Peter Kenyon
CEO at RAMSDENS HOLDINGS PLC
Replay available
Interim Results Investor Presentation hosted by Ramsdens Holdings (LSE:RFX) on Investor Meet Company, held 2025-06-05.
On 6ix: 6ix.com/event/ramsdens-holdings-plc-rfx-interim-results-investor-presentation
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:00 Good afternoon, and welcome to the RAMSDENS HOLDINGS PLC Interim Results Investor Presentation. Today's recorded meeting. Investors will be in listen only mode. Questions are encouraged and can be submitted at any time by the Q and A tab situated in the right hand corner of your screen. Just simply type in your question and press send. Company may not be in a position to answer any question received during the meeting itself. However, the company can review all questions submitted and publish responses where it's appropriate to do so. Before we begin, we'd like to submit the following poll.
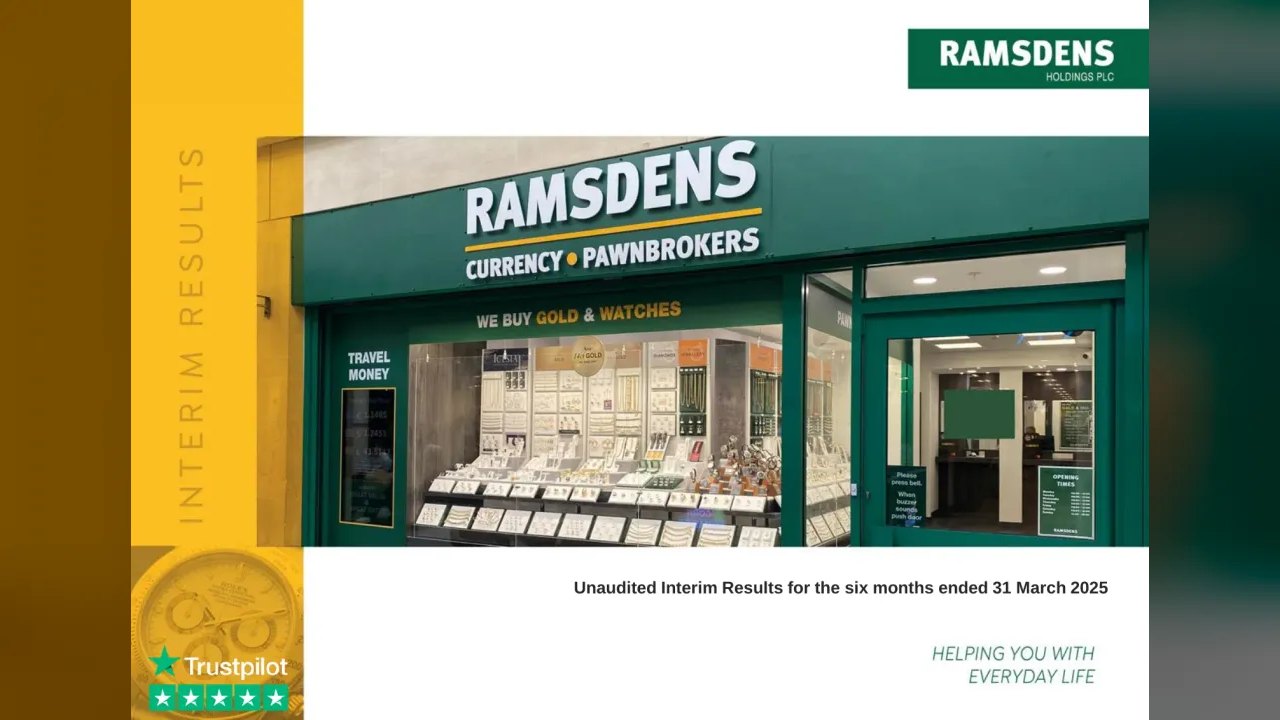
0:28 I'd now like to hand you over to Peter Kenyon, CEO. Good afternoon, sir. Thank you. Welcome, everybody. Thank you for your time in getting to if you'd to know more about RAMSDENS and how we're trading. So I'll go through the the presentation and obviously welcome questions from everybody at the end. So that's a nice picture of a store. Moving on, you got the disclaimer inside of our York store. So a bit of an overview of RAMSDENS, if you like, and where we've come from. So you look at the top left graph, profit before tax, a bit of a nice staircase, obviously, interrupted by COVID. But the right hand bar is the last twelve months. So h two f y twenty four, h one f y twenty five is about 13,500,000.
1:22 We draw that out really just to give you some thoughts around the gold price and where, underlyingly, the business is is comfortable at and and where it moves from, you know, thereafter. The right hand side, again, you've got a staircase of the of the interim dividend, in the dark green. And in f y twenty five, you have, for the very first time, an interim special dividend. We'll come back to it, but that's really recognizing that at this moment in time, we feel we've got a following wind with the gold price that might not last forever and therefore want to, recognize and reward shareholders with some of that extra profit we are making. Strong financial position. Again, just three highlights for you. We'll put more detail on it, but solid balance sheet, 54.7 net assets, of which 7,400,000 is net cash and then 19% return on equity. So quite an efficient balance sheet.
2:20 Diversified income streams, you can see the four key cost schemes that we have, quite a balanced pie chart. Now, you know, again, it's a it's a good solid position for the business. It means that we are countercyclical and generally have done quite well in whatever the circumstances have been economically. Moving on. So top left there, strong foundations. You got that financial base. We've got cash to invest. We can leverage off our head office cost base. We are a cash generative business. The computer systems are our own. I have four developers with a fifth joining me, on Monday. All of our websites are integrated to our core operating system.
3:08 If you were a customer in any one of our stores, that staff member would be able to see what you've done through the history of your relationship with RAMSDENS. So it's a very good system designed for our own own use. Certainly, two or three of our IT guys are geniuses in developing that system. We have a strong customer brand. We've worked hard at advertising. We have a strong presence on the high street, and that's a good differentiator when you think about some of the website operators that we'll come and talk about later. There's a trust in that you can walk through our front door and have a conversation with somebody face to face. We've been kind to enough to and worked hard to achieve a five star trust pilot rating.
3:55 I think I've got a great you know, the the staff I've gotta recognize the staff here. They are superb. They try every single day to help customers with whatever they need help in. We have a strong culture. We look after customers. We adhere to the customer duty ethos. You know, the FCA authorization is embedded in the business, so we've got good governance. You know, we've got a new chair in Simon. Chris Muir has joined the board. He's brought different dynamics to to the board. He's asked a lot of good challenging questions, and, obviously, hopefully, that'll improve the business as we move forward. Low staff turnover, investing in our people, and that's how we're trying to to grow the business.
4:37 And talking about growing the business, our strategy really is unchanged. I've probably shuffled the order of these these icons. So on the left of the page, you've got drive growth from the core estate and grow the online presence. They're now slightly linked together because they're very complementary. You know, the pawnbroken website that was launched in November 24 and our gold buying website website launched in February 25 are very much about driving customers into stores, and we can come back to those. If you look at our foreign currency operation, again, when we get to foreign currency, it's about click and collect. So the customer's collecting the currency in the store. And then the jewelry also the jewelry website acts not only as a profit center in its own right, but it's also a a catalog for all the stores to see what watches we've got, what range of new jewelry we've got, and what secondhand jewelry we've got. So, these are both complimentary.
5:38 We've opened a few stores, in recent years. They're far from mature. And on that point, my mature stores are far from mature. They've still got opportunities to grow, and that drive that we have is something that will continue, that continuous improvement. We've we've added new services. So the the multicurrency card, was launched in September 23. That's grown to 25,000 cards in issue now. We've got the international money transfer service, which soft launched in February, And we can relocate some stores, odd ones and two. We were forced into one in Elgin during the year, and we've got a major refurbishment of our store in Musselburgh happening right at this moment. On the right hand side, we have an established store model.
6:27 That model works. I only have one store that, if you like, is in that is it worth it test, and whether I should close it or not. The rest of them are absolutely contributing to head office costs and beyond that. So we had a hiatus that was really government change of government led. With the change of government, new policies, what would they do? Budget has been and gone. You know, we know that they have changed the rules around employers, national insurance. That to ourselves is about a 750,000, £800,000 annual cost. But from a growth perspective, it was what would it do to the high streets? Which retailers are saying what? How are they overcoming it? Some have closed stores.
7:16 Some are putting up prices. So we've take that, if you like, is a new dynamic taking into our assessment of new locations. You know, it's very much about who we're gonna be next to. Will we be there tomorrow? And will we locate in an area of a town that is it remains, if you like, the community and and the heartland of that of that town. So, we've done a lot of research. I've got three more in legals. We've opened two, and we have a significant opportunity to expand. So growth strategy isn't changing. Maybe had a pause on new stores, but it's definitely now kicking on again. And then the last one there is something usually crops up with an acquisition. Most pawn brokers are enjoying the gold price currently. So, you know, that's a bit hard to to ask them to sell at the moment, but, you know, we we lie and wait, so to speak, to the right day. We have cash to invest, and I'm sure my my phone number will be on speed dial should someone want to leave the market.
8:18 So we've said in our r and s, profits expected to exceed 15,000,000 following a a record first half. You've got the financial highlights that are there on screen. I don't propose to go through them because Martin will, but it's a great performance across the four core income streams. Two new stores that have opened, two websites, the IMTs and the cards is mentioned there. And if you like an outlook, if you like a quick, again, overview where we sit, the board is confident of the future. We'll deliver on our growth strategy and and and long may that continue increasing. In fact, that staircase I mentioned of of profitability and rewarding shareholders. So what I'll do is pass on to Martin to run through the financials.
9:09 Thank you, Peter. As you can see in the p and l, we'll we'll run through it fairly quickly. We do have a slide on each income stream individually where we get into more detail. But revenue up 18% for the six months, 51,600,000, which is up from 43.8. That 18% growth in revenue is pretty much filtered through to gross profit. You can see gross profit up 20%. So, obviously, the big drivers of that growth is is the purchase of precious metals at 30% and jewelry retail at 18%, but it's pleasing to see all four key income streams with growth during h '1. In terms of store numbers, there's approximately two stores extra, if you like, this year compared to last year. So that's a little bit of the increase in in admin costs, but the bigger part of that increase is the cost of people. So the the real living wage, which is our entry level pay, went up 10% in 2024, which is a big part of that increase in admin expenses.
10:15 Obviously, what we do have to look forward to in April 25 is a that 5% increase, which is now being put through under further national insurance cost, but that's not in this this h one period. We have managed to pay down some of the RCF and the finance cost. You can see the benefit of that £100,000 reduction in h one compared to last year. And our profit before tax, 6,100,000, is up over 50% on the same period last year. We've got the pie chart there again just showing the mix of that gross profit, which is very balanced across the four income streams.
10:55 So looking at each segment individually, so gold buying or precious metals buying has been by far the biggest growth factor in h one, and that's been heavily influenced by the gold price. So you can see in the chart in the top left, the average gold price in the period was £26.22. That's the 9 carat sterling gold price rather than the dollar price, which is often quoted in the media. You can see that's up substantially. It's around 30% up from last year at 1945.
11:28 The price today is actually close to £30. I think it's over £30. So you can see it's moved up again substantially post period compared to the average in the period, which has also led to us, as Peter said, upgrading the full year outlook, particularly for this segment. We have launched a new website, so it was around February time when that went live. We've seen very good traffic to that website. So we used to have a gold buying website as part of our wider company website, which had other services on there. By separating it out, it's obviously got a more focus to it, and the volume of traffic has been very strong. And we've we've also seen volumes of gold purchased increase post period end, which has led to that upgrade for the full year.
12:17 We do have a choice when we buy gold. What we do with it, we can scrap it or we can retail it. So we always have that consideration of whether we repair it, refurbish it to retail, and whether we scrap it. And the differential
12:30 in gold price to retail price is often a big factor in that and also the number of stores that we open. So if we open lots of stores, we obviously then would need to stock up more. So that's just something to be aware of in terms of that choice. And, obviously, you know, falling gold price, we could retail more of that stock and take more of that higher profit level because the, you know, the the the value of the differential is much higher in that position. You can see the gold prices sustained that growth right throughout the period, and it's done enough for for several years now, actually. And that's leading to a higher gross profit margin. So because we buy it on probably a four to six week cycle in terms of when we buy the gold and when we sell the gold, you can see the gross margin improvement as well during the period as well as the the revenue improvement.
13:23 And therefore, the margin has got better during this first six months.
13:29 Moving on to revenue of jewelry retail, which has been, again, very, very positive. 18% growth in revenue and 18% growth in gross profit. So that's showing that we've been able to manage the margins across the various products and still keep that margin despite the input cost, particularly for the jury side of retail, having that higher price, higher input cost. The pie chart in the bottom right of the of the slide just shows how the the makeup of the the revenue is is mixed. So we've had about a third of the revenue is premium watches. Now in the premium watches space, prices have been relatively consistent. So, obviously, very little impact from any gold price change.
14:14 And what's happened here is we've probably sold less higher value watches. We've bought more watches at a lower value, and the average ticket is probably reduced very slightly. The growth in watches, therefore, is really lots of growth through volume. It's around 19% up, so it's slightly higher than the the overall average, And that's been very, very successful. If you look at the other two parts, the jury parts, which make up two thirds of the revenue, a lot more of that growth has come through pricing. So because the gold price is higher, we put our prices up because the input cost has gone up to maintain our margin. And whilst we've seen small incremental growth in volume, the rest of that growth has come through increased in pricing.
15:00 We still have very, very good value for money. We still have the opportunity if we wanted to to increase prices further given the continued increase in the gold price. Retail has been a real success for several years. You can see the chart in the bottom left, which shows the growth of retail both in store and online, and that's continued. That momentum has been very strong. And we've continued to invest in the stock levels to support that. So it's around 1,700,000 of extra retail stock in the half year, and there's around 700,000 extra of gold stock if you like to support the the gold purchasing segment as well. So that investment has continued. And if the revenue momentum continues, we'll continue to invest in inventory moving forward.
15:49 The website is due another refresh as well, so we're investing in the website. And the website growth is 17% in the half year, so very close to the same as the stores. So both stores and website both performing very strongly.
16:06 Moving on to Pawnbroken. You can see here that gross profit is up 11%. Revenue is only up 4%, and the anomaly there, if you like, is that the the revenue recognizes credit losses. There's an expected credit loss that you've got to account for using IFRS nine, which is a very complicated formula. But, effectively, the increased gold price has meant that there's lower expected credit losses, and therefore, the gross up, if you like, to revenue is much lower. But, certainly, the the interest generation of the book is very similar. The the interest rates we charge customers are the same as a year ago, and the book has generally been higher than it was in h one in the prior year. And the book is relatively flat from the year end. So if you take September to March, the the book is relatively flat.
16:55 It's slightly higher in terms of in debt lending, but they're slightly better, managed, if you like, in terms of the expired book. There's less expired lending in there, which is less income generating. So what we've seen in terms of lending is very good lending. We've seen slightly better repayment rates, and that's offset that what would have been growth. And we've also had an incentive to to to customers or an encouragement to to customers to repay some of their loans where they're looking to reborrow. So this has been something we've been trying to do for probably the last twelve months, which is to where a customer needs more time to pay, helping them help themselves by paying down some of that capital to help them get their goods back quicker. This is gonna help our long term payments of our loan book and actually help that customer reborrow in the future.
17:50 But it does have a short term impact into the the loan book in this period. We've launched a new website for pawnbroken. Now, again, a bit like the gold buying website. A lot of this is to attract customers to the stores. So the the Pawnbroken website was launched in November, but we've really started to try and push that in terms of customer acquisition towards the end of the period and into h two. So these websites, including the goal buying website, have seen very, very strong traffic, and contributing, to good post period end performance.
18:30 Foreign currency exchange has been, you know, 1% increase in terms of gross profit. It's 2% in revenue. And we've seen a moving parts here are that sales growth has been pretty good. We've seen two and a half percent increase in currency sold, and that's more customers taking slightly lower amounts of currency each. So there's been a slight reduction in the amount taken abroad, and we think that's down to the, you know, purchasing power of the customer having less disposable income. And because they've taken less, they've actually brought less back, and our purchases are down because of that unless people have sold their currency back to us. So purchases down from 8,800,000, they're down to 8,200,000.
19:15 Now whilst that's only a small proportion of the currency exchange, it is at a higher margin, so it does disproportionately reduce the commission level across the segment. But we do we have been on that curve downwards for purchases now for a couple of years. So we are hopeful that once that flattens out, that the growth that we're seeing through sales will give a bit more momentum into this segment. The other areas, we've added on into this segment are the the currency card, which was launched last year. There's now 25,000 cards in issue. That's increased from 17,000. And, obviously, we're approaching the key summer months, where we'll have the opportunity to continue to grow that currency card, volume into the into that period.
20:03 We've also launched a money transfer service in house. So this is a an FCA regulated product, which we used to use a third party to pass leads across to. We now have that facility to do those transactions in house, and that will help us build that business going forward over the next few years. So into the cash flow, I guess, to recap in terms of the the business model and the cash generation of our our stores is that, you know, the business is very cash generative. When you open a store, we pay the CapEx. It's typically 250,000 CapEx, 250,000 working capital to put the jewelry, the FX, a bit lending into the store, and then all the profitability comes through in real cash.
20:52 So what happens then is that profitability that we've seen in h one has been very much come through as operating cash flow. You can see 5,100,000 of operating cash. We've invested in inventory. That's the biggest working capital movement there, 2,400,000. 1.7 of that is to support the the inventory in retail, and it's around 700,000 in terms of the precious metals, volumes, and increased pricing, which increases the cost in the cycle, for that product. We've only opened two stores in the in the period, so the CapEx is relatively low compared to previous years. As Peter said, we paused store openings really as we looked at the what the high street environment was, and we pretty much started again, on a six to eight new stores into the future from from now onwards.
21:45 We pay both dividends in h one. It's important to to remember that when you look at our half year cash flow, so 3,600,000 there out as dividend paid, which means h two is obviously very, very cash generative. And h two actually has the seasonally stronger currency period as well. Therefore, you'll see that the cash generation come through particularly strongly at that time. We pay the dividends in October and March, which is outside of the currency season to support that cash need into currency into the tools. We've declared an ordinary dividend up 25% to support that increase in in profitability. The philosophy of the business is is up to 50% of our profit out as dividend, and we typically pay that one third and two thirds across the interim and final.
22:32 We have recognized the fact that profit is higher because of the the increase in gold buying and that continued post period end. And therefore, we've introduced for the first time a special dividend to recognize the fact that, you know, we wanna continue that dividend philosophy. We'll have an eye on any potential reduction in gold price into the future that we wanna be able to measure, you know, a consistently growing dividend, a progressive dividend despite that. So that's that's how we've approached that. The RCF, you can see in the period as well, just to mention there, 5,500,000 reduction in RCF, which we're able to reduce given the strong cash generation in the half year. Onto the balance sheet.
23:20 We've had a very strong balance sheet. We obviously, that reinvestment of half of the profits over the years keeps growing the balance sheet, 54,700,000. Despite that continual growth in the balance sheet, we do have still have very strong return on equity. It's around 19% for the last twelve months. When you look at the asset classes in the balance sheet, it's important to remember we book all of our inventory at cost. You know, the precious metals inventory and the retail inventory, especially the pre owned jewelry, is again a substantial value below the gold price. Trade and receivables is the pawnbroken debtors. And, again, you know, the increase in gold price means the security held behind that is extremely strong. The cash balance of 10,300,000 in the balance sheet does include the currency.
24:06 That's around 4,000,000. There is a very cash intensive cycle to run the business. You do need to hold a lot of cash in the stores in either currency or sterling to buy gold each day, to sell currency each day. And therefore, that's why we do borrow at the same time as having that level of cash in the business. Okay. So a quick summary. We think we've got a robust business model, diversified income streams that have, if you like, enabled the growth that you can see in the two graphs on the right hand side. You know, we keep talking about a staircase, and both have a very strong staircase, again, excluding COVID. Profitability for the half year, 54% up, forecasting over 15,000,000 for the year, strong balance sheet, increasing dividend.
24:59 People say are kind enough to say that we have a strong management team. I know I've got a very strong management team support supporting both Martin and I, and we have a track record of delivering growth. The board does remain confident that we can continue to grow RAMSDENS well into the future. And that, ladies and gentlemen, is all we've got to say at the moment. We'll go through the appendices, and we're happy to take questions. Fantastic. Thank you very much indeed. Ladies and gentlemen, on that note, please do continue to submit your questions just using the Q and A tab situated on the right hand corner of your screen. But just while the team take a few moments to review those questions submitted today, I'd like to remind you the recording of the presentation, along with a copy of the slides and the published Q and A, can be accessed via your dashboard.
25:46 Peter, Martin, as you can see, we've had a number of questions submitted, both prior to the presentation and during the presentation. If I may just ask you to click on that q and a tab, where appropriate to do so, read out the question, give you a response, and I'll pick up from you at the end. Thank you. Right. Question one. Firstly, thank you for making ourselves accessible to to investors to engage at IMC today. You're welcome. If you're not already done so, could you help us understand how productive the various new websites are in developing new or refreshed income streams, new customer interest? I appreciate, of course, you don't want to give the competition too much detail. Just a couple of numbers I would probably happy to share. If you take our pawnbroking website and we take it, like, say the visitors that that site, that has doubled in the last three months.
26:37 And if I take our gold buying website, which has come off the RAMSDENS for cash environment we talked about, and it's got SEO, it's got a little bit of pay per click in in May where we learned some lessons. The volume of people visiting that site has tripled, and then most of the people on that website are going to the branch locator page. And therefore, we lose when they leave the site there because we haven't got their details. We are actually losing the the the true conversion, but we believe our websites are helping both pawnbroking and gold buying. Alright. One. It's cash agency. Yeah. I can't read the So the question is, you know, first cash if we acquire acquire an agency, how do we think that will affect Yeah.
27:30 Sorry. Yeah. RAMSDENS. So sorry. Move this out screens. Move that right. How will First Cash's acquisition of HNT impact RAMSDENS? What is the risk of overexpansion and lower profits for the industry? How will First Cash's acquisition of HNT impact RAMSDENS? Well, the first act first impact is it's done wonders for the share price with First Cash paying 12 times PE for the HNT business. You can see why they've done that because they are at a multiple of over 20, I believe, in The States. What is the risk of overexpansion and more profits for the industry? I'm not really seeing that. I think, you know, the the industry now is about 880 pound broken stores in The UK.
28:21 I don't see overexpansion. I think that, you know, stores will continue to to to incrementally grow throughout the industry from ourselves, from HNT, from from cash converters, and probably a couple of independents. So I think it's it's positive news overall. Interim results announcement, the reason for the total loan book falling by 1% is due to a refocused initiative in f y twenty five to encourage customers to repay part of their loan capital if they needed more time to pay off their loan. A, could you please provide details on how this scheme works? B, if a loan is past due and the customer repays part of the loan capital, will this loan be reclassified from past due to in date? And if yes, what is the percentage? Right. Okay. So if a customer wants more time to repay so their loan has expired typically.
29:18 They don't want to lose their goods, and they historically, and I'm going years back here, would just pay the interest and renew into a new loan. Now we have for four years encouraged the customer to pay some of that capital off when they renew. However, in the last nine months ish, we have changed this IT system, the prompt that the cashier gets to ask the customer, and that change in process and the question that we have asked the customer has taken the 40% of customers who paid something off their capital up to close to 90%. And that 90% of the people is probably that increase has probably lowered our loan book by about two and a half percent during the last six months.
30:14 But it is a new loan agreement, so it swaps into a new loan agreement. And, yes, it obviously is not then past due. Is it the long term wish of the board at RAMSDENS to concentrate on store openings in the South Of England with that part of the country being underrepresented in terms of the number of RAMSDENS stores, especially compared to your main competitor, HNT? South of England is an opportunity for us. The Northwest is an opportunity. The Midlands is an opportunity for us. So it is just one of the areas that we are looking to grow. And, you know, you'll see where we where we plant flags over the next, you know, one to two years of of that store store growth.
31:00 Am I correct in believing that after the substantial increase in the share price of RAMSDENS HOLDINGS in recent months that the board would not consider buying back shares for cancellation at these levels and would prefer to use the money towards opening new stores possibly in the south of the country. Well, we've always said that that it's about crudely half out in dividend, half in to invest in the future growth of RAMSDENS. We think that gets a good balance of rewarding shareholders, and it gives us a good, if you like, chunk of income to, and cash to grow the business. Until we run out of areas to grow the business, I don't think that we would be looking to buy shares back. Why the low this year in store openings?
31:49 You consistently opened about two a year as a comfortable limit. Cover that one off. Change of government. Didn't know what would happen to the high streets. We're gonna be back to six to eight stores moving forward. Oh, I'm sorry. Again, things pages slip there. It moves when we get more questions added in. Right. Andrew has asked, cyber attacks are very much in the news. Can you provide some color in respect of RAMSDENS preparedness? Or trust me, my IT director gets this asked this quite a lot. You know, we think we're prepared. We have, a a a a system, dual factor authentication, multifactor authentication, different layers of security.
32:40 We think we have a good defense, but I don't want anybody to test that. But we know from that our data is absolutely encrypted at rest, so, you know, we sleep easy with that one. Why is there no interest income despite having net cash and short term deposits? That's an interesting question. Is it on the amount of interest receivable? We we don't show it separately. The you know, we don't you know, our our cash moves through the accounts very quickly. We hold a lot of physical cash as well. So we don't, you know, we don't store our cash away in the in savings accounts. Okay. Do you have any concerns regarding stronger competition post the HNT takeover?
33:29 No. Did you consider doing a share buyback rather than paying a special dividend? We've considered share buybacks in the past, and we thought share a special dividend was the right thing to do. If the gold price stays at the current level for the rest of the year, should we assume that current forecast might need to be revised upwards? Oh, well, I thought we'd put a bullish upgrade in from 13.1 to, well, over 13 to over 15. You know, who knows? We're trying to push that profit up as much as I can every single day. So I think that's a a watch and see. Obviously, if we're very successful, the profits will go up.
34:16 Are you the fifth largest jeweler in The UK? Not to my knowledge. I don't know how that is is calculated. Someone did try and tell me I was in the top 10, but I I quickly went through a couple of jewelers and said, maybe not. So I don't know really where we actually sit. I know that we are consciously improving our jewelry retailing. No. Okay. Right. New in house international money transfer service soft launched in February 2025. Given that income from the Western Union transfer service has been in slow decline for the last three years, What opportunity do you see in this in house money transfer service?
35:05 On a side note, thank you for the great performance. I will obviously, you're welcome for that one. So international money transfers is a bank to bank transfer. So if any of you got houses abroad, you should be using RAMSDENS currency to make the transfer into, for example, your Spanish bank account. Western Union is where you come into our store and you pay cash or card over the counter, and the cash is remitted digitally, and the customer collects cash in another Western Union outlet somewhere in the world. So Western Union is very cash to cash with a little bit of bank transfers, where our international money transfers is very much bank to bank, and it's aimed at UK residents who may be import, export, or or have, you know, houses abroad.
35:58 A significant reason for the excellent interim results was the high price of gold. Nobody can tell for sure the future, not least in relation to the price of gold. But taking into account your experience regarding financial matters, would you expect in one year's time the price of gold to be higher or lower than its current record levels? You know what? I've been wrong on this one so many times. I wouldn't want to guess. All I would say is we budget and forecast with a fall in mind. How do you think the buyout of HNT will affect your trading? I don't think it'll have any impact. Any plans for further franchising? No. Did you say loan book value was fairly even between h one and h two?
36:47 I'd I'd expect h two to be much higher given it includes the Christmas period when you think more people need short term funds. Our h one includes Christmas. It shifted a little bit. I mean, there isn't much seasonality into pawnbroking at all and in in our business. And it used to be that the loans increased, January, February when the bills landed after Christmas, but we have seen December lending tick up. There isn't I say there isn't really a a seasonality in our pawnbroking business. Are the outstanding loan days going down? Are customers paying the loans down back quicker sooner?
37:35 Alright. That's a question that's very probably driven out of HNT and some of the data that they share. Personally, I think it's it's not the best measure. It's to do with how many people actually repay and when they repay. So the statistics that we look at are how many people pay us back in month one that is slightly increased. It's about 23, 24% borrow for less than a month. And we look at the number of customers who repay overall, and that's inched up from about 70 86% to 88. So we don't do that calculation. Is FX a declining trade now everyone uses credit cards?
38:27 As explained, John, you know, our sales of foreign currency have been increasing. You know, the the currency exchange has increased. The number of transactions have increased. The ATV is slightly down. So, you know, more people are getting more cash from RAMSDENS. Julian, your pawnbroking rates look considerably above H and Ts. Is this correct? Any reason for it? Our pawnbroking interest rates are considerably less than H and Ts, and I don't know what data you are looking at, Julian. And I think the two that I left on screen, we've answered. You have indeed. You have indeed, and you've actually covered off every single question you've had come through. So thank you very much indeed for that. And, of course, any further questions do come through, the team will have the ability to review those. And we'll publish responses where appropriate to do so on the Investor Meet company platform.
39:28 Before redirecting investors to provide you with their feedback, which is important to you and the team, Peter, if I may just ask you for a few closing comments, please? Yeah. I I look. I feel as though we've actually rattled through through those questions. I don't know whether that's testament to the presentation. And if you like, our open, transparent way of sharing the information as best we can, And therefore, there was fewer questions this time. But, you know, thank you for showing an interest in RAMSDENS. We think we have a very, very good business. We have opportunities to grow, and hopefully, we will continue to do that, and we'll continue to reward shareholders with dividends and, you know, hopefully, value growth as well. Have a good, evening all. Fantastic. Thank you both for updating investors today. Can I please ask investors not to close this session? It should be automatically redirected to provide your feedback in order the team can better understand your views and expectations.
40:21 This will only take a few moments to complete, and I'm sure it's greatly valued by the company. On behalf of the management team of RAMSDENS HOLDINGS PLC, we'd like to thank you for attending today's presentation. That concludes today's session, and good evening to you.
Follow Ramsdens Holdings PLC into a list and get an email when it puts out news.
CEO at RAMSDENS HOLDINGS PLC
CFO at RAMSDENS HOLDINGS PLC