PremierWest Bancorp — Merger or Acquisition (October 2007)
17 slides from PremierWest Bancorp's merger presentation, Oct 22, 2007
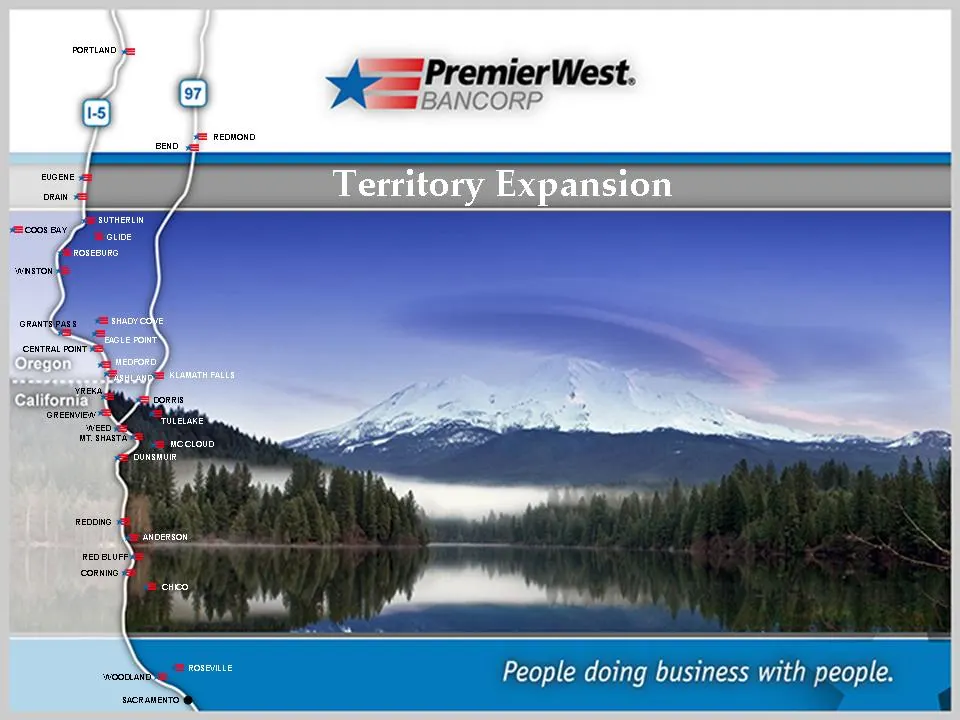
Slide 1: PremierWest Bancorp
+4 PremierWest. PS mag BANCORP People doing business with people.
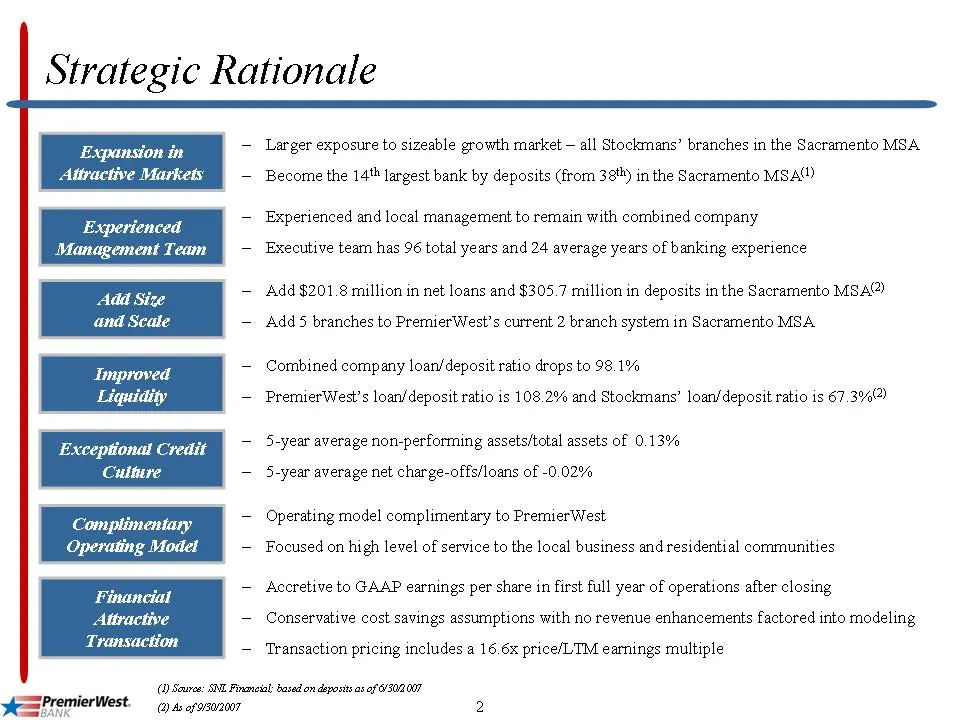
Slide 2: Strategic Rationale
Strategic Rationale pansion Attractive Markets Experienced Management Team Add Size and Scate Improved Ligue Exceptionat “di Culture Financial Aftractive Transaction Larger exposure to sizeable growth market — all Stockmans’ branches in the Sacramento MSA Become the 14" largest bank by deposits (fro
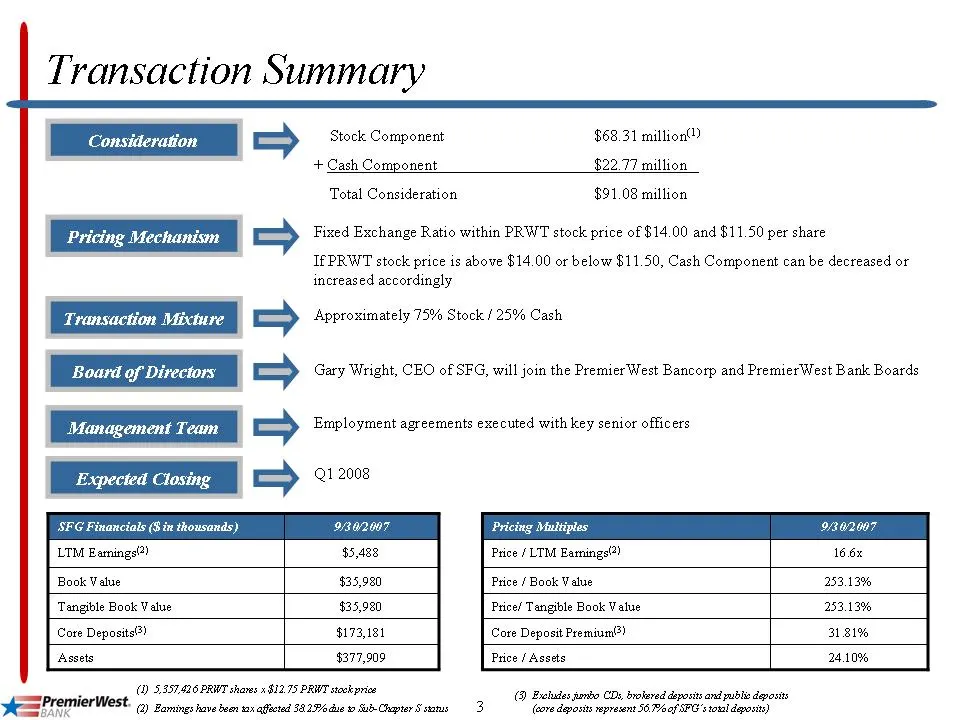
Slide 3: Transaction Summary
Transaction Summary Consideration a Pricing Mechanism Transaction Mixture Board of Directors Management Team QVHUGVGVY Expected Closing SFG Financials (Bin thousands) Stock Component + Cash Component $68.31 million) $22.77 million Total Consideration $91.08 million Fixed Exchange Ratio within PRWT s
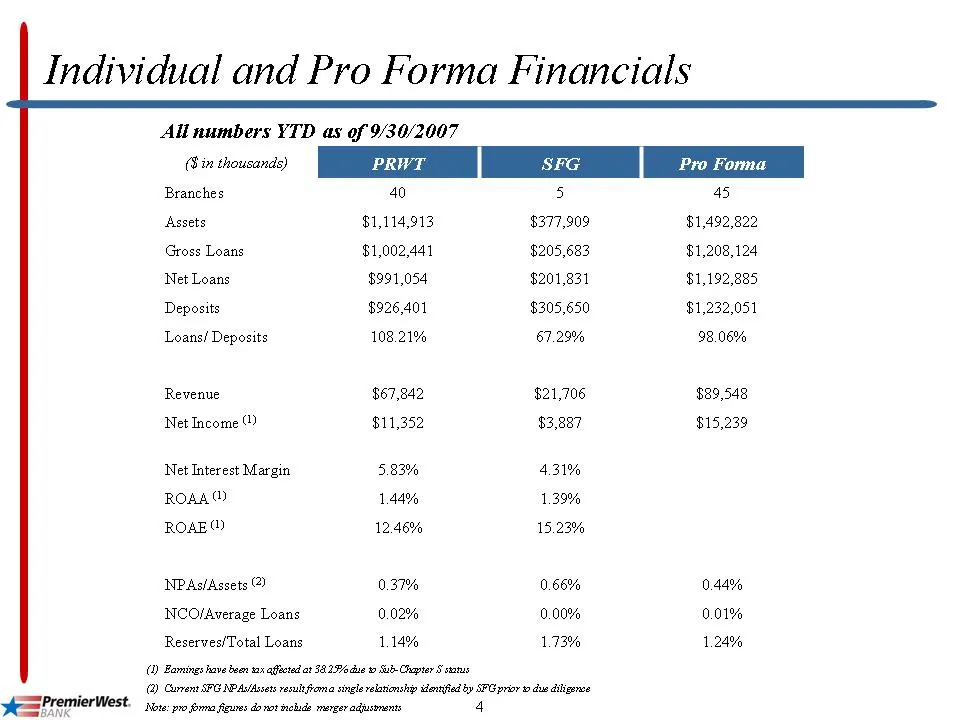
Slide 4: Individual and Pro Forma Financials
Individual and Pro Forma Financials All numbers YTD as of 9/30/2007 Branches 40 Assets $1,114,913 Gross Loans $1,002,441 ‘Net Loans $991,054 Deposits $926,401 Loans/ Deposits 108.21% Revenue $67,842 Net Income ( $11,352 Net Interest Margin 5.83% ROAA® 1.44% ROAE® 12.46% NPAsiAssets @ 0.37% NCO/Avera
Slide 5: Experienced Senior Management
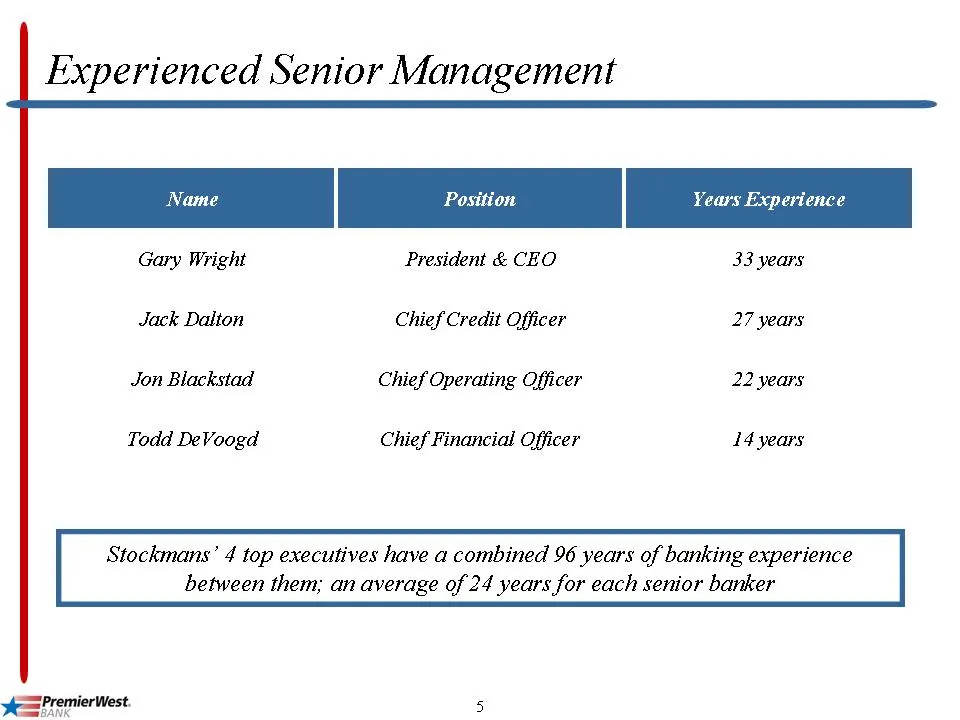
Experienced Senior Management Postion : ees Gary Wright President & CEO 33 years Jack Dalton Chief Credit Officer 27 years Jon Blackstad Chief Operating Officer 22 years Todd DeVoogd Chief Financial Officer 14 years Stockmans’ 4 top executives have a combined 96 years of banking experience between t
Slide 6: Geographic Footprint
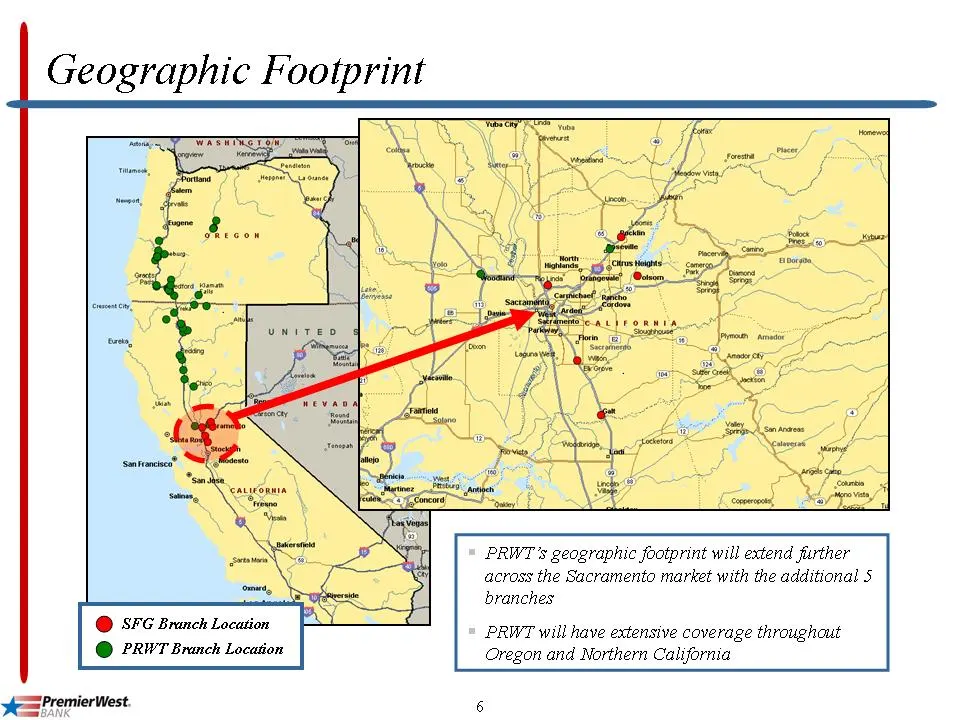
Geographic Footprint ee —_ ee Red pipet, 4 PRWT’s geographic footprint will extend further across the Sacramento market with the additional 5 branches PRWT will have extensive coverage throughout Oregon and Northern California
Slide 7: Market Growth
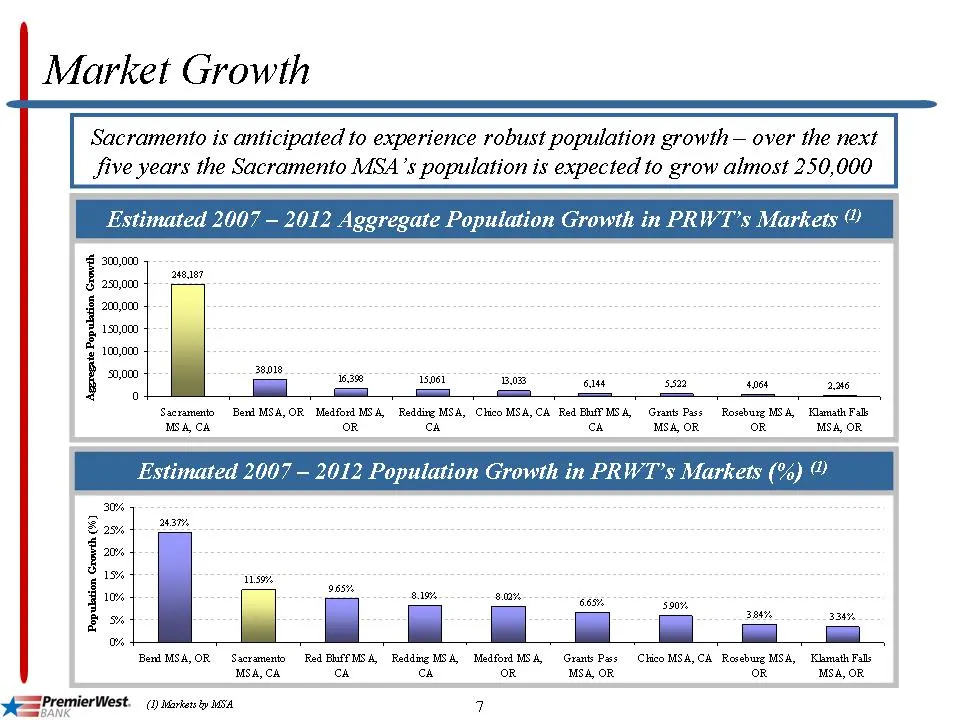
Market Growth Sacramento is anticipated to experience robust population growth — over the next five years the Sacramento MSA’s population is expected to grow almost 250,000 Estimated 2007 — 2012 Aggregate Population Growth in PRWT’s Markets © mp Baw joe from Fm ee i ga " = aid BOB 6144 5522 4064 en]
Slide 8: Market Size
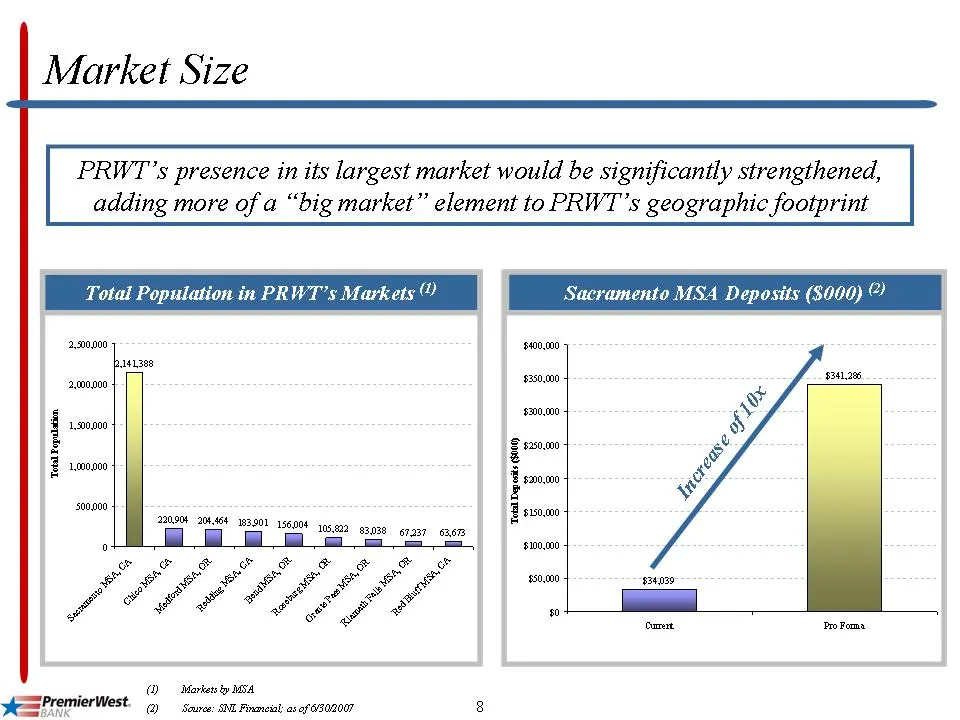
Market Size PRWT’s presence in its largest market would be significantly strengthened, adding more of a “big market” element to PRWT’s geographic footprint Total Population in PRWT’s Markets? Sacramento MSA Deposits ($000) © 2.500900 900,00 1381388 $581,286 2.000000 350.0 200,00 1.00000 $230.0 ‘Tota
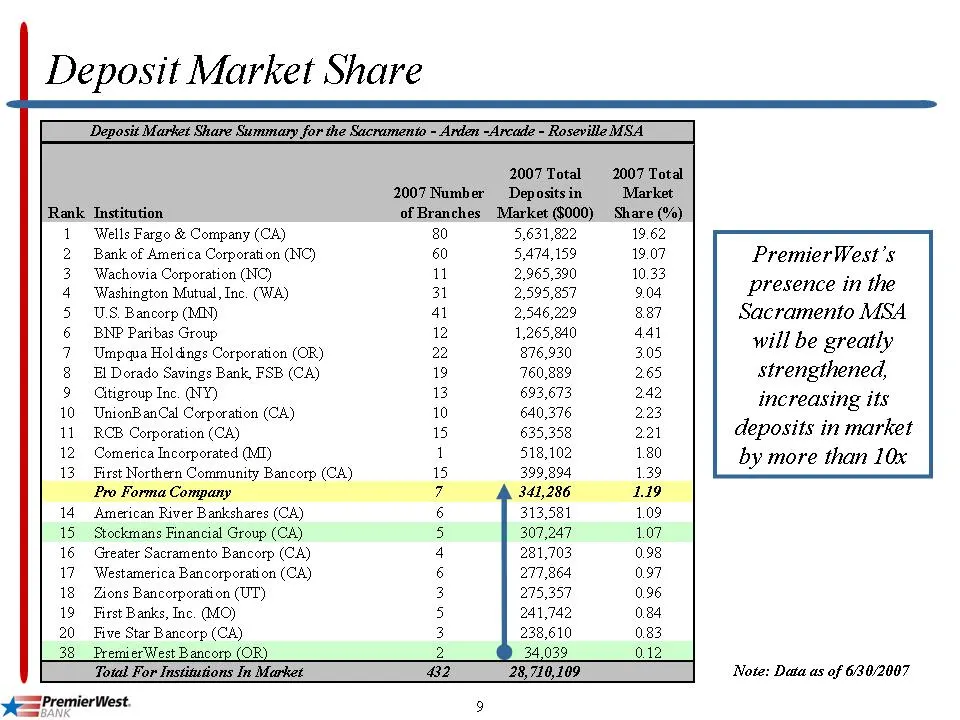
Slide 9: Deposit Market Share
Deposit Market Share Deposti Market Share Summary for the Sacramento - Arden -Arcade - Roseville MSA 2007 Total 2007 Total 2007Number Depositsin Market Rank Institution of Branches Market ($000) Share (%) 1 Wells Fargo & Company (CA) 80 5,631,822 19.62 2 Bank of America Corporation (NC) 60 5,474,159
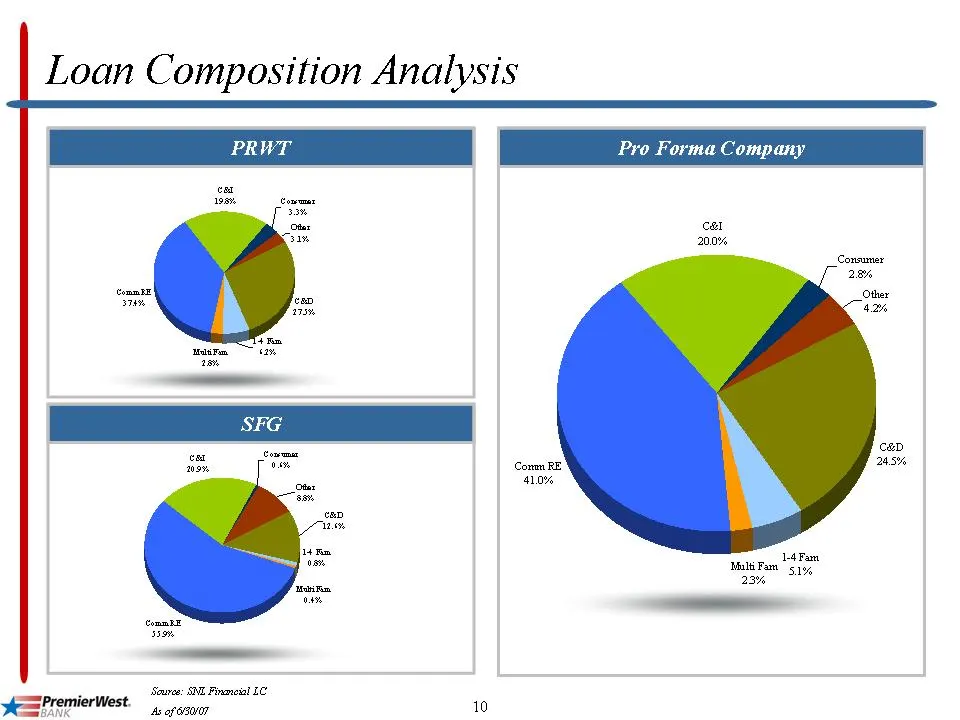
Slide 10: Loan Composition Analysis
Loan Composition Analysis cat 200% 14Fam, Malt Fam “sy 23% Scuroe: SNE Finanoal EC As of OSVOT 10
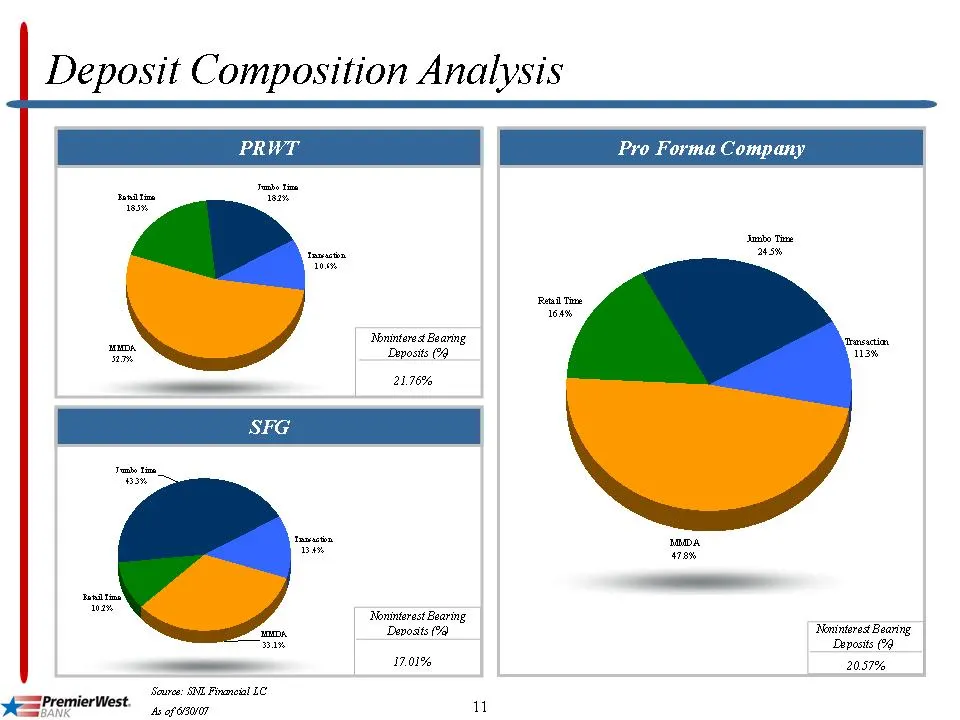
Slide 11: Deposit Composition Analysis
Deposit Composition Analysis Rbninterest Bearing cn Deposits (24 21.76% iis ‘Noninterest Bearing an Davoats 20 ‘Nonintored Bearing =a eposits (24 17.01% 2057% —premierwest, 2% NFmeal IC ePremierWest. sever "
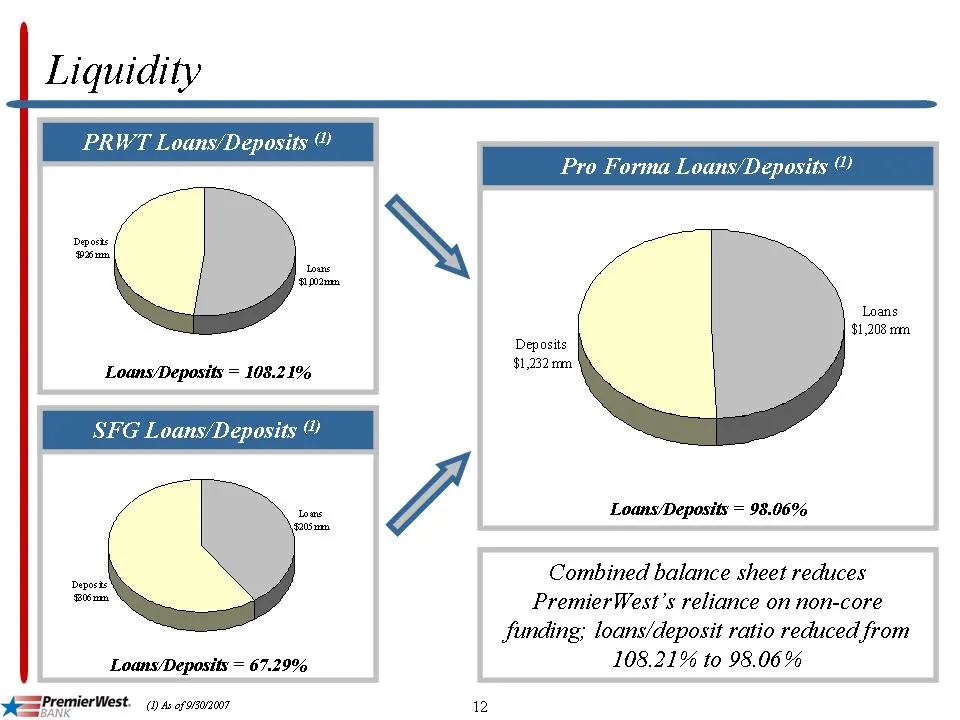
Slide 12: Liquidity
Liquidity PRWT Loans/Deposits ® Deposts mm Lous ‘1pm Loans/Deposits = 108.2 1% SFG Loans/Deposits © Leas 3205 Deposits ‘E06mm Loans/Deposits = 67.29% eS PremierWest (ys aros0z007 re Forma Loans/Depos Loans $1,208 rom \ G @ Loans/Deposits = 98.06% Combined balance sheet reduces PremierWest’s reliance
Slide 13: Credit Quality
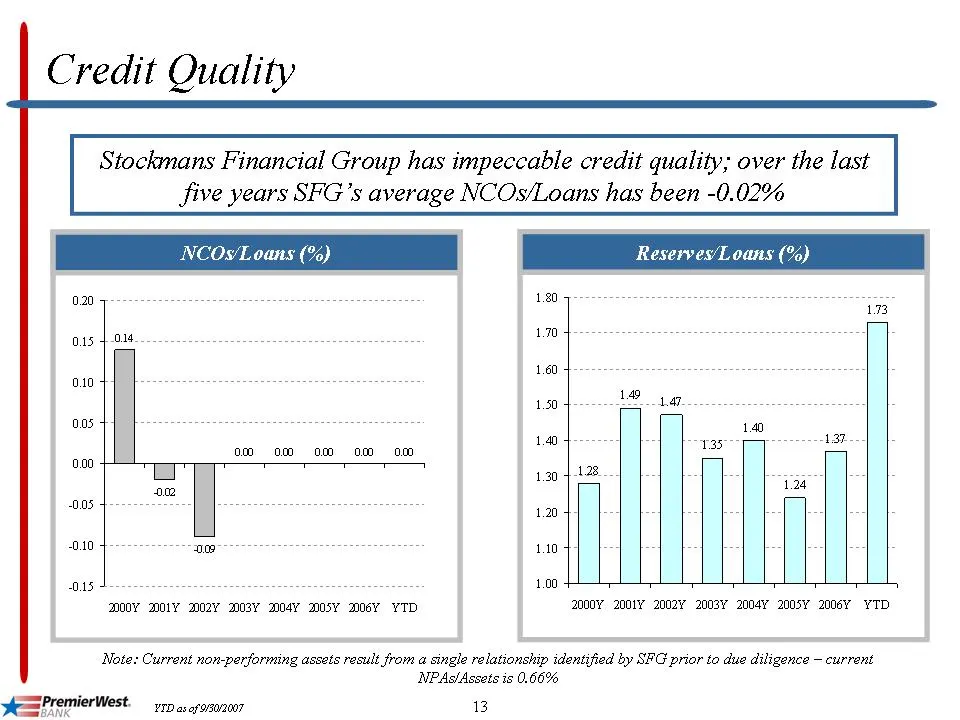
Credit Quality Stockmans Financial Group has impeccable credit quality; over the last five years SFG’s average NCOs/Loans has been -0.02% 20 o1s {ou oo ons om ono ao ogo ono o.oo 0.05 0.15 MOOY MOY mY MOBY wO4Y wOSY mosey YTD Reserves/Loans (% 1.80 1.70 1.60 1.50 1.40 1.30 1.20 1.10 1.00 + 173 a een
Slide 14: Returns on Assets & Equity
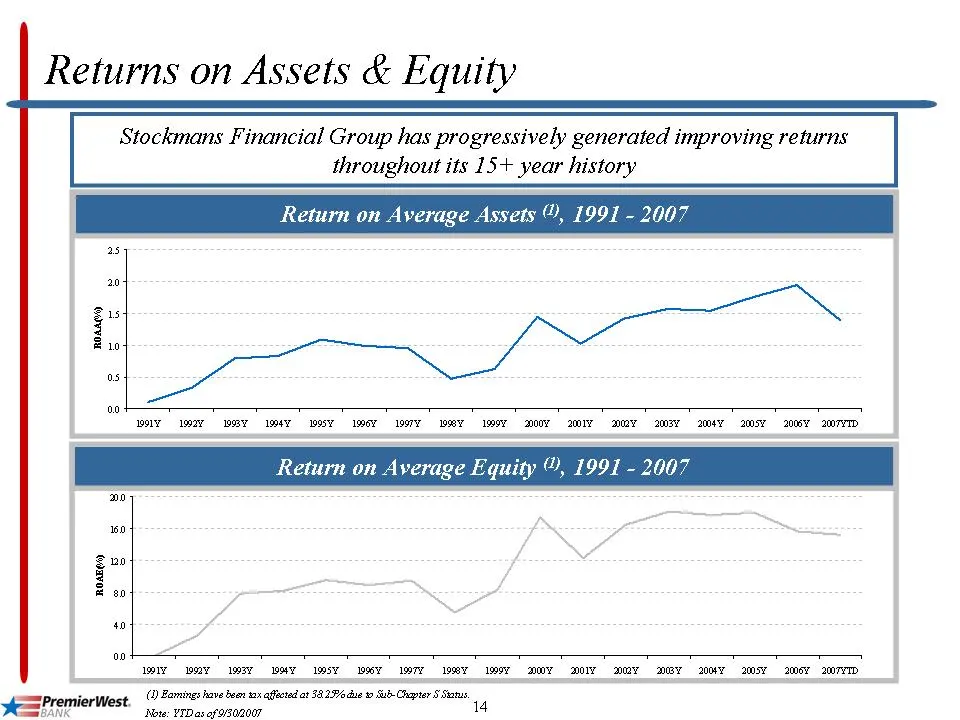
yes PremierWest. SANK (Note: YTDas of 802007 Returns on Assets & Equity Stockmans Financial Group has progressively generated improving returns throughout its 15+ year history | Return on Average Assets ©, 1991 - 2007 as OY we WEY IY osy er oY wy Impey ono) amy) oMmY amy aay amy nosy amrTD Return on
Slide 15: Manageable Execution Risk
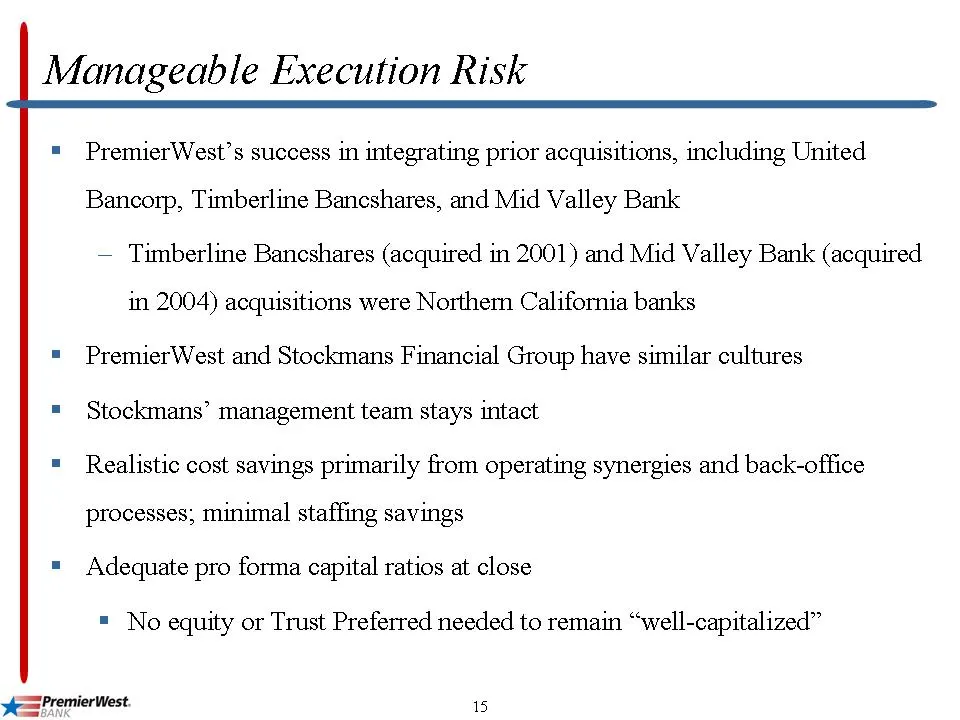
Manageable Execution Risk = PremierWest’s success in integrating prior acquisitions, including United Bancorp, Timberline Bancshares, and Mid Valley Bank — Timberline Bancshares (acquired in 2001) and Mid Valley Bank (acquired. in 2004) acquisitions were Northern California banks = PremierWest and S
Slide 16: Consistent with Territory Growth Strategy
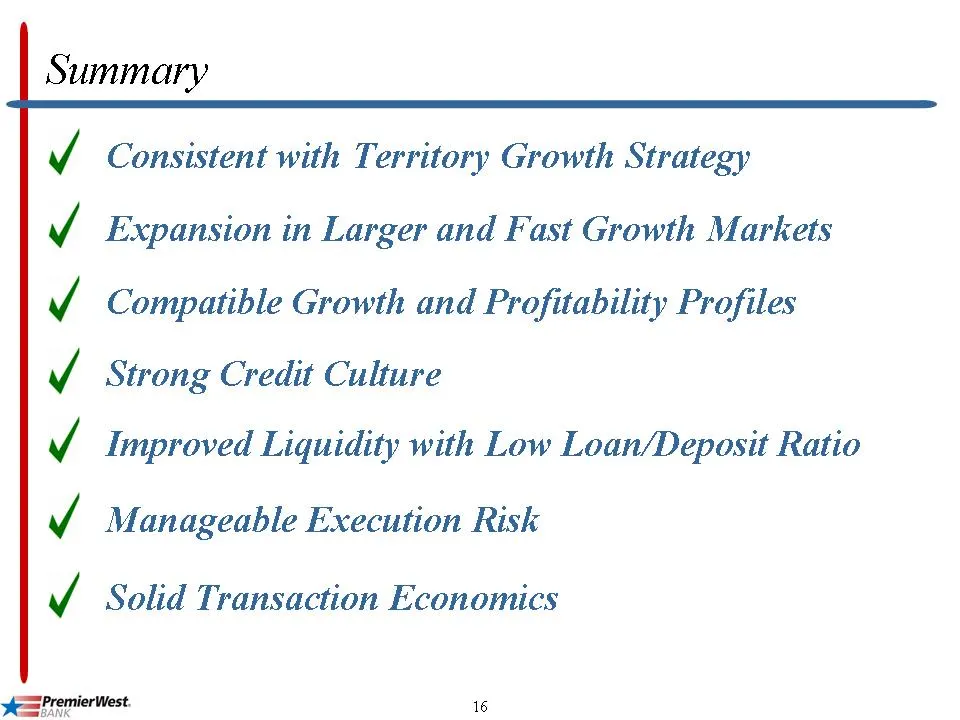
Consistent with Territory Growth Strategy Expansion in Larger and Fast Growth Markets Compatible Growth and Profitability Profiles Strong Credit Culture Improved Liquidity with Low Loan/Deposit Ratio Manageable Execution Risk / Vv / / / V / yes PremierWest. 16 Solid Transaction Economics
Slide 17: Forward-Looking Statements and Additional Information
Forward-Looking Statements and Additional Information = This presentation includes forward-looking statements within the meaning of the “Safe-Harbor” provisions afthe Private Securities Litigation Reform Act of 1995, which management believes are a Denefi to Shareholders. These statements are necess
Source: SEC EDGAR · 8-K filed Oct 22, 2007
More decks from PremierWest Bancorp
 Shareholder Meeting (May 2011)27 slides · May 26, 2011
 Shareholder Meeting (May 2010)29 slides · May 28, 2010
 D.A. Davidson & Co. Annual Financial Services Conference 201027 slides · May 12, 2010
 IPO Roadshow (February 2010)28 slides · Feb 18, 2010
 Shareholder Meeting (June 2009)27 slides · Jun 24, 2009
 Sandler O'Neill 2009 West Coast Financial Services Conference16 slides · Feb 26, 2009