PremierWest Bancorp — Shareholder Meeting (May 2010)
29 slides from PremierWest Bancorp's shareholder meeting presentation, May 28, 2010
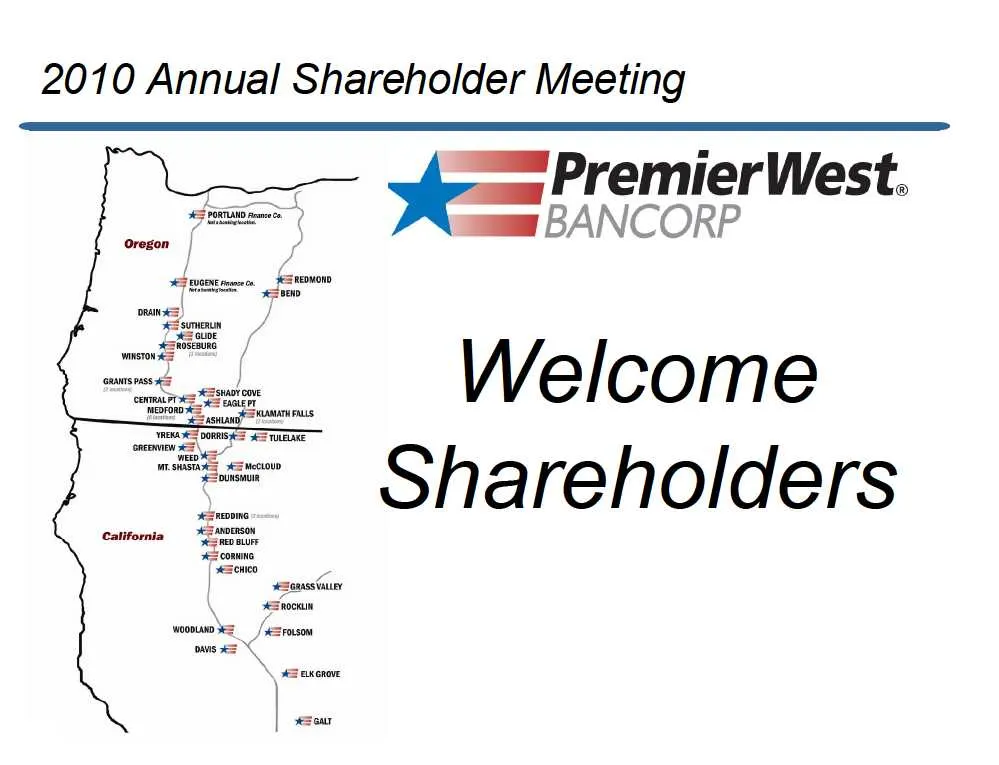
Slide 1: 2010 Annual Shareholder Meeting
2010 Annual Shareholder Meeting ===" PremierWest. eum BANCORP Welcome Shareholders
Slide 2: Introductions
Introductions
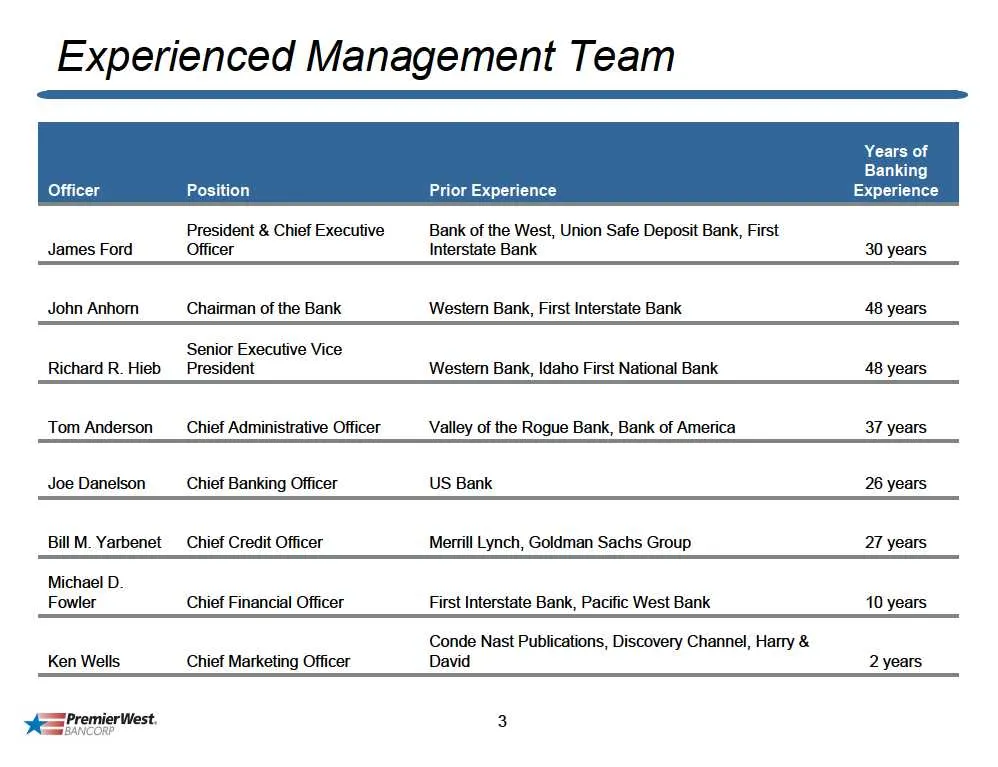
Slide 3: Experienced Management Team
Experienced Management Team Years of Banking Officer Position Prior Experience Experience President & Chief Executive Bank of the West, Union Safe Deposit Bank, First James Ford Officer Interstate Bank 30 years John Anhorn Chairman of the Bank Western Bank, First Interstate Bank 48 years: Senior Exe
Slide 4: Management's Report
Management's Report ee PremierWest
Slide 5: Forward Looking Statement Disclosure
Forward Looking Statement Disclosure This presentation may include “forward-looking statements” about PremierWest. Forward-looking statements generally include financial projections; descriptions of plans or objectives of management for future operations, products or services; forecasts of future ec
Slide 6: Net Income (Loss) Available to Common Shareholders / Loan Loss Provision
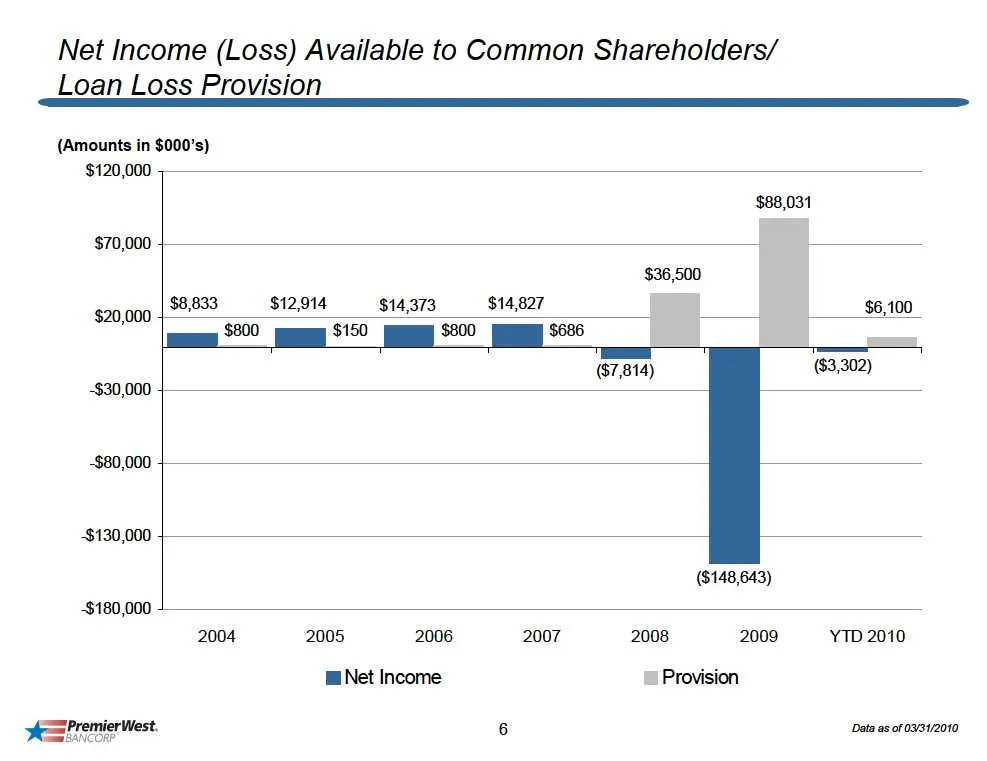
Net Income (Loss) Available to Common Shareholders/ Loan Loss Provision (Amounts in $000’s) $120,000 $88,031 $70,000 $36,500 $20,000 {$2833 $12,914 $14,373, $14,827 $6,100 {ummm $200 $*50 ER $200 E86 © ($7,814) ($3,302) -$30,000 -$80,000 -$130,000 ($148,643) -$180,000 2004 2005 2006 2007 2008 2009 Y
Slide 7: Core Deposit Franchise
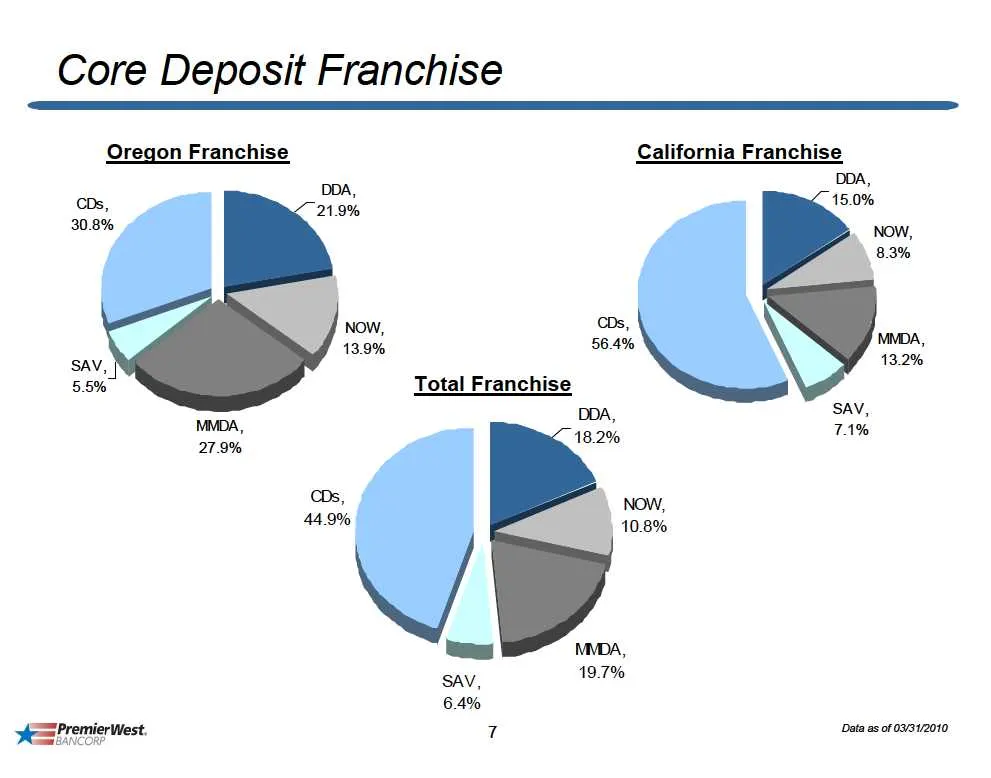
Core Deposit Franchise Oregon Franchise California Franchise Total Franchise 6.4% Sling west T ata 2s oF 09012010
Slide 8: Core Deposit Franchise
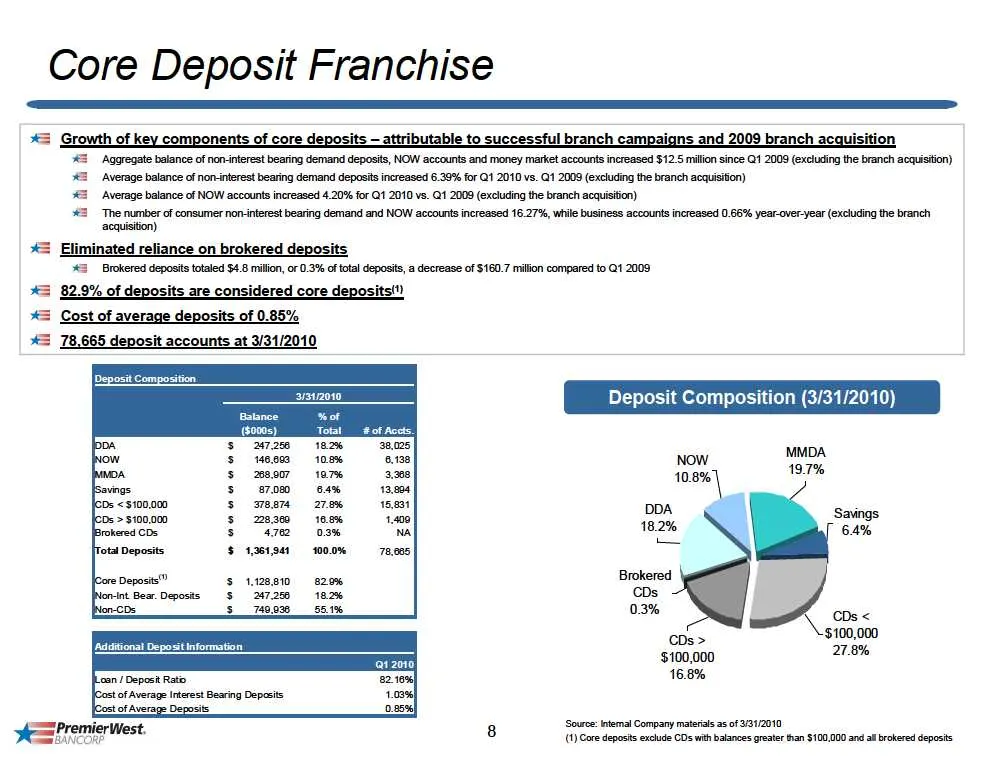
Core Deposit Franchise += Growth of key components of core deposits — attributable to successful branch campaigns and 2009 branch acquisition ‘Aggregate balance of nor interest bearing demand deposits, NOW accounts and money market accounts increased $12.5 milion since Q1 2008 (excluding the branch
Slide 9: Banking Footprint with Strong Market Share
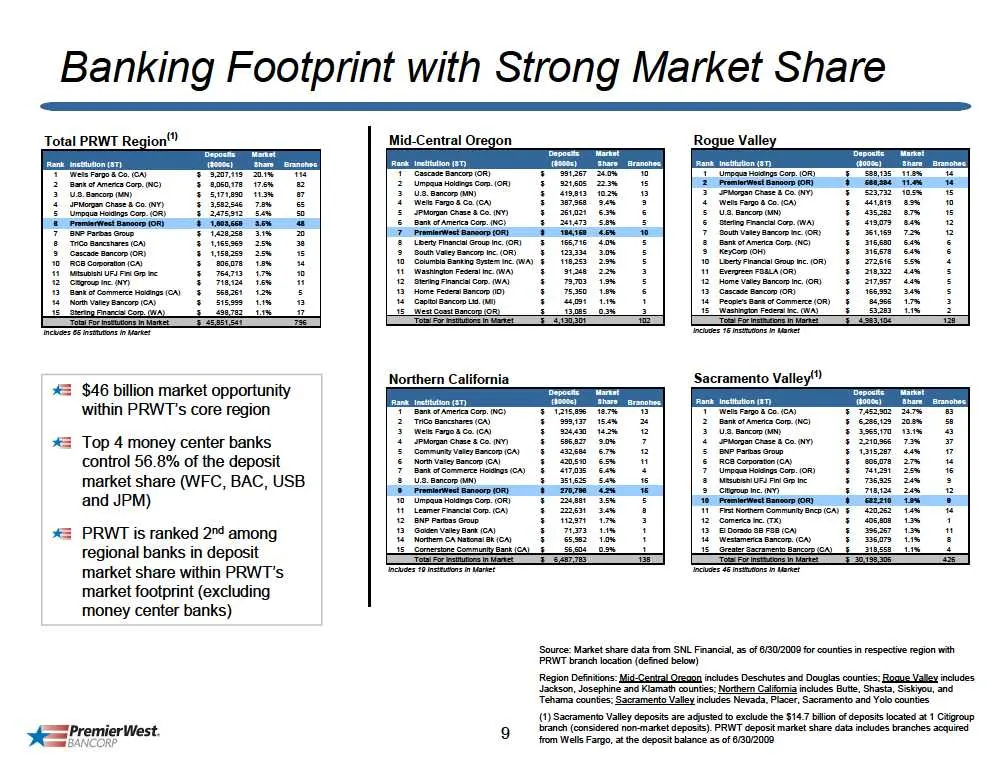
Banking Footprint with Strong Market Share id-Central Oregon Rogue Valley aime : 2 ieee igigs i | [Smee i gs 42 $46 billion market opportunity within PRWT's core region 4 Top 4 money center banks : tiie i 2 control 56.8% of the deposit ® a market share (WFC, BAC, USB = dee ae and JPM) 3 Sais F| a 4
Slide 10: Liquidity Profile Strong liquidity position
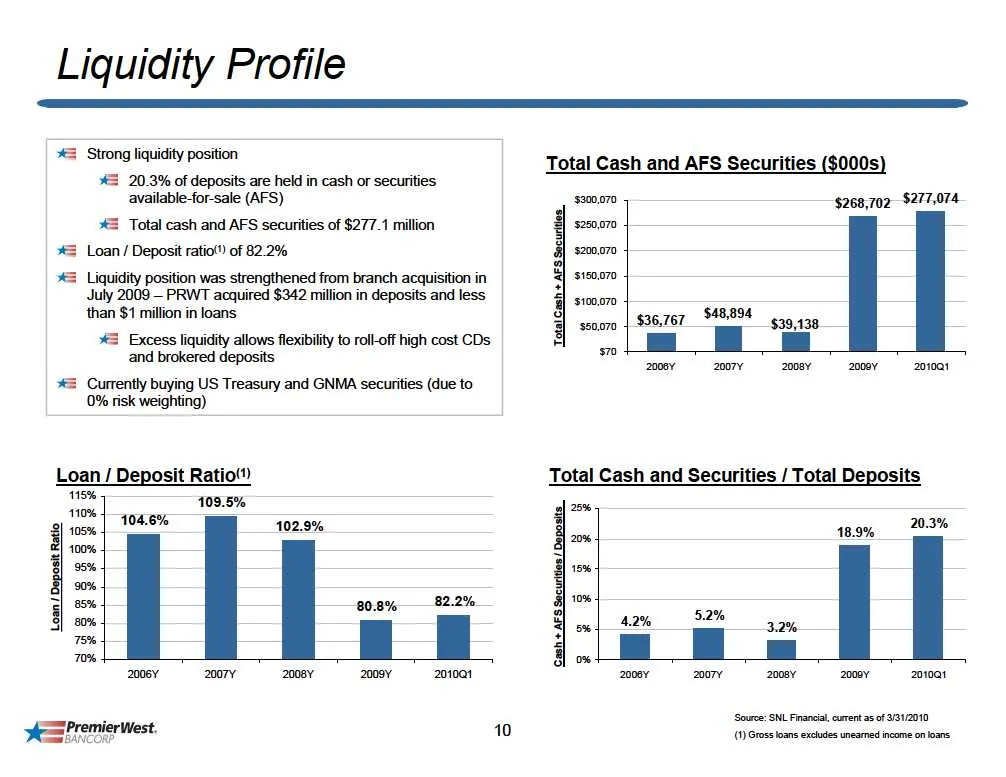
Liquidity Profile 4 Strong liquidity position Total Cash and AFS Securities ($000s) 42 20.3% of deposits are held in cash or securities available-for-sale (AFS) ‘se00.070 $268,702 $277,074 42 Total cash and AFS securities of $277.1 million | s2s0.970 #3 Loan / Deposit ratio!) of 82.2% s200070 FH 3 L
Slide 11: Peer Comparison
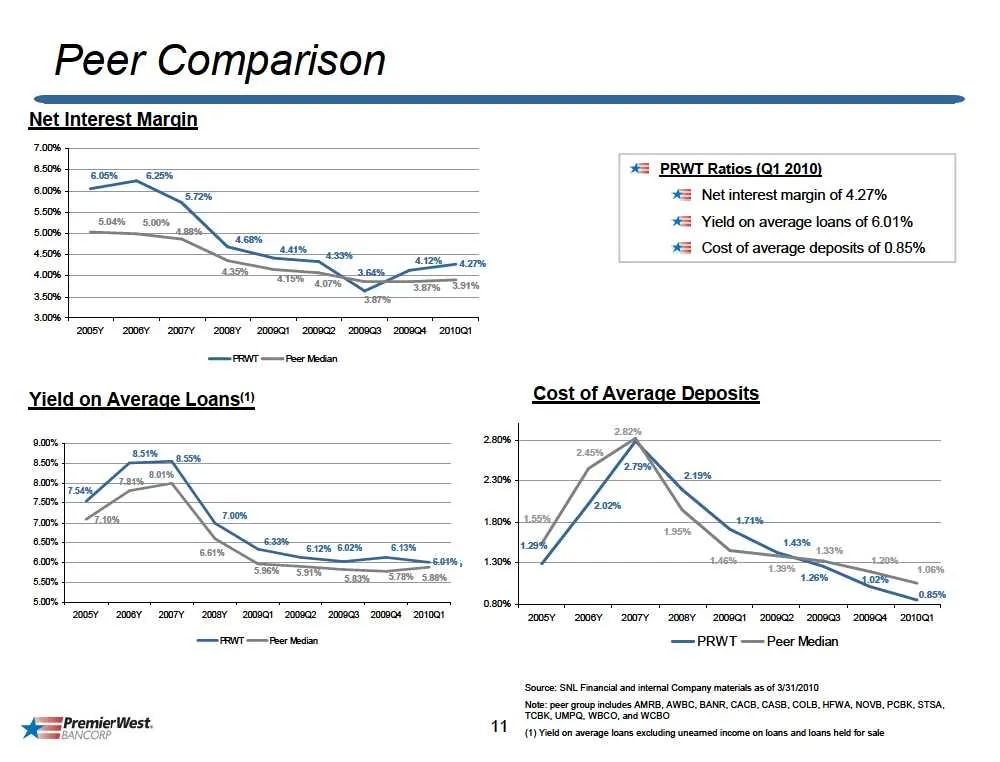
Peer Comparison Net Interest Marai 700% ose 42 PRWT Ratios (Q1 2010) ams 42 Net interest margin of 4.27% oe 42 Yield on average loans of 6.01% ie 4 Cost of average deposits of 0.85% 00x | 50% 200% zaosr anoey " 2an7¥ " aoeey " apoaat ”2ooec2 ” aooecn”axmecs "2o10ct rrr Peer ian Yield on Average Loan
Slide 12: Loan Portfolio by Region
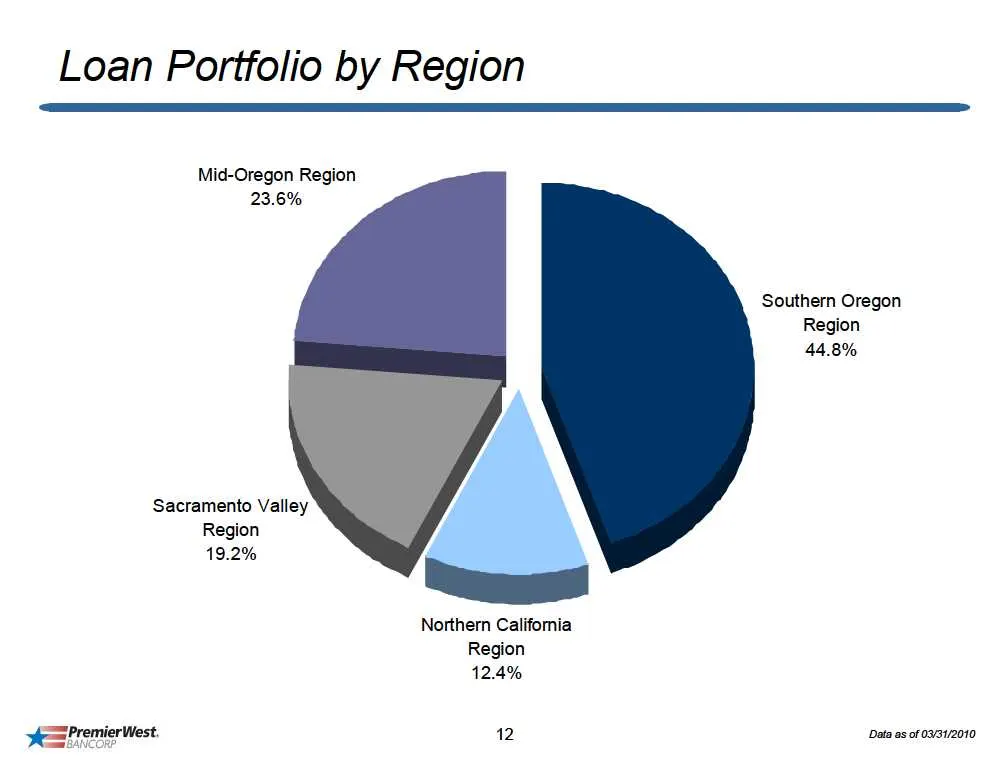
Loan Portfolio by Region Mid-Oregon Region 23.6% Southern Oregon Region 44.8% Sacramento Valley Region 19.2% Northern Califomia Region 12.4% es PremierWest. 12 Data as of 0331/2010 thier
Slide 13: Diversified Loan Portfolio
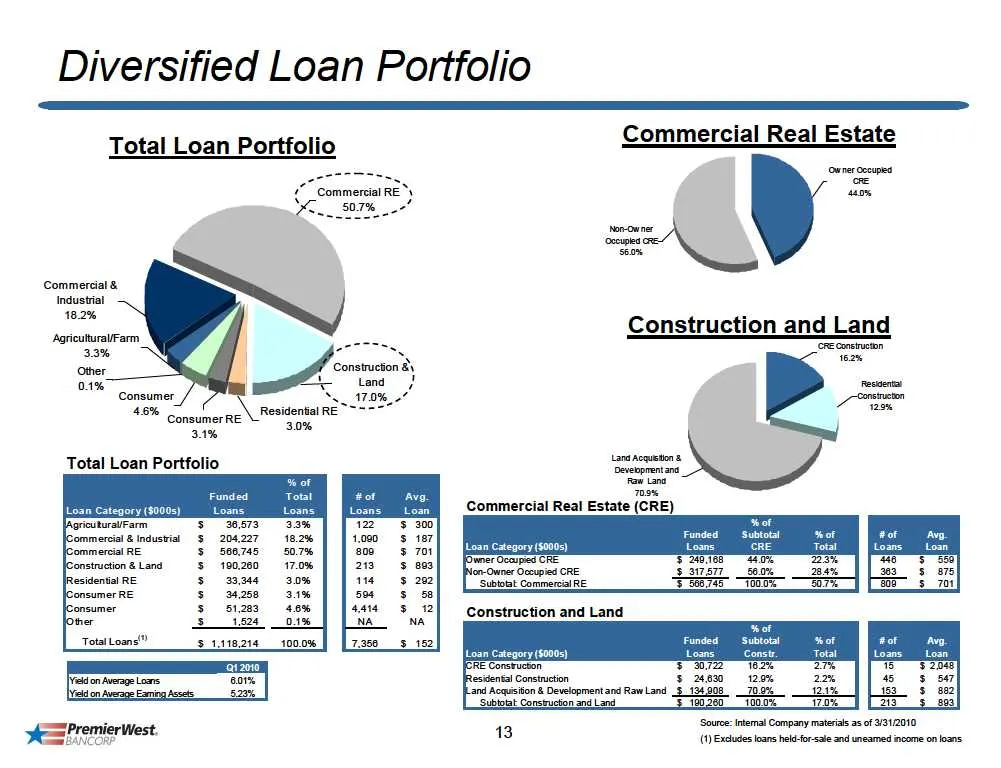
Diversified Loan Portfolio Total Loan Portfo! Commercial Real Estate ae. 4 owner occupa «Commercial RE“ So 507% 2? industrial 18.2% . Construction and Land aricuturalFarm _onsuucvon and’hand 7 on Constructon &\ ie Land escent Ss 170% 2 48% Residental RE~~=~" aa Consumer re \ Resident 3.1% . Lar Auto
Slide 14: Detailed Commercial Real Estate Portfolio
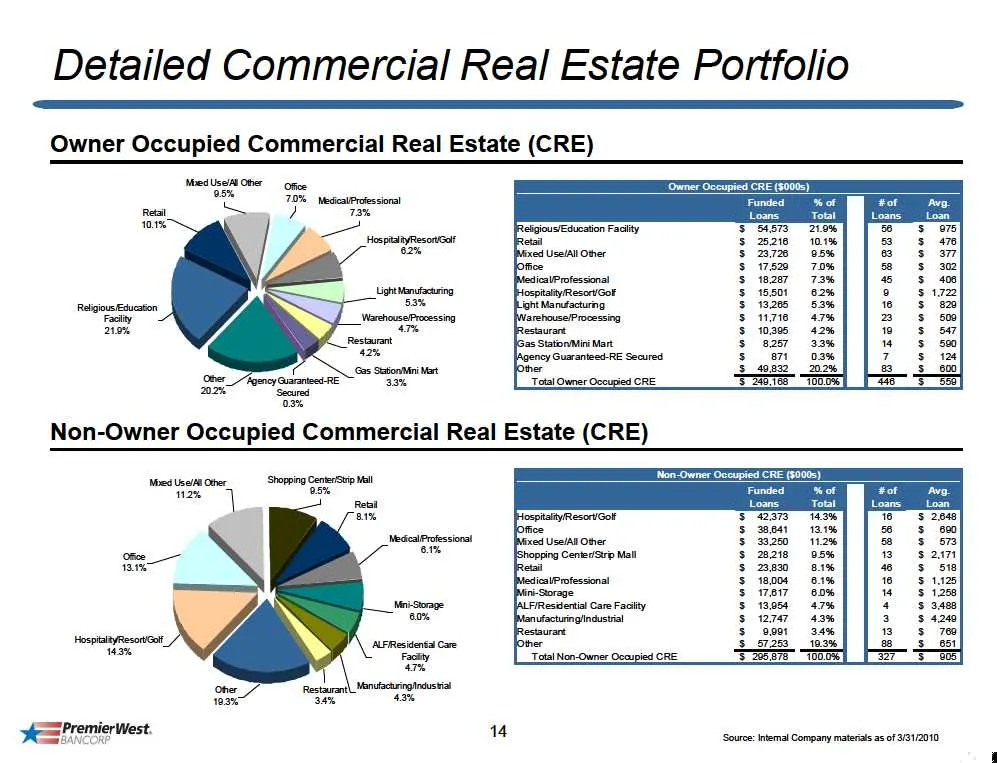
Detailed Commercial Real Estate Portfolio Owner Occupied Commercial Real Estate (CRE) (Owner Occupied CRE ($0005) Funded of Total 28 3 a se 46 a 16 a ‘secured ‘om Non-Owner Occupied Commercial Real Estate (CRE) eS rrerer west. 4 Soc: heal Conary mate of 47912010
Slide 15: Detailed Construction and Land Portfolio
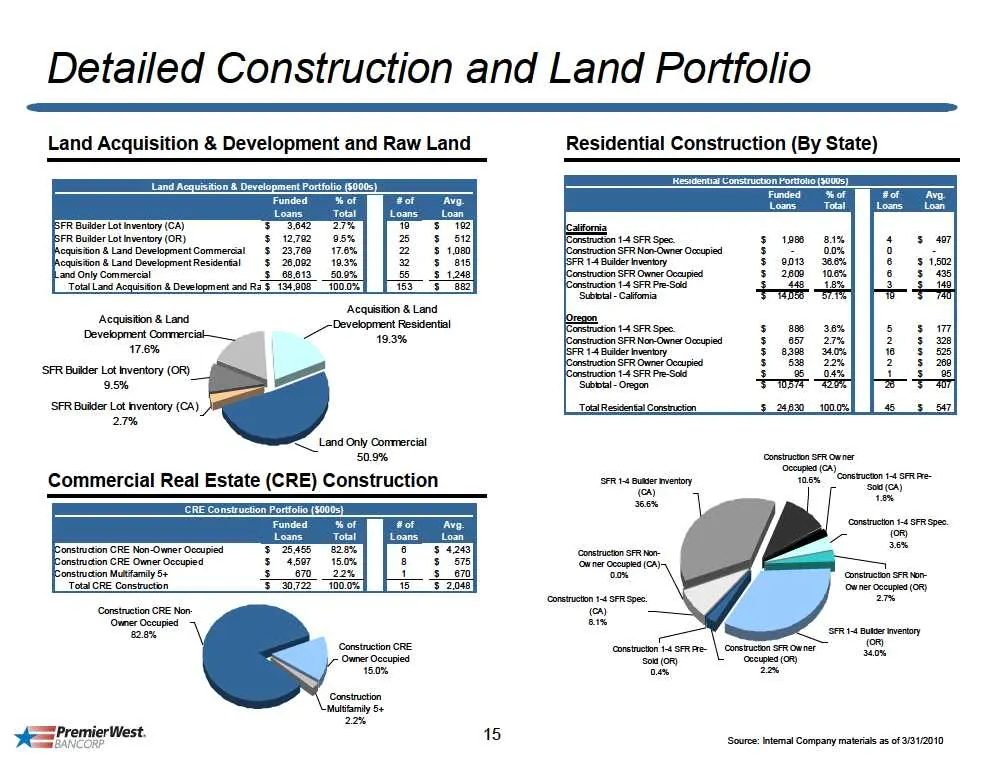
Detailed Construction and Land Portfolio Land Acquisition & Development and Raw Land Residential Construction (By State) Hesiential Construction Fotovo (3005) Finded ot eons Tefal Land Acquisition & Development Portfalio (000s) Funded % of Loans Total BFR Builder Lot inventory (CA) [SFR Buider Lot i
Slide 16: Credit Quality
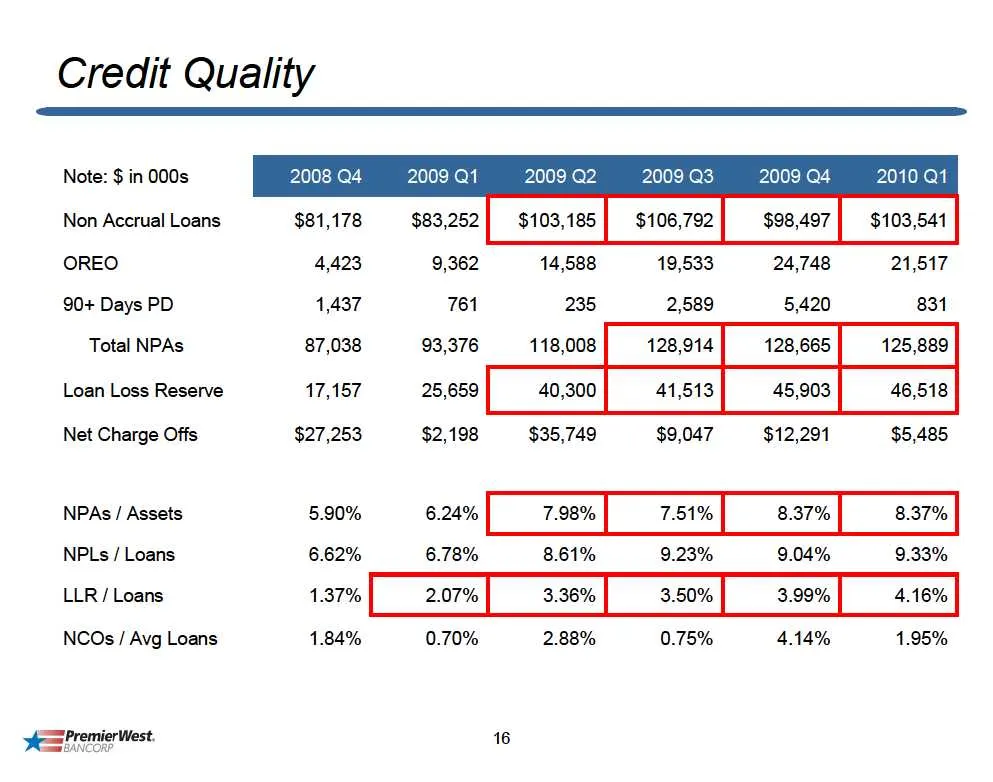
Credit Quality 2009 Q1 2009 Q2 2009 Q3 2009 Q4 2010 Q1 2008 Q4 Note: $ in 000s Non Accrual Loans $81,178 $83,252} $103,185} $106,792 $98,497 | $103,541 OREO 4,423 9,362 14,588 19,533 24,748 21,517 90+ Days PD 1,437 761 235 2,589 5,420 831 Total NPAs 87,038 93,376 118,008] + 128,914] 128,665] 125,880
Slide 17: Geography of Credit Issues
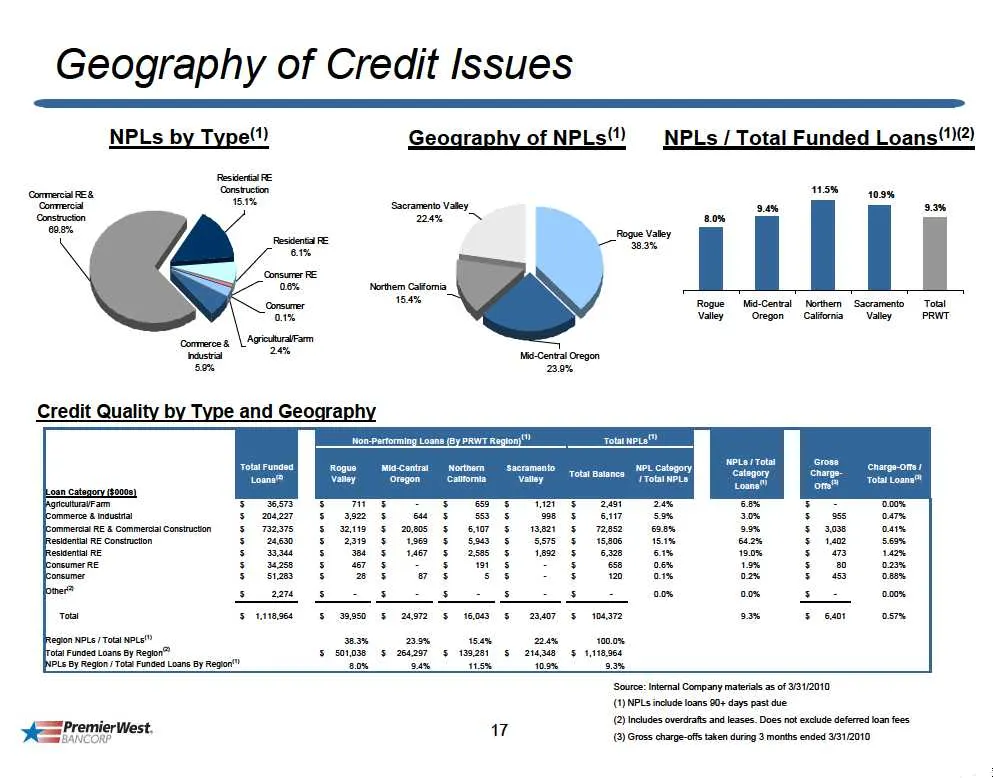
Geography of Credit Issues NPLs by Type) Geography of NPLs) NPLs/Total Funded Loans((2) Grenctn 15% toy Sacramento Vatey ae 23% ms == oy e a roan ge ce ee Consumer eH Rogue Mid-Central Northen Sacramento Total ms = oe eae on Brtoming Loans (8y PRWT Region)” yotunois!™ oll Fun Rogue mia-contrtNortnem
Slide 18: Update on PremierWest
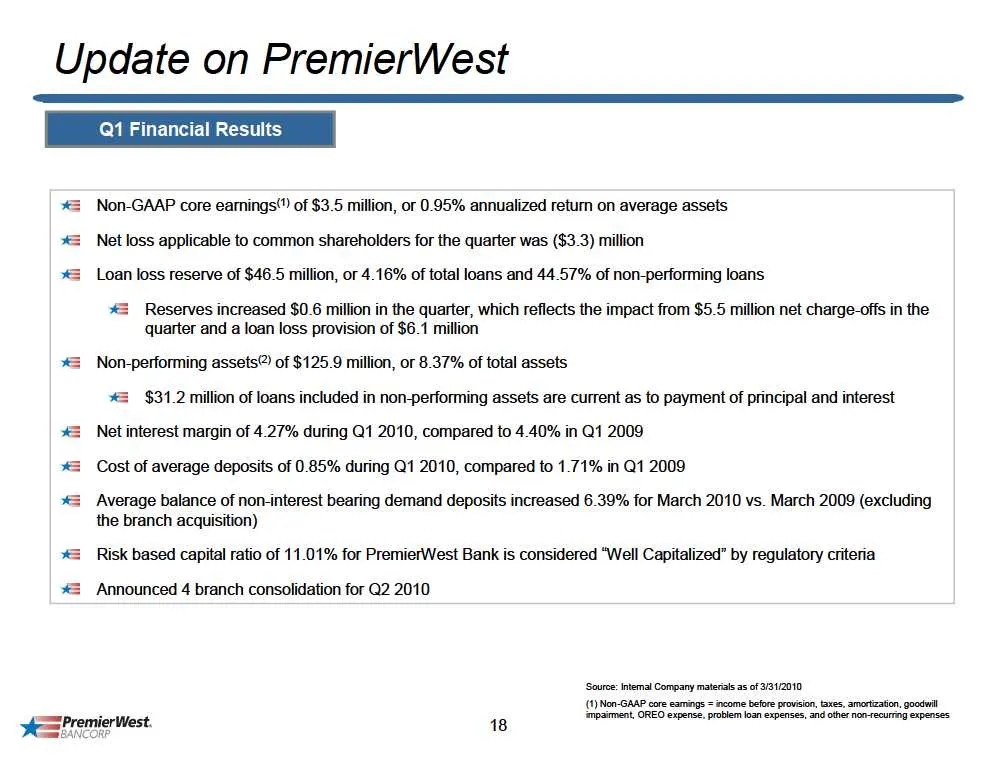
Update on PremierWest ii Non-GAAP core earings" of $3.5 million, or 0.95% annualized retun on average assets Net loss applicable to common shareholders for the quarter was ($3.3) million Loan loss reserve of $46.5 million, or 4.16% of total loans and 44.57% of non-performing loans 42 Reserves increa
Slide 19: Long-Term Strategic Initiatives
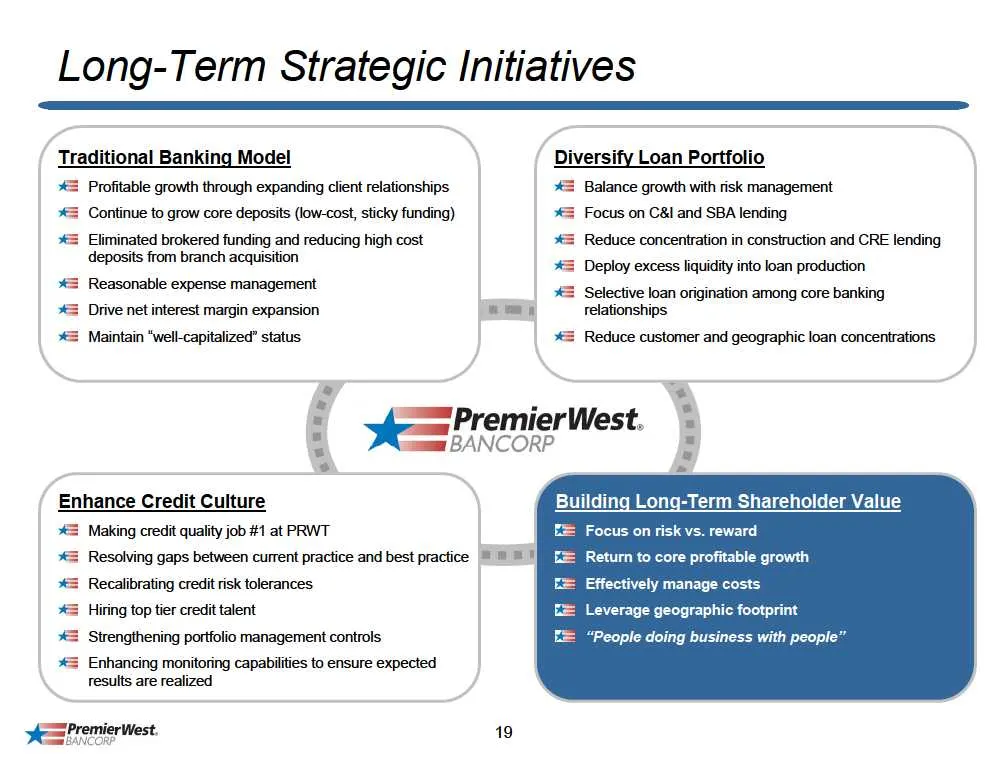
Long-Term Strategic Initiatives Fa ~ / Traditional Banking Model Profitable growth through expanding client relationships Continue to grow core deposits (low-cost, sticky funding) Eliminated brokered funding and reducing high cost deposits from branch acquisition Reasonable expense management iversi
Slide 20: Capital Snapshot
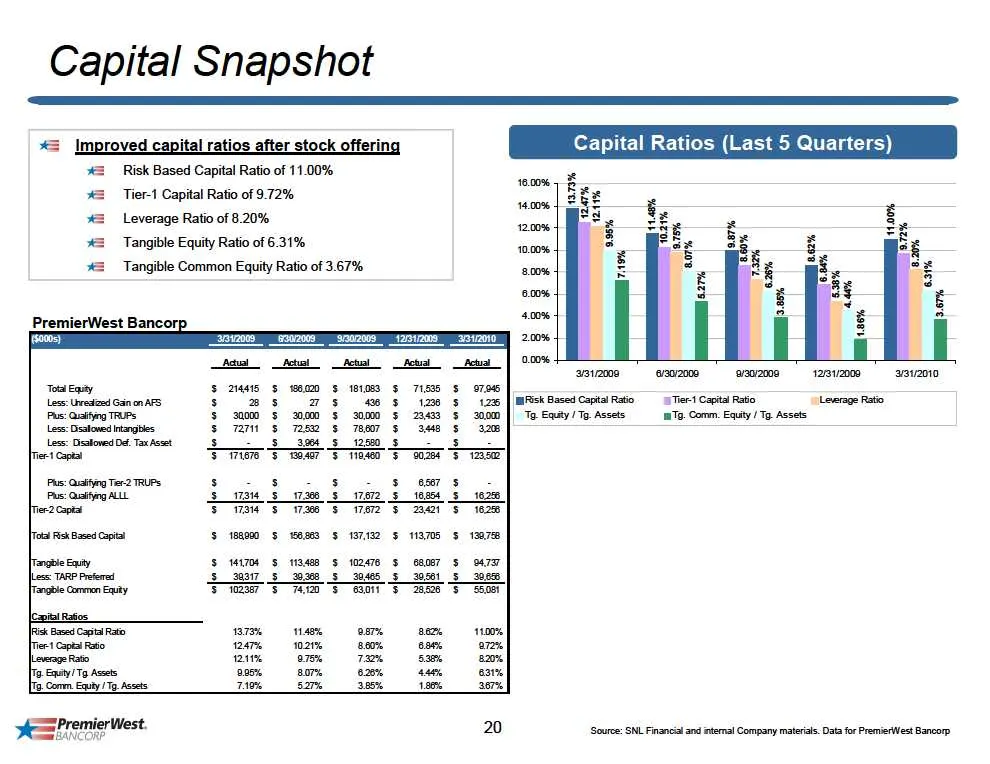
Capital Snapshot = Improved ital ratios after stock offerin: 42 Risk Based Capital Ratio of 11.00% 10.0% 42 Tier Capital Ratio of 9.72% 14.00% 42 _ Leverage Ratio of 8.20% t2c0% 42 Tangible Equity Ratio of 6.31% aa 42 Tangible Common Equity Ratio of 3.67% ame 00% 4.00% PremierWest Bancorp seveme " a
Slide 21: Ownership
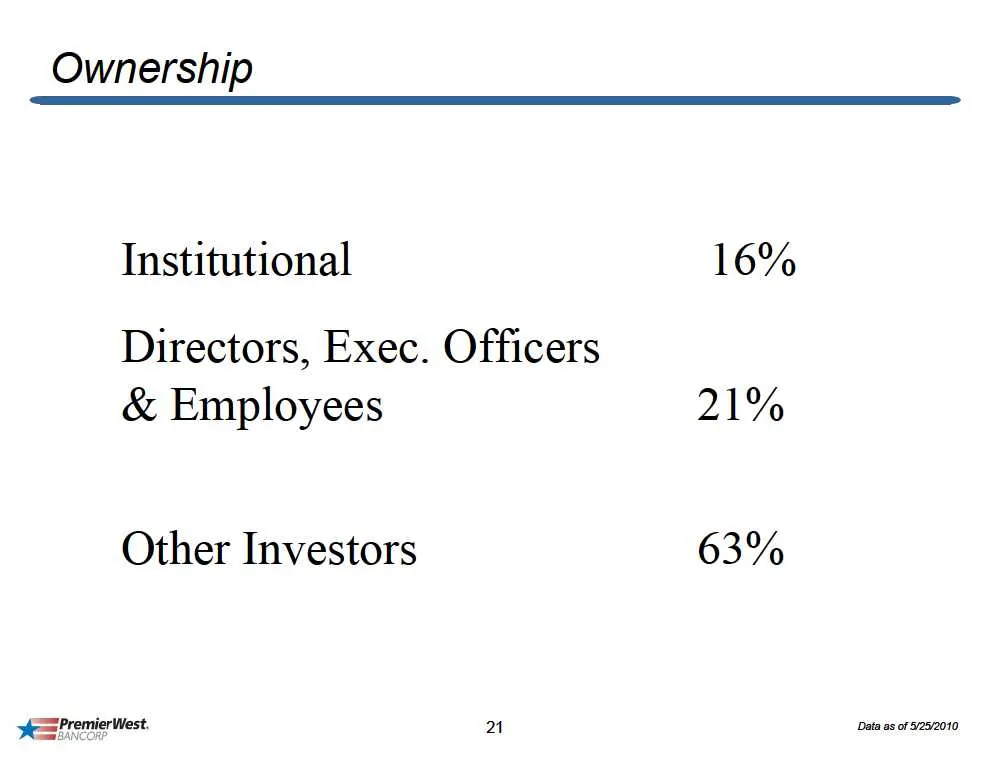
Ownership Institutional 16% Directors, Exec. Officers & Employees 21% Other Investors 63% ee PremierWest. a1 Data as of 52572010
Slide 22: 2010 - 2011 Plans
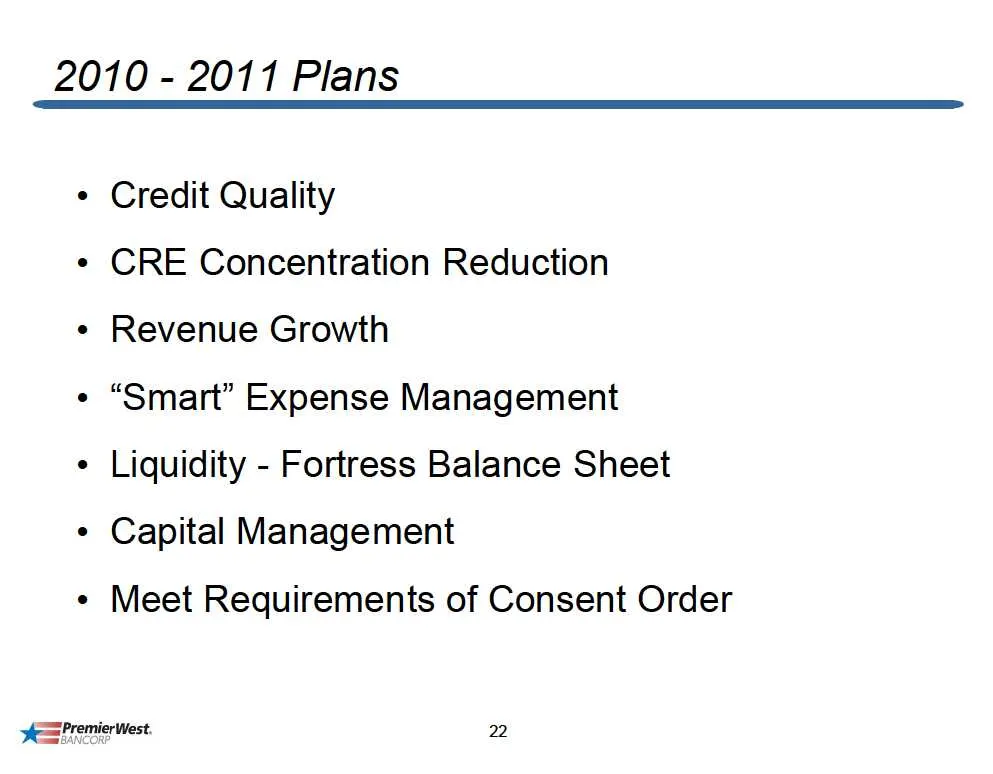
2010 - 2011 Plans Credit Quality CRE Concentration Reduction Revenue Growth “Smart” Expense Management Liquidity - Fortress Balance Sheet Capital Management Meet Requirements of Consent Order ee PremierWest 22
Slide 23: Key Consent Order Requirements for PremierWest Bank
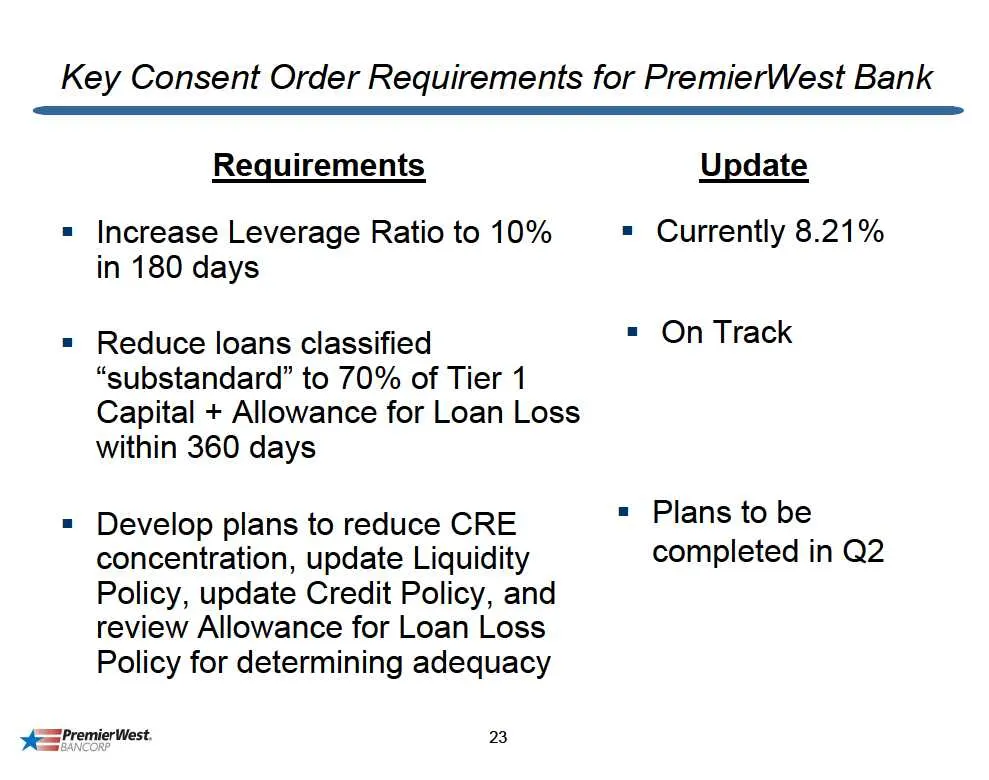
Key Consent Order Requirements for PremierWest Bank Requirements Update = Increase Leverage Ratio to 10% = Currently 8.21% in 180 days = Reduce loans classified * On Track “substandard” to 70% of Tier 1 Capital + Allowance for Loan Loss within 360 days Develop plans to reduce CRE * Plans to be conce
Slide 24: Proposals for Action by Shareholders
Proposals for Action by Shareholders
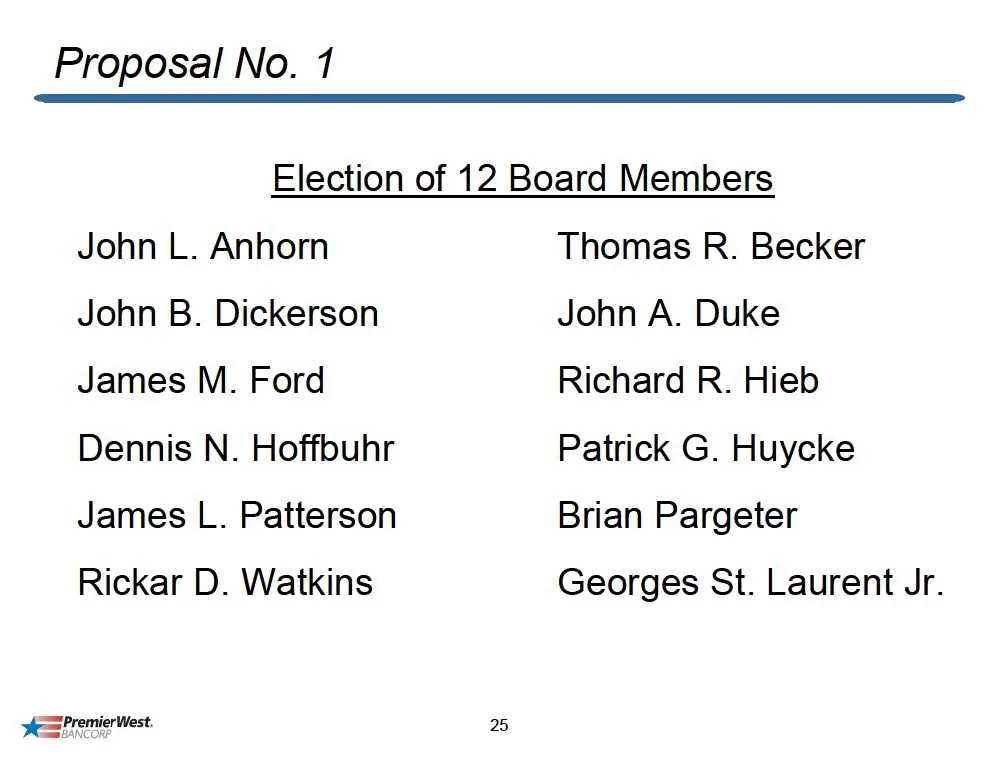
Slide 25: Proposal: Election of Board Members
Proposal No. 1 Election of 12 Board Members John L. Anhorn John B. Dickerson James M. Ford Dennis N. Hoffbuhr James L. Patterson Rickar D. Watkins eS PremierWest 25 Thomas R. Becker John A. Duke Richard R. Hieb Patrick G. Huycke Brian Pargeter Georges St. Laurent Jr.
Slide 26: Proposal: Ratify Appointment of Moss Adams LLP
Proposal No. 2 Ratify Appointment of Moss Adams LLP as Independent Public Accountants ee PremierWest 26
Slide 27: Proposal: Advisory Vote on Executive Compensation
Proposal No. 3 Advisory Vote on Executive Compensation Arrangements and Policies ea PremierWest. 7
Slide 28: VOTE
VOTE
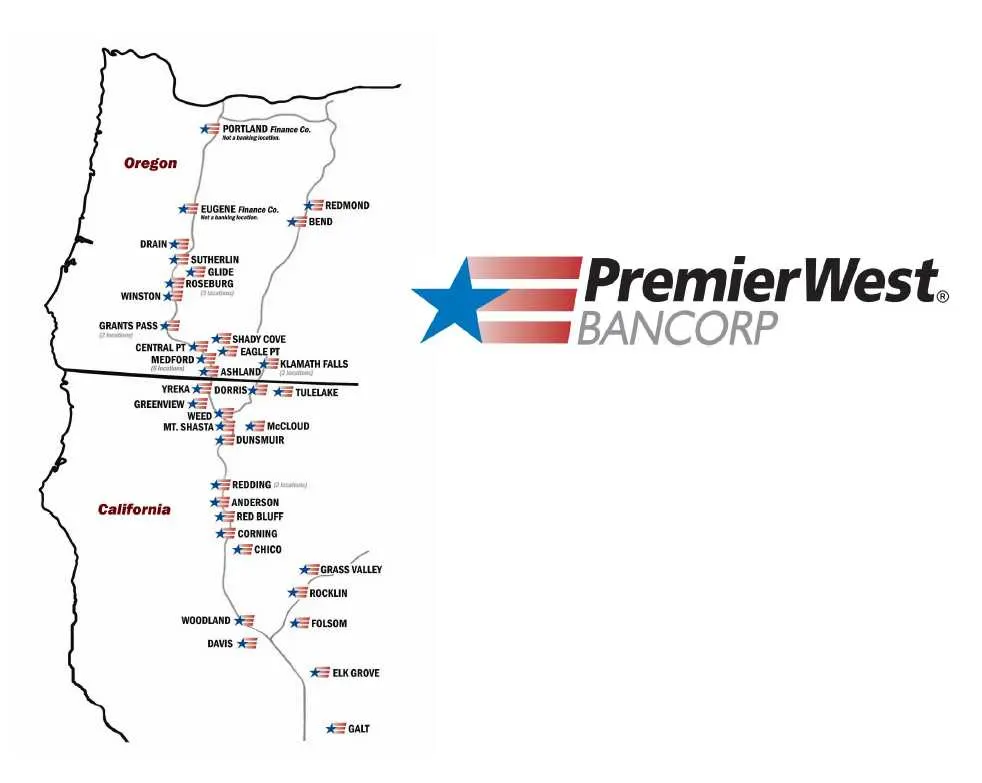
Slide 29: AAT FAS
1 AAT FAS EAGLE PT YREKA AES DORRIS AS eS TULELIRE oneenview = \__* ‘WEED MI.SHASTAES 5 MeCLOUD California eS DUNSMUIR ) esreoine ES ANDERSON SES RED BLUFF eS connina [sesentco Z Sams aie ( Soca =a js = __/eroisom aus 65 AS EK GROVE Scar === PremierWest. sums BANCORP
Source: SEC EDGAR · 8-K filed May 28, 2010
More decks from PremierWest Bancorp
 Shareholder Meeting (May 2011)27 slides · May 26, 2011
 D.A. Davidson & Co. Annual Financial Services Conference 201027 slides · May 12, 2010
 IPO Roadshow (February 2010)28 slides · Feb 18, 2010
 Shareholder Meeting (June 2009)27 slides · Jun 24, 2009
 Sandler O'Neill 2009 West Coast Financial Services Conference16 slides · Feb 26, 2009
 D.A. Davidson & Co. Conference (February 2009)13 slides · Feb 19, 2009