DNB Financial — Investor Presentation (August 2013)
59 slides from DNB Financial's investor presentation, Aug 21, 2013
Slide 1: Investor Overview Presentation
Investor Overview Presentation
Slide 2: Forward-looking statements & additional information
Forward-looking statements: Certain statements contained in this presentation are forward-looking in nature. These include all statements about DNB's plans, objectives, expectations and other statements that are not historical facts, and usually use words such as "expect," "anticipate," "believe" an
Slide 3: Table of Contents
I. Corporate Overview (Pages 4-9) II. Strong Market Drives Opportunity (Pages 10-21) III. Consistent Performance, Stable Growth & Financial Trends (Pages 22-38) IV. The Differentiators: Operationally Unique (Pages 39-42) V. Experienced Management and Board Leadership (Pages 43-47) VI. Invest in DNBF
Slide 4: Corporate Overview
CORPORATE OVERVIEW Founded: 1860, The oldest National Bank in the greater Philadelphia Region Headquarters: Downingtown, Chester County, Pennsylvania NASDAQ Ticker: DNBF Total Assets: $668 million Deposits: $562 million Total Equity: $57 million Branch Offices: 13 Share Price: $17.94 (7/31/13) Marke
Slide 5: Compelling Investment Opportunity
COMPELLING INVESTMENT OPPORTUNITY Snapshot June 30, 2013 • High quality footprint in affluent Chester and Delaware Counties, Pennsylvania • Attractive valuation with room to grow o Price to LTM’s Earnings: 9.57X - Peers @ 12.2X o Price to TBV: 111% - Peers @ 124% • Book value per share has grown fro
Slide 6: Compelling Investment Opportunity
COMPELLING INVESTMENT OPPORTUNITY • Serving growing, diversified and affluent markets in Chester and Delaware Counties, Pennsylvania • Well capitalized, highly liquid, with clean, conservative balance sheet • Well positioned to grow to $1 billion-plus in assets • Low-cost core deposits funds lending
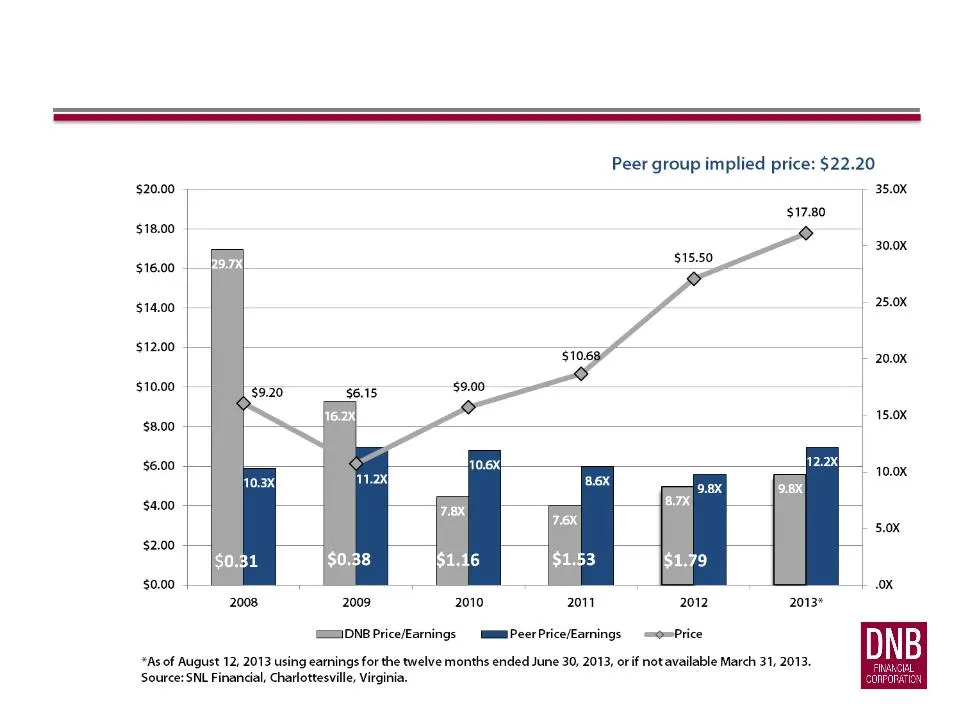
Slide 7: Historical Stock Price and Price to Earnings Ratios Compared to Peers
$1.82 HISTORICAL STOCK PRICE AND PRICE TO EARNINGS RATIOS COMPARED TO PEERS
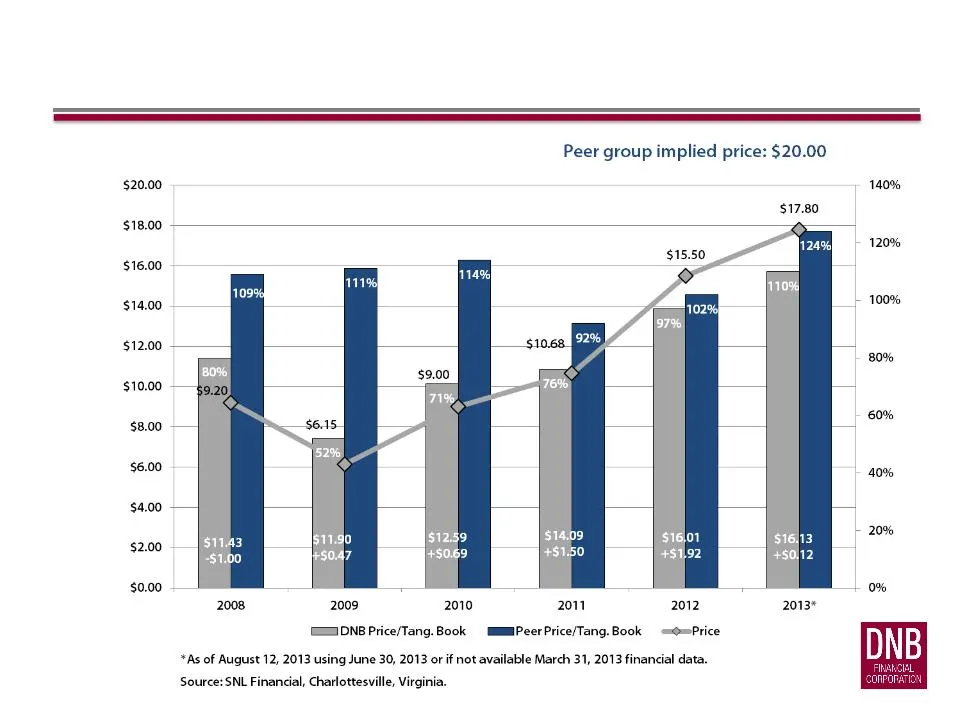
Slide 8: Historical Stock Price and Price to Tangible Book Ratios Compared to Peers
HISTORICAL STOCK PRICE AND PRICE TO TANG. BOOK RATIOS COMPARED TO PEERS
Slide 9: Key Initiatives & Milestones
• Successful balance sheet restructure in early 2010 - ahead of the curve • Purchased Boothwyn, PA branch in June 2012 • One of the 19 banks nationwide to be named to KBW Honor Roll for 3 successive years • Increased dividend in first quarter 2013 KEY INITIATIVES & MILESTONES o Significantly reduced
Slide 10: Strong Market Drives Opportunity
Strong Market Drives Opportunity
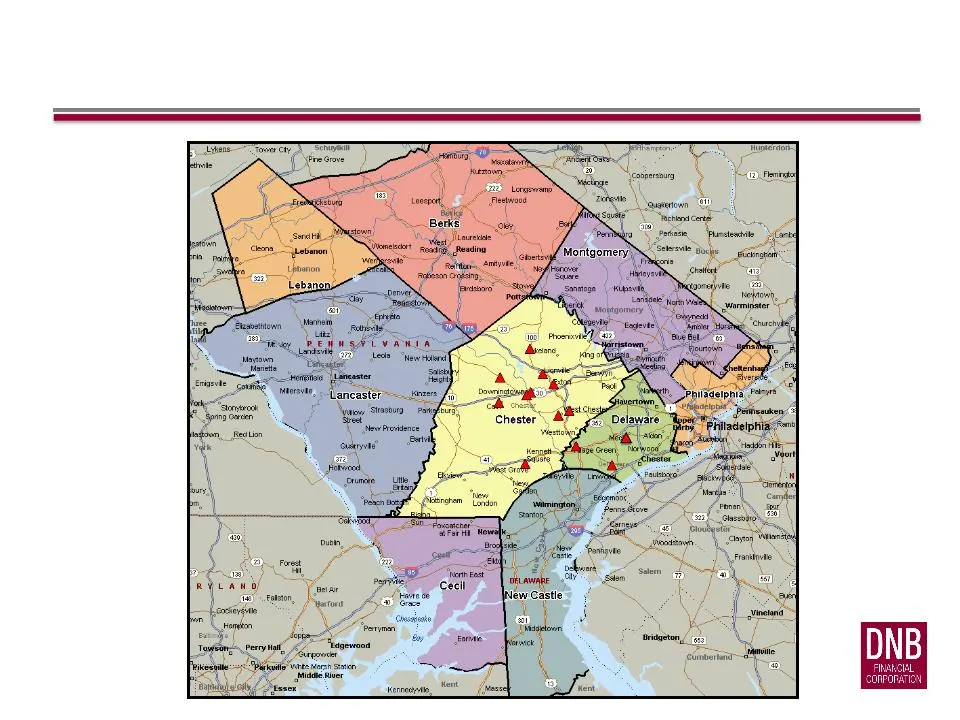
Slide 11: Established Presence in Attractive Southeastern Pennsylvania Market
ESTABLISHED PRESENCE IN ATTRACTIVE SOUTHEASTERN PENNSYLVANIA MARKET
Slide 12: Banking Market Overview
County # of Branches Total Deposits in Market ($000) Total Population 2012 (Actual) Population Change 2011- 2012 (%) Projected Population Change 2012- 2017 (%) Median HH Income 2012 ($) Projected HH Income Change 2012- 2017 (%) Chester 191 10,777,700 506,575 0.74% 5.33% 86,265 13.27% Delaware 173 11
Slide 13: Market Overview and Demographics
MARKET OVERVIEW AND DEMOGRAPHICS Largest Market: Chester County, PA • Fast Growing: Population 506,575 in 2012, representing an increase of 73,074 from the 2000 Census • Best Educated in PA: Of the population 25 years or older, 93% are high school graduates, 48% have a bachelor’s degree or higher an
Slide 14: Growing Banking Presence: Delaware County, PA
Growing Banking Presence: Delaware County, PA • Population 561,098 in 2012, representing an increase of 8,805 from the 2000 Census • Of the population 25 years or older, 92% are high school graduates, 35% have a bachelor’s degree or higher, and 15% have a graduate or professional degree (U.S. Census
Slide 15: Strategy to Serve Our Markets and Grow
• Continue to attract low cost core deposits • Grow fee revenue as a percentage of total revenues by investing in new business lines, building full client relationships and maximizing significant untapped cross-sell potential • Build relationship banking in retail and commercial while providing a co
Slide 16: DNB vs Competitors: Deposit Market Share
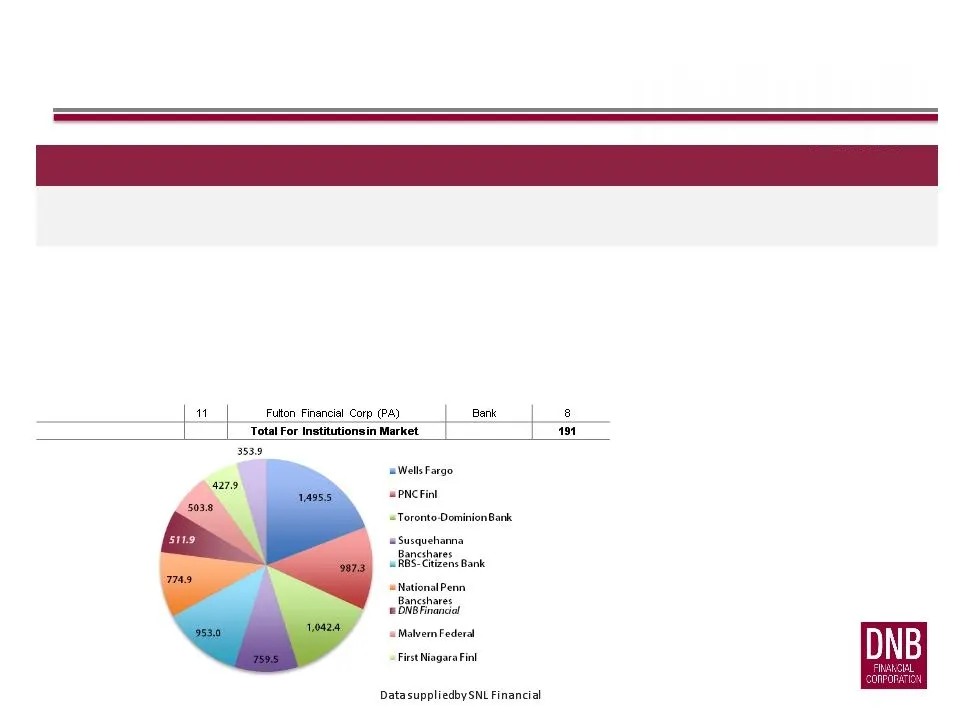
Chester County, PA 2012 Rank 2011 Rank Institution (ST) Type 2012 Number of Branches 2012 Total Deposits in Market ($M) 2012 Total Market Share (%) 2011 Total Deposits in Market ($M) 2011 Total Market Share (%) 1 1 Wells Fargo & Co. (CA) Bank 17 1,495.5 13.88 1,418.7 13.30 2 3 Toronto-Dominion Bank
Slide 17: Balanced Deposit Mix: Five Quarters of Core Deposit Growth
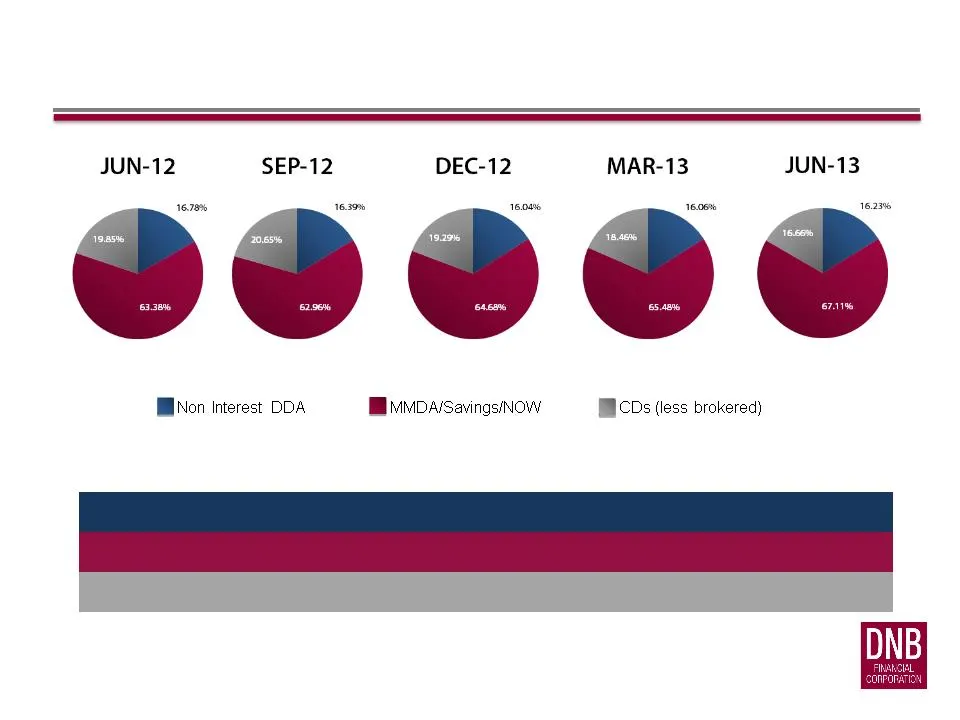
Jun-12 Sep-12 Dec-12 Mar-13 Jun-13 Non Interest DDA 16.78% 16.39% 16.04% 16.06% 16.23% MMDA/Savings/NOW 63.38% 62.96% 64.68% 65.48% 67.11% CDs (less brokered) 19.85% 20.65% 19.29% 18.46% 16.66% BALANCED DEPOSIT MIX: FIVE QUARTERS OF CORE DEPOSIT GROWTH
Slide 18: High Level of Low Cost Core Deposits
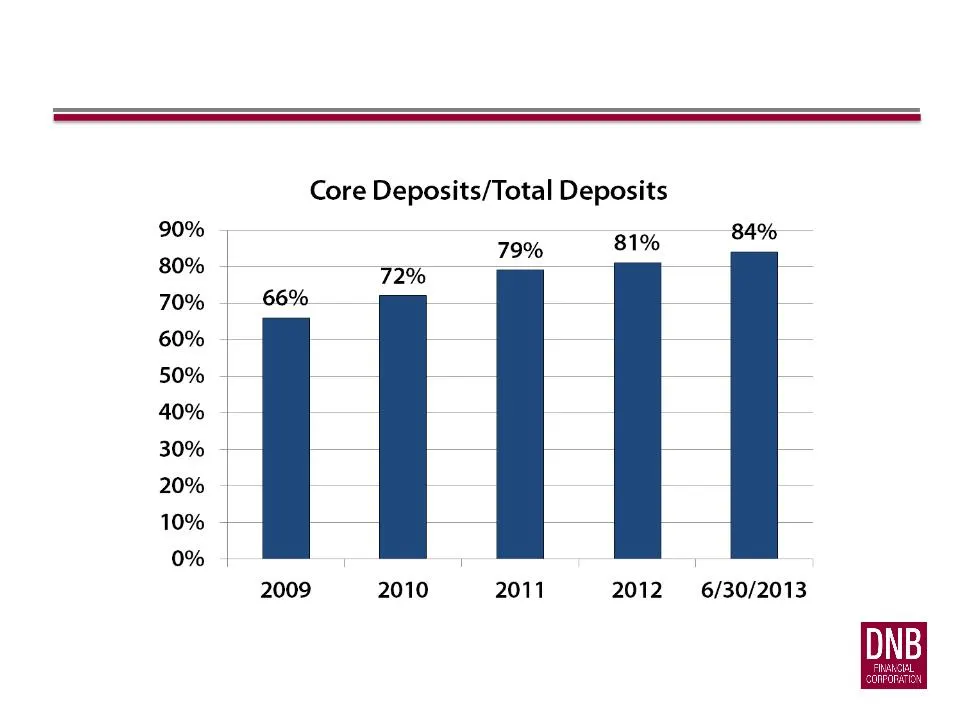
HIGH LEVEL OF LOW COST CORE DEPOSITS
Slide 19: Detailed Loan Portfolio Composition
Loan Type $ Balance Percent Commercial RE OO 84,798 21.76% Commercial RE NOO 78,172 20.05% Residential 1-4 59,747 15.33% Commercial & Industrial 50,428 12.94% Residential 5+ 25,489 6.54% SBA/USDA Guaranteed 29,911 7.67% Construction 17,023 4.37% Home Equity LOC 18,931 4.86% Municipal/Govt/Non-Profit
Slide 20: Balanced Loan Portfolio
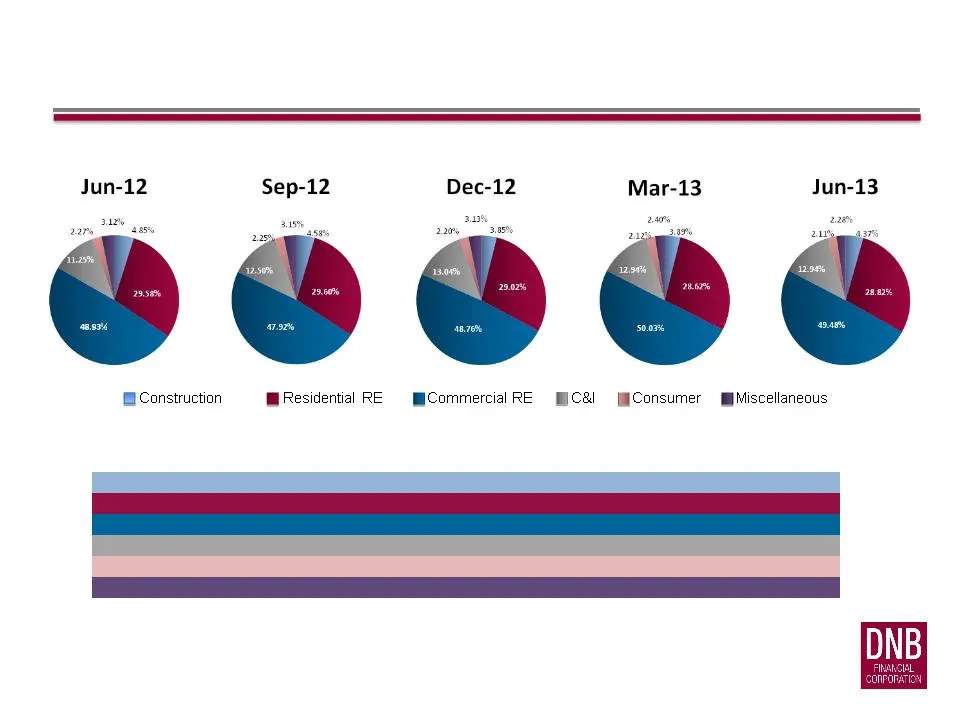
Jun-12 Sep-12 Dec-12 Mar-13 Jun-13 Construction 4.85% 4.58% 3.85% 3.89% 4.37% Residential RE 29.58% 29.60% 29.02% 28.62% 28.82% Commercial RE 48.93% 47.92% 48.76% 50.03% 49.48% C&I 11.25% 12.50% 13.04% 12.94% 12.94% Consumer 2.27% 2.25% 2.20% 2.12% 2.11% Miscellaneous 3.12% 3.15% 3.13% 2.40% 2.28% R
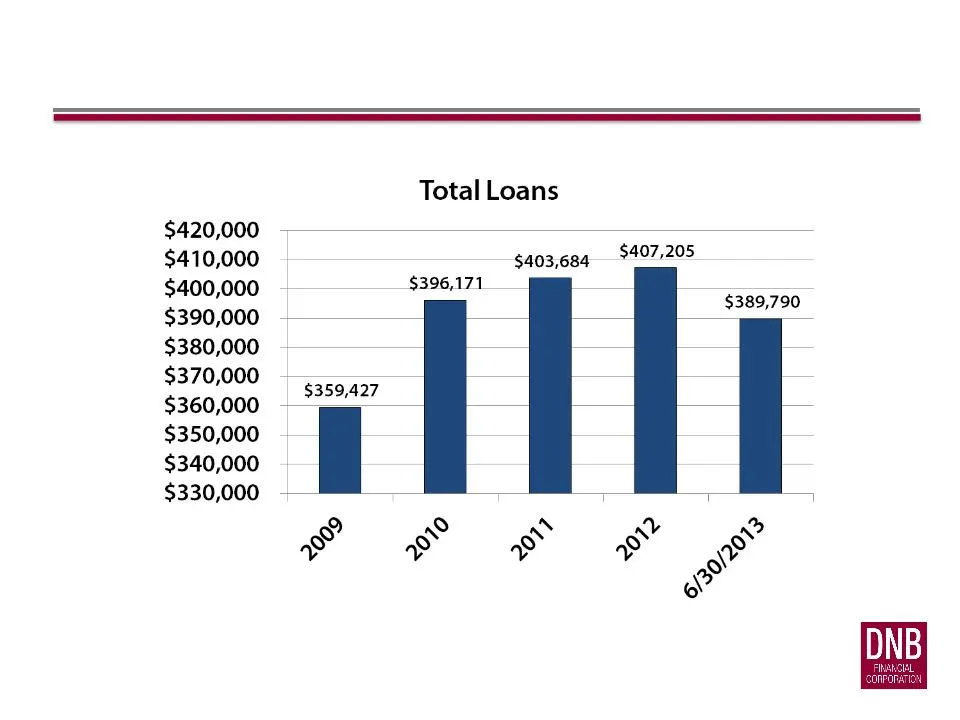
Slide 21: Total Loans
$420,000 $410,000 $400,000 $390,000 - $380,000 $370,000 $360,000 $350,000 $340,000 $330,000 Total Loans $403,684 $407,205 $396,171 $389,790 $359,427 | ! U T T 1 2 © RS a > SS SF LS
Slide 22: DNB's Financial Strength, Consistent Performance, Stable Growth and Financial Trends
DNB’s Financial Strength, Consistent Performance, Stable Growth and Financial Trends
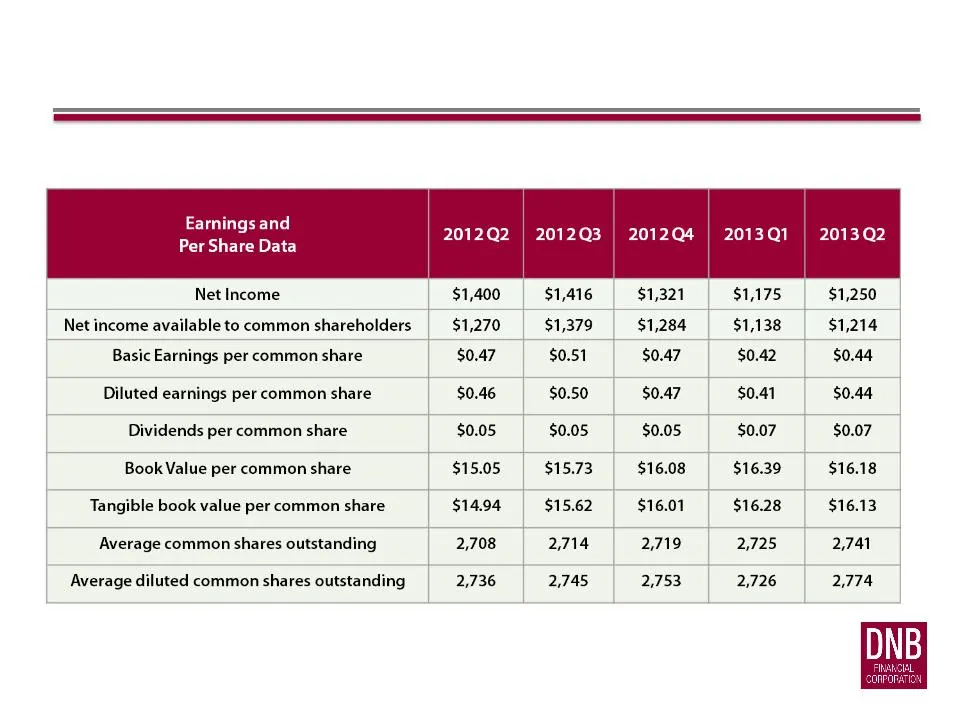
Slide 23: Earnings and Per Share Data
Eamings and Per Share Data 2012Q2 | 2012Q3 2013Q1 2013Q2 Net Income $1,400 $1,416 $1,321 $1,175 $1,250 Net income available to common shareholders $1,270 $1,379 $1,284 $1,138 $1,214 Basic Earnings per common share $0.47 $0.51 $0.47 $0.42 $0.44 Diluted earnings per common share $0.46 $0.50 $0.47 $0.4
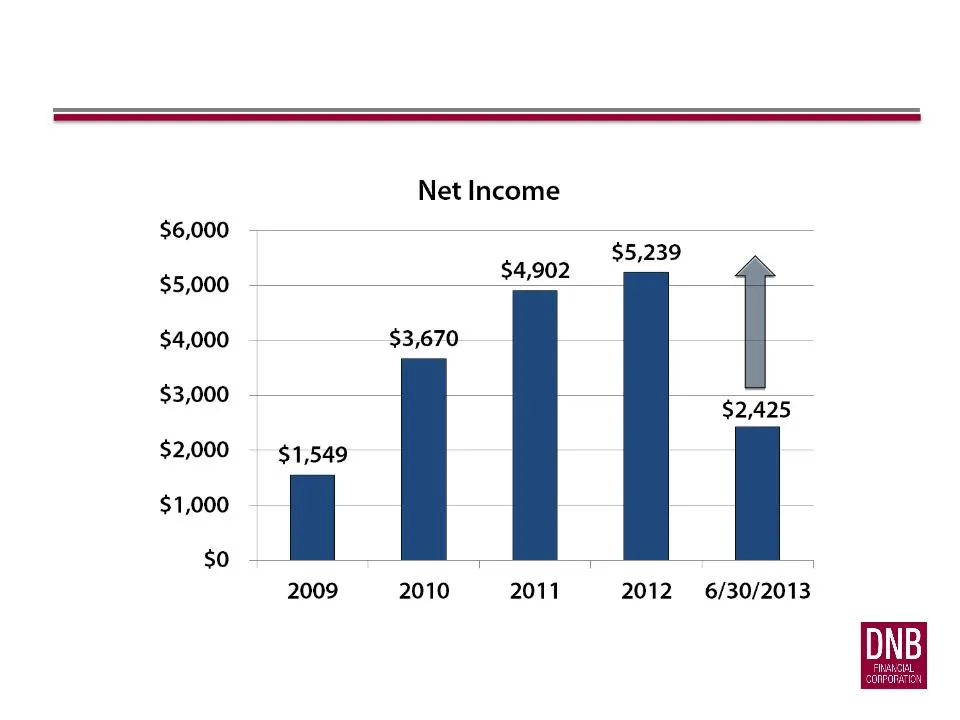
Slide 24: Net Income
Net Income $6,000 $5,239 $5,000 $4,902 $4,000 $3,670 33/000 $2,425 $2,000 $1,549 $1,000 i $0 ' + 1 2009 2010 2011 2012 6/30/2013
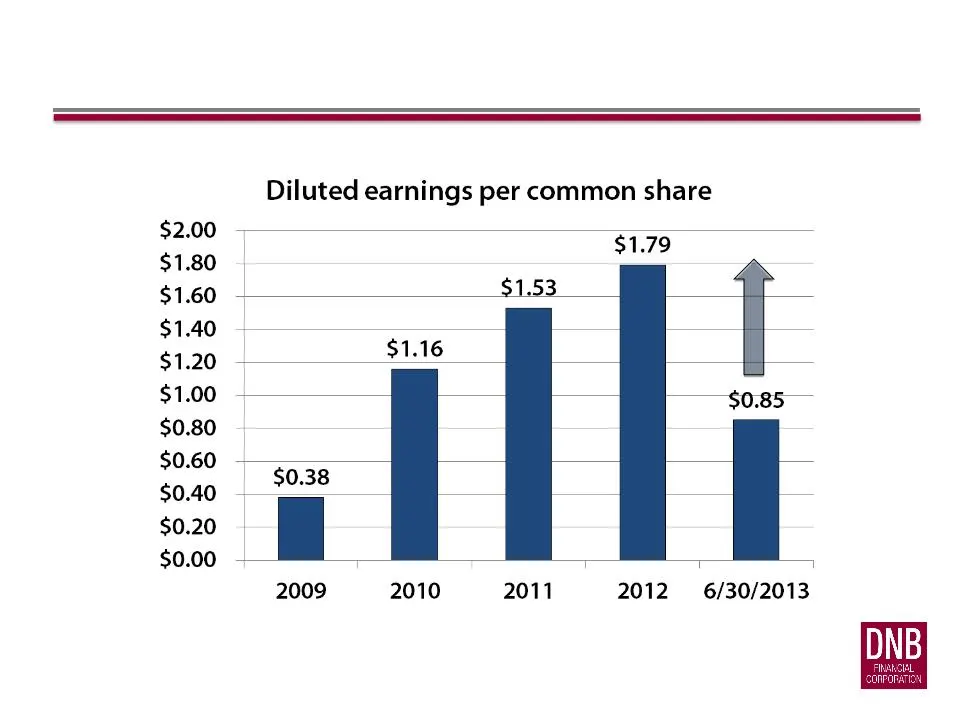
Slide 25: Diluted earnings per common share
Diluted earnings per common share $2.00 $1.80 $1.60 | $1.53 $1.40 1 $1.20 $1.16 $1.00 $0.85 $0.80 $0.60 $0.40 038 _— | — : $0.20 | $0.00 2009 2010 2011 2012 6/30/2013 $1.79
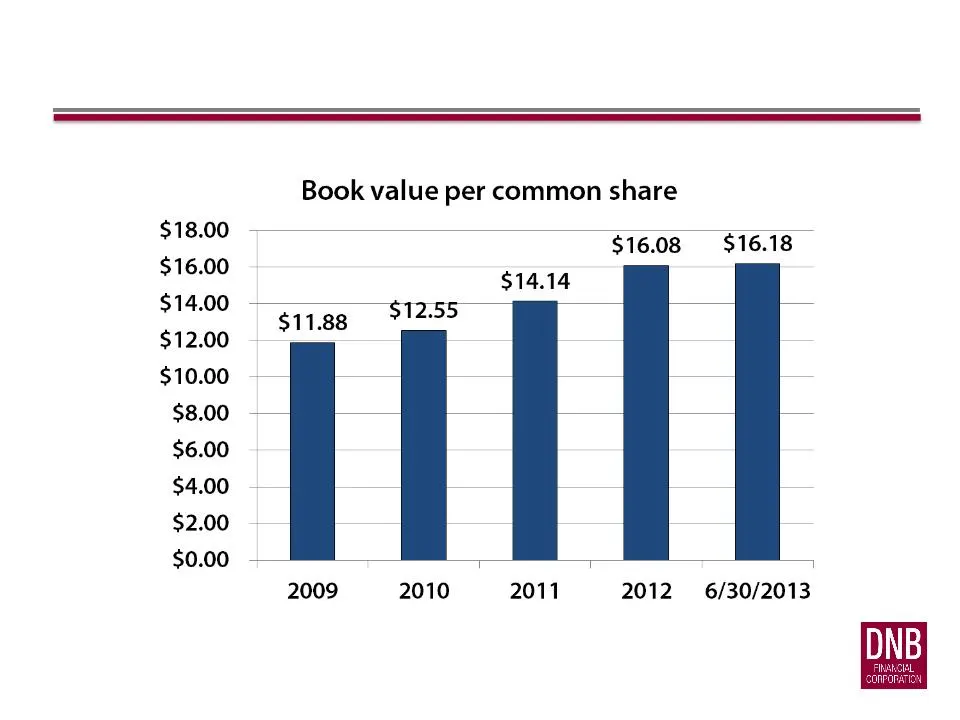
Slide 26: Book value per common share
Book value per common share $16.08 $16.18 $14.14 $11.88 $12.55 2009 2010 2011 2012 6/30/2013
Slide 27: Executive Summary: Performance Ratios
Performance Ratios 2012 Q2 2012 Q3 2012 Q4 2013 Q1 2013 Q2 Return on average assets 0.91% 0.89% 0.83% 0.74% 0.76% Return on average equity 10.51% 10.23% 9.26% 8.32% 8.60% Return on average tangible equity 10.54% 10.29% 9.31% 8.36% 8.65% Net interest margin 3.78% 3.80% 3.55% 3.32% 3.35% Efficiency ra
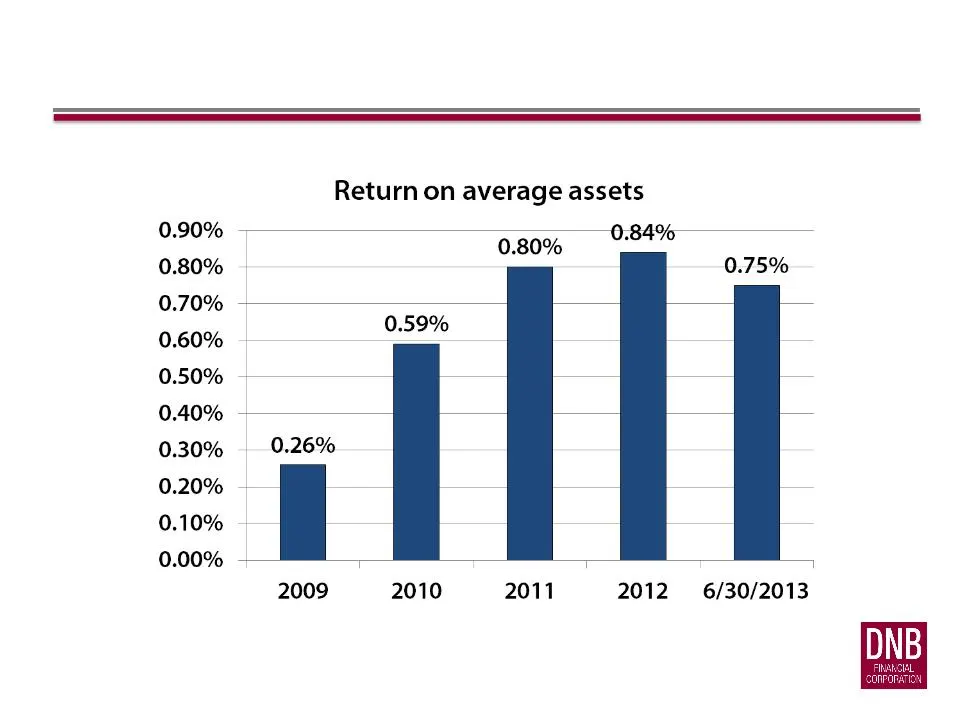
Slide 28: Return on average assets
Return on average assets 0.80% 0.75% 0.59% 0.26% 2009 2010 2011 2012 6/30/2013
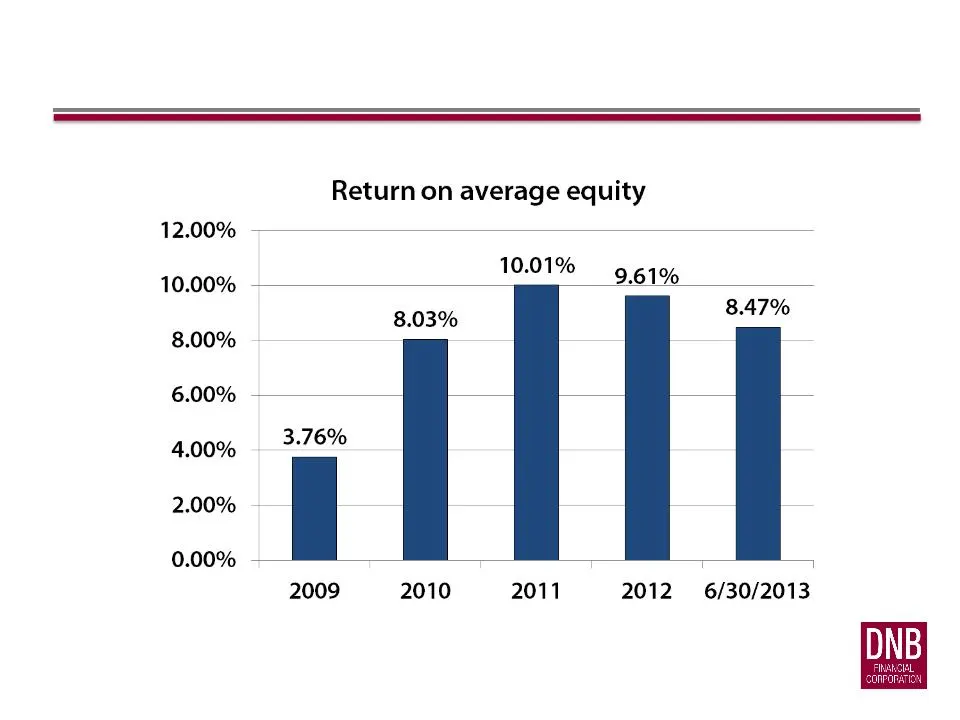
Slide 29: Return on average equity
12.00% 10.00% 8.00% 6.00% 4.00% 2.00% 0.00% Return on average equity 10.01% 9 610% 8.03% 8.47% 3.76% 2009 2010 2011 2012 6/30/2013
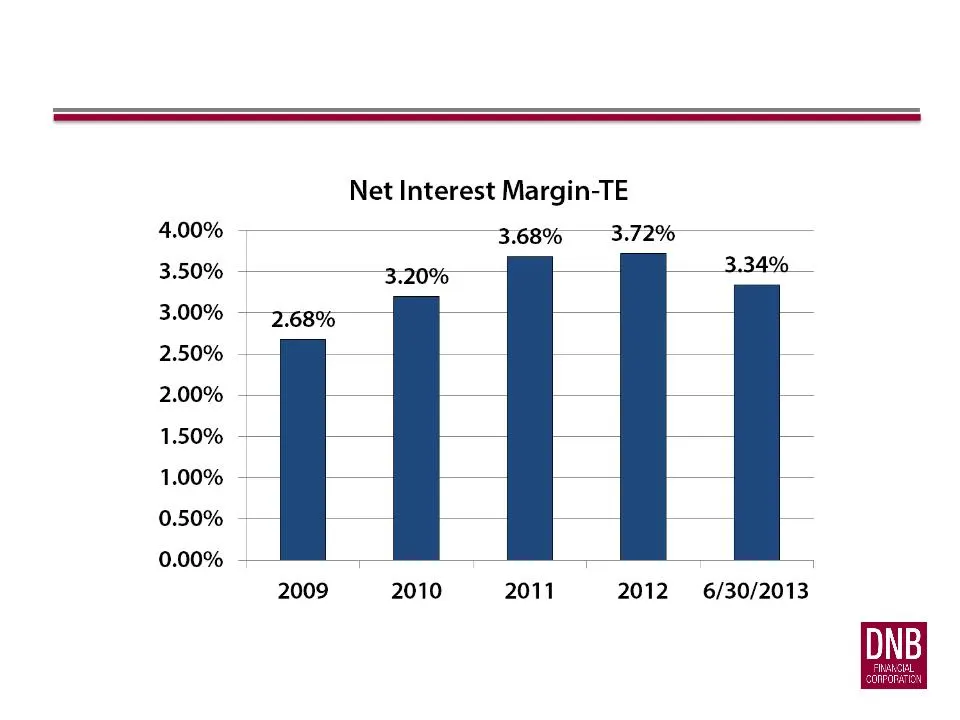
Slide 30: Net Interest Margin-TE
Net Interest Margin-TE 4.00% 3.68% 3.72% 3.50% 3.20% Y 3.00% 68% 2.50% - | u 2.00% 1.50% 1.00% 0.50% | 0.00% ; : : 2009 2010 2011 2012 6/30/2013
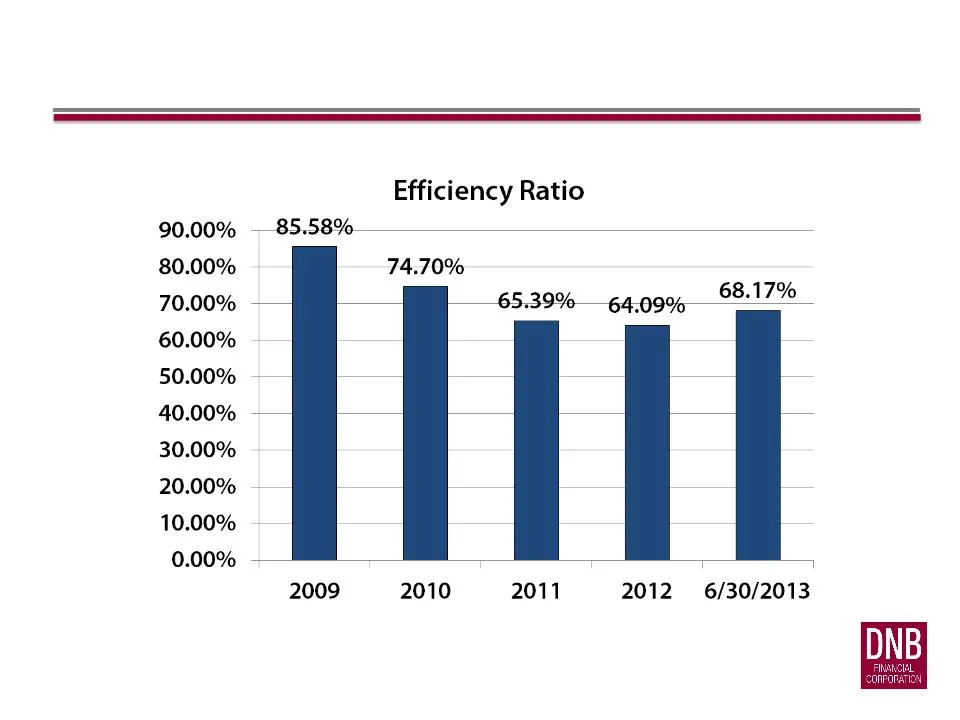
Slide 31: Efficiency Ratio
Efficiency Ratio 90.00% 85.58% 80.00% 74.70% 70.00% 60.00% 50.00% 40.00% 30.00% 20.00% 10.00% 0.00% i 68.17% 2009 2010 2011 2012 6/30/2013
Slide 32: Executive Summary: Asset Quality Ratios
Asset Quality Ratios 2012 Q2 2012 Q3 2012 Q4 2013 Q1 2013 Q2 Net Charge-offs to average loans 0.40% 0.03% -0.10% -0.11% 0.82% Non-performing loans/Total loans 2.21% 2.45% 2.63% 4.05% 2.60% Allowance for credit loss/Total loans 1.53% 1.63% 1.72% 1.77% 1.72% Allowance for credit loss/Non-performing lo
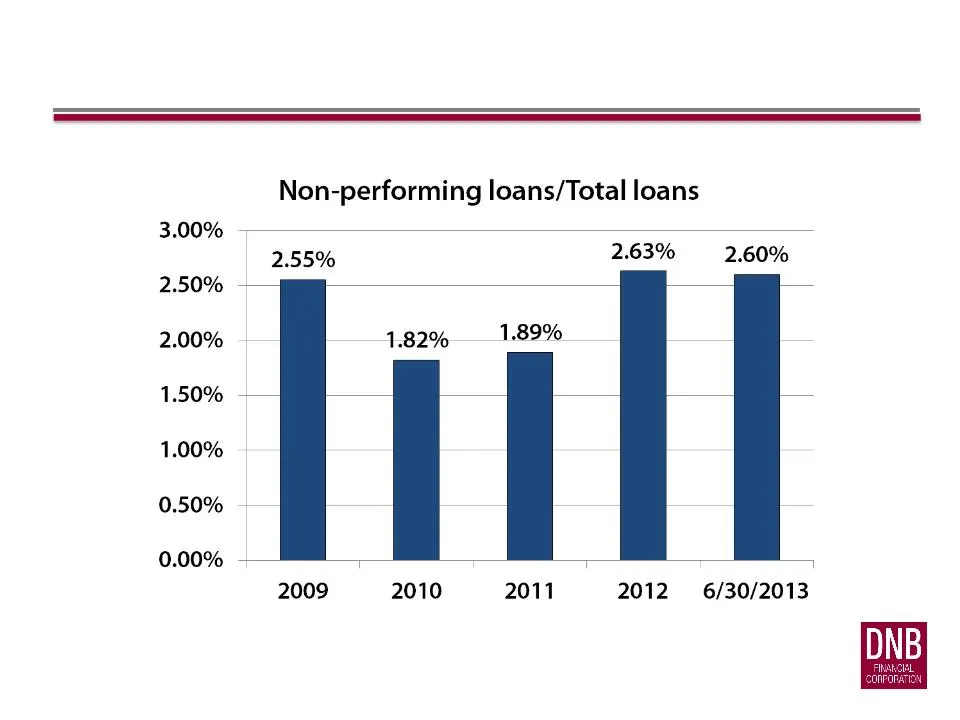
Slide 33: Non-performing loans/Total loans
Non-performing loans/Total loans 2.55% 2.63% 2.60% 1.82% 1.89% 2009 2010 2011 2012 6/30/2013
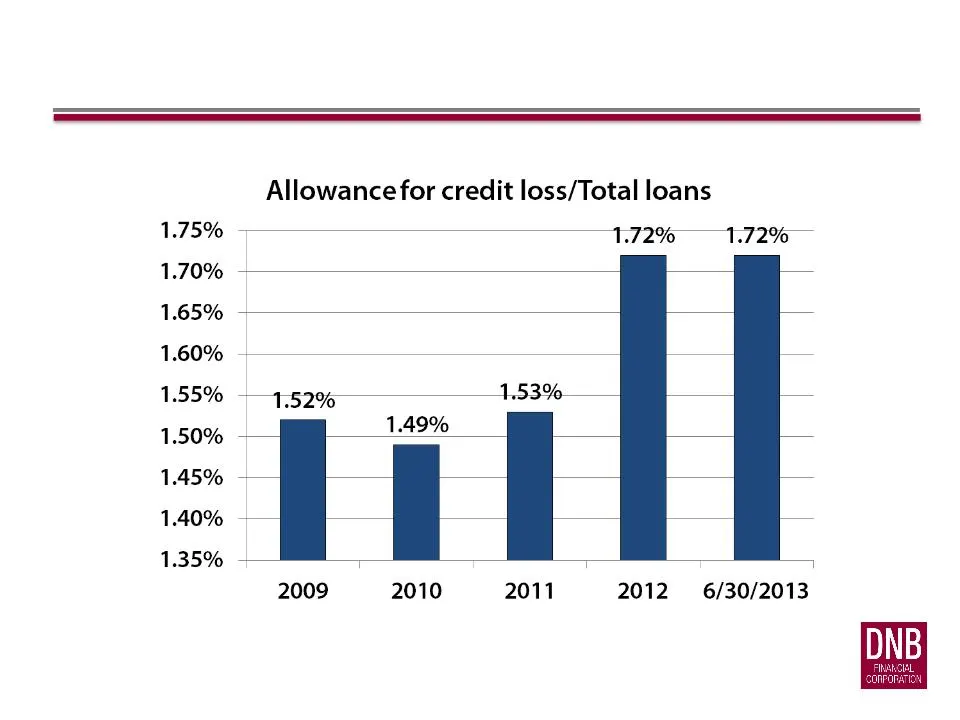
Slide 34: Allowance for credit loss/Total loans
1.75% 1.70% 1.65% 1.60% - 1.55% 1.50% 1.45% 1.40% 1.35% Allowance for credit loss/Total loans 1.72% 1.52% 1.53% | 1.49% i] 2009 2010 2011 2012 6/30/2013
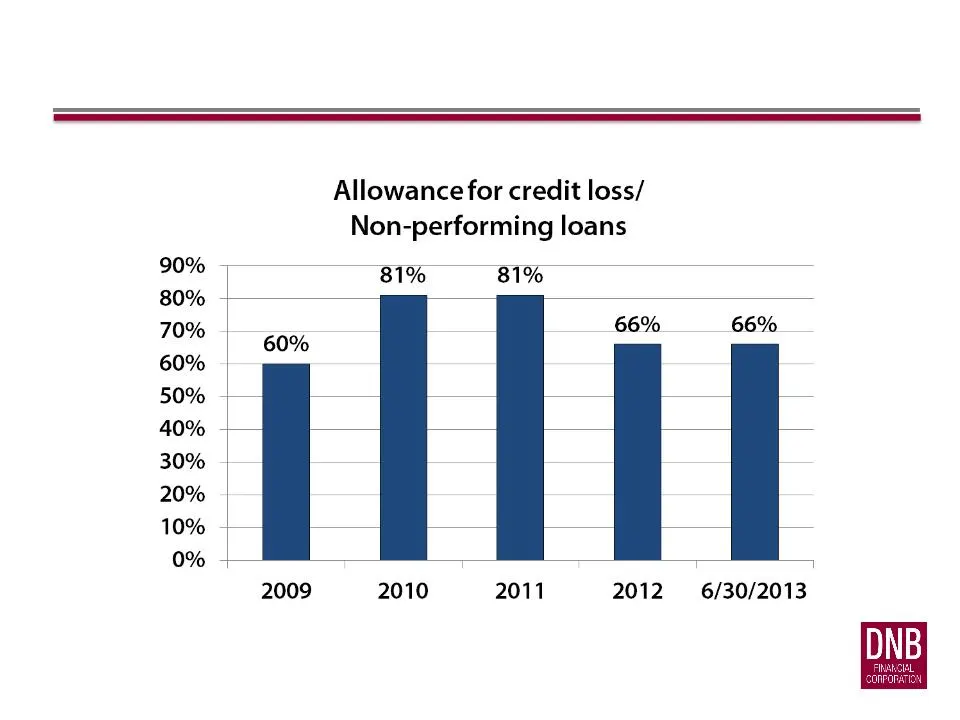
Slide 35: Allowance for credit loss/Non-performing loans
90% 80% 70% 60% 50% 40% 30% 20% 10% 0% Allowance for credit loss/ Non-performing loans 81% 81% 66% 66% | 2009 2010 2011 2012 = 6/30/2013
Slide 36: Executive Summary: Capital Ratios
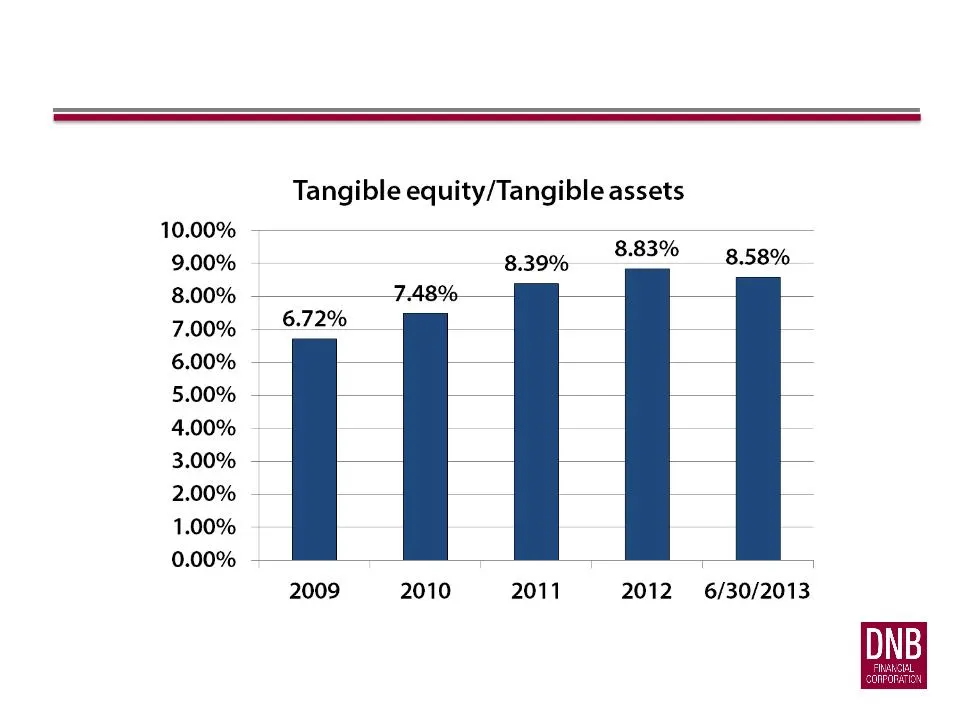
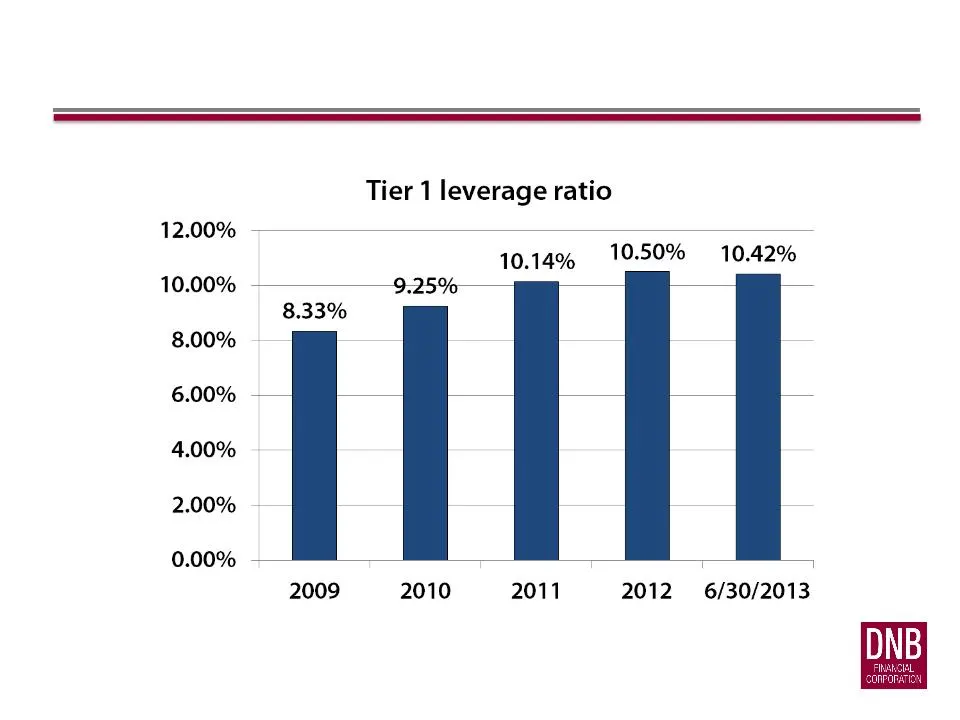
Capital Ratios 2012 Q2 2012 Q3 2012 Q4 2013 Q1 2012 Q2 Total equity/Total assets 8.47% 8.89% 8.87% 8.98% 8.60% Tangible equity/Tangible assets 8.43% 8.85% 8.83% 8.94% 8.58% Tangible common equity/Tangible assets 6.38% 6.78% 6.80% 6.92% 6.63% Tier 1 leverage ratio 10.22% 10.31% 10.50% 10.48% 10.42% T
Slide 37: Tangible equity/Tangible assets
Tangible equity/Tangible assets 10.00% 9.00% 8.30% °83% a.se% 8.00% FABY 7.00% 6.72% 6.00% 5.00% 4.00% 3.00% 2.00% - 1.00% 0.00% T 1 2009 2010 2011 2012 6/30/2013
Slide 38: Tier 1 leverage ratio
Tier 1 leverage ratio 12.00% 10.14% 10-50% 10.42% 10.00% 8.33% 8.00% 6.00% 4.00% 2.00% 0.00% 2009 2010 2011 2012 6/30/2013
Slide 39: The Differentiators: Operationally Unique
The Differentiators: Operationally Unique
Slide 40: Enterprise Risk Management
ENTERPRISE RISK MANAGEMENT • Led by William Hieb, President & Chief Risk and Credit Officer • Integration across financial, operational, strategic and compliance • Committee-driven decision-making process • Management • Board of Directors • Internal Control Redundancies • Accountability
Slide 41: Enterprise Risk Management
ENTERPRISE RISK MANAGEMENT • Corporate goal of building and maintaining a fortress balance sheet • Strong asset quality • Strong levels of liquidity with contingency planning • Superior ALCO process
Slide 42: Proactive Investment Portfolio Management
PROACTIVE INVESTMENT PORTFOLIO MANAGEMENT • Three tiered/segmented investment portfolio o Liquidity o Intermediate o Income • Manage liquidity and cash flows better • Maneuverability - Asset mix shifts • Opportunistic • Facilitates strong earnings • Consistent with ERM
Slide 43: Experienced Management and Board Leadership
Experienced Management and Board Leadership
Slide 44: Experienced Management Team
EXPERIENCED MANAGEMENT TEAM William S. Latoff - Chairman & Chief Executive Officer 41 years experience in finance, public accounting, real estate and automotive industries. Director since 1998, Chairman of the Board since 2003 and CEO since 2004. Chairman of the Executive and Board Loan Committees.
Slide 45: Experienced Management Team
EXPERIENCED MANAGEMENT TEAM Albert J. Melfi, Jr. - Executive Vice President & Chief Lending Officer 39 years experience in the commercial banking industry with a concentration in middle market and CRE lending. Joined DNB in 2006 and is directly responsible for all commercial and personal lending. Pr
Slide 46: Experienced Management Team
EXPERIENCED MANAGEMENT TEAM James F. Gagliano - Director of Retail Services and Cash Management Mr. Gagliano has 20 years of retail banking and financial services experience. James joined DNB First in 2013 and is directly responsible for DNB First's retail branches & cash management. Prior experienc
Slide 47: Experienced Management Team
EXPERIENCED MANAGEMENT TEAM Frank S. Monterosso - Senior Vice President of Operations 23 years of experience in operations management with a concentration in electronic commerce, payment solutions and banking. Joined DNB in 2008 and is directly responsible for IT and deposit operations. Prior experi
Slide 48: Invest in DNB Financial
Invest in DNB Financial
Slide 49: Last 12 Months DNBF Stock Performance
Security or Index Return-Last 12 Months DNBF* 35.91% NASDAQ Bank Index* 32.71% KBW Bank Index* 40.55% LAST 12 MONTHS-DNBF STOCK PERFORMANCE Closing price on June 29, 2012: $13.50 Closing price on June 28, 2013: $17.71 * Source: Bloomberg
Slide 50: Investor Relations Contact
INVESTOR RELATIONS CONTACT Gerald F. Sopp 484.359.3138 gsopp@dnbfirst.com http://investors.dnbfirst.com/ For more information, Investors may contact:
Slide 51: Thank You
THANK YOU
Slide 52: Investment Analysis for DNB Financial Corporation
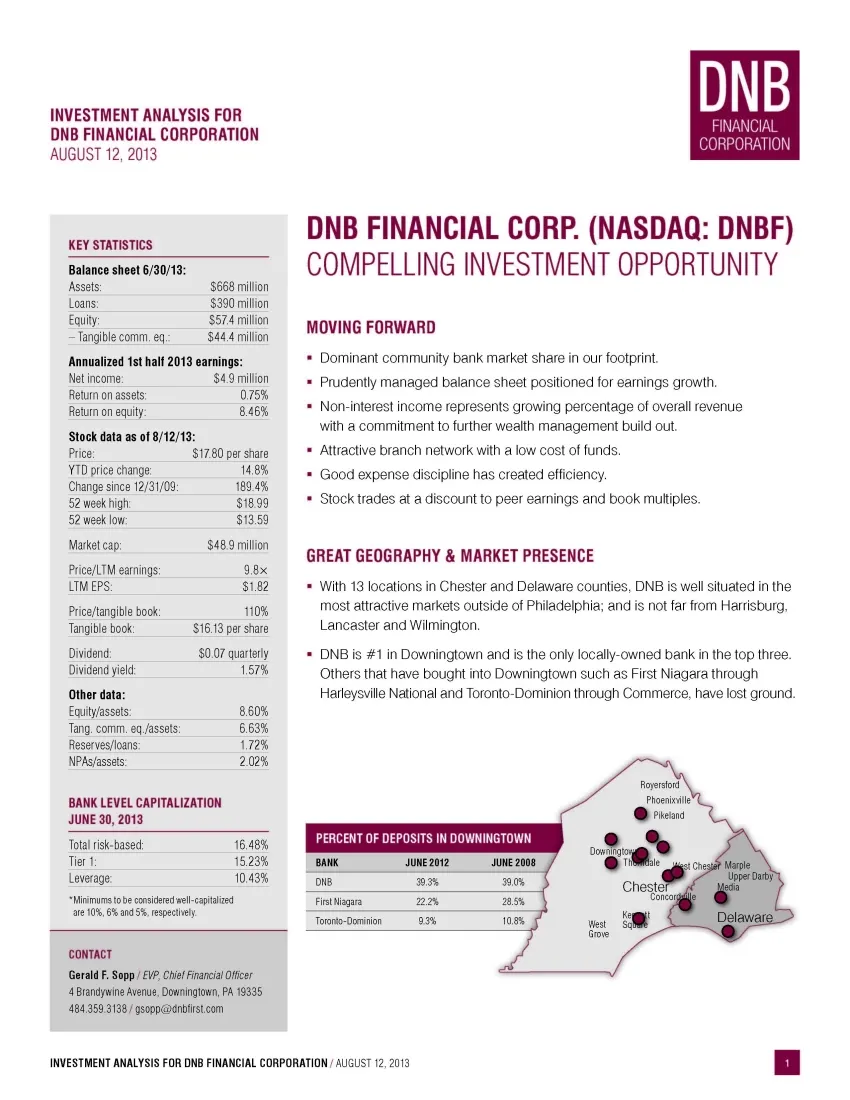
INVESTMENT ANALYSIS FOR DNB FINANCIAL CORPORATION AUGUST 12, 2013 KEY STATISTICS Balance sheet 6/30/13: Assets: 668 million Loans: $390 million Equity: $574 milion = Tangible comm. e9 $44.4 million Annualized ‘st half 2013 earnings: Net income: $49 milion Return on assets: 075% Return on equity 8.46
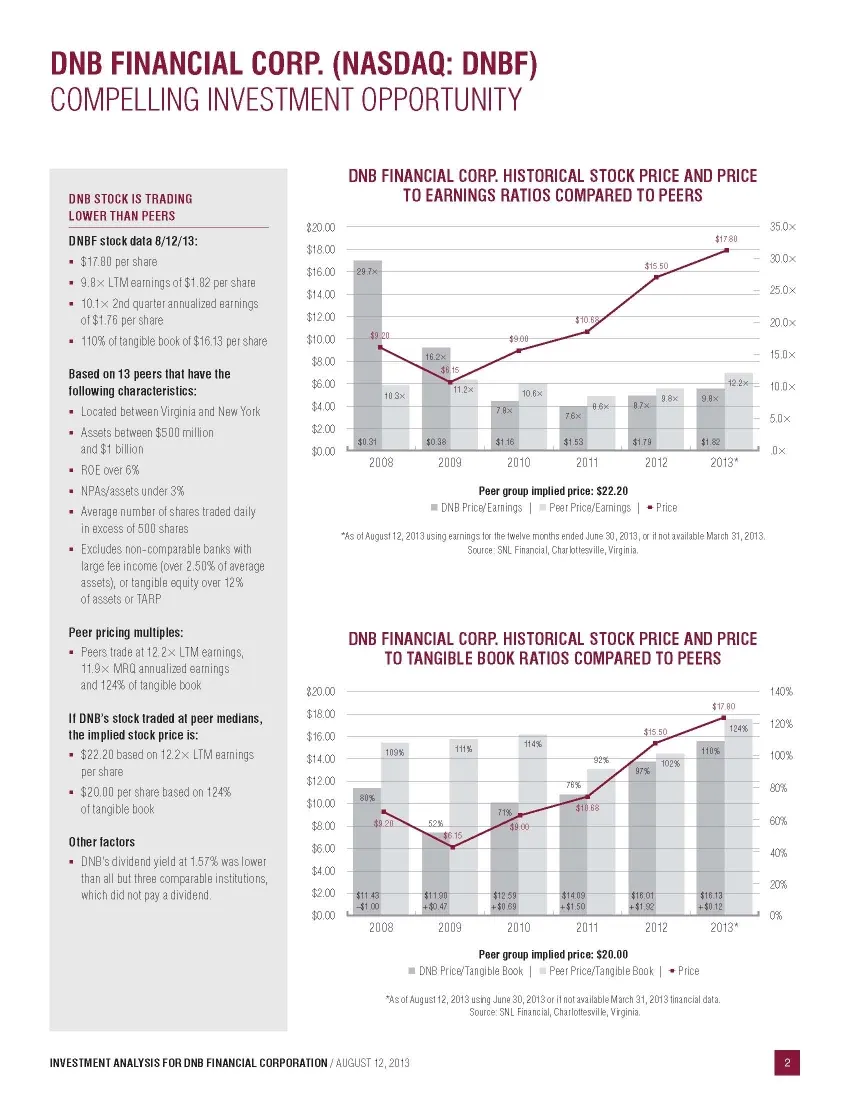
Slide 53: DNB Stock Is Trading Lower Than Peers
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY DNB STOCK IS TRADING LOWER THAN PEERS DNBF stock data 8/12/13: = $1780 par share + 9.8% LTMeamnings of $1.82 per share 40.1% 2nd quarter annualized earnings, of $1.76 per share “110% of tanaible book of $16.13 pet share Based on 13
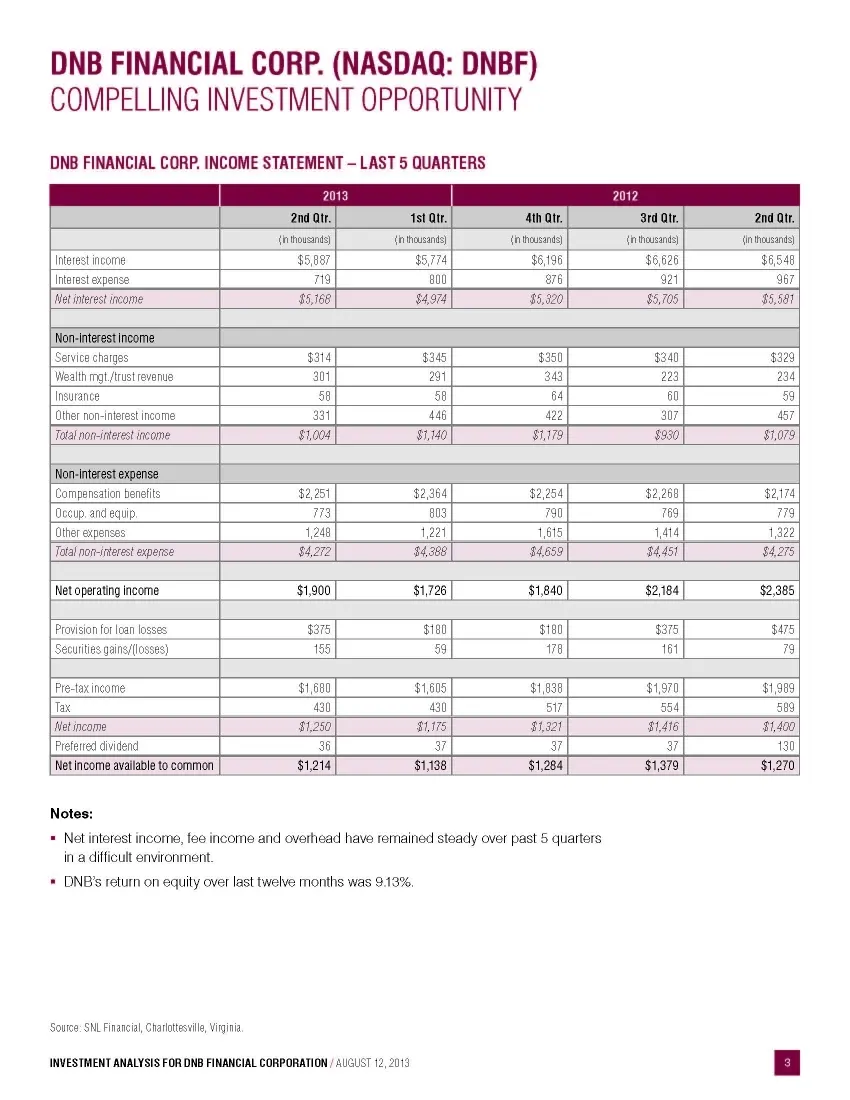
Slide 54: DNB Financial Corp. Income Statement - Last 5 Quarters
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY DNB FINANCIAL CORP. INCOME STATEMENT — LAST 5 QUARTERS 2013 2012 2nd Qtr. 4st tr. ath tr, anda. 2nd at. {ious {inns {iiaands) {inthands) finds) Interest income $5,087 95,774 96,195 $6,626, $6548 Interest expense 719 00 76 921 or et
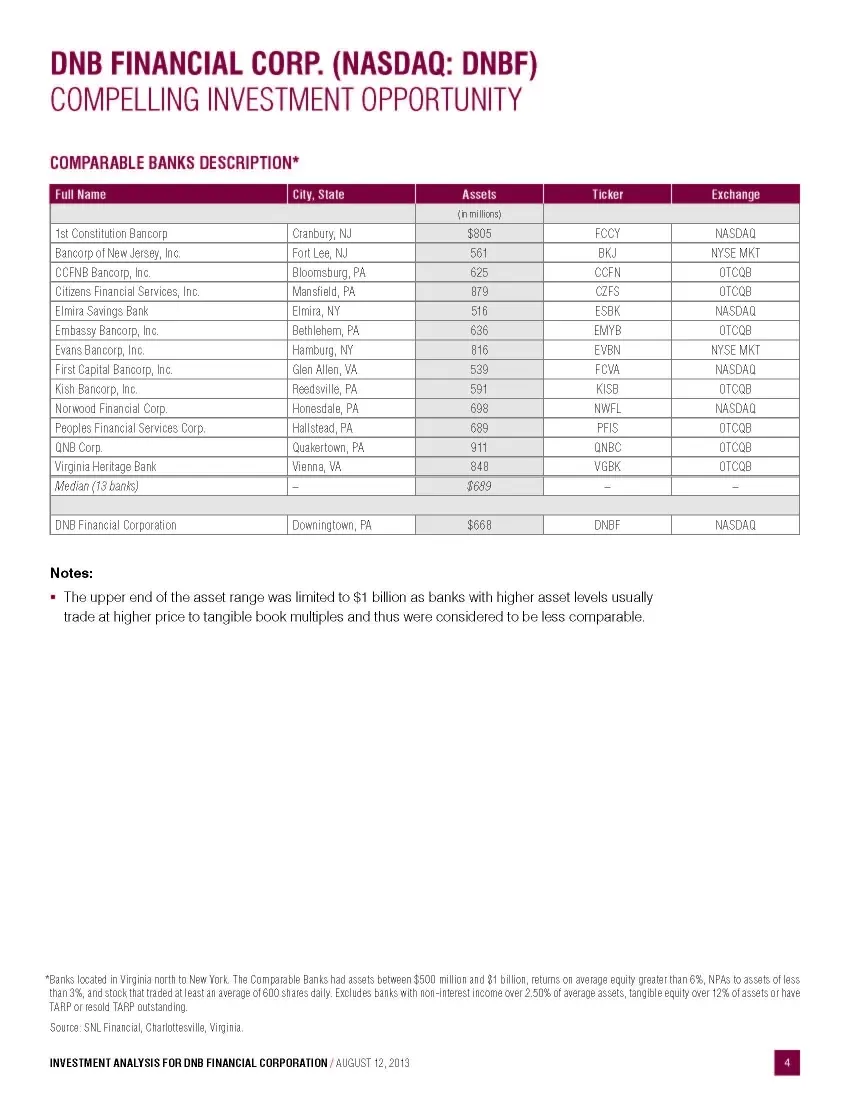
Slide 55: Comparable Banks Description
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY COMPARABLE BANKS DESCRIPTION* Aimilins) ‘st Constitution Bancorp Cranbury, NA $005 Foor NASDAQ, Bancorpot New Jersey, no Fort Le, Nd 561 8K NYSE MKT CCOFNB Bancorp, ne Bloomsburg, PA 625 CCFN orcas Citizens Financial Services, In M
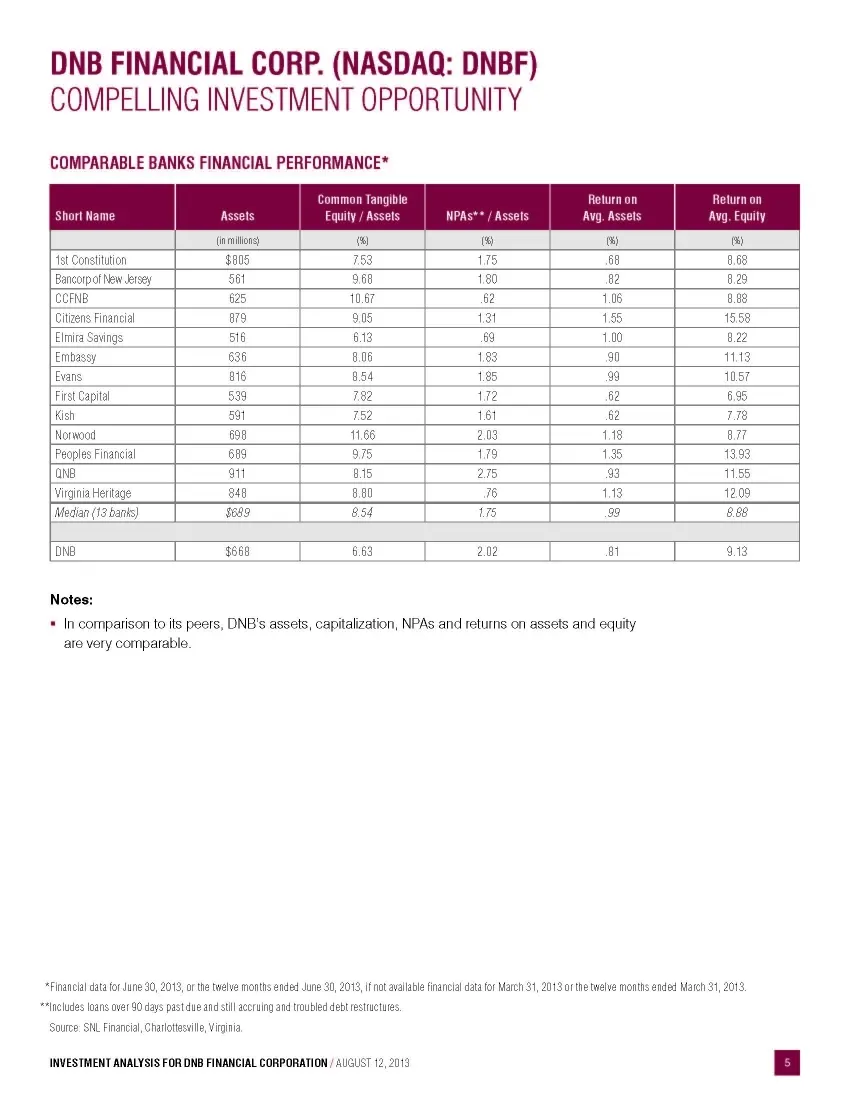
Slide 56: Comparable Banks Financial Performance
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY COMPARABLE BANKS FINANCIAL PERFORMANCE* Common Tangible Return on Short Name Equity / Assets NPAS** / Assels Avg, Asset Comins m (si ny “st Constitution $005 753 175 8 Bancorpot New sey SE 9.68 180 7 CORN, 5 0.7 a 106 Cites Financi
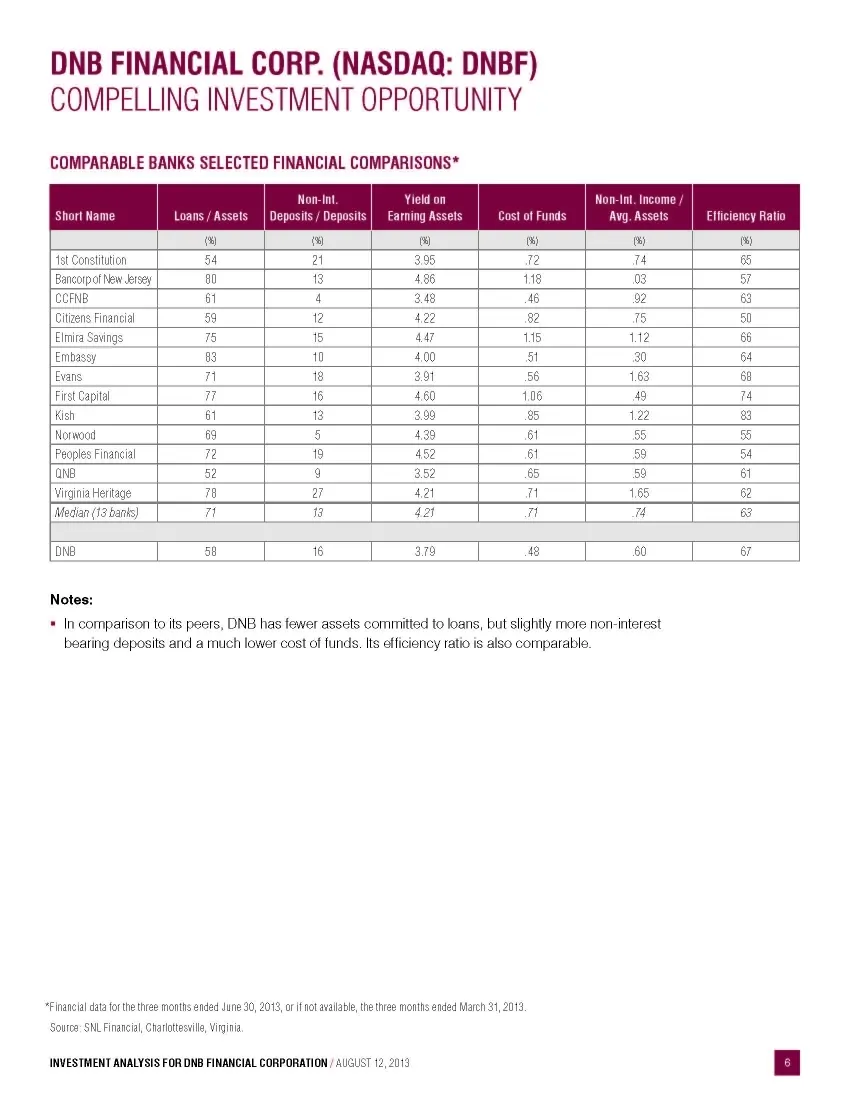
Slide 57: Comparable Banks Selected Financial Comparisons
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY COMPARABLE BANKS SELECTED FINANCIAL COMPARISONS* Non-nt Yield on Non- Int In D Earning Asset Cost of Fund Avg, Asset Efficiency Ratio oy ny ry “st Constitution 54 21 3.95 72 74 6 Bancorpot New sey 0 8 4.96 118 08 57 CORN, a 4 38 4%
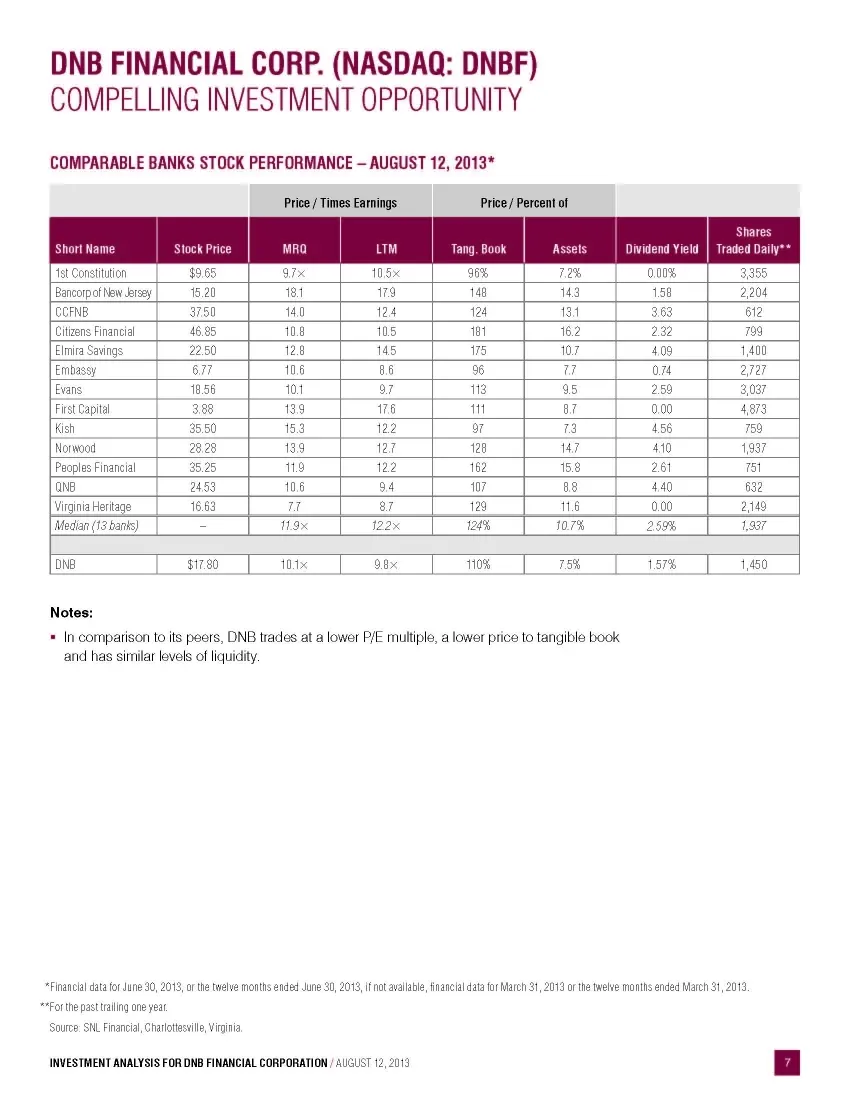
Slide 58: Comparable Banks Stock Performance - August 12, 2013
DNB FINANCIAL CORP. (NASDAQ: DNBF) COMPELLING INVESTMENT OPPORTUNITY COMPARABLE BANKS STOCK PERFORMANCE — AUGUST 12, 2013* Price / Times Earnings Price/ Percent of Stock Price wRQ ‘st Constitution 99.65 8x 10⁵% 72% 0.00% 3.355 Banoopofhew pissy] 15.20 8 119 143 58 2204 CORN. 3750 140 Tea 134 3.68 61
Slide 59: Contact
CONTACT Gerald F. Sopp EVP, Chief Financial Officer 4 Brandywine Avenue Downingtown, PA 19335 484,359.3138 gsopp@dnbfirst.com FORWARD-LOOKING STATEMENTS: ject fac pect" “antiipat,"“belleve™ avaliable al the vith regard epost levels (6) changes in lve in general, national (3) changes asa result of ne
Source: SEC EDGAR · 8-K filed Aug 21, 2013
More decks from DNB Financial Corporation
 Investor Presentation (August 2018)32 slides · Aug 7, 2018
 Shareholder Meeting (April 2016)31 slides · Apr 27, 2016
 Merger or Acquisition (April 2016)23 slides · Apr 5, 2016
 Investor Presentation (September 2015)47 slides · Sep 23, 2015
 Investor Presentation (September 2014)42 slides · Sep 2, 2014
 Investor Presentation (March 2014)59 slides · Mar 5, 2014