PetroQuest Energy — Investor Presentation (August 2014)
32 slides from PetroQuest Energy's investor presentation, Aug 13, 2014
Slide 1: PetroQuest Energy, Inc. August 2014
oe Energy, Inc. August 2014
Slide 2: Forward Looking Statements
Forward Looking Statements 2 This presentation contains "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. These forward-looking statements are subject to certain risks, trends
Slide 3: Our Properties
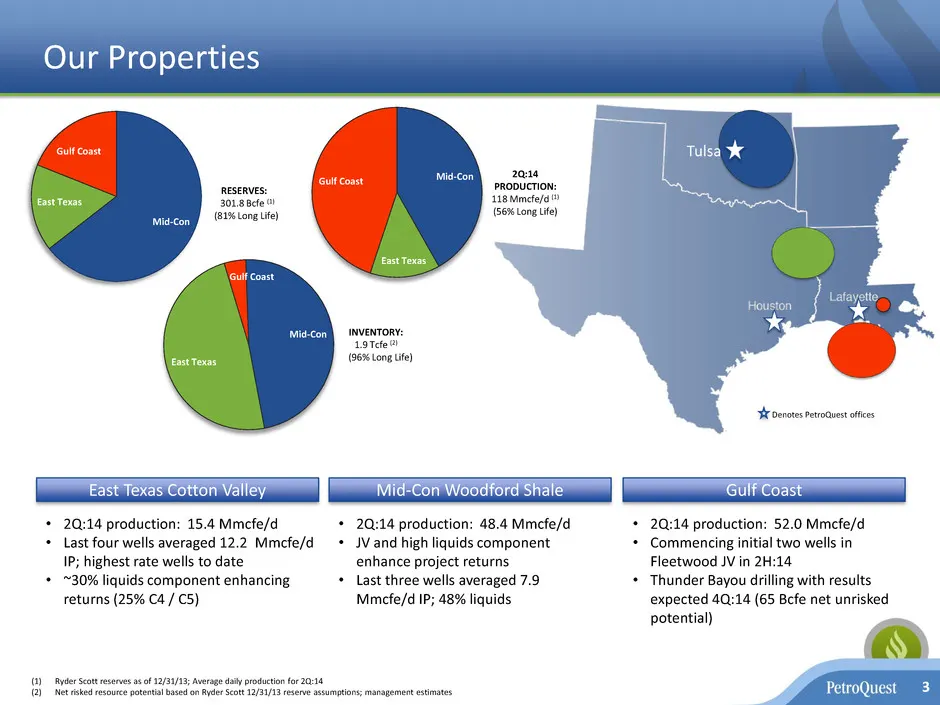
(1) Ryder Scott reserves as of 12/31/13; Average daily production for 2Q:14 (2) Net risked resource potential based on Ryder Scott 12/31/13 reserve assumptions; management estimates Our Properties 3 Mid-Con East Texas Gulf Coast 2Q:14 PRODUCTION: 118 Mmcfe/d (1) (56% Long Life) Mid-Con East Texas Gu
Slide 4: Industry Activity - Cotton Valley Trend
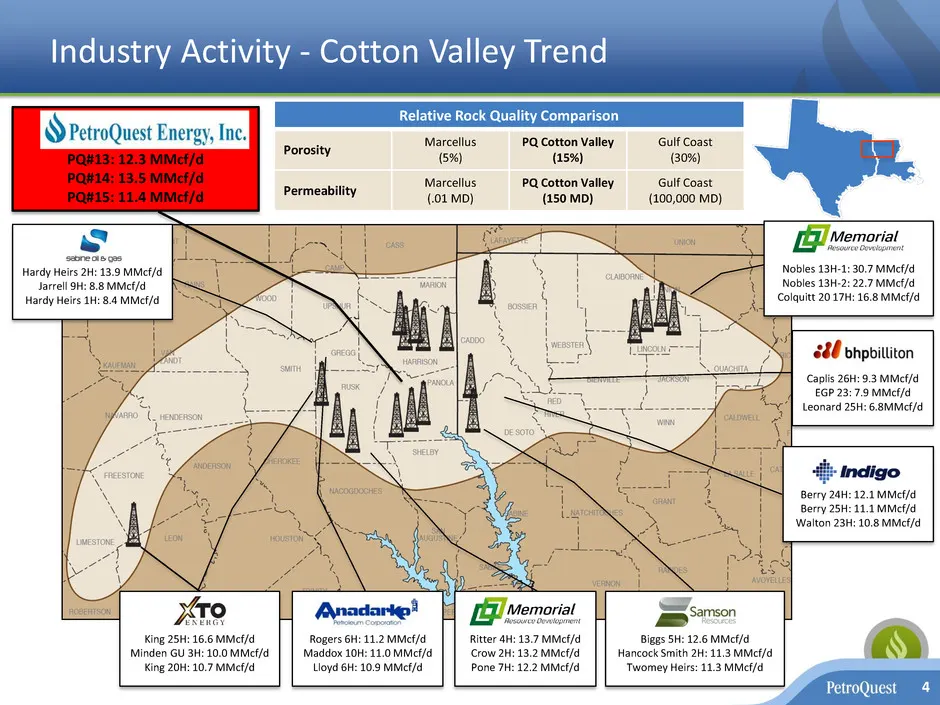
Industry Activity - Cotton Valley Trend 4 Caplis 26H: 9.3 MMcf/d EGP 23: 7.9 MMcf/d Leonard 25H: 6.8MMcf/d Nobles 13H-1: 30.7 MMcf/d Nobles 13H-2: 22.7 MMcf/d Colquitt 20 17H: 16.8 MMcf/d Berry 24H: 12.1 MMcf/d Berry 25H: 11.1 MMcf/d Walton 23H: 10.8 MMcf/d PQ#13: 12.3 MMcf/d PQ#14: 13.5 MMcf/d PQ#1
Slide 5: Cotton Valley Horizontal – Horizontal Uplift
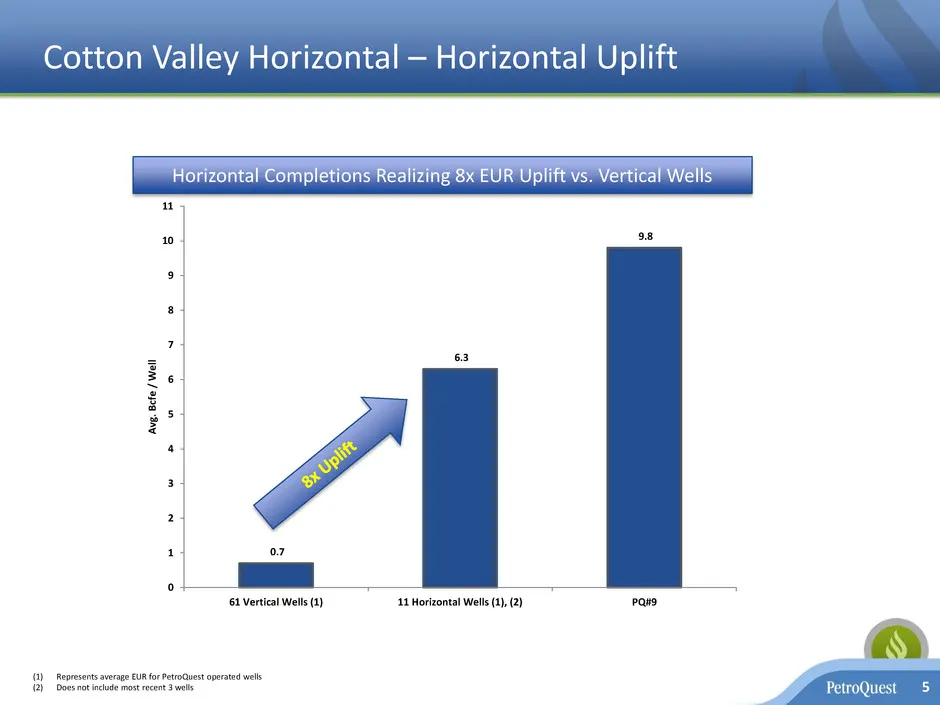
0.7 6.3 9.8 0 1 2 3 4 5 6 7 8 9 10 11 61 Vertical Wells (1) 11 Horizontal Wells (1), (2) PQ#9 Av g. B cfe / W el l Cotton Valley Horizontal – Horizontal Uplift 5 Horizontal Completions Realizing 8x EUR Uplift vs. Vertical Wells (1) Represents average EUR for PetroQuest operated wells (2) Does not in
Slide 6: Cotton Valley Horizontal – Moving Up the Curve
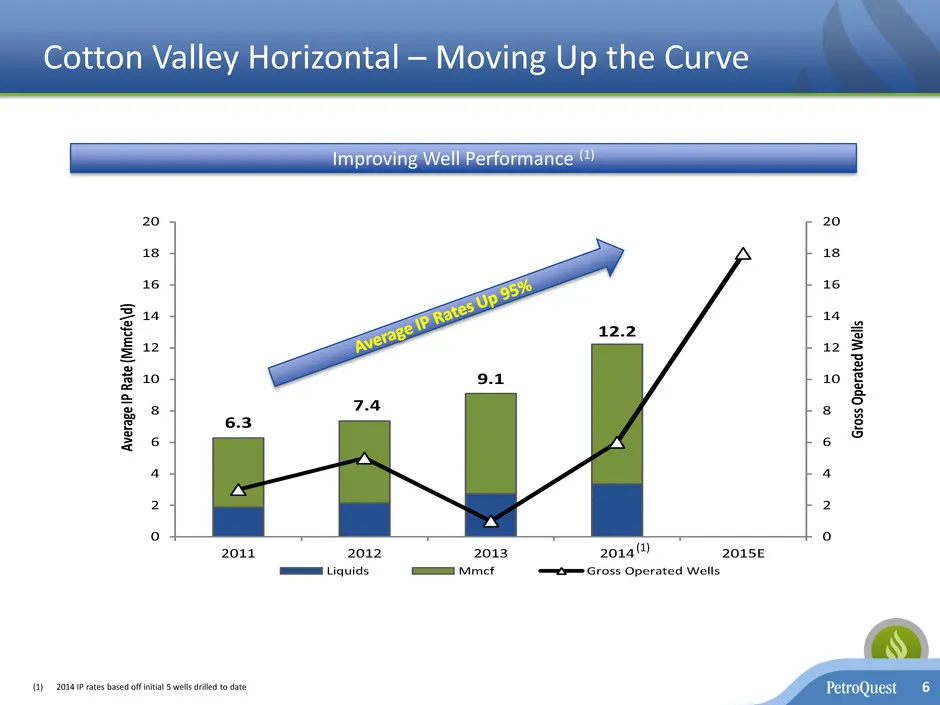
6.3 7.4 9.1 12.2 0 2 4 6 8 10 12 14 16 18 20 0 2 4 6 8 10 12 14 16 18 20 2011 2012 2013 2014 2015E Gro ss O pe rat ed W ells Av erag e IP Ra te (M mcf e\d ) Liquids Mmcf Gross Operated Wells Cotton Valley Horizontal –Moving Up the Curve 6 Improving Well Performance (1) (1) 2014 IP rates based off in
Slide 7: Cotton Valley Horizontal – Increasing EURs
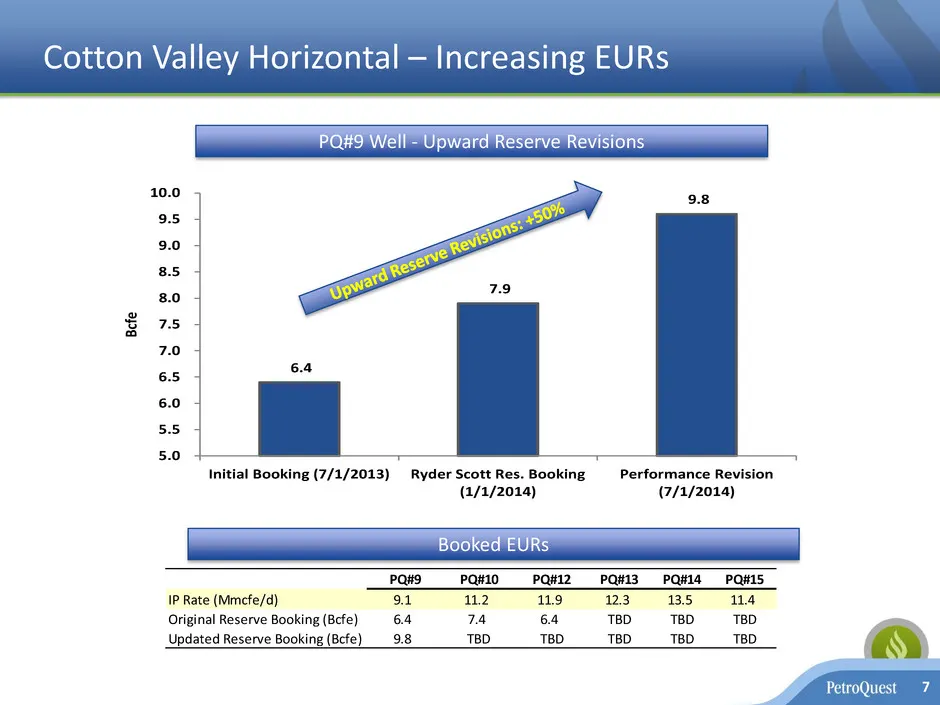
6.4 7.9 9.8 5.0 5.5 6.0 6.5 7.0 7.5 8.0 8.5 9.0 9.5 10.0 Initial Booking (7/1/2013) Ryder Scott Res. Booking (1/1/2014) Performance Revision (7/1/2014) Bcf e Cotton Valley Horizontal – Increasing EURs 7 PQ#9 Well - Upward Reserve Revisions Booked EURs PQ#9 PQ#10 PQ#12 PQ#13 PQ#14 PQ#15 IP Rate (Mmcf
Slide 8: Cotton Valley Horizontal Economics
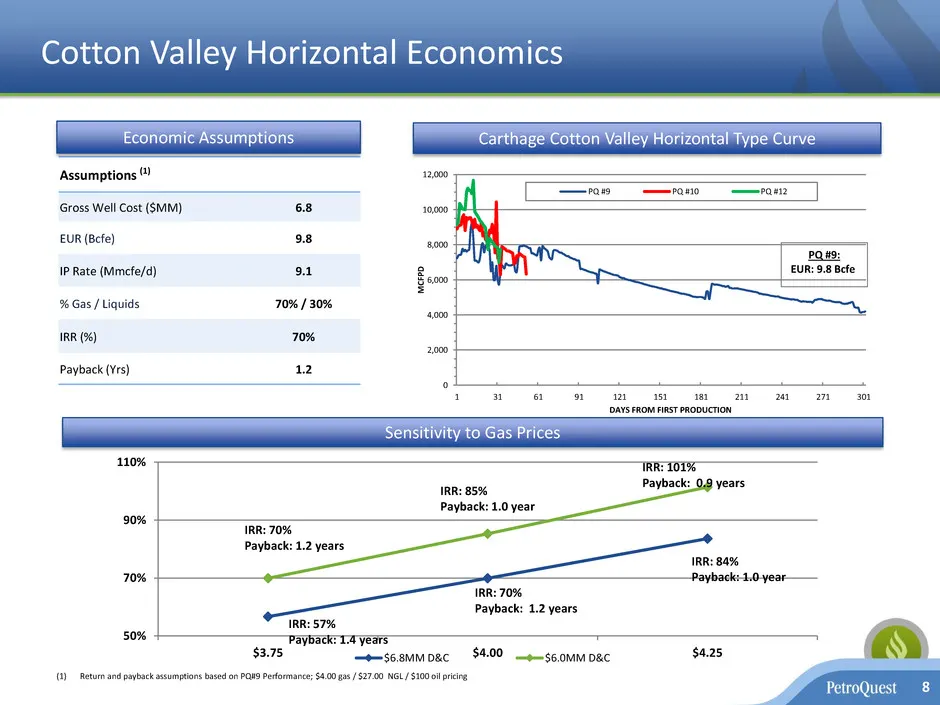
Cotton Valley Horizontal Economics 8 Assumptions (1) Gross Well Cost ($MM) 6.8 EUR (Bcfe) 9.8 IP Rate (Mmcfe/d) 9.1 % Gas / Liquids 70% / 30% IRR (%) 70% Payback (Yrs) 1.2 (1) Return and payback assumptions based on PQ#9 Performance; $4.00 gas / $27.00 NGL / $100 oil pricing Sensitivity to Gas Price
Slide 9: Cotton Valley Horizontal Planned Activity and Inventory
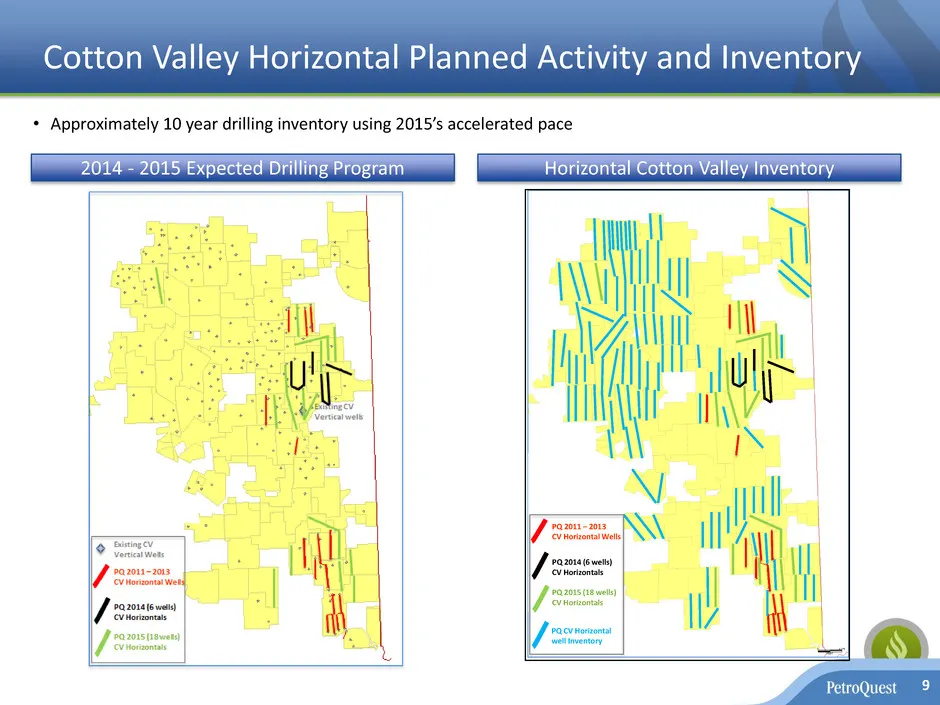
Cotton Valley Horizontal Planned Activity and Inventory 9 2014 - 2015 Expected Drilling Program Horizontal Cotton Valley Inventory • Approximately 10 year drilling inventory using 2015’s accelerated pace PQ 2015 (18 wells) CV Horizontals PQ 2014 (6 wells) CV Horizontals PQ 2011 – 2013 CV Horizontal
Slide 10: Cotton Valley Drilling to Unlock NAV
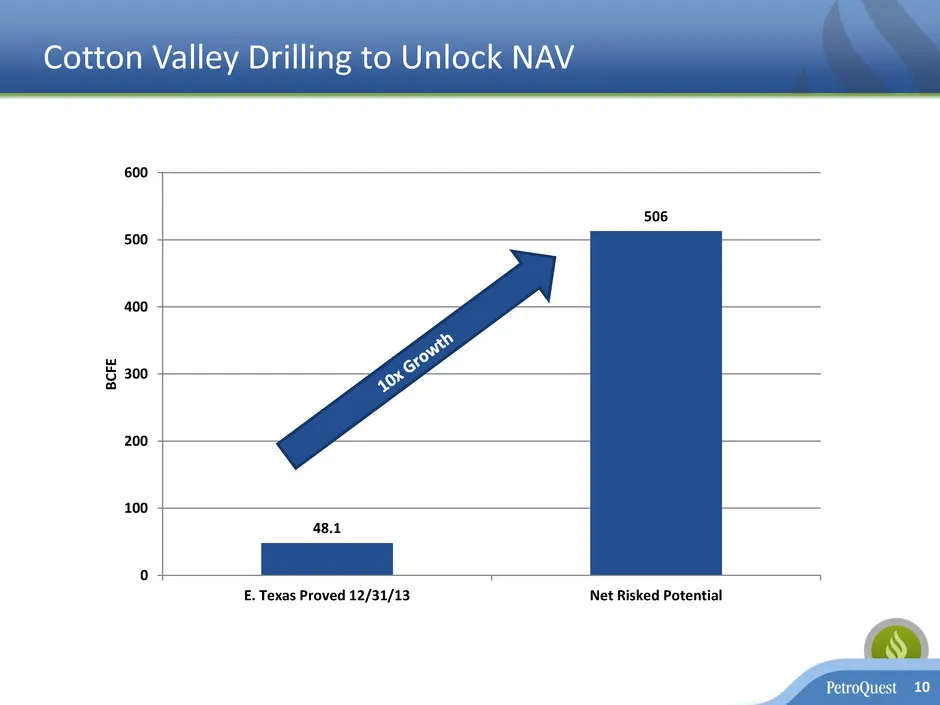
Cotton Valley Drilling to Unlock NAV 10 48.1 506 0 100 200 300 400 500 600 E. Texas Proved 12/31/13 Net Risked Potential BCF E
Slide 11: Mid-Continent Woodford Shale
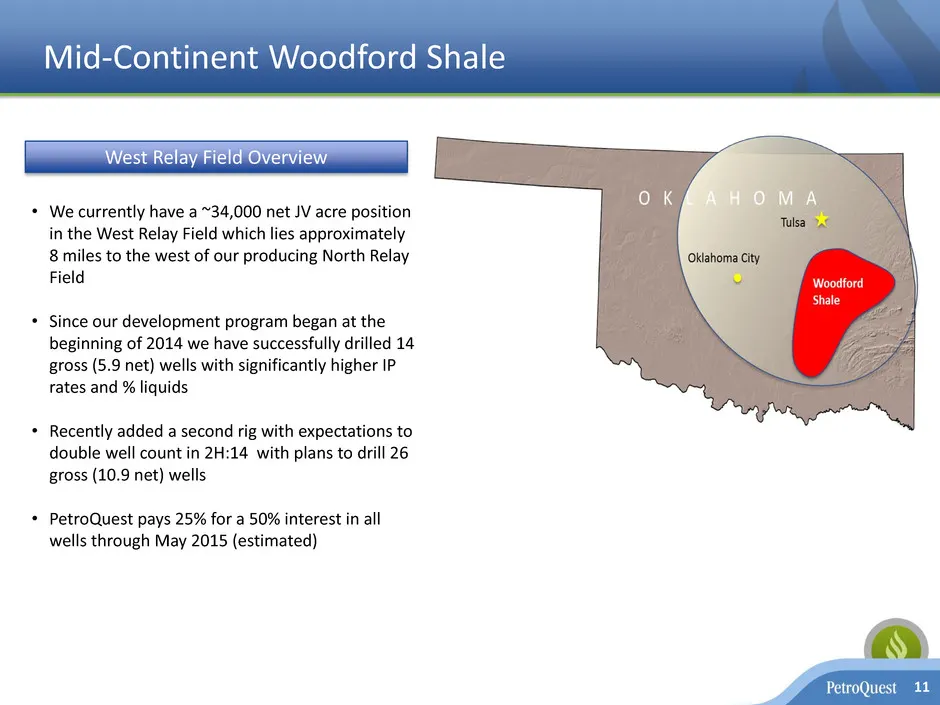
Mid-Continent Woodford Shale 11 • We currently have a ~34,000 net JV acre position in the West Relay Field which lies approximately 8 miles to the west of our producing North Relay Field • Since our development program began at the beginning of 2014 we have successfully drilled 14 gross (5.9 net) we
Slide 12: Woodford Position – Ramping Up Development
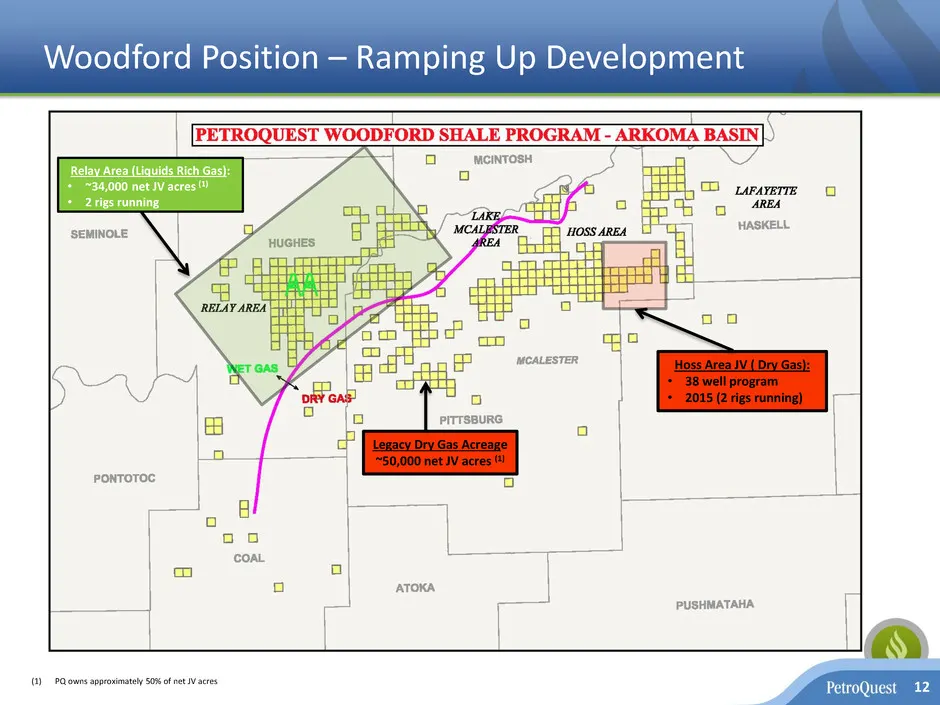
Woodford Position – Ramping Up Development 12 Legacy Dry Gas Acreage ~50,000 net JV acres (1) Relay Area (Liquids Rich Gas): • ~34,000 net JV acres (1) • 2 rigs running Hoss Area JV ( Dry Gas): • 38 well program • 2015 (2 rigs running) (1) PQ owns approximately 50% of net JV acres
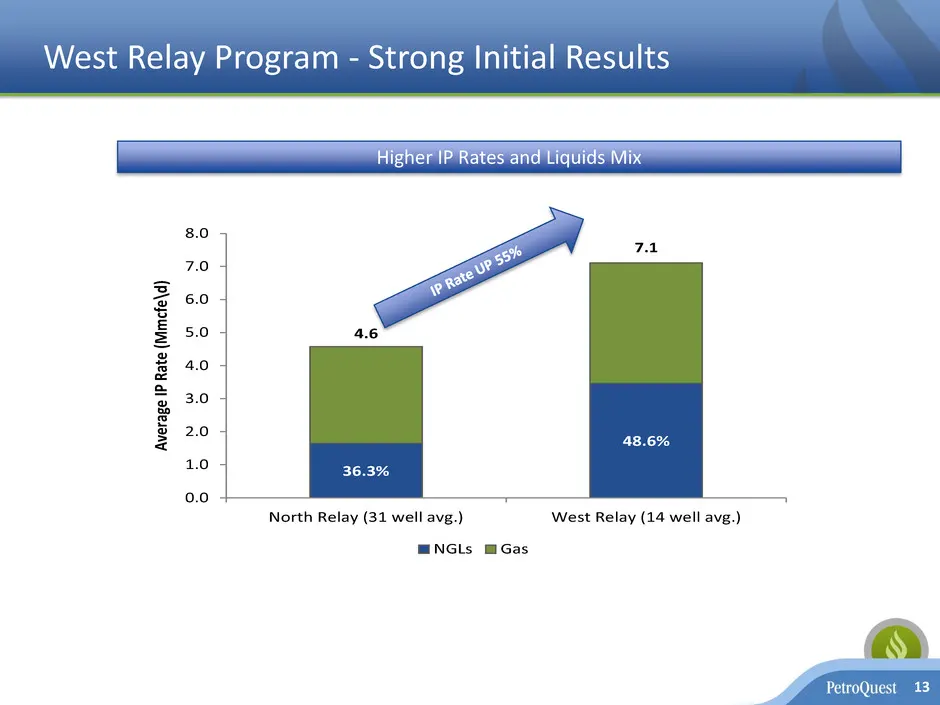
Slide 13: West Relay Program - Strong Initial Results
36.3% 48.6% 4.6 7.1 0.0 1.0 2.0 3.0 4.0 5.0 6.0 7.0 8.0 North Relay (31 well avg.) West Relay (14 well avg.) Av era ge IP Rat e ( Mm cfe \d ) NGLs Gas West Relay Program - Strong Initial Results 13 Higher IP Rates and Liquids Mix
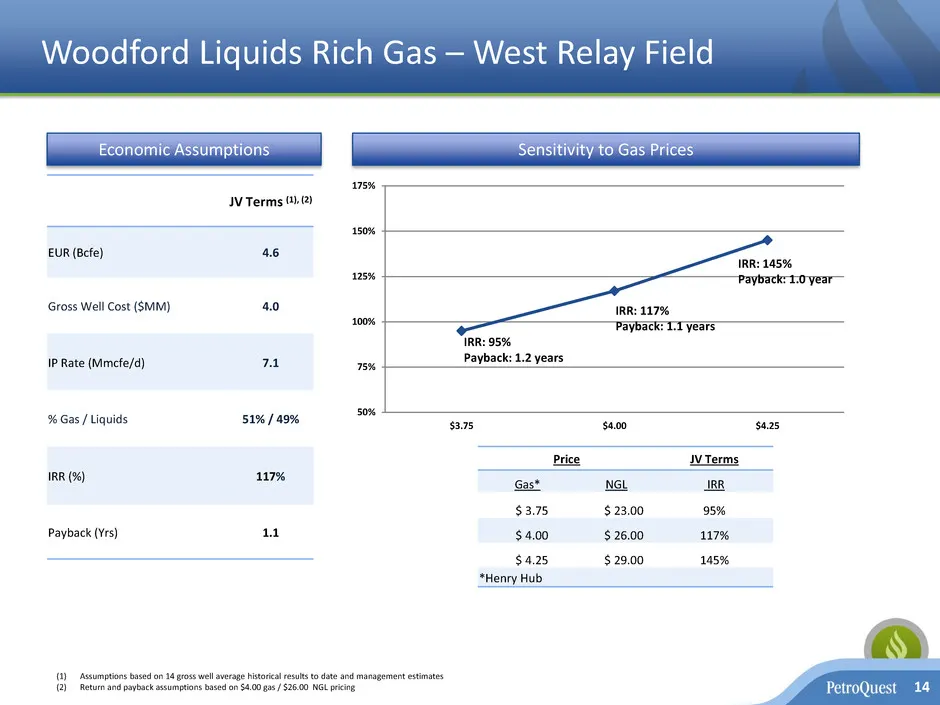
Slide 14: Woodford Liquids Rich Gas – West Relay Field
Woodford Liquids Rich Gas –West Relay Field 14 Price JV Terms Gas* NGL IRR $ 3.75 $ 23.00 95% $ 4.00 $ 26.00 117% $ 4.25 $ 29.00 145% *Henry Hub JV Terms (1), (2) EUR (Bcfe) 4.6 Gross Well Cost ($MM) 4.0 IP Rate (Mmcfe/d) 7.1 % Gas / Liquids 51% / 49% IRR (%) 117% Payback (Yrs) 1.1 Sensitivity to Ga
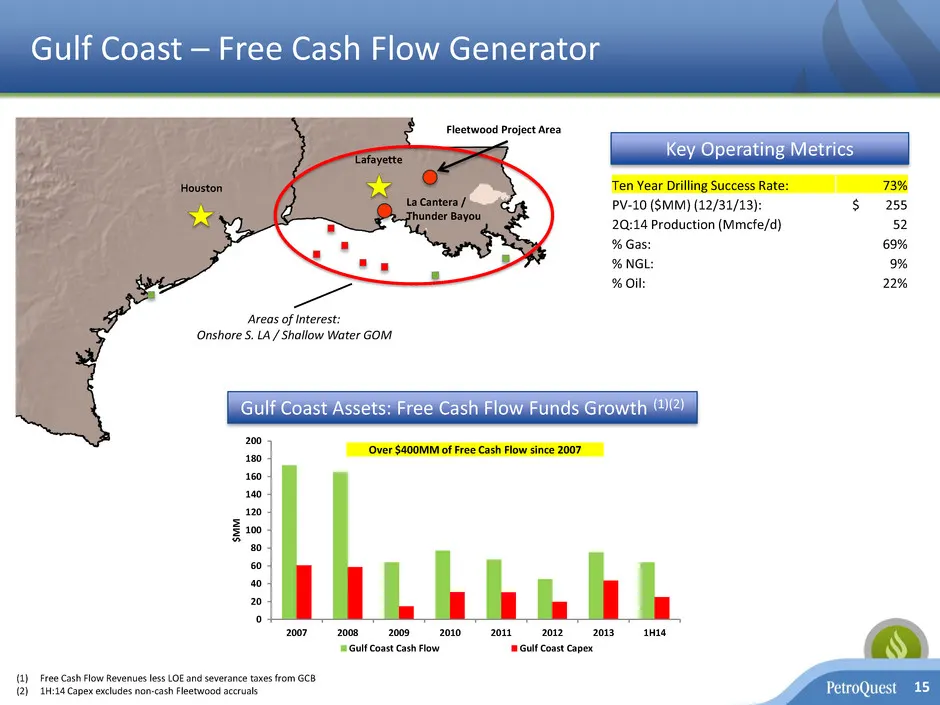
Slide 15: Gulf Coast – Free Cash Flow Generator
Gulf Coast – Free Cash Flow Generator 15 Houston Lafayette Areas of Interest: Onshore S. LA / Shallow Water GOM Key Operating Metrics Fleetwood Project Area (1) Free Cash Flow Revenues less LOE and severance taxes from GCB (2) 1H:14 Capex excludes non-cash Fleetwood accruals Gulf Coast Assets: Free
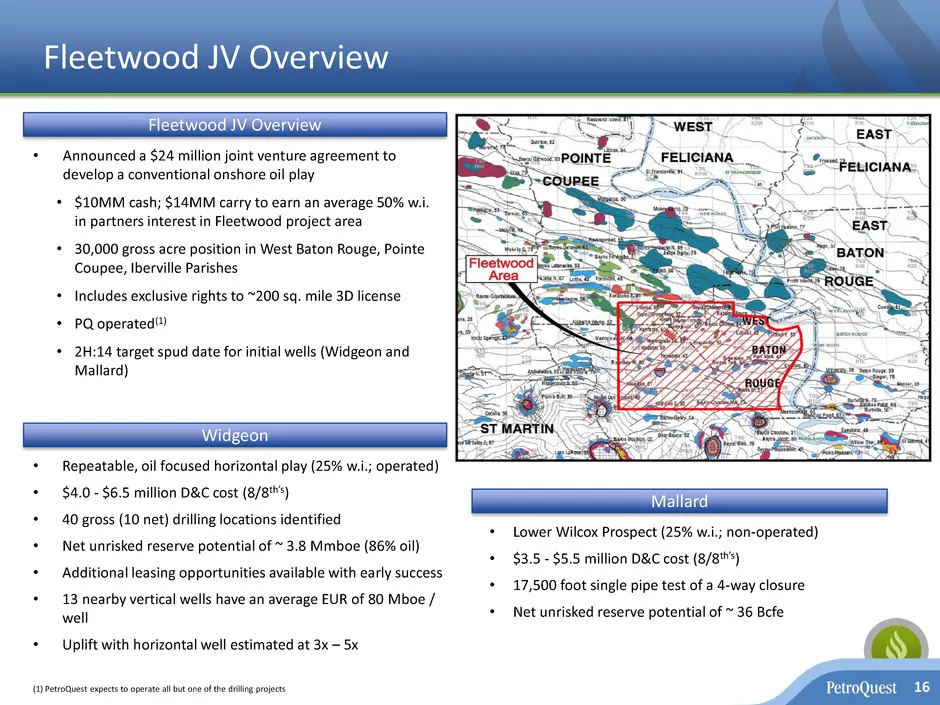
Slide 16: Fleetwood JV Overview
Fleetwood JV Overview • Announced a $24 million joint venture agreement to develop a conventional onshore oil play • $10MM cash; $14MM carry to earn an average 50% w.i. in partners interest in Fleetwood project area • 30,000 gross acre position in West Baton Rouge, Pointe Coupee, Iberville Parishes
Slide 17: LaCantera/Thunder Bayou Deeper Pool Tests
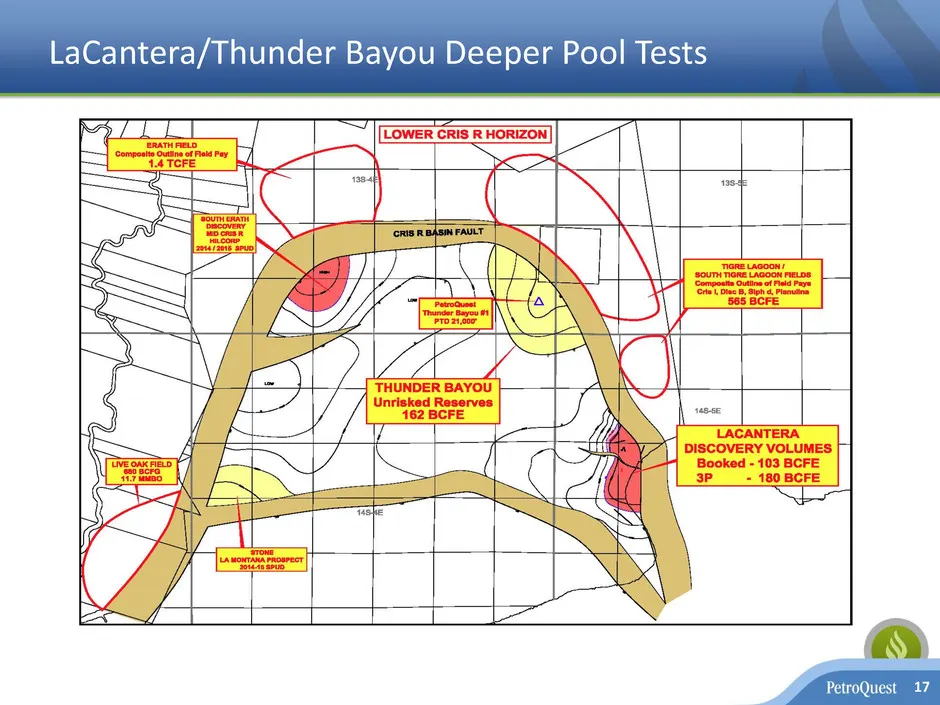
LaCantera/Thunder Bayou Deeper Pool Tests 17
Slide 18: LaCantera/Thunder Bayou Stratigraphic Cross Sections
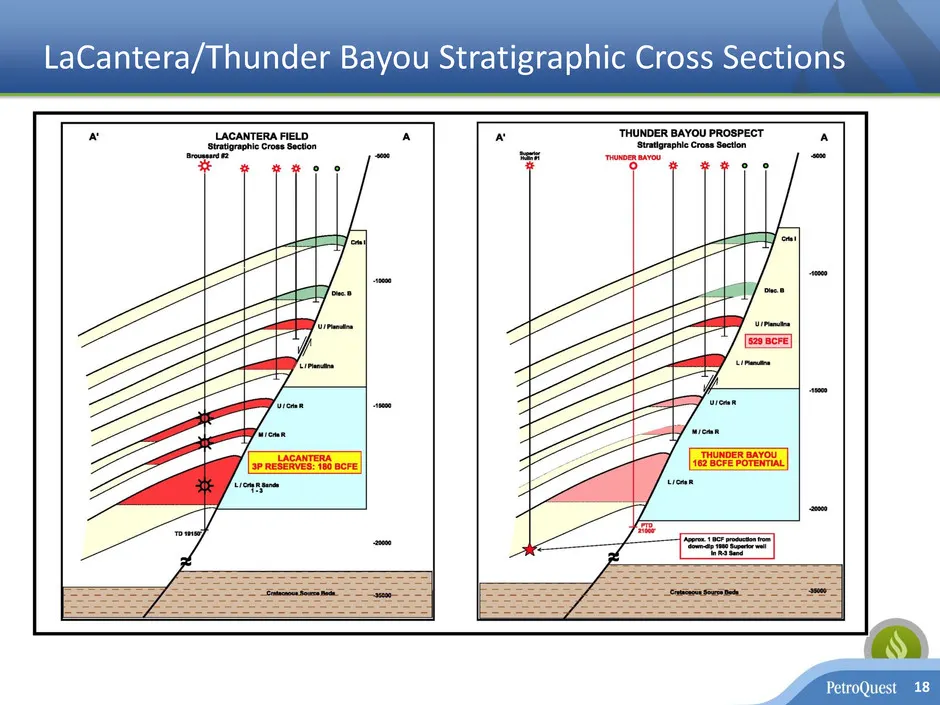
LaCantera/Thunder Bayou Stratigraphic Cross Sections 18
Slide 19: PQ Operated Gulf Coast Drilling Summary
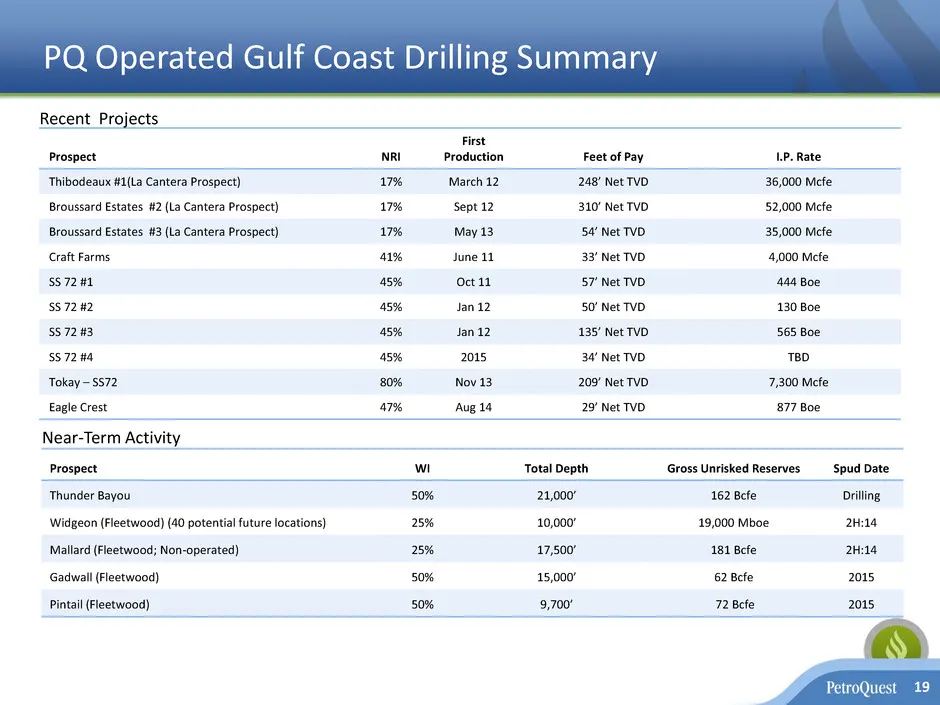
PQ Operated Gulf Coast Drilling Summary Prospect WI Total Depth Gross Unrisked Reserves Spud Date Thunder Bayou 50% 21,000’ 162 Bcfe Drilling Widgeon (Fleetwood) (40 potential future locations) 25% 10,000’ 19,000 Mboe 2H:14 Mallard (Fleetwood; Non-operated) 25% 17,500’ 181 Bcfe 2H:14 Gadwall (Fleetw
Slide 20: Liquids Production Will Drive Cash Margin Expansion
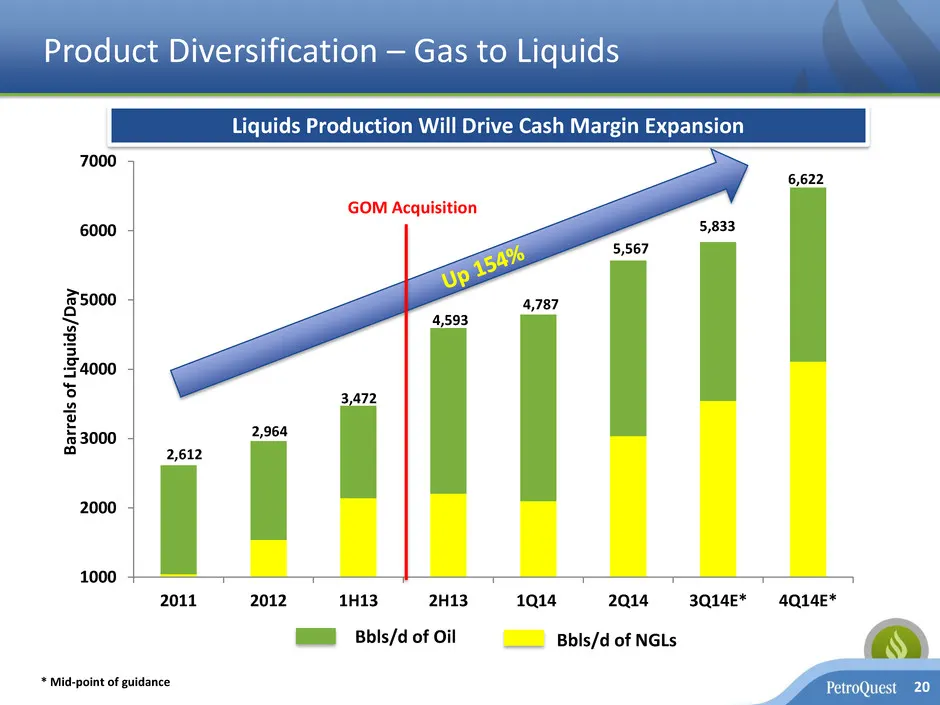
20 Liquids Production Will Drive Cash Margin Expansion Bbls/d of Oil Bbls/d of NGLs Product Diversification – Gas to Liquids 3,889 1000 2000 3000 4000 5000 6000 7000 2011 2012 1H13 2H13 1Q14 2Q14 3Q14E* 4Q14E* 2,612 2,964 3,472 4,593 4,787 GOM Acquisition 6,622 B ar re ls of L iq u id s/D ay * Mid-p
Slide 21: Significant Sequential Cash Flow Growth
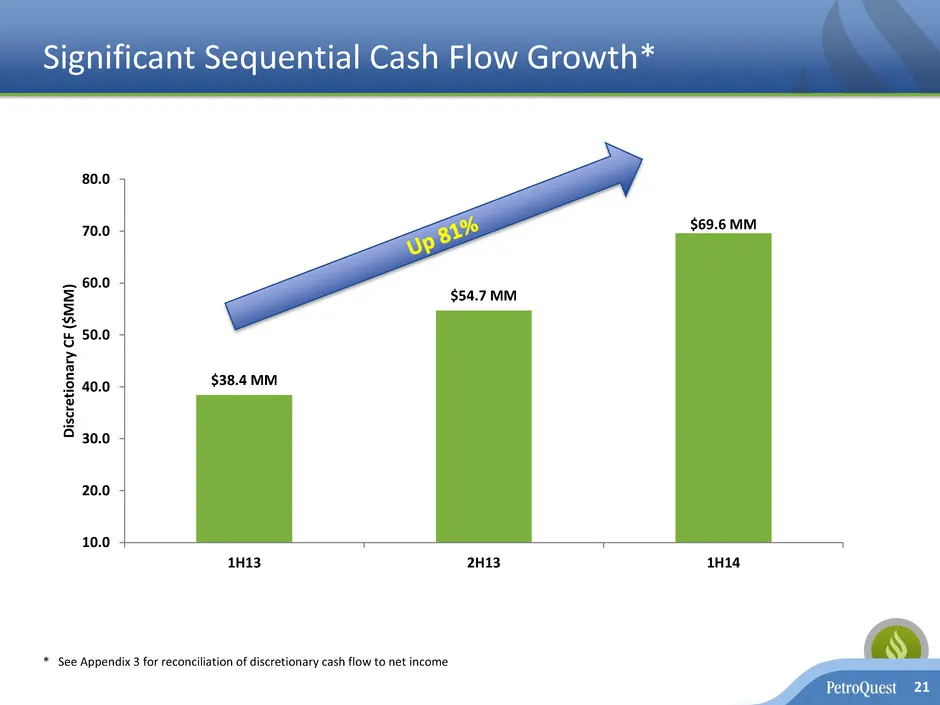
Significant Sequential Cash Flow Growth* 21 $38.4 MM $54.7 MM $69.6 MM 10.0 20.0 30.0 40.0 50.0 60.0 70.0 80.0 1H13 2H13 1H14 D iscr et io n ar y CF ($ M M ) * See Appendix 3 for reconciliation of discretionary cash flow to net income
Slide 22: Operating & Financial Metrics
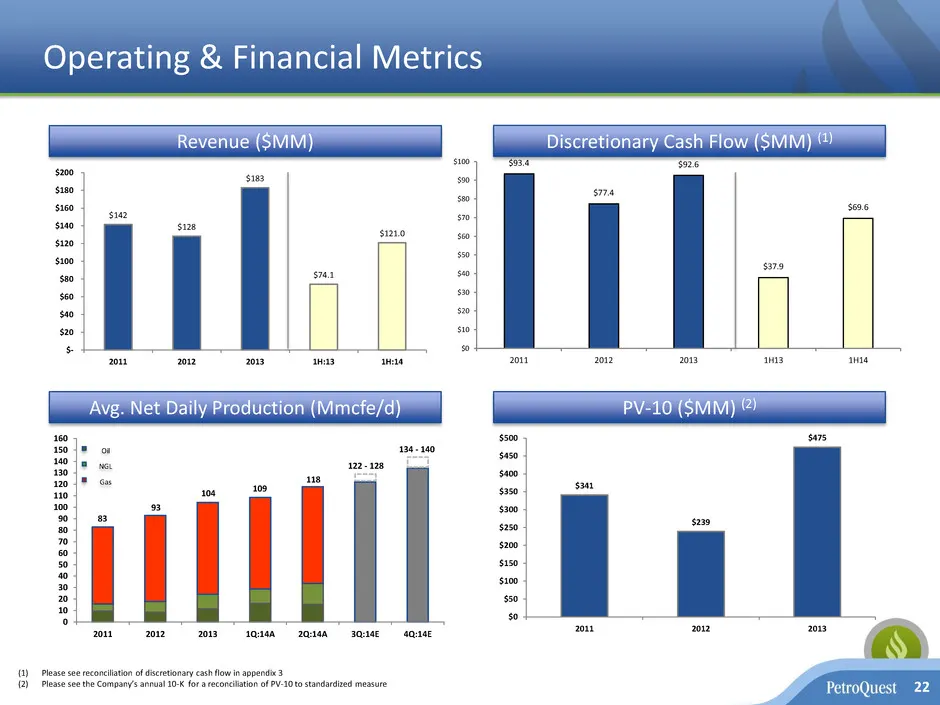
$142 $128 $183 $74.1 $121.0 $- $20 $40 $60 $80 $100 $120 $140 $160 $180 $200 2011 2012 2013 1H:13 1H:14 Operating & Financial Metrics 22 Revenue ($MM) Avg. Net Daily Production (Mmcfe/d) PV-10 ($MM) (2) Discretionary Cash Flow ($MM) (1) (1) Please see reconciliation of discretionary cash flow in app
Slide 23: Debt Metrics – Poised for Improvement with Growing Cash Flow Profile
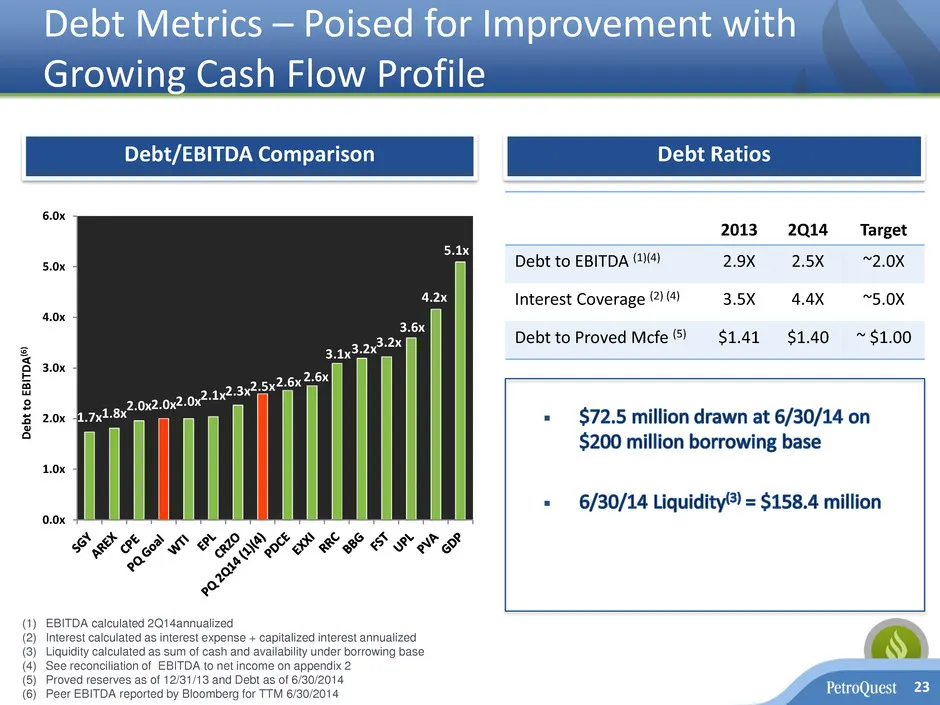
Debt Metrics – Poised for Improvement with Growing Cash Flow Profile 23 Debt/EBITDA Comparison 2013 2Q14 Target Debt to EBITDA (1)(4) 2.9X 2.5X ~2.0X Interest Coverage (2) (4) 3.5X 4.4X ~5.0X Debt to Proved Mcfe (5) $1.41 $1.40 ~ $1.00 (1) EBITDA calculated 2Q14annualized (2) Interest calculated as
Slide 24: Relative Market Valuation
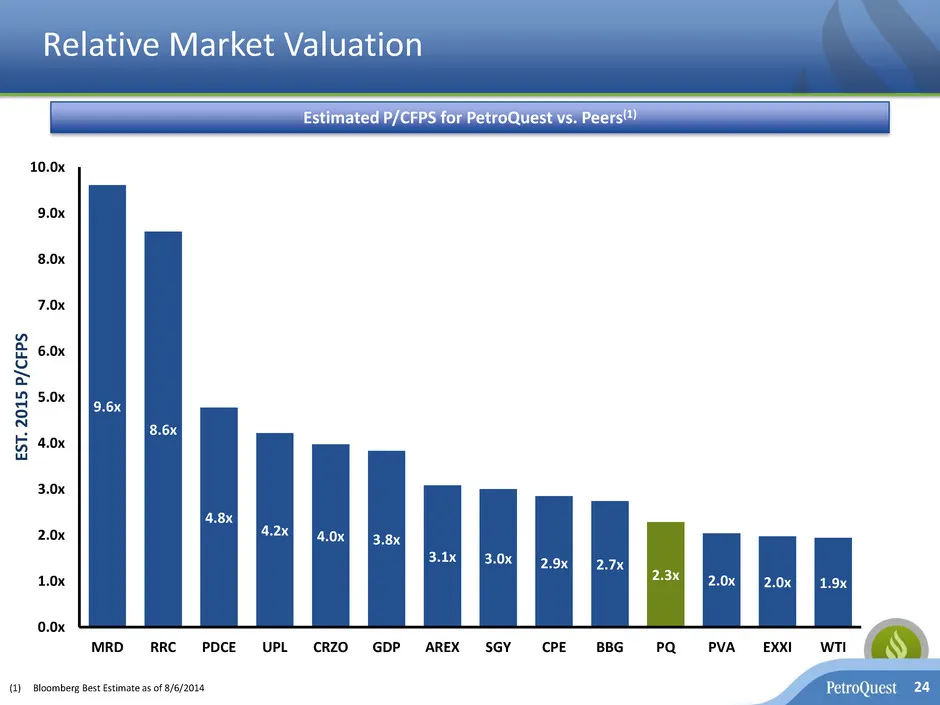
Relative Market Valuation 24 Estimated P/CFPS for PetroQuest vs. Peers(1) 9.6x 8.6x 4.8x 4.2x 4.0x 3.8x 3.1x 3.0x 2.9x 2.7x 2.3x 2.0x 2.0x 1.9x 0.0x 1.0x 2.0x 3.0x 4.0x 5.0x 6.0x 7.0x 8.0x 9.0x 10.0x MRD RRC PDCE UPL CRZO GDP AREX SGY CPE BBG PQ PVA EXXI WTI ES T. 20 1 5 P /CFP S (1) Bloomberg Best
Slide 25: The Opportunity
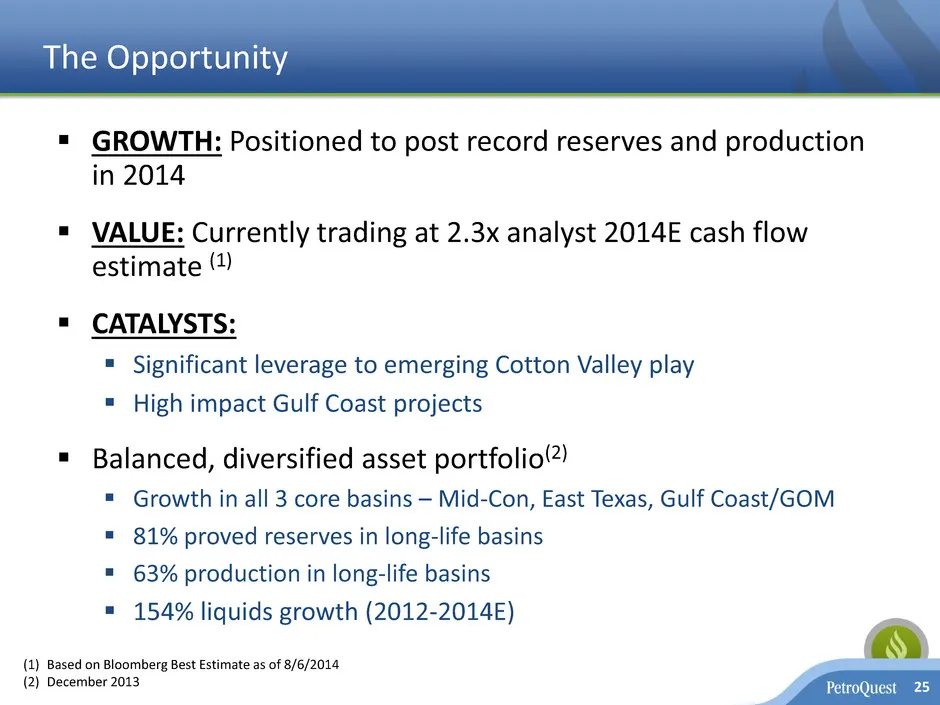
The Opportunity GROWTH: Positioned to post record reserves and production in 2014 VALUE: Currently trading at 2.3x analyst 2014E cash flow estimate (1) CATALYSTS: Significant leverage to emerging Cotton Valley play High impact Gulf Coast projects Balanced, diversified asset portfolio(2)
Slide 26: Appendix
26 Appendix
Slide 27: Appendix - Hedging Positions
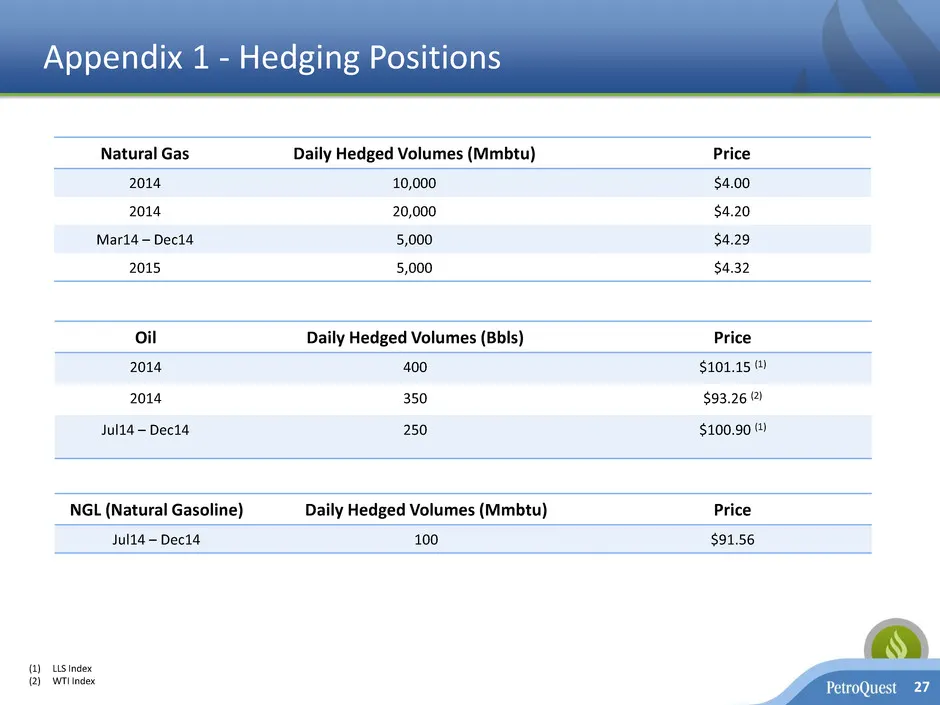
Appendix 1 - Hedging Positions 27 Natural Gas Daily Hedged Volumes (Mmbtu) Price 2014 10,000 $4.00 2014 20,000 $4.20 Mar14 – Dec14 5,000 $4.29 2015 5,000 $4.32 Oil Daily Hedged Volumes (Bbls) Price 2014 400 $101.15 (1) 2014 350 $93.26 (2) Jul14 – Dec14 250 $100.90 (1) (1) LLS Index (2) WTI Index NGL
Slide 28: Appendix - Adjusted EBITDA
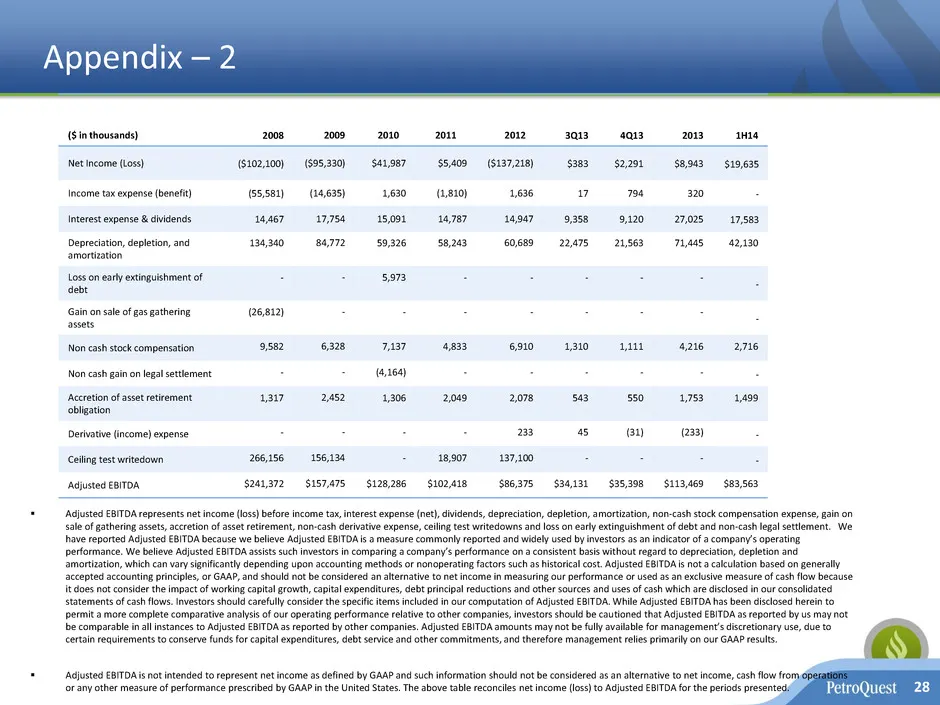
Appendix – 2 Adjusted EBITDA represents net income (loss) before income tax, interest expense (net), dividends, depreciation, depletion, amortization, non-cash stock compensation expense, gain on sale of gathering assets, accretion of asset retirement, non-cash derivative expense, ceiling test wri
Slide 29: Appendix - Discretionary Cash Flow Reconciliation
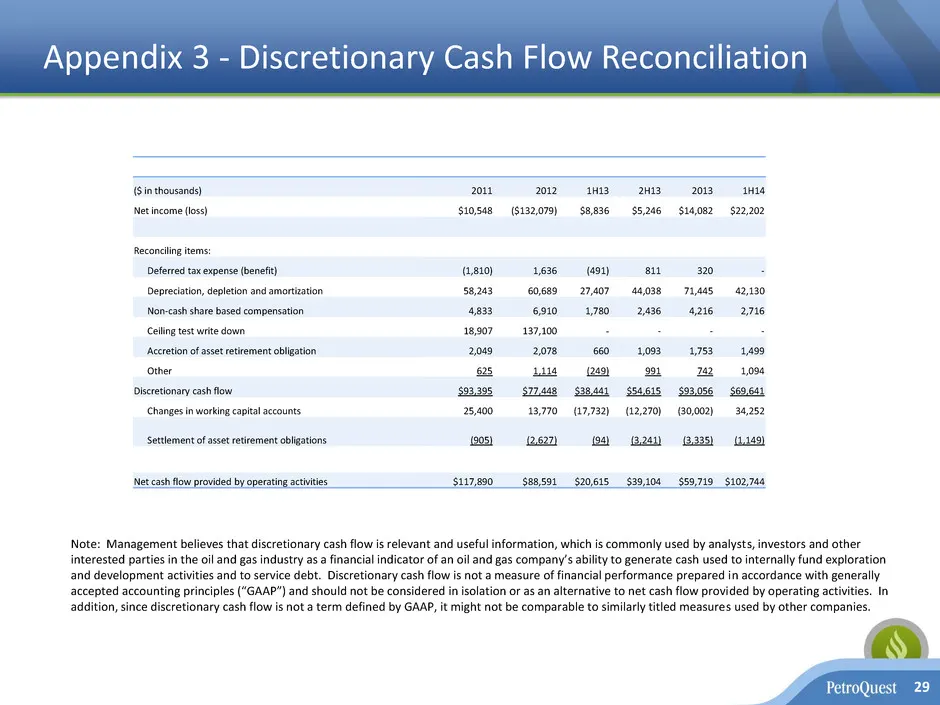
Appendix 3 - Discretionary Cash Flow Reconciliation ($ in thousands) 2011 2012 1H13 2H13 2013 1H14 Net income (loss) $10,548 ($132,079) $8,836 $5,246 $14,082 $22,202 Reconciling items: Deferred tax expense (benefit) (1,810) 1,636 (491) 811 320 - Depreciation, depletion and amortization 58,243 60,689
Slide 30: Appendix - Fleetwood – Widgeon Sensitivity to Well Cost
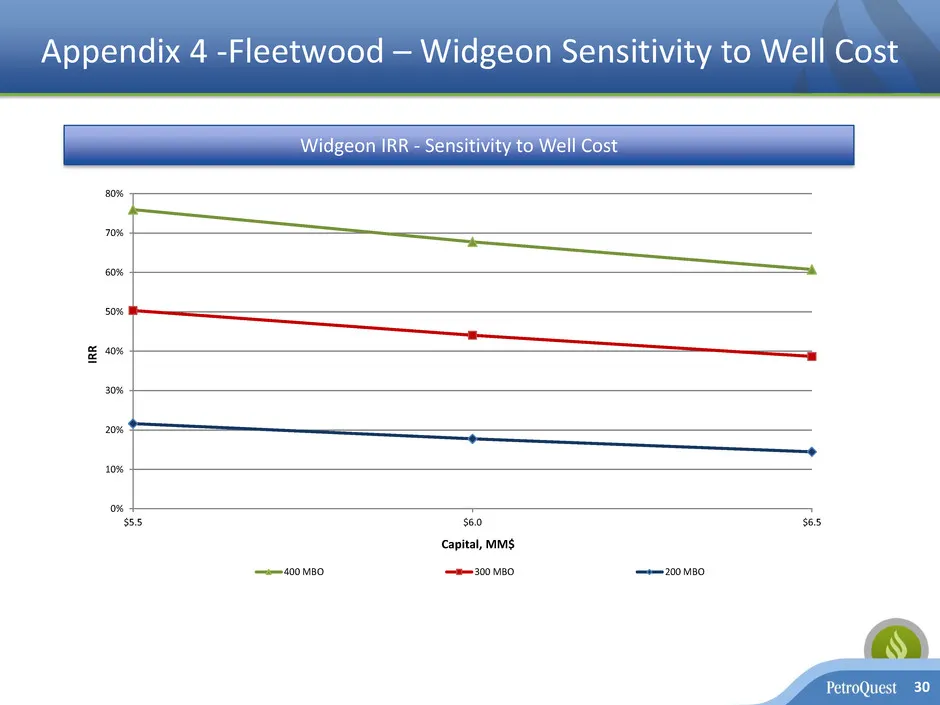
Appendix 4 -Fleetwood –Widgeon Sensitivity to Well Cost 30 Widgeon IRR - Sensitivity to Well Cost 0% 10% 20% 30% 40% 50% 60% 70% 80% $5.5 $6.0 $6.5 IR R Capital, MM$ 400 MBO 300 MBO 200 MBO
Slide 31: Appendix - Woodford Dry Gas – Hoss Field Joint Venture
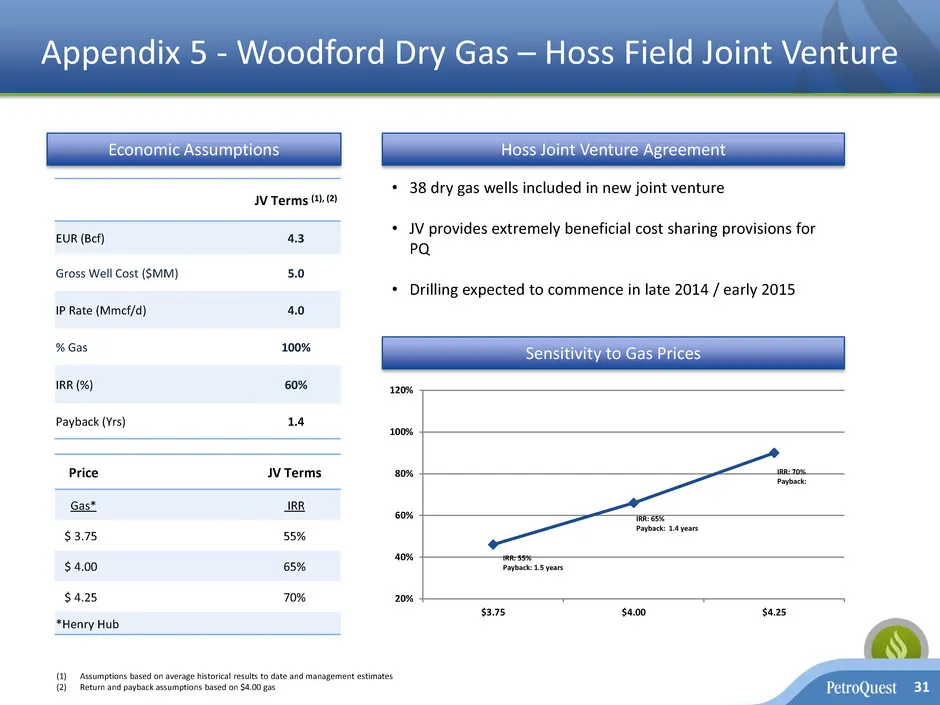
Appendix 5 - Woodford Dry Gas – Hoss Field Joint Venture 31 Price JV Terms Gas* IRR $ 3.75 55% $ 4.00 65% $ 4.25 70% *Henry Hub JV Terms (1), (2) EUR (Bcf) 4.3 Gross Well Cost ($MM) 5.0 IP Rate (Mmcf/d) 4.0 % Gas 100% IRR (%) 60% Payback (Yrs) 1.4 • 38 dry gas wells included in new joint venture • J
Slide 32: Company Information
Company Information 32 400 East Kaliste Saloom Road, Suite 6000 Lafayette, Louisiana 70508 Phone: (337) 232-7028 Fax: (337) 232-0044 www.petroquest.com This presentation contains "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E
Source: SEC EDGAR · 8-K filed Aug 13, 2014
More decks from PetroQuest Energy Inc
 Corporate Update (June 2019)15 slides · Jun 19, 2019
 Investor Presentation (November 2018)16 slides · Nov 7, 2018
 Investor Presentation (July 2018)29 slides · Jul 10, 2018
 Investor Presentation (December 2017)6 slides · Dec 20, 2017
 Investor Presentation (January 2017)28 slides · Jan 9, 2017
 Investor Presentation (April 2016)29 slides · Apr 5, 2016