M3, Inc. · TSE:2413
M3 — FY2023 Q3 Earnings Presentation
46 slides from M3's earnings presentation, Jan 31, 2024
Slide 1: M3, Inc. Presentation Material January 2024
M3, Inc. Presentation Material January 2024 Copyright © 2024 M3, Inc. All rights reserved. 0
Slide 2: Forward-looking statements disclaimer
The following presentation contains forecasts, future plans, management targets and other forward-looking projections relating to M3, Inc. and/or its group. These statements are drawn from assumptions of future events based on data currently available to us, and there exist possibilities that such a
Slide 3: FY2023 Q1-Q3 Consolidated Results
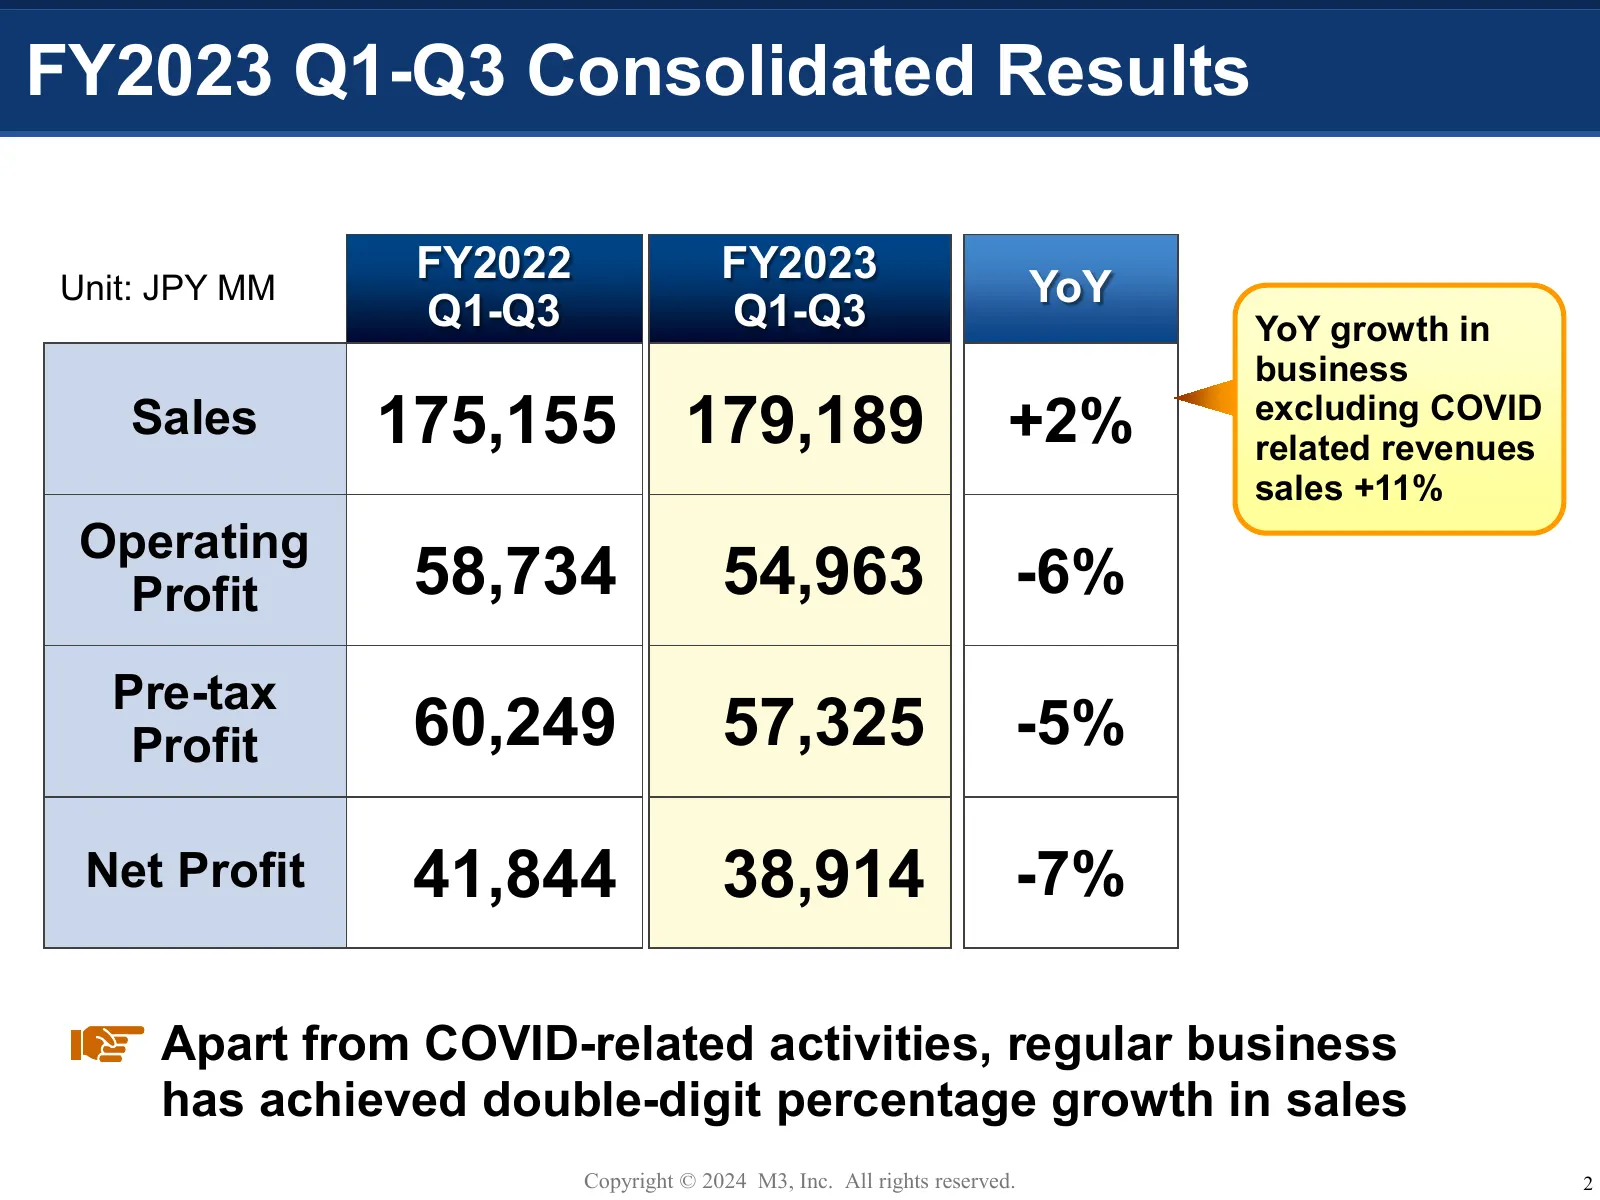
FY2023 Q1-Q3 Consolidated Results FY2022 FY2023 Unit: JPY MM YoY Q1-Q3 Q1-Q3 YoY growth in business Sales 175,155 179,189 +2% excluding COVID related revenues sales +11% Operating Profit 58,734 54,963 -6% Pre-tax Profit 60,249 57,325 -5% Net Profit 41,844 38,914 -7% Apart from COVID-related activiti
Slide 4: Consolidated Sales Trends and COVID Impact
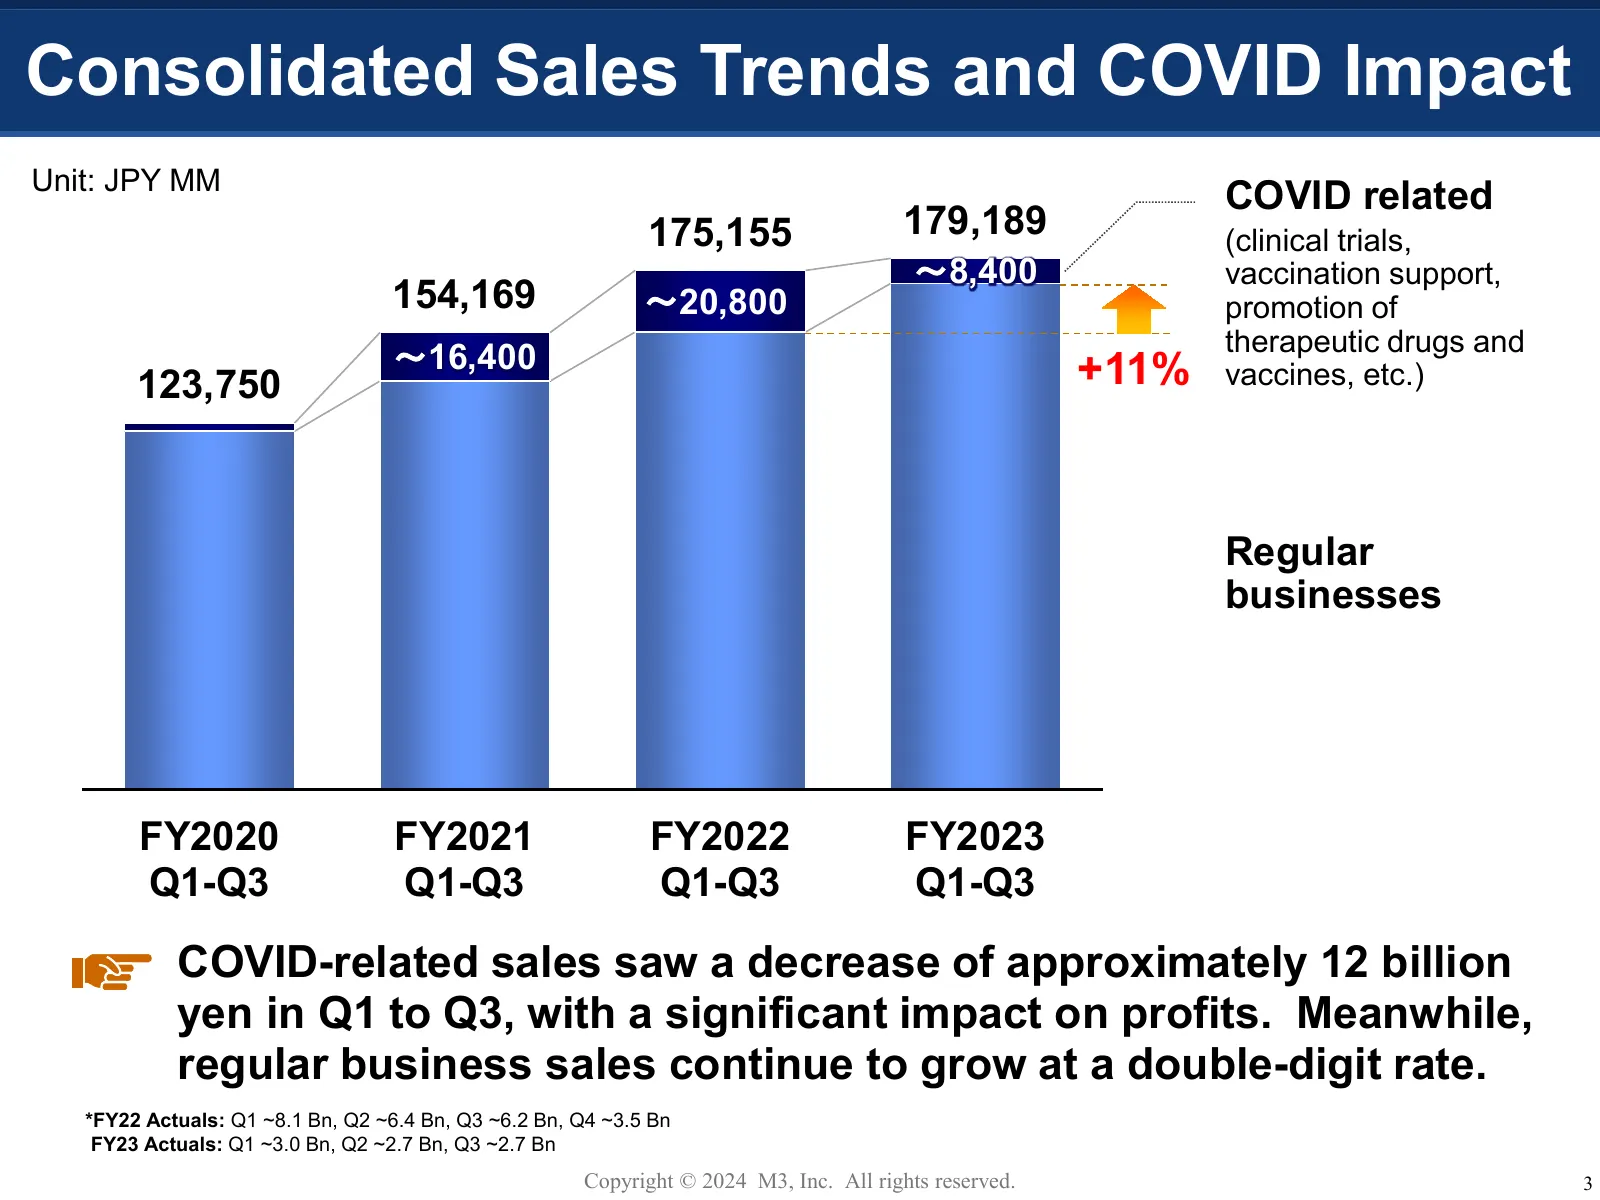
Consolidated Sales Trends and COVID Impact Unit: JPY MM COVID related 175,155 179,189 (clinical trials, ~8,400 vaccination support, 154,169 ~20,800 promotion of therapeutic drugs and 123,750 ~16,400 +11% vaccines, etc.) Regular businesses FY2020 FY2021 FY2022 FY2023 Q1-Q3 Q1-Q3 Q1-Q3 Q1-Q3 COVID-rel
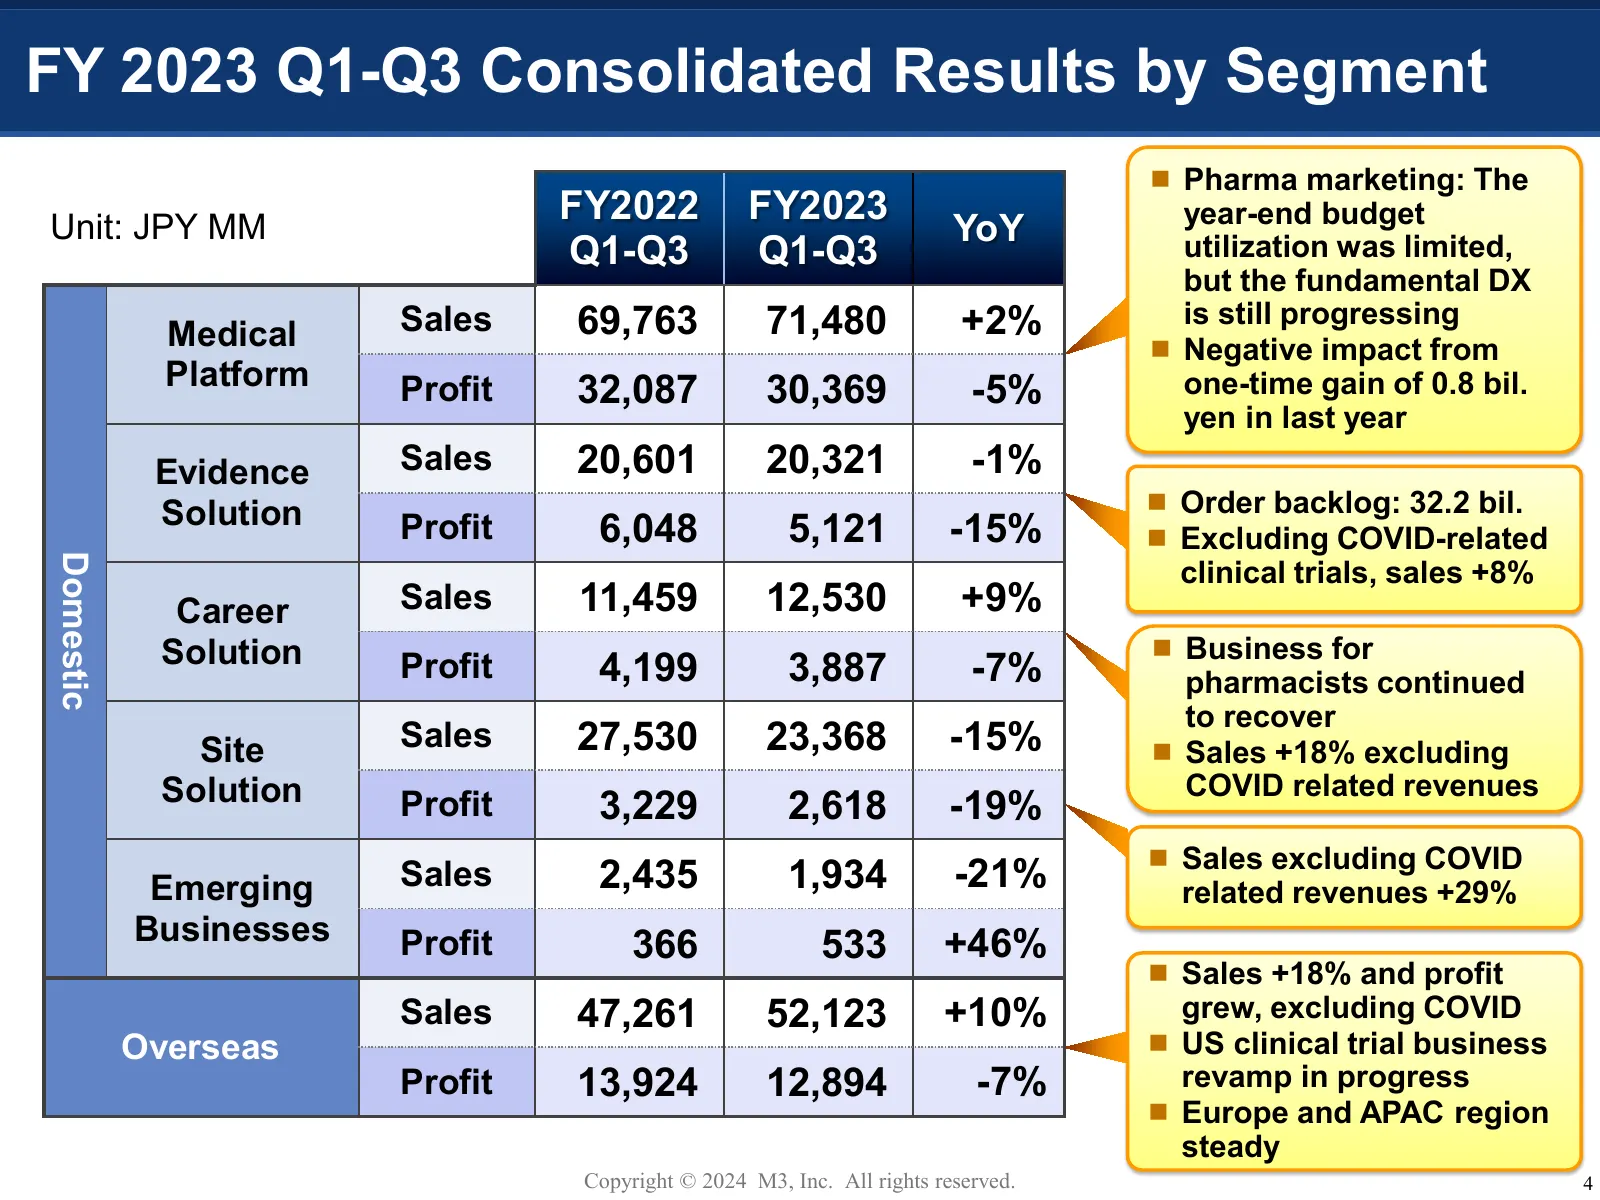
Slide 5: FY2023 Q1-Q3 Consolidated Results by Segment
FY 2023 Q1-Q3 Consolidated Results by Segment Pharma marketing: The FY2022 FY2023 year-end budget Unit: JPY MM YoY Q1-Q3 Q1-Q3 utilization was limited, but the fundamental DX Sales 69,763 71,480 +2% is still progressing Medical Negative impact from Platform Profit 32,087 30,369 -5% one-time gain
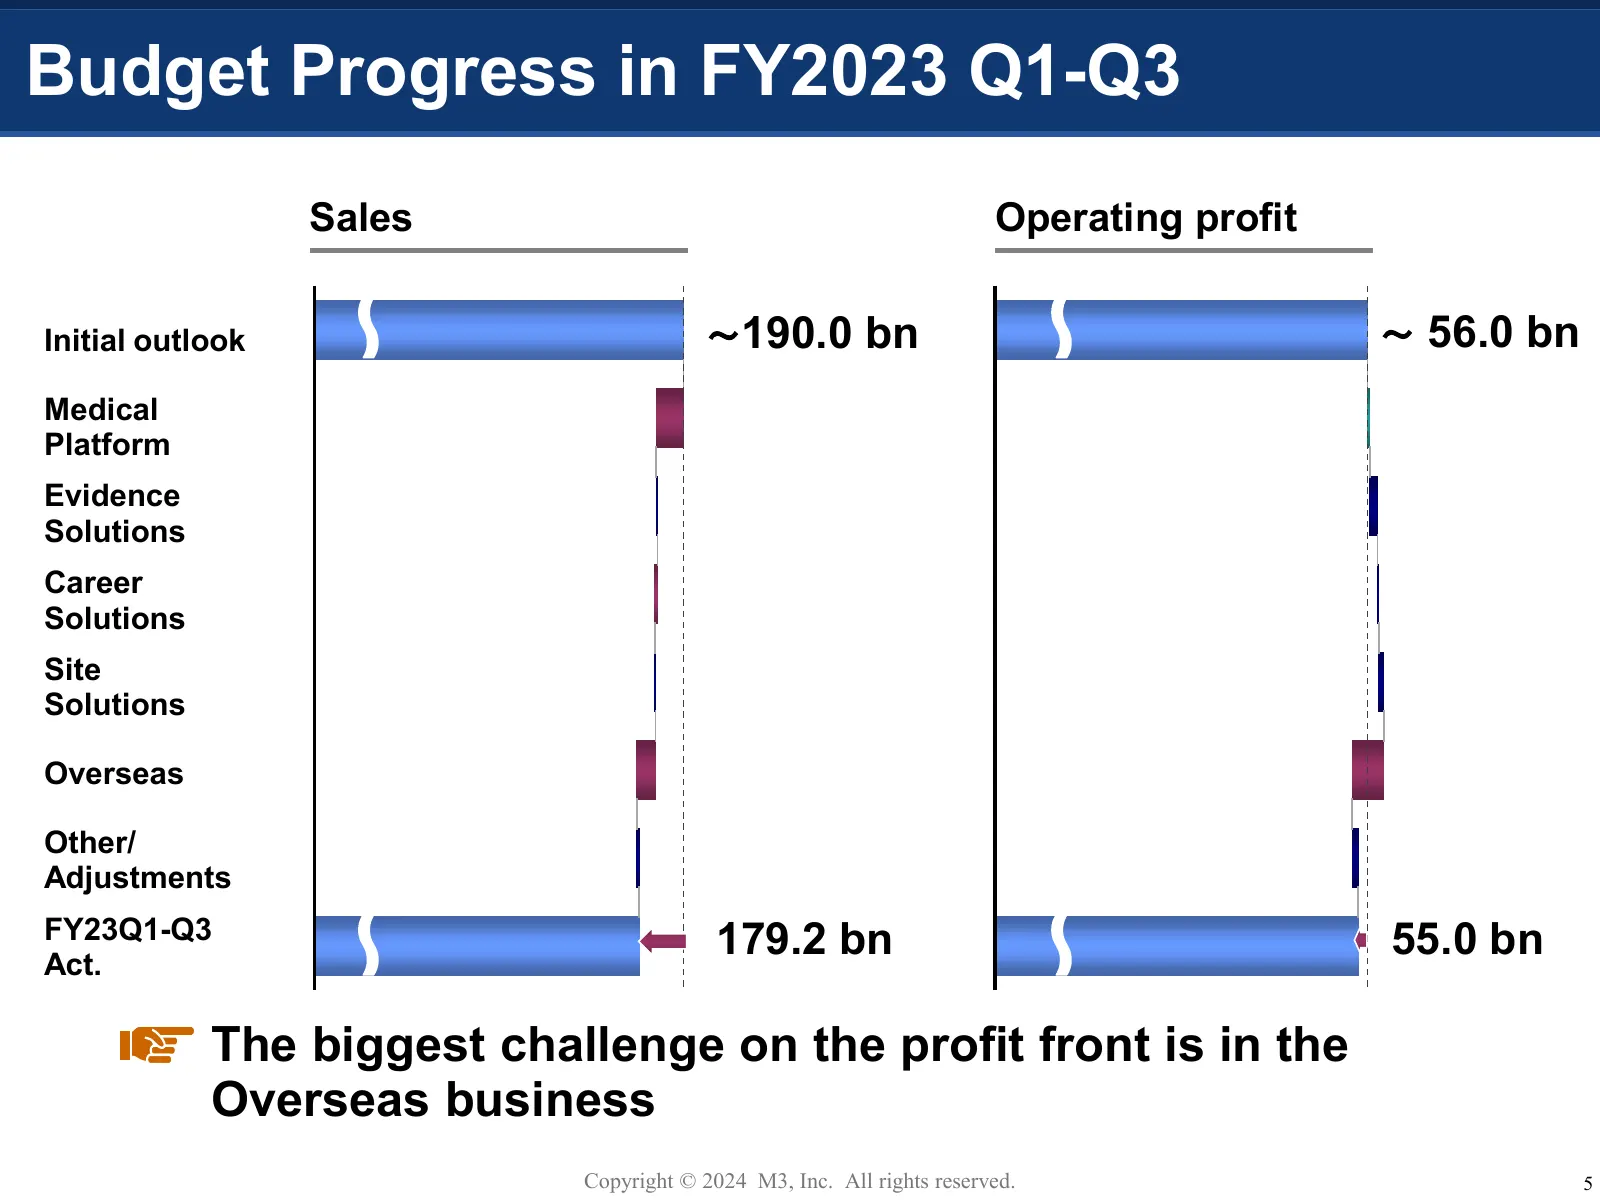
Slide 6: Budget Progress in FY2023 Q1-Q3
Budget Progress in FY2023 Q1-Q3 Sales Operating profit Initial outlook ~190.0 bn ~ 56.0 bn Medical Platform Evidence Solutions Career Solutions Site Solutions Overseas Other/ Adjustments FY23Q1-Q3 179.2 bn 55.0 bn Act. The biggest challenge on the profit front is in the Overseas business Copyright ©
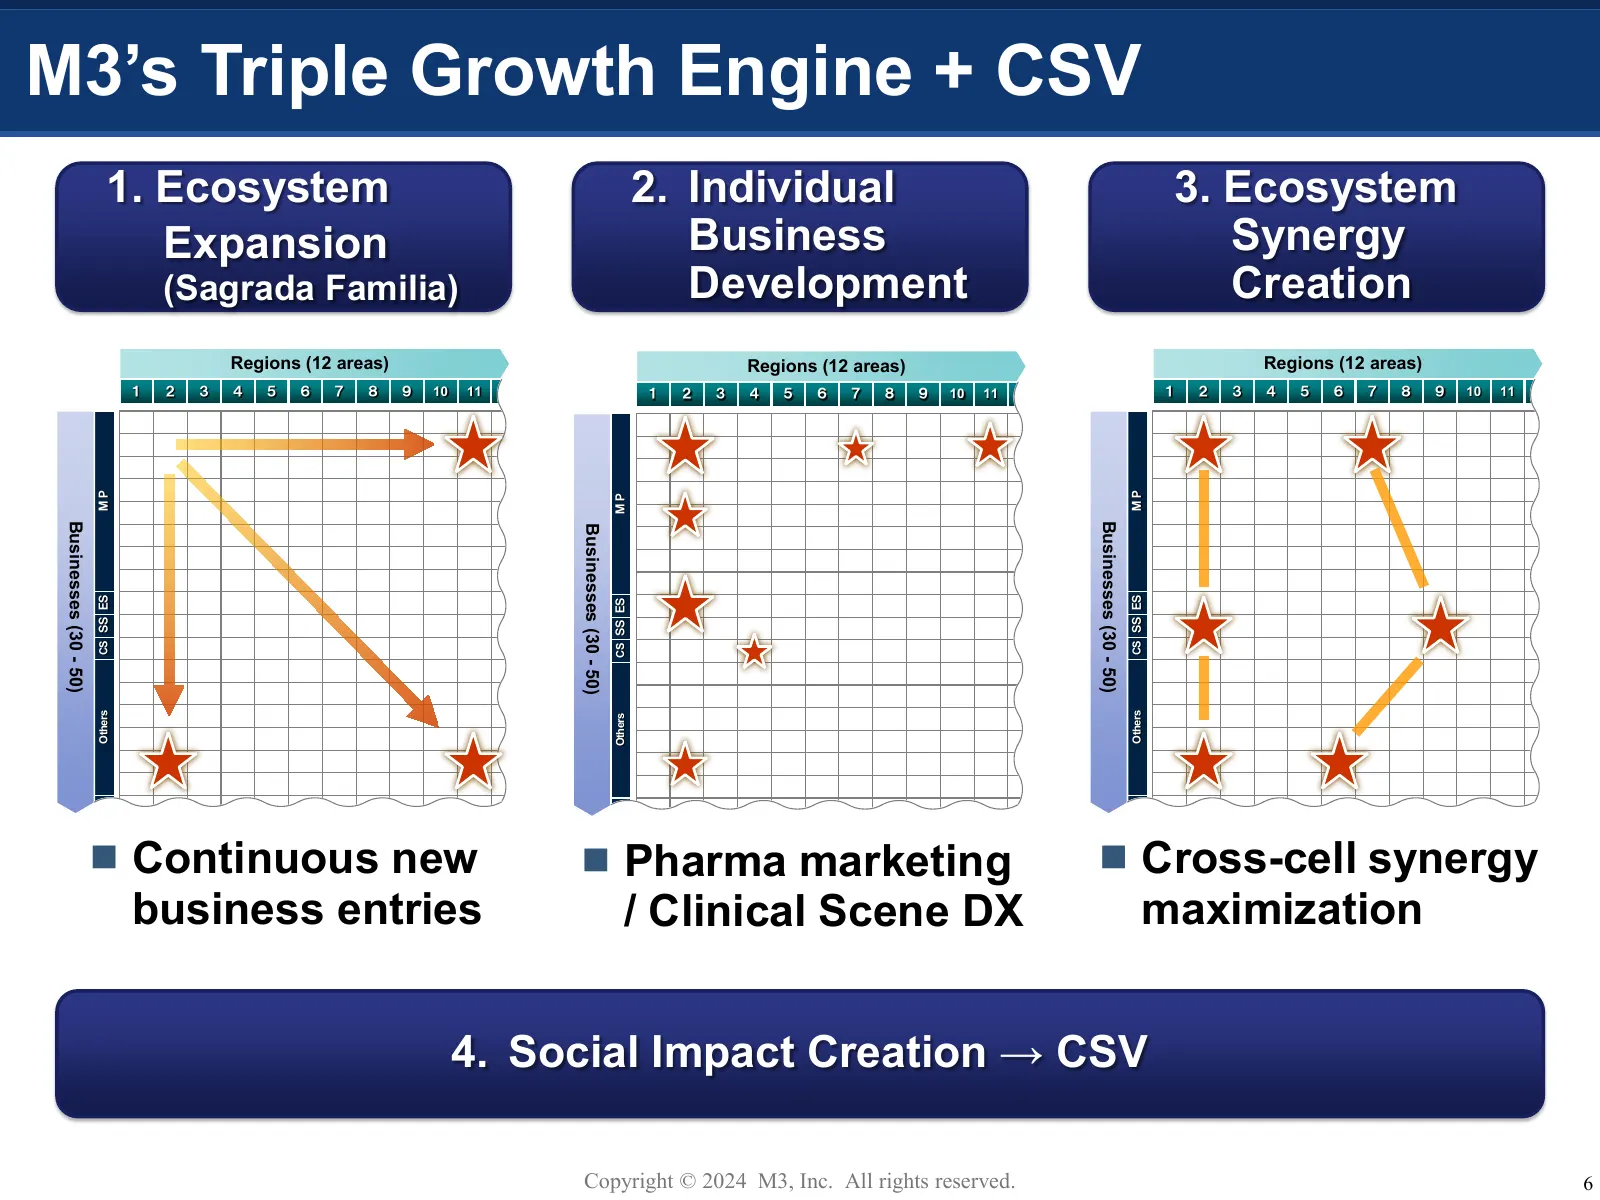
Slide 7: M3's Triple Growth Engine + CSV
M3’s Triple Growth Engine + CSV 1. Ecosystem 2. Individual 3. Ecosystem Expansion Business Synergy (Sagrada Familia) Development Creation Regions (12 areas) Regions (12 areas) Regions (12 areas) 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 MP MP MP Businesses (30 - 50) Bus
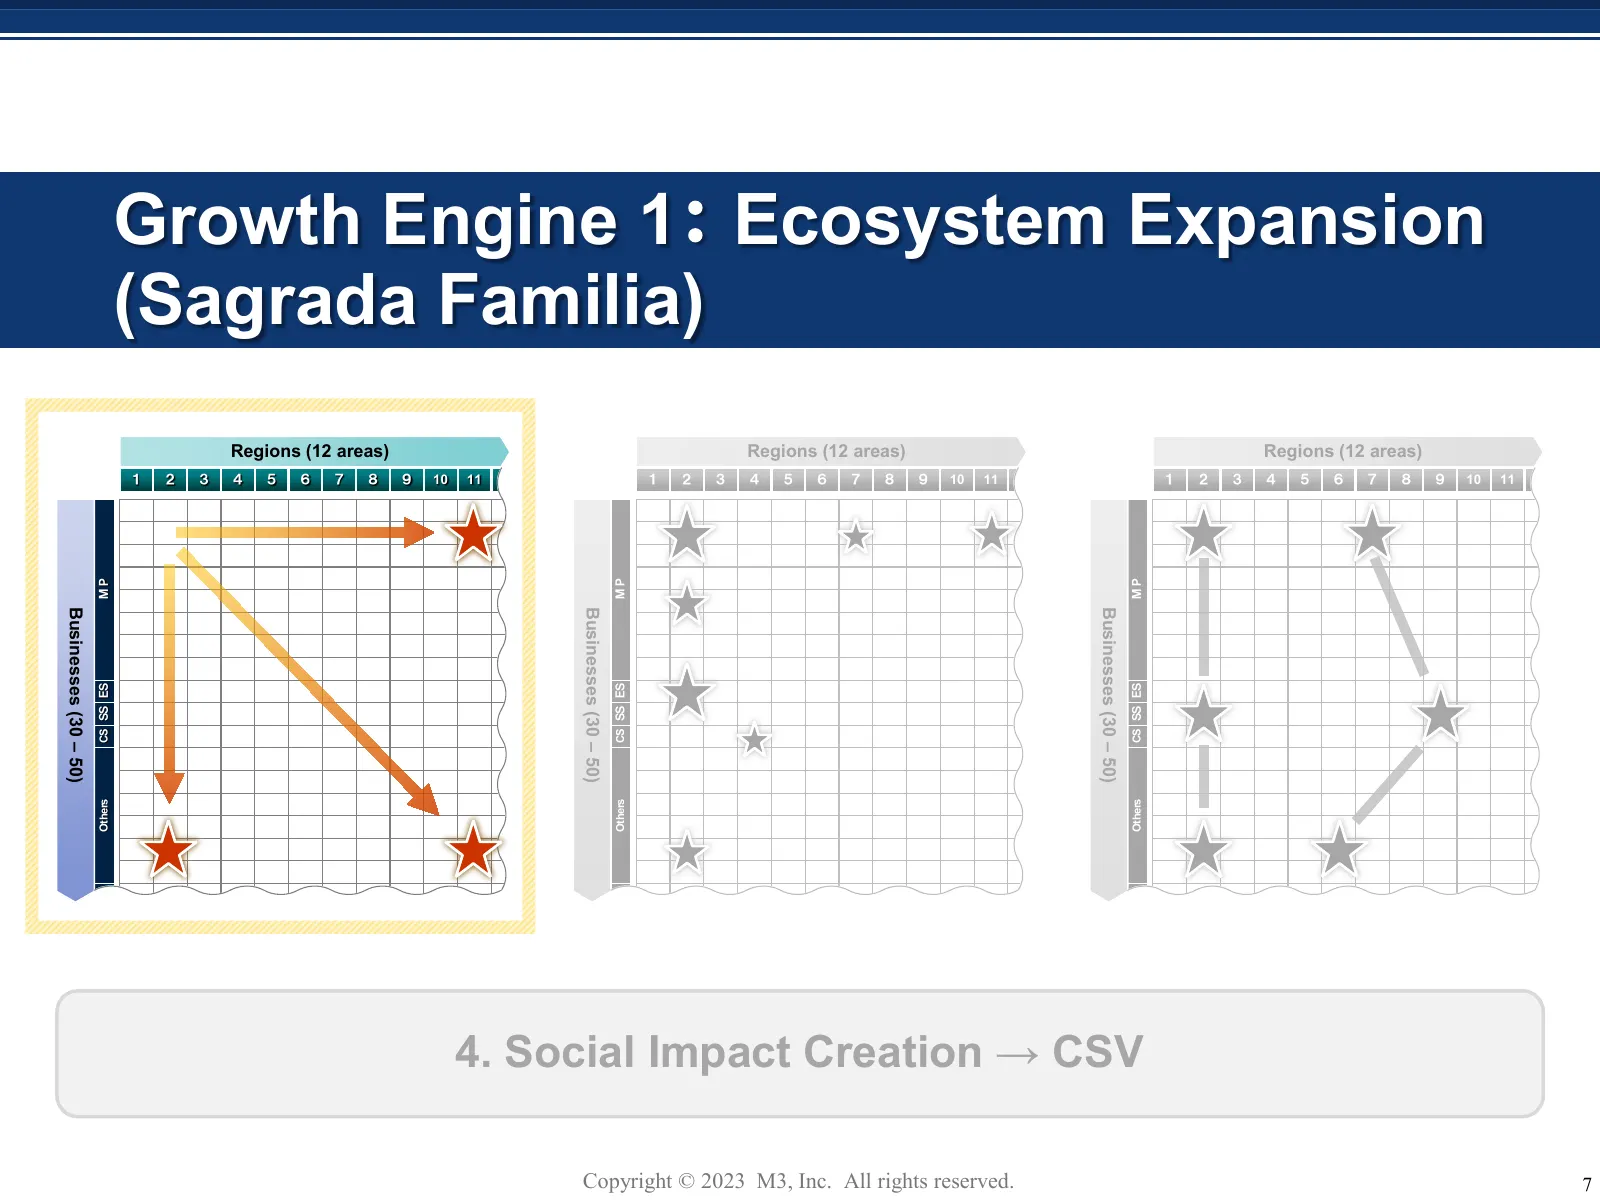
Slide 8: Growth Engine 1: Ecosystem Expansion (Sagrada Familia)
Growth Engine 1: Ecosystem Expansion (Sagrada Familia) Regions (12 areas) Regions (12 areas) Regions (12 areas) 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 MP MP MP Businesses (30 – 50) Businesses (30 – 50) Businesses (30 – 50) CS SS ES CS SS ES CS SS ES Others Others Oth
Slide 9: Leverage 3 Major Resources to Solve Healthcare Issues
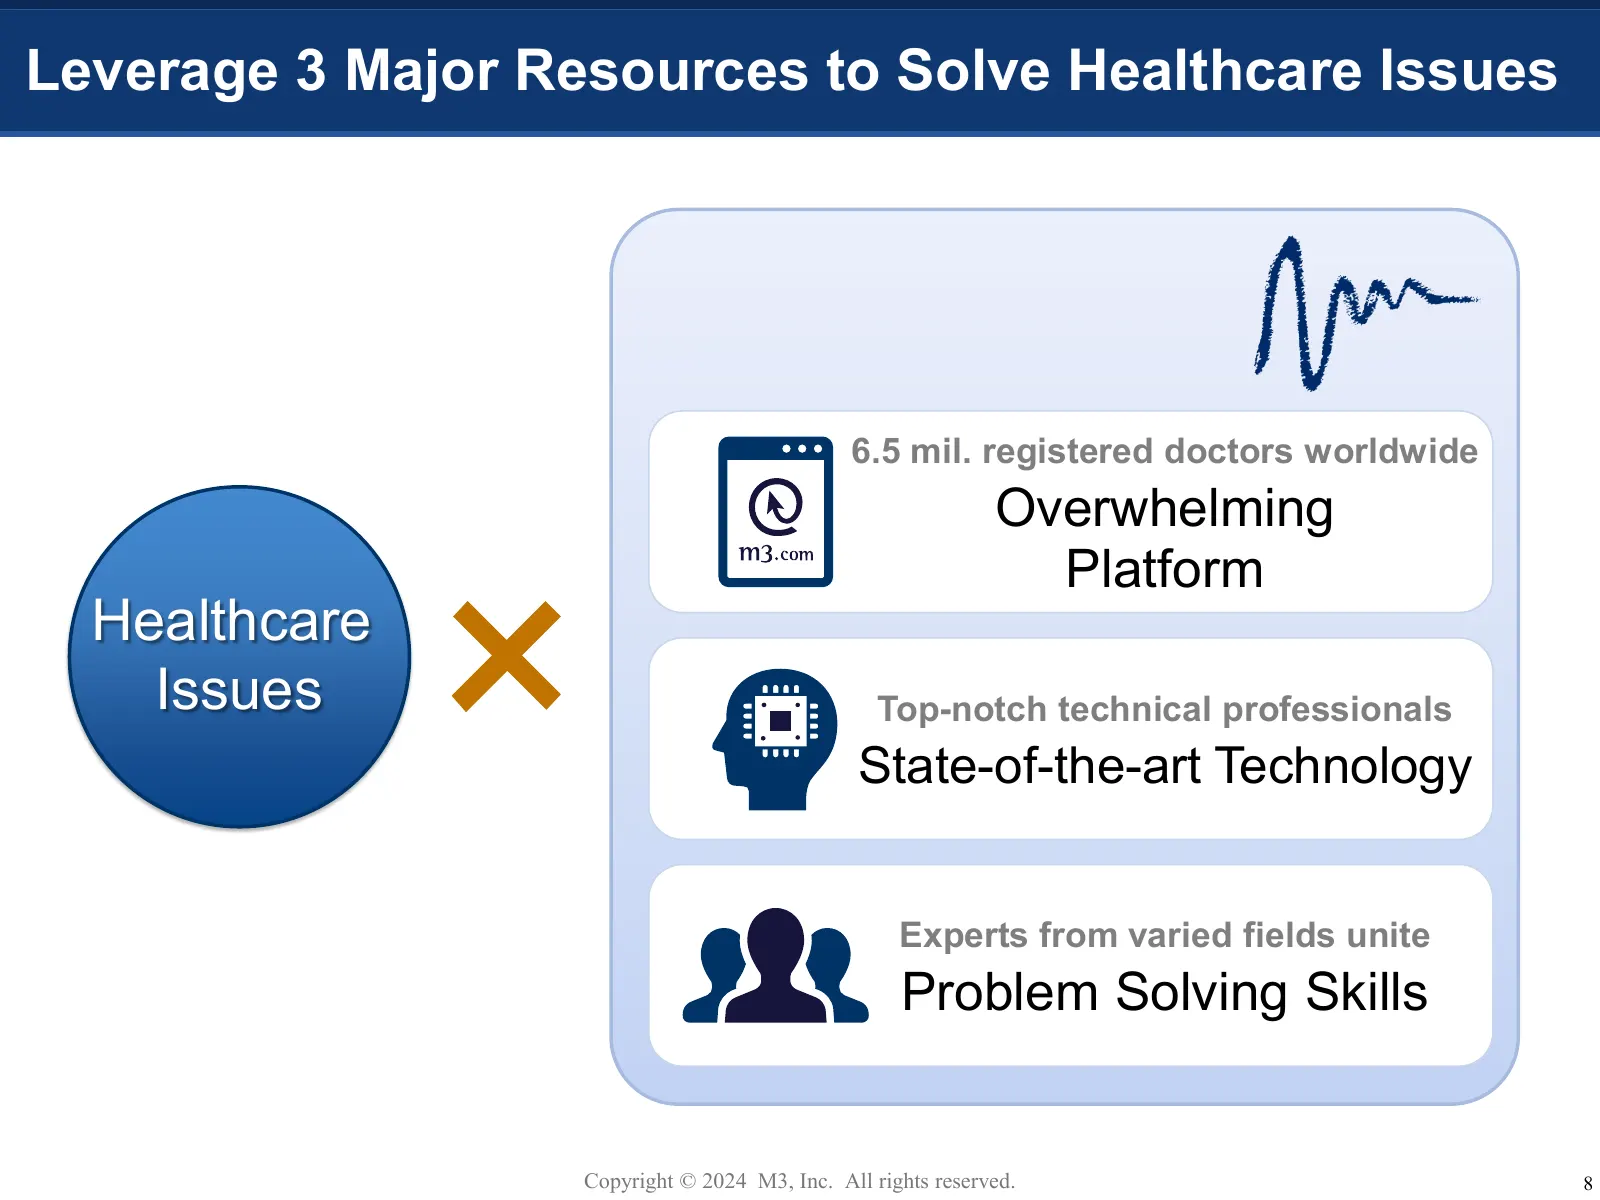
Leverage 3 Major Resources to Solve Healthcare Issues 6.5 mil. registered doctors worldwide Overwhelming Platform Healthcare Issues × Top-notch technical professionals State-of-the-art Technology Experts from varied fields unite Problem Solving Skills Copyright © 2024 M3, Inc. All rights reserved. 8
Slide 10: Business Scope Expansion and Growth Potential
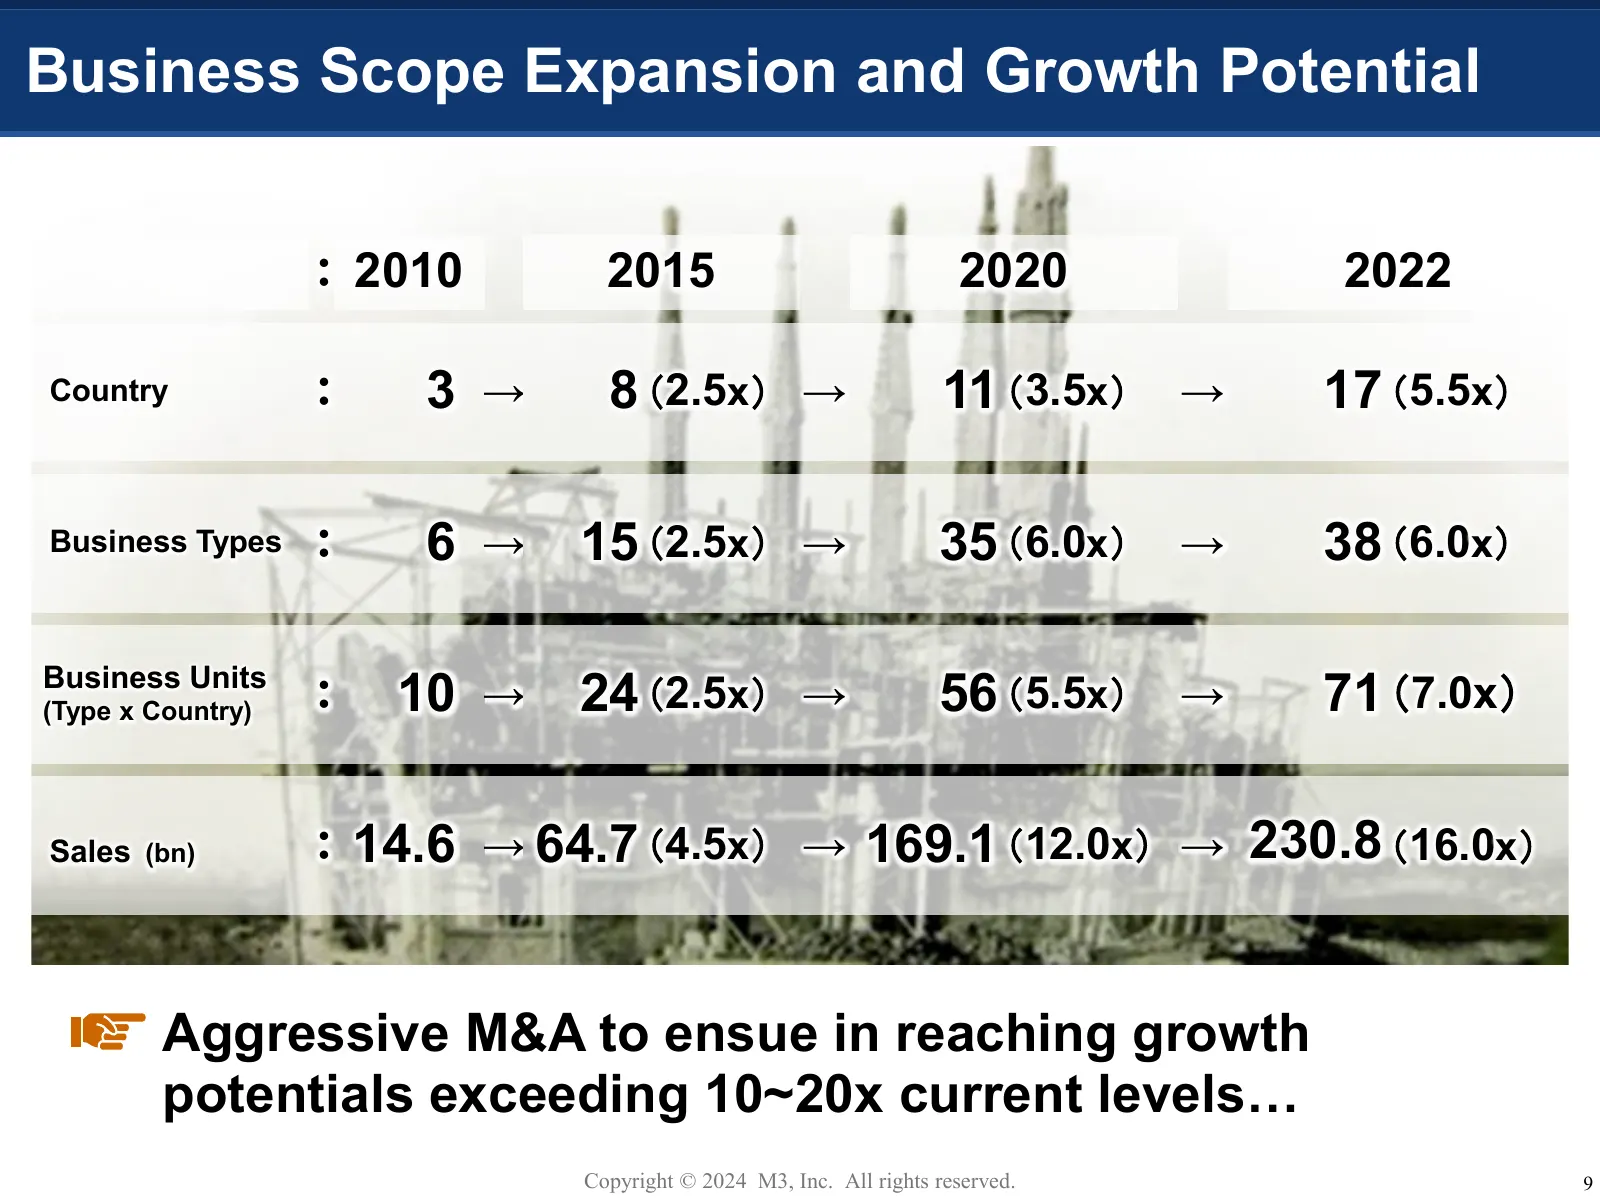
Business Scope Expansion and Growth Potential : 2010 2015 2020 2022 Country : 3 → 8 (2.5x) → 11 (3.5x) → 17 (5.5x) Business Types : 6 → 15 (2.5x) → 35 (6.0x) → 38 (6.0x) Business Units (Type x Country) : 10 → 24 (2.5x) → 56 (5.5x) → 71 (7.0x) Sales (bn) : 14.6 → 64.7 (4.5x) → 169.1 (12.0x) → 230.8 (
Slide 11: Growth Image per Business Expansion Phases
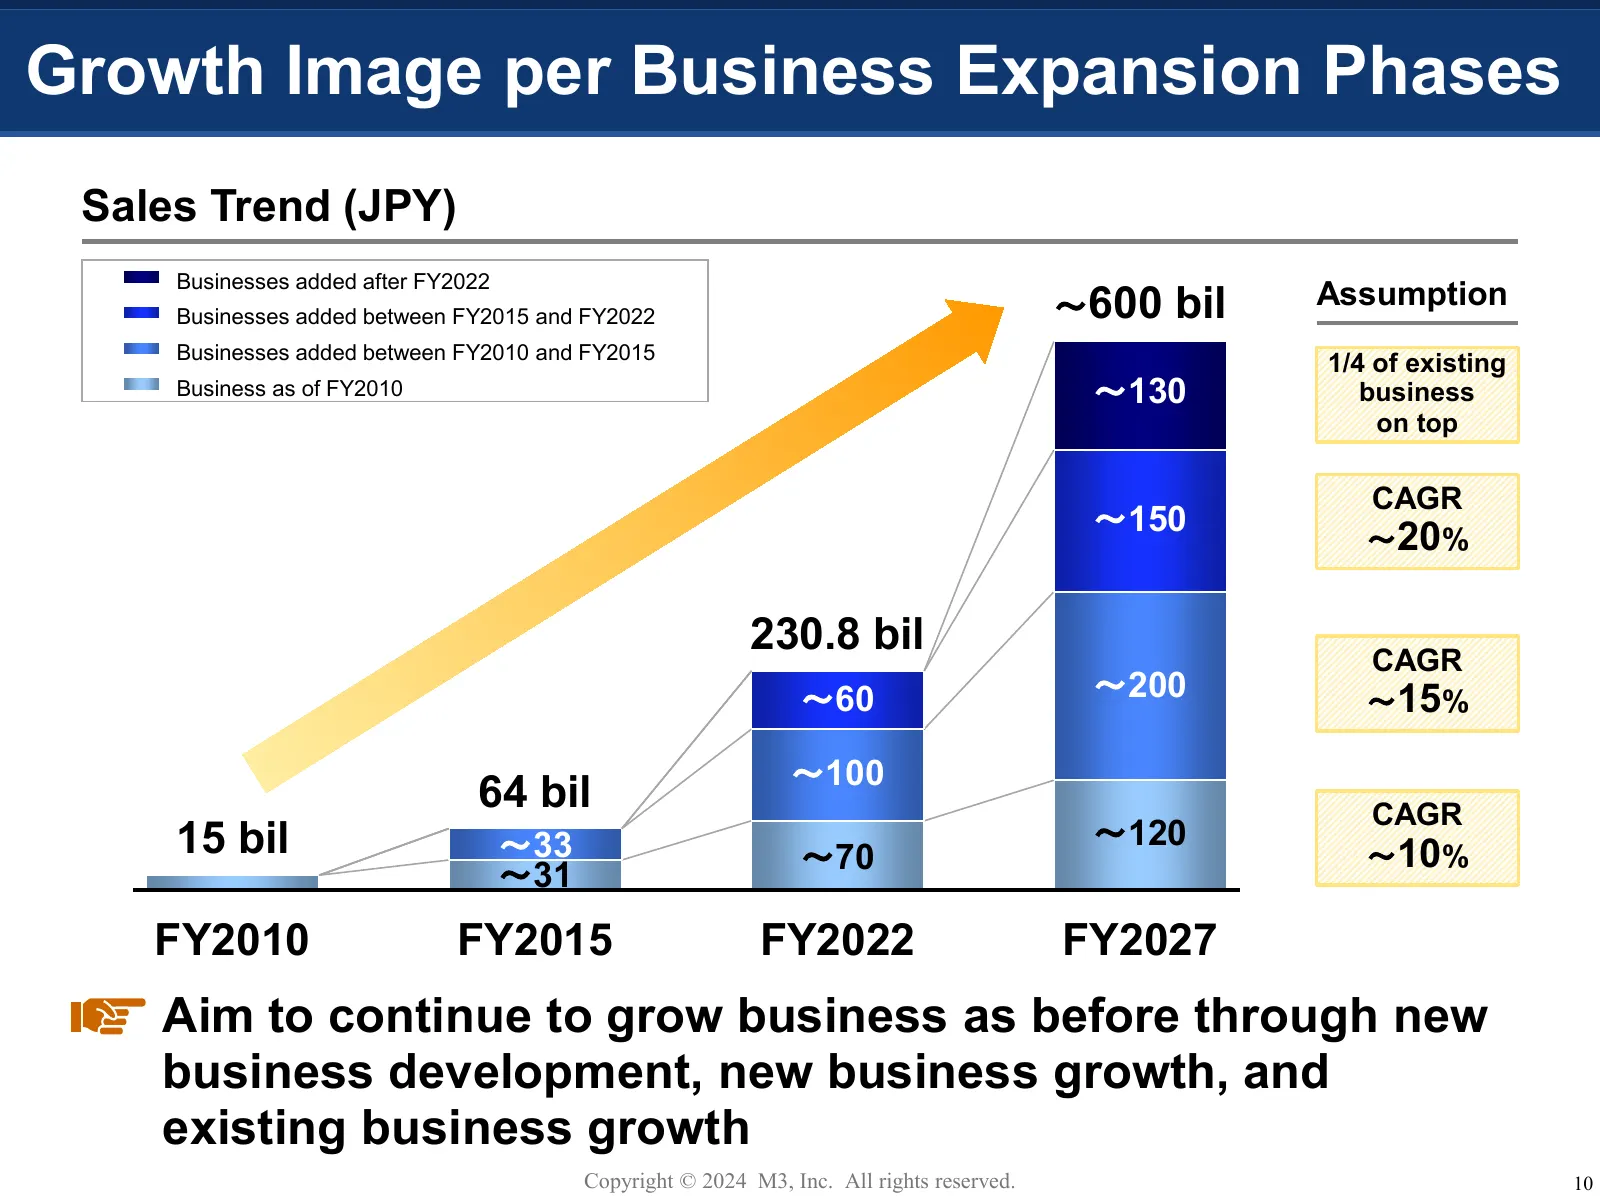
Growth Image per Business Expansion Phases Sales Trend (JPY) Businesses added after FY2022 ~600 bil Assumption Businesses added between FY2015 and FY2022 Businesses added between FY2010 and FY2015 1/4 of existing Business as of FY2010 ~130 business on top CAGR ~150 ~20% 230.8 bil CAGR ~60 ~200 ~15%
Slide 12: Sales Composition Ratio: Past and Future Image
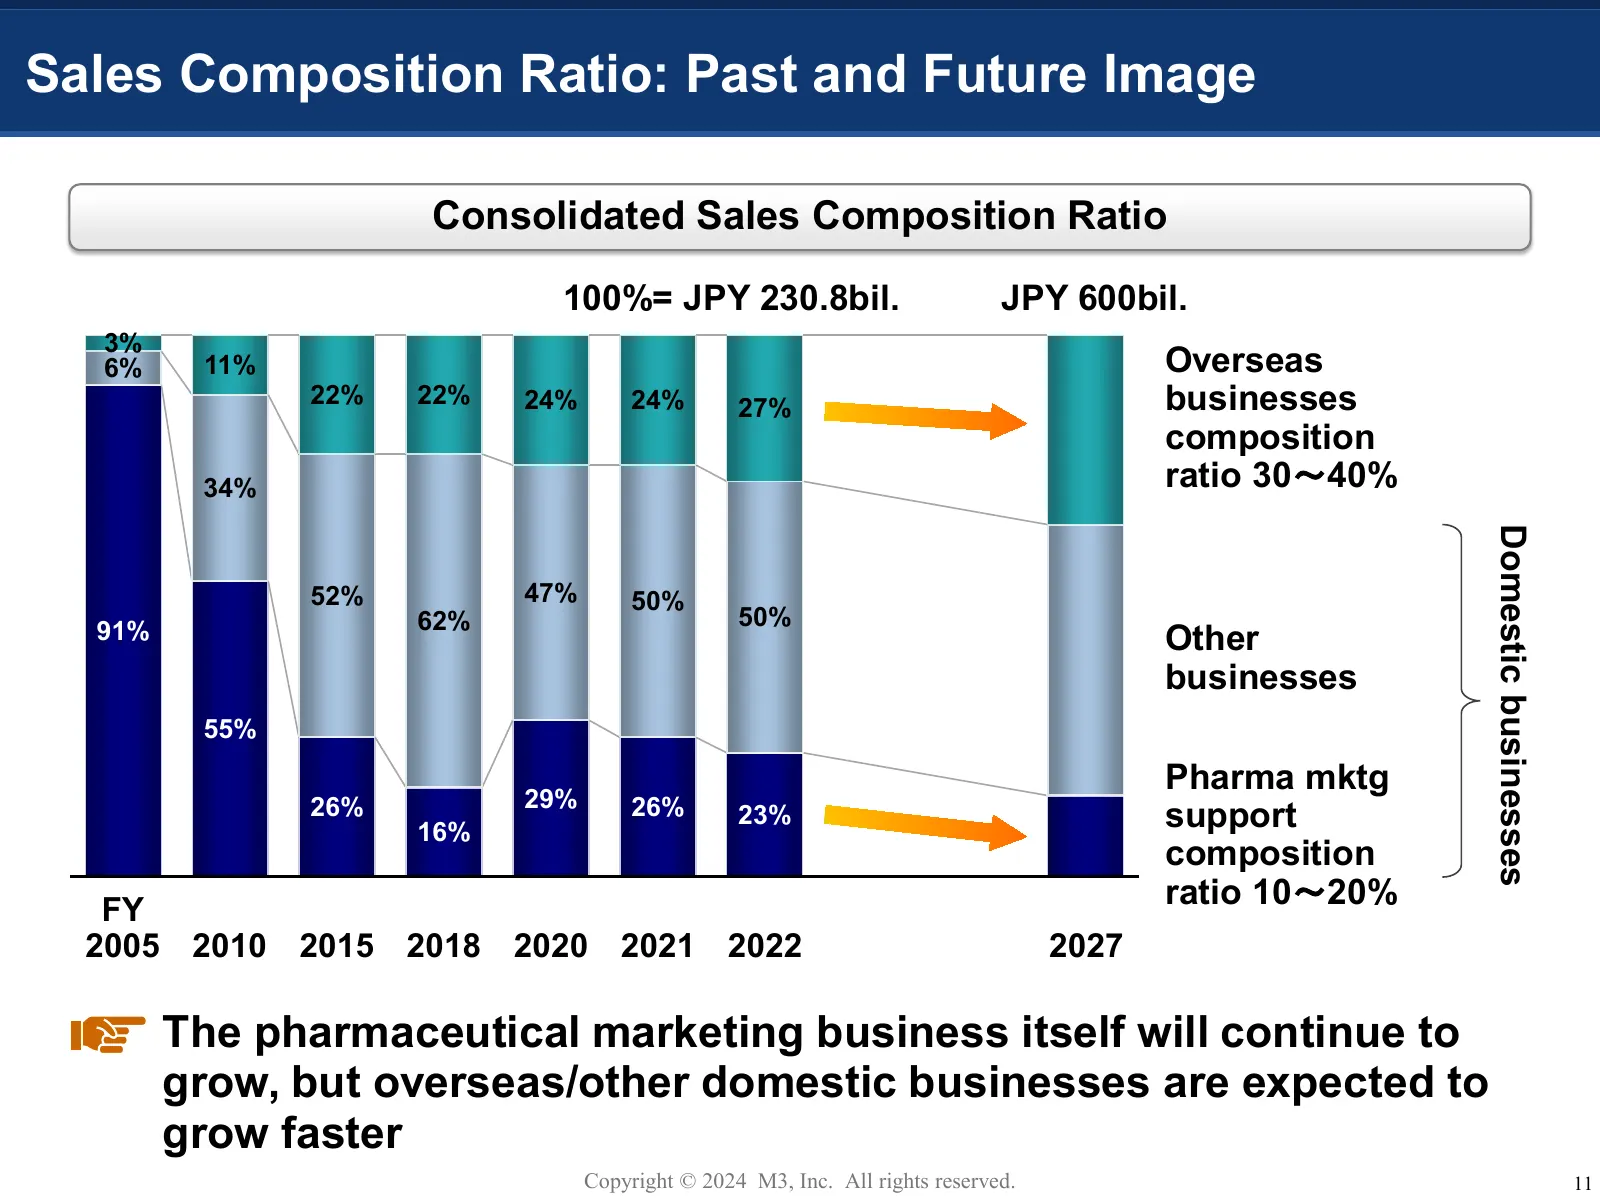
Sales Composition Ratio: Past and Future Image Consolidated Sales Composition Ratio 100%= JPY 230.8bil. JPY 600bil. 3% 6% 11% Overseas 22% 22% 24% 24% 27% businesses composition 34% ratio 30~40% Domestic businesses 52% 47% 50% 62% 50% 91% Other businesses 55% Pharma mktg 26% 29% 26% 16% 23% support
Slide 13: Trend in M&A Volume: Programmatic M&A Strategy
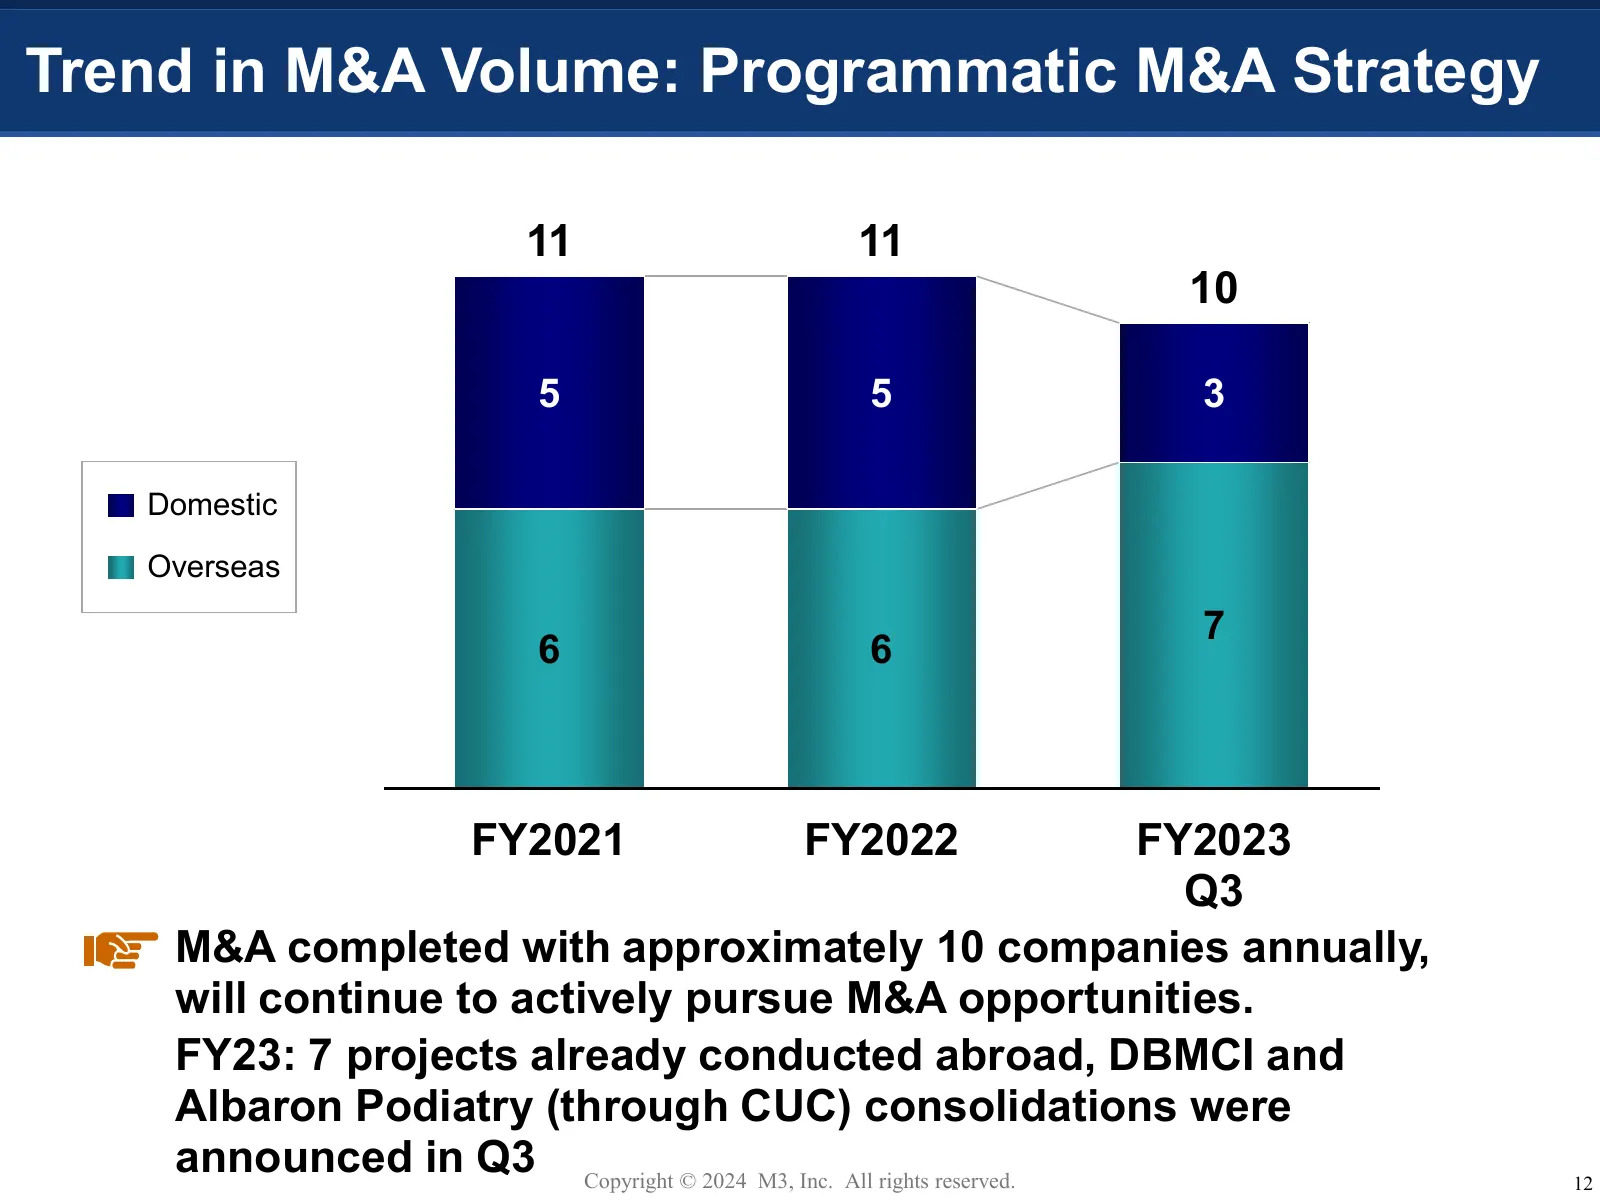
Trend in M&A Volume: Programmatic M&A Strategy 11 11 10 5 5 3 Domestic Overseas 7 6 6 FY2021 FY2022 FY2023 Q3 M&A completed with approximately 10 companies annually, will continue to actively pursue M&A opportunities. FY23: 7 projects already conducted abroad, DBMCI and Albaron Podiatry (through CUC
Slide 14: Business Expansion Creation Flow
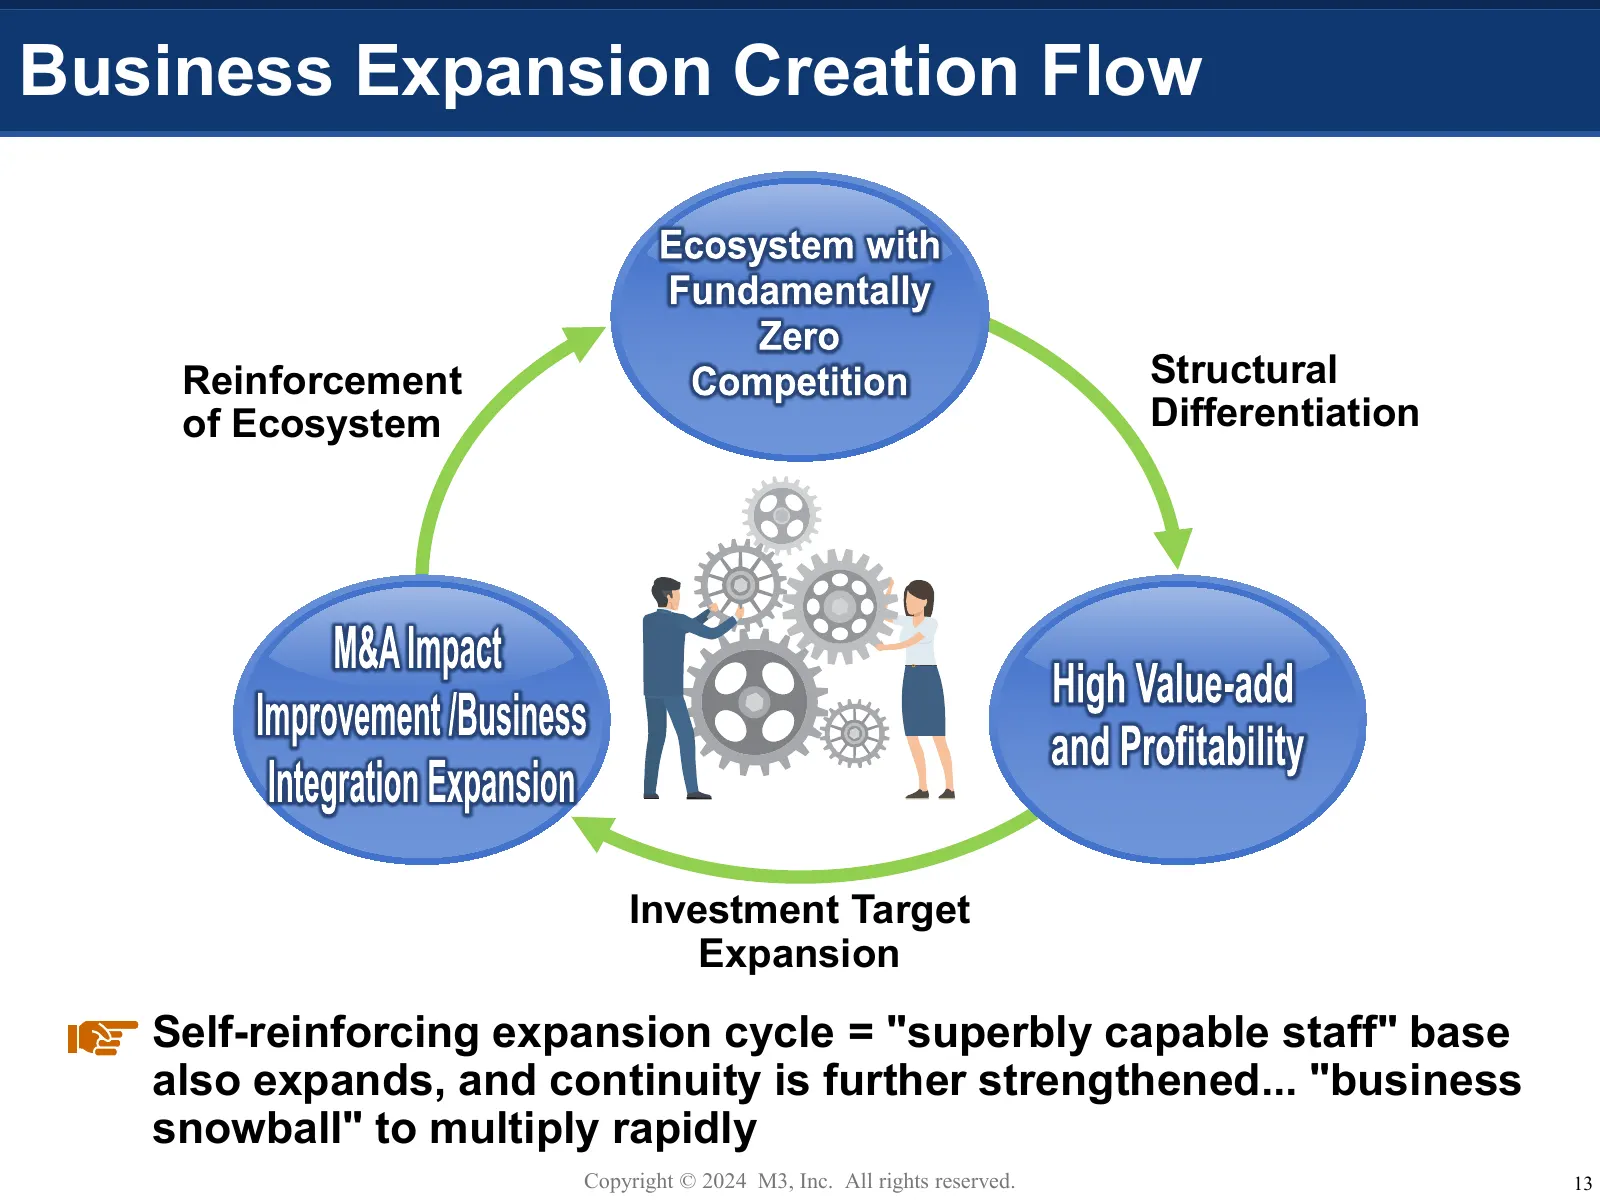
Business Expansion Creation Flow Reinforcement Structural of Ecosystem Differentiation Investment Target Expansion Self-reinforcing expansion cycle = "superbly capable staff" base also expands, and continuity is further strengthened... "business snowball" to multiply rapidly Copyright © 2024 M3, Inc
Slide 15: Growth Engine 2: Individual Business Development
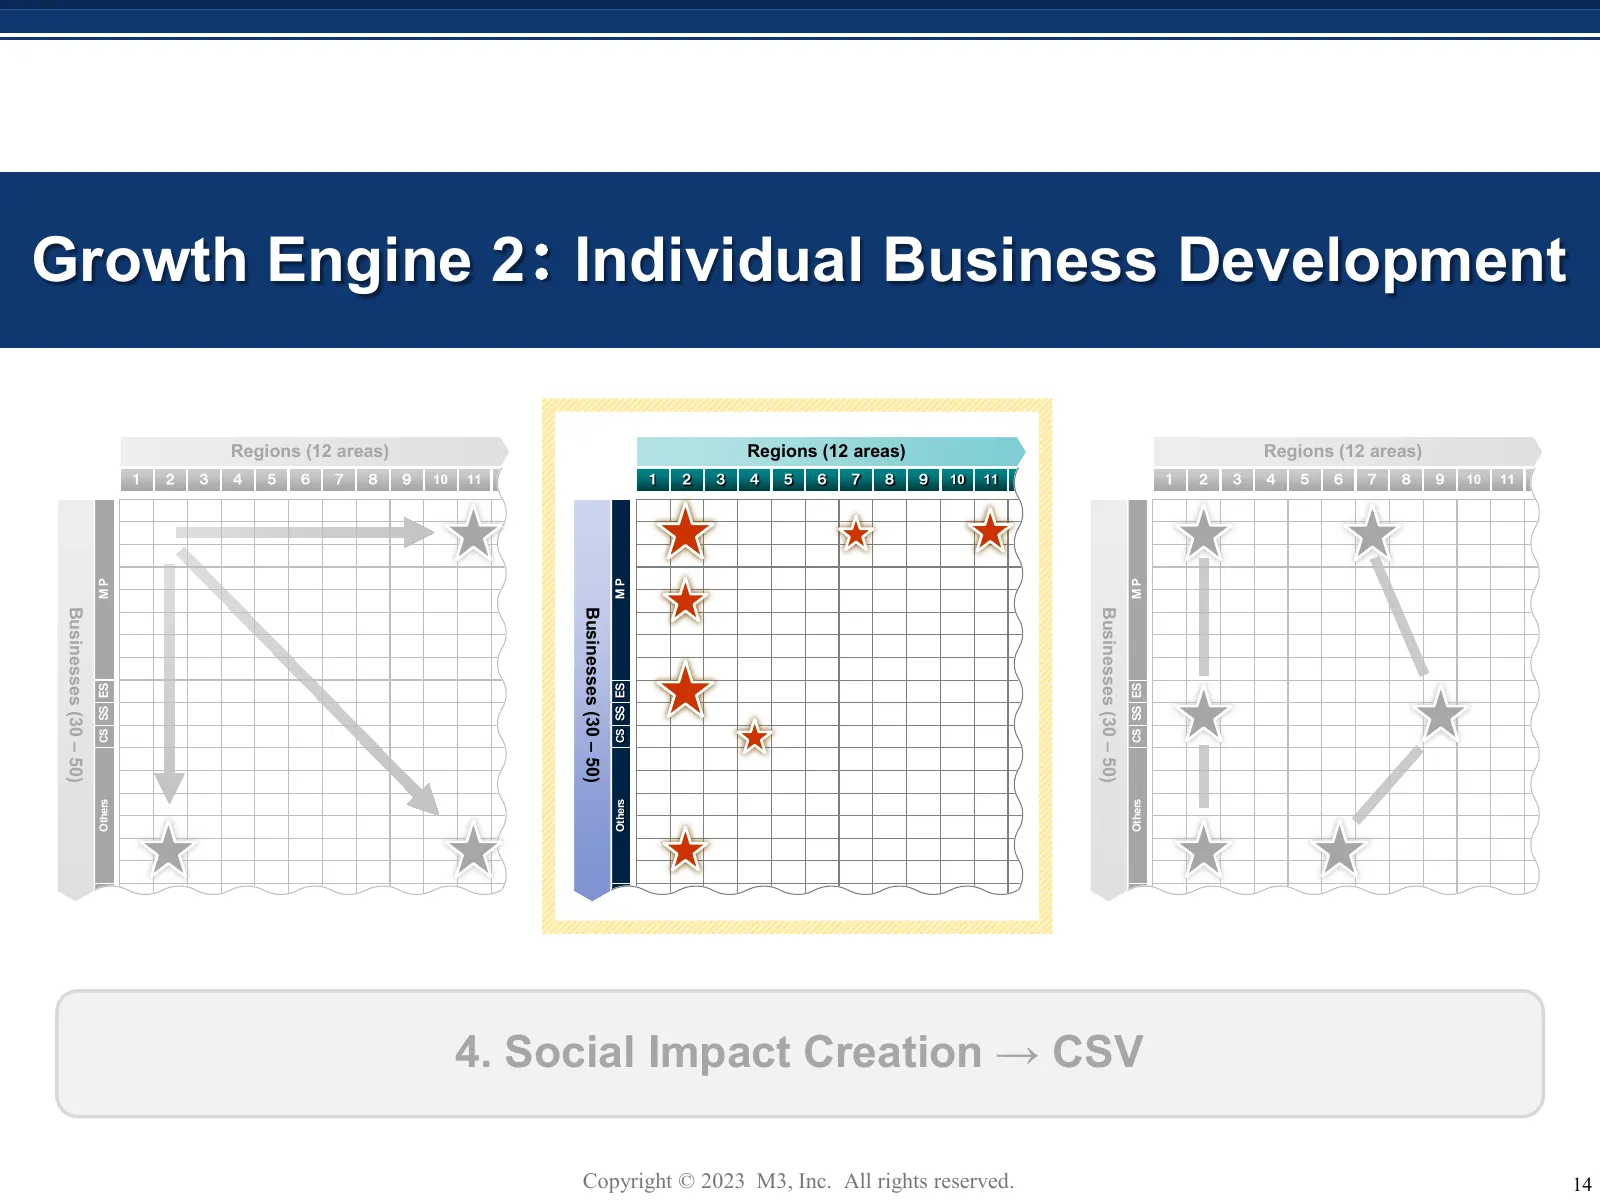
Growth Engine 2: Individual Business Development Regions (12 areas) Regions (12 areas) Regions (12 areas) 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 MP MP MP Businesses (30 – 50) Businesses (30 – 50) Businesses (30 – 50) CS SS ES CS SS ES CS SS ES Others Others Others 4.
Slide 16: Pharmaceutical Sales & Marketing DX
Pharmaceutical Sales & Marketing DX Copyright © 2024 M3, Inc. All rights reserved. 15
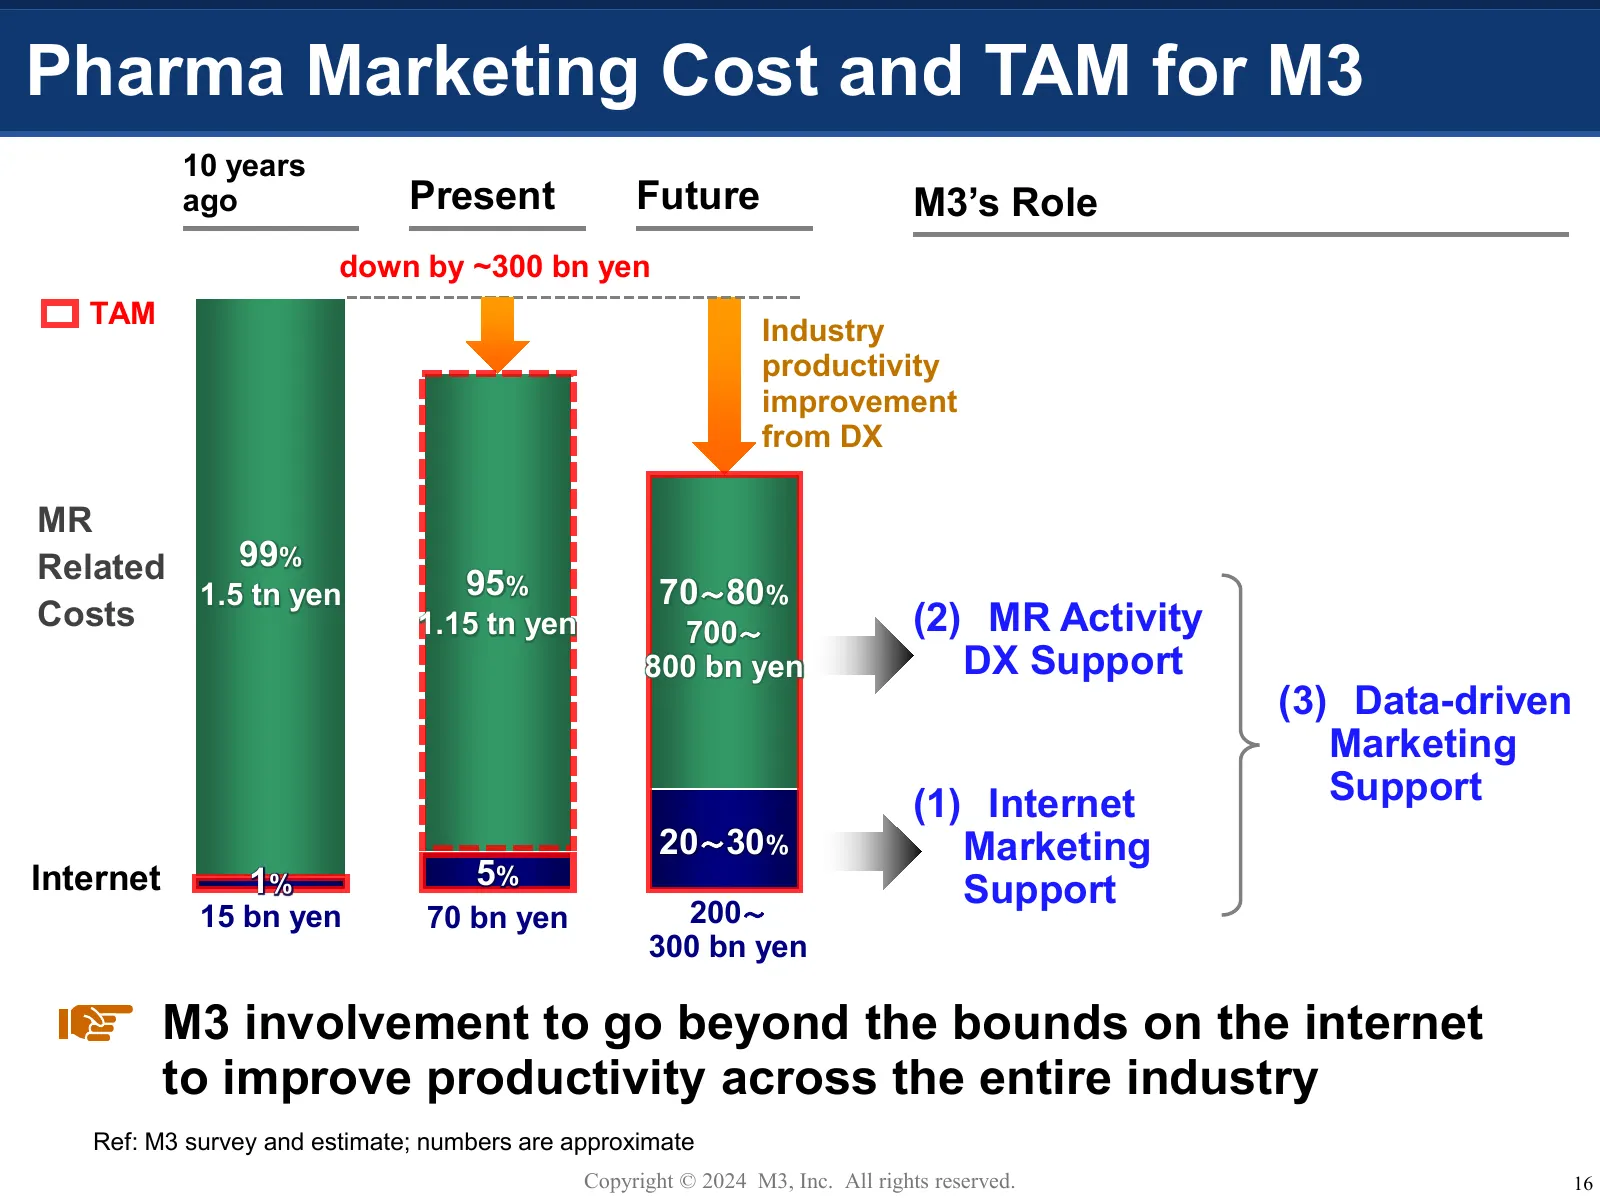
Slide 17: Pharma Marketing Cost and TAM for M3
Pharma Marketing Cost and TAM for M3 10 years ago Present Future M3’s Role down by ~300 bn yen TAM Industry productivity improvement from DX MR Related 99% 1.5 tn yen 95% 70~80% Costs 1.15 tn yen 700~ (2) MR Activity 800 bn yen DX Support (3) Data-driven Marketing (1) Internet Support 20~30% Marketi
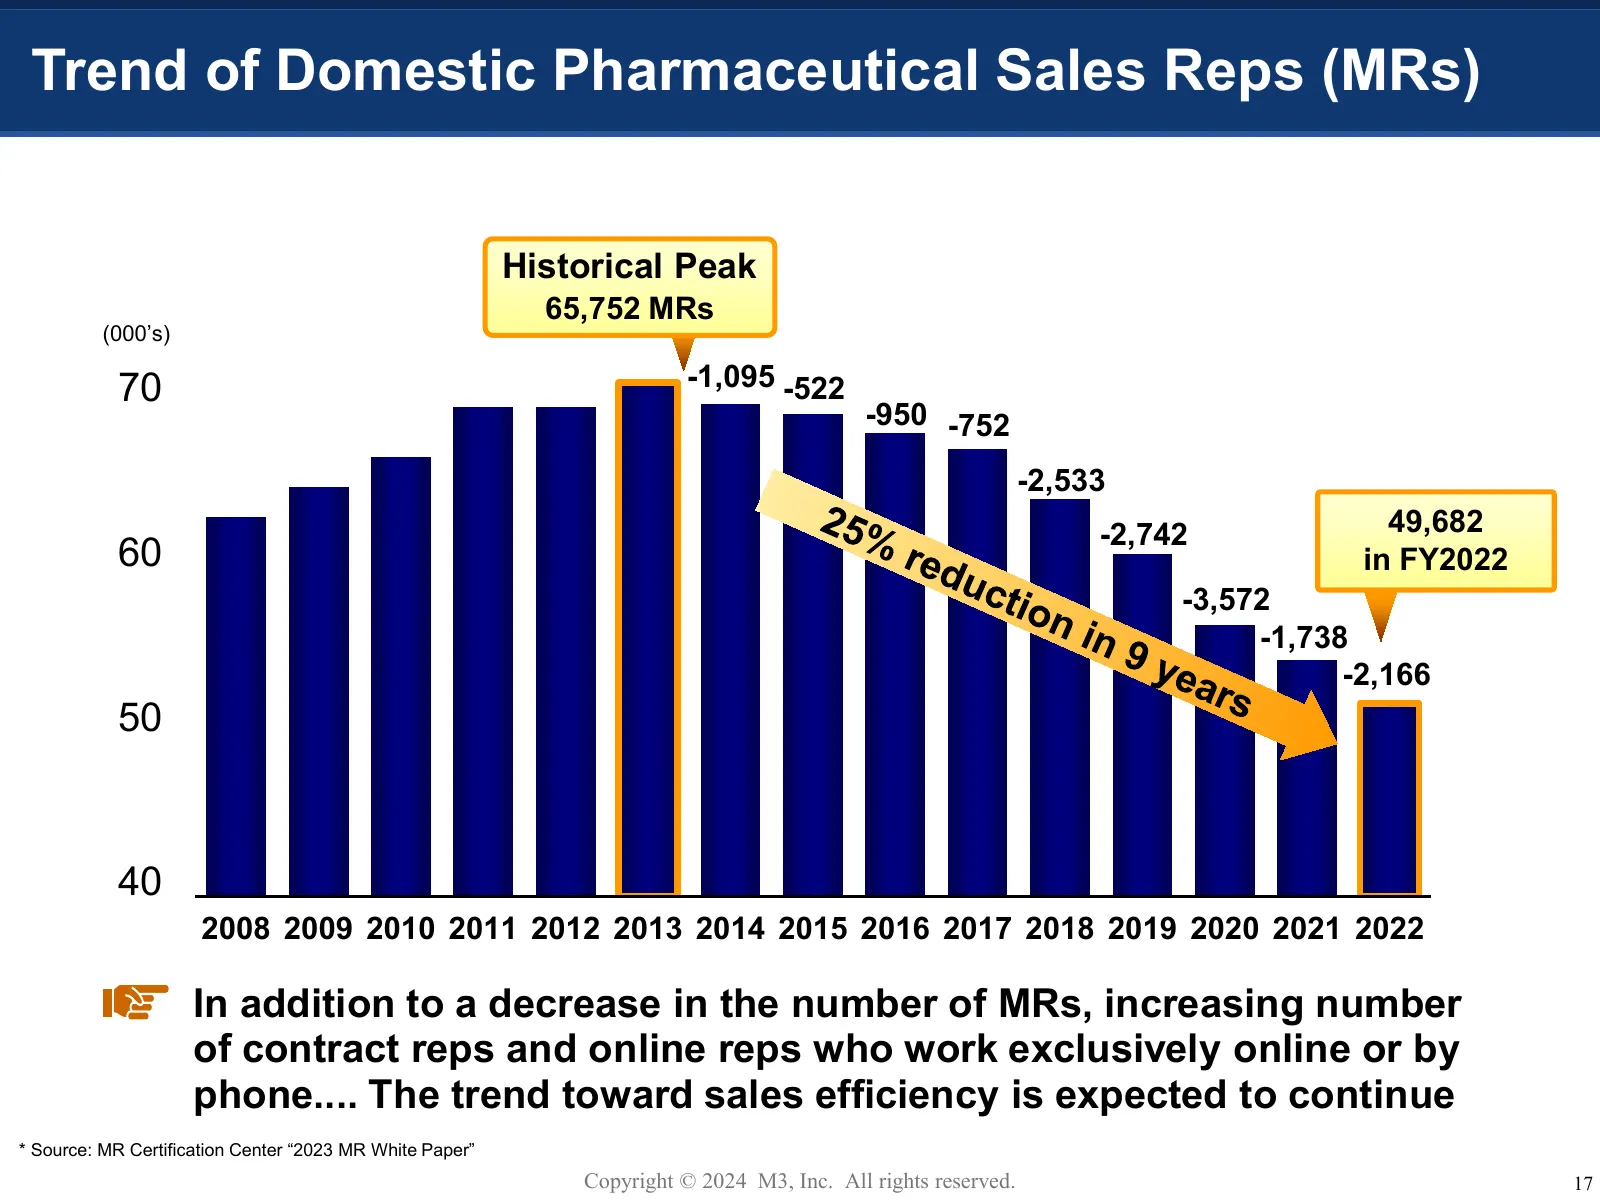
Slide 18: Trend of Domestic Pharmaceutical Sales Reps (MRs)
Trend of Domestic Pharmaceutical Sales Reps (MRs) Historical Peak 65,752 MRs (000’s) 70 -1,095 -522 -950 -752 -2,533 -2,742 49,682 60 in FY2022 -3,572 -1,738 -2,166 50 40 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 In addition to a decrease in the number of MRs, increa
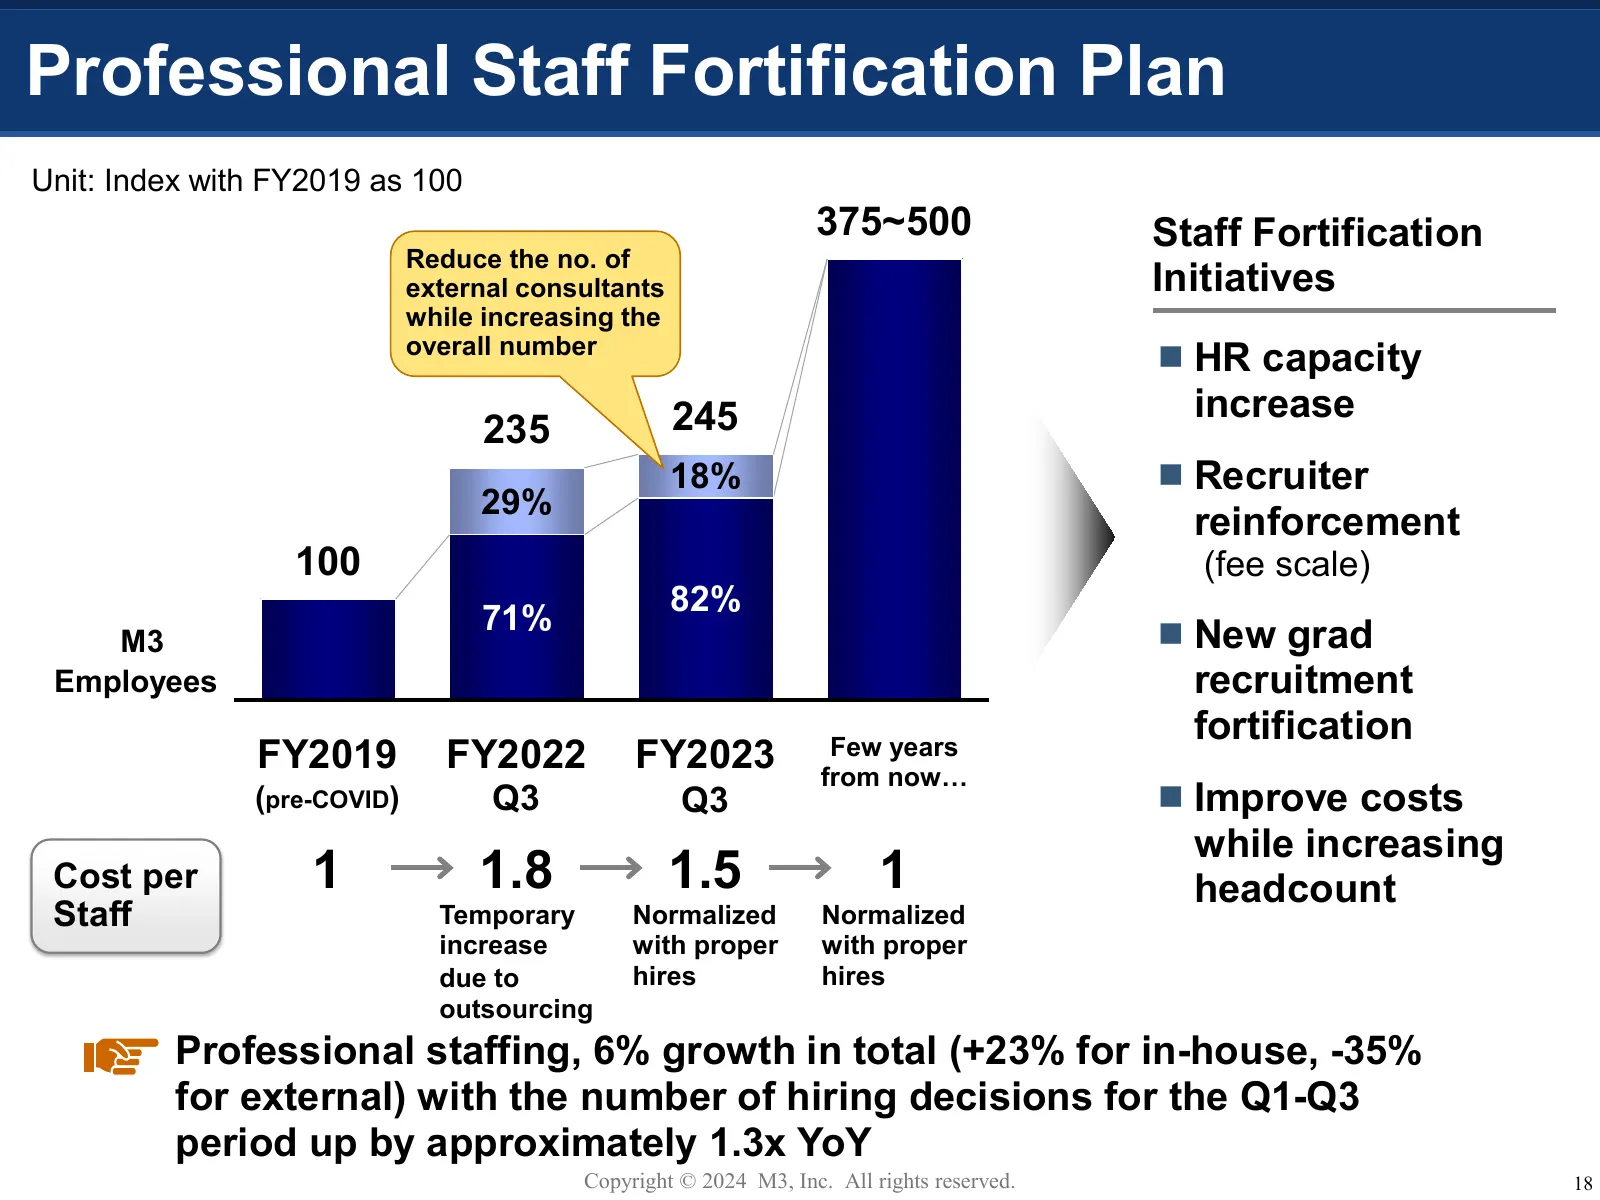
Slide 19: Professional Staff Fortification Plan
Professional Staff Fortification Plan Unit: Index with FY2019 as 100 375~500 Staff Fortification Reduce the no. of external consultants Initiatives while increasing the overall number HR capacity 245 increase 235 18% Recruiter 29% reinforcement 100 (fee scale) 82% 71% M3 New grad Employees rec
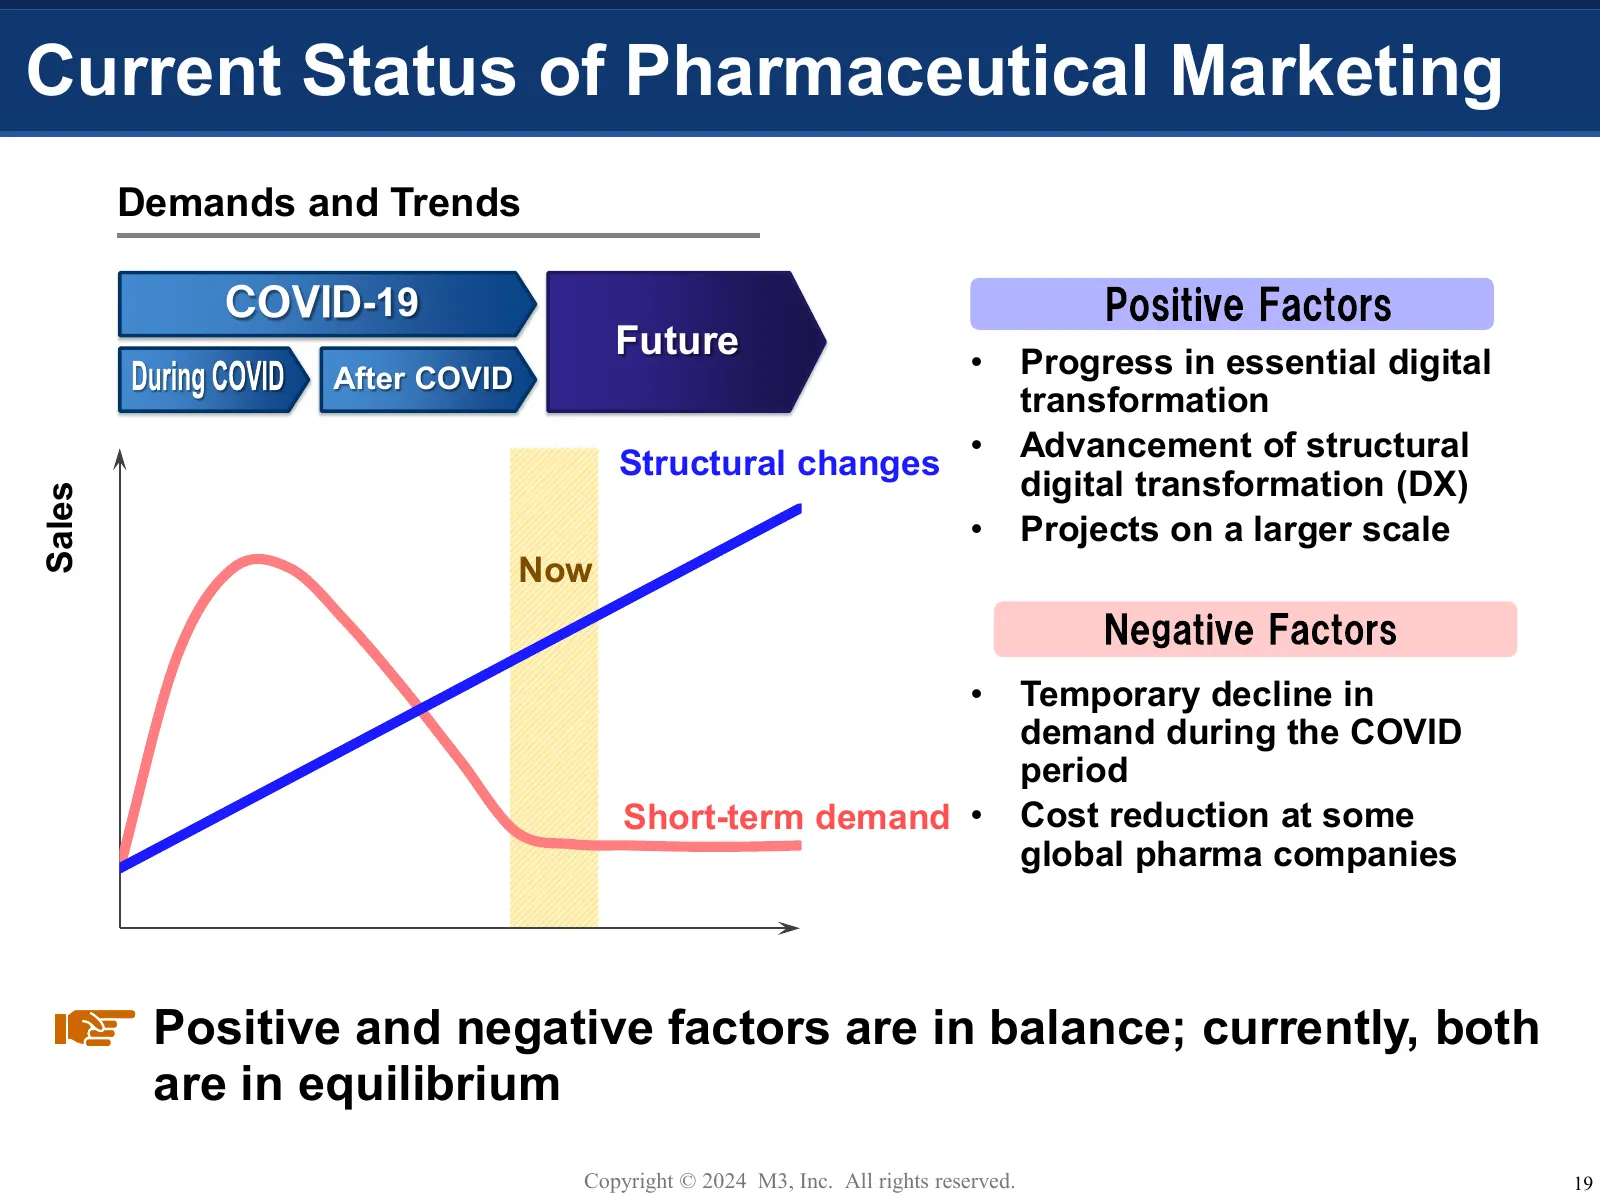
Slide 20: Current Status of Pharmaceutical Marketing
Current Status of Pharmaceutical Marketing Demands and Trends COVID-19 Future After COVID • Progress in essential digital transformation Structural changes • Advancement of structural digital transformation (DX) Sales • Projects on a larger scale Now • Temporary decline in demand during the COVID pe
Slide 21: As a Strategic Partner to Pharma Companies
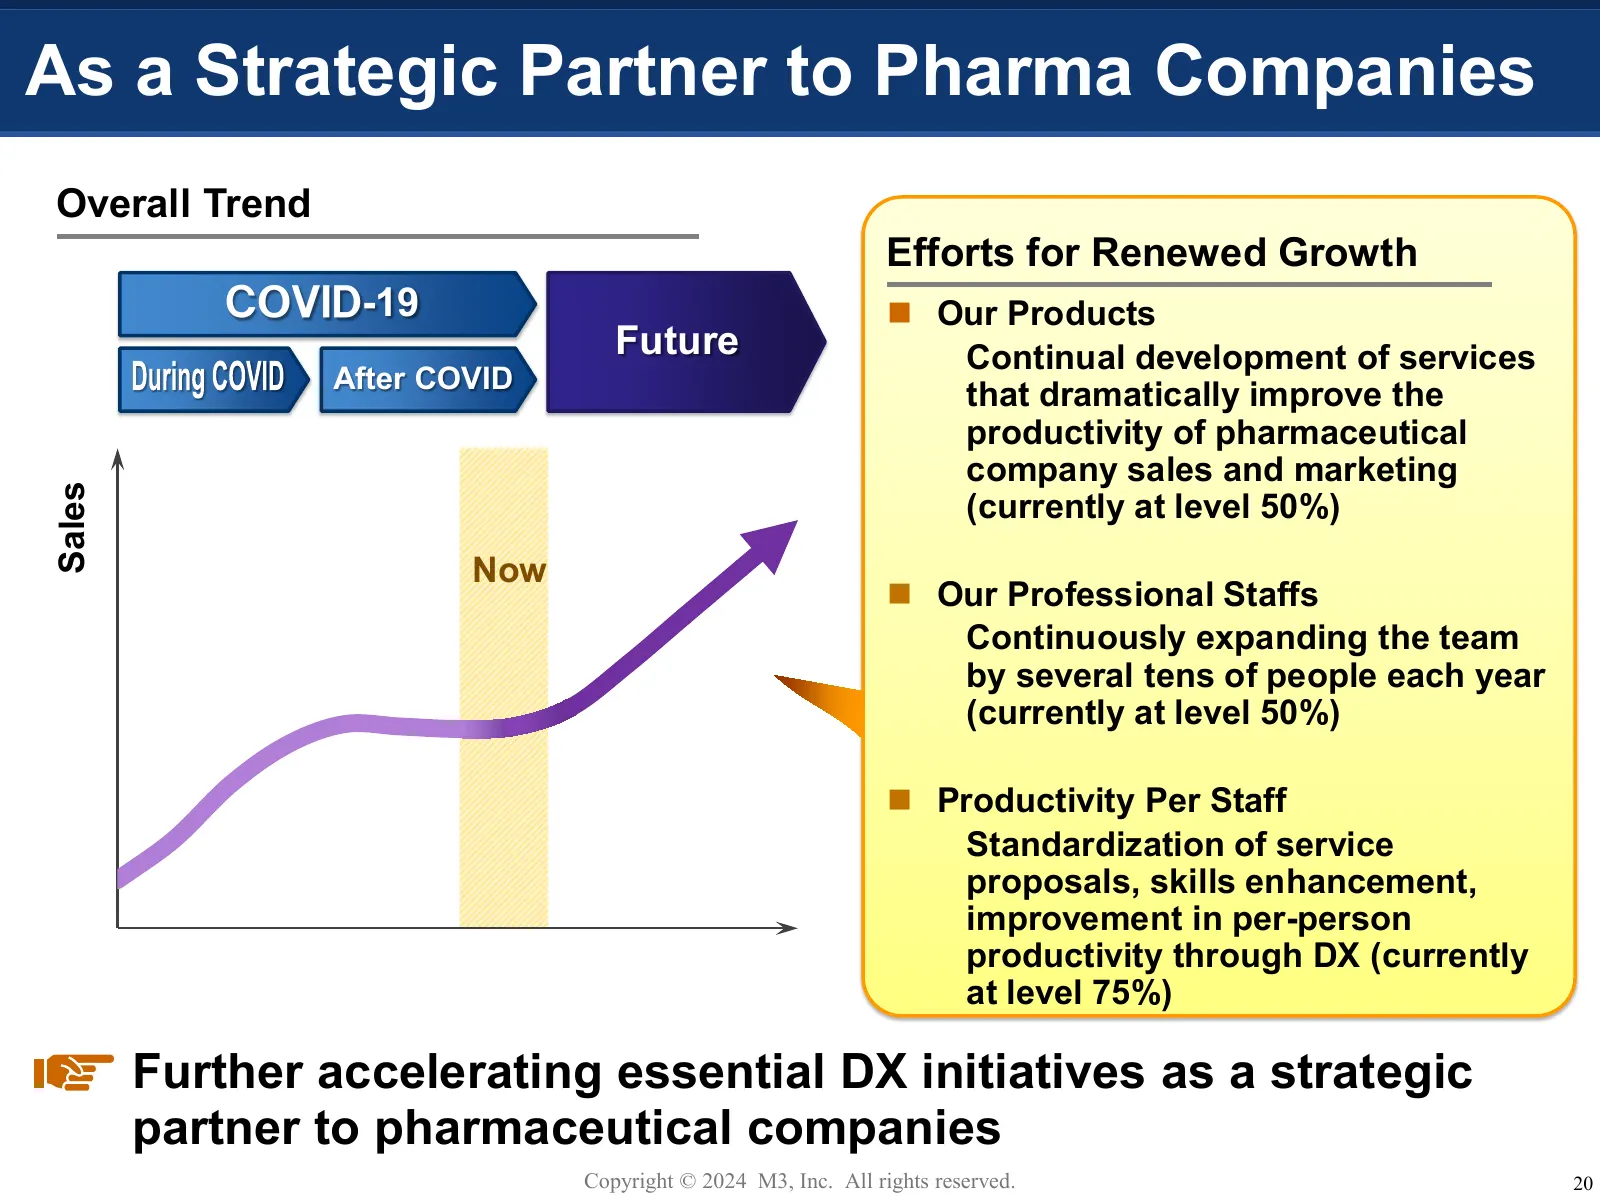
As a Strategic Partner to Pharma Companies Overall Trend Efforts for Renewed Growth COVID-19 Our Products Future Continual development of services After COVID that dramatically improve the productivity of pharmaceutical company sales and marketing Sales (currently at level 50%) Now Our Professio
Slide 22: DX of the Clinical Scene
DX of the Clinical Scene Copyright © 2024 M3, Inc. All rights reserved. 21
Slide 23: DX of Clinics: Creating a New Patient Experience
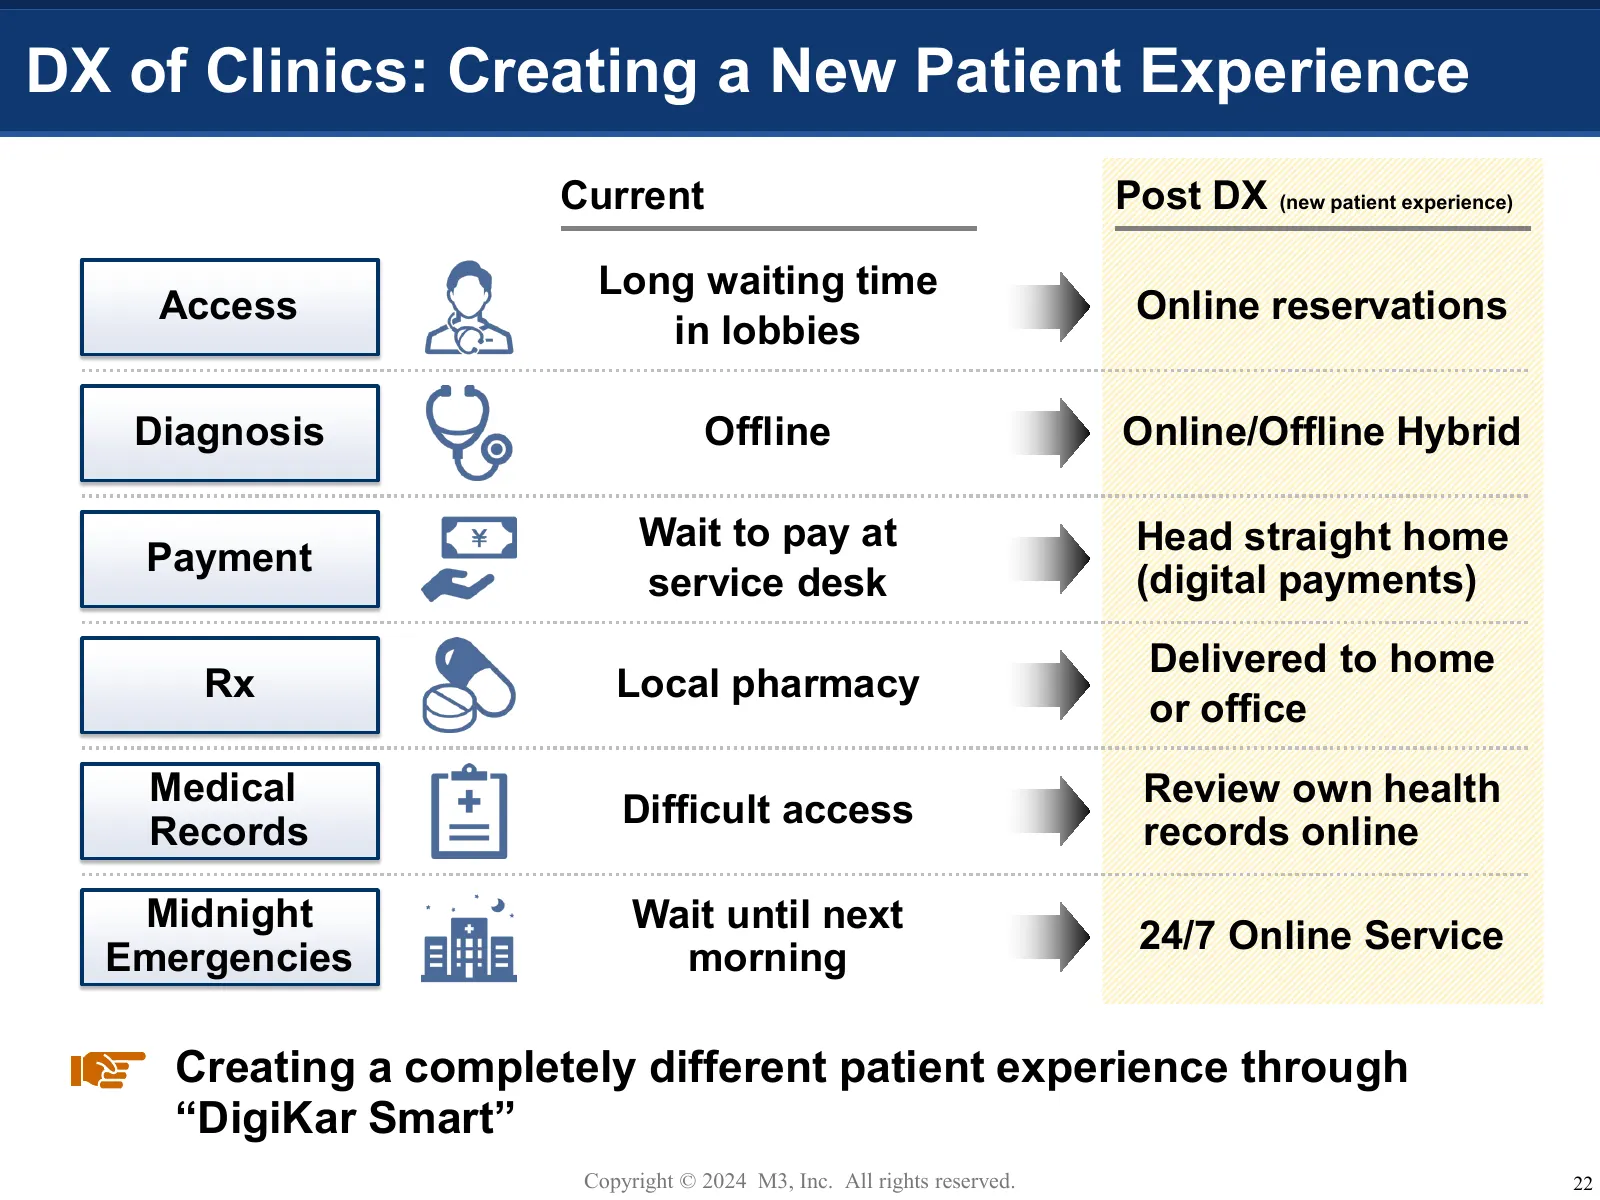
DX of Clinics: Creating a New Patient Experience Current Post DX (new patient experience) Long waiting time Access Online reservations in lobbies Diagnosis Offline Online/Offline Hybrid Wait to pay at Head straight home Payment service desk (digital payments) Delivered to home Rx Local pharmacy or o
Slide 24: M3 DigiKar EHR Growth
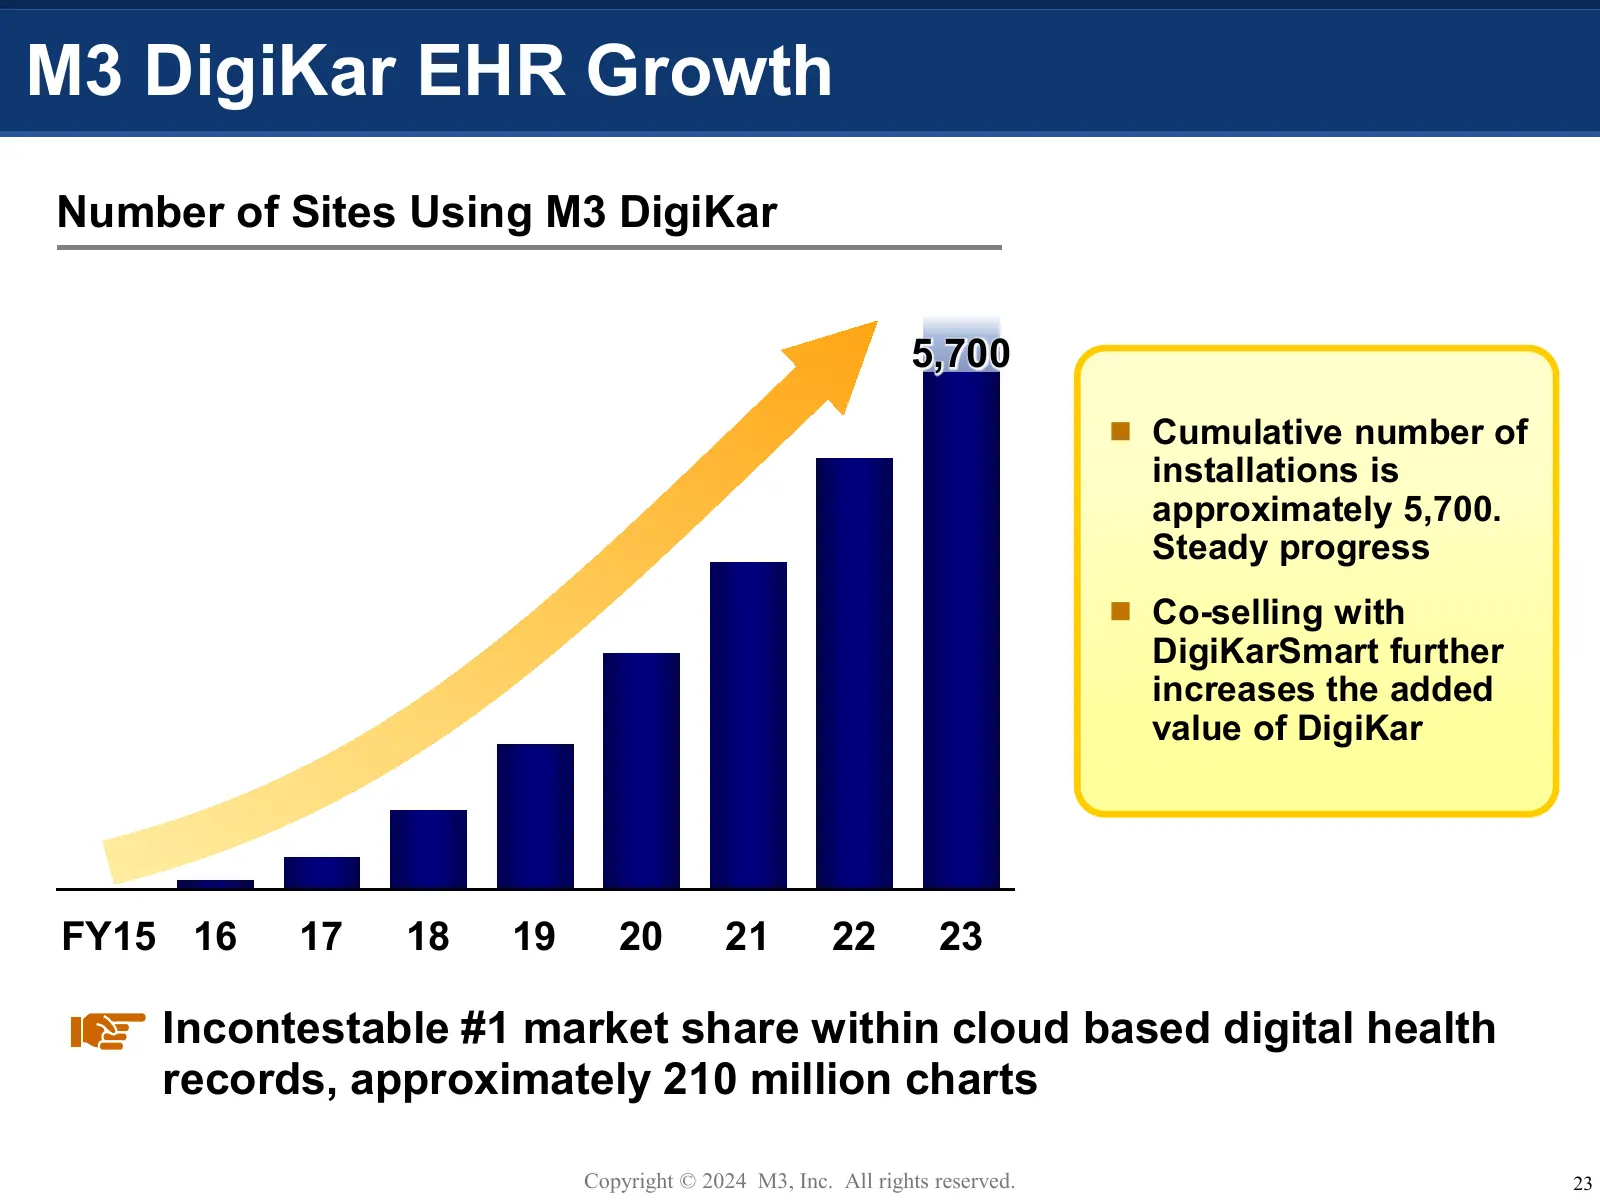
M3 DigiKar EHR Growth Number of Sites Using M3 DigiKar 5,700 Cumulative number of installations is approximately 5,700. Steady progress Co-selling with DigiKarSmart further increases the added value of DigiKar FY15 16 17 18 19 20 21 22 23 Incontestable #1 market share within cloud based digital
Slide 25: DX of Clinics: DigiKar Smart
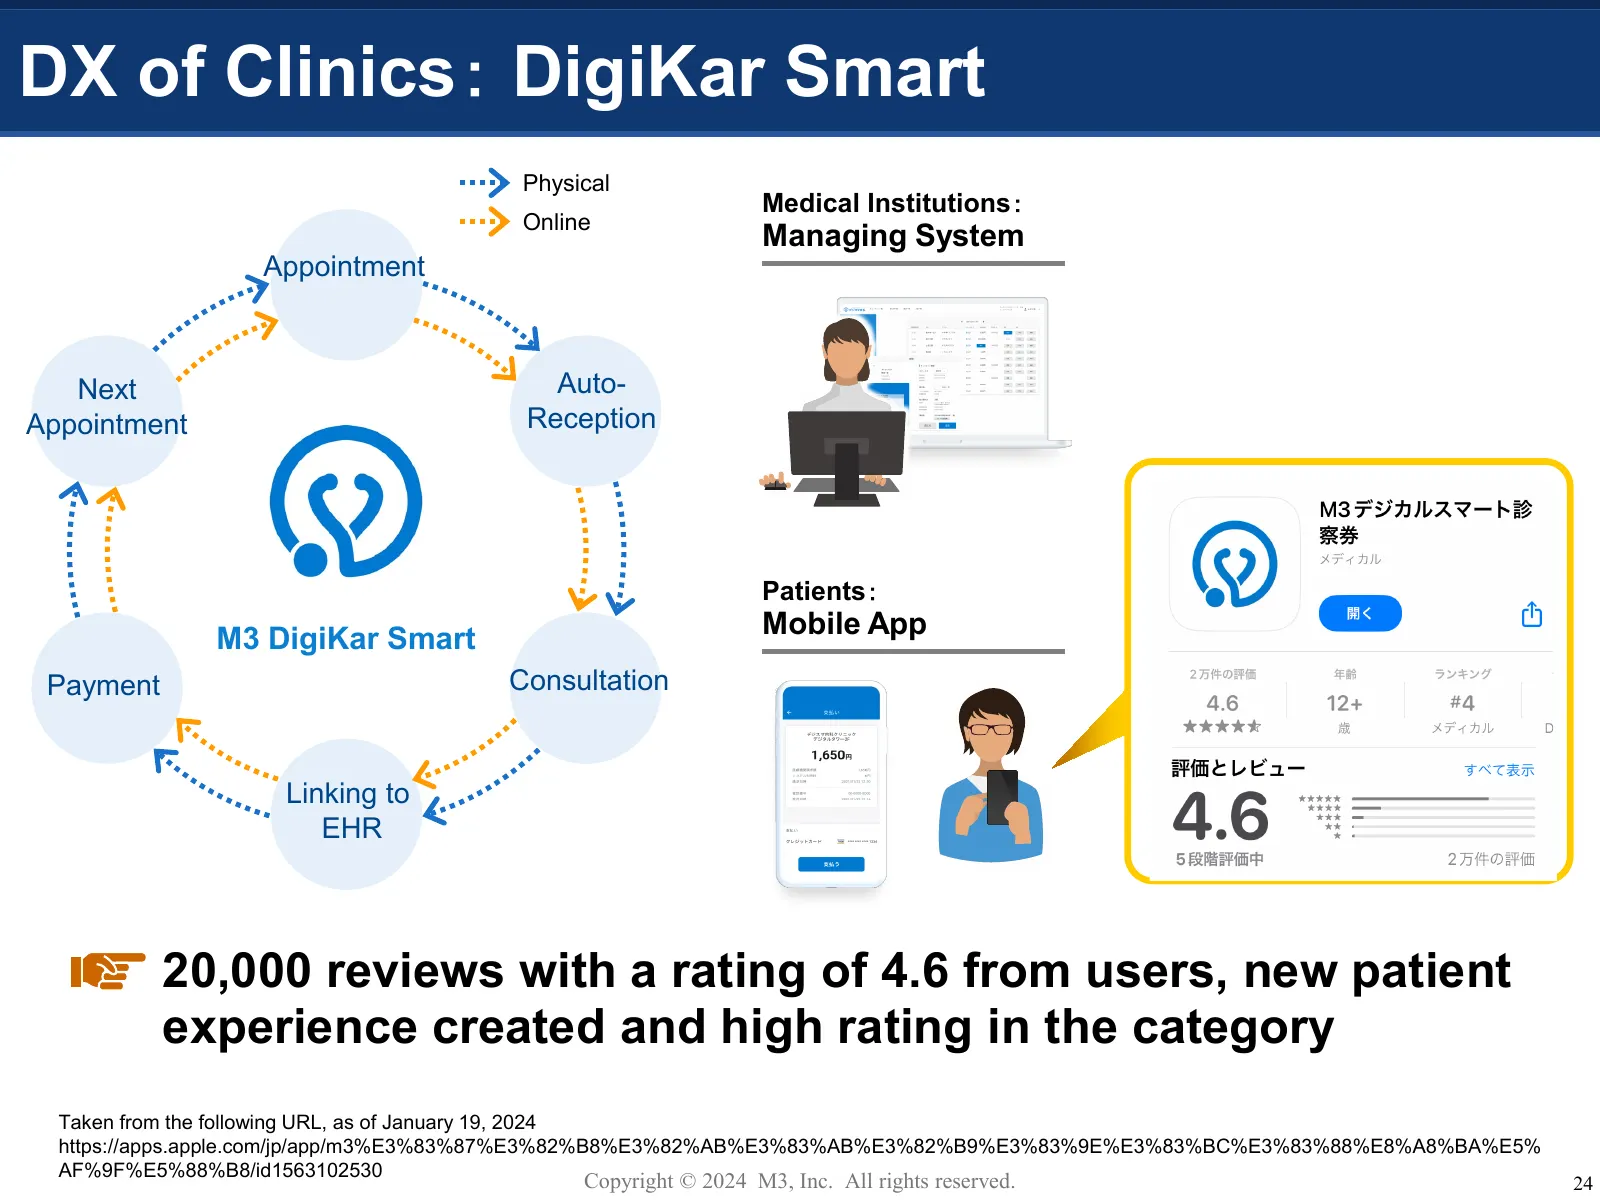
DX of Clinics: DigiKar Smart Physical Medical Institutions: Online Managing System Appointment Next Auto- Appointment Reception Patients: M3 DigiKar Smart Mobile App Payment Consultation Linking to EHR 20,000 reviews with a rating of 4.6 from users, new patient experience created and high rating in
Slide 26: No. of DigiKar Smart Users
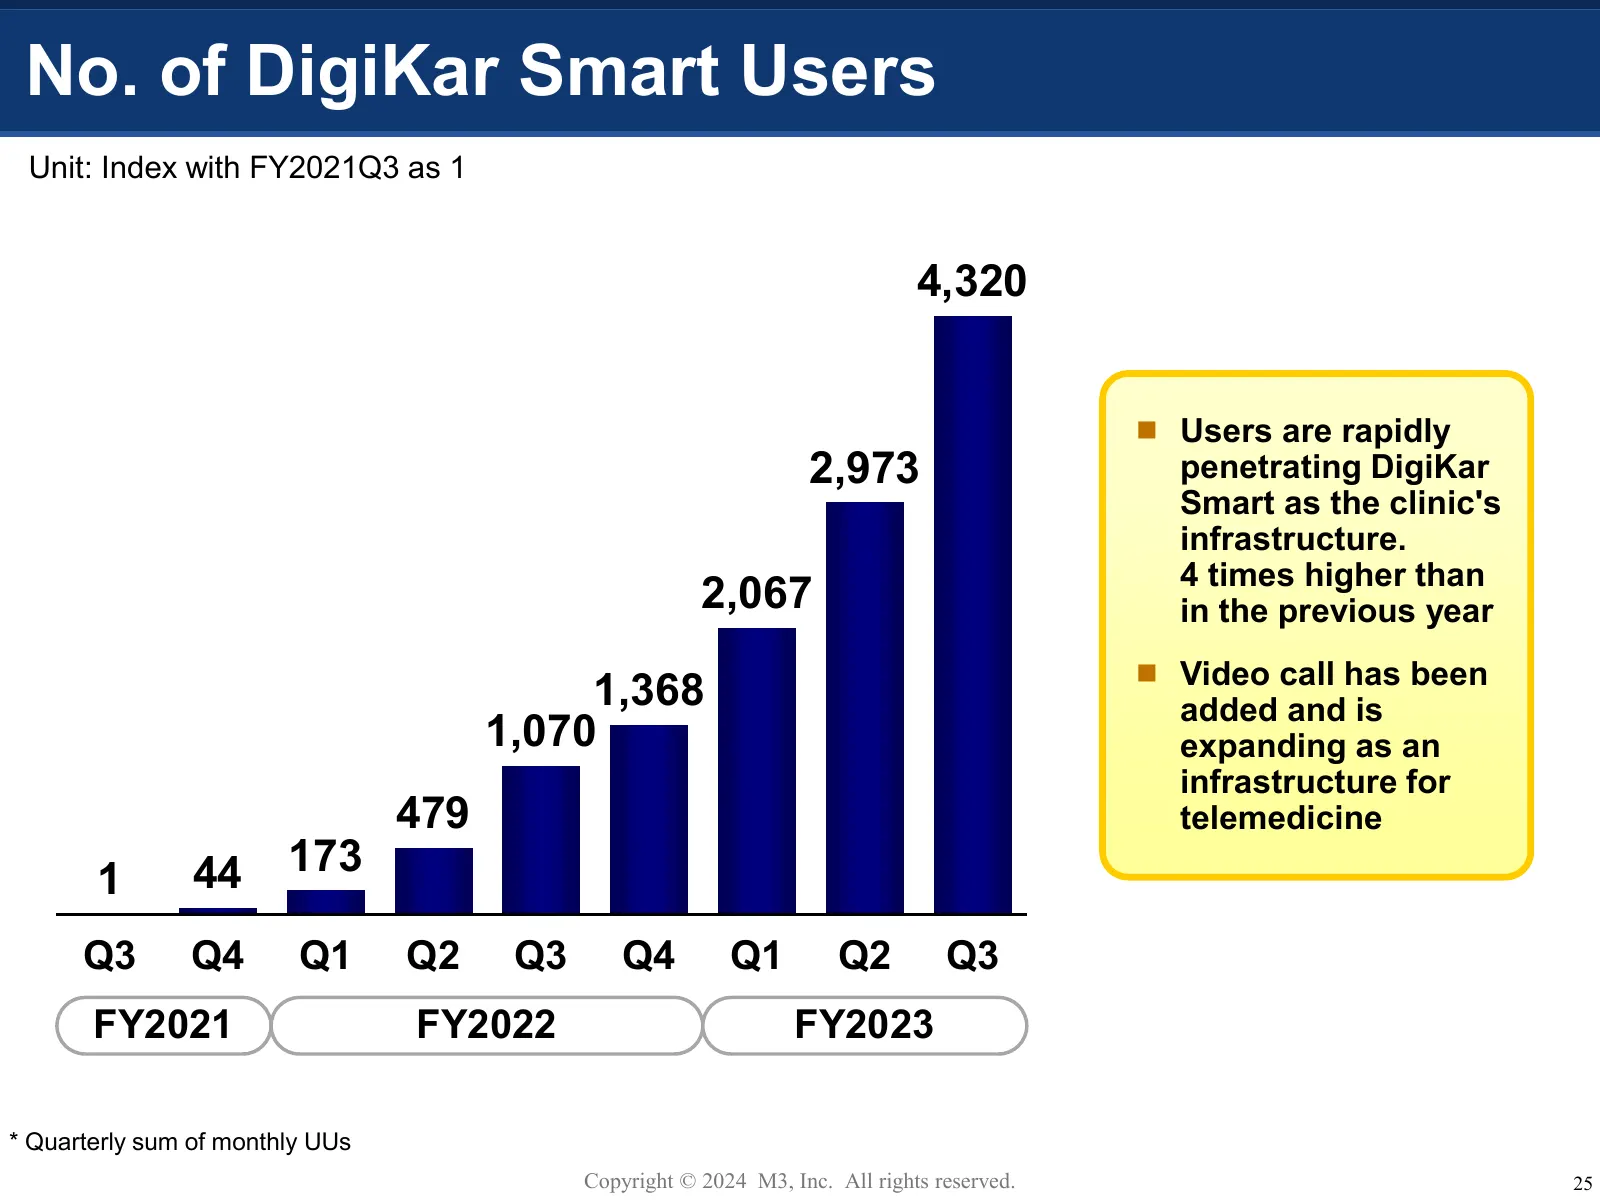
No. of DigiKar Smart Users Unit: Index with FY2021Q3 as 1 4,320 Users are rapidly 2,973 penetrating DigiKar Smart as the clinic's infrastructure. 4 times higher than 2,067 in the previous year Video call has been 1,368 added and is 1,070 expanding as an infrastructure for 479 telemedicine 44 173
Slide 27: Ecosystem Synergy: Medical Data Business
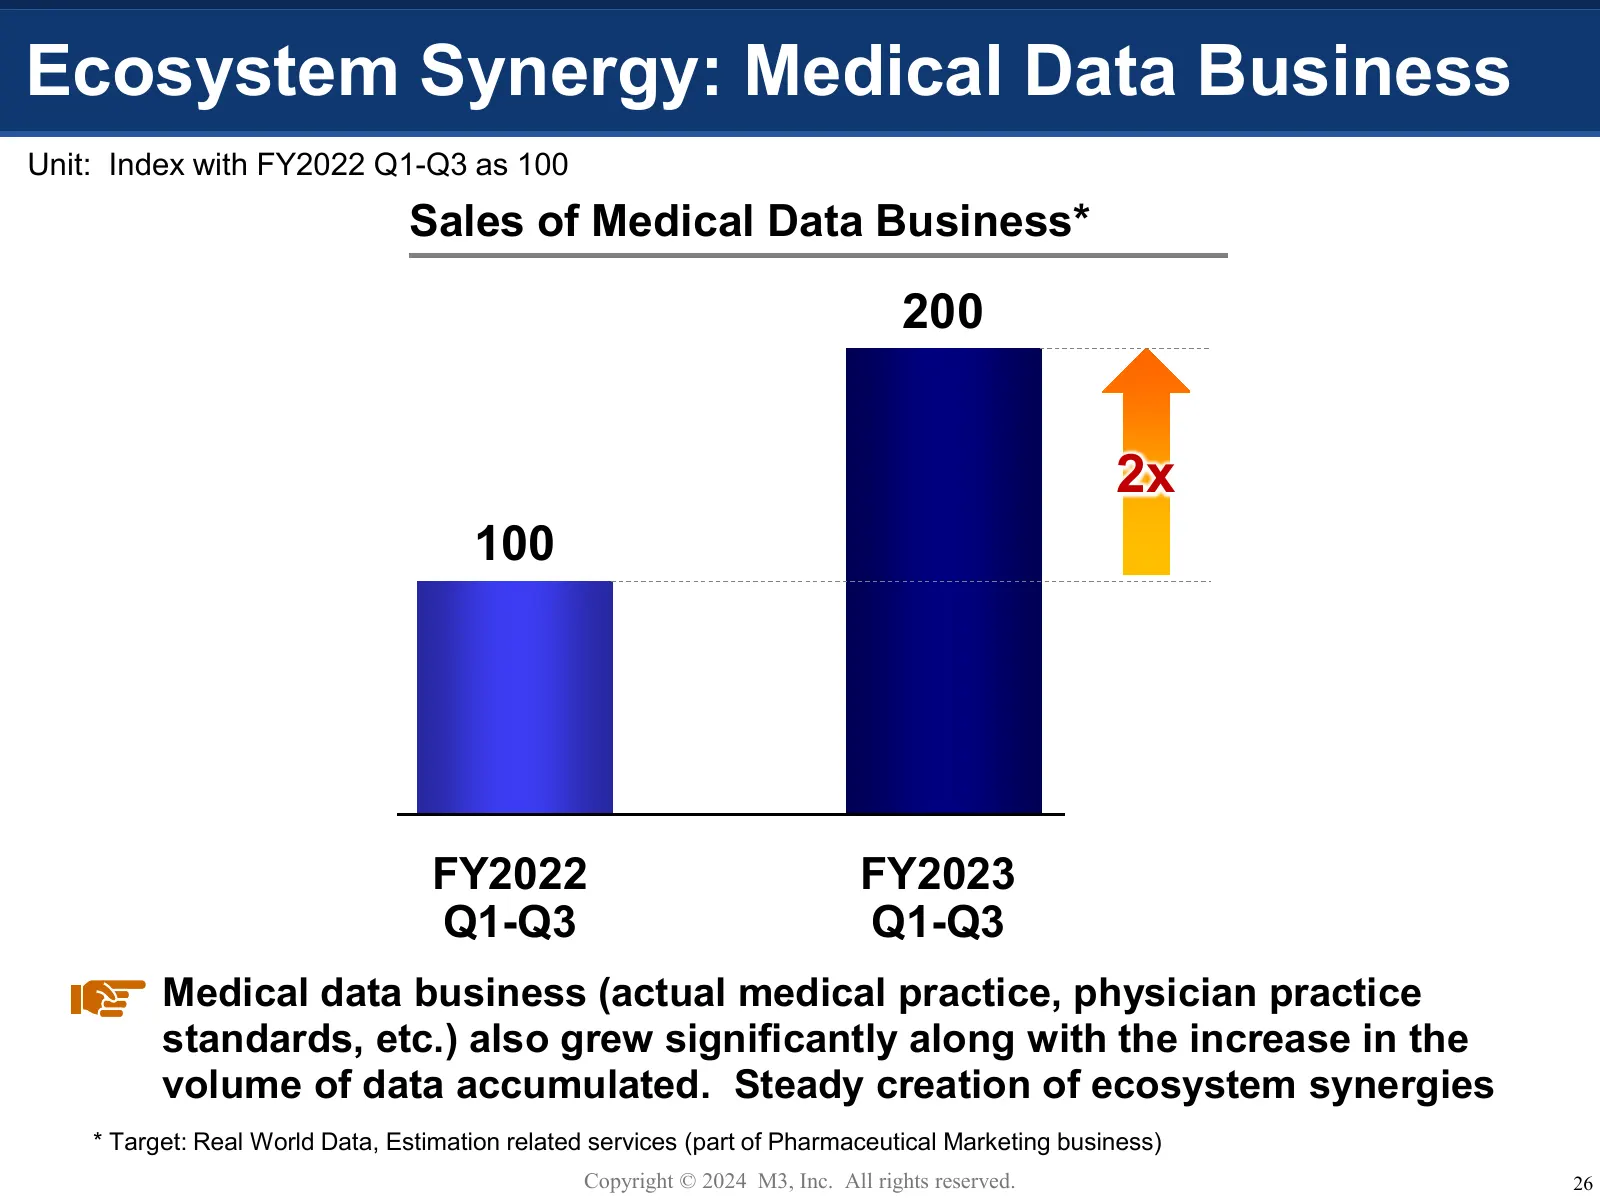
Ecosystem Synergy: Medical Data Business Unit: Index with FY2022 Q1-Q3 as 100 Sales of Medical Data Business* 200 2x 100 FY2022 FY2023 Q1-Q3 Q1-Q3 Medical data business (actual medical practice, physician practice standards, etc.) also grew significantly along with the increase in the volume of data
Slide 28: Number of Clinics Covered by M3 Group
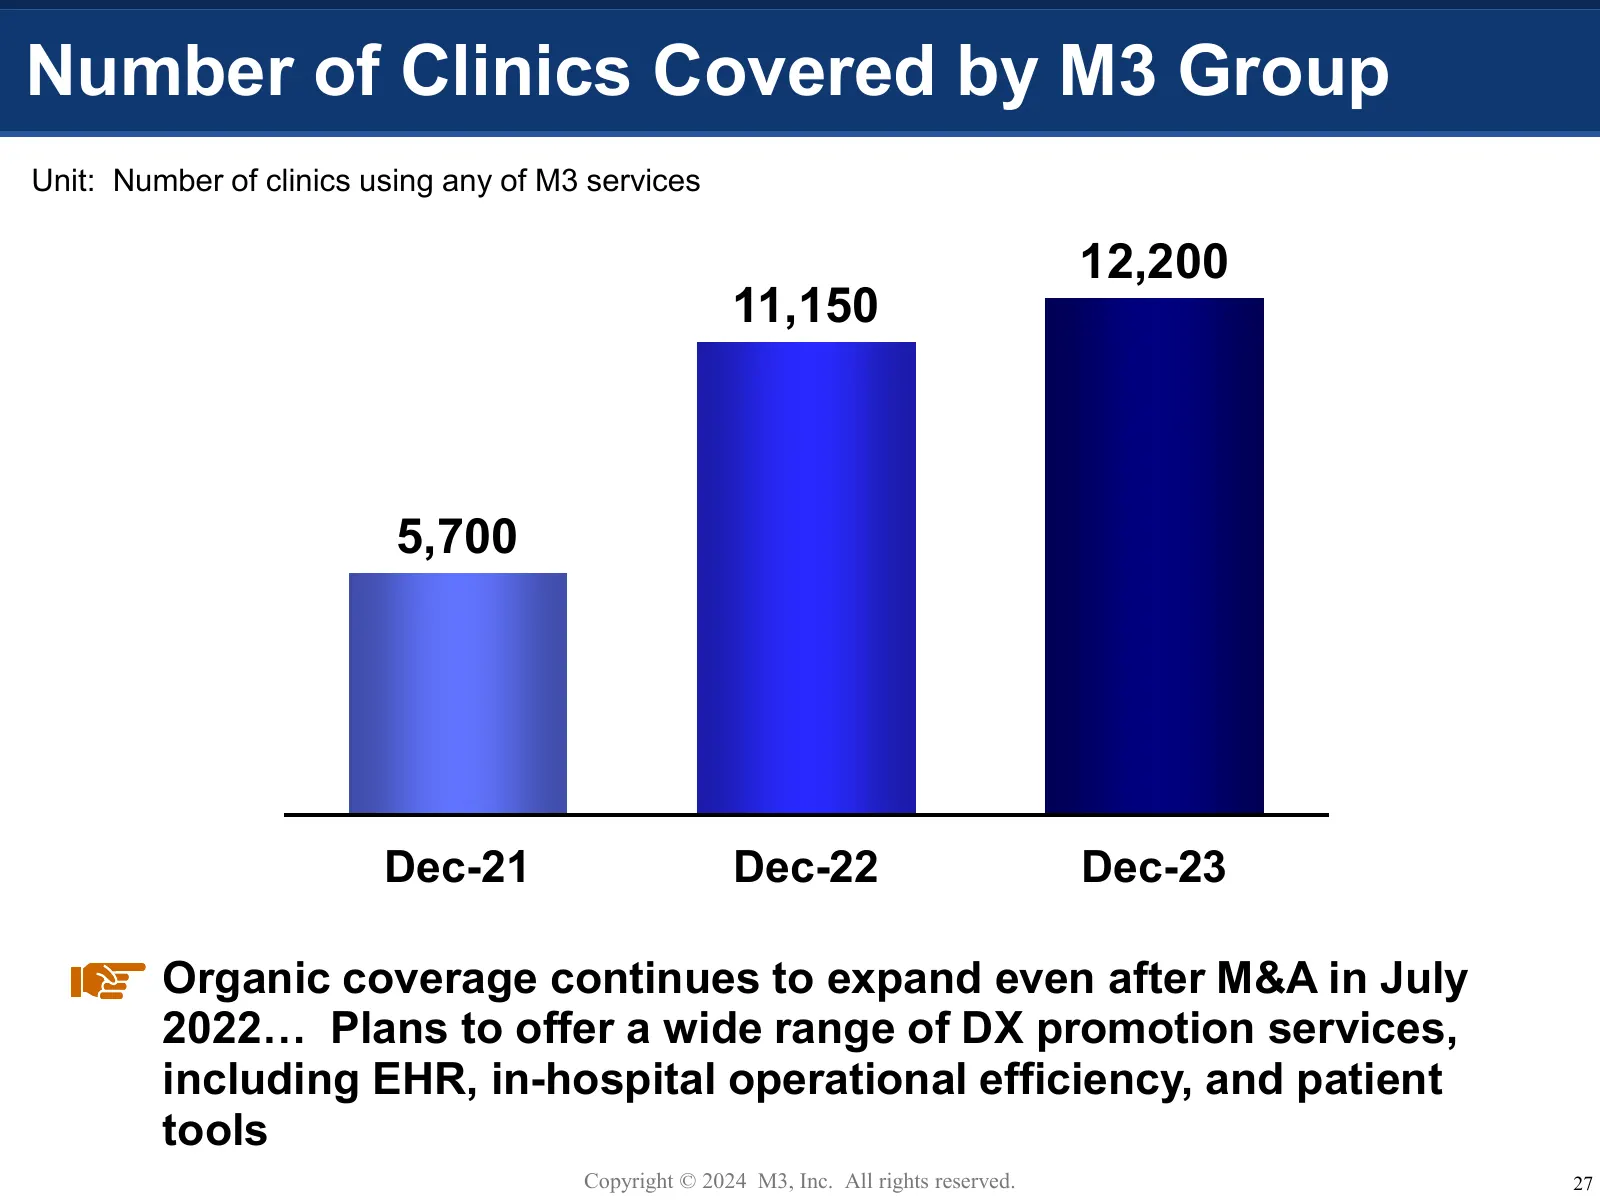
Number of Clinics Covered by M3 Group Unit: Number of clinics using any of M3 services 12,200 11,150 5,700 Dec-21 Dec-22 Dec-23 Organic coverage continues to expand even after M&A in July 2022… Plans to offer a wide range of DX promotion services, including EHR, in-hospital operational efficiency, a
Slide 29: Overseas
Overseas Copyright © 2024 M3, Inc. All rights reserved. 28
Slide 30: Number of Doctor Members and Panelists (Global)
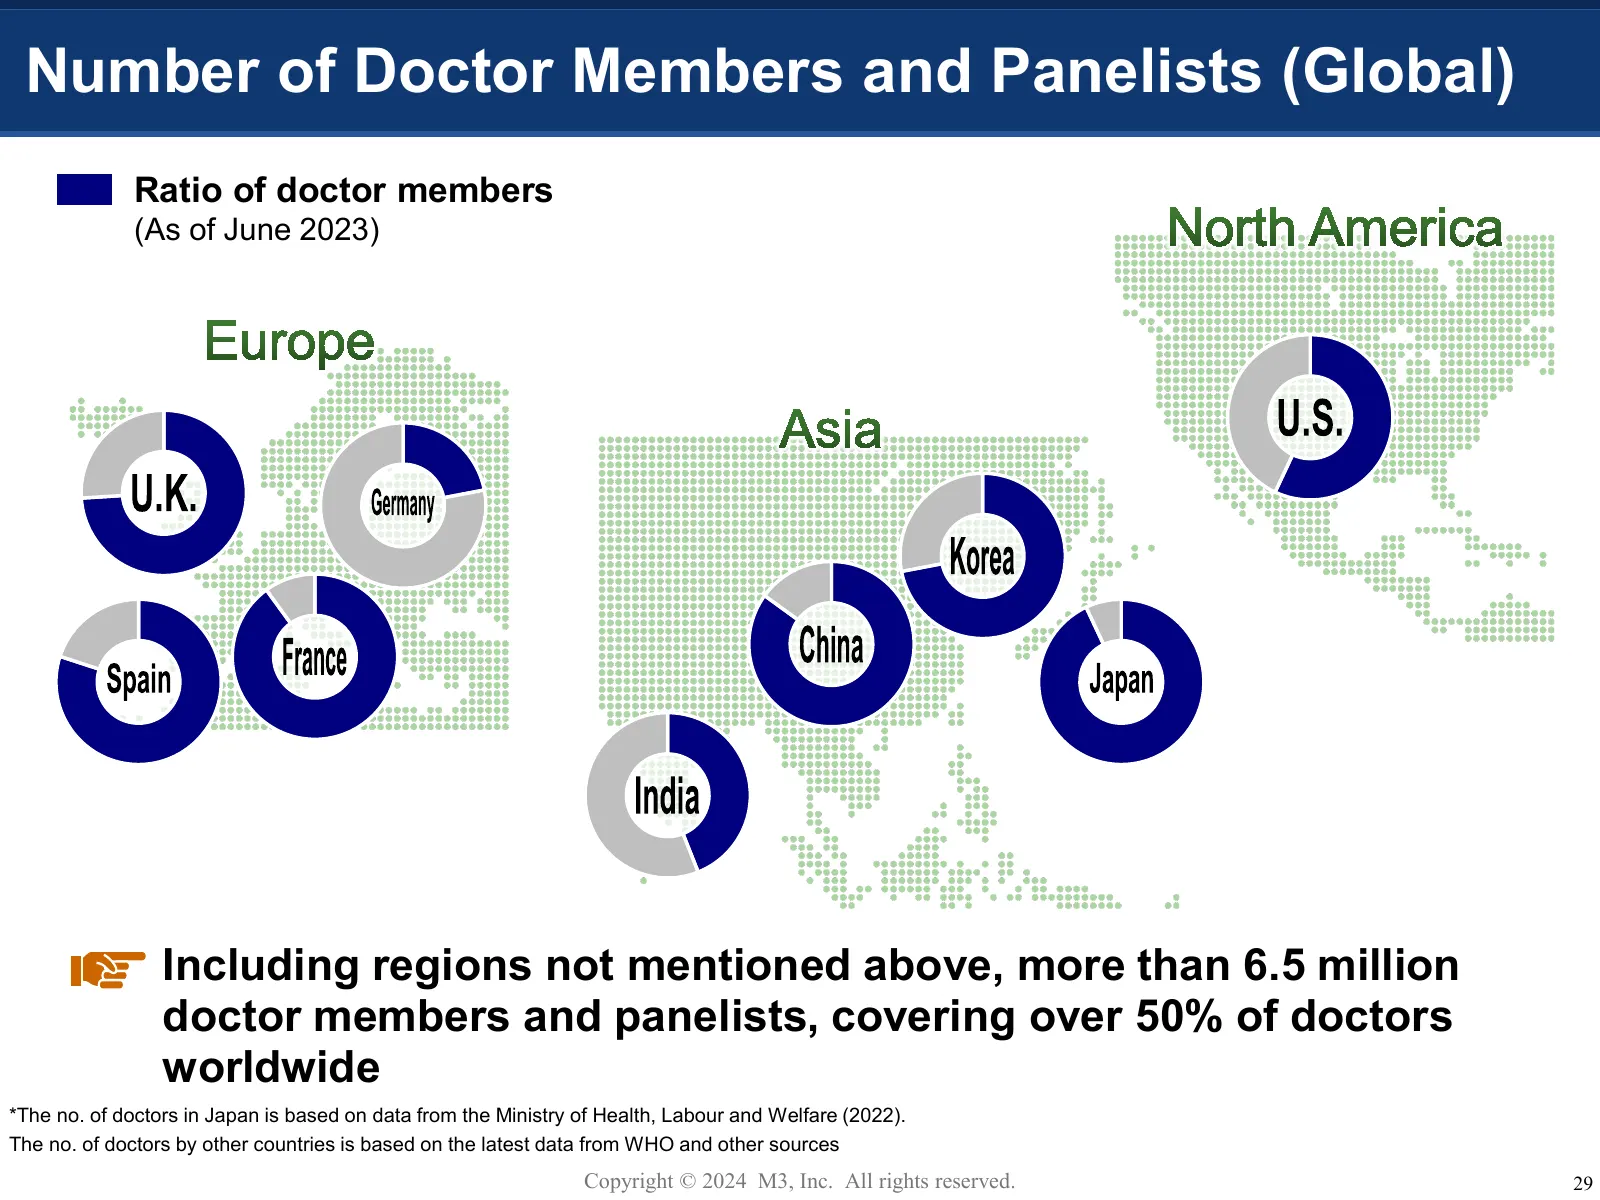
Number of Doctor Members and Panelists (Global) Ratio of doctor members (As of June 2023) Including regions not mentioned above, more than 6.5 million doctor members and panelists, covering over 50% of doctors worldwide *The no. of doctors in Japan is based on data from the Ministry of Health, Labou
Slide 31: Overseas Segment: Sales by Region
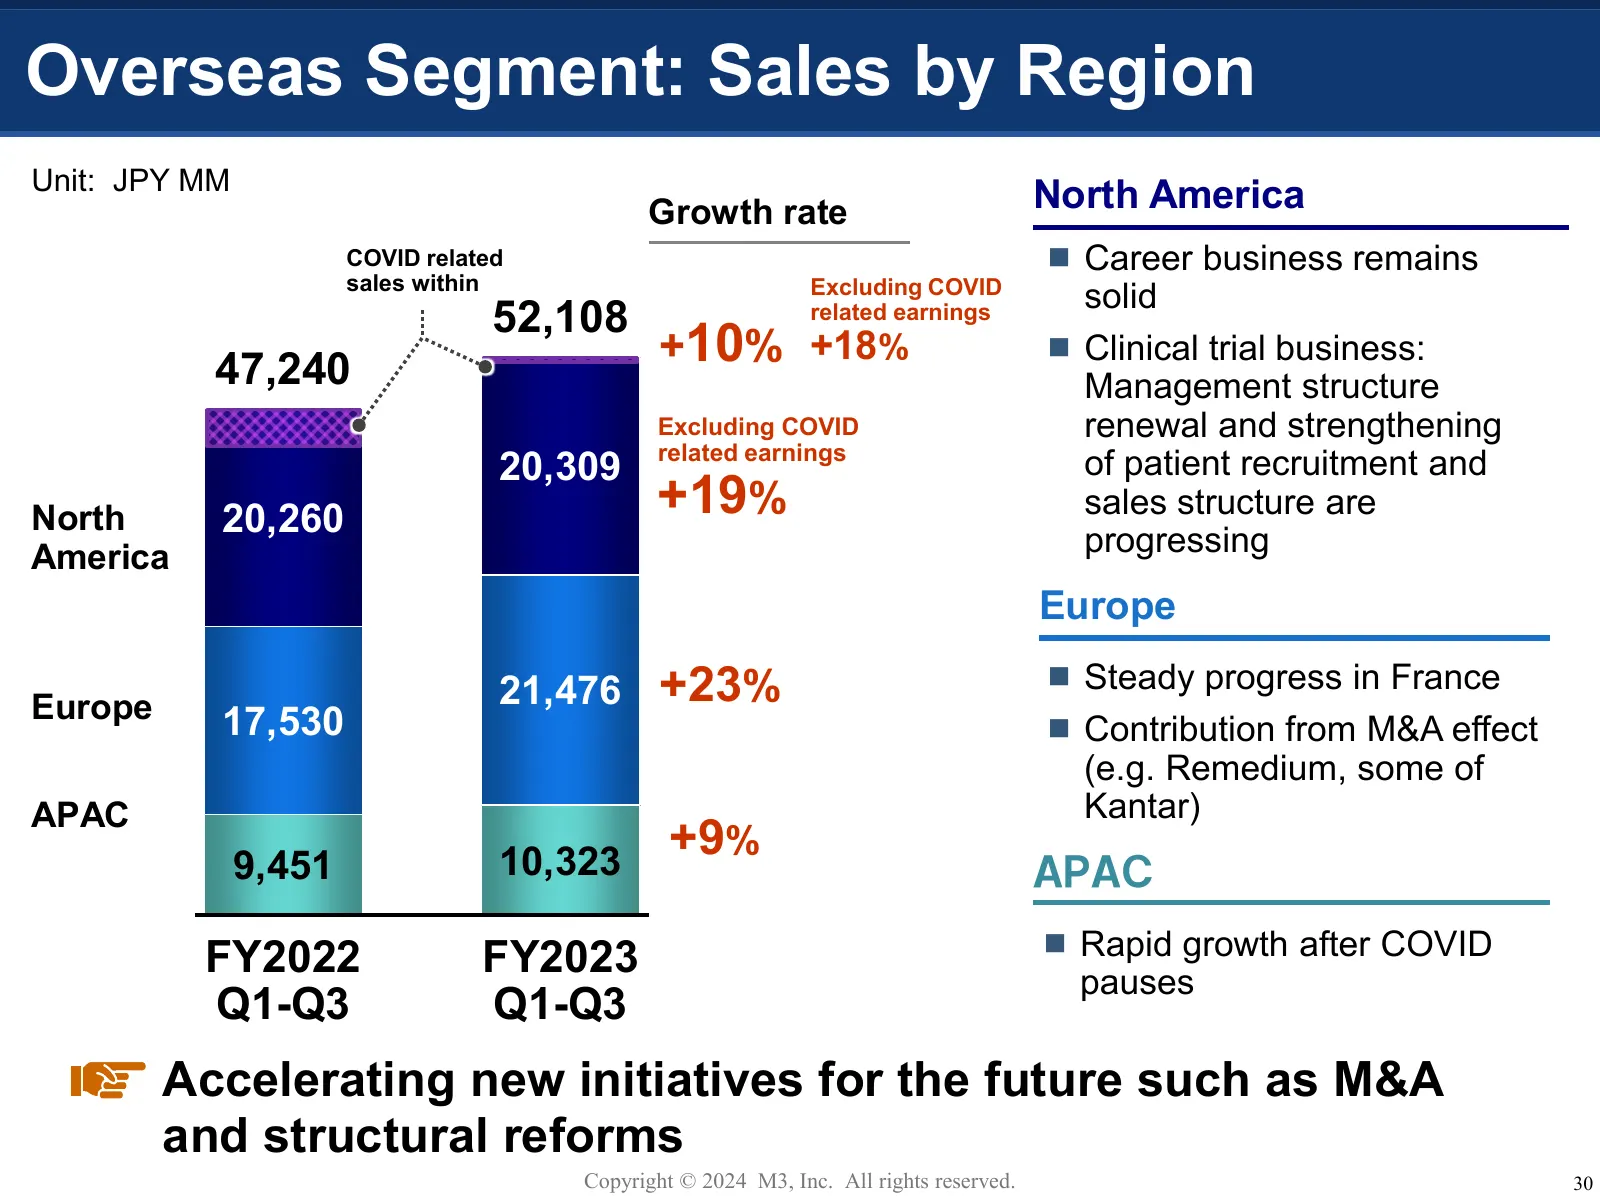
Overseas Segment: Sales by Region Unit: JPY MM Growth rate North America COVID related Career business remains sales within Excluding COVID solid 52,108 related earnings +10% +18% Clinical trial business: 47,240 Management structure Excluding COVID renewal and strengthening related earnings 20,3
Slide 32: Overseas Growth Trends by Business
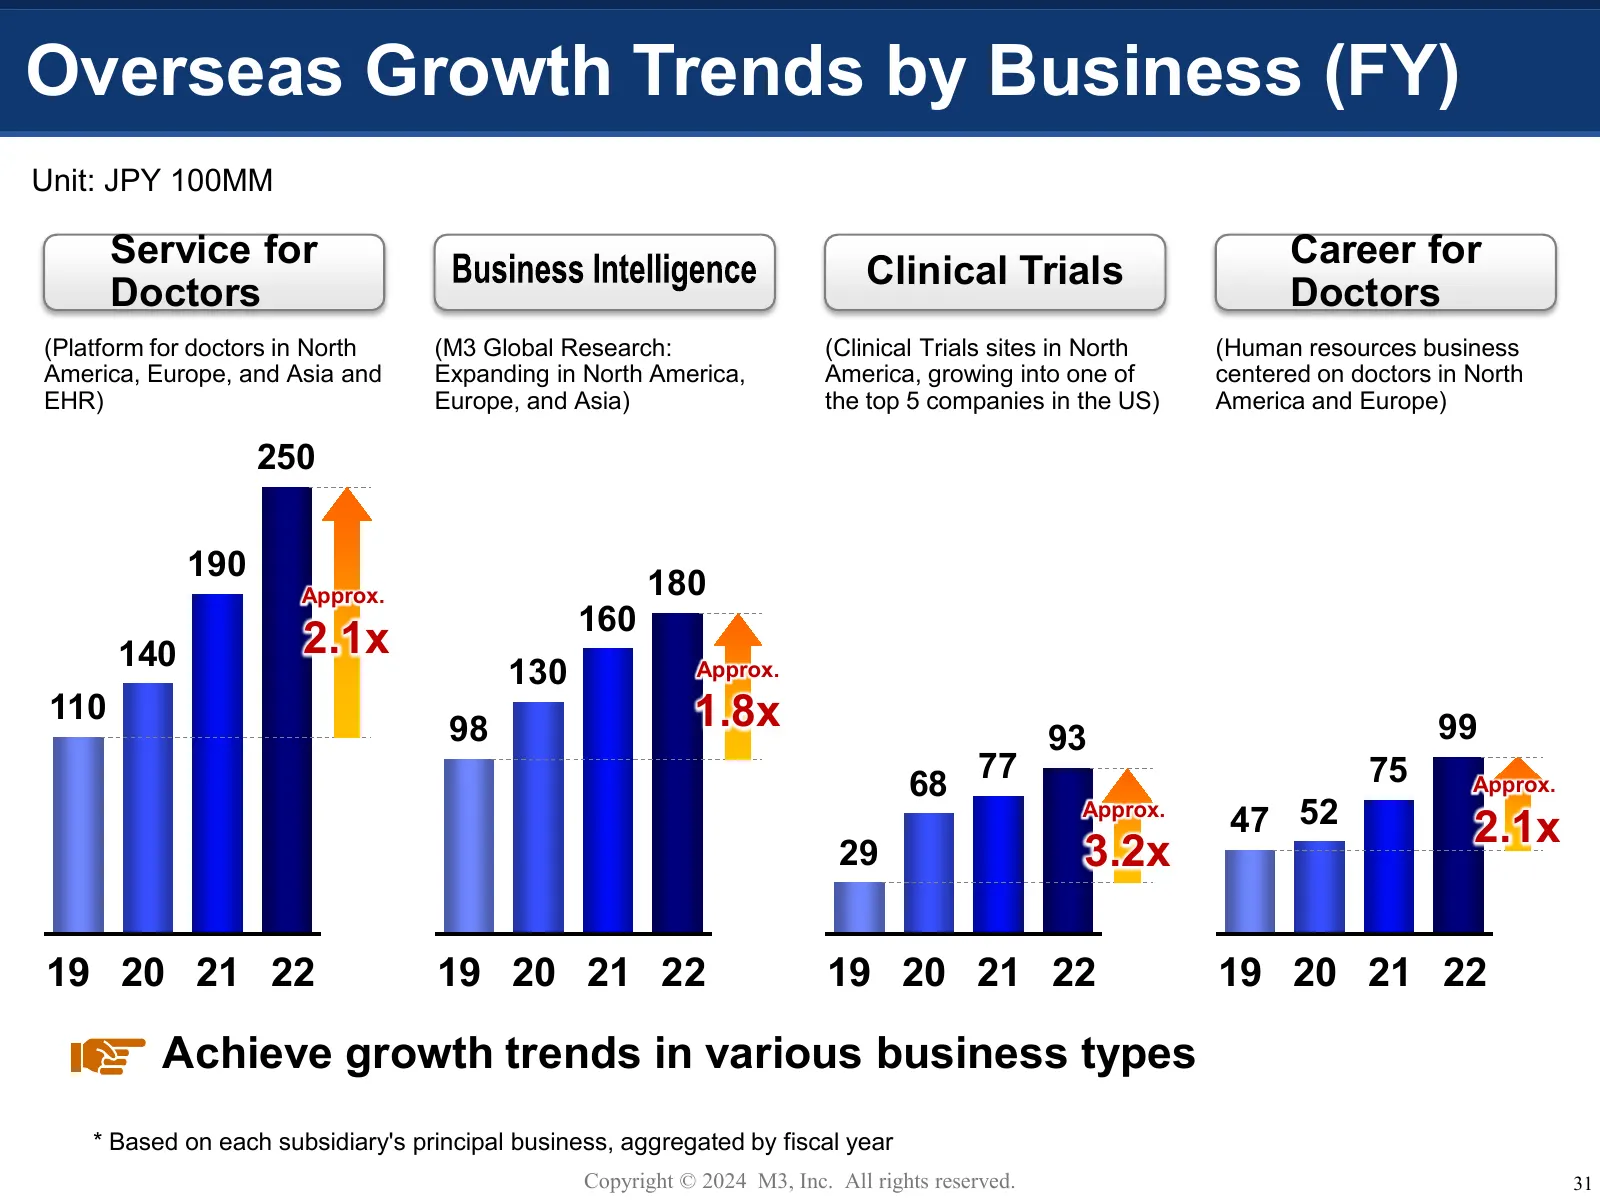
Overseas Growth Trends by Business (FY) Unit: JPY 100MM Service for Career for Clinical Trials Doctors Doctors (Platform for doctors in North (M3 Global Research: (Clinical Trials sites in North (Human resources business America, Europe, and Asia and Expanding in North America, America, growing into
Slide 33: Consolidation of DBMCI in India
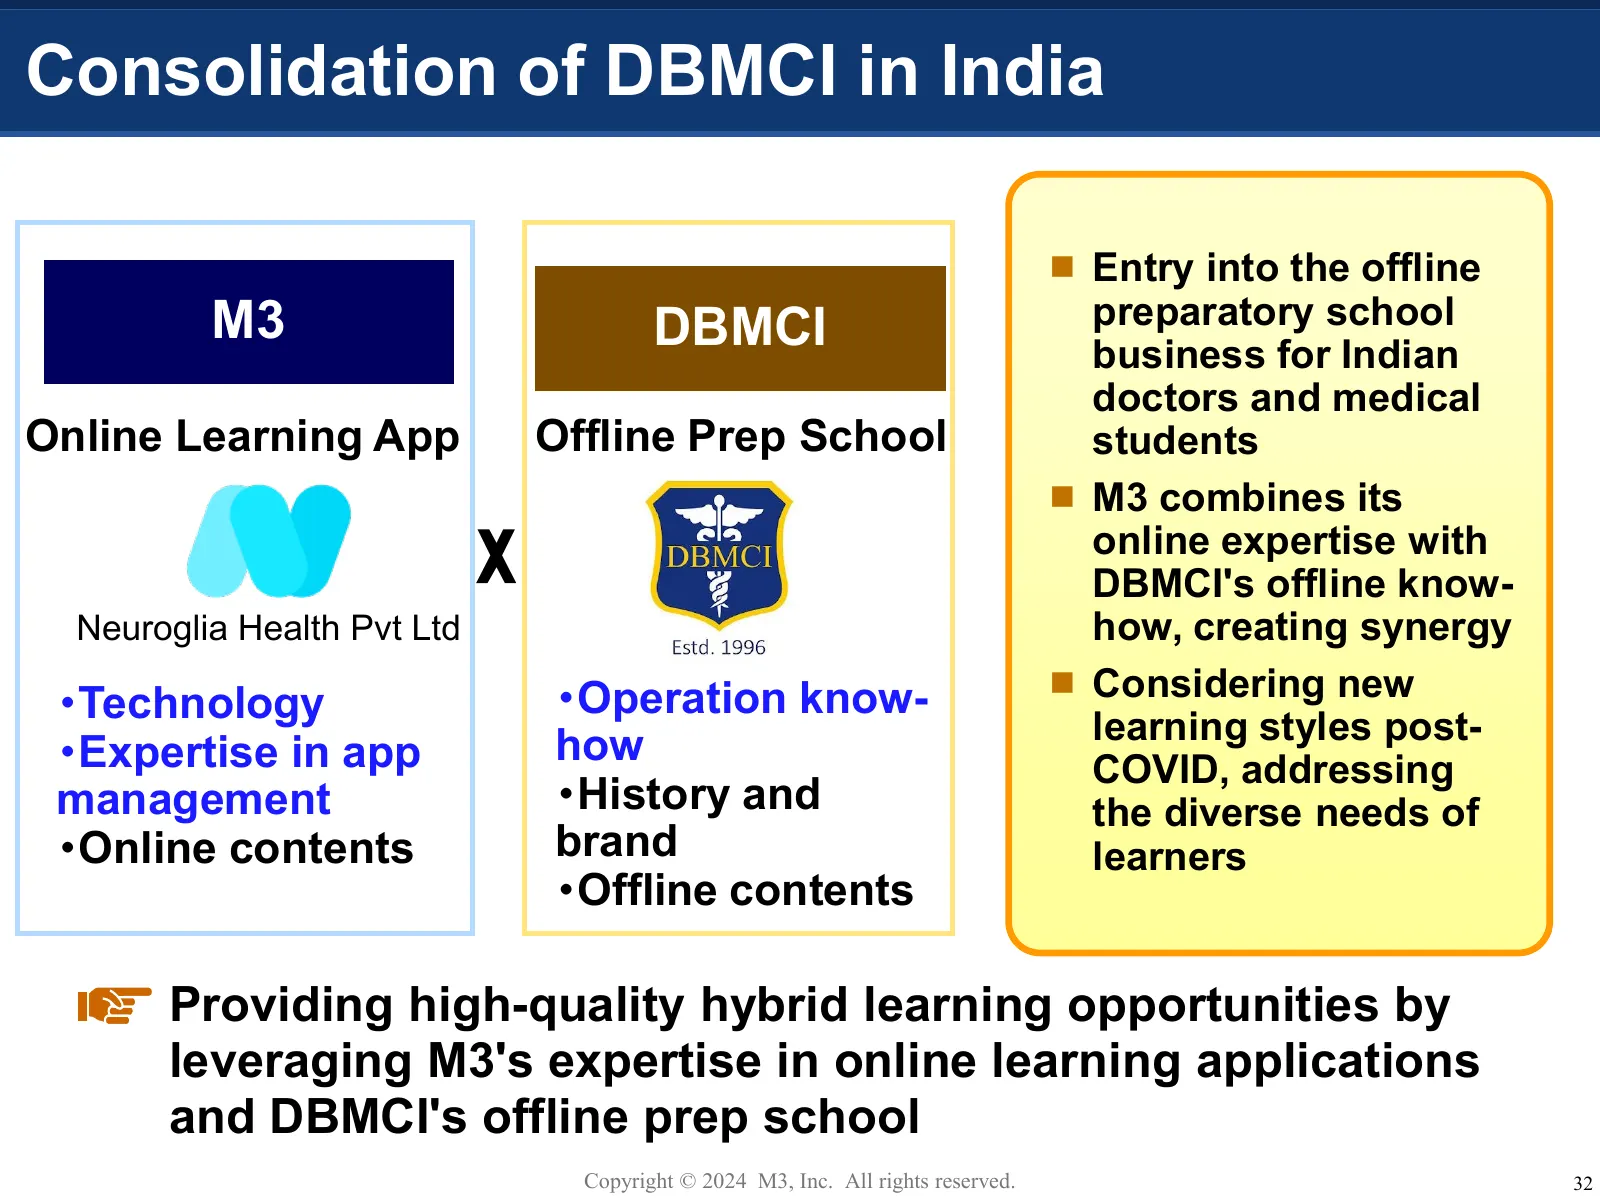
Consolidation of DBMCI in India Entry into the offline M3 DBMCI preparatory school business for Indian doctors and medical Online Learning App Offline Prep School students M3 combines its x online expertise with DBMCI's offline know- Neuroglia Health Pvt Ltd how, creating synergy ・Operation know
Slide 34: Growth Engine 3: Ecosystem Synergy Creation
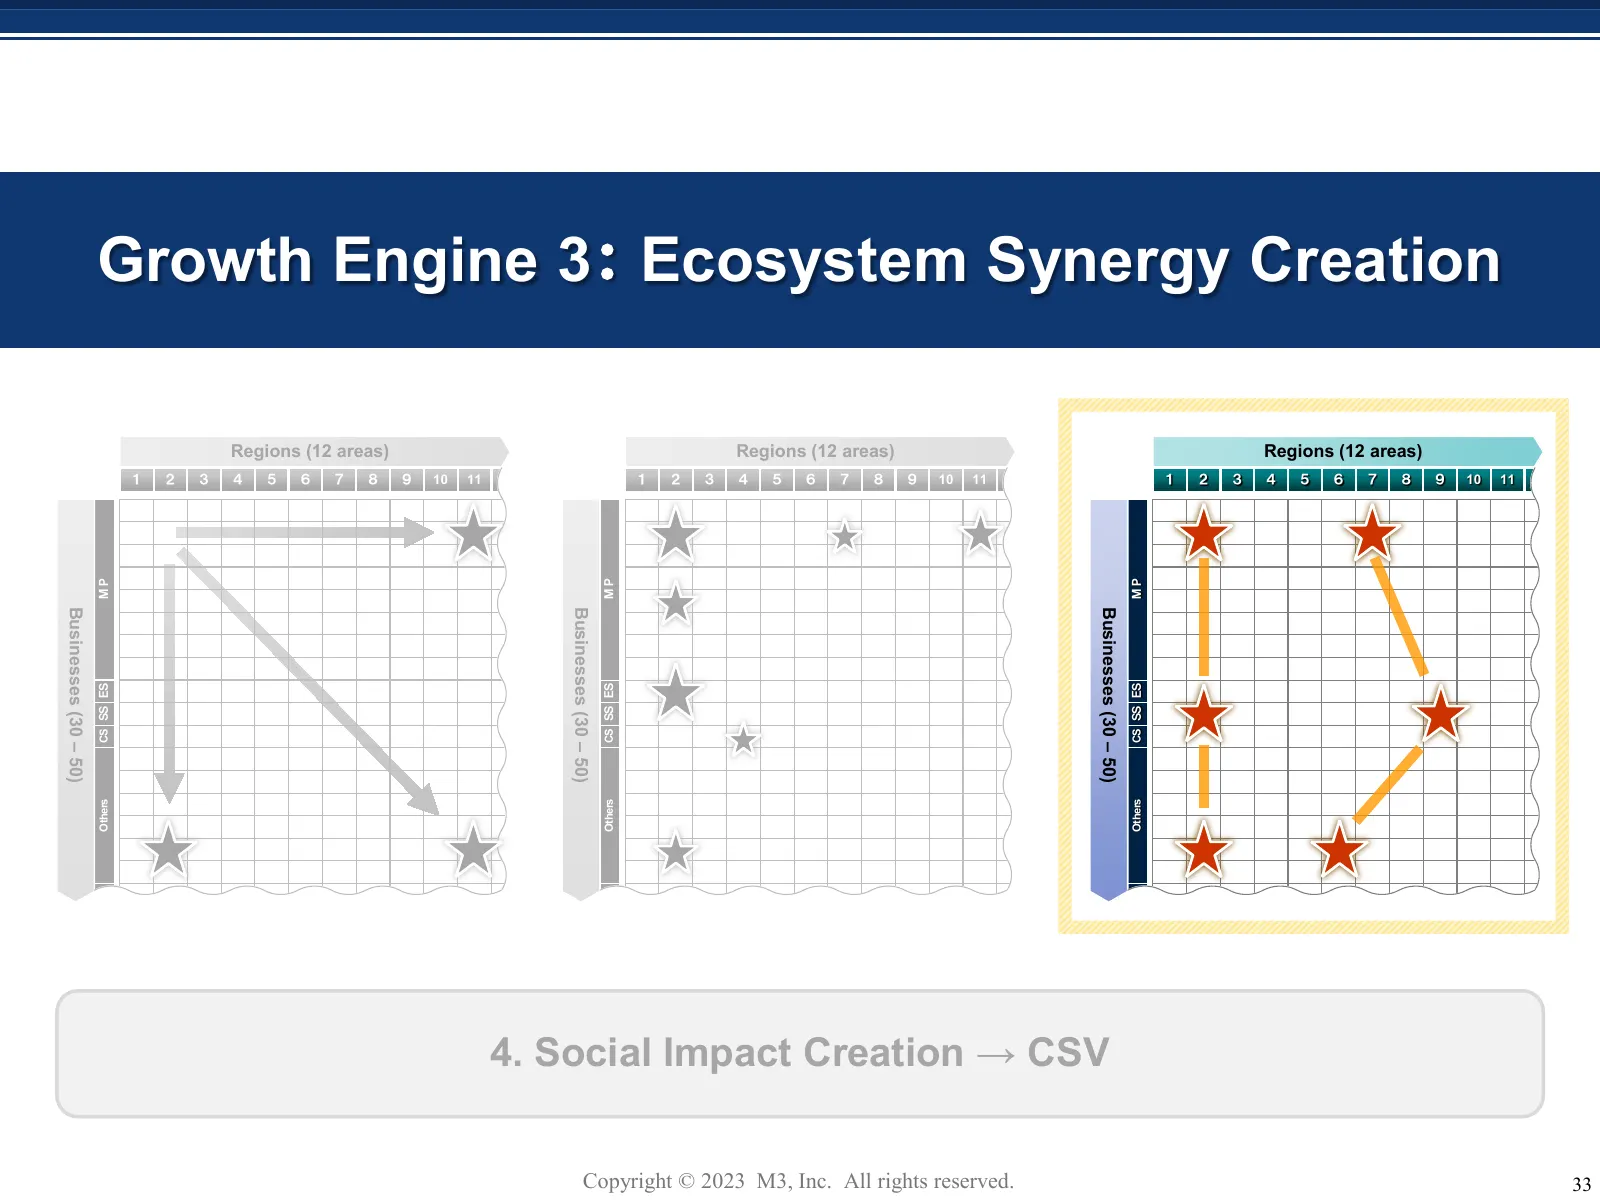
Growth Engine 3: Ecosystem Synergy Creation Regions (12 areas) Regions areas) Regions (12 areas) Regions (12 areas) 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 MP MP MP Businesses (30 Businesses Businesses (30 – 50) Businesses (30 CS SS ES CS SS ES CS SS ES (30 –– 50) ( –
Slide 35: Business Scope Expansion and Growth Potential
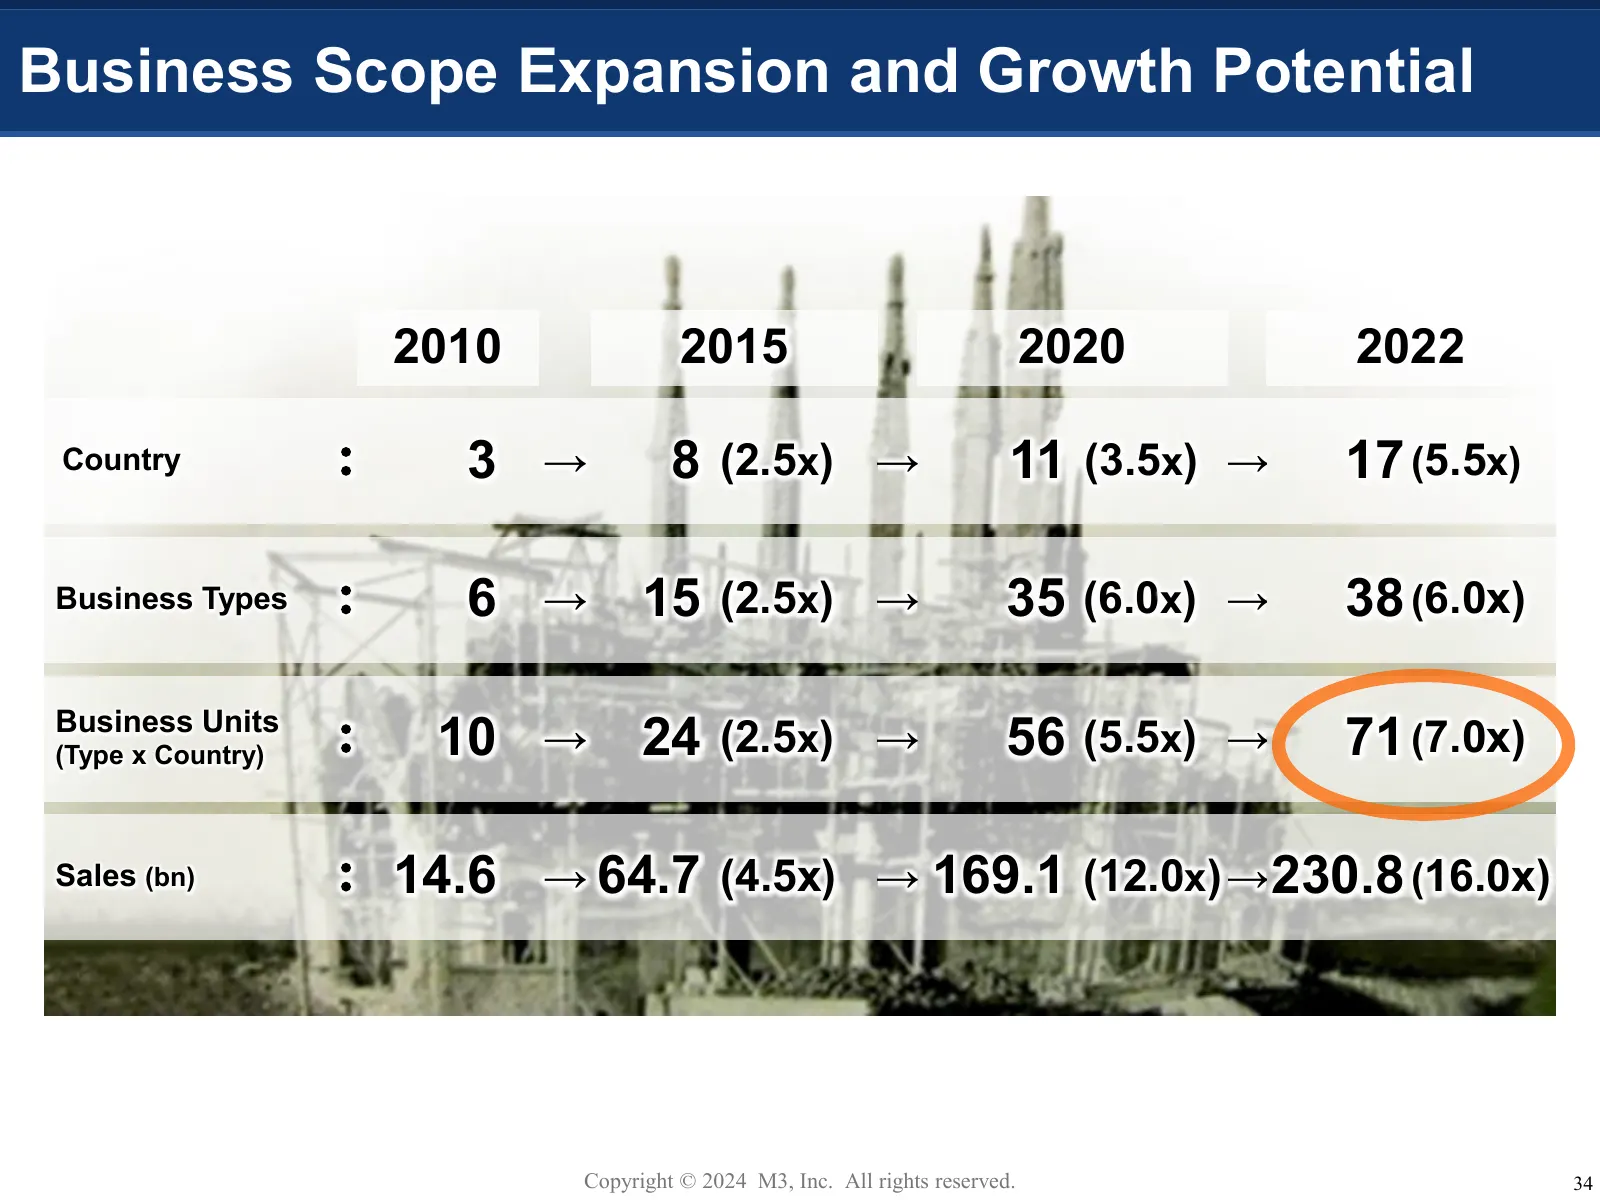
Business Scope Expansion and Growth Potential 2010 2015 2020 2022 Country : 3 → 8 (2.5x) → 11 (3.5x) → 17 (5.5x) Business Types : 6 → 15 (2.5x) → 35 (6.0x) → 38 (6.0x) Business Units (Type x Country) : 10 → 24 (2.5x) → 56 (5.5x) → 71 (7.0x) Sales (bn) : 14.6 → 64.7 (4.5x) → 169.1 (12.0x)→ 230.8 (16.
Slide 36: Cross-Business Synergy Creation Potential
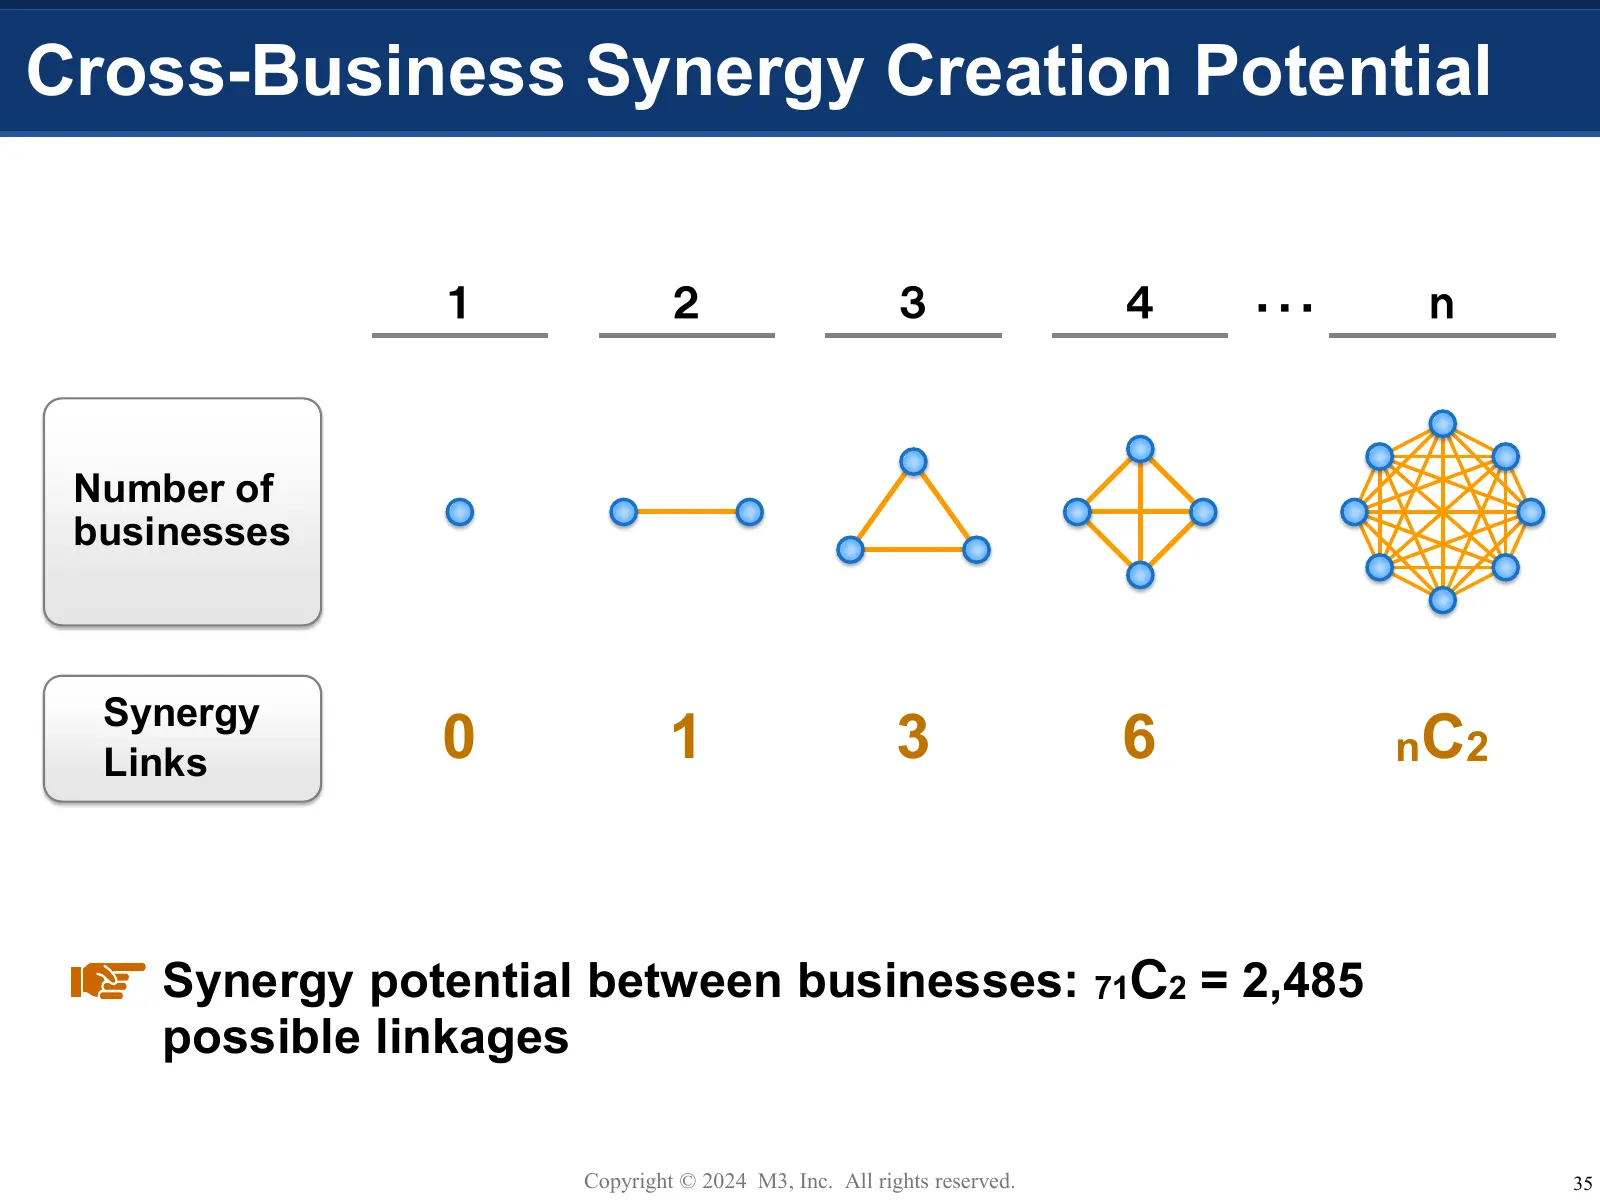
Cross-Business Synergy Creation Potential 1 2 3 4 ・・・ n Number of businesses Synergy Links 0 1 3 6 nC2 Synergy potential between businesses: 71C2 = 2,485 possible linkages Copyright © 2024 M3, Inc. All rights reserved. 35
Slide 37: Ecosystem Synergy Value Creation
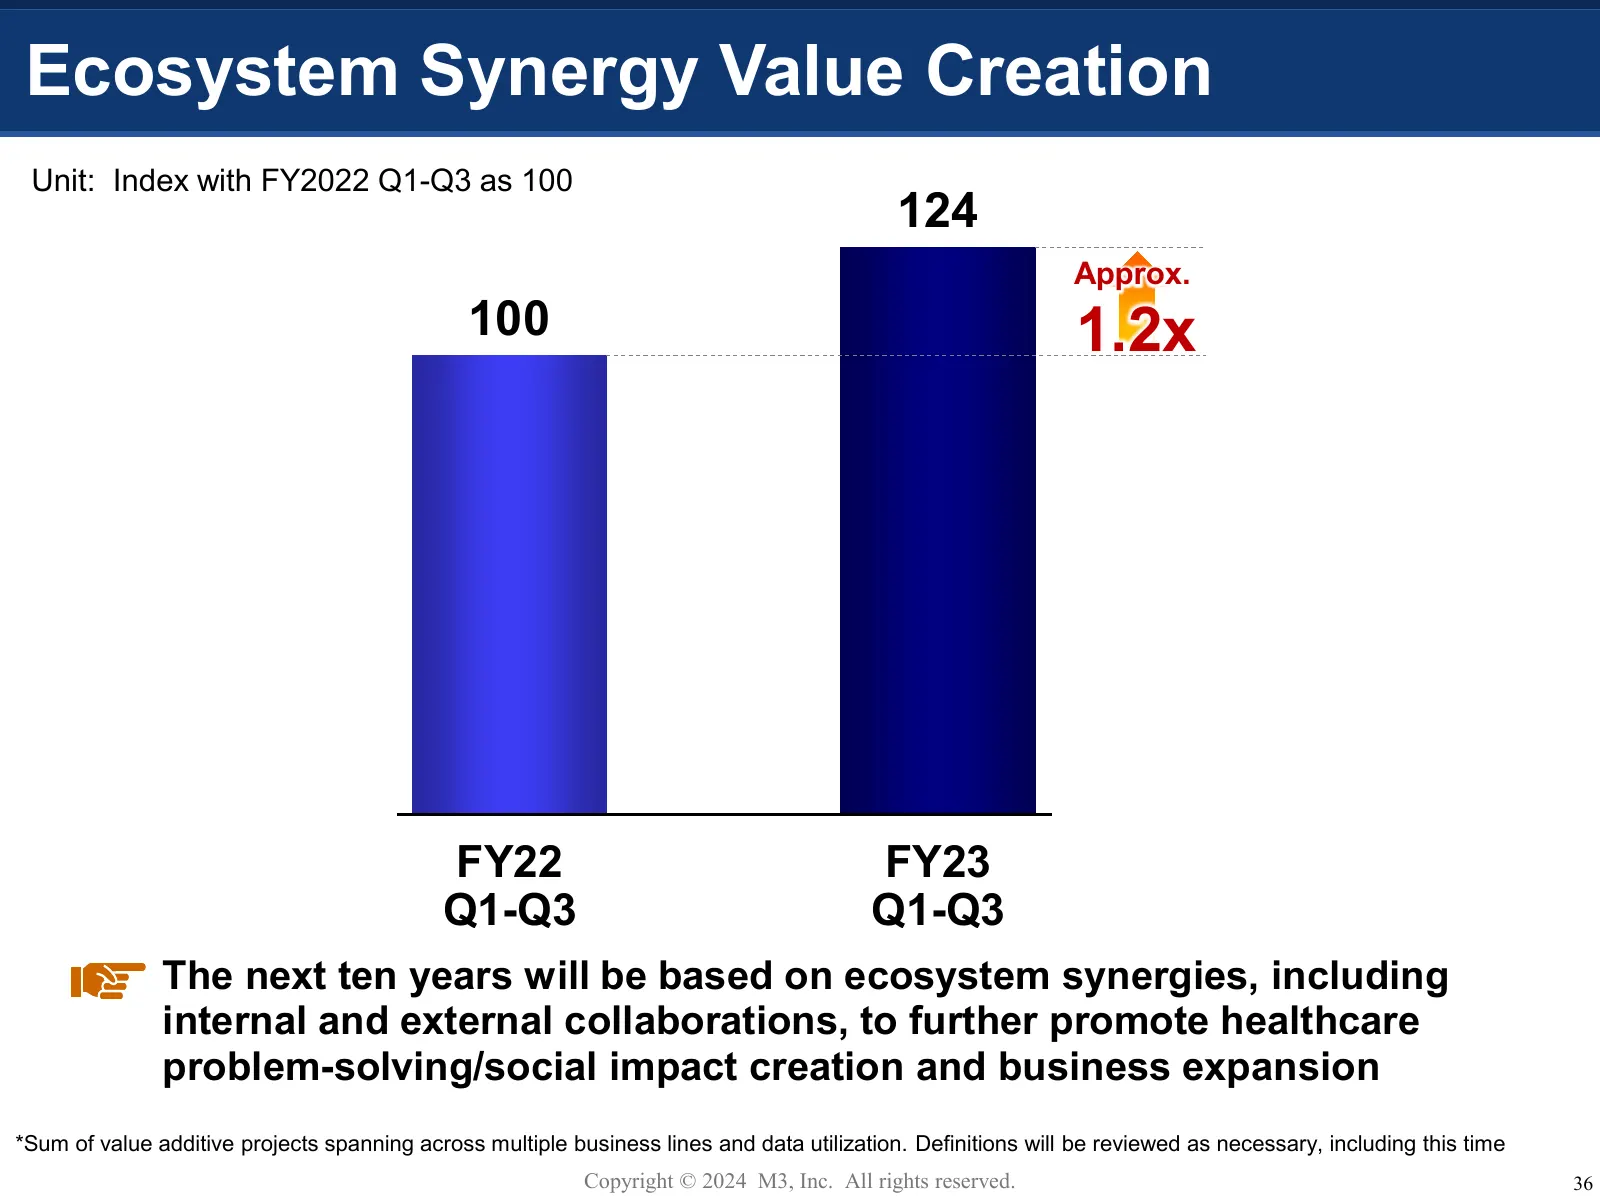
Ecosystem Synergy Value Creation Unit: Index with FY2022 Q1-Q3 as 100 124 Approx. 100 1.2x FY22 FY23 Q1-Q3 Q1-Q3 The next ten years will be based on ecosystem synergies, including internal and external collaborations, to further promote healthcare problem-solving/social impact creation and business
Slide 38: The White Jack Project
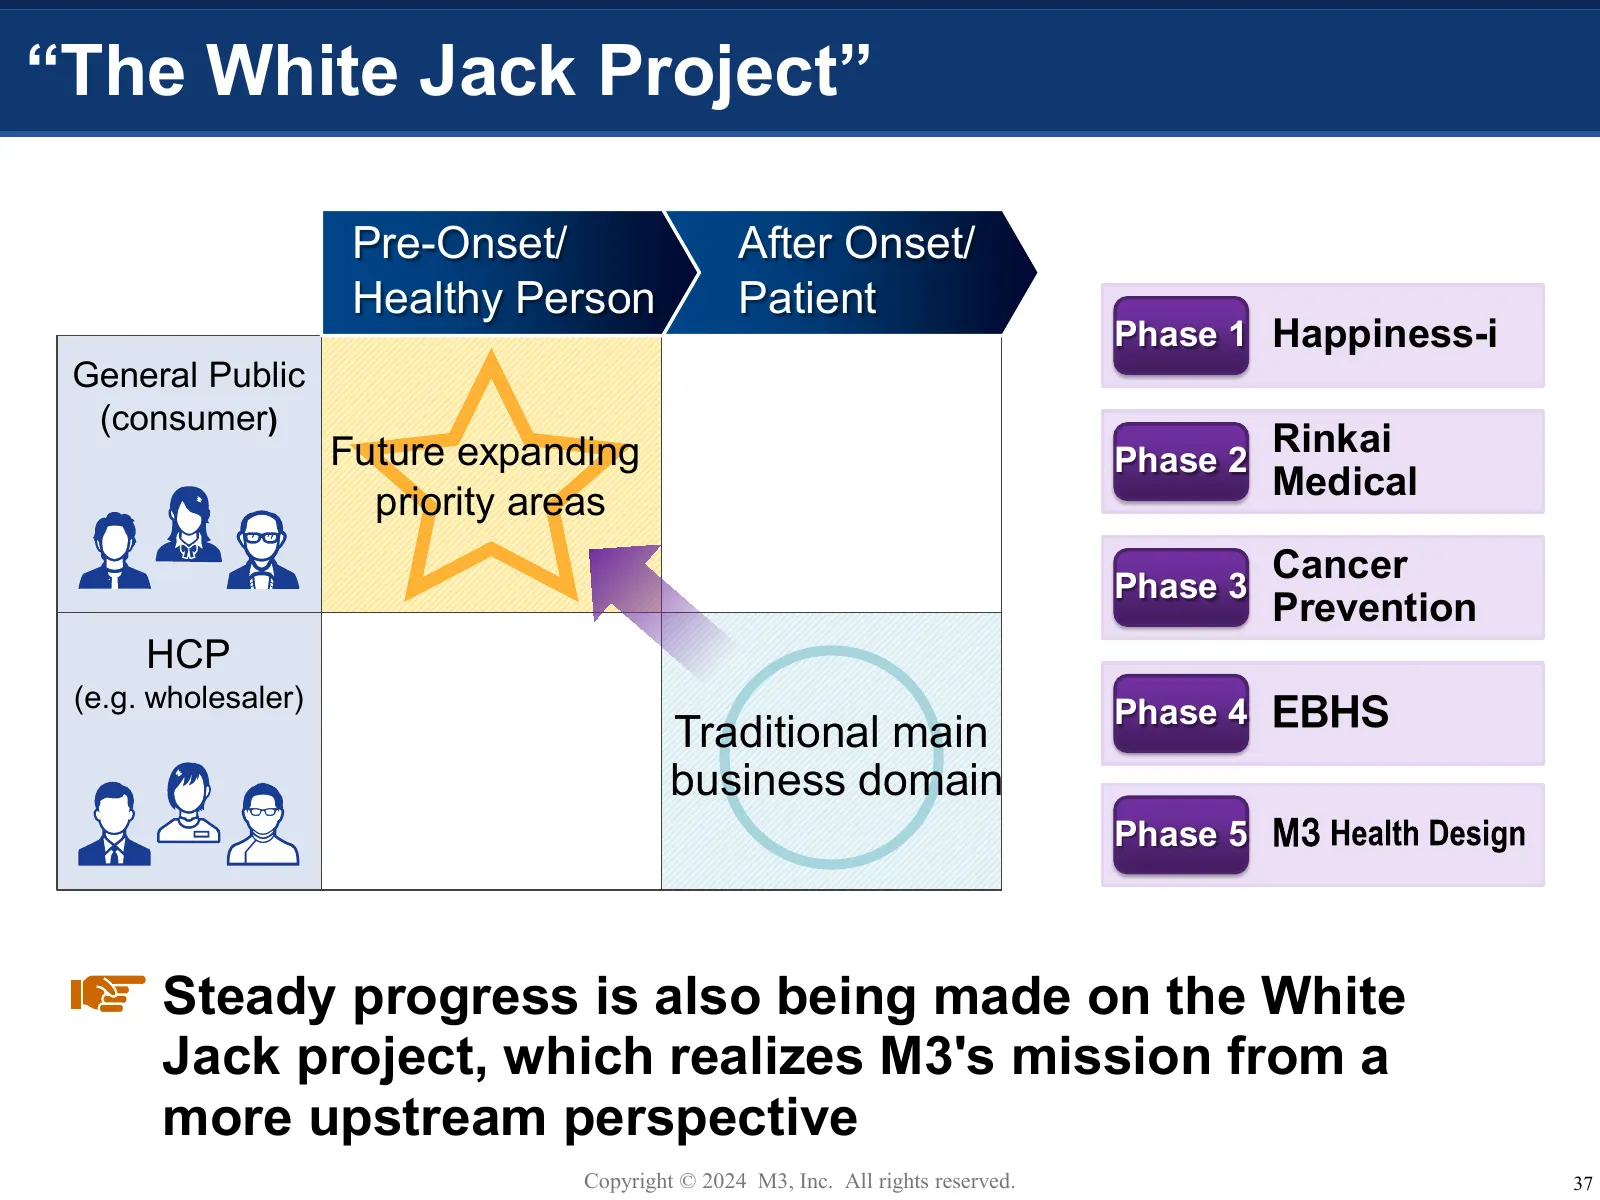
“The White Jack Project” Pre-Onset/ After Onset/ Healthy Person Patient Phase 1 Happiness-i General Public (consumer) Future expanding Rinkai Phase 2 Medical priority areas Cancer Phase 3 Prevention HCP (e.g. wholesaler) Phase 4 EBHS Traditional main business domain Phase 5 Steady progress is also b
Slide 39: Expand Coverage of Enterprise Services
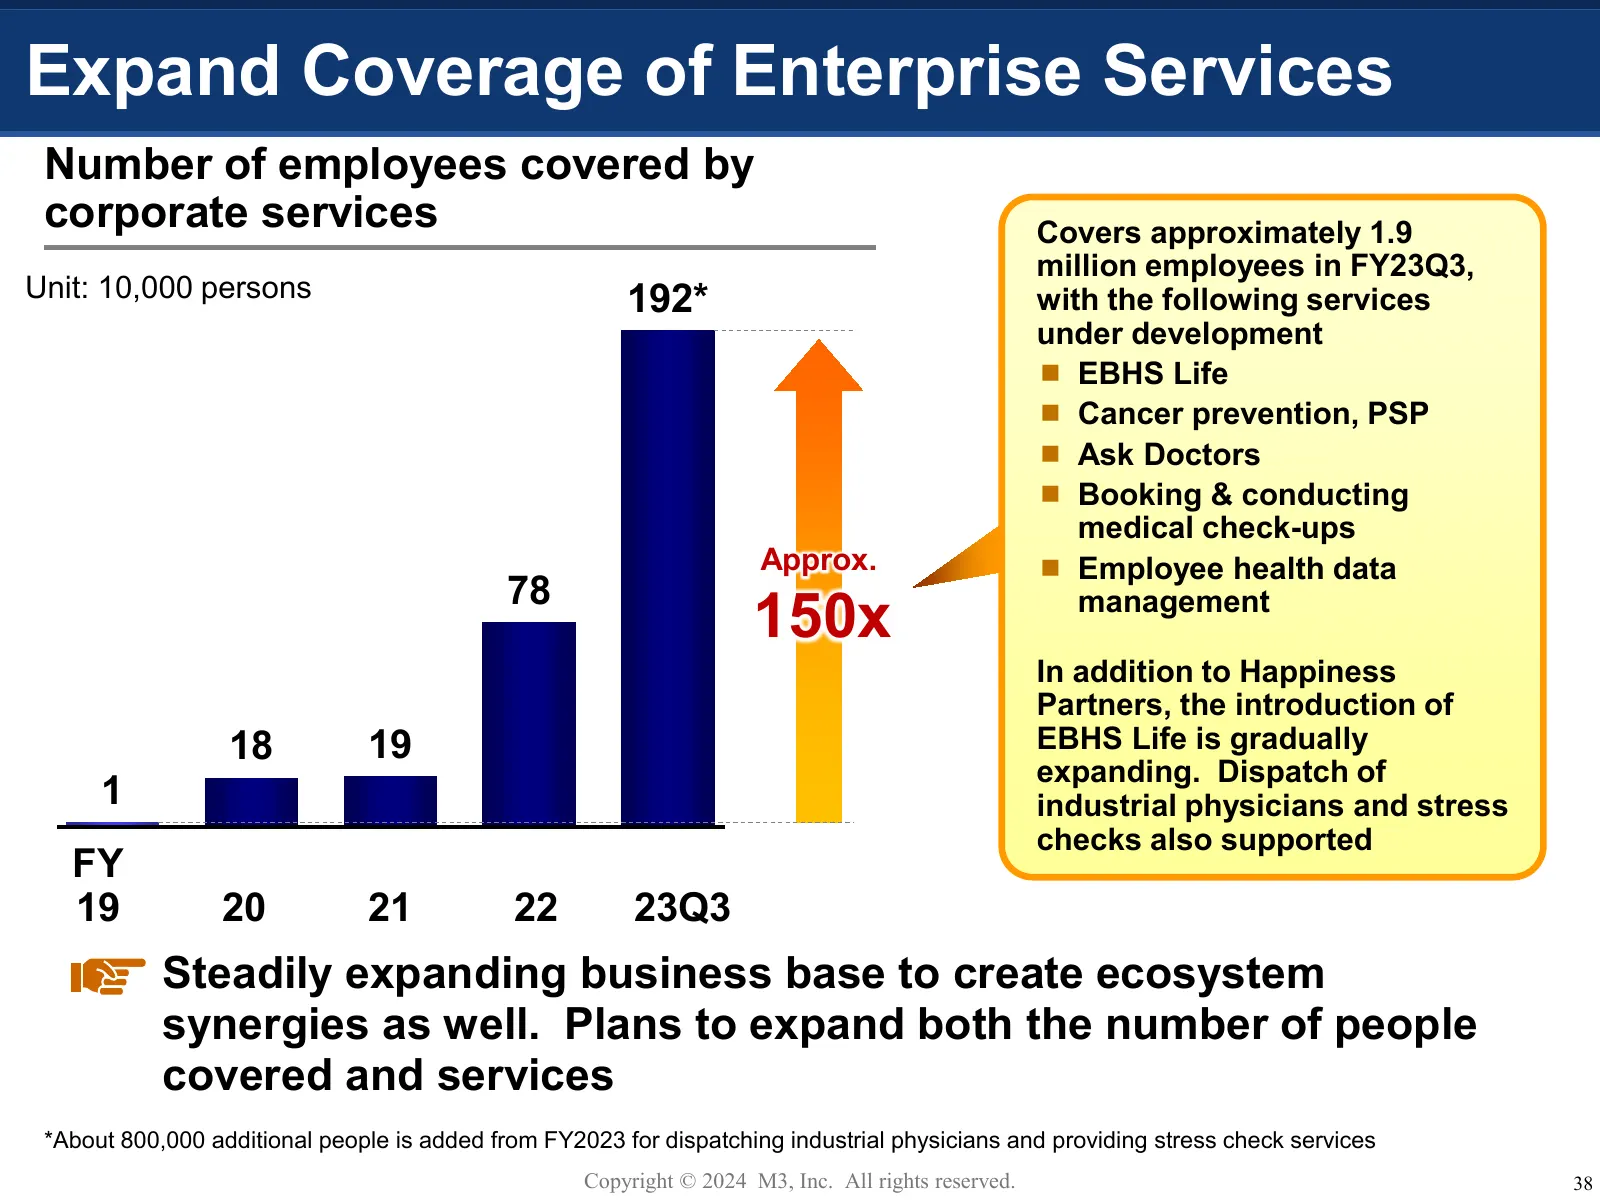
Expand Coverage of Enterprise Services Number of employees covered by corporate services Covers approximately 1.9 million employees in FY23Q3, Unit: 10,000 persons 192* with the following services under development EBHS Life Cancer prevention, PSP Ask Doctors Booking & conducting medical che
Slide 40: Status of Tender Offer for Benefit One
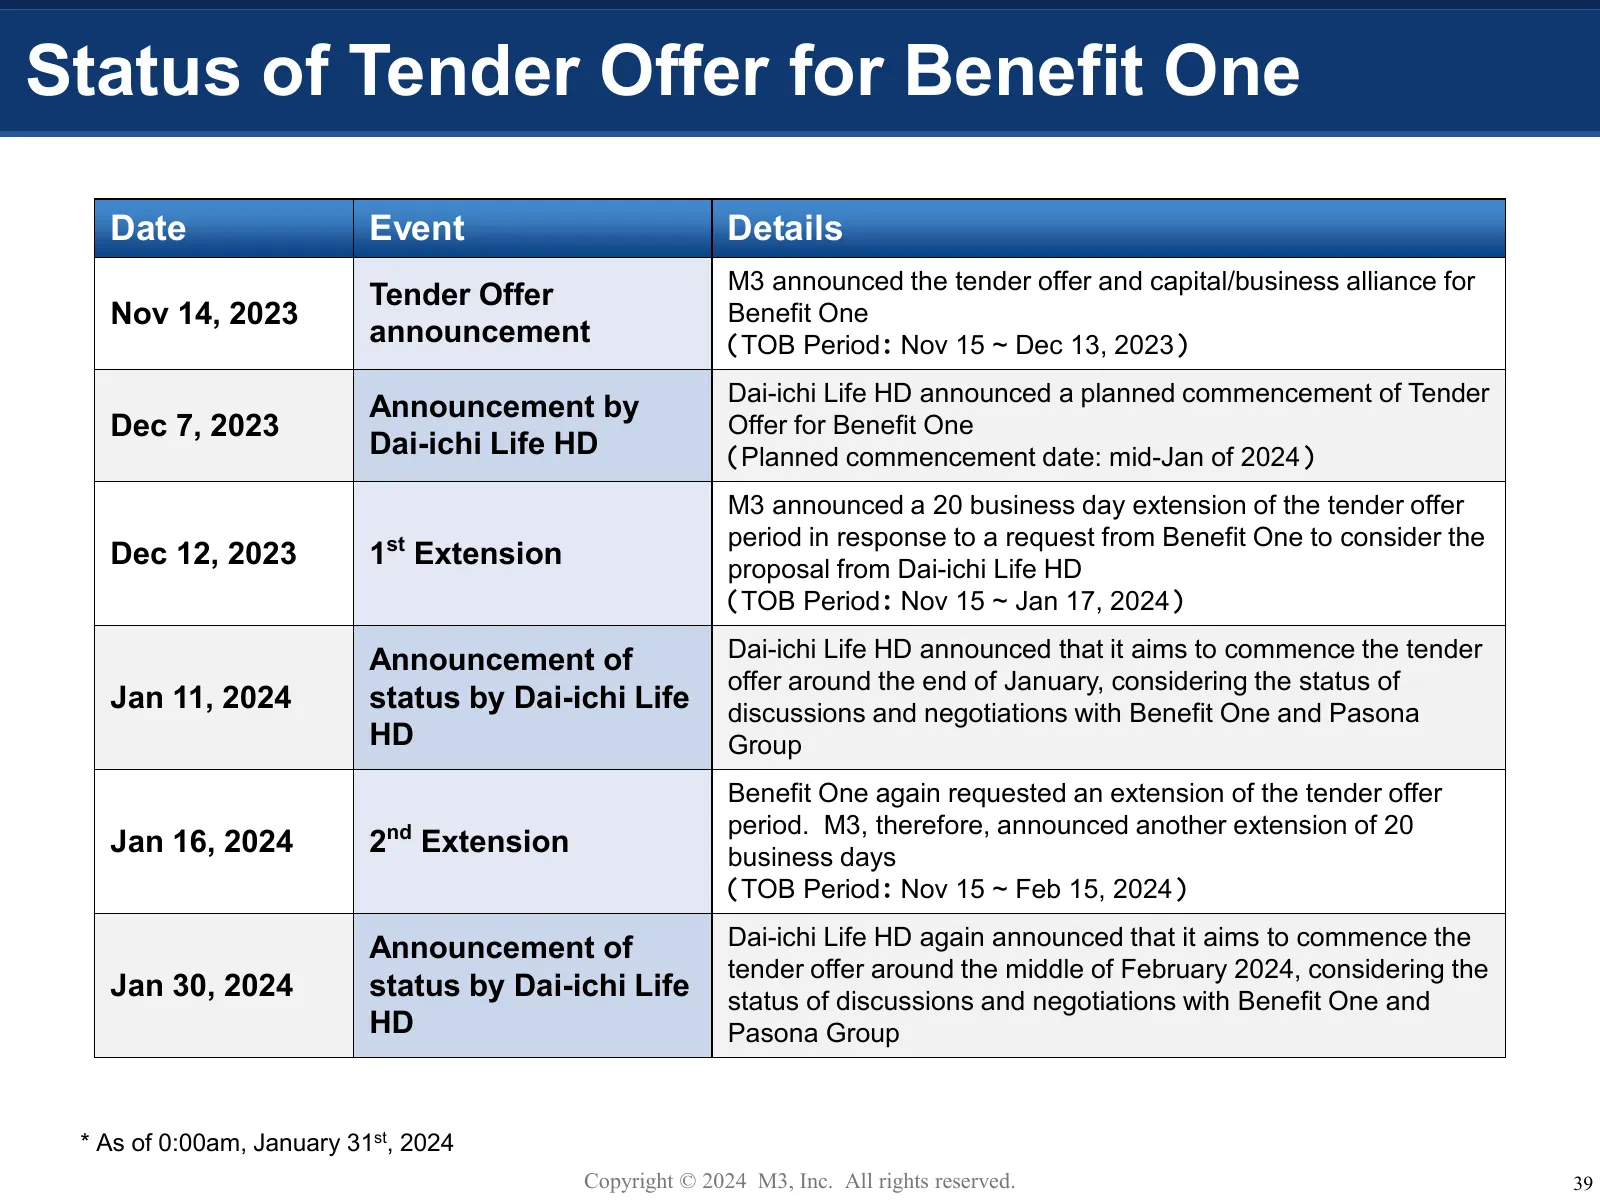
Status of Tender Offer for Benefit One Date Event Details M3 announced the tender offer and capital/business alliance for Tender Offer Nov 14, 2023 Benefit One announcement (TOB Period: Nov 15 ~ Dec 13, 2023) Dai-ichi Life HD announced a planned commencement of Tender Announcement by Dec 7, 2023 Off
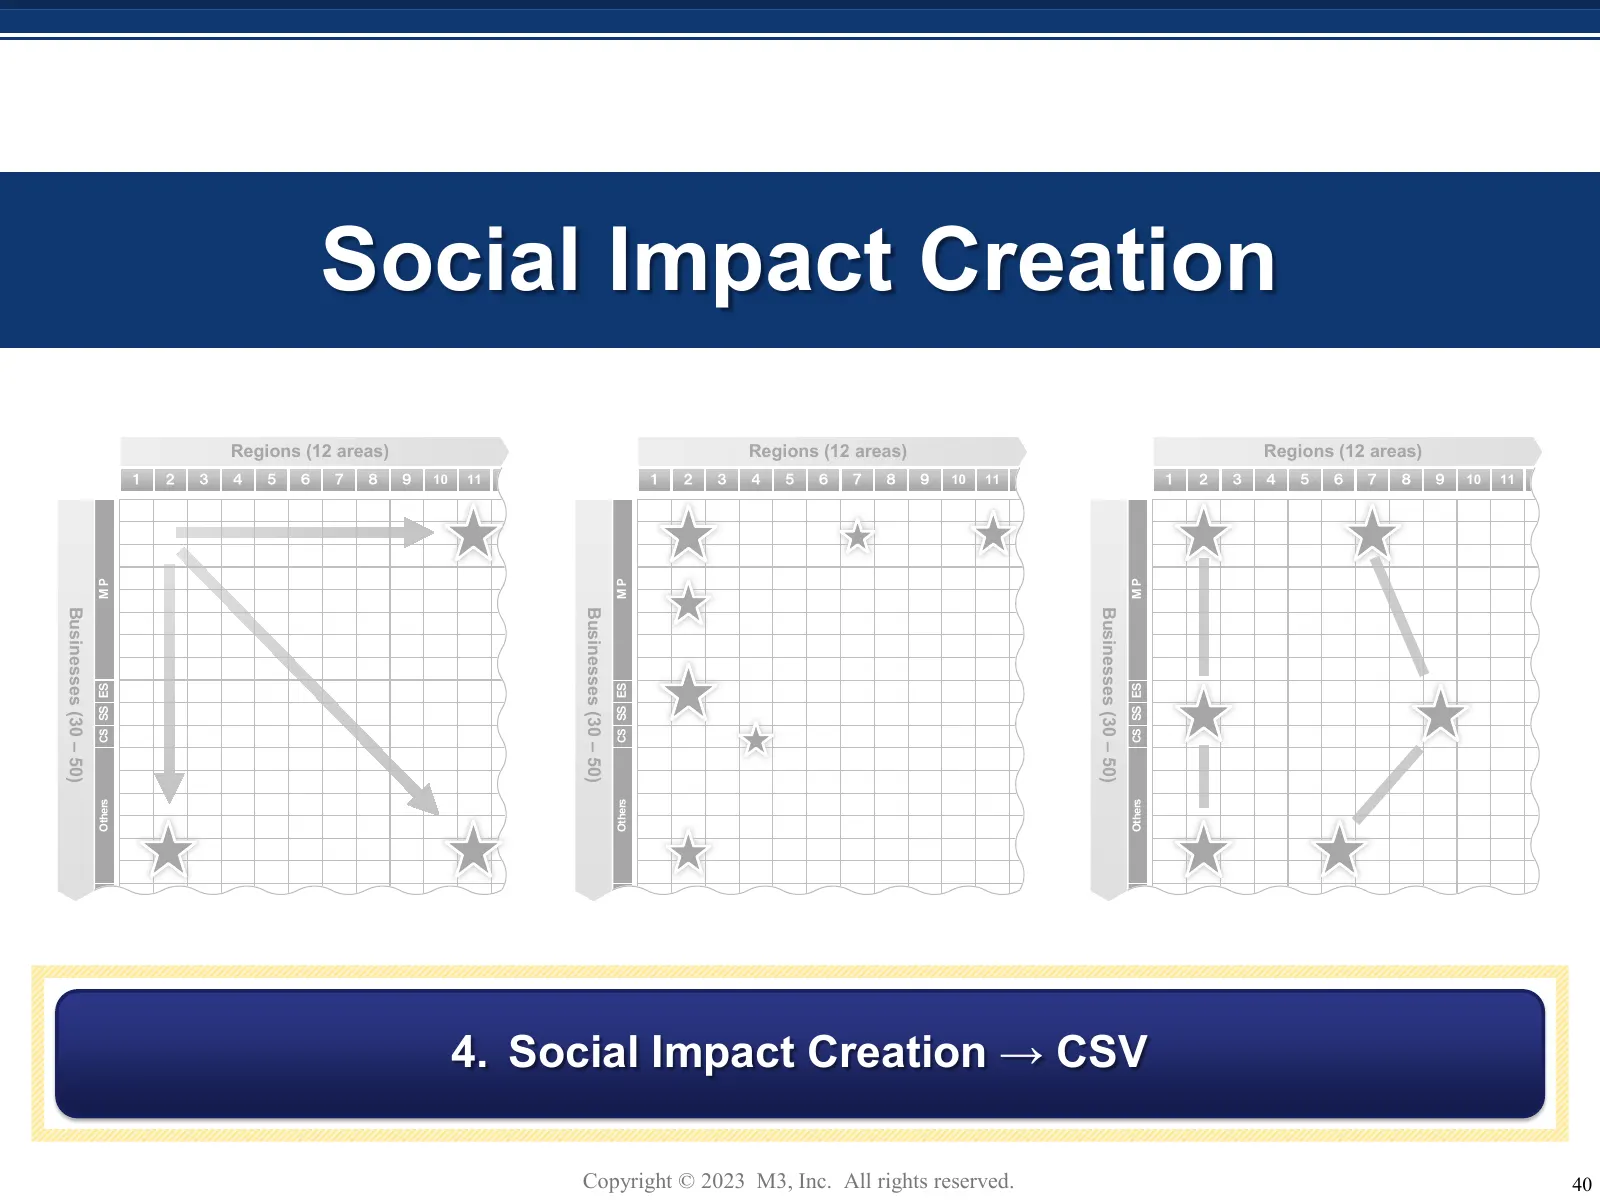
Slide 41: Social Impact Creation
Social Impact Creation Regions (12 areas) Regions areas) Regions (12 areas) Regions (12 areas) 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 1 2 3 4 5 6 7 8 9 10 11 MP MP MP Businesses (30 Businesses Businesses (30 – 50) Businesses (30 CS SS ES CS SS ES CS SS ES (30 –– 50) ( – 50)) 30 50 50) Other
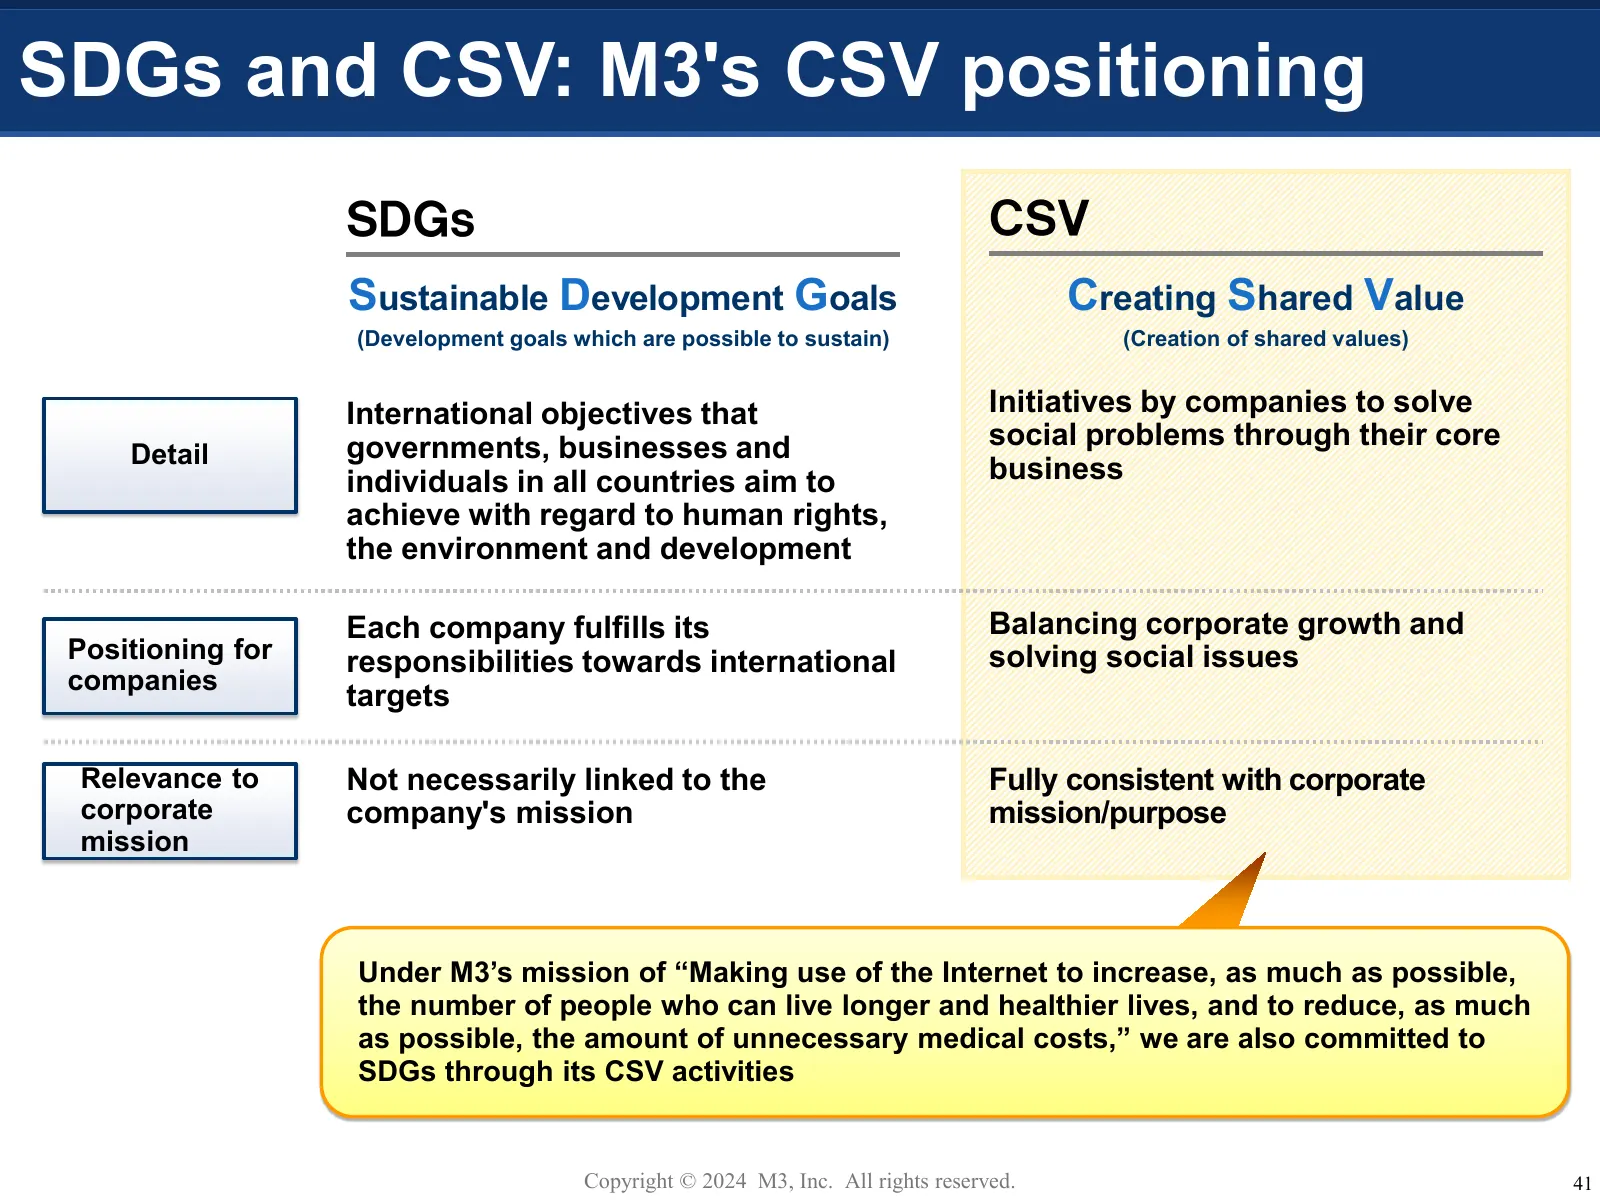
Slide 42: SDGs and CSV: M3's CSV positioning
SDGs and CSV: M3's CSV positioning SDGs CSV Sustainable Development Goals Creating Shared Value (Development goals which are possible to sustain) (Creation of shared values) International objectives that Initiatives by companies to solve governments, businesses and social problems through their core
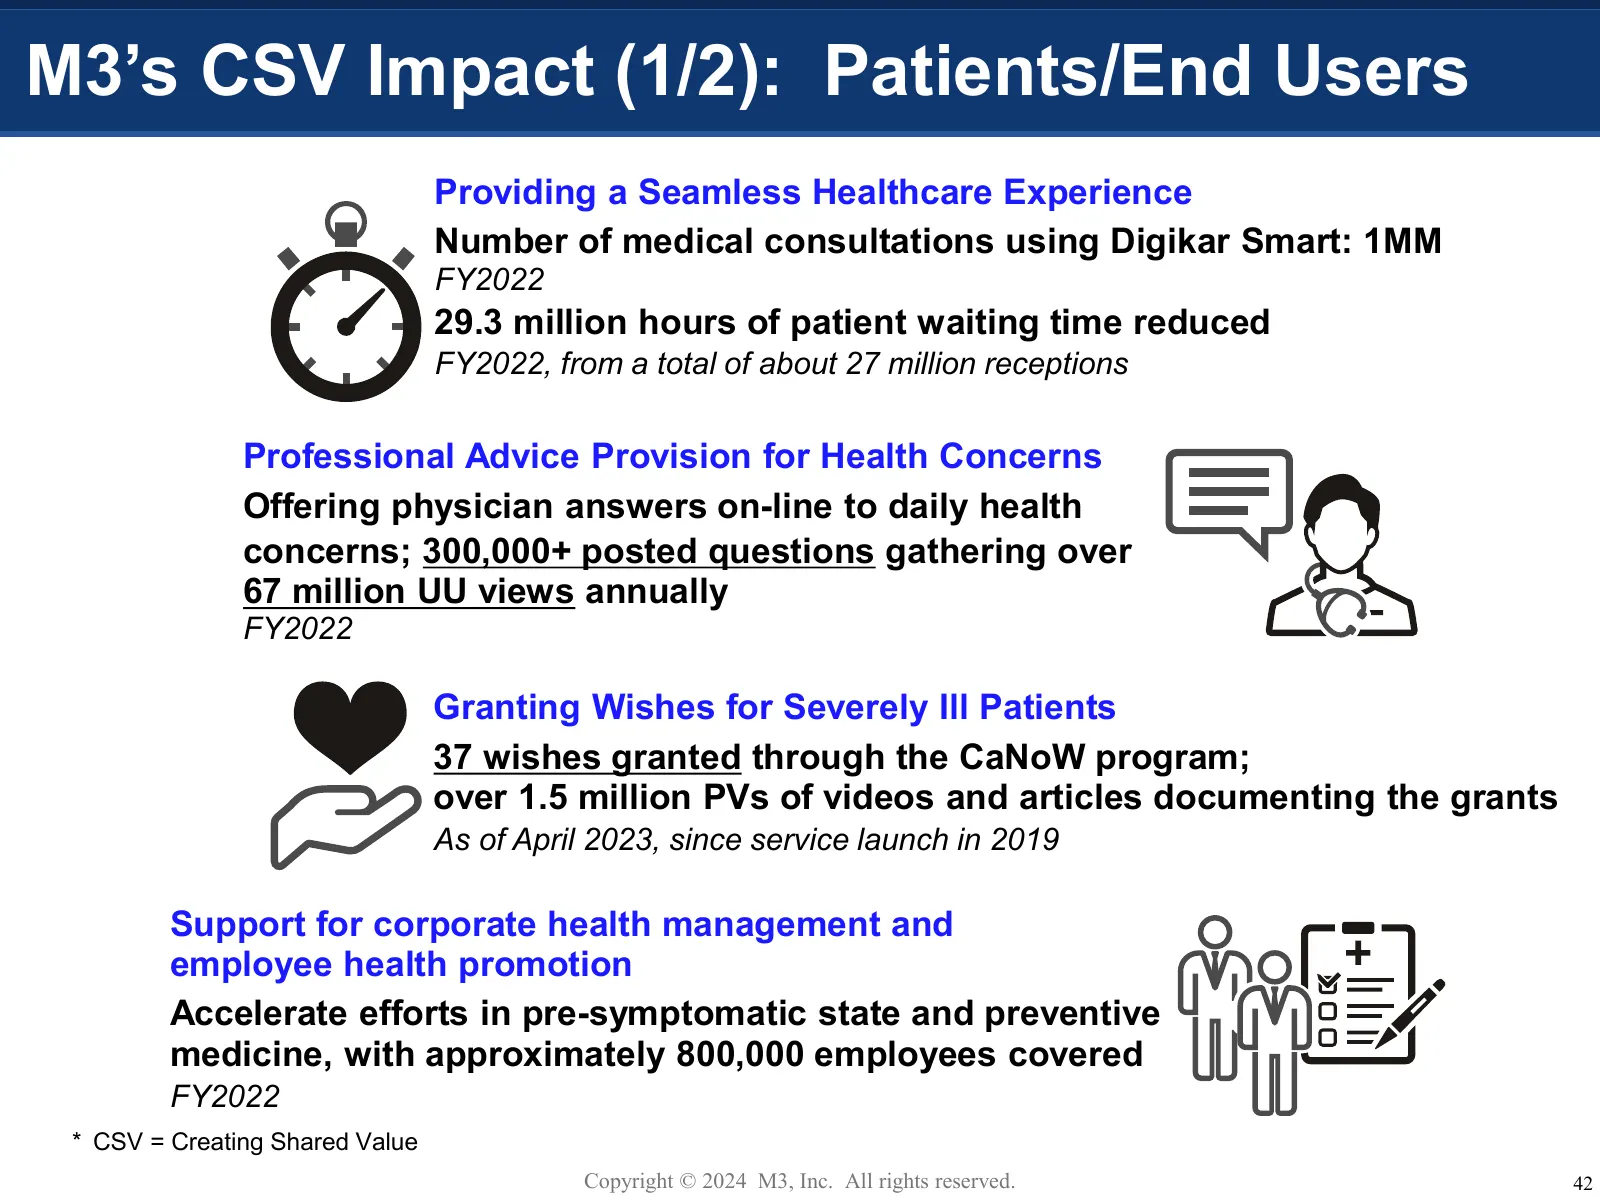
Slide 43: M3's CSV Impact (1/2): Patients/End Users
M3’s CSV Impact (1/2): Patients/End Users Providing a Seamless Healthcare Experience Number of medical consultations using Digikar Smart: 1MM FY2022 29.3 million hours of patient waiting time reduced FY2022, from a total of about 27 million receptions Professional Advice Provision for Health Concern
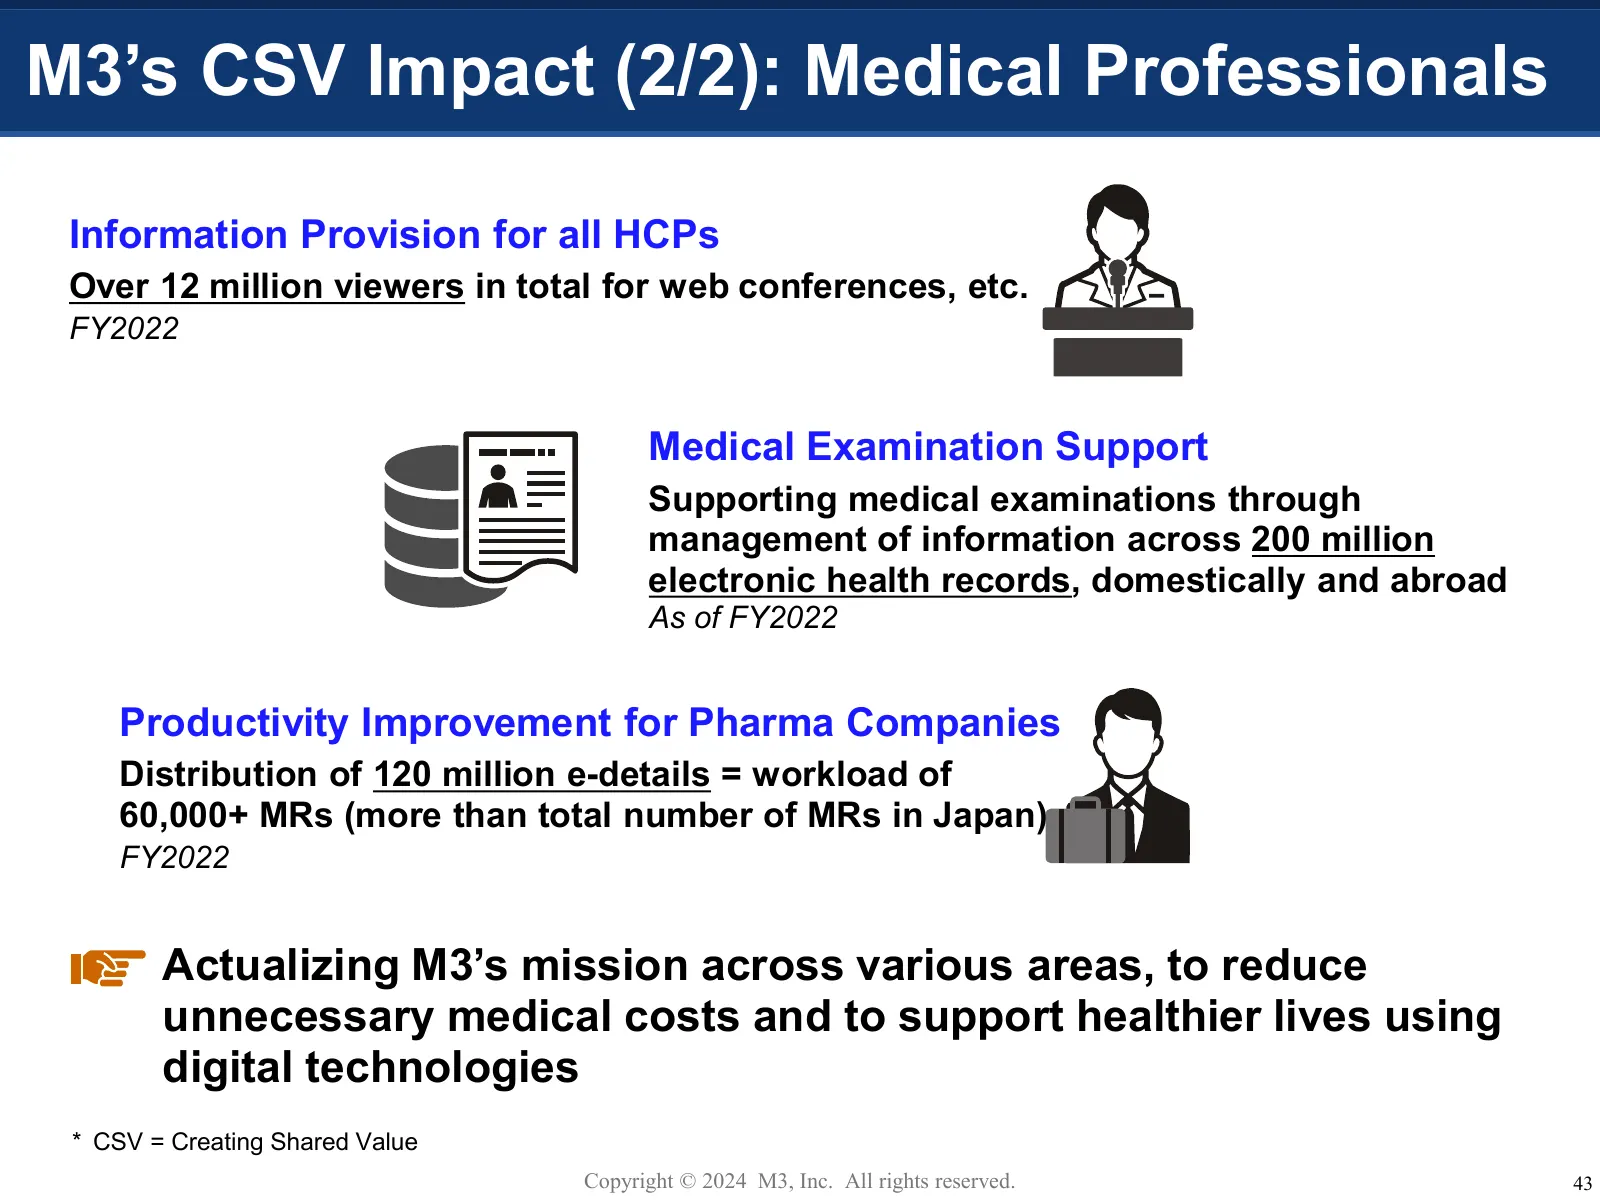
Slide 44: M3's CSV Impact (2/2): Medical Professionals
M3’s CSV Impact (2/2): Medical Professionals Information Provision for all HCPs Over 12 million viewers in total for web conferences, etc. FY2022 Medical Examination Support Supporting medical examinations through management of information across 200 million electronic health records, domestically a
Slide 45: FY2023 Outlook
FY2023 Outlook Copyright © 2024 M3, Inc. All rights reserved. 44
Slide 46: Annual Results
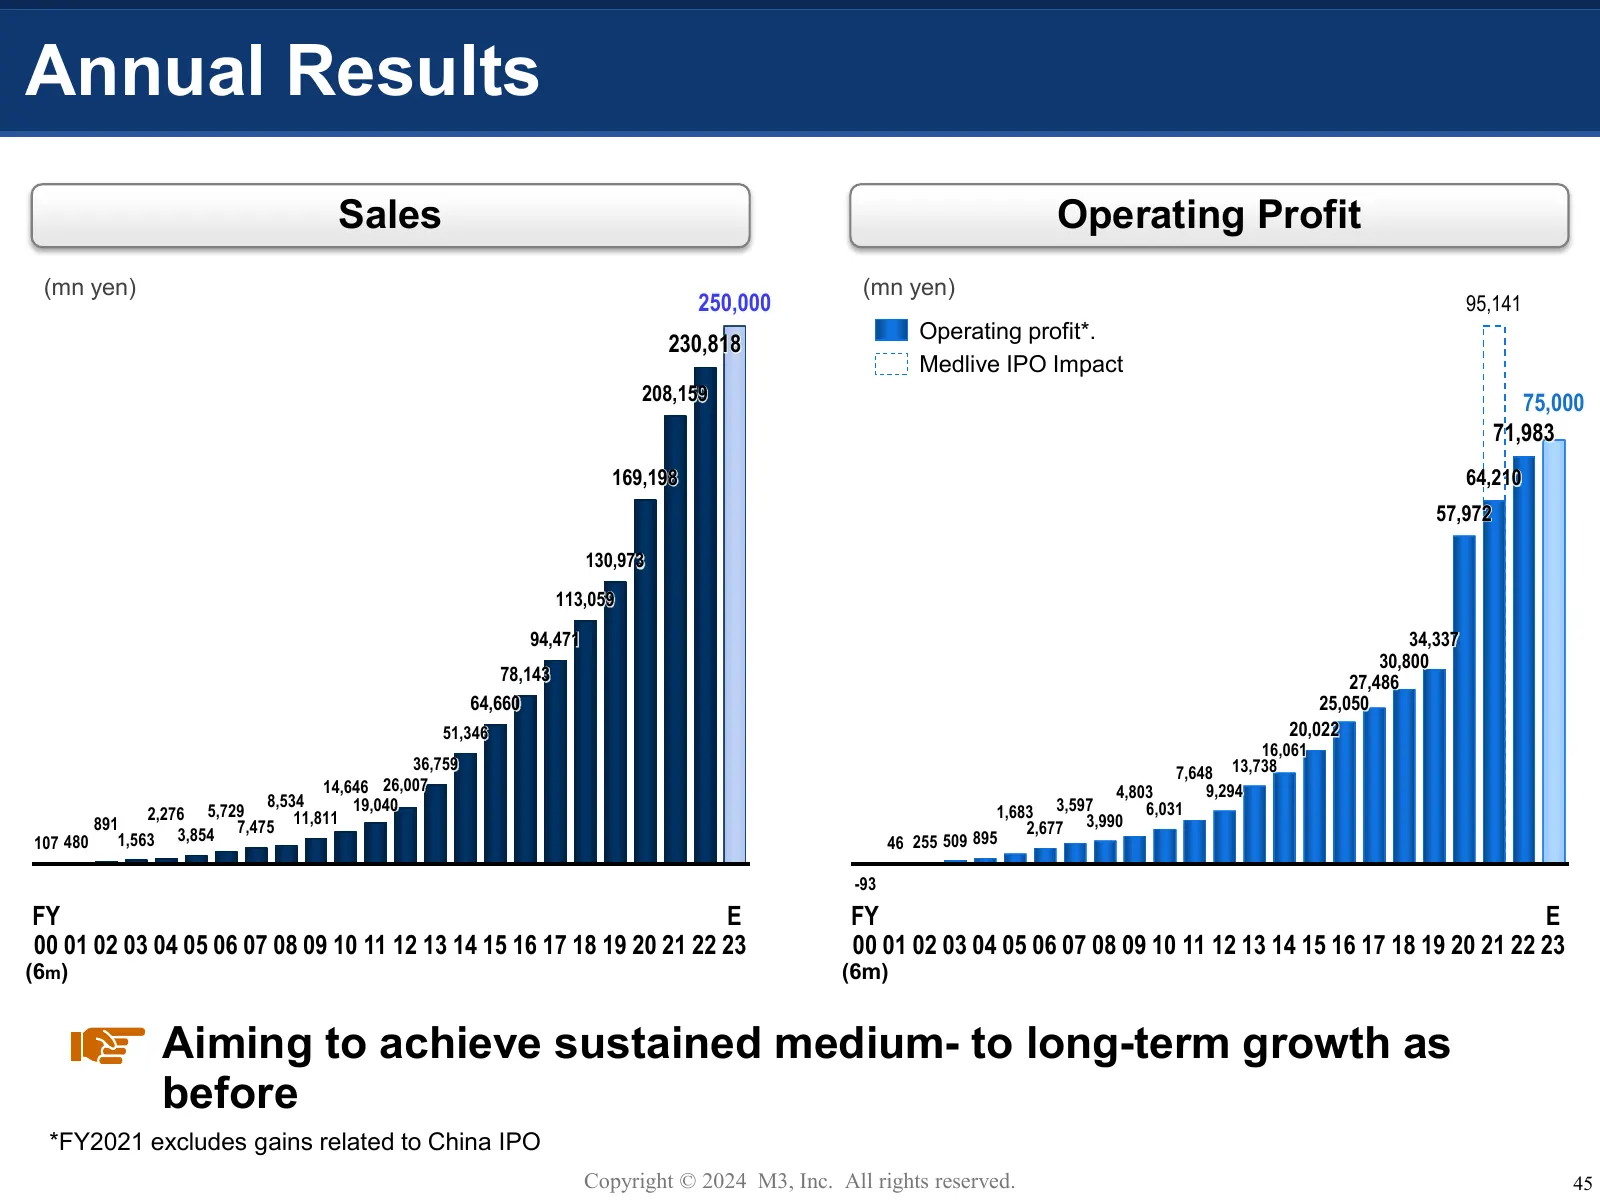
Annual Results Sales Operating Profit (mn yen) (mn yen) 250,000 95,141 Operating profit*. 230,818 Medlive IPO Impact 208,159 75,000 71,983 169,198 64,210 57,972 130,973 113,059 94,471 34,337 30,800 78,143 27,486 64,660 25,050 51,346 20,022 16,061 36,759 7,648 13,738 14,646 26,007 4,803 9,294 8,534 1
Source: Internet Archive copy of corporate.m3.com
More decks from M3, Inc.
 Investor Presentation (November 2026)8 slides · Nov 20, 2026
 H1 FY2026 Earnings Presentation44 slides · Nov 4, 2026
 Q2 FY2026 Earnings Presentation44 slides · Nov 4, 2026
 Q1 FY2026 Earnings Presentation42 slides · Aug 6, 2026
 Merger or Acquisition (June 2026)14 slides · Jun 5, 2026
 FY2025 Earnings Presentation54 slides · May 1, 2026