Transcript
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:04 Hello everyone and thank you for joining us today for this live White Gold Corp presentation. We're joined by David D'Onofrio, CEO, and Donovan Pellet, President of White Gold Corp. I'm sure you're all excited to hear their commentary on today's announcement of the PEA results for the White Gold Project, follow the discussion. They will be available to answer your questions, so do, if you have any questions, please submit them throughout the presentation using the chat box in the bottom of your screen.
0:30 Also, if you'd like to have a more involved conversation with the team, when we close off today, there will be a meeting request pop up that will appear on screen. So simply submit that request and I'll pass it along to the White Gold team and one of them will connect with you personally. As always, this event is being recorded and will be available for replay shortly after we conclude. With that said, David, the floor is yours. I'm just going to be in the back screen managing the deck, but the floor is yours. Thank you so much, Kyle. It is great to be here today. We have announced a tremendous milestone for our company. First and foremost, really want to thank and congratulate all of our supporters and stakeholders that have helped us to get here. I have with us Donovan Pollitt, a recent new addition to our team who's been able to add a tremendous amount of value in a very short period of time and we're incredibly enthused about the additional value that he will be able to add going forward.
1:30 Dylan Langeau, our newly added rock star, pun intended, unfortunately cannot be here. He is on a plane up to the Yukon to go find more Gold. So we gave him a pass for that. As people likely know, but I'm always keen to remind viewers, what is White Gold? We are an exploration and development company. Our projects are in the Yukon in Canada, in the Klondike District. This is the area made famous 125-years ago, which was the epicentre of the notorious Gold Rush that has now seen over 20Moz of Placer Gold mined in this district. However, it was not until just recently when Sean Ryan, our partner and co-founder, was the first person to be able to really unlock the value there and crack the code on how to discover hard rock sources of this Placer Gold and additional bedrock-style deposits.
2:32 Our company, following his guidance over the last number of years, has continued to be very successful. We have delineated a 3Moz resource. It is the highest grade deposit in the Yukon with a significant upside for growth on the deposits itself and within the immediately surrounding area. What's I believe as or even more exciting than the success we've had to date is the size of our land package. When Sean realized what indicators were indicative of this type of resources, he then took that technique and data exploration approach and tested basically the entire region. He deployed one of the largest soil sampling protocols ever.
3:20 And from that, he then hand-selected and curated the portfolio, which White Gold owns today. It consists of 21 properties covering 300,000 hectares. We believe it truly is a district scale opportunity. We are in very early days, I believe, of unlocking these potential. And we're also fortunate now in a time where we've started to see the area come into development. We have a neighbour to the south of us, Tallamore. They own the Coffee to Project, which was another of Sean Ryan's discoveries. It is an incredible deposit. It is very advanced. It is fully funded to head into production, which they believe can start as early as the beginning of next year. This exciting opportunity, which in theory was so attractive and exciting 10-years ago when White Gold was created, is now becoming a reality.
4:16 We've now advanced these projects to this very material milestone of being able to put economics around it with our maiden PEA. And at the same time, we're as or more excited about the continued upside for this project based on historic and ongoing drilling and the future potential we see on the projects and within our other properties. With that, I will turn it over to Donovan to dive into the PEA and we can continue our discussion as we go forward here. Thanks, David. I appreciate that. It's exciting to be able to tell you all today about our maiden PEA on the White Gold deposit. This has been months in the making and we're happy to go over it with you here today. If we could advance to the next slide, please, I'd appreciate it. What we're talking about here is a simple truck and shovel operation, open pit only, that has an NPV of $1.9Bn at $3,600 Gold.
5:15 We've already had feedback on the conservatism of some of the assumptions we've used in this, but we think this is an excellent starting point for making everybody aware of the value that is already in this deposit on a resource that is from 2-years ago. So you can start to see that there's a fast payback period of 1.7 years based on the higher grade, the higher grade profile of this deposit. And I think that's something that really differentiates it from some other things in the market right now. The 38% after-tax IRR is also compelling. And as I mentioned, this is just a starting point. This is two thirds of the known resource on what we have currently mapped into a nine-year mine life. And I think it's a great position to build on. So if we can move to the next slide, please. I think when we start to apply a higher Gold price, like US$4,500 an ounce, you start to see an after-tax NPV5 of US$3Bn.
6:17 So this is really where, I mean, You start putting close to spot prices in, this is very compelling. I think a lot of people didn't understand the value of the deposit. And I think even with a fully loaded CapEx and a bunch of conservative assumptions, we deliberately derated the first year of production to 85% because I don't know 1 deposit that has started at 100% production capacity in the first year. We deliberately put all of the capital requirements in to get to what we think would be a 12,000 ton a day operation. So this is a great starting point for a district that, as David mentioned, is huge. This year we are completing 15,000 to 20,000m of drilling in the goals of expanding these deposits, either along strike or at depth, which is lower risk, higher probability drilling. Again, no guarantees of success, but more likely than Greenfield exploration.
7:21 And we think that this is a district. We have 4 really great deposits that comprise the resource and all of them are open in every direction. I've said it on previous calls, I'll say it again. David mentioned Dylan Longille, who joined the company last year. Dylan joined from Great Bear Resources, then Kinross. Dylan was on the discovery hole at Great Bear. He stayed with Great Bear until about 4Moz and stayed on with Kinross to drill it up to 7Moz. I can't personally think of a better person to drill our deposit from 3Moz upwards. We want to show you today that a lot of people throw around the millions of ounces numbers as though, you know, that's pocket change. Already what we have is very compelling and is not reflected in the current shareplace. You've seen that this morning, had a nice response to the release of this.
8:13 I think as people sink their teeth further into this and realise that there are 25 targets currently on our property package, there's a lot of room to grow what we have and not just grow the market cap, grow the value per share. The entire point of this year's drilling program is to increase the ounces per share and to increase the value per share. And this PEA is 1 of 3 legs of value creation that we set out on this year to increase your value per share. Can we move to the next slide, please? So going through it, as I mentioned, it's a 12,000 ton a day project. That is not absolutely enormous. It's not the same size as some of the biggest pits in Canada, but it's not a small project either. It's a real project.
9:07 We've got a 1.54-gram head grade, and that's really the differentiator on this versus a lot of other open pit projects,
9:15 almost a 50% higher average head grade than a lot of other things out there. As I mentioned, this is only incorporating about two thirds of the total resource that's currently identified. And we deliberately did not proceed with an underground scenario in this. It's just open pit. There is potential for underground. We could have proceeded with an underground scenario here, but Dylan's in the process of identifying more mineralization at depth and a long strike on the Golden Saddle. And I think it would have been premature to include it in this. I think it's another lever for value creation going forward and it's something that we can look at in subsequent studies.
9:57 This is a fully baked, all-in cost, processing at US$27 a tonne. Some people will look at that and say, isn't it US$20 in Timmins? And it is, but we've included the fact that we're going to need to move diesel to site. That's going to be higher power generation costs. So when you look at this PEA, you should look at it and think this is well considered by someone who would look at the real economics around building something like this and it stands on its own as is, let alone all of the upside we feel is in the property package to be identified this season, next season and many seasons to come. So I'm quite excited to be going over this right now. I think this is an exciting juncture for the company and I don't know if we want to go to the next slide and talk about the Gold price sensitivity on this.
10:51 But yeah, as we start to look at the base case sensitivity, even with an after-tax NPV at $3,600, I think it's compelling, but you start to look at $4,200 and $4,500 and it becomes extremely compelling. So if you're bullish on the gold price going forward, I think this project only gets better. And I think with added exploration upside added to this, it will make these numbers even better. So I think the next most important thing to look at after this is the next slide talking about location and infrastructure. This is a very small percentage of the property package that Sean Ryan assembled. This is a truly spectacular property package.
11:38 You know, it's mind boggling how big it is and how much gold could be hiding there. We're just looking at a very small section in that small little rectangle in the middle with the 2 Gold stars and that's not even fully identified within that rectangle. You can see we're immediately to the north of the coffee deposit, which is now being developed by Talamore and not too far from the casino deposit for Western Copper and Gold. This is a very exciting time to be involved with this project because Talamore proceeding towards production with their coffee deposit and upgrading the Northern Access Road, which is the green road connecting Dawson to the coffee deposit. This is a very exciting time to have our study come out because we feel that this district is just getting going and it's just getting started.
12:33 I'm trying to think if there are any points to cover other than that. If we move to the next slide, maybe we can cover the mineral resource estimate. So, again, it's a higher grade resource and that's what enabled the faster payback period and the higher grade production profile, as well as a competitive all-in sustaining cost per ounce, but only
12:58 60% of our current resources in this PEA. So our goal is to increase this resource and increase the economics over time. But again, we wanted to give institutional investors and retail investors some parameters, be it operating parameters, OPEX, CAPEX, timelines in order to make their own models and come up, do their own math in order to understand the value that's already in the ground, that's already been identified. If we can move forward to the next slide on processing, This is a simple processing flow sheet. It's crush and grind, 12,000t a day, 87% average recovery and these are base metallurgical assumptions. There's potential to improve them with detailed metallurgical testing going forward. But again, this is a starting point, not an ending point.
13:50 We haven't, we're not standing on our tippy toes. This is, there's a lot of room for improvement. This is just to put some meat on the bone so everybody can understand what's already there.
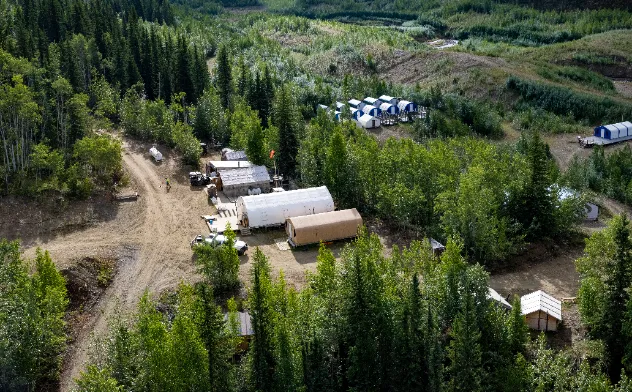
14:03 But yeah, carbon leach flow sheet, the golden saddle in the VG actually average about 92% in leach recovery. So that's very, it's very promising for future developments and growth of those zones. If we can move forward to the project infrastructure slide. This should give everybody a very good example. This is like a zoom in on that little rectangle we had on the property wide package. This is this is a very small portion of the property package. There's a lot more gold to be found on these properties. This shows you open pit highlights where the engineered tailing storage facility would be in the yellow and brown. All the infrastructure required for production with onsite power plant, bulk fuel storage, full camp, an airstrip big enough to land a 737 for rotational crews to come into and out of, and an access road tie into the northern access route for moving equipment and materials to site.
15:12 So this should give you a good idea of the scale of the infrastructure that's contemplated with this. But if you look at our corporate presentation, you'll also see that across this entire plan view, there are soil geochem showings across the entire property. So there's a lot of room to grow this deposit and iterate on this plan. The best part of this plan was that there are multiple locations to put a milling facility. There are multiple locations to put a tailings management facility. This is just 1 study and it's showing that there are many paths forward for this deposit and this is one of them, but we think it's very promising based on what we've seen so far. If we could move to the next slide with a breakdown of the capital.
16:02 The PEA contemplates, this is a breakdown of the capital costs associated with developing this deposit. These are larger numbers, but I think realistic numbers. I think anybody who's trying to develop something in this part of the world needs to give realistic numbers that this is going to be a big operation and it's going to have a nice size ticket cost with it. But as you can see with the revenues and the payback period and the NPV, it's all well worth it.
16:37 You're seeing the lump of most of the costs in the mining and the mineral processing, but infrastructure such as power plant also plays a pretty large role in getting this up and running. The good news is that once a mill like this is established, is that any incremental feed that is found in the district, which I believe there's lots of, should all just be subject to operating costs and then flow to the bottom line. So I think this is actually a really great place to start because a 12,000 ton a day mill could run, I think for decades, if exploration is successful and you keep finding satellite zones to feed it. And I think that has appeal to larger operators who have a longer view than just after you discount something for 10 years and an NPV5, the 11th year doesn't have too much value.
17:29 But anybody who's been in this game long enough knows you want multi-cycle assets to be able to benefit from multiple gold prices. And I believe this asset has that. So I think this is really great. If we could move on to project opportunities on the next slide.
17:47 So like I mentioned before, this is a great slide because I showed you a slide with all the infrastructure and this is almost the same view, but showing a lot of the soil geochem
18:01 heat maps of where Gold has been found in the surface, overlaid with where a lot of our zones are, the Golden Saddle zone, the Arc zone, Hawaiian Surprise. So what you're seeing here is just how big the system is. And we barely started drilling it. There's only 90,000m. David, are you going to jump in? I think that's exactly what you're going to say. We cannot underscore enough our views on the growth potential of this project. In the past number of years, we have been focusing on identifying new potential zones of mineralization using the same protocols that Sean Ryan has developed that has been so successful. And that is what has donated.
18:46 We see 25 targets on this one project alone. As you go North of the river where we have the VG zone, there's another, at least a dozen different targets on the areas where the work has been done. The system is continuing to look to be bigger and bigger. Dylan has identified potential where these zones could be connecting at depth. But in the past couple of years, what the strategy has been, after we identified the zone, we did enough work to demonstrate that there'll be a small resource there. We then left it to go find the next one and the next one waiting for the opportunity when the market and it made sense for us to raise the appropriate amount of capital to go back and follow up. As Donovan said, we are viewing this, we operate as investors. We are looking to grow the value per share in our company. And that is where we are today.
19:37 We are in that position where we have our largest drill program in the history of our company underway. It is orders of magnitude of anything that we've done in the past, 70 to 80% of that is focused on growing known zones, which should be the highest probability type drilling. However, we do have a number of new targets, which look very perspective that are drill ready, that we're looking to be able to drill this year. We'll likely do another webinar with Dylan who can talk some more about those, especially once we start to get results in the near future. But this to me, like as happy and as excited as I was to see the economics we had as a base case. What's so compelling is the continued upside potential of this property alone, let alone the latent value in the balance of our district, which I believe now is gonna, you know, we'll see the leverage to unlock it with the infrastructure that's coming in as part of the development of the Talamore project being that northern access gateway. It allows us to have road access to all our properties and become a hub and spoke type production model, which is what you typically see in these evolving camps and Val d'Or, Timmins and some of these other different places. So the setup is really great. We're doing the work.
20:53 We're funded. We have the team in place to do it. And the stars have really aligned. And as I've said many times, When we looked to evaluate projects with the Power 1 Group, who are partnering with Sean, White Gold really checked all the boxes in terms of potential. Now those potentials are becoming reality. We're in a great jurisdiction. It's just gotten better. There's a new conservative government, very pro-mining. We see permits happening. We're very fortunate to have great relationships with our First Nation partners who are also supportive of the work that we're doing, as well as that of the other companies. We're in a supportive commodity environment. And most importantly, we're in a geological terrain that I believe is as a more
21:36 perspective than anywhere else in Canada. It's just that we are now starting to do the work 50 years later than some of these best areas in Quebec and Ontario. So Our vision in day 1 was that this White Gold offered the potential to own the majority of a new camp within 1 company. And we're starting to see that vision becoming more probable and becoming a reality. Today was a great first step. And I think our best days really, really could be ahead of us here. I think that's a great, great summary of it right there.
22:10 You know, I think looking at this right now, we mentioned Sean Ryan as a, you know, the person who put this all together and we've benefited greatly from his expertise. We continue to benefit from his expertise as a board member and contributor to the group. I'd also be remiss actually if I didn't spend a few minutes talking about the whole team that works under Dylan. We've actually got a lot of excellent geologists come from very well-known companies working with Dylan on this and everybody's very excited about all the different places we can find more Gold. There's a solid group of people making this all happen. It's not just the people you see on these webinars. So the team is bigger. There are about 40 people in the camp right now making the 3 drills turning work.
23:00 It takes a lot of people to make these things happen. And it takes a lot of years to make these things happen too. I mean, every overnight success is usually 5, 10 years in the making and white Gold is no different. People have been slogging away at this for a long time And we finally got the stars aligning for us with the commodity price, with the equity markets, with the geology.
23:27 So, this is a very good time to be bringing this project forward, especially with, as David mentioned, our neighbours at Talamard proceeding to production. I think these are the opportunities. As I said, resource conversion, the more we can drill and update our MRE either later this year or sometimes next year, depending on the timing of the assays, that's all upside. Underground, I mentioned underground. There is already an underground. There is a scenario already mapped out, but it wasn't included in this because I believe Dylan had a great pull last year over 3g, just over 50m. This year we're putting a lot more holes to try and expand that underground thing, underground mineralization. That's something for the future. That's all upside. That's not in this.
24:14 Metallurgical optimization, that's for down the road. District, We talked about the 25 zones in the district and the satellite feed. Maybe we can move to the next slide because this just shows how everything is open. Ryan Surprise, open along strike. Arc trying to drill down beneath the deposit. All things that could potentially add resources and lower the strip ratio, which is fantastic. And then Gold Saddle, as you can see the arrow pointing down and to the right, that's Dillon's drilling at depth, trying to see what happens there. Across the river on the top left, we have the VG, which is also getting drilled this year, which is a very high-grade zone actually, and could potentially add to this as well.
25:01 If we could move to the next slide on pure comparisons, I think this is a great slide showing the weighted average grade. It just shows where white gold sits. It just shows there's opportunity for enterprise value per ounce re-rate. I think that's a cornerstone of this. I think this is under-owned by institutions. It's under-owned by retail. And this PEA, as well as drill results, is part of our campaign to re-educate everyone
25:30 on the value proposition of this deposit. I think this is an important slide to look at and an important slide to digest. If we can keep finding high-grade, we're just going to try and play to our strengths and push this harder. If we can spend the next slide talking about the critical mineral spin out. David, do you want to handle this? Yes, for sure. This again plays to the value of owning this enormous land package, which frankly, I do not think you'd ever be able to go and recreate today. This was curated by Sean Ryan over 15-years. We're very fortunate that in the Yukon, it's relatively inexpensive to maintain these claims. I think in other areas around the world, it just wouldn't be possible.
26:16 That ability to keep these claims has allowed us to do significant amounts of work over the last several years. We're a Gold-focused company. We've been set out to find these different potential mineralized bodies of Gold. However, while doing that work over the last several years, we've identified some very compelling and prospective targets that were rich in minerals other than Gold, primarily Copper, Molybdenum, Tungsten, Antimony and some of these other very topical, critical minerals. As people I'm sure are aware, metals and minerals have not only become politicized, they become weaponized. We've seen south of the border, tremendous amounts of attention and capital from the current administration being invested directly into this. In our area is the casino deposit owned by Western Copper and Gold. It's one of, if not the largest undeveloped copper projects in Canada.
27:18 That is of national importance, has been specifically referenced from the Prime Minister's office. So it really shouldn't come as a surprise that this area could be fertile in other types of minerals. After the identification of these opportunities, we've continued to test them and they've really been verified as bona fide targets. Being in the shadow of this big project that really should come as no surprise. And furthermore, there's a very significant Copper Belt, which starts at the Southern end of our project and continues South along the Big Creek Fault. This hosts a number of other very well-known deposits, including the Minto, Selkirk and Carmax with Cascadia.
28:06 We've done geophysical work, following on our geochemical discovery of these targets. That has only further validated the potential. They've really lined up. So we're now at a point where we want to ensure that these targets can get the attention and the expertise that they deserve. What that led us to was a decision to isolate these properties into a new company with the shares of that company to be distributed to our White Gold shareholders. The vote for that is actually tomorrow and if approved shareholders of White Gold will get 1 share of this new company called W2 Critical Minerals Corp for every 5 shares of white gold that they own. The specific record date is not defined post our special meeting, assuming it's approved. It'll then go through the process with the courts in exchange for final approvals.
29:03 So at some point, potentially in the coming weeks, we'll know exactly that record date. I believe that these properties are very prospective and we're very enthused about their potential. So again, this is another attribute of the value of this land package. And this other reason supporting our decision to do this, again, thinking as shareholders first, if our company is still trading at a significant discount to its peer group on a dollar per ounce basis, just for our Gold resources, which are of the highest grade, some of the highest growth potential, some of the closest path to production, that means we're really getting no value whatsoever for these properties. So by spinning them into a new company, distributing the shares to our shareholders, that will unlock value for our shareholders. So I believe this is a very perspective project portfolio and it is a great way to unlock some additional value for our shareholders.
30:17 Great. Maybe we should move on to some questions if there are any. Yeah, perfect. I can moderate them. There have been quite a few questions. We'll start from the top here. Great presentation, by the way, gentlemen. Quick question regarding the processing. What is the grind size assumption in the study? I'm gonna have to answer that in a minute. I just need a second to pull it up. Yeah, no problem. No problem. I can move on to the next one while you do that. The press release mentions capacity to accept feed. What is mil capacity versus the average 12,000 tons per day throughput? The mil spec for just over 12,000 tons a day I would be running pretty much at 100% or 95% capacity.
31:08 Perfect. And then can you speak to the Delta from the MRE recovery assumption of 85% for a study of 72% for ARK and Ryan's. 85% is typically the average across everything. So you've got a split between 92% in gold saddle and then, and then 70, low 70s for ARK and Ryan. That's just the difference between the average of the 2, but the bulk of the tonnes is at 92% recovery in the Gold, Saddle and VG. Just to touch on that a little further, what's really interesting, the Gold, Saddle and the VG, that makes up about 80% of our resource, so 92% recovery. It's fabulous. The ARK and the Ryan's, the metallurgical evaluation that was a big part of our current PEA, they were able to significantly optimise that from what had been identified 10 years ago. We believe that there's additional opportunity for continual optimization.
32:11 And that is actually quite exciting for me to hear because these are very big targets with lots of growth potential. However, in the past, they didn't get the attention because people or the team thought with that type of recovery, why would you bother investing your drill dollars there? Just keep chasing the super high-grade stuff with the great recoveries. The ARK, for example, it's a kilometre and a half of a footprint. It's only been drilled down to 100m deep. The ability to grow that significantly is very compelling. And we believe that's something that can be done on a low cost basis. So this successful optimization study really opened our eyes to the potential for the ARK and the Ryan's and many of the other targets which have similar looking type signatures.
33:04 Great, thank you, David. Let's move on to another question here. I have one question on drilling. How much has been drilled and included in the PEA? How much drilling is drilled and not included? And how much drilling is funded and left to do? I can answer that. Everything in the PEA was based on 90,000m of drilling to date. Last year, about 2,500m was drilled, which was not included in the PEA. This year, the plan is to complete 15,000 to 20,000m of drilling. And I give a range on that because frankly, it's been difficult organising logistics in the territory, but we're hopeful we're going to hit the midpoint of that range. So to answer the question, the 90,000m of drilling is what the resource for this PEA was based on. The date of that resource estimate was August 19th, 2025, if you go on to CDAR.
34:00 Again, all the drilling from last summer came in after November 1st, 2025, and that was press released, but was not included in this PEA. And all the drilling from this year will be released later this year and hopefully included in a mineral resource estimate update in due course. And just to add to that, there's also 7,000m of drilling that was discovered by our team through our hanging wall section of the Golden Saddle, which we are in the process of re-logging and will be assayed this year. So it's a very significant amount of what I'll call free metres we can look for results for. And anything we find there will be accretive to the size of the resource and potential economics. Any colour on the 9 to 1 strip ratios, maybe in terms of how they differ between the 4 pits and pit slope assumptions used to get there?
34:54 Yeah, so the 9 to 1 pit is an average across several pits. There are 4 zones incorporated in this study. The 9 to 1 is an interesting number because it's a little higher than most people would expect. But that's just a testament to how profitable everything is now and how deep the pits ran due to running scenarios at $3,600. You could run a lower tonnage scenario, say an 8,000t a day scenario for almost a similar NPV, but slightly lower with a lower strip. However, due to Gold economics being what they are, We elected to run a 12,000t a day scenario for full NPV maximization here. Again, the best part of this deposit is that it's scalable across a lot of different parameters.
35:41 So you could run something closer to a 6.5t, 7.1t strip at an 8,000t a day operation for a lower total number of ounces. But the fact that the Gold price is where it is and the profitability is there allows us to push the pits deeper and take more waste. So it's a good question. The other thing I will point out is that a long strike drilling at Ryan Surprise, VG and any drilling sort of above 200m in arc should bring down that strip ratio because it would add in-pit material. Plus on top of that, on slide 11 of our July presentation, there's a plan view of all the unassayed drill material from underworld drilling days that is currently being re-assayed.
36:27 Anything above 0.38g a ton that is in the current pit model, that is in the current pit model is not, that is in the current pit in this PEA has not been factored in, and that could further reduce the pit strip ratio. Right, makes sense. Well, there's another question regarding this, so we'll stay on topic here. On the higher strip, does that mean part of the underground resources are being incorporated into the PEA pits? No, no, the underground would be a totally separate thing below a certain level. That's for another chapter for another day. I think Dylan's drilling is nowhere close to being done on that, and that's for the future. Regarding the economics, was seasonality of materials factored in, in brackets, this individual says, regarding shorter season and materials, et cetera?
37:18 Yeah, that's right. You have to talk about winter access roads or barge crossings in summer, barge deliveries of materials in summer. That was all factored in. There's a lot of logistics around setting up the big operation here. But yes, those were heavily discussed and incorporated into all the planning of this PEA. One question here. Are there deleterious minerals? Are there deleterious minerals? None in Golden Saddle and VG. There's a little bit of sulphide and Carbon that's sub-optimal in Ryan's prize and art, but nothing that can't be surmounted with a bit of metallurgy. And so that's the best answer.
38:11 Upon registration, there's questions submitted and I have one here. Any plans to uplist to New York Stock Exchange or NASDAQ? David, I'll let you handle that. And listen, these are good considerations, right? We're in a world now where all of a sudden, you know, different capital markets care about these gold companies. Something worth considering, Some of our other Power 1 companies have done it and seen a lot of success. So nothing in the immediate future. But listen, as shareholders, we're always open to ways to optimise the value of our investment. Looks like another question regarding the strip ratio here. One last one on strip. Can you speak to the pit slopes per pit that were assumed in the PEA shows? I don't have the exact numbers in front of me and I don't want to misspeak. I don't think extensive geotechnical work was done to optimise pit slope angles, I think is the safest answer to your question.
39:12 Is that an area for further reduction of pit strip going forward? I believe so. I think you need to have pretty extensive geotechnical drilling, joint mapping, joint characterization and everything to come up with ultimate pit slope angles. And that was not done because this is a PEA. This is a first pass. I think a generalized angle was picked by our engineering consultants that seemed reasonable for the district. And again, I don't think this was done to a PFS or a definitive feasibility study level. This is just a first pass. I just want to take a moment for people that came in a little later here. When we close off, there is a request meeting button. So obviously it was a very thorough press release. And if you want to meet with the White Coat team, you can hit that request meeting button. And as always, White Coat does have their book and link and all their press releases.
40:03 So very easily accessible company, just something to keep in mind with that. Please, we'd love to speak to interested parties, shareholders, stakeholders, by all means, we'd love to speak to people directly. Yeah, exactly. Now, Donovan, did you end up reaching out to that team member regarding their grind size? I don't have the answer, but if the gentleman or lady who asked the question wants to follow up with me later today via that link, I should have the answer by the end of the day. Great. We are getting a little long in the tooth here. We have one more question and then I'll pass it over to you gentlemen for closing remarks. Can you expand on the mine schedule? You mentioned that in year 1, you are only scheduling 85% production levels. Yeah, I mean, this again, this is a conceptual study, but like when I was on the buy side, you'd always see things that would start at 100%, which I've never seen actually happen. So the idea here was to de-rate the production in the first year to 85%.
40:58 Would it be 85%? I don't know. But would it maybe 80%, maybe 90%, maybe 75%? The idea is to give you a taste that this is actually, these considerations were made and factored in. This isn't standing on our tippy toes, trying to stretch for value. There's a lot of value already in this with conservative assumptions. And concessions were made, fully loaded diesel costs were brought into the power, the milling costs were reasonably high, and this thing still generates a very large NPV. So I think with further refinement, with further optimization, there's more low-hanging fruit to pick here. But the goal here was credibility and the goal here was, you know, ability to stand up for this study to stand on its own without modification.
41:47 So yeah, I think 85 is a good number to pick because there are always issues in startup and we wanted you to know that we'd consider that. All right, gentlemen, congratulations on this news. I will pass it over to David maybe for any closing remarks here, but a great update. And thank you everyone for attending and submitting your questions. It always makes it a lot more engaging of a conversation. So thank you for that. But David, over to you for any last words. Yeah, thanks so much. We really appreciate the opportunity to talk to shareholders and stakeholders. We're all in this together. Today was a very important milestone as we continue on our journey to unlock what I think is one of the most prolific areas in Canada as we continue to see this area move into development.
42:35 The historic past of 20 million ounces of placer gold, the success of our exploration program, I really do believe we're in the very early days of delivering further value. We have done a tremendous start, we have a tremendous team and I really want to communicate our gratefulness and that there will be a lot to look forward to over the coming balance of the year and into the future as we start to release, grow results and look to unlock value through these other levers, including introducing our story to the institutional community and working hard to make White Gold the best company it possibly can be. As I mentioned from the beginning, I think it really is a special company with a very unique opportunity. I personally have never seen something with as much potential as White Coast. So thrilled to be here, privileged to be here. Thank you to everyone for joining. Thank you to our team and our supporters and please stay tuned.