Nstar — Barclays CEO Energy-Power Conference 2011
32 slides from Nstar's conference presentation, Sep 8, 2011
Slide 1: Barclays CEO Energy-Power Conference
Barclays CEO Energy-Power Conference September 8, 2011 Jim Judge Senior Vice President and CFO David McHale Executive Vice President and CFO
Slide 2: NU Safe Harbor Provisions
NU Safe Harbor Provisions This presentation contains statements concerning NU’s expectations, beliefs, plans, objectives, goals, strategies, assumptions of future events, future financial performance or growth and other statements that are not historical facts. These statements are “forward-looking
Slide 3: NU Safe Harbor Provisions
NU Safe Harbor Provisions Information Concerning Forward-Looking Statements Relating to the NU–NSTAR Merger Additional Information and Where To Find It In addition to historical information, this communication may contain a number of “forward-looking statements” as defined in the Private Securities
Slide 4: NSTAR Safe Harbor Provisions
NSTAR Safe Harbor Provisions Information Concerning Forward-Looking Statements Additional Information and Where to Find It In addition to historical information, this presentation may contain a number of “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995.
Slide 5: Topics for Today
Topics for Today • NU Update – Transmission projects – Financial performance • Merger Update • NSTAR Financial Update
Slide 6: A Compelling Combination – Creates Largest Utility Company in New England
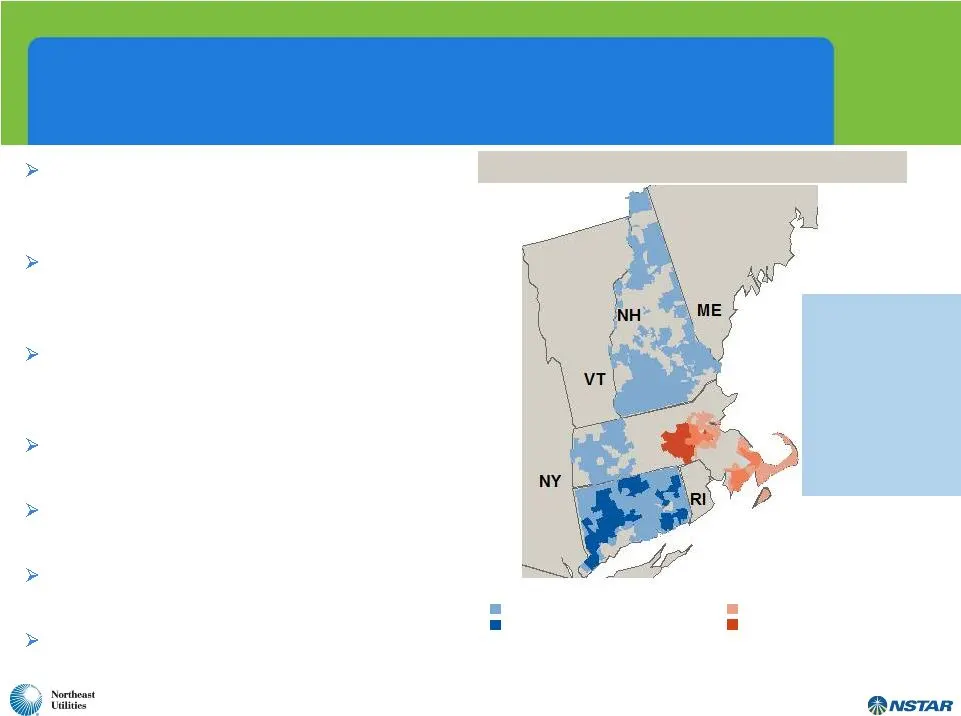
A Compelling Combination – Creates Largest Utility Company in New England Significant infrastructure investment opportunities combined with balance sheet strength provides for substantial growth potential Larger, diverse and better positioned to support economic growth and state public policy initia
Slide 7: Transmission Update
Transmission Update
Slide 8: NEEWS Projects Advance Current Status Report
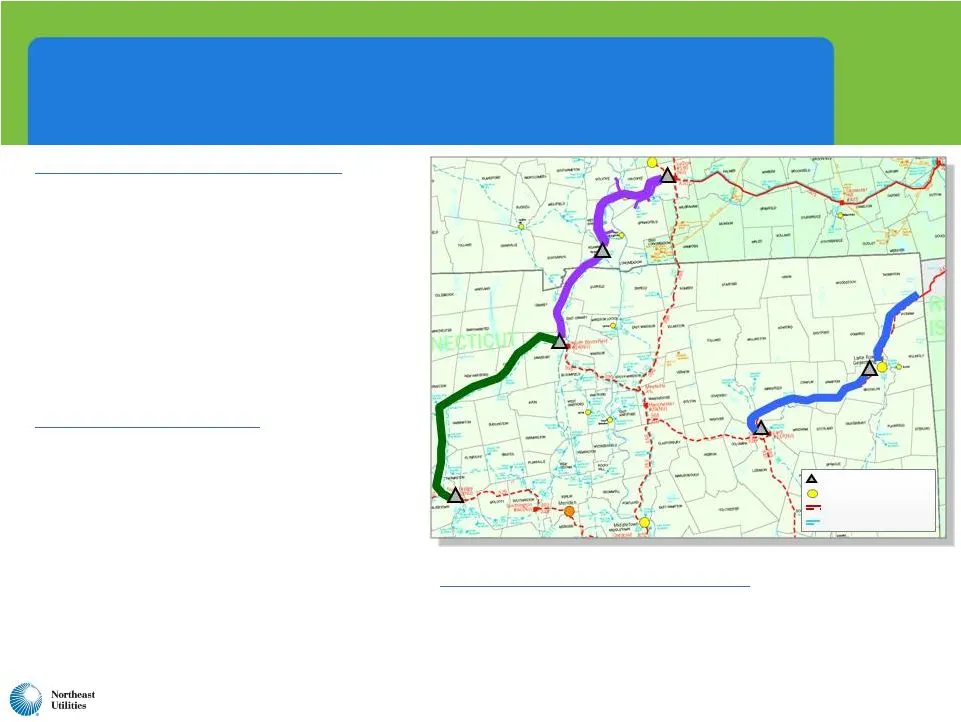
NEEWS Projects Advance Current Status Report • Substation construction commenced in MA in Dec. 2010; in CT in July/August 2011 • Commenced overhead site work in MA in February 2011 • Commence overhead construction in CT in early 2012 following receipt of environmental permits • Projected in-service:
Slide 9: Northern Pass Transmission – a $1.1 Billion Capital Investment
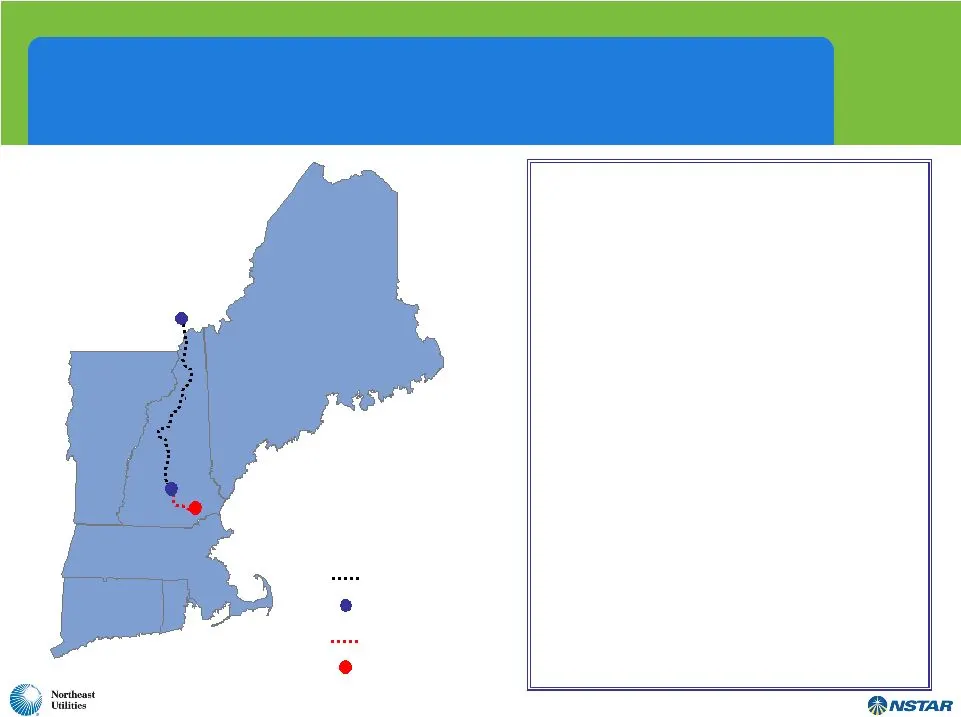
Northern Pass Transmission – a $1.1 Billion Capital Investment ´ • To be owned by Northern Pass Transmission LLC - NU (75%) and NSTAR (25%) • 1,200 MW transfer capability • Northern terminus at Des Cantons (Québec), southern terminus in Franklin (New Hampshire) • Québec terminal will convert the pow
Slide 10: Review of FERC-Approved Transmission ROEs
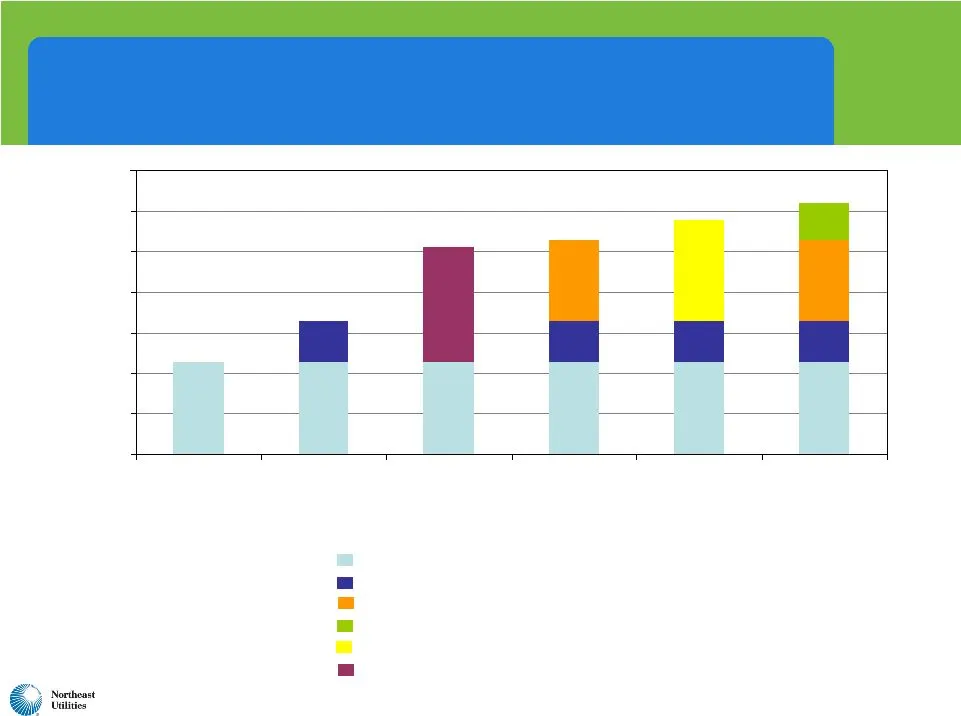
Review of FERC-Approved Transmission ROEs 10.00% 10.50% 11.00% 11.50% 12.00% 12.50% 13.00% 13.50% Local Network Service Regional Network Service Base Northern Pass 2005-2008 Regional Projects NEEWS M-N Underground NU’s Local Network Service Tariff ROE NE RTO Incentive adder of 50 basis points on PTF
Slide 11: NU Financial Update
NU Financial Update
Slide 12: NU – Strong First Half Earnings
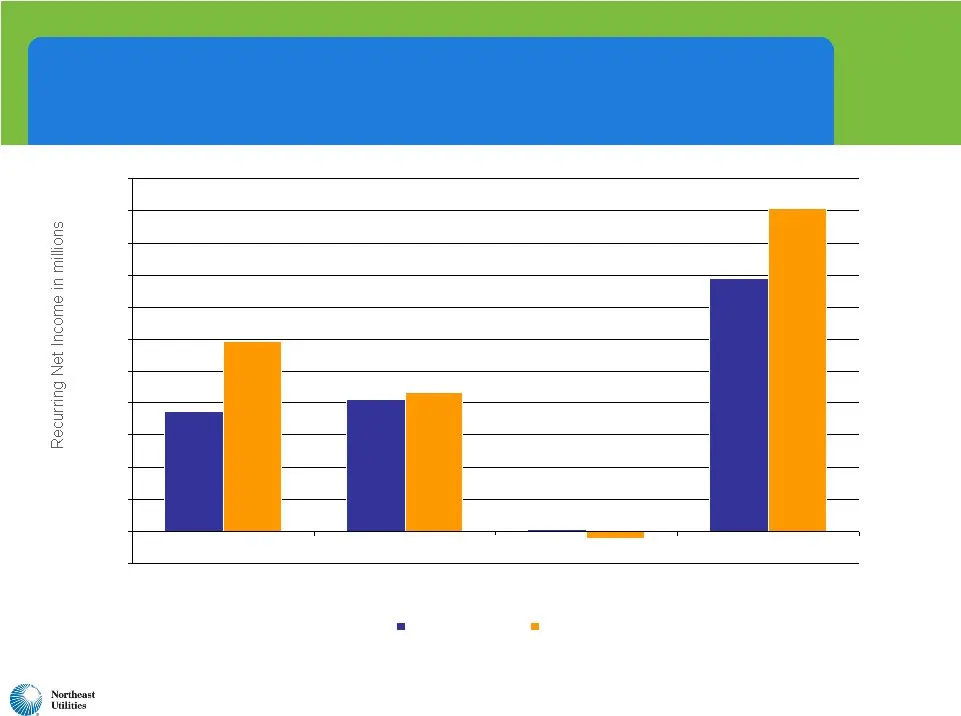
NU – Strong First Half Earnings $82.1 $158.2 $1.1 $75.0 $200.9 -$4.5 $86.9 $118.5 -$20.0 $0.0 $20.0 $40.0 $60.0 $80.0 $100.0 $120.0 $140.0 $160.0 $180.0 $200.0 $220.0 1H 2010 1H 2011 Distribution/Generation Transmission Parent/Other Total *Excludes $9.5 million of after-tax merger-related expenses i
Slide 13: 2009 and 2010 Results and Standalone 2011 Guidance
2009 and 2010 Results and Standalone 2011 Guidance 2009 Actual 2010 Actual Revised 2011 Guidance NU Consolidated EPS (GAAP) $1.91 $2.19 $2.10 - $2.20 Distribution/Generation $0.92 $1.16 $1.30 - $1.35 Transmission $0.95 $1.00 $1.05 – $1.10 Competitive $0.09 $0.05 N/A NU Parent/Other ($0.05) ($0.05)*
Slide 14: NU – Improved Earnings Have Resulted in Rising Dividends
NU – Improved Earnings Have Resulted in Rising Dividends $0.825 $0.775 $0.725 $0.95 $1.025 $1.10 5 62.5% 48.7% 44.3% 49.7% $2.16 ³ $1.86² $1.16¹ $1.59 Payout ratios EPS Dividends paid/declared per share Excludes net income of competitive businesses, one-time CL&P tax reduction Excludes litigation se
Slide 15: Merger Update
Merger Update
Slide 16: Status of Merger Approvals
Status of Merger Approvals Securities and Exchange Commission Shareholders Department of Justice Federal Communications Commission Federal Energy Regulatory Commission Maine DPUC Massachusetts DPU Nuclear Regulatory Commission Approvals Received Applications Pending Connecticut PURA New Hampshire PU
Slide 17: Massachusetts Hearings on Merger
Massachusetts Hearings on Merger • Hearings ended July 28 • Net benefits study anticipates $784M in net savings over 10 years Elimination of duplicative efforts Adoption of best practices Attrition/retirements – 350 positions over time • Attorney General’s focus: Customer benefits • Other intervener
Slide 18: NSTAR Financial Update
NSTAR Financial Update
Slide 19: NSTAR's Solid First Half Exceeds Expectations
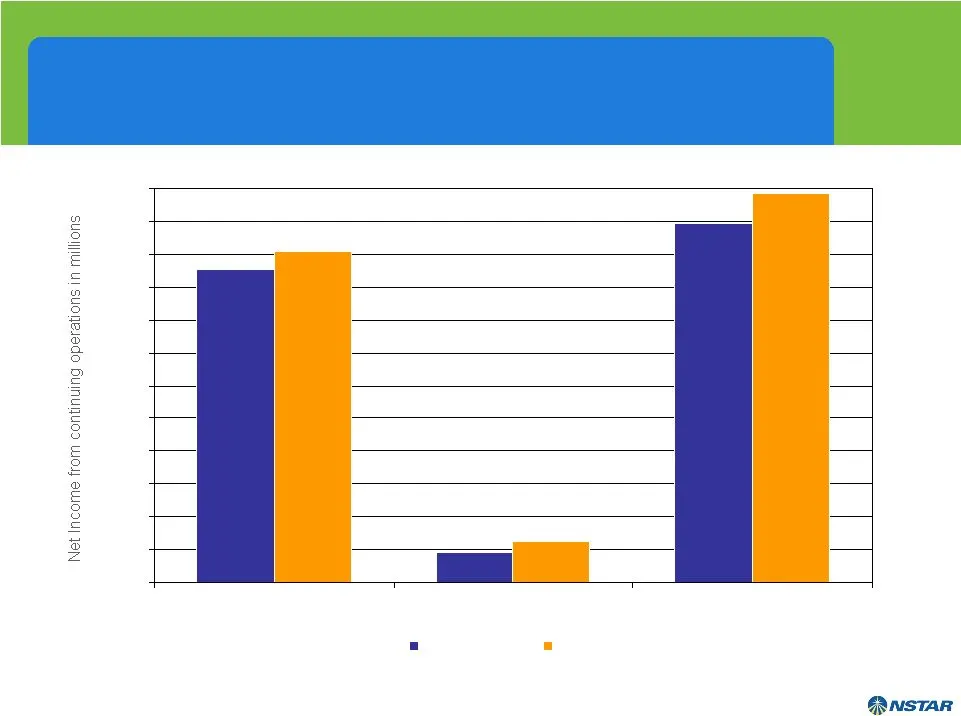
NSTAR’s Solid First Half Exceeds Expectations EPS $1.19 EPS $1.07 $14.0 $114.5 $100.5 $123.4 $17.6 $105.8 $5.0 $15.0 $25.0 $35.0 $45.0 $55.0 $65.0 $75.0 $85.0 $95.0 $105.0 $115.0 $125.0 Electric Gas Consolidated 1H 2010 1H 2011 Note: Results reflect continuing operations excluding merger-related cos
Slide 20: NSTAR System Has Significant Transmission Investment Ahead
NSTAR System Has Significant Transmission Investment Ahead • Transmission Rate Base is expected to double within 5 years to approximately $1.6 billion • Growth/reliability spending averages $100 million per year • Incremental Major Projects: – Cape Cod Line – Boston 345kV Connection – Mid Cape Line
Slide 21: Highest Credit Rating in the Industry
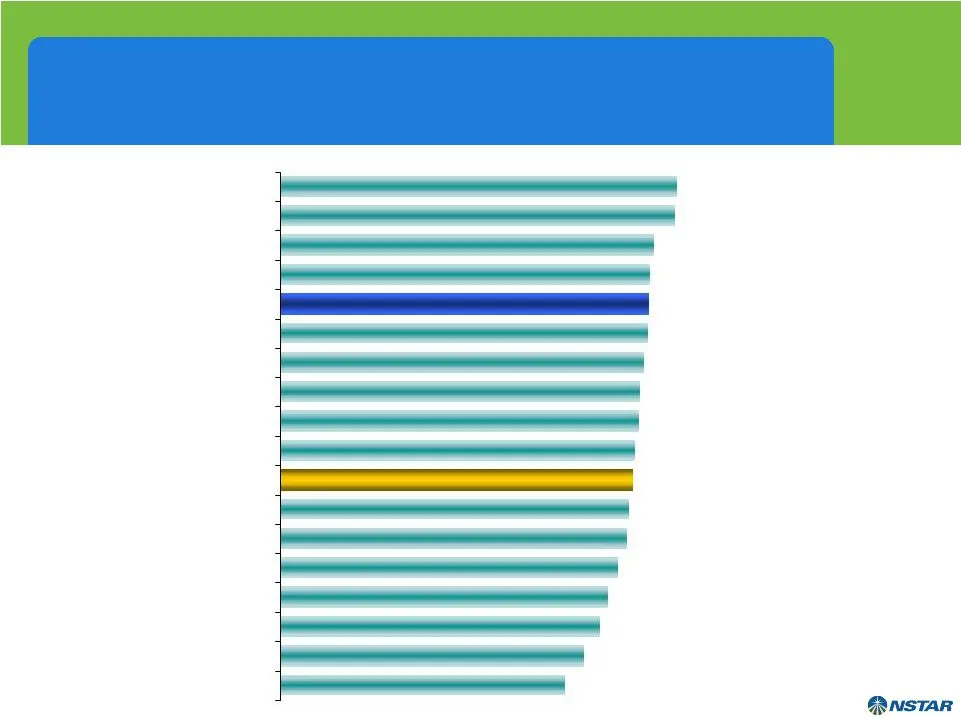
Highest Credit Rating in the Industry #1 NSTAR A+ *As published by EEI NSTAR A+ Southern Company A Consolidated Edison, Inc. A- Dominion Resources, Inc. A- DPL Inc. A- Duke Energy Corporation A- Energy East Corporation A- NextEra Energy, Inc. A- KeySpan Corp. A- Niagara Mohawk Power Corporation A- V
Slide 22: J.D. Power Survey Recognizes Customer Service Efforts
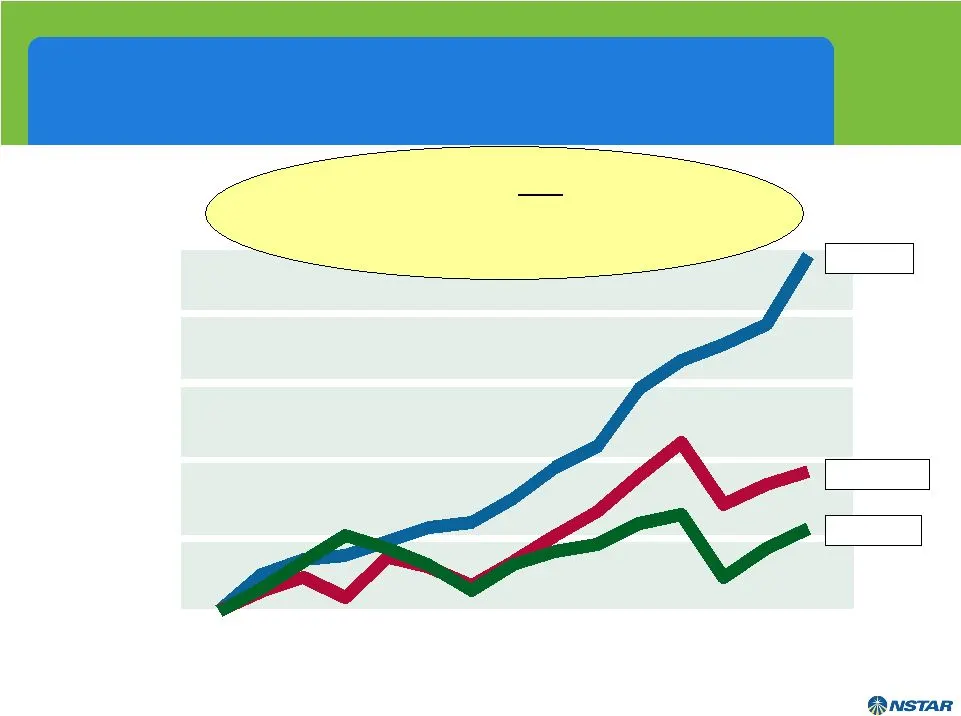
J.D. Power Survey Recognizes Customer Service Efforts Company A Company B Company C Company D NSTAR Company E Company F Company G Company H Company I EAST LARGE AVERAGE Company J Company K Company L Company M Company N Company O Company P
Slide 23: NSTAR Total Shareholder Return Outperforms the Industry
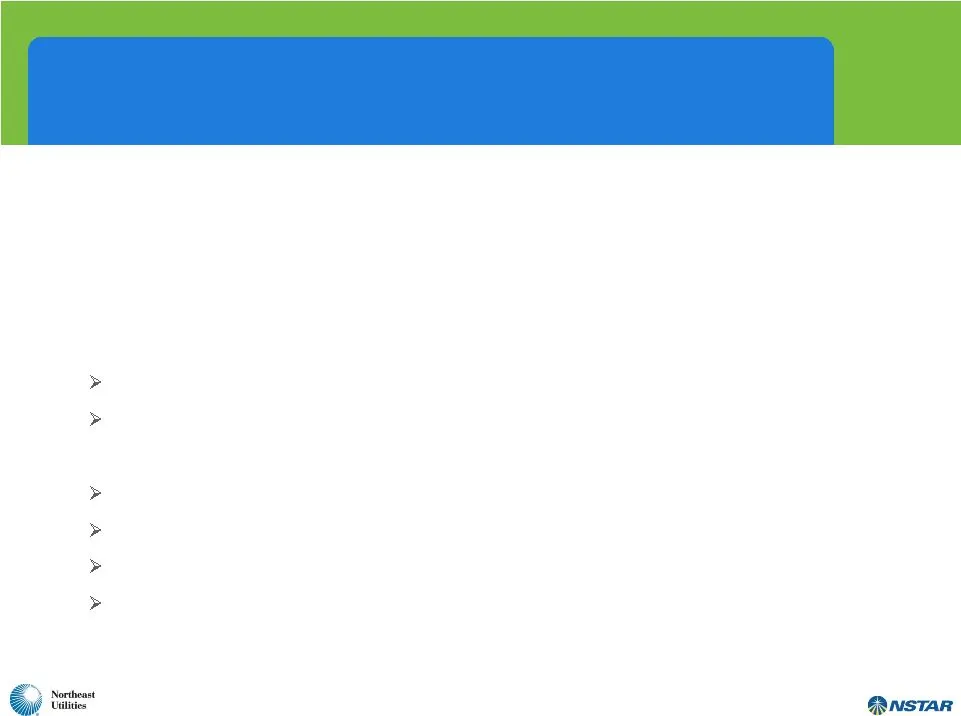
NSTAR Total Shareholder Return Outperforms the Industry $1,000 $2,000 $3,000 $4,000 $5,000 $6,000 Only Company in Any Industry to Deliver 14 Consecutive Years of Positive Total Shareholder Return S&P 500 Utility Index NSTAR
Slide 24: Key Takeaways on the Merger
Key Takeaways on the Merger • Combines two highly successful energy delivery companies with similar strategies • Matches NSTAR’s distribution expertise and strong cash flows with NU’s nationally recognized transmission organization and significant investment opportunities • Larger, diverse and bette
Slide 25: Appendix
Appendix
Slide 26: Improved Results Due In Part to Resolution of All Three Electric Distribution Rate Cases
Improved Results Due In Part to Resolution of All Three Electric Distribution Rate Cases • Five-year settlement approved by NHPUC on 6/28/2010 • $45.5 million increase on 7/1/10 in addition to 8/1/09 temporary increase of $25.6 million • $2.3 million decrease on 7/1/11 • 2012 & 2013 projected increa
Slide 27: Yankee Gas Rate Decision Less Supportive
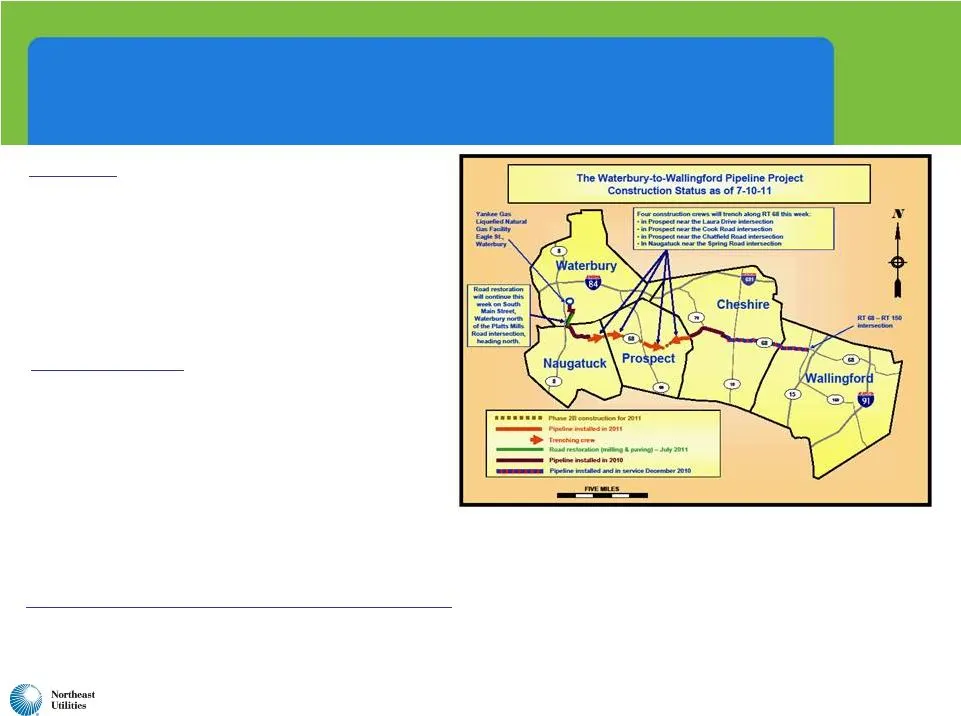
Yankee Gas Rate Decision Less Supportive The Good • Supported full projected cost of Waterbury to Wallingford line • Supported ramp-up to $40 million annual spending for pipeline replacement • Authorized capital structure of 52.2% equity; 47.8% debt The Not So Good • 8.83% authorized ROE • First-yea
Slide 28: NU Weather-Adjusted Retail Sales Trends
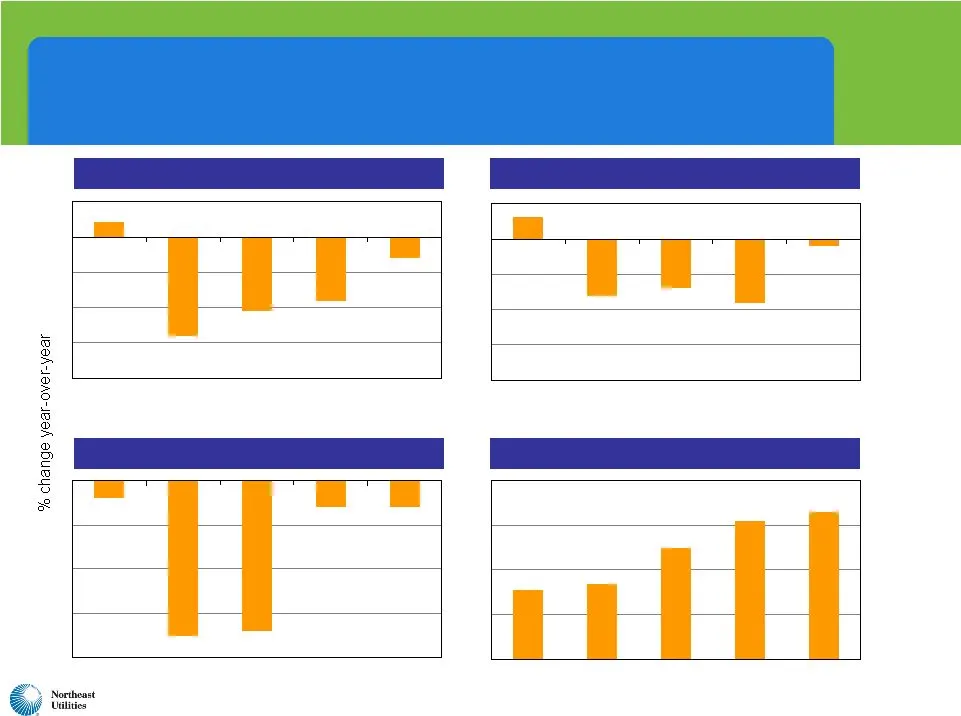
NU Weather-Adjusted Retail Sales Trends CL&P PSNH WMECO Yankee Gas (firm) -2.8 -2.1 -1.8 -0.6 0.4 2011 YTD -1.4 -1.8 -0.2 -1.6 0.6 2011 YTD -0.6 -0.6 -3.4 -3.5 -0.4 2011 YTD 3.4 6.2 6.6 5.0 3.1 2011 YTD
Slide 29: 2006 – 2011 NU Consolidating EPS GAAP / Non-GAAP Reconciliation
2006 – 2011 NU Consolidating EPS GAAP / Non-GAAP Reconciliation (0.20) (0.06) N/A N/A N/A N/A NU-NSTAR Merger Expenses N/A 0.09 N/A N/A N/A N/A NU Tax Settlement $2.19 N/A N/A N/A $2.16 0.05 $2.11 (0.05) 2.16 1.00 $1.16 2010 Actual $2.10 - $2.20 N/A N/A N/A $2.30 – $2.40 N/A $2.30 – $2.40 (0.05) 2.3
Slide 30: NSTAR…20 Consecutive Years of Operating Earnings Growth
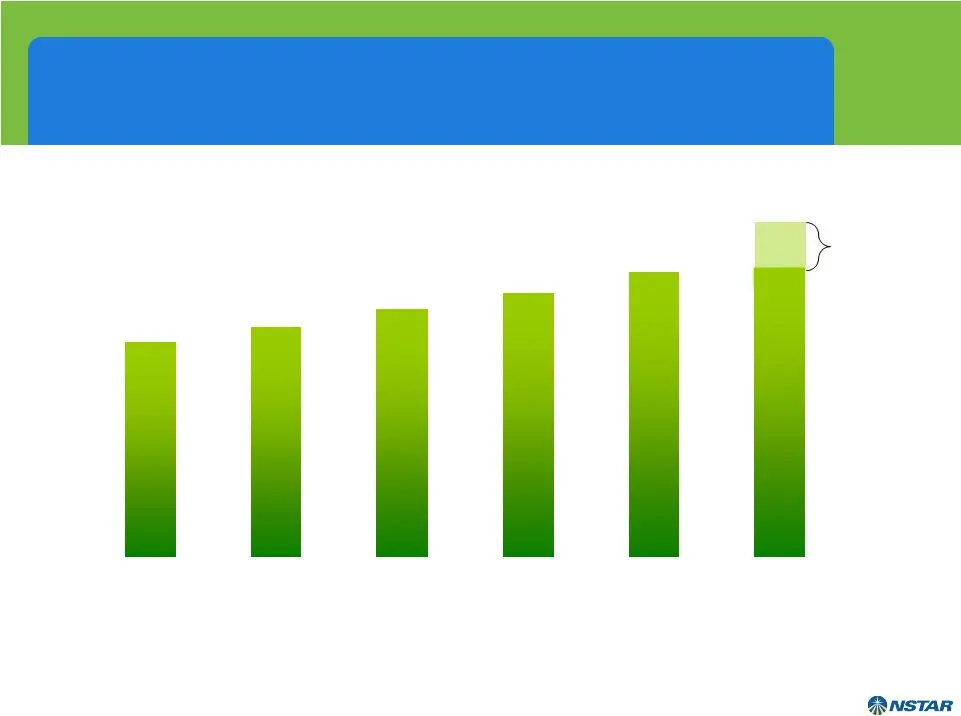
NSTAR…20 Consecutive Years of Operating Earnings Growth $1.93 $2.07 $2.22 $2.37 $2.56 Guidance $2.60 – $2.75
Slide 31: NSTAR – Consistent, Above Average Dividend Growth
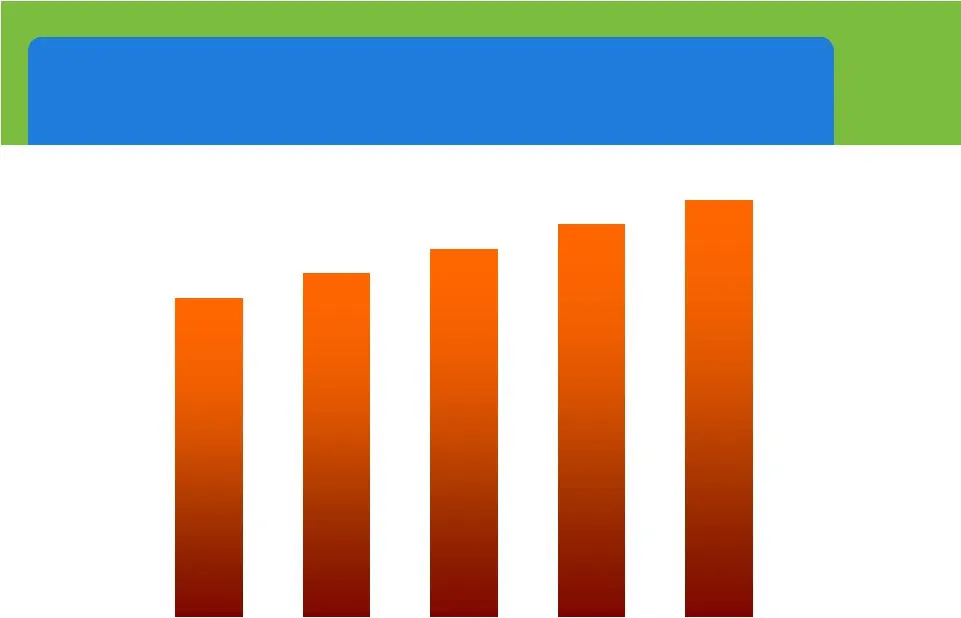
NSTAR – Consistent, Above Average Dividend Growth …13 Consecutive Years of Increase… $1.30 $1.40 $1.50 $1.60 $1.70
Slide 32: NSTAR Rate Cases
NSTAR Rate Cases • Effective January 1, 2006 to December 31, 2012 • Customers’ overall delivery rates flat • Annual inflation-adjusted distribution rate change offset by transition charge • Allowed ROE of 10.5% (8.5% to 12.5% band) • Recovery of Incremental Safety & Reliability Program Costs • Inclu
Source: SEC EDGAR · 425 filed Sep 8, 2011
More decks from Nstar
 Merger or Acquisition (February 2012)38 slides · Feb 29, 2012
 EEI Financial Conference 201151 slides · Nov 7, 2011
 EEI Financial Conference 201149 slides · Nov 7, 2011
 Williams Capital East Coast Conference 201137 slides · Aug 10, 2011
 Deutsche Bank Conference (May 2011)24 slides · May 11, 2011
 Merger or Acquisition (March 2011)44 slides · Mar 10, 2011