Teppco Partners LP — MLP Investor Conference 2002
31 slides from Teppco Partners LP's conference presentation, Mar 12, 2002
Slide 1: TEPPCo MLP Investor Conference
(iW TEPPCo MLP Investor Conference New York, NY March 12, 2002
Slide 2: Forward-looking Statements
Forward-looking Statements Except for the historical information contained herein, this document contains forward-looking statements regarding the Partnership, including projections, estimates, forecasts, plans, and objectives. Although management believes that all such statements are based upon rea
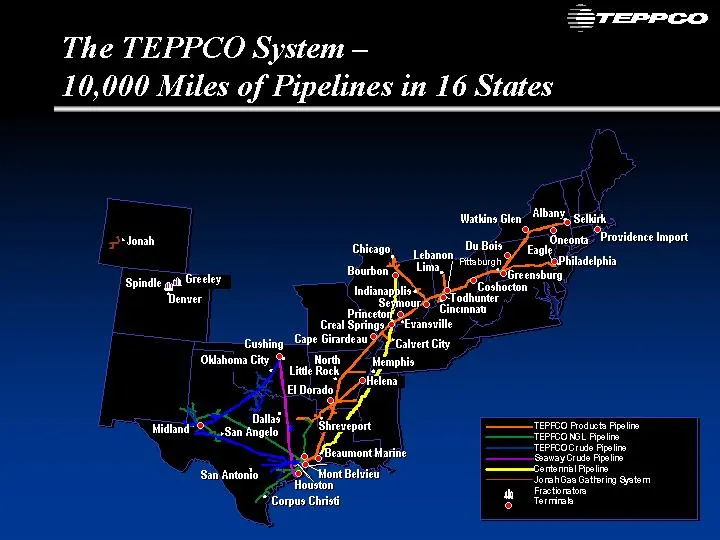
Slide 3: The TEPPCO System — 10,000 Miles of Pipelines in 16 States
The TEPPCO System — 10,000 Miles of Pipelines in 16 States Sia 7 domah Z ‘Bneonts:\ Providence Import Spindle gat 6reley Denver Cushing Cape Girardeau ‘Oklahoma City North emphis 9S a ath Z Meme Widland@\garanace ) > Shrevenort TEPFCO Frodurt Pstine LTEPFCO NBL Pline TEPFCOCrute Fpl eaumont Marine S
Slide 4: TEPPCO has become a full range provider of logistics services
TEPPCO has become a full range provider of logistics services to the petroleum industry + As one of the largest pipeline master limited partnerships, with $1.8 billion in assets, TEPPCO has substantial positions in three major petroleum industry sectors -— UPSTREAM Crude oil marketing, transportatio
Slide 5: TEPPCO has grown significantly since the partnership was formed in 1990
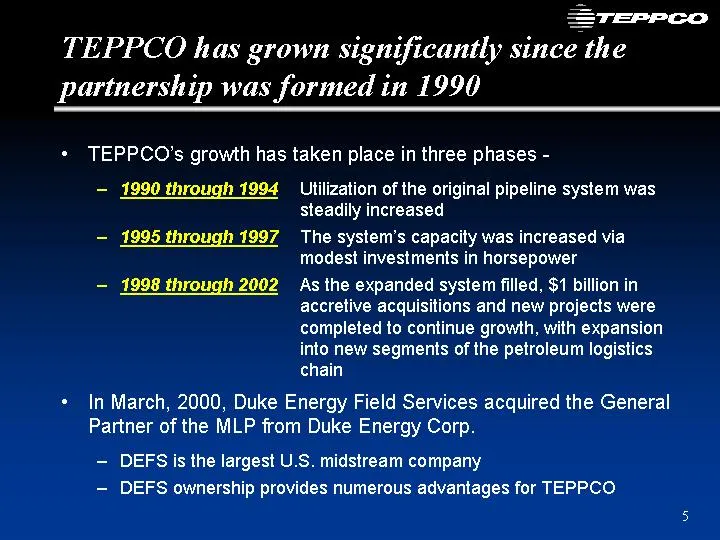
TEPPCO has grown significantly since the partnership was formed in 1990 + TEPPCO's growth has taken place in three phases - - 1990 through 1994 Utilization of the original pipeline system was steadily increased - 1995 through 1997 The system's capacity was increased via modest investments in horsepo
Slide 6: DEFS, owner of the TEPPCO GP, is owned by two energy companies
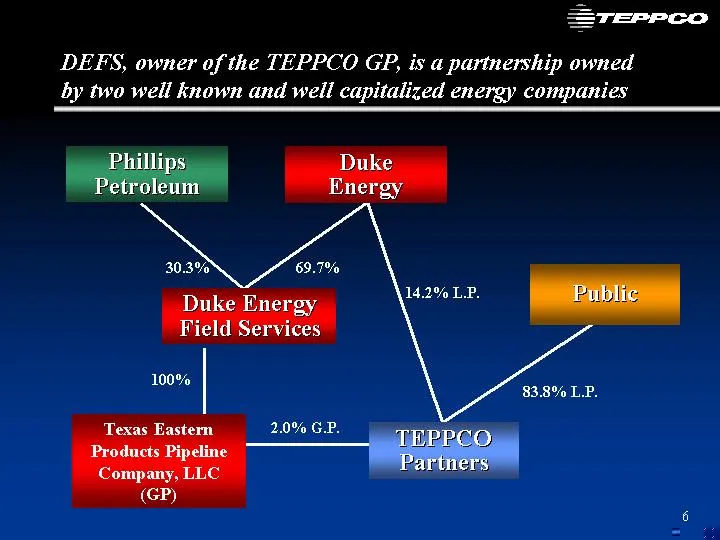
DEFS, owner of the TEPPCO GP, is a partnership owned by two well known and well capitalized energy companies 142% LP. 83.8% LP. 2.0% GP.
Slide 7: Business diversification has been a benefit of TEPPCO's growth strategy
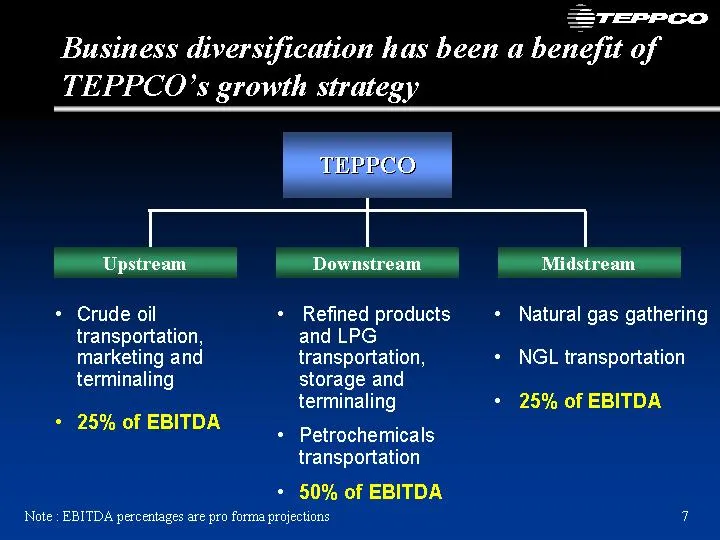
Business diversification has been a benefit of TEPPCO’s growth strategy re es * Crude oil + Refined products + Natural gas gathering transportation, and LPG marketing and transportation, + NGL transportation terminaling storage and terminaling + 25% of EBITDA ° 259 25%e,0L EBITDA + Petrochemicals tr
Slide 8: TEPPCO's assets are strategically positioned to capitalize on market opportunities
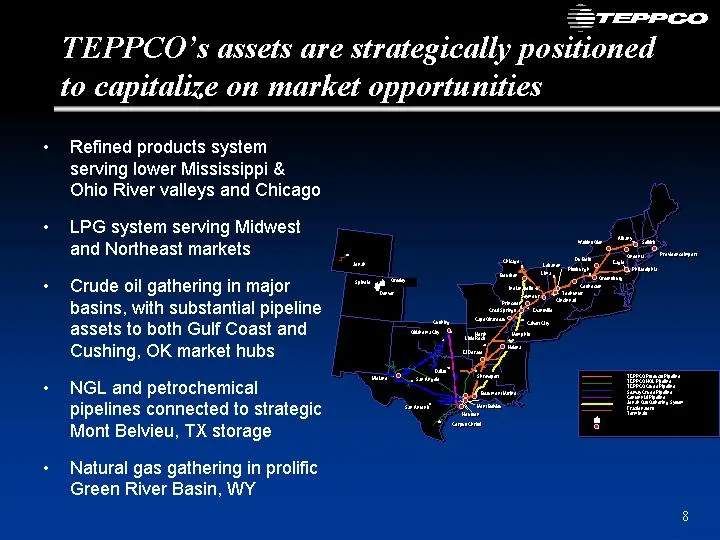
TEPPCO’s assets are strategically positioned to capitalize on market opportunities Refined products system serving lower Mississippi & Ohio River valleys and Chicago LPG system serving Midwest and Northeast markets Crude oil gathering in major basins, with substantial pipeline assets to both Gulf Co
Slide 9: Significant Upstream Achievements in 2001
Significant Upstream Achievements in 2001 + Excellent gathering, marketing and transportation results - Benefited from favorable location and quality differentials + P+ (location differential) was strong + Sweet to sour price differentials were wide - Enhanced results in Red River basin with a strat
Slide 10: Significant Midstream Achievements in 2001
Significant Midstream Achievements in 2001 + The midstream sector is an area TEPPCO has been evaluating because of the large group of assets available, many with growth potential + Jonah acquisition marked substantial, attractive entry to natural gas gathering business - New, high quality assets in
Slide 11: Significant Downstream Achievements in 2001
Significant Downstream Achievements in 2001 Maximized products pipeline system utilization - Record summer LPG movements driven by favorable propane market conditions - Strong refined products movements due to chronic Midwest supply shortage and refinery outages + Market based rates implemented for
Slide 12: Significant Financial Achievements in 2001
Significant Financial Achievements in 2001 + Record earnings and EBITDA + Completed $246 million in equity offerings + Successful debt restructuring - Positioned partnership for growth by increasing credit facility to $700 million + Increased distribution by 9.5% to $2.30 per unit on an annualized b
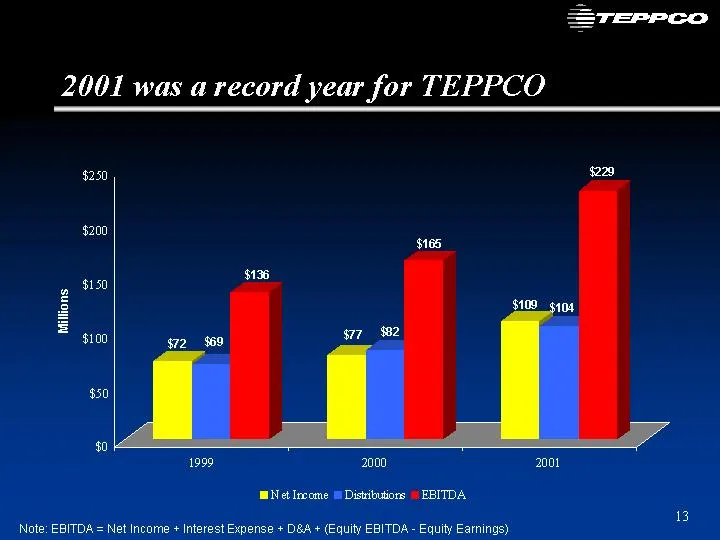
Slide 13: 2001 was a record year for TEPPCO
2001 was a record year for TEPPCO Millions $250 $200 $150 $100 $50 0 1999 2000 2001 Net Iecome M Distitutions EBITDA 13 Net Income + Interest Expense + D&A + (Equity EBITDA - Equity Earnings)
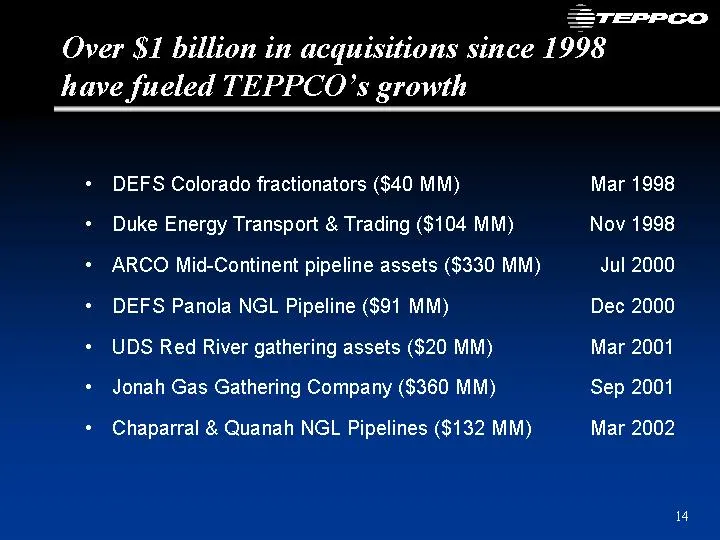
Slide 14: Over $1 billion in acquisitions since 1998 have fueled growth
Over $1 billion in acquisitions since 1998 have fueled TEPPCO’s growth + DEFS Colorado fractionators ($40 MM) + Duke Energy Transport & Trading ($104 MM) + ARCO Mid-Continent pipeline assets ($330 MM) + DEFS Panola NGL Pipeline ($91 MM) + UDS Red River gathering assets ($20 MM) + Jonah Gas Gathering
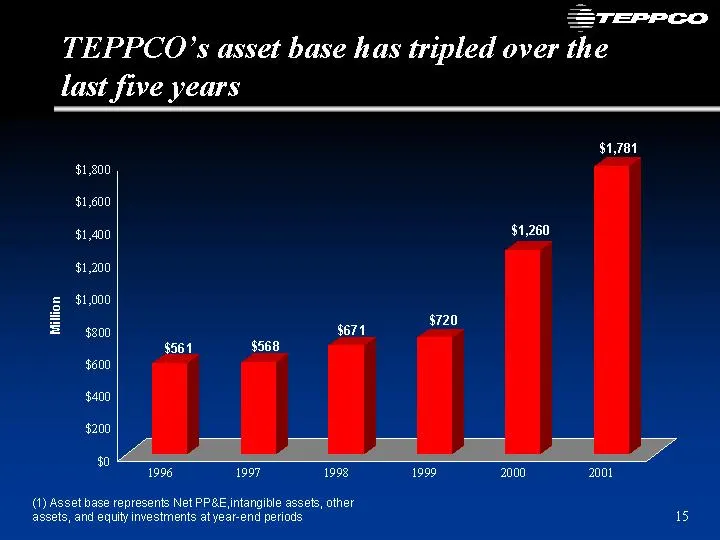
Slide 15: TEPPCO's asset base has tripled over the last five years
TEPPCO’s asset base has tripled over the last five years $1,781 en) $1,600 $1,400 $1,200 = $1,000 $800 $600 $400 $200 $0 1996 1997 1998 1999 2000 2001 (1) Asset base represents Net PP&E,intangible assets, other assets, and equity investments at year-end periods 15
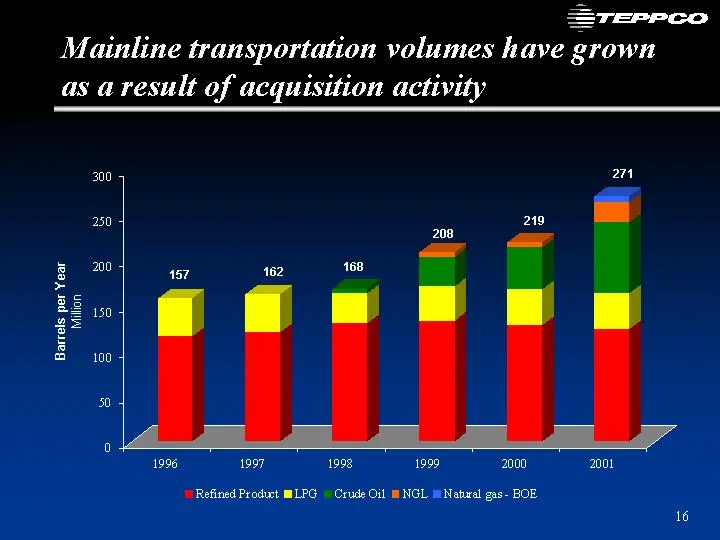
Slide 16: Mainline transportation volumes have grown as a result of acquisition activity
Mainline transportation volumes have grown as a result of acquisition activity Barrels per Year Million 1996 1997 1998 1999 2000 2001 | Refined Prodint MLPG Crude Oil m NGL m Nabwal gas- BOE 16
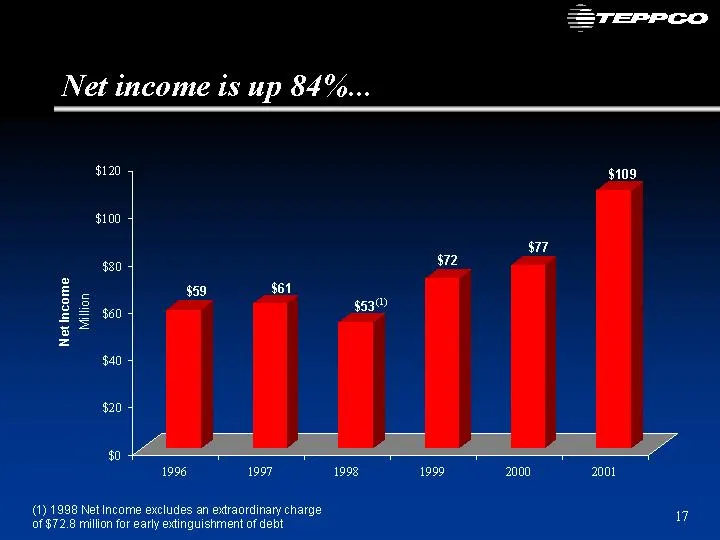
Slide 17: Net income is up 84%...
Net income is up 84%... $120 $100 $20 $60 Net Income Million $40 $20 0 1996 1997 1998 1999 2000 2001 (1) 1998 Net Income excludes an extraordinary charge ie of $72.8 million for early extinguishment of debt
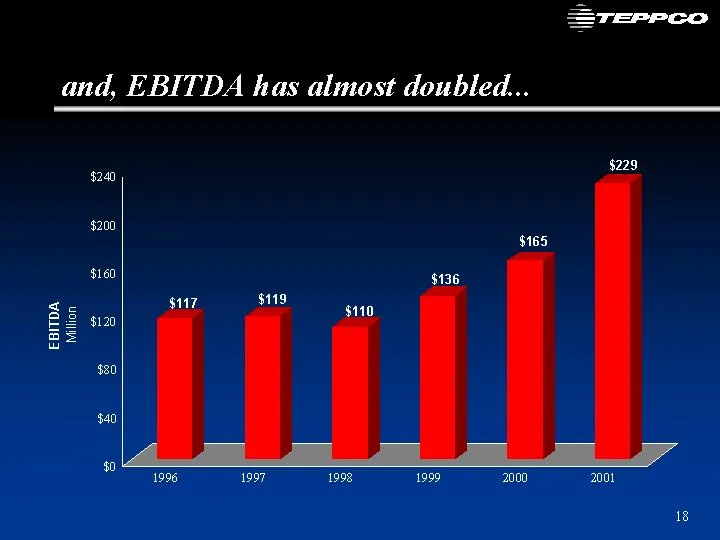
Slide 18: and, EBITDA has almost doubled...
and, EBITDA has almost doubled... EBITDA Million 229 $240 : $200 $160 $120 $80 $40 0 1996 1997 1998 1999 2000 2001 18
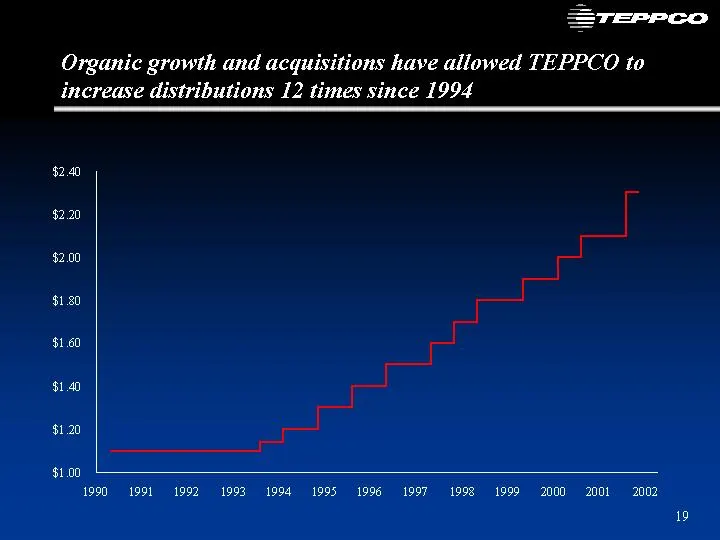
Slide 19: Organic growth and acquisitions have allowed TEPPCO to increase distributions
Organic growth and acquisitions have allowed TEPPCO to increase distributions 12 times since 1994 240 $220 $2.00 = $1.80 $1.60 140 $120 $1.00 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 20012002 19
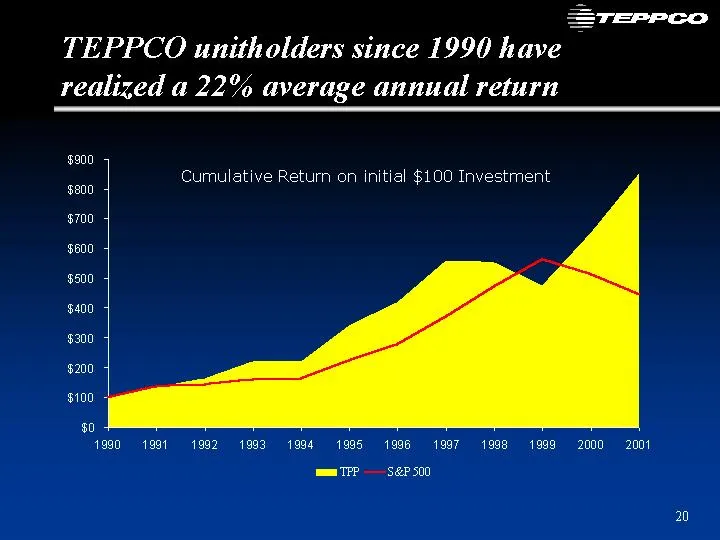
Slide 20: TEPPCO unitholders since 1990 have realized a 22% average annual return
TEPPCO unitholders since 1990 have realized a 22% average annual return a Cumulative Return on initial $100 Investment $700 $600 $600 $400 $300 $200 $100 $0 1990 1991 1992 1993 1994 1996 1996 1997 1998 1939 2000 2001 mmm TPP S@P500 20
Slide 21: Upstream Strategy - find synergies, reduce costs, improve margins, enhance Seaway
Upstream Strategy - find synergies, reduce costs, improve margins, enhance Seaway + One of the keys to a successful gathering and marketing effort will be increasing efficiency. TEPPCO plans to: - Look for strategic acquisition opportunities in the geographic areas where it currently has operations
Slide 22: Midstream Strategy - Grow Jonah, increase use of NGL pipelines
Midstream Strategy - Grow Jonah, increase use of NGL pipelines, find new opportunities + The Jonah acquisition has considerable upside - Gas production continues to increase — New “step out areas” are being developed —- Recent dip in gas prices has had little impact - Jonah will provide additional i
Slide 23: Downstream Strategy - Start up Centennial, optimize the TEPPCO system
Downstream Strategy - Start up Centennial, optimize the TEPPCO system, and selectively expand delivery capability Centennial Pipeline will be in service by the end of the first quarter 2002. CPL is important to TEPPCO: - Strategically Allows TEPPCO to participate in the incremental capacity to its c
Slide 24: Downstream Strategy - cont'd
Downstream Strategy - cont’ + With additional capacity available on the TEPPCO system, new delivery opportunities and expansions may be feasible - Expansion of the LPG system to the Northeast is under consideration — Renewed interest in jet fuel deliveries to additional locations — Well positioned t
Slide 25: Financial Strategy - Fund expansions and acquisitions while improving the balance sheet
Financial Strategy - Fund expansions and acquisitions while improving the balance sheet * Debt Successful offering of $500 million in senior debt completed in February, 2002 Bank credit line is adequate to support acquisition activity Maintain a reasonable balance between fixed and floating rate deb
Slide 26: Overall Partnership Strategy - improve service, maintain assets, grow, reward investors
Overall Partnership Strategy - improve service, maintain assets, grow, reward investors + Expand and improve service in current markets + Maintain the integrity of the asset base + Pursue growth balanced between internal projects and accretive acquisitions in the range of $300 - $400 million annuall
Slide 27: Strategic relationship with DEFS provides substantial opportunities for TEPPCO
Strategic relationship with DEFS provides substantial opportunities for TEPPCO DEFS is the largest midstream company in the U.S - Twice as big as #2 — Natural gas gathering systems, storage and intrastate gas pipelines - NGL pipelines and fee-based gas processing facilities Asset purchases from DEFS
Slide 28: TEPPCO's 2002 outlook with assets currently in place
TEPPCO’s 2002 outlook with assets currently in place + EBITDA: $240 - $260 million - Includes Chaparral & Quanah Pipelines — Full year of Jonah Gas Gathering System + Net Income: $90 - $110 million * Earnings Per Unit: $1.50 - $1.85 * Capital expenditures: $74 million — Includes $27 million maintena
Slide 29: Factors that could impact TEPPCO's 2002 performance
Factors that could impact TEPPCO’s 2002 performance + Refined products and petrochemicals demand - Overall economic conditions and travel patterns - Market adjustments to Centennial Pipeline start-up + Winter weather and Canadian pricing impacts on LPG + Crude prices and differentials + Natural gas
Slide 30: A few words about transparency
A few words about transparency + Our corporate governance model is one of full disclosure + We show allocations to the LP’s and the GP and report EPU after allocations to the GP + Everything TEPPCO owns is on the balance sheet - Seaway and Centennial interests accounted for on equity method + There
Slide 31: TEPPCO is well positioned for continued growth
TEPPCO is well positioned for continued growth + Strong asset position with attractive growth potential + Experienced personnel with customer service orientation + Growth opportunities from alignment with DEFS + Financial strength to fund growth initiatives + Strict corporate governance to ensure co
Source: SEC EDGAR · 8-K filed Mar 12, 2002
More decks from Teppco Partners LP
 Morgan Stanley MLP Reception (October 2009)26 slides · Oct 7, 2009
 Master Limited Partnerships Investor Conference (September 2009)27 slides · Sep 16, 2009
 Wells Fargo Retail Meeting (September 2009)27 slides · Sep 15, 2009
 Barclays Capital CEO Energy/Power Conference 200929 slides · Sep 9, 2009
 Merger or Acquisition (August 2009)29 slides · Aug 26, 2009
 Wachovia Securities Investor Presentation (June 2007)51 slides · Jun 1, 2007