Teppco Partners LP — Morgan Stanley MLP Reception (October 2009)
26 slides from Teppco Partners LP's conference presentation, Oct 7, 2009
Slide 1: Morgan Stanley MLP Reception
Morgan Stanley MLP Reception October 6, 2009 Randy Fowler Executive Vice President and CFO © Allrights reserved. Enterprise Products Partners L.P.
Slide 2: Forward Looking Statements
Forward Looking Statements This presentation contains forward-looking statements and information based on Enterprise's beliefs and those of its general partner, as well as assumptions made by and information currently available to them. When used in this presentation, words such as “anticipate,” “pr
Slide 3: Investor Notice
Investor Notice In connection with the proposed merger, Enterprise has filed a registration statement on Form S-4 (Registration No. 333-161185), which includes a prospectus of Enterprise and a proxy statement of TEPPCO and other materials, with the Securities and Exchange Commission (“SEC”). INVESTO
Slide 4: Key Investment Considerations
Key Investment Considerations [Ez @ Large, diversified, integrated midstream energy system servicing producers and consumers of natural gas, NGLs and crude oil «Approximately $23 billion enterprise value; more than $19 billion in assets; $13 billion in equity market capitalization «Accesses some of
Slide 5: Significant Management Ownership
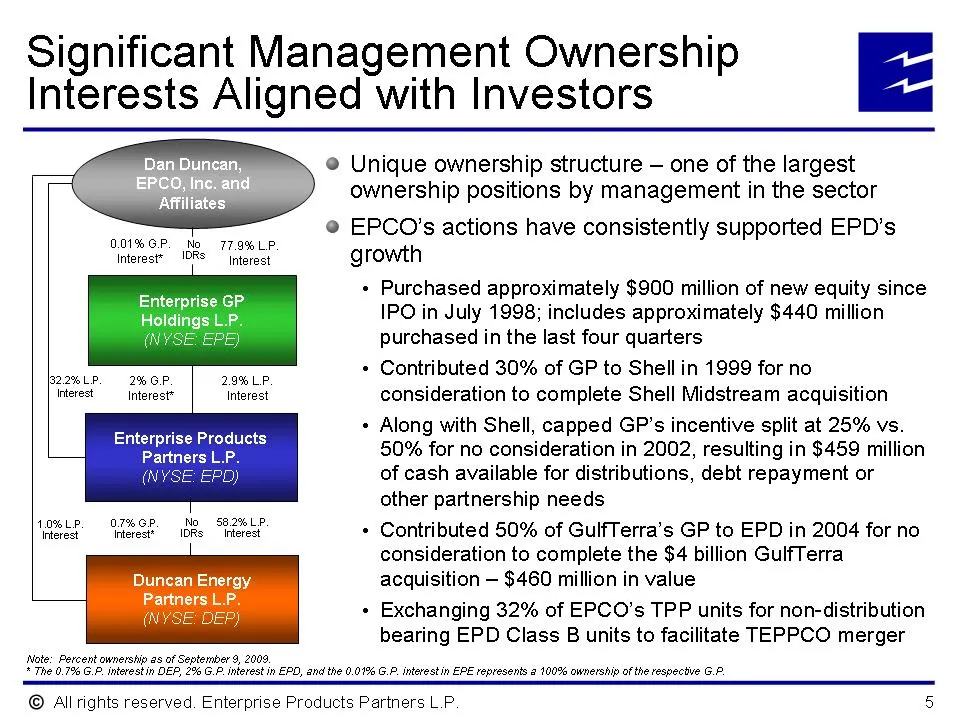
Significant Management Ownership Interests Aligned with Investors O01%GP. No 77.9%LP. Interest™ !ORS Interest Enterprise GP Holdings L.P. B22%LP. 2% GP. Interest Interest” 2.9% LP. No $8.2%LP. 10%LP. 07% GP. IRs “Interest Interest’ Interest Duncan Energy Partners L.P. Note: Percent aunership as of S
Slide 6: Leading Business Positions Integrated Across Midstream Energy Value Chain
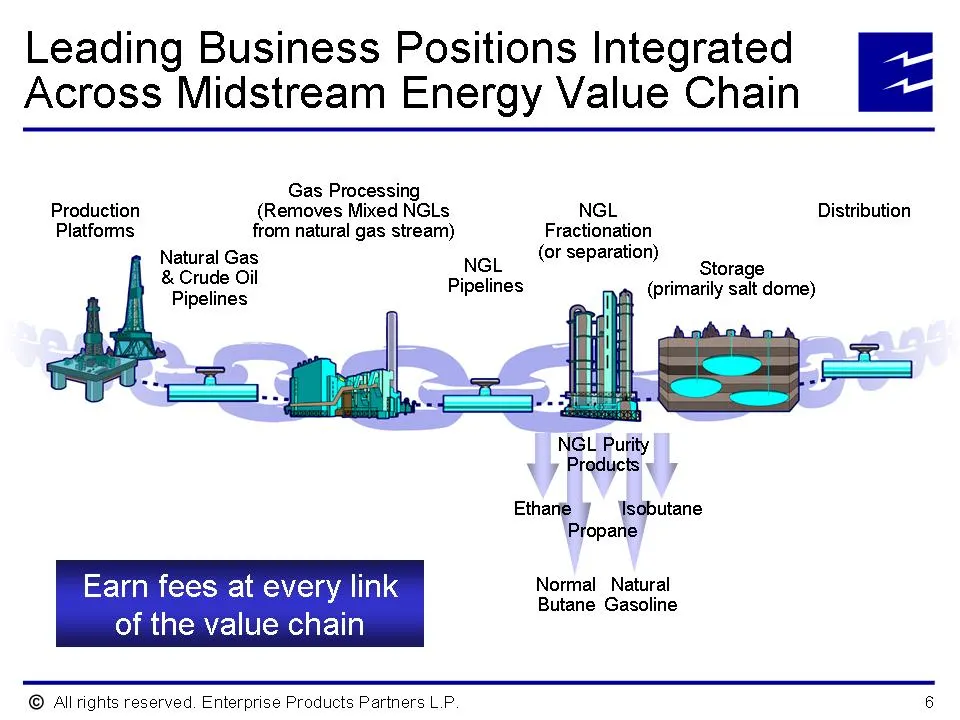
Leading Business Positions Integrated [ Across Midstream Energy Value Chain Gas Processing Production (Removes Mixed NGLs NGL Distribution Platforms from natural gas stream) Fractionation Natural Gas No. (orseparation) Storage & Crude Oil peli sve Pipelines Pipelines (primarily salt dome) NGL Purity
Slide 7: EPD / TPP Pro Forma System Map
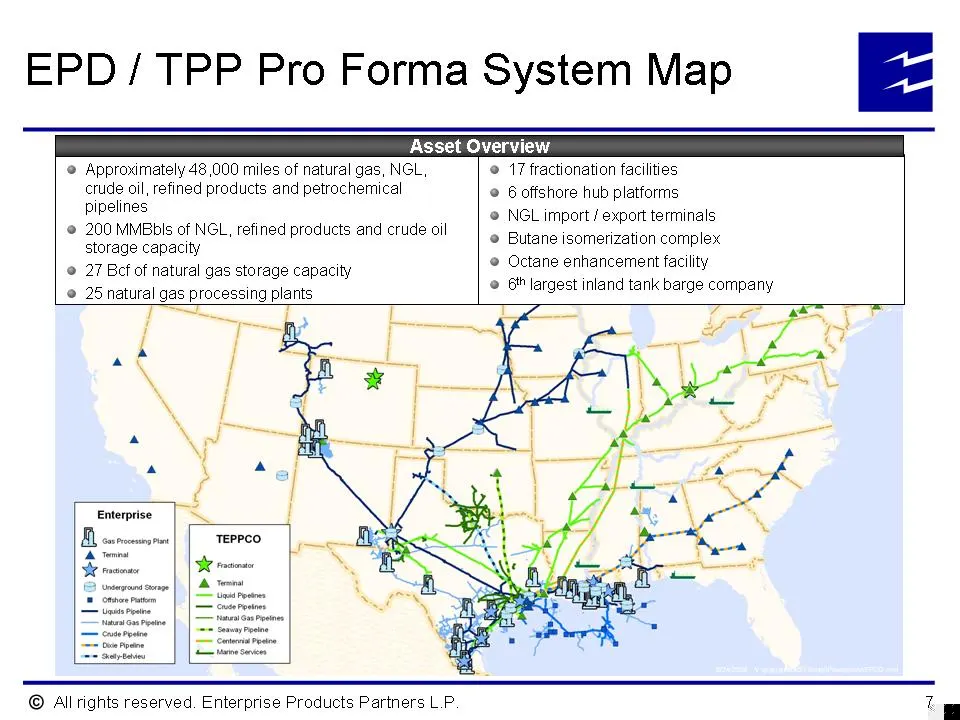
EPD / TPP Pro Forma System Map Asset Overview Approximately 48,000 miles of natural gas, NGL, 17 fractionation facilities crude oil, refined products and petrochemical 6 offshore hub platforms Pipelines NGL import / export terminals © 200 MMBbIs of NGL, refined products and crude oil Butane isomeriz
Slide 8: Geographic and Business Diversification Provide Multiple Earnings Streams
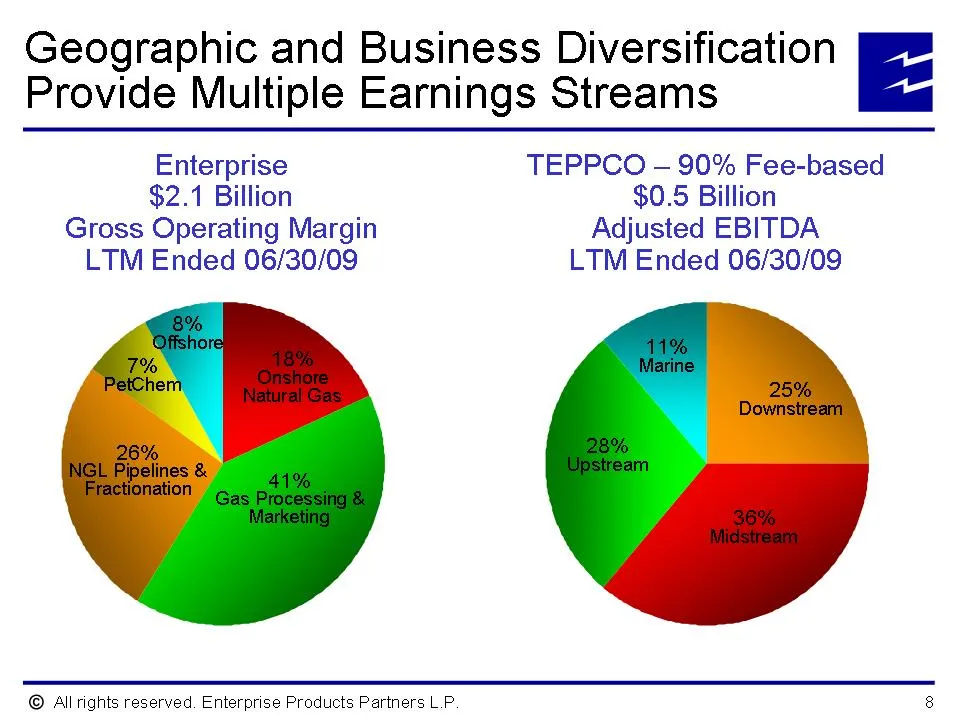
Geographic and Business Diversification [ Provide Multiple Earnings Streams Enterprise TEPPCO — 90% Fee-based $2.1 Billion $0.5 Billion Gross Operating Margin Adjusted EBITDA LTM Ended 06/30/09 LTM Ended 06/30/09 © Allrights reserved. Enterprise Products Partners L.P. 8
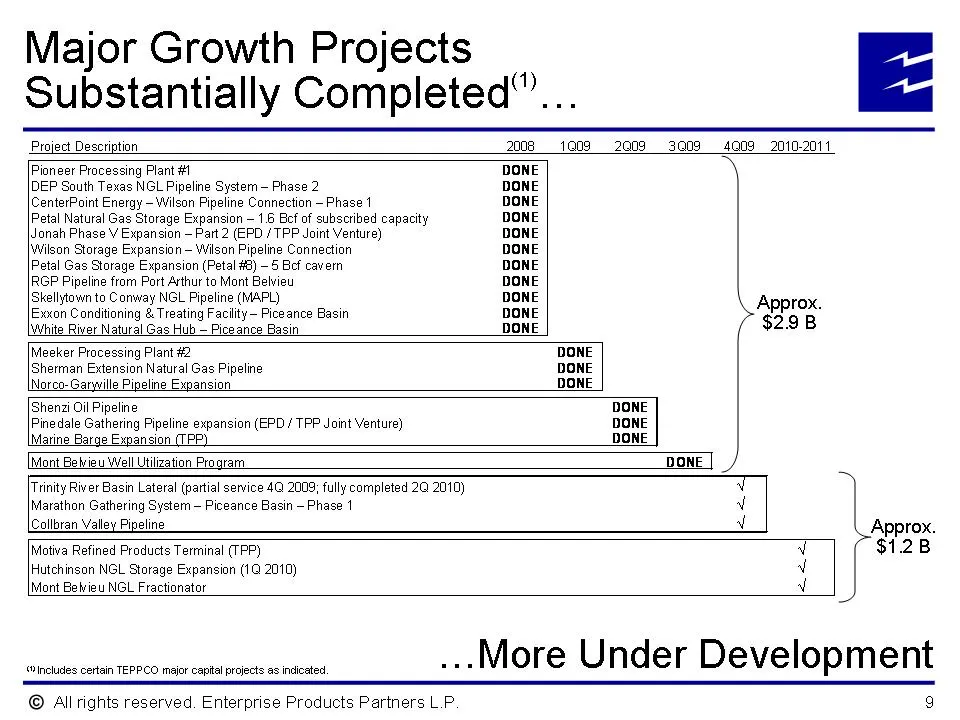
Slide 9: Major Growth Projects
Major Growth Projects Substantially Completed”... Project Description 2008109 2009 _3G09 4009 2010-2011 Pioneer Processing Plant #1 DONE DEP South Texas NGL Pipeline System - Phase 2 DONE JCenterPoint Energy — Wilson Pipeline Connection - Phase 1 DONE Petal Natural Gas Storage Expansion — 1.6 Bcf of
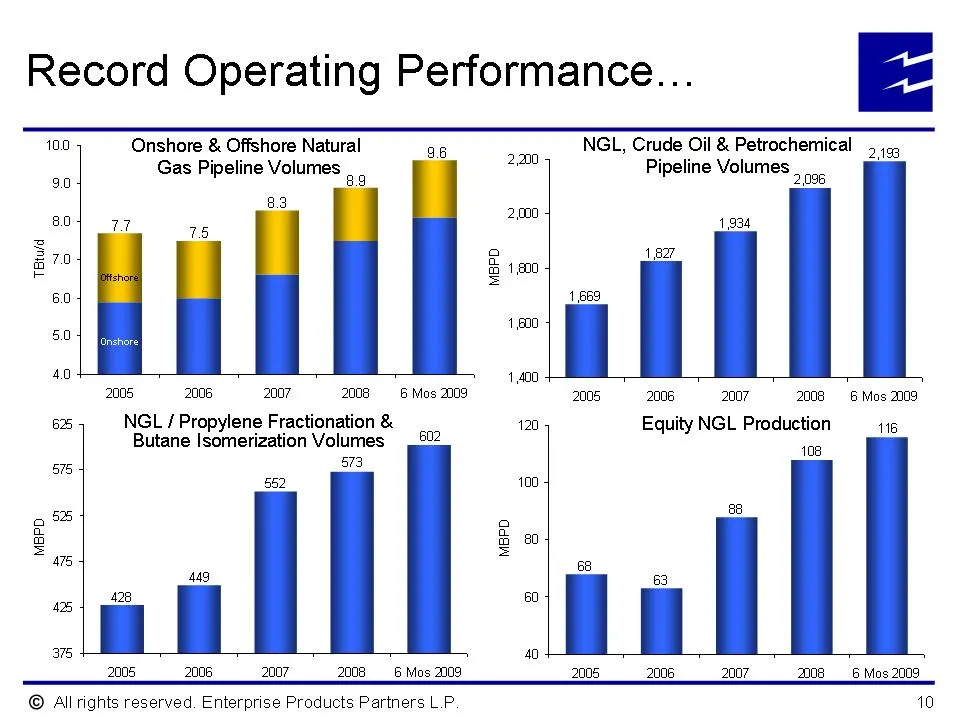
Slide 10: Record Operating Performance
Record Operating Performance... 100 Onshore & Offshore Natural NGL, Crude Oil & Petrochemical 5 jo Gas Pipeline Volumes Pipeline Volumes 89 2,096 é e 2005 2008 2007 2008 6 Mos 2009 2005 2008 2007 2008/6 Mos 2009 65 NGL / Propylene Fractionation & 120 Equity NGL Production 116 Butane Isomerization Vo
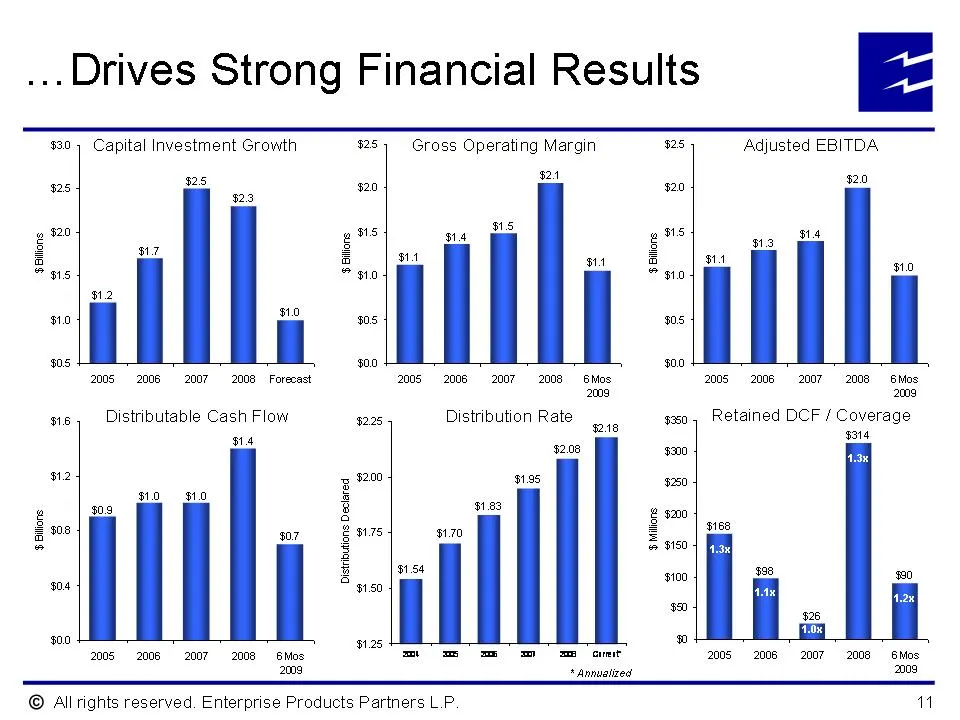
Slide 11: ...Drives Strong Financial Results
...Drives Strong Financial Results 330) Capital Investment Growth 325) Gross Operating Margin 928 Adjusted EBITDA ga 925 325 920 920 ee 923 ms ms oe e e wo is si a ° $0 ° $0 12 so uD sos 90s sas soo soo 200s 2006-2007 «2008 Forecast 200s 200820072008 «Sas 200s 2008 ©2007-2008” BMs 20a 20a 18 Distrib
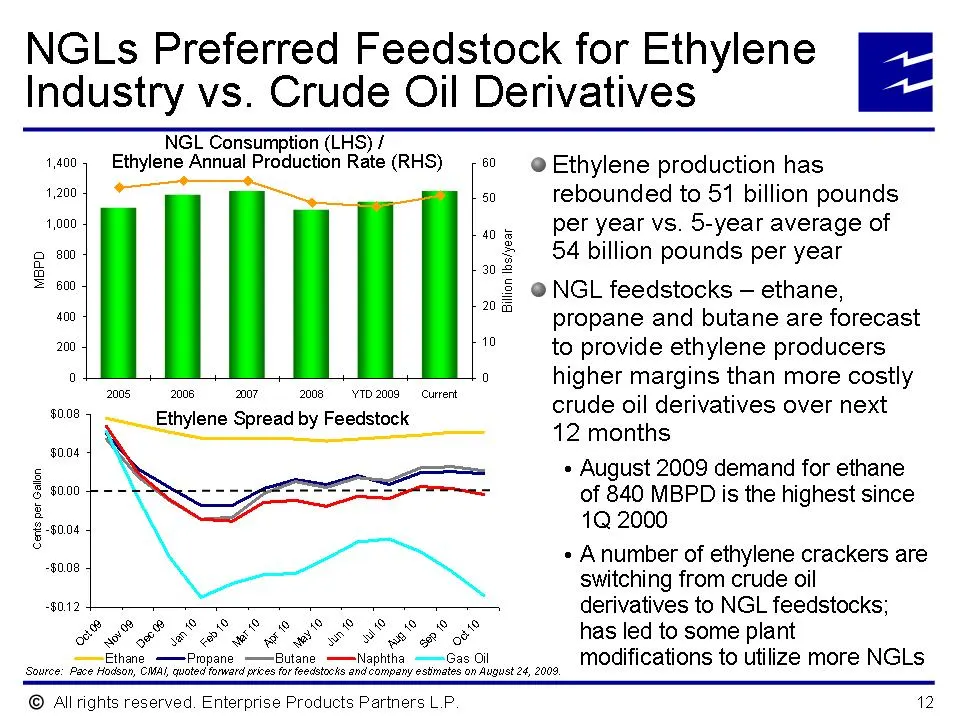
Slide 12: NGLs Preferred Feedstock for Ethylene
NGLs Preferred Feedstock for Ethylene Industry vs. Crude Oil Derivatives MBPD Certs per Gallon 4,400 4,200 4,000 NGL Consumption (LHS) / Ethylene Annual Production Rate (RHS) 60 2008 2006 07 2008 current Ethylene Spread by Feedstock ‘yD 2008 60 Billion Ibs/year Pea posh ao a ge co gS sg? og FS of CF
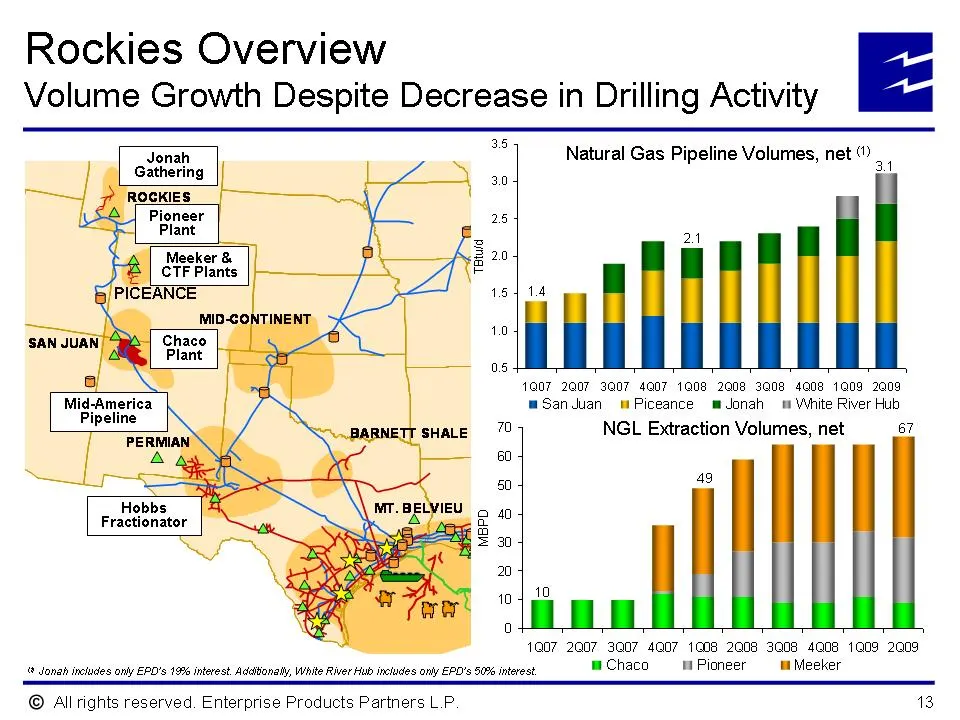
Slide 13: Rockies Overview
Rockies Overview Volume Growth Despite Decrease in Drilling Activity 36 a Jonah Natural Gas Pipeline Volumes, net “ 31 Gathering ROGKIES Pioneer Meeker & CTF Plants SAN JUAN 1Q07 2007 3007 4007 1908 2008 3008 4a08 1909 2009 Mid-America mSanJuan wu Piceance mJonah = White River Hub Pipeline 7 NGL Ext
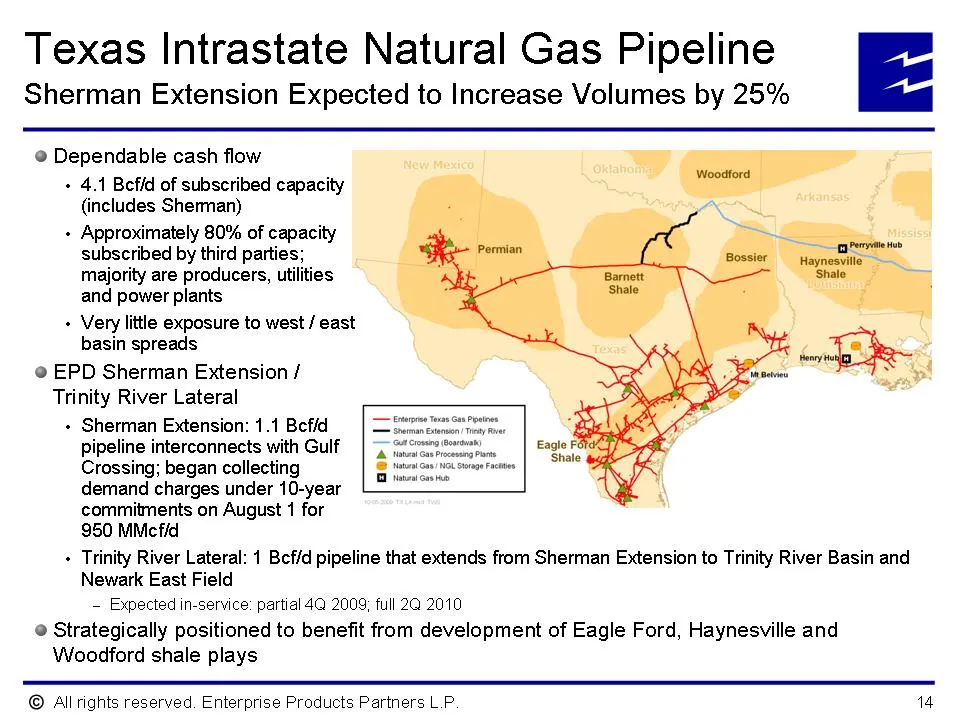
Slide 14: Texas Intrastate Natural Gas Pipeline
Texas Intrastate Natural Gas Pipeline Sherman Extension Expected to Increase Volumes by 25% © Dependable cash flow New Men | onan + 4.1 Befid of subscribed capacity LL a (includes Sherman) Sean ae + Approximately 80% of capacity subscribed by third parties; majority are producers, utilities and powe
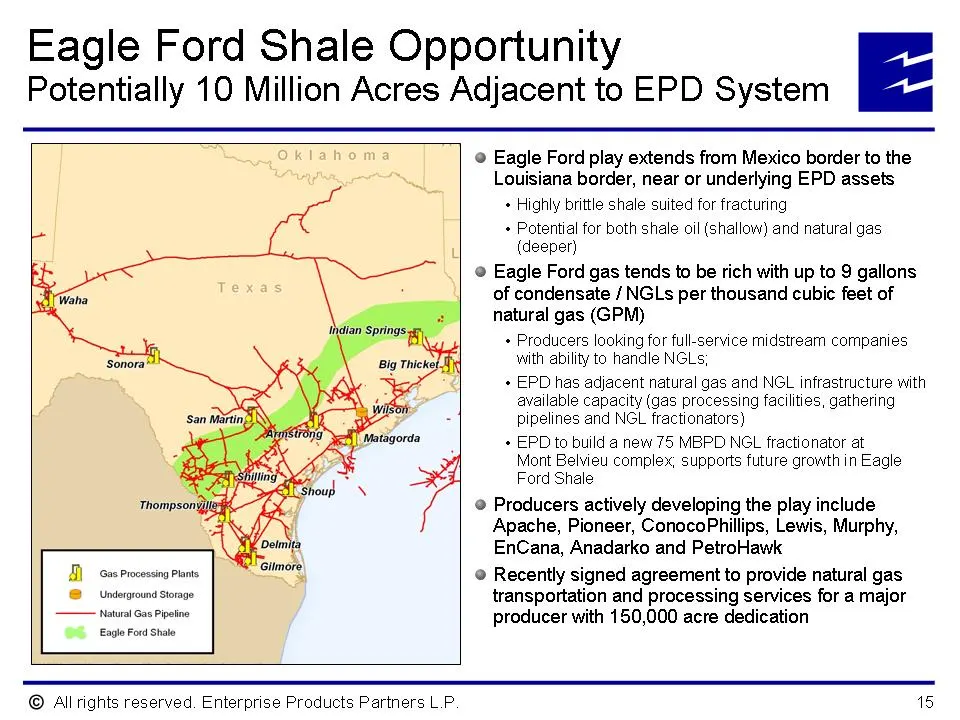
Slide 15: Eagle Ford Shale Opportunity
Eagle Ford Shale Opportunity Potentially 10 Million Acres Adjacent to EPD System Oklahoma eT Gimore —— Gas Processing Plants Underground Storage Natural Gas Pipeline Eagle Ford Shale a @ Eagle Ford play extends from Mexico border to the Louisiana border, near or underlying EPD assets + Highly brittl
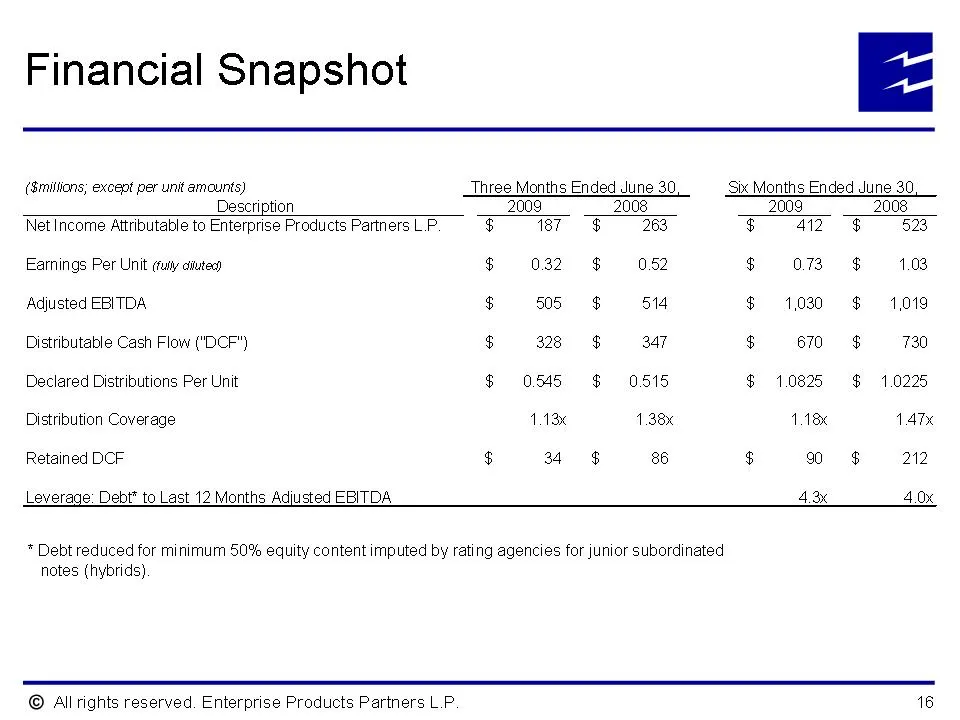
Slide 16: Financial Snapshot
Financial Snapshot (millions; except per unit amounts) Three Months Ended June 30, ‘Six Months Ended June 30, Description 2009 2008 2009 2008 Net Income Attributable to Enterprise Products Partners LP. $ 87 $ 263 $ 412 ¢ 523 Earnings Per Unit ¢ruty ciiutes) $ 032 ¢ 0.52 $ 073 $ 1.03 Adjusted EBITDA.
Slide 17: Substantial Financial Flexibility Added by Eliminating GP's 50% IDR
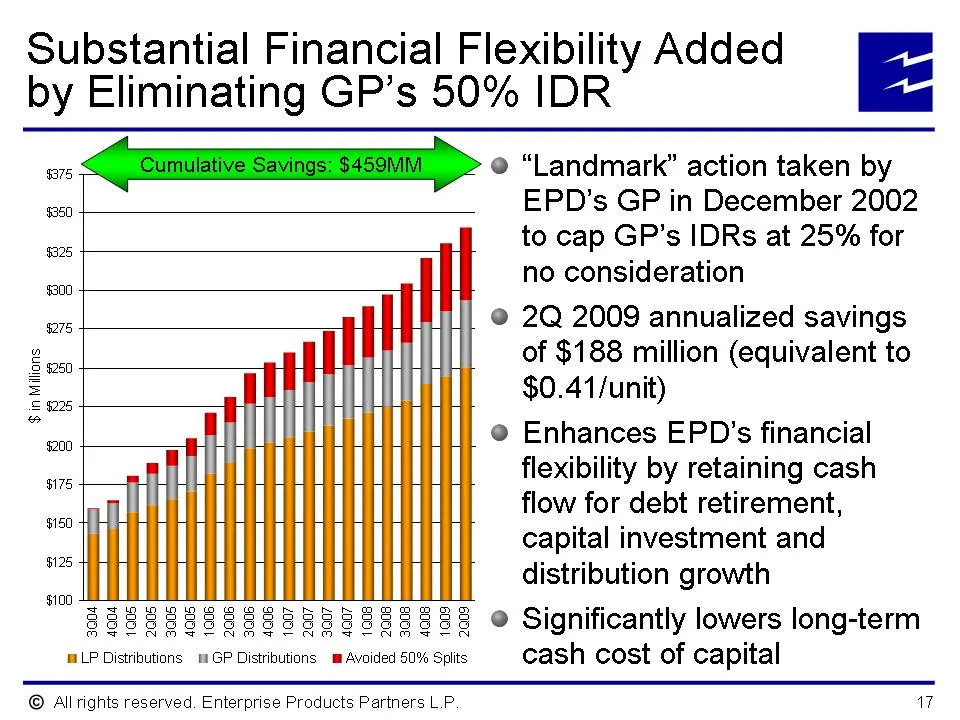
Substantial Financial Flexibility Added by Eliminating GP’s 50% IDR 575 Gham,» @ “Landmark” action taken by EPD’s GP in December 2002 $350 $ in Millions, 6 8 $200 + 5175 4 $150 $125, $100 Avoided 50% Splits LP Distributions 1m GP Distributions © Allrights reserved. Enterprise Products Partners L.P.
Slide 18: History of Providing Distribution Growth While Retaining Capital
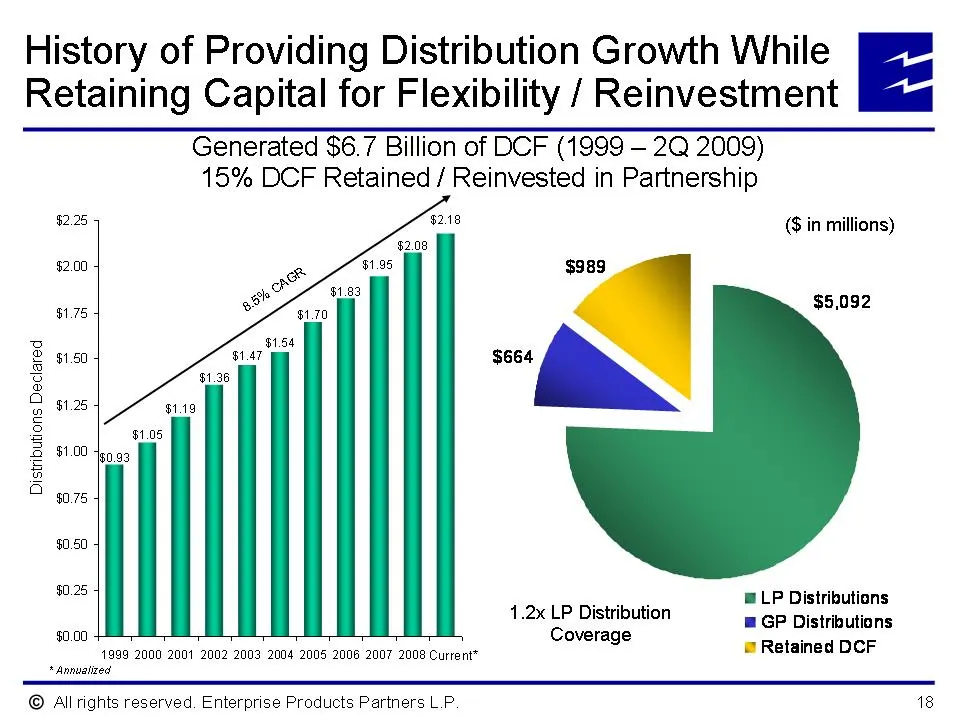
History of Providing Distribution Growth While Retaining Capital for Flexibility / Reinvestment Generated $6.7 Billion of DCF (1999 — 2Q 2009) 15% DCF Retained / Reinvested in Partnership tae Gin millions) $2.00 $1.75 $5,092 2 5 $1.50 3 2 91.25 5 3B $1.00 9 $0.75 $0.50 a Sea toul LP Distributions Be
Slide 19: Proven Track Record
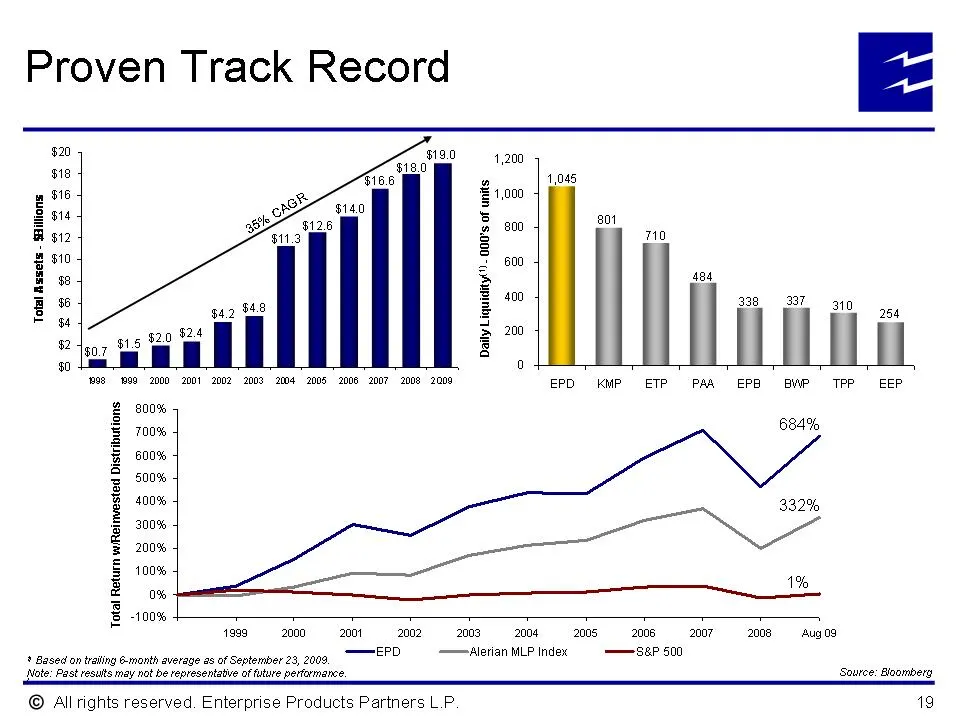
Proven Track Record sa #18 . 9 516 i 2514 s Bs g #510 f a $ Eos > a2 5 Fa a 2 2 z 0 wie "wie go 012020204 00500207 208 “2000 EPD KMP ETP PAA EPE BWP TPP EEP 2 800% = 700% § so0% S 500% os 5 200% 5 100% i 1% 2 ow B -100% + seo 2000-=«2001=002=«200 «200420052006 = «2007008 PD = —Aletian NLP index sep
Slide 20: Non-GAAP Reconciliations
Non-GAAP Reconciliations © Allrights reserved. Enterprise Products Partners L.P.
Slide 21: Non-GAAP Financial Measures
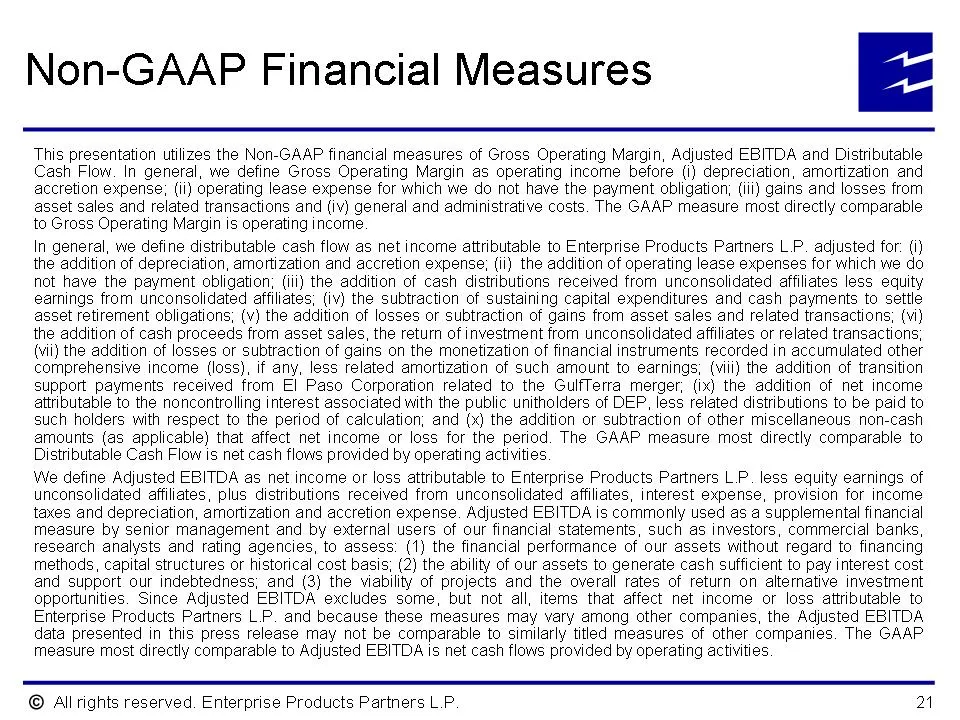
Non-GAAP Financial Measures This presentation utilizes the Non-GAAP financial measures of Gross Operating Margin, Adjusted EBITDA and Distributable Cash Flow. In general, we define Gross Operating Margin as operating income before (i) depreciation, amortization and accretion expense; (ii) operating
Slide 22: Non-GAAP Reconciliations
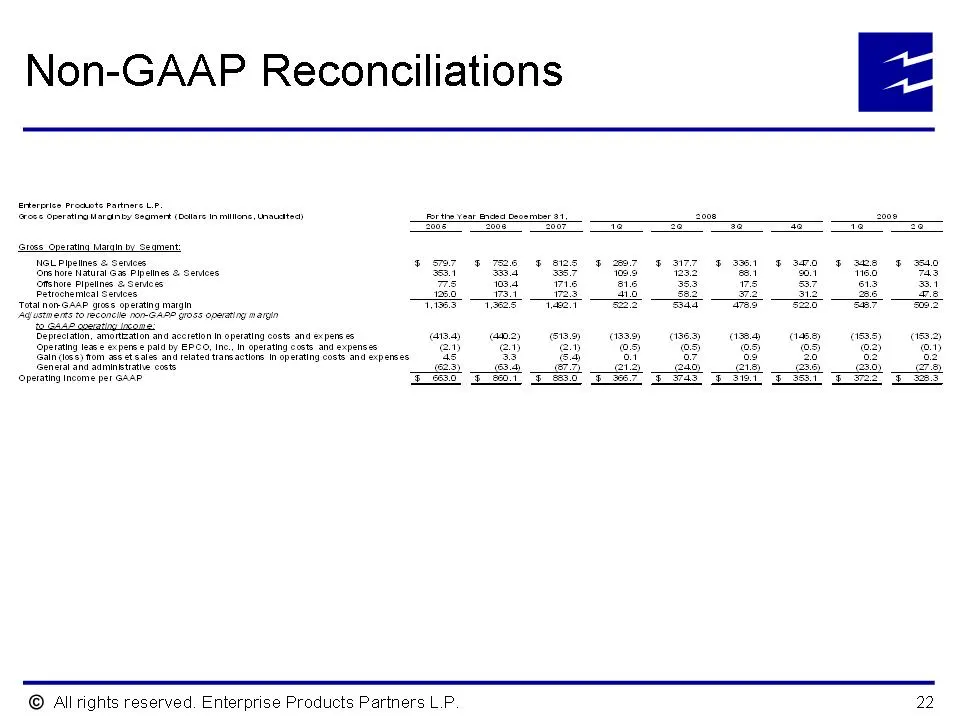
Non-GAAP Reconciliations ieee operating Man by Seument NGL Ppatnes & Sertoss ‘ore hoe Natural Gas Pipelines & Sences apap carne Depreciation, amorteation and aoctetion in opetating costs and e< pes 2s ating lee 2:panee pad by EPCS, Ino. n operating costs and spans es is) Rosette an sate ase In opaat
Slide 23: Non-GAAP Reconciliations
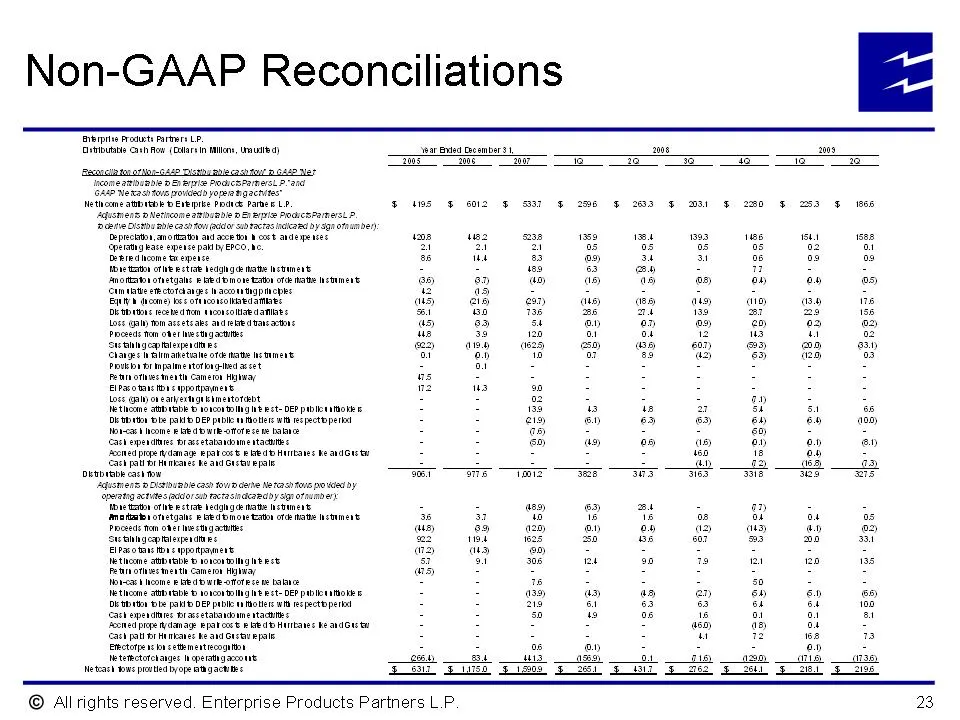
Non-GAAP Reconciliations There heat rar LP. (Guts Hera) ve powcads yore mgacnsts netucane aabeepk beverpike Pace Famer LP $495 § oO? § SBF § 25 F aHs $F mS F 2D B53 FHS ‘ecto anomto ad soto heart andes cee ios te es nT no) perma eave opens pally E20, 4c 2 21 0 os 08 0s 02 Dreiedicone tremens es ua 9
Slide 24: Non-GAAP Reconciliations
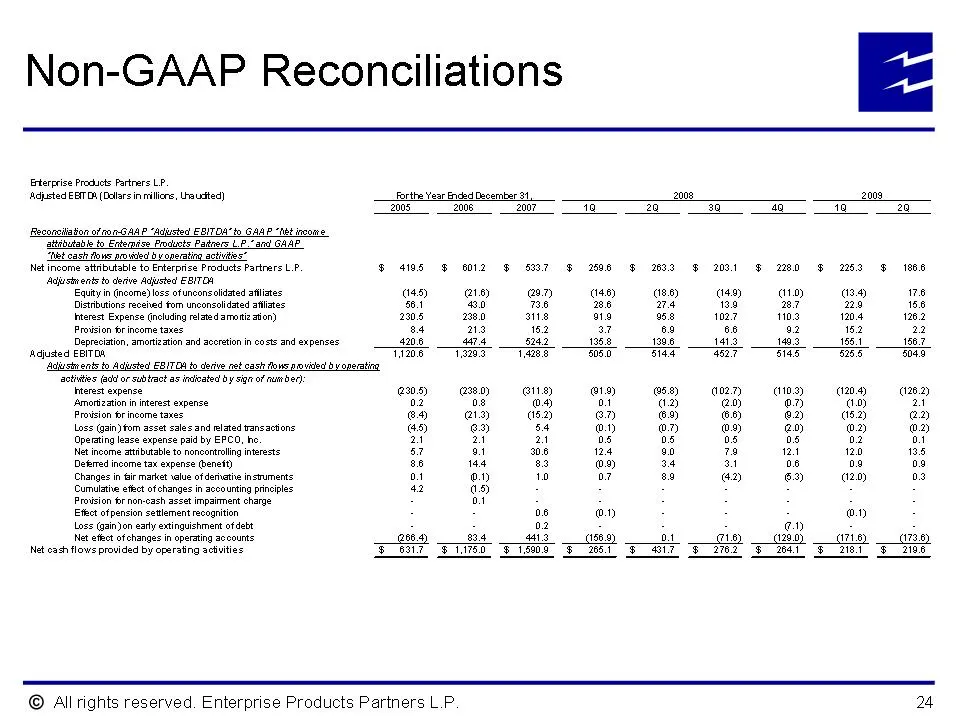
Non-GAAP Reconciliations Erterprise Products Partrers LP. Adjsted EBTOA (Dallas in illers, Urauted) forthe Vear Ended Dasember $1 2009 2009 200s 2008 2007 rT 2 3 ro} rT 2 econsilaion of 00-6 AAP “Aused! EBITDA” ty GAAP “tt income saidutable to Entemice Prcuots Patrers UP." and GAAP "At cash four ars
Slide 25: TPP Non-GAAP Financial Measures
TPP Non-GAAP Financial Measures [Ez This presentation includes Adjusted EBITDA, which is a non-GAAP financial measure. This non-GAAP financial measure should not be considered as an alternative to GAAP measures such as net income, operating income, cash flow from operating activities or any other me
Slide 26: Non-GAAP Reconciliations
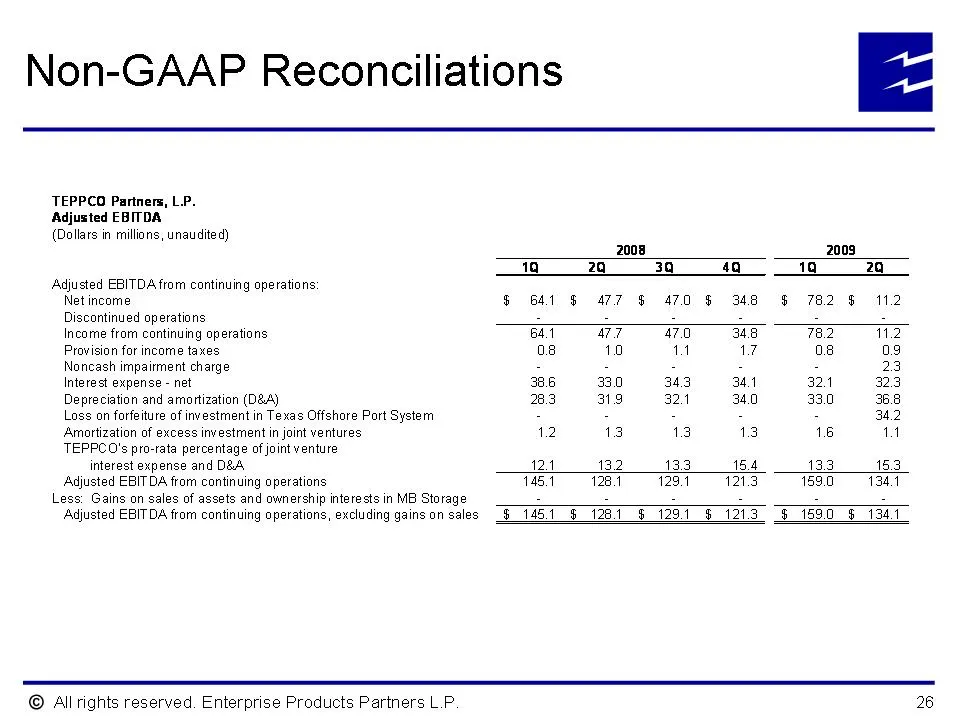
Non-GAAP Reconciliations TEPPCO Partners, LP. Adjusted EBITDA (Dollars in millions, unaudited) 2008 2003 710 20 30 40 1a 20 Adjusted EBITDA from continuing operations: Net income § G41 § 477 § 470 § MB § 782 § 112 Discontinued operations - - - - - - Income fram continuing operations aT WT qo mB 782
Source: SEC EDGAR · 425 filed Oct 7, 2009
More decks from Teppco Partners LP
 Master Limited Partnerships Investor Conference (September 2009)27 slides · Sep 16, 2009
 Wells Fargo Retail Meeting (September 2009)27 slides · Sep 15, 2009
 Barclays Capital CEO Energy/Power Conference 200929 slides · Sep 9, 2009
 Merger or Acquisition (August 2009)29 slides · Aug 26, 2009
 Wachovia Securities Investor Presentation (June 2007)51 slides · Jun 1, 2007
 Investor Day (March 2007)75 slides · Mar 29, 2007