Emami Limited · NSE:EMAMILTD
Emami — Investor Presentation (January 2010)
46 slides from Emami's investor presentation, January 2010
Slide 1: Investor Presentation January 2010
Investor Presentation January’ 2010 Confidential 1
Slide 2: Disclaimer
Disclaimer This Confidential Presentation (“CP”) contains proprietary and confidential information regarding Emami Limited ((or “EMAMI”).) The CP is prepared by Emami Limited based on the published information available and has not independently verified any of the information contained herein.
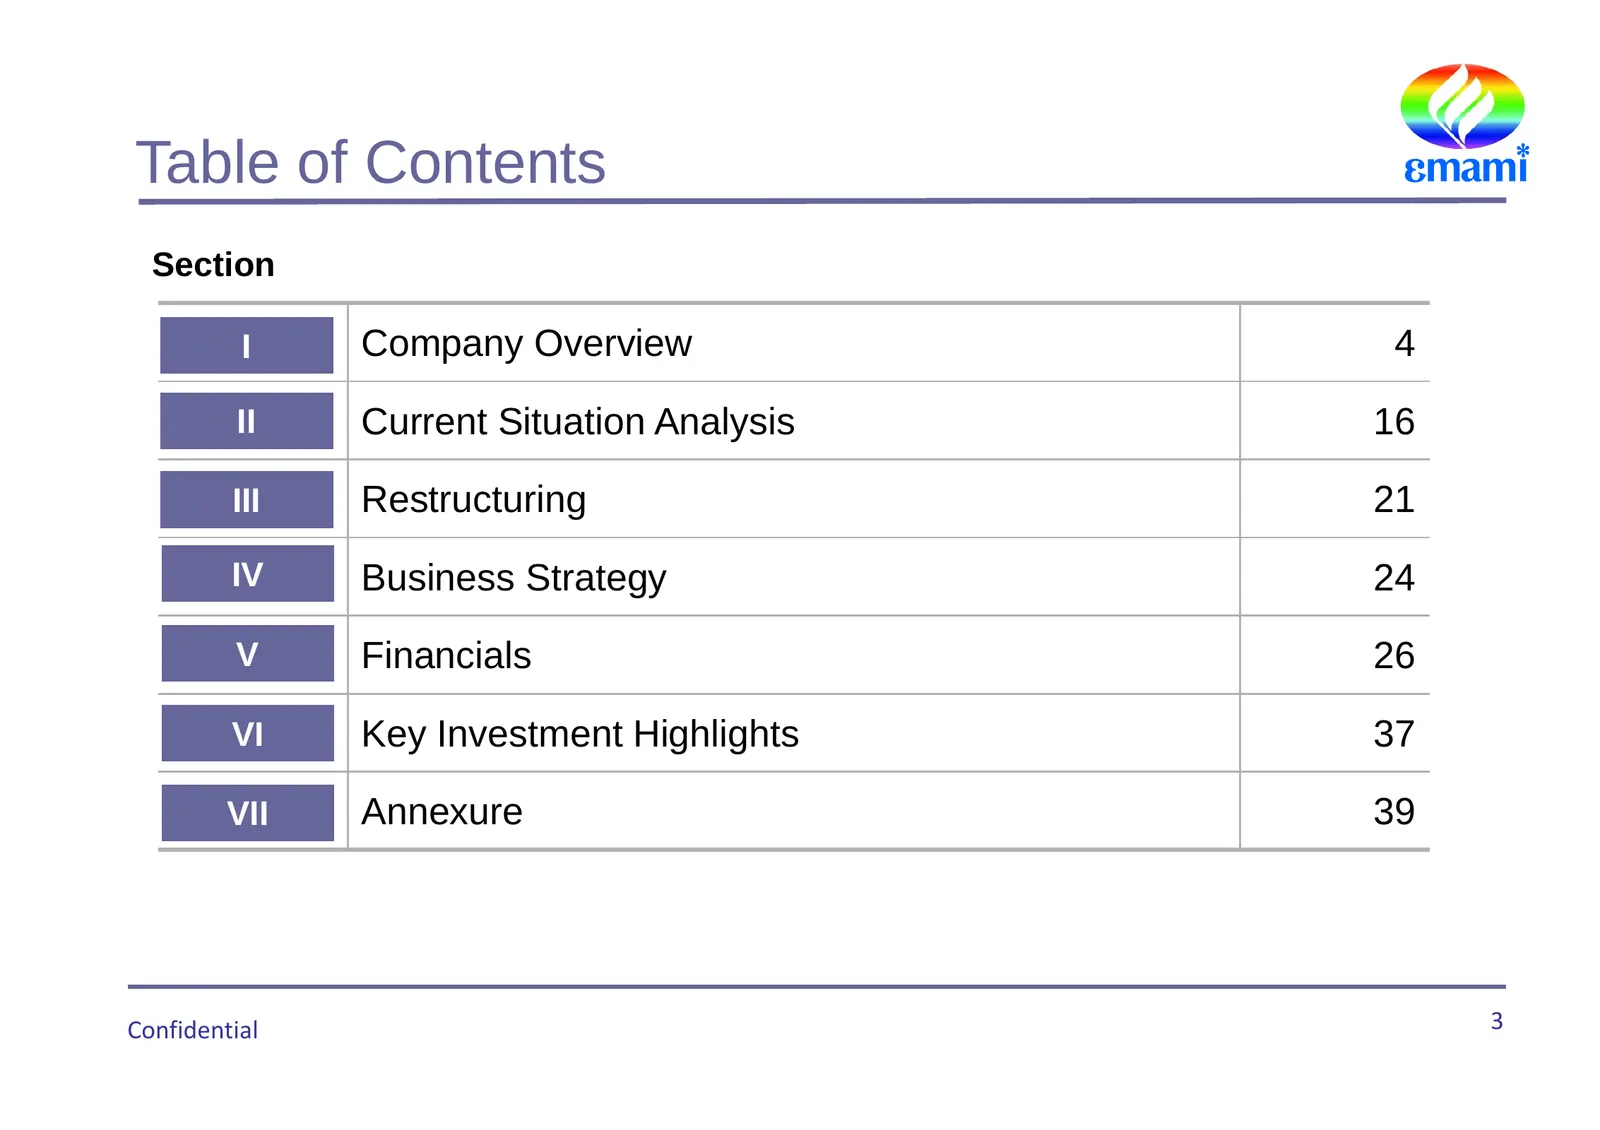
Slide 3: Table of Contents
Table of Contents Section I Company Overview 4 II y Current Situation Analysis 16 III Restructuring 21 IV B i Business Strategy St t 24 V Financials 26 VI Key Investment Highlights 37 VII Annexure 39 Confidential 3
Slide 4: Company Overview
Section: I Company Overview Confidential 4
Slide 5: Company Overview
Company Overview Emami Limited, the flagship company of the Emami Group, is a leading FMCG player in India The Company is promoted by Kolkata-based industrialists, Mr. R.S. Agarwal and Mr. R.S. Goenka Emami has been in the health, beauty and personal care products space since the last 30 years
Slide 6: Business Philosophy
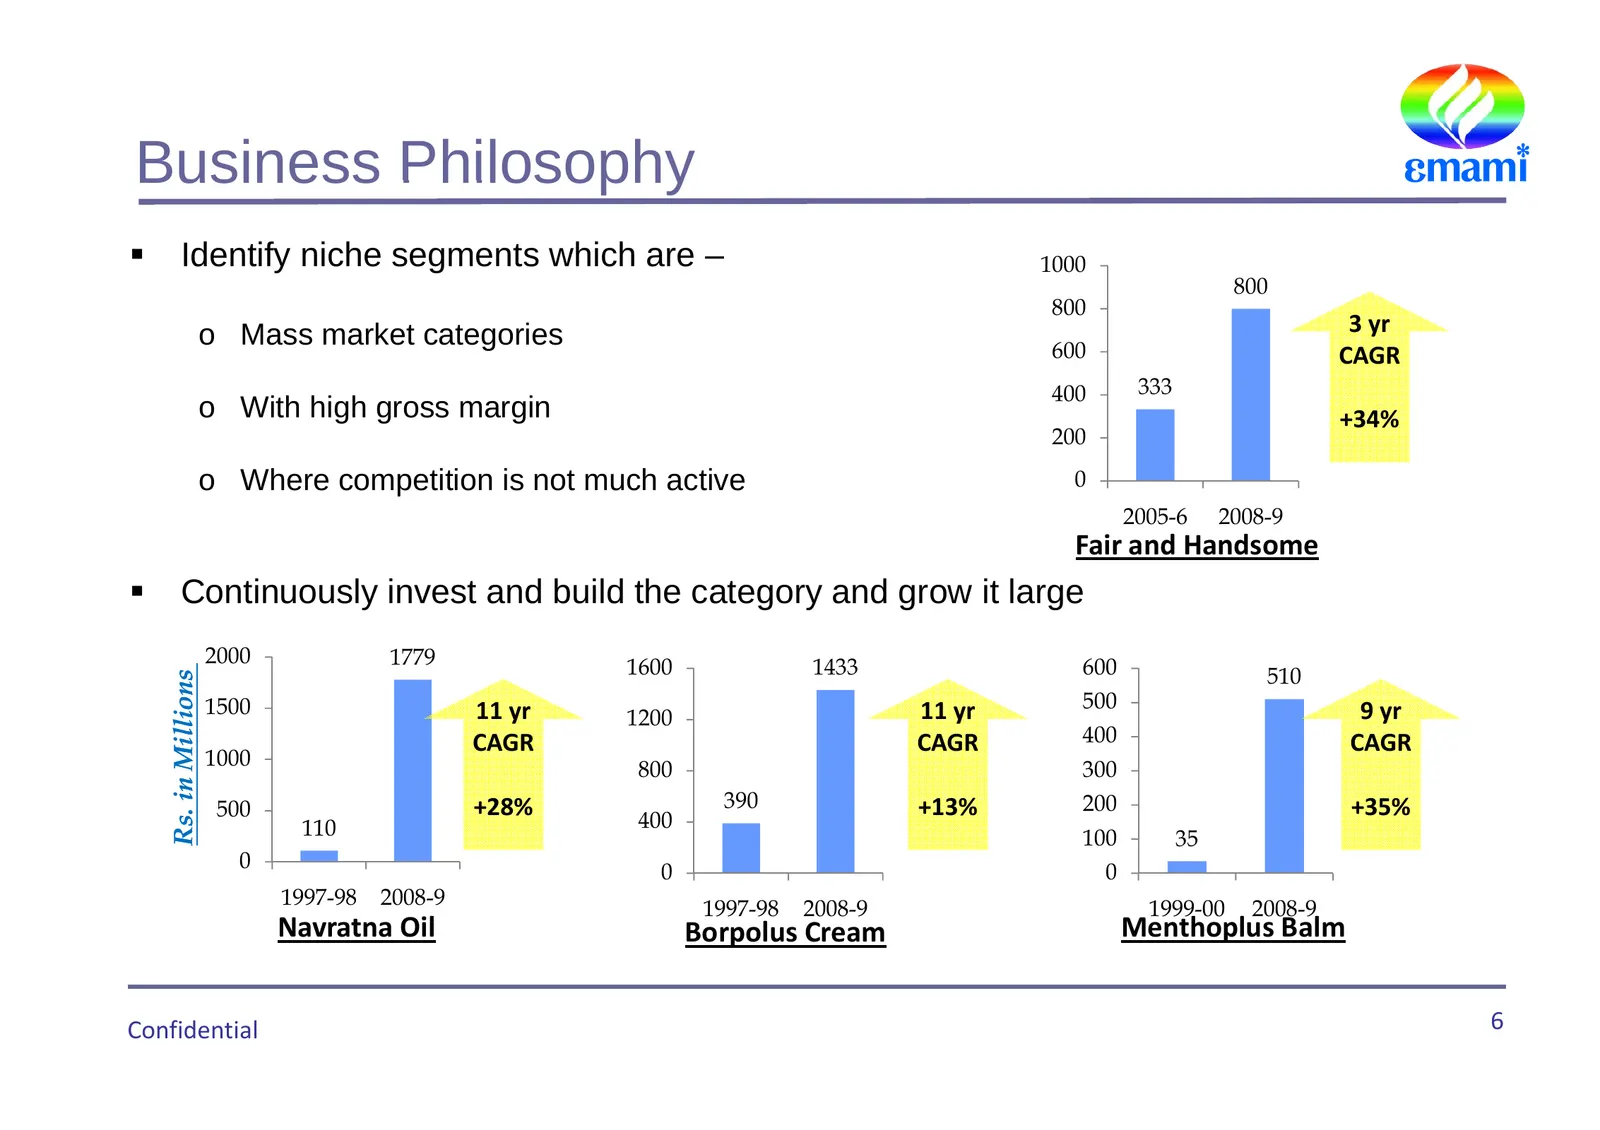
Business Philosophy Identify niche segments which are – 1000 800 800 o Mass market categories 3 yr 600 CAGR 400 333 o With high gross margin +34% 200 o Where competition is not much active 0 2005-6 2008-9 Fair and Handsome Continuously invest and build the category and grow it large 2000 1779 16
Slide 7: Snapshot of power brands
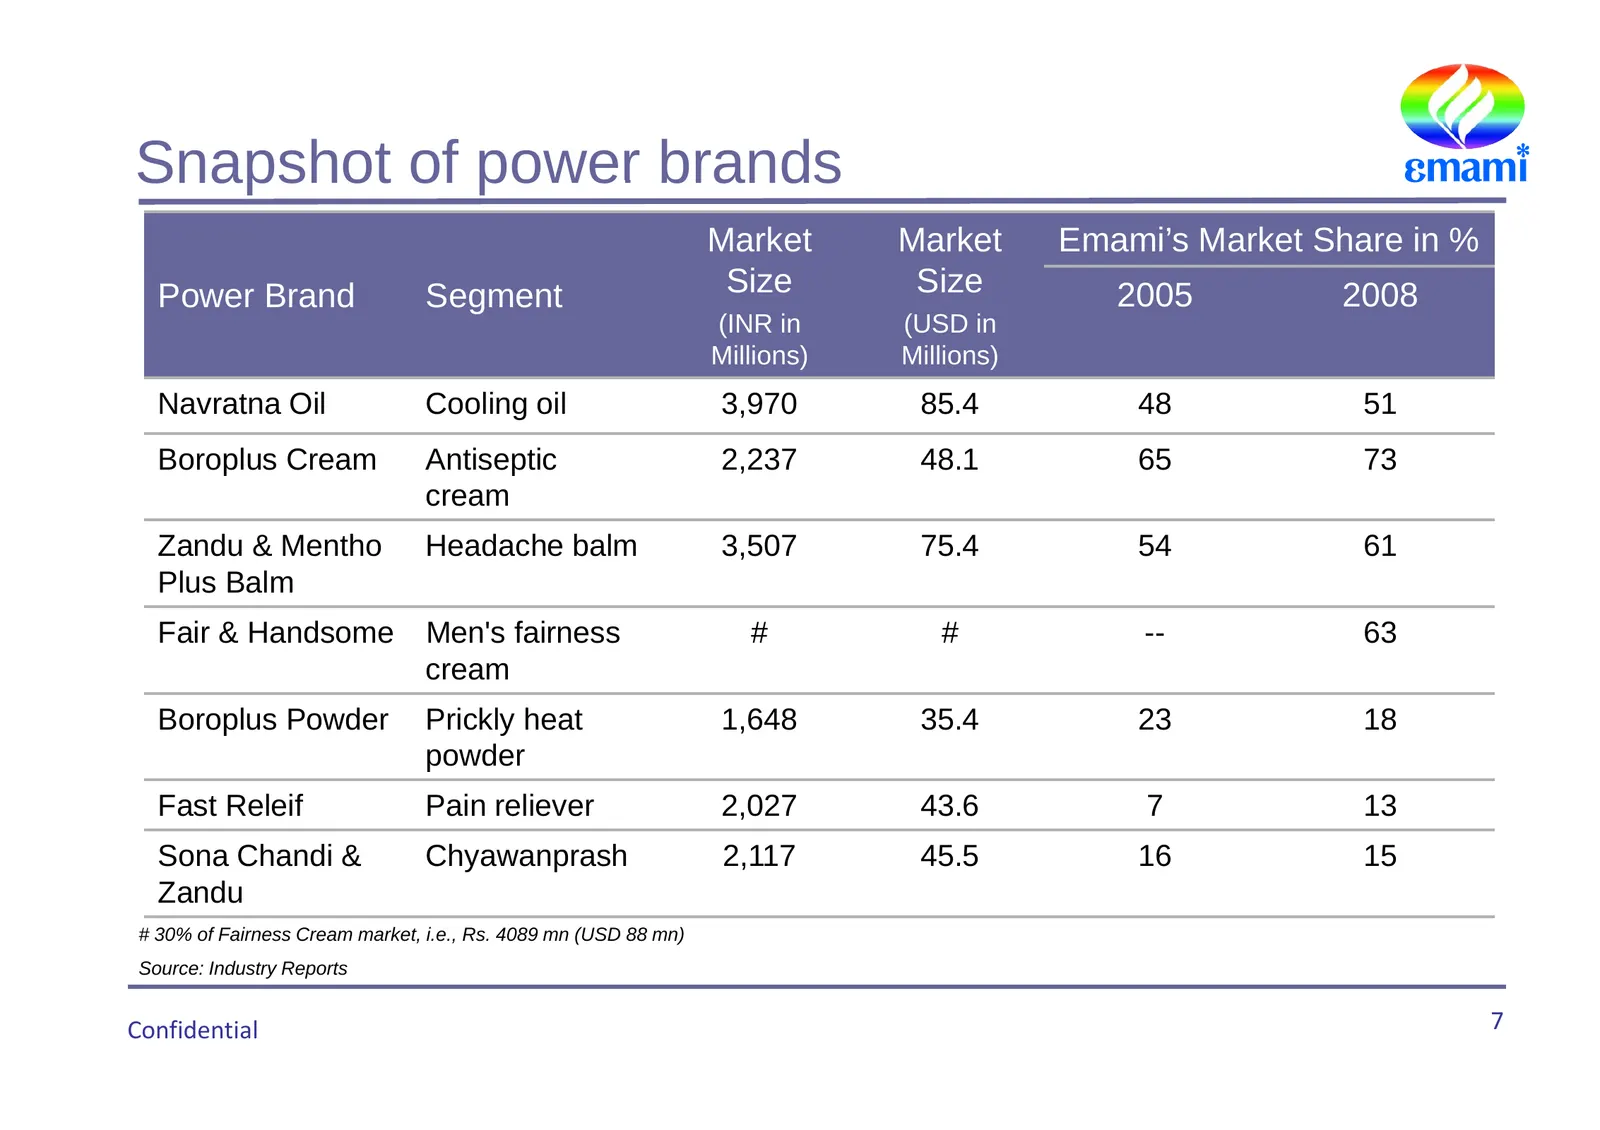
Snapshot of power brands Market Market Emami’s Market Share in % Power Brand Segment g Size Size 2005 2008 (INR in (USD in Millions) Millions) Navratna Oil Cooling oil 3,970 85.4 48 51 Boroplus Cream Antiseptic 2,237 48.1 65 73 cream Zandu & Mentho Headache balm 3,507 75.4 54 61 Plus Balm Fair & Han
Slide 8: Domestic reach
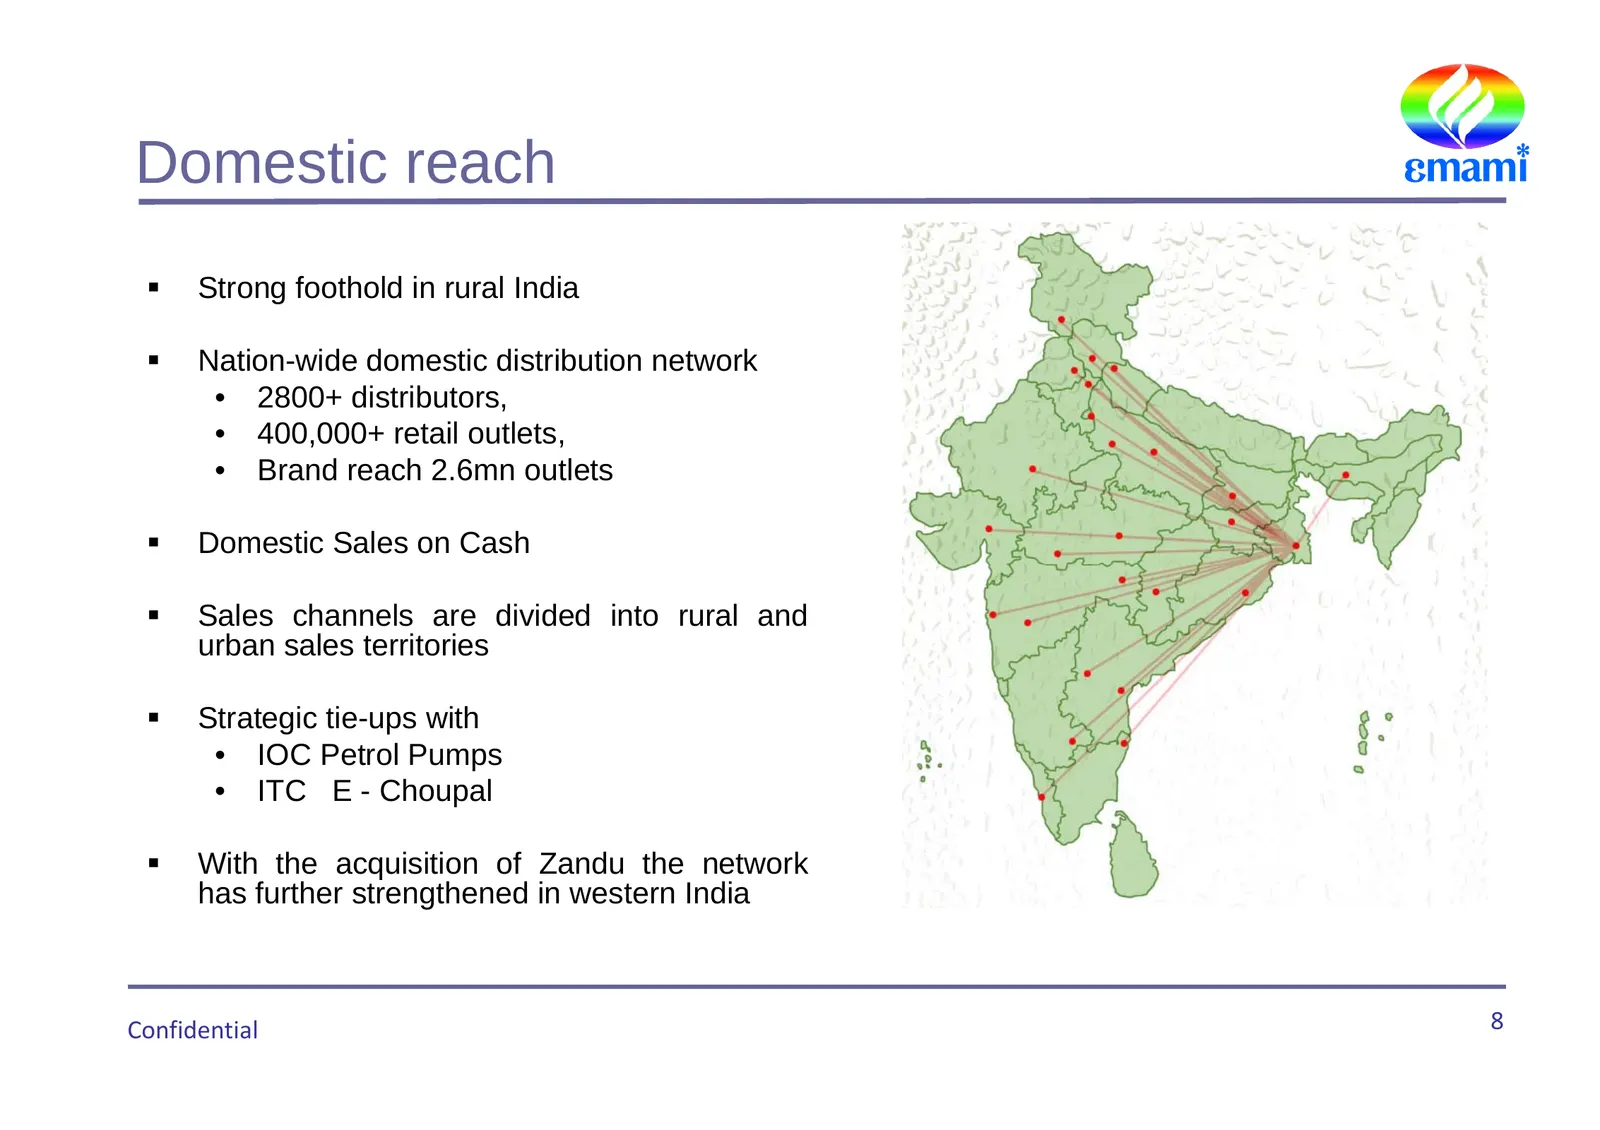
Domestic reach Strong foothold in rural India Nation-wide domestic distribution network • 2800+ distributors, • 400,000+ 400 000+ retail outlets outlets, • Brand reach 2.6mn outlets Domestic Sales on Cash Sales channels are divided into rural and urban sales territories Strategic tie-ups w
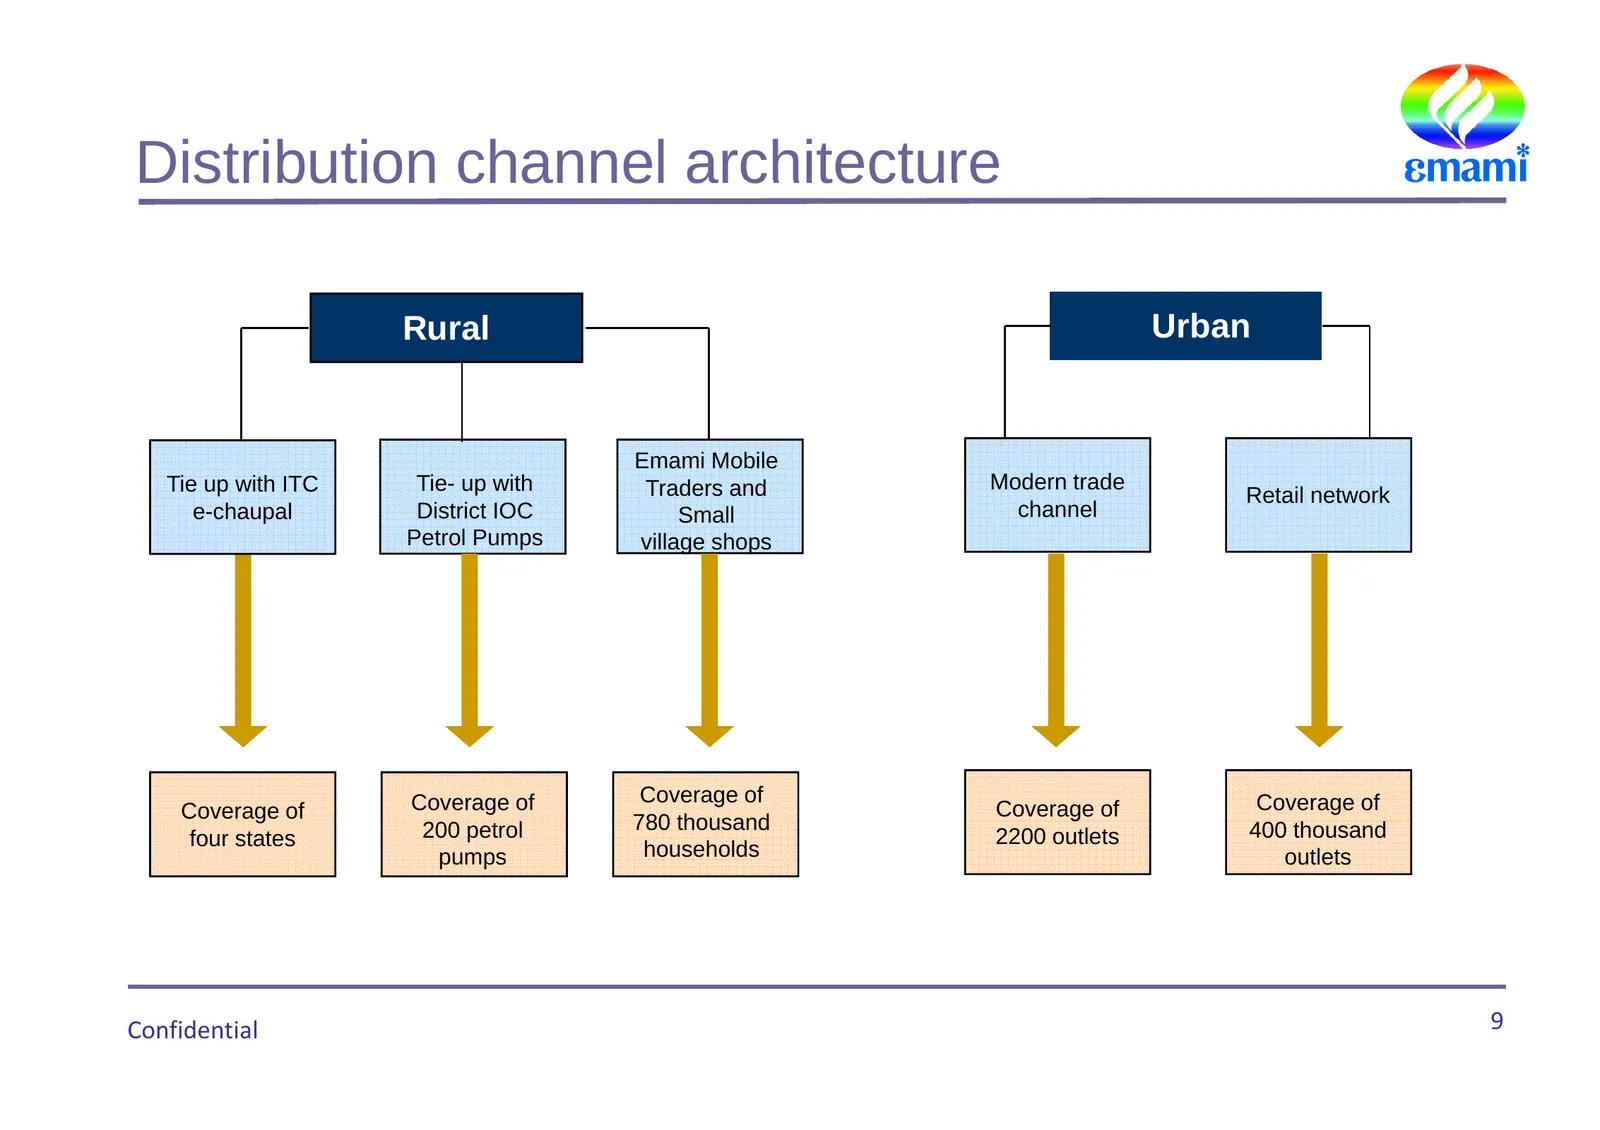
Slide 9: Distribution channel architecture
Distribution channel architecture Rural Urban Emami Mobile Tie up with ITC Tie- up with Traders and Modern trade Retail network e-chaupal District IOC Small channel Petrol Pumps village shops Coverage of Coverage of Coverage of Coverageg of Coverage g of 200 petrol 780 thousand 400 thousand four sta
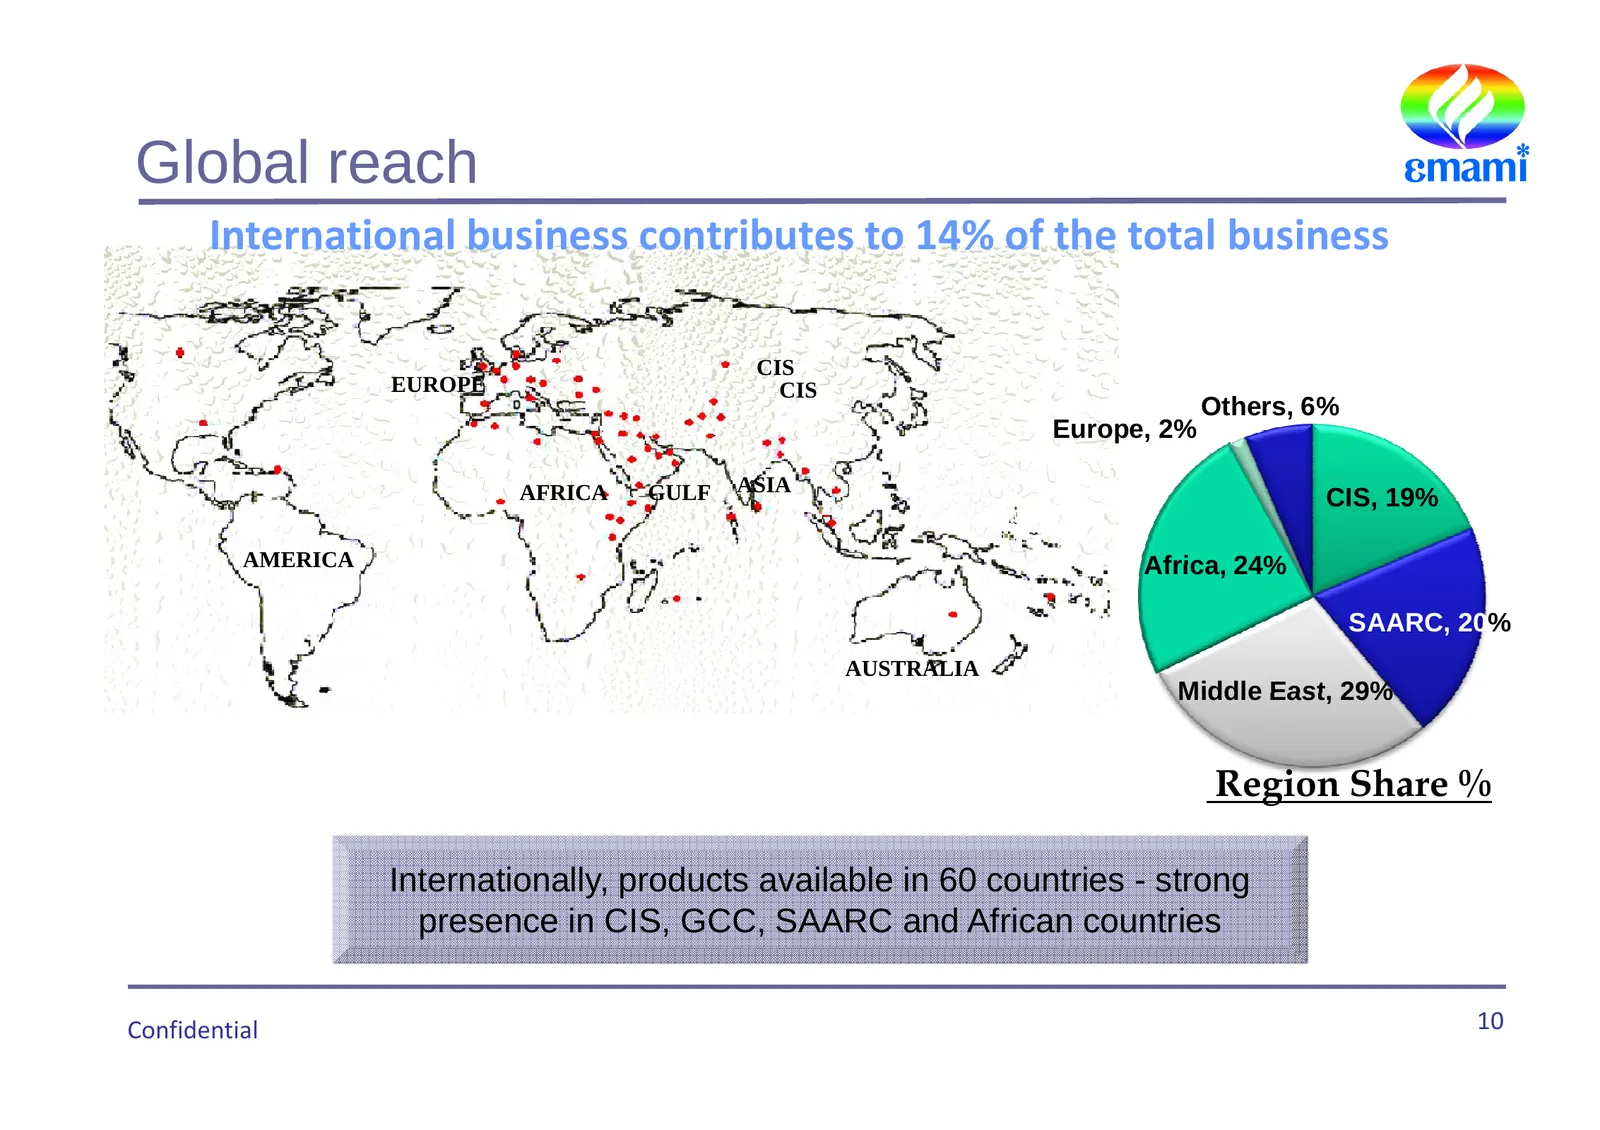
Slide 10: Global reach
Global reach International business contributes to 14% of the total business CIS EUROPE CIS Others, 6% Europe, 2% AFRICA GULF ASIA CIS, 19% AMERICA Africa 24% Africa, SAARC, 20% AUSTRALIA East 29% Middle East, Region Share % Internationally, products available in 60 countries - strong presence in CI
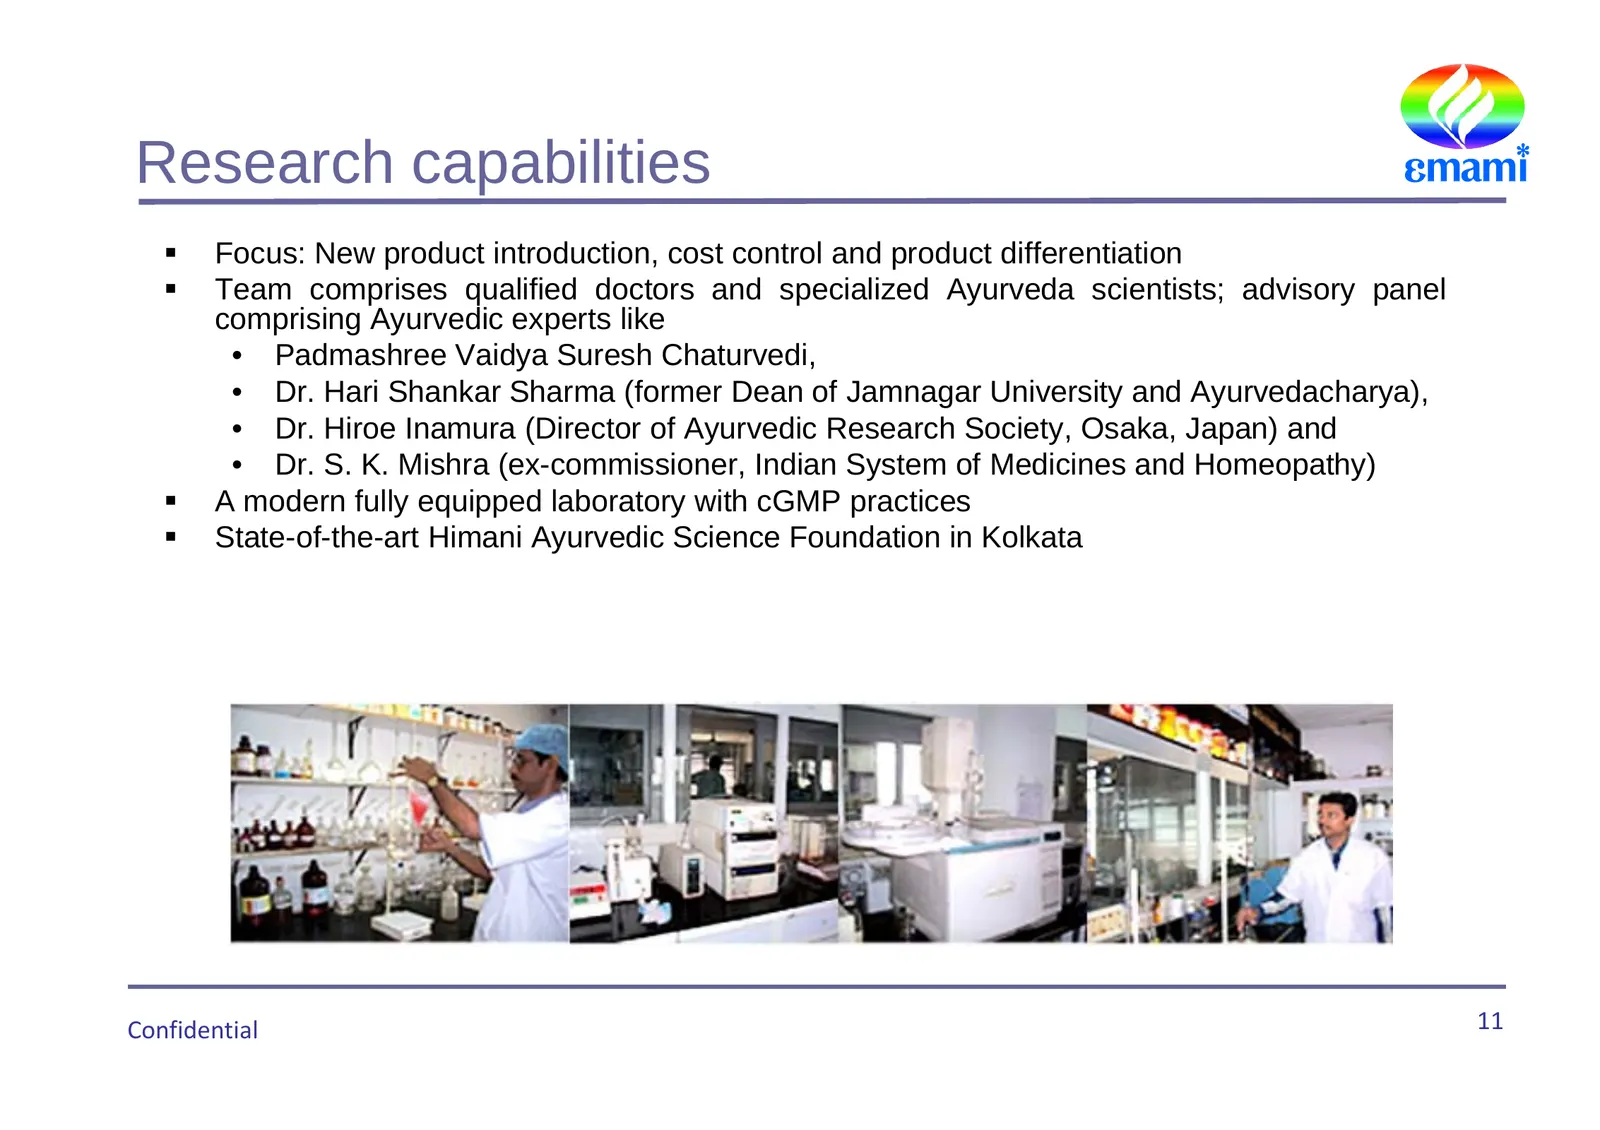
Slide 11: Research capabilities
Research capabilities Focus: New product introduction, cost control and product differentiation Team comprises qualified doctors and specialized Ayurveda scientists; advisory panel comprising i i Ayurvedic A di experts t like lik • Padmashree Vaidya Suresh Chaturvedi, • Dr. Hari Shankar Sharma (
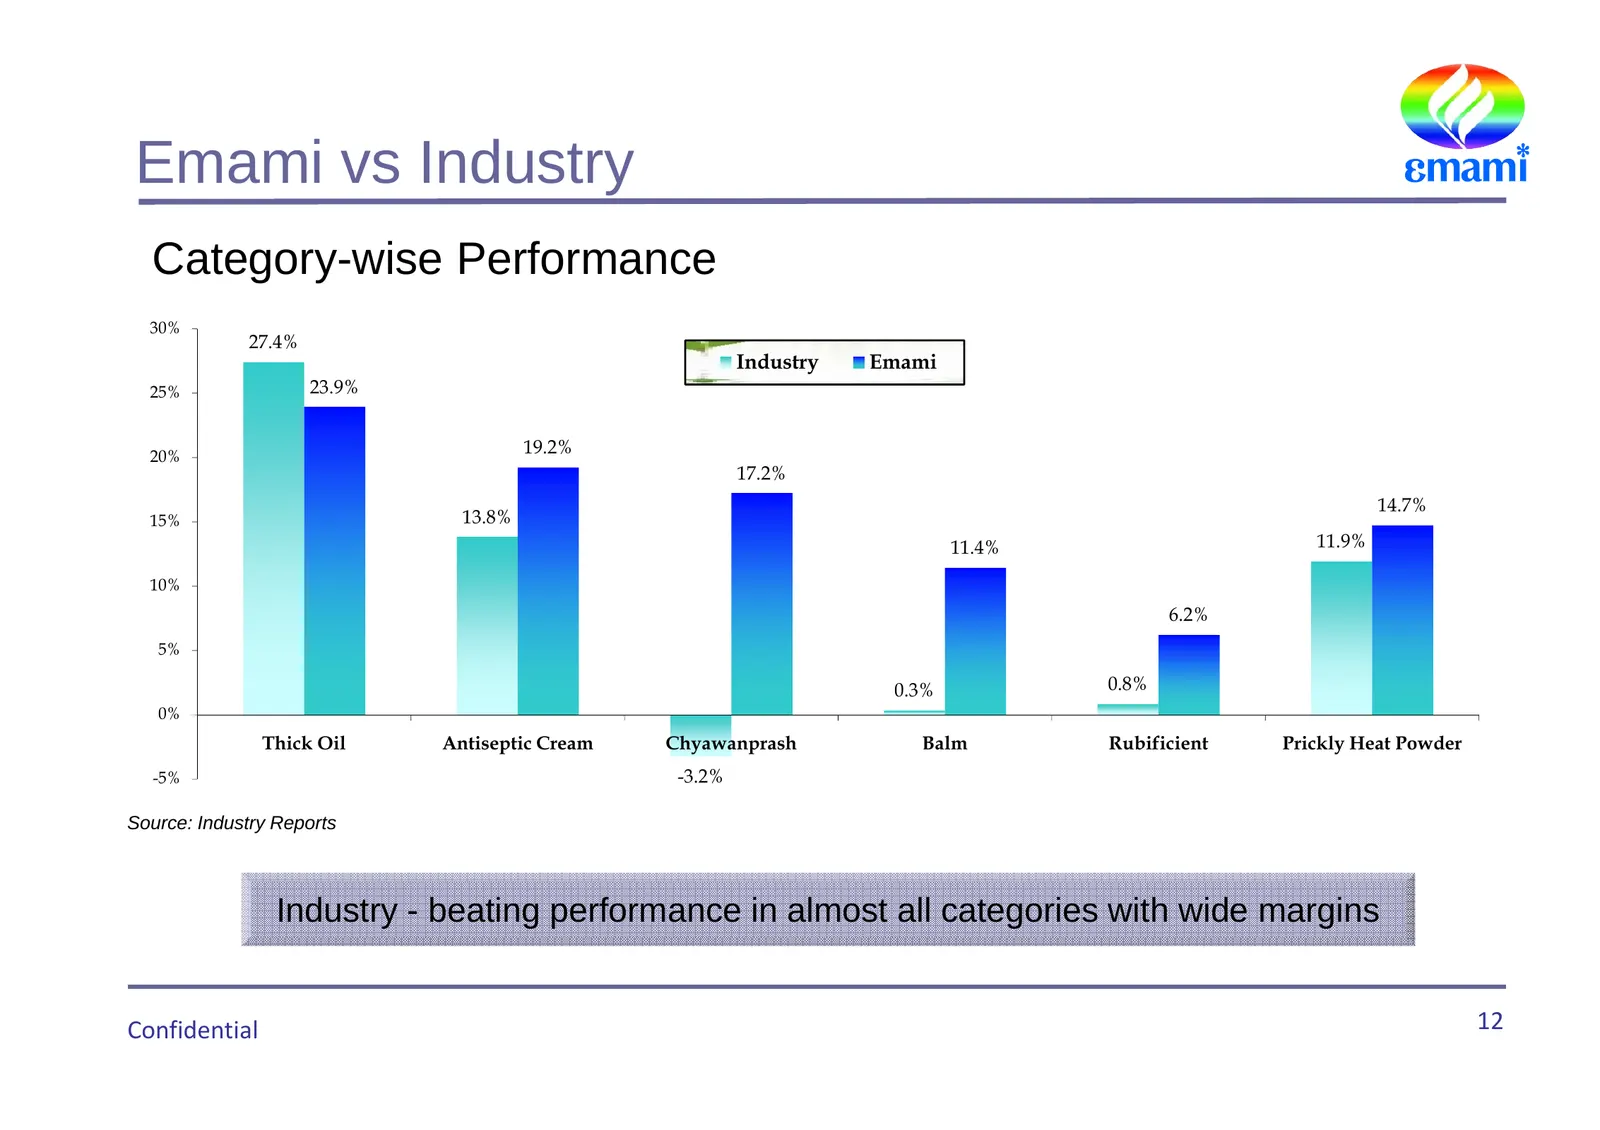
Slide 12: Emami vs Industry
Emami vs Industry Category-wise Performance 30% 27.4% Industry Emami 25% 23.9% 20% 19.2% 17.2% 14.7% 15% 13.8% 11.4% 11.9% 10% 6.2% 5% 0 3% 0.3% 0.8% 0% Thick Oil Antiseptic Cream Chyawanprash Balm Rubificient Prickly Heat Powder -5% -3.2% Source: Industry Reports Industry - beating performance in a
Slide 13: Low penetration: Big opportunity
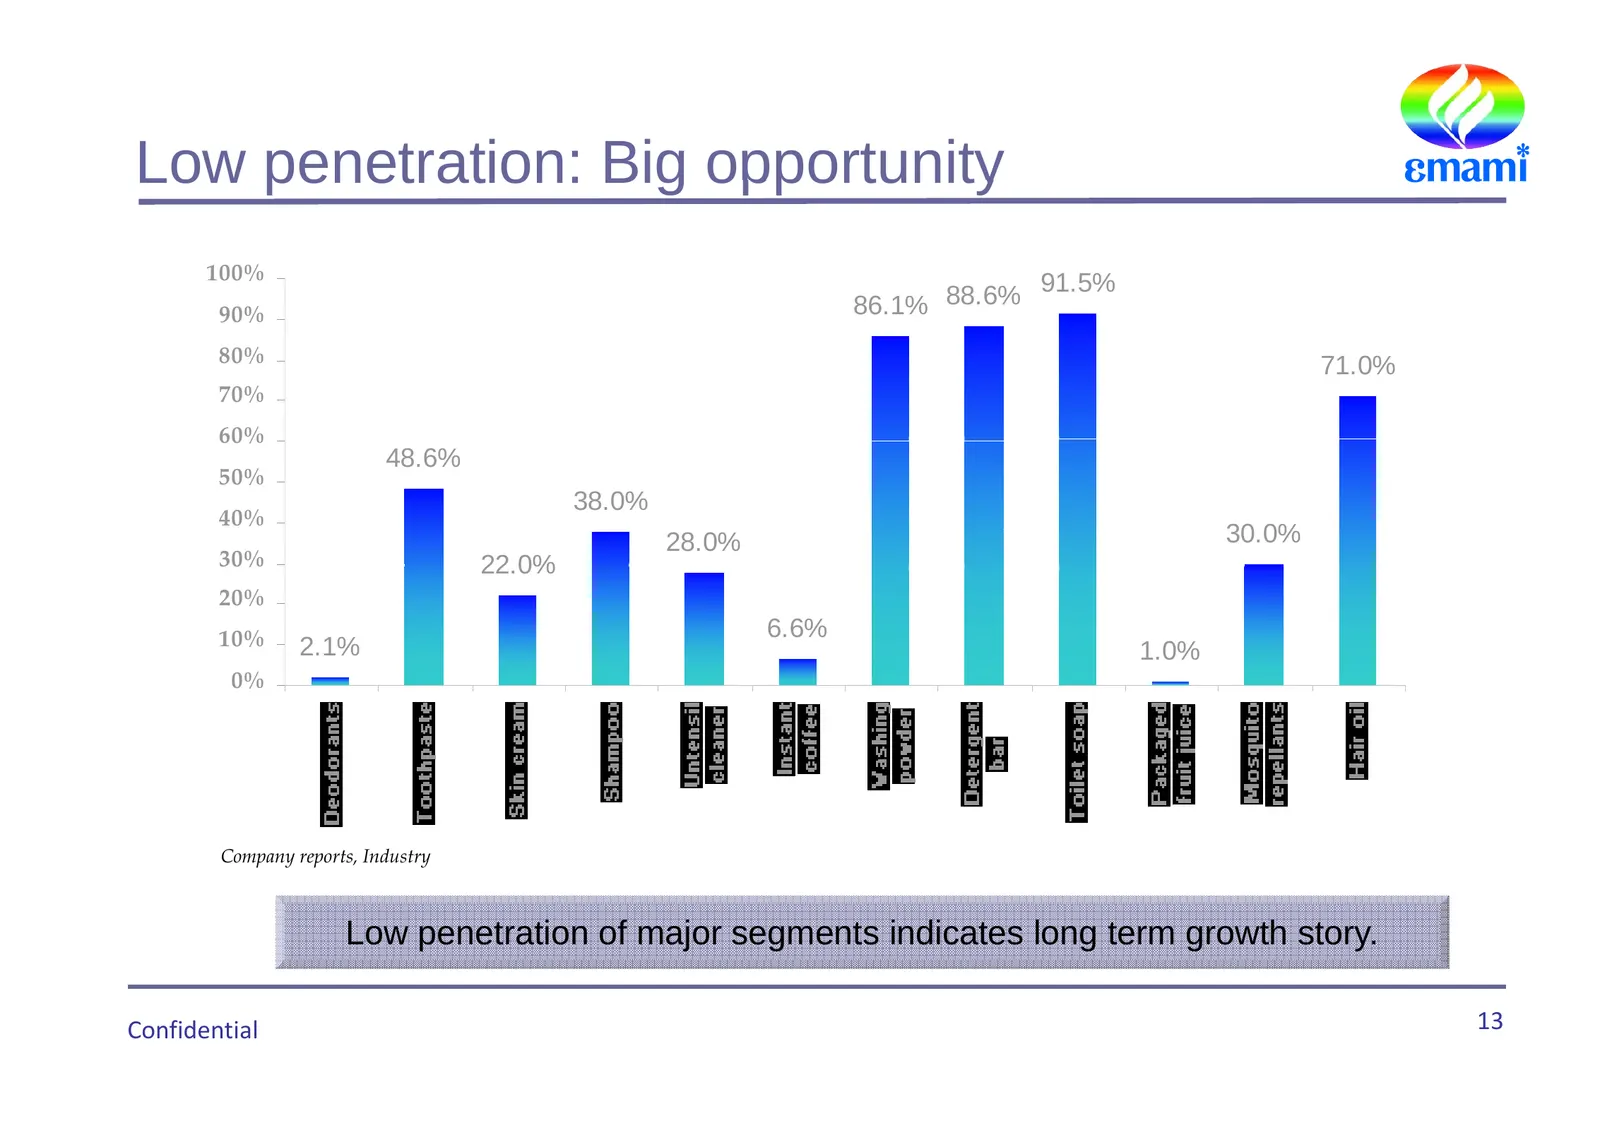
Low penetration: Big opportunity 100% 91.5% 90% 86 1% 88.6% 86.1% 80% 71.0% 70% 60% 48.6% 50% 38.0% 40% 28.0% 30.0% 30% 22 0% 22.0% 20% 10% 6.6% 2.1% 1.0% 0% Company reports, Industry Low p penetration of major j segments g indicates long g term g growth story. y Confidential 13
Slide 14: New launches
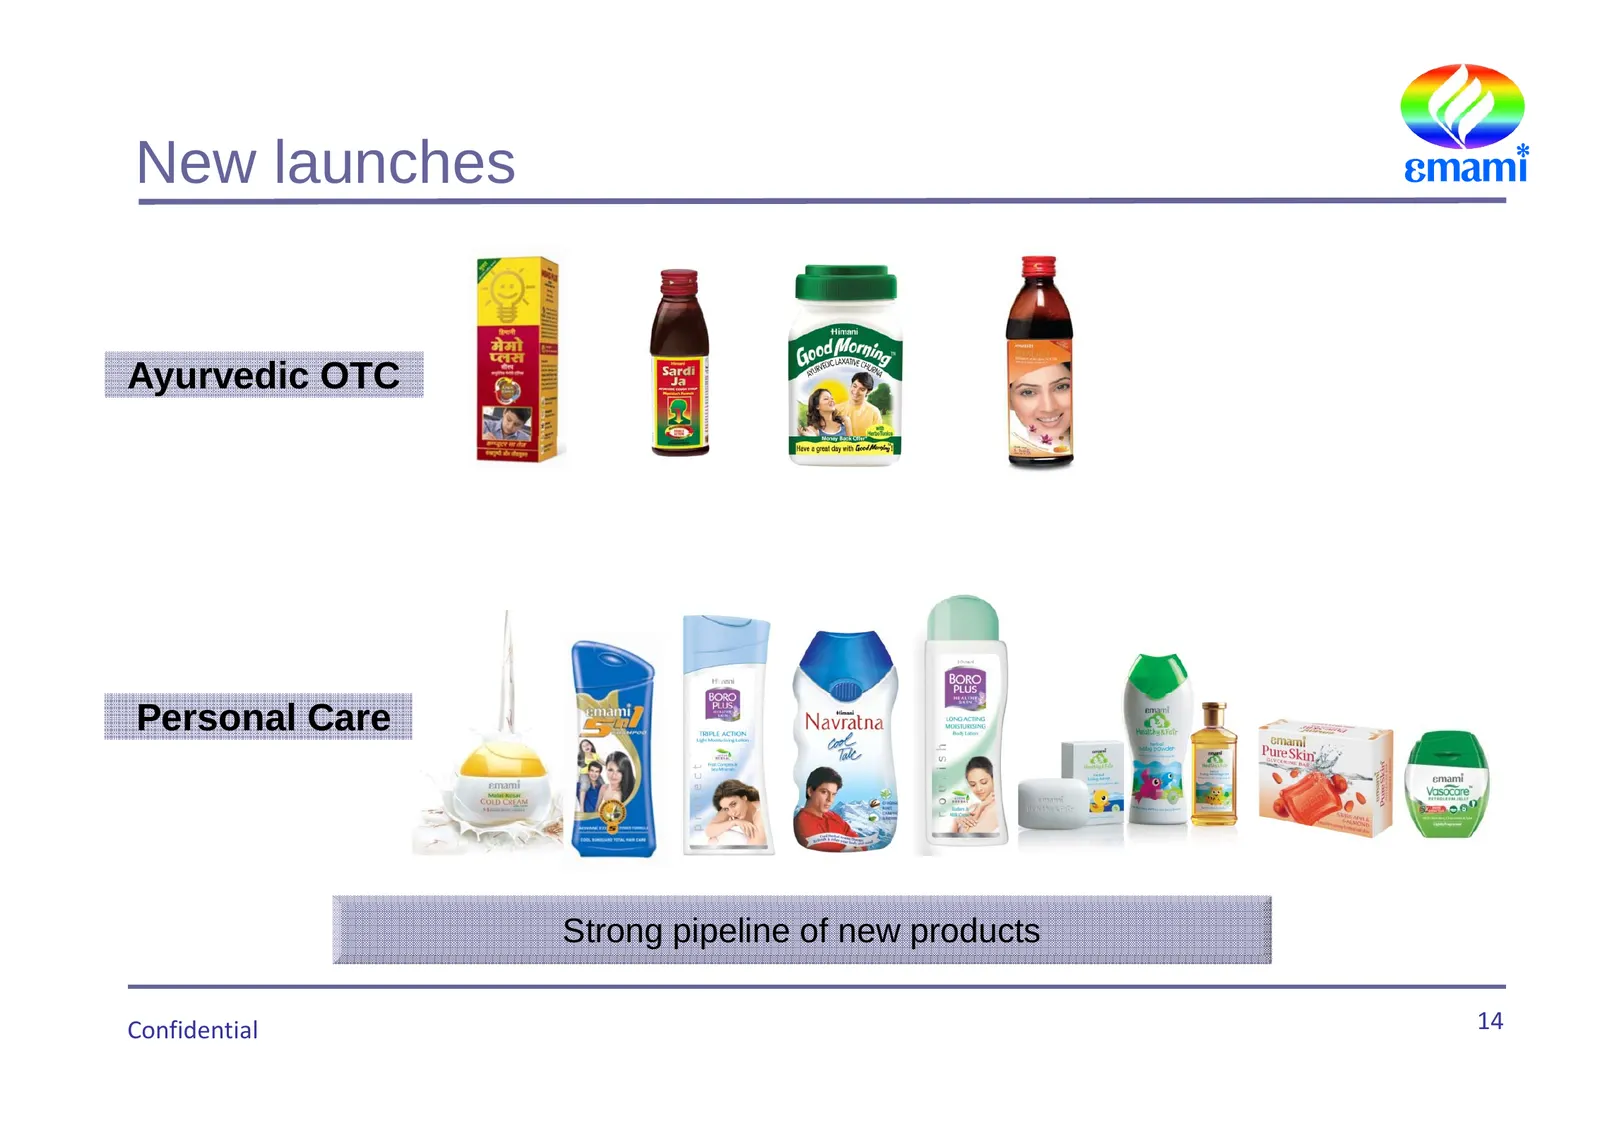
New launches Ayurvedic OTC Personal Care Strong g pipeline of new products Confidential 14
Slide 15: Current shareholding pattern
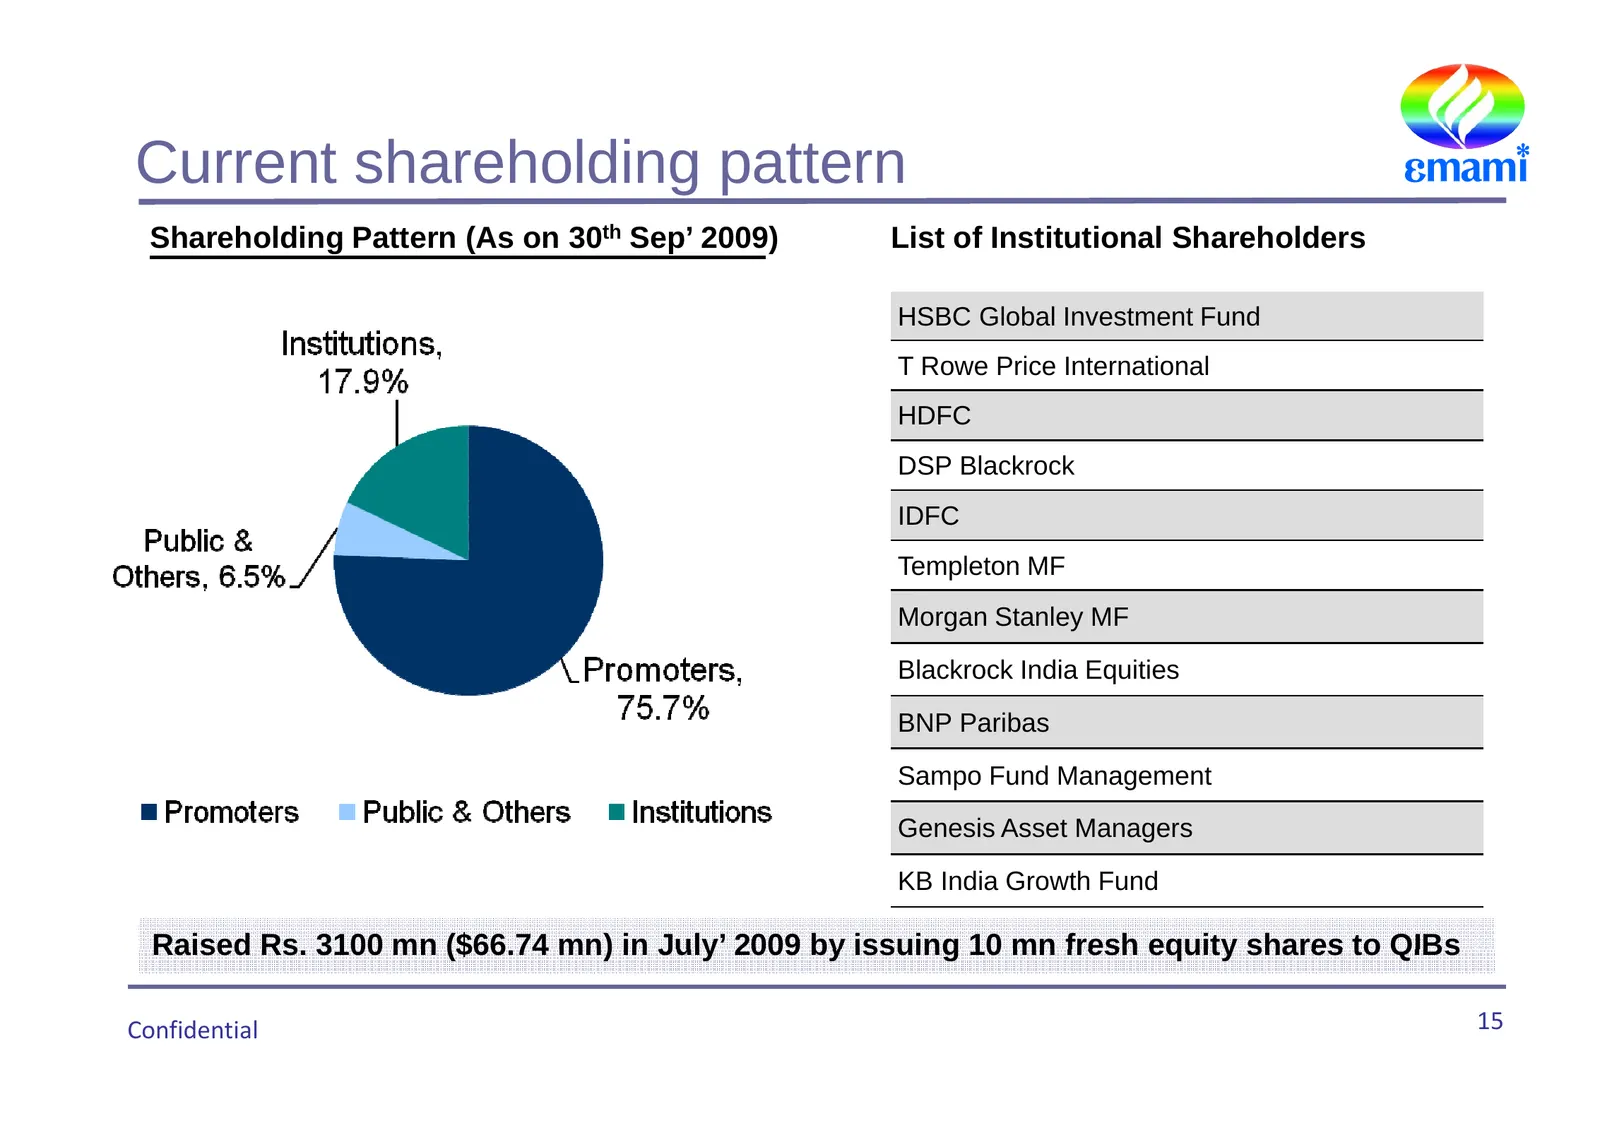
Current shareholding pattern Shareholding Pattern (As on 30th Sep’ 2009) List of Institutional Shareholders HSBC Global Gl b l IInvestment t tFFund d T Rowe Price International HDFC DSP Blackrock IDFC Templeton MF Morgan Stanley MF Blackrock India Equities BNP Paribas Sampo Fund Management G Genesis
Slide 16: Current Situation Analysis
Section: II Current Situation Analysis Confidential 16
Slide 17: The Zandu acquisition
The Zandu acquisition Century old household name in India and a leading Ayurveda healthcare company It is a strategic fit for Emami with a strong research and development base in Ayurveda • Emami acquired 68 91% stake in Zandu 68.91% Leadership position in pain balm (rubificient) category for
Slide 18: Zandu brands
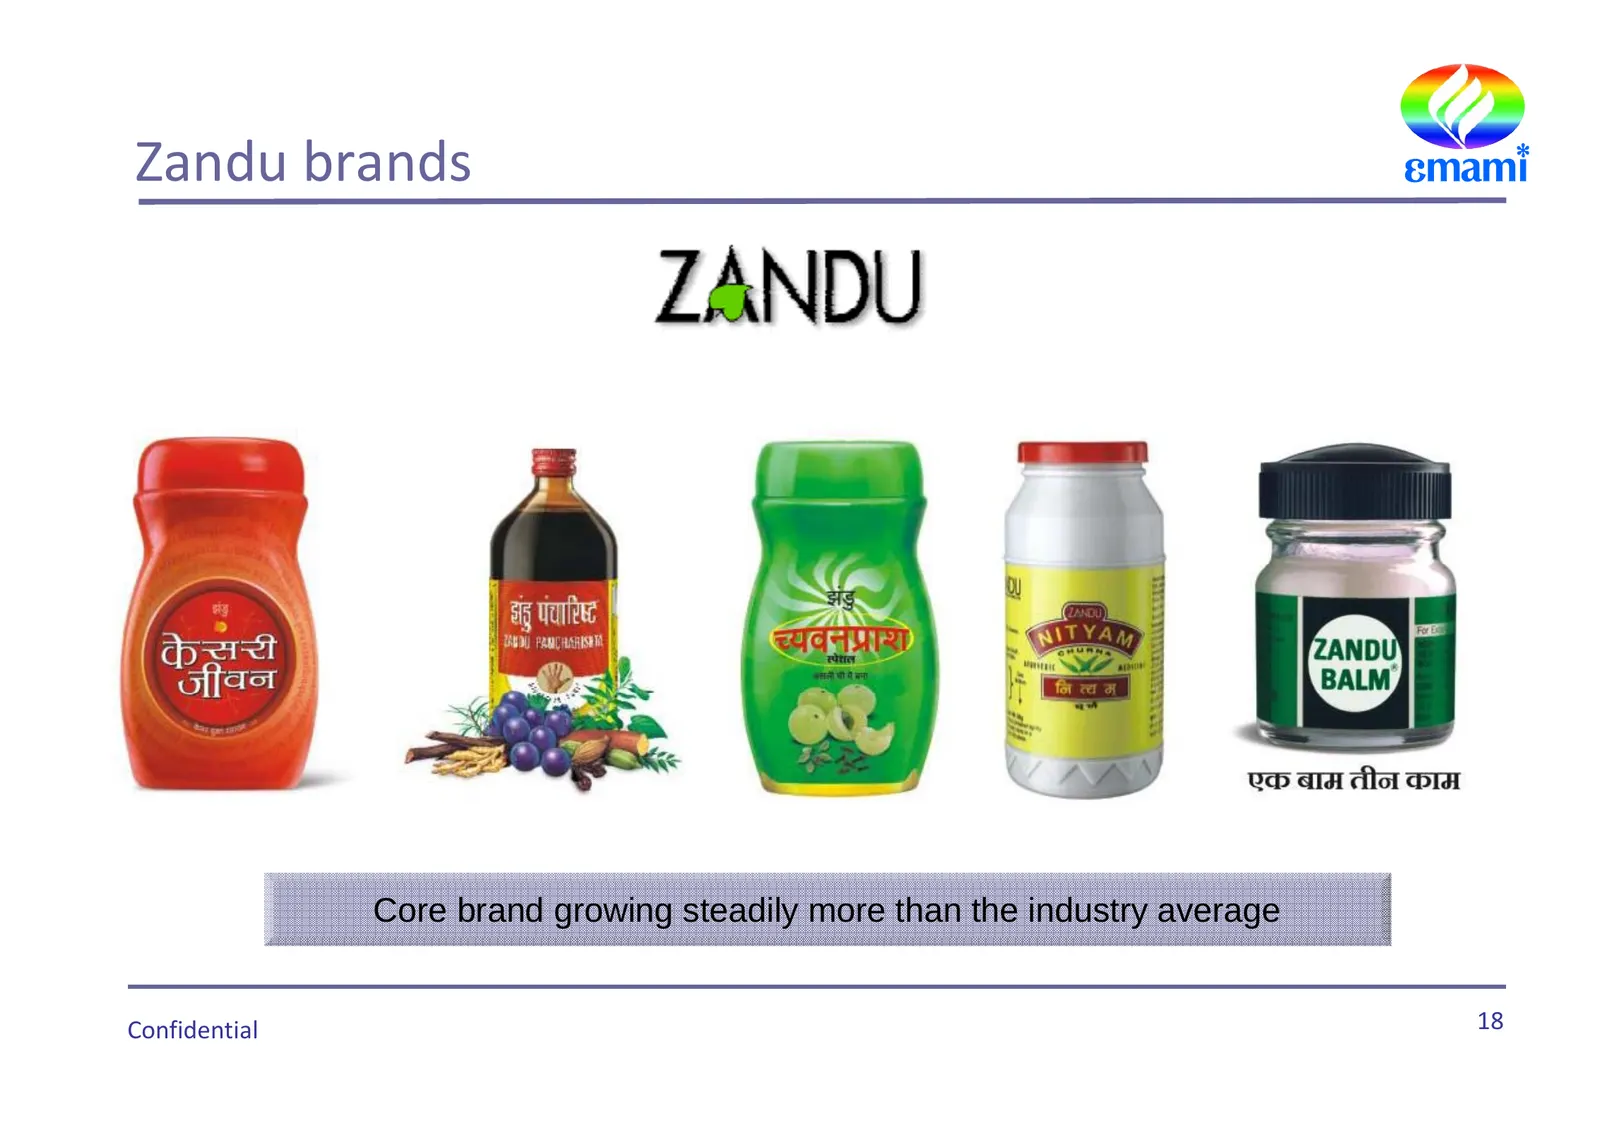
Zandu brands Core brand growing steadily more than the industry average Confidential 18
Slide 19: Strategic initiatives
Strategic initiatives Various strategic initiatives undertaken to enhance value Effective April 2009, 2009 production commenced at Pantnagar unit in the tax free zone of Uttaranchal Increase in Sales relaisations at Zandu for reduction in trade margins by around 10%. More focus on the core bus
Slide 20: Marketing initiatives
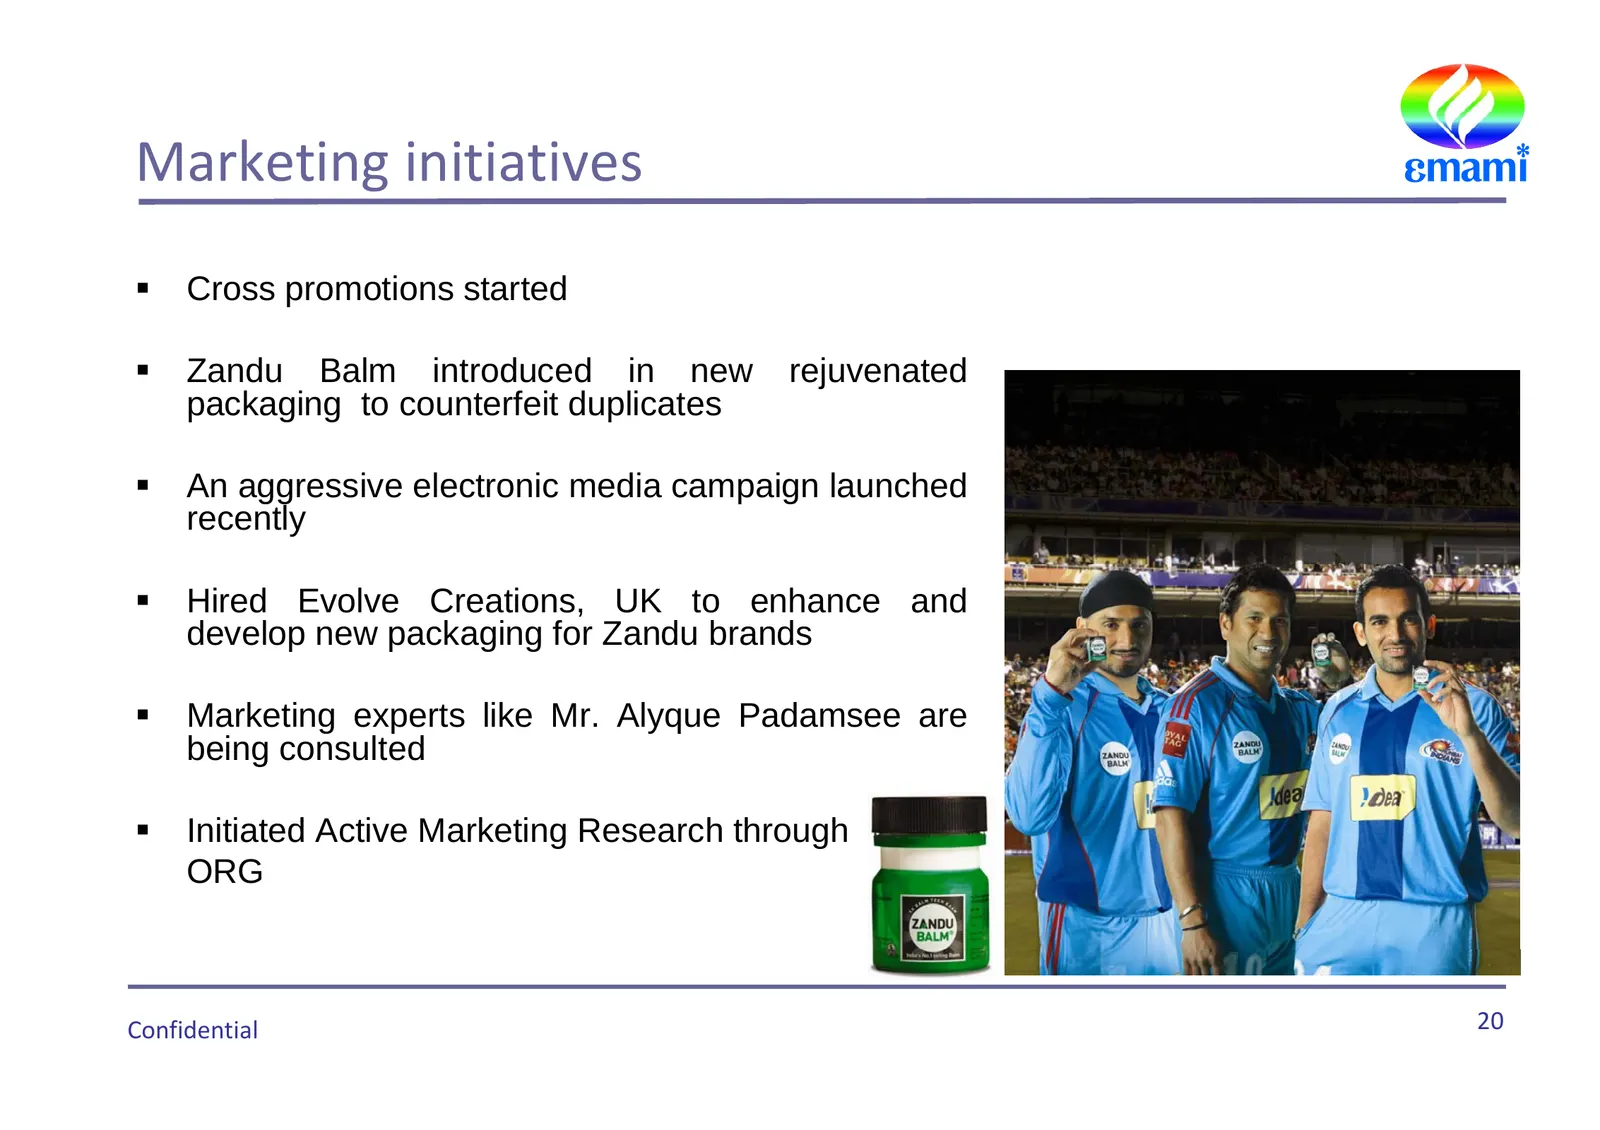
Marketing initiatives Cross promotions started Zandu Balm introduced in new rejuvenated packaging to counterfeit duplicates An aggressive electronic media campaign launched recently Hired Evolve Creations, UK to enhance and develop new packaging for Zandu brands Marketing experts like Mr.
Slide 21: Restructuring
Section: III Restructuring Confidential 21
Slide 22: Restructuring
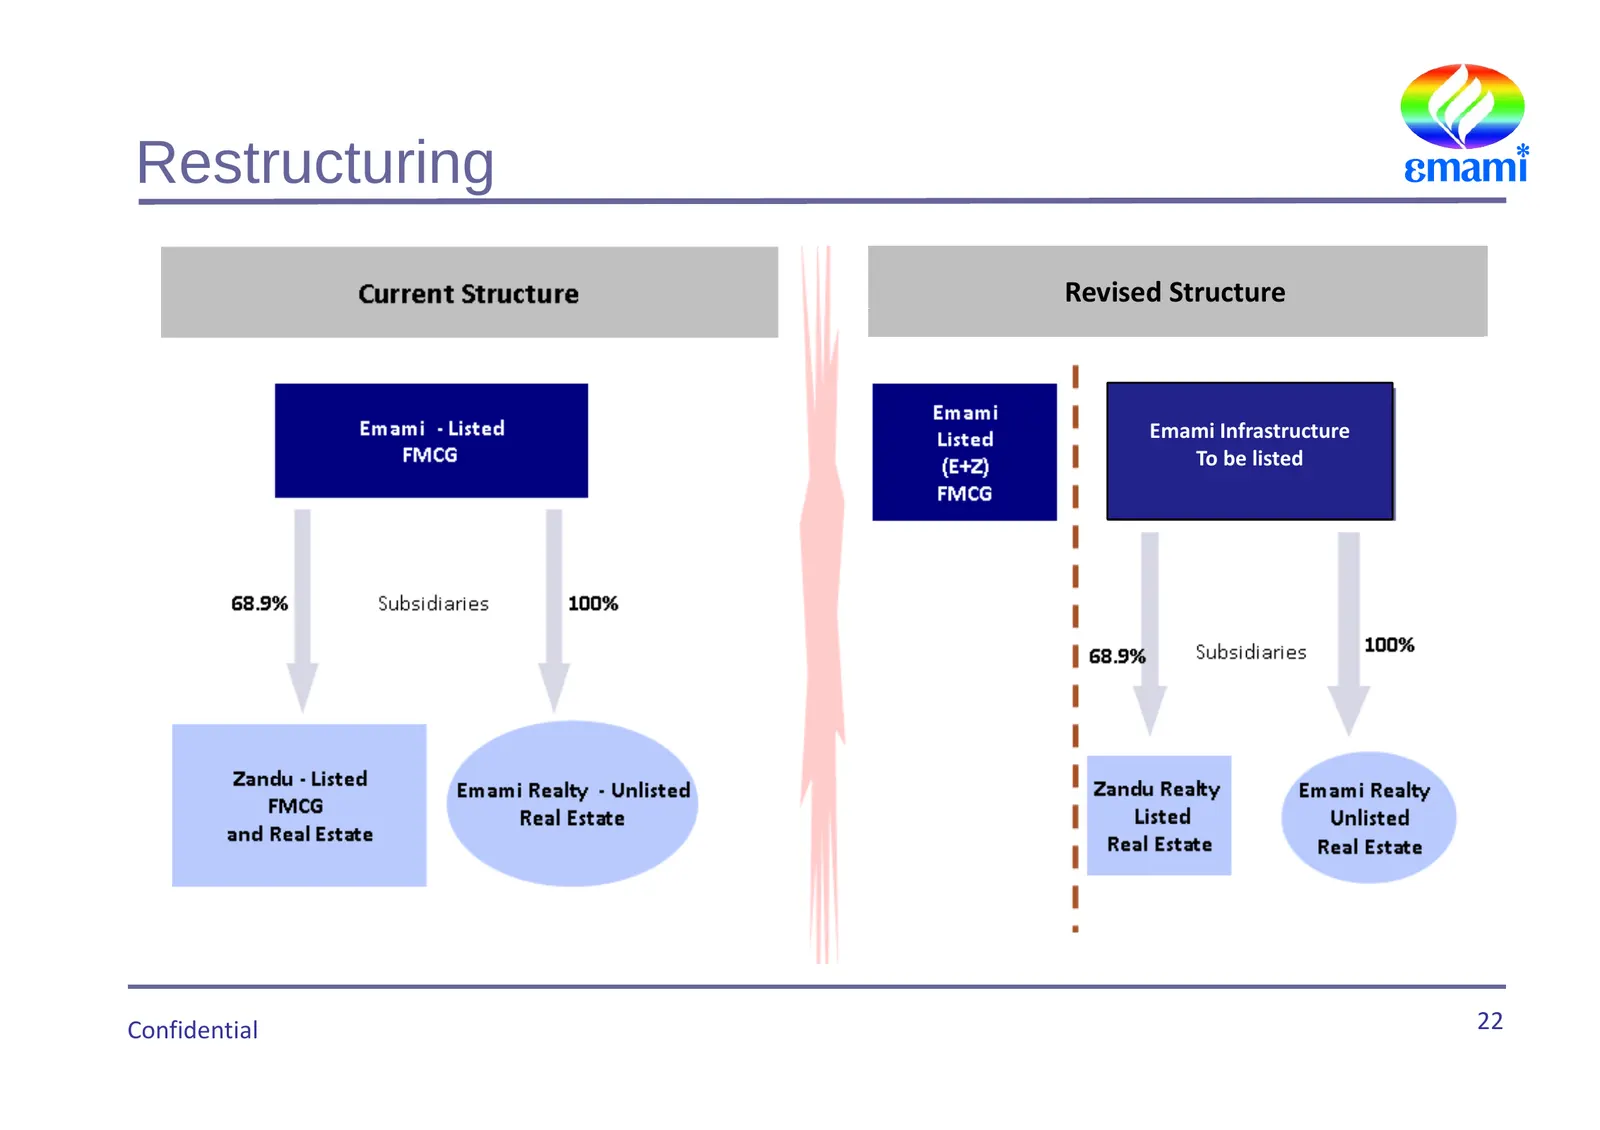
Restructuring Revised Structure Emami Infrastructure To be listed Confidential 22
Slide 23: Restructuring (Contd.) Share Swap Details
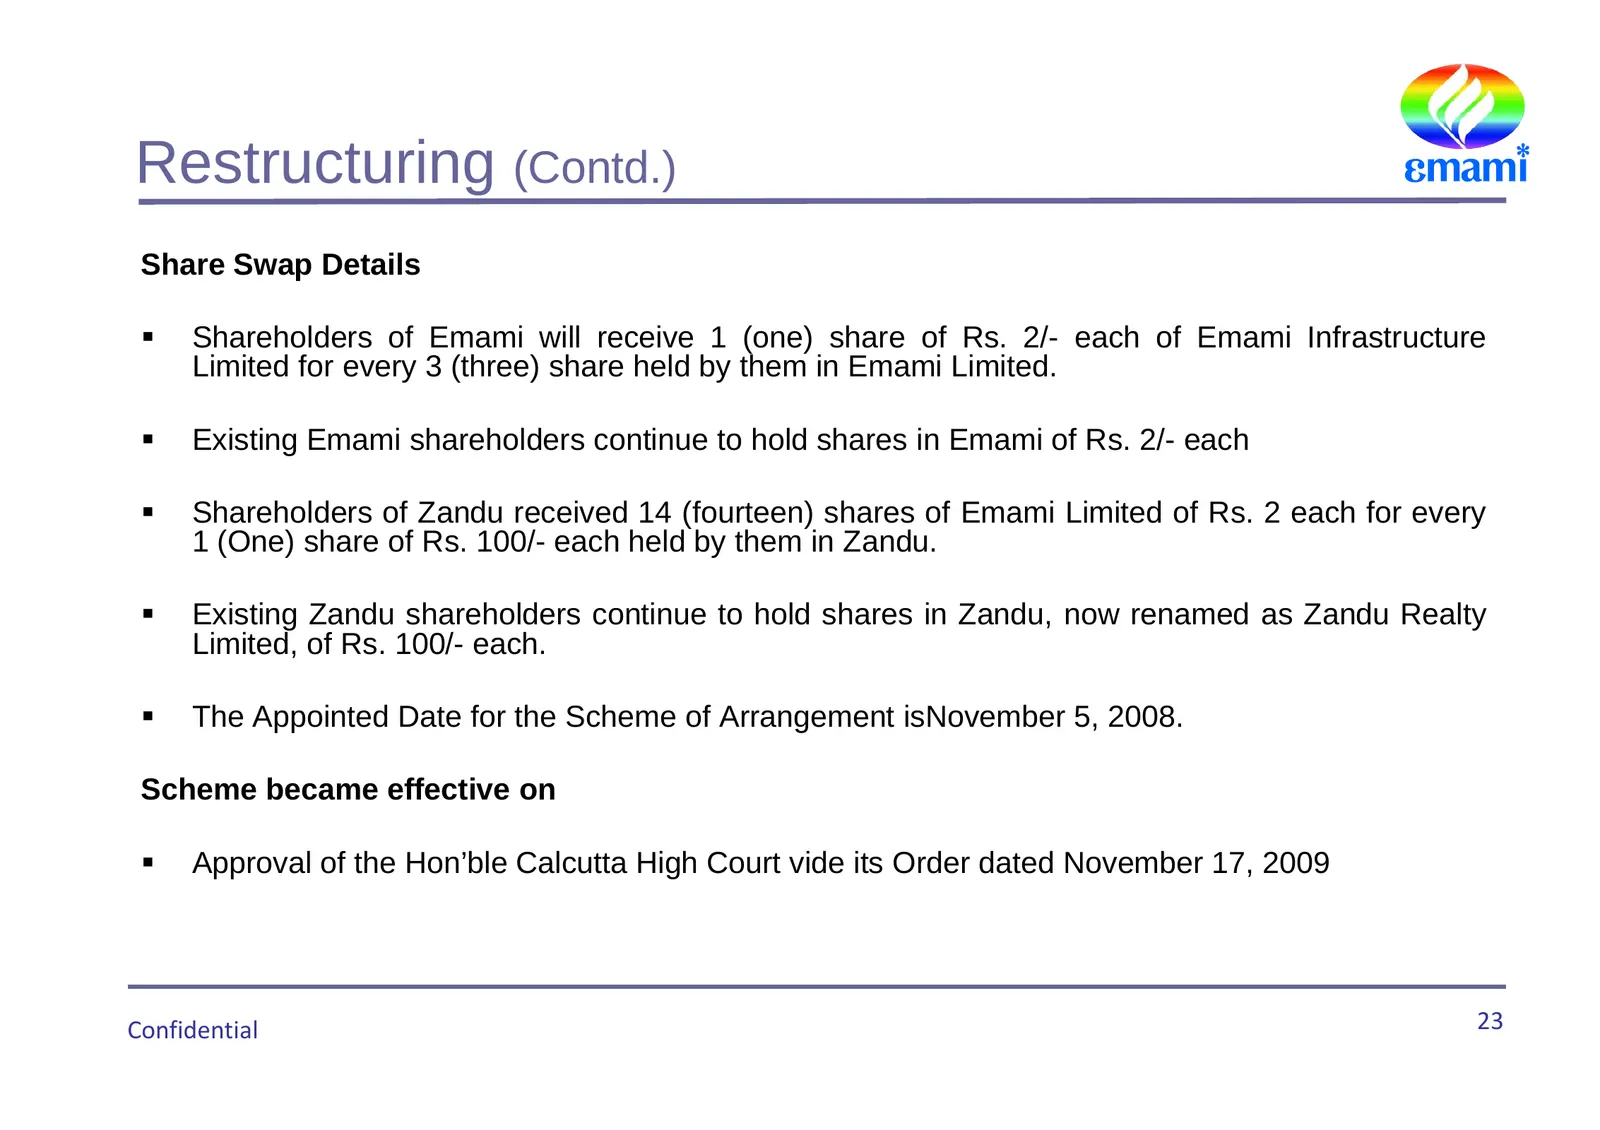
Restructuring (Contd.) Share Swap Details Shareholders of Emami will receive 1 (one) share of Rs. 2/- each of Emami Infrastructure Limited for every 3 (three) share held by them in Emami Limited. Existing Emami shareholders continue to hold shares in Emami of Rs. Rs 2/- 2/ each Shareholders of
Slide 24: Business Strategy
Section: IV Business Strategy Confidential 24
Slide 25: Business Strategy
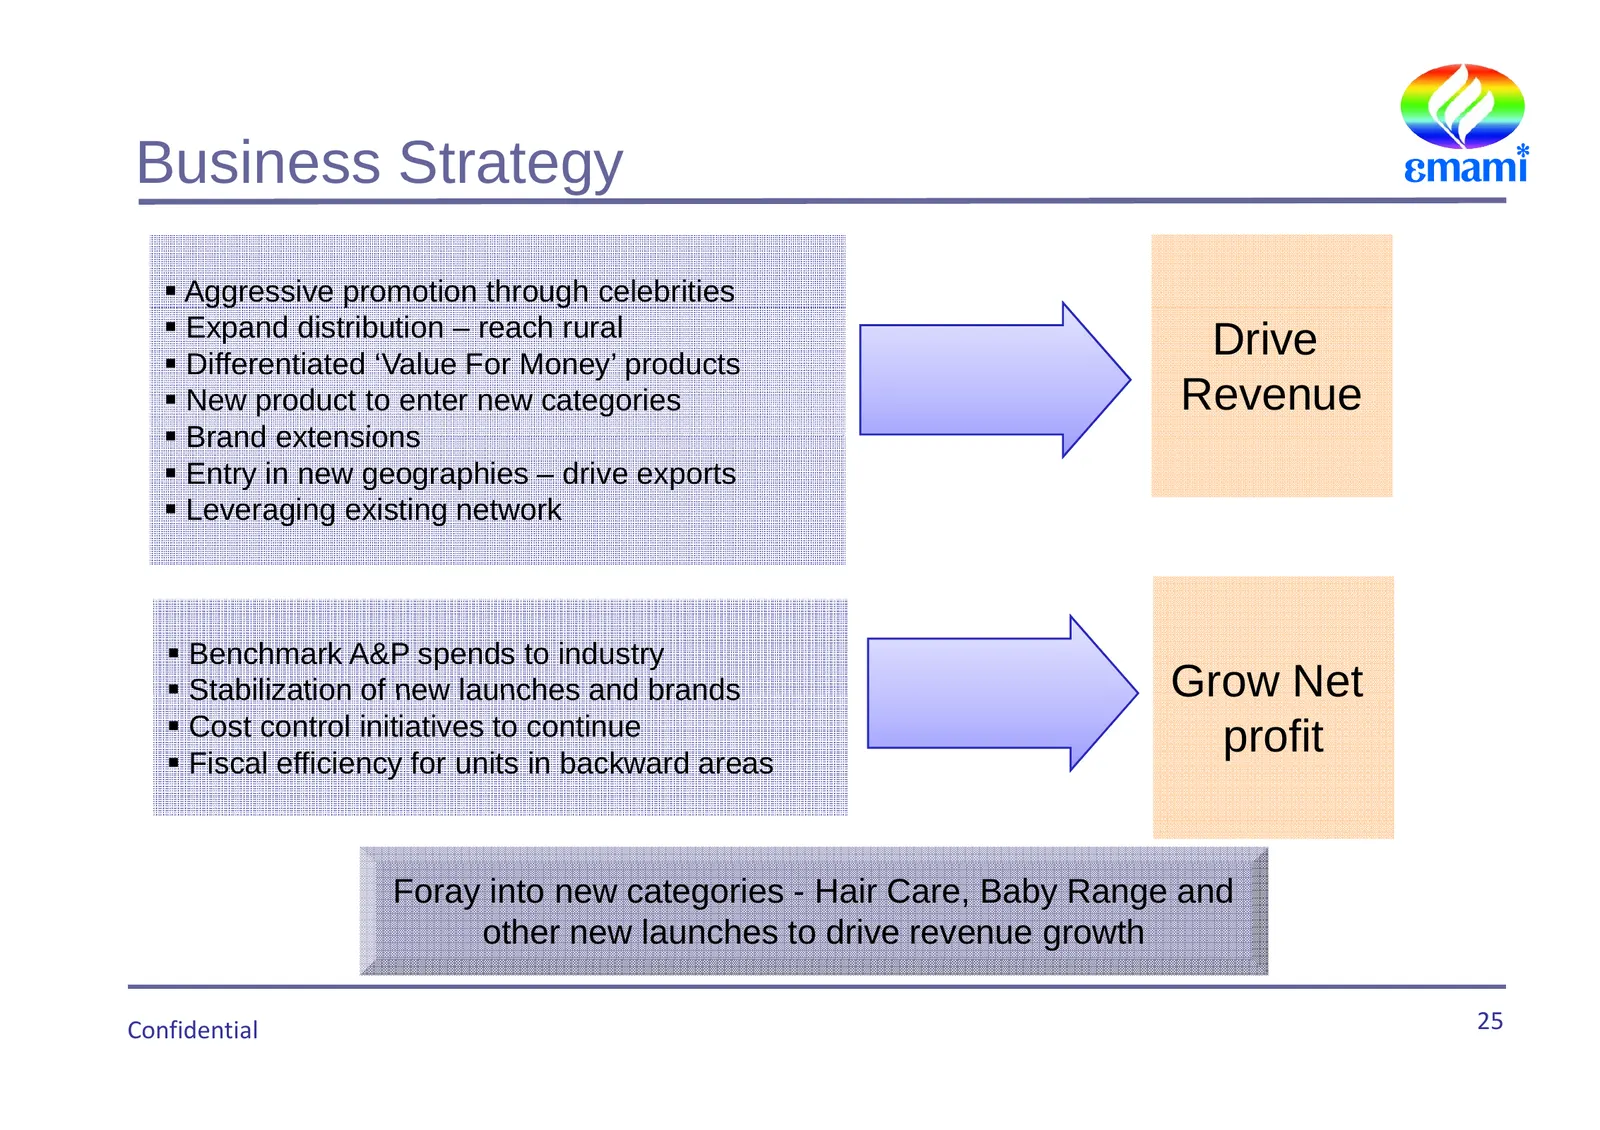
Business Strategy Aggressive promotion through celebrities Expand distribution – reach rural Differentiated ‘Value For Money’ products Drive New product to enter new categories Revenue Brand extensions Entry in new geographies – drive exports Leveraging existing network Benchmark A&P
Slide 26: Financials
Section: V Financials Confidential 26
Slide 27: Consistent growth ….. topline
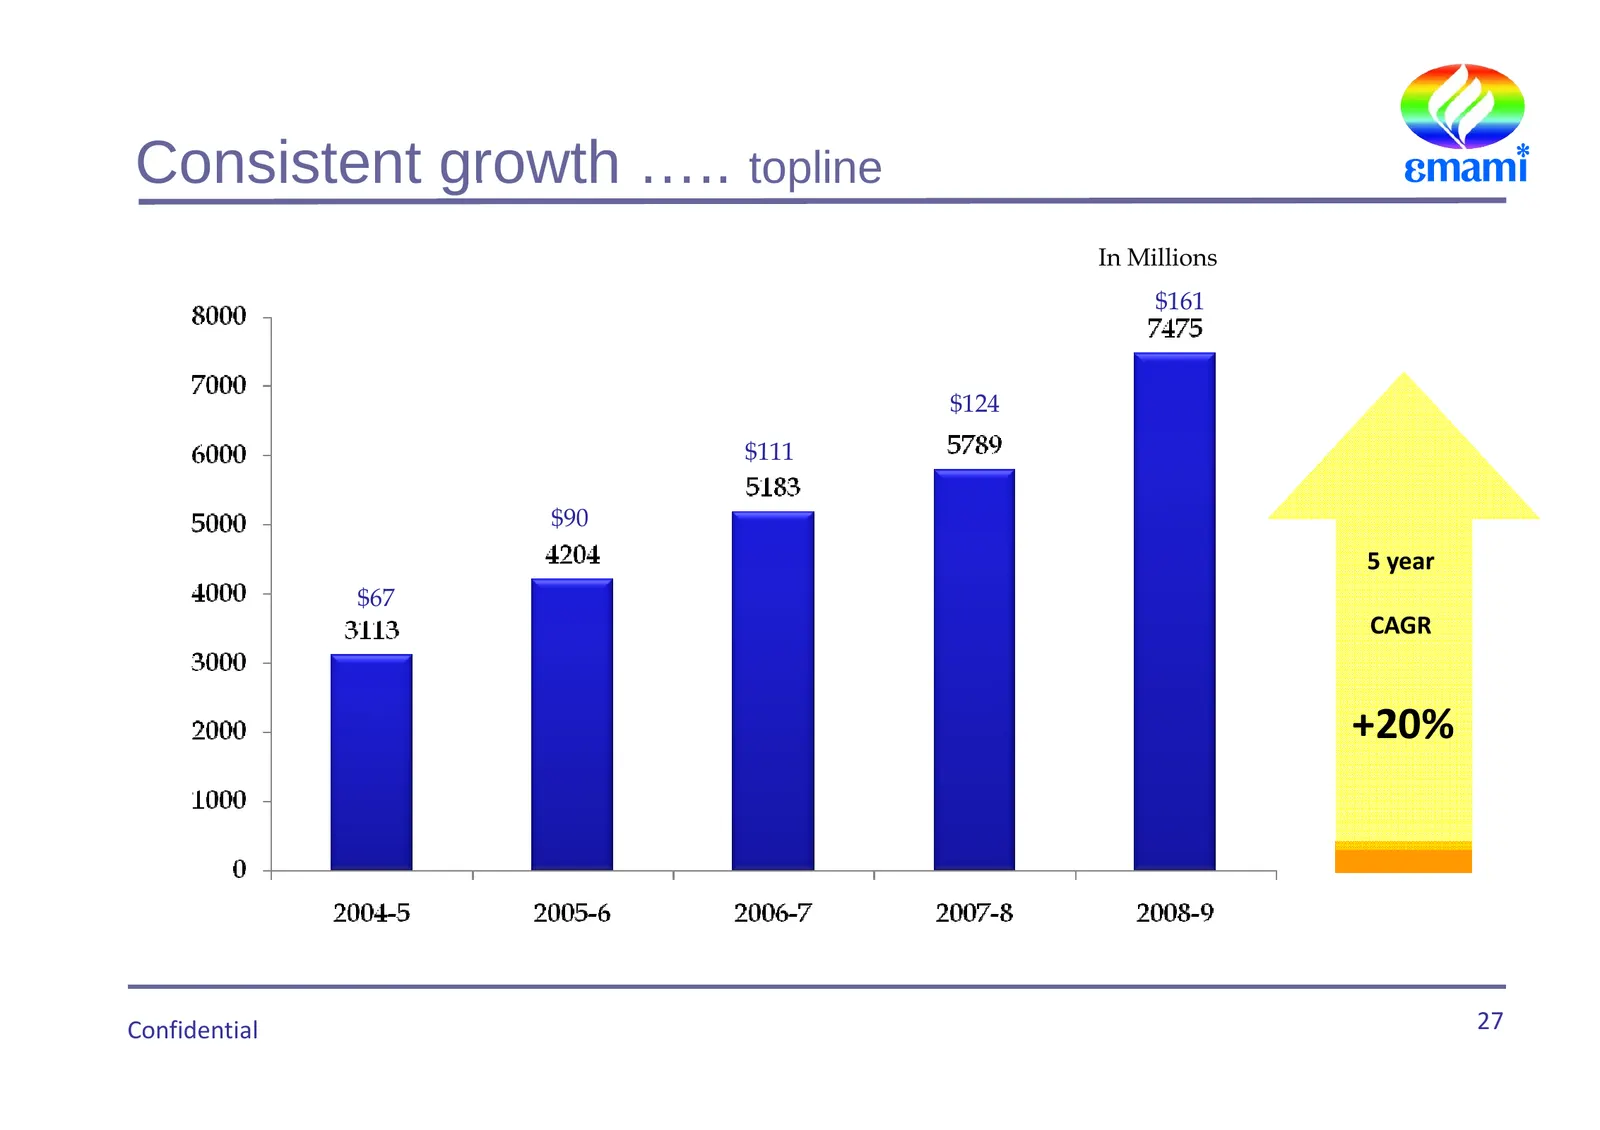
Consistent growth ….. topline In Millions $161 $124 $111 $90 5 year $67 CAGR +20% Confidential 27
Slide 28: Consistent growth ….. EBIDTA
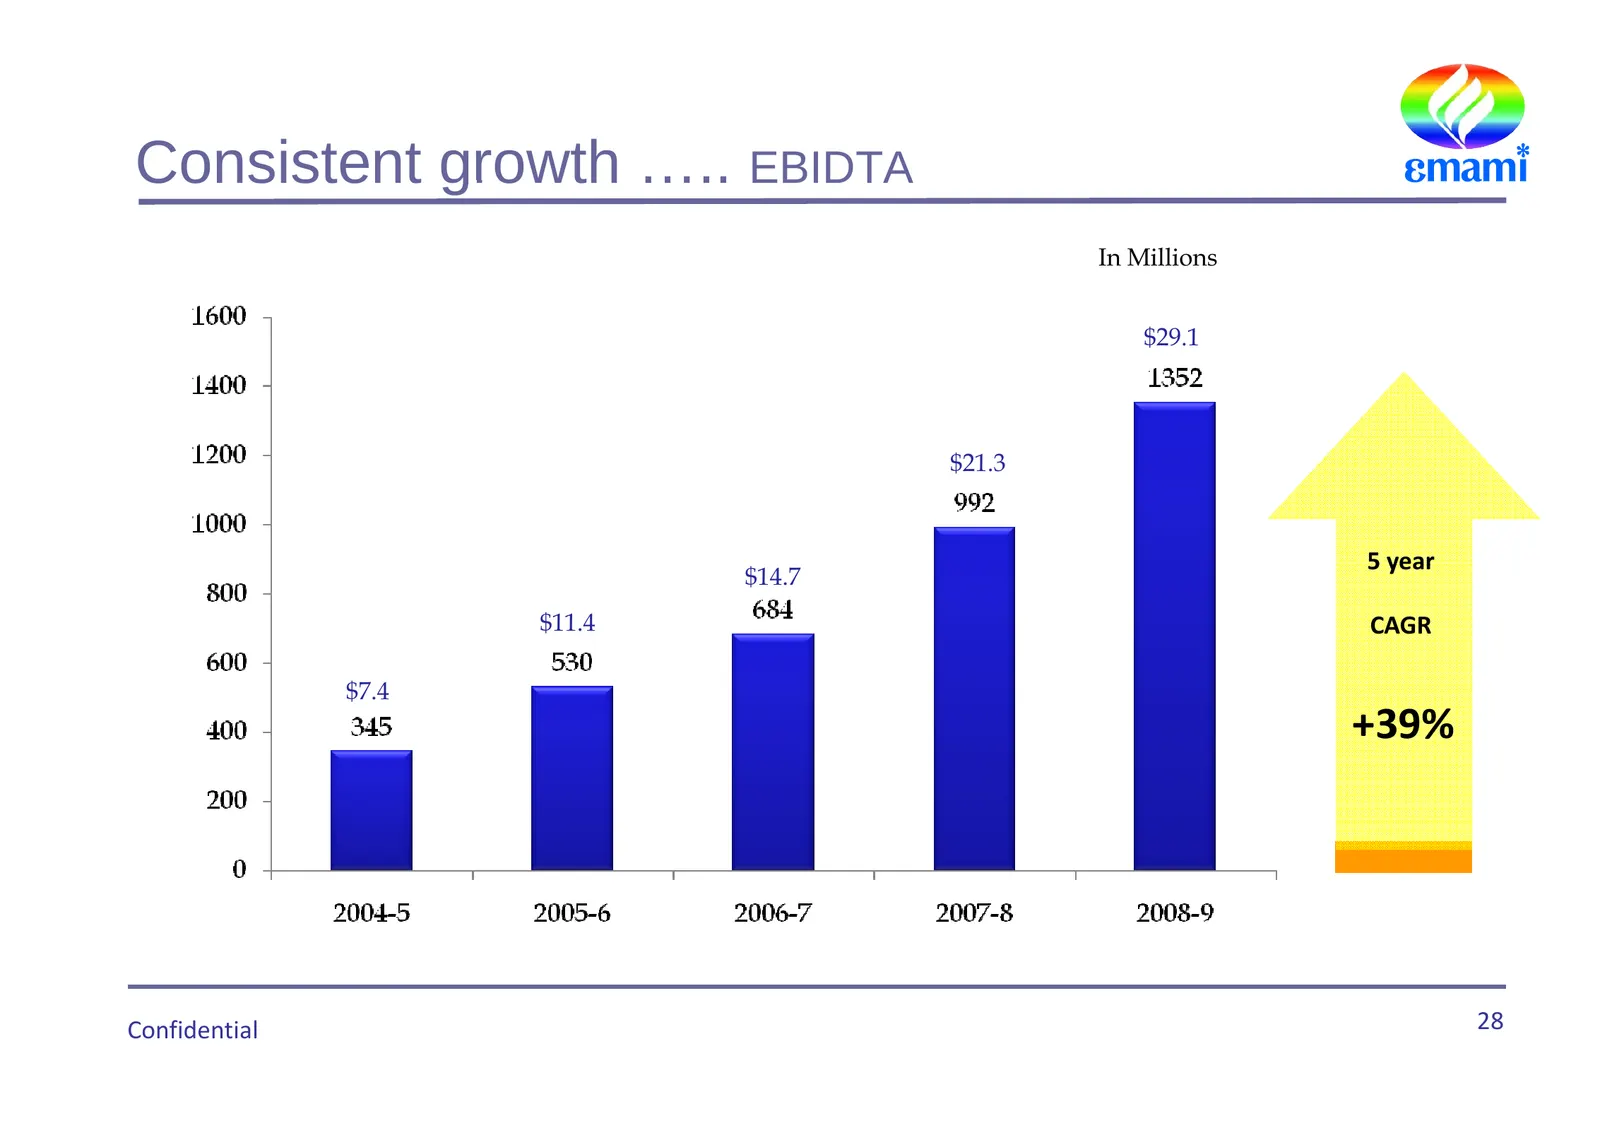
Consistent growth ….. EBIDTA In Millions $29.1 $21.3 5 year $14.7 $11.4 CAGR $7 4 $7.4 +39% Confidential 28
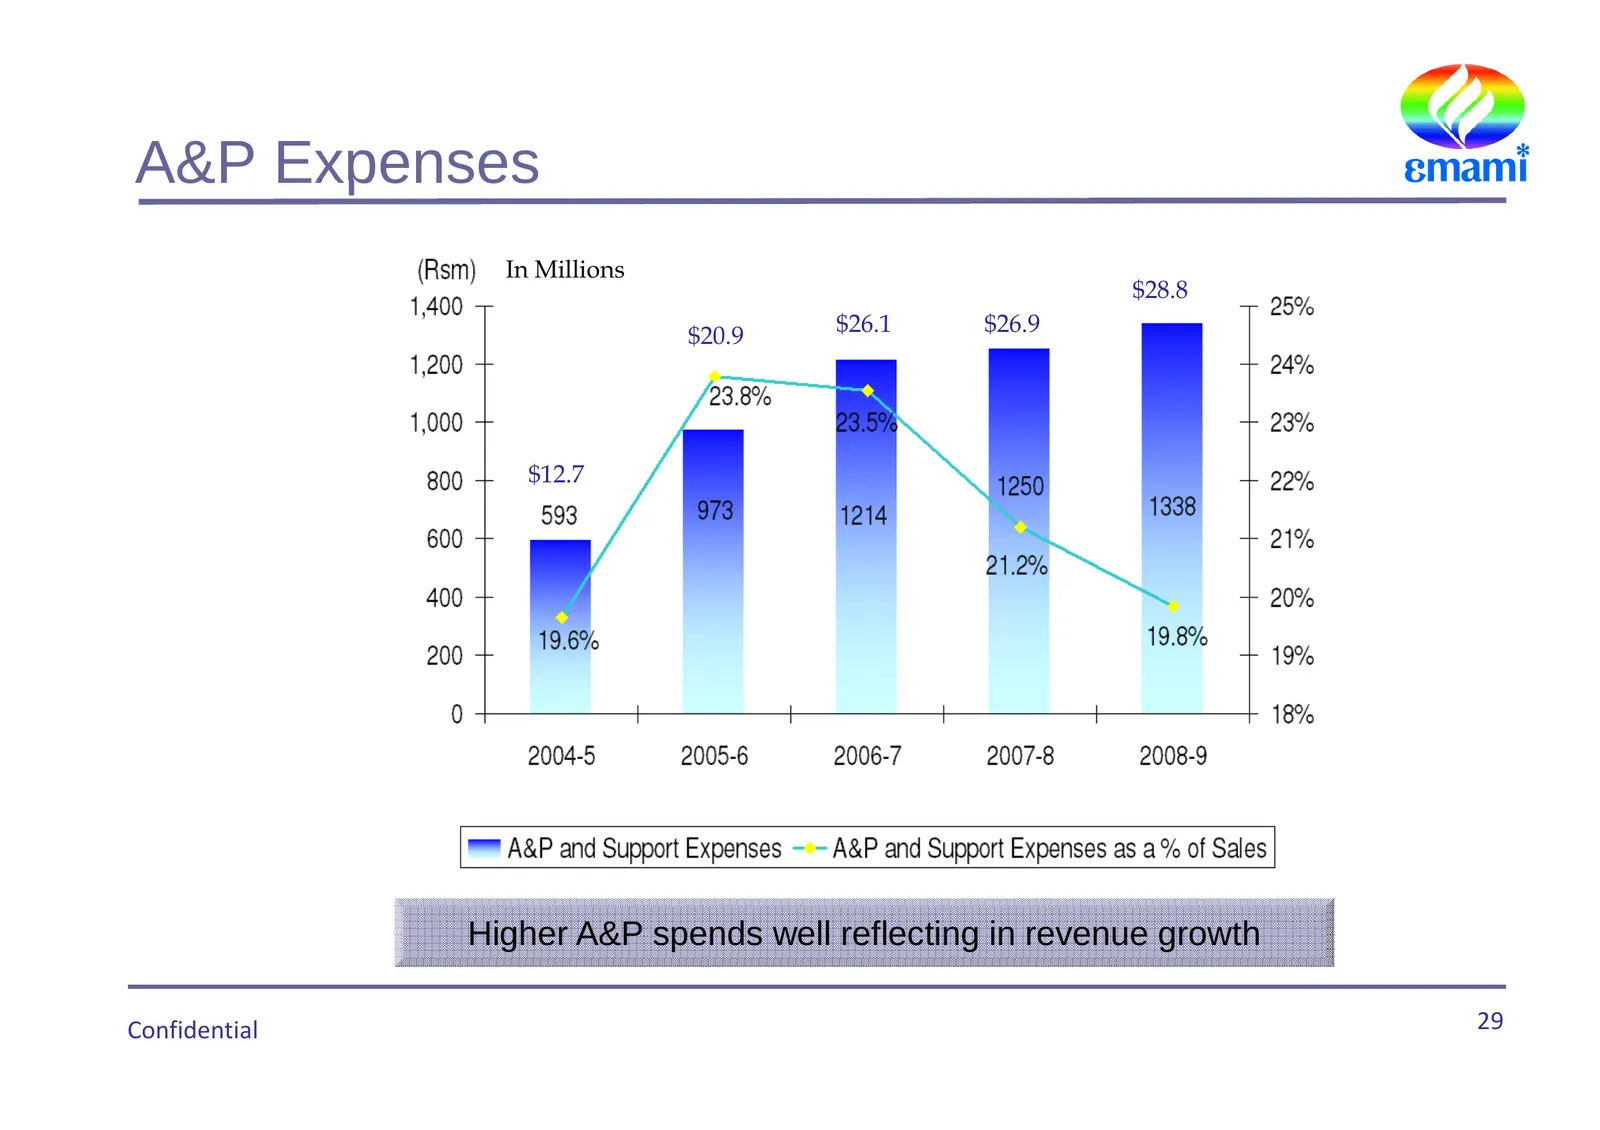
Slide 29: A&P Expenses
A&P Expenses In Millions $28.8 $20.9 $26.1 $26.9 $12.7 Higher g A&P spends p well reflecting g in revenue g growth Confidential 29
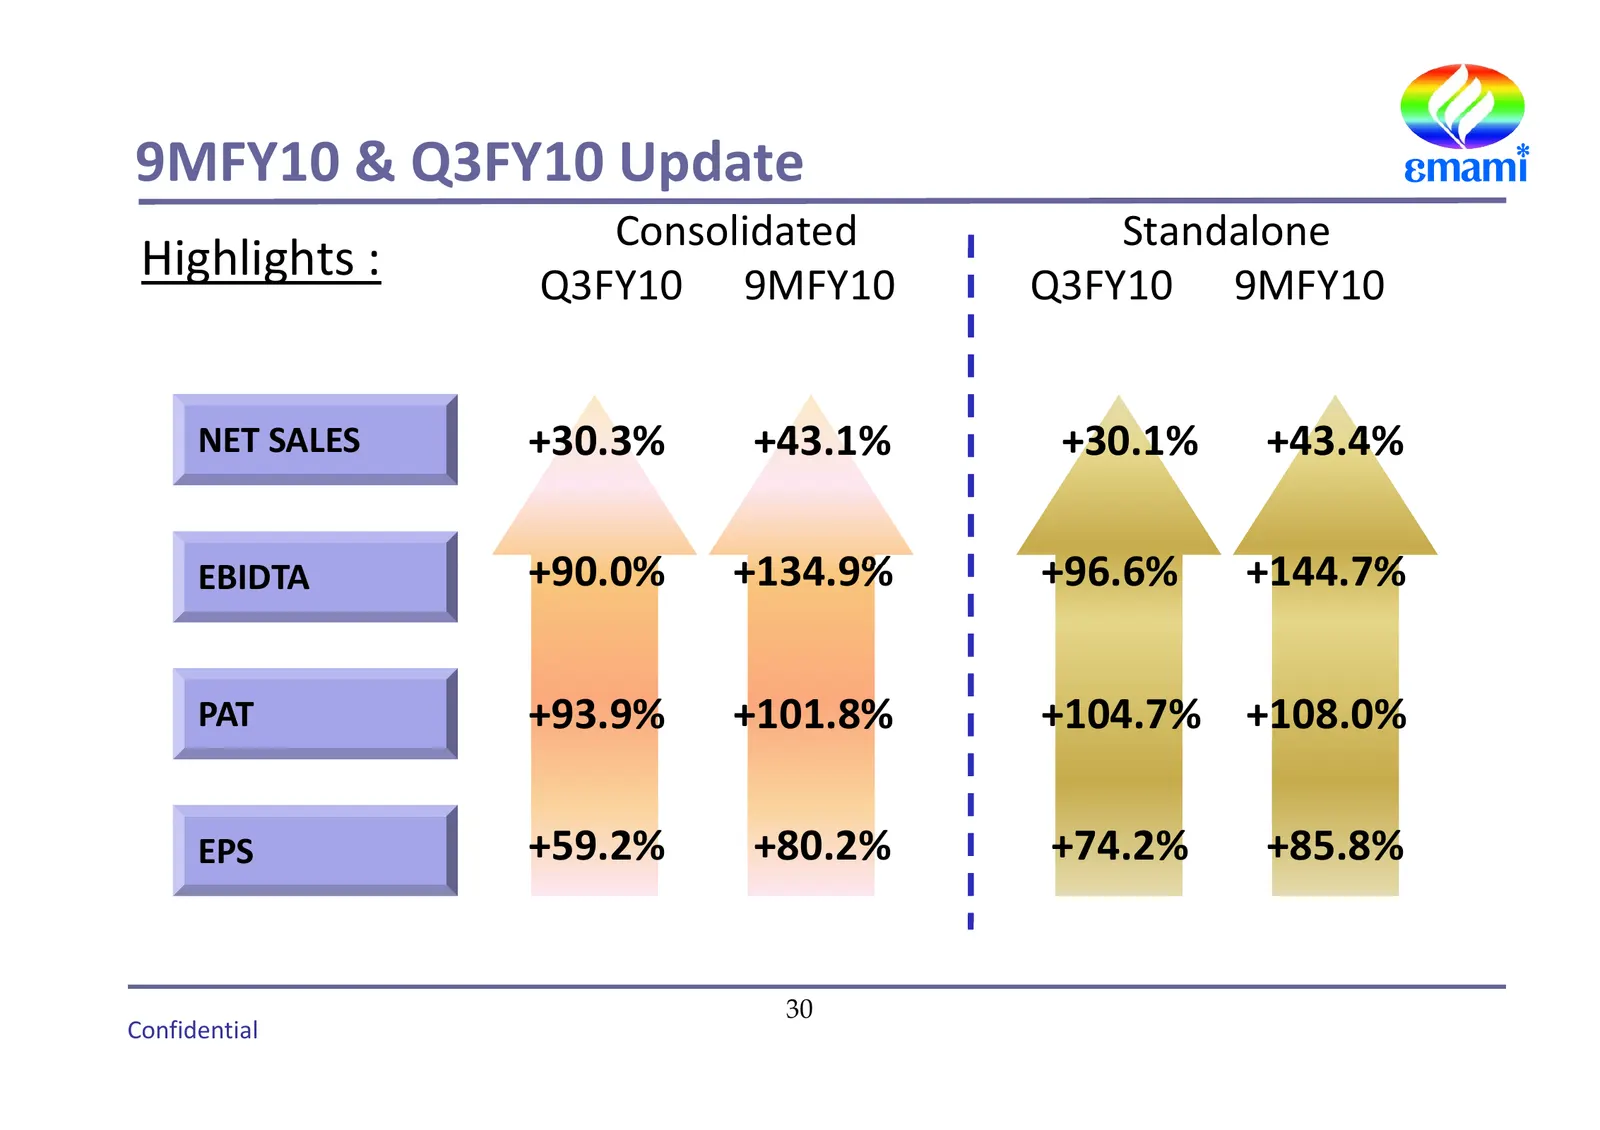
Slide 30: 9MFY10 & Q3FY10 Update
9MFY10 & Q3FY10 Update Consolidated Standalone Highlights : Q3FY10 9MFY10 Q3FY10 9MFY10 NET SALES +30 3% +30.3% +43 1% +43.1% +30 1% +30.1% +43 4% +43.4% EBIDTA +90 0% +90.0% +134 9% +134.9% +96 6% +96.6% +144 7% +144.7% PAT +93.9% +101.8% +104.7% +108.0% EPS +59.2% +80.2% +74.2% +85.8% 30 Confident
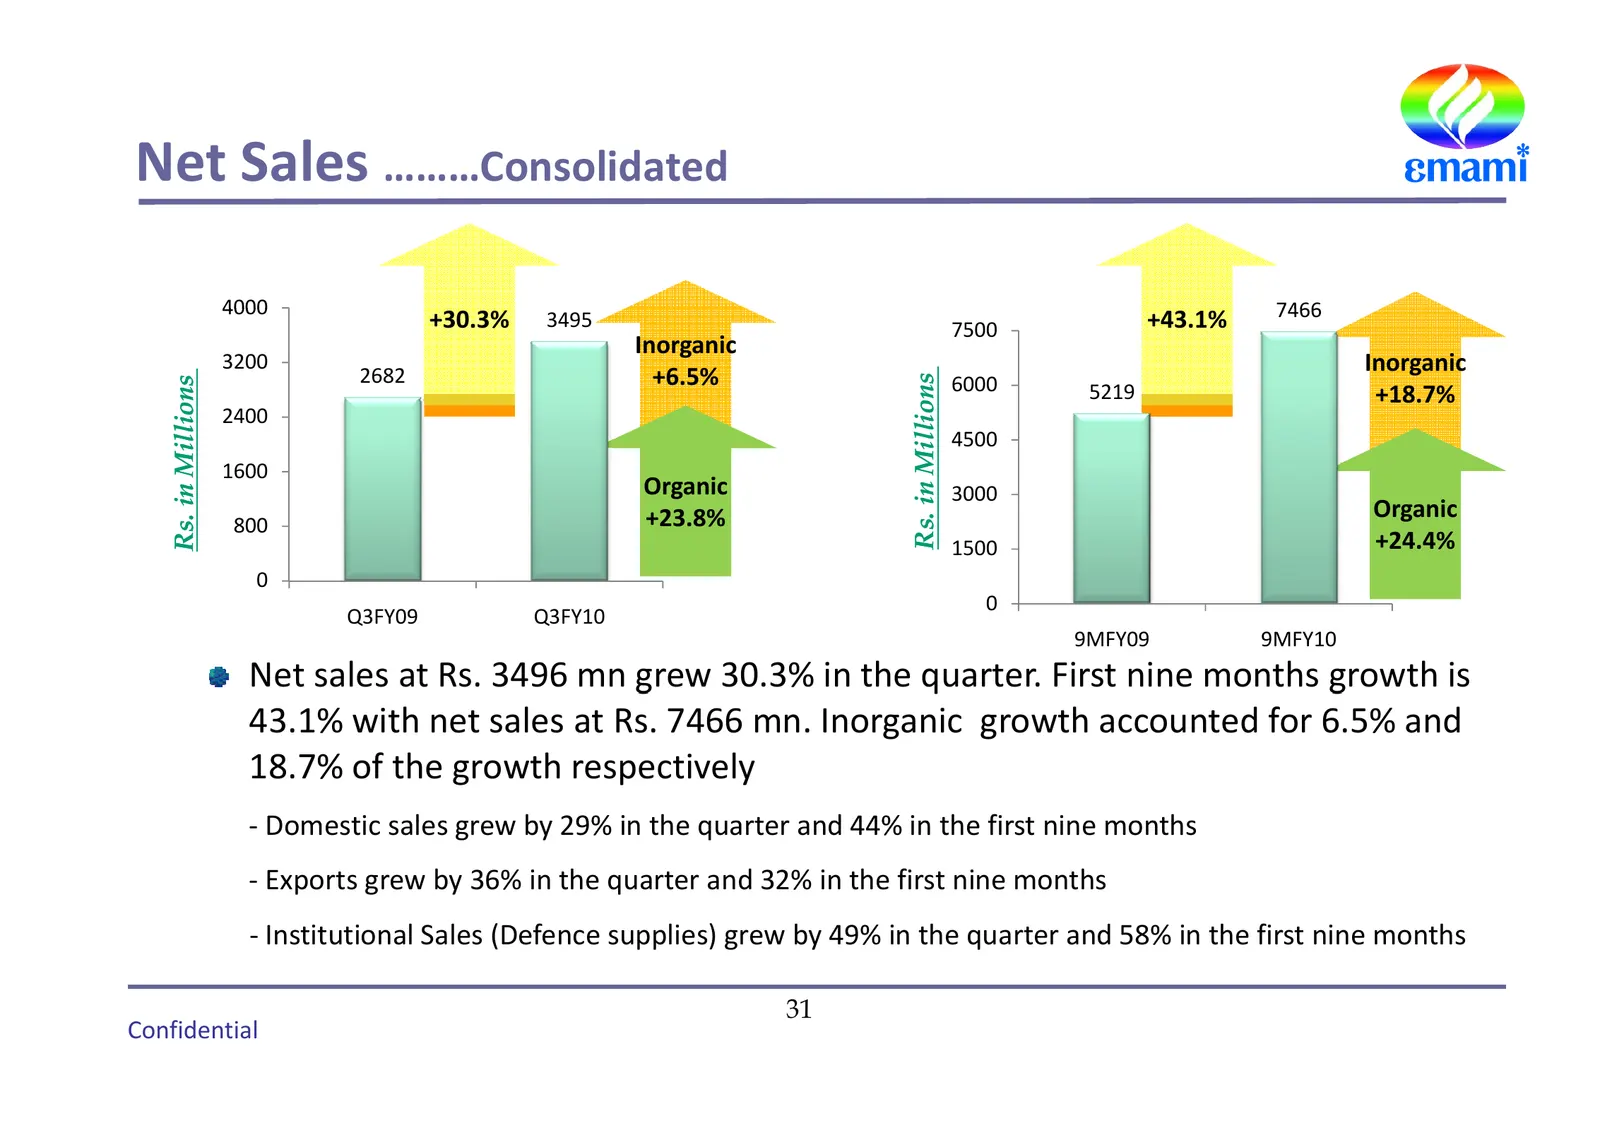
Slide 31: Net Sales Consolidated
Net Sales ………Consolidated 4000 7466 +30.3% 3495 7500 +43.1% Inorganic 3200 Inorganic 2682 +6.5% Rs. in Milllions 6000 Rs. in Milllions 5219 +18.7% 2400 4500 1600 Organic 3000 +23.8% Organic 800 1500 +24.4% 0 0 Q3FY09 Q3FY10 9MFY09 9MFY10 Net sales at Rs. 3496 mn ggrew 30.3% in the q quarter. First n
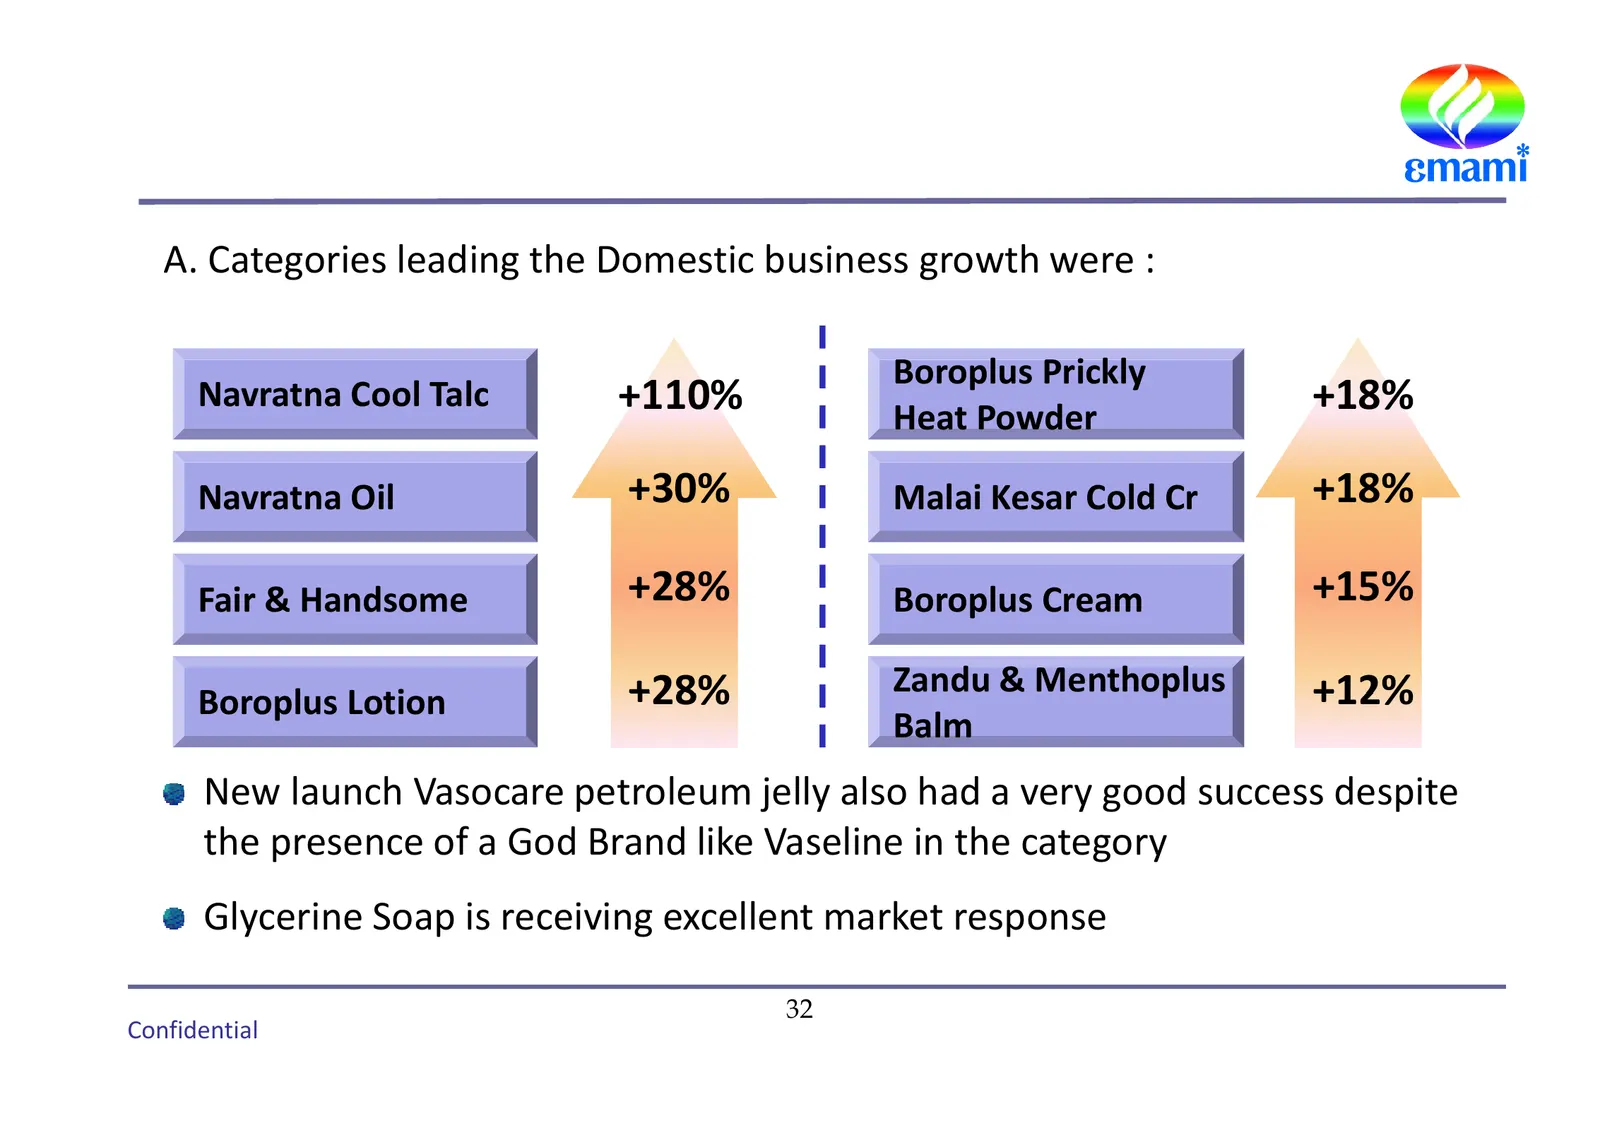
Slide 32: Categories leading the Domestic business growth
A. Categories leading the Domestic business growth were : Boroplus Prickly Navratna Cool Talc +110% Heat Powder +18% Navratna Oil +30% Malai Kesar Cold Cr +18% Fair & Handsome +28% Boroplus Cream +15% +28% Zandu & Menthoplus p +12% B l LLotion Boroplus ti Balm New launch Vasocare petroleum jelly als
Slide 33: International Business and Institutional Business growth
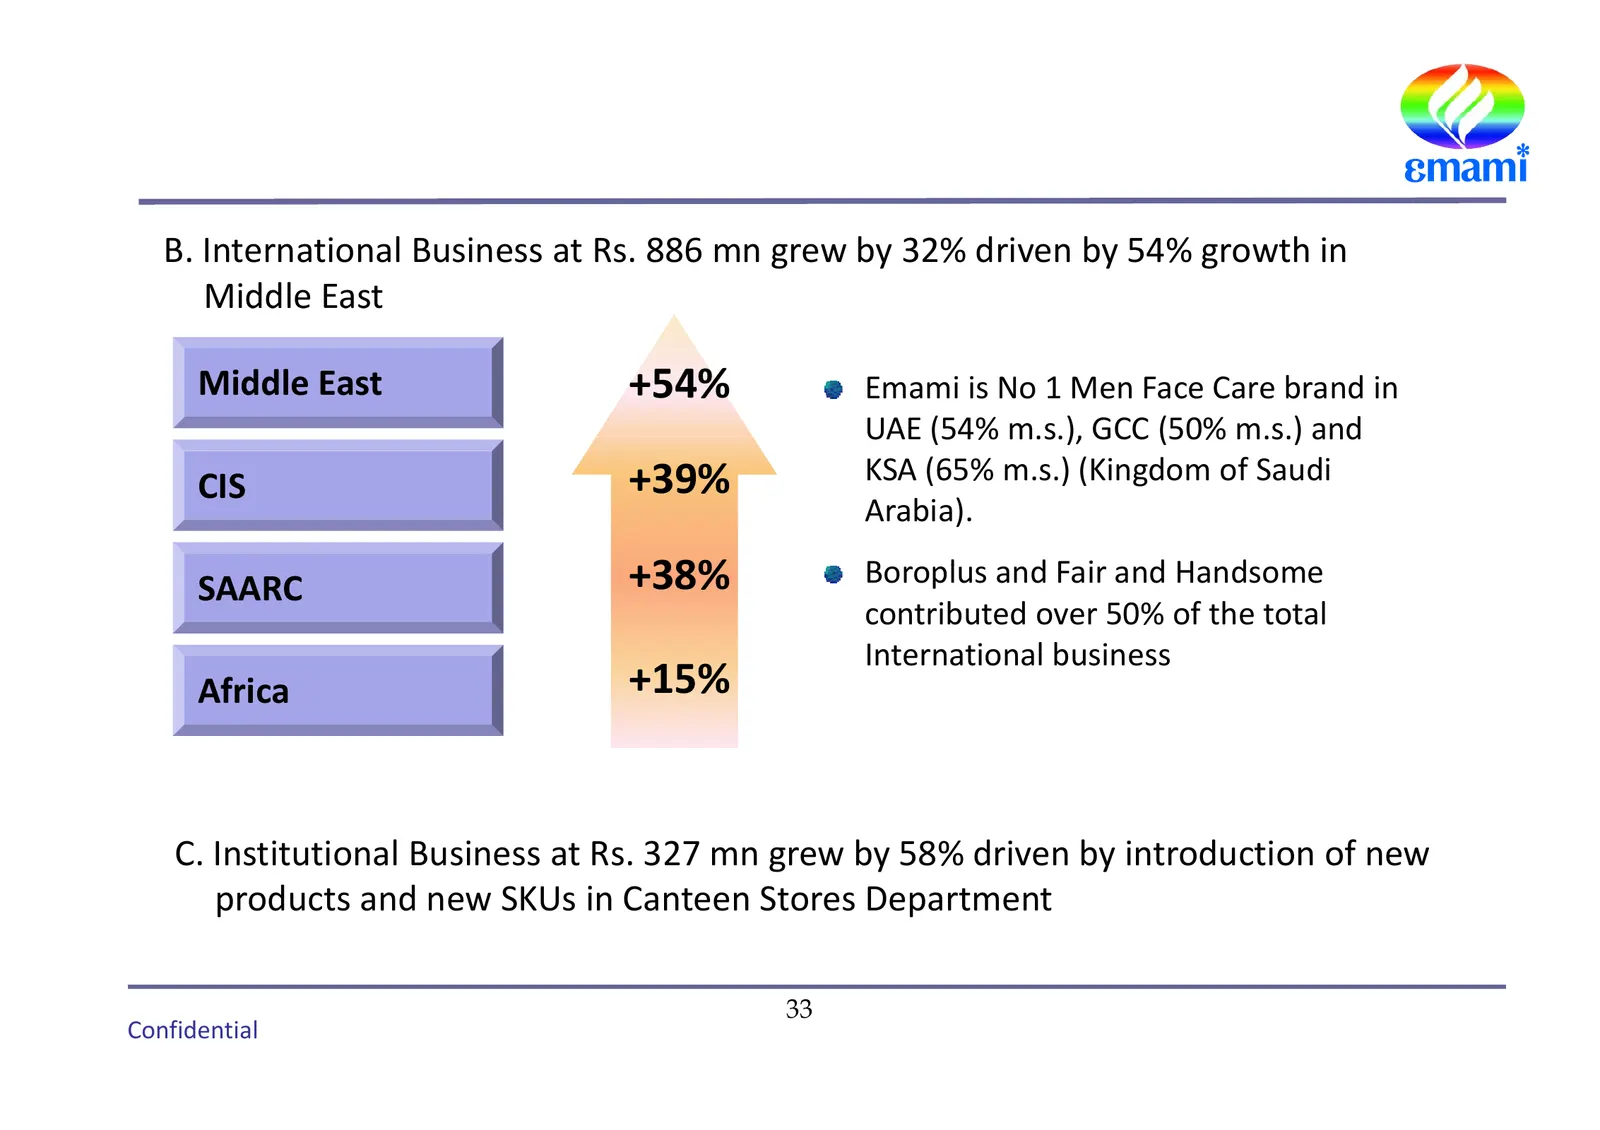
B. International Business at Rs. 886 mn grew by 32% driven by 54% growth in Middle dd e East as Middle East +54% Emami is No 1 Men Face Care brand in UAE (54% m.s.), GCC (50% m.s.) and +39% KSA (65% m.s.) (Kingdom of Saudi CIS Arabia). SAARC +38% 38% Boroplus B l and d FFair i and dHHandsome d contr
Slide 34: Earnings Consolidated
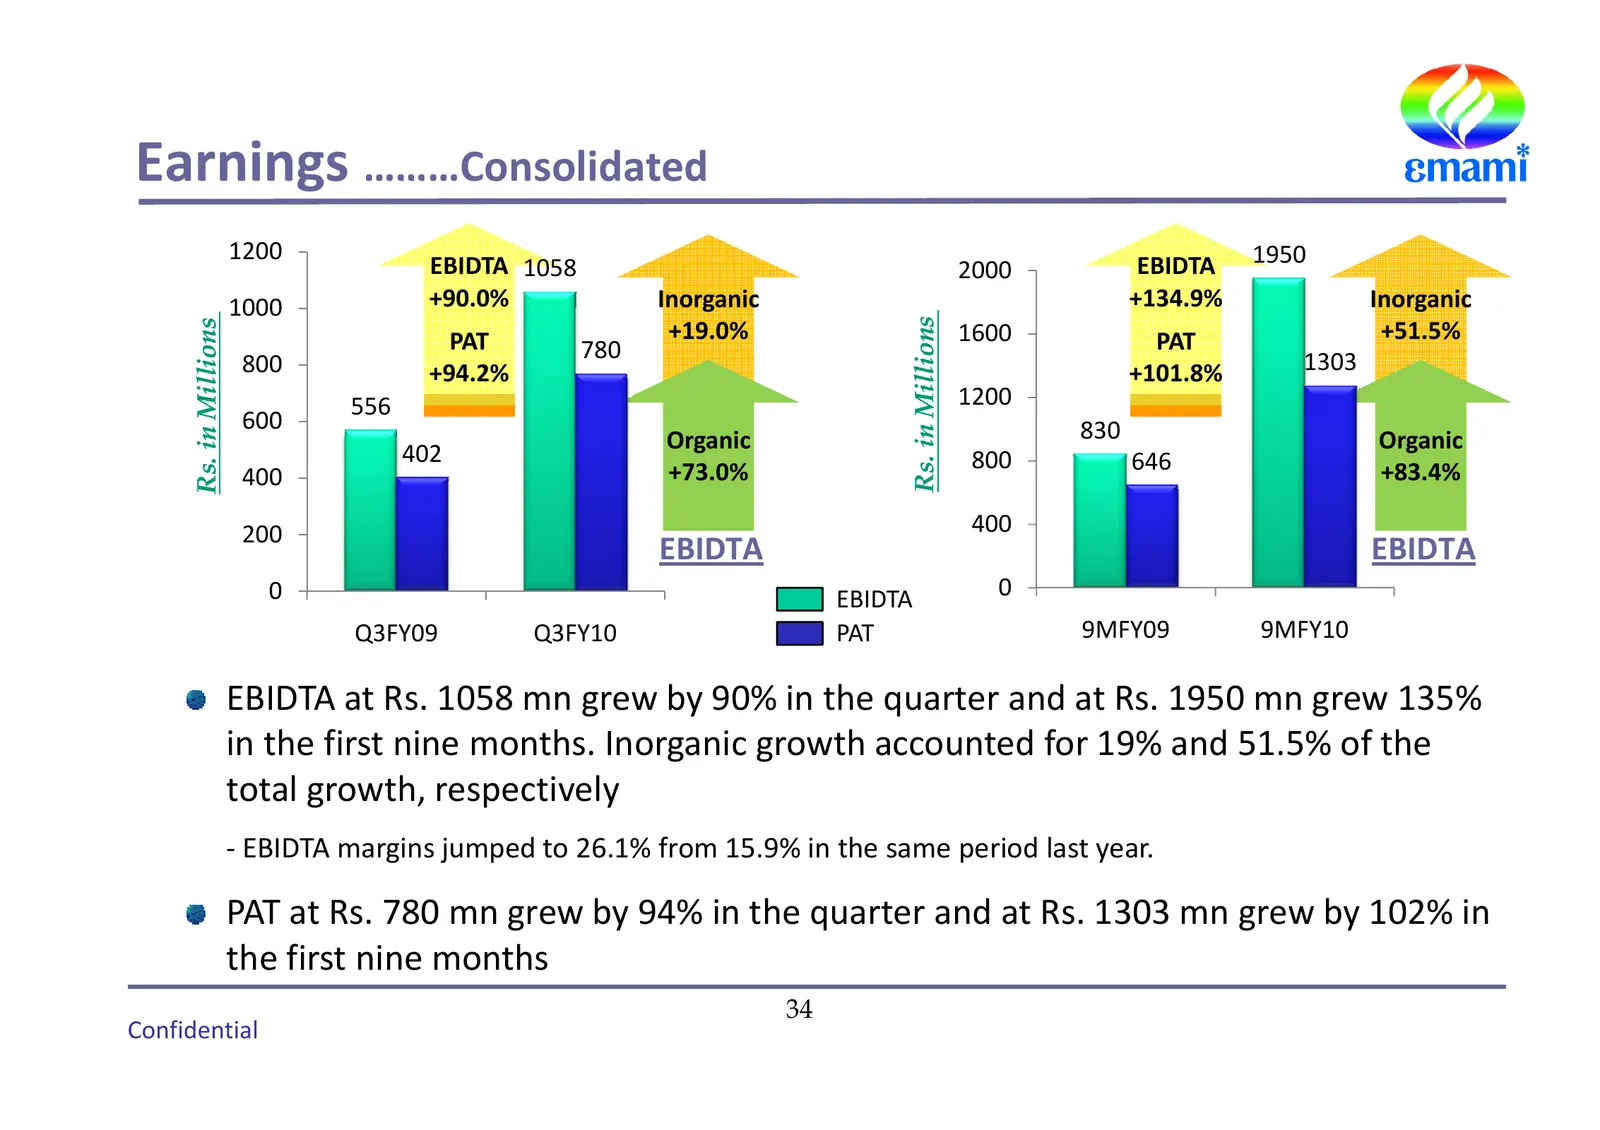
Earnings ………Consolidated 1200 1950 EBIDTA 1058 2000 EBIDTA 1000 +90.0% Inorganic g +134.9% Inorganic g n Millions n Millions PAT +19.0% 1600 PAT +51.5% 780 1303 800 +94.2% +101.8% 556 1200 600 830 Rs. in Rs. in Organic Organic 402 800 646 400 +73.0% +83.4% 200 400 EBIDTA EBIDTA 0 EBIDTA 0 Q3FY09 Q3F
Slide 35: 9MFY10 Consolidated Financials
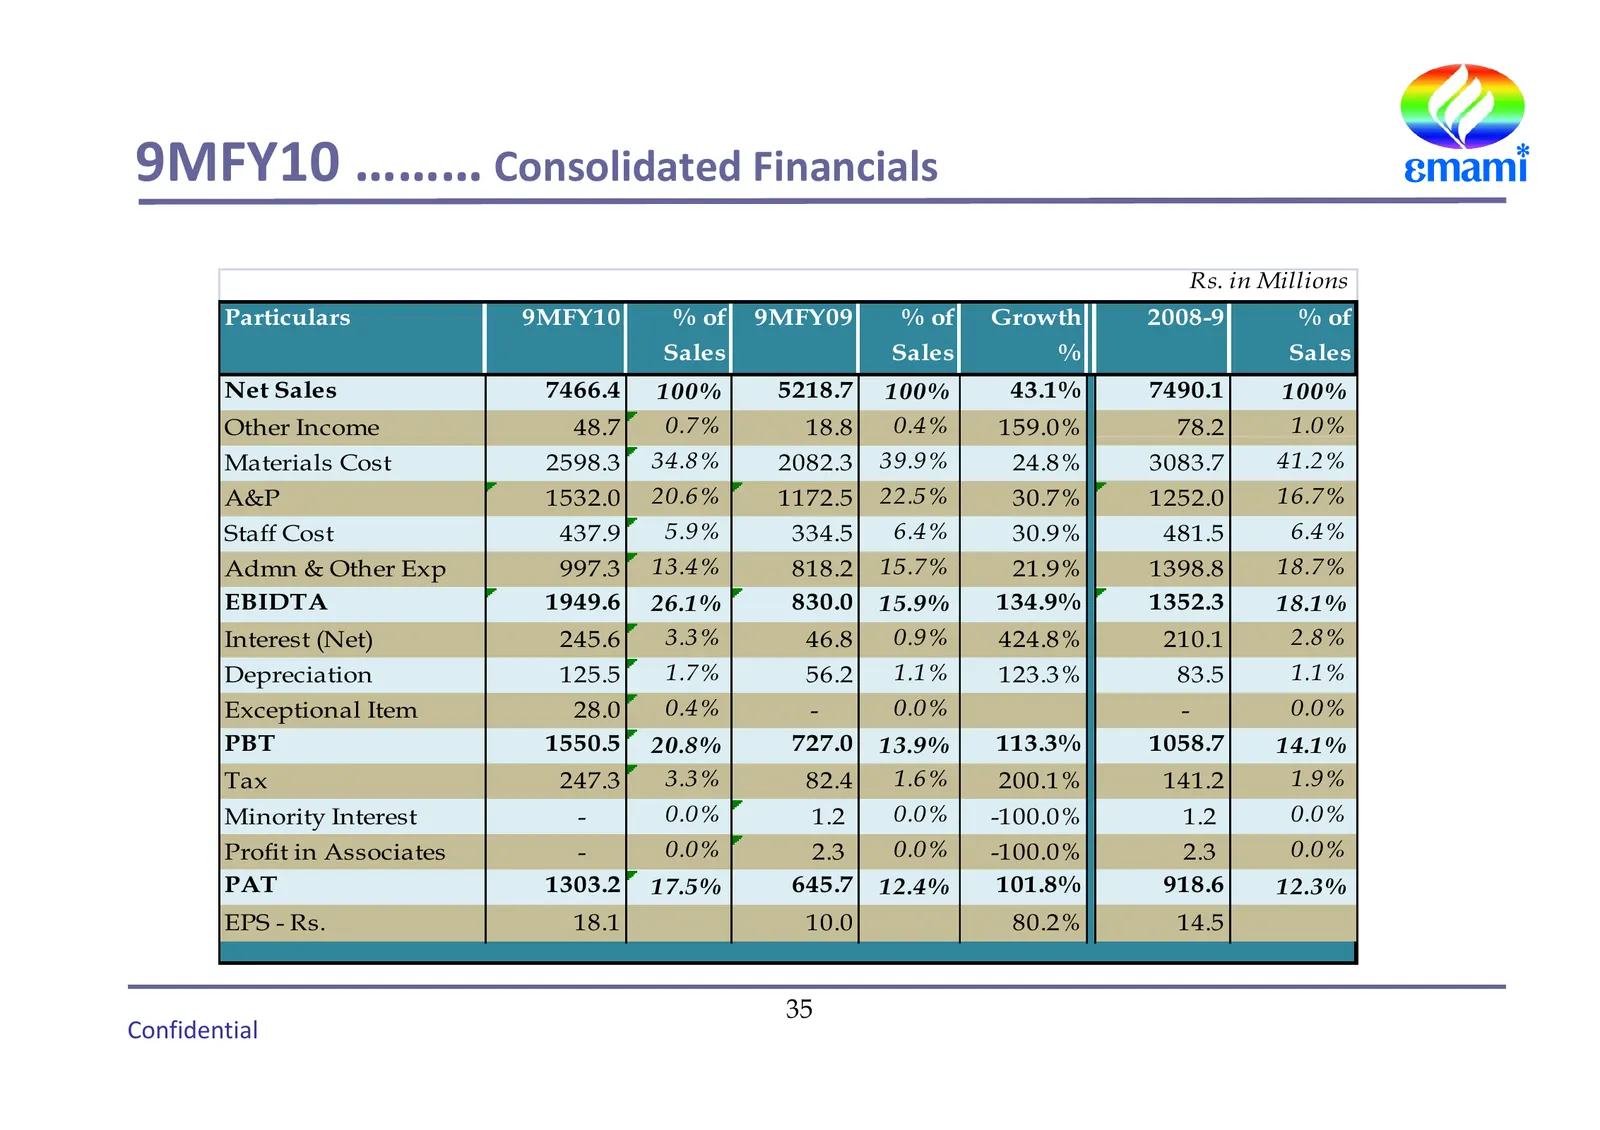
9MFY10 ……… Consolidated Financials Rs. in Millions Particulars 9MFY10 % of 9MFY09 % of Growth 2008-9 % of Sales Sales % Sales Net Sales 7466.4 100% 5218.7 100% 43.1% 7490.1 100% Other Income 48.7 0.7% 18.8 0.4% 159.0% 78.2 1.0% Materials Cost 2598.3 34.8% 2082.3 39.9% 24.8% 3083.7 41.2% A&P 1532.0 2
Slide 36: Q3FY10 Consolidated Financials
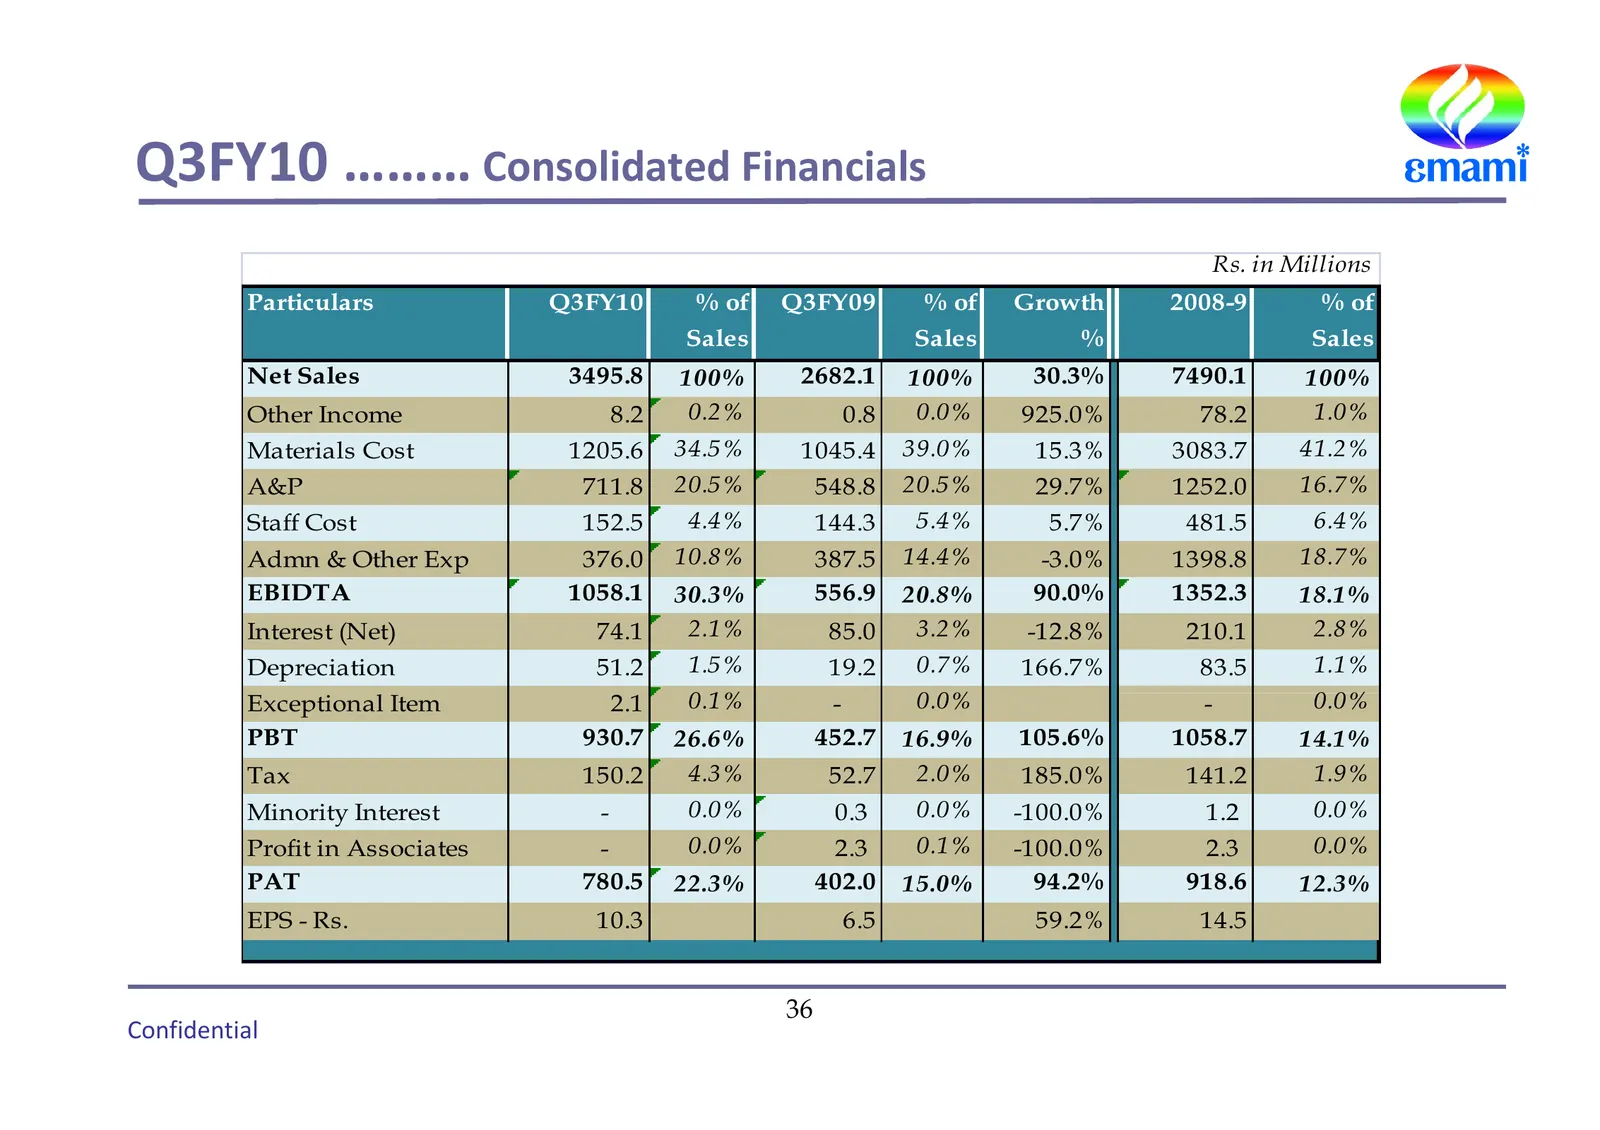
Q3FY10 ……… Consolidated Financials Rs. in Millions Particulars Q3FY10 % of Q3FY09 % of Growth 2008-9 2008 9 % of Sales Sales % Sales Net Sales 3495.8 100% 2682.1 100% 30.3% 7490.1 100% Other Income 8.2 0.2% 0.8 0.0% 925.0% 78.2 1.0% Materials Cost 1205.6 34.5% 1045.4 39.0% 15.3% 3083.7 41.2% A&P 711
Slide 37: Key Investment Highlights
Section: VI Key Investment Highlights Confidential 37
Slide 38: Key investment highlights
Key investment highlights Fastest growing FMCG company Niche category player + innovator – in Therapeutic and Ayurvedic segment - strong entry barriers for the competition The top four Brands does not face any serious competition With the acquisition of Zandu, we have one the strongest Ayurv
Slide 39: Annexure
Section: VII Annexure Confidential 39
Slide 40: Fair and Handsome Cream
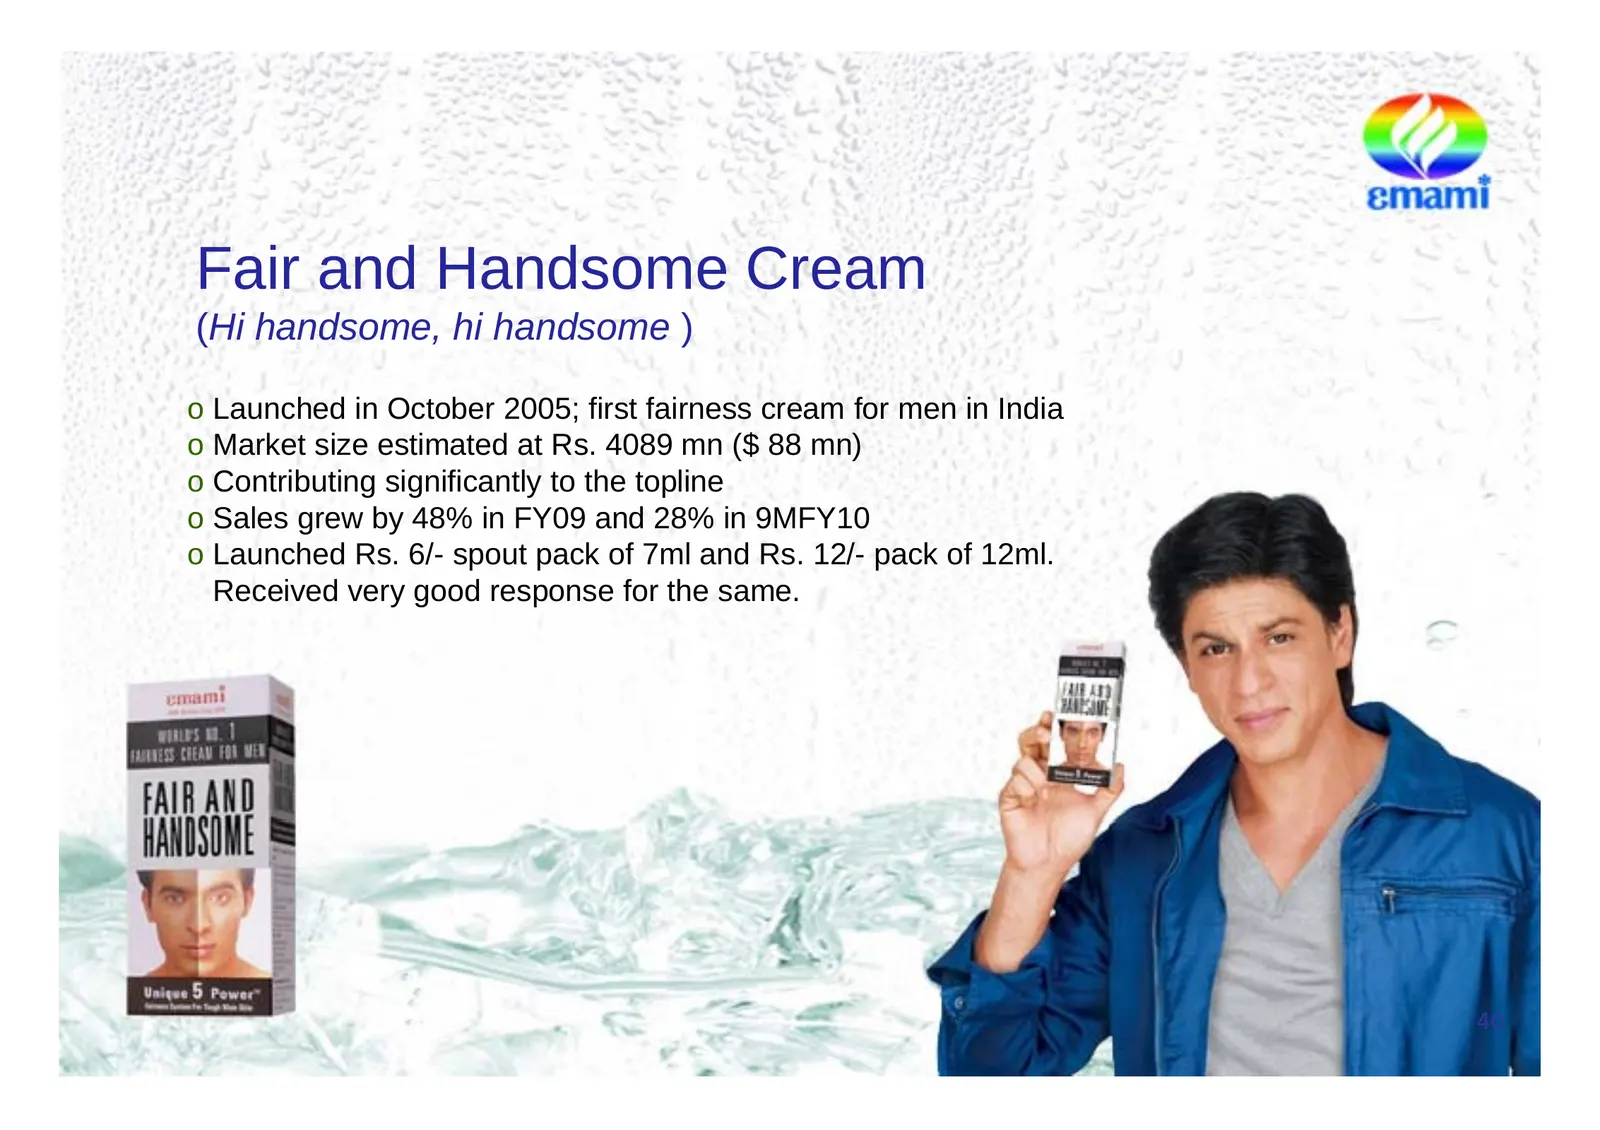
Fair and Handsome Cream (Hi handsome, hi handsome ) o Launched in October 2005; first fairness cream for men in India o Market M k t size i estimated ti t d att RRs. 4089 mn ($ 88 mn)) o Contributing significantly to the topline o Sales grew by 48% in FY09 and 28% in 9MFY10 o Launched au c ed Rs.s 6
Slide 41: Boroplus Antiseptic Cream
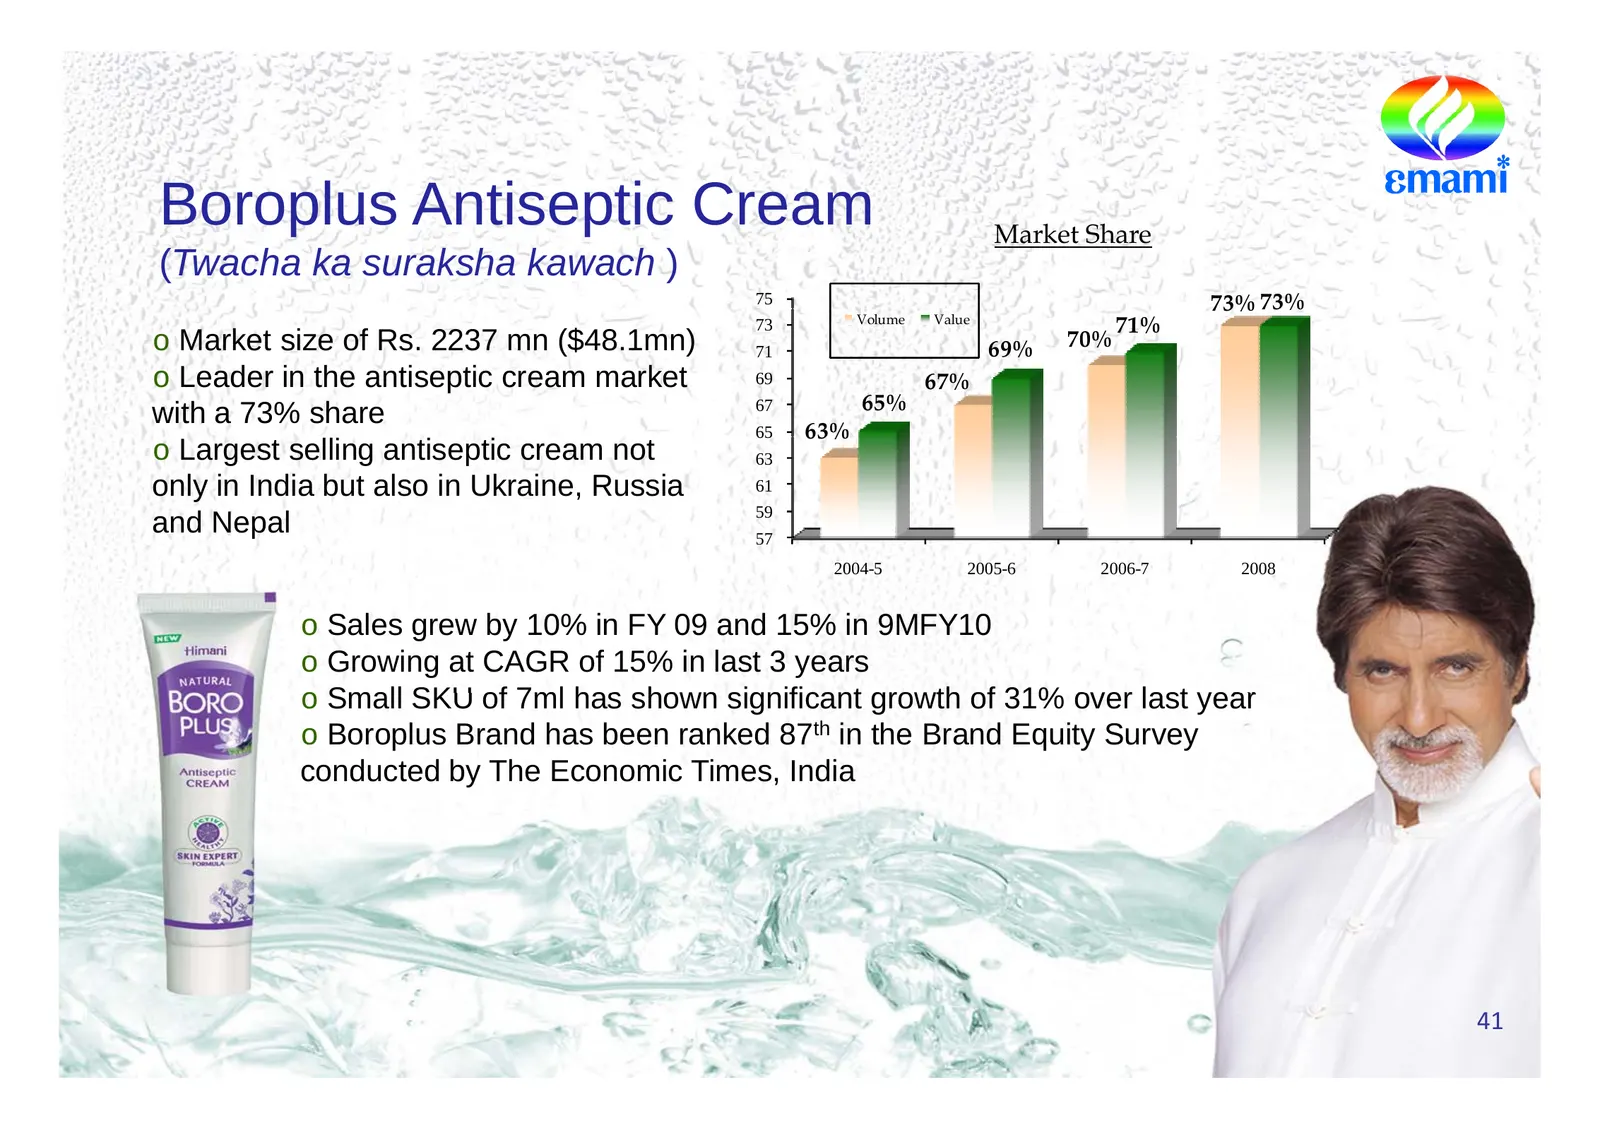
Boroplus Antiseptic Cream Market Share (Twacha ka suraksha kawach ) 75 73% 73% Volume Value 73 71% o Market size of Rs. 2237 mn ($48.1mn) 71 69% 70% o Leader in the antiseptic cream market 69 67% 67 65% with a 73% share 65 63% o Largest selling antiseptic cream not 63 only in India but also in Ukrai
Slide 42: Navratna Oil
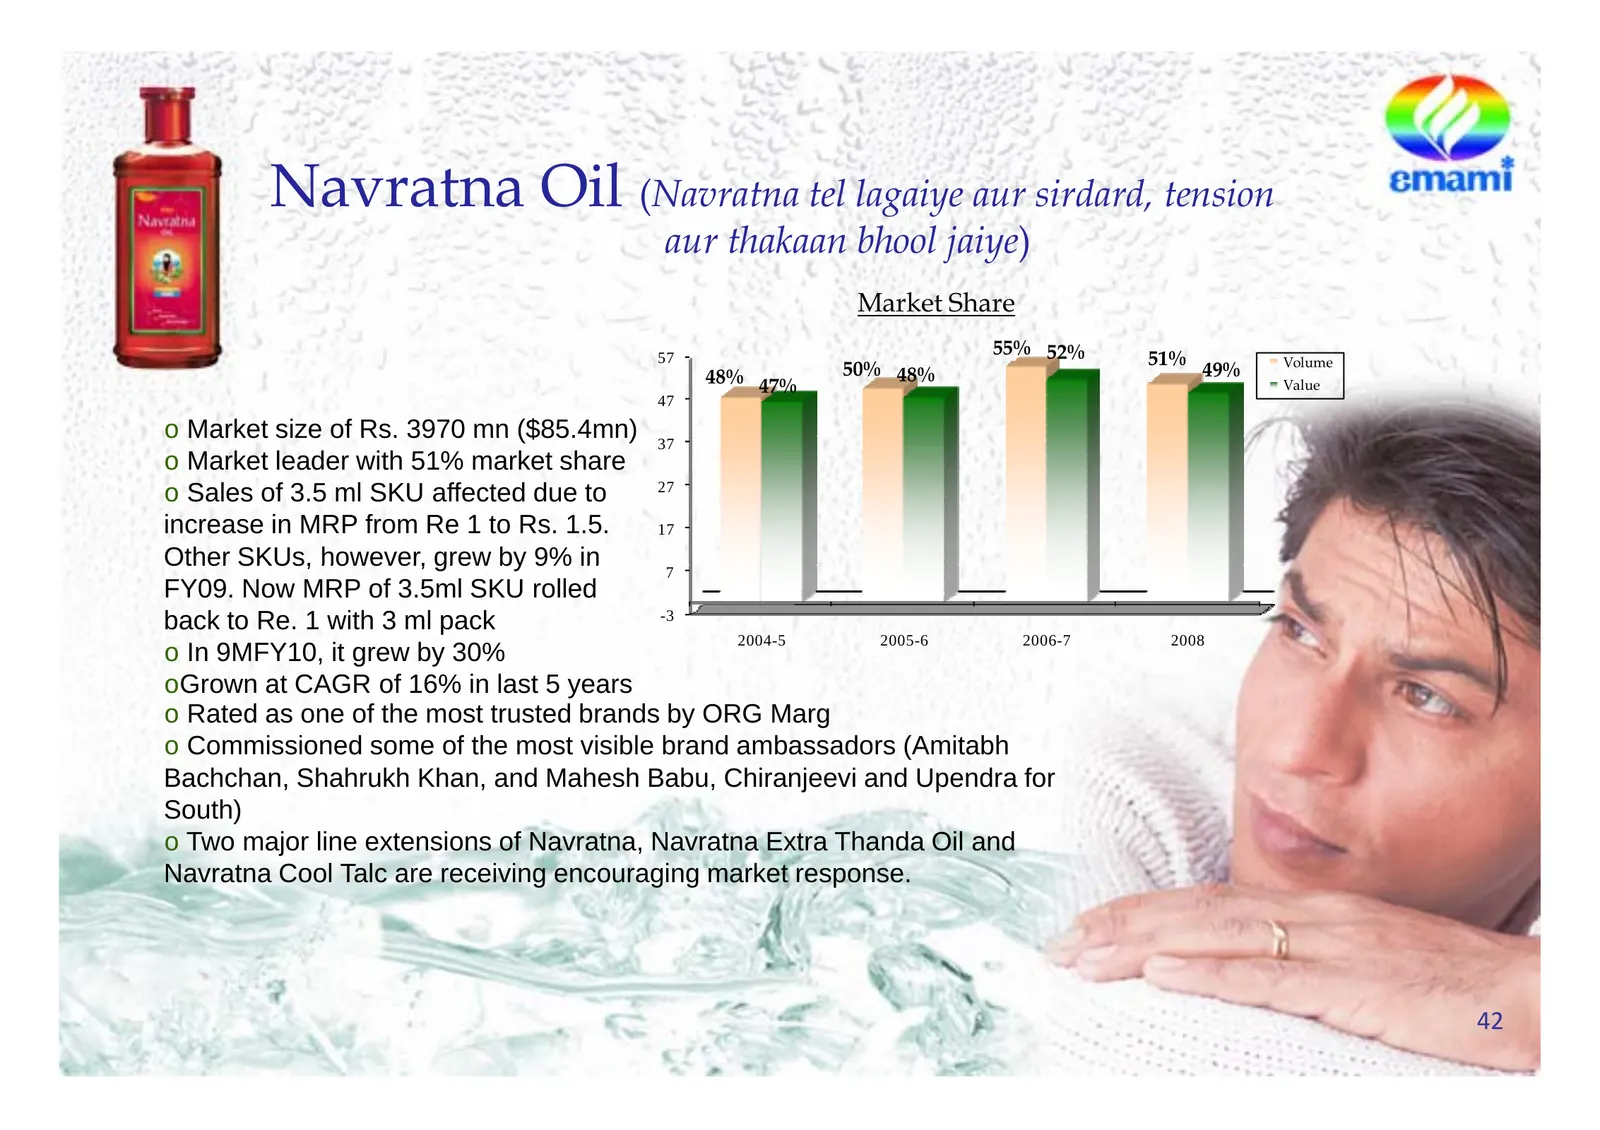
Navratna Oil (Navratna (N tell lagaiye l i aur sirdard, i d d tension i aur thakaan bhool jaiye) Market Share 55% 52% 57 51% Volume 48% 47% 50% 48% 49% Value 47 o Market size of Rs. 3970 mn ($85.4mn) 37 o Market leader with 51% market share 27 o Sales of 3.5 ml SKU affected due to increase in MRP fr
Slide 43: Mentho Plus Balm
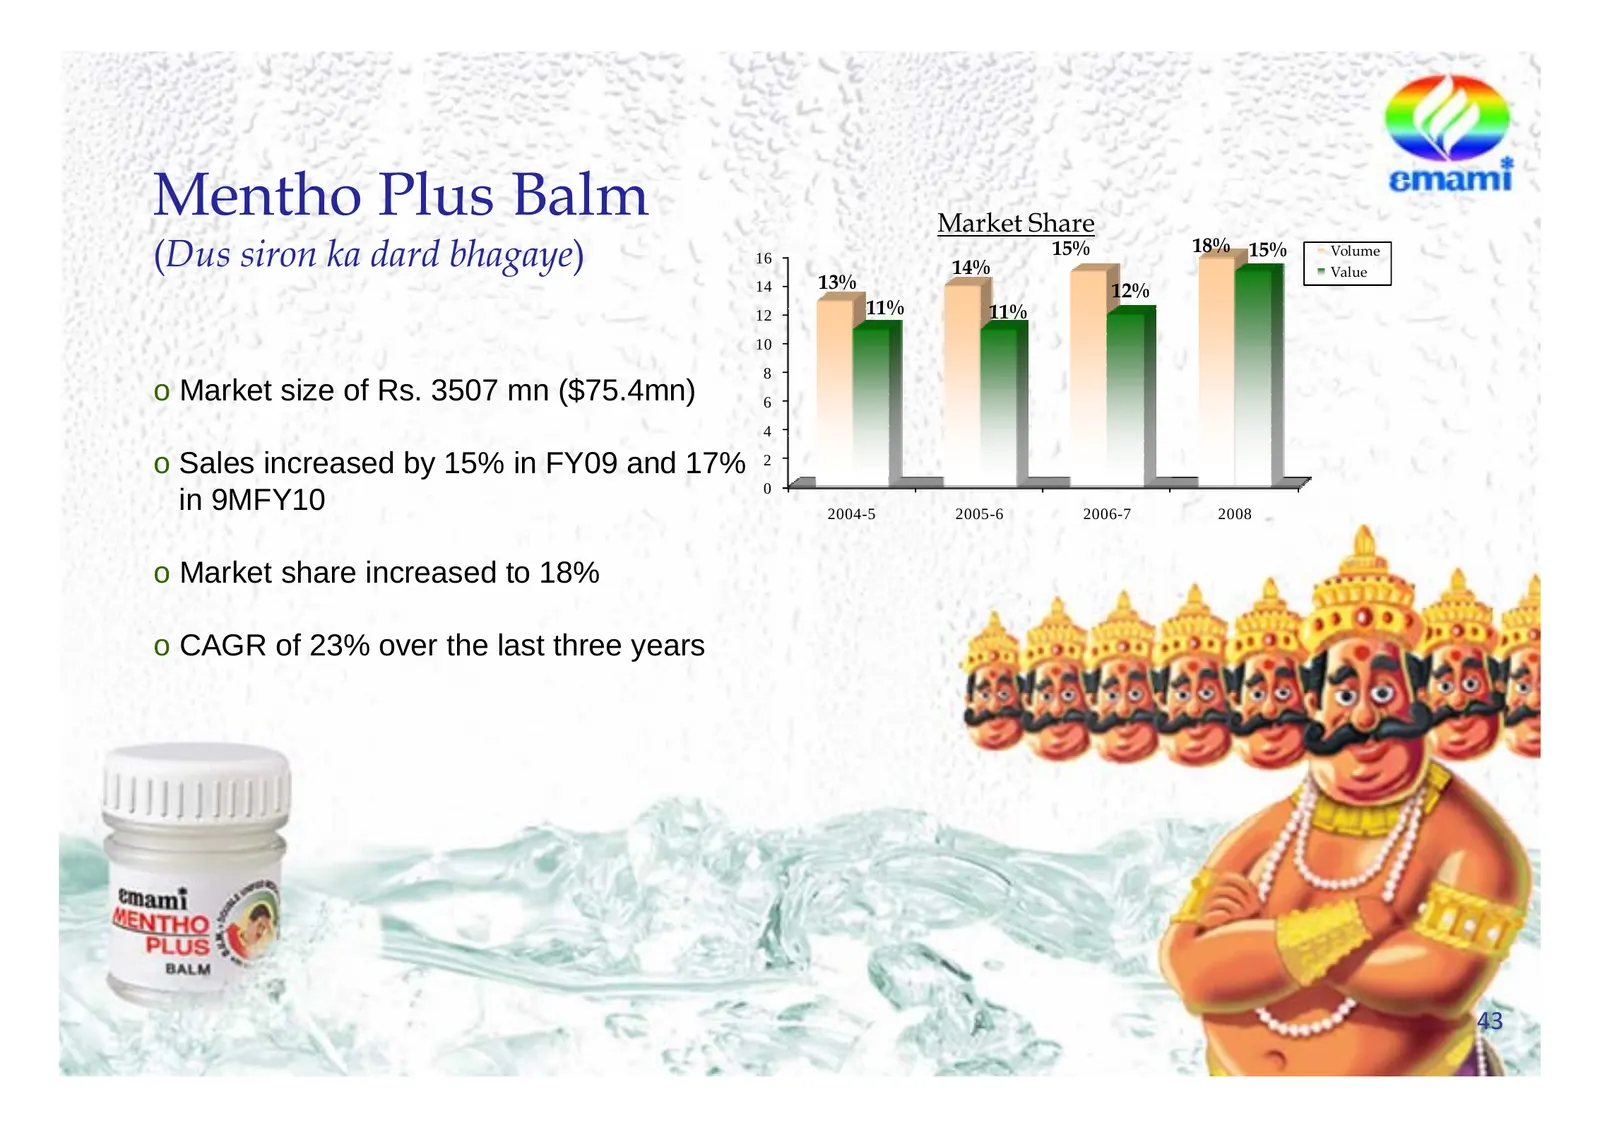
M th Plus Mentho Pl B Balm l Market Share (Dus siron ka dard bhagaye) 16 14% 15% 18% 15% Volume Value 14 13% 12% 12 11% 11% 10 8 o Market size of Rs. 3507 mn ($75.4mn) 6 4 o Sales increased by 15% in FY09 and 17% 2 0 in 9MFY10 2004-5 2005-6 2006-7 2008 o Market M k t share h increased i d to t 18% o
Slide 44: Sona Chandi Chyawanprash
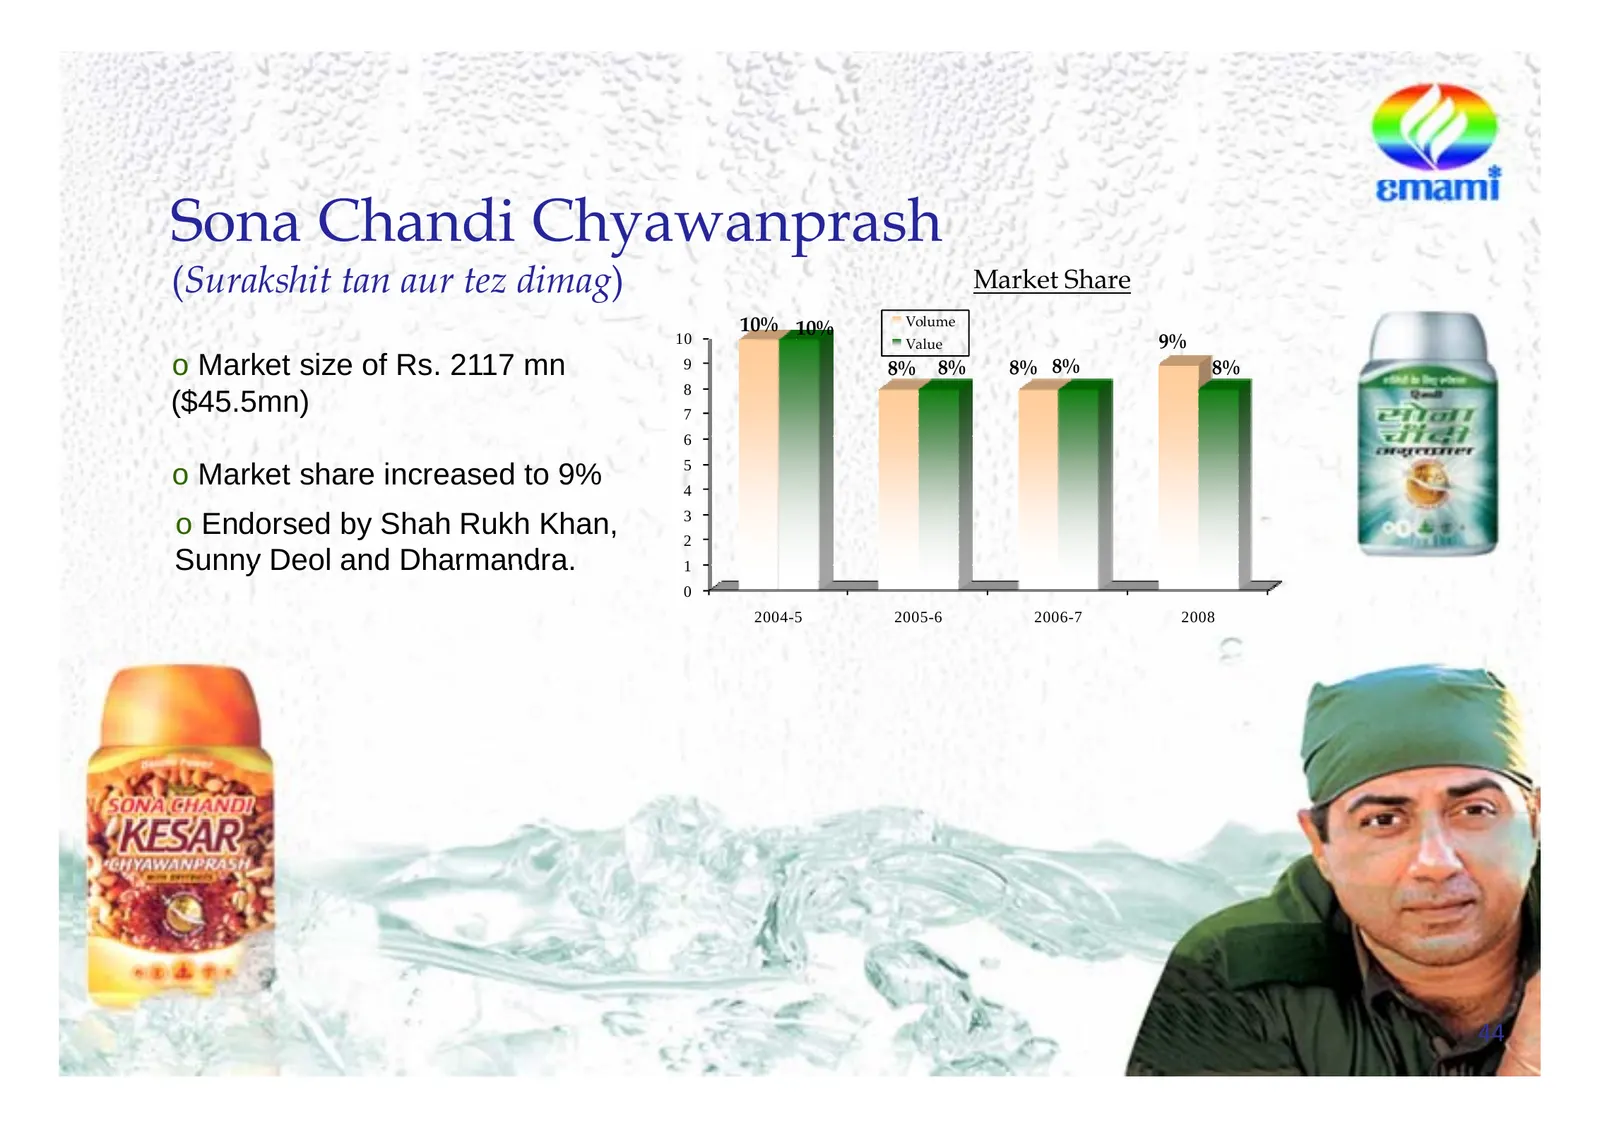
Sona Chandi Chyawanprash (Surakshit tan aur tez dimag) Market Share 10% 10% Volume 10 Value 9% o Market size of Rs. 2117 mn 9 8% 8% 8% 8% 8% 8 ($45.5mn) 7 6 5 o Market share increased to 9% 4 3 o Endorsed by Shah Rukh Khan, 2 Sunny Deol and Dharmandra Dharmandra. 1 0 2004-5 2005-6 2006-7 2008 Confid
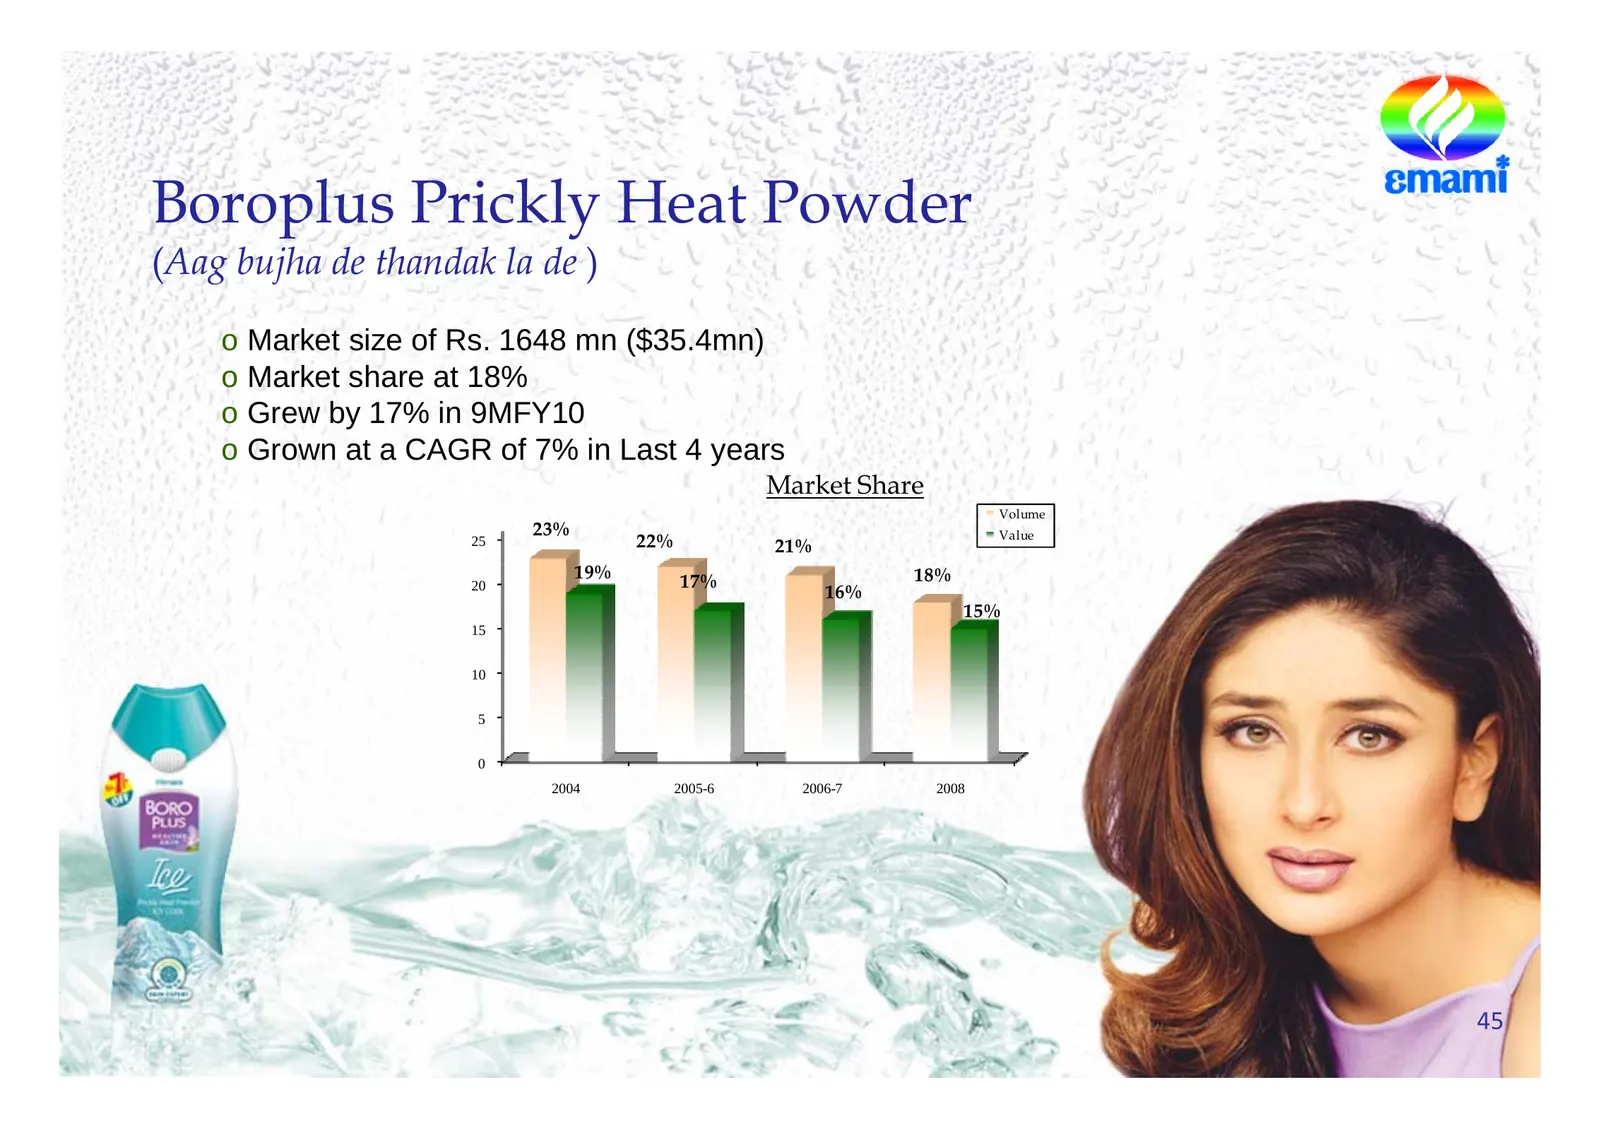
Slide 45: Boroplus Prickly Heat Powder
Boroplus l Prickly kl Heat Powder d (Aag bujha de thandak la de ) o Market size of Rs. 1648 mn ($35.4mn) o Market share at 18% o Grew by 17% in 9MFY10 o Grown at a CAGR of 7% in Last 4 years Market Share Volume 23% Value 25 22% 21% 19% 17% 18% 20 16% 15% 15 10 5 0 2004 2005-6 2006-7 2008 Confidentia
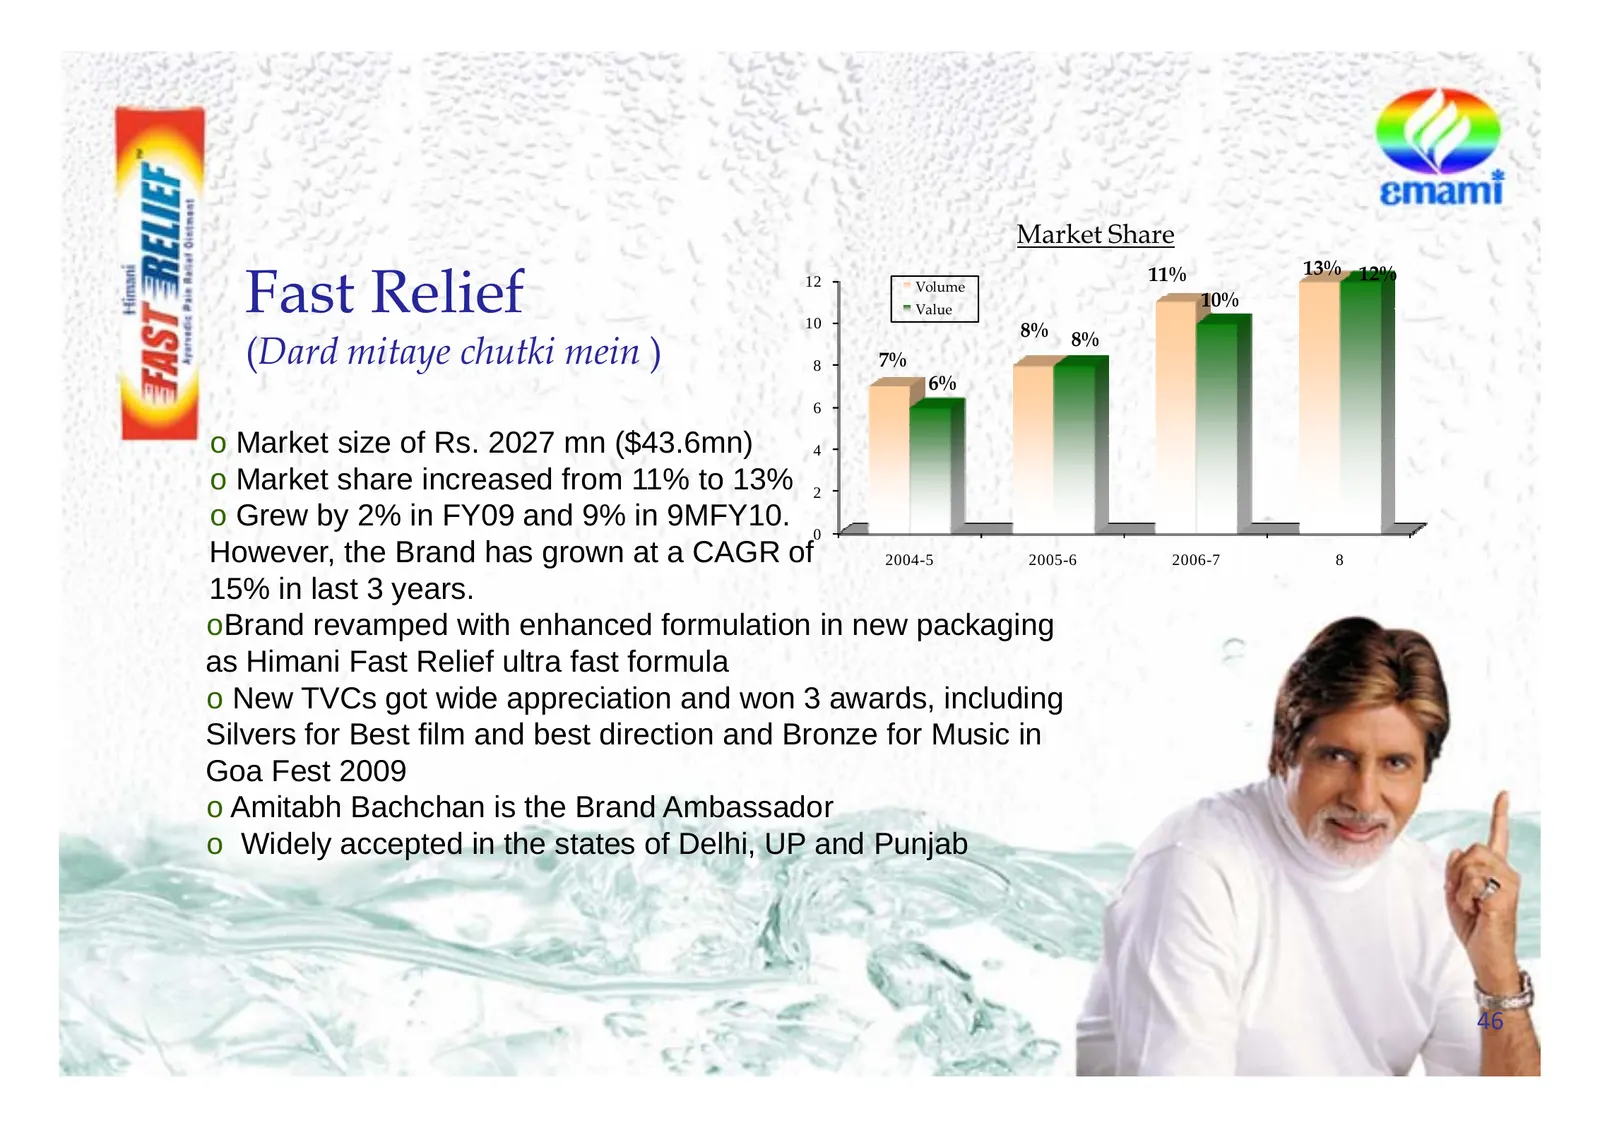
Slide 46: Fast Relief
Market Share Fast Relief 11% 13% 12% 12 Volume Value 10% 10 8% 8% (Dard mitaye chutki mein ) 8 7% 6% 6 o Market M k t sizei off Rs. R 2027 mn ($43.6mn) ($43 6 ) 4 o Market share increased from 11% to 13% 2 o Grew by 2% in FY09 and 9% in 9MFY10. 0 However,, the Brand has grown g at a CAGR of 2004-55
Source: Internet Archive copy of emamiltd.in
More decks from Emami Limited
 Q2 FY27 Earnings Presentation25 slides · Nov 5, 2026
 Q1 FY27 Earnings Presentation18 slides · Aug 4, 2026
 Q4 FY2026 Earnings Presentation22 slides · May 21, 2026
 Nuvama India Conference 2026 & IIFL's 17th Enterprising India Global Investors' Conference22 slides · Feb 6, 2026
 Q3 FY2026 Earnings Presentation22 slides · Feb 5, 2026
 Q2 FY26 Earnings Presentation21 slides · Nov 10, 2025