Universal Robina Corp. · PSE:URC
Universal Robina — Q3 2008 Earnings Presentation
10 slides from Universal Robina's earnings presentation, August 2008
Slide 1: Year-to-Date Q3 FY2008 Financial Results
Year-to-Date Q3 FY2008 Financial Results August 2008
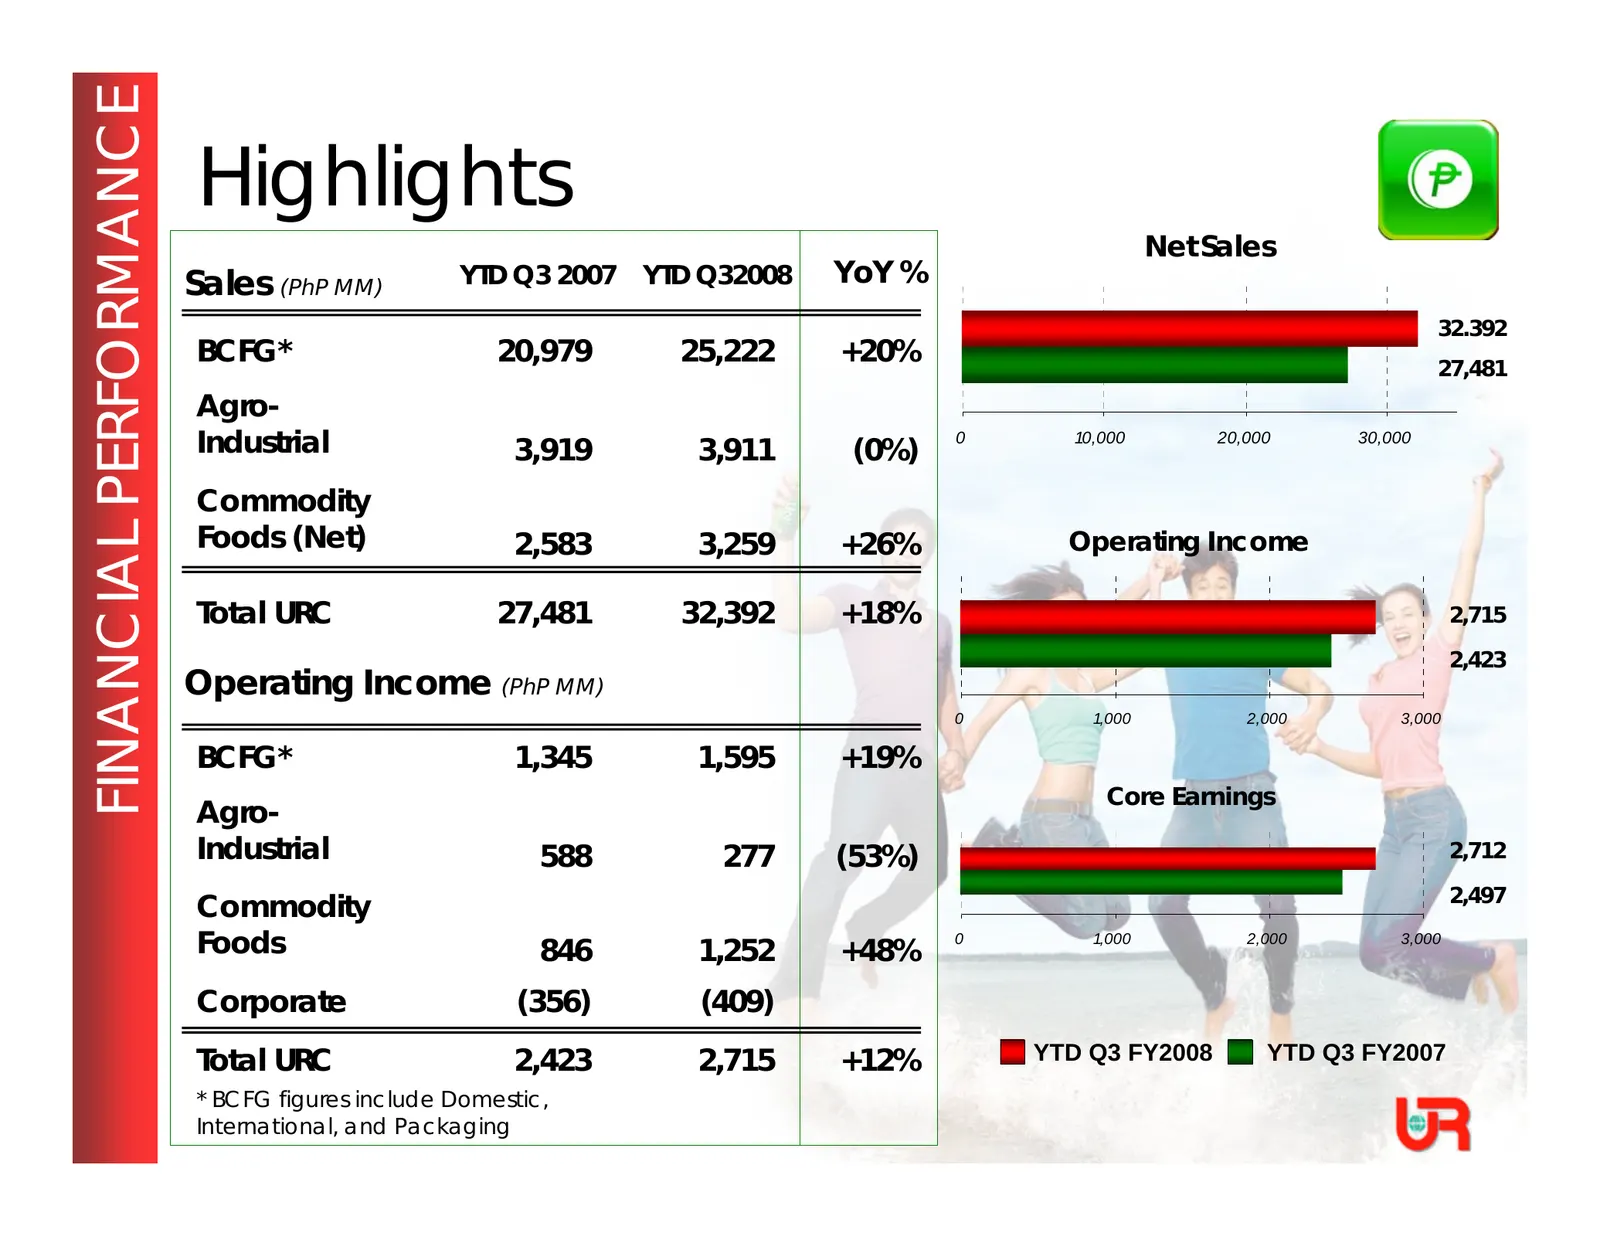
Slide 2: Financial Performance Highlights
FINANCIAL PERFORMANCE Highlights Net Sales Sales (PhP MM) YTD Q3 2007 YTD Q32008 YoY % 32.392 BCFG* 20,979 25,222 +20% 27,481 Agro- Industrial 3,919 3,911 (0%) 0 10,000 20,000 30,000 Commodity Foods (Net) 2,583 3,259 +26% Operating Income Total URC 27,481 32,392 +18% 2,715 2,423 Operating Income (Ph
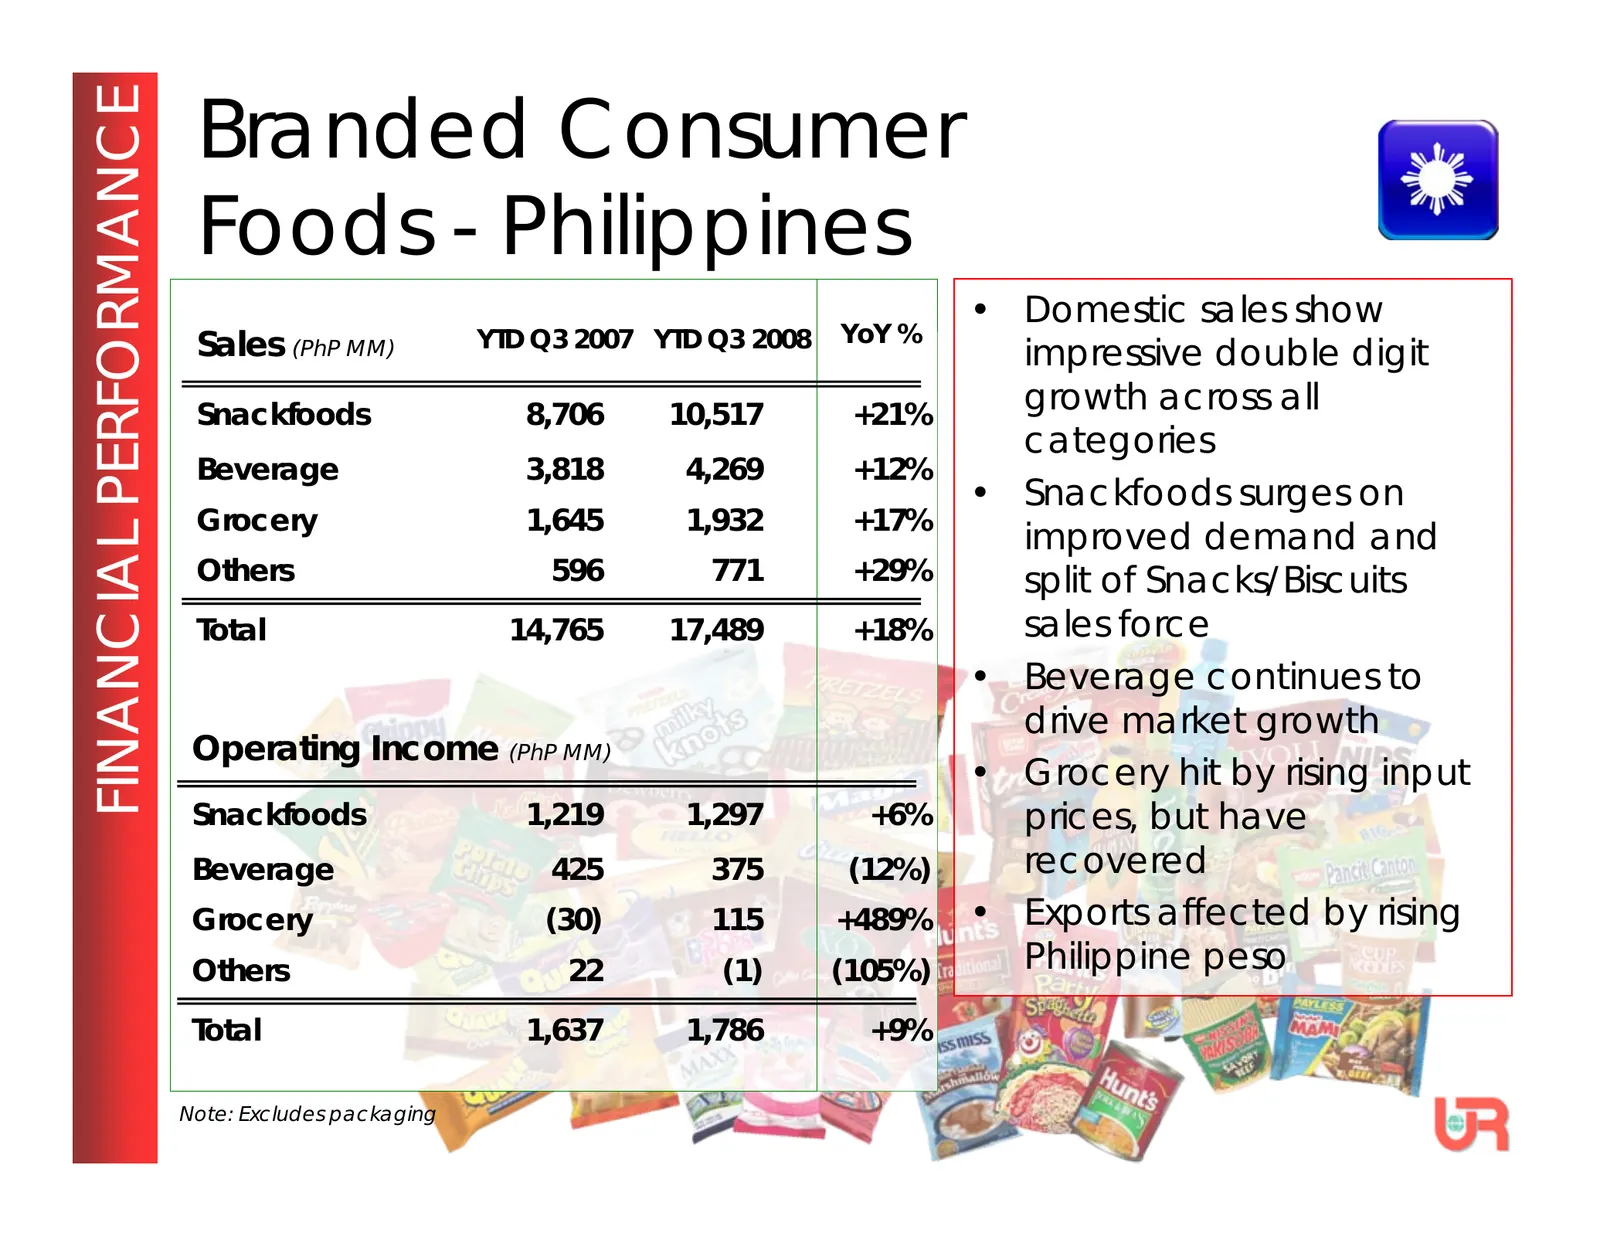
Slide 3: Branded Consumer Foods - Philippines
FINANCIAL PERFORMANCE Branded Consumer Foods - Philippines • Domestic sales show YoY % Sales (PhP MM) YTD Q3 2007 YTD Q3 2008 impressive double digit Snackfoods 8,706 10,517 +21% growth across all categories Beverage 3,818 4,269 +12% • Snackfoods surges on Grocery 1,645 1,932 +17% improved demand an
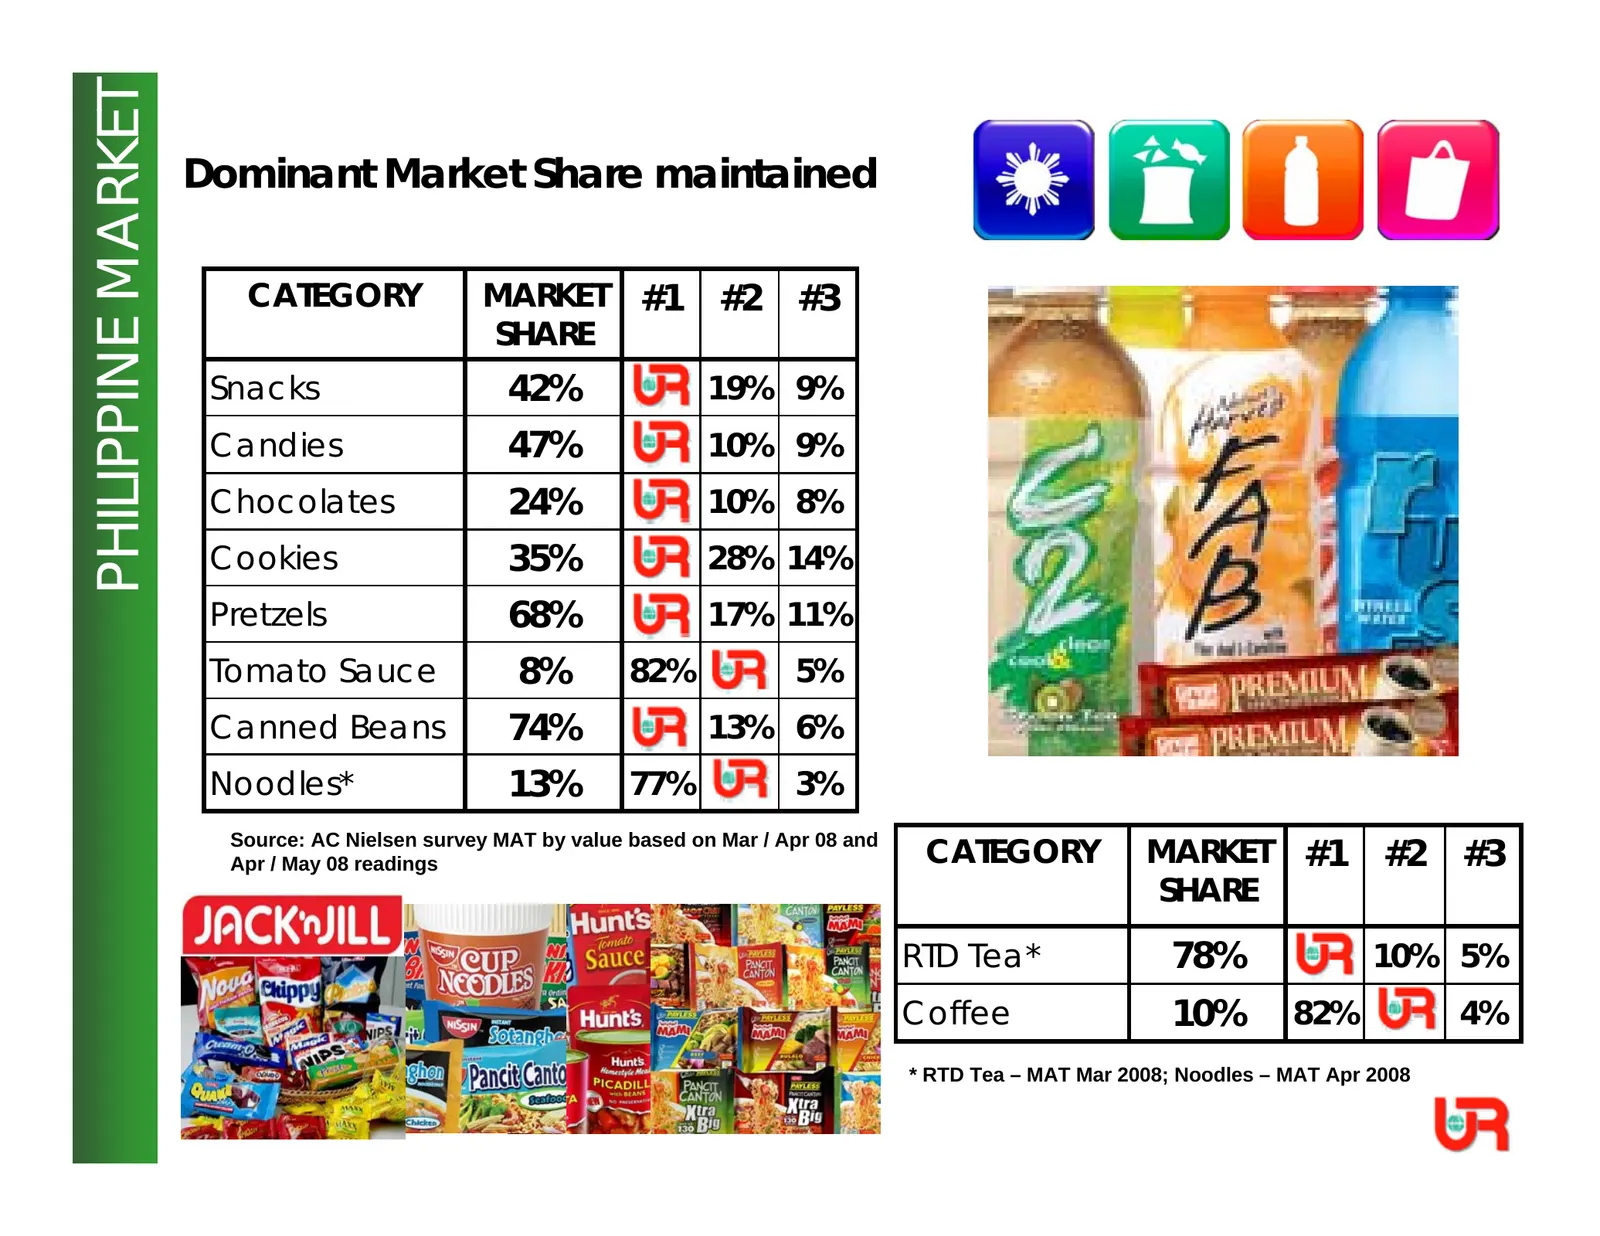
Slide 4: Philippine Market: Dominant Market Share Maintained
PHILIPPINE MARKET Dominant Market Share maintained CATEGORY MARKET #1 #2 #3 SHARE Snacks 42% 19% 9% Candies 47% 10% 9% Chocolates 24% 10% 8% Cookies 35% 28% 14% Pretzels 68% 17% 11% Tomato Sauce 8% 82% 5% Canned Beans 74% 13% 6% Noodles* 13% 77% 3% CATEGORY MARKET #1 #2 #3 Source: AC Nielsen survey
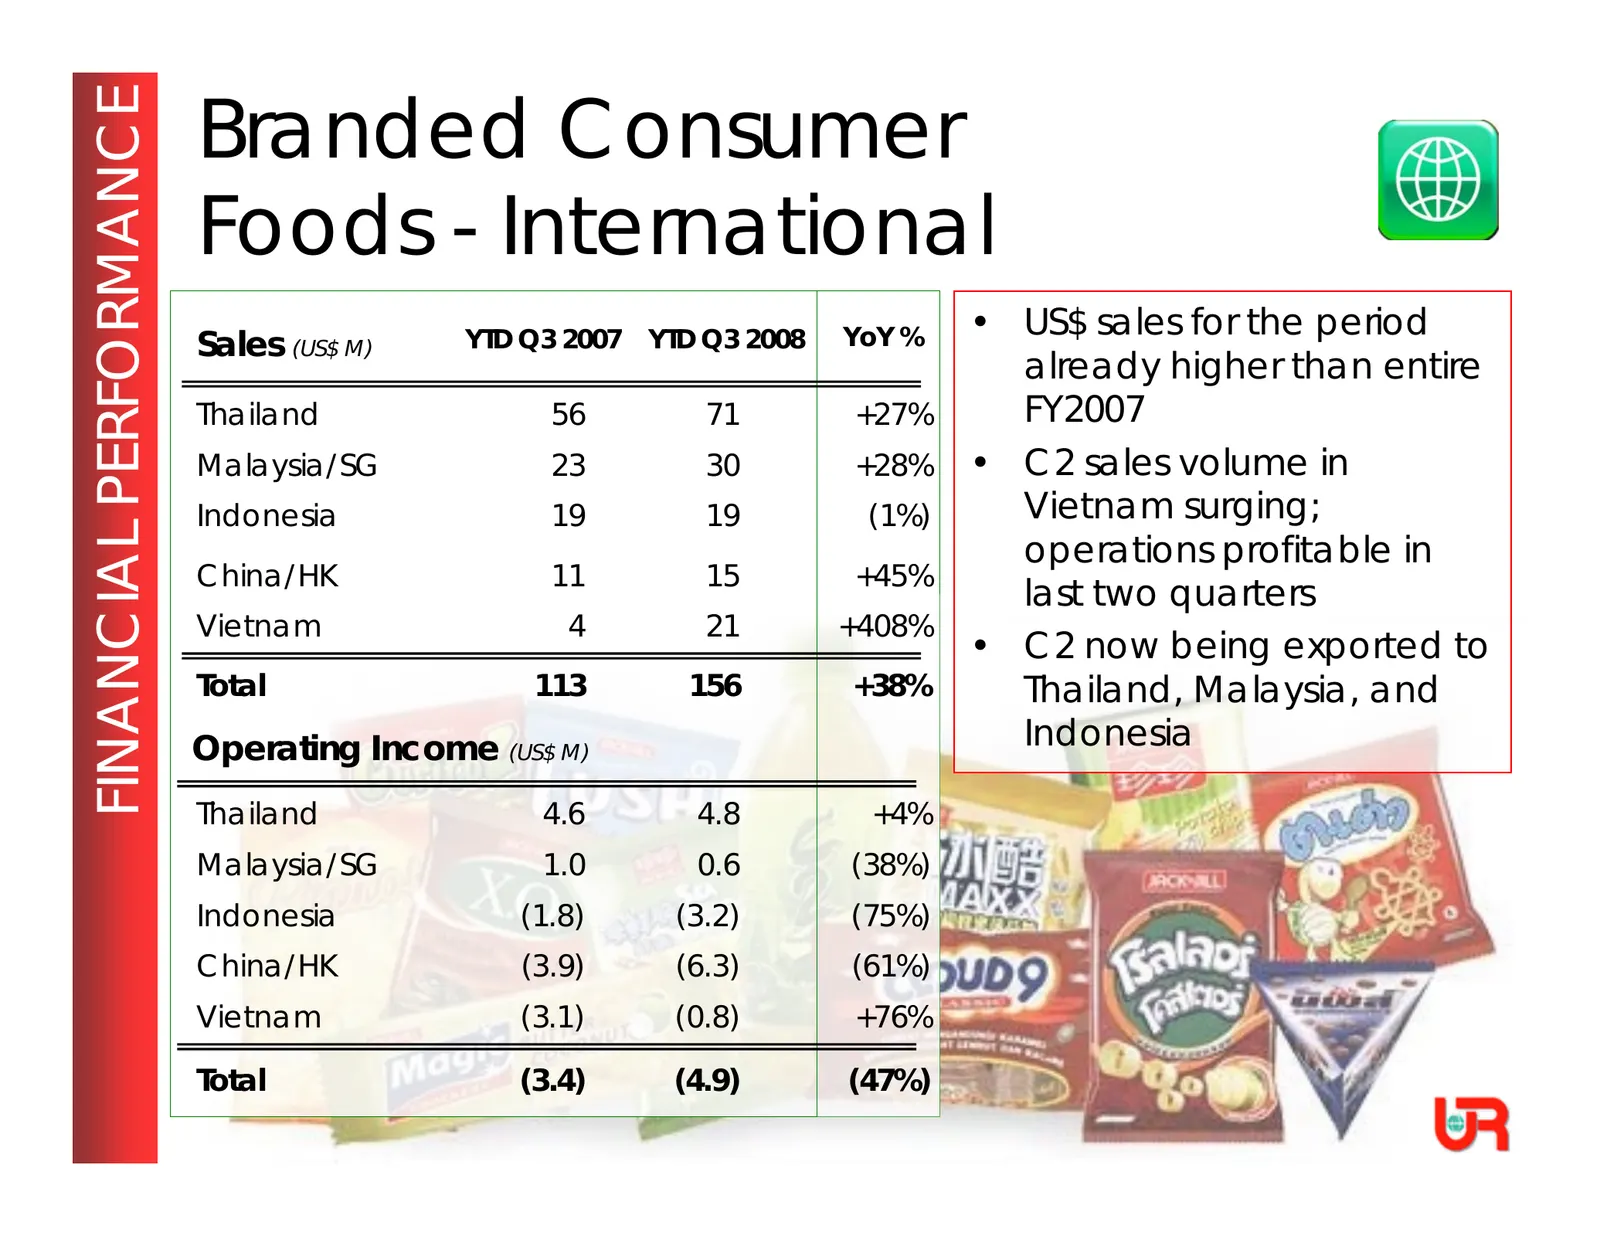
Slide 5: Branded Consumer Foods - International
FINANCIAL PERFORMANCE Branded Consumer Foods - International YoY % • US$ sales for the period Sales (US$ M) YTD Q3 2007 YTD Q3 2008 already higher than entire Thailand 56 71 +27% FY2007 Malaysia/SG 23 30 +28% • C2 sales volume in Indonesia 19 19 (1%) Vietnam surging; operations profitable in China/H
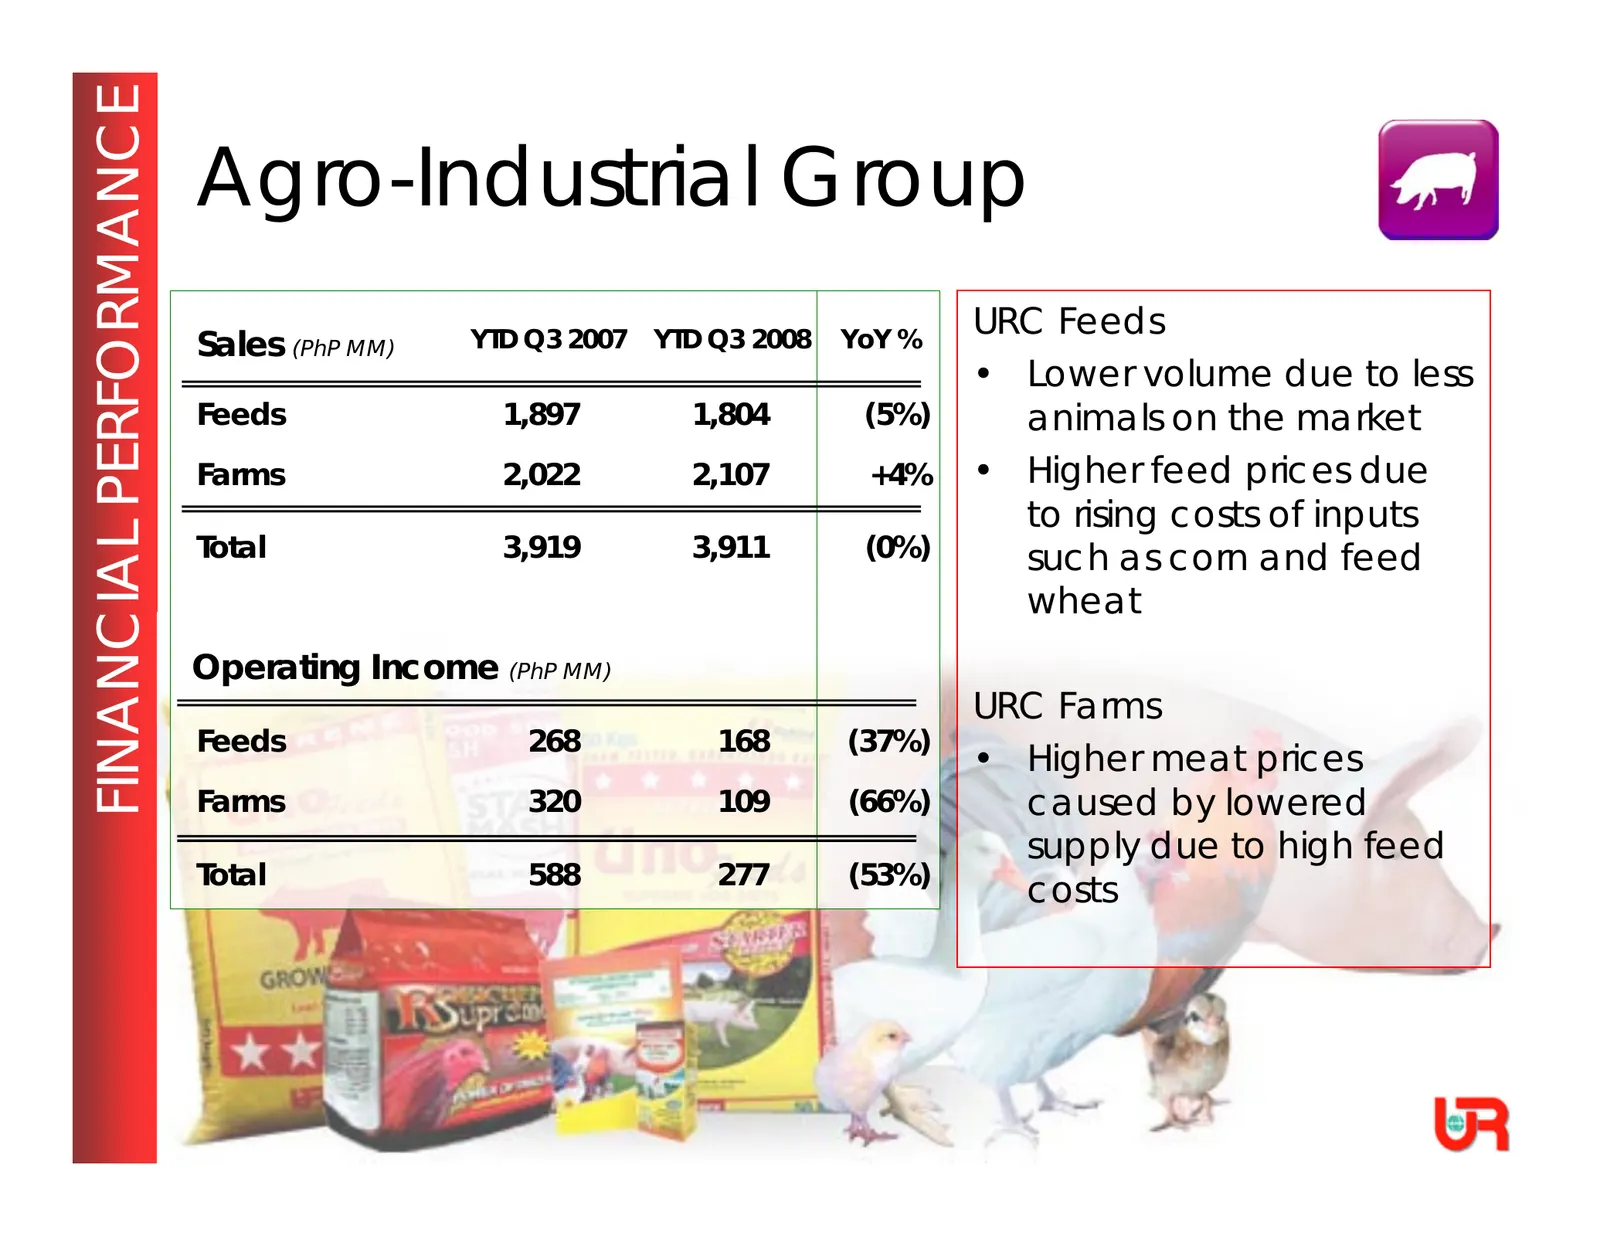
Slide 6: Agro-Industrial Group
FINANCIAL PERFORMANCE Agro-Industrial Group URC Feeds Sales (PhP MM) YTD Q3 2007 YTD Q3 2008 YoY % • Lower volume due to less Feeds 1,897 1,804 (5%) animals on the market Farms 2,022 2,107 +4% • Higher feed prices due to rising costs of inputs Total 3,919 3,911 (0%) such as corn and feed wheat Opera
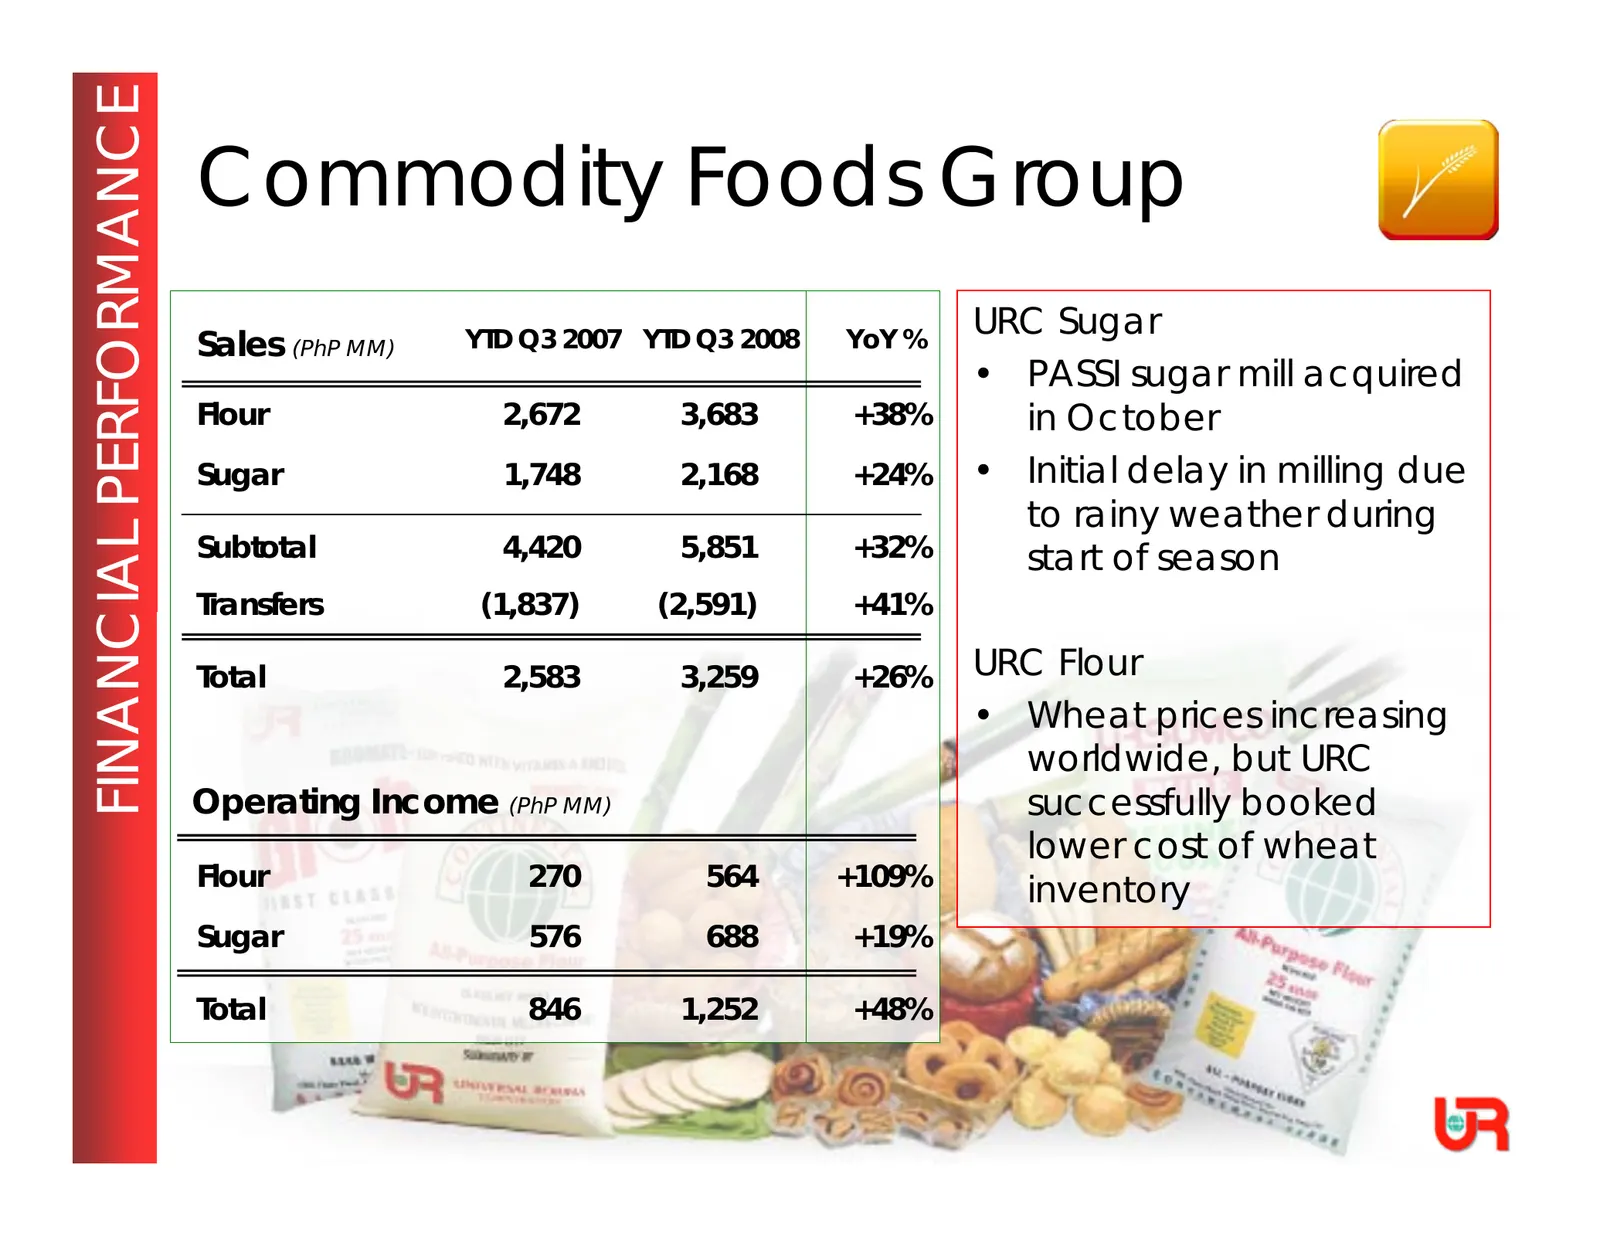
Slide 7: Commodity Foods Group
FINANCIAL PERFORMANCE Commodity Foods Group URC Sugar Sales (PhP MM) YTD Q3 2007 YTD Q3 2008 YoY % • PASSI sugar mill acquired Flour 2,672 3,683 +38% in October Sugar 1,748 2,168 +24% • Initial delay in milling due to rainy weather during Subtotal 4,420 5,851 +32% start of season Transfers (1,837) (
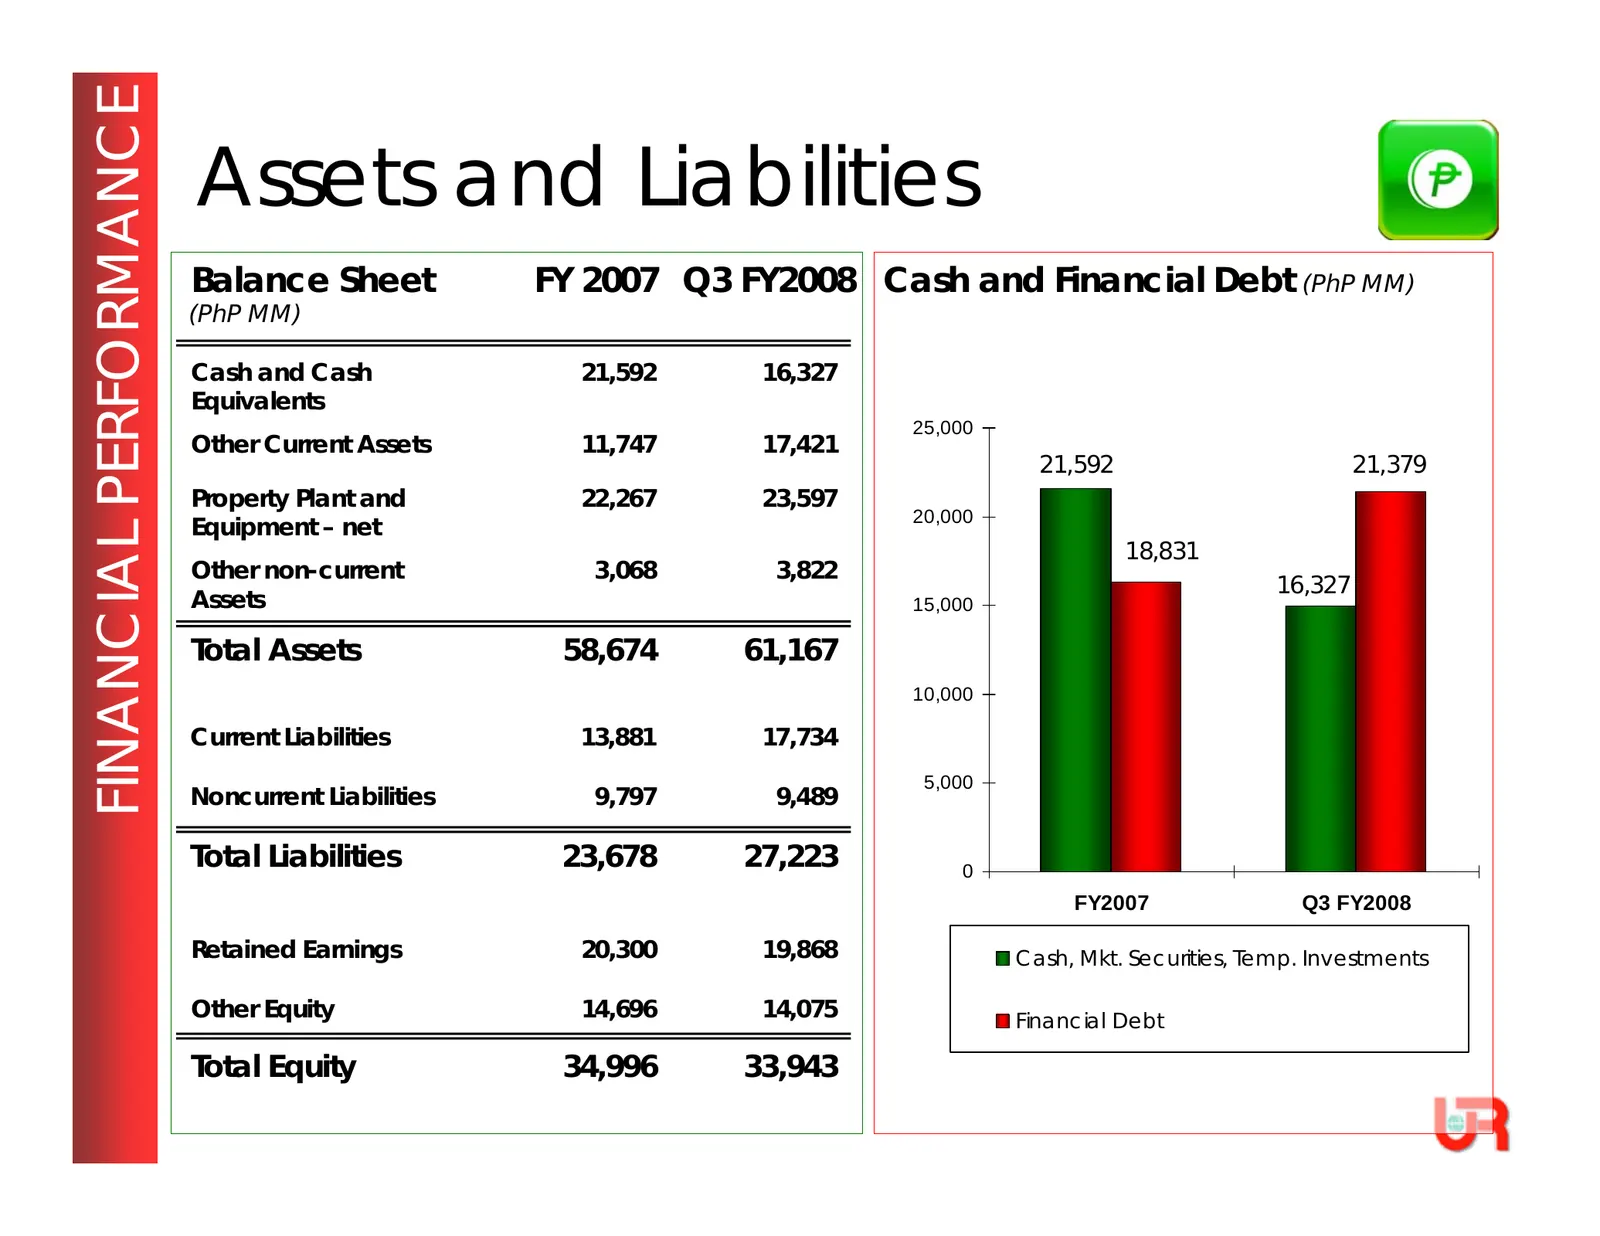
Slide 8: Assets and Liabilities
FINANCIAL PERFORMANCE Assets and Liabilities Balance Sheet FY 2007 Q3 FY2008 Cash and Financial Debt (PhP MM) (PhP MM) Cash and Cash 21,592 16,327 Equivalents 25,000 Other Current Assets 11,747 17,421 21,592 21,379 Property Plant and 22,267 23,597 20,000 Equipment – net 18,831 Other non-current 3,06
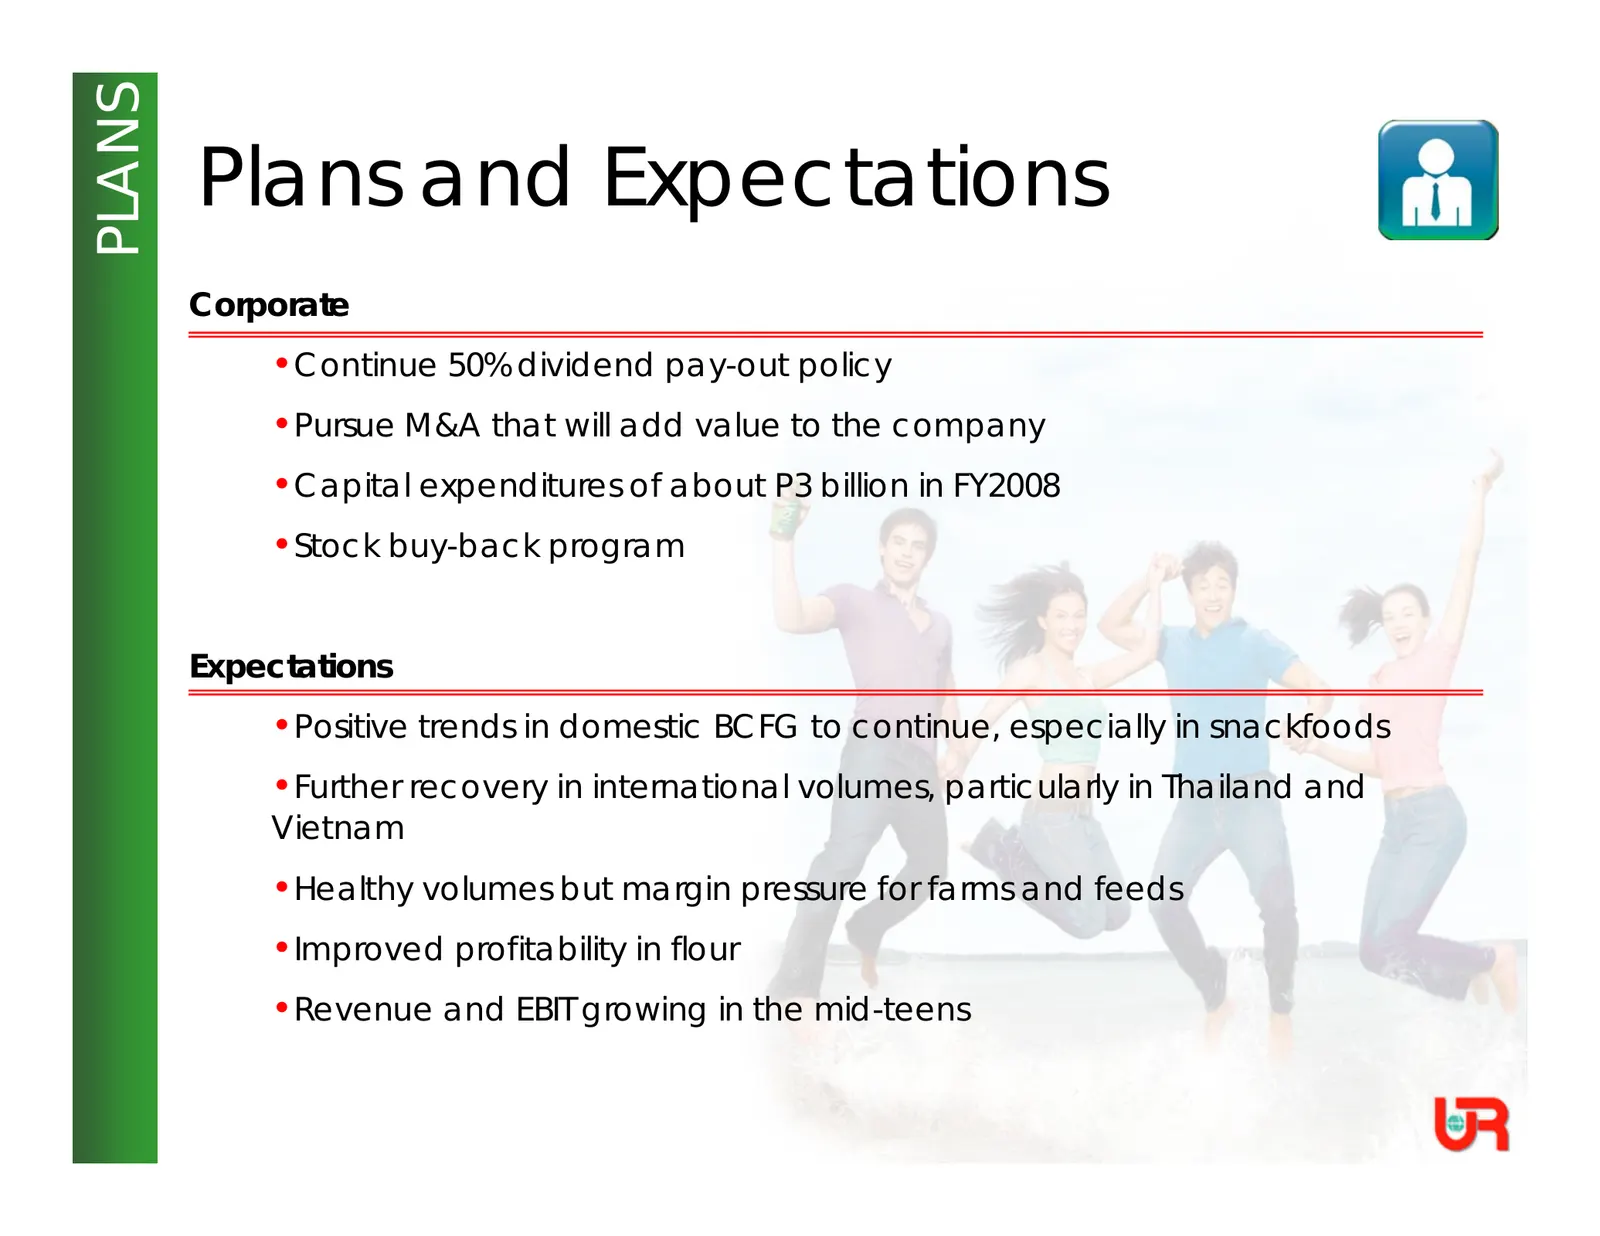
Slide 9: Plans and Expectations
PLANS Plans and Expectations Corporate •Continue 50% dividend pay-out policy •Pursue M&A that will add value to the company •Capital expenditures of about P3 billion in FY2008 •Stock buy-back program Expectations •Positive trends in domestic BCFG to continue, especially in snackfoods •Further recove
Slide 10: The End
3 UNIVERSAL ROBINA CORPORATION The End
Source: company website
More decks from Universal Robina Corp.
 Q3 2026 Earnings Presentation20 slides · Nov 5, 2026
 Q2 2026 Earnings Presentation20 slides · Aug 6, 2026
 Q1 2026 Earnings Presentation19 slides · May 7, 2026
 Q4 2025 Earnings Presentation22 slides · Mar 13, 2026
 Q3 2025 Earnings Presentation19 slides · Nov 6, 2025
 H1 2025 Earnings Presentation19 slides · Aug 8, 2025