Wheeling Pittsburgh — Proxy Contest (July 2006)
34 slides from Wheeling Pittsburgh's proxy contest presentation, Jul 26, 2006
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 (Amendment No. ) Filed by the Registrant ¨ Filed by a Party other than the Registrant x Check the appropriate box: ¨ Preliminary Proxy
Slide 2: Fee paid previously with preliminary materials
¨ Fee paid previously with preliminary materials. ¨ Check box if any part of the fee is offset as provided by Exchange Act Rule 0-11(a)(2) and identify the filing for which the offsetting fee was paid previously. Identify the previous filing by registration statement number, or the Form or Schedule
Slide 3: Investor presentation posted to Esmark's website
The following investor presentation has been posted to Esmark’s website at http://www.esmark.com. * * *
Slide 4: July 26, 2006 Esmark
JULY 26, 2006 + ESMARK A Steel Services Family m™
Slide 5: Important proxy statement information
Esmark, together with the other participants indicated below, filed a preliminary proxy statement with the SEC on July 21, 2006 relating to the solicitation of proxies for the election of a slate of director nominees at the 2006 annual meeting of stockholders of Wheeling-Pitt, which has not yet been
Slide 6: Agenda
Agenda Page Overview 2 Strategic vision 7 Overview of Esmark 18 Overview of Wheeling-Pitt 22 Conclusion 29 2
Slide 7: Esmark has proposed a new slate of directors
Esmark has proposed a new slate of directors to ensure proper consideration of its combination proposal with Wheeling-Pitt Esmark has presented a proposal to the Board of Directors of Wheeling-Pittsburgh Corporation (“Wheeling-Pitt”) to combine the two companies. Wheeling-Pitt has rejected this prop
Slide 8: Overview of the proposed transaction
Overview of the proposed transaction Wheeling-Pitt would issue 26.5 million new common shares to Esmark stockholders valued at approximately $473 million, based on the closing share price of $17.86 as of July 14, 2006 The proposed transaction would value Esmark at approximately $273 million and refl
Slide 9: Esmark is nominating a talented and diverse slate of nominees
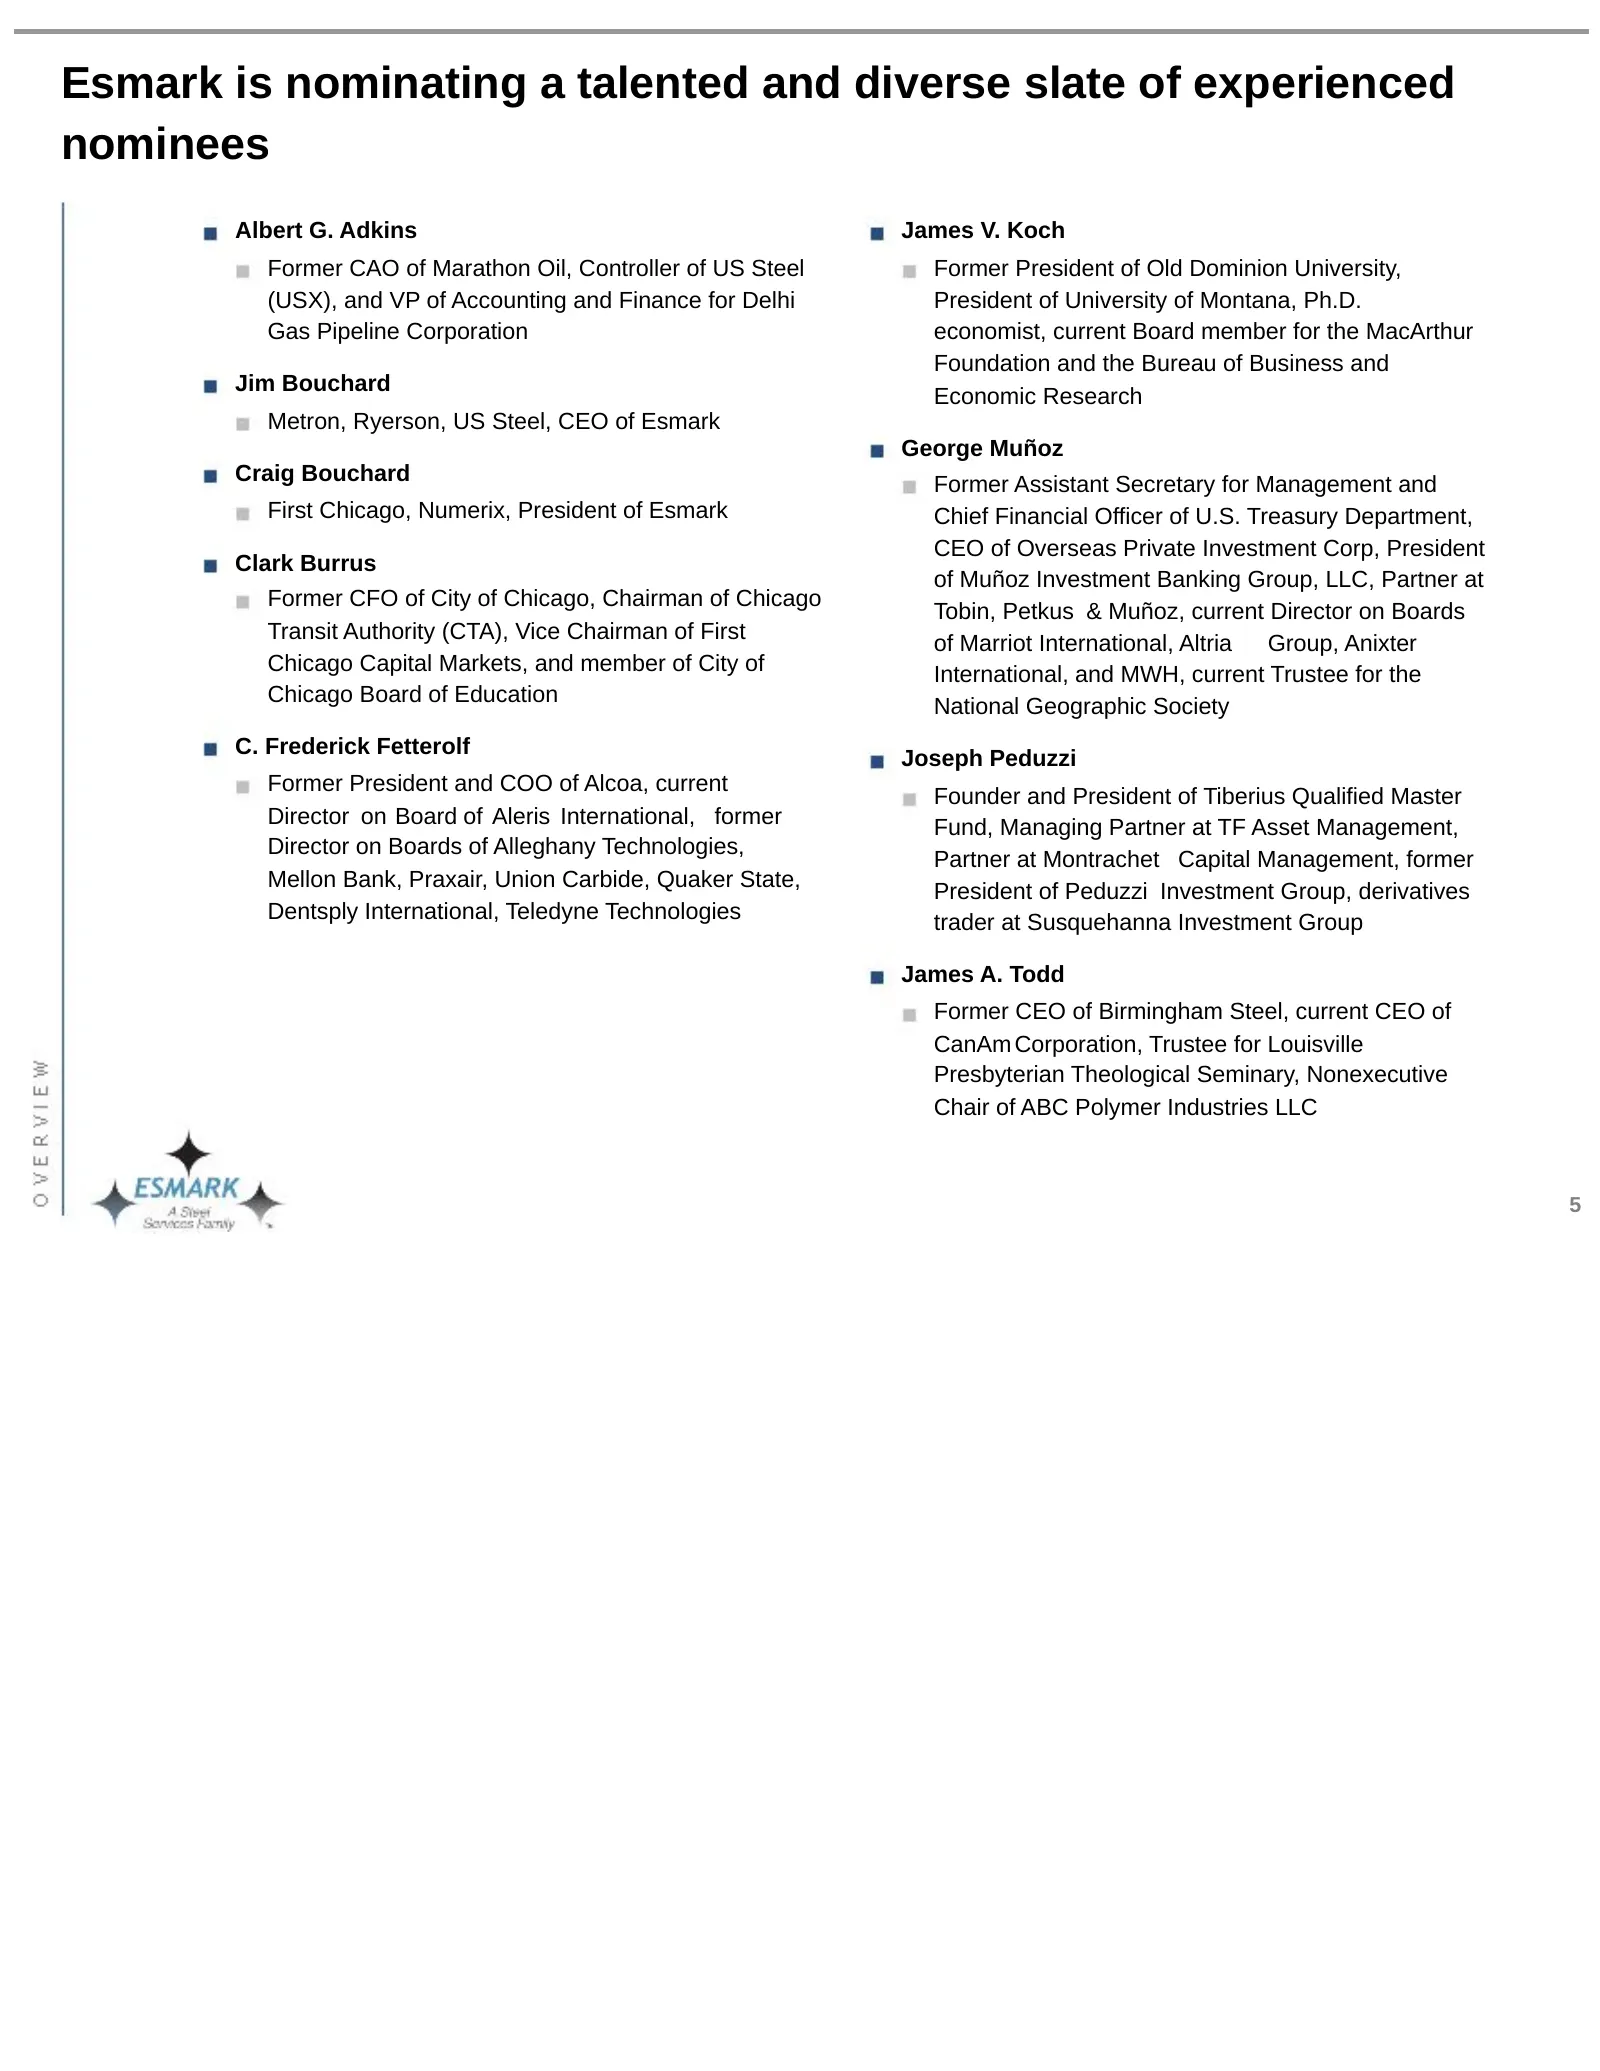
Esmark is nominating a talented and diverse slate of experienced nominees Albert G. Adkins James V. Koch Former CAO of Marathon Oil, Controller of US Steel Former President of Old Dominion University, (USX), and VP of Accounting and Finance for Delhi President of University of Montana, Ph.D. Gas Pip
Slide 10: The proposed executive management team
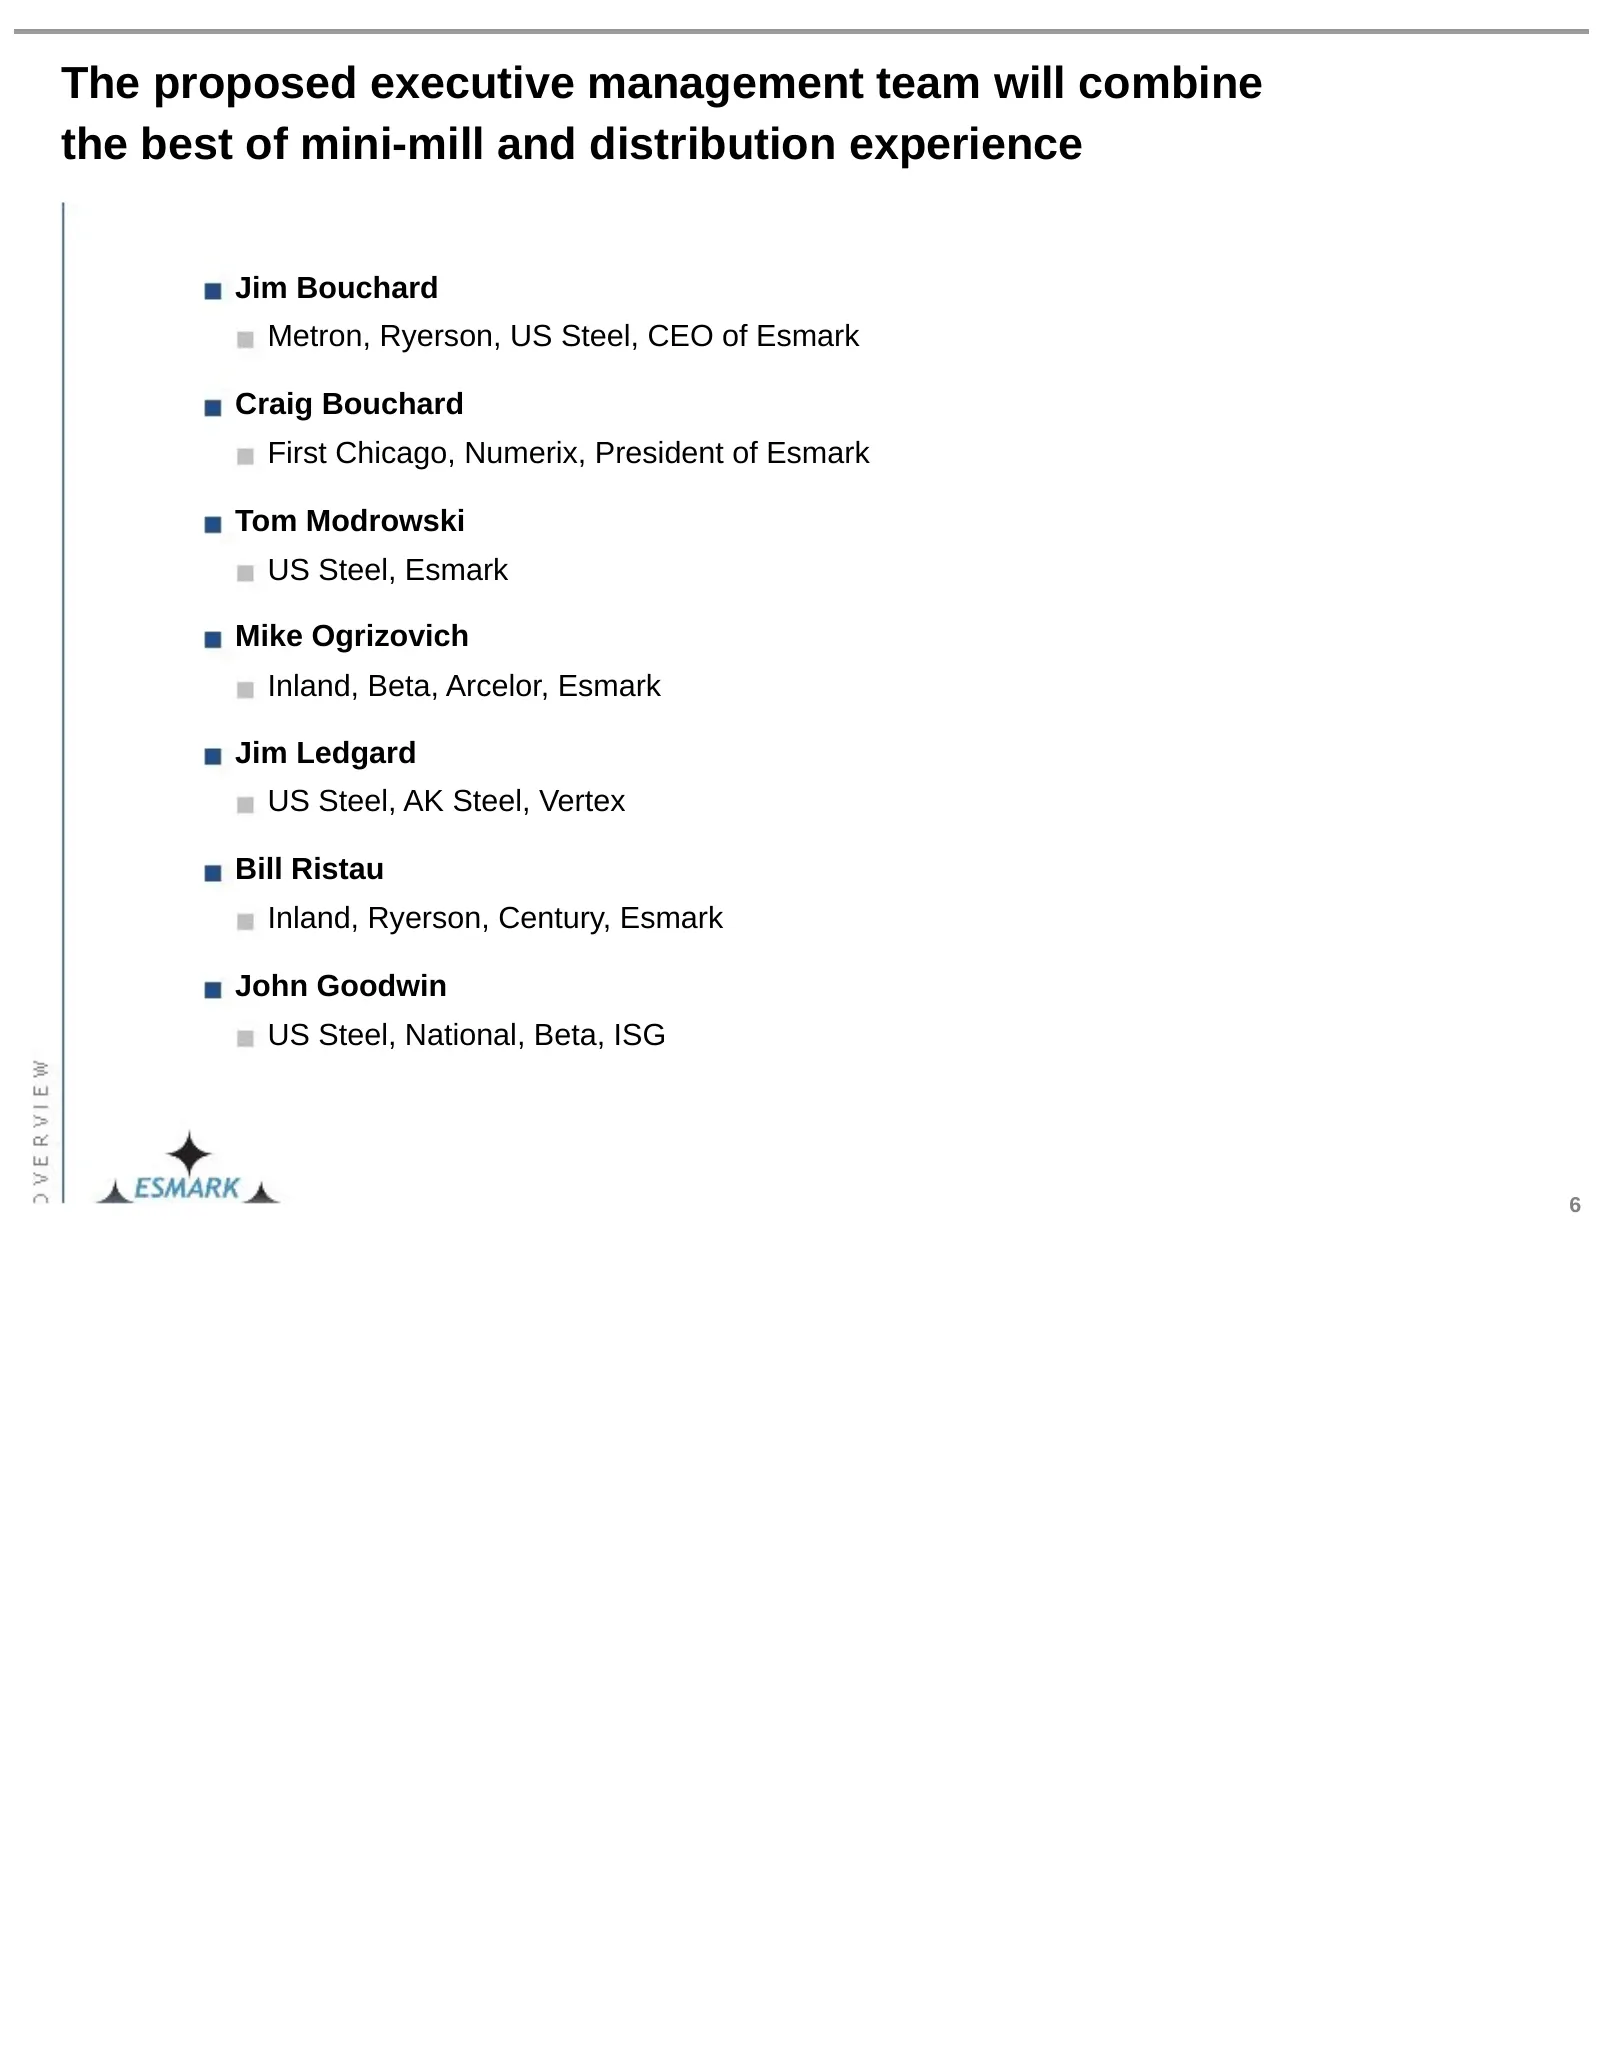
The proposed executive management team will combine the best of mini-mill and distribution experience Jim Bouchard Metron, Ryerson, US Steel, CEO of Esmark Craig Bouchard First Chicago, Numerix, President of Esmark Tom Modrowski US Steel, Esmark Mike Ogrizovich Inland, Beta, Arcelor, Esmark Jim Ledg
Slide 11: Agenda
Agenda Page Overview 2 Strategic vision 7 Overview of Esmark 18 Overview of Wheeling-Pitt 22 Conclusion 29 7
Slide 12: The combination would create a strong model for growth and profitability
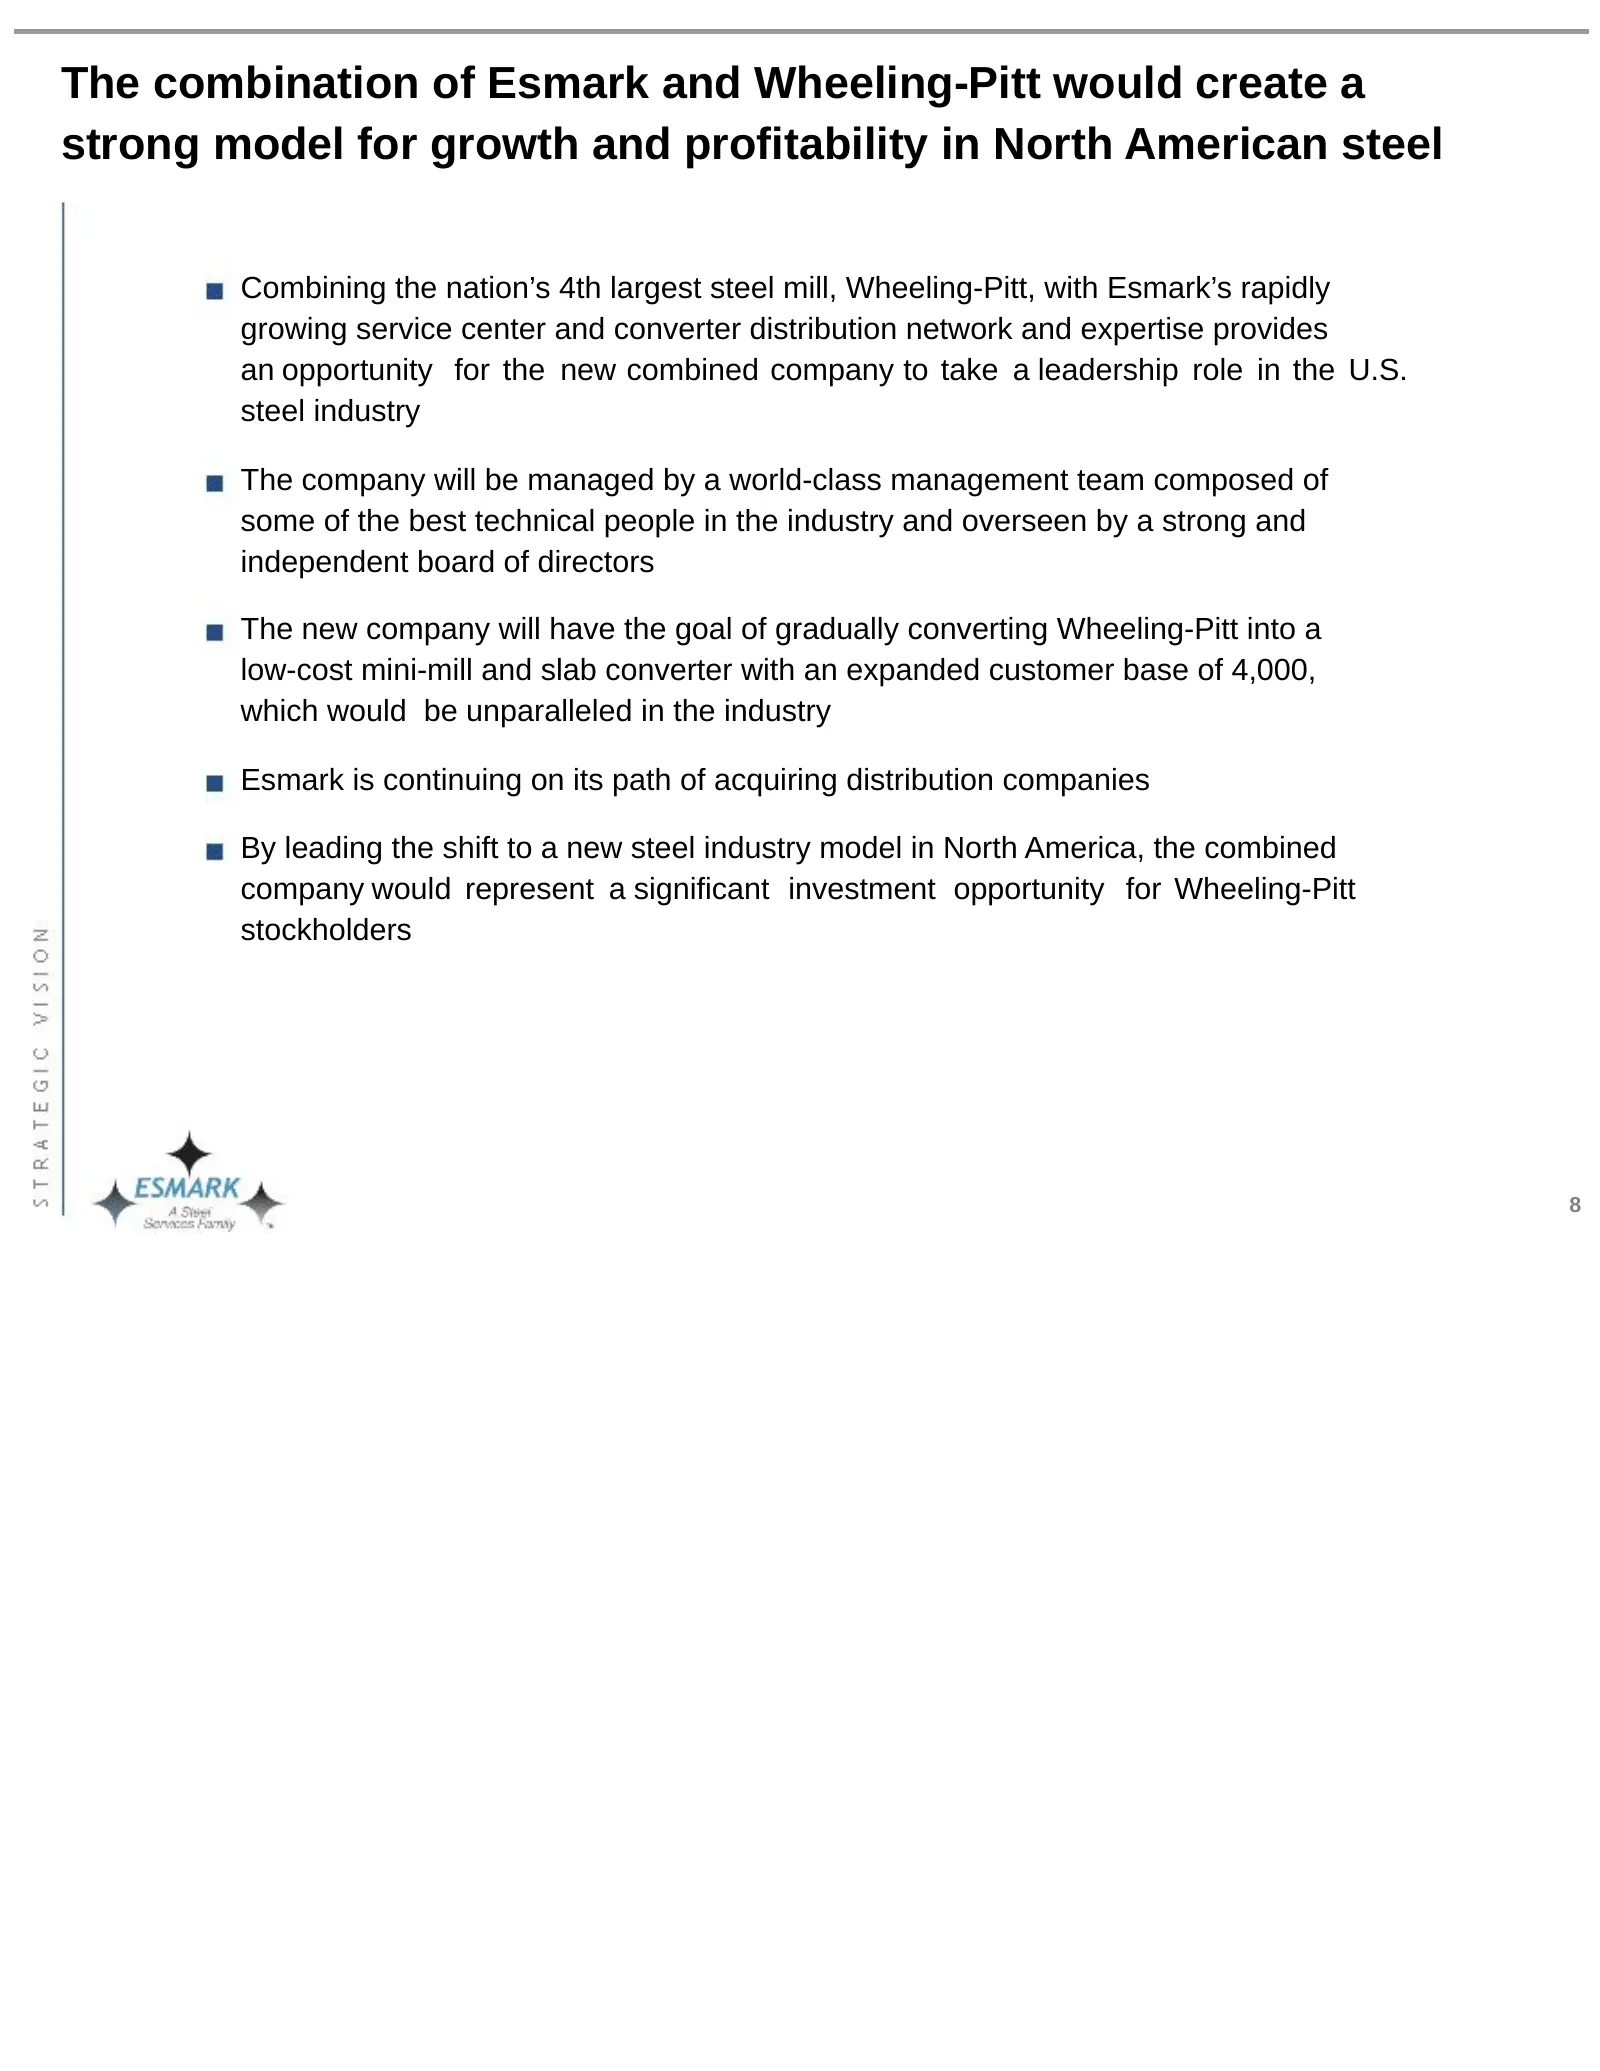
The combination of Esmark and Wheeling-Pitt would create a strong model for growth and profitability in North American steel Combining the nation’s 4th largest steel mill, Wheeling-Pitt, with Esmark’s rapidly growing service center and converter distribution network and expertise provides an opportu
Slide 13: The combination is consistent with Esmark's strategy
The combination is consistent with Esmark’s strategy Build a “niche” regional steel company Combine mill and service center strengths Service a diverse and profitable customer segment Target a more profitable business mix of 75% downstream, 25% mini-mill Expand product offerings and market scope Ext
Slide 14: Esmark has been rapidly growing its business
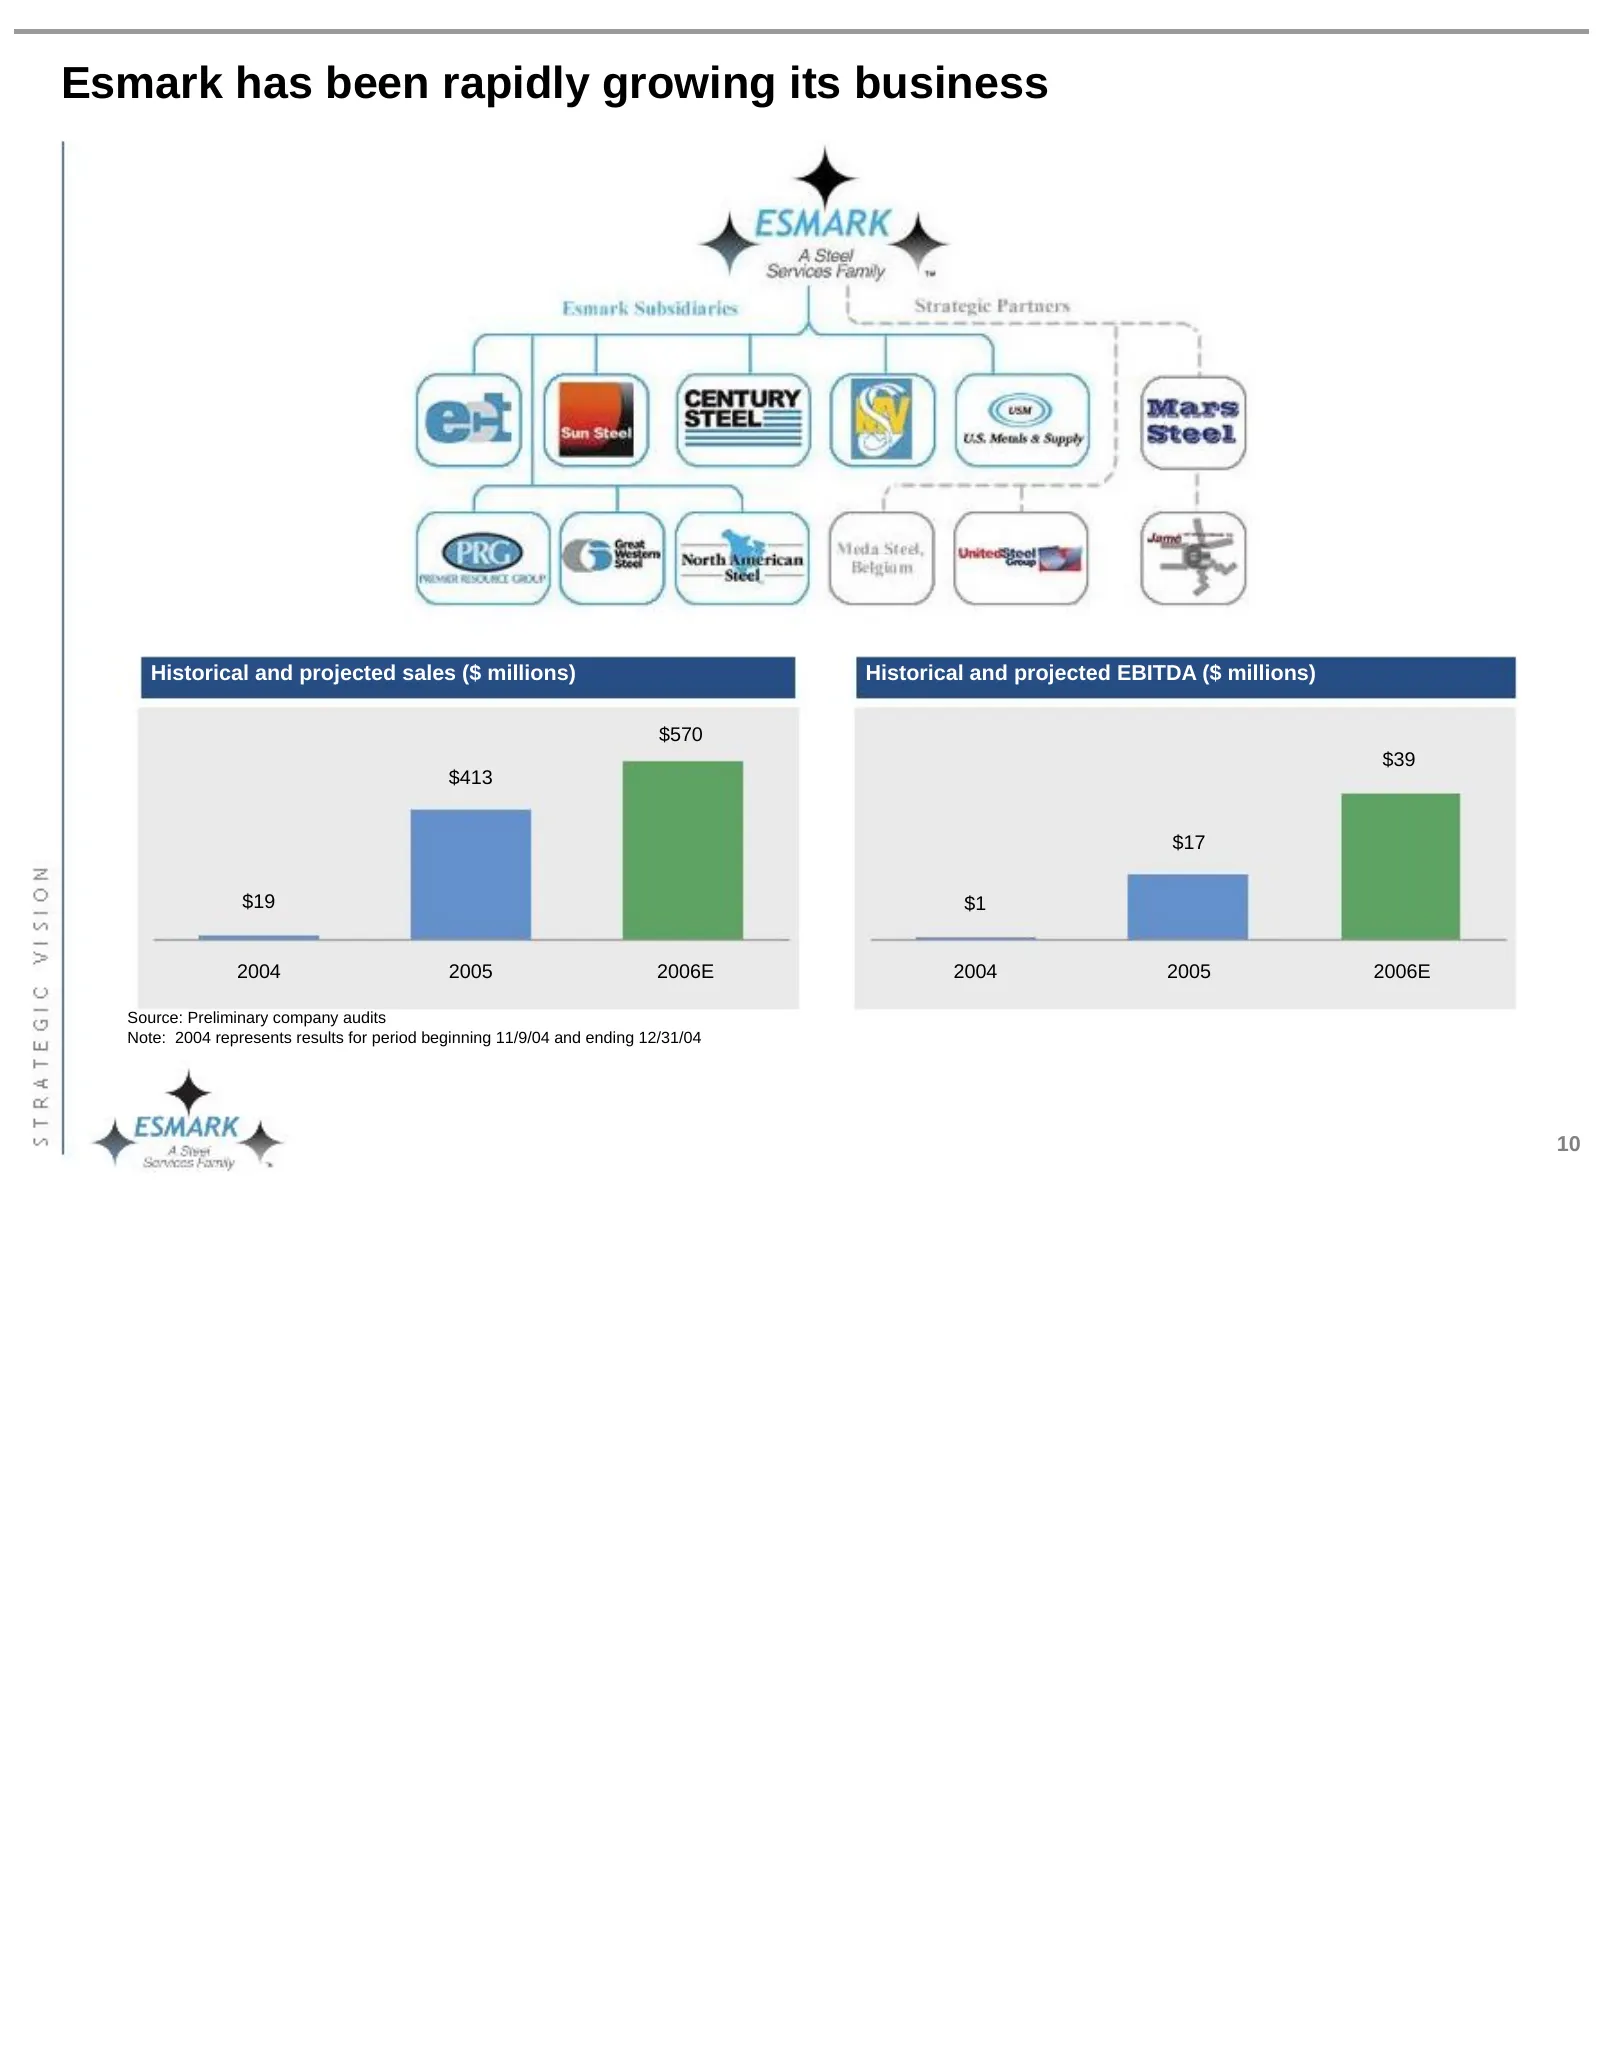
Esmark has been rapidly growing its business Historical and projected sales ($ millions) Historical and projected EBITDA ($ millions) $570 $39 $413 $17 $19 $1 2004 2005 2006E 2004 2005 2006E Source: Preliminary company audits Note: 2004 represents results for period beginning 11/9/04 and ending 12/3
Slide 15: The combination would create a leader in the U.S. steel marketplace
The combination would create a leader in the U.S. steel marketplace with operational and commercial competitive advantages Transaction merits Supply chain integration Esmark management has a proven and profitable distribution platform with significant growth opportunities ahead Current industry dyna
Slide 16: Opportunities should be significant
Opportunities should be significant Slab Esmark intends to invest in and efficiently use the Hot Strip Mill with a incremental goal of converting over one million tons of slabs per year profit Wheeling-Pitt has been burdened by credit and purchasing limitations Purchasing while Esmark’s financial st
Slide 17: Esmark is confident it can secure a competitive slab agreement
Esmark is confident it can secure a competitive slab agreement for the new company based on strategic discussions Esmark currently has a longstanding commercial relationship with MAN Ferrostaal Incorporated (“Ferrostaal”), an operating subsidiary of MAN AG, a publicly traded company with approximate
Slide 18: Improved product mix provides opportunity for multiple expansion
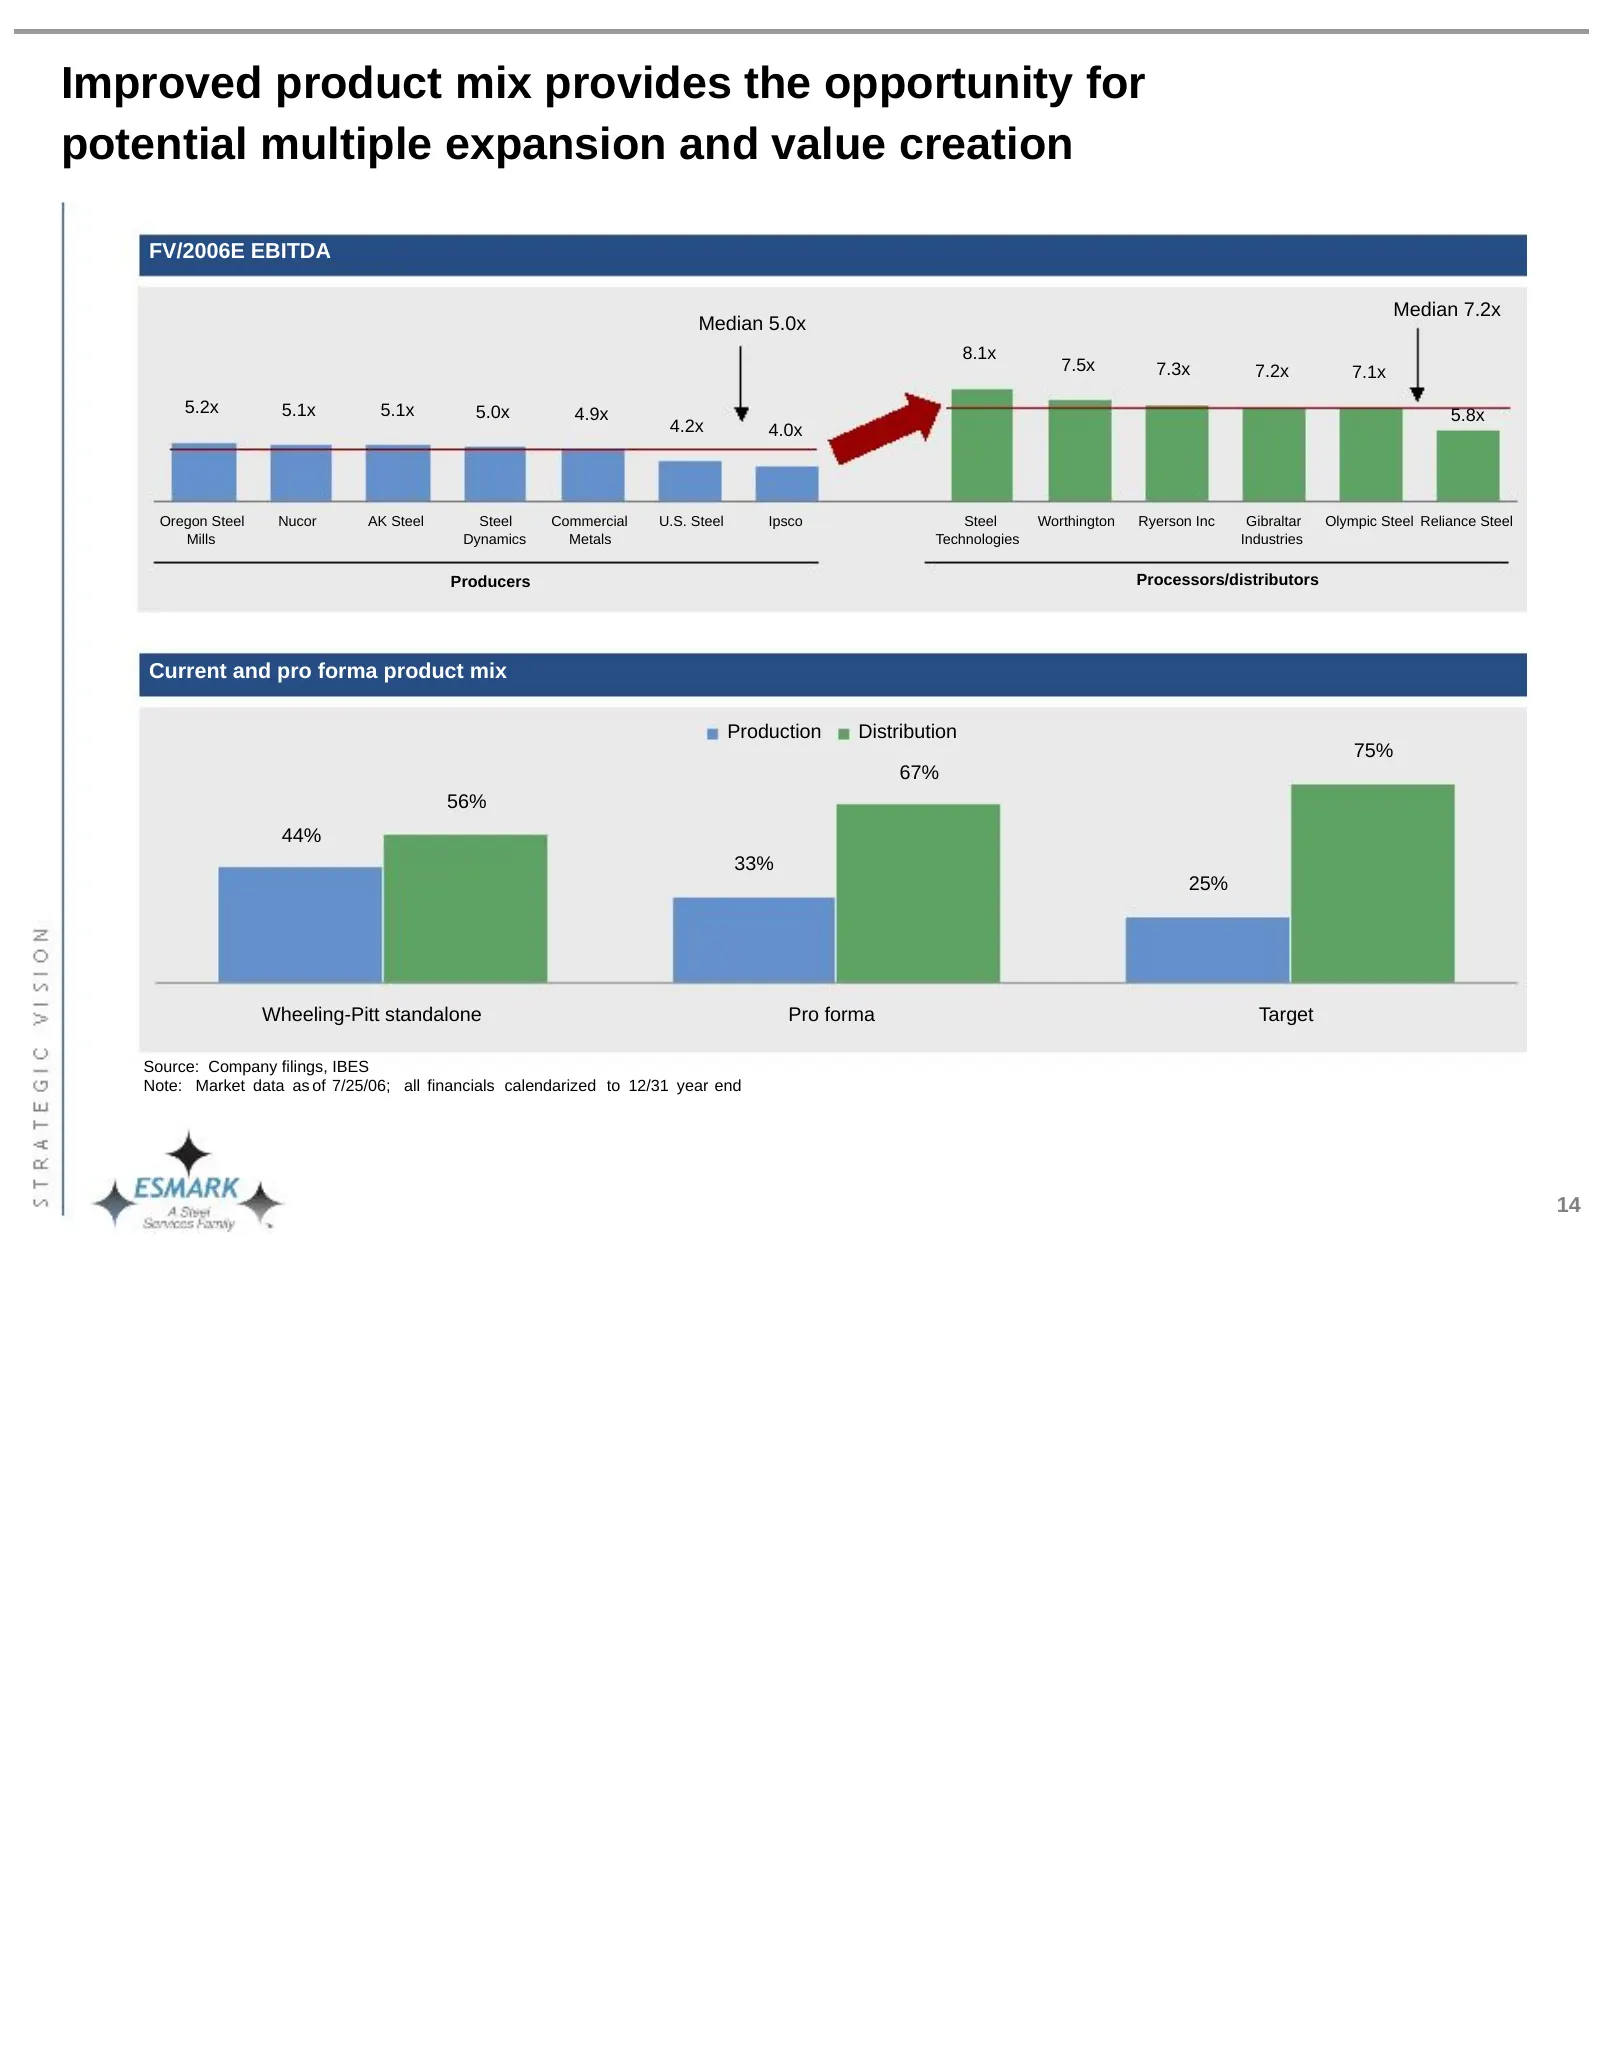
Improved product mix provides the opportunity for potential multiple expansion and value creation FV/2006E EBITDA Median 7.2x Median 5.0x 8.1x 7.5x 7.3x 7.2x 7.1x 5.2x 5.1x 5.1x 5.0x 4.9x 5.8x 4.2x 4.0x Oregon Steel Nucor AK Steel Steel Commercial U.S. Steel Ipsco Steel Worthington Ryerson Inc Gibra
Slide 19: A combination would improve Wheeling-Pitt's financial flexibility
A combination with Esmark would significantly improve Wheeling-Pitt’s financial flexibility Through the combination Esmark would contribute: Over $200 million of liquidity No long-term debt Business with 2006 projected EBITDA of $39 million New $350 million revolving credit facility for combined com
Slide 20: The combined company would have a strong regional presence
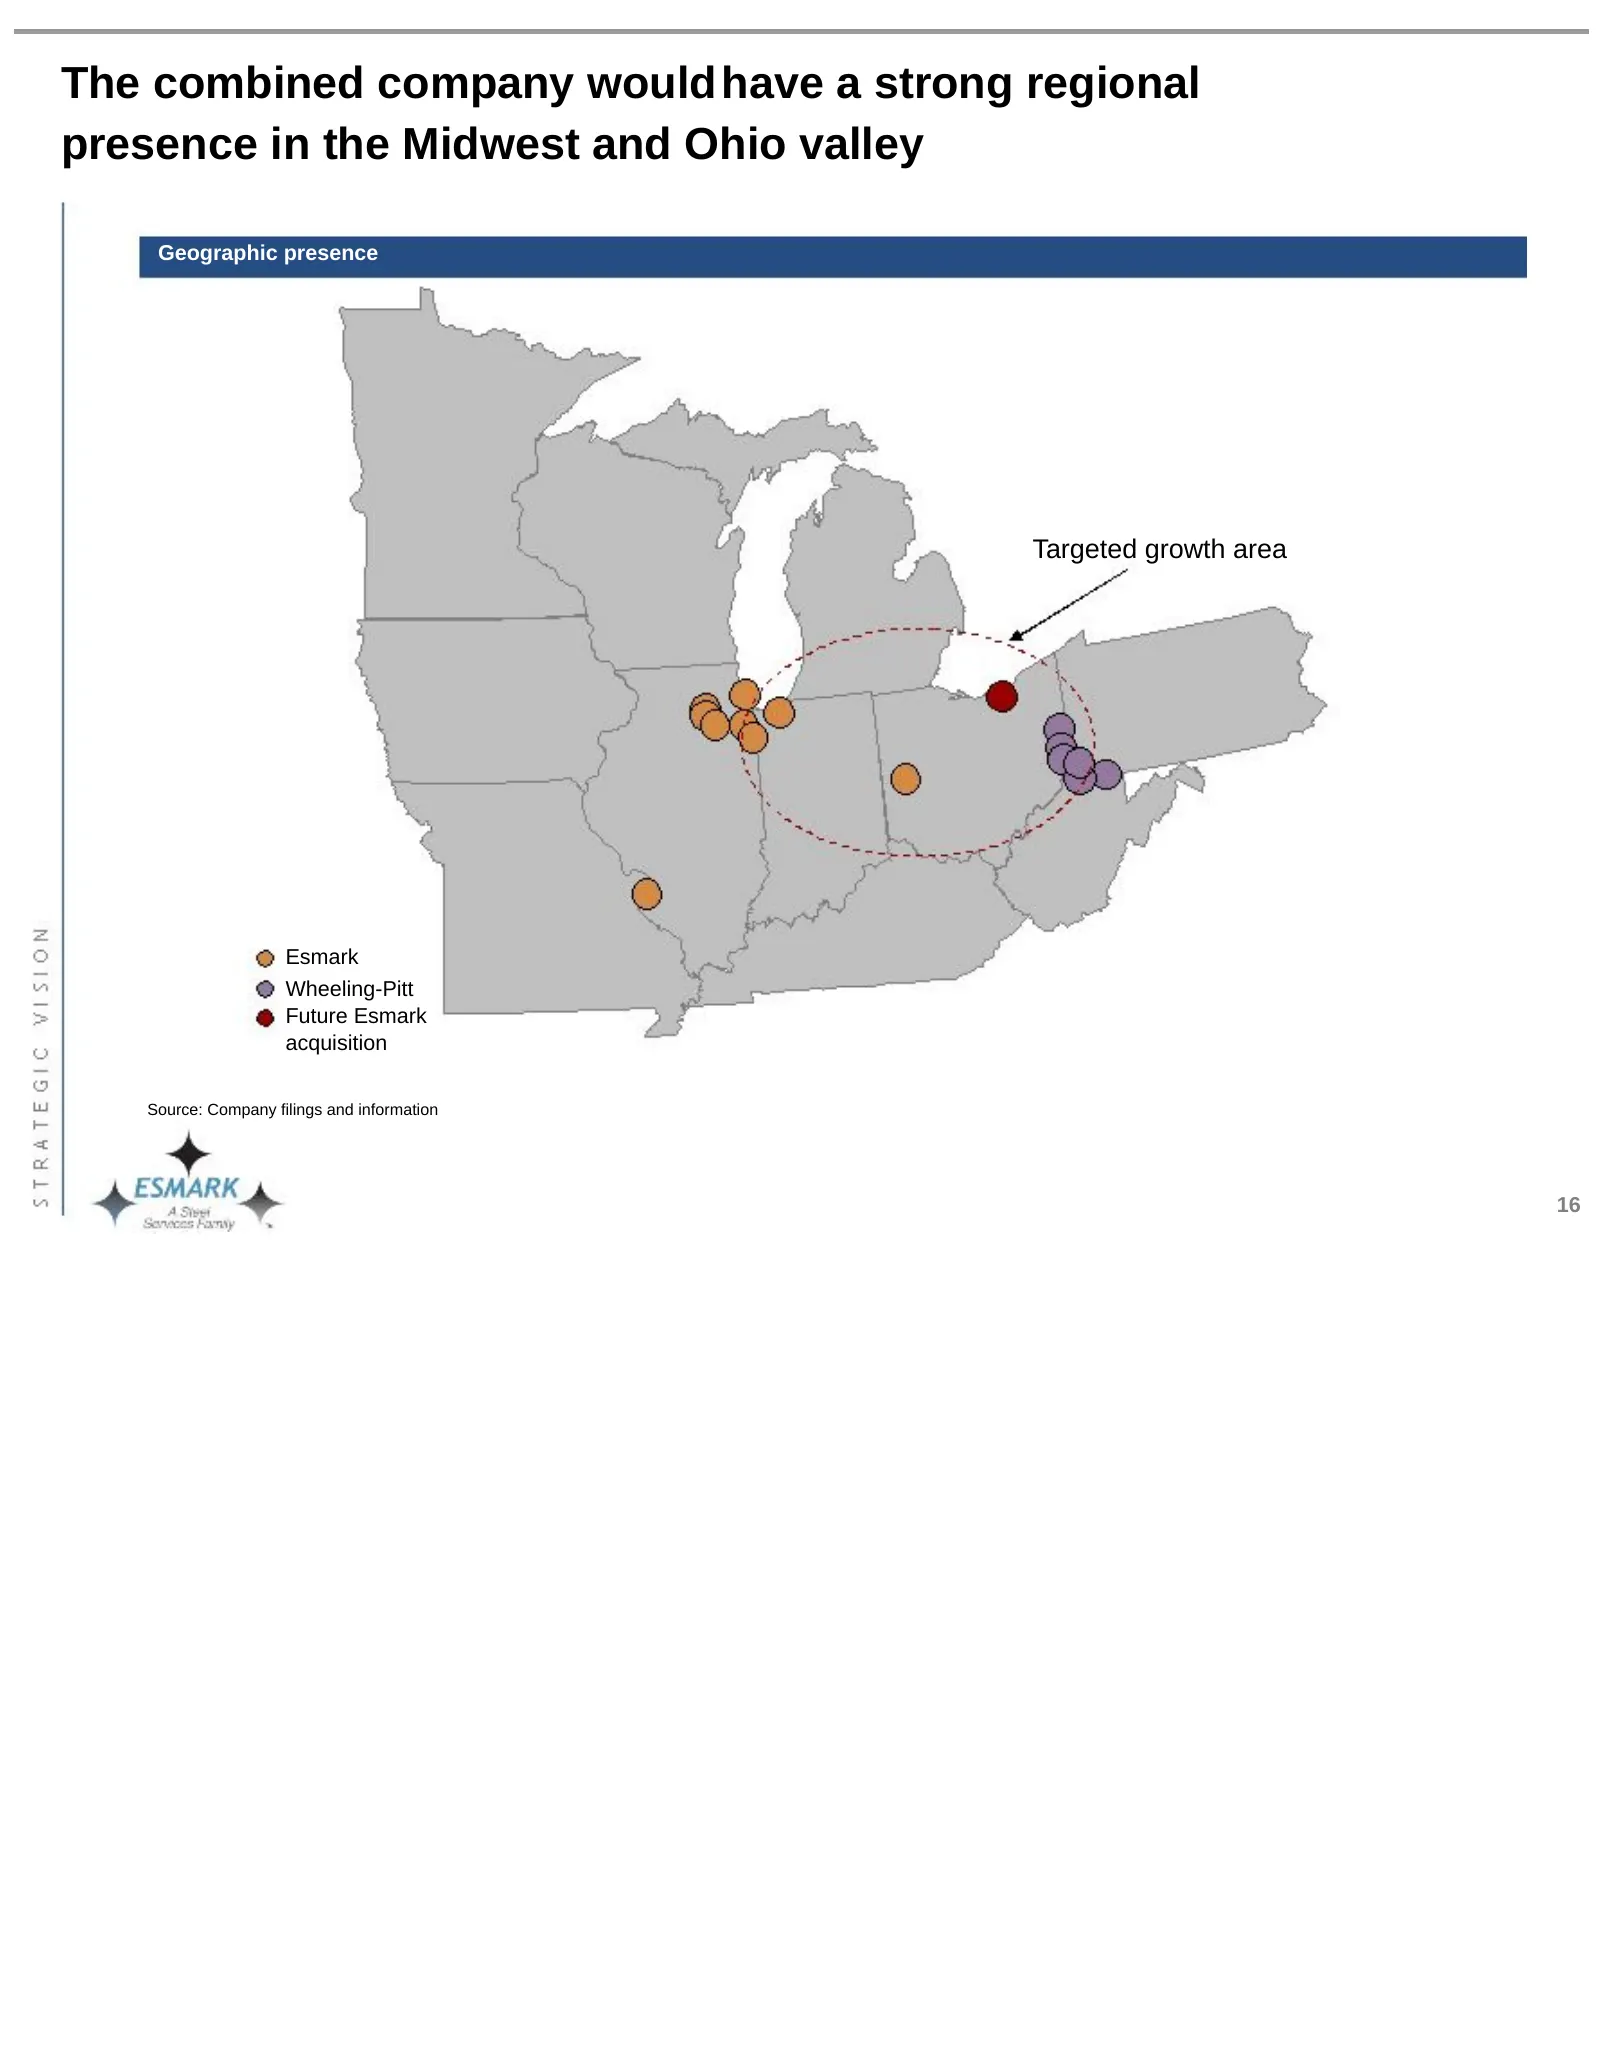
The combined company would have a strong regional presence in the Midwest and Ohio valley Geographic presence Targeted growth area Esmark Wheeling-Pitt Future Esmark acquisition Source: Company filings and information 16
Slide 21: The combined company would represent a significant investment opportunity
The combined company would represent a significant investment opportunity for stockholders Wheeling-Pitt's $2 billion mini-mill linked with Esmark's $570 million low-cost and proven service center and converter down stream company We are asking for your support to elect our proposed slate of directo
Slide 22: Agenda
Agenda Page Overview 2 Strategic vision 7 Overview of Esmark 18 Overview of Wheeling-Pitt 22 Conclusion 29 18
Slide 23: Esmark has been a successful consolidator
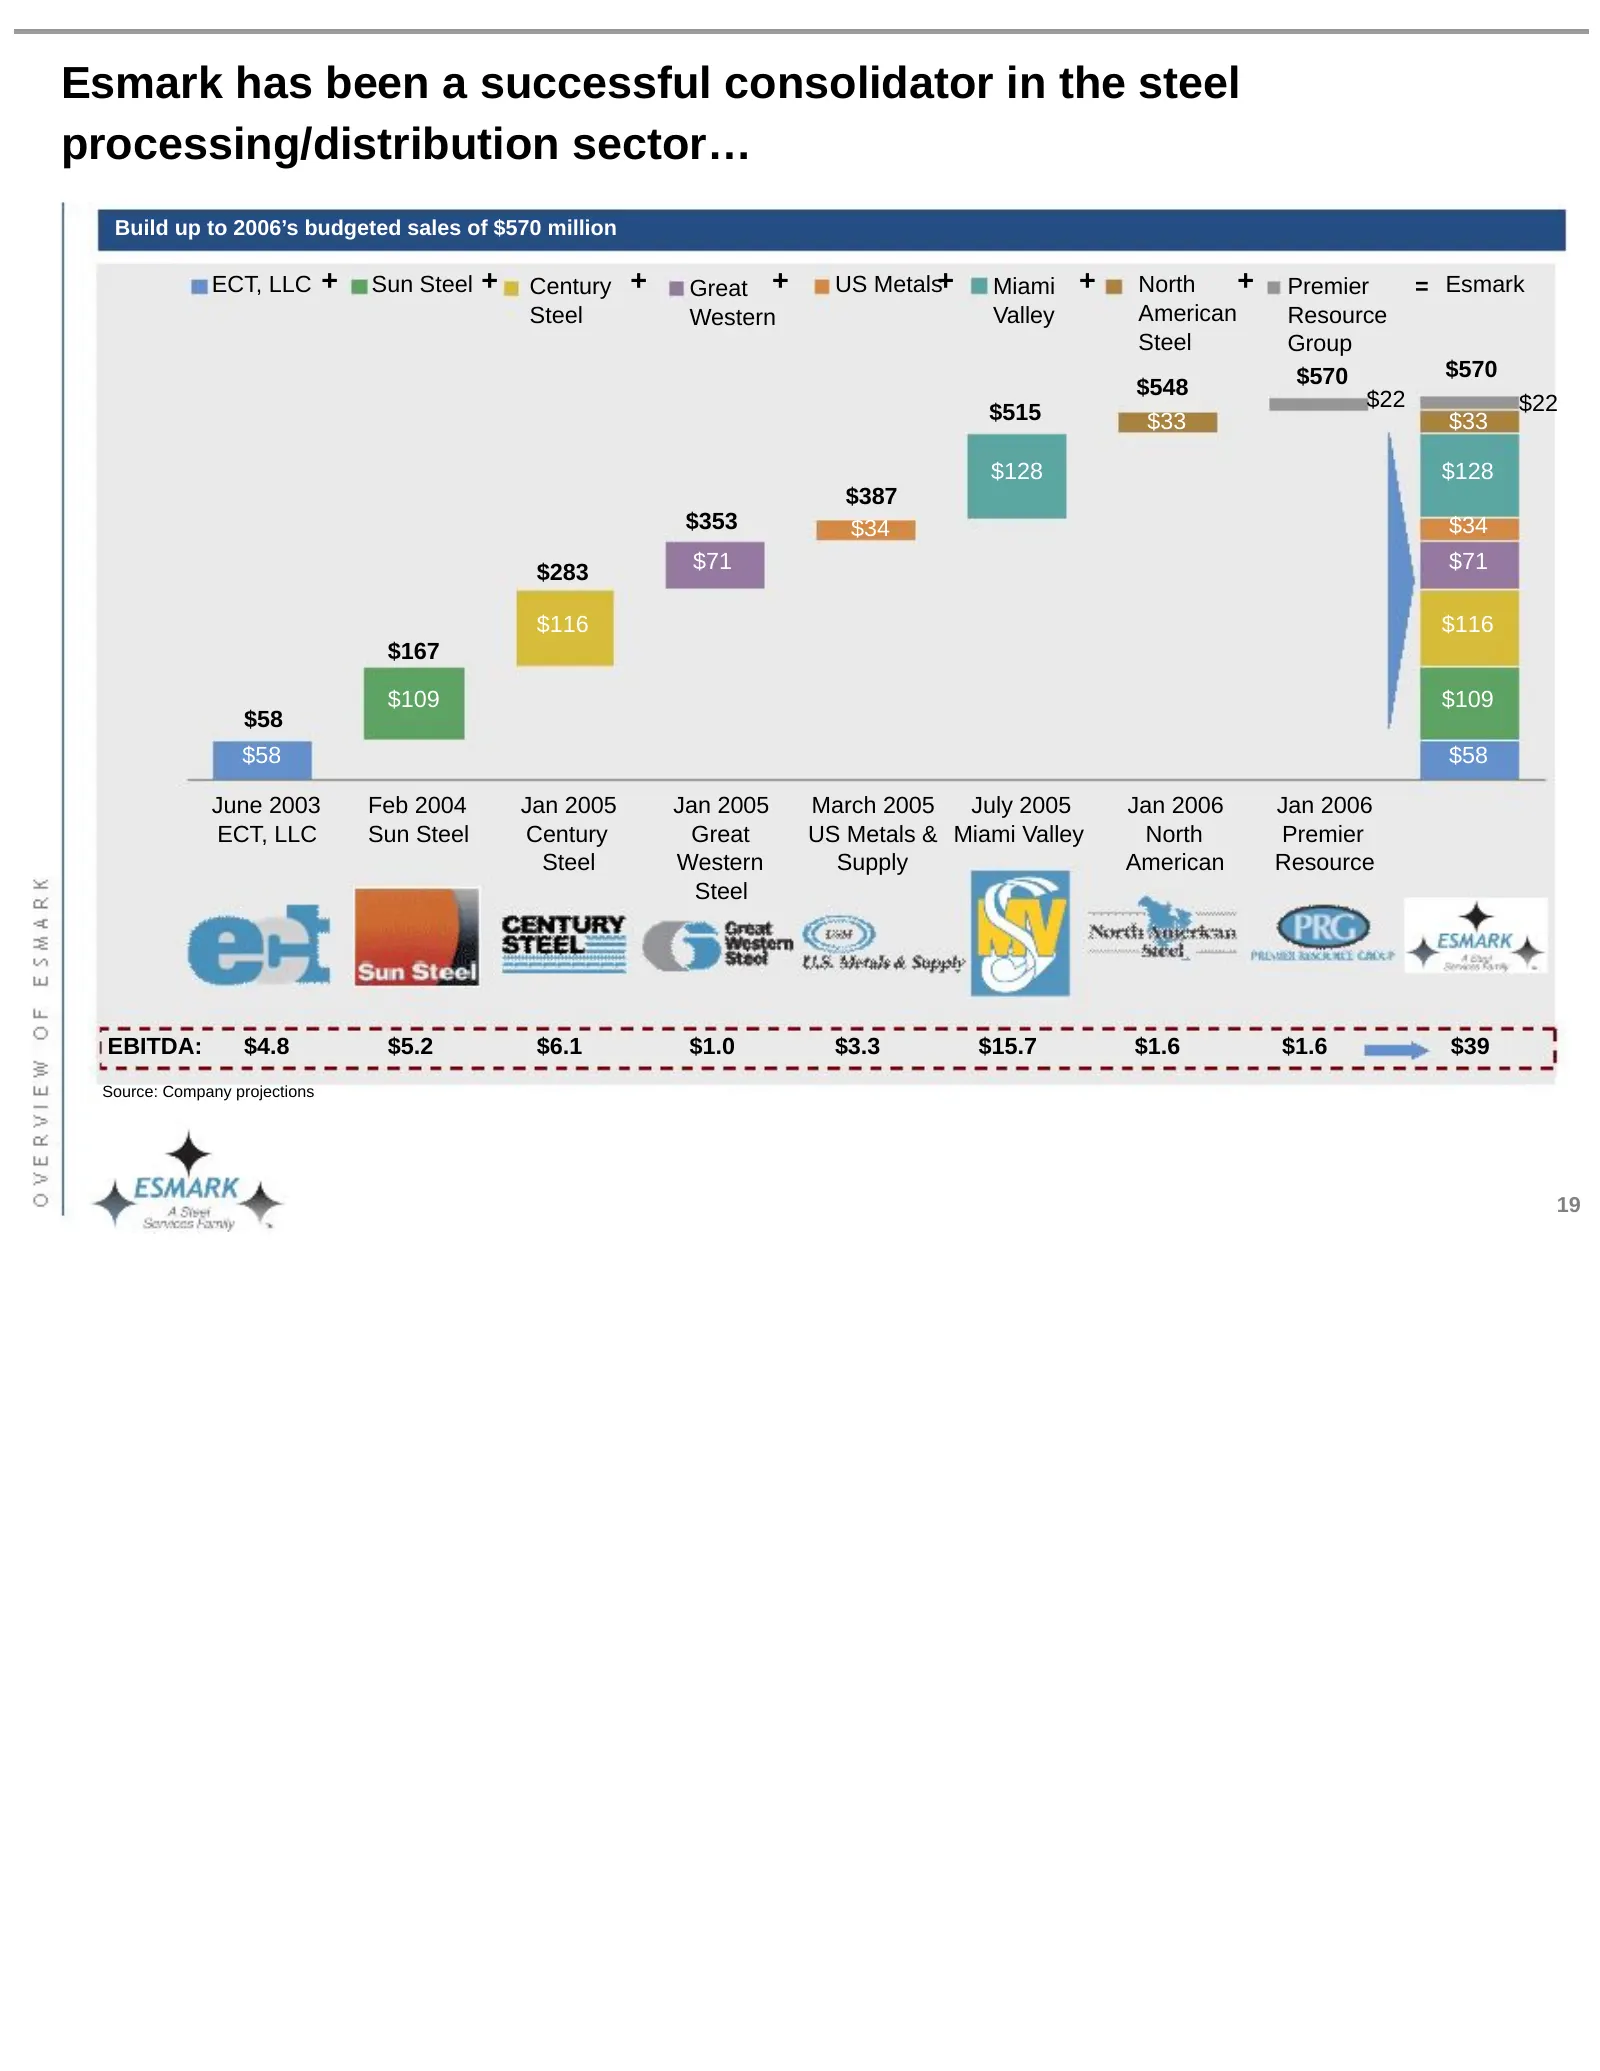
Esmark has been a successful consolidator in the steel processing/distribution sector… Build up to 2006’s budgeted sales of $570 million ECT, LLC + Sun Steel + Century + Great + US Metals+ Miami + North + Premier = Esmark Steel Western Valley American Resource Steel Group $570 $570 $548 $22 $22 $515
Slide 24: Esmark positioned among leading U.S. service centers
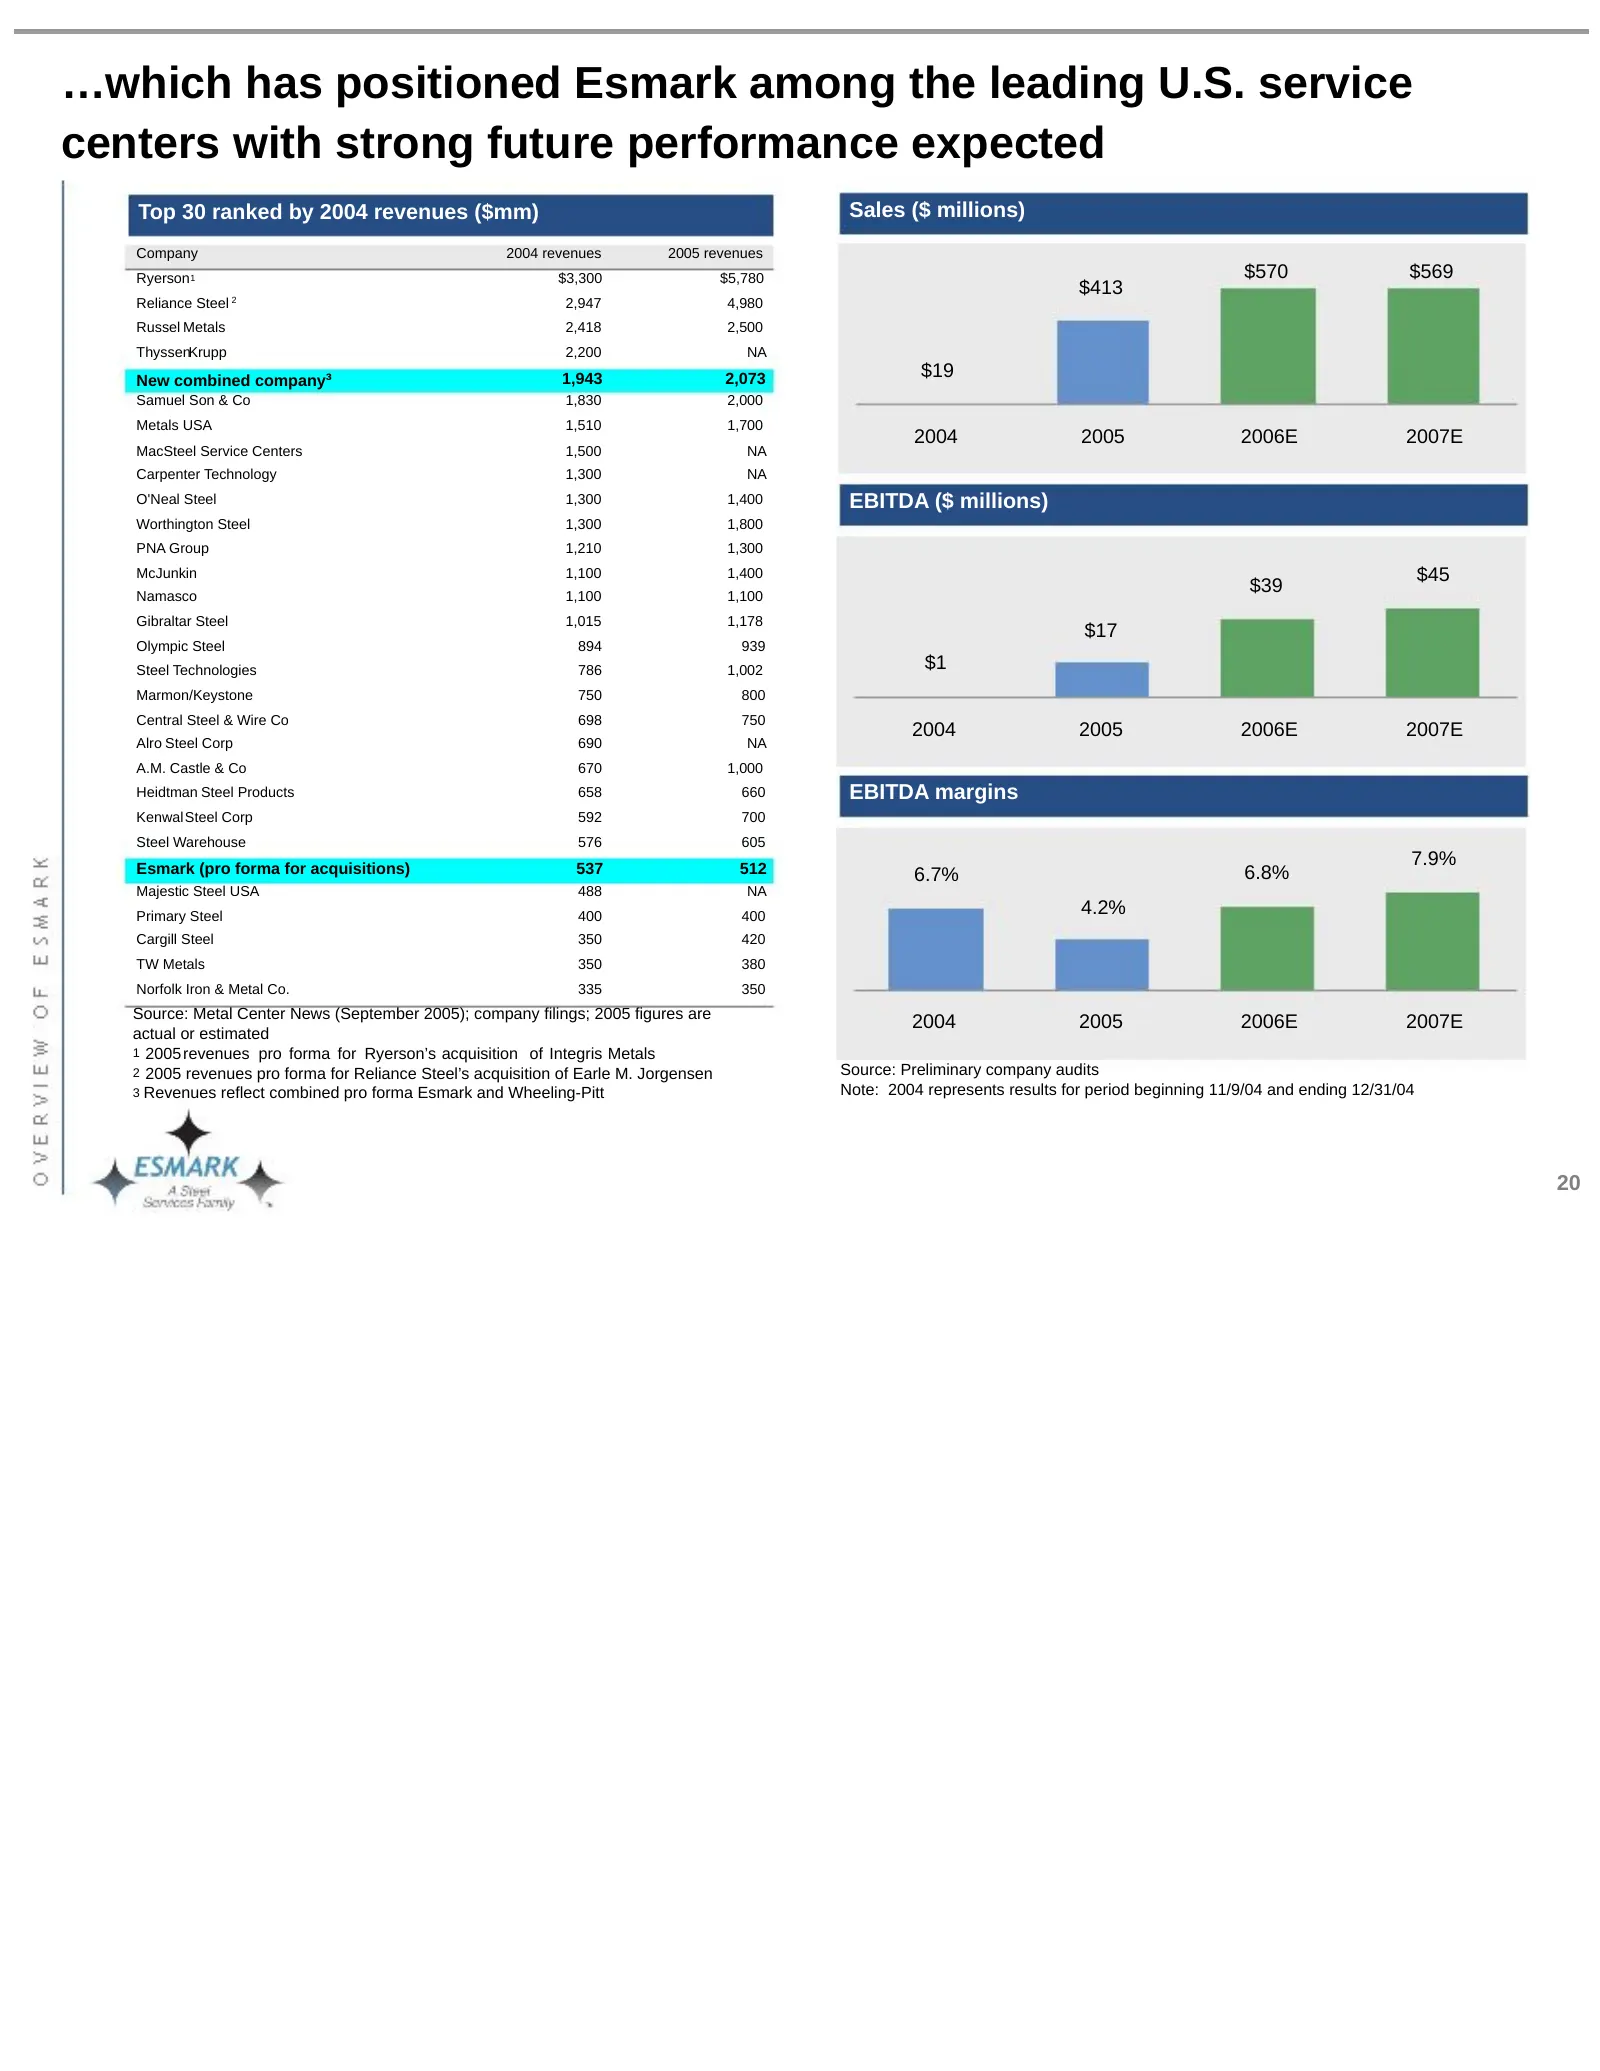
…which has positioned Esmark among the leading U.S. service centers with strong future performance expected Top 30 ranked by 2004 revenues ($mm) Sales ($ millions) Company 2004 revenues 2005 revenues Ryerson1 $3,300 $5,780 $570 $569 $413 Reliance Steel 2 2,947 4,980 Russel Metals 2,418 2,500 Thyssen
Slide 25: Esmark's proposed valuation is in line with public market comparables
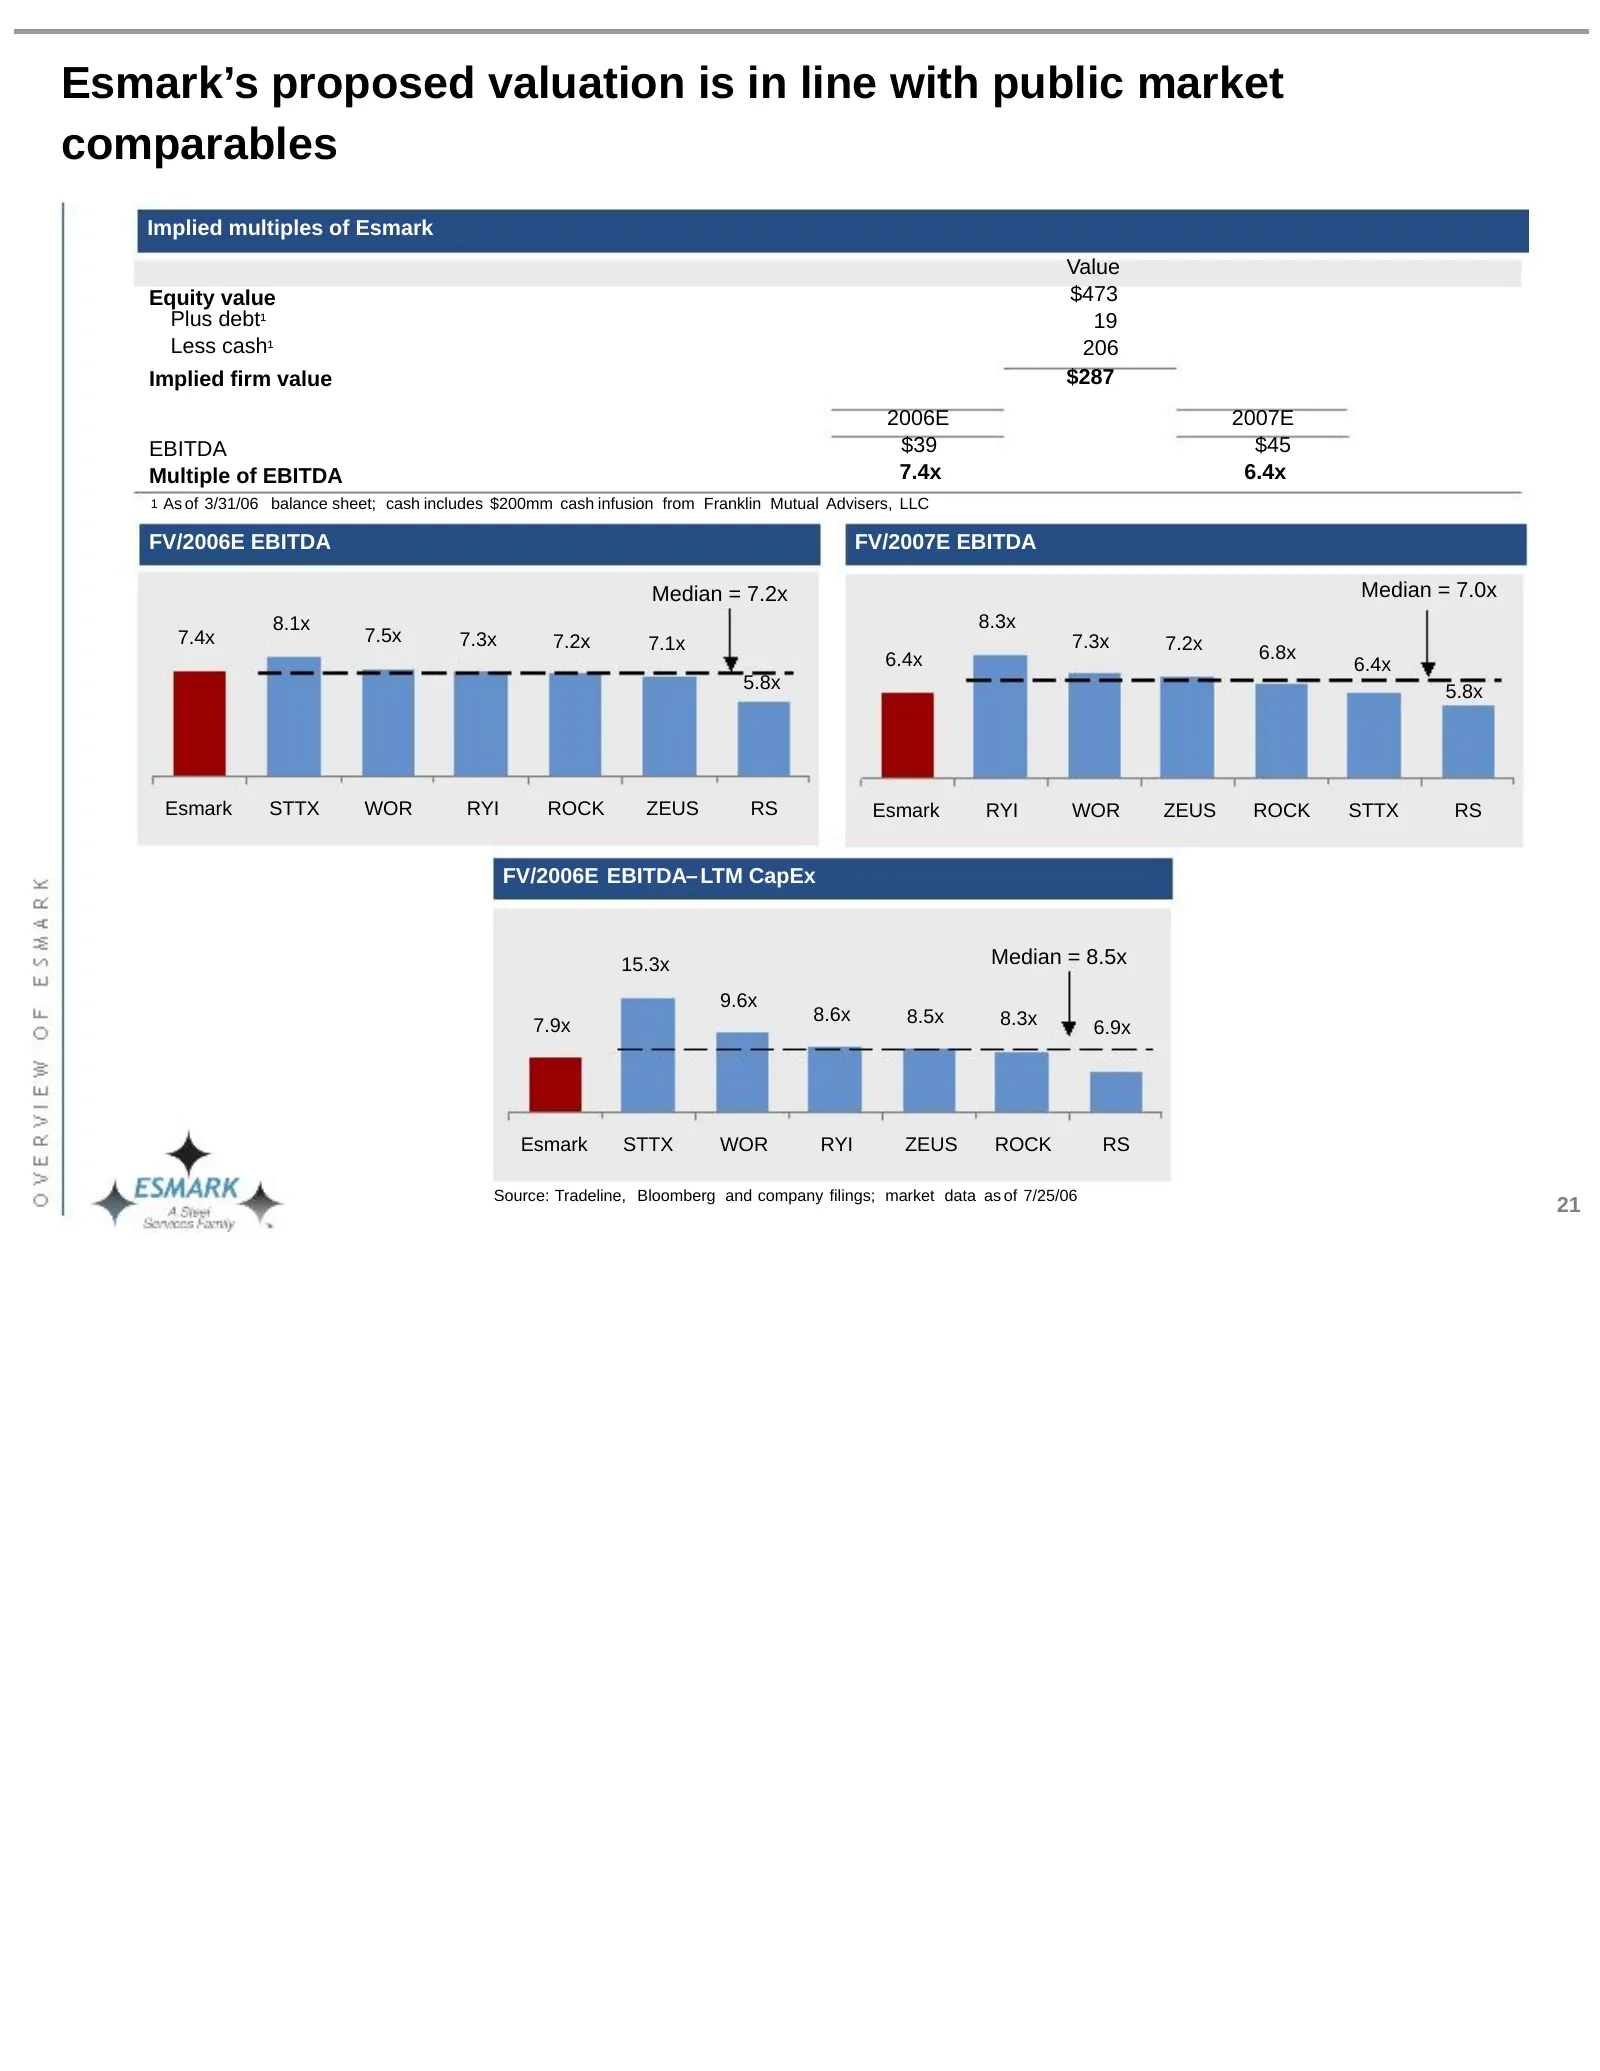
Esmark’s proposed valuation is in line with public market comparables Implied multiples of Esmark Value Equity value $473 Plus debt¹ 19 Less cash¹ 206 Implied firm value $287 2006E 2007E EBITDA $39 $45 Multiple of EBITDA 7.4x 6.4x 1 As of 3/31/06 balance sheet; cash includes $200mm cash infusion fro
Slide 26: Agenda
Agenda Page Overview 2 Strategic vision 7 Overview of Esmark 18 Overview of Wheeling-Pitt 22 Conclusion 29 22
Slide 27: Wheeling-Pitt's performance has lagged despite a strong steel market
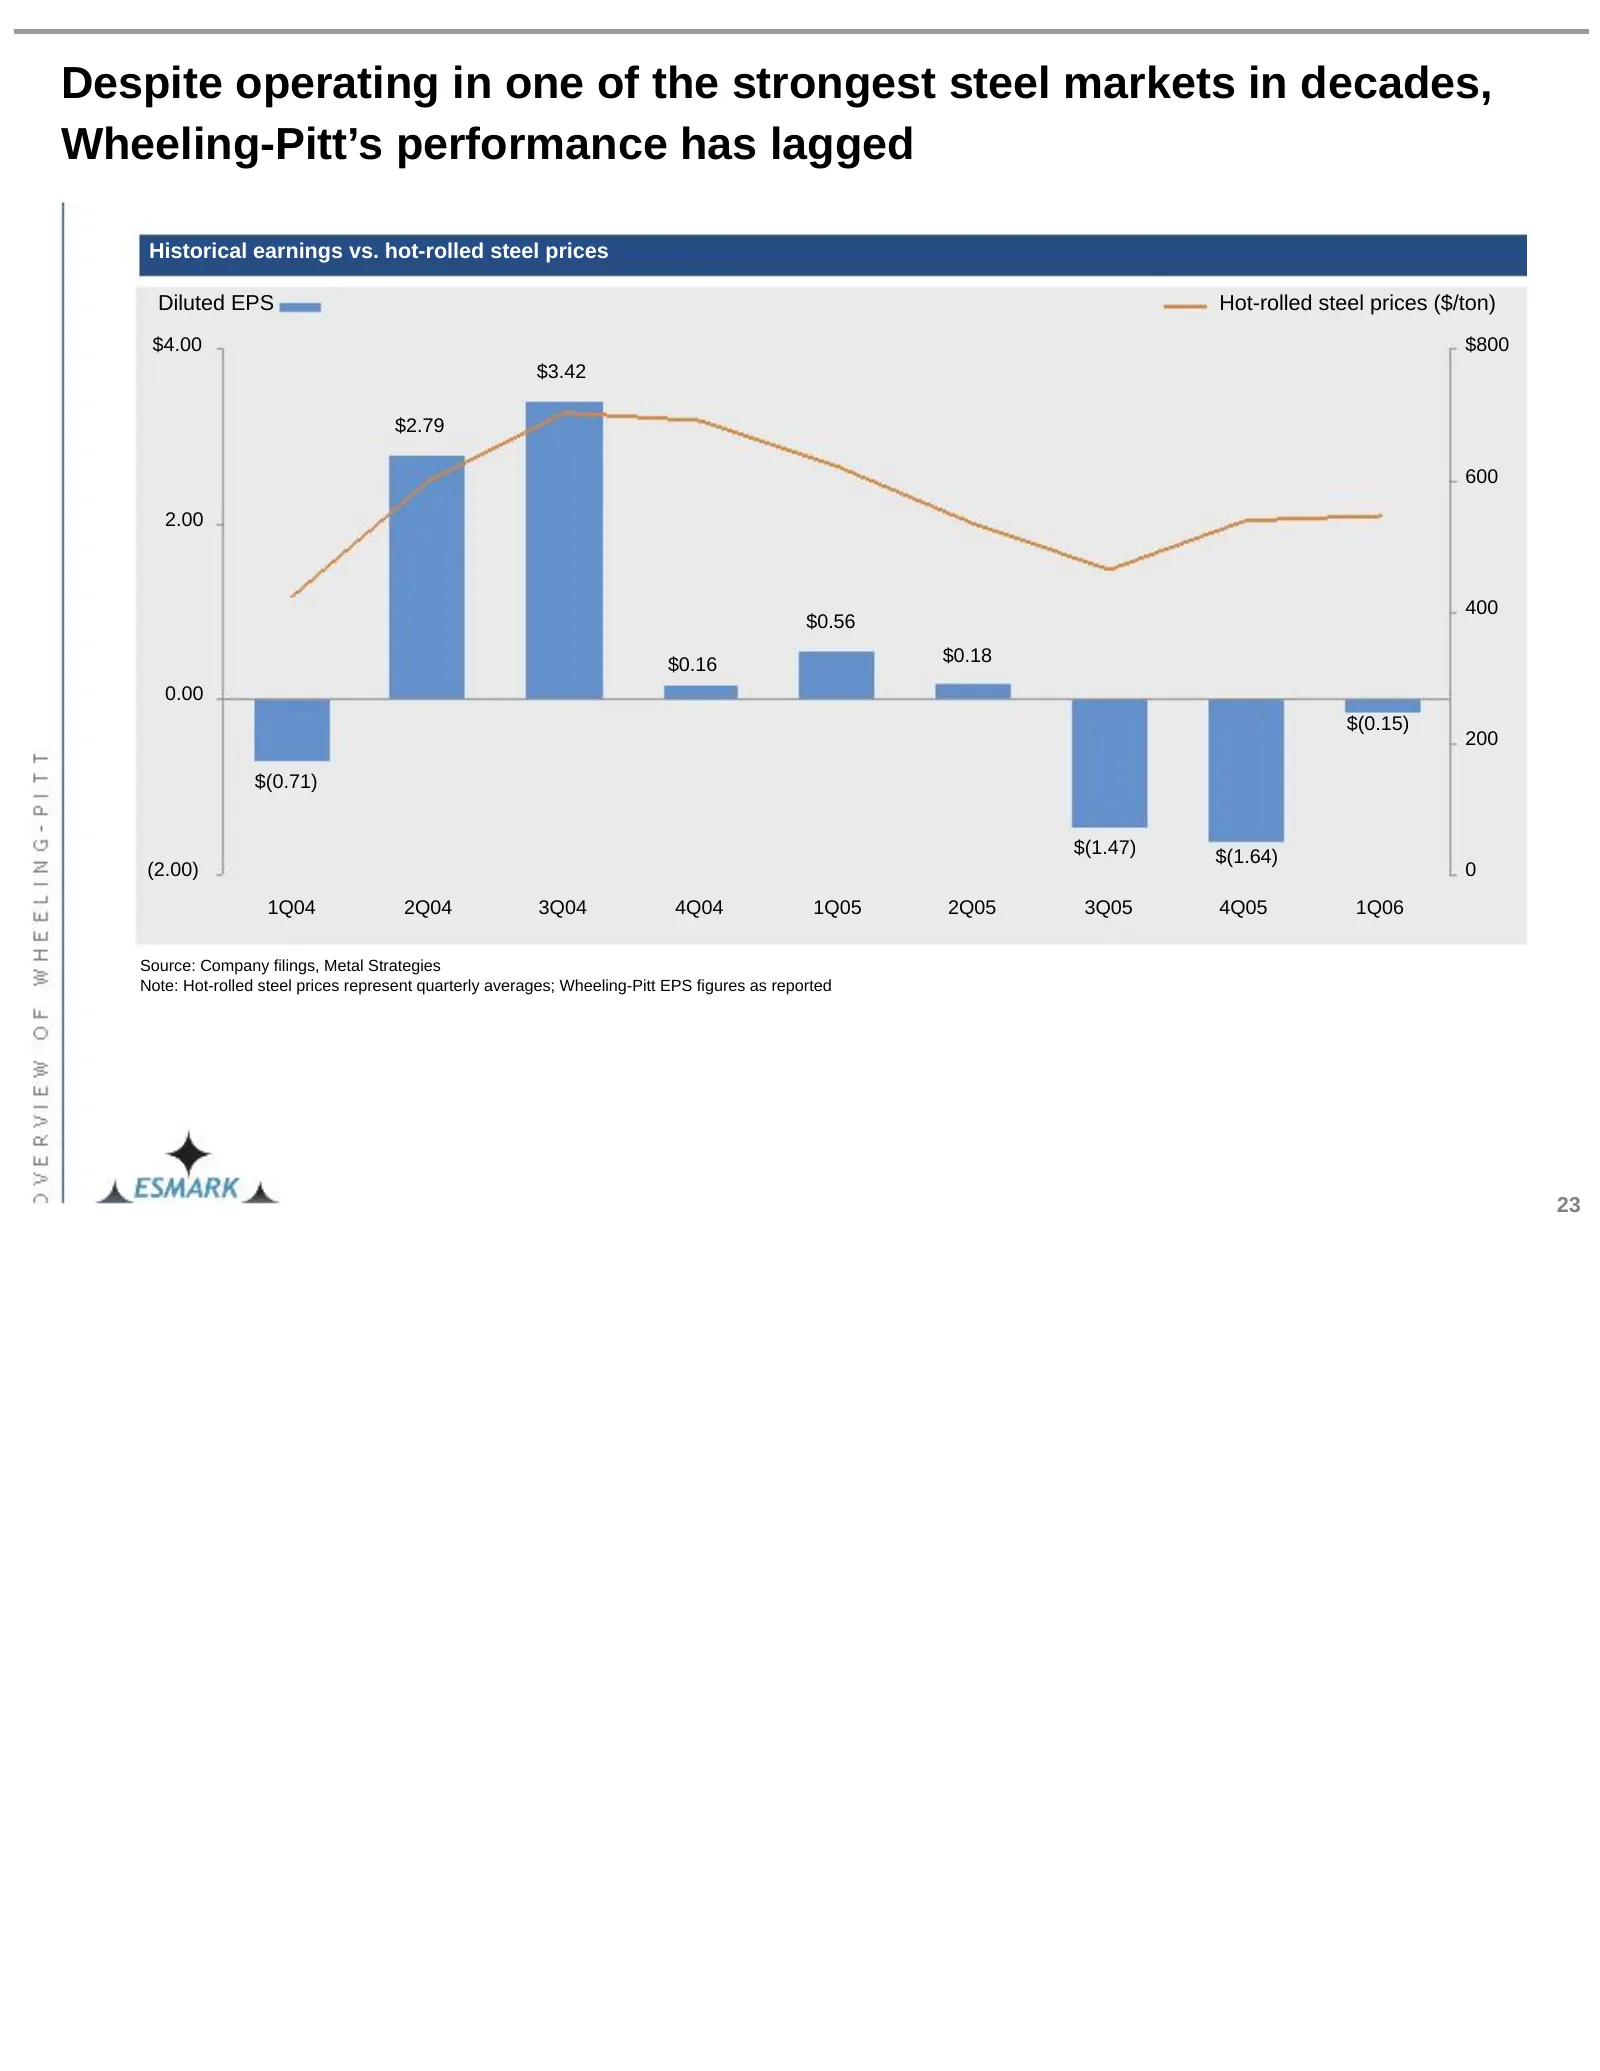
Despite operating in one of the strongest steel markets in decades, Wheeling-Pitt’s performance has lagged Historical earnings vs. hot-rolled steel prices Diluted EPS Hot-rolled steel prices ($/ton) $4.00 $800 $3.42 $2.79 600 2.00 400 $0.56 $0.16 $0.18 0.00 $(0.15) 200 $(0.71) $(1.47) $(1.64) (2.00)
Slide 28: Industry peers were more successful in meeting Street expectations
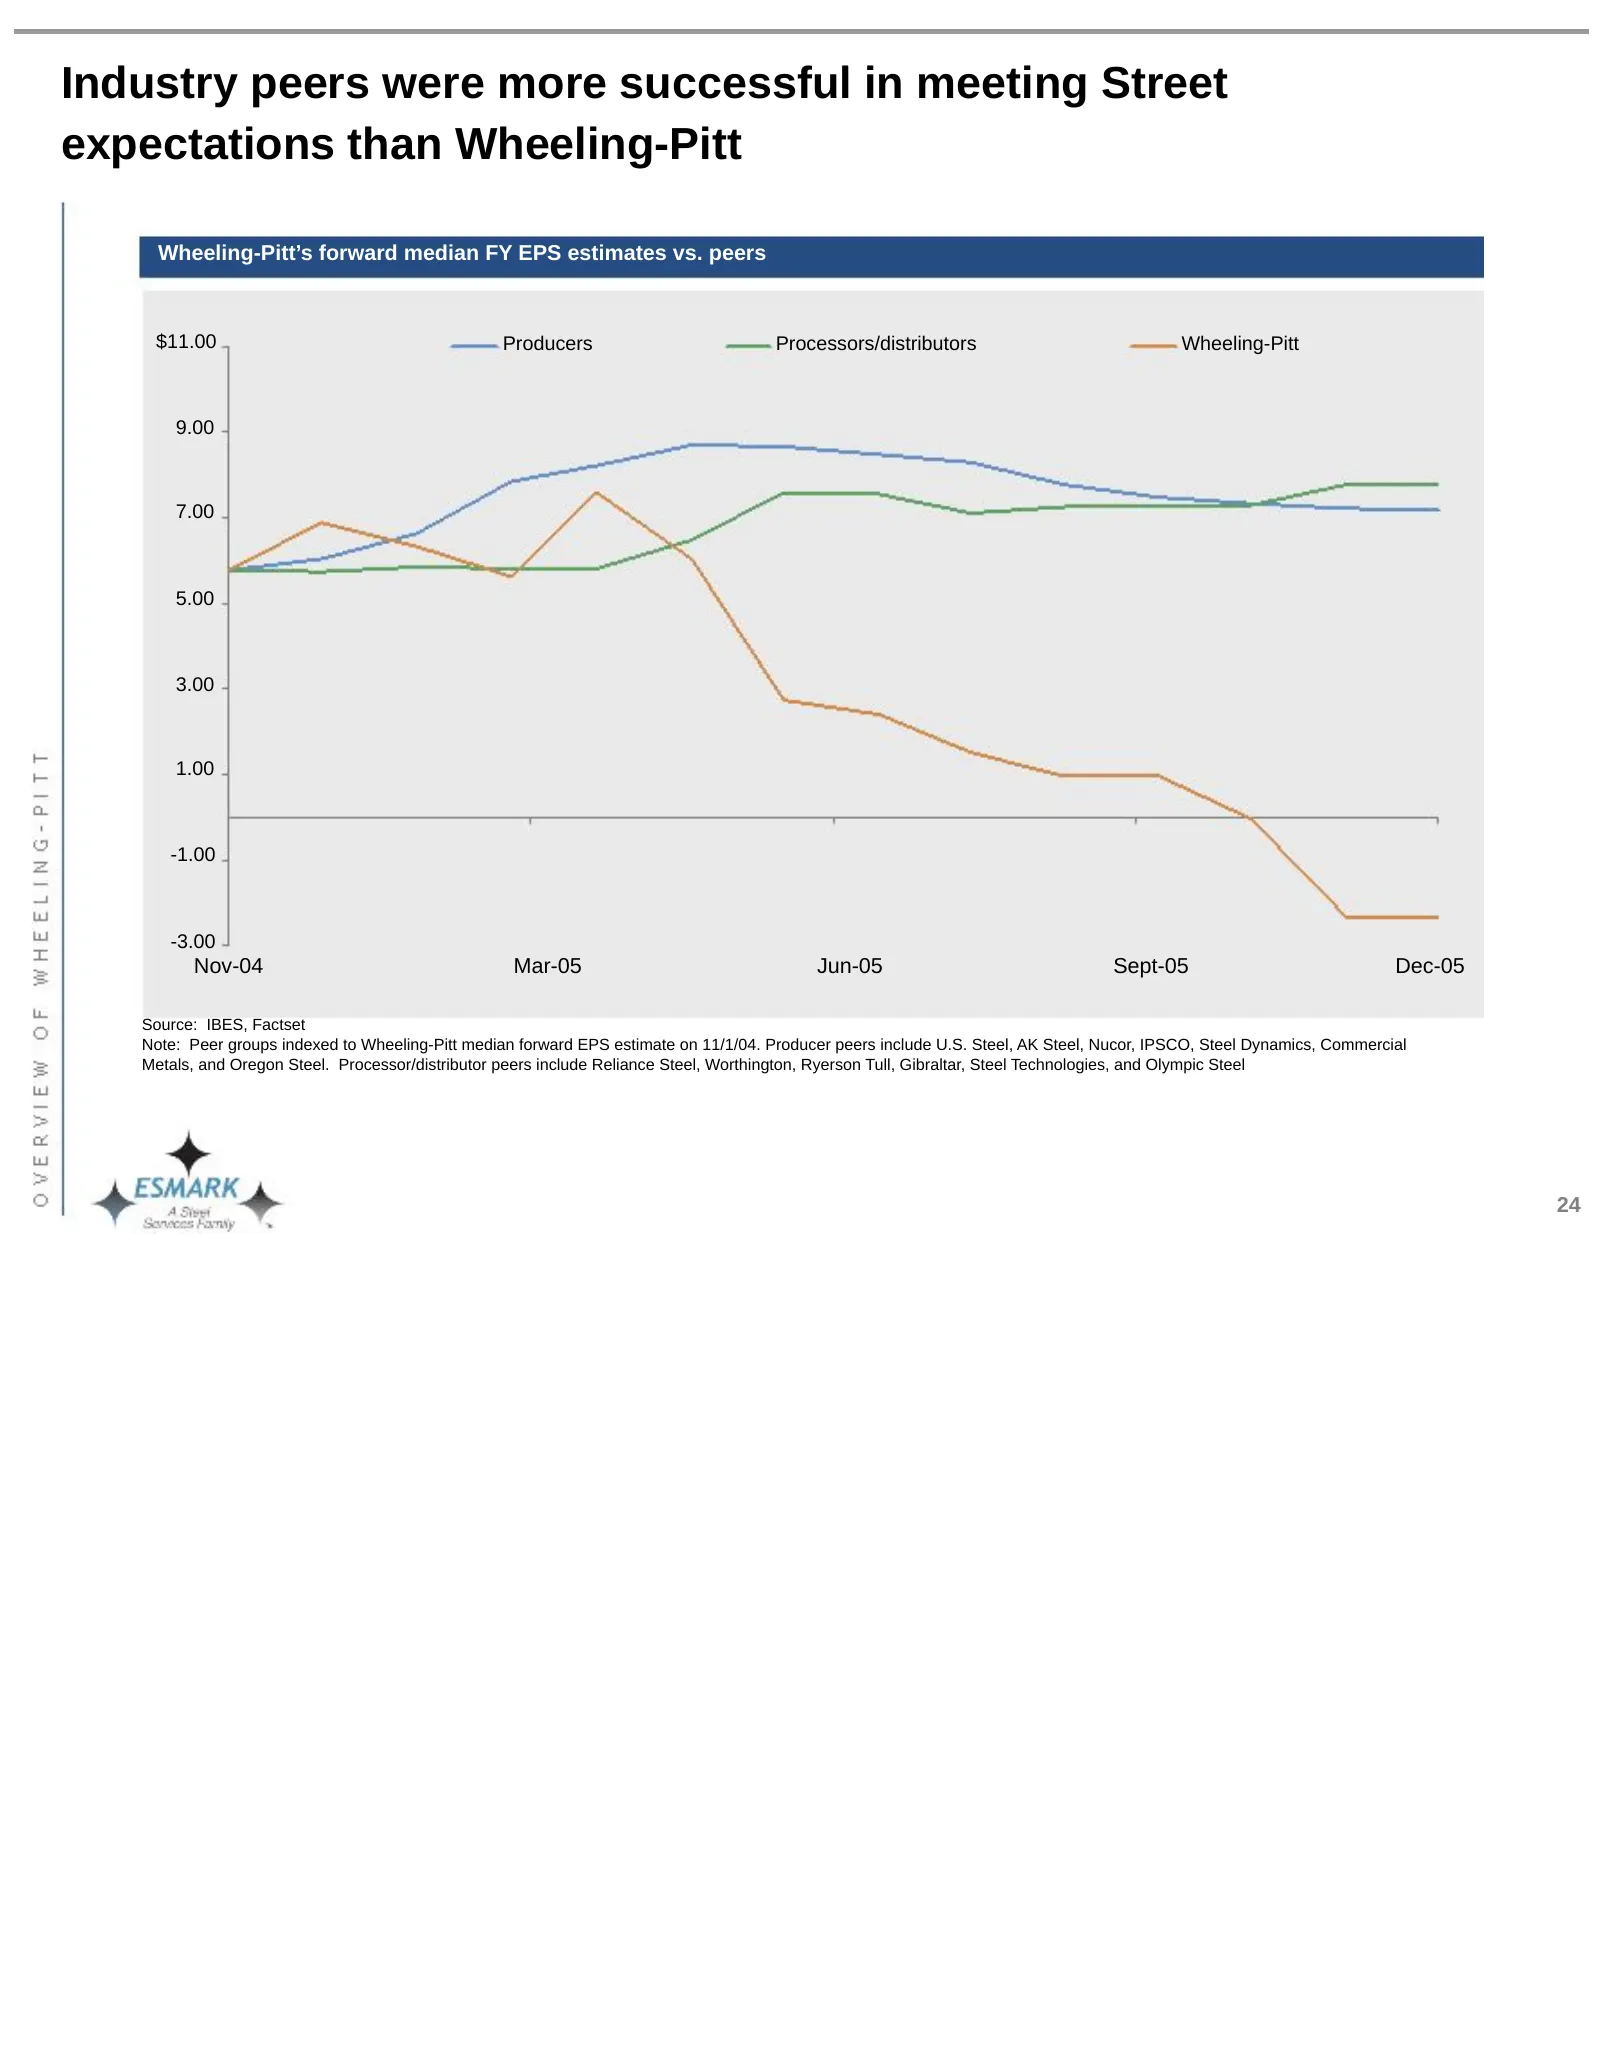
Industry peers were more successful in meeting Street expectations than Wheeling-Pitt Wheeling-Pitt’s forward median FY EPS estimates vs. peers $11.00 Producers Processors/distributors Wheeling-Pitt 9.00 7.00 5.00 3.00 1.00 -1.00 -3.00 Nov-04 Mar-05 Jun-05 Sept-05 Dec-05 11/1/04 2/7/05 5/17/05 8/24/
Slide 29: Wheeling-Pitt's performance has been plagued by a number of factors
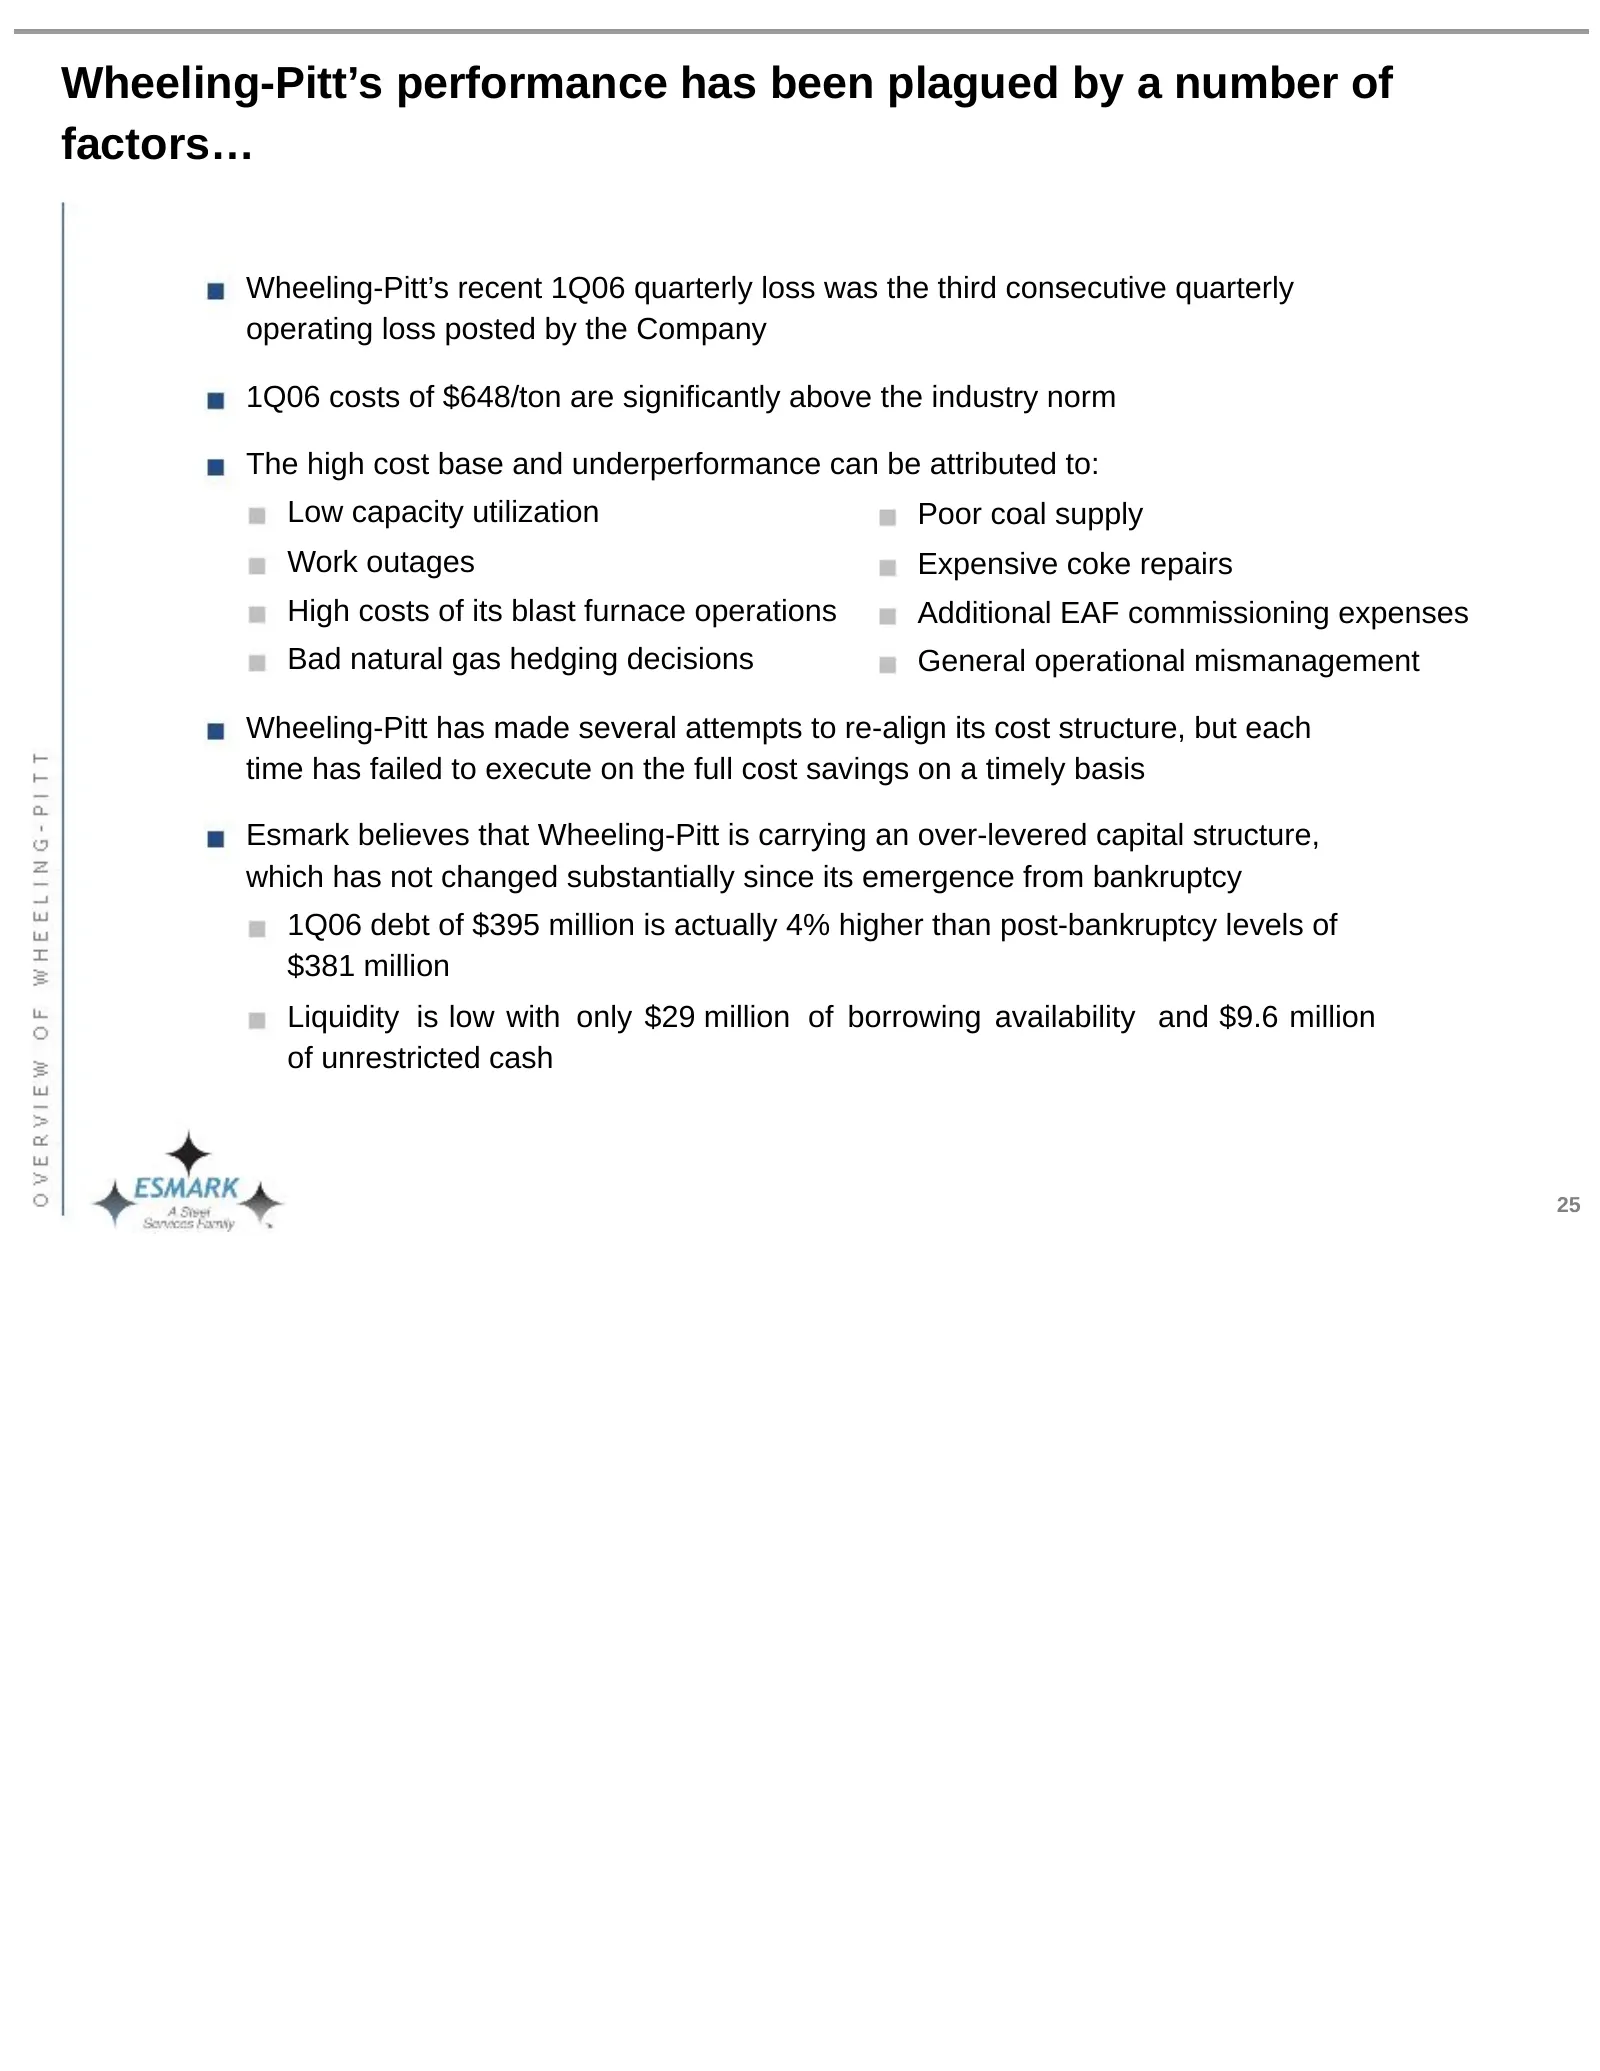
Wheeling-Pitt’s performance has been plagued by a number of factors… Wheeling-Pitt’s recent 1Q06 quarterly loss was the third consecutive quarterly operating loss posted by the Company 1Q06 costs of $648/ton are significantly above the industry norm The high cost base and underperformance can be att
Slide 30: Wheeling-Pitt has operated with a highly levered capital structure
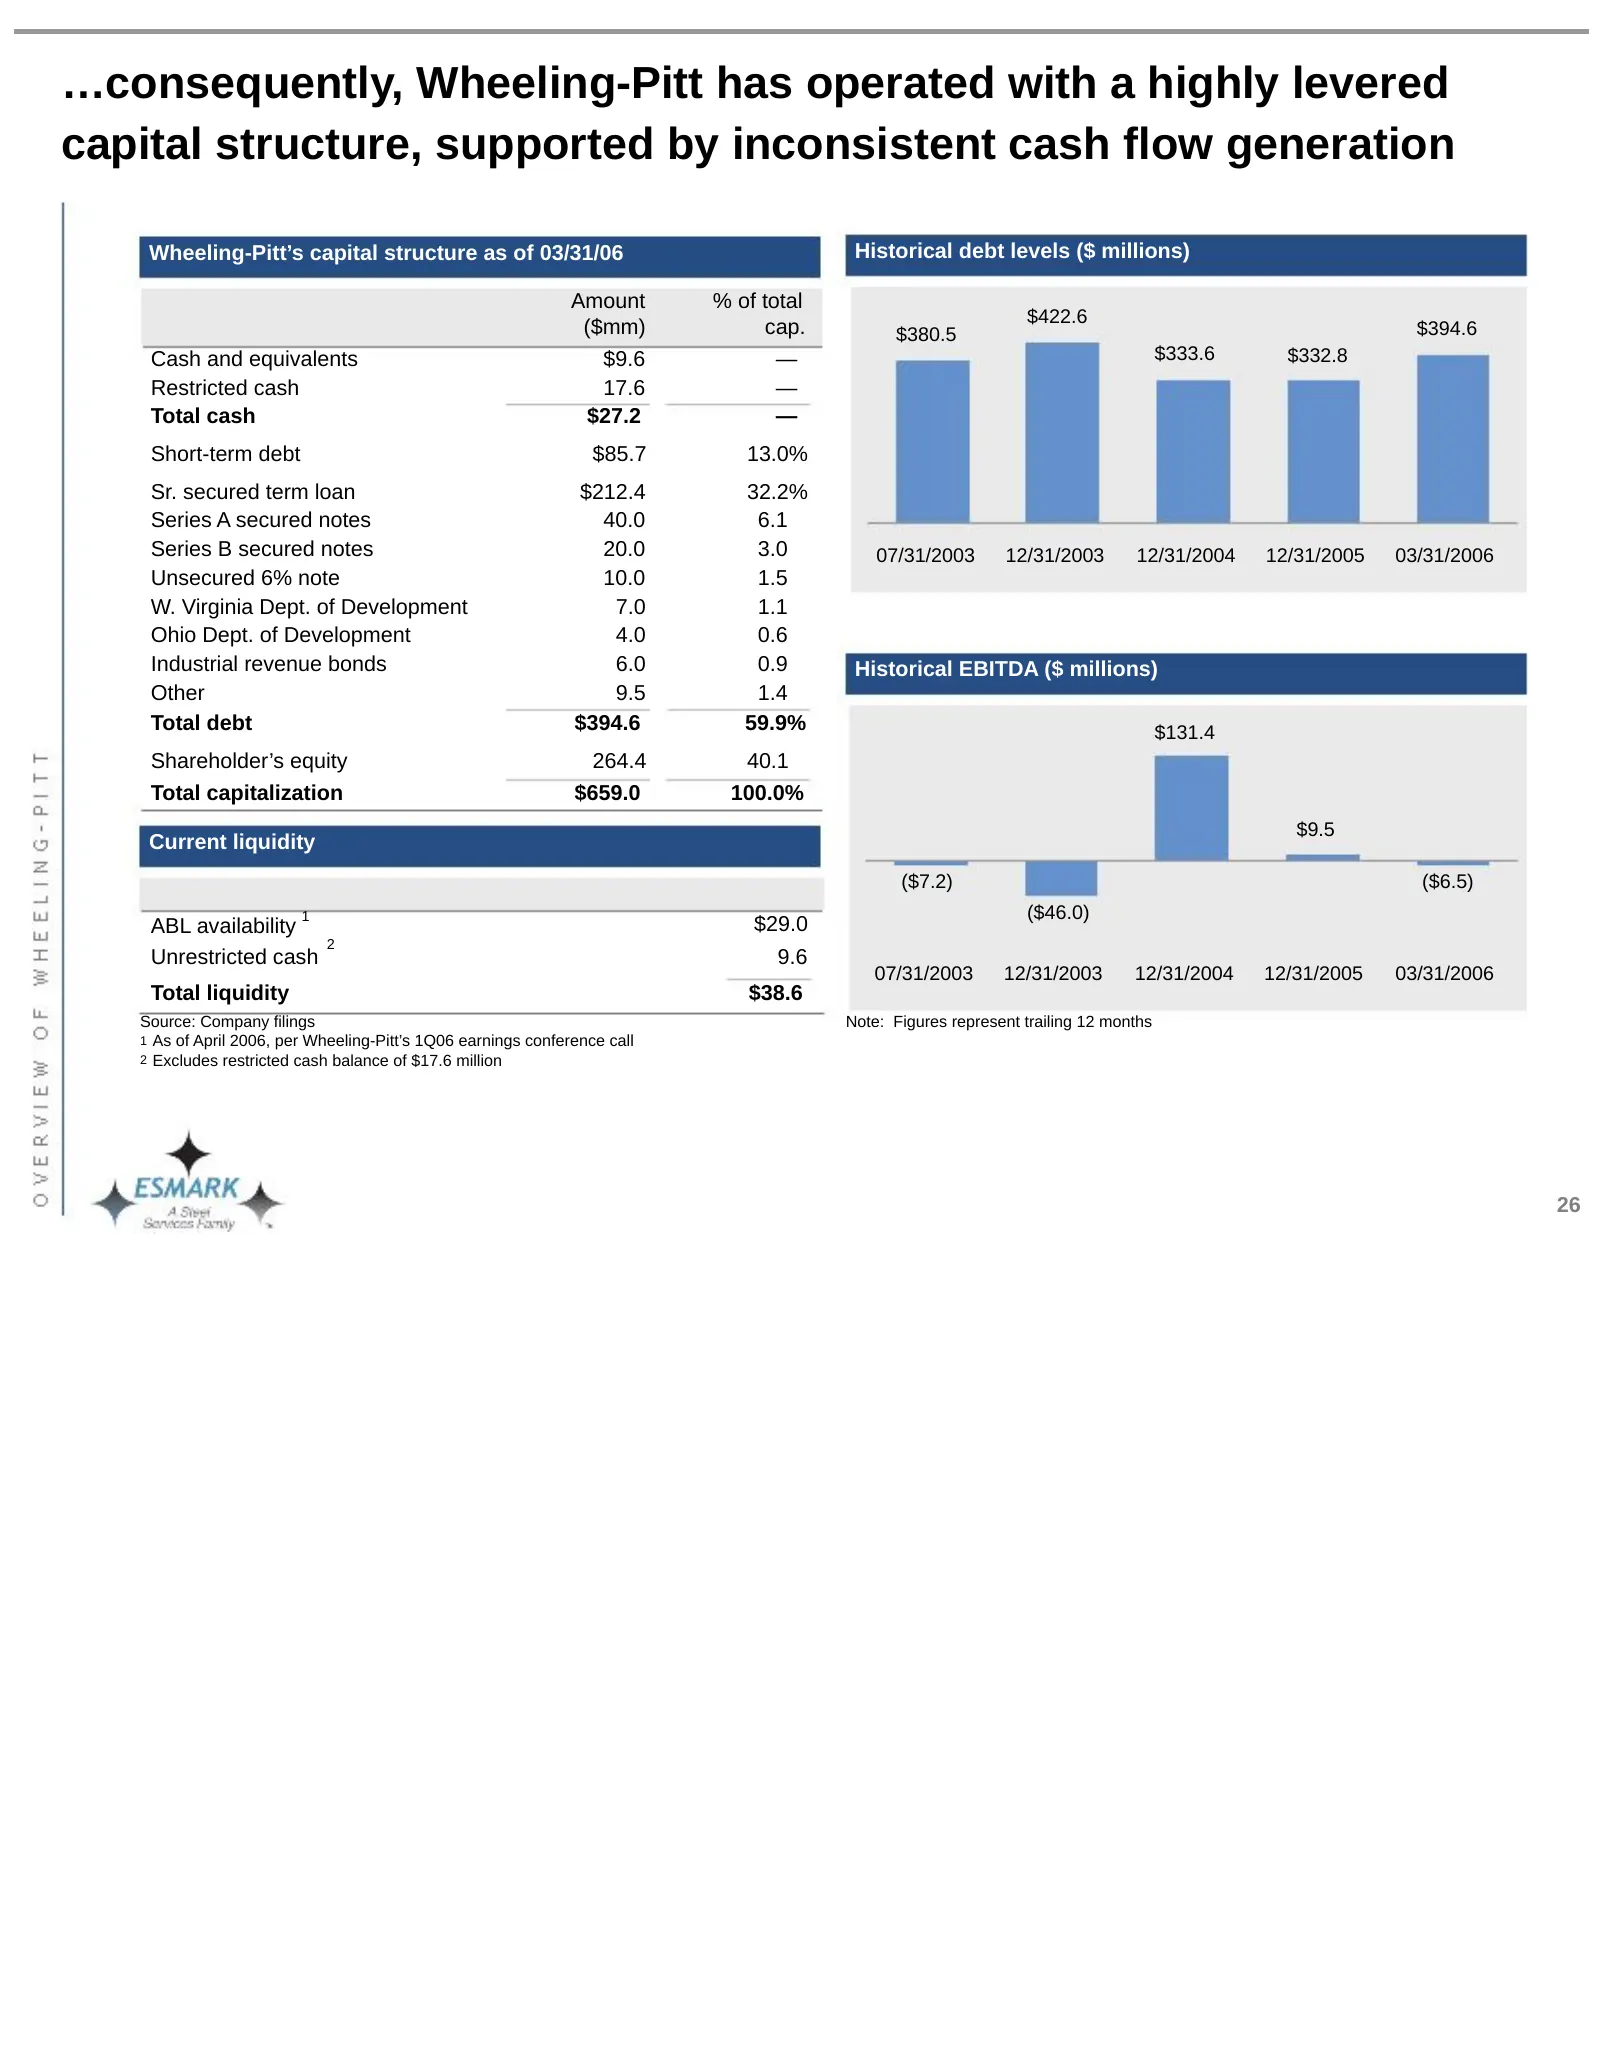
…consequently, Wheeling-Pitt has operated with a highly levered capital structure, supported by inconsistent cash flow generation Wheeling-Pitt’s capital structure as of 03/31/06 Historical debt levels ($ millions) Amount % of total $422.6 ($mm) cap. $380.5 $394.6 Cash and equivalents $9.6 — $333.6
Slide 31: Management and board dealing with non-value enhancing issues
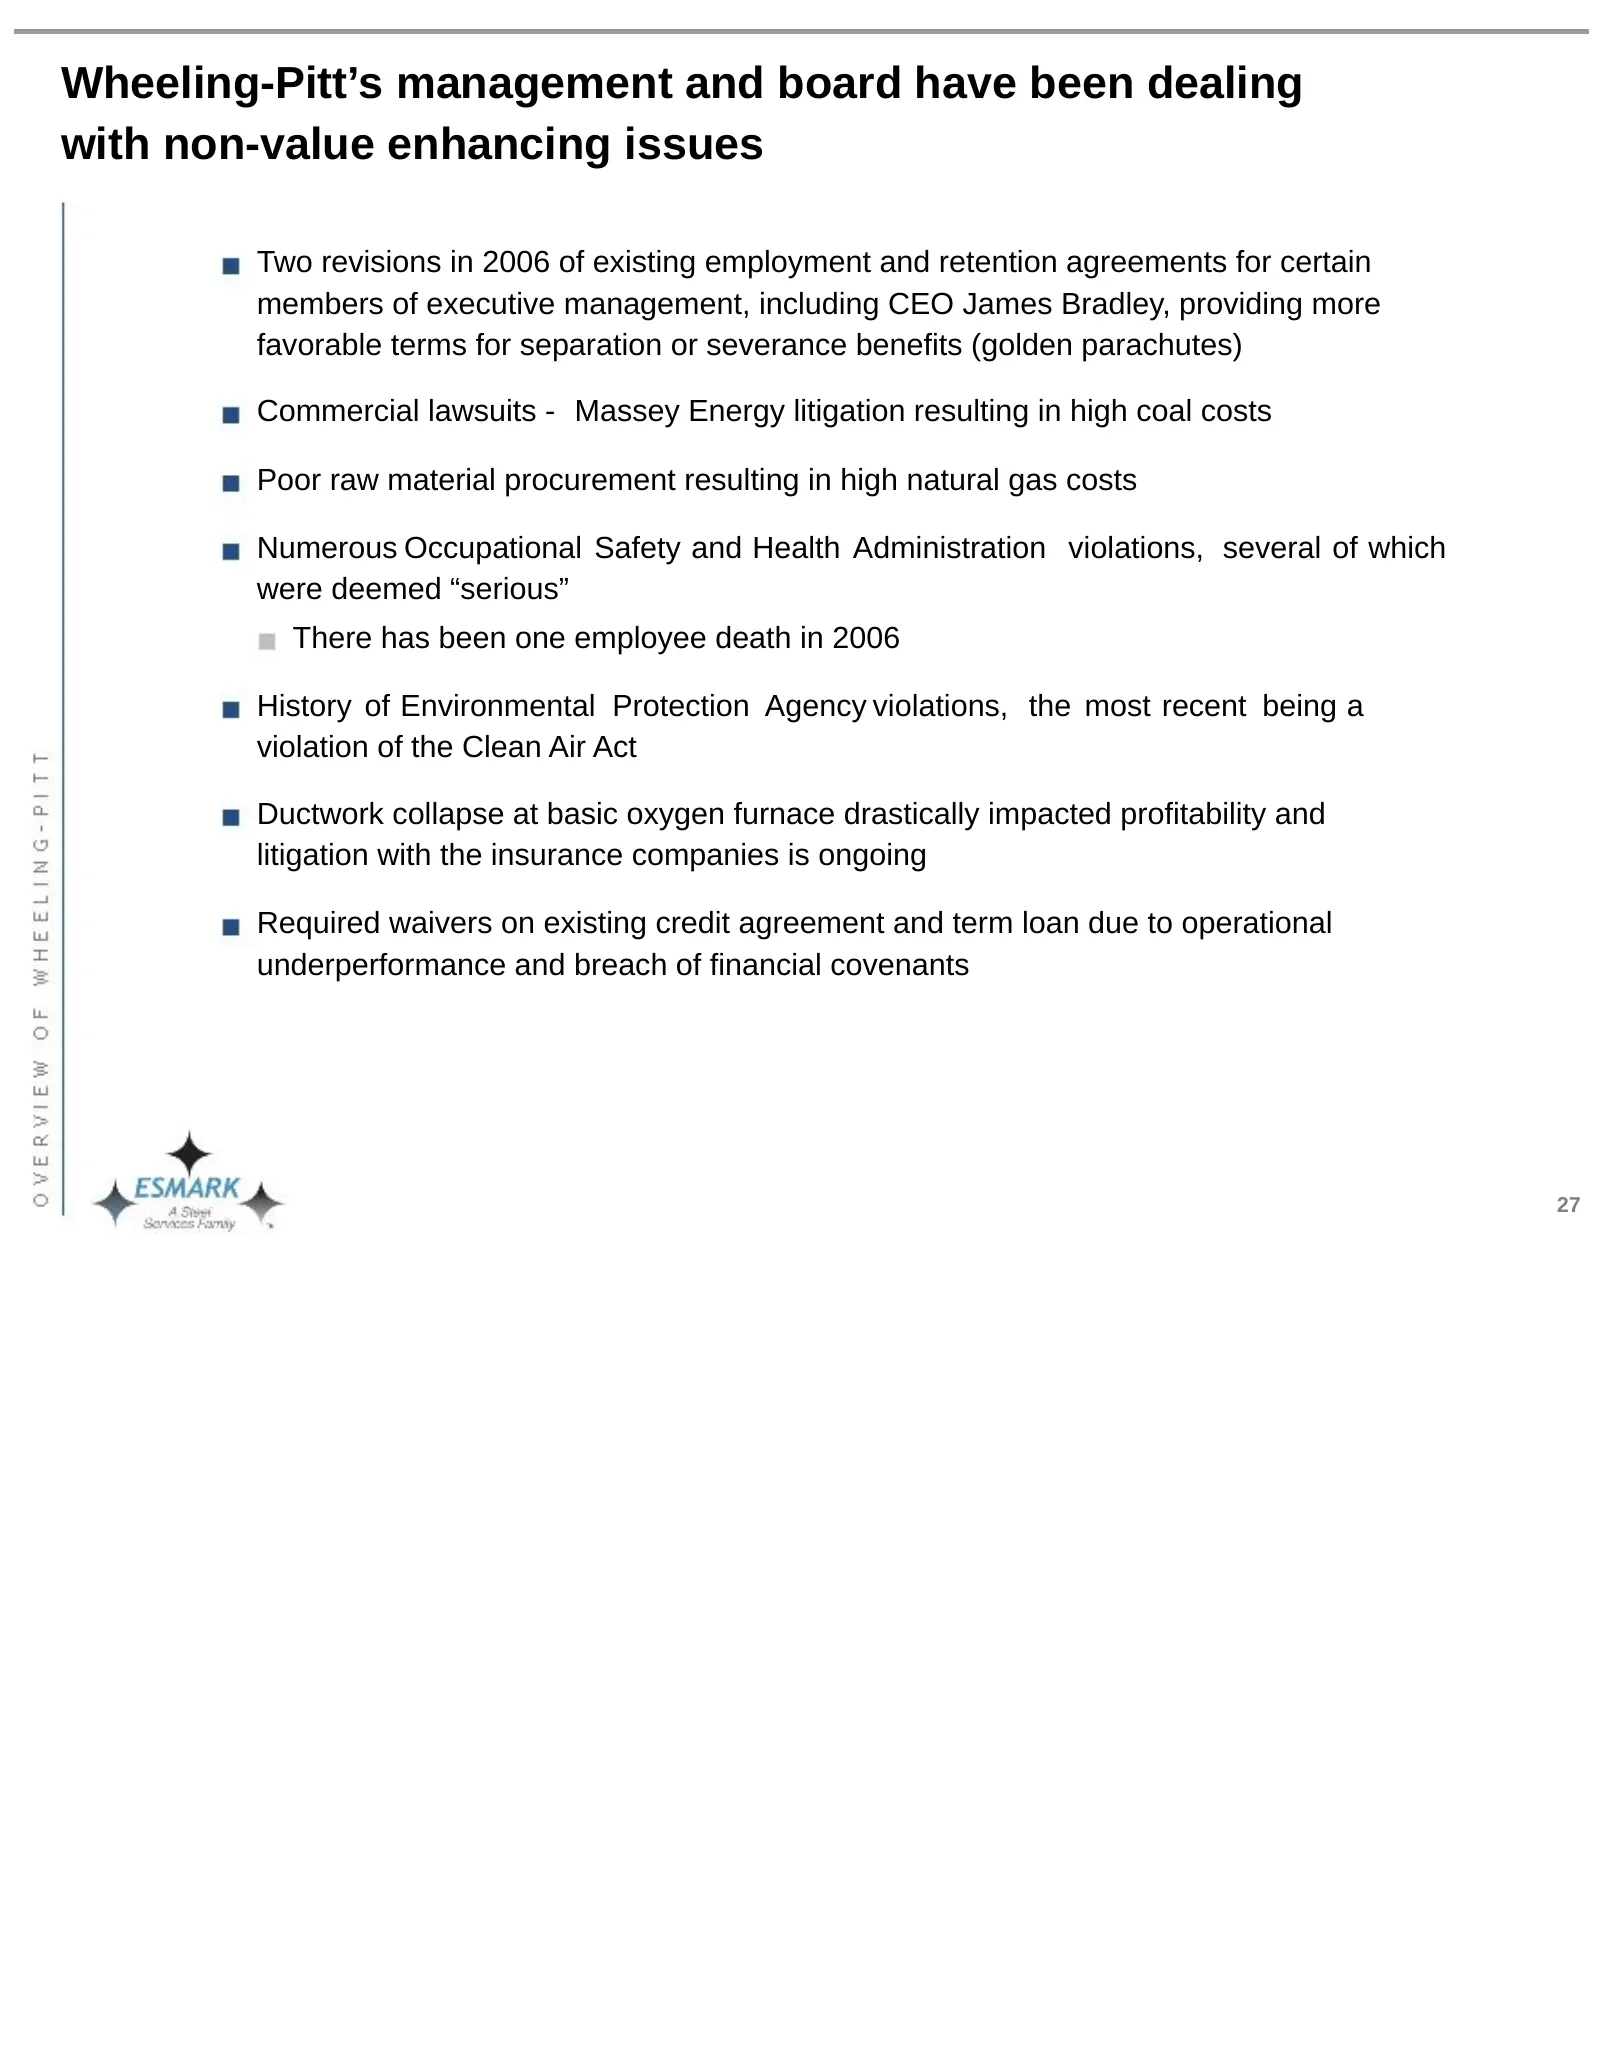
Wheeling-Pitt’s management and board have been dealing with non-value enhancing issues Two revisions in 2006 of existing employment and retention agreements for certain members of executive management, including CEO James Bradley, providing more favorable terms for separation or severance benefits (
Slide 32: Wheeling-Pitt's announcements regarding CSN
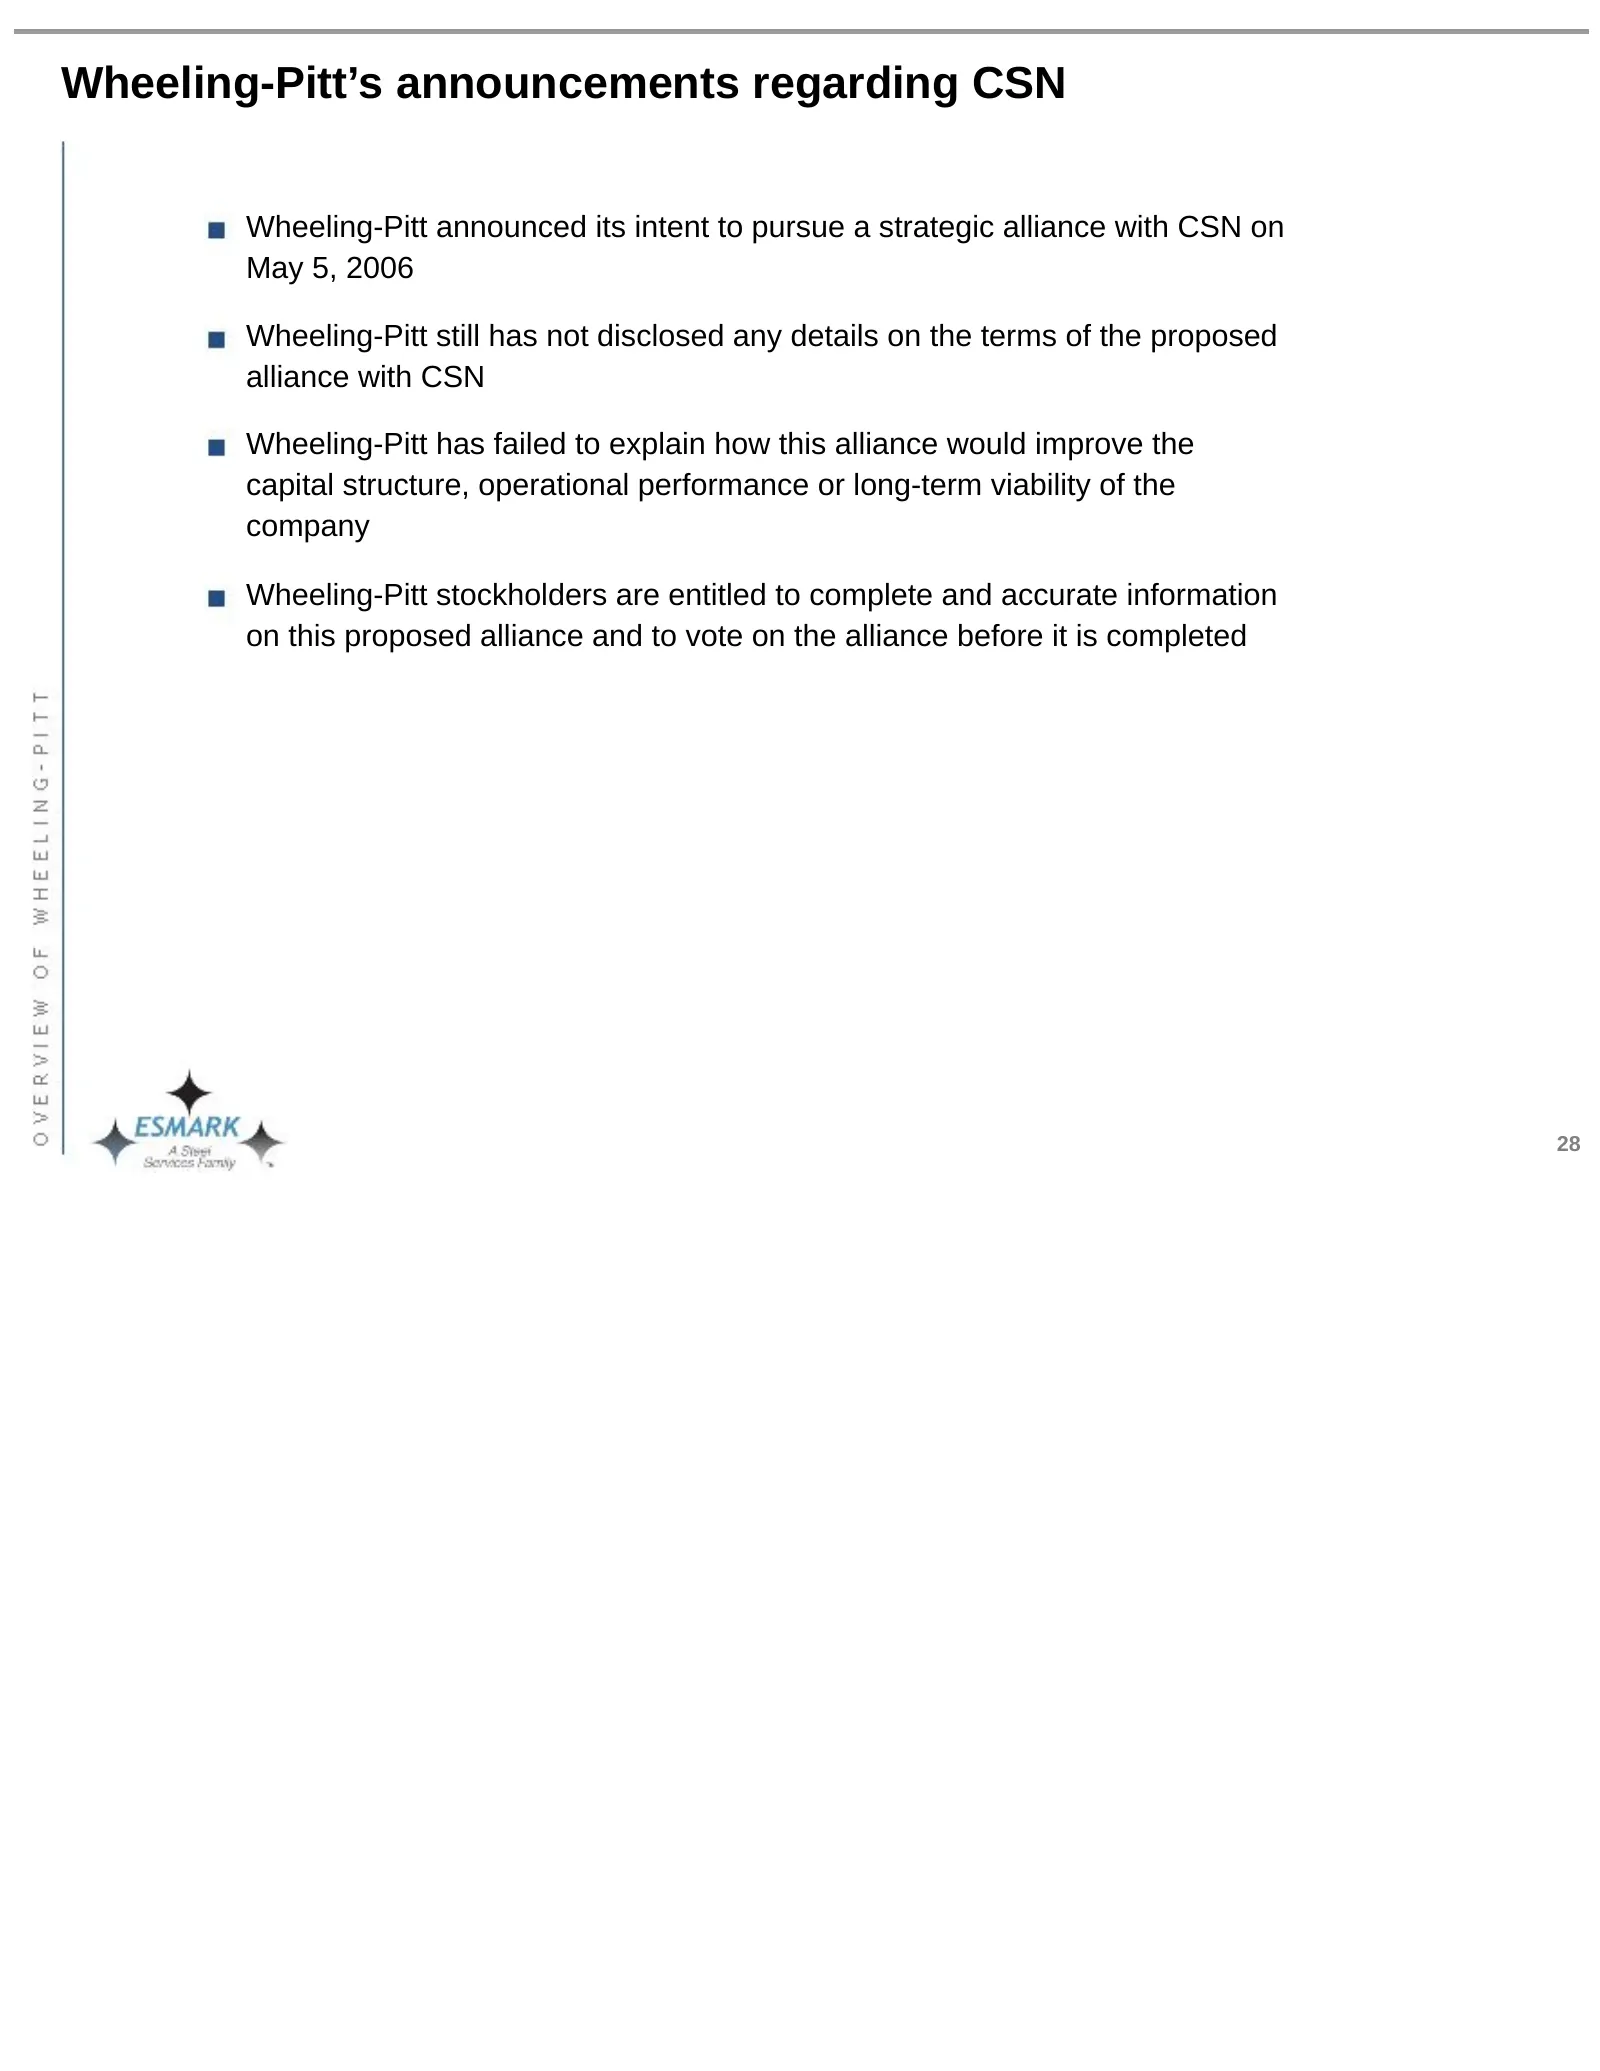
Wheeling-Pitt’s announcements regarding CSN Wheeling-Pitt announced its intent to pursue a strategic alliance with CSN on May 5, 2006 Wheeling-Pitt still has not disclosed any details on the terms of the proposed alliance with CSN Wheeling-Pitt has failed to explain how this alliance would improve t
Slide 33: Agenda
Agenda Page Overview 2 Strategic vision 7 Overview of Esmark 18 Overview of Wheeling-Pitt 22 Conclusion 29 29
Slide 34: Conclusion Questions and Answers
Conclusion Esmark would like to thank you for the opportunity to meet and discuss the potentially exciting future for Wheeling-Pitt and its stockholders We ask for your support to ensure that our slate of directors is elected so that our proposal receives due consideration Questions and Answers 30
Source: SEC EDGAR · DFAN14A filed Jul 26, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (December 2006)22 slides · Dec 7, 2006
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)40 slides · Nov 7, 2006
 Proxy Contest (November 2006)44 slides · Nov 6, 2006
 Proxy Contest (September 2006)21 slides · Sep 29, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006