Wheeling Pittsburgh — Merger or Acquisition (December 2006)
22 slides from Wheeling Pittsburgh's merger presentation, Dec 7, 2006
Slide 1: Filed by Esmark Incorporated pursuant to Rule 425
Filed by Esmark Incorporated. Pursuant to Rule 425 under the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 of the Securities Exchange Act of 1934 Subject Company: Wheeling-Pittsburgh Corporation Commission File No.: 000-50300
Slide 2: Global Steel CEO Forum: The Esmark Vision
Goldman Sachs D E CEM B ER 7 , 2 0 0 6 Global Steel CEO Forum "THE ESMARK VISION" James P. Bouchard –Chairman and CEO, Esmark Inc.
Slide 3: Forward-looking statements
This presentation contains forward-looking statements relating to Esmark Incorporated (“Esmark”). These forward-looking statements are based on current expectations and assumptions that are subject to risks and uncertainties that could cause actual results to differ materially. These risks and uncer
Slide 4: Service center carbon flat rolled inventory and shipments
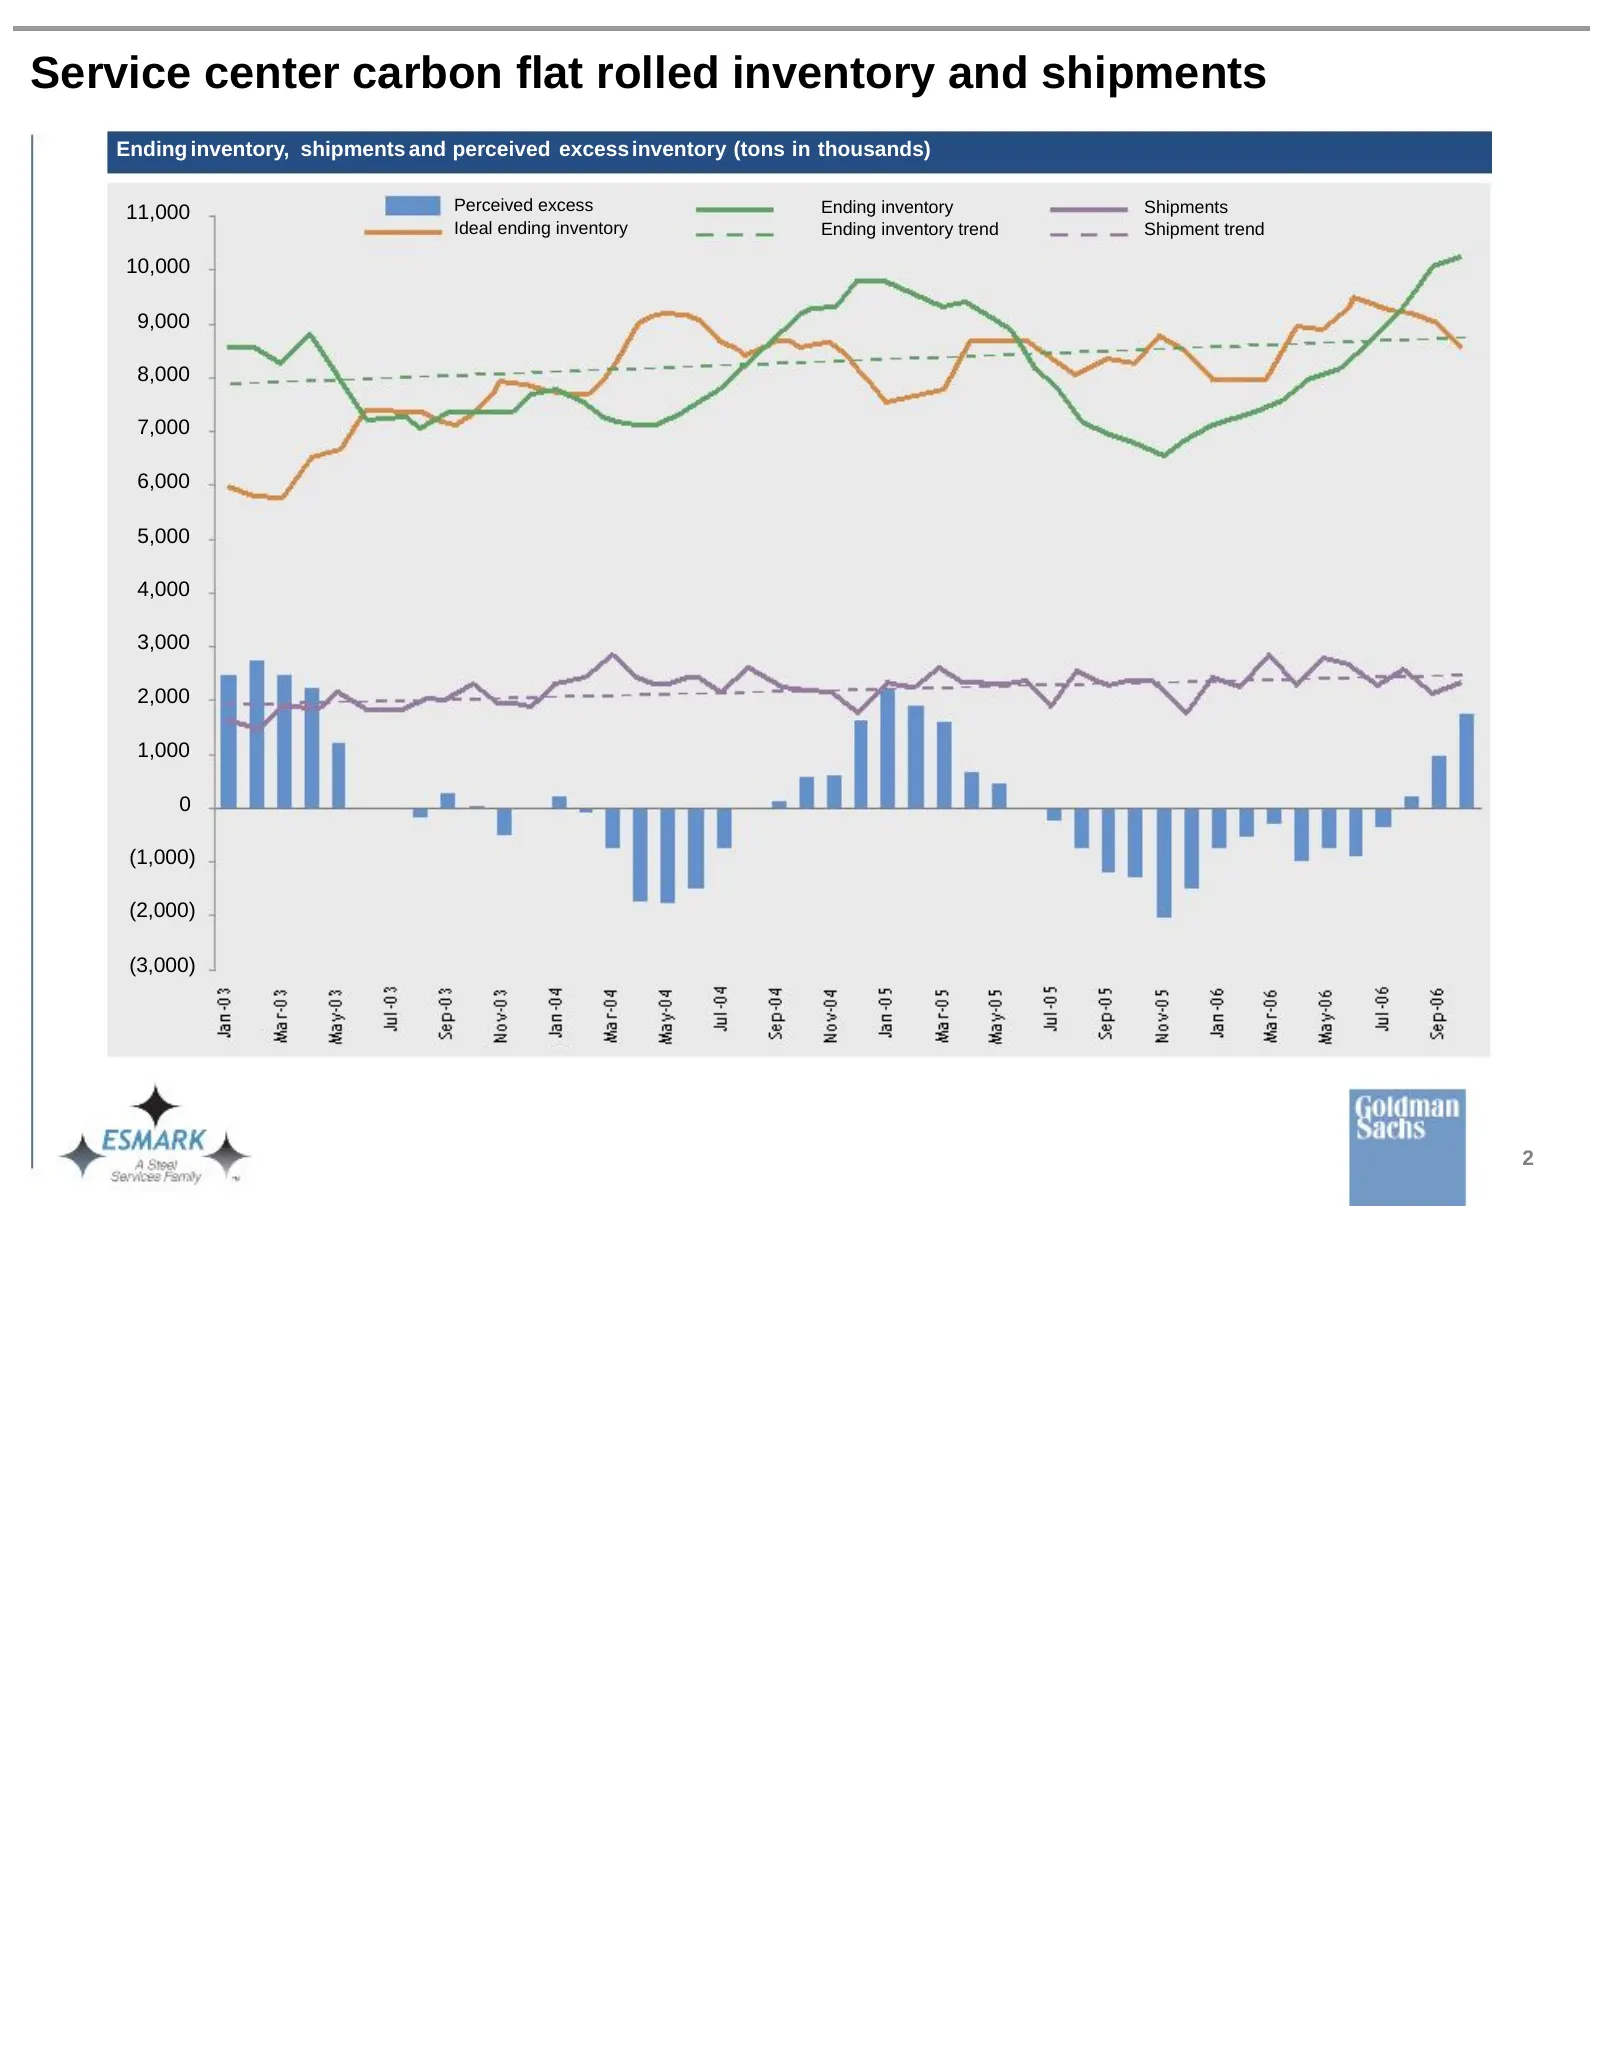
Service center carbon flat rolled inventory and shipments Ending inventory, shipments and perceived excess inventory (tons in thousands) 11,000 Perceived excess Ending inventory Shipments Ideal ending inventory Ending inventory trend Shipment trend 10,000 9,000 8,000 7,000 6,000 5,000 4,000 3,000 2,
Slide 5: Current inventory trends
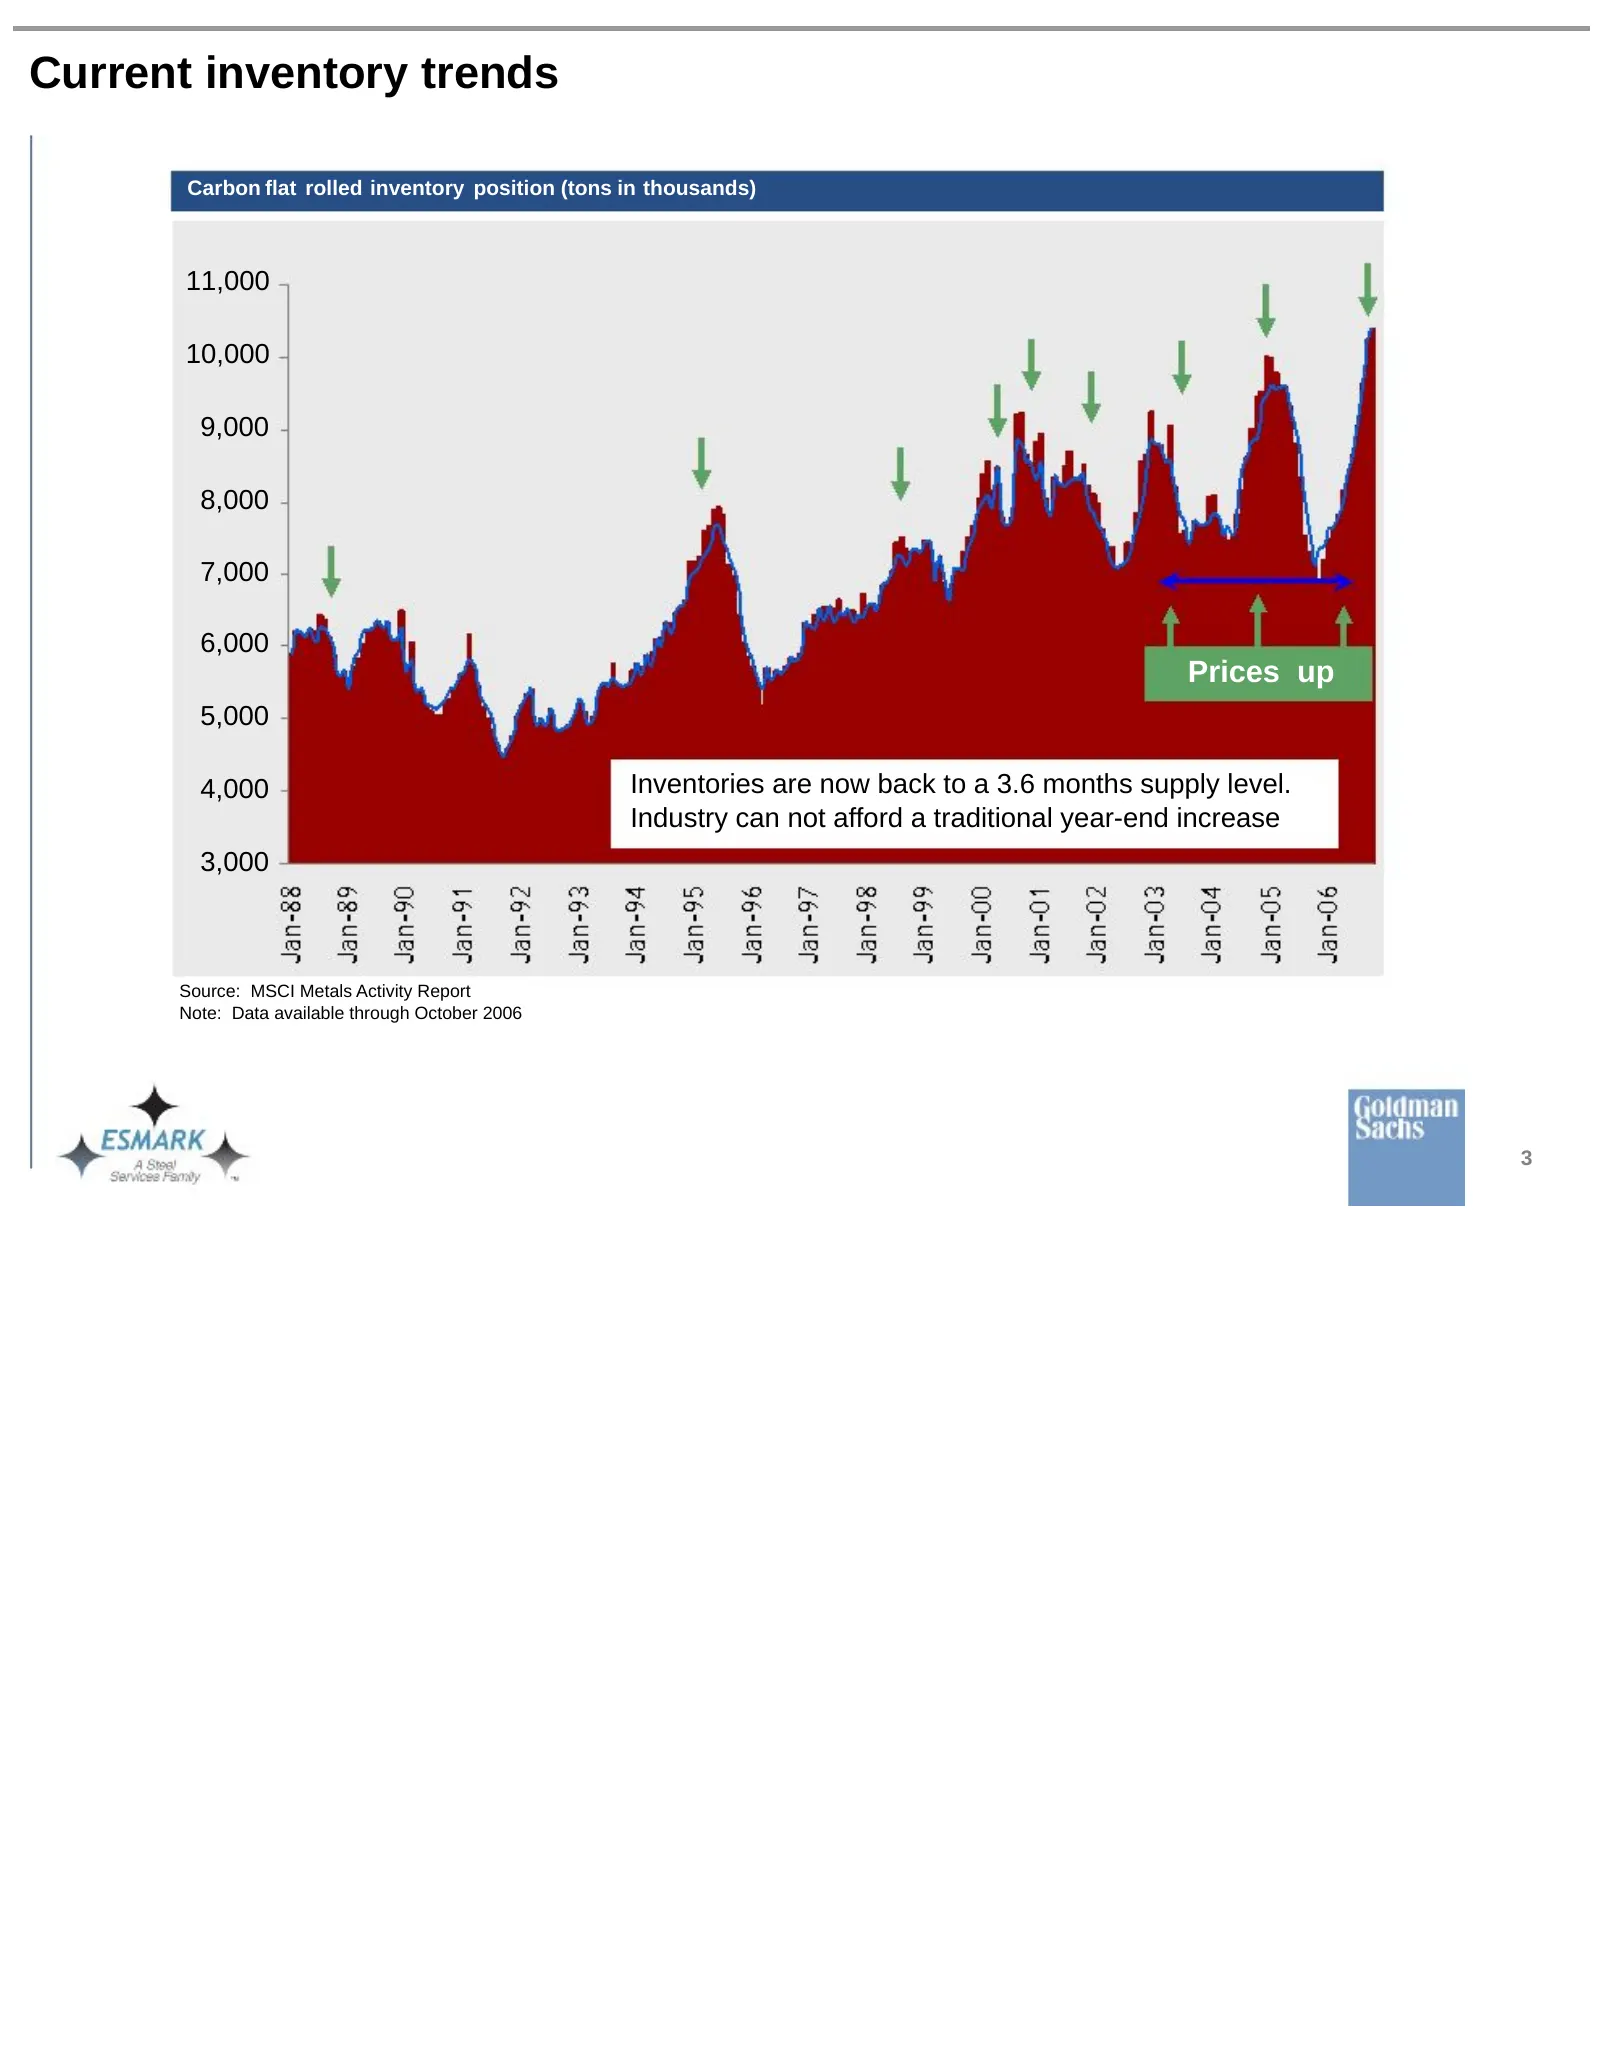
Current inventory trends Carbon flat rolled inventory position (tons in thousands) 11,000 10,000 9,000 8,000 7,000 6,000 Prices up 5,000 4,000 Inventories are now back to a 3.6 months supply level. Industry can not afford a traditional year-end increase 3,000 Source: MSCI Metals Activity Report Note
Slide 6: Esmark – acquisition strategy
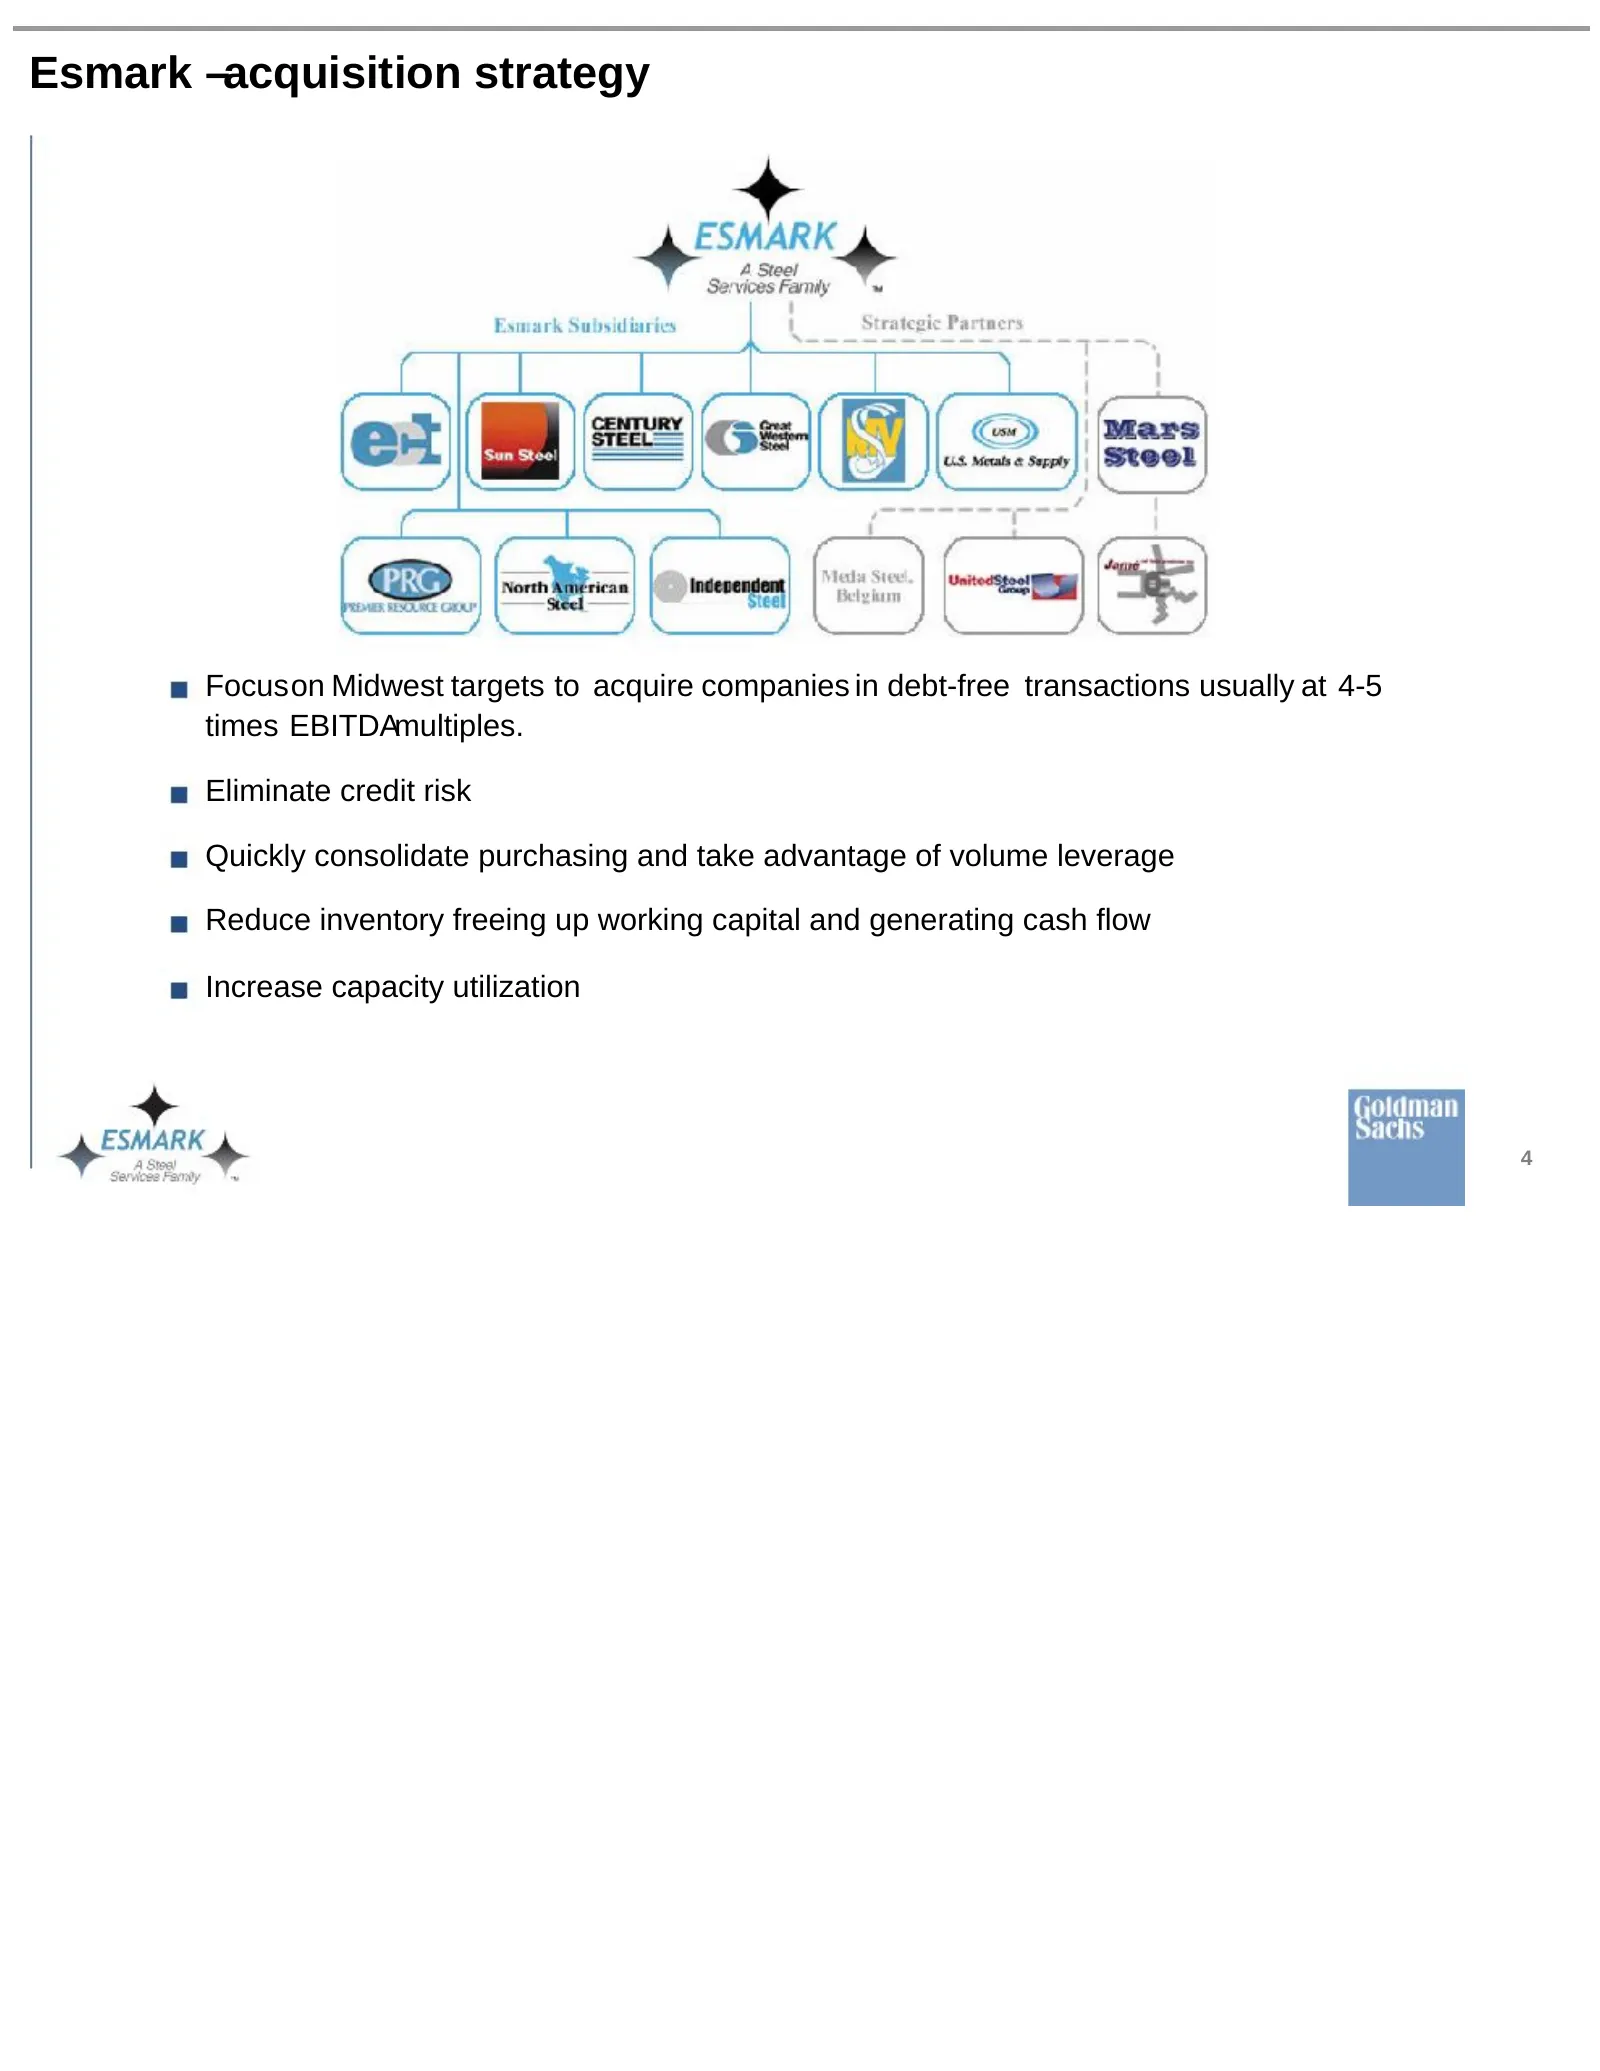
Esmark –acquisition strategy Focuson Midwest targets to acquire companies in debt-free transactions usually at 4-5 times EBITDAmultiples. Eliminate credit risk Quickly consolidate purchasing and take advantage of volume leverage Reduce inventory freeing up working capital and generating cash flow In
Slide 7: Esmark acquisition timeline – pro forma 2006
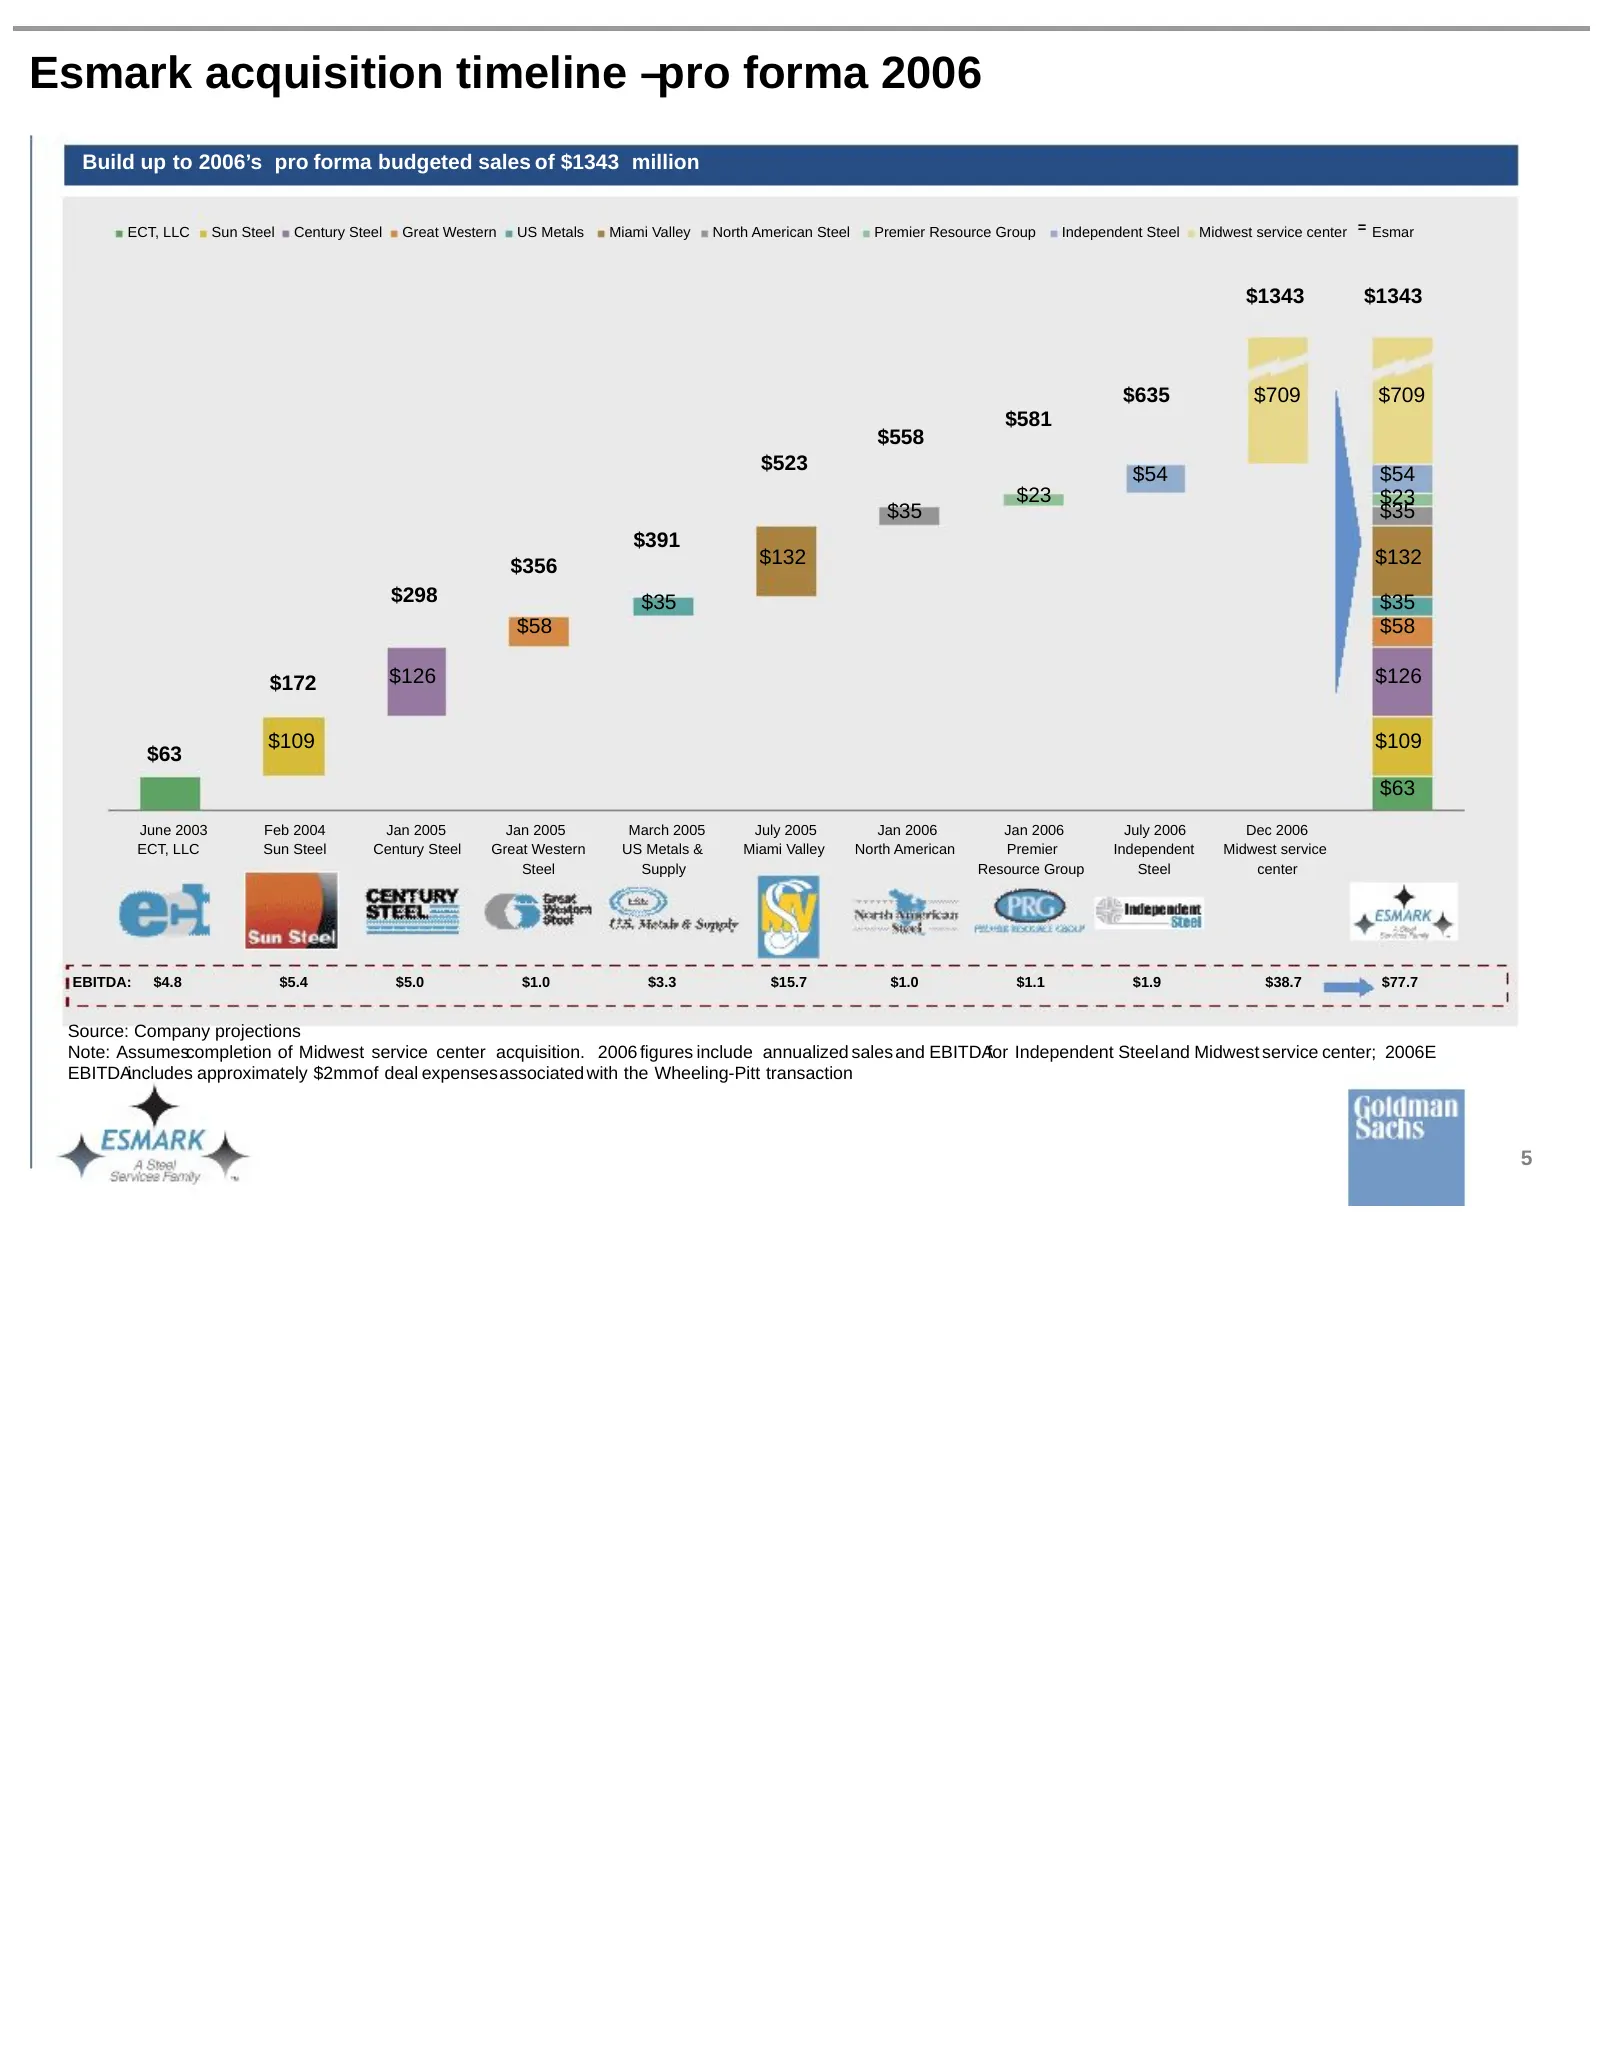
Esmark acquisition timeline –pro forma 2006 Build up to 2006’s pro forma budgeted sales of $1343 million ECT, LLC Sun Steel Century Steel Great Western US Metals Miami Valley North American Steel Premier Resource Group Independent Steel Midwest service center = Esmar $1343 $1343 $635 $709 $709 $581
Slide 8: Esmark acquisition timeline – pro forma 2007
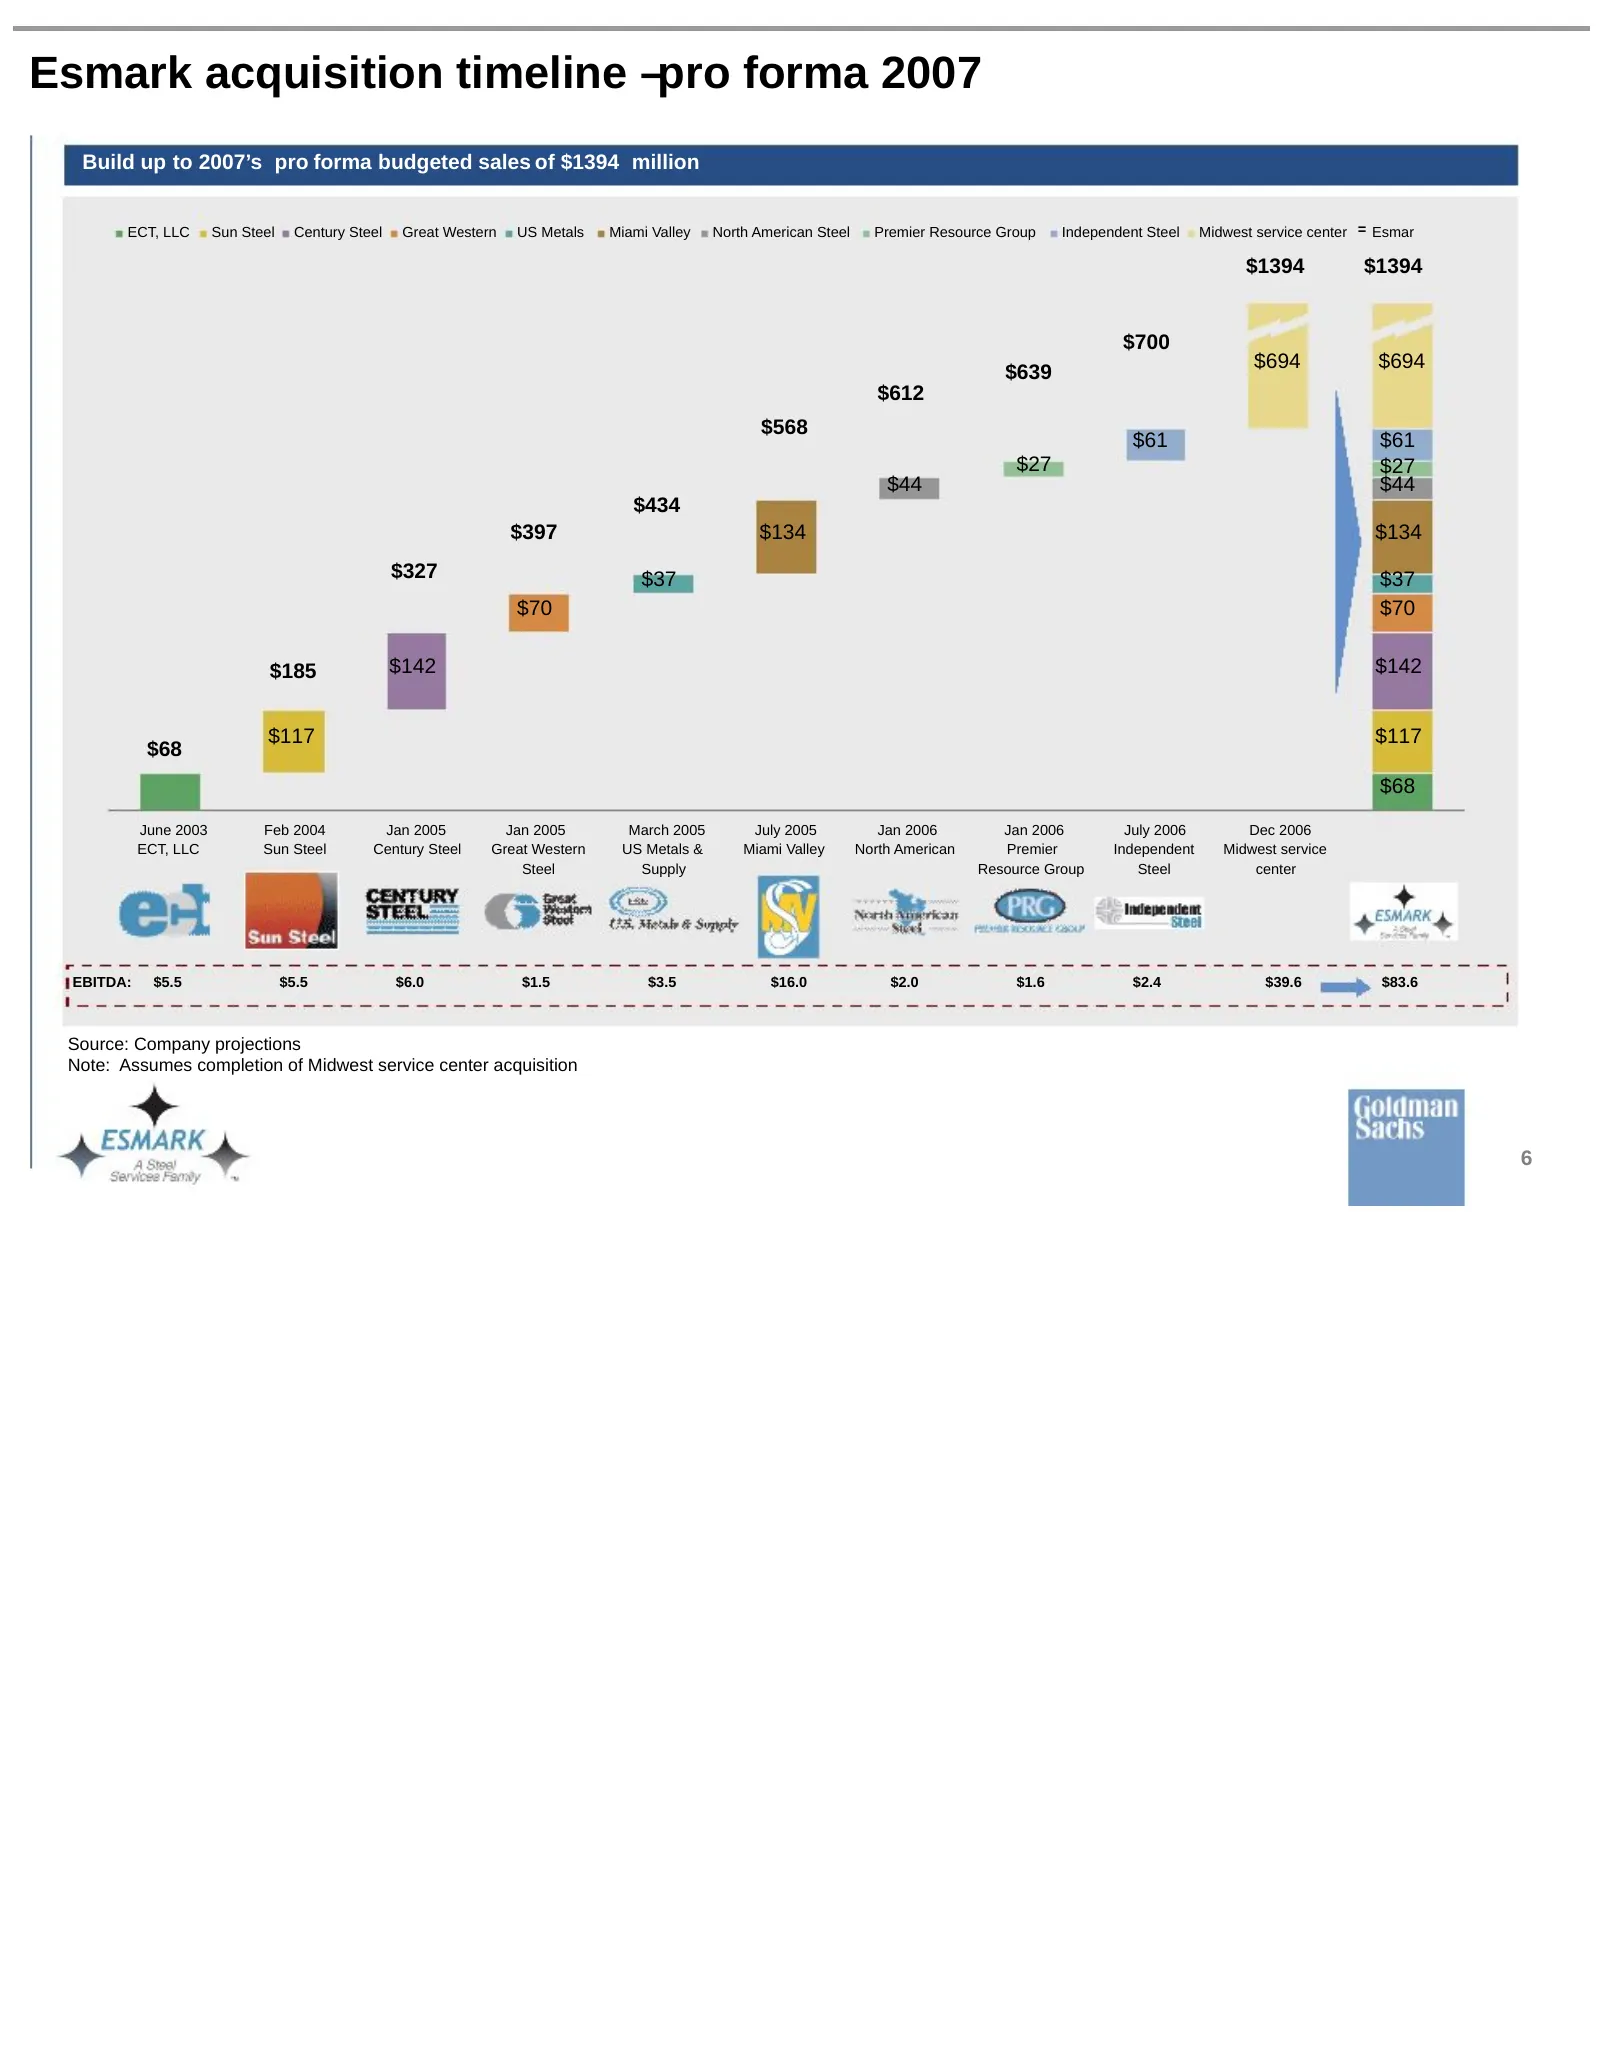
Esmark acquisition timeline –pro forma 2007 Build up to 2007’s pro forma budgeted sales of $1394 million ECT, LLC Sun Steel Century Steel Great Western US Metals Miami Valley North American Steel Premier Resource Group Independent Steel Midwest service center = Esmar $1394 $1394 $700 $694 $694 $639
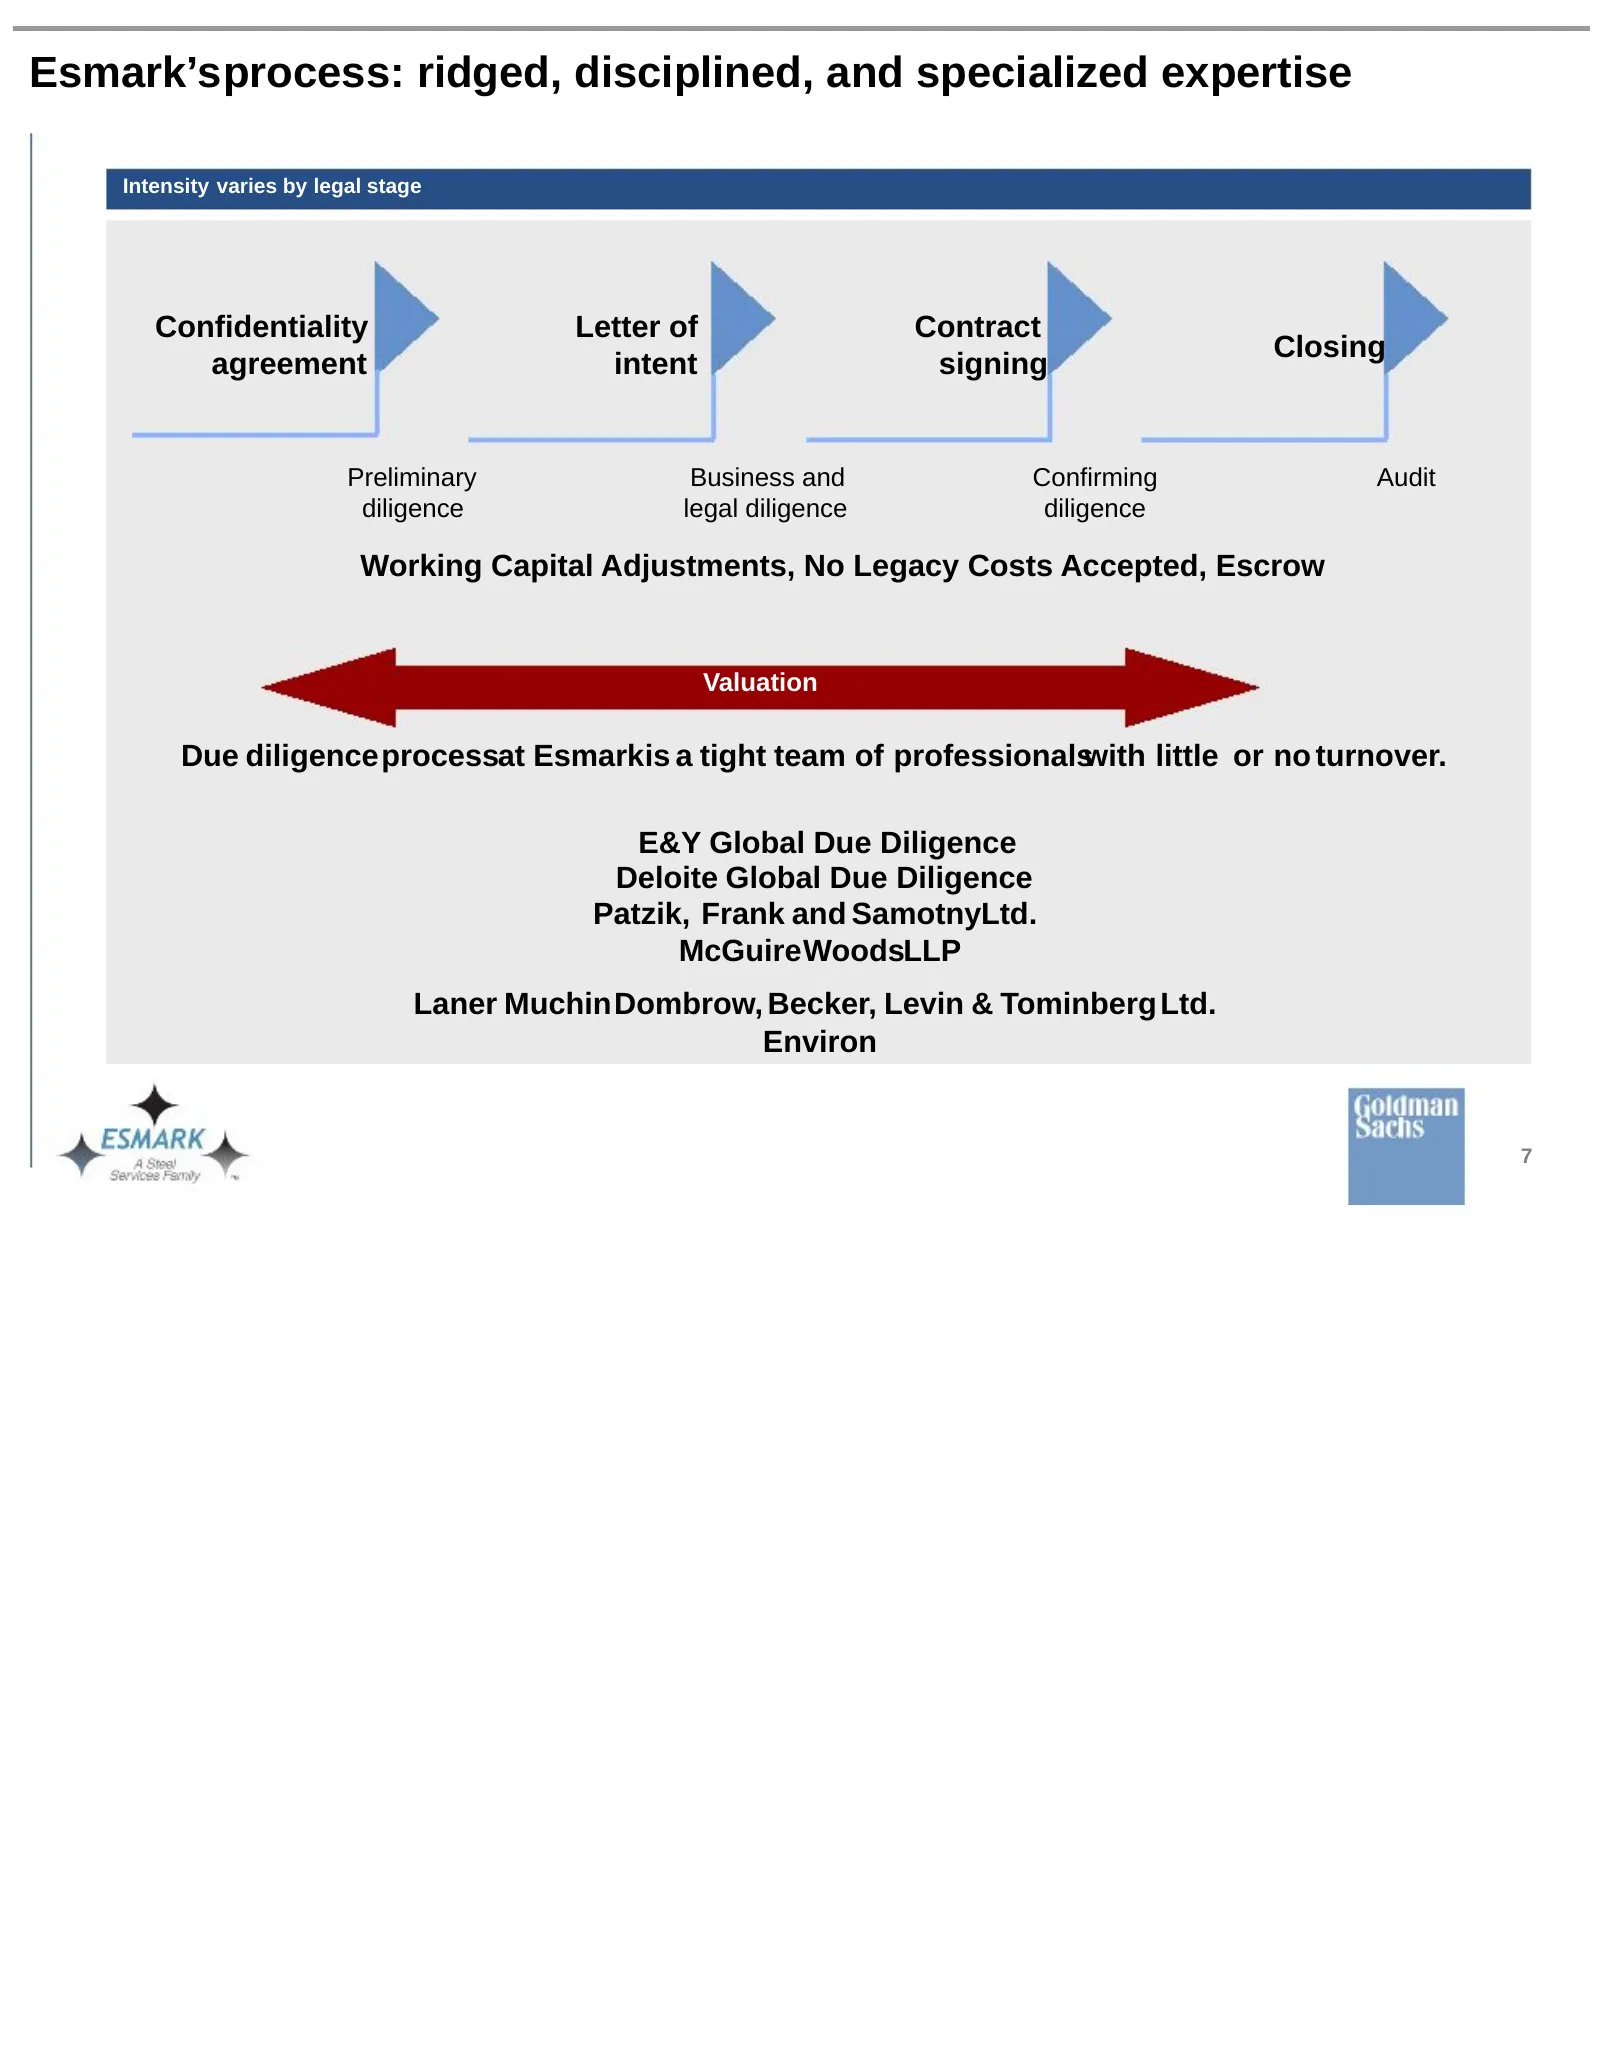
Slide 9: Esmark's process: rigid, disciplined, and specialized expertise
Esmark’sprocess: ridged, disciplined, and specialized expertise Intensity varies by legal stage Confidentiality Letter of Contract Closing agreement intent signing Preliminary Business and Confirming Audit diligence legal diligence diligence Working Capital Adjustments, No Legacy Costs Accepted, Esc
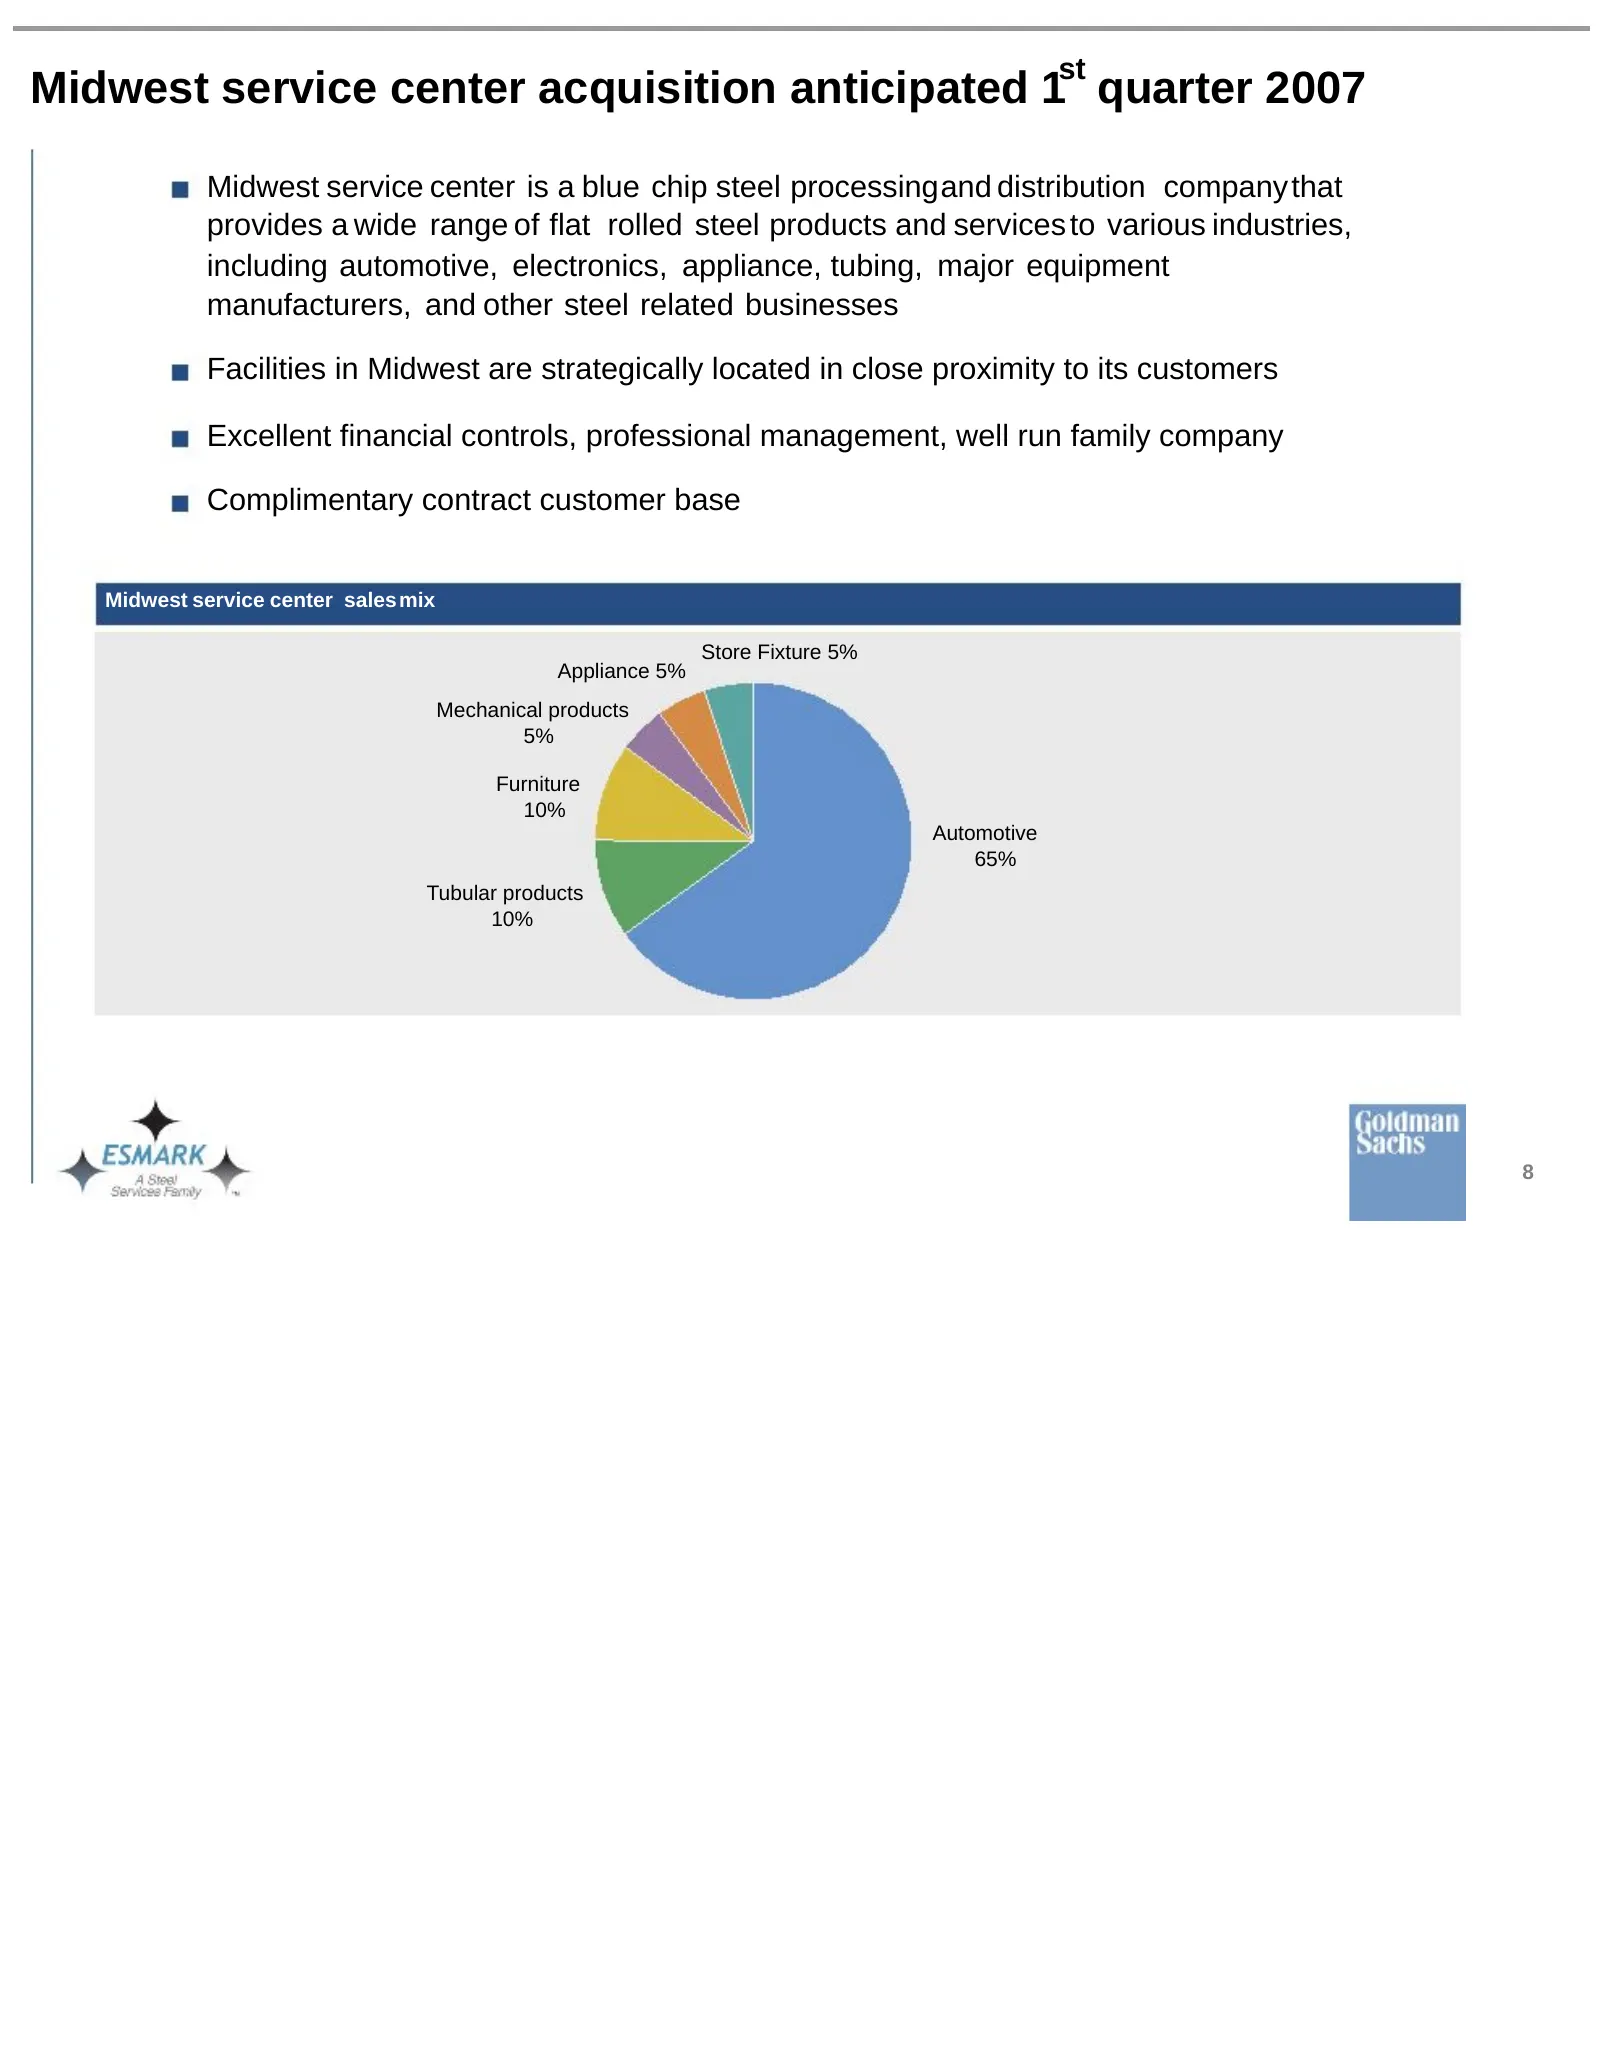
Slide 10: Midwest service center acquisition anticipated 1st quarter 2007
st Midwest service center acquisition anticipated 1 quarter 2007 Midwest service center is a blue chip steel processingand distribution company that provides a wide range of flat rolled steel products and services to various industries, including automotive, electronics, appliance, tubing, major equ
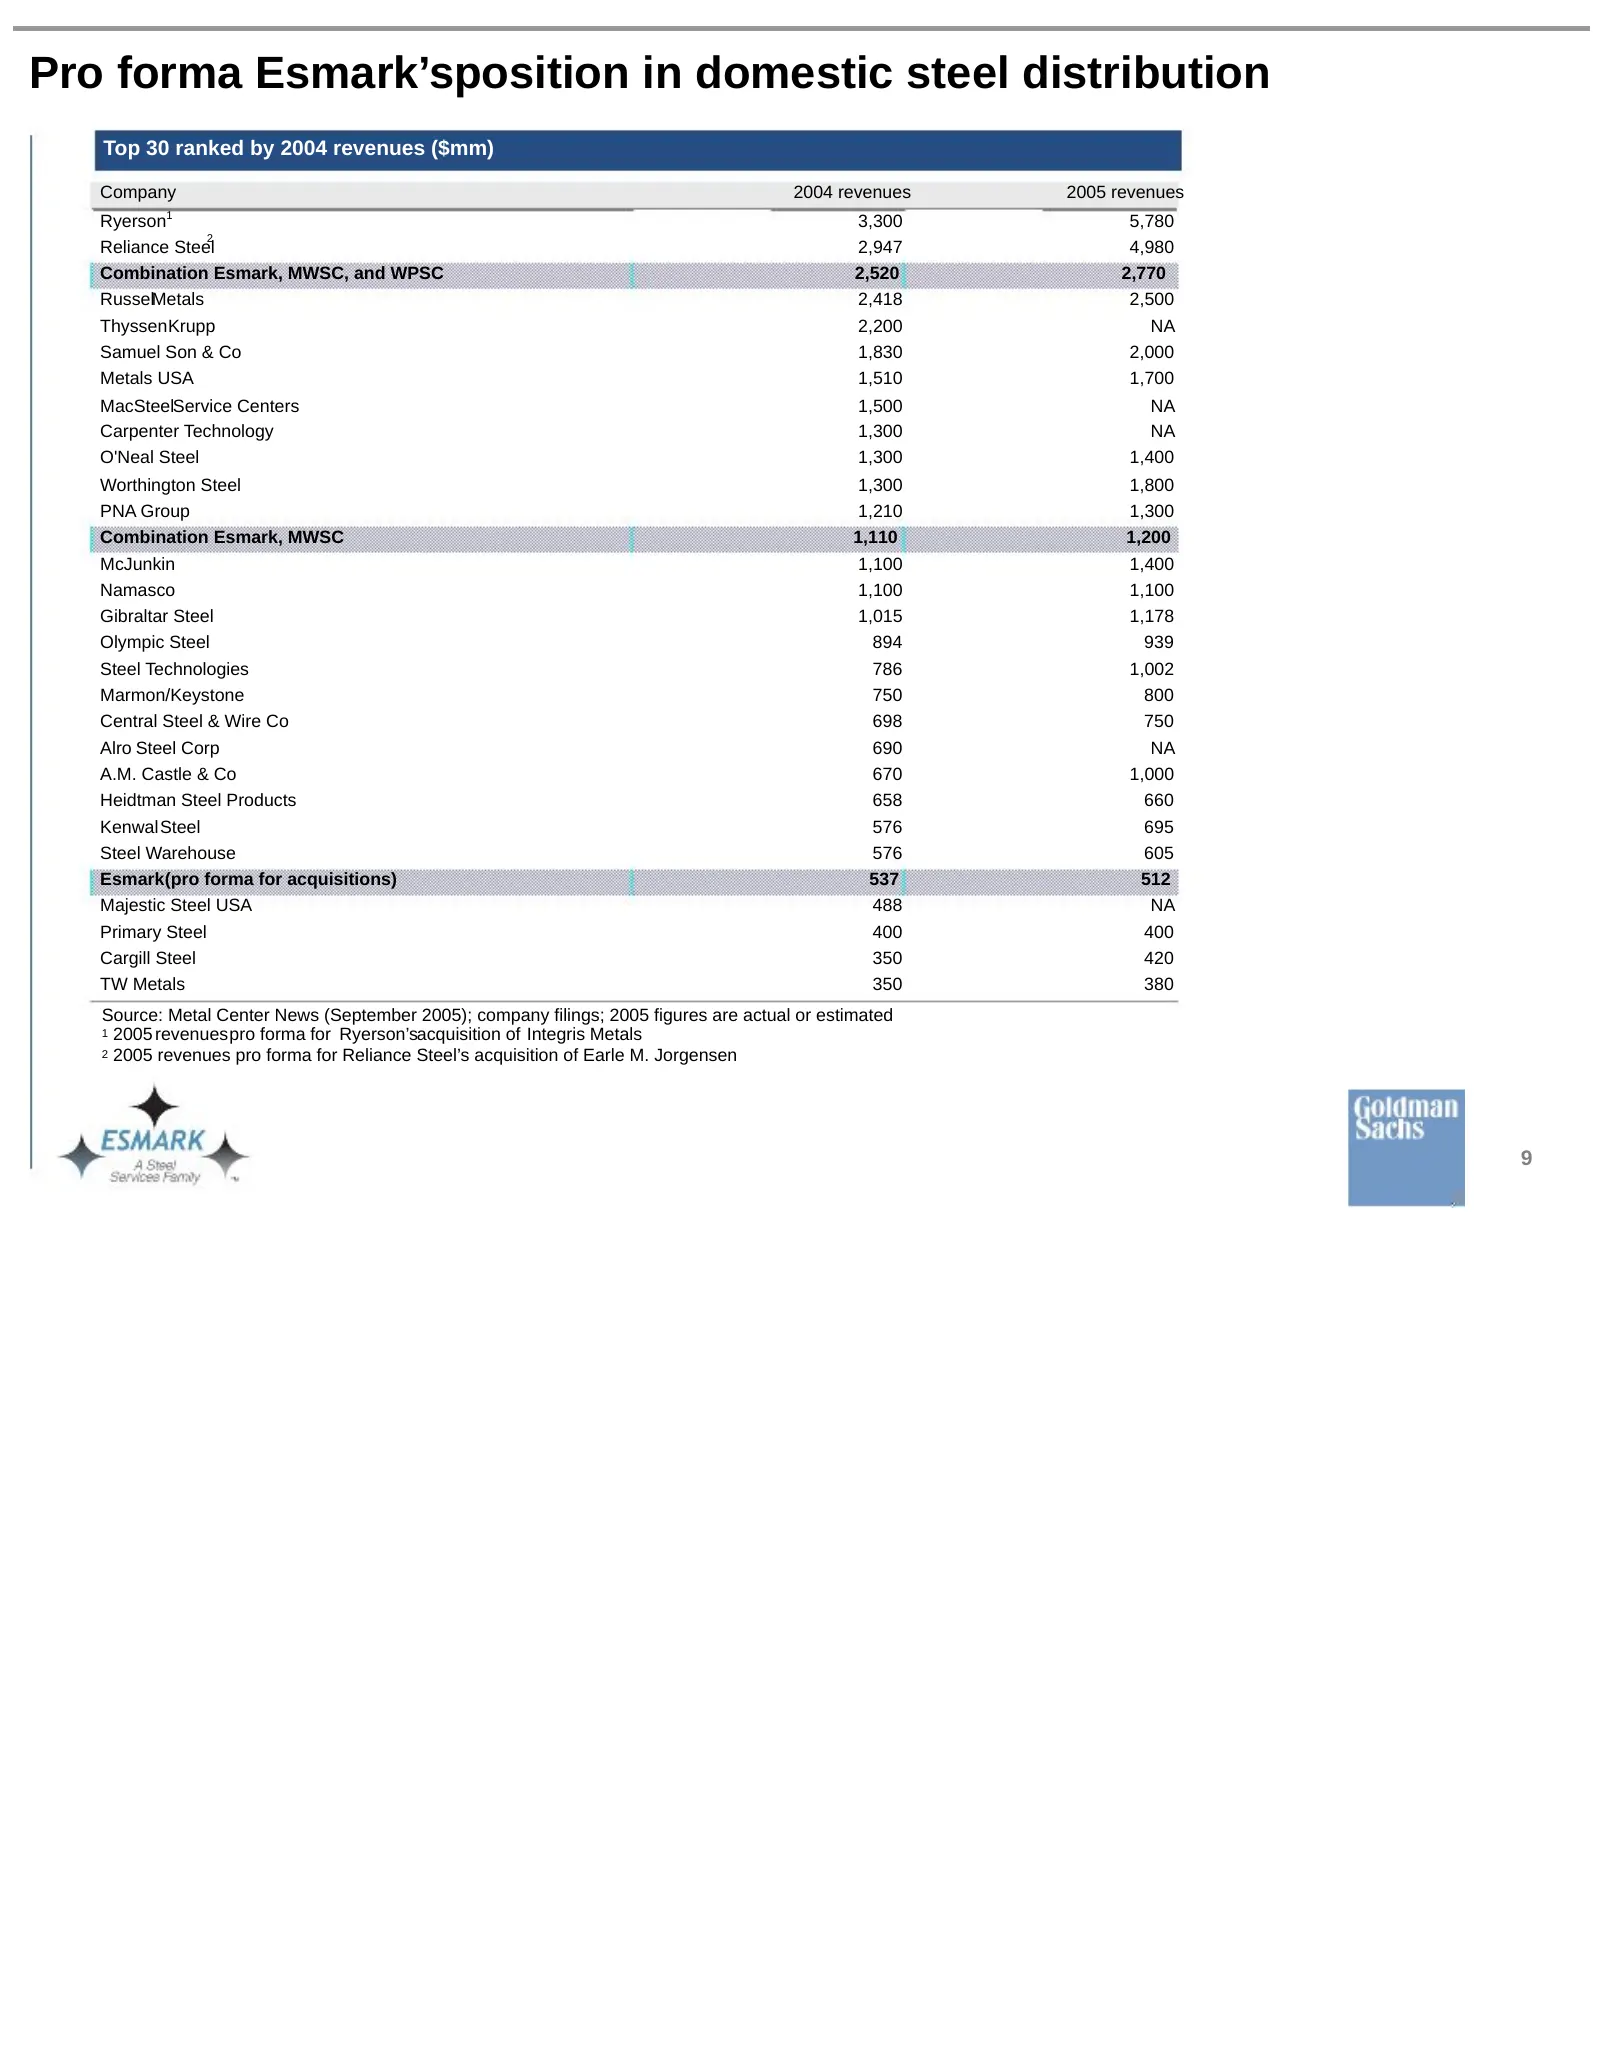
Slide 11: Pro forma Esmark's position in domestic steel distribution
Pro forma Esmark’sposition in domestic steel distribution Top 30 ranked by 2004 revenues ($mm) Company 2004 revenues 2005 revenues Ryerson1 3,300 5,780 2 Reliance Steel 2,947 4,980 Combination Esmark, MWSC, and WPSC 2,520 2,770 RusselMetals 2,418 2,500 ThyssenKrupp 2,200 NA Samuel Son & Co 1,830 2,0
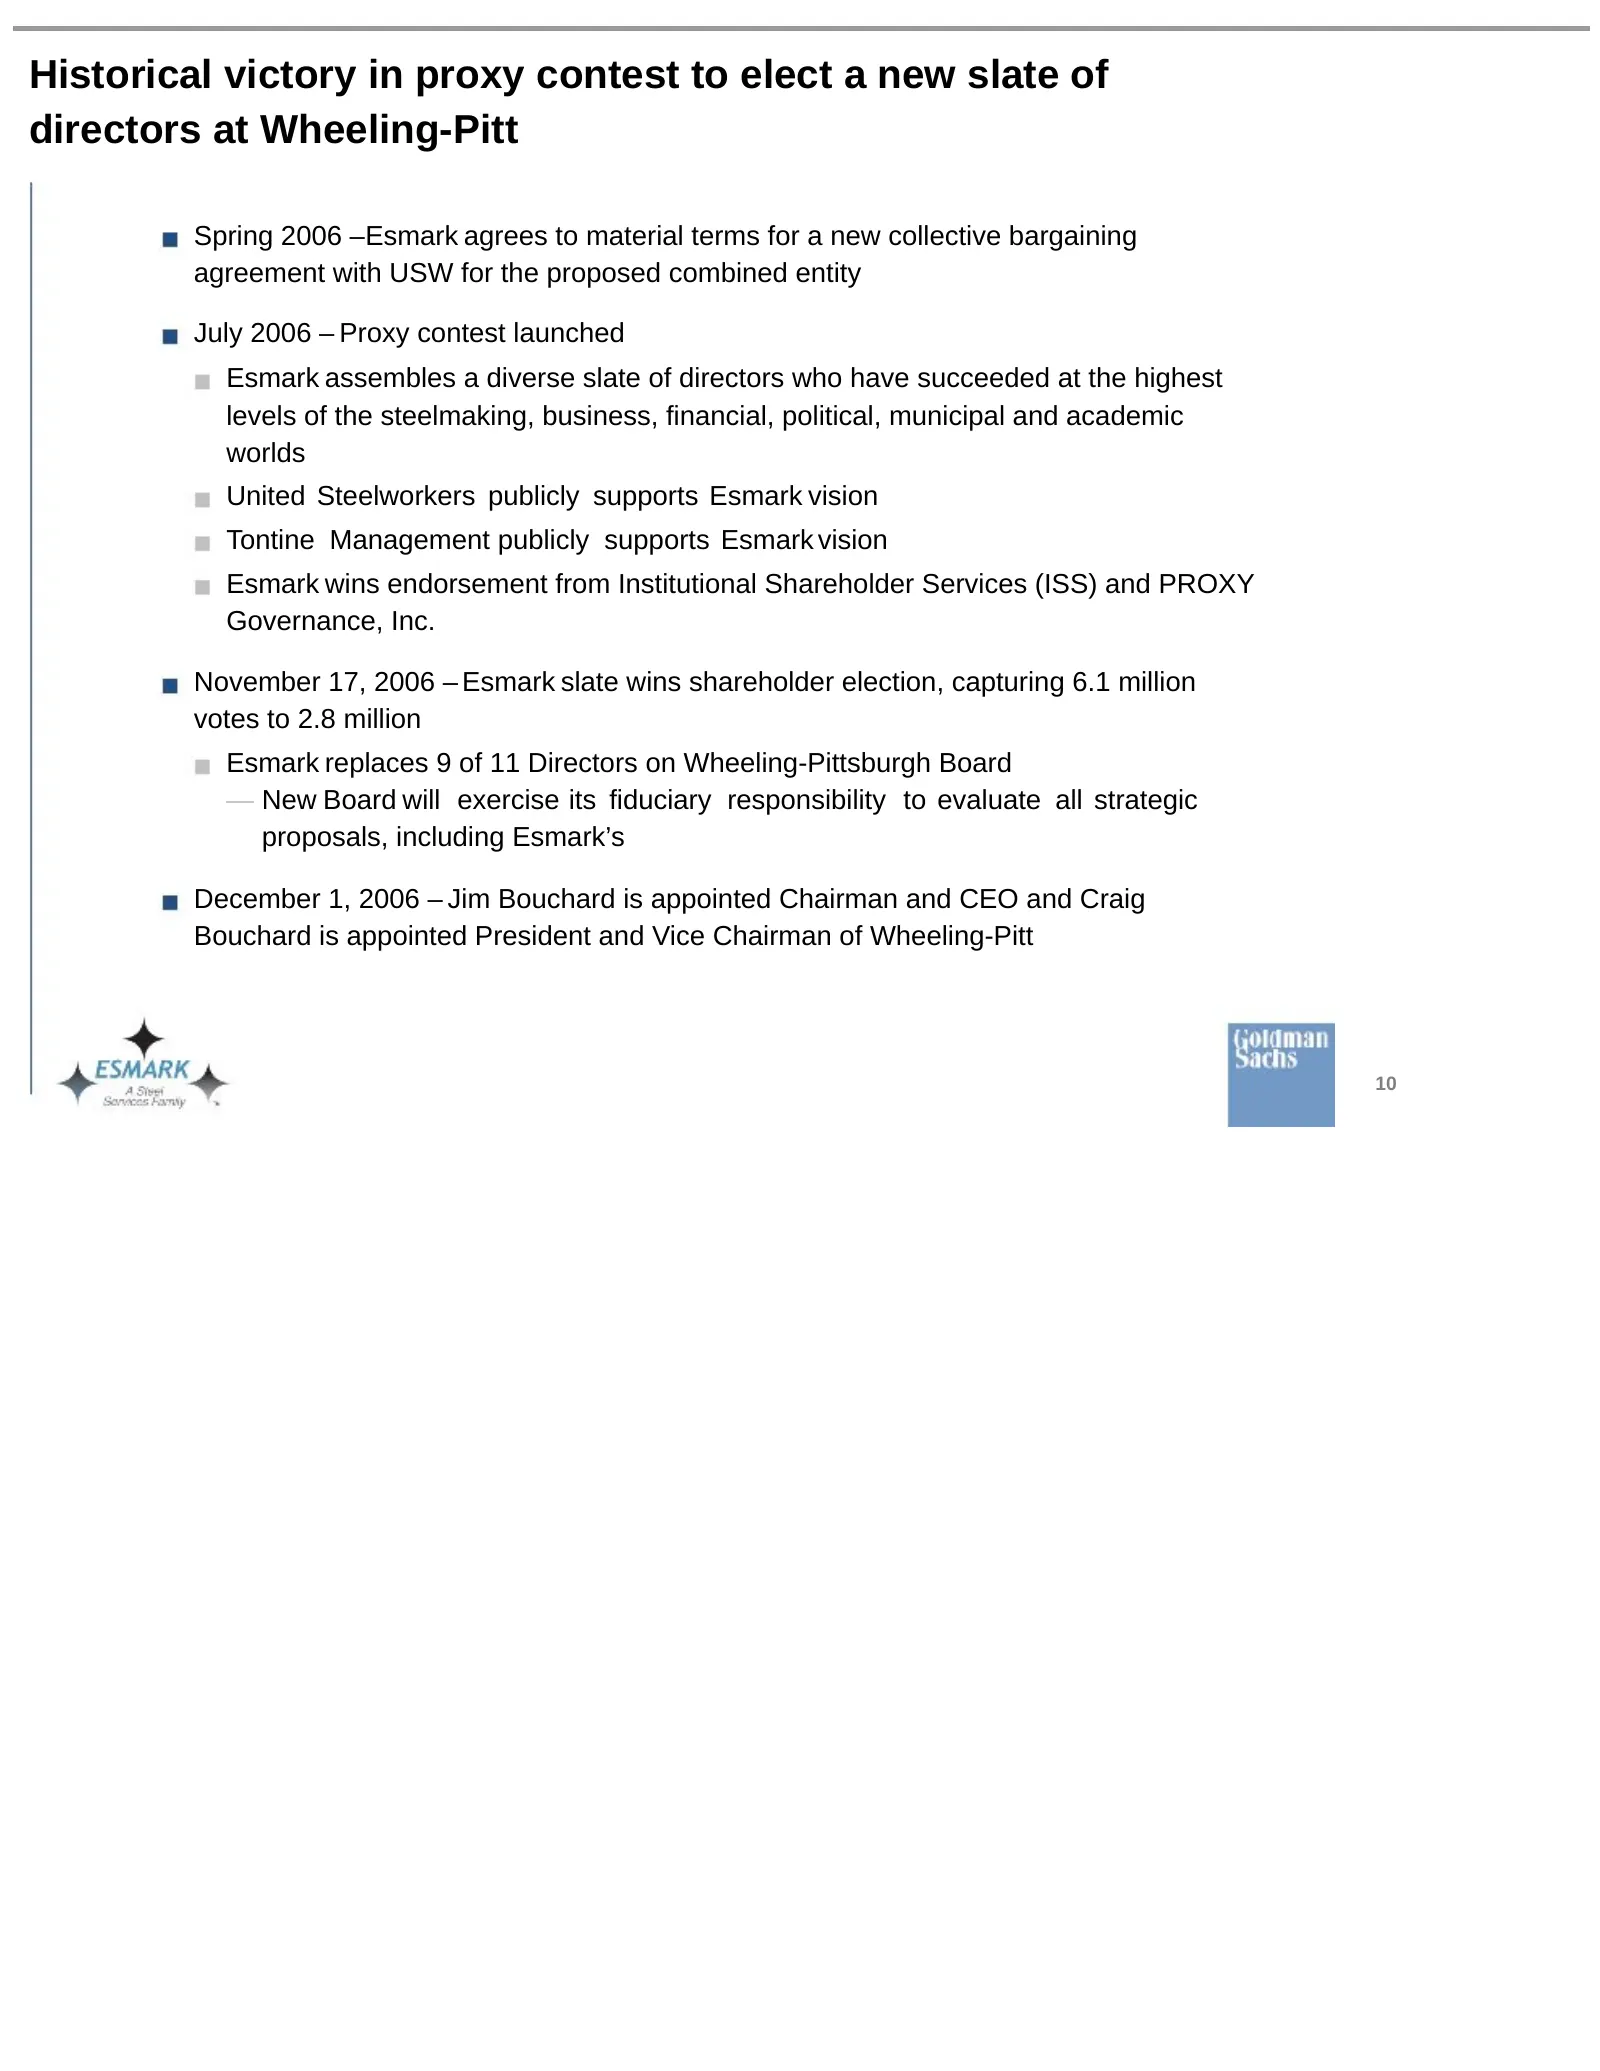
Slide 12: Historical victory in proxy contest at Wheeling-Pitt
Historical victory in proxy contest to elect a new slate of directors at Wheeling-Pitt Spring 2006 –Esmark agrees to material terms for a new collective bargaining agreement with USW for the proposed combined entity July 2006 – Proxy contest launched Esmark assembles a diverse slate of directors who
Slide 13: Where does a mill fit in the Esmark strategy?
Where does a mill fit in the Esmark strategy? Esmarkis committed to changing the steel supply chain model in North America The company will be managedby a proven team composedof some of the best technical people in the industry The proposed new company will transform Wheeling-Pitt into a converter o
Slide 14: Financial logic: high distribution multiple post WPSC
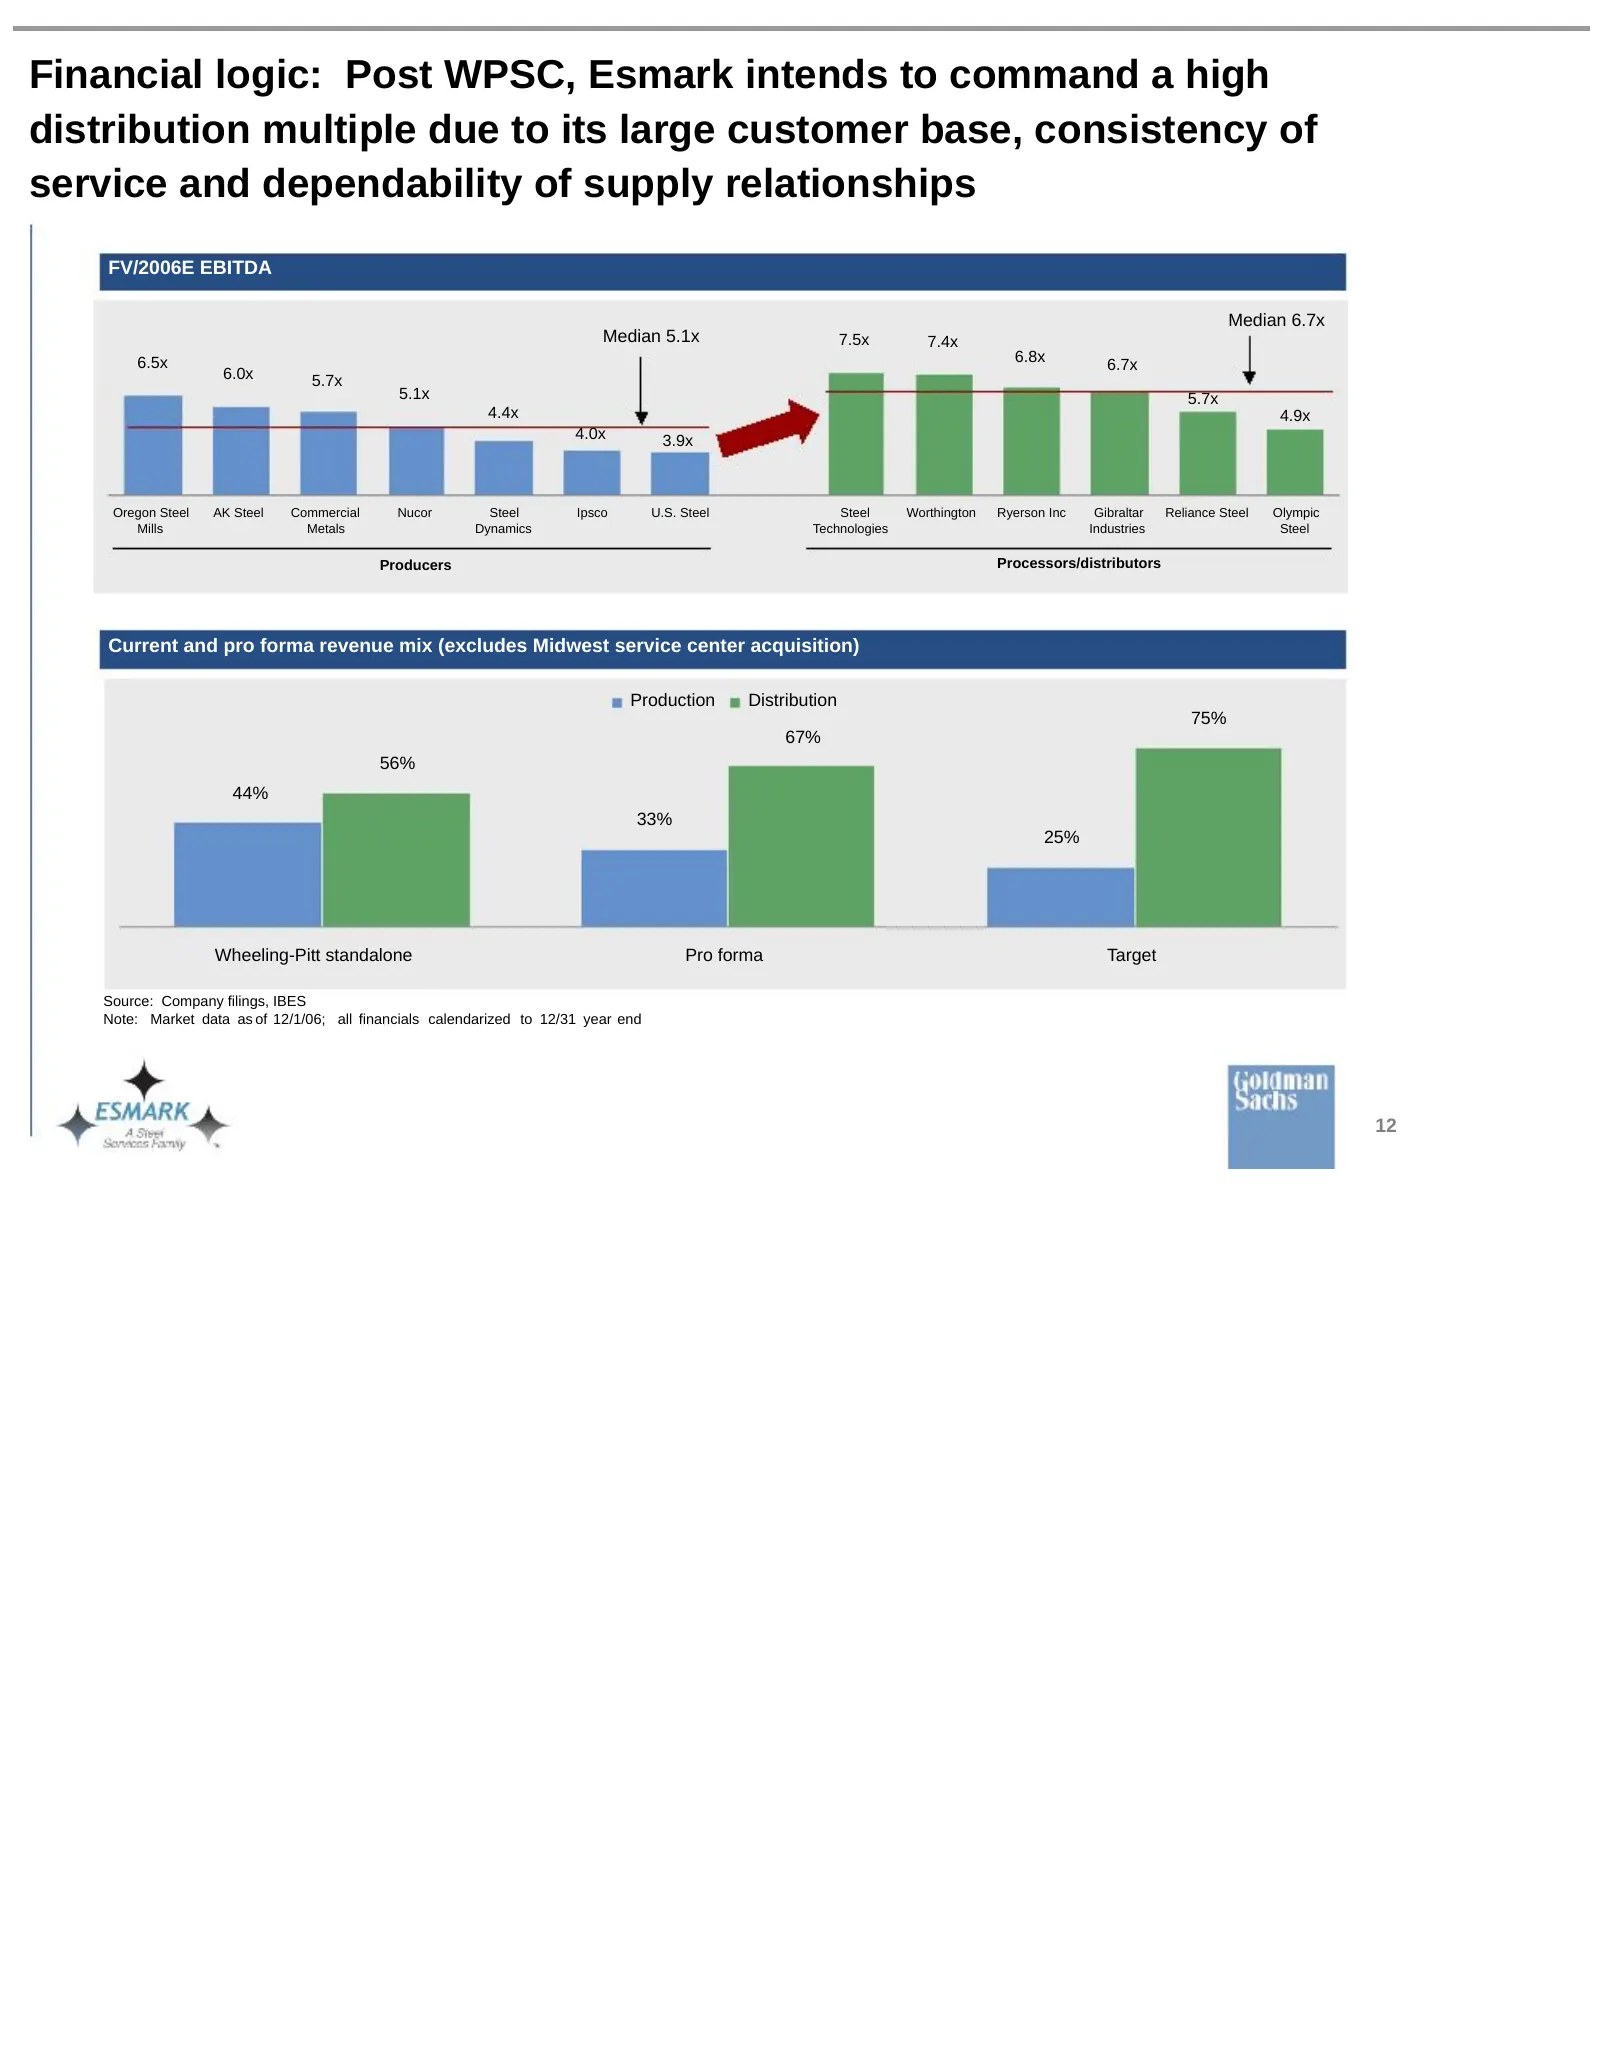
Financial logic: Post WPSC, Esmark intends to command a high distribution multiple due to its large customer base, consistency of service and dependability of supply relationships FV/2006E EBITDA Median 6.7x Median 5.1x 7.5x 7.4x 6.5x 6.8x 6.7x 6.0x 5.7x 5.1x 5.7x 4.4x 4.9x 4.0x 3.9x Oregon Steel AK
Slide 15: Strategy for Wheeling-Pitt
Strategy for Wheeling-Pitt There are three basic requirements for a small regional steel producer like Wheeling- Pitt to succeed: High capacity utilization even in down markets Low-cost producer (shut down blast furnace and import slabs) Large, diverse and loyal customer base EsmarkStrategy for Whee
Slide 16: The combination would create a leader in the U.S. steel marketplace
The combination would create a leader in the U.S. steel marketplace with operational and commercial competitive advantages Transaction merits Supply chain integration Esmark management has a proven and profitable distribution platform with significant growth opportunities ahead Current industry dyna
Slide 17: A combination with Esmark would improve Wheeling-Pitt's financial flexibility
A combination with Esmark would significantly improve Wheeling-Pitt’s financial flexibility Through the combination Esmarkwould contribute: Esmark intends to invest in and efficiently use the Hot Strip Mill with a goal of converting over 1.4 million tons of slabs per year Wheeling-Pitt has been burd
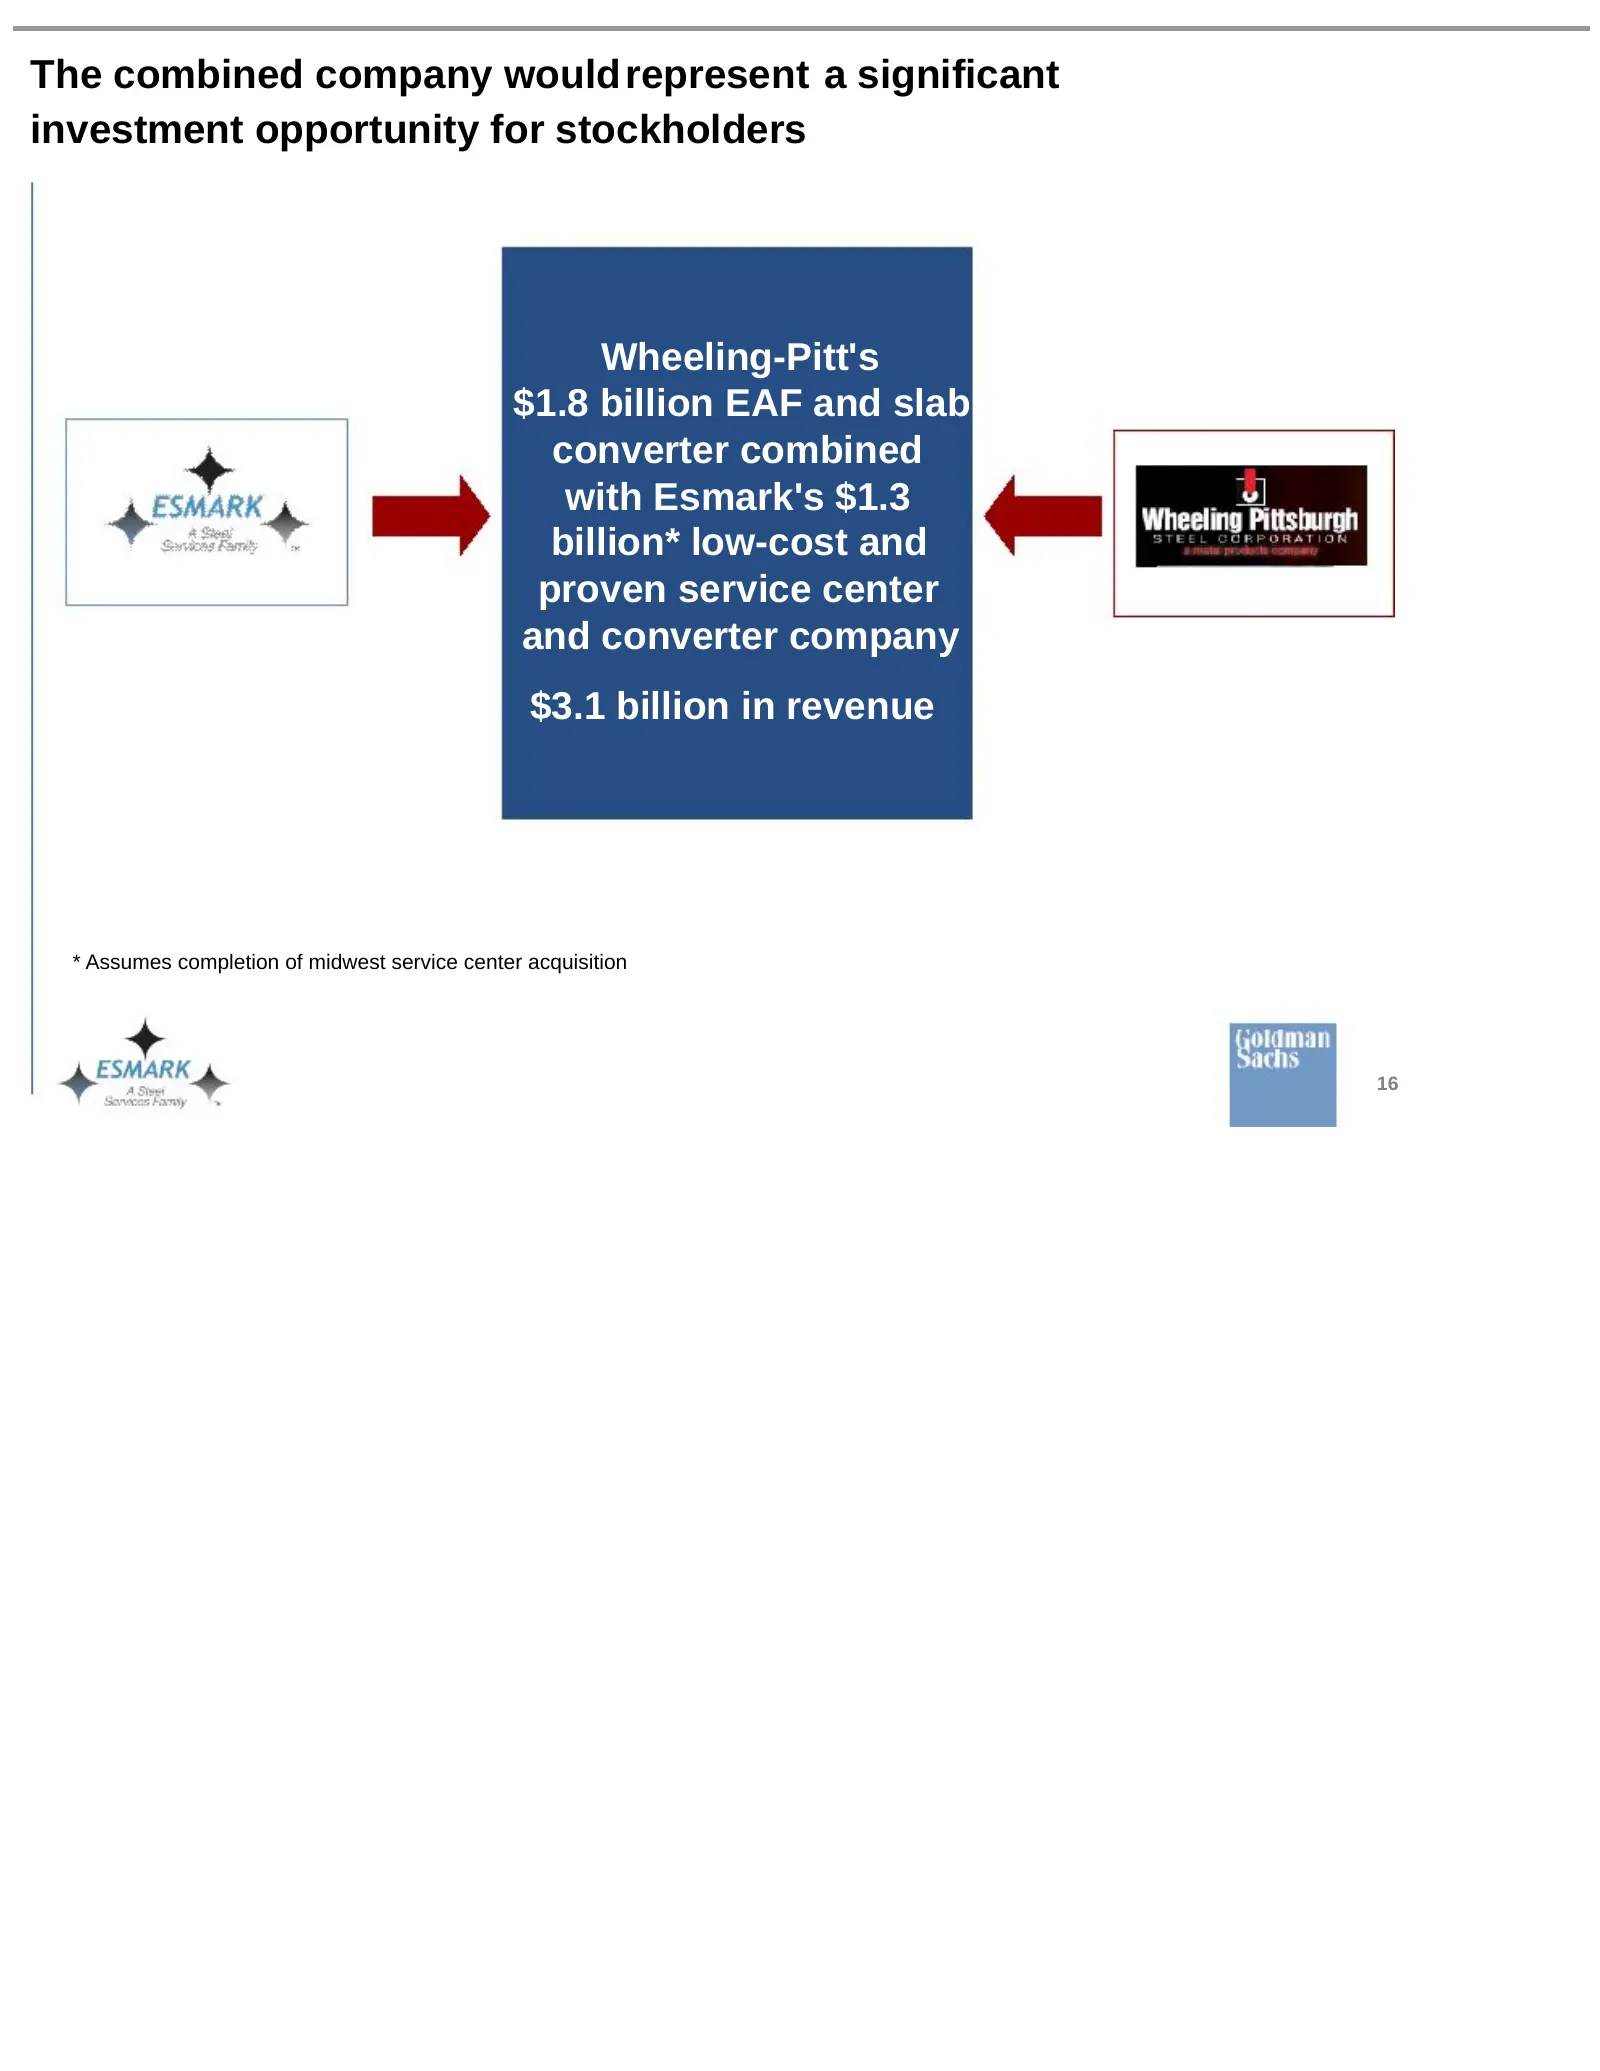
Slide 18: The combined company would represent a significant investment opportunity
The combined company would represent a significant investment opportunity for stockholders Wheeling-Pitt's $1.8 billion EAF and slab converter combined with Esmark's $1.3 billion* low-cost and proven service center and converter company $3.1 billion in revenue * Assumes completion of midwest service
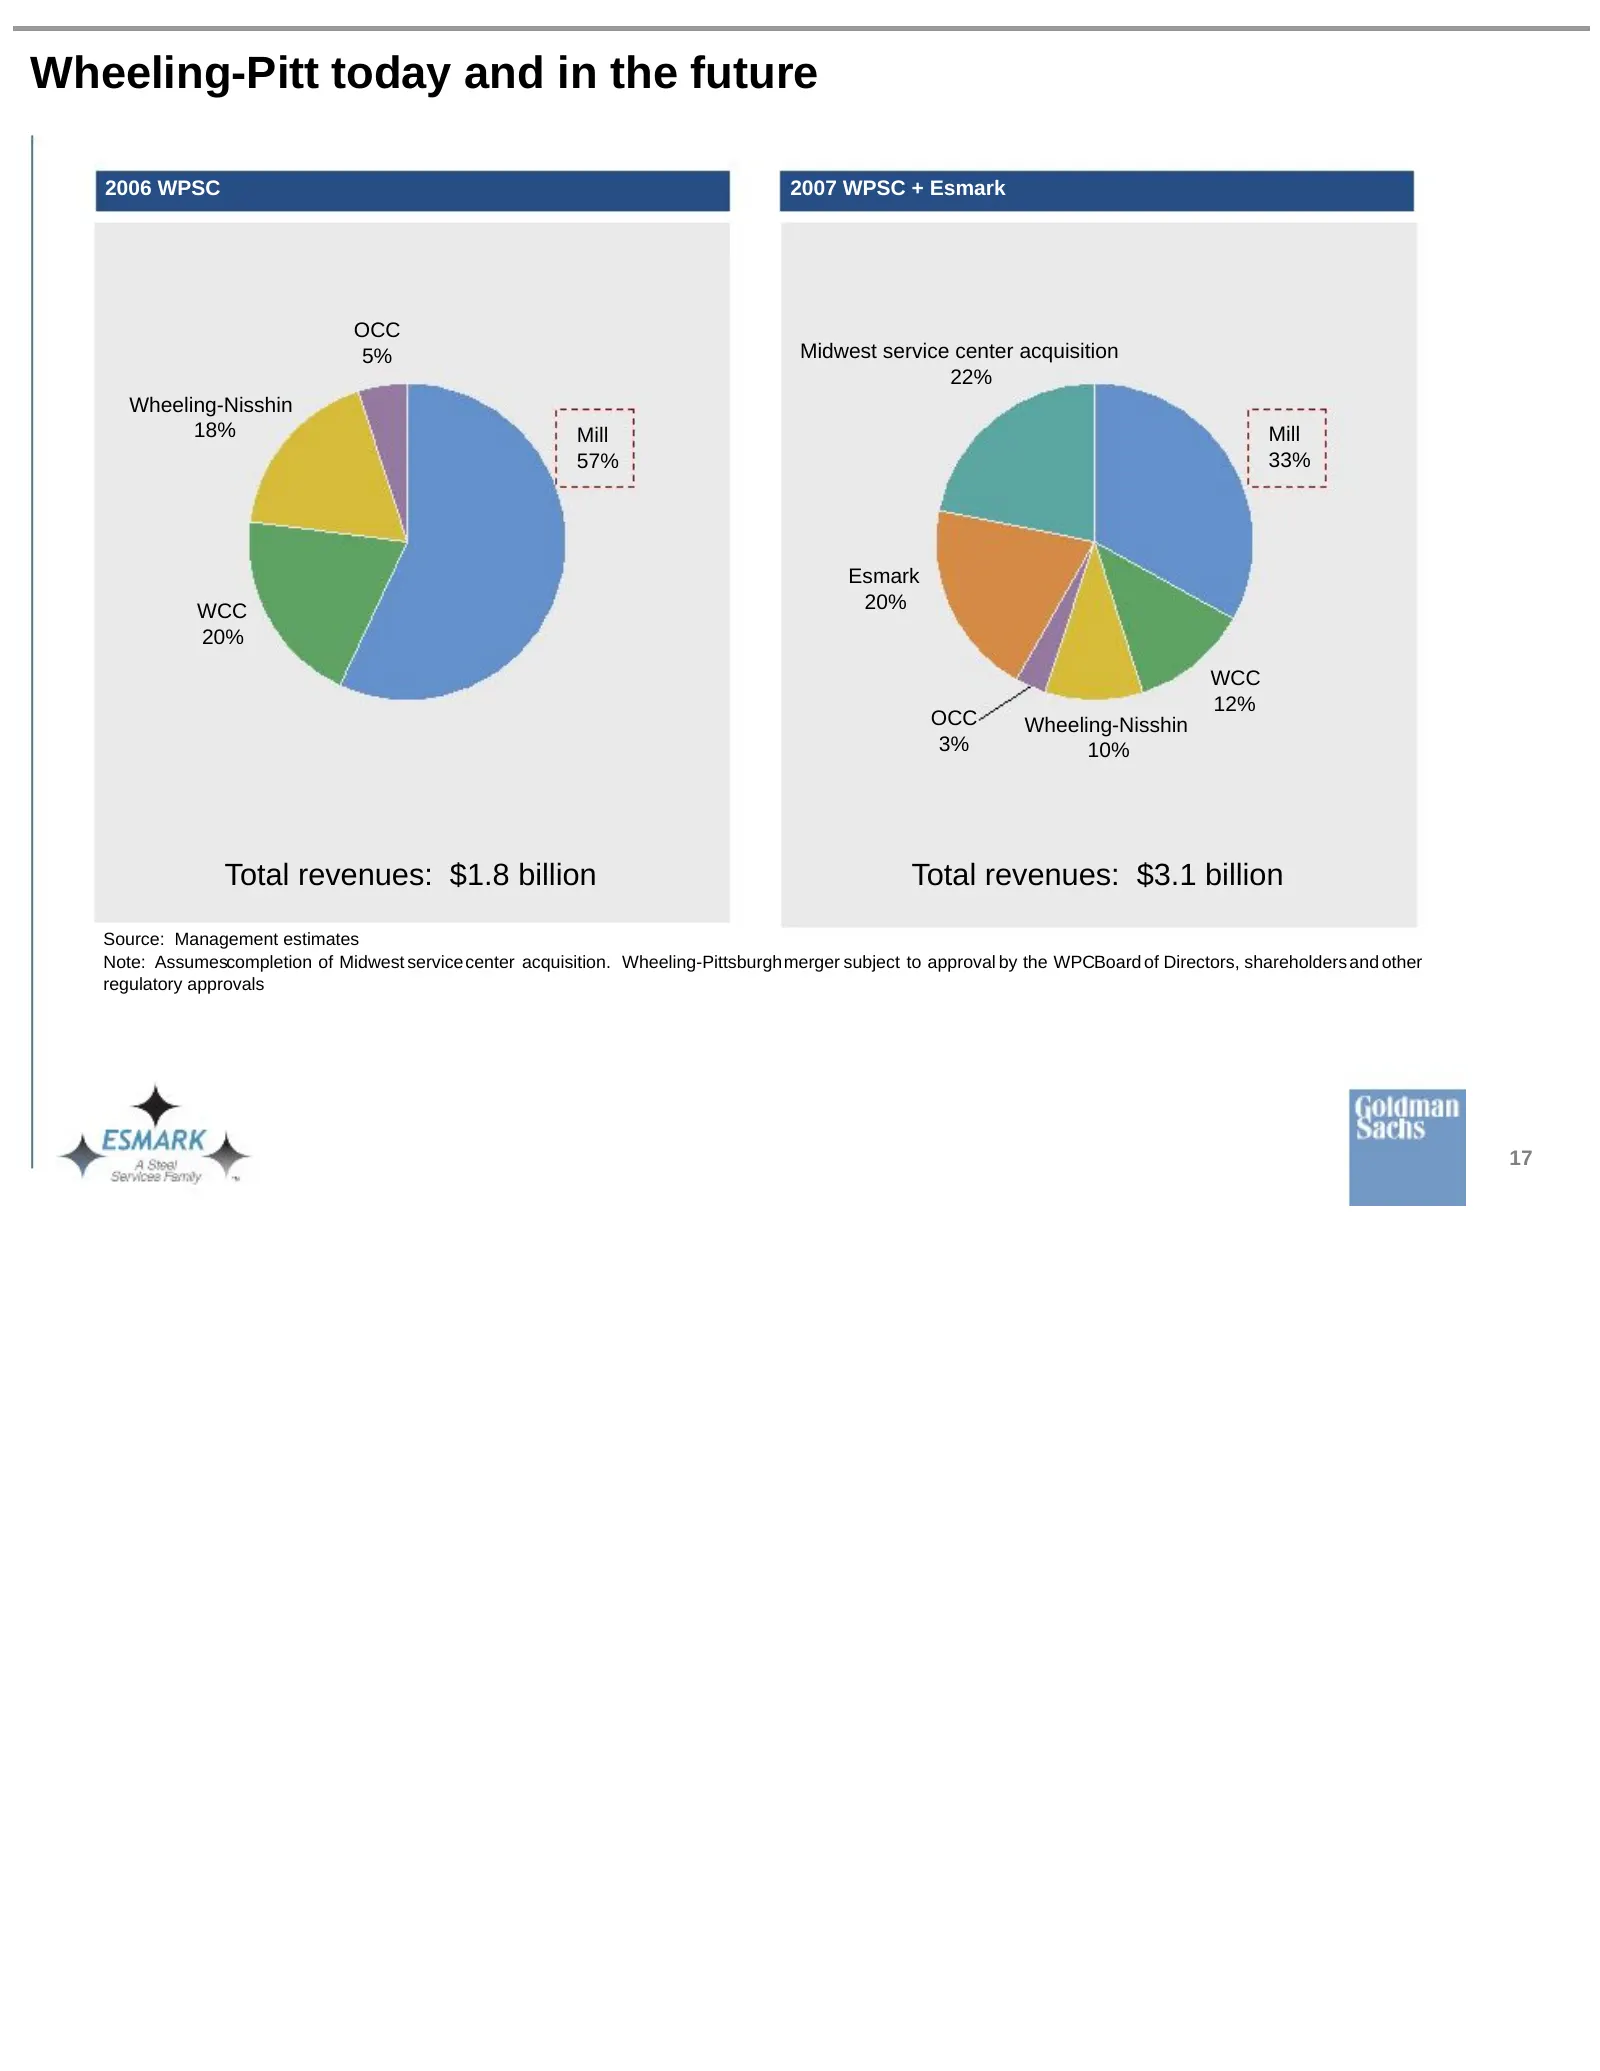
Slide 19: Wheeling-Pitt today and in the future
Wheeling-Pitt today and in the future 2006 WPSC 2007 WPSC + Esmark OCC 5% Midwest service center acquisition 22% Wheeling-Nisshin 18% Mill Mill 57% 33% Esmark WCC 20% 20% WCC 12% OCC Wheeling-Nisshin 3% 10% Total revenues: $1.8 billion Total revenues: $3.1 billion Source: Management estimates Note:
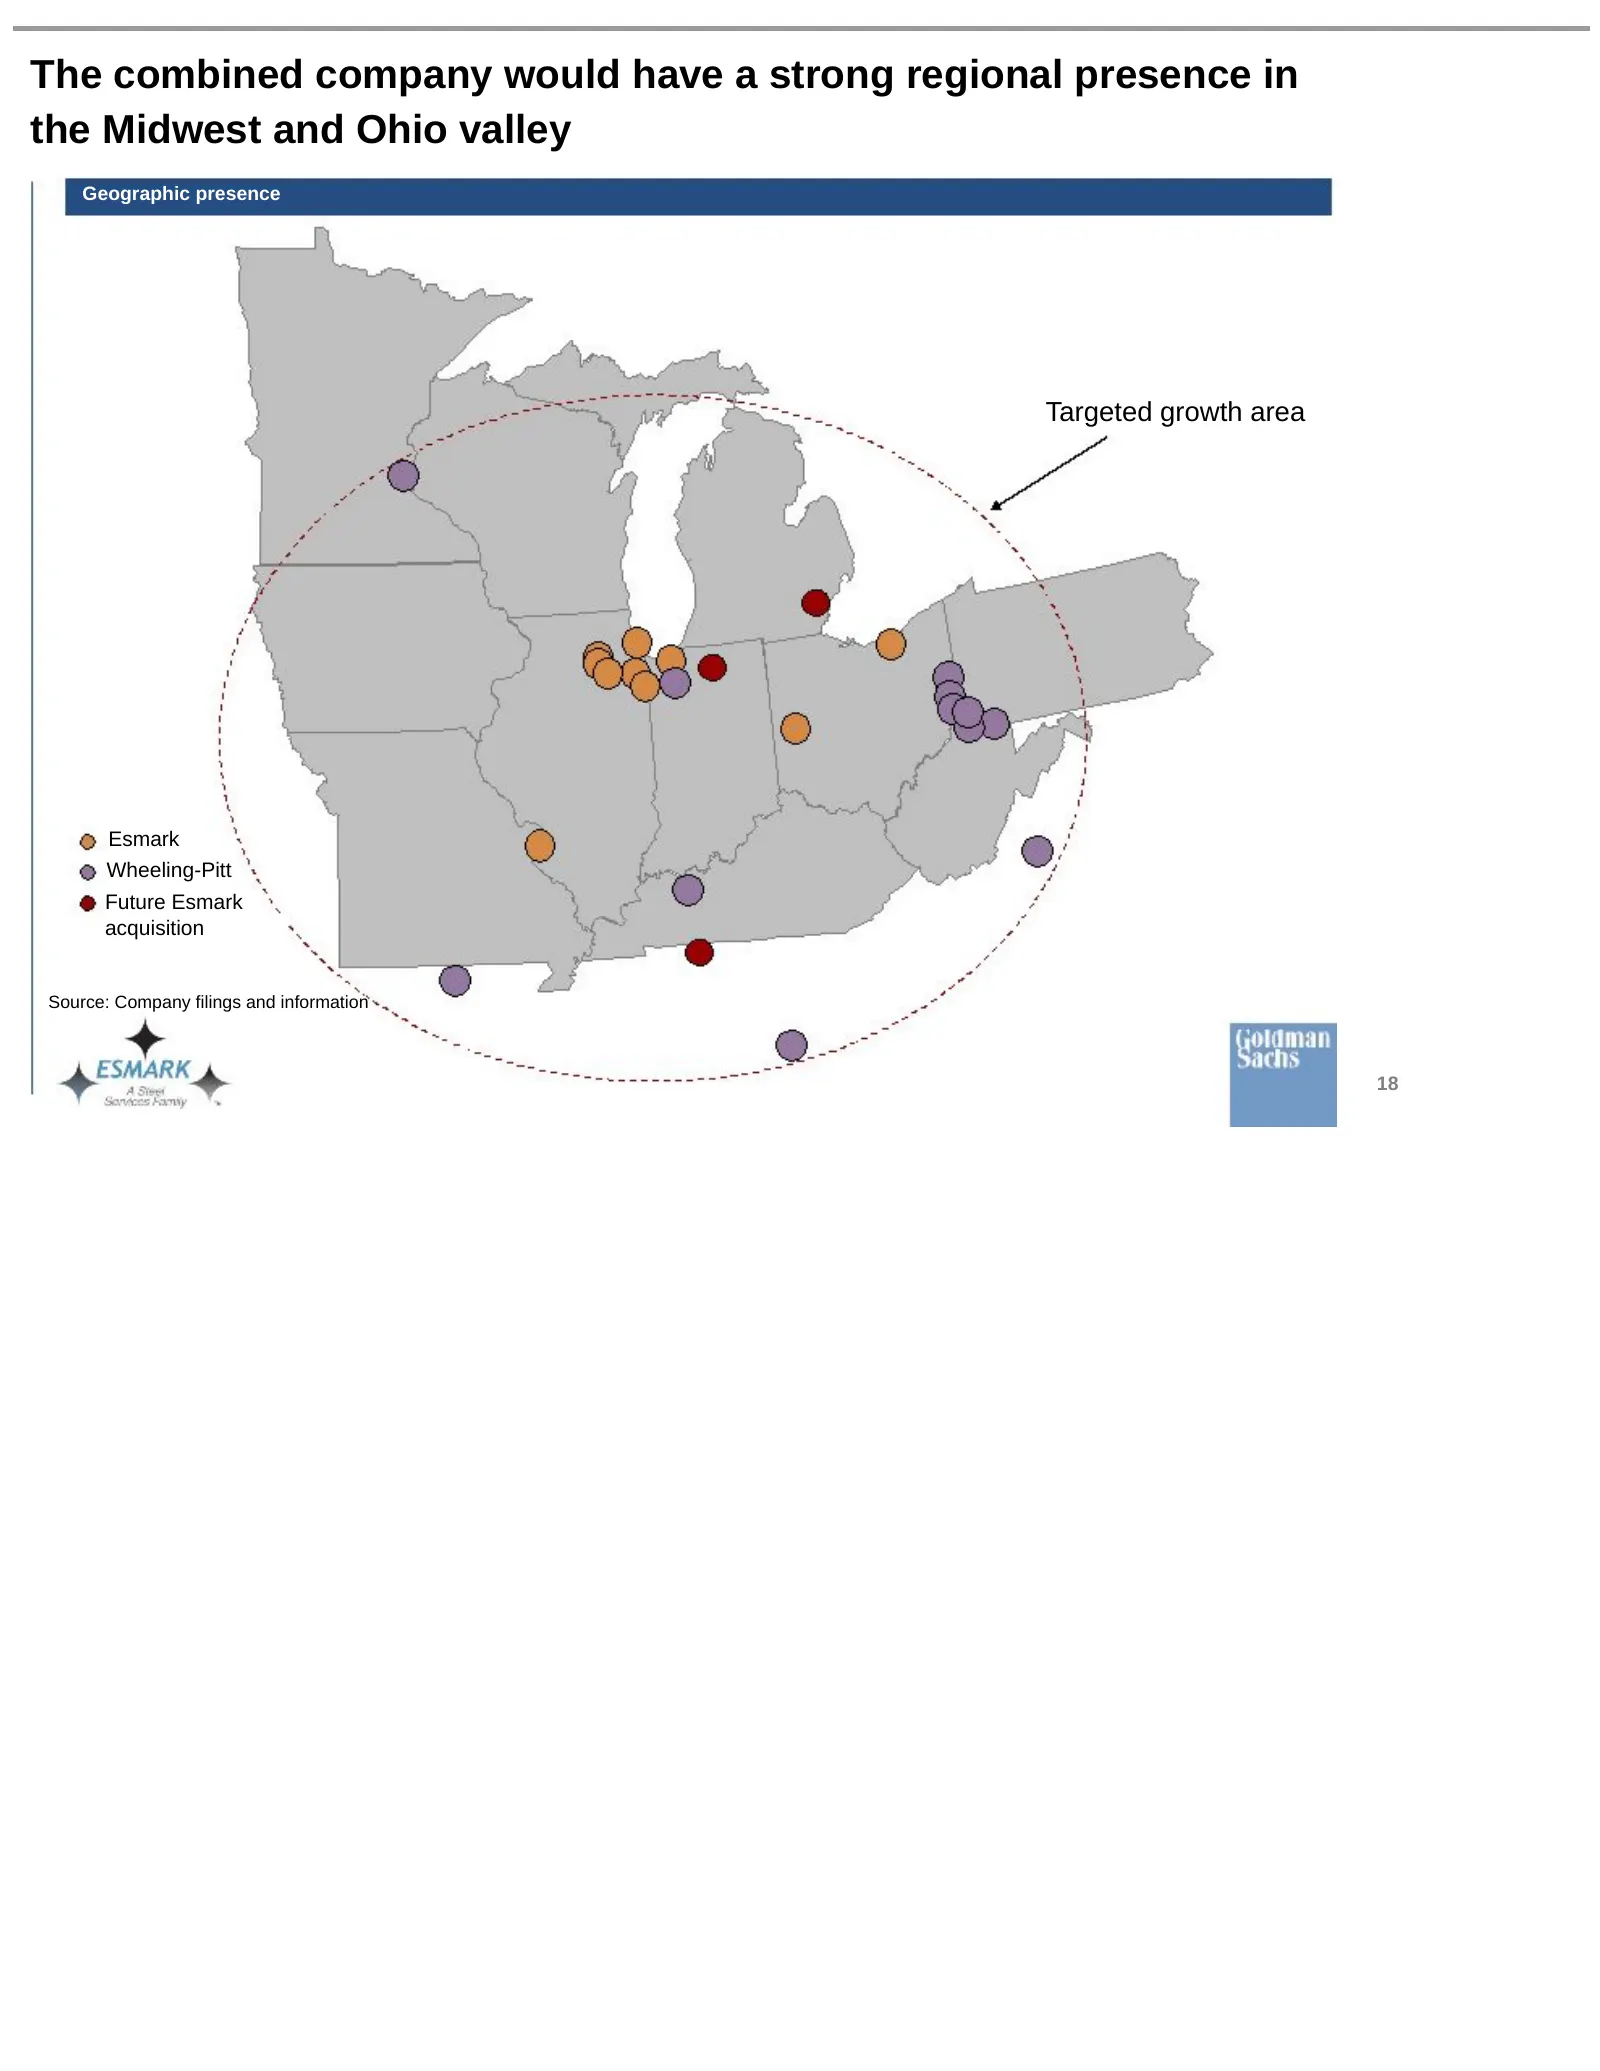
Slide 20: The combined company would have a strong regional presence
The combined company would have a strong regional presence in the Midwest and Ohio valley Geographic presence Targeted growth area Esmark Wheeling-Pitt Future Esmark acquisition Source: Company filings and information 18
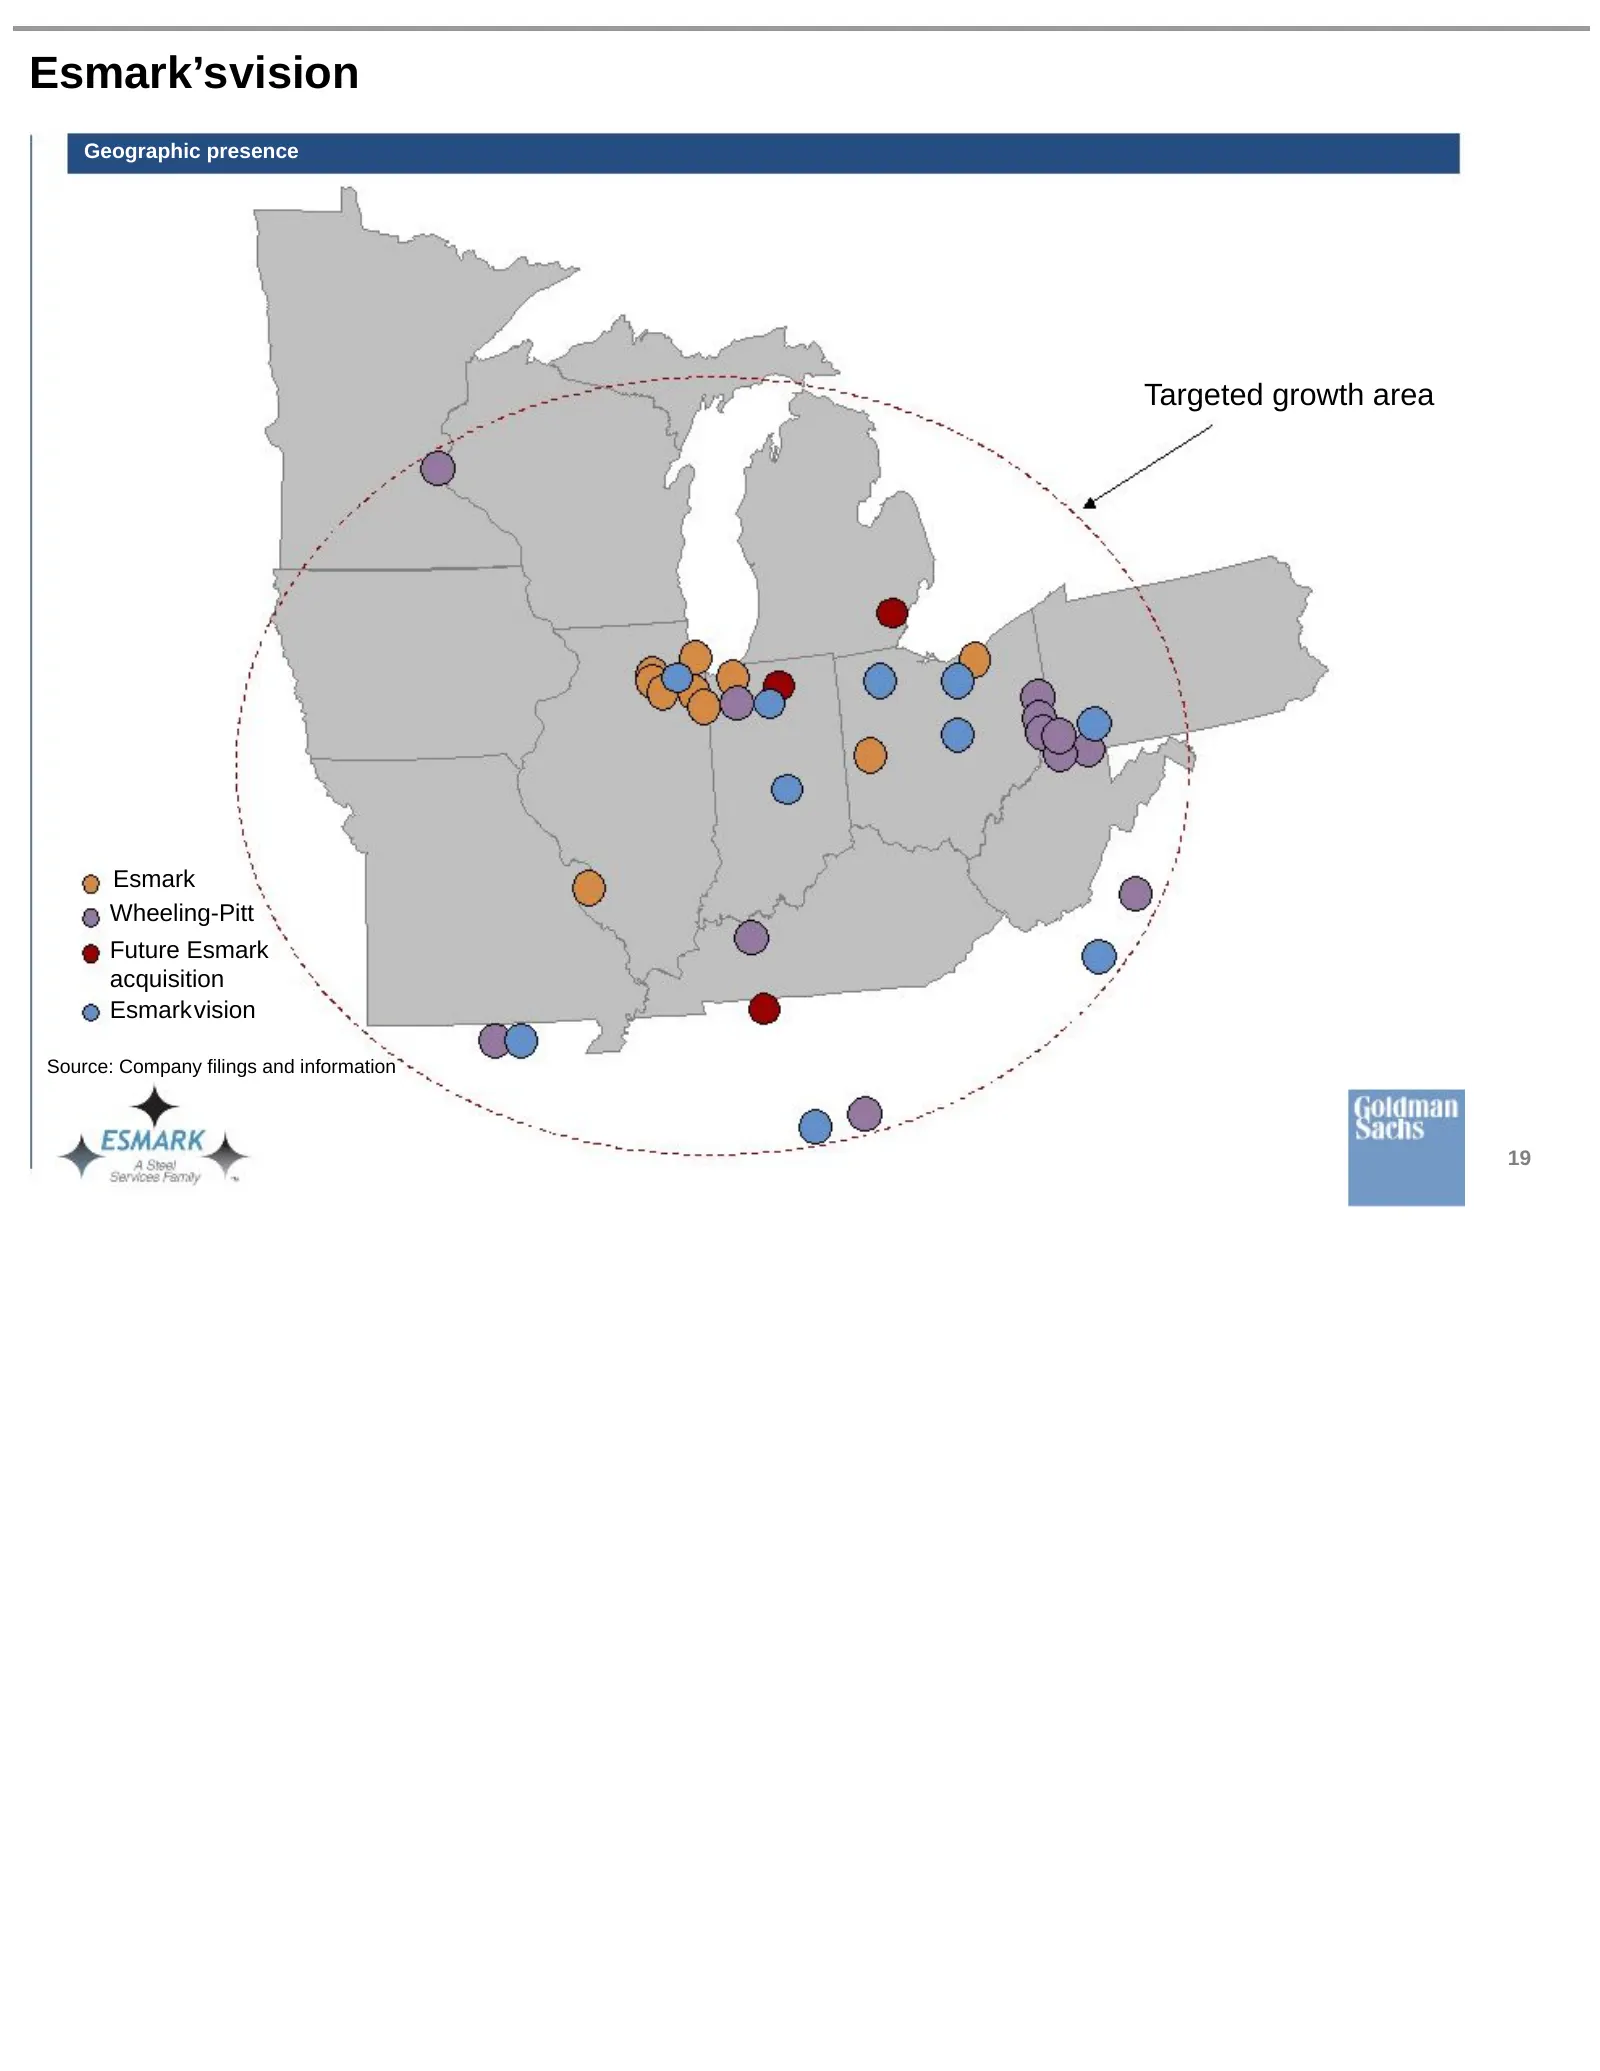
Slide 21: Esmark's vision
Esmark’svision Geographic presence Targeted growth area Esmark Wheeling-Pitt Future Esmark acquisition Esmarkvision Source: Company filings and information 19
Slide 22: Conclusion; Questions / Answers
Conclusion Questions / Answers 20
Source: SEC EDGAR · 425 filed Dec 7, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)40 slides · Nov 7, 2006
 Proxy Contest (November 2006)44 slides · Nov 6, 2006
 Proxy Contest (September 2006)21 slides · Sep 29, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006
 KeyBanc Conference 200647 slides · Sep 13, 2006