Wheeling Pittsburgh — Proxy Contest (November 2006)
40 slides from Wheeling Pittsburgh's proxy contest presentation, Nov 7, 2006
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 Filed by the Registrant ¨ Filed by a Party other than the Registrant x Check the appropriate box: ¨ Preliminary Proxy Statement ¨ Conf
Slide 2: Form, Schedule or Registration Statement No.
(2) Form, Schedule or Registration Statement No.: (3) Filing Party: (4) Date Filed:
Slide 3: Esmark Presentation, November 2006
NOVEMBER 2006 + ESMARK A Steel Services Family ™ Presentation
Slide 4: Forward-looking statements
This presentation contains forward-looking statements. These forward-looking statements are based on current expectations and assumptions that are subject to risks and uncertainties that could cause actual results to differ materially. These risks and uncertainties include the ability to successfull
Slide 5: Agenda
Agenda Page Executive summary and director slate 2 Wheeling-Pitt has overpromised and underperformed 13 Esmark’s Strategic vision and operating plan 21 Conclusion 33 2
Slide 6: Existing Board and management have failed to address the Company's problems
Wheeling-Pitt’s existing Board of Directors and senior management have failed to address the Company’s problems Despite operating in one of the strongest steel environments in decades, Wheeling-Pitt’s strategy, led by Jim Bradley, has resulted in one of the highest cost structures in the industry an
Slide 7: The USWA opposes Wheeling-Pitt's merger with CSN
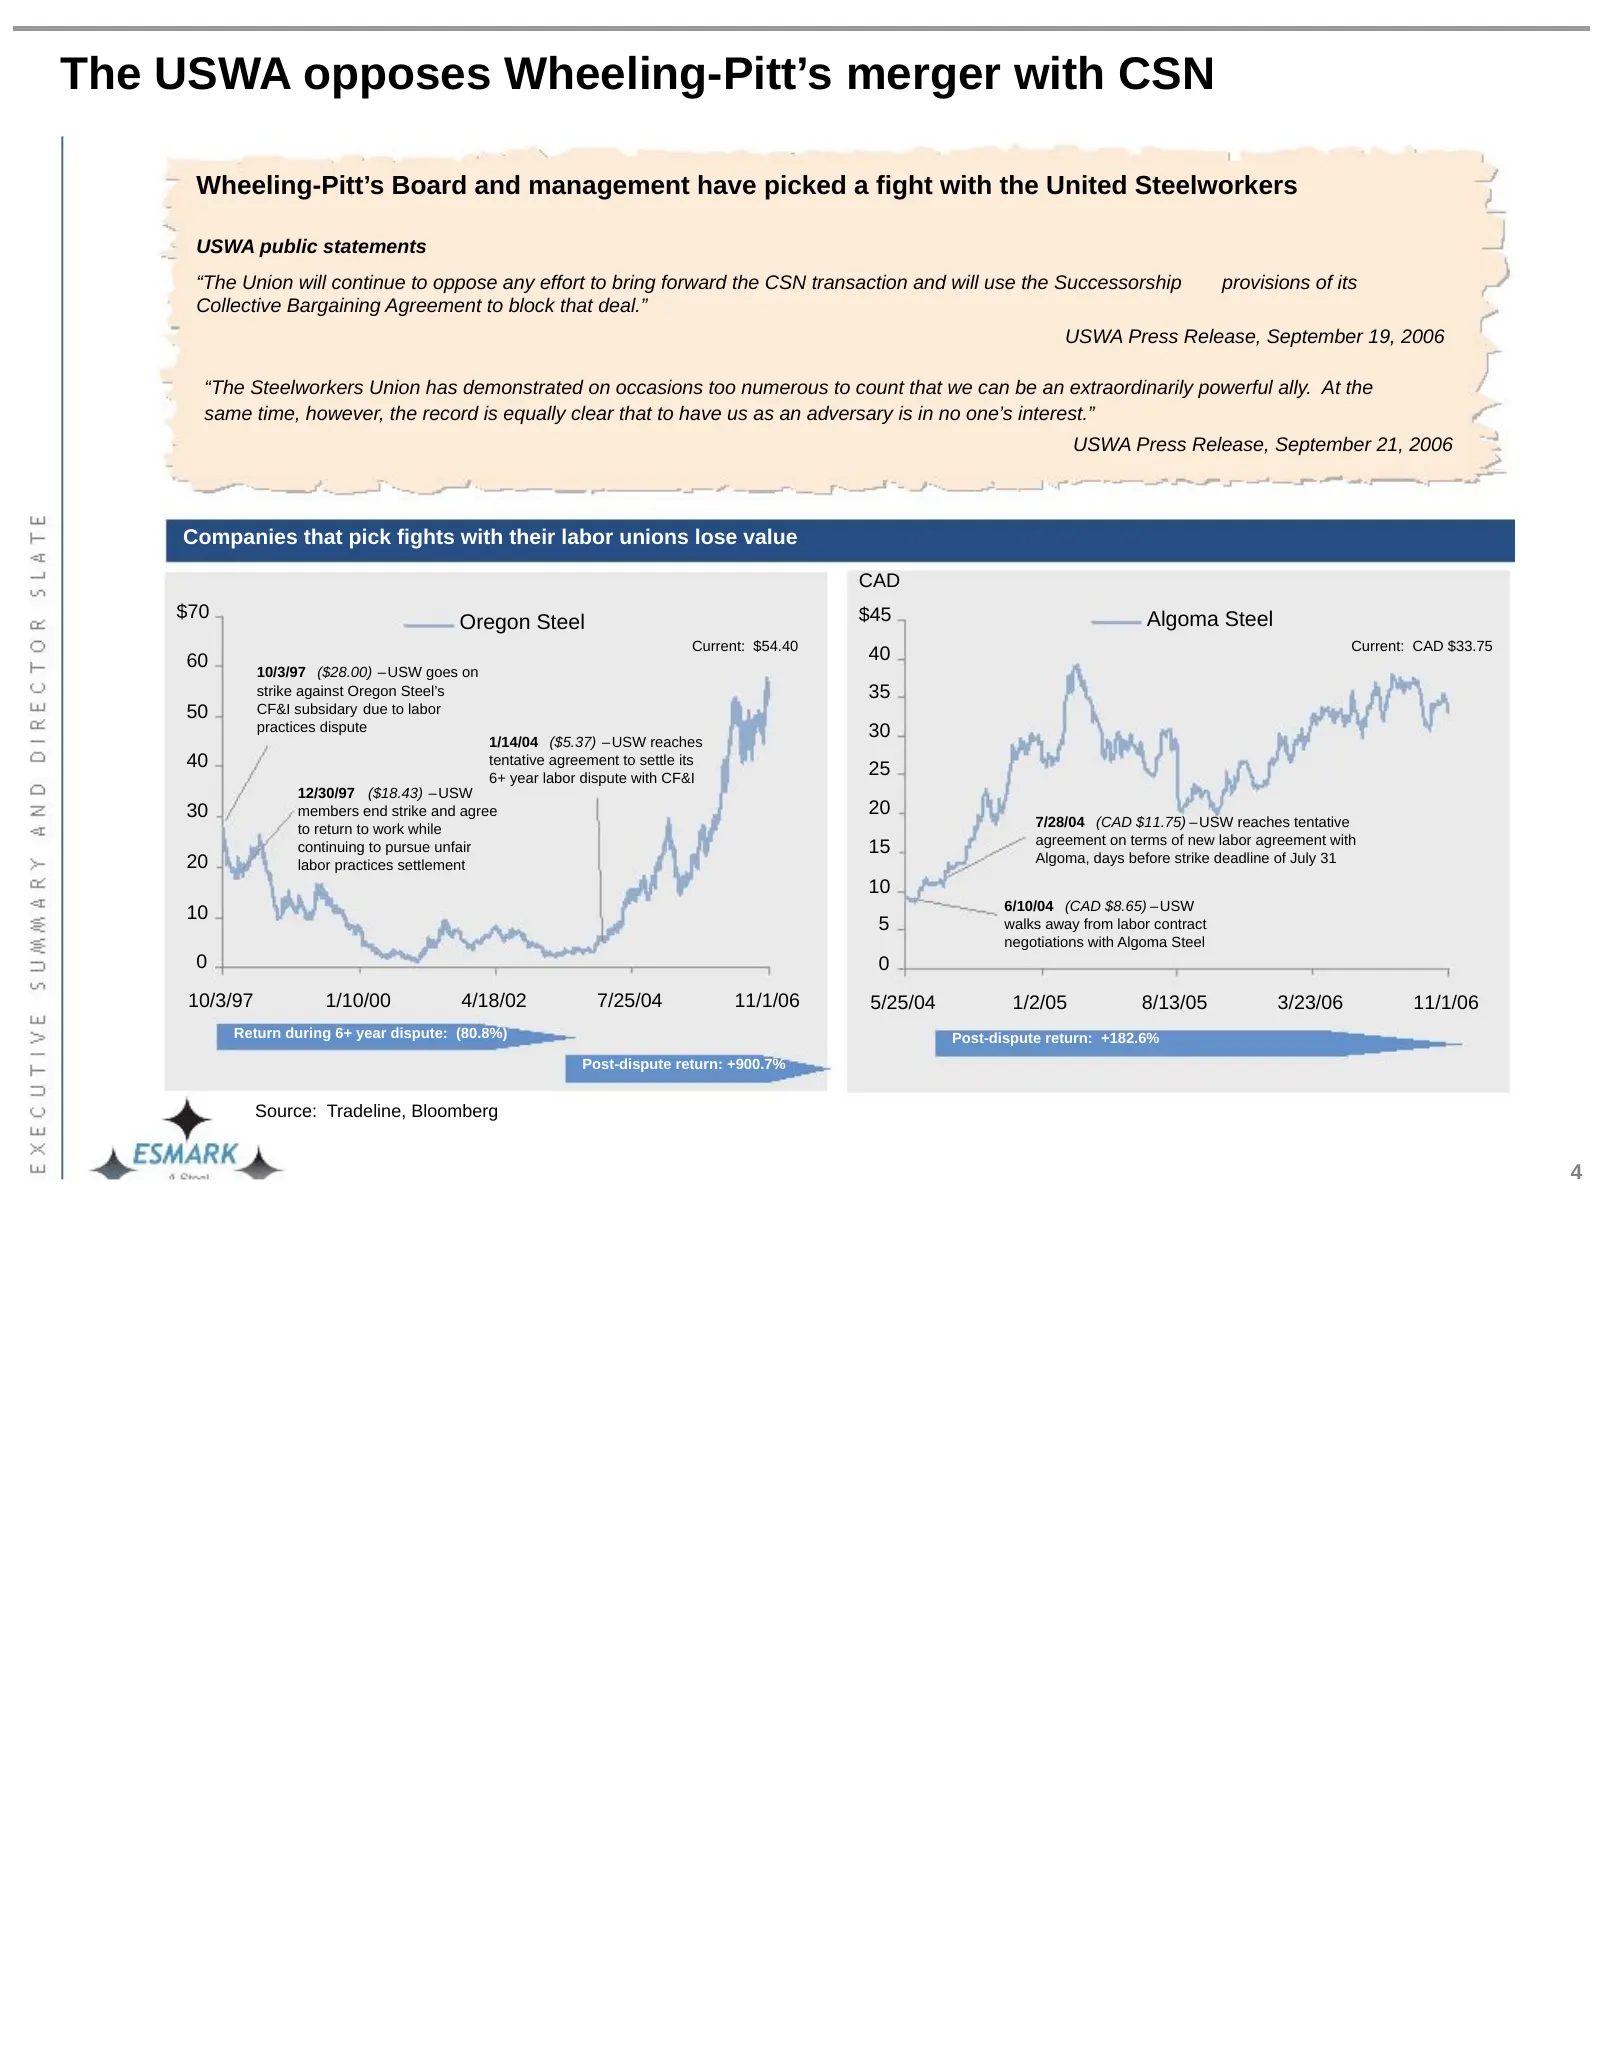
The USWA opposes Wheeling-Pitt’s merger with CSN Wheeling-Pitt’s Board and management have picked a fight with the United Steelworkers USWA public statements “The Union will continue to oppose any effort to bring forward the CSN transaction and will use the Successorship provisions of its Collective
Slide 8: Wheeling-Pitt's Board slate is a temporary Board
Wheeling-Pitt’s Board slate is a temporary Board Since the existing Board has approved the CSN merger, they are a temporary Board If the CSN merger is consummated, the Wheeling-Pitt Board will change by the terms of the agreement Who are the Directors? — Jim Bradley as Chairman — 3 CSN Directors — 2
Slide 9: Esmark has proposed a new slate of directors
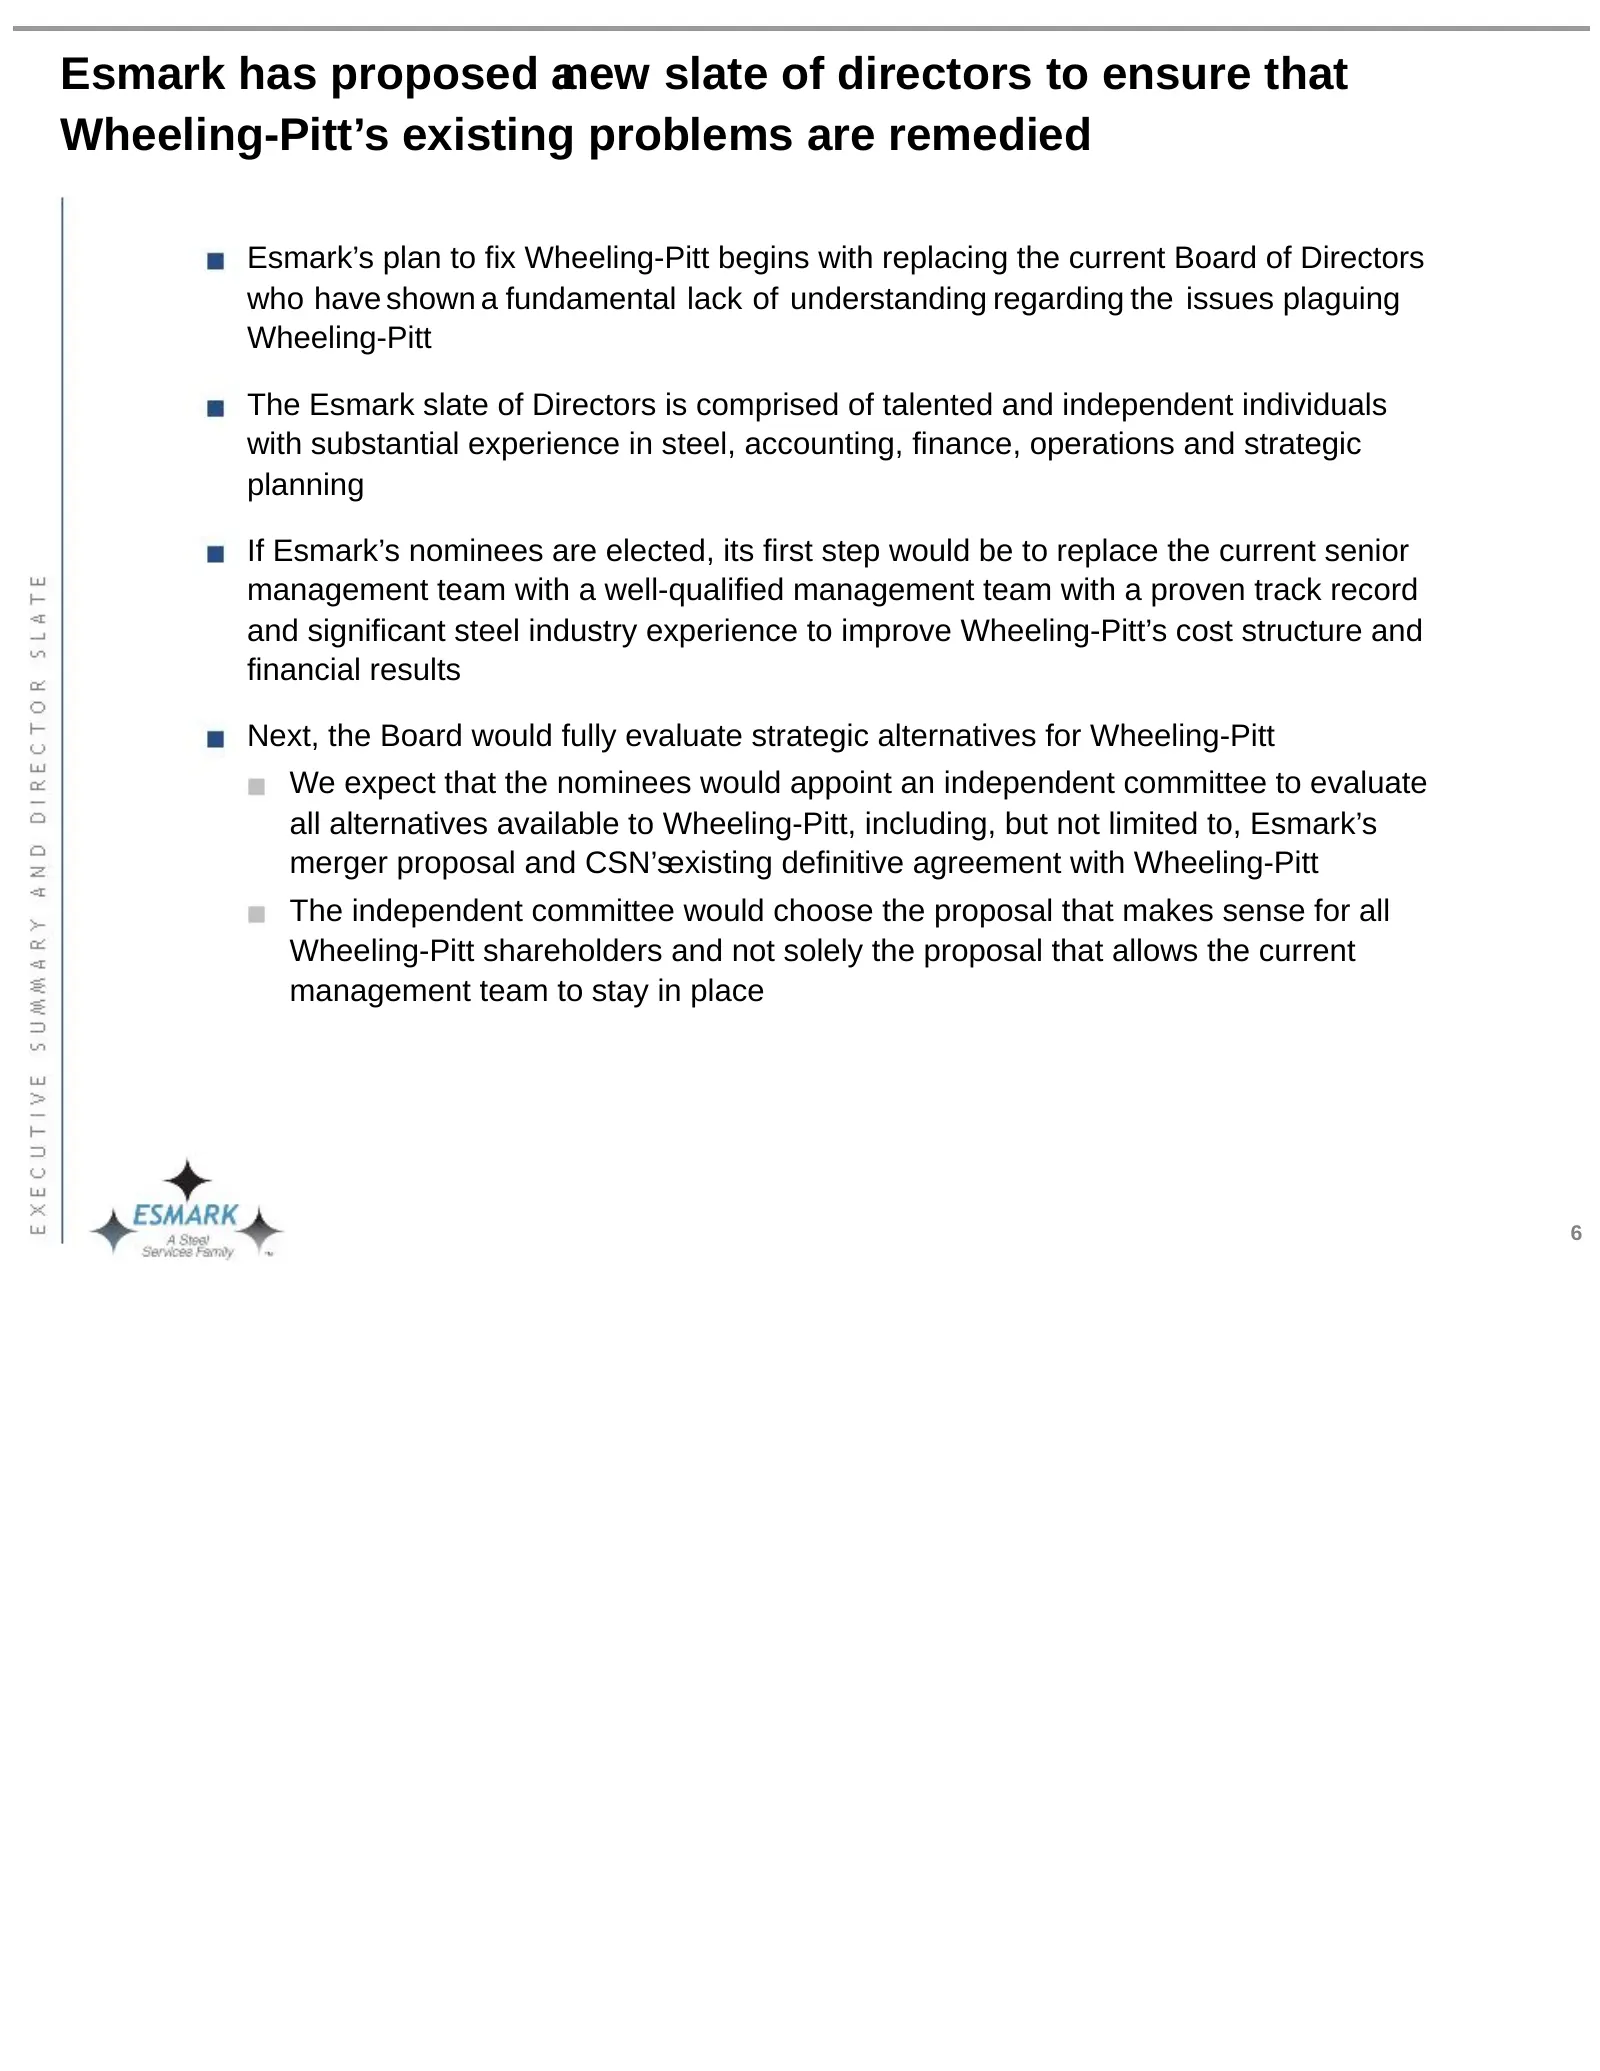
Esmark has proposed anew slate of directors to ensure that Wheeling-Pitt’s existing problems are remedied Esmark’s plan to fix Wheeling-Pitt begins with replacing the current Board of Directors who have shown a fundamental lack of understanding regarding the issues plaguing Wheeling-Pitt The Esmark
Slide 10: Esmark is nominating a talented and diverse slate of experienced nominees
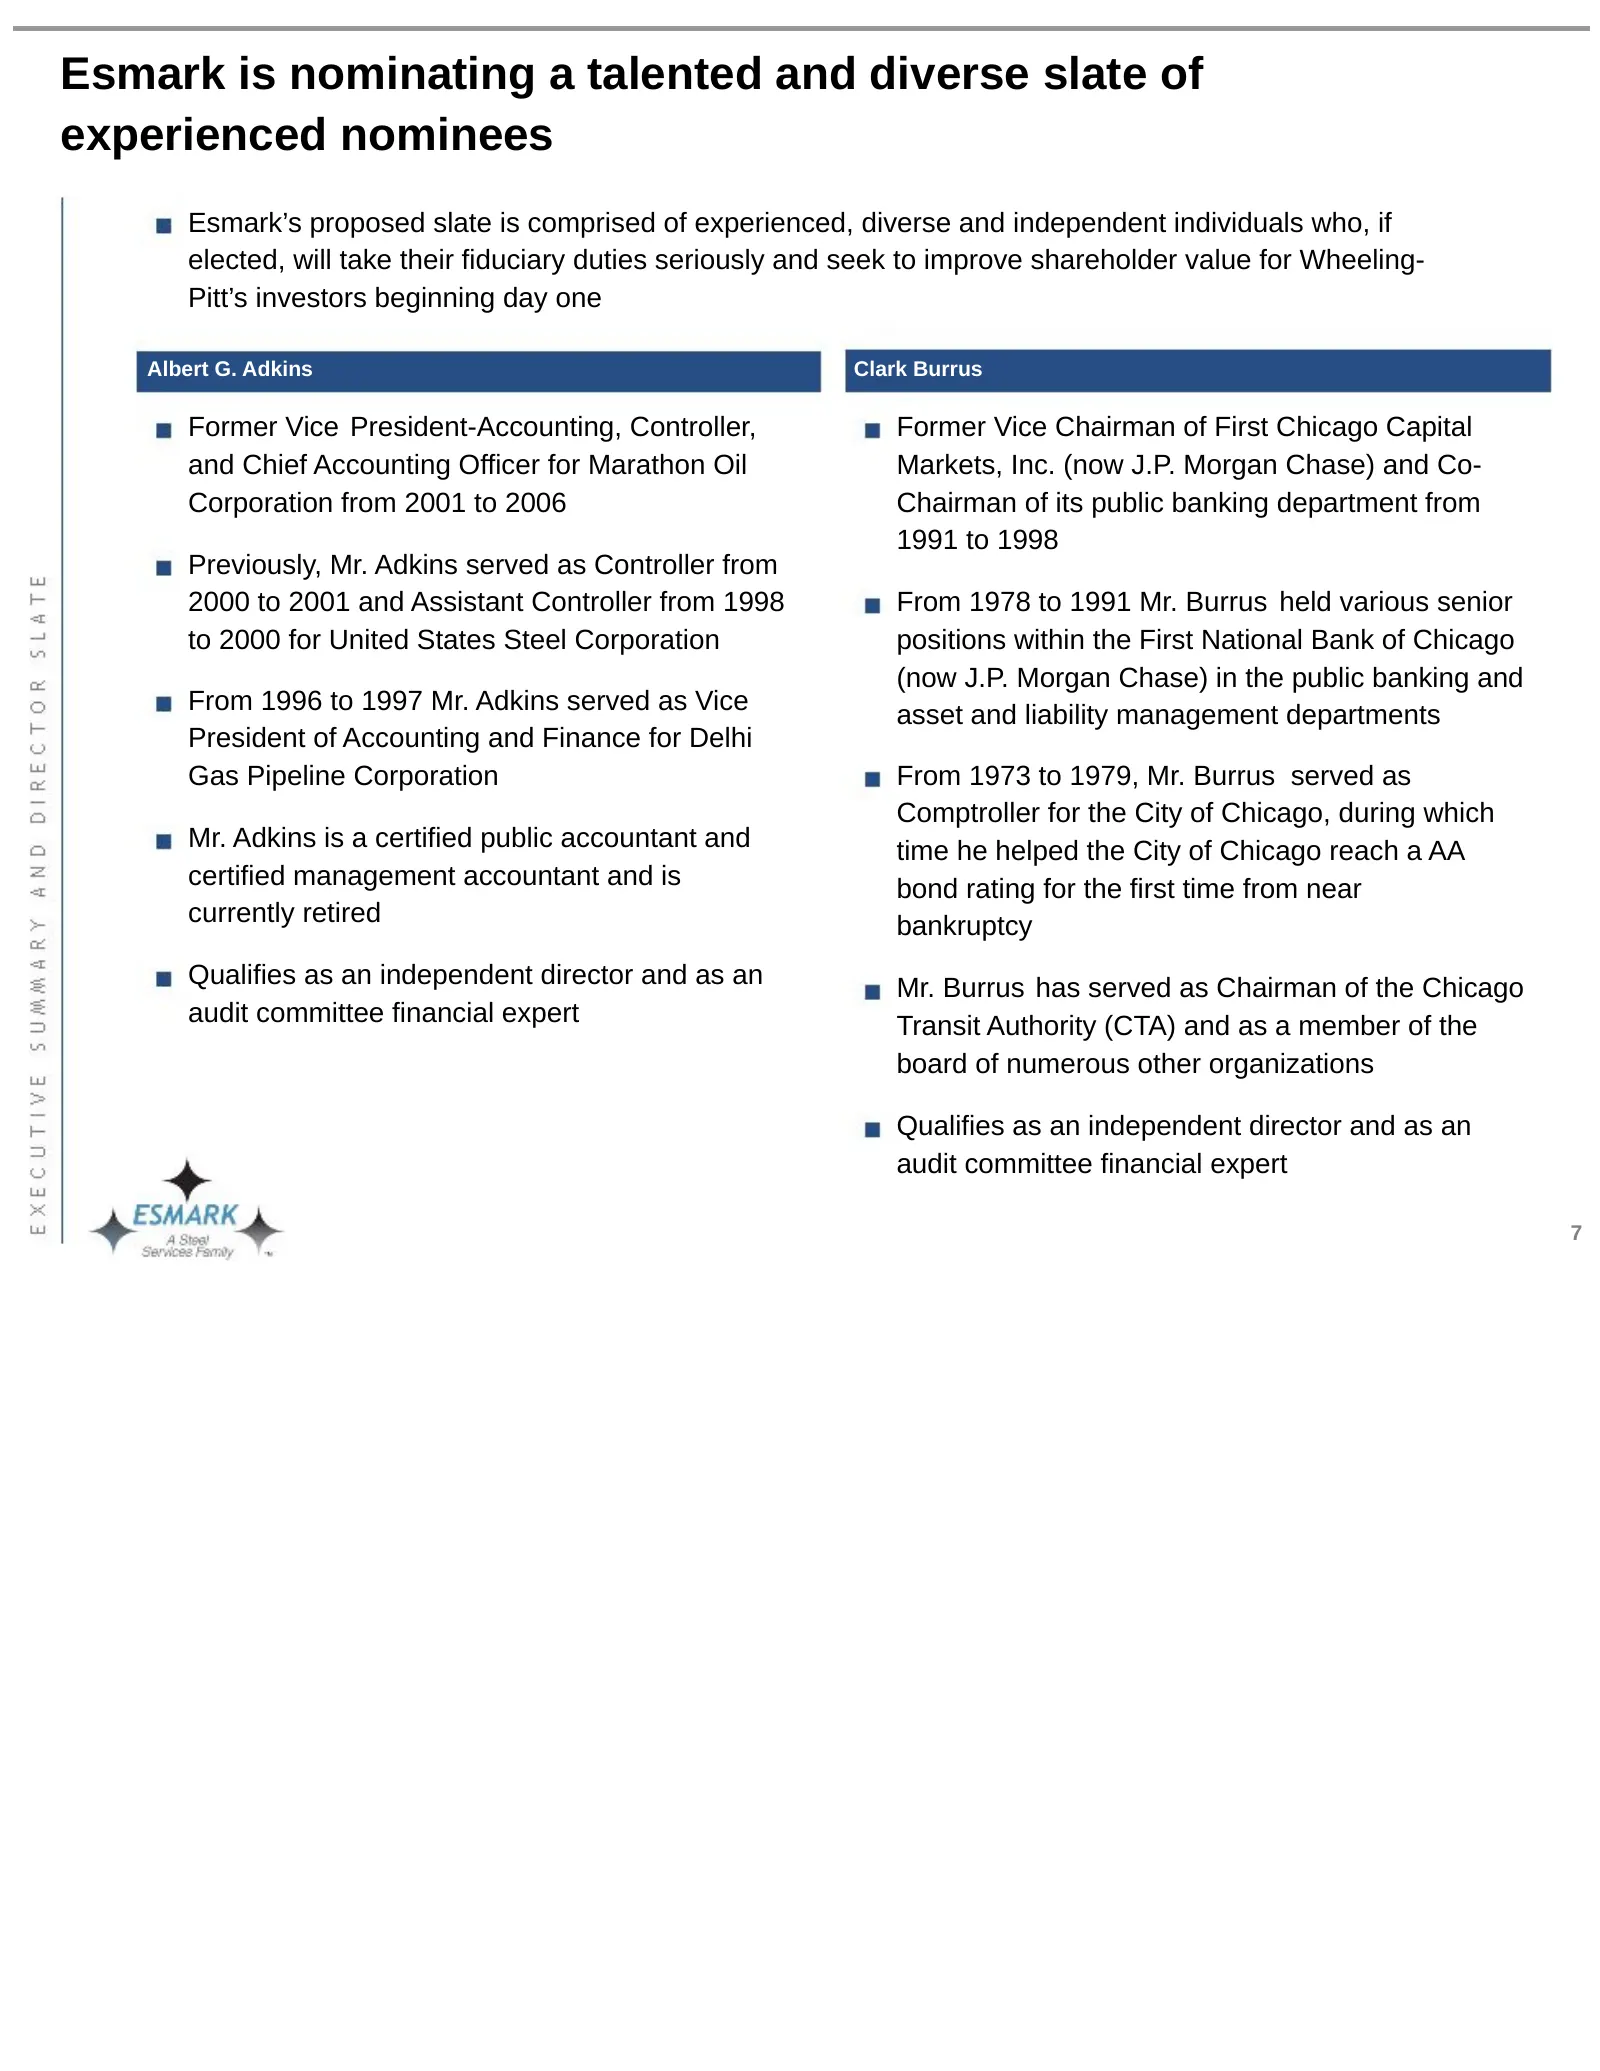
Esmark is nominating a talented and diverse slate of experienced nominees Esmark’s proposed slate is comprised of experienced, diverse and independent individuals who, if elected, will take their fiduciary duties seriously and seek to improve shareholder value for Wheeling- Pitt’s investors beginnin
Slide 11: Nominees (cont'd.)
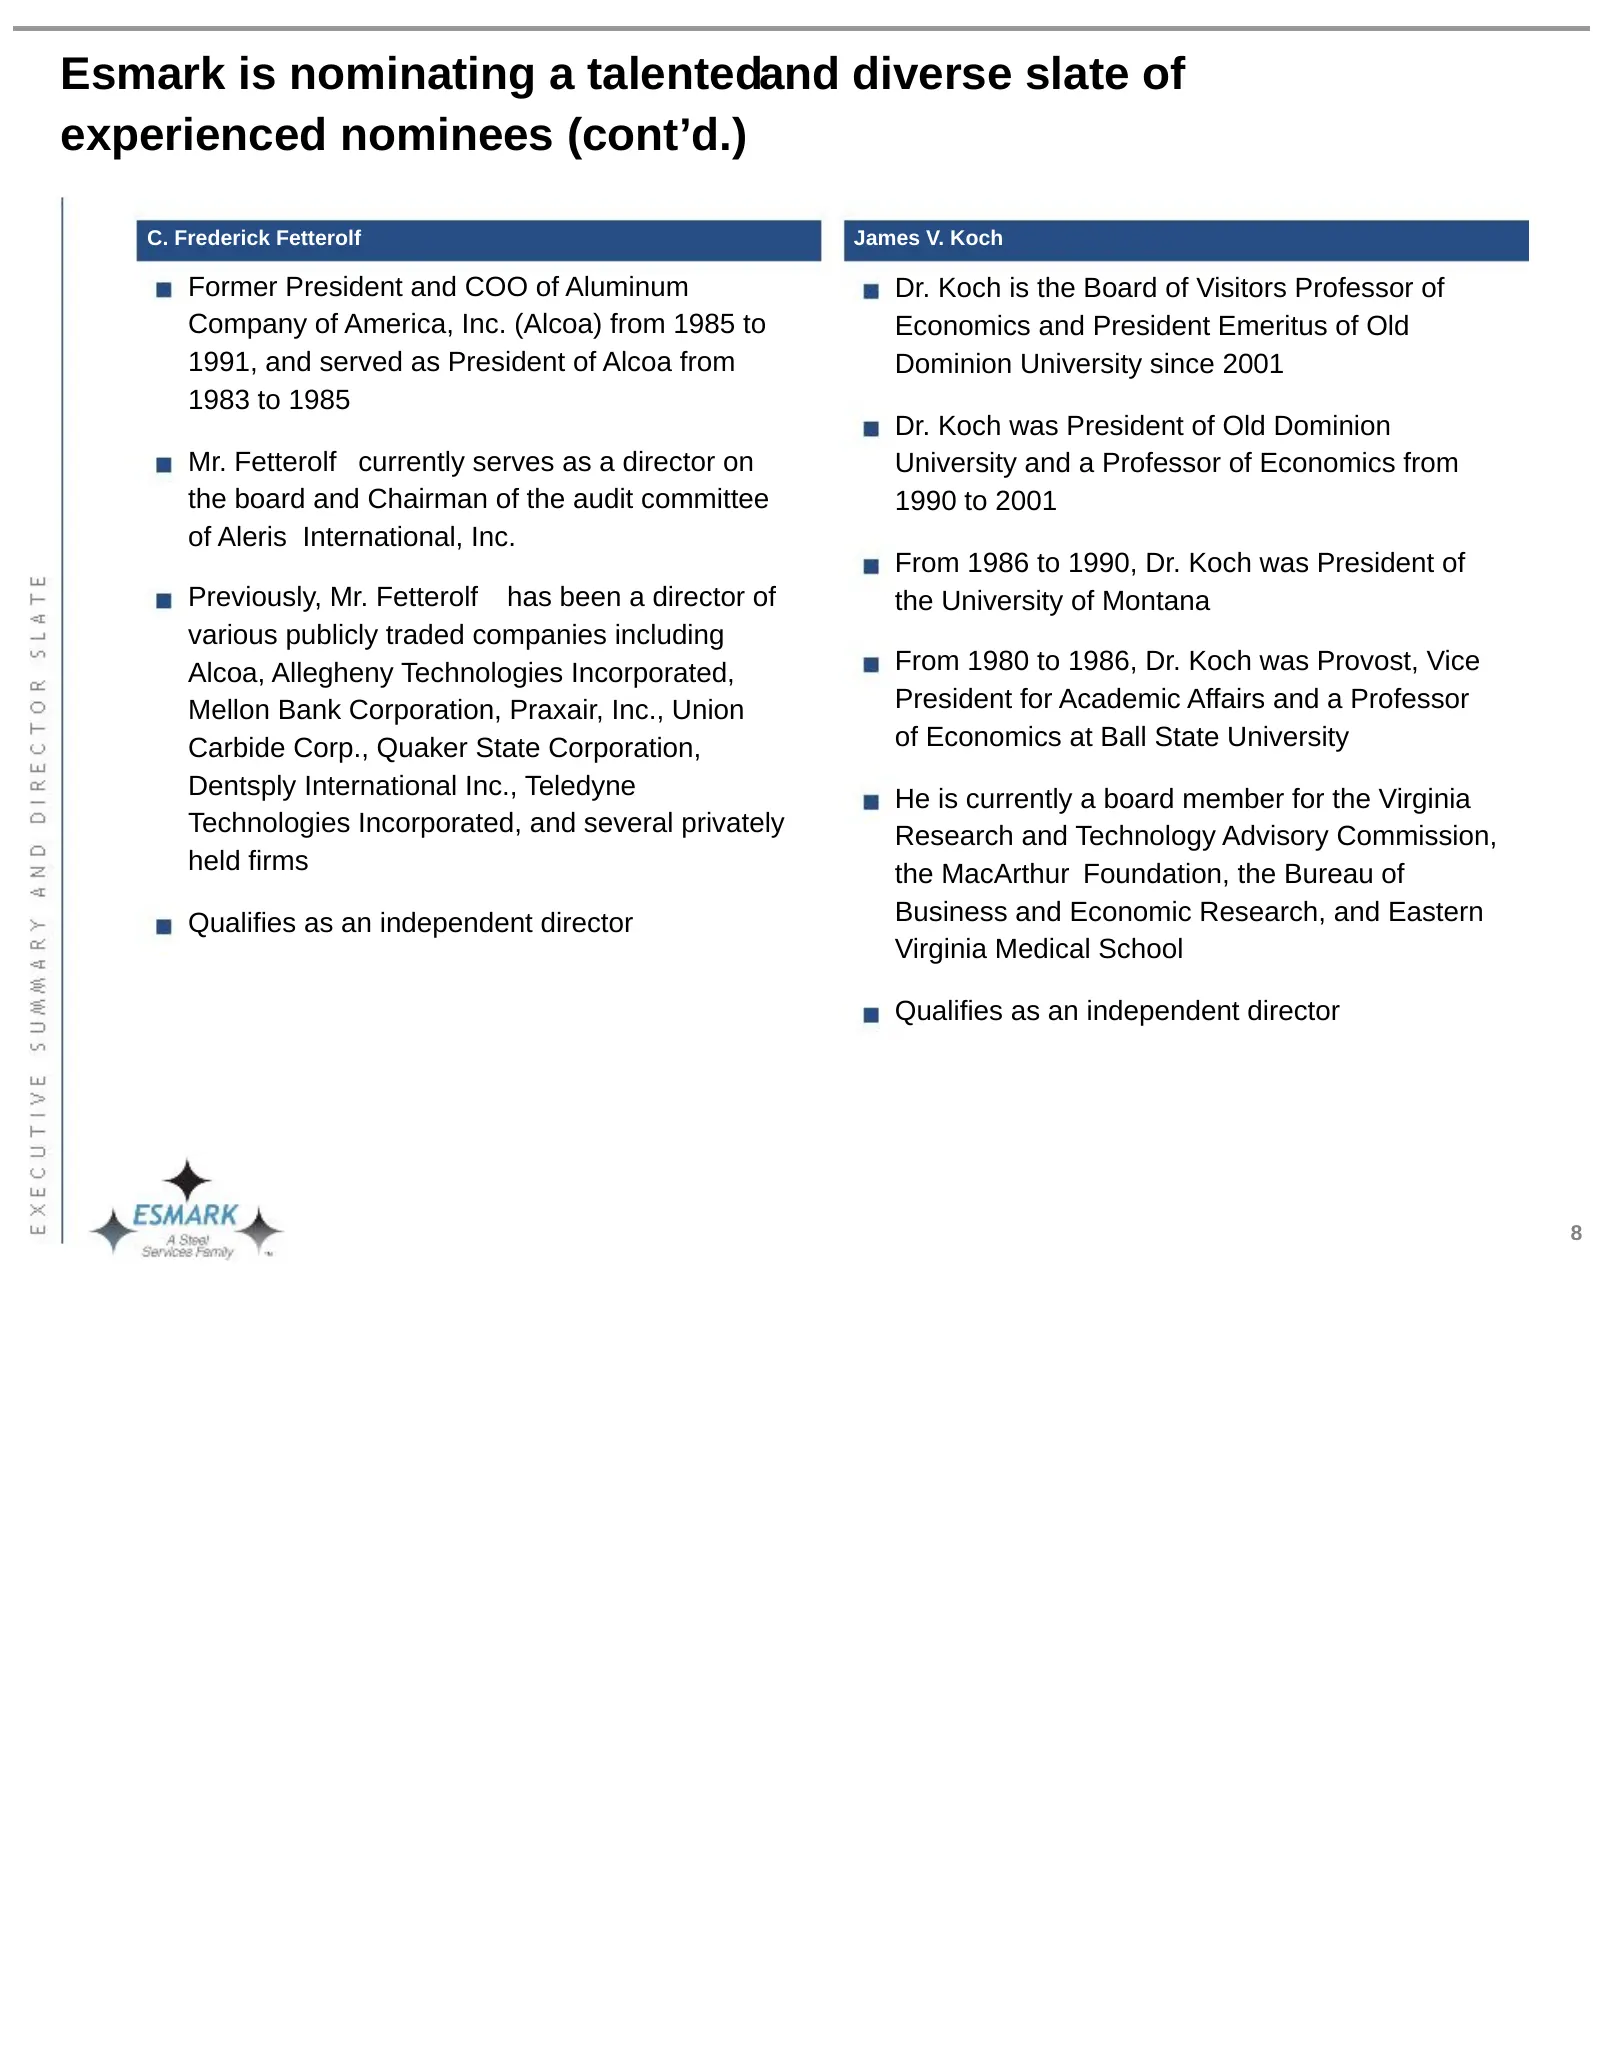
Esmark is nominating a talentedand diverse slate of experienced nominees (cont’d.) C. Frederick Fetterolf James V. Koch Former President and COO of Aluminum Dr. Koch is the Board of Visitors Professor of Company of America, Inc. (Alcoa) from 1985 to Economics and President Emeritus of Old 1991, and
Slide 12: Nominees (cont'd.)
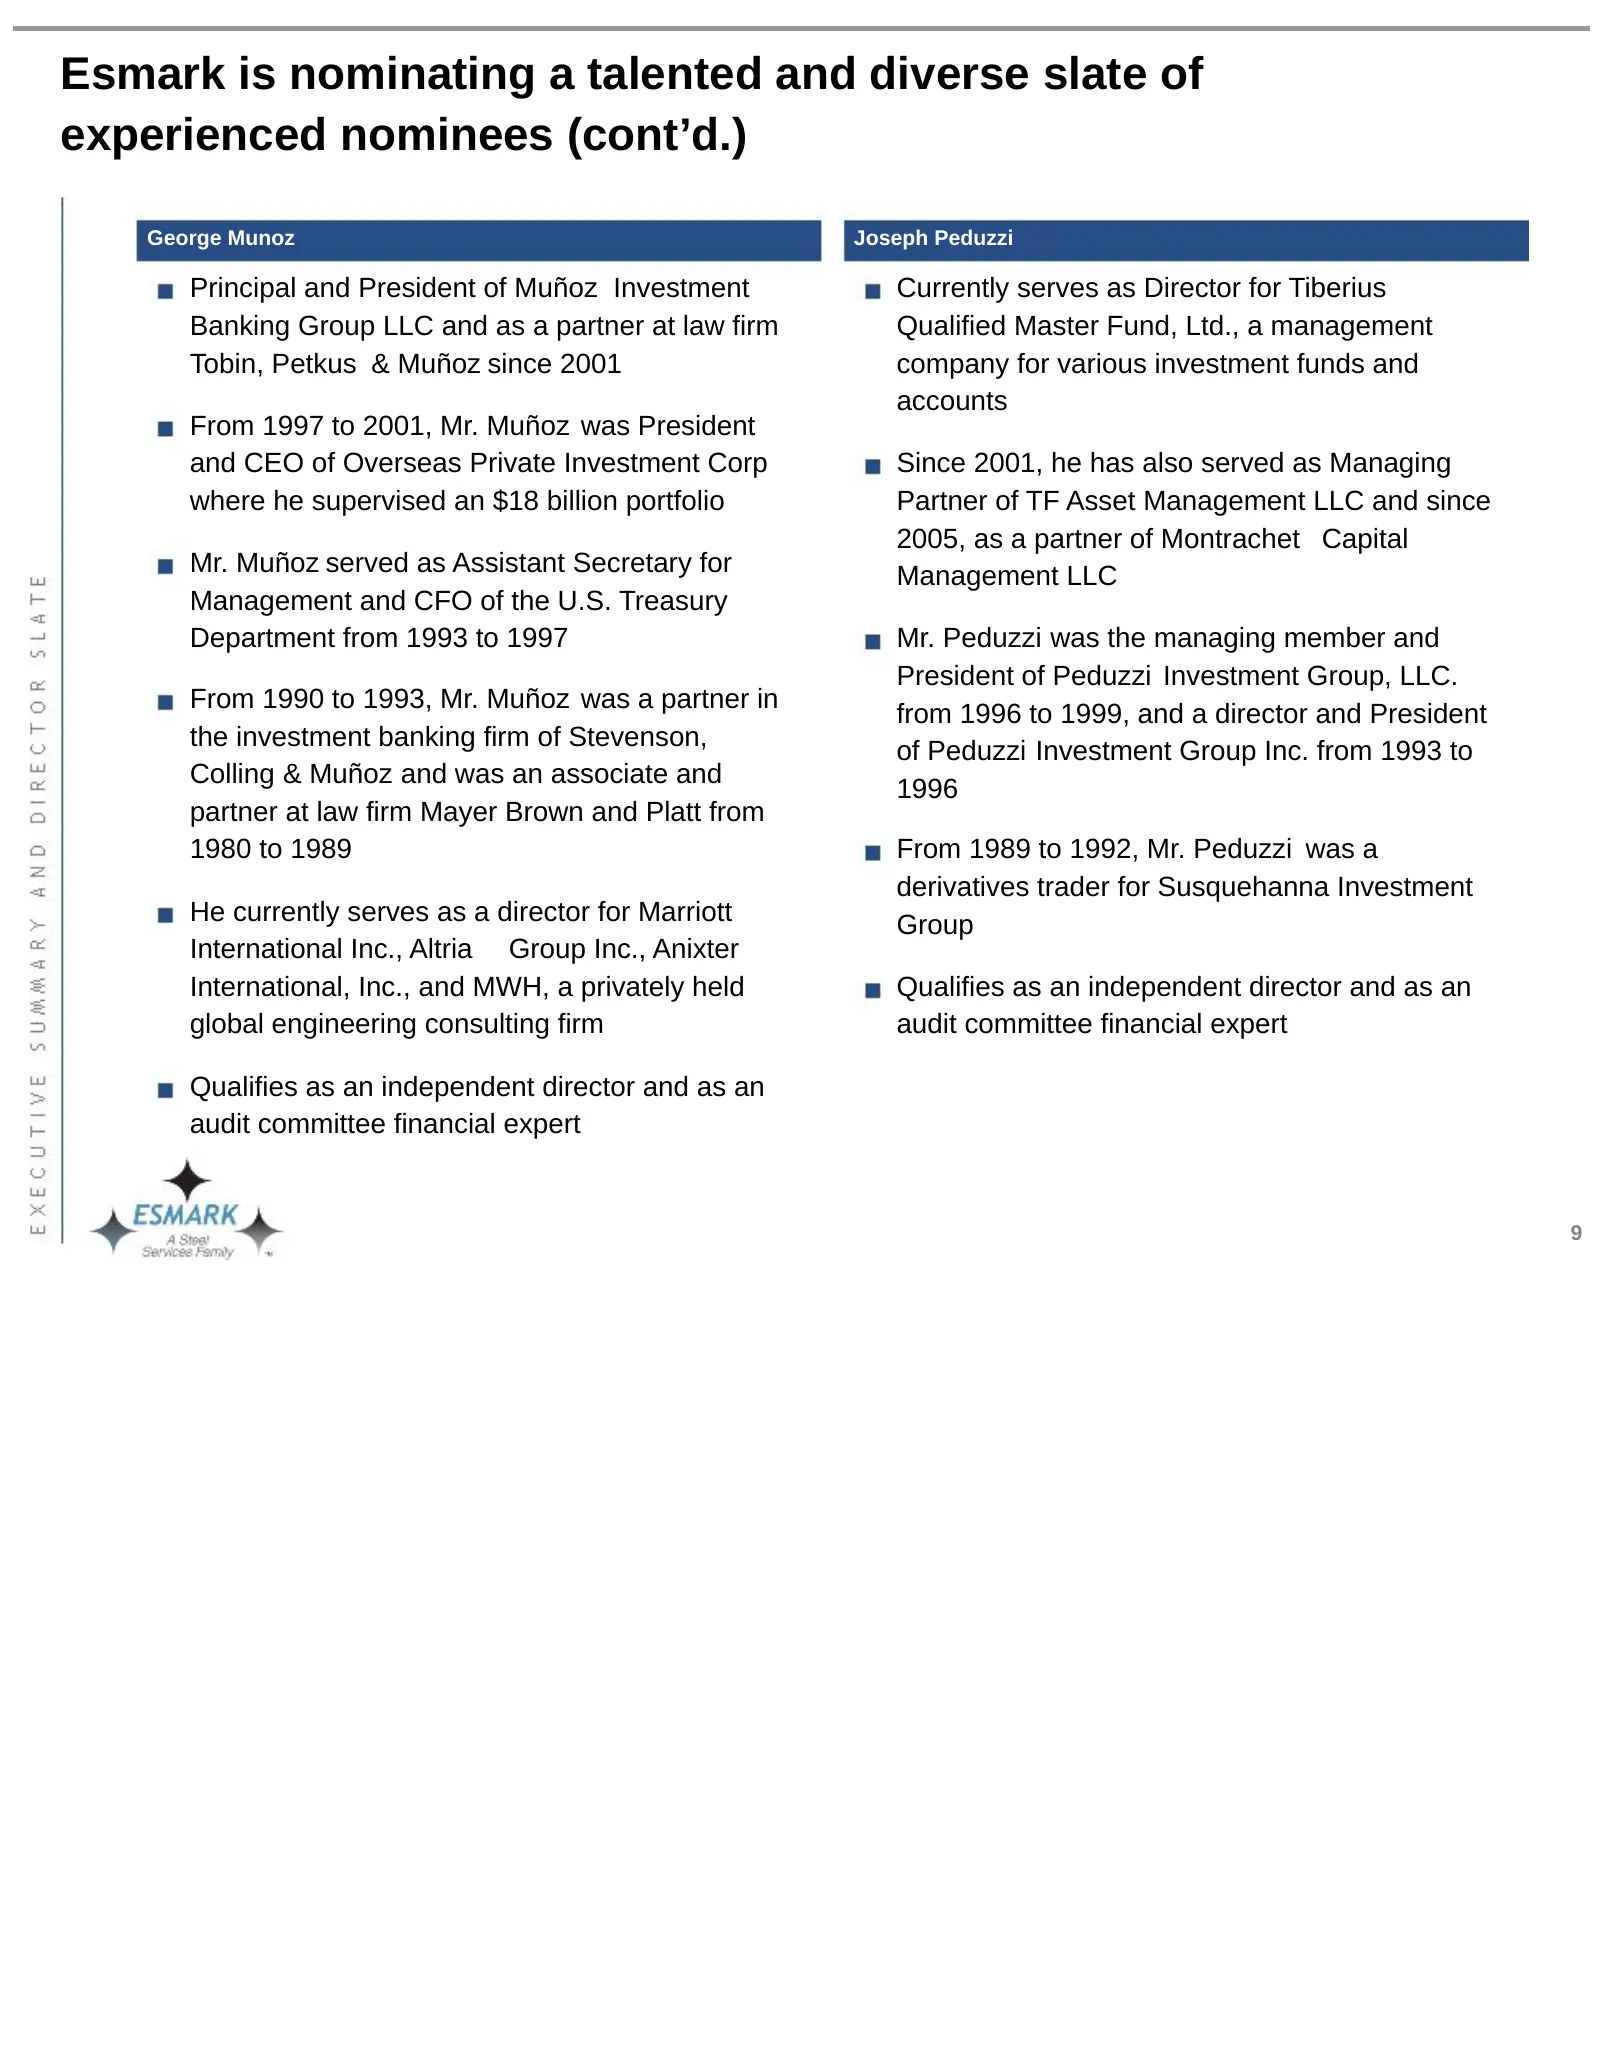
Esmark is nominating a talented and diverse slate of experienced nominees (cont’d.) George Munoz Joseph Peduzzi Principal and President of Muñoz Investment Currently serves as Director for Tiberius Banking Group LLC and as a partner at law firm Qualified Master Fund, Ltd., a management Tobin, Petkus
Slide 13: Nominees (cont'd.)
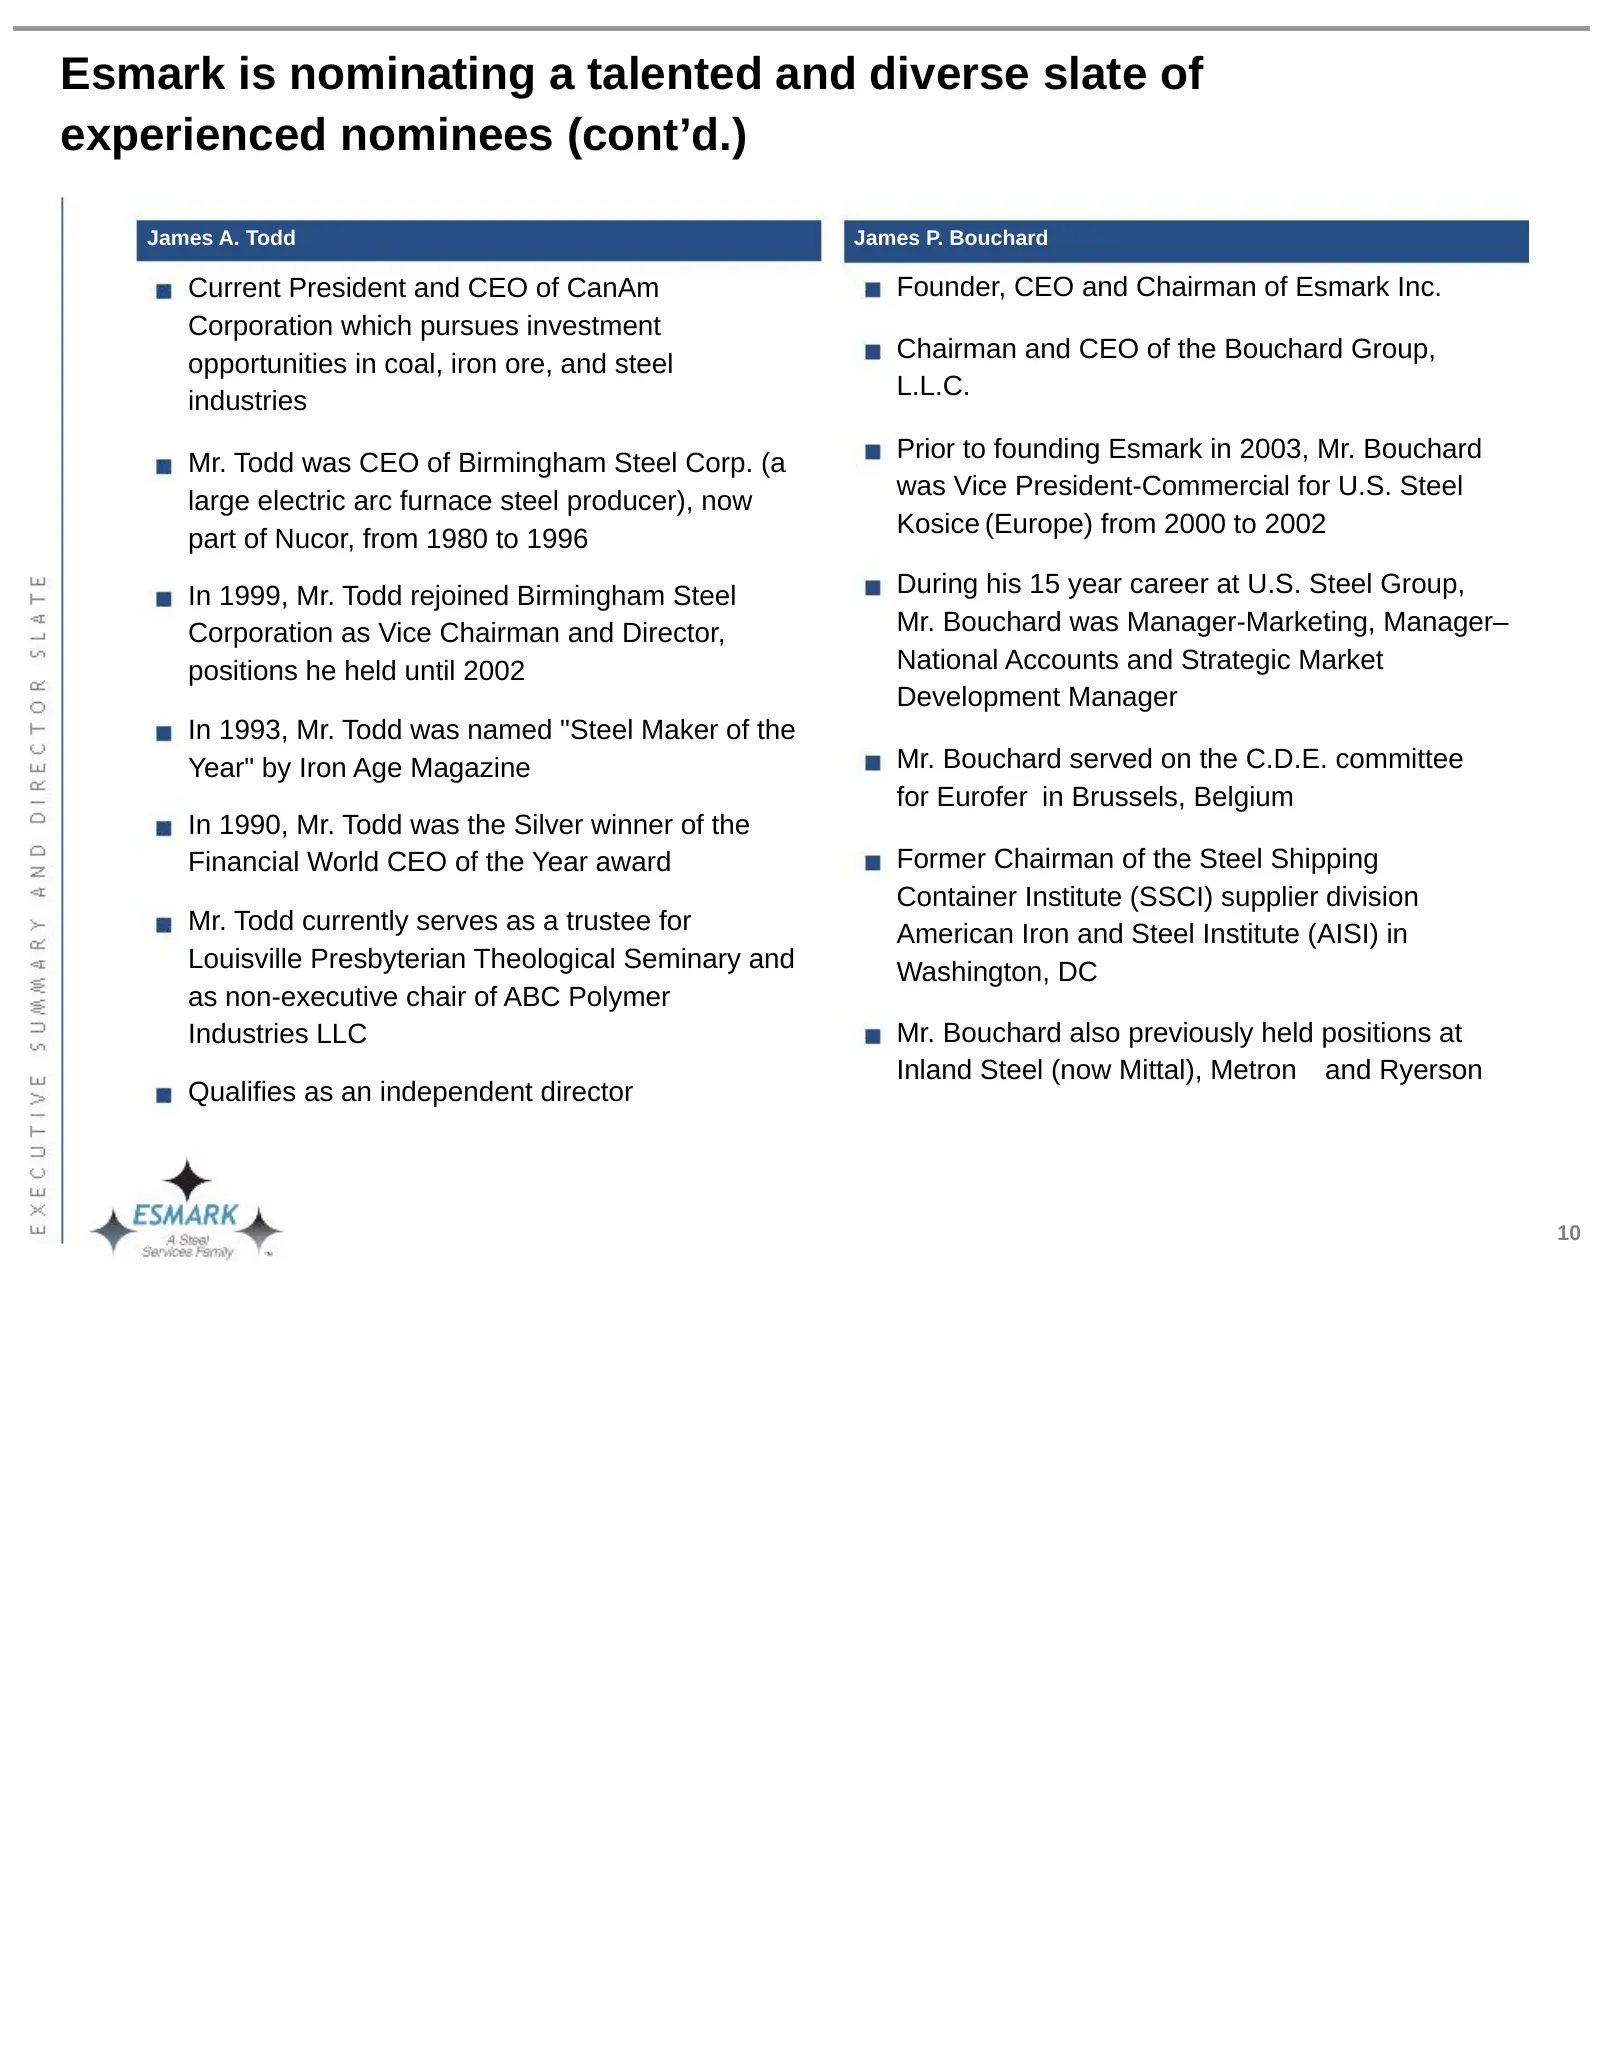
Esmark is nominating a talented and diverse slate of experienced nominees (cont’d.) James A. Todd James P. Bouchard Current President and CEO of CanAm Founder, CEO and Chairman of Esmark Inc. Corporation which pursues investment Chairman and CEO of the Bouchard Group, opportunities in coal, iron ore
Slide 14: Nominees (cont'd.)
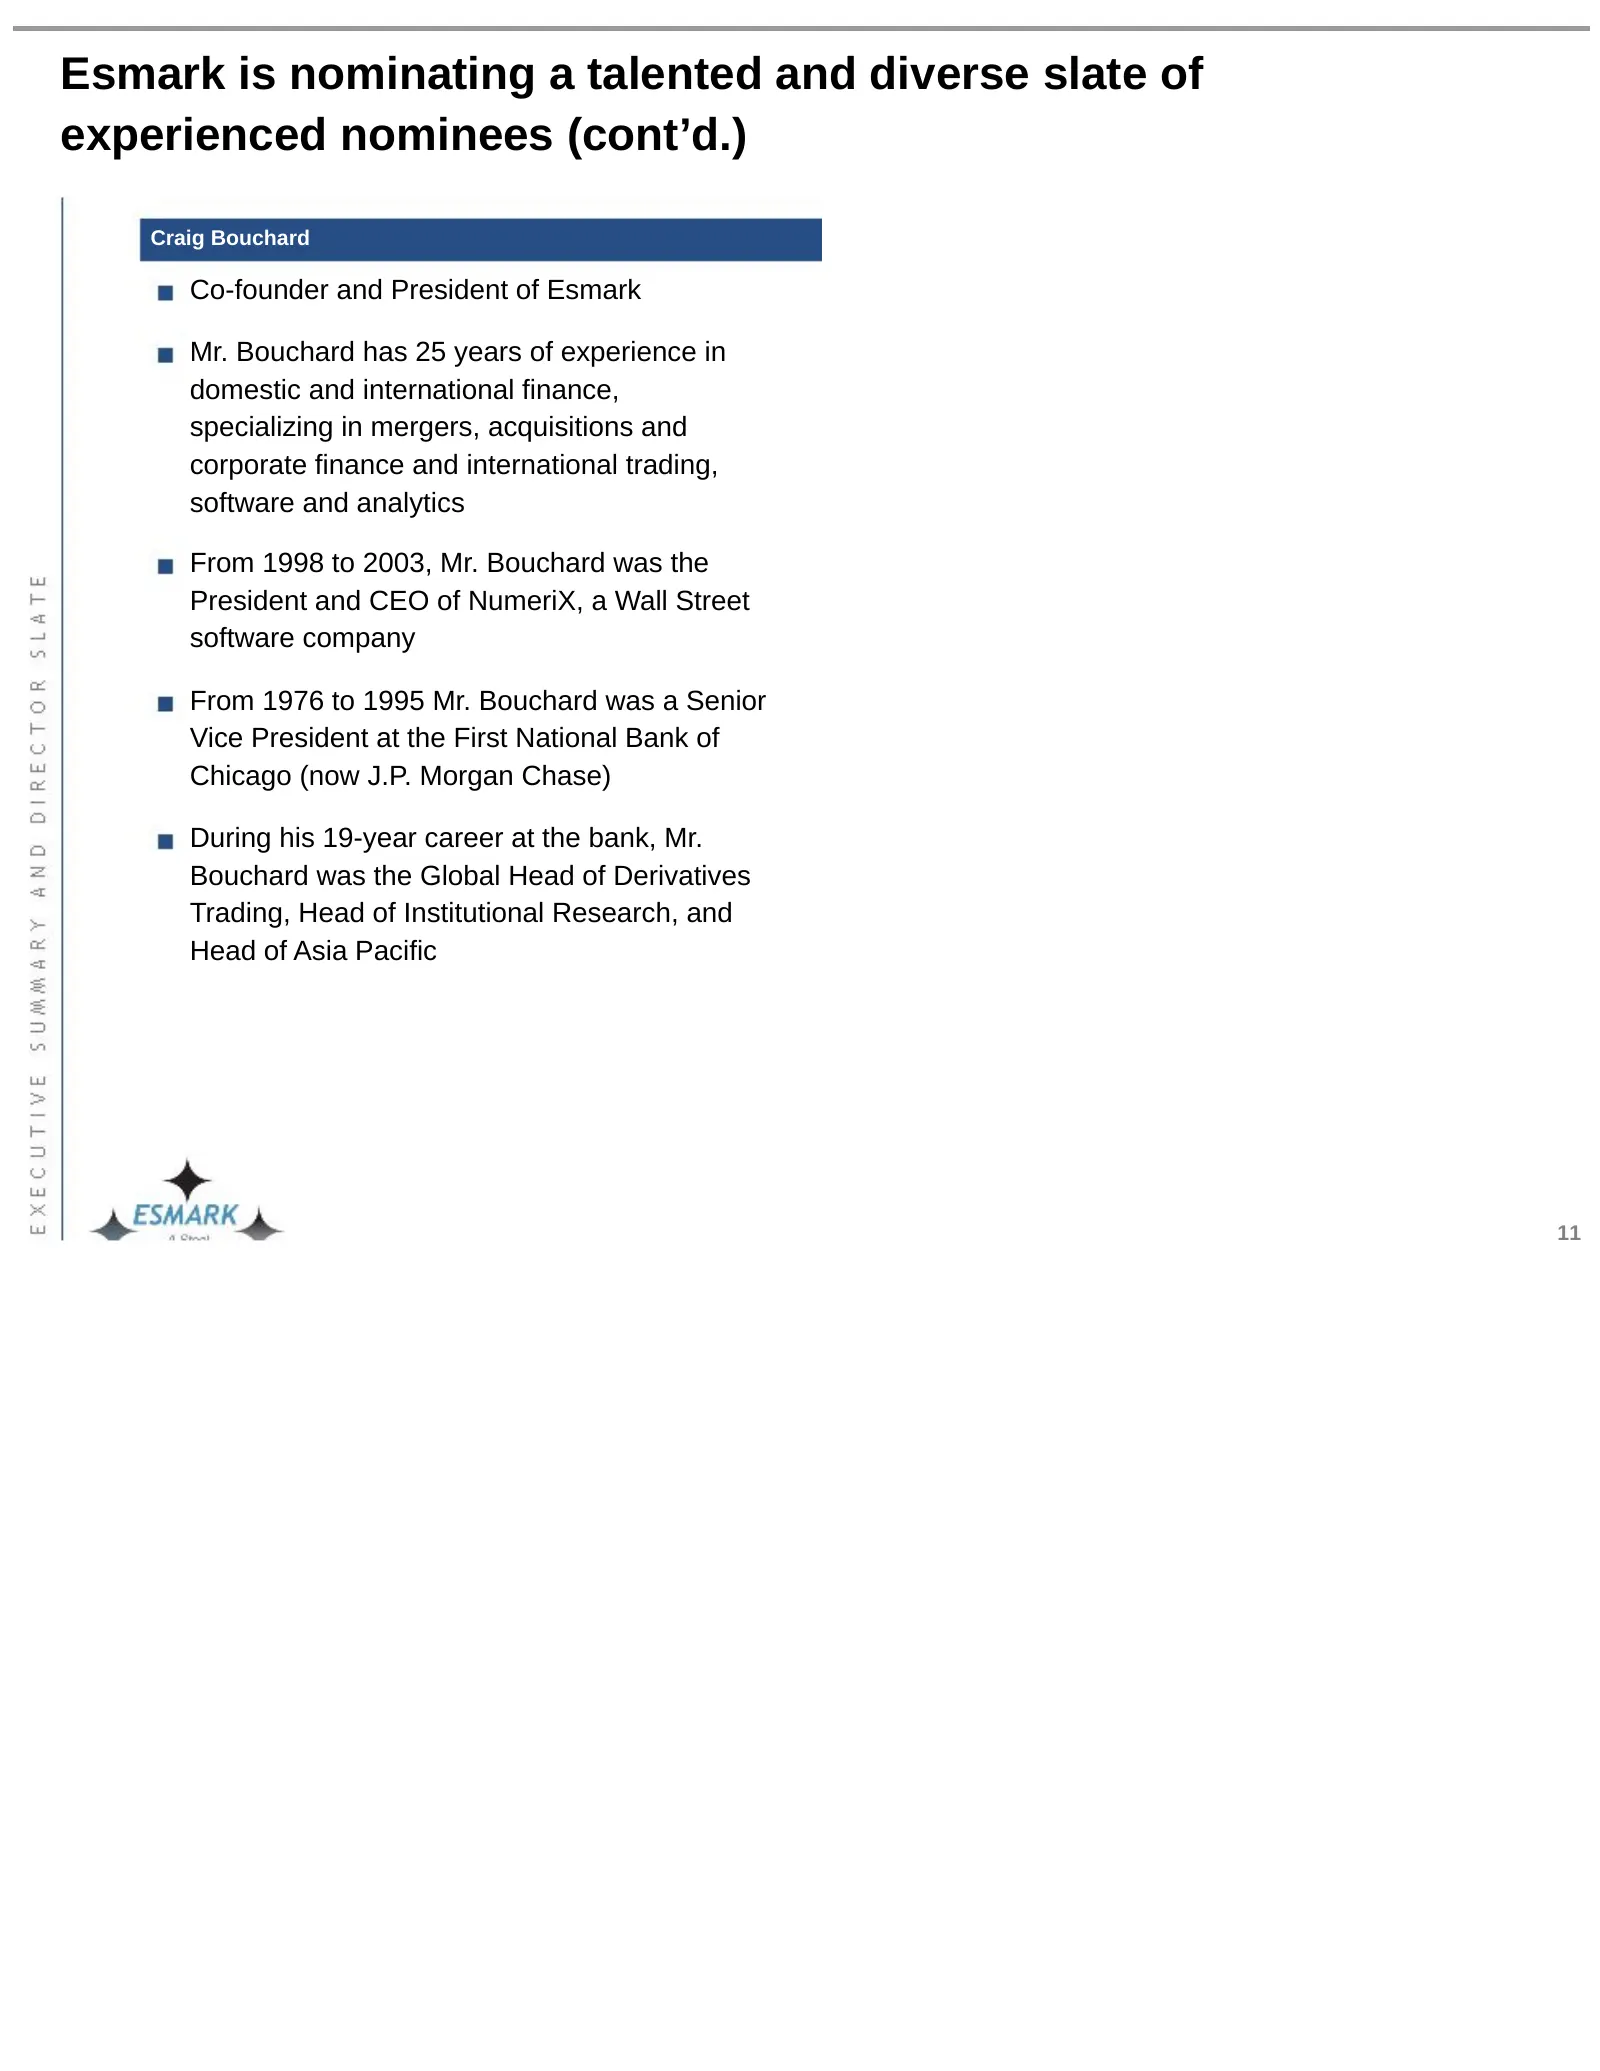
Esmark is nominating a talented and diverse slate of experienced nominees (cont’d.) Craig Bouchard Co-founder and President of Esmark Mr. Bouchard has 25 years of experience in domestic and international finance, specializing in mergers, acquisitions and corporate finance and international trading,
Slide 15: Esmark's proposed slate would bring depth, experience and strategic vision
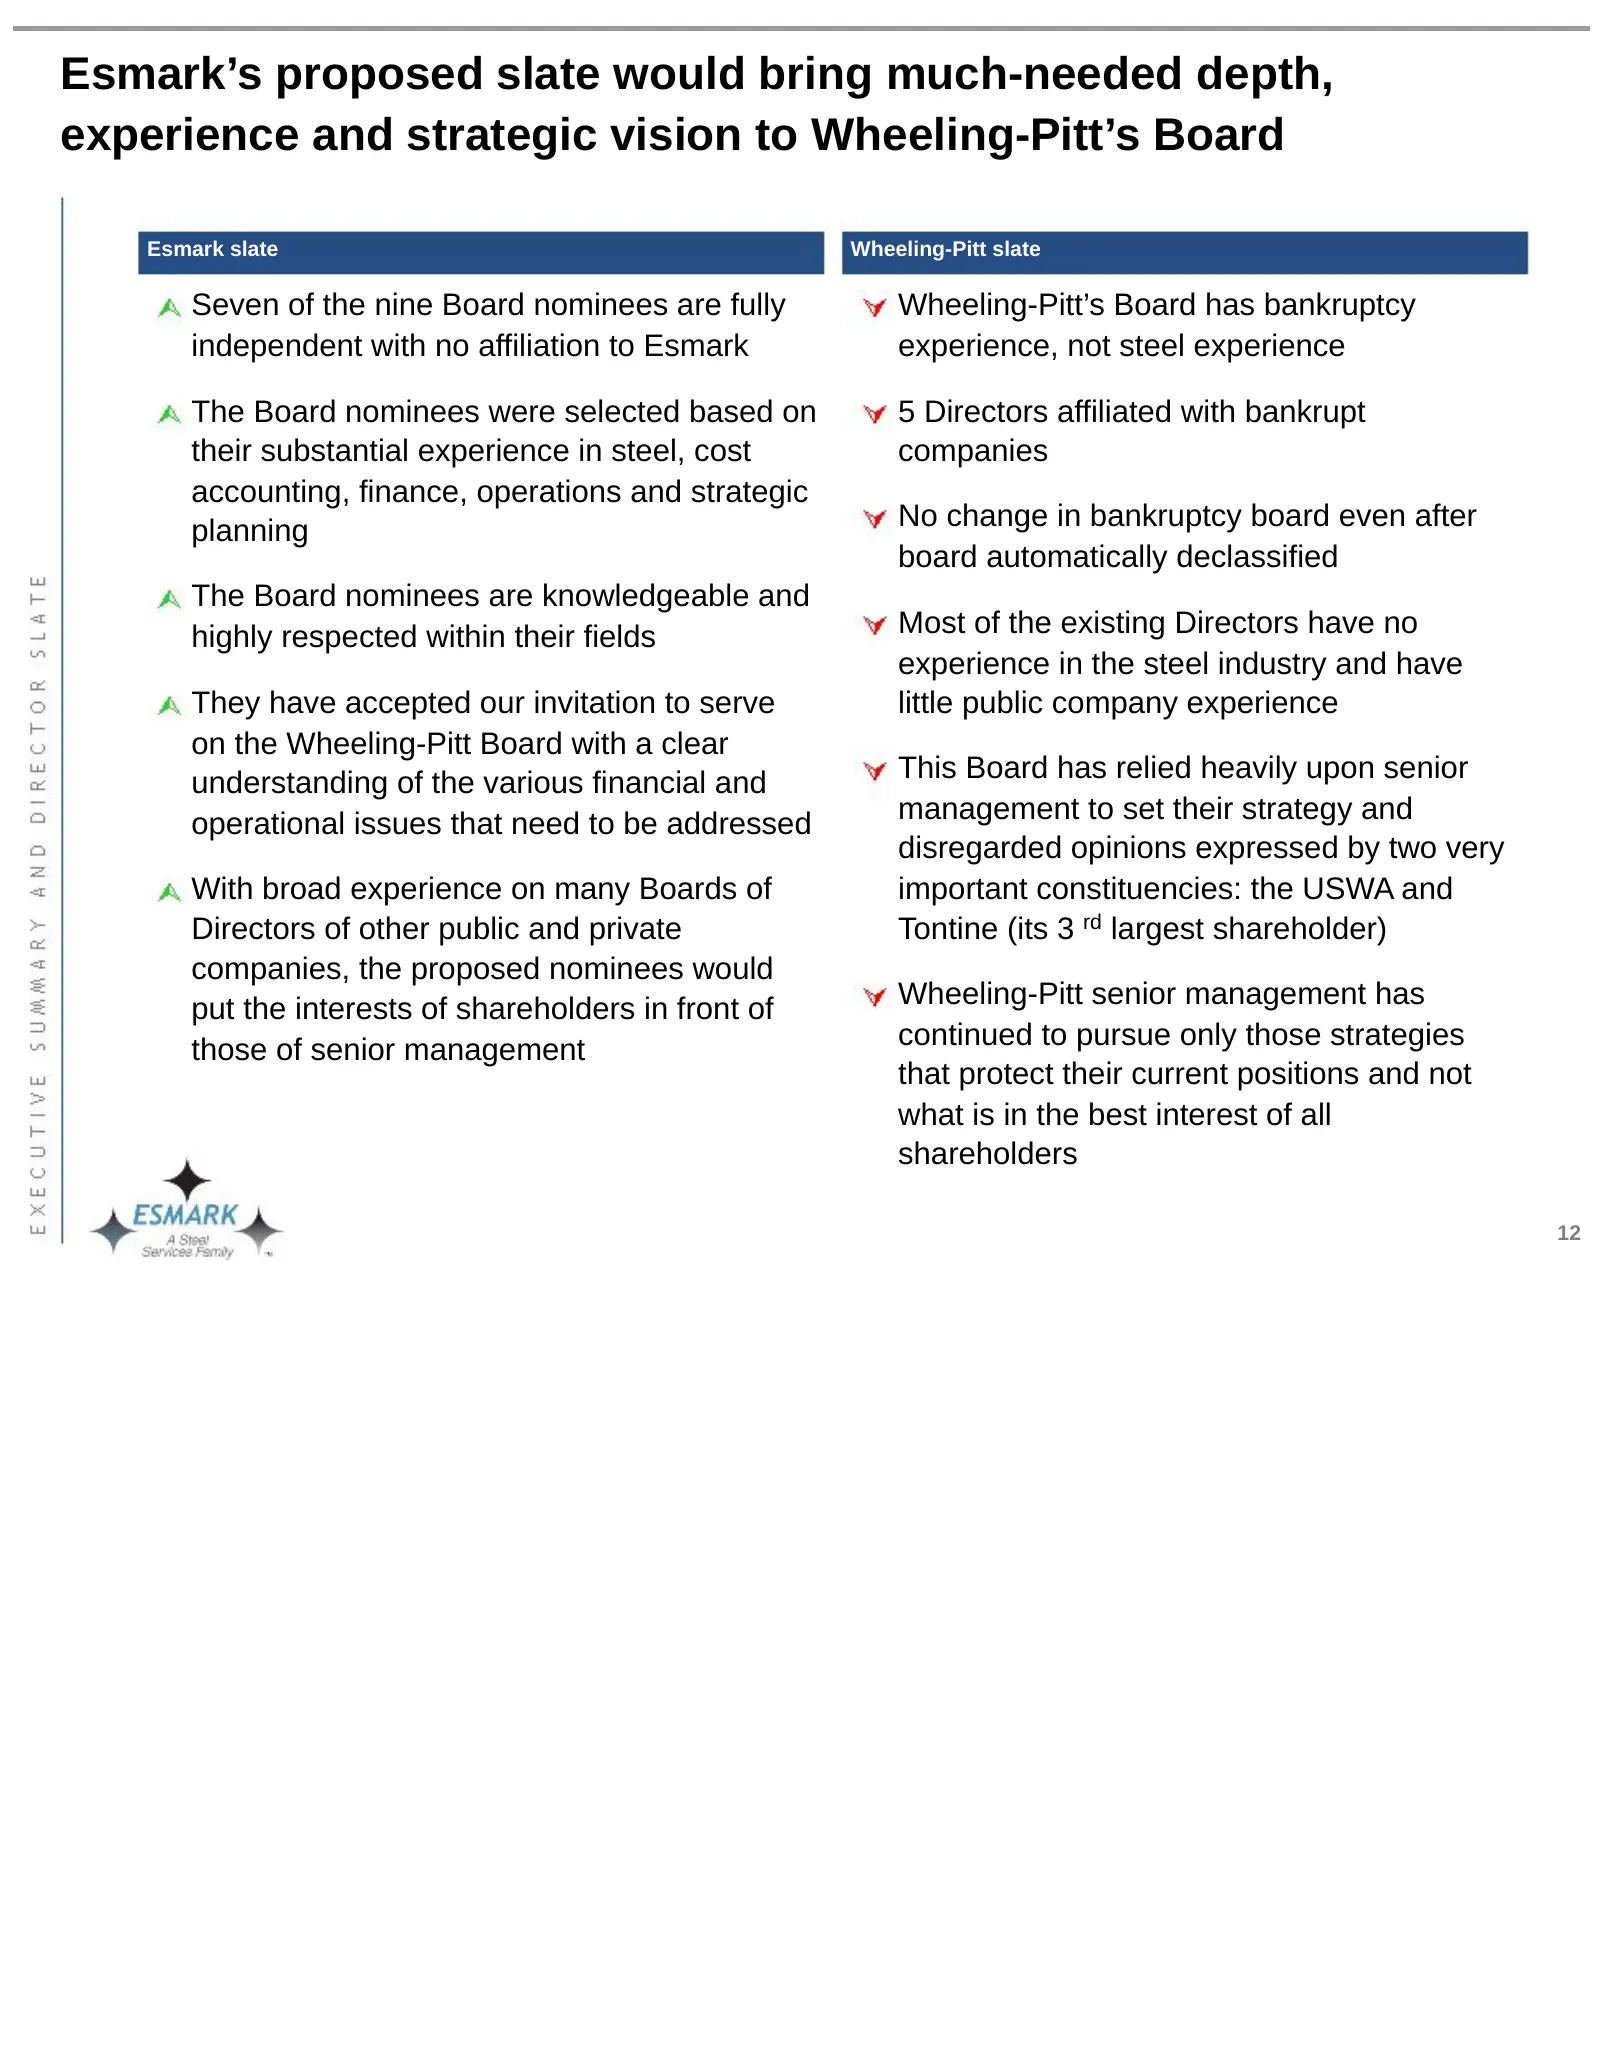
Esmark’s proposed slate would bring much-needed depth, experience and strategic vision to Wheeling-Pitt’s Board Esmark slate Wheeling-Pitt slate Seven of the nine Board nominees are fully Wheeling-Pitt’s Board has bankruptcy independent with no affiliation to Esmark experience, not steel experience
Slide 16: Agenda
Agenda Page Executive summary and director slate 2 Wheeling-Pitt hasoverpromisedand underperformed 13 Esmark’s Strategic vision and operating plan 21 Conclusion 33 13
Slide 17: Wheeling-Pitt has underperformed its peers and the broader market indices
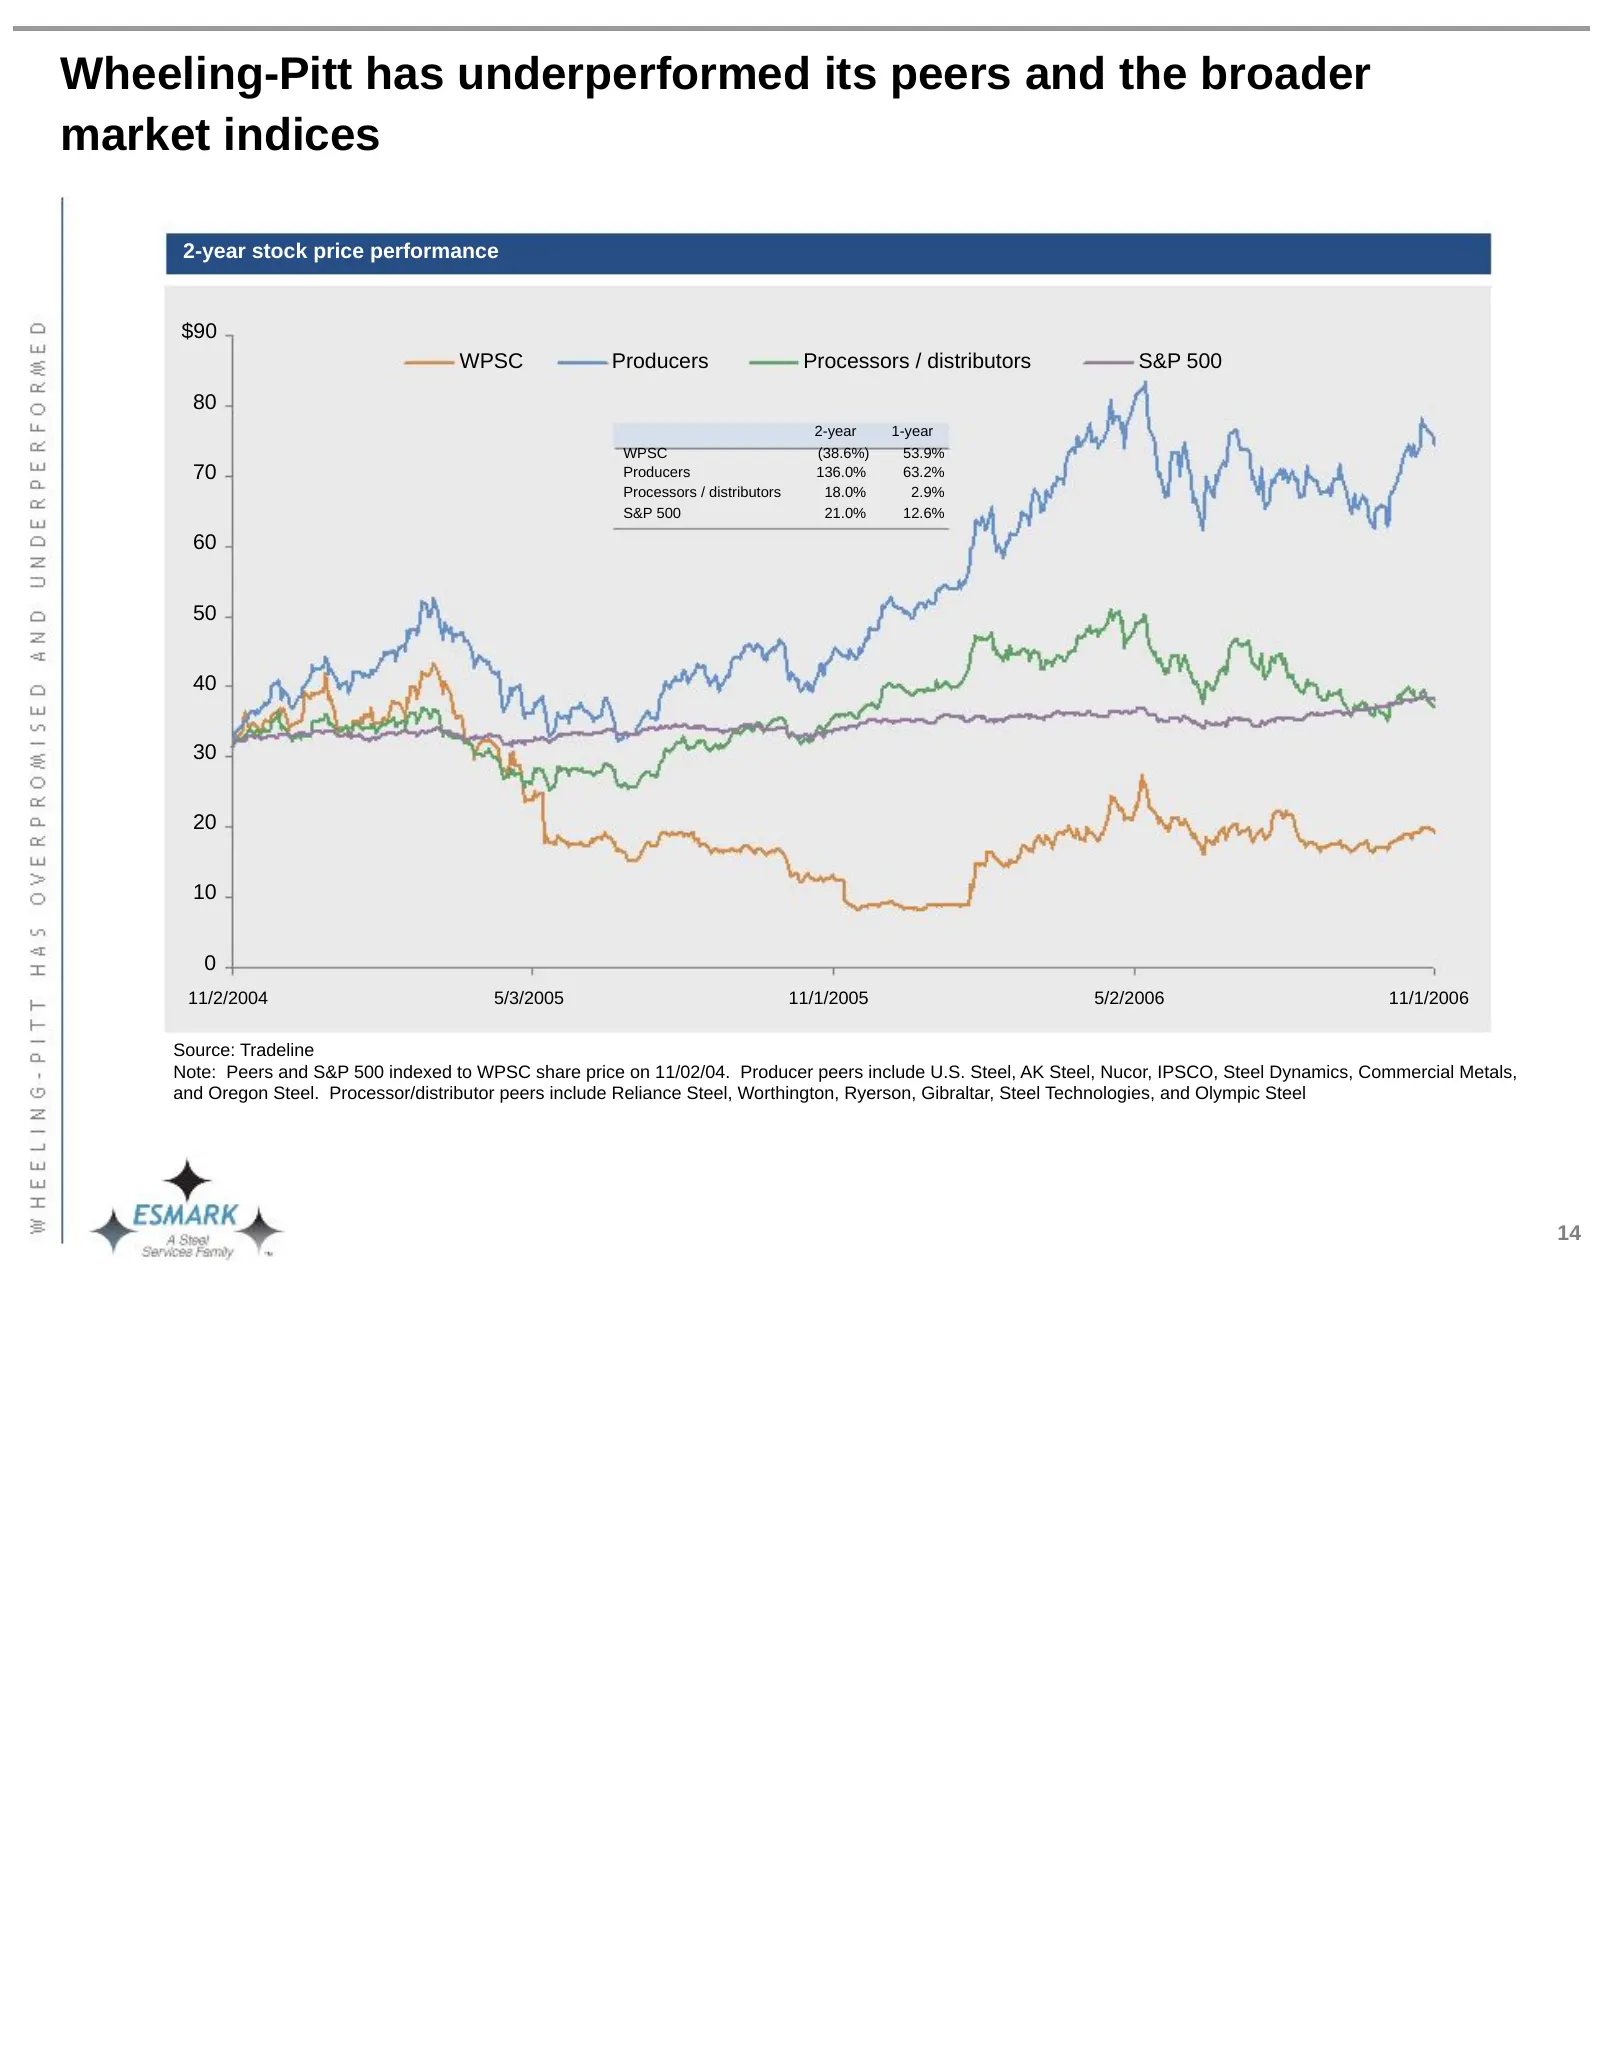
Wheeling-Pitt has underperformed its peers and the broader market indices 2-year stock price performance $90 WPSC Producers Processors / distributors S&P 500 80 2-year 1-year WPSC (38.6%) 53.9% 70 Producers 136.0% 63.2% Processors / distributors 18.0% 2.9% S&P 500 21.0% 12.6% 60 50 40 30 20 10 0 11/
Slide 18: Operational performance has lagged despite strong steel markets
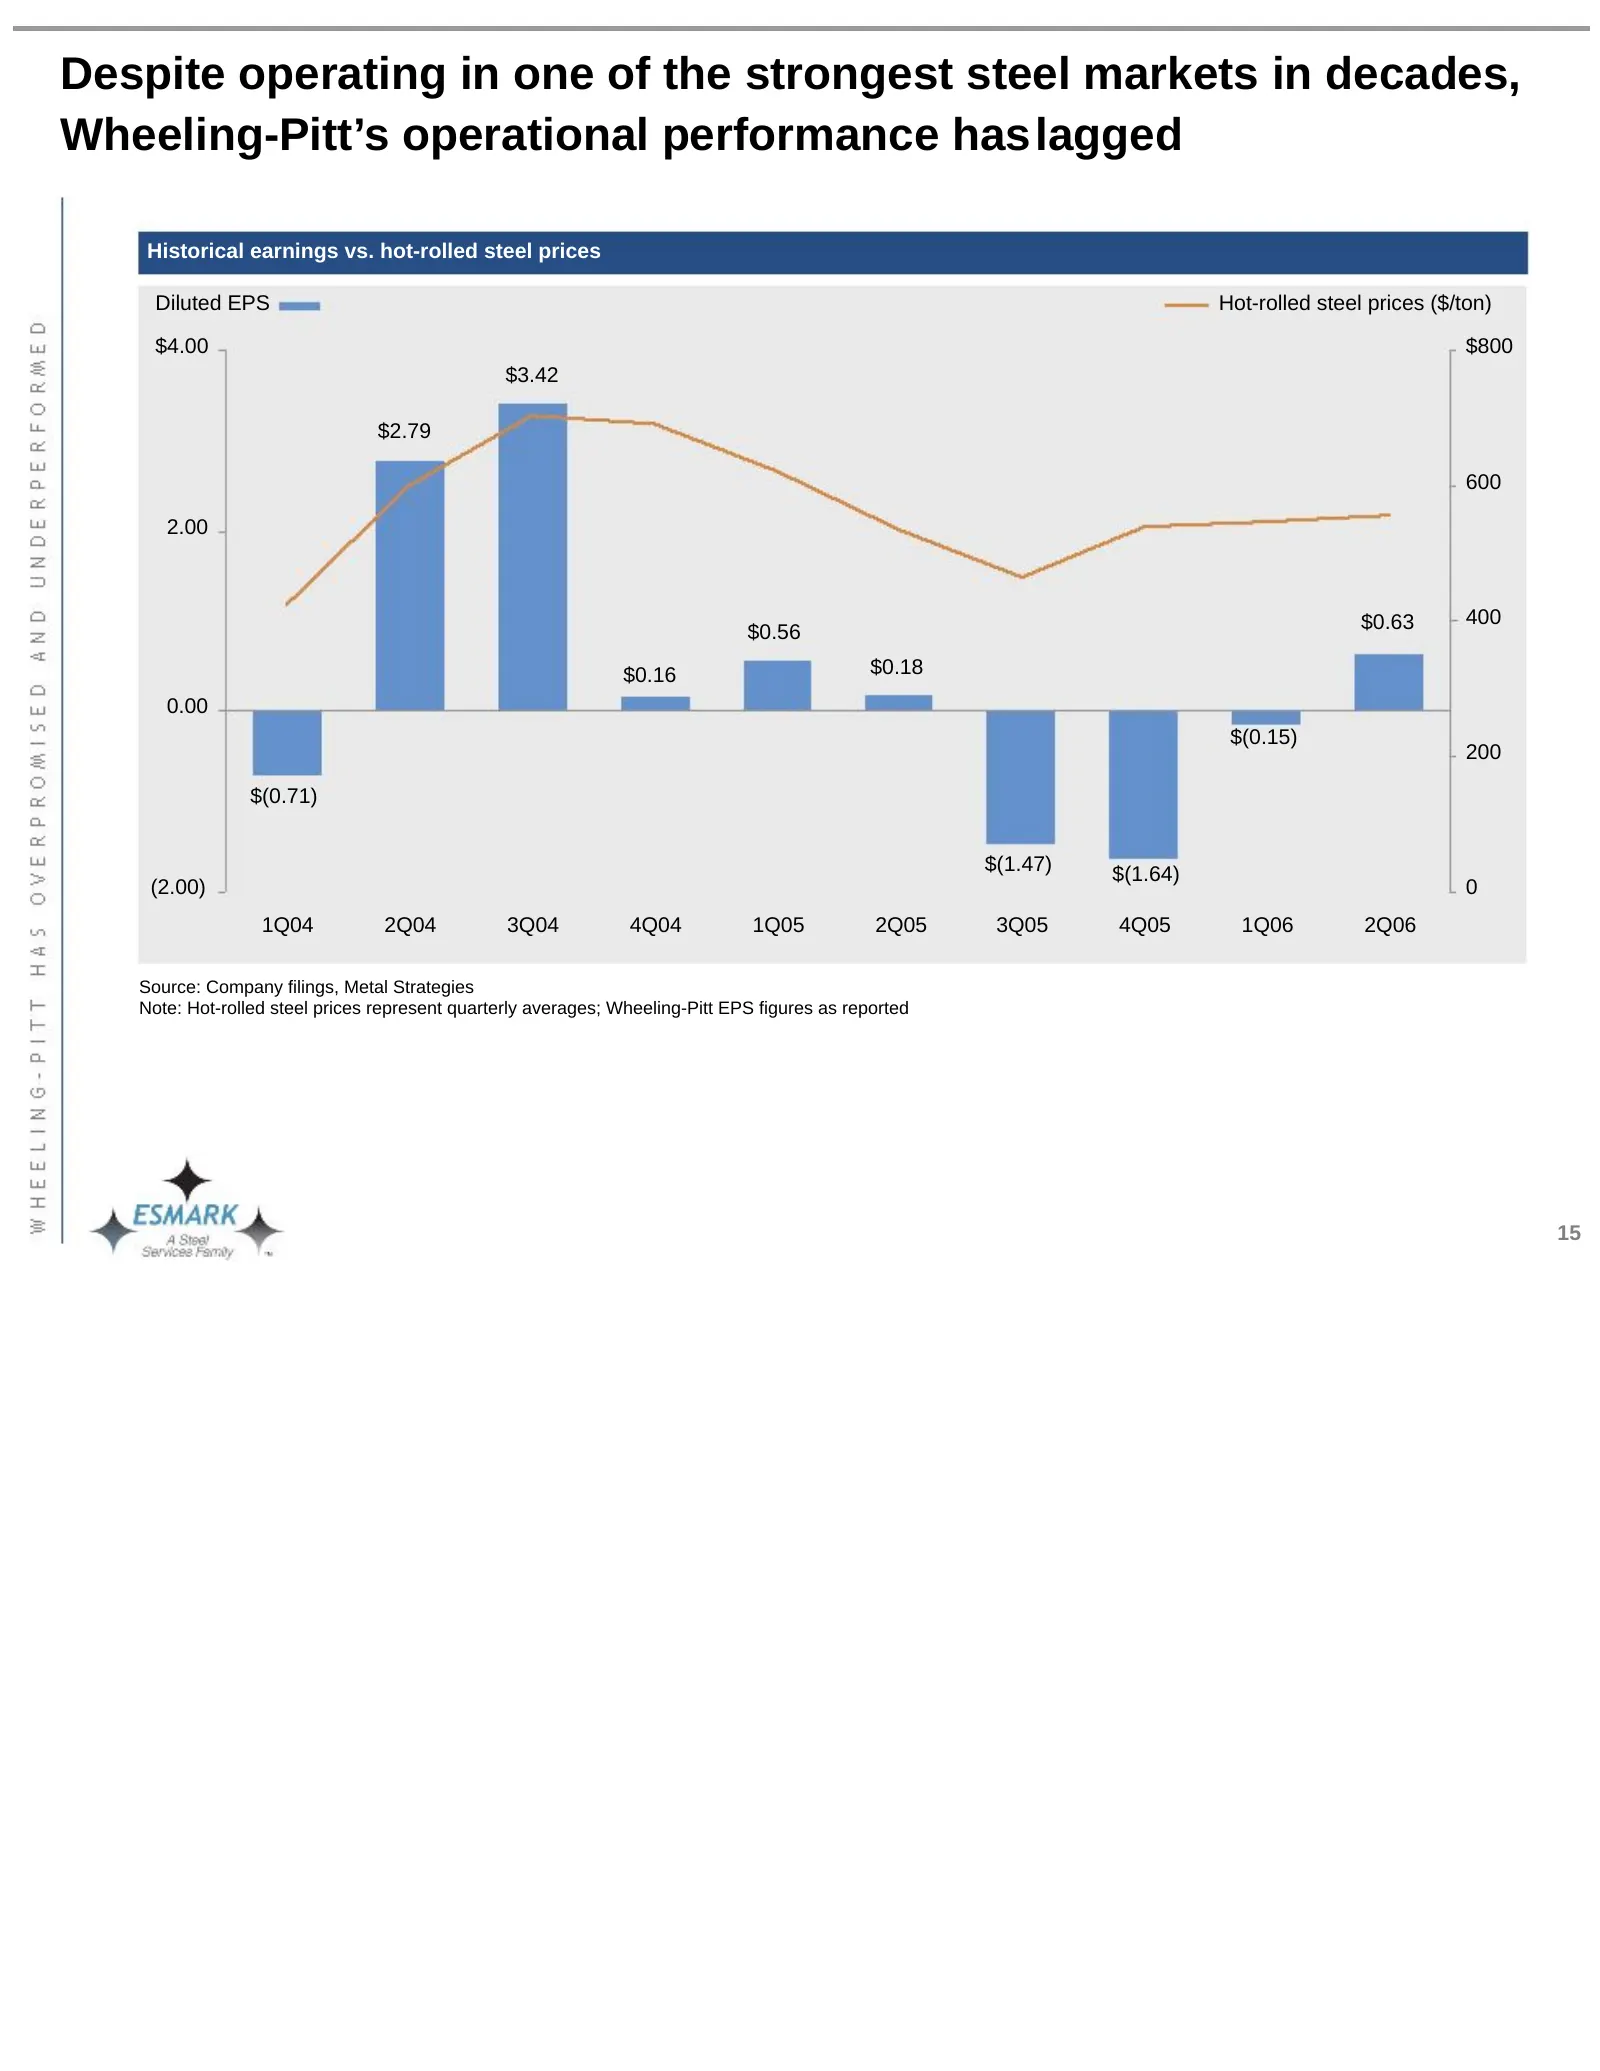
Despite operating in one of the strongest steel markets in decades, Wheeling-Pitt’s operational performance haslagged Historical earnings vs. hot-rolled steel prices Diluted EPS Hot-rolled steel prices ($/ton) $4.00 $800 $3.42 $2.79 600 2.00 $0.63 400 $0.56 $0.16 $0.18 0.00 $(0.15) 200 $(0.71) $(1.4
Slide 19: Industry peers were more successful in meeting Street expectations
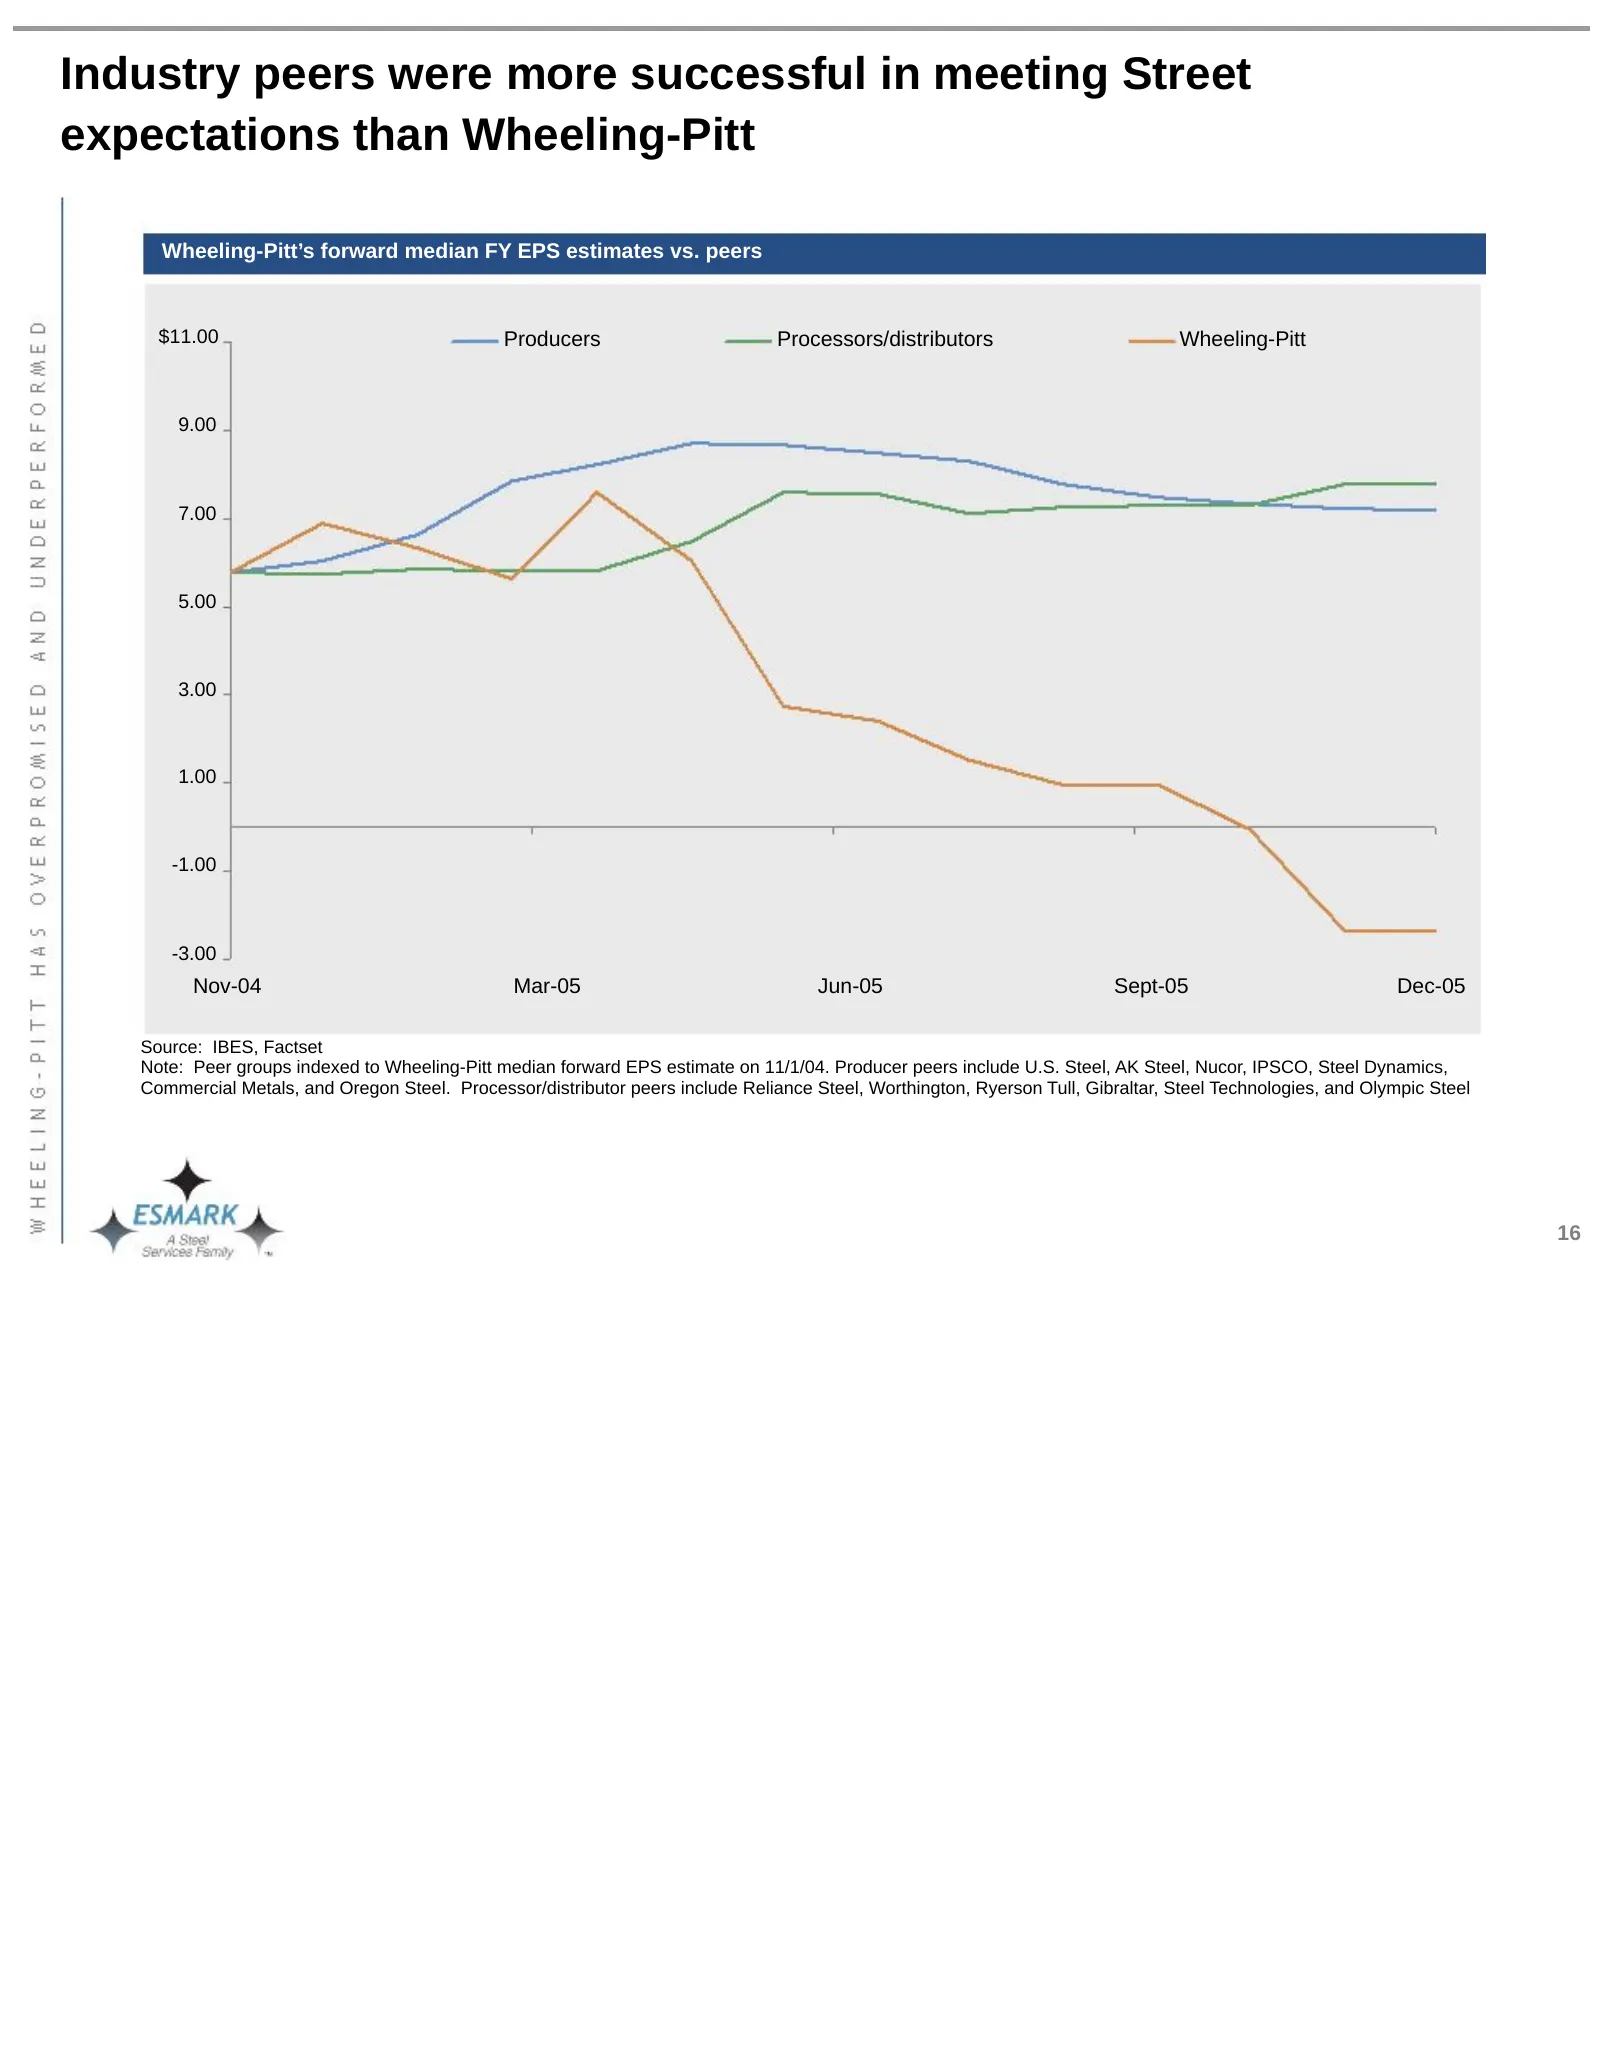
Industry peers were more successful in meeting Street expectations than Wheeling-Pitt Wheeling-Pitt’s forward median FY EPS estimates vs. peers $11.00 Producers Processors/distributors Wheeling-Pitt 9.00 7.00 5.00 3.00 1.00 -1.00 -3.00 Nov-04 11/1/04 Mar-05 2/7/05 Jun-05 5/17/05 Sept-05 8/24/05 Dec-
Slide 20: Wheeling-Pitt's performance has been plagued by a number of factors
Wheeling-Pitt’s performance has been plagued by a number of factors… Despite Wheeling-Pitt posting a profit in 2Q06, this came after three consecutive quarterly operating losses posted by the Company and continues to lag behind industry peers. Anticipated 3Q profit will also lag 2Q06 costs of $651/t
Slide 21: Highly levered capital structure with inconsistent cash flow
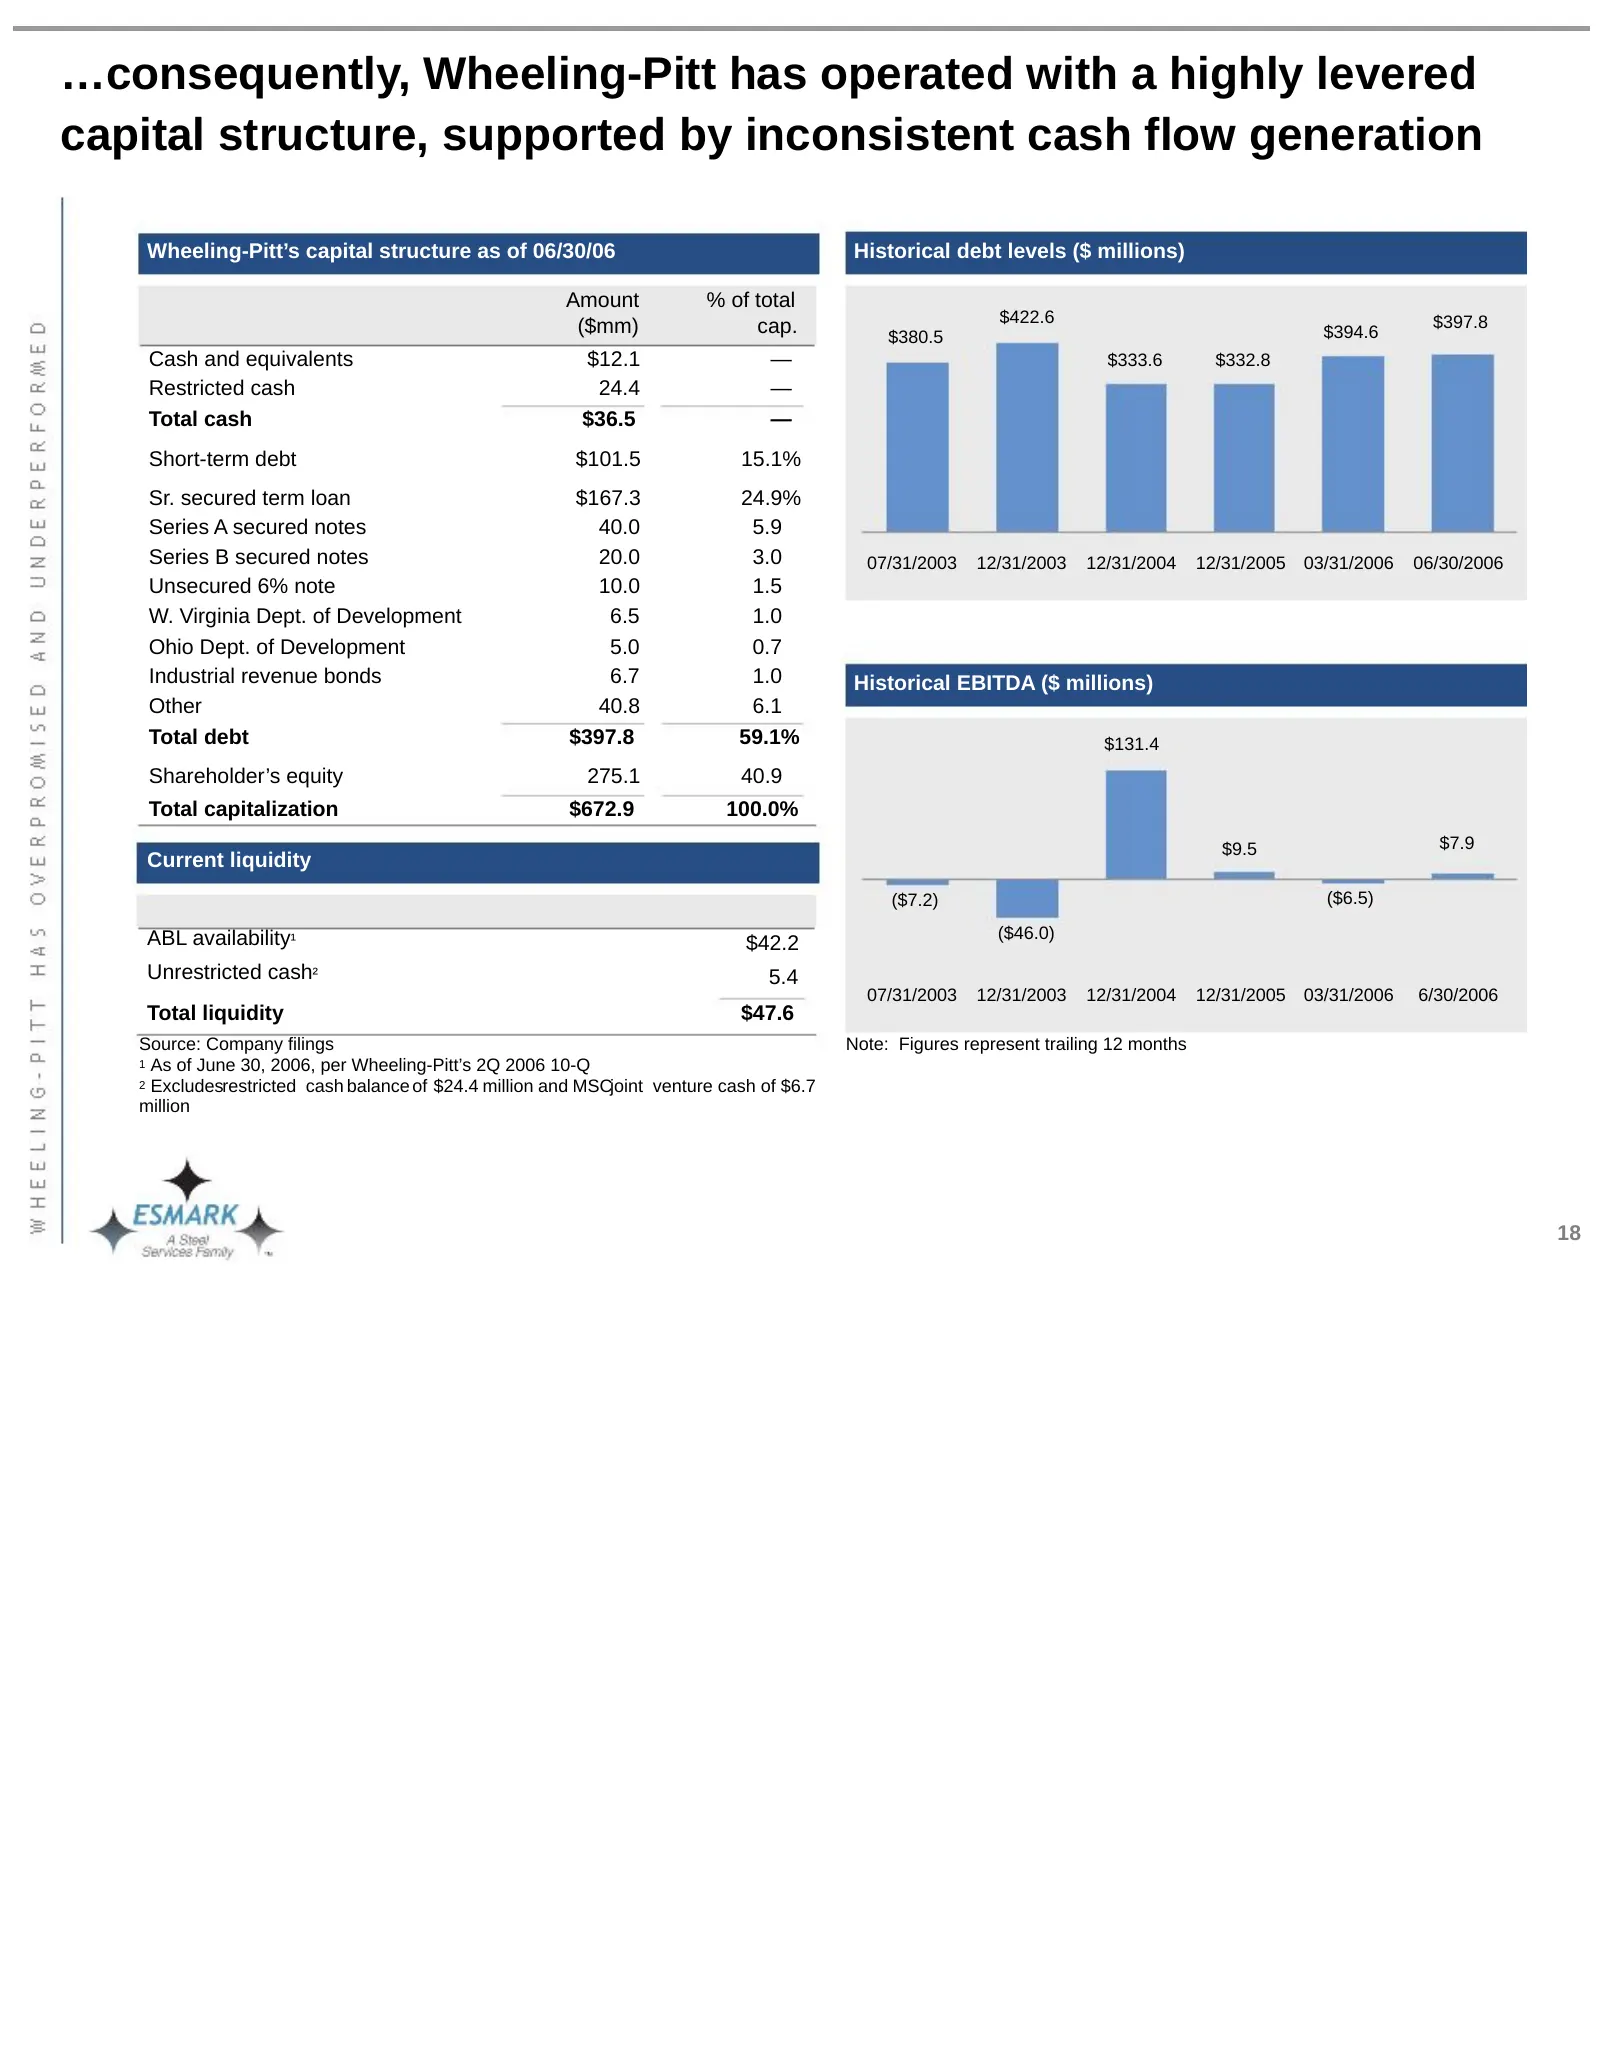
…consequently, Wheeling-Pitt has operated with a highly levered capital structure, supported by inconsistent cash flow generation Wheeling-Pitt’s capital structure as of 06/30/06 Historical debt levels ($ millions) Amount % of total $422.6 $397.8 ($mm) cap. $380.5 $394.6 Cash and equivalents $12.1 —
Slide 22: Wheeling-Pitt remains the highest cost producer
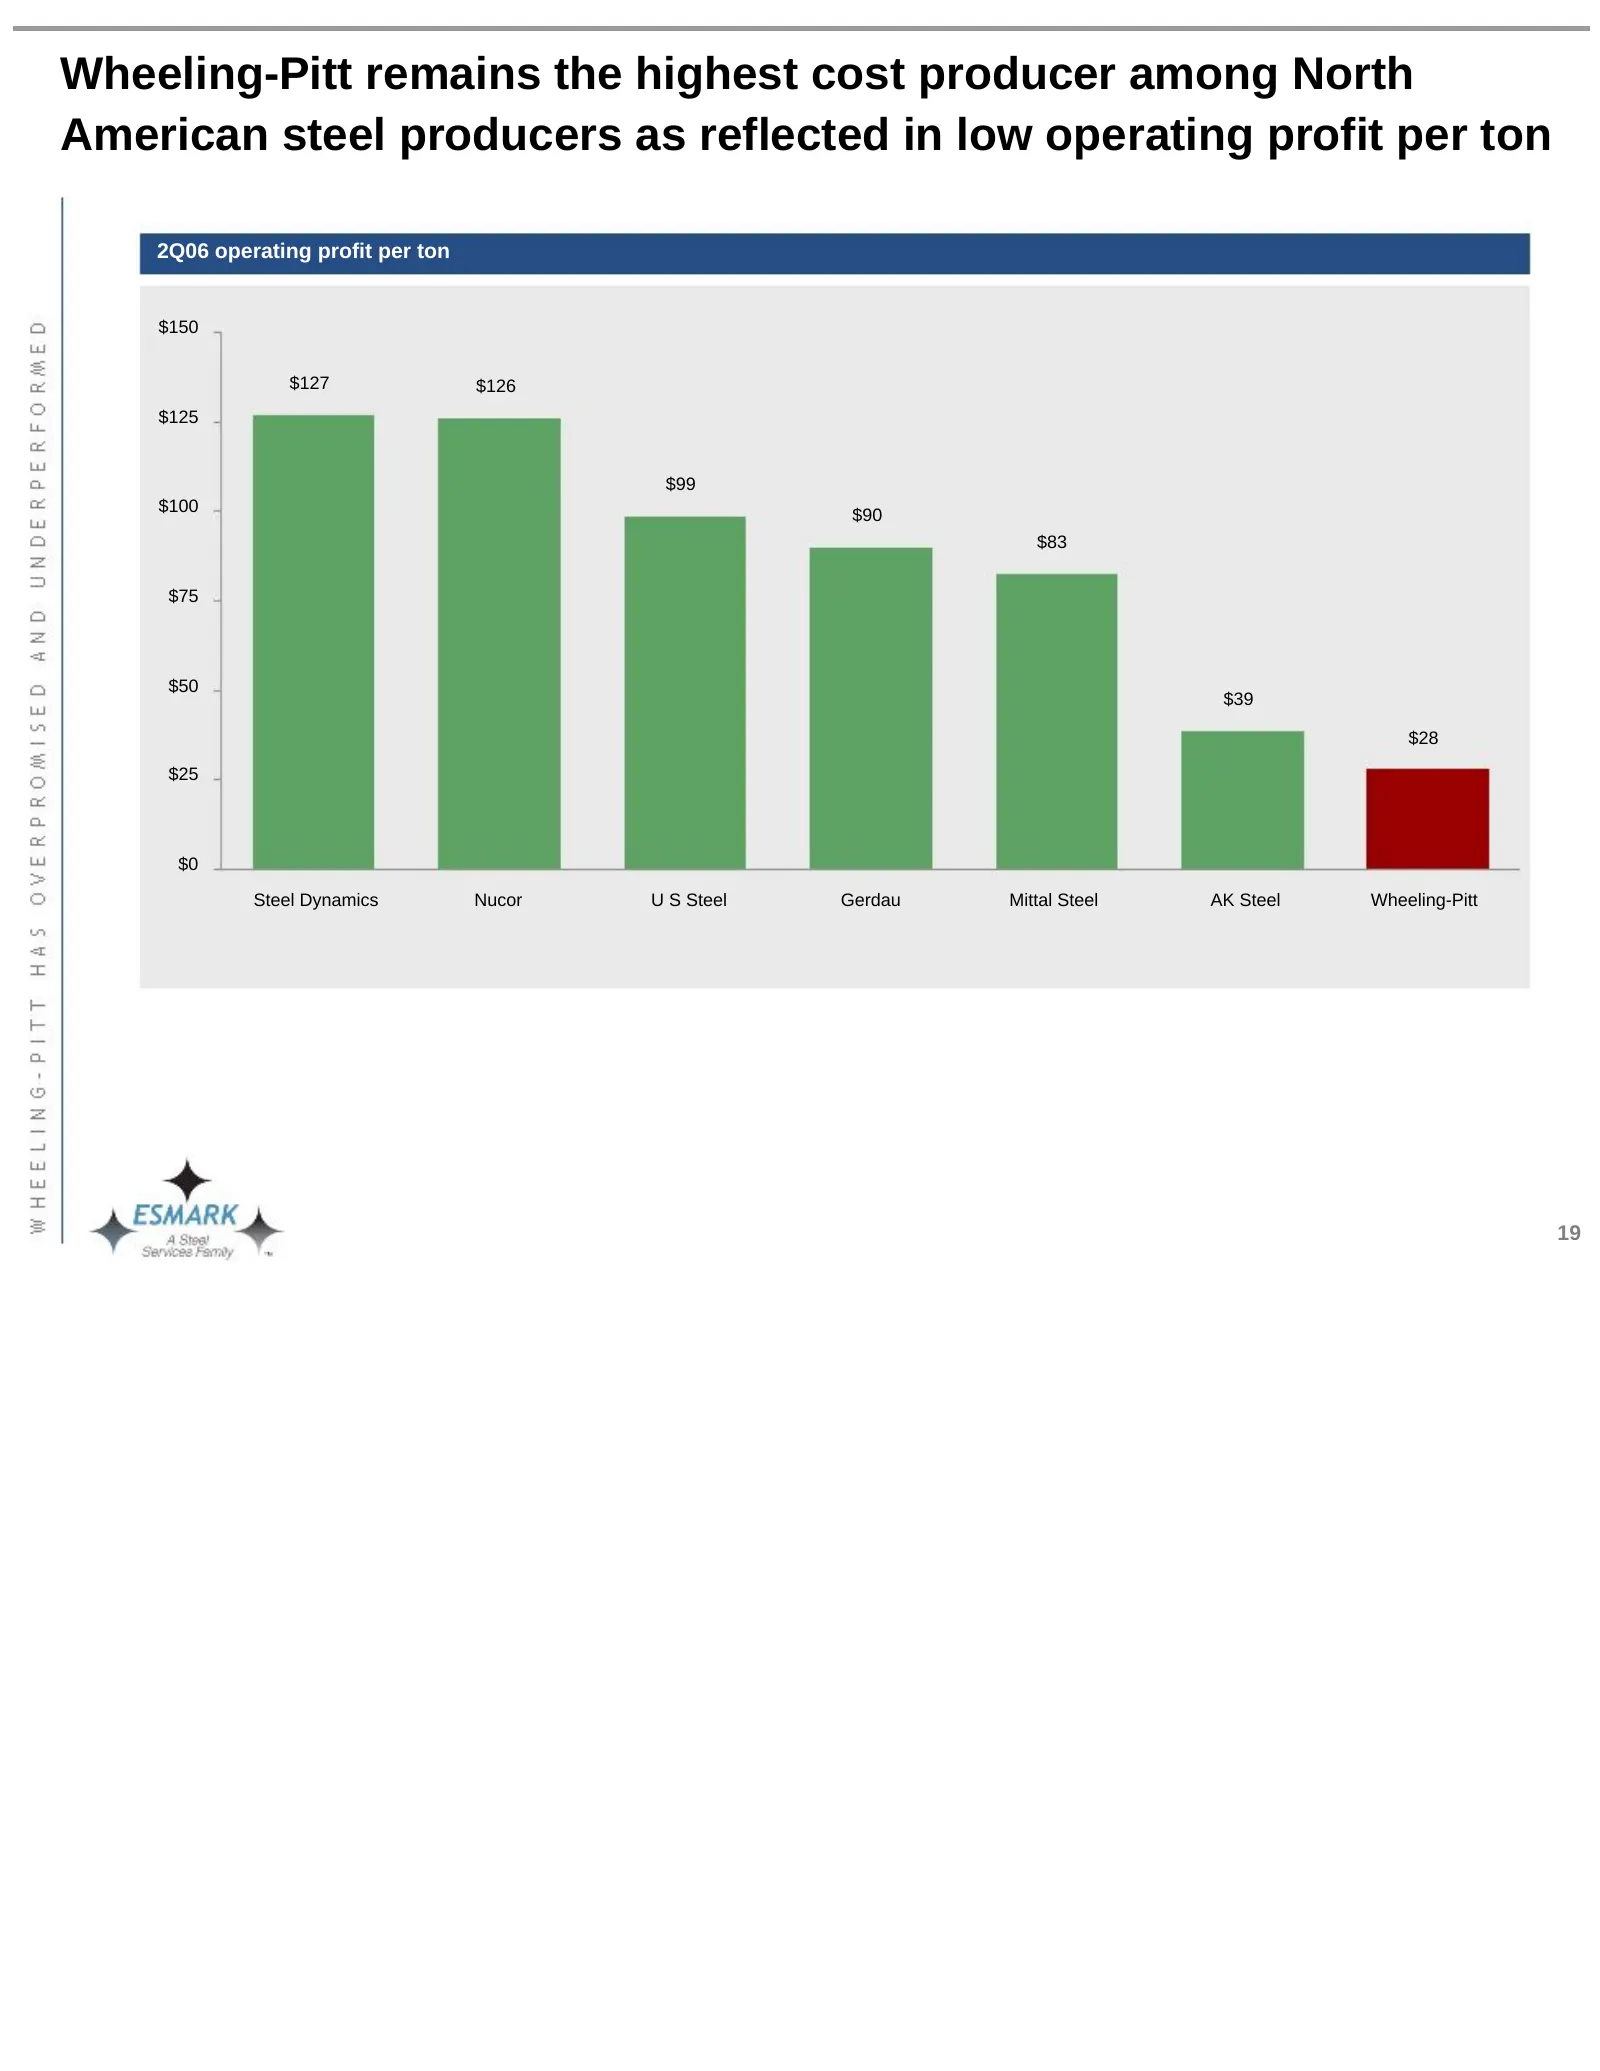
Wheeling-Pitt remains the highest cost producer among North American steel producers as reflected in low operating profit per ton 2Q06 operating profit per ton $150 $127 $126 $125 $99 $100 $90 $83 $75 $50 $39 $28 $25 $0 Steel Dynamics Nucor U S Steel Gerdau Mittal Steel AK Steel Wheeling-Pitt 19
Slide 23: Specific examples of Wheeling-Pitt's operating failures
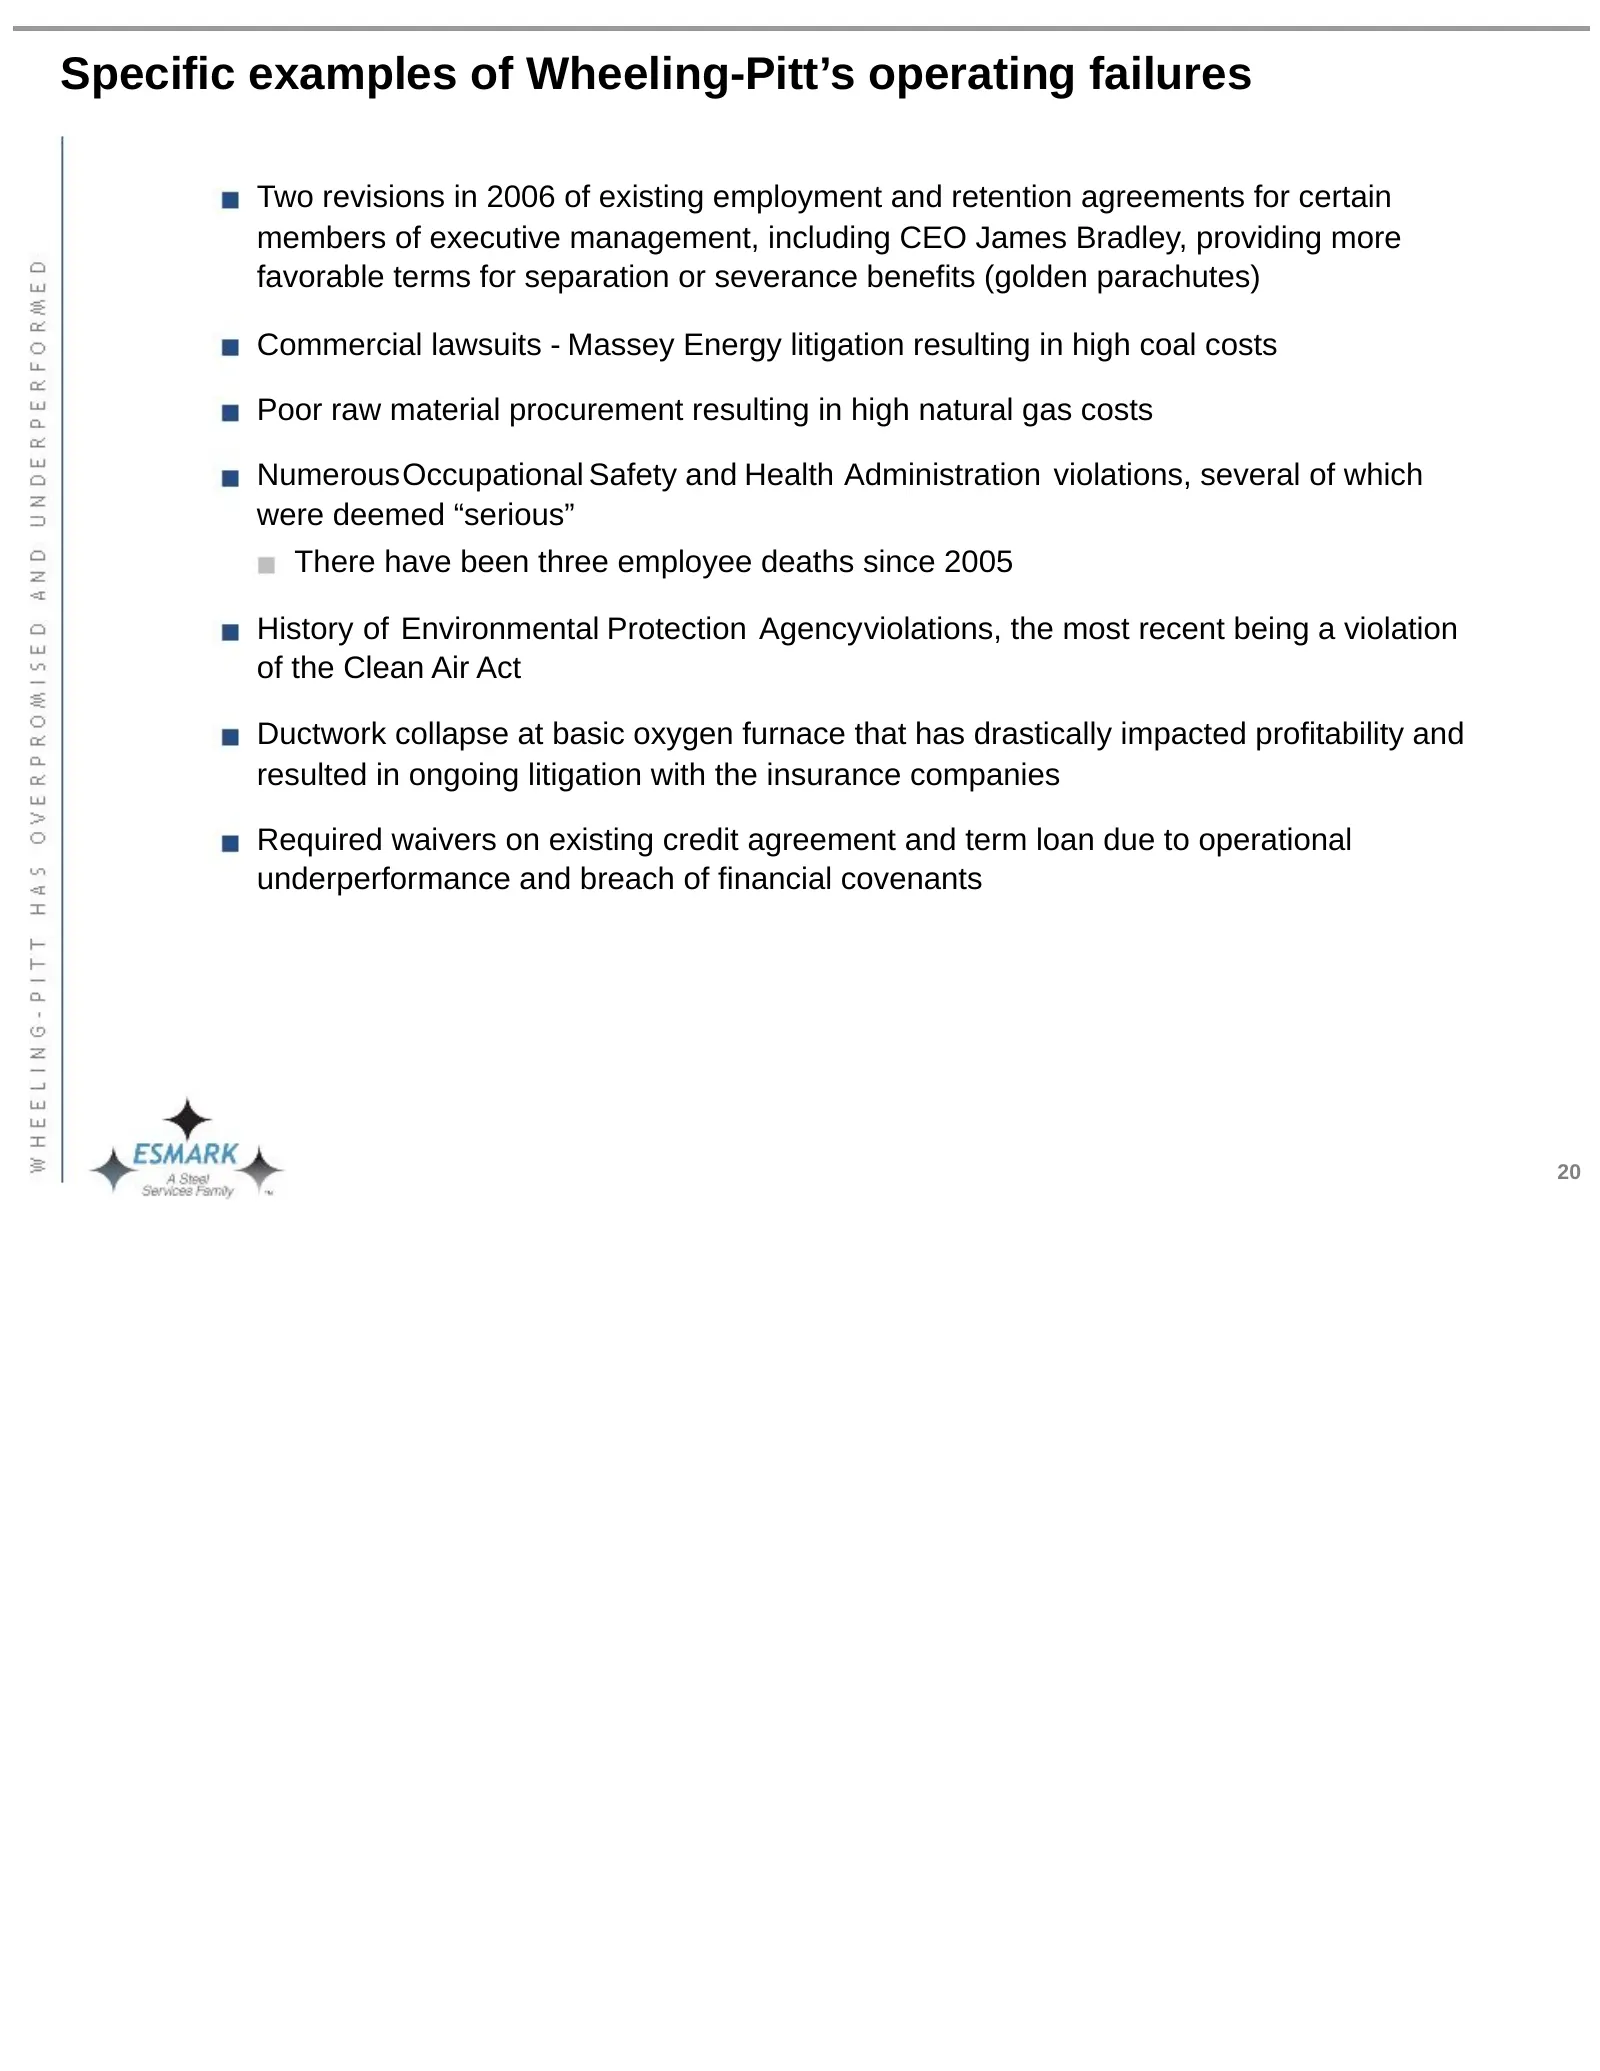
Specific examples of Wheeling-Pitt’s operating failures Two revisions in 2006 of existing employment and retention agreements for certain members of executive management, including CEO James Bradley, providing more favorable terms for separation or severance benefits (golden parachutes) Commercial l
Slide 24: Agenda
Agenda Page Executive summary and director slate 2 Wheeling-Pitt has overpromised and underperformed 13 Esmark’s Strategic vision and operating plan 21 Conclusion 33 21
Slide 25: Strategy for Wheeling-Pitt
Strategy for Wheeling-Pitt There are three basic requirements for a small regional steel producer like Wheeling- Pitt to succeed: Strong partnership with its Union Low-cost producers Large, diverse and loyal customer base Strategy for Wheeling-Pitt Build a “niche” regional steel company Combine mill
Slide 26: Esmark's process to fix Wheeling-Pitt
Esmark’s process to fix Wheeling-Pitt Step 1: Replace current Board of Directors with new slate of talented, experienced, and independent individuals Step 2: Replace current management with well-qualified team that has a proven track record and significant steel industry experience Step 3: Appoint a
Slide 27: Esmark's proposed executive management team
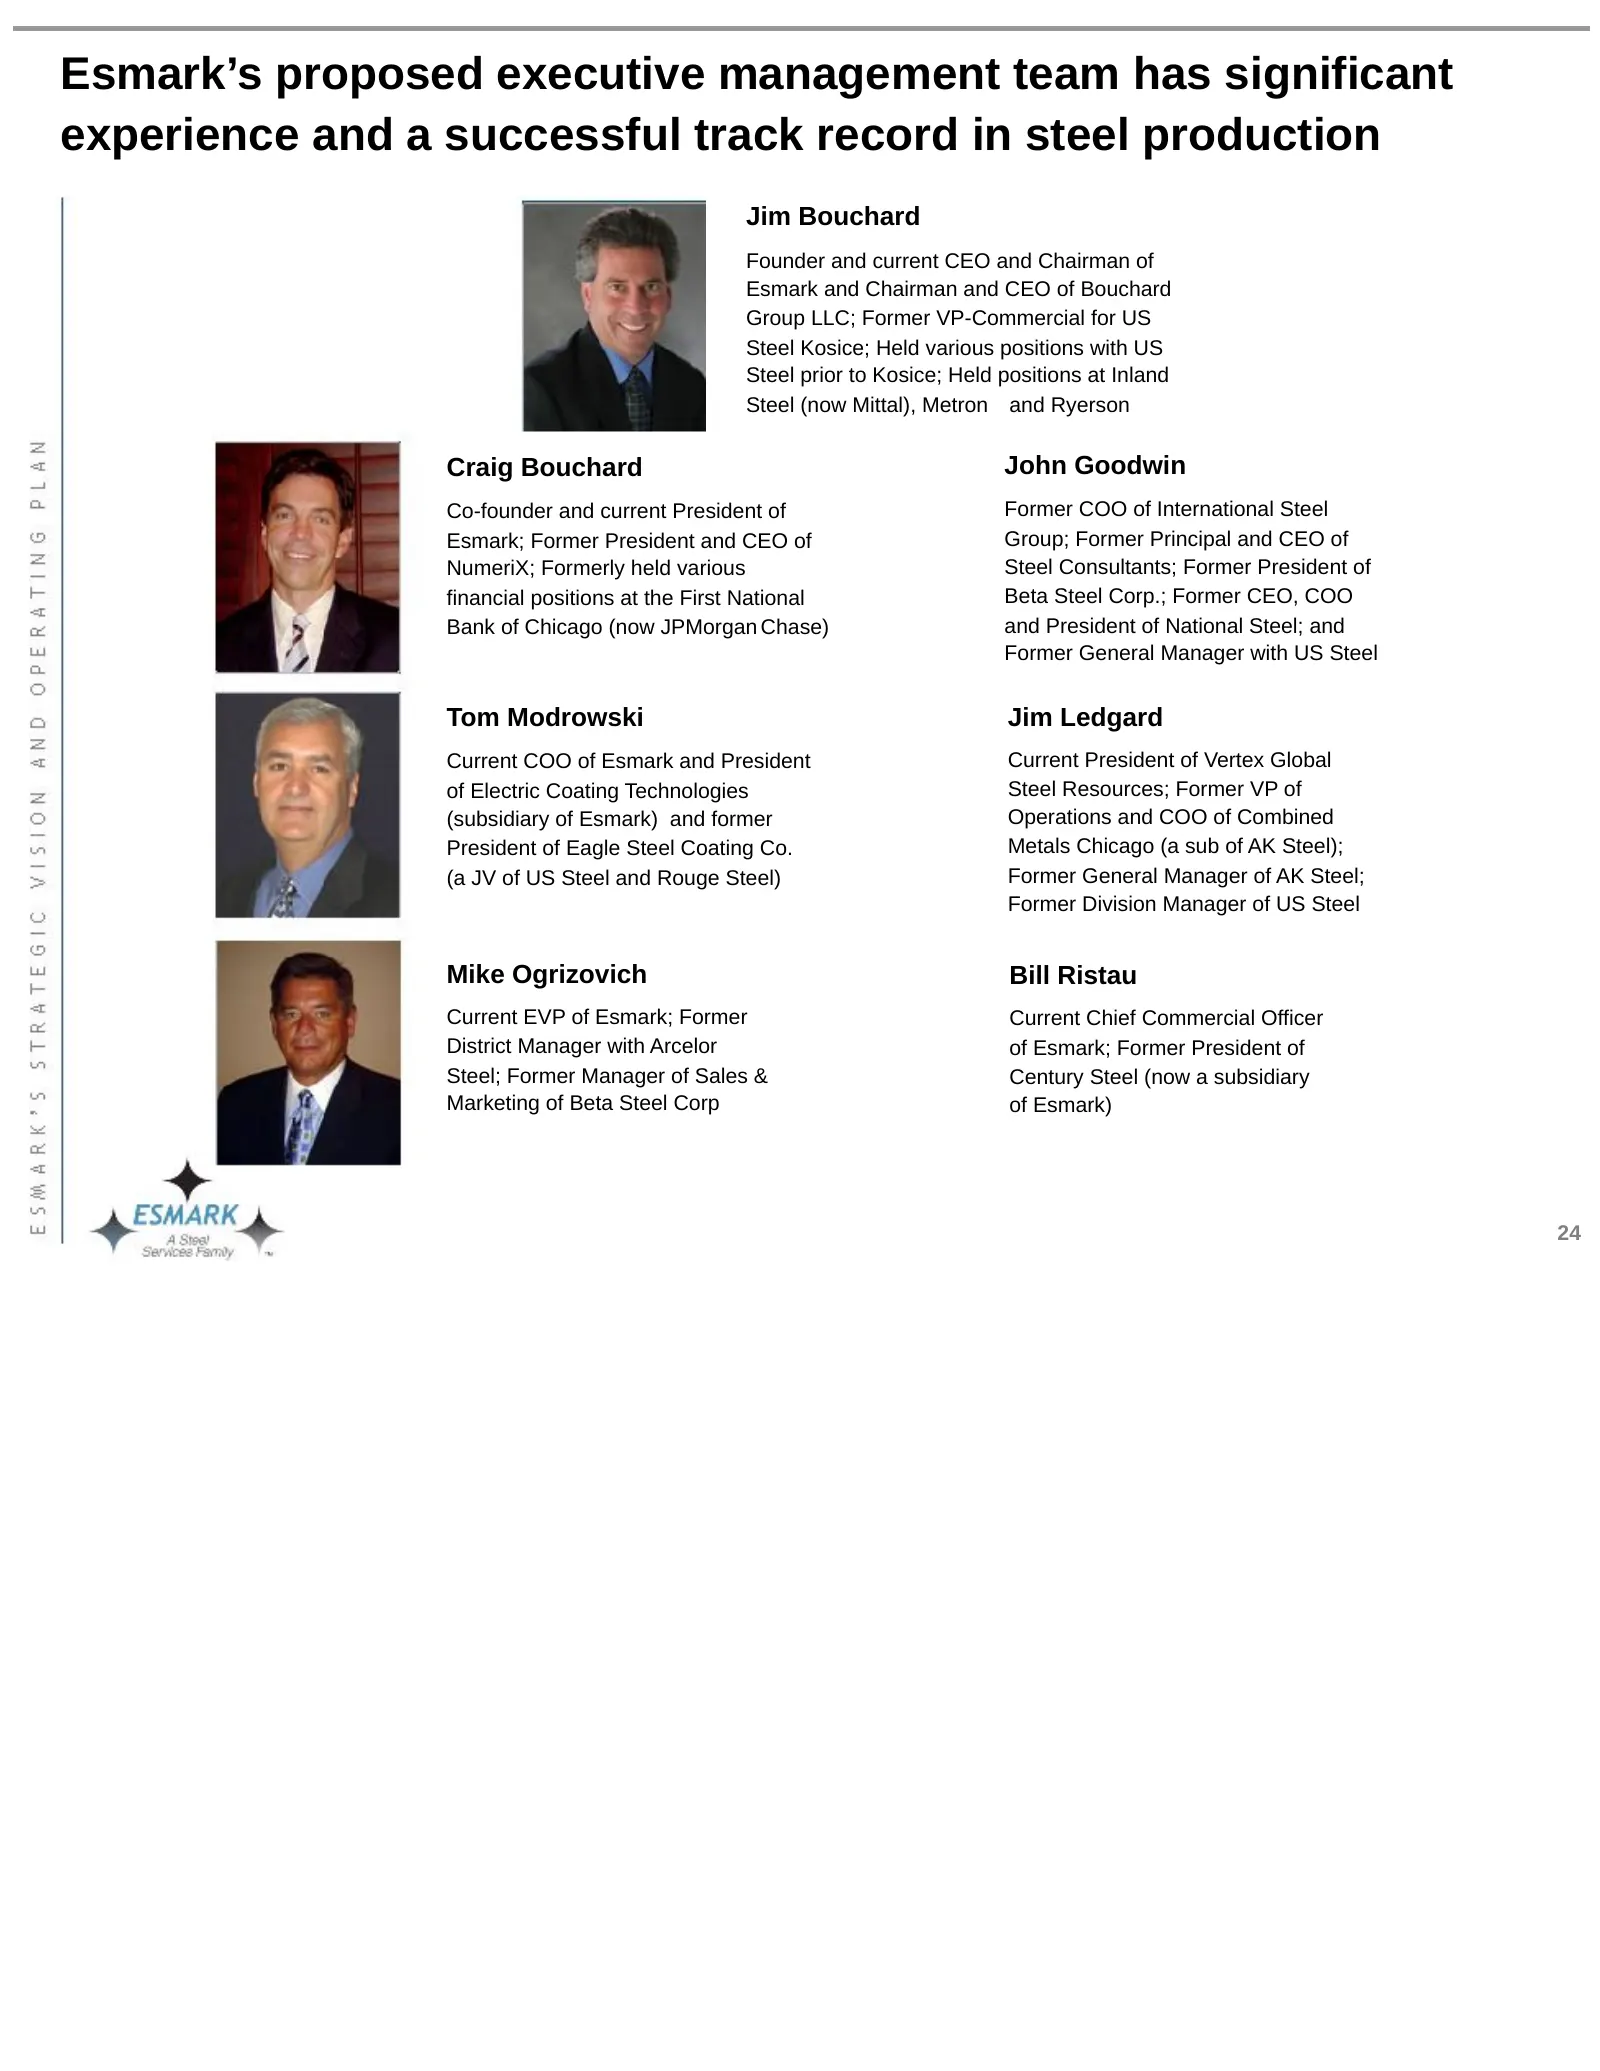
Esmark’s proposed executive management team has significant experience and a successful track record in steel production Jim Bouchard Founder and current CEO and Chairman of Esmark and Chairman and CEO of Bouchard Group LLC; Former VP-Commercial for US Steel Kosice; Held various positions with US St
Slide 28: Esmark's current proposal
Esmark’s current proposal Wheeling-Pitt would issue 16.5 million new common shares to Esmark shareholders valued at approximately $295 million, based on the closing share price of $17.86 as of July 14, 2006 and Esmark’s valuation as of the same date* Esmark has arranged in principle new credit facil
Slide 29: Combination would create a strong model for growth and profitability
The combination of Esmark and Wheeling-Pitt would create a strong model for growth and profitability in North American steel Combining the nation’s 4th largest steel mill, Wheeling-Pitt, with Esmark’s rapidly growing service center and converter distribution network provides an opportunity for the n
Slide 30: Esmark has been rapidly growing its business
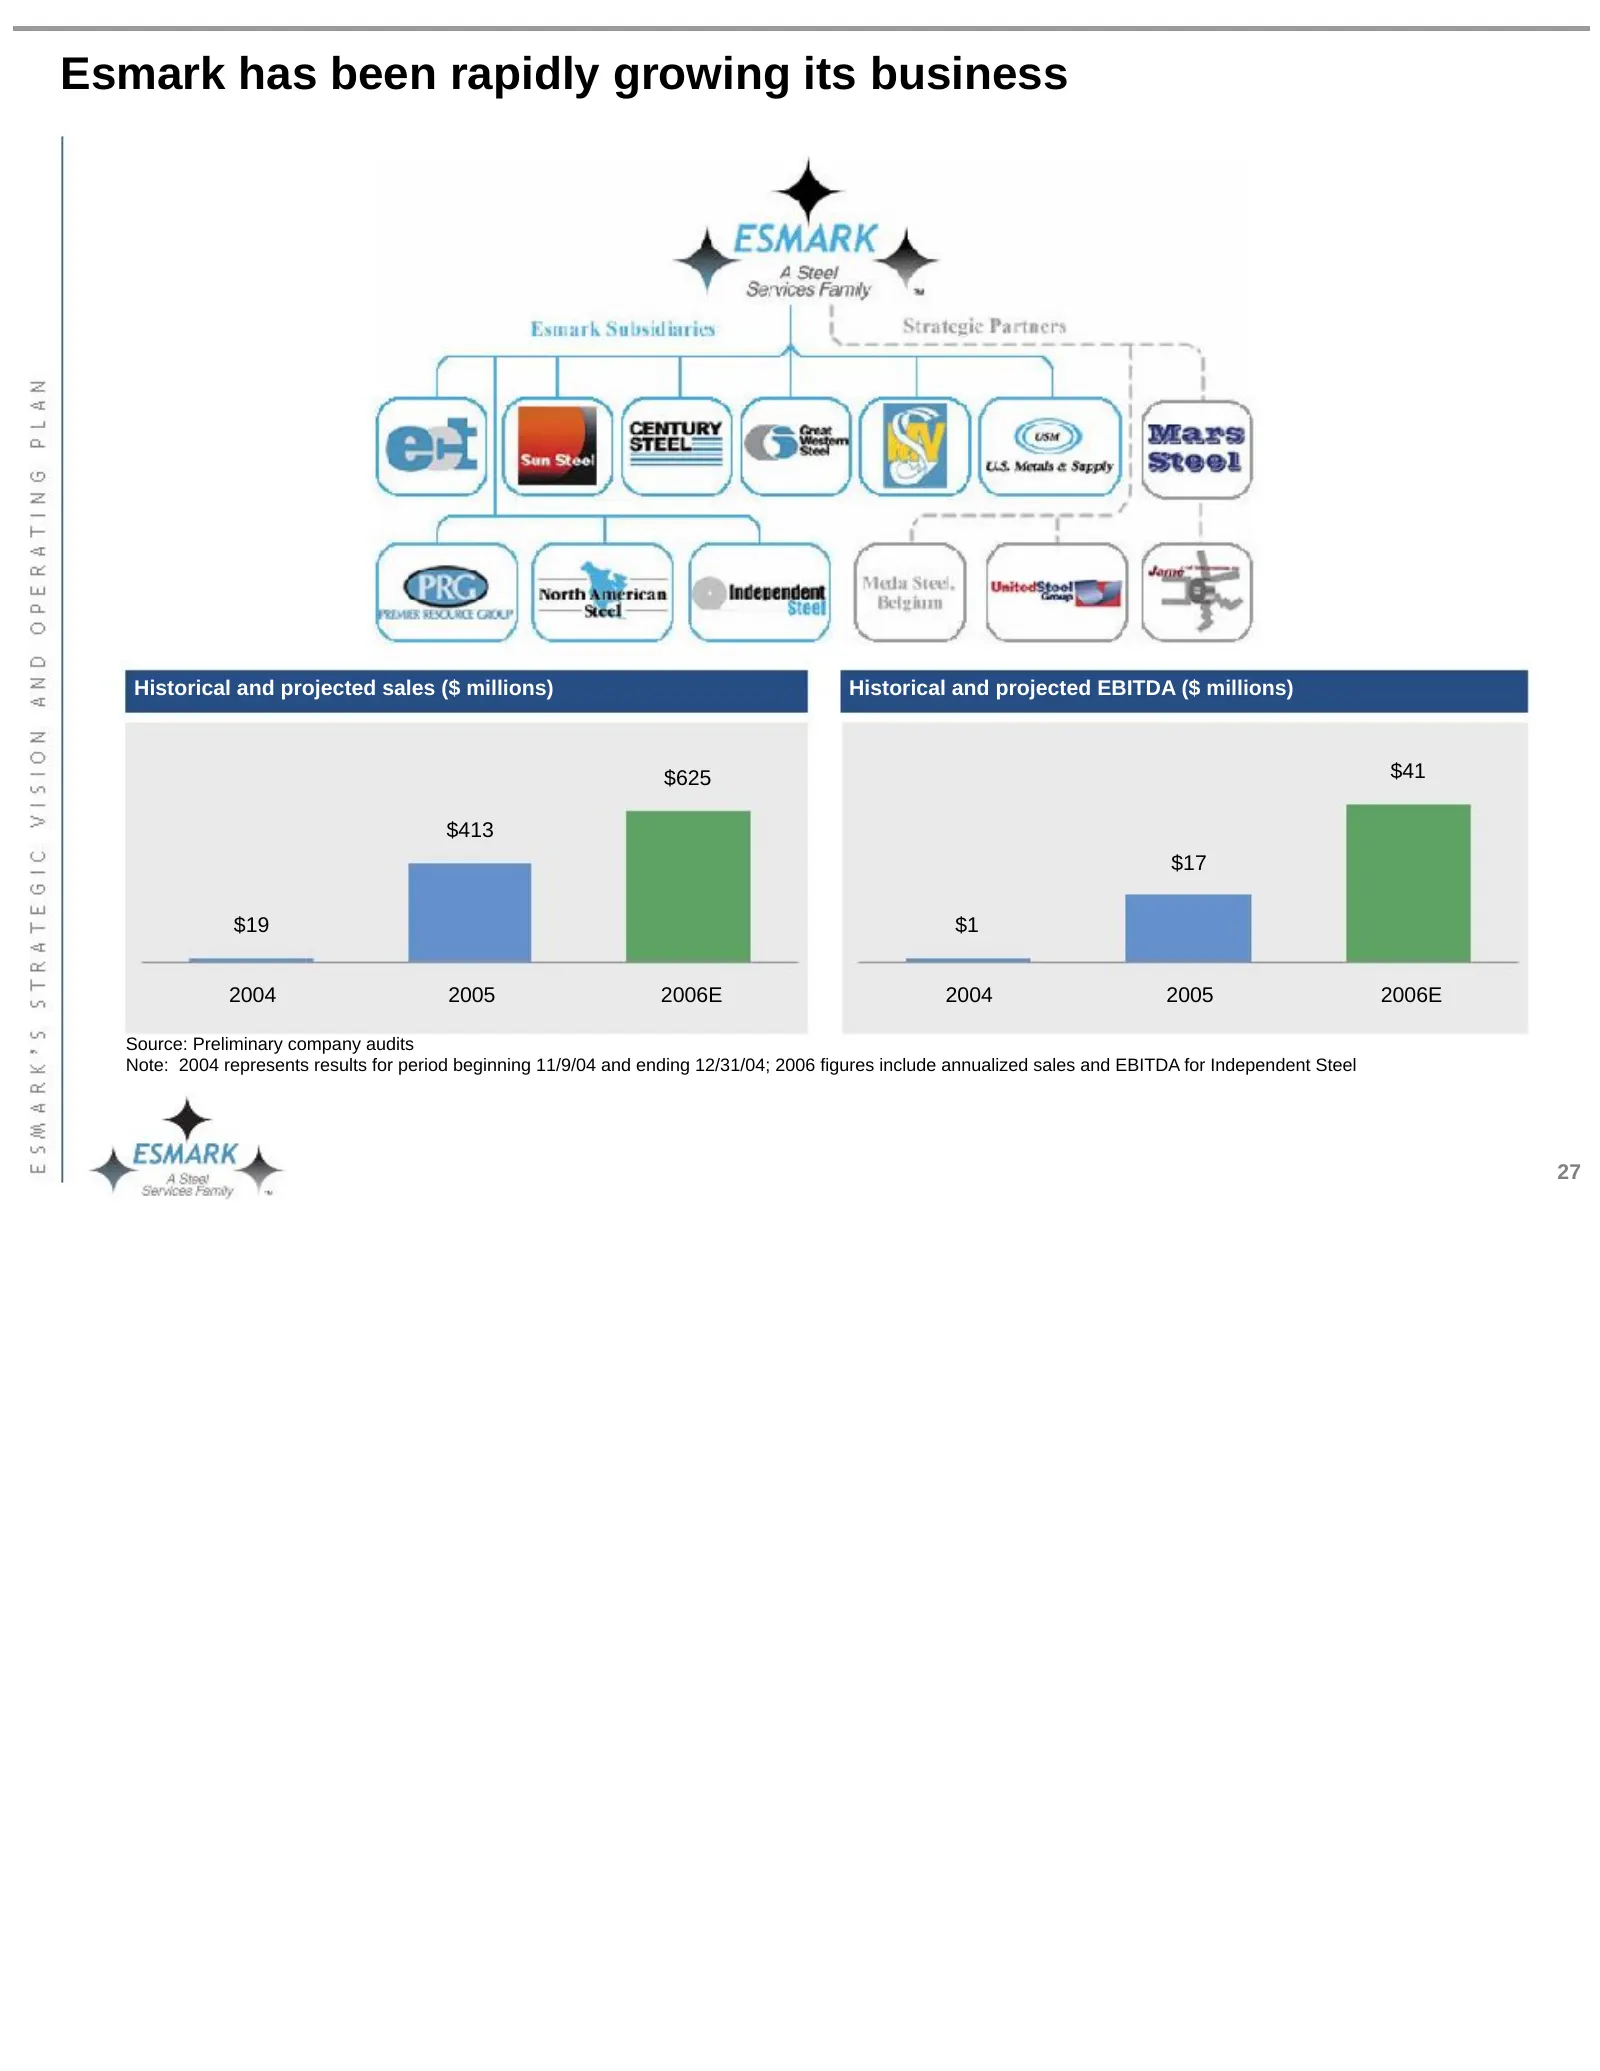
Esmark has been rapidly growing its business Historical and projected sales ($ millions) Historical and projected EBITDA ($ millions) $625 $41 $413 $17 $19 $1 2004 2005 2006E 2004 2005 2006E Source: Preliminary company audits Note: 2004 represents results for period beginning 11/9/04 and ending 12/3
Slide 31: Combination would create a leader with competitive advantages
The combination would create a leader in the U.S. steel marketplace with operational and commercial competitive advantages Transaction merits Supply chain integration Esmark management has a profitable distribution platform with significant growth opportunities Esmark aspires to be the first distrib
Slide 32: Opportunities should be significant
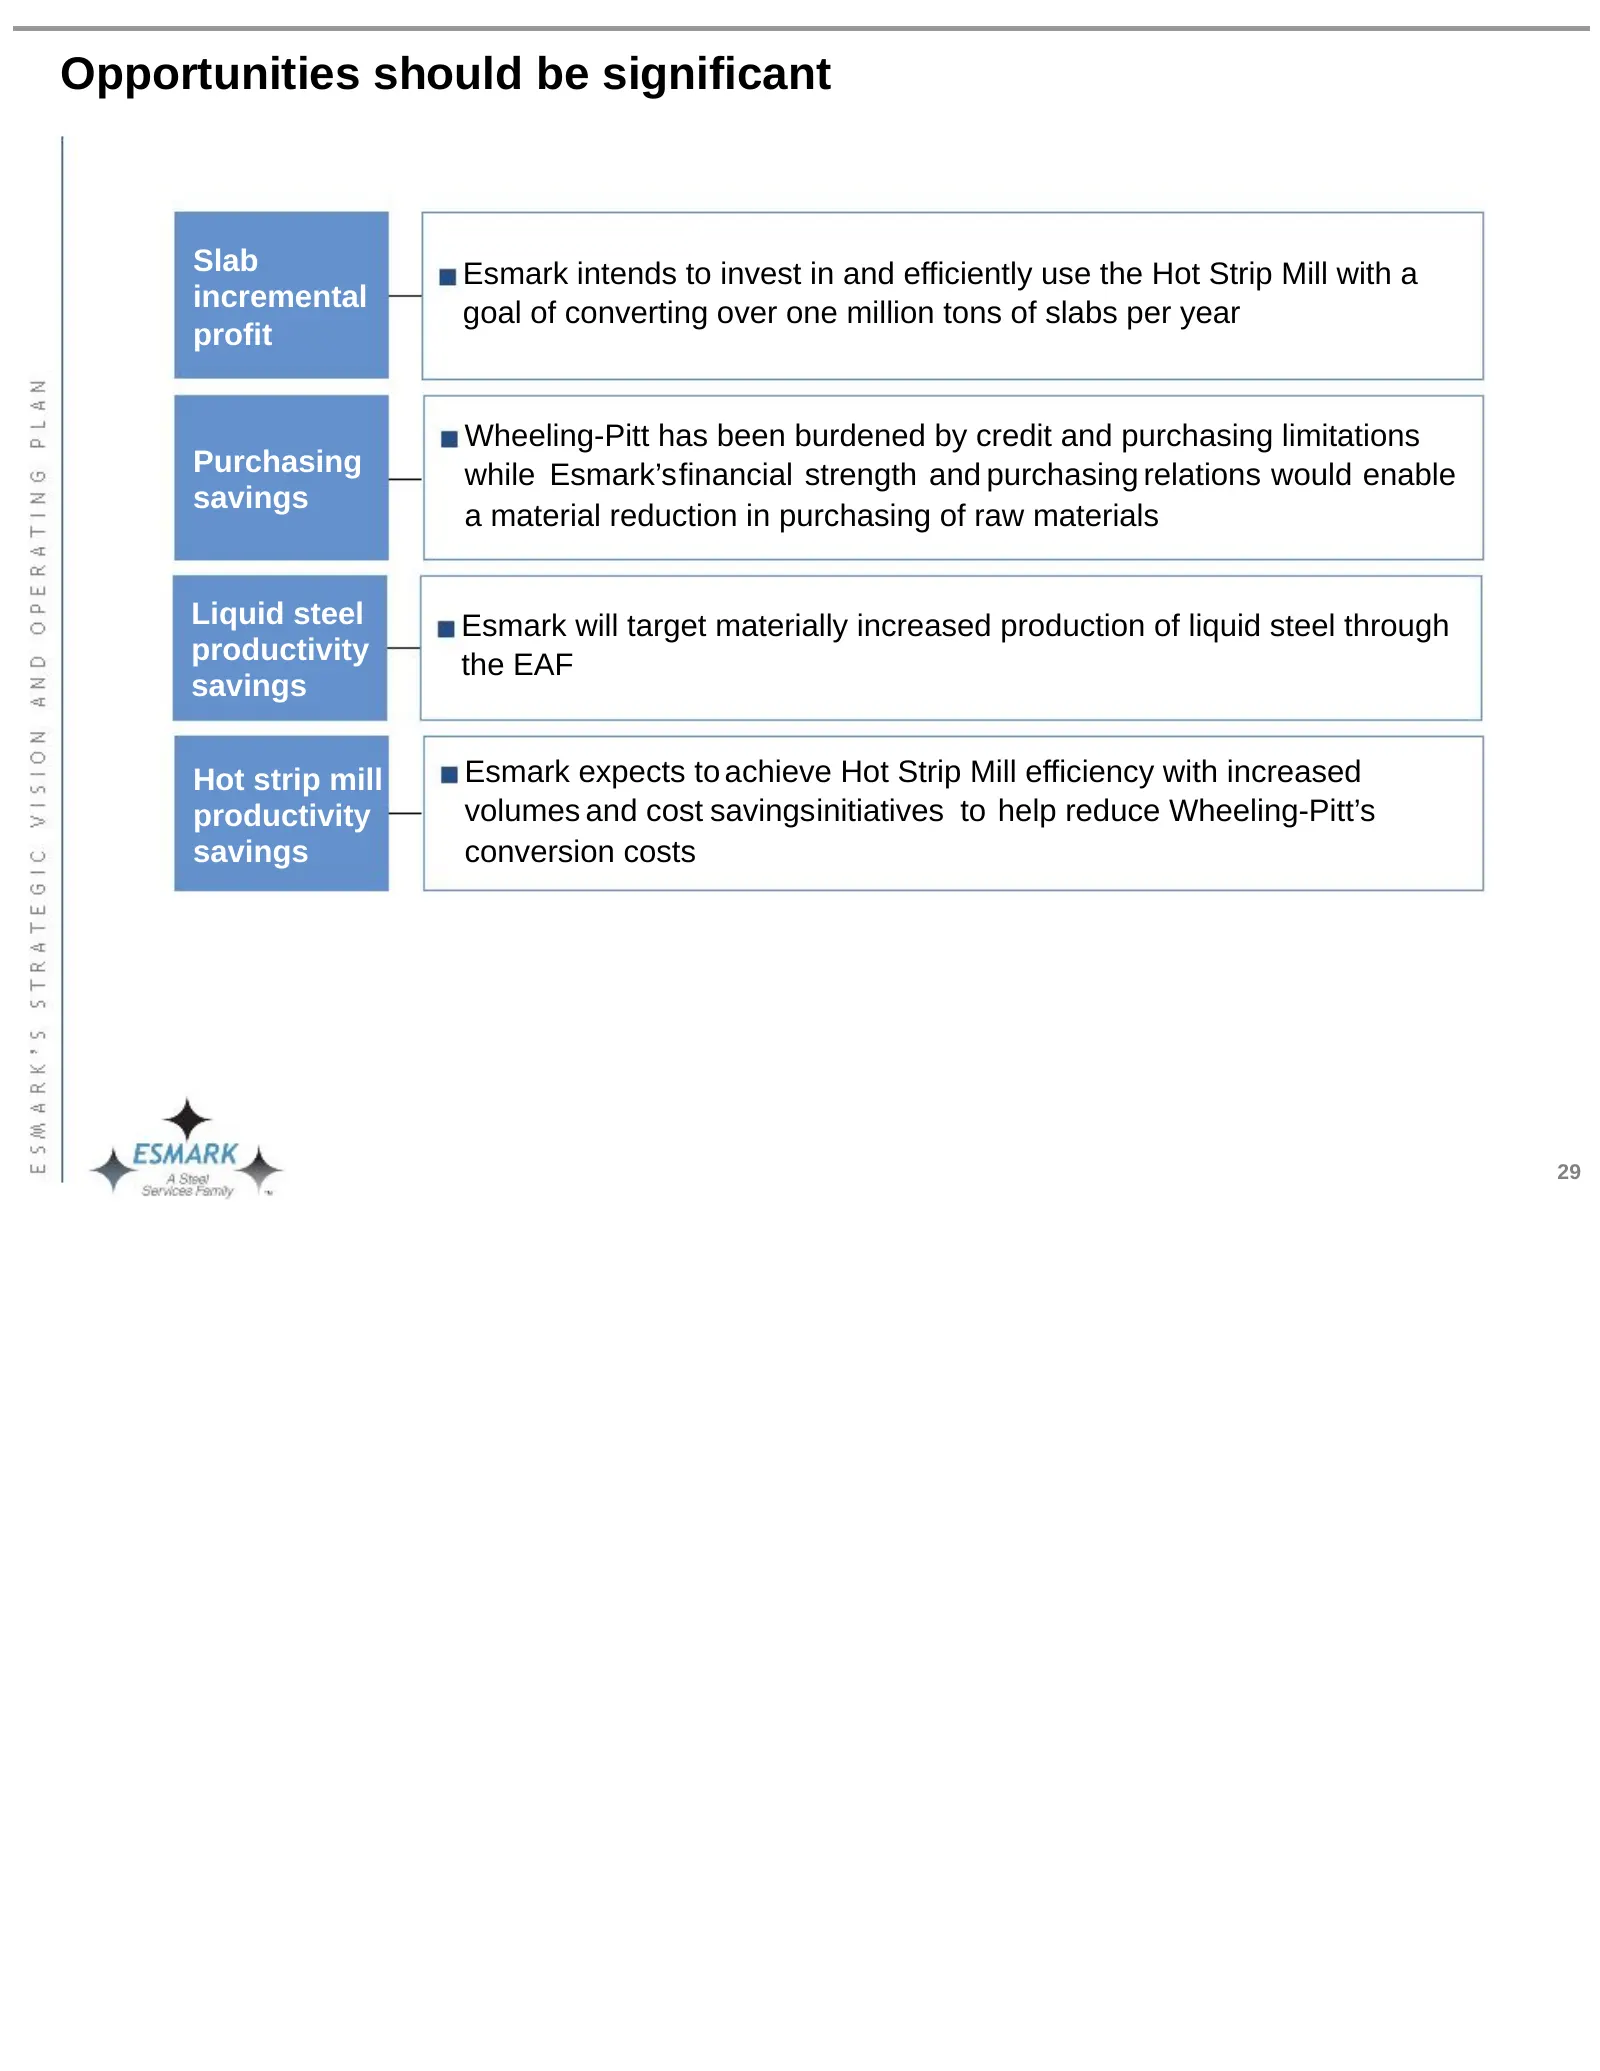
Opportunities should be significant Slab Esmark intends to invest in and efficiently use the Hot Strip Mill with a incremental goal of converting over one million tons of slabs per year profit Wheeling-Pitt has been burdened by credit and purchasing limitations Purchasing while Esmark’sfinancial str
Slide 33: Competitive slab arrangement with two leading steel producers
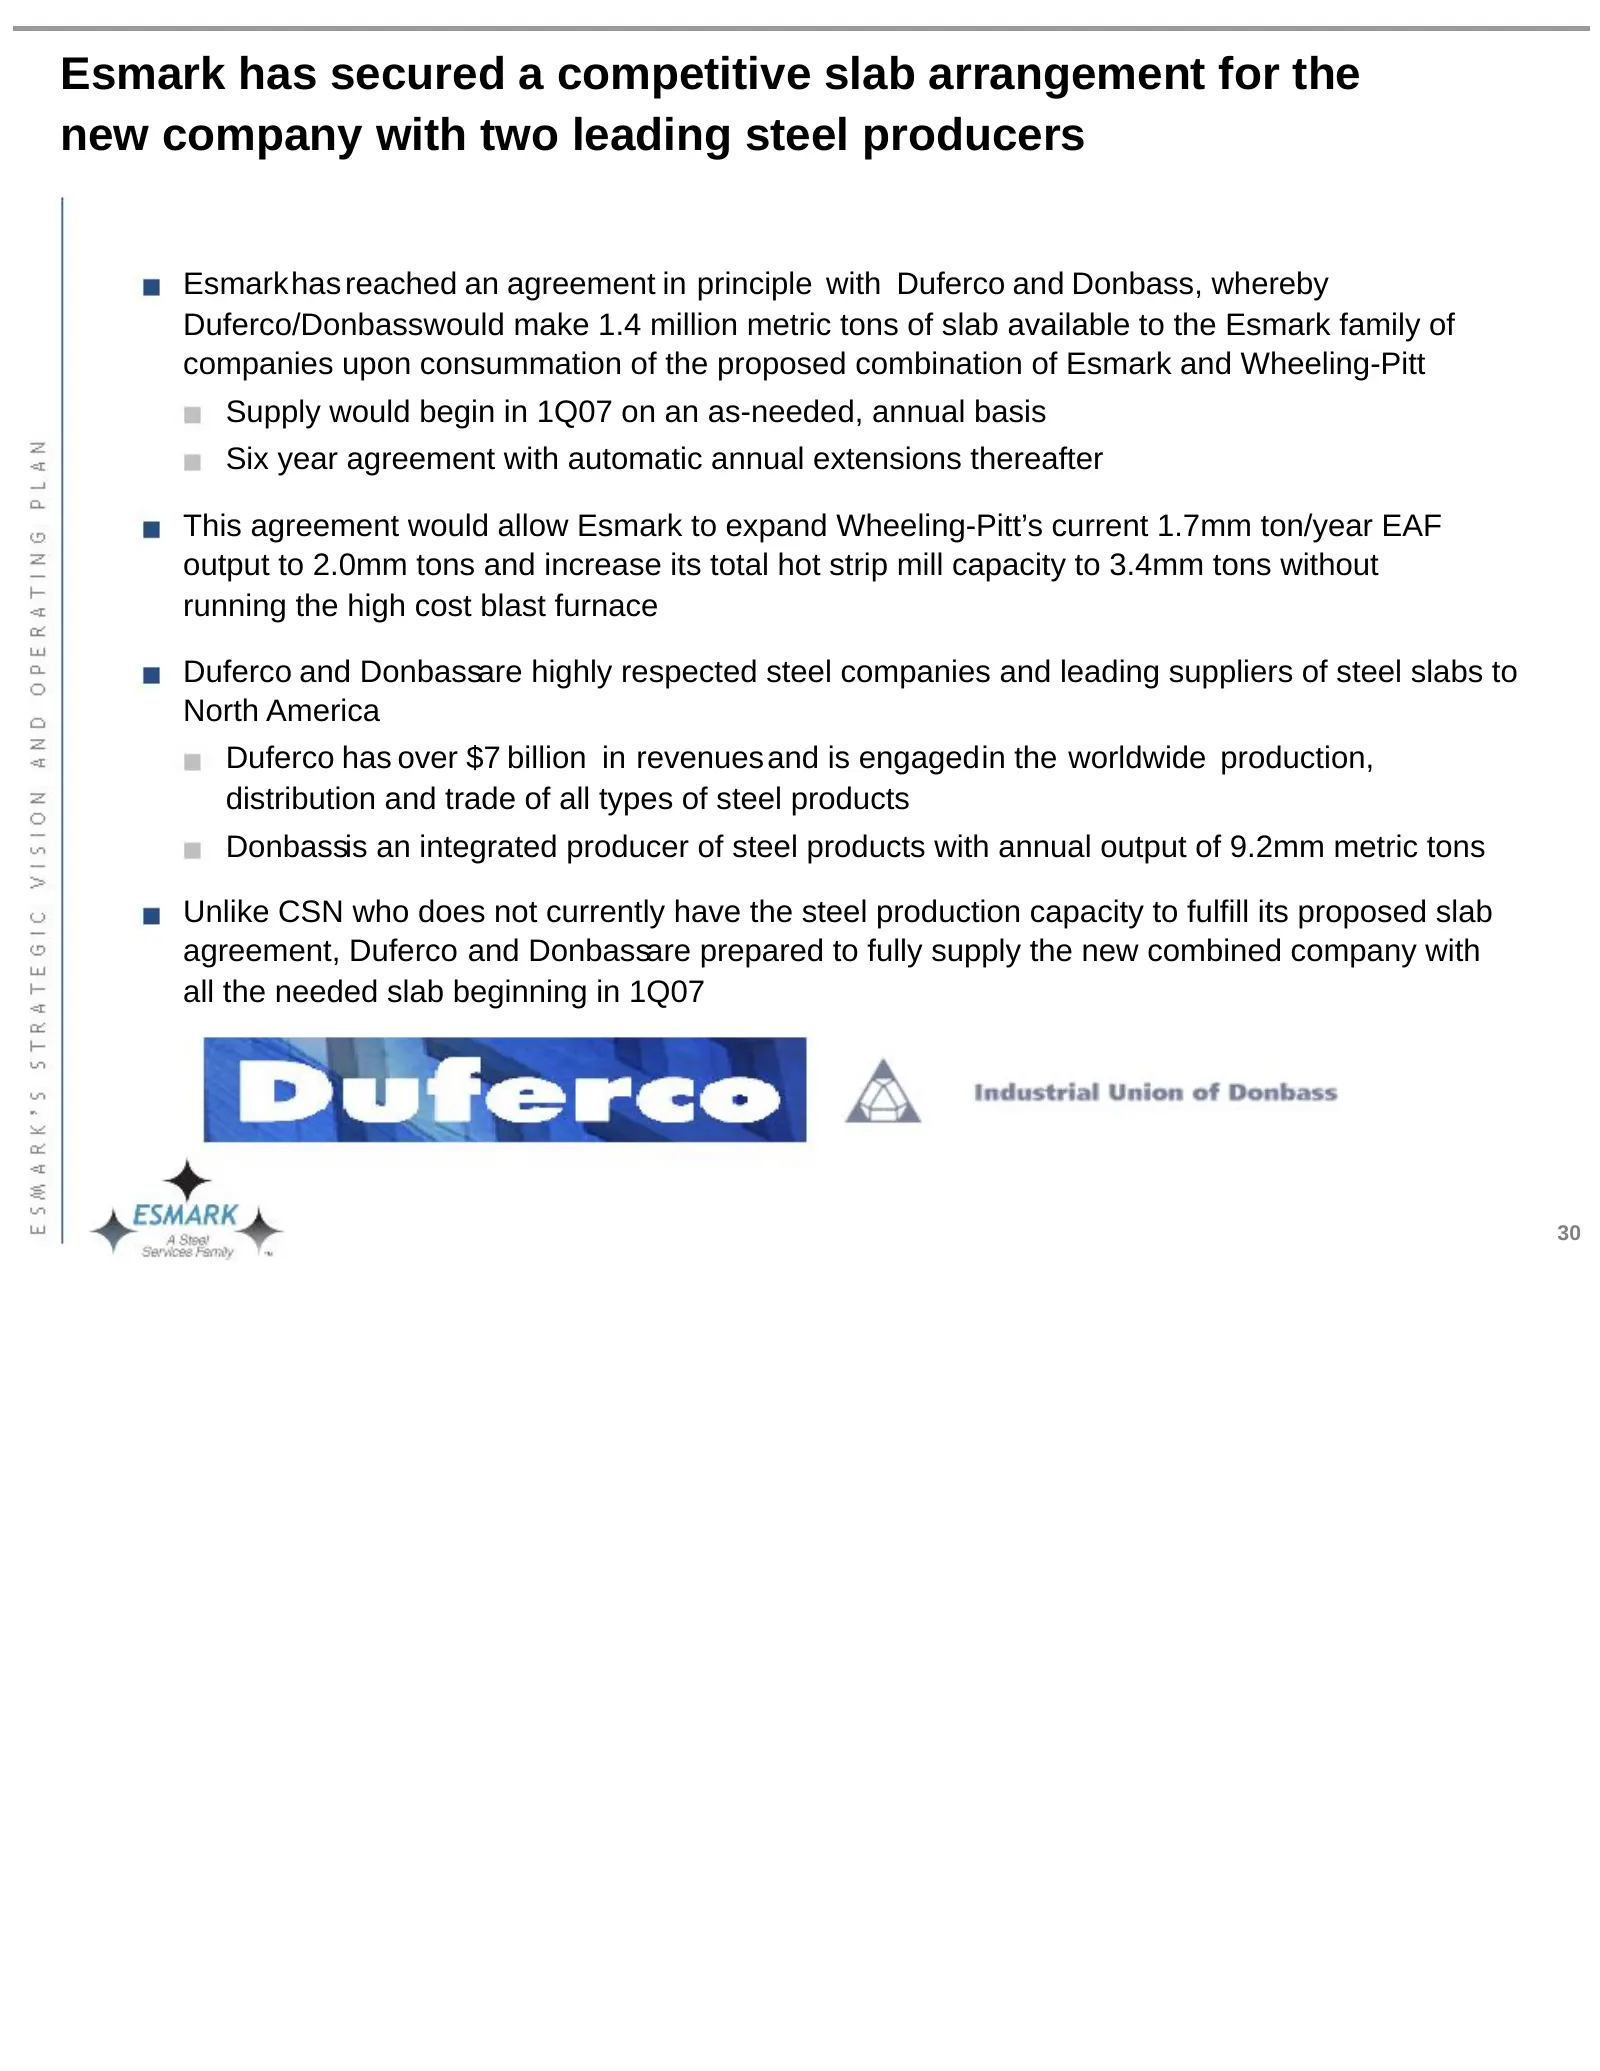
Esmark has secured a competitive slab arrangement for the new company with two leading steel producers Esmarkhas reached an agreement in principle with Duferco and Donbass, whereby Duferco/Donbasswould make 1.4 million metric tons of slab available to the Esmark family of companies upon consummation
Slide 34: Improved product mix provides potential multiple expansion
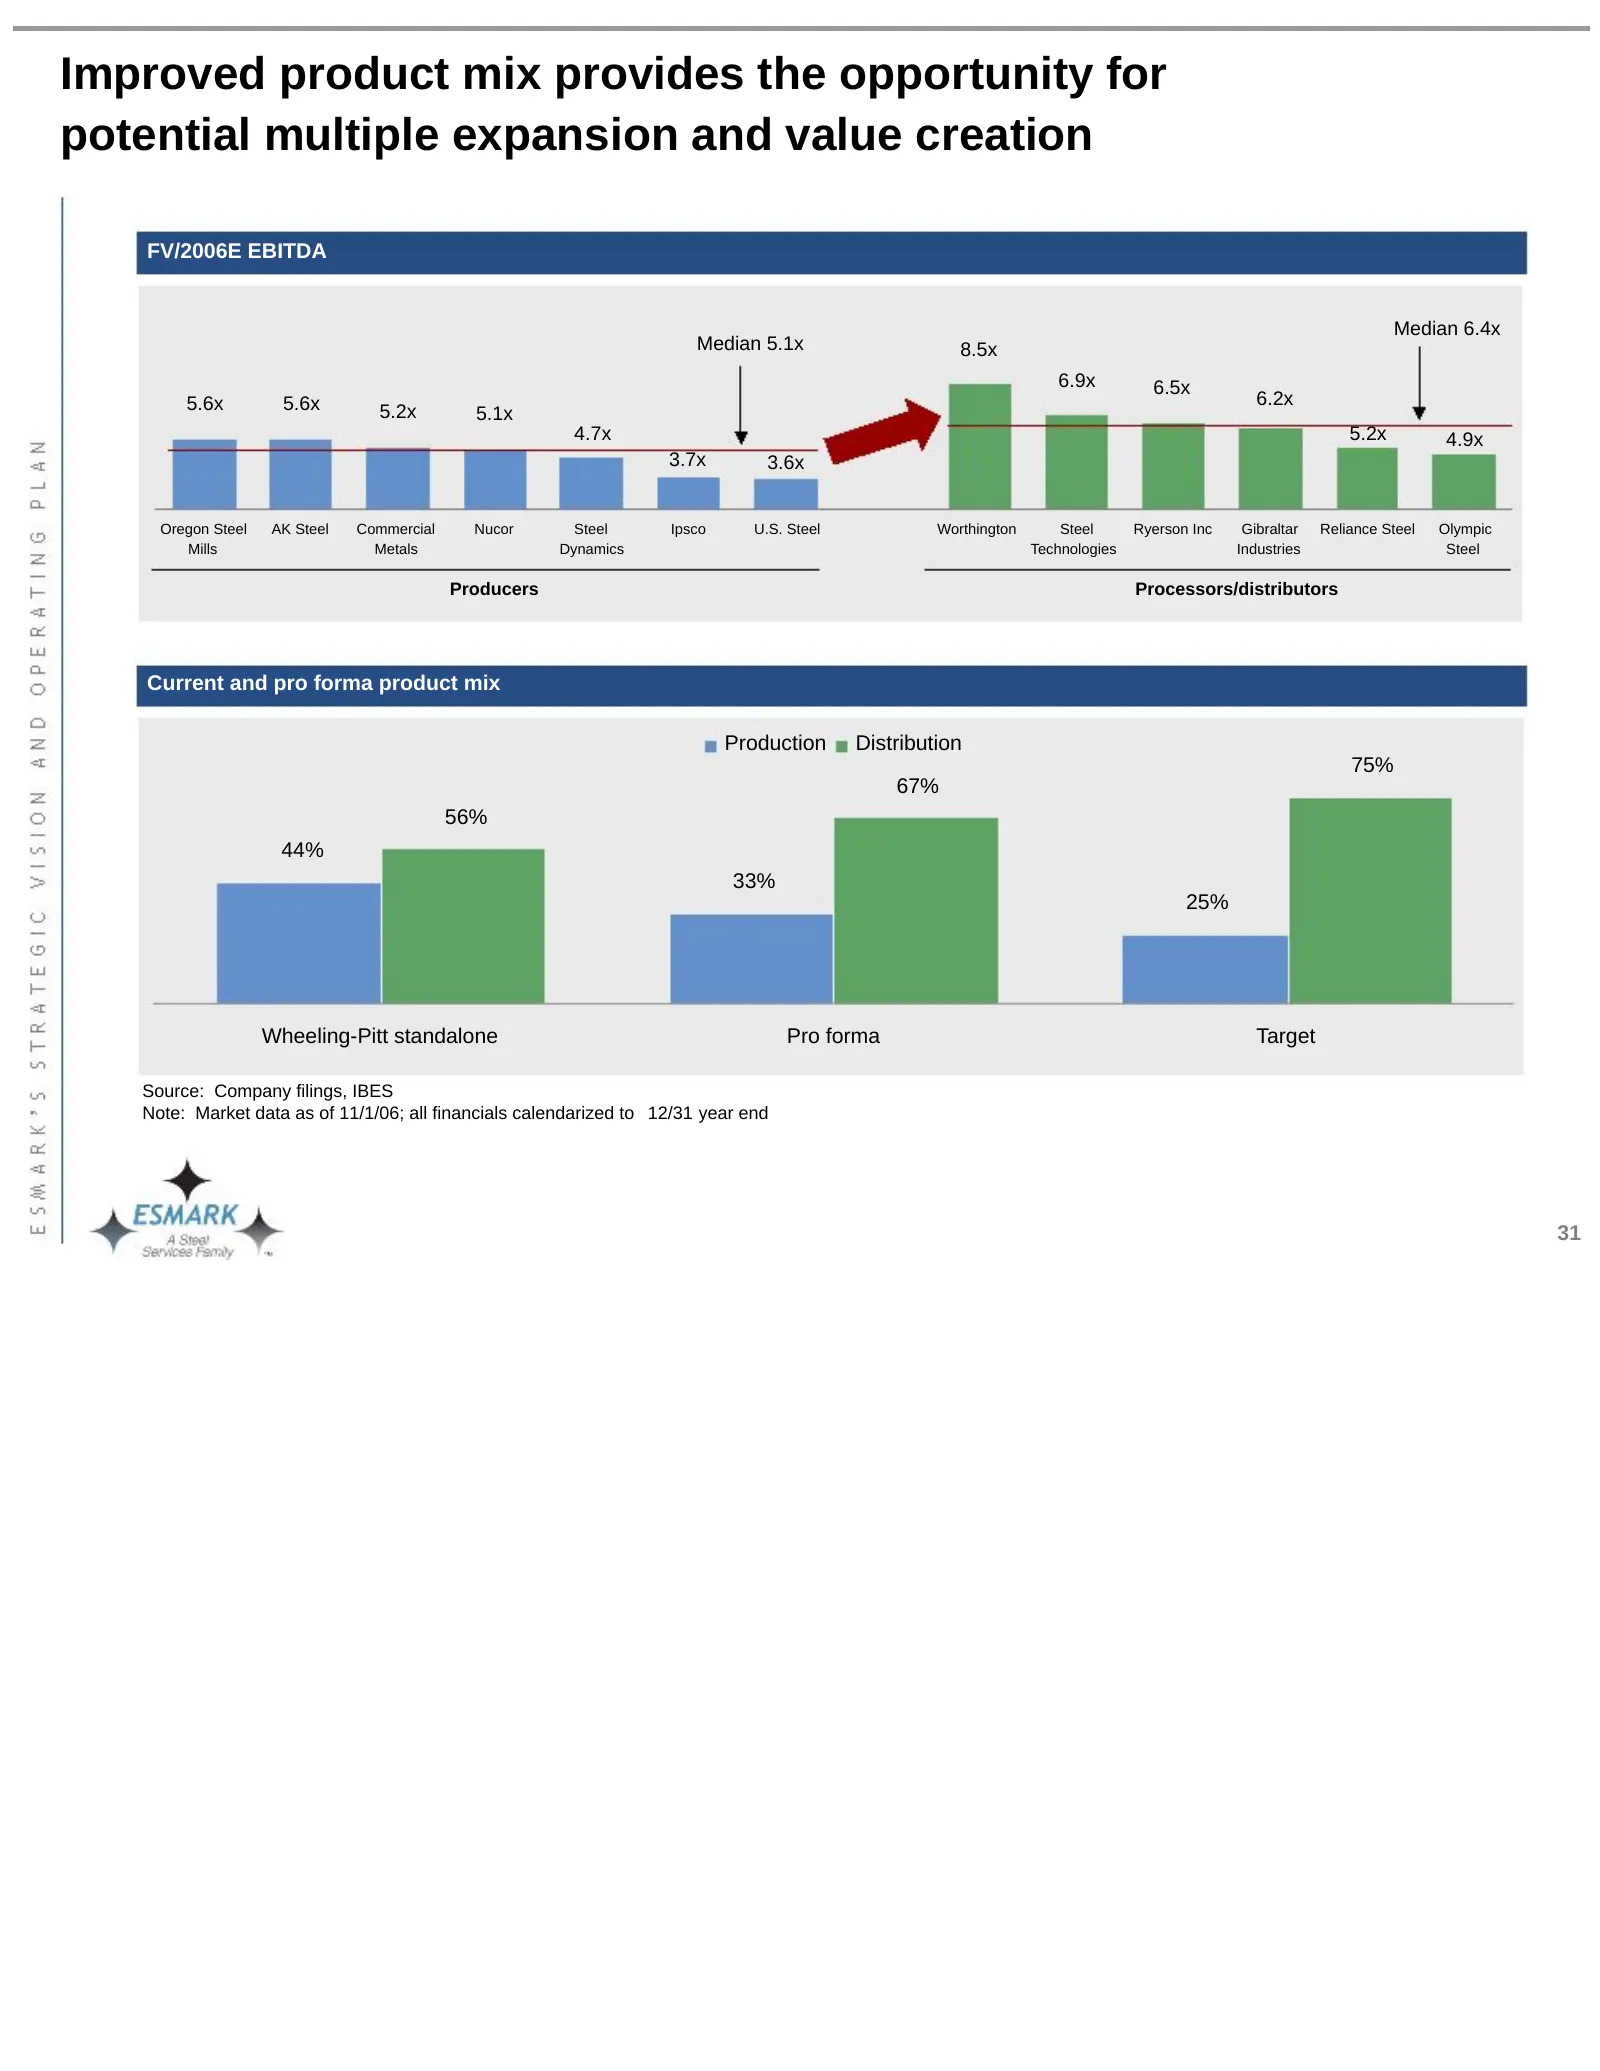
Improved product mix provides the opportunity for potential multiple expansion and value creation FV/2006E EBITDA Median 6.4x Median 5.1x 8.5x 6.9x 6.5x 5.6x 5.6x 6.2x 5.2x 5.1x 4.7x 5.2x 4.9x 3.7x 3.6x Oregon Steel AK Steel Commercial Nucor Steel Ipsco U.S. Steel Worthington Steel Ryerson Inc Gibra
Slide 35: Combination would improve Wheeling-Pitt's financial flexibility
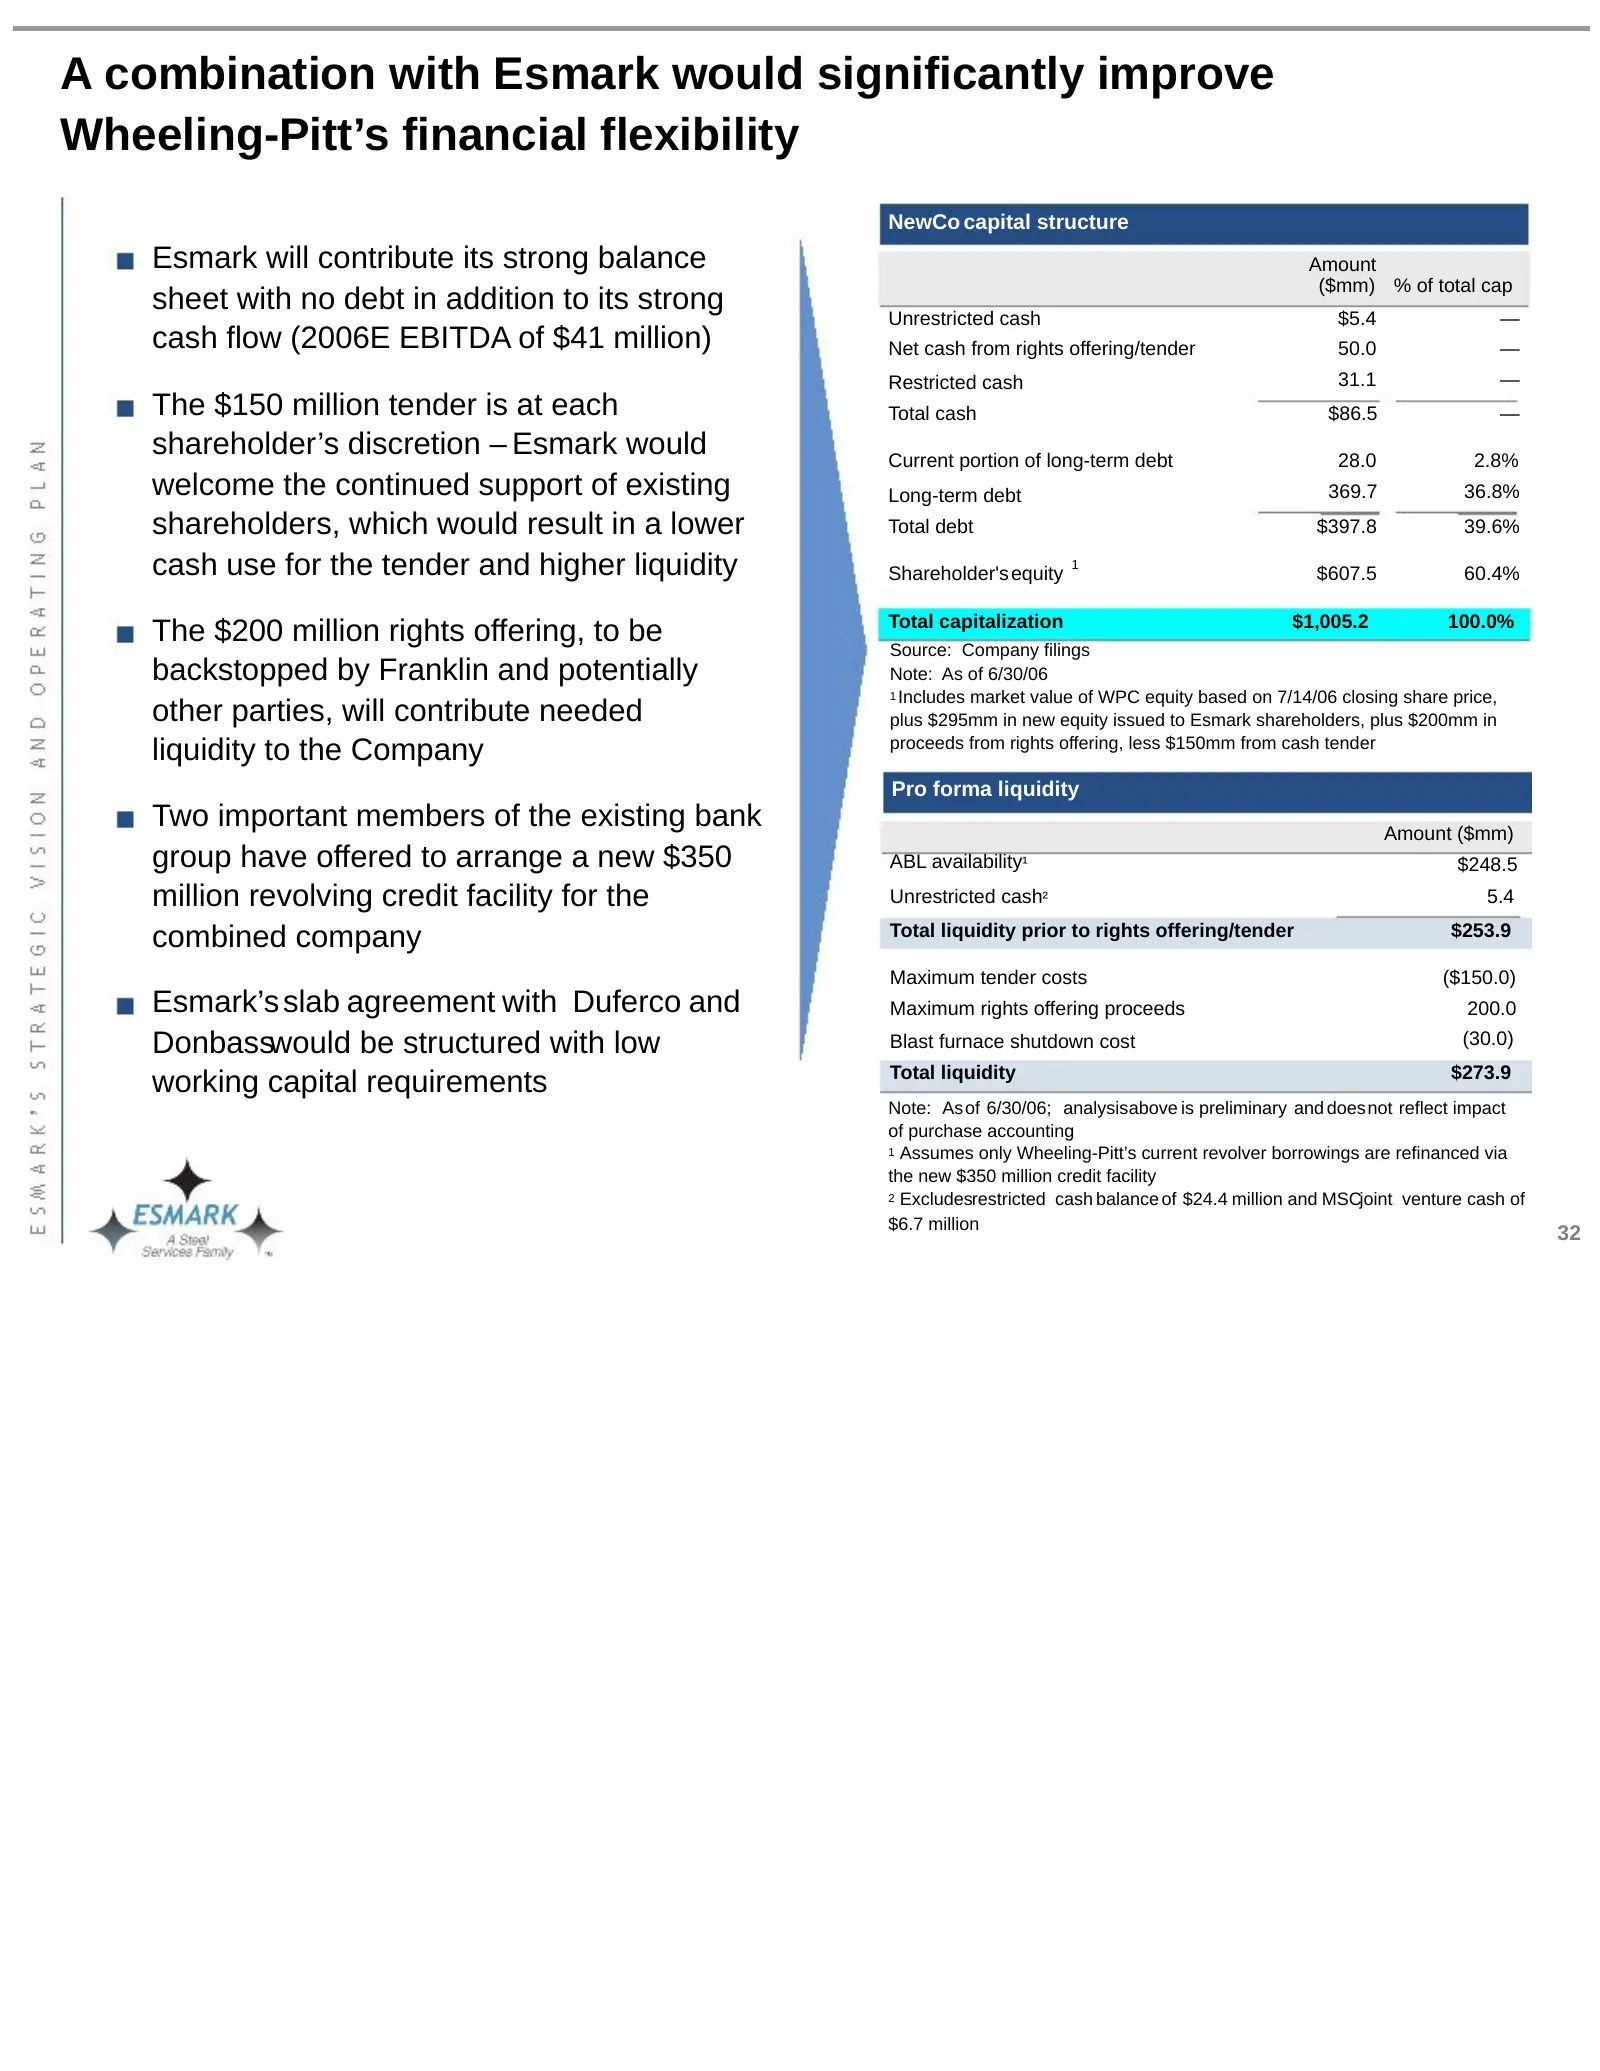
A combination with Esmark would significantly improve Wheeling-Pitt’s financial flexibility NewCo capital structure Esmark will contribute its strong balance Amount ($mm) % of total cap sheet with no debt in addition to its strong Unrestricted cash $5.4 — cash flow (2006E EBITDA of $41 million) Net
Slide 36: Agenda
Agenda Page Executive summary and director slate 2 Wheeling-Pitt has overpromised and underperformed 13 Esmark’s Strategic vision and operating plan 21 Conclusion 33 33
Slide 37: Two largest stakeholders support Esmark's slate of directors
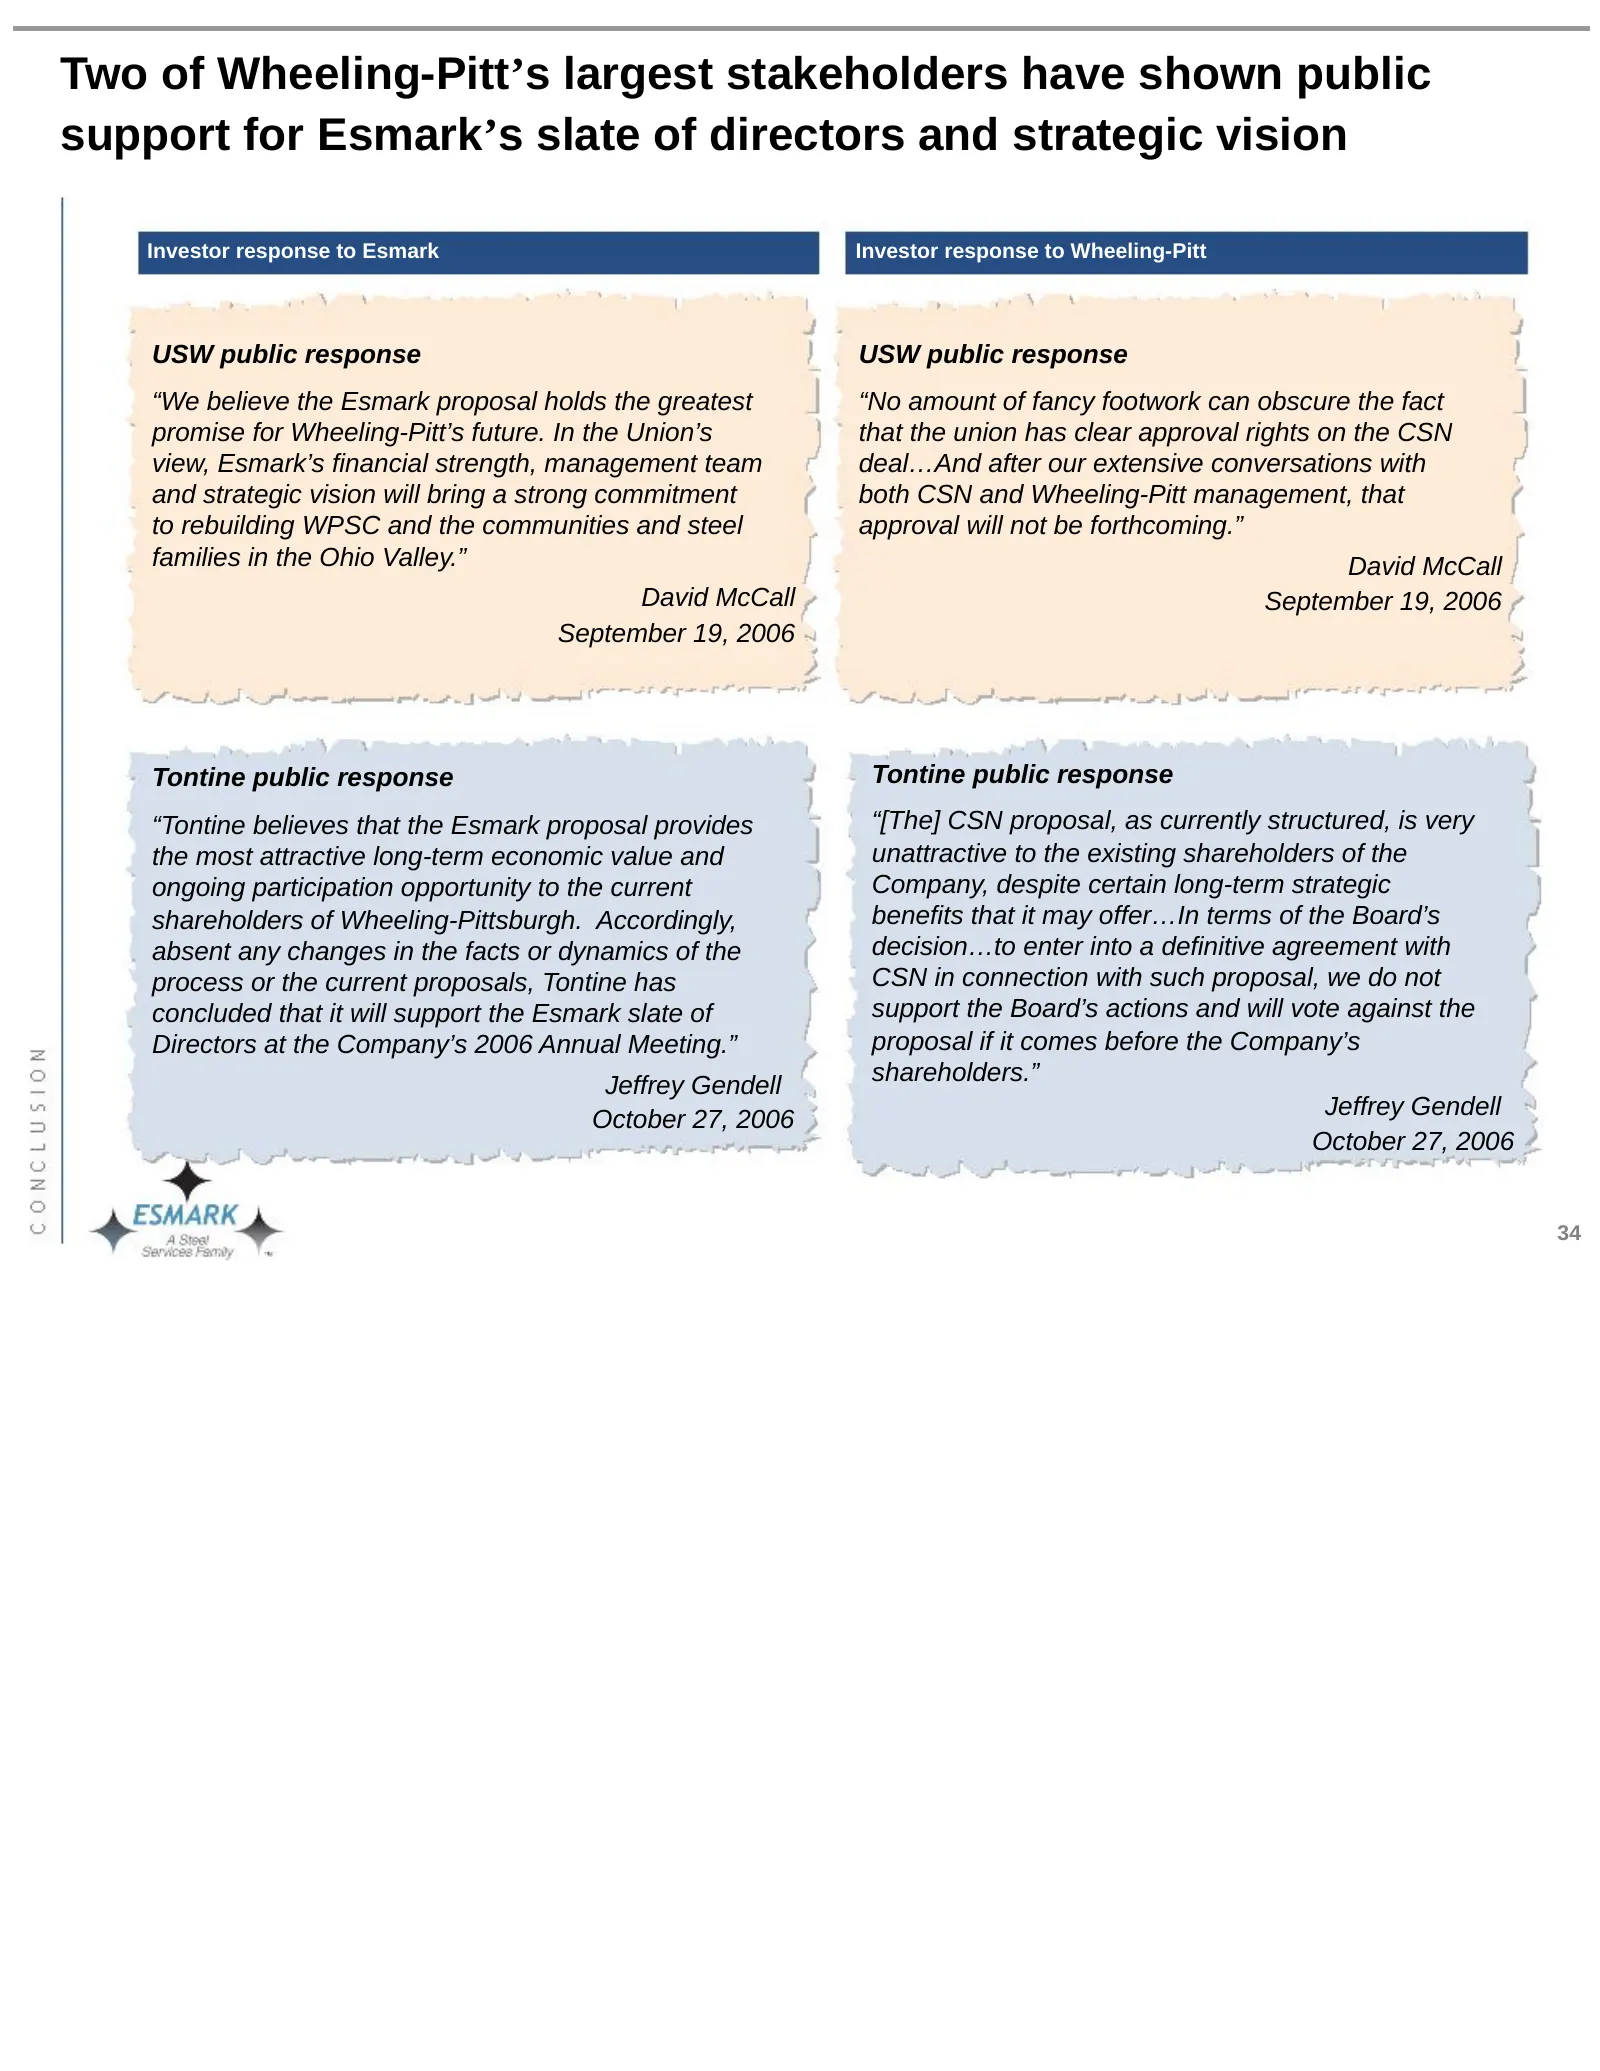
Two of Wheeling-Pitt’s largest stakeholders have shown public support for Esmark’s slate of directors and strategic vision Investor response to Esmark Investor response to Wheeling-Pitt USW public response USW public response “We believe the Esmark proposal holds the greatest “No amount of fancy foo
Slide 38: The CSN deal is the wrong next step for Wheeling-Pitt
The CSN deal is the wrongnext step for Wheeling-Pitt Combination of two historically unprofitable businesses and unsubstantiated value for Heartland The Heartland assets being merged with Wheeling-Pitt in the proposed strategic arrangement with CSN are being valued at approximately $300 million (bas
Slide 39: Electing the Esmark nominees is the right next step
Electing the Esmarknominees is the right next step for Wheeling-Pitt Union and Tontine-supported proposal We highly encourage investors to look at the strong, union-supported Esmark proposal Tontine Management, LLC has also expressed public support of the Esmark slate of directors and strategic visi
Slide 40: Conclusion, Questions and Answers
Conclusion Esmark would like to thank you for the opportunity to meet and discuss the potentially exciting future for Wheeling-Pitt and its shareholders Questions and Answers 37
Source: SEC EDGAR · DFAN14A filed Nov 7, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (December 2006)22 slides · Dec 7, 2006
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)44 slides · Nov 6, 2006
 Proxy Contest (September 2006)21 slides · Sep 29, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006
 KeyBanc Conference 200647 slides · Sep 13, 2006