Wheeling Pittsburgh — Proxy Contest (November 2006)
44 slides from Wheeling Pittsburgh's proxy contest presentation, Nov 6, 2006
Slide 1: The Transformation of Wheeling-Pittsburgh
The Transformation of Wheeling-Pittsburgh November 2006
Slide 2: Forward-looking statements
The information contained in this presentation, other than historical information, consists of forward-looking statements within the meaning of Section 27A of the Securities Act and Section 21E of the Securities Exchange Act. In particular, statements containing estimates or projections of future op
Slide 3: Table of Contents
Table of Contents Section 1 Background and Process 3 Section 2 CSN Strategic Alliance 8 2.A Transaction Summary 9 2.B Strategic Advantages 14 2.C Financial Advantages 21 2.D Transaction Details 27 Section 3 Proposal Comparison - CSN vs Esmark 30 Section 4 Conclusion/Timeline 35 Appendix A Operating
Slide 4: Background and Process
Section 1 Background and Process
Slide 5: Dramatic Changes to Steel Industry's Landscape
Dramatic Changes to Steel Industry's Landscape... .... Have significantly contributed to defining WPSC's Strategic Goals Consolidation and Globalization Steel Sector has witnessed significant consolidation, giving the industry's emerging behemoths a variety of strategic business advantages: broader
Slide 6: Wheeling-Pittsburgh's Strategic Goals
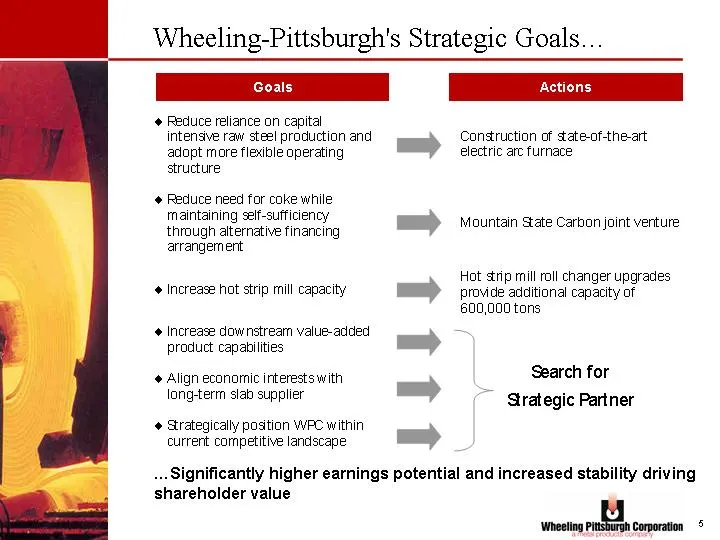
Wheeling-Pittsburgh's Strategic Goals... Actions Goals ....Significantly higher earnings potential and increased stability driving shareholder value
Slide 7: Extensive and Rigorous Search Process
Extensive and Rigorous Search Process Conducted exploratory talks with 9 parties regarding strategic alternatives in most recent 18 months and signed confidentiality agreements with 8 parties Proposals received from CSN and Esmark CSN proposal and business plan jointly developed with WPC with clear
Slide 8: Search Process Timeline
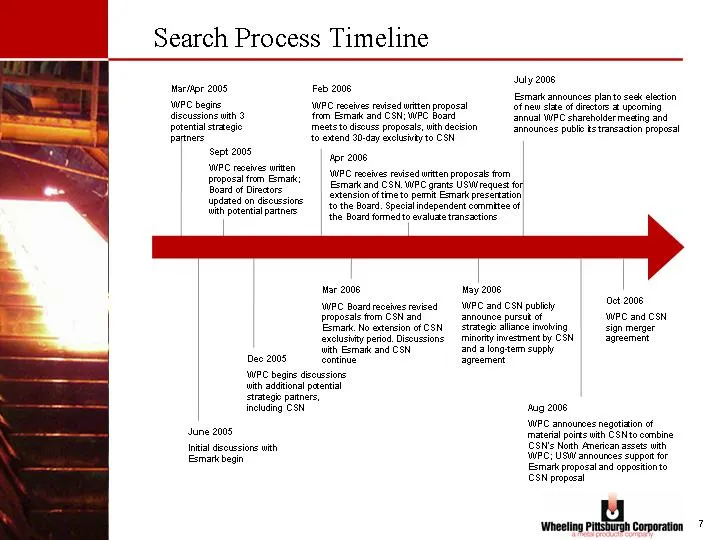
Search Process Timeline Mar/Apr 2005 WPC begins discussions with 3 potential strategic partners Feb 2006 WPC receives revised written proposal from Esmark and CSN; WPC Board meets to discuss proposals, with decision to extend 30-day exclusivity to CSN Mar 2006 WPC Board receives revised proposals fr
Slide 9: CSN Strategic Alliance
Section 2 CSN Strategic Alliance
Slide 10: Transaction Summary
Section 2.A Transaction Summary
Slide 11: Transaction Summary
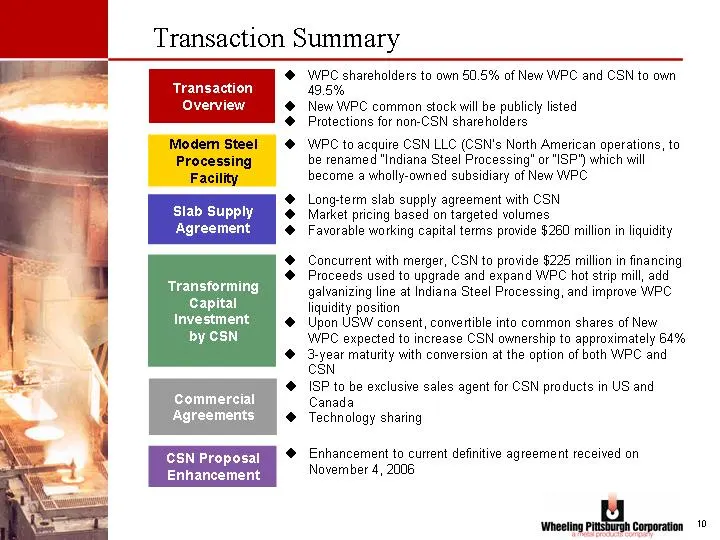
Transaction Summary Transaction Overview Transforming Capital Investment by CSN Slab Supply Agreement WPC shareholders to own 50.5% of New WPC and CSN to own 49.5% New WPC common stock will be publicly listed Protections for non-CSN shareholders Long-term slab supply agreement with CSN Market pricin
Slide 12: Pro Forma Ownership and Corporate Structure at Closing
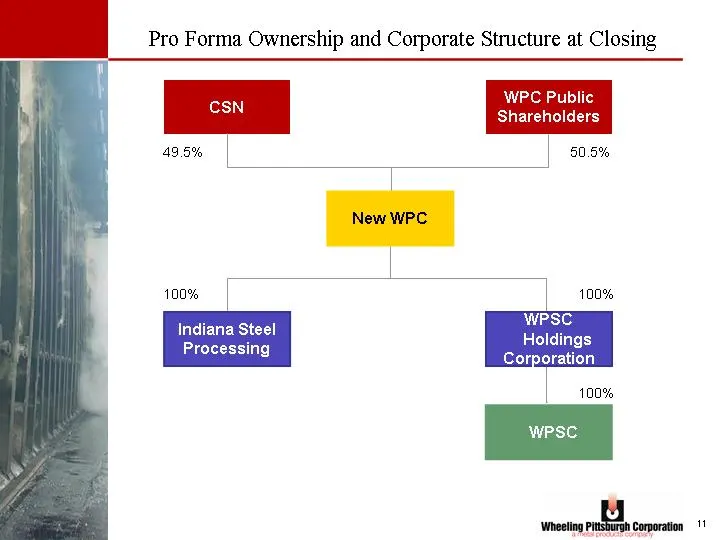
Pro Forma Ownership and Corporate Structure at Closing CSN WPC Public Shareholders New WPC Indiana Steel Processing WPSC Holdings Corporation WPSC 100% 100% 100% 49.5% 50.5%
Slide 13: Enhanced CSN Proposal Received on November 4, 2006
Enhanced CSN Proposal Received on November 4, 2006 Enhancements by CSN to existing definitive agreement with WPC "responsive" to issues raised by current shareholders Provides shareholders "choice" to participate in the future upside of the transaction and /or immediately monetize their position at
Slide 14: Governance Provisions and Shareholder Rights
Governance Provisions and Shareholder Rights New WPC Board of Directors to consist of 11 directors 5 independent directors from existing independent WPC directors 2 USW directors James Bradley 3 directors designated by CSN Board will be staggered with a mix of independent and CSN directors to preser
Slide 15: Strategic Advantages
Section 2.B Strategic Advantages
Slide 16: CSN as Strategic Partner Provides Compelling Industrial Logic
CSN as Strategic Partner Provides Compelling Industrial Logic Hot strip mill upgrade increases capacity to 4.0mm tons energy efficient new furnace will drive a competitive cost structure through gas savings additional throughput of 600,000 tons reduces costs per ton significant operating efficiencie
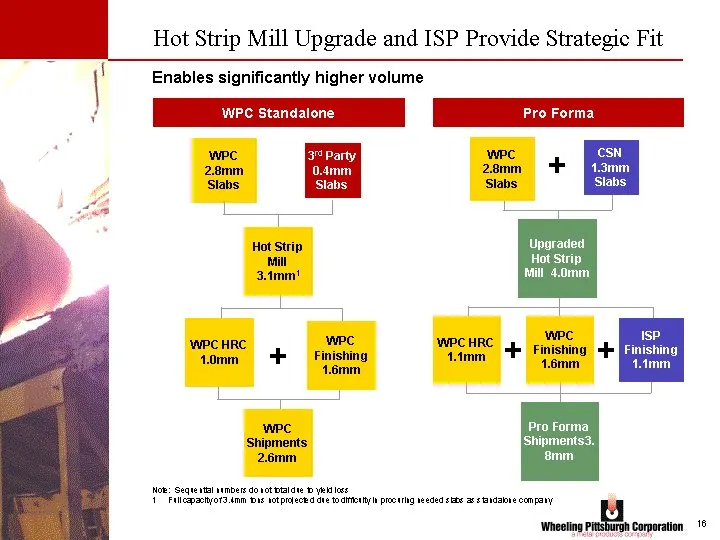
Slide 17: Hot Strip Mill Upgrade and ISP Provide Strategic Fit
Hot Strip Mill Upgrade and ISP Provide Strategic Fit WPC Standalone Pro Forma CSN 1.3mm Slabs + + WPC 2.8mm Slabs Upgraded Hot Strip Mill 4.0mm Pro Forma Shipments3. 8mm ISP Finishing 1.1mm + WPC Finishing 1.6mm WPC HRC 1.1mm Note: Sequential numbers do not total due to yield loss 1 Full capacity of
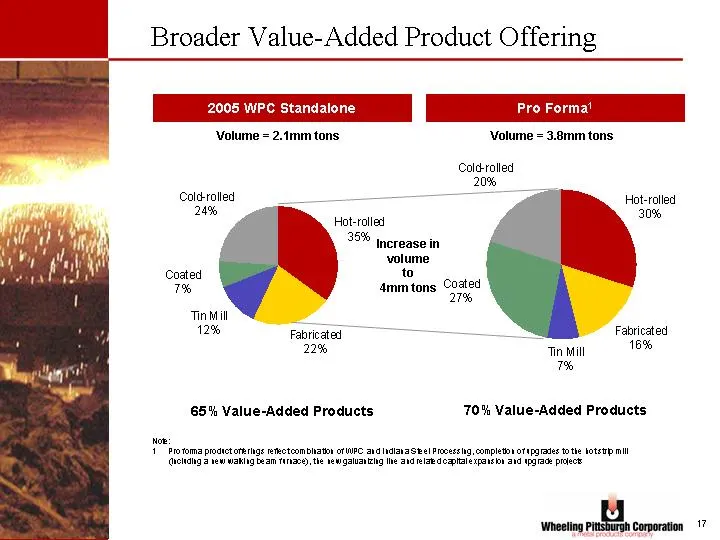
Slide 18: Broader Value-Added Product Offering
Broader Value-Added Product Offering 65% Value-Added Products 70% Value-Added Products 2005 WPC Standalone Pro Forma1 Increase in volume to 4mm tons Note: 1 Pro forma product offerings reflect combination of WPC and Indiana Steel Processing, completion of upgrades to the hot strip mill (including a
Slide 19: Favorable Long-Term Slab Supply Agreement
Favorable Long-Term Slab Supply Agreement Significantly Augments Raw Steel Capacity 10-year slab supply agreement with CSN Market price 4-6 weeks of CSN's inventory on site Favorable working capital terms WPC's current raw steel production is limited to 2.8 million tons annually New WPC upgraded hot
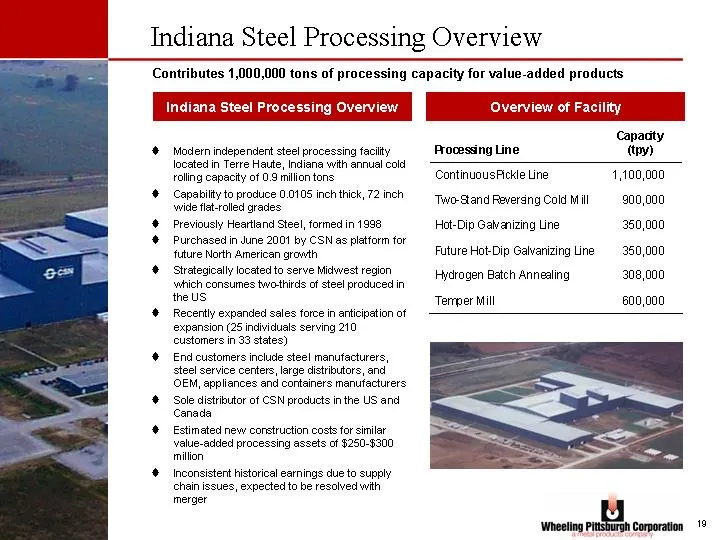
Slide 20: Indiana Steel Processing Overview
Contributes 1,000,000 tons of processing capacity for value-added products Indiana Steel Processing Overview Indiana Steel Processing Overview Overview of Facility Modern independent steel processing facility located in Terre Haute, Indiana with annual cold rolling capacity of 0.9 million tons Capab
Slide 21: Transforming Capital-Cash Into Company Immediately
Enables funding for timely expansion and modernization at a level beyond WPC's access to capital 3-year $225 million note payable to CSN provides potential for ultimate equity infusion Use of proceeds in strategic capital investments, to pay down debt and to enhance liquidity $75 million for hot str
Slide 22: Financial Advantages
Section 2.C Financial Advantages
Slide 23: Significant Pro Forma Earnings Potential
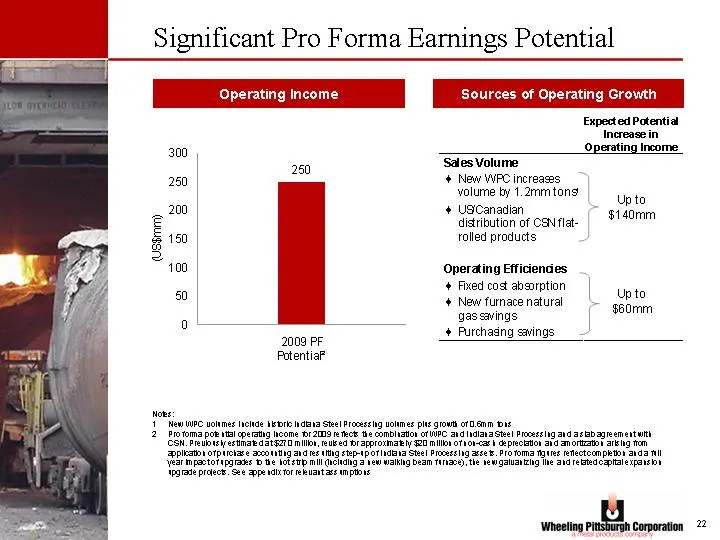
Significant Pro Forma Earnings Potential Operating Income Sources of Operating Growth Up to Notes: 1 New WPC volumes include historic Indiana Steel Processing volumes plus growth of 0.6mm tons 2 Pro forma potential operating income for 2009 reflects the combination of WPC and Indiana Steel Processin
Slide 24: Significant Pro Forma Earnings Potential
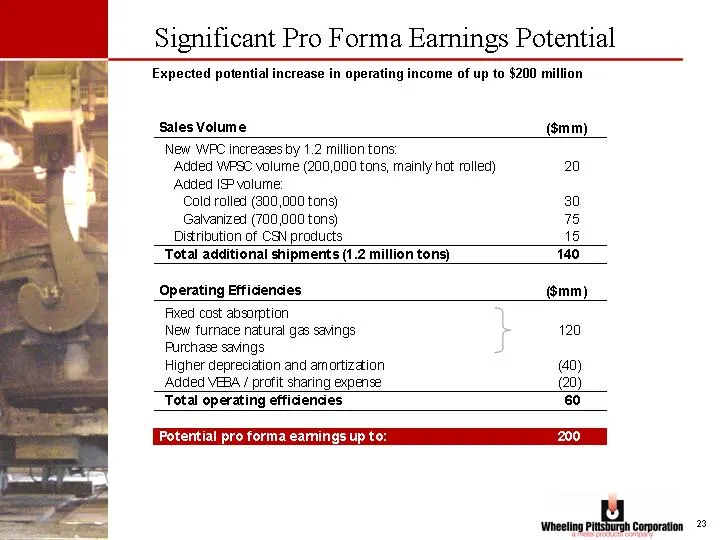
Significant Pro Forma Earnings Potential Expected potential increase in operating income of up to $200 million
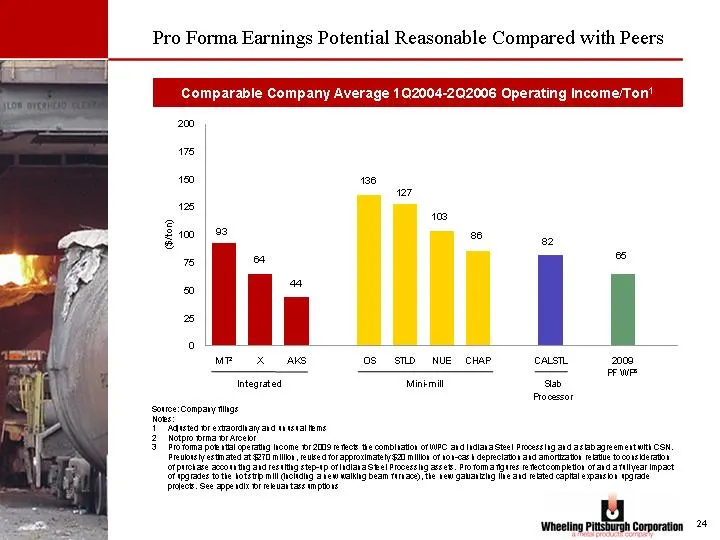
Slide 25: Pro Forma Earnings Potential Reasonable Compared with Peers
Pro Forma Earnings Potential Reasonable Compared with Peers Comparable Company Average 1Q2004-2Q2006 Operating Income/Ton1 Source: Company filings Notes: 1 Adjusted for extraordinary and unusual items 2 Not pro forma for Arcelor 3 Pro forma potential operating income for 2009 reflects the combinatio
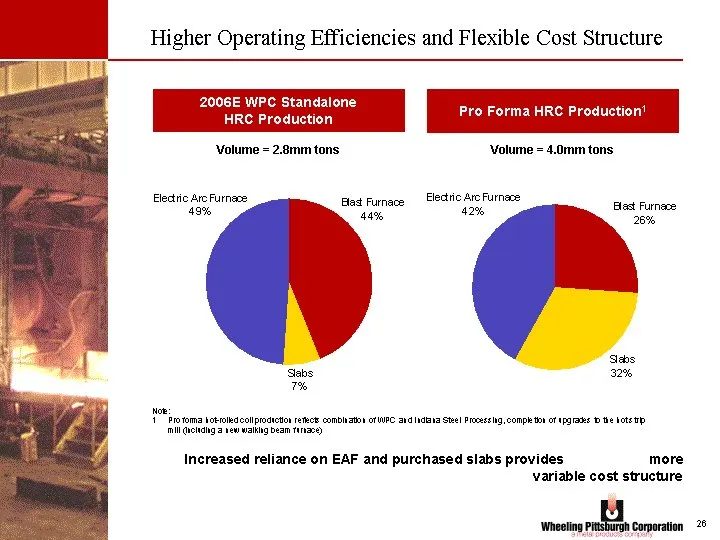
Slide 26: Higher Operating Efficiencies and Flexible Cost Structure
Higher Operating Efficiencies and Flexible Cost Structure Increased reliance on EAF and purchased slabs provides more variable cost structure 2006E WPC Standalone HRC Production Pro Forma HRC Production1 Note: 1 Pro forma hot-rolled coil production reflects combination of WPC and Indiana Steel Proce
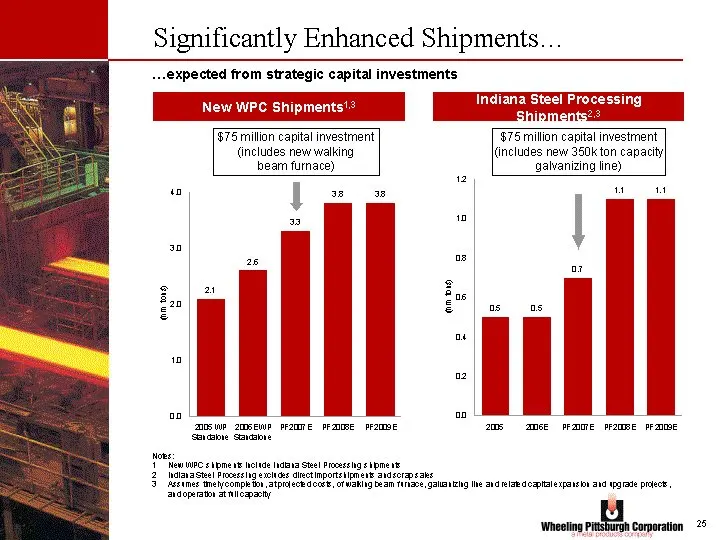
Slide 27: Significantly Enhanced Shipments
Significantly Enhanced Shipments... ....expected from strategic capital investments New WPC Shipments1,3 Indiana Steel Processing Shipments2,3 $75 million capital investment (includes new walking beam furnace) $75 million capital investment (includes new 350k ton capacity galvanizing line) Notes: 1
Slide 28: Transaction Details
Section 2.D Transaction Details
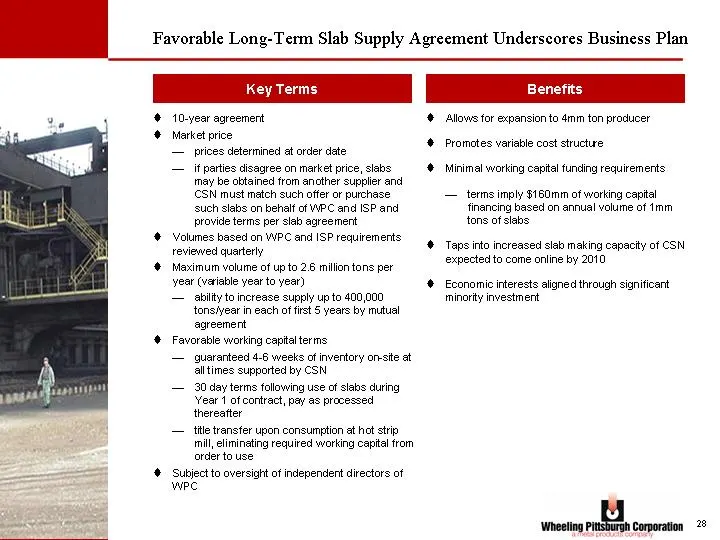
Slide 29: Slab Supply Agreement Key Terms and Benefits
10-year agreement Market price prices determined at order date if parties disagree on market price, slabs may be obtained from another supplier and CSN must match such offer or purchase such slabs on behalf of WPC and ISP and provide terms per slab agreement Volumes based on WPC and ISP requirements
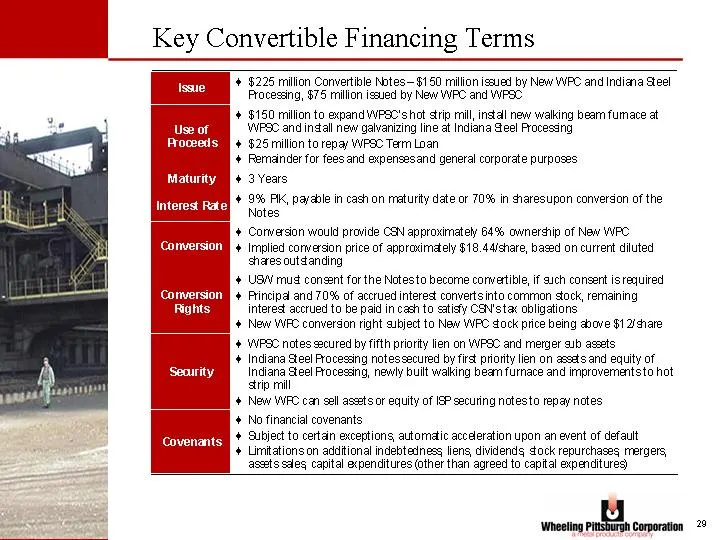
Slide 30: Key Convertible Financing Terms
Key Convertible Financing Terms
Slide 31: Proposal Comparison - CSN vs Esmark
Section 3 Proposal Comparison - CSN vs Esmark
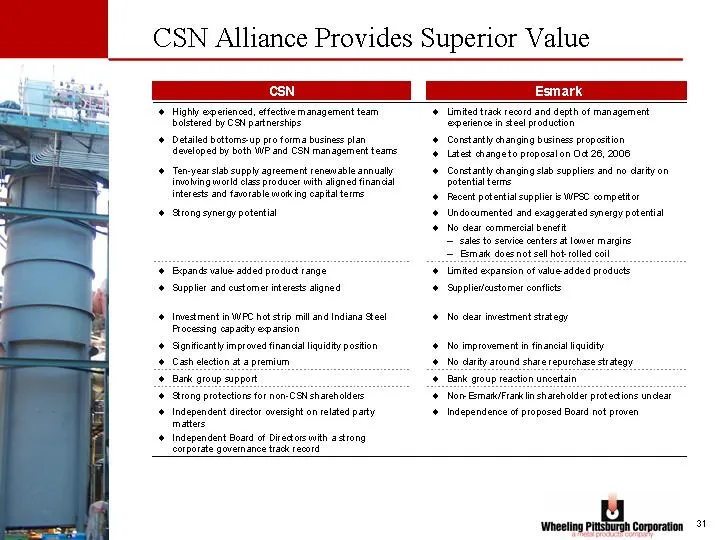
Slide 32: CSN Alliance Provides Superior Value
CSN Alliance Provides Superior Value
Slide 33: Superior Pro Forma Financial and Liquidity Position
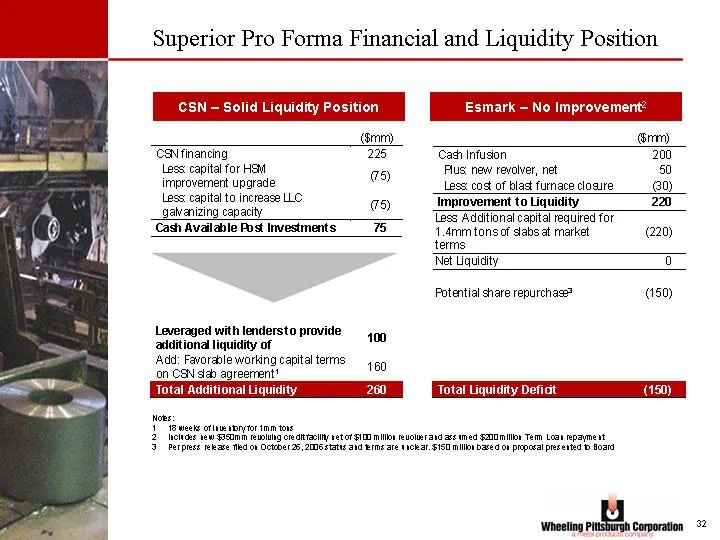
CSN - Solid Liquidity Position Esmark - No Improvement2 Notes: 1 18 weeks of inventory for 1mm tons 2 Includes new $350mm revolving credit facility net of $100 million revolver and assumed $200 million Term Loan repayment 3 Per press release filed on October 26, 2006 status and terms are unclear. $1
Slide 34: United Steelworkers and the VEBA
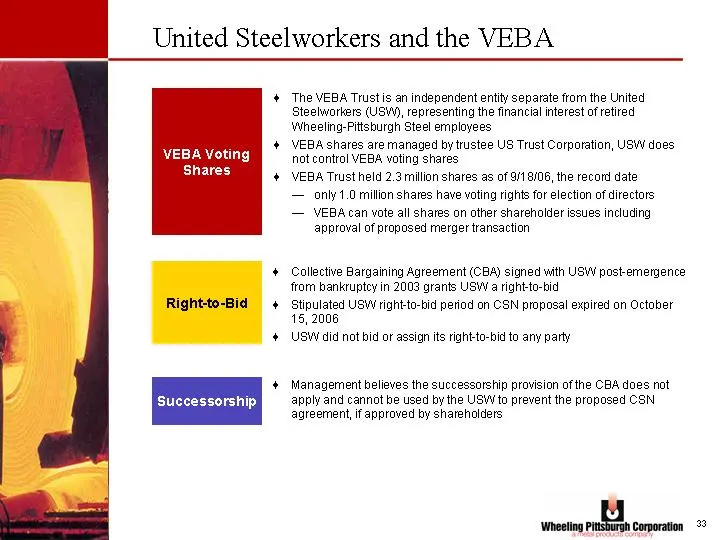
United Steelworkers and the VEBA The VEBA Trust is an independent entity separate from the United Steelworkers (USW), representing the financial interest of retired Wheeling-Pittsburgh Steel employees VEBA shares are managed by trustee US Trust Corporation, USW does not control VEBA voting shares VE
Slide 35: CSN Is The Right Next Step for WPC
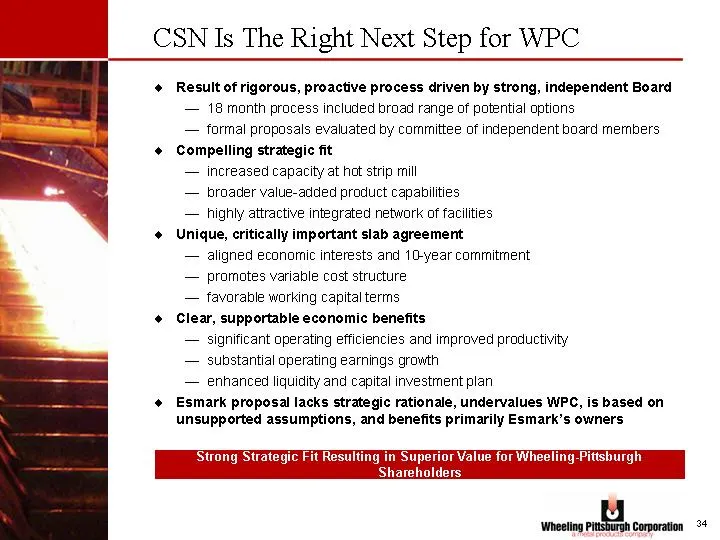
CSN Is The Right Next Step for WPC Result of rigorous, proactive process driven by strong, independent Board 18 month process included broad range of potential options formal proposals evaluated by committee of independent board members Compelling strategic fit increased capacity at hot strip mill b
Slide 36: Conclusion/Timeline
Section 4 Conclusion/Timeline
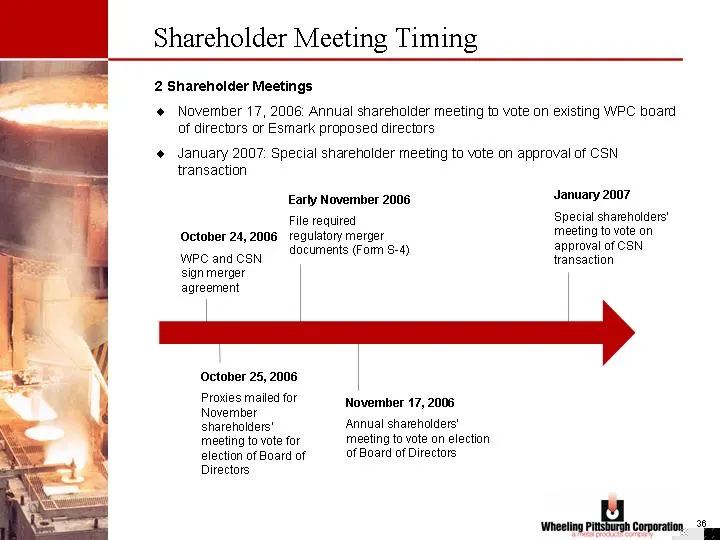
Slide 37: Shareholder Meeting Timing
October 24, 2006 WPC and CSN sign merger agreement November 17, 2006 Annual shareholders' meeting to vote on election of Board of Directors January 2007 Special shareholders' meeting to vote on approval of CSN transaction Shareholder Meeting Timing 2 Shareholder Meetings November 17, 2006: Annual sh
Slide 38: Existing Board Continues to Practice Good Governance
Existing Board Continues to Practice Good Governance... Visited and listened to large shareholders after August 3rd announcement Had numerous communications with large shareholders regarding impression of alternatives (WPC and CSN) Extended right-to-bid period for USW or assignee for 5 weeks; provid
Slide 39: Existing Board's Practice of Good Governance and Transparency
Existing Board's Practice of Good Governance and Transparency Ensures Best Value for All Shareholders Re-election of existing Board maintains shareholder options shareholder acceptance of proposed CSN merger is still being assessed further CSN proposal changes possible during two weeks before annual
Slide 40: Operating Assumptions
Appendix A Operating Assumptions
Slide 41: Assumptions For Operating Earnings Potential
Assumptions For Operating Earnings Potential Overall the projections are based upon market conditions in the steel industry which have existed to date in 2006 and those that we expect to prevail for the balance of the year for Wheeling Pittsburgh Corporation except as otherwise described below opera
Slide 42: CSN Overview
Appendix B CSN Overview
Slide 43: CSN Overview
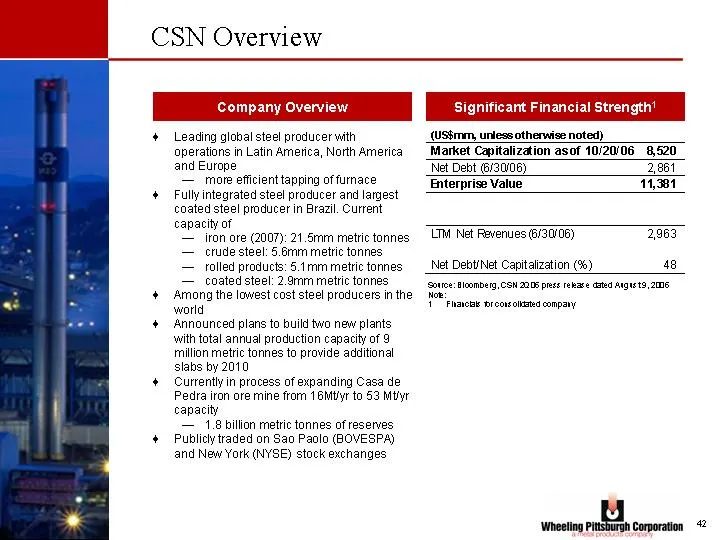
CSN Overview Leading global steel producer with operations in Latin America, North America and Europe more efficient tapping of furnace Fully integrated steel producer and largest coated steel producer in Brazil. Current capacity of iron ore (2007): 21.5mm metric tonnes crude steel: 5.6mm metric ton
Slide 44: Wheeling oR Corporation
Wheeling oR Corporation
Source: SEC EDGAR · DEFA14A filed Nov 6, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (December 2006)22 slides · Dec 7, 2006
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)40 slides · Nov 7, 2006
 Proxy Contest (September 2006)21 slides · Sep 29, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006
 KeyBanc Conference 200647 slides · Sep 13, 2006