Inland Real Estate — Investor Presentation (November 2011)
31 slides from Inland Real Estate's investor presentation, Nov 15, 2011
Slide 1: Investor Presentation Third Quarter 2011
Investor Presentation Third Quarter 2011 www.inlandrealestate.com NYSE: IRC November 2011
Slide 2: IRC Snapshot Profile
IRC SNAPSHOT PROFILE Inception 1994; self-administered and self-managed 2000; listed on NYSE June 2004 Target Upper Midwest markets 83% of retail SF in high density infill locations in Chicago & Minneapolis MSAs 159 Neighborhood, Community, Power, Lifestyle centers and single-tenant properties 1 14
Slide 3: Experienced Leadership Team
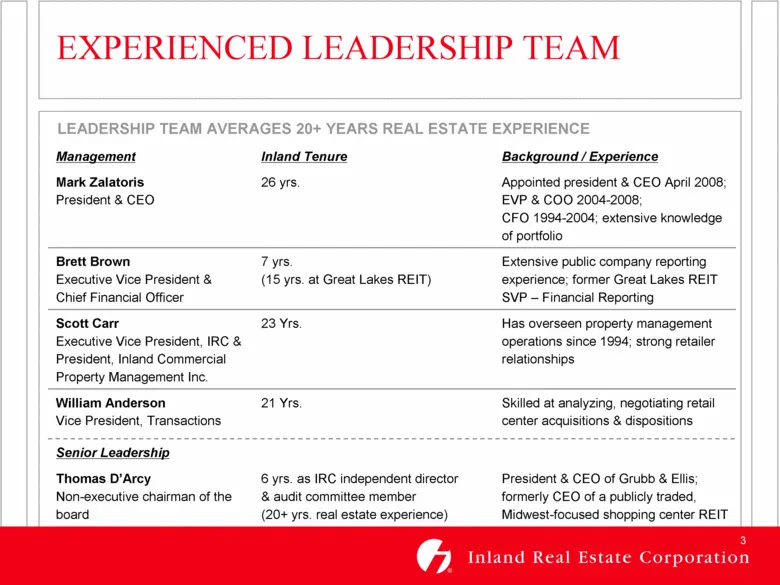
EXPERIENCED LEADERSHIP TEAM Management Inland Tenure Background / Experience Mark Zalatoris President & CEO 26 yrs. Appointed president & CEO April 2008; EVP & COO 2004-2008; CFO 1994-2004; extensive knowledge of portfolio Brett Brown Executive Vice President & Chief Financial Officer 7 yrs. (15 yrs
Slide 4: Operating Strategy: Defensive Portfolio
OPERATING STRATEGY Defensive portfolio – primarily value and necessity retail Centers with grocer / drug / discount component 77% of total portfolio retail gross leasable area (GLA) Resilient Midwest markets Strong demographics dense populations, high incomes, diverse economies High barriers to entr
Slide 5: Operating Strategy: Leasing and Portfolio Management
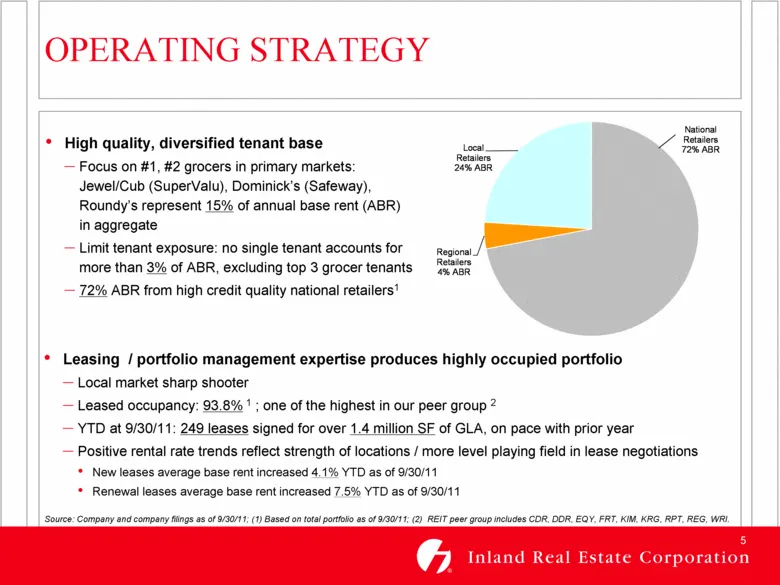
OPERATING STRATEGY Leasing / portfolio management expertise produces highly occupied portfolio Local market sharp shooter Leased occupancy: 93.8% 1 ; one of the highest in our peer group 2 YTD at 9/30/11: 249 leases signed for over 1.4 million SF of GLA, on pace with prior year Positive rental rate
Slide 6: Operating Strategy: Strong Balance Sheet Focus
OPERATING STRATEGY Strong balance sheet focus Sources of opportunity capital in place: $300 MM credit facilities includes $150 MM line of credit; competitive terms, matures June 2014 ATM equity program established in ‘09: sold $32.5 MM in common stock as of 9/30/11; authorized to issue up to $100 MM
Slide 7: Core Markets
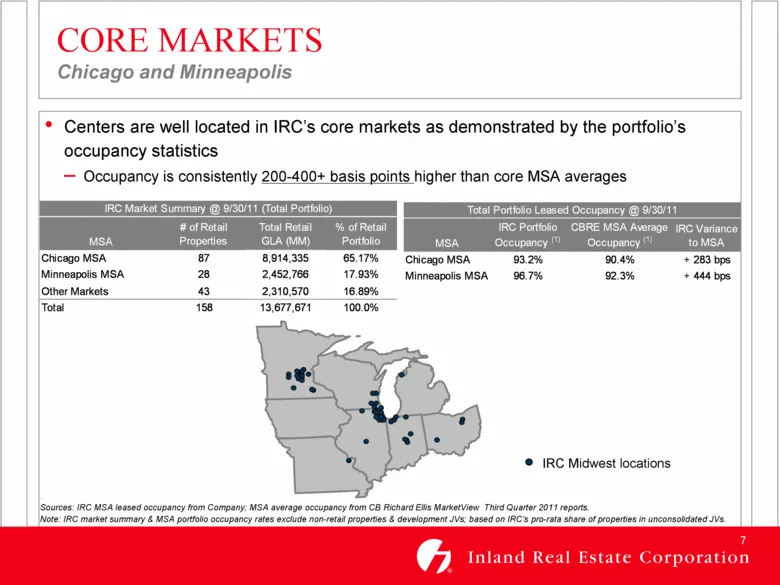
CORE MARKETS Chicago and Minneapolis. Sources: IRC MSA leased occupancy from Company; MSA average occupancy from CB Richard Ellis MarketView Third Quarter 2011 reports. Note: IRC market summary & MSA portfolio occupancy rates exclude non-retail properties & development JVs; based on IRC’s pro-rata s
Slide 8: Chicago Market Snapshot
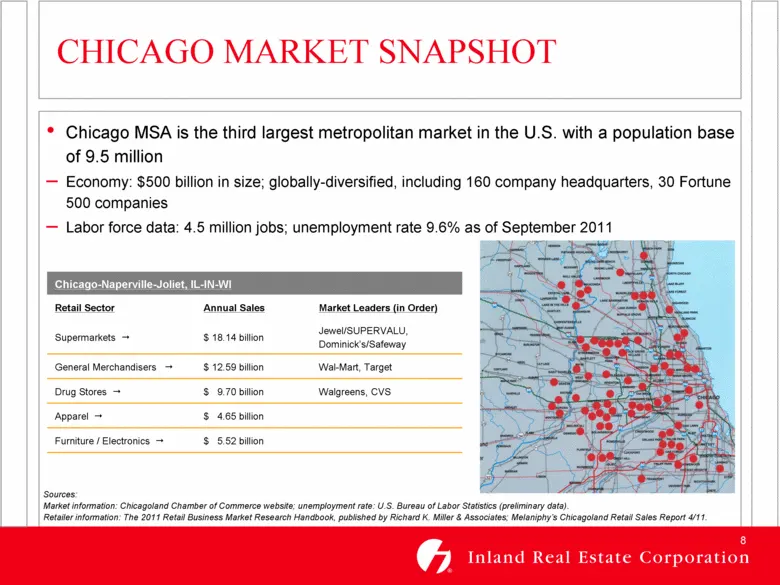
Chicago MSA is the third largest metropolitan market in the U.S. with a population base of 9.5 million Economy: $500 billion in size; globally-diversified, including 160 company headquarters, 30 Fortune 500 companies Labor force data: 4.5 million jobs; unemployment rate 9.6% as of September 2011 CHI
Slide 9: Minneapolis Market Snapshot
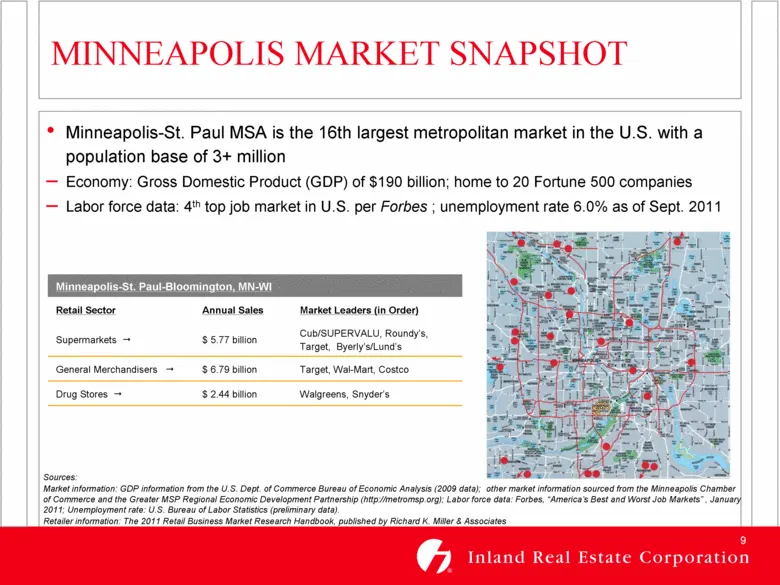
MINNEAPOLIS MARKET SNAPSHOT Sources: Market information: GDP information from the U.S. Dept. of Commerce Bureau of Economic Analysis (2009 data); other market information sourced from the Minneapolis Chamber of Commerce and the Greater MSP Regional Economic Development Partnership (http://metromsp.o
Slide 10: Dominant REIT in Primary Markets
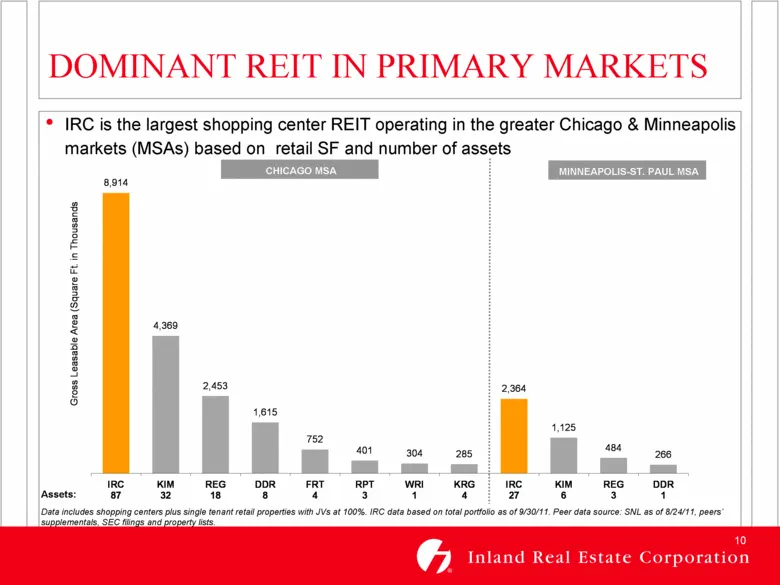
Assets: DOMINANT REIT IN PRIMARY MARKETS IRC is the largest shopping center REIT operating in the greater Chicago & Minneapolis markets (MSAs) based on retail SF and number of assets MINNEAPOLIS-ST. PAUL MSA Data includes shopping centers plus single tenant retail properties with JVs at 100%. IRC da
Slide 11: Strong Market Demographics
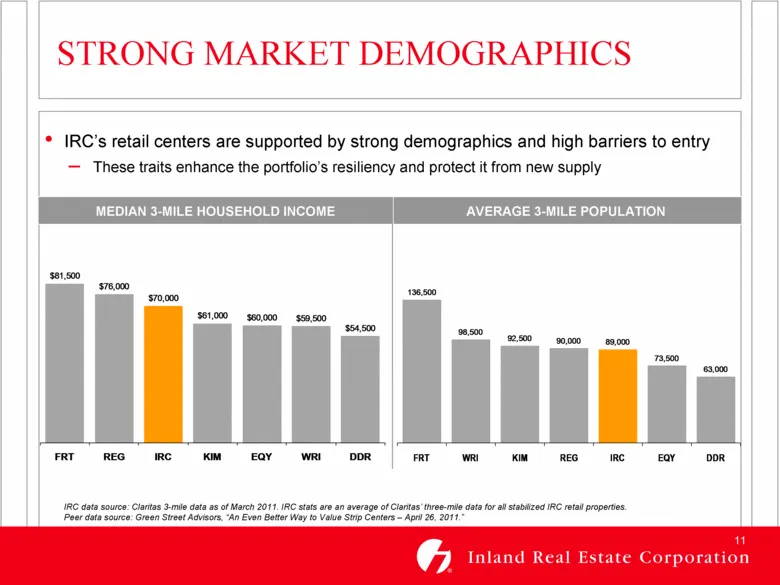
STRONG MARKET DEMOGRAPHICS IRC data source: Claritas 3-mile data as of March 2011. IRC stats are an average of Claritas’ three-mile data for all stabilized IRC retail properties. Peer data source: Green Street Advisors, “An Even Better Way to Value Strip Centers – April 26, 2011.” IRC’s retail cente
Slide 12: Total Portfolio Composition
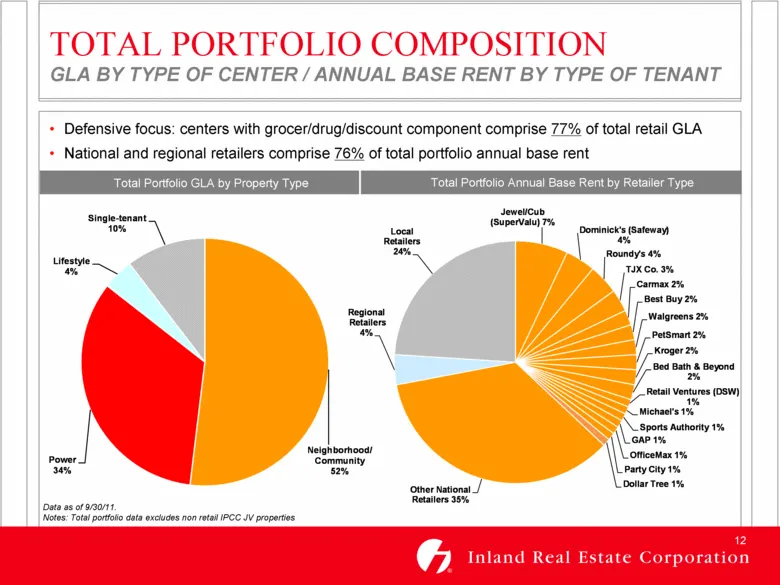
TOTAL PORTFOLIO COMPOSITION GLA BY TYPE OF CENTER / ANNUAL BASE RENT BY TYPE OF TENANT (1) Data as of 9/30/11. Notes: Total portfolio data excludes non retail IPCC JV properties Total Portfolio GLA by Property Type Total Portfolio Annual Base Rent by Retailer Type Defensive focus: centers with groce
Slide 13: Diversified Tenant Base
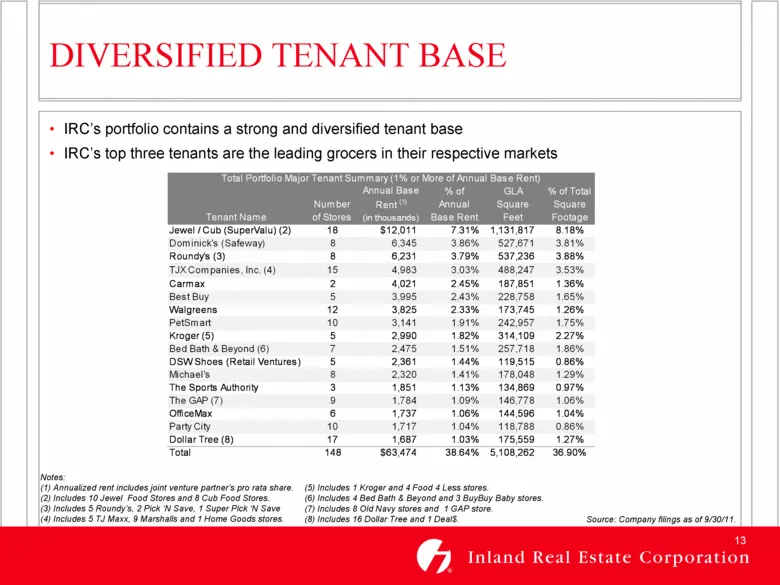
DIVERSIFIED TENANT BASE IRC’s portfolio contains a strong and diversified tenant base IRC’s top three tenants are the leading grocers in their respective markets Source: Company filings as of 9/30/11. Notes: (1) Annualized rent includes joint venture partner’s pro rata share. (2) Includes 10 Jewel F
Slide 14: Operating Fundamentals: Rent Spreads
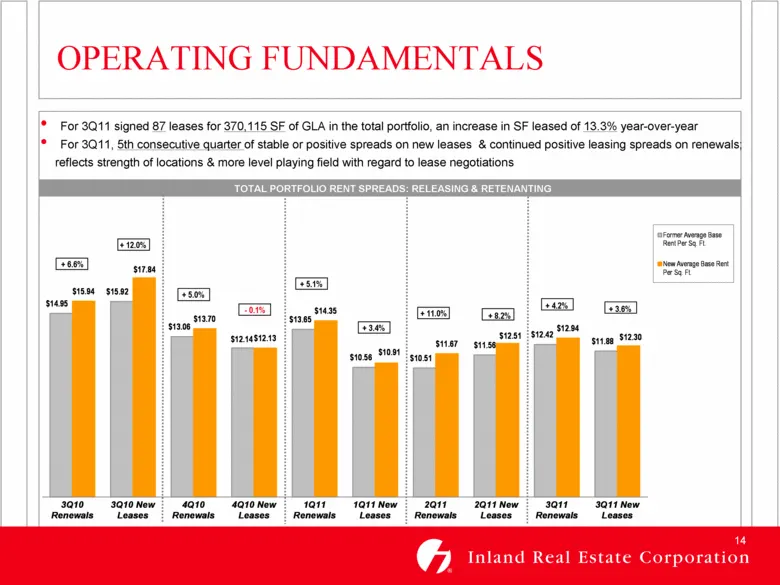
For 3Q11 signed 87 leases for 370,115 SF of GLA in the total portfolio, an increase in SF leased of 13.3% year-over-year For 3Q11, 5th consecutive quarter of stable or positive spreads on new leases & continued positive leasing spreads on renewals; reflects strength of locations & more level playing
Slide 15: Well Staggered Lease Expirations
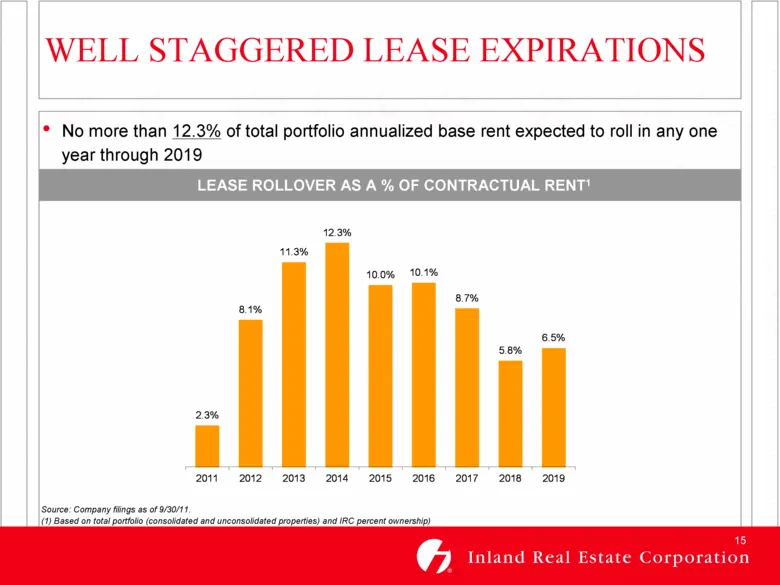
WELL STAGGERED LEASE EXPIRATIONS No more than 12.3% of total portfolio annualized base rent expected to roll in any one year through 2019 Source: Company filings as of 9/30/11. (1) Based on total portfolio (consolidated and unconsolidated properties) and IRC percent ownership) LEASE ROLLOVER AS A %
Slide 16: Leasing Efficiencies
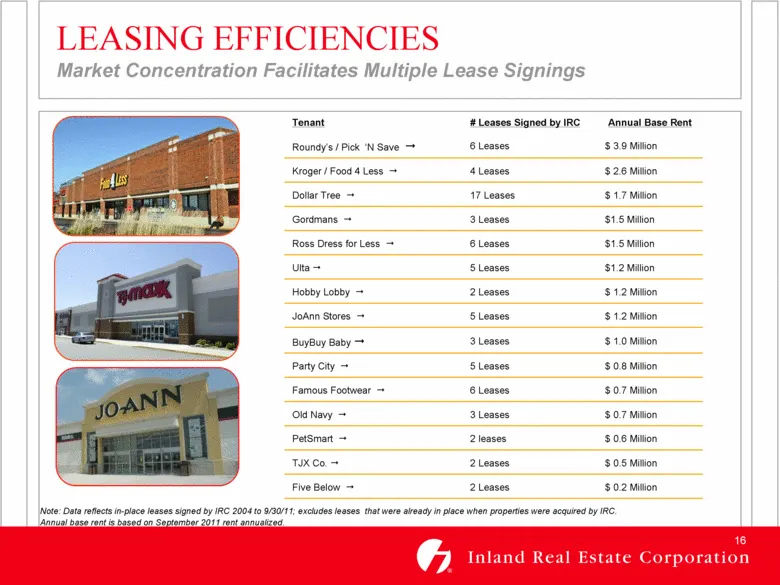
Tenant # Leases Signed by IRC Annual Base Rent Roundy’s / Pick ‘N Save 6 Leases $ 3.9 Million Kroger / Food 4 Less 4 Leases $ 2.6 Million Dollar Tree 17 Leases $ 1.7 Million Gordmans 3 Leases $1.5 Million Ross Dress for Less 6 Leases $1.5 Million Ulta 5 Leases $1.2 Million Hobby Lobby 2 Leases $ 1.2
Slide 17: Growth from Existing Portfolio: Completed Initiatives
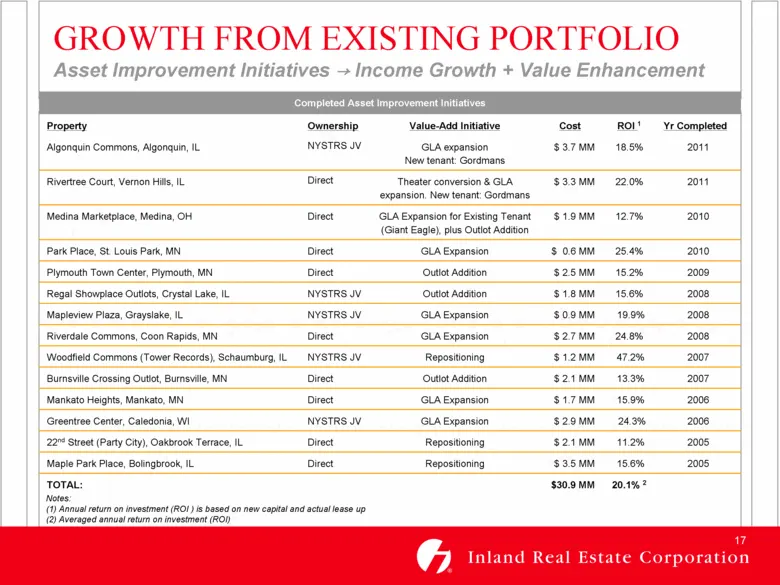
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives Income Growth + Value Enhancement Completed Asset Improvement Initiatives Property Ownership Value-Add Initiative Cost ROI 1 Yr Completed Algonquin Commons, Algonquin, IL NYSTRS JV GLA expansion New tenant: Gordmans $ 3.7 MM 18.5% 2011 Riv
Slide 18: Growth from Existing Portfolio: In-Process Initiatives
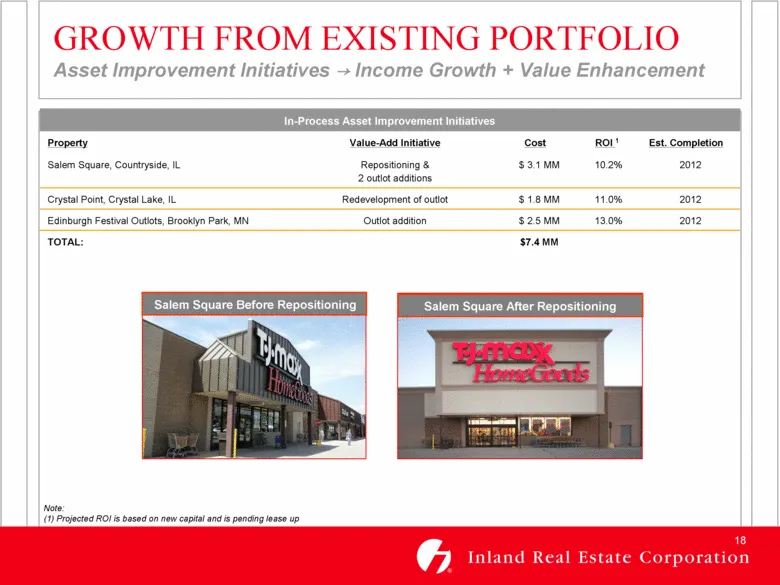
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives Income Growth + Value Enhancement In-Process Asset Improvement Initiatives Property Value-Add Initiative Cost ROI 1 Est. Completion Salem Square, Countryside, IL Repositioning & 2 outlot additions $ 3.1 MM 10.2% 2012 Crystal Point, Crystal
Slide 19: Development Projects
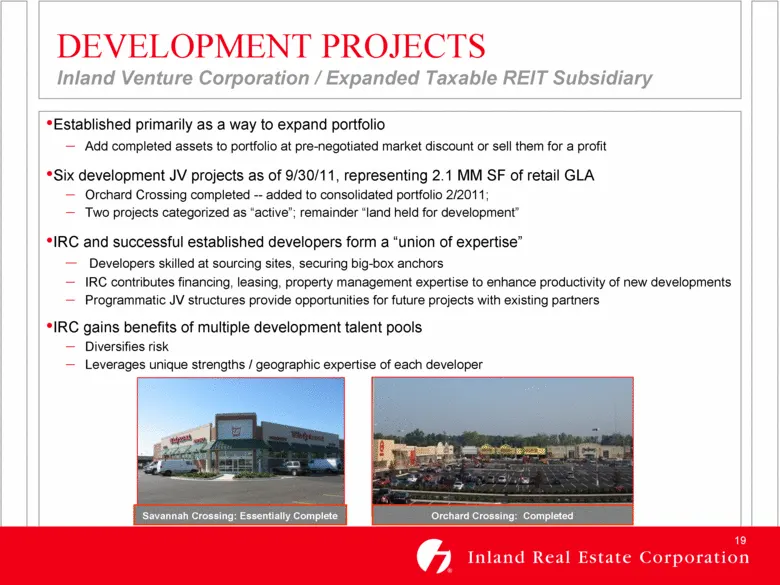
Savannah Crossing: Essentially Complete DEVELOPMENT PROJECTS Inland Venture Corporation / Expanded Taxable REIT Subsidiary Established primarily as a way to expand portfolio Add completed assets to portfolio at pre-negotiated market discount or sell them for a profit Six development JV projects as o
Slide 20: Acquisition History
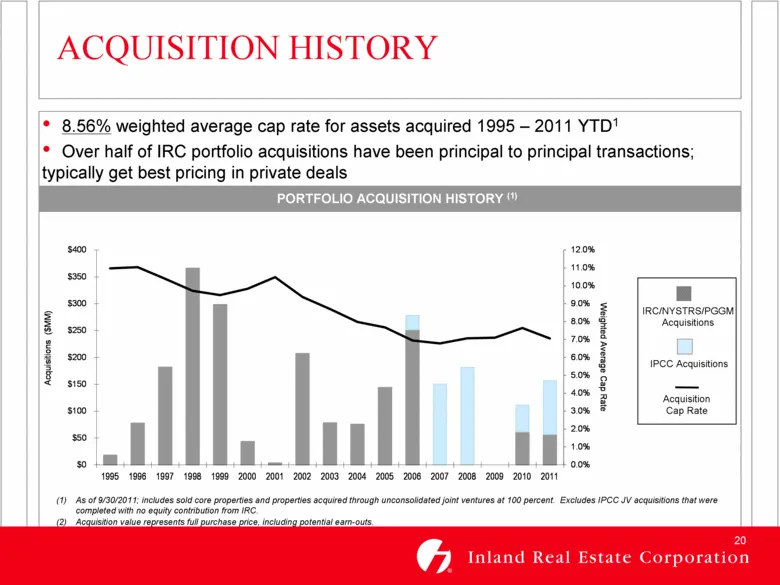
(1) As of 9/30/2011; includes sold core properties and properties acquired through unconsolidated joint ventures at 100 percent. Excludes IPCC JV acquisitions that were completed with no equity contribution from IRC. (2) Acquisition value represents full purchase price, including potential earn-outs
Slide 21: Maintaining a Strong Balance Sheet
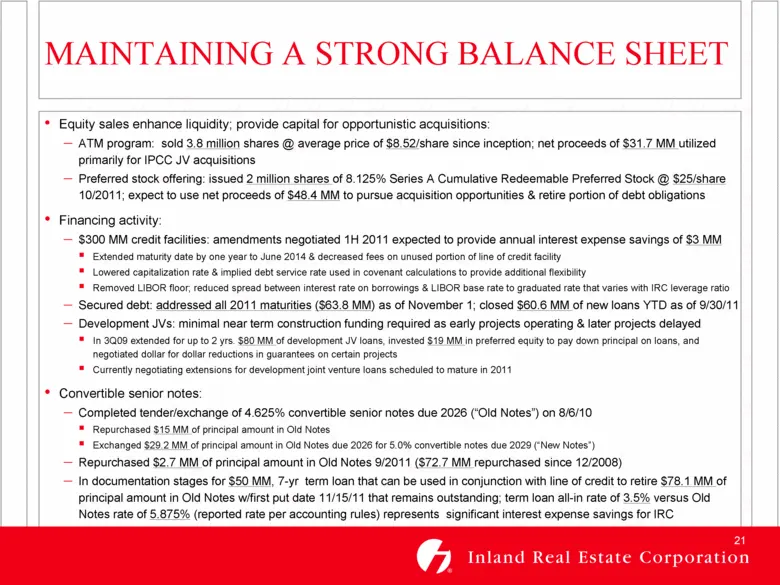
MAINTAINING A STRONG BALANCE SHEET Equity sales enhance liquidity; provide capital for opportunistic acquisitions: ATM program: sold 3.8 million shares @ average price of $8.52/share since inception; net proceeds of $31.7 MM utilized primarily for IPCC JV acquisitions Preferred stock offering: issue
Slide 22: Consolidated Debt Maturities
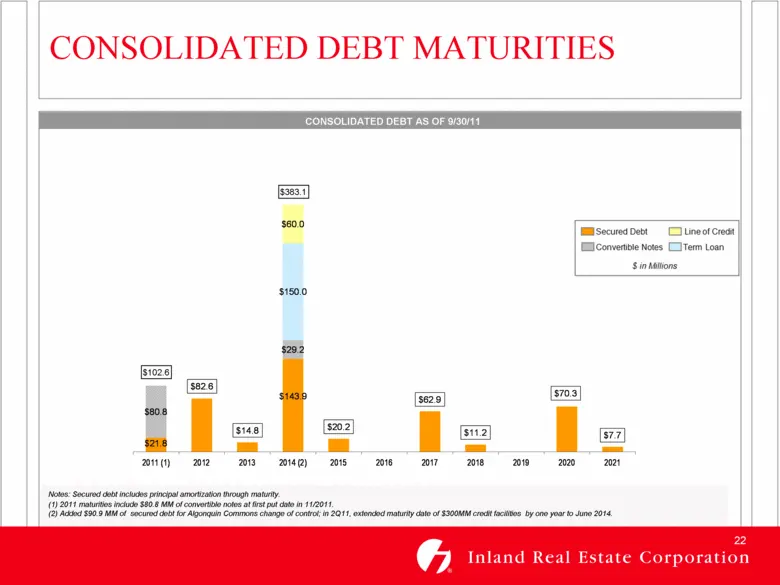
CONSOLIDATED DEBT MATURITIES Notes: Secured debt includes principal amortization through maturity. (1) 2011 maturities include $80.8 MM of convertible notes at first put date in 11/2011. (2) Added $90.9 MM of secured debt for Algonquin Commons change of control; in 2Q11, extended maturity date of $3
Slide 23: Joint Venture Strategies
JOINT VENTURE STRATEGIES Diversify Capital Resources + Expand Platform + Drive Future Growth Asset Management and Asset Based Joint Venture Strategies Retail Focus IRC Knowledge High Quality Partners ‘Union of Expertise’ Long-term Asset Management Role Value-enhancing
Slide 24: Asset Management Joint Venture: IPCC
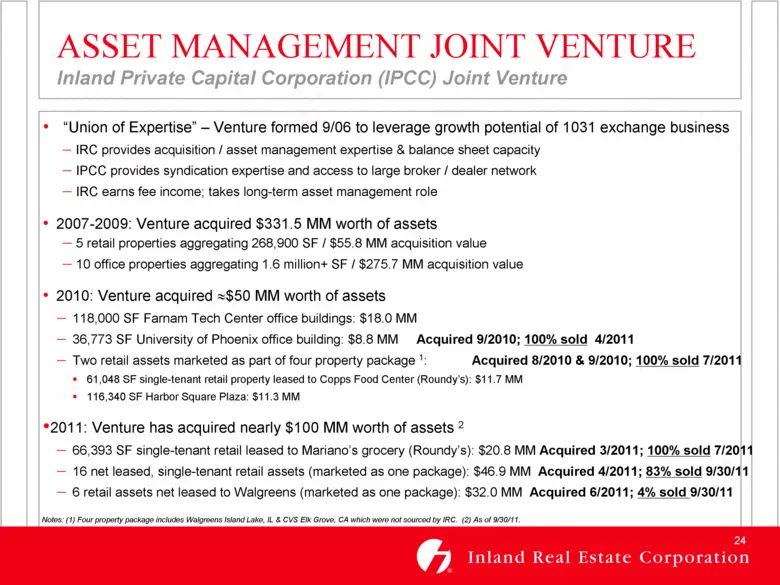
ASSET MANAGEMENT JOINT VENTURE Inland Private Capital Corporation (IPCC) Joint Venture “Union of Expertise” – Venture formed 9/06 to leverage growth potential of 1031 exchange business IRC provides acquisition / asset management expertise & balance sheet capacity IPCC provides syndication expertise
Slide 25: Asset-Based Joint Venture: NYSTRS
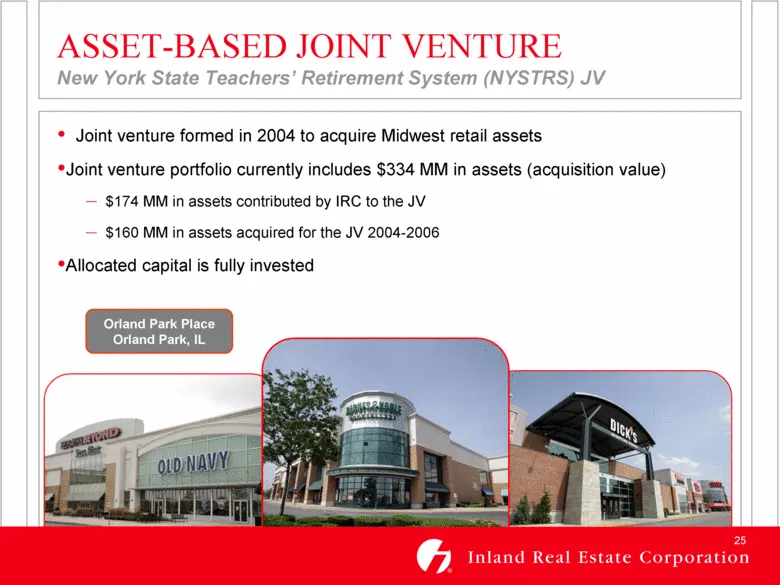
ASSET-BASED JOINT VENTURE New York State Teachers’ Retirement System (NYSTRS) JV Joint venture formed in 2004 to acquire Midwest retail assets Joint venture portfolio currently includes $334 MM in assets (acquisition value) $174 MM in assets contributed by IRC to the JV $160 MM in assets acquired fo
Slide 26: Strategic Joint Venture with PGGM
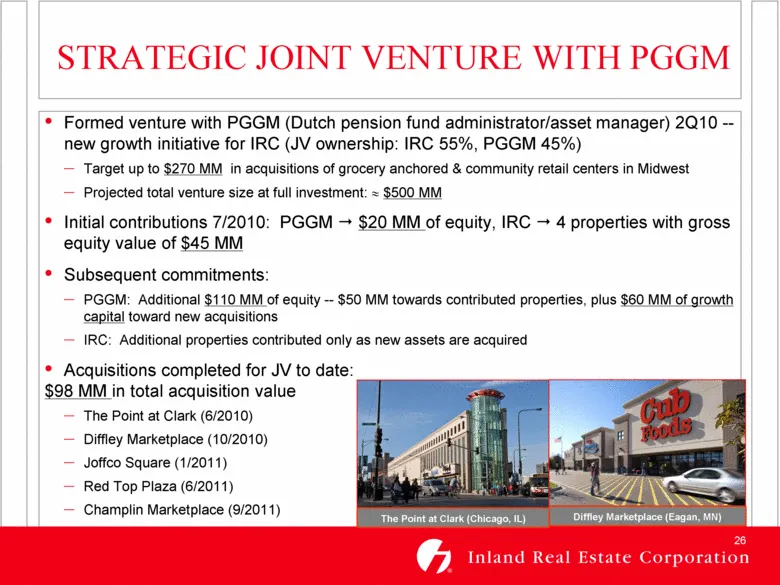
STRATEGIC JOINT VENTURE WITH PGGM Formed venture with PGGM (Dutch pension fund administrator/asset manager) 2Q10 -- new growth initiative for IRC (JV ownership: IRC 55%, PGGM 45%) Target up to $270 MM in acquisitions of grocery anchored & community retail centers in Midwest Projected total venture s
Slide 27: PGGM Joint Venture Structure
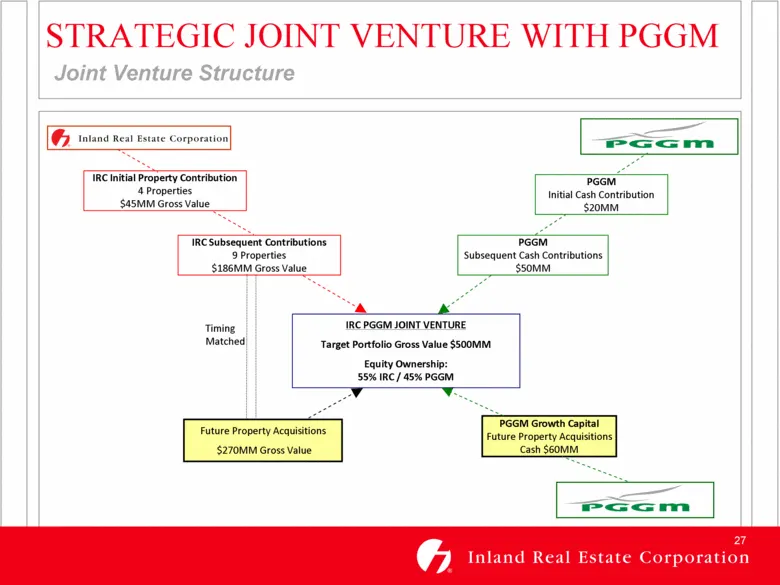
STRATEGIC JOINT VENTURE WITH PGGM Joint Venture Structure IRC Subsequent Contributions 9 Properties $186MM Gross Value PGGM Subsequent Cash Contributions $50MM PGGM Growth Capital Future Property Acquisitions Cash $60MM Future Property Acquisitions $270MM Gross Value IRC PGGM JOINT VENTURE Target Po
Slide 28: PGGM Joint Venture Benefits
STRATEGIC JOINT VENTURE WITH PGGM Unique Joint Venture Provides Benefits IRC-PGGM joint venture is immediately accretive way to generate up to $130 MM of growth capital Monetizes equity value of IRC assets while retaining operating control Gains on sale become IRC contributions toward new acquisitio
Slide 29: Joint Venture Fee Income
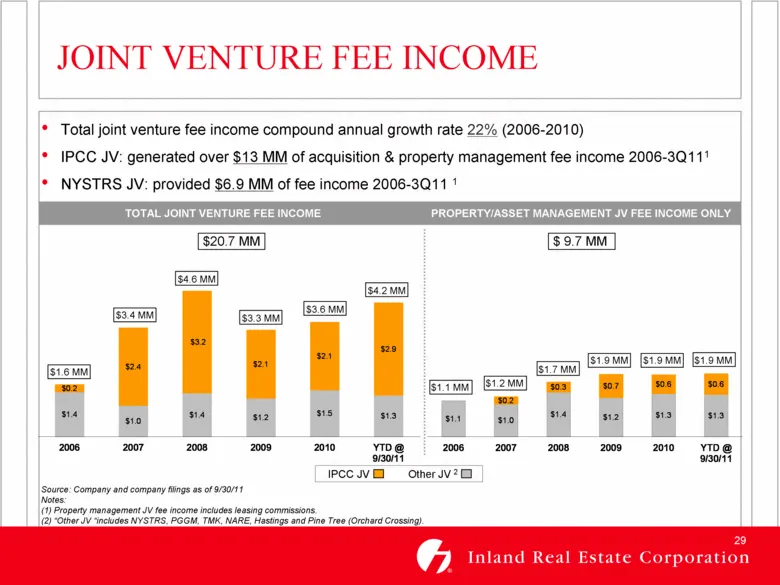
$3.4 MM $3.3 MM $1.6 MM $4.6 MM $3.6 MM $4.2 MM JOINT VENTURE FEE INCOME Total joint venture fee income compound annual growth rate 22% (2006-2010) IPCC JV: generated over $13 MM of acquisition & property management fee income 2006-3Q111 NYSTRS JV: provided $6.9 MM of fee income 2006-3Q11 1 Source:
Slide 30: Summary
IRC has built a solid foundation for future growth Necessity & value-based retail in high barrier to entry markets should outperform other retail real estate over time Centers impacted by big-box vacancies have been re-tenanted with high credit quality, best-in-class retailers that drive additional
Slide 31: Forward-Looking Statements
FORWARD-LOOKING STATEMENTS Certain statements in this presentation constitute "forward-looking statements" within the meaning of the Federal Private Securities Litigation Reform Act of 1995. These forward-looking statements are not historical facts but are the intent, belief or current expectations
Source: SEC EDGAR · 8-K filed Nov 15, 2011
More decks from Inland Real Estate Corp
 Investor Presentation (November 2015)30 slides · Nov 17, 2015
 Investor Presentation (September 2015)29 slides · Sep 16, 2015
 Investor Presentation (June 2015)29 slides · Jun 9, 2015
 Investor Presentation (May 2015)26 slides · May 15, 2015
 Investor Presentation (February 2015)26 slides · Feb 24, 2015
 Investor Presentation (November 2014)26 slides · Nov 5, 2014