Teppco Partners LP — A. G. Edwards Energy Conference 2004
34 slides from Teppco Partners LP's conference presentation, Mar 24, 2004
Slide 1: TEPPCO Partners, L.P. – A. G. Edwards Energy Conference
TEPPCO Partners, L.P. A. G. Edwards Energy Conference Boston, MA March 24, 2004
Slide 2: Forward-looking Statements
Forward-looking Statements m= The material and information furnished in this presentation contains forward-looking statements as such are described within various provisions of the Federal Securities Laws. Forward-looking statements include projections, estimates, forecasts, plans and objectives and
Slide 3: TEPPCO Partners, L.P.
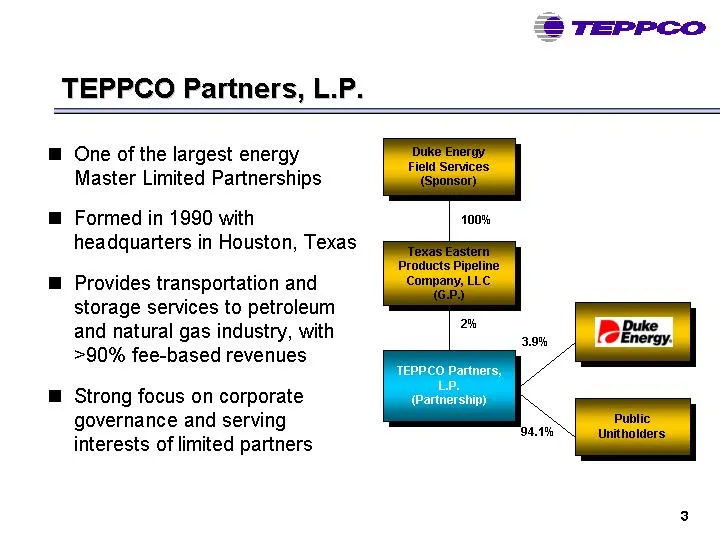
I i) TEPPCO Partners, L.P. m@ One of the largest energy Master Limited Partnerships m@ Formed in 1990 with headquarters in Houston, Texas ™@ Provides transportation and storage services to petroleum and natural gas industry, with >90% fee-based revenues TEPPCO Partners, LP. ™@ Strong focus on corpor
Slide 4: The Sponsor: Duke Energy Field Services
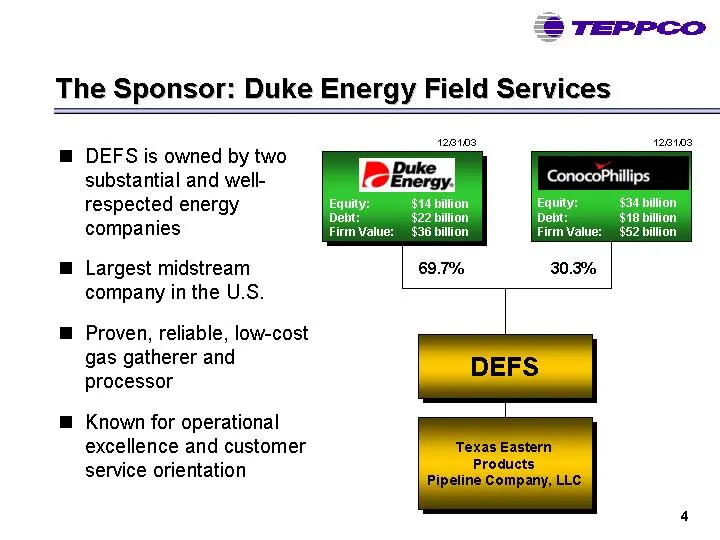
The Sponsor: Duke Energy Field Services DEFS is owned by two substantial and well- respected energy companies Largest midstream company in the U.S. Proven, reliable, low-cost gas gatherer and processor Known for operational excellence and customer service orientation 126103 120103 ConocoPhillips Equ
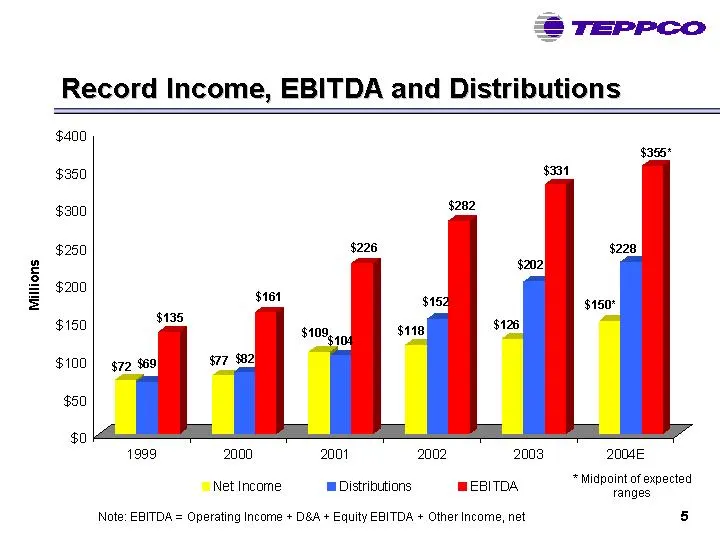
Slide 5: Record Income, EBITDA and Distributions
g 5 Record Income, EBITDA and Distributions $400 $360 $200 $260 $200 $150 $100 $50 $0 1999 2000 2001 2002 2008 2004E * Midpoint of expected Net Income Distributions EBITDA enbee Note: EBITDA = Operating Income + D&A + Equity EBITDA + Other Income, net 5
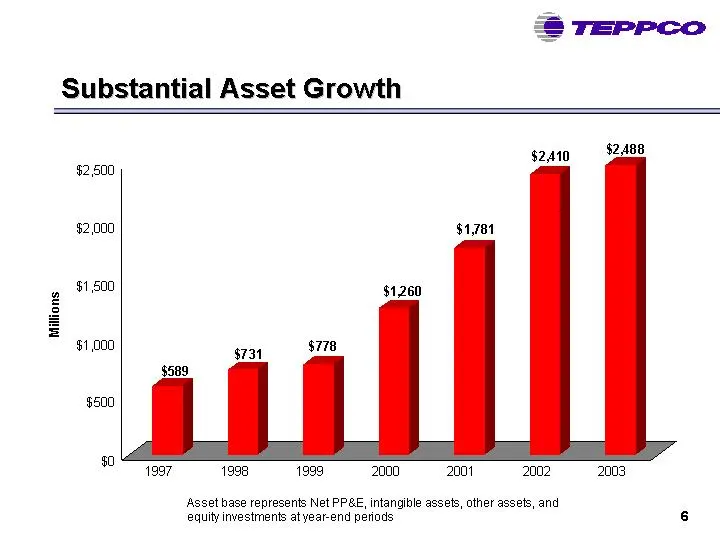
Slide 6: Substantial Asset Growth
Substantial Asset Growth $2,500 $2,000 $1,500 $1,000 $600 $0 1997 1998 1999 2000 2001 2002 2008 Asset base represents Net P&E, intangible assets, other assets, and equity investments at year-end periods 6
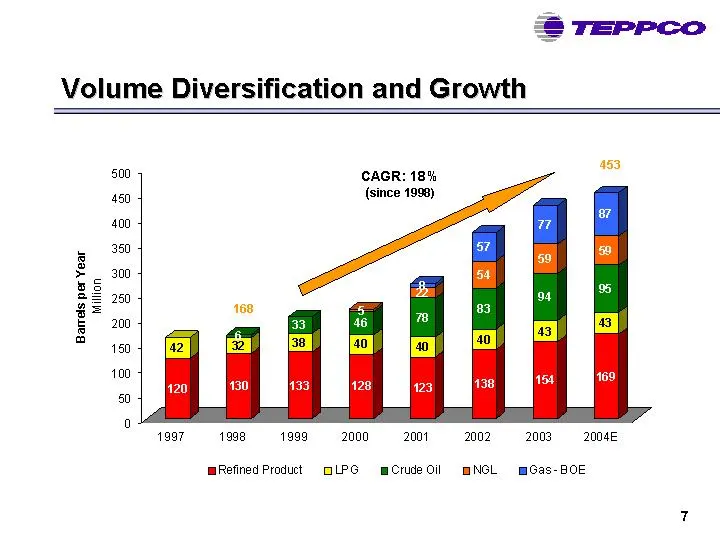
Slide 7: Volume Diversification and Growth CAGR: 18%
Volume Diversification and Growth 453 500 CAGR: 18% (since 1998) Barrels per Year 1997 998 1999 2000S 2001) 20022003204: wRefined Product OLPG mCrudecil gNGL mGas-BOE
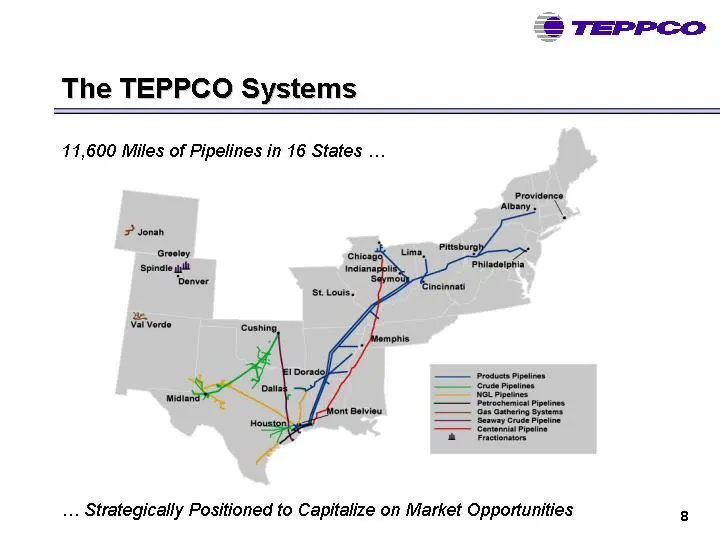
Slide 8: The TEPPCO Systems
The TEPPCO Systems 11,600 Miles of Pipelines in 16 States ... ... Strategically Positioned to Capitalize on Market Opportunities 8
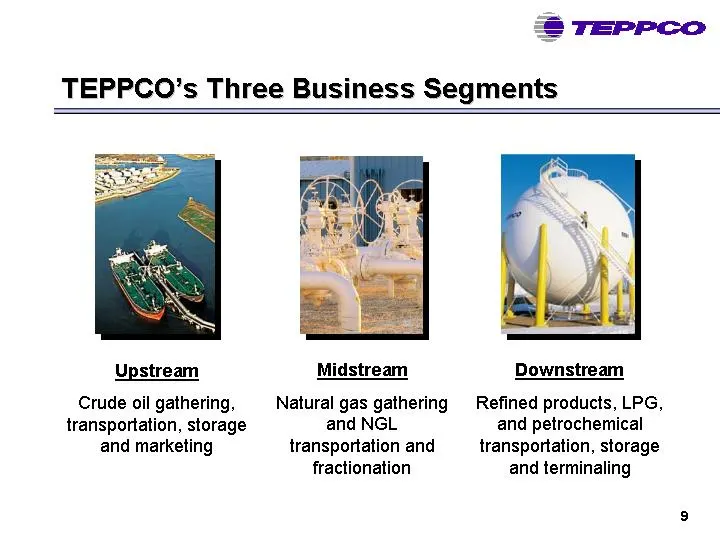
Slide 9: Upstream Midstream Downstream
Upstream Midstream Downstream Crude oil gathering, Natural gas gathering Refined products, LPG, transportation, storage and NGL and petrochemical and marketing transportation and transportation, storage fractionation and terminaling
Slide 10: TEPPCO Corporate Strategy
TEPPCO Corporate Strategy @ Focus on internal growth prospects — Increase throughput on our pipeline systems — Expand / upgrade existing assets and construct new pipeline and gathering systems ™ Target accretive acquisitions in our core businesses that provide growth potential — Utilize competitive
Slide 11: TEPPCO's Upstream Business
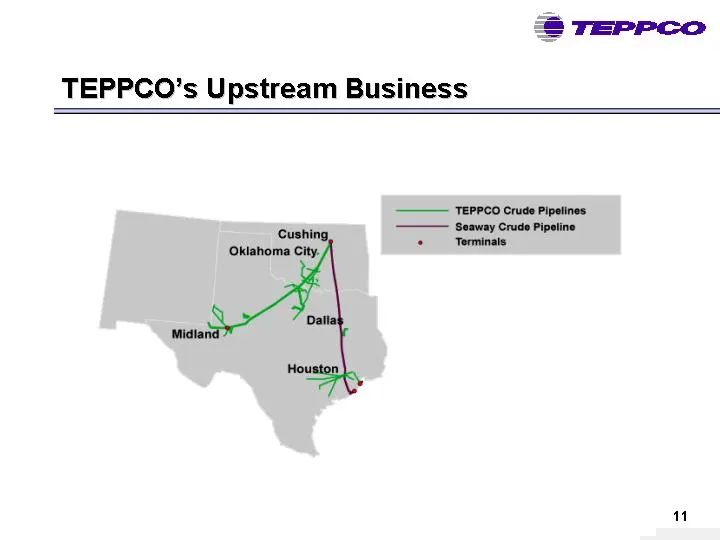
TEPPCO’s Upstream Business —— TEPPCO Crude Pipelines Eee ee Oklahoma City, Dal "
Slide 12: Upstream EBITDA Contribution
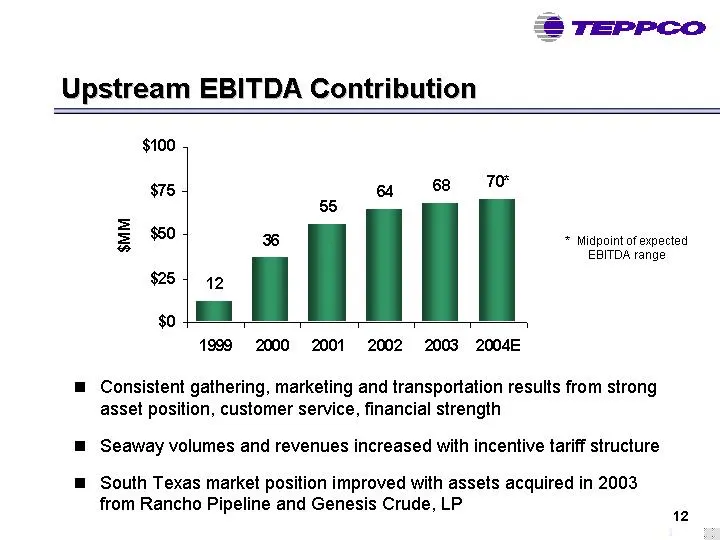
$100 Upstream EBITDA Contribution $75 68 70 55 $60 6 | 1 | oo |= 1999 2000 «2001 2002 2003 2004E 64 $MM * Midpoint of expected EBITDA range = Consistent gathering, marketing and transportation results from strong asset position, customer service, financial strength ™ Seaway volumes and revenues incr
Slide 13: Upstream Strategy
Upstream Strategy @ Strengthen market position around existing asset base — Focus activity in West Texas, South Texas and Red River areas — Increase margins by improving/expanding services and reducing costs through asset optimization ™@ Pursue strategic acquisitions to complement existing assets @
Slide 14: TEPPCO's Midstream Business
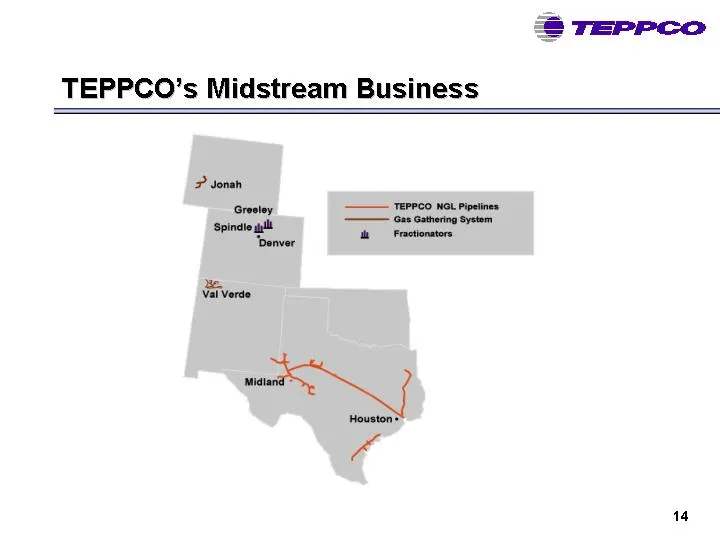
TEPPCO’s Midstream Business P Jonah ince —— areca rates SSS spinal os Diener Be Usiverde 4 14
Slide 15: Midstream EBITDA Contribution
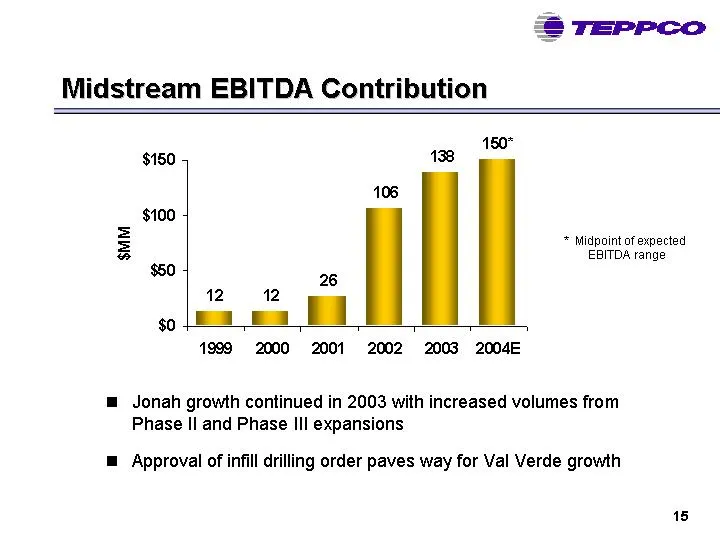
Midstream EBITDA Contribution 150" $150 138 106 $100 = + Midpoint ofexectes 3 EBITDA range $0 28 12 12 so | —__ a 1999 2000 «2001 «2002 2003 2004E @ Jonah growth continued in 2003 with increased volumes from Phase II and Phase III expansions @ Approval of infill drilling order paves way for Val Verd
Slide 16: Midstream Strategy
Midstream Strategy @ Strong portfolio of high quality assets in prolific gas producing basins — Assets positioned in basins playing an increasingly vital role in the United States’ domestic gas supply @ Realize full potential of existing assets — Increase throughput on Val Verde, Jonah and Chaparral
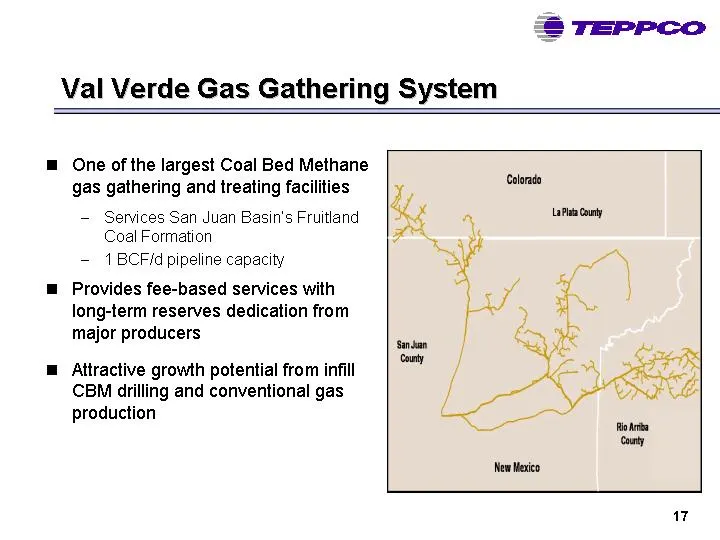
Slide 17: Val Verde Gas Gathering System
Val Verde Gas Gathering System ™ One of the largest Coal Bed Methane gas gathering and treating facilities - Services San Juan Basin's Fruitland Coal Formation - 1BCFid pipeline capacity m Provides fee-based services with long-term reserves dedication from major producers ™@ Attractive growth potent
Slide 18: Val Verde Growth Potential
Val Verde Growth Potential @ Near-term volume growth from Coal Bed Methane infill drilling — New Mexico Oil Conservation Division issued order in July 2003 approving 160-acre spacing in all areas of the Fruitland Coal Formation — Volumes from infill wells dedicated to Val Verde and within footprint
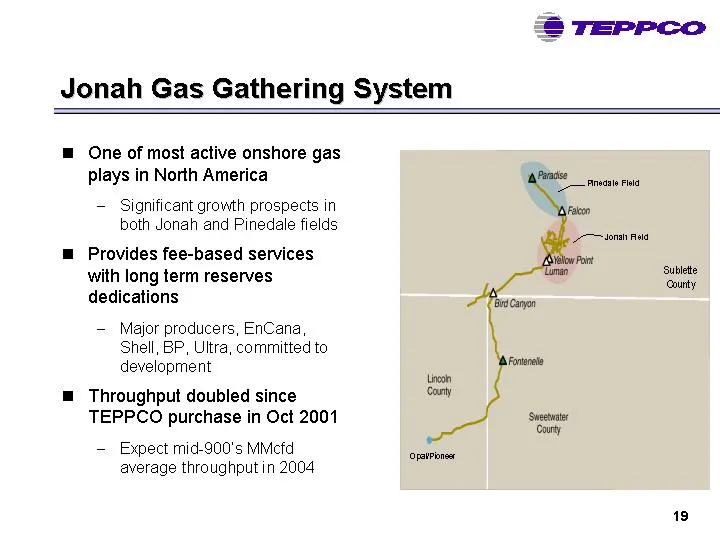
Slide 19: Jonah Gas Gathering System
Jonah Gas Gathering System ™ One of most active onshore gas plays in North America Sawaal Fa — Significant growth prospects in both Jonah and Pinedale fields m Provides fee-based services with long term reserves dedications lon ena Fs Pont Sublete county — Major producers, EnCana, Shell, BP, Ultra,
Slide 20: Phase III Expansion and Pioneer Plant
Phase Ill Expansion and Pioneer Plant @ Phase III Expansion has increased system capacity to 1.2 Befd — >90% of gas dedicated life of lease from wellhead to Bird Canyon — Obtained increased long haul dedications from major producers m@ Improved system reliability with Pioneer Processing Plant and Op
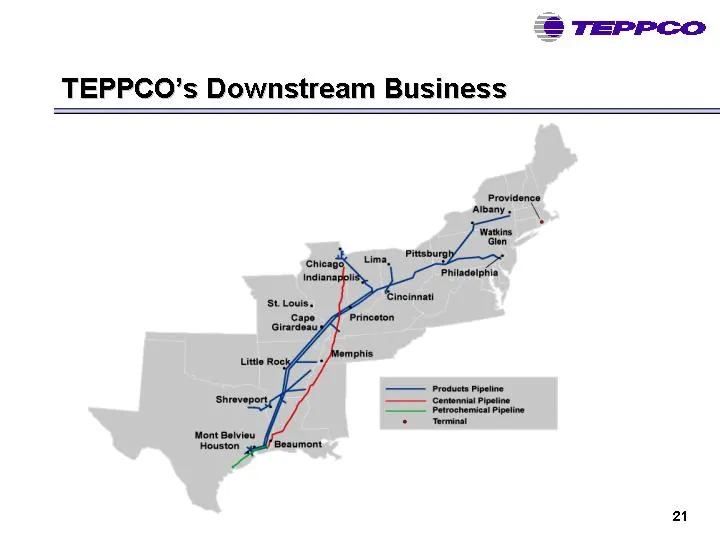
Slide 21: TEPPCO's Downstream Business
TEPPCO’s Downstream Business Mont Belview Houston a Beaumont 2
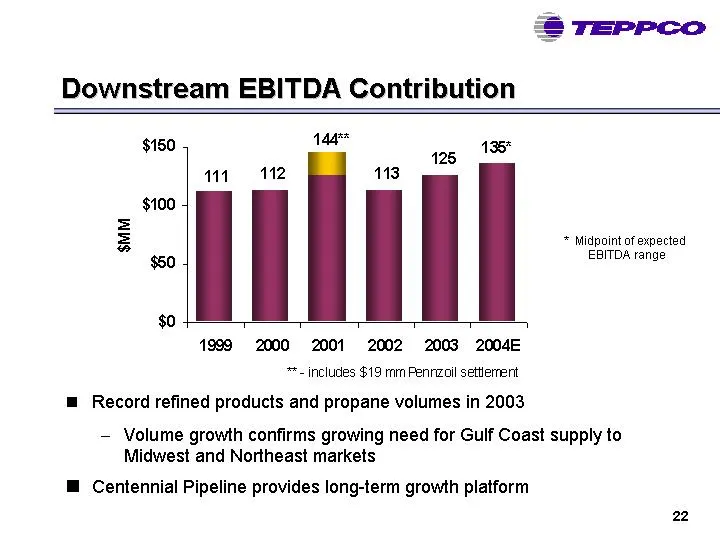
Slide 22: Downstream EBITDA Contribution
Downstream EBITDA Contribution 150 144" 7 $ 5 18 m2 113 $100 = zB * Midpoint of expected $60 EBITDA range $0 1999 2000 «2001 +2002 2003 2004E *- includes $19 rm Fenrzoil settlerrent, @ Record refined products and propane volumes in 2003 = Volume growth confirms growing need for Gulf Coast supply to
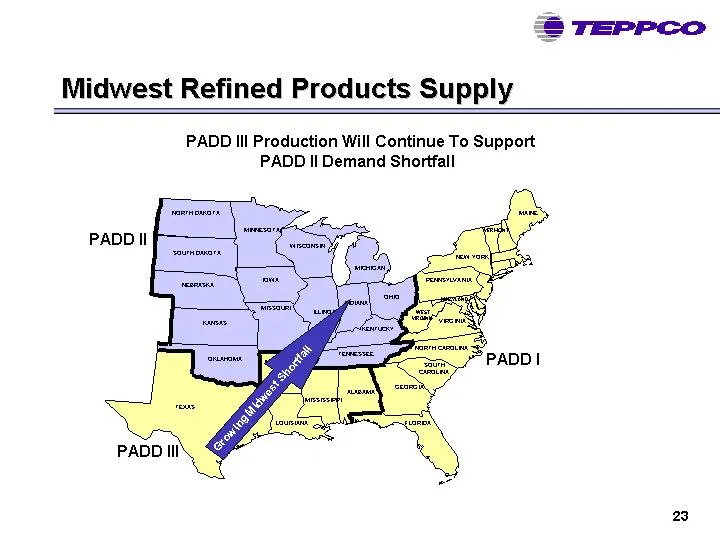
Slide 23: Midwest Refined Products Supply
Midwest Refined Products Supply PADD Ill Production Will Continue To Support PADD II Demand Shortfall PADD Il 23
Slide 24: Downstream Strategy
Downstream Strategy m@ Utilize TEPPCO and Centennial Pipeline systems to serve growing Midwest supply shortfall — Acquisition of capacity lease and increased ownership position improves ability to optimize operations and customer service @ Centennial is a key investment for TEPPCO, providing substan
Slide 25: Integrity Management Program
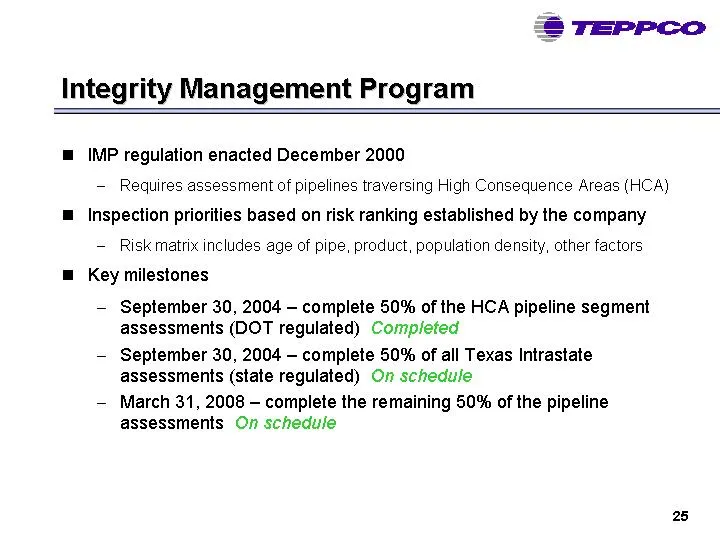
Integrity Management Program @ IMP regulation enacted December 2000 — Requires assessment of pipelines traversing High Consequence Areas (HCA) @ Inspection priorities based on risk ranking established by the company = Risk matrix includes age of pipe, product, population density, other factors @ Key
Slide 26: Link to searchable text of slide shown above
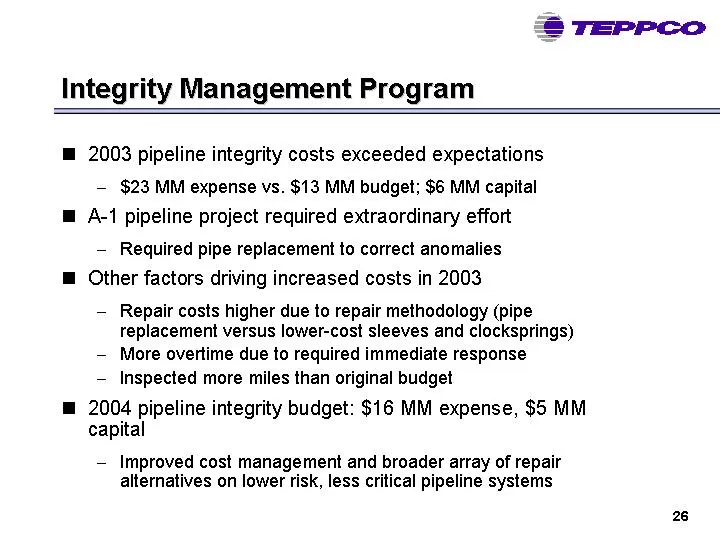
Link to searchable text of slide shown above
Slide 27: Balance Sheet and Distribution Coverage
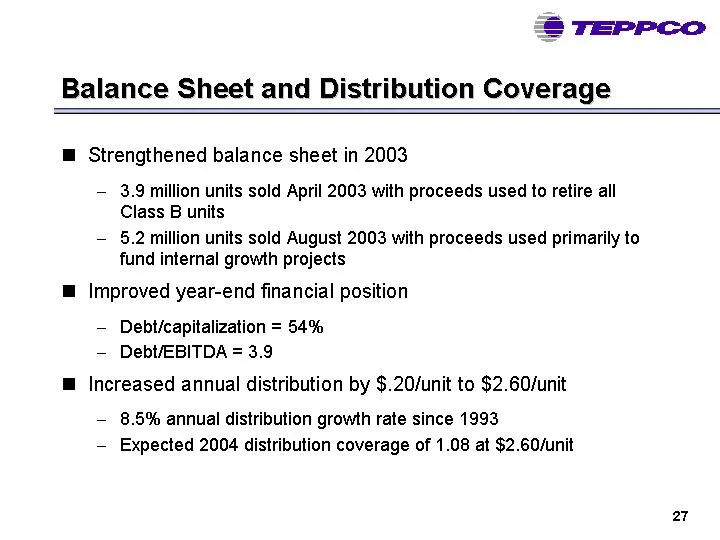
Balance Sheet and Distribution Coverage @ Strengthened balance sheet in 2003 — 3.9 million units sold April 2003 with proceeds used to retire all Class B units — 5.2 million units sold August 2003 with proceeds used primarily to fund internal growth projects @ Improved year-end financial position —
Slide 28: Consistent distribution growth since 1993
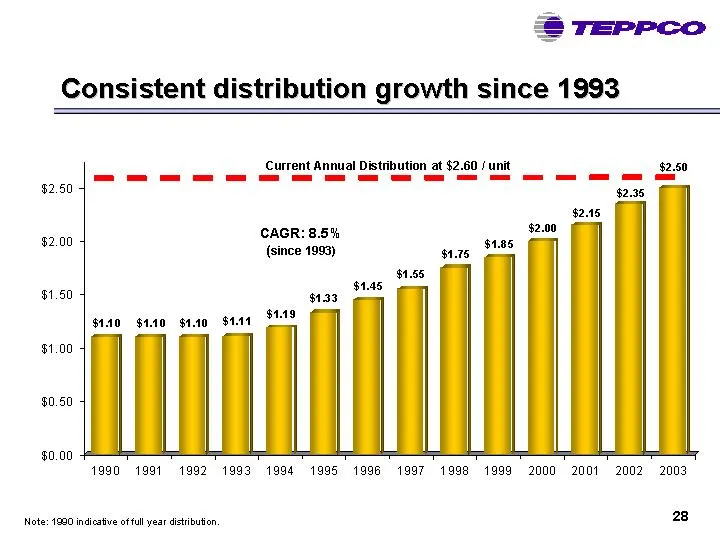
A TEPPCO Consistent distribution growth since 1993 Current Annual Distribution at $2.60 / unit $2.50 apes $2.35 $2.00 CAGR: 8.5% (since 1993) 1:50 $133 giao stan saan $1t1 S449 $1.00 $0.50 $0.00 1990 1991 1992 1993 1994 1995 1998 1997 1998 1999 2000 2001 2002 2003 Note: 1000 indcative of ful year at
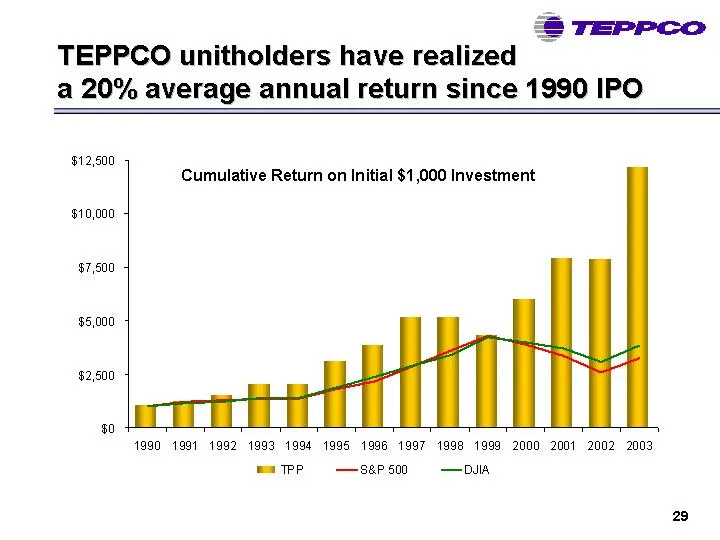
Slide 29: TEPPCO unitholders have realized a 20% average annual return
TEPPCO unitholders have realized a 20% average annual return since 1990 IPO $12,500 Cumulative Return on Initial $1,000 Investment $10,000 $7,500 $6,000 $2,500 80 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 ma TPP | =—saP500 —DuJA 29
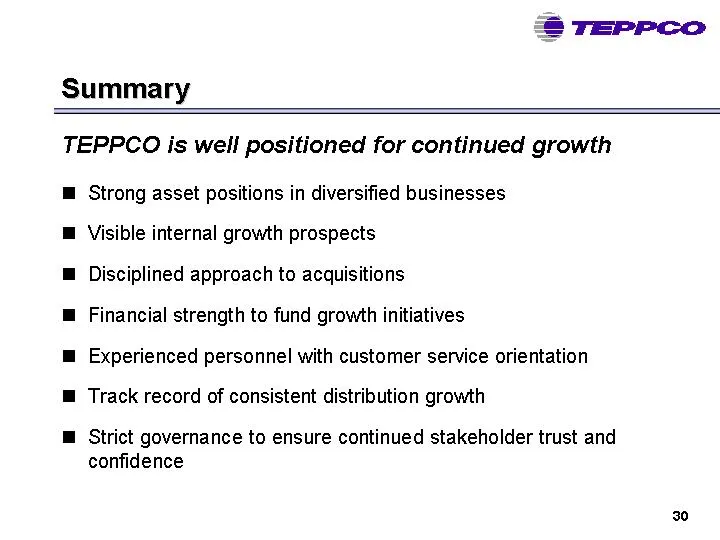
Slide 30: Summary
Summary TEPPCO is well positioned for continued growth Strong asset positions in diversified businesses Visible internal growth prospects Disciplined approach to acquisitions Financial strength to fund growth initiatives Experienced personnel with customer service orientation Track record of consist
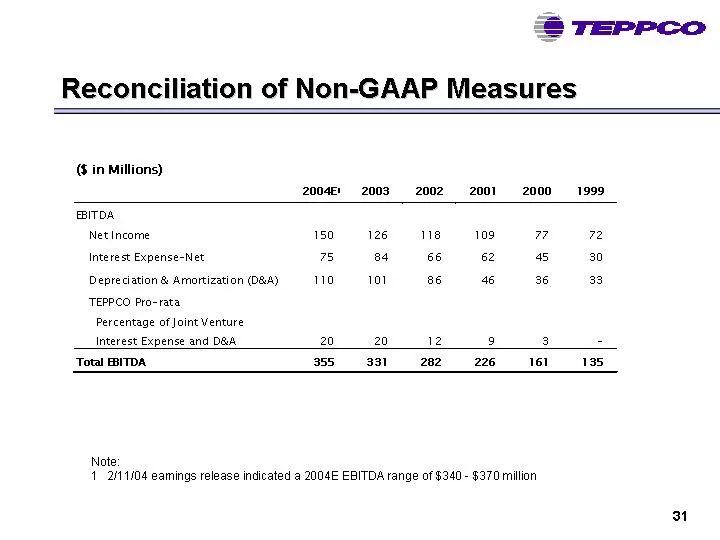
Slide 31: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures TEPPCO in Millions) 2004 2003 2002 2001-2000 _—+1999 EBITDA Net income 15012618109 77 72 Interest Expense-Net 75 8466 62 45 30 Depreciation & Amortization (D&A) «110.101 86 46 36 33 TEPPCO Pro-rata Percentage of Joint Venture Interest Expense and D&A 20 20 12 8 a
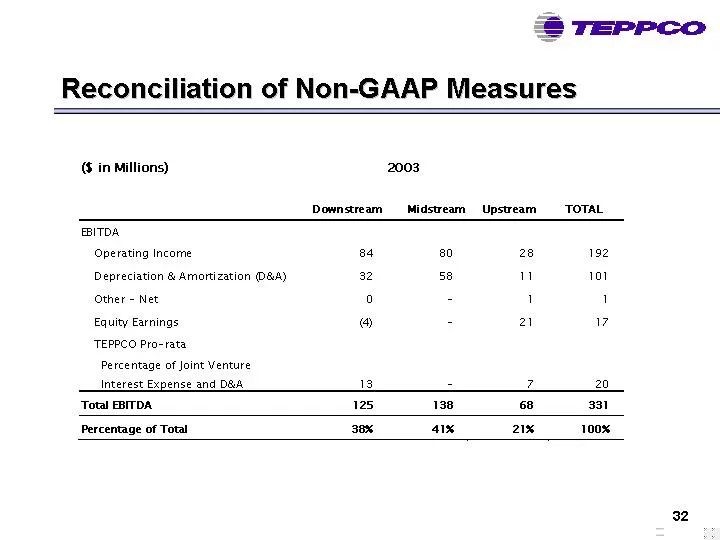
Slide 32: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures TEPPCO G in Millions) 2003 Downstream Midstream Upstream TOTAL EBITDA Operating Income 84 80 28 192 Depreciation & Amortization D&A) 32 58 u 101 Other - Net 0 - 1 1 Equity Earnings ® - 21 7 TEPPCO Pro-rata Percentage of Joint Venture Interest Expense and D&A, 13 =
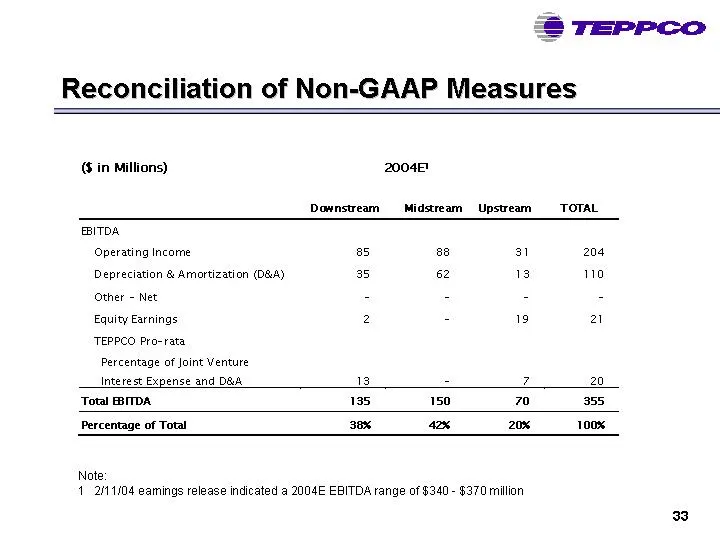
Slide 33: Reconciliation of Non-GAAP Measures
TEPPCO Reconciliation of Non-GAAP Measures in Millions) 200481 Downstream Midstream Upstream TOTAL EBITDA Operating Income 85 88 a1 204 Depreciation & Amortization (O&A) 35 62 13 no Other - Net s s 5 x Equity Earnings 2 - 19 21 TEPPCO Pro-rata Percentage of Joint Venture Interest Expense and D&A 13
Slide 34: Searchable text section of graphics
Searchable text section of graphics shown above TEP PCO Partners, L.P. A. G. Edwards Energy Conference Boston, MA March 24, 2004 [LOGO] [ LOG O] Forward-looking Statements • The material and information furnished in this presentation contains forward-looking statements as such are described within v
Source: SEC EDGAR · 8-K filed Mar 24, 2004
More decks from Teppco Partners LP
 Morgan Stanley MLP Reception (October 2009)26 slides · Oct 7, 2009
 Master Limited Partnerships Investor Conference (September 2009)27 slides · Sep 16, 2009
 Wells Fargo Retail Meeting (September 2009)27 slides · Sep 15, 2009
 Barclays Capital CEO Energy/Power Conference 200929 slides · Sep 9, 2009
 Merger or Acquisition (August 2009)29 slides · Aug 26, 2009
 Wachovia Securities Investor Presentation (June 2007)51 slides · Jun 1, 2007