Alliance Bankshares — Q1 2007 Earnings Presentation
31 slides from Alliance Bankshares's earnings presentation, May 17, 2007
Slide 1: Alliance Bankshares cover
Vi Ce Bank shares king is today. And tomorrow.
Slide 2: Who We Are
WHO WE ARE Diversified banking organization in one of the most desirable, affluent markets in the country $629.9 million in total assets as of March 31, 2007; opened for business in November 1998 Five banking branches, a wealth management team, a Loan Processing Office and a three- location full ser
Slide 3: Who We Are
WHO WE ARE Emphasis on small to medium sized businesses with complementary, full service consumer services Broad array of financial services products Insurance lines include P&C, Life, Health, Homeowners, Auto, etc... Responsive and experienced management Strong credit culture and discipline
Slide 4: Why We Are Different
WHY WE ARE DIFFERENT Competitive Approach Speed & Responsiveness We meet or exceed customer timelines Execution & Reliability We deliver on our commitments Customization & Flexibility We adjust our products to meet customer needs while meeting our own financial objectives
Slide 5: Who We Are: Management
WHO WE ARE Thomas A. Young, Jr., President and Chief Executive Officer 37 years of banking experience Paul M. Harbolick, Jr., CPA Executive Vice President and Chief Financial Officer 25 years of financial experience Frank H. Grace, III, Executive Vice President 27 years of banking experience Craig W
Slide 6: Who We Are: Management
WHO WE ARE Thomas Patrick Danaher, President, Alliance Insurance Agency 25 years of insurance experience John B. McKenney, III, Senior Vice President, Chief Credit Officer 28 years of banking experience Michael C. O'Grady, Senior Vice President, Director of Commercial Banking 32 years of banking exp
Slide 7: Board of Directors
BOARD OF DIRECTORS Comprised of regional business leaders including CPAs, Insurance, Association and Construction Professionals, Alliance's Board of Directors represents a distinguished collection of innovative, yet fiscally conservative individuals.
Slide 8: Our Market Area
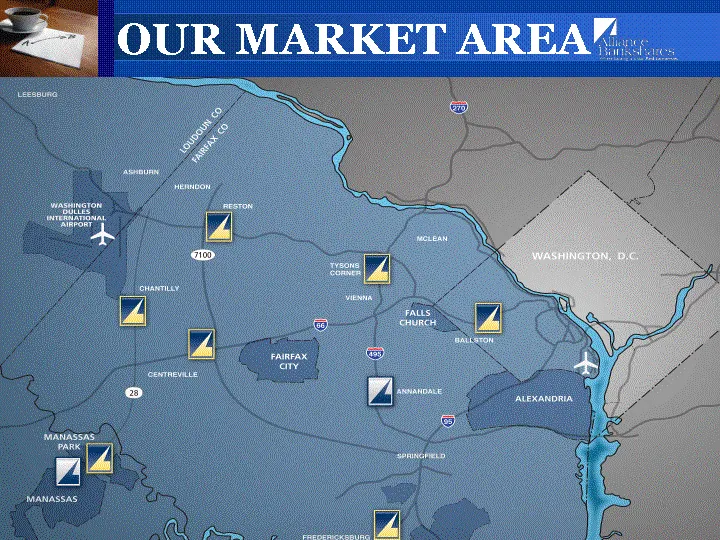
OUR MARKET AREA
Slide 9: Our Market Area
OUR MARKET AREA Strong job growth: 71,200 net new jobs in 2006 Median household income of $74,700 - second highest in the country At 2.9%, the area has the lowest unemployment rate in the nation Presence of Federal Government acts as a stabilizing force in the local employment base Center for Region
Slide 10: Regional Housing
REGIONAL HOUSING Inventories hit record levels in 2006 Month-over-the-year price changes turned negative in July 2006 Anticipate inventory levels to return to normal by end of 2007 or 1st Quarter 2008 Price changes are likely to remain in negative territory Price increases expected to return to hist
Slide 11: Regional Housing
REGIONAL HOUSING Recent market trends show soft housing market continues Average days on market as of March 2007 was 113 compared to 64 in March 2006 Average sales price in March 2007 was $498,000 compared to $503,000 in March 2006 Home sales in the first quarter 2007 were 7,414 or 9.4% lower than t
Slide 12: Alliance Impacts
ALLIANCE IMPACTS Lower account balances of core title companies Average DDA down $32.2MM 1Q07 compared to 1Q06 Funding of balance sheet migrates from demand deposit level to market rate funding (cds, funds purchased and FHLB advances) Compounds margin squeeze Less active residential real estate lend
Slide 13: Alliance Action Steps
ALLIANCE ACTION STEPS Refocused energies into expanding core market niche Senior Executive deployed to lead the effort Expanded calling team Effective use of technology to bring the bank to the client Close monitoring of existing residential real estate portfolio Tighter credit standards applied Exp
Slide 14: Alliance Action Steps: Diversify Revenue
ALLIANCE ACTION STEPS Diversify revenue base with insurance revenue Core agency in place 1/1/06; Battlefield agency in place 1/1/07; FIG agency acquired 4/5/07 Exited stand alone mortgage banking division in late 2006 Created a small focused self contained mortgage banking unit 5 active experienced
Slide 15: Alliance Action Steps: Balance Sheet Restructuring
ALLIANCE ACTION STEPS Balance sheet restructuring in 2Q07 and beyond Delever balance sheet by $75MM Rebalance investment and trading portfolios Target balances of $30MM and $75MM respectively Update portfolio yields to current market via lower volatility products Reduce size of wholesale funding por
Slide 16: Alliance Action Steps: Stock Buyback
ALLIANCE ACTION STEPS Common stock buyback initiative Up to 300,000 shares may be purchased under the program (approximately 5.4% of currently outstanding shares) Program includes public and private transactions Authorized for one year Enhanced shareholder value We believe the common stock is underv
Slide 17: Our Performance
OUR PERFORMANCE
Slide 18: Total Assets
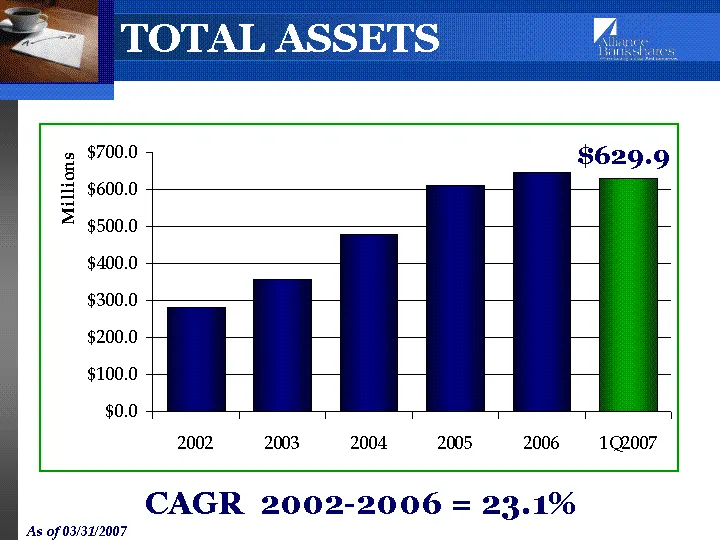
$629.9 CAGR 2002-2006 = 23.1% As of 03/31/2007 TOTAL ASSETS
Slide 19: Total Loans
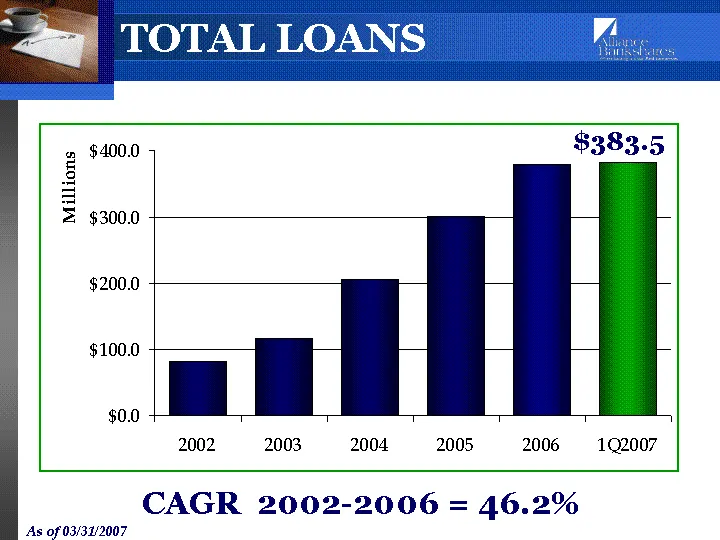
TOTAL LOANS CAGR 2002-2006 = 46.2% As of 03/31/2007 $383.5
Slide 20: Credit Quality
CREDIT QUALITY $1.3MM of loans with a specific allocation of the allowance as of 3/31/07 Allowance for loan losses as of 3/31/07 was 1.17% Net Charge Offs of $212,000 for the first quarter of 2007 Net Charge Offs to Average Loans were .06%
Slide 21: Total Investments
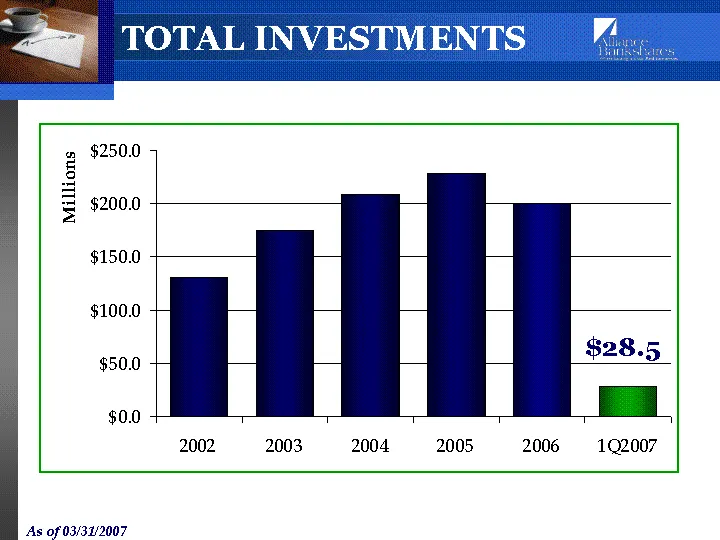
TOTAL INVESTMENTS As of 03/31/2007 $28.5
Slide 22: Trading Assets
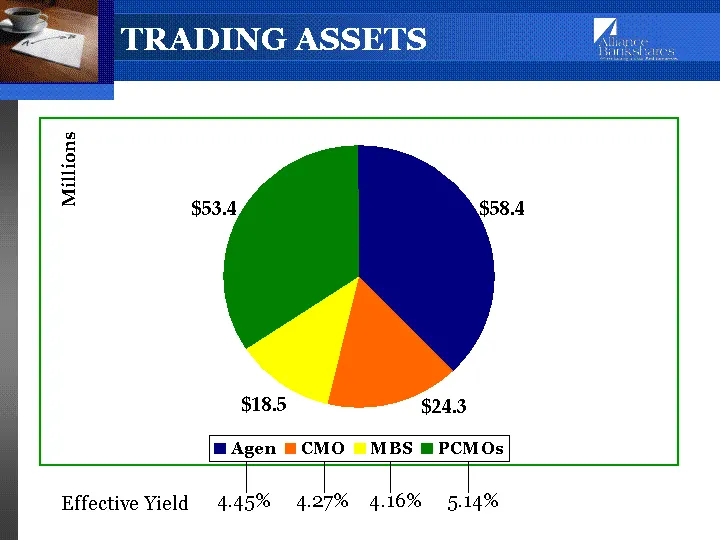
TRADING ASSETS Millions $24.3 $53.4 $58.4 $18.5 4.45% 4.27% 4.16% 5.14% Effective Yield
Slide 23: Total Deposits
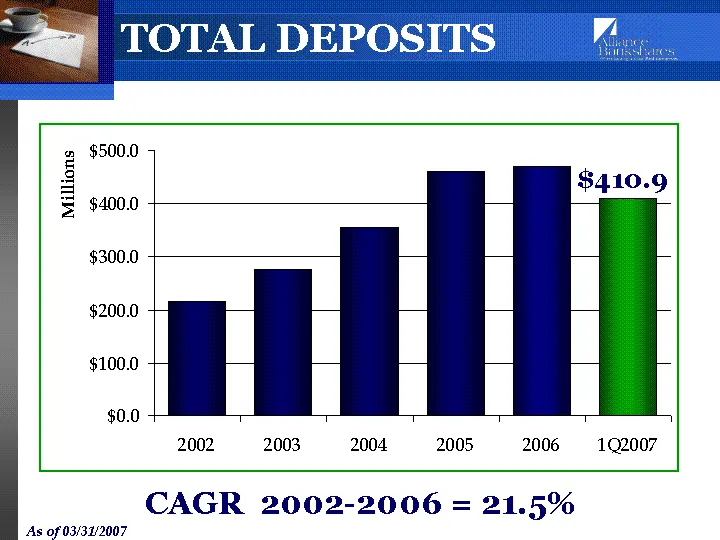
TOTAL DEPOSITS CAGR 2002-2006 = 21.5% As of 03/31/2007 $410.9
Slide 24: Deposit Composition
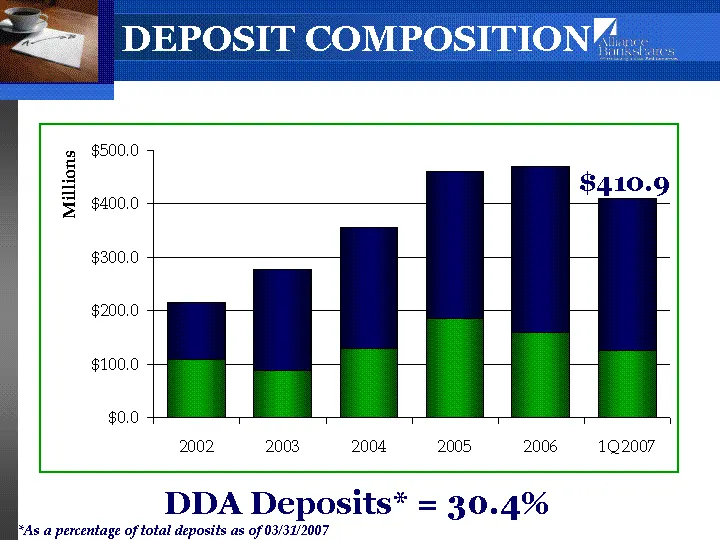
DEPOSIT COMPOSITION DDA Deposits* = 30.4% *As a percentage of total deposits as of 03/31/2007 $410.9
Slide 25: Millions
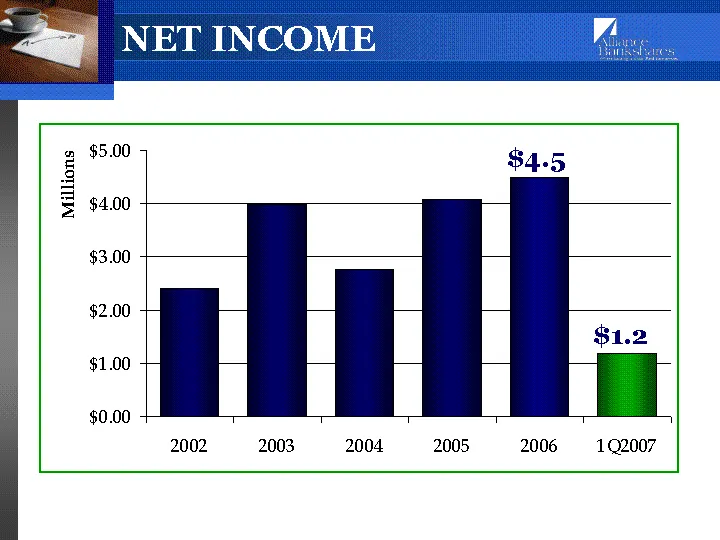
Millions $5.00 4 $4.00 $3.00 $2.00 $1.00 $0.00 $4.5 2002 2003 2004 2005 2006 1Q2007
Slide 26: Earnings Per Share, Diluted
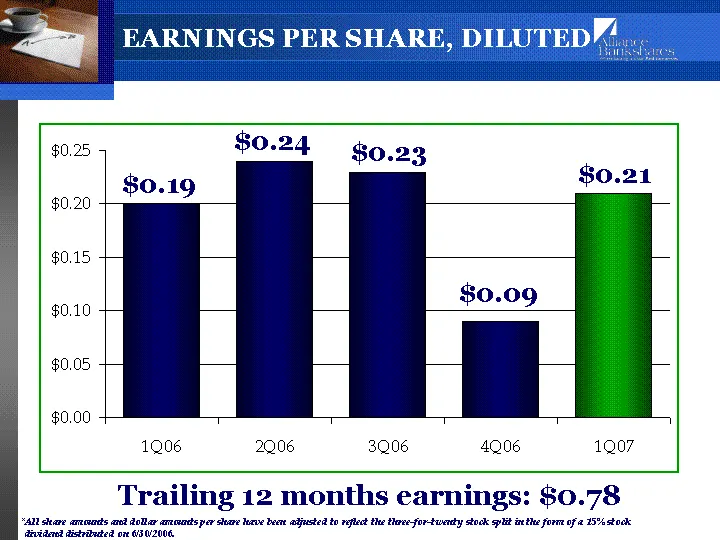
EARNINGS PER SHARE, DILUTED $0.19 $0.23 $0.24 $0.09 $0.21 *All share amounts and dollar amounts per share have been adjusted to reflect the three-for-twenty stock split in the form of a 15% stock dividend distributed on 6/30/2006. Trailing 12 months earnings: $0.78
Slide 27: Looking Ahead
LOOKING AHEAD Experienced local management team leading the company through the challenging real estate cycle Understands the balance between client relationships, growth and long-term shareholder value Open strategically located branches Fredericksburg is a top priority Leverage insurance company o
Slide 28: Attractive Long-Term Valuation
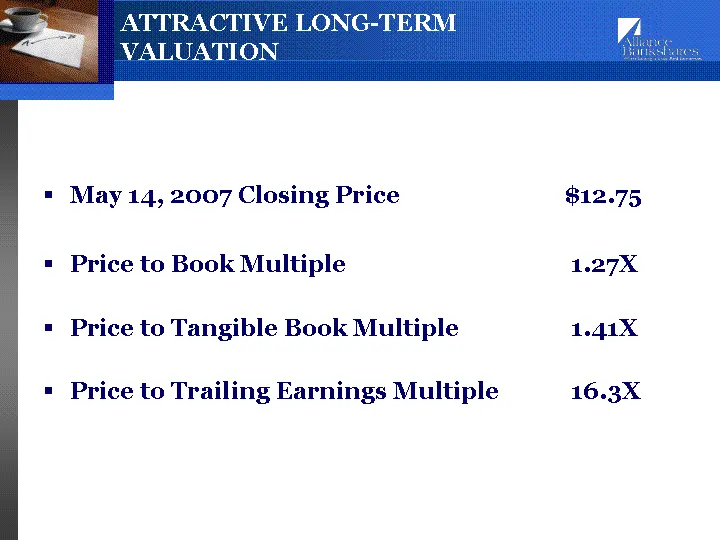
ATTRACTIVE LONG-TERM VALUATION May 14, 2007 Closing Price $12.75 Price to Book Multiple 1.27X Price to Tangible Book Multiple 1.41X Price to Trailing Earnings Multiple 16.3X
Slide 29: Why Alliance?
WHY ALLIANCE ? Great long-term marketplace Federal government spending makes Metropolitan, Washington D.C. very attractive Challenging real estate cycle is difficult to predict but should be nearing the end of the cycle Strong experienced management team Focused and consistent business expansion Tre
Slide 30: Forward Looking Statements
Forward Looking Statements This presentation and other communications and statements by the Company and its management may contain "forward-looking statements," including statements about our beliefs, plans, objectives, goals, expectations, estimations and intentions. These statements are not guaran
Slide 31: Thank you
Thank you for your and interest in our company. Visit us on-line at www.alliancebankva.com
Source: SEC EDGAR · 8-K filed May 17, 2007
More decks from Alliance Bankshares Corp
 FBR Fall Investor Conference 201146 slides · Nov 29, 2011
 Stifel Nicolaus Bank Conference (November 2011)51 slides · Nov 2, 2011
 Merger or Acquisition (September 2011)48 slides · Sep 19, 2011
 Q1 2009 Earnings Presentation13 slides · May 8, 2009
 Investor Presentation (August 2007)34 slides · Aug 13, 2007
 Investor Presentation (December 2006)36 slides · Dec 7, 2006