Inland Real Estate — Investor Presentation (June 2010)
32 slides from Inland Real Estate's investor presentation, Jun 8, 2010
Slide 1: Inland Real Estate Corporation Investor Presentation June 2010
Inland Real Estate Corporation Investor Presentation June 2010 www.inlandrealestate.com NYSE: IRC
Slide 2: Contemplated offer to exchange or purchase 4.625% Convertible Senior Notes
The Company’s contemplated offer to exchange or purchase all of its outstanding 4.625% Convertible Senior Notes due 2026 (the “Old Notes”) has not yet commenced. The Company will file a Tender Offer Statement on Schedule TO and related exhibits, including a letter of transmittal and consent, with th
Slide 3: IRC Snapshot Profile
IRC SNAPSHOT PROFILE Inception 1994; self-administered and self-managed 2000; listed on NYSE June 2004 Target Upper Midwest markets Total Portfolio: 84% of SF in high density infill locations in Chicago & Minneapolis MSAs 140 Neighborhood, Community, Power, Lifestyle centers and single-tenant proper
Slide 4: Experienced Leadership Team
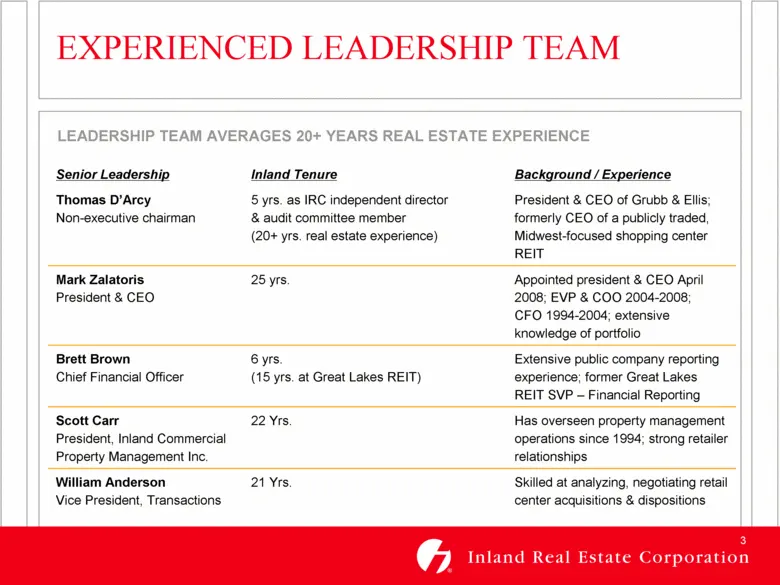
EXPERIENCED LEADERSHIP TEAM Senior Leadership Inland Tenure Background / Experience Thomas D’Arcy Non-executive chairman 5 yrs. as IRC independent director & audit committee member (20+ yrs. real estate experience) President & CEO of Grubb & Ellis; formerly CEO of a publicly traded, Midwest-focused
Slide 5: Operating Strategy
OPERATING STRATEGY Defensive Portfolio – primarily value and necessity retail Centers with grocer / drug / discount component 61% of total portfolio retail GLA Resilient Midwest Markets Strong demographics dense populations, diverse economies, high incomes High barriers to entry Portfolio Scale in c
Slide 6: Operating Strategy
OPERATING STRATEGY Source: Company and company filings as of 3/31/10 Strong balance sheet focus 2009 equity raise: $106.4 MM net proceeds ATM program established: issue up to $100 MM in common stock 2009 dividend paid adjusted to approximate REIT taxable income; monthly dividend $0.0475/sh (5/2010)
Slide 7: Core Markets: Chicago and Minneapolis
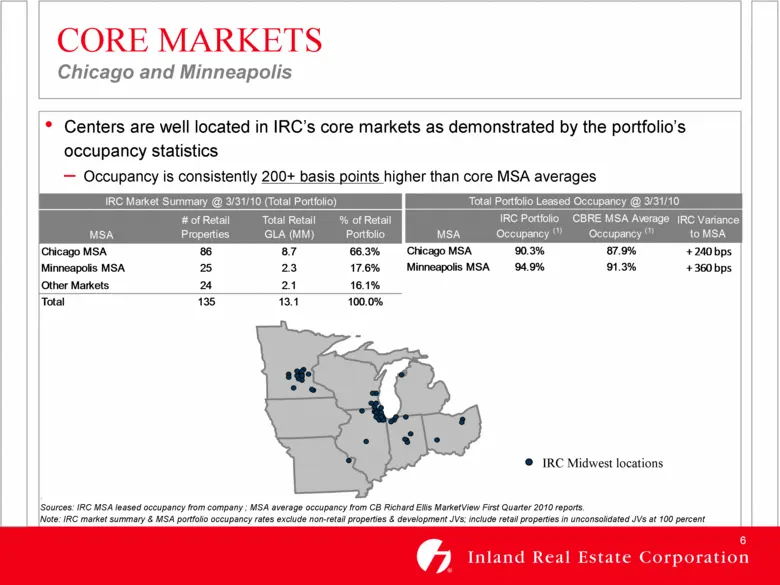
CORE MARKETS Chicago and Minneapolis Sources: IRC MSA leased occupancy from company ; MSA average occupancy from CB Richard Ellis MarketView First Quarter 2010 reports. Note: IRC market summary & MSA portfolio occupancy rates exclude non-retail properties & development JVs; include retail properties
Slide 8: Chicago Market Snapshot
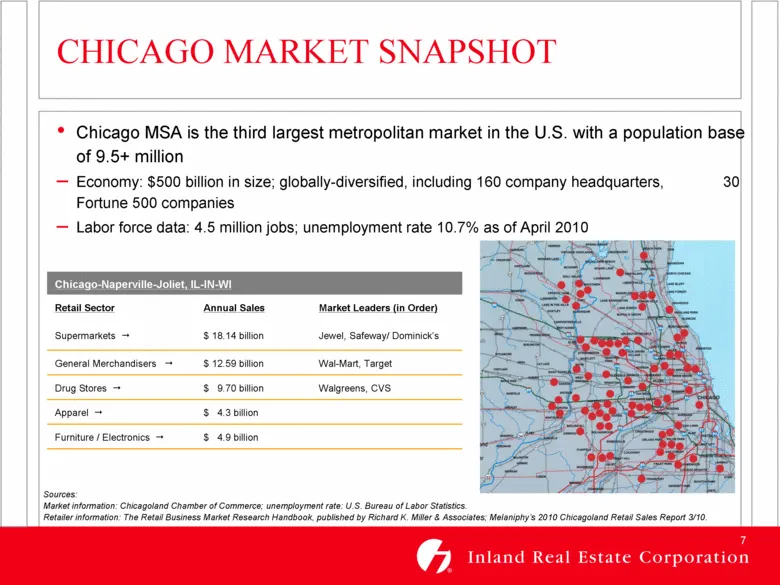
CHICAGO MARKET SNAPSHOT Sources: Market information: Chicagoland Chamber of Commerce; unemployment rate: U.S. Bureau of Labor Statistics. Retailer information: The Retail Business Market Research Handbook, published by Richard K. Miller & Associates; Melaniphy’s 2010 Chicagoland Retail Sales Report
Slide 9: Chicago Market Shopping Center REIT Ownership
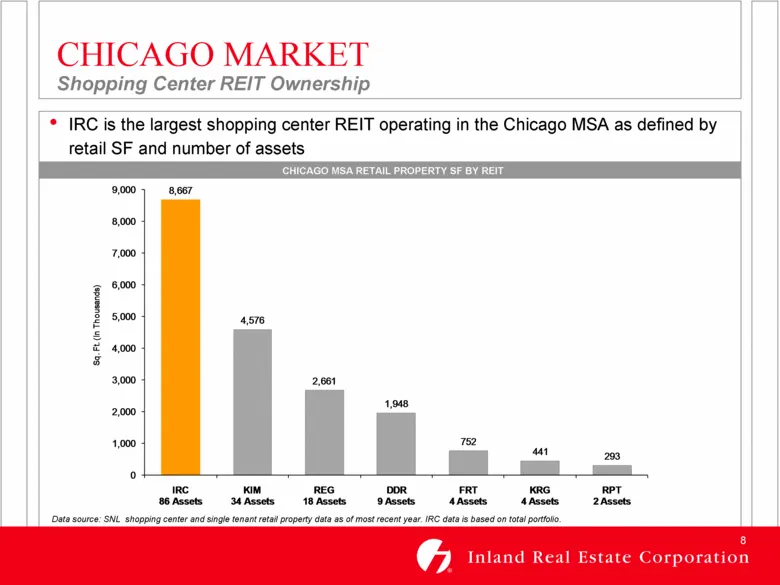
CHICAGO MARKET Shopping Center REIT Ownership Data source: SNL shopping center and single tenant retail property data as of most recent year. IRC data is based on total portfolio. IRC is the largest shopping center REIT operating in the Chicago MSA as defined by retail SF and number of assets CHICAG
Slide 10: Minneapolis Market Snapshot
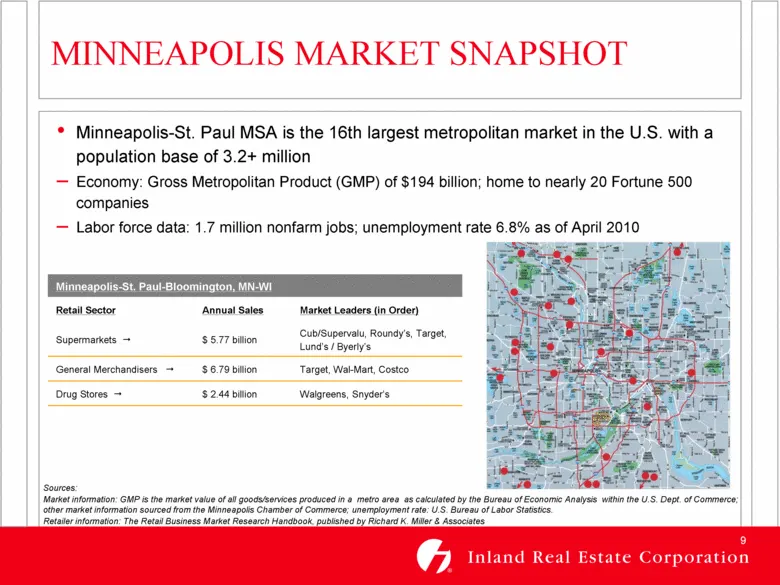
MINNEAPOLIS MARKET SNAPSHOT Sources: Market information: GMP is the market value of all goods/services produced in a metro area as calculated by the Bureau of Economic Analysis within the U.S. Dept. of Commerce; other market information sourced from the Minneapolis Chamber of Commerce; unemployment
Slide 11: Minneapolis Market Shopping Center REIT Ownership
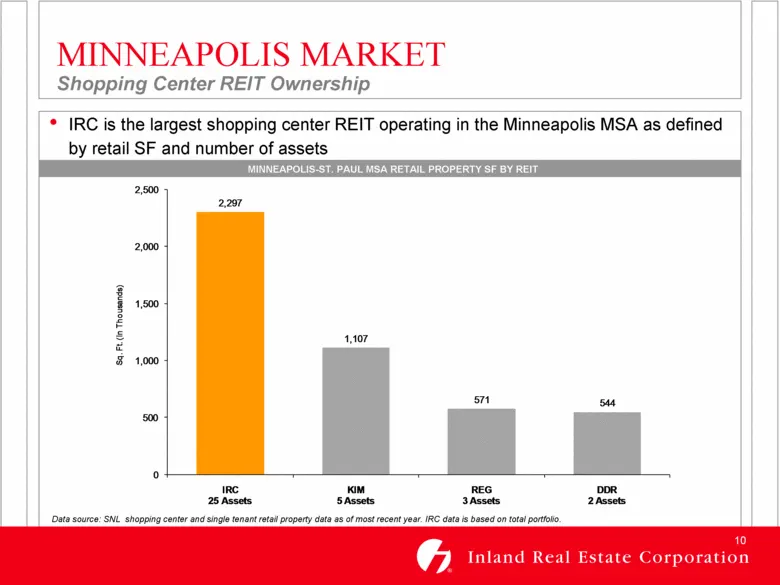
MINNEAPOLIS MARKET Shopping Center REIT Ownership IRC is the largest shopping center REIT operating in the Minneapolis MSA as defined by retail SF and number of assets MINNEAPOLIS-ST. PAUL MSA RETAIL PROPERTY SF BY REIT Data source: SNL shopping center and single tenant retail property data as of mo
Slide 12: Strong Market Demographics
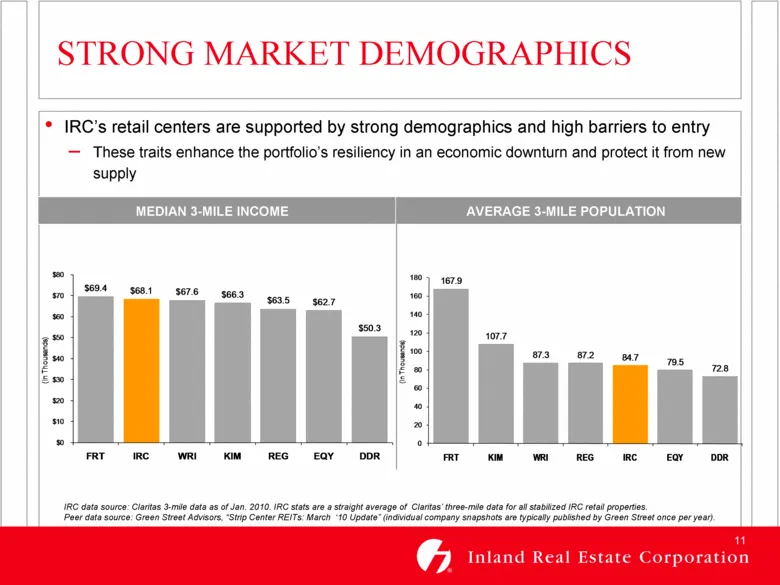
STRONG MARKET DEMOGRAPHICS IRC data source: Claritas 3-mile data as of Jan. 2010. IRC stats are a straight average of Claritas’ three-mile data for all stabilized IRC retail properties. Peer data source: Green Street Advisors, “Strip Center REITs: March ‘10 Update” (individual company snapshots are
Slide 13: Total Portfolio Composition
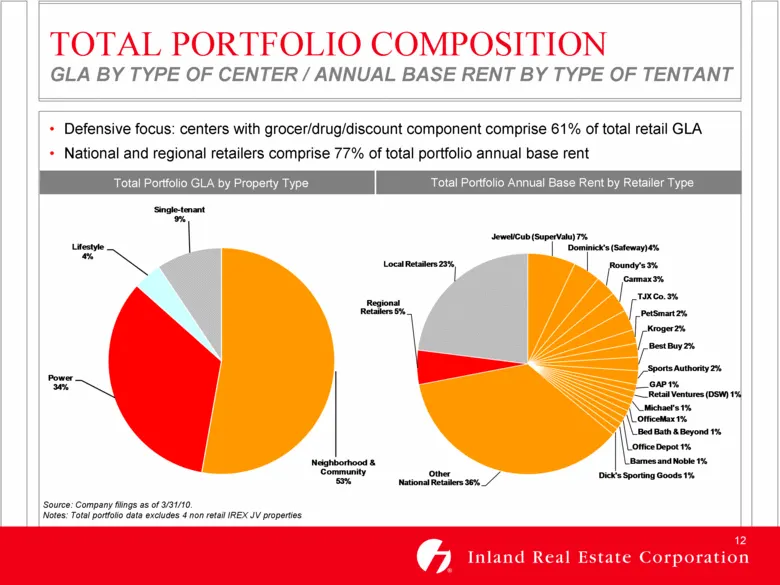
TOTAL PORTFOLIO COMPOSITION GLA BY TYPE OF CENTER / ANNUAL BASE RENT BY TYPE OF TENTANT (1) Source: Company filings as of 3/31/10. Notes: Total portfolio data excludes 4 non retail IREX JV properties Defensive focus: centers with grocer/drug/discount component comprise 61% of total retail GLA Nation
Slide 14: Diversified Tenant Base
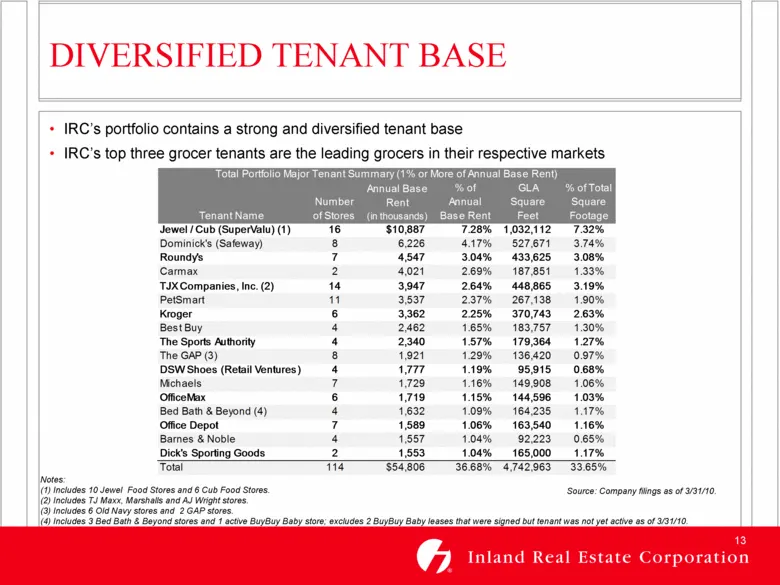
DIVERSIFIED TENANT BASE IRC’s portfolio contains a strong and diversified tenant base IRC’s top three grocer tenants are the leading grocers in their respective markets (1) Notes: (1) Includes 10 Jewel Food Stores and 6 Cub Food Stores. (2) Includes TJ Maxx, Marshalls and AJ Wright stores. (3) Inclu
Slide 15: Leasing activity and rent spreads
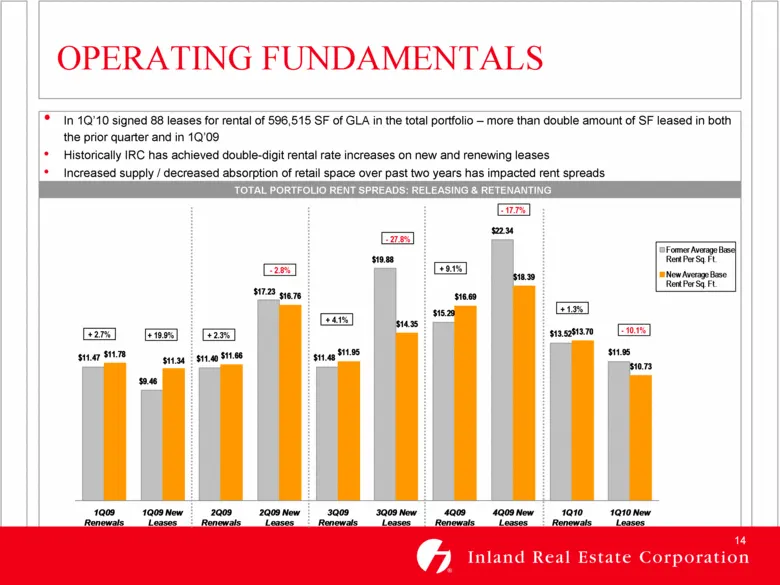
In 1Q’10 signed 88 leases for rental of 596,515 SF of GLA in the total portfolio – more than double amount of SF leased in both the prior quarter and in 1Q’09 Historically IRC has achieved double-digit rental rate increases on new and renewing leases Increased supply / decreased absorption of retail
Slide 16: Well Staggered Lease Expirations
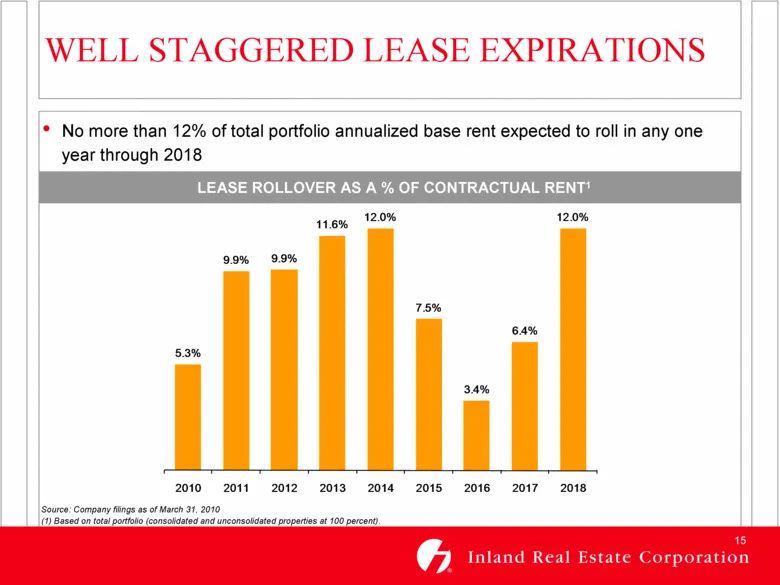
WELL STAGGERED LEASE EXPIRATIONS No more than 12% of total portfolio annualized base rent expected to roll in any one year through 2018 Source: Company filings as of March 31, 2010 (1) Based on total portfolio (consolidated and unconsolidated properties at 100 percent). LEASE ROLLOVER AS A % OF CONT
Slide 17: Leasing Efficiencies
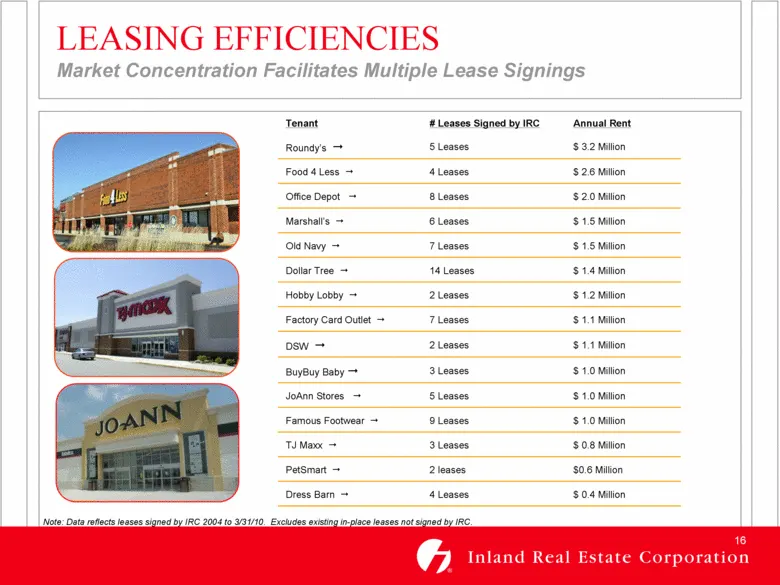
Tenant # Leases Signed by IRC Annual Rent Roundy’s 5 Leases $ 3.2 Million Food 4 Less 4 Leases $ 2.6 Million Office Depot 8 Leases $ 2.0 Million Marshall’s 6 Leases $ 1.5 Million Old Navy 7 Leases $ 1.5 Million Dollar Tree 14 Leases $ 1.4 Million Hobby Lobby 2 Leases $ 1.2 Million Factory Card Outle
Slide 18: Meeting Operational Challenges: Big Box Vacancies
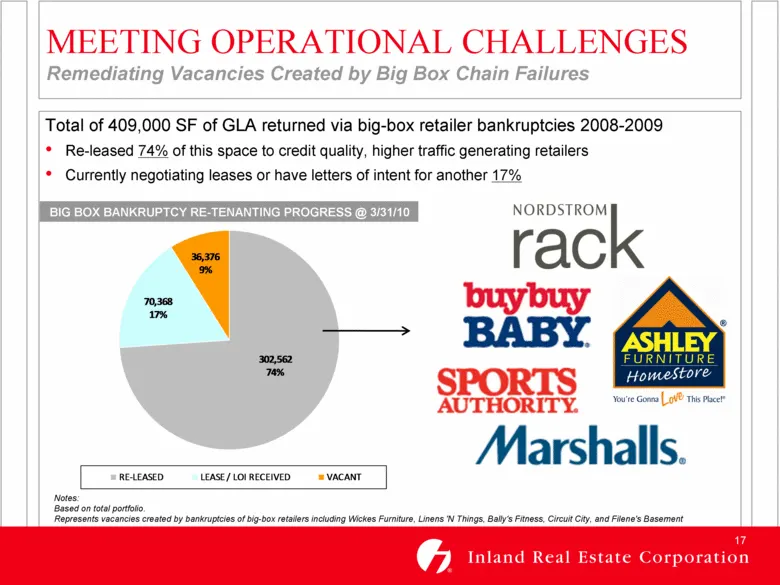
MEETING OPERATIONAL CHALLENGES Remediating Vacancies Created by Big Box Chain Failures Total of 409,000 SF of GLA returned via big-box retailer bankruptcies 2008-2009 Re-leased 74% of this space to credit quality, higher traffic generating retailers Currently negotiating leases or have letters of in
Slide 19: Growth from Existing Portfolio: Completed Initiatives
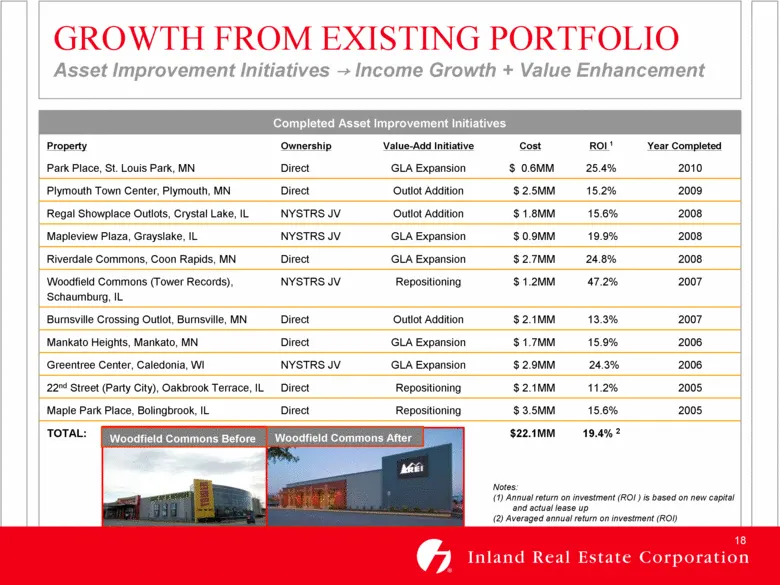
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives Income Growth + Value Enhancement Completed Asset Improvement Initiatives Property Ownership Value-Add Initiative Cost ROI 1 Year Completed Park Place, St. Louis Park, MN Direct GLA Expansion $ 0.6MM 25.4% 2010 Plymouth Town Center, Plymou
Slide 20: Growth from Existing Portfolio: In-Process Initiatives
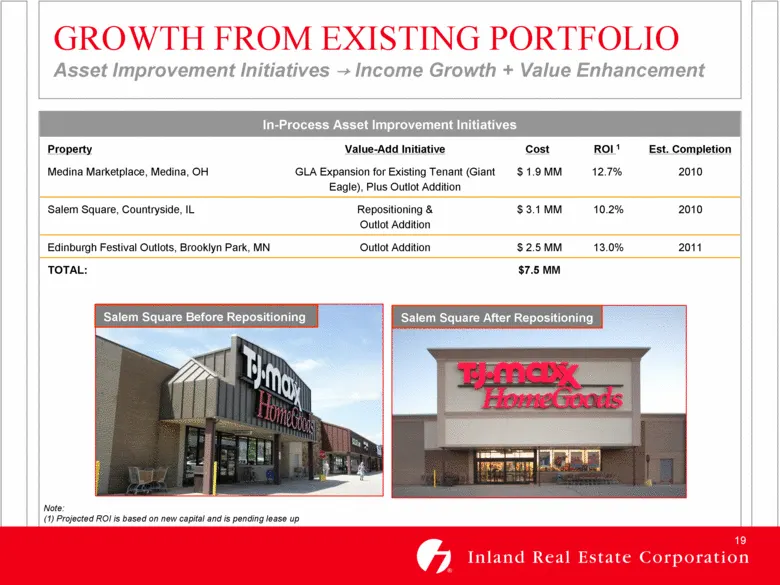
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives Income Growth + Value Enhancement In-Process Asset Improvement Initiatives Property Value-Add Initiative Cost ROI 1 Est. Completion Medina Marketplace, Medina, OH GLA Expansion for Existing Tenant (Giant Eagle), Plus Outlot Addition $ 1.9
Slide 21: Development Projects
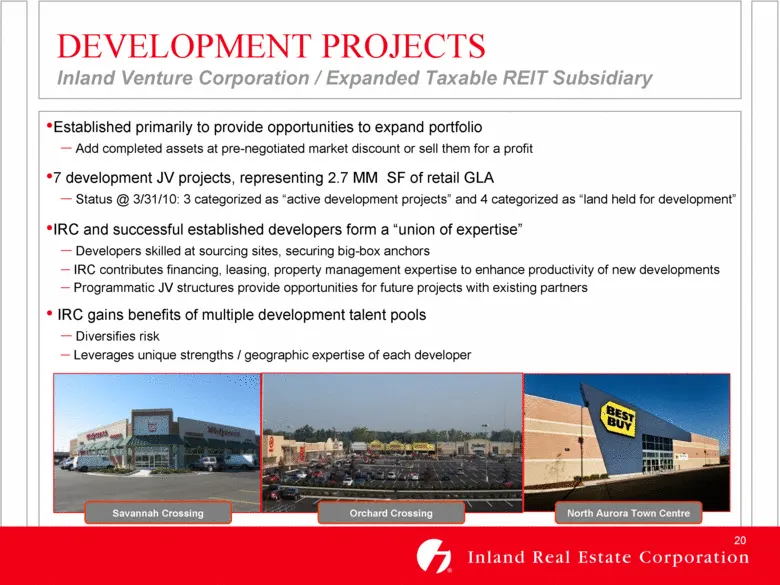
DEVELOPMENT PROJECTS Inland Venture Corporation / Expanded Taxable REIT Subsidiary Established primarily to provide opportunities to expand portfolio Add completed assets at pre-negotiated market discount or sell them for a profit 7 development JV projects, representing 2.7 MM SF of retail GLA Statu
Slide 22: Acquisition History
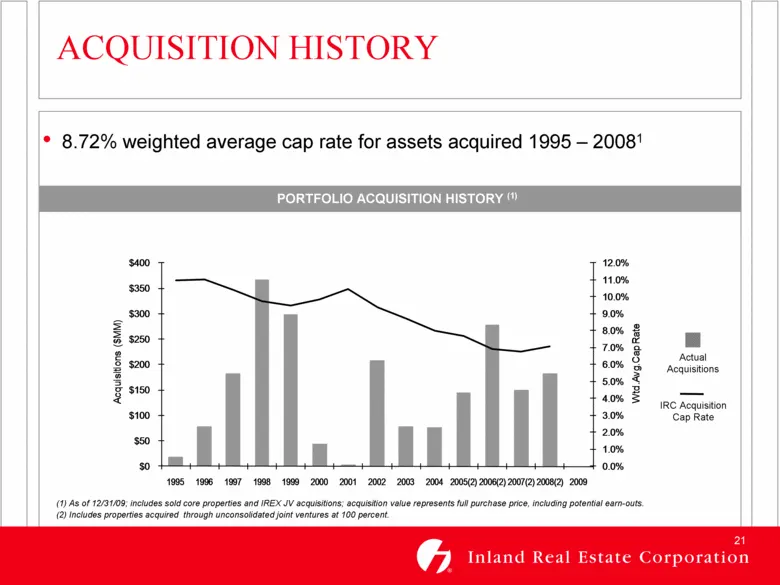
(1) As of 12/31/09; includes sold core properties and IREX JV acquisitions; acquisition value represents full purchase price, including potential earn-outs. (2) Includes properties acquired through unconsolidated joint ventures at 100 percent. ACQUISITION HISTORY 8.72% weighted average cap rate for
Slide 23: Maintaining a Strong Balance Sheet
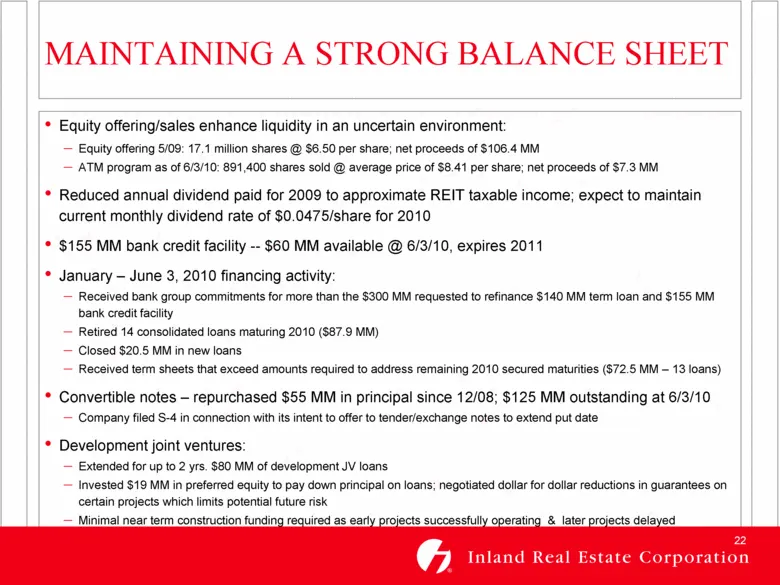
MAINTAINING A STRONG BALANCE SHEET Equity offering/sales enhance liquidity in an uncertain environment: Equity offering 5/09: 17.1 million shares @ $6.50 per share; net proceeds of $106.4 MM ATM program as of 6/3/10: 891,400 shares sold @ average price of $8.41 per share; net proceeds of $7.3 MM Red
Slide 24: Consolidated Debt Maturities
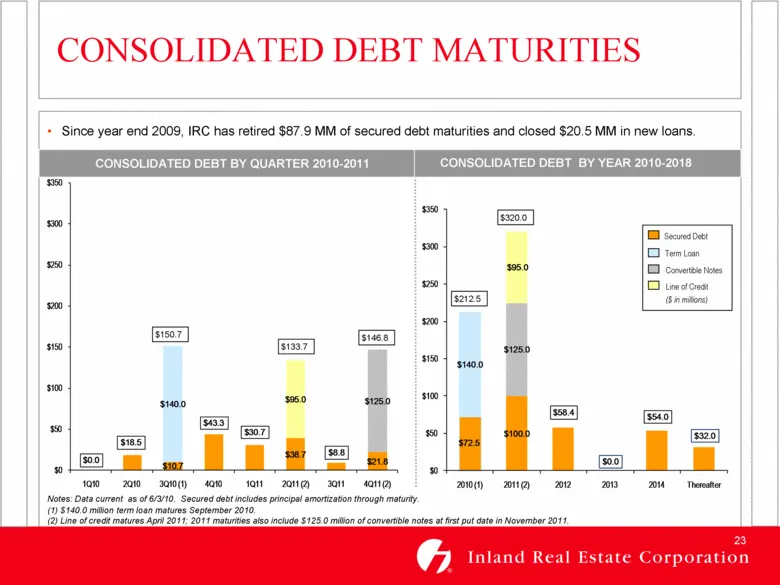
$320.0 CONSOLIDATED DEBT MATURITIES Since year end 2009, IRC has retired $87.9 MM of secured debt maturities and closed $20.5 MM in new loans. Notes: Data current as of 6/3/10. Secured debt includes principal amortization through maturity. (1) $140.0 million term loan matures September 2010. (2) Lin
Slide 25: Pro Forma Consolidated Debt Maturities
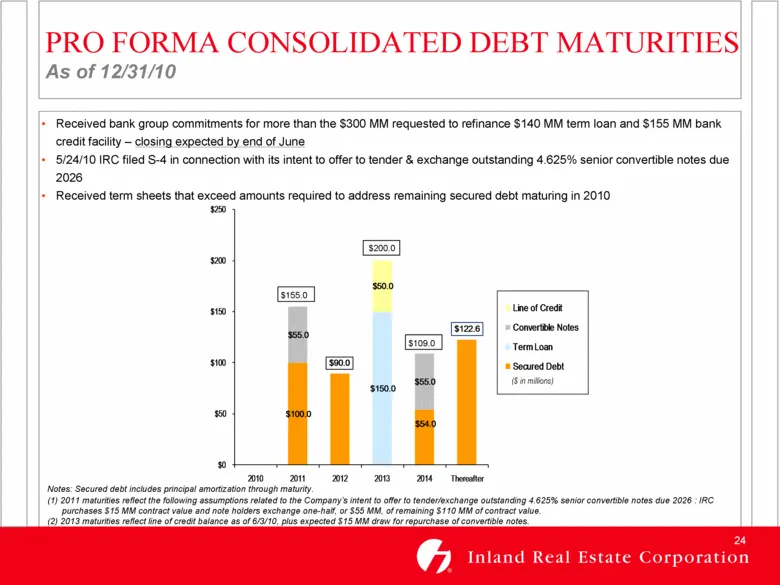
$155.0 PRO FORMA CONSOLIDATED DEBT MATURITIES As of 12/31/10 Received bank group commitments for more than the $300 MM requested to refinance $140 MM term loan and $155 MM bank credit facility – closing expected by end of June 5/24/10 IRC filed S-4 in connection with its intent to offer to tender &
Slide 26: Joint Venture Strategies
JOINT VENTURE STRATEGIES Diversify Capital Resources + Expand Platform + Drive Future Growth Asset Management and Asset Based Joint Venture Strategies Retail Focus IRC Knowledge High Quality Partners ‘Union of Expertise’ Long-term Asset Management Role Value-enhancing
Slide 27: Asset-Based Joint Venture: NYSTRS
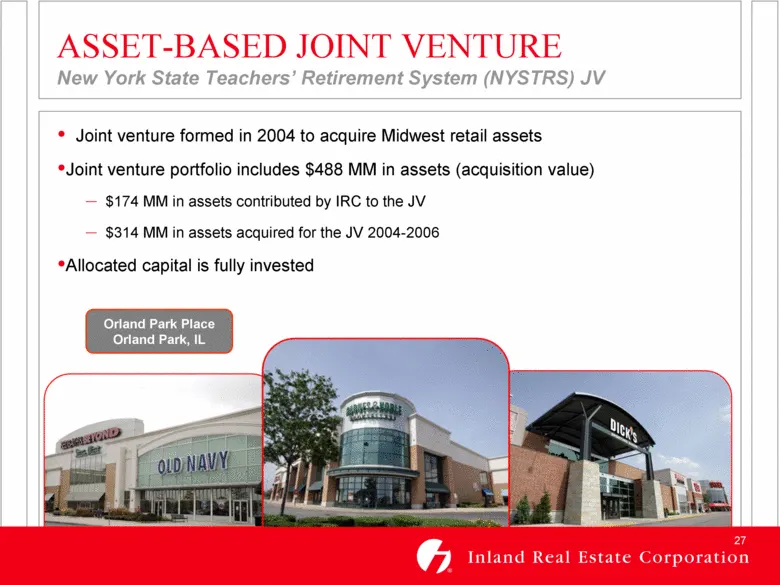
ASSET-BASED JOINT VENTURE New York State Teachers’ Retirement System (NYSTRS) JV Joint venture formed in 2004 to acquire Midwest retail assets Joint venture portfolio includes $488 MM in assets (acquisition value) $174 MM in assets contributed by IRC to the JV $314 MM in assets acquired for the JV 2
Slide 28: Strategic Joint Venture with PGGM
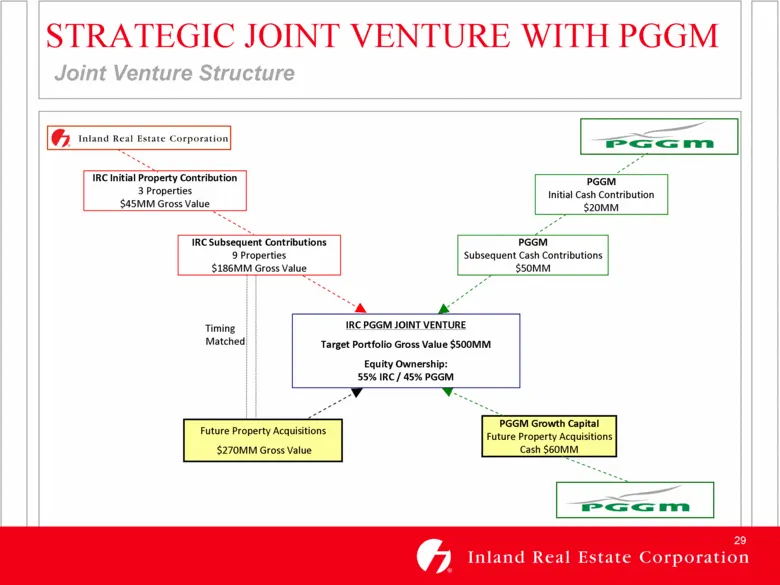
STRATEGIC JOINT VENTURE WITH PGGM Joint Venture Structure IRC Subsequent Contributions 9 Properties $186MM Gross Value PGGM Subsequent Cash Contributions $50MM PGGM Growth Capital Future Property Acquisitions Cash $60MM Future Property Acquisitions $270MM Gross Value IRC PGGM JOINT VENTURE Target Po
Slide 29: Strategic Joint Venture with PGGM: Benefits
STRATEGIC JOINT VENTURE WITH PGGM Unique Joint Venture Structure Provides Benefits IRC-PGGM joint venture is immediately accretive way to generate up to $130 MM of growth capital Monetizes equity value of IRC assets while maintaining operating control Gains on sale become IRC contributions toward ne
Slide 30: Joint Venture Fee Income
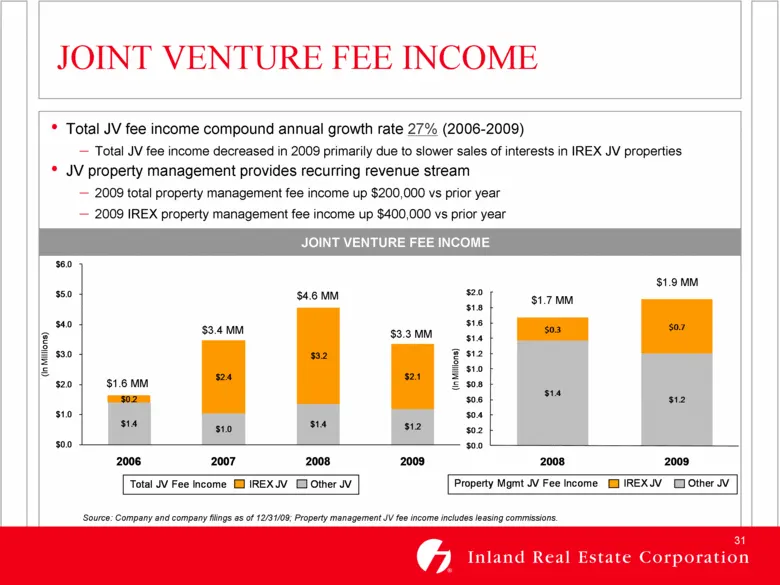
JOINT VENTURE FEE INCOME JOINT VENTURE FEE INCOME $1.6 MM $3.4 MM $4.6 MM Total JV fee income compound annual growth rate 27% (2006-2009) Total JV fee income decreased in 2009 primarily due to slower sales of interests in IREX JV properties JV property management provides recurring revenue stream 20
Slide 31: IRC is well positioned to weather current conditions
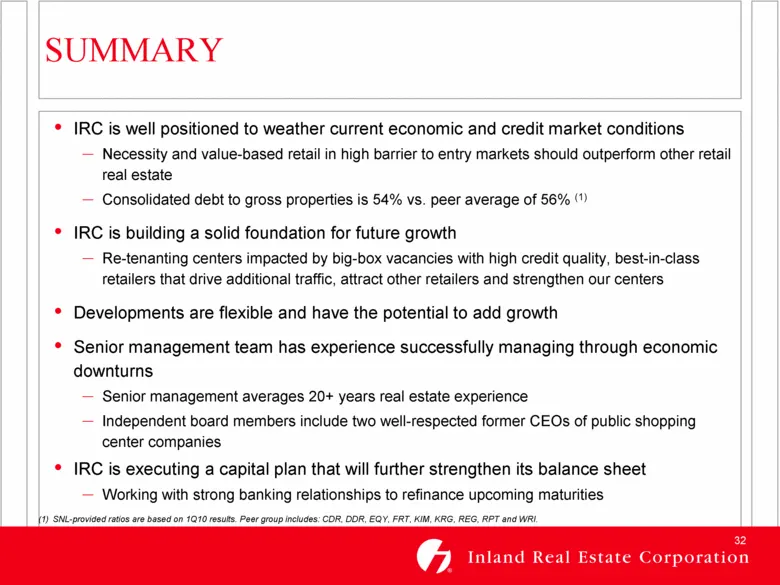
IRC is well positioned to weather current economic and credit market conditions Necessity and value-based retail in high barrier to entry markets should outperform other retail real estate Consolidated debt to gross properties is 54% vs. peer average of 56% (1) IRC is building a solid foundation for
Slide 32: Forward-Looking Statements
FORWARD-LOOKING STATEMENTS These presentation materials may contain "forward-looking statements" within the meaning of the Federal Private Securities Litigation Reform Act of 1995. Forward-looking statements are statements that are not historical, including statements regarding management's intentio
Source: SEC EDGAR · 8-K filed Jun 8, 2010
More decks from Inland Real Estate Corp
 Investor Presentation (November 2015)30 slides · Nov 17, 2015
 Investor Presentation (September 2015)29 slides · Sep 16, 2015
 Investor Presentation (June 2015)29 slides · Jun 9, 2015
 Investor Presentation (May 2015)26 slides · May 15, 2015
 Investor Presentation (February 2015)26 slides · Feb 24, 2015
 Investor Presentation (November 2014)26 slides · Nov 5, 2014