Emmi AG · SIX:EMMN
Emmi — Helvea Swiss Equities Conference 2012
43 slides from Emmi's conference presentation, Jan 12, 2012
Slide 1: Emmi: On track for further growth
Emmi: On track for further growth Helvea conference, Bad Ragaz Reto Conrad, CFO Emmi Schweiz AG Bad Ragaz, 12 January 2012
Slide 2: Emmi in brief
Emmi in brief Key success drivers Investments and innovation Key financials and outlook Appendix
Slide 3: Independent and successful in open markets
Independent and successful in open markets Strategy and vision Vision § Long-term success as an independent company in open markets Market positioning § No. 1 among Swiss milk processors § The top company for Swiss cheese, both within Switzerland and abroad § A leading company in Europe for premium
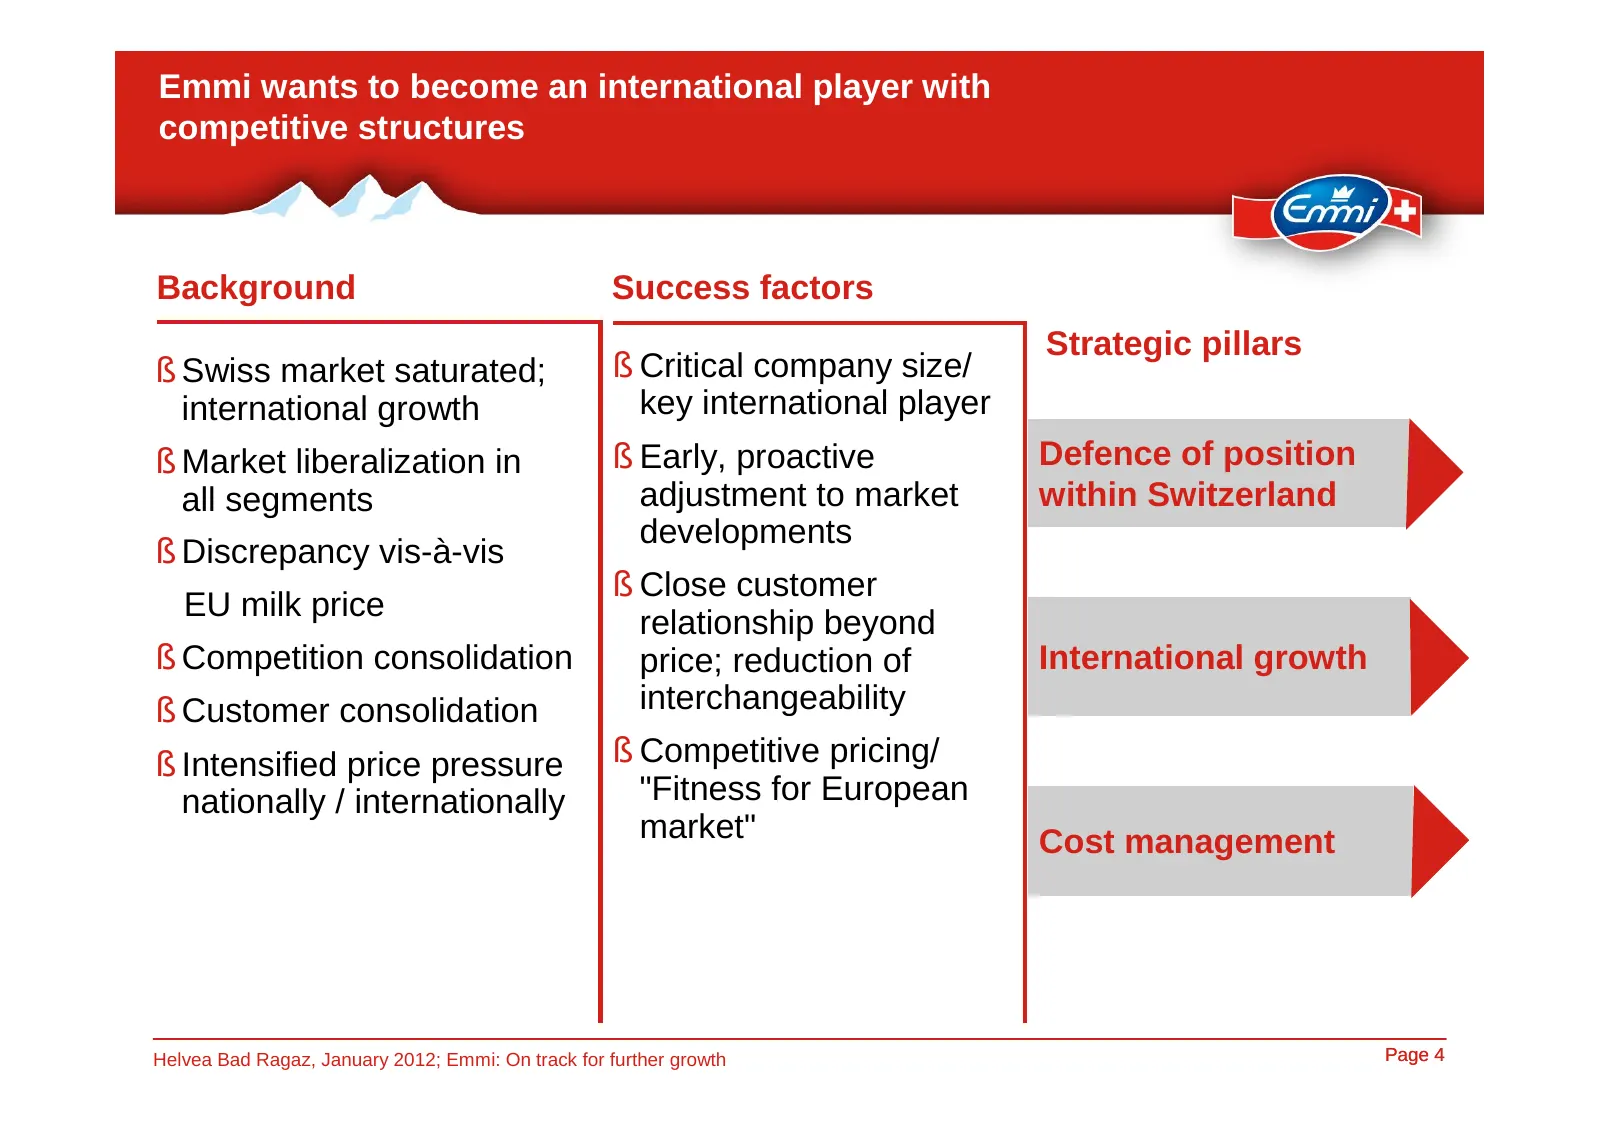
Slide 4: Emmi wants to become an international player with competitive structures
Emmi wants to become an international player with competitive structures Background Success factors Strategic pillars § Swiss market saturated; § Critical company size/ international growth key international player § Market liberalization in § Early, proactive Defence of position all segments adjust
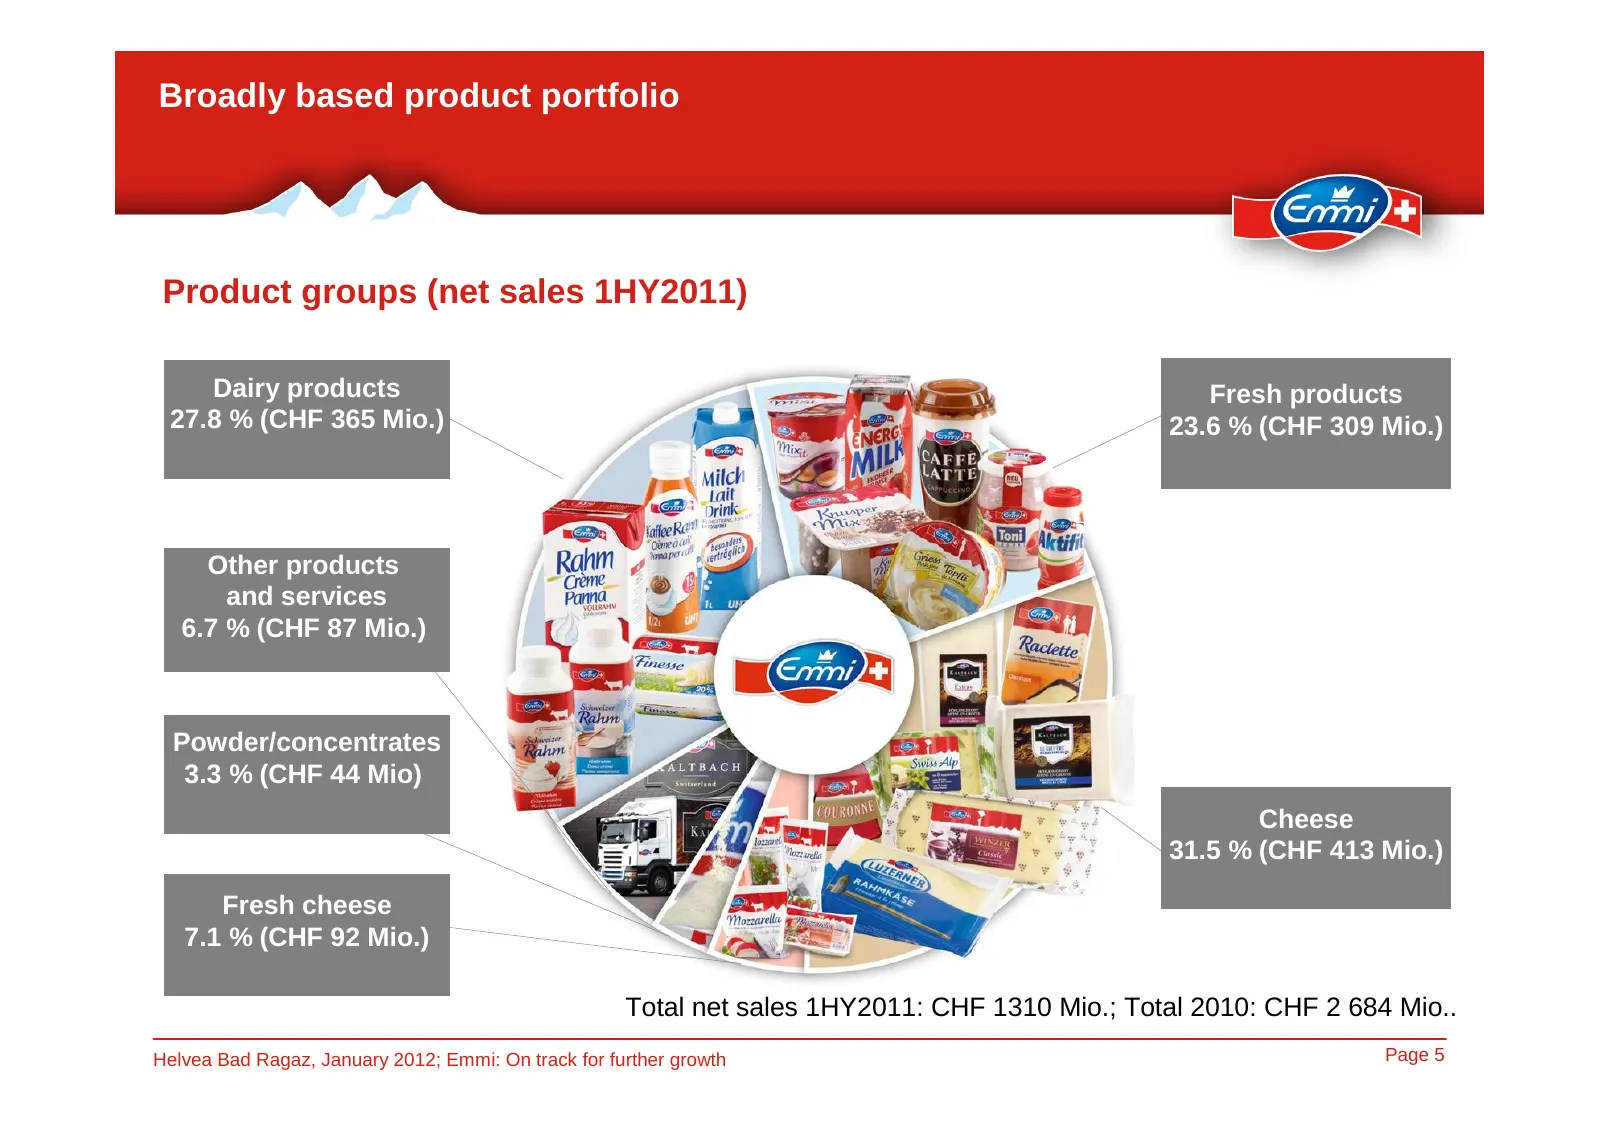
Slide 5: Broadly based product portfolio
Broadly based product portfolio Product groups (net sales 1HY2011) Dairy products Fresh products 27.8 % (CHF 365 Mio.) 23.6 % (CHF 309 Mio.) Other products and services 6.7 % (CHF 87 Mio.) Powder/concentrates 3.3 % (CHF 44 Mio) Cheese 31.5 % (CHF 413 Mio.) Fresh cheese 7.1 % (CHF 92 Mio.) Total net
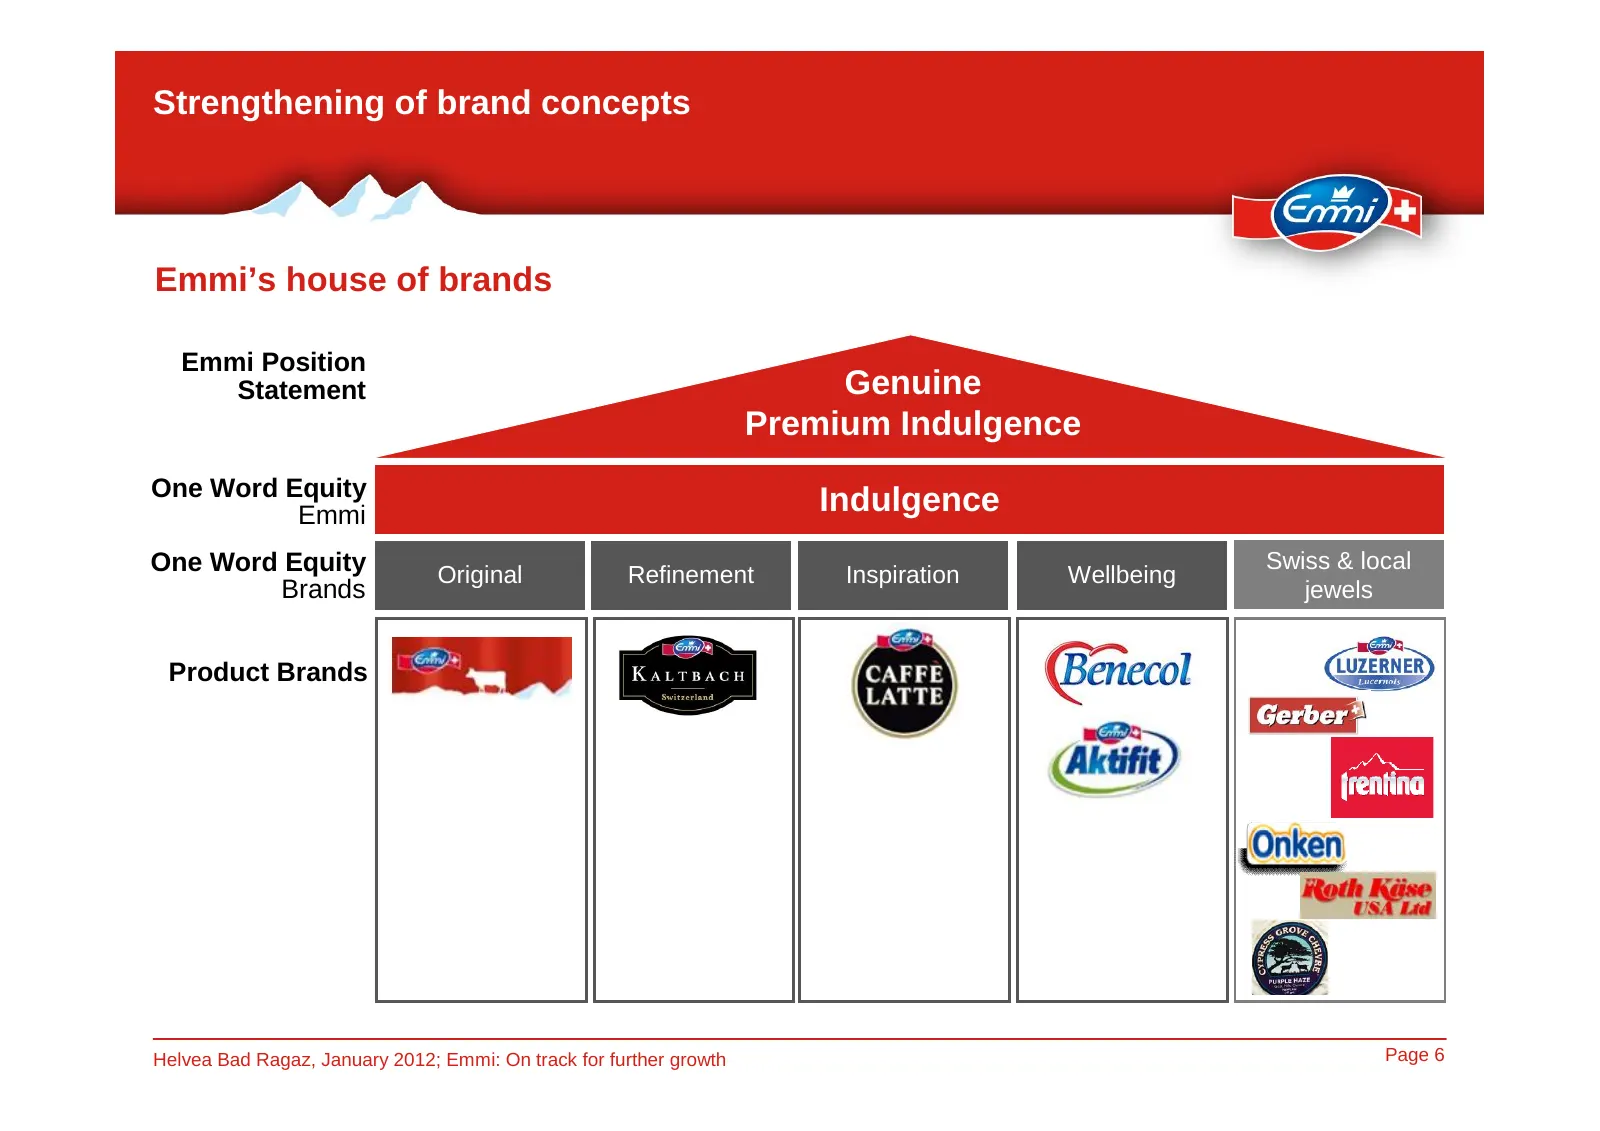
Slide 6: Strengthening of brand concepts
Strengthening of brand concepts Emmi’s house of brands Emmi Position Statement Genuine Premium Indulgence One Word Equity Emmi Indulgence One Word Equity Swiss & local Original Refinement Inspiration Wellbeing Brands jewels Product Brands Helvea Bad Ragaz, January 2012; Emmi: On track for further gr
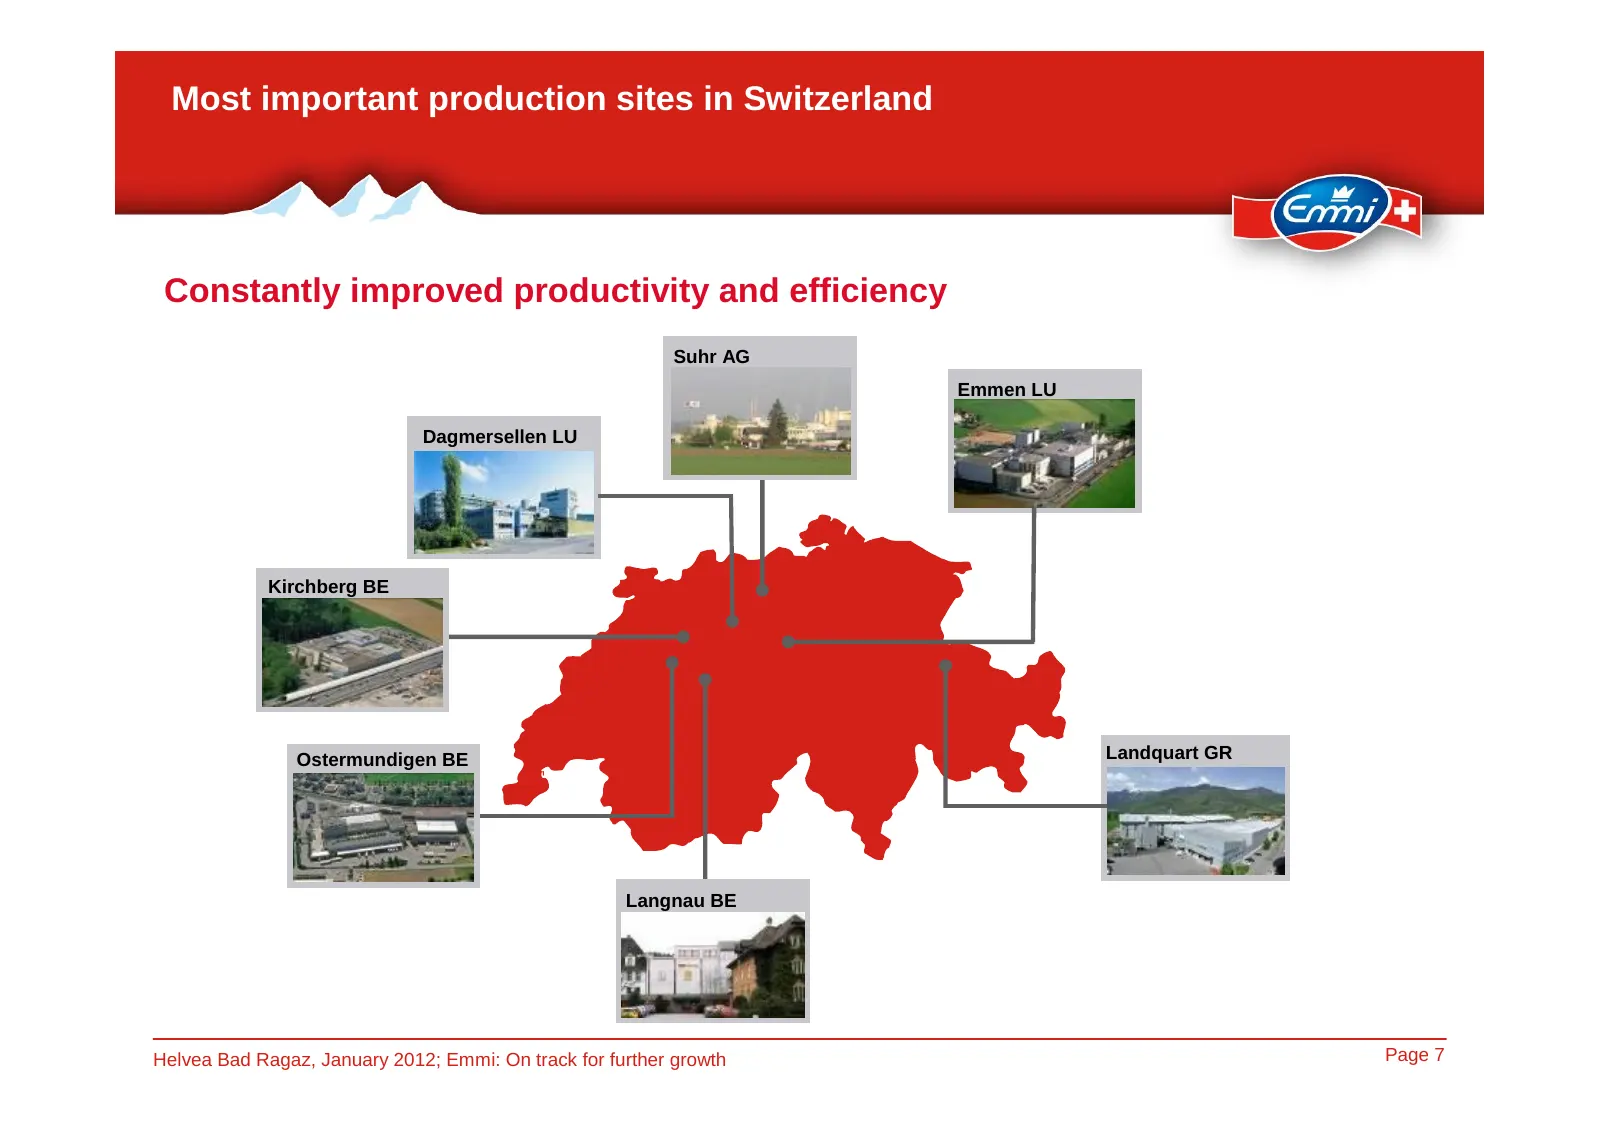
Slide 7: Most important production sites in Switzerland
Most important production sites in Switzerland Constantly improved productivity and efficiency Suhr AG Emmen LU Dagmersellen LU Kirchberg Kirchberg BEBE Ostermundigen BE Landquart GR Langnau BE Helvea Bad Ragaz, January 2012; Emmi: On track for further growth Page 7
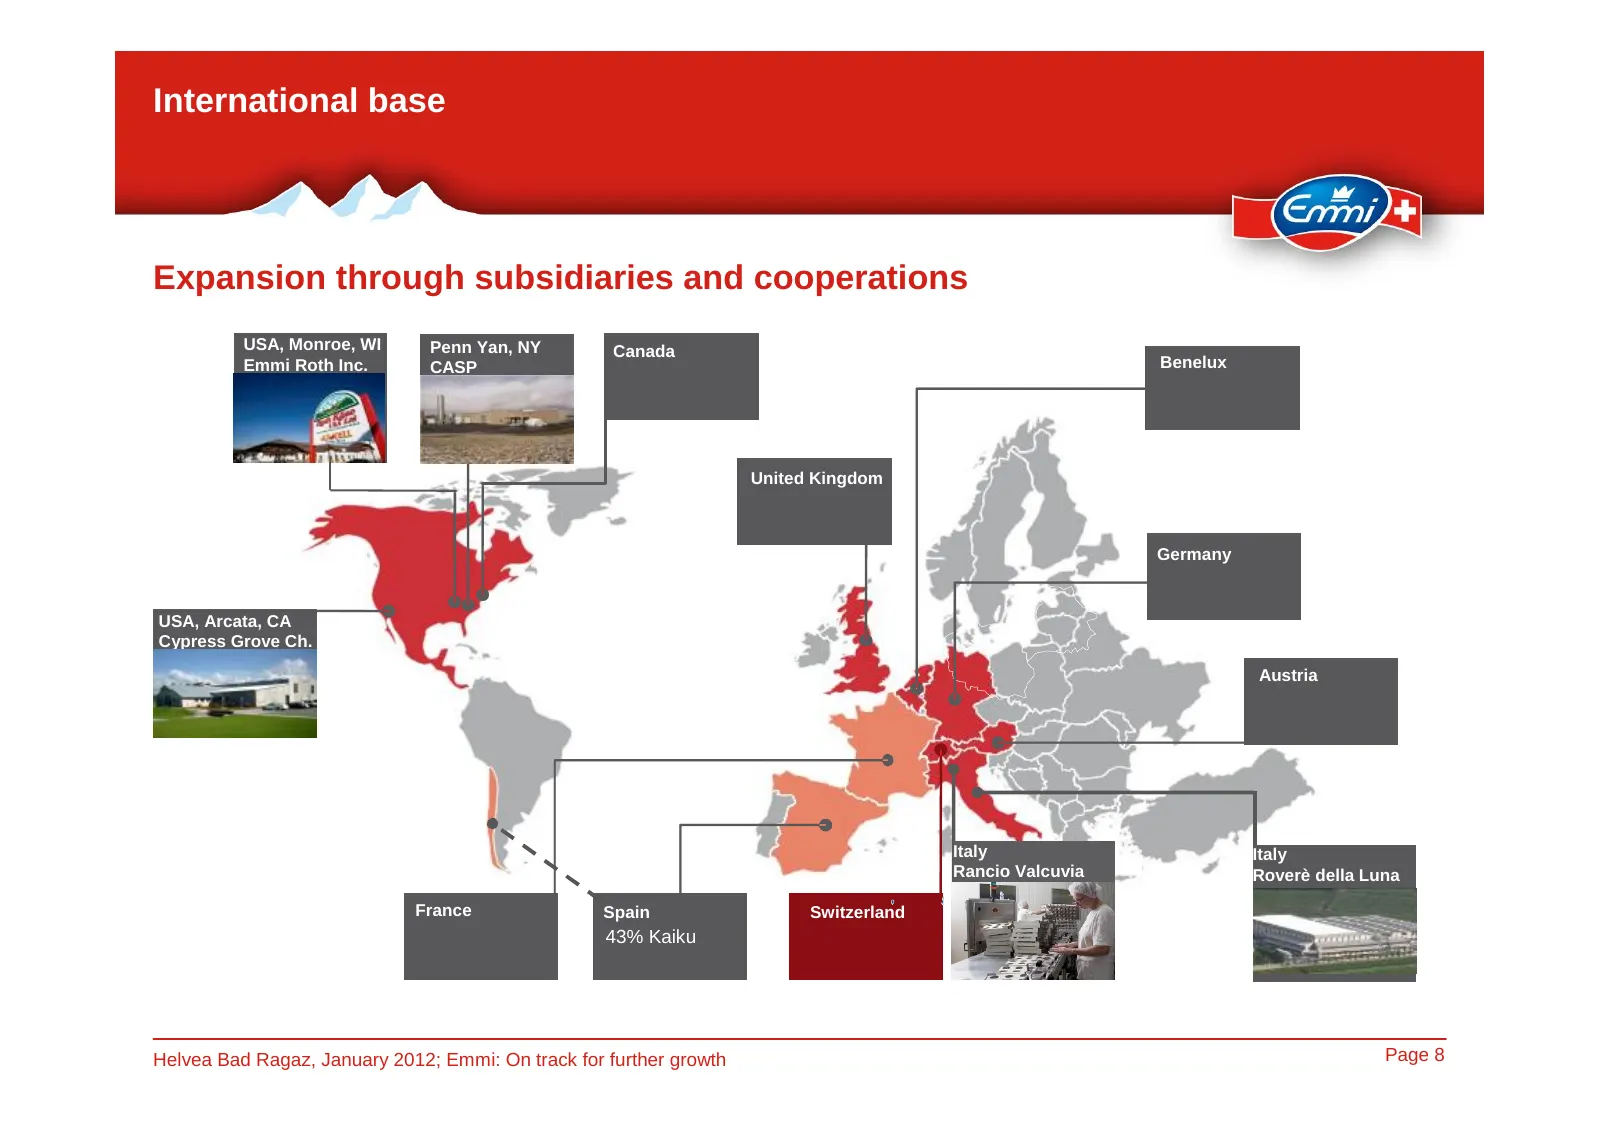
Slide 8: International base
International base Expansion through subsidiaries and cooperations USA, Monroe, WI Penn Yan, NY Canada Emmi Roth Inc. CASP Benelux United Kingdom Germany USA, Arcata, CA Cypress Grove Ch. Austria Italy Italy Rancio Valcuvia Roverè della Luna France Spain Switzerland 43% Kaiku Helvea Bad Ragaz, Janua
Slide 9: Key success drivers: Acquisitions and innovation
Emmi in brief Key success drivers Acquisitions and innovation Key financials and outlook Appendix
Slide 10: Focus in 2011
Focus in 2011 CH: Optimized product portfolio; Intl: mix of local products and Swiss exports Switzerland: Strong brand concepts International: Successful acquisitions § Organic growth with high value brands § Extended distribution with recently acquired local brands (Onken, Roth, § Successful launch
Slide 11: Key brand: Emmi Caffè Latte
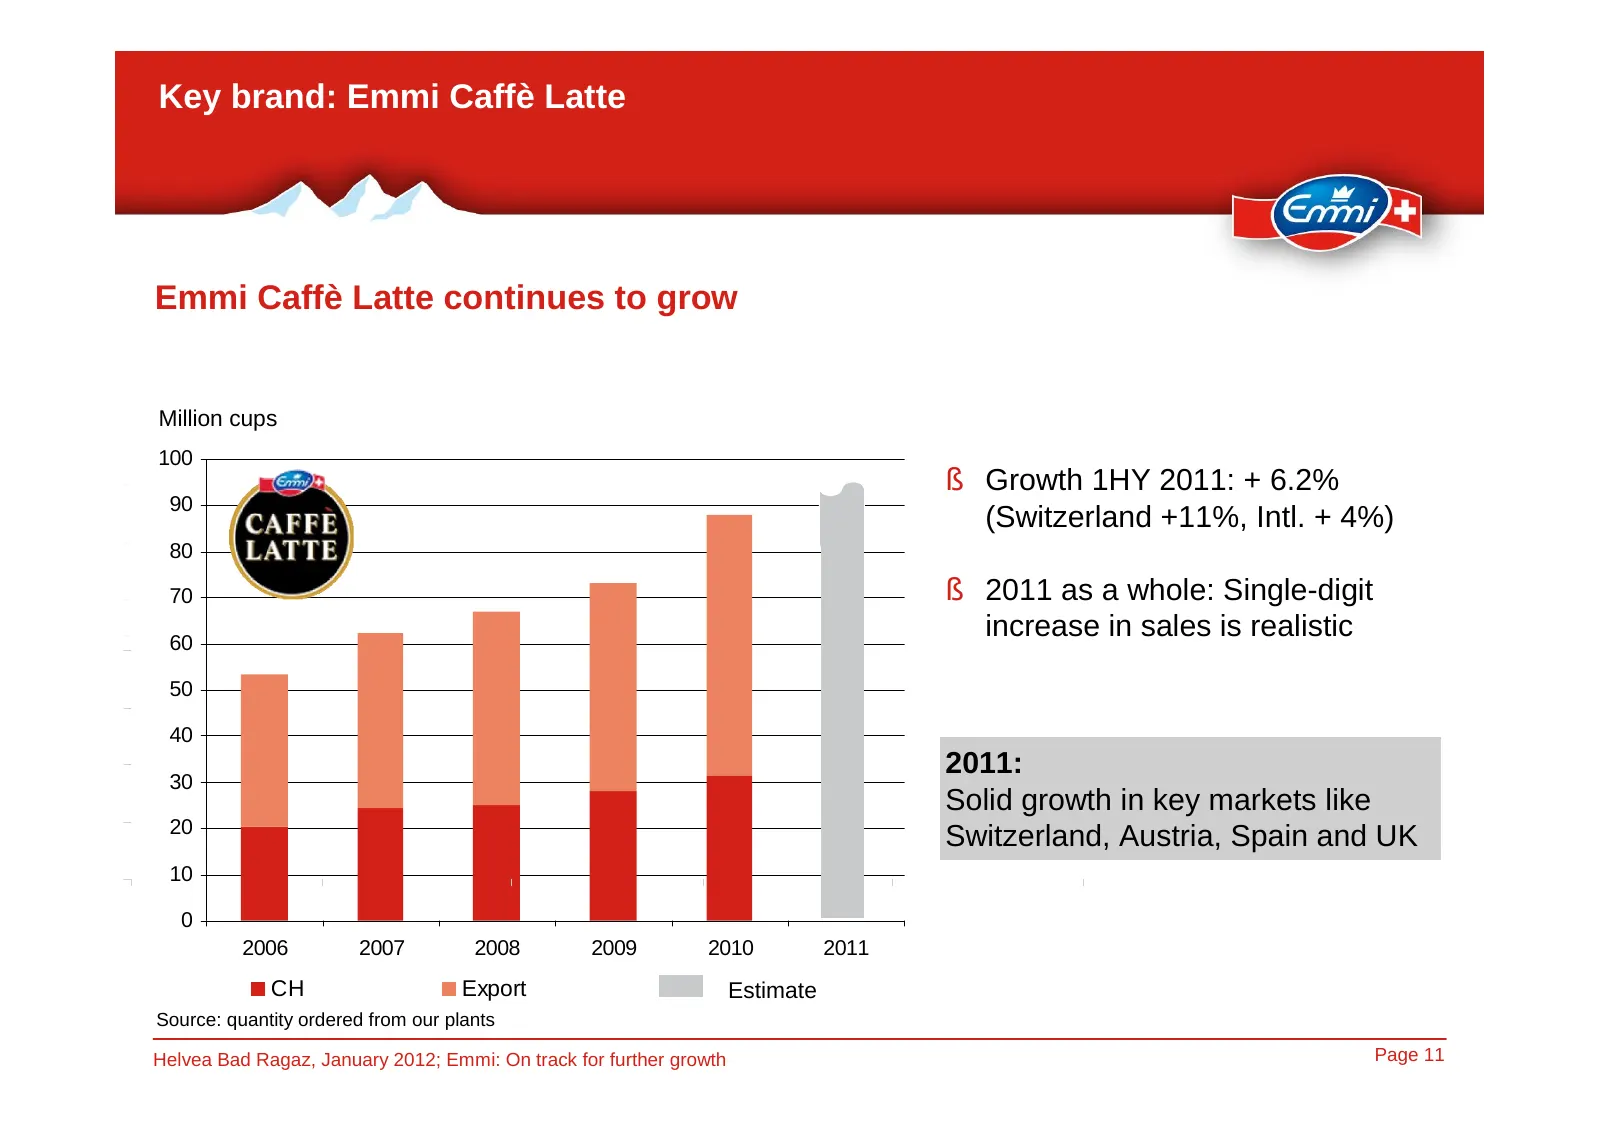
Key brand: Emmi Caffè Latte Emmi Caffè Latte continues to grow Million cups 100 § Growth 1HY 2011: + 6.2% 90 (Switzerland +11%, Intl. + 4%) 80 70 § 2011 as a whole: Single-digit 60 increase in sales is realistic 50 40 2011: 30 Solid growth in key markets like 20 Switzerland, Austria, Spain and UK 10
Slide 12: Recently acquired: Key brand Onken
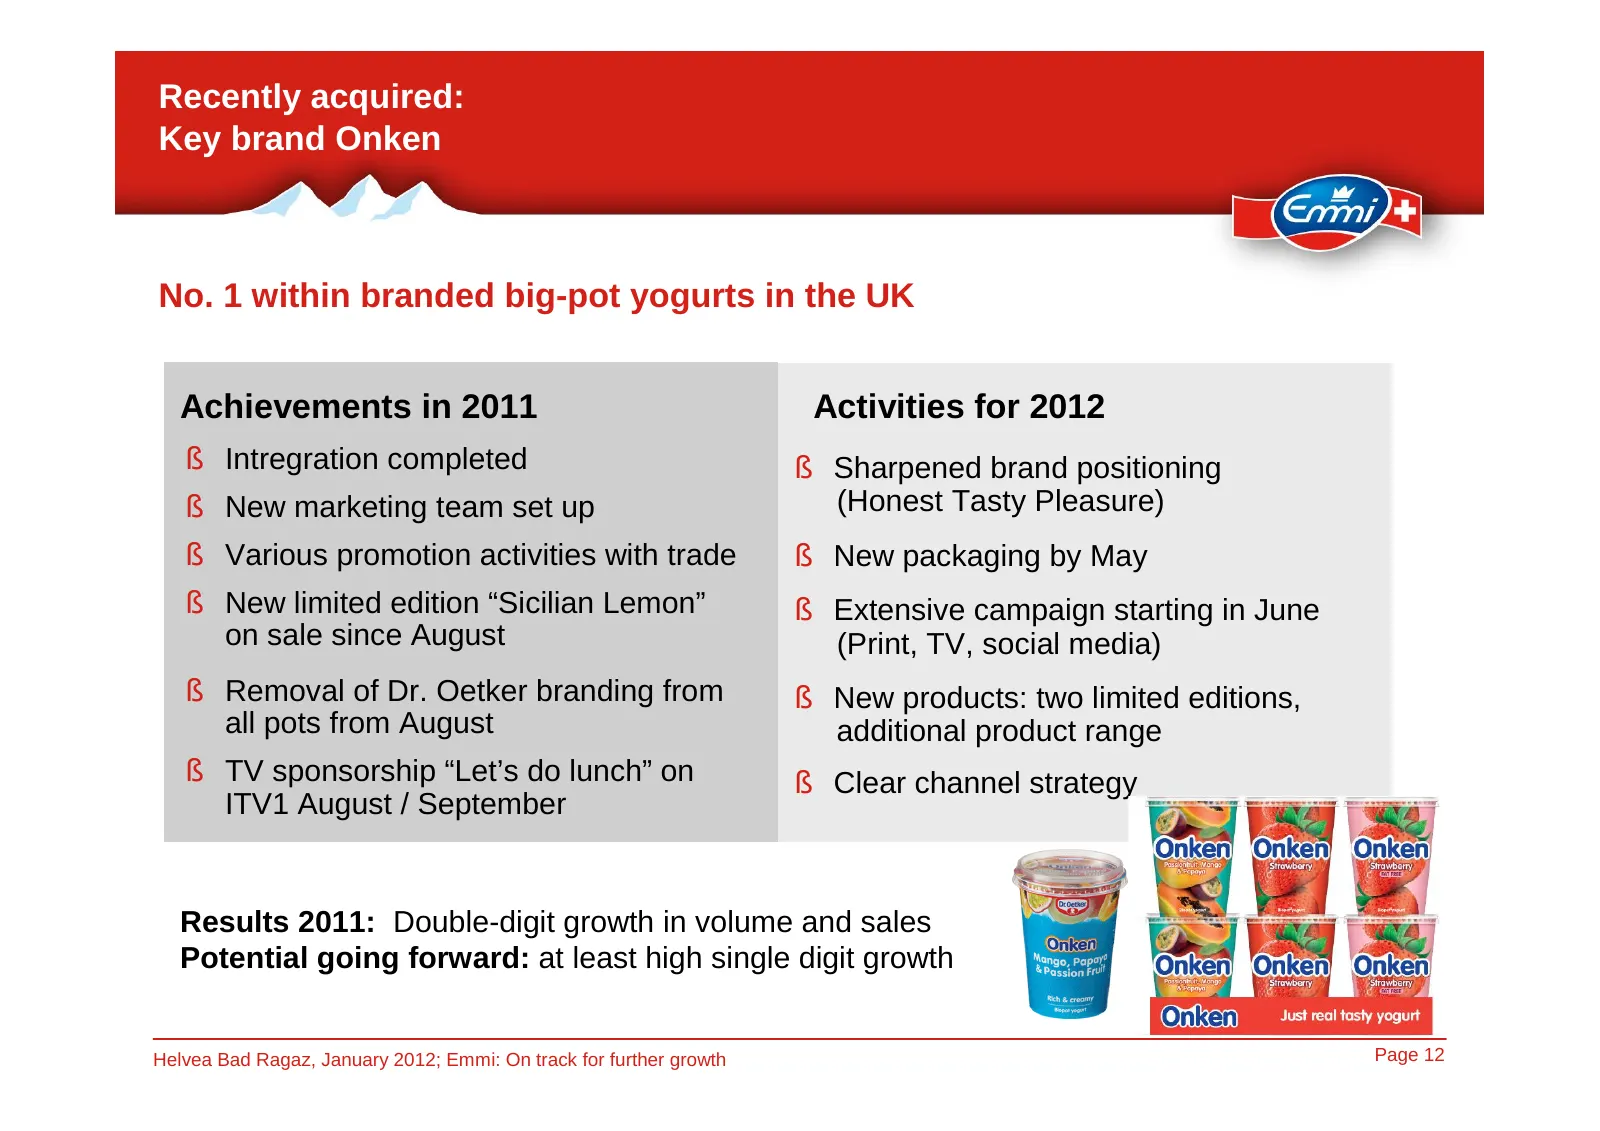
Recently acquired: Key brand Onken No. 1 within branded big-pot yogurts in the UK Achievements in 2011 Activities for 2012 § Intregration completed § Sharpened brand positioning § New marketing team set up (Honest Tasty Pleasure) § Various promotion activities with trade § New packaging by May § New
Slide 13: Recently acquired: Key brand Roth cheese
Recently acquired: Key brand Roth cheese US market: Wide range of cheese and fresh products Achievements in 2011 Activities for 2012 § Sales specialization: food service, Positioning as the expert for specialty cheese retail and specialty retail § Cheese education program in the food § Increasing ra
Slide 14: Emmi-Roth USA: Cheese experts for the food service industry
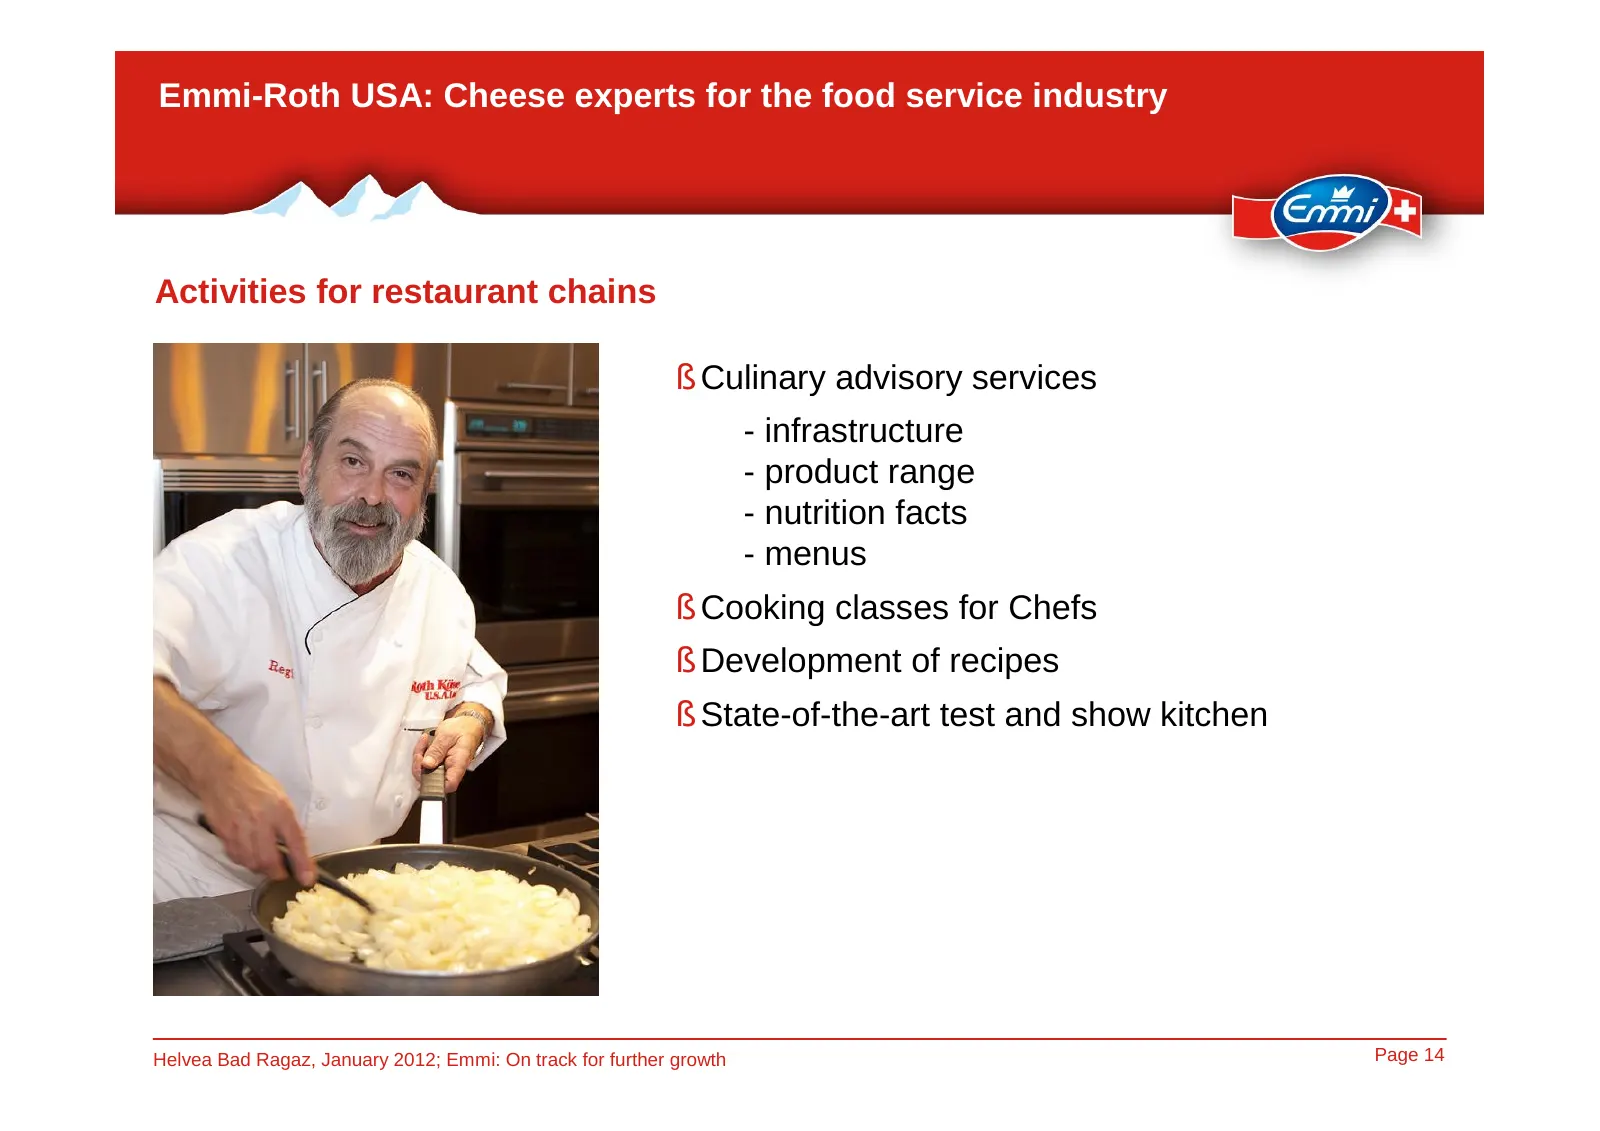
Emmi-Roth USA: Cheese experts for the food service industry Activities for restaurant chains § Culinary advisory services - infrastructure - product range - nutrition facts - menus § Cooking classes for Chefs § Development of recipes § State-of-the-art test and show kitchen Helvea Bad Ragaz, January
Slide 15: Recently acquired: Key brand Cypress Grove Chèvre
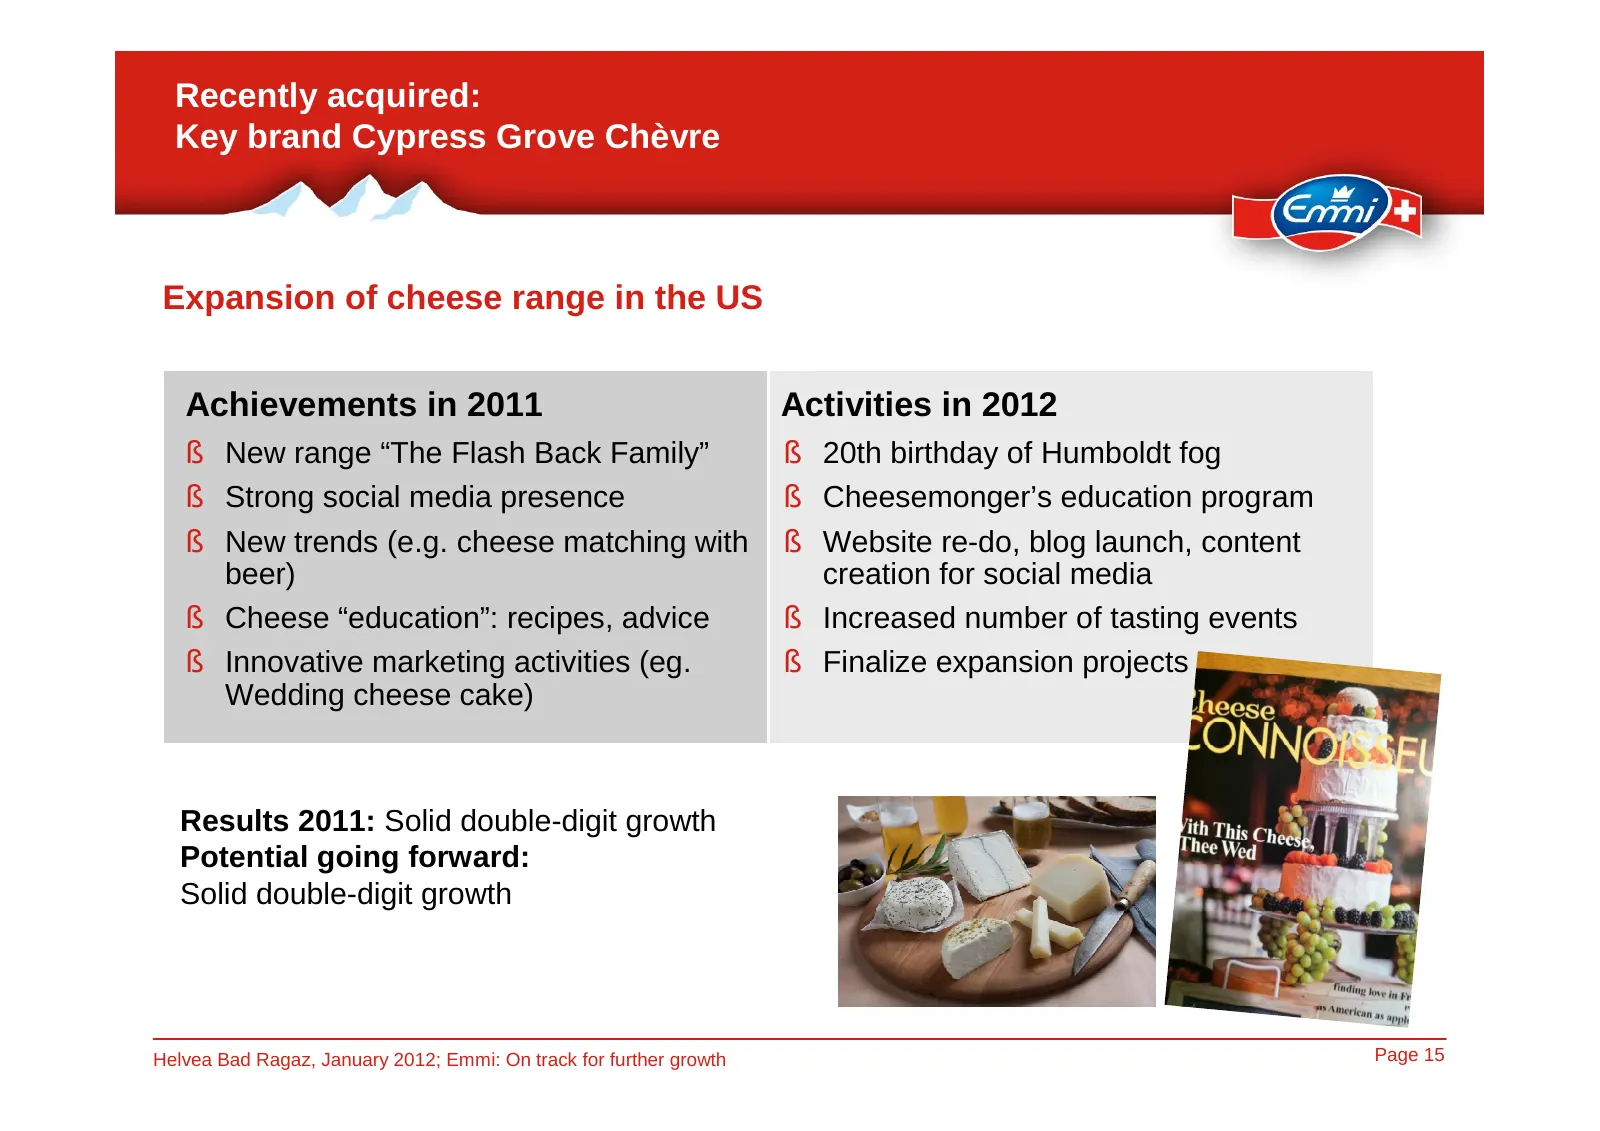
Recently acquired: Key brand Cypress Grove Chèvre Expansion of cheese range in the US Achievements in 2011 Activities in 2012 § New range “The Flash Back Family” § 20th birthday of Humboldt fog § Strong social media presence § Cheesemonger’s education program § New trends (e.g. cheese matching with
Slide 16: Recently acquired: Key brand Bontà Divina
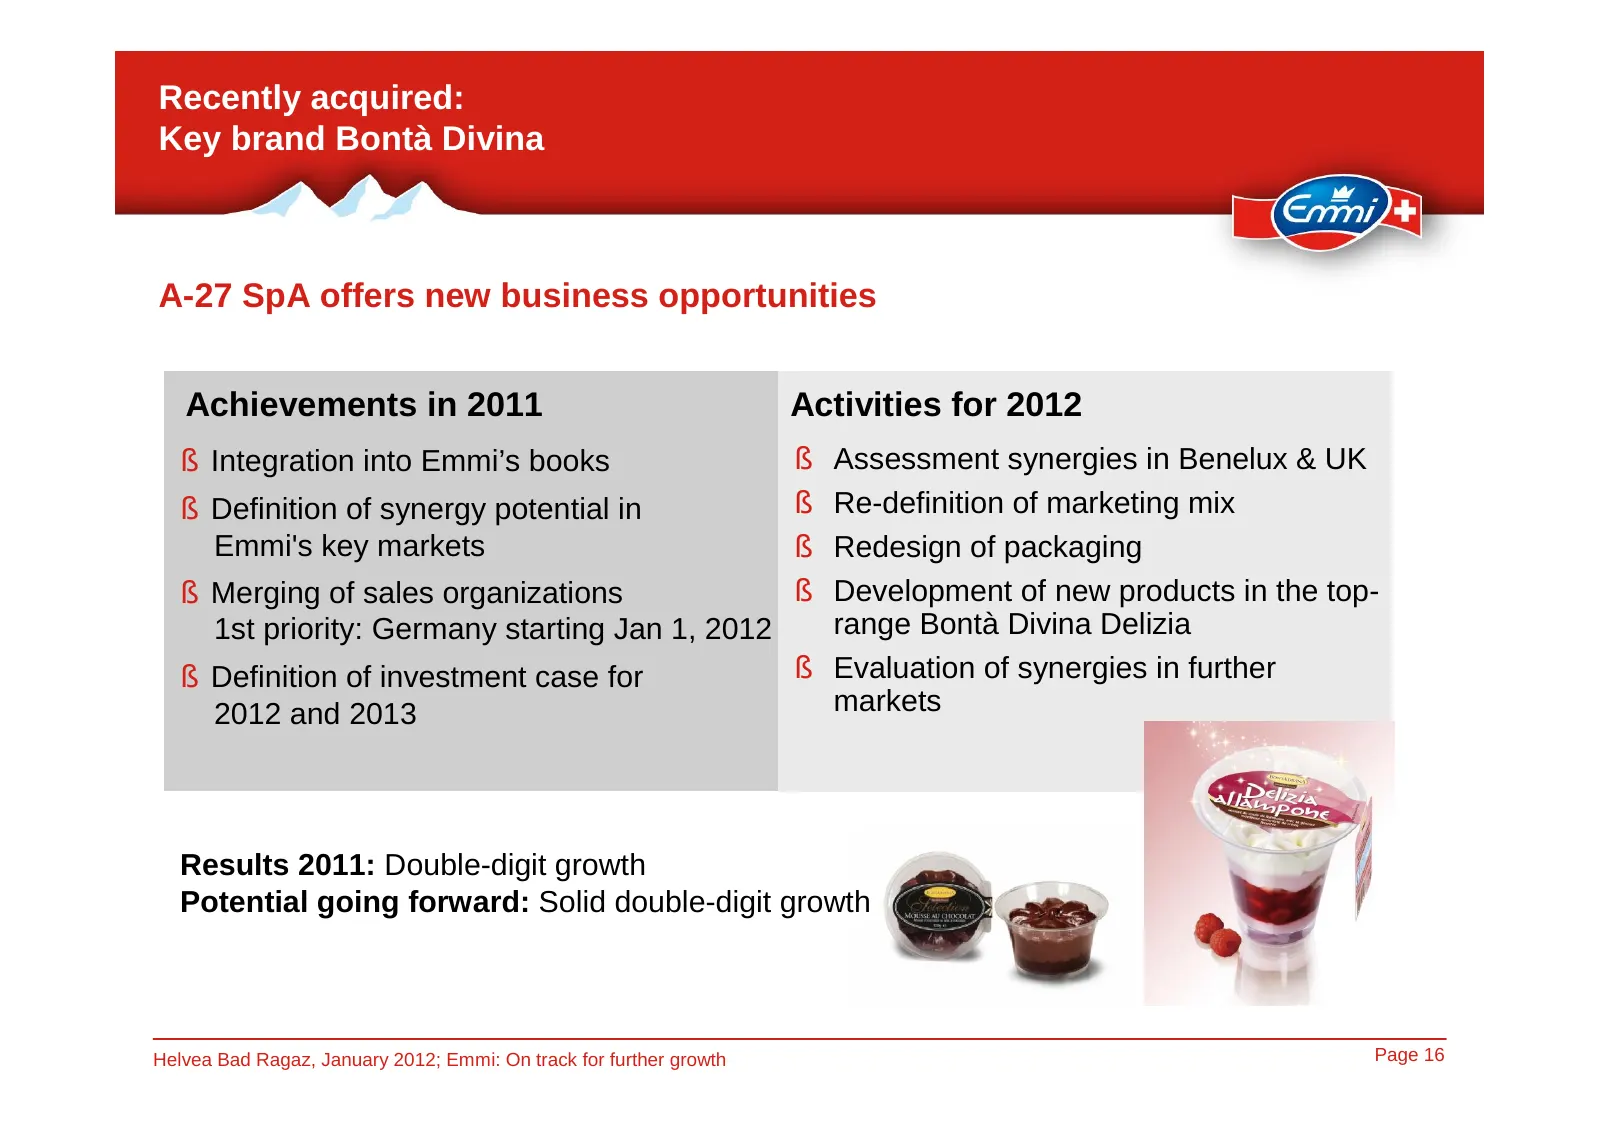
Recently acquired: Key brand Bontà Divina A-27 SpA offers new business opportunities Achievements in 2011 Activities for 2012 § Integration into Emmi’s books § Assessment synergies in Benelux & UK § Definition of synergy potential in § Re-definition of marketing mix Emmi's key markets § Redesign of
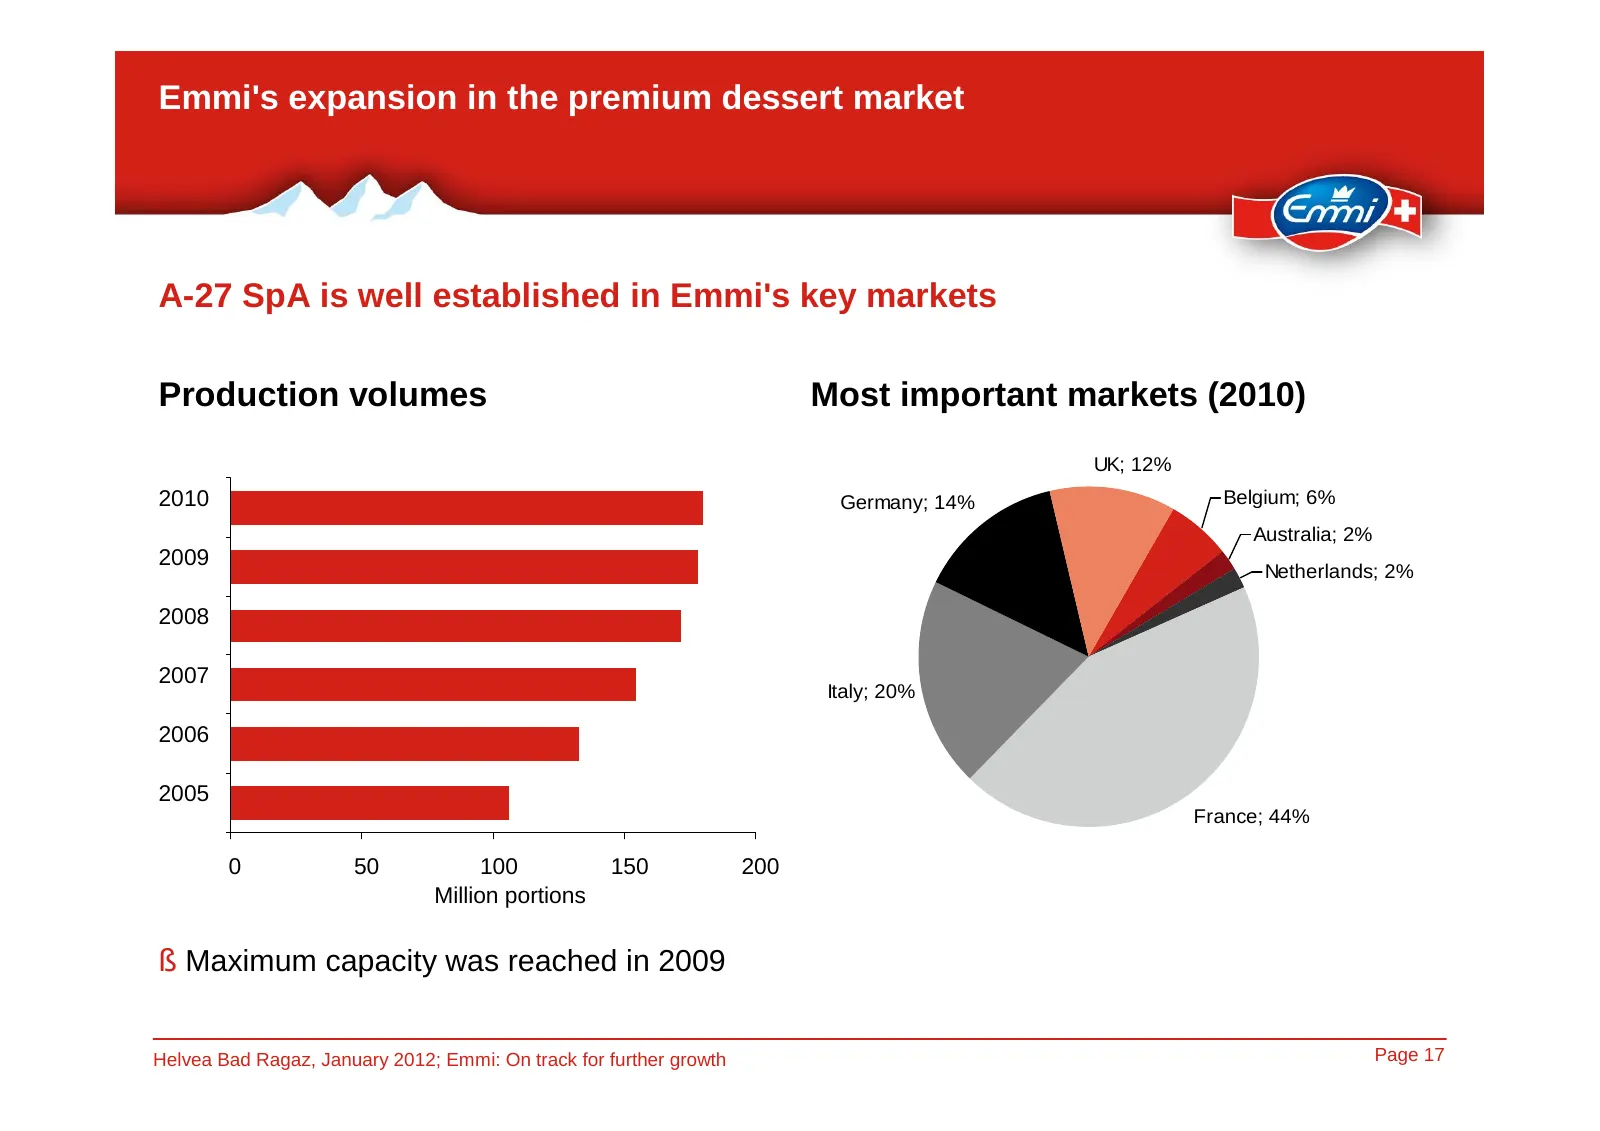
Slide 17: Emmi's expansion in the premium dessert market
Emmi's expansion in the premium dessert market A-27 SpA is well established in Emmi's key markets Production volumes Most important markets (2010) UK; 12% 2010 Germany; 14% Belgium; 6% Australia; 2% 2009 Netherlands; 2% 2008 2007 Italy; 20% 2006 2005 France; 44% 0 50 100 150 200 Million portions § M
Slide 18: Investments and innovation
Emmi in brief Key success drivers Investments and innovation Key financials and outlook Appendix
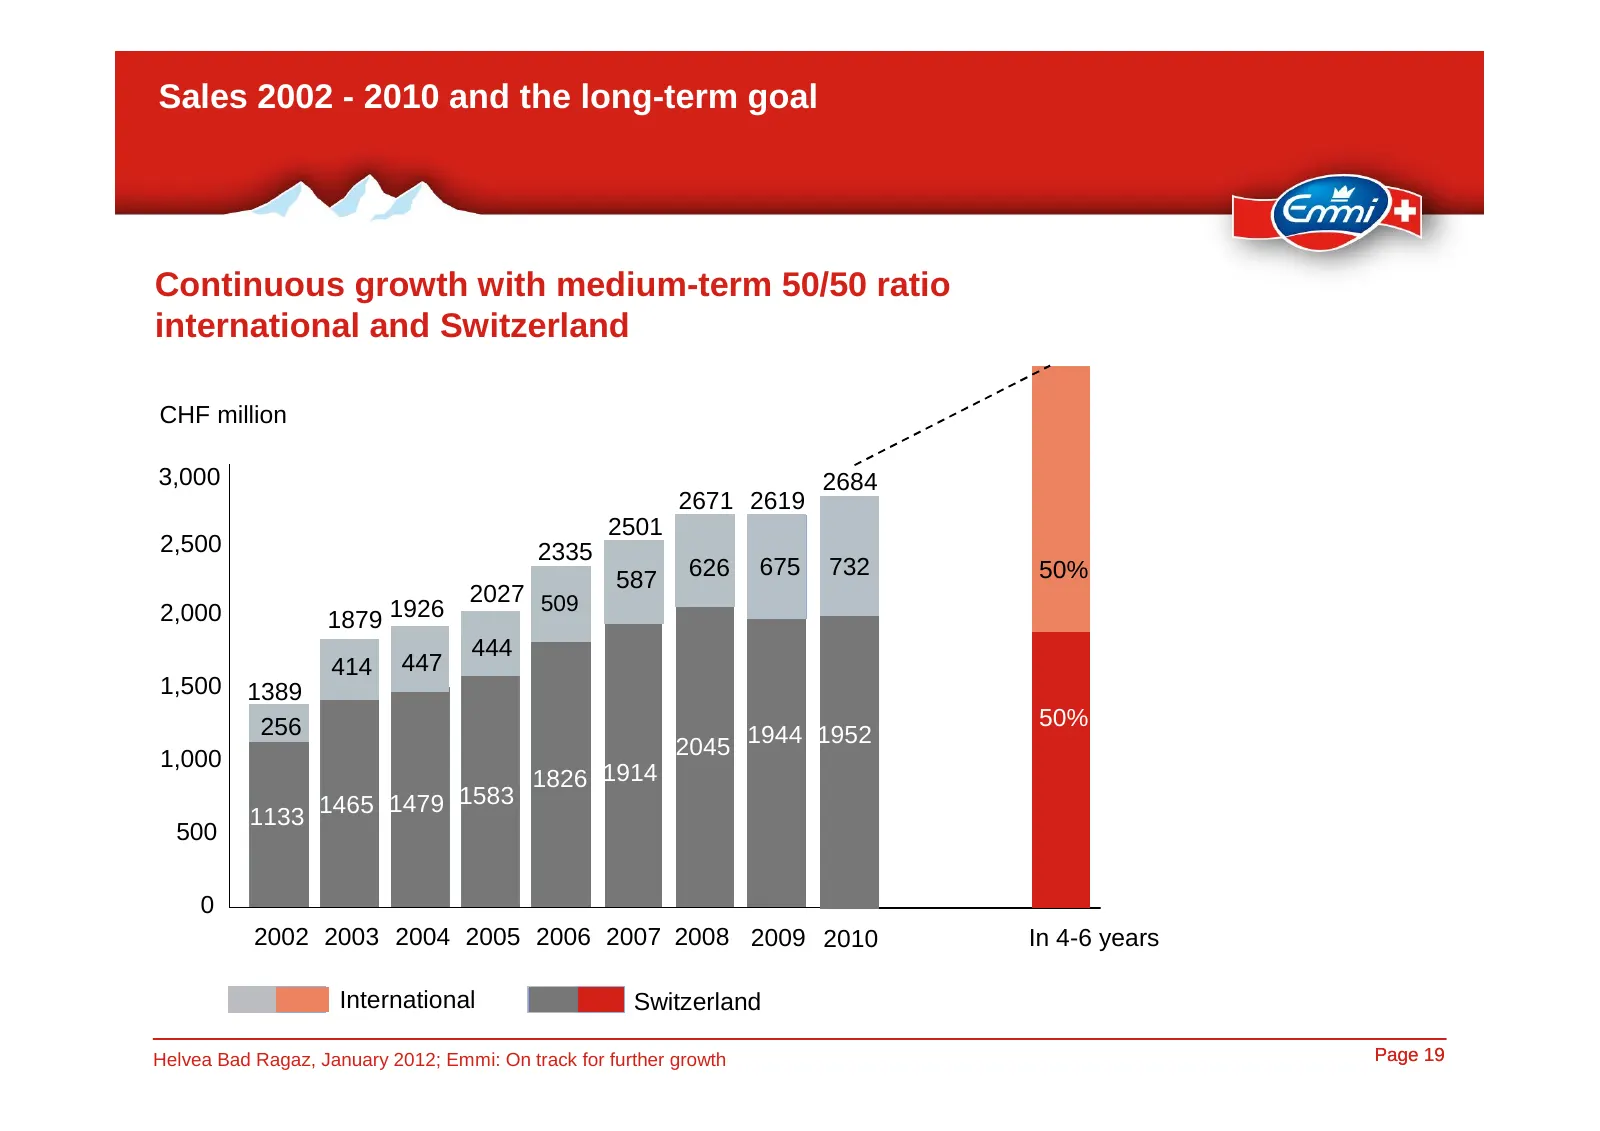
Slide 19: Sales 2002 - 2010 and the long-term goal
Sales 2002 - 2010 and the long-term goal Continuous growth with medium-term 50/50 ratio international and Switzerland CHF million 3,000 2684 2671 2619 2501 2,500 2335 626 675 732 50% 587 2027 509 2,000 1879 1926 444 414 447 1,500 1389 256 50% 1,000 2045 1944 1952 1826 1914 1465 1479 1583 1133 500 0
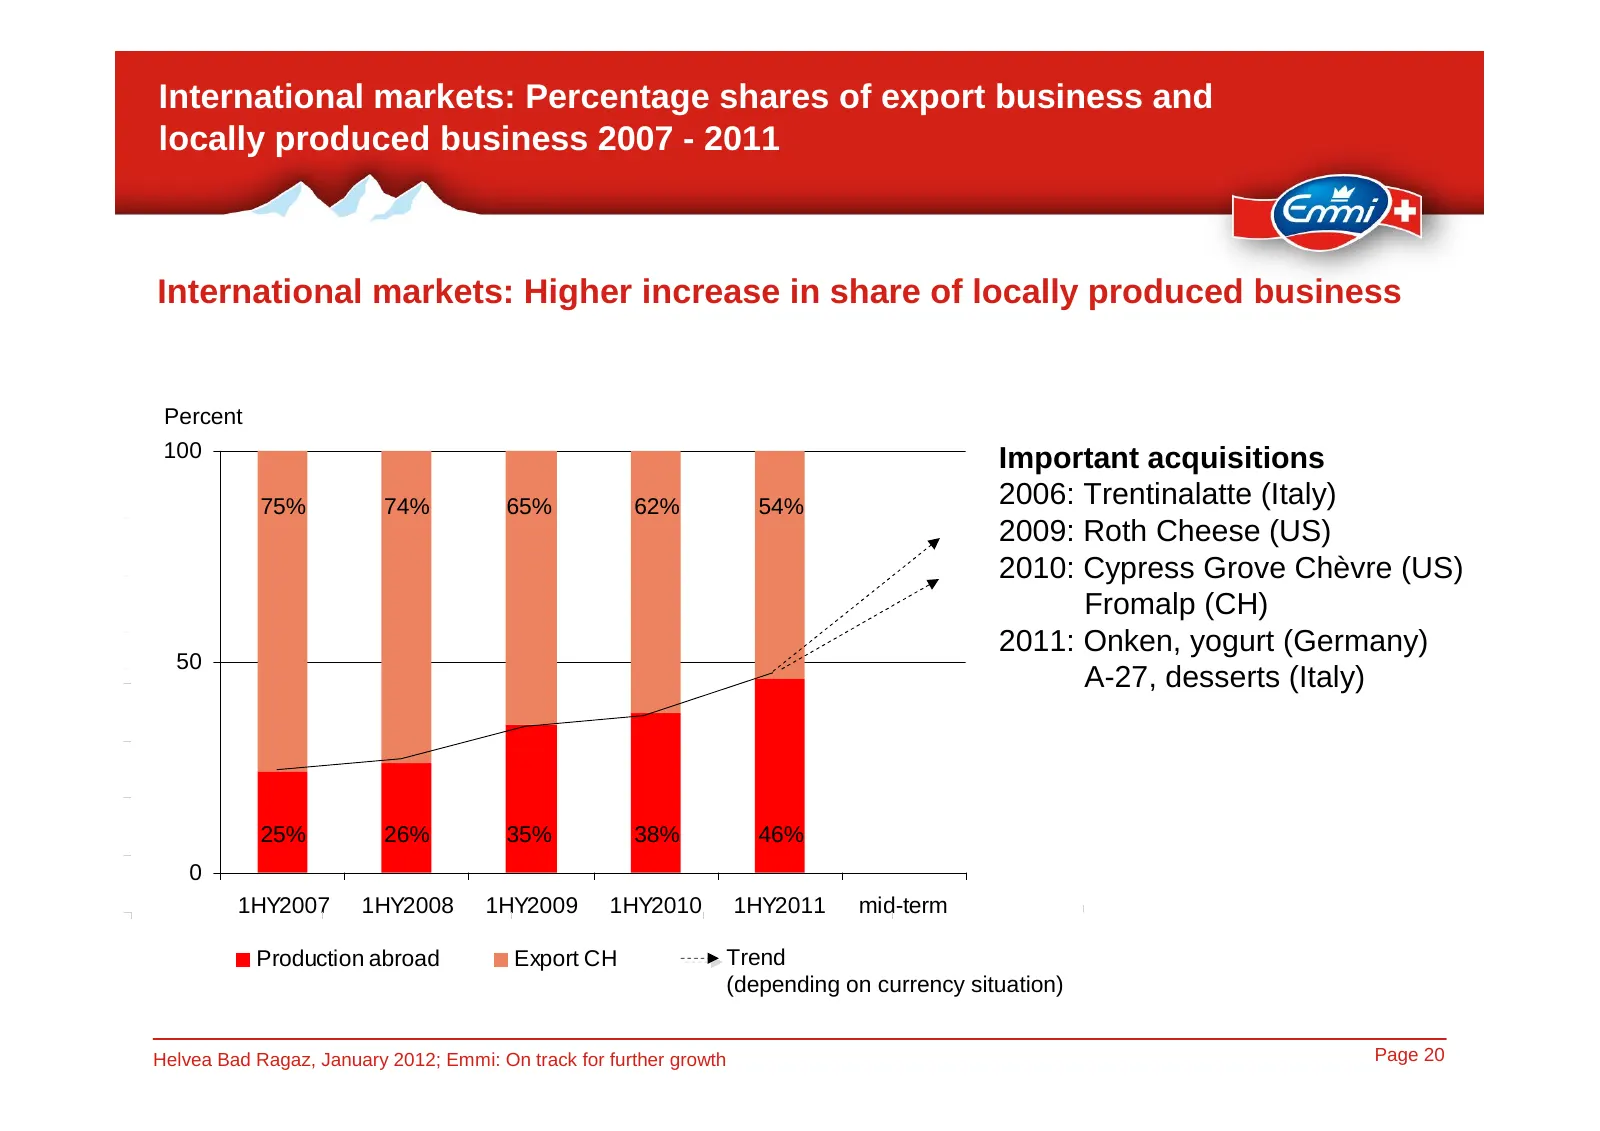
Slide 20: International markets: shares of export and locally produced business
International markets: Percentage shares of export business and locally produced business 2007 - 2011 International markets: Higher increase in share of locally produced business Percent 100 Important acquisitions 75% 74% 65% 62% 54% 2006: Trentinalatte (Italy) 2009: Roth Cheese (US) 2010: Cypress G
Slide 21: Investments for further growth: Italy
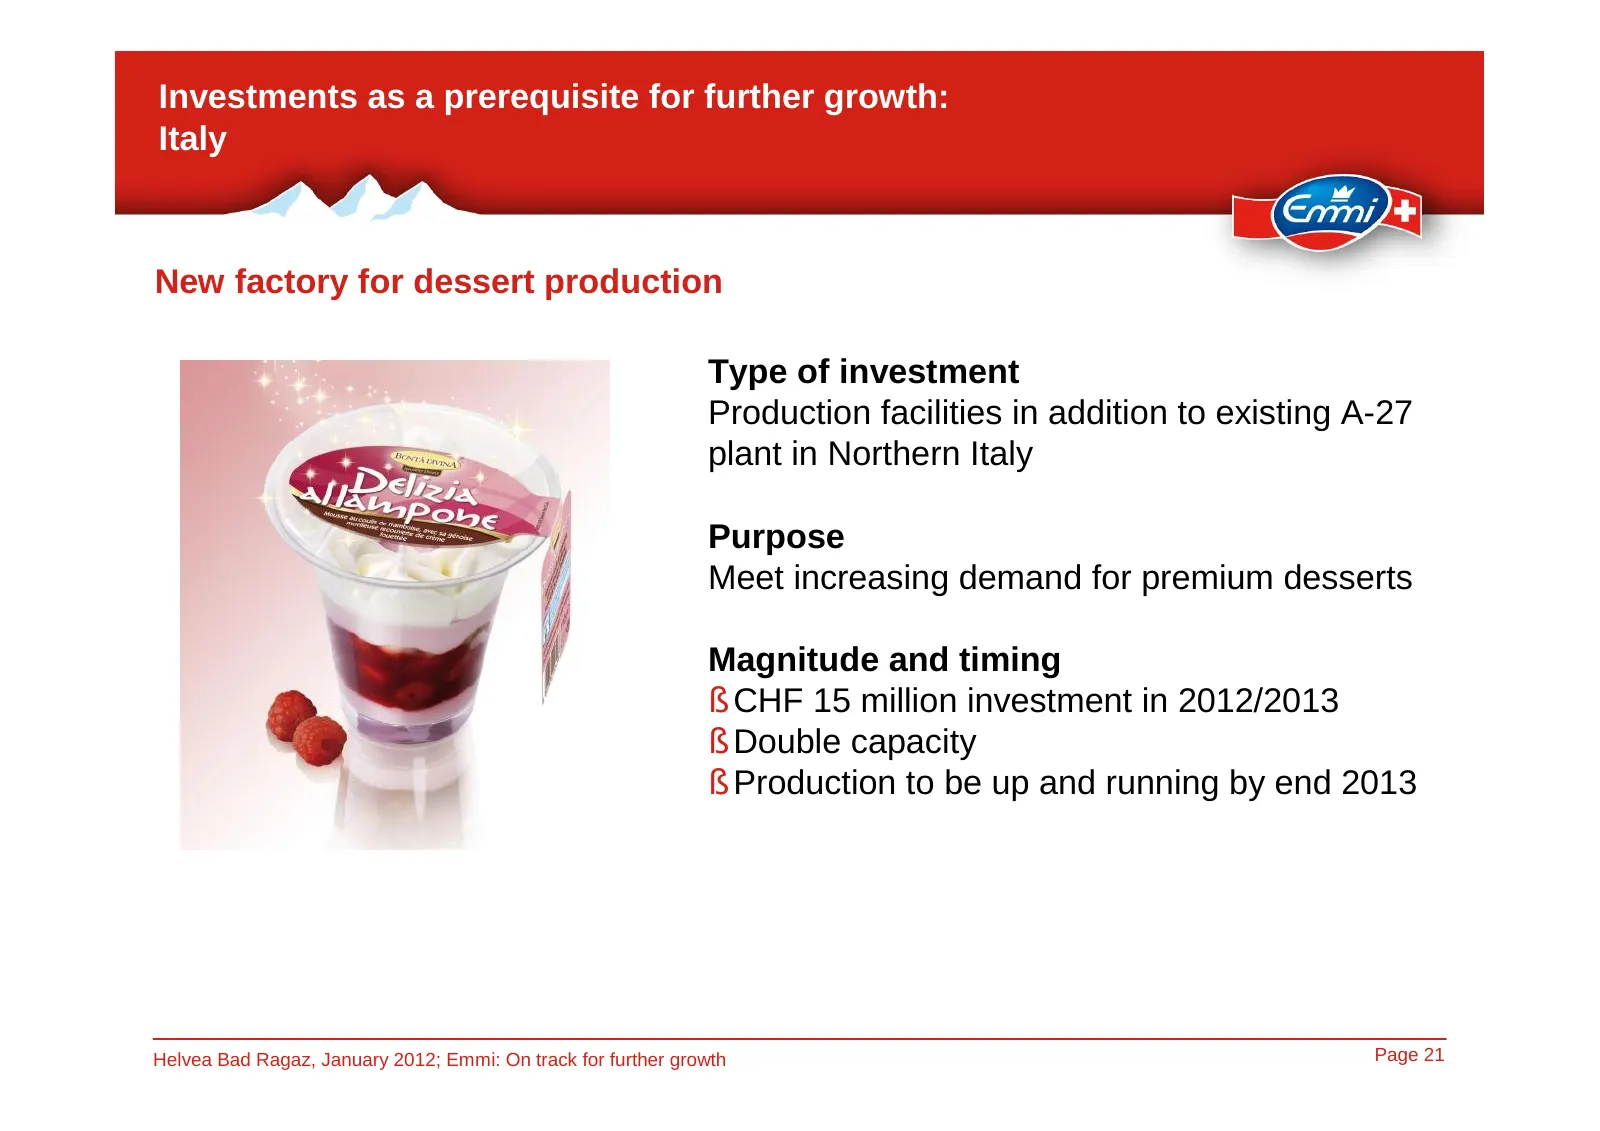
Investments as a prerequisite for further growth: Italy New factory for dessert production Type of investment Production facilities in addition to existing A-27 plant in Northern Italy Purpose Meet increasing demand for premium desserts Magnitude and timing § CHF 15 million investment in 2012/2013 §
Slide 22: Investments for further growth: USA
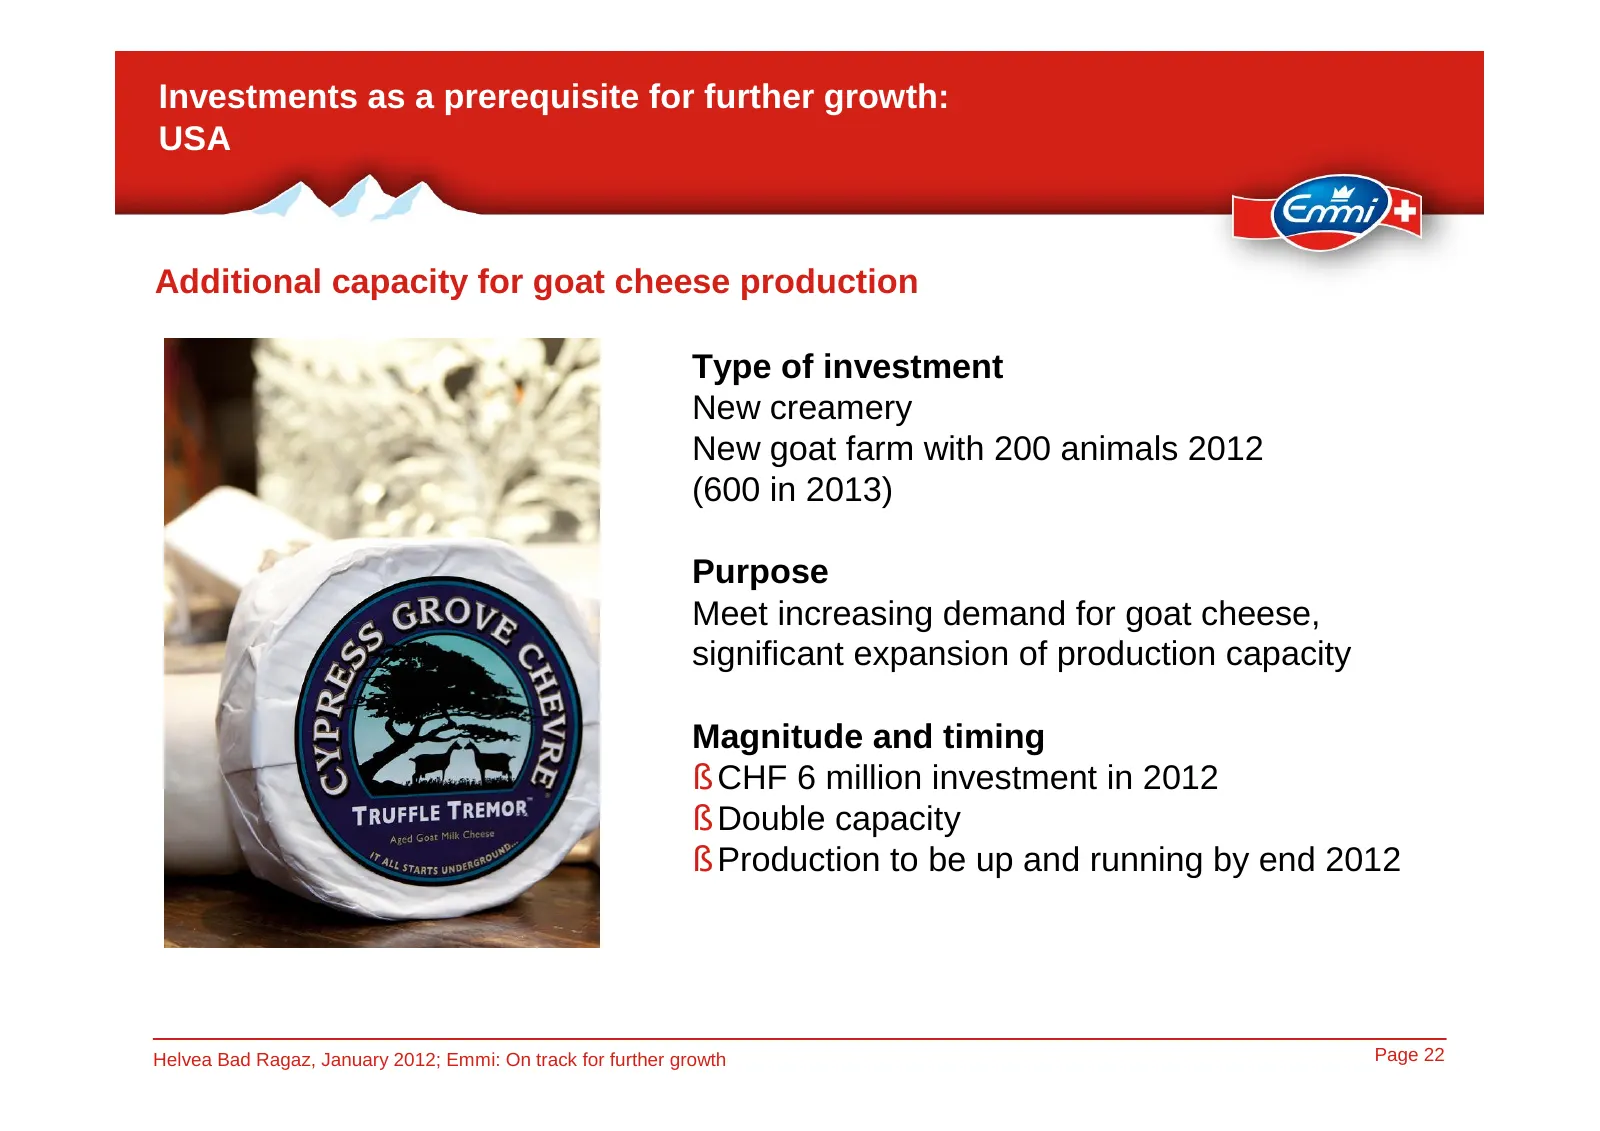
Investments as a prerequisite for further growth: USA Additional capacity for goat cheese production Type of investment New creamery New goat farm with 200 animals 2012 (600 in 2013) Purpose Meet increasing demand for goat cheese, significant expansion of production capacity Magnitude and timing § C
Slide 23: Investments for further growth: Switzerland, Kaltbach
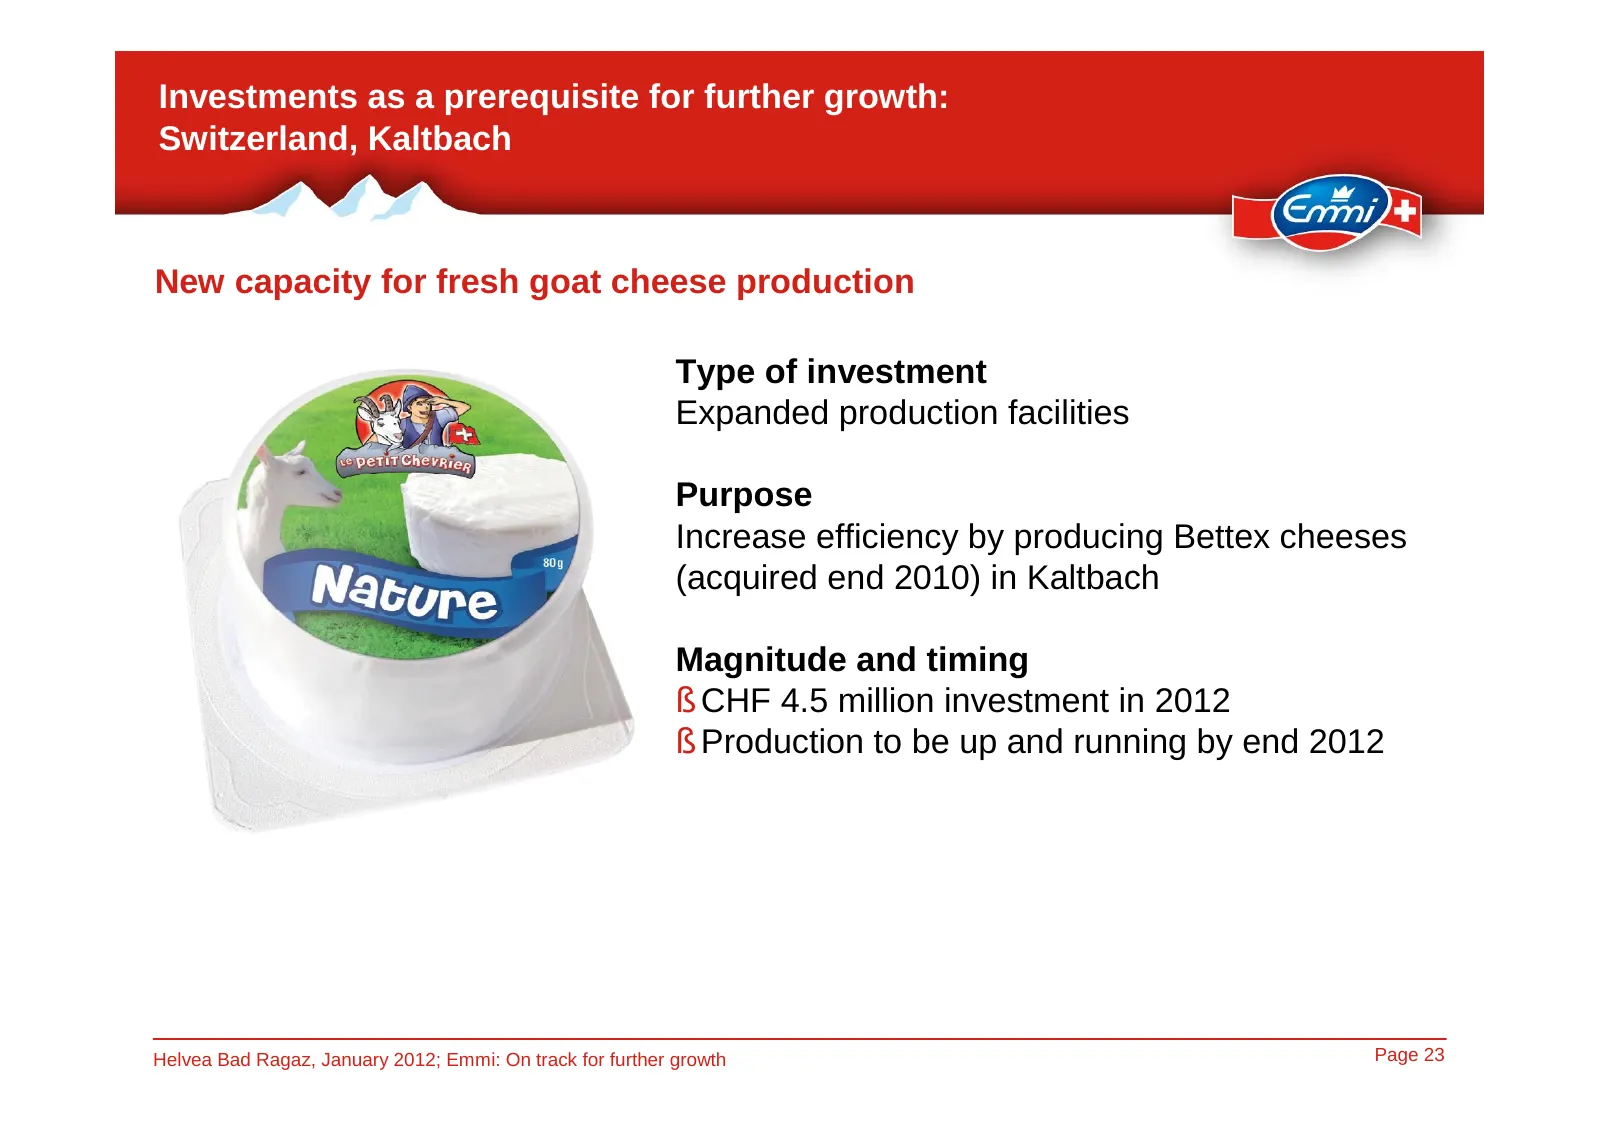
Investments as a prerequisite for further growth: Switzerland, Kaltbach New capacity for fresh goat cheese production Type of investment Expanded production facilities Purpose Increase efficiency by producing Bettex cheeses (acquired end 2010) in Kaltbach Magnitude and timing § CHF 4.5 million inves
Slide 24: Investments for further growth: Switzerland, Saignelégier
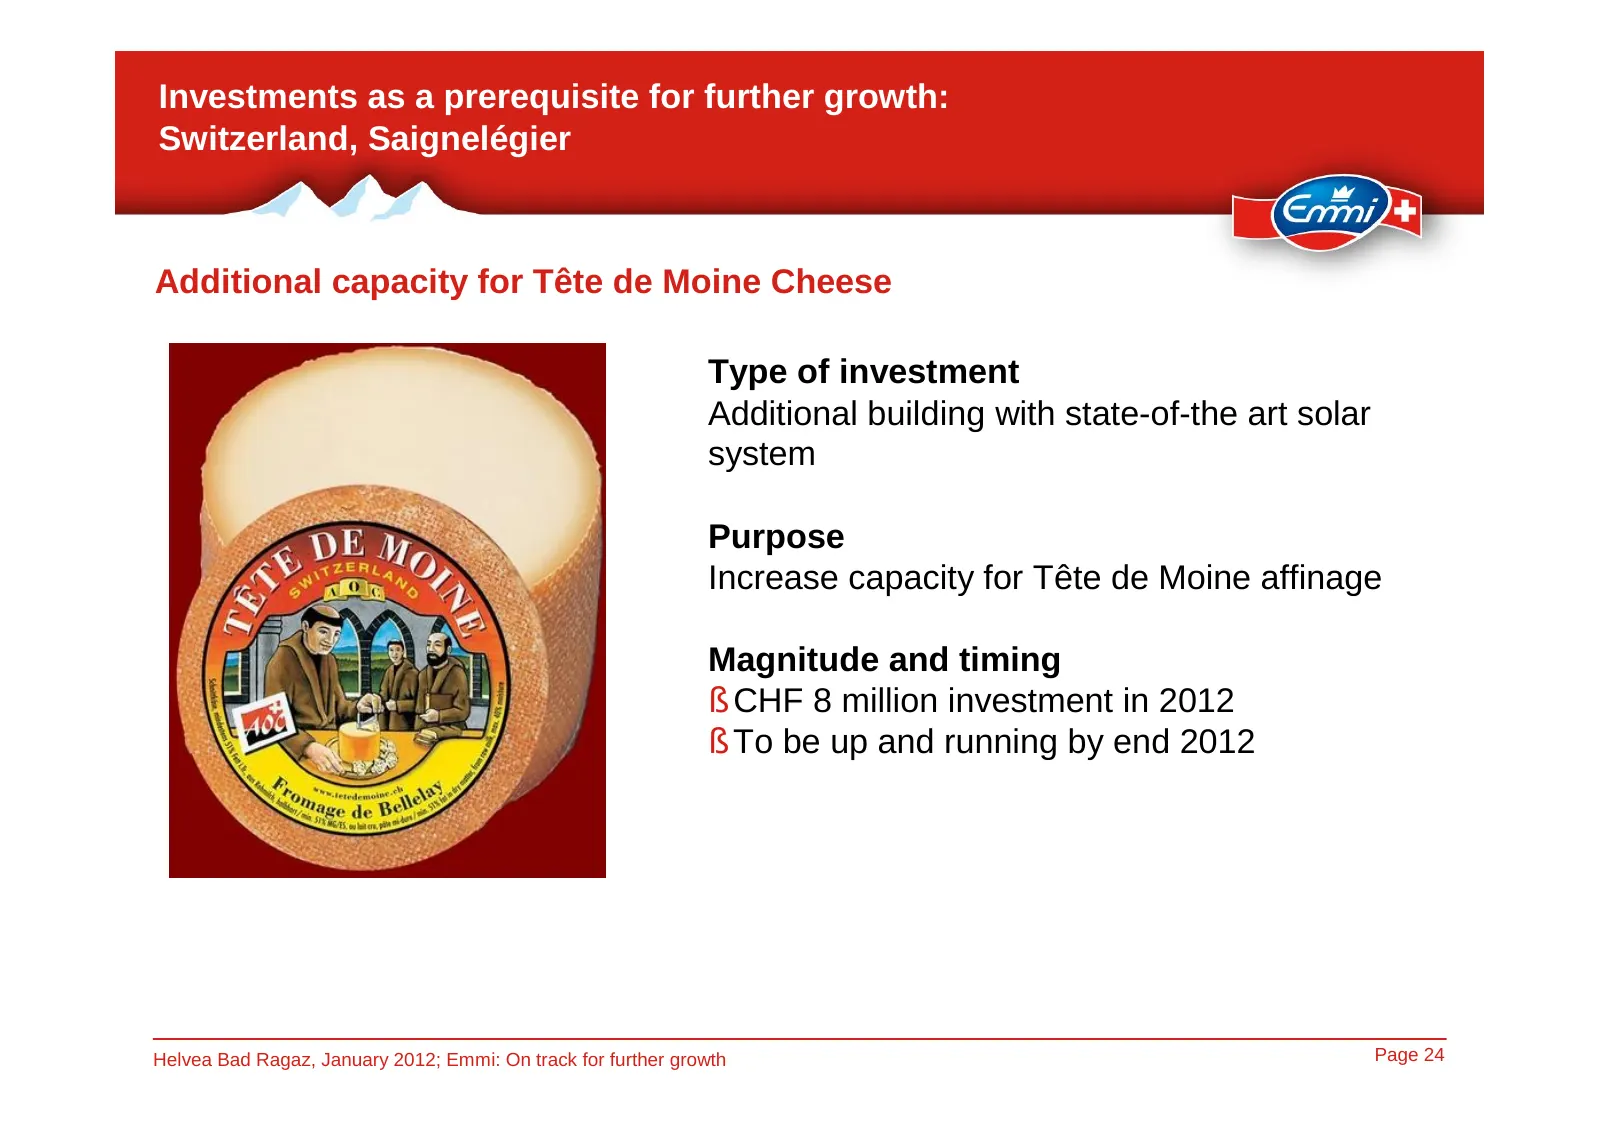
Investments as a prerequisite for further growth: Switzerland, Saignelégier Additional capacity for Tête de Moine Cheese Type of investment Additional building with state-of-the art solar system Purpose Increase capacity for Tête de Moine affinage Magnitude and timing § CHF 8 million investment in 2
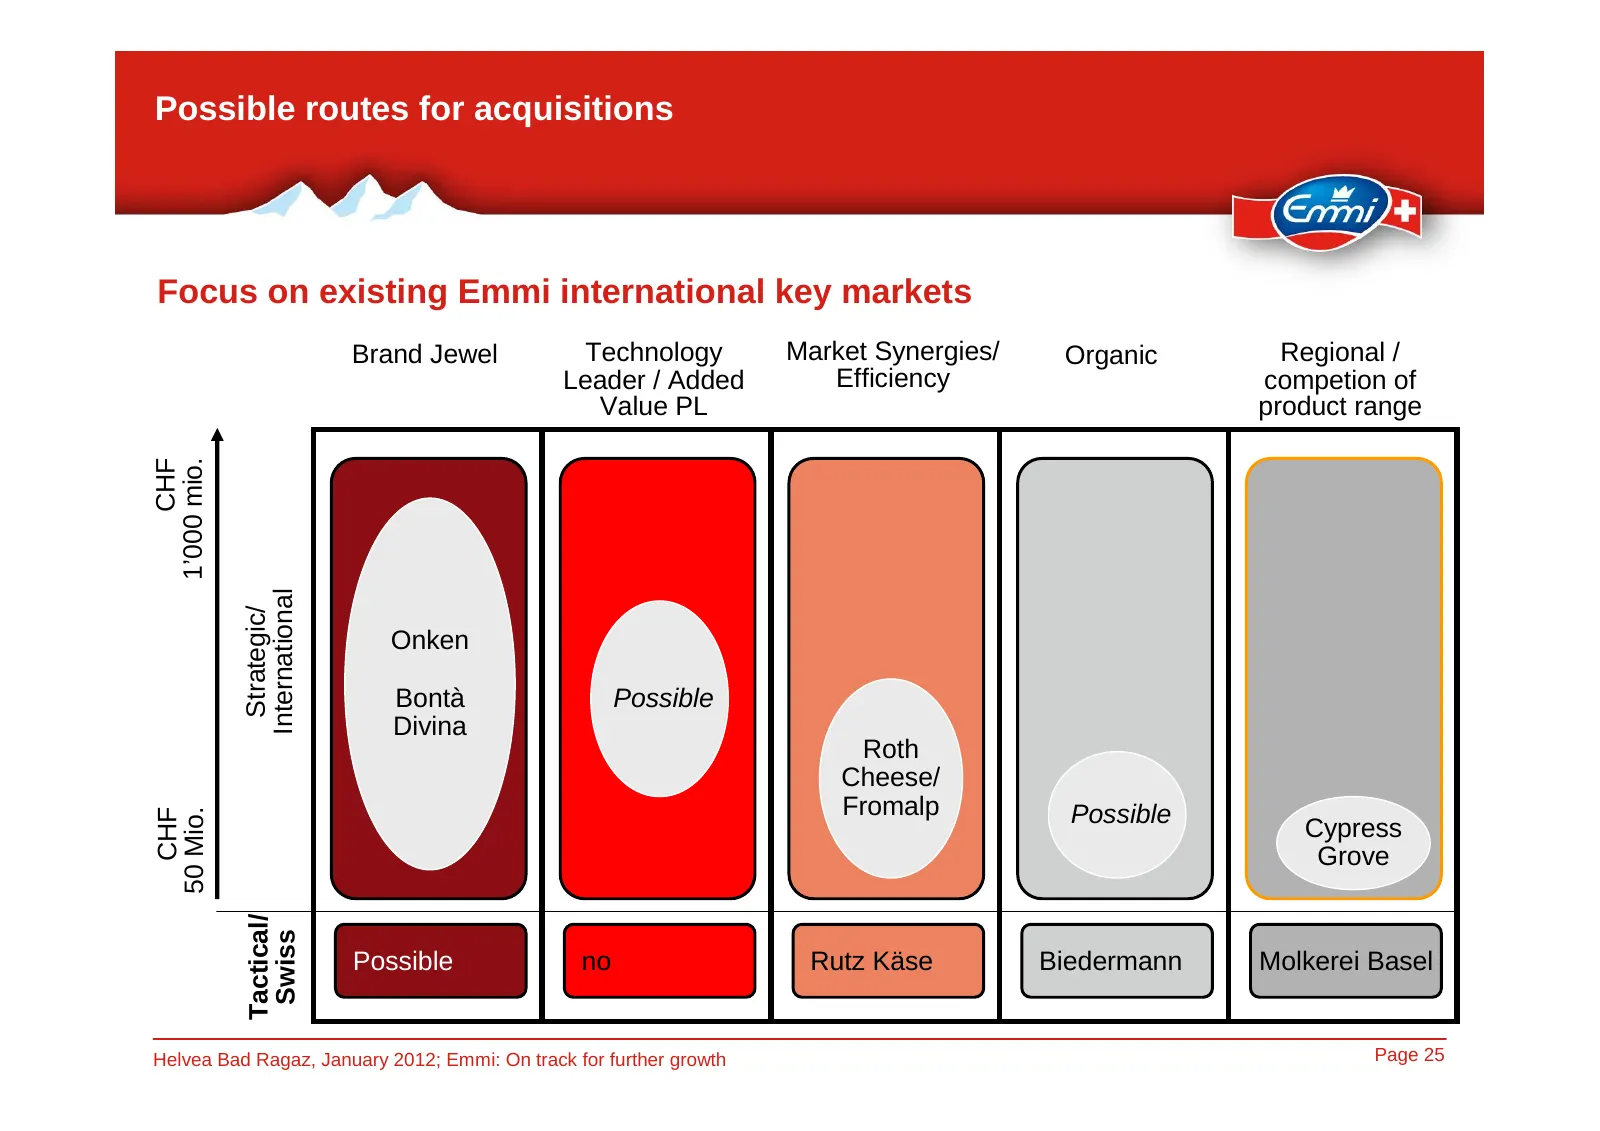
Slide 25: Possible routes for acquisitions
Possible routes for acquisitions Focus on existing Emmi international key markets Brand Jewel Technology Market Synergies/ Organic Regional / Leader / Added Efficiency competion of Value PL product range CHF 1’000 mio. International Strategic/ Onken Bontà Possible Divina Roth Cheese/ Fromalp Possibl
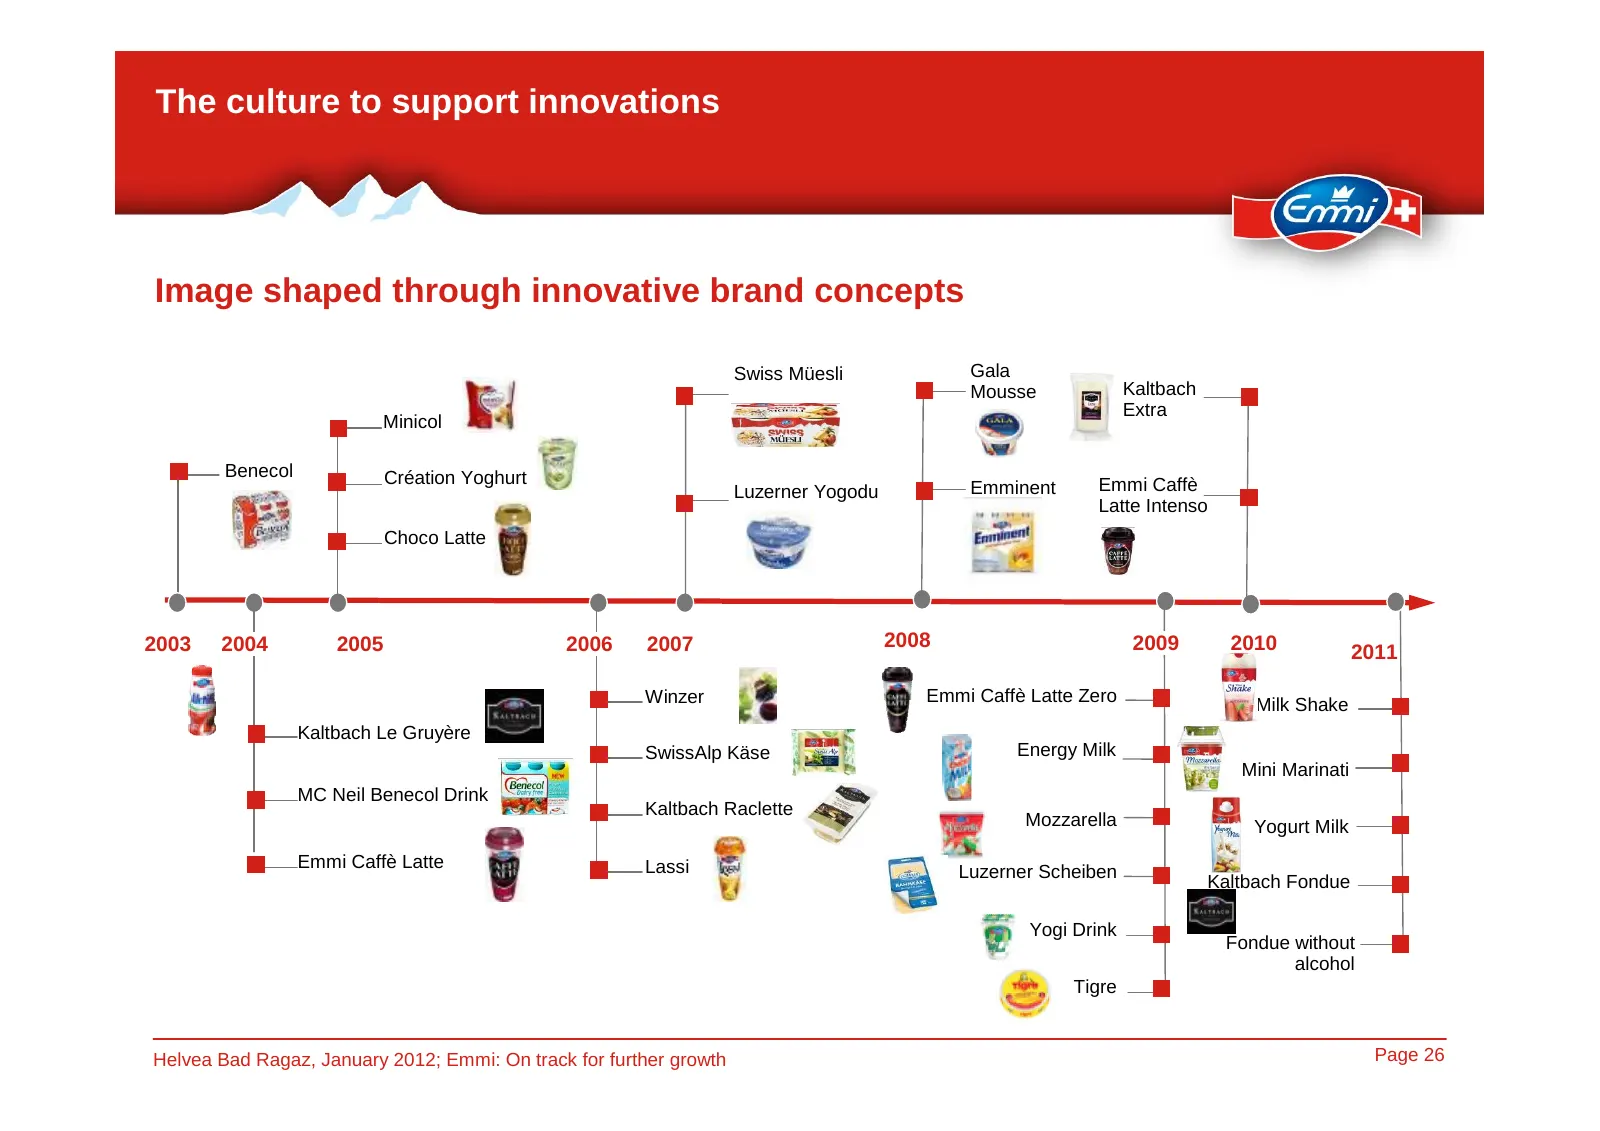
Slide 26: The culture to support innovations
The culture to support innovations Image shaped through innovative brand concepts Swiss Müesli Gala Mousse Kaltbach Extra Minicol Benecol Création Yoghurt Luzerner Yogodu Emminent Emmi Caffè Latte Intenso Choco Latte 2003 2004 2005 2006 2007 2008 2009 2010 2011 Winzer Emmi Caffè Latte Zero Milk Shak
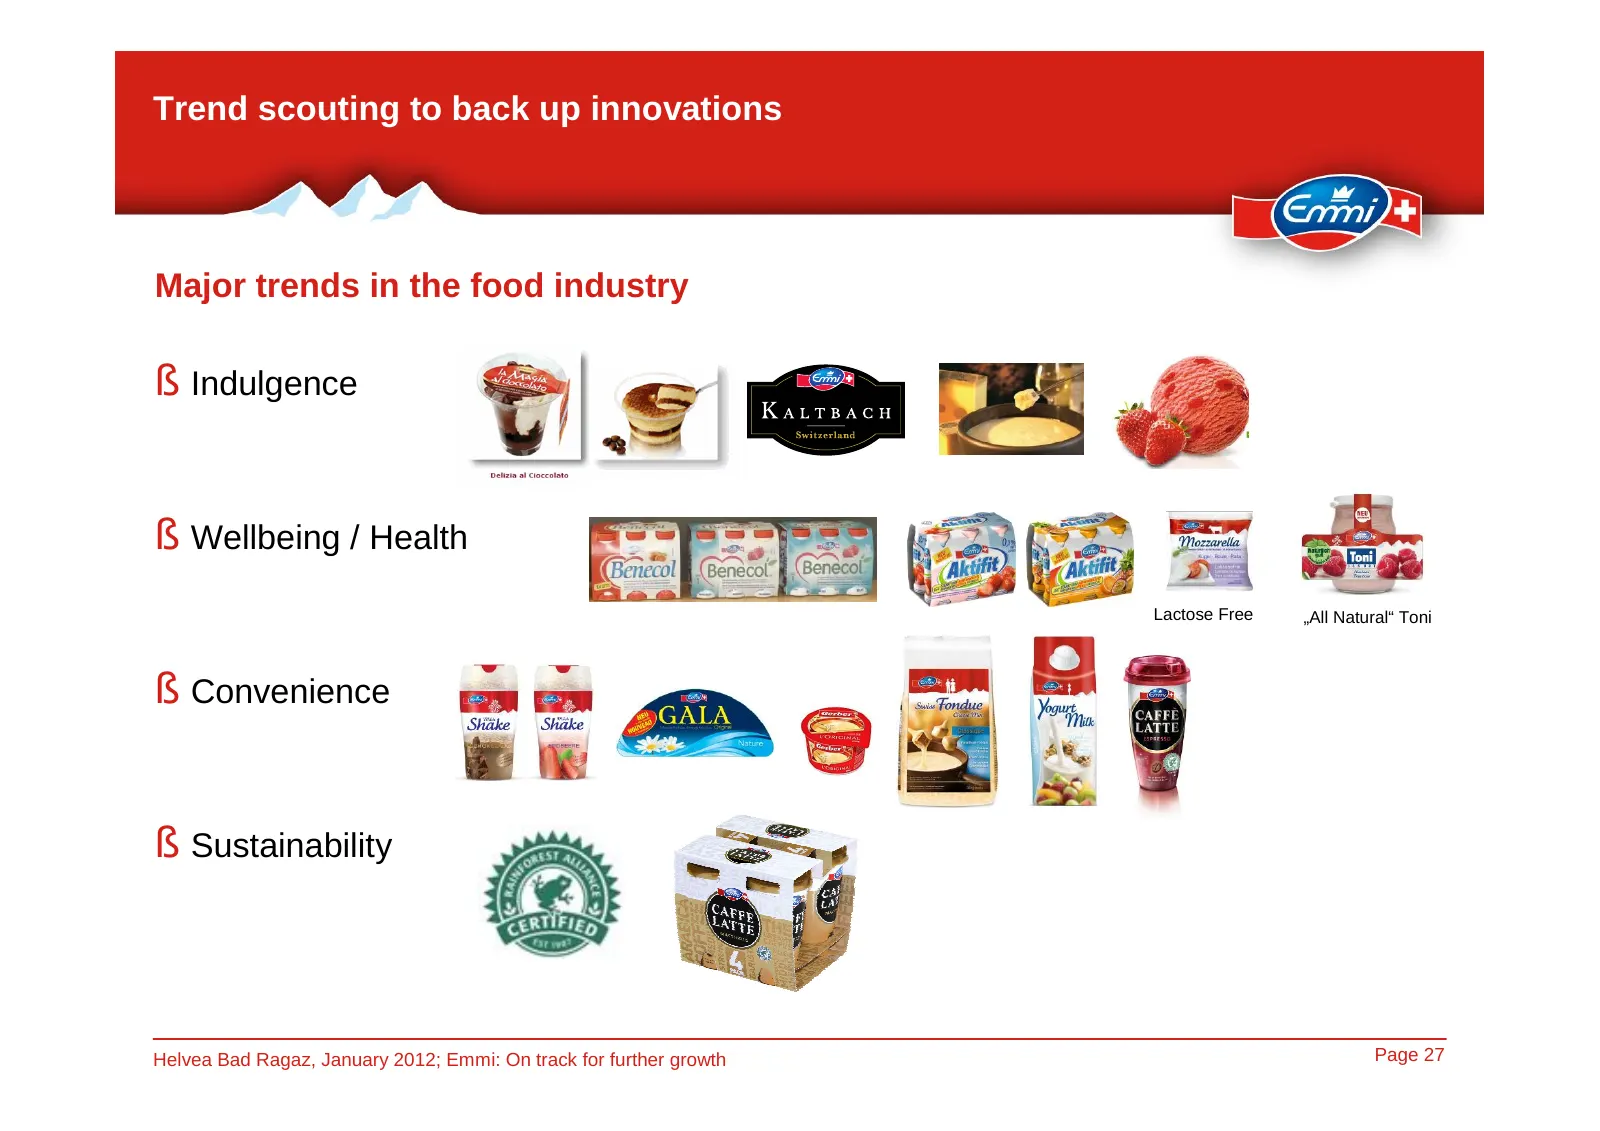
Slide 27: Trend scouting to back up innovations
Trend scouting to back up innovations Major trends in the food industry § Indulgence § Wellbeing / Health Lactose Free „All Natural“ Toni § Convenience § Sustainability Helvea Bad Ragaz, January 2012; Emmi: On track for further growth Page 27
Slide 28: Key financials and outlook
Emmi in brief Key success drivers Investments and innovation Key financials and outlook Appendix
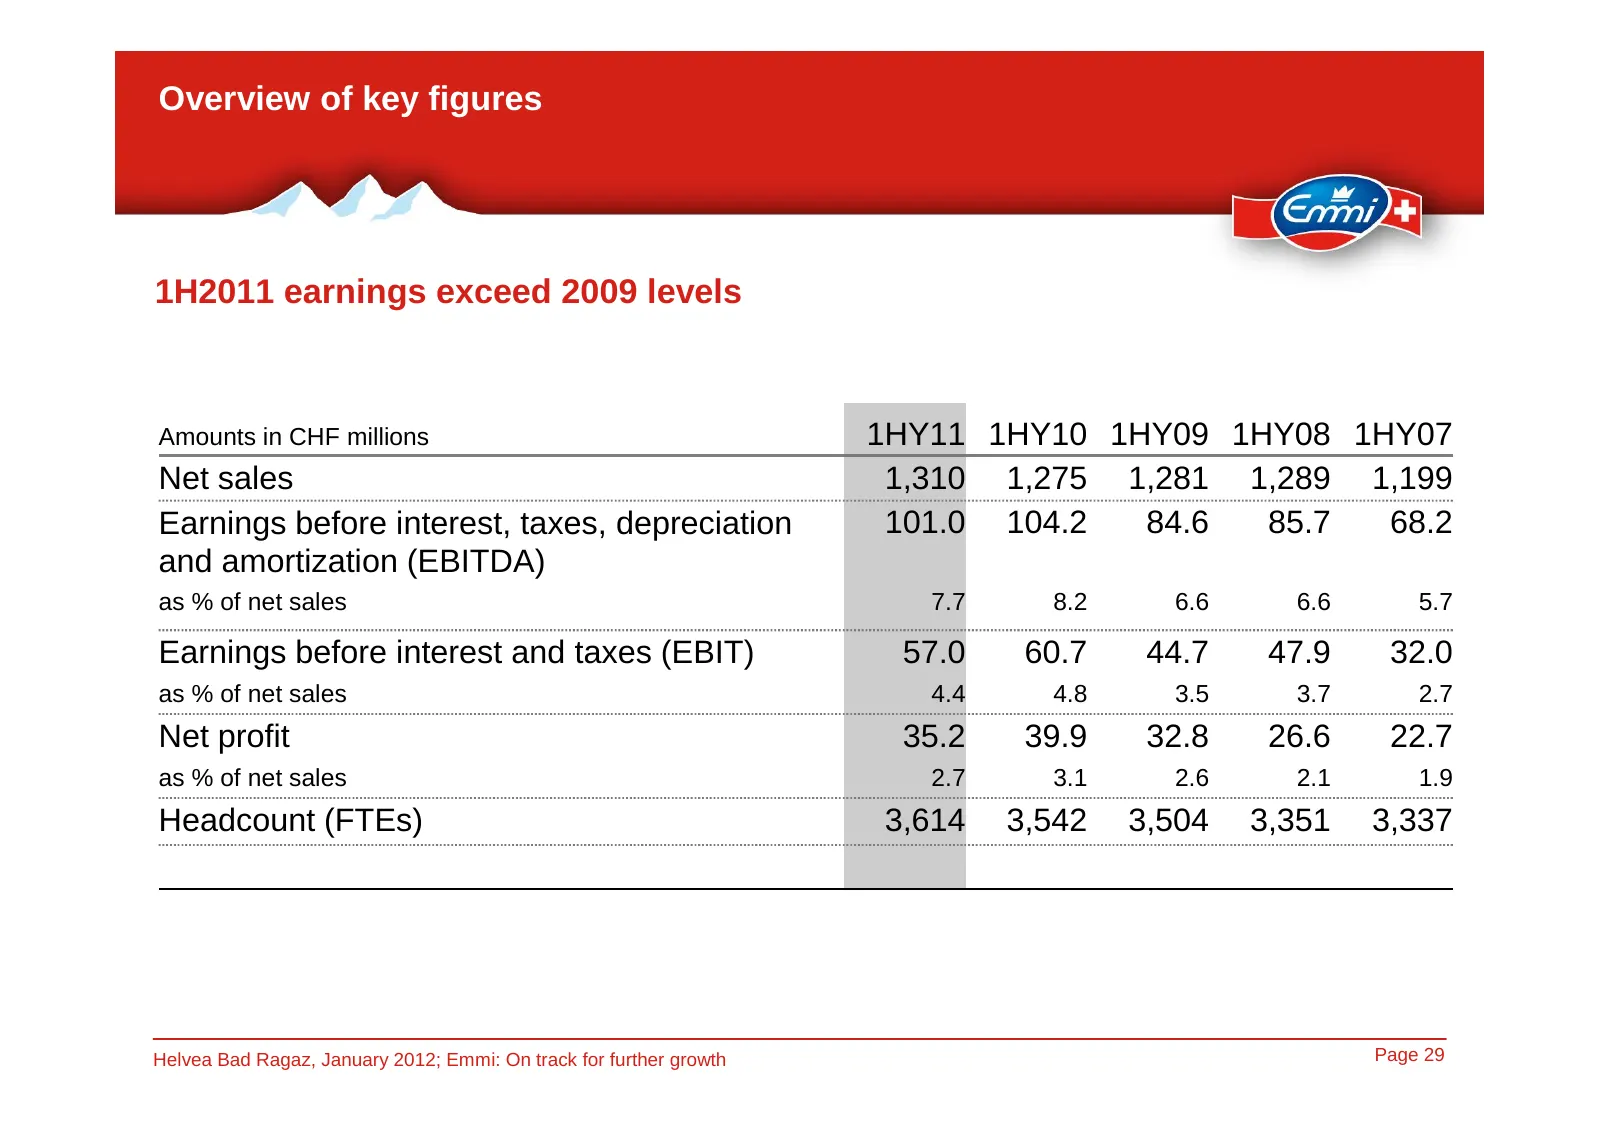
Slide 29: Overview of key figures
Overview of key figures 1H2011 earnings exceed 2009 levels Amounts in CHF millions 1HY11 1HY10 1HY09 1HY08 1HY07 Net sales 1,310 1,275 1,281 1,289 1,199 Earnings before interest, taxes, depreciation 101.0 104.2 84.6 85.7 68.2 and amortization (EBITDA) as % of net sales 7.7 8.2 6.6 6.6 5.7 Earnings b
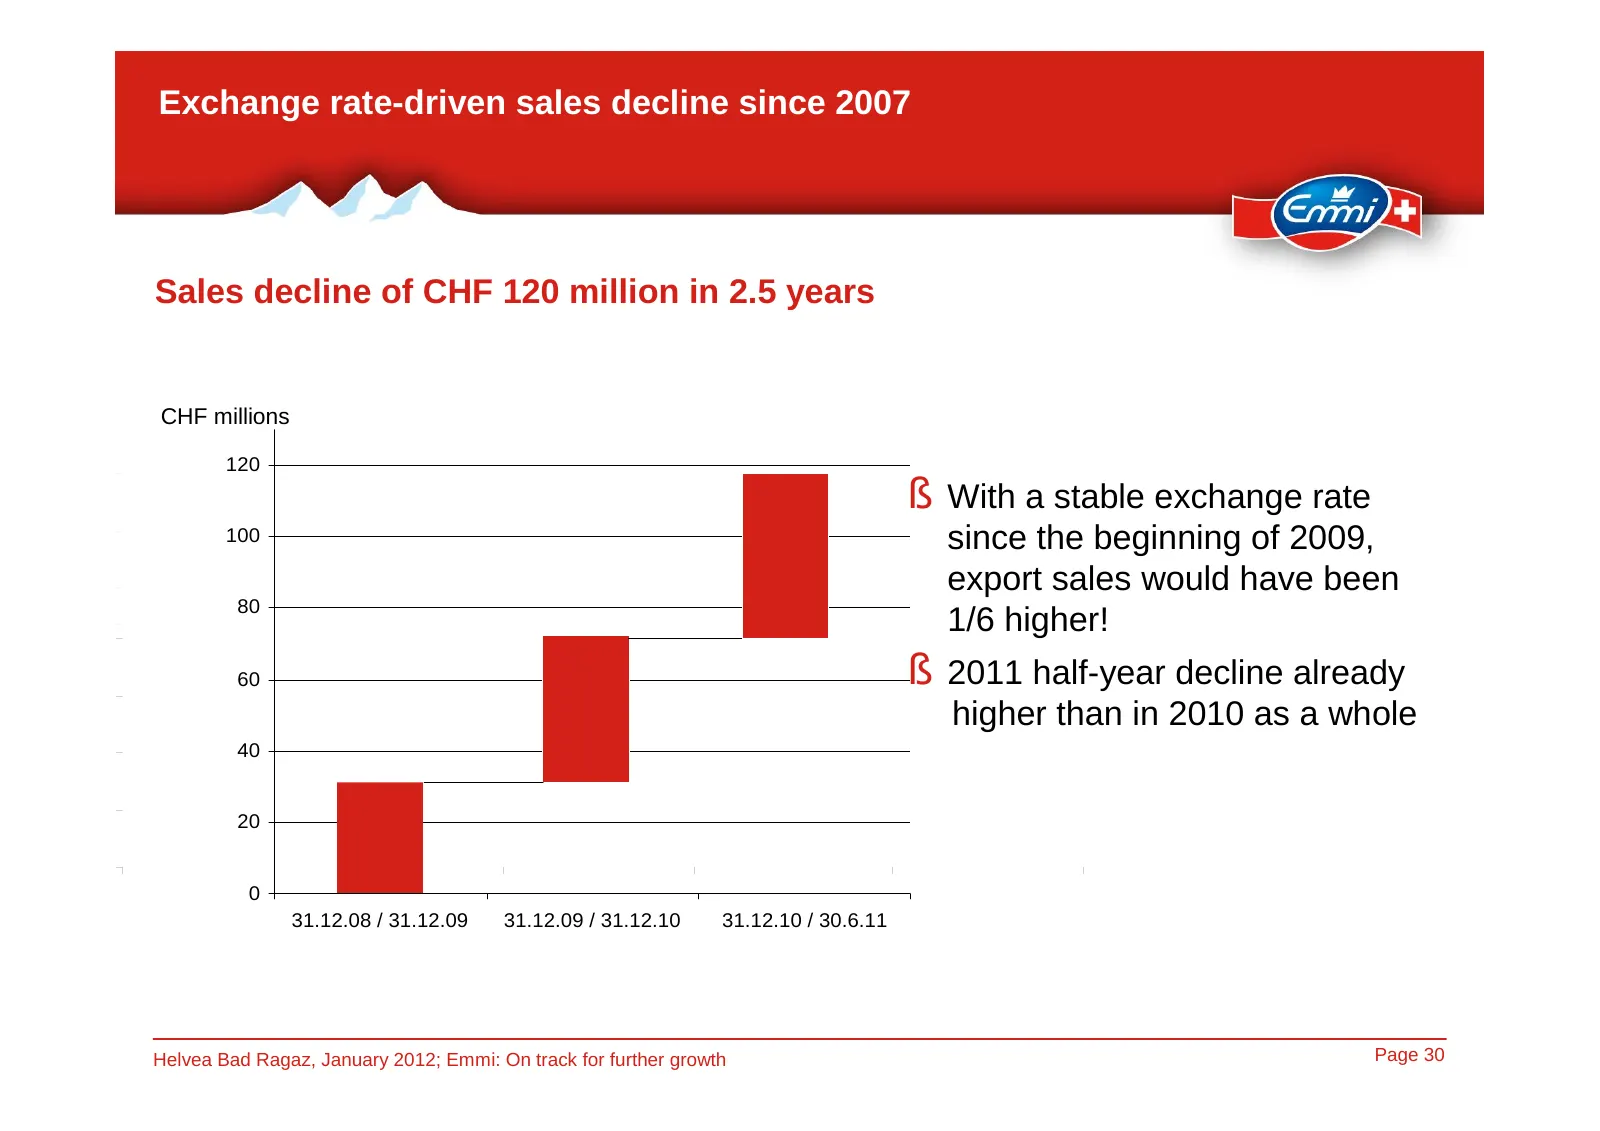
Slide 30: Exchange rate-driven sales decline since 2007
Exchange rate-driven sales decline since 2007 Sales decline of CHF 120 million in 2.5 years CHF millions 120 § With a stable exchange rate 100 since the beginning of 2009, export sales would have been 80 1/6 higher! 60 § 2011 half-year decline already higher than in 2010 as a whole 40 20 0 31.12.08
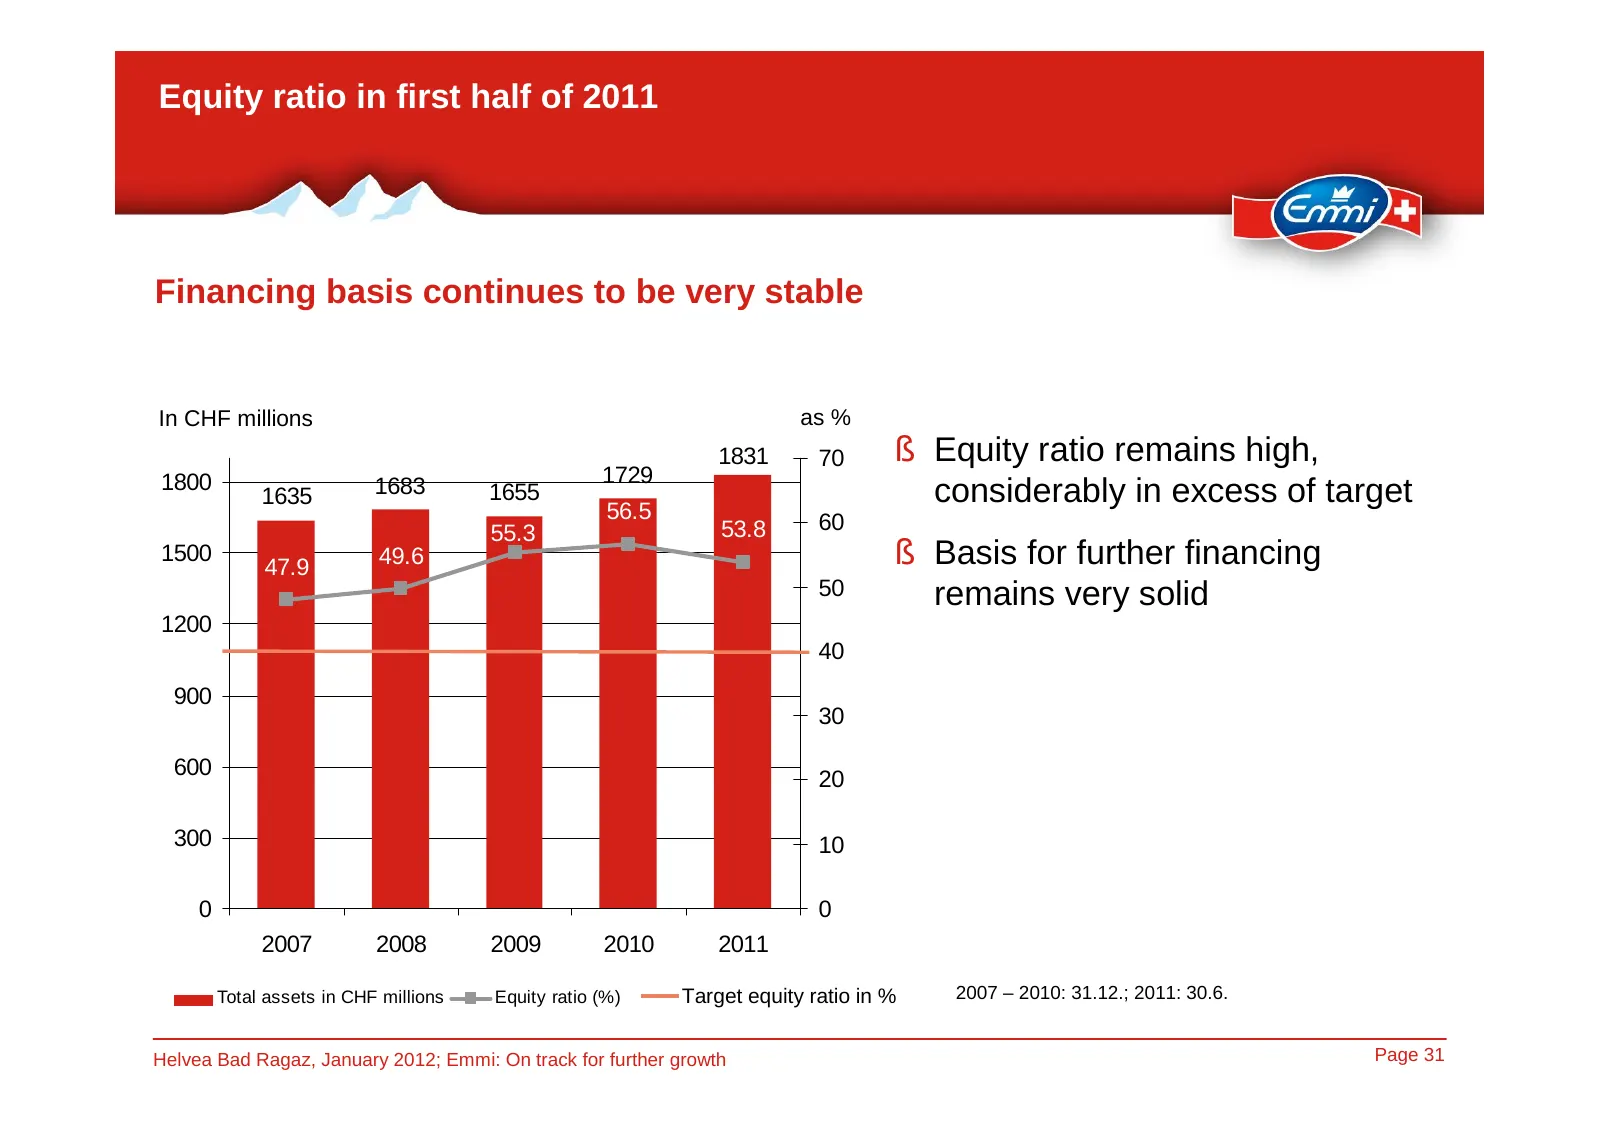
Slide 31: Equity ratio in first half of 2011
Equity ratio in first half of 2011 Financing basis continues to be very stable In CHF millions as % 1831 70 § Equity ratio remains high, 1800 1683 1729 1635 1655 considerably in excess of target 56.5 60 55.3 53.8 1500 47.9 49.6 § Basis for further financing 50 remains very solid 1200 40 900 30 600 2
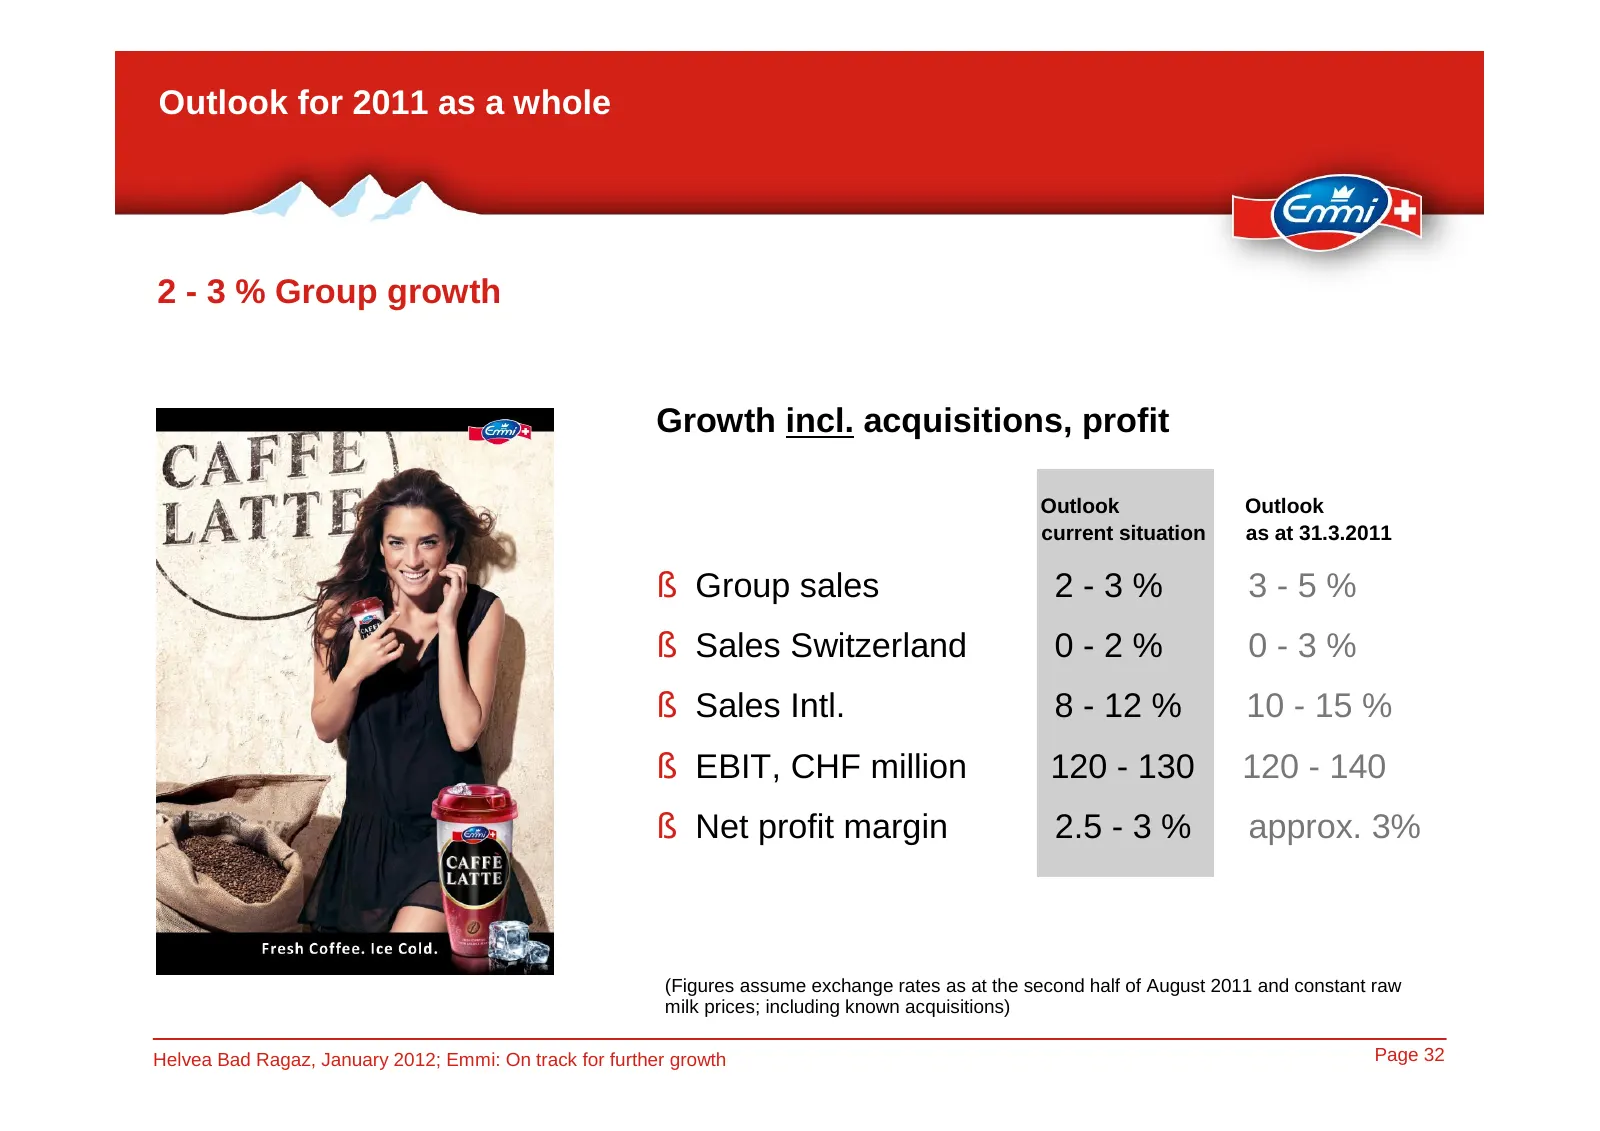
Slide 32: Outlook for 2011 as a whole
Outlook for 2011 as a whole 2 - 3 % Group growth Growth incl. acquisitions, profit Outlook Outlook current situation as at 31.3.2011 § Group sales 2-3% 3-5% § Sales Switzerland 0-2% 0-3% § Sales Intl. 8 - 12 % 10 - 15 % § EBIT, CHF million 120 - 130 120 - 140 § Net profit margin 2.5 - 3 % approx. 3%
Slide 33: Medium-term objectives
Medium-term objectives 2 – 3 % organic growth per year at Group level Growth without acquisitions, profit § Group sales 2–3% § Sales in Switzerland stable § International sales 6–8% § Net profit margin 2.5 – 3.5 % No change from outlook as per 25 March 2011 (Figures assume constant exchange rates an
Slide 34: Alpine skiing is the perfect fit for Emmi
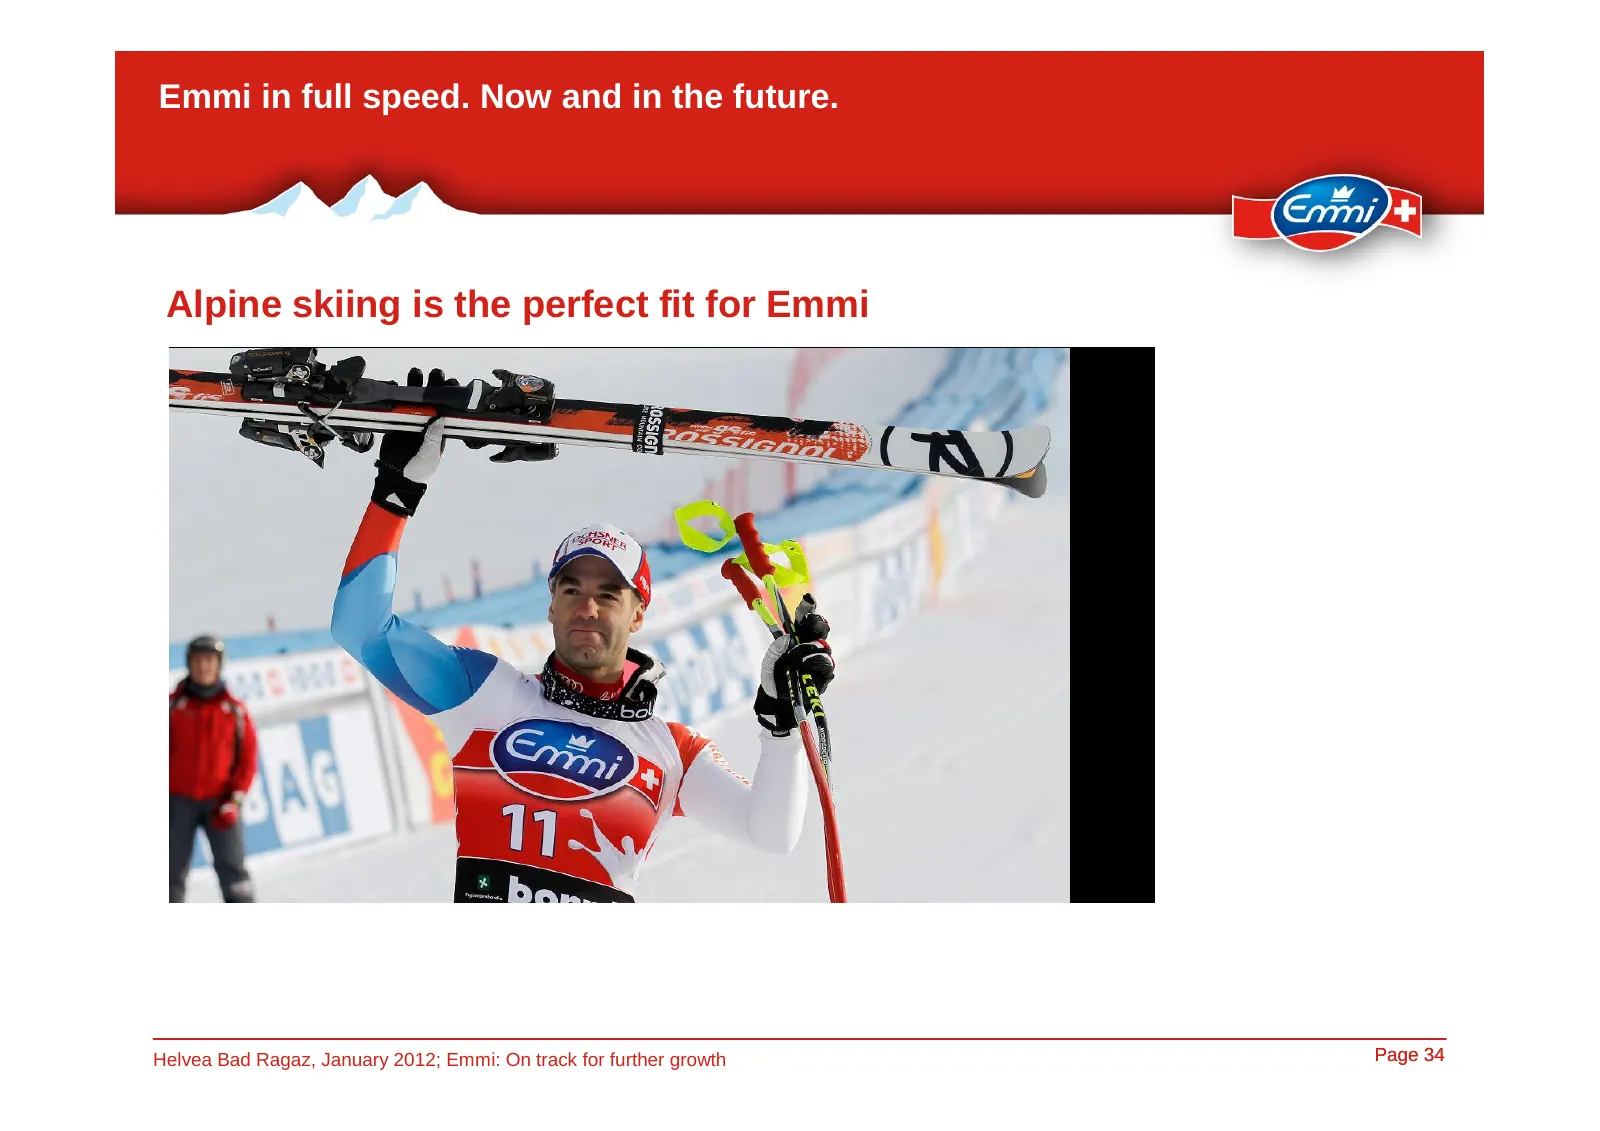
Emmi in full speed. Now and in the future. Alpine skiing is the perfect fit for Emmi Helvea Bad Ragaz, January 2012; Emmi: On track for further growth Page 34
Slide 35: Appendix 1: Sustainability
Das erste Flussigjogurt = der Schweiz
Slide 36: Sustainability is a high priority
Sustainability is a high priority Emmi’s first sustainability report § Emmi started its sustainability initiatives back in the early nineties § The sustainability report complies with the Global Reporting Initiative (GRI) standards (reporting level C+) § The report is available in German and English
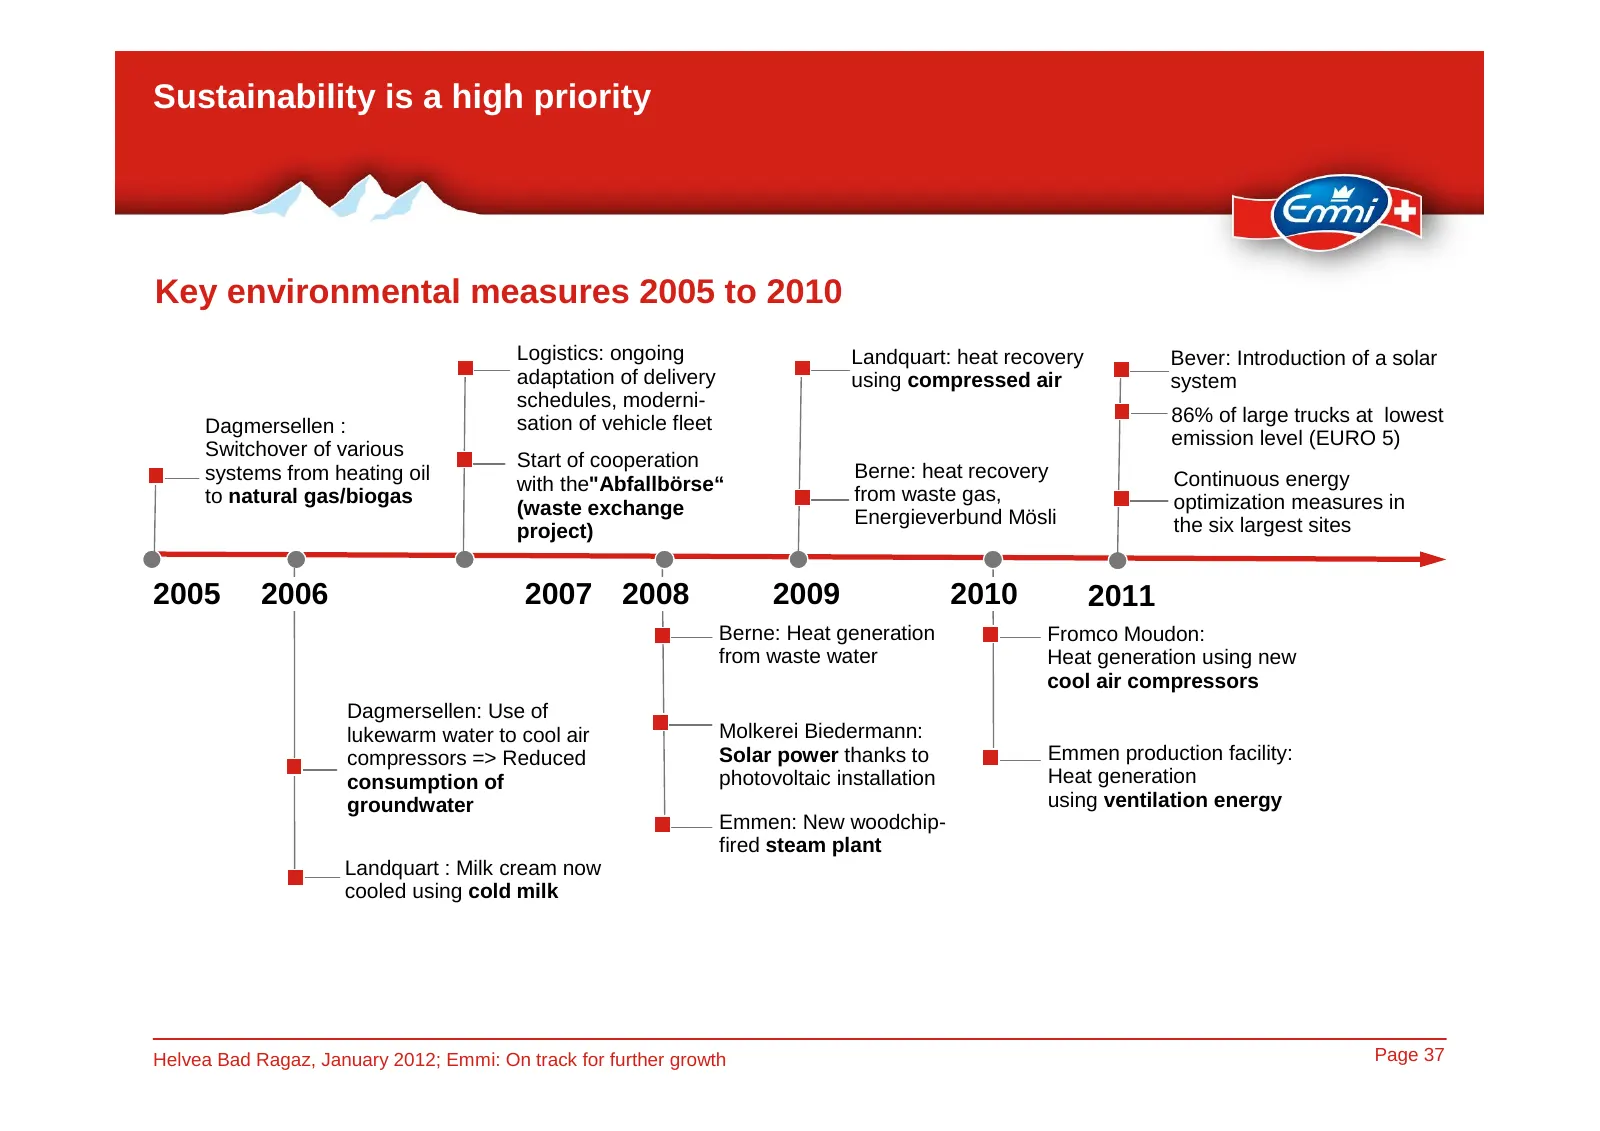
Slide 37: Key environmental measures 2005 to 2010
Sustainability is a high priority Key environmental measures 2005 to 2010 Logistics: ongoing Landquart: heat recovery Bever: Introduction of a solar adaptation of delivery using compressed air system schedules, moderni- sation of vehicle fleet 86% of large trucks at lowest Dagmersellen : emission le
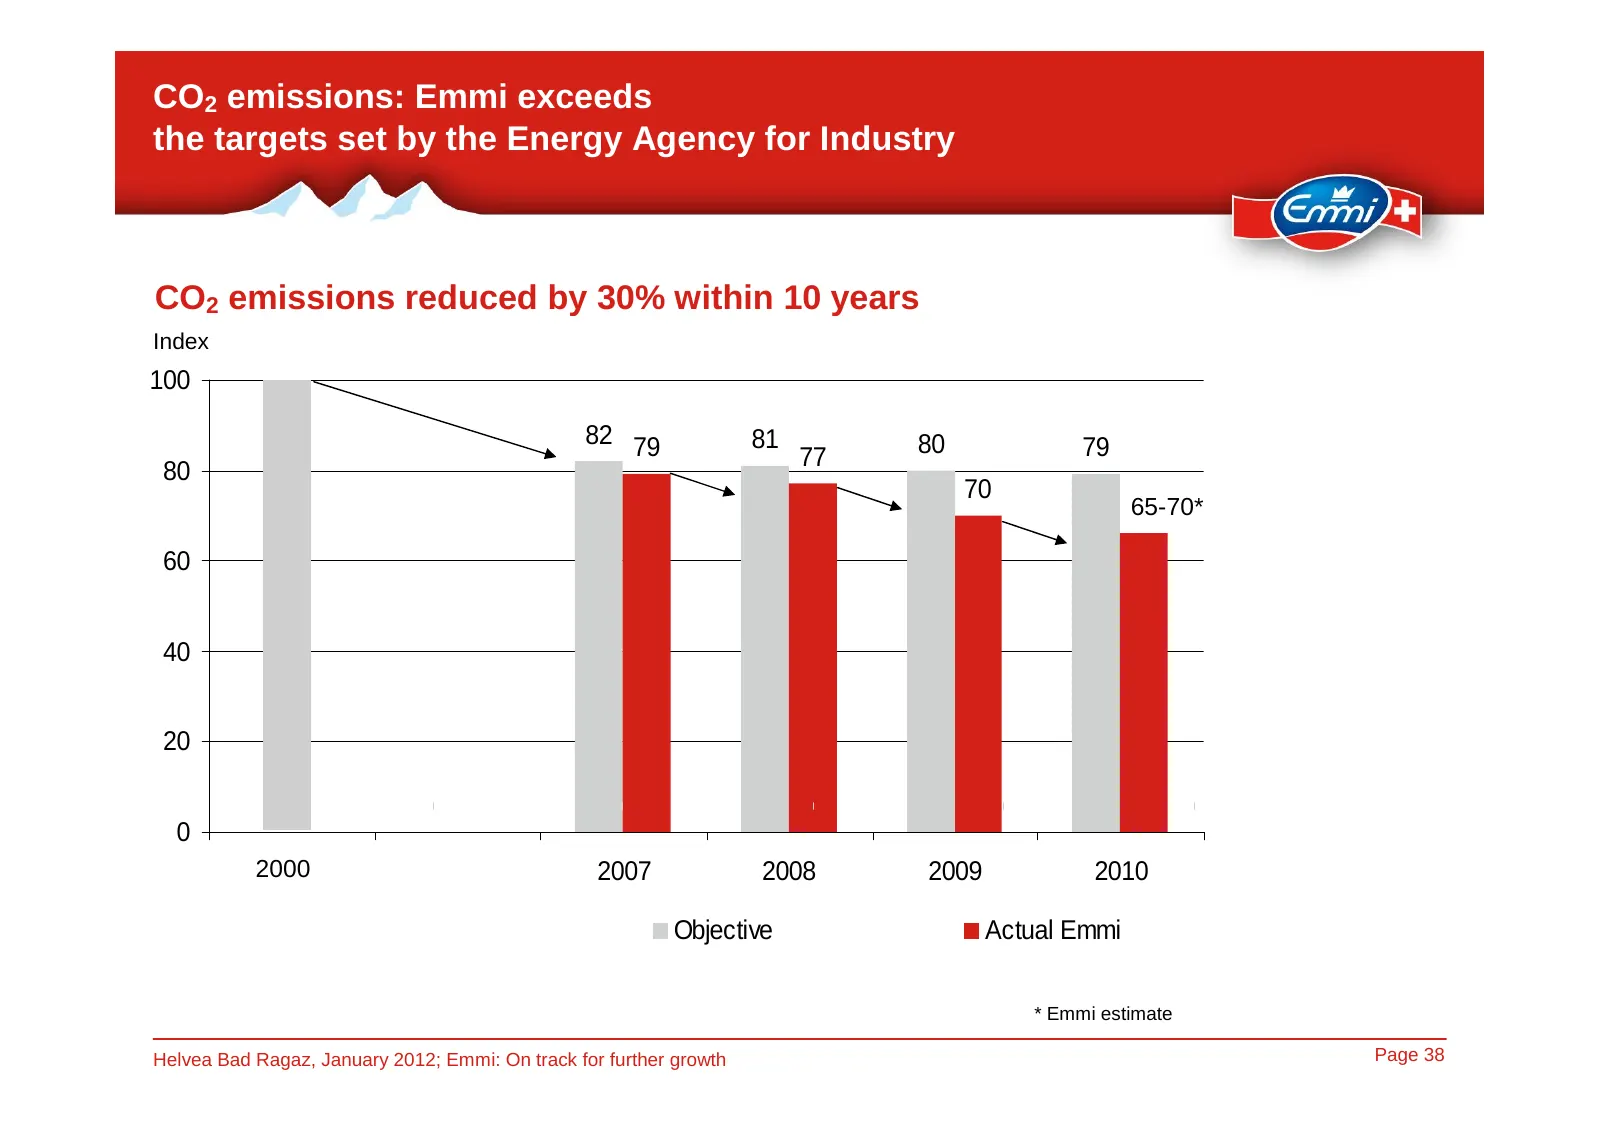
Slide 38: CO2 emissions: Emmi exceeds targets set by the Energy Agency
CO2 emissions: Emmi exceeds the targets set by the Energy Agency for Industry CO2 emissions reduced by 30% within 10 years Index 100 82 79 81 80 79 77 80 70 65-70* 60 40 20 0 2000 2007 2008 2009 2010 Objective Actual Emmi * Emmi estimate Helvea Bad Ragaz, January 2012; Emmi: On track for further gro
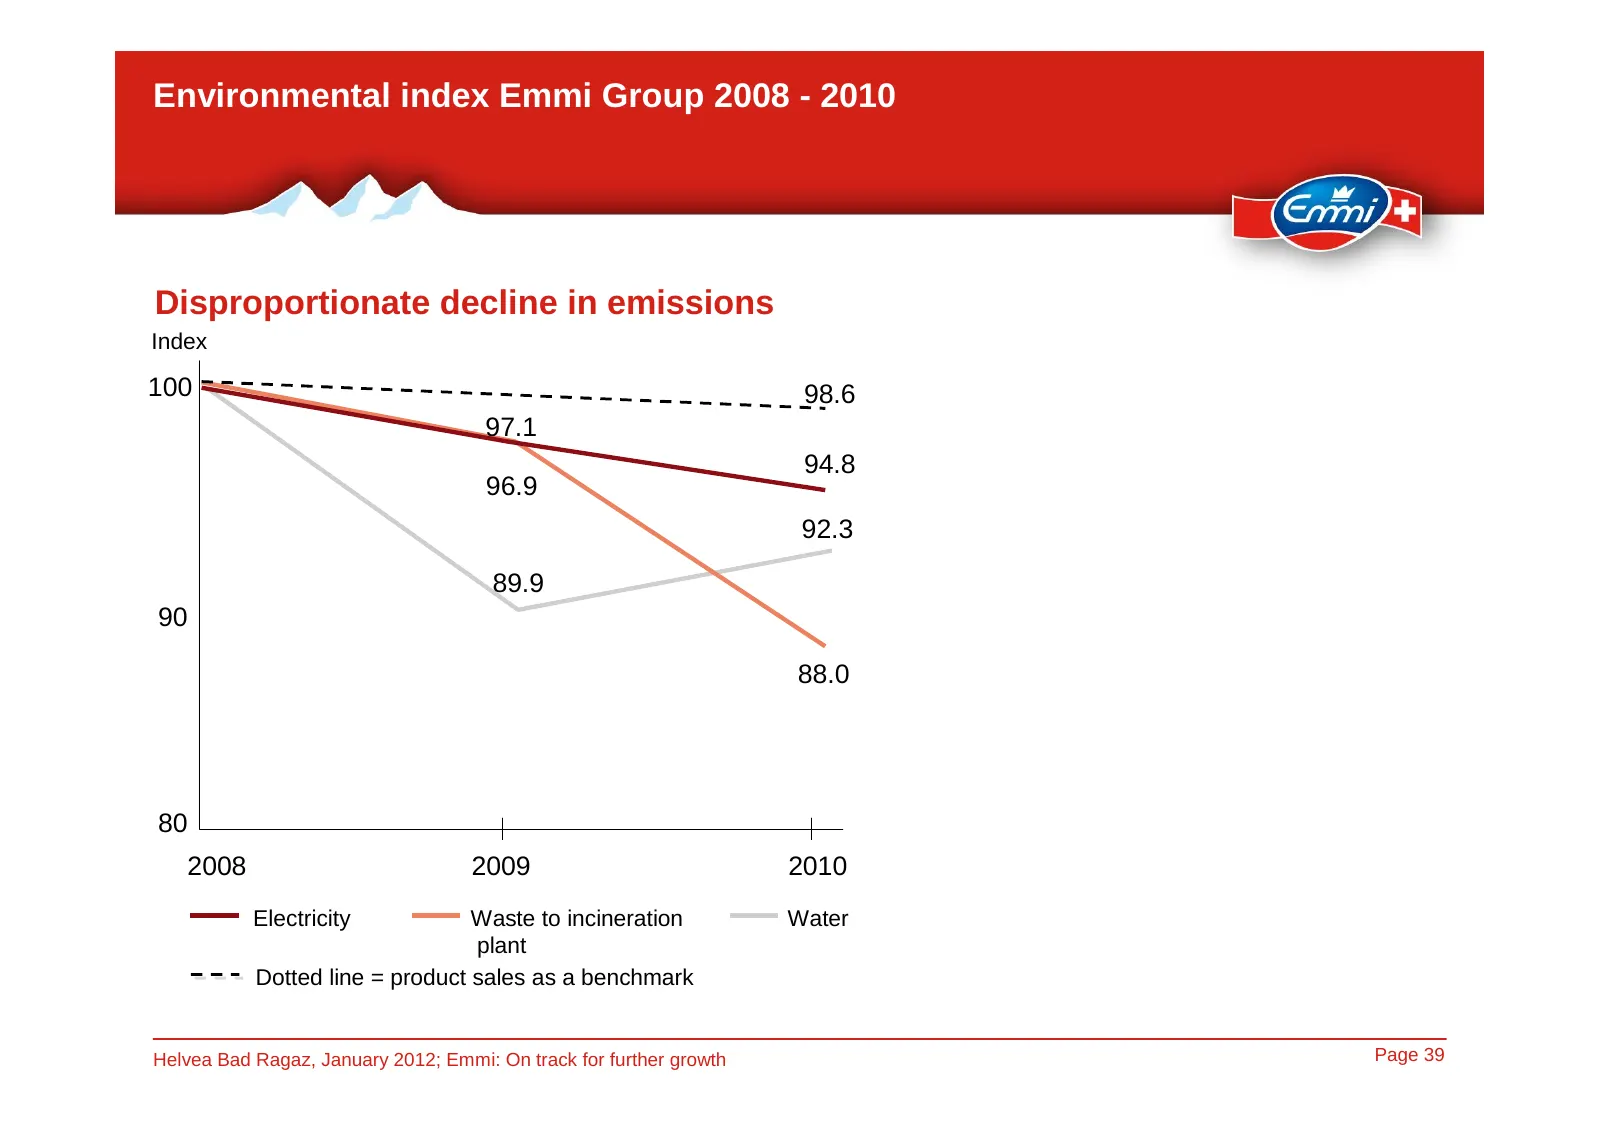
Slide 39: Environmental index Emmi Group 2008 - 2010
Environmental index Emmi Group 2008 - 2010 Disproportionate decline in emissions Index 100 98.6 97.1 94.8 96.9 92.3 89.9 90 88.0 80 2008 2009 2010 Electricity Waste to incineration Water plant Dotted line = product sales as a benchmark Helvea Bad Ragaz, January 2012; Emmi: On track for further growt
Slide 40: Appendix 2: Market background
Appendix 2: Market background
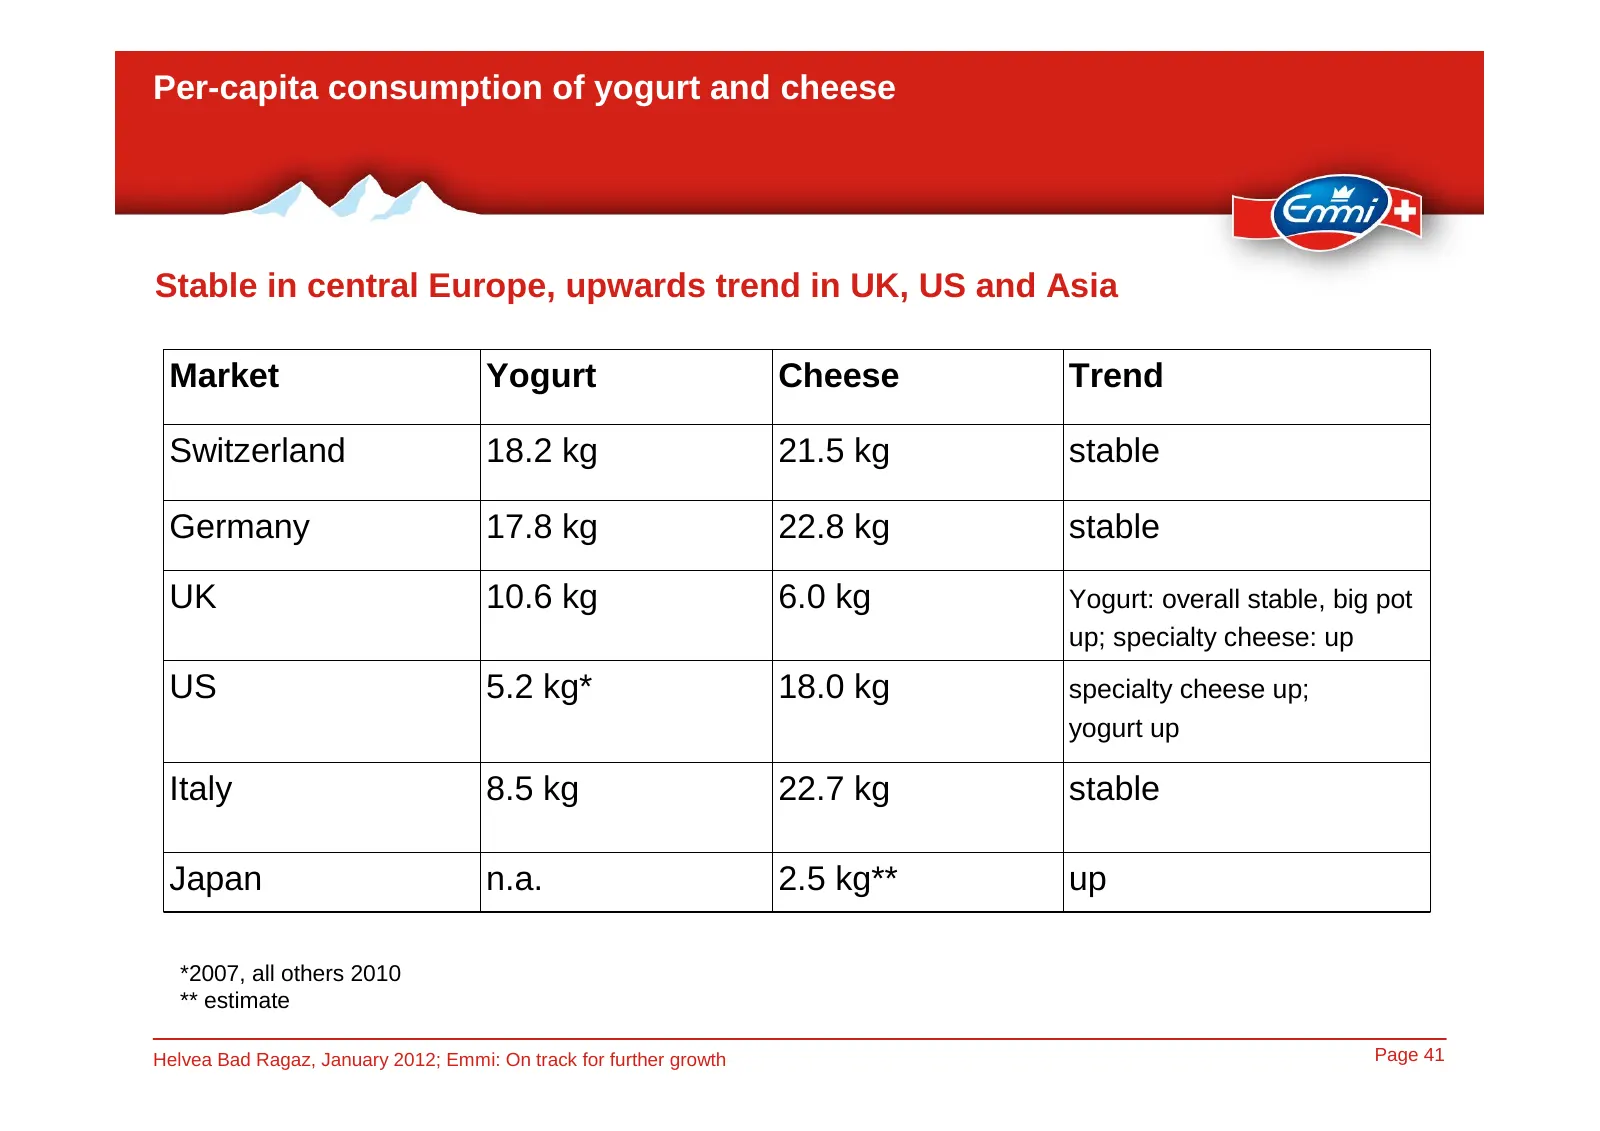
Slide 41: Per-capita consumption of yogurt and cheese
Per-capita consumption of yogurt and cheese Stable in central Europe, upwards trend in UK, US and Asia Market Yogurt Cheese Trend Switzerland 18.2 kg 21.5 kg stable Germany 17.8 kg 22.8 kg stable UK 10.6 kg 6.0 kg Yogurt: overall stable, big pot up; specialty cheese: up US 5.2 kg* 18.0 kg specialty
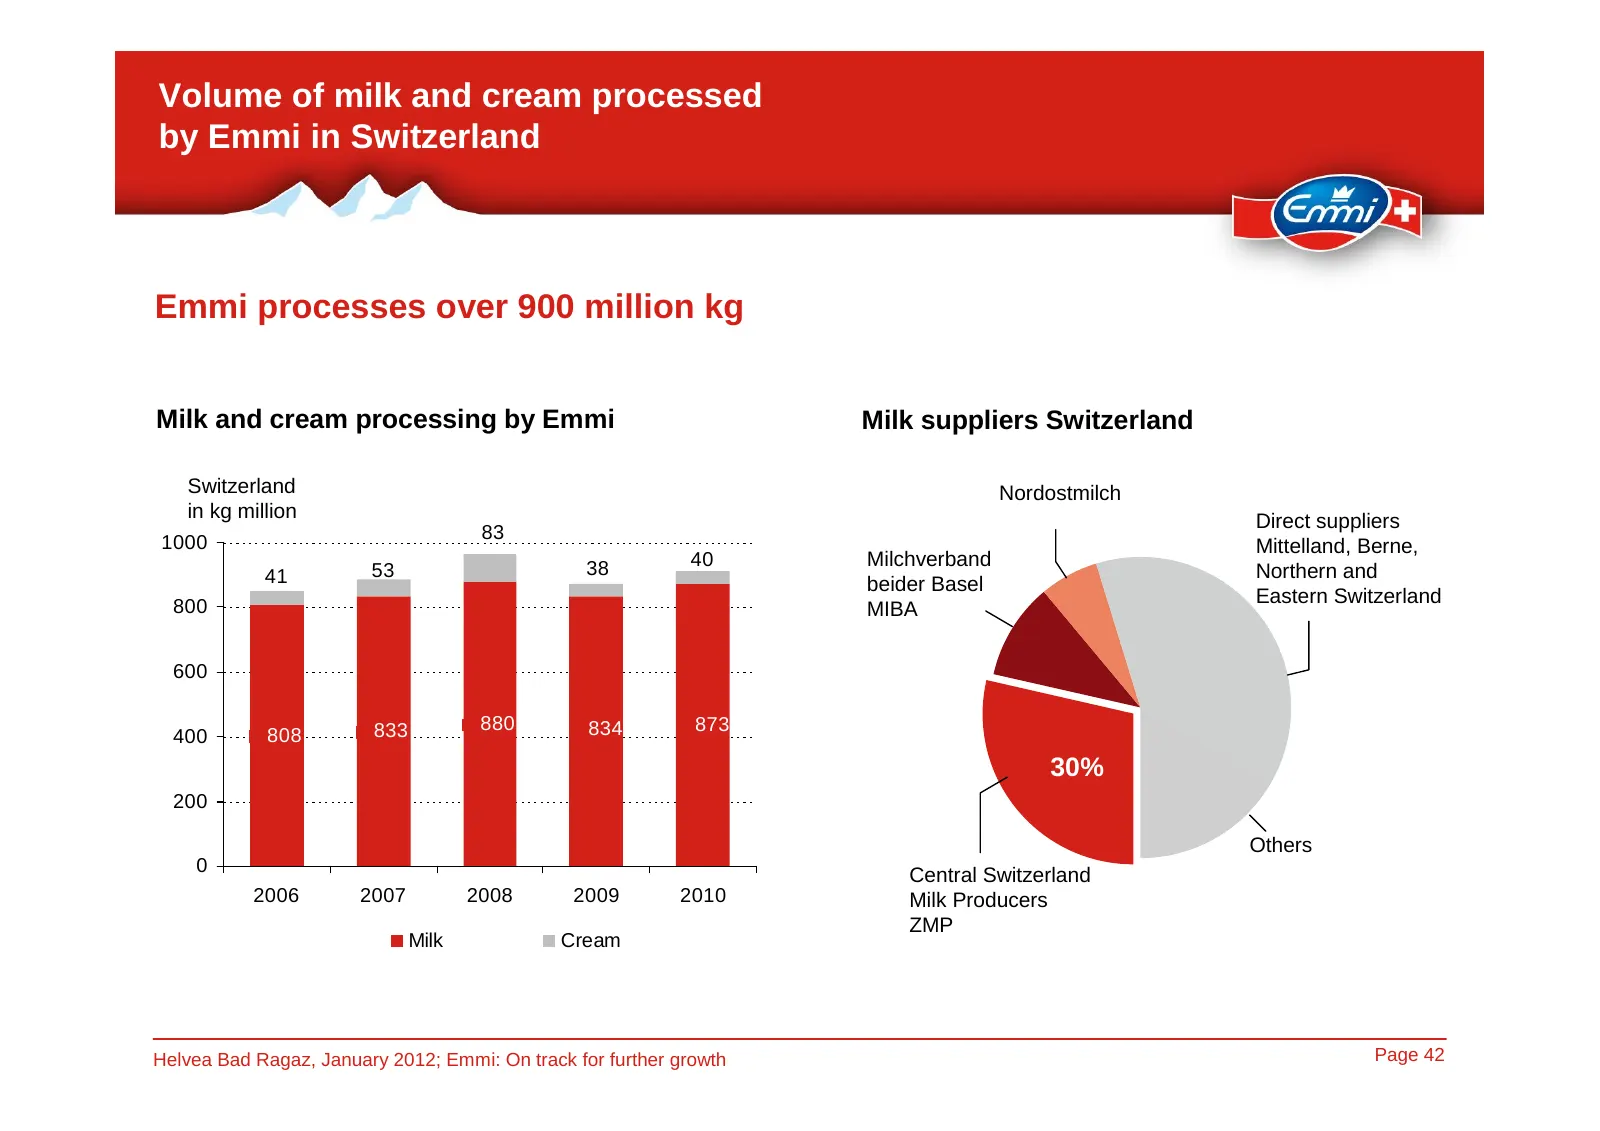
Slide 42: Volume of milk and cream processed by Emmi in Switzerland
Volume of milk and cream processed by Emmi in Switzerland Emmi processes over 900 million kg Milk and cream processing by Emmi Milk suppliers Switzerland Switzerland Nordostmilch in kg million Direct suppliers 1000 83 Mittelland, Berne, 38 40 Milchverband 41 53 Northern and beider Basel 800 Eastern
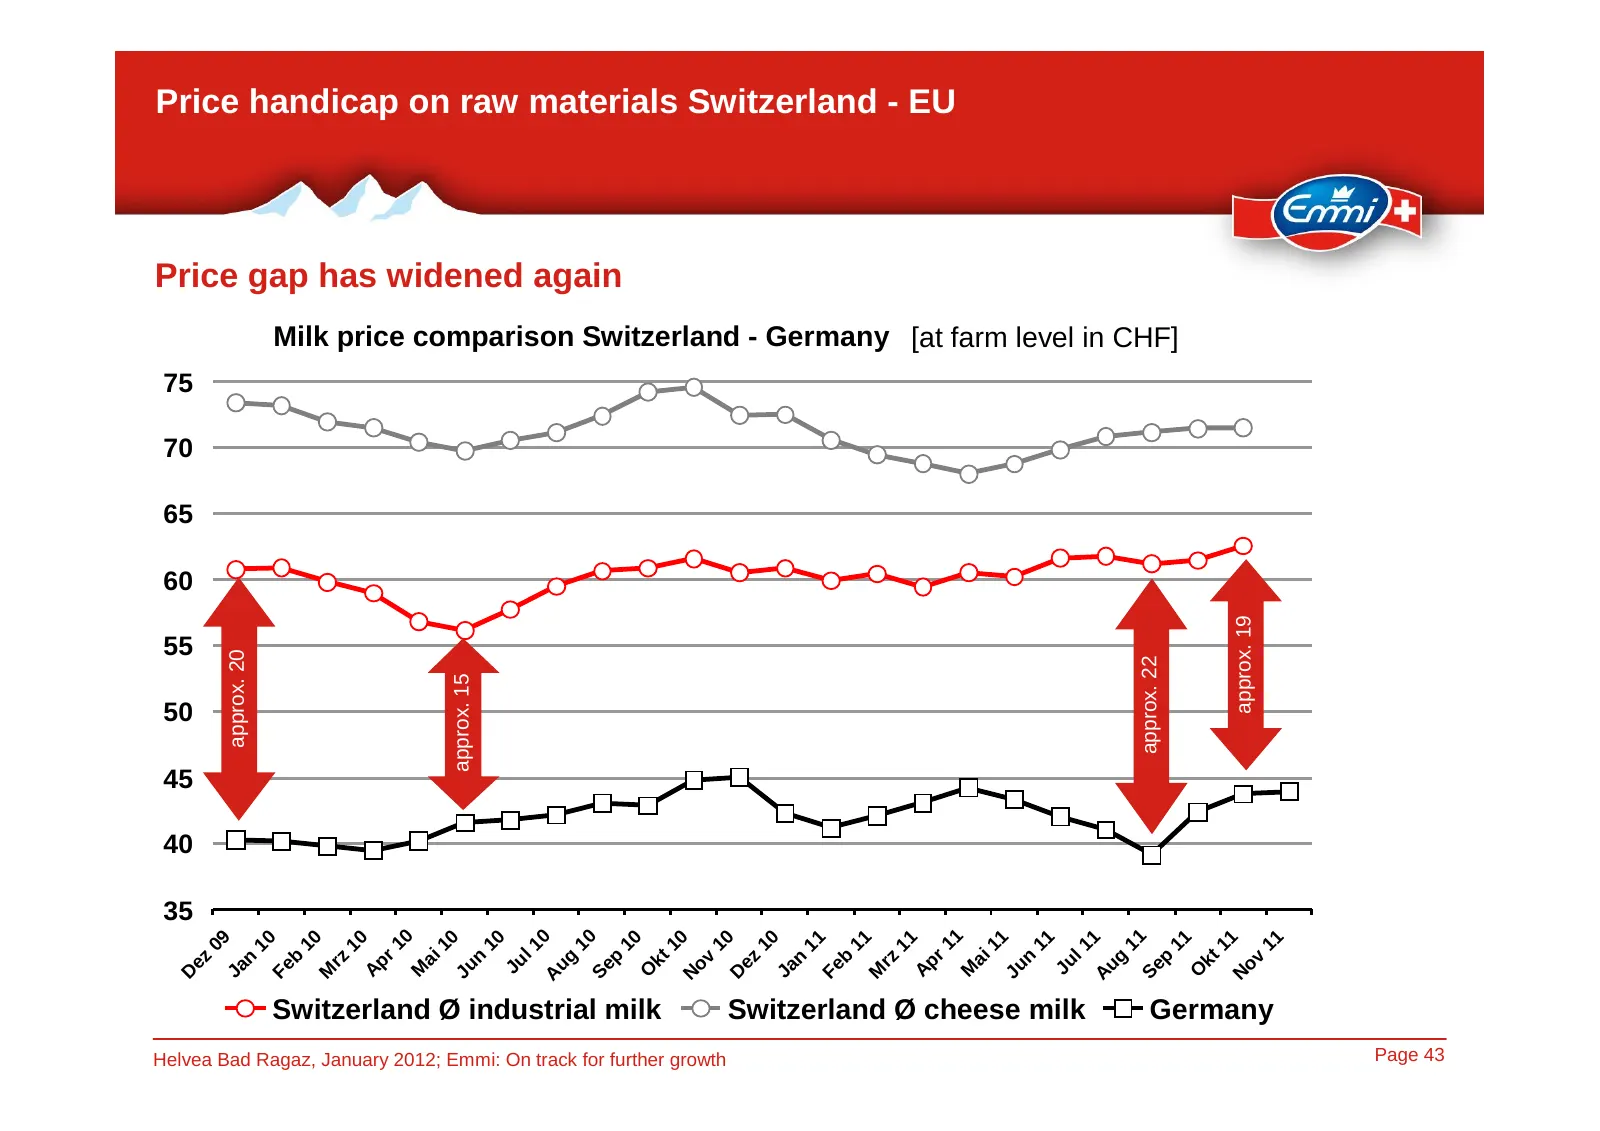
Slide 43: Price handicap on raw materials Switzerland - EU
Price handicap on raw materials Switzerland - EU Price gap has widened again Milk price comparison Switzerland - Germany [at farm level in CHF] 75 70 65 60 approx. 19 55 approx. 20 approx. 22 approx. 15 50 45 40 35 10 1 11 10 Au 0 10 11 10 11 Au 1 N 0 N 1 10 11 09 10 10 10 11 11 10 11 10 11 r1 1 1 l
Source: Internet Archive copy of group.emmi.com
More decks from Emmi AG
 Swiss Equities Conference 202637 slides · Jan 14, 2026
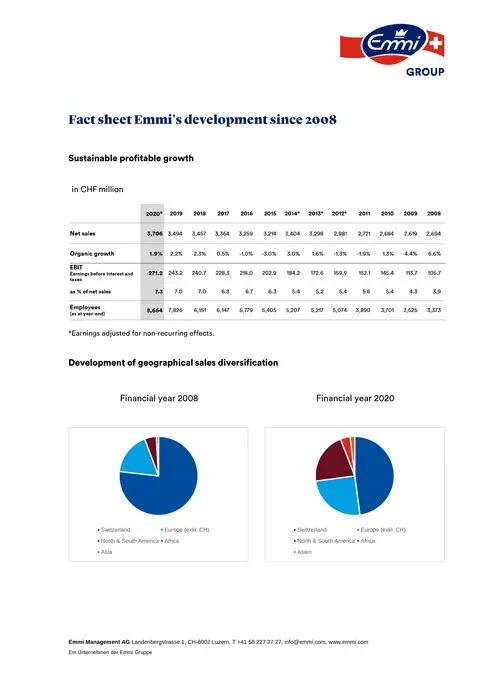 Fact Sheet (September 2021)4 slides · Sep 9, 2021
 FY2016 Earnings Presentation48 slides · Mar 22, 2017
 H1 2016 Earnings Presentation32 slides · Aug 23, 2016
 Emmi Gruppe — FY2015 Earnings Presentation54 slides · Mar 24, 2016
 Investor Day (November 2015)15 slides · Nov 3, 2015