SI Financial — Investor Presentation (May 2011)
30 slides from SI Financial's investor presentation, May 5, 2011
Slide 1: Investor Presentation
Investor Presentation May 5, 2011
Slide 2: Forward Looking Statements
Forward Looking Statements This presentation contains forward-looking statements, which can be identified by the use of words such as “believes,” “expects,” “anticipates,” “estimates” or similar expressions. These forward-looking statements include, but are not limited to: u statements of our goals,
Slide 3: Use of Non-GAAP Financial Measures
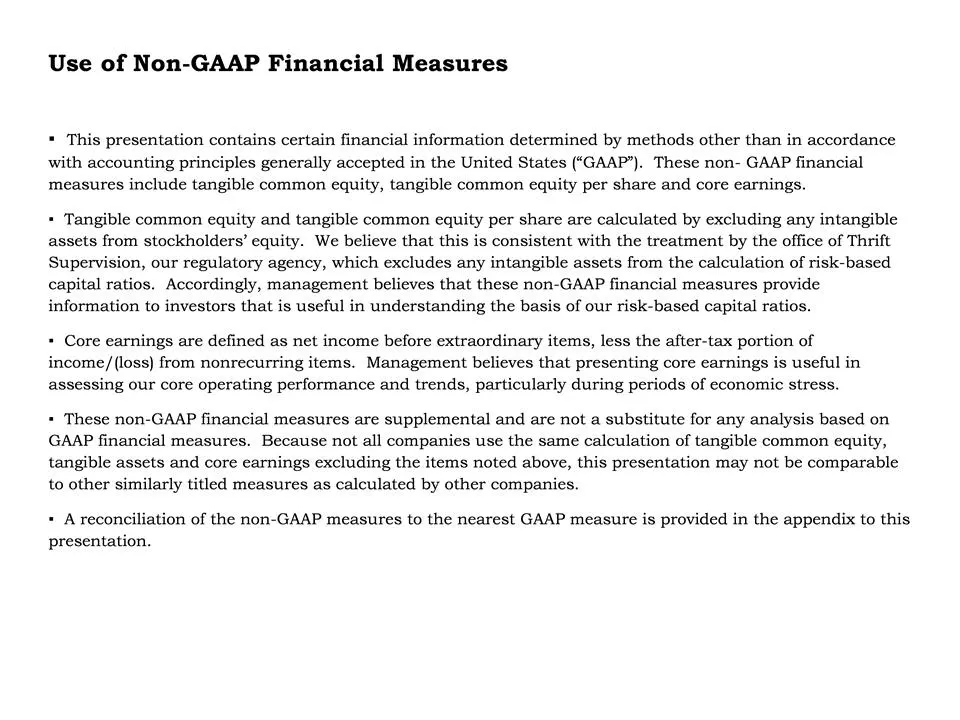
Use of Non-GAAP Financial Measures * This presentation contains certain financial information determined by methods other than in accordance with accounting principles generally accepted in the United States (“GAAP”). These non- GAAP financial measures include tangible common equity, tangible common
Slide 4: Market Summary as of 05/02/11
Issuer: SI Financial Group, Inc. Listing / Ticker: Nasdaq Global Market / “SIFI” Market Price Per Share: $9.95 Shares Outstanding: 10,576,302 Market Capitalization: $105.2 million Tangible Book Value Per Share: $11.80 Price to Tangible Book Value: 84.3% Dividend Yield: 1.2% Market Summary as of 05/0
Slide 5: Company Overview
Company Overview
Slide 6: Company History
Company History u Headquartered in Willimantic, CT u Established in 1842 u Total assets in 1995: $252 million u Total assets at 3/31/11: $929 million
Slide 7: Experienced Management Team
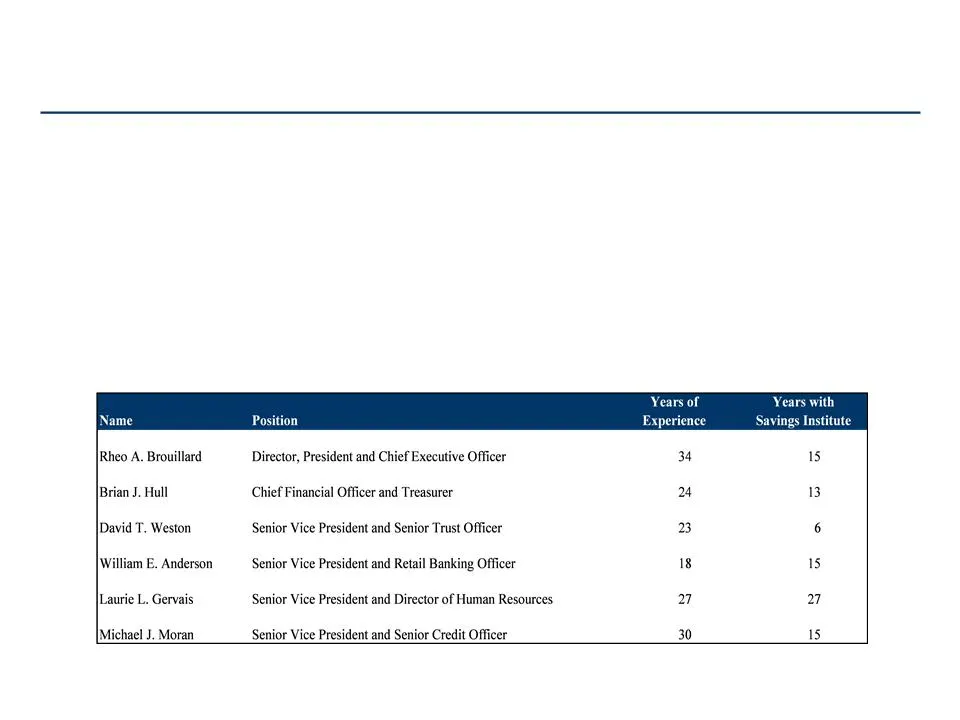
Experienced Management Team u Savings Institute’s management team is comprised of experienced individuals that have operated through various credit cycles and have executed the Bank’s growth strategy u 156 years of Banking Experience, 91 years at SIBT u CEO, CFO and SCO with 88 years of commercial b
Slide 8: Company Profile
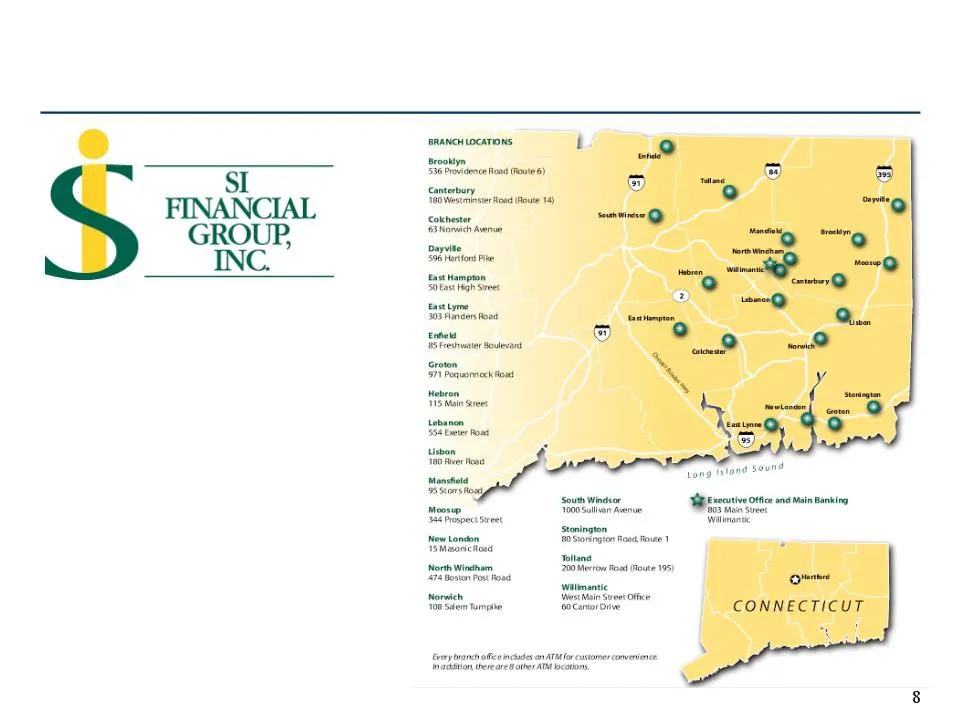
Company Profile Headquartered in Willimantic, CT, SI Financial reorganized to a two-tier mutual holding company in 2000 and sold a minority interest in 2004. In 2011, SI Financial completed their 2nd step conversion. As of December 31, 2010 / March 31, 2011 : u Total assets: $926.4 M / $929.4 M u To
Slide 9: Market Area Overview
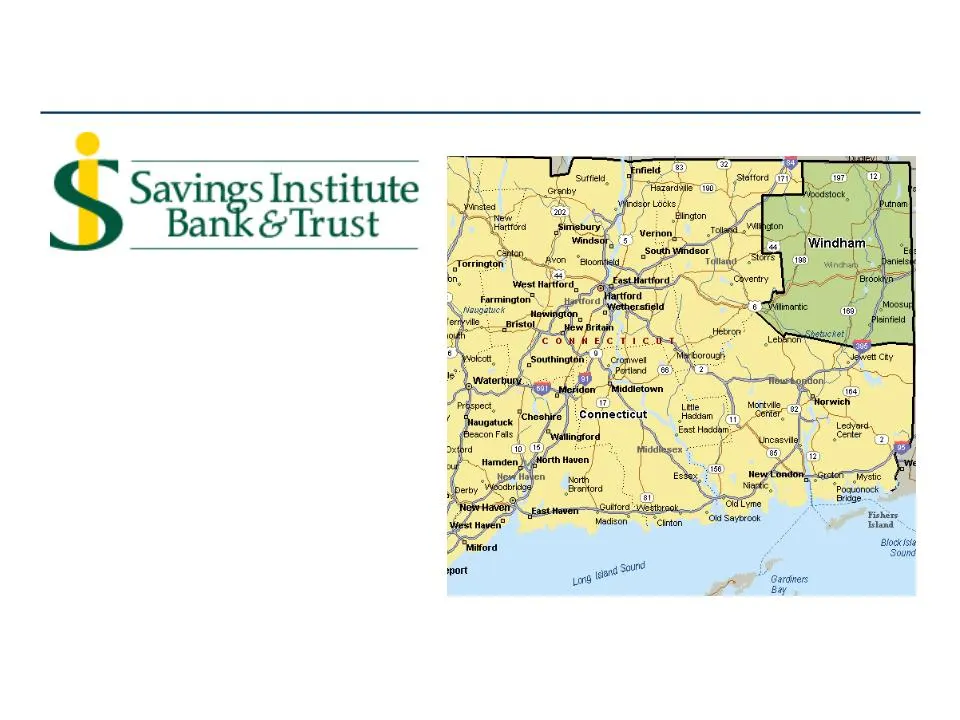
Market Area Overview u Savings Institute operates 21 full-service community banking locations in Windham, New London, Tolland, Hartford and Middlesex counties in Connecticut u 30 miles east of Hartford, Connecticut u Diverse economy primarily oriented to the educational, service, entertainment, manu
Slide 10: Market Area Presence
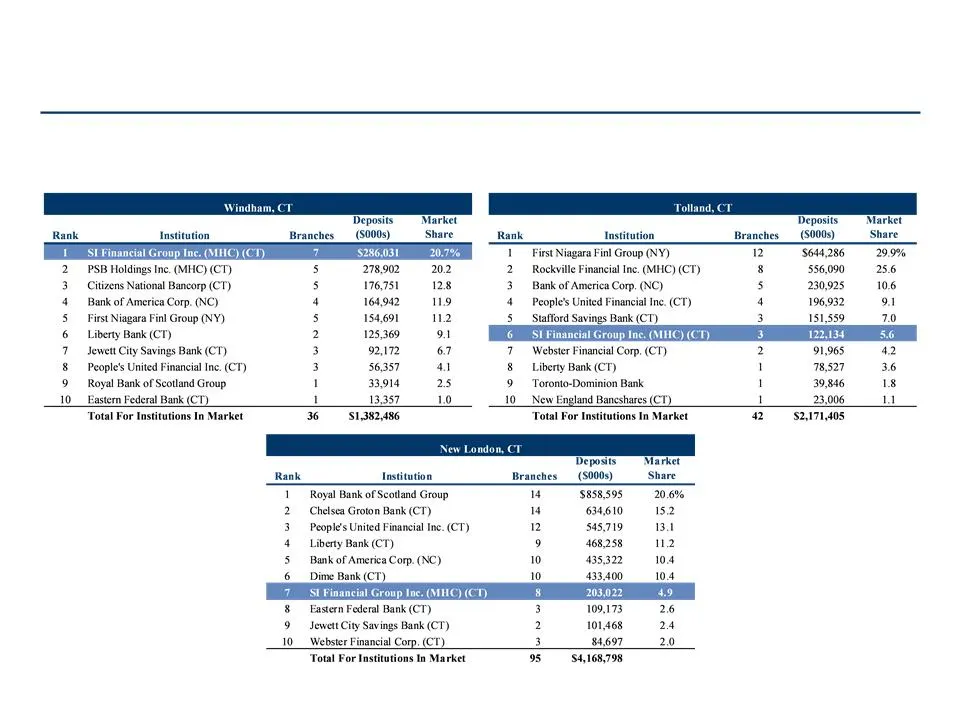
Market Area Presence u Savings Institute is among the top 10 banks by market share in 3 of the 5 counties in which it does business Source: FDIC. Data as of 6/30/10.
Slide 11: Business Strategy
Business Strategy u Continue community oriented focus by offering a full range of financial products and services to its customers u Optimize future growth opportunities by executing a proven business model and by seeking acquisition opportunities in areas in or adjacent to existing market area u Ac
Slide 12: Acquisition Opportunities
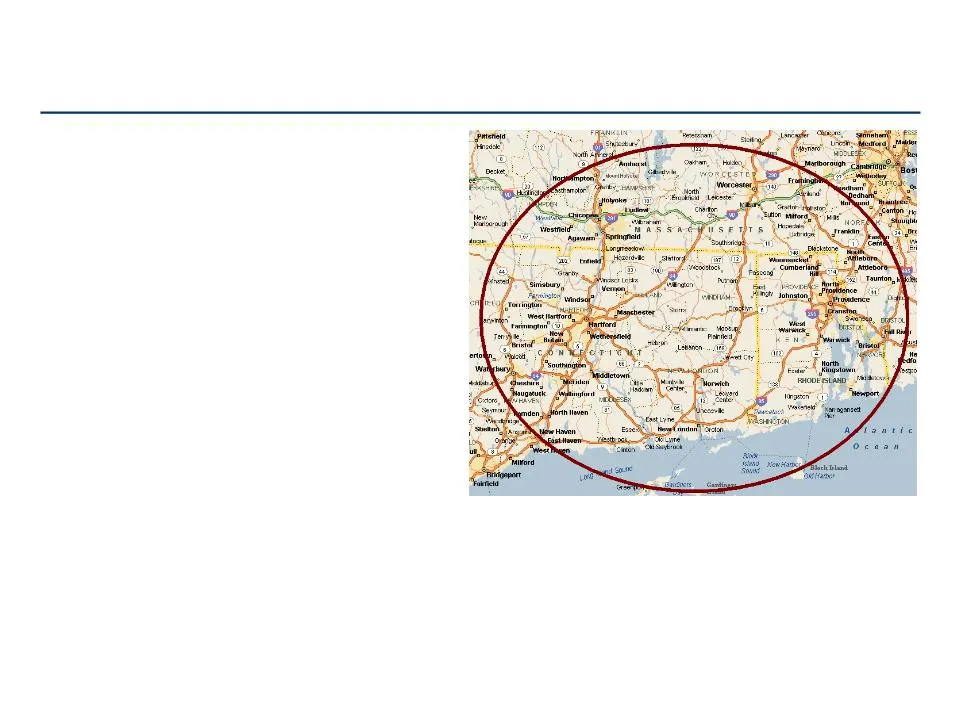
Acquisition Opportunities u In Connecticut, Rhode Island and Massachusetts there are approximately 26 public and private banks and thrifts with assets between $100 million and $500 million u 11 are de novo u 4 have TARP outstanding u 2 have Texas ratios of greater than 50%* u On a selective basis Sa
Slide 13: Financial Highlights
Financial Highlights
Slide 14: Franchise Growth
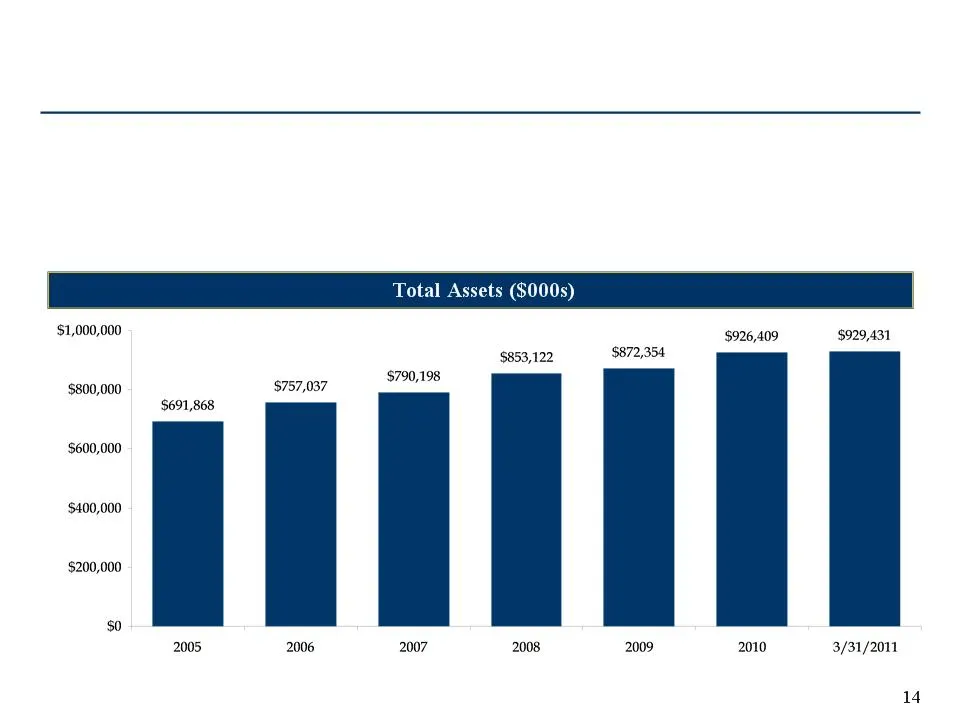
Franchise Growth u Savings Institute has grown organically and through acquisitions, resulting in an asset CAGR from 2005 to 2010 of 6.0% u Since 2005 has acquired 2 branches, opened 4 branches and relocated or renovated 6 existing branches, expanding market presence in Tolland, New London, Hartford
Slide 15: Diversified Loan Portfolio
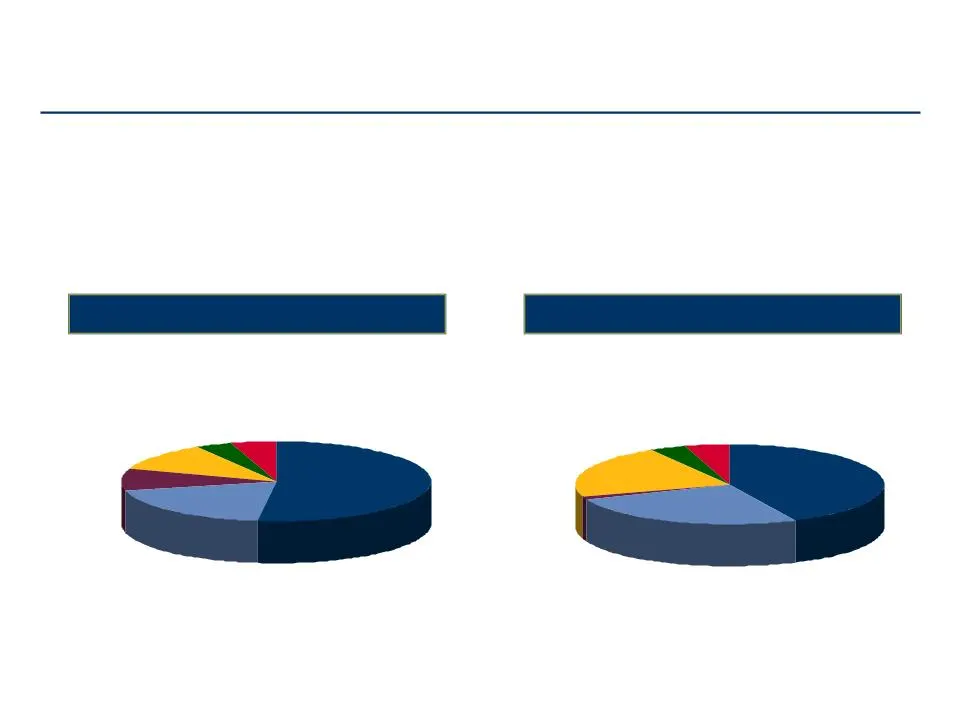
At March 31, 2011 At December 31, 2005 Diversified Loan Portfolio u Savings Institute has diversified its portfolio mix by increasing commercial real estate, multi-family and commercial business lending while maintaining prudent underwriting practices u Increased focus on SBA and USDA guaranteed com
Slide 16: Commercial Loan Concentrations
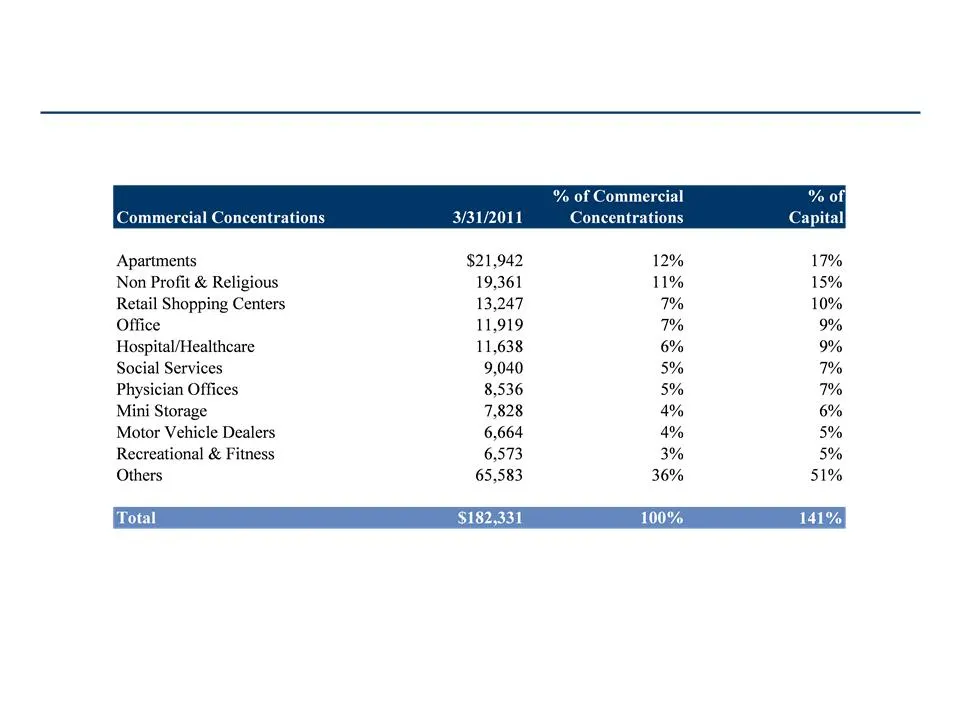
Commercial Loan Concentrations Commercial loan concentration includes CRE, Multi-family and C&I loans Dollars in thousands
Slide 17: Asset Quality Trends
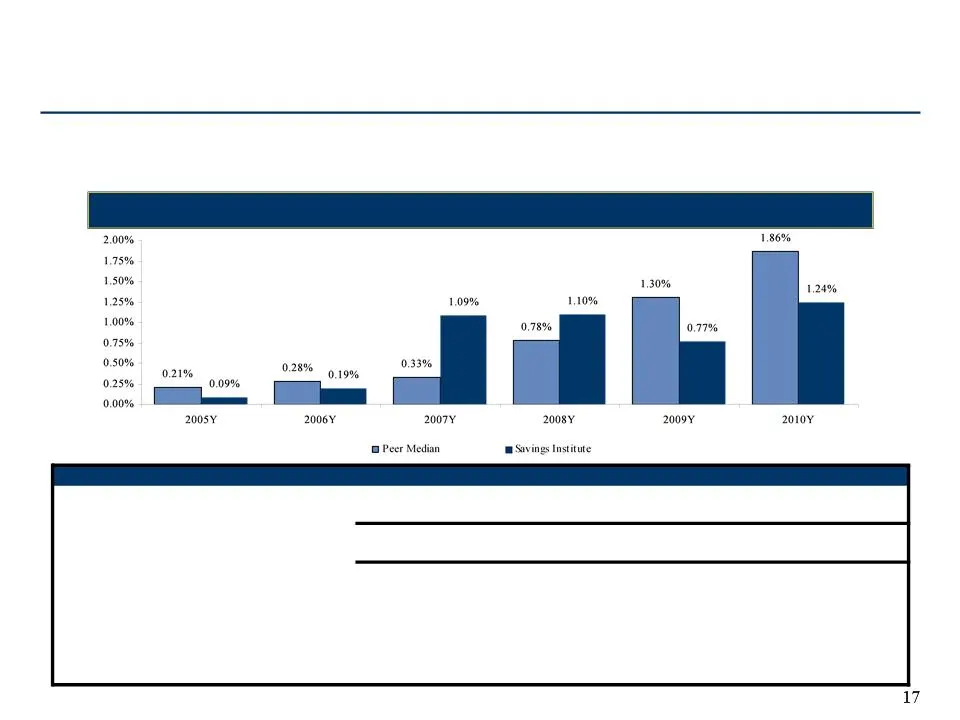
NPAs and TDRs/Assets 2005 2006 2007 2008 2009 2010 3/31/2011 Asset Quality Trends u Savings Institute has maintained high asset quality with solid reserve coverage u Aggressive early recognition of nonperforming loans Peer group comprised of all publicly traded banks and thrifts in Connecticut. Tota
Slide 18: Non Performing Asset Breakdown
30-59 days 60-89 days Non At 3/31/11 Accruing Accruing Accrual OREO Total $3,306 $13 $6,173 $830 Non Performing Asset Breakdown Dollars in thousands 1-4 Family Residential $2,417 $11 $4,079 $190 CRE and Multi-family 1,992 Other Commercial Home Equity Other Consumer Excludes Purchased SBA/USDA Loans
Slide 19: Securities Portfolio
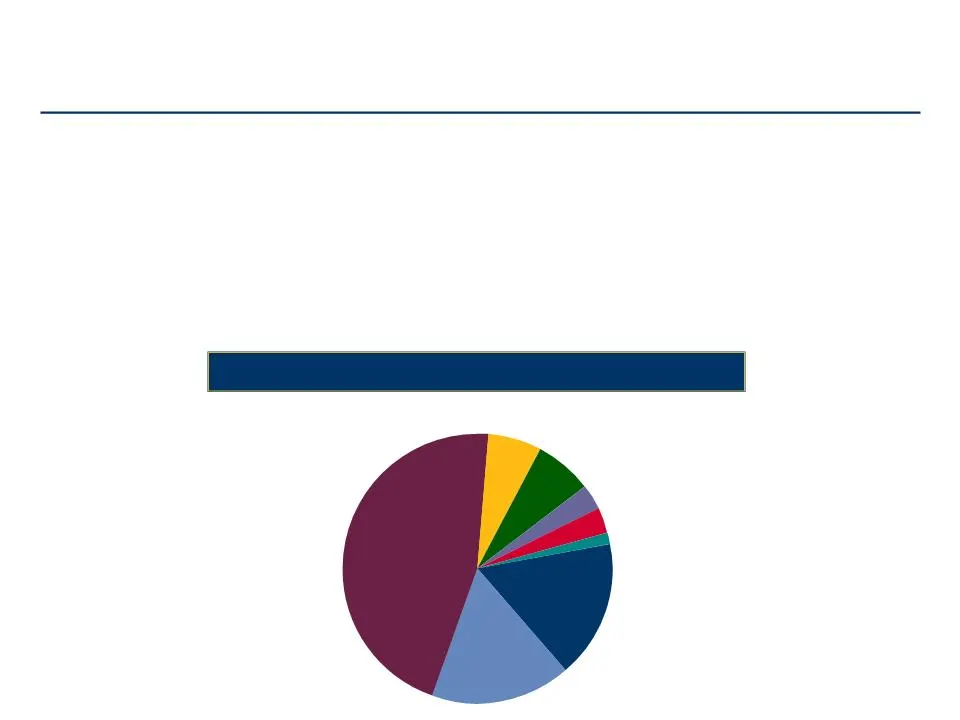
March 31, 2011 Securities Portfolio u Savings Institute maintains a diversified securities portfolio totaling $217 million as of March 31, 2011 u Savings Institute has previously taken $2.3 million in OTTI charges on 3 pooled trust preferred securities and one non agency MBS u Savings Institute perf
Slide 20: Deposit Mix
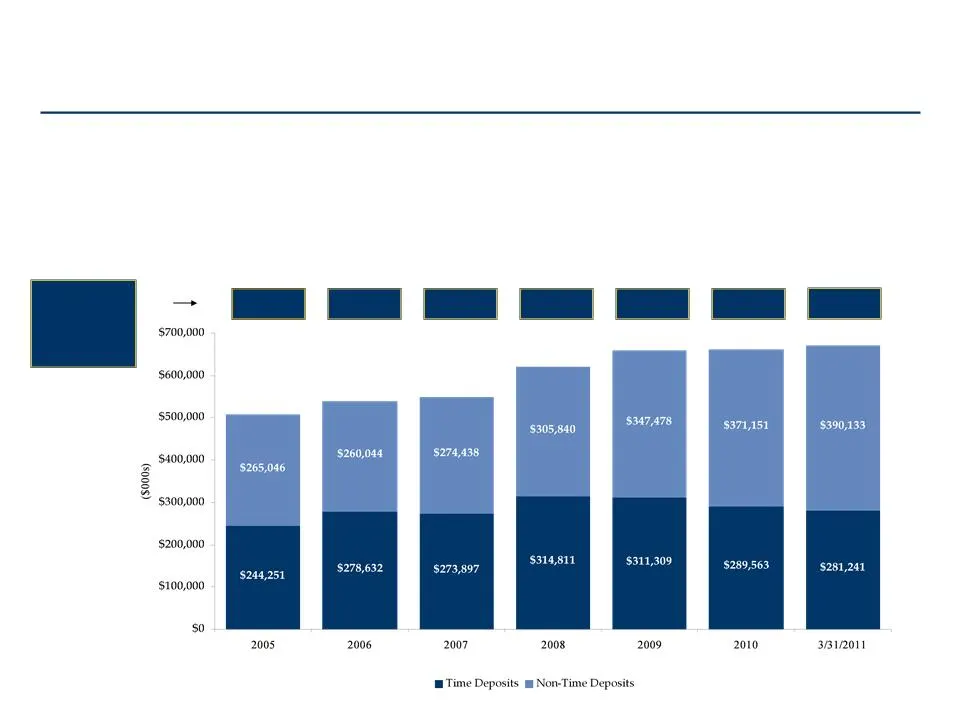
Cost of Interest Bearing Deposits 1.98% 2.74% 3.19% 2.85% 2.25% 1.55% 1.28% Deposit Mix u Savings Institute has grown deposits and emphasized the growth of core deposits through investments to its branch network, new product offerings and attracting commercial deposits from small and medium size bus
Slide 21: Electronic Banking
Electronic Banking Transactions at SIBT ATMs 195,229 190,790 Debit Signature Transactions 466,042 513,614 Debit POS/ATM Transactions 522,519 555,505 On Line Bill Pay Transactions 78,954 82,292 eStatement Accounts 7,796 9,524 Consumer Online Customers 10,989 13,021 Business Online Customers
Slide 22: Mortgage Banking
Mortgage Banking Dollars in thousands u Savings Institute has recently started selling mortgage loans but has been retaining the servicing portion and receives a fee for doing so. Residential Mortgage Loans Originated $17,314,000 $25,094,000 Sold 7,624,000 19,844,000 Residential Loans Sold / Service
Slide 23: Core Profitability
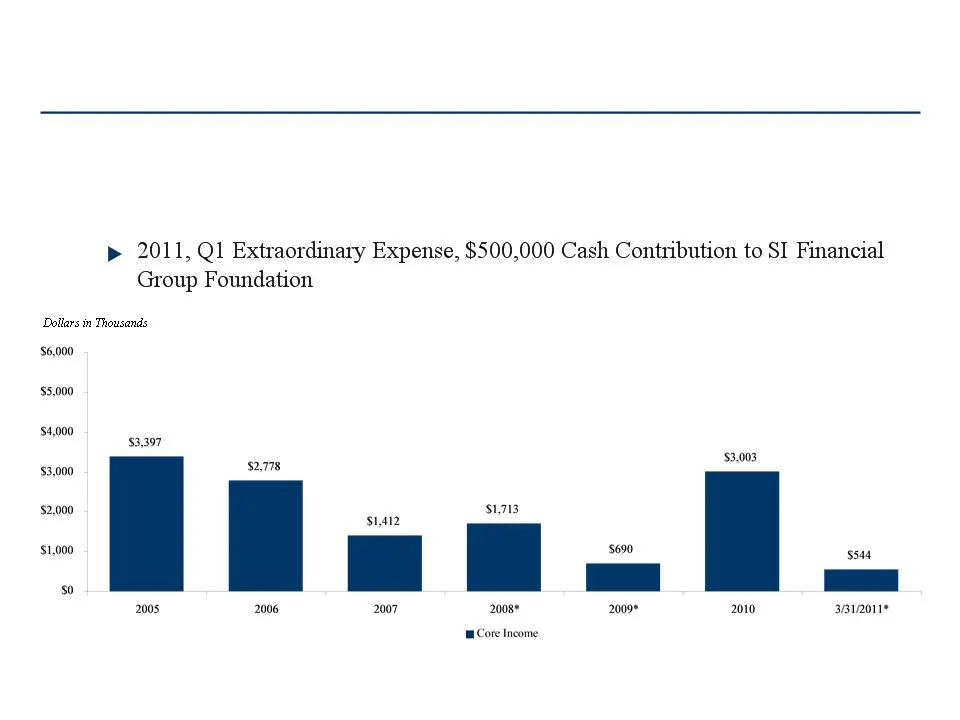
Core Profitability u Core earnings have remained profitable, after excluding the following events: u 2008 write down on securities of $7.1 million u 2009 FDIC special assessment of $393,000 * Excludes events as noted above.
Slide 24: Strong Capital Profile
Minimum Actual Strong Capital Profile (1) Represents bank level data. u Through internal capital generation Savings Institute has remained well capitalized throughout the current economic crisis u As a result of our recent 2 nd step offering, Savings Institute continues to have a strong capital base
Slide 25: Stock Buybacks and Dividends
Stock Buybacks and Dividends u Since completing our MHC offering in December 2004, SI Financial has repurchased approximately 786,000 shares u Approximately 15.6% of original offering u Between March 2005 and March 2011 SI Financial has paid stockholders a total of $0.72 in quarterly dividends u Qua
Slide 26: Investment Merits
Investment Merits u Community-oriented bank with experienced management team u Managed company through different credit cycles u Executed various bank and non-bank acquisitions u Strong asset quality track record and reserve coverage levels u Strong core deposit base u Diversified loan portfolio u I
Slide 27: Trading Multiples
SIFI Average Median Average Median Peer Group (1) New England Thrifts Trading Multiples (1) Peer Group consists of Nationwide thrifts with assets between $500M and $1.5B and market caps between $75M and $125M. Data as of May 2, 2011 Source: SNL Financial Price $9.95 Price / Earnings NM 19.80x 14.76x
Slide 28: Appendix I: Non-GAAP Financial Measures
Appendix I: Non-GAAP Financial Measures
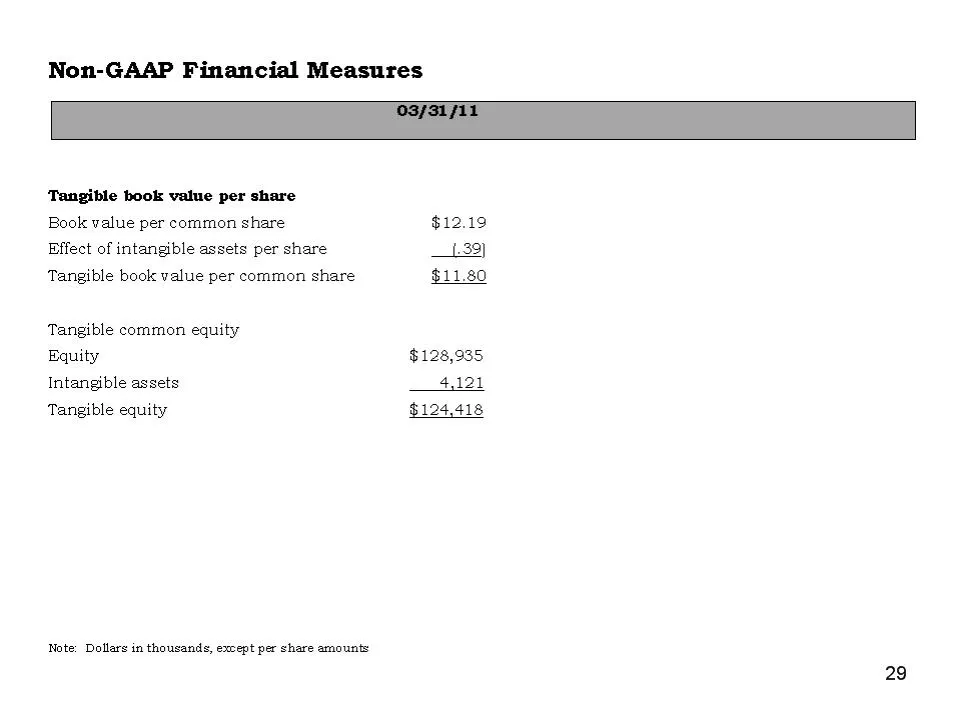
Slide 29: Non-GAAP Financial Measures
Non-GAAP Financial Measures Tangible book value per share Book value per common share $12.19 Effect of intangible assets per share 39 Tangible book value per common share $11.80 Tangible common equity Equity $128,935 Intangible assets 4,121 Tangible equity $124,418 Note: Dollars in thousands, except
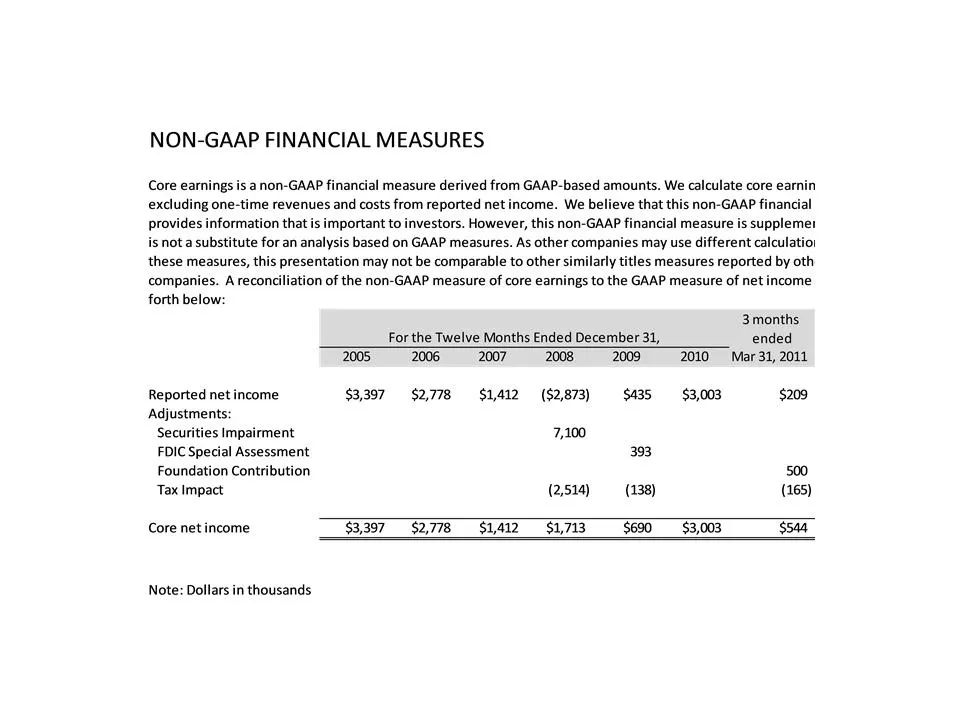
Slide 30: Non-GAAP Financial Measures
NON-GAAP FINANCIAL MEASURES Core earnings is a non-GAAP financial measure derived from GAAP-based amounts. We calculate core earni excluding one-time revenues and costs from reported net income. We believe that this non-GAAP financial provides information that is important to investors. However, thi
Source: SEC EDGAR · 8-K filed May 5, 2011
More decks from SI Financial Group Inc
 Merger or Acquisition (December 2018)13 slides · Dec 11, 2018
 Investor Presentation (September 2018)18 slides · Sep 20, 2018
 Shareholder Meeting (May 2018)19 slides · May 9, 2018
 Investor Presentation (May 2017)18 slides · May 10, 2017
 Investor Presentation (May 2016)19 slides · May 11, 2016
 Shareholder Meeting (May 2015)19 slides · May 13, 2015