
21 October 2026
Gelion plc
("Gelion", the "Company" or the "Group")
Final results to 30 June 2026
Gelion is seeking to replace the critical minerals in current Lithium-ion battery cathode materials with the Company’s Nano-Encapsulated Sulfur (NES™), a material that is low cost and designed to drop-in to existing global manufacturing lines. Gelion’s NES™ is made from sulfur, which is abundant, mining-free, and free from supply chain constraints.
Gelion (LSE: GELN), the sulfur battery technology company, announces its audited final results for the year ended 30 June 2026.
Financial performance
- Total income of £2.5 million (FY25: £2.7 million), 17.1% better than analyst consensus1, primarily comprising increasing UK and Australian government grants and R&D tax incentives/credits, funding approximately 63.2% of Group R&D expenditure, up from 49.8% in FY25.
- Adjusted EBITDA loss2 of £4.4 million (FY25: £4.1 million), 10.4% better than analyst consensus, reflecting continued investment in the Group's NES™ technology development, strategic collaborations and commercialisation activities.
- Strong balance sheet with pro forma cash and cash equivalents3 of £9.6 million (30 June 2025: £4.1 million), 21.1% higher than analyst consensus and nil debt, reflecting disciplined capital management and the successful completion of an oversubscribed £9.9 million net capital raise in 2025, providing a strong platform to support the Group’s next phase of growth and commercialisation.
1Analyst consensus is based on the latest published forecasts available to the Company from covering analysts as at 30 June 2026 and represents the mean of those forecasts (where applicable) on a comparable basis.
2Adjusted EBITDA loss is a non-statutory measure. The calculation method is shown in Note 29.
3Pro forma cash and cash equivalents is a non-statutory measure. The calculation method is shown in Note 29.
Operational and strategic progress
- Sulfur Battery Technology Development: Commenced a £2.6 million ARENA-funded sulfur battery development programme (incl. additional funding made available in March 2026), secured funding and established a partnership with the University of Nottingham for a solid-state pouch cell prototyping line, achieved target 4Q areal capacity in sulfur coin cells, and advanced three U.S. lithium-sulfur patents.
- Strategic Partnerships and Collaborative Development Programmes: Executed a Collaboration Agreement with TDK Corporation and subsequently expanded its scope following strong NES™ CAM performance results, secured APC funding for a lithium-sulfur project with QinetiQ UK, signed a three-year £1.8 million grant-funded collaboration with Nissan Technical Centre Europe and the University of Oxford.
- U.S. Market Entry: Entered the U.S. market through a strategic collaboration with the National Laboratory of the Rockies (NLR) to advance NES™ sulfur cathode technology and support development of a domestic U.S. supply chain.
- NES™ CAM Technology and Manufacturing Development: Completed Max Planck technology transfer and scaled NES™ CAM production in Australia, introduced NES™ CAM as a drop-in cathode solution for lithium-ion and sodium-ion battery manufacturing, and secured an exclusive global commercial licence for NES™ cathode intellectual property from Max Planck Innovation GmbH.
- Financial Position and Leadership Capability: Completed an oversubscribed £10.5 million gross capital raise (£9.9 million net), appointed Professor Rachid Yazami as Technology Advisor and Matt Wood as Chief Executive Officer, with John Wood continuing as Senior Advisor.
Post-period end highlights
- Expanded Commercial Engagements: Entered into a £2.0 million funded development and scale-up agreement with Mitsui Kinzoku Co. Ltd. to validate NES™ CAM across automotive, stationary storage, consumer electronics, aerospace and defence applications, and signed a material testing agreement with a top-15 global automotive OEM and a co-funded proof of concept agreement with a top-five global automotive OEM to evaluate NES™ sulfur cathode technology and NES™ CAM for electric vehicle battery applications.
- Validated NES™ for Defence Applications: Successfully completed the APC-funded ARMD4 programme, with lithium-sulfur pouch cells incorporating NES™ completing representative drone mission profiles and demonstrating stable cycling, high-power performance and operation under demanding conditions.
- Strengthened Intellectual Property Portfolio: Secured six new patent grants, including three in the United States, two in Europe and one in Asia, strengthening protection for Gelion's sulfur battery technology across key global markets.
- Strong Independent U.S. Validation of NES™ Battery Technology: Independent NLR testing under the CRADA validated NES™ performance, with cells retaining 92% of reference capacity at a 20-fold higher cycling rate, supporting further validation and potential qualification for defence, aerospace and drone applications.
Matt Wood, CEO of Gelion, commented: "2026 has been an important transition year for Gelion, marked by continued advancements in our sulfur battery technology and growing commercial validation of our NES™ cathode platform through partnerships with leading global industrial and battery sector participants. These partnerships, together with the milestones achieved across our technology programmes, demonstrate the progress we have made in positioning Gelion's technologies for commercial deployment.
"Having joined Gelion as CEO in June, I would like to recognise John Wood's outstanding contribution to the Company. Under John's leadership, Gelion established a world-class sulfur battery technology platform, secured strategic partnerships with globally recognised organisations and laid the foundations for the Company's transition towards commercialisation.
"The momentum has continued after the period end, with new agreements signed with Mitsui Kinzoku and leading global automotive OEMs. Supported by a strengthened balance sheet, strong partner engagement and a clear focus on commercial execution, we are confident in our strategy and the opportunity ahead. As we move from technology validation towards customer programmes, qualification and scale-up, our focus remains on converting our technological leadership into commercial adoption and long-term shareholder value."
Annual Report
The FY Annual Report can be viewed and downloaded from the Company's website:
https://gelion.com/investors/financial-reports-documents-notices/.
Investor Presentation
Investors are reminded that an investor presentation will take place at 0900h BST on Thursday, 22 October 2026 on the Investor Meet Company platform, hosted by Matt Wood, CEO, Amit Gupta, CFO and Louis Adriaenssens, CTO. The presentation is open to all existing and prospective shareholders.
Registration: https://www.investormeetcompany.com/gelion-plc/register-investor
Questions may be submitted in advance through the Investor Meet Company dashboard up to 0800h BST on the day of the presentation, or at any time during the live event. Investors who already follow Gelion on the platform will be automatically invited.
For more information, please visit Next-Generation Sulfur Battery Technologies | Gelion or contact:
|
Gelion plc |
via Tavistock |
|
Strand Hanson Limited (Nominated and Financial Adviser) |
+44 (0) 20 7409 3494 |
|
Oberon Capital (Joint Broker) |
+44 (0) 20 3179 5300 |
|
Allenby Capital Limited (Joint Broker) Jos Pinnington / Lauren Wright (Sales and Corporate Broking) Alex Brearley / Ashur Joseph (Corporate Finance) |
+44 (0) 20 3328 5656 |
|
Tavistock (Financial & Corporate PR) |
+44 20 7920 3150 |
Market Abuse Regulation
This announcement contains inside information for the purposes of Article 7 of EU Regulation No. 596/2014, which forms part of United Kingdom domestic law by virtue of the European Union (Withdrawal) Act 2018, as amended.
About Gelion
Gelion plc (LSE: GELN) is an advanced battery materials company developing next-generation cathode technologies for lithium-ion and lithium-sulfur batteries. Its proprietary Nano-Encapsulated Sulfur (NES™) cathode active material is designed to replace conventional critical-mineral cathodes with abundant sulfur, delivering higher energy density while remaining compatible with existing battery manufacturing infrastructure.
The Company's strategy is to commercialise NES™ through partnerships with leading industrial companies and battery manufacturers, enabling adoption within established global supply chains across automotive, defence, device and other high-performance applications. Gelion works with Tier One industrial partners including TDK and Mitsui Kinzoku (Japan), QinetiQ and Nissan (UK), Top 15 Global Automotive Manufacturer, Top 5 Global Automotive Manufacturer, and National Laboratory of the Rockies (NLR) (US), and Max Planck Institute of Colloids and Interfaces (MPI) (Germany).
Chairman's Statement
This has been a pivotal year for Gelion, as the Company has strengthened the technical, commercial and strategic foundations required to advance its technology towards market deployment. We achieved important technical milestones, expanded our global network of strategic partners and continued to build momentum across key markets as demand grows for secure, sustainable and high-performance battery technologies.
A key milestone during the year was the demonstration of stable cycling performance from Gelion’s proprietary sulfur cathode active material (CAM) at an industry-recognised performance benchmark. This breakthrough reinforces the potential of Gelion’s technology to deliver high-energy-density, low-cost sulfur-based batteries for a range of commercial applications, and the business is now positioned for accelerated growth under the leadership of Matt Wood, Gelion’s new CEO.
Partnerships and commercial progress
Gelion has continued to strengthen its partnerships, delivering samples of its NES™ CAM formulations to TDK in Japan and to QinetiQ in the UK, an important step in executing the Company’s partnership-led commercialisation strategy and demonstrating its ability to produce material at volumes consistent with pouch cell demonstration requirements.
We also saw strong testing results from Gelion’s Nano-Encapsulated Sulfur (NES™) Cathode Active Material (CAM) platform, supporting an expansion of the Collaboration Agreement scope with TDK Corporation announced earlier in the year. Strong cycling performance in lithium-metal pouch and graphitic anode cells demonstrates the technology’s potential for drones, electric vehicles and integration into existing manufacturing lines.
Gelion strengthened its innovation pipeline during the year by commencing a three-year collaboration with Nissan Technical Centre Europe and the University of Oxford to accelerate the development of solid-state lithium-sulfur battery technology. Backed by Innovate UK grant funding, the programme highlights the strength of the Company’s technology and its growing network of strategic partners.
In June 2026, Gelion entered into a strategic Cooperative Research and Development Agreement (CRADA) with the U.S. Department of Energy’s (DOE) National Laboratory of the Rockies (NLR), marking an important step in the Company’s expansion into the U.S. energy storage market. The collaboration will support the advancement of Gelion’s NES™ sulfur cathode technology from prototype towards commercialisation, validating NES™ performance and a domestic U.S. supply chain for next-generation lithium-sulfur batteries.
The Group also secured exclusive global commercial rights to key intellectual property from Max-Planck-Innovation, covering nano-encapsulated sulfur cathode technology and novel nano-confined anode materials, representing another important step in transitioning to market deployment.
Post year-end, Gelion signed a £2 million funded joint development agreement with Mitsui Kinzoku to validate NES™ cathode active material and support a potential pathway to commercial-scale production and distribution in selected Asian markets.
Leadership and key appointments
The appointment of Matt Wood as Chief Executive Officer was an important moment for the Company, reflecting the Board’s confidence in Gelion’s next phase of growth as it transitions from technology development to commercial execution. Matt joined the Board on 30 June 2026, succeeding John Wood. Under John’s leadership, Gelion established a world-class battery materials platform and built the strong technical, commercial and strategic foundations for future growth.
On behalf of the Board, I thank John for his outstanding leadership, vision and dedication to the Company, and I am delighted that he will continue to support Gelion as Senior Advisor, ensuring continuity across key strategic relationships.
Matt brings extensive international leadership experience and a strong track record of scaling advanced industrial businesses. His appointment strengthens Gelion’s ability to execute its commercial strategy as the Company builds on its technology leadership, deepens relationships with global partners and advances the commercial deployment of its NES™ platform. The Board looks forward to working closely with Matt as we continue to create long-term value for shareholders.
We were also pleased to welcome Professor Rachid Yazami as Technology Advisor. As a globally recognised pioneer in lithium-ion battery technology, his appointment further strengthens Gelion’s technical expertise as the Company advances the commercial development of its next-generation battery materials.
Positioned for scale-up
During the year, the Group raised £9.9m (net of costs) via an oversubscribed placing, subscription and retail offer and the Australian Renewable Energy Agency (ARENA) expanded its existing funding agreement to accelerate the commercial execution of the Company’s sulfur CAM through its Advanced Commercial Prototyping Centre. This increased funding will support the scale-up of fabrication capabilities, expanded testing and integration activities, strengthening Gelion’s pathway towards commercial deployment and global supply chain development.
As governments and industry place increasing emphasis on sovereign, secure and sustainable battery supply chains, Gelion remains focused on translating its technology leadership into scalable commercial opportunities that support long-term global growth. The Group continues to build momentum across its core markets of Japan, the UK, Australia and the United States, while expanding opportunities in high-value applications.
Gelion enters the coming year with strong technical momentum, an expanding portfolio of strategic partnerships and a clear pathway towards commercial growth. While significant opportunities remain ahead, the Board believes the Company is well positioned to translate its differentiated technology into scalable commercial outcomes and create sustainable long-term value for shareholders.
Dr Steve Mahon
Chairman
CEO's Report
It is a privilege to write my first CEO Report for Gelion following my recent appointment. While this report reflects a period that was led by my predecessor, John Wood, I would like to begin by recognising his outstanding contribution to the Company. Under John’s leadership, Gelion built upon its strong foundations to establish a world-class sulfur battery technology platform, secured strategic partnerships with globally recognised organisations and laid the foundations for the Company’s transition towards commercialisation. As I assume stewardship of the Company, I am grateful to John and pleased that he will continue to support the business as a Senior Advisor during this next phase of growth.
2026 marked an important transition for Gelion, as we moved beyond demonstrating the performance of our sulfur battery technologies towards validating their commercial potential through leading industry partnerships and continued technical breakthroughs, specifically:
- The successful completion of the Advanced Route to Market Demonstrator 4 (ARMD4) programme with QinetiQ independently demonstrated that NES™ cells using lithium-metal anodes maintained stable performance beyond 200 charge-discharge cycles and repeatedly completed representative drone mission profiles requiring rapid bursts of power, with limited degradation. These results provide application-specific performance data to support qualification by defence and aerospace customers; and
- In parallel, NES™ full cells using graphitic anodes achieved more than 750 cycles at 1C, demonstrating compatibility with established lithium-ion architectures and providing battery manufacturers with a stronger technical basis for qualification within their existing platforms. This led to expansion of scope with TDK to include commercially applied anode-types including graphitic anodes.
Together, these results address critical customer qualification requirements and advance NES™ towards partner-led development programmes, customer adoption and commercial deployment in cells with both lithium-metal anodes for defence applications and graphitic anodes for applications such as commercial drones, electric vehicles and consumer electronics.
Our focus throughout the year has been to:
- Accelerate the commercial validation of our sulfur battery technologies through strategic partnerships with leading global battery manufacturers and industrial collaborators
- Advance our technology platform from laboratory innovation towards scalable manufacturing by demonstrating compatibility with existing battery production infrastructure
- Build the foundations for long-term growth by strengthening our intellectual property through new patents and securing exclusive licencing with Max Planck Institute, expanding our global supply chain relationships and deploying capital with discipline
I am pleased to report that we have delivered meaningful progress against each of these priorities.
Building commercial momentum
During the year we have significantly strengthened our commercial and technical position through a series of important milestones. Our collaboration with TDK evolved into a full collaboration agreement and continues to generate exceptional technical results, with expanded testing further validating the performance of our sulfur cathode technology. We also announced a three-year collaborative project with Nissan to integrate Gelion’s NES™ sulfur cathode into next-generation solid-state electric vehicle (EV) batteries, alongside securing an exclusive licence agreement with Max-Planck-Innovation GmbH that further strengthens our intellectual property position and access to world-leading sulfur battery technologies.
These relationships are further complemented by continued progress with:
- QinetiQ through the APC funded ARMD4 programme in the UK,
- Nissan Europe solid-state battery programme through the UK Battery Innovation Programme (BIP) funding;
- Advanced Commercial Prototype Centre (ACPC) programme funded by ARENA in Australia.
Together, these collaborations demonstrate growing confidence from industry leaders and government agencies in Gelion’s technology and its commercial potential.
Advancing our technology
Technically, this year has been one of our strongest to date. We achieved several important breakthroughs in lithium-sulfur performance with our NES™ cathode, including reaching our target areal capacity, successfully transferring the Max-Planck Institute (MPI) technology into Gelion’s development programme and expanding production of our sulfur cathode active material. We also introduced our sulfur cathode active material as a true “drop-in” solution capable of integrating with existing manufacturing infrastructure, significantly lowering barriers to commercial adoption.
Our technology platform continues to differentiate itself by combining high energy density with the use of abundant, low-cost and more sustainable materials. Rather than requiring fundamental changes to existing infrastructure, our sulfur cathode technology is designed to work alongside established production processes, creating an attractive route to industrial scale deployment. Further U.S. patent advances and the appointment of Professor Rachid Yazami as Technology Advisor reinforced both the strength of our already strong intellectual property portfolio and the scientific foundations underpinning our technology.
Commercial validation and broadening our platform
Commercial validation continues to accelerate. Beyond our work with TDK, Nissan and QinetiQ, we announced a transformational collaboration agreement with Mitsui Kinzoku and entered the United States market through collaboration with the National Laboratory of the Rockies to validate Gelion’s sulfur cathode materials for the rapidly developing U.S. battery ecosystem. These partnerships provide independent validation of our technology whilst creating multiple pathways towards future commercial deployment.
Capital allocation and financial strength
Throughout the year we maintained our disciplined approach to capital allocation. Non-dilutive government funding remained an important part of our development strategy, supporting technology advancement in both Australia and the United Kingdom while allowing shareholder capital to be deployed efficiently. We successfully completed an oversubscribed equity fundraise, including strong participation through the retail offer, raising approximately £9.9 million (net of costs). The success of the fundraising reflects continued investor confidence in Gelion’s strategy and provides the financial resource to accelerate commercial execution.
The Company also took decisive steps to sharpen its strategic focus and direct resources towards its highest-value growth opportunities. Following a review of priorities and market conditions, the Company commenced a strategic review of the Battery Minerals recycling business including identifying an investor or a partner and decided to discontinue the Integration Solutions business. These actions enable Gelion to concentrate capital, management attention and execution capability on the development and commercialisation of NES™ sulfur cathode materials, which the Board believes offer the strongest potential for long-term value creation.
Looking ahead
As I assume the role of Chief Executive Officer, I do so at an exciting point in Gelion’s development. The Company has evolved from a technology-led organisation into one increasingly focused on commercialisation, supported by a strong intellectual property portfolio, world-class scientific capability and a growing network of strategic partners across the global battery ecosystem.
Gelion is entering an important new phase of commercial progression, moving from technology validation towards contracted customer programmes and revenue generation. The funded programmes with Mitsui Kinzoku and a top-five global automotive OEM are expected to generate commercial revenue in FY27, albeit initially modest, while strengthening strategic customer relationships and advancing NES™ qualification, scale-up and broader market adoption.
Looking ahead, our priorities remain clear. We will continue to advance commercial prototype pouch cells, execute on and further expand customer validation programmes, proceed with the scale-up NES™ sulfur cathode material production and deepen relationships with leading battery manufacturers and OEMs across Europe, Asia and North America. As the battery industry seeks lower-cost, higher-performance and more sustainable chemistries, we believe Gelion is exceptionally well positioned to become an important technology partner within the global battery supply chain.
I would like to thank John for his vision, leadership and commitment in establishing the partnerships on which Gelion will build its next chapter. I am also grateful to our employees, Board, partners and shareholders for their continued support. As we advance, my focus will be on executing our commercial strategy with discipline, deepening our customer and manufacturing partnerships, and translating our technology leadership into long-term shareholder value. I am excited for the opportunities ahead and look forward to leading Gelion through its next phase of growth.
Matt Wood
Chief Executive Officer
CFO’s Review
Overview
FY26 was a year of strategic transformation for Gelion, as we sharpened our focus on commercialising our sulfur battery technology. We expanded our strategic partnership base, secured independent third-party validation of our NES™ sulfur CAM and established our U.S. operations as a platform for market entry. We also secured additional non-dilutive funding, reducing reliance on equity markets to finance our development roadmap. During the year and subsequent to year end, we also took steps to simplify the Group’s portfolio and concentrate capital and management resources on Gelion’s core sulfur commercialisation opportunity.
Gelion entered FY26 with clearer strategic priorities and finished the year in a materially stronger financial position, with a pro forma cash position of approximately £9.6 million, underpinned by the successful capital raise completed during the year, additional grant funding and tax incentives. This provides a strong platform from which to pursue commercial growth opportunities in FY27.
Financial Performance
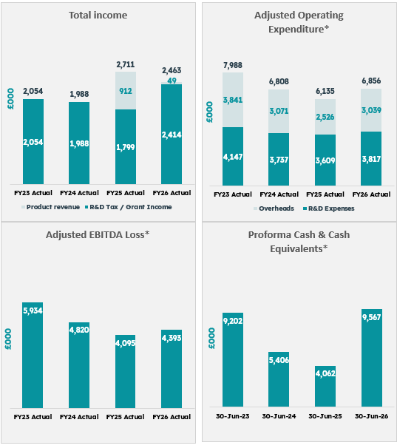
Total income for FY26 was £2.5 million (FY25: £2.7 million) largely reflecting grant income received from UK and Australian government-supported research and development programmes. Revenue from contracts with customers reduced significantly in FY26, reflecting the completion of the prior year Integration Solutions project and the Group’s decision to wind down this offering following a review of strategic priorities and market conditions. This decision is expected to reduce non-core revenue contribution but preserve capital and management capacity for NES™ sulfur cathode commercialisation.
Key financial metrics
* Represents non-statutory measures with calculation method shown in Note 29
A key measure of Gelion’s capital efficiency is the extent to which external funding supports innovation. During FY26, other income principally comprising of grants and R&D tax incentives represented approximately 63.2% of the Group’s total R&D expenditure, up from 49.8% in FY25, driven by the ARMD4 programme, the ARENA linked ACPC grant and Australian R&D tax incentive claims. This improvement reflects our continued success in securing non-dilutive funding from governments and research collaborators in the UK and Australia. By funding a significant proportion of development activity through government and associated entities, we accelerate innovation while reducing reliance on shareholder capital.
Research and development expenditure was £3.8 million (FY25: £3.6 million). While the overall level of investment remained broadly consistent, the composition of our R&D activities evolved significantly. In FY25, development expenditure supported both sulfur and zinc-based technology platforms. Following a strategic review of priorities and market opportunities, FY26 investment was directed predominantly towards advancing our sulfur technology, reflecting management’s confidence in its commercial potential, scalability and ability to address large and rapidly growing global energy storage markets.
Business overheads increased to £3.0 million (FY25: £2.5 million), reflecting investment in business development incl. US expansion, strategic partnerships and activities supporting Gelion’s transition from technology development to commercialisation and an increase in executive/ non-executive remuneration. During the year, the Company progressed strategic collaborations with TDK, Nissan and QinetiQ, and secured the MPI licence. Together, these organisations span key parts of the battery value chain, from advanced materials through to end-user applications, providing increasing external validation of Gelion’s sulfur technology and expanding potential pathways to commercialisation.
Post year-end, Gelion also executed a strategic agreement with Mitsui Kinzoku, further extending its commercial network. Together, these initiatives are building multiple pathways to future commercial value, including joint development agreement (JDA) income, licensing income and an active pipeline of commercial discussions.
Adjusted EBITDA loss increased to £4.4 million (FY25: £4.1 million), reflecting reduced contribution from Integration Solutions, together with increased investment in commercialisation activities. These impacts were partially offset by higher grant income, R&D tax incentives and other non-dilutive funding.
Operating loss before non-recurring items was £5.5 million (FY25: £5.3 million). Non-recurring costs of £1.1 million (FY25: £0.8 million) comprised capital raising costs, non-cash losses associated with intellectual property portfolio impairment and other strategic initiatives undertaken during the year. Operating loss after non-recurring items was £6.7 million (FY25: £6.0 million).
Statement of Financial Position
Gelion’s balance sheet strengthened considerably during FY26, with net assets increasing by 47% to £14.6 million (FY25: £10.0 million).
Cash and cash equivalents increased to £7.6 million at 30 June 2026 (FY25: £2.7 million), reflecting successful capital raising activities and continued grant funding support. On a pro forma basis, available liquidity stood at approximately £9.6 million (FY25: £4.1 million) which includes cash and cash equivalents, expected R&D tax incentive receipts of £1.4 million, grant receivables of £0.5 million and other government tax receivables of £0.1 million.
Intangible assets and goodwill totalled £5.7 million (FY25: £6.1 million), while property, plant and equipment increased to £1.1 million (FY25: £0.9 million) as the Company continued investing in development and scale-up capabilities.
The strengthening of the balance sheet provides Gelion with increased financial flexibility as it advances the commercialisation of its sulfur battery technologies and supports the execution of its strategic growth plans.
Capital Management
During the year, Gelion strengthened its capital position through an equity net fundraising of £9.9 million, completed in November 2025 at 20p per share, to fund continued sulfur technology development, commercialisation activities and U.S. market entry. This was complemented by the non-dilutive funding secured during the year (see R&D expenditure above), reflecting our continued focus on minimising reliance on shareholder capital wherever possible.
Capital allocation remains focused on extending the Group’s runway and prioritising investment behind NES™ sulfur cathode commercialisation. The decisions to wind down Integration Solutions and commence a formal sale process for Battery Minerals Ltd are consistent with this approach, reducing non-core capital requirements and supporting a more focused, capital-efficient business model.
Foreign Currency
Gelion operates across Australia, the United Kingdom and the United States, resulting in exposure to foreign currency movements. Gelion’s currency risk profile remains well-controlled, supported by active management of procurement and funding streams. As we look to broader commercial expansion, further currency risk mitigation strategies will be deployed as required.
Outlook
FY26 marked an important transition in Gelion’s evolution from technology development towards commercial execution. During the year, the Company expanded its strategic partnership base, strengthened third-party validation of its NES™ sulfur cathode technology and established a stronger financial platform to support the next phase of growth.
With a focused sulfur strategy, significant industry validation and £9.6 million of pro forma cash and cash equivalents, Gelion enters FY27 with a clearer pathway to commercialisation. Our priorities are to deepen strategic partnerships, progress partner-led scale-up and licensing opportunities and deploy capital with discipline towards the activities most closely aligned with long-term value creation.
FY27 is expected to mark an important step in the Group’s commercial progression, with modest commercial revenue expected to be recognised from both the funded Mitsui Kinzoku joint development programme and the funded proof-of-concept agreement with a top-five global automotive OEM. These programmes demonstrate Gelion’s increasing ability to convert strategic customer engagement and technology validation into contracted commercial activity and revenue.
The steps taken to simplify the Group’s portfolio support this approach by preserving capital, sharpening execution focus and aligning resources behind Gelion’s core sulfur platform. The progress achieved during FY26 gives us confidence that Gelion is better positioned to translate its technology leadership into sustainable commercial outcomes and long-term shareholder value.
Amit Gupta
Chief Financial Officer
|
Year ended 30 June | ||||
|
Notes |
2026 £’000 |
2025 £’000 | ||
|
Revenue from contracts with customers |
4 |
49 |
912 | |
|
Other income |
5 |
2,414 |
1,799 | |
|
Total income |
2,463 |
2,711 | ||
|
Research and development expenses |
6 |
(3,817) |
(3,609) | |
|
Business overheads |
6 |
(3,039) |
(2,526) | |
|
Direct costs |
- |
(671) | ||
|
Share-based payments expense |
(558) |
(574) | ||
|
Depreciation and amortisation |
(585) |
(593) | ||
|
Operating loss before exceptional and non-recurring items |
6 |
(5,536) |
(5,262) | |
|
Exceptional and non-recurring items: |
7 |
|||
|
Loss on write-off of IP intangibles and disposal of property, plant and equipment |
(532) |
(346) | ||
|
Capital raising and acquisition related costs |
(199) |
(301) | ||
|
Business restructure and other costs |
(411) |
(114) | ||
|
Total exceptional and non-recurring items |
(1,142) |
(761) | ||
|
Operating loss |
(6,678) |
(6,023) | ||
|
Finance costs |
(10) |
(27) | ||
|
Finance income |
215 |
47 | ||
|
Loss on ordinary activities before taxation |
(6,473) |
(6,003) | ||
|
Tax income |
9 |
20 |
19 | |
|
Loss on ordinary activities after taxation |
(6,453) |
(5,984) | ||
|
Total loss for the year attributable to equity holders of the parent | ||||
|
Other comprehensive income: |
||||
|
Items that may be reclassified to profit or loss |
||||
|
- - Exchange gains/(losses) arising on translation of foreign operations |
10 |
604 |
(556) | |
|
Total comprehensive loss for the year attributable to equity holders of the parent |
(5,849) |
(6,540) | ||
|
Loss per share (basic and diluted) attributable to the equity holders (pence) |
12 |
(3.1) |
(4.1) | |
The above results relate entirely to continuing activities.
The accompanying notes form part of this financial information.
Consolidated Balance Sheet|
As at 30 June | |||
|
Notes |
2026 £’000 |
2025 £’000 | |
|
Assets |
|||
|
Non-current assets |
|||
|
Intangible assets |
13 |
5,717 |
6,104 |
|
Property, plant and equipment |
15 |
1,071 |
874 |
|
Current assets |
|||
|
Cash and cash equivalents |
17 |
7,550 |
2,661 |
|
Other receivables |
18 |
2,451 |
1,719 |
|
Total Assets |
16,789 |
11,358 | |
|
Liabilities |
|||
|
Current liabilities |
|||
|
Trade and other payables |
16, 19 |
1,277 |
1,014 |
|
Non-current liabilities |
|||
|
Trade and other payables |
16, 19 |
89 |
72 |
|
Deferred grant income |
20 |
519 |
- |
|
Deferred tax liabilities |
21 |
281 |
301 |
|
Total liabilities |
2,166 |
1,387 | |
|
Net assets |
14,623 |
9,971 | |
|
Equity |
|||
|
Issued capital |
22 |
229 |
177 |
|
Share premium account |
22 |
38,306 |
28,415 |
|
Other reserves |
22 |
10,057 |
8,895 |
|
Capital reduction reserve |
22 |
11,194 |
11,194 |
|
Accumulated losses |
(45,163) |
(38,710) | |
|
Total equity |
14,623 |
9,971 | |
The financial statements of Gelion Plc, company registration number 09796512, were approved by the Directors and authorised for issue on 20 October 2026.
The accompanying notes form part of this financial information.
Dr Steve Mahon
Chairman
Consolidated Statement of Cash Flows|
Year ended 30 June | |||
|
Notes |
2026 £’000 |
2025 £’000 | |
|
Cash flow from operating activities |
|||
|
Loss for the year before tax |
(6,473) |
(6,003) | |
|
Adjustments for: |
|||
|
Depreciation & amortisation |
6 |
585 |
593 |
|
Finance costs |
10 |
27 | |
|
Finance income |
(215) |
(47) | |
|
Loss on disposal of property, plant and equipment and write-off of IP intangibles |
7 |
532 |
346 |
|
Share-based payments expense |
23 |
558 |
574 |
|
Changes in operating assets/liabilities |
|||
|
Decrease in receivables |
81 |
239 | |
|
(Increase)/Decrease in prepayments |
(118) |
9 | |
|
Increase /(Decrease) in payables |
70 |
(193) | |
|
Net cash used in operating activities |
(4,970) |
(4,455) | |
|
Cash flows from investing activities |
|||
|
Purchase of intangible assets |
(203) |
(318) | |
|
Sale of property, plant and equipment |
1 |
2 | |
|
Purchase of tangible property, plant and equipment |
(487) |
(165) | |
|
Grant income received against equipment |
138 |
- | |
|
Interest received |
193 |
46 | |
|
Net cash used in investing activities |
(358) |
(435) | |
|
Cash flows from financing activities |
|||
|
Proceeds from issue of shares |
22 |
10,500 |
4,420 |
|
Transaction costs of issue of shares |
22 |
(557) |
(451) |
|
Repayment of leasing liabilities |
(30) |
(16) | |
|
Net cash generated from financing activities |
9,913 |
3,953 | |
|
Net increase/(decrease) in cash held |
4,585 |
(937) | |
|
Cash and cash equivalents at beginning of financial year |
2,661 |
3,792 | |
|
Effect of exchange rate changes |
304 |
(194) | |
|
Cash and cash equivalents at end of financial year |
17 |
7,550 |
2,661 |
The accompanying notes form part of this financial information.
Consolidated Statement of Changes in Equity|
Share capital |
Share premium |
Accumulated losses |
Capital reduction reserve |
Other reserves |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 |
£’000 | |
|
Balance at 1 July 2024 |
136 |
24,487 |
(32,726) |
11,194 |
8,877 |
11,968 |
|
Loss on ordinary activities after taxation |
- |
- |
(5,984) |
- |
- |
(5,984) |
|
Other comprehensive income |
– |
– |
– |
– |
(556) |
(556) |
|
Total comprehensive loss for the year |
- |
- |
(5,984) |
- |
(556) |
(6,540) |
|
Contributions by and distributions to owners: | ||||||
|
Share-based payment charge |
- |
- |
- |
- |
574 |
574 |
|
Shares issued during the period |
41 |
4,379 |
- |
- |
- |
4,420 |
|
Costs of shares issued |
- |
(451) |
- |
- |
- |
(451) |
|
Total contributions by and distributions to owners: |
41 |
3,928 |
- |
- |
574 |
4,543 |
|
Balance at 30 June 2025 |
177 |
28,415 |
(38,710) |
11,194 |
8,895 |
9,971 |
|
Balance at 1 July 2025 |
177 |
28,415 |
(38,710) |
11,194 |
8,895 |
9,971 |
|
Loss on ordinary activities after taxation |
- |
- |
(6,453) |
- |
- |
(6,453) |
|
Other comprehensive income |
- |
- |
- |
- |
604 |
604 |
|
Total comprehensive loss for the year |
- |
- |
(6,453) |
- |
604 |
(5,849) |
|
Contributions by and distributions to owners: | ||||||
|
Share-based payment charge |
- |
- |
- |
- |
558 |
558 |
|
Shares issued during the period |
52 |
10,448 |
- |
- |
- |
10,500 |
|
Costs of shares issued |
- |
(557) |
- |
- |
- |
(557) |
|
Total contributions by and distributions to owners: |
52 |
9,891 |
- |
- |
558 |
10,501 |
|
Balance at 30 June 2026 |
229 |
38,306 |
(45,163) |
11,194 |
10,057 |
14,623 |
The accompanying notes form part of this financial information.
Notes to The Consolidated Financial Statements1. General Information
Gelion Plc (‘Gelion’ or the ‘Company’) is a 100% owner of:
• Gelion Technologies Pty Limited, an Australian subsidiary that conducts research and development in respect of lithium-sulfur battery technology; and
• Gelion Europe Limited (previously OXLiD Limited), a UK subsidiary which is involved in the research and development of lithium-sulfur battery technology; and
• Battery Minerals Limited, a UK subsidiary which is involved in the recycling of lithium-ion battery technology; and
• OXLiD Limited, a UK non-trading subsidiary; and
• Gelion US Corp., a US subsidiary which is involved in the research and development of lithium-sulfur battery technology; and
• Gelion Integrated Solutions Pty Limited, a non-trading Australian subsidiary that provides renewable battery storage systems for grid, commercial and industrial applications.
Gelion Plc is a public limited company, limited by shares, incorporated and domiciled in England and Wales. The Company was incorporated on 26 September 2015. The registered office of the Company is at C/O External Services Limited, Central House 20 Central Avenue, St Andrews Business Park, Norwich, United Kingdom, NR7 0HR. The registered company number is 09796512.
Gelion Plc was incorporated as Gelion UK Limited. On 12 November 2021, the Company was re-registered as a public limited company under the Companies Act and its name was changed to Gelion Plc.
The Board, Directors and management referred to in this document refers to the Board, Directors and management of Gelion.
2. Accounting Policies
2.1 Basis of preparation
The principal accounting policies applied in the preparation of the Group financial statements are set out below. These policies have been consistently applied to the period presented, unless otherwise stated.
These financial statements have been prepared in accordance with UK adopted International Accounting Standards and the requirements of the Companies Act 2006 as applicable to companies reporting under International Financial Reporting Standards (IFRS).
The preparation of financial statements in compliance with UK-adopted International Accounting Standards requires the use of certain critical accounting estimates. It also requires Group management to exercise judgement in applying the Group’s accounting policies. The areas where significant judgements and estimates have been made in preparing the financial statements and their effect are disclosed in note 2.20.
These financial statements are presented in Great British Pounds (GBP) unless otherwise stated, which is the Company’s presentational currency and the parent company’s functional currency. Amounts are rounded to the nearest thousand, unless otherwise stated. The functional currency of the subsidiaries are Great British Pounds (GBP), Australian Dollars (AUD) and United States Dollars (USD). Some numerical figures included in this Annual Report have been subject to rounding adjustments. The policies adopted for translation of the subsidiary’s assets, liabilities, income and expenses are set out in note 2.17.
2.2 Basis of consolidation
The consolidated financial statements consolidate the financial statements of Gelion Plc and of its subsidiary undertakings drawn up to each reporting date.
Where the Company has control over an investee, it is classified as a subsidiary. The Company controls an investee if all three of the following elements are present: power over the investee, exposure to variable returns from the investee, and the ability of the investor to use its power to affect those variable returns. Control is reassessed whenever facts and circumstances indicate that there may be a change in any of the elements of control.
Profit or loss and each component of other comprehensive income are attributed to the equity holders of the parent of the Group. When necessary, adjustments are made to the financial statements of subsidiaries to bring their accounting policies in line with the Group’s accounting policies. All intra-group assets and liabilities, equity, income, expenses and cash flows relating to transactions between members of the Group are eliminated in full on consolidation.
The following were subsidiary undertakings of the Group:
|
Name |
Registered office |
Class of shares |
Holding |
|
Gelion Technologies Pty Limited |
Australia |
Ordinary A |
100% |
|
Gelion Europe Limited |
UK |
Ordinary A |
100% |
|
Battery Minerals Limited |
UK |
Ordinary A |
100% |
|
OXLiD Limited |
UK |
Ordinary A |
100% |
|
Gelion US Corp. |
USA |
Ordinary A |
100% |
|
Gelion Integrated Solutions Pty Limited |
Australia |
Ordinary A |
100% |
The shareholdings are held directly except for Gelion Integrated Solutions Pty Limited which is held indirectly through Gelion Technologies Pty Limited.
The registered office of Gelion Technologies Pty Limited and Gelion Integrated Solutions Pty Limited is Level 16, 101 Miller Street, North Sydney, NSW, 2060, Australia.
The registered office of Gelion Europe Limited, Battery Minerals Limited and OXLiD Limited is C/O External Services Limited, Central House 20 Central Avenue, St Andrews Business Park, Norwich, United Kingdom, NR7 0HR.
The registered office of Gelion US Corp. is 251 Little Falls Drive, in the City of Wilmington, County of New Castle 19808, State of Delaware, the United Sates of America.
2.3 Going concern
The financial statements have been prepared on a going concern basis which assumes that the Group will have sufficient funds available to enable it to continue to trade for the foreseeable future being a period of at least 12 months from the date of approval of these financial statements. In making their assessment that this assumption is correct, the Directors have undertaken an in-depth review of the business, its current prospects, and cash resources as set out below. The Company is a holding entity and as such its going concern is dependent on the Group therefore the going concern assessment for the Company was performed as part of the Group’s assessment.
The Directors have reviewed the cash flow forecast for the period to 31 December 2027. The Group meets its normal working capital requirements through existing cash resources which, at 30 June 2026, comprised £7.6 million in cash at bank, £1.4 million in receivables from the Australian and UK R&D tax credits, £0.5 million in grant receivables and £0.1 million in other tax receivables from the Australian and the UK tax authorities. The Groups pro forma cash position at 30 June 2026 therefore equals £9.6 million (“Pro forma Cash”). In addition, the Group also has access to a R&D loan facility of £1.0 million maturing in November 2027, and which remains undrawn at the date of approval of these financial statements.
The Directors have also considered a possible downside sensitivity of a 10% increase in non-controllable operating costs (excluding payroll). Under this scenario the business would still have adequate financial resources to continue for at least 12 months from the date of approval of these financial statements. In addition, the Directors have identified further mitigating actions to reduce cash outflows, including reductions in uncommitted discretionary operating expenditure.
After due consideration of the forecast and current cash resources, the Directors confirm that they are satisfied that the Group and Company will be able to continue to operate and meet its liabilities as they fall due over the going concern period to 31 December 2027. Accordingly, the Board has concluded that the going concern basis of preparation of the Group and Company Financial Statements is appropriate and that there are no material uncertainties that would cast doubt on that basis of preparation.
2.4 Revenue
Under IFRS 15, an entity recognises revenue when a performance obligation is satisfied, i.e. when control of the goods or services underlying the particular performance obligation is transferred to the customer.
Revenue is measured at the fair value of the consideration received or receivable.
The BESS (Battery Energy Storage System) contracts are fixed-price and are treated as a single performance obligation, as the components and related services are highly interdependent and do not have standalone value to the customer. Revenue is recognised at a point in time, which occurs when control of the completed system transfers to the customer, typically upon delivery, customer acceptance, and/or installation.
Judgement is required in assessing the point at which control transfers, including consideration of contractual acceptance provisions and the customer’s ability to direct the use of, and obtain the benefits from the system.
Amounts invoiced are recorded as trade receivables when the right to payment is unconditional. Where revenue recognised at the year end date is more than amounts invoiced, the Group recognises accrued income for the difference. Prior to the point of revenue recognition, costs incurred are recorded as work-in-progress within inventory. Advance payments from customers are recognised as contract liabilities and are released to revenue when the performance obligation is satisfied.
2.5 Other income
Other income includes:
- Government grants: Government grants are recognised when there is reasonable assurance that the Group will comply with the conditions attaching to the grants and that the grants will be received.
Government grants related to the acquisition of property, plant and equipment are recognised as deferred income and released to profit or loss on a systematic basis over the useful lives of the related assets.
Government grants related to eligible operating expenditure are recognised in profit or loss as other income on a systematic basis over the periods in which the Group recognises the related expenses for which the grants are intended to compensate.
In assessing whether there is reasonable assurance that the conditions attaching to a grant will be met, the Group considers the relevant grant terms and milestones, eligible expenditure incurred, progress against the applicable project requirements, historical claim outcomes and correspondence with the relevant granting authority.
Government grants are subject to conditions set out in the relevant funding agreements, including eligible expenditure requirements, achievement of project milestones and deliverables, and ongoing reporting and compliance obligations.
At the reporting date, certain funded projects are ongoing, and the Group continues to have obligations relating to future milestones, eligible expenditure and reporting requirements.
Amounts relating to future expenditure or conditions not yet satisfied are not recognised as income. Management is not aware of any material breach of grant conditions at the reporting date that would require repayment of recognised grant amounts.
- R&D tax incentives (Australia): primarily relate to research and development incentives. This represents a refundable tax offset that is available on eligible R&D expenditure incurred by the Group. These are not recognised until there is reasonable assurance that the Group will comply with the conditions attaching to them and that the incentives will be received. Government grants that are receivable as compensation for expenses or losses already incurred or for the purpose of giving immediate financial support to the Group with no future related costs are recognised in profit or loss in the period in which they become receivable.
- R&D tax credits (UK): The Group claims R&D Expenditure Credit (‘RDEC’) on the costs it incurs in its research and development projects. RDEC is considered taxable income and therefore the Group records the RDEC under Other income in the statement of comprehensive income, and the associated tax charge levied against this income is recorded in the taxation line. The income is recognised on the performance model under IAS 20 ‘Accounting for Government Grants and Disclosures’.
- Enhanced R&D Intensive Support (“ERIS”) UK: The Group claims Enhanced R&D Intensive Support (“ERIS”) in respect of qualifying research and development expenditure incurred by its loss-making UK R&D intensive subsidiaries. The resulting payable tax credit is recognised under Other income in the statement of comprehensive income in accordance with IAS 20.
2.6 Taxation
The income tax expense or benefit for the period is the tax payable on the current periods taxable income based on the national income tax rate for each jurisdiction, adjusted by changes in deferred tax assets and liabilities attributable to temporary differences, unused tax losses and adjustments recognised for prior periods where applicable.
Deferred tax assets relating to temporary differences and unused tax losses are recognised only to the extent that it is probable that future taxable profit will be available against which the benefits of the deferred tax asset can be utilised. Deferred tax assets and liabilities are offset when there is a legally enforceable right to offset current tax assets and liabilities and when the deferred tax balances relate to the same taxation authority.
Current tax assets and tax liabilities are offset where the entity has a legally enforceable right to offset and intends either to settle on a net basis, or to realise the asset and settle the liability simultaneously.
Current and deferred tax is recognised in profit or loss, except to the extent that it relates to items recognised in other comprehensive income or directly in equity. In this case, the tax is also recognised in other comprehensive income or directly in equity, respectively.
2.7 Earnings/loss per share
Basic earnings/loss per share
Basic earnings/loss per share is calculated by dividing:
- the profit or loss attributable to owners of Gelion Plc, excluding any costs of servicing equity other than Ordinary Shares; by
- the weighted average number of Ordinary Shares outstanding during the financial year, adjusted for bonus elements in Ordinary Shares issued during the financial year.
Diluted earnings/loss per share
Diluted earnings/loss per share adjusts the figures used in the determination of basic earnings/loss per share to take into account:
- the after-income tax effect of interest and other financing costs associated with dilutive potential Ordinary Shares; and
- the weighted average number of shares assumed to have been issued for no consideration in relation to dilutive potential Ordinary Shares.
2.8 Cash and cash equivalents
For the purpose of presentation in the Statement of Cash Flows, cash and cash equivalents includes cash on hand, deposits held at call with financial institutions, other short-term highly liquid investments with original maturities of three months or less that are readily convertible to known amounts of cash and which are subject to an insignificant risk of changes in value, and bank overdrafts. Term deposits that are held for a period of less than three months form a part of cash and cash equivalents.
2.9 Property, plant and equipment
Plant and equipment are stated at historical cost less accumulated depreciation and impairment. Historical cost includes expenditure that is directly attributable to the acquisition of the items.
Depreciation is calculated on a straight-line basis to write off the net cost of each item of property, plant and equipment (excluding land) over their expected useful lives as follows:
Plant and equipment 3–7 years
Office furniture and equipment 3 years
Leasehold improvements are depreciated over the unexpired period of the lease or the estimated useful life of the assets, whichever is shorter.
The residual values, useful lives and depreciation methods are reviewed, and adjusted if appropriate, at each reporting date.
An item of property, plant and equipment is derecognised upon disposal or when there is no future economic benefit to the Group. Gains and losses between the carrying amount and the disposal proceeds are taken to profit or loss.
2.10 Right-of-use assets
A right-of-use asset is recognised at the commencement date of a lease. The right-of-use asset is measured at cost, which comprises the initial amount of the lease liability, adjusted for, as applicable, any lease payments made at or before the commencement date net of any lease incentives received, any initial direct costs incurred, and, except where included in the cost of inventories, an estimate of costs expected to be incurred for dismantling and removing the underlying asset, and restoring the site or asset.
Right-of-use assets are depreciated on a straight-line basis over the unexpired period of the lease or the estimated useful life of the asset, whichever is the shorter. Where the Group expects to obtain ownership of the leased asset at the end of the lease term, the depreciation is calculated over its estimated useful life. Right-of-use assets are subject to impairment or adjusted for any remeasurement of lease liabilities.
The Group has elected not to recognise a right-of-use asset and corresponding lease liability for short-term leases with terms of 12 months or less. Lease payments on these assets are expensed to profit or loss as incurred.
2.11 Intangible assets
Research and development
Research and development expenditure is recognised as an expense as incurred. No research and development costs have been capitalised to date given the stage of the business.
Development expenditure is recognised as an expense except those costs incurred on development projects can be capitalised as intangible assets to the extent that such expenditure is expected to generate future economic benefits.
Patents and trademarks
Separately acquired trademarks and patents are recognised at historical cost. Patents have a finite life and are subsequently carried at cost less accumulated amortisation. Separately acquired trademarks are shown at historical cost. They are considered to have infinite lives and are assessed for impairment at each year end. The Group amortises intangible assets with a limited useful life using the straight-line method over their expected useful lives as follows:
Patents 15–20 years
Disposal of intangible assets
When an intangible asset, such as a patent, is disposed of or no longer expected to generate future economic benefits, it is derecognized from the financial statements. The profit or loss on disposal is determined as the difference between the carrying amount of the asset at the time of disposal and the proceeds from its disposal.
The Group may dispose of intangible assets through various methods, including but not limited to sale, abandonment, or expiration of the asset's legal rights. The method of disposal is chosen based on the circumstances at the time of disposal. Any gain or loss on the disposal of an intangible asset is recognized in the statement of profit or loss in the period in which the disposal occurs.
2.12 Impairment of non-financial assets
Goodwill and intangible assets with indefinite useful economic lives are tested for impairment annually at the financial year-end. Other non-financial assets are reviewed for impairment whenever events or changes in circumstances indicate that the carrying amount may not be recoverable. An impairment loss is recognised for the amount by which the asset’s carrying amount exceeds its recoverable amount.
2.13 Trade and other payables
These amounts represent liabilities for goods and services provided to the Group prior to the end of the financial year and which are unpaid. Due to their short-term nature, they are measured at amortised cost and are not discounted. The amounts are unsecured and are usually paid within 30 days of recognition.
2.14 Financial instruments
IFRS 9 requires an entity to address the classification, measurement and recognition of financial assets and liabilities.
- Classification
The Group classifies its financial assets in the following measurement categories:
- those to be measured at amortised cost.
The classification depends on the Group’s business model for managing the financial assets and the contractual terms of the cash flows.
The Group classifies financial assets as at amortised cost only if both of the following criteria are met:
- the asset is held within a business model whose objective is to collect contractual cash flows; and
- the contractual terms give rise to cash flows that are solely payment of principal and interest.
- Recognition
Purchases and sales of financial assets are recognised on trade date (that is, the date on which the Group commits to purchase or sell the asset). Financial assets are derecognised when the rights to receive cash flows from the financial assets have expired or have been transferred and the Group has transferred substantially all the risks and rewards of ownership.
- Measurement
At initial recognition, the Group measures a financial asset at its fair value plus, in the case of a financial asset not at fair value through profit or loss (FVPL), transaction costs that are directly attributable to the acquisition of the financial asset.
Transaction costs of financial assets carried at FVPL are expensed in profit or loss.
- Tax receivables
Australian R&D tax receivables
Management has assessed that tax receivables arising from a refundable tax offset from Australian Taxation Office, for eligible R&D expenditure, are recognised at the value claimed. These receivables are expected to be collected in a short-term period and the Directors have assessed that the receivables are not impaired. This is based on Australian government credit rating (AAA) and successful historical collection of tax receivables.
UK R&D tax receivables
Management has assessed that tax receivables arising from UK Research and Development (“R&D”) tax relief claims with HM Revenue & Customs (“HMRC”), including the Research and Development Expenditure Credit (“RDEC”) scheme in the prior year and Enhanced R&D Intensive Support (“ERIS”) in the current year, are recognised at the amounts expected to be recovered.
These receivables are expected to be collected within a short-term period and the Directors have assessed that the receivables are not impaired, having regard to the nature of the counterparty as a UK government authority and the Group’s historical experience of successfully recovering R&D tax amounts from HMRC.
2.15 Share-based payments
The Group provides benefits to its employees in the form of share-based payments, whereby employees render services in exchange for shares or rights over shares (equity-settled transactions) in the parent entity.
The cost of these equity-settled transactions with employees is measured by reference to the fair value of the equity instruments at the date at which they are granted. The fair value is determined using a Black- Scholes model.
The cost of these equity-settled transactions is recognised as an expense, with a corresponding increase in equity, over the period in which the service conditions are fulfilled (the vesting period), ending on the date on which the relevant employees become fully entitled to the award (the vesting date).
At each subsequent reporting date until vesting, the cumulative charge to profit and loss is the product of:
- the grant date fair value of the award;
- the current best estimate of the number of awards that will vest;
- the expired portion of the vesting period; and
- the removal of any fair value attributable to share options that have contractually lapsed or expired.
The charge to profit and loss for the period is the cumulative amount as calculated above less the amounts already charged in previous periods. There is a corresponding entry to the share-based payment reserve in equity.
If a share-based payment arrangement is modified, the minimum expense recognised over the vesting period is the original fair value. If the modification increases fair value, the additional fair value is recognised over the remaining vesting period.
2.16 Exceptional and non-recurring items
The Group considers certain unusual or infrequent items that either because of their size or their nature, or relevance to the business as are non-recurring and disclose separately to report the underlying performance of the business. For an item to be considered as a separate item, it must initially meet at least one of the following criteria:
- It is a significant item, which may cross more than one accounting period.
- It has been directly incurred as a result of either an acquisition / divestment or funding related or arises from a major business change.
- It is unusual in nature, e.g. outside the normal course of business.
If an item meets at least one of the criteria, the Board, through the Audit and Risk Committee, then exercises judgement as to whether the item should be classified as an allowable adjustment to IFRS performance measures and disclosed separately.
2.17 Foreign currency translation
The functional currency of each company in the Group is that of the primary economic environment in which the entity operates. Monetary assets and liabilities denominated in foreign currencies are translated into the functional currency at the rates of exchange ruling at the period end. Transactions in foreign currencies are recorded at the rate ruling at the date of the transaction.
On consolidation, the assets and liabilities of the Group entities that have a functional currency different to the presentational currency are translated into GBP at the closing rate at the date of the Statement of Financial Position. Income and expenses for each statement of profit or loss are translated at average exchange rates for the period. Exchange differences are recognised in other comprehensive income and accumulated in a foreign exchange translation reserve.
2.18 Contributed equity
Ordinary Shares are classified as equity. Incremental costs directly attributable to the issue of new shares are deducted from the share premium account.
Retained losses includes all current and prior period results.
2.19 Input taxes
Revenues, expenses and assets are recognised net of the amount of associated goods and services tax (GST) in Australia or value added tax (VAT) in the UK, unless the sales tax incurred is not recoverable from the taxation authority. In this case it is recognised as part of the cost of acquisition of the asset or as part of the expense.
Receivables and payables are stated inclusive of the amount of sales tax receivable or payable. The net amount of sales tax recoverable from, or payable to, the taxation authority is included with other receivables or payables in the balance sheet.
Cash flows are presented on a net basis. The sales tax components of cash flows arising from investing or financing activities which are recoverable from, or payable to the taxation authority, are presented as operating cash flows.
2.20 Critical accounting judgements and key sources of estimation uncertainty
The preparation of the financial information requires the use of accounting estimates which, by definition, will seldom equal the actual results. Management also needs to exercise judgement in the process of applying the Group’s accounting policies. The areas involving a high degree of judgement or complexity, or areas of assumptions and estimates are:
Critical accounting judgements
- Revenue recognition
The Group treats each fixed-price BESS contract as a single performance obligation satisfied at a point in time. Revenue is measured when the performance obligation is satisfied and control is transferred to the customer. Management judgement is required to assess the point at which control transfers, taking into account contractual terms and the customer’s ability to use and obtain benefits from the system.
- Australian R&D tax incentives
From 1 July 2011, the Australian Taxation Office has provided a tax incentive, in the form of a refundable tax offset of 43.5%, for eligible research and development expenditure. Management has assessed its research and development activities and expenditure and applied judgement in determining which expenses are likely to be eligible under the scheme. For the period ended 30 June 2026 the Group has recorded other income of £1,128,000 (2025: £1,209,000) based on expected tax refunds to be received from the government (recognised under Other receivables).
- UK R&D Tax reliefs: R&D expenditure credit (RDEC) Scheme and Enhanced R&D Intensive Support (“ERIS”) Scheme
Gelion Europe Limited and Battery Minerals are both eligible to claim Research and Development Expenditure Credit (RDEC) under the SMEs programme and ERIS Scheme. For the period ending 30 June 2026, Management has assessed eligible R&D expenses and has recognised £261,000 under ERIS (2025: £102,000 under RDEC) in other income from expected tax refunds (recognised under Other receivables).
- Recognition of a deferred tax asset
The Group has incurred tax losses in both Australia and the UK in each of the periods reported in these financial statements. No deferred tax asset has been recognised in respect of these losses, as the Directors believe that there is not sufficient certainty over future profits that would utilise them.
Key sources of estimation uncertainty
- Estimation of useful lives of intangible assets
The Group determines the estimated useful lives of its finite-life intangible assets and the related amortisation expense. For patents, useful lives are determined with reference to the expected period of economic benefit, including the remaining legal life of the patent. Patents are amortised over useful lives of between 15 and 20 years.
- Management considers that the useful lives applied remain appropriate at the reporting date and does not consider a material change in those useful lives to be reasonably possible in the foreseeable future.
The key assumption for trademarks is they have an infinite life as they do not have an expiration date.
- Impairment of goodwill and patents
The Group performs an annual impairment test for goodwill acquired through business combinations, comparing its carrying amount to its recoverable amount at the reporting date. The recoverable amount of goodwill is determined for the Group as a whole based on its FVLCTS (Fair Value Less Cost of Disposal) method. Fair value is estimated with reference to the Group’s market capitalisation at the reporting date. Management considers this approach to provide the most reliable indication of fair value given the Group’s listed status on AIM. Any impairment loss is recognised immediately in the income statement and is not subsequently reversed.
- The Group assesses impairment of patents at each reporting date by evaluating conditions specific to the Group and to the particular asset that may lead to impairment. If an impairment trigger is identified, the recoverable amount of the asset is determined. To date, impairment has been recognized on capitalised patents for patent applications that have either lapsed, been rejected or written off. In these instances, the Group fully impairs the carrying amount of patent at that date.
- Recognition of equity-settled share-based payments
The cost of equity-settled share-based payment transactions with employees is measured by reference to the fair value of the equity instruments at the date at which they are granted. The fair value is determined using a Black-Scholes model. The Group had adopted the graded vesting approach, whereby a larger proportion of the total expense is recognised in earlier vesting periods which then decreases in the subsequent years. Please refer to note 23 for the key assumptions and inputs used in the model to determine the fair values at each measurement date.
2.21 Standards, amendments and interpretations to existing standards that are effective for the first time in the financial year
During the year ended 30 June 2026, Gelion has adopted the following new IFRSs (including amendments thereto) and IFRIC interpretations that became effective for the first time.
|
Standard |
Effective date, annual period beginning on or after |
|
Lack of exchangeability (Amendment to IAS 21 The Effects of Changes in Foreign Exchange Rates) |
1 January 2025 |
Their adoption has not had any material impact on the disclosures or amounts reported in the financial information.
Standards issued but not yet effective:
There are a number of standards, amendments to standards, and interpretations which have been issued by the IASB that are effective in future accounting periods that the Group has decided not to adopt early.
|
Standard |
Effective date, annual period beginning on or after |
|
Amendments to the Classification and Measurement of Financial Instruments (Amendments to IFRS 9 Financial Instruments) |
1 January 2026 |
|
Annual Improvements to IFRS Accounting Standards – Volume 11 |
1 January 2026 |
|
Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 9 and IFRS 7) |
1 January 2026 |
|
IFRS 18 Presentation and Disclosure in Financial Statements |
1 January 2027 |
|
IFRS 19 Subsidiaries without Public Accountability: Disclosures |
1 January 2027 |
|
Translation to a Hyperinflationary Presentation Currency (IAS 21 The Effects of Changes in Foreign Exchange Rates) |
1 January 2027 |
|
IFRS 20 Regulatory Assets and Regulatory Liabilities |
1 January 2029 |
As at 30 June 2026, IFRS 18 and IFRS 19, together with the amendments effective from 1 January 2026 listed above, had been endorsed for use in the United Kingdom. Translation to a Hyperinflationary Presentation Currency (Amendments to IAS 21) was subsequently endorsed for use in the United Kingdom on 30 September 2026. IFRS 20 Regulatory Assets and Regulatory Liabilities had not yet been endorsed for use in the United Kingdom.
The Directors are evaluating the impact that the above new standards and amendments may have on the Group's financial statements. The Group does not currently expect the adoption of these standards and amendments, other than IFRS 18, to have a material impact on its financial statements.
3. Segment Reporting
Operating segments are reported in a manner consistent with the internal reporting provided to the chief operating decision-maker.
The chief operating decision-maker, who is responsible for allocating resources and assessing performance of the operating segments, has been identified as the Board as a whole.
In the opinion of the Directors, during each of the two-years ended 30 June, Gelion operated in the single business segment of battery research and development. Therefore, there is one operating segment which is considered to be the Group.
Geographical disclosure
|
UK |
Australia |
As at 30 June 2026 £’000 |
UK |
Australia |
As at 30 June 2025 £’000 | |
|
Non-current assets |
||||||
|
Goodwill |
2,804 |
- |
2,804 |
2,804 |
- |
2,804 |
|
Intangible assets |
1,122 |
1,791 |
2,913 |
1,198 |
2,102 |
3,300 |
|
Property, plant and equipment |
178 |
893 |
1,071 |
171 |
703 |
874 |
|
Total income |
||||||
|
Revenue from contracts with customers |
- |
49 |
49 |
- |
912 |
912 |
|
Other income |
835 |
1,579 |
2,414 |
590 |
1,209 |
1,799 |
|
Depreciation and amortisation |
(165) |
(420) |
(585) |
(129) |
(464) |
(593) |
|
Finance income (interest) |
52 |
163 |
215 |
8 |
39 |
47 |
|
Operating loss |
(2,505) |
(4,173) |
(6,678) |
(1,933) |
(4,090) |
(6,023) |
4. Revenue from Contracts with Customers
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Revenue from contracts with customers |
49 |
912 |
|
Total Revenue from contracts with customers |
49 |
912 |
In FY2025, the Group recognised revenue of £912k from the installation of two 2MWh BESS for Group Energy Pty Limited (a Borg Group company). The remaining £49k has been recognised in FY2026 upon completion of final commissioning activities.
5. Other Income
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
R&D tax concessions |
1,389 |
1,311 |
|
Grant income |
1,025 |
488 |
|
Total other income |
2,414 |
1,799 |
The subsidiaries incur R&D expenditure which qualifies for relief under a tax incentive scheme provided by the Australian Taxation Office, as well as the Enhanced R&D Intensive Support (ERIS) Scheme by HMRC in FY26, the R&D expenditure credit (RDEC) Scheme by HMRC in FY25. Management estimates the expenditure each year relevant to approved R&D activities in respect of which a claim can be made at each reporting date. The accounting policy in respect of recognition of this income is detailed in note 2.5 and the key accounting judgements applied are detailed in note 2.20.
For Gelion Europe Limited and Battery Minerals Limited, the subsidiaries recognise grant income which relates to approved grant funding through the Faraday Battery Challenge (FBC) and the Advanced Propulsion Centre (APC) programs. The grant funding is recognised on an accrual basis and are claimed either on a monthly or a quarterly basis with the funds received in the month after the claim submission.
For Gelion Technologies Pty Limited, grant income relating to operating expenditure is recognised in profit or loss as eligible expenditure is incurred in delivering the ACPC (ARENA) project. Grant income relating to capital expenditure is recognised initially as deferred income and subsequently recognised in profit or loss on a systematic basis over the useful life of the related assets, matching the periods in which the associated depreciation expense is recognised.
6. Operating loss before exceptional and non-recurring items
|
Year ended 30 June | |||
|
Notes |
2026 |
2025 | |
|
Revenue from contracts with customers |
49 |
912 | |
|
Direct costs |
- |
(671) | |
|
R&D tax concessions |
5 |
1,389 |
1,311 |
|
Grant income |
5 |
1,025 |
488 |
|
Depreciation and amortisation |
13, 15 |
(585) |
(593) |
|
Employee benefits |
11 |
(4,533) |
(4,269) |
|
R&D expenses |
(1,344) |
(1,275) | |
|
Out of which: |
|||
|
External R&D services |
(404) |
(500) | |
|
R&D materials, consumables & other |
(523) |
(428) | |
|
Rent for laboratories |
(417) |
(347) | |
|
Business overheads and other expenses |
(1,537) |
(1,165) | |
|
Total operating loss before exceptional and non-recurring items |
(5,536) |
(5,262) | |
During the year, the Group reviewed the classification of laboratory rental expenses. These costs were previously presented within business overheads and have been reclassified to research and development expenses.
£347,000 of laboratory rental expenses for the year ended 30 June 2025 have been reclassified from business overheads to research and development expenses.
The reclassification better reflects the nature and use of the laboratory facilities, which are primarily used for the Group’s research and development activities, and provides more relevant and consistent presentation of R&D expenditure. Management does not consider the reclassification to represent the correction of a prior-period error. The laboratory rent was appropriately recognised as an expense in prior periods. There has been no change to the recognition of the expenditure, the measurement of the expenditure or the timing of recognition.
The reclassification has no impact on the Group’s total expenses, loss before tax, net assets or cash flows for the year ended 30 June 2025.
7. Exceptional and non-recurring items
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Acquisition related costs |
111 |
211 |
|
Capital raising costs |
88 |
90 |
|
Loss on disposal of Property, Plant and Equipment |
2 |
47 |
|
Loss on write-off of IP intangibles |
530 |
299 |
|
Business restructure |
- |
88 |
|
Other |
411 |
26 |
|
Total exceptional and non-recurring items |
1,142 |
761 |
Exceptional and non-recurring costs in FY26 include write-off of IP intangibles, US operations initial establishment costs, executive recruitment costs, deferred consideration in relation to the Gelion Europe Limited acquisition and capital raise costs. These have been separately disclosed to assist the user of the financial information to understand and compare the underlying results of the Company.
Other expenses of £411k included £200k of US business establishment costs, legal fees towards grant funding and business development expenses, and £150k of executive recruitment fees.
Exceptional and non-recurring costs in FY25 include write-off of IP intangibles, deferred consideration in relation to the Gelion Europe Limited acquisition, capital raise costs and one-off costs relating to an organisational restructure.
8. Auditors’ Remuneration
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Fees payable to the Company’s auditors for the statutory audit of the Company’s annual financial statements |
109 |
104 |
|
Fees payable to the Company’s auditors and its associates for the audits of the Company’s subsidiaries |
46 |
43 |
|
Non-audit services |
||
|
Taxation and other services |
1 |
2 |
|
Total auditors’ remuneration |
156 |
149 |
9. Taxation
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
The taxation income for the year is made up as follows: |
||
|
Corporation taxation on the results for the year |
(20) |
(19) |
|
Taxation income for the year |
(20) |
(19) |
|
Numerical reconciliation of income tax expense to accounting loss: |
||
|
Loss for the year before income tax |
(6,473) |
(6,003) |
|
Prima facie tax benefit on loss from ordinary activities @ 25% |
(1,618) |
(1,501) |
|
Add/(less) tax effect of: |
||
|
Non-deductible expenditure |
1,188 |
880 |
|
R&D tax offsets |
(282) |
(302) |
|
Tax losses incurred but not recognised |
692 |
904 |
|
Total taxation income |
(20) |
(19) |
Non-deductible expenses include share-based payments and expenditure subject to R&D tax incentive.
Estimated tax losses of £18,150,000 (2025: £15,156,000) are available for relief against future profits. No deferred tax asset has been provided for in the accounts based on the estimated tax losses. The estimated tax losses per jurisdiction is as follows and do not have an expiry date in each of these jurisdictions:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Estimated tax losses arising in the UK |
4,953 |
3,934 |
|
Estimated tax losses arising in Australia |
13,197 |
11,222 |
|
Total tax losses available to carry forward |
18,150 |
15,156 |
The standard rate of corporation tax in Australia, where the subsidiary is based, is 25% (2025: 25%).
As per note 2.6, deferred tax assets have not been recognised on the basis the Company is not forecasted to make a profit for the foreseeable future.
10. Exchange Gains and Losses Arising on Translation of Foreign Operations
Gelion Technologies Pty Limited, a battery technology development business incorporated in Australia, was merged into Gelion UK Limited in 2016 so as to maximise operational synergies and generate further cost savings.
A gain or loss through other comprehensive income arises on translation of the subsidiary’s assets and liabilities from Australian Dollars to GBP as part of the consolidation process at year end.
11. Employee Benefit Expenses
Employee benefit expenses (including Directors) comprise:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Salaries and wages including taxes |
3,565 |
3,350 |
|
Defined contribution pension cost |
294 |
276 |
|
Employer’s national insurance expense |
116 |
69 |
|
Share-based payment expense |
558 |
574 |
|
Total employee benefits expense (note 6) |
4,533 |
4,269 |
Average Employee Numbers
|
2026 |
2025 | |
|
R&D |
25 |
24 |
|
Systems & Engineering |
5 |
6 |
|
Administration |
16 |
16 |
|
Average number of employees |
46 |
46 |
|
Employee headcount at period end |
50 |
42 |
Key management personnel
Directors and key management personnel compensation
The total remuneration paid (including bonus accruals) to the Directors and key management personnel of the Group during the year are as follows:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Salaries and wages including taxes |
649 |
684 |
|
Defined contribution pension cost |
30 |
45 |
|
Employer’s national insurance expense |
30 |
17 |
|
Share-based payment expense |
140 |
233 |
|
Total key management personnel costs |
849 |
979 |
The Directors and senior management represent key management personnel. Further details of Directors’ remunerations are given in the Directors’ Remuneration Report. The highest paid Director during the year received total remuneration of £254,071 (2025: £201,268). No share options were exercised by Directors during the financial year ended 30 June 2026.
12. Loss Per Share
|
Year ended 30 June |
|
2026 £’000 |
2025 £’000 | |
|
Loss after tax |
£6,453,000 |
£5,984,000 |
|
Weighted average number of shares (number) |
210,977,856 |
146,797,706 |
|
Loss per share (pence) |
3.1p |
4.1p |
The calculation of the loss per share is based on the loss for the financial period after taxation of £6,453,000 (2025: £5,984,000) and on the weighted average of 210,977,856 (2025: 146,797,706) Ordinary Shares in issue during the period.
In FY26, the parent company issued 52,569,673 shares, majority of which relates:
- 52,500,000 ordinary shares issued at a price of 20 pence per share
- 69,673 shares issued in lieu of options exercised.
This increase in the number of Ordinary Shares has resulted in the weighted average number of shares in the year to June 2026 to increase to 210,977,856 (2025: 146,797,706).
There were 17,300,962 share options outstanding at 30 June 2026 (2025: 14,468,083). The impact of these options would be to reduce the diluted loss per share and therefore they are antidilutive. Hence, the diluted loss per share reported for the periods under review is the same as the loss per share.
13. Intangible Assets
|
Patents £’000 |
Trademarks £’000 |
Goodwill £’000 |
Total £’000 | |
|
At 30 June 2024 |
4,056 |
21 |
2,804 |
6,881 |
|
Cost |
||||
|
Additions |
318 |
- |
- |
318 |
|
Write-offs |
(341) |
- |
- |
(341) |
|
Difference on foreign exchange |
(242) |
(4) |
- |
(246) |
|
At 30 June 2025 |
3,791 |
17 |
2,804 |
6,612 |
|
Additions |
262 |
3 |
- |
265 |
|
Write-offs |
(664) |
- |
- |
(664) |
|
Difference on foreign exchange |
205 |
1 |
- |
206 |
|
At 30 June 2026 |
3,594 |
21 |
2,804 |
6,419 |
|
Amortisation |
||||
|
At 30 June 2024 |
267 |
– |
- |
267 |
|
Amortisation |
308 |
- |
- |
308 |
|
Write-offs |
(42) |
- |
- |
(42) |
|
Difference on foreign exchange |
(25) |
- |
- |
(25) |
|
At 30 June 2025 |
508 |
- |
- |
508 |
|
Amortisation |
293 |
- |
- |
293 |
|
Write-offs |
(134) |
- |
- |
(134) |
|
Difference on foreign exchange |
35 |
- |
- |
35 |
|
At 30 June 2026 |
702 |
- |
- |
702 |
|
Carrying amount |
||||
|
At 30 June 2025 |
3,283 |
17 |
2,804 |
6,104 |
|
At 30 June 2026 |
2,892 |
21 |
2,804 |
5,717 |
14. Goodwill and impairment
In accordance with IFRS requirements, the Group performs an annual impairment test to assess whether goodwill has suffered any impairment. As at 30 June 2026, goodwill was tested for impairment using the FVLCTS (Fair Value Less Cost of Disposal) method. The closing share price at 30 June 2026 was 18 pence giving a market capitalisation of £41.3 million which is £26.70 million higher than the Net Assets of the Group on this date. The share price would need to have dropped below 6 pence for the market value to be below the Net Asset value of the Group at that date. Based on the above, no impairment loss was identified in relation to goodwill. Since 30 June 2026, the share price of Gelion Plc has traded across a high-low range of 12.5p and 19.75p per share.
On 29th November 2023, the Group recognised goodwill of £2,804,447 following the acquisition of Gelion Europe. The intellectual property, technical know-how and other synergies arising from the acquisition are expected to benefit the Group’s operations across both Australia and the United Kingdom rather than Gelion Europe on a standalone basis. Accordingly, for impairment testing purposes, goodwill has been allocated to the group of CGUs comprising the Australian and UK operations that are expected to benefit from the synergies of the acquisition.
15. Property, Plant and Equipment
|
Office furniture and equipment |
Plant and equipment |
Right-of-use assets |
Leasehold improvements |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 | |
|
Cost |
|||||
|
At 30 June 2024 |
92 |
1,726 |
427 |
106 |
2,351 |
|
Additions |
67 |
98 |
53 |
- |
218 |
|
Disposals |
(1) |
(240) |
- |
- |
(241) |
|
Difference on foreign exchange |
(12) |
(138) |
(37) |
(10) |
(197) |
|
At 30 June 2025 |
146 |
1,446 |
443 |
96 |
2,131 |
|
Additions |
5 |
416 |
- |
4 |
425 |
|
Disposals |
(2) |
(16) |
(413) |
(26) |
(457) |
|
Difference on foreign exchange |
14 |
122 |
23 |
9 |
168 |
|
At 30 June 2026 |
163 |
1,968 |
53 |
83 |
2,267 |
|
Depreciation |
|||||
|
At 30 June 2024 |
72 |
699 |
419 |
92 |
1,282 |
|
Charge for the year |
13 |
257 |
12 |
3 |
285 |
|
Accumulated depreciation on disposal |
(1) |
(191) |
- |
- |
(192) |
|
Difference on foreign exchange |
(7) |
(65) |
(38) |
(8) |
(118) |
|
At 30 June 2025 |
77 |
700 |
393 |
87 |
1,257 |
|
Charge for the year |
18 |
243 |
27 |
4 |
292 |
|
Accumulated depreciation on disposal |
(2) |
(13) |
(413) |
(26) |
(454) |
|
Difference on foreign exchange |
7 |
64 |
23 |
7 |
101 |
|
At 30 June 2026 |
100 |
994 |
30 |
72 |
1,196 |
|
Carrying amount |
|||||
|
At 30 June 2025 |
69 |
746 |
50 |
9 |
874 |
|
At 30 June 2026 |
63 |
974 |
23 |
11 |
1,071 |
16. Leases
The Group has lease contracts in respect of leasehold property used in its operations. These leases have lease terms of between two and three years.
There is no leasehold property recognised by the Group in the two years ended 30 June 2026 presented in these financial statements other than those recognised as right-of-use assets. Therefore, for the carrying amount of right-of-use assets at each reporting date and movements in each year ended refer to note 15.
Set out below are the carrying amounts of lease liabilities (included under trade and other payables) and the movements during each year ended 30 June:
|
2026 |
2025 | |
|
Balance as at 1 July |
45 |
8 |
|
Additions |
- |
53 |
|
Interest |
3 |
1 |
|
Payments |
(30) |
(16) |
|
Difference on foreign exchange |
- |
(1) |
|
Balance as at 30 June |
18 |
45 |
The maturity analysis of lease liabilities is disclosed in note 24.
The following are the amounts recognised in profit or loss:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Depreciation expense of right-of-use assets |
27 |
12 |
|
Interest expense on lease liabilities |
3 |
1 |
|
Total amount recognised in profit or loss |
30 |
13 |
17. Cash and Cash Equivalents
|
As at 30 June | ||
|
2026 |
2025 | |
|
Cash at bank |
7,550 |
2,661 |
|
Total Cash and Cash Equivalents |
7,550 |
2,661 |
Cash at bank including short-term deposits < 3 months comprises balances held by Gelion Plc, Gelion Europe Limited, Battery Minerals Limited and Gelion Technologies Pty Limited current bank accounts.
18. Other Receivables
|
As at 30 June | ||
|
2026 |
2025 | |
|
Other receivables: |
||
|
R&D tax incentive |
1,426 |
1,256 |
|
Government grant receivable |
528 |
- |
|
Prepayments |
406 |
119 |
|
VAT/GST receivable |
63 |
145 |
|
Other debtors |
28 |
199 |
|
Total other receivables |
2,451 |
1,719 |
The amounts are measured at amortised cost using the effective interest method in line with IFRS 9.
R&D tax incentives are granted by the Australian Taxation Office and the HMRC in the form of refundable tax offsets. The key judgements applied in the recognition of this receivable are detailed in note 2.20.
Government grant receivables included £414,000 relating to ARENA grant funding and £114,000 relating to Innovate UK grant funding, which were both received subsequent to the reporting period ending 30 June 2026.
Prepayments include advance payments of £187,000 for the purchase of equipment for the ARENA project. The equipment generally has a lead time of approximately three to six months for delivery, installation and commissioning.
The Directors consider that the carrying value of other receivables approximates to their fair value.
19. Trade and Other Payables
Due within one year
|
As at 30 June | ||
|
2026 |
2025 | |
|
Trade payables |
661 |
546 |
|
Accruals |
380 |
291 |
|
Employee liabilities including employment taxes |
218 |
150 |
|
Lease liabilities |
18 |
27 |
|
1,277 |
1,014 | |
Due in more than one year
|
As at 30 June | ||
|
2026 |
2025 | |
|
Lease liabilities |
- |
18 |
|
Provision for long service leave |
89 |
54 |
|
89 |
72 | |
Trade payables and accruals principally comprise amounts outstanding for trade purchases and continuing costs. The Directors consider that the carrying value amount of trade and other payables approximates to their fair value. Please refer to note 24 for further details.
20. Deferred grant income
|
2026 |
2025 | |
|
Balance as at 1 July |
- |
- |
|
Deferred grant income |
515 |
- |
|
Credit to profit or loss |
(8) |
- |
|
Difference on foreign exchange |
12 |
|
|
Balance as at 30 June |
519 |
- |
During the year, the Group received government grant funding from the Australian Renewable Energy Agency (“ARENA”) in relation to the acquisition of capital assets. An amount of £515k was recognised as Deferred grant income, with £8k released to profit or loss during the year over the useful lives of the related assets.
21. Deferred tax
Deferred tax liability of £281k represents the carrying amount of the deferred tax liability recognised on Gelion Europe’s technology-based intangibles at the time of acquisition.
|
2026 £’000 |
2025 £’000 | |
|
Balance as at 1 July |
301 |
320 |
|
Credit to profit or loss |
(20) |
(19) |
|
Balance as at 30 June |
281 |
301 |
22. Issued Capital and Reserves
Share capital and premium
|
Ref. |
Number of shares |
Share capital |
Share premium | ||
|
£’000 |
£’000 | ||||
|
Balance as at 1 July 2024 |
136,010,603 |
136 |
24,487 | ||
|
Shares issued during the period |
a/b |
40,812,264 |
41 |
4,379 | |
|
Cost of shares issued |
c |
- |
- |
(451) | |
|
Exercise of share options |
28,916 |
- |
- | ||
|
Balance as at 30 June 2025 |
176,851,783 |
177 |
28,415 | ||
|
Shares issued during the period |
d |
52,500,000 |
52 |
10,448 | |
|
Cost of shares issued |
e |
- |
- |
(557) | |
|
Exercise of share options |
69,673 |
- |
- | ||
|
Balance as at 30 June 2026 |
229,421,456 |
229 |
38,306 | ||
Year ended 30 June 2025
- On 20 December 2024, 11,397,837 new ordinary shares of £0.001 have been issued at a price of 15 pence per share. On 3 January 2025, 1,033,334 new ordinary shares of £0.001 have been issued at a price of 15 pence per share.
- On 6 May 2025, 28,381,093 new ordinary shares of £0.001 have been issued at a price of 9 pence per share.
- Transaction costs incurred in the issuing of shares in the period ended 30 June 2025 of £541,000 of which £451,000 was offset against share premium and £90,000 was expensed.
Year ended 30 June 2026
- On 7 November 2025, 52,500,000 new ordinary shares of £0.001 have been issued at a price of 20 pence per share.
- Transaction costs incurred in the issuing of shares in the period ended 30 June 2026 of £645,000 of which £557,000 was offset against share premium and £88,000 was expensed.
Nature and purpose of other reserves
Other reserves
Share-based payments reserve
The share-based payments reserve is used to recognise the value of equity-settled share-based payments provided to employees, including key management personnel, as part of their remuneration. Refer to note 23 for further details of these plans.
Foreign currency translation reserve
The subsidiary’s functional currency is AUD and therefore on consolidation a foreign exchange gain or loss on translation of net assets is recognised through other comprehensive income at each reporting date. These gains or losses are accumulated in a foreign currency translation reserve.
Capital reduction reserve
Immediately following the Second Bonus Issue in FY22, the balance standing to the credit of the share premium account was cancelled and the amount so cancelled was credited to a distributable reserve called the ‘capital reduction reserve’.
Merger relief reserve
On 29th November 2023, the Company completed the acquisition of 100% of ordinary shares of Gelion Europe Limited, the transaction consideration involved a combination of cash and the issuance of 10,508,582 ordinary shares in Gelion. The investment was recognised at fair value, and the excess of the fair value over the nominal value of the issued share capital is recorded within equity as a merger relief reserve.
Other reserves:
|
Share-based payment reserve £’000 |
Foreign currency translation reserve £’000 |
Merger relief reserve £’000 |
Total other reserves £’000 | |
|
Balance at 1 July 2024 |
6,497 |
(210) |
2,590 |
8,877 |
|
Foreign currency translation reserve movement |
- |
(556) |
– |
(556) |
|
Share-based payment charge |
574 |
– |
– |
574 |
|
Balance at 30 June 2025 |
7,071 |
(766) |
2,590 |
8,895 |
|
Balance at 1 July 2025 |
7,071 |
(766) |
2,590 |
8,895 |
|
Foreign currency translation reserve movement |
- |
604 |
– |
604 |
|
Share-based payment charge |
558 |
- |
– |
558 |
|
Balance at 30 June 2026 |
7,629 |
(162) |
2,590 |
10,057 |
23. Share-Based Payments
The Directors recognise the role of the Group’s staff in contributing to its overall success and the importance of the Group’s ability to incentivise and motivate its employees. Therefore, the Directors believe that certain employees should be given the opportunity to participate and take a financial interest in the success of the Company, aligning employees’ interests with shareholders and Company goals.
In July 2022, the Board introduced a new Share Option Plan. The plan is designed to motivate and incentivise key talent to assist the Group in achieving its strategic aims whilst remaining consistent with its tolerance for risk, all set within delegated limits set out during the IPO.
These options are structured as nominal cost options. The options will normally vest in three equal tranches over three years, subject to continued employment.
Share-based payment expenses are calculated using the graded vesting method, whereby a larger proportion of the total expense is recognised in earlier vesting periods and decreases in the subsequent years. This expense recognition pattern aligns with the economics of these awards, as employees render a greater proportion of the services required to earn the awards during the initial vesting periods.
Issued during the year ended 30 June 2026
• On 31 August 2025, 727,265 options were granted that will vest in three equal tranches, the first anniversary being 31 August 2026, followed by annual vesting on 31 August 2027 and 31 August 2028. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
• On 1 December 2025, 1,494,887 options were granted that will vest in three equal tranches, the first anniversary being 31 August 2026, followed by annual vesting on 31 August 2027 and 31 August 2028. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
• On the 15 January 2026, 450,000 options were granted under an Unapproved share option scheme to Technology Advisor Prof. Rachid Yazami that will vest in three equal tranches, the first anniversary being 15 January 2027, followed by annual vesting on 15 January 2028 and 15 January 2029, subject to continuing as an advisor to Gelion PLC. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the fifth anniversary of the grant.
• On 3 March 2026, 270,400 options were granted to John Wood that vested in full on 30 June 2026. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
Issued during the year ended 30 June 2025
• On the 6 January 2025, 300,000 options were granted under an Unapproved share option scheme to Director Dr Graham Cooley that will vest in three equal tranches, the first anniversary being 6 January 2026, followed by annual vesting on 6 January 2027 and 6 January 2028, subject to continuing to be a Director of the Group. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
• On the 15 March 2025, 1,500,000 options were granted under an Unapproved share option scheme to advisor Prof. Markus Antonietti that will vest in three equal tranches, the first anniversary being 15 March 2026, followed by annual vesting on 15 March 2027 and 15 March 2028, subject to continuing as an advisor to Gelion PLC. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the fifth anniversary of the grant.
• On 25 March 2025, 706,899 options were granted that will vest in three equal tranches, the first anniversary being 31 August 2025, followed by annual vesting on 31 August 2026 and 31 August 2027. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
• On 30 April 2025, 1,113,737 options were granted that will vest in three equal tranches, the first anniversary being 31 August 2025, followed by annual vesting on 31 August 2026 and 31 August 2027. The options were granted with the exercise price of 0.1 pence and will be exercisable up to the tenth anniversary of the grant.
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Share-based payment expense recognised |
558 |
574 |
|
Total share-based payment expense |
558 |
574 |
Summary of movements in awards:
|
New Share Option Plan Number ’000s |
2021 and prior Original Share Option Plan Number ’000s |
Unapproved Share Option Plan Number ’000s |
Weighted average exercise price £ | |
|
Outstanding at 30 June 2024 |
5,556 |
5,583 |
- |
0.16 |
|
Exercisable at 30 June 2024 |
1,674 |
5,583 |
- |
0.24 |
|
Granted |
1,821 |
– |
1,800 |
0.00 |
|
Forfeited |
(263) |
– |
– |
0.00 |
|
Exercised |
(29) |
– |
– |
0.00 |
|
Expired |
- |
– |
– |
– |
|
Outstanding at 30 June 2025 |
7,085 |
5,583 |
1,800 |
0.12 |
|
Exercisable at 30 June 2025 |
3,909 |
5,583 |
- |
0.19 |
|
Granted |
2,493 |
- |
450 |
0.00 |
|
Forfeited/Cancelled |
- |
- |
- |
0.00 |
|
Exercised |
(70) |
- |
- |
0.00 |
|
Expired |
- |
(40) |
- |
0.22 |
|
Outstanding at 30 June 2026 |
9,508 |
5,543 |
2,250 |
0.10 |
|
Exercisable at 30 June 2026 |
5,715 |
5,543 |
600 |
0.15 |
The range of exercise prices for options outstanding at the end of the year was £0.001 to £1.45 (2025: £0.001 to £1.45).
The weighted average remaining contractual life for the share options outstanding as at 30 June 2026 was 5.00 years (2025: 5.74 years).
Of the total number of options outstanding at 30 June 2026, 11,857,308 (2025: 9,491,963) had vested and were exercisable.
The weighted average fair value of the options granted in the year was £0.21 (2025: £0.11).
The Black-Scholes option pricing model was used to value the share-based payment awards granted in the year as it was considered that this approach would result in materially accurate estimate of the fair value of options granted. The following table lists the inputs to the models used for share option plans:
|
2026* |
2025 | |
|
Weighted average fair values at the measurement date |
£0.21 |
£0.11 |
|
Weighted average exercise price |
£0.001 |
£0.001 |
|
Expected volatility (%) |
n/a |
n/a |
|
Risk-free interest rate (%) |
n/a |
n/a |
|
Expected life of share options (years) |
10 |
10 |
*2026 Options that were granted represent nominal cost options with an exercise price of £0.001. Nominal cost options fair value, under the Black-Scholes option pricing model, equals the share price at grant date, therefore expected volatility and risk-free interest rate have no impact on the valuation. In the year ended 30 June 2026 2,942,552 options (2025: 3,620,636) were granted at an exercise price of £0.001 (2025: £0.001). The total share-based payment expense for the year was £558,000 (2025: £574,000).
24. Financial Instruments and Risk Management
Capital risk management
The Group manages its capital to ensure it will be able to continue as a going concern while maximising the return to stakeholders. The overall strategy of the Group is to minimise costs and liquidity risk.
The capital structure of the Group consists of equity attributable to equity holders of the Group, comprising issued share capital, and retained earnings as disclosed in the Consolidated Statement of Changes of Equity.
The Group is exposed to a number of risks through its normal operations, the most significant of which are credit, currency and liquidity risks. The management of these risks is vested to the Board of Directors.
Credit risk
Credit risk is the risk of financial loss to the Group if a customer or counterparty to a financial instrument fails to meet its contractual obligations and arises principally from the Group’s receivables from customers. Indicators that there is no reasonable expectation of recovery include, amongst others, failure to make contractual payments for a period of greater than 120 days past due. There were no receivables from customers as at end of June 2026.
The carrying amount of financial assets represents the maximum credit exposure.
The principal financial assets of the Group are bank balances including short-term deposits. The Group deposits surplus liquid funds with counterparty banks that have high credit ratings, and the Directors consider the credit risk to be minimal. The Group’s maximum exposure to credit by class of individual financial instrument is shown in the table below:
|
As at 30 June |
|||||||||
|
2026 |
2026 |
2025 |
2025 |
||||||
|
£’000 |
£’000 |
£’00 |
£’000 |
||||||
|
Cash and cash equivalents |
7,550 |
7,550 |
2,661 |
2,661 |
|||||
|
7,550 |
7,550 |
2,661 |
2,661 |
||||||
|
As at 30 June | |||||||||
|
2026 |
2026 |
2025 |
2025 | ||||||
|
£’000 |
£’000 | ||||||||
|
Royal Bank of Scotland |
A+ |
2,571 |
A+ |
1,334 | |||||
|
HSBC UK |
A+ |
- |
A+ 24 | ||||||
|
Commonwealth Bank of Australia |
A+ |
4,979 |
A+ |
1,303 | |||||
|
7,550 |
2,661 | ||||||||
The Group monitors the credit ratings of counterparties regularly and at the reporting date does not expect any losses from non-performance by the counterparties. For all financial assets to which the impairment requirements have not been applied, the carrying amount represents the maximum exposure to credit loss.
Currency risk
The Group operates in a global market with income and costs possibly arising in a number of currencies (AUD, USD, GBP) and is exposed to foreign currency risk arising from commercial transactions, acquiring Property, Plant and Equipment and laboratory materials and consumables, as well as translation of net investment in foreign subsidiaries. Exposure to commercial transactions arise from sales or purchases by operating companies in currencies other than the companies’ functional currency. Currency exposures are reviewed regularly. The Group has signed an agreement with financial institution in FY23, to set forward exchange rate contracts to provide certainty in terms of cash flow forecasts.
The Group has a limited level of exposure to foreign exchange risk through their foreign currency denominated cash balances and a portion of the Group’s costs being incurred in Australian Dollar. Accordingly, movements in the Great British Pounds exchange rate against these currencies could have a detrimental effect on the Group’s results primarily for reporting purposes.
Currency risk is managed by maintaining some cash deposits in currencies other than Great British Pounds, particularly those currencies where future expenditure is forecasted. The table below shows the currency profiles of cash and cash equivalents:
|
As at 30 June | ||
|
2026 |
2025 | |
|
Cash, cash equivalents and term deposits |
||
|
US Dollars |
199 |
214 |
|
Great British Pounds |
2,571 |
1,358 |
|
Australian Dollars |
4,780 |
1,089 |
|
7,550 |
2,661 | |
Liquidity risk
Liquidity risk is the risk that the Group will encounter difficulty in meeting the obligations associated with its financial liabilities that are settled by delivering cash or another financial asset. The Group’s approach to managing liquidity is to ensure, as far as possible, that it will have sufficient liquidity to meet its liabilities when they are due, under both normal and stressed conditions, without incurring unacceptable losses or risking damage to the Group’s reputation.
The Group seeks to manage liquidity risk by regularly reviewing cash flow budgets and forecasts to ensure that sufficient liquidity is available to meet foreseeable needs and to invest cash assets safely and profitably. The Group deems there is sufficient liquidity for the foreseeable future.
The Group had cash and cash equivalents at period end as below:
|
As at 30 June | ||
|
2026 |
2025 | |
|
Cash and cash equivalents |
7,550 |
2,661 |
|
7,550 |
2,661 | |
The table below sets out the maturity profile of the Group’s financial liabilities at each year end:
Year ended 30 June 2026
|
Due in less than one month |
Due between one and three months |
Due between three months and one year |
Due between one year and five years |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 | |
|
Trade and other payables |
1,242 |
- |
- |
- |
1,242 |
|
Lease liabilities |
- |
7 |
12 |
- |
19 |
|
Provision for Long Service Leave |
- |
- |
- |
89 |
89 |
|
1,242 |
7 |
12 |
89 |
1,350 |
Year ended 30 June 2025
|
Due in less than one month |
Due between one and three months |
Due between three months and one year |
Due between one year and five years |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 | |
|
Trade and other payables |
965 |
- |
22 |
- |
987 |
|
Lease liabilities |
- |
7 |
22 |
19 |
48 |
|
Provision for Long Service Leave |
- |
- |
- |
54 |
54 |
|
965 |
7 |
44 |
73 |
1,089 |
25. Capital Commitments
As at 30 June 2026, the Group had capital commitments of £597,000 (2025: nil), relating to committed expenditure under the ARENA project, primarily for laboratory equipment and project-related assets. These commitments represent contracted amounts not yet recognised as liabilities at the reporting date and are expected to be incurred during FY27.
26. Related Party Transactions
Other than the remuneration to key management personnel outlined in note 11 of these financial statements, there are the following related party transactions:
Management and R&D service fees of £10,655 (2025: £43,089) were paid to Thomas Maschmeyer Consulting Pty Limited, a company with a common director (Prof Thomas Maschmeyer).
Remuneration of £38,983 (2025: £26,866) was paid to a fixed term employee for services provided to the company. The employee is a related person of a Group Director who resigned on June 30, 2026.
Remuneration of key management personnel
The remuneration of the Directors, who are the key management personnel of the Group, is set out in aggregate in note 11 for each of the categories specified in IAS 24.
27. Events Subsequent to Year End
Subsequent to year end, the Group entered into a funded joint development agreement with Mitsui Kinzoku Co. Ltd. to validate its NES™ Cathode Active Material. The agreement provides for £2.0 million of milestone-based funding.
28. Control
In the opinion of the Directors there is no single ultimate controlling party.
29. Alternative Performance Measures (APM)
The below non-IFRS performance measures have been used. These measures are additional to IFRS measures and may not be comparable with other companies. APMs should not be viewed in isolation but as a supplementary information.
In determining whether an item should be presented as an allowable adjustment to IFRS measures, the Group considers items which are significant either because of their size or their nature, and which are exceptional and non-recurring. For an item to be considered as an allowable adjustment to IFRS measures, it must initially meet at least one of the following criteria:
- It is a significant item, which may cross more than one accounting period.
- It has been directly incurred as a result of either an acquisition / divestment or arises from a major business change.
- It is unusual in nature, e.g. outside the normal course of business.
If an item meets at least one of the criteria, the Board, through the Audit and Risk Committee, then exercises judgement as to whether the item should be classified as an allowable adjustment to IFRS performance measures. These adjustments have been defined as:
- Transaction costs - Costs incurred in relation to capital raising, acquisition or divestment
- Loss on disposal of property, plant and equipment and write-off of IP intangibles
- Share based payments expense – Non-cash employee incentives
- Business restructure and other items - restructuring expenses, incorporation costs incurred towards initial geographical expansion, support required for grant funding applications, executive recruitment costs etc.
Use: Provides a consistent measure of the profits from the core business activities. The Company believes these APMs are widely used by securities analysts, investors and other interested parties to evaluate the profitability of companies. This measure is closely tracked by management to evaluate the Company’s operating performance and to make financial, strategic and operating decisions and because it may help investors to understand and evaluate, in the same manner as management, the underlying trends in the Company’s operational performance on a comparable basis, period on period.
Measures
- Adjusted EBITDA loss is calculated by excluding Capital raising and acquisition related costs, Loss on disposal of Property, Plant and Equipment and write-off of IP intangibles, Share based payments, Business restructure and Depreciation and Amortisation from Operating loss:
Reconciliation:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Operating loss |
(6,678) |
(6,023) |
|
Adjustments |
||
|
Loss on disposal of fixed assets and write-off of IP intangibles |
532 |
346 |
|
Share-based payments expense |
558 |
574 |
|
Depreciation and amortisation |
585 |
593 |
|
Capital raising and acquisition related costs |
199 |
301 |
|
Business restructure and other |
411 |
114 |
|
Adjusted EBITDA loss |
(4,393) |
(4,095) |
- Adjusted Operating loss is calculated by excluding Loss on disposal of Property, Plant and Equipment, write-off of IP intangibles, Transaction costs and Business restructure costs from Operating loss.
Reconciliation:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Operating loss |
(6,678) |
(6,023) |
|
Adjustments |
||
|
Loss on disposal of Property, Plant and Equipment and write-off of IP intangibles |
532 |
346 |
|
Capital raising and acquisition related costs |
199 |
301 |
|
Business restructure and other |
411 |
114 |
|
Adjusted operating loss |
(5,536) |
(5,262) |
- Adjusted loss after taxation is calculated by excluding exceptional and non-recurring expenses from reported loss from ordinary activities after taxation.
Reconciliation:
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Loss on ordinary activities after taxation |
(6,453) |
(5,984) |
|
Adjustments |
||
|
Loss on disposal of Property, Plant and Equipment and write-off of IP intangibles |
532 |
346 |
|
Capital raising and acquisition related costs |
199 |
301 |
|
Business restructure and other |
411 |
114 |
|
Adjusted loss after taxation |
(5,311) |
(5,223) |
- Proforma cash and cash equivalents is calculated by including R&D tax incentive, RDEC/ERIS receivables, grant receivables and other tax receivables from the Australian and the UK tax authorities.
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Cash and cash equivalents |
7,550 |
2,661 |
|
R&D tax incentive receivable from the Australian Government |
1,154 |
1,159 |
|
ERIS/RDEC from the UK government |
272 |
97 |
|
Grant receivable from the Australian government |
414 |
- |
|
Grant receivable from the UK government |
114 |
- |
|
Other tax receivables |
63 |
145 |
|
Proforma cash and cash equivalents |
9,567 |
4,062 |
- Underlying net cash use is calculated by including net cash used in operating activities, purchase of IP intangibles and property, plant and equipment, adjusted for exceptional and non-recurring items.
|
Year ended 30 June | ||
|
2026 |
2025 | |
|
Net cash used in operating activities |
(4,970) |
(4,455) |
|
Purchase of tangible Property, Plant and Equipment |
(487) |
(165) |
|
Cash used for IP intangibles |
(203) |
(318) |
|
Capital raising and acquisition related costs |
199 |
222 |
|
Business restructure and other |
411 |
114 |
|
Underlying net cash use |
(5,050) |
(4,602) |
|
As at 30 June | |||
|
Notes |
2026 £’000 |
2025 £’000 | |
|
Assets |
|||
|
Non-current assets |
|||
|
Investment in subsidiary |
4 |
38,052 |
32,465 |
|
Current assets |
|||
|
Cash and cash equivalents |
2,437 |
1,170 | |
|
Other receivables |
5 |
133 |
253 |
|
Total assets |
40,622 |
33,888 | |
|
Liabilities |
|||
|
Current liabilities |
|||
|
Trade and other payables |
6 |
360 |
252 |
|
Total liabilities |
360 |
252 | |
|
Net assets |
40,262 |
33,636 | |
|
Equity |
|||
|
Issued capital |
7 |
229 |
177 |
|
Share premium account |
7 |
38,306 |
28,415 |
|
Share-based payment reserve |
7 |
7,629 |
7,071 |
|
Capital reduction reserve |
7 |
11,194 |
11,194 |
|
Merger relief reserve |
2,511 |
2,511 | |
|
Accumulated losses |
(19,607) |
(15,732) | |
|
Total equity |
40,262 |
33,636 | |
As permitted by Section 408 of the Companies Act 2006, no income statement or statement of comprehensive income is presented for the Company.
The Company recorded a loss for the financial year ended 30 June 2026 of £3,875,000 (2025: loss of £1,102,000).
The financial statements of Gelion Plc, company registration number 09796512, were approved by the Directors and authorised for issue on 20 October 2026.
Dr Steve Mahon
Chairman
Parent Company Statement of Changes in Equity|
Share capital |
Share premium |
Accumulated losses |
Capital reduction reserve |
Share-based payment reserve |
Merger relief reserve |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 |
£’000 |
£’000 | |
|
Balance at 1 July 2024 |
136 |
24,487 |
(14,630) |
11,194 |
6,496 |
2,511 |
30,194 |
|
Total comprehensive loss for the period |
(1,102) |
(1,102) | |||||
|
Contributions by and distributions to owners: |
|||||||
|
Share-based payment charge |
- |
- |
- |
- |
575 |
- |
575 |
|
Shares issued during the period |
41 |
4,379 |
- |
- |
- |
- |
4,420 |
|
Costs of share issued |
- |
(451) |
- |
- |
- |
- |
(451) |
|
Total contributions by and distributions to owners |
41 |
3,928 |
575 |
4,544 | |||
|
Balance at 30 June 2025 |
177 |
28,415 |
(15,732) |
11,194 |
7,071 |
2,511 |
33,636 |
|
Balance at 1 July 2025 |
177 |
28,415 |
(15,732) |
11,194 |
7,071 |
2,511 |
33,636 |
|
Total comprehensive loss for the period |
- |
- |
(3,875) |
- |
- |
- |
(3,875) |
|
Contributions by and distributions to owners: |
|||||||
|
Share-based payment charge |
- |
- |
- |
- |
558 |
- |
558 |
|
Shares issued during the period |
52 |
10,448 |
- |
- |
- |
- |
10,500 |
|
Costs of share issued |
- |
(557) |
- |
- |
- |
- |
(557) |
|
Total contributions by and distributions to owners: |
52 |
9,891 |
558 |
10,501 | |||
|
Balance at 30 June 2026 |
229 |
38,306 |
(19,607) |
11,194 |
7,629 |
2,511 |
40,262 |
1. General Information
Gelion Plc (‘Gelion’ or the ‘Company’) is a 100% owner of Australian and UK subsidiaries that conducts research and development in respect of lithium-sulfur battery technology and the recycling of lithium-ion battery technology.
Gelion is a public limited company, limited by shares, incorporated and domiciled in England and Wales. The Company was incorporated on 26 September 2015. The registered office of the Company is at C/O External Services Limited, Central House 20 Central Avenue, St Andrews Business Park, Norwich, United Kingdom, NR7 0HR. The registered company number is 09796512.
Gelion Plc was incorporated as Gelion UK Ltd. On 12 November 2021, the Company was re-registered as a public limited company under the Companies Act and its name was changed to Gelion Plc.
The Board, Directors and management referred to in this document refers to the Board, Directors and management of Gelion.
2. Accounting Policies
2.1. Basis of preparation
These separate financial statements have been prepared in accordance with Financial Reporting Standard 101, ‘Reduced Disclosure Framework’ (FRS 101). The financial statements have been prepared under the historical cost convention and in accordance with the Companies Act 2006.
The preparation of financial statements in compliance with FRS 101 requires the use of certain critical accounting estimates. It also requires Group management to exercise judgement in applying the Group's accounting policies. The areas where significant judgements and estimates have been made in preparing the financial statements and their effect are disclosed in note 2.20 of the consolidated financial statements.
The following exemptions from the requirements of IFRS have been applied in the preparation of these financial statements, in accordance with FRS 101:
- Paragraphs 45(b) and 46 to 52 of IFRS 2 – Share-Based Payment
- IFRS 7 – Financial Instruments (Disclosures)
- Paragraphs 91 to 99 of IFRS 13 – Fair Value Measurement
- The following paragraphs of IAS 1 – Presentation of Financial Statements
- 10(d) – Statement of cash flows
- 16 – Statement of compliance with all IFRS
- 38A – Requirement for minimum of two primary statements, including cash flow statements
- 38B-D – Additional comparative information
- 111 – Statement of cash flows information
- 134-136 – Capital management disclosures
- IAS 7 – Statement of cash flows
- Paragraph 17 of IAS 24 – Related party disclosures relating to key management personnel
- The requirement of IAS 24 – Related party transactions relating to transactions between group members
These financial statements are presented in Great British Pounds (GBP) unless otherwise stated, which is the Company’s presentational and functional currency. Amounts are rounded to the nearest thousand, unless otherwise stated.
2.2. Significant accounting policies
The accounting policies of the Company are the same as those of the Group which are set out in the relevant Notes to the Consolidated Financial Statements, except that it has no policy in respect of consolidation and investments in subsidiaries are carried at historical cost, less any provisions for impairment.
2.3. Critical judgements and key sources of estimation uncertainty
As noted in note 2.20 to the consolidated financial statements the preparation of the financial statements requires management to make estimates and assumptions that affect the reported results. Company specific critical judgements and estimates are as follows:
Impairment of investments in subsidiaries.
The Company is making significant investments into Gelion Technologies Pty and Gelion Europe Limited to assist with the development and deployment of its technologies. The Company incorporated Battery Minerals Ltd for the purpose of developing advanced hydrometallurgy solutions to improve the efficiency of critical metal recycling from battery production scrap and end-of-life-cells and is largely funded through government grants and on a long-term expects this to be independently funded. In assessing the carrying value of this asset for impairment, the Directors will at the end of each reporting period assess whether there is any indication that an asset may be impaired including the Investment in Subsidiary. The assessment will consider indications for potential impairment and assess the impairment amount with reference to the recoverable amount and carrying amount of the asset.
The determination of the recoverable amount of investments in subsidiary companies involves significant estimation uncertainty. In estimating FVLCTS, key inputs include the share price used in the market capitalisation-based valuation and estimated disposal costs. A lower share price or higher disposal costs could reduce the recoverable amount, resulting in additional impairment and a material adjustment to the carrying amounts within the next financial year.
2.4. Share-based payments
The Group provides benefits to its employees in the form of share-based payments, whereby employees render services in exchange for shares or rights over shares (equity-settled transactions) in the parent entity as per note 2.15 of the consolidated financial statements. The only difference to that policy is that the costs relating to share-based payments is capitalised in the parent as part of the investment in the Group’s subsidiaries, as it relates to employees of those subsidiaries.
3. Results for the Year
The Company recorded a loss for the financial year ended 30 June 2026 of £3,875,000 (2025: loss £1,102,000). The auditors’ remuneration for audit and other services is disclosed in note 8 to the consolidated financial statements.
4. Investments in Subsidiaries
The following were subsidiary undertakings of the Group:
|
Name |
Registered office |
Class of shares |
Holding |
|
Gelion Technologies Pty Limited |
Australia |
Ord A |
100% |
|
Gelion Europe Limited |
UK |
Ord A |
100% |
|
Battery Minerals Limited |
UK |
Ord A |
100% |
|
OXLiD Limited |
UK |
Ord A |
100% |
|
Gelion US Corp. |
USA |
Ord A |
100% |
|
Gelion Integrated Solutions Pty Limited |
Australia |
Ord A |
100% |
The shareholdings are held directly except for Gelion Integrated Solutions Pty Limited which is held through Gelion Technologies Pty Limited.
The registered office of Gelion Technologies Pty Limited is Level 16, 101 Miller Street, North Sydney, NSW 2060.
The registered office of Gelion Europe Limited, OXLiD Limited and Battery Minerals Limited is C/O External Services Limited, Central House 20 Central Avenue, St Andrews Business Park, Norwich, United Kingdom, NR7 0HR.
The registered office of Gelion US Corp. is 251 Little Falls Drive, in the City of Wilmington, County of New Castle 19808, State of Delaware, the United Sates of America.
|
Gelion Technologies Pty Ltd |
Gelion Europe Limited |
Battery Minerals Limited |
Total | |
|
£’000 |
£’000 |
£’000 |
£’000 | |
|
Cost |
||||
|
At 30 June 2024 |
34,047 |
4,163 |
- |
38,210 |
|
Additions – equity subscription |
4,759 |
500 |
230 |
5,489 |
|
Additions – share-based payment charge |
378 |
152 |
- |
530 |
|
At 30 June 2025 |
39,184 |
4,815 |
230 |
44,229 |
|
Additions – equity subscription |
6,400 |
900 |
330 |
7,630 |
|
Additions – share-based payment charge |
367 |
42 |
10 |
419 |
|
At 30 June 2026 |
45,951 |
5,757 |
570 |
52,278 |
|
Impairment and other |
||||
|
At 30 June 2024 |
11,764 |
- |
- |
11,764 |
|
Impairment |
- |
- |
- |
- |
|
At 30 June 2025 |
11,764 |
- |
- |
11,764 |
|
Impairment |
1,719 |
289 |
454 |
2,462 |
|
At 30 June 2026 |
13,483 |
289 |
454 |
14,226 |
|
Carrying amount |
||||
|
At 30 June 2025 |
27,420 |
4,815 |
230 |
32,465 |
|
At 30 June 2026 |
32,468 |
5,468 |
116 |
38,052 |
Share-based payment charges capitalised relate to the share-based payment charges incurred by the parent company for options granted by the parent to the employees of the subsidiary.
As for the impairment of the investment, please refer further to note 4.1.
4.1. Impairment of Investments in Subsidiaries
The Company tests the net recoverable amounts of assets annually for impairment, or more frequently if there are indicators of impairment. During the year, Management considered the recoverability of its investments in subsidiaries, which is disclosed in Note 4. The subsidiaries continue to operate, incurring research and development activity and generate losses, which is seen as temporary. The fair value measurement of the investments is classified as Level 2 under IFRS 13.
Based on this, the directors considered that the market capitalisation less relevant adjustments as a proxy in the ‘fair value less costs to sell’ method is more reliable and applicable in assessing the impairment of investments in subsidiaries.
The market capitalisation of the Group on 30 June 2026 was £41.3 million (229,421,456 shares at a share price of 18.0 pence). This was adjusted for the parent company’s cash balance of £2.4 million and net payables of £0.2 million, together with disposal costs of £1.0 million, resulting in an indicative carrying value of £38.1 million.
In comparing the cost of the total investment £40.5 million, the indicative carrying value of £38.1 million represents £2.4 million impairment to be recognised in the current year. Following the impairment of £0.4 million of Battery Minerals Limited, the remaining impairment charge of £2 million has been proportionately allocated to Gelion Technologies Pty Limited and Gelion Europe Limited.
Battery Minerals Limited was incorporated on 16 February 2024. At 30 June 2026, the carrying amount of the Company’s investment in Battery Minerals Limited before impairment was £0.6 million. Following management’s assessment that the subsidiary is not core to the Group’s operations, the Company undertook an impairment review. The investment’s recoverable amount was assessed at £0.1 million (FVLCS), equal to the subsidiary’s net asset value at that date. Accordingly, an impairment loss of £0.4 million was recognised in profit or loss in the Company’s separate financial statements, reducing the investment’s carrying amount to £0.1 million.
The table below illustrates the sensitivity of the impairment charge to key assumptions used in determining FVLCTS
Share Price Sensitivity
|
Change in share price |
FVLCTS (£’m) |
Impairment charge (£’m) |
|
+20% |
46.4 |
- |
|
+10% |
42.2 |
- |
|
(10%) |
34.0 |
6.5 |
|
(20%) |
29.8 |
10.7 |
Costs of Disposal Sensitivity
|
Additional costs of disposal |
FVLCTS (£’m) |
Impairment charge (£’m) |
|
+1% |
37.7 |
2.8 |
|
+2% |
37.3 |
3.2 |
Since 30 June 2026, the share price of Gelion Plc has traded across a high-low range of 12.5p and 19.75p per share. If this exercise was undertaken on 13 October 2026, the impairment would increase by £10.6 million to £13.0 million.
The Company will continue to assess the recoverable amount of its investments in subsidiaries annually or whenever there are indications of impairment, in accordance with IAS 36. Any subsequent changes in the recoverable amount and impairment losses will be recognized in the financial statements in the periods in which they occur.
5. Trade and Other Receivables
|
As at 30 June | ||
|
2026 |
2025 | |
|
Amounts receivable from Group companies |
15 |
184 |
|
Prepayments |
63 |
26 |
|
Other debtors |
55 |
43 |
|
133 |
253 | |
The amounts are measured at amortised cost using the effective interest method in line with IFRS 9. There were no term deposits for a period greater than three months as of June 2026.
6. Trade and Other Payables
Due within one year
|
As at 30 June | ||
|
2026 |
2025 | |
|
Trade payables |
193 |
86 |
|
Amounts owed to Group companies |
22 |
1 |
|
Accruals |
145 |
165 |
|
360 |
252 | |
7. Share Capital
Details of the Company’s share capital are as set out in note 22 to the consolidated financial statements.
Details of the Company’s share premium account and other reserves are as set out in note 22 to the consolidated financial statements.
Details of the movements in retained earnings are set out in the parent company Statement of Changes in Equity.
Corporate Information|
Company number |
09796512 | |
|
Directors |
||
|
Executive |
Matt Wood Amit Gupta | |
|
Non-Executive |
Dr Steve Mahon Prof. Thomas Maschmeyer Joycelyn Morton Michael Davie Graham Cooley | |
|
Secretary |
Billy French | |
|
Registered Office |
C/O External Services Limited, Central House 20 Central Avenue, St Andrews Business Park, Norwich, United Kingdom, NR7 0HR | |
|
Website |
www.gelion.com | |
|
Advisers |
||
|
Independent auditors |
BDO LLP 55 Baker Street, London W1U 7EU www.bdo.co.uk | |
|
Solicitors to the Company |
Fieldfisher LLP Riverbank House, 2 Swan Lane, London EC4R 3TT | |
|
Nominated and financial adviser |
Strand Hanson Limited 26 Mount Row, London W1K 3SQ | |
|
Joint brokers |
Oberon Capital Nightingale House, 6 Duke Street St James's, London SW1Y 6BN | |
|
Allenby Capital Limited 5 St Helen's Pl, London EC3A 6AB | ||
|
Registrars |
MUFG Pension & Market Services 29 Wellington Street, Leeds LS1 4DL | |
|
Public relations |
Tavistock +44 20 7920 3150 gelion@tavistock.co.uk | |
-ends-
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.