STORE Capital — Morgan Stanley 2nd Annual Net Lease Summit 2015
27 slides from STORE Capital's conference presentation, Apr 16, 2015
Slide 1: Morgan Stanley 2nd Annual Net Lease Summit
Morgan Stanley 2nd Annual Net Lease Summit April 17, 2015 The LEADER in Middle Market Real Estate Capital Solutions S T O R E capital
Slide 2: Forward-looking statements
This presentation may include forward-looking statements and include comments with respect to our objectives and strategies, and the results of our operations and our business. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. T
Slide 3: STORE Overview
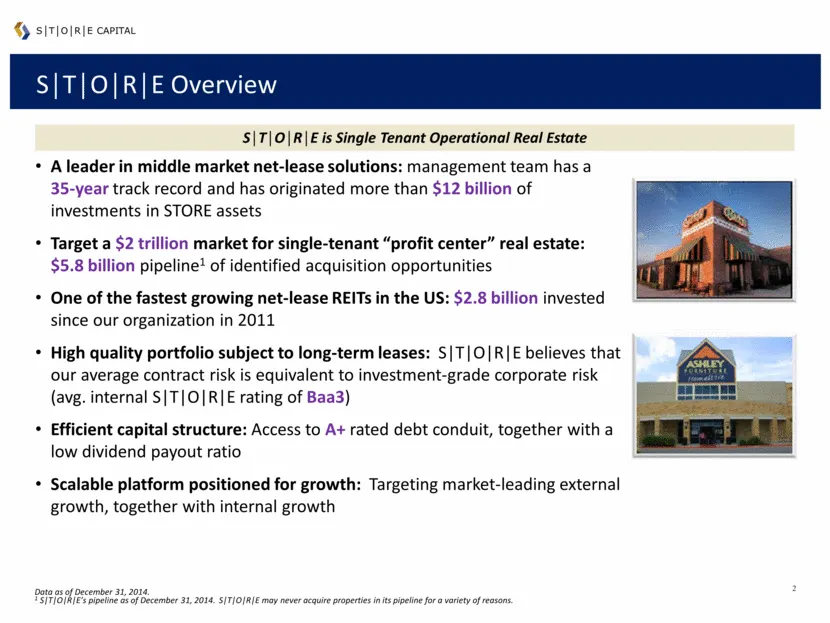
S T O R E Overview A leader in middle market net-lease solutions: management team has a 35-year track record and has originated more than $12 billion of investments in STORE assets Target a $2 trillion market for single-tenant “profit center” real estate: $5.8 billion pipeline1 of identified acquisi
Slide 4: Experienced Leadership Team with a Proven Track Record
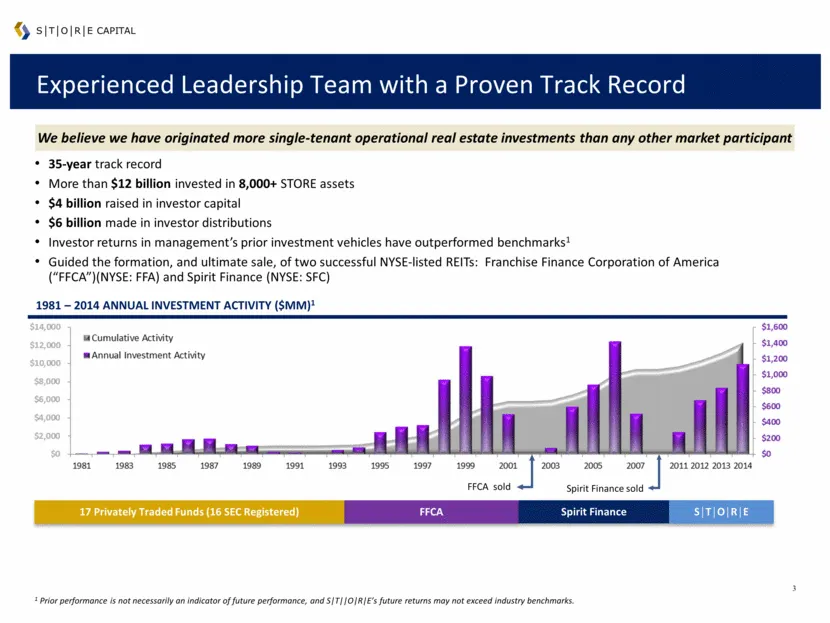
Experienced Leadership Team with a Proven Track Record 35-year track record More than $12 billion invested in 8,000+ STORE assets $4 billion raised in investor capital $6 billion made in investor distributions Investor returns in management’s prior investment vehicles have outperformed benchmarks1 G
Slide 5: Experienced Leadership Team with a Proven Track Record
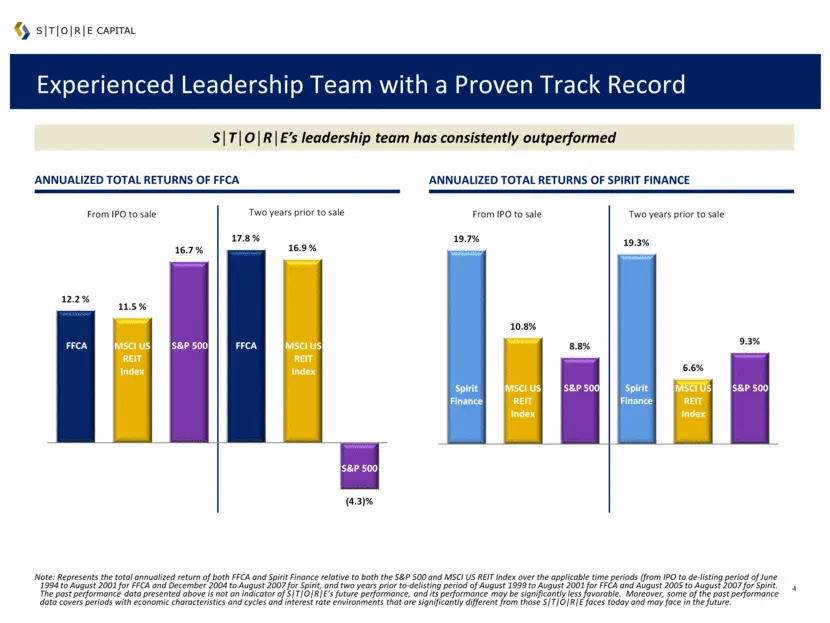
Experienced Leadership Team with a Proven Track Record ANNUALIZED TOTAL RETURNS OF SPIRIT FINANCE S T O R E’s leadership team has consistently outperformed ANNUALIZED TOTAL RETURNS OF FFCA S T O R E capital Note: Represents the total annualized return of both FFCA and Spirit Finance relative to both
Slide 6: Target Market Exceeding $2 Trillion in Size
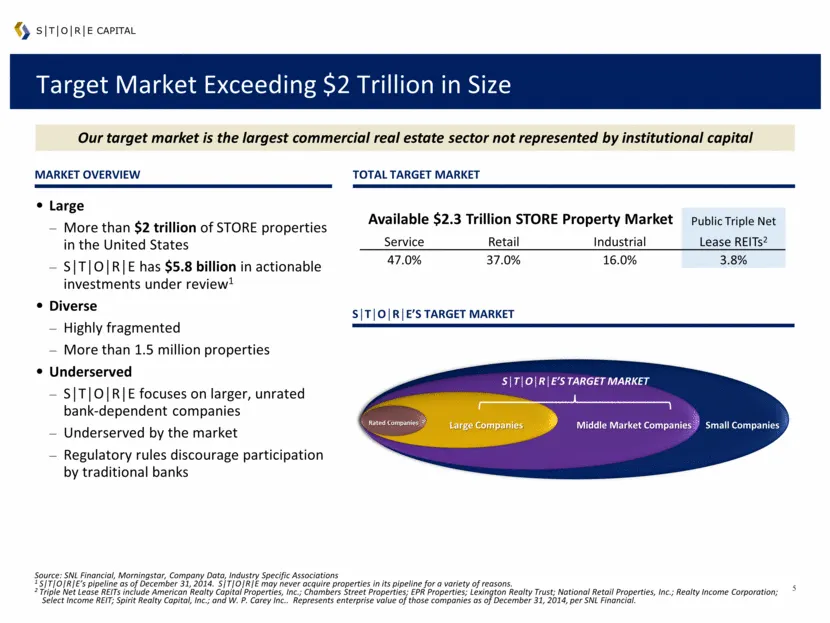
Target Market Exceeding $2 Trillion in Size Large More than $2 trillion of STORE properties in the United States S T O R E has $5.8 billion in actionable investments under review1 Diverse Highly fragmented More than 1.5 million properties Underserved S T O R E focuses on larger, unrated bank-depende
Slide 7: Superior Direct Origination Platform
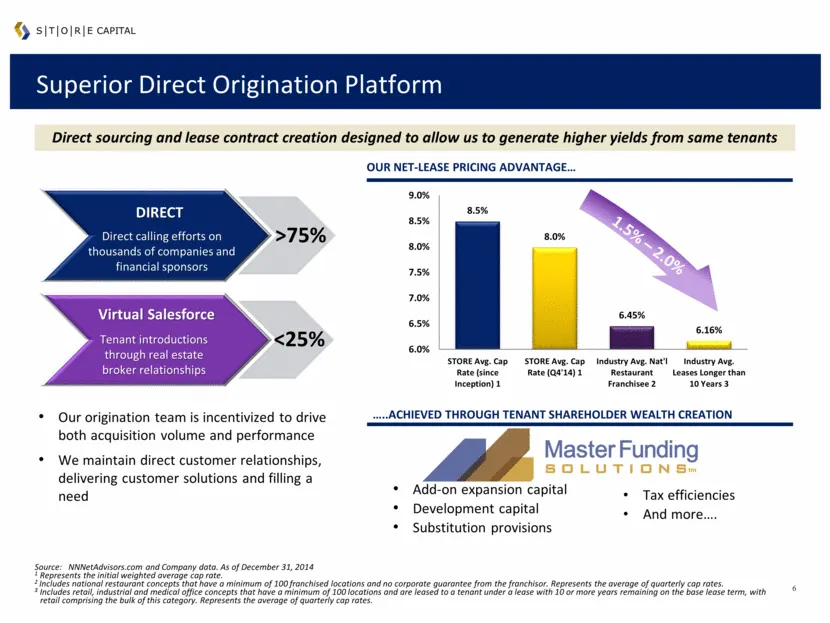
..Achieved through tenant shareholder wealth creation Add-on expansion capital Development capital Substitution provisions Tax efficiencies And more . tm Superior Direct Origination Platform Our origination team is incentivized to drive both acquisition volume and performance We maintain direct cust
Slide 8: We have a $5.8 billion Pipeline of Potential Investments
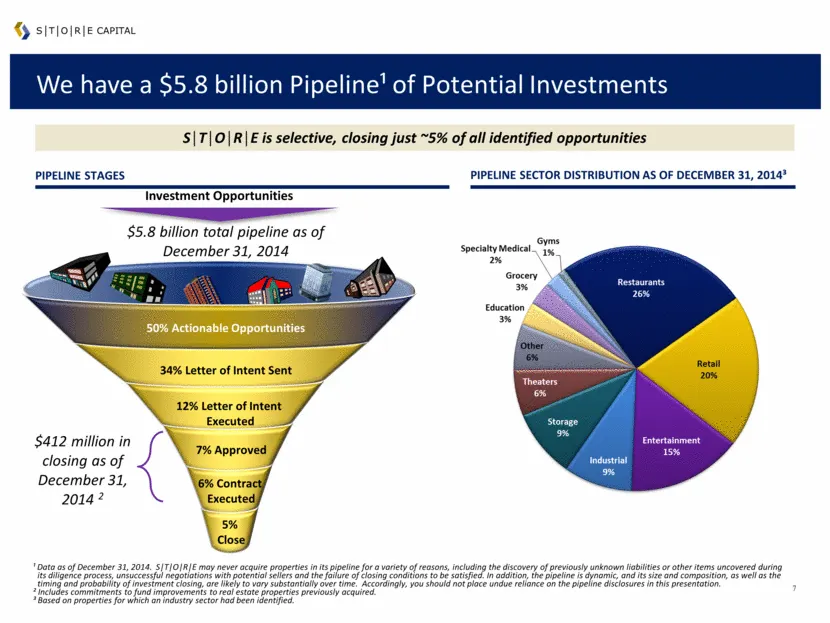
We have a $5.8 billion Pipeline¹ of Potential Investments ¹ Data as of December 31, 2014. S T O R E may never acquire properties in its pipeline for a variety of reasons, including the discovery of previously unknown liabilities or other items uncovered during its diligence process, unsuccessful neg
Slide 9: Stable and Attractive Lease Rates
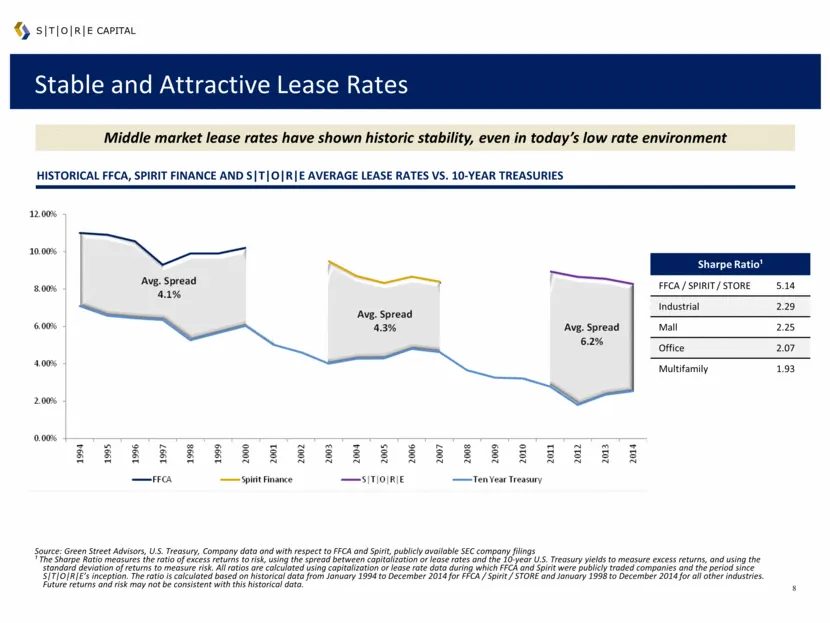
Stable and Attractive Lease Rates Middle market lease rates have shown historic stability, even in today’s low rate environment Historical FFCA, Spirit FINANCE and S T O R E average Lease Rates vs. 10-Year Treasuries Source: Green Street Advisors, U.S. Treasury, Company data and with respect to FFCA
Slide 10: STORE Contracts vs. Investment Grade Tenant Leases
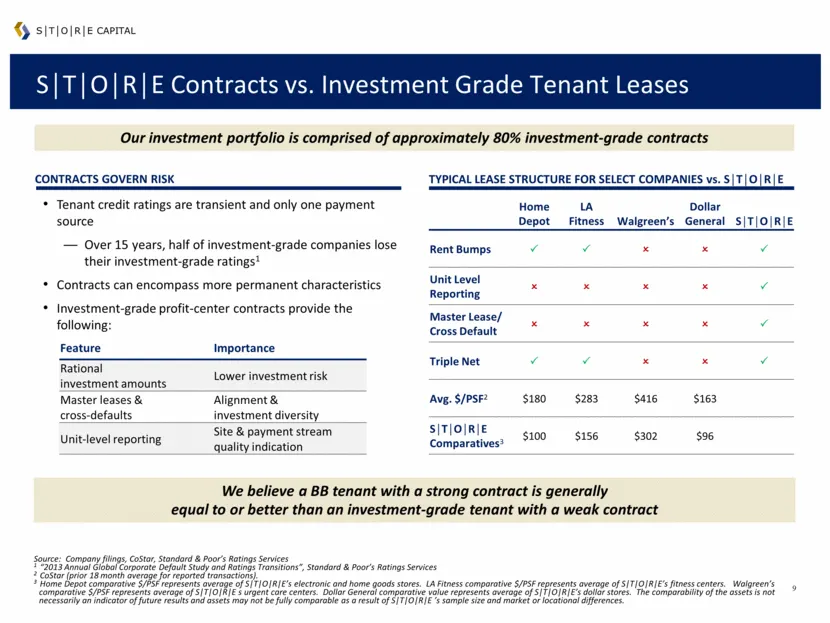
S T O R E Contracts vs. Investment Grade Tenant Leases S T O R E CAPITAL TYPICAL LEASE STRUCTURE FOR SELECT COMPANIES vs. S T O R E Tenant credit ratings are transient and only one payment source Over 15 years, half of investment-grade companies lose their investment-grade ratings1 Contracts can enc
Slide 11: Time-Tested Underwriting Approach
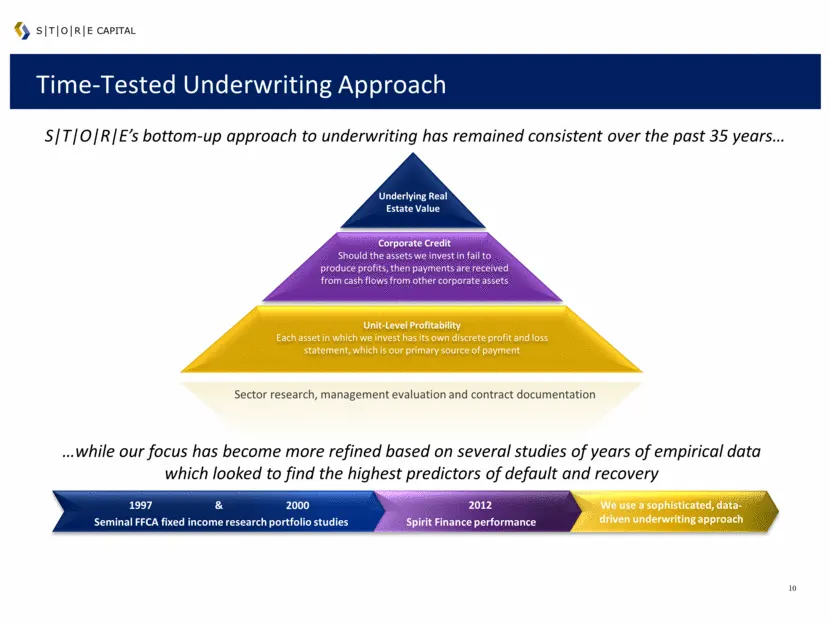
Time-Tested Underwriting Approach S T O R E’s bottom-up approach to underwriting has remained consistent over the past 35 years Unit-Level Profitability Each asset in which we invest has its own discrete profit and loss statement, which is our primary source of payment Corporate Credit Should the as
Slide 12: FFCA 1997 and 2000 Default Studies
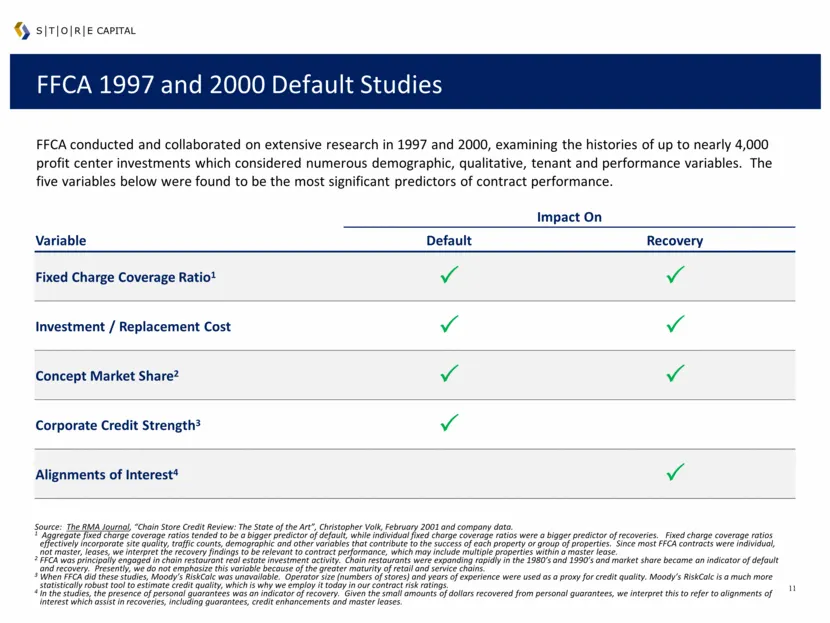
FFCA 1997 and 2000 Default Studies S T O R E CAPITAL FFCA conducted and collaborated on extensive research in 1997 and 2000, examining the histories of up to nearly 4,000 profit center investments which considered numerous demographic, qualitative, tenant and performance variables. The five variable
Slide 13: Risk Management – The STORE Score
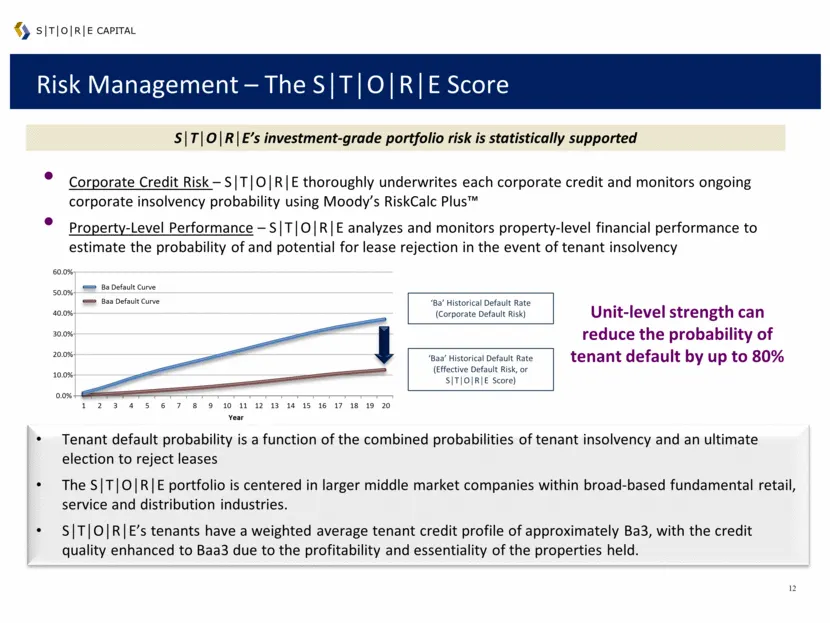
Risk Management – The S T O R E Score S T O R E capital Corporate Credit Risk – S T O R E thoroughly underwrites each corporate credit and monitors ongoing corporate insolvency probability using Moody’s RiskCalc Plus™ Property-Level Performance – S T O R E analyzes and monitors property-level financ
Slide 14: Cutting-Edge Servicing Platform
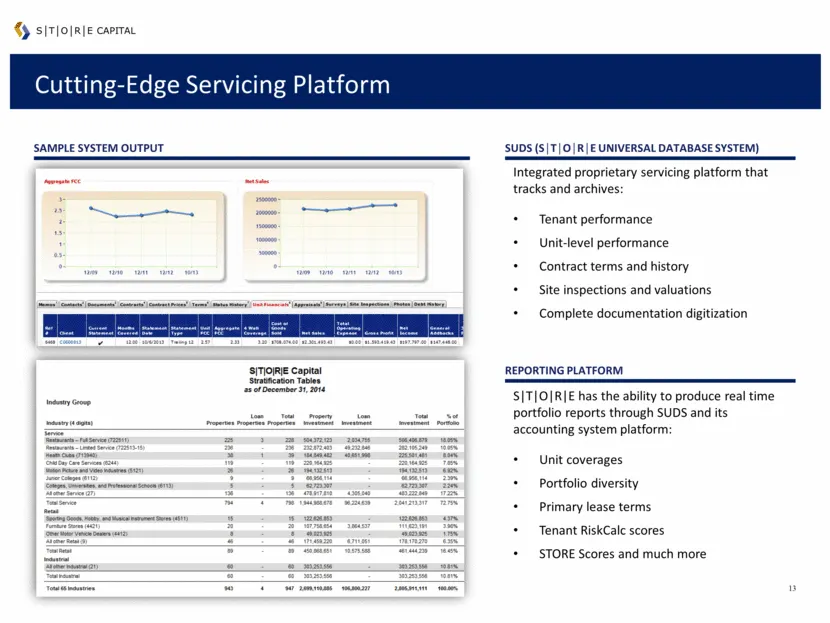
Cutting-Edge Servicing Platform SUDS (S T O R E UNIVERSAL DATABASE SYSTEM) Integrated proprietary servicing platform that tracks and archives: Tenant performance Unit-level performance Contract terms and history Site inspections and valuations Complete documentation digitization Reporting platform S
Slide 15: Portfolio – At a Glance
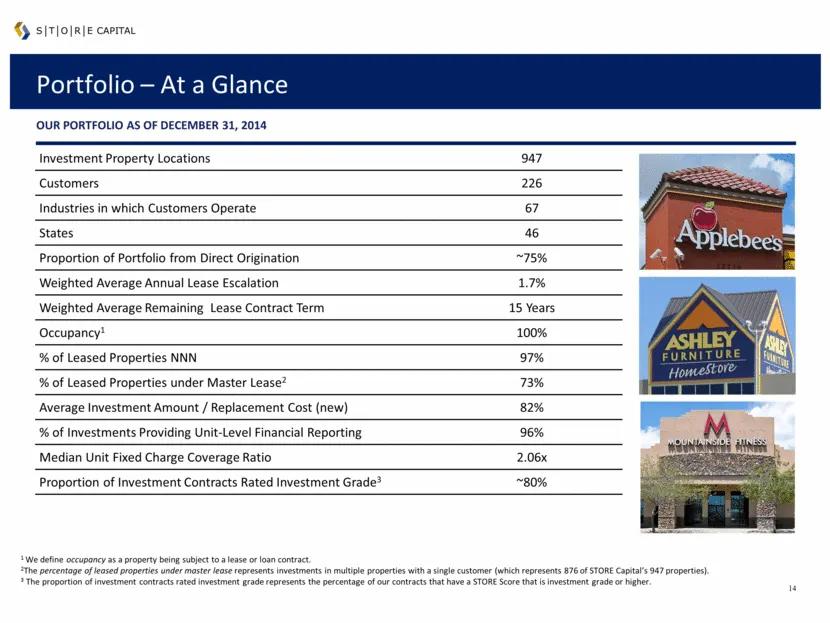
Portfolio – At a Glance OUR PORTFOLIO as of DECEMBER 31, 2014 Investment Property Locations 947 Customers 226 Industries in which Customers Operate 67 States 46 Proportion of Portfolio from Direct Origination ~75% Weighted Average Annual Lease Escalation 1.7% Weighted Average Remaining Lease Contrac
Slide 16: Diversified Across Geographies
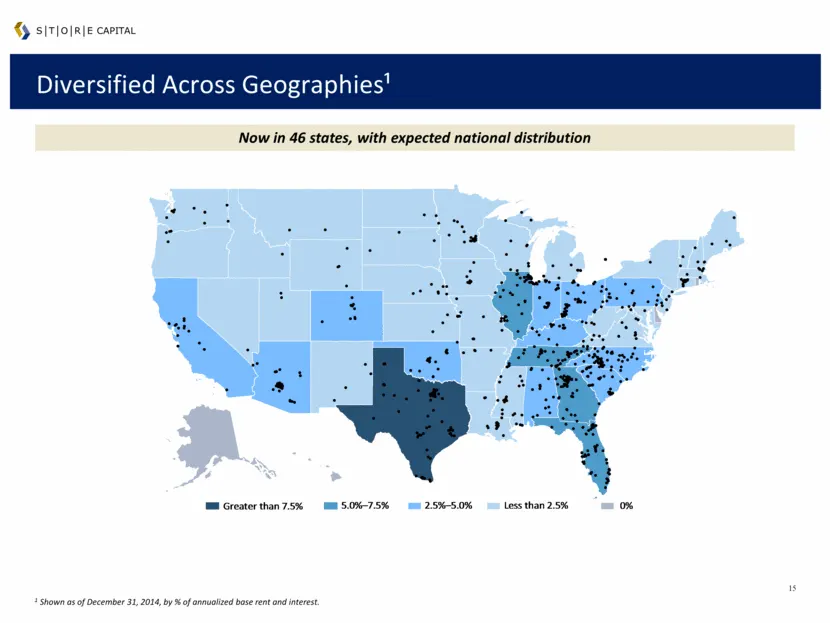
Diversified Across Geographies¹ Now in 46 states, with expected national distribution S T O R E capital 1 Shown as of December 31, 2014, by % of annualized base rent and interest. G r e at e r t h a n 7.5% 5.0% – 7.5% 2.5% – 5.0% L e ss t h a n 2.5% 0% — — — — — — — — — — — — — — — — — — — — — — — —
Slide 17: Diversified Across Tenants and Industries
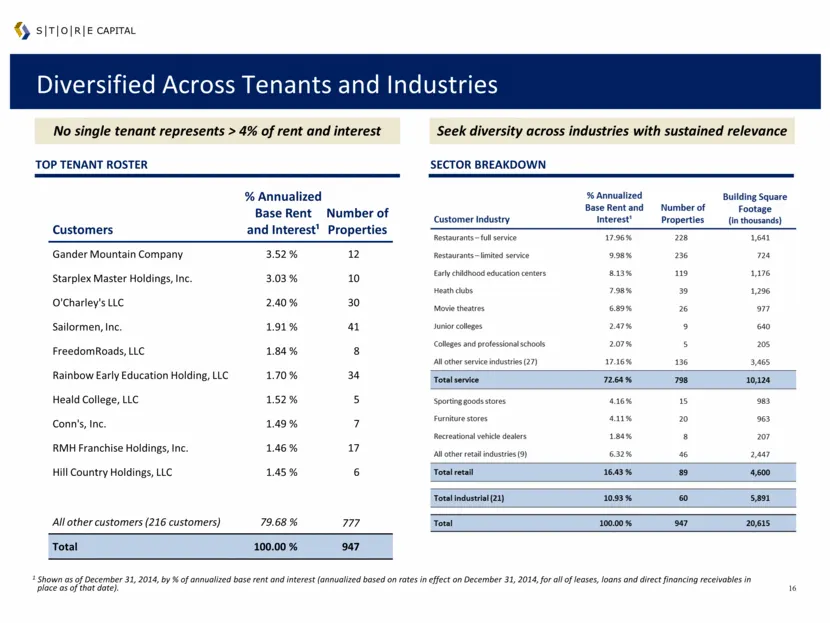
Diversified Across Tenants and Industries No single tenant represents > 4% of rent and interest TOP TENANT ROSTER Sector breakdown Seek diversity across industries with sustained relevance S T O R E capital Customers % Annualized Base Rent and Interest¹ Number of Properties Gander Mountain Company 3
Slide 18: Proprietary and Intensive Contract Monitoring System
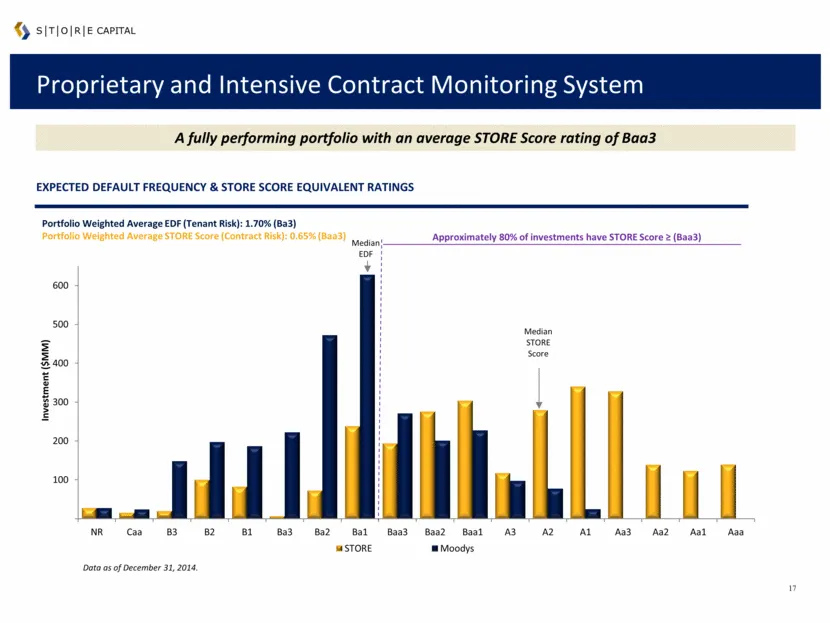
Proprietary and Intensive Contract Monitoring System A fully performing portfolio with an average STORE Score rating of Baa3 S T O RE capital Data as of December 31, 2014. Expected default frequency & STORE score equivalent Ratings 100 200 300 400 500 600 NR Caa B3 B2 B1 Ba3 Ba2 Ba1 Baa3 Baa2 Baa1 A
Slide 19: Flexible, Conservative Capital Structure
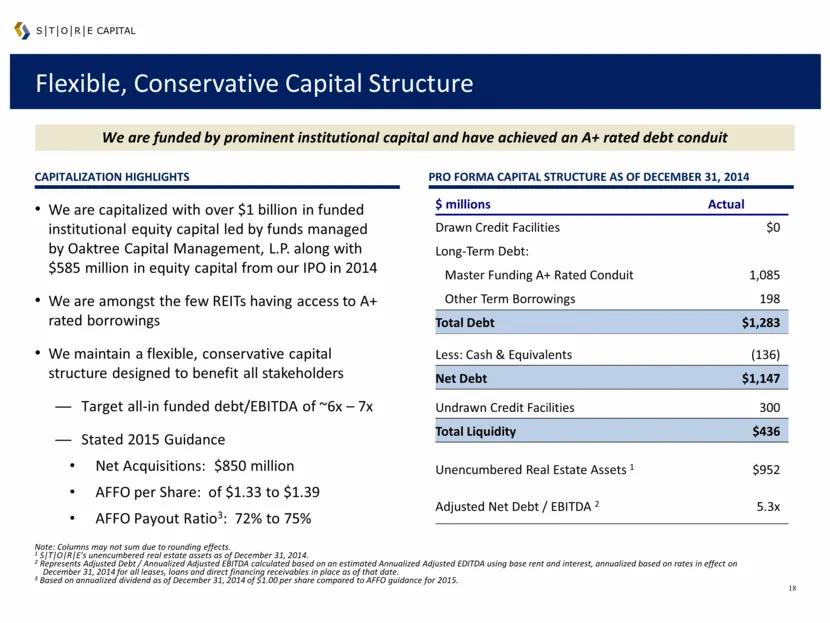
Flexible, Conservative Capital Structure CAPITALIZATION HIGHLIGHTS PRO FORMA CAPITAL STRUCTURE as of DEcember 31, 2014 S T O R E capital We are funded by prominent institutional capital and have achieved an A+ rated debt conduit We are capitalized with over $1 billion in funded institutional equity
Slide 20: Greater Access to Capital at a Lower Cost
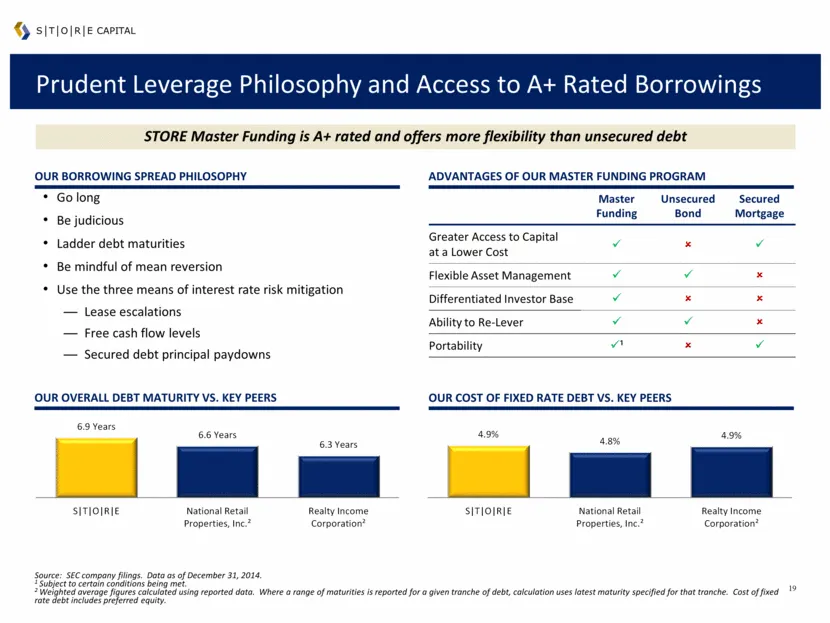
Master Funding Unsecured Bond Secured Mortgage Greater Access to Capital at a Lower Cost ü û ü Flexible Asset Management ü ü û Differentiated Investor Base ü û û Ability to Re-Lever ü ü û Portability ü¹ û ü Prudent Leverage Philosophy and Access to A+ Rated Borrowings Source: SEC company filings. Da
Slide 21: STORE's Performance
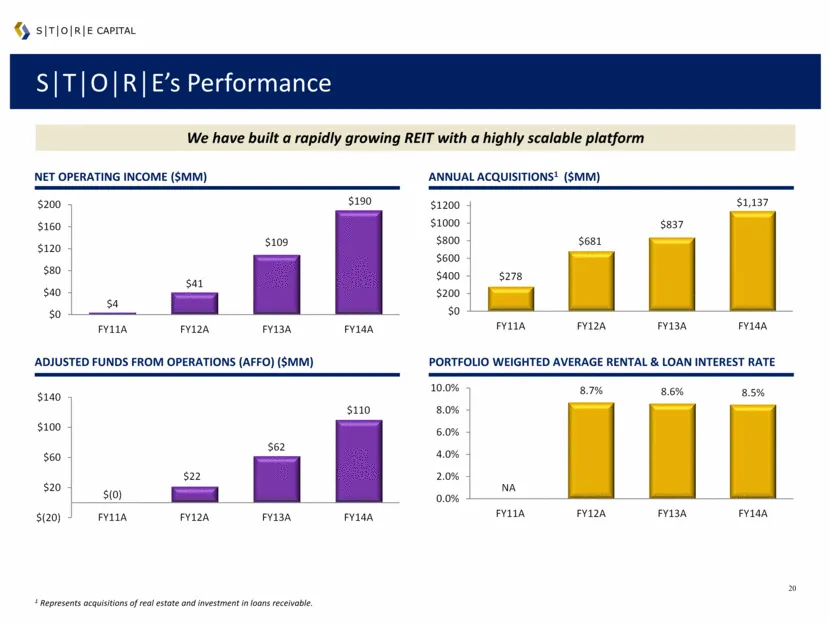
S T O R E’s Performance ADJUSTED Funds From Operations (AFFO) ($MM) Portfolio weighted average Rental & Loan Interest rate Net Operating Income ($MM) ANNUAL ACQUISITIONS1 ($MM) We have built a rapidly growing REIT with a highly scalable platform S T O R E capital 1 Represents acquisitions of real es
Slide 22: High Quality Portfolio
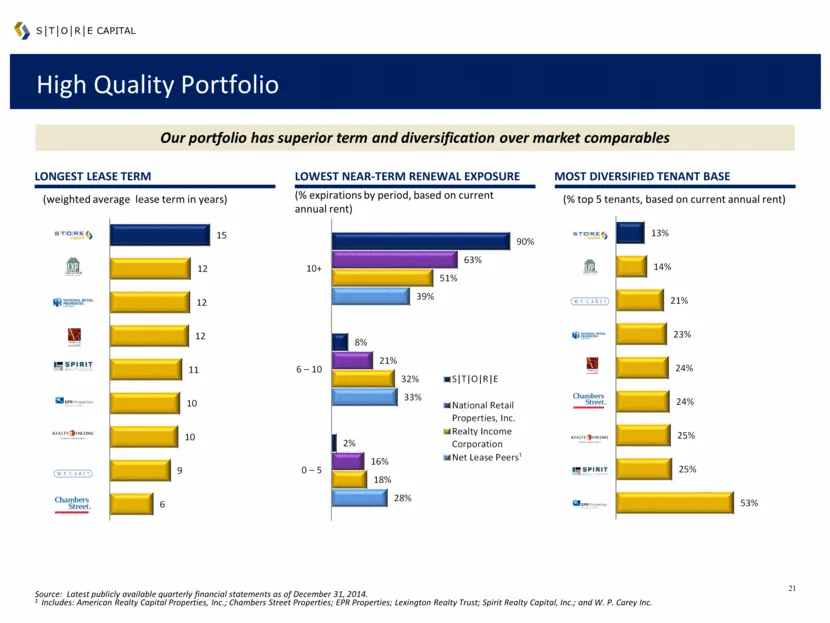
High Quality Portfolio Most Diversified Tenant Base Source: Latest publicly available quarterly financial statements as of December 31, 2014. 1 Includes: American Realty Capital Properties, Inc.; Chambers Street Properties; EPR Properties; Lexington Realty Trust; Spirit Realty Capital, Inc.; and W.
Slide 23: Our Dividend Policy and Growth
Our Dividend Policy and Growth Dividend policy S T O R E capital We have a current annual dividend rate of $1.00 per share Represents a 4.3% yield1 Stated target future AFFO payout ratio of ~75% Expected sources of AFFO Growth Internal Driven by reinvestment of excess cash flow post dividend payment
Slide 24: STORE is a Highly Compelling Risk-Adjusted Return Story
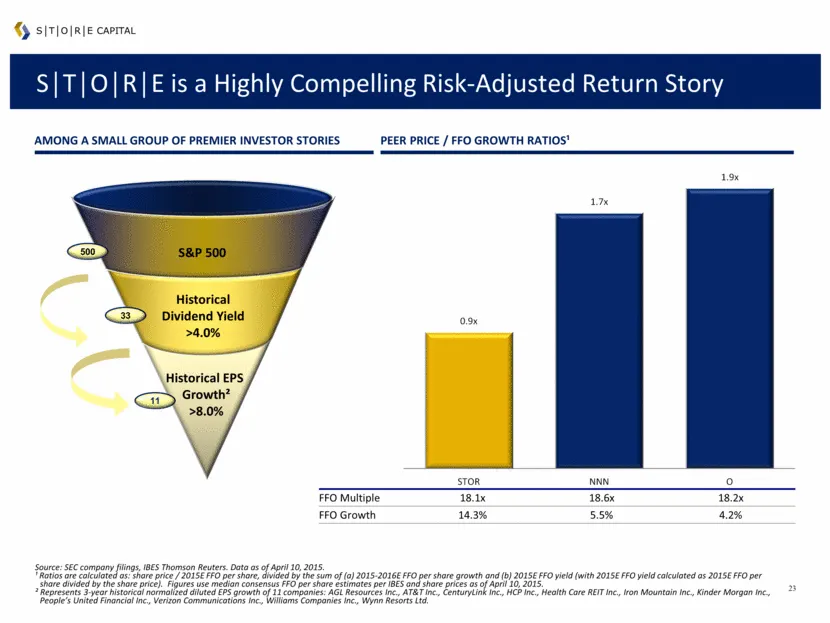
FFO Multiple 18.1x 18.6x 18.2x FFO Growth 14.3% 5.5% 4.2% Historical EPS Growth² >8.0% 11 33 Historical Dividend Yield >4.0% S T O R E is a Highly Compelling Risk-Adjusted Return Story S T O R E capital Source: SEC company filings, IBES Thomson Reuters. Data as of April 10, 2015. ¹ Ratios are calcul
Slide 25: Board and Corporate Governance
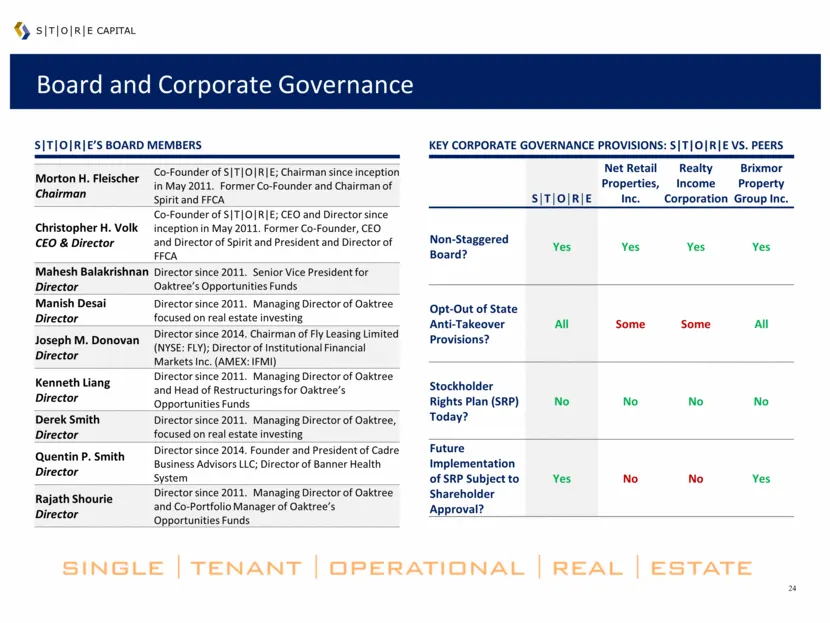
Board and Corporate Governance S T O R E capital Key corporate governance provisions: S T O R E vs. peers S T O R E’s board members Morton H. Fleischer Chairman Co-Founder of S T O R E; Chairman since inception in May 2011. Former Co-Founder and Chairman of Spirit and FFCA Christopher H. Volk CEO &
Slide 26: IPO Overview
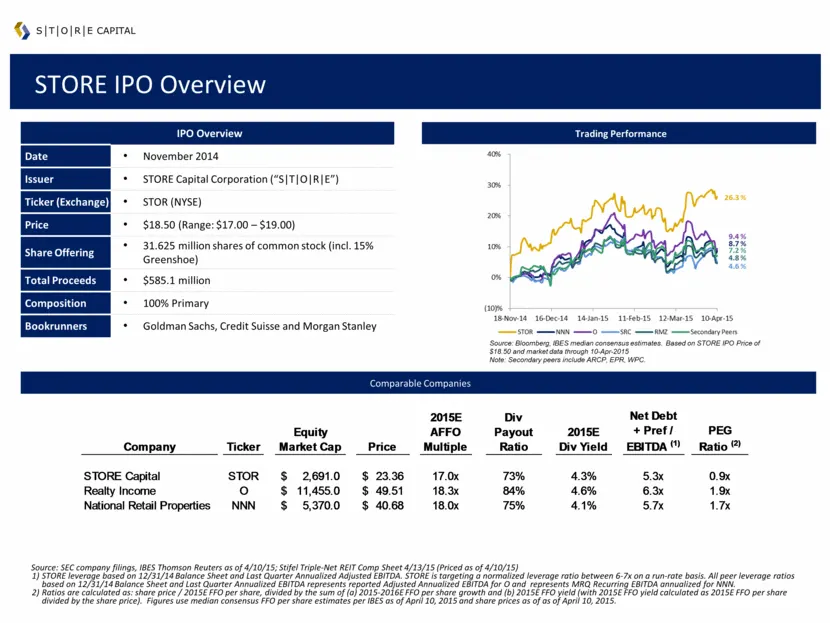
IPO Overview Date November 2014 Issuer STORE Capital Corporation (“S T O R E”) Ticker (Exchange) STOR (NYSE) Price $18.50 (Range: $17.00 – $19.00) Share Offering 31.625 million shares of common stock (incl. 15% Greenshoe) Total Proceeds $585.1 million Composition 100% Primary Bookrunners Goldman Sac
Slide 27: Investment Highlights
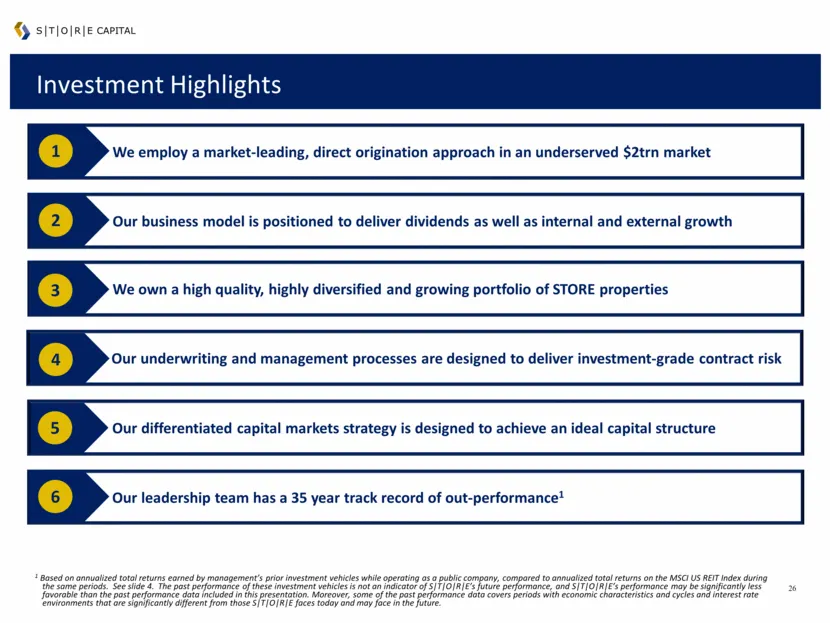
Investment Highlights Our business model is positioned to deliver dividends as well as internal and external growth 2 We employ a market-leading, direct origination approach in an underserved $2trn market 1 S T O R E capital Our leadership team has a 35 year track record of out-performance1 6 4 Our
Source: SEC EDGAR · 8-K filed Apr 16, 2015
More decks from STORE Capital Corp
 Q2 2023 Earnings Presentation10 slides · Aug 4, 2023
 Q2 2022 Earnings Presentation26 slides · Aug 3, 2022
 Q2 2022 Earnings Presentation22 slides · Aug 3, 2022
 Q1 2022 Earnings Presentation26 slides · May 4, 2022
 Q1 2022 Earnings Presentation22 slides · May 4, 2022
 Q4 2021 Earnings Presentation33 slides · Feb 23, 2022