Entegra Financial — Non-Deal Roadshow (November 2016)
50 slides from Entegra Financial's roadshow presentation, Nov 4, 2016
Slide 1: Fall 2016 Investor Meetings
Z Entegra FINANCIAL Fall 2016 Investor Meetings
Slide 2: Forward Looking Statements
The discussions included in this document may contain “forward - looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 , including Section 21 E of the Securities Exchange Act of 1934 and Section 27 A of the Securities Act of 1933 . Such statements involve kno
Slide 3: Non-GAAP Measurements
Statements included in this document include non - GAAP financial measures and should be read along with the accompanying tables in Appendix A to our quarterly earnings release, which provide a reconciliation of non - GAAP financial measures to GAAP financial measures . This document discusses finan
Slide 4: Who We Are
Who We Are
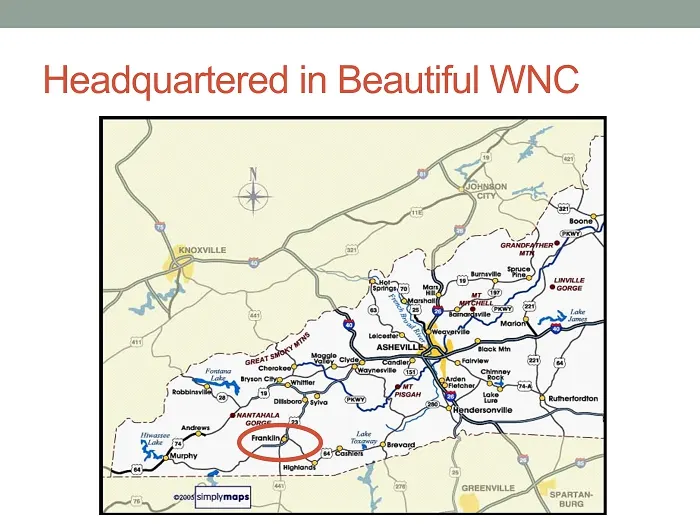
Slide 5: Headquartered in Beautiful WNC
Headquartered in Beautiful WNC
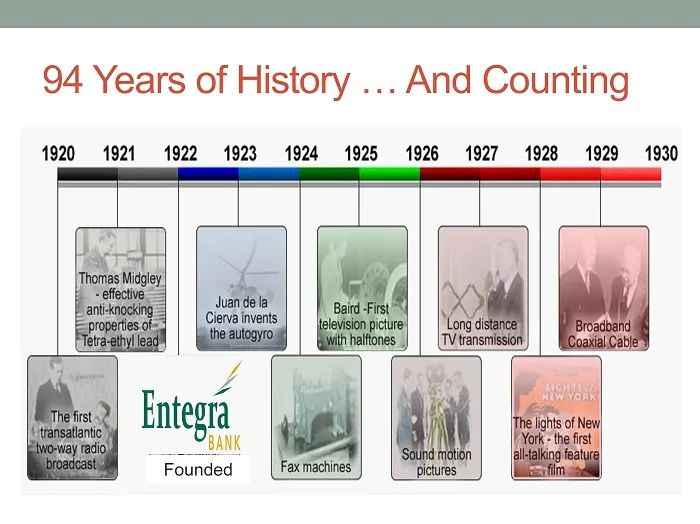
Slide 6: Years of History … And Counting
94 Years of History … And Counting Founded
Slide 7: Thrift Charter, But ....
Thrift Charter, But ….
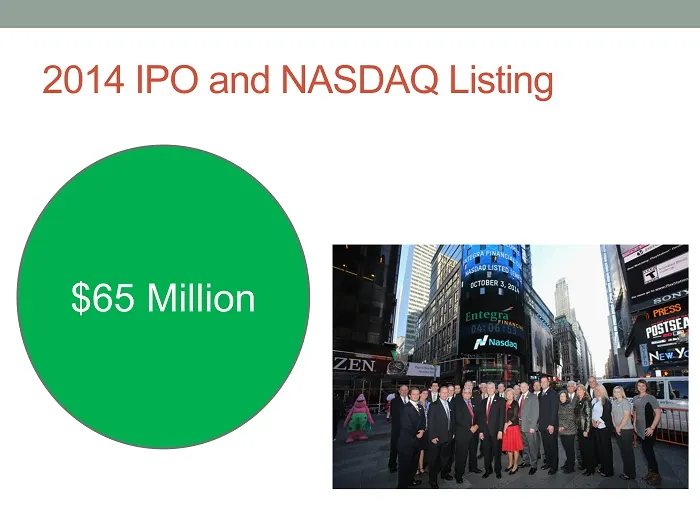
Slide 8: 2014 IPO and NASDAQ Listing $65 Million
2014 IPO and NASDAQ Listing $65 Million
Slide 9: What's In A Name? Integrity
What’s In A Name? Integrity (Noun) “the quality of being honest and having strong moral principles ; moral uprightness . ”
Slide 10: Integrity: More Important Than Ever
Integrity: More Important Than Ever
Slide 11: Experienced Executive Team
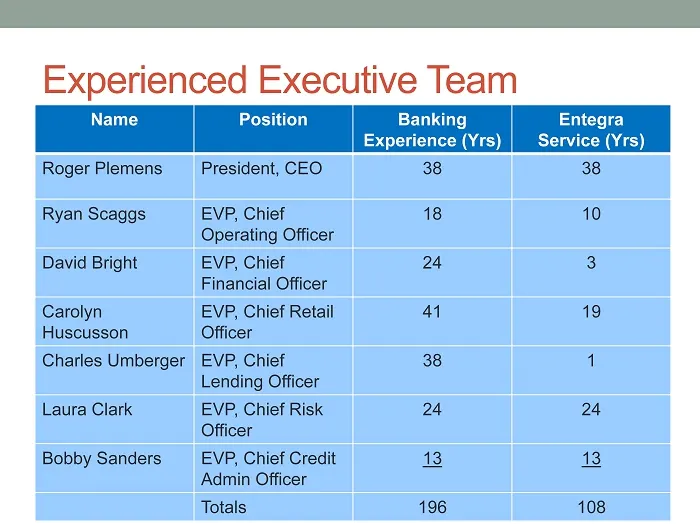
Experienced Executive Team Name Position Banking Experience ( Yrs ) Entegra Service ( Yrs ) Roger Plemens President, CEO 38 38 Ryan Scaggs EVP, Chief Operating Officer 18 10 David Bright EVP, Chief Financial Officer 24 3 Carolyn Huscusson EVP, Chief Retail Officer 41 19 Charles Umberger EVP, Chief L
Slide 12: Solid Stock Performance
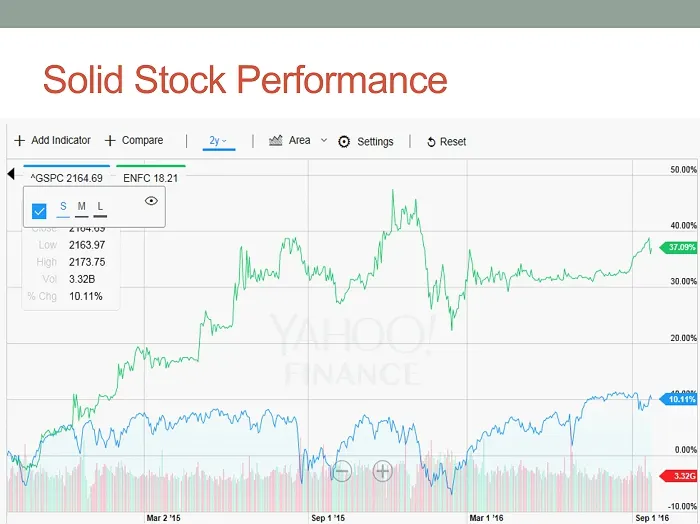
OO Solid Stock Performance + Addindcator + Compare | _2y-_ | wt rea» @ setings | 9 Reset —=— mel sGSPC 216469 ENFC 18.21 oo ry os Sep 16
Slide 13: Attractively Valued
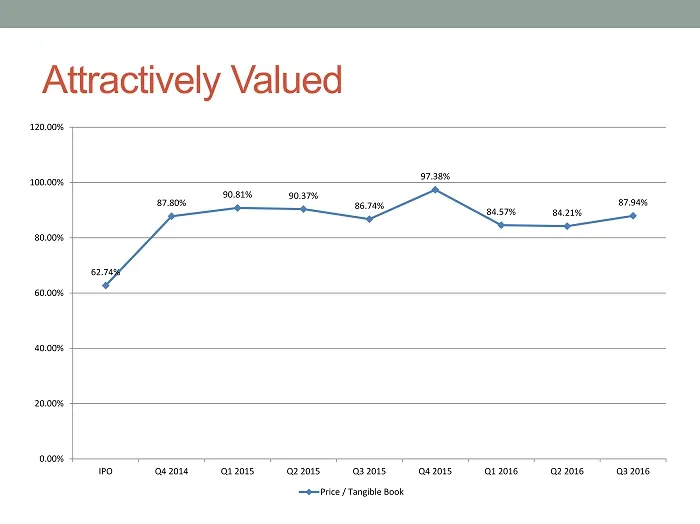
Attractively Valued 62.74% 87.80% 90.81% 90.37% 86.74% 97.38% 84.57% 84.21% 87.94% 0.00% 20.00% 40.00% 60.00% 80.00% 100.00% 120.00% IPO Q4 2014 Q1 2015 Q2 2015 Q3 2015 Q4 2015 Q1 2016 Q2 2016 Q3 2016 Price / Tangible Book
Slide 14: SNL – One of the Feel-Good Stories
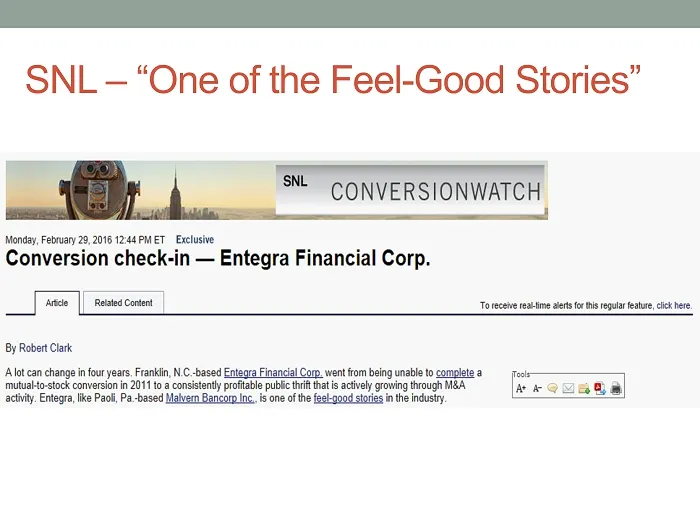
SNL – “One of the Feel - Good Stories”
Slide 15: #2 Legacy Deposit Market Share
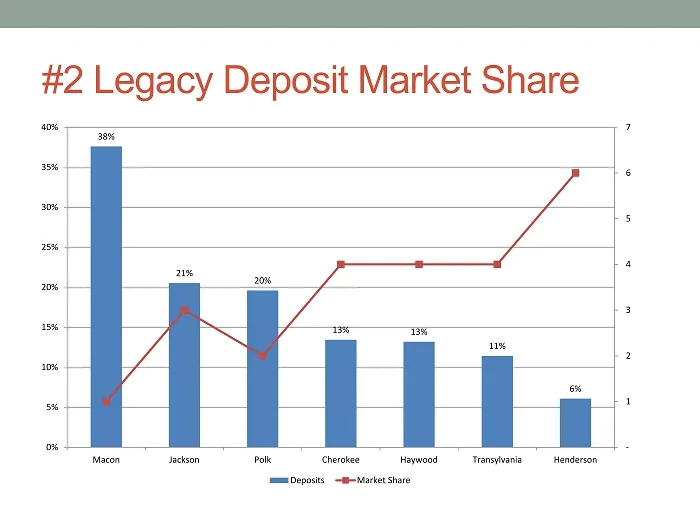
#2 Legacy Deposit Market Share 38% 21% 20% 13% 13% 11% 6% - 1 2 3 4 5 6 7 0% 5% 10% 15% 20% 25% 30% 35% 40% Macon Jackson Polk Cherokee Haywood Transylvania Henderson Deposits Market Share
Slide 16: NOL Protection Plan Limits 5% Investors
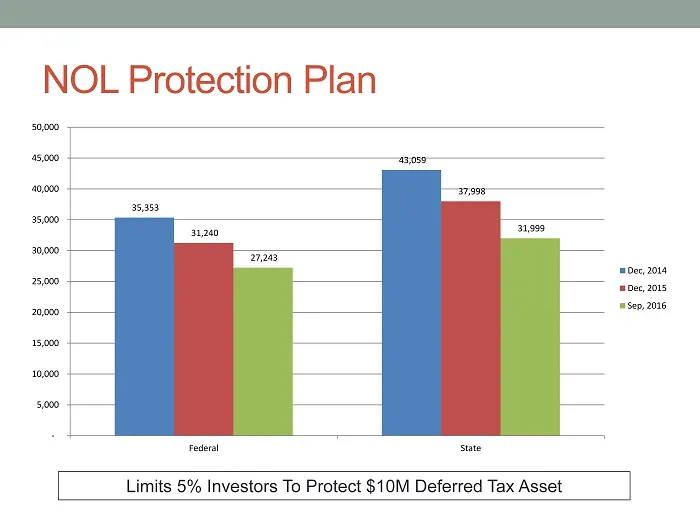
NOL Protection Plan Limits 5% Investors To Protect $10M Deferred Tax Asset 35,353 43,059 31,240 37,998 27,243 31,999 - 5,000 10,000 15,000 20,000 25,000 30,000 35,000 40,000 45,000 50,000 Federal State Dec, 2014 Dec, 2015 Sep, 2016
Slide 17: Strategy Summary
Strategy Summary
Slide 18: Continued Execution of Strategic Plan
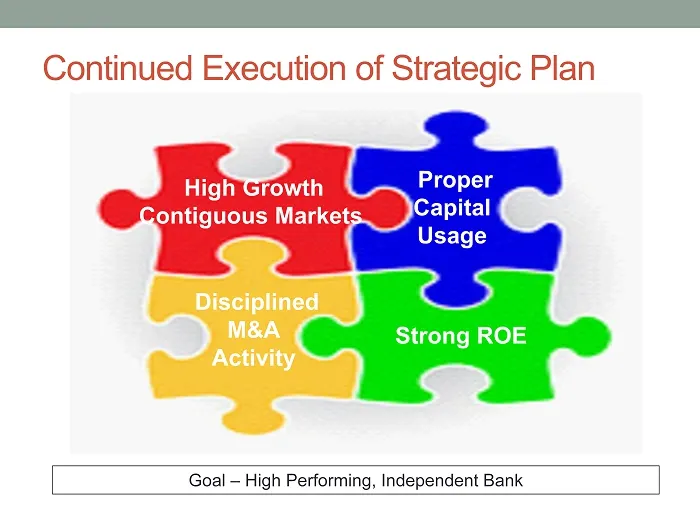
Continued Execution of Strategic Plan High Growth Contiguous Markets Disciplined M&A Activity Strong ROE Proper Capital Usage Goal – High Performing, Independent Bank
Slide 19: Proper Capital Usage
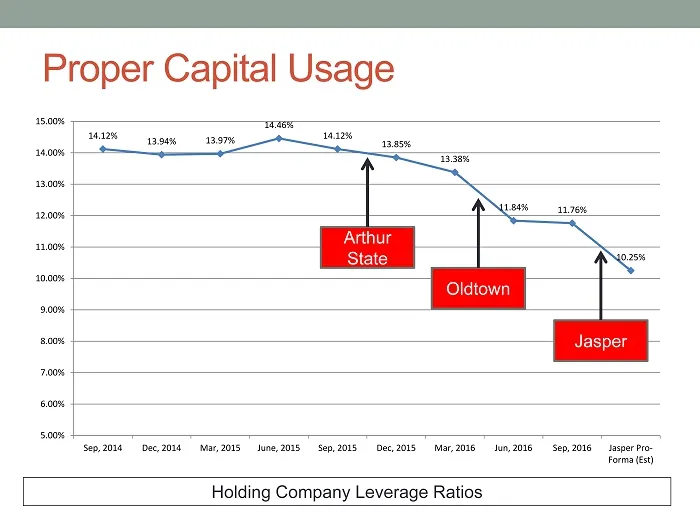
Proper Capital Usage 14.12% 13.94% 13.97% 14.46% 14.12% 13.85% 13.38% 11.84% 11.76% 10.25% 5.00% 6.00% 7.00% 8.00% 9.00% 10.00% 11.00% 12.00% 13.00% 14.00% 15.00% Sep, 2014 Dec, 2014 Mar, 2015 June, 2015 Sep, 2015 Dec, 2015 Mar, 2016 Jun, 2016 Sep, 2016 Jasper Pro- Forma (Est) Holding Company Levera
Slide 20: Disciplined Acquisitions
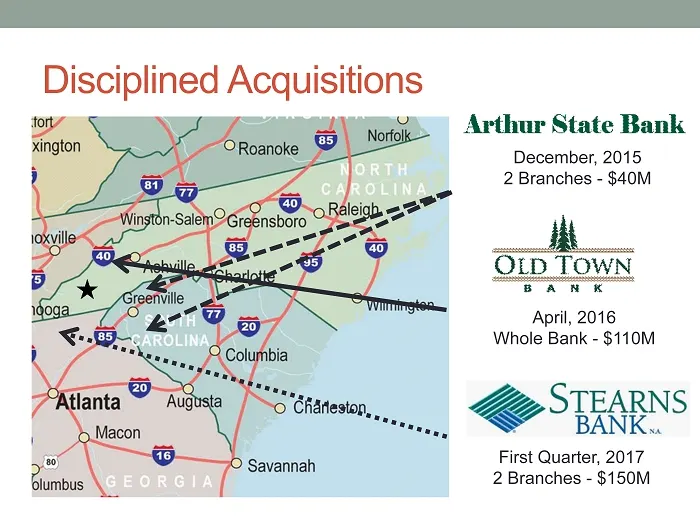
Disciplined Acquisitions December, 2015 2 Branches - $40M April, 2016 Whole Bank - $110M First Quarter, 2017 2 Branches - $150M
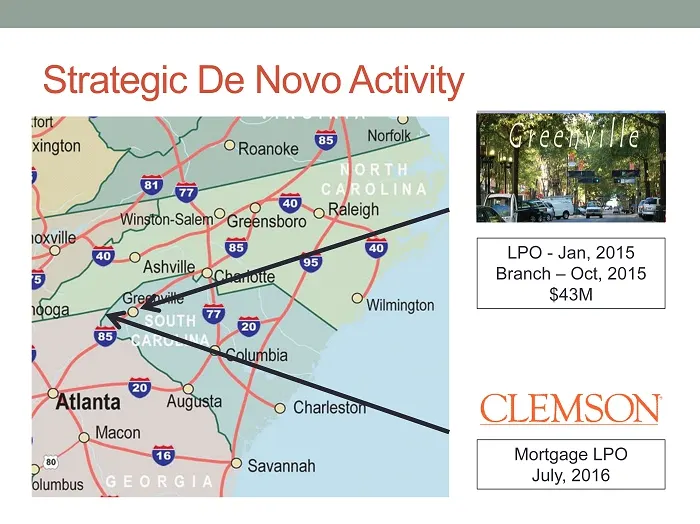
Slide 21: Strategic De Novo Activity
Strategic De Novo Activity Mortgage LPO July, 2016 LPO - Jan, 2015 Branch – Oct, 2015 $43M
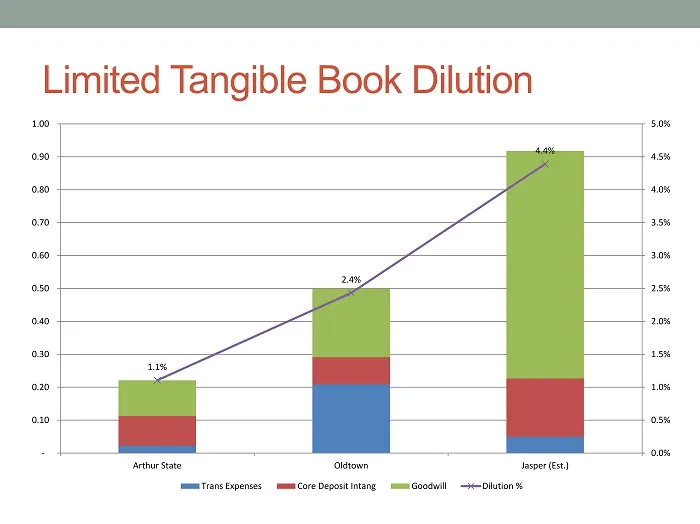
Slide 22: Limited Tangible Book Dilution
Limited Tangible Book Dilution 1.1% 2.4% 4.4% 0.0% 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% 3.5% 4.0% 4.5% 5.0% - 0.10 0.20 0.30 0.40 0.50 0.60 0.70 0.80 0.90 1.00 Arthur State Oldtown Jasper (Est.) Trans Expenses Core Deposit Intang Goodwill Dilution %
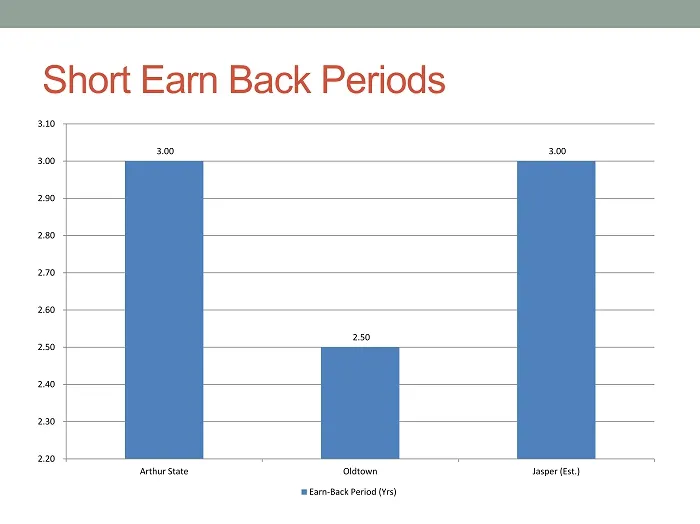
Slide 23: Short Earn Back Periods
Short Earn Back Periods 3.00 2.50 3.00 2.20 2.30 2.40 2.50 2.60 2.70 2.80 2.90 3.00 3.10 Arthur State Oldtown Jasper (Est.) Earn-Back Period (Yrs)
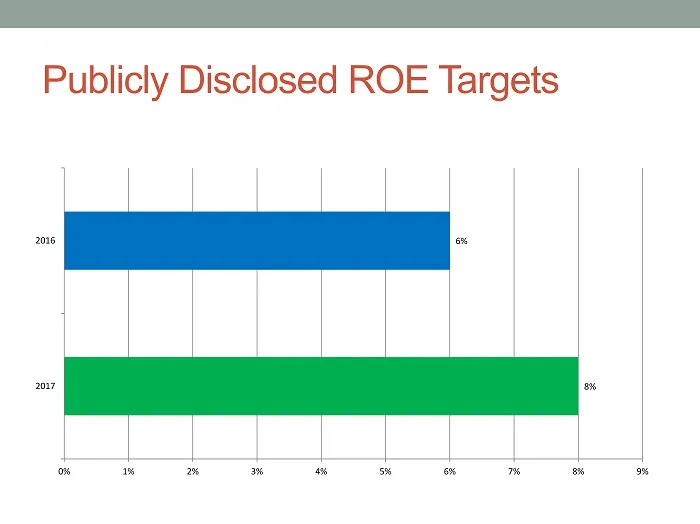
Slide 24: Publicly Disclosed ROE Targets
Publicly Disclosed ROE Targets 8% 6% 0% 1% 2% 3% 4% 5% 6% 7% 8% 9% 2017 2016
Slide 25: Research Coverage
Research Coverage SANDLER O'NEILL + PARTNERS
Slide 26: What About Share Repurchases?
What About Share Repurchases? • Other opportunities • F ranchise value • Upside potential • Fund stock compensation
Slide 27: Market Overview
Market Overview
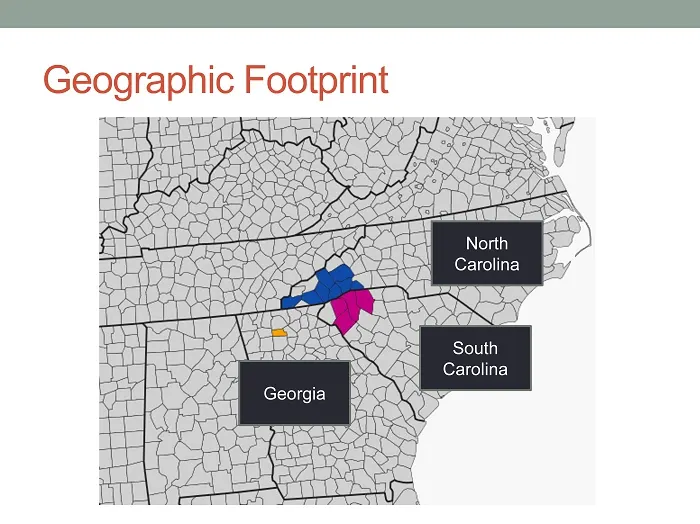
Slide 28: Geographic Footprint
Geographic Footprint South Carolina North Carolina Georgia
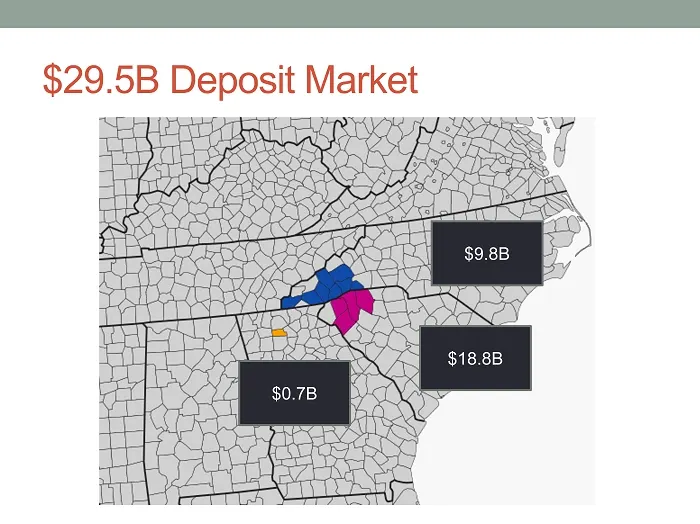
Slide 29: $29.5B Deposit Market
$29.5B Deposit Market $18.8B $9.8B $0.7B
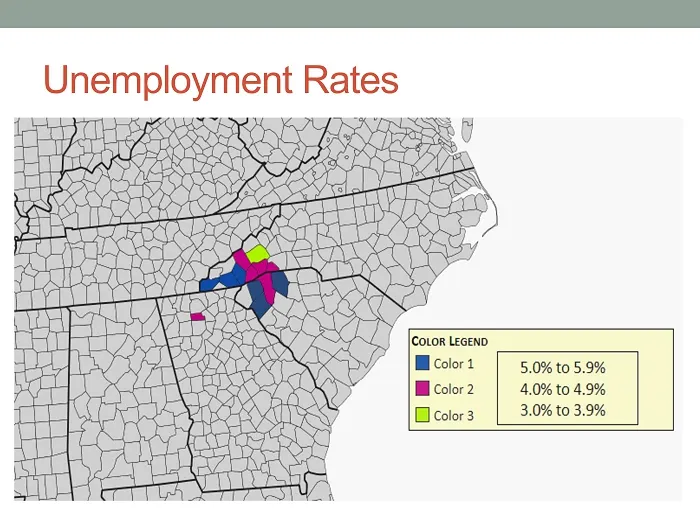
Slide 30: Unemployment Rates
ON Unemployment Rates |COLOR LEGEND Wi color 1 5.0% to 5.9% Wi color 2 4.0% to 4.9% Bicotor3 3.0% to 3.9%
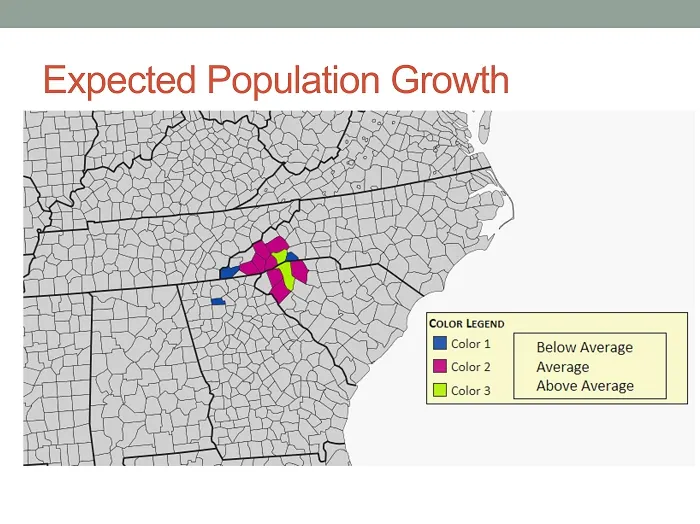
Slide 31: Expected Growth
Expecte {1 ws [coor teen Wi color 1 Below Average Hicolor2 | Average [colors | Above Average
Slide 32: Financial Overview
Financial Overview
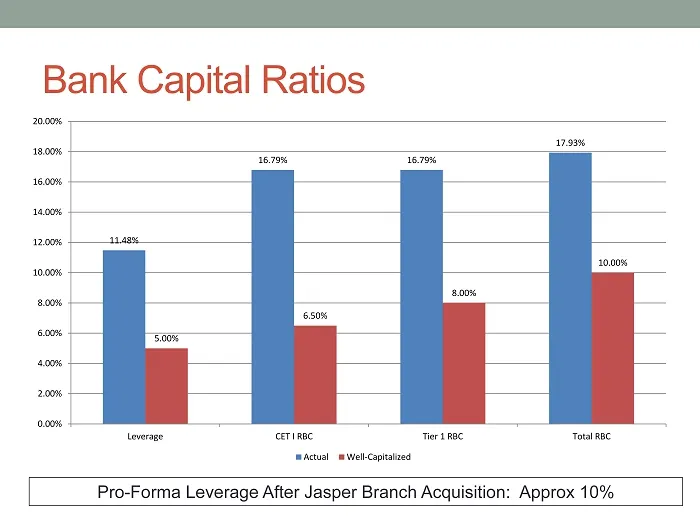
Slide 33: Bank Capital Ratios
Bank Capital Ratios Pro - Forma Leverage After Jasper Branch Acquisition: Approx 10% 11.48% 16.79% 16.79% 17.93% 5.00% 6.50% 8.00% 10.00% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% 18.00% 20.00% Leverage CET I RBC Tier 1 RBC Total RBC Actual Well-Capitalized
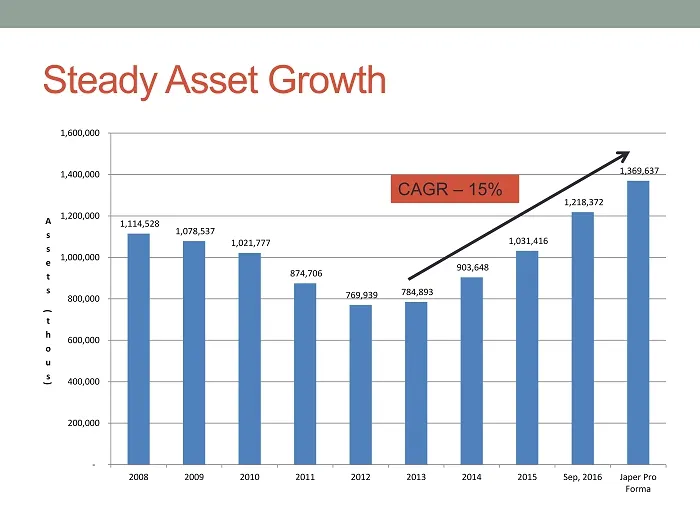
Slide 34: Steady Asset Growth
Steady Asset Growth 1,114,528 1,078,537 1,021,777 874,706 769,939 784,893 903,648 1,031,416 1,218,372 1,369,637 - 200,000 400,000 600,000 800,000 1,000,000 1,200,000 1,400,000 1,600,000 2008 2009 2010 2011 2012 2013 2014 2015 Sep, 2016 Japer Pro Forma A s s e t s ( t h o u s ) CAGR – 15%
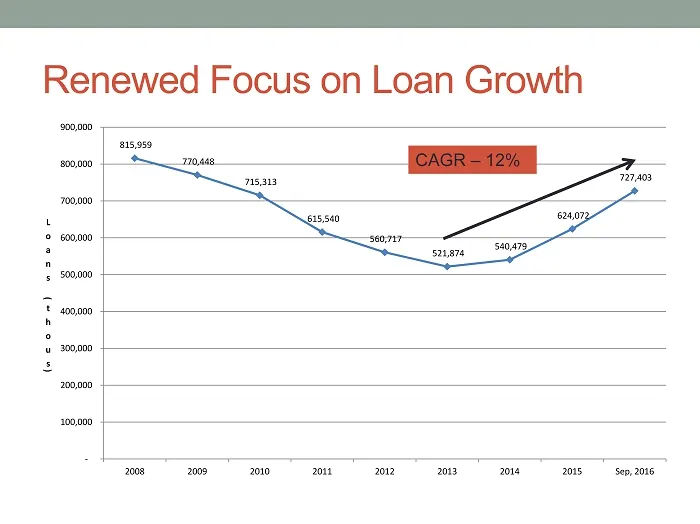
Slide 35: Renewed Focus on Loan Growth
Renewed Focus on Loan Growth 815,959 770,448 715,313 615,540 560,717 521,874 540,479 624,072 727,403 - 100,000 200,000 300,000 400,000 500,000 600,000 700,000 800,000 900,000 2008 2009 2010 2011 2012 2013 2014 2015 Sep, 2016 L o a n s ( t h o u s ) CAGR – 12%
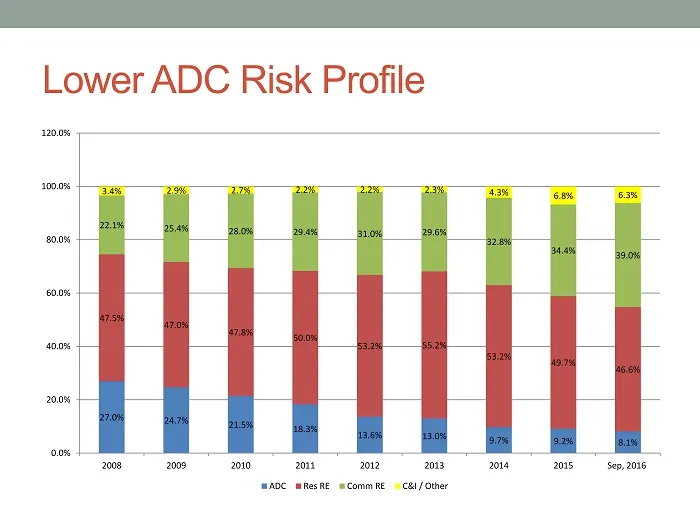
Slide 36: Lower ADC Risk Profile
Lower ADC Risk Profile 27.0% 24.7% 21.5% 18.3% 13.6% 13.0% 9.7% 9.2% 8.1% 47.5% 47.0% 47.8% 50.0% 53.2% 55.2% 53.2% 49.7% 46.6% 22.1% 25.4% 28.0% 29.4% 31.0% 29.6% 32.8% 34.4% 39.0% 3.4% 2.9% 2.7% 2.2% 2.2% 2.3% 4.3% 6.8% 6.3% 0.0% 20.0% 40.0% 60.0% 80.0% 100.0% 120.0% 2008 2009 2010 2011 2012 2013
Slide 37: ADC / CRE Within Regulatory Limits
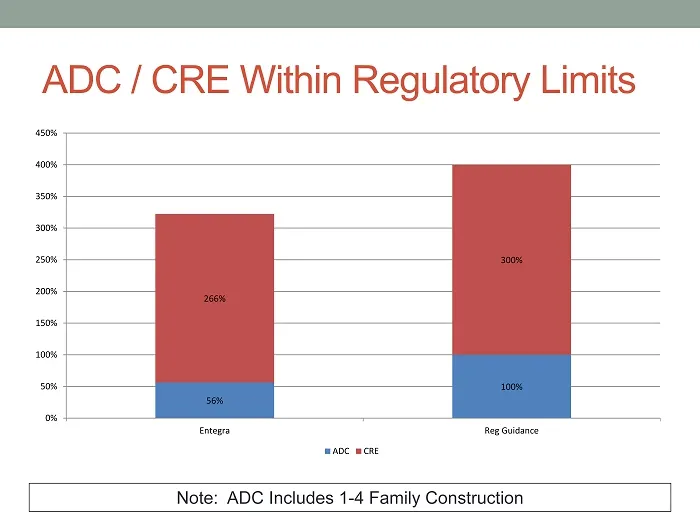
ADC / CRE Within Regulatory Limits Note: ADC Includes 1 - 4 Family Construction 56% 100% 266% 300% 0% 50% 100% 150% 200% 250% 300% 350% 400% 450% Entegra Reg Guidance ADC CRE
Slide 38: Growing Deposits w/ Minimal Brokered
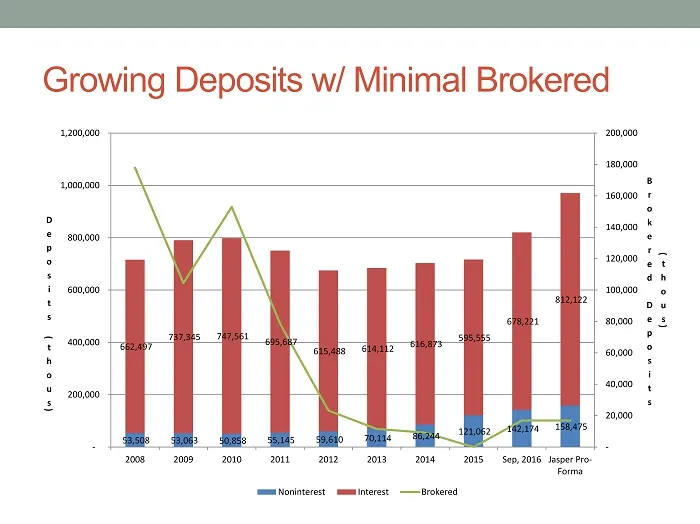
Growing Deposits w / Minimal Brokered 53,508 53,063 50,858 55,145 59,610 70,114 86,244 121,062 142,174 158,475 662,497 737,345 747,561 695,687 615,488 614,112 616,873 595,555 678,221 812,122 - 20,000 40,000 60,000 80,000 100,000 120,000 140,000 160,000 180,000 200,000 - 200,000 400,000 600,000 800,0
Slide 39: Focus on Core Deposits
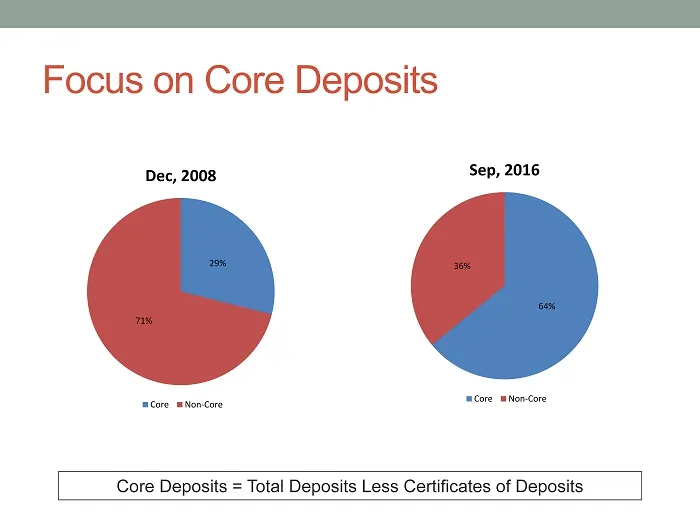
Focus on Core Deposits Core Deposits = Total Deposits Less Certificates of Deposits 29% 71% Dec, 2008 Core Non-Core 64% 36% Sep, 2016 Core Non-Core
Slide 40: Core Deposit Benefits
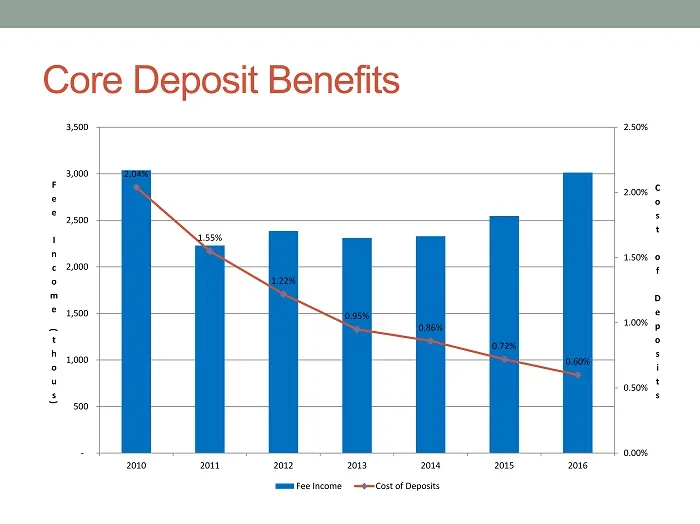
Core Deposit Benefits 2.04% 1.55% 1.22% 0.95% 0.86% 0.72% 0.60% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% - 500 1,000 1,500 2,000 2,500 3,000 3,500 2010 2011 2012 2013 2014 2015 2016 C o s t o f D e p o s i t s F e e I n c o m e ( t h o u s ) Fee Income Cost of Deposits
Slide 41: Improving Earnings
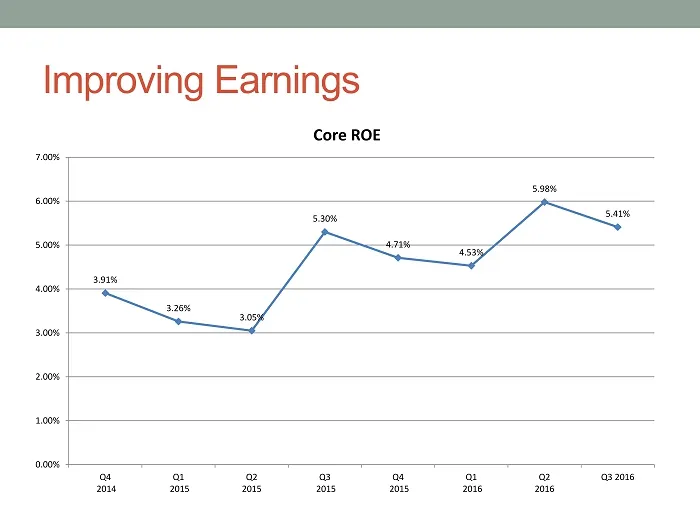
Improving Earnings 3.91% 3.26% 3.05% 5.30% 4.71% 4.53% 5.98% 5.41% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 7.00% Q4 2014 Q1 2015 Q2 2015 Q3 2015 Q4 2015 Q1 2016 Q2 2016 Q3 2016 Core ROE
Slide 42: Margin Driving Higher Earnings
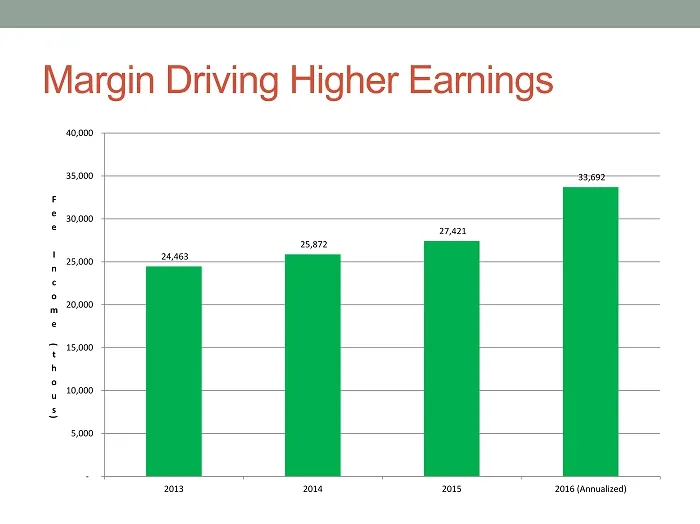
Margin Driving Higher Earnings 24,463 25,872 27,421 33,692 - 5,000 10,000 15,000 20,000 25,000 30,000 35,000 40,000 2013 2014 2015 2016 (Annualized) F e e I n c o m e ( t h o u s )
Slide 43: Disciplined Expense Control
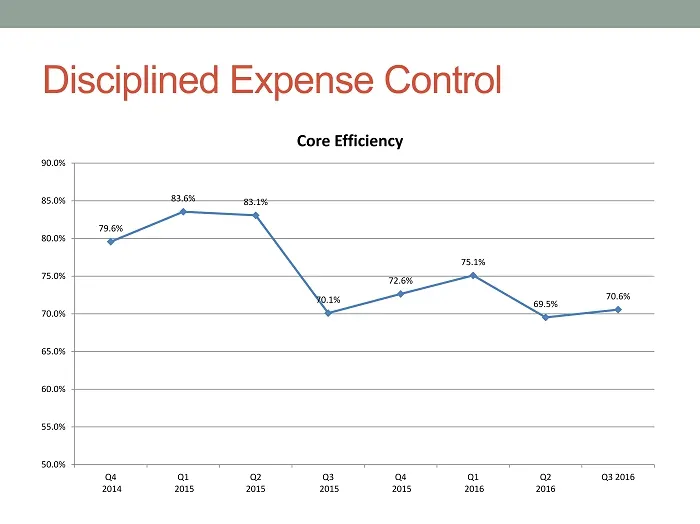
Disciplined Expense Control 79.6% 83.6% 83.1% 70.1% 72.6% 75.1% 69.5% 70.6% 50.0% 55.0% 60.0% 65.0% 70.0% 75.0% 80.0% 85.0% 90.0% Q4 2014 Q1 2015 Q2 2015 Q3 2015 Q4 2015 Q1 2016 Q2 2016 Q3 2016 Core Efficiency
Slide 44: Credit Losses Continue to Decline
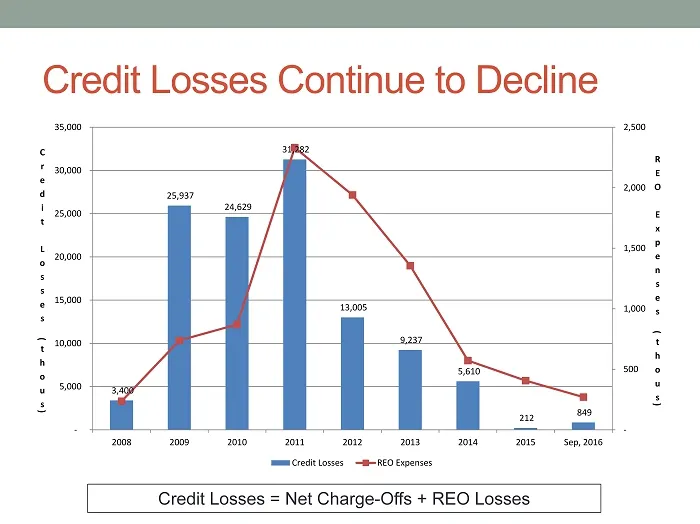
Credit Losses Continue to Decline Credit Losses = Net Charge - Offs + REO Losses 3,400 25,937 24,629 31,282 13,005 9,237 5,610 212 849 - 500 1,000 1,500 2,000 2,500 - 5,000 10,000 15,000 20,000 25,000 30,000 35,000 2008 2009 2010 2011 2012 2013 2014 2015 Sep, 2016 R E O E x p e n s e s ( t h o u s )
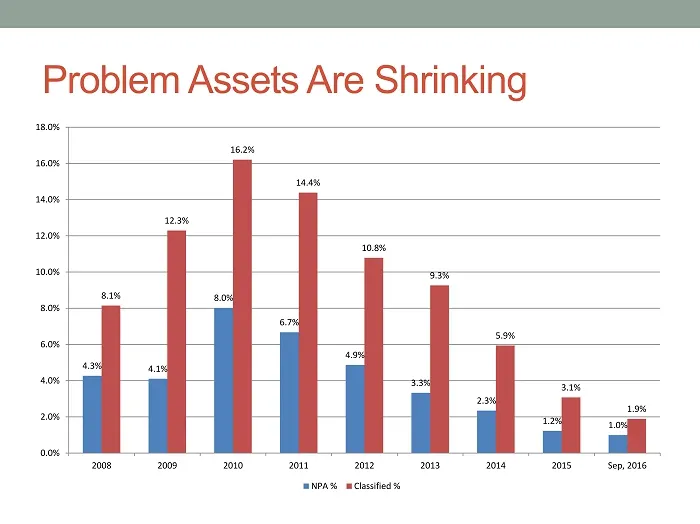
Slide 45: Problem Assets Are Shrinking
Problem Assets Are Shrinking 4.3% 4.1% 8.0% 6.7% 4.9% 3.3% 2.3% 1.2% 1.0% 8.1% 12.3% 16.2% 14.4% 10.8% 9.3% 5.9% 3.1% 1.9% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 18.0% 2008 2009 2010 2011 2012 2013 2014 2015 Sep, 2016 NPA % Classified %
Slide 46: Summary
Summary
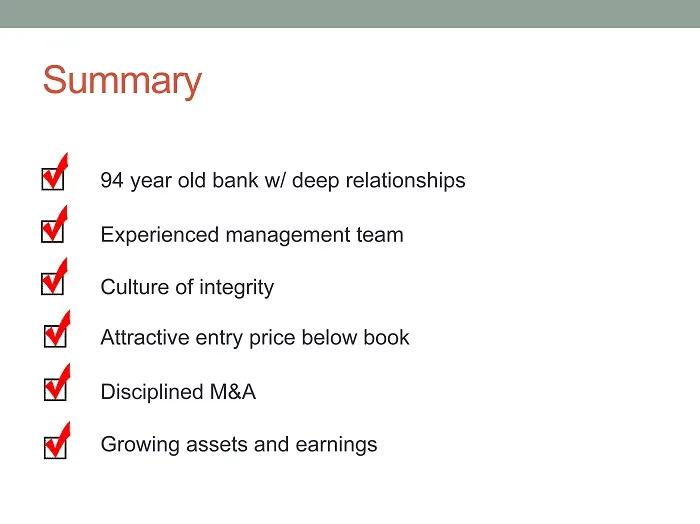
Slide 47: Summary
Summary 94 year o ld bank w/ deep relationships Experienced management team Culture of integrity Attractive entry price below book Disciplined M&A Growing assets and earnings
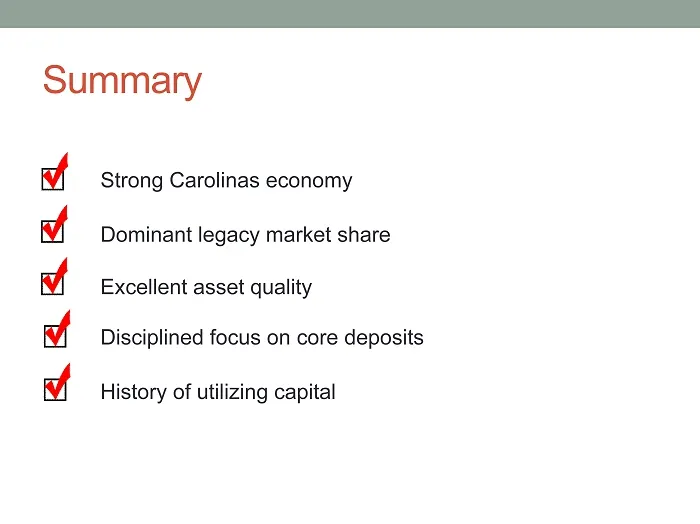
Slide 48: Summary
Summary Strong Carolinas economy Dominant legacy market share Excellent asset quality Disciplined focus on core deposits History of utilizing capital
Slide 49: GAAP Appendix
GAAP Appendix
Slide 50: GAAP Ratios
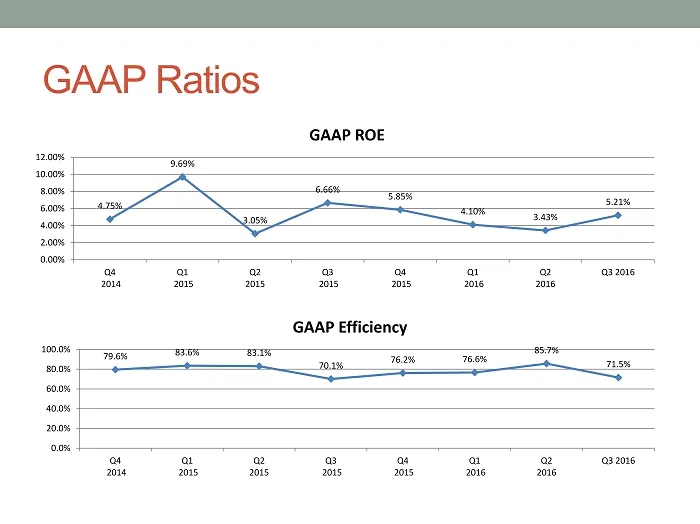
GAAP Ratios 4.75% 9.69% 3.05% 6.66% 5.85% 4.10% 3.43% 5.21% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% Q4 2014 Q1 2015 Q2 2015 Q3 2015 Q4 2015 Q1 2016 Q2 2016 Q3 2016 GAAP ROE 79.6% 83.6% 83.1% 70.1% 76.2% 76.6% 85.7% 71.5% 0.0% 20.0% 40.0% 60.0% 80.0% 100.0% Q4 2014 Q1 2015 Q2 2015 Q3 2015 Q4 2015
Source: SEC EDGAR · 8-K filed Nov 4, 2016
More decks from Entegra Financial Corp
 Merger or Acquisition (February 2019)21 slides · Feb 6, 2019
 Q4 2018 Earnings Presentation17 slides · Jan 24, 2019
 Merger or Acquisition (January 2019)25 slides · Jan 16, 2019
 Q3 2018 Earnings Presentation14 slides · Oct 18, 2018
 Investor Presentation (September 2018)48 slides · Sep 17, 2018
 Q2 2018 Earnings Presentation10 slides · Jul 19, 2018