Sterling Financial Corp
Sterling Financial — Q1 2013 Earnings Presentation
30 slides from Sterling Financial's earnings presentation, May 7, 2013
Slide 1: Management Update First Quarter 2013
Management Update First Quarter 2013 NASDAQ Ticker: STSA Spokane, Washington www.sterlingfinancialcorporation.com
Slide 2: Safe Harbor
Safe Harbor (1) The Reform Act defines the term "forward-looking statements" to include: statements of management plans and objectives, statements regarding the future economic performance, and projections of revenues and other financial data, among others. The Reform Act precludes liability for ora
Slide 3: 2013 Sterling Franchise at a Glance
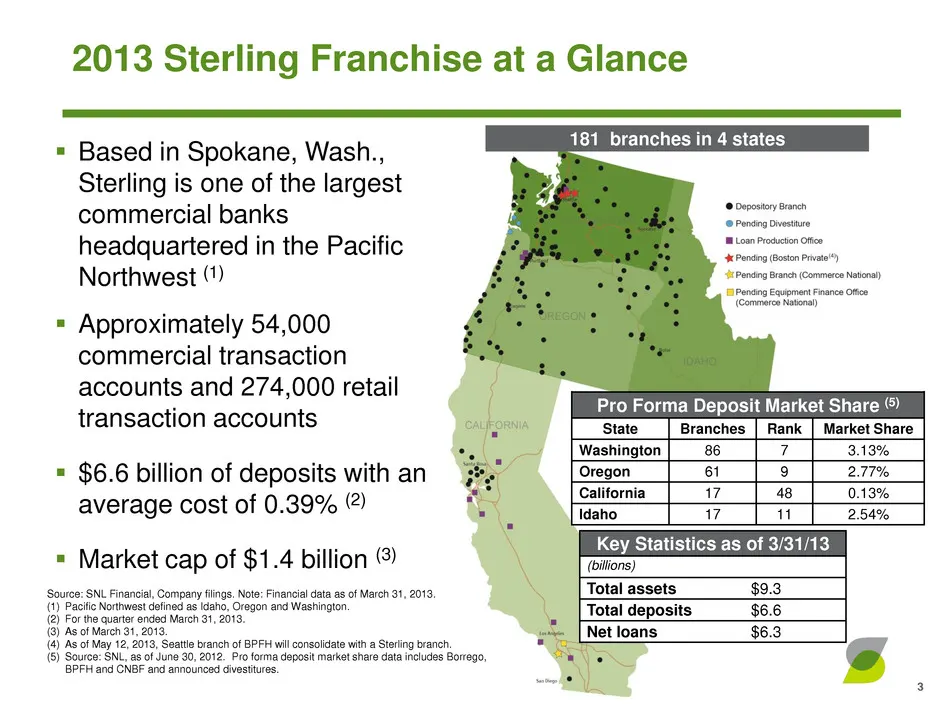
Key Statistics as of 3/31/13 (billions) Total assets $9.3 Total deposits $6.6 Net loans $6.3 2013 Sterling Franchise at a Glance 3 Based in Spokane, Wash., Sterling is one of the largest commercial banks headquartered in the Pacific Northwest (1) Approximately 54,000 commercial transaction accou
Slide 4: Key Operating Objectives and Performance Trends
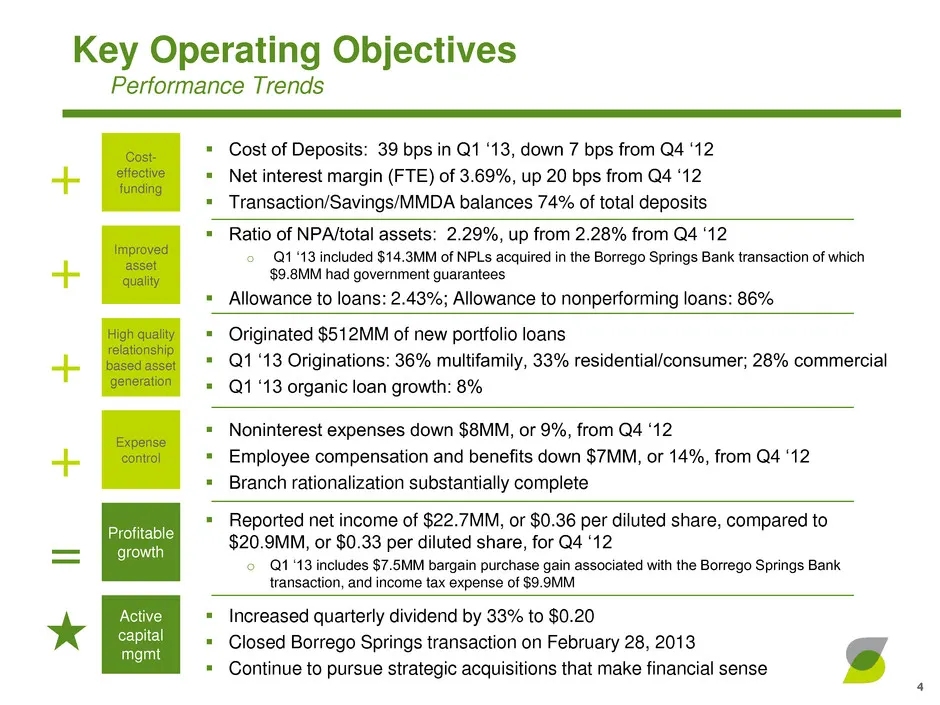
Key Operating Objectives Performance Trends Cost of Deposits: 39 bps in Q1 ‘13, down 7 bps from Q4 ‘12 Net interest margin (FTE) of 3.69%, up 20 bps from Q4 ‘12 Transaction/Savings/MMDA balances 74% of total deposits Ratio of NPA/total assets: 2.29%, up from 2.28% from Q4 ‘12 o Q1 ‘13 includ
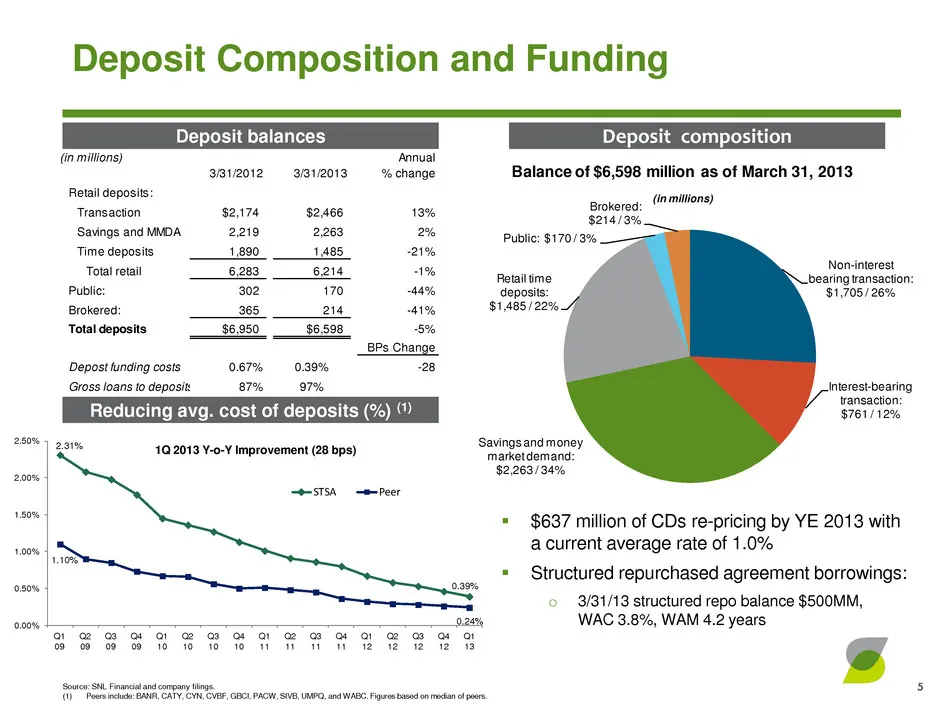
Slide 5: Deposit Composition and Funding
Non-interest bearing transaction: $1,705 / 26% Interest-bearing transaction: $761 / 12% Savings and money market demand: $2,263 / 34% Retail time deposits: $1,485 / 22% Public: $170 / 3% Brokered: $214 / 3% Balance of $6,598 million as of March 31, 2013 (in millions) (in millions) 3/31/2012 3/31/201
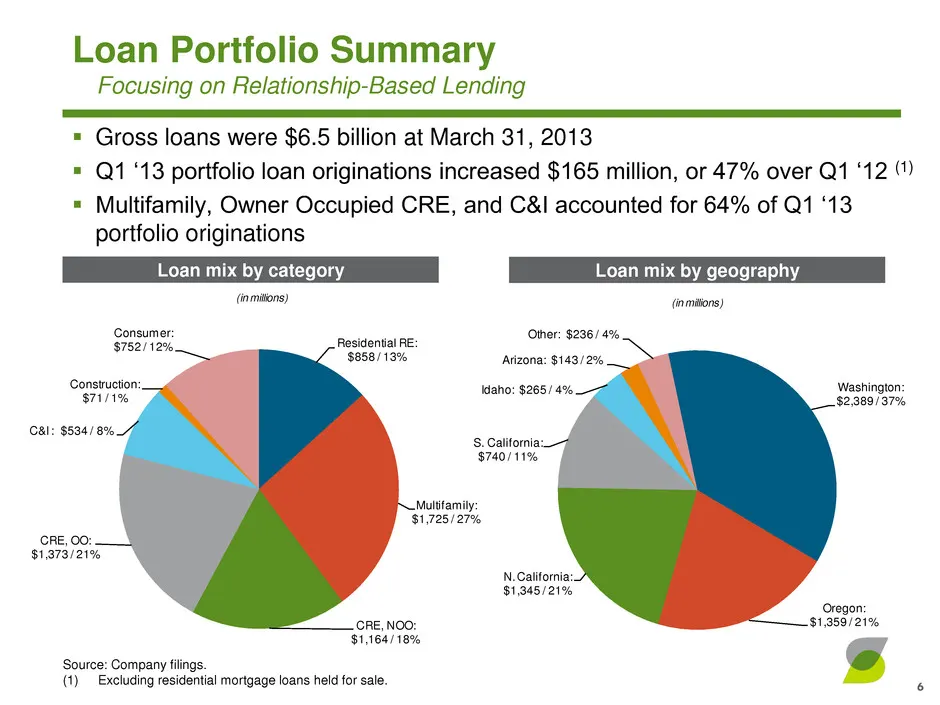
Slide 6: Loan Portfolio Summary
Washington: $2,389 / 37% Oregon: $1,359 / 21% N. California: $1,345 / 21% S. California: $740 / 11% Idaho: $265 / 4% Arizona: $143 / 2% Other: $236 / 4% (in millions) Residential RE: $858 / 13% Multifamily: $1,725 / 27% CRE, NOO: $1,164 / 18% CRE, OO: $1,373 / 21% C&I : $534 / 8% Construction: $71 /
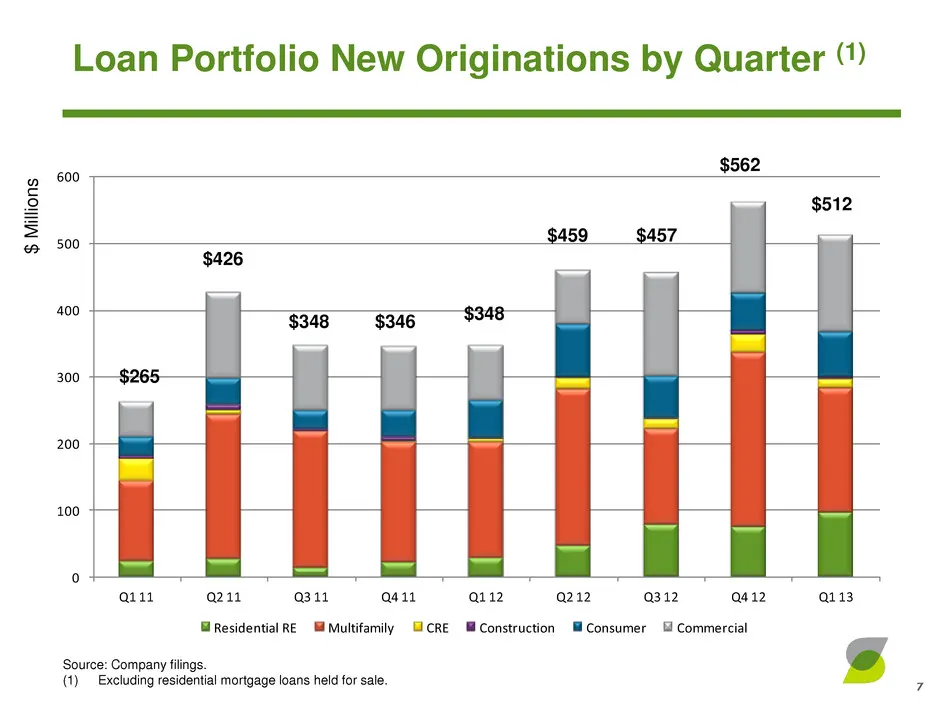
Slide 7: Loan Portfolio New Originations by Quarter
0 100 200 300 400 500 600 Q1 11 Q2 11 Q3 11 Q4 11 Q1 12 Q2 12 Q3 12 Q4 12 Q1 13 Residential RE Multifamily CRE Construction Consumer Commercial 7 $265 $348 $346 $348 $426 Source: Company filings. (1) Excluding residential mortgage loans held for sale. Loan Portfolio New Originations by Quarter (1) $
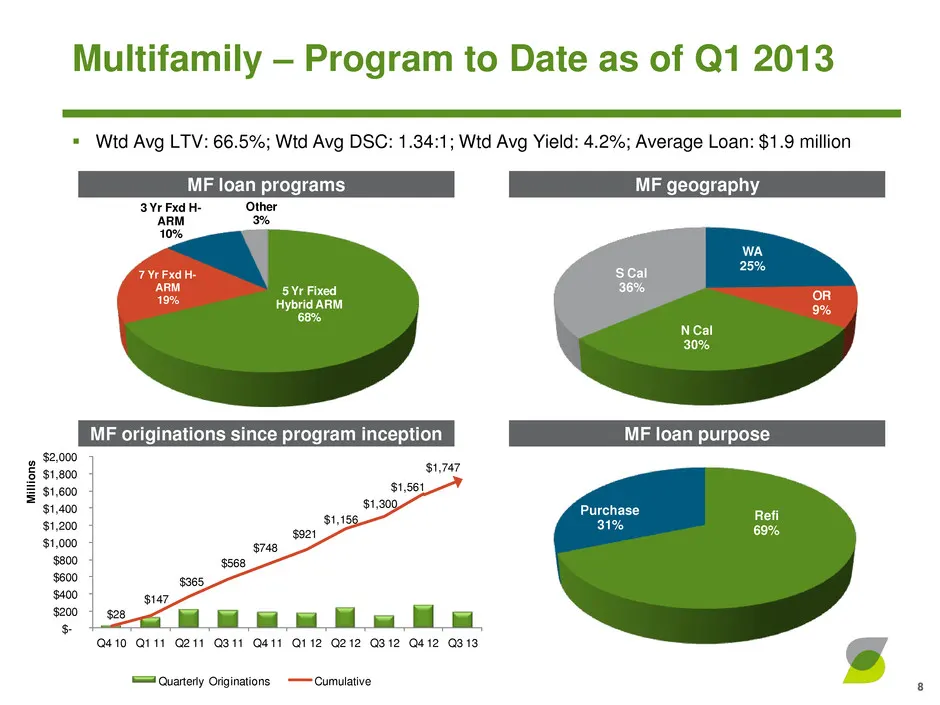
Slide 8: Multifamily – Program to Date as of Q1 2013
WA 25% OR 9% N Cal 30% S Cal 36% 5 Yr Fixed Hybrid ARM 68% 7 Yr Fxd H- ARM 19% 3 Yr Fxd H- ARM 10% Other 3% Refi 69% Purchase 31% Multifamily – Program to Date as of Q1 2013 8 MF loan programs MF geography MF loan purpose MF originations since program inception Wtd Avg LTV: 66.5%; Wtd Avg DSC: 1.3
Slide 9: Expense Control and Operating Efficiency Drivers
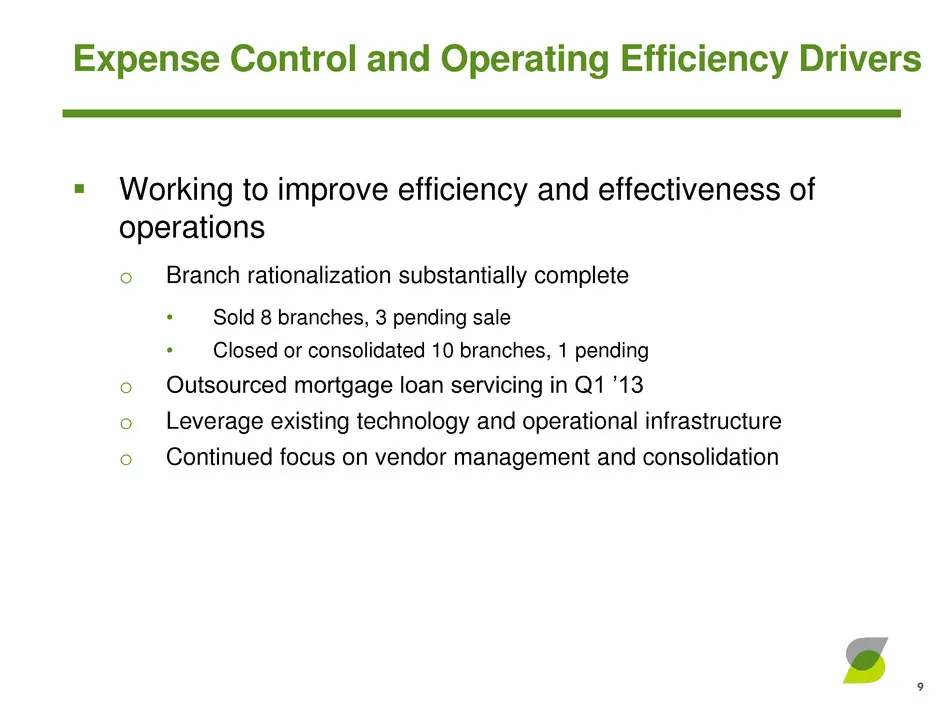
Working to improve efficiency and effectiveness of operations o Branch rationalization substantially complete • Sold 8 branches, 3 pending sale • Closed or consolidated 10 branches, 1 pending o Outsourced mortgage loan servicing in Q1 ’13 o Leverage existing technology and operational infrastructu
Slide 10: Asset Quality Metrics Comparable to Peers
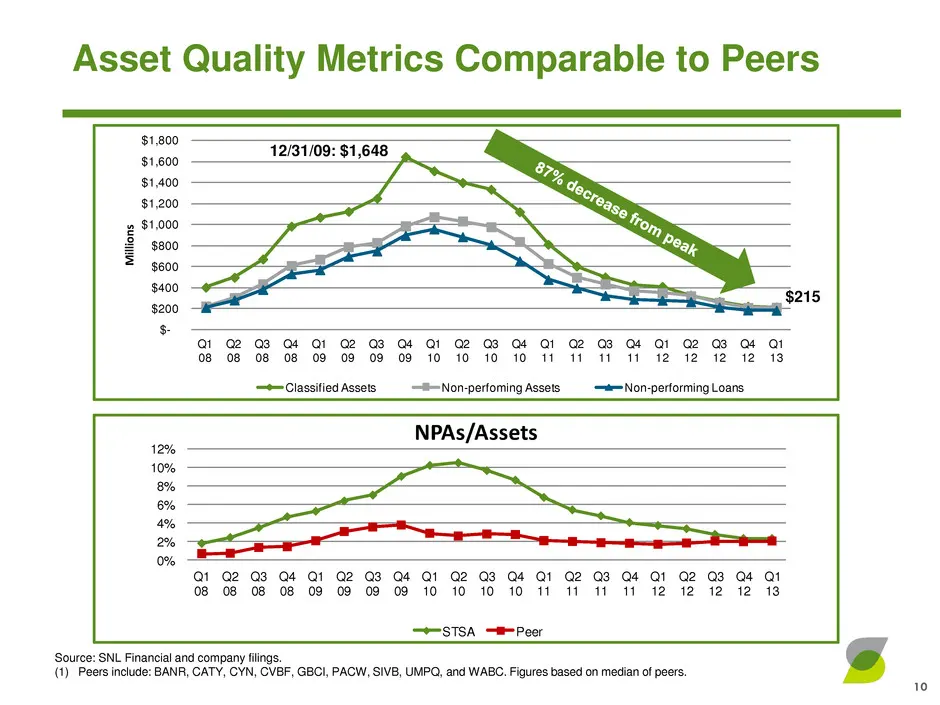
10 Asset Quality Metrics Comparable to Peers Source: SNL Financial and company filings. (1) Peers include: BANR, CATY, CYN, CVBF, GBCI, PACW, SIVB, UMPQ, and WABC. Figures based on median of peers. 0% 2% 4% 6% 8% 10% 12% Q1 08 Q2 08 Q3 08 Q4 08 Q1 09 Q2 09 Q3 09 Q4 09 Q1 10 Q2 10 Q3 10 Q4 10 Q1 11 Q
Slide 11: Non-performing Loan (NPL) Flow Analysis
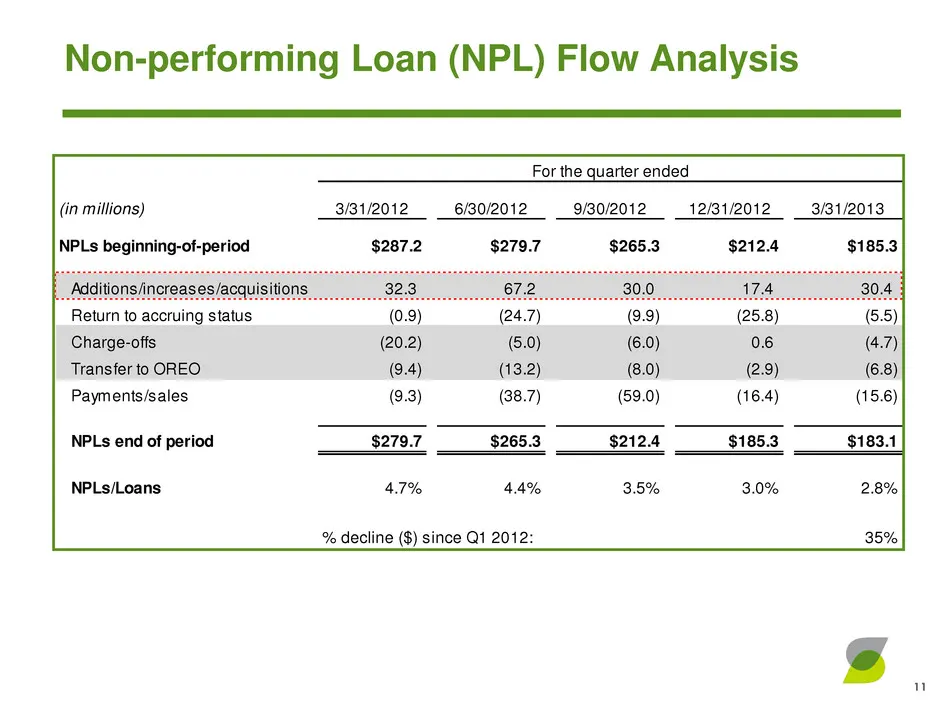
(in millions) 3/31/2012 6/30/2012 9/30/2012 12/31/2012 3/31/2013 NPLs beginning-of-period $287.2 $279.7 $265.3 $212.4 $185.3 Additions/increases/acquisitions 32.3 67.2 30.0 17.4 30.4 Return to accruing status (0.9) (24.7) (9.9) (25.8) (5.5) Charge-offs (20.2) (5.0) (6.0) 0.6 (4.7) Transfer to OREO (
Slide 12: OREO Flow Analysis
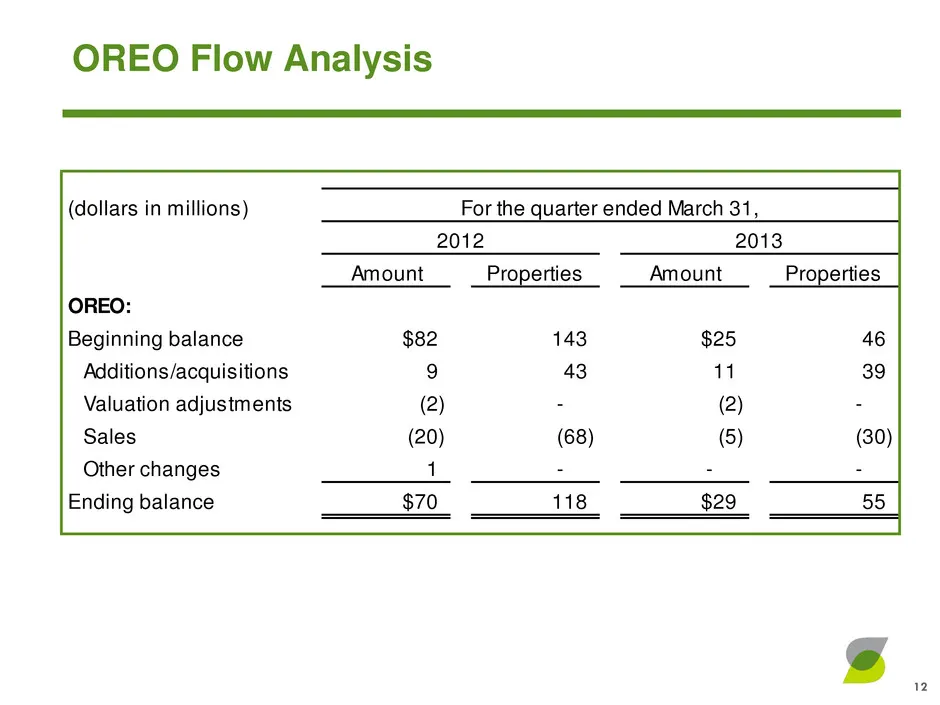
(dollars in millions) Amount Properties Amount Properties OREO: Beginning balance $82 143 $25 46 Additions/acquisitions 9 43 11 39 Valuation adjustments (2) - (2) - Sales (20) (68) (5) (30) Other changes 1 - - - Ending balance $70 118 $29 55 2012 2013 For the quarter ended March 31, OREO Flow Analys
Slide 13: Summary
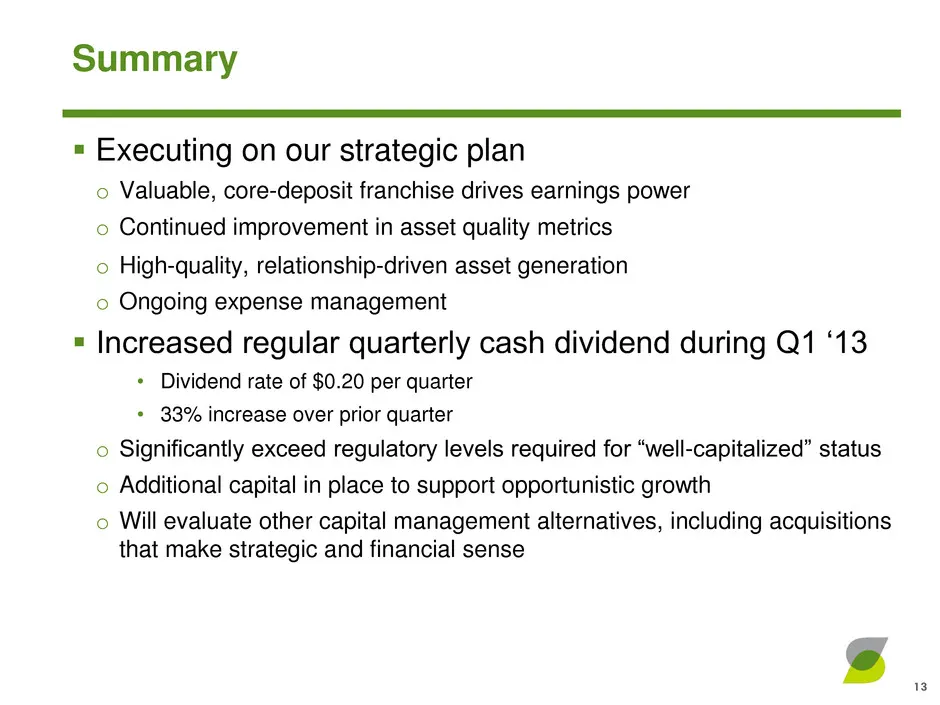
Summary Executing on our strategic plan o Valuable, core-deposit franchise drives earnings power o Continued improvement in asset quality metrics o High-quality, relationship-driven asset generation o Ongoing expense management Increased regular quarterly cash dividend during Q1 ‘13 • Dividend r
Slide 14: Investor and Media Contacts
NASDAQ Ticker: STSA Spokane, Washington www.sterlingfinancialcorporation.com Investor Contact Media Contact Patrick Rusnak Cara Coon Chief Financial Officer VP/Communications and Public Affairs Director (509) 227-0961 (509) 626-5348 patrick.rusnak@bankwithsterling.com cara.coon@bankwithsterling.com
Slide 15: Earnings Release Supplement
Earnings Release Supplement For the Quarter and Quarter Ended March 31,2013
Slide 16: Acquisition of Borrego Springs Bank, N.A.
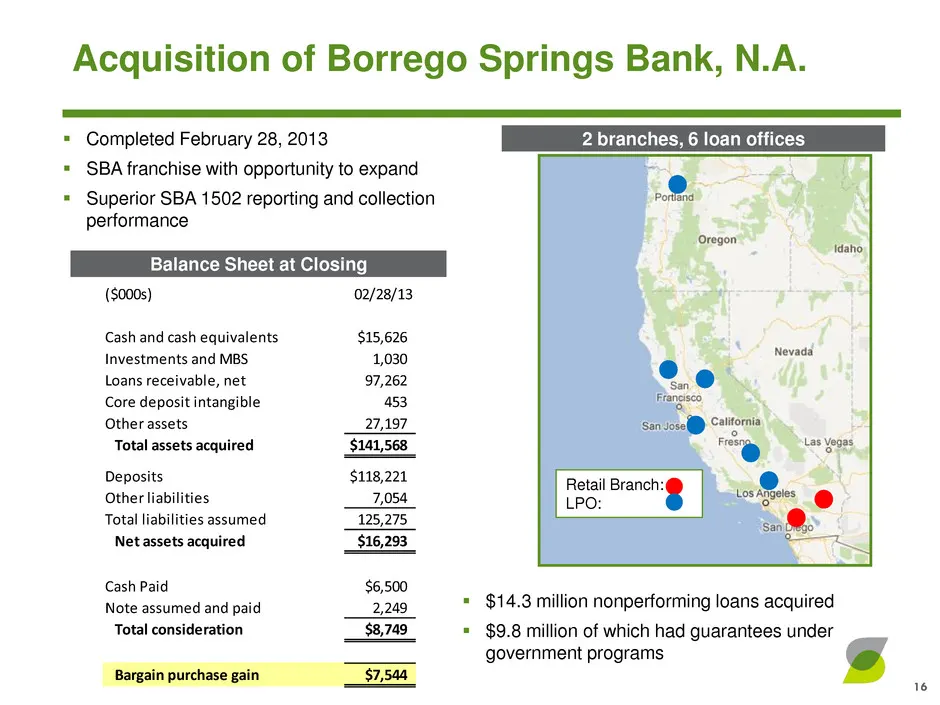
($000s) 02/28/13 Cash and cash equivalents $15,626 Investments and MBS 1,030 Loans receivable, net 97,262 Core deposit intangible 453 Other assets 27,197 Total assets acquired $141,568 Deposits $118,221 Other liabilities 7,054 Total liabilities assumed 125,275 Net assets acquired $16,293 Cash Paid $
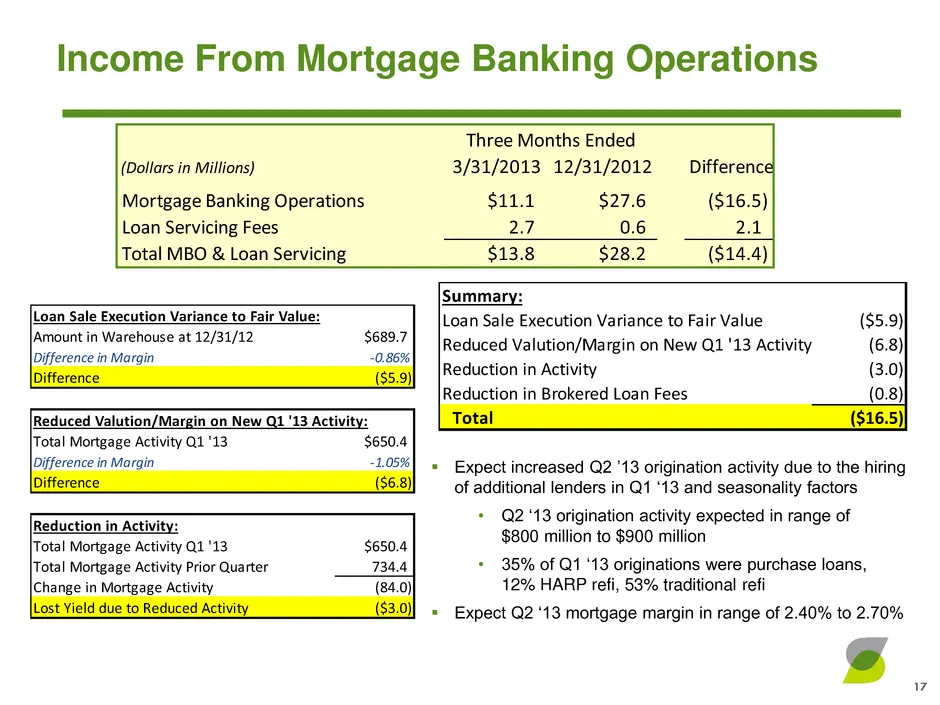
Slide 17: Income From Mortgage Banking Operations
Summary: Loan Sale Execution Variance to Fair Value ($5.9) Reduced Valution/Margin on New Q1 '13 Activity (6.8) Reduction in Activity (3.0) Reduction in Brokered Loan Fees (0.8) Total ($16.5) Income From Mortgage Banking Operations 17 (Dollars in Millions) 3/31/2013 12/31/2012 Difference Mortgage Ba
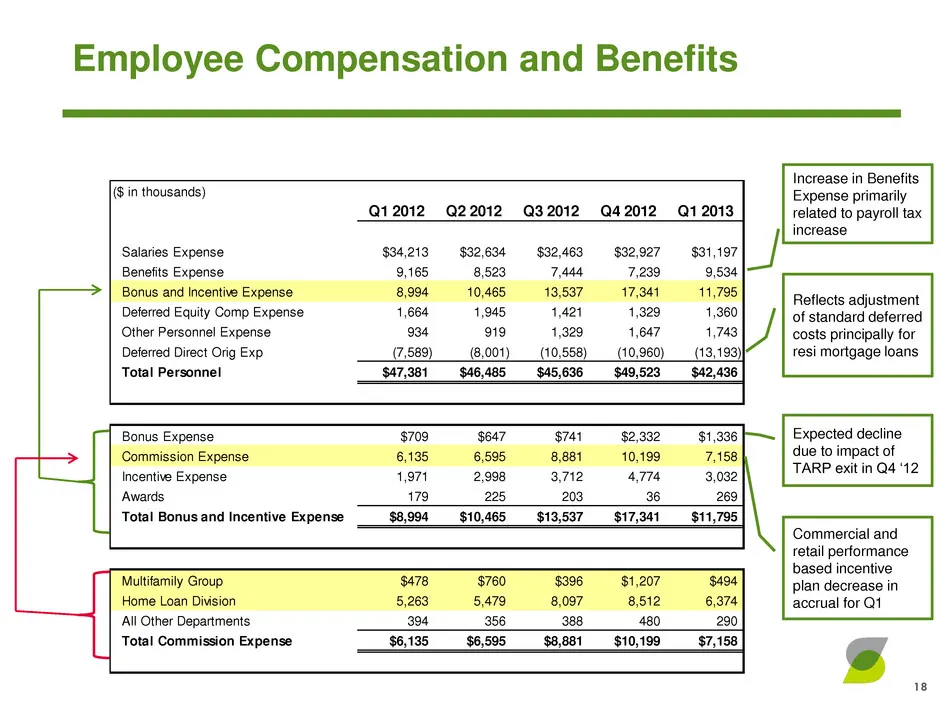
Slide 18: Personnel and Compensation Expense
($ in thousands) Q1 2012 Q2 2012 Q3 2012 Q4 2012 Q1 2013 Salaries Expense $34,213 $32,634 $32,463 $32,927 $31,197 Benefits Expense 9,165 8,523 7,444 7,239 9,534 Bonus and Incentive Expense 8,994 10,465 13,537 17,341 11,795 Deferred Equity Comp Expense 1,664 1,945 1,421 1,329 1,360 Other Personnel Ex
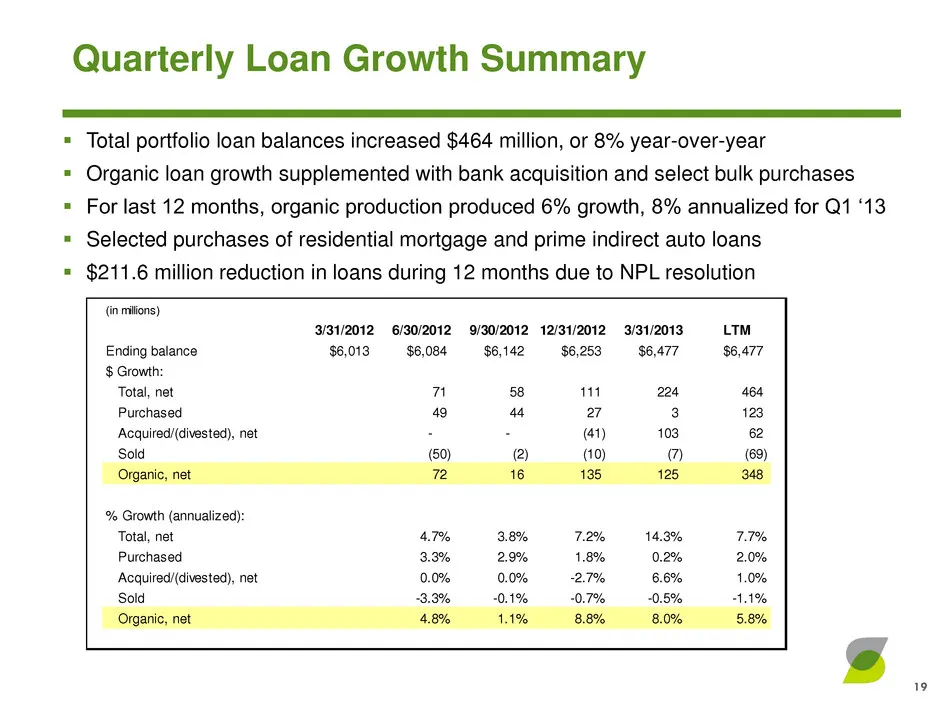
Slide 19: Quarterly Loan Growth Summary
(in millions) 3/31/2012 6/30/2012 9/30/2012 12/31/2012 3/31/2013 LTM Ending balance $6,013 $6,084 $6,142 $6,253 $6,477 $6,477 $ Growth: Total, net 71 58 111 224 464 Purchased 49 44 27 3 123 Acquired/(divested), net - - (41) 103 62 Sold (50) (2) (10) (7) (69) Organic, net 72 16 135 125 348 % Growth (
Slide 20: Appendix
STERLING” FINANCIAL CORPORATION APPENDIX
Slide 21: Capital Compared to Peers
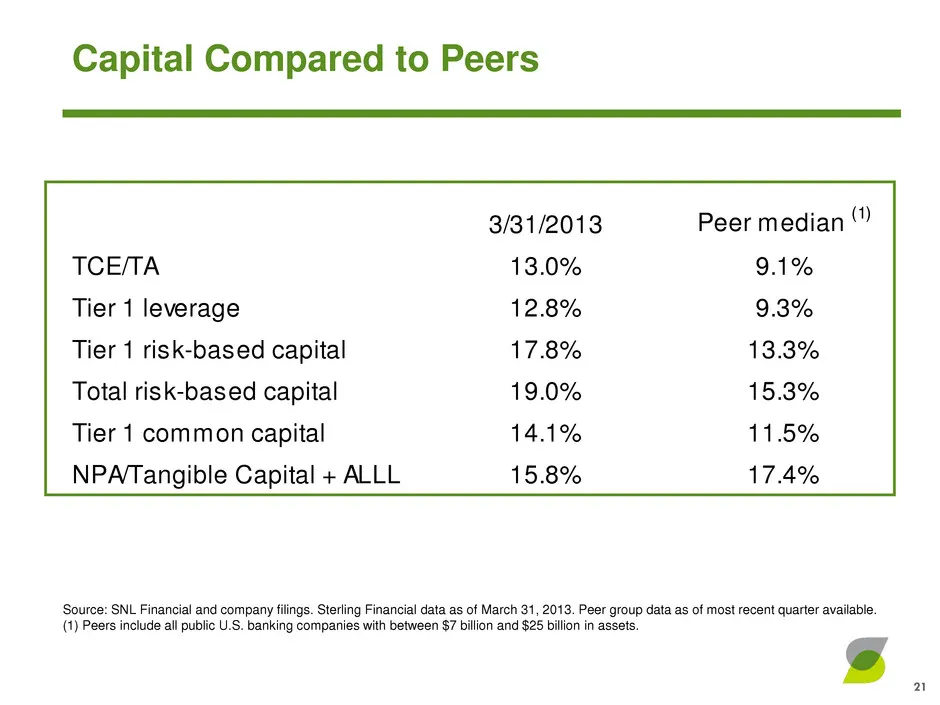
3/31/2013 Peer median (1) TCE/TA 13.0% 9.1% Tier 1 leverage 12.8% 9.3% Tier 1 risk-based capital 17.8% 13.3% Total risk-based capital 19.0% 15.3% Tier 1 common capital 14.1% 11.5% NPA/Tangible Capital + ALLL 15.8% 17.4% Capital Compared to Peers Source: SNL Financial and company filings. Sterling Fi
Slide 22: Quarterly Financial Summary
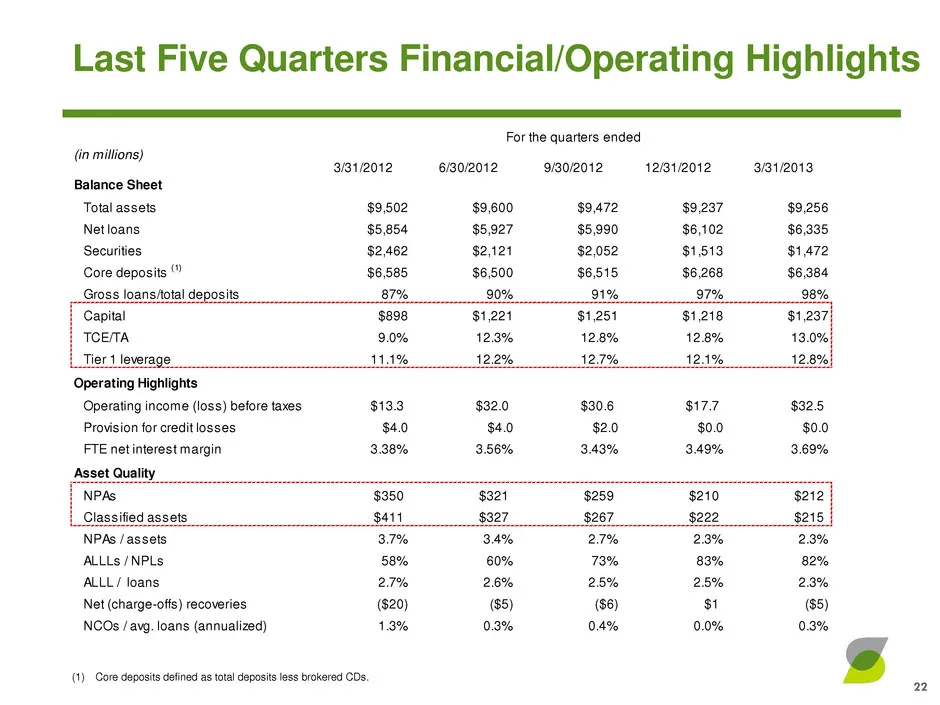
For the quarters ended (in millions) 3/31/2012 6/30/2012 9/30/2012 12/31/2012 3/31/2013 Balance Sheet Total assets $9,502 $9,600 $9,472 $9,237 $9,256 Net loans $5,854 $5,927 $5,990 $6,102 $6,335 Securities $2,462 $2,121 $2,052 $1,513 $1,472 Core deposits (1) $6,585 $6,500 $6,515 $6,268 $6,384 Gross
Slide 23: Investment Portfolio Overview
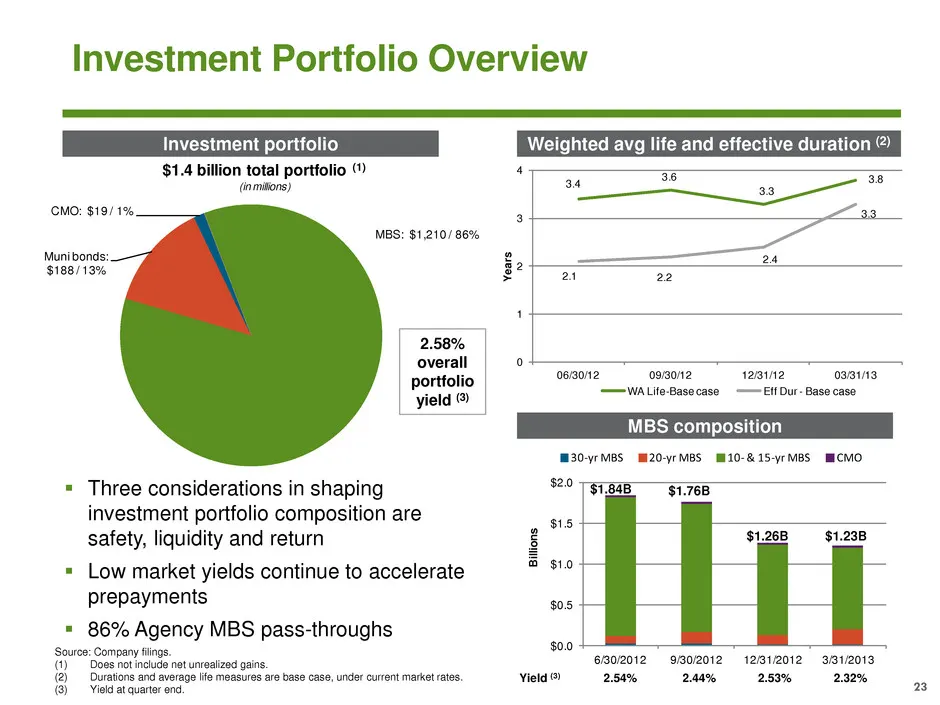
$0.0 $0.5 $1.0 $1.5 $2.0 6/30/2012 9/30/2012 12/31/2012 3/31/2013 Bi llio ns 30-yr MBS 20-yr MBS 10- & 15-yr MBS CMO MBS: $1,210 / 86% Muni bonds: $188 / 13% CMO: $19 / 1% $1.4 billion total portfolio (1) (in millions) 3.4 3.6 3.3 3.8 2.1 2.2 2.4 3.3 0 1 2 3 4 06/30/12 09/30/12 12/31/12 03/31/13 Ye
Slide 24: Loan Portfolio – CRE Non-Owner-Occupied Includes Multifamily
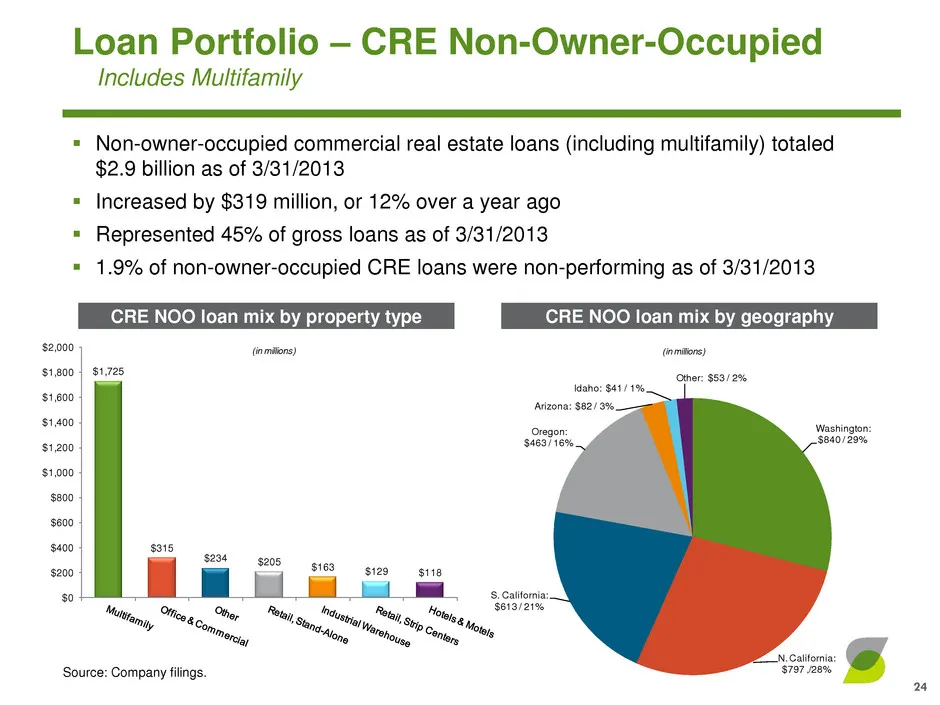
Washington: $840 / 29% N. California: $797 ,/28% S. California: $613 / 21% Oregon: $463 / 16% Arizona: $82 / 3% Idaho: $41 / 1% Other: $53 / 2% (in millions) Loan Portfolio – CRE Non-Owner-Occupied Includes Multifamily Non-owner-occupied commercial real estate loans (including multifamily) totaled
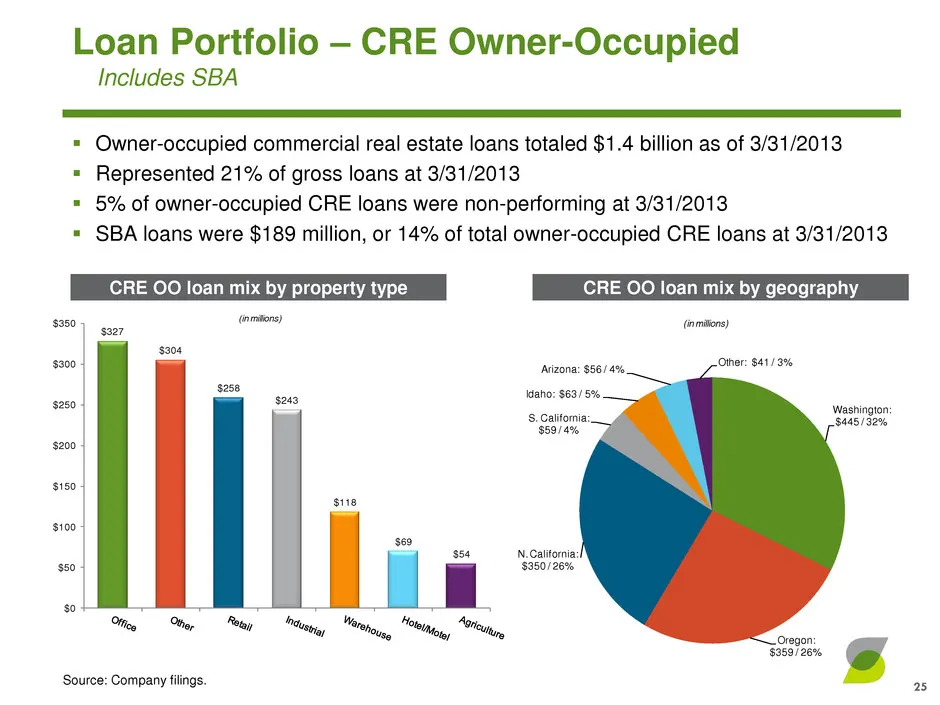
Slide 25: Loan Portfolio – CRE Owner-Occupied Includes SBA
Washington: $445 / 32% Oregon: $359 / 26% N. California: $350 / 26% S. California: $59 / 4% Idaho: $63 / 5% Arizona: $56 / 4% Other: $41 / 3% (in millions) Loan Portfolio – CRE Owner-Occupied Includes SBA Owner-occupied commercial real estate loans totaled $1.4 billion as of 3/31/2013 Represente
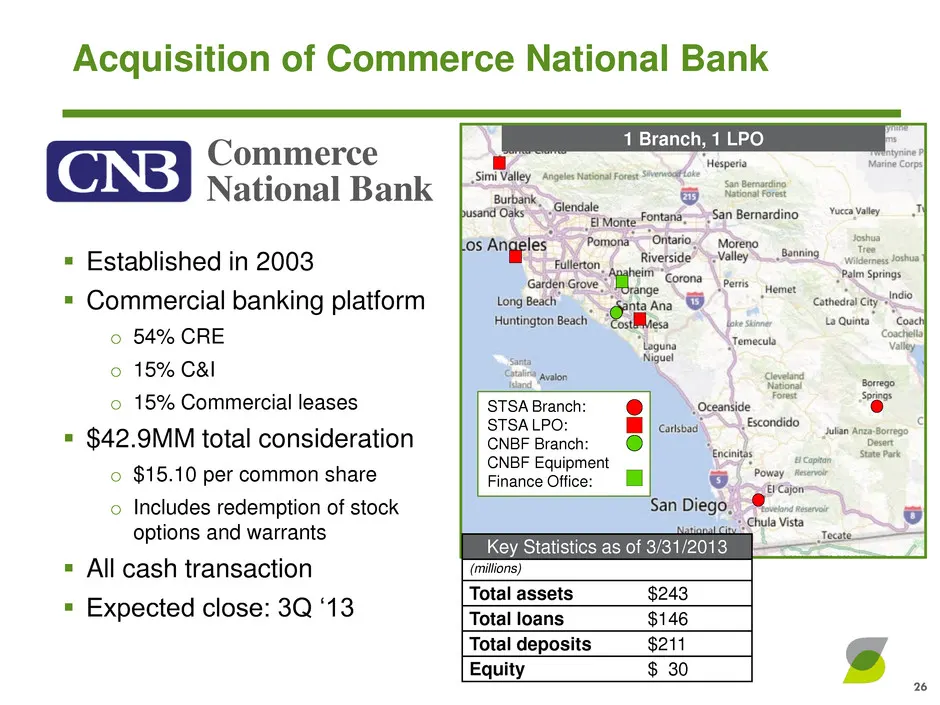
Slide 26: Acquisition of Commerce National Bank
Key Statistics as of 3/31/2013 (millions) Total assets $243 Total loans $146 Total deposits $211 Equity $ 30 Acquisition of Commerce National Bank 26 Established in 2003 Commercial banking platform o 54% CRE o 15% C&I o 15% Commercial leases $42.9MM total consideration o $15.10 per common shar
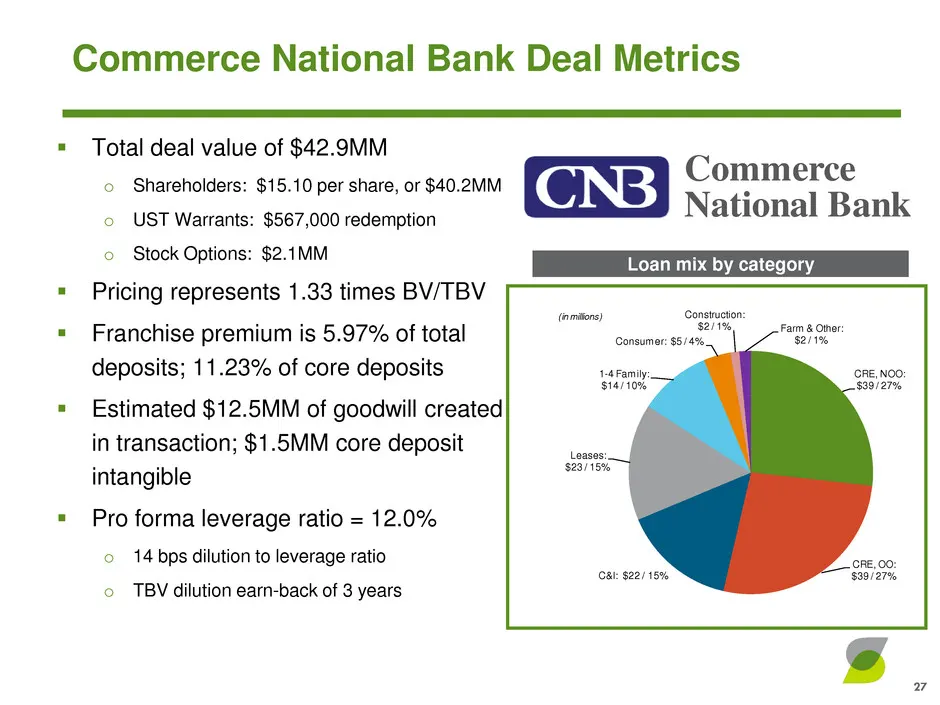
Slide 27: Commerce National Bank Deal Metrics
CRE, NOO: $39 / 27% CRE, OO: $39 / 27%C&I: $22 / 15% Leases: $23 / 15% 1-4 Family: $14 / 10% Consumer: $5 / 4% Construction: $2 / 1% Farm & Other: $2 / 1% (in millions) Commerce National Bank Deal Metrics Total deal value of $42.9MM o Shareholders: $15.10 per share, or $40.2MM o UST Warrants: $567
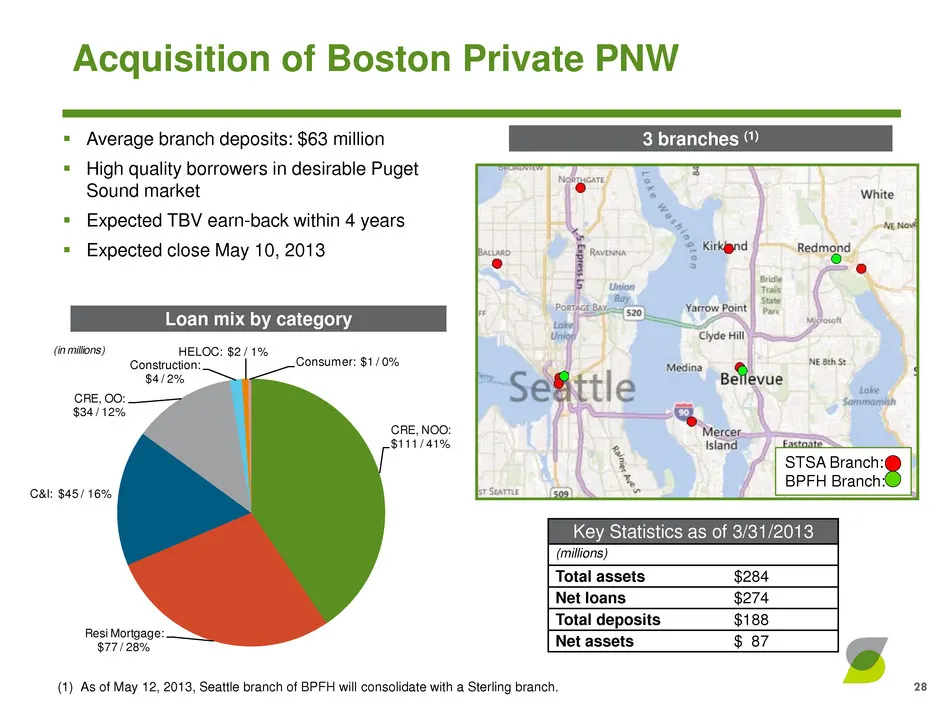
Slide 28: Acquisition of Boston Private PNW
Key Statistics as of 3/31/2013 (millions) Total assets $284 Net loans $274 Total deposits $188 Net assets $ 87 Acquisition of Boston Private PNW 28 Average branch deposits: $63 million High quality borrowers in desirable Puget Sound market Expected TBV earn-back within 4 years Expected close
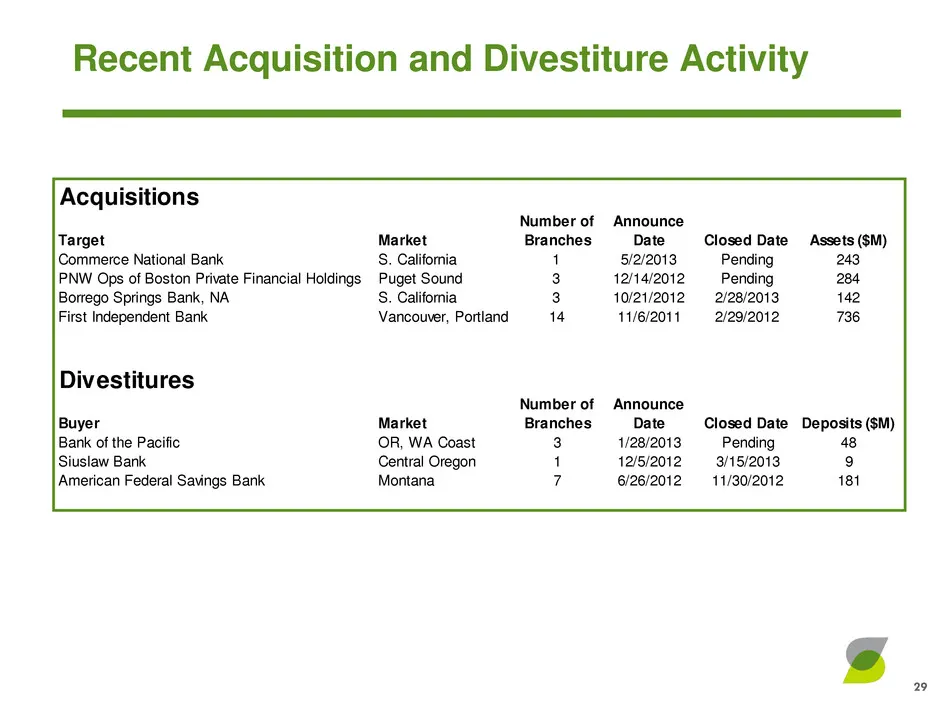
Slide 29: Recent Acquisition and Divestiture Activity
Acquisitions Target Market Number of Branches Announce Date Closed Date Assets ($M) Commerce National Bank S. California 1 5/2/2013 Pending 243 PNW Ops of Boston Private Financial Holdings Puget Sound 3 12/14/2012 Pending 284 Borrego Springs Bank, NA S. California 3 10/21/2012 2/28/2013 142 First In
Slide 30: Investor and Media Contacts
NASDAQ Ticker: STSA Spokane, Washington www.sterlingfinancialcorporation.com Investor Contact Media Contact Patrick Rusnak Cara Coon Chief Financial Officer VP/Communications and Public Affairs Director (509) 227-0961 (509) 626-5348 patrick.rusnak@bankwithsterling.com cara.coon@bankwithsterling.com
Source: SEC EDGAR · 8-K filed May 7, 2013
More decks from Sterling Financial Corp
 Q3 2013 Earnings Presentation6 slides · Oct 24, 2013
 Merger or Acquisition (September 2013)20 slides · Sep 12, 2013
 Merger or Acquisition (September 2013)20 slides · Sep 12, 2013
 Q2 2013 Earnings Presentation27 slides · Jul 30, 2013
 Q2 2013 Earnings Presentation8 slides · Jul 25, 2013
 Q1 2013 Earnings Presentation6 slides · Apr 24, 2013