Sterling Financial Corp
Sterling Financial — Merger or Acquisition (September 2013)
20 slides from Sterling Financial's merger presentation, Sep 12, 2013
Slide 1: Umpqua and Sterling: Combining to create the West Coast's largest community bank
Umpqua and Sterling: Combining to create the West Coast’s largest community bank Improved return on capital, increased scale and superior execution Strategic merger September 11, 2013 UMPQUA eo B-A-N°K STERLINGBANK
Slide 2: Safe harbor statement
Safe harbor statement This presentation includes forward-looking statements within the meaning of the “Safe-Harbor” provisions of the Private Securities Litigation Reform Act of 1995, which management believes are a benefit to shareholders. These statements are necessarily subject to risk and uncert
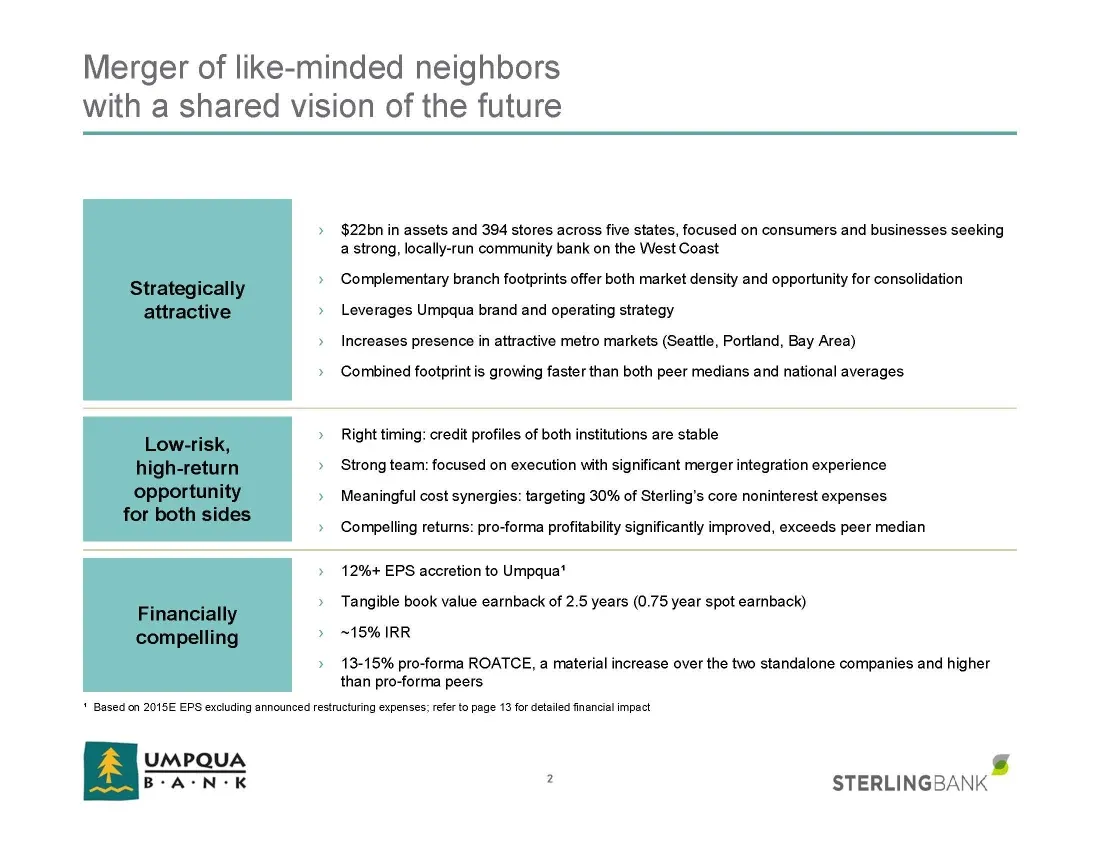
Slide 3: Merger of like-minded neighbors with a shared vision of the future
Merger of like-minded neighbors with a shared vision of the future >» $22bn in assets and 394 stores across five states, focused on consumers and businesses seeking a strong, locally-run community bank on the West Coast > Complementary branch footprints offer both market density and opportunity for
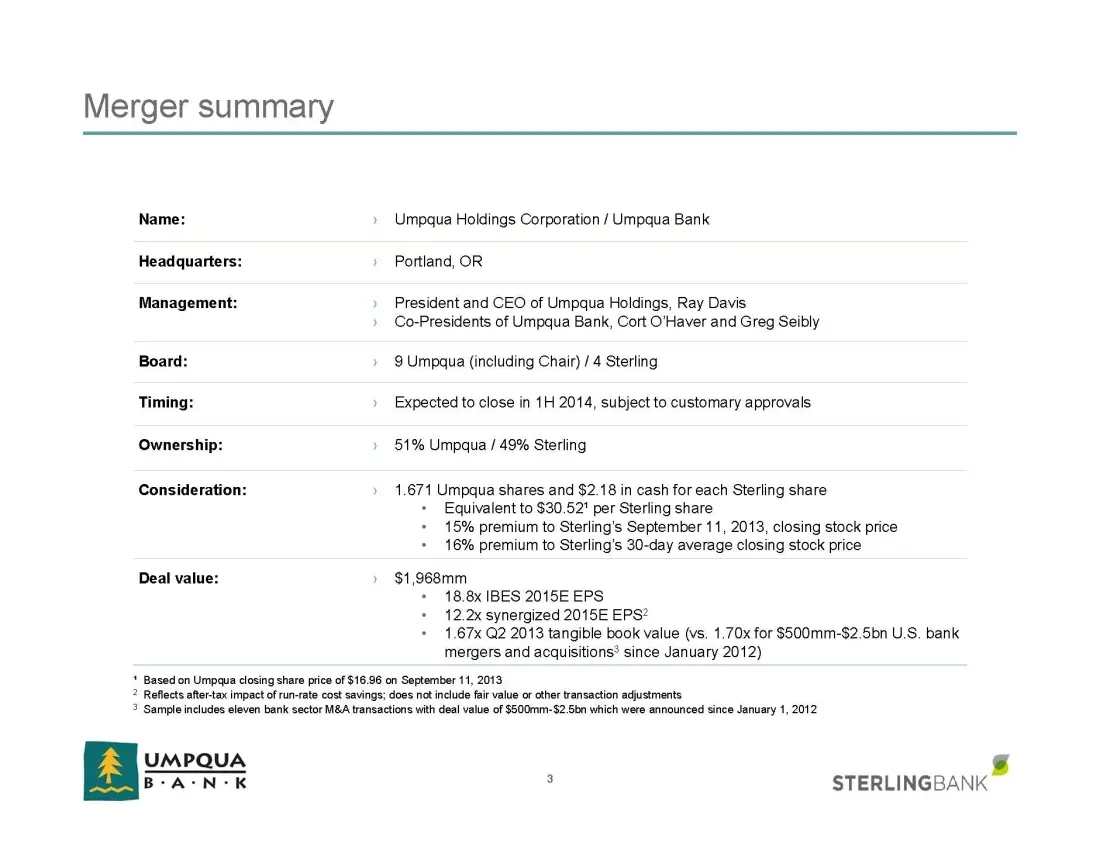
Slide 4: Merger summary
Merger summary Name: Umpqua Holdings Corporation / Umpqua Bank Headquarters: Portland, OR Management: » President and CEO of Umpqua Holdings, Ray Davis Co-Presidents of Umpqua Bank, Cort O’Haver and Greg Seibly Board: 9 Umpqua (including Chair) / 4 Sterling Timing: Expected to close in 1H 2014, subj
Slide 5: Strategic fit
Strategic fit UMPQUA sg B-A-N-K * STERLINGBANK
Slide 6: Natural partners with scale in complementary geographies and business lines
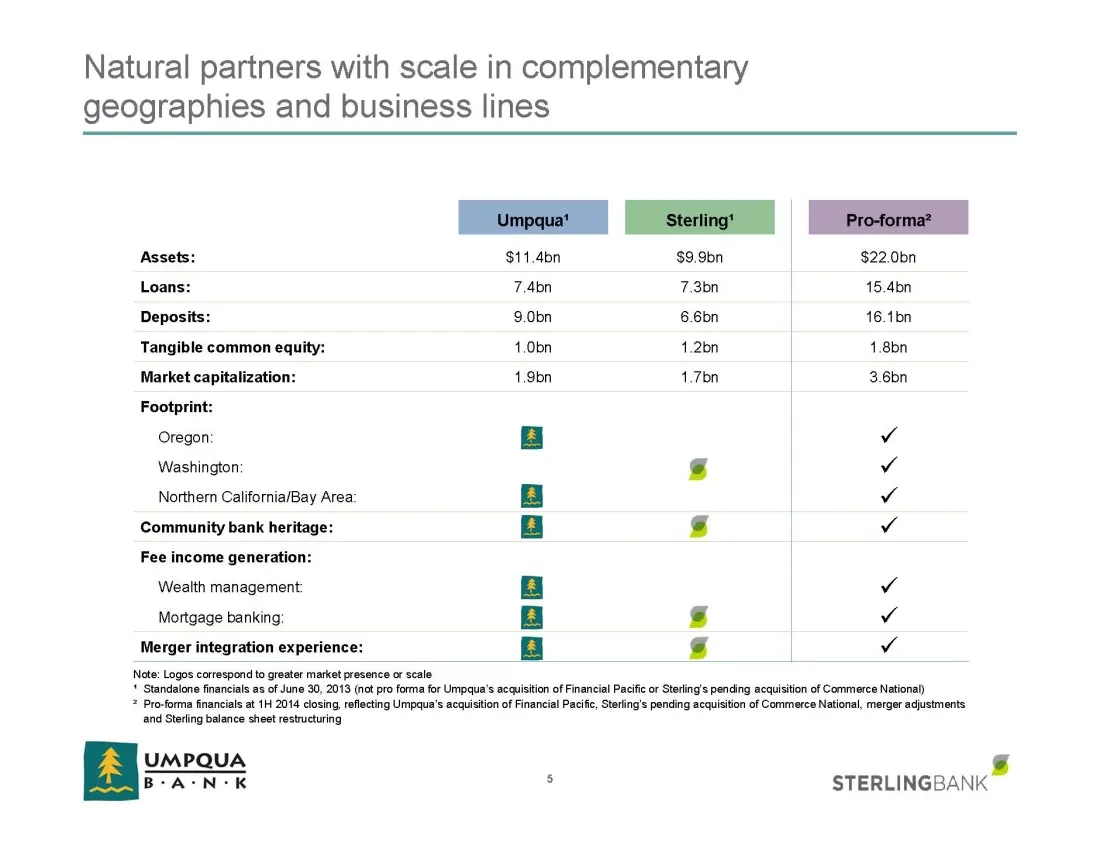
Natural partners with scale in complementary geographies and business lines Assets: $11.4bn $9.9bn $22.0bn Loans: 7.Abn 7.3bn 15.4bn Deposits: 9.0bn 6.6bn 16.1bn Tangible common equity: 4.0bn 1.2bn 1.8bn Market capitalization: 4.9bn 1.7bn 3.6bn Footprint: Oregon: B v Washington: v Northern Californi
Slide 7: Highly complementary and diversifying loan and deposit profiles
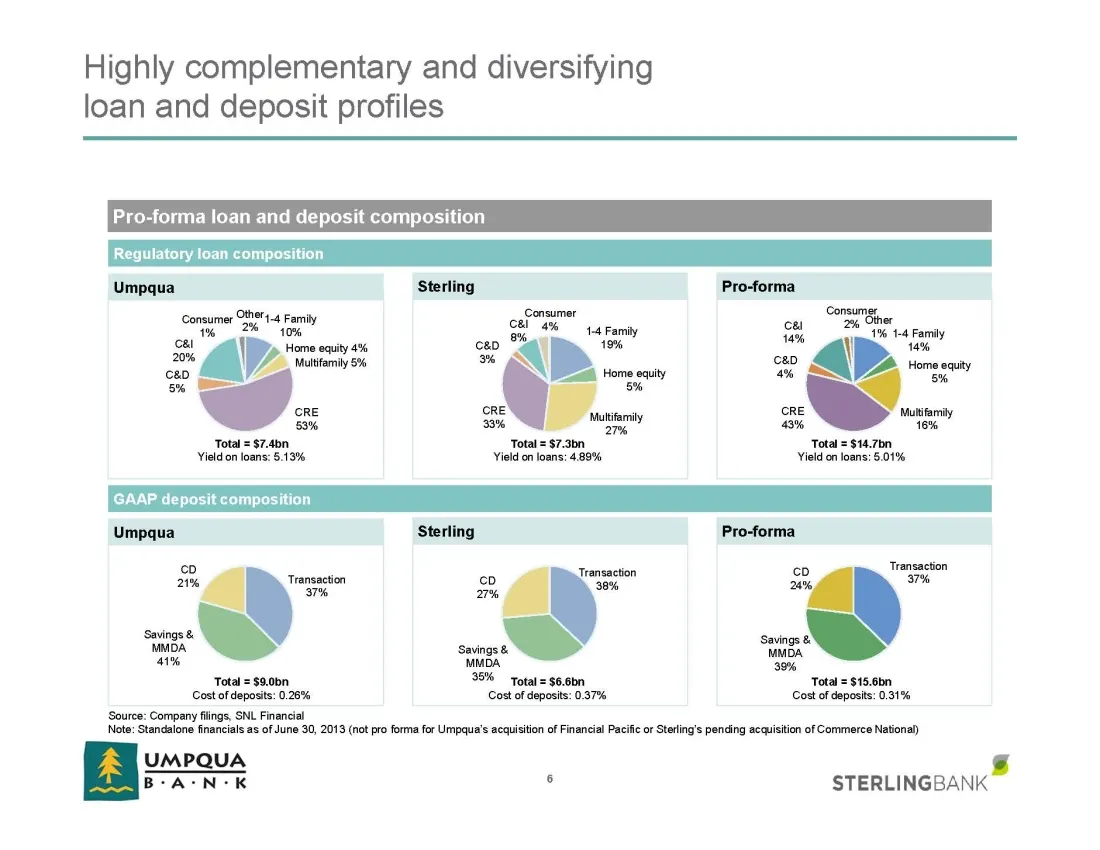
Highly complementary and diversifying loan and deposit profiles Regulatory loan composition Umpqua Sterling Pro-forma ote consumer ‘Consumer her. Family cer 1% 2% 10% 6% fe amity bed ay cal \ Home equity 4% ceo 19% 20% Za Multifamily 5% % ome weauty cao BE re sity =, 5% cre cre a cre vuntanty ou om
Slide 8: Enhanced scale and regional leadership
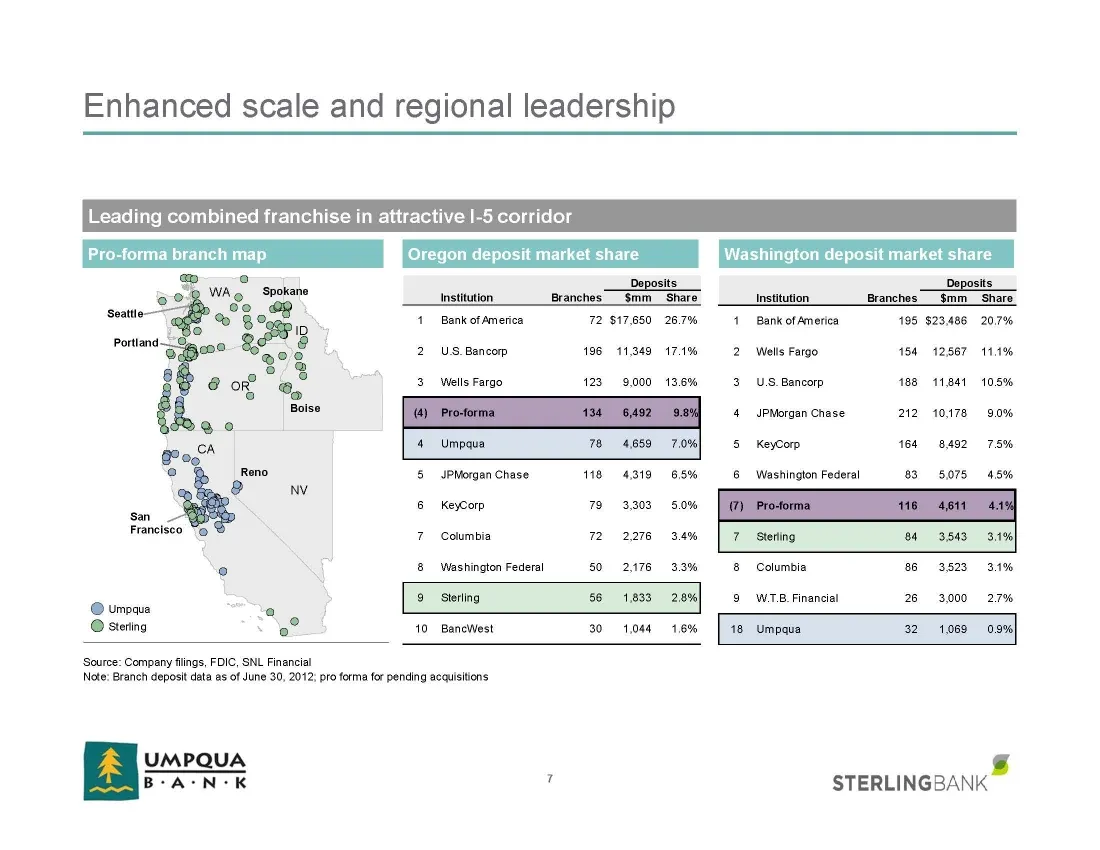
Enhanced scale and regional leadership Leading combined franchise in attractive I-5 corridor Pro-forma branch map Oregon deposit market share Washington deposit market share ° Deposits Institution Institution Branches $mm_ Share 1 Bank of America 72 $17,850 267% 1 Bankof America 195 $23.486 207% 2 U
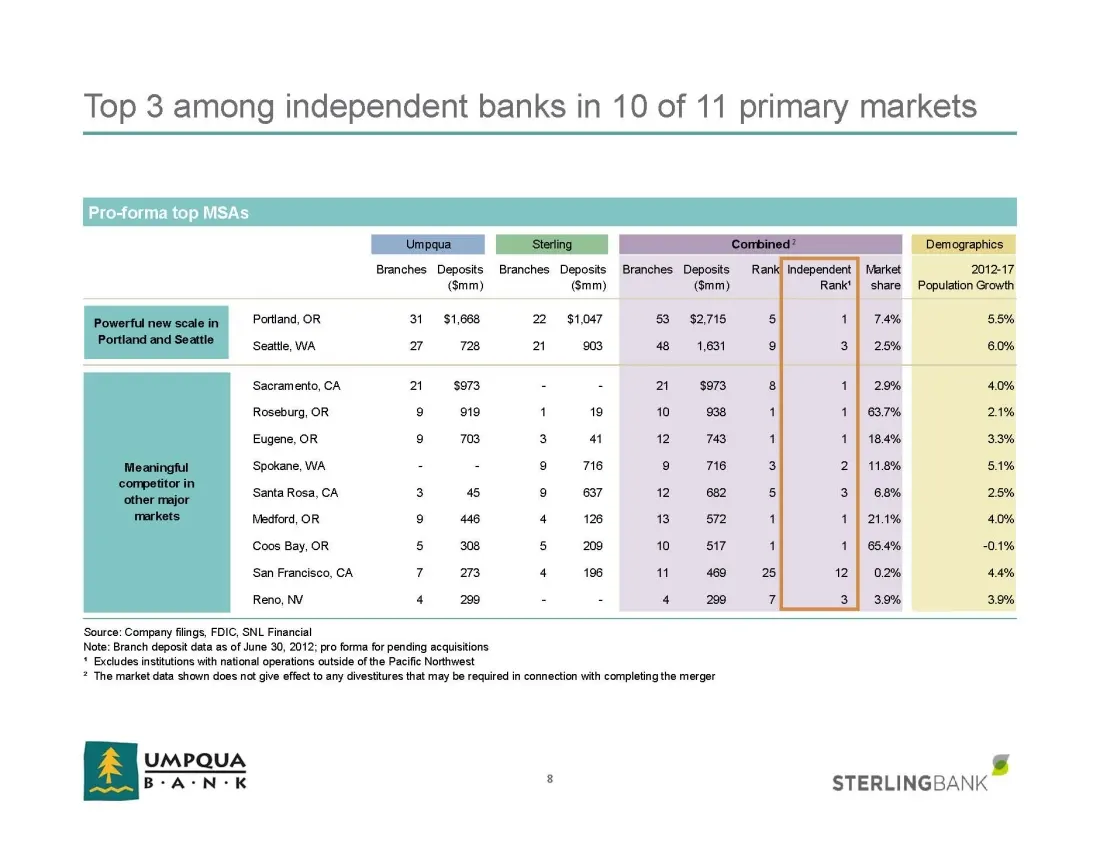
Slide 9: Top among independent banks in primary markets
Top 3 among independent banks in 10 of 11 primary markets Pro-forma top MSAs Branches Deposits Branches Deposits Branches Deposits Rank| independent | Market (Smm) (Smm) (mm) Rank’ | share Portland, OR 31 $1,668 22 $1,047 83 $2,715 5 1) 74% | ae’ rie inn ‘Sacramento, CA 21 $973 - - 2 $973 8 1) 29% R
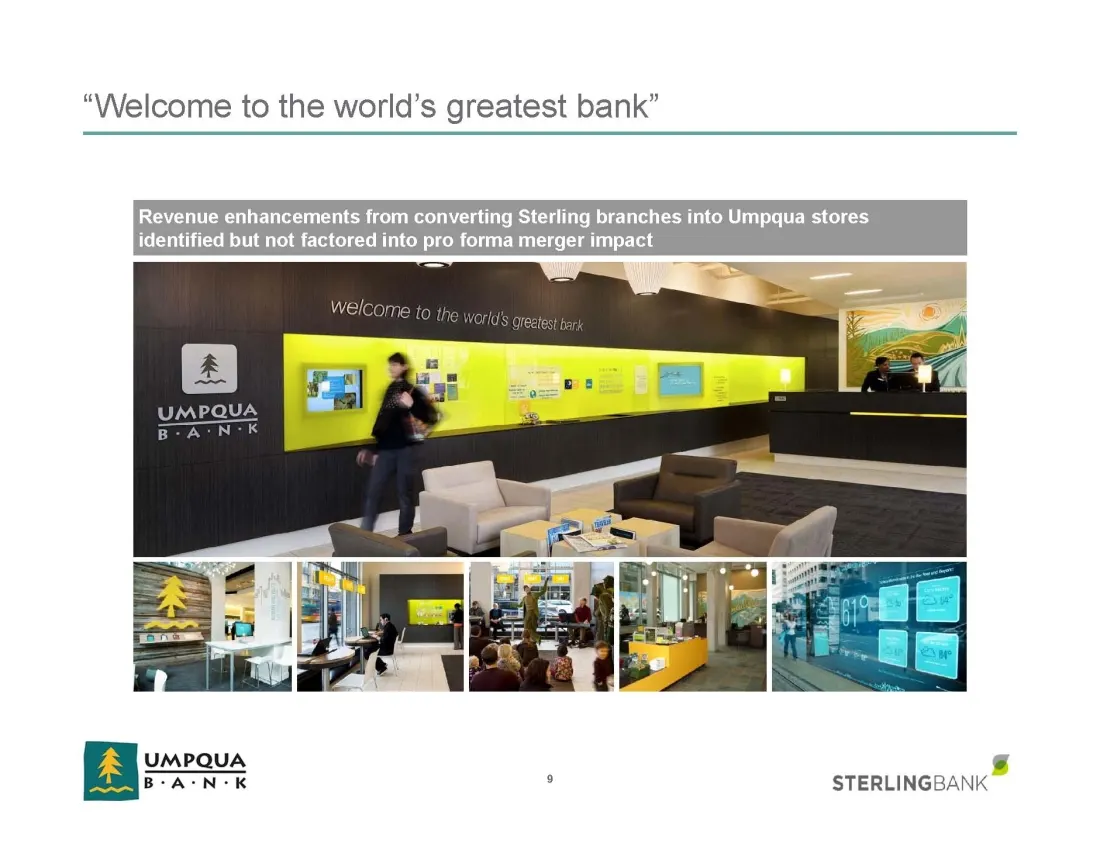
Slide 10: Welcome to the world's greatest bank
“Welcome to the world’s greatest bank” Revenue enhancements from converting Ste: ranches into Umpqua stores identified but not factored into pro forma merger impact e ; STERLINGBANK
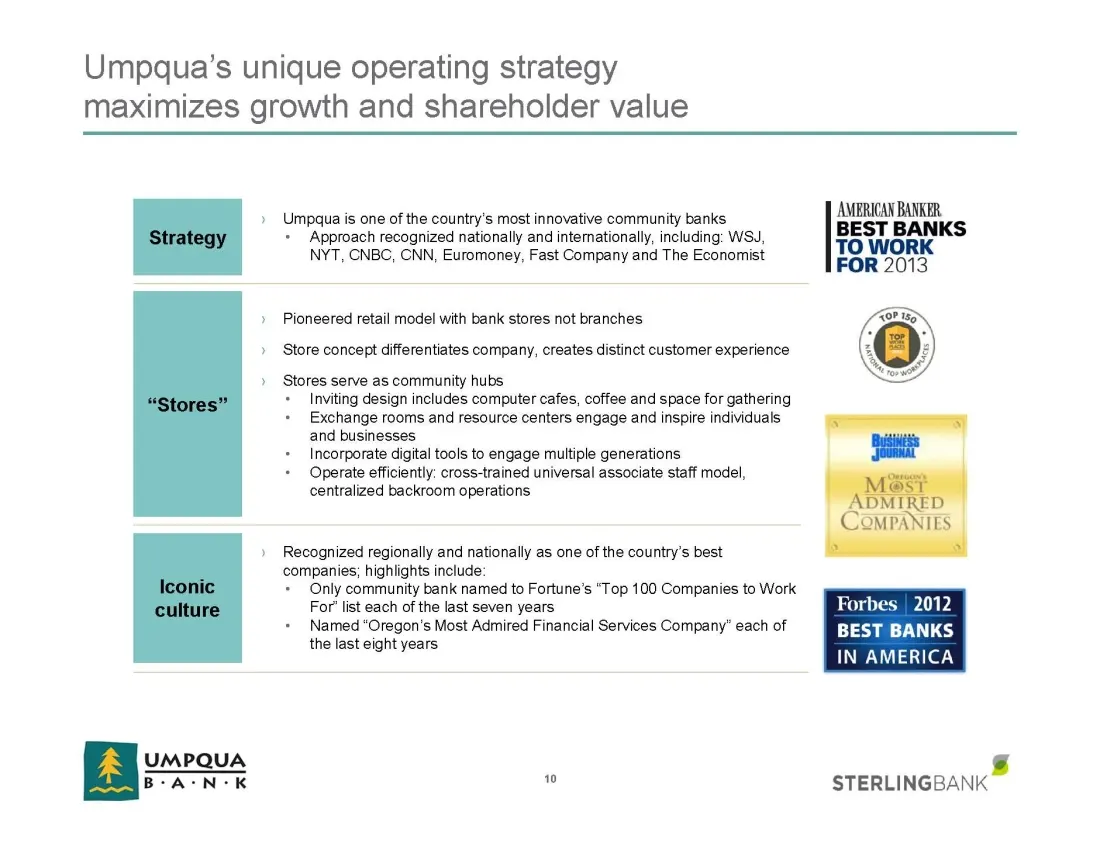
Slide 11: Umpqua's unique operating strategy maximizes growth and shareholder value
Umpqua’s unique operating strategy maximizes growth and shareholder value » Umpqua is one of the country's most innovative community banks Se ‘Approach recognized nationally and intemationally, including: WS., NYT, CNBC, CNN, Euromoney, Fast Company and The Economist FOR 2013 » Pioneered retail mode
Slide 12: Financially compelling combination
Financially compelling combination UMPQUA s B-A-N-K a STERLINGBANK
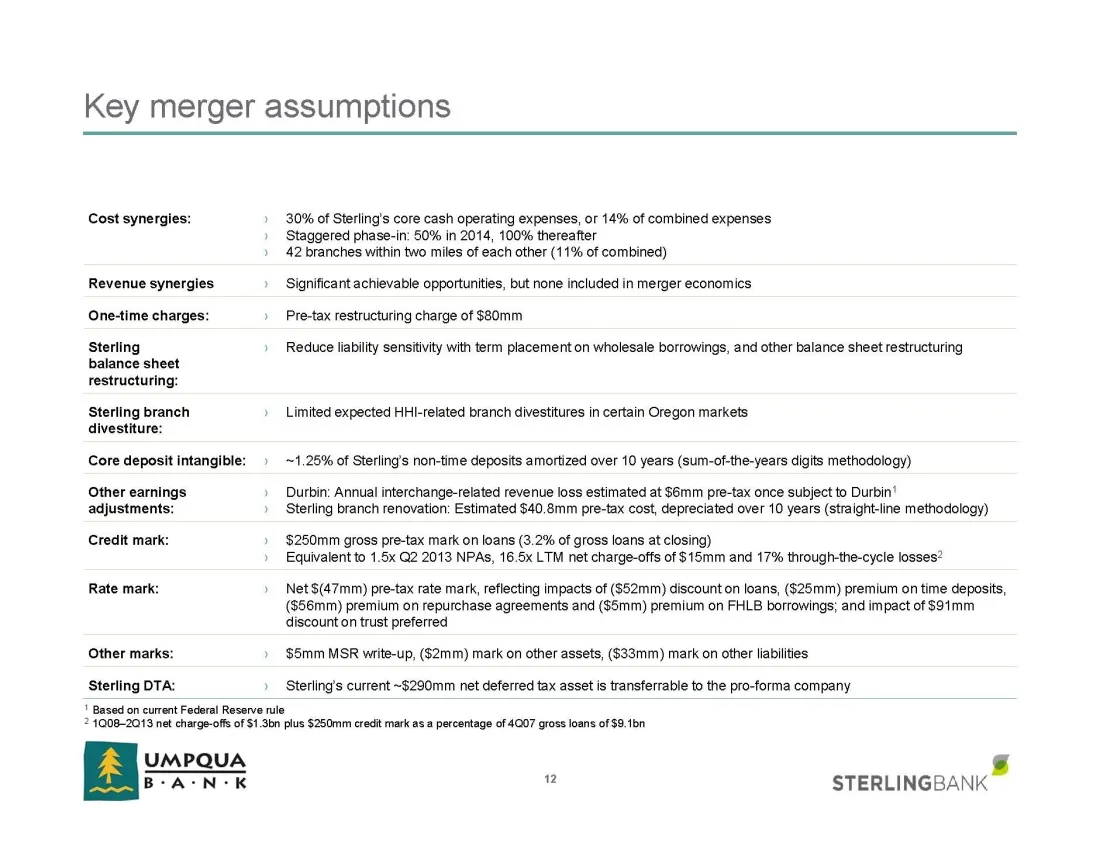
Slide 13: Key merger assumptions
Key merger assumptions Cost synergies: 30% of Sterling's core cash operating expenses, or 14% of combined expenses ‘Staggered phase-in: 50% in 2014, 100% thereafter » 42 branches within two miles of each other (11% of combined) Revenue synergies ‘Significant achievable opportunities, but none includ
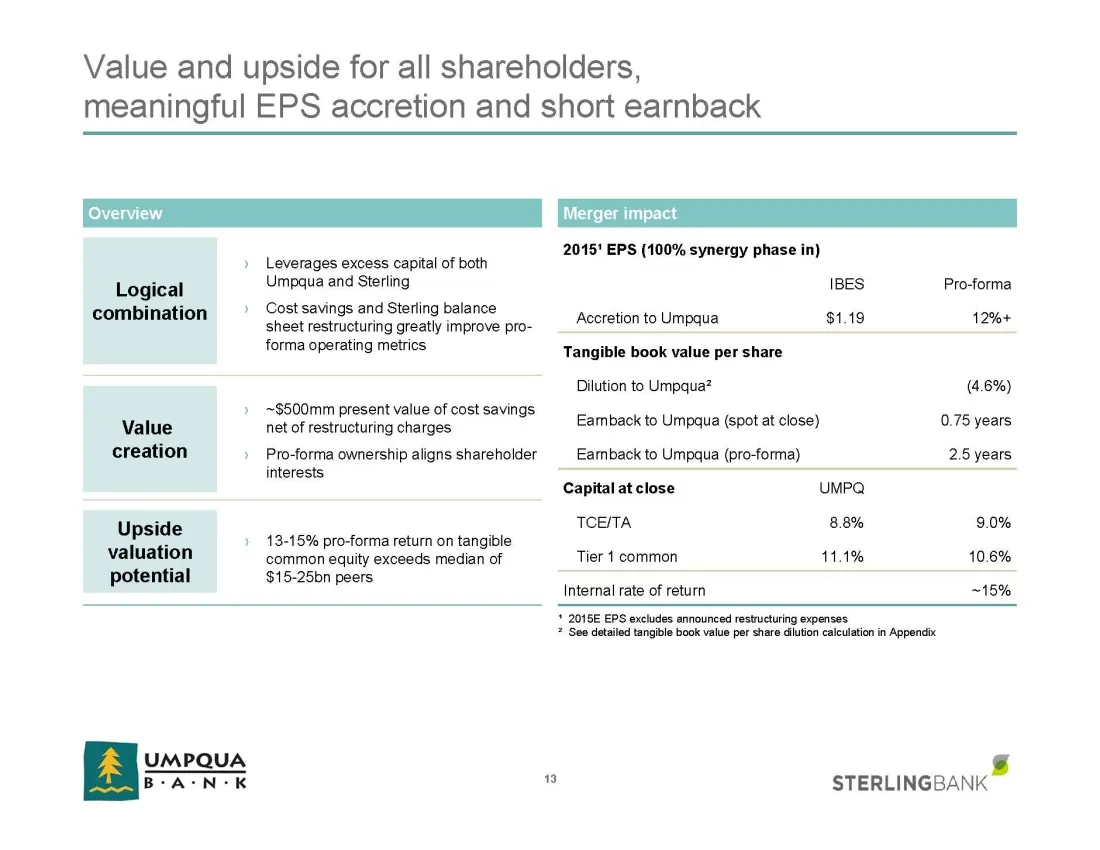
Slide 14: Value and upside for all shareholders, meaningful EPS accretion and short earnback
Value and upside for all shareholders, meaningful EPS accretion and short earnback Overview Logical combination ~ Value creation > Upside valuation potential Leverages excess capital of both Umpqua and Sterling Cost savings and Sterling balance sheet restructuring greatly improve pro- forma operatin
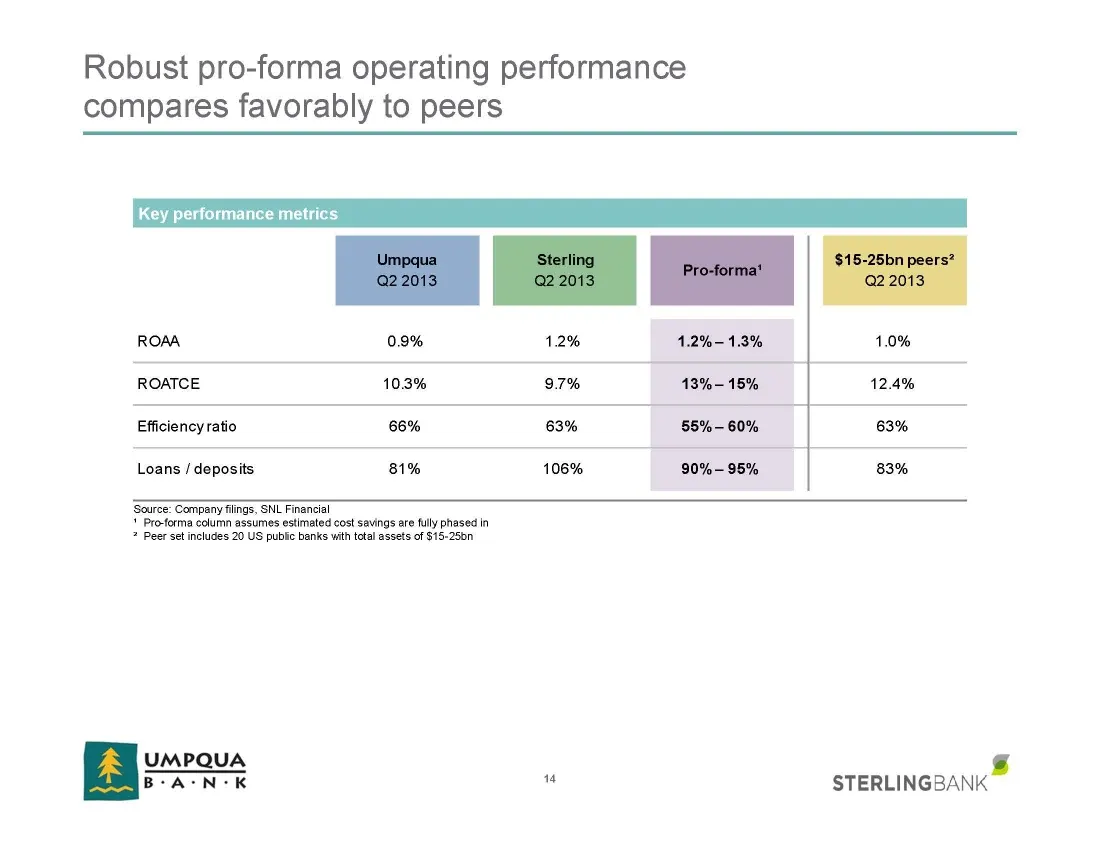
Slide 15: Robust pro-forma operating performance compares favorably to peers
Robust pro-forma operating performance compares favorably to peers Key performance metrics ROAA 0.9% 12% 1.2% — 1.3% 1.0% ROATCE 103% 9.7% 13% — 15% 12.4% Efficiency ratio 66% 63% 55% - 60% 63% Loans / deposits 81% 106% 90% — 95% 83% ‘Source: Company flings, SNL Financial * Pro-forma column assumes
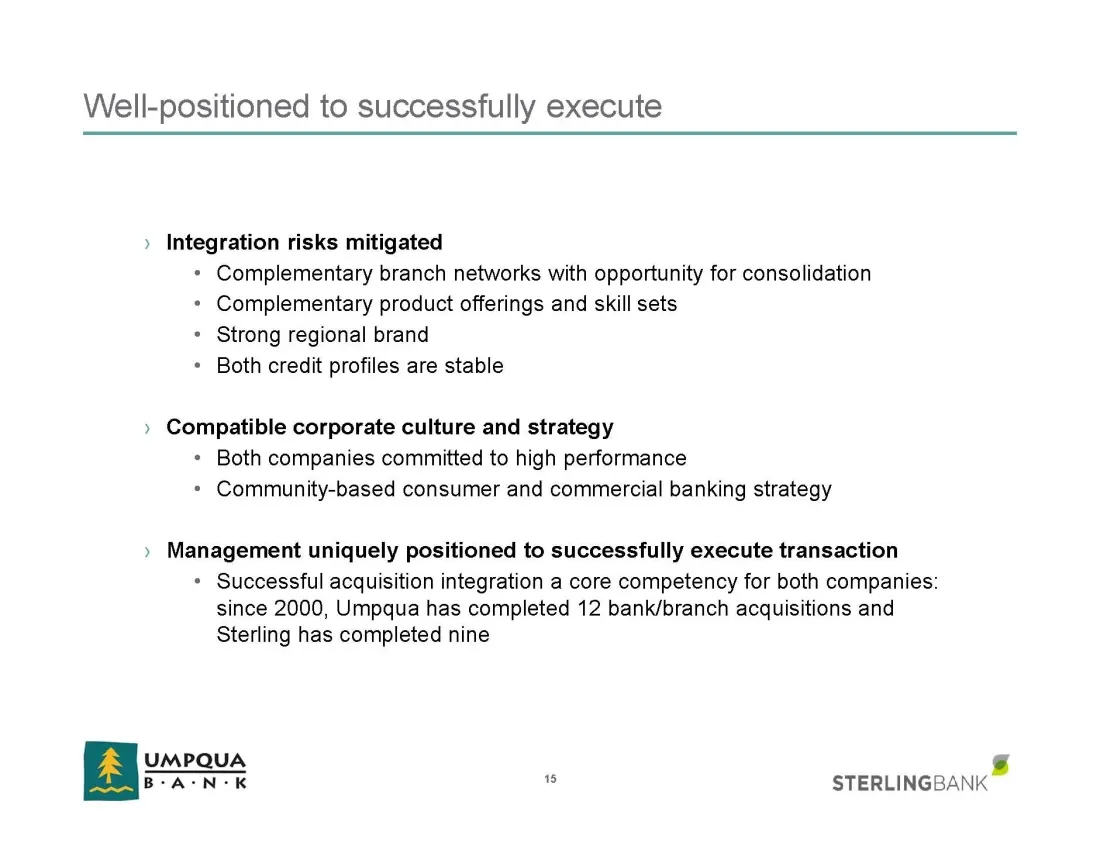
Slide 16: Well-positioned to successfully execute
Well-positioned to successfully execute ) Integration risks mitigated * Complementary branch networks with opportunity for consolidation * Complementary product offerings and skill sets * Strong regional brand * Both credit profiles are stable » Compatible corporate culture and strategy + Both compa
Slide 17: Merger summary
Merger summary STERLINGBANK®
Slide 18: Appendix
Appendix UMPQUA sg B-A-N-K « STERLINGBANK
Slide 19: Thorough reciprocal due diligence completed
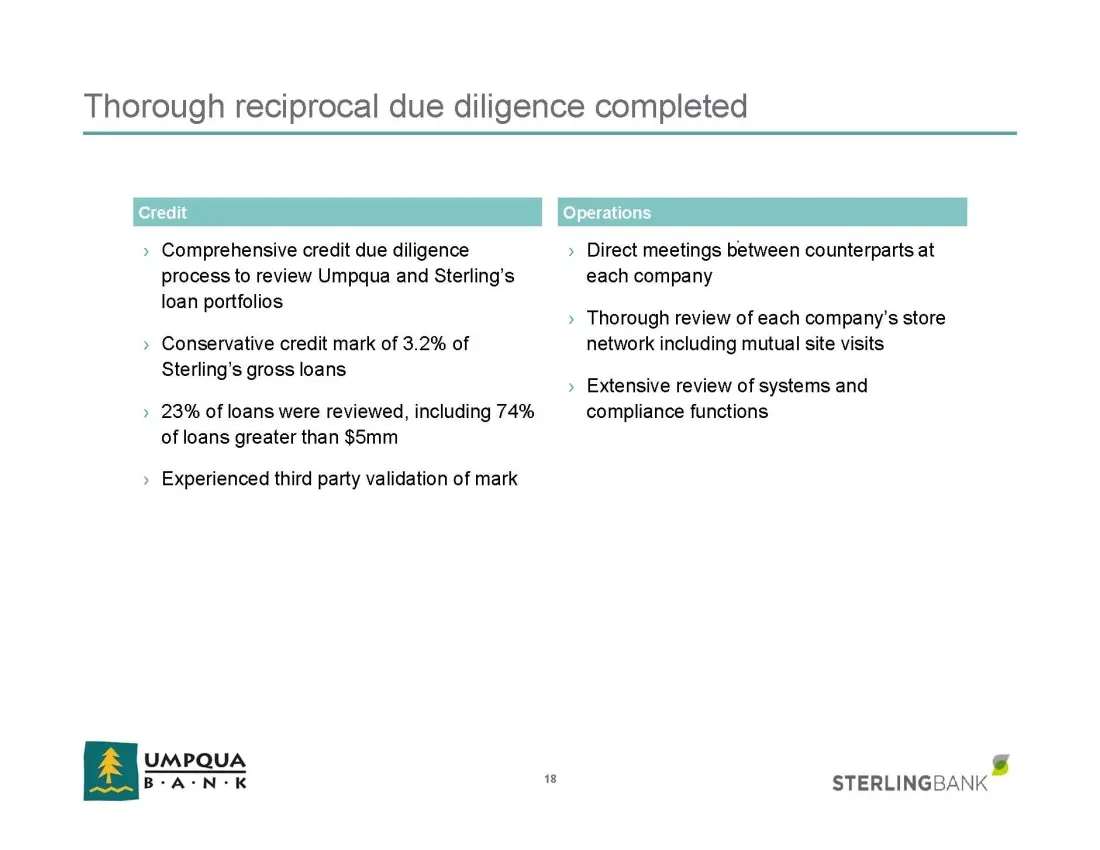
Thorough reciprocal due diligence completed Foret persons > Comprehensive credit due diligence > Direct meetings between counterparts at process to review Umpqua and Sterling's each company loan portfolios . >» Thorough review of each company’s store >» Conservative credit mark of 3.2% of network in
Slide 20: Tangible book value per share dilution detail
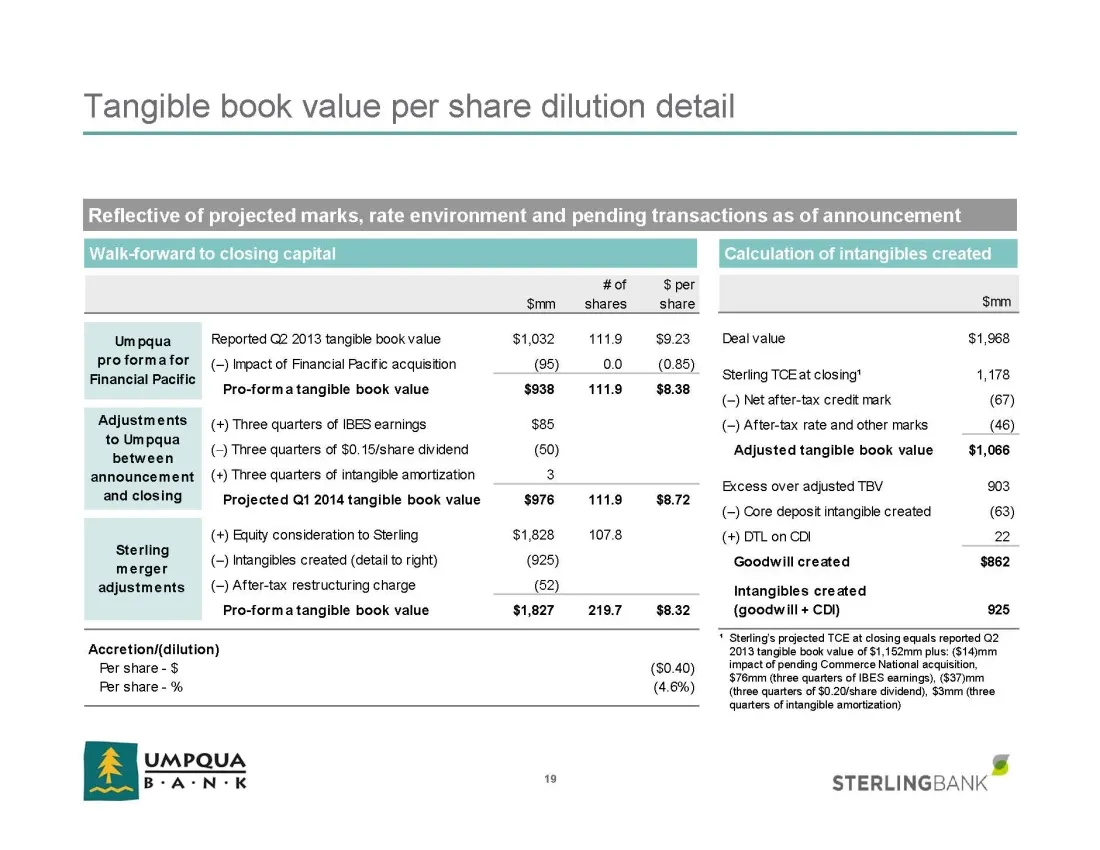
Tangible book value per share dilution detail Reflective of projected marks, rate environment and pending transactions as of announcement’ Walk-forward to closing capital Calculation of intangibles created #of Sper $mm__shares __share mm Umpqua _-Reported G2 2013 tangible book value $1,032 1119 $9.2
Source: SEC EDGAR · 425 filed Sep 12, 2013
More decks from Sterling Financial Corp
 Q3 2013 Earnings Presentation6 slides · Oct 24, 2013
 Merger or Acquisition (September 2013)20 slides · Sep 12, 2013
 Q2 2013 Earnings Presentation27 slides · Jul 30, 2013
 Q2 2013 Earnings Presentation8 slides · Jul 25, 2013
 Q1 2013 Earnings Presentation30 slides · May 7, 2013
 Q1 2013 Earnings Presentation6 slides · Apr 24, 2013