STORE Capital — Q3 2017 Earnings Presentation
53 slides from STORE Capital's earnings presentation, Nov 2, 2017
Slide 1: Foundational Distinction: 2017 Third Quarter Investor Presentation
el ty Foundational Distinction 2017 Third Quarter Investor Presentation
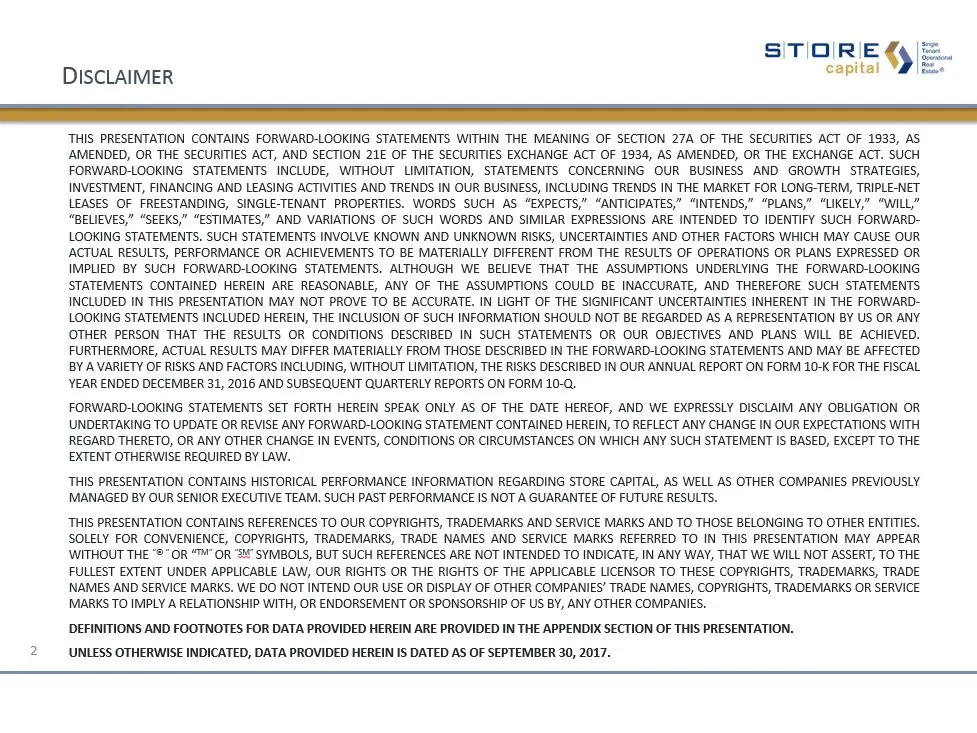
Slide 2: Disclaimer
Disclaimer This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, or the Securities Act, and Section 21E of the Securities Exchange Act of 1934, as amended, or the Exchange Act. Such forward-looking statements include, witho
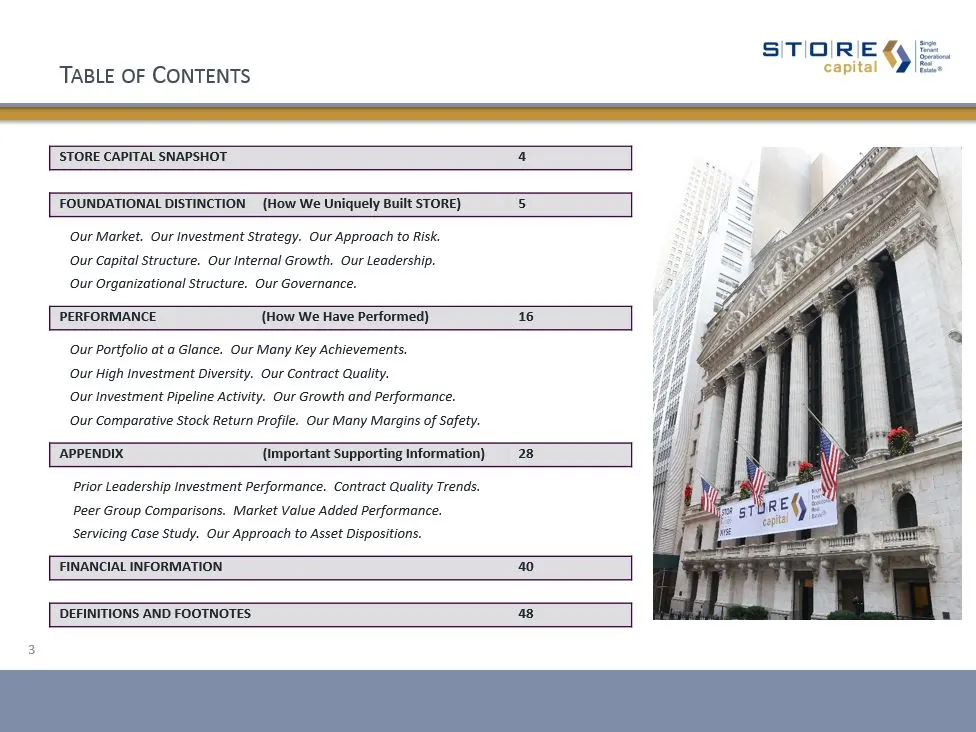
Slide 3: Table of Contents
3 STORE CAPITAL SNAPSHOT 4 FOUNDATIONAL DISTINCTION (How We Uniquely Built STORE) 5 Our Market. Our Investment Strategy. Our Approach to Risk. Our Capital Structure. Our Internal Growth. Our Leadership. Our Organizational Structure. Our Governance. PERFORMANCE (How We Have Performed) 16 Our Portfoli
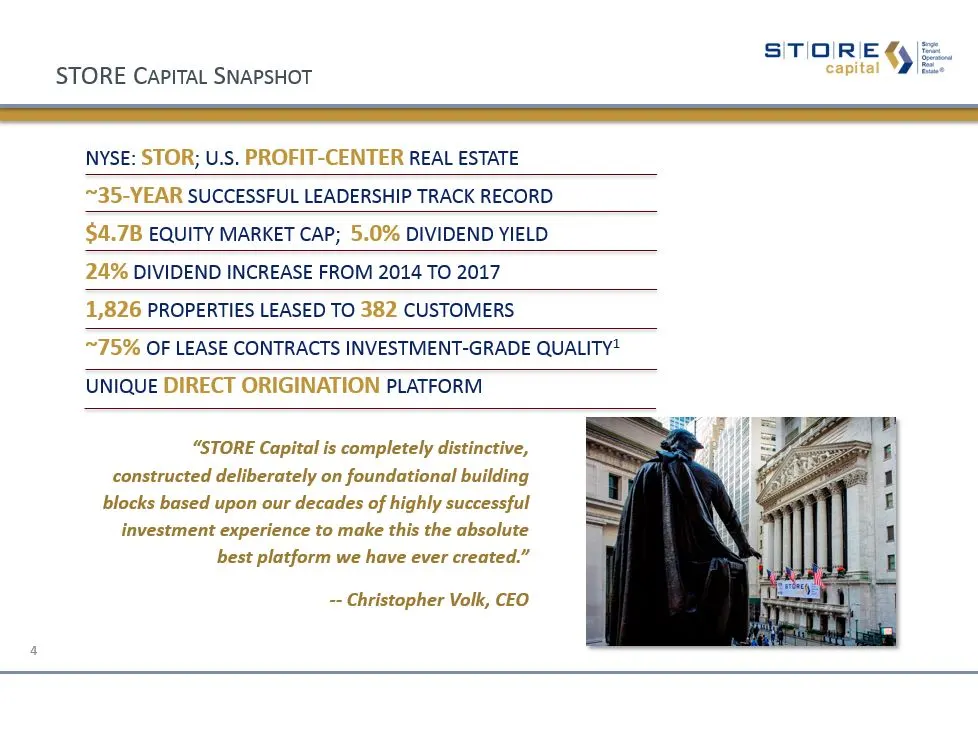
Slide 4: STORE Capital Snapshot
STORE Capital Snapshot NYSE: STOR; U.S. PROFIT-CENTER REAL ESTATE ~35-YEAR SUCCESSFUL LEADERSHIP TRACK RECORD $4.7B EQUITY MARKET CAP; 5.0% DIVIDEND YIELD24% DIVIDEND INCREASE FROM 2014 TO 20171,826 PROPERTIES LEASED TO 382 CUSTOMERS ~75% OF LEASE CONTRACTS INVESTMENT-GRADE QUALITY1 UNIQUE DIRECT OR
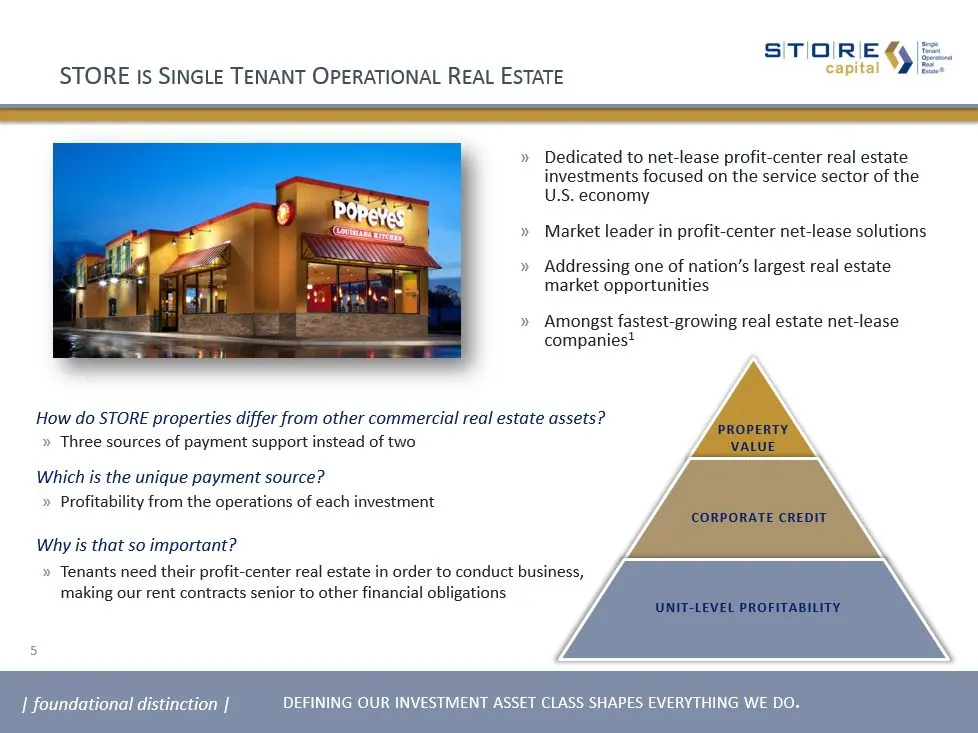
Slide 5: Net-lease profit-center real estate investments
Dedicated to net-lease profit-center real estate investments focused on the service sector of the U.S. economyMarket leader in profit-center net-lease solutionsAddressing one of nation’s largest real estate market opportunitiesAmongst fastest-growing real estate net-lease companies1 Why is that so i
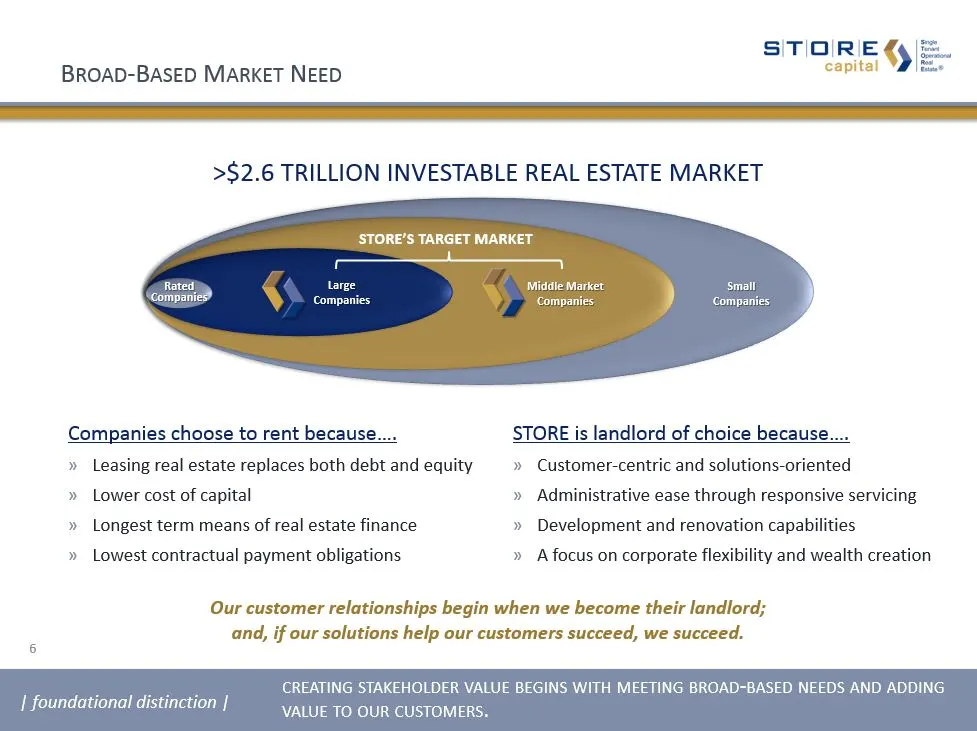
Slide 6: Broad-Based Market Need
Broad-Based Market Need 6 Rated Large Middle Market Companies choose to rent because….Leasing real estate replaces both debt and equityLower cost of capitalLongest term means of real estate financeLowest contractual payment obligations STORE is landlord of choice because….Customer-centric and soluti
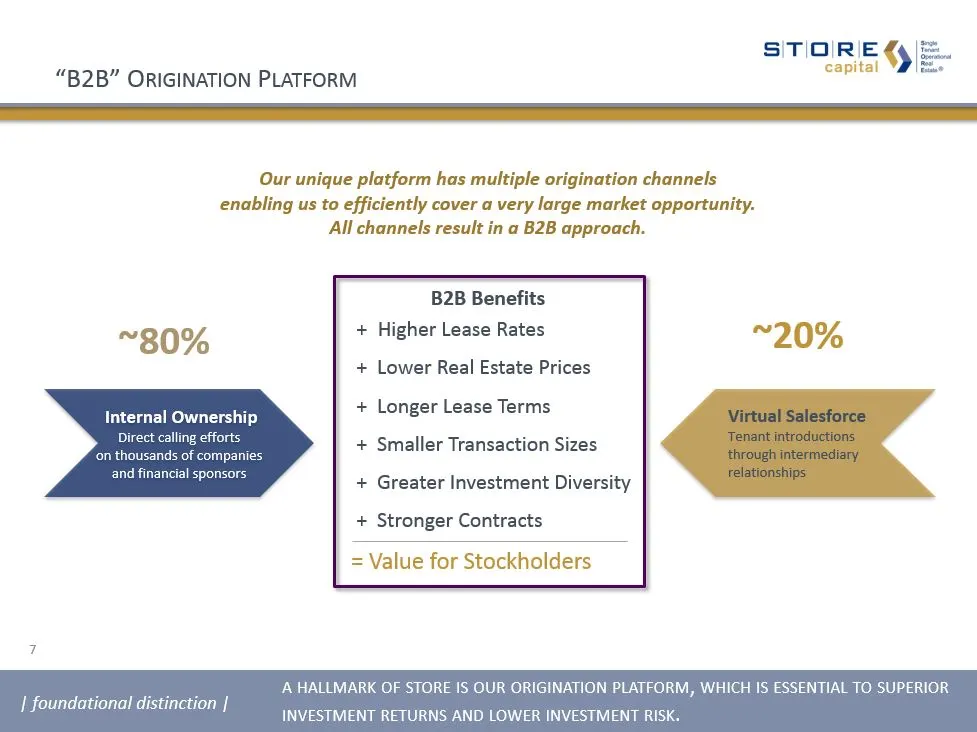
Slide 7: B2B Origination Platform
Internal OwnershipDirect calling efforts on thousands of companies and financial sponsors ~80% ~20% B2B Benefits + Higher Lease Rates+ Lower Real Estate Prices+ Longer Lease Terms+ Smaller Transaction Sizes + Greater Investment Diversity+ Stronger Contracts Our unique platform has multiple originati
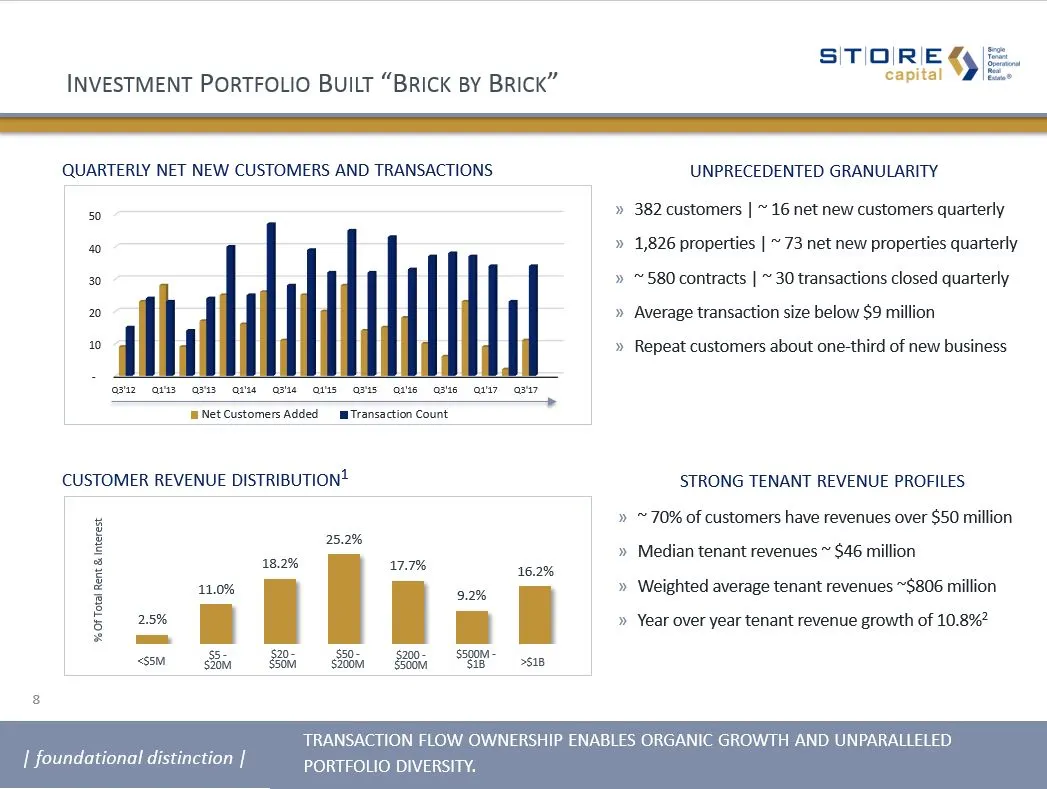
Slide 8: Investment Portfolio Built Brick by Brick
Investment Portfolio Built “Brick by Brick” quarterly net new customers and transactions unprecedented granularity | foundational distinction | transaction flow ownership enables organic growth and unparalleled portfolio diversity. 8 customer revenue distribution1 % Of Total Rent & Interest 382 cust
Slide 9: Lease Contracts Define Investment Risk
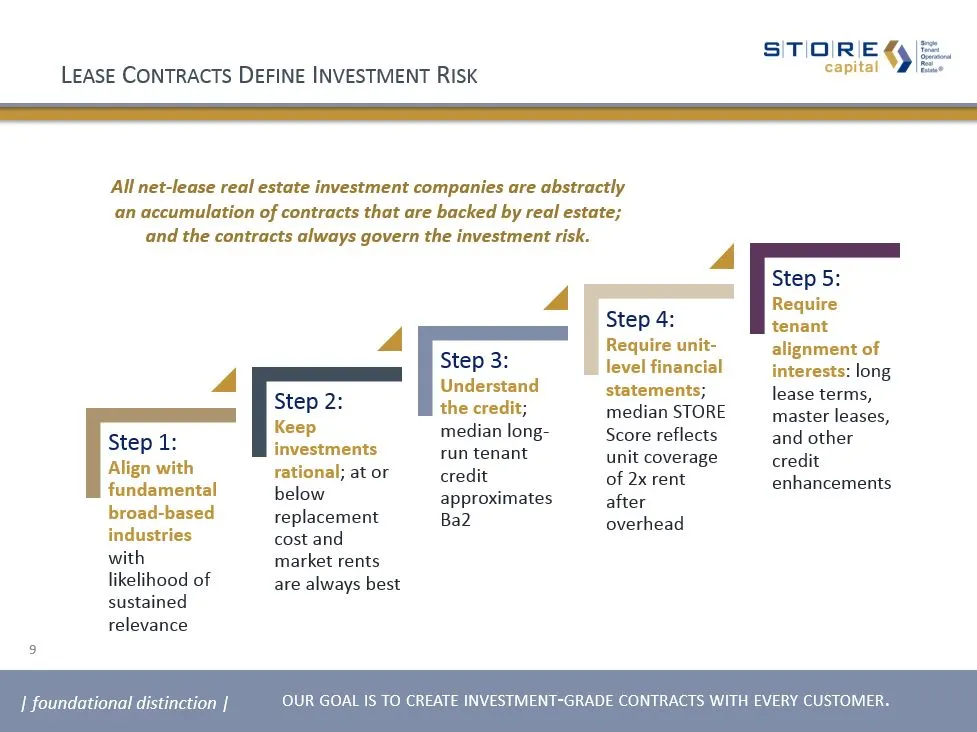
Lease Contracts Define Investment Risk All net-lease real estate investment companies are abstractly an accumulation of contracts that are backed by real estate; and the contracts always govern the investment risk. | foundational distinction | our goal is to create investment-grade contracts with ev
Slide 10: Capital Structure Leadership
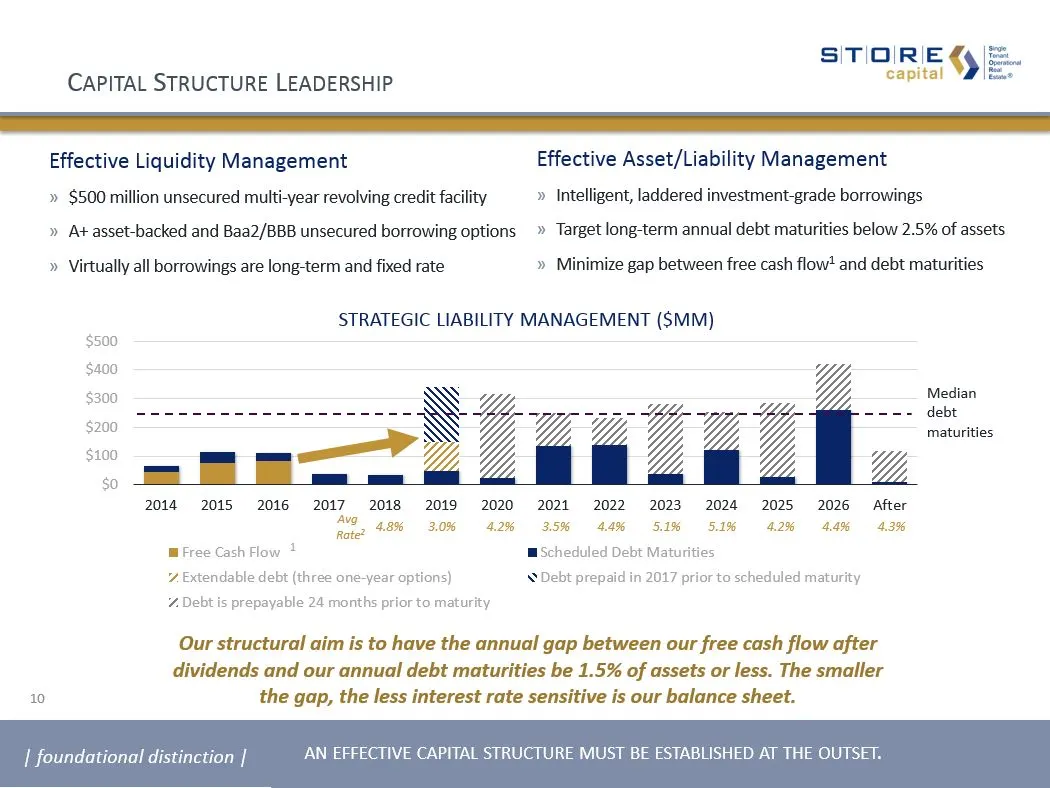
Capital Structure Leadership | foundational distinction | an effective capital structure must be established at the outset. 10 Effective Liquidity Management$500 million unsecured multi-year revolving credit facilityA+ asset-backed and Baa2/BBB unsecured borrowing optionsVirtually all borrowings are
Slide 11: Complementary Investment-Grade Debt Options
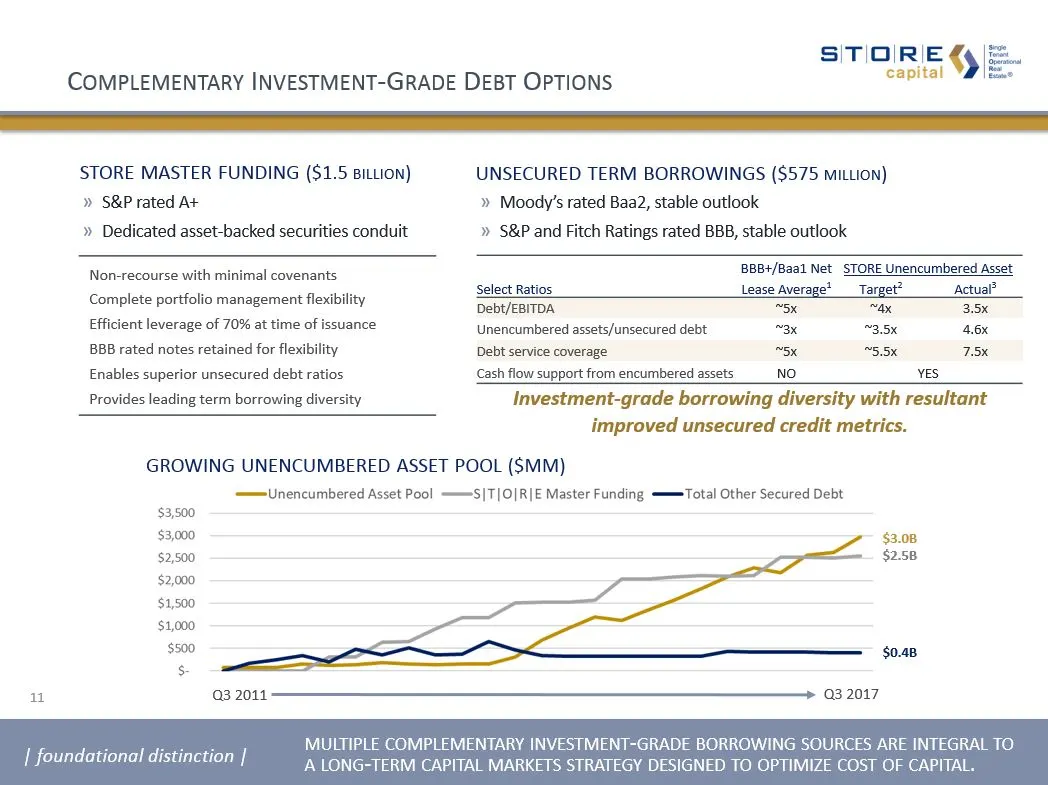
Complementary Investment-Grade Debt Options growing unencumbered asset pool ($MM) store master funding ($1.5 billion) S&P rated A+Dedicated asset-backed securities conduit unsecured term borrowings ($575 million) | foundational distinction | multiple complementary investment-grade borrowing sources
Slide 12: Internal Growth Strategy
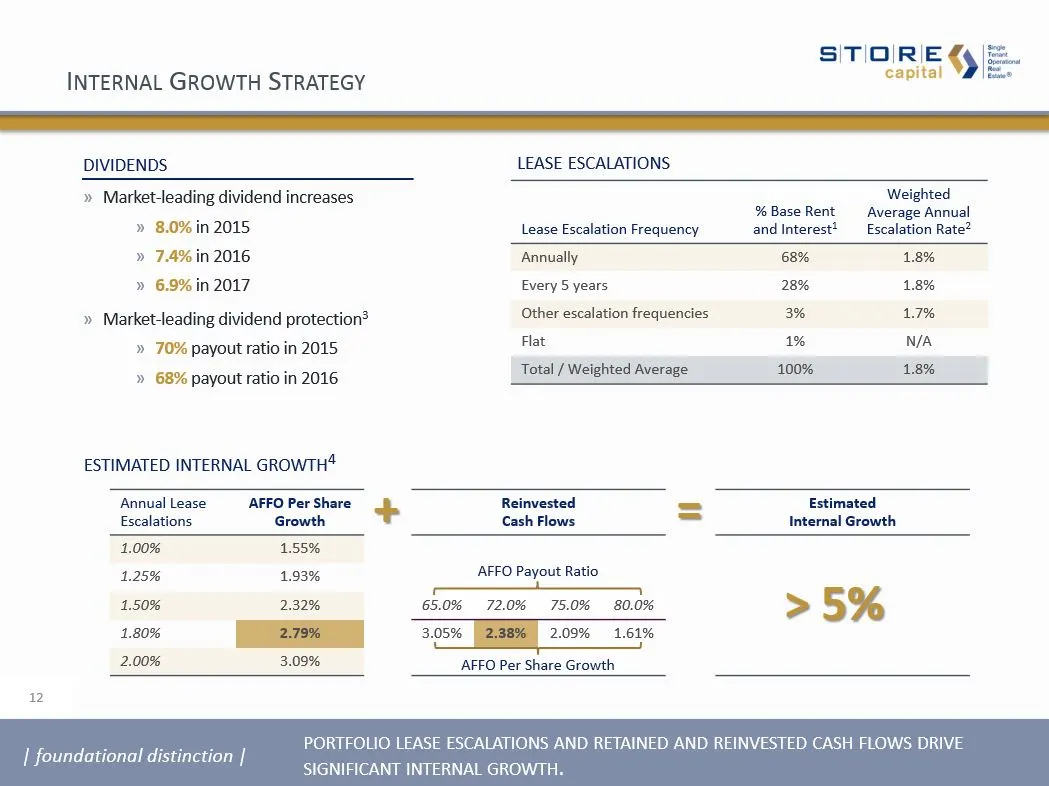
12 Internal Growth Strategy Lease Escalation Frequency % Base Rent and Interest1 Weighted Average Annual Escalation Rate2 Annually 68% 1.8% Every 5 years 28% 1.8% Other escalation frequencies 3% 1.7% Flat 1% N/A Total / Weighted Average 100% 1.8% lease escalations dividends Market-leading dividend i
Slide 13: Unrivaled Leadership
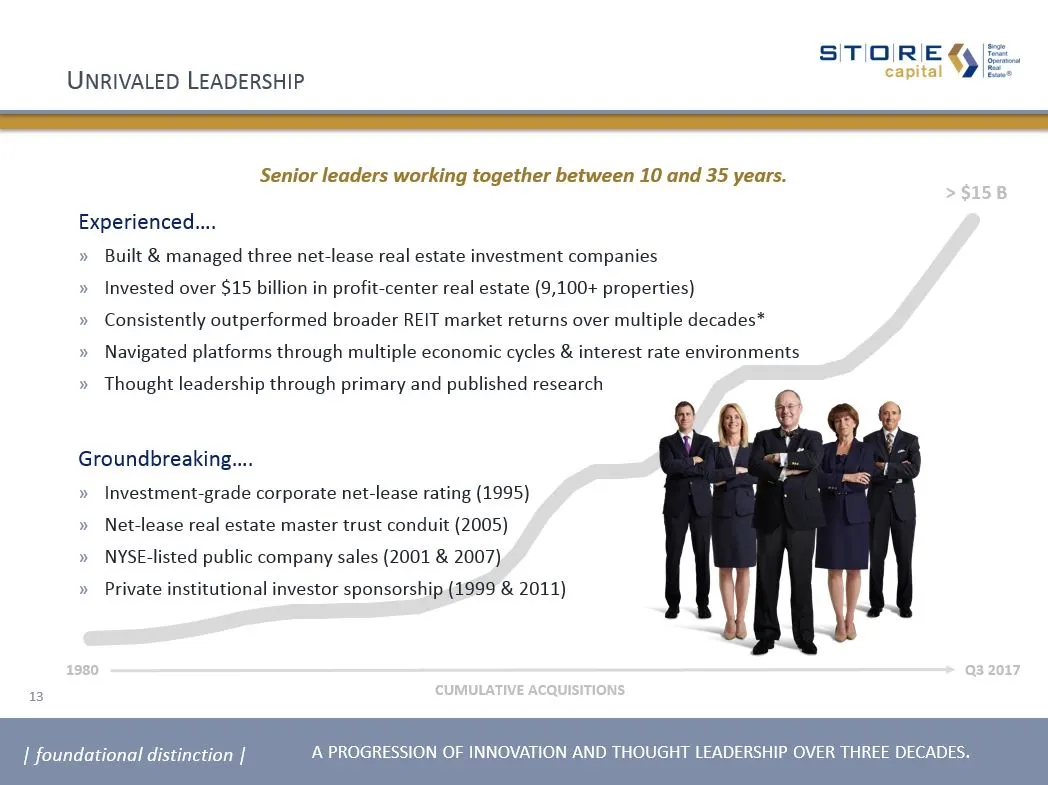
13 Unrivaled Leadership Experienced….Built & managed three net-lease real estate investment companiesInvested over $15 billion in profit-center real estate (9,100+ properties)Consistently outperformed broader REIT market returns over multiple decades*Navigated platforms through multiple economic cyc
Slide 14: Efficient and Scalable Platform
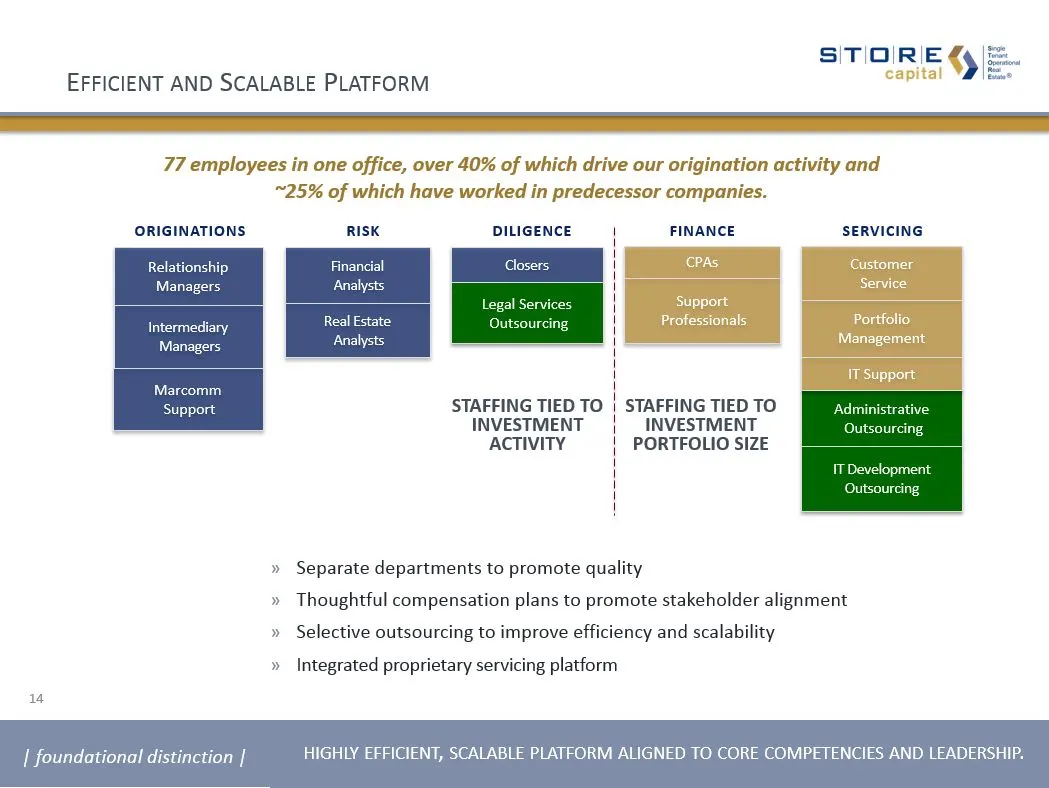
77 employees in one office, over 40% of which drive our origination activity and ~25% of which have worked in predecessor companies. originations servicing diligence finance risk RelationshipManagers Intermediary Managers Closers Financial Analysts Real Estate Analysts CPAs Support Professionals Cus
Slide 15: Best in Class Corporate Governance
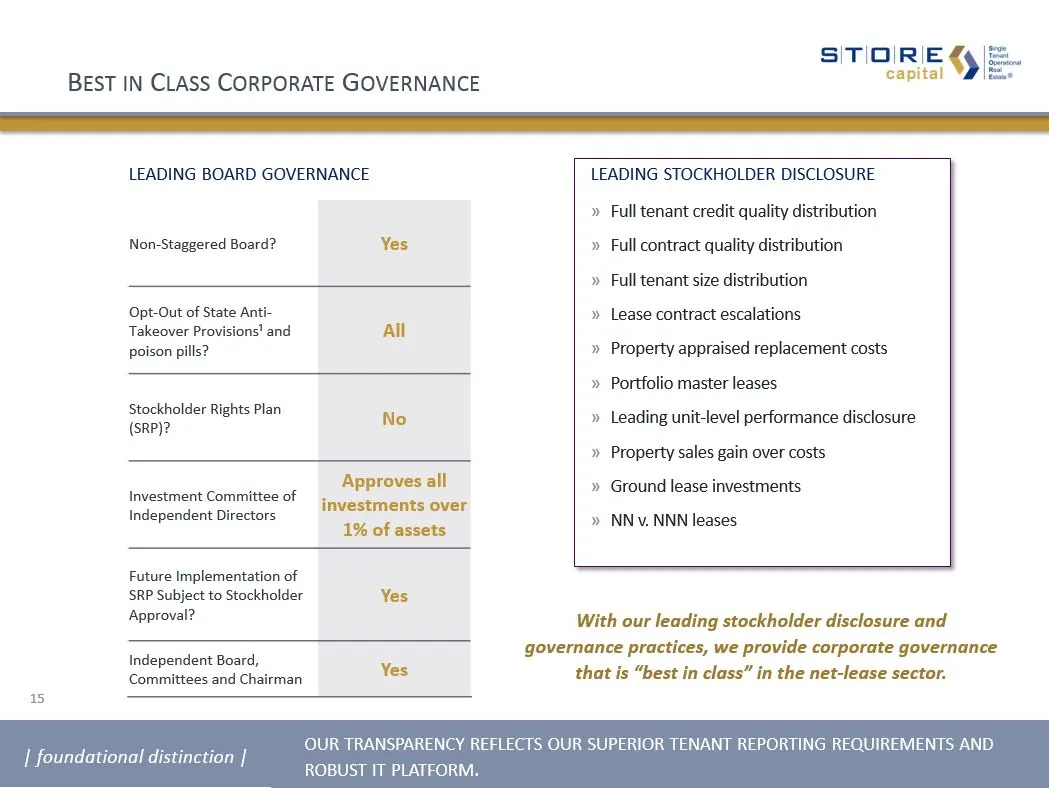
Best in Class Corporate Governance Non-Staggered Board? Yes Opt-Out of State Anti-Takeover Provisions¹ and poison pills? All Stockholder Rights Plan (SRP)? No Investment Committee of Independent Directors Approves all investments over 1% of assets Future Implementation of SRP Subject to Stockholder
Slide 16: Portfolio at a Glance
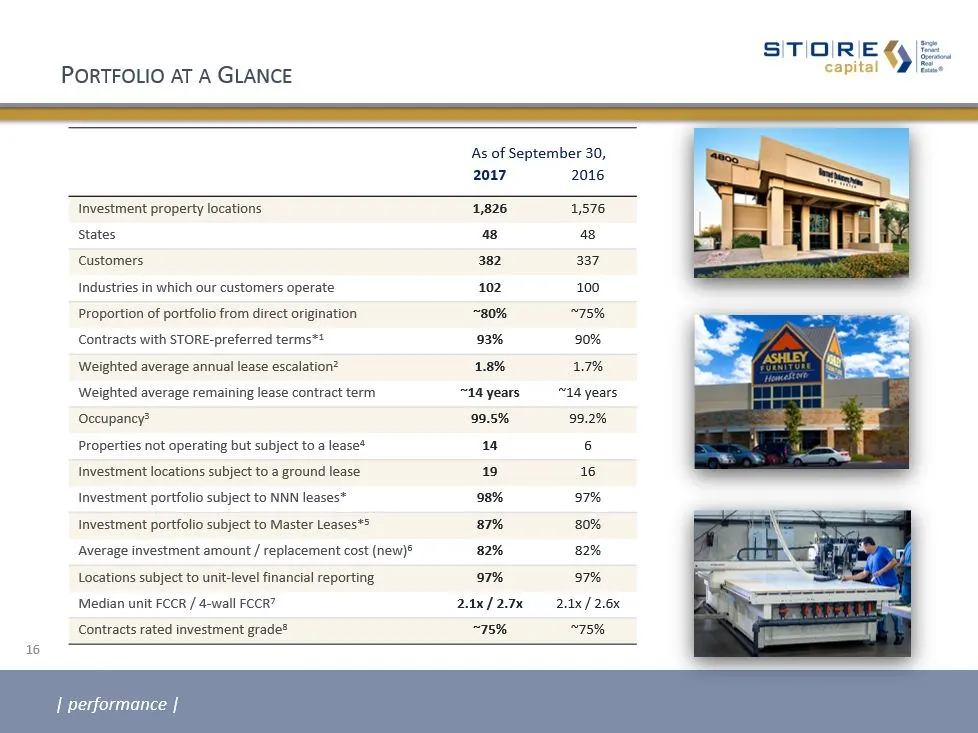
Portfolio at a Glance As of September 30, 2017 2016 Investment property locations 1,826 1,576 States 48 48 Customers 382 337 Industries in which our customers operate 102 100 Proportion of portfolio from direct origination ~80% ~75% Contracts with STORE-preferred terms*1 93% 90% Weighted average ann
Slide 17: Key Achievements As A Public Company
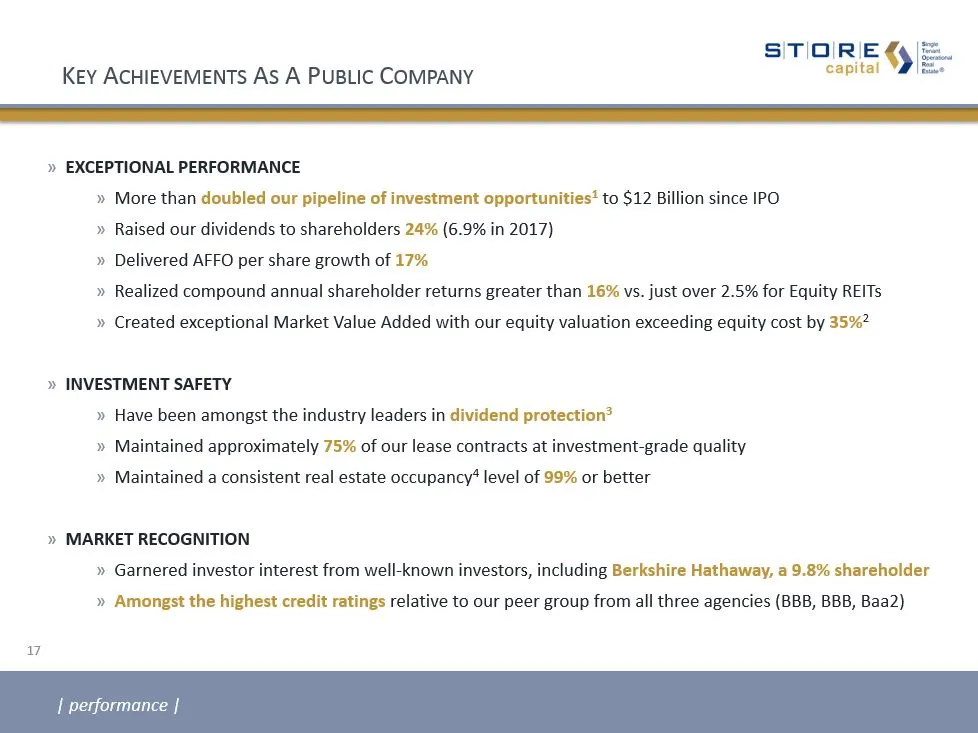
Key Achievements As A Public Company EXCEPTIONAL PERFORMANCEMore than doubled our pipeline of investment opportunities1 to $12 Billion since IPORaised our dividends to shareholders 24% (6.9% in 2017)Delivered AFFO per share growth of 17% Realized compound annual shareholder returns greater than 16%
Slide 18: Diversification Across Industry Groups
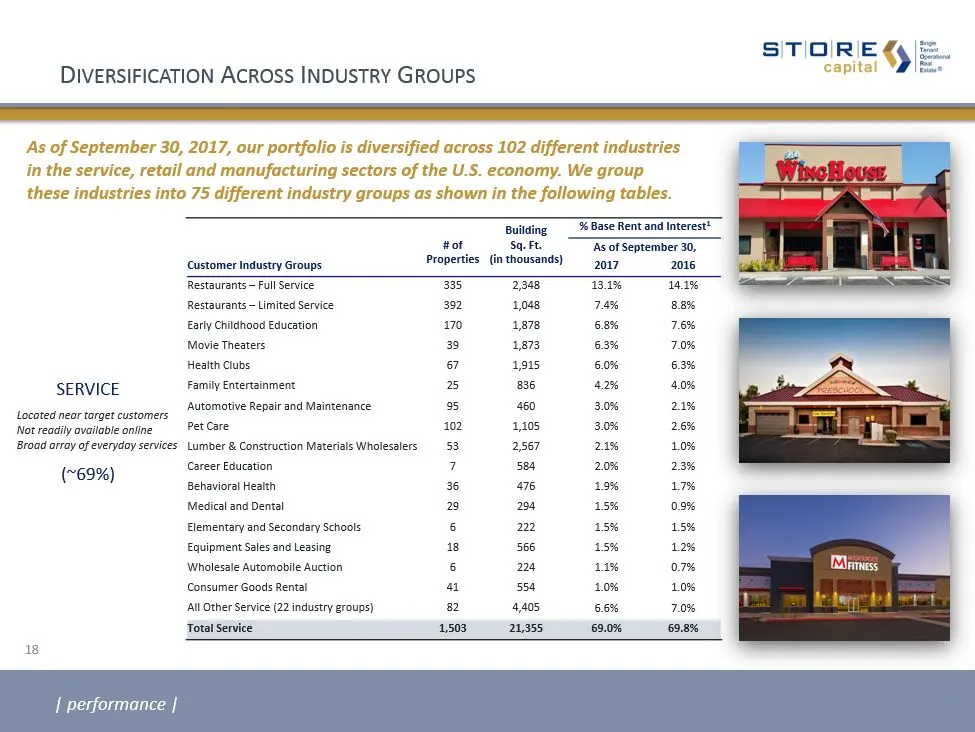
Diversification Across Industry Groups Building % Base Rent and Interest1 # ofProperties Sq. Ft. (in thousands) As of September 30, Customer Industry Groups 2017 2016 Restaurants – Full Service 335 2,348 13.1% 14.1% Restaurants – Limited Service 392 1,048 7.4% 8.8% Early Childhood Education 170 1,87
Slide 19: Diversification Across Industry Groups (continued)
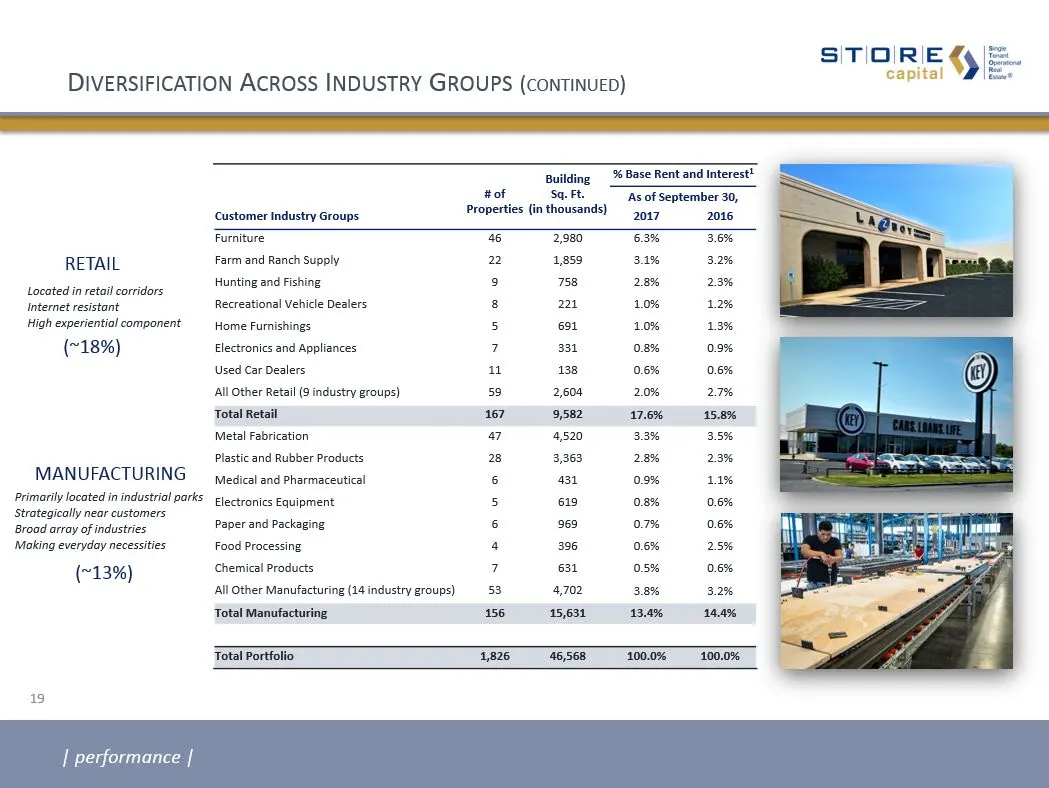
Diversification Across Industry Groups (continued) 19 Building % Base Rent and Interest1 # ofProperties Sq. Ft. (in thousands) As of September 30, Customer Industry Groups 2017 2016 Furniture 46 2,980 6.3% 3.6% Farm and Ranch Supply 22 1,859 3.1% 3.2% Hunting and Fishing 9 758 2.8% 2.3% Recreational
Slide 20: Top Customers
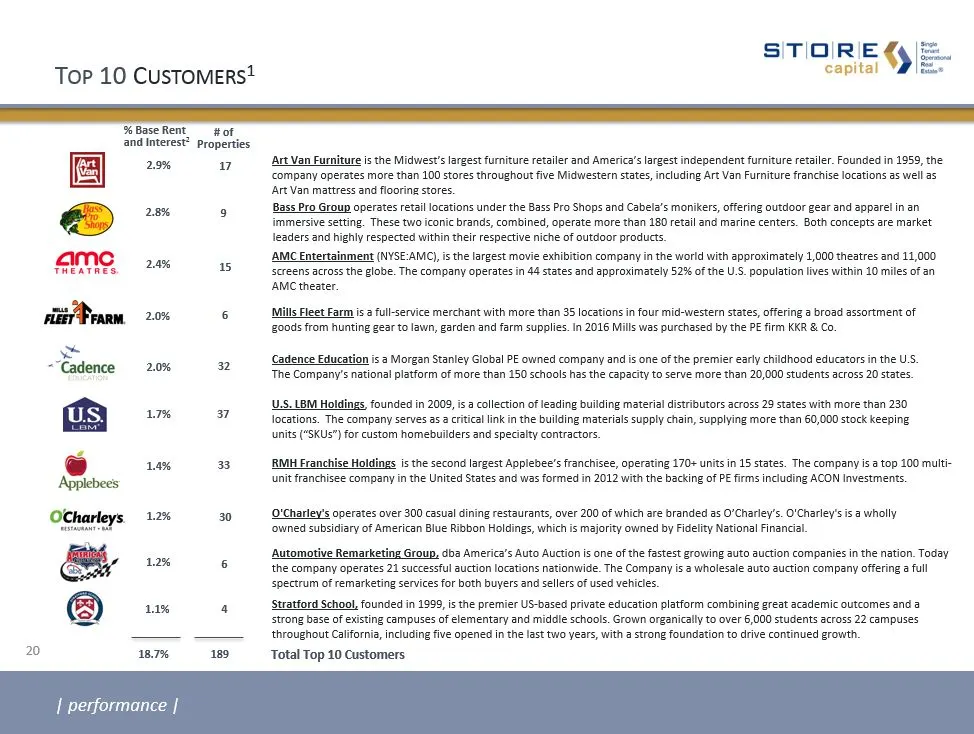
20 Top 10 Customers1 AMC Entertainment (NYSE:AMC), is the largest movie exhibition company in the world with approximately 1,000 theatres and 11,000 screens across the globe. The company operates in 44 states and approximately 52% of the U.S. population lives within 10 miles of an AMC theater. Caden
Slide 21: Diversification Across Geographies
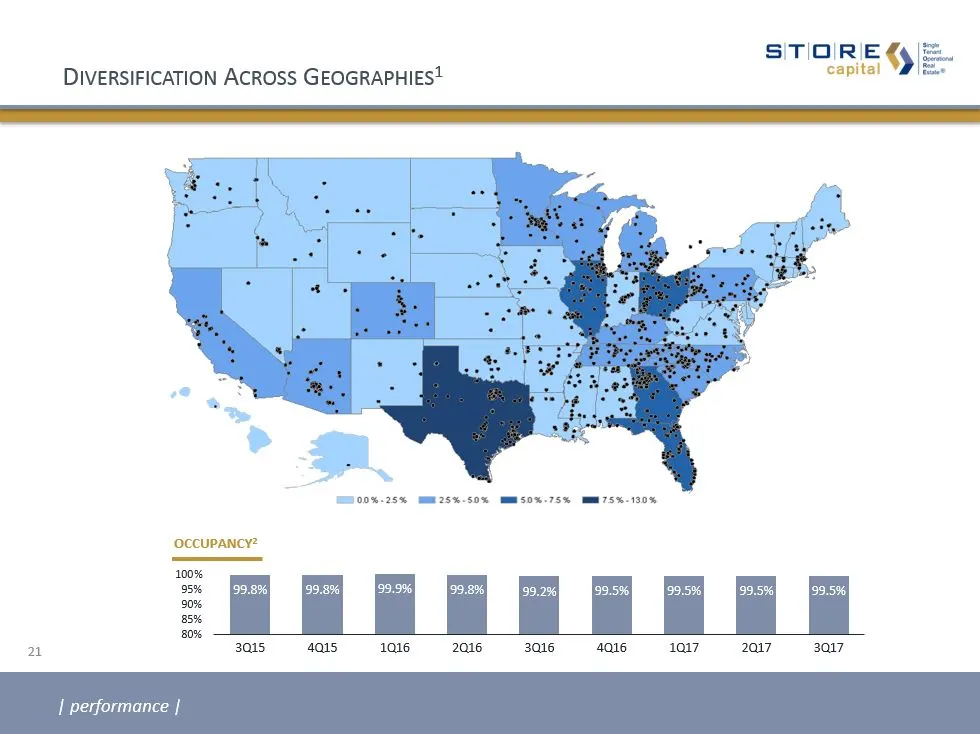
Diversification Across Geographies1 | performance | 21 OCCUPANCY2
Slide 22: ~75% of Contracts Investment-Grade in Quality
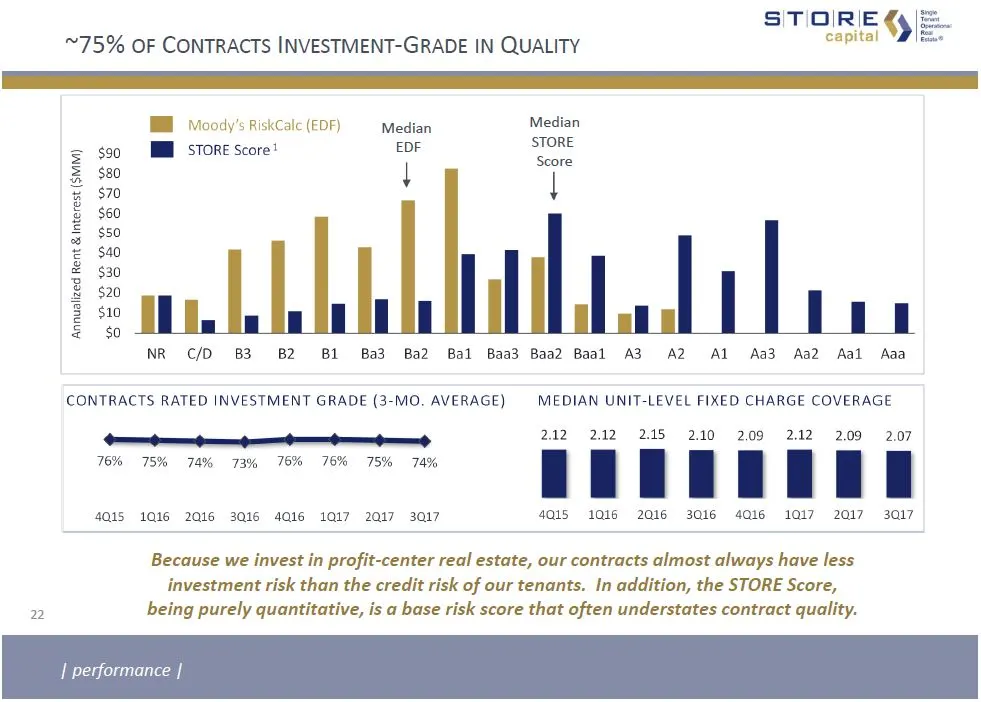
~75% of Contracts Investment-Grade in Quality Because we invest in profit-center real estate, our contracts almost always have less investment risk than the credit risk of our tenants. In addition, the STORE Score, being purely quantitative, is a base risk score that often understates contract quali
Slide 23: Investment Pipeline Activity
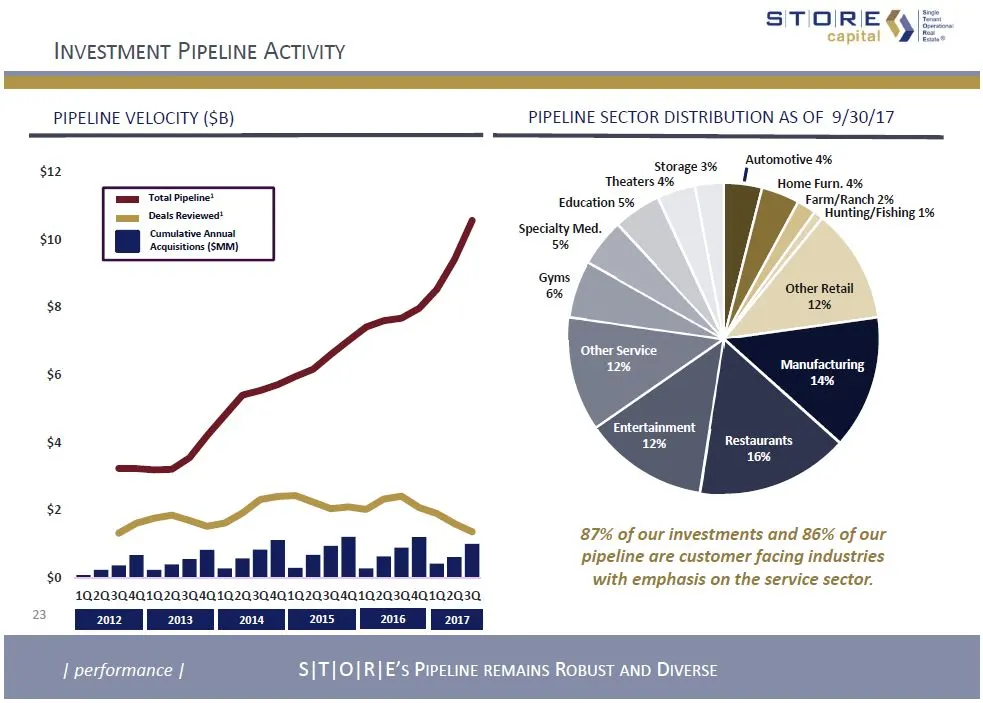
23 Investment Pipeline Activity Total Pipeline1 Deals Reviewed1 Cumulative Annual Acquisitions ($MM) 2012 2013 2014 2015 2016 2017 PIPELINE VELOCITY ($B) PIPELINE SECTOR DISTRIBUTION AS OF 9/30/17 87% of our investments and 86% of our pipeline are customer facing industries with emphasis on the serv
Slide 24: Growth and Performance
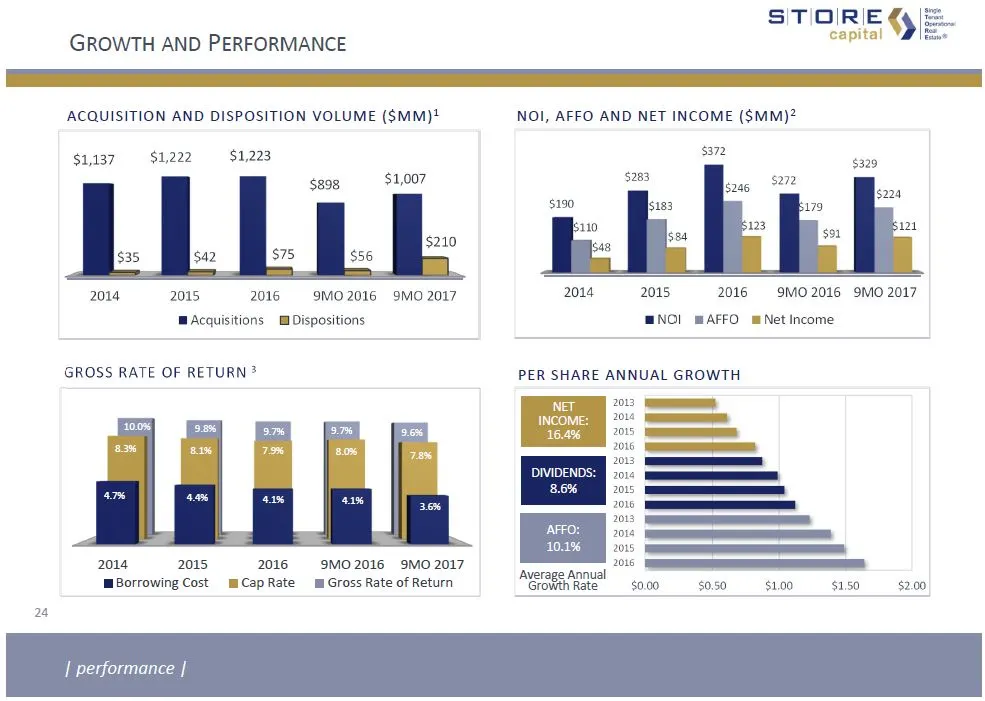
24 NOI, AFFO AND NET INCOME ($MM)2 Growth and Performance | performance | PER SHARE ANNUAL GROWTH NET INCOME:16.4% DIVIDENDS:8.6% AFFO:10.1% Average Annual Growth Rate ACQUISITION AND DISPOSITION VOLUME ($MM)1 GROSS RATE OF RETURN 3 5.6% 5.3% 5.4% 5.6% 4.1% 4.7% 4.4% 4.1% 9.7% 8.3% 8.1% 7.9% 8.0% 10
Slide 25: Total Return Built on Both Yield & Growth
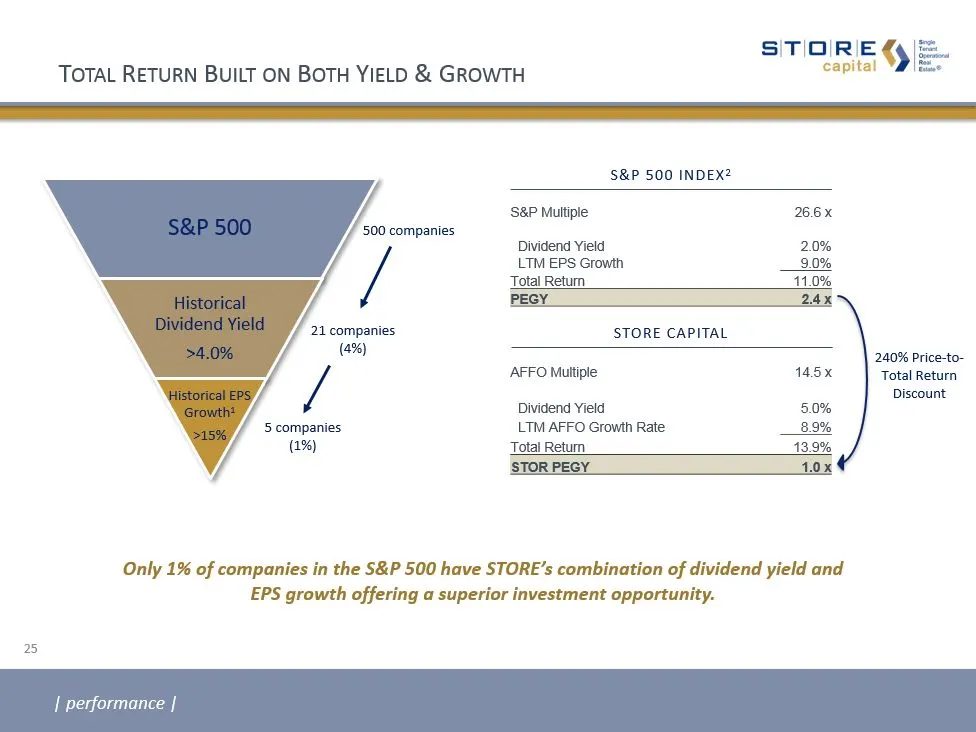
Total Return Built on Both Yield & Growth | performance | 25 500 companies 21 companies(4%) 5 companies(1%) Only 1% of companies in the S&P 500 have STORE’s combination of dividend yield and EPS growth offering a superior investment opportunity. 240% Price-to-Total Return Discount S&P 500 INDEX2 S&P
Slide 26: Margins of Safety
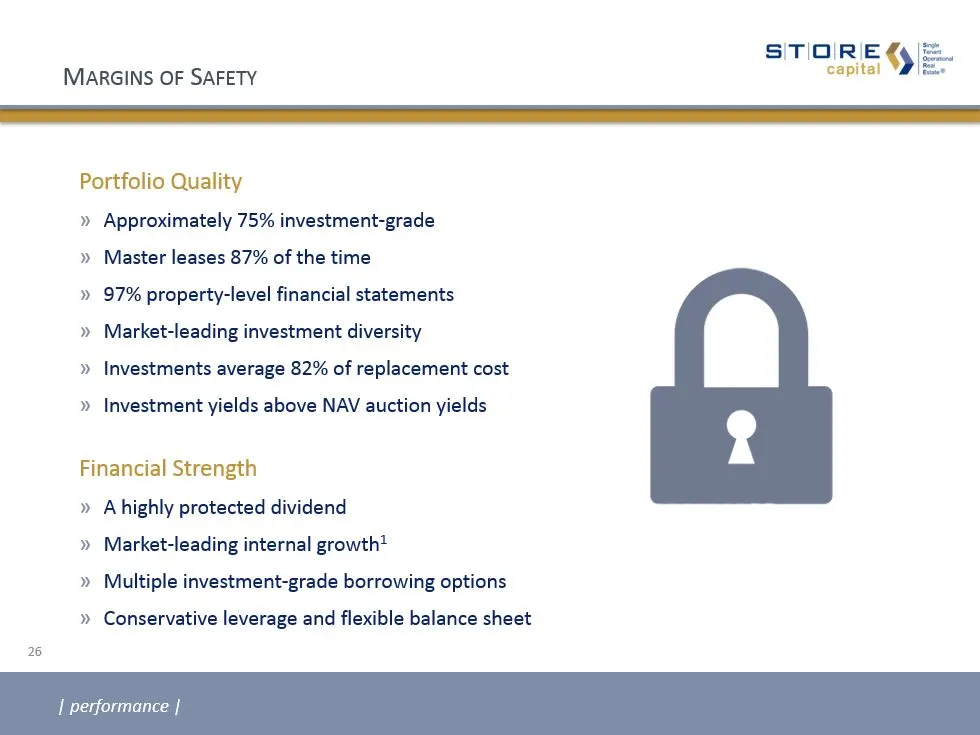
Margins of Safety Portfolio QualityApproximately 75% investment-gradeMaster leases 87% of the time97% property-level financial statementsMarket-leading investment diversityInvestments average 82% of replacement costInvestment yields above NAV auction yields Financial StrengthA highly protected divid
Slide 27: Distinction
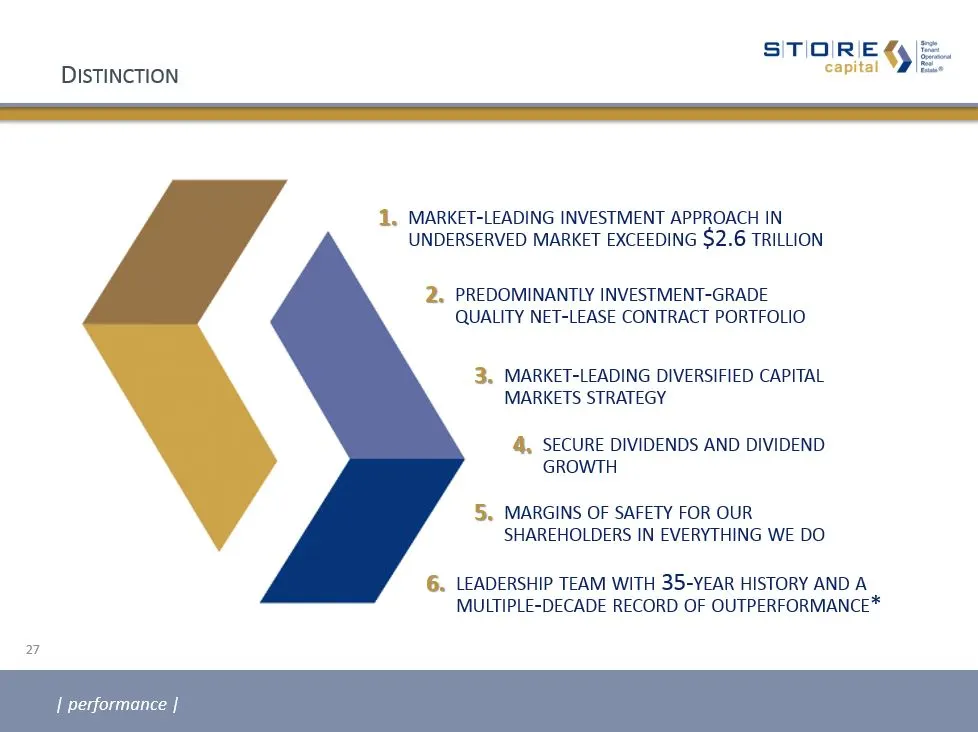
Distinction market-leading investment approach in underserved market exceeding $2.6 trillion 1. predominantly investment-grade quality net-lease contract portfolio 2. market-leading diversified capital markets strategy 3. secure dividends and dividend growth 4. margins of safety for our shareholders
Slide 28: Appendix
el ty Appendix
Slide 29: Management Team Performance
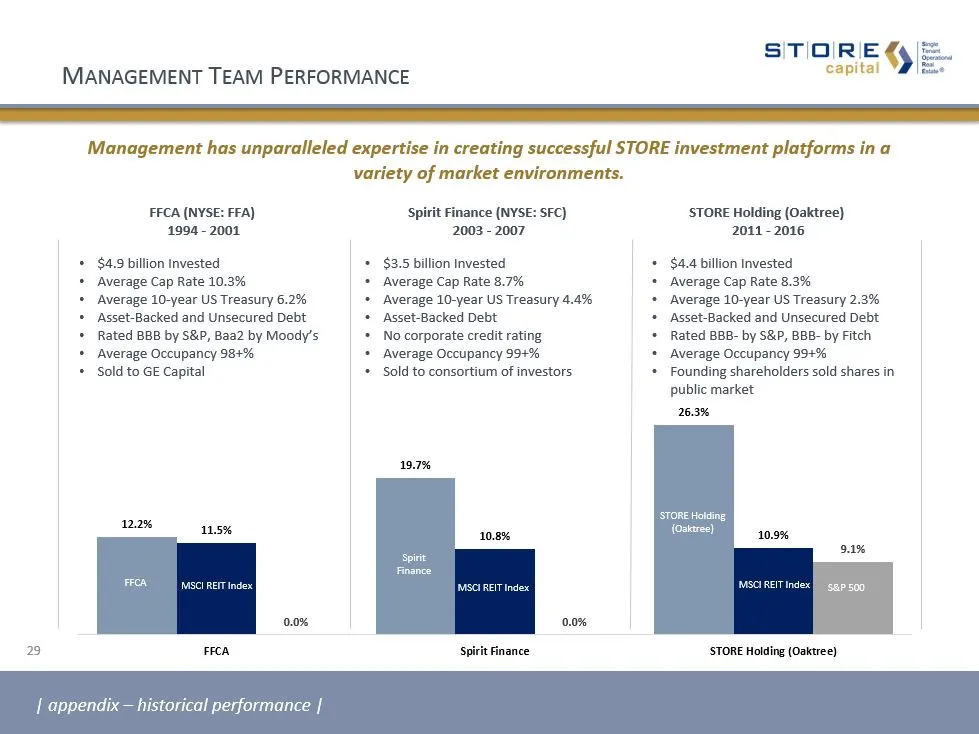
FFCA (NYSE: FFA) 1994 - 2001 Spirit Finance (NYSE: SFC) 2003 - 2007 STORE Holding (Oaktree) 2011 - 2016 Management Team Performance | appendix – historical performance | Management has unparalleled expertise in creating successful STORE investment platforms in a variety of market environments. 29 $4
Slide 30: Stable and Attractive Lease Rates and Risk-Adjusted Returns
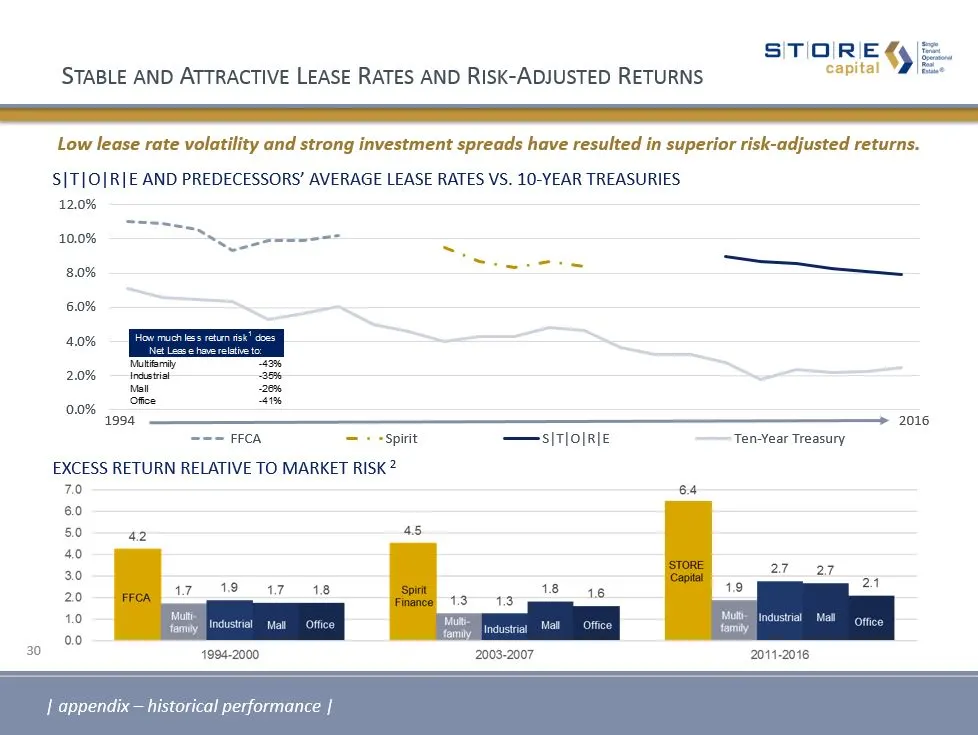
| appendix – historical performance | 30 1994 2016 Stable and Attractive Lease Rates and Risk-Adjusted Returns Low lease rate volatility and strong investment spreads have resulted in superior risk-adjusted returns. S|T|O|R|E and predecessors’ average Lease Rates vs. 10-Year Treasuries Excess Return
Slide 31: Marginal Equity Returns on Net Lease Real Estate Investments
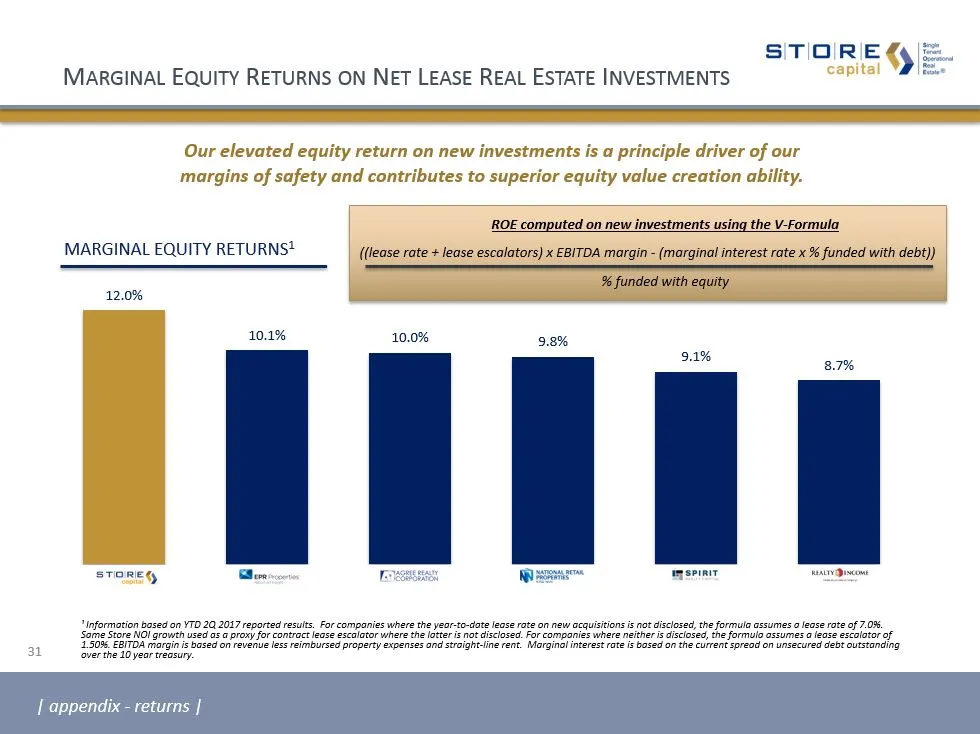
¹ Information based on YTD 2Q 2017 reported results. For companies where the year-to-date lease rate on new acquisitions is not disclosed, the formula assumes a lease rate of 7.0%. Same Store NOI growth used as a proxy for contract lease escalator where the latter is not disclosed. For companies whe
Slide 32: Comparative Value Creation STORE vs. Peers
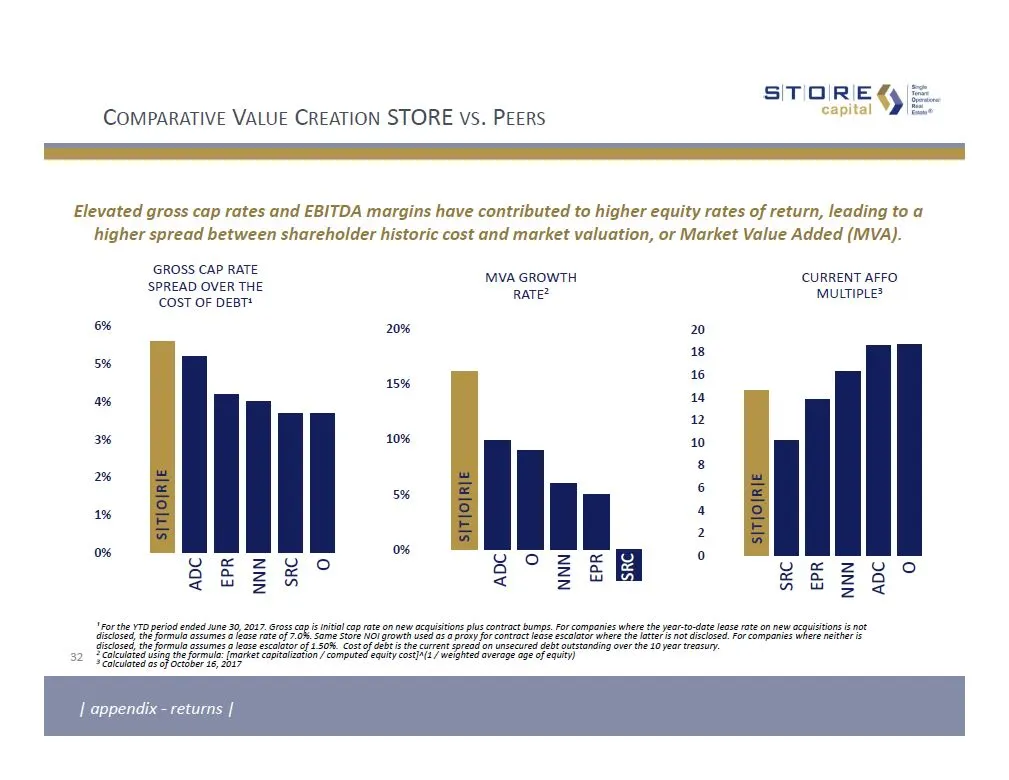
| appendix - returns | 32 ADCEPRNNNSRCO ADCONNNEPRSRC SRCEPRNNNADCO GROSS Cap Rate SPREAD over the cost of debt1 MVA Growth Rate2 CURRENT AFFO Multiple3 S|T|O|R|E S|T|O|R|E S|T|O|R|E Elevated gross cap rates and EBITDA margins have contributed to higher equity rates of return, leading to a higher sp
Slide 33: Consistent Contract Quality
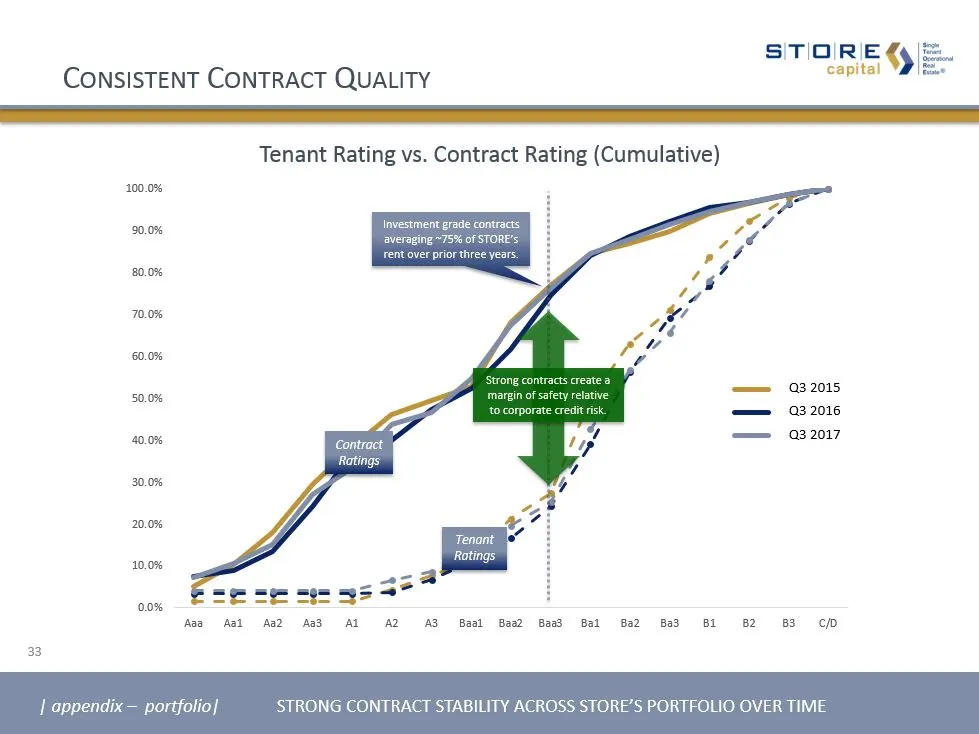
Consistent Contract Quality STRONG CONTRACT STABILITY ACROSS STORE’S PORTFOLIO OVER TIME 33 Investment grade contracts averaging ~75% of STORE’s rent over prior three years. Tenant Rating vs. Contract Rating (Cumulative) Strong contracts create a margin of safety relative to corporate credit risk. C
Slide 34: Most Diversified Tenant Base
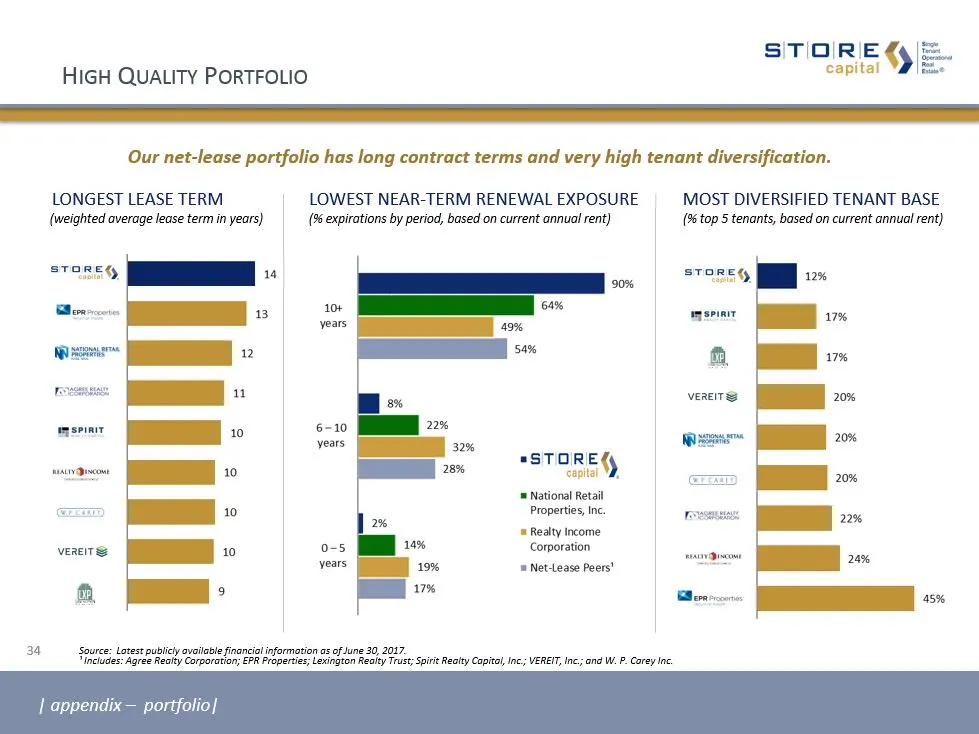
Most Diversified Tenant Base Source: Latest publicly available financial information as of June 30, 2017. ¹ Includes: Agree Realty Corporation; EPR Properties; Lexington Realty Trust; Spirit Realty Capital, Inc.; VEREIT, Inc.; and W. P. Carey Inc. (weighted average lease term in years) Longest Lease
Slide 35: Stable and Growing Cash Flow
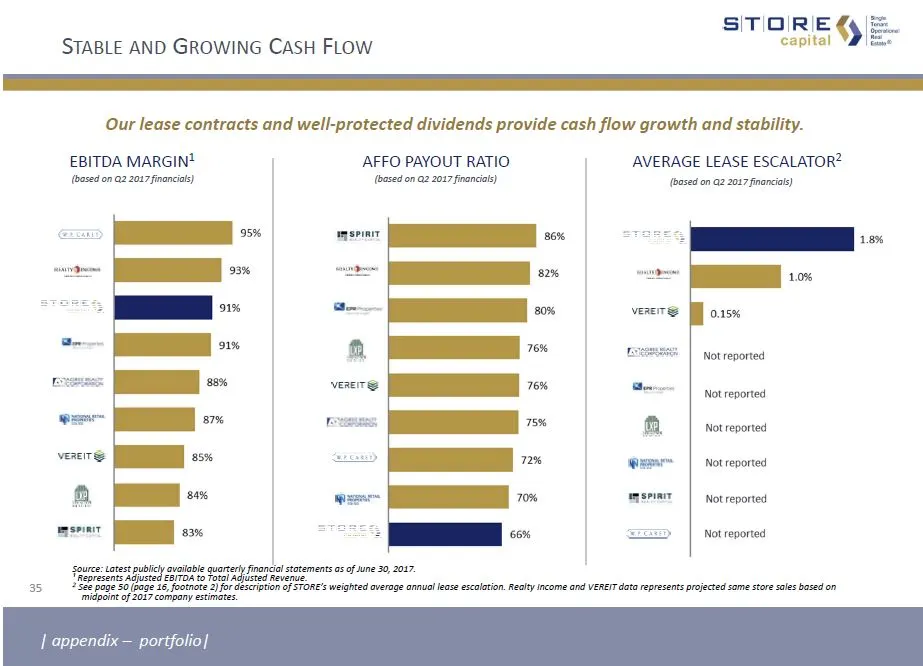
ebitda margin1 Average Lease escalator2 Source: Latest publicly available quarterly financial statements as of June 30, 2017. ¹ Represents Adjusted EBITDA to Total Adjusted Revenue.2 See page 50 (page 16, footnote 2) for description of STORE’s weighted average annual lease escalation. Realty Income
Slide 36: Case Study: National Restaurant Chain Bankruptcy
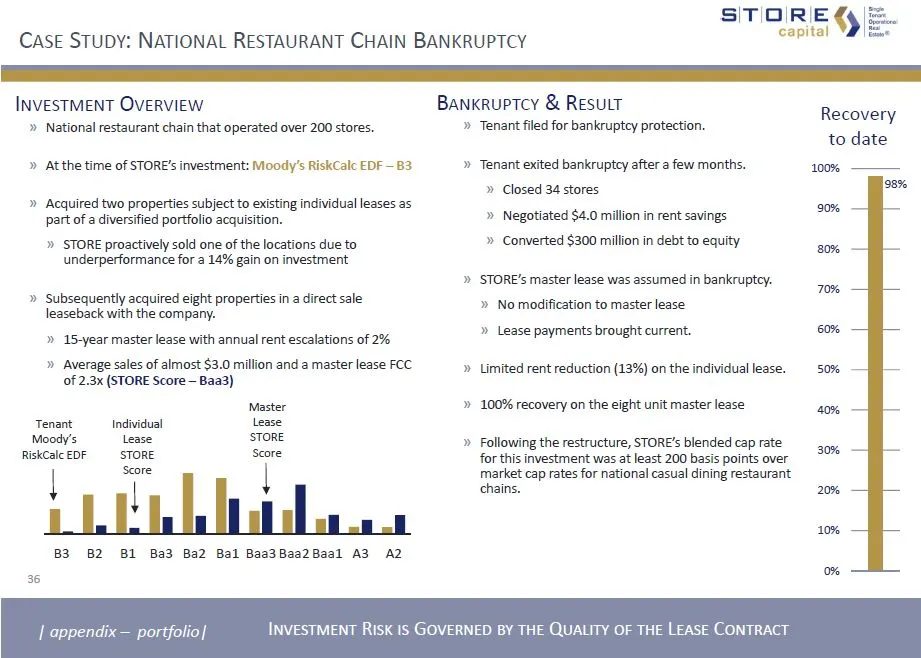
Case Study: National Restaurant Chain Bankruptcy Investment Overview National restaurant chain that operated over 200 stores.At the time of STORE’s investment: Moody’s RiskCalc EDF – B3Acquired two properties subject to existing individual leases as part of a diversified portfolio acquisition.STORE
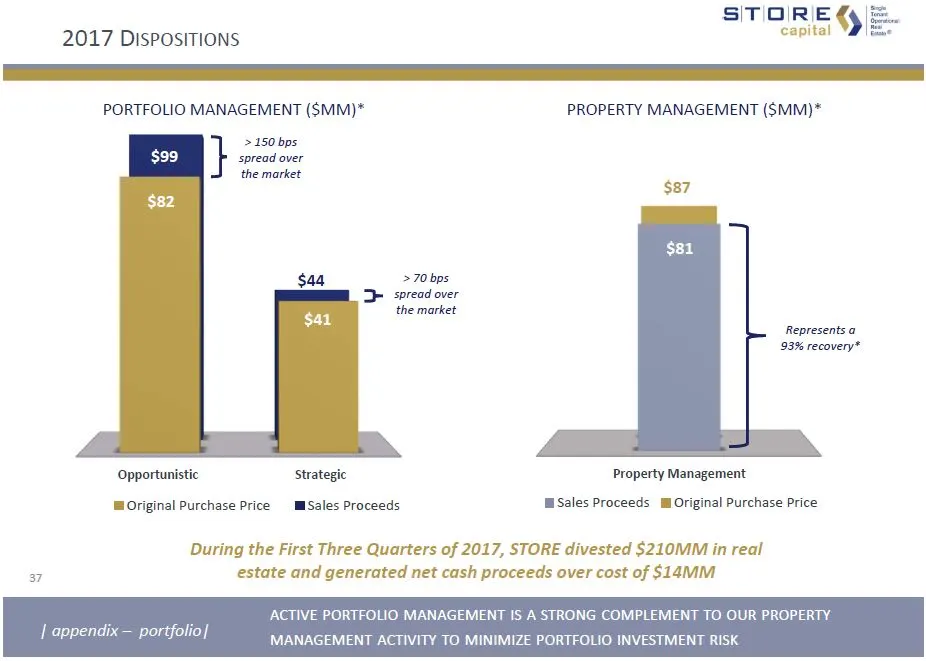
Slide 37: 2017 Dispositions
2017 Dispositions active portfolio management is a strong complement to our property management activity to minimize portfolio investment risk During the First Three Quarters of 2017, STORE divested $210MM in real estate and generated net cash proceeds over cost of $14MM > 150 bps spread over the ma
Slide 38: Executive Management Team
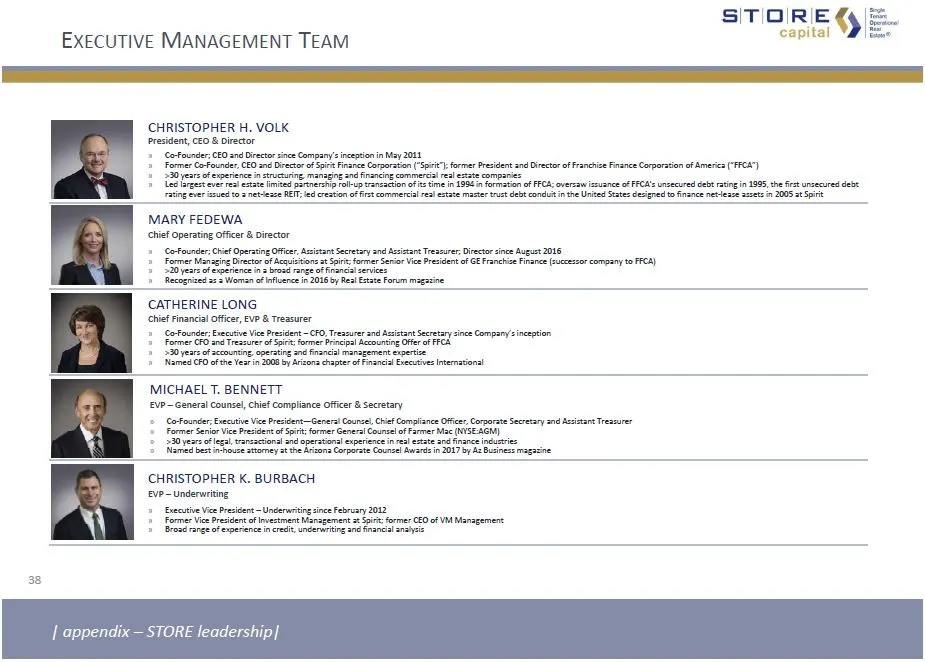
38 Executive Management Team | appendix – STORE leadership| MARY FEDEWAChief Operating Officer & DirectorCo-Founder; Chief Operating Officer, Assistant Secretary and Assistant Treasurer; Director since August 2016Former Managing Director of Acquisitions at Spirit; former Senior Vice President of GE
Slide 39: Board of Directors
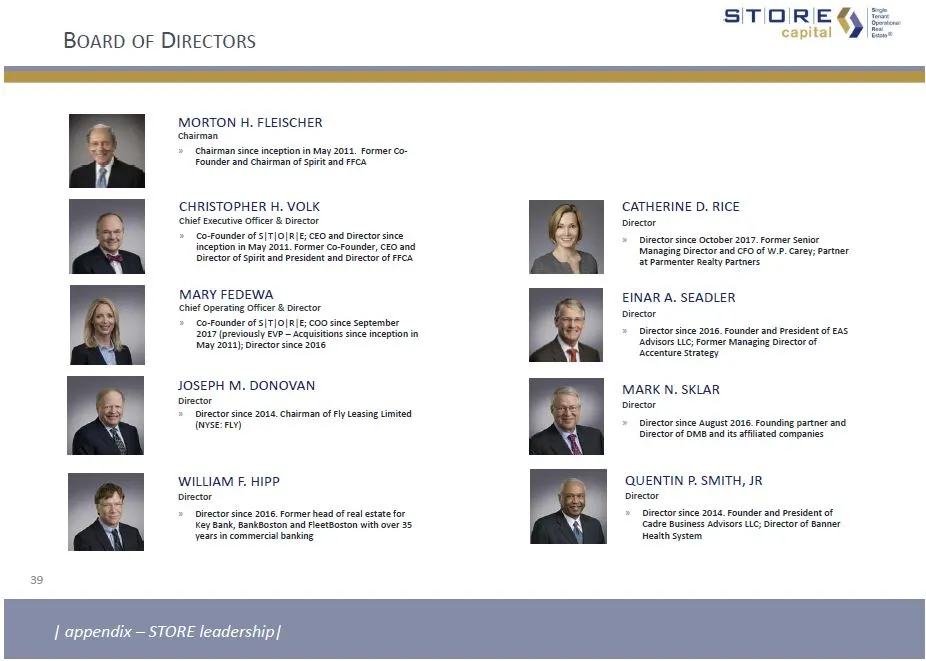
39 Board of Directors MORTON H. FLEISCHERChairmanChairman since inception in May 2011. Former Co-Founder and Chairman of Spirit and FFCA MARY FEDEWAChief Operating Officer & DirectorCo-Founder of S|T|O|R|E; COO since September 2017 (previously EVP – Acquisitions since inception in May 2011); Directo
Slide 40: Financial Information
S|T| aE ty Financial Information
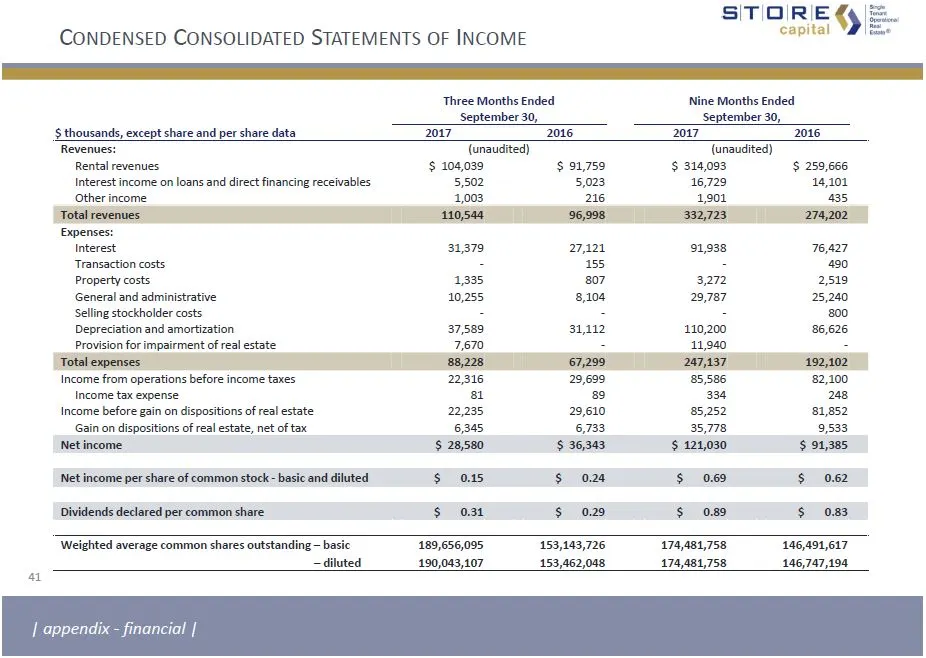
Slide 41: Condensed Consolidated Statements of Income
41 Condensed Consolidated Statements of Income Three Months Ended Nine Months Ended September 30, September 30, $ thousands, except share and per share data 2017 2016 2017 2016 Revenues: (unaudited) (unaudited) Rental revenues $ 104,039 $ 91,759 $ 314,093 $ 259,666 Interest income on loans and direc
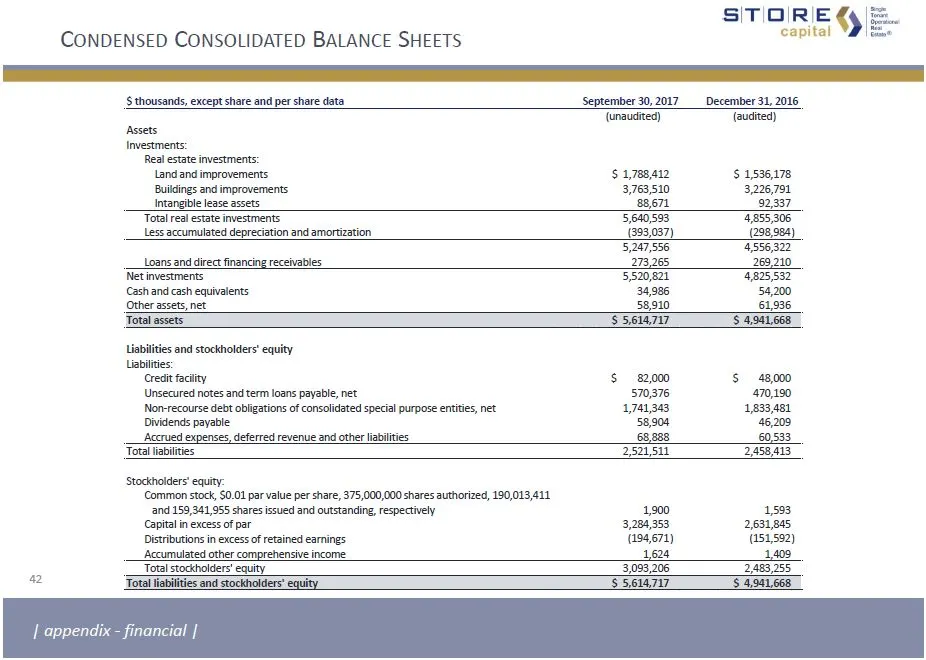
Slide 42: Condensed Consolidated Balance Sheets
Condensed Consolidated Balance Sheets $ thousands, except share and per share data September 30, 2017 December 31, 2016 (unaudited) (audited) Assets Investments: Real estate investments: Land and improvements $ 1,788,412 $ 1,536,178 Buildings and improvements 3,763,510 3,226,791 Intangible lease ass
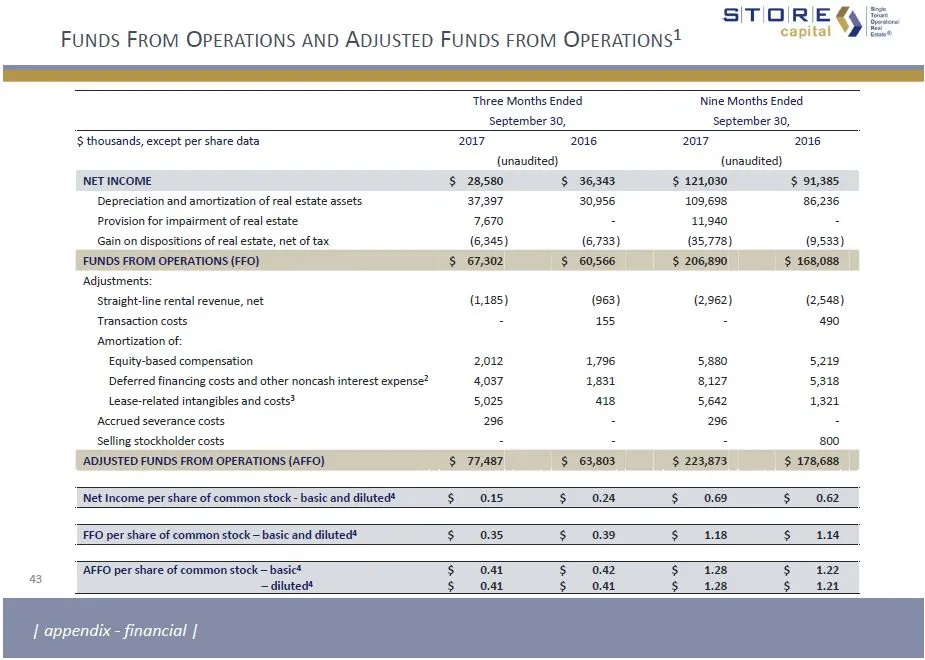
Slide 43: Funds From Operations and Adjusted Funds from Operations
Funds From Operations and Adjusted Funds from Operations1 Three Months Ended Nine Months Ended September 30, September 30, $ thousands, except per share data 2017 2016 2017 2016 (unaudited) (unaudited) NET INCOME $ 28,580 $ 36,343 $ 121,030 $ 91,385 Depreciation and amortization of real estate asset
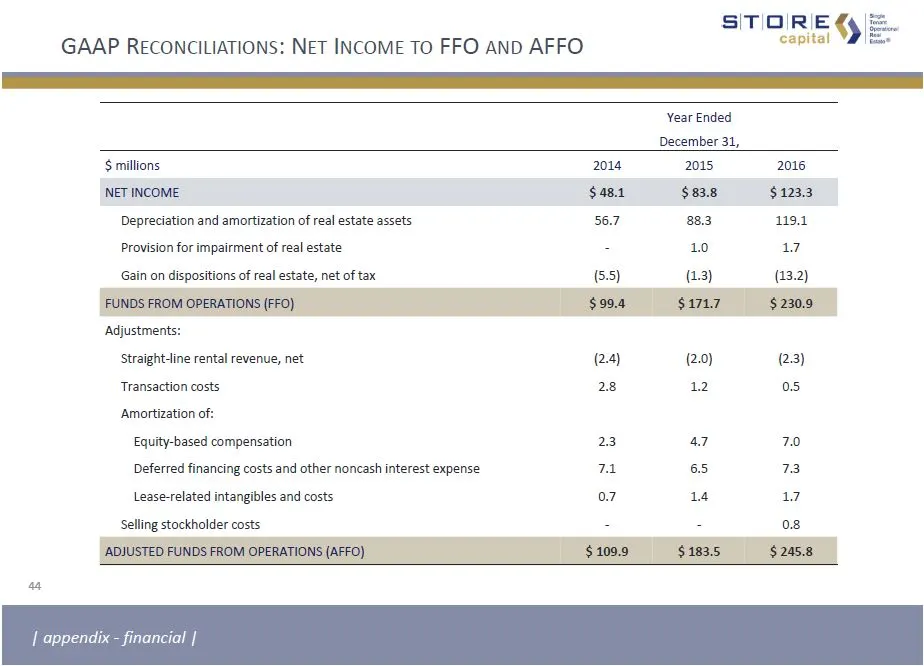
Slide 44: GAAP Reconciliations: Net Income to FFO and AFFO
GAAP Reconciliations: Net Income to FFO and AFFO 44 Year Ended December 31, $ millions 2014 2015 2016 NET INCOME $ 48.1 $ 83.8 $ 123.3 Depreciation and amortization of real estate assets 56.7 88.3 119.1 Provision for impairment of real estate - 1.0 1.7 Gain on dispositions of real estate, net of tax
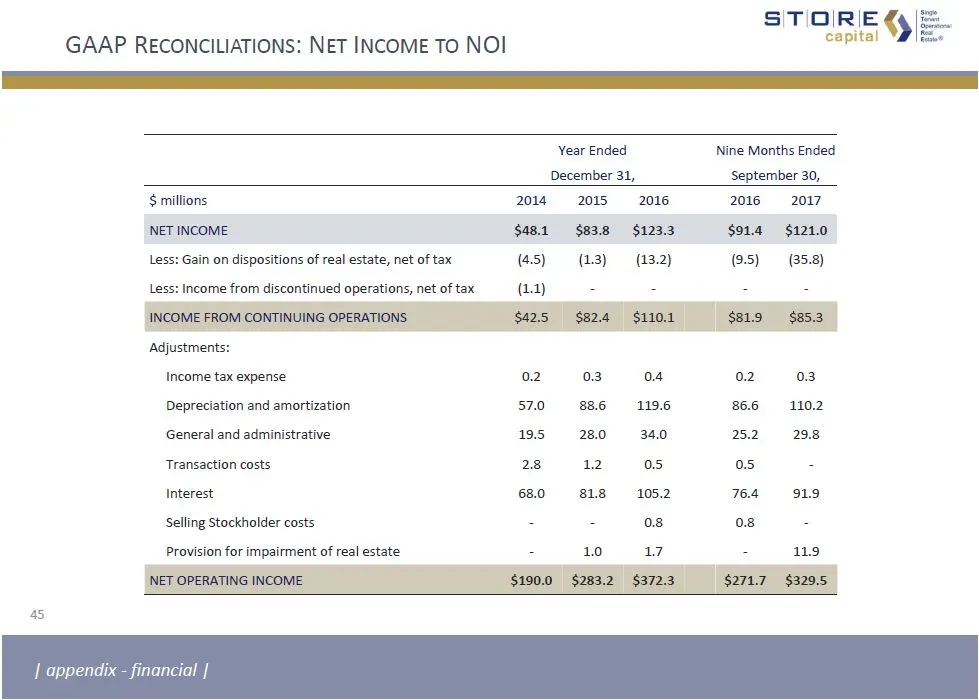
Slide 45: GAAP Reconciliations: Net Income to NOI
GAAP Reconciliations: Net Income to NOI 45 Year Ended Nine Months Ended December 31, September 30, $ millions 2014 2015 2016 2016 2017 NET INCOME $48.1 $83.8 $123.3 $91.4 $121.0 Less: Gain on dispositions of real estate, net of tax (4.5) (1.3) (13.2) (9.5) (35.8) Less: Income from discontinued opera
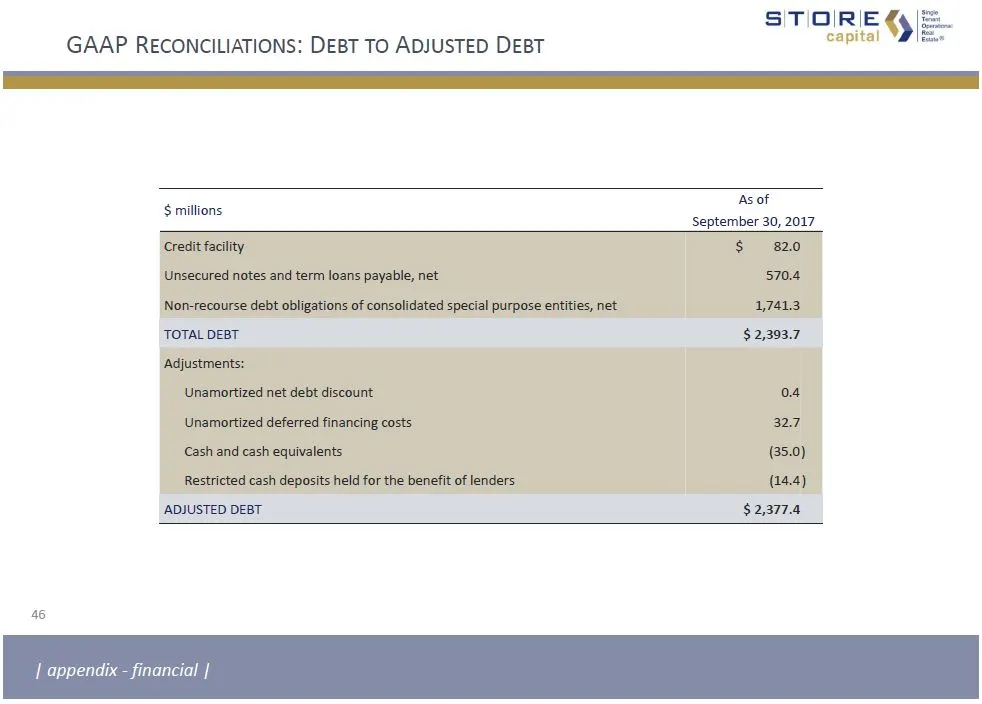
Slide 46: GAAP Reconciliations: Debt to Adjusted Debt
GAAP Reconciliations: Debt to Adjusted Debt 46 $ millions As of September 30, 2017 Credit facility $ 82.0 Unsecured notes and term loans payable, net 570.4 Non-recourse debt obligations of consolidated special purpose entities, net 1,741.3 TOTAL DEBT $ 2,393.7 Adjustments: Unamortized net debt disco
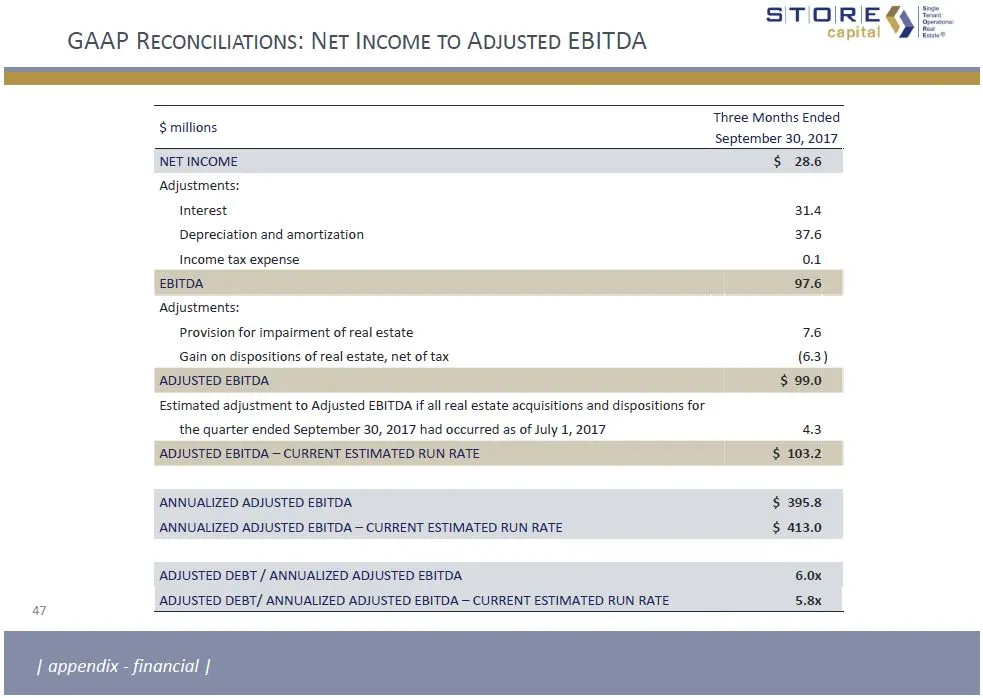
Slide 47: GAAP Reconciliations: Net Income to Adjusted EBITDA
GAAP Reconciliations: Net Income to Adjusted EBITDA 47 $ millions Three Months Ended September 30, 2017 NET INCOME $ 28.6 Adjustments: Interest 31.4 Depreciation and amortization 37.6 Income tax expense 0.1 EBITDA 97.6 Adjustments: Provision for impairment of real estate 7.6 Gain on dispositions of
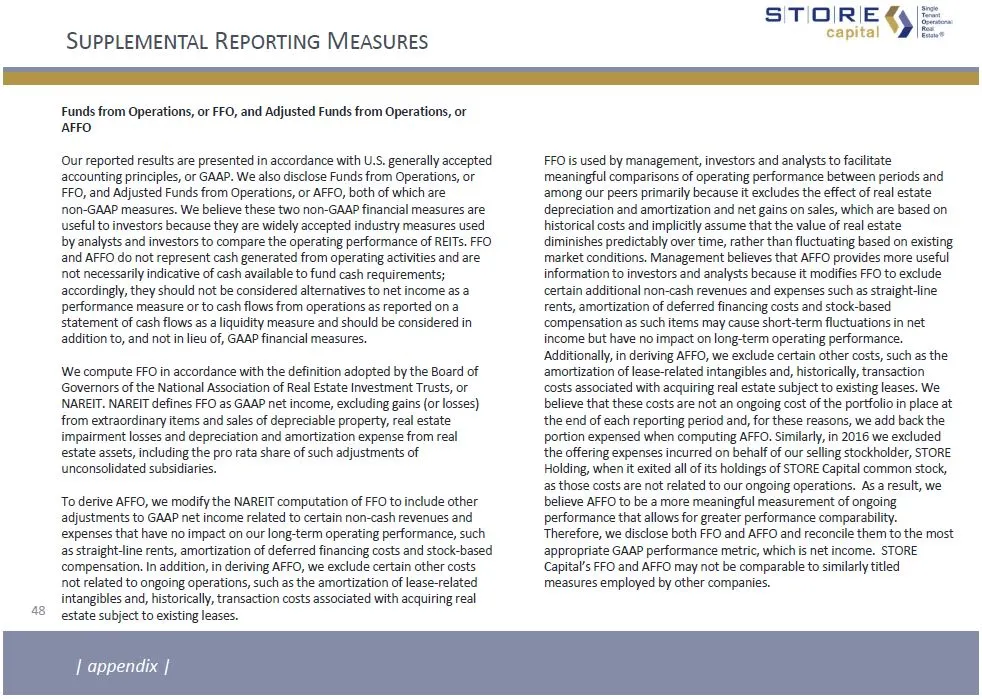
Slide 48: Supplemental Reporting Measures
48 Supplemental Reporting Measures Funds from Operations, or FFO, and Adjusted Funds from Operations, or AFFO Our reported results are presented in accordance with U.S. generally accepted accounting principles, or GAAP. We also disclose Funds from Operations, or FFO, and Adjusted Funds from Operatio
Slide 49: Supplemental Reporting Measures
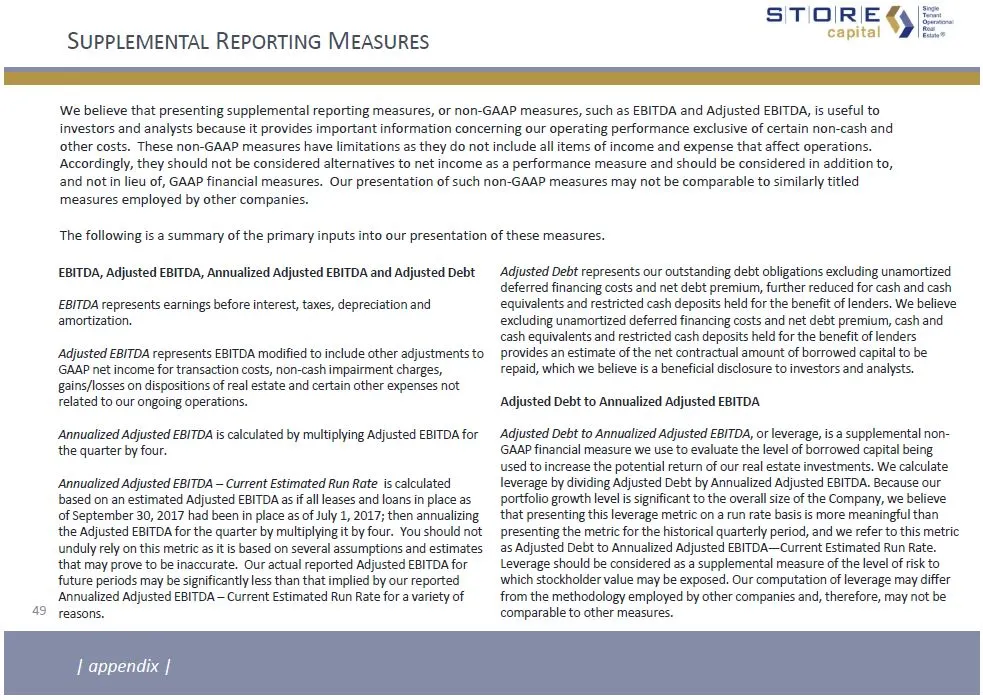
49 Supplemental Reporting Measures We believe that presenting supplemental reporting measures, or non-GAAP measures, such as EBITDA and Adjusted EBITDA, is useful to investors and analysts because it provides important information concerning our operating performance exclusive of certain non-cash an
Slide 50: Footnotes
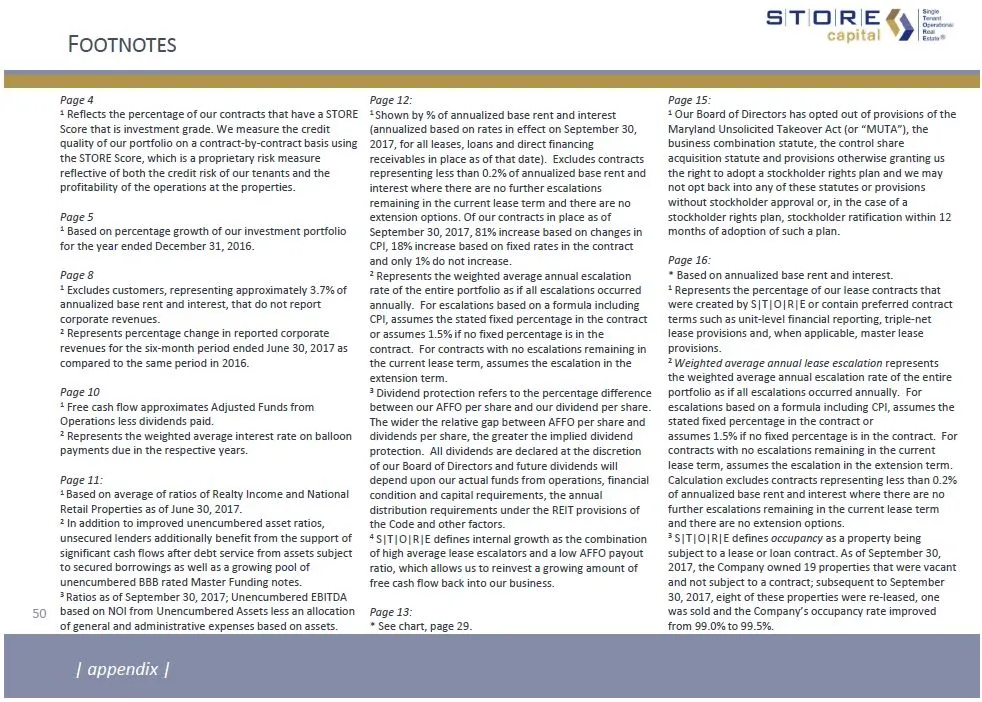
50 Footnotes Page 41 Reflects the percentage of our contracts that have a STORE Score that is investment grade. We measure the credit quality of our portfolio on a contract-by-contract basis using the STORE Score, which is a proprietary risk measure reflective of both the credit risk of our tenants
Slide 51: Footnotes
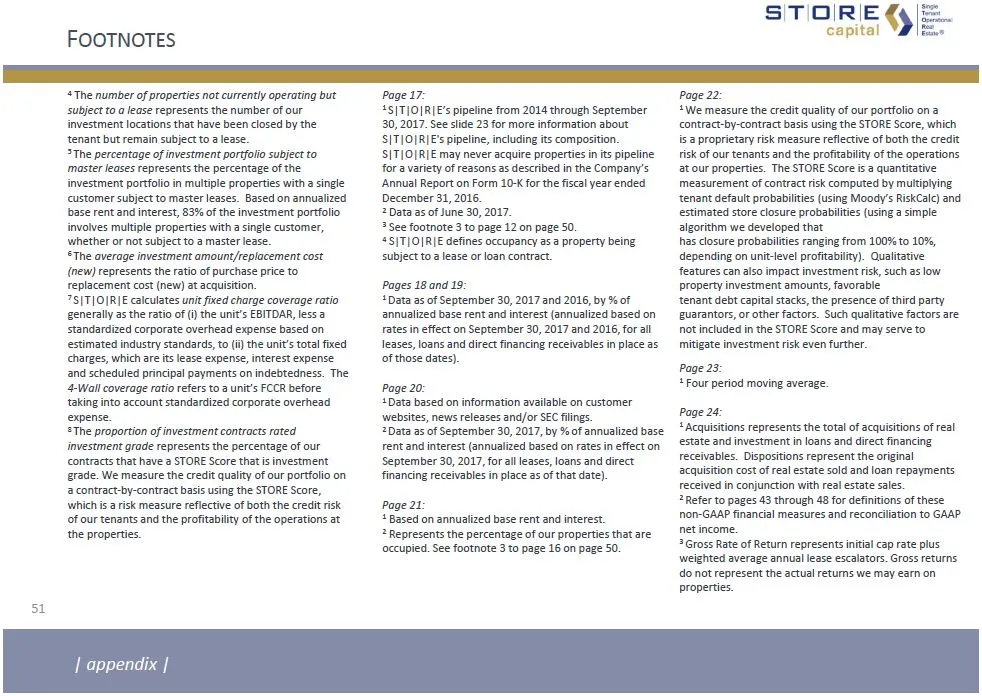
Footnotes | appendix | 51 4 The number of properties not currently operating but subject to a lease represents the number of our investment locations that have been closed by the tenant but remain subject to a lease.5 The percentage of investment portfolio subject to master leases represents the per
Slide 52: Footnotes
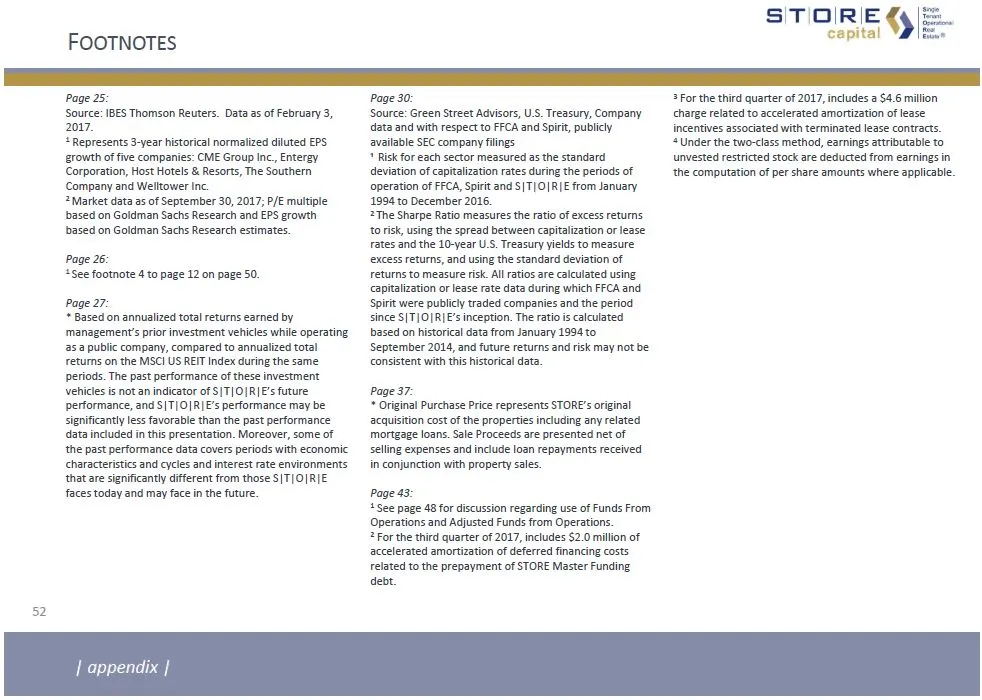
Footnotes | appendix | 52 Page 25:Source: IBES Thomson Reuters. Data as of February 3, 2017.1 Represents 3-year historical normalized diluted EPS growth of five companies: CME Group Inc., Entergy Corporation, Host Hotels & Resorts, The Southern Company and Welltower Inc.2 Market data as of September
Slide 53: Investor and Media Contacts
Investor and Media ContactsFinancial Profiles, Inc.Moira Conlon, 310.622.8220Tricia Ross, 310.622.8226STORECapital@finprofiles.com Corporate Headquarters8377 East Hartford Drive, Suite 100Scottsdale, Arizona 85255480.256.1100www.STOREcapital.com
Source: SEC EDGAR · 8-K filed Nov 2, 2017
More decks from STORE Capital Corp
 Q2 2023 Earnings Presentation10 slides · Aug 4, 2023
 Q2 2022 Earnings Presentation26 slides · Aug 3, 2022
 Q2 2022 Earnings Presentation22 slides · Aug 3, 2022
 Q1 2022 Earnings Presentation26 slides · May 4, 2022
 Q1 2022 Earnings Presentation22 slides · May 4, 2022
 Q4 2021 Earnings Presentation33 slides · Feb 23, 2022