Middleburg Financial — Shareholder Meeting (May 2013)
26 slides from Middleburg Financial's shareholder meeting presentation, May 1, 2013
Slide 1: Annual Meeting May 1, 2013
> Middleburg “>” Financial Corporation Annual Meeting May 1, 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements a) Certain information contained in this discussion may include “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21K of the Securilies Exchange Act of 1934, as amended. These forward-looking statcments re
Slide 3: Agenda
Agenda * MFC 2012 Review * 2013 Priorities )
Slide 4: Mission
fae a Mission > To provide high quality financial solutions which aid individuals and businesses in achieving their aspirations, and in so doing, contribute to the welfare of our communities, provide a rewarding work environment for our employees and earn a superior return for our shareholders.
Slide 5: 2012 Performance
2012 Performance (
Slide 6: Key Indicators
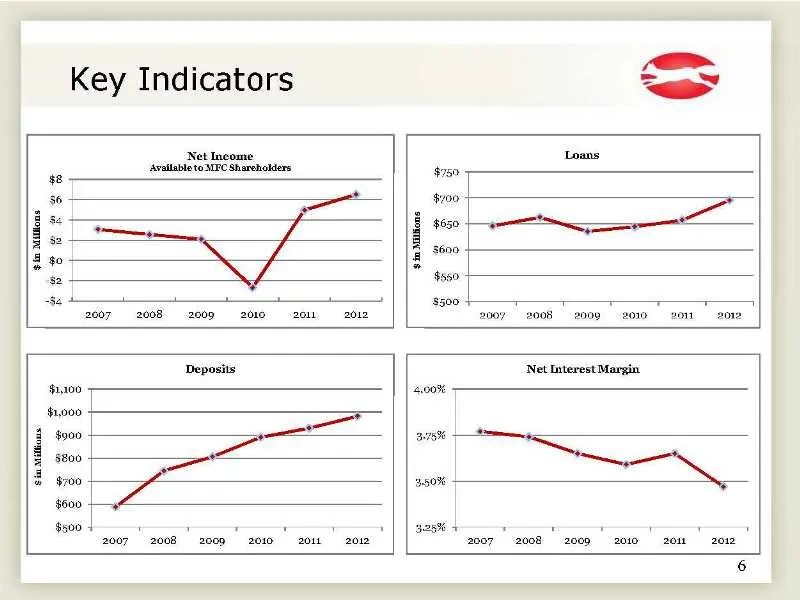
Key Indicators ( = $8 $750 36 $700 i is {<<} $2 $5507 = mia Siu Millions 2007 2008 ©2009 2010 zo 201 6
Slide 7: Key Indicators
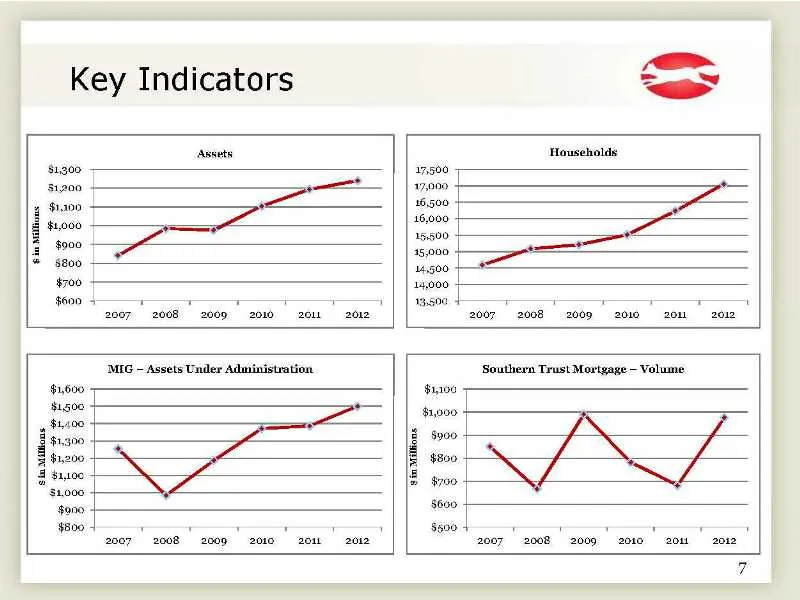
Key Indicators a) Assets Households 81900 51200 z fi200 § tooo 3 #900 * 5800 4700 $500} yp 9 5 + | | 5500 > 2007 | 2008 | 2009 | 2010 | ell 2012 2007 2008 2009 2010202012 MIG ~ Assets Under Administration Southern Trust Mortgage — Volume fo 7 8,900 2 sv00 4 2 s200 $700 + $600 | $800 Y © , , r 1 $500
Slide 8: Well Capitalized
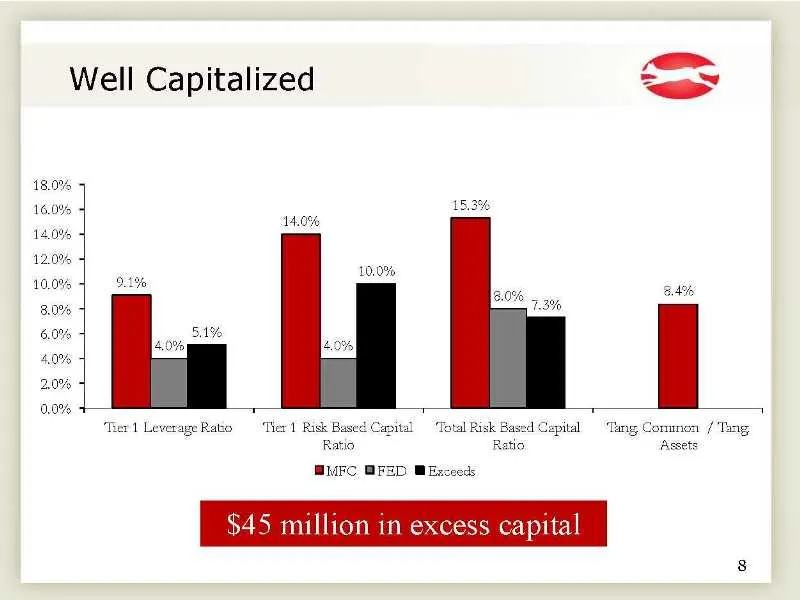
Well Capitalized S> 18.0% 16.0% 14.0% 14.0% 12.0% spies 10.0% 4 9.1% ad 8.0% 6.0% 4.0% 2.0% 0.0% 4 “Ter 1 Leverage Ratio ‘Tang, Common / Tang Assets MMFC BFED MExcecd: $45 million in excess capi
Slide 9: Q1 2013 Results
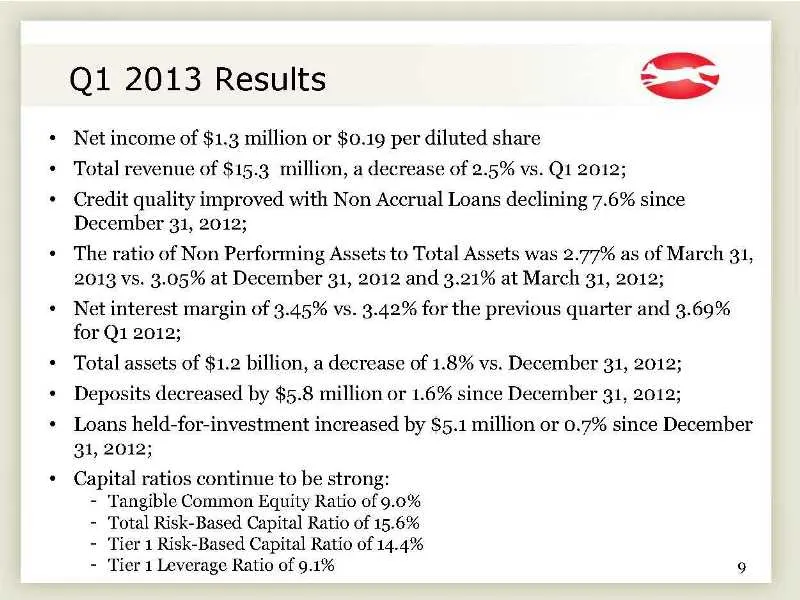
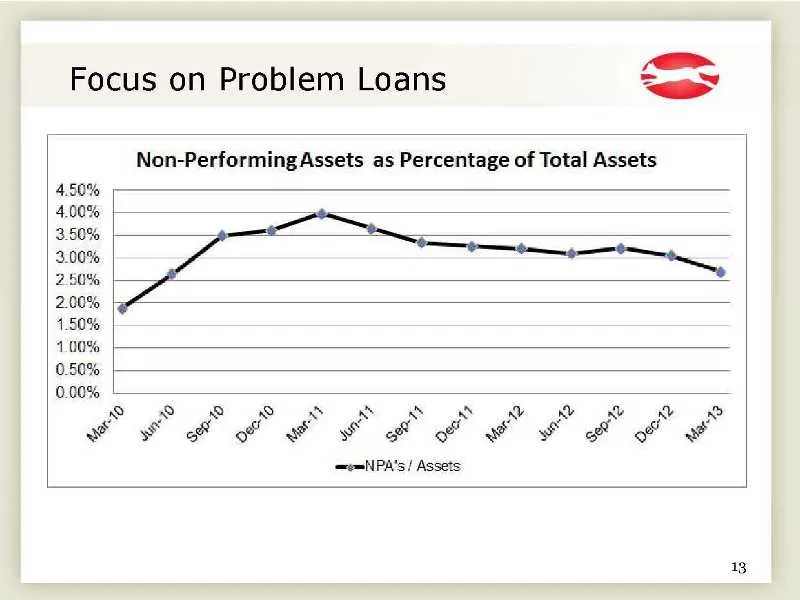
Qi 2013 Results —_ ( Net income of $1.3 million or $0.19 per diluted share Total revenue of $15.3 million, a decrease of 2.5% vs. Qt 2012; Credit quality improved with Non Accrual Loans declining 7.6% since December 31, 2012; The ratio of Non Performing Assets to Total Assets was 2.77% as of March 3
Slide 10: 2013 Outlook
2013 Outlook () 10
Slide 11: 2012 Priorities
2012 Priorities 1. Focus on problem loans 2. Increase revenue 3. Improve productivity () 1
Slide 12: Focus on Problem Loans
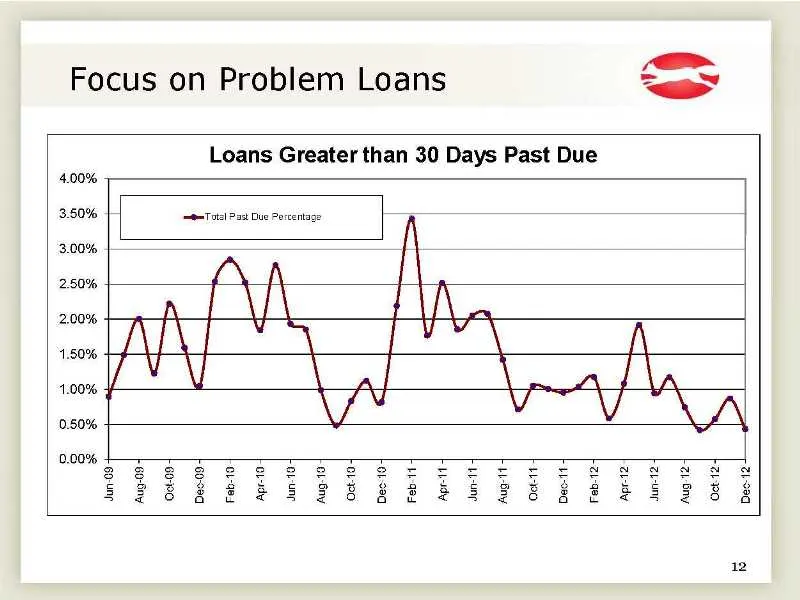
Focus on Problem Loans () Loans Greater than 30 Days Past Due me Toial Pas Due Percentage \w oats Oct-12, 12
Slide 13: Focus on Problem Loans
) Focus on Problem Loans — ( 4.50% 4.00% 3.50% 3.00% 2.50% 2.00% 4.50% 1.00% 0.50% 0.00% Non-PerformingAssets as Percentage of Total Assets Rs > © © 8 BP SF YF SF YP WM HM HM DM | eS HK Kw KH Me Fe KM men NPAs / Assets 13
Slide 14: Increase Revenue
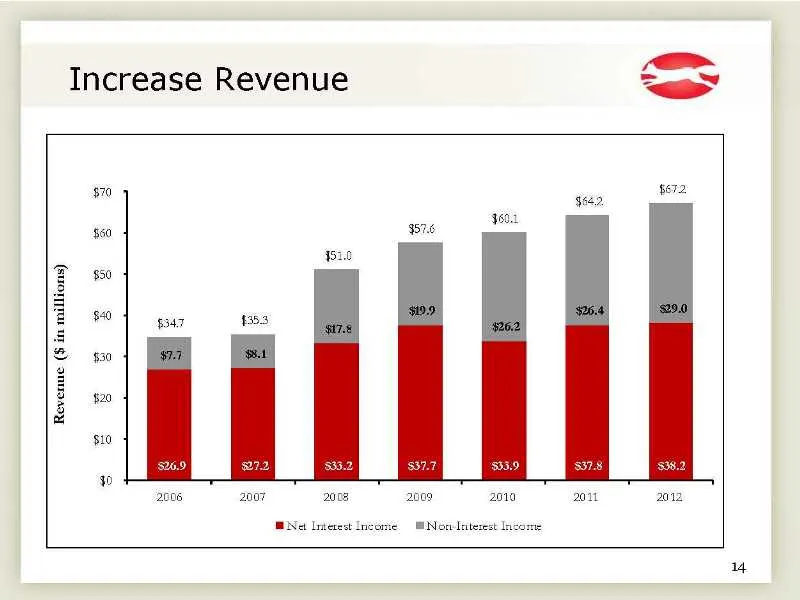
Increase Revenue Revenme ($ in millions) $70 $60 $50 $40 $0 $20 $10 $547 53 10 $602 $7.6 022, $672 2006 208 Net Imerest Income 2009 2ni0 iNew Interest Income ania
Slide 15: Improve Productivity
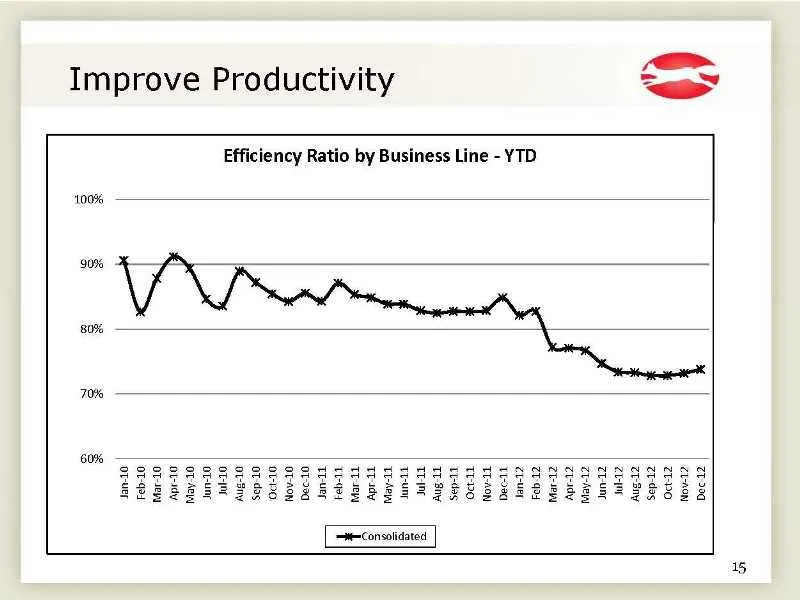
Improve Productivity — ( 100% Efficiency Ratio by Business Line - YTD 222 Consolidated 5
Slide 16: 2012 Priorities
() 2012 Priorities 1. Focus on problem loans 2. Increase revenue 3. Improve productivity PLEASED BUT NOT SATISFIED 16
Slide 17: 2013 Priorities
2013 Priorities 1. Focus on problem loans 2. Increase revenue 3. Improve productivity (
Slide 18: 2013 Priorities: Focus on problem loans
) 2013 Priorities > ( 1. Focus on problem loans — Nearly $6 million related to problem loans and other-real- estate-owned — Improvements in problem loans directly impact bottom line 18
Slide 19: 2013 Priorities: Increase revenue
2013 Priorities S 2. Increase revenue — Focus on loan growth: 70% loan-to-deposit ratio ensures adequate funds for growth — Improve loan yields through pricing and mix
Slide 20: 2013 Priorities: Improve productivity
) 2013 Priorities > ( 3. Improve productivity — Continued focus on efficiency ratio — Deliver operational savings through improved efficiency
Slide 21: Recognition
Recognition + J. Bradley Davis ( 21
Slide 22: Recognition
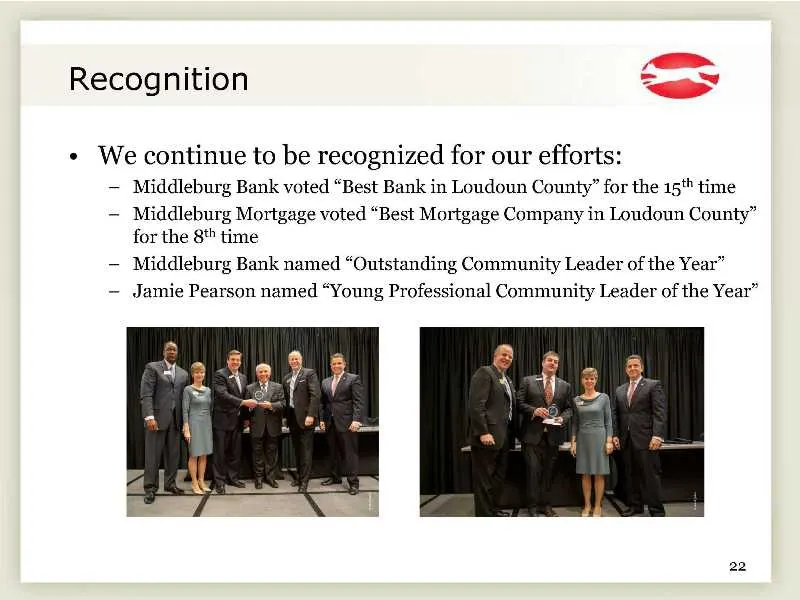
Recognition — ¢ We continue to be recognized for our efforts: ~ Middleburg Bank voted “Best Bank in Loudoun County” for the 15" time — Middleburg Mortgage voted “Best Mortgage Company in Loudoun County” for the 8*" time — Middleburg Bank named “Outstanding Community Leader of the Year” — Jamie Pears
Slide 23: Summary
nad Summary a) Well positioned for sustained performance: Diverse set of financial solutions meets clients’ diverse needs; Expanded geography reduces dependence on any one region; Technology solutions reduces cost of service delivery and provides clients with greater convenience; Improved operationa
Slide 24: Annual Meeting May 1, 2013
> Middleburg “>” Financial Corporation Annual Meeting May 1, 2013
Slide 25: 25
25
Slide 26: Middleburg Financial Corporation
> Middleburg <>’ Financial Corporation
Source: SEC EDGAR · 8-K filed May 1, 2013
More decks from Middleburg Financial Corp
 Merger or Acquisition (October 2016)19 slides · Oct 24, 2016
 Shareholder Meeting (May 2016)24 slides · May 4, 2016
 Investor Presentation (September 2015)33 slides · Sep 18, 2015
 Shareholder Meeting (May 2015)24 slides · May 6, 2015
 Shareholder Meeting (May 2014)22 slides · May 9, 2014
 Shareholder Meeting (May 2012)27 slides · May 2, 2012