Middleburg Financial — Merger or Acquisition (October 2016)
19 slides from Middleburg Financial's merger presentation, Oct 24, 2016
Slide 1: Creating Virginia's Premier Bank - Investor Presentation
ACCESS NATIONAL BANK Middleburg Bank The Difference is Access. Neighbors You Can Bank On™ Creating Virginia’s Premier Bank Investor Presentation October 24, 2016
Slide 2: Forward Looking Statements
FORWARD LOOKING STATEMENTS The information presented herein contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding Access National Corporation’s (“Access”) and Middleburg Financial Corporation's (“Middleburg”) expectations or predic
Slide 3: Additional Information
ADDITIONAL INFORMATION Additional Information About the Proposed Transaction and Where to Find It Investors are urged to review carefully and consider all public filings by Access and Middleburg with the Securities and Exchange Commission (the “SEC’), including but not limited to their Annual Report
Slide 4: Transaction Rationale
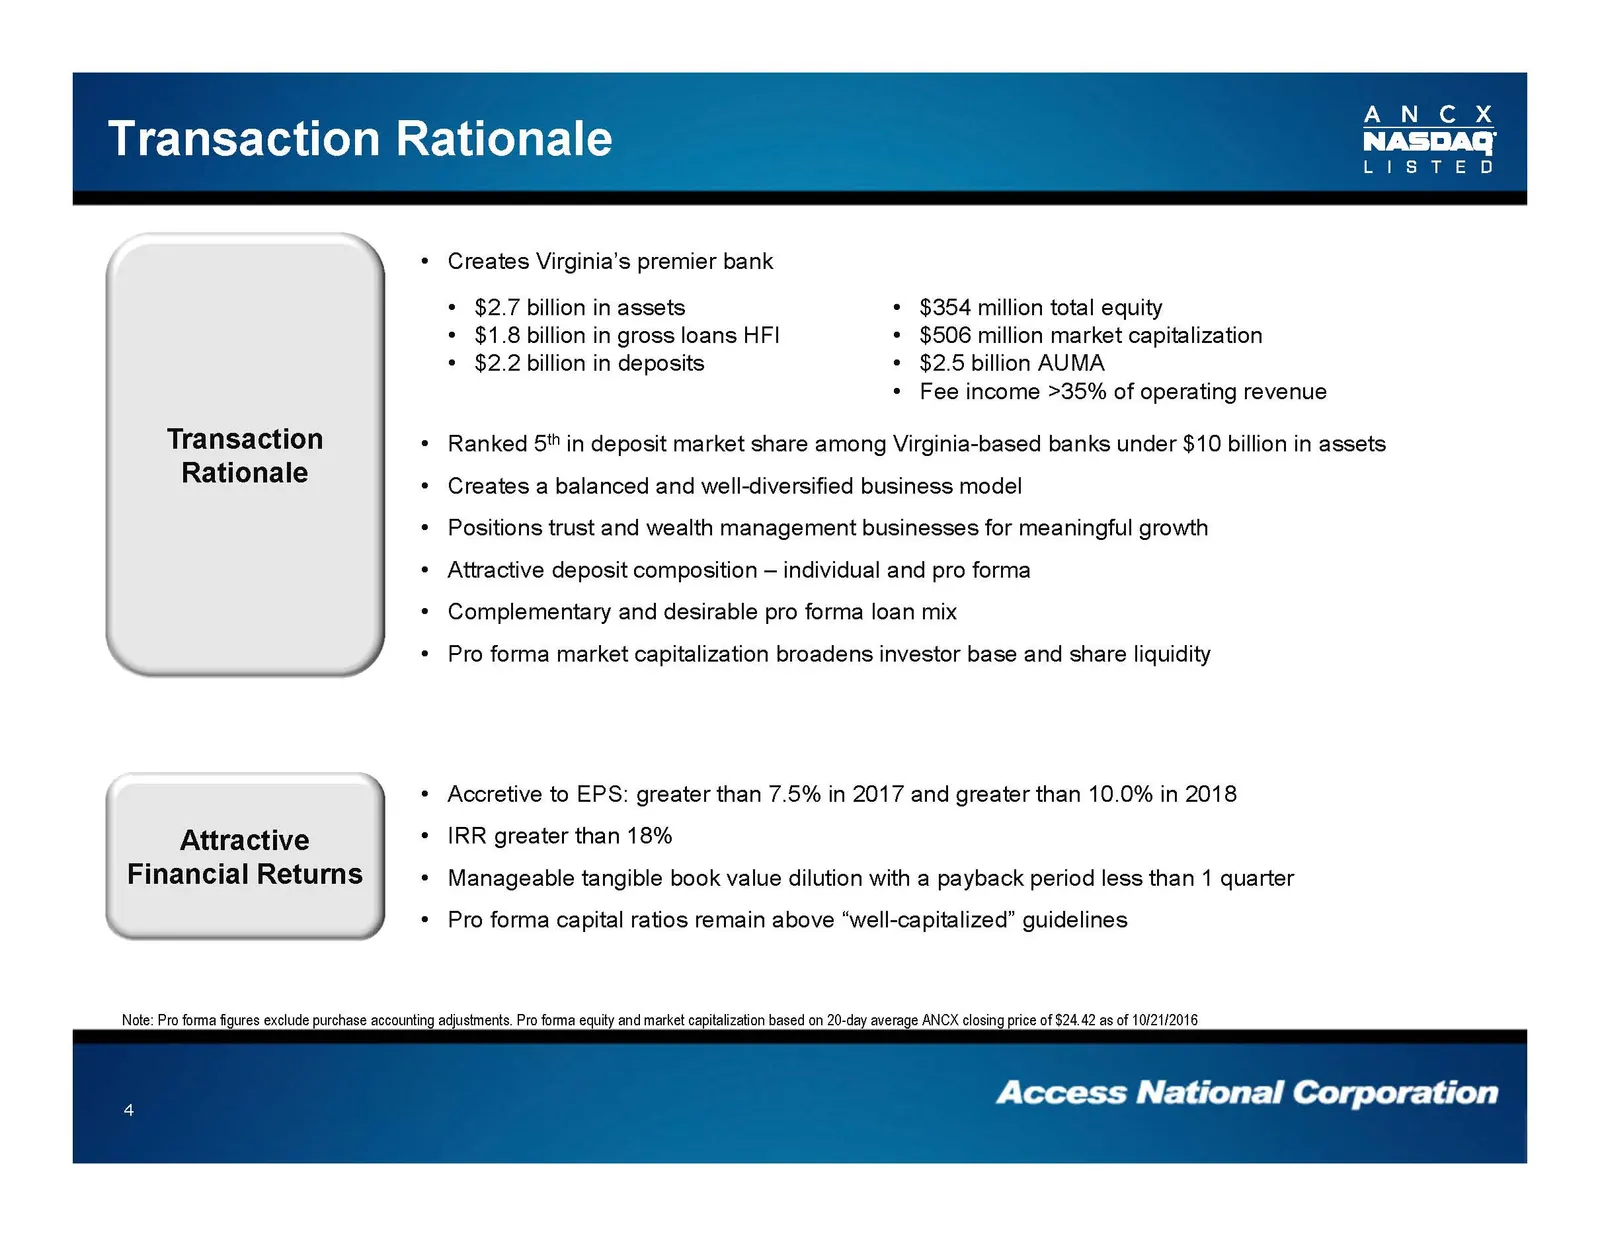
Transaction Rationale Transaction Rationale oY Attractive Financial Returns Note: Pro forma figures exclude purchase accounting adjustments. Pro forma equity and market capitalization based on 20-day average ANCX closing price of $24.42 as of 10/21/2016 Creates Virginia’s premier bank * $2.7 billion
Slide 5: A Transformational Strategic Merger in Virginia
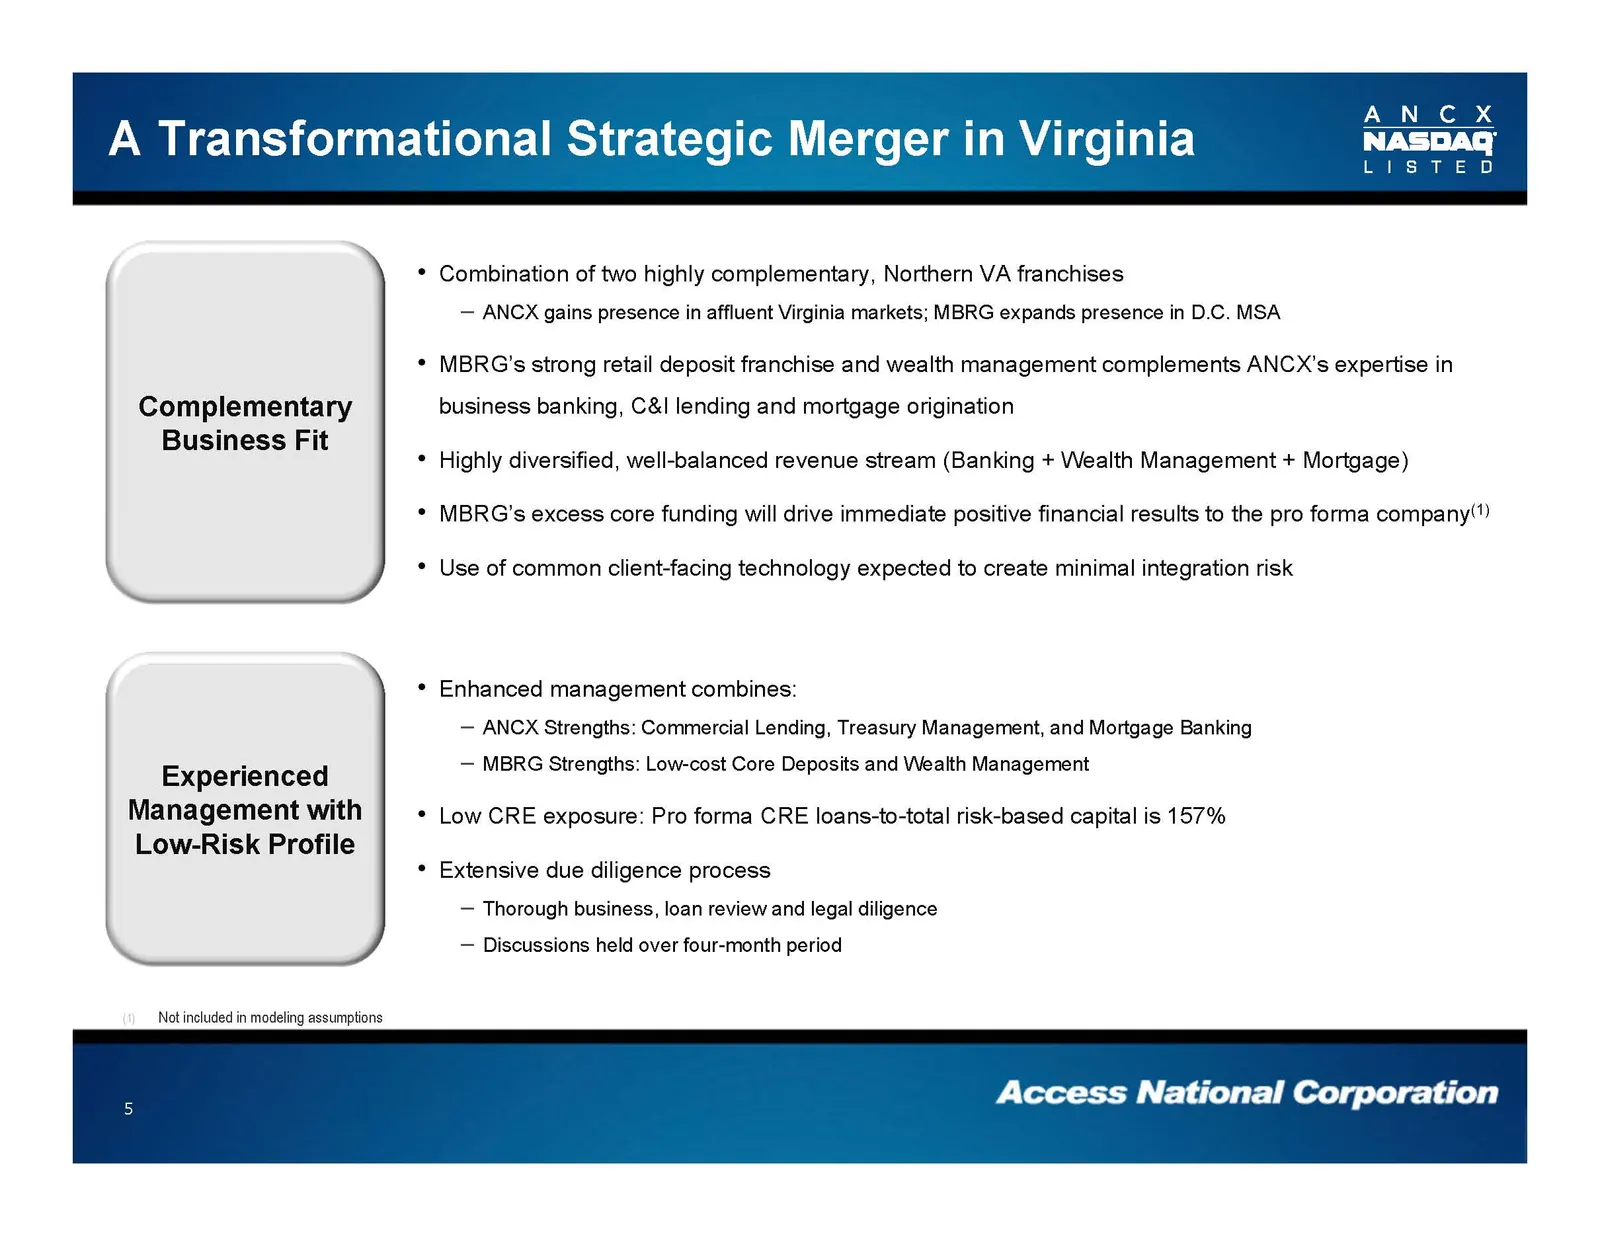
A Transformational Strategic Merger in Virginia » * Combination of two highly complementary, Northern VA franchises — ANCX gains presence in affluent Virginia markets; MBRG expands presence in D.C. MSA * MBRG's strong retail deposit franchise and wealth management complements ANC%’s expertise in Com
Slide 6: Overview of Merger Partners
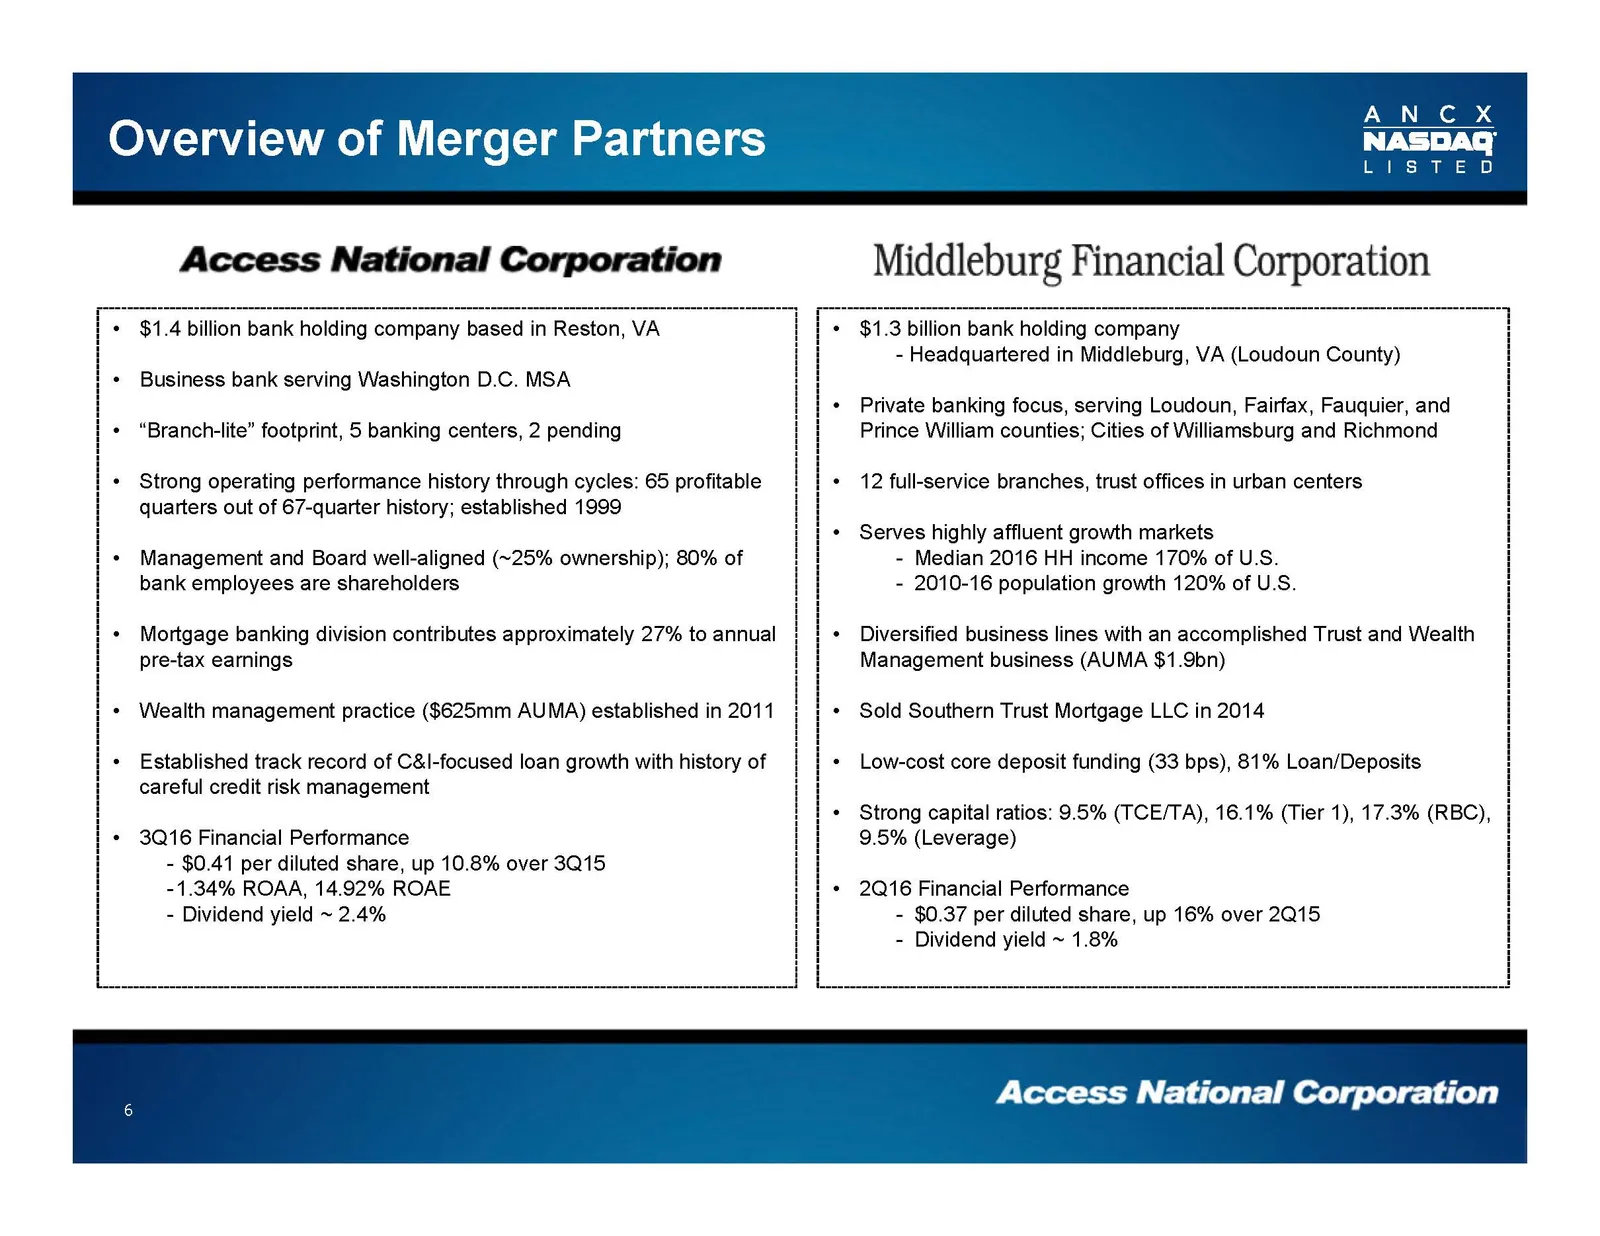
Overview of Merger Partners Access National Corporation Middleburg Financial Corporation * $1.4 billion bank holding company based in Reston, VA + Business bank serving Washington D.C. MSA + “Branch-lite” footprint, 5 banking centers, 2 pending * Strong operating performance history through cycles:
Slide 7: Transaction Summary
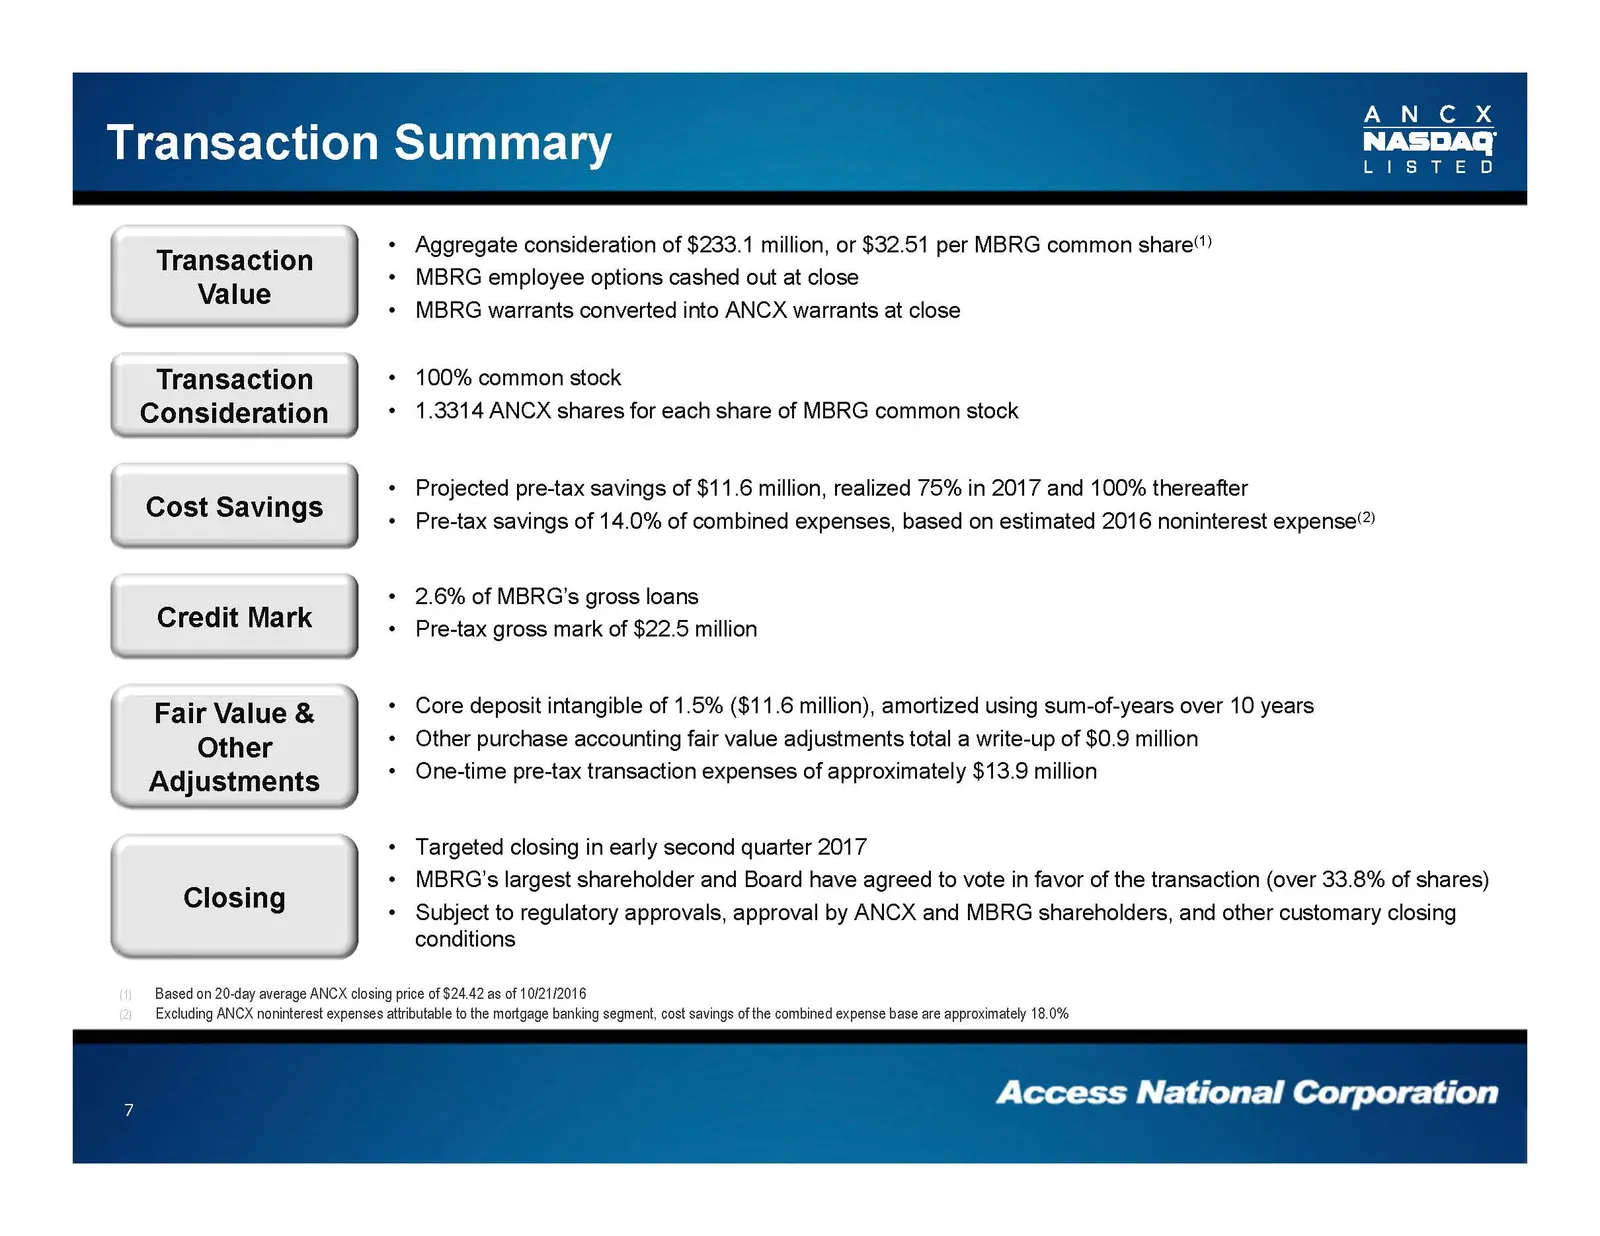
Transaction Summary Transaction Value ds Transaction Consideration Cost Savings a Credit Mark —_—_ Fair Value & Other Adjustments es Closing —— Based on 20-day average ANCX closing price of $24.42 as of 10/21/2016 Aggregate consideration of $233.1 million, or $32.51 per MBRG common share MBRG employ
Slide 8: Strong EPS Accretion, IRR & Robust Capital
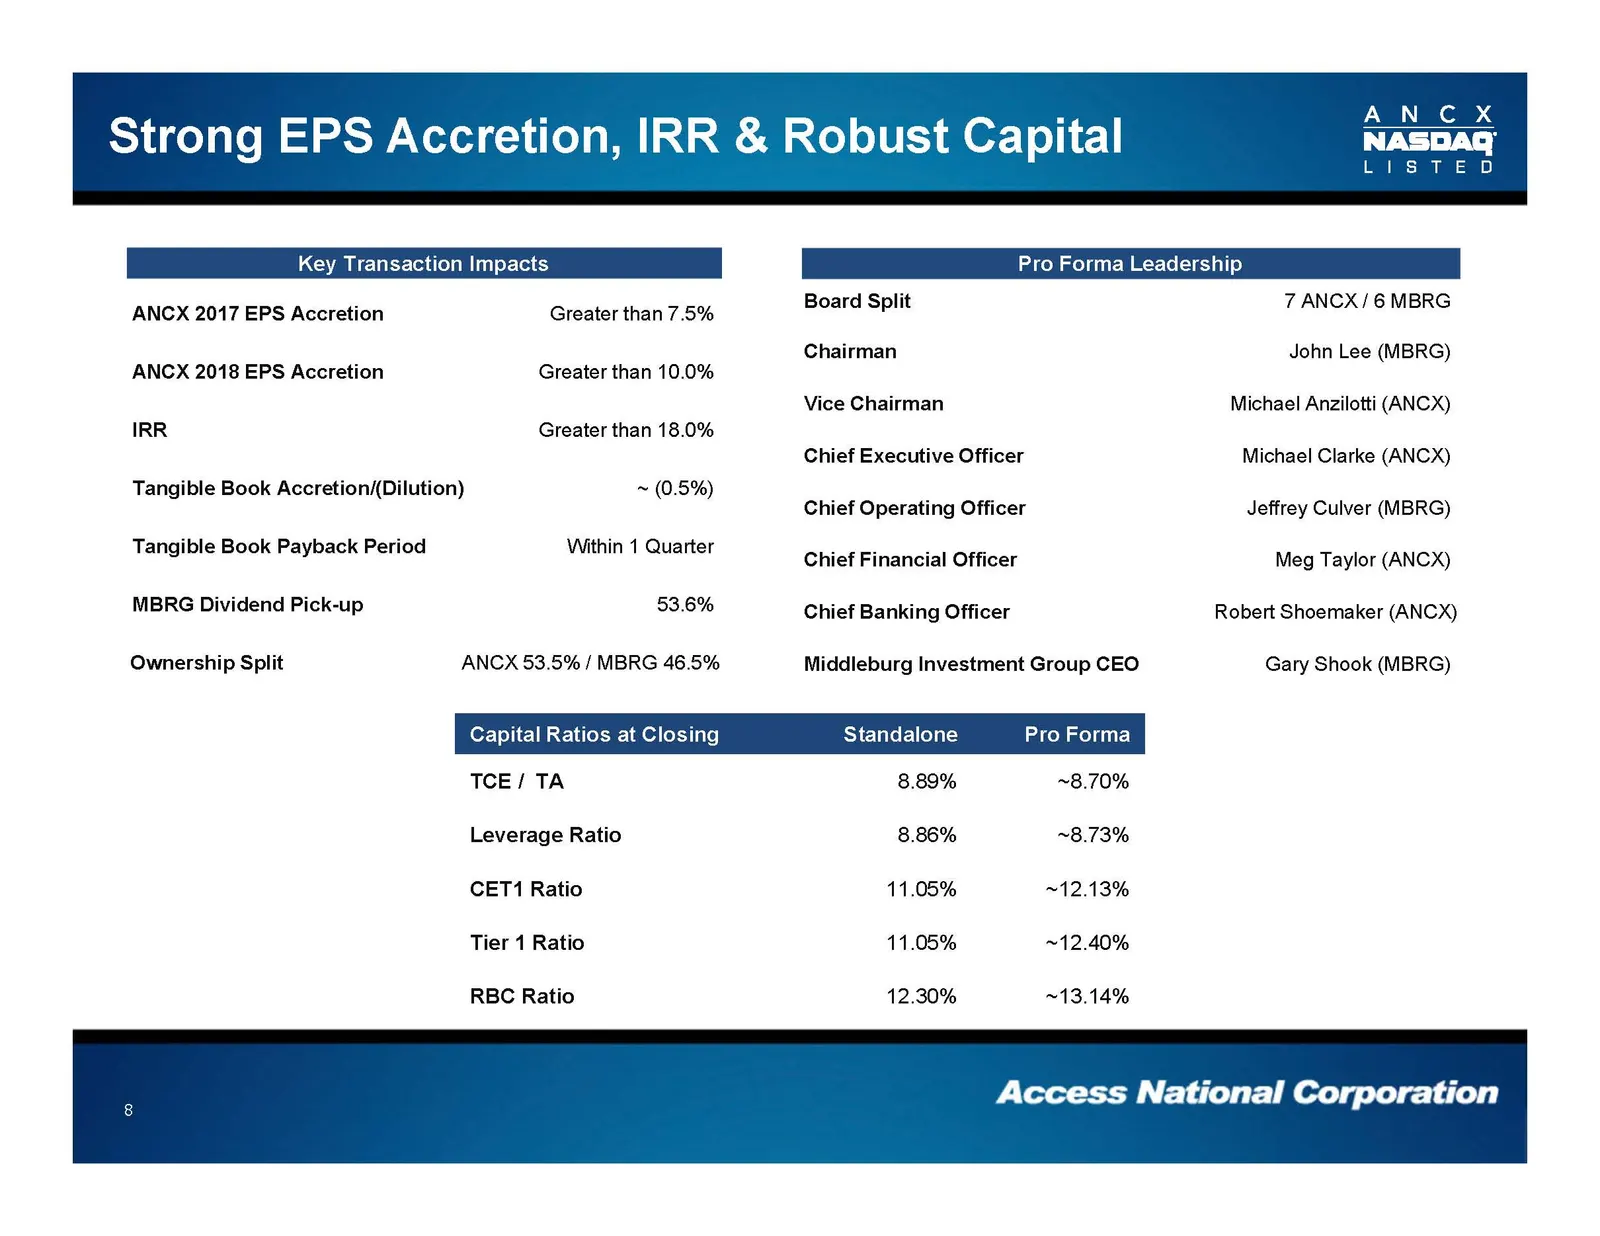
Strong EPS Accretion, IRR & Robust Capital Key Transaction Impacts ANCX 2017 EPS Accretion Greater than 7.5% ANCX 2018 EPS Accretion Greater than 10.0% IRR Greater than 18.0% Tangible Book Accretion/(Dilution) ~ (0.5%) Tangible Book Payback Period Within 1 Quarter MBRG Dividend Pick-up 53.6% Ownersh
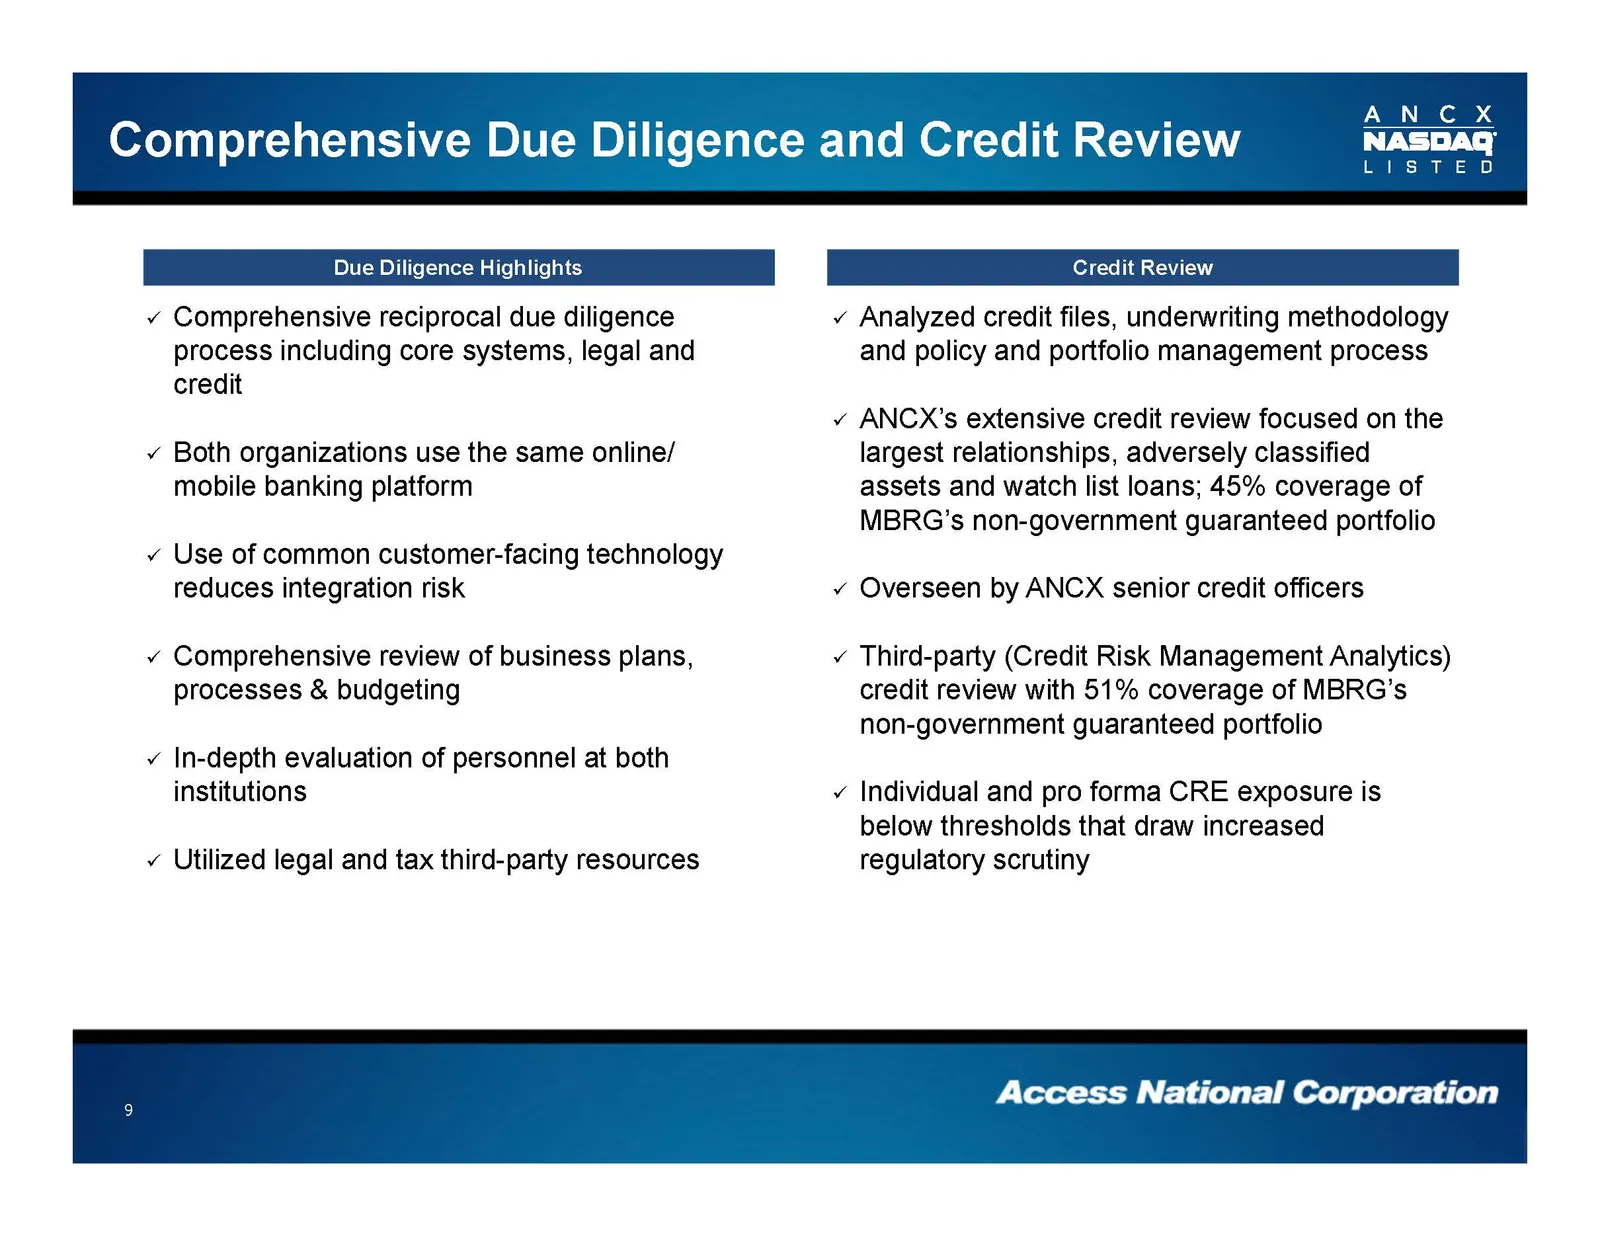
Slide 9: Comprehensive Due Diligence and Credit Review
Comprehensive Due Diligence and Credit Review Due Diligence Highlights Credit Review v Comprehensive reciprocal due diligence v Analyzed credit files, underwriting methodology process including core systems, legal and and policy and portfolio management process credit v ANCX’s extensive credit revie
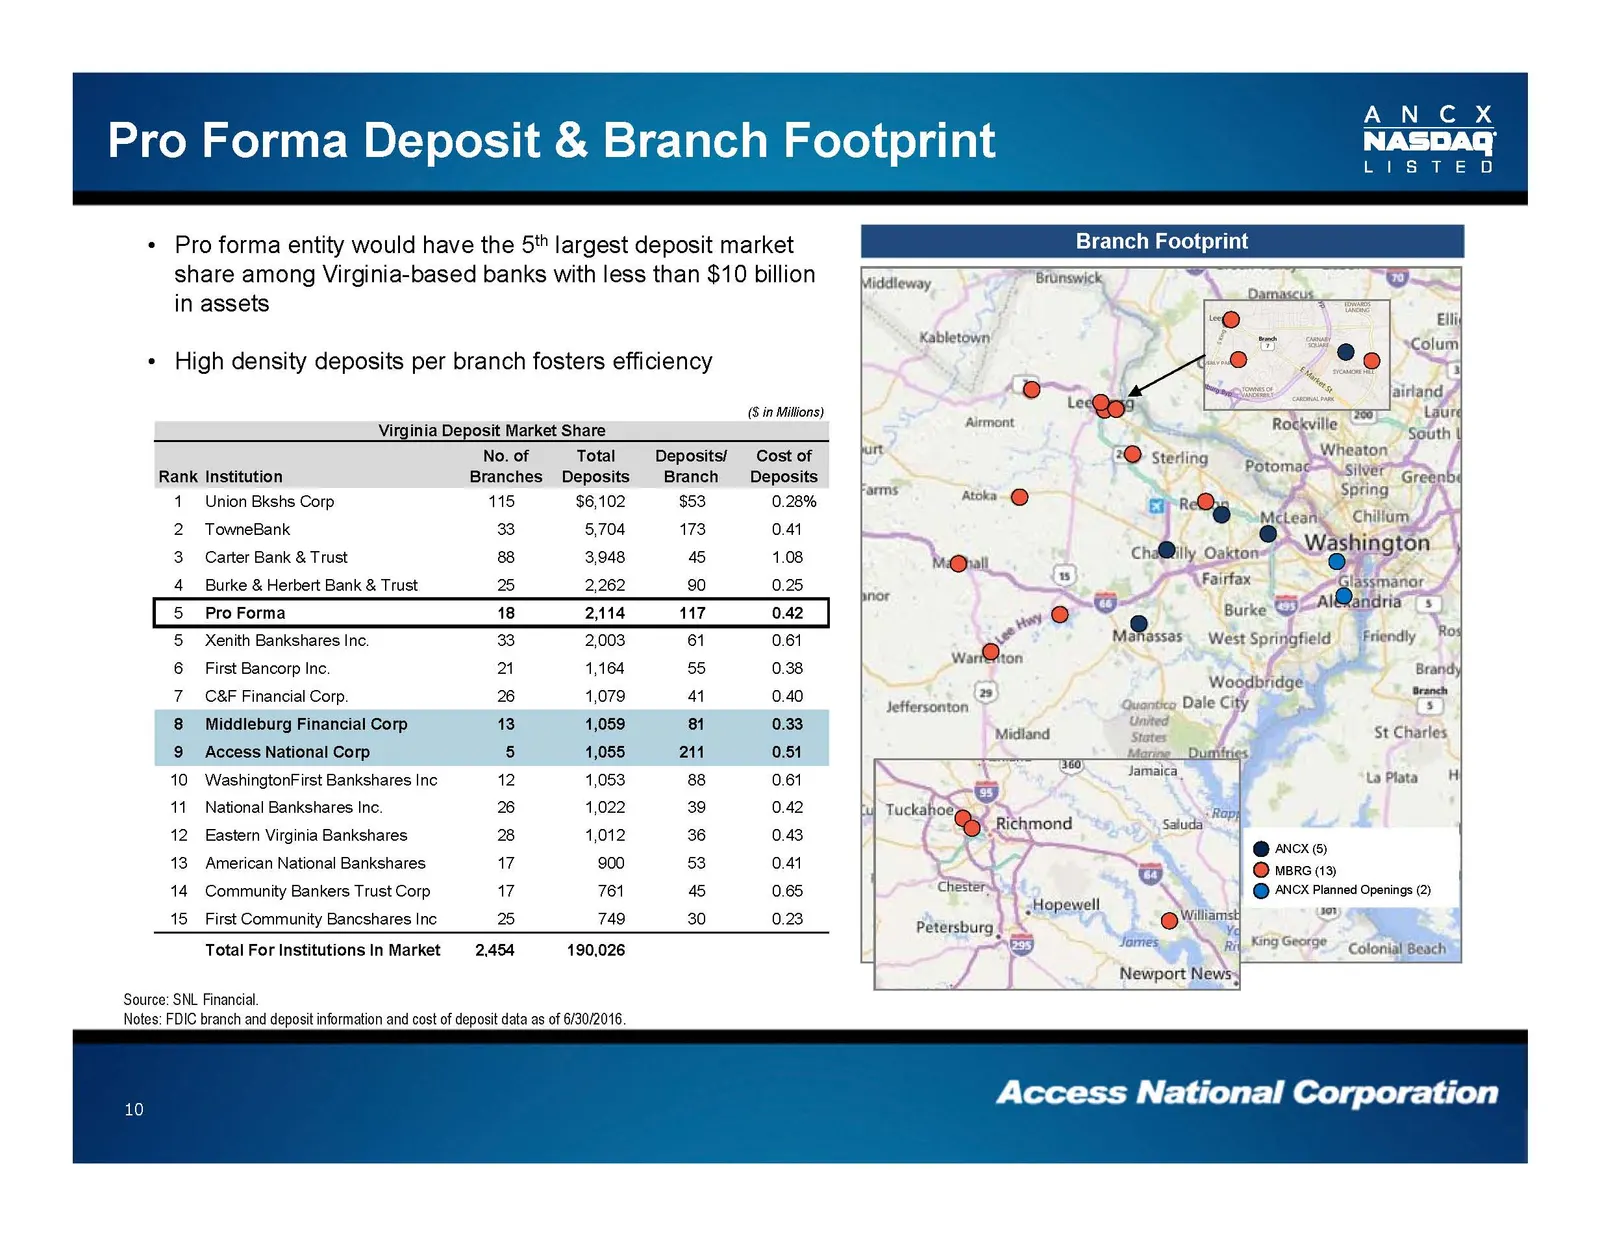
Slide 10: Pro Forma Deposit & Branch Footprint
Pro Forma Deposit & Branch Footprint + Pro forma entity would have the 5t* largest deposit market share among Virginia-based banks with less than $10 billion [iiddtewey, Brunswick in assets Kabletown + High density deposits per branch fosters efficiency oe ? ta~<e (S in Millions) dlncit ~ oe Virgini
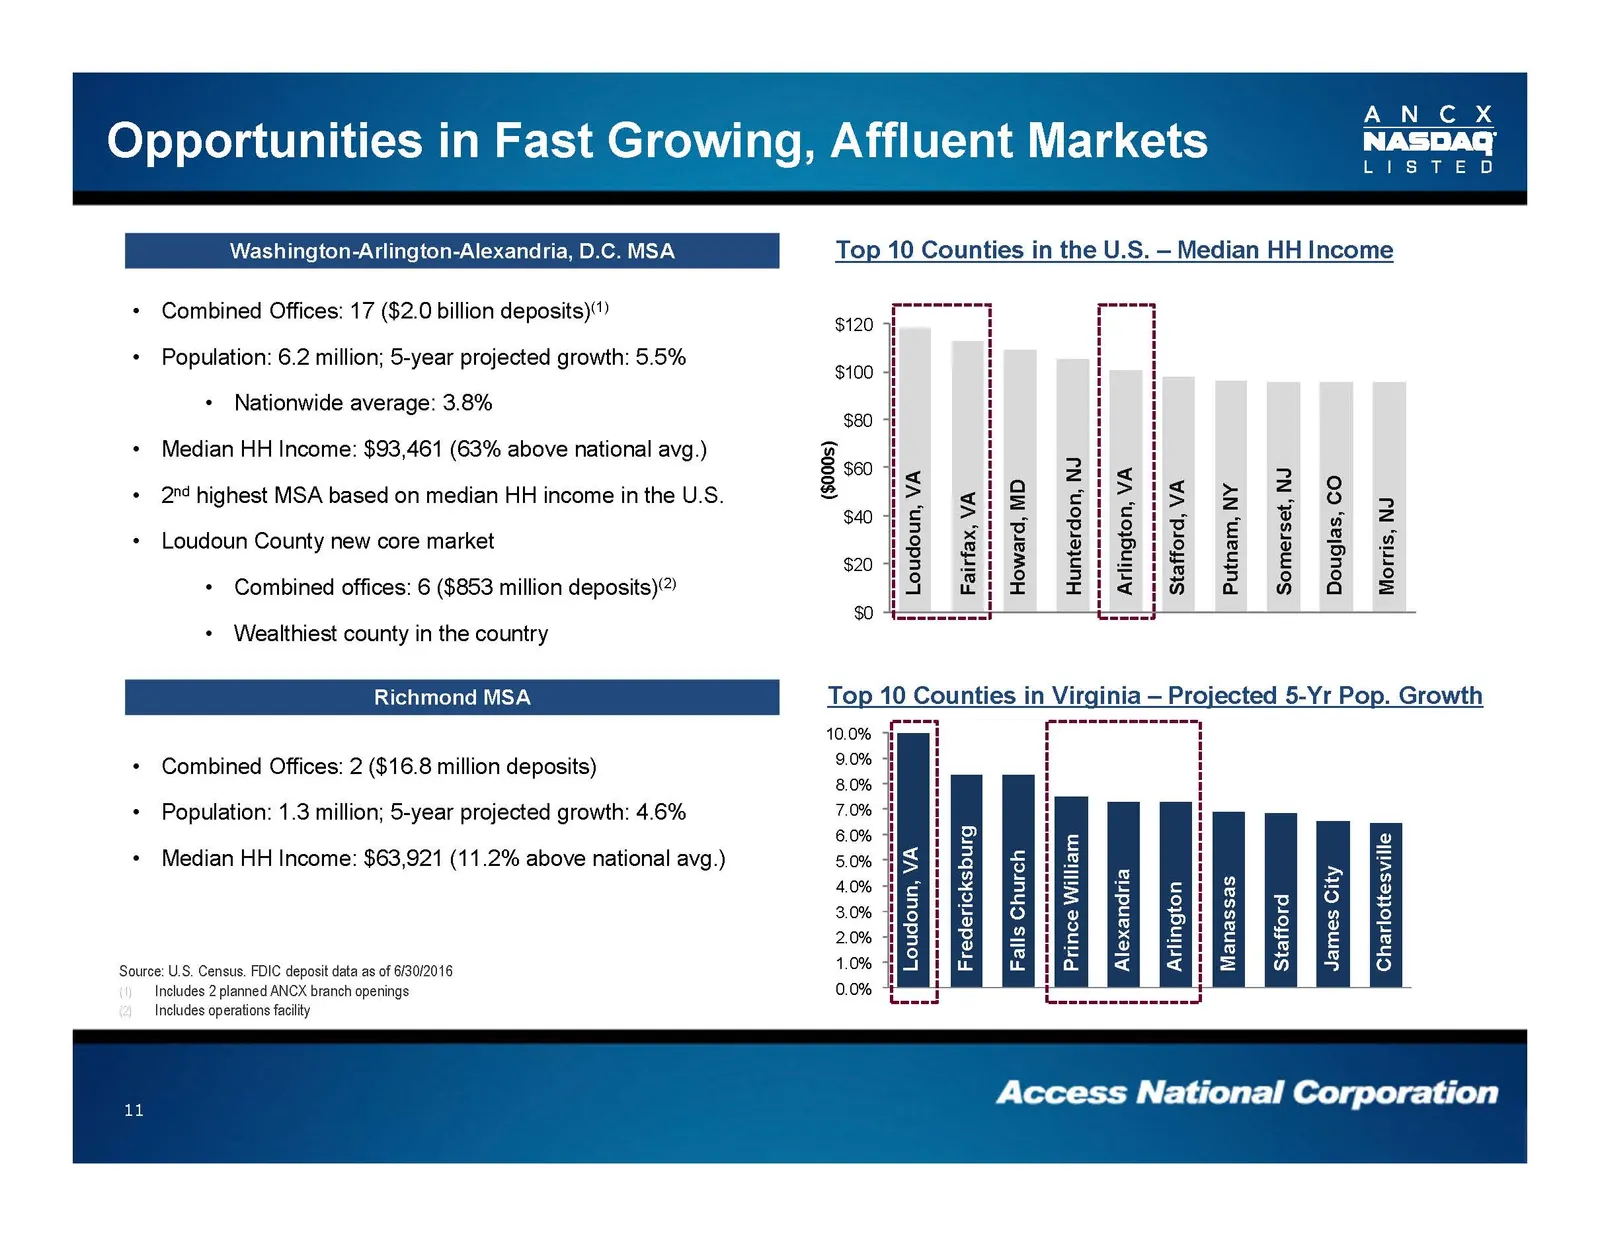
Slide 11: Washington-Arlington-Alexandria, D.C. MSA Top Counties in the U.S. — Median HH Income
Washington-Arlington-Alexandria, D.C. MSA Top 10 Counties in the U.S. — Median HH Income * Combined Offices: 17 ($2.0 billion deposits) $120 | H i + Population: 6.2 million; 5-year projected growth: 5.5% $100 H / H i + Nationwide average: 3.8% H H $60 H * Median HH Income: $93,461 (63% above nationa
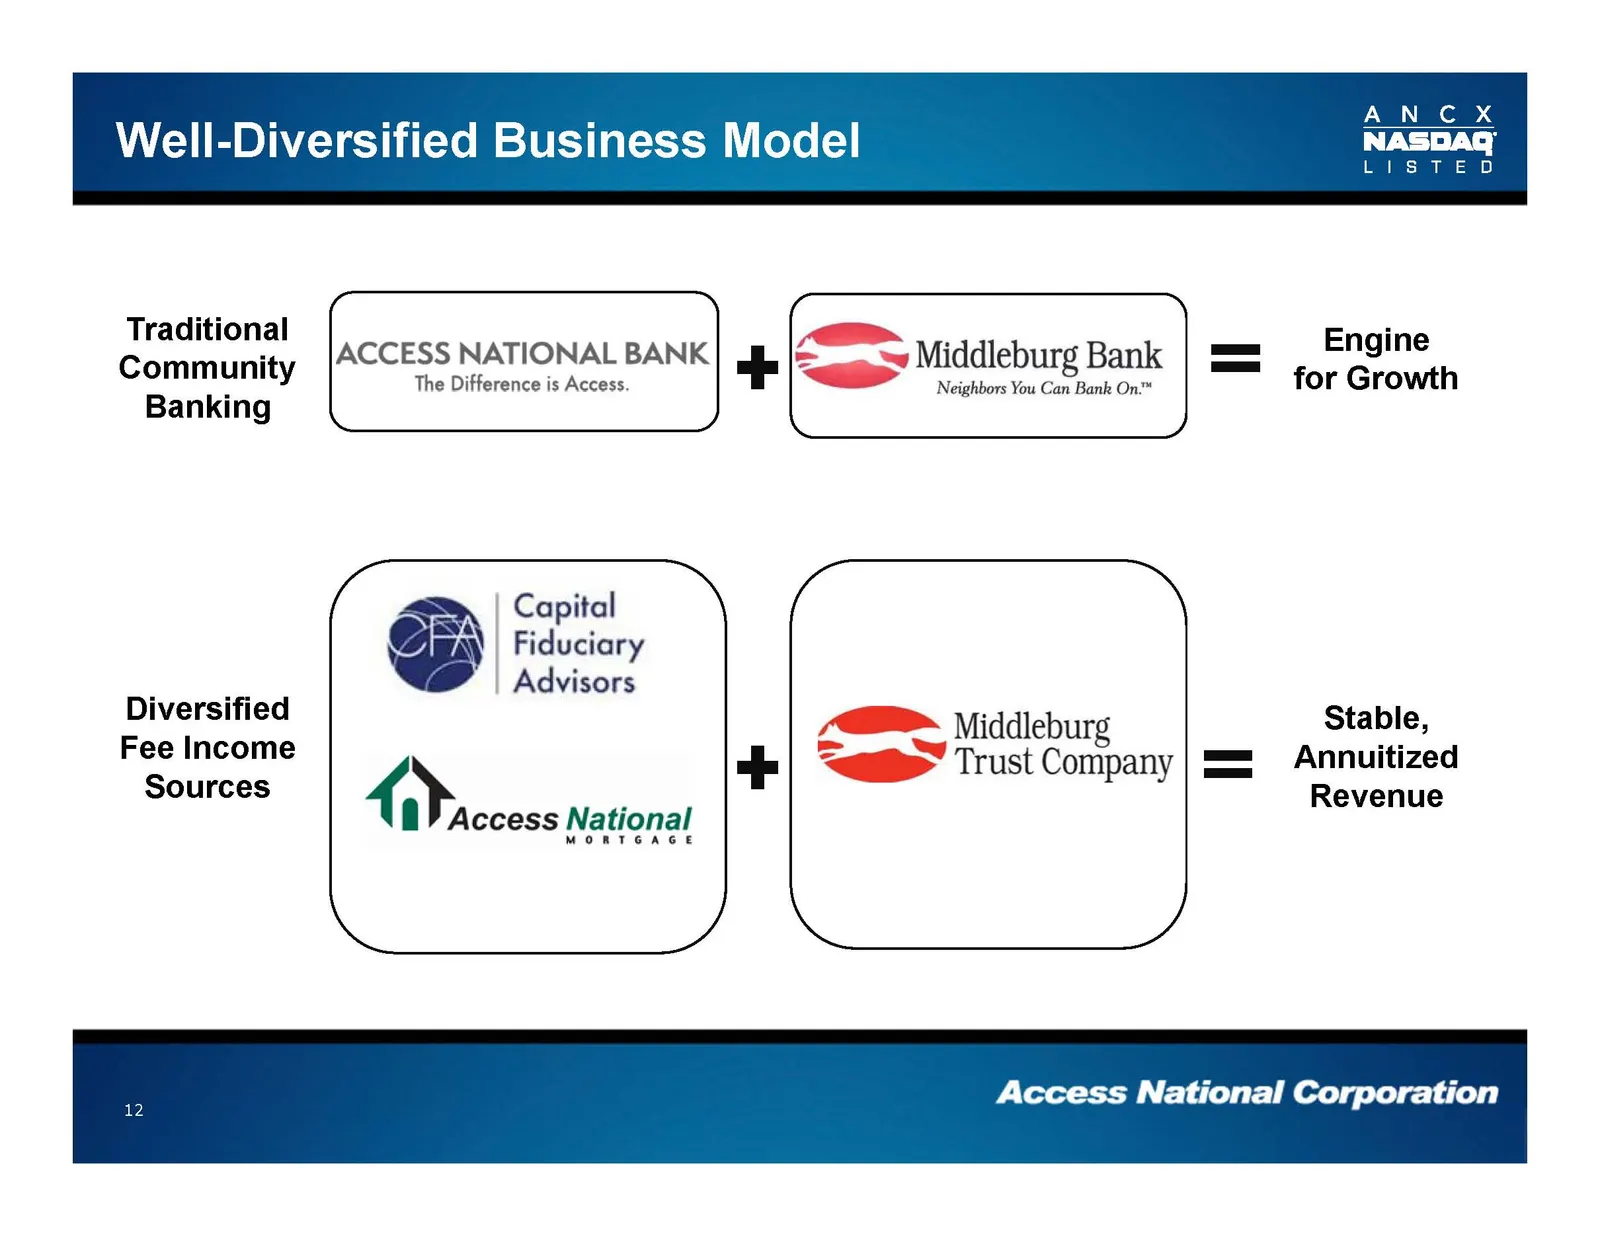
Slide 12: Well-Diversified Business Model
Well-Diversified Business Model Traditional ~~, Engine +, |ACCESS NATIONAL BANK| og | Middleburg Bank | = 9 Community The Difference is Access. + a Neighbors You re On™ for Growth anking Capital > CAA Fiduciary . . Advisors Fes income AP Middleburg Stable, | <a Trust Company | == = Annuitized Source
Slide 13: Attractive Fee Revenue Mix
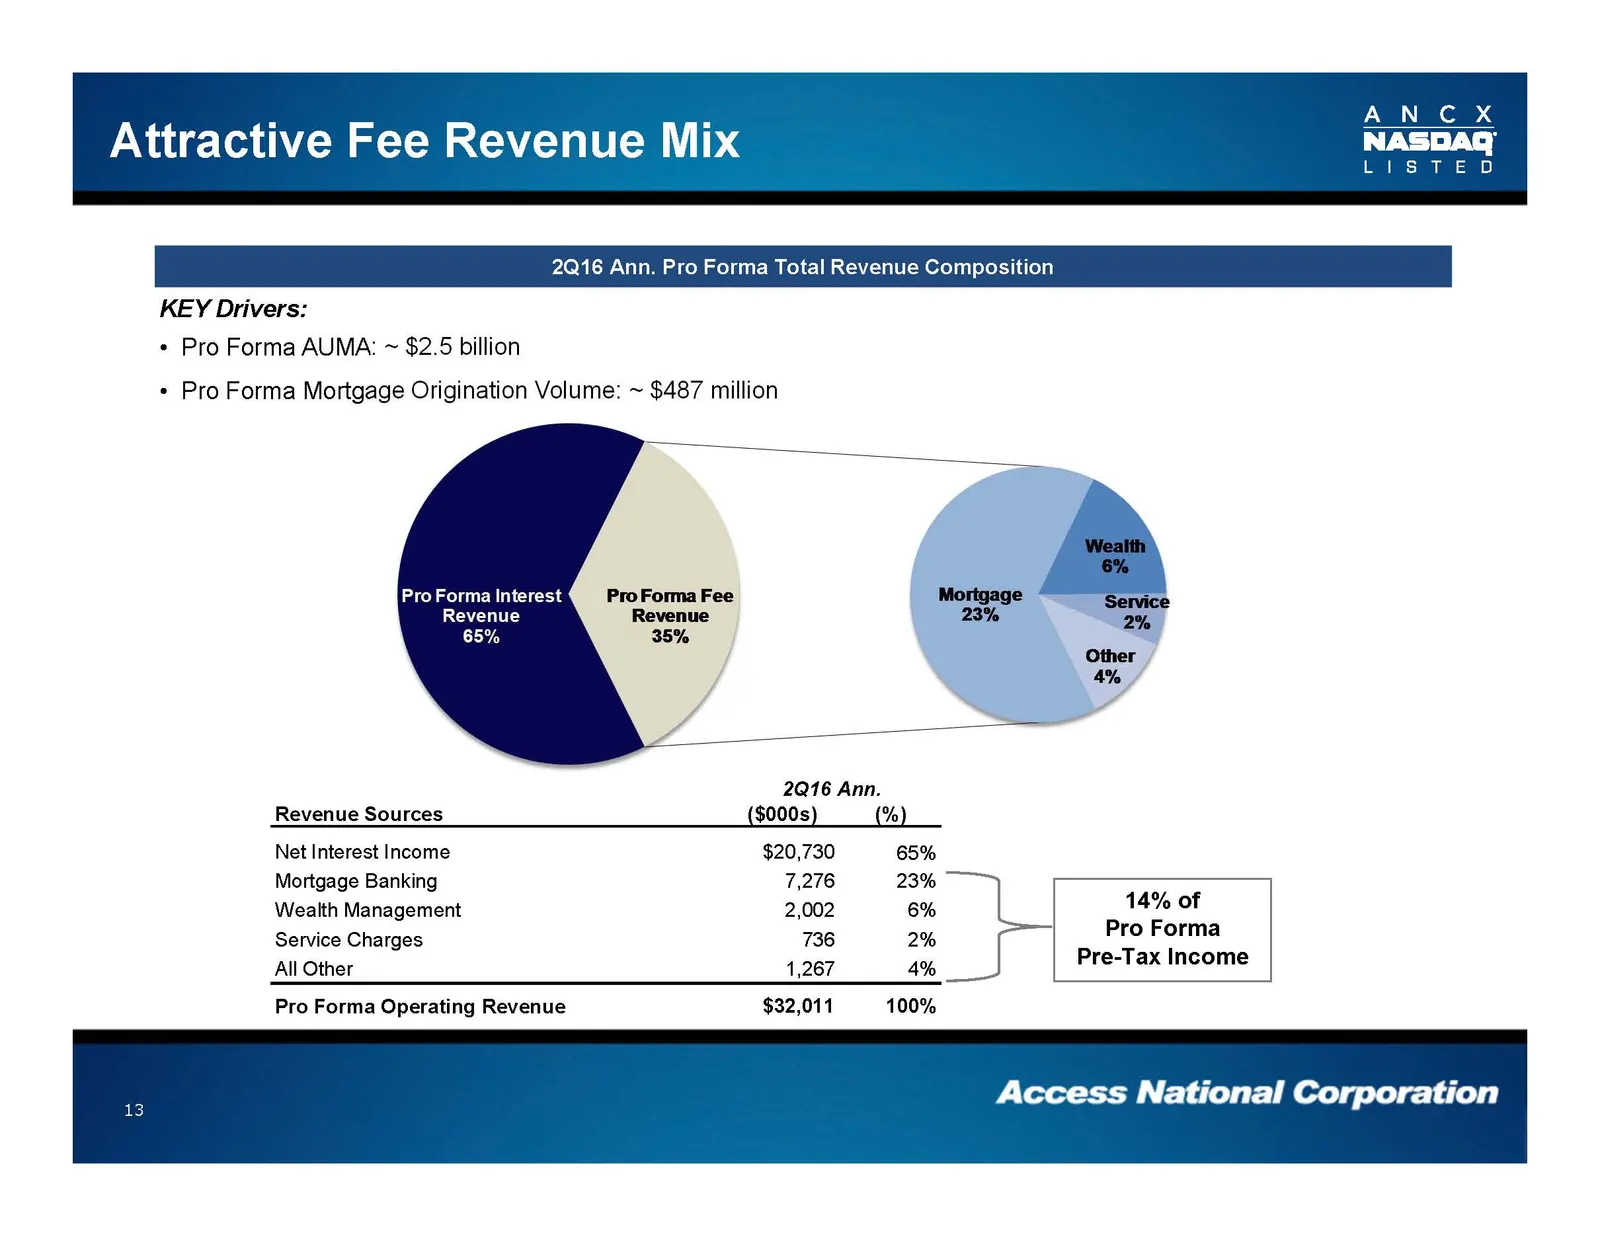
Attractive Fee Revenue Mix KEY Drivers: * Pro Forma AUMA: ~ $2.5 billion 2Q16 Ann. Pro Forma Total Revenue Composi ¢ Pro Forma Mortgage Origination Volume: ~ $487 million Pro Forma Interest ProForma Fee Mortgage e Revenue Revenue 23% 2% 65% 35% Other 4% 2Q16 Ann. Revenue Sources ($000s) (%) Net Inte
Slide 14: Pro Forma Loan and Deposit Composition
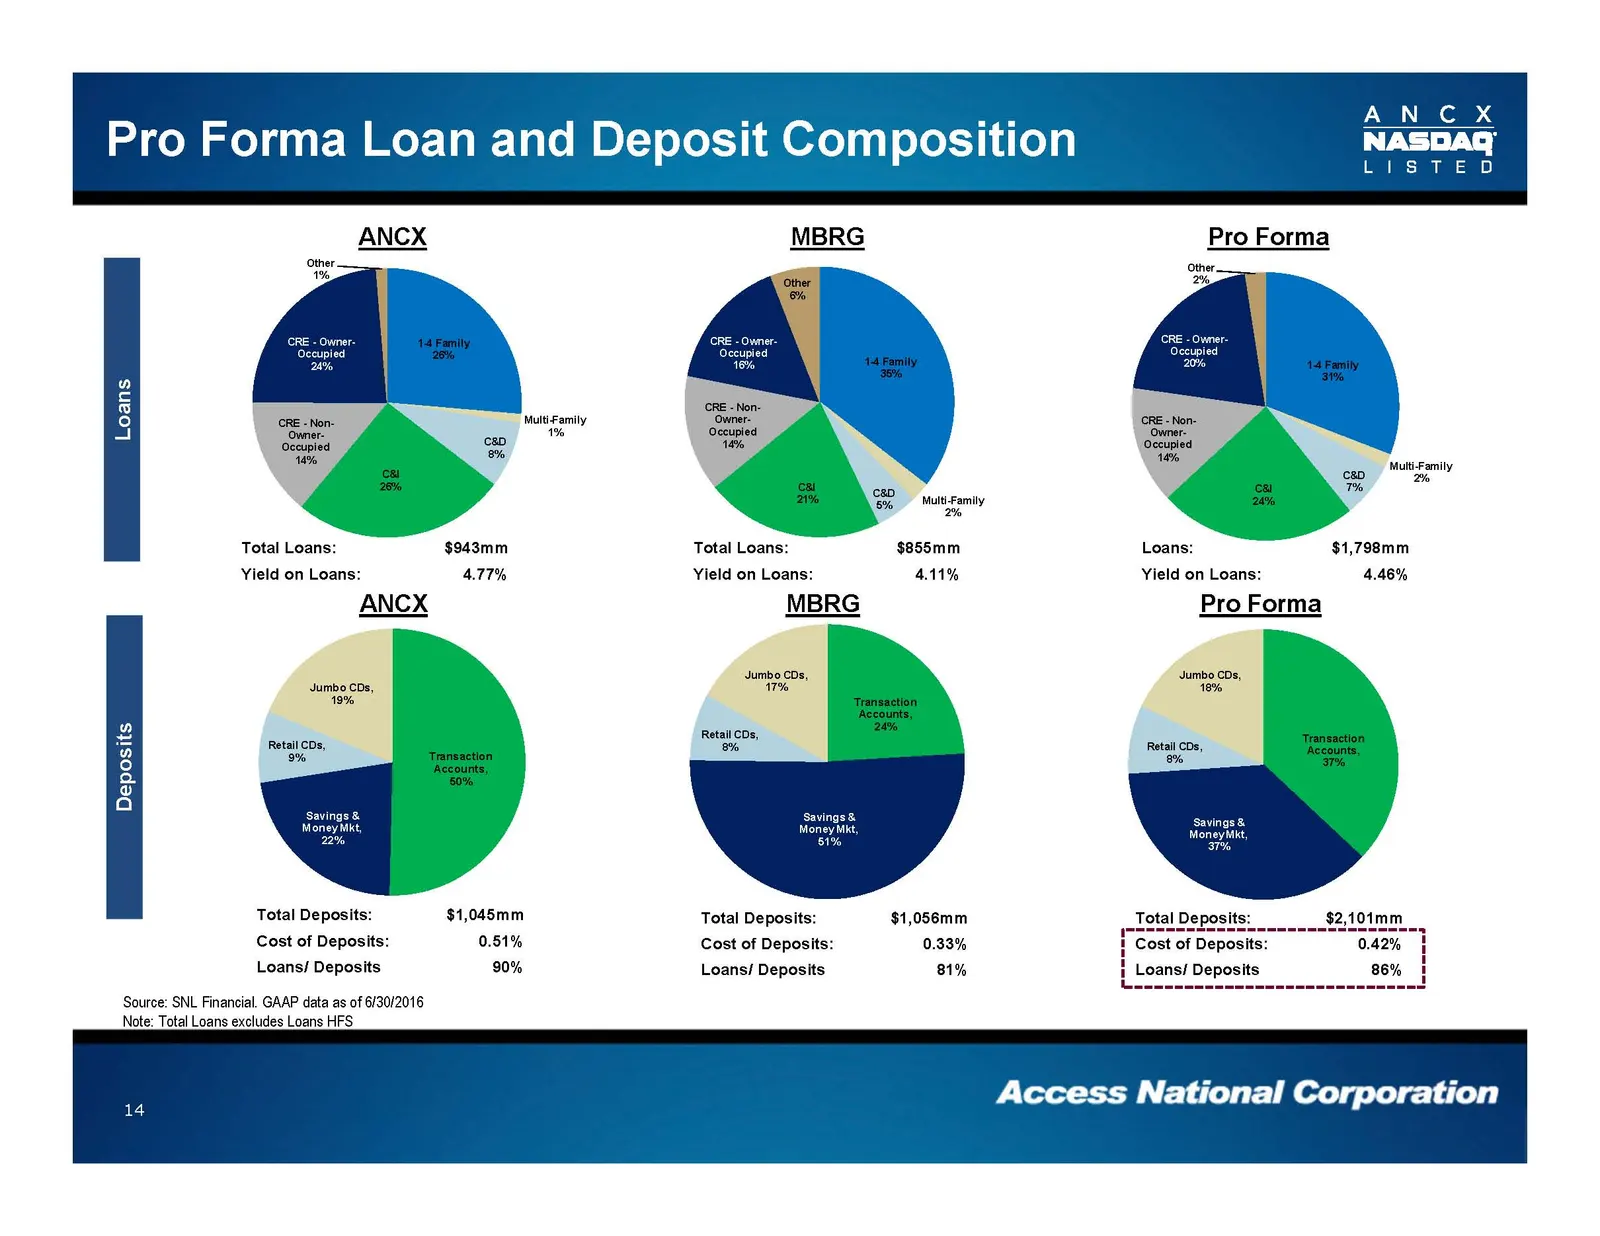
Pro Forma Loan and Deposit Composition a i= S 8 I] TotalLoans: -———-$943mm Yield on Loans: 4.77% ANCX Jumbo CDs, i 136 2 = Retall CDs, Q 9% ‘Transaction 3 iaecounts, 2 20% a Total Deposits: $1,045mm Cost of Deposits: 0.51% Loans/ Deposits 90% Source: SNL Financial. GAAP data as of 6/30/2016 Note: To
Slide 15: Pro Forma Company Joins High-Performing Peer Group
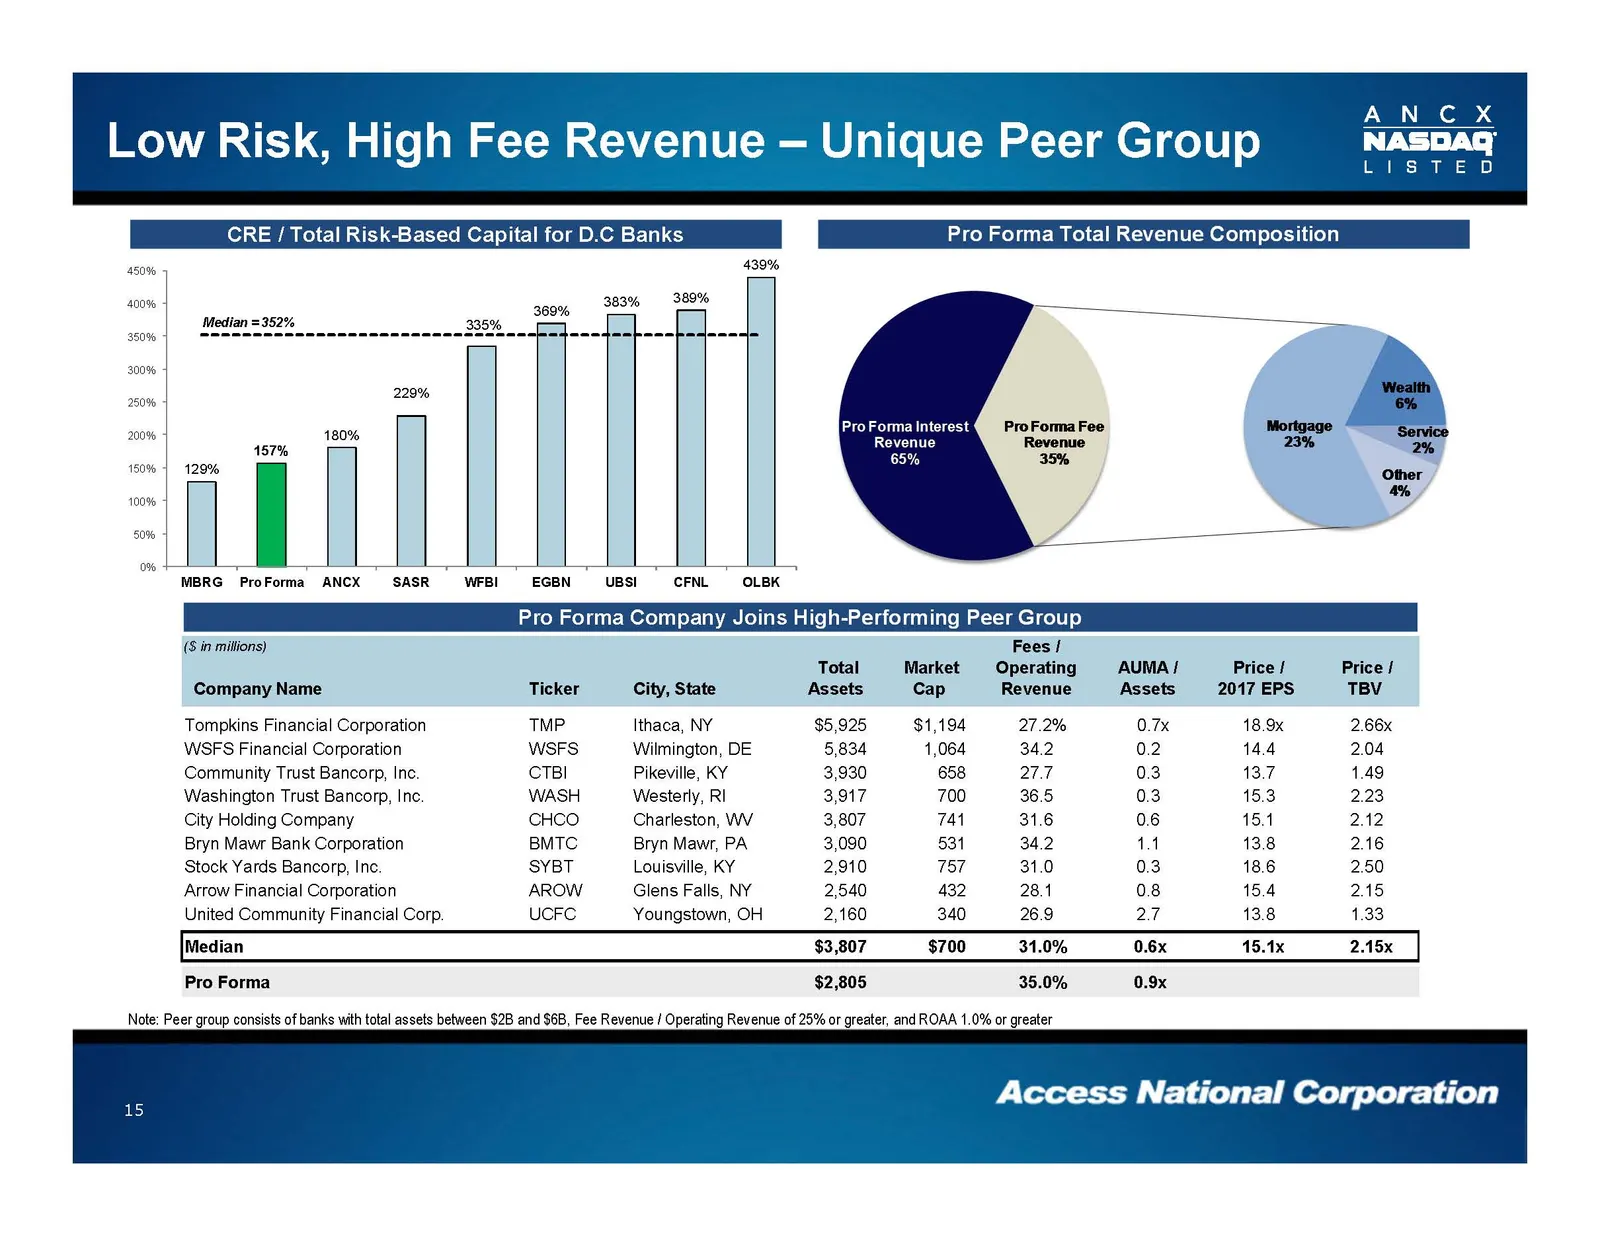
450% 40096 350% 300% 250% 200% 160% 100% 0% 439% | / 369% = Se Median =352% 335% a | 229% rs POCICCs® ProFormaFee Mortgage 157% Revenue Revenue 23% mw 65% 35% 129% Other | ° “MBRG Proforma ANCX SASR WFBI EGBN UBSI | CFNL OLBK — Pro Forma Company Joins Hig rforming Peer Group (3 in millions) Fees / T
Slide 16: Future Opportunities
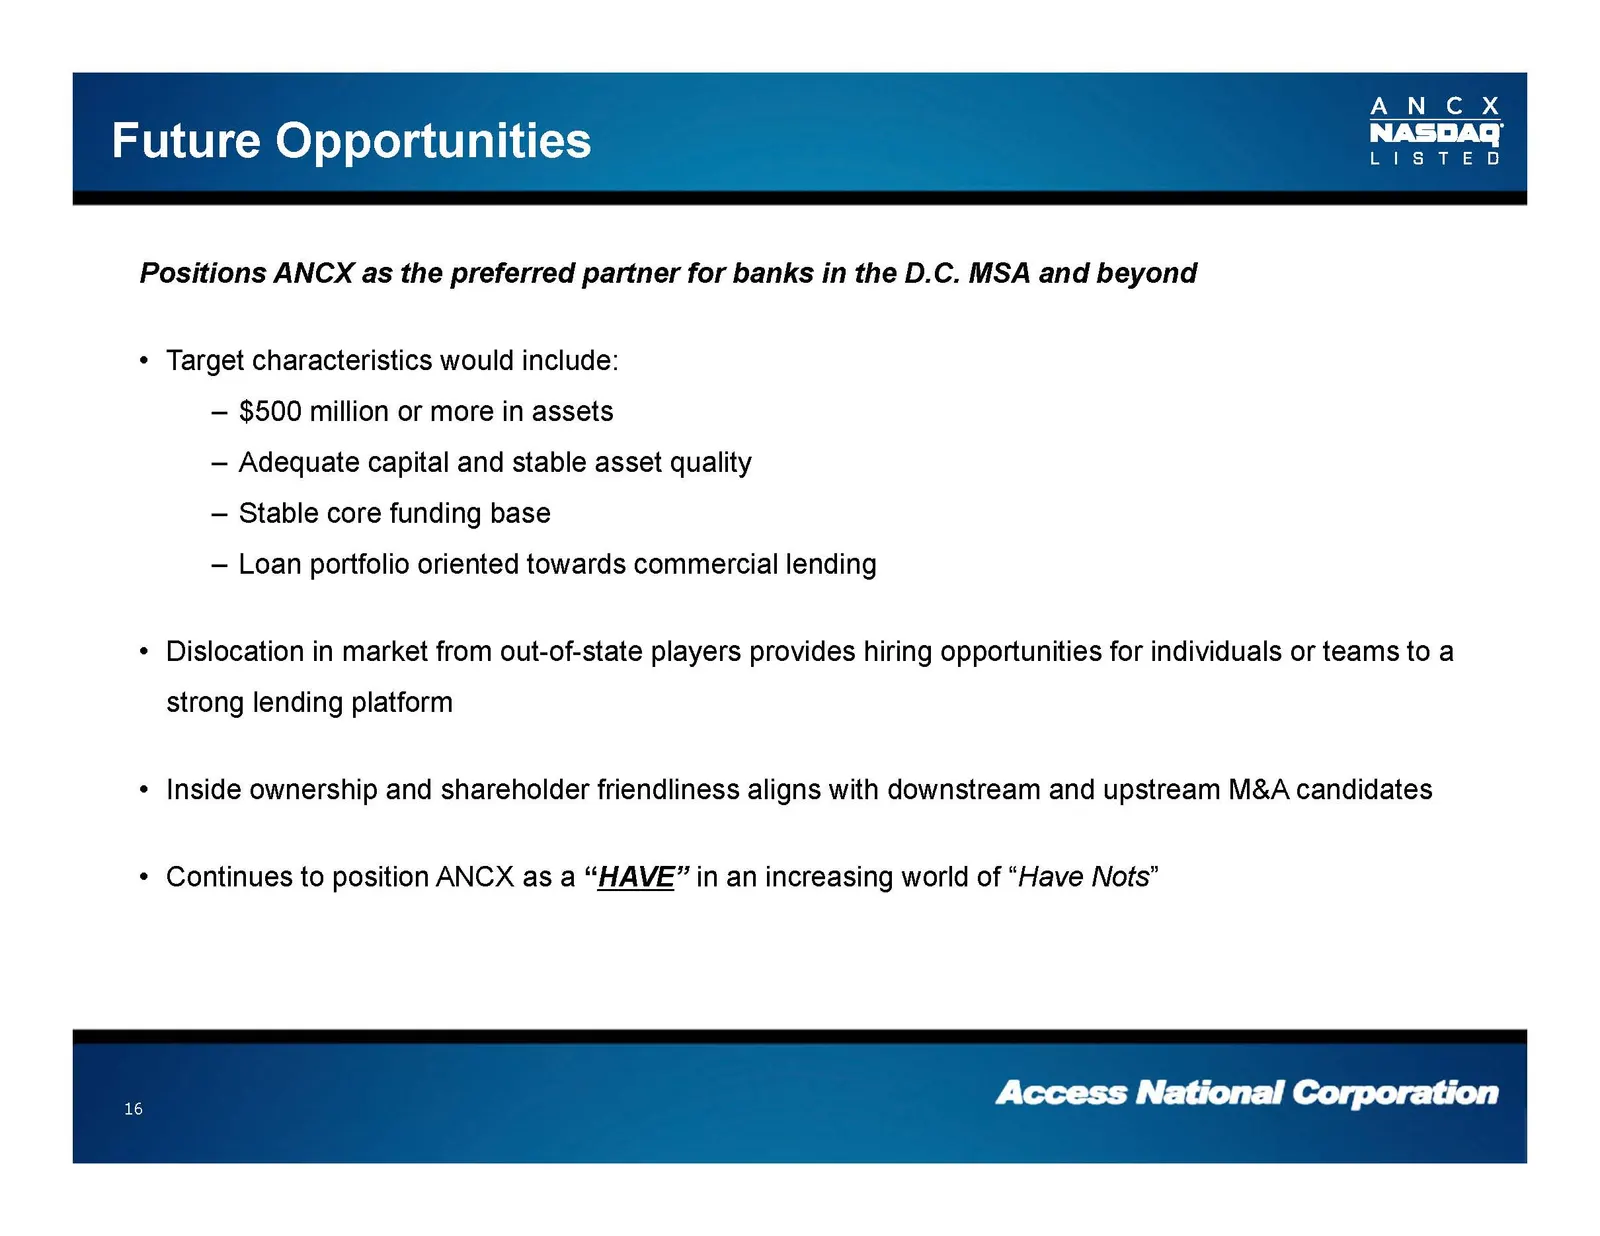
Future Opportunities Positions ANCX as the preferred partner for banks in the D.C. MSA and beyond Target characteristics would include: — $500 million or more in assets — Adequate capital and stable asset quality — Stable core funding base — Loan portfolio oriented towards commercial lending * Dislo
Slide 17: Transaction Summary
Transaction Summary v Merger of Complementary Business Models Delivers a better-scaled, comprehensive product and services set to Virginia communities Positions wealth management and trust business for expansion (pro forma AUMA of approximately $2.5 billion) Pro forma size enables deeper penetration
Slide 18: ANCX Ownership Presents Meaningful Upside
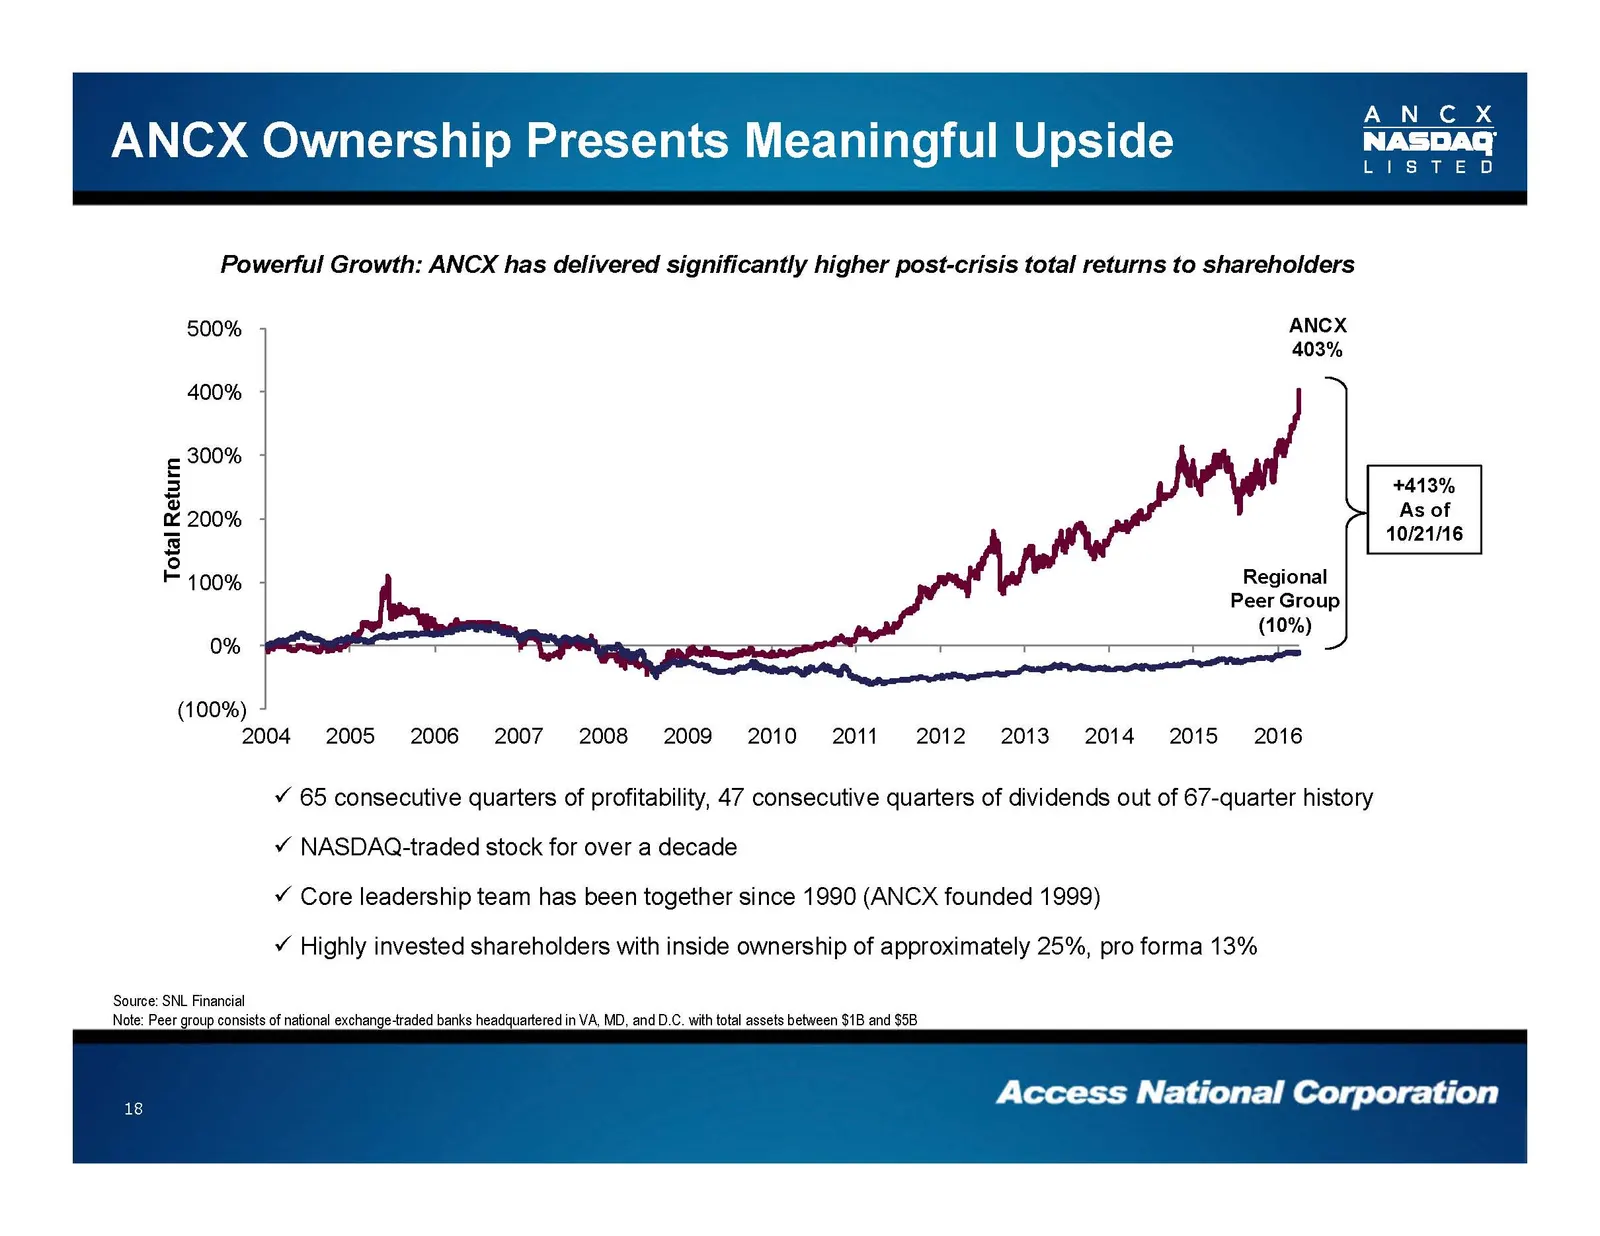
ANCX Ownership Presents Meaningful Upside Powerful Growth: ANCX has delivered significantly higher post-crisis total returns to shareholders 500% ANCX 403% 400% ¢ 300% 2 +413% 2 As of = 200% 10/216 ° : F 400% Regional Peer Group (10%) 0% r T T , — (100%) 2004 «2005 2006 2007 2008 2009 2010 2011 2012
Slide 19: Contacts
CONTACTS Visitors are welcome! Michael W. Clarke Meg M. Taylor, CPA President and CEO, Access National Corporation EVP, CFO CEO, Access National Bank megtaylor@AccessNationalBank.com mclarke@AccessNationalBank.com Sheila M. Linton VP, Corporate Secretary Investor Relations slinton@AccessNationalBank
Source: SEC EDGAR · 8-K filed Oct 24, 2016
More decks from Middleburg Financial Corp
 Shareholder Meeting (May 2016)24 slides · May 4, 2016
 Investor Presentation (September 2015)33 slides · Sep 18, 2015
 Shareholder Meeting (May 2015)24 slides · May 6, 2015
 Shareholder Meeting (May 2014)22 slides · May 9, 2014
 Shareholder Meeting (May 2013)26 slides · May 1, 2013
 Shareholder Meeting (May 2012)27 slides · May 2, 2012