INX — Kaufman Brothers Conference 2007
28 slides from INX's conference presentation, May 16, 2007
Slide 1: Kaufman Brothers Conference
Kaufman Brothers Conference Mark Hilz President & COO May 16, 2007 INX Inc. Nasdaq: INXI www.INXI.com
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, including future operating results expectations. Statements associated with words such as “anticipate,” “believe,” “expect,” “hope,” “should,
Slide 3: INX Inc. (Nasdaq: INXI)
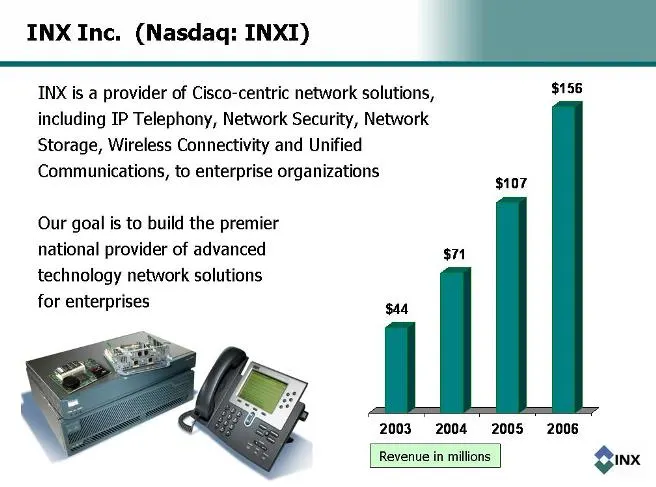
INX Inc. (Nasdaq: INXI) $44 $71 $107 $156 2003 2004 2005 2006 INX is a provider of Cisco-centric network solutions, including IP Telephony, Network Security, Network Storage, Wireless Connectivity and Unified Communications, to enterprise organizations Our goal is to build the premier national provi
Slide 4: INX Inc. (Nasdaq: INXI)
INX Inc. (Nasdaq: INXI) NASDAQ: INXI Shares Outstanding: 6.7MM Float: 4.8MM Diluted shares: 7.7MM Diluted market cap: ~$77MM 90-day avg. volume: ~35,000 Headquarters: Houston, Texas Only public company focused on delivering Cisco IP Telephony to enterprises Profitable, with 3-year compound annual gr
Slide 5: Management
Management Jim Long – Chairman & CEO – founded the company in 1982. Mark Hilz – President & COO – experience as CEO of larger public company; acquisitions experience; served on INX board prior to joining management in July 2000. Brian Fontana – CFO – since January 2005; experience as CFO with larger
Slide 6: Mass Adoption Of IP Telephony By Enterprises Is Just Beginning
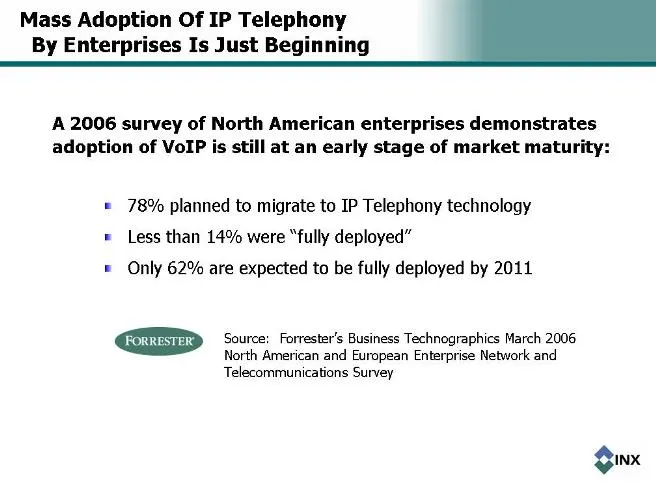
Mass Adoption Of IP Telephony By Enterprises Is Just Beginning A 2006 survey of North American enterprises demonstrates adoption of VoIP is still at an early stage of market maturity: 78% planned to migrate to IP Telephony technology Less than 14% were “fully deployed” Only 62% are expected to be fu
Slide 7: Increasing IP Network Importance & Complexity Drives Demand For INX Solutions
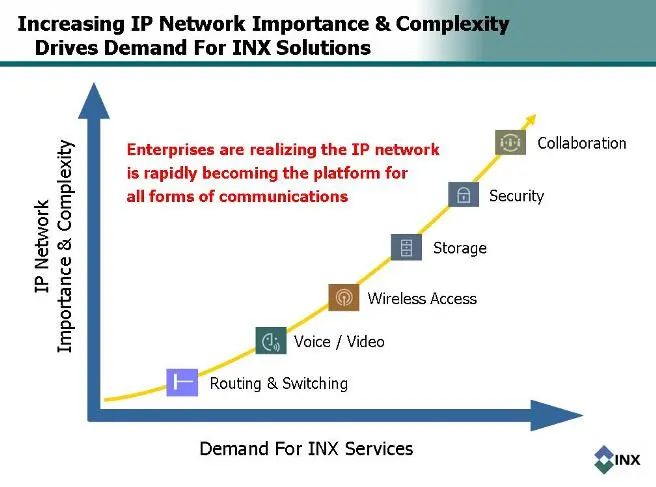
Increasing IP Network Importance & Complexity Drives Demand For INX Solutions Enterprises are realizing the IP network is rapidly becoming the platform for all forms of communications IP Network Importance & Complexity Collaboration Security Storage Wireless Access Voice Video Routing & Switching De
Slide 8: Revenue Sources & Mix
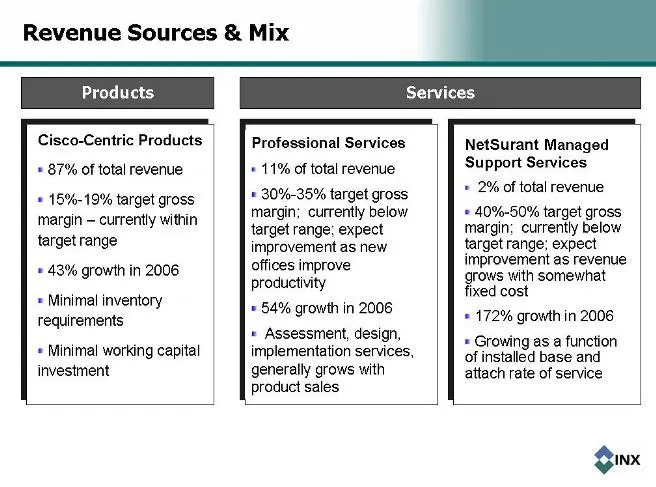
Revenue Sources & Mix Cisco-Centric Products 87% of total revenue 15%-19% target gross margin – currently within target range 43% growth in 2006 Minimal inventory requirements Minimal working capital investment Professional Services 11% of total revenue 30%-35% target gross margin; currently below t
Slide 9: NetSurant Managed Support Services A Competitive Advantage
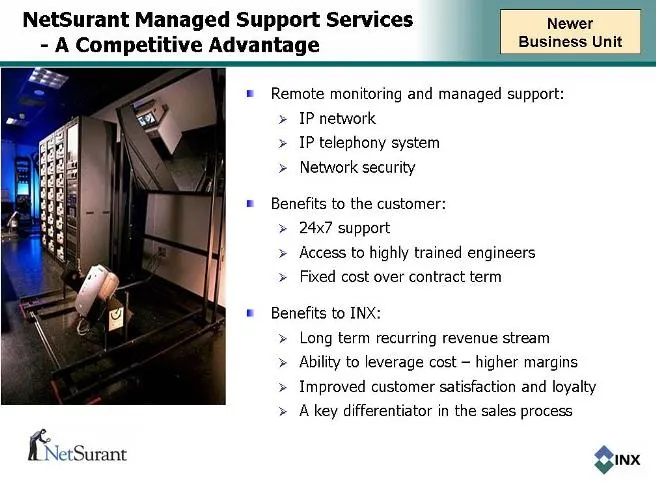
NetSurant Managed Support Services A Competitive Advantage Remote monitoring and managed support: IP network IP telephony system Network security Benefits to the customer: 24x7 support Access to highly trained engineers Fixed cost over contract term Benefits to INX: Long term recurring revenue strea
Slide 10: NetSurant Managed Support Services Recurring Service Revenue
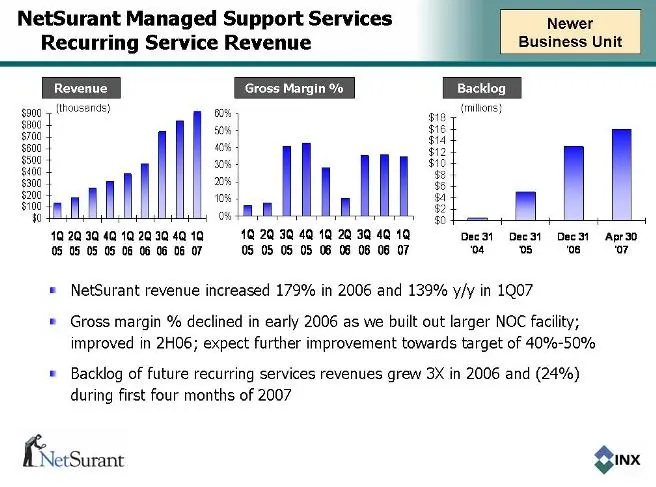
NetSurant Managed Support Services Recurring Service Revenue $0 $100 $200 $300 $400 $500 $600 $700 $800 $900 1Q 05 2Q 05 3Q 05 4Q 05 1Q 06 2Q 06 3Q 06 4Q 06 1Q 07 $0 $2 $4 $6 $8 $10 $12 $14 $16 $18 Dec 31 '04 Dec 31 '05 Dec 31 '06 Apr 30 '07 NetSurant revenue increased 179% in 2006 and 139% y/y in 1
Slide 11: RouteStep Communications Business Unit
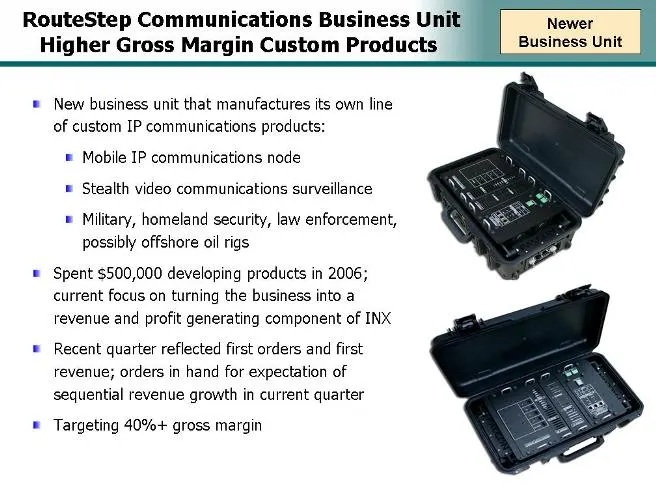
RouteStep Communications Business Unit Higher Gross Margin Custom Products New business unit that manufactures its own line of custom IP communications products: Mobile IP communications node Stealth video communications surveillance Military, homeland security, law enforcement, possibly offshore oi
Slide 12: Our Longer-Term Financial Expectations
Our Longer-Term Financial Expectations We believe the industry we are participating in is growing at 20%-30% We expect to grow faster than industry growth rates over the long run by: gaining market share because of our focus and expertise increasing revenue per customer by selling to larger customer
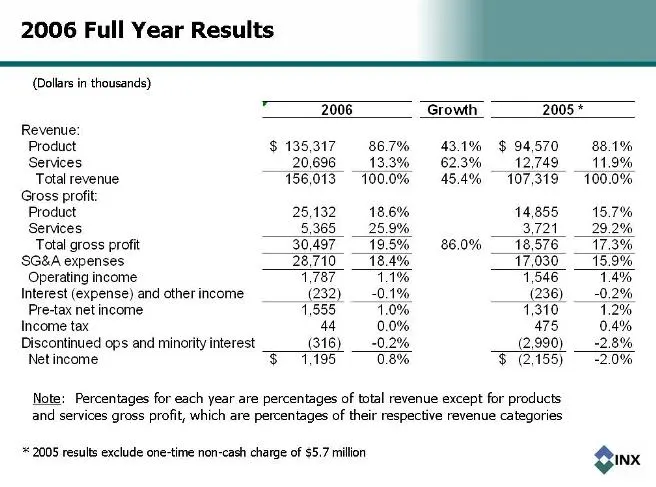
Slide 13: 2006 Full Year Results
2006 Full Year Results (Dollars in thousands) 2006 Growth 2005 * Revenue: Product $135,317 86.7% 43.1% $94,570 88.1% Services 20,696 13.3% 62.3% 12,749 11.9% Total revenue ‘ .0% 45.4% — 107; 100.0% Gross profit: Product 25,132 18.6% 14855 15.7% Services 5.365 25.9% 3,721 _ 29.2% Total gross profit 3
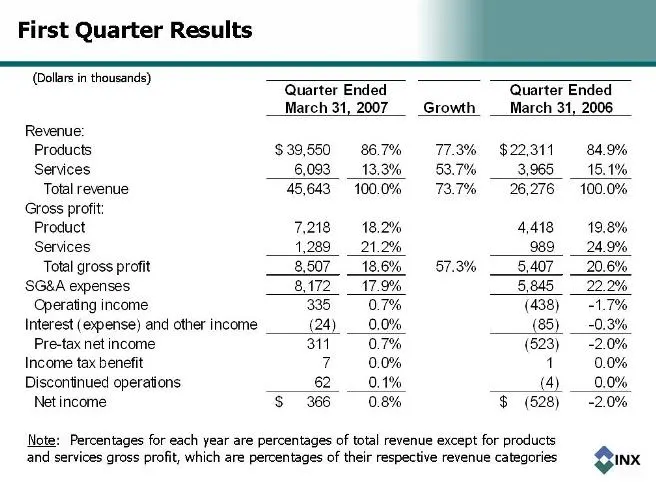
Slide 14: First Quarter Results
First Quarter Results Growth Revenue: Products 39,550 $ 86.7% 77.3% 22,311 $ 84.9% Services 6,093 13.3% 53.7% 3,965 15.1% Total revenue 45,643 100.0% 73.7% 26,276 100.0% Gross profit: Product 7,218 18.2% 4,418 19.8% Services 1,289 21.2% 989 24.9% Total gross profit 8,507 18.6% 57.3% 5,407 20.6% SG&A
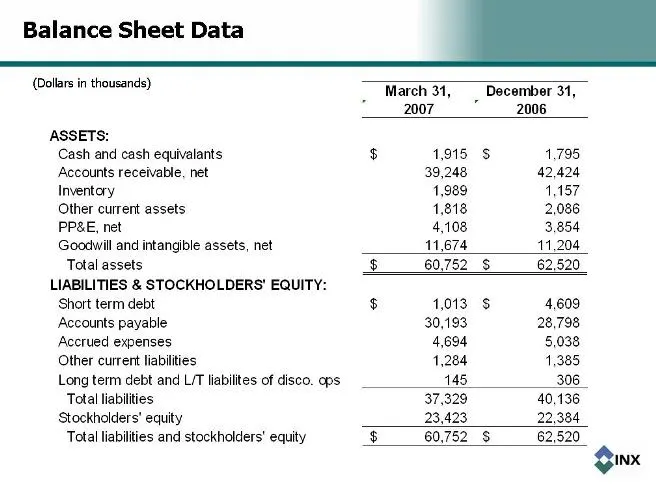
Slide 15: Balance Sheet Data
Balance Sheet Data March 31, December 31, 2007 2006 ASSETS: Cash and cash equivalants 1,915 $ 1,795 $ Accounts receivable, net 39,248 42,424 Inventory 1,989 1,157 Other current assets 1,818 2,086 PP&E, net 4,108 3,854 Goodwill and intangible assets, net 11,674 11,204 Total assets 60,752 $ 62,520 $ L
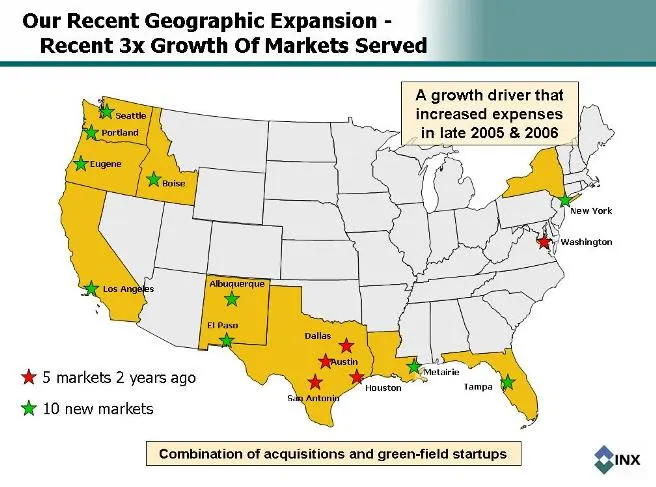
Slide 16: Our Recent Geographic Expansion
Our Recent Geographic Expansion - Recent 3x Growth Of Markets Served A growth driver that increased expenses in late 2005 & 2006 Seattle Portland Eugene Boise Los Angeles Albuquerque El Paso Dallas Austin San Antonio Houston Metairie Tampa Washington New York 5 markets 2 years ago 10 new markets Com
Slide 17: Increasing Number and Size of Customers
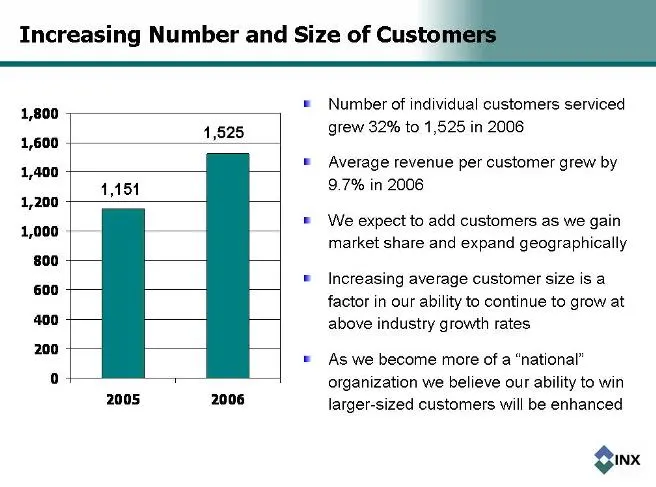
Increasing Number and Size of Customers 0 200 400 600 800 1,000 1,200 1,400 1,600 1,800 2005 2006 Number of individual customers serviced grew 32% to 1,525 in 2006 Average revenue per customer grew by 9.7% in 2006 We expect to add customers as we gain market share and expand geographically Increasin
Slide 18: Blue Chip Customer Base (page 1 of 2)
Blue Chip Customer Base (page 1 of 2) Corporate Contractor to Other Cisco Partners
Slide 19: Blue Chip Customer Base (page 2 of 2)
Blue Chip Customer Base (page 2 of 2) Government Education (Deemphasized In 2006)
Slide 20: Planned Decrease In Education Business Masked Strength Of Business In 2006
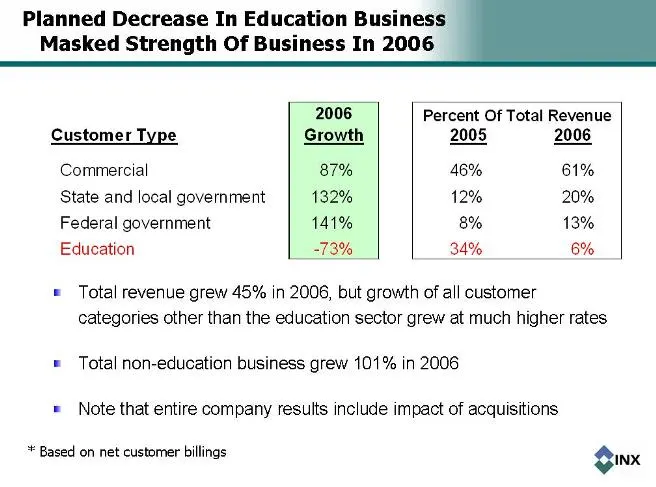
Planned Decrease In Education Business Masked Strength Of Business In 2006 Customer Type Commercial 87% 46% 61% State and local government 132% 12% 20% Federal government 141% 8% 13% Education -73% 34% 6% Growth Percent Of Total Revenue 2006 2005 2006 Total revenue grew 45% in 2006, but growth of al
Slide 21: Acquisitions
Acquisitions 3 acquisitions in past 2 years (all more than 1 year ago) All acquisitions have been successful and accretive We add value to acquired operations due to our balance sheet, industry focus and expertise and relationship with Cisco For most recently reported quarter, revenue from the acqui
Slide 22: Our Two 2005 Acquisitions Performed Well
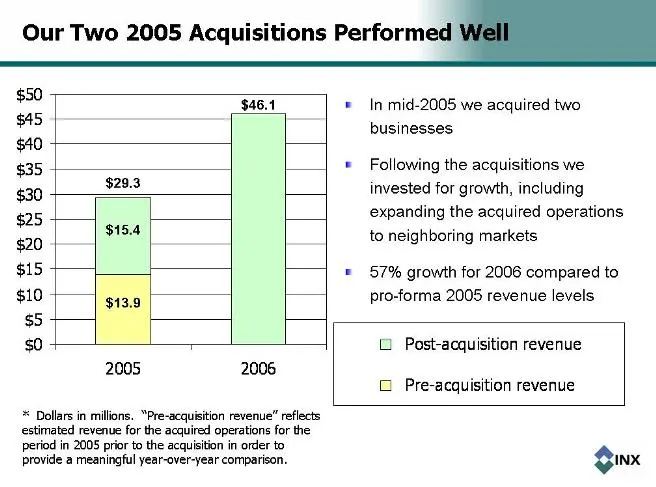
Our Two 2005 Acquisitions Performed Well $0 $5 $10 $15 $20 $25 $30 $35 $40 $45 $50 2005 2006 Post-acquisition revenue Pre-acquisition revenue In mid-2005 we acquired two businesses Following the acquisitions we invested for growth, including expanding the acquired operations to neighboring markets 5
Slide 23: Sources Of Revenue Growth in Q1-07
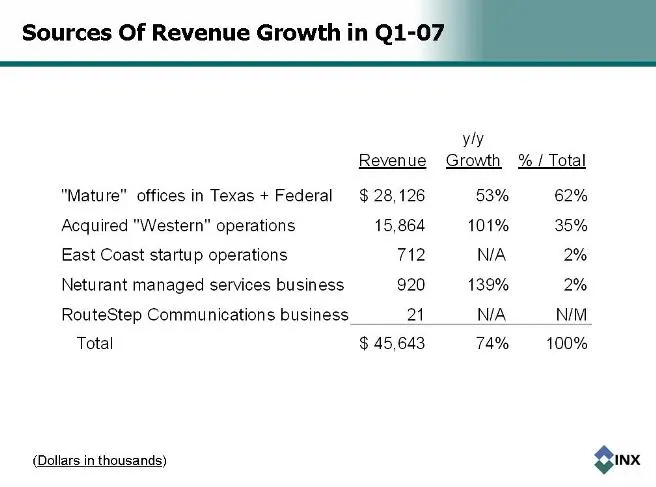
Sources Of Revenue Growth in Q1-07 (Dollars in thousands) y/y Revenue Growth % / Total "Mature" offices in Texas + Federal 28,126 $ 53% 62% Acquired "Western" operations 15,864 101% 35% East Coast startup operations 712 N/A 2% Neturant managed services business 920 139% 2% RouteStep Communications b
Slide 24: Business Component Operating Profitability
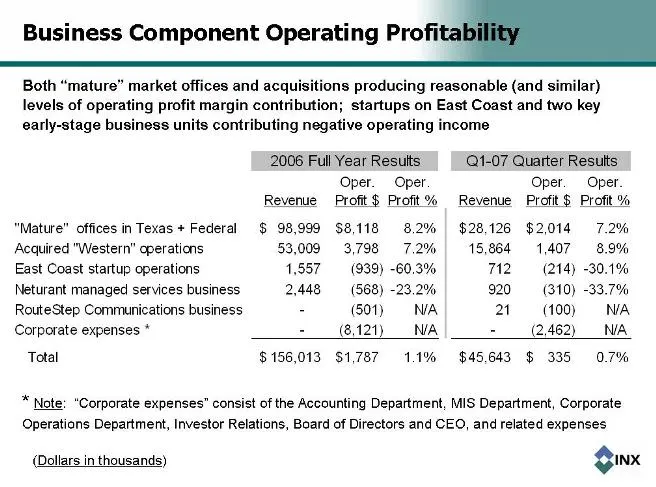
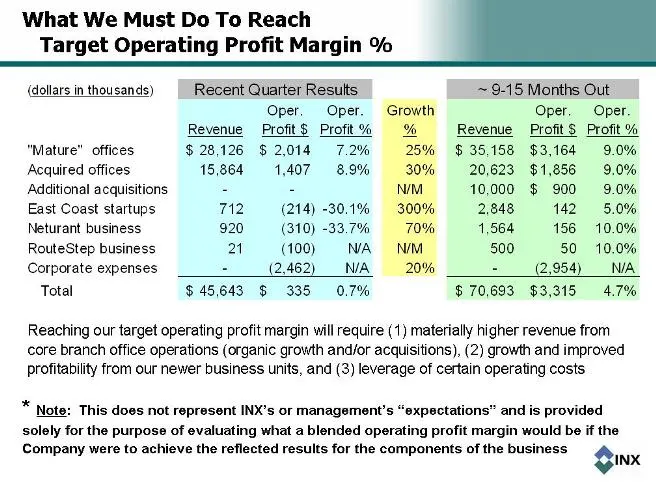
Business Component Operating Profitability Both “mature” market offices and acquisitions producing reasonable (and similar) levels of operating profit margin contribution; startups on East Coast and two key early-stage business units contributing negative operating income Note : “Corporate expenses”
Slide 25: What We Must Do To Reach Target Operating Profit Margin %
What We Must Do To Reach Target Operating Profit Margin % (dollars in thousands) Oper. Oper. Growth Oper. Oper. Revenue Profit $ Profit % % Revenue Profit $ Profit % "Mature" offices 28,126 $ 2,014 $ 7.2% 25% 35,158 $ 3,164 $ 9.0% Acquired offices 15,864 1,407 8.9% 30% 20,623 1,856 $ 9.0% Additional
Slide 26: Operating Expenses / Sales %
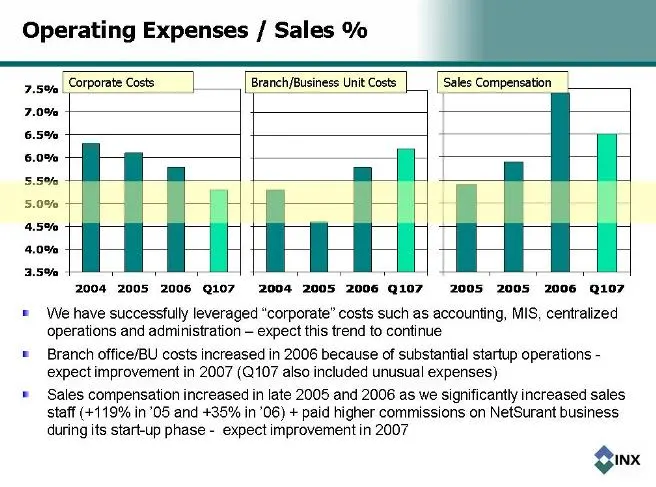
Operating Expenses / Sales % 3.5% 4.0% 4.5% 5.0% 5.5% 6.0% 6.5% 7.0% 7.5% 2004 2005 2006 Q107 Sales Compensation 3.5% 4.0% 4.5% 5.0% 5.5% 6.0% 6.5% 7.0% 7.5% 2004 2005 2006 Q107 Corporate Costs Branch/Business Unit Costs 2005 2005 2006 Q107 We have successfully leveraged “corporate” costs such as ac
Slide 27: Financial Highlights
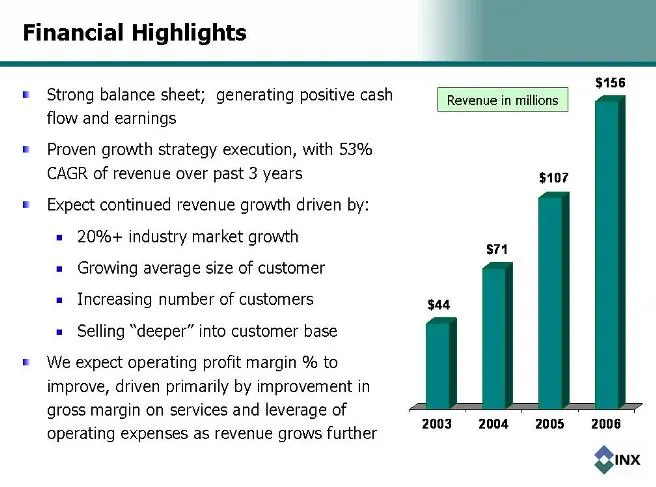
Financial Highlights Strong balance sheet; generating positive cash flow and earnings Proven growth strategy execution, with 53% CAGR of revenue over past 3 years Expect continued revenue growth driven by: 20%+ industry market growth Growing average size of customer Increasing number of customers Se
Slide 28: Stockholder Advantages
Stockholder Advantages Mass implementation of VoIP technology by enterprises should drive industry growth IP communications is a multi-billion dollar, rapidly growing market Cisco is the dominant manufacturer and INX is the only pure play public company focused on delivering Cisco VoIP solutions for
Source: SEC EDGAR · 8-K filed May 16, 2007
More decks from INX Inc
 Merger or Acquisition (November 2011)10 slides · Nov 1, 2011
 Rodman & Renshaw Global Investment Conference 201120 slides · Sep 13, 2011
 Shareholder Meeting (July 2011)15 slides · Jul 19, 2011
 Q1 2011 Earnings Presentation15 slides · Jul 13, 2011
 FY2010 Earnings Presentation28 slides · Jun 6, 2011
 Corporate Update (November 2010)24 slides · Nov 10, 2010