Carmila SA · EURONEXT:CARM
Carmila SA — H1 2020 Earnings Presentation
43 slides from Carmila SA's earnings presentation, Jul 30, 2020
Slide 1: 2020 half-year results
3 0 J u l y 2 0 2 0 2020 half-year results
Slide 2: Introduction
Introduction 2 Alcobendas - Madrid Bay 2- (Spain) France
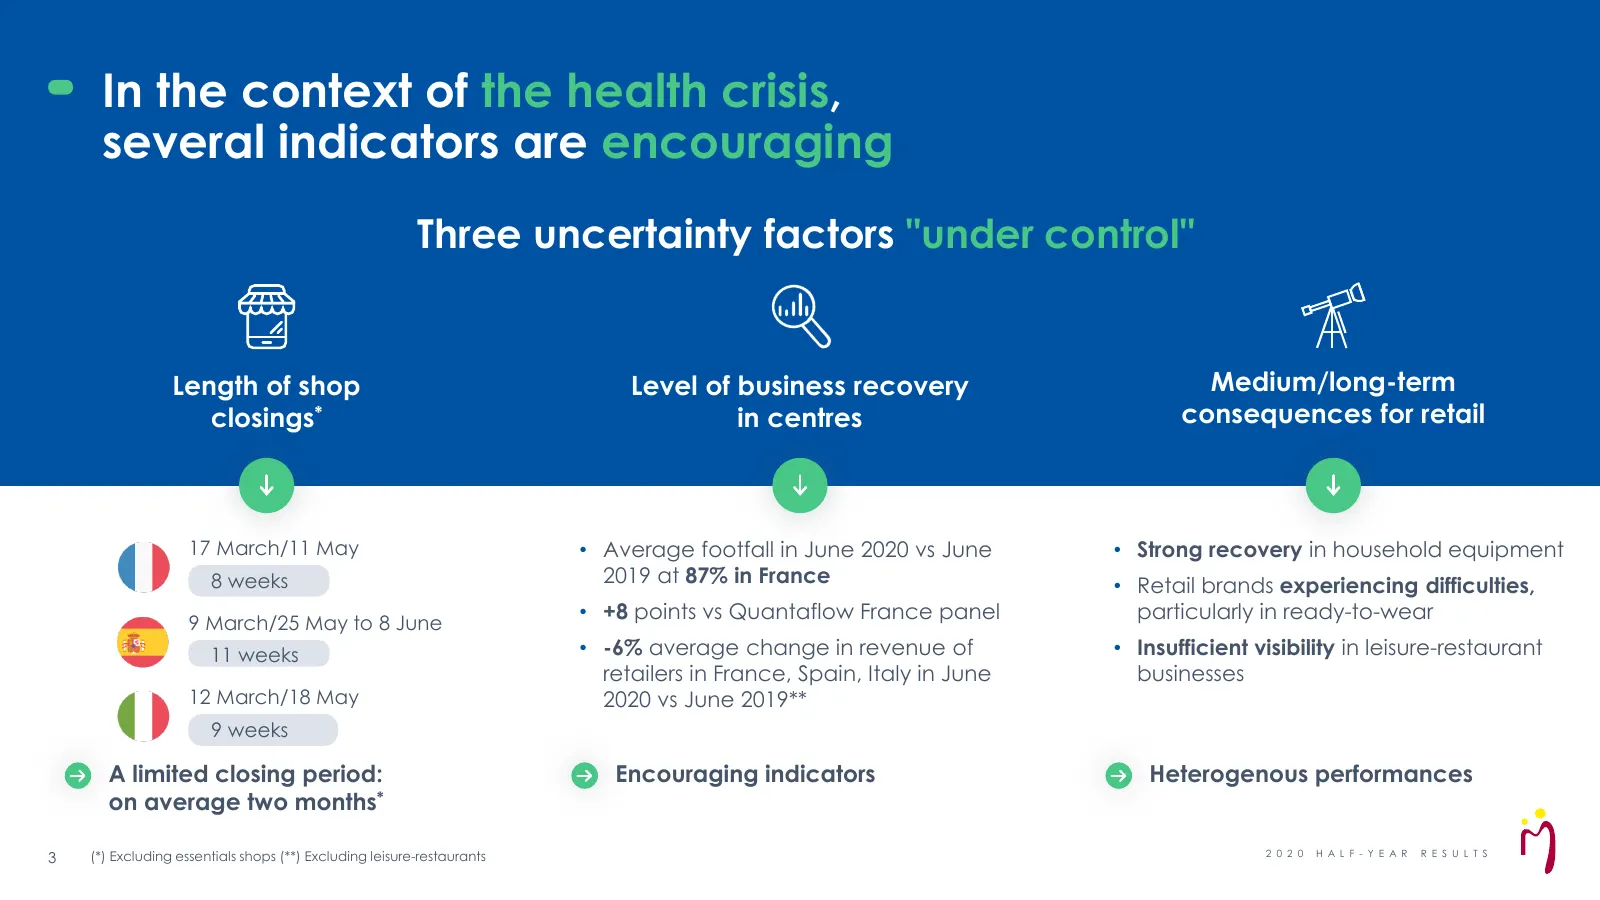
Slide 3: In the context of the health crisis, several indicators are encouraging
In the context of the health crisis, several indicators are encouraging Three uncertainty factors "under control" Length of shop Level of business recovery Medium/long-term closings* in centres consequences for retail 17 March/11 May • Average footfall in June 2020 vs June • Strong recovery in house
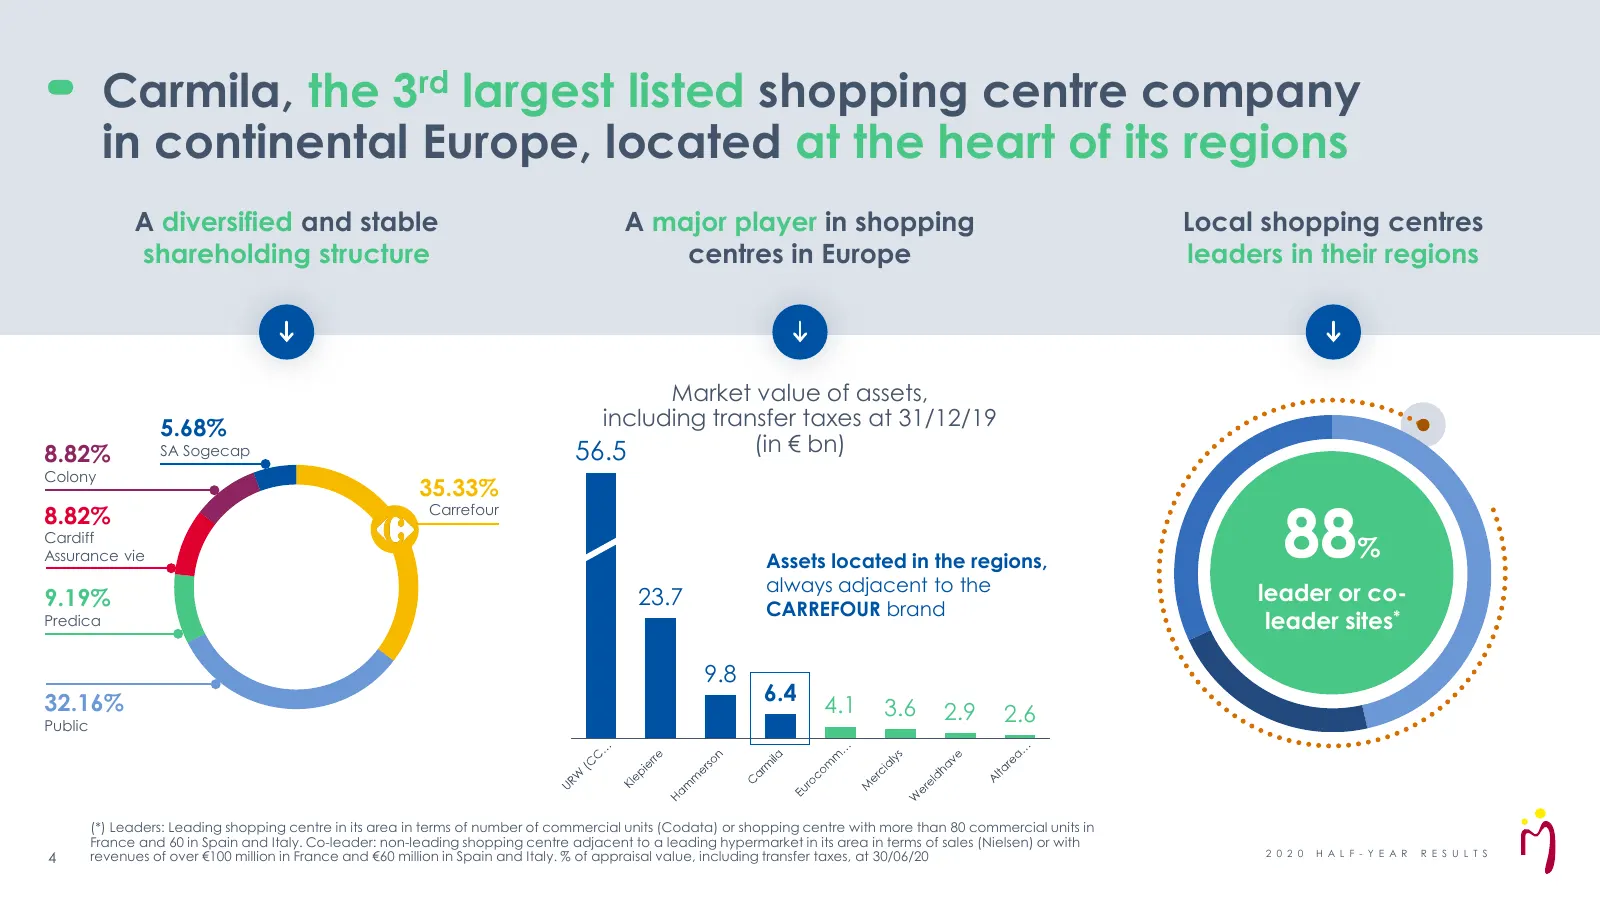
Slide 4: Carmila, the 3rd largest listed shopping centre company in continental Europe
Carmila, the 3rd largest listed shopping centre company in continental Europe, located at the heart of its regions A diversified and stable A major player in shopping Local shopping centres shareholding structure centres in Europe leaders in their regions Market value of assets, including transfer t
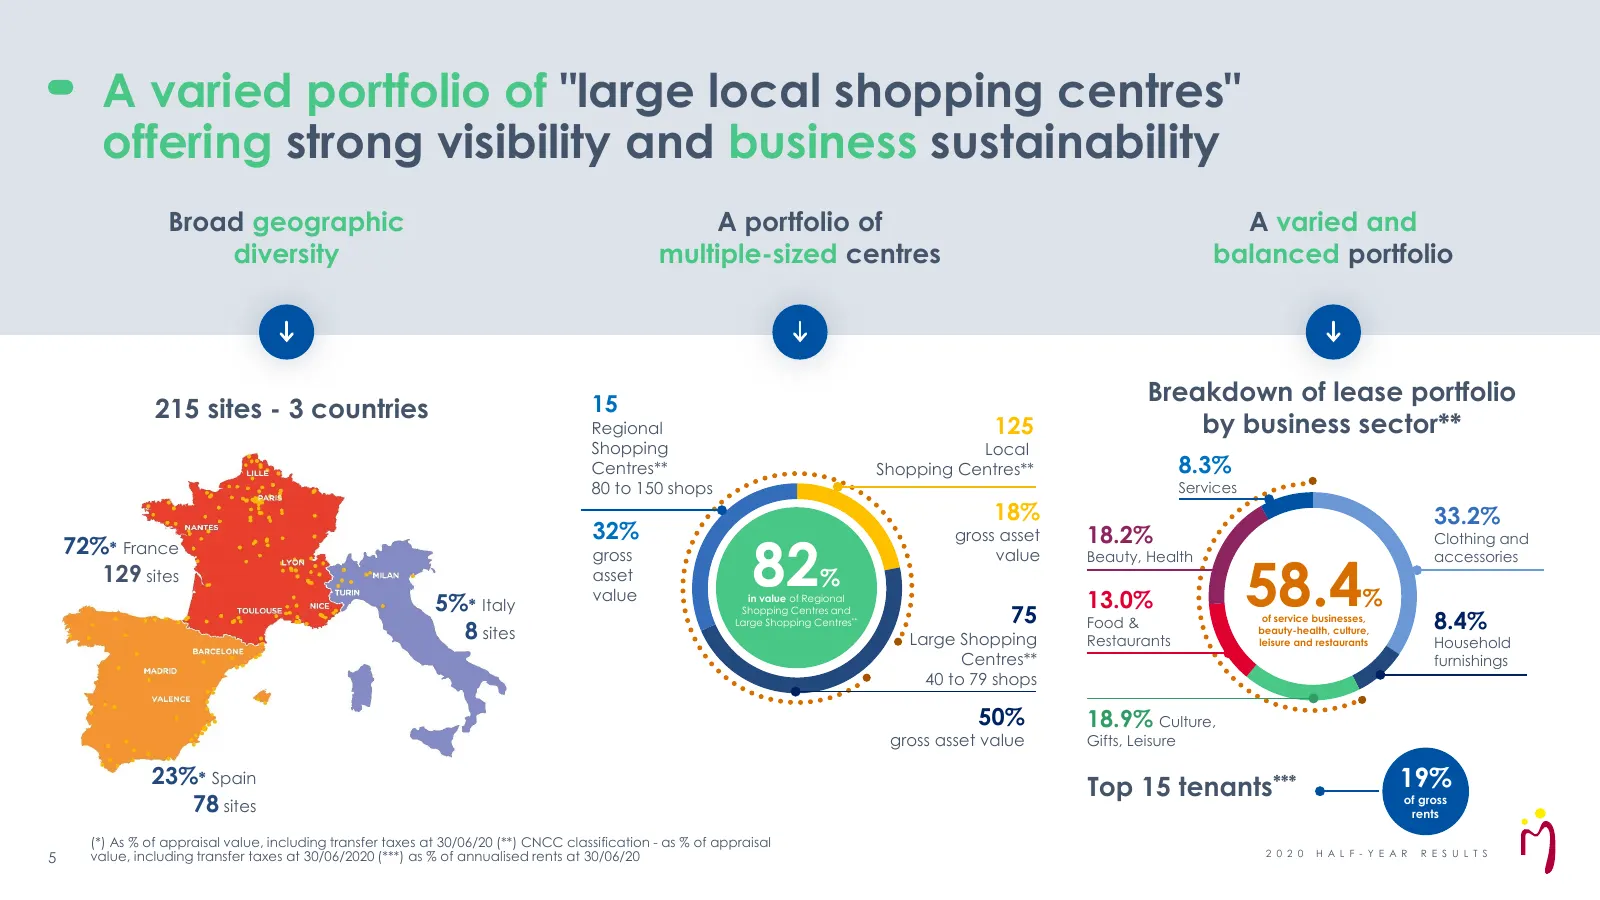
Slide 5: A varied portfolio of large local shopping centres
A varied portfolio of "large local shopping centres" offering strong visibility and business sustainability Broad geographic A portfolio of A varied and diversity multiple-sized centres balanced portfolio 15 Breakdown of lease portfolio 215 sites - 3 countries Regional 125 by business sector** Shopp
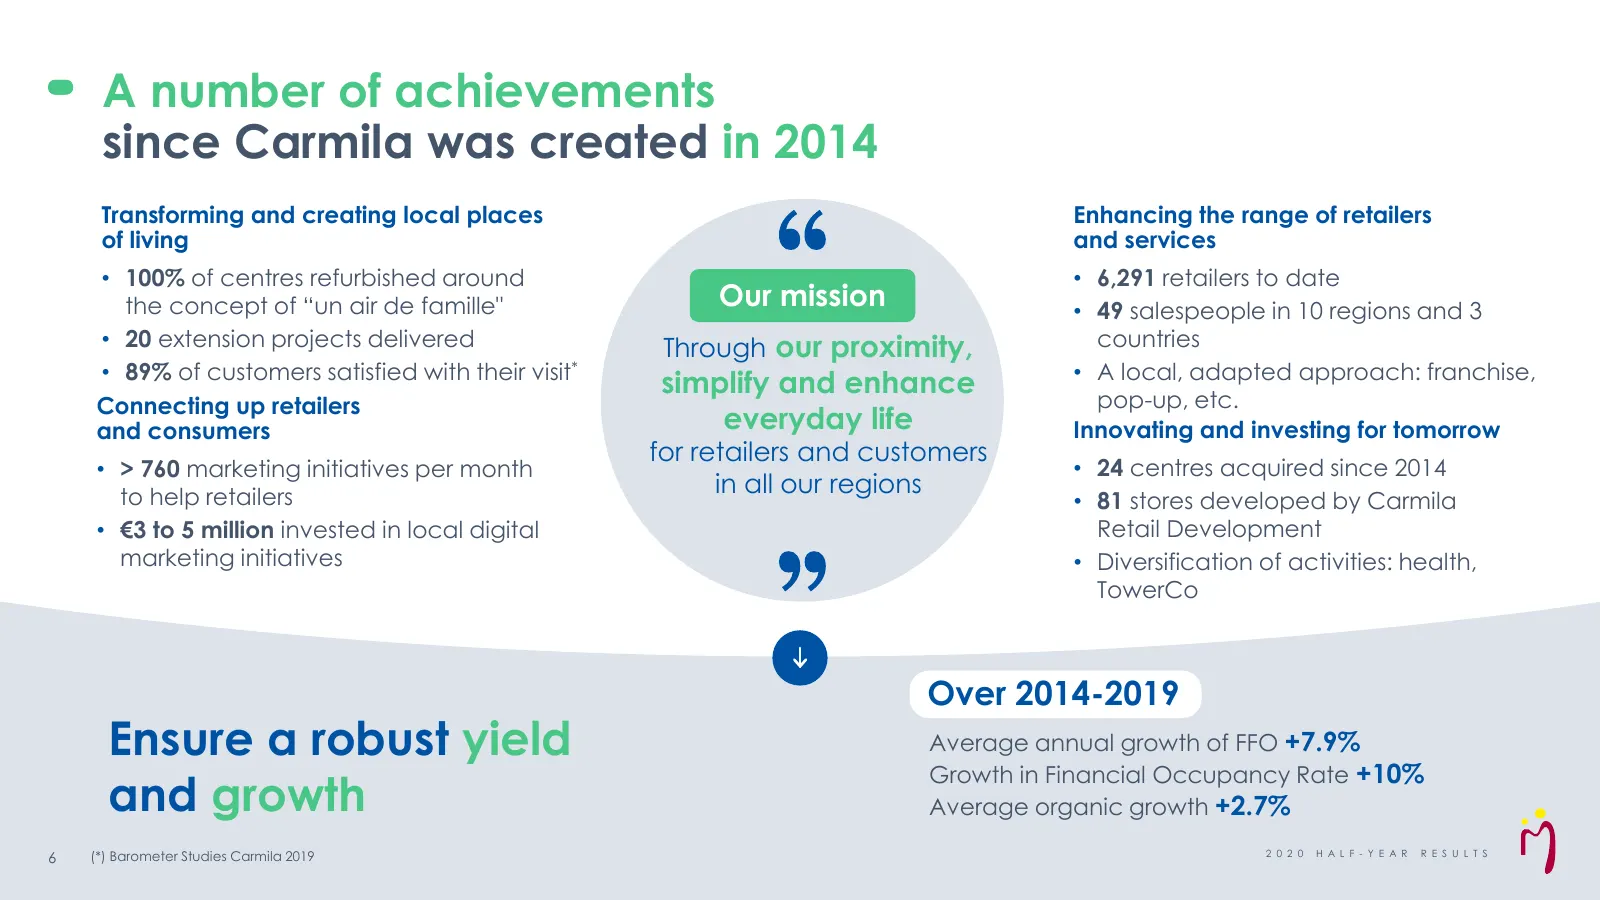
Slide 6: A number of achievements since Carmila was created in 2014
A number of achievements since Carmila was created in 2014 Transforming and creating local places Enhancing the range of retailers of living and services • 100% of centres refurbished around • 6,291 retailers to date the concept of “un air de famille" Our mission • 49 salespeople in 10 regions and 3
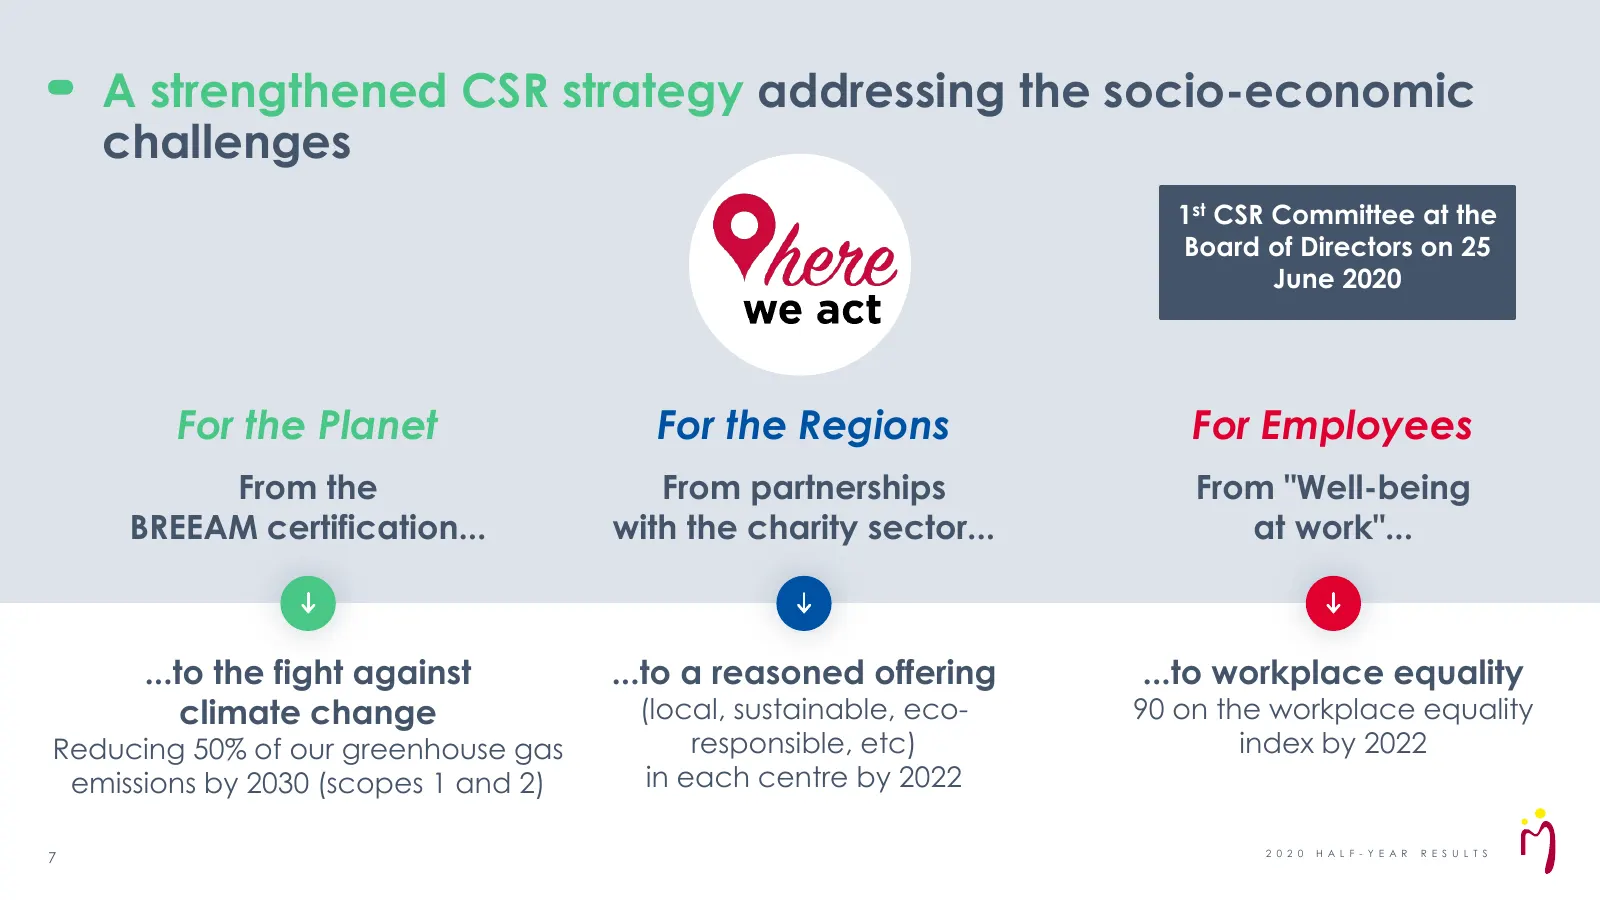
Slide 7: A strengthened CSR strategy addressing the socio-economic challenges
A strengthened CSR strategy addressing the socio-economic challenges 1st CSR Committee at the Board of Directors on 25 June 2020 For the Planet For the Regions For Employees From the From partnerships From "Well-being BREEAM certification... with the charity sector... at work"... ...to the fight aga
Slide 8: Activity during the 1st half of 2020
Activity during the 1st half of 2020 8 BayOrléans 2 – Torcy Place Collégien Brianza d’Arc -(France) Italy
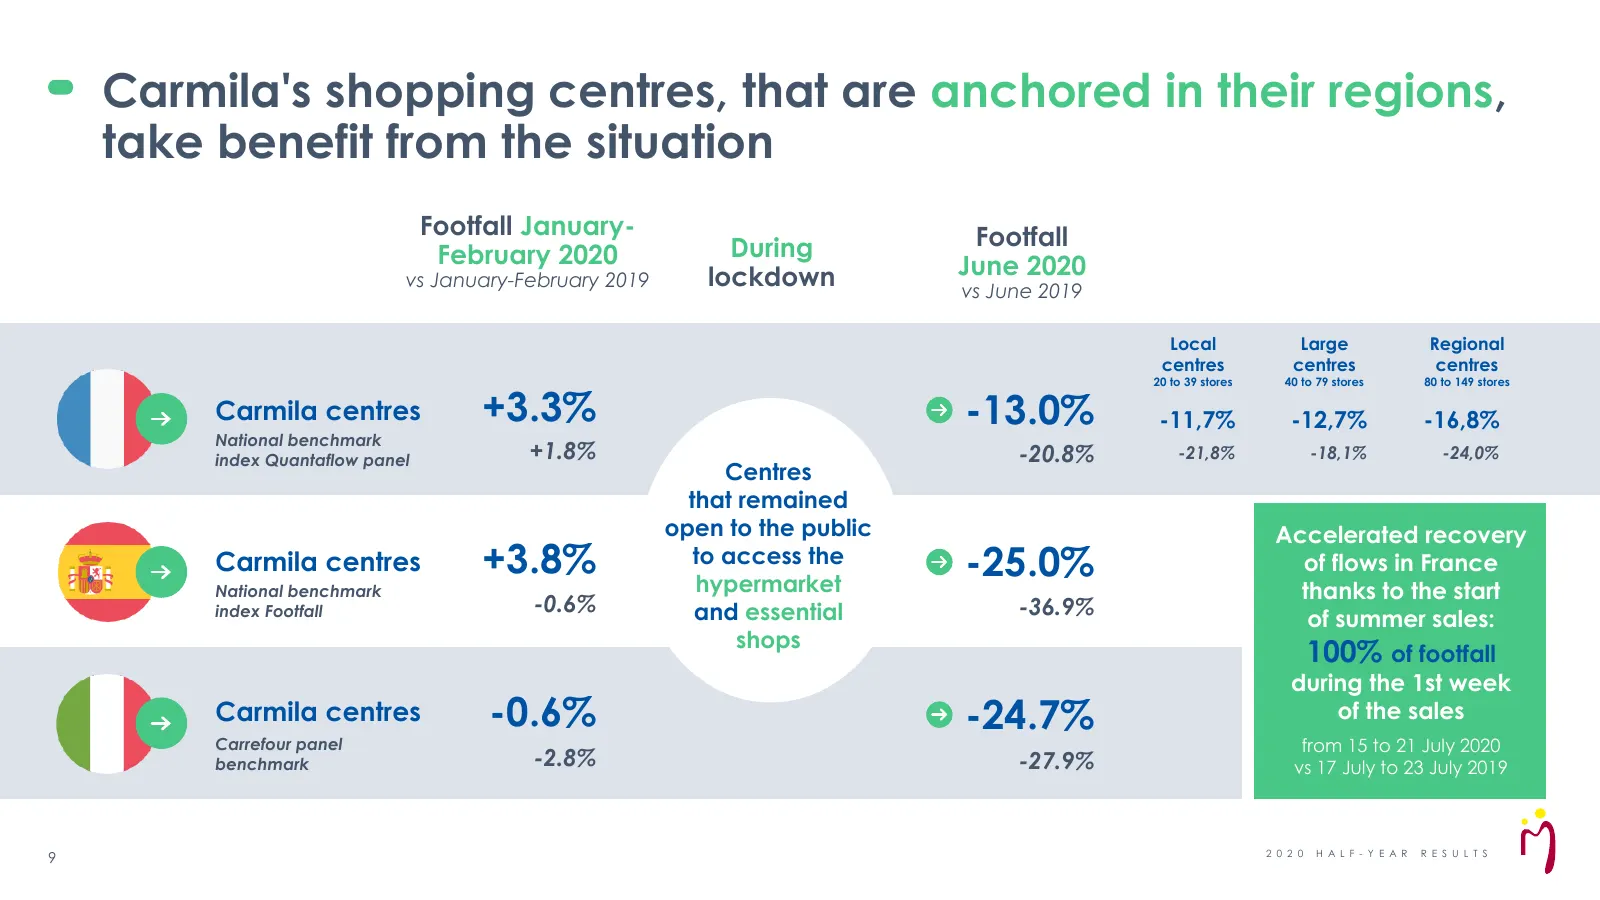
Slide 9: Carmila's shopping centres take benefit from the situation
Carmila's shopping centres, that are anchored in their regions, take benefit from the situation Footfall January- Footfall February 2020 During vs January-February 2019 lockdown June 2020 vs June 2019 Local Large Regional centres centres centres 20 to 39 stores 40 to 79 stores 80 to 149 stores Carmi
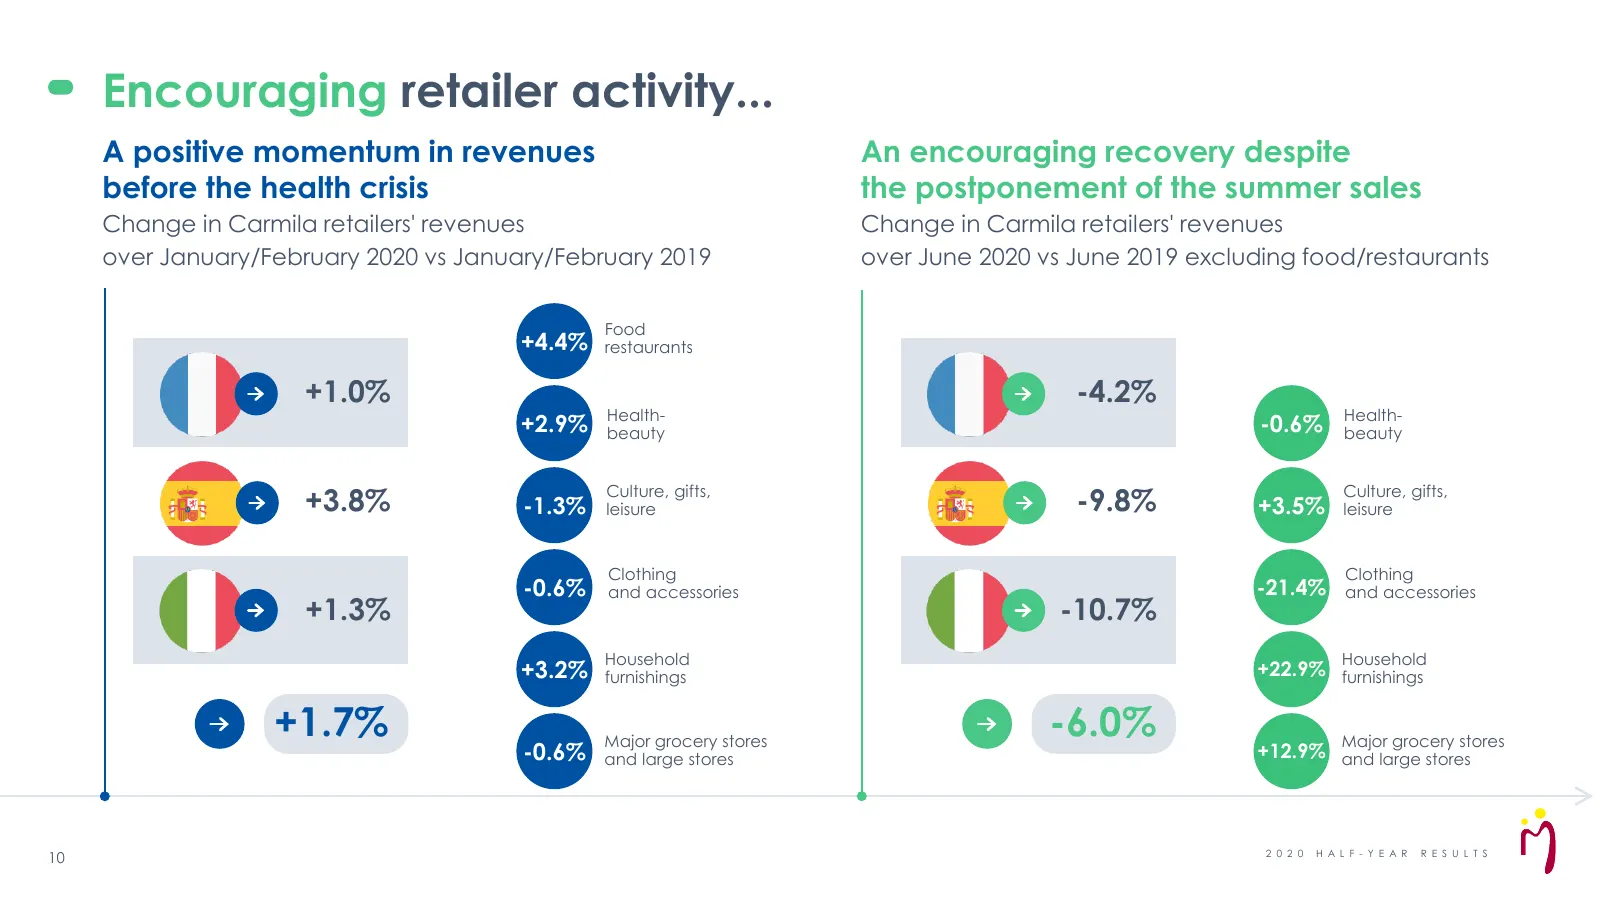
Slide 10: Encouraging retailer activity
Encouraging retailer activity... A positive momentum in revenues An encouraging recovery despite before the health crisis the postponement of the summer sales Change in Carmila retailers' revenues Change in Carmila retailers' revenues over January/February 2020 vs January/February 2019 over June 202
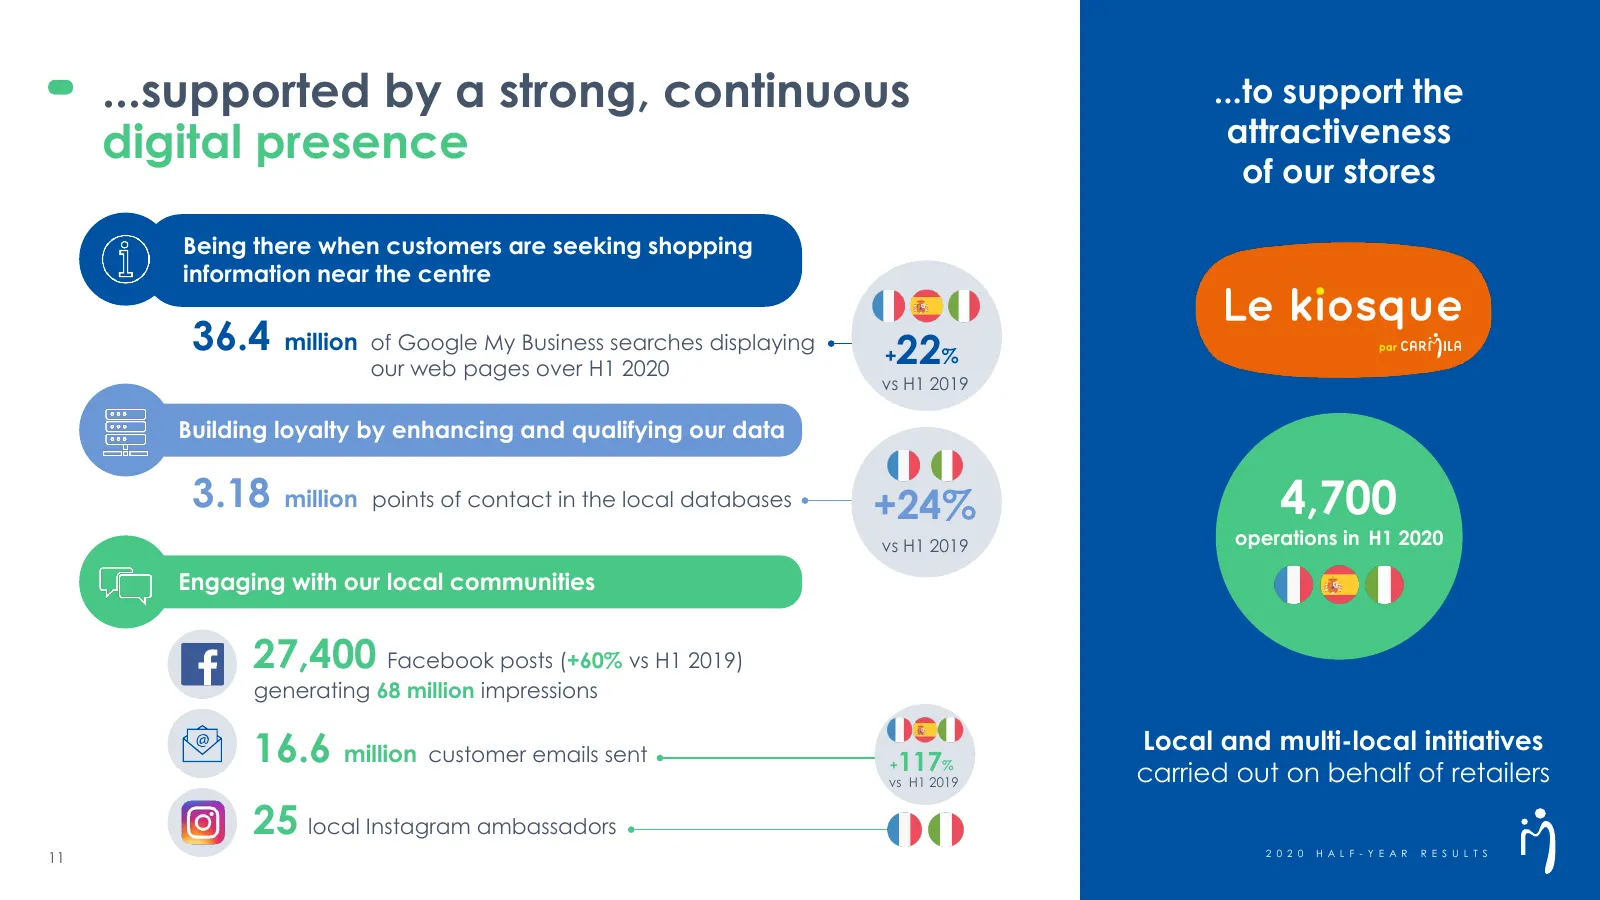
Slide 11: Supported by a strong, continuous digital presence
...supported by a strong, continuous ...to support the digital presence attractiveness of our stores Being there when customers are seeking shopping information near the centre 36.4 million of Google My Business searches displaying +22% our web pages over H1 2020 vs H1 2019 Building loyalty by enhan
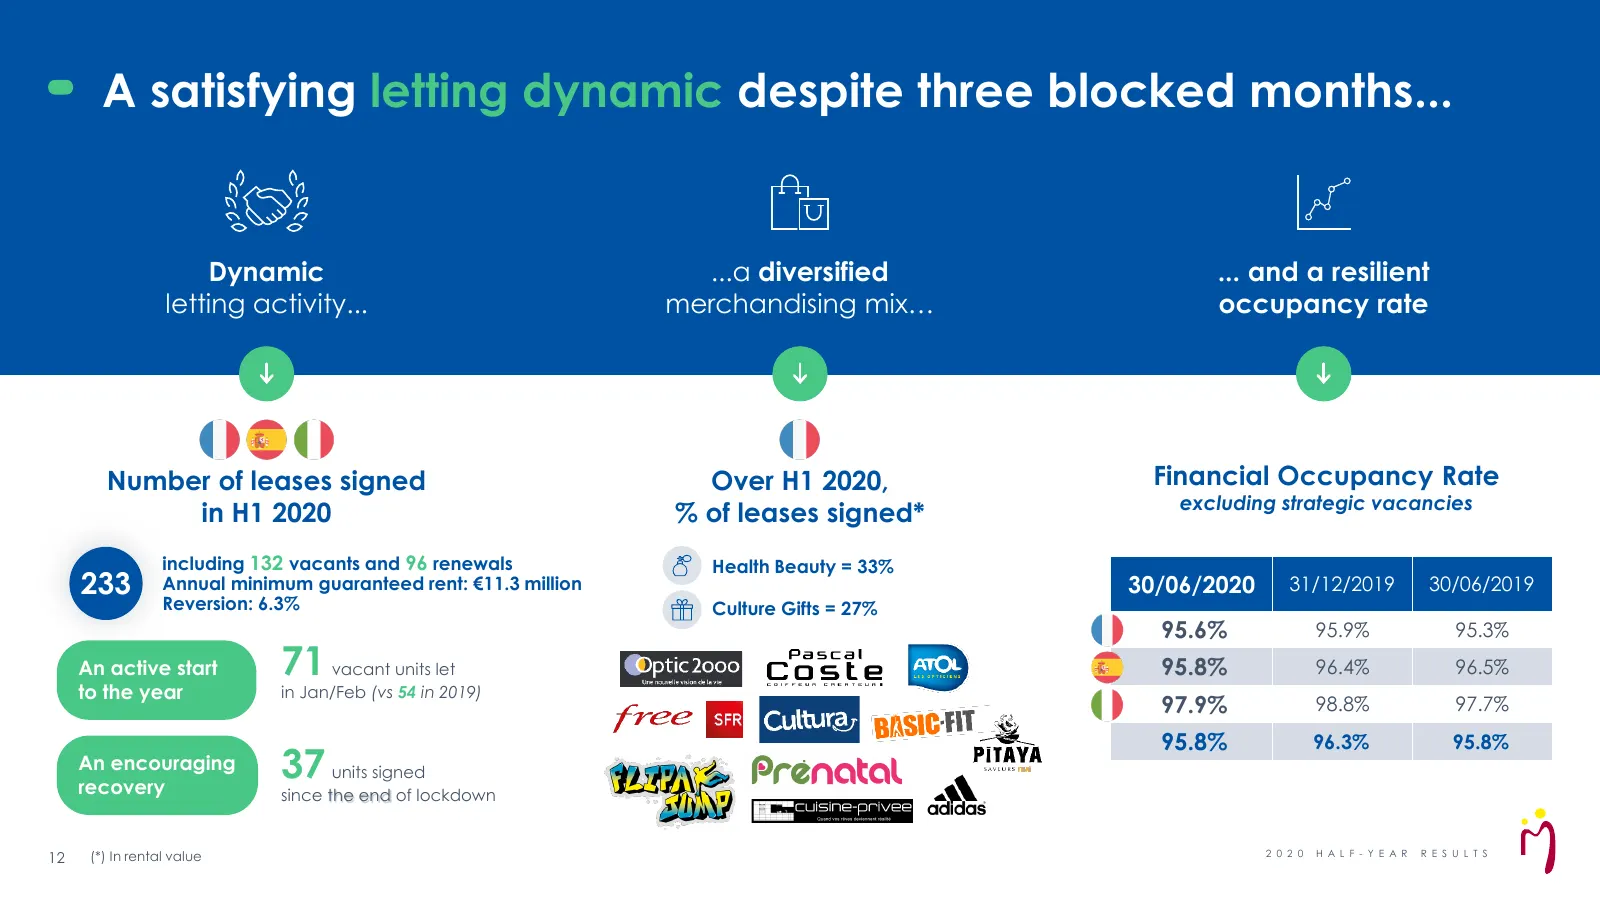
Slide 12: A satisfying letting dynamic despite three blocked months
A satisfying letting dynamic despite three blocked months... Dynamic ...a diversified ... and a resilient letting activity... merchandising mix… occupancy rate Number of leases signed Over H1 2020, Financial Occupancy Rate excluding strategic vacancies in H1 2020 % of leases signed* including 132 va
Slide 13: Extensive coverage and multi-local approach
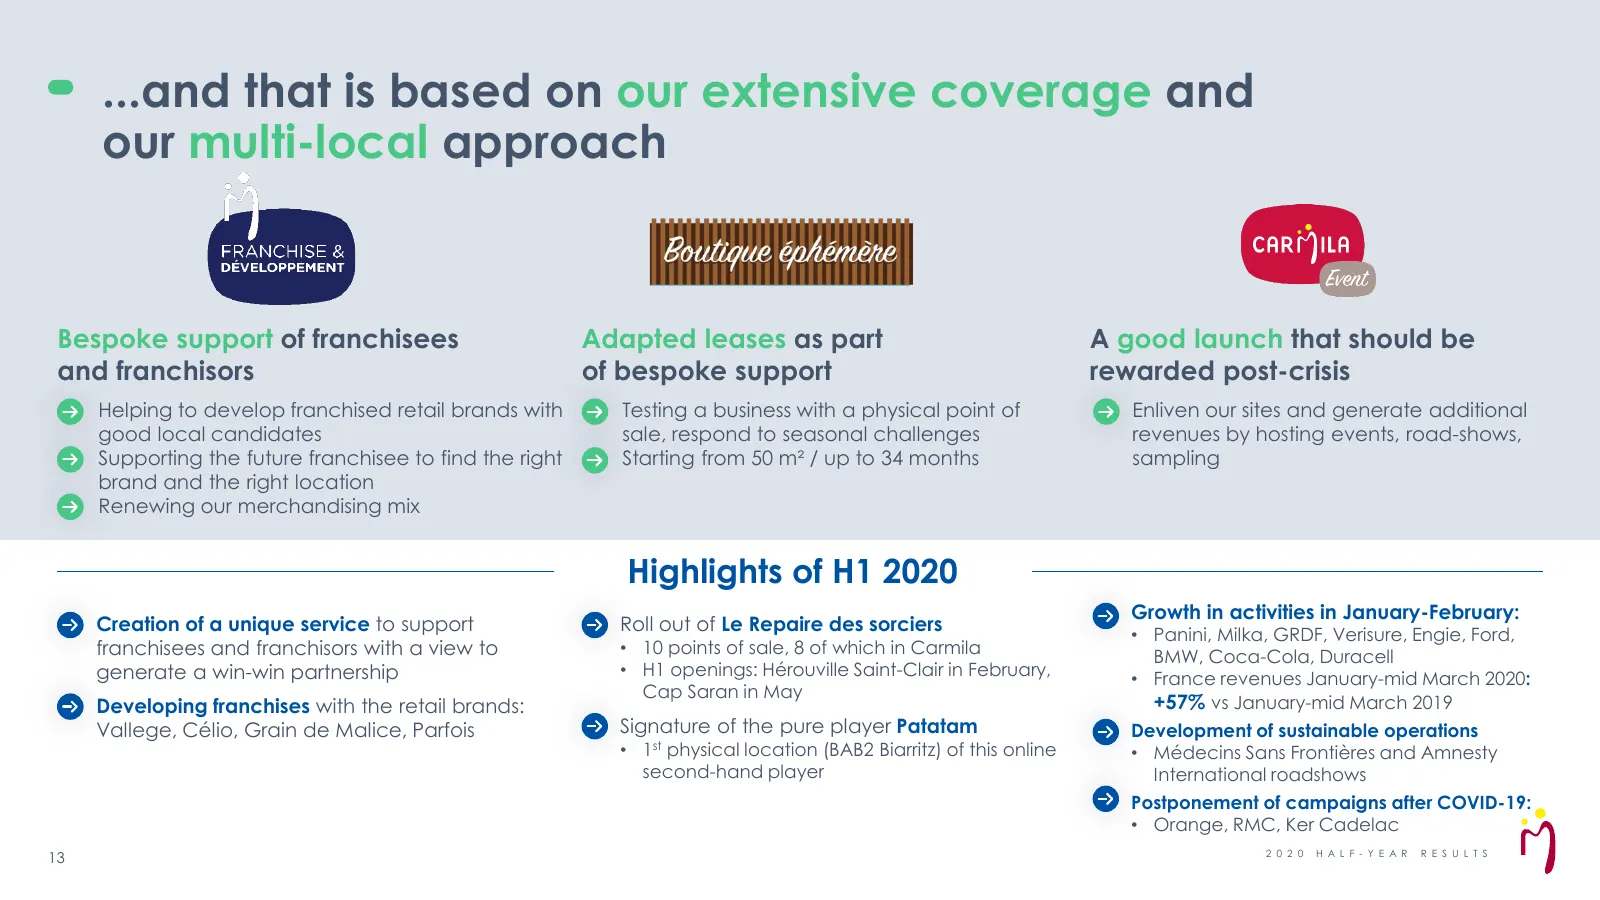
...and that is based on our extensive coverage and our multi-local approach Bespoke support of franchisees Adapted leases as part A good launch that should be and franchisors of bespoke support rewarded post-crisis Helping to develop franchised retail brands with • Testing a business with a physical
Slide 14: Concrete results from the Here we act CSR programme
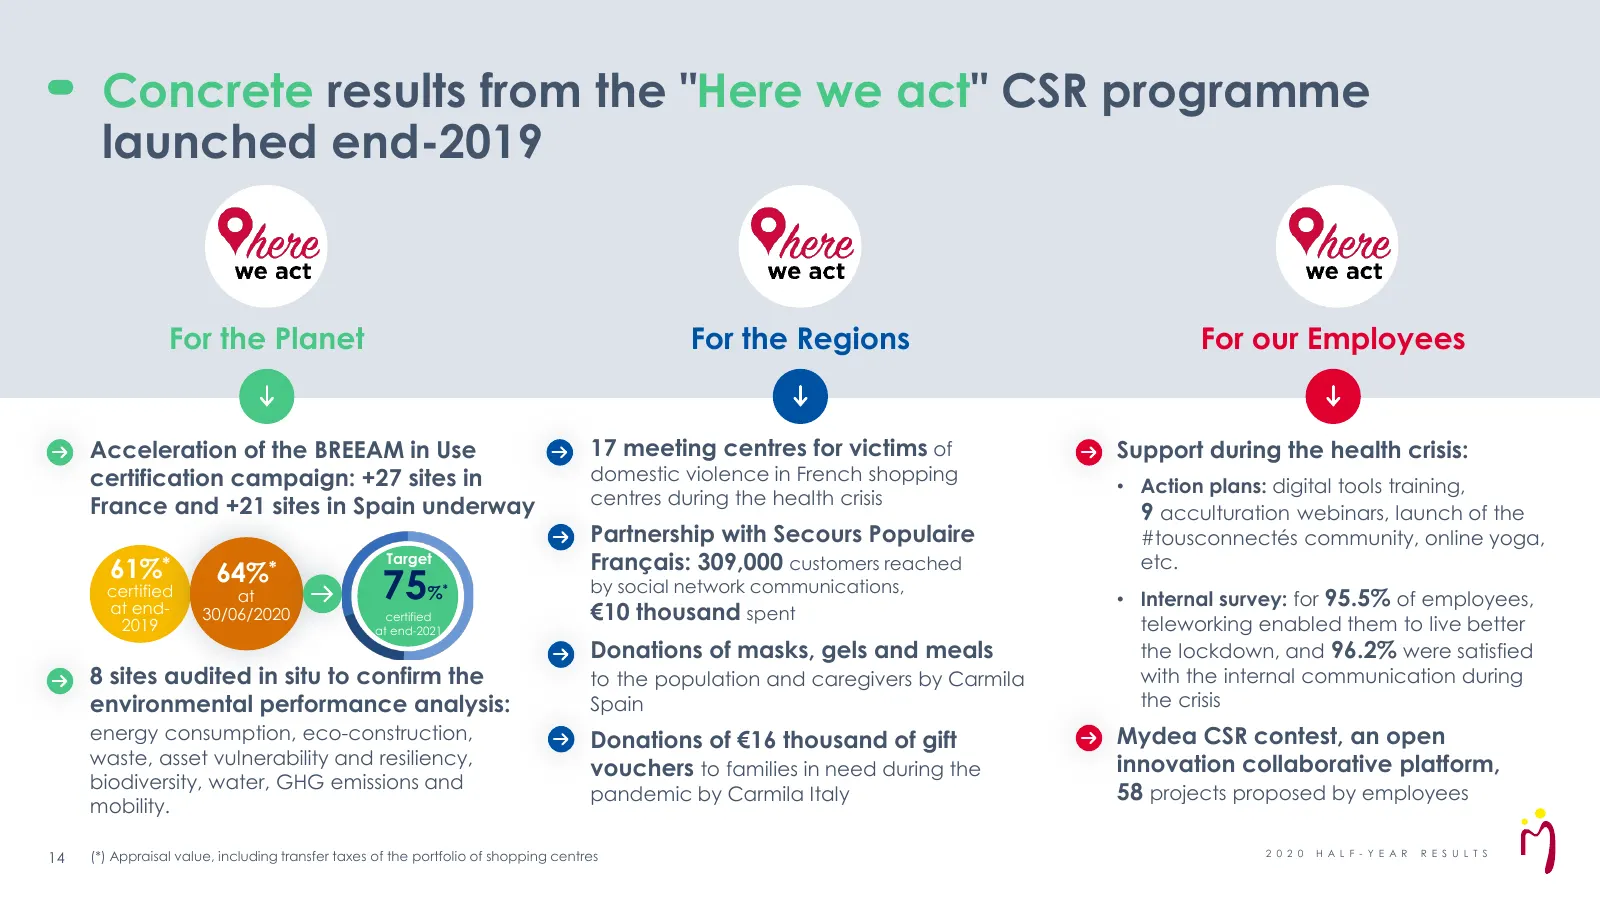
Concrete results from the "Here we act" CSR programme launched end-2019 For the Planet For the Regions For our Employees Acceleration of the BREEAM in Use 17 meeting centres for victims of Support during the health crisis: certification campaign: +27 sites in domestic violence in French shopping • A
Slide 15: Operational excellence at the heart of the health crisis
Operational excellence at the heart of the health crisis 15 Bay 2 Torcy BAB2Collégien – Biarritz -(France) France
Slide 16: Proactive management during the shutdown period
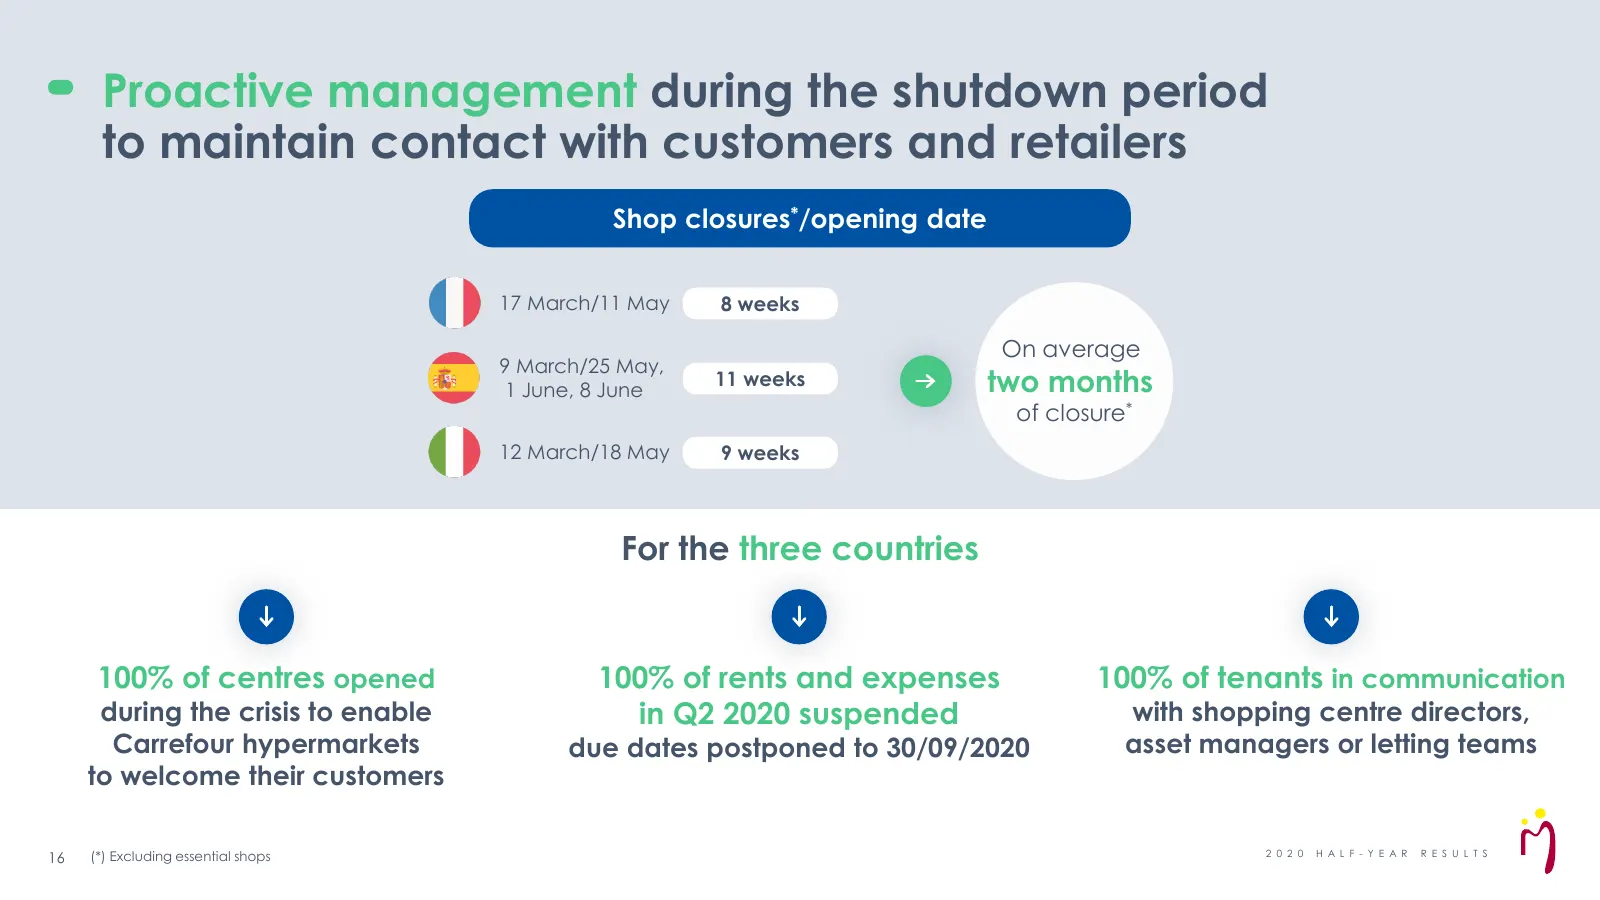
Proactive management during the shutdown period to maintain contact with customers and retailers Shop closures*/opening date 17 March/11 May 8 weeks On average 9 March/25 May, 1 June, 8 June 11 weeks two months of closure* 12 March/18 May 9 weeks For the three countries 100% of centres opened 100% o
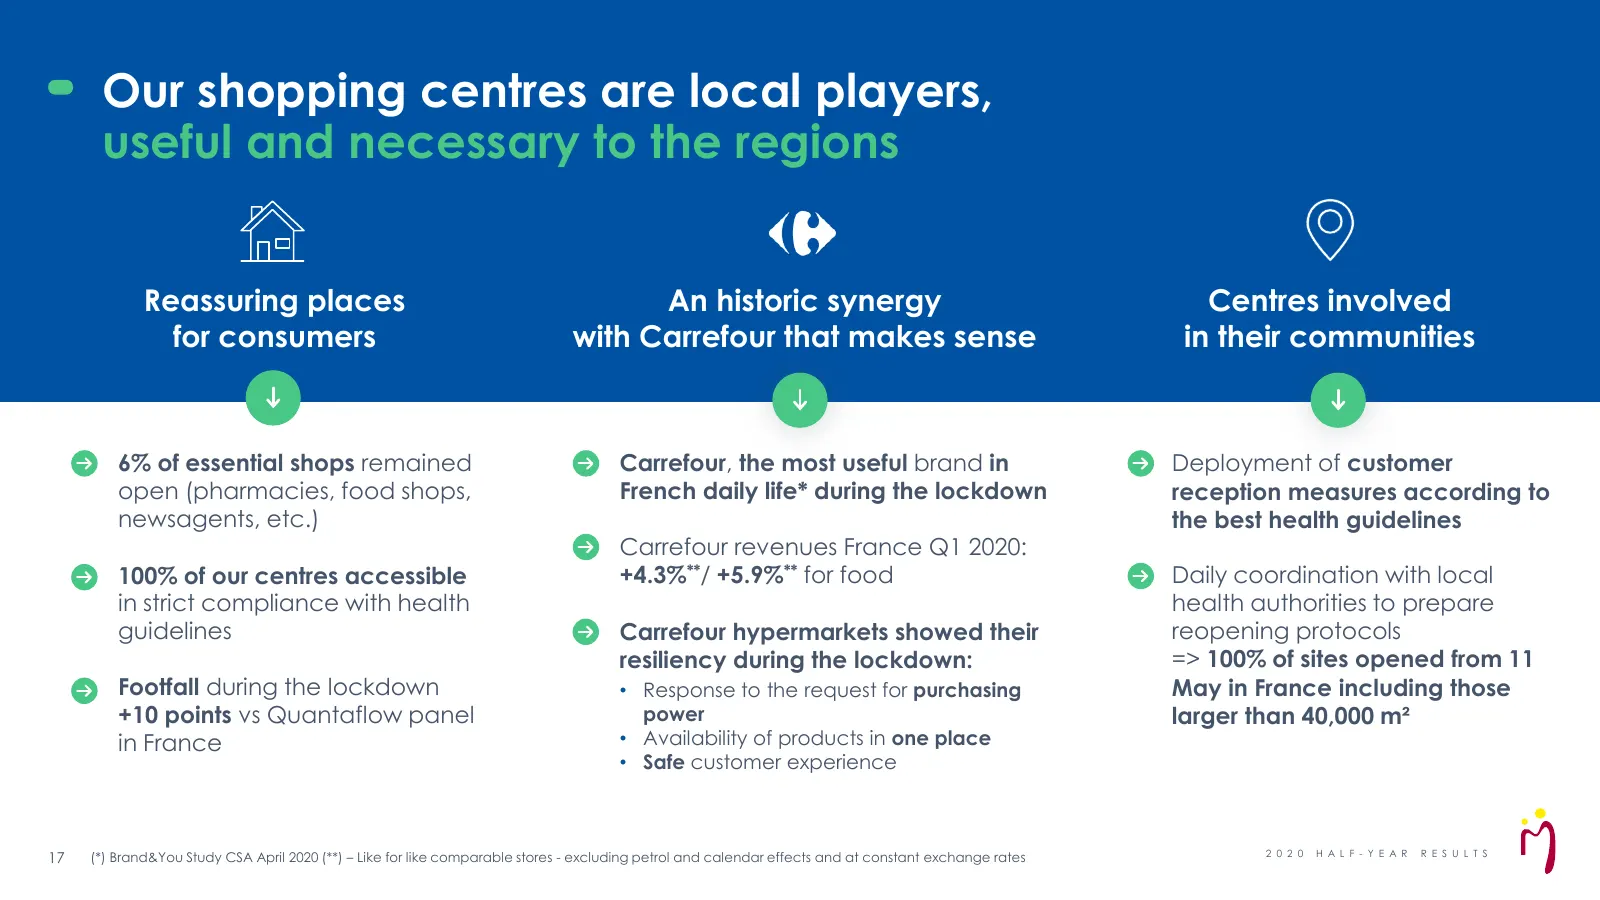
Slide 17: Our shopping centres are local players, useful and necessary to the regions
Our shopping centres are local players, useful and necessary to the regions Reassuring places An historic synergy Centres involved for consumers with Carrefour that makes sense in their communities 6% of essential shops remained Carrefour, the most useful brand in Deployment of customer open (pharma
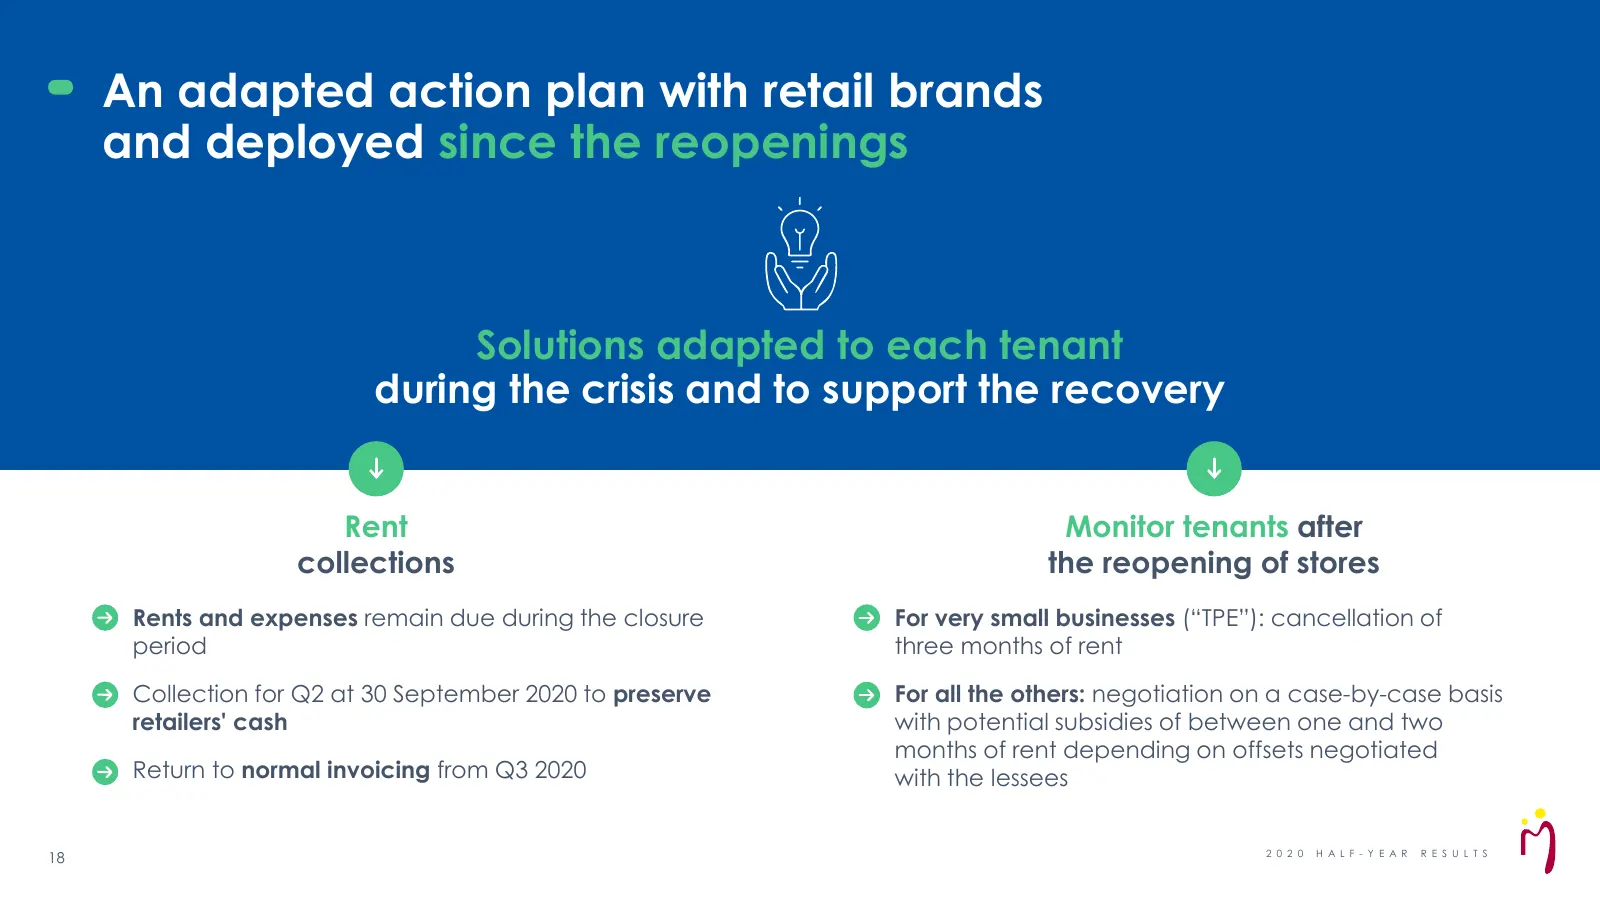
Slide 18: An adapted action plan with retail brands
An adapted action plan with retail brands and deployed since the reopenings Solutions adapted to each tenant during the crisis and to support the recovery Rent Monitor tenants after collections the reopening of stores Rents and expenses remain due during the closure For very small businesses (“TPE”)
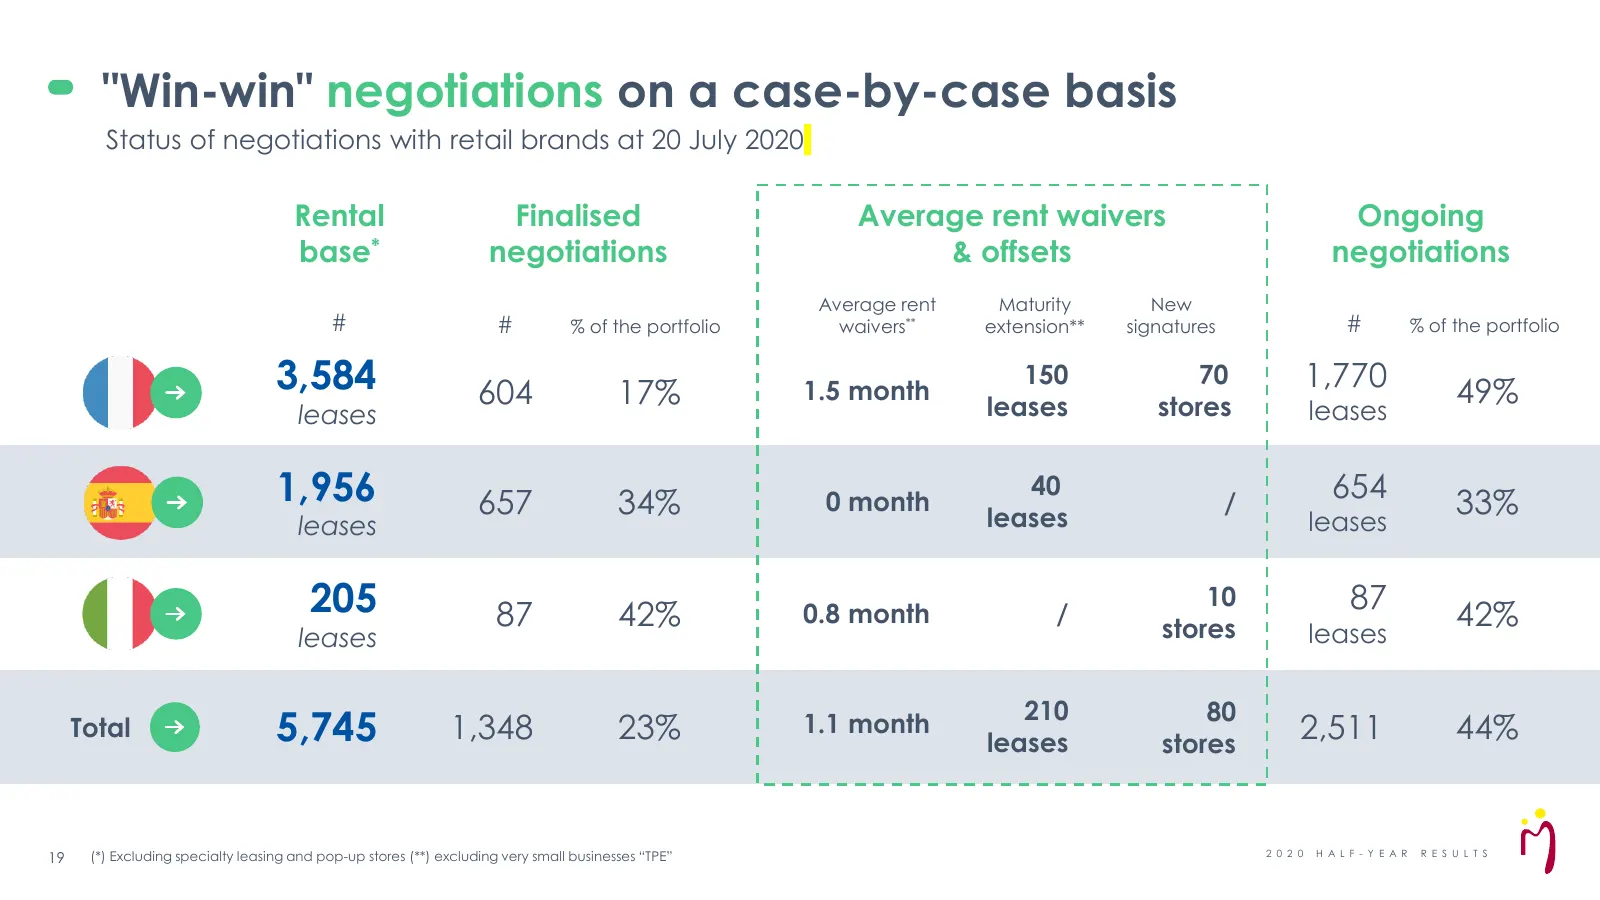
Slide 19: Win-win negotiations on a case-by-case basis
"Win-win" negotiations on a case-by-case basis Status of negotiations with retail brands at 20 July 2020 Rental Finalised Average rent waivers Ongoing base* negotiations & offsets negotiations Average rent Maturity New # # % of the portfolio waivers** extension** signatures # % of the portfolio 3,58
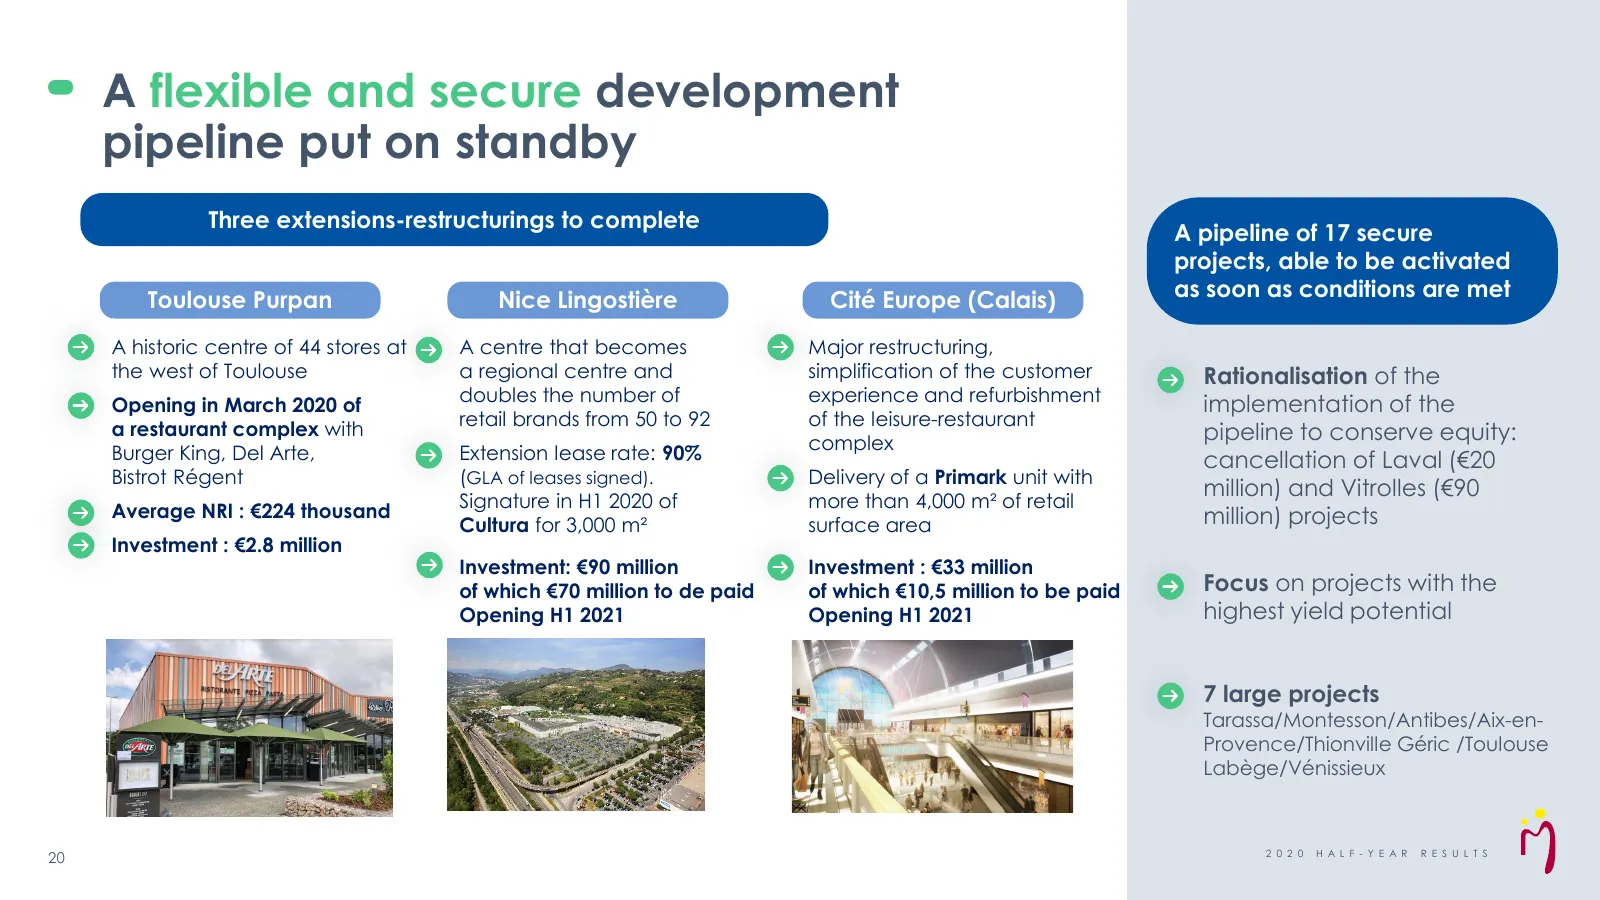
Slide 20: A flexible and secure development pipeline put on standby
A flexible and secure development pipeline put on standby Three extensions-restructurings to complete A pipeline of 17 secure projects, able to be activated Toulouse Purpan Nice Lingostière Cité Europe (Calais) as soon as conditions are met A historic centre of 44 stores at A centre that becomes Maj
Slide 21: Financial results
Financial results 21 BAB2 – Biarritz - France
Slide 22: An atypical half-year marked by the impacts of the health crisis
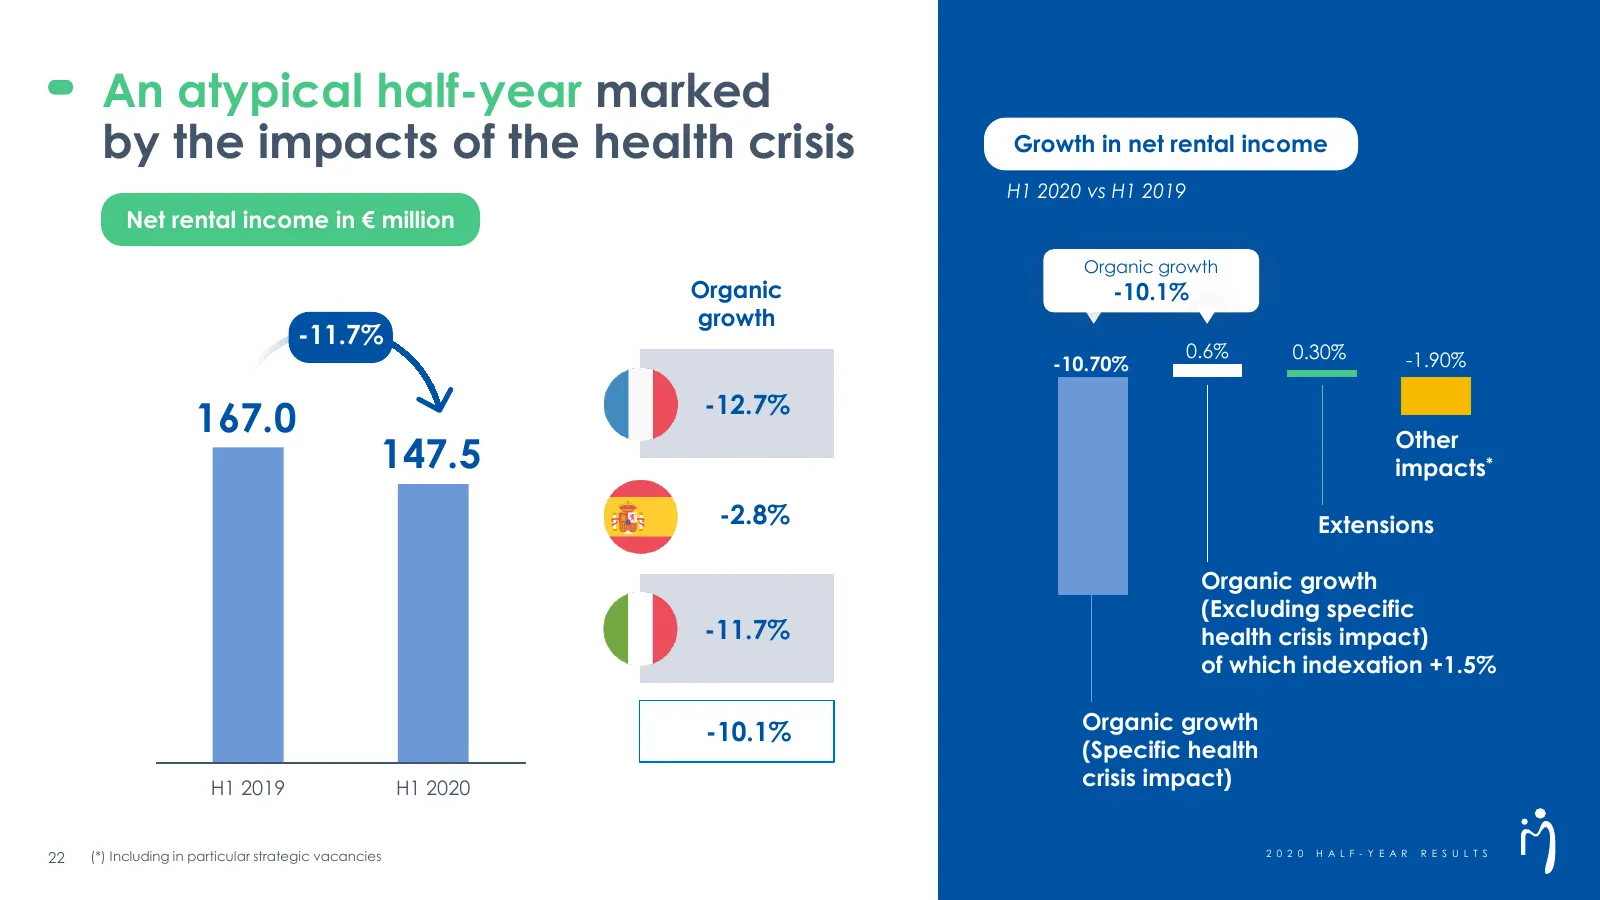
An atypical half-year marked by the impacts of the health crisis Growth in net rental income H1 2020 vs H1 2019 Net rental income in € million Organic growth Organic -10.1% growth -11.7% 0.6% 0.30% -1.90% -10.70% -12.7% 167.0 Other 147.5 impacts* -2.8% Extensions Organic growth (Excluding specific -
Slide 23: EBITDA down 13.7%
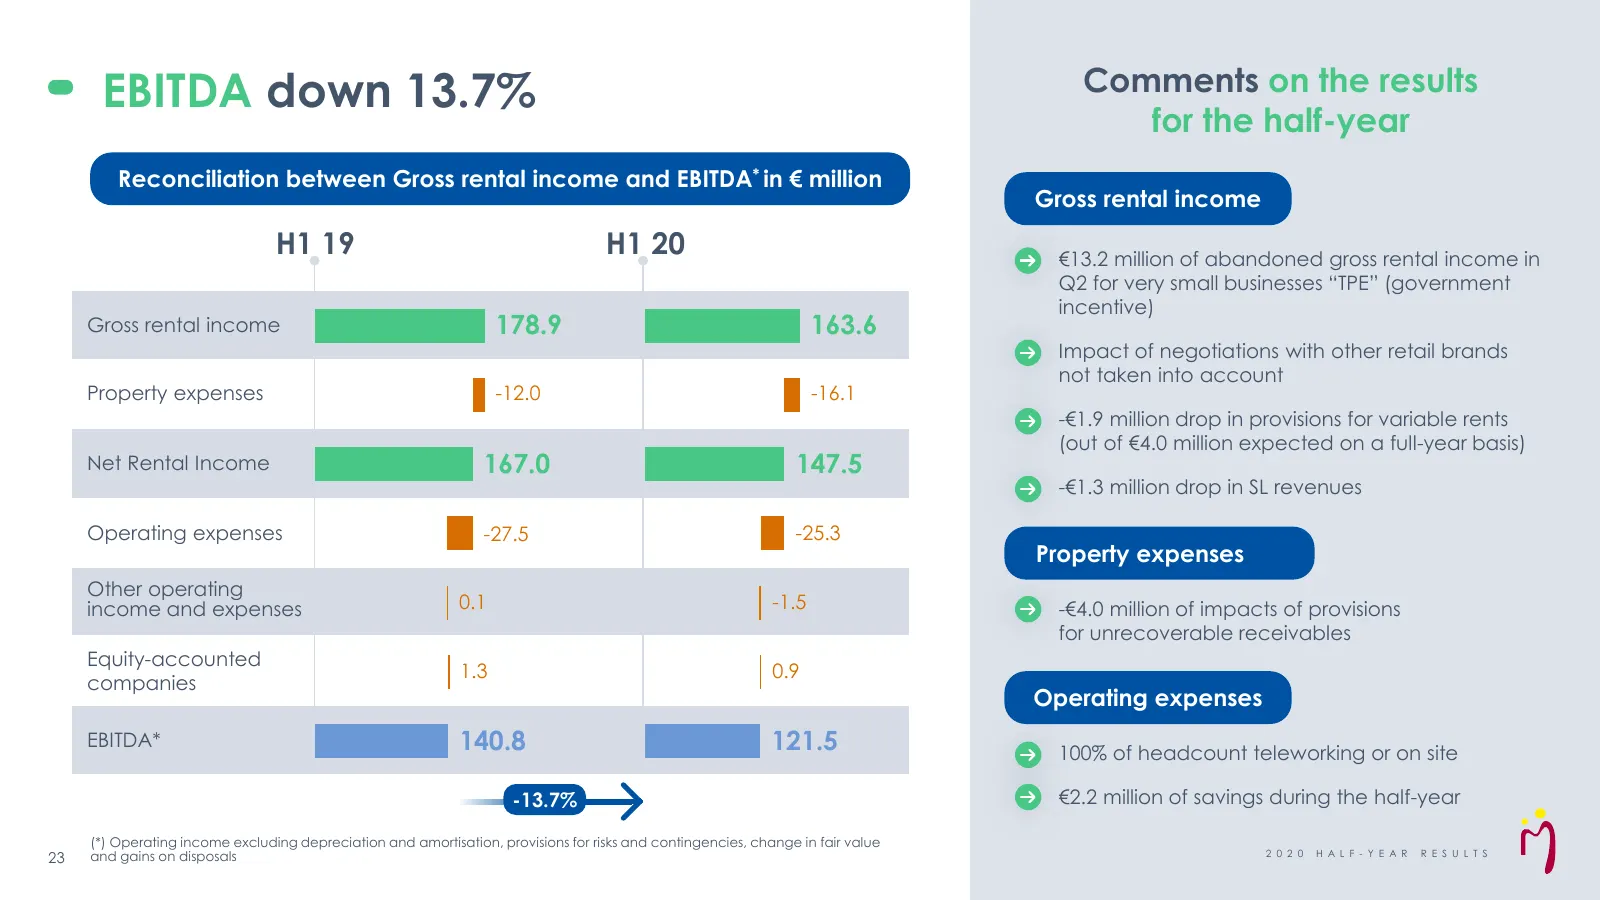
EBITDA down 13.7% Comments on the results for the half-year Reconciliation between Gross rental income and EBITDA* in € million Gross rental income H1 19 H1 20 €13.2 million of abandoned gross rental income in Q2 for very small businesses “TPE” (government incentive) Gross rental income 178.9 163.6
Slide 24: Recurring earnings limited decline
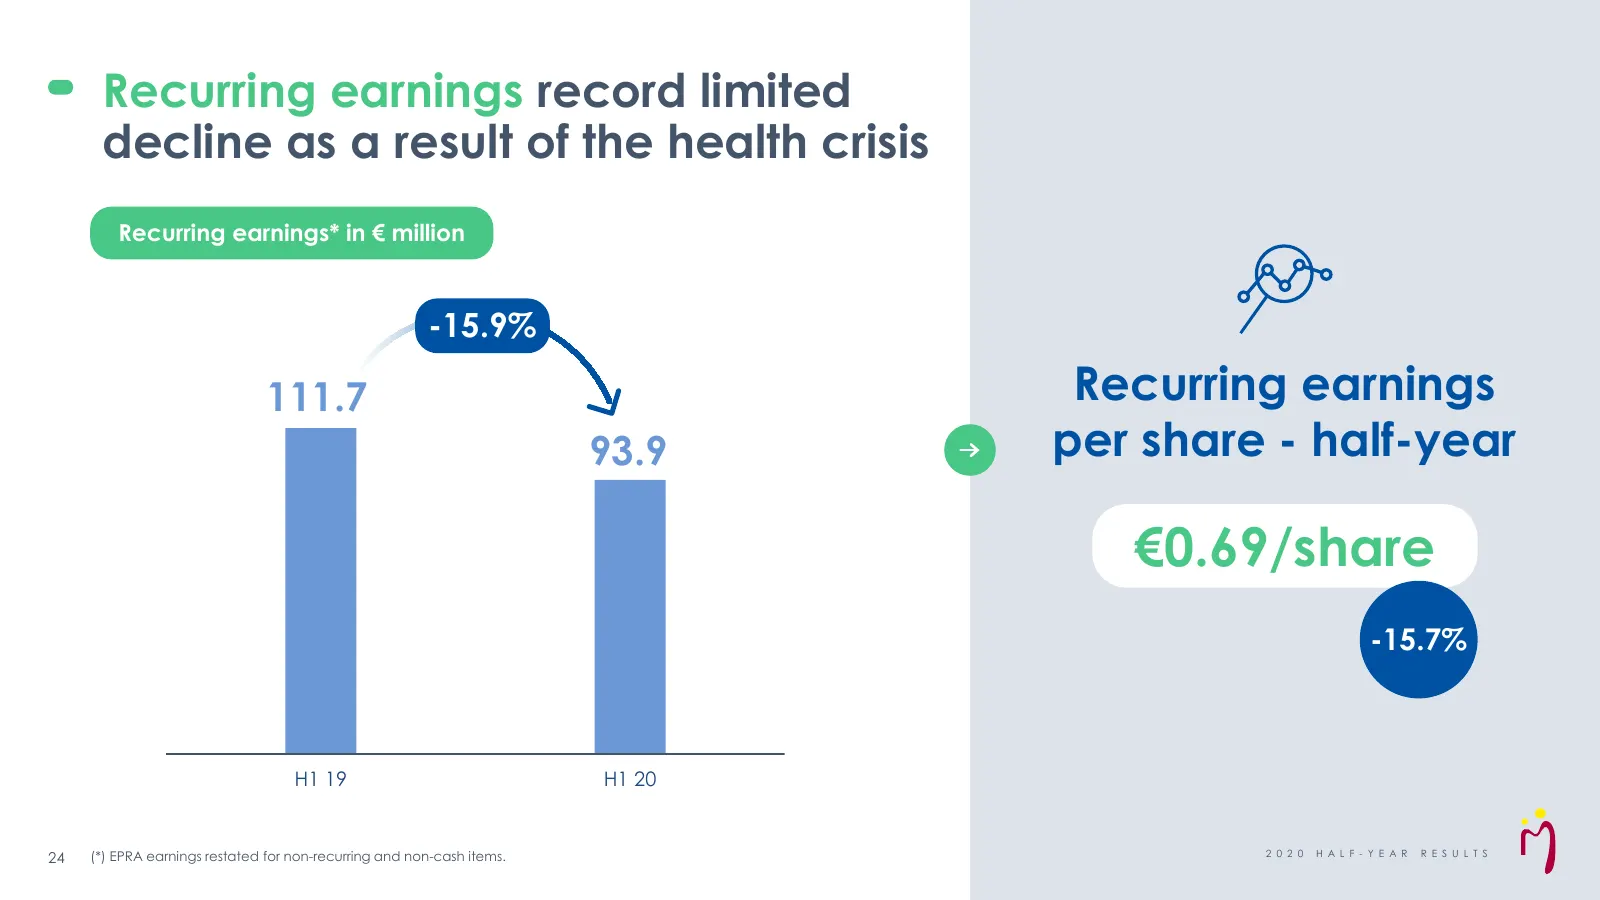
Recurring earnings record limited decline as a result of the health crisis Recurring earnings* in € million -15.9% 111.7 Recurring earnings 93.9 per share - half-year €0.69/share -15.7% H1 19 H1 20 (*) EPRA earnings restated for non-recurring and non-cash items. 2 0 2 0 H A L F - Y E A R R E S U L T
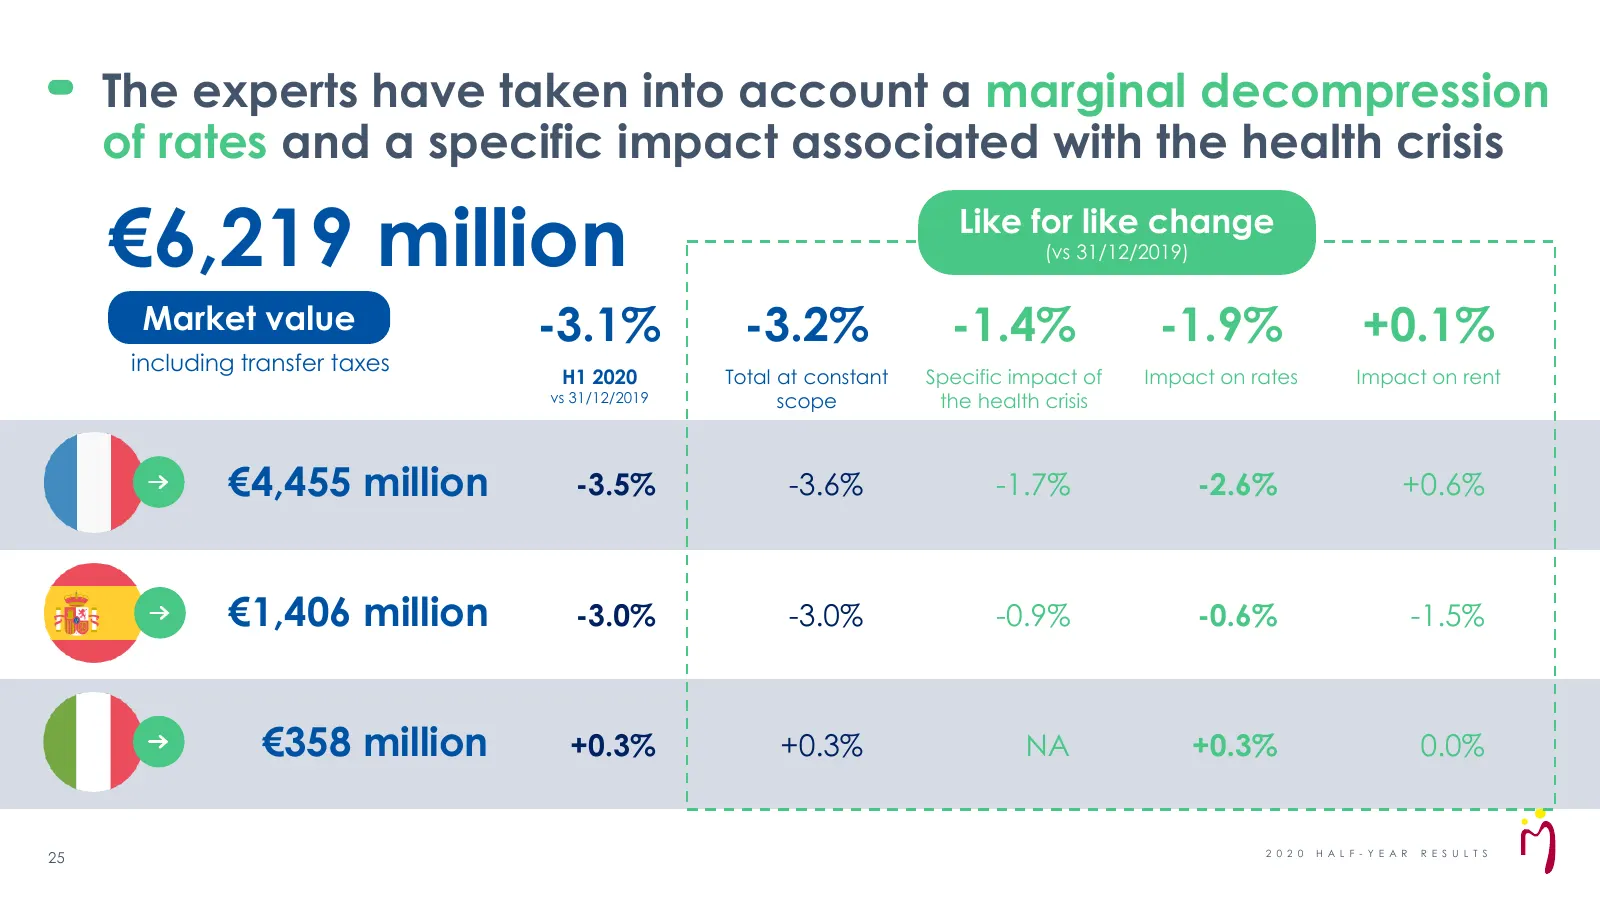
Slide 25: Portfolio market value €6,219 million
The experts have taken into account a marginal decompression of rates and a specific impact associated with the health crisis €6,219 million Like for like change (vs 31/12/2019) Market value -3.1% -3.2% -1.4% -1.9% +0.1% including transfer taxes H1 2020 Total at constant Specific impact of Impact on
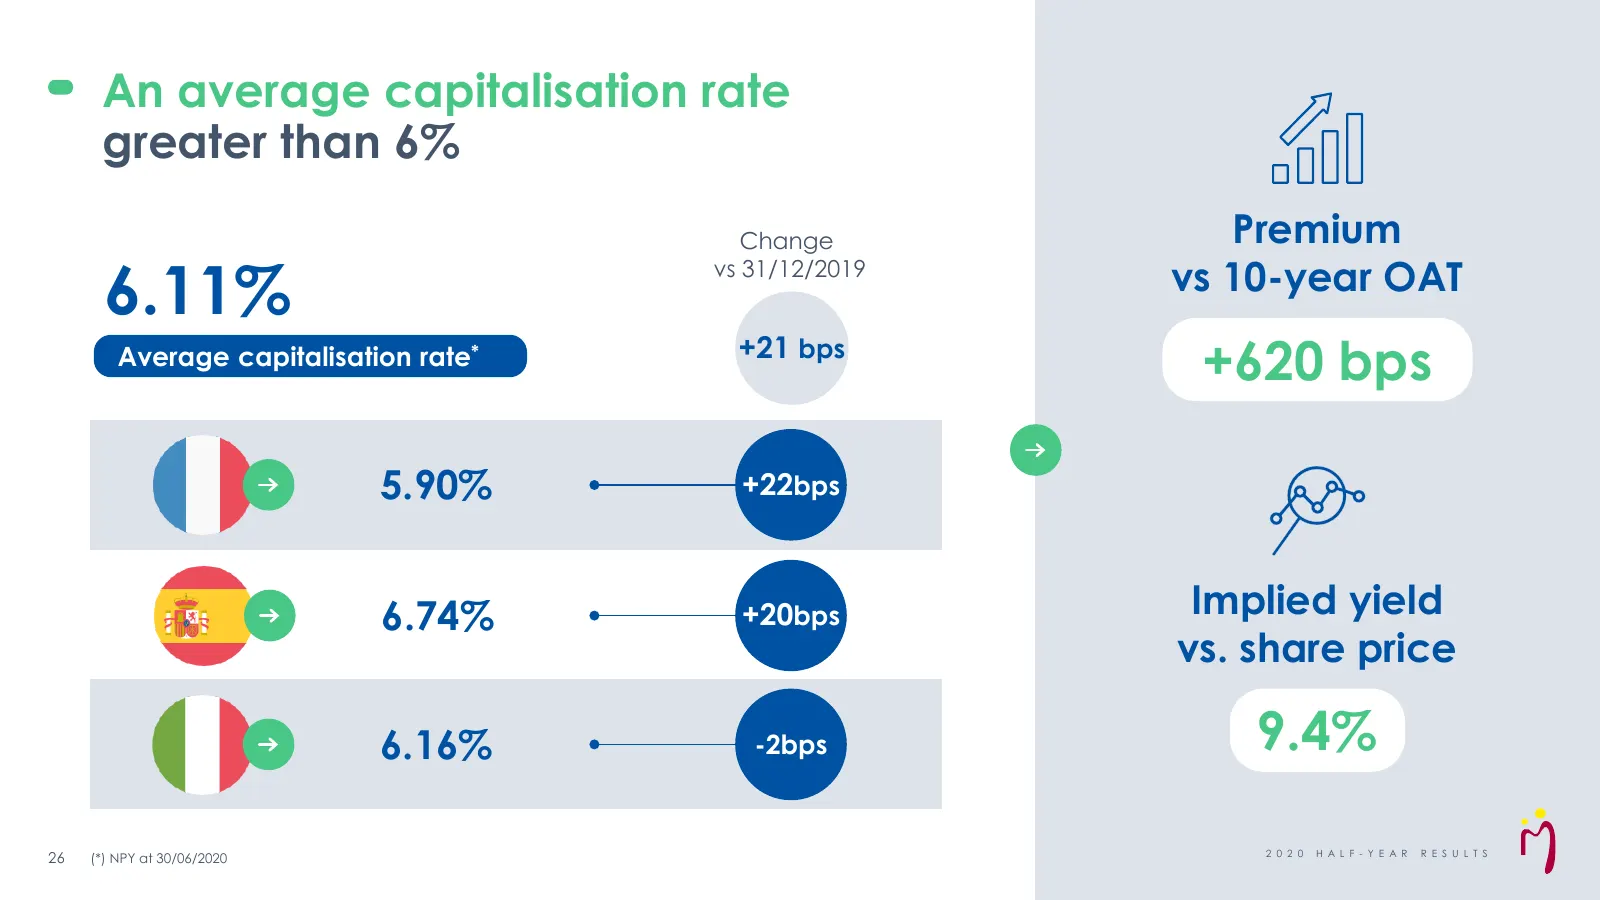
Slide 26: An average capitalisation rate greater than 6%
An average capitalisation rate greater than 6% Change Premium 6.11% vs 10-year OAT vs 31/12/2019 5,91% Average capitalisation rate* +21 bps +620 bps 5.90% +22bps 6.74% +20bps Implied yield vs. share price 6.16% -2bps 9.4% 2 0 2 0 H A L F - Y E A R R E S U L T S 26 (*) NPY at 30/06/2020
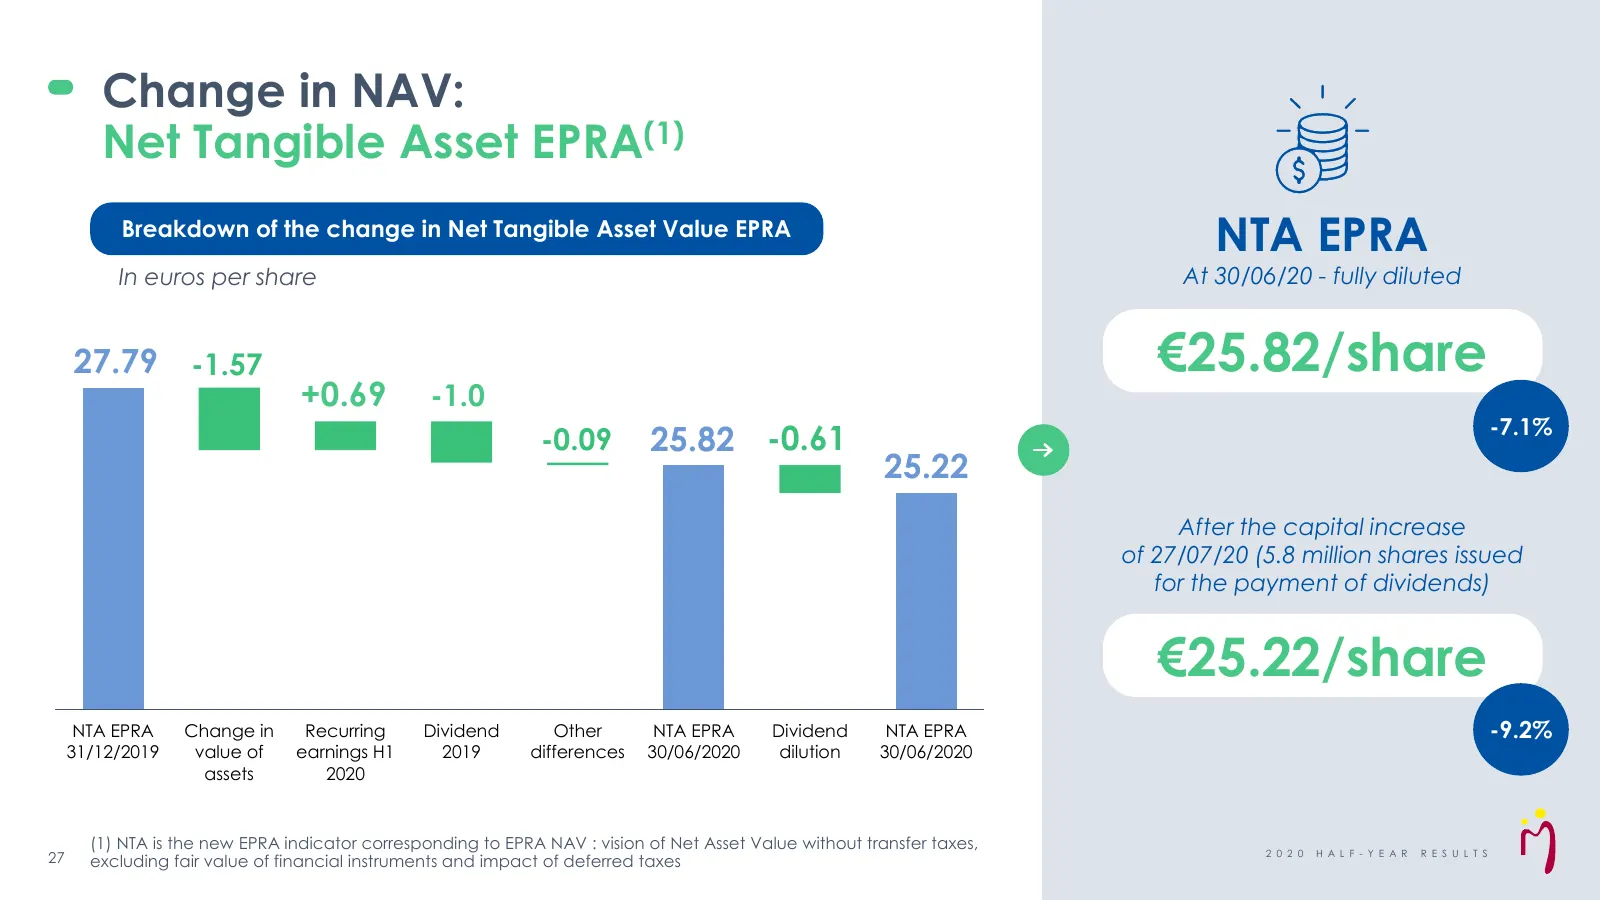
Slide 27: Change in NAV: Net Tangible Asset EPRA
Change in NAV: Net Tangible Asset EPRA(1) Breakdown of the change in Net Tangible Asset Value EPRA NTA EPRA In euros per share At 30/06/20 - fully diluted 27.79 -1.57 €25.82/share +0.69 -1.0 -7.1% -0.09 25.82 -0.61 25.22 After the capital increase of 27/07/20 (5.8 million shares issued for the payme
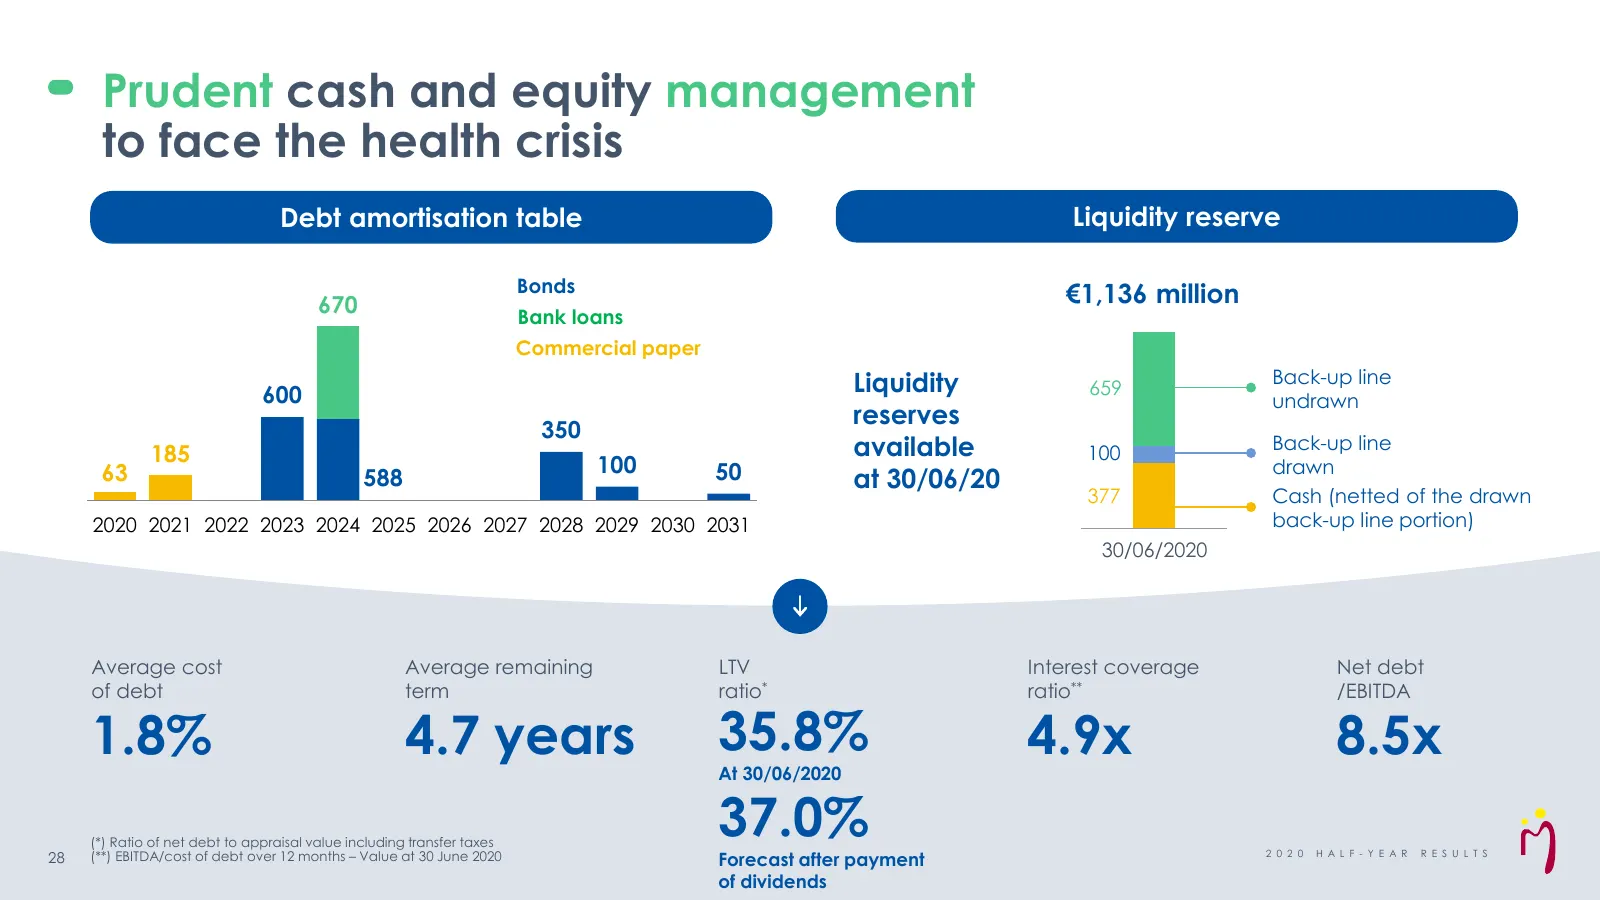
Slide 28: Prudent cash and equity management to face the health crisis
Prudent cash and equity management to face the health crisis Debt amortisation table Liquidity reserve Bonds €1,136 million 670 Bank loans Commercial paper 600 Liquidity 659 Back-up line undrawn reserves 350 185 available 100 Back-up line 63 100 50 drawn 588 at 30/06/20 377 Cash (netted of the drawn
Slide 29: €132 million in equity reinforcements related to the adjusted dividend
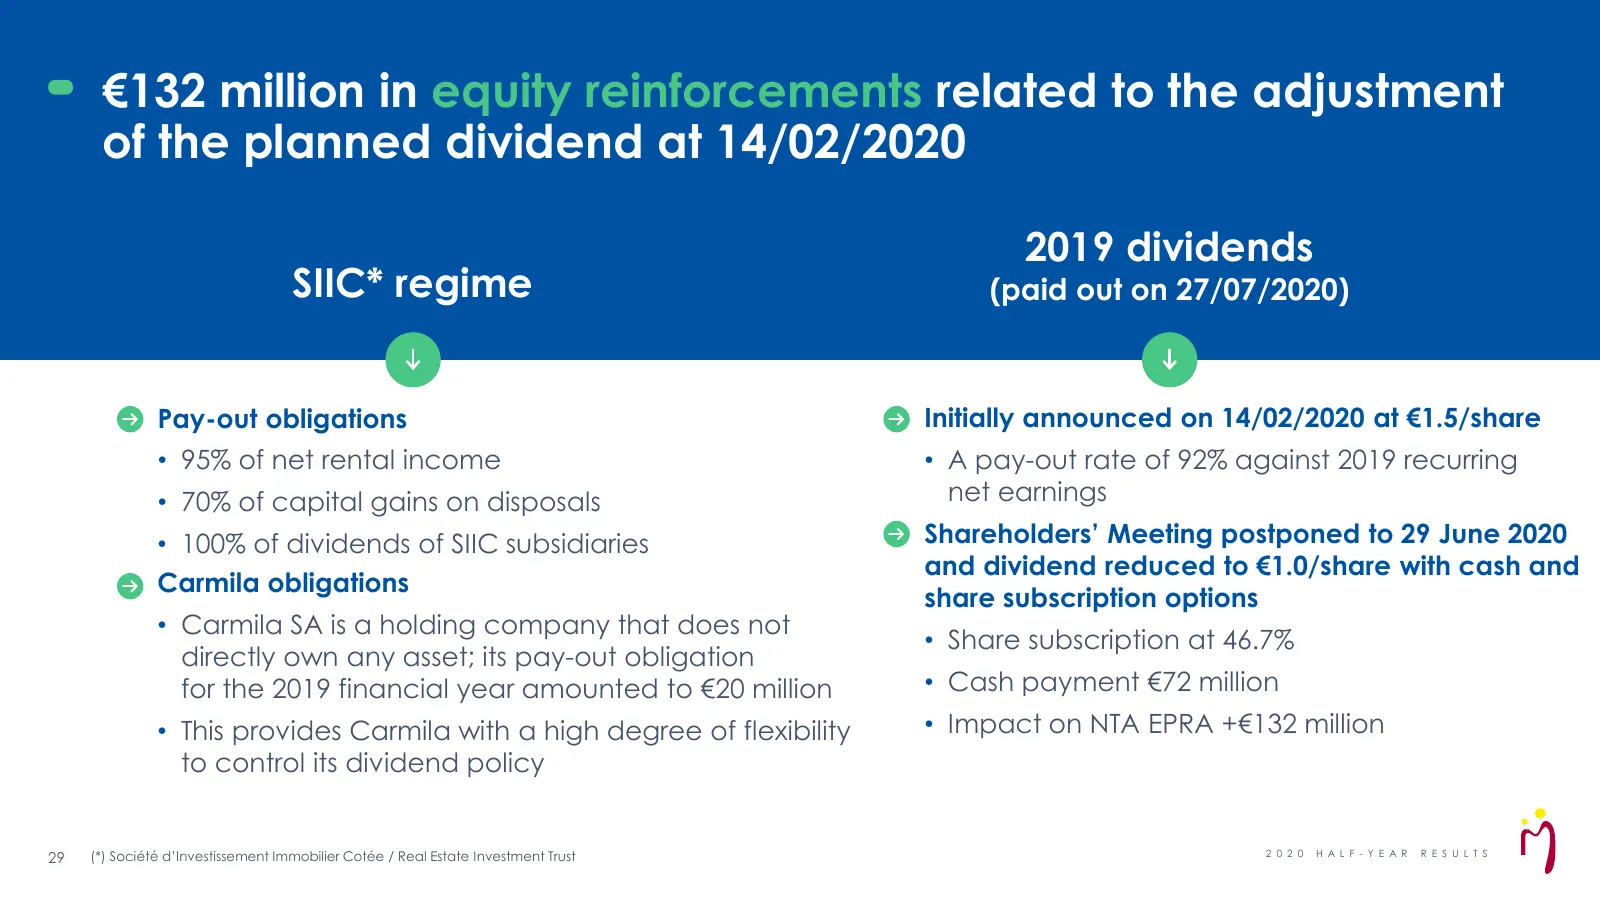
€132 million in equity reinforcements related to the adjustment of the planned dividend at 14/02/2020 2019 dividends SIIC* regime (paid out on 27/07/2020) Pay-out obligations Initially announced on 14/02/2020 at €1.5/share • 95% of net rental income • A pay-out rate of 92% against 2019 recurring • 7
Slide 30: Carmila's specific advantages
Carmila’s specific advantages 30 Nice Lingostière (Extensions) – France
Slide 31: Proximity as a differentiating and value-creating advantage
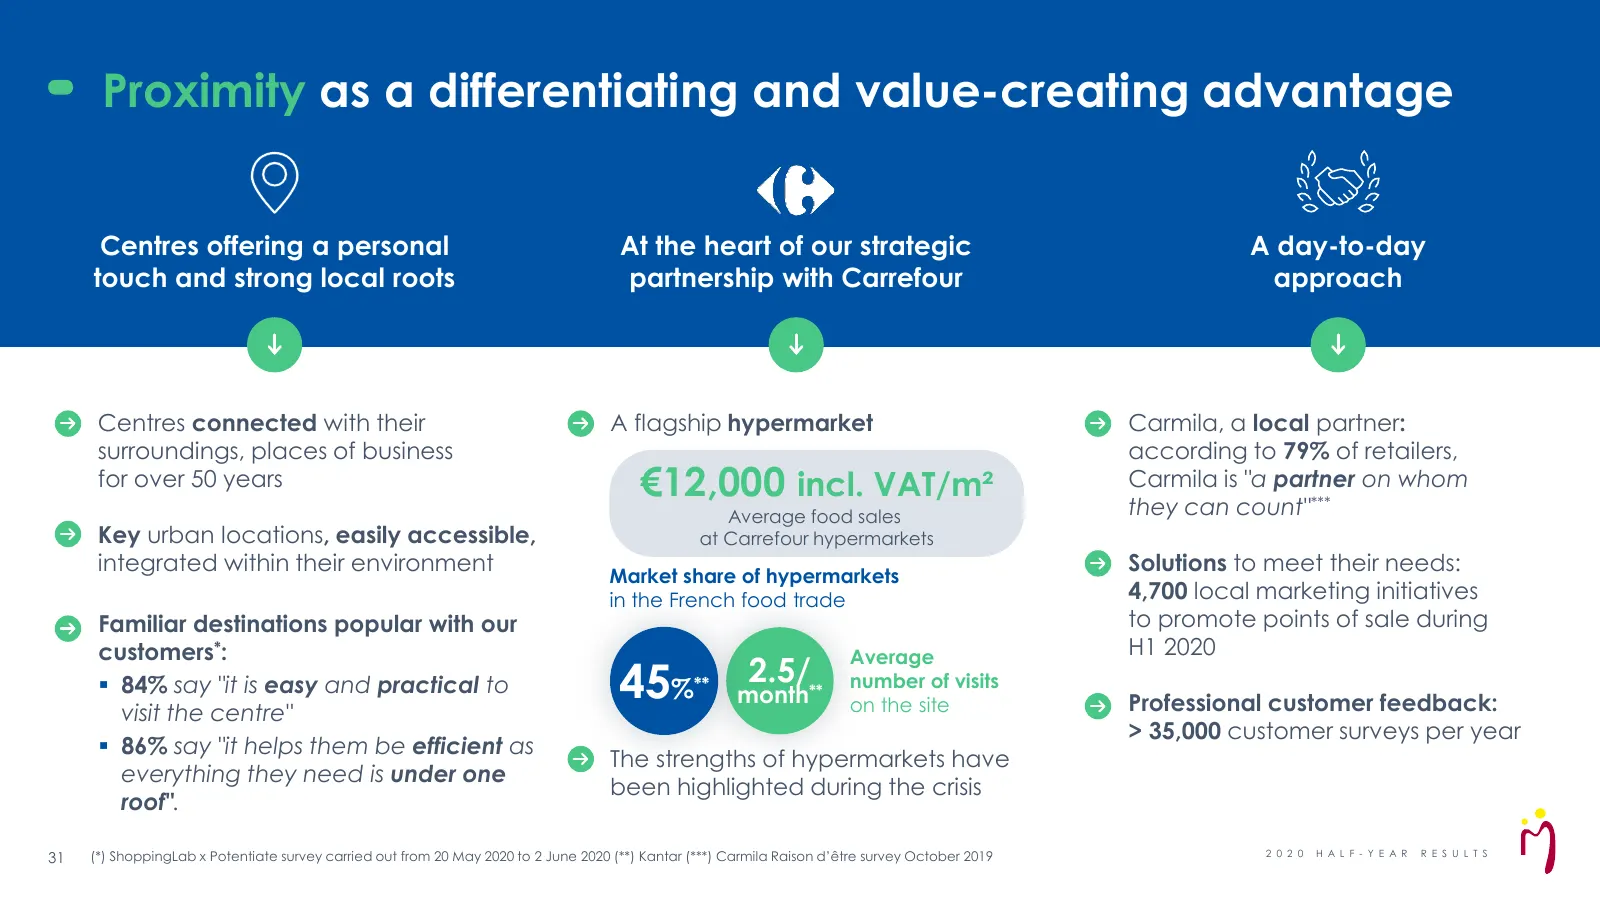
Proximity as a differentiating and value-creating advantage Centres offering a personal At the heart of our strategic A day-to-day touch and strong local roots partnership with Carrefour approach Centres connected with their A flagship hypermarket Carmila, a local partner: surroundings, places of bu
Slide 32: Proximity, the most suited shopping centre business model
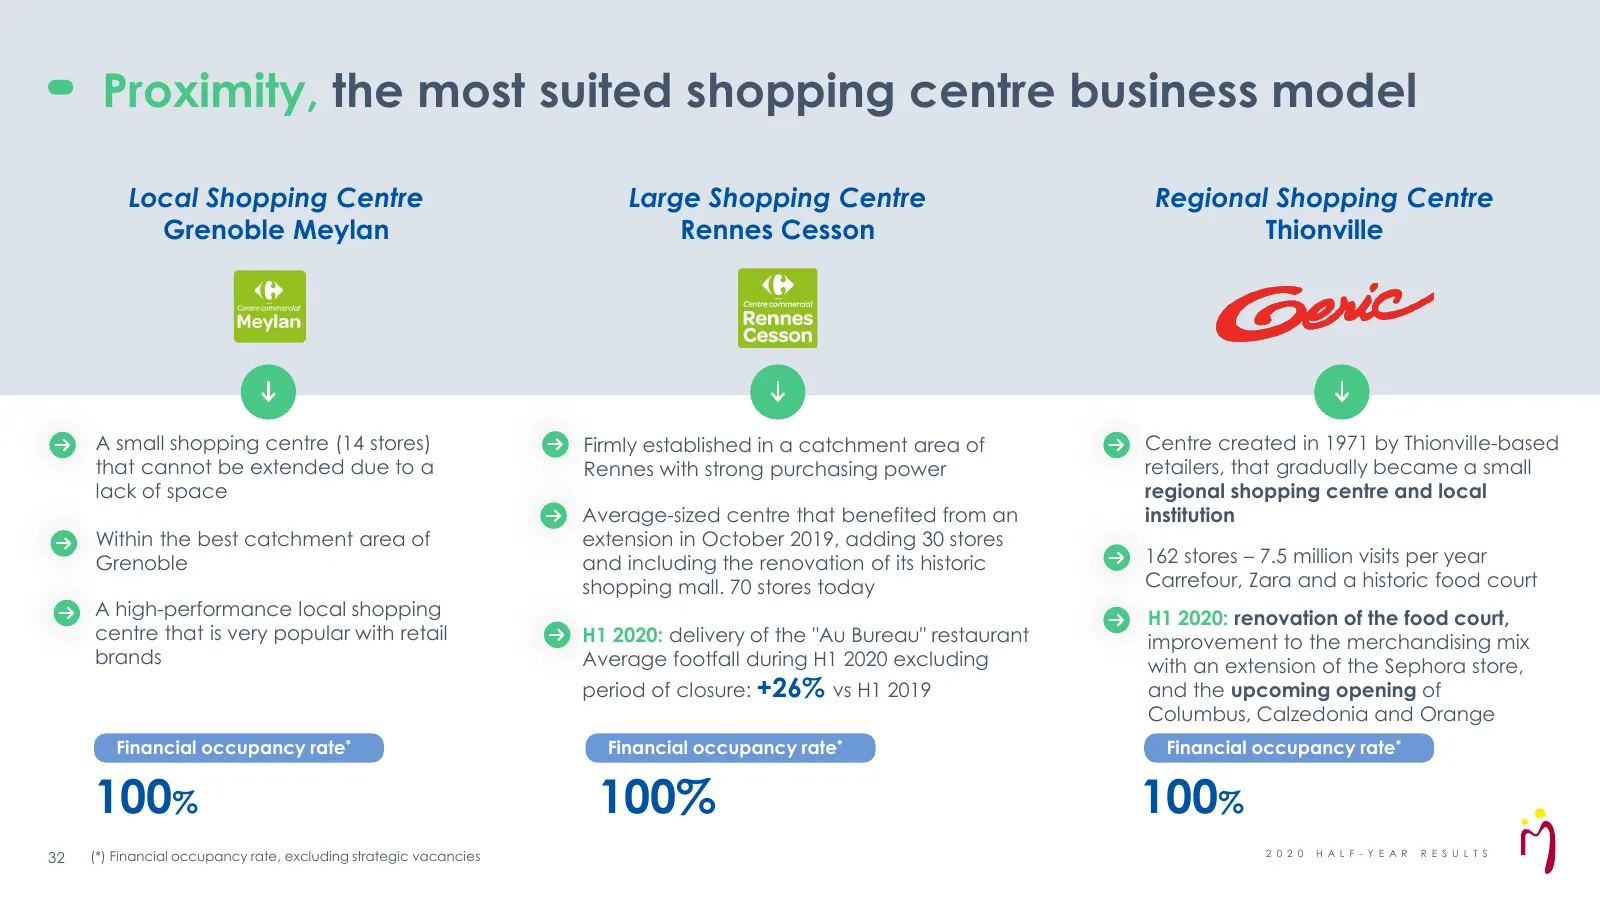
Proximity, the most suited shopping centre business model Local Shopping Centre Large Shopping Centre Regional Shopping Centre Grenoble Meylan Rennes Cesson Thionville • A small shopping centre (14 stores) Firmly established in a catchment area of Centre created in 1971 by Thionville-based that cann
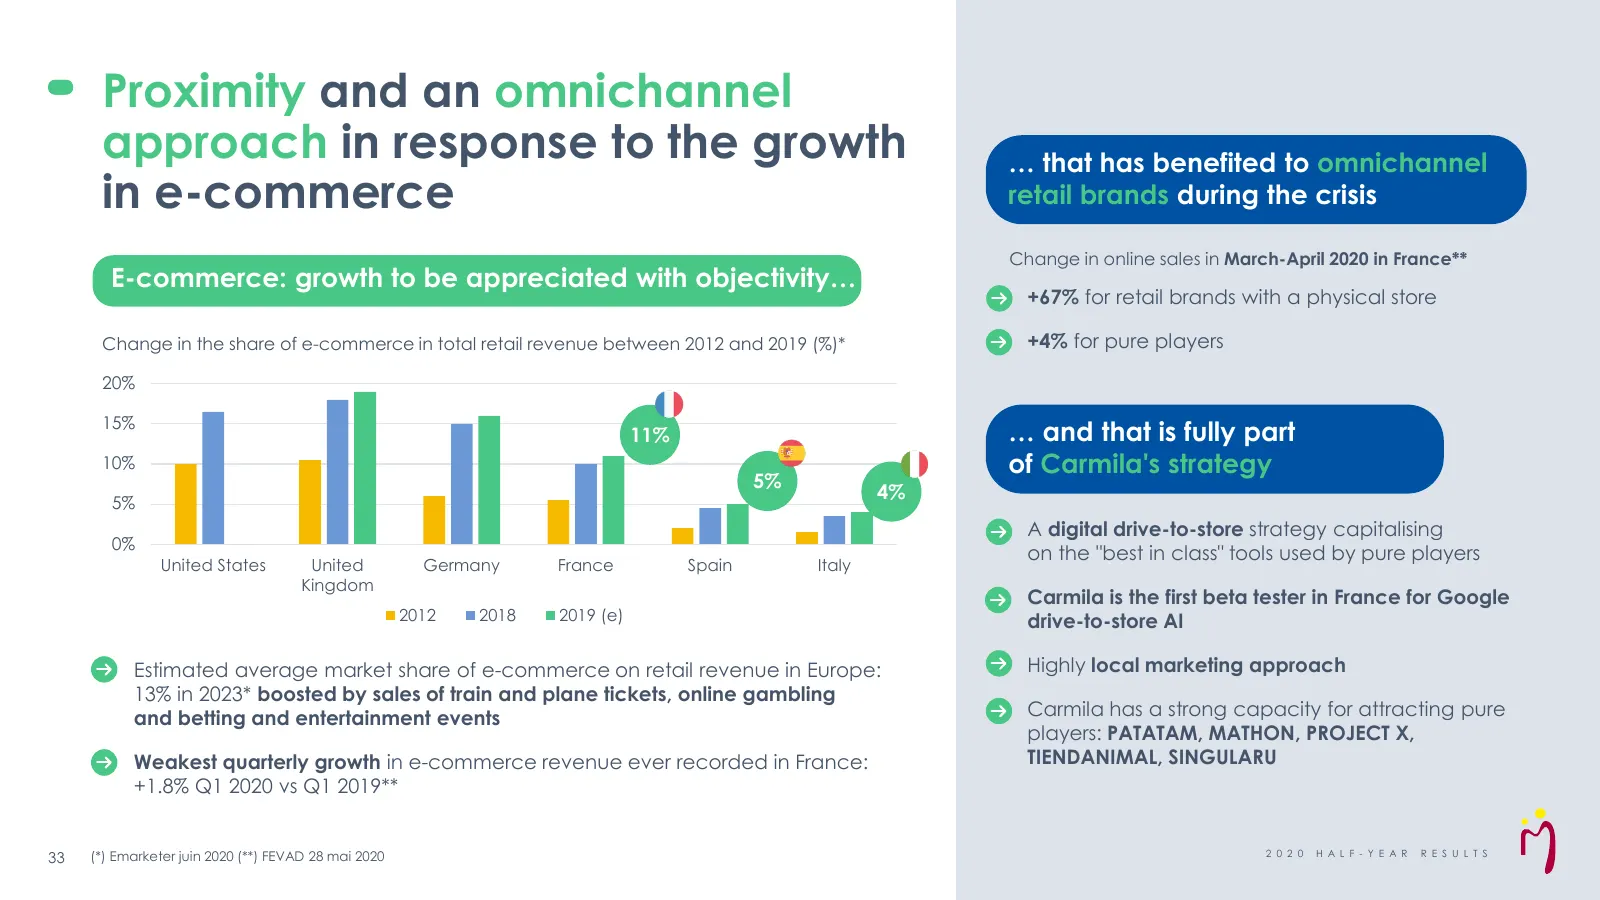
Slide 33: Proximity and an omnichannel approach in response to e-commerce
Proximity and an omnichannel approach in response to the growth … that has benefited to omnichannel in e-commerce retail brands during the crisis Change in online sales in March-April 2020 in France** E-commerce: growth to be appreciated with objectivity… +67% for retail brands with a physical store
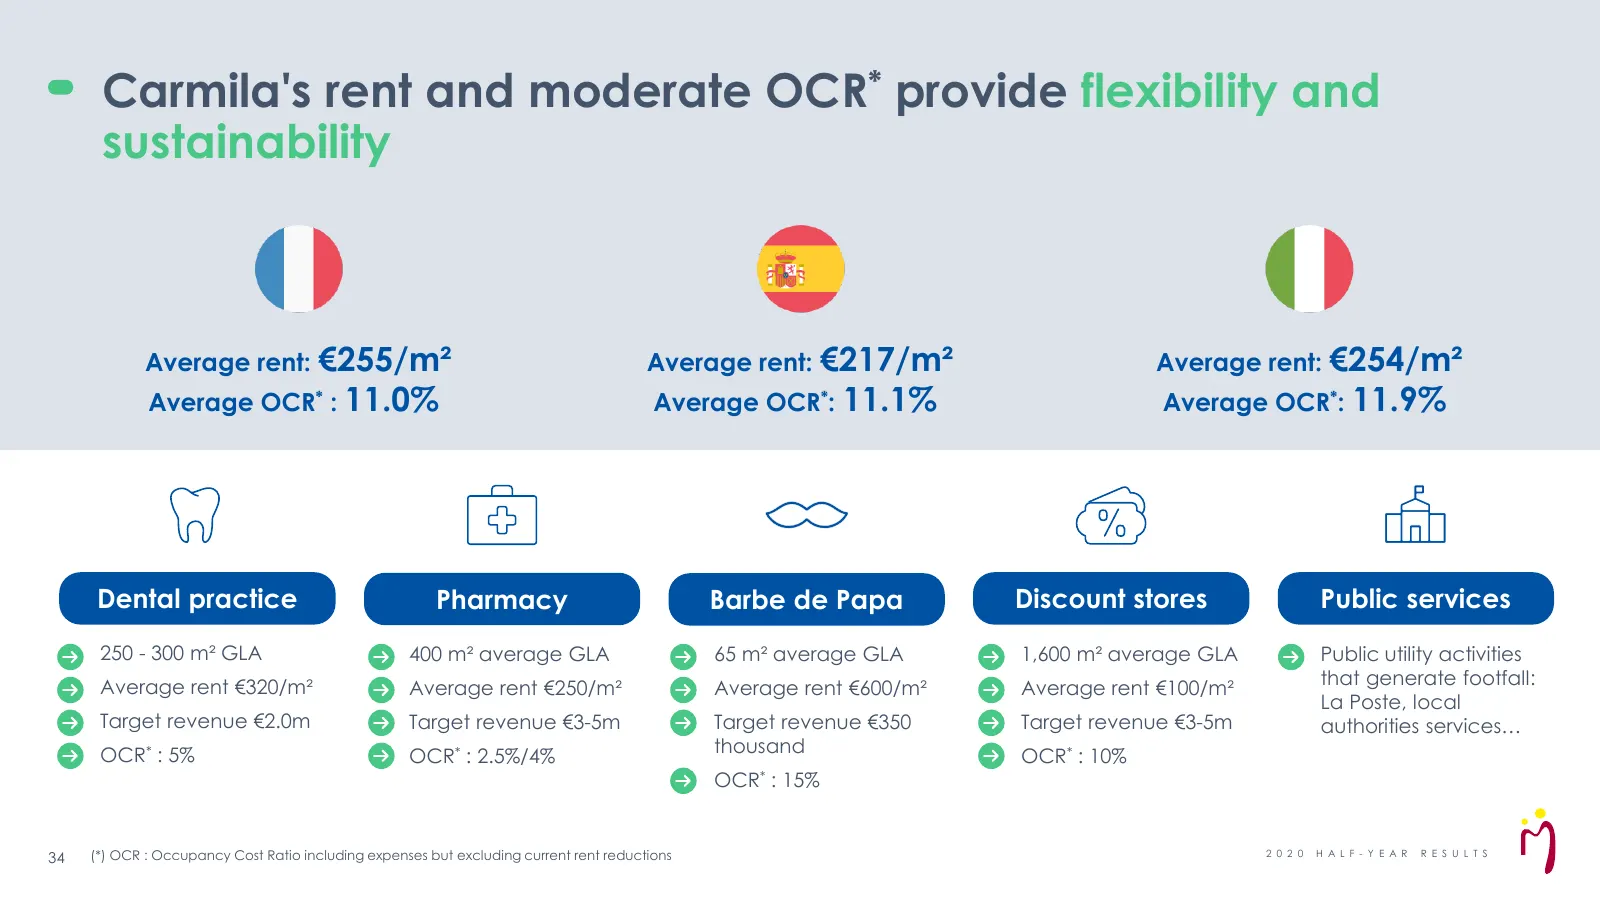
Slide 34: Carmila's rent and moderate OCR provide flexibility and sustainability
Carmila's rent and moderate OCR* provide flexibility and sustainability Average rent: €255/m² Average rent: €217/m² Average rent: €254/m² Average OCR* : 11.0% Average OCR*: 11.1% Average OCR*: 11.9% Dental practice Pharmacy Barbe de Papa Discount stores Public services 250 - 300 m² GLA 400 m² averag
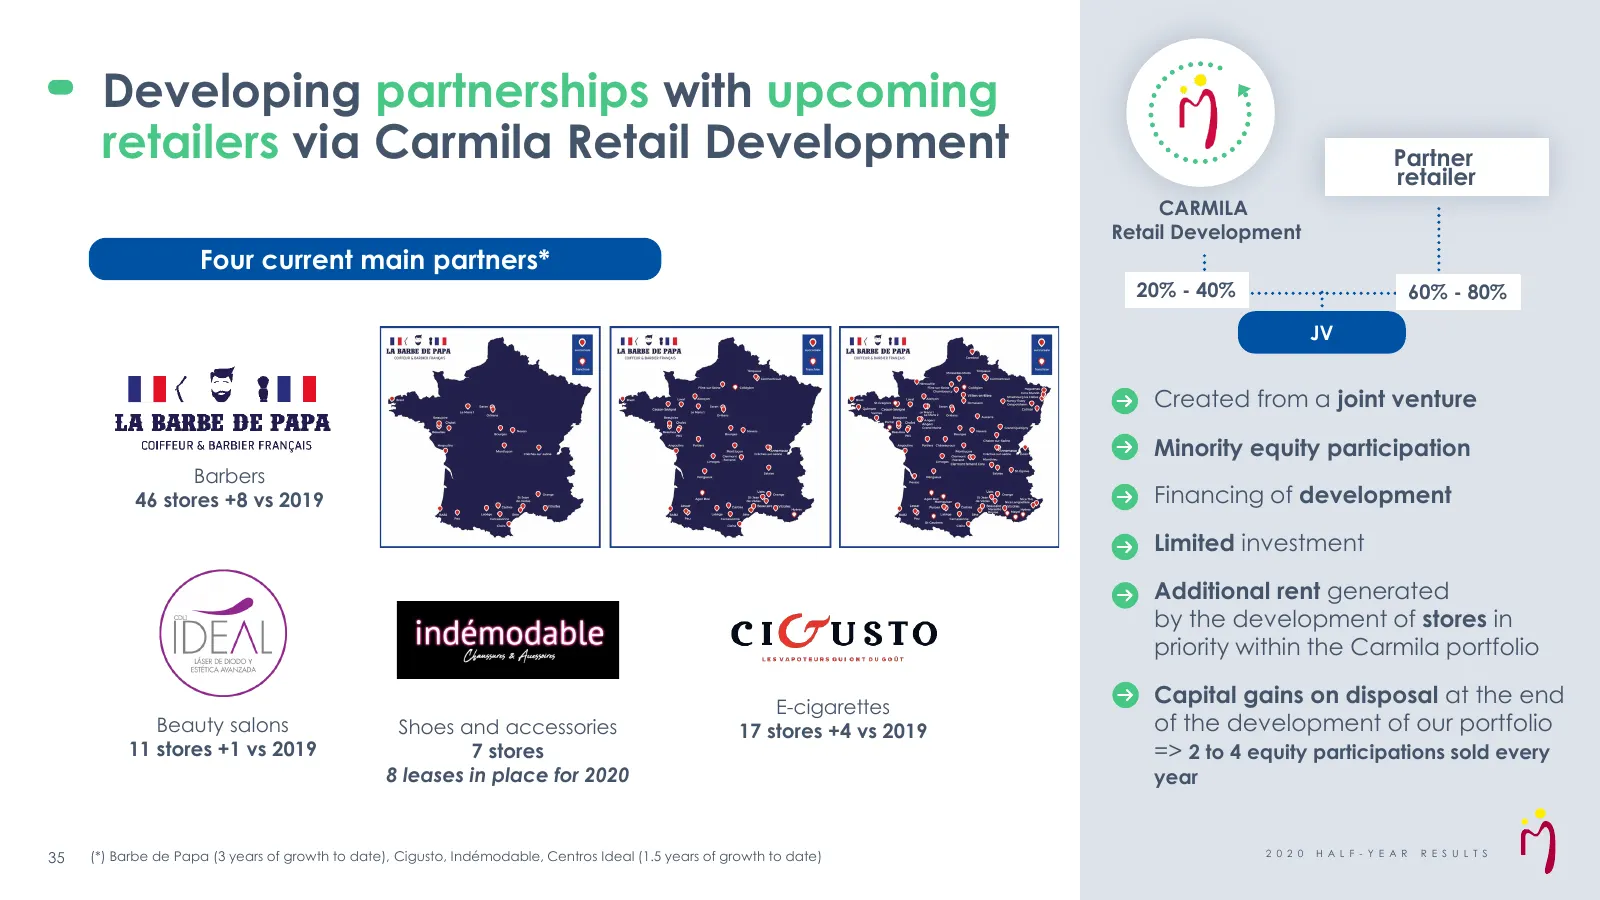
Slide 35: Developing partnerships with upcoming retailers via Carmila Retail Development
Developing partnerships with upcoming retailers via Carmila Retail Development Partner retailer CARMILA Retail Development Four current main partners* 20% - 40% 60% - 80% JV Created from a joint venture Minority equity participation Barbers 46 stores +8 vs 2019 Financing of development Limited inves
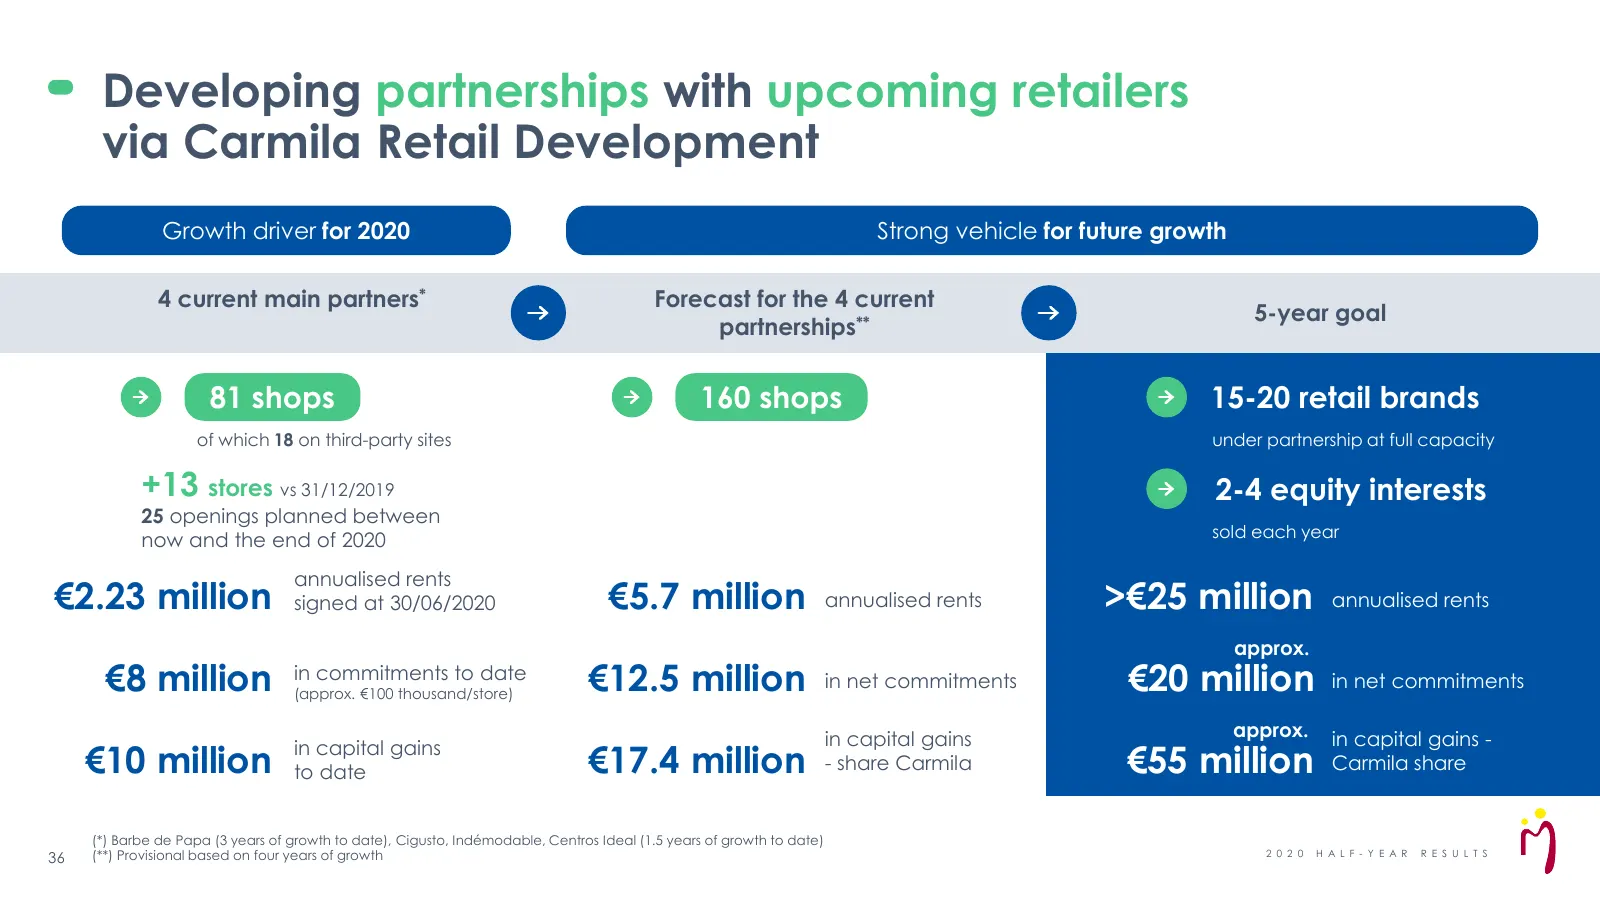
Slide 36: Developing partnerships with upcoming retailers via Carmila Retail Development
Developing partnerships with upcoming retailers via Carmila Retail Development Growth driver for 2020 Strong vehicle for future growth 4 current main partners* Forecast for the 4 current 5-year goal partnerships** 81 shops 160 shops 15-20 retail brands of which 18 on third-party sites under partners
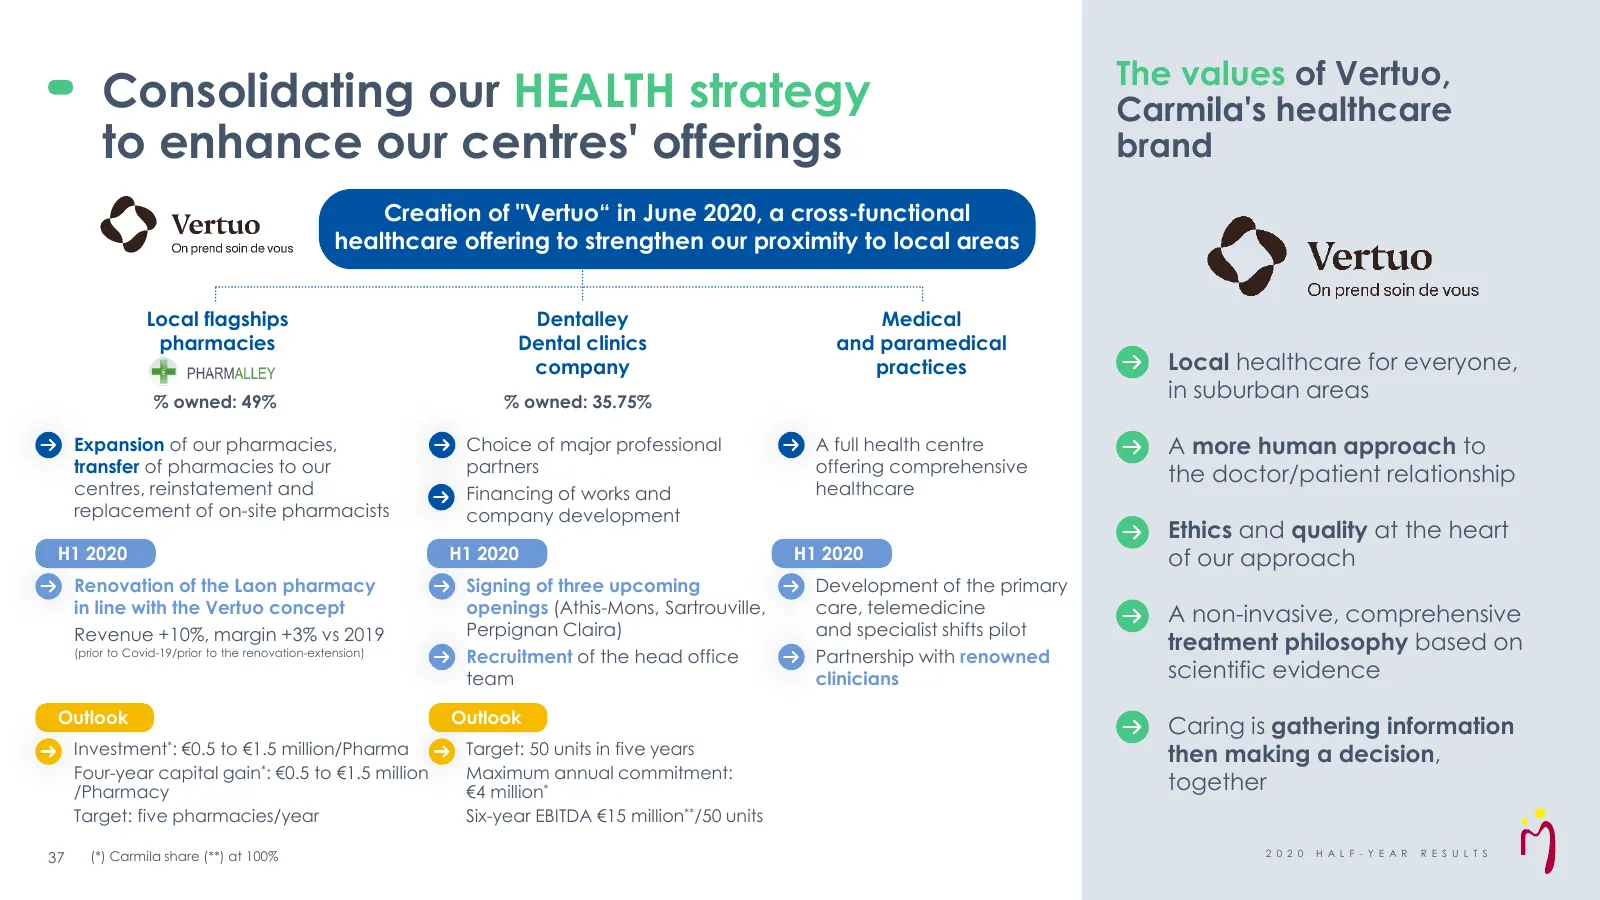
Slide 37: Consolidating our HEALTH strategy to enhance our centres' offerings
The values of Vertuo, Consolidating our HEALTH strategy Carmila's healthcare to enhance our centres' offerings brand Creation of "Vertuo“ in June 2020, a cross-functional healthcare offering to strengthen our proximity to local areas Local flagships Dentalley Medical pharmacies Dental clinics and pa
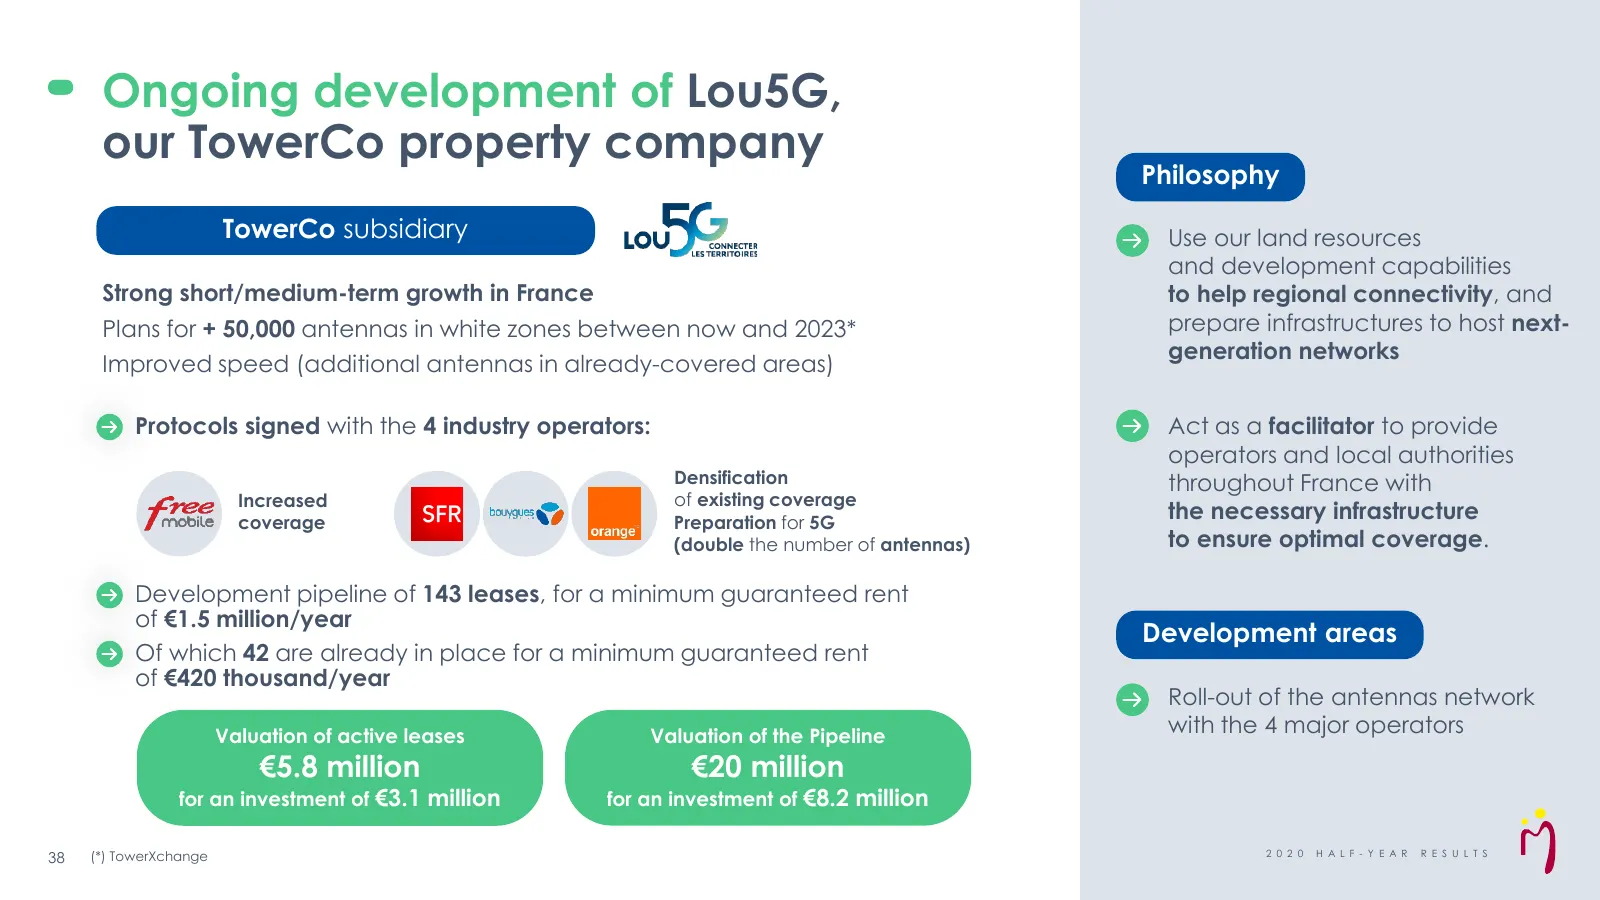
Slide 38: Ongoing development of Lou5G, our TowerCo property company
Ongoing development of Lou5G, our TowerCo property company Philosophy TowerCo subsidiary Use our land resources and development capabilities Strong short/medium-term growth in France to help regional connectivity, and Plans for + 50,000 antennas in white zones between now and 2023* prepare infrastru
Slide 39: Conclusion
Conclusion 39
Slide 40: Shopping centres are under threat but quality will triumph
NATIXIS research note of 25 June 2020 Shopping centres are under threat but quality will triumph over the crisis and e-commerce R É S U L T A T S S E M E S T R I E L S 2 0 2 0 40
Slide 41: Our purpose statement as a guiding principle
Our purpose statement as a guiding principle At Carmila, proximity is at the heart of everything we do. We provide everybody with access to a reasoned offering of everyday useful products and services. Approval We connect retailers and customers as closely as possible to living areas. by the Shareho
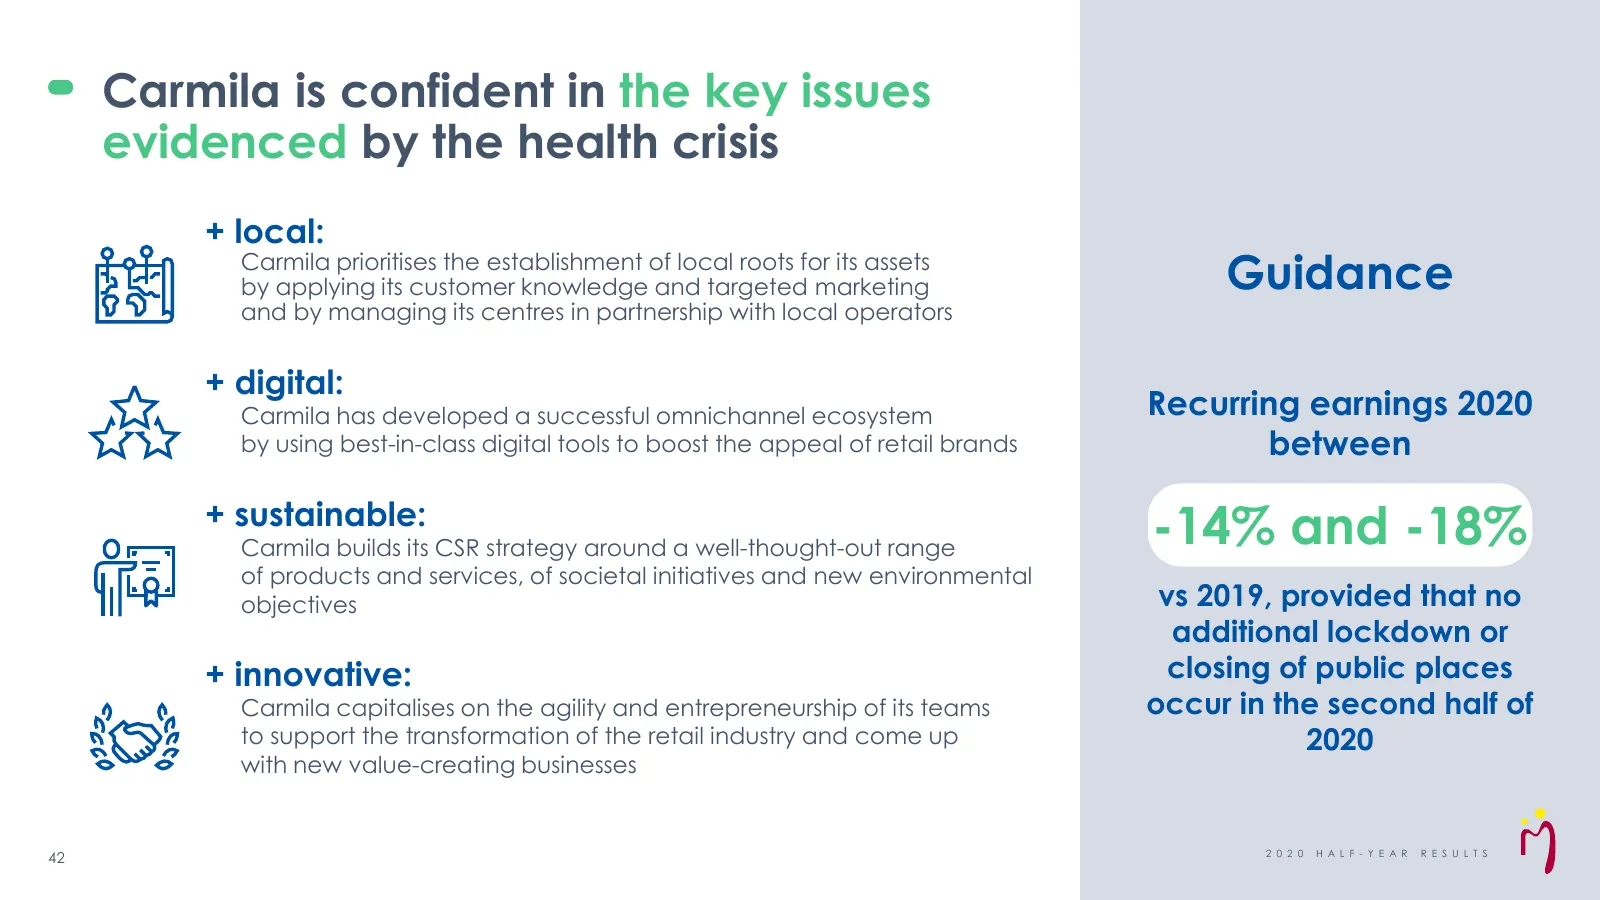
Slide 42: Carmila is confident in the key issues evidenced by the health crisis
Carmila is confident in the key issues evidenced by the health crisis + local: Carmila prioritises the establishment of local roots for its assets by applying its customer knowledge and targeted marketing Guidance and by managing its centres in partnership with local operators + digital: Carmila has
Slide 43: 2020 half-year results
3 0 J u l y 2 0 2 0 2020 half-year results
Source: Internet Archive copy of carmila.com
More decks from Carmila SA
 H1 2026 Earnings Presentation39 slides · Jul 29, 2026
 Shareholder Meeting (May 2026)71 slides · May 13, 2026
 FY2025 Earnings Presentation43 slides · February 2026
 H1 2025 Earnings Presentation44 slides · Jul 22, 2025
 Shareholder Meeting (May 2025)79 slides · May 14, 2025
 FY2024 Earnings Presentation43 slides · Feb 11, 2025