Ubiquitel — Merger or Acquisition (May 2006)
15 slides from Ubiquitel's merger presentation, May 23, 2006
Slide 1: Acquisition by Sprint Nextel: Fair Value, Best Strategic Alternative
ded piquitel Acquisition by Sprint Nextel: Fair Value, Best Strategic Alternative May 2006
Slide 2: Safe Harbor Provisions
deJoiquitet Safe Harbor Provisions Annumber of the matters discussed in this document that are not historical or current facts deal with potential future circumstances and developments, in particular, information regarding the acquisition of UbiquiTel Inc. and its projected 2006 and 2007 operating p
Slide 3: Additional Disclosure
deJoiquitet Additional Disclosure In connection with the proposed acquisition and required stockholder approval, UbiquiTel has filed with the SEC a definitive proxy statement. The proxy statement will be mailed to the stockholders of UbiquiTel. UbiquiTel's stockholders are urged to read the proxy st
Slide 4: Acquisition by Sprint Nextel: Best Course For UbiquiTel Stockholders
deJoiquitet Acquisition by Sprint Nextel Best Course For UbiquiTel Stockholders > Uncertain Prospects After Sprint Nextel Merger Led To Exploration of Strategic Alternatives - Challenging operating environment ~ Prospect of continuing litigation with uncertain timing/outcome > Sale To Sprint Nextel
Slide 5: Challenging Operating Environment
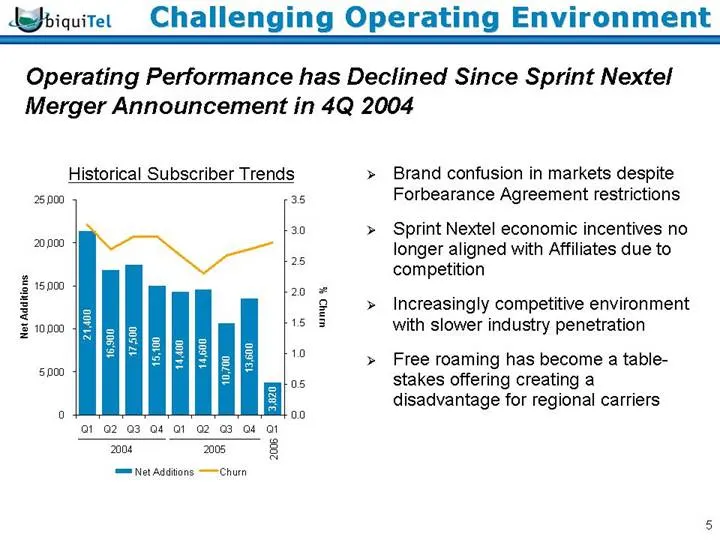
J oiquitet Challenging Operating Environment Operating Performance has Declined Since Sprint Nextel Merger Announcement in 4Q 2004 Historical Subscriber Trends 2500 35 a0 2op00 25 3B 20 Not Additions a 500 or a2 03 a4 a1 a2 a3 at at 200 ms «8 = Net Adgtions —churn wun v Brand confusion in markets de
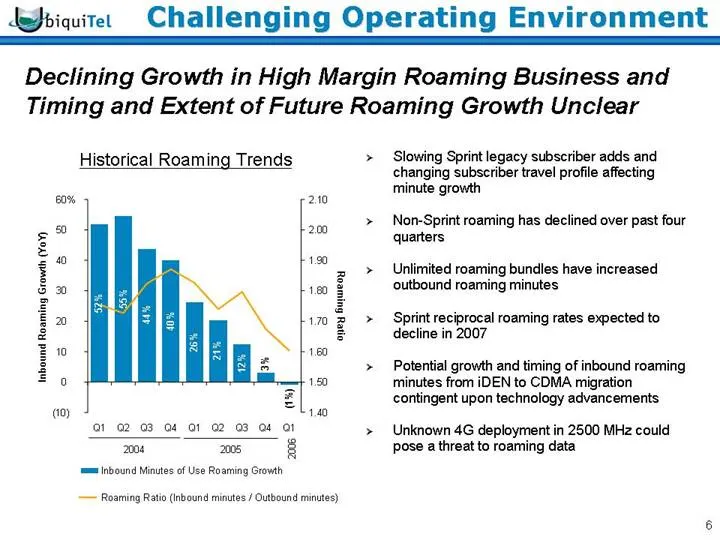
Slide 6: Challenging Operating Environment: Declining Roaming Growth
J biquitet Challenging Operating Environment Declining Growth in High Margin Roaming Business and Timing and Extent of Future Roaming Growth Unclear Inbound Roaming Growth (YoY) 60% 10) Historical Roaming Trends 210 ‘ney Suyweoy Oo 8 oO @ oO OF 205 g ‘mm Inbound Minutes of Use Roaming Growth 20 — Ro
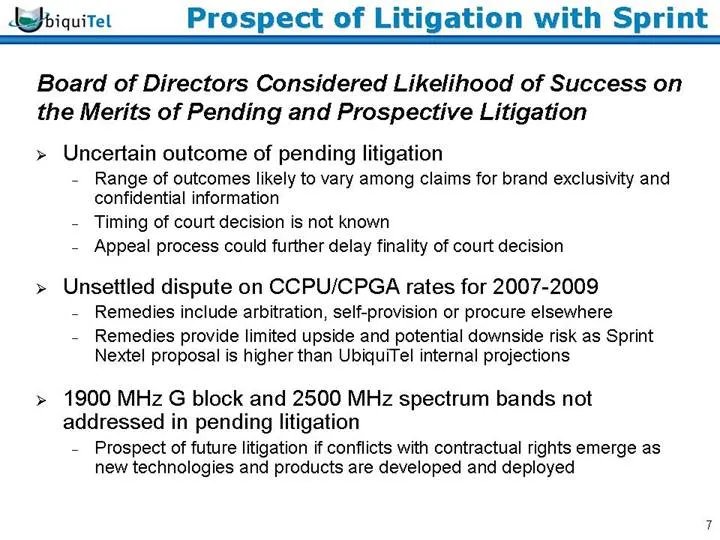
Slide 7: Prospect of Litigation with Sprint
deJbiquitet Prospect of Litigation with Sprint Board of Directors Considered Likelihood of Success on the Merits of Pending and Prospective Litigation > Uncertain outcome of pending litigation ~ Range of outcomes likely to vary among claims for brand exclusivity and confidential information - Timing
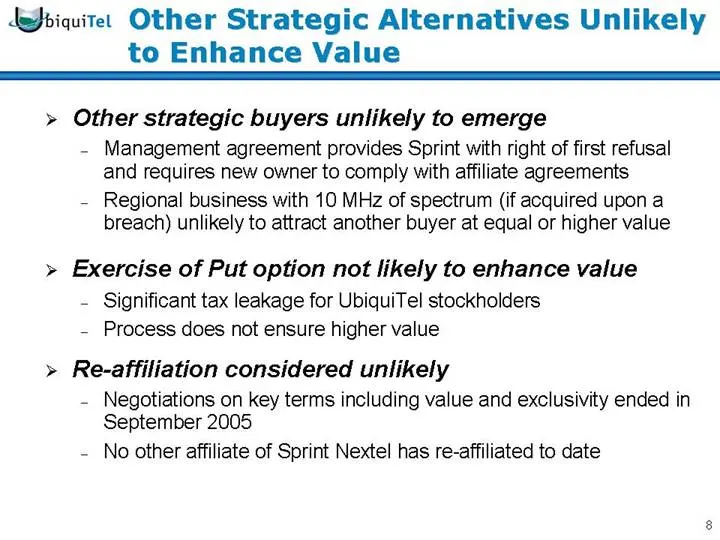
Slide 8: Other Strategic Alternatives Unlikely to Enhance Value
driquite' Other Strategic Alternatives Unlikely to Enhance Value > Other strategic buyers unlikely to emerge - Management agreement provides Sprint with right of first refusal and requires new owner to comply with affiliate agreements ~ Regional business with 10 MHz of spectrum (if acquired upon a b
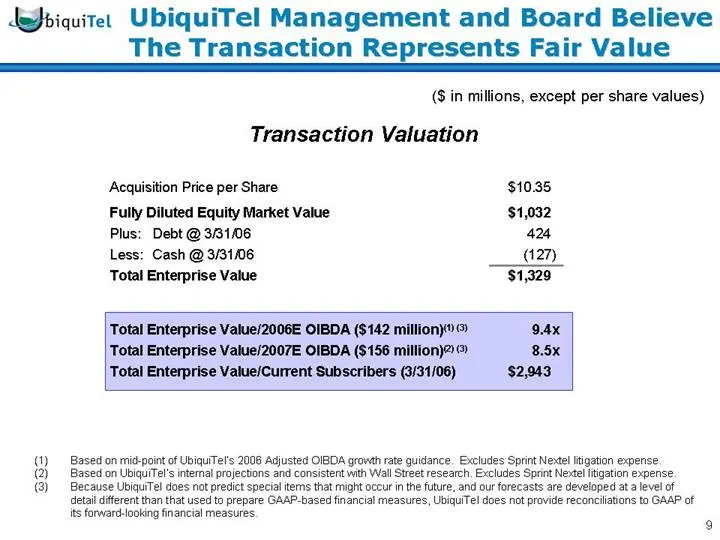
Slide 9: The Transaction Represents Fair Value
dJriquitet UbiquiTel Management and Board Believe The Transaction Represents Fair Value ($ in millions, except per share values) Transaction Valuation Acquisition Price per Share $1035 Fully Diluted Equity Market Value $1,032 Plus: Debt @ 36106 424 Less: Cash @ 3/3106 (127) Total Enterprise Value $1
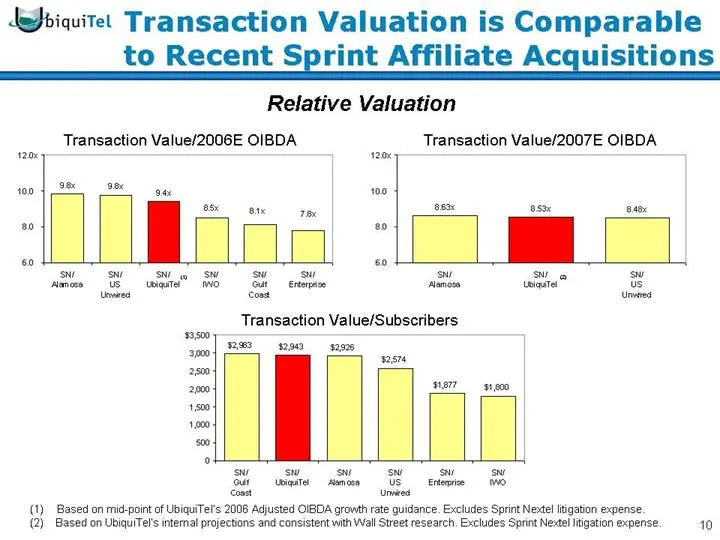
Slide 10: Transaction Valuation is Comparable to Recent Sprint Affiliate Acquisitions
dg¥biquite’ Transaction Valuation is Comparable to Recent Spr nt Affiliate Acqu ons Relative Valuation Transaction Value/2006E OIBDA Transaction Value/2007E OIBDA 2m 109 oo fea 20 60 Ca ee ee ow a ances US miguel” AO Guten nose eit ites const Transaction Value/Subscribers www Gat weigiTel Aanoee US
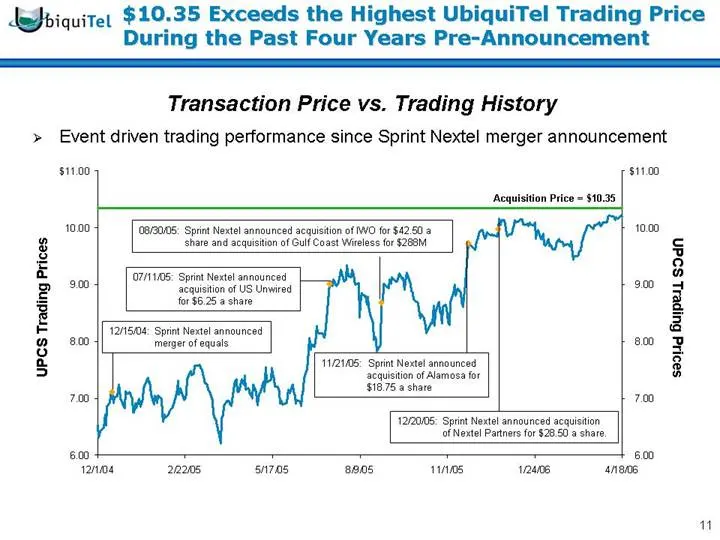
Slide 11: $10.35 Exceeds the Highest UbiquiTel Trading Price Pre-Announcement
deJoiquitet $10.35 Exceeds the Highest UbiquiTel Trading Price During the Past Four Years Pre-Announcement » Event driven trading performance since Sprint Nextel merger announcement UPCS Trading Prices oem Transaction Price vs. Trading History 1000 9.00 ao 700 600 rn sit00 Acquistion Price ~ $10.35
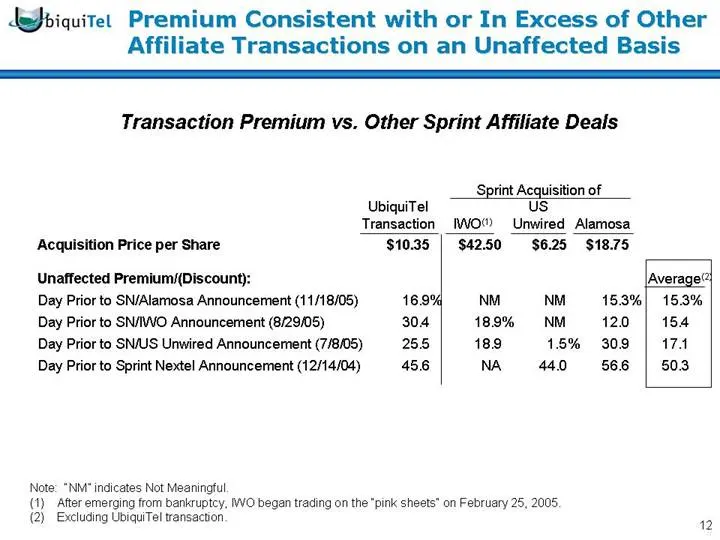
Slide 12: Premium Consistent with or In Excess of Other Affiliate Transactions
dJoiquitet. Premium Consistent with or In Excess of Other Affiliate Transactions on an Unaffected Basis Transaction Premium vs. Other Sprint Affiliate Deals Sprint Acquisition of UbiquiTel US Transaction [WO Unwired Alamosa Acquisition Price per Share $10.35 | $4250 $6.25 $18.75 Unaffected Premium/(
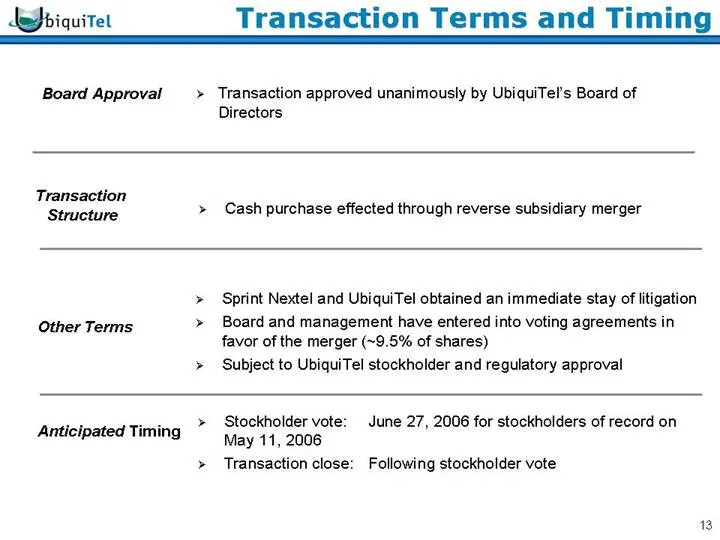
Slide 13: Transaction Terms and Timing
bp quiTel Transaction Terms and Timing Board Approval » Transaction approved unanimously by UbiquiTel’s Board of Directors Transaction - SEIS. > Cash purchase effected through reverse subsidiary merger Sprint Nextel and UbiquiTel obtained an immediate stay of litigation Other Terms Board and managem
Slide 14: Acquisition by Sprint Nextel Provides Fair Value, Best Strategic Alternative
Wriquiter Acquisition by Sprint Nextel Provides Fair Value, Best Strategic Alternative >» $10.35 in Cash Today Provides Fair Value to UbiquiTel Stockholders - Comparable to Recent Sprint Nextel Affiliate Transactions - Highest UPCS Stock Price in Past 4 Years Pre-Announcement > Best Available Strate
Slide 15: Searchable text section of graphics shown above
Searchable text section of graphics shown above [LOGO] Acquisition by Sprint Nextel: Fair Value, Best Strategic Alternative May 2006 [LOGO] Safe Harbor Provisions A number of the matters discussed in this document that are not historical or current facts deal with potential future circumstances and
Source: SEC EDGAR · 8-K filed May 23, 2006