Somerset Hills Bancorp — Shareholder Meeting (April 2010)
25 slides from Somerset Hills Bancorp's shareholder meeting presentation, Apr 28, 2010
Slide 1: Annual Meeting of Stockholders April 28, 2010
Annual Meeting of Stockholders April 28, 2010 1
Slide 2: Forward-Looking Statements
2 Forward-Looking Statements This investor presentation contains certain forward-looking statements which are based on certain assumptions and describe future plans, strategies and expectations of the Company. These forward-looking statements are generally identified by use of the words "believe," "
Slide 3: Company Profile
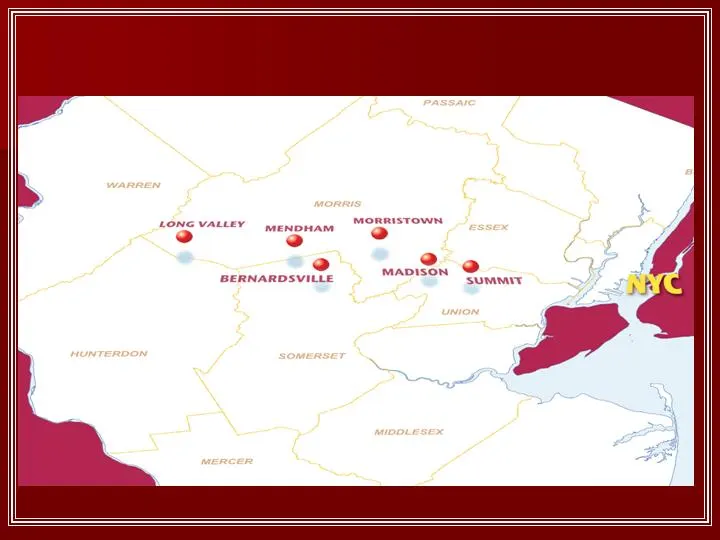
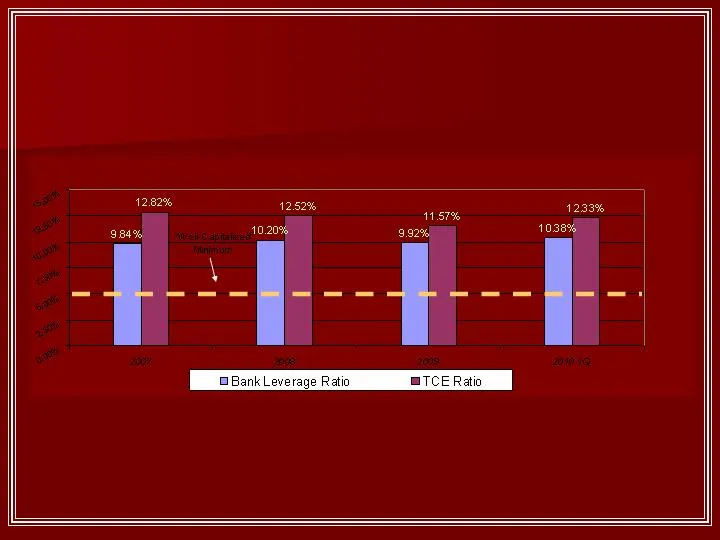
3 Company Profile Commercial banking franchise in Northern NJ; founded in 1998 Six branches located in one of the Nation’s wealthiest regions A relationship-based commercial and consumer lender $330 million in assets at year-end 2009 Strong capital; tangible common equity ratio above 12% Sound asset
Slide 4: Bernardsville
es 2 BERNARDSVILLE eo e
Slide 5: Valuable New Jersey Franchise
5 Valuable New Jersey Franchise Superior Asset Quality We rank #1 out of 26 in asset quality versus NJ Banks (see note) Rank based on SOMH nonperforming asset ratio of .08% versus NJ average of 2.20% Exceptional Deposit Mix We rank #1 in deposit mix Rank based on SOMH core (non-CD) deposits percenta
Slide 6: Balance Sheet Trends
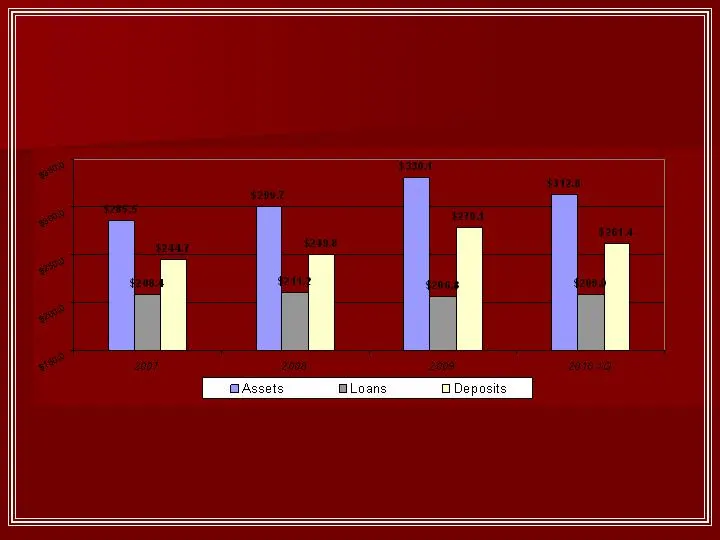
6 Balance Sheet Trends ($ millions)
Slide 7: Net Income
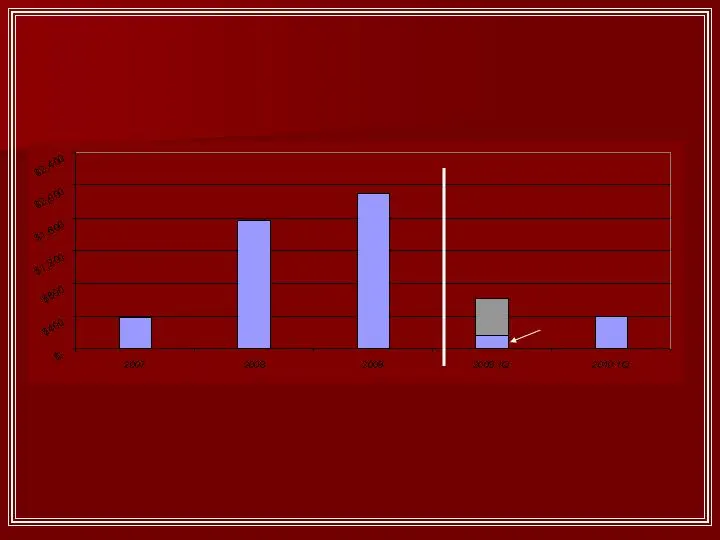
$ 619 7 Net Income ($ thousands) $ 382 $ 1,894 $ 1,566 $ 410 $ 161* _____ * $161 excludes a first qtr. 2009 BOLI benefit, net of a retirement plan liability, resulting from the death of our former CFO.
Slide 8: Capital Strength
8 Capital Strength At period-end
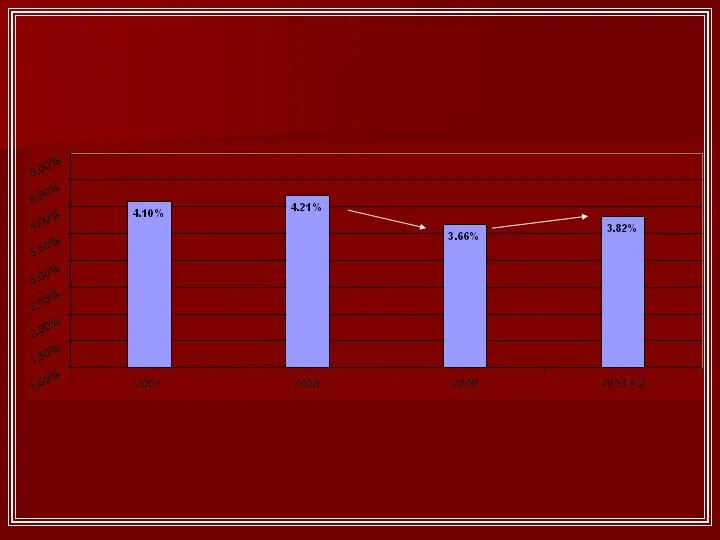
Slide 9: Net Interest Margin
Reflects strategy to increase liquidity Reflects partial unwinding of strategy 9 Net Interest Margin Note : Net interest margin reflected on a fully-taxable equivalent basis
Slide 10: Positioned for Rising Rates
10 Positioned for Rising Rates Strategic decision to position bank for rising rates Maintain relatively large overnight holdings rather than reach for yield Our fixed rate residential exposure (both securities and loans) remains low–15% of total assets Potential impact of rising interest rates on ou
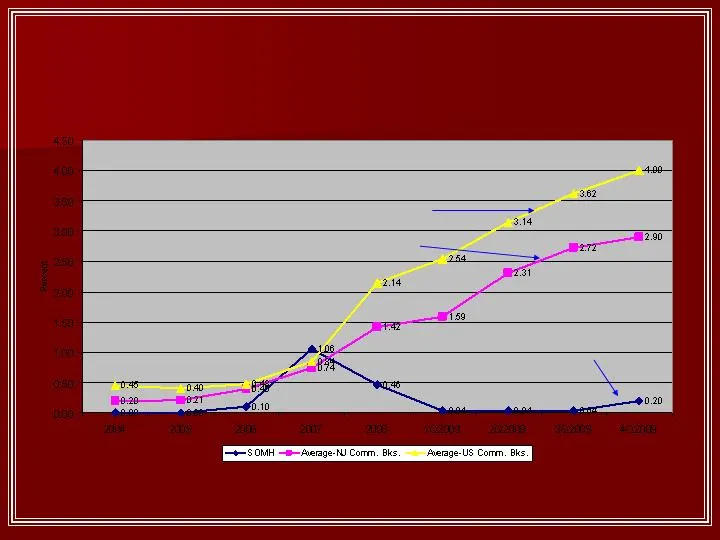
Slide 11: Nonperforming Asset Ratio vs. Industry
11 Nonperforming Asset Ratio vs. Industry Source: SNL Financial. Commercial banks between $100mm and $1billion in total assets. SOMH U.S. Community Banks NJ Community Banks
Slide 12: Asset Quality
12 Asset Quality ( How do we do it?) Conservative Credit Culture Strict Underwriting standards (Low LTV, Recourse, etc.) Philosophy of “careful growth” since inception in 1998 High level of owner-occupied collateral resulting from a focus on professional fields such as lawyers, doctors and accountan
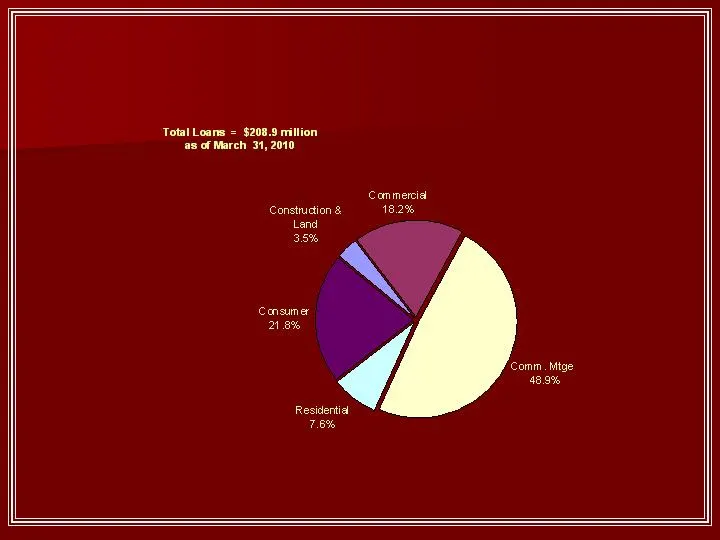
Slide 13: Total Loans
Total Loans = $208.9 rrllion ‘as of March 34, 2010 Commercial Constudions 182% teed an% Consumer \ nee , Residertiad 7.8% ‘Comm. Mige 48.9%
Slide 14: Commercial Mortgage Portfolio
14 Commercial Mortgage Portfolio Portfolio totals $102.0 million as of March 31, 2010 We’ve never had a loss in this portfolio 100% of portfolio is secured by NJ properties Diversified exposure with $695,000 average loan size Weighted average LTV at origination less than 50% Approx. 64% of portfolio
Slide 15: Commercial Loan Portfolio
15 Commercial Loan Portfolio Portfolio totals $38.0 million as of March 31, 2010 As of 3/31/10, no nonperforming loans and one loan ($182,000) past due more than 30 days Average loan size approx. $200,000 reflecting a diverse local customer base, with strong cross sell and referral opportunities Vir
Slide 16: Consumer Loan Portfolio
16 Consumer Loan Portfolio $45.5 million outstanding as of March 31, 2009 (98% Home Equity) Historical charge-offs in home equity portfolio = ZERO No loans past due more than 30 days Nonaccrual loans only 0.23% of total portfolio 100% in State of NJ Self-originated, individually underwritten in-hous
Slide 17: Residential Mortgage Lending
17 Residential Mortgage Lending Residential portfolio totals $15.9 million at 3/31/10 Primarily “accommodation” jumbos to local high net worth individuals Current avg. LTV is less than 40% No nonperformers or past-due more than 30 days at 3/31/10 We have never had a loss in this portfolio Sullivan F
Slide 18: Deposit Mix
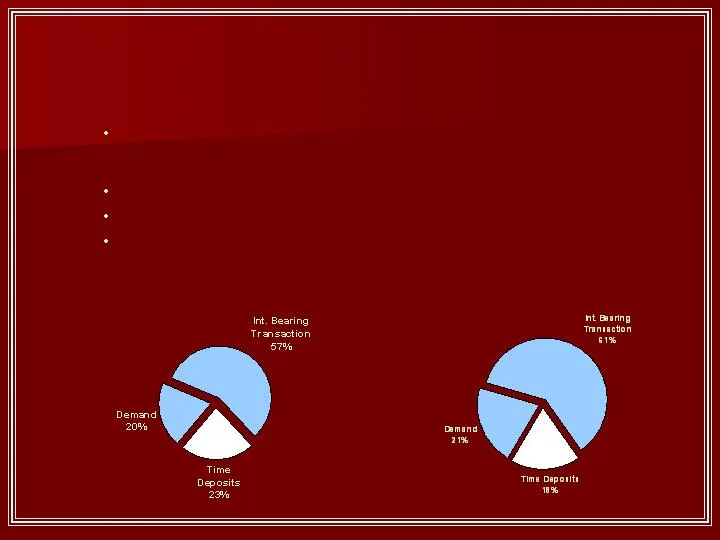
Year-end 2008 Year-end 2009 18 Deposit Mix - Currently, more than 82% of Deposits are “Core” Our definition of core excludes all time deposits - Key drivers of growth in Core: relationship banking paramount checking escrow control product - Time Deposits decreasing and returning to historical levels
Slide 19: Core Deposits
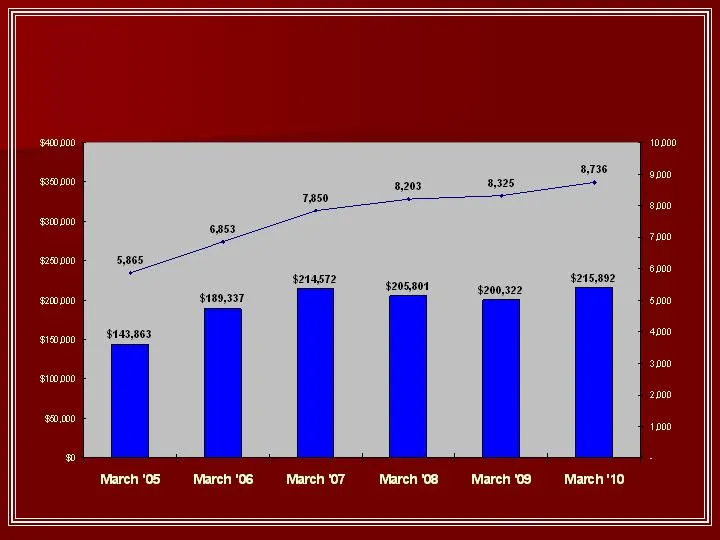
19 Core Deposits ($ thousands) # of Core Accounts Total Core Deposit Balances
Slide 20: Paramount Checking Account
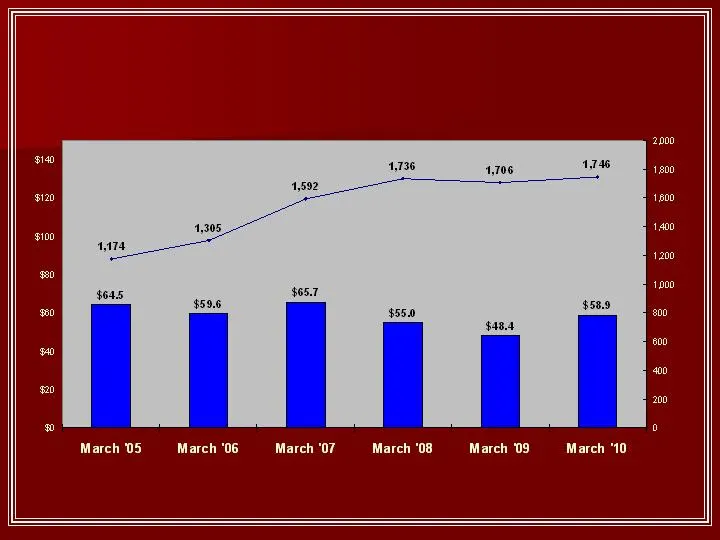
20 Paramount Checking Account ($ thousands) Average Balance per Account # of Paramount Accounts
Slide 21: Expense Control
special assessment in 2009) FDIC Assessment (including a $140 Total -9.9% (153) 1,542 1,389 Other, incl. outside consultants -7.6% (41) 540 499 Data Processing and Telecom -27.7% (76) 274 198 Advertising/Promotion -1.8% $ (35) $ 1,917 $ 1,882 Occupancy Expense Control-Areas of Focus 21 Expense Contr
Slide 22: Embracing Technology
22 Embracing Technology We utilize technology to increase efficiency and improve customer service New and improved website Our Retail and Business Modules have streamlined functionality and an updated “look” We are the first community bank in the country to implement Trusteer’s Rapport product Remot
Slide 23: TARP Preferred issuance and redemption
23 On January 16, 2009 SOMH issued “TARP Preferred” $7.4 million in capital proceeds to Holding Company 163,065 warrants to purchase common stock at $6.82 Reasons for Issuing Perception that only the strongest community banks would be approved Encouraged by the regulators to participate Possibly pro
Slide 24: Dividends
24 Cash Dividend Today we declared a quarterly cash dividend of 5 cents per share Dividend Yield of 2.4% (assuming $8.25 share price) Stock Dividend Today we declared a 5% stock dividend This is our 8 th Stock Dividend in 9 years. Dividends
Slide 25: Summary
25 Our staff is highly experienced Each of our key executives, and a majority of our staff, has significant industry experience at both large and community-based banks Our balance sheet is strong Asset quality metrics among the best in the Nation We operate in one of the wealthiest regions in the U.
Source: SEC EDGAR · 8-K filed Apr 28, 2010
More decks from Somerset Hills Bancorp
 Shareholder Meeting (May 2013)10 slides · May 8, 2013
 Merger or Acquisition (February 2013)32 slides · Feb 7, 2013
 Merger or Acquisition (January 2013)13 slides · Jan 29, 2013
 Shareholder Meeting (April 2012)25 slides · Apr 19, 2012
 Investor Presentation (November 2011)26 slides · Nov 1, 2011
 Shareholder Meeting (April 2011)29 slides · Apr 26, 2011