Somerset Hills Bancorp — Shareholder Meeting (April 2011)
29 slides from Somerset Hills Bancorp's shareholder meeting presentation, Apr 26, 2011
Slide 1: Annual Meeting of Stockholders
Annual Meeting of Stockholders April 27, 2011
Slide 2: Forward-Looking Statements
Forward-Looking Statements This investor presentation contains certain forward-looking statements which are based on certain assumptions and describe future plans, strategies and expectations of the Company. These forward-looking statements are generally identified by use of the words “believe,” “ex
Slide 3: Company Profile
Company Profile Commercial banking franchise in Northern NJ; founded in 1998 A relationship-based lender located in one of the Nation’s wealthiest regions $329 million in assets at year-end 2010 Strong capital; tangible common equity ratio 12.0% Sound asset quality; greater than 99.9% of all loans a
Slide 4: Branch Network
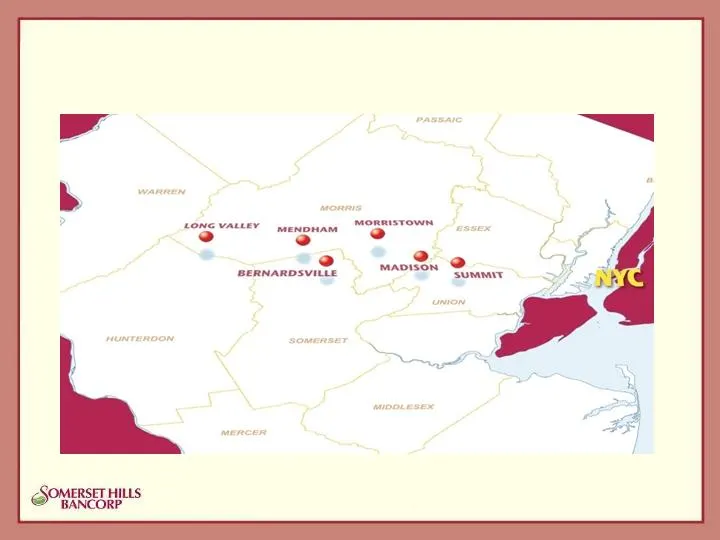
Branch Network Phil.
Slide 5: Valuable New Jersey Franchise
Valuable New Jersey Franchise Superior asset quality We rank #1 out of 28 in asset quality versus NJ Banks (see note) Rank based on SOMH nonperforming asset ratio of 0.08% versus NJ average of 2.88% Exceptional deposit mix We rank #2 out of 28 in deposit mix Rank based on SOMH core (non-CD) deposits
Slide 6: Balance Sheet Trends
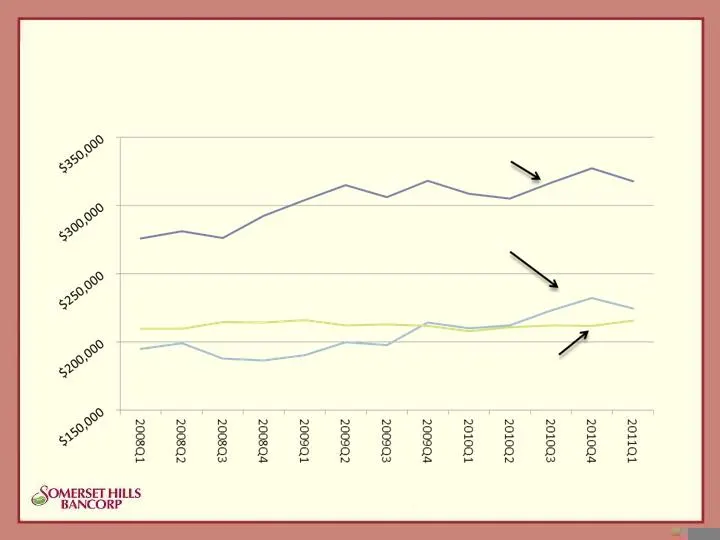
Balance Sheet Trends ($ thousands, quarterly avg.) Total Assets Core Deposits Loans
Slide 7: Net Income Trend
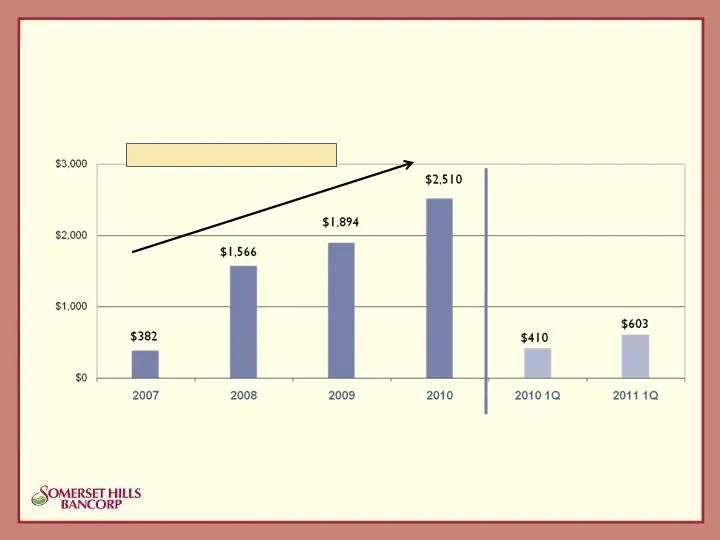
Net Income Trend ($ thousands) Strong Earnings Momentum
Slide 8: Profitability Ratios (Annual)
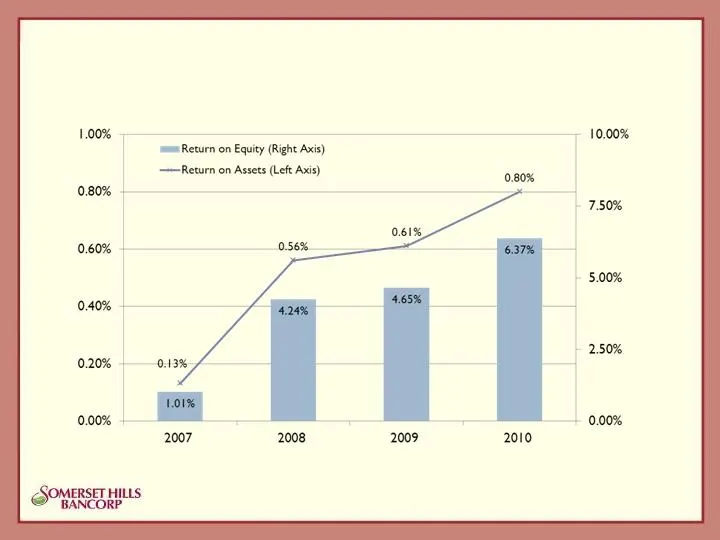
Profitability Ratios (Annual)
Slide 9: Profitability Ratios (1st Quarter)
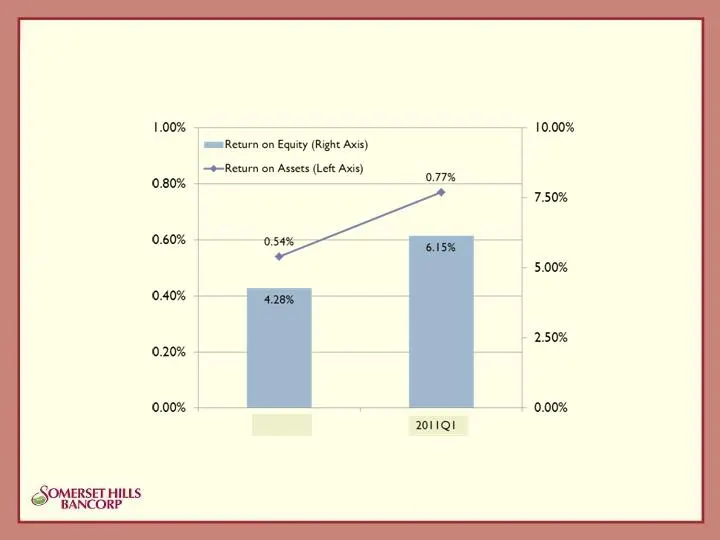
Profitability Ratios (1 st Quarter) 2010Q1
Slide 10: Net Interest Margin Trend
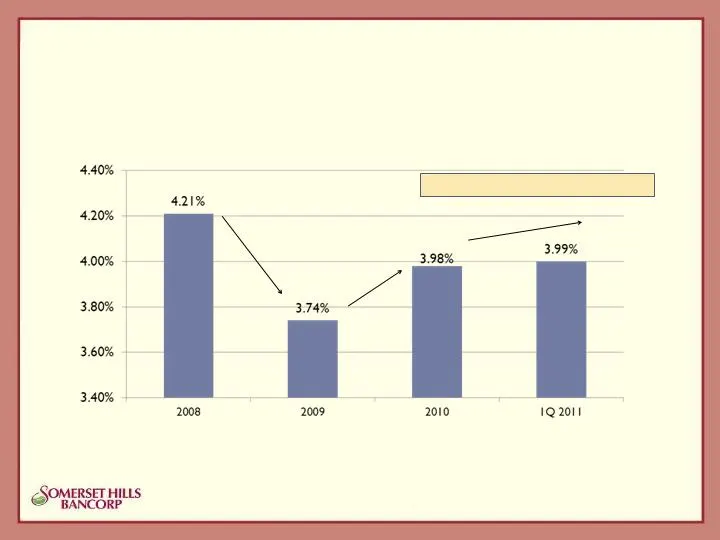
Net Interest Margin Trend Reflects strategy to increase liquidity Unwinding of strategy Loan growth Working our way back to 4.00%+
Slide 11: Operating Efficiency
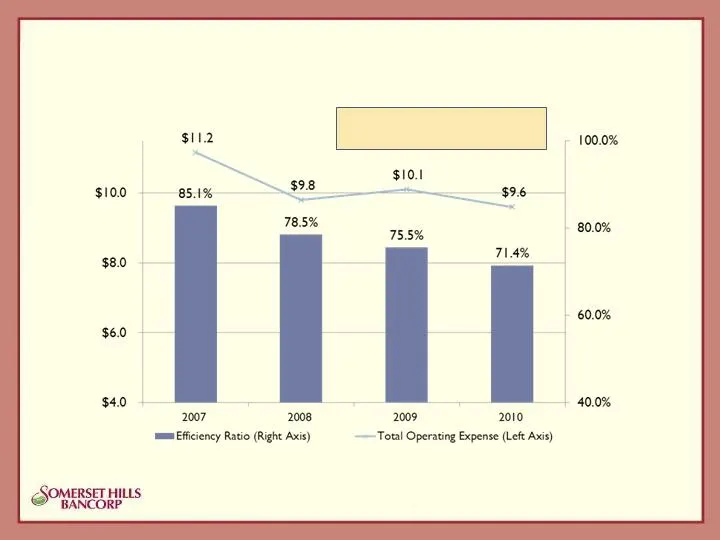
Operating Efficiency ($ millions) Always determined to do more with less
Slide 12: Capital Strength
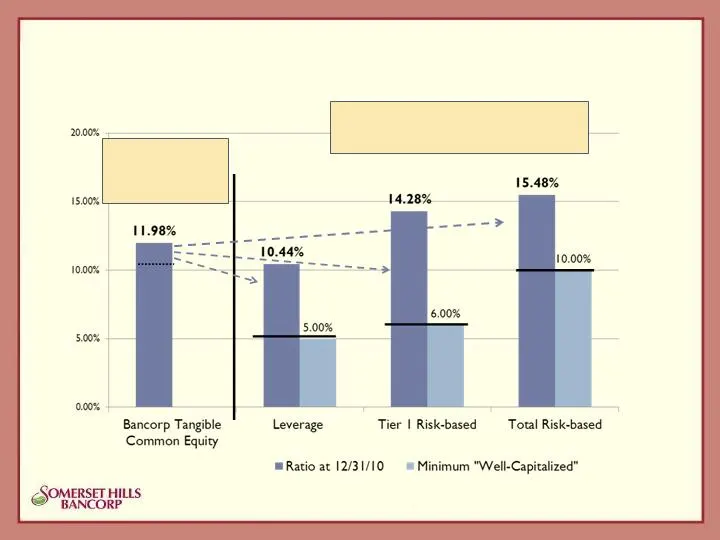
Capital Strength An additional $4+ million of capital is held at holding company. All regulatory capital ratios are more than 500 bps in excess of well- capitalized levels.
Slide 13: Credit Quality
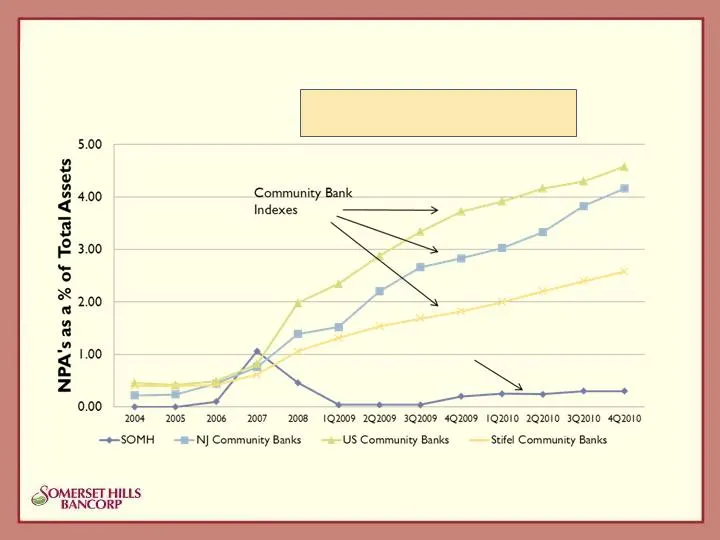
Credit Quality Source: SNL Financial. Commercial banks between $100mm and $1billion in total assets. SNL’s definition of nonperforming assets includes troubled debt restructurings. Somerset Hills Bank Somerset Hills has significantly less problem assets
Slide 14: Asset Quality-How Do We Do It?
Asset Quality-How Do We Do It? Credit Culture Conservative Strict Underwriting standards (Low LTV, Recourse, etc.) Philosophy of “careful growth” since inception in 1998 Owner-occupied collateral - focusing on professionals (e.g., lawyers, accountants, doctors) Economic Strength of Operating Area Ou
Slide 15: Loan Mix at Year-end 2010
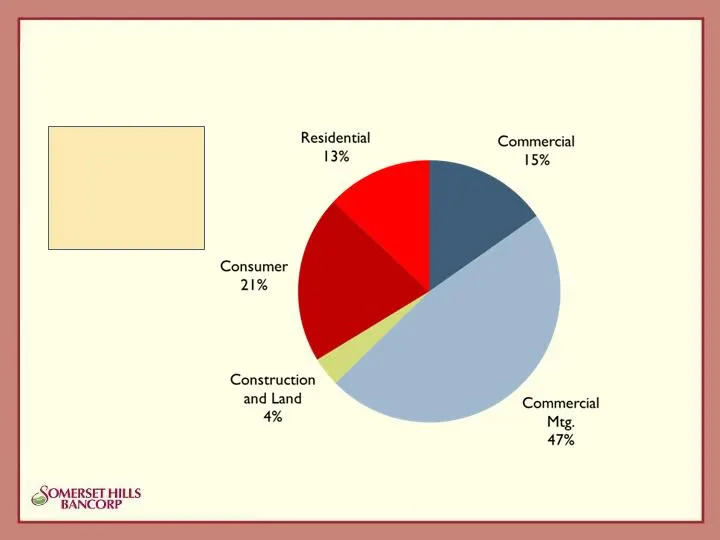
Loan Mix at Year-end 2010 Total Loan Portfolio = $207.1 million Well-diversified by Loan Type
Slide 16: Commercial Mortgage Portfolio
Commercial Mortgage Portfolio (information as of December 31, 2010) Portfolio totals $98.2 million We’ve never had a loss in this portfolio 100% of portfolio is secured by NJ properties Diversified with $659,000 average exposure per loan Average LTV at origination was 57% Approximately 56% of portfo
Slide 17: Commercial Loan Portfolio
Commercial Loan Portfolio (information as of December 31, 2010) Portfolio totals $31.6 million No nonperforming loans Average loan size of less than $200,000 reflecting a diverse local customer base, with strong cross sell and referral opportunities Virtually all commercial loans supported by person
Slide 18: Consumer Loan Portfolio
$42.9 million outstanding (98% Home Equity) Historical charge-offs in home equity portfolio = ZERO No nonaccrual loans 100% in State of NJ Self-originated, individually underwritten in-house We do not use automated underwriting models Majority originated with a CLTV of 50% to 65%; maximum of 80% 85%
Slide 19: Residential Mortgage Lending
Residential Mortgage Lending (information as of December 31, 2010) Residential portfolio totals $26.9 million Primarily “accommodation” jumbos to local high net worth individuals Avg. LTV of portfolio at origination is less than 50% No nonaccrual or loans past-due 30 days or more We have never had a
Slide 20: Investment Portfolio at Year-end 2010
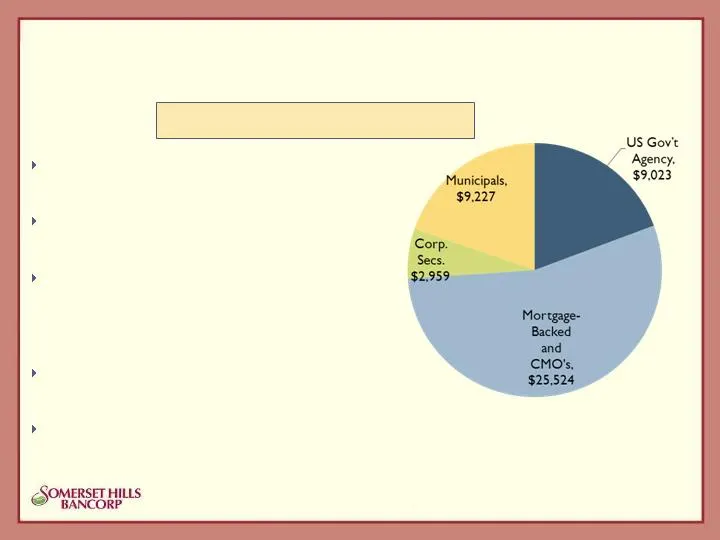
Investment Portfolio at Year-end 2010 We have never taken an OTTI charge , largely due to our conservative investment philosophy We avoid reaching for yield and stick to high quality investments Approximately 75% of the portfolio is guaranteed by U.S. Gov’t/Agencies The fair market value of our muni
Slide 21: Liquidity
Liquidity As a financial institution and, in particular, a community bank, we pay close attention to liquidity management. Currently, approximately 10% of the balance sheet ($30-$35 million) is held at the Federal Reserve in an overnight position We have substantial amounts of collateral, both secur
Slide 22: Positioned for Rising Interest Rates
Positioned for Rising Interest Rates We maintain a relatively large volume of overnight holdings We have avoided reaching for yield in our securities portfolio The duration of our loan portfolio is approximately 2 years Our residential exposure (both securities and loans) remains low–approx. 17% of
Slide 23: Deposit Funding
Deposit Funding Our business model relies almost exclusively on core and other local deposits Core deposit (i.e., non-time) balances comprised 85% of total deposits, best in NJ Relationship-driven commercial non-interest bearing demand accounts Paramount account, an attractive interest-bearing check
Slide 24: Deposit Mix Trends
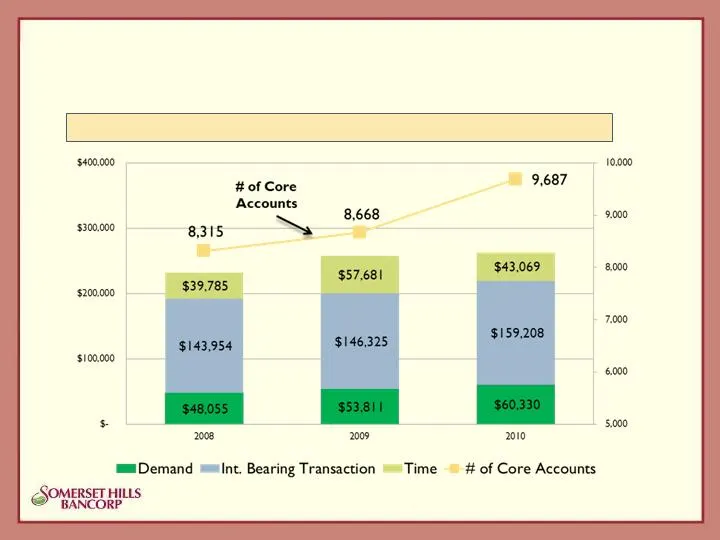
Deposit Mix Trends ($ thousands, annual averages) Core Deposits have increased by 14.3% over the past two years.
Slide 25: Expense Control
Expense Control ($ thousands) Increase/(Decrease) Amount Pct. Occupancy $ 1,664.9 $ 1,881.6 $ (216.7) -11.5% Printing, Stat & Supplies 133.2 186.0 (52.9) -28.4% Legal Fees 38.4 85.9 (47.5) -55.3% Correspondent Bank Fees 58.6 94.0 (35.4) -37.6% Audits and Exams 261.1 286.3 (25.2) -8.8% Telephone 68.9
Slide 26: Technology
Technology As a community bank, we generally do not implement cutting-edge technology; however, we have the capability to deploy cost-effective technology, whenever advantageous We recently enhanced our debit card fraud detection systems. We are the first community bank to implement Trusteer’s Rappo
Slide 27: Dividends
Yesterday, we declared a quarterly cash dividend of 6 cents per share Represents a dividend yield of 2.7% (assuming $8.75 share price) We were one of just a handful of banks nationwide that raised its cash dividend in 2010. Our financial strength and performance bode well for potentially higher cash
Slide 28: Summary: unique and valuable community banking franchise
We have a unique and valuable community banking franchise We operate in one of the wealthiest regions in the Nation Our asset quality metrics are among the best We have a superior deposit mix We are strongly capitalized We are positioned well for a higher rate environment Our staff is highly experie
Slide 29: Somerset Hills Bancorp
OMERSET HILLS Ss BANCORP
Source: SEC EDGAR · 8-K filed Apr 26, 2011
More decks from Somerset Hills Bancorp
 Shareholder Meeting (May 2013)10 slides · May 8, 2013
 Merger or Acquisition (February 2013)32 slides · Feb 7, 2013
 Merger or Acquisition (January 2013)13 slides · Jan 29, 2013
 Shareholder Meeting (April 2012)25 slides · Apr 19, 2012
 Investor Presentation (November 2011)26 slides · Nov 1, 2011
 Shareholder Meeting (April 2010)25 slides · Apr 28, 2010