QMed — Investor Presentation (February 2007)
20 slides from QMed's investor presentation, Feb 13, 2007
Slide 1: QMed, Inc. Managing the Chronically Ill
QMed, Inc. Managing the Chronically Ill
Slide 2: Forward Looking Statements
This presentation contains “forward-looking statements” as that term is defined in the Private Securities Litigation Reform Act of 1995. These statements involve risks and uncertainties that may cause results to differ materially from those set forth in the statements. No forward-looking statement c
Slide 3: Guidance for SNP Revenue
Our guidance for 2007 is $38.5 - $44 Million revenue for New Jersey and South Dakota chronics alone (~3%) Chronic Population defined as CAD, Heart Failure & Stroke Fundamentals South Dakota New Jersey Population 112,994 276,796 Chronic Population 19,840 68,100 % Chronics 17.6% 24.6% Total All Popula
Slide 4: Special Needs Plans
Medicare Modernization Act (MMA) established Special Needs Plans for Duals, Institutionalized, and Chronically Ill individuals who have special needs QMedCare is primarily oriented to operating SNPs for those with chronic conditions e.g CAD, CHF, Stroke Risk adjusted payments (RAPS) from Medicare Th
Slide 5: Illustrative Risk Score Levels for A Typical Medicare Eligible
1.00 Average Medicare 0.92 Non-Institutionalized/Non-Medicaid 1.90 Institutionalized 1.29 Dual Eligible (Medicare/Medicaid) Nationwide Risk Score Eligibility Category Illustrative Risk Score Levels for A Typical Medicare Eligible
Slide 6: Political & Regulatory Outlook
We believe that the outlook for Medicare SNPs continues to improve We remain active on Capitol Hill and at CMS CMS marketing regulations are slowly evolving to assist SNPs All parties understand that chronics spend the lion’s share of Medicare funds Medicare can save money by removing artificial ove
Slide 7: QMed Background for SNP Success
Successful Medical & Disease Management FFS and capitated markets Seniors and commercial members with cardiovascular disease Demonstration projects with CMS IT systems include electronic medical records, expert system analytics, physician engagement, detailed reporting QMed Background for SNP Succes
Slide 8: QMed Background for SNP Success
Our Medicare Special Needs Plans are based on this expertise We are a “Care Model”, not a “Contracting Model” Plan We manage the top line RAPS management tool We manage the bottom line Clinical algorithms for physician decision support C3 – Community Coordinated Care for patients linked to all provi
Slide 9: Why QMed's SNPs are Special
1.0 or less 1.5-2.3 RAPs $350+ (NJ + SD) $125 (NJ) $101 (SD) Patient Value Proposition Non-engaging Engaging Provider Interest No coverage or Generics Only Brand and Generic Part D and Donut hole Chronic Avoidance Chronically Ill Enrollment Discounted Contracts Quality Of Care Model Standard Medicar
Slide 10: Early Lessons
Price and design for seniors post Part D Understand CMS marketing guidelines Engage the selling broker community Engage physicians and hospitals Execute above peers Enrollment Manage RAPS for Top Line Medical Management for the bottom line Early Lessons
Slide 11: Keys to Enrollment – Recruitment Strategy
Meet the needs of hospitals Meet the needs of physicians Meet the needs of patients Market, market, market – intelligence based on regional and local dynamics Keys to Enrollment – Recruitment Strategy
Slide 12: Patient Value Proposition
Cost of Coverage Comparison HLP (QMed) Wellmark HeartLine Plus $101.00 Supplemental Premium included $140.00 Part D thru donut hole (option 3) included $110.30 Total Cost of Coverage $101.00 $250.30 Monthly Savings 59.6% $149.30 Cost of Coverage Comparison QMed AARP QMedCare $125.00 Approx. Supplime
Slide 13: Comprehensive Marketing
Strategic relationships with nearly 300 senior products brokers Work with the hospital systems to endorse the program to physicians Physicians can now tell their patients about our SNP health, drug and cost benefits Understand local market dynamics Easy and concise messaging to Medicare Beneficiarie
Slide 14: So, How are we doing…?
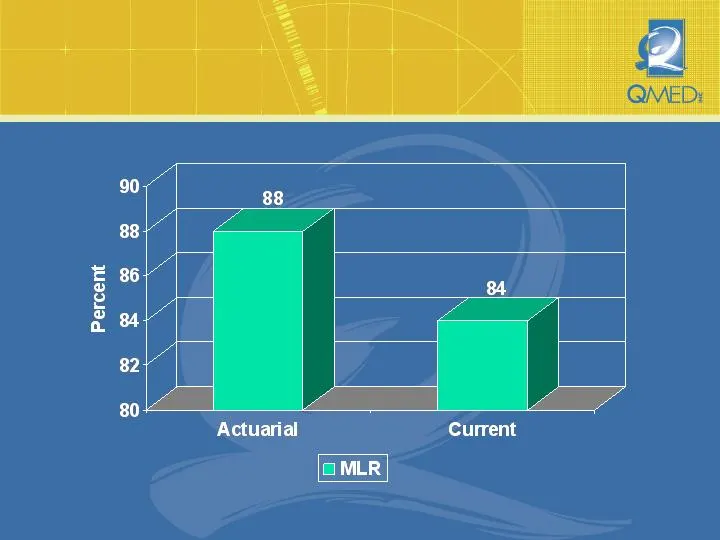
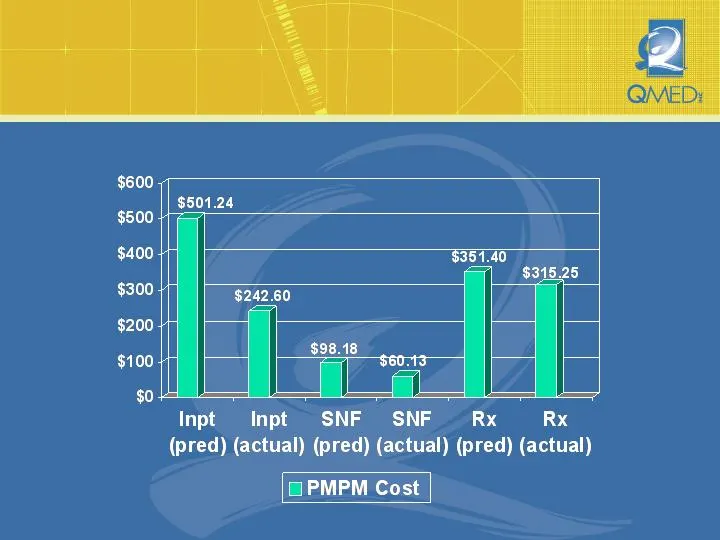
This is based on 1500 member months, average LOTIP 6 months So, How are we doing…?
Slide 15: So, How are we doing …?
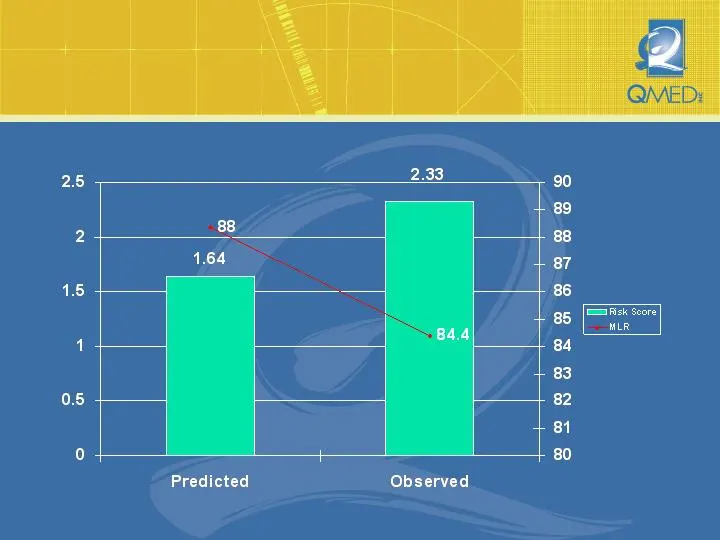
This is based on 1500 member months, average LOTIP 6 months So, How are we doing …?
Slide 16: So, How are we doing … RAPs?
This is based on 1500 member months, average LOTIP 6 months So, How are we doing … RAPs?
Slide 17: Unique Infrastructure
Systems identifying “Gaps in Care” – Proactively identifying Gaps to concentrate care efforts for members cost effectively Systems for RAPS payments – Chart review identification for proper reimbursement for managing risk underwriting, maintain revenue with balanced budget act Enhancements to Broade
Slide 18: Investment Perspective
Right Product – Right Time – Right Price – Right Care Model Industry leading IT backbone Market is Large 90k targets of opportunity = $1.8 BILLION (NJ +SD) Dual SNP in April 2007 in SD Expansion probable in 2008 Experienced Motivated Management Team SNP 2007 Guidance $38.5 - $44 Million Investment P
Slide 19: Investment Perspective
We will deliver performance in the fastest growing most important segment in healthcare. Investment Perspective
Slide 20: QMed Inc. Managing the Chronically Ill
QMed Inc. Managing the Chronically Ill
Source: SEC EDGAR · 8-K filed Feb 13, 2007