Entegra Financial — Shareholder Meeting (May 2015)
33 slides from Entegra Financial's shareholder meeting presentation, May 21, 2015
Slide 1: 2015 Shareholder Meeting
ee a Entegra FINANCIAL 2015 Shareholder Meeting
Slide 2: Forward Looking Statements
Forward Looking Statements Information in this presentation may contain “forward-looking statements”. Such statements involve known and unknown risks, uncertainties and other factors that may cause actual results to differ materially. Forward-looking statements are often characterized by the use of
Slide 3: Executive Management
Executive Management
Slide 4: Experienced Executive Team
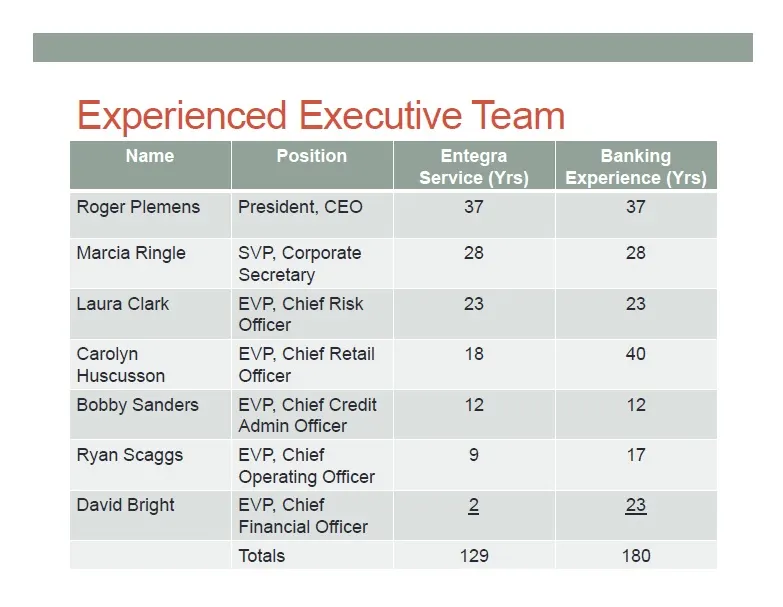
Experienced Executive Team Name Position Entegra Service (Yrs) Banking Experience (Yrs) Roger Plemens President, CEO 37 37 Marcia Ringle SVP, Corporate Secretary 28 28 Laura Clark EVP, Chief Risk Officer 23 23 Carolyn Huscusson EVP, Chief Retail Officer 18 40 Bobby Sanders EVP, Chief Credit Admin Of
Slide 5: Strategic Overview
Strategic Overview
Slide 6: Successful Capital Raise
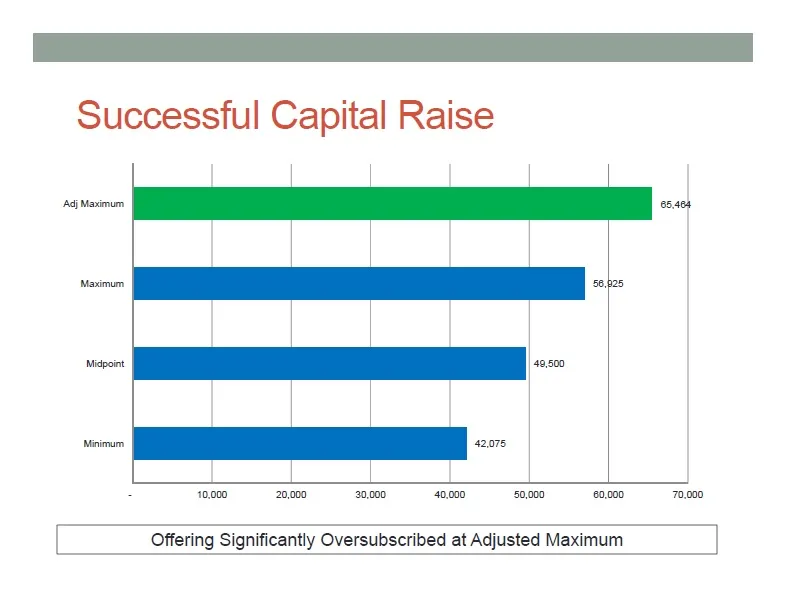
Successful Capital Raise Adj Maximum Midpoint Maximum Minimum 65,464 42,075 49,500 56,925 - 10,000 20,000 30,000 40,000 50,000 60,000 70,000 Offering Significantly Oversubscribed at Adjusted Maximum
Slide 7: Years of History … And Counting
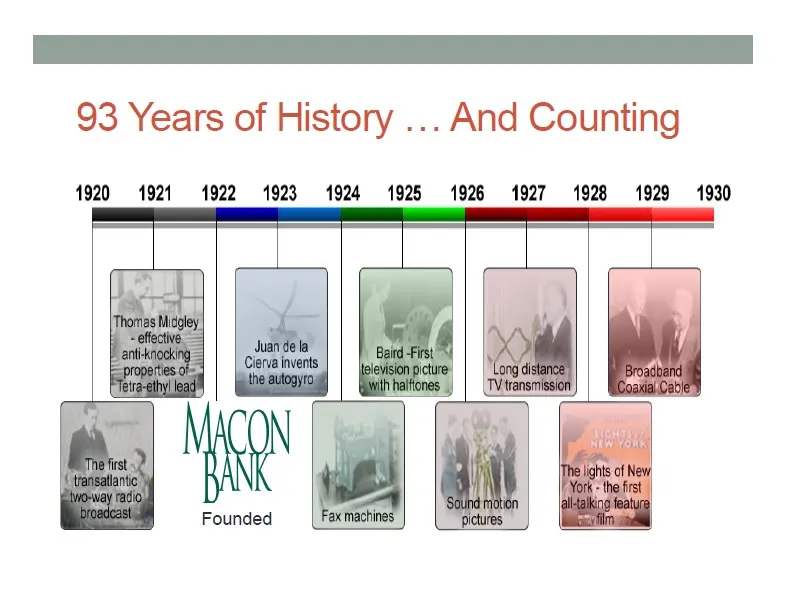
93 Years of History … And Counting
Slide 8: FDIC / State of NC / Federal Reserve Written Agreement / Consent Order MOU
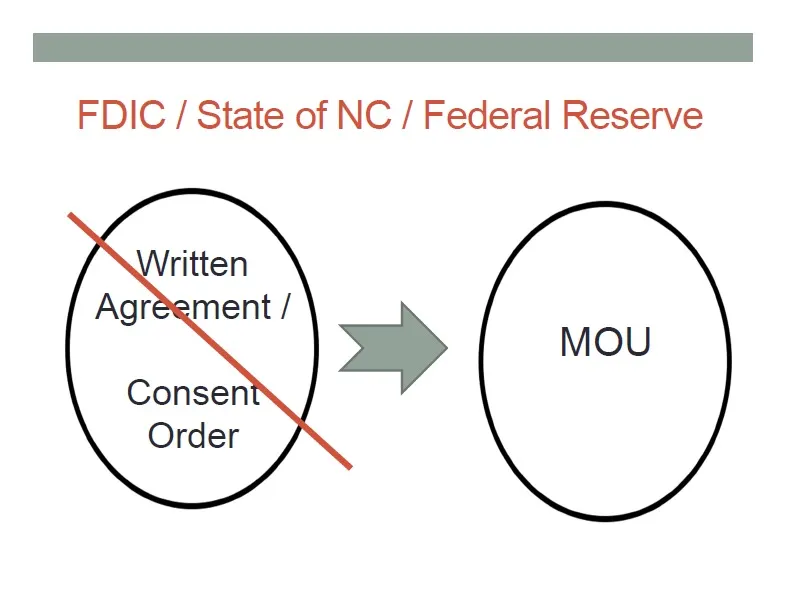
FDIC / State of NC / Federal Reserve Written Agreement / Consent Order MOU
Slide 9: Expanding Footprint
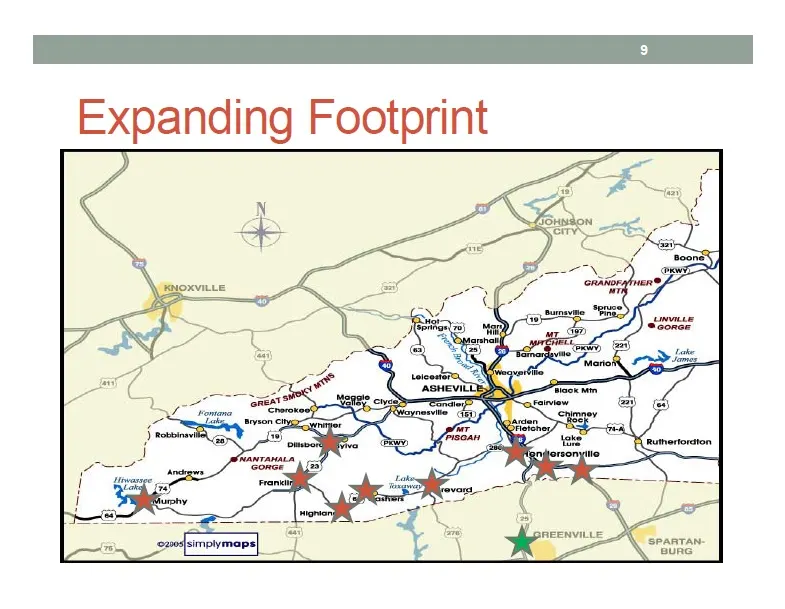
Expanding Footprint ee, Ct o2io4fsimplymaps|
Slide 10: Greenville, SC Regional HQ
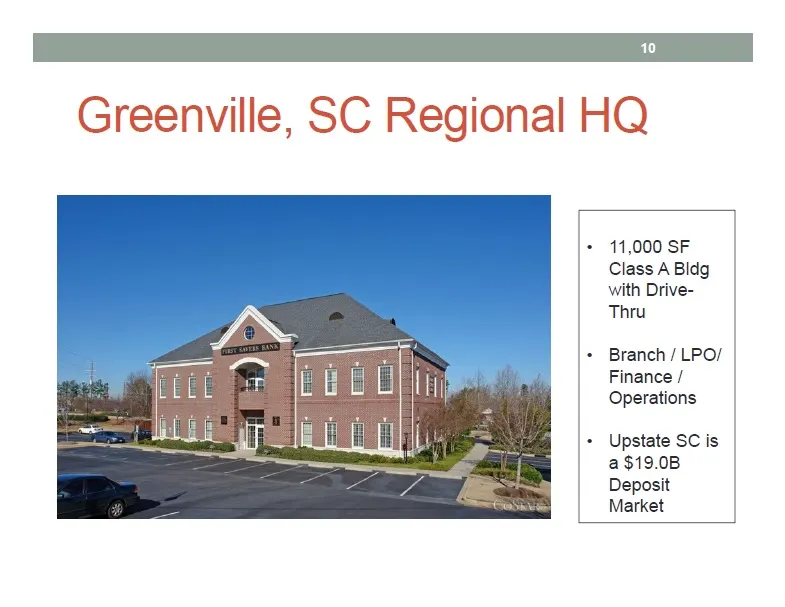
Greenville, SC Regional HQ 11,000 SF Class A Bldg with Drive- Thru • Branch / LPO/ Finance / Operations • Upstate SC is a $19.0B Deposit Market
Slide 11: Bank Rebranding (Q3 2015)
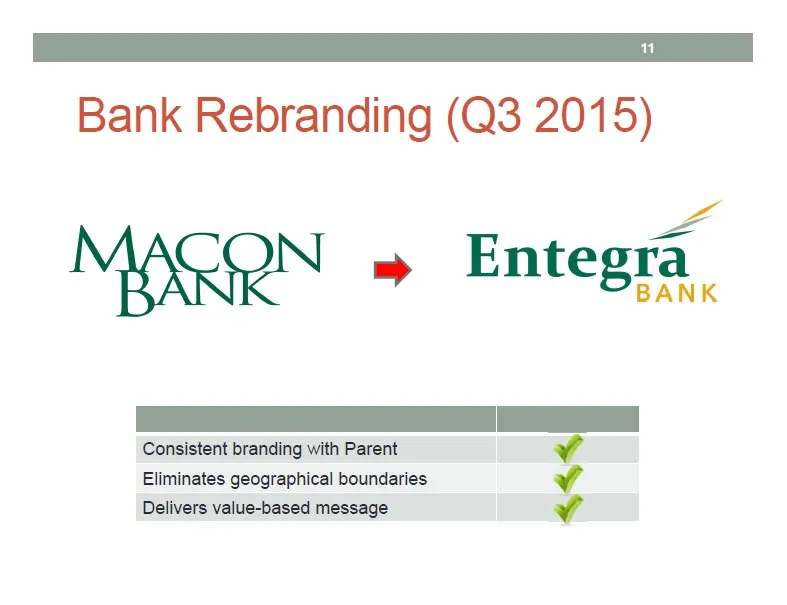
Bank Rebranding (Q3 2015) Consistent branding with Parent Eliminates geographical boundaries Delivers value-based message
Slide 12: Enterprise Risk Management ERM: Implementation Process Underway
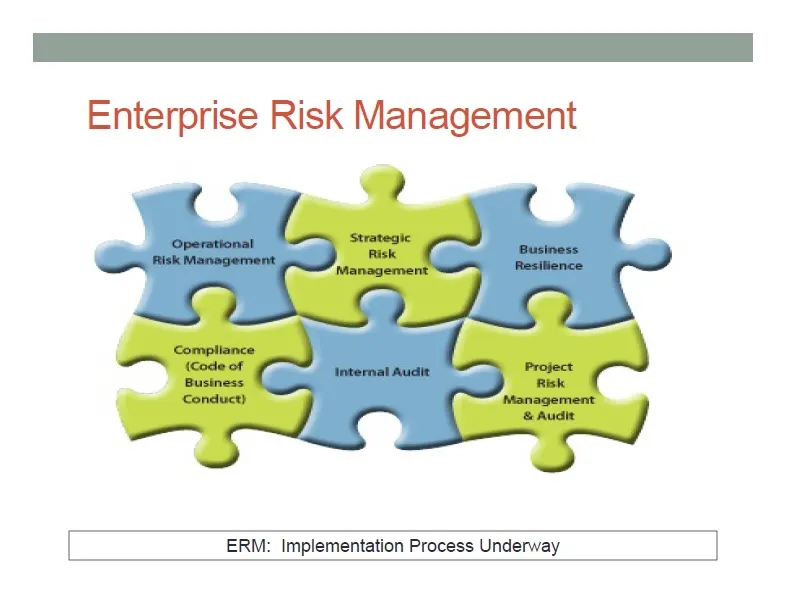
Enterprise Risk Management ERM: Implementation Process Underway
Slide 13: Continued Strong Deposit Market Share
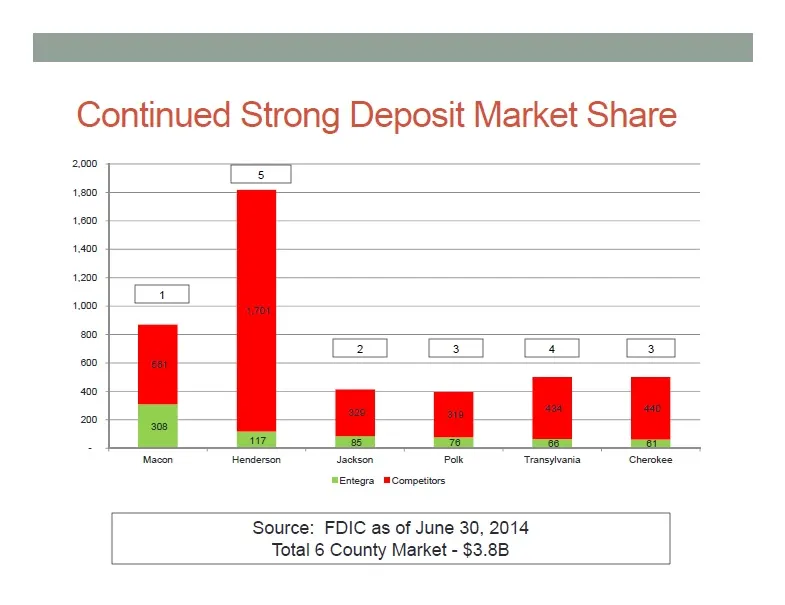
Continued Strong Deposit Market Share - 200 400 600 800 1,000 1,200 1,400 1,600 1,800 2,000 1 5 2 3 4 3 561 1,701 329 319 434 440 308 117 85 76 66 61 Macon Henderson Jackson Polk Transylvania Cherokee Entegra Competitors Source: FDIC as of June 30, 2014 Total 6 County Market - $3.8B
Slide 14: Top Deposit Market Share
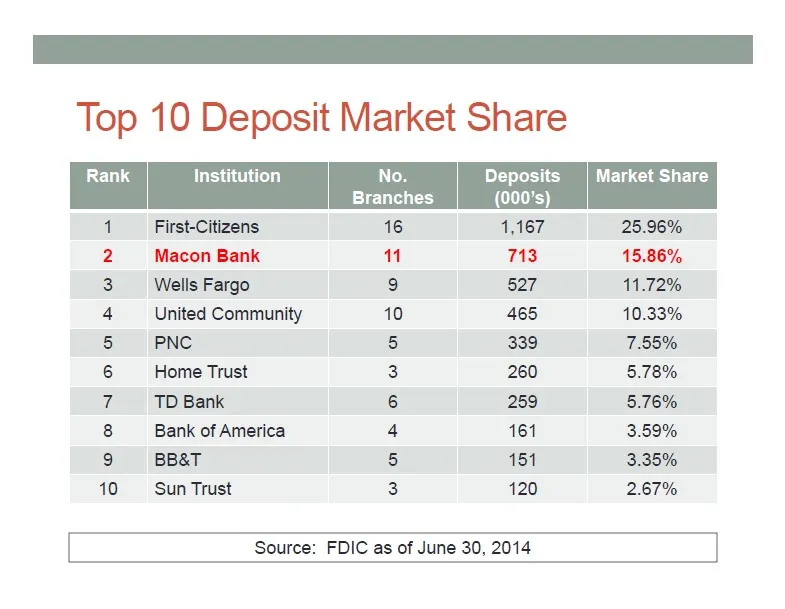
Top 10 Deposit Market Share Rank Institution No. Branches Deposits (000’s) Market Share 1 First-Citizens 16 1,167 25.96% 2 Macon Bank 11 713 15.86% 3 Wells Fargo 9 527 11.72% 4 United Community 10 465 10.33% 5 PNC 5 339 7.55% 6 Home Trust 3 260 5.78% 7 TD Bank 6 259 5.76% 8 Bank of America 4 161 3.5
Slide 15: Financial Overview
Financial Overview
Slide 16: A Lot of Good News ....
A Lot of Good News ....
Slide 17: Well Capitalized Under BASEL III
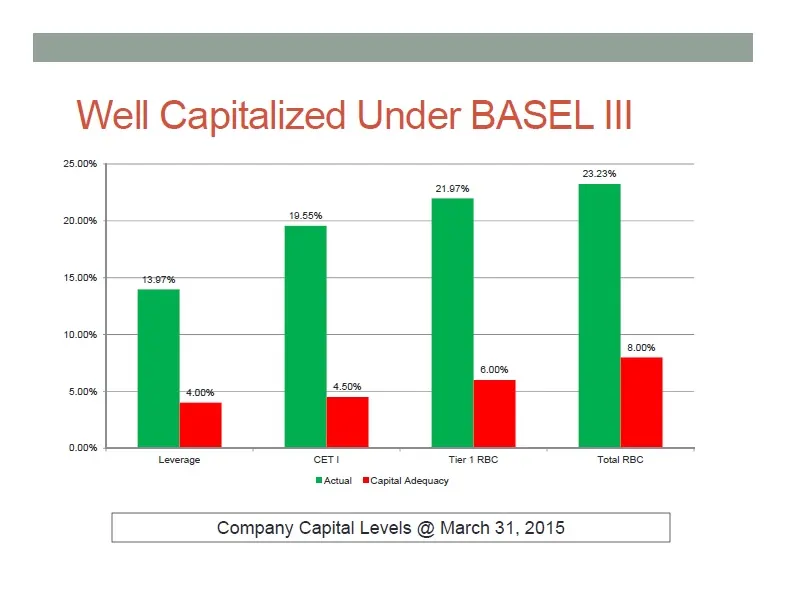
Well Capitalized Under BASEL III 0.00% 5.00% 10.00% 15.00% 20.00% 25.00% 13.97% 19.55% 21.97% 23.23% 4.00% 4.50% 6.00% 8.00% Leverage CET I Tier 1 RBC Total RBC Actual Capital Adequacy Company Capital Levels @ March 31, 2015
Slide 18: We Are Growing Again
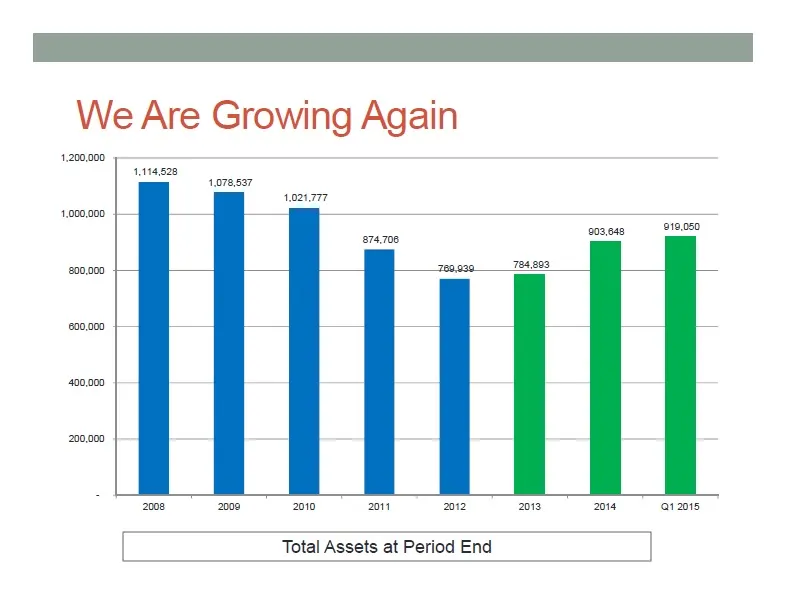
We Are Growing Again 200,000 400,000 600,000 800,000 1,000,000 1,200,000 1,114,528 1,078,537 1,021,777 874,706 769,939 784,893 903,648 919,050 2008 2009 2010 2011 2012 2013 2014 Q1 2015 Total Assets at Period End
Slide 19: Loan Balance Trends
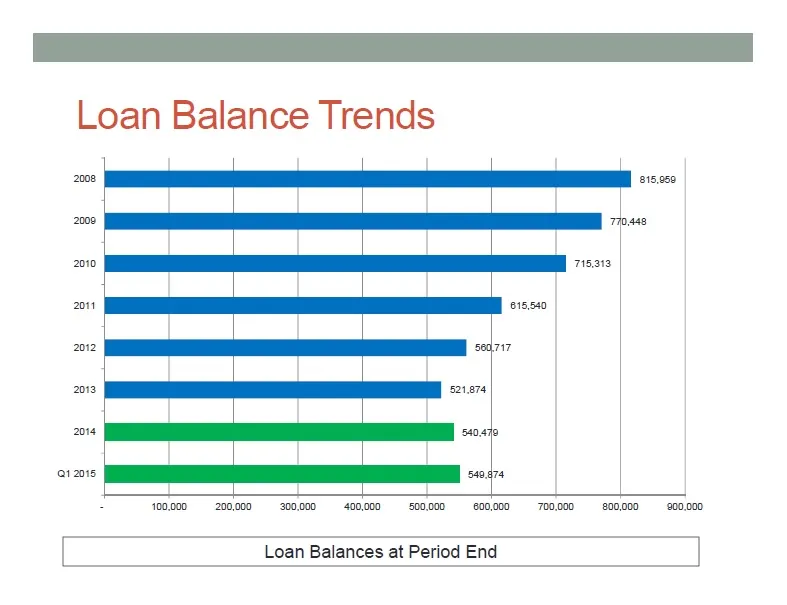
Loan Balance Trends 2014 2013 2012 2011 2010 2009 2008 Q1 2015 540,479 521,874 560,717 615,540 715,313 770,448 815,959 549,874 100,000 200,000 300,000 400,000 500,000 600,000 700,000 800,000 900,000 Loan Balances at Period End
Slide 20: Loan Composition Trends
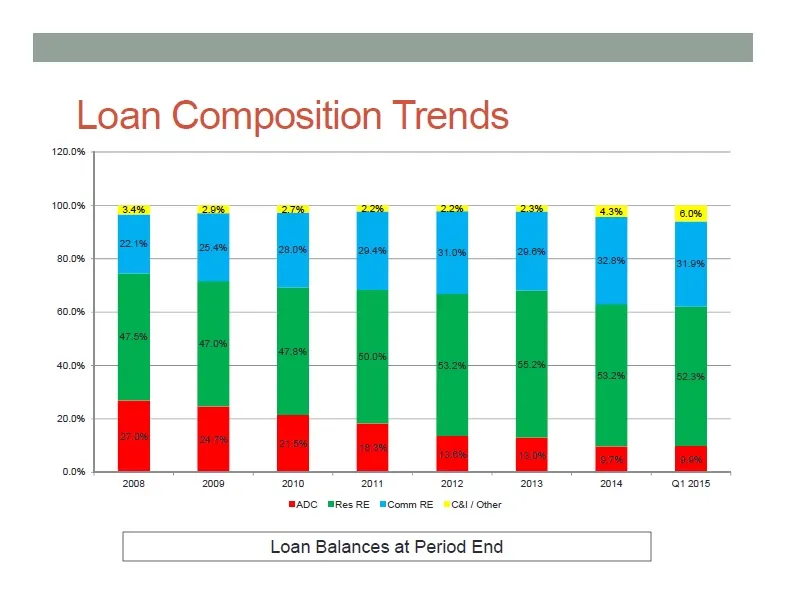
Loan Composition Trends 20.0% 40.0% 60.0% 80.0% 100.0% 120.0% 0.0% 3.4% 2.9% 2.7% 2.2% 2.2% 2.3% 4.3% 6.0% 22.1% 25.4% 28.0% 29.4% 31.0% 29.6% 32.8% 31.9% 47.5% 47.0% 47.8% 50.0% 53.2% 55.2% 53.2% 52.3% 27.0% 24.7% 21.5% 18.3% 13.6% 13.0% 9.7% 9.9% 2008 2009 2010 2011 2012 2013 2014 Q1 2015 ADC Res
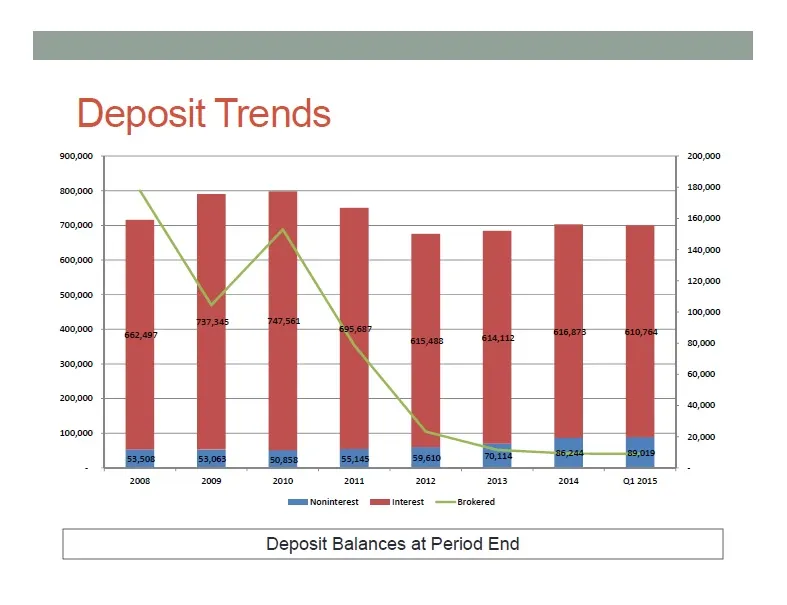
Slide 21: Deposit Trends
Deposit Trends 100,000 200,000 300,000 400,000 500,000 600,000 700,000 800,000 900,000 40,000 60,000 80,000 100,000 120,000 140,000 160,000 180,000 200,000 20,000 662,497 737,345 747,561 695,687 615,488 614,112 616,873 610,764 53,508 53,063 50,858 55,145 59,610 70,114 86,244 89,019 2008 2009 2010 20
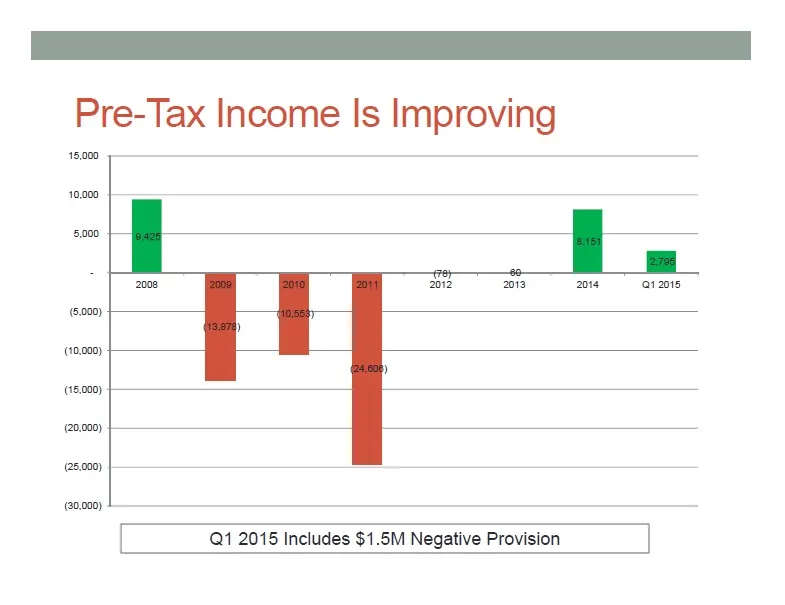
Slide 22: Pre-Tax Income Is Improving
Pre-Tax Income Is Improving (25,000) (20,000) (15,000) (10,000) (5,000) - 5,000 10,000 15,000 (30,000) 9,425 (13,878) (10,553) (24,606) (78) 60 8,151 2,795 2008 2009 2010 2011 2012 2013 2014 Q1 2015 Q1 2015 Includes $1.5M Negative Provision
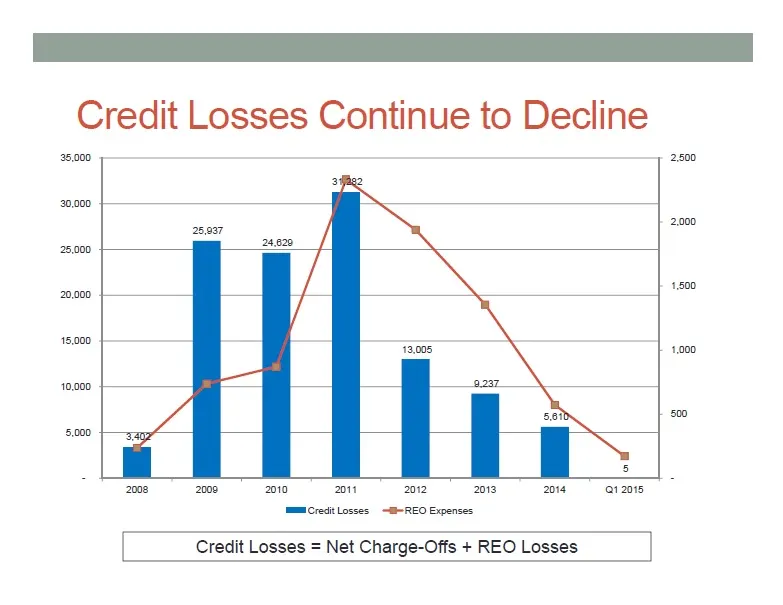
Slide 23: Credit Losses Continue to Decline
Credit Losses Continue to Decline 10,000 15,000 20,000 25,000 30,000 35,000 5,000 3,402 25,937 24,629 31,282 13,005 9,237 5,610 5 2008 2009 2010 2011 2012 2013 2014 Q1 2015 500 1,000 1,500 2,000 2,500 Credit Losses REO Expenses Credit Losses = Net Charge-Offs + REO Losses
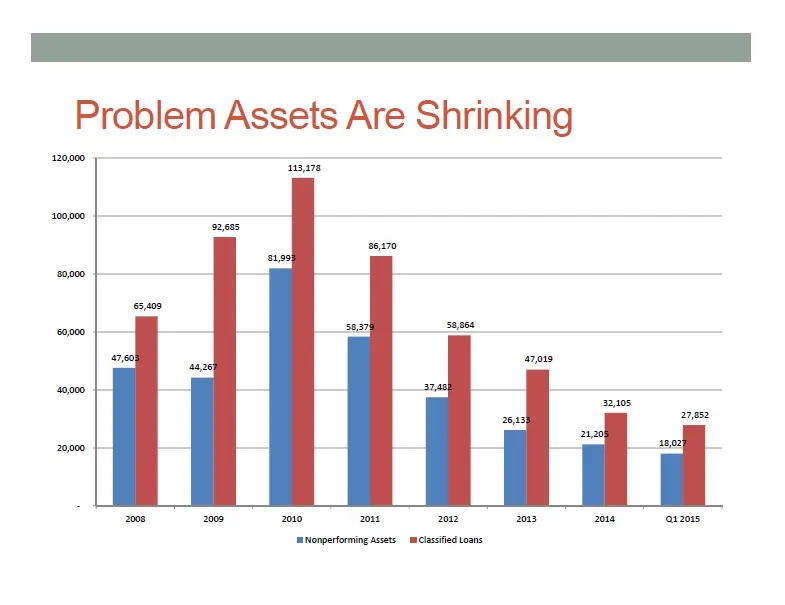
Slide 24: Problem Assets Are Shrinking
Problem Assets Are Shrinking 20,000 40,000 60,000 80,000 100,000 120,000 47,603 44,267 81,993 58,379 37,482 26,133 21,205 18,027 65,409 92,685 113,178 86,170 58,864 47,019 32,105 27,852 2008 2009 2010 2011 2012 2013 2014 Q1 2015 Nonperforming Assets Classified Loans
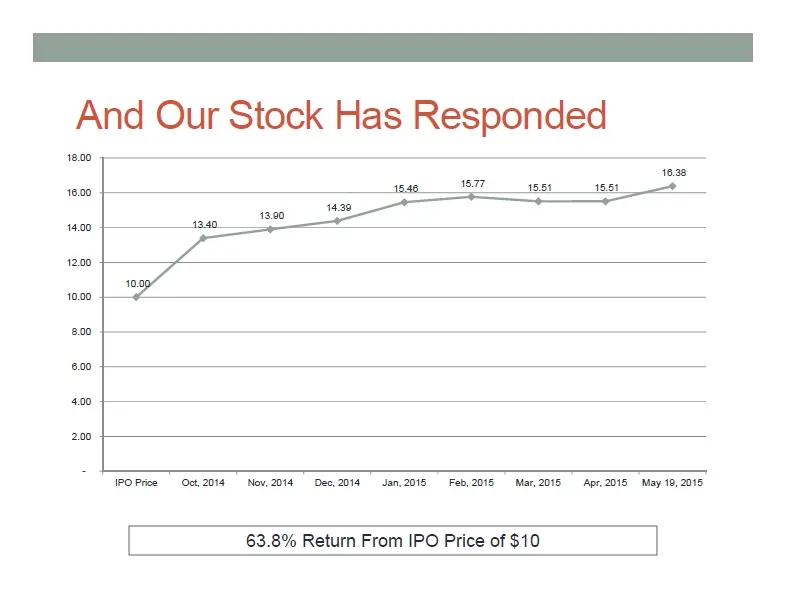
Slide 25: And Our Stock Has Responded
And Our Stock Has Responded 2.00 4.00 6.00 8.00 10.00 12.00 14.00 16.00 18.00 10.00 13.40 13.90 14.39 15.46 15.77 15.51 15.51 16.38 IPO Price Oct, 2014 Nov, 2014 Dec, 2014 Jan, 2015 Feb, 2015 Mar, 2015 Apr, 2015 May 19, 2015 63.8% Return From IPO Price of $10
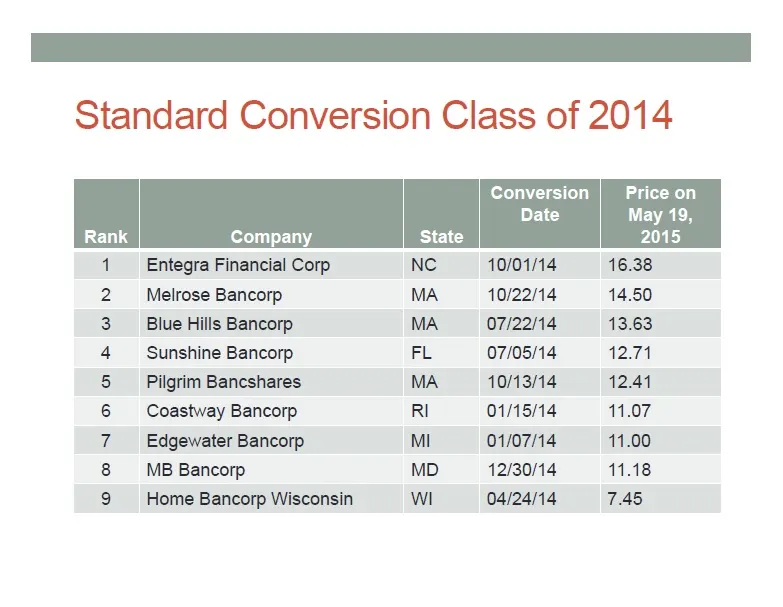
Slide 26: Standard Conversion Class of 2014
Standard Conversion Class of 2014 Rank Company State Conversion Date Price on May 19, 2015 1 Entegra Financial Corp NC 10/01/14 16.38 2 Melrose Bancorp MA 10/22/14 14.50 3 Blue Hills Bancorp MA 07/22/14 13.63 4 Sunshine Bancorp FL 07/05/14 12.71 5 Pilgrim Bancshares MA 10/13/14 12.41 6 Coastway Banc
Slide 27: But, We Remain Focused On....
But, We Remain Focused On....
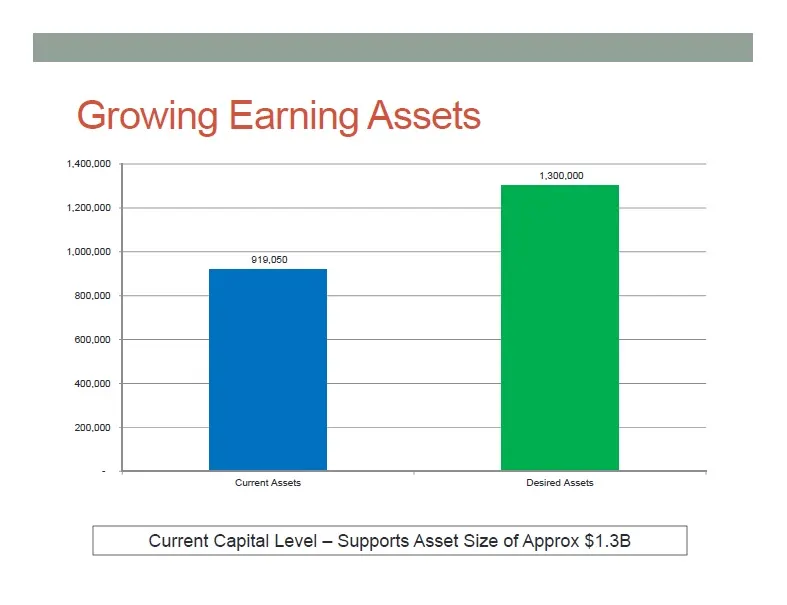
Slide 28: Growing Earning Assets
Growing Earning Assets 200,000 400,000 600,000 800,000 1,000,000 1,200,000 1,400,000 919,050 1,300,000 Current Assets Desired Assets Current Capital Level – Supports Asset Size of Approx $1.3B
Slide 29: Continued Reduction in Deposit Costs
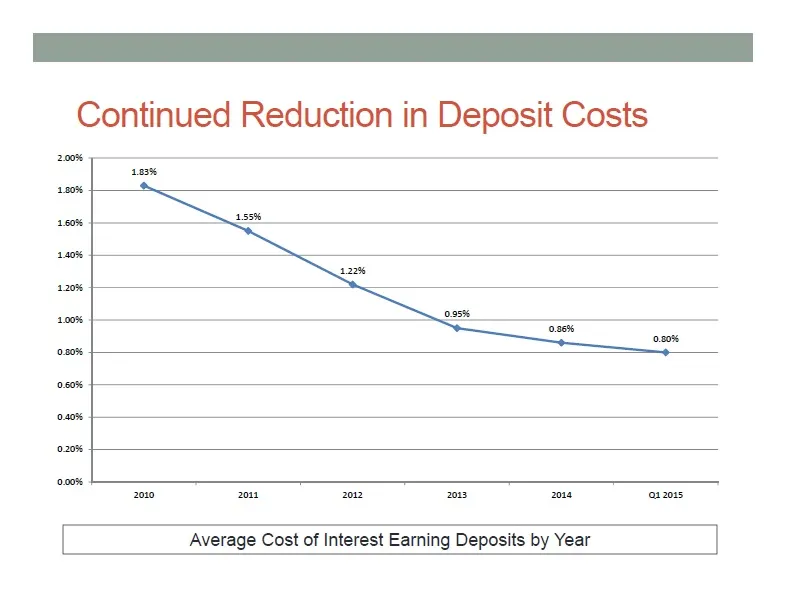
Continued Reduction in Deposit Costs 0.00% 0.20% 0.40% 0.60% 0.80% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% 1.83% 1.55% 1.22% 0.95% 0.86% 0.80% 2010 2011 2012 2013 2014 Q1 2015 Average Cost of Interest Earning Deposits by Year
Slide 30: Managing our Capital
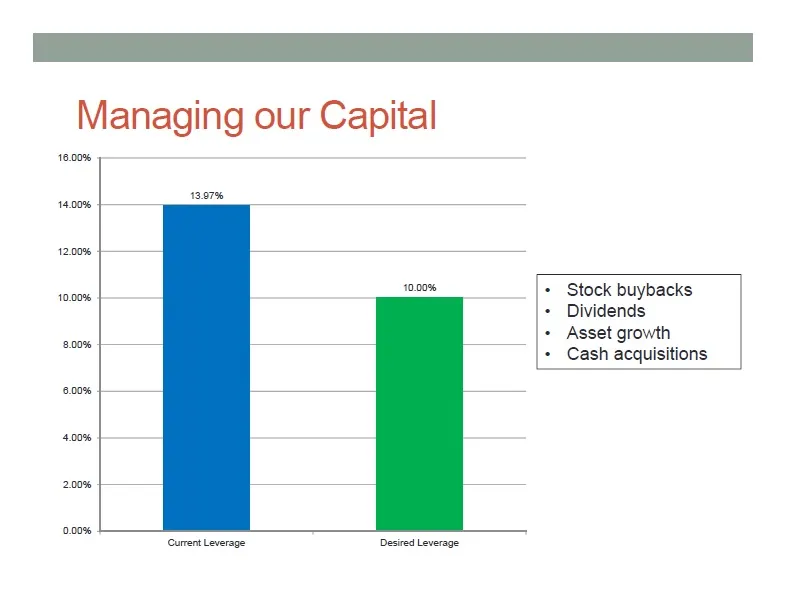
Managing our Capital 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% 13.97% 10.00% Current Leverage Desired Leverage Stock buybacks • Dividends • Asset growth • Cash acquisitions
Slide 31: Increasing Fee Income
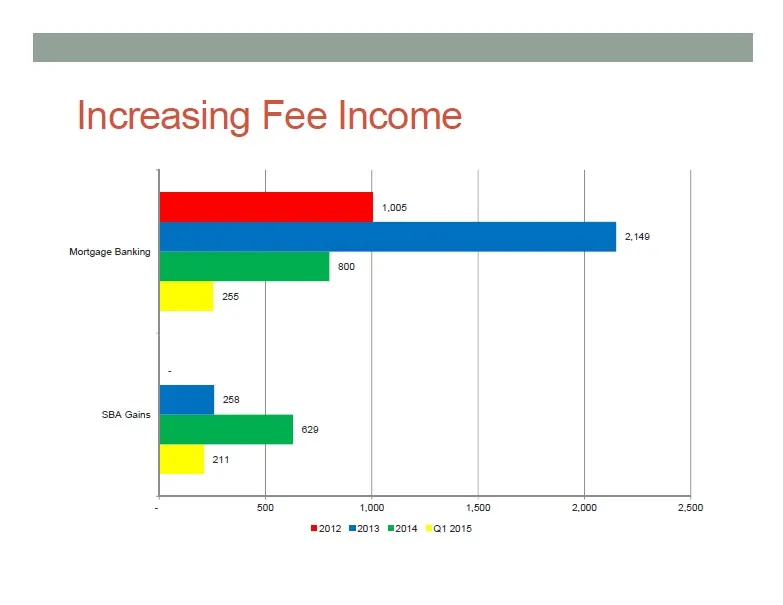
Increasing Fee Income 211 255 629 800 258 2,149 - 1,005 - 500 1,000 1,500 2,000 2,500 SBA Gains Mortgage Banking 2012 2013 2014 Q1 2015
Slide 32: Summary
Summary
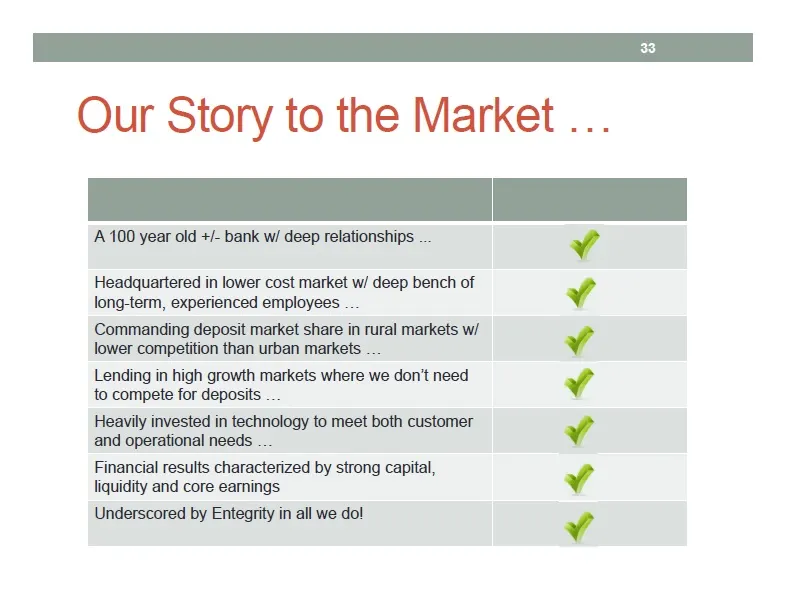
Slide 33: Our Story to the Market
Our Story to the Market … A 100 year old +/- bank w/ deep relationships ... Headquartered in lower cost market w/ deep bench of long-term, experienced employees … Commanding deposit market share in rural markets w/ lower competition than urban markets … Lending in high growth markets where we don’t
Source: SEC EDGAR · 8-K filed May 21, 2015
More decks from Entegra Financial Corp
 Merger or Acquisition (February 2019)21 slides · Feb 6, 2019
 Q4 2018 Earnings Presentation17 slides · Jan 24, 2019
 Merger or Acquisition (January 2019)25 slides · Jan 16, 2019
 Q3 2018 Earnings Presentation14 slides · Oct 18, 2018
 Investor Presentation (September 2018)48 slides · Sep 17, 2018
 Q2 2018 Earnings Presentation10 slides · Jul 19, 2018