Xeta Technologies — Southwest IDEAS Conference 2010
25 slides from Xeta Technologies's conference presentation, Nov 10, 2010
Slide 1: Investor Presentation, Southwest IDEAS Conference November 10, 2010
Investor Presentation Southwest IDEAS Conference November 10, 2010
Slide 2: Forward-looking statements
Portions of this presentation contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements include information concerning our possible or assumed future results of operations, as well as trends and conditions in our markets
Slide 3: XETA at a Glance
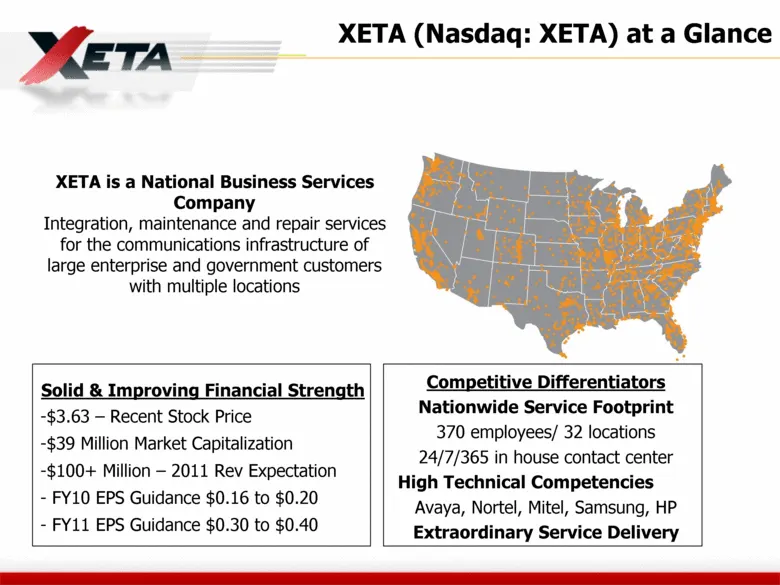
XETA is a National Business Services Company Integration, maintenance and repair services for the communications infrastructure of large enterprise and government customers with multiple locations Solid & Improving Financial Strength $3.63 – Recent Stock Price $39 Million Market Capitalization $100+
Slide 4: Razor and Razor Blade Model
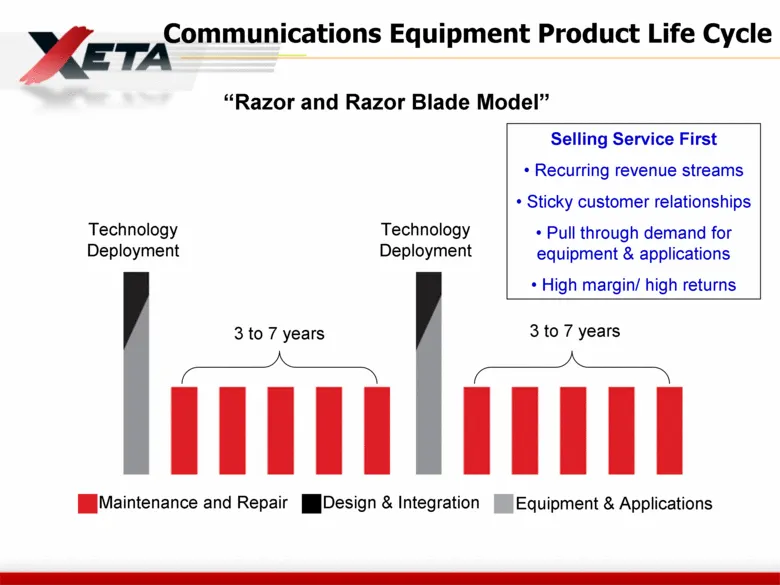
“Razor and Razor Blade Model” Selling Service First Recurring revenue streams Sticky customer relationships Pull through demand for equipment & applications High margin/ high returns Maintenance and Repair Design & Integration Equipment & Applications 3 to 7 years Communications Equipment Product Li
Slide 5: What Do We Do
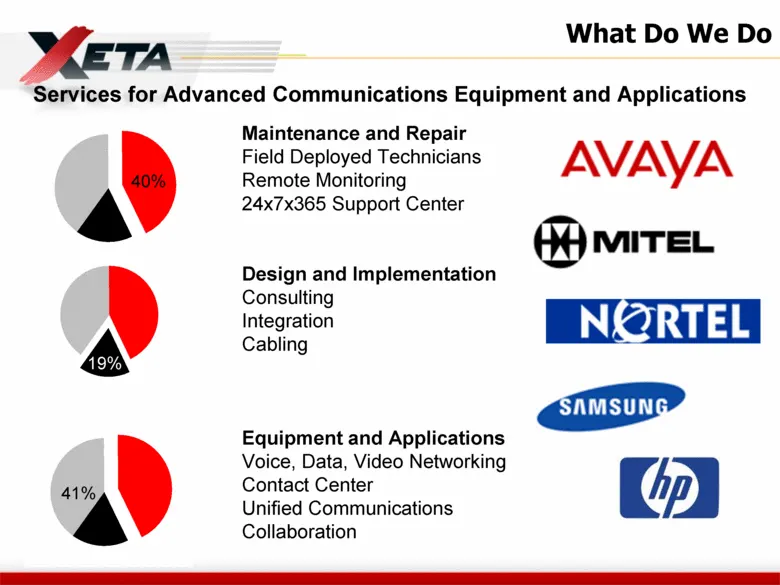
Maintenance and Repair Field Deployed Technicians Remote Monitoring 24x7x365 Support Center Design and Implementation Consulting Integration Cabling Equipment and Applications Voice, Data, Video Networking Contact Center Unified Communications Collaboration Services for Advanced Communications Equip
Slide 6: Investment Considerations
Taking Market Share: Well-positioned to acquire significant market share and grow at double digit rates. Improving Profitability: Shift in the revenue mix and operating leverage.targeted EBITDA of 10% to 12% vs. 6.1% during first 9 months of FY10. Razor/ Razor blade Model - Recurring Revenue Increas
Slide 7: Size of Addressable Market
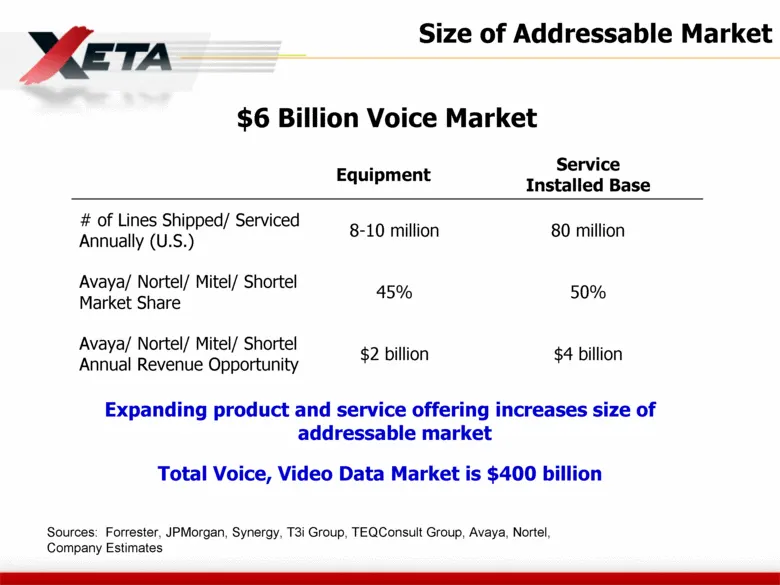
Size of Addressable Market $6 Billion Voice Market Sources: Forrester, JPMorgan, Synergy, T3i Group, TEQConsult Group, Avaya, Nortel, Company Estimates Equipment Service Installed Base # of Lines Shipped/ Serviced Annually (U.S.) 8-10 million 80 million Avaya/ Nortel/ Mitel/ Shortel Market Share 45%
Slide 8: Competitively Differentiated – Why XETA?
Competitively Differentiated – Why XETA? Highest Competencies with Multiple Leading Vendors
Slide 9: Competitively Differentiated – Why XETA? Customers
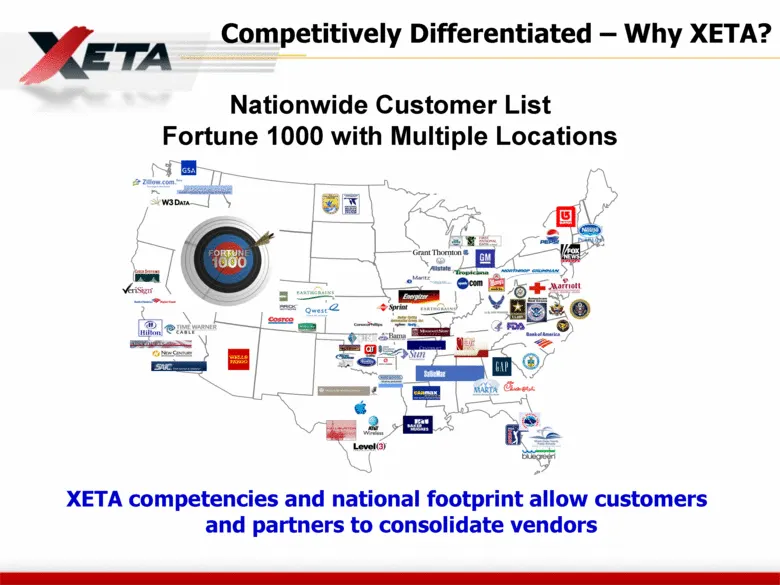
XETA competencies and national footprint allow customers and partners to consolidate vendors Nationwide Customer List Fortune 1000 with Multiple Locations Competitively Differentiated – Why XETA?
Slide 10: Growth Opportunity - Acquire Market Share
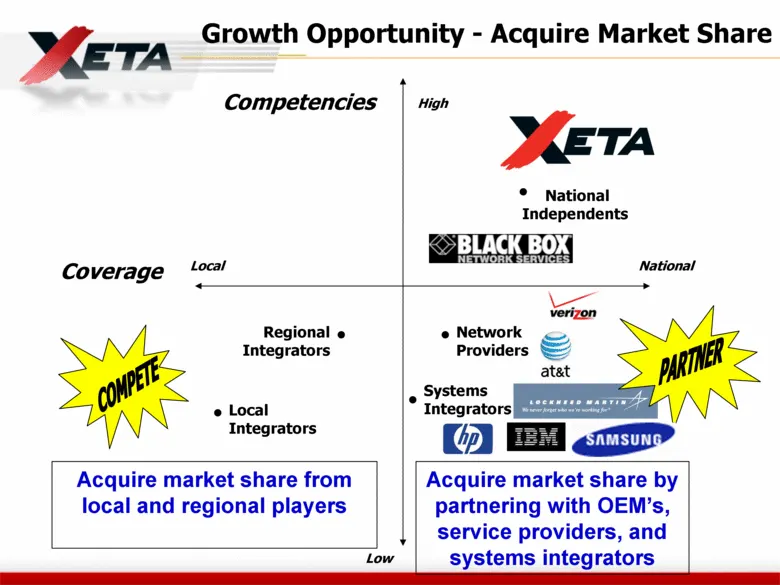
National Independents Regional Integrators Systems Integrators Network Providers Local Integrators Competencies Coverage Growth Opportunity - Acquire Market Share Acquire market share from local and regional players Acquire market share by partnering with OEM’s, service providers, and systems integr
Slide 11: Acquire Market Share – Unique Wholesale Model
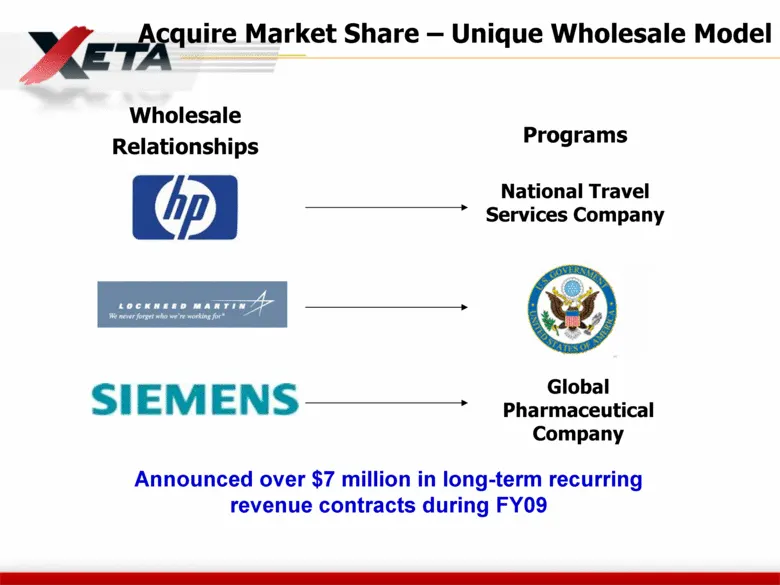
Wholesale Relationships Programs Acquire Market Share – Unique Wholesale Model National Travel Services Company Global Pharmaceutical Company Announced over $7 million in long-term recurring revenue contracts during FY09
Slide 12: XETA's Unique Position
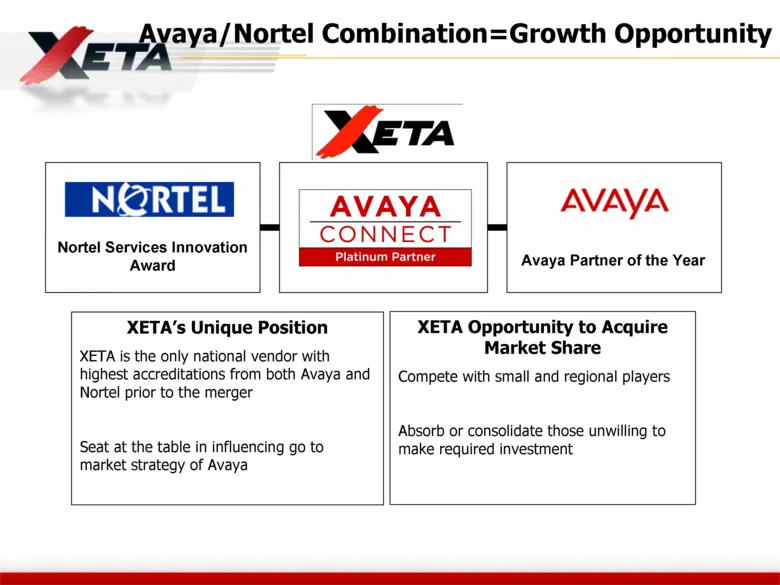
Nortel Services Innovation Award XETA’s Unique Position XETA is the only national vendor with highest accreditations from both Avaya and Nortel prior to the merger Seat at the table in influencing go to market strategy of Avaya Avaya Partner of the Year Avaya/Nortel Combination=Growth Opportunity XE
Slide 13: Accelerate Growth Through Acquisitions
Favorable conditions for accretive acquisitions Economic Conditions have stressed weaker players XETA well positioned to be an active consolidator Acquisitions during FY10 Add more than $20 million in revenue during FY11 Efficiencies of Scale – Cost synergies and earnings leverage will drive accreti
Slide 14: Revenue Mix Shift
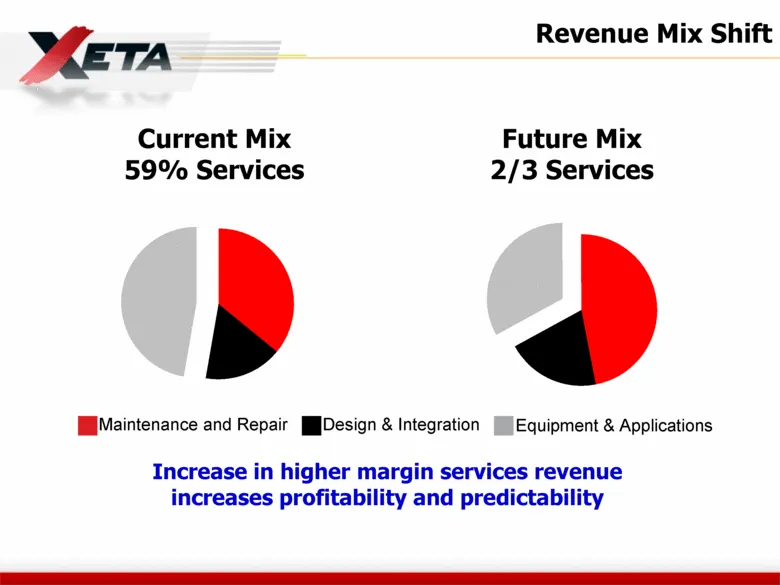
Revenue Mix Shift Current Mix 59% Services Future Mix 2/3 Services Increase in higher margin services revenue increases profitability and predictability Design & Integration Equipment & Applications Maintenance and Repair
Slide 15: Total Revenue – Historical Trends
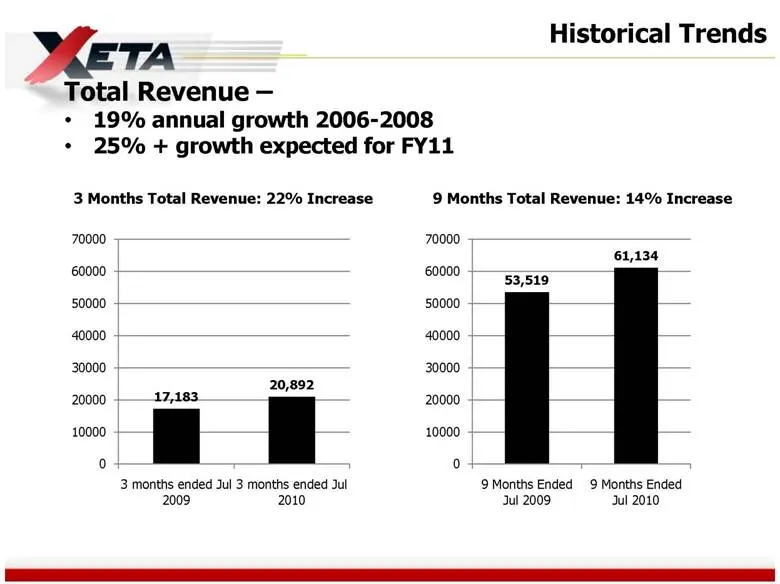
Total Revenue – 19% annual growth 2006-2008 25% + growth expected for FY11 Historical Trends 3 Months Total Revenue: 22% Increase 9 Months Total Revenue: 14% Increase
Slide 16: Service Revenue – Historical Trends
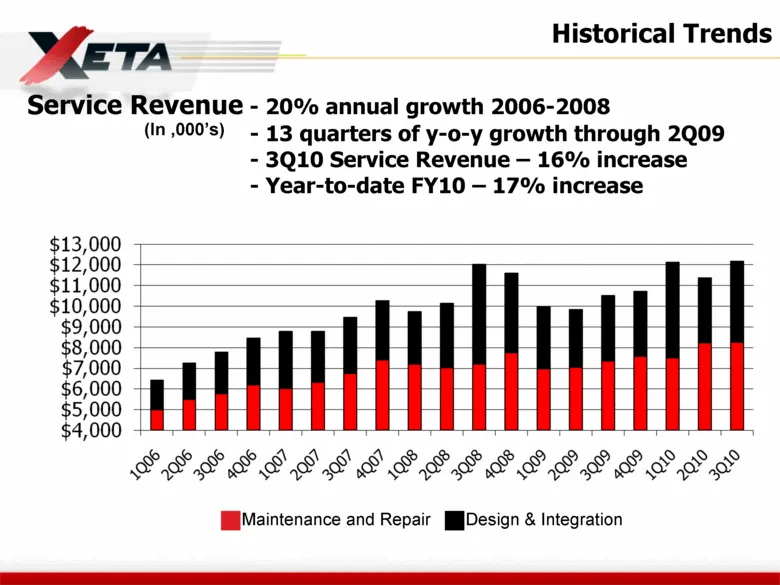
Service Revenue - 20% annual growth 2006-2008 - 13 quarters of y-o-y growth through 2Q09 - 3Q10 Service Revenue – 16% increase - Year-to-date FY10 – 17% increase (In ,000’s) Historical Trends Maintenance and Repair Design & Integration
Slide 17: Targeted Operating Results
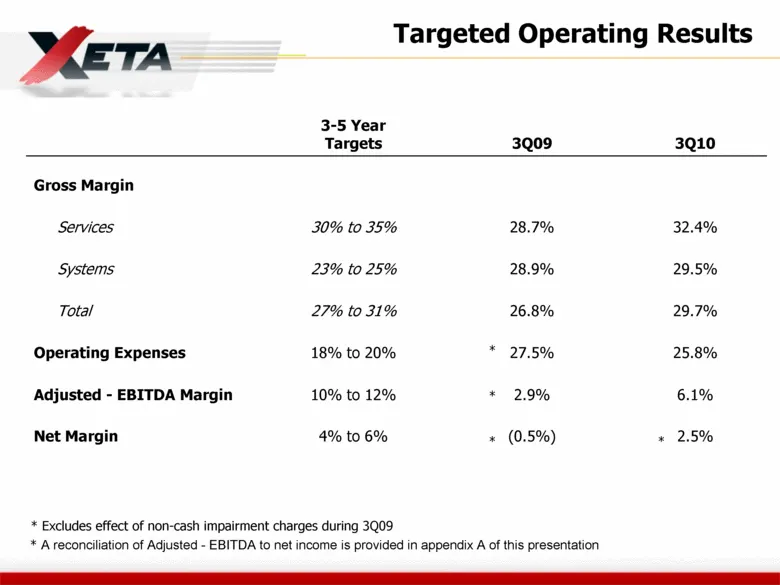
3-5 Year Targets 3Q09 3Q10 Gross Margin Services 30% to 35% 28.7% 32.4% Systems 23% to 25% 28.9% 29.5% Total 27% to 31% 26.8% 29.7% Operating Expenses 18% to 20% 27.5% 25.8% Adjusted - EBITDA Margin 10% to 12% 2.9% 6.1% Net Margin 4% to 6% (0.5%) 2.5% Targeted Operating Results * * * * * Excludes ef
Slide 18: Systems Gross Margin Target – 23% to 25%
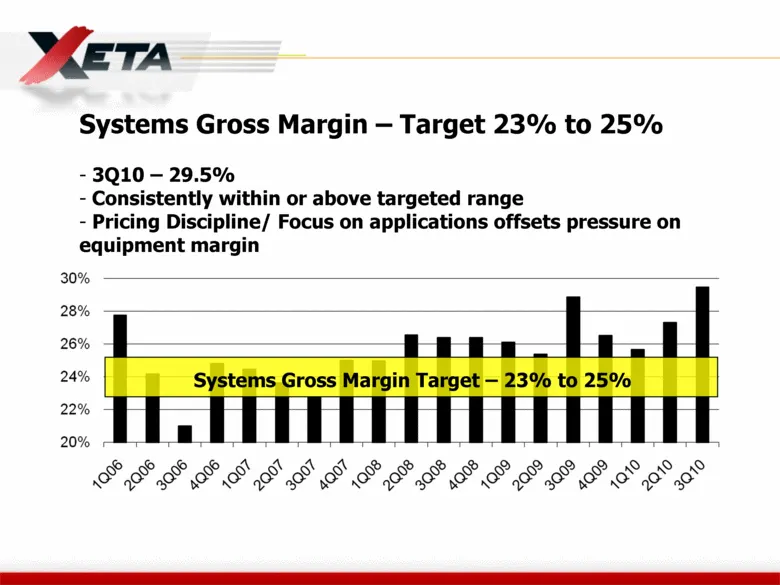
Systems Gross Margin Target – 23% to 25% Systems Gross Margin – Target 23% to 25% 3Q10 – 29.5% Consistently within or above targeted range Pricing Discipline/ Focus on applications offsets pressure on equipment margin
Slide 19: Services Gross Margin Target – 30% to 35%
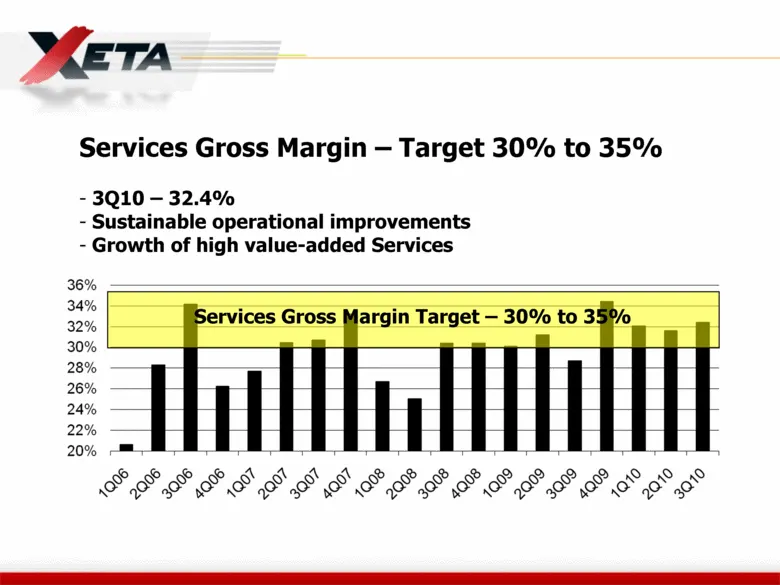
Services Gross Margin Target – 30% to 35% Services Gross Margin – Target 30% to 35% 3Q10 – 32.4% Sustainable operational improvements Growth of high value-added Services
Slide 20: Overall Gross Margin Target – 27% to 31%
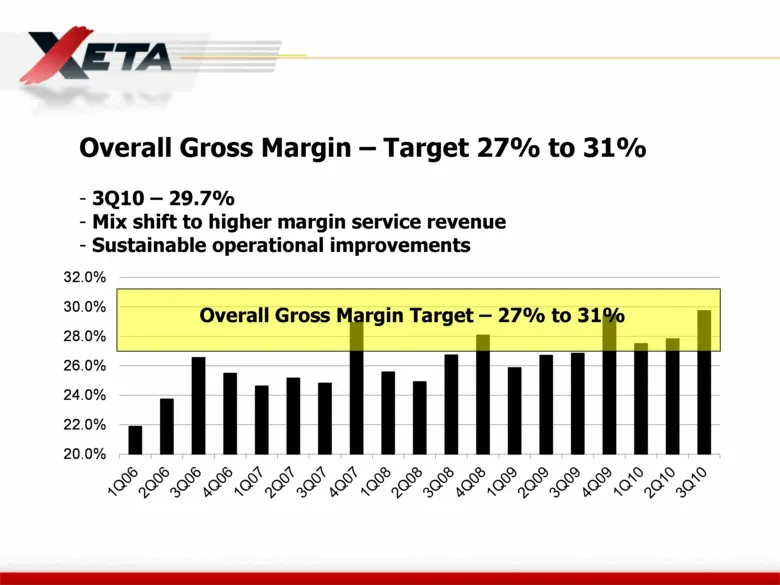
Overall Gross Margin Target – 27% to 31% Overall Gross Margin – Target 27% to 31% 3Q10 – 29.7% Mix shift to higher margin service revenue Sustainable operational improvements 20.0% 22.0% 24.0% 26.0% 28.0% 30.0% 32.0%
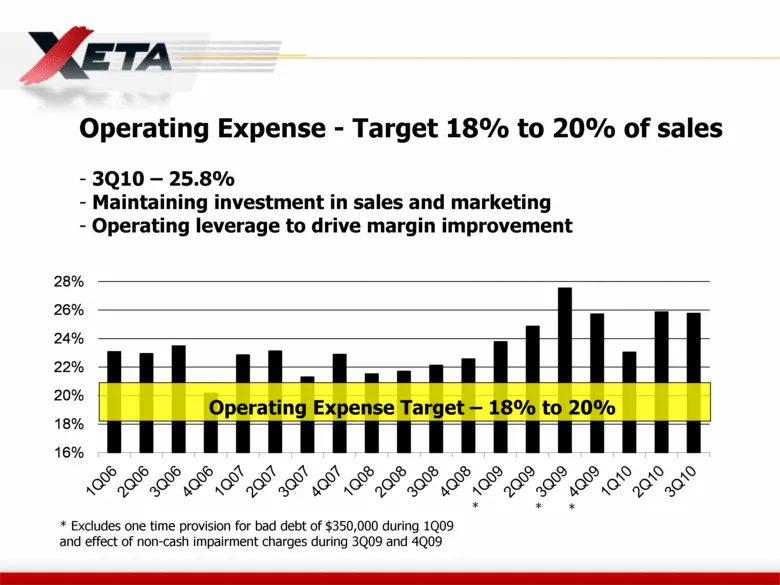
Slide 21: Operating Expense Target – 18% to 20%
Operating Expense Target – 18% to 20% Operating Expense - Target 18% to 20% of sales 3Q10 – 25.8% Maintaining investment in sales and marketing Operating leverage to drive margin improvement * * * Excludes one time provision for bad debt of $350,000 during 1Q09 and effect of non-cash impairment char
Slide 22: Financials – Balance Sheet
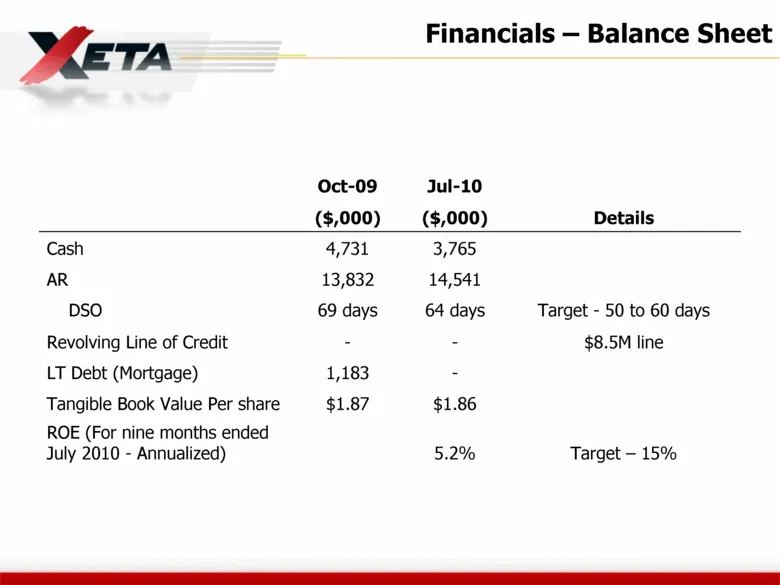
Financials – Balance Sheet Oct-09 Jul-10 ($,000) ($,000) Details Cash 4,731 3,765 AR 13,832 14,541 DSO 69 days 64 days Target - 50 to 60 days Revolving Line of Credit - - $8.5M line LT Debt (Mortgage) 1,183 - Tangible Book Value Per share $1.87 $1.86 ROE (For nine months ended July 2010 - Annualized
Slide 23: Investment Considerations
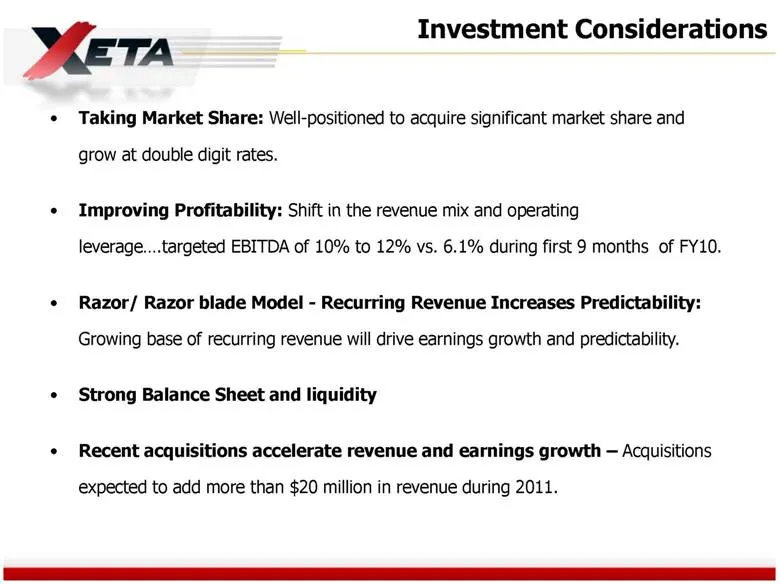
Taking Market Share: Well-positioned to acquire significant market share and grow at double digit rates. Improving Profitability: Shift in the revenue mix and operating leverage.targeted EBITDA of 10% to 12% vs. 6.1% during first 9 months of FY10. Razor/ Razor blade Model - Recurring Revenue Increas
Slide 24: Southwest IDEAS Conference November 10, 2010
Investor Presentation Southwest IDEAS Conference November 10, 2010
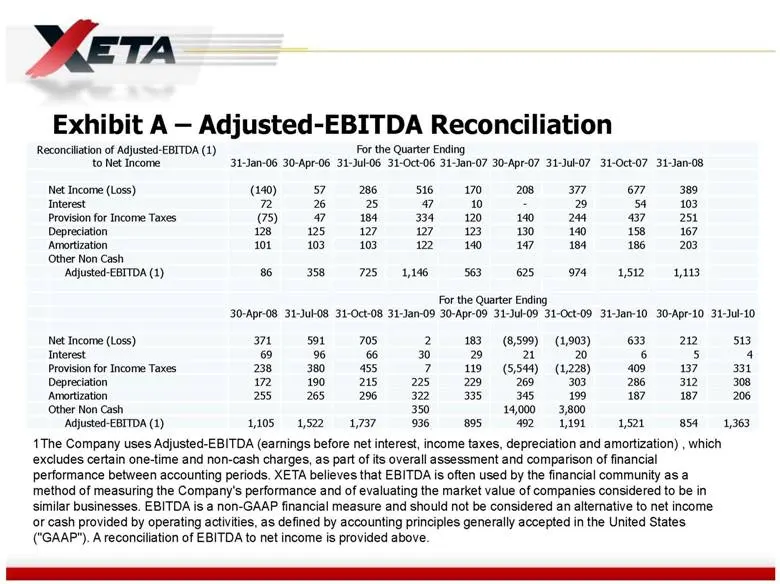
Slide 25: Exhibit A – Adjusted-EBITDA Reconciliation
Exhibit A – Adjusted-EBITDA Reconciliation 1The Company uses Adjusted-EBITDA (earnings before net interest, income taxes, depreciation and amortization) , which excludes certain one-time and non-cash charges, as part of its overall assessment and comparison of financial performance between accountin
Source: SEC EDGAR · 8-K filed Nov 10, 2010
More decks from Xeta Technologies Inc
 Midwest IDEAS Conference 201025 slides · Aug 31, 2010
 ROTH 22nd Annual Growth Stock Conference 201027 slides · Mar 17, 2010
 Southwestern Showcase Investor Conference (November 2008)25 slides · Nov 19, 2008
 B. Riley & Co. Investor Conference 200824 slides · Apr 2, 2008
 Investor Presentation (November 2007)22 slides · Nov 14, 2007