Alpha Natural Resources — Tuohy Brothers' 4th Annual Energy Conference (August 2013)
26 slides from Alpha Natural Resources's conference presentation, Aug 5, 2013
Slide 1: Alpha Natural Resources European Investor Presentation
1 Alpha Natural Resources European Investor Presentation August 5, 2013 Alpha Natural Resources Tuohy Brothers’ 4th Annual Energy Conference
Slide 2: Forward-Looking Statements
2 Forward-Looking Statements Statements in this presentation which are not statements of historical fact are “forward-looking statements” within the Safe Harbor provision of the Private Securities Litigation Reform Act of 1995. Such statements are not guarantees of future performance. Many factors c
Slide 3: Leading U.S. Producer with Global Reach
3 • Leading US supplier and exporter of metallurgical coal with expertise in blending and optimization Globally # 3 in metallurgical coal by shipment volume Exports $2.9 billion or 42% of total revenues in 2012 • One of the most regionally diversified producers in the US • More export terminal c
Slide 4: Overview: Strategy to Create an Industry Leader
4 Alpha Natural Resources European Investor Presentation Alpha Natural Resources Overview Strategy to Create an Industry Leader
Slide 5: Focus on Three-Pronged Strategy
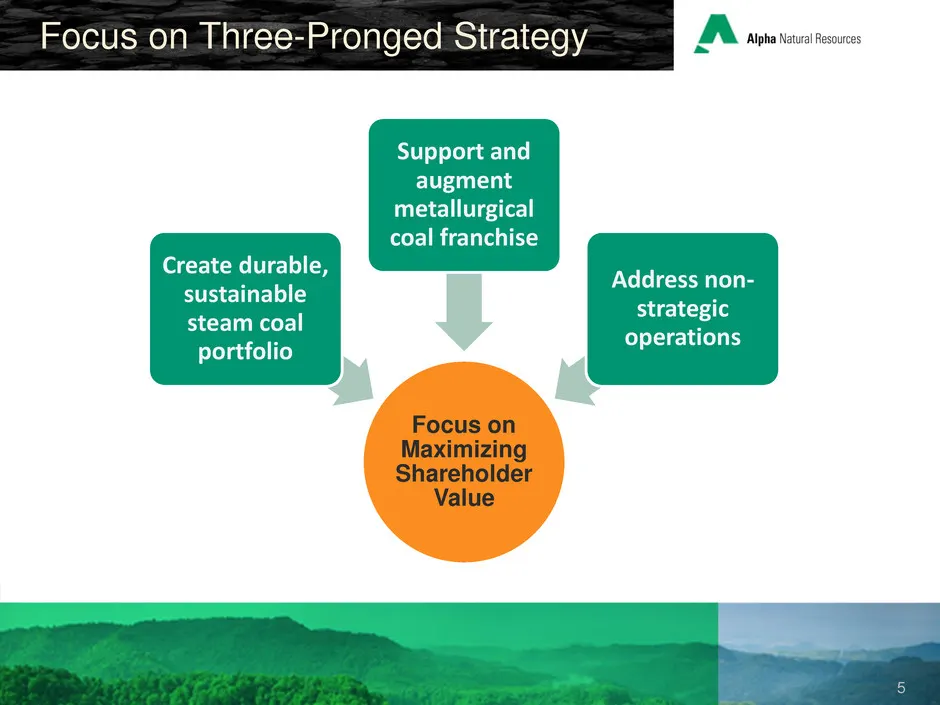
5 Focus on Three-Pronged Strategy Focus on Maximizing Shareholder Value Create durable, sustainable steam coal portfolio Support and augment metallurgical coal franchise Address non- strategic operations
Slide 6: Strategic Repositioning: Decisive Action
6 Strategic Repositioning: Decisive Action Adjusted production and shipments in response to current market & pricing environment Expecting 2013 shipment volumes of approximately 83-91mm tons* Implemented cost containment initiatives throughout company Strategic repositioning announced in Septe
Slide 7: Leading Global Supplier
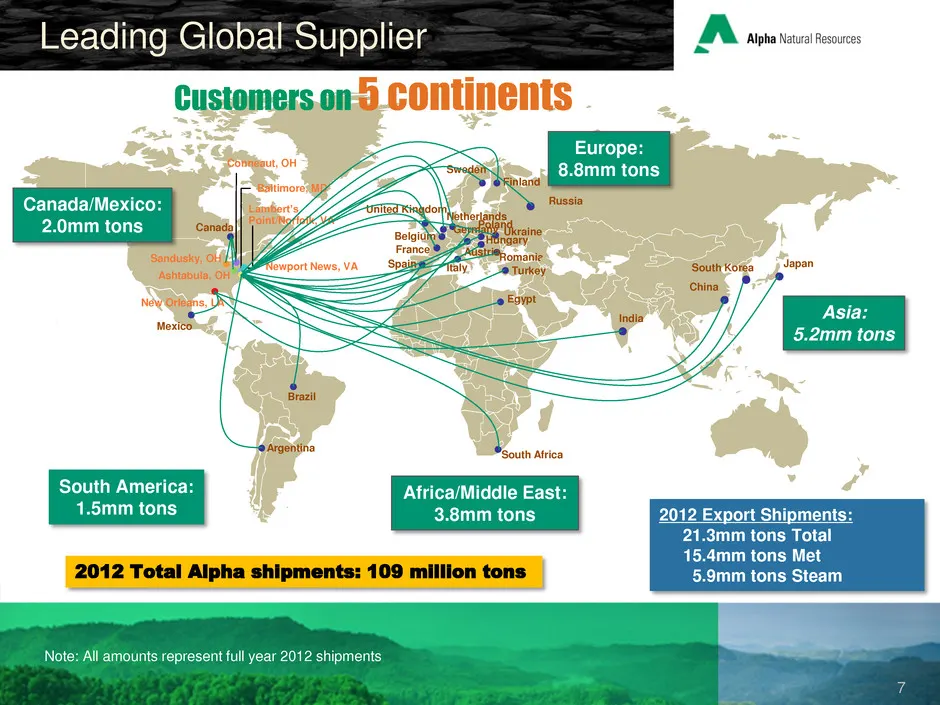
7 Leading Global Supplier Belgium Brazil Romania Canada France Egypt Sweden Netherlands Ukraine Spain Turkey United Kingdom Sandusky, OH Conneaut, OH Newport News, VA Lambert’s Point/Norfolk, VA Baltimore, MD Ashtabula, OH Russia New Orleans, LA Argentina Mexico Finland India Japan South Africa Chin
Slide 8: Logistics Flexibility Through Port Diversity
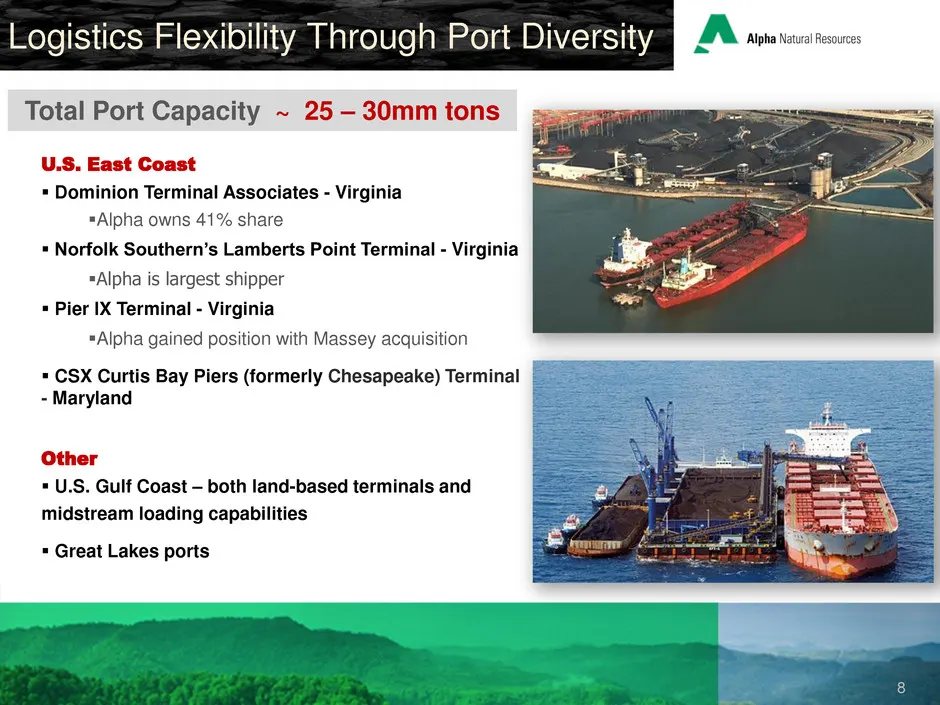
8 Logistics Flexibility Through Port Diversity Total Port Capacity ~ 25 – 30mm tons U.S. East Coast Dominion Terminal Associates - Virginia Alpha owns 41% share Norfolk Southern’s Lamberts Point Terminal - Virginia Alpha is largest shipper Pier IX Terminal - Virginia Alpha gained position w
Slide 9: Operational Diversification: Western and Eastern Coal Operations
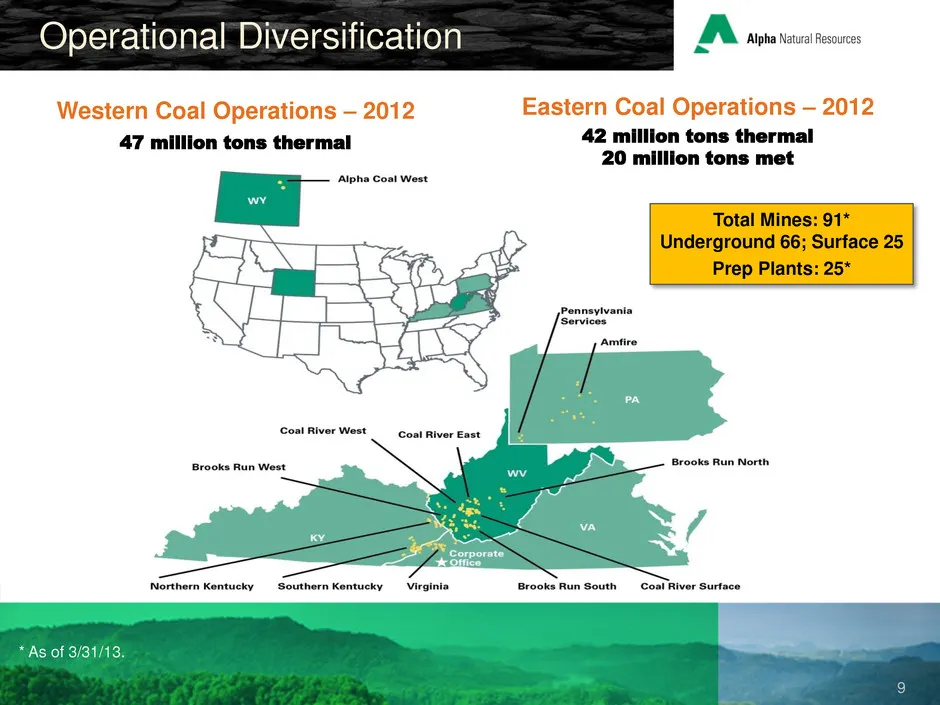
9 Operational Diversification Western Coal Operations – 2012 47 million tons thermal Eastern Coal Operations – 2012 42 million tons thermal 20 million tons met Total Mines: 91* Underground 66; Surface 25 Prep Plants: 25* * As of 3/31/13.
Slide 10: Operational Diversification: Revenue Mix and Reserves
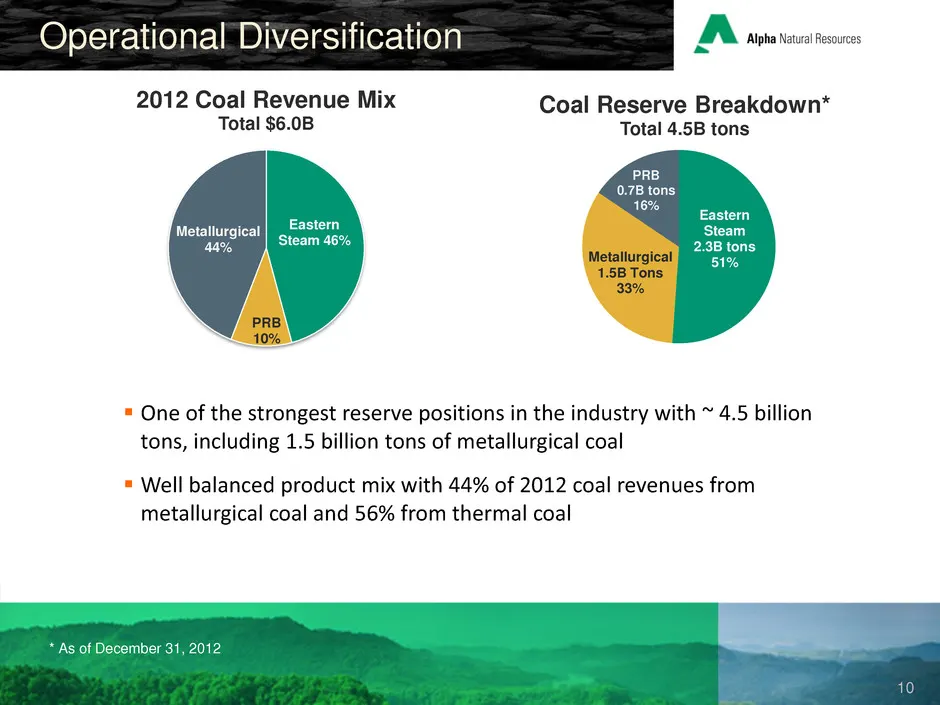
10 Operational Diversification * As of December 31, 2012 Eastern Steam 46% PRB 10% Metallurgical 44% 2012 Coal Revenue Mix Total $6.0B Eastern Steam 2.3B tons 51% Metallurgical 1.5B Tons 33% PRB 0.7B tons 16% Coal Reserve Breakdown* Total 4.5B tons One of the strongest reserve positions in the ind
Slide 11: Multiple Organic Met Coal Opportunities
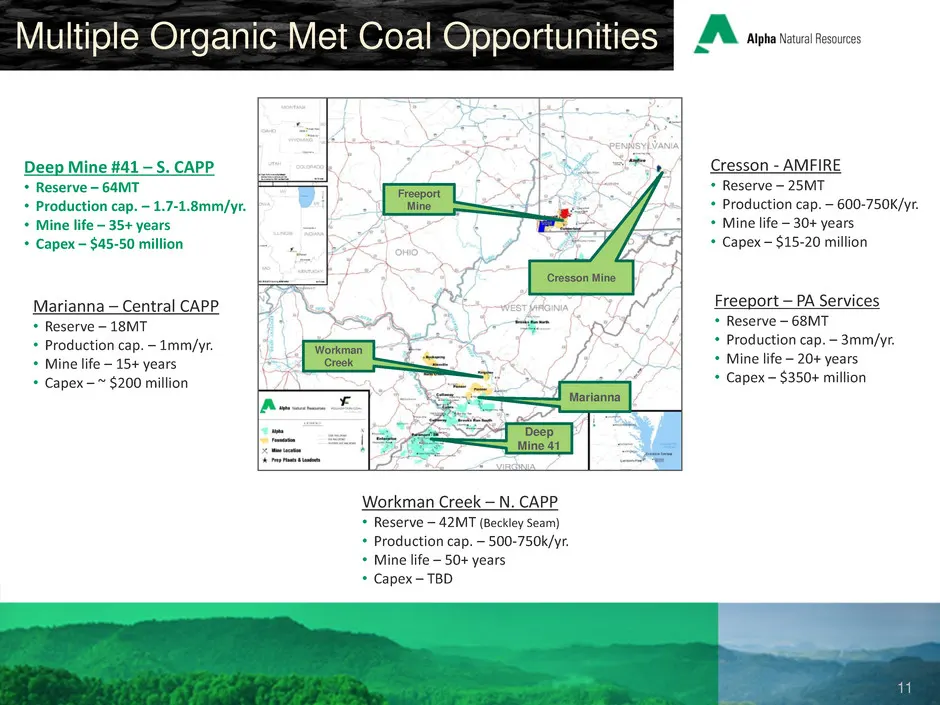
11 Multiple Organic Met Coal Opportunities Freeport – PA Services • Reserve – 68MT • Production cap. – 3mm/yr. • Mine life – 20+ years • Capex – $350+ million Cresson - AMFIRE • Reserve – 25MT • Production cap. – 600-750K/yr. • Mine life – 30+ years • Capex – $15-20 million Workman Creek – N. CAPP •
Slide 12: Market Overview: BRICS Drive Global Growth
12 Alpha Natural Resources European Investor Presentation Market Overview BRICS Drive Global Growth
Slide 13: Asia Drives Thermal Demand
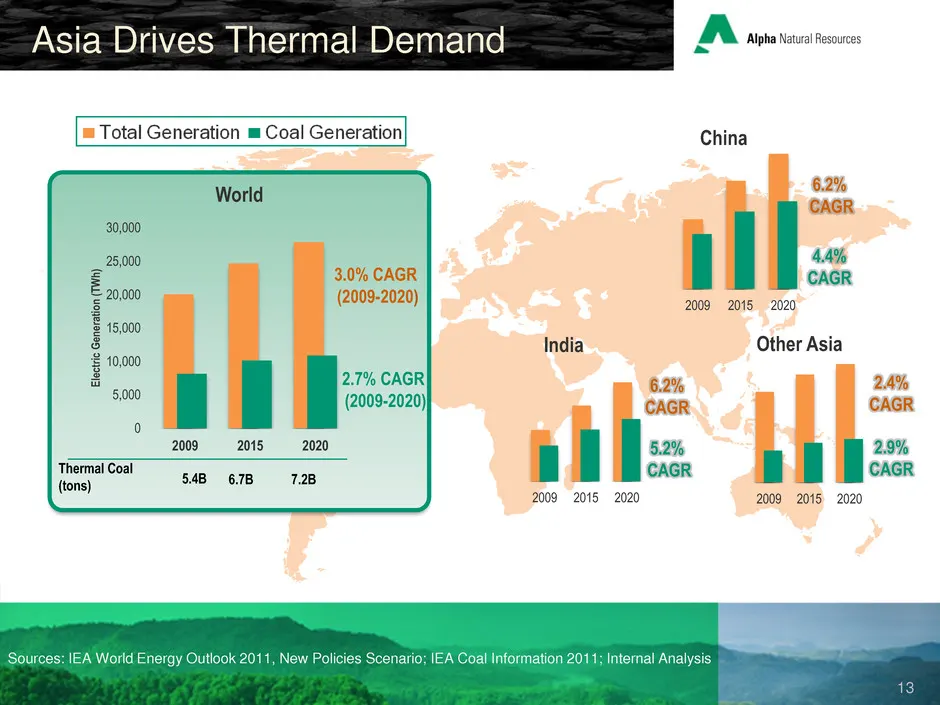
13 Asia Drives Thermal Demand Sources: IEA World Energy Outlook 2011, New Policies Scenario; IEA Coal Information 2011; Internal Analysis 2009 2015 2020 India 6.2% CAGR 5.2% CAGR 2009 2015 2020 China 4.4% CAGR 6.2% CAGR 0 5,000 10,000 15,000 20,000 25,000 30,000 2009 2015 2020 El ec tri c Ge n er at
Slide 14: Developing Nations Need Met Coal
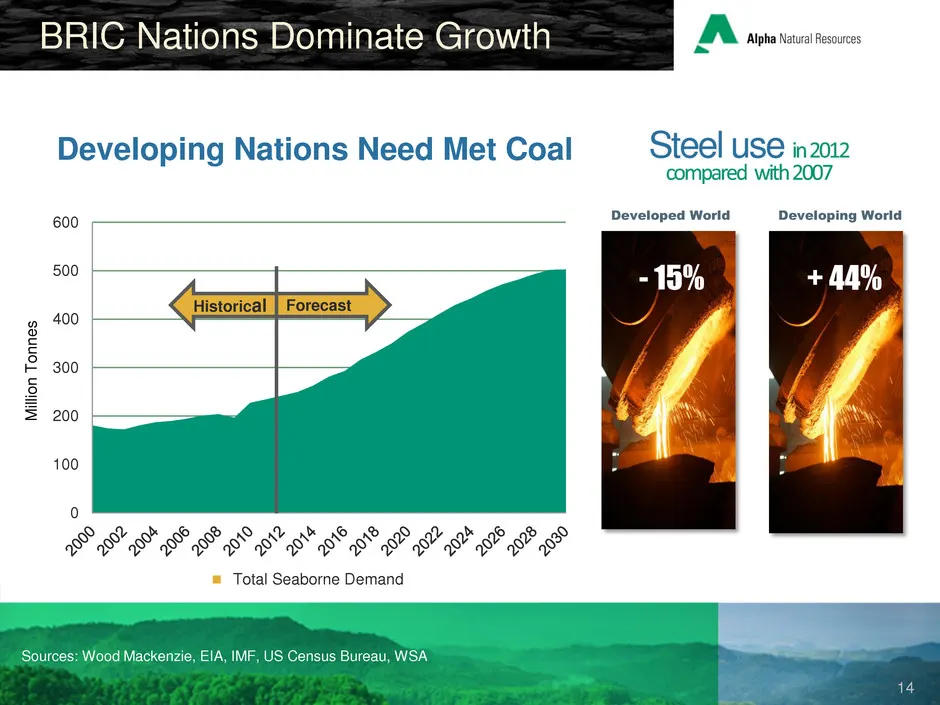
14 0 100 200 300 400 500 600 Total Seaborne Demand M ill io n T o n n e s - 15% Developed World Developing World + 44% BRIC Nations Dominate Growth Steel use in 2012 compared with 2007 Sources: Wood Mackenzie, EIA, IMF, US Census Bureau, WSA Developing Nations Need Met Coal Forecast Historical
Slide 15: Global Met Cutbacks May Increase
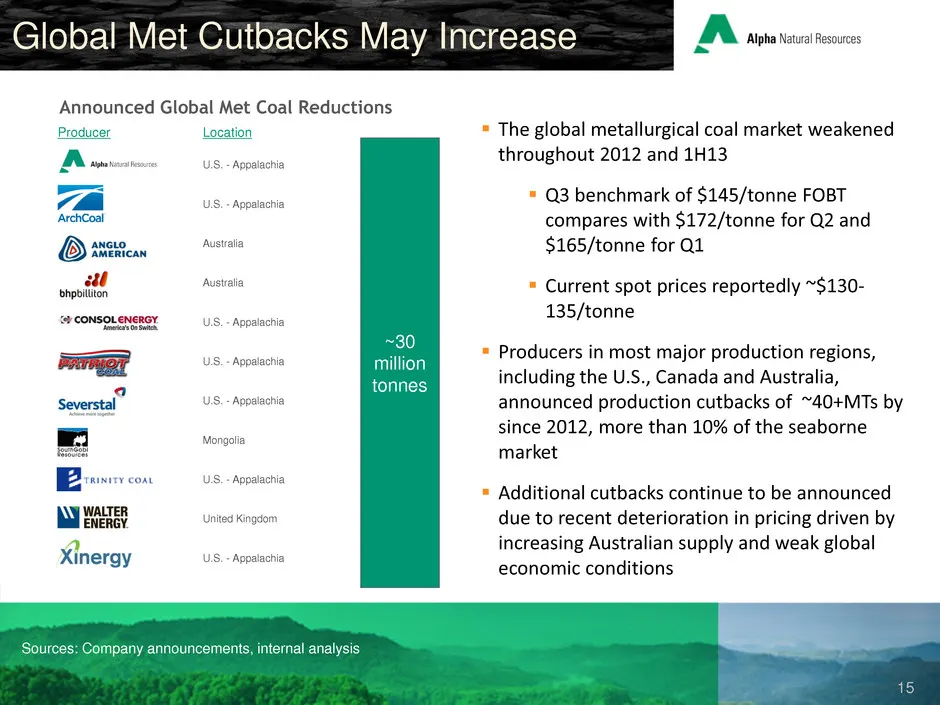
15 Global Met Cutbacks May Increase Sources: Company announcements, internal analysis Announced Global Met Coal Reductions ~30 million tonnes U.S. - Appalachia U.S. - Appalachia Australia Australia U.S. - Appalachia U.S. - Appalachia U.S. - Appalachia Mongolia U.S. - Appalachia United Kingdom U.S. -
Slide 16: U.S. Steam Mixed; CAPP Issues Persist
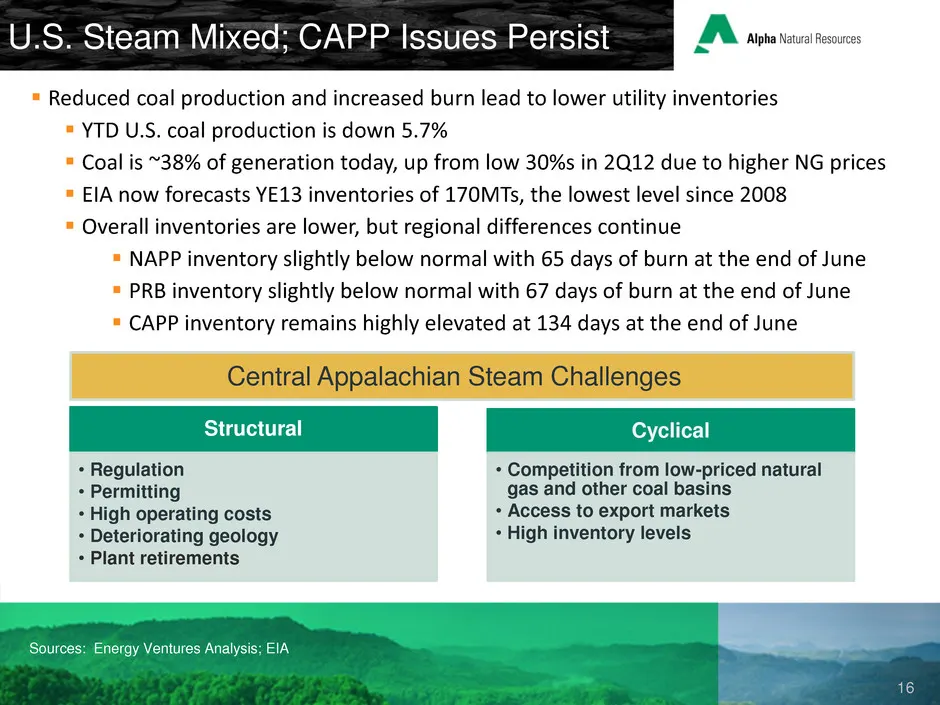
16 Reduced coal production and increased burn lead to lower utility inventories YTD U.S. coal production is down 5.7% Coal is ~38% of generation today, up from low 30%s in 2Q12 due to higher NG prices EIA now forecasts YE13 inventories of 170MTs, the lowest level since 2008 Overall invento
Slide 17: Regulation Causing Coal Unit Retirements
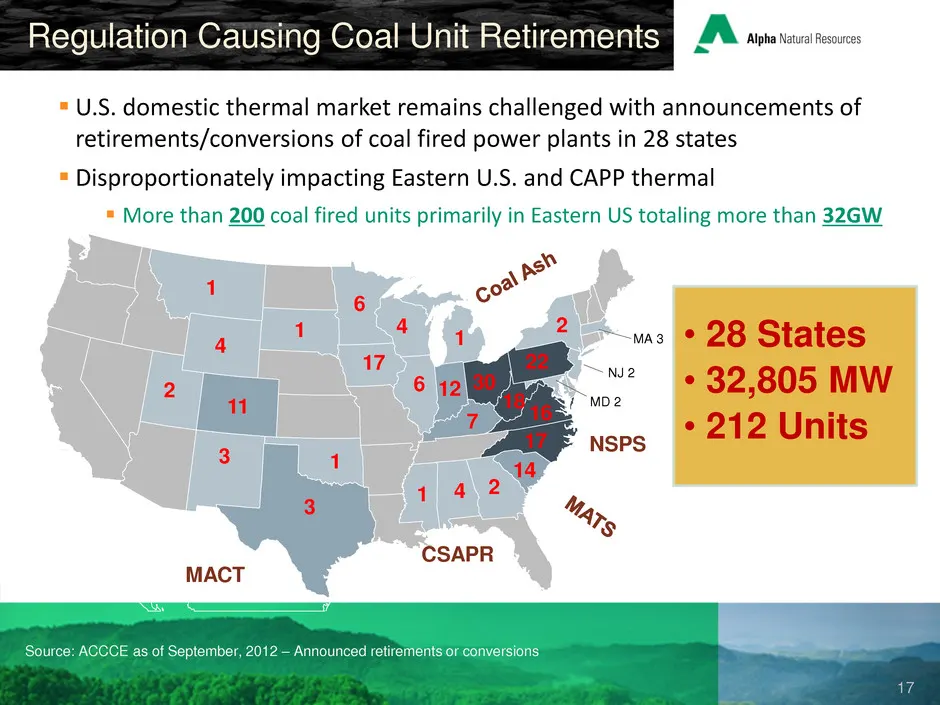
17 Regulation Causing Coal Unit Retirements • 28 States • 32,805 MW • 212 Units Source: ACCCE as of September, 2012 – Announced retirements or conversions MA 3 MD 2 NJ 2 22 14 16 17 18 30 17 6 1 3 4 2 3 2 4 1 6 4 12 7 11 1 MACT NSPS CSAPR 1 2 1 U.S. domestic thermal market remains challenged with
Slide 18: Financial Overview: Resources to Enhance Shareholder Value
18 Alpha Natural Resources European Investor Presentation Financial Overview Resources to Enhance Shareholder Value
Slide 19: ANR: Historical Financial Results
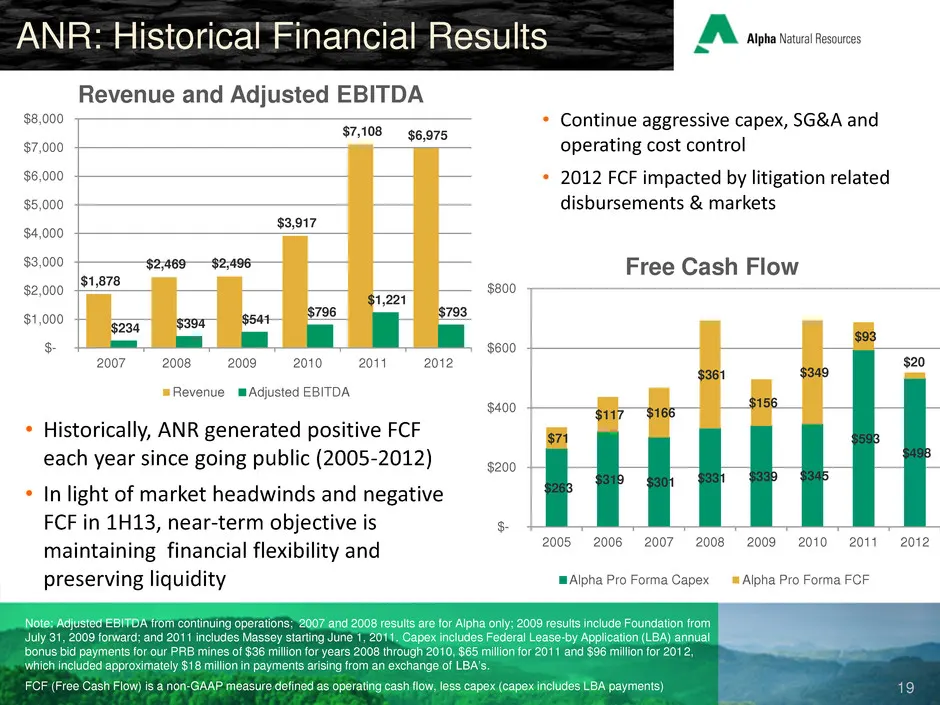
19 Note: Adjusted EBITDA from continuing operations; 2007 and 2008 results are for Alpha only; 2009 results include Foundation from July 31, 2009 forward; and 2011 includes Massey starting June 1, 2011. Capex includes Federal Lease-by Application (LBA) annual bonus bid payments for our PRB mines of
Slide 20: Liquidity & Debt Profile
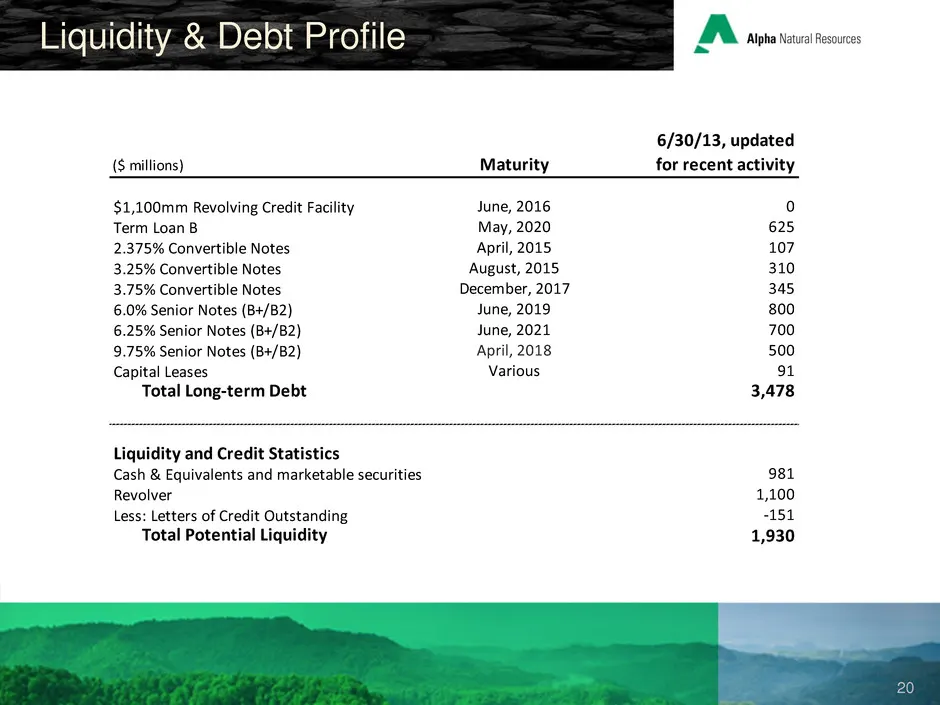
20 Liquidity & Debt Profile Maturity 6/30/13, updated for recent activity June, 2016 0 May, 2020 625 April, 2015 107 August, 2015 310 December, 2017 345 June, 2019 800 June, 2021 700 April, 2018 500 Various 91 Total Long-term Debt 3,478 981 1,100 -151 Total Potential Liquidity 1,930 ($ millions) $1,
Slide 21: Well-Positioned for Future Growth
21 Leading global met producer with consistent performance enhanced by product and regional diversification o #3 globally in metallurgical coal More export capacity than any other US producer allows Alpha to take advantage of growing seaborne demand Prudent capital expenditure management with
Slide 22: Appendices
22 www.alphanr.com Appendices
Slide 23: Reconciliation: Use of Non-GAAP Measures
23 Reconciliation Use of Non-GAAP Measures In addition to the results prepared in accordance with generally accepted accounting principles in the United States (GAAP) provided throughout this press release, Alpha has presented the following non-GAAP financial measures, which management uses to gauge
Slide 24: Reconciliation: Guidance
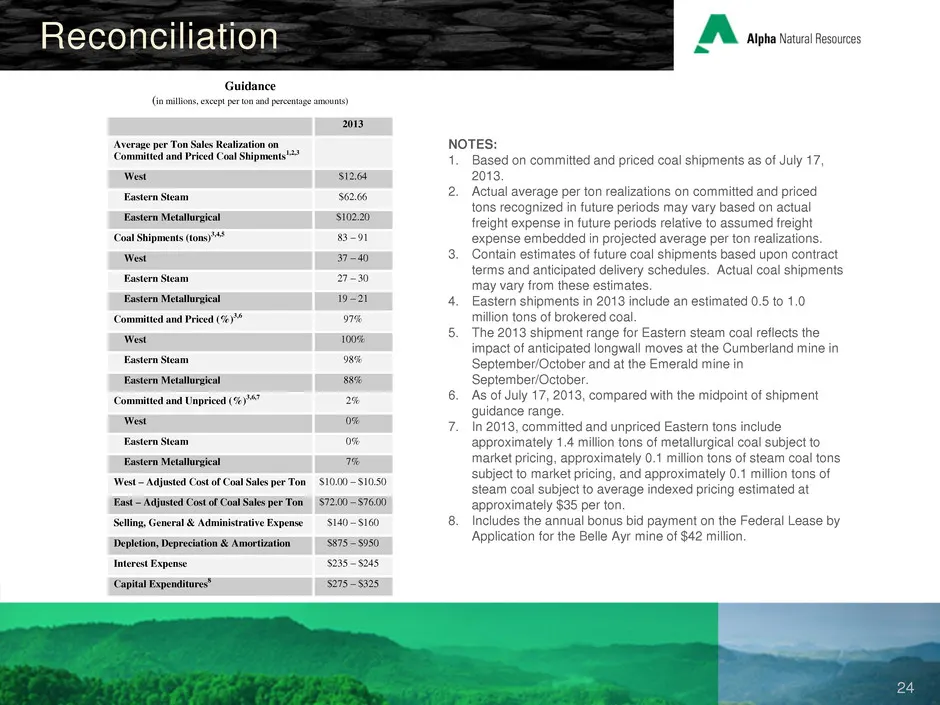
24 Reconciliation Guidance (in millions, except per ton and percentage amounts) 2013 Average per Ton Sales Realization on Committed and Priced Coal Shipments1,2,3 West $12.64 Eastern Steam $62.66 Eastern Metallurgical $102.20 Coal Shipments (tons)3,4,5 83 – 91 West 37 – 40 Eastern Steam 27 – 30 East
Slide 25: Reconciliation of Adjusted EBITDA
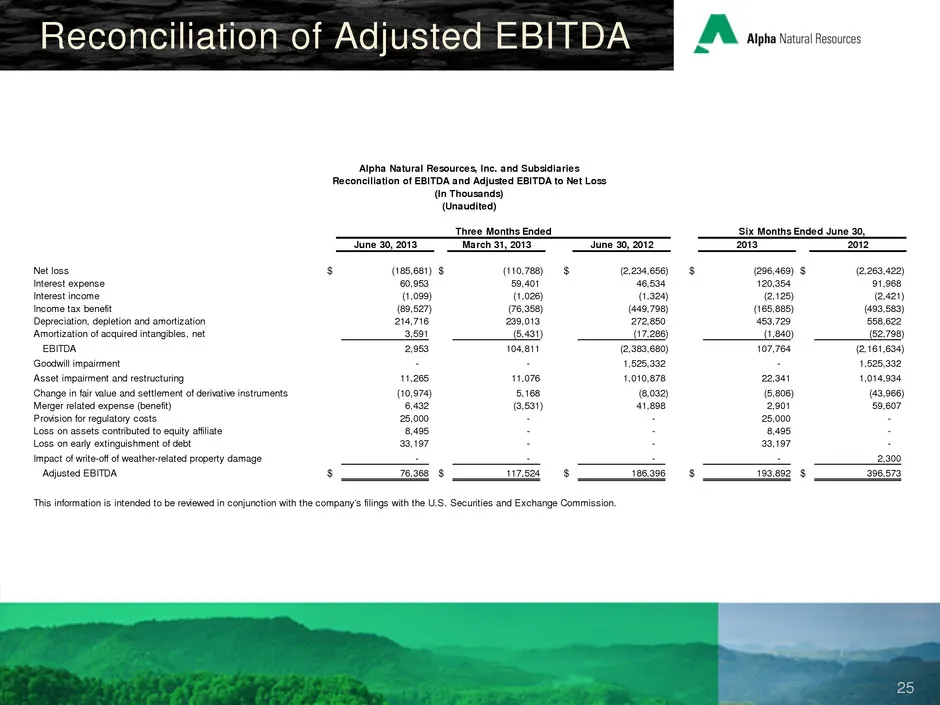
25 Reconciliation of Adjusted EBITDA June 30, 2013 March 31, 2013 June 30, 2012 2013 2012 Net loss $ (185,681) $ (110,788) $ (2,234,656) $ (296,469) $ (2,263,422) Interest expense 60,953 59,401 46,534 120,354 91,968 Interest income (1,099) (1,026) (1,324) (2,125) (2,421) Income tax benefit (89,527)
Slide 26: Reconciliation of Adjusted Income
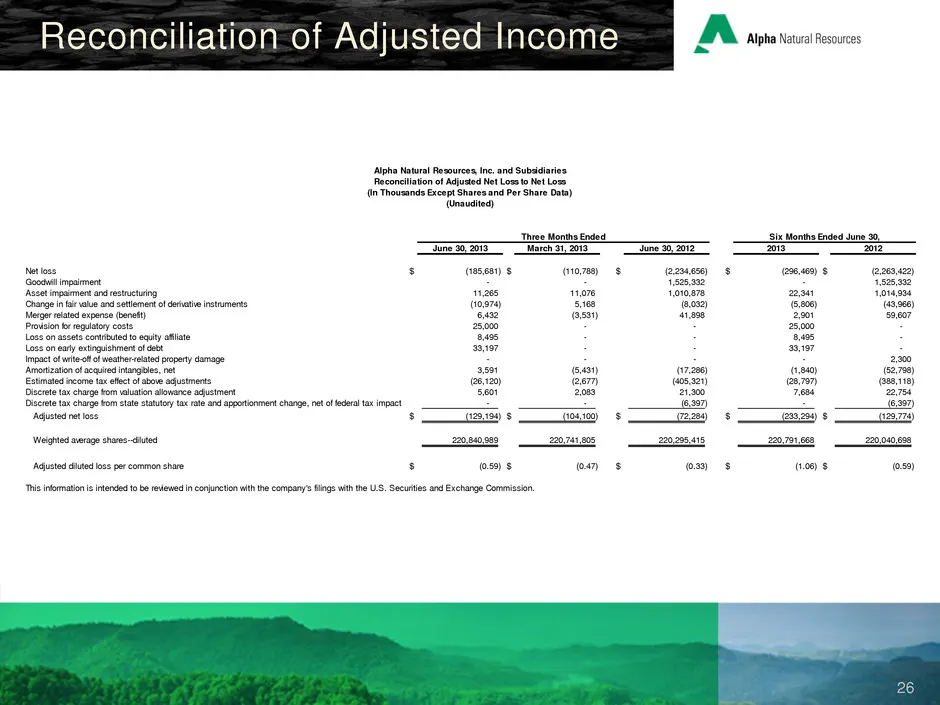
26 Reconciliation of Adjusted Income June 30, 2013 March 31, 2013 June 30, 2012 2013 2012 Net loss $ (185,681) $ (110,788) $ (2,234,656) $ (296,469) $ (2,263,422) Goodwill impairment - - 1,525,332 - 1,525,332 Asset impairment and restructuring 11,265 11,076 1,010,878 22,341 1,014,934 Change in fair
Source: SEC EDGAR · 8-K filed Aug 5, 2013
More decks from Alpha Natural Resources Inc
 J.P. Morgan Global High Yield & Leveraged Finance Conference (February 2015)36 slides · Feb 23, 2015
 Barclays CEO Energy-Power Conference 201435 slides · Sep 2, 2014
 2014 BMO 23rd Global Metals and Mining Conference; Sterne Agee 2014 Boston Executive Summi33 slides · Jun 17, 2014
 2014 BMO 23rd Global Metals and Mining Conference / Brean Capital 2014 Global Resources &30 slides · May 28, 2014
 2014 BMO 23rd Global Metals and Mining Conference30 slides · Feb 24, 2014
 J.P. Morgan Global High Yield & Leveraged Finance Conference (February 2013)27 slides · Feb 25, 2013