Teladoc Health, Inc. · NYSE:TDOC
Teladoc Health — Investor Day (March 2020)
152 slides from Teladoc Health's investor day presentation, Mar 5, 2020
Slide 1: Investor Day
INVESTOR Telagoc. Dayenn
Slide 2: Safe harbor
Safe harbor + This presentation contains, and our officers may make, "forwarelooking'" statements that are based on our managements beliefs and ossumptions and on information curently available to management. These forwerc-ocking slotementsinclude, without limitation, information concerning possible
Slide 3: Transforming how people access healthcare around the world
At Teladoc Health, we are transforming how people access healthcare around the world. We are creating a new kind of healthcare experience – one with greater convenience, outcomes, and value.
Slide 4: Welcome and Overview
© © © Teladoc. leXeze) oO © © Welcome @) © oO and Overview COO wersaere ooo O00 —
Slide 5: The Only Comprehensive Virtual Care Solution
The Only Comprehensive Virtual Care Solution Industry Leader with Differentiated Assets, Capabilities and Scale Track Record of Delivering Strong Revenue Growth Global Leadership Position Across Channels Durable Business with Compelling Financial Model Positioned to Broaden Role in Healthcare Delive
Slide 6: Guided by shared values
We are guided by shared values 6 We are passionate about taking care of people We are committed to unsurpassed quality We keep our promises We lead with integrity , accountability , and transparency We stand up for what’s right We strive to create value We respect each other and value succeeding tog
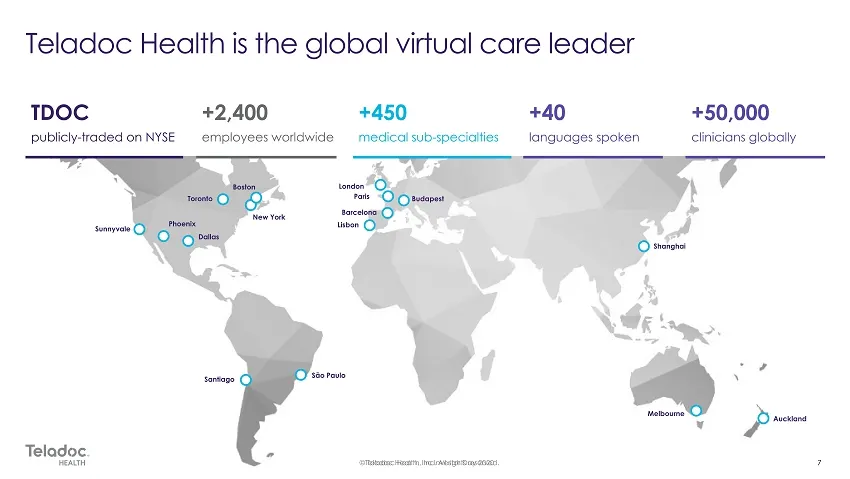
Slide 7: Office locations
Melbourne Toronto Boston Phoenix Dallas
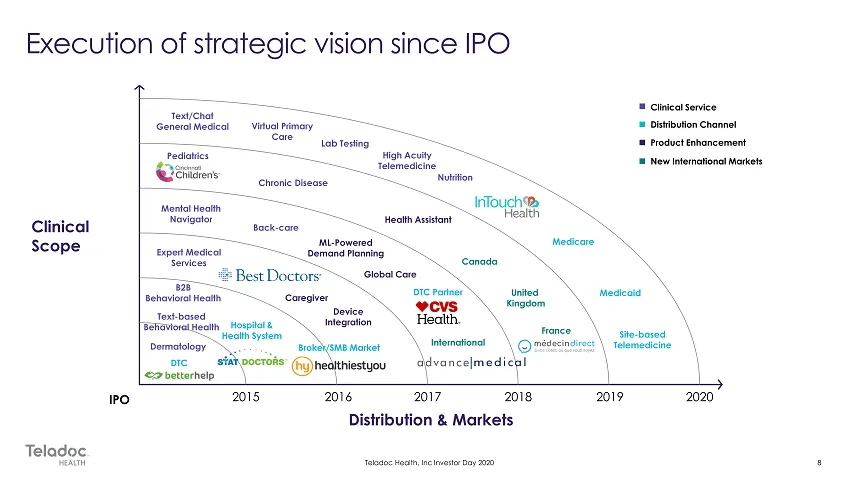
Slide 8: Services and capabilities
Dermatology Hospital & Health System Text - based Behavioral Health DTC Caregiver Expert Medical Services Device Integration Global Care International DTC Partner Mental Health Navigator Back - care ML - Powered Demand Planning Chronic Disease Health Assistant Pediatrics Canada United Kingdom France
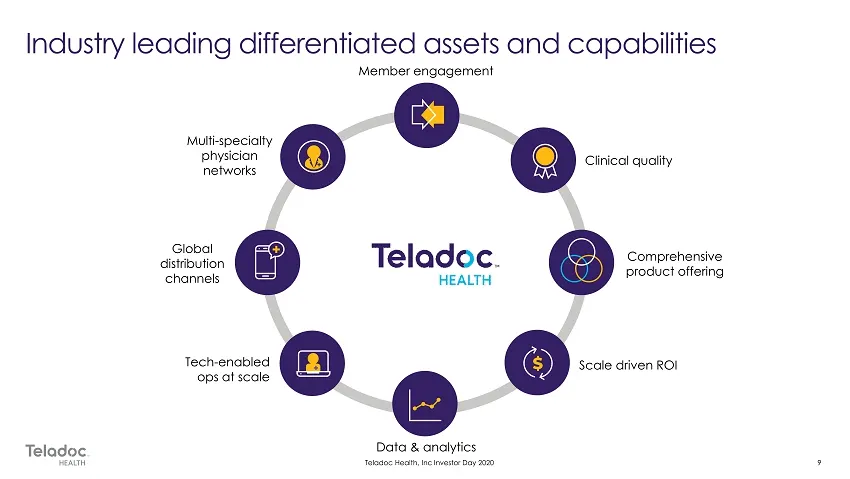
Slide 9: Industry leading differentiated assets and capabilities
Industry leading differentiated assets and capabilities Member engagement ‘Multi-specialty piysilen Clinical quality networks distibution Teladoc. Comprehensive channels HEALTH Pr a Tech-enabled Scale driven ROI ops al scale Teladoc Data & analytics
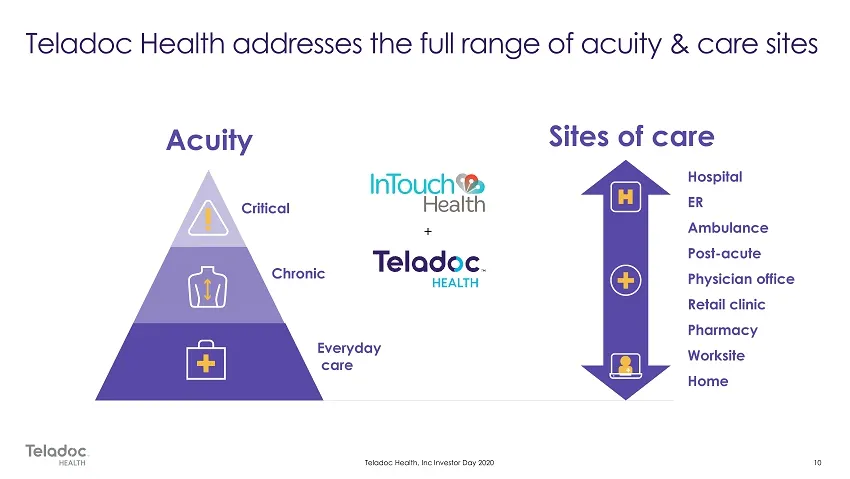
Slide 10: Acuity and sites of care
Acuity Critical Chronic Everyday care Sites of care Hospital ER Ambulance Post - acute Physician office Retail clinic Pharmacy Worksite Home
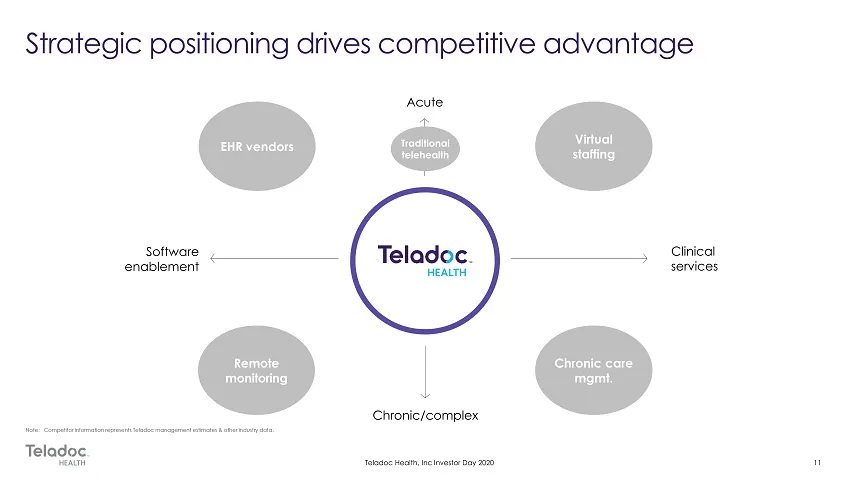
Slide 11: Competitive comparison
Note: Competitor information represents Teladoc management estimates & other industry data.
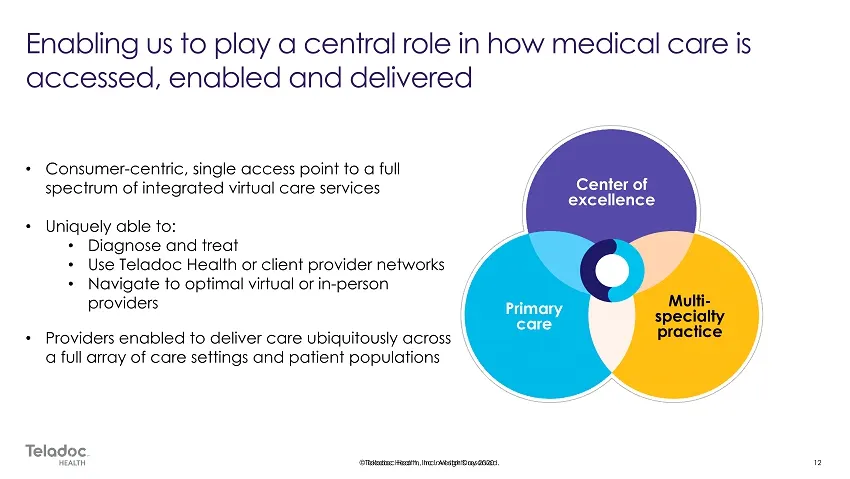
Slide 12: Central role in how medical care is accessed and delivered
Enabling us to play a central role in how medical care is accessed, enabled and delivered + Consumer-centric, single access point to a full spectrum of integrated virtual care services Center of excellence + Uniquely able to: + Diagnose and treat + Use Teladoc Health or client provider networks + Na
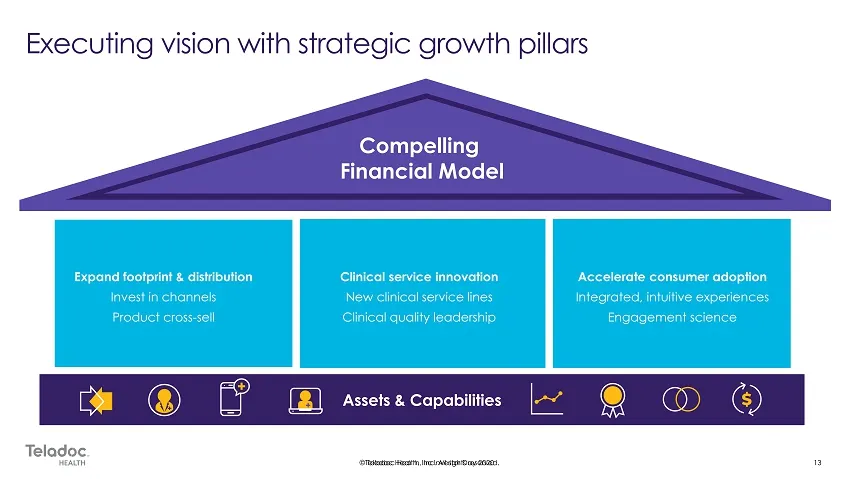
Slide 13: Assets and capabilities
Assets & Capabilities Expand footprint & distribution Invest in channels Product cross - sell Clinical service innovation New clinical service lines Clinical quality leadership Accelerate consumer adoption Integrated, intuitive experiences Engagement science Compelling Financial Model Compelling Fin
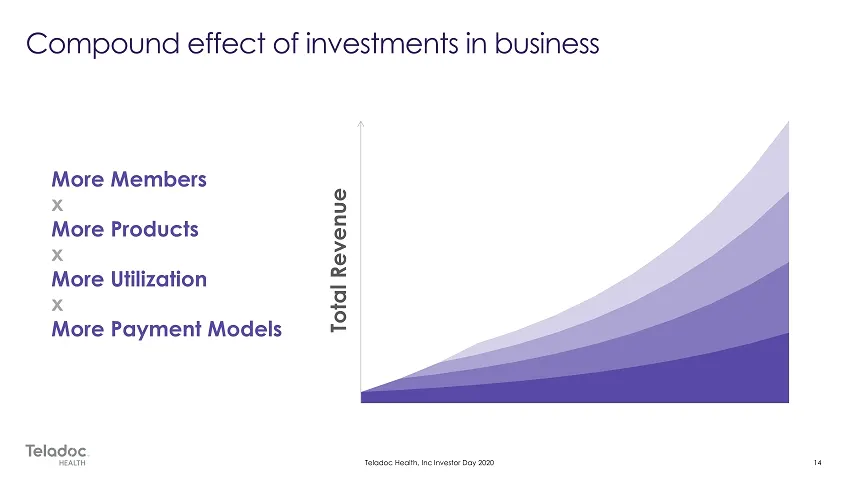
Slide 14: Revenue growth drivers
Total Revenue x More Members x More Products x More Utilization x More Payment Models
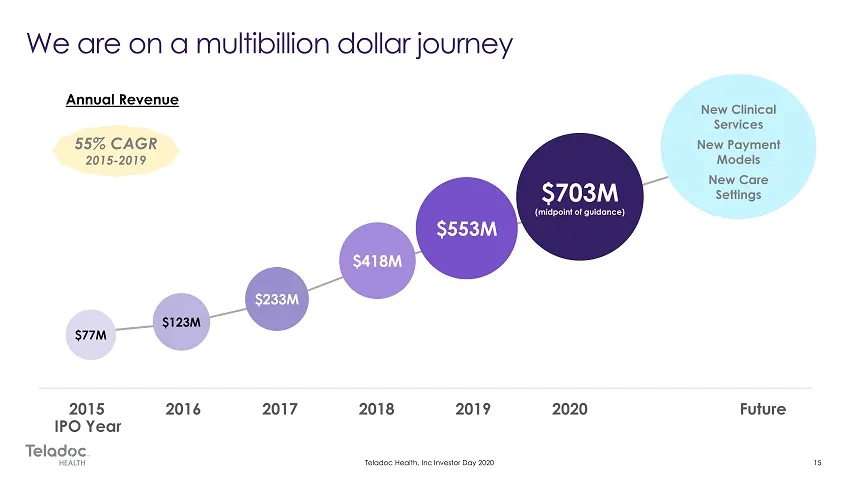
Slide 15: Annual revenue 2015-2019
2015 2016 2017 2018 2019 2020 Future New Clinical Services New Payment Models New Care Settings $77M $123M $233M $418M IPO Year Annual Revenue 55% CAGR 2015 - 2019
Slide 16: Teladoc Health Case Study
Teladoc Health Case Study Teladoc
Slide 17: Client case study overview
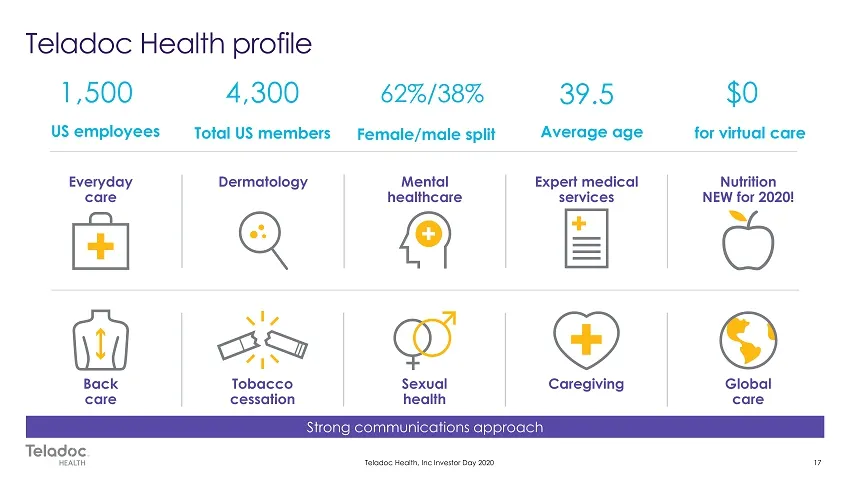
Dermatology Mental healthcare Expert medical services Nutrition NEW for 2020! Everyday care US employees Total US members Back care Caregiving Sexual health Tobacco cessation Global care 1,500 4,300 for virtual care $0 62%/38% 39.5 Female/male split Average age
Slide 18: Strong engagement and utilization
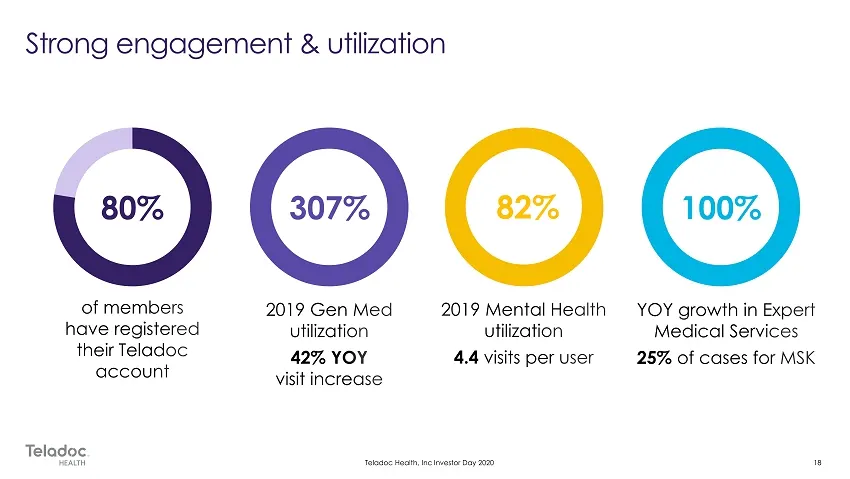
Strong engagement & utilization 80% 82% of members 2019 Gen Med 2019 Mental Health have registered utilization utilization mel Teladee 42% YOY 4.4 visits per user account visit increase Teladoc 100% YOY growth in Expert Medical Services 25% of cases for MSK
Slide 19: Claims cost comparison
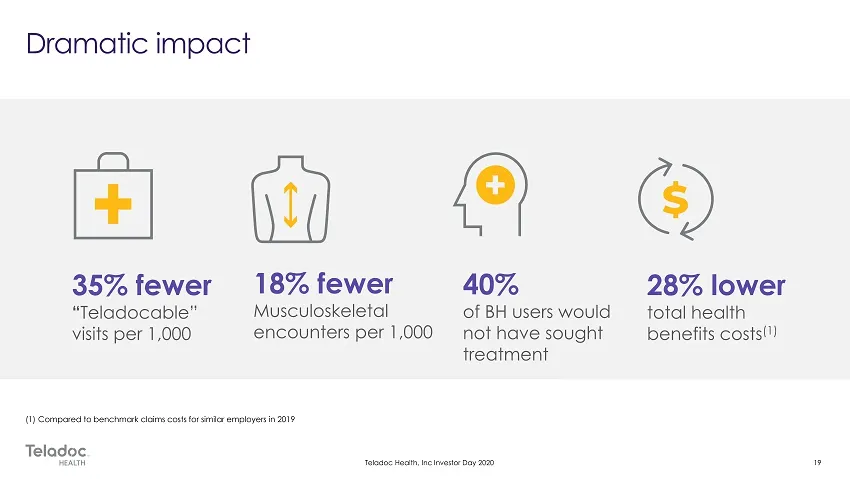
(1) Compared to benchmark claims costs for similar employers in 2019
Slide 20: Total access and visits
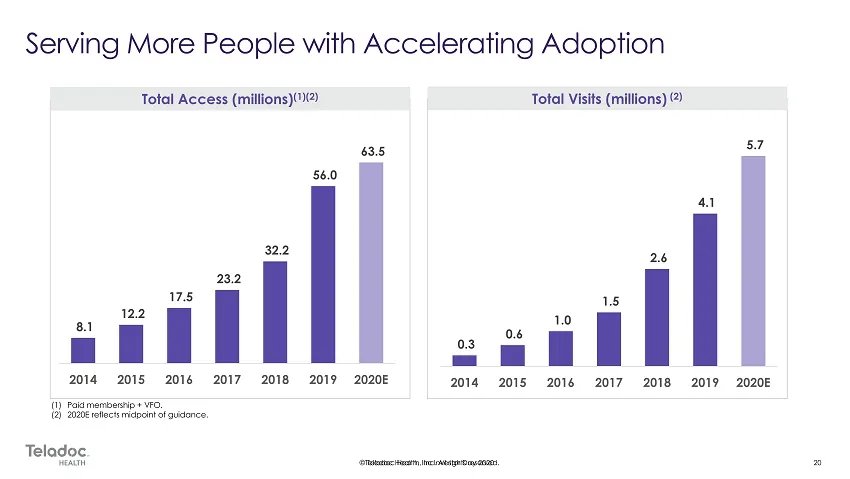
(1) Paid membership + VFO. (2) 2020E reflects midpoint of guidance. Total Access (millions) (1)(2) Total Visits (millions) (2) 8.1 12.2 17.5 23.2 32.2 56.0 63.5 2014 2015 2016 2017 2018 2019 2020E 0.3 0.6 1.0 1.5 2.6 4.1 5.7 2014 2015 2016 2017 2018 2019 2020E
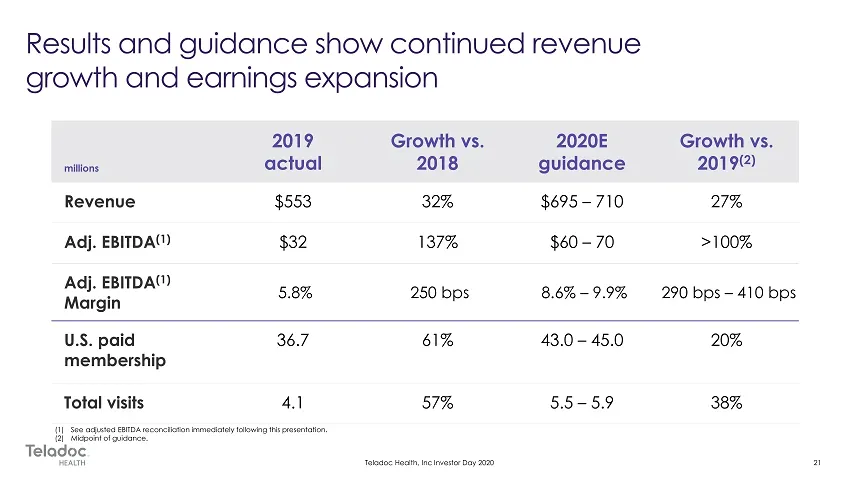
Slide 21: Adjusted EBITDA margin
5.8% 250 bps 8.6% 9.9 % 290 bps 410 bps (1) See adjusted EBITDA reconciliation immediately following this presentation. (2) Midpoint of guidance.
Slide 22: Playbook for growth
C eke) OOo Oo C o0000 Playbook for growth David Sides Chief Operating Officer Telodoe INVESTOR
Slide 23: Key themes
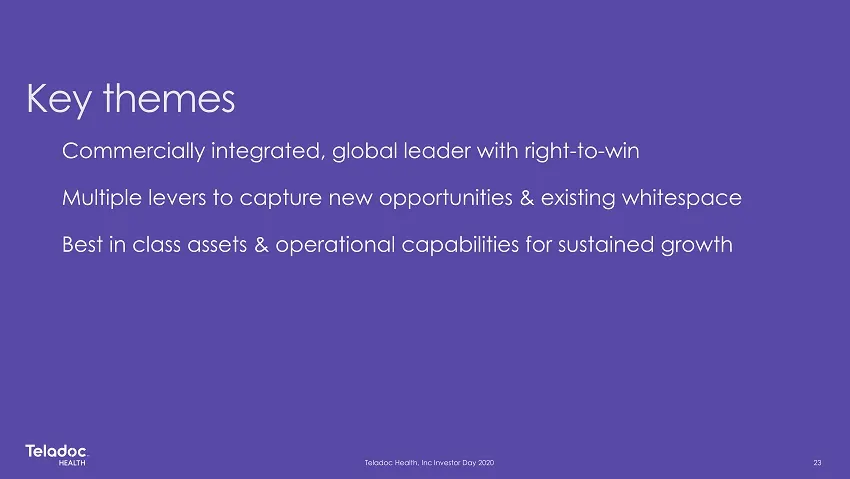
Key themes Commercially integrated, global leader with right-to-win Multiple levers to capture new opportunities & existing whitespace Best in class assets & operational capabilities for sustained growth Teladoc.
Slide 24: Assets and capabilities
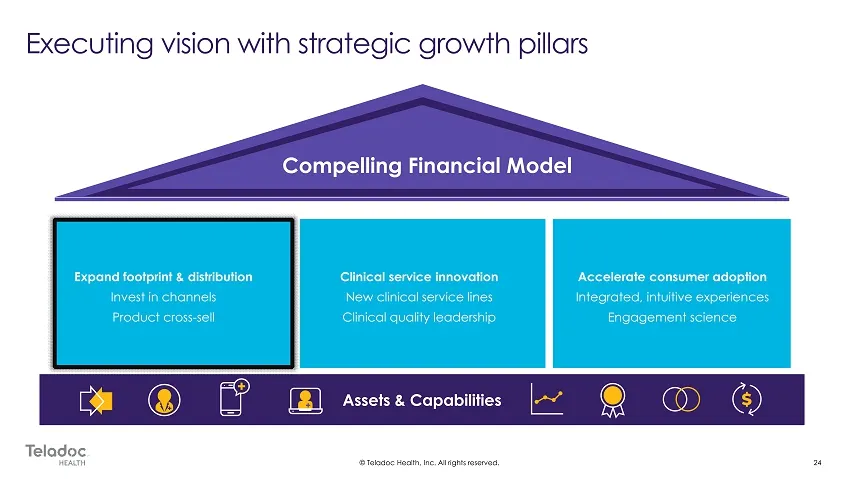
Assets & Capabilities Expand footprint & distribution Invest in channels Product cross - sell Clinical service innovation New clinical service lines Clinical quality leadership Accelerate consumer adoption Integrated, intuitive experiences Engagement science Compelling Financial Model
Slide 25: Distribution channels
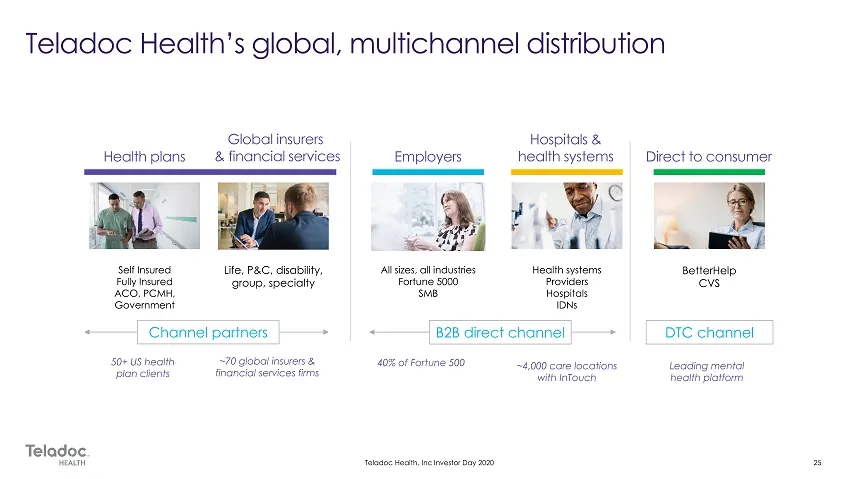
Direct to consumer Health plans Channel partners Employers Global insurers & financial services Hospitals & health systems B2B direct channel DTC channel 50+ US health plan clients ~70 global insurers & financial services firms 40% of Fortune 500 ~4,000 care locations with InTouch Leading mental hea
Slide 26: International opportunity
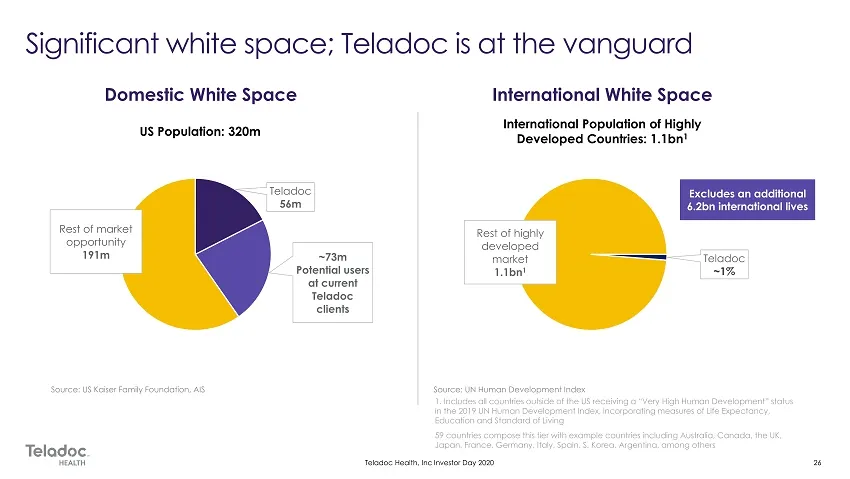
~1% 1. Includes all countries outside of the US receiving a “Very High Human Development” status in the 2019 UN Human Development Index, incorporating measures of Life Expectancy, Education and Standard of Living 59 countries compose this tier with example countries including Australia, Canada, the
Slide 27: Winning with an integrated commercial model
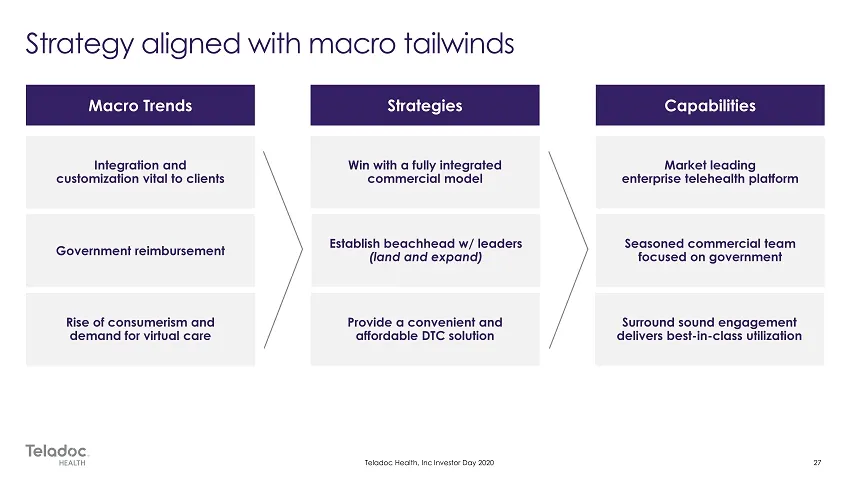
Integration and customization vital to clients Government reimbursement Rise of consumerism and demand for virtual care Win with a fully integrated commercial model Surround sound engagement delivers best - in - class utilization Provide a convenient and affordable DTC solution Market leading enterp
Slide 28: Employer views on virtual care
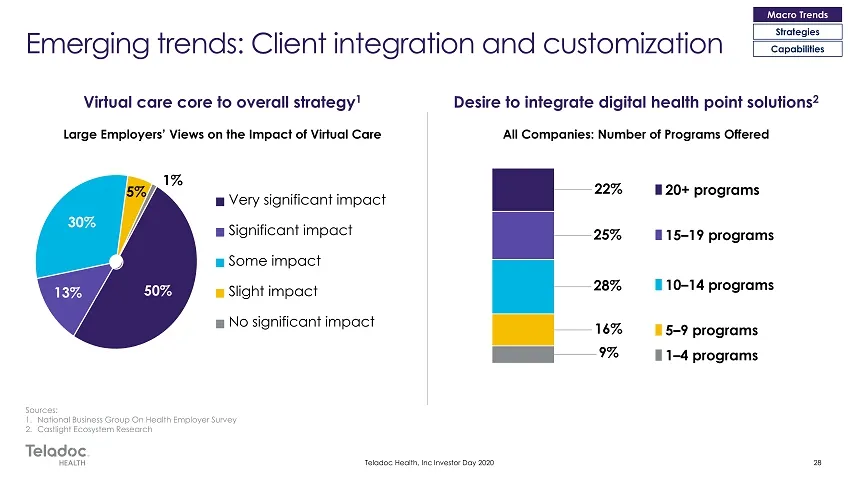
9% 16% 28% 25% 22% 20+ programs 15 – 19 programs 10 – 14 programs 5 – 9 programs 1 – 4 programs Large Employers’ Views on the Impact of Virtual Care 1. 2. 5% 1% All Companies: Number of Programs Offered Strategies Capabilities
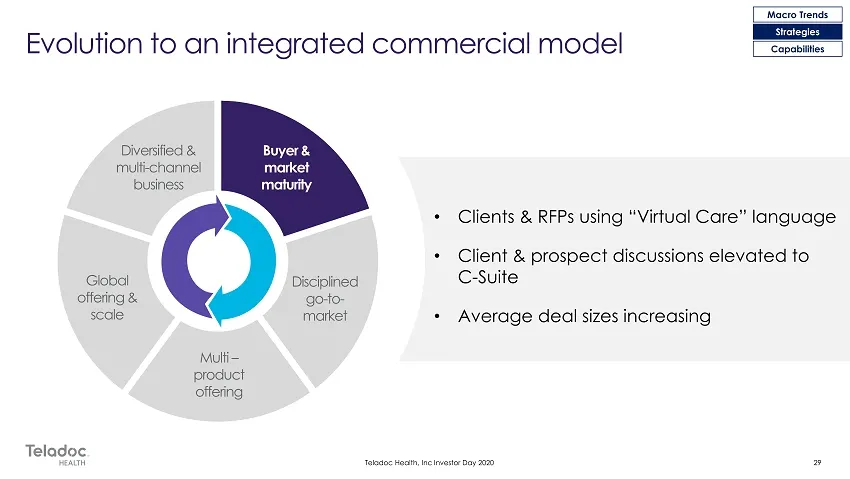
Slide 29: Macro Trends, Strategies, Capabilities
Macro Trends Strategies Capabilities
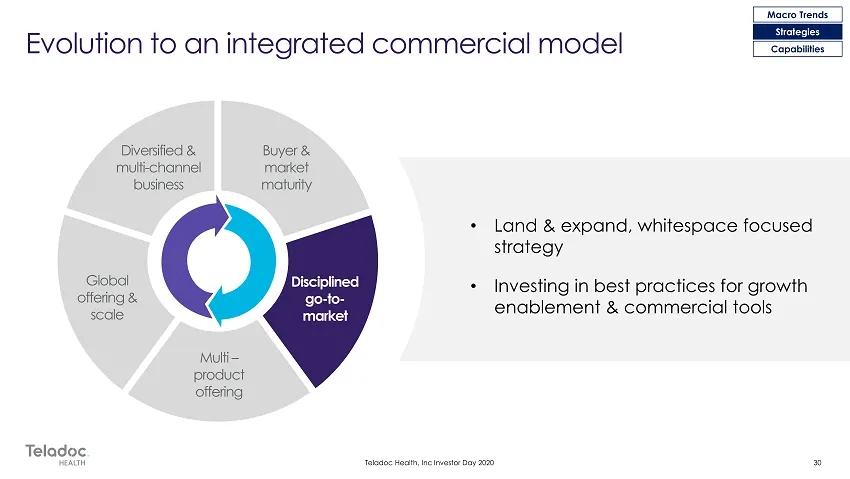
Slide 30: Disciplined go-to-market
Disciplined go - to - market Macro Trends Strategies Capabilities
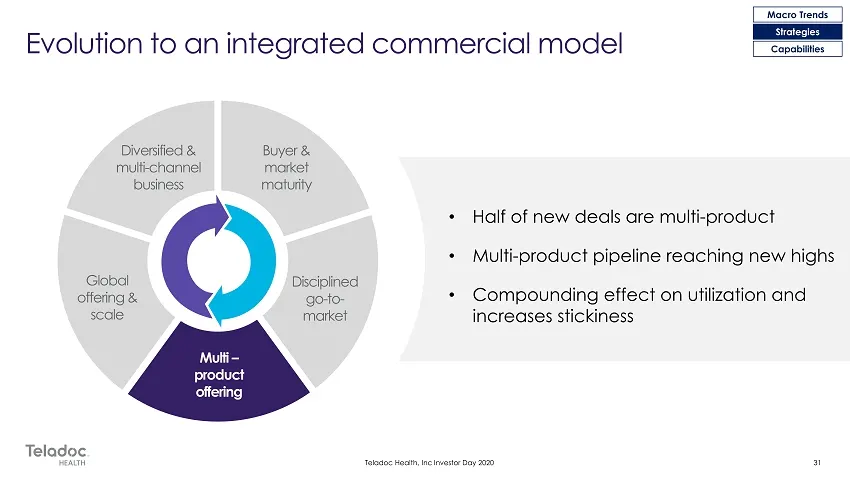
Slide 31: Macro Trends, Strategies, Capabilities
Macro Trends Strategies Capabilities
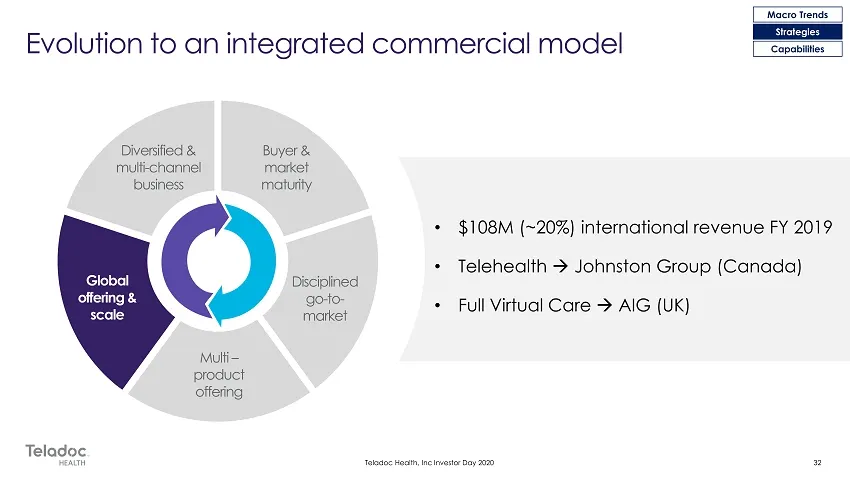
Slide 32: International revenue
• $108M (~20%) international revenue FY 2019 Macro Trends Strategies Capabilities
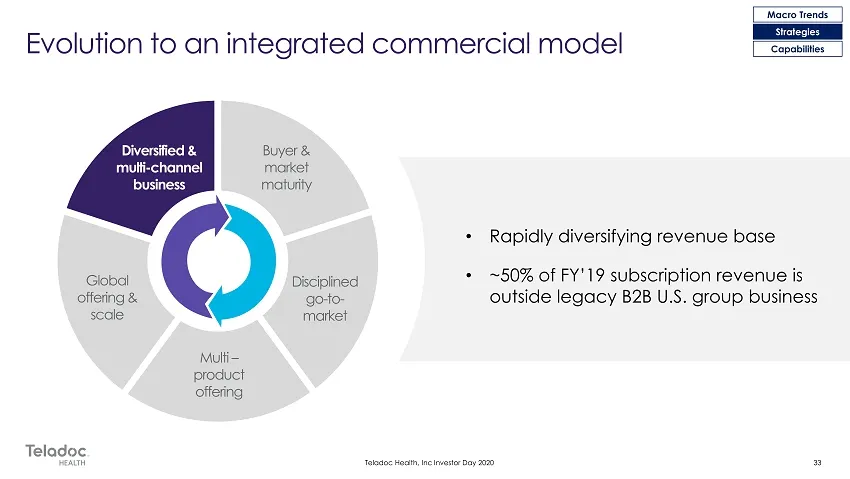
Slide 33: Subscription revenue mix
• ~50% of FY’19 subscription Macro Trends Strategies Capabilities
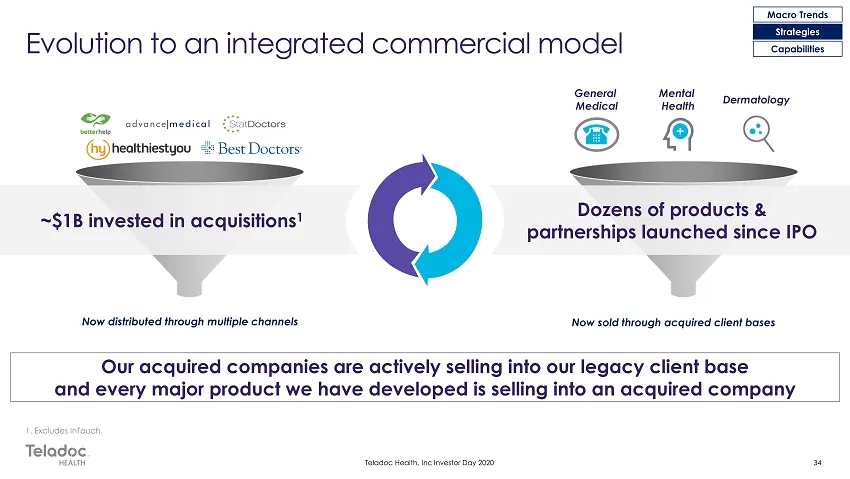
Slide 34: Multiple distribution channels
Macro Trends Strategies Capabilities Now distributed through multiple channels Now sold through acquired client bases Mental Health General Medical Dermatology
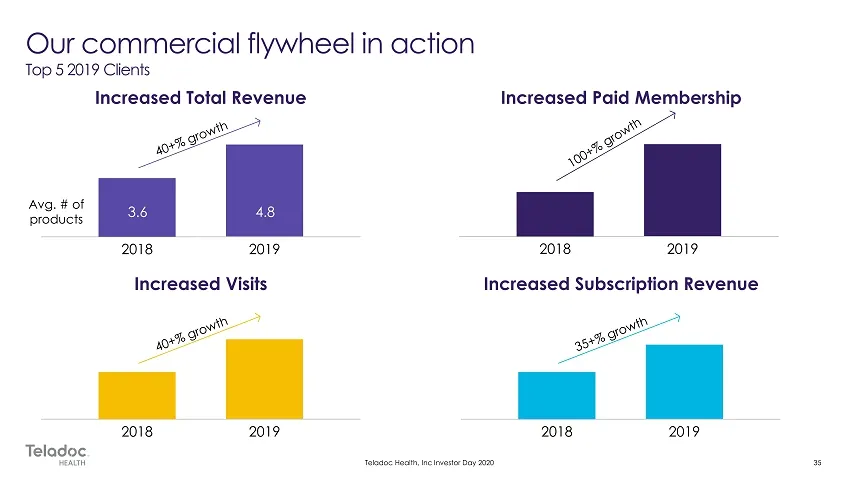
Slide 35: Commercial flywheel in action
Our commercial flywheel in action Top 5 2019 Clients Increased Total Revenue Increased Paid Membership 7 a Ae x Avg. # of 2 products 2018 2019 2018 2019 Increased Visits Increased Subscription Revenue ot ee 2018 2019
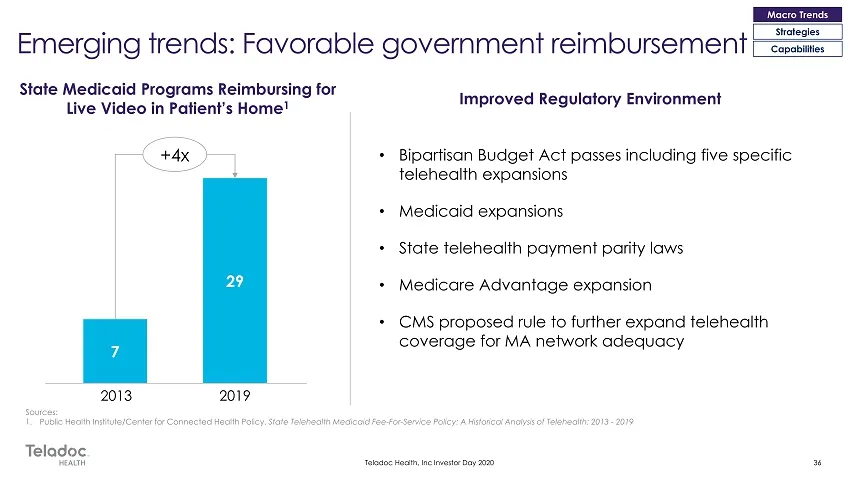
Slide 36: Government telehealth policy tailwinds
• Bipartisan Budget Act passes including five specific telehealth expansions • Medicaid expansions • State telehealth payment parity laws • Medicare Advantage expansion • CMS proposed rule to further expand telehealth coverage for MA network adequacy 1. 7 29 Strategies Capabilities
Slide 37: Macro Trends, Strategies, Capabilities
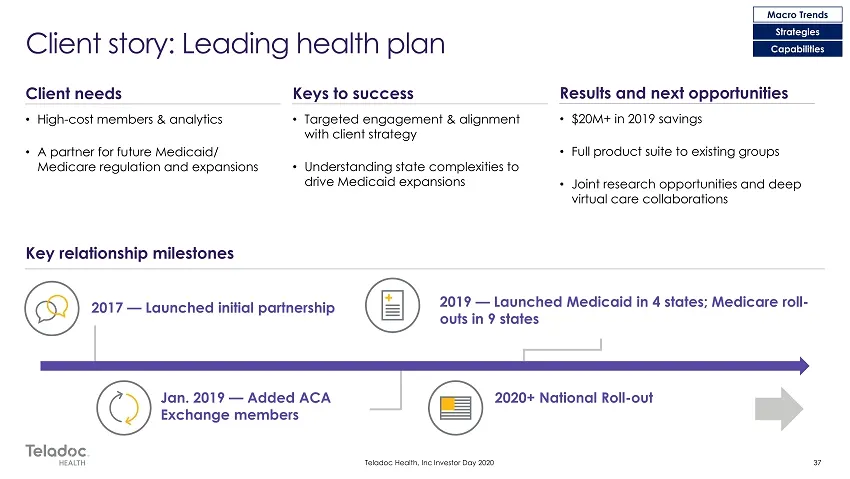
Macro Trends Strategies Capabilities
Slide 38: Emerging trends: consumer habits shifting
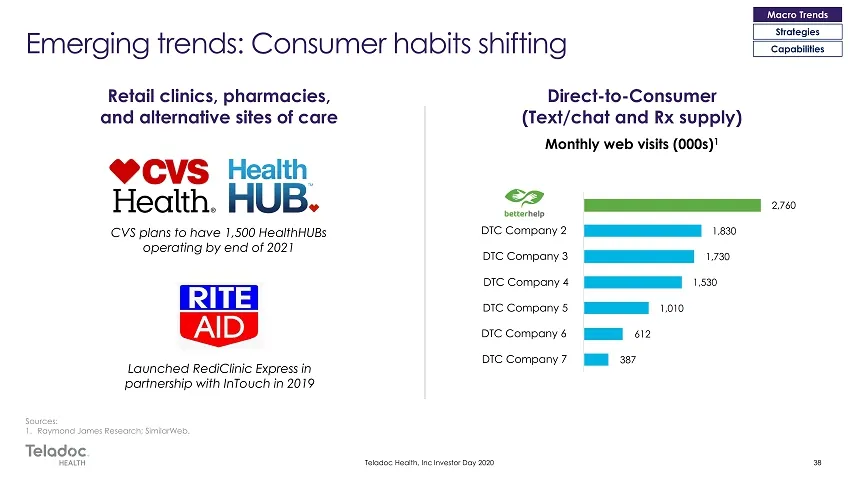
Emerging trends: Consumer habits shifting oe Retail clinics, pharmacies, Direct-to-Consumer and alternative sites of care (Text/chat and Rx supply) Monthly web visits (000s)! CVS Health Health. HUB. Po eo CVS plans fo have 1,500 HealthHUBs CIC Compory? TTT 530 ‘operating by end of 2021 DIC Companys
Slide 39: Visits per member, revenue/CAC, LTV
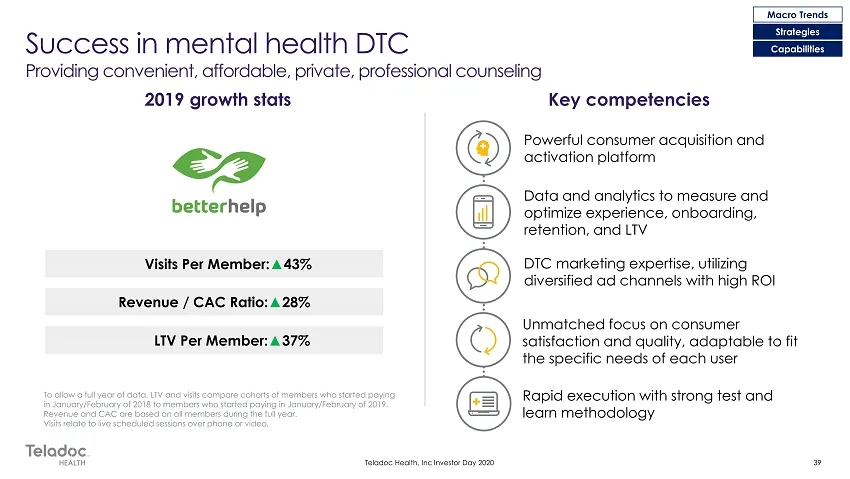
Visits Per Member: ▲ 43% Revenue / CAC Ratio: ▲ 28% LTV Per Member: ▲ 37% Macro Trends Strategies Capabilities
Slide 40: Macro Trends, Strategies, Capabilities
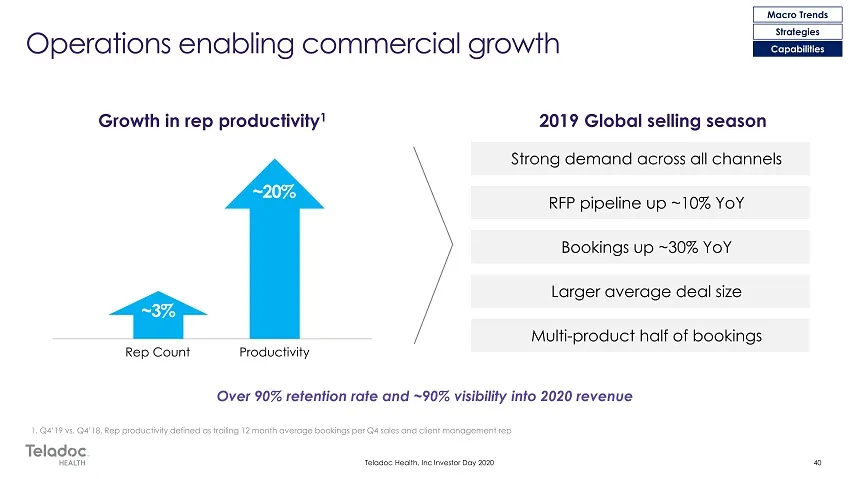
Macro Trends Strategies Capabilities ~20% ~3%
Slide 41: Assets and capabilities
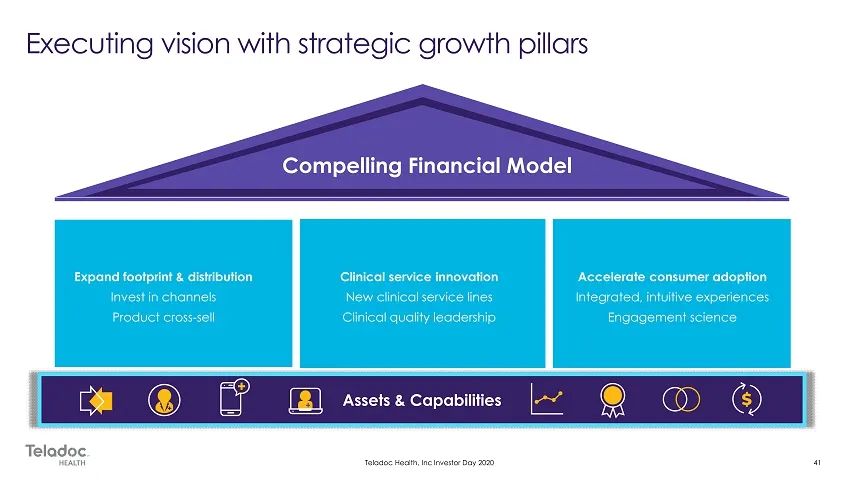
Assets & Capabilities Expand footprint & distribution Invest in channels Product cross - sell Clinical service innovation New clinical service lines Clinical quality leadership Accelerate consumer adoption Integrated, intuitive experiences Engagement science Compelling Financial Model
Slide 42: Macro Trends, Strategies, Capabilities
Macro Trends Strategies Capabilities
Slide 43: Macro Trends, Strategies, Capabilities
Macro Trends Strategies Capabilities
Slide 44: Macro Trends, Strategies, Capabilities
Macro Trends Strategies Capabilities
Slide 45: Summary
Summary Commercially integrated, global leader with right-to-win Multiple levers to capture new opportunities & existing whitespace Best in class assets & operational capabilities for sustained growth Teladoc.
Slide 46: Member engagement
Teladoc. HEALTH Member engagement Stephany Verstraete Chief Marketing Officer
Slide 47: Summary
Summary Adoption is accelerating across sponsored and DTC populations, and we're uniquely capturing the demand Expansion of multi-service eligibility drives activation growth Our scale, tenure and expertise build an unmatched base of activated users, creating a flywheel dynamic that fuels utilizatio
Slide 48: Leading consumer engagement
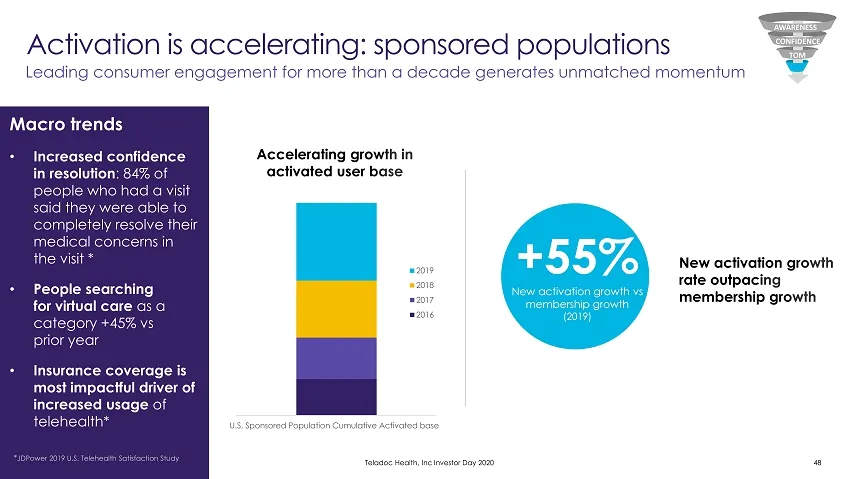
U.S. Sponsored Population Cumulative Activated base 2019 2018 2017 2016 Leading consumer engagement for more than a decade generates unmatched momentum New activation growth vs membership growth (2019) * JDPower 2019 U.S. Telehealth Satisfaction Study AWARENESS CONFIDENCE TOM
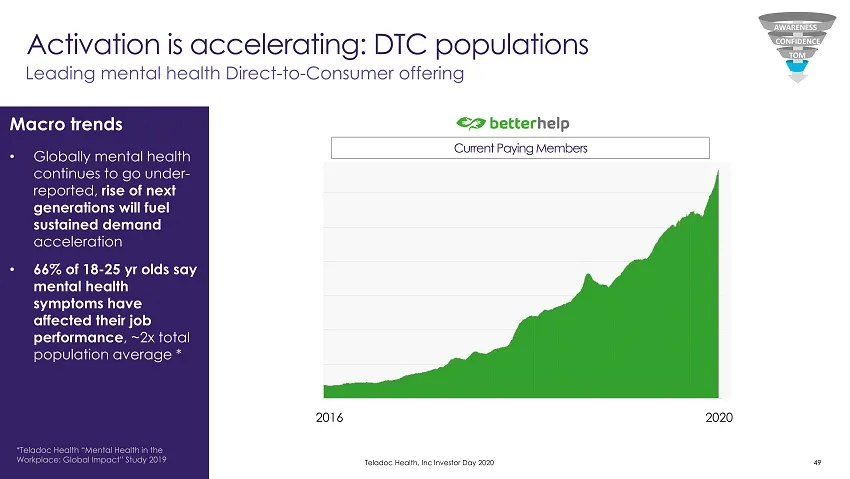
Slide 49: Mental health awareness study
AWARENESS CONFIDENCE TOM *Teladoc Health “Mental Health in the Workplace: Global Impact” Study 2019
Slide 50: BetterHelp test and learn strategies
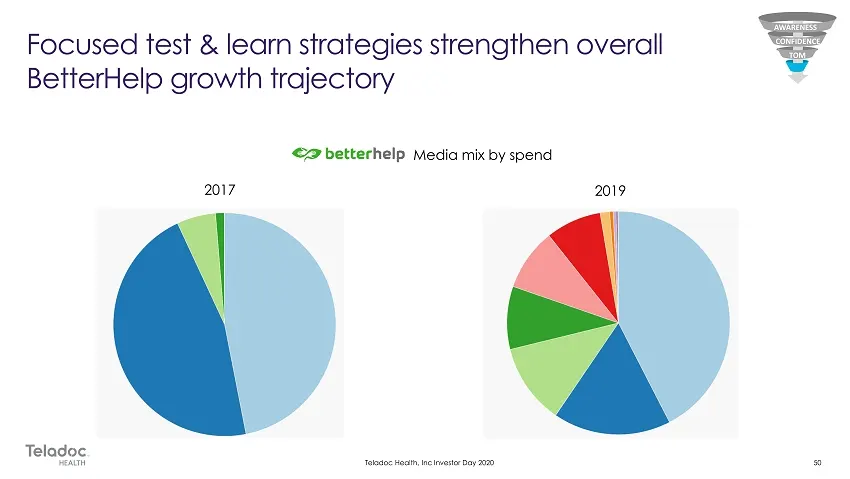
Focused test & learn strategies strengthen overall BetterHelp growth trajectory a betterhelp Media mix by spend 2017 2019 Teladoc
Slide 51: Core user profile
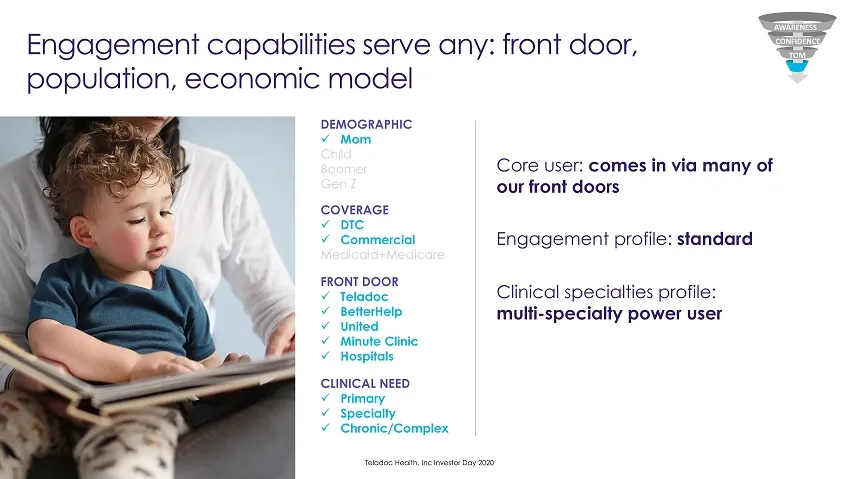
Core user: comes in via many of our front doors Engagement profile: standard Clinical specialties profile: multi - specialty power user DEMOGRAPHIC x Mom Child Boomer Gen Z COVERAGE x DTC x Commercial Medicaid+Medicare CLINICAL NEED x Primary x Specialty x Chronic/Complex FRONT DOOR x Teladoc x Bett
Slide 52: Emerging user: child covered by Medicaid
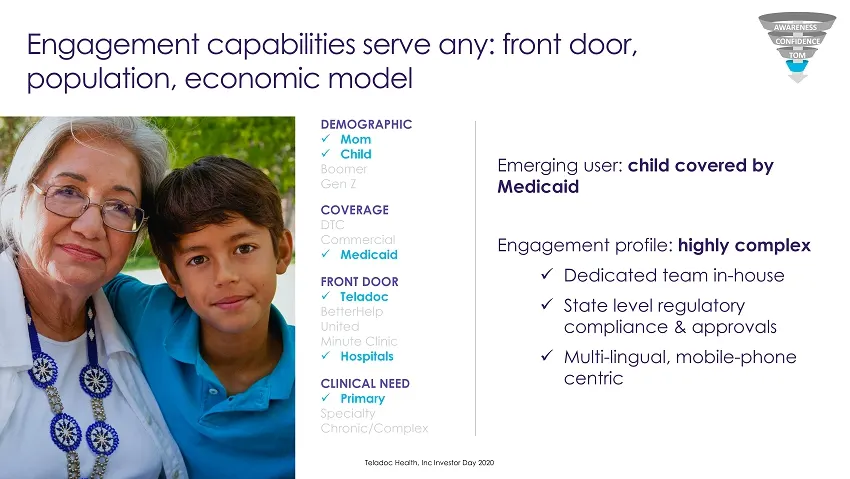
DEMOGRAPHIC x Mom x Child Boomer Gen Z COVERAGE DTC Commercial x Medicaid CLINICAL NEED x Primary Specialty Chronic/Complex FRONT DOOR x Teladoc BetterHelp United Minute Clinic x Hospitals Emerging user: child covered by Medicaid Engagement profile: highly complex x Dedicated team in - house x State
Slide 53: Emerging user: retiree
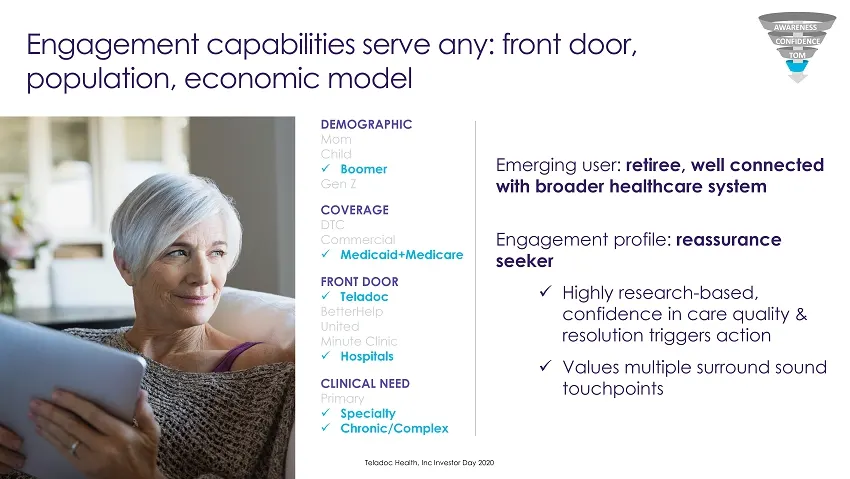
DEMOGRAPHIC Mom Child x Boomer Gen Z COVERAGE DTC Commercial x Medicaid+Medicare CLINICAL NEED Primary x Specialty x Chronic/Complex FRONT DOOR x Teladoc BetterHelp United Minute Clinic x Hospitals Emerging user: retiree, well connected with broader healthcare system Engagement profile: reassurance
Slide 54: Power user of the future
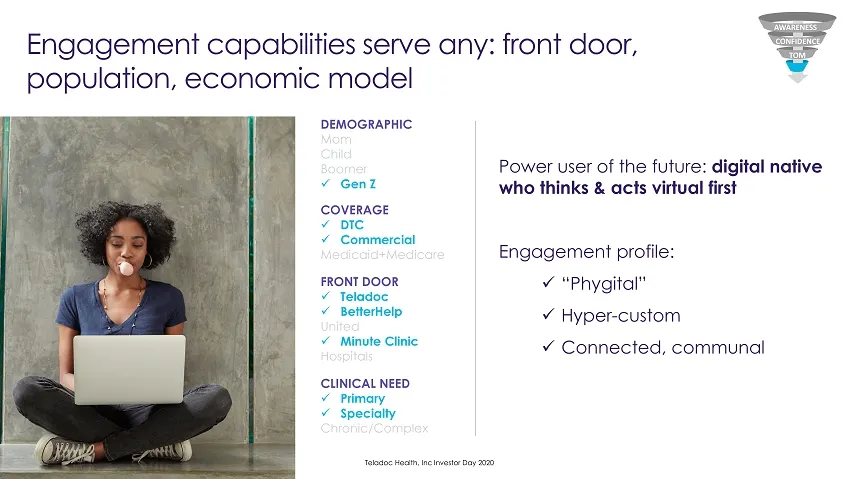
DEMOGRAPHIC Mom Child Boomer x Gen Z COVERAGE x DTC x Commercial Medicaid+Medicare CLINICAL NEED x Primary x Specialty Chronic/Complex FRONT DOOR x Teladoc x BetterHelp United x Minute Clinic Hospitals Power user of the future: digital native who thinks & acts virtual first Engagement profile: x “ P
Slide 55: Flywheel dynamic
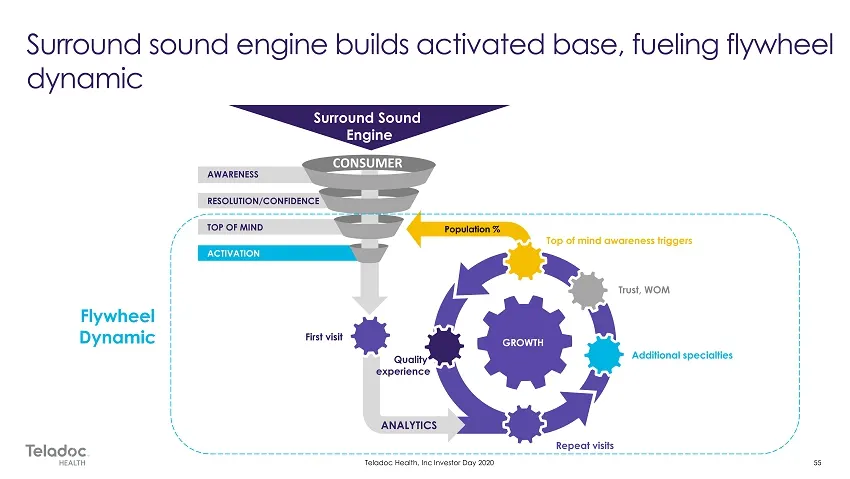
First visit AWARENESS RESOLUTION/CONFIDENCE TOP OF MIND ACTIVATION CONSUMER Population % Repeat visits Top of mind awareness triggers GROWTH Additional specialties Quality experience Trust, WOM ANALYTICS Flywheel Dynamic
Slide 56: Flywheel dynamic
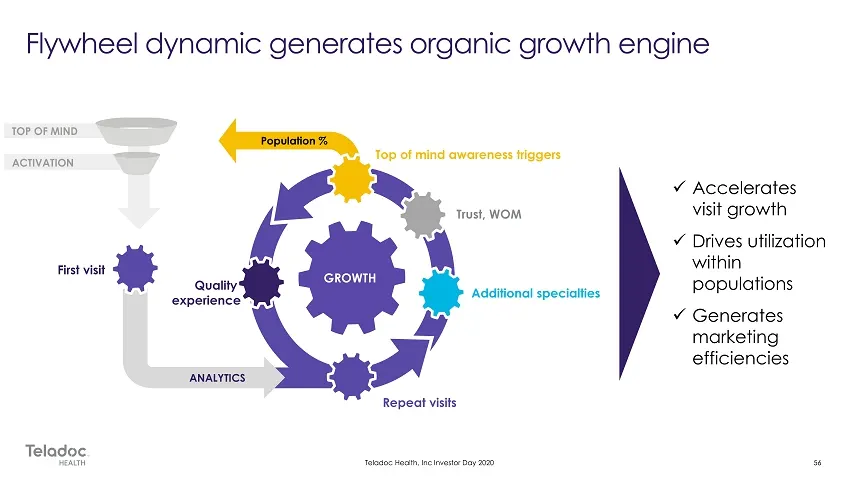
Population % Repeat visits Top of mind awareness triggers GROWTH Additional specialties Quality experience Trust, WOM First visit ANALYTICS
Slide 57: Utilization following product additions
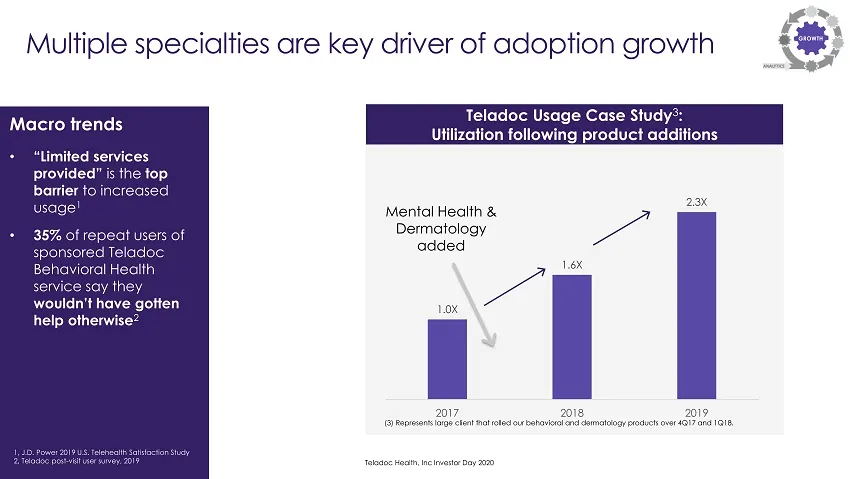
Teladoc Usage Case Study 3 : Utilization following product additions 1.0X 1.6X 2.3X 2017 2018 2019 (3) Represents large client that rolled our behavioral and dermatology products over 4Q17 and 1Q18. GROWTH 1 2 1, J.D. Power 2019 U.S. Telehealth Satisfaction Study 2, Teladoc post - visit user survey,
Slide 58: First visits and repeat visits
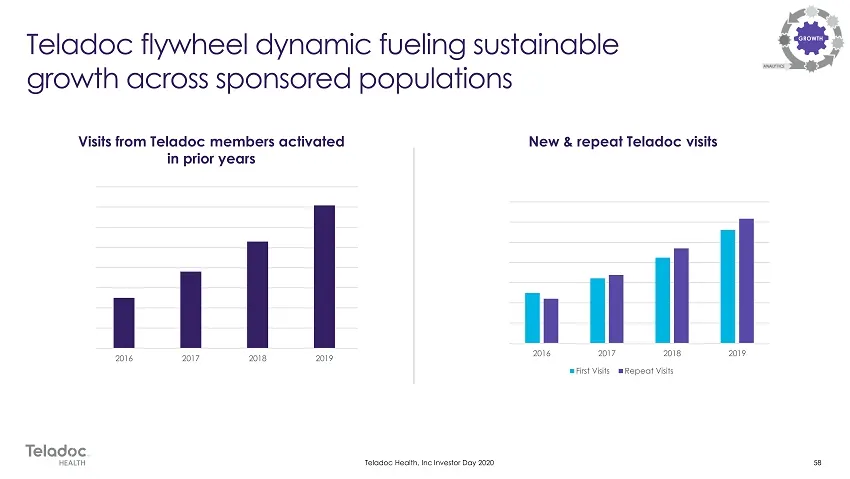
0 100,000 200,000 300,000 400,000 500,000 600,000 700,000 800,000 2016 2017 2018 2019 0 200,000 400,000 600,000 800,000 1,000,000 1,200,000 1,400,000 2016 2017 2018 2019 First Visits Repeat Visits GROWTH
Slide 59: New vs activated member visit advertising cost
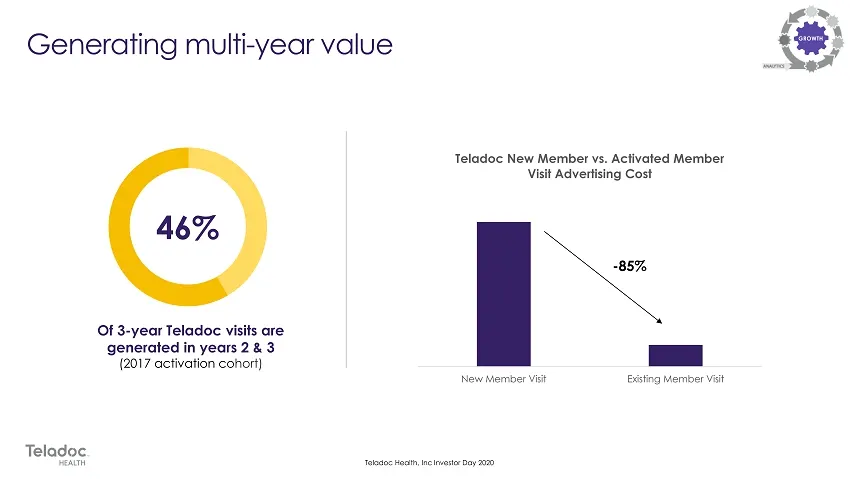
New Member Visit Existing Member Visit Teladoc New Member vs. Activated Member Visit Advertising Cost - 85% Of 3 - year Teladoc visits are generated in years 2 & 3 GROWTH
Slide 60: Revenue from members using over 3 months
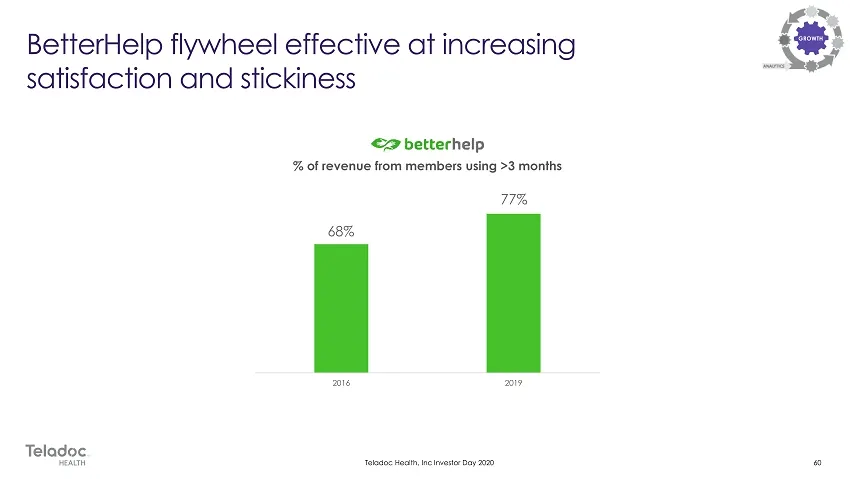
GROWTH 2016 2019 % of revenue from members using >3 months 68% 77%
Slide 61: Summary
Summary Adoption is accelerating across sponsored and DTC populations, and we're uniquely capturing the demand Expansion of multi-service eligibility drives activation growth Our scale, tenure and expertise build an unmatched base of activated users, creating a flywheel dynamic that fuels utilizatio
Slide 62: Product strategy
Teladoc. HEALTH Product strategy Dan Trencher SVP of Product & Corporate Strategy
Slide 63: Key themes
Key themes Driving evolution in the virtual care industry, and continuing to lead through innovation Reimagining care delivery across spectrum of Primary and Specialty Care Strategy resonating in market
Slide 64: Teladoc has driven the evolution of virtual care
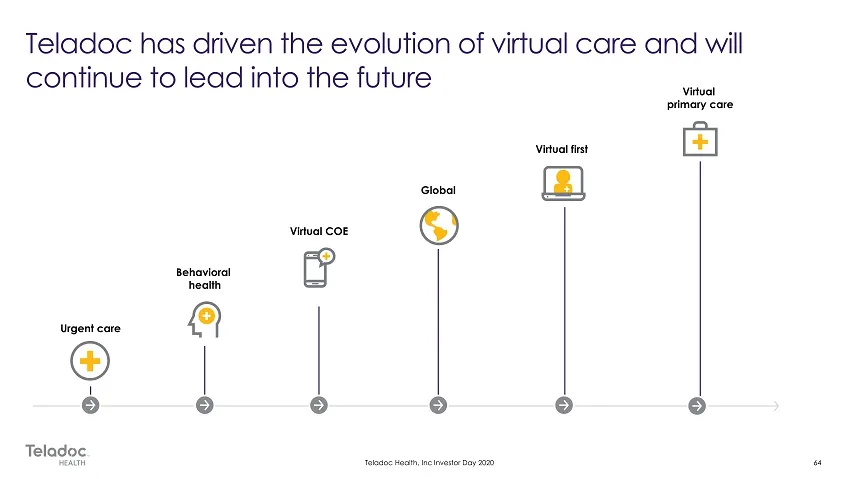
Teladoc has driven the evolution of virtual care and will continue to lead into the future Virtual fst a Virtual primary care a +
Slide 65: Paradigm shift for virtual care
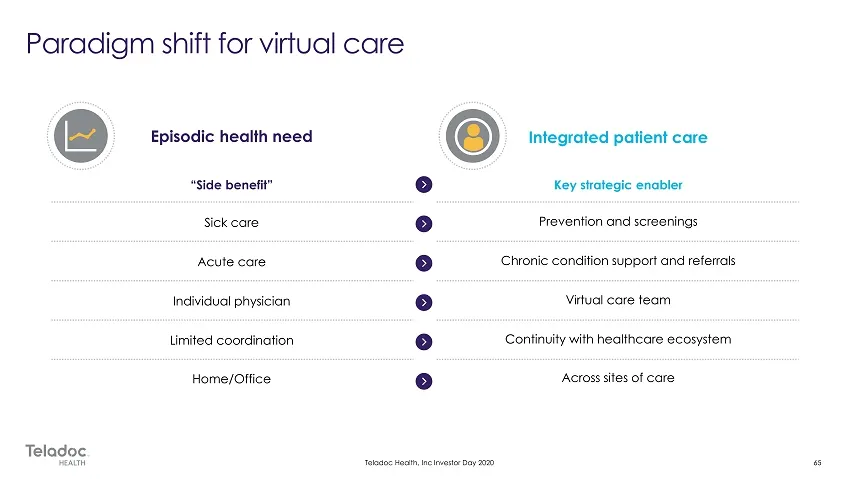
Paradigm shift for virtual care Episodic health need Integrated patient care “Side benefit” (>) Key strategic enabler Sick care ° Prevention and screenings Acute care [>] ‘Chronic condition support and referrals Individual physician ° Virtual care team Limited coordination ° Continuity with healthca
Slide 66: Central role in medical care
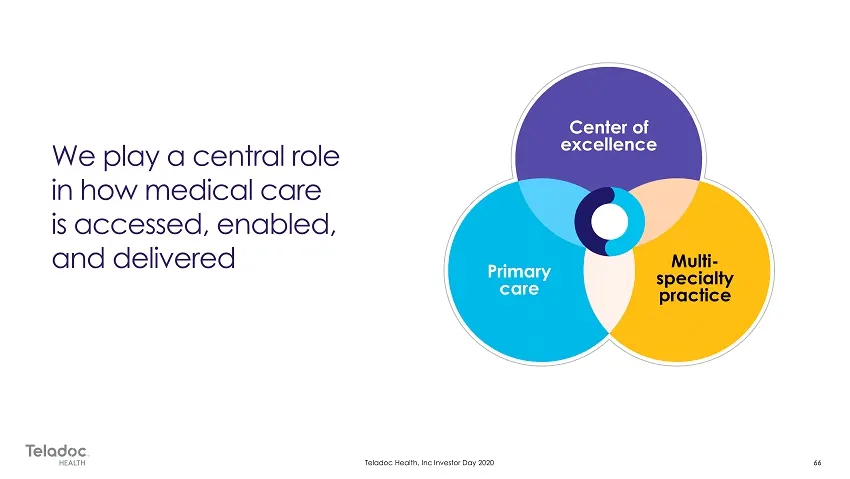
We play a central role in how medical care is accessed, enabled, and delivered Teladoc Center of excellence Primary care
Slide 67: Primary care access and disease burden
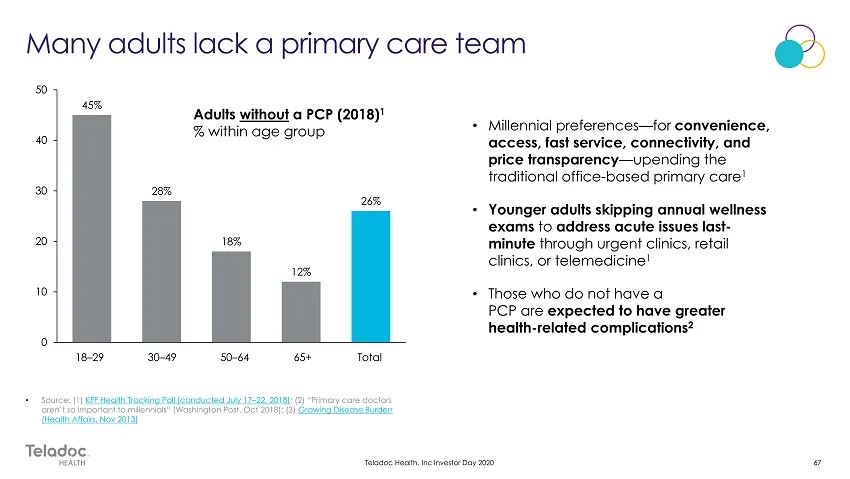
45% 28% 18% 12% 26% 0 10 20 30 40 50 • • • • KFF Health Tracking Poll (conducted July 17 – 22, 2018) Growing Disease Burden (Health Affairs, Nov 2013)
Slide 68: VPC: reimagining primary care
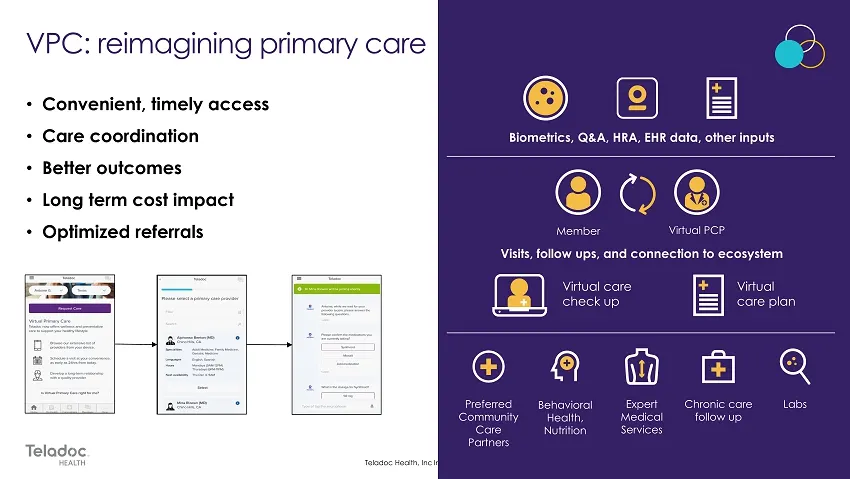
VPC: reimagining primary care + Convenient, timely access Care coordination metrics, Q&A, HRA, EHR data, other inputs + Better outcomes + Long term cost impact © © Q) Optimized referrals Member Virtual PCP Visits, follow ups, and connection to ecosystem ae [SS Teladoc
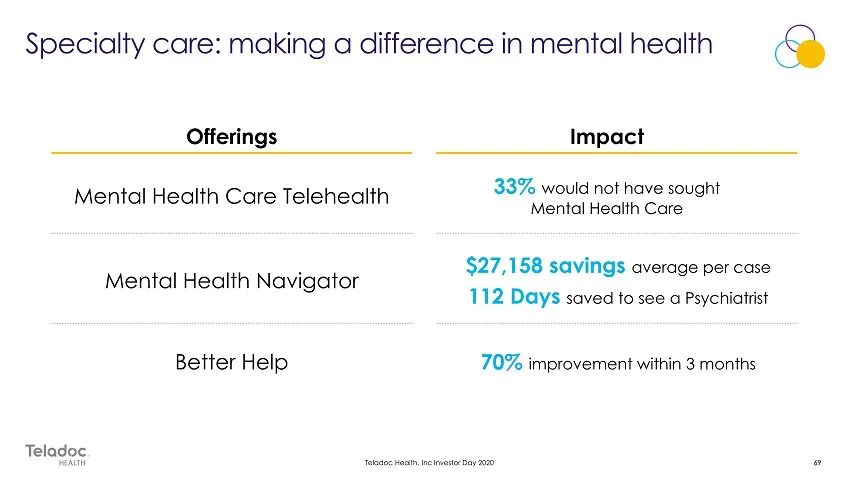
Slide 69: 70% improvement within months
70% improvement within 3 months
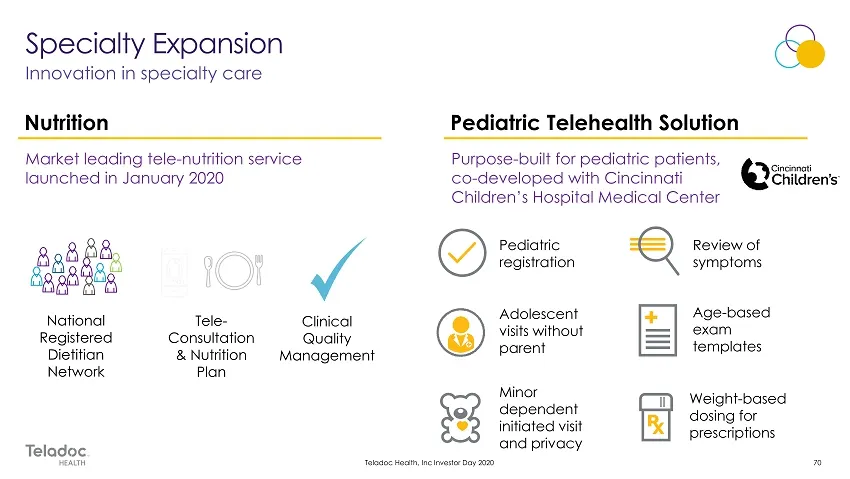
Slide 70: Nutrition and pediatric telehealth
Nutrition Market leading tele - nutrition service launched in January 2020 Pediatric Telehealth Solution Purpose - built for pediatric patients, co - developed with Cincinnati Children’s Hospital Medical Center Age - based exam templates Pediatric registration Adolescent visits without parent Review
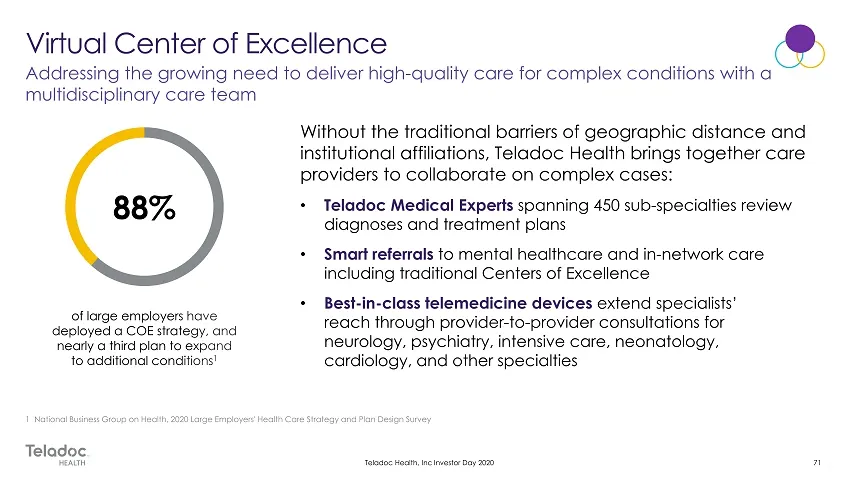
Slide 71: Virtual Center of Excellence
Virtual Center of Excellence Addressing the growing need to deliver high-quality care for complex conditions with a multidisciplinary care team Without the traditional barriers of geographic distance and institutional affiliations, Teladoc Health brings together care providers to collaborate on comp
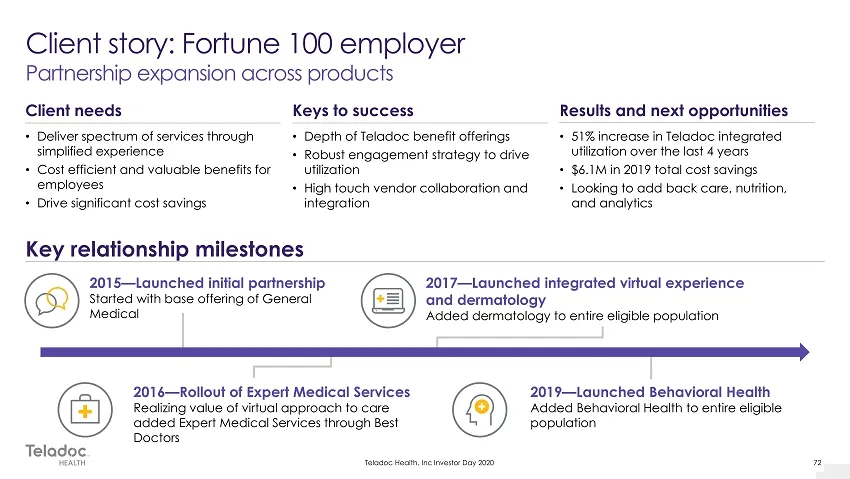
Slide 72: Client story: Fortune employer
Client story: Fortune 100 employer Partnership expansion across products Client needs Keys to success + Deliver spectrum of services through + Depth of Teladoc benefit offerings simpitied experience + Robust engagement strategy to drive + Cost efficient and valuable benefits for utilization employee
Slide 73: New clinical services, payment models, care settings
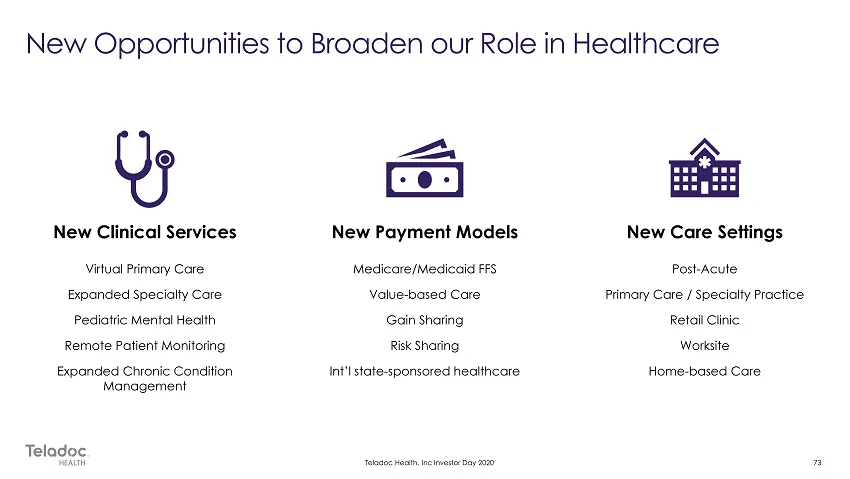
New Clinical Services Virtual Primary Care Expanded Specialty Care Pediatric Mental Health Remote Patient Monitoring Expanded Chronic Condition Management New Payment Models Medicare/Medicaid FFS Value - based Care Gain Sharing Risk Sharing Int’l state - sponsored healthcare New Care Settings Post -
Slide 74: Key themes
Key themes Driving evolution in the virtual care industry, and continuing to lead through innovation Reimagining care delivery across spectrum of Primary and Specialty Care Strategy resonating in market
Slide 75: Quality and patient experience
O00 oe0000 o0000 Teladoc. HEALTH Quality & patient experience Lew Levy, MD FACP. Chief Medical Officer Telodoe INVESTOR
Slide 76: Key takeaways
Key Takeaways We have industry leading clinical quality assets and capabilities Our global presence and scale unlocks the power of data and analytics Teladoc's clinical leadership across the spectrum of acuity is a true competitive differentiator
Slide 77: Abby: a 15-year-old dancer with back pain
Abby A 15-year-old dancer with back pain Teladoc.
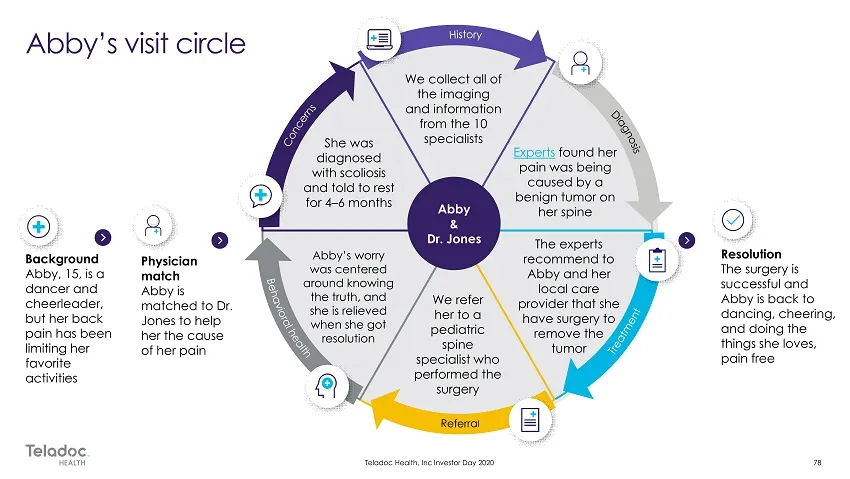
Slide 78: Abby's visit circle
Abby's visit circle ® Background Abby, 15,i8 0 dancer and cheerleader, but her back pain has been limiting her favorite activities Teladoc We collect all of the imaging and information from the 10 specialists She was Experts found dy" diagnosed J with scoliosis Pain was being @ ees 5 icomed by a. Q
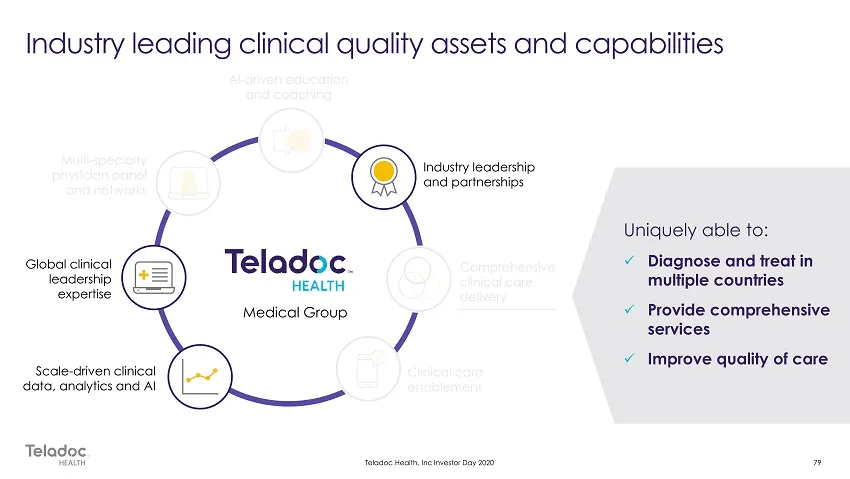
Slide 79: Industry leading clinical quality assets and capabilities
Industry leading clinical quality assets and capabilities = Global clinical leadership expertise Teladoc. HEALTH Medical Group Scale-driven clinical data, anaiytics and Al Teladoc. Industry leadership and partnerships Uniquely able to: a Diagnose and treat in multiple countries Provide comprehensive
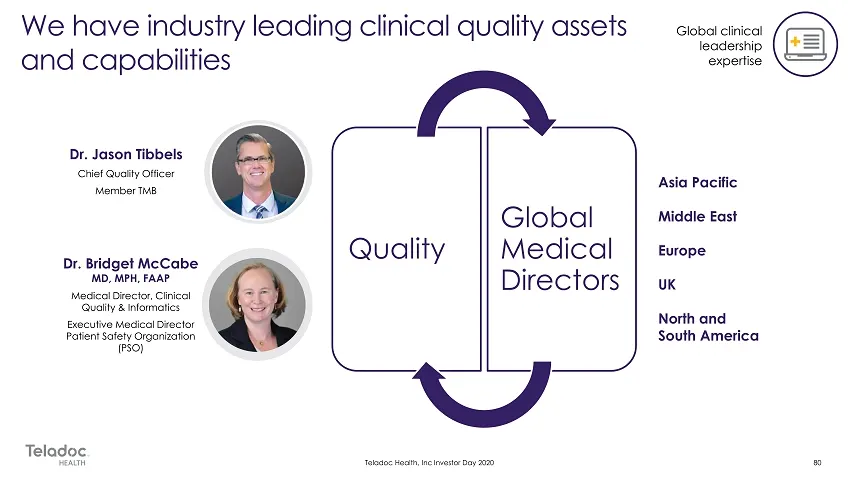
Slide 80: Clinical quality leadership
We have industry leading clinical quality assets and capabilities Dr. Jason Tibbels Chief Quaity Officer Member TM Dr. Bridget McCabe (MD, MPH, FAAP Medical Direcior, Cinical Qual & informatics Executive Medical Diector Patient Safety Organization (P30) Teladoc. fN Global Medical Directors Quality G
Slide 81: Global scale unlocks data and analytics
Our global presence and scale unlocks the __ scoe-awencnca © ° eon power of data and analytics + Leveraging the data of market leading 4M+ annual visits * Controlling pharmacy spend through targeted outreach + Harnessing voice data through Al: Learning key elements of optimized outcomes and patient
Slide 82: COVID-19 case study
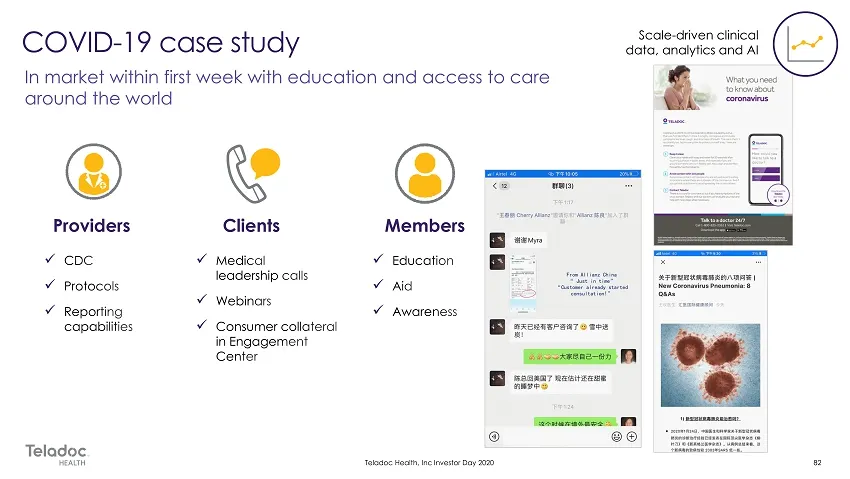
COVID-19 case study dite. snevicsone Al In market within first week with education and access to care around the world Providers Clients Members vy coc ¥ Medical ¥ Education = leadership calls 2 Y Protocols P Y aio | Y Webinars Y Reporting Y Awareness copobiiities ¥ Consumer collateral B gersrsero n
Slide 83: Clinical leadership and partnerships
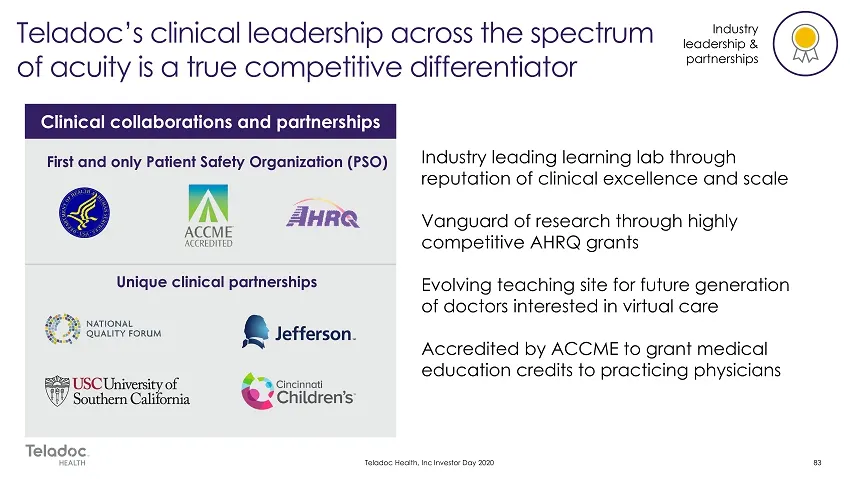
Teladoc’s clinical leadership across the speCtrUM .qa.%6"Y of acuity is a true competitive differentiator partnerships Clinical collaborations and partnerships First and only Patient Safety Organization (PSO) Industry leading learning lab through reputation of clinical excellence and scale @ iy | AH
Slide 84: Summary
Summary We have industry leading clinical quality assets and capabilities Our global presence and scale unlocks the power of data and analytics Teladoc's clinical leadership across the spectrum of acuity is a true competitive differentiator
Slide 85: Client insights
Teladoc. Client insights
Slide 86: Chuck Divita
Chuck Divita Executive Vice President, Commercial Markets + Leads commercial health insurance business + Former Senior Vice President and Chief Financial Officer of GMHC + Nearly 10+ current and former board appointments GUIDEWELL
Slide 87: Introducing InTouch Health
© oO © Teladoc. 0o0o0 ™ © © oO Introducin @) © © InTouch Health 6) @) @) Jason Gorevic, Chief Executive Officer O00 000 —
Slide 88: Why facility-based telemedicine? Why InTouch?
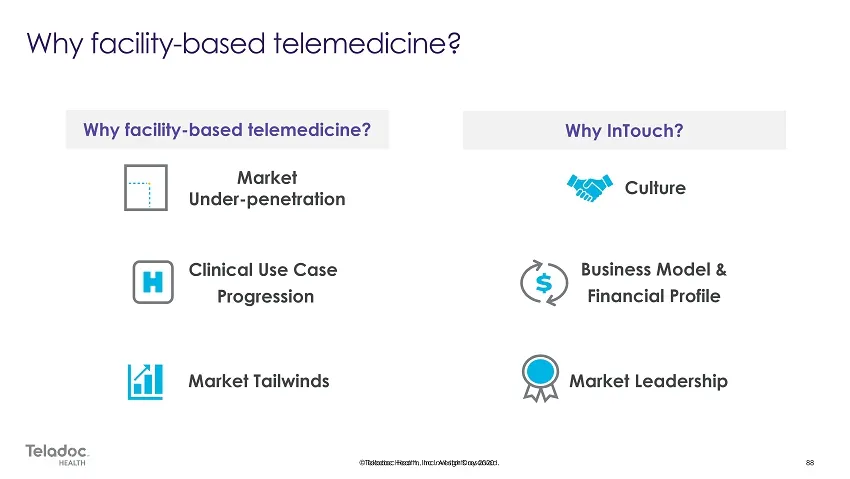
Why facility - based telemedicine? Why InTouch? Market Under - penetration Clinical Use Case Progression Market Tailwinds Culture Business Model & Financial Profile Market Leadership
Slide 89: Industry leader in provider-to-provider consultations
Industry leader in critical, provider - to - provider consultations Award winning, medical - grade telehealth devices #1 Virtual Care Platform by KLAS Research
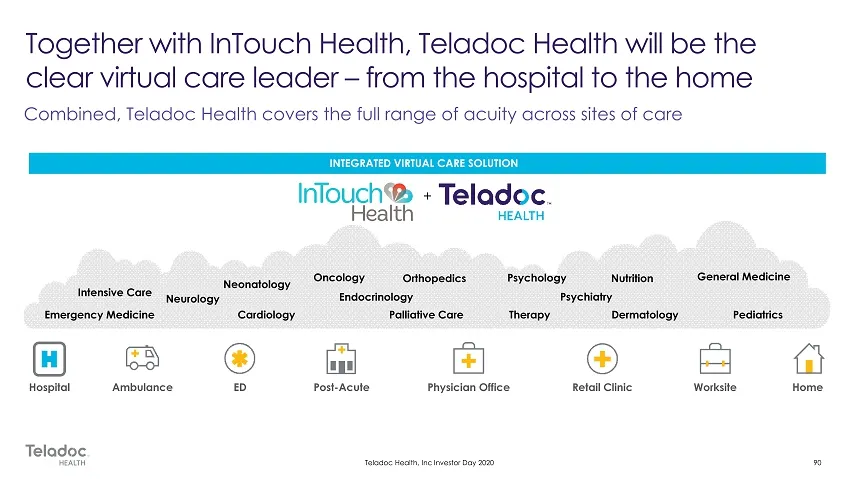
Slide 90: Integrated virtual care solution
Home Worksite Retail Clinic Physician Office Post - Acute ED Ambulance Hospital INTEGRATED VIRTUAL CARE SOLUTION Neonatology Psychology Nutrition Cardiology Oncology Neurology Emergency Medicine Psychiatry Dermatology Intensive Care Pediatrics Therapy Orthopedics Endocrinology General Medicine Palli
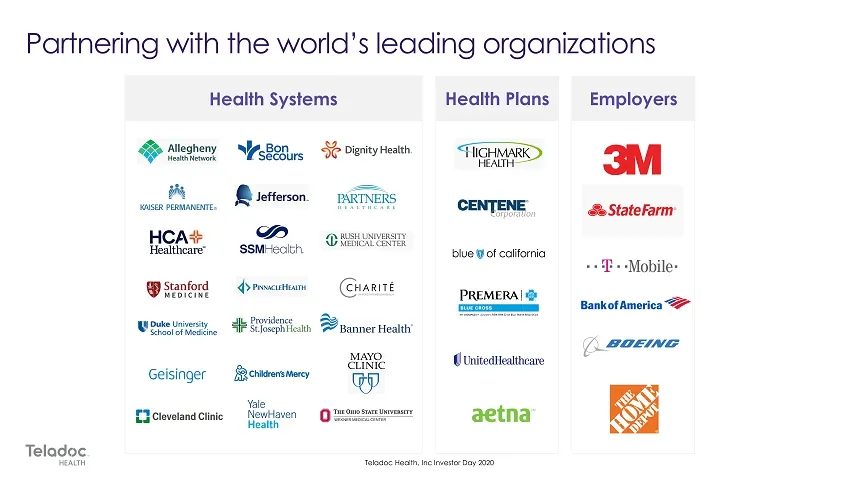
Slide 91: Health Plans, Health Systems, Employers
Health Plans Health Systems Employers
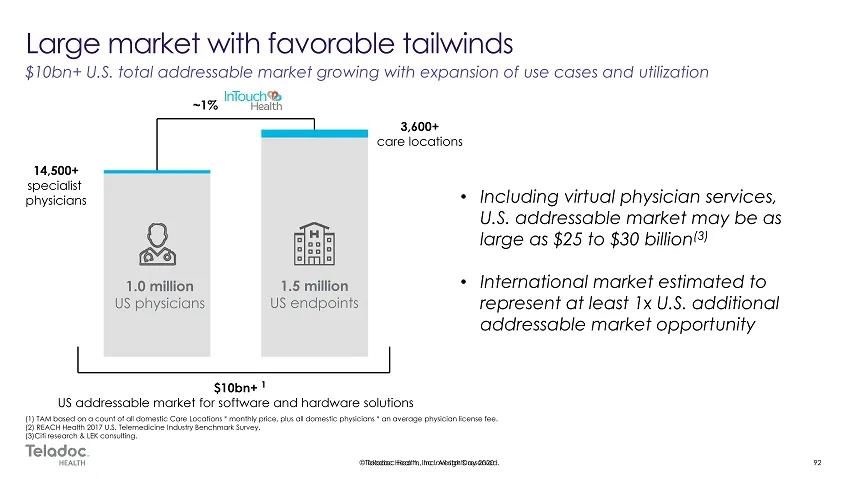
Slide 92: US addressable market for InTouch
(1) TAM based on a count of all domestic Care Locations * monthly price, plus all domestic physicians * an average physician lice ns e fee. (2) REACH Health 2017 U.S. Telemedicine Industry Benchmark Survey. (3) Citi research & LEK consulting. 1.0 million US physicians 1.5 million US endpoints 14,500
Slide 93: InTouch Health overview
O00 o0000 o0000 InTouch Health overview Joe DeVivo, InTouch Health Chief Executive Officer Telodoe INVESTOR
Slide 94: Key themes
Key themes InTouch combines market leading software, hardware, and networking solutions to create the most comprehensive site-based virtual care solution on the market Combined organization is positioned to lead the virtualization of healthcare across care settings InTouch Health has compelling fina
Slide 95: $3.5 trillion of annual US spend
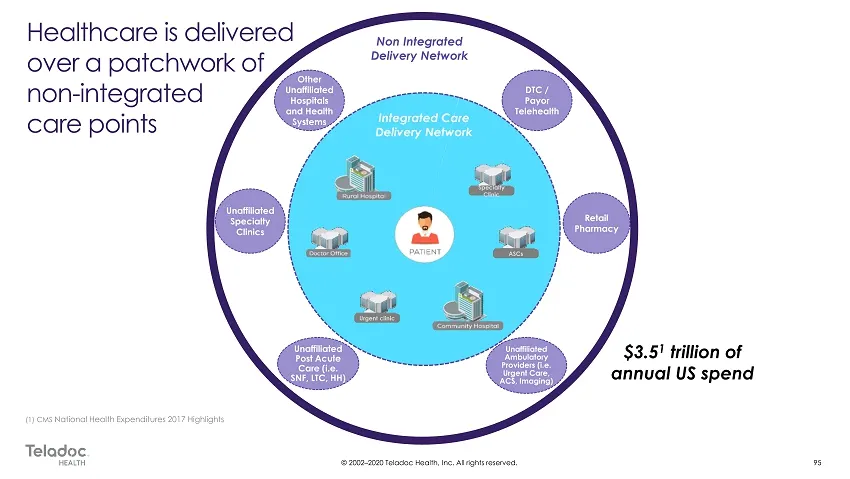
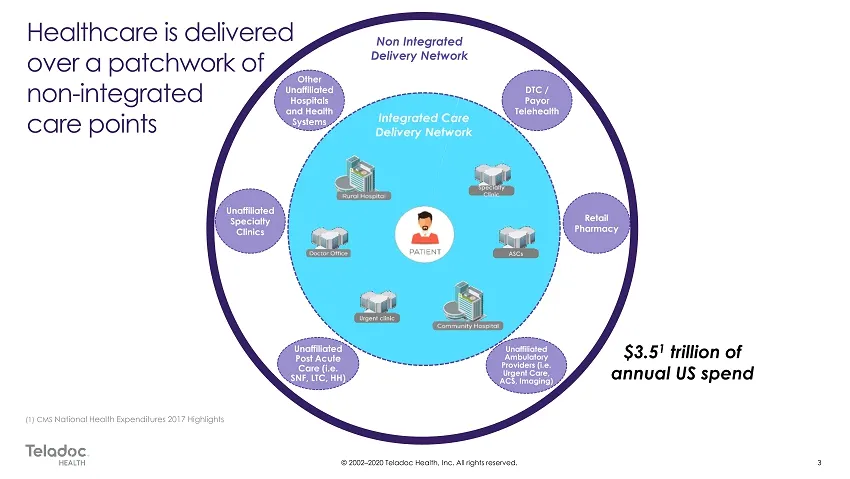
$3.5 1 trillion of annual US spend Non Integrated Delivery Network Unaffiliated Post Acute Care (i.e. SNF, LTC, HH) Retail Pharmacy Other Unaffiliated Hospitals and Health Systems Unaffiliated Specialty Clinics Integrated Care Delivery Network Urgent clinic Specialty Clinic ASCs Unaffiliated Ambulat
Slide 96: Connecting doctors anywhere to patients anywhere
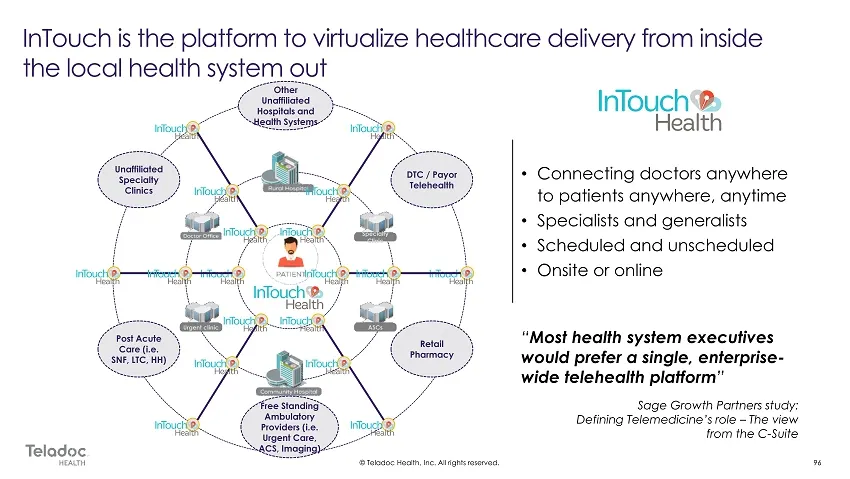
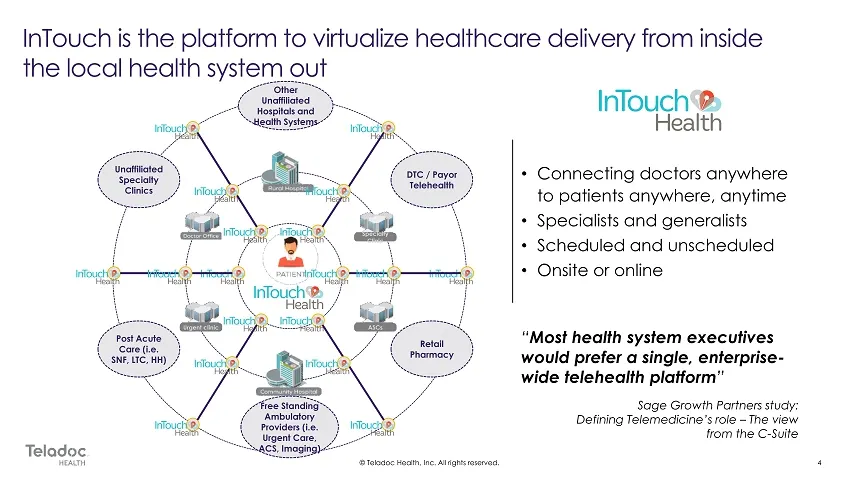
• Connecting doctors anywhere to patients anywhere, anytime • Specialists and generalists • Scheduled and unscheduled • Onsite or online Other Unaffiliated Hospitals and Health Systems DTC / Payor Telehealth Retail Pharmacy Free Standing Ambulatory Providers (i.e. Urgent Care, ACS, Imaging) Unaffili
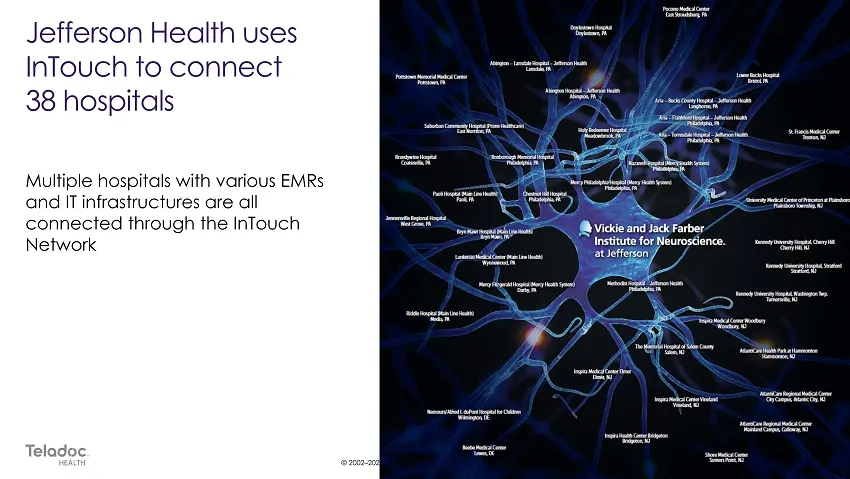
Slide 97: InTouch Network connects hospitals
Multiple hospitals with various EMRs and IT infrastructures are all connected through the InTouch Network
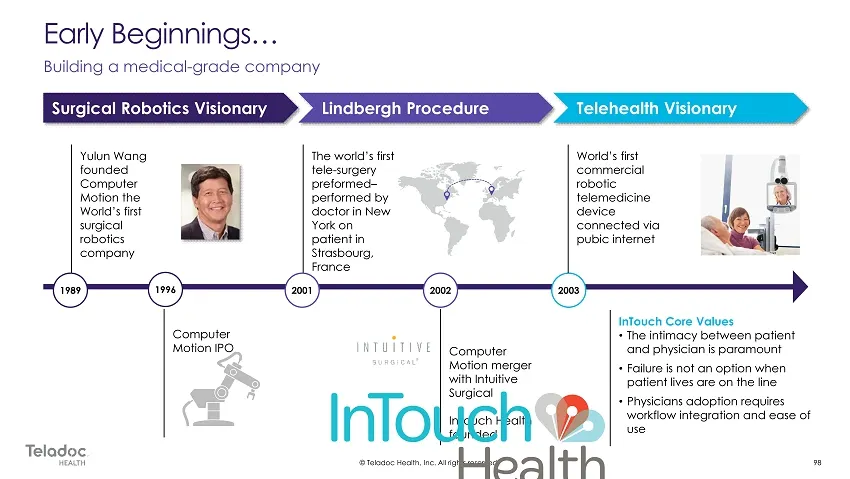
Slide 98: InTouch history
1989 Yulun Wang founded Computer Motion the World’s first surgical robotics company The world’s first tele - surgery preformed – performed by doctor in New York on patient in Strasbourg, France 2001 2002 Computer Motion merger with Intuitive Surgical InTouch Health founded 1996 Computer Motion IPO S
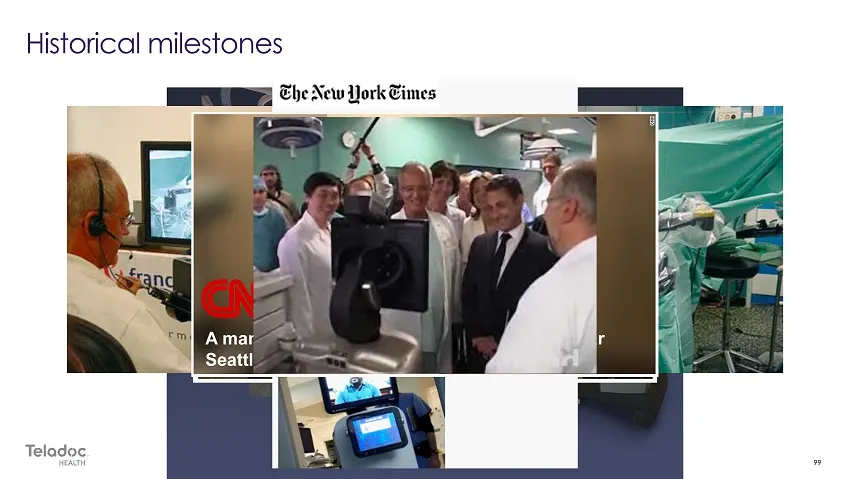
Slide 99: Coronavirus patient treated by robot
A man diagnosed with Wuhan coronavirus near Seattle is being treated largely by a robot
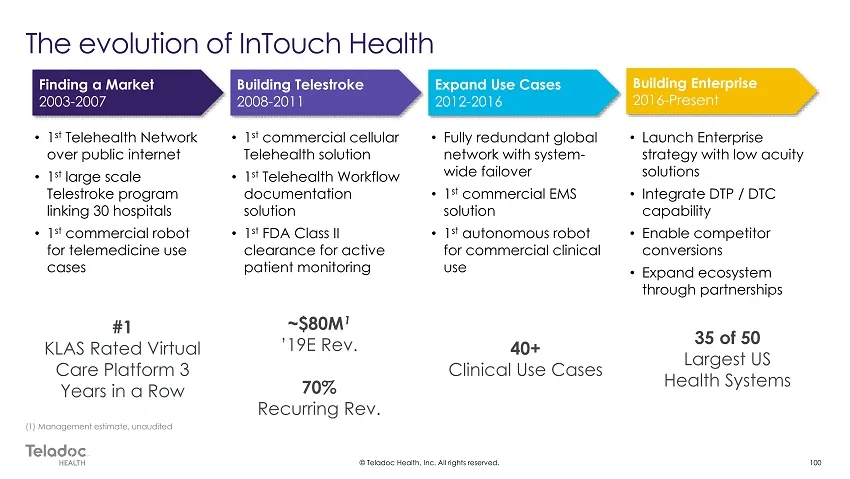
Slide 100: InTouch market stages and metrics
Finding a Market 2003 - 2007 Building Telestroke 2008 - 2011 Expand Use Cases 2012 - 2016 Building Enterprise 2016 - Present #1 KLAS Rated Virtual Care Platform 3 Years in a Row ~$80M 1 ’19E Rev. 70% Recurring Rev. 40+ Clinical Use Cases 35 of 50 Largest US Health Systems (1) Management estimate, un
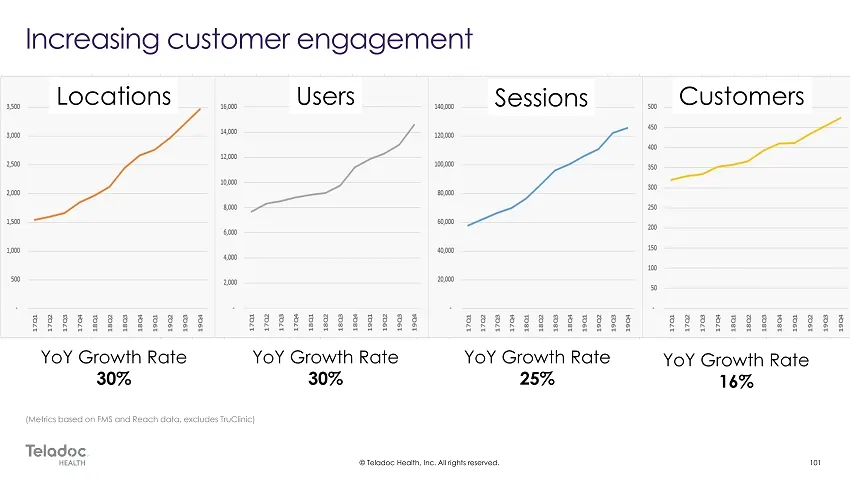
Slide 101: Growth in locations, users, sessions, customers
(Metrics based on FMS and Reach data, excludes TruClinic) YoY Growth Rate 30% YoY Growth Rate 25% YoY Growth Rate 16% YoY Growth Rate 30% Locations Users Sessions Customers
Slide 102: Striving for excellence in teleneonatology
Striving for Excellence in TELENEONATOLOGY JENNIFER FANG, MD, MS Medical Director Teleneonatology BETH KREOFSKY, MBA Operations Manager Teleneonatology
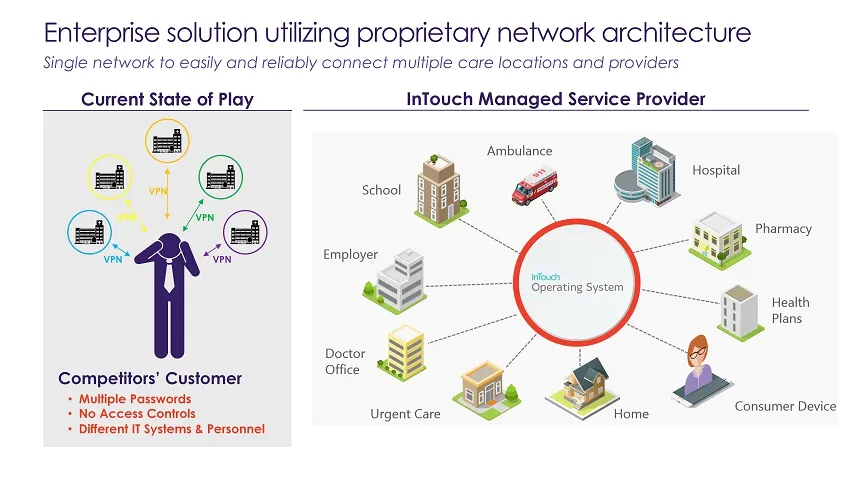
Slide 103: Managed service provider vs competitors' customer
103 InTouch Managed Service Provider Competitors’ Customer • Multiple Passwords • No Access Controls • Different IT Systems & Personnel Current State of Play VPN VPN VPN VPN VPN
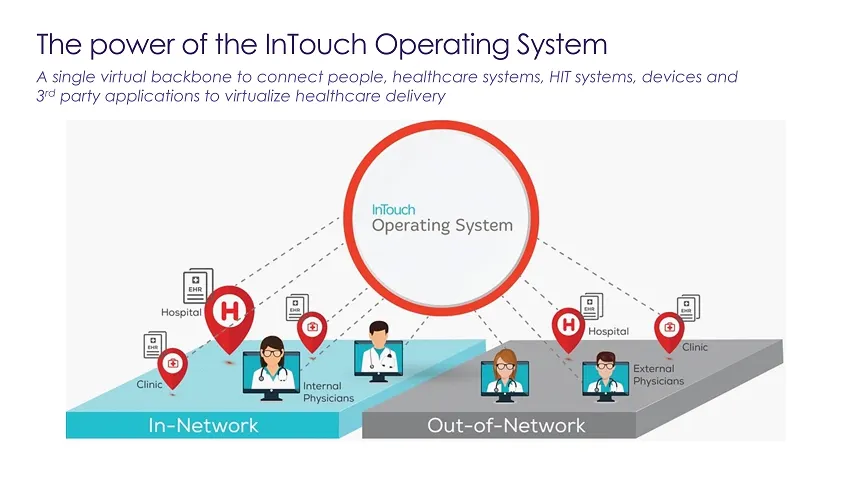
Slide 104: Single virtual backbone
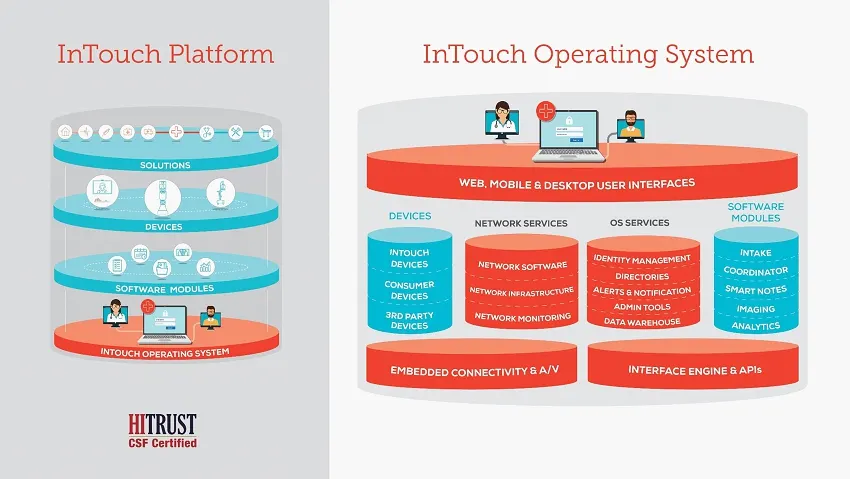
104 A single virtual backbone to connect people, healthcare systems, HIT systems, devices and 3 rd party applications to virtualize healthcare delivery
Slide 105: InTouch Platform
InTouch Platform > oO HITRUST CSF Certified InTouch Operating System ‘SOFTWARE DEVICE: Mt aed [NETWORK SERVICES ‘osservices jODULES EMBEDDED CONNECTIVITY BA/V INTERFACE ENGINE & APIs
Slide 106: Partnerships with Intuitive Surgical and GE
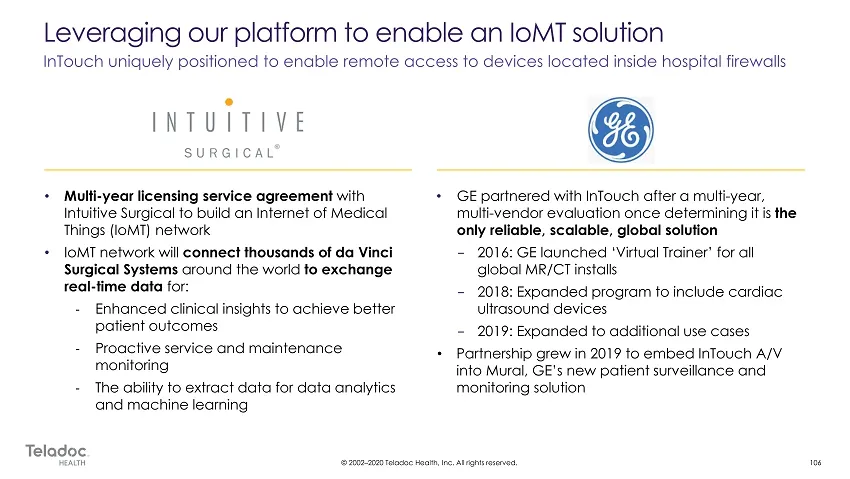
• Multi - year licensing service agreement with Intuitive Surgical to build an Internet of Medical Things (IoMT) network • IoMT network will connect thousands of da Vinci Surgical Systems around the world to exchange real - time data for: - Enhanced clinical insights to achieve better patient outcom
Slide 107: Emergent and scheduled primary and specialty services
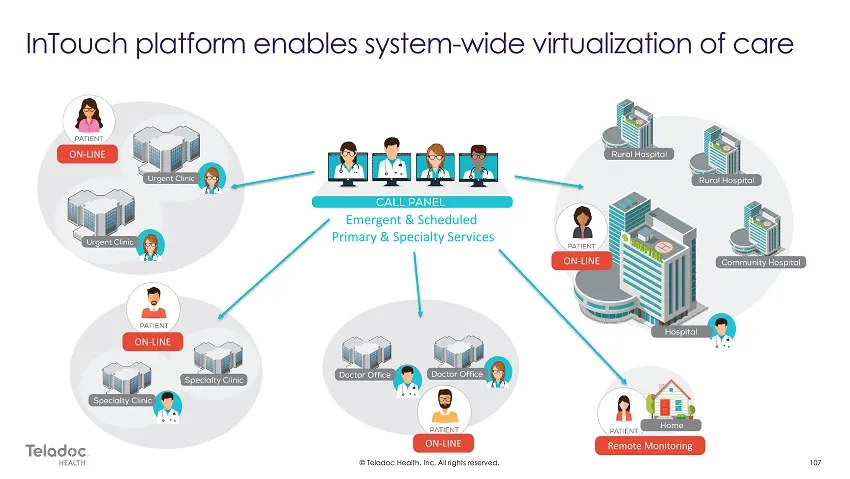
Emergent & Scheduled Primary & Specialty Services ON - LINE ON - LINE ON - LINE ON - LINE Remote Monitoring
Slide 108: Software and devices
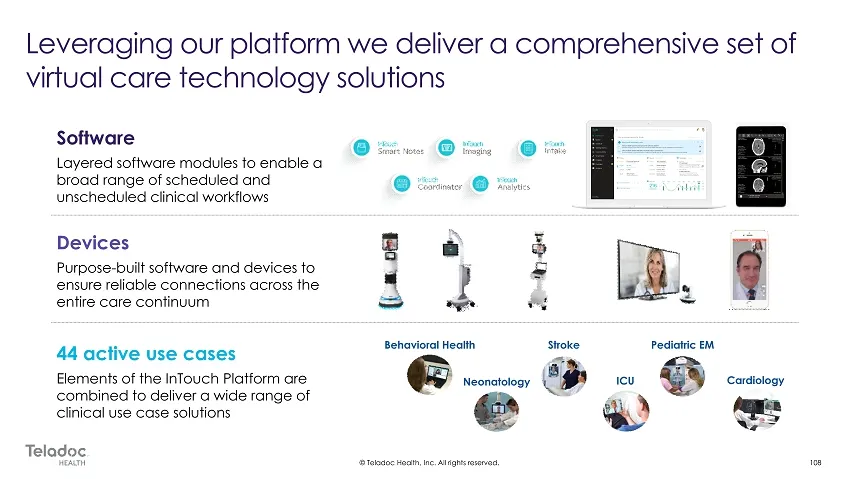
Software Layered software modules to enable a broad range of scheduled and unscheduled clinical workflows Devices Purpose - built software and devices to ensure reliable connections across the entire care continuum 44 active use cases Elements of the InTouch Platform are combined to deliver a wide r
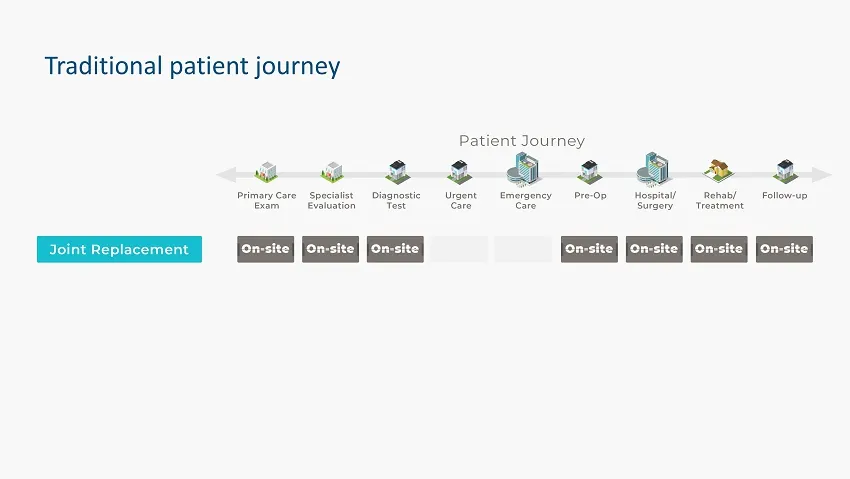
Slide 109: Traditional patient journey
Traditional patient j ourney
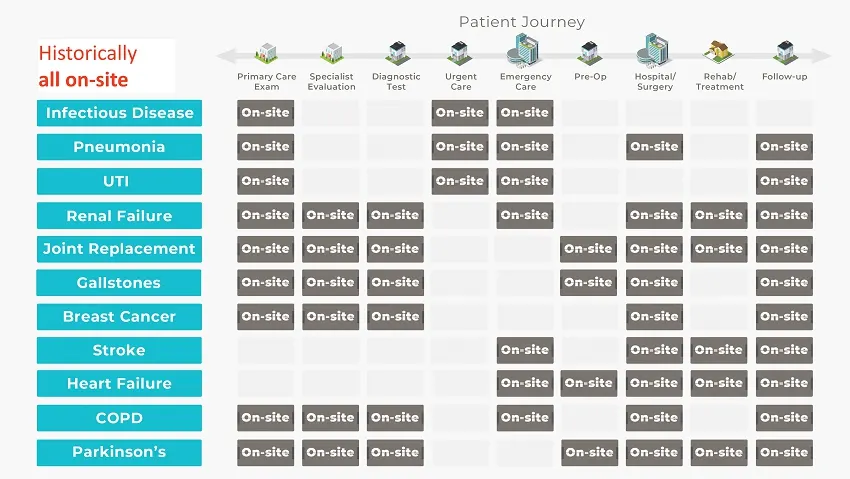
Slide 110: Patient journey: historically all on-site
Historically all on-site Patient Journey
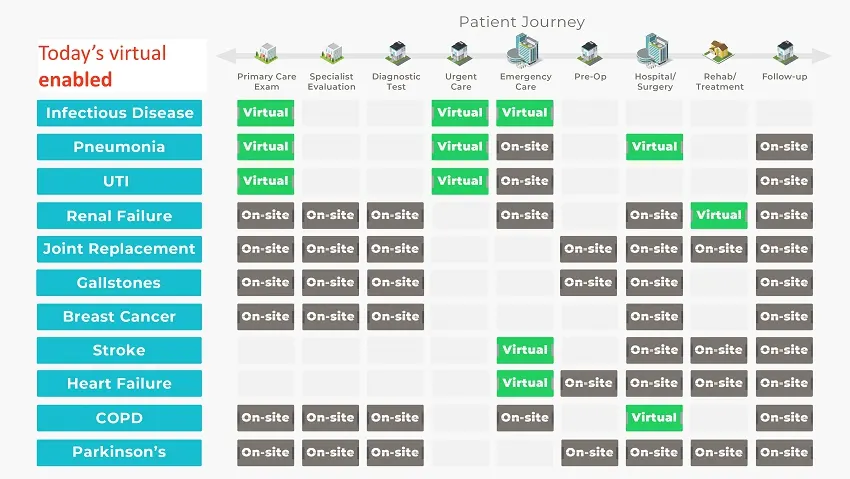
Slide 111: Patient journey: today's virtual
Patient Journey 2424 4 Today’s virtual ie :
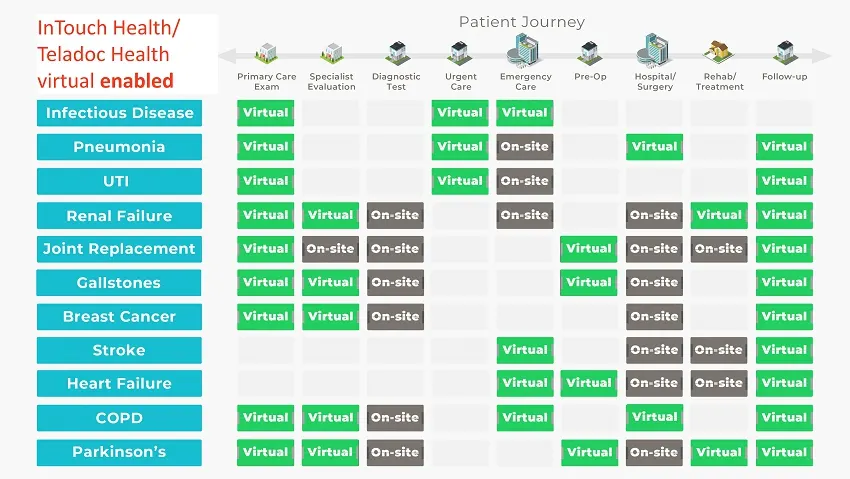
Slide 112: Virtual enabled patient journey
InTouch Health/ Teladoc Health virtual enabled
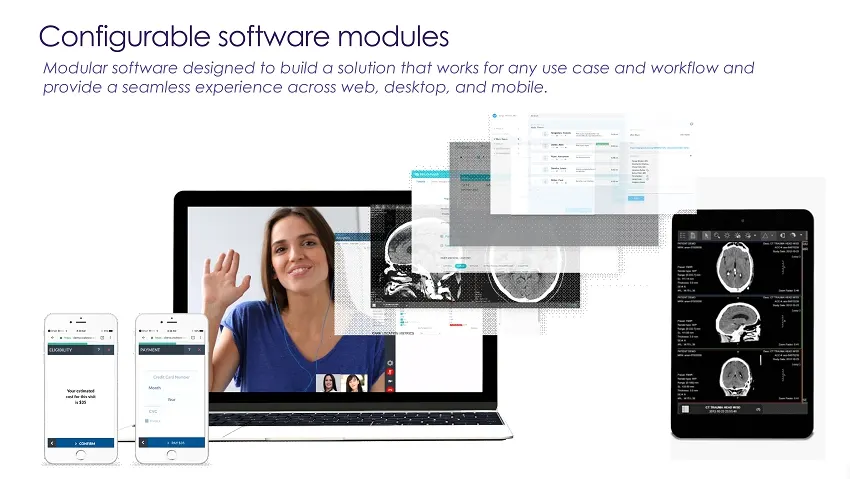
Slide 113: Modular software
113 Modular software designed to build a solution that works for any use case and workflow and provide a seamless experience across web, desktop, and mobile.
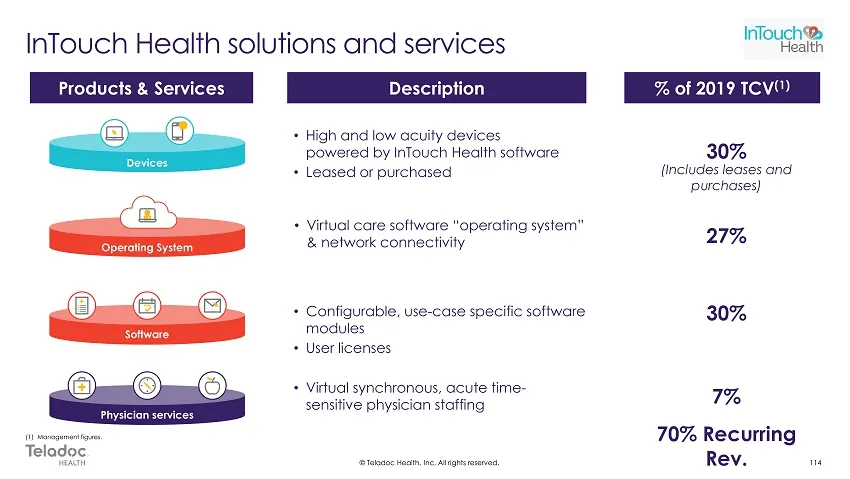
Slide 114: Products and services
Products & Services Description % of 2019 TCV (1) • High and low acuity devices powered by InTouch Health software • Leased or purchased Devices • Configurable, use - case specific software modules • User licenses Software • Virtual synchronous, acute time - sensitive physician staffing Physician se
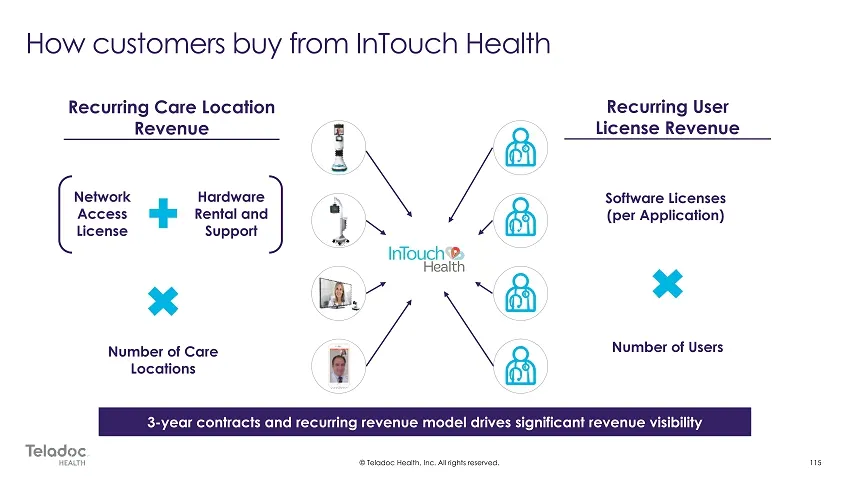
Slide 115: Recurring revenue model
3 - year contracts and recurring revenue model drives significant revenue visibility Recurring Care Location Revenue Number of Care Locations Network Access License Hardware Rental and Support Number of Users Software Licenses (per Application) Recurring User License Revenue
Slide 116: #1 Virtual Care Platform
#1 Virtual Care Platform For the third year in a row, InTouch Health is recognized as Best in KLAS for Virtual Care Platforms in the “2020 Best in KLAS: Software & Service” report #1 Direct to Consumer Teladoc Health won the J.D. Power award for Highest Telehealth Satisfaction with Direct to Consume
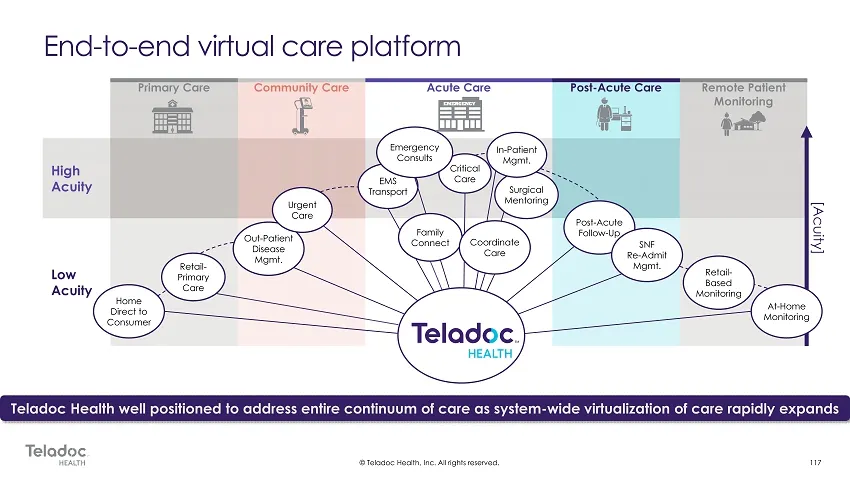
Slide 117: Continuum of care
Primary Care Community Care Acute Care Post - Acute Care Remote Patient Monitoring High Acuity Low Acuity Home Direct to Consumer Out - Patient Disease Mgmt. Retail - Based Monitoring Post - Acute Follow - Up SNF Re - Admit Mgmt. Retail - Primary Care Urgent Care EMS Transport Critical Care Surgical
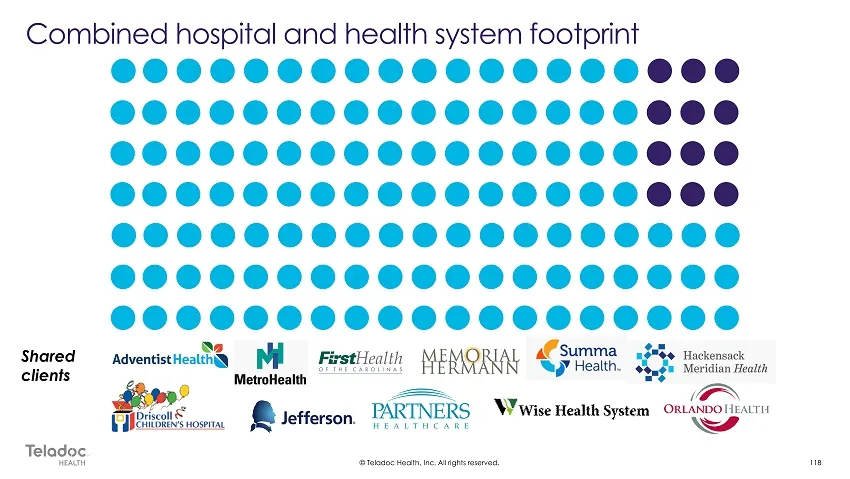
Slide 118: Combined hospital and health system footprint
Combined hospital and health system footprint 0000000800080 8080888888 Shared —adventnteat NB Firstlfenlty MEMORIAL ACSumMA abe toons NOP Health. $35 seriian Hearn clients MetroHealth a an Faleasts, a Jefferson. PARTNERS —W Wise Health system ano Teladoc
Slide 119: How InTouch and Teladoc Health deliver value for health systems
Teladoc. HEALTH How InTouch & Teladoc Health deliver value for health systems Jefferson Health ‘okeleke) C Oo000 — OO0000
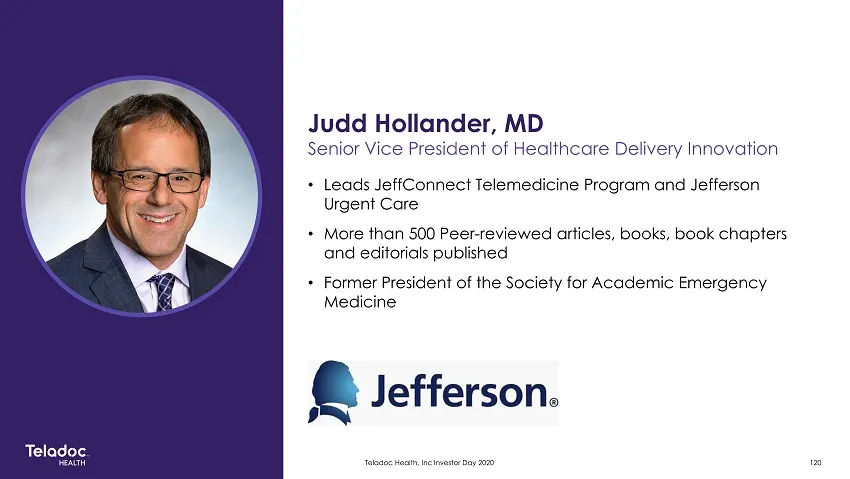
Slide 120: Judd Hollander, MD
Judd Hollander, MD Senior Vice President of Healthcare Delivery Innovation + Leads JeffConnect Telemedicine Program and Jefferson Urgent Care + More than 500 Peer-reviewed articles, books, book chapters and editorials published + Former President of the Society for Academic Emergency Medicine a Jeff
Slide 121: Financial overview
Teladoc. HEALTH Financial overview Mala Murthy, Chief Financial Officer
Slide 122: Key themes
Key themes We have a demonstrated history of meeting or exceeding financial targets Compelling financial model, with a foundation for sustained growth & margin expansion Positive free cash flow generation for continued investment in growth & operational excellence
Slide 123: Compelling financial model
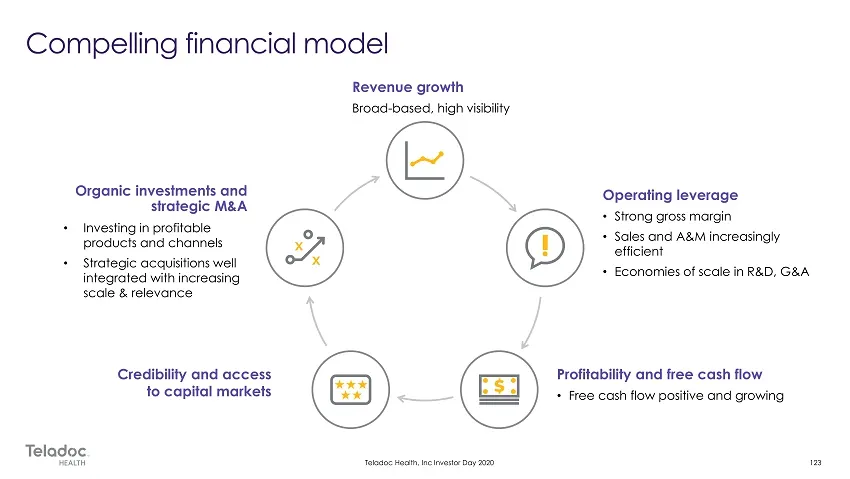
Compelling financial model Revenue growth Broad-based, high visibility Organic investments and Operating leverage strategic M&A + Strong gross morgin + Investing in profitable soevon aan nah products and channels ales cn increasingly Siratesi i fi efficient + Strategic acquisitions wel . integrated
Slide 124: Membership, revenue and EBITDA growth
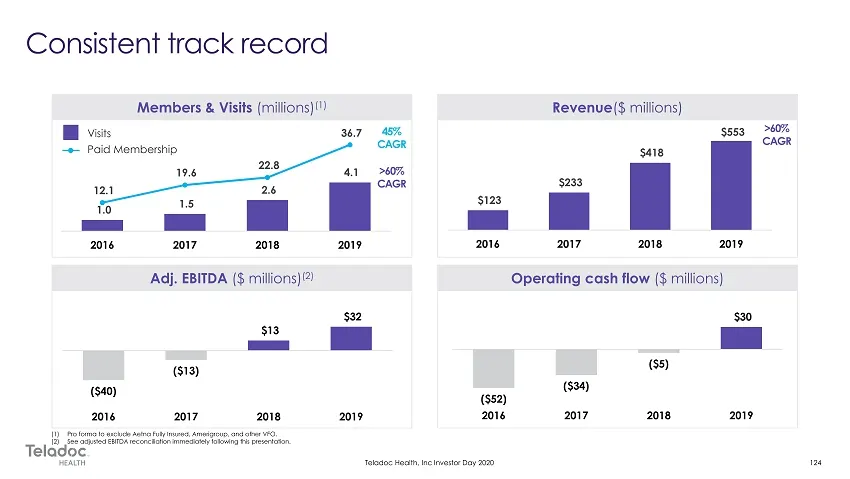
>60% CAGR 45% CAGR >60% CAGR (1) Pro forma to exclude Aetna Fully Insured, Amerigroup, and other VFO. (2) See adjusted EBITDA reconciliation immediately following this presentation. 1.0 1.5 2.6 4.1 12.1 19.6 22.8 36.7 2016 2017 2018 2019 $123 $233 $418 $553 2016 2017 2018 2019 ($40) ($13) $13 $32 20
Slide 125: Adjusted EBITDA margin
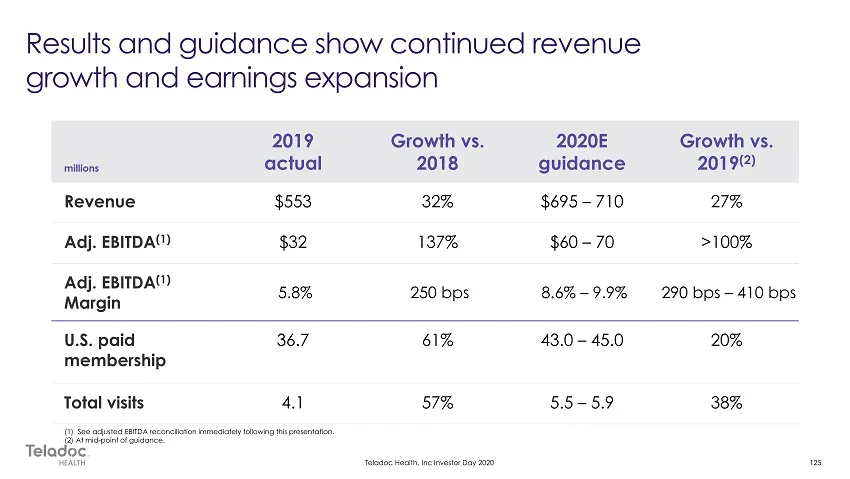
5.8% 250 bps 8.6% 9.9 % 290 bps 410 bps (1) See adjusted EBITDA reconciliation immediately following this presentation. (2) At mid - point of guidance.
Slide 126: Revenue and subscription mix
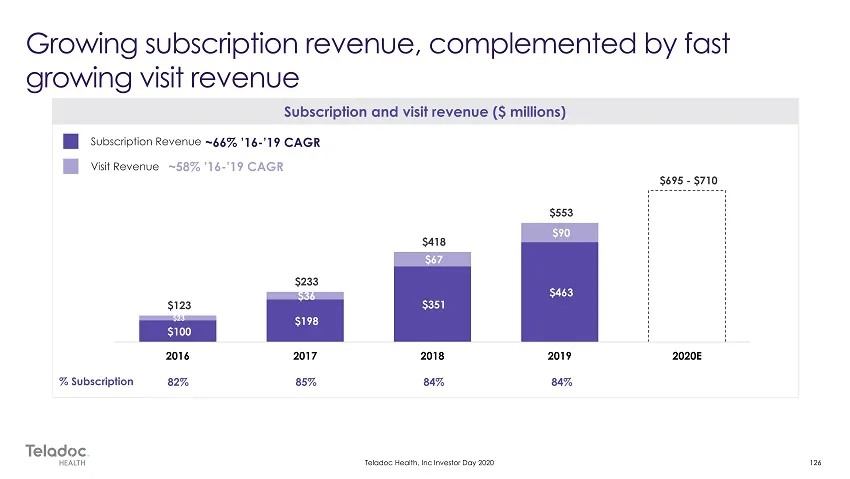
$100 $198 $351 $463 $23 $36 $67 $90 $123 $233 $418 $553 $695 - $710 2016 2017 2018 2019 2020E ~58% ’16 - ’19 CAGR 82% 85% 84% 84% % Subscription
Slide 127: Global, diversified, deeper client penetration
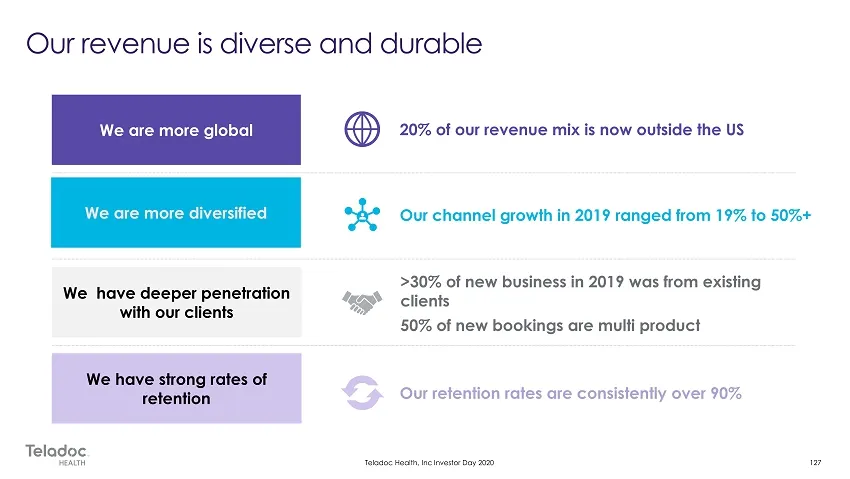
• 20% of our revenue mix is now outside the US We are more global • Our channel growth in 2019 ranged from 19% to 50%+ • >30% of new business in 2019 was from existing clients • 50% of new bookings are multi product We are more diversified We have deeper penetration with our clients • Our retention
Slide 128: Membership and average PMPM
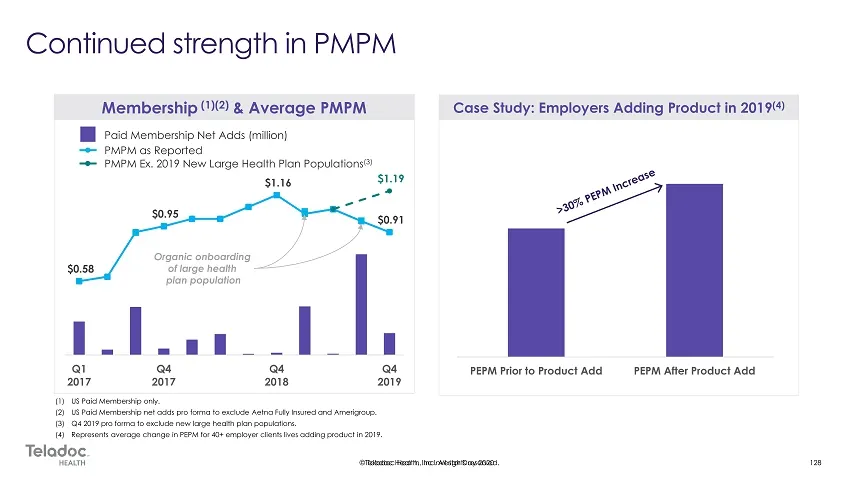
$0.58 $0.95 $1.16 $0.91 $1.19 Q1 2017 Q4 2017 Q4 2018 Q4 2019 Membership (1)(2) & Average PMPM (1) US Paid Membership only. (2) US Paid Membership net adds pro forma to exclude Aetna Fully Insured and Amerigroup. (3) Q4 2019 pro forma to exclude new large health plan populations. (4) Represents aver
Slide 129: Utilization and paid visits
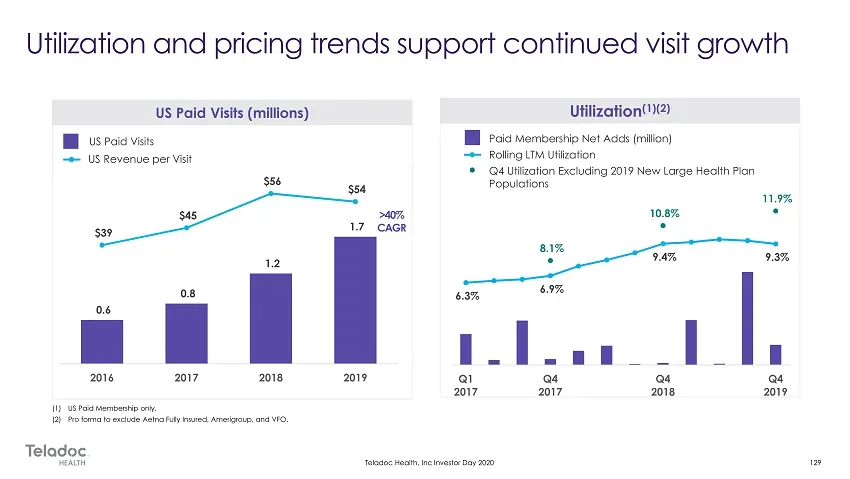
6.3% 6.9% 9.4% 9.3% 8.1% 10.8% 11.9% Q1 2017 Q4 2017 Q4 2018 Q4 2019 (1) US Paid Membership only. (2) Pro forma to exclude Aetna Fully Insured, Amerigroup, and VFO. US Paid Visits (millions) >40% CAGR Utilization (1)(2) 0.6 0.8 1.2 1.7 $39 $45 $56 $54 2016 2017 2018 2019
Slide 130: Gross profit and margin
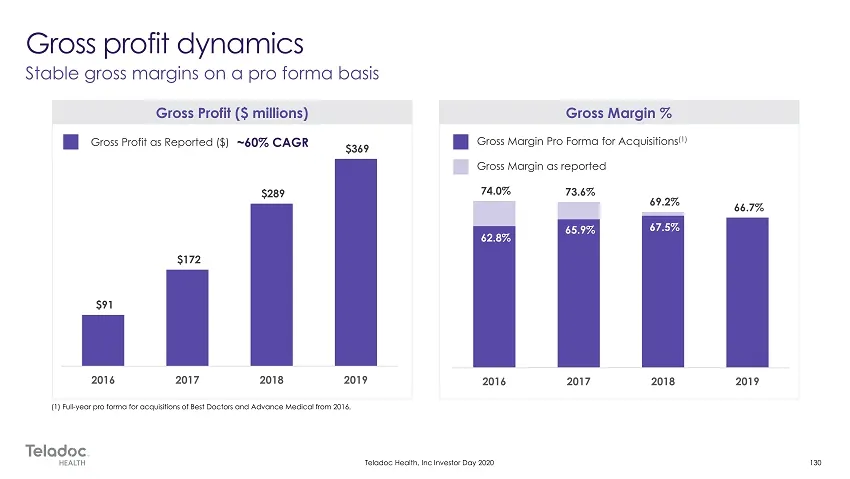
Gross Margin % Gross Profit ($ millions) $91 $172 $289 $369 2016 2017 2018 2019 62.8% 65.9% 67.5% 74.0% 73.6% 69.2% 66.7% 2016 2017 2018 2019
Slide 131: Gross margin drivers
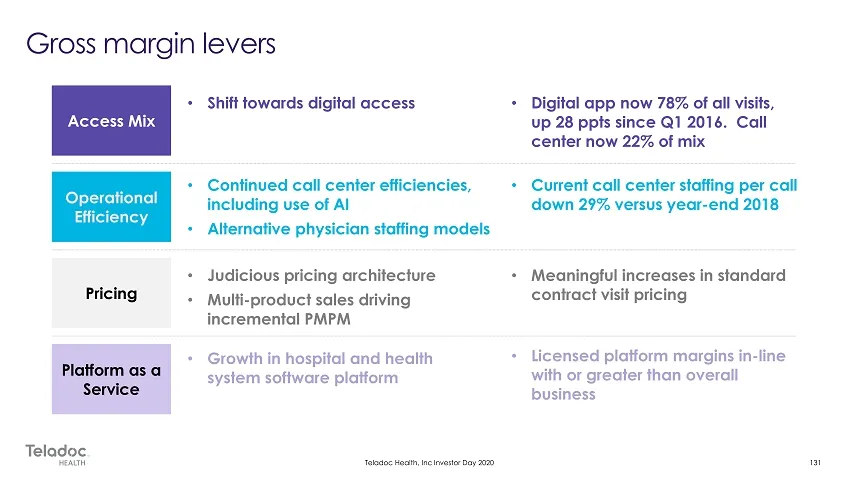
• Digital app now 78% of all visits, up 28 ppts since Q1 2016. Call center now 22% of mix • Continued call center efficiencies, including use of AI • Alternative physician staffing models Access Mix • Current call center staffing per call down 29% versus year - end 2018 • Meaningful increases in sta
Slide 132: Operating expense leverage
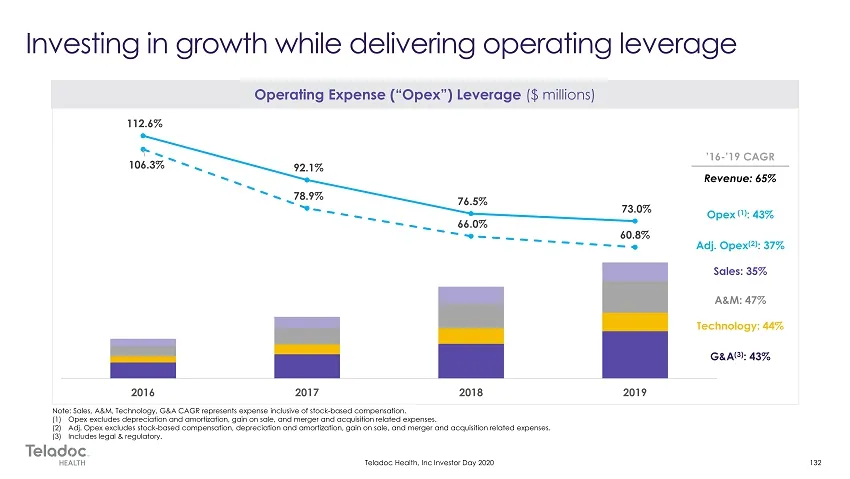
112.6% 92.1% 76.5% 73.0% 106.3% 78.9% 66.0% 60.8% 2016 2017 2018 2019 Sales: 35% G&A (3) : 43% A&M: 47% Technology: 44% Note: Sales, A&M, Technology, G&A CAGR represents expense inclusive of stock - based compensation. (1) Opex excludes depreciation and amortization, gain on sale, and merger and acq
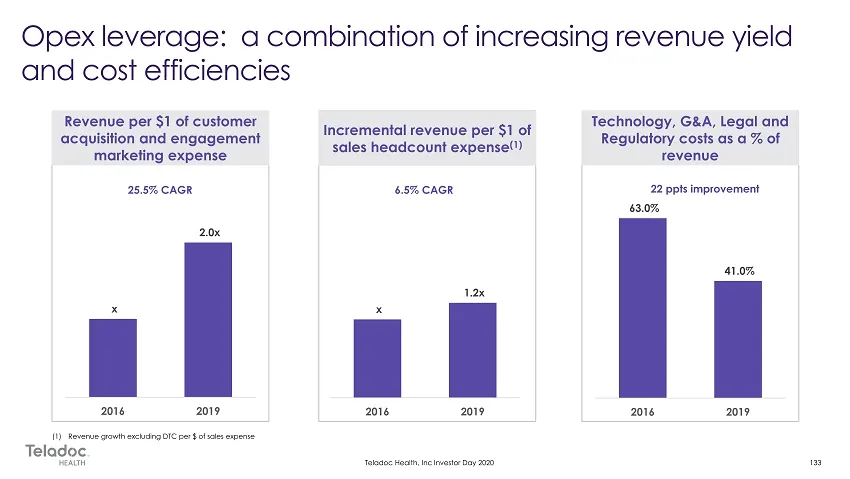
Slide 133: Sales efficiency
x 2.0x 2016 2019 25.5% CAGR 6.5% CAGR 22 ppts improvement (1) Revenue growth excluding DTC per $ of sales expense x 1.2x 2016 2019 63.0% 41.0% 2016 2019
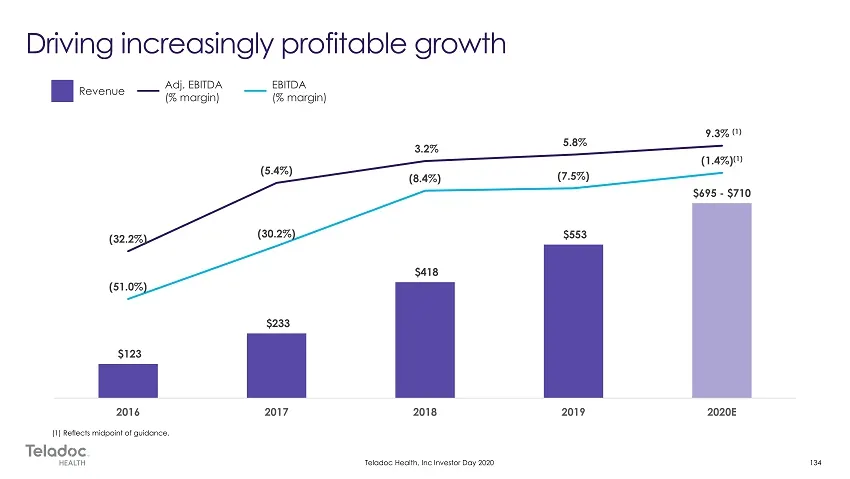
Slide 134: Revenue and adjusted EBITDA margin
$123 $233 $418 $553 $695 - $710 (32.2%) (5.4%) 3.2% 5.8% 9.3% (1) (51.0%) (30.2%) (8.4%) (7.5%) (1.4%) (1) 2016 2017 2018 2019 2020E
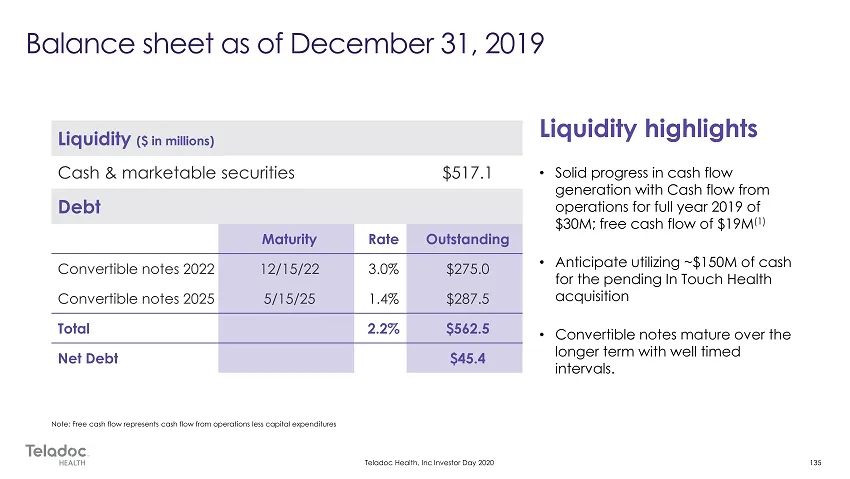
Slide 135: Liquidity highlights
Liquidity highlights • Solid progress in cash flow generation with Cash flow from operations for full year 2019 of $30M; free cash flow of $19M (1) • Anticipate utilizing ~$150M of cash for the pending In Touch Health acquisition • Convertible notes mature over the longer term with well timed interv
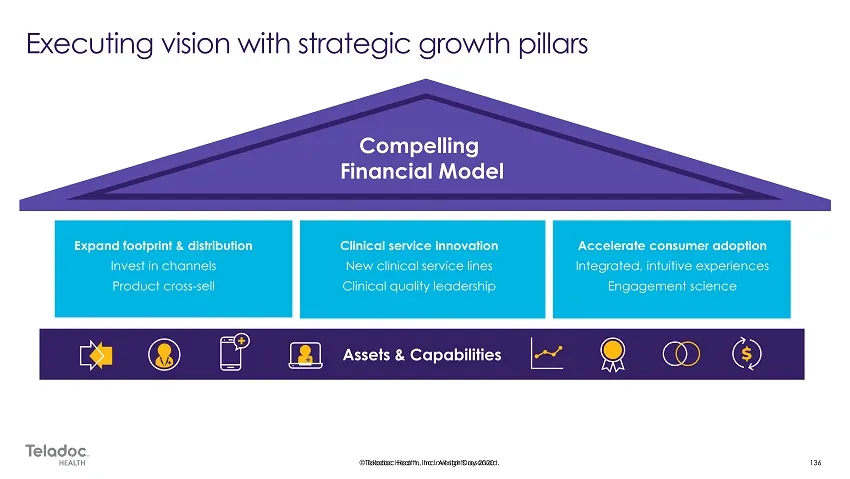
Slide 136: Assets and capabilities
Assets & Capabilities Expand footprint & distribution Invest in channels Product cross - sell Clinical service innovation New clinical service lines Clinical quality leadership Accelerate consumer adoption Integrated, intuitive experiences Engagement science Compelling Financial Model Compelling Fin
Slide 137: Growth levers and innovation
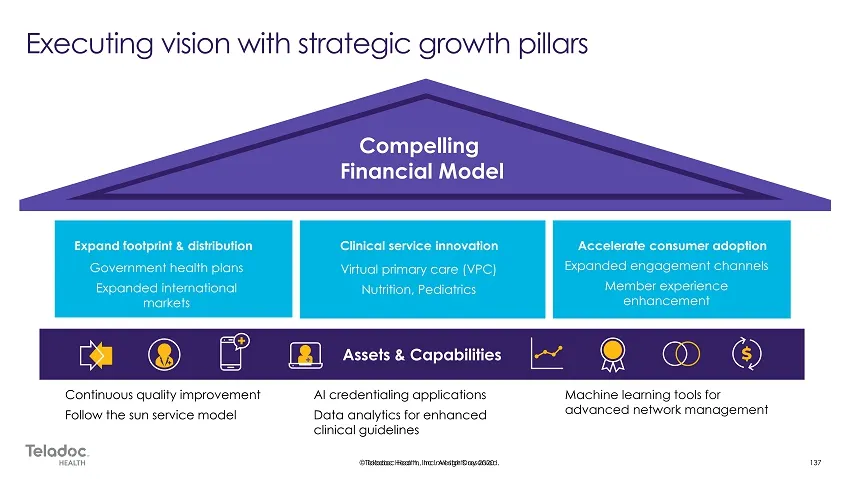
Assets & Capabilities Compelling Financial Model Compelling Financial Model Machine learning tools for advanced network management Expand footprint & distribution Clinical service innovation Accelerate consumer adoption Government health plans Expanded international markets Virtual primary care (VPC
Slide 138: Visit growth by service
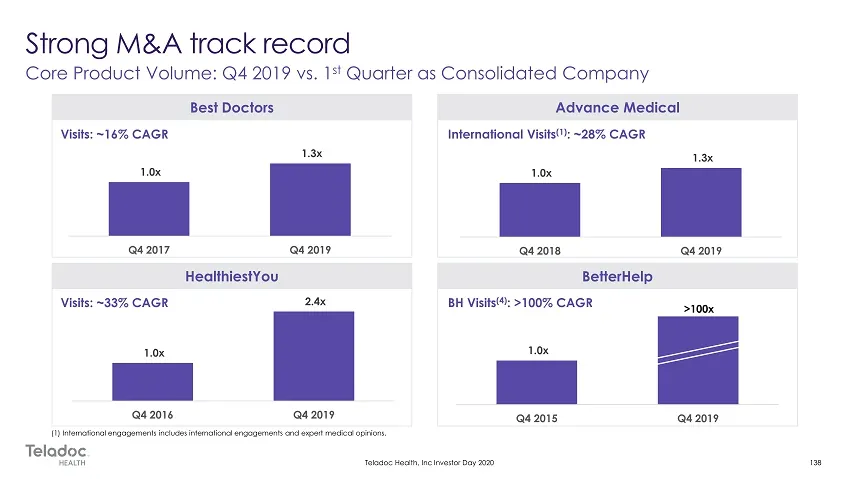
1.0x 1.3x Q4 2017 Q4 2019 1.0x 1.3x Q4 2018 Q4 2019 1.0x 2.4x Q4 2016 Q4 2019 1.0x Q4 2015 Q4 2019 (1 ) International engagements includes international engagements and expert medical opinions. Visits: ~16% CAGR Visits: ~33% CAGR International Visits (1) : ~28% CAGR BH Visits (4) : >100% CAGR
Slide 139: Adjusted EBITDA
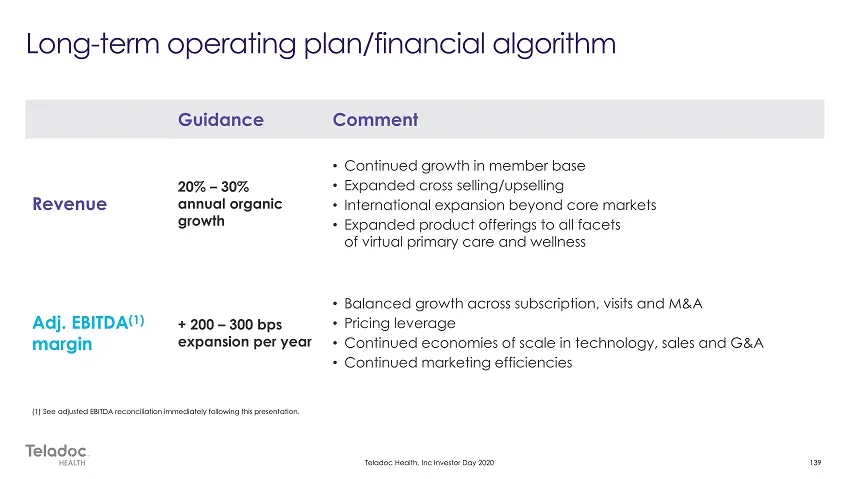
(1) See adjusted EBITDA reconciliation immediately following this presentation.
Slide 140: Summary
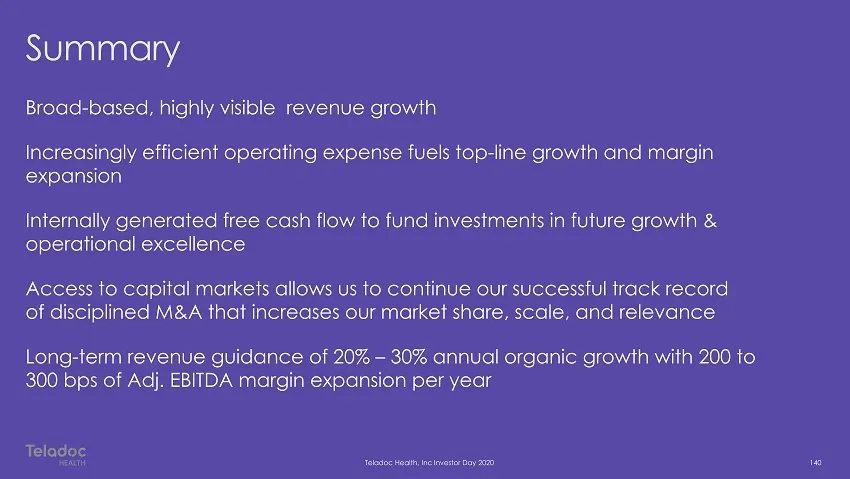
Summary Broad-based, highly visible revenue growth Increasingly efficient operating expense fuels top-line growth and margin expansion Internally generated free cash flow to fund investments in future growth & operational excellence Access to capital markets allows us to continue our successful trac
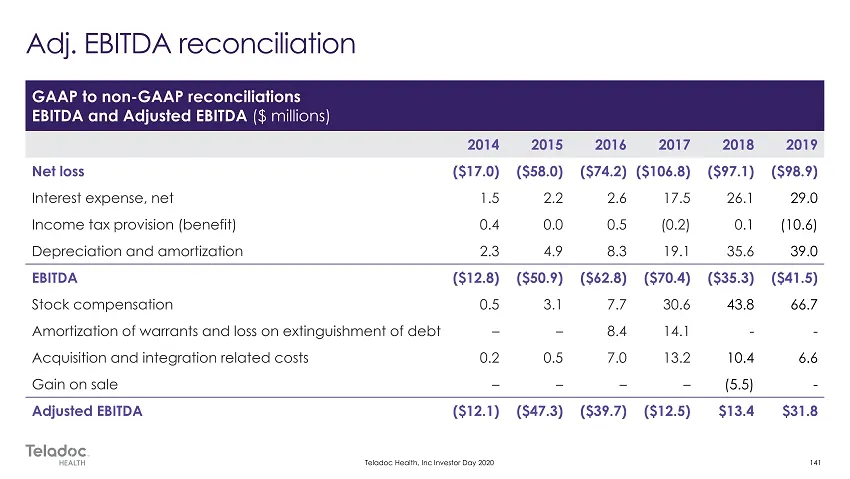
Slide 141: Adjusted EBITDA reconciliation
($98.9) 29.0 (10.6) 39.0 ($41.5) 43.8 66.7 - - 10.4 6.6 (5.5) -
Slide 142: Investor Day
INVESTOR Telagoc. Dayenn
Slide 143: InTouch Health Innovation
InTouch Health Innovation Teladoc.
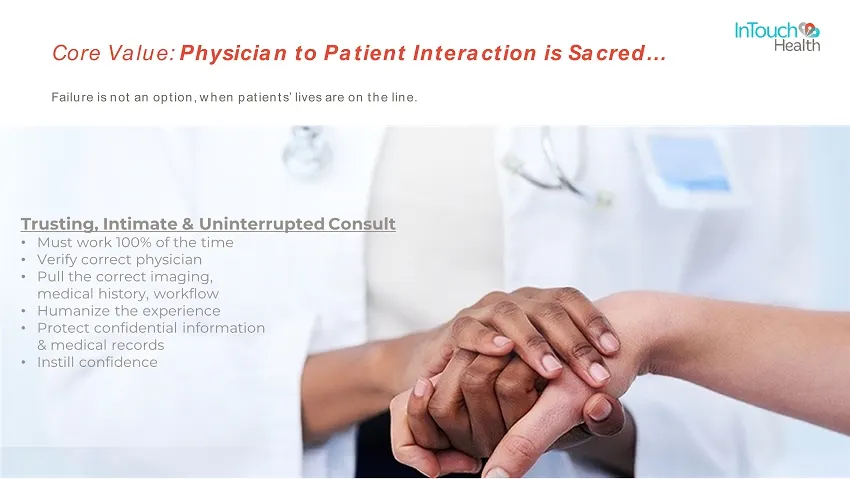
Slide 144: Core value: physician to patient interaction is sacred
Core Value: Physician to Patient Interaction is Sacred… Failure is not an option, when patients’ lives are on the line.
Slide 145: $3.5 trillion of annual US spend
$3.5 1 trillion of annual US spend Non Integrated Delivery Network Unaffiliated Post Acute Care (i.e. SNF, LTC, HH) Retail Pharmacy Other Unaffiliated Hospitals and Health Systems Unaffiliated Specialty Clinics Integrated Care Delivery Network Urgent clinic Specialty Clinic ASCs Unaffiliated Ambulat
Slide 146: Connecting doctors anywhere to patients anywhere
• Connecting doctors anywhere to patients anywhere, anytime • Specialists and generalists • Scheduled and unscheduled • Onsite or online Other Unaffiliated Hospitals and Health Systems DTC / Payor Telehealth Retail Pharmacy Free Standing Ambulatory Providers (i.e. Urgent Care, ACS, Imaging) Unaffili
Slide 147: Reputation for the most reliable network
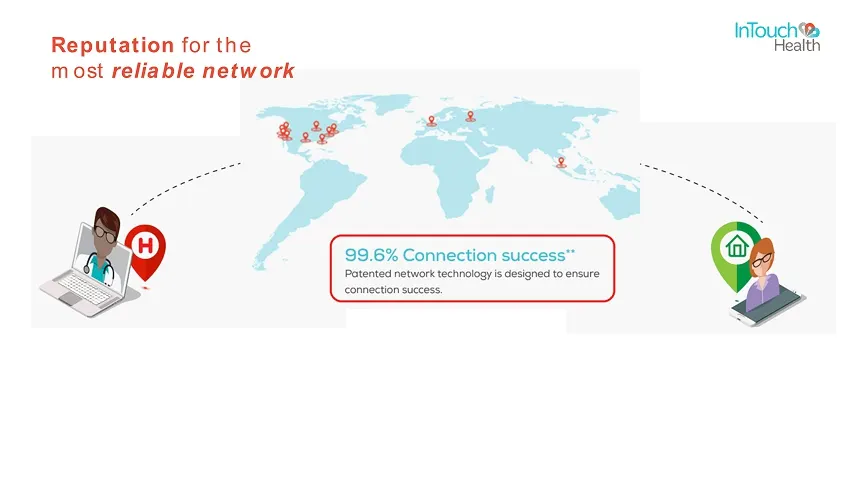
Reputation for the most reliable network
Slide 148: Every use case, one platform
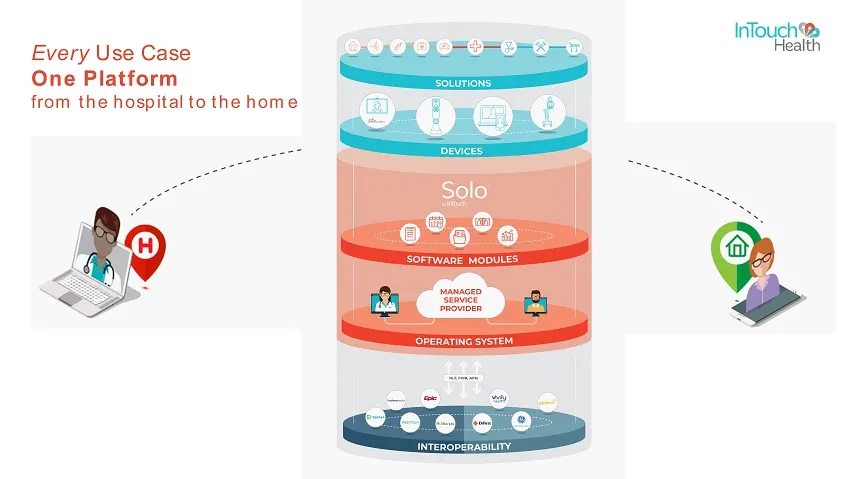
Every Use Case One Platform from the hospital to the home
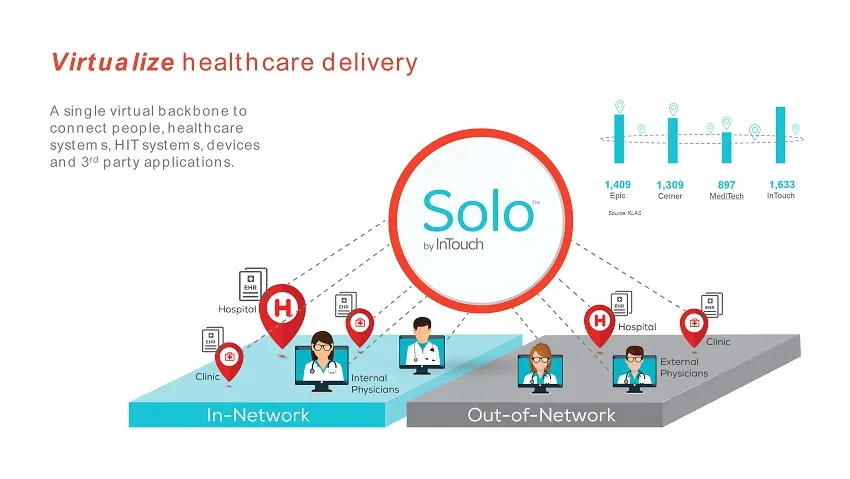
Slide 149: Virtualize healthcare delivery
Virtualize healthcare delivery A single virtual backbone to connect people, healthcare systems, HIT systems, devices and 3 rd party applications.
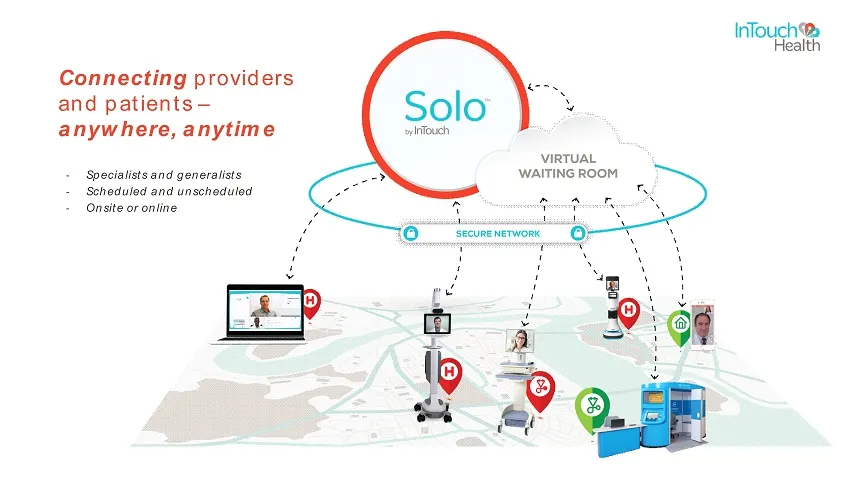
Slide 150: Connecting providers and patients
Connecting providers and patients – anywhere, anytime - Specialists and generalists - Scheduled and unscheduled - Onsite or online
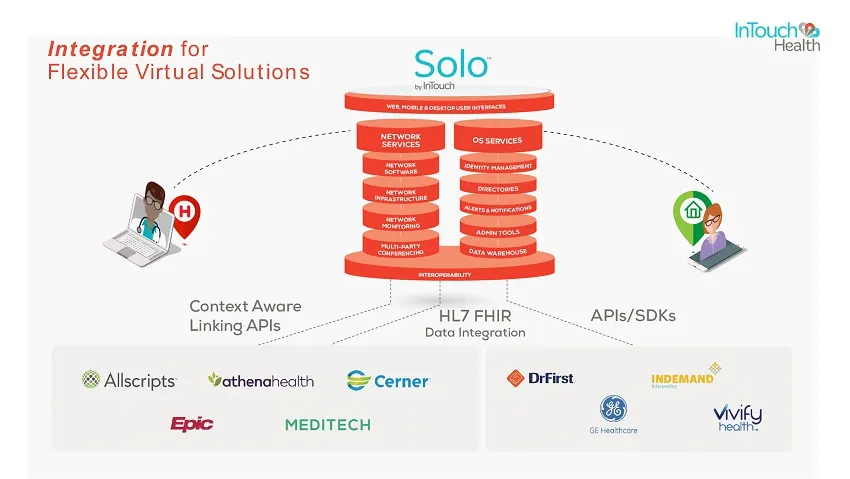
Slide 151: Integration for flexible virtual solutions
Integration for Flexible Virtual Solutions
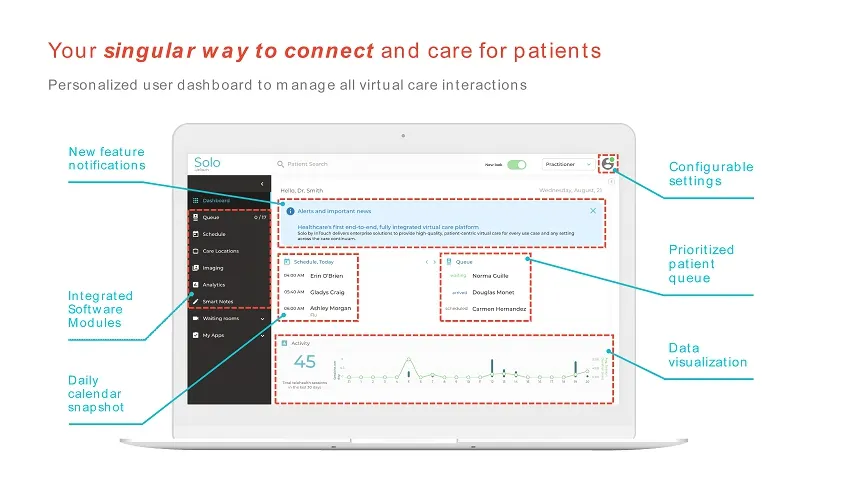
Slide 152: Your singular way to connect and care for patients
Your singular way to connect and care for patients Personalized user dashboard to manage all virtual care interactions Configurable settings Data visualization Integrated Software Modules New feature notifications Daily calendar snapshot Prioritized patient queue
Source: SEC EDGAR · 8-K filed Mar 5, 2020
More decks from Teladoc Health, Inc.
 Q3 2026 Earnings Presentation14 slides · Oct 28, 2026
 Investor Presentation (2026)52 slides · Oct 19, 2026
 Q2 2026 Earnings Presentation14 slides · Jul 29, 2026
 Q1 2026 Earnings Presentation14 slides · Apr 29, 2026
 Q4 2025 Earnings Presentation13 slides · Feb 25, 2026
 44th Annual J.P. Morgan Healthcare Conference 202619 slides · Jan 12, 2026