SITE Centers Corp. · NYSE:SITC
SITE Centers — JDN Realty — Merger or Acquisition (November 2002)
24 slides from SITE Centers's merger presentation, Nov 6, 2002
Slide 1: Filed by Developers Diversified Realty Corporation Pursuant to Rule 425
Filed by Developers Diversified Realty Corporation Pursuant to Rule 425 under the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 under the Securities Exchange Act of 1934 Subject Company: JDN Realty Corporation Registration Statement No. 333-100889 This filing relates to the followi
Slide 2: JDN Realty Corporation Merger Agreement with Developers Diversified Realty Corporation
JDN Realty Corporation Merger Agreement with Developers Diversified Realty Corporation
Slide 3: Background of the Merger
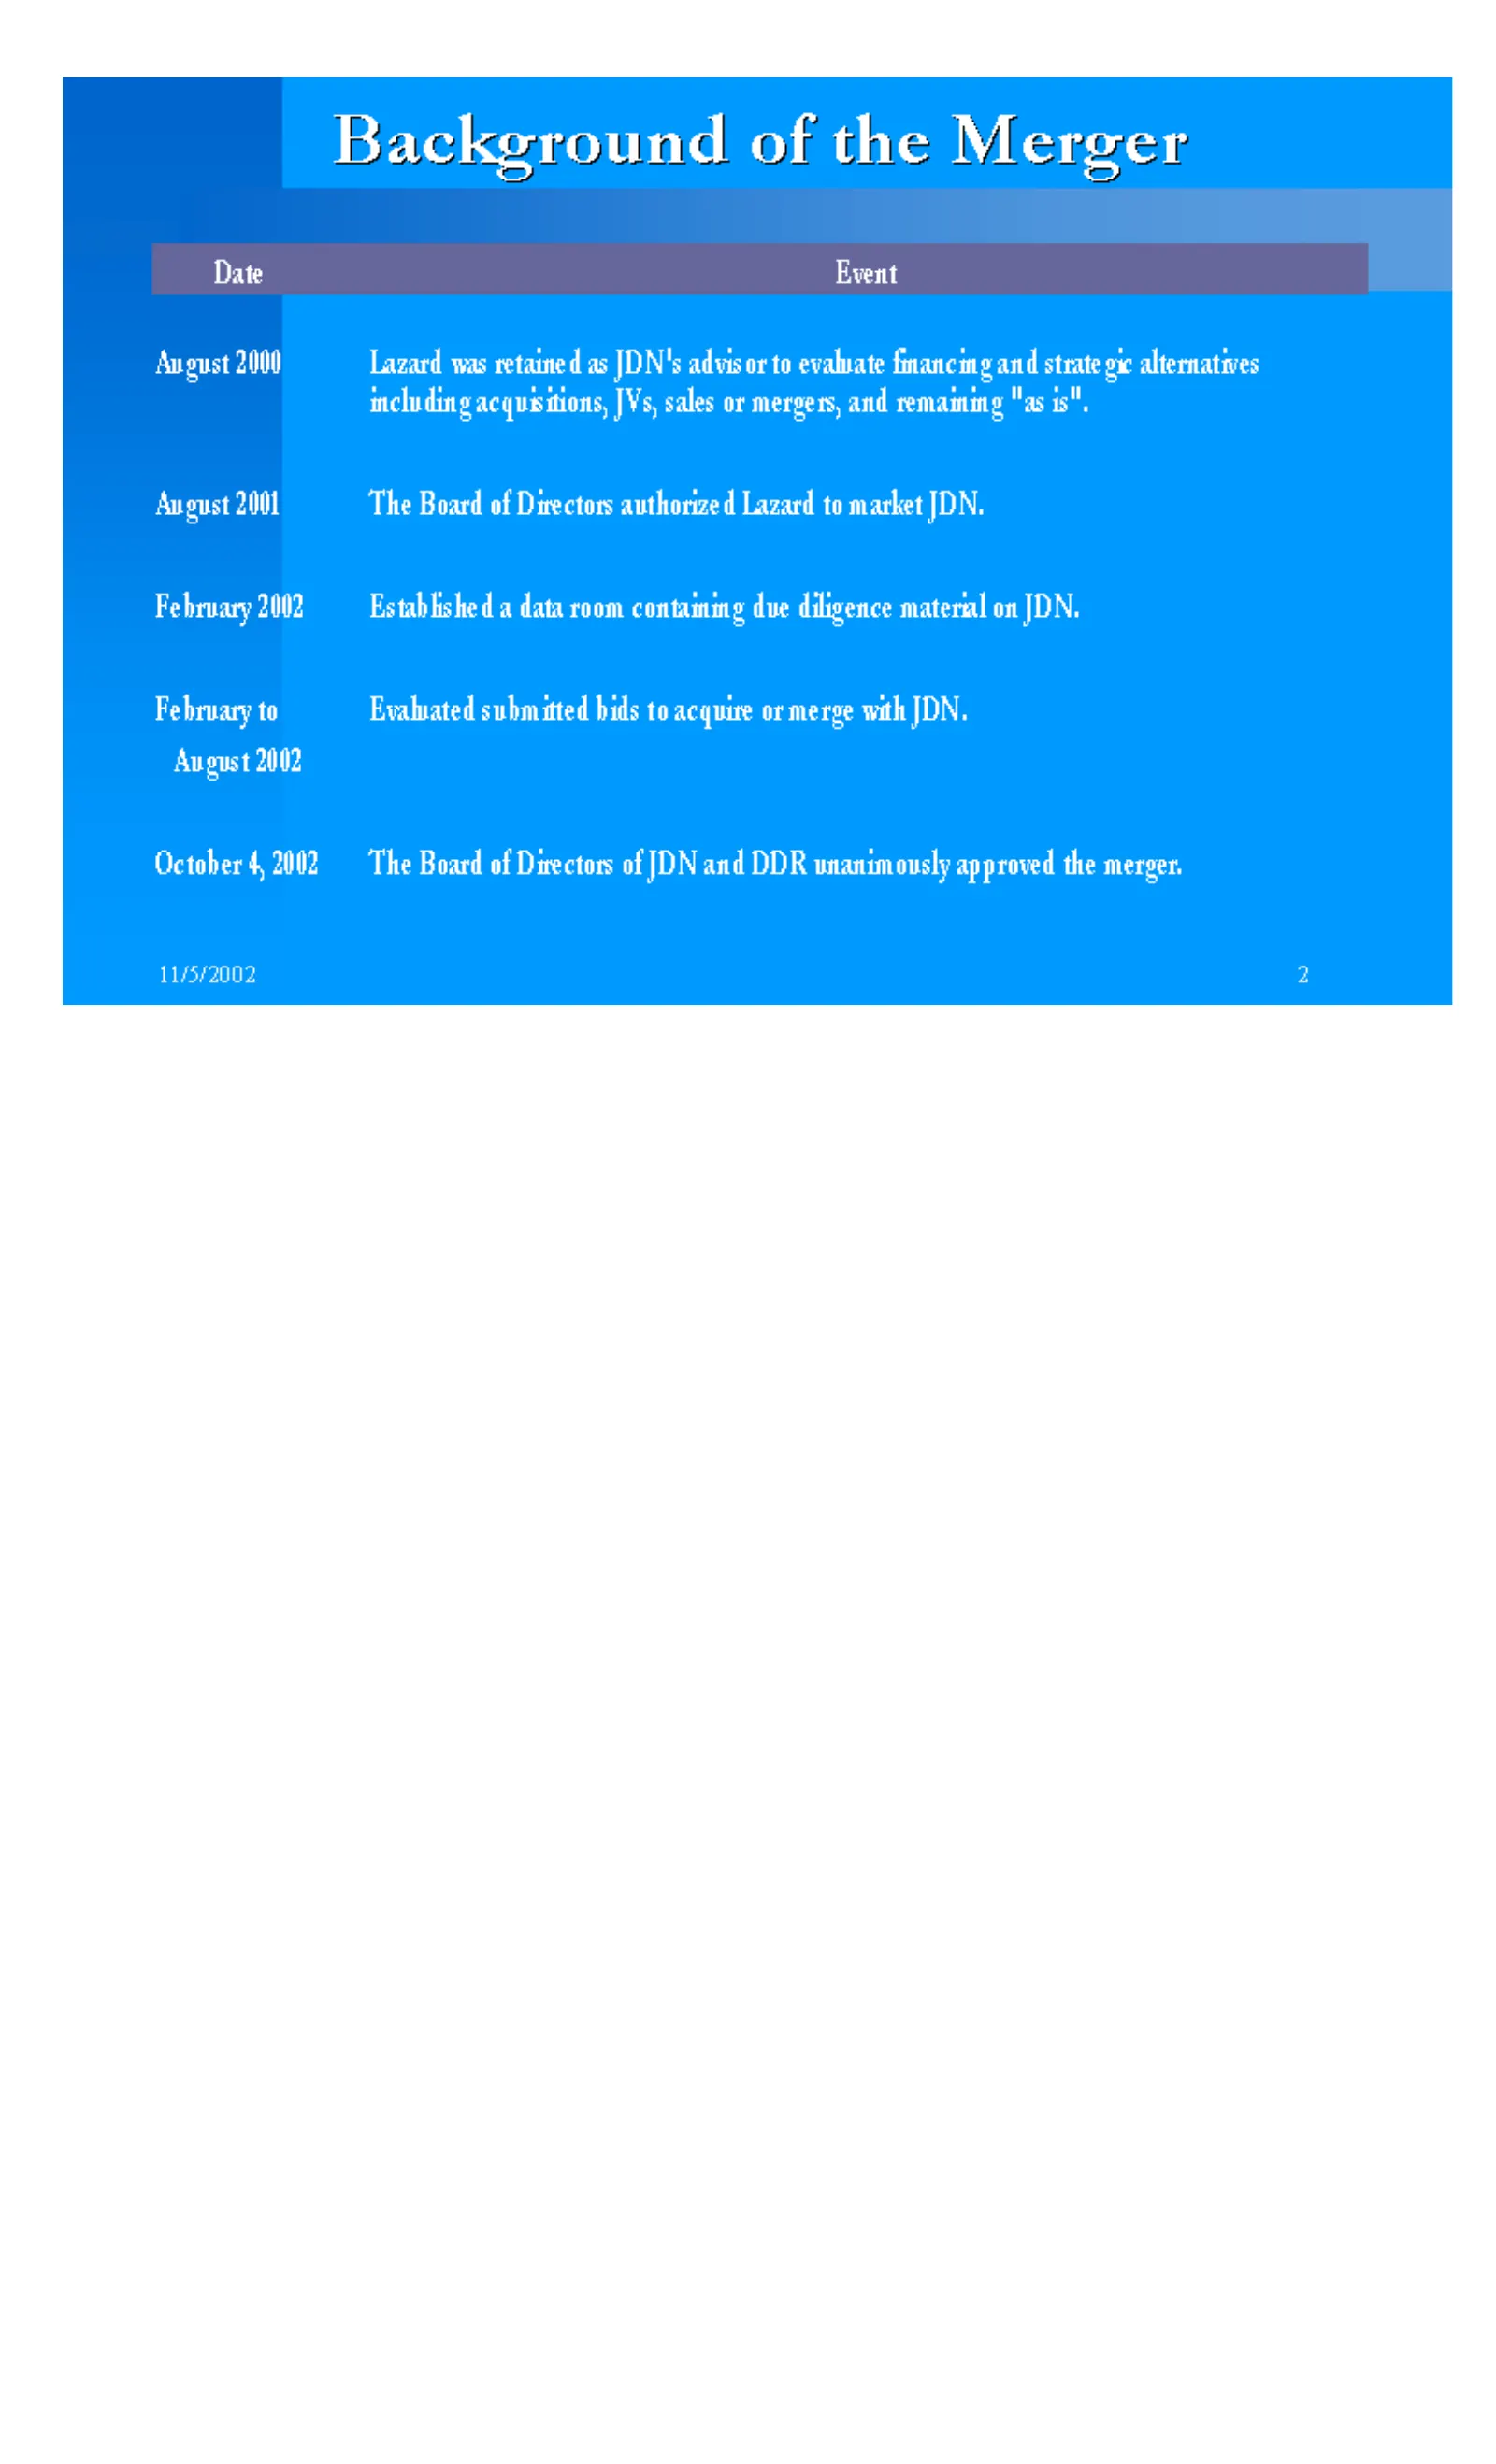
Background of the Merger
Slide 4: Summary of Terms of Merger
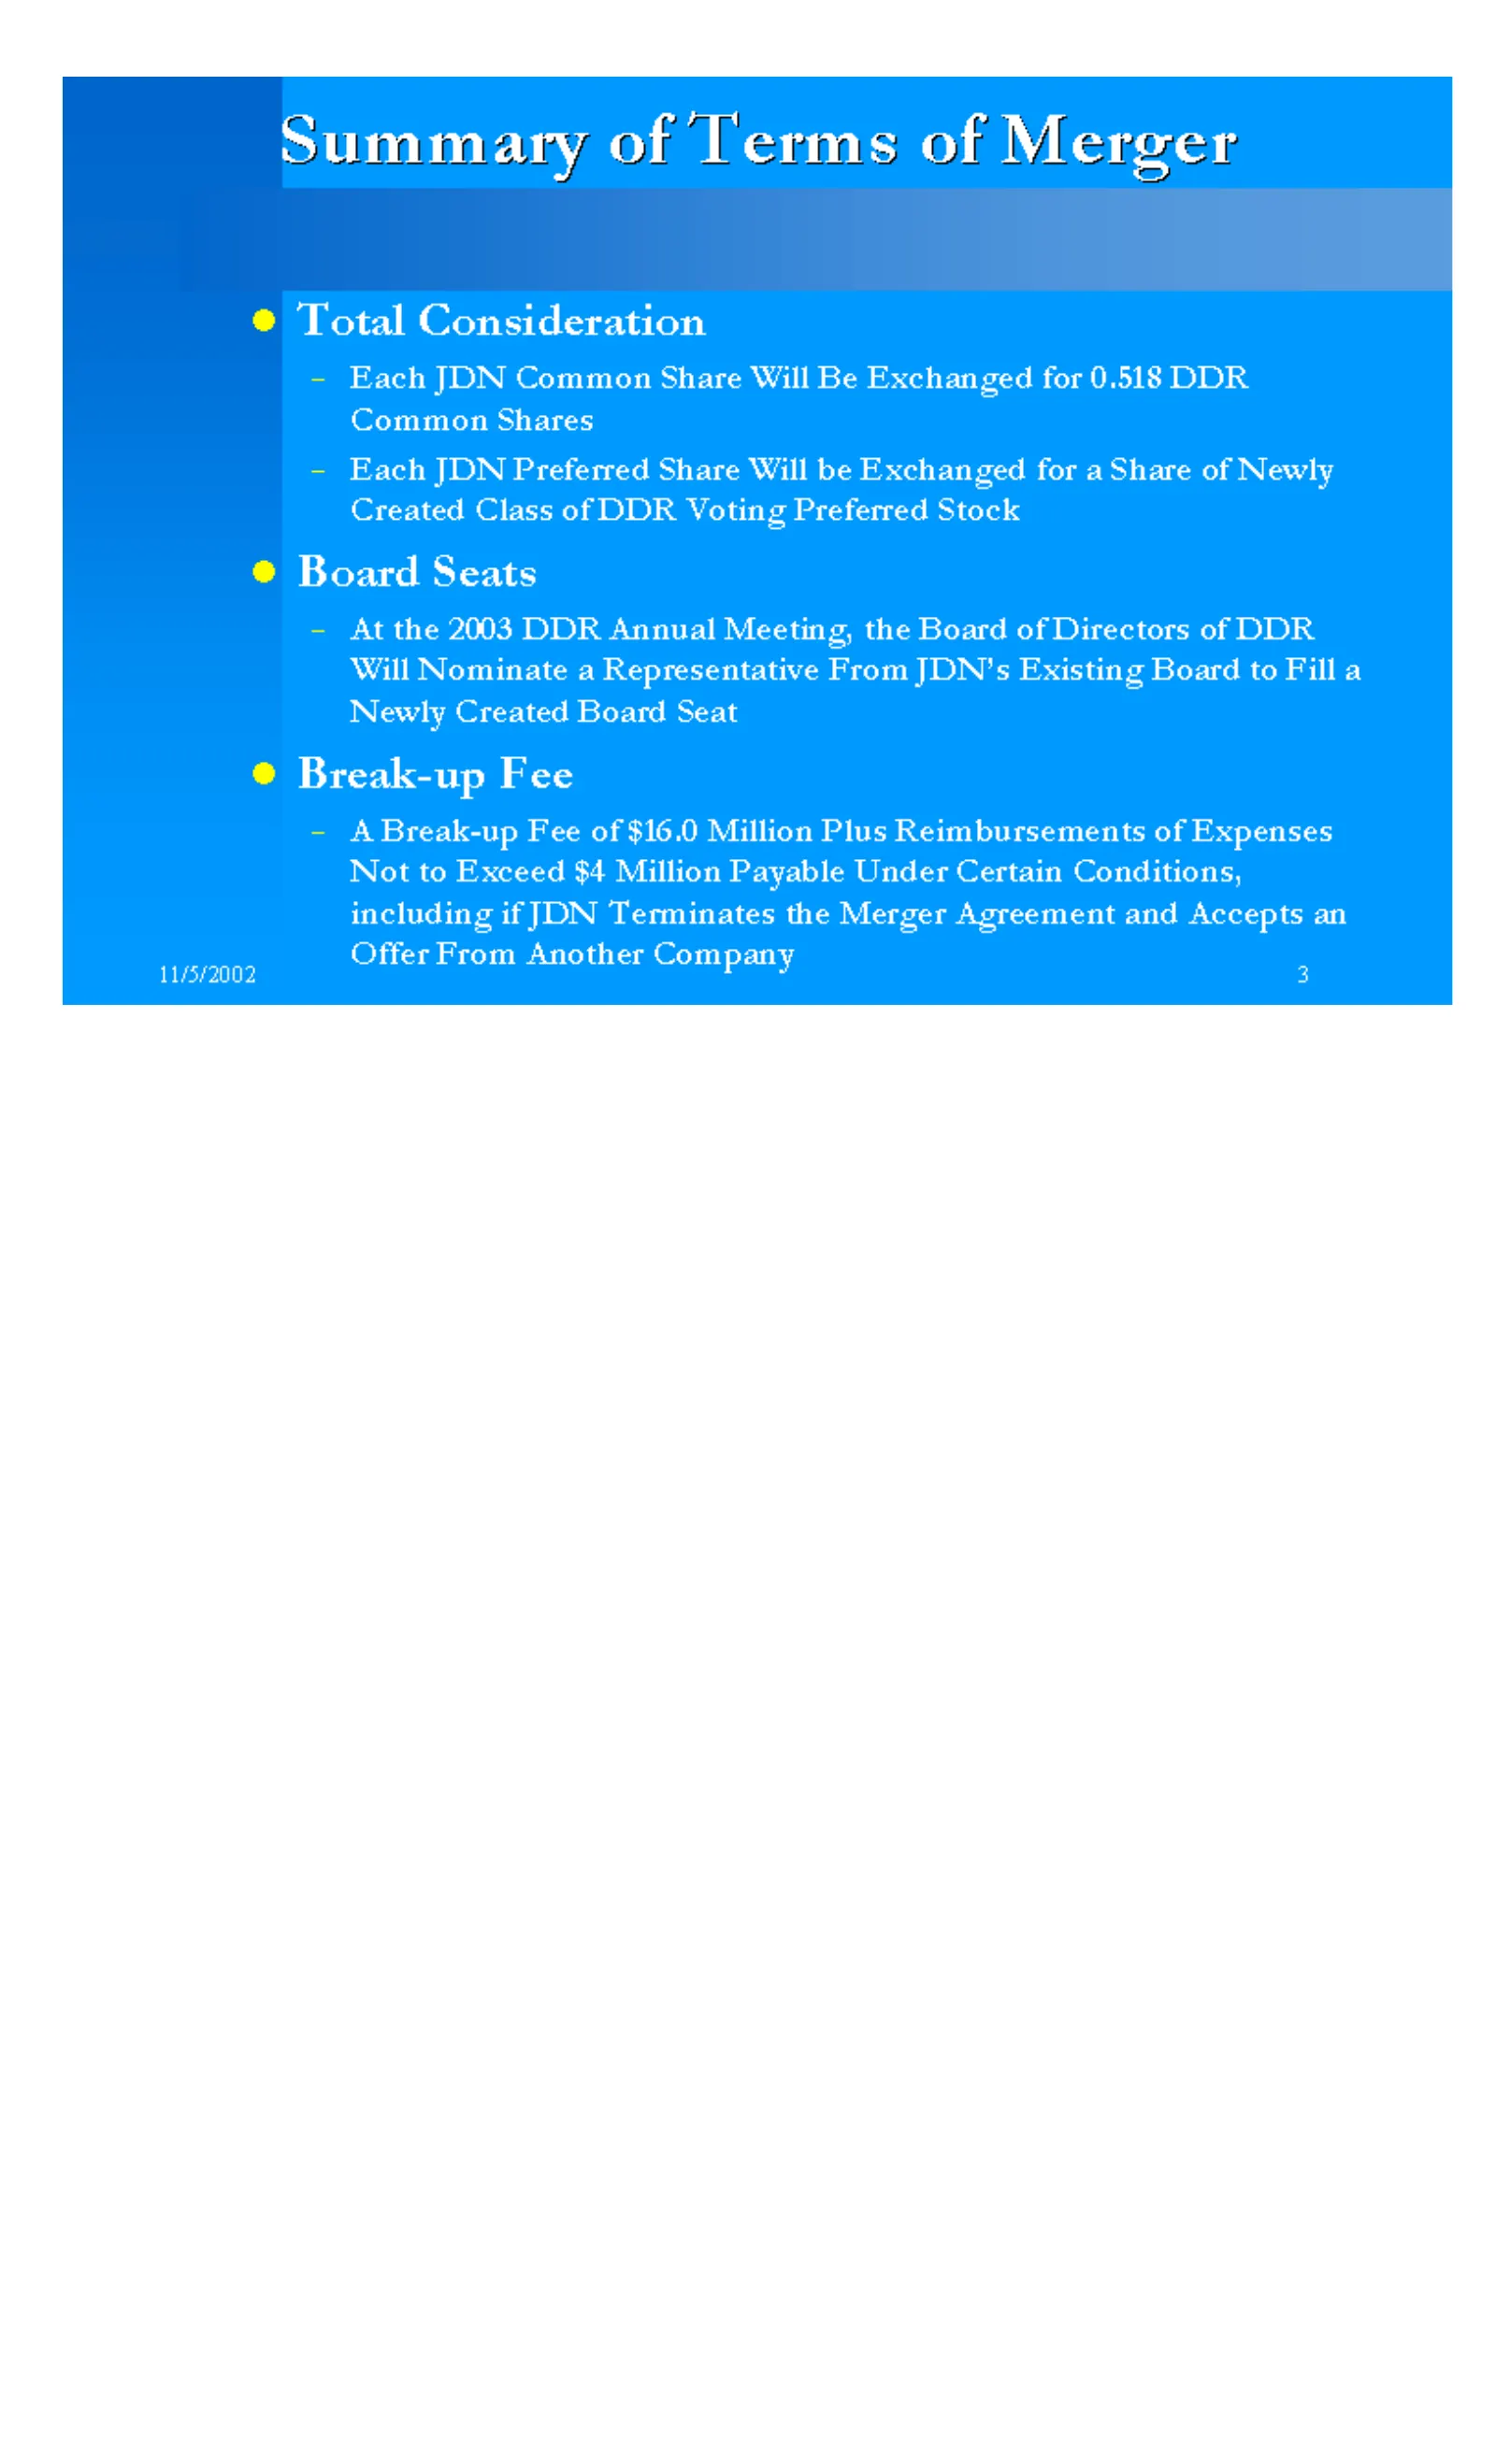
Summary of Terms of Merger Total Consideration Each JDN Common Share Will Be Exchanged for 0.518 DDR Common Shares Each JDN Preferred Share Will be Exchanged for a Share of Newly Created Class of DDR Voting Preferred Stock Board Seats At the 2003 DDR Annual Meeting, the Board of Directors of DDR Wil
Slide 5: Summary of Terms of Merger: Dividend and Closing
Summary of Terms of Merger Dividend JDN Cannot Pay Dividends On Its Common Stock Until It Has Entered Into a Closing Agreement With the Internal Revenue Service Confirming JDN Compliance With Certain Technical Requirements for Qualification As a REIT JDN’s Dividends Will Be Reduced by the Amount of
Slide 6: Pricing Considerations
(1) As of September 30, 2002 Pricing Considerations 37 Companies Approached By JDN Public and Private REITs, Equity Funds, and Public and Private Companies Reviewed JDN Companies Submitted Initial Bids to Acquire or Merge with JDN at Prices Ranging from $9.67 to $13.15 Per Share DDR Offered Best Opp
Slide 7: Strategic Rationale
Strategic Rationale Creates One of the Largest Shopping Center REITs Improves JDN’s Cost of and Access to Capital Enhances National Platform Enhances Acquisition and Development Capabilities Improves Liquidity of Stock for Shareholders Opportunity to Realize Cost Synergies
Slide 8: Strategic Rationale: Historical FFO and Dividend Growth
Strategic Rationale Strong Historical FFO Per Share Growth Rate Strong Historical Dividend Per Share Growth Rate Reduces JDN Shareholders’ Financing and Strategic Risks
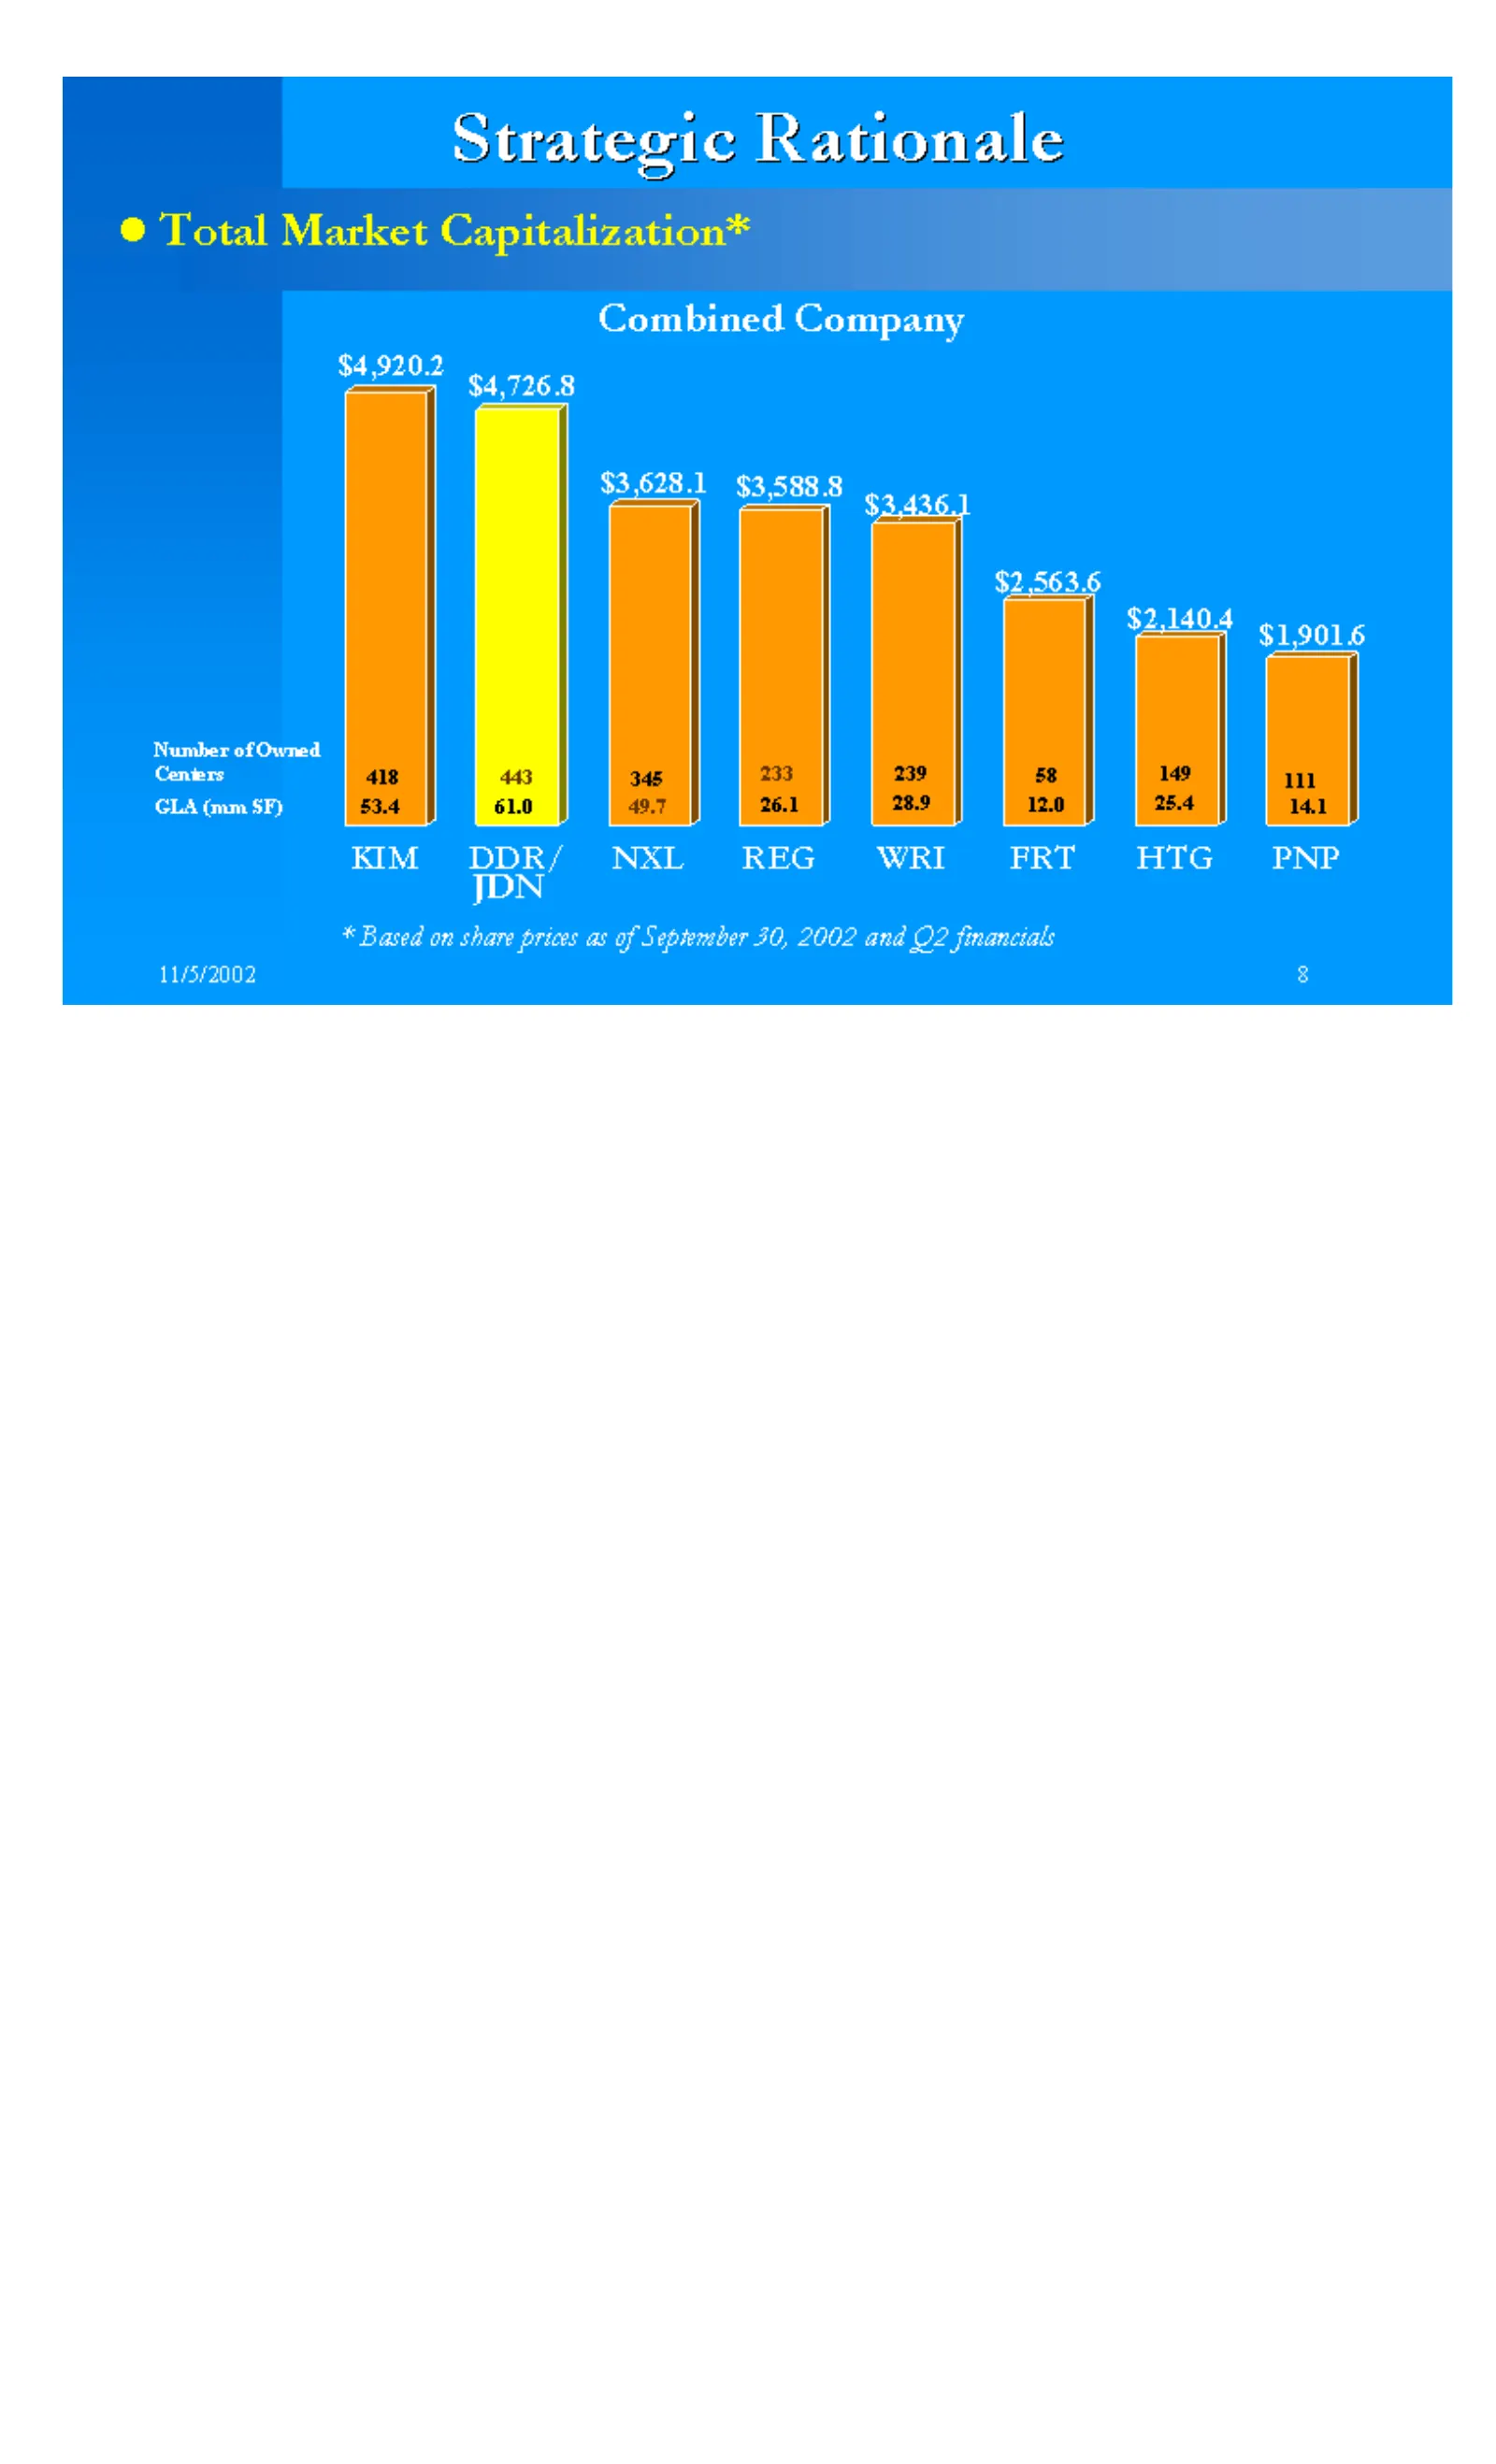
Slide 9: Strategic Rationale: Market Capitalization Versus Peers
Strategic Rationale KIM DDR/ NXL REG WRI FRT HTG PNP 4920.2 4726.8 3628.1 3588.8 3436.1 2563.6 2140.4 1901.6 Number of Owned Centers GLA (mm SF) 53.4 61.0 239 28.9 58 12.0 111 14.1 149 25.4 345 49.7 233 26.1 418 443 Total Market Capitalization* Combined Company JDN * Based on share prices as of Sept
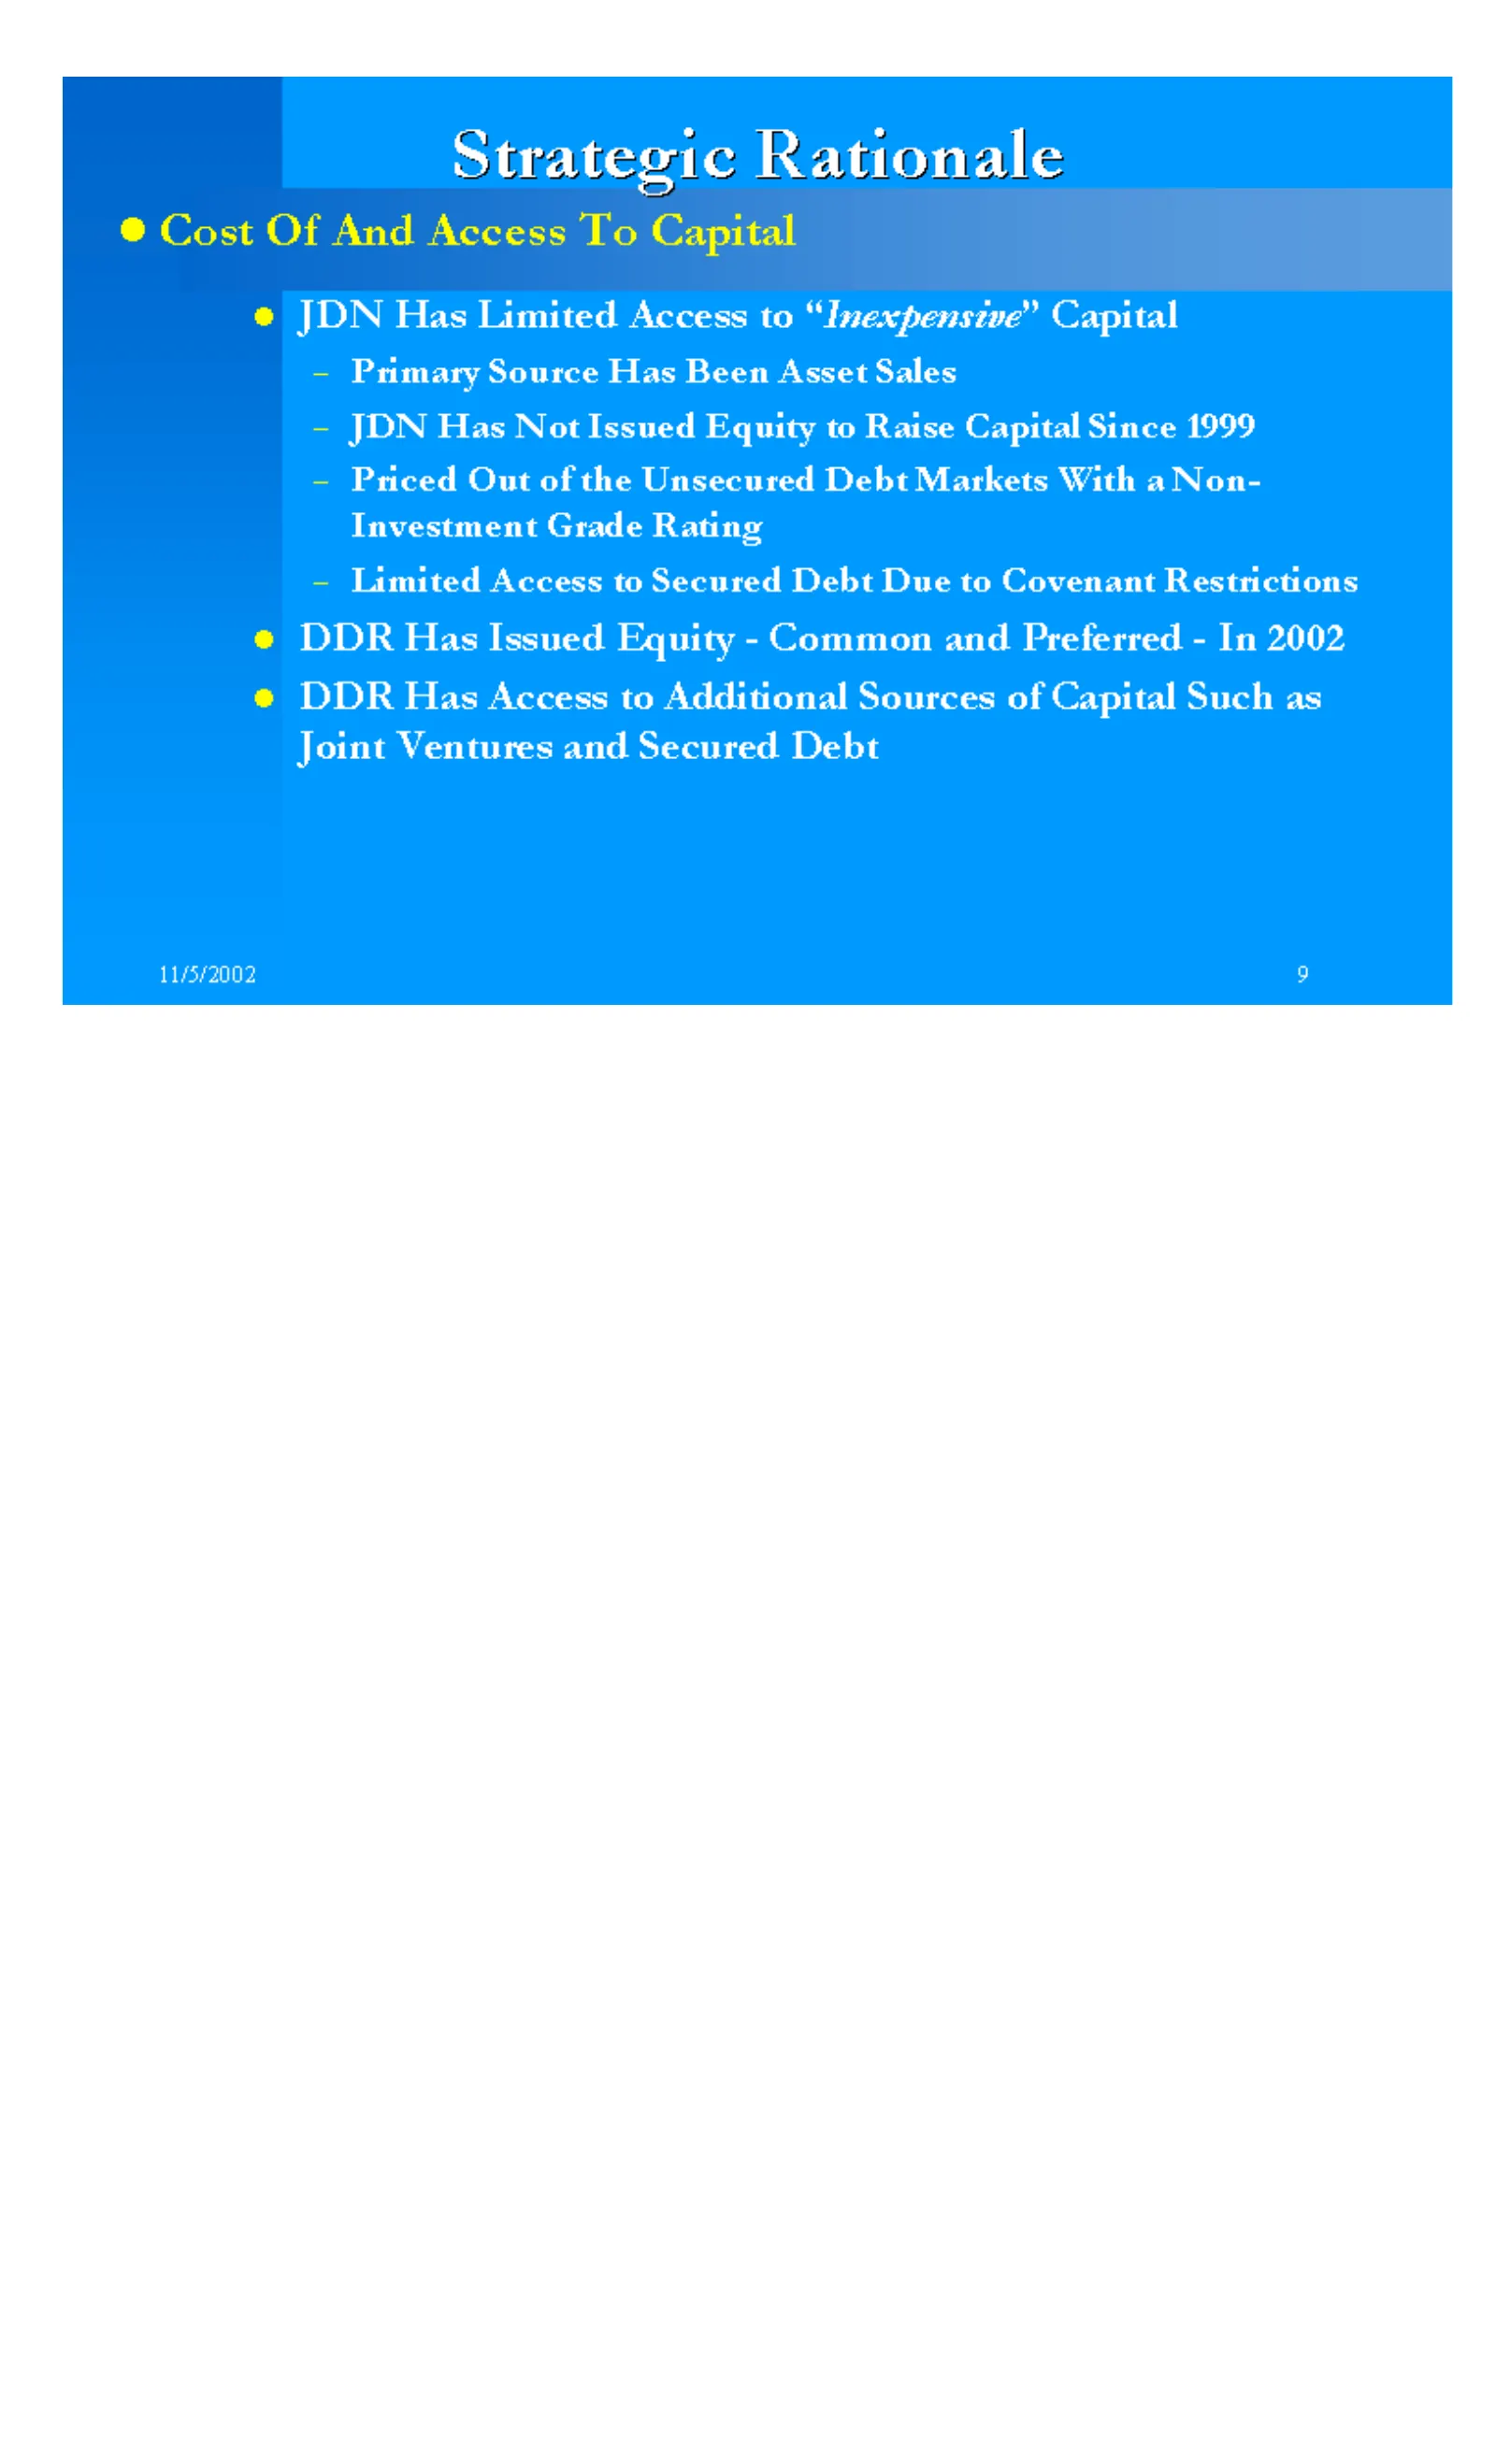
Slide 10: Cost of and Access to Capital
Strategic Rationale JDN Has Limited Access to "Inexpensive" Capital Primary Source Has Been Asset Sales JDN Has Not Issued Equity to Raise Capital Since 1999 Priced Out of the Unsecured Debt Markets With a Non- Investment Grade Rating Limited Access to Secured Debt Due to Covenant Restrictions DDR H
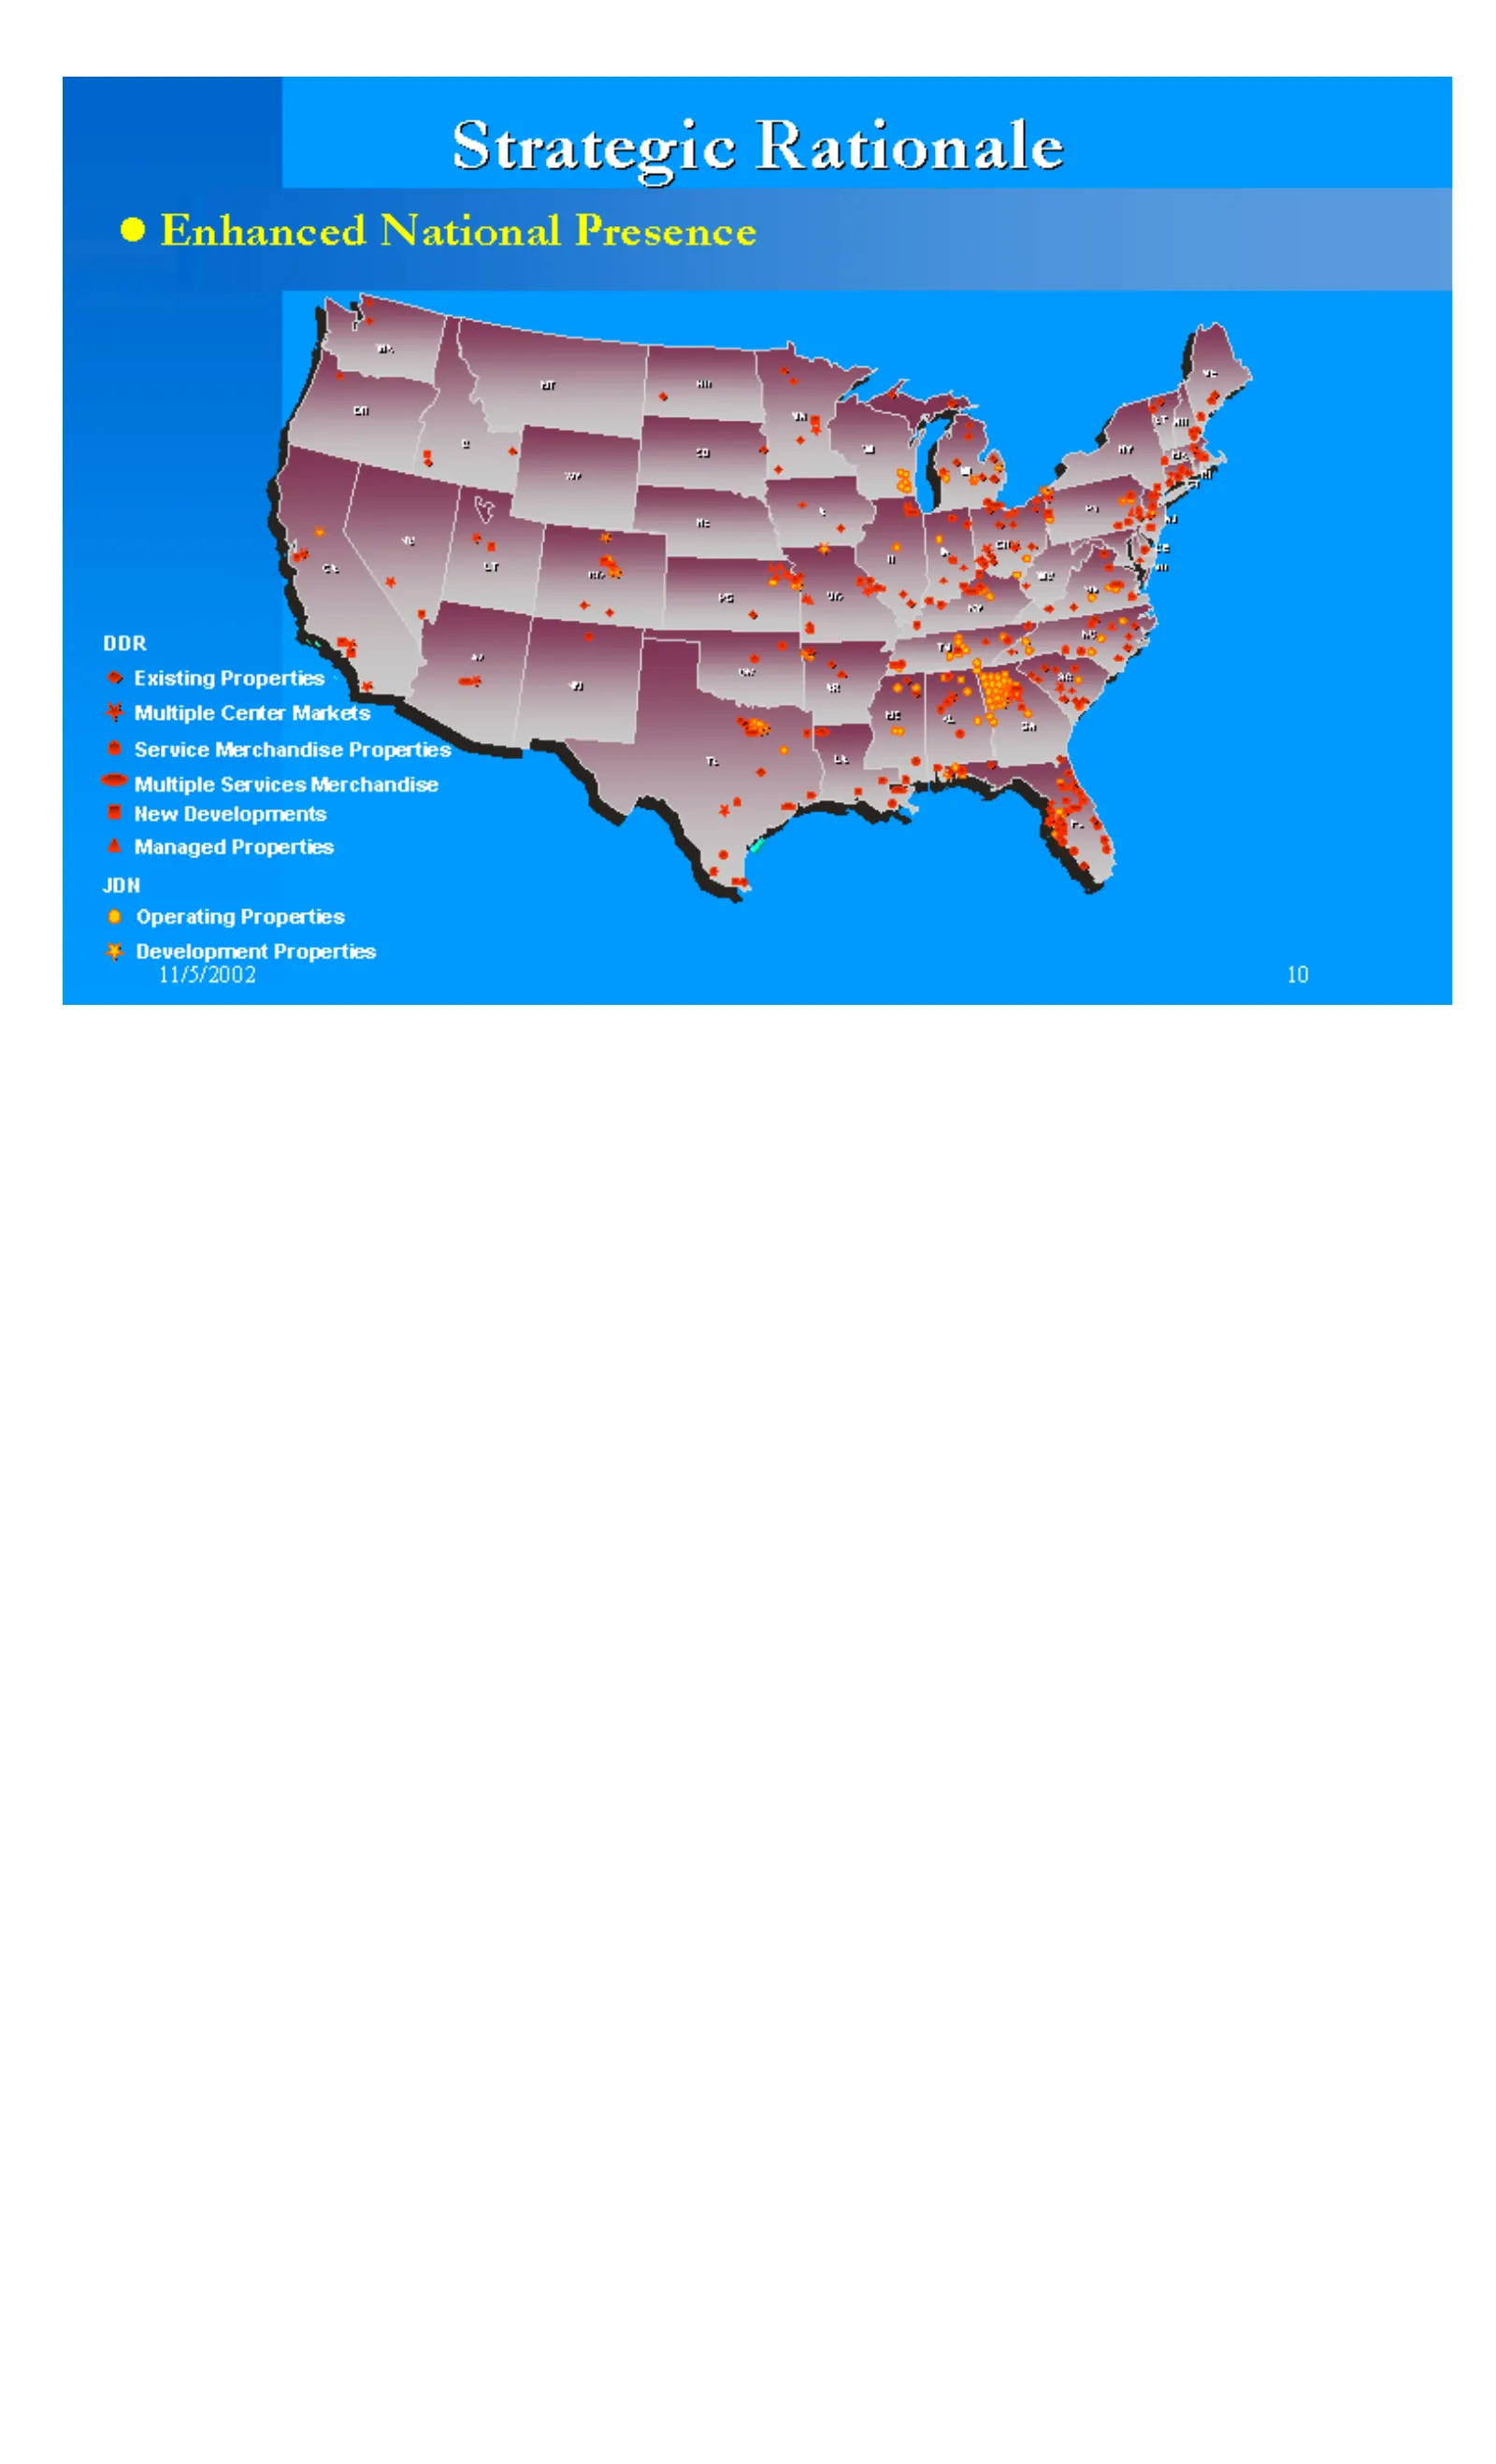
Slide 11: Enhanced National Presence
Strategic Rationale Existing Properties Multiple Center Markets Service Merchandise Properties Multiple Services Merchandise New Developments Managed Properties Operating Properties Development Properties DDR JDN Enhanced National Presence
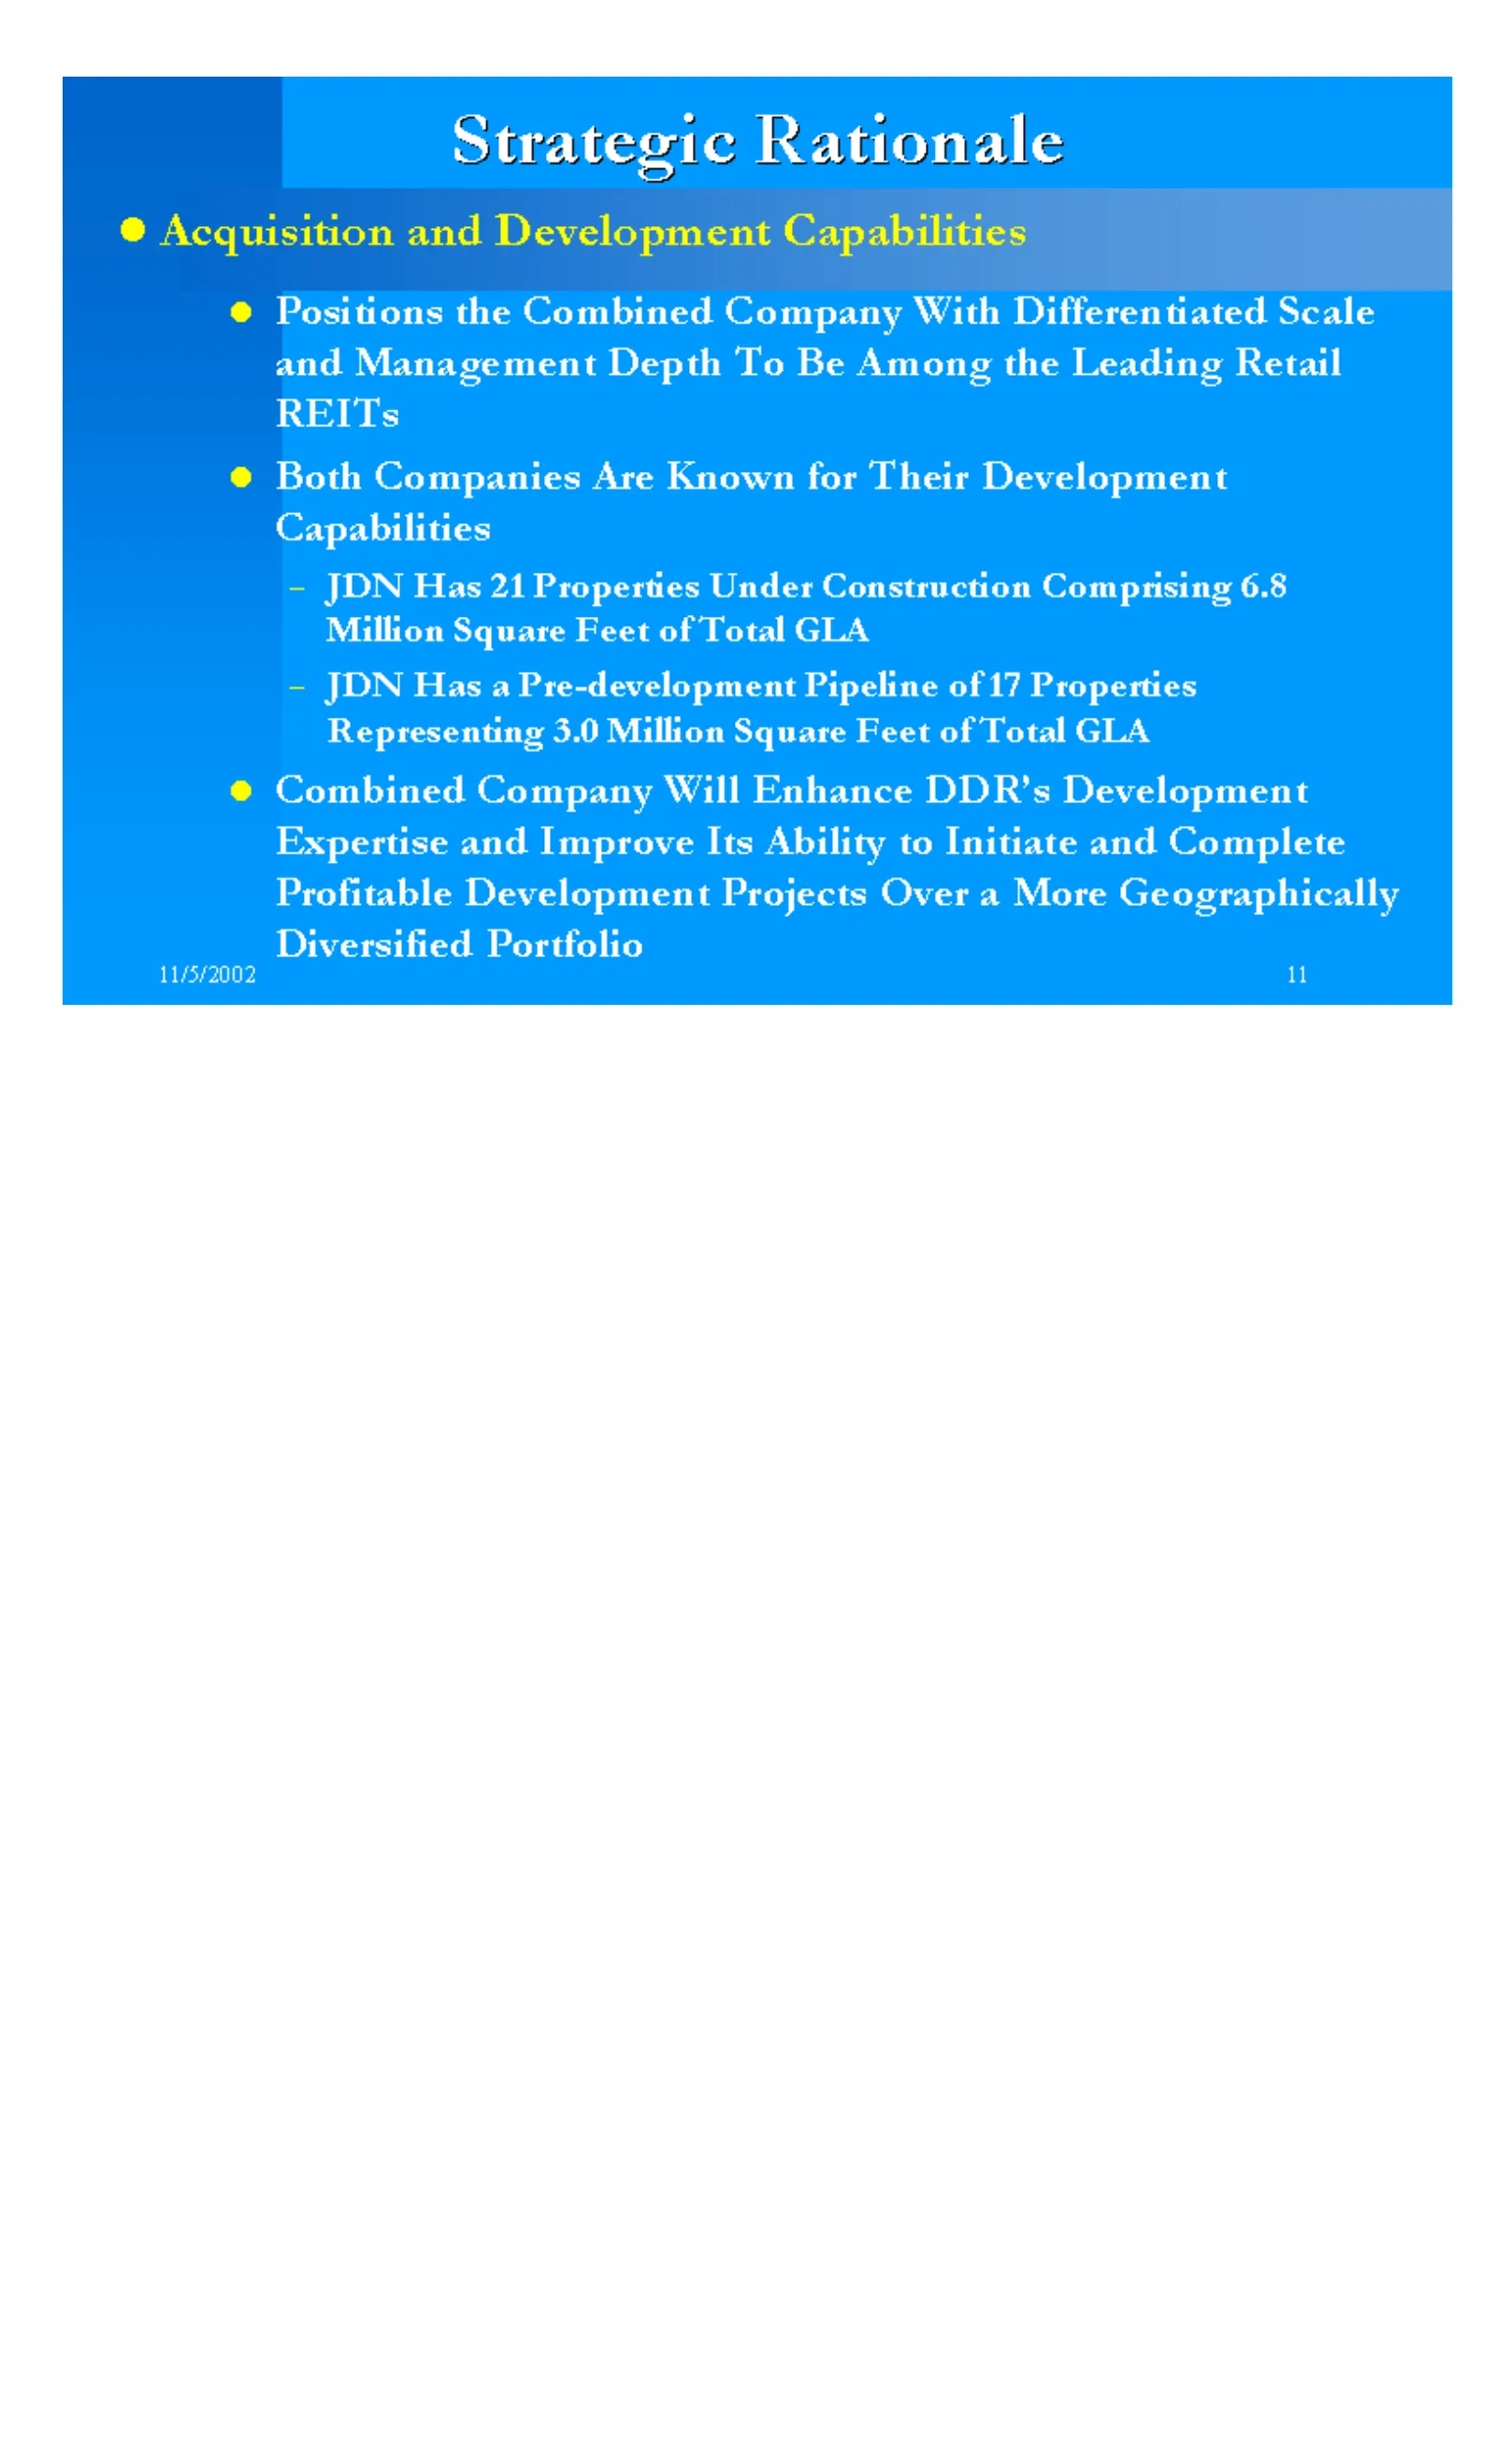
Slide 12: Acquisition and Development Capabilities
Strategic Rationale Positions the Combined Company With Differentiated Scale and Management Depth To Be Among the Leading Retail REITs Both Companies Are Known for Their Development Capabilities JDN Has 21 Properties Under Construction Comprising 6.8 Million Square Feet of Total GLA JDN Has a Pre-de
Slide 13: Increased Liquidity
Strategic Rationale The Trading Volume of the Combined Company is Expected to Be Nearly Five Times JDN’s Existing Trading Volume Increased Liquidity
Slide 14: Cost Synergies
Strategic Rationale Economies of Scale To Be Realized From Merger Provides an Accretive Transaction to JDN’s Shareholders Due to Cost Synergies General and Administrative Savings of $9 Million Interest Expense Savings of $6 Million Significant Development Company Savings as Well Cost Synergies
Slide 15: Accretion in FFO Per Share
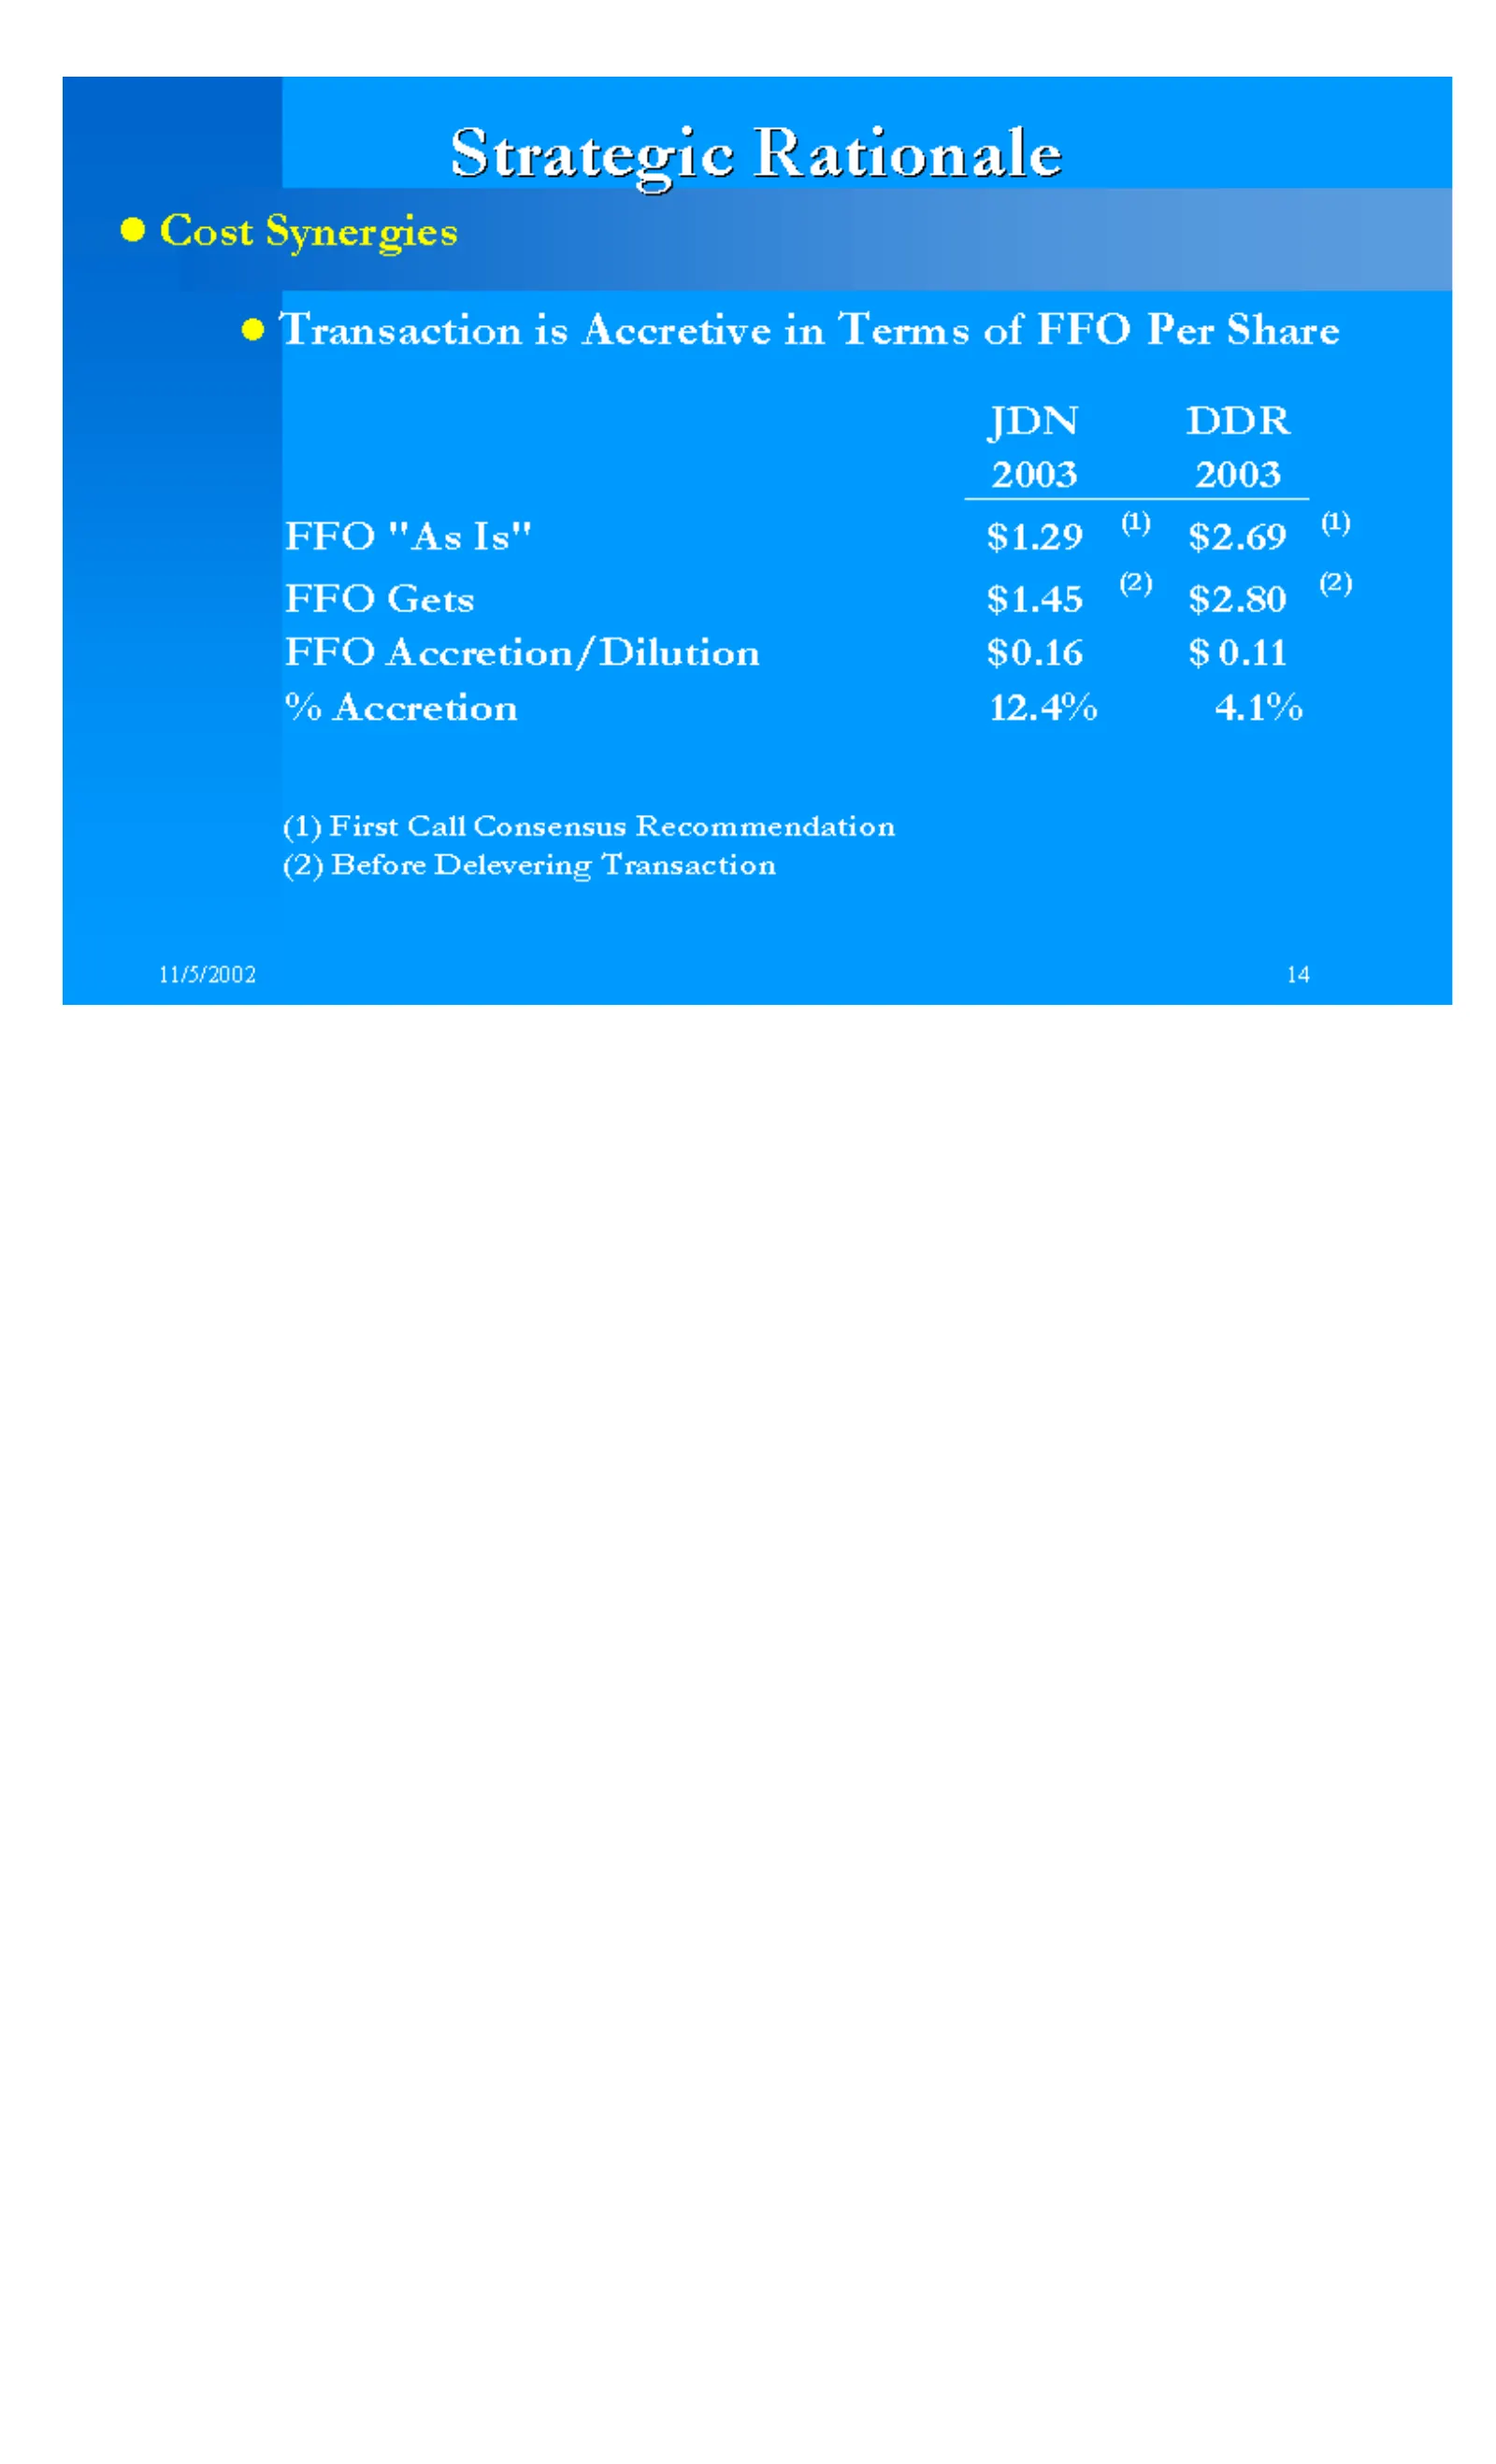
Strategic Rationale Cost Synergies Transaction is Accretive in Terms of FFO Per Share
Slide 16: DDR FFO Per Share Growth Rate
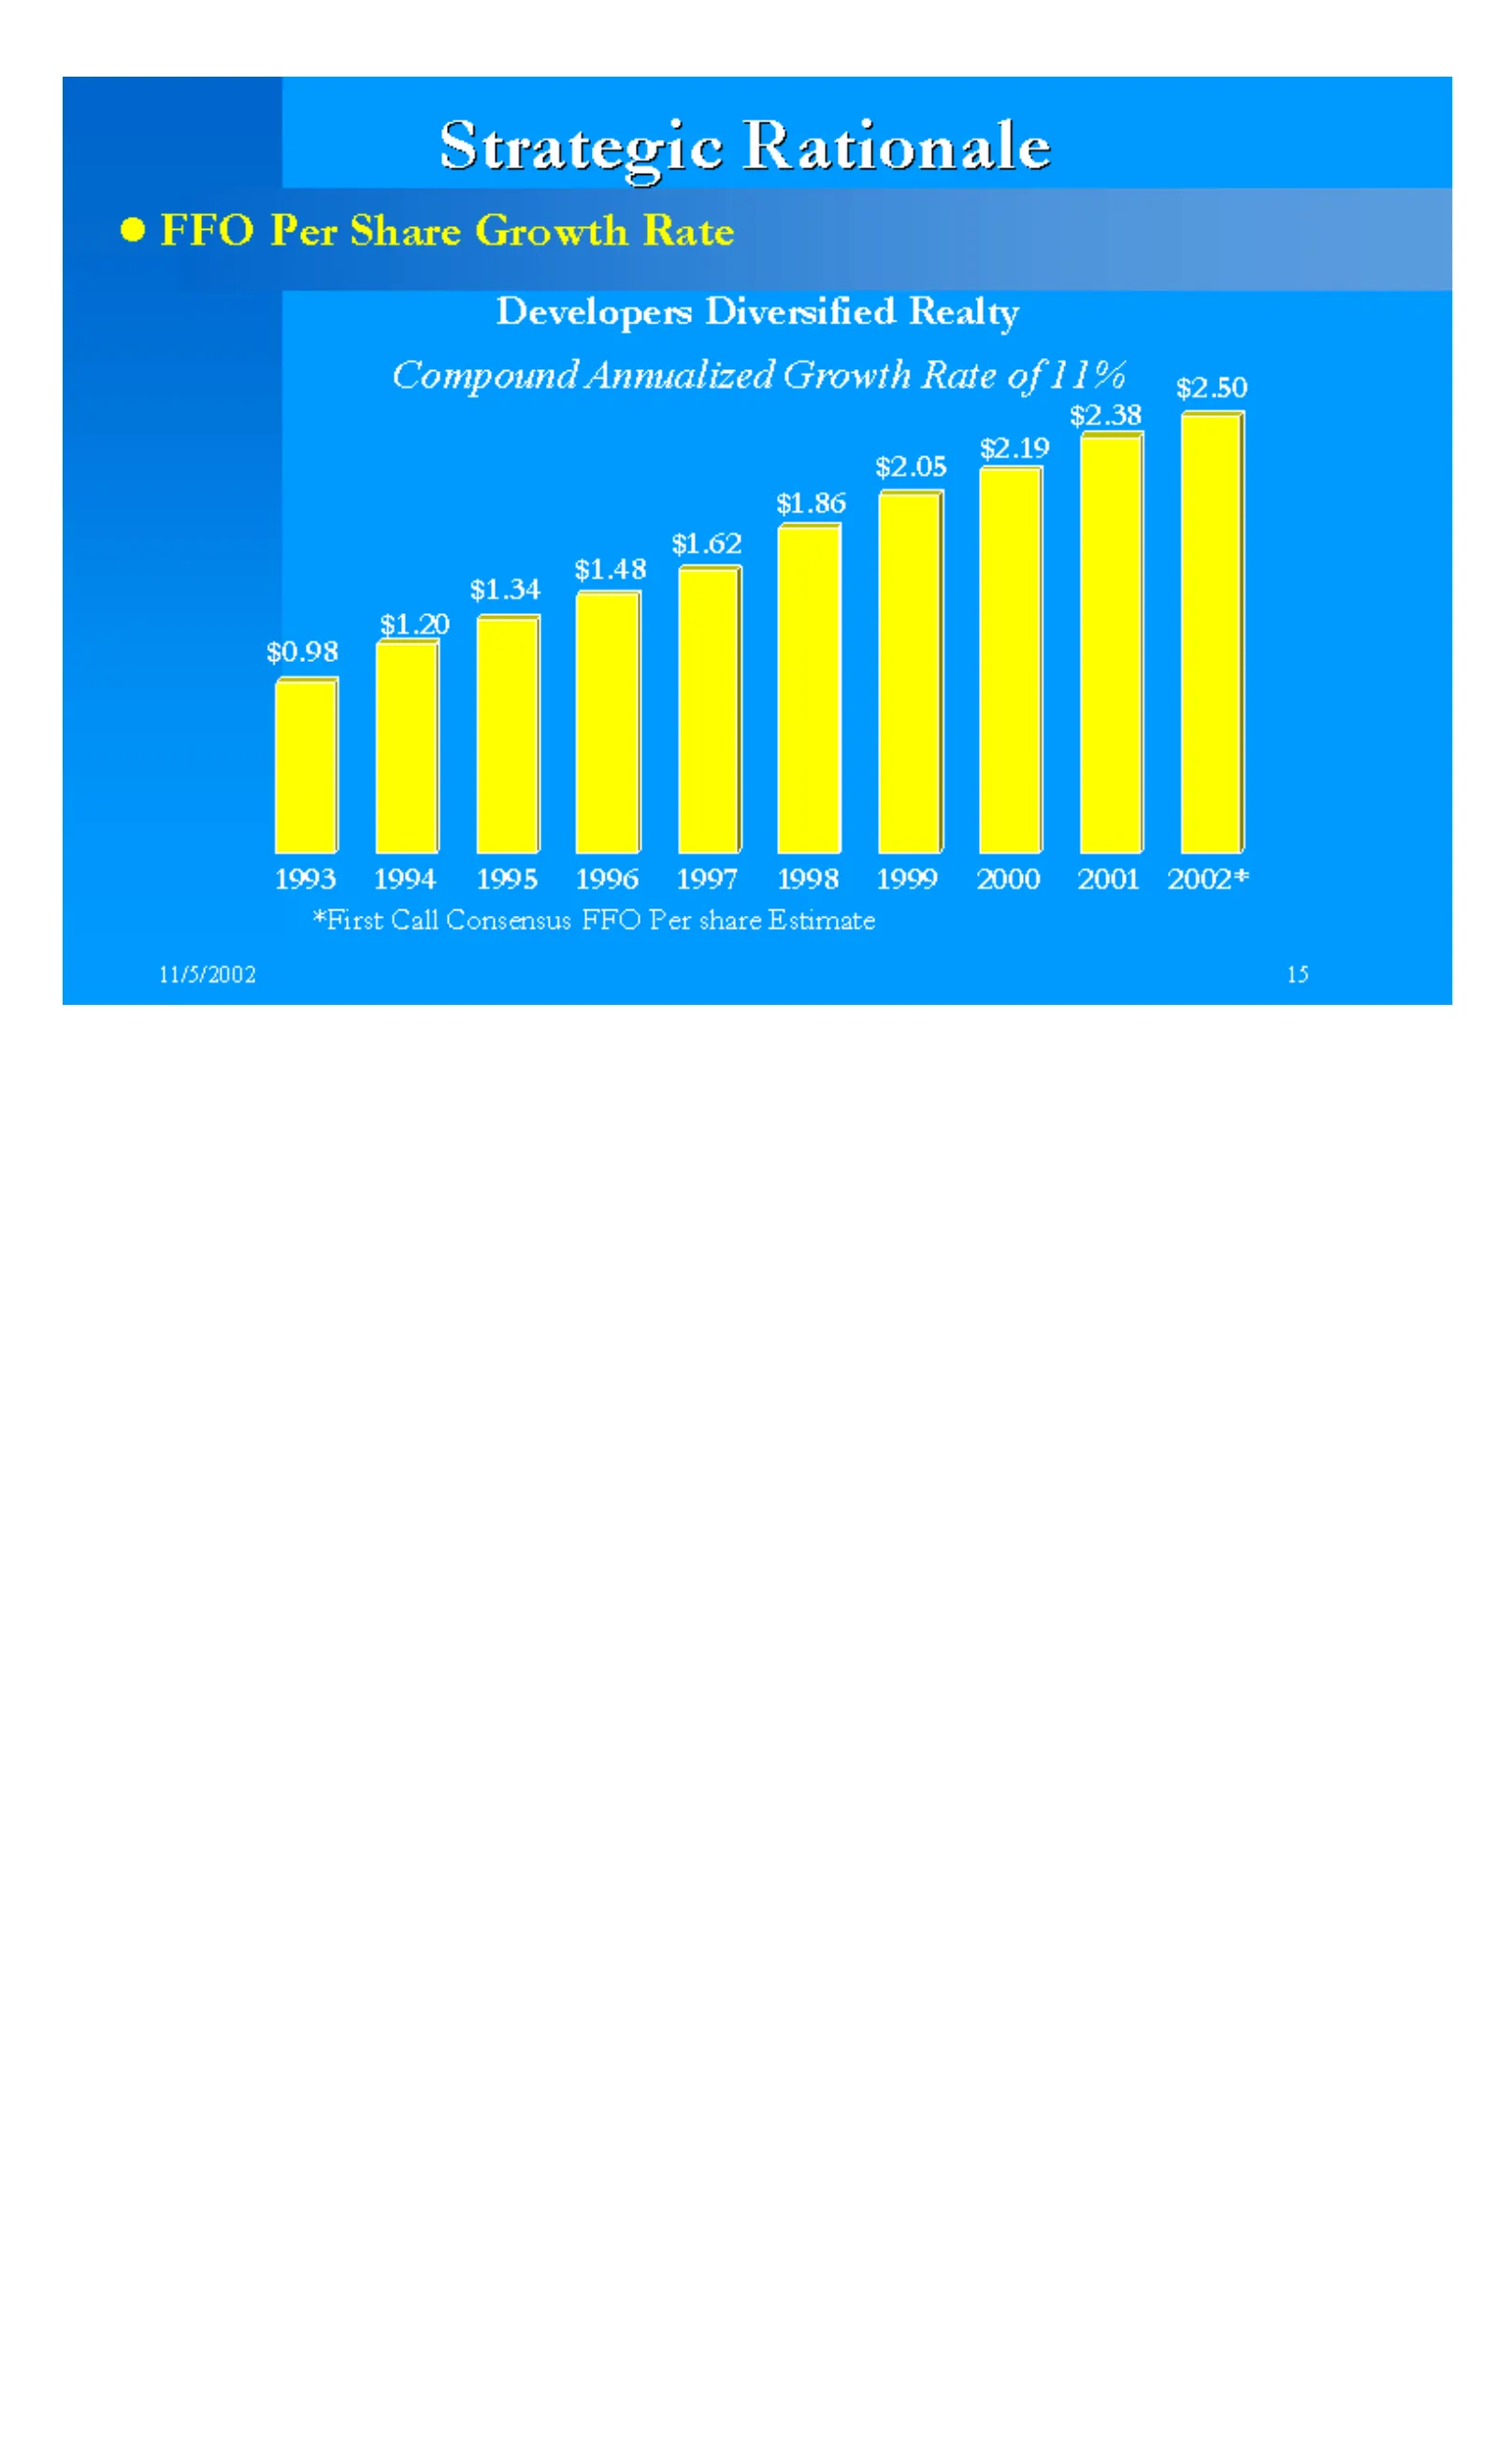
Strategic Rationale 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002* DDR 0.98 1.2 1.34 1.48 1.62 1.86 2.05 2.19 2.38 2.5 Compound Annualized Growth Rate of 11% *First Call Consensus FFO Per share Estimate FFO Per Share Growth Rate Developers Diversified Realty
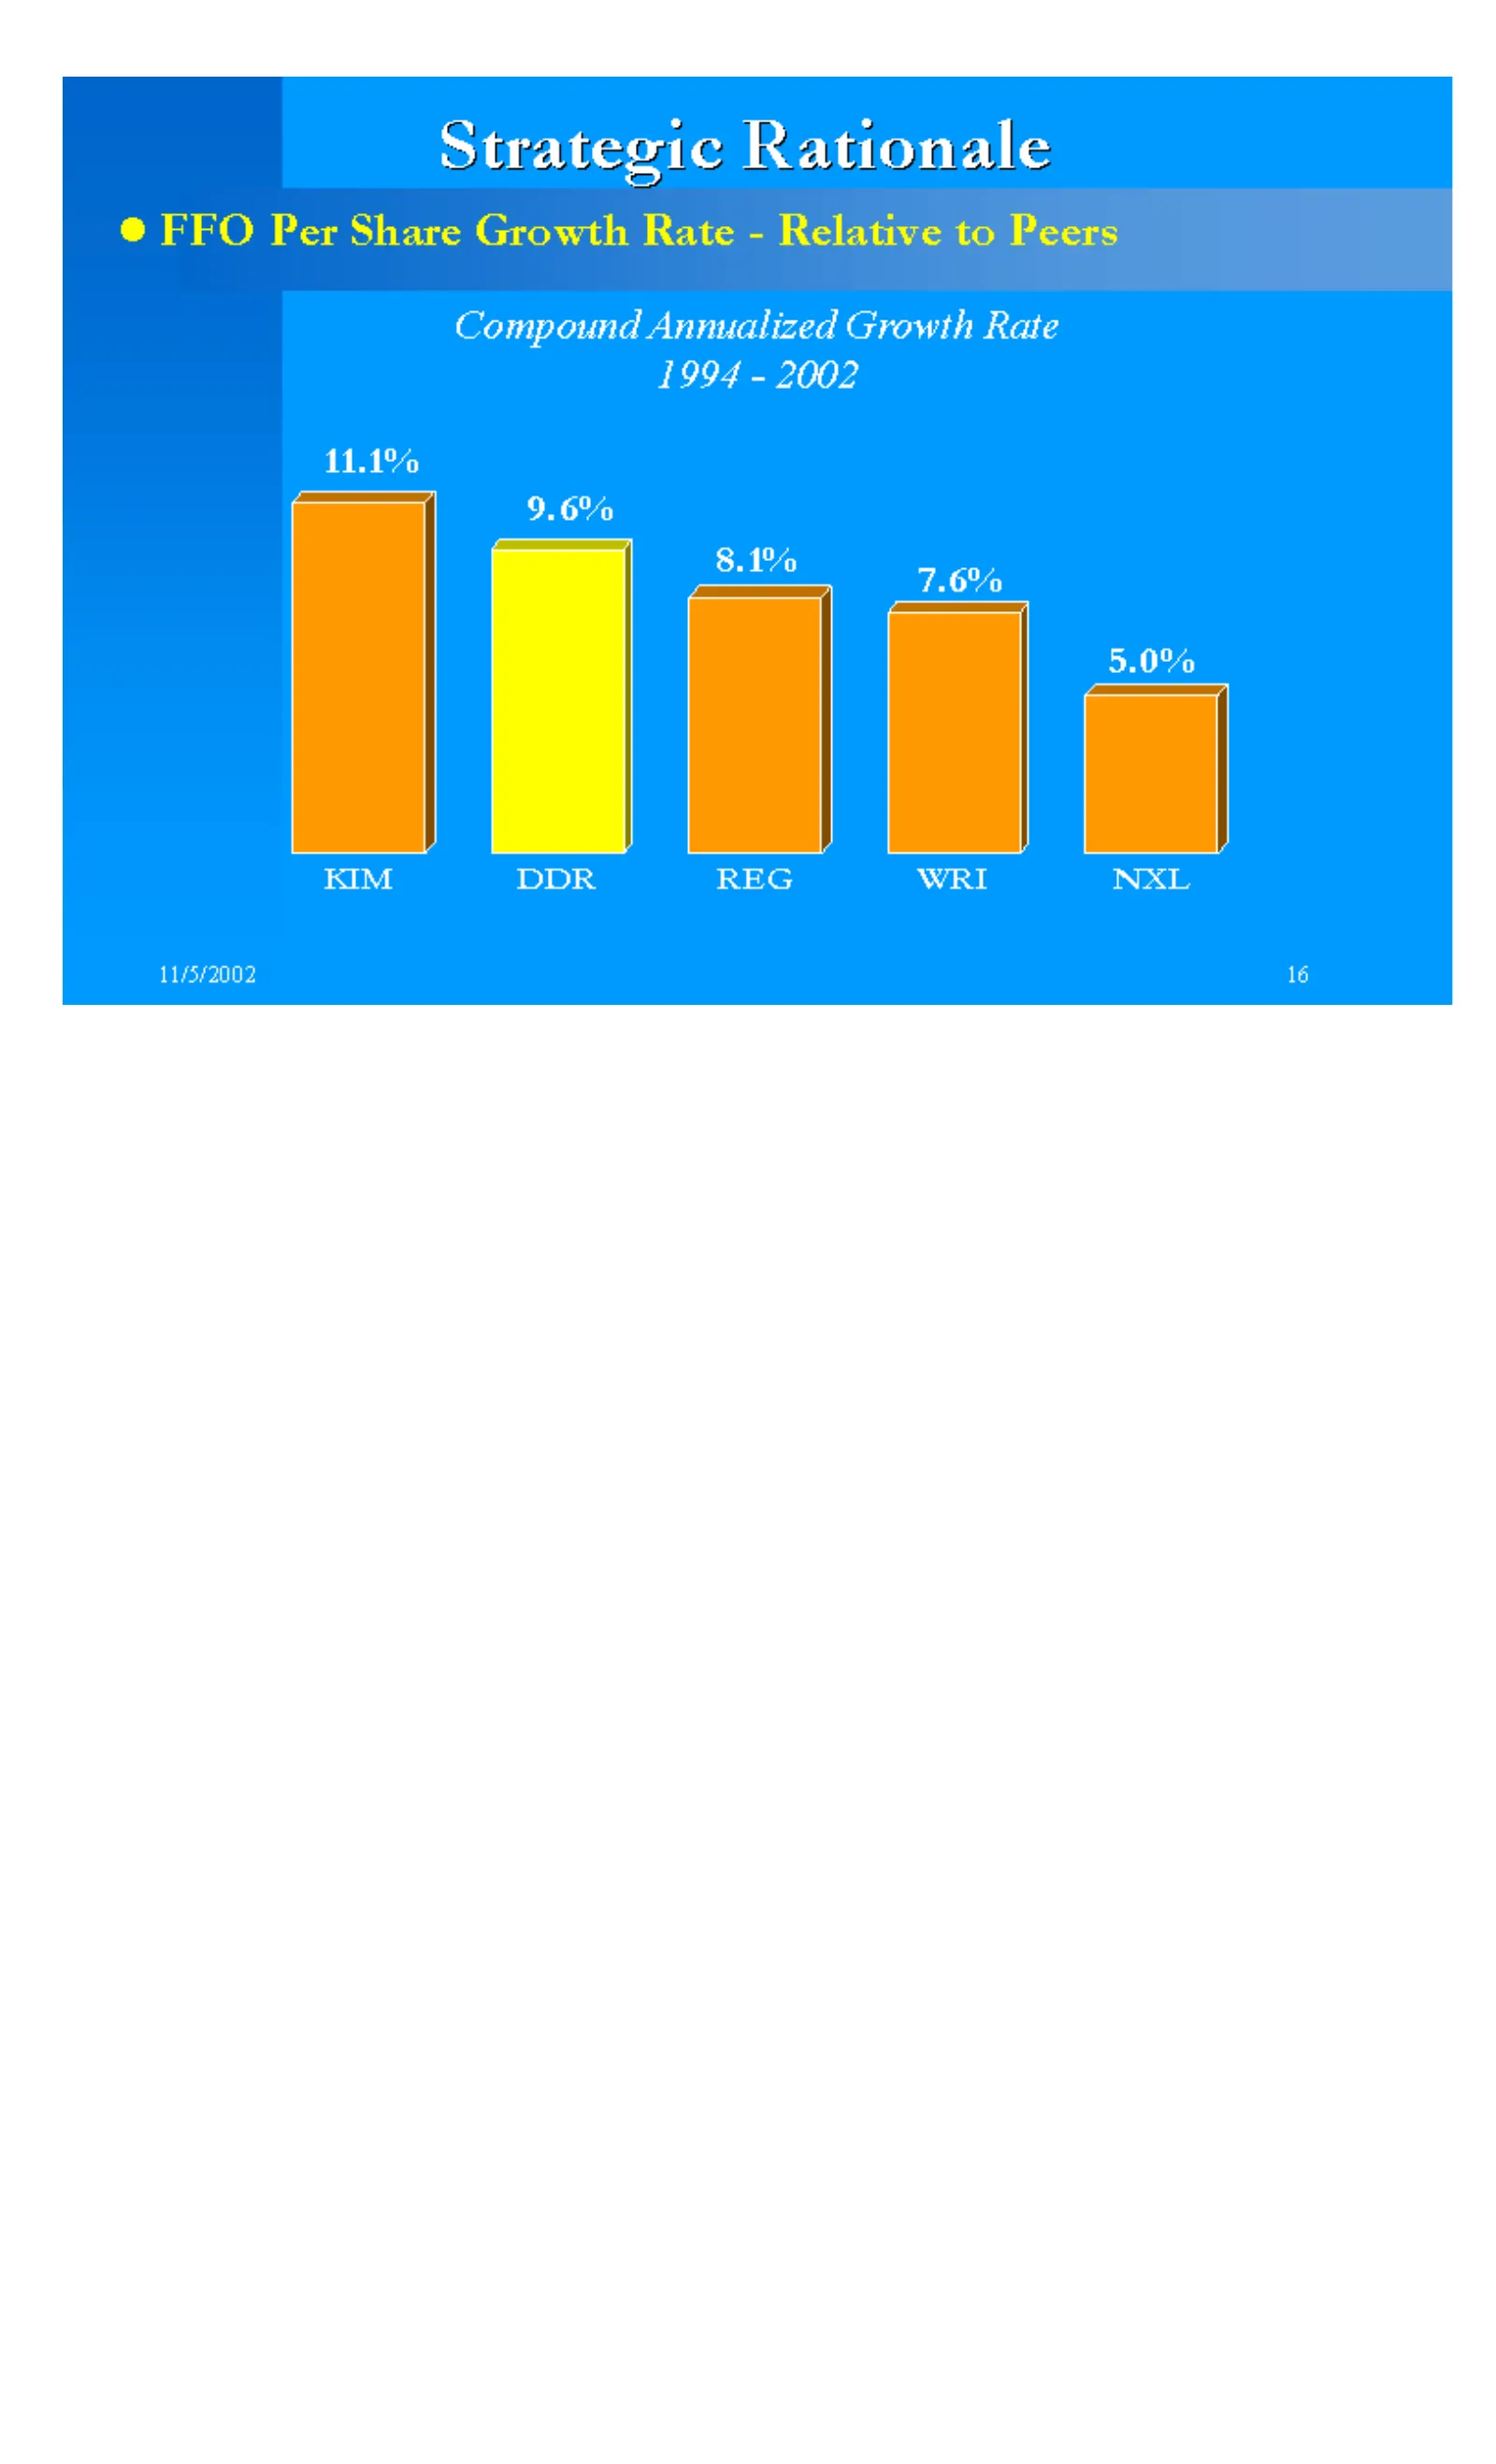
Slide 17: FFO Per Share Growth Rate Relative to Peers
Strategic Rationale KIM DDR REG WRI NXL 0.111 0.096 0.081 0.076 0.05 Compound Annualized Growth Rate 1994 - 2002 FFO Per Share Growth Rate - Relative to Peers
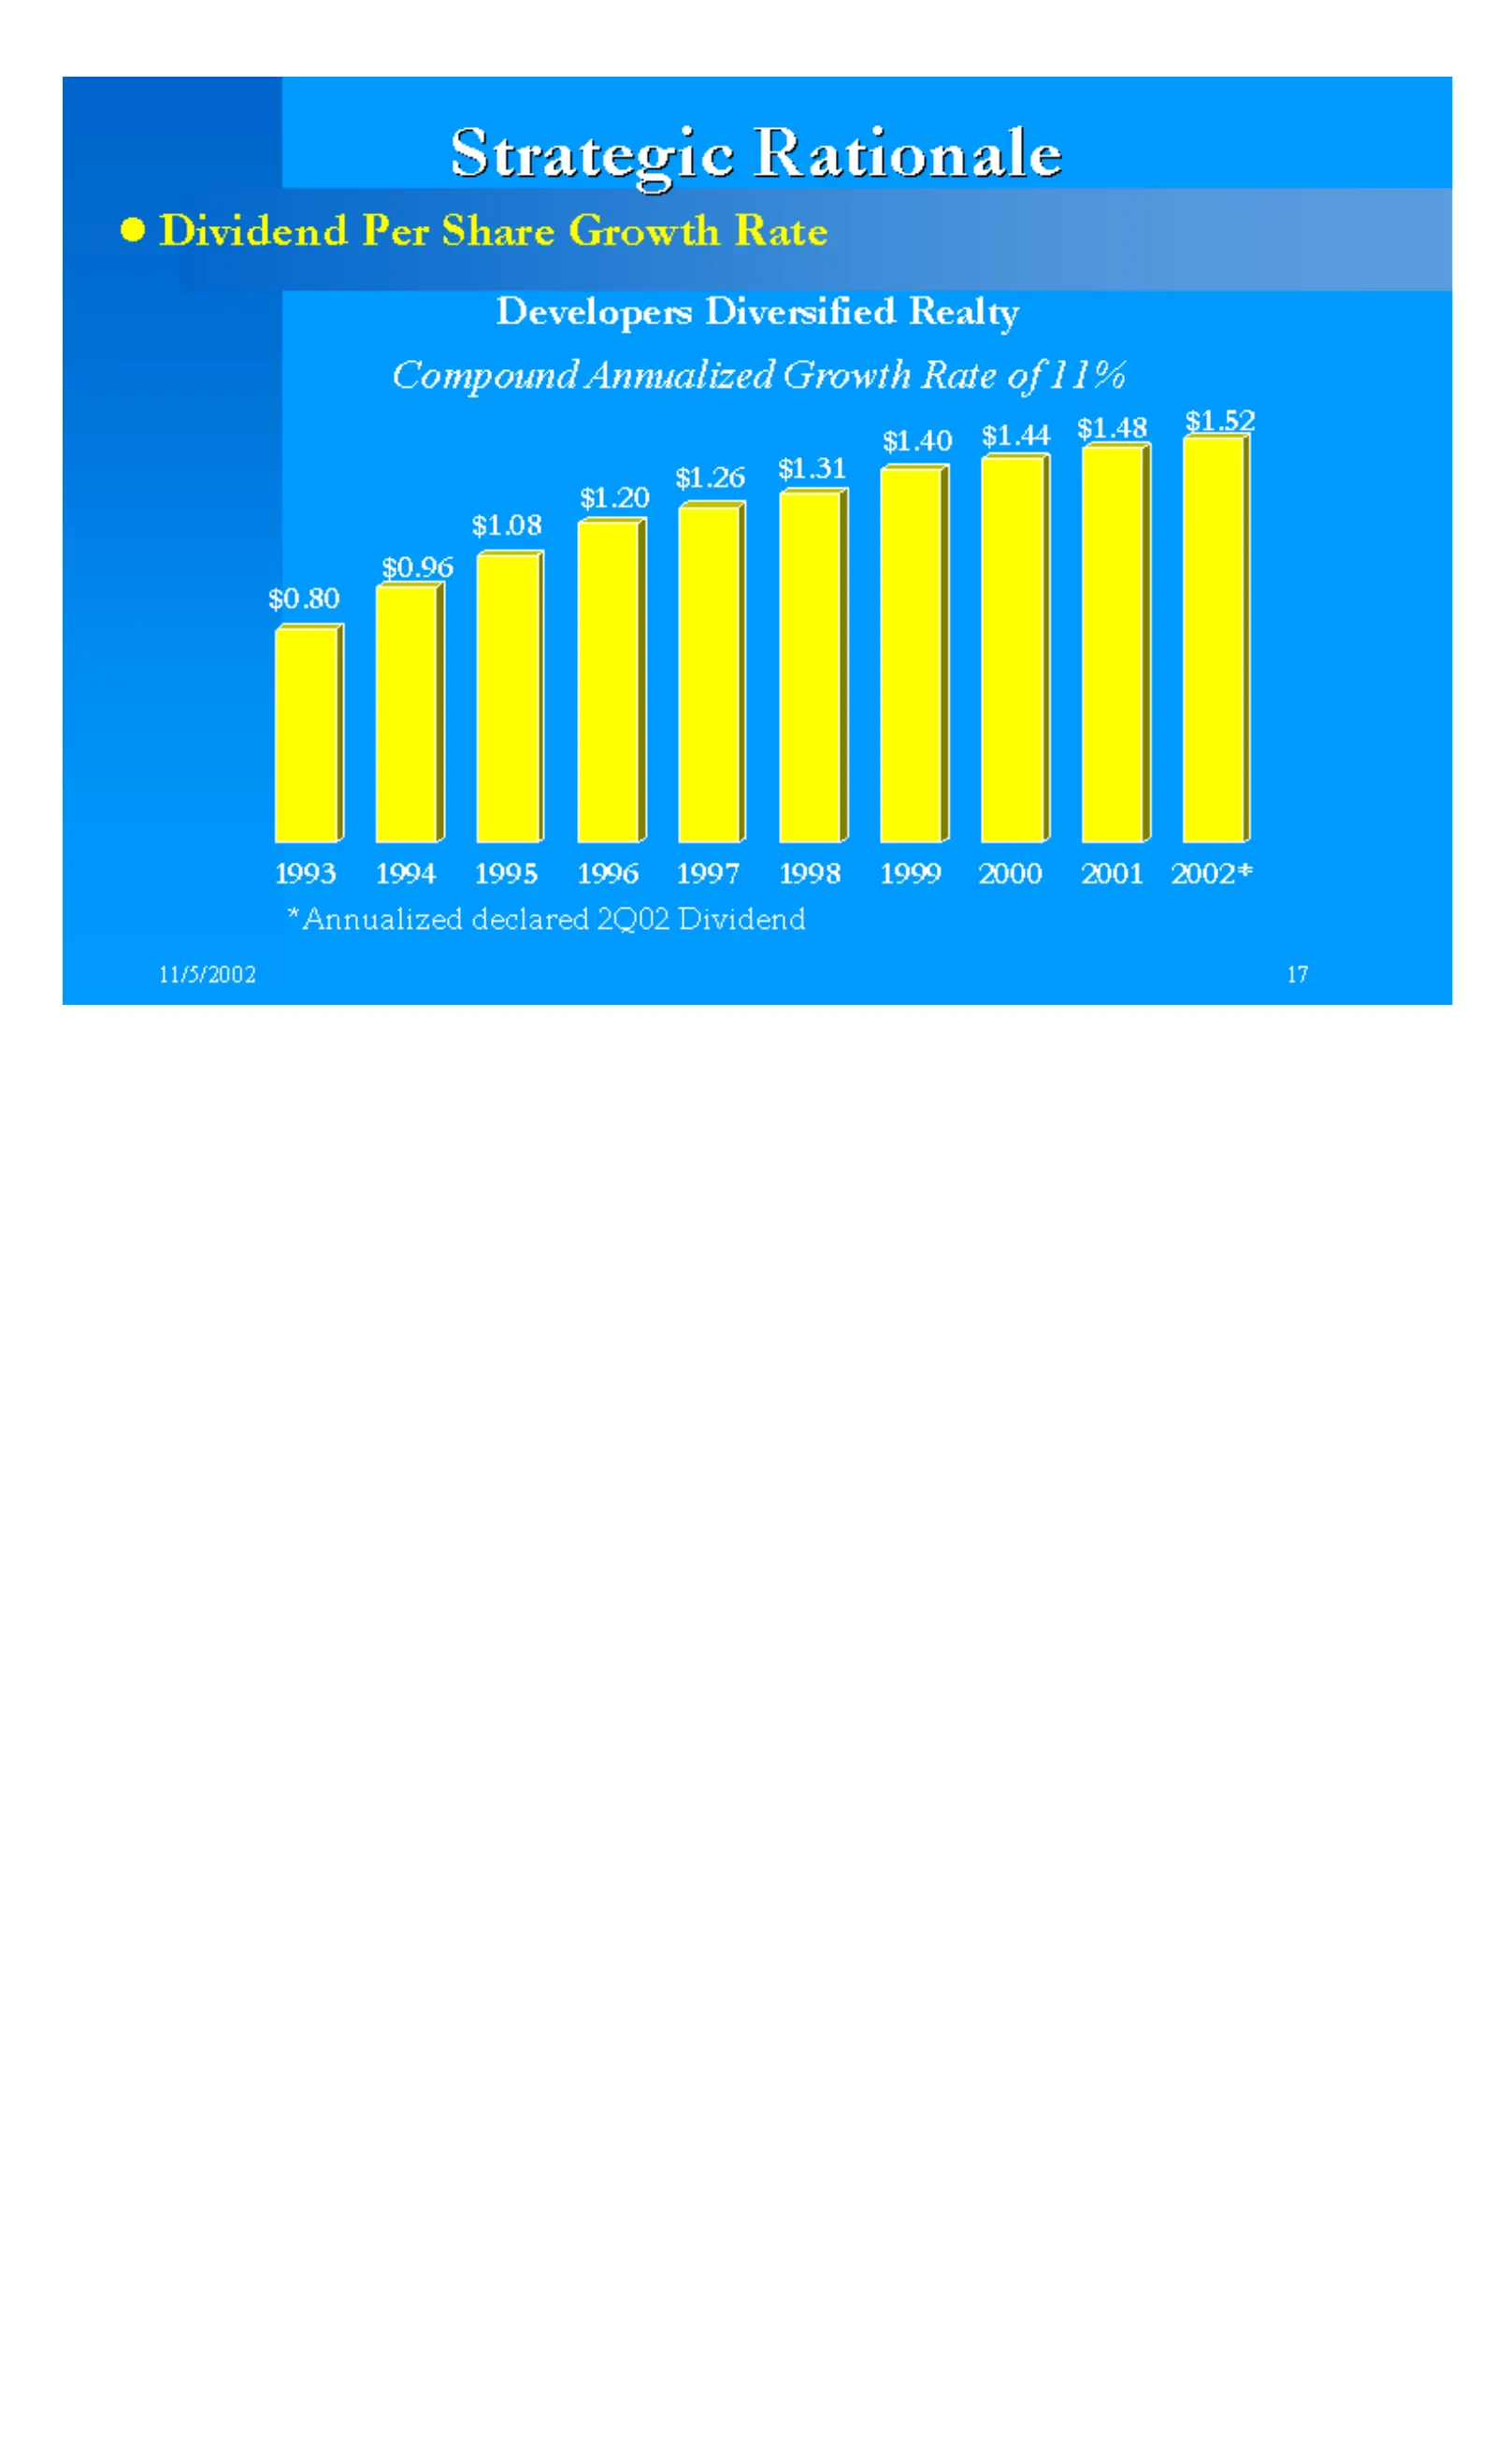
Slide 18: DDR Dividend Per Share Growth Rate
Strategic Rationale 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002* DDR 0.8 0.96 1.08 1.2 1.26 1.31 1.4 1.44 1.48 1.52 *Annualized declared 2Q02 Dividend Dividend Per Share Growth Rate Developers Diversified Realty Compound Annualized Growth Rate of 11%
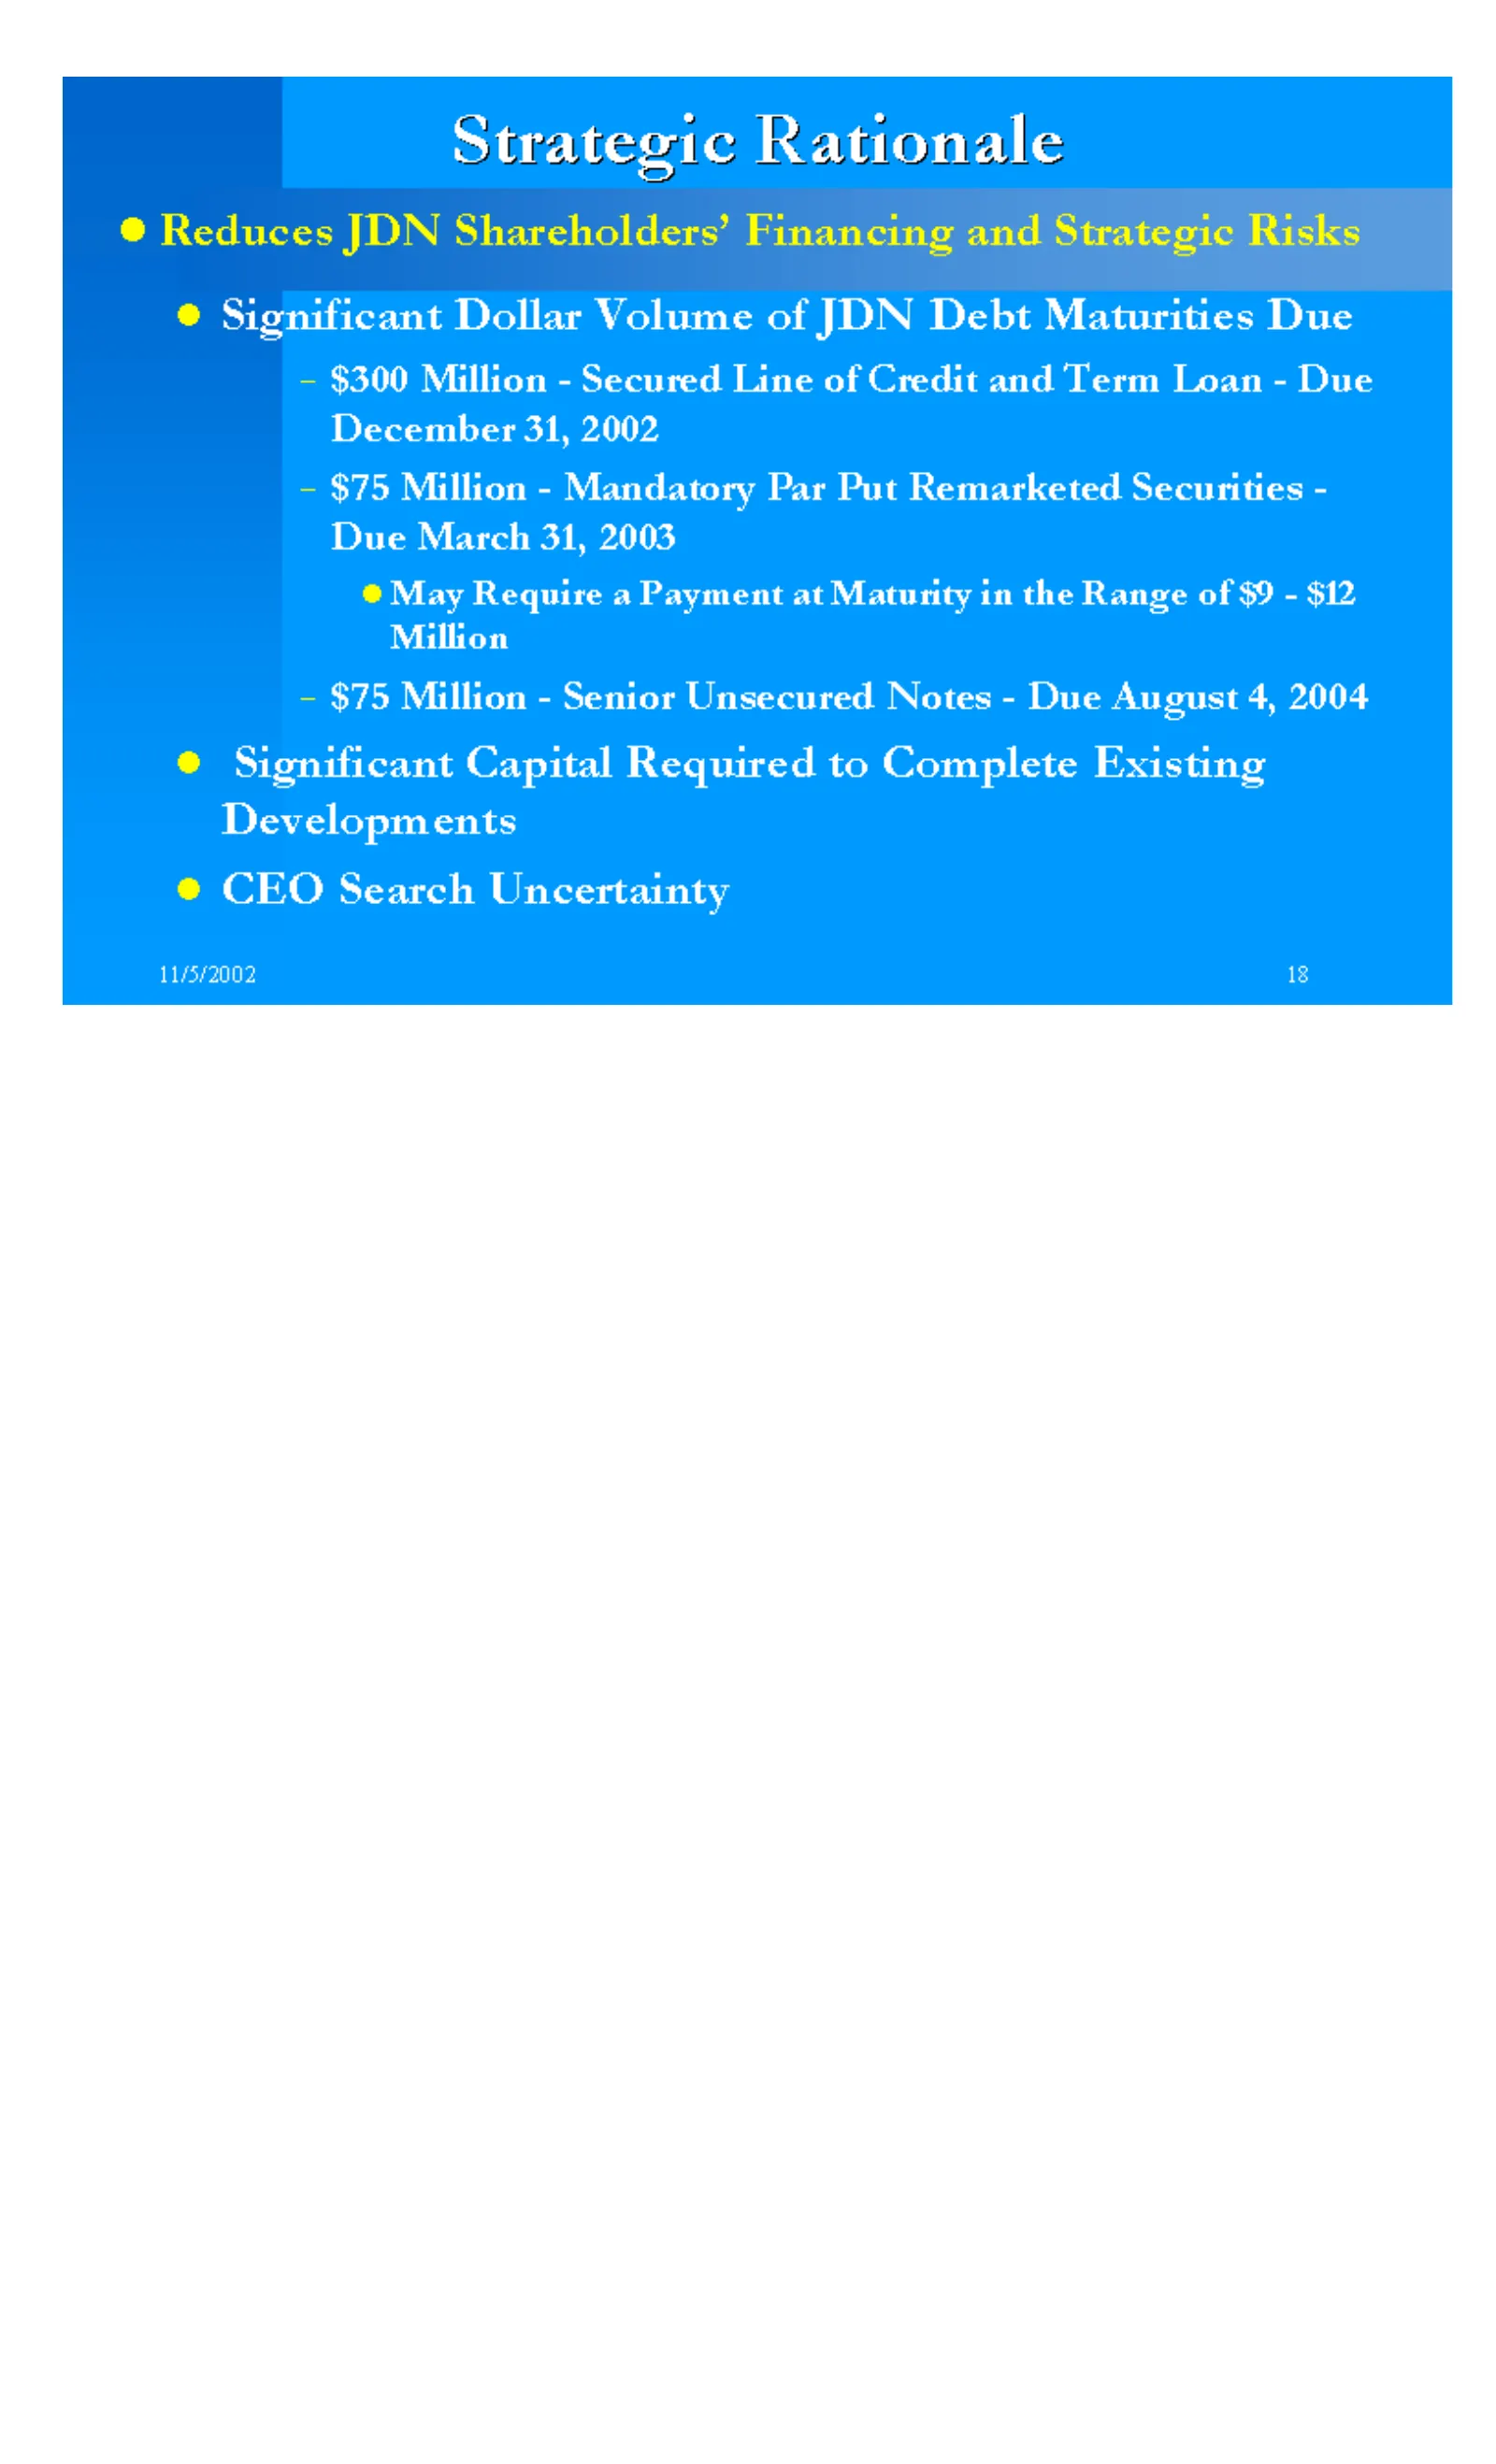
Slide 19: Significant JDN Debt Maturities Due
Strategic Rationale Significant Dollar Volume of JDN Debt Maturities Due $300 Million - Secured Line of Credit and Term Loan - Due December 31, 2002 $75 Million - Mandatory Par Put Remarketed Securities - Due March 31, 2003 May Require a Payment at Maturity in the Range of $9 - $12 Million $75 Milli
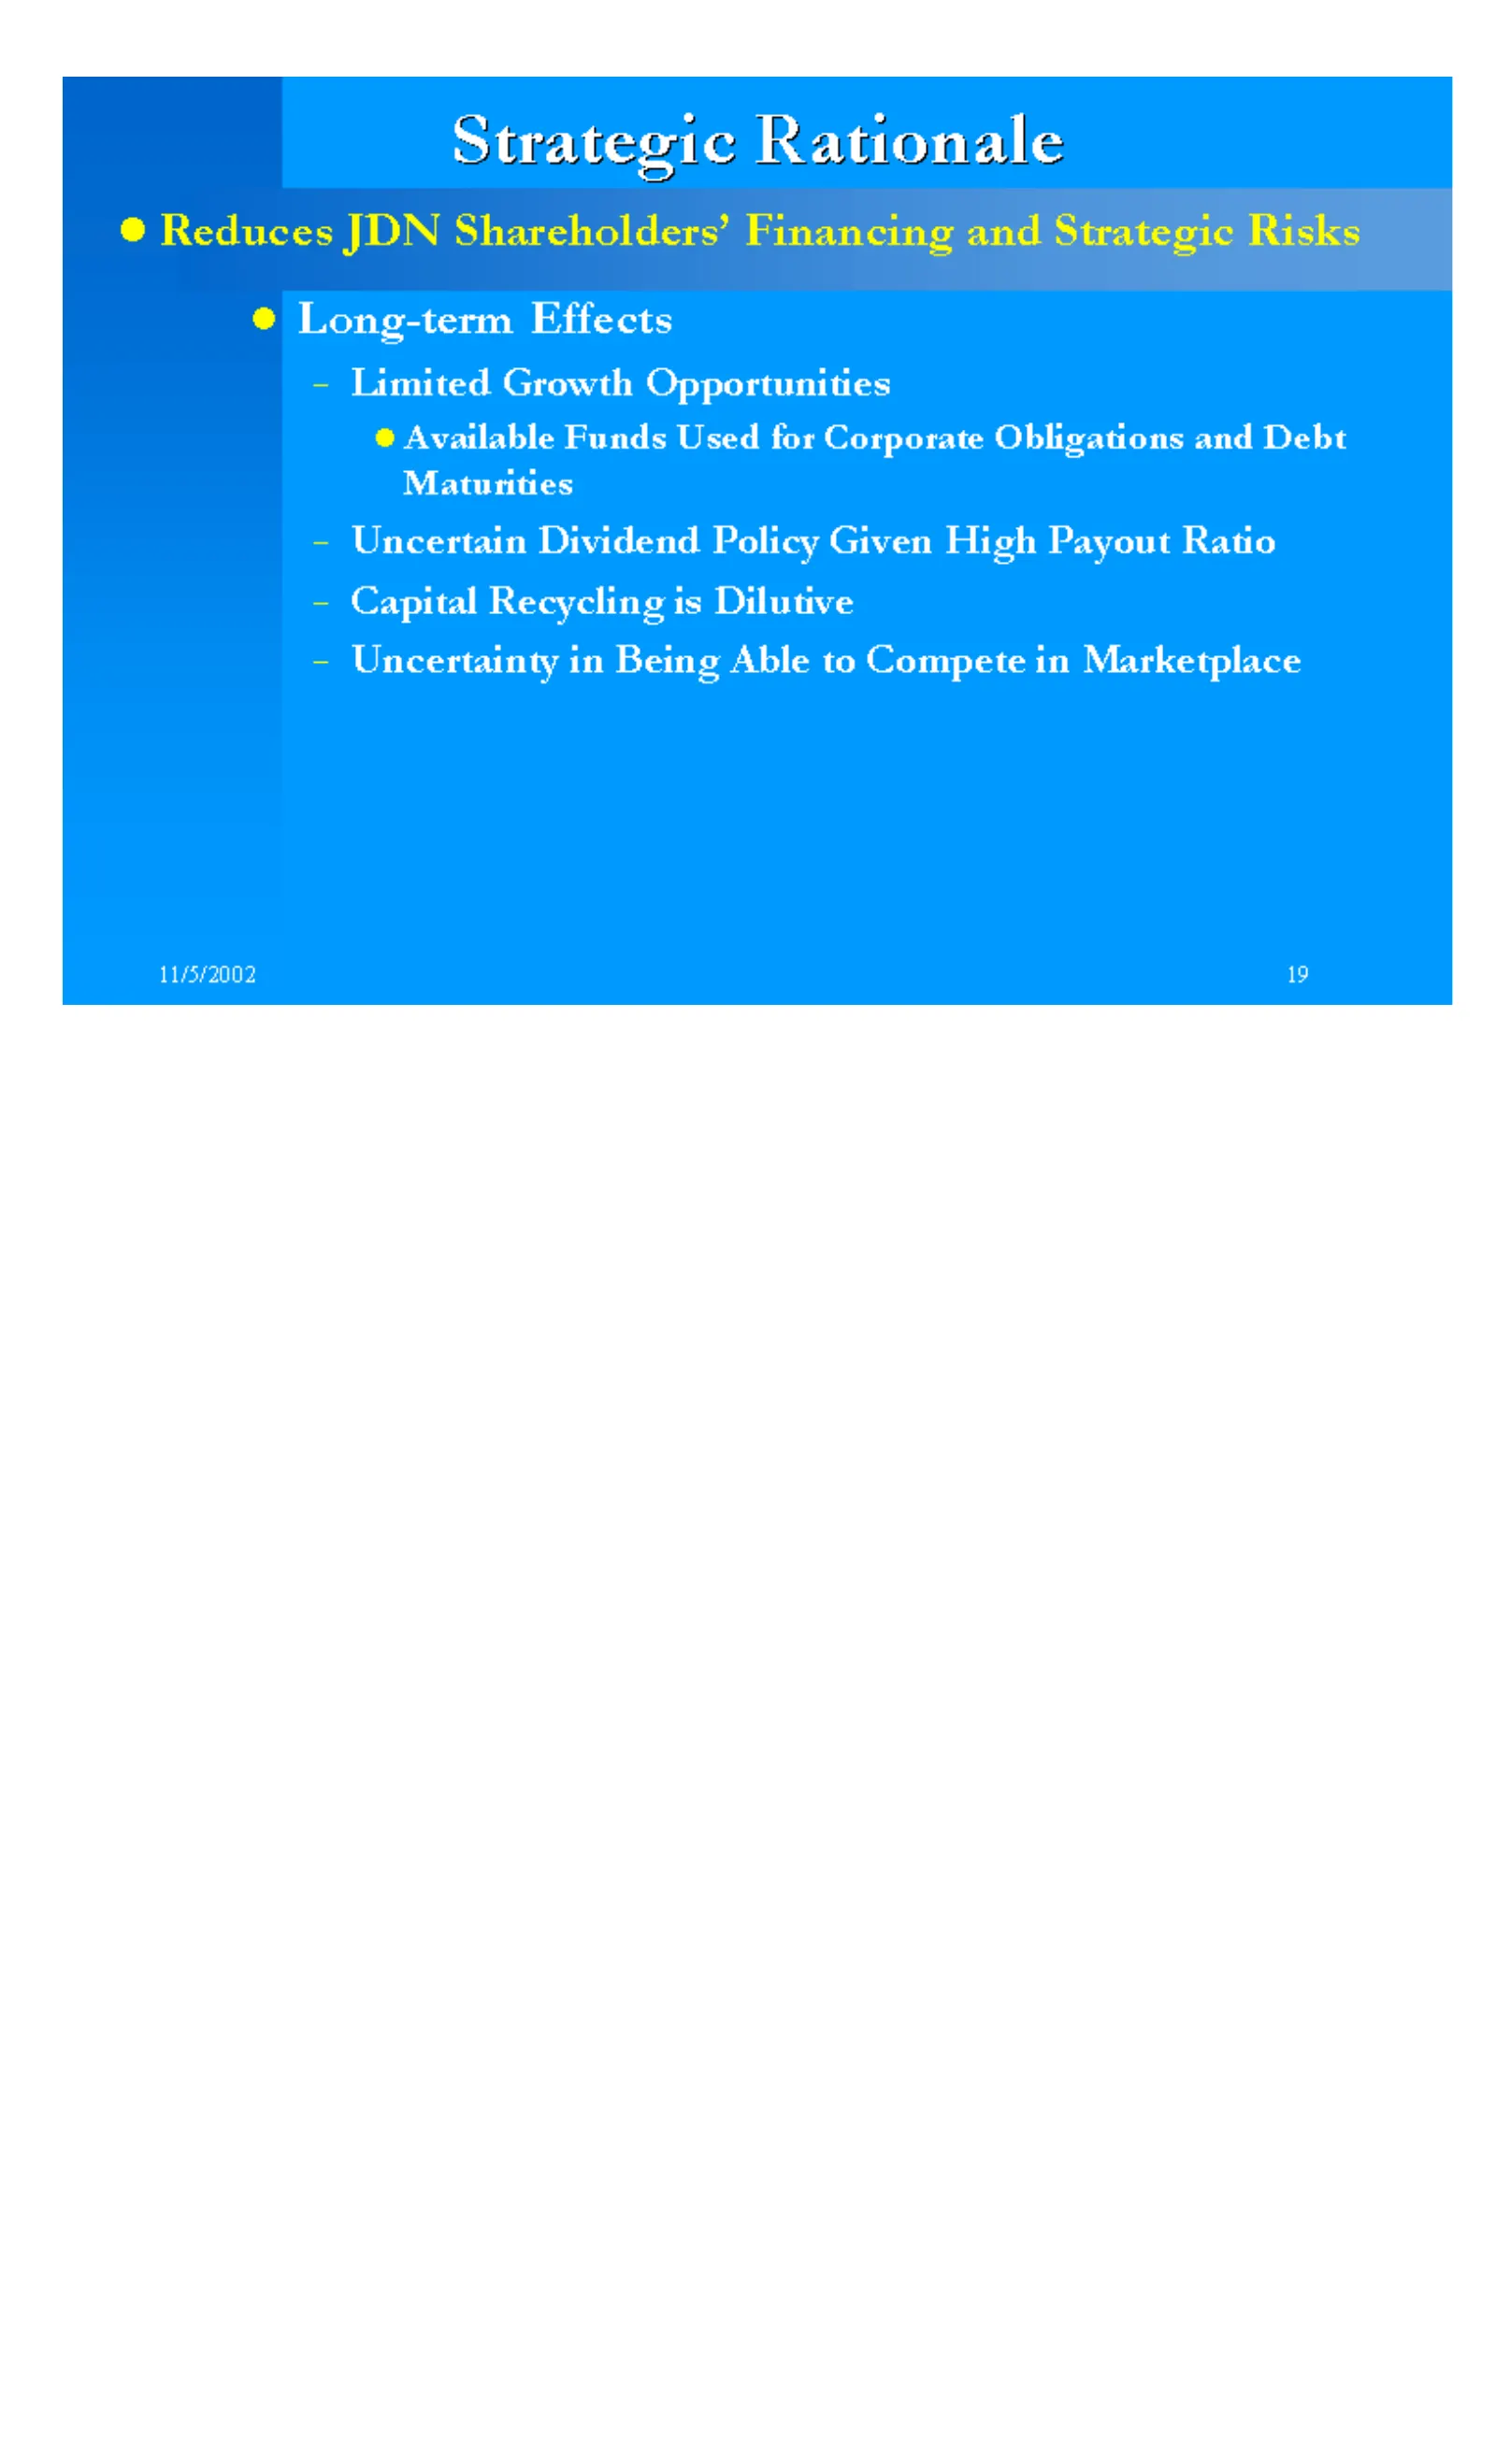
Slide 20: Long-term Effects on JDN
Strategic Rationale Long-term Effects Limited Growth Opportunities Available Funds Used for Corporate Obligations and Debt Maturities Uncertain Dividend Policy Given High Payout Ratio Capital Recycling is Dilutive Uncertainty in Being Able to Compete in Marketplace Reduces JDN Shareholders’ Financin
Slide 21: What JDN's Shareholders Will Get
JDN’s Shareholders Will Get A Company That Has Had Solid Earnings Growth A Company That Has Annually Increased Its Dividend A Company That Has The Development Capabilities To Maximize The Value Of Current Projects A Company That Has a Strong Balance Sheet and Access to the Capital Markets A Company
Slide 22: Forward Looking Statement
Forward Looking Statement JDN Realty Corporation considers the portions of the information contained in this presentation and statements made in connection with this presentation, with respect to the Company’s beliefs and expectations of the outcome of future events, to be forward-looking statements
Slide 23: Forward Looking Statement: Registration Statement and Proxy Information
Forward Looking Statement DDR has filed a registration statement on Form S-4, containing a joint proxy statement/prospectus and other relevant documents concerning the proposed merger transaction between DDR and JDN with the SEC. YOU ARE URGED TO READ THE REGISTRATION STATEMENT CONTAINING THE JOINT
Slide 24: Forward Looking Statement: Participants in Solicitation
Forward Looking Statement DDR and JDN, and their respective directors and executive officers and other members of their management and employees, may be deemed to be participants in the solicitation of proxies from the stockholders of DDR and JDN in connection with the merger. Information about the
Source: SEC EDGAR · 425 filed Nov 6, 2002
More decks from SITE Centers Corp.
 Merger or Acquisition (September 2024)32 slides · Sep 17, 2024
 Q2 2024 Earnings Presentation39 slides · Jul 30, 2024
 Q1 2024 Earnings Presentation28 slides · Apr 30, 2024
 Citi Global Property CEO Conference 202442 slides · March 2024
 Q4 2023 Earnings Presentation29 slides · Feb 13, 2024
 Merger or Acquisition (November 2023)42 slides · Nov 1, 2023