CLEVELAND--(BUSINESS WIRE)-- TFS Financial Corporation (NASDAQ: TFSL) (the "Company"), the holding company for Third Federal Savings and Loan Association of Cleveland (the "Association"), today announced results for the three months and six months ended March 31, 2022.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20220428006194/en/
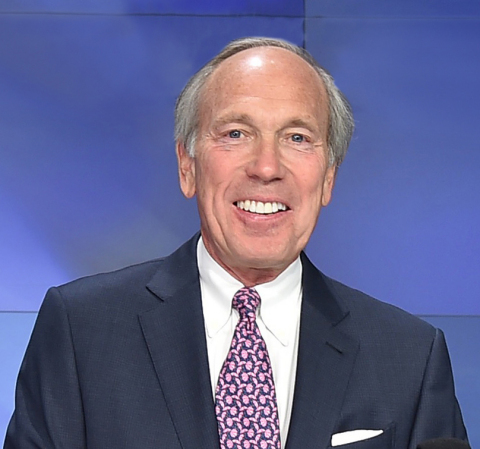
Chairman and CEO Marc A. Stefanski (Photo: Business Wire)
“While we are starting to see the impact of rising interest rates on refinances, our strength and stability allows us to continue our aggressive pursuit of purchase mortgages and equity lines of credit,” said Chairman and CEO, Marc A. Stefanski. "As a result, we’ve had a 50 percent increase in purchases, and a 30 percent increase in equity line originations compared to the first two quarters last year.”
Highlights - Second Quarter Fiscal Year 2022
- Reported net income of $15.8 million
- Continued improvement of net interest margin to 1.82%
- Generated $453 million of loan growth
- Maintained strong asset quality and recorded a $1 million release of provision for credit losses
- Paid a $0.2825 dividend per share
The Company reported net income of $15.8 million for the quarter ended March 31, 2022 compared to net income of $16.1 million for the quarter ended December 31, 2021. Net interest income increased compared to the prior quarter, net gain on sale of loans decreased, non-interest expense increased and there was a decrease in the release of provision for credit losses. Net income of $32.0 million was reported for the six months ended March 31, 2022 compared to net income of $48.0 million for the six months ended March 31, 2021. The change primarily consisted of a decrease in net gain on sale of loans and a decrease in the release of provision for credit losses, partially offset by an increase in net interest income and a decrease in non-interest expense.
Net interest income increased $4.9 million, or 8.5%, to $62.7 million for the quarter ended March 31, 2022 from $57.8 million for the quarter ended December 31, 2021. Net interest income increased by $3.4 million, or 2.9%, to $120.6 million, for the six months ended March 31, 2022 from $117.2 million for the six months ended March 31, 2021. The increases were primarily due to growth in the average balances of loans and decreased costs of funding. Borrowings that matured during the periods were replaced with lower cost funding and the majority of maturing certificates of deposits either repriced at lower interest rates or migrated to lower-priced non-maturity deposits. The interest rate spread for the quarter ended March 31, 2022 was 1.71% compared to 1.57% for the quarter ended December 31, 2021 and 1.54% for the quarter ended March 31, 2021. The net interest margin was 1.82%, 1.69%, and 1.67% for the quarters ended March 31, 2022, December 31, 2021 and March 31, 2021, respectively.
During the quarter ended March 31, 2022, there was a $1.0 million release of provision from the allowance for credit losses, bringing the total release of provision to $3.0 million for the six months ended March 31, 2022. A $6.0 million release of provision was recorded for the six months ended March 31, 2021. During both current and prior year periods, releases of provisions were primarily due to recoveries exceeding charge-offs and improvements in the economic trends and forecasts used to estimate credit losses for the reasonable and supportable periods. The allowance for credit losses was $90.9 million, or 0.69% of total loans receivable, at March 31, 2022 and included a $26.6 million liability for unfunded commitments. At September 30, 2021, the allowance for credit losses was $89.3 million, or 0.71% of total loans receivable and included a $25.0 million liability for unfunded commitments. The Company recorded $2.7 million and $4.7 million of net loan recoveries for the quarter and six months ended March 31, 2022, respectively, compared to $1.4 million and $2.6 million of net loan recoveries for the quarter and six months ended March 31, 2021, respectively.
Total loan delinquencies decreased $2.1 million to $22.9 million, or 0.17% of total loans receivable, at March 31, 2022 from $25.0 million, or 0.20% of total loans receivable, at December 31, 2021 and decreased $1.8 million from $24.7 million at September 30, 2021. Non-accrual loans decreased $4.1 million to $39.3 million, or 0.30% of total loans, at March 31, 2022 from $43.4 million at December 31, 2021 and decreased $4.7 million from $44.0 million, or 0.35% of total loans, at September 30, 2021.
Non-interest income decreased $2.6 million to $5.6 million for the quarter ended March 31, 2022 from $8.2 million for the quarter ended December 31, 2021. The decrease was primarily due to a $2.1 million decrease in net gain on the sale of loans and a $0.7 million decrease in death benefits from bank owned life insurance contracts. Non-interest income decreased $23.5 million to $13.7 million for the six months ended March 31, 2022 from $37.2 million for the six months ended March 31, 2021, mainly due to a decrease in the net gain on the sale of loans. There were $101.7 million of loans sold at a net gain of $2.3 million during the six months ended March 31, 2022 compared to $517.5 million of loans sold at a net gain of $25.4 million during the six months ended March 31, 2021.
Total non-interest expense increased $2.3 million, to $50.0 million for the quarter ended March 31, 2022, from $47.7 million for the quarter ended December 31, 2021. The increase was spread between marketing expense, third-party costs on loan originations and compensation expense. Total non-interest expense decreased $2.9 million, to $97.6 million for the six months ended March 31, 2022, from $100.5 million for the six months ended March 31, 2021. The decrease mainly consisted of a $2.7 million decrease in other operating expenses and a $1.6 million decrease in compensation expense, partially offset by a $1.1 million increase in marketing costs. The decrease in other operating expenses included a $1.6 million positive variance related to actuarial calculations on the defined benefit plan and a $1.1 million decrease in third-party costs for loan originations.
Total assets increased by $523.4 million, or 3.7%, to $14.58 billion at March 31, 2022 from $14.06 billion at September 30, 2021. This change was mainly the result of new loan origination levels exceeding the total of loan sales and principal repayments, partially offset by a decrease in cash and cash equivalents.
Cash and cash equivalents decreased $117.6 million, or 24%, to $370.7 million at March 31, 2022 from $488.3 million at September 30, 2021. The decrease can be attributed to the reinvestment of liquid assets into loan products.
Loans held for investment, net of allowance and deferred loan expenses, increased $626.9 million, or 5.0%, to $13.14 billion at March 31, 2022 from $12.51 billion at September 30, 2021, primarily due to the level of loans originated and held for investment. The residential core mortgage loan portfolio increased $451.5 million, to $10.73 billion, and home equity loans and lines of credit increased $161.2 million, to $2.38 billion, during the six months ended March 31, 2022. Total first mortgage loan originations were $1.74 billion for the six months ended March 31, 2022 and $2.06 billion for the six months ended March 31, 2021 and included $587.0 of purchase originations during the current fiscal year-to-date period compared to $392.2 million during the same period last year. New equity line of credit commitments were $1.03 billion and $786.3 million, respectively, for the six months ended March 31, 2022 and March 31, 2021.
Deposits increased $14.7 million, or less than 1%, to $9.01 billion at March 31, 2022 from $8.99 billion at September 30, 2021. The increase was the result of a $271.8 million increase in checking accounts and a $72.8 million increase in savings accounts, partially offset by a $317.4 million decrease in certificates of deposit ("CDs") and a $11.7 million decrease in money market deposit accounts for the six months ended March 31, 2022. Total deposits included $453.9 million and $492.0 million of brokered CDs and $200.0 million and $0 of brokered checking accounts at March 31, 2022 and September 30, 2021, respectively. Brokered checking accounts were added during the quarter ended March 31, 2022, as an alternative source of funding in the management of interest rate risk.
Borrowed funds, all from the FHLB, increased $463.5 million, or 15.0%, to $3.56 billion at March 31, 2022 from $3.09 billion at September 30, 2021. The increase was primarily used to fund loan growth. During the six months ended March 31, 2022, additions included $590.0 million of overnight advances and $250.0 million of long term advances, partially offset by principal repayments. Also, during the six-month period, $250.0 million of 90 day advances and their related swap contracts matured and were paid off. The total balance of borrowed funds at March 31, 2022 consisted of $590.0 million of overnight advances, $888.3 million of term advances with a weighted average maturity of approximately 2.5 years and $2.1 billion of term advances, aligned with interest rate swap contracts, with a remaining weighted average effective maturity of approximately 2.4 years.
Total shareholders' equity increased $63.5 million, or 3.7%, to $1.80 billion at March 31, 2022 from $1.73 billion at September 30, 2021. Activity reflects $32.0 million of net income, a $57.0 million decrease in accumulated other comprehensive loss and $4.8 million of positive adjustments related to our stock compensation and employee stock ownership plans, reduced by $29.1 million of quarterly dividends and $1.2 million of repurchases of common stock. The decrease in accumulated other comprehensive loss is primarily due to a net positive change in unrealized gains and losses on swap contracts. During the six months ended March 31, 2022, a total of 69,059 shares of our common stock were repurchased at an average cost of $17.23 per share. The Company's eighth stock repurchase program allows for a total of 10,000,000 shares to be repurchased, with 5,822,020 shares remaining to be repurchased at March 31, 2022.
The Company declared and paid a quarterly dividend of $0.2825 per share during each the first and second quarters of the current fiscal year. As a result of a mutual member vote, Third Federal Savings and Loan Association of Cleveland, MHC (the "MHC"), the mutual holding company that owns approximately 81% of the outstanding stock of the Company, was able to waive its receipt of its share of the dividend paid. Under Federal Reserve regulations, the MHC is required to obtain the approval of its members every 12 months for the MHC to waive its right to receive dividends. As a result of a July 13, 2021 member vote and the subsequent non-objection of the Federal Reserve, the MHC has the approval to waive the receipt of up to a total of $1.13 per share of possible dividends to be declared on the Company's common stock, including up to $0.2825 in dividends during the three months ending June 30, 2022. The MHC has conducted the member vote to approve the dividend waiver each of the past eight years under Federal Reserve regulations and for each of those eight years, approximately 97% of the votes cast were in favor of the waiver.
The Association operates under the capital requirements for the standardized approach of the Basel III capital framework for U.S. banking organizations (“Basel III Rules”). At March 31, 2022 all of the Association's capital ratios substantially exceed the amounts required for the Association to be considered "well capitalized" for regulatory capital purposes. The Association’s Tier 1 leverage ratio was 10.99%, its Common Equity Tier 1 and Tier 1 ratios, as calculated under the fully phased-in Basel III Rules, were each 19.30% and its total capital ratio was 19.85%. Additionally, the Company's Tier 1 leverage ratio was 12.66%, its Common Equity Tier 1 and Tier 1 ratios were each 22.24% and its total capital ratio was 22.79%. The current capital ratios of the Association reflect the dilutive impact of $56.0 million of dividends that the Association paid to the Company, its sole shareholder, during the quarter ended December 31, 2021. Because of its intercompany nature, these dividends had no impact on the Company's capital ratios or its consolidated statement of condition.
Presentation slides as of March 31, 2022 will be available on the Company's website, www.thirdfederal.com, under the Investor Relations link within the "Recent Presentations" menu, beginning April 29, 2022. The Company will not be hosting a conference call to discuss its operating results.
Third Federal Savings and Loan Association is a leading provider of savings and mortgage products, and operates under the values of love, trust, respect, a commitment to excellence and fun. Founded in Cleveland in 1938 as a mutual association by Ben and Gerome Stefanski, Third Federal’s mission is to help people achieve the dream of home ownership and financial security. It became part of a public company in 2007 and celebrated its 80th anniversary in May, 2018. Third Federal, which lends in 25 states and the District of Columbia, is dedicated to serving consumers with competitive rates and outstanding service. Third Federal, an equal housing lender, has 21 full service branches in Northeast Ohio, five lending offices in Central and Southern Ohio, and 16 full service branches throughout Florida. As of March 31, 2022, the Company’s assets totaled $14.58 billion.
Forward Looking Statements |
|
This report contains forward-looking statements, which can be identified by the use of such words as estimate, project, believe, intend, anticipate, plan, seek, expect and similar expressions. These forward-looking statements include, among other things: |
|
● |
statements of our goals, intentions and expectations; |
● |
statements regarding our business plans and prospects and growth and operating strategies; |
● |
statements concerning trends in our provision for credit losses and charge-offs on loans and off-balance sheet exposures; |
● |
statements regarding the trends in factors affecting our financial condition and results of operations, including asset quality of our loan and investment portfolios; and |
● |
estimates of our risks and future costs and benefits. |
These forward-looking statements are subject to significant risks, assumptions and uncertainties, including, among other things, the following important factors that could affect the actual outcome of future events: |
|
● |
significantly increased competition among depository and other financial institutions; |
● |
inflation and changes in the interest rate environment that reduce our interest margins or reduce the fair value of financial instruments; |
● |
general economic conditions, either globally, nationally or in our market areas, including employment prospects, real estate values and conditions that are worse than expected; |
● |
the strength or weakness of the real estate markets and of the consumer and commercial credit sectors and its impact on the credit quality of our loans and other assets, and changes in estimates of the allowance for credit losses; |
● |
decreased demand for our products and services and lower revenue and earnings because of a recession or other events; |
● |
changes in consumer spending, borrowing and savings habits; |
● |
adverse changes and volatility in the securities markets, credit markets or real estate markets; |
● |
our ability to manage market risk, credit risk, liquidity risk, reputational risk, and regulatory and compliance risk; |
● |
our ability to access cost-effective funding; |
● |
legislative or regulatory changes that adversely affect our business, including changes in regulatory costs and capital requirements and changes related to our ability to pay dividends and the ability of Third Federal Savings, MHC to waive dividends; |
● |
changes in accounting policies and practices, as may be adopted by the bank regulatory agencies, the Financial Accounting Standards Board or the Public Company Accounting Oversight Board; |
● |
the adoption of implementing regulations by a number of different regulatory bodies, and uncertainty in the exact nature, extent and timing of such regulations and the impact they will have on us; |
● |
our ability to enter new markets successfully and take advantage of growth opportunities, and the possible short-term dilutive effect of potential acquisitions or de novo branches, if any; |
● |
our ability to retain key employees; |
● |
future adverse developments concerning Fannie Mae or Freddie Mac; |
● |
changes in monetary and fiscal policy of the U.S. Government, including policies of the U.S. Treasury and the FRS and changes in the level of government support of housing finance; |
● |
the continuing governmental efforts to restructure the U.S. financial and regulatory system; |
● |
the ability of the U.S. Government to remain open, function properly and manage federal debt limits; |
● |
changes in policy and/or assessment rates of taxing authorities that adversely affect us or our customers; |
● |
changes in accounting and tax estimates; |
● |
changes in our organization, or compensation and benefit plans and changes in expense trends (including, but not limited to trends affecting non-performing assets, charge-offs and provisions for credit losses); |
● |
the inability of third-party providers to perform their obligations to us; |
● |
the effects of global or national war, conflict or acts of terrorism; |
● |
civil unrest; |
● |
cyber-attacks, computer viruses and other technological risks that may breach the security of our websites or other systems to obtain unauthorized access to confidential information, destroy data or disable our systems; and |
● |
the impact of wide-spread pandemic, including COVID-19, and related government action, on our business and the economy. |
Because of these and other uncertainties, our actual future results may be materially different from the results indicated by any forward-looking statements. Any forward-looking statement made by us in this report speaks only as of the date on which it is made. We undertake no obligation to publicly update any forward-looking statements, whether as a result of new information, future developments or otherwise, except as may be required by law. |
|
TFS FINANCIAL CORPORATION AND SUBSIDIARIES |
|||||||||||
CONSOLIDATED STATEMENTS OF CONDITION (unaudited) |
|||||||||||
(In thousands, except share data) |
|||||||||||
March 31, 2022 |
December 31, 2021 |
September 30, 2021 |
|||||||||
ASSETS |
|||||||||||
Cash and due from banks |
$ |
24,395 |
$ |
23,885 |
$ |
27,346 |
|||||
Other interest-earning cash equivalents |
346,276 |
384,124 |
460,980 |
||||||||
Cash and cash equivalents |
370,671 |
408,009 |
488,326 |
||||||||
Investment securities available for sale |
443,222 |
423,842 |
421,783 |
||||||||
Mortgage loans held for sale |
— |
38,064 |
8,848 |
||||||||
Loans held for investment, net: |
|||||||||||
Mortgage loans |
13,150,338 |
12,659,957 |
12,525,687 |
||||||||
Other loans |
2,589 |
2,705 |
2,778 |
||||||||
Deferred loan expenses, net |
47,372 |
45,954 |
44,859 |
||||||||
Allowance for credit losses on loans |
(64,324 |
) |
(63,576 |
) |
(64,289 |
) |
|||||
Loans, net |
13,135,975 |
12,645,040 |
12,509,035 |
||||||||
Mortgage loan servicing rights, net |
8,464 |
8,761 |
8,941 |
||||||||
Federal Home Loan Bank stock, at cost |
162,783 |
162,783 |
162,783 |
||||||||
Real estate owned, net |
131 |
131 |
289 |
||||||||
Premises, equipment, and software, net |
35,417 |
36,364 |
37,420 |
||||||||
Accrued interest receivable |
30,908 |
30,320 |
31,107 |
||||||||
Bank owned life insurance contracts |
300,268 |
298,398 |
297,332 |
||||||||
Other assets |
93,050 |
80,799 |
91,586 |
||||||||
TOTAL ASSETS |
$ |
14,580,889 |
$ |
14,132,511 |
$ |
14,057,450 |
|||||
LIABILITIES AND SHAREHOLDERS’ EQUITY |
|||||||||||
Deposits |
$ |
9,008,347 |
8,933,279 |
$ |
8,993,605 |
||||||
Borrowed funds |
3,555,325 |
3,180,614 |
3,091,815 |
||||||||
Borrowers’ advances for insurance and taxes |
95,199 |
143,338 |
109,633 |
||||||||
Principal, interest, and related escrow owed on loans serviced |
33,034 |
35,655 |
41,476 |
||||||||
Accrued expenses and other liabilities |
93,236 |
86,255 |
88,641 |
||||||||
Total liabilities |
12,785,141 |
12,379,141 |
12,325,170 |
||||||||
Commitments and contingent liabilities |
|||||||||||
Preferred stock, $0.01 par value, 100,000,000 shares authorized, none issued and outstanding |
— |
— |
— |
||||||||
Common stock, $0.01 par value, 700,000,000 shares authorized; 332,318,750 shares issued |
3,323 |
3,323 |
3,323 |
||||||||
Paid-in capital |
1,748,589 |
1,746,992 |
1,746,887 |
||||||||
Treasury stock, at cost |
(768,304 |
) |
(767,457 |
) |
(768,035 |
) |
|||||
Unallocated ESOP shares |
(33,584 |
) |
(34,667 |
) |
(35,751 |
) |
|||||
Retained earnings—substantially restricted |
856,555 |
855,318 |
853,657 |
||||||||
Accumulated other comprehensive loss |
(10,831 |
) |
(50,139 |
) |
(67,801 |
) |
|||||
Total shareholders’ equity |
1,795,748 |
1,753,370 |
1,732,280 |
||||||||
TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY |
$ |
14,580,889 |
$ |
14,132,511 |
$ |
14,057,450 |
|||||
TFS FINANCIAL CORPORATION AND SUBSIDIARIES |
|||||||||||||||||||
CONSOLIDATED STATEMENTS OF INCOME (unaudited) |
|||||||||||||||||||
(In thousands, except share and per share data) |
|||||||||||||||||||
For the three months ended |
|||||||||||||||||||
March 31, 2022 |
December 31, 2021 |
September 30, 2021 |
June 30, 2021 |
March 31, 2021 |
|||||||||||||||
INTEREST AND DIVIDEND INCOME: |
|||||||||||||||||||
Loans, including fees |
$ |
91,125 |
$ |
90,119 |
$ |
92,002 |
$ |
93,584 |
$ |
96,175 |
|||||||||
Investment securities available for sale |
1,355 |
960 |
1,041 |
828 |
966 |
||||||||||||||
Other interest and dividend earning assets |
981 |
1,011 |
1,033 |
979 |
814 |
||||||||||||||
Total interest and dividend income |
93,461 |
92,090 |
94,076 |
95,391 |
97,955 |
||||||||||||||
INTEREST EXPENSE: |
|||||||||||||||||||
Deposits |
16,896 |
19,251 |
21,617 |
23,461 |
24,545 |
||||||||||||||
Borrowed funds |
13,824 |
14,995 |
15,061 |
14,852 |
14,999 |
||||||||||||||
Total interest expense |
30,720 |
34,246 |
36,678 |
38,313 |
39,544 |
||||||||||||||
NET INTEREST INCOME |
62,741 |
57,844 |
57,398 |
57,078 |
58,411 |
||||||||||||||
PROVISION (RELEASE) FOR CREDIT LOSSES |
(1,000 |
) |
(2,000 |
) |
(2,000 |
) |
(1,000 |
) |
(4,000 |
) |
|||||||||
NET INTEREST INCOME AFTER PROVISION FOR CREDIT LOSSES |
63,741 |
59,844 |
59,398 |
58,078 |
62,411 |
||||||||||||||
NON-INTEREST INCOME: |
|||||||||||||||||||
Fees and service charges, net of amortization |
2,568 |
2,404 |
2,156 |
2,491 |
2,460 |
||||||||||||||
Net gain on the sale of loans |
113 |
2,187 |
4,305 |
3,423 |
8,911 |
||||||||||||||
Increase in and death benefits from bank owned life insurance contracts |
2,222 |
2,911 |
2,146 |
2,361 |
3,807 |
||||||||||||||
Other |
688 |
652 |
74 |
1,174 |
530 |
||||||||||||||
Total non-interest income |
5,591 |
8,154 |
8,681 |
9,449 |
15,708 |
||||||||||||||
NON-INTEREST EXPENSE: |
|||||||||||||||||||
Salaries and employee benefits |
26,862 |
26,515 |
26,912 |
26,945 |
26,672 |
||||||||||||||
Marketing services |
6,551 |
5,626 |
4,043 |
4,073 |
5,325 |
||||||||||||||
Office property, equipment and software |
6,824 |
6,639 |
6,453 |
6,427 |
6,395 |
||||||||||||||
Federal insurance premium and assessments |
2,276 |
2,012 |
2,233 |
2,139 |
2,323 |
||||||||||||||
State franchise tax |
1,237 |
1,224 |
1,202 |
1,151 |
1,159 |
||||||||||||||
Other expenses |
6,225 |
5,657 |
6,603 |
7,115 |
6,936 |
||||||||||||||
Total non-interest expense |
49,975 |
47,673 |
47,446 |
47,850 |
48,810 |
||||||||||||||
INCOME BEFORE INCOME TAXES |
19,357 |
20,325 |
20,633 |
19,677 |
29,309 |
||||||||||||||
INCOME TAX EXPENSE |
3,512 |
4,185 |
3,618 |
3,696 |
6,300 |
||||||||||||||
NET INCOME |
$ |
15,845 |
$ |
16,140 |
$ |
17,015 |
$ |
15,981 |
$ |
23,009 |
|||||||||
Earnings per share |
|||||||||||||||||||
Basic |
$ |
0.06 |
$ |
0.06 |
$ |
0.06 |
$ |
0.06 |
$ |
0.08 |
|||||||||
Diluted |
$ |
0.06 |
$ |
0.06 |
$ |
0.06 |
$ |
0.06 |
$ |
0.08 |
|||||||||
Weighted average shares outstanding |
|||||||||||||||||||
Basic |
277,423,493 |
277,225,121 |
276,982,904 |
276,864,229 |
276,716,978 |
||||||||||||||
Diluted |
278,819,539 |
278,903,373 |
278,880,379 |
278,931,432 |
278,593,303 |
||||||||||||||
TFS FINANCIAL CORPORATION AND SUBSIDIARIES |
|||||||
CONSOLIDATED STATEMENTS OF INCOME (unaudited) |
|||||||
(In thousands, except share and per share data) |
|||||||
For the Six Months Ended |
|||||||
March 31, |
|||||||
2022 |
2021 |
||||||
INTEREST AND DIVIDEND INCOME: |
|||||||
Loans, including fees |
$ |
181,244 |
$ |
196,301 |
|||
Investment securities available for sale |
2,315 |
1,953 |
|||||
Other interest and dividend earning assets |
1,992 |
1,630 |
|||||
Total interest and dividend income |
185,551 |
199,884 |
|||||
INTEREST EXPENSE: |
|||||||
Deposits |
36,147 |
52,241 |
|||||
Borrowed funds |
28,819 |
30,489 |
|||||
Total interest expense |
64,966 |
82,730 |
|||||
NET INTEREST INCOME |
120,585 |
117,154 |
|||||
PROVISION (RELEASE) FOR CREDIT LOSSES |
(3,000 |
) |
(6,000 |
) |
|||
NET INTEREST INCOME AFTER PROVISION FOR CREDIT LOSSES |
123,585 |
123,154 |
|||||
NON-INTEREST INCOME: |
|||||||
Fees and service charges, net of amortization |
4,972 |
4,955 |
|||||
Net gain on the sale of loans |
2,300 |
25,354 |
|||||
Increase in and death benefits from bank owned life insurance contracts |
5,133 |
5,454 |
|||||
Other |
1,340 |
1,406 |
|||||
Total non-interest income |
13,745 |
37,169 |
|||||
NON-INTEREST EXPENSE: |
|||||||
Salaries and employee benefits |
53,377 |
55,010 |
|||||
Marketing services |
12,177 |
11,058 |
|||||
Office property, equipment and software |
13,463 |
12,830 |
|||||
Federal insurance premium and assessments |
4,288 |
4,713 |
|||||
State franchise tax |
2,461 |
2,310 |
|||||
Other expenses |
11,882 |
14,618 |
|||||
Total non-interest expense |
97,648 |
100,539 |
|||||
INCOME BEFORE INCOME TAXES |
39,682 |
59,784 |
|||||
INCOME TAX EXPENSE |
7,697 |
11,773 |
|||||
NET INCOME |
$ |
31,985 |
$ |
48,011 |
|||
Earnings per share |
|||||||
Basic |
$ |
0.11 |
$ |
0.17 |
|||
Diluted |
$ |
0.11 |
$ |
0.17 |
|||
Weighted average shares outstanding |
|||||||
Basic |
277,323,217 |
276,464,037 |
|||||
Diluted |
278,864,945 |
278,291,638 |
|||||
TFS FINANCIAL CORPORATION AND SUBSIDIARIES |
|||||||||||||||||||||||||||||||||
AVERAGE BALANCES AND YIELDS (unaudited) |
|||||||||||||||||||||||||||||||||
Three Months Ended |
Three Months Ended |
Three Months Ended |
|||||||||||||||||||||||||||||||
March 31, 2022 |
December 31, 2021 |
March 31, 2021 |
|||||||||||||||||||||||||||||||
Average Balance |
Interest Income/ Expense |
Yield/ Cost (1) |
Average Balance |
Interest Income/ Expense |
Yield/ Cost (1) |
Average Balance |
Interest Income/ Expense |
Yield/ Cost (1) |
|||||||||||||||||||||||||
(Dollars in thousands) |
|||||||||||||||||||||||||||||||||
Interest-earning assets: |
|||||||||||||||||||||||||||||||||
Interest-earning cash equivalents |
$ |
337,915 |
$ |
161 |
0.19 |
% |
$ |
494,186 |
$ |
190 |
0.15 |
% |
$ |
494,161 |
$ |
127 |
0.10 |
% |
|||||||||||||||
Investment securities |
4,044 |
11 |
1.09 |
% |
2,932 |
9 |
1.23 |
% |
— |
— |
— |
% |
|||||||||||||||||||||
Mortgage-backed securities |
432,012 |
1,344 |
1.24 |
% |
421,358 |
951 |
0.90 |
% |
435,847 |
966 |
0.89 |
% |
|||||||||||||||||||||
Loans (2) |
12,845,756 |
91,125 |
2.84 |
% |
12,582,758 |
90,119 |
2.86 |
% |
12,892,195 |
96,175 |
2.98 |
% |
|||||||||||||||||||||
Federal Home Loan Bank stock |
162,783 |
820 |
2.01 |
% |
162,783 |
821 |
2.02 |
% |
158,930 |
687 |
1.73 |
% |
|||||||||||||||||||||
Total interest-earning assets |
13,782,510 |
93,461 |
2.71 |
% |
13,664,017 |
92,090 |
2.70 |
% |
13,981,133 |
97,955 |
2.80 |
% |
|||||||||||||||||||||
Noninterest-earning assets |
475,938 |
512,102 |
548,229 |
||||||||||||||||||||||||||||||
Total assets |
$ |
14,258,448 |
$ |
14,176,119 |
$ |
14,529,362 |
|||||||||||||||||||||||||||
Interest-bearing liabilities: |
|||||||||||||||||||||||||||||||||
Checking accounts |
$ |
1,292,977 |
293 |
0.09 |
% |
$ |
1,151,600 |
265 |
0.09 |
% |
$ |
1,062,894 |
296 |
0.11 |
% |
||||||||||||||||||
Savings accounts |
1,869,103 |
485 |
0.10 |
% |
1,835,361 |
557 |
0.12 |
% |
1,724,978 |
760 |
0.18 |
% |
|||||||||||||||||||||
Certificates of deposit |
5,788,249 |
16,118 |
1.11 |
% |
5,944,470 |
18,429 |
1.24 |
% |
6,394,643 |
23,489 |
1.47 |
% |
|||||||||||||||||||||
Borrowed funds |
3,282,890 |
13,824 |
1.68 |
% |
3,175,158 |
14,995 |
1.89 |
% |
3,352,317 |
14,999 |
1.79 |
% |
|||||||||||||||||||||
Total interest-bearing liabilities |
12,233,219 |
30,720 |
1.00 |
% |
12,106,589 |
34,246 |
1.13 |
% |
12,534,832 |
39,544 |
1.26 |
% |
|||||||||||||||||||||
Noninterest-bearing liabilities |
238,884 |
312,104 |
306,556 |
||||||||||||||||||||||||||||||
Total liabilities |
12,472,103 |
12,418,693 |
12,841,388 |
||||||||||||||||||||||||||||||
Shareholders’ equity |
1,786,345 |
1,757,426 |
1,687,974 |
||||||||||||||||||||||||||||||
Total liabilities and shareholders’ equity |
$ |
14,258,448 |
$ |
14,176,119 |
$ |
14,529,362 |
|||||||||||||||||||||||||||
Net interest income |
$ |
62,741 |
$ |
57,844 |
$ |
58,411 |
|||||||||||||||||||||||||||
Interest rate spread (1)(3) |
1.71 |
% |
1.57 |
% |
1.54 |
% |
|||||||||||||||||||||||||||
Net interest-earning assets (4) |
$ |
1,549,291 |
$ |
1,557,428 |
$ |
1,446,301 |
|||||||||||||||||||||||||||
Net interest margin (1)(5) |
1.82 |
% |
1.69 |
% |
1.67 |
% |
|||||||||||||||||||||||||||
Average interest-earning assets to average interest-bearing liabilities |
112.66 |
% |
112.86 |
% |
111.54 |
% |
|||||||||||||||||||||||||||
Selected performance ratios: |
|||||||||||||||||||||||||||||||||
Return on average assets (1) |
0.44 |
% |
0.46 |
% |
0.63 |
% |
|||||||||||||||||||||||||||
Return on average equity (1) |
3.55 |
% |
3.67 |
% |
5.45 |
% |
|||||||||||||||||||||||||||
Average equity to average assets |
12.53 |
% |
12.40 |
% |
11.62 |
% |
|||||||||||||||||||||||||||
| (1) | Annualized. |
|
| (2) | Loans include both mortgage loans held for sale and loans held for investment. |
|
| (3) | Interest rate spread represents the difference between the yield on average interest-earning assets and the cost of average interest-bearing liabilities. |
|
| (4) | Net interest-earning assets represent total interest-earning assets less total interest-bearing liabilities. |
|
| (5) | Net interest margin represents net interest income divided by total interest-earning assets. |
TFS FINANCIAL CORPORATION AND SUBSIDIARIES |
||||||||||||||||||||||
AVERAGE BALANCES AND YIELDS (unaudited) |
||||||||||||||||||||||
Six Months Ended |
Six Months Ended |
|||||||||||||||||||||
March 31, 2022 |
March 31, 2021 |
|||||||||||||||||||||
Average Balance |
Interest Income/ Expense |
Yield/ Cost (1) |
Average Balance |
Interest Income/ Expense |
Yield/ Cost (1) |
|||||||||||||||||
(Dollars in thousands) |
||||||||||||||||||||||
Interest-earning assets: |
||||||||||||||||||||||
Interest-earning cash equivalents |
$ |
416,050 |
$ |
351 |
0.17 |
% |
$ |
485,375 |
$ |
255 |
0.11 |
% |
||||||||||
Mortgage-backed securities |
426,685 |
2,295 |
1.08 |
% |
441,696 |
1,953 |
0.88 |
% |
||||||||||||||
Loans (2) |
12,714,257 |
181,244 |
2.85 |
% |
12,991,561 |
196,301 |
3.02 |
% |
||||||||||||||
Federal Home Loan Bank stock |
162,783 |
1,641 |
2.02 |
% |
147,861 |
1,375 |
1.86 |
% |
||||||||||||||
Total interest-earning assets |
13,719,775 |
185,531 |
2.70 |
% |
14,066,493 |
199,884 |
2.84 |
% |
||||||||||||||
Noninterest-earning assets |
494,020 |
536,771 |
||||||||||||||||||||
Total assets |
$ |
14,213,795 |
$ |
14,603,264 |
||||||||||||||||||
Interest-bearing liabilities: |
||||||||||||||||||||||
Checking accounts |
$ |
1,222,288 |
558 |
0.09 |
% |
$ |
1,040,353 |
617 |
0.12 |
% |
||||||||||||
Savings accounts |
1,852,232 |
1,042 |
0.11 |
% |
1,693,536 |
1,674 |
0.20 |
% |
||||||||||||||
Certificates of deposit |
5,866,360 |
34,547 |
1.18 |
% |
6,444,083 |
49,950 |
1.55 |
% |
||||||||||||||
Borrowed funds |
3,229,024 |
28,819 |
1.78 |
% |
3,411,955 |
30,489 |
1.79 |
% |
||||||||||||||
Total interest-bearing liabilities |
12,169,904 |
64,966 |
1.07 |
% |
12,589,927 |
82,730 |
1.31 |
% |
||||||||||||||
Noninterest-bearing liabilities |
275,494 |
341,727 |
||||||||||||||||||||
Total liabilities |
12,445,398 |
12,931,654 |
||||||||||||||||||||
Shareholders’ equity |
1,771,885 |
1,671,610 |
||||||||||||||||||||
Total liabilities and shareholders’ equity |
$ |
14,217,283 |
$ |
14,603,264 |
||||||||||||||||||
Net interest income |
$ |
120,565 |
$ |
117,154 |
||||||||||||||||||
Interest rate spread (3) |
1.63 |
% |
1.53 |
% |
||||||||||||||||||
Net interest-earning assets (4) |
$ |
1,549,871 |
$ |
1,476,566 |
||||||||||||||||||
Net interest margin (5) |
1.76 |
% |
1.67 |
% |
||||||||||||||||||
Average interest-earning assets to average interest-bearing liabilities |
112.74 |
% |
111.73 |
% |
||||||||||||||||||
Selected performance ratios: |
||||||||||||||||||||||
Return on average assets |
0.45 |
% |
0.66 |
% |
||||||||||||||||||
Return on average equity |
3.61 |
% |
5.74 |
% |
||||||||||||||||||
Average equity to average assets |
12.46 |
% |
11.45 |
% |
||||||||||||||||||
| (1) | Annualized. |
|
| (2) | Loans include both mortgage loans held for sale and loans held for investment. |
|
| (3) | Interest rate spread represents the difference between the yield on average interest-earning assets and the cost of average interest-bearing liabilities. |
|
| (4) | Net interest-earning assets represent total interest-earning assets less total interest-bearing liabilities. |
|
| (5) | Net interest margin represents net interest income divided by total interest-earning assets. |
View source version on businesswire.com: https://www.businesswire.com/news/home/20220428006194/en/
Jennifer Rosa (216) 429-5037
Source: Third Federal Savings and Loan