Aberdeen Group plc · LSE:ABDN
Aberdeen — Standard Life Bank — Debt Investor Presentation (May 2005)
32 slides from Aberdeen's debt investor presentation, May 2005
Slide 1: Debt Capital Roadshow May 2005
Debt Capital Roadshow May 2005
Slide 2: Contents
Contents 1. Executive Summary 2. Standard Life Bank 3. Financials 4. Strategic Review & Demutualisation 5. Indicative Terms of the Offering 1
Slide 3: 1. Executive Summary
P | STANDARD LIFE BANK® L< 1. Executive Summary
Slide 4: Executive Summary
Executive Summary Inaugural capital issue for Standard Life Bank Core part of Standard Life group Builds on established brand Technologically advanced telephone and internet-based mortgage lender and savings bank Outstanding asset quality Well placed for continuing profitable growth Committed to inv
Slide 5: 2. Standard Life Bank
2. Standard Life Bank 4
Slide 6: Standard Life Bank
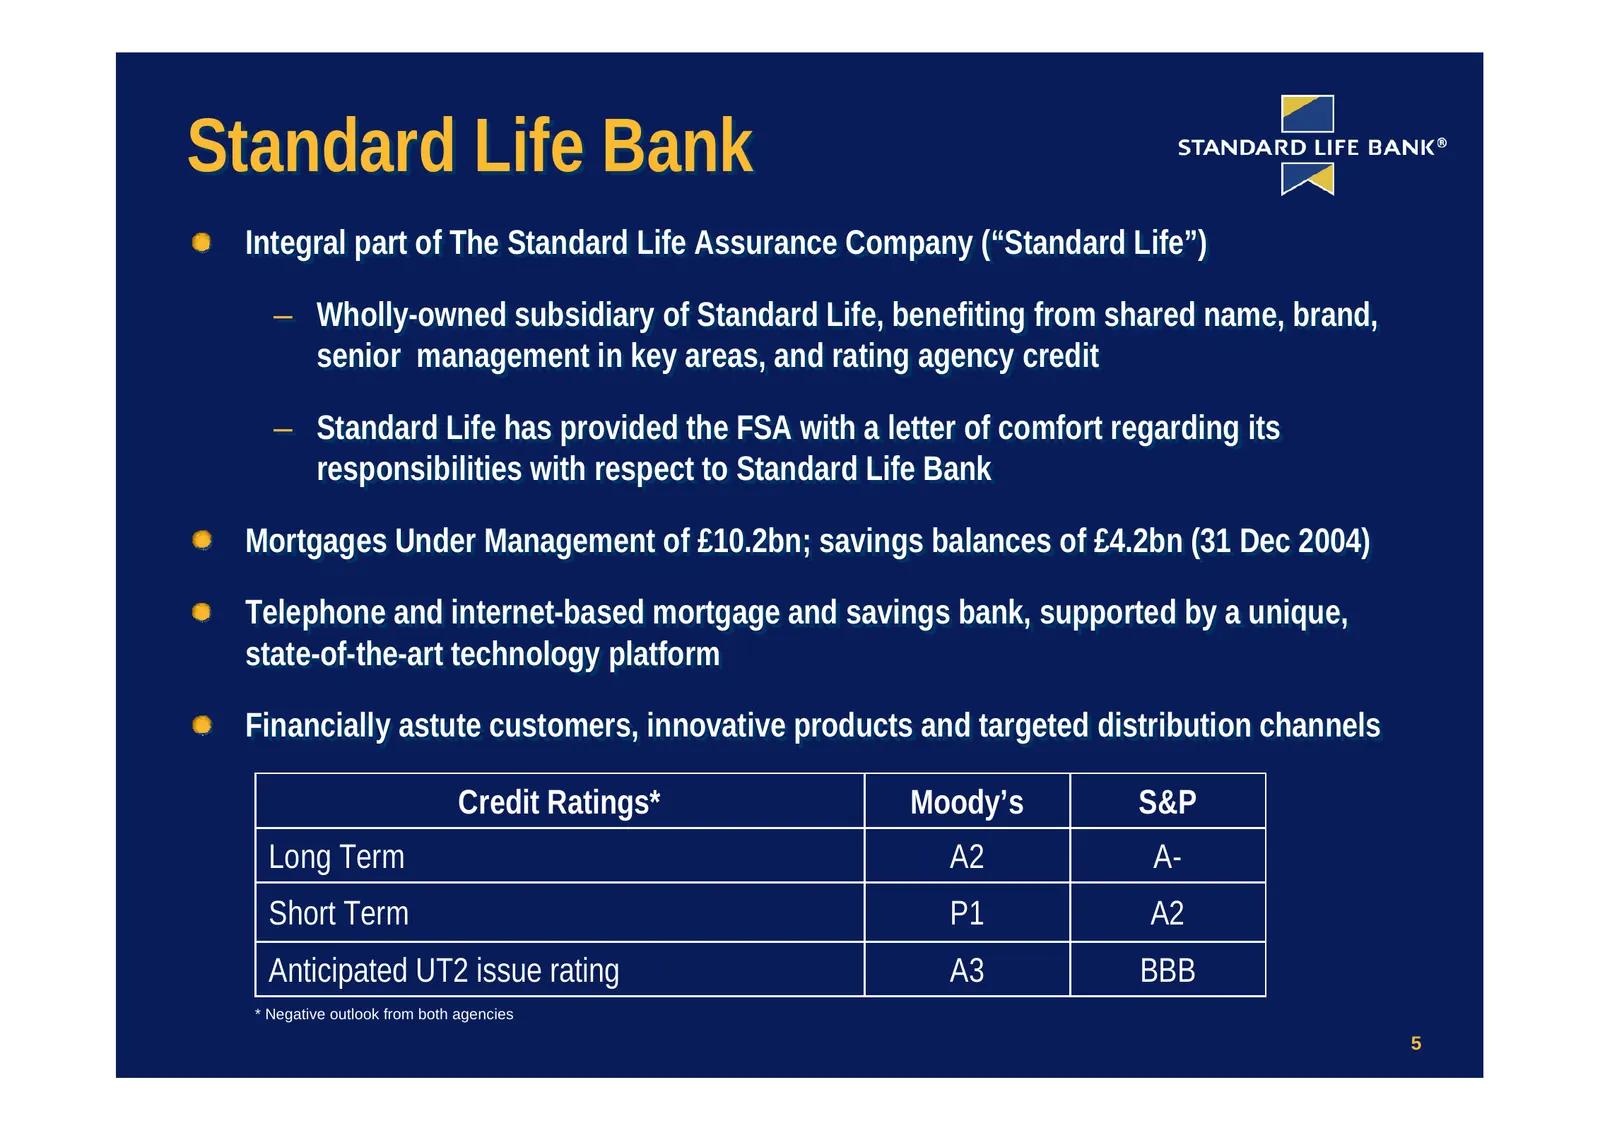
Standard Life Bank Integral Integral part part of of The The Standard Standard Life Life Assurance Assurance Company Company (“Standard (“Standard Life”) Life”) –– Wholly-owned Wholly-owned subsidiary subsidiary of of Standard Standard Life, Life, benefiting benefiting from from shared shared name,
Slide 7: Operating Objectives
Operating Objectives Complete Standard Life group’s suite of key long-term financial products Originate a ‘Superior Prime’ residential mortgage book Engage customers with innovative products Provide an appropriate return to Standard Life Safeguard and enhance the Standard Life brand & values 5 year
Slide 8: Standard Life Bank's Customer Proposition – Freestyle Finance
Standard Life Bank’s Customer Proposition – Freestyle Finance High quality, flexible mortgage products offering financial planning capability Sophisticated underwriting techniques Competitively-priced , transparent retail savings Clearly defined audience of financially-astute customers and their adv
Slide 9: Products
Products Core Core product product is is the the Freestyle Freestyle®® range range -- flexible flexible mortgages mortgages designed designed as as financial financial planning tools, incorporating offsetting, cash reserve and overpayments planning tools, incorporating offsetting, cash reserve and o
Slide 10: Distribution Channels
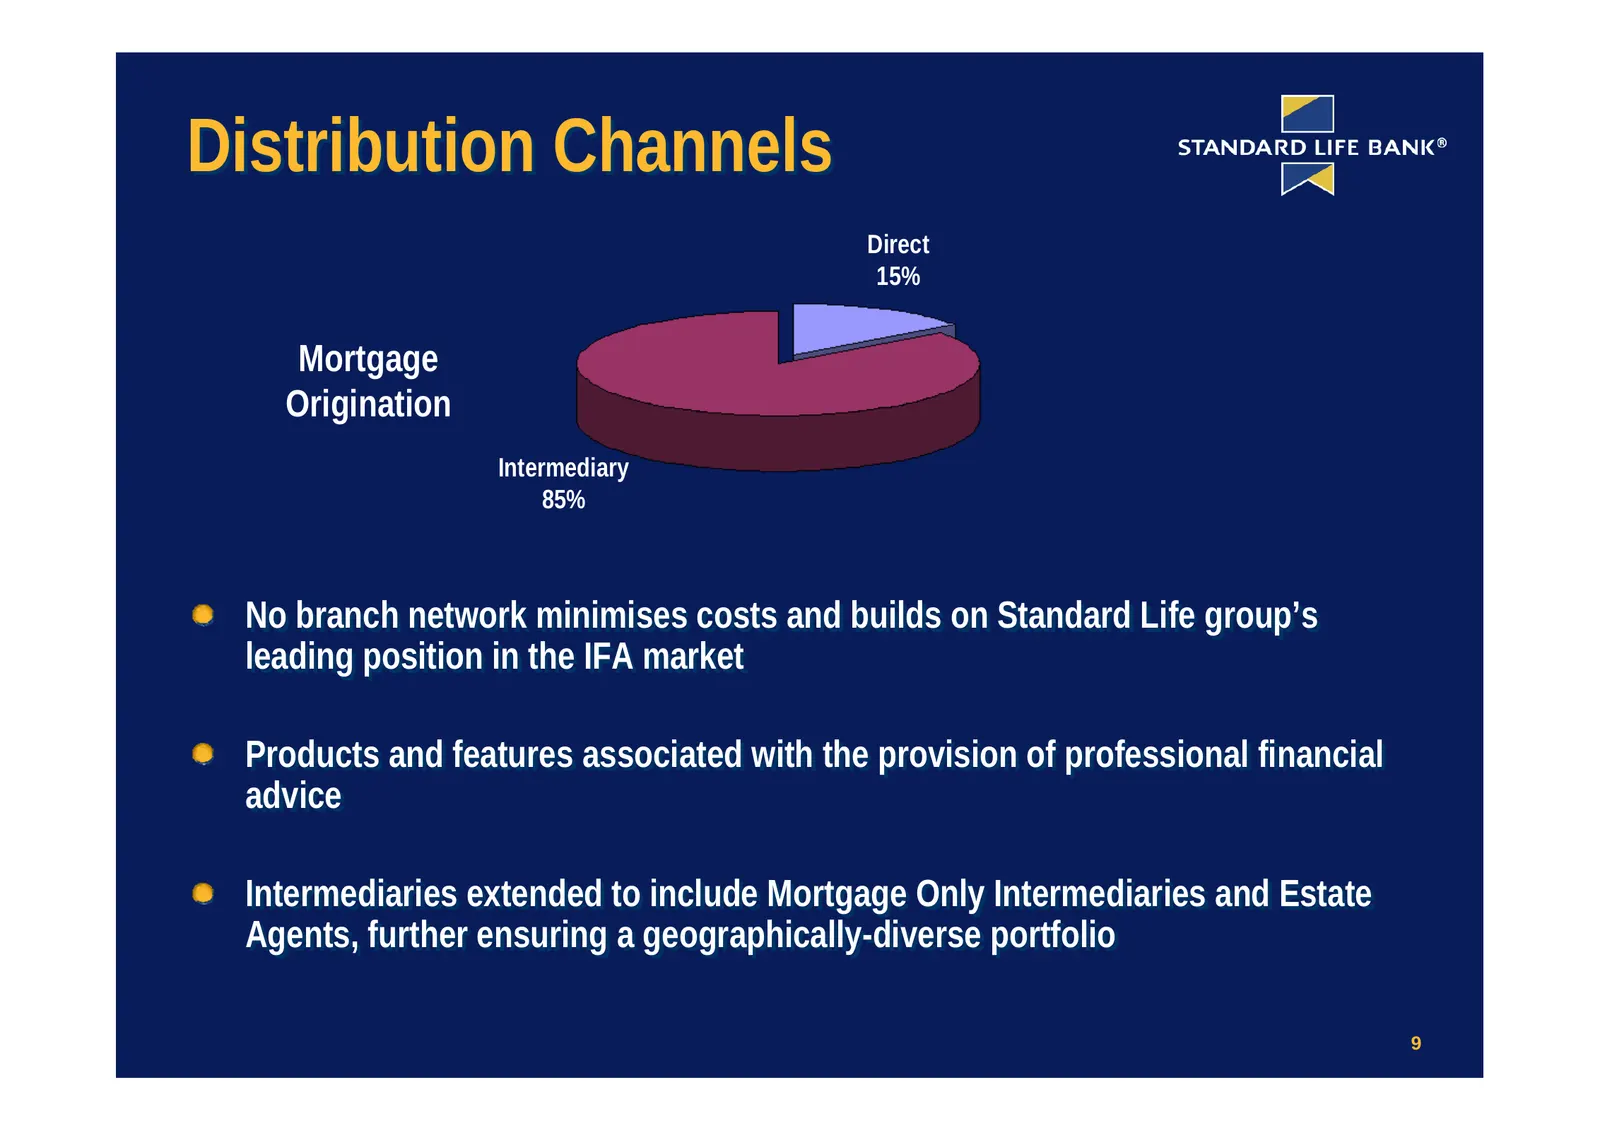
Distribution Channels Direct 15% Mortgage Origination Intermediary 85% No branch network minimises costs and builds on Standard Life group’s leading position in the IFA market Products and features associated with the provision of professional financial advice Intermediaries extended to include Mort
Slide 11: Mortgage Underwriting
Mortgage Underwriting Fully automated process Decisions incorporate credit score, affordability, bespoke underwriting rules and fraud management Offers based on affordability not income multiples Highly experienced underwriters compliment automated process All valuations involve full site visit by I
Slide 12: Mortgage Customer Profile
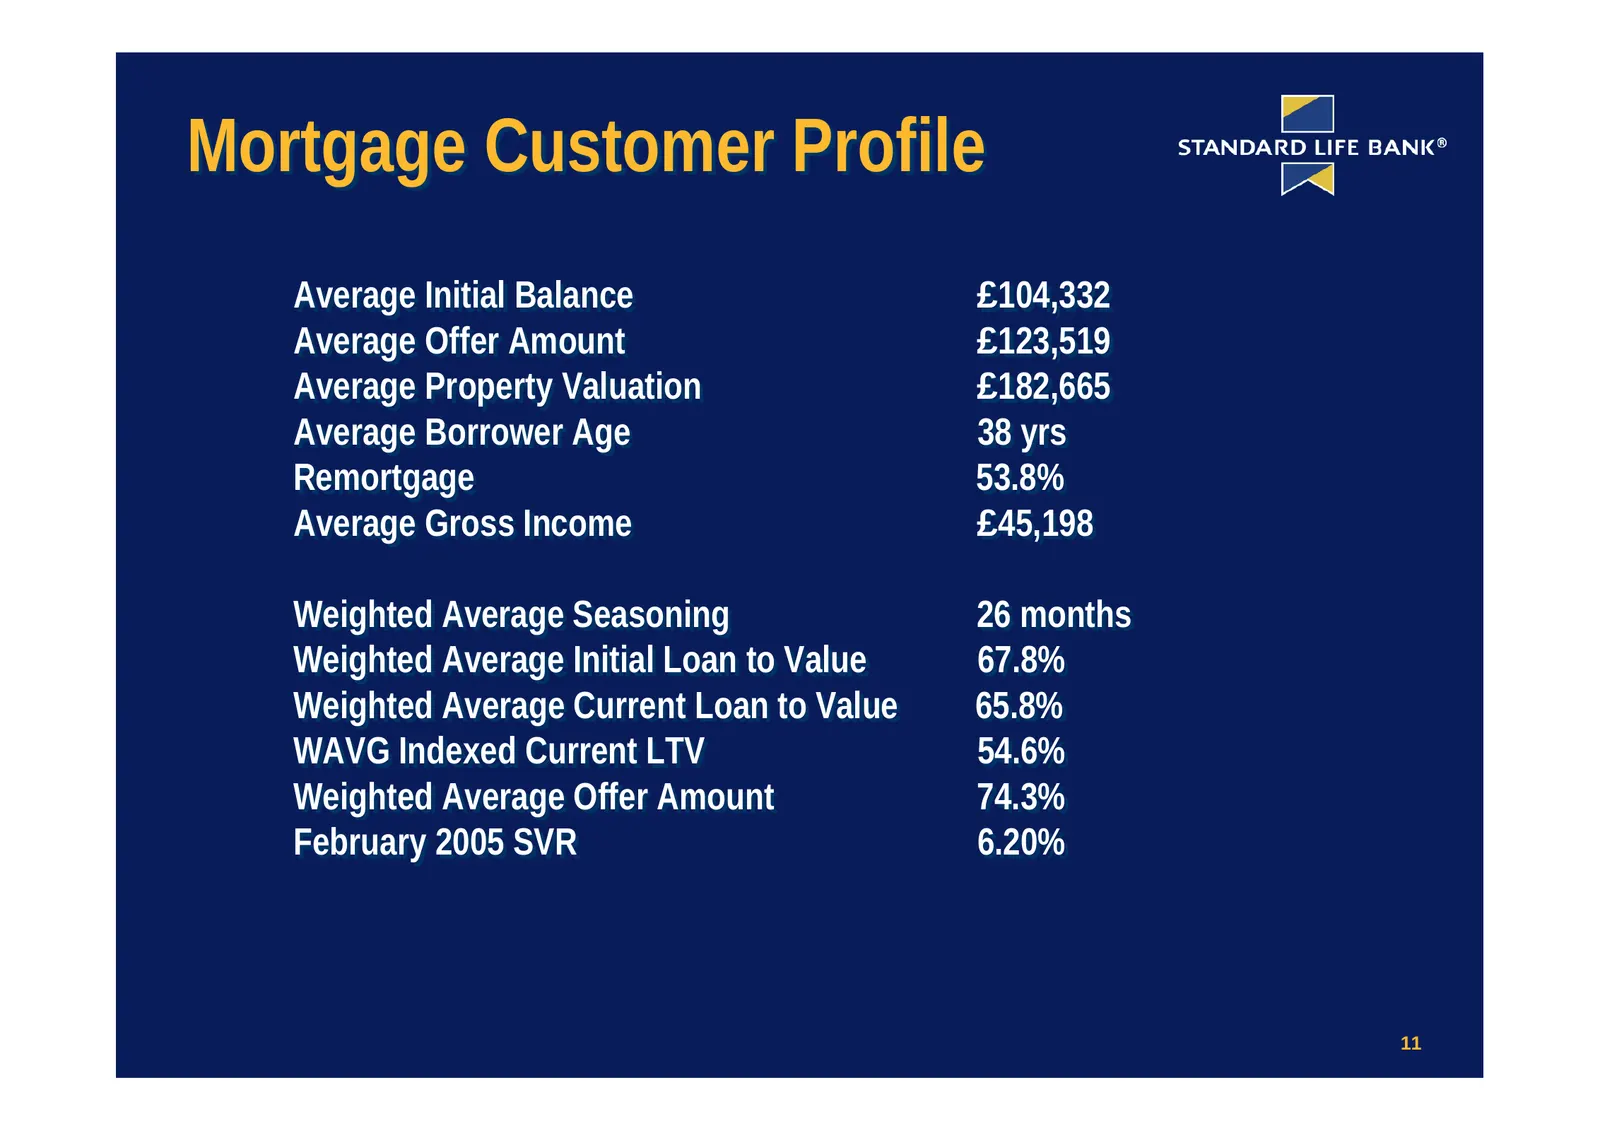
Mortgage Customer Profile Average Initial Balance £104,332 Average Offer Amount £123,519 Average Property Valuation £182,665 Average Borrower Age 38 yrs Remortgage 53.8% Average Gross Income £45,198 Weighted Average Seasoning 26 months Weighted Average Initial Loan to Value 67.8% Weighted Average Cu
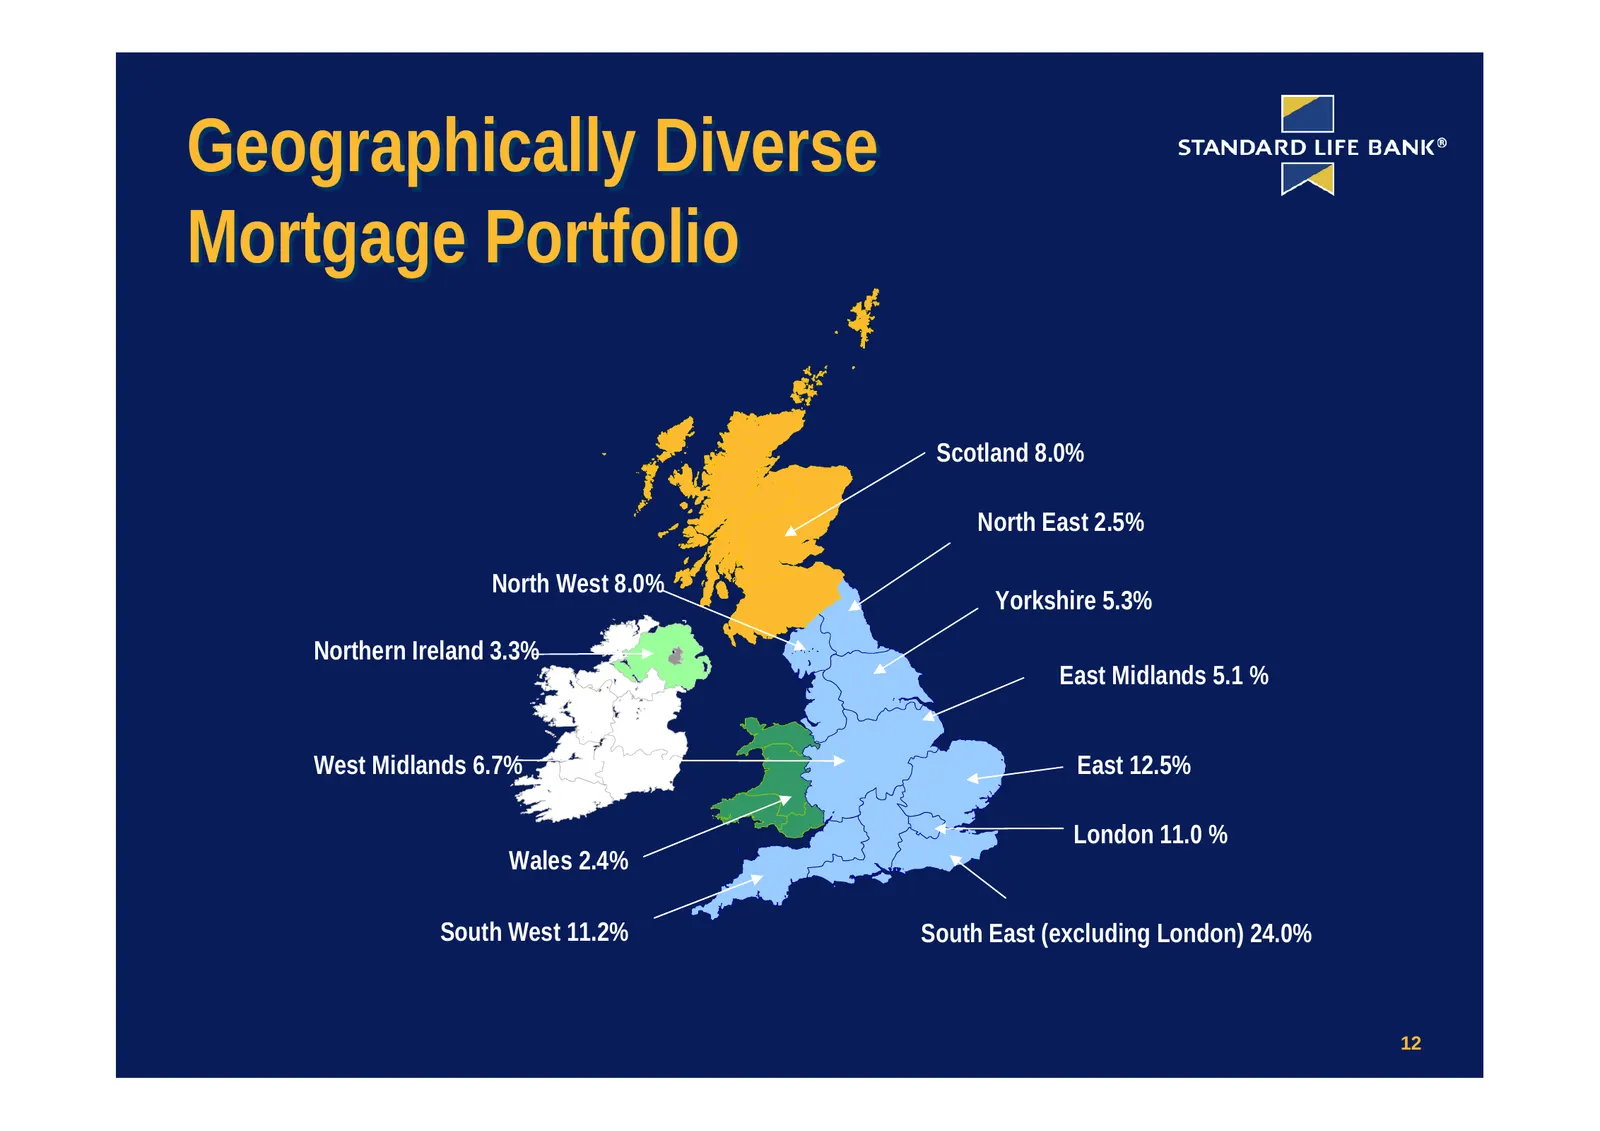
Slide 13: Geographically Diverse Mortgage Portfolio
Geographically Diverse Mortgage Portfolio Scotland 8.0% North East 2.5% North West 8.0% Yorkshire 5.3% Northern Ireland 3.3% East Midlands 5.1 % West Midlands 6.7% East 12.5% London 11.0 % Wales 2.4% South West 11.2% South East (excluding London) 24.0% 12
Slide 14: Pro-Active Arrears Management
Pro-Active Arrears Management Arrears levels are monitored daily Highly reactive customer contact strategies, utilising loan behaviour and score cards (both internal and external). Resulting high “roll rates” reflected in low level of arrears Experienced arrears management staff and cross-training i
Slide 15: 3. Financials
P | STANDARD LIFE BANK® L< 3. Financials
Slide 16: Key Financials
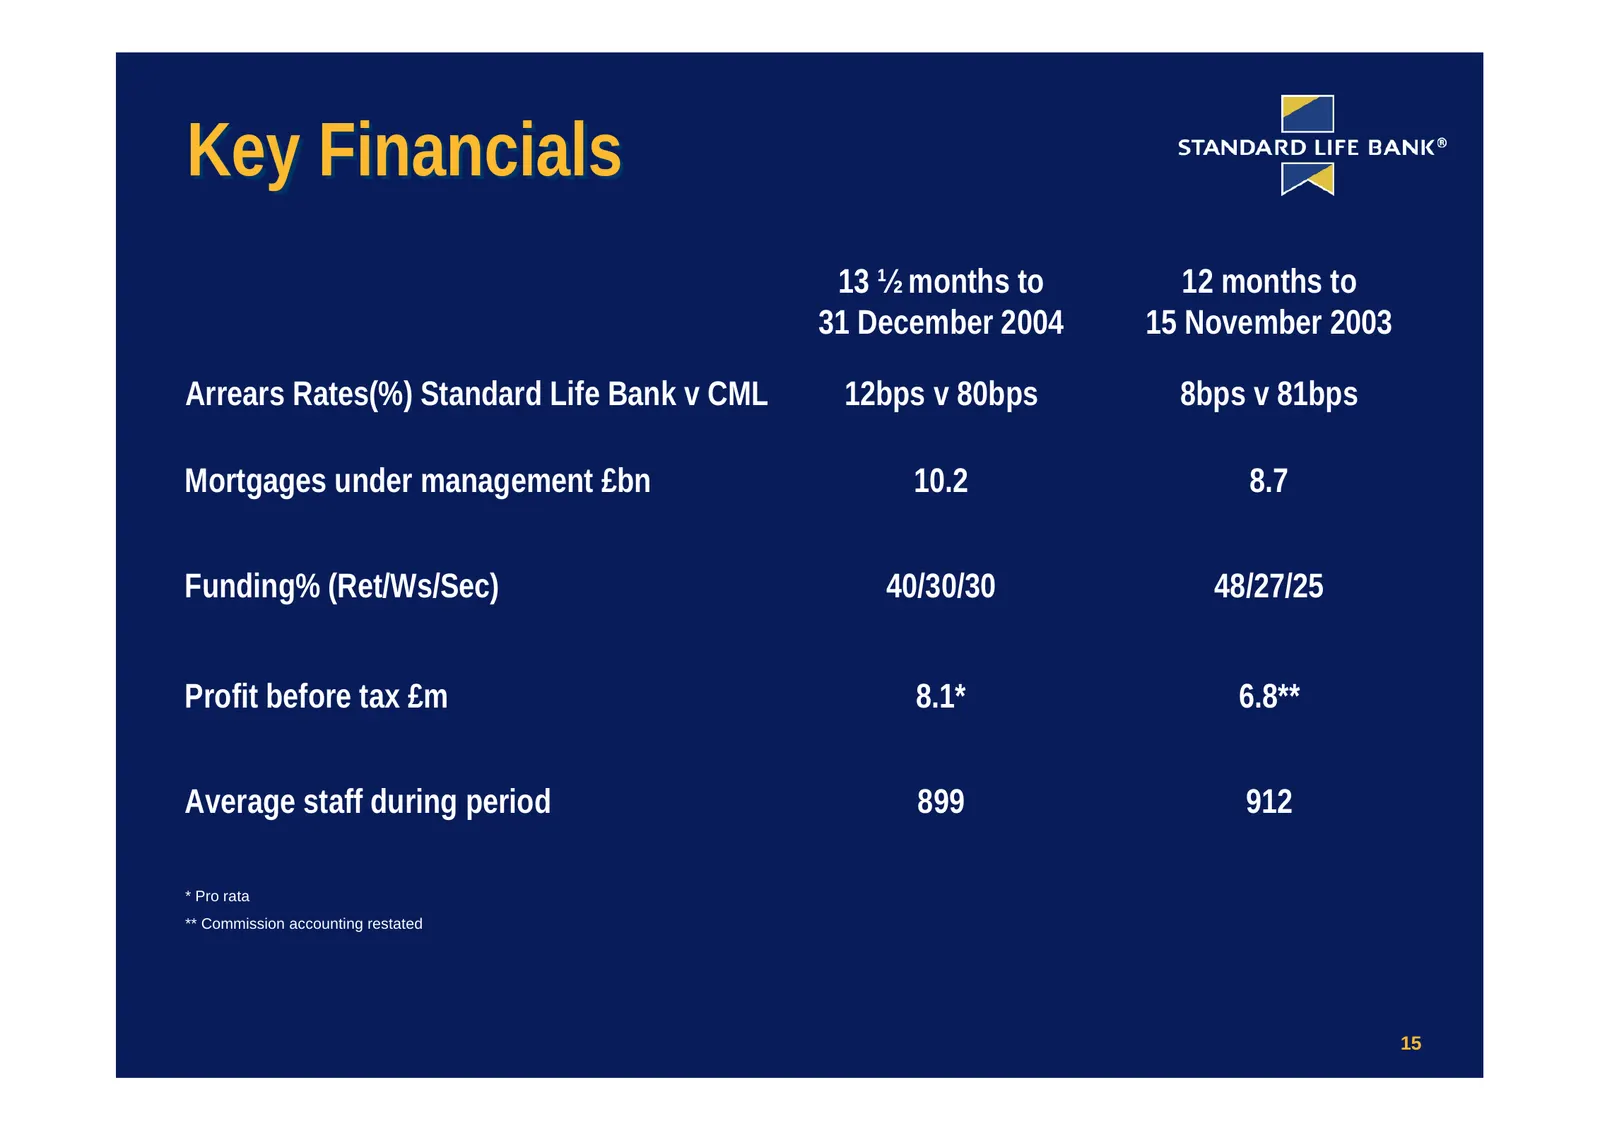
Key Financials 13 ½ months to 12 months to 31 December 2004 15 November 2003 Arrears Rates(%) Standard Life Bank v CML 12bps v 80bps 8bps v 81bps Mortgages under management £bn 10.2 8.7 Funding% (Ret/Ws/Sec) 40/30/30 48/27/25 Profit before tax £m 8.1* 6.8** Average staff during period 899 912 * Pro
Slide 17: Exceptional Arrears Performance
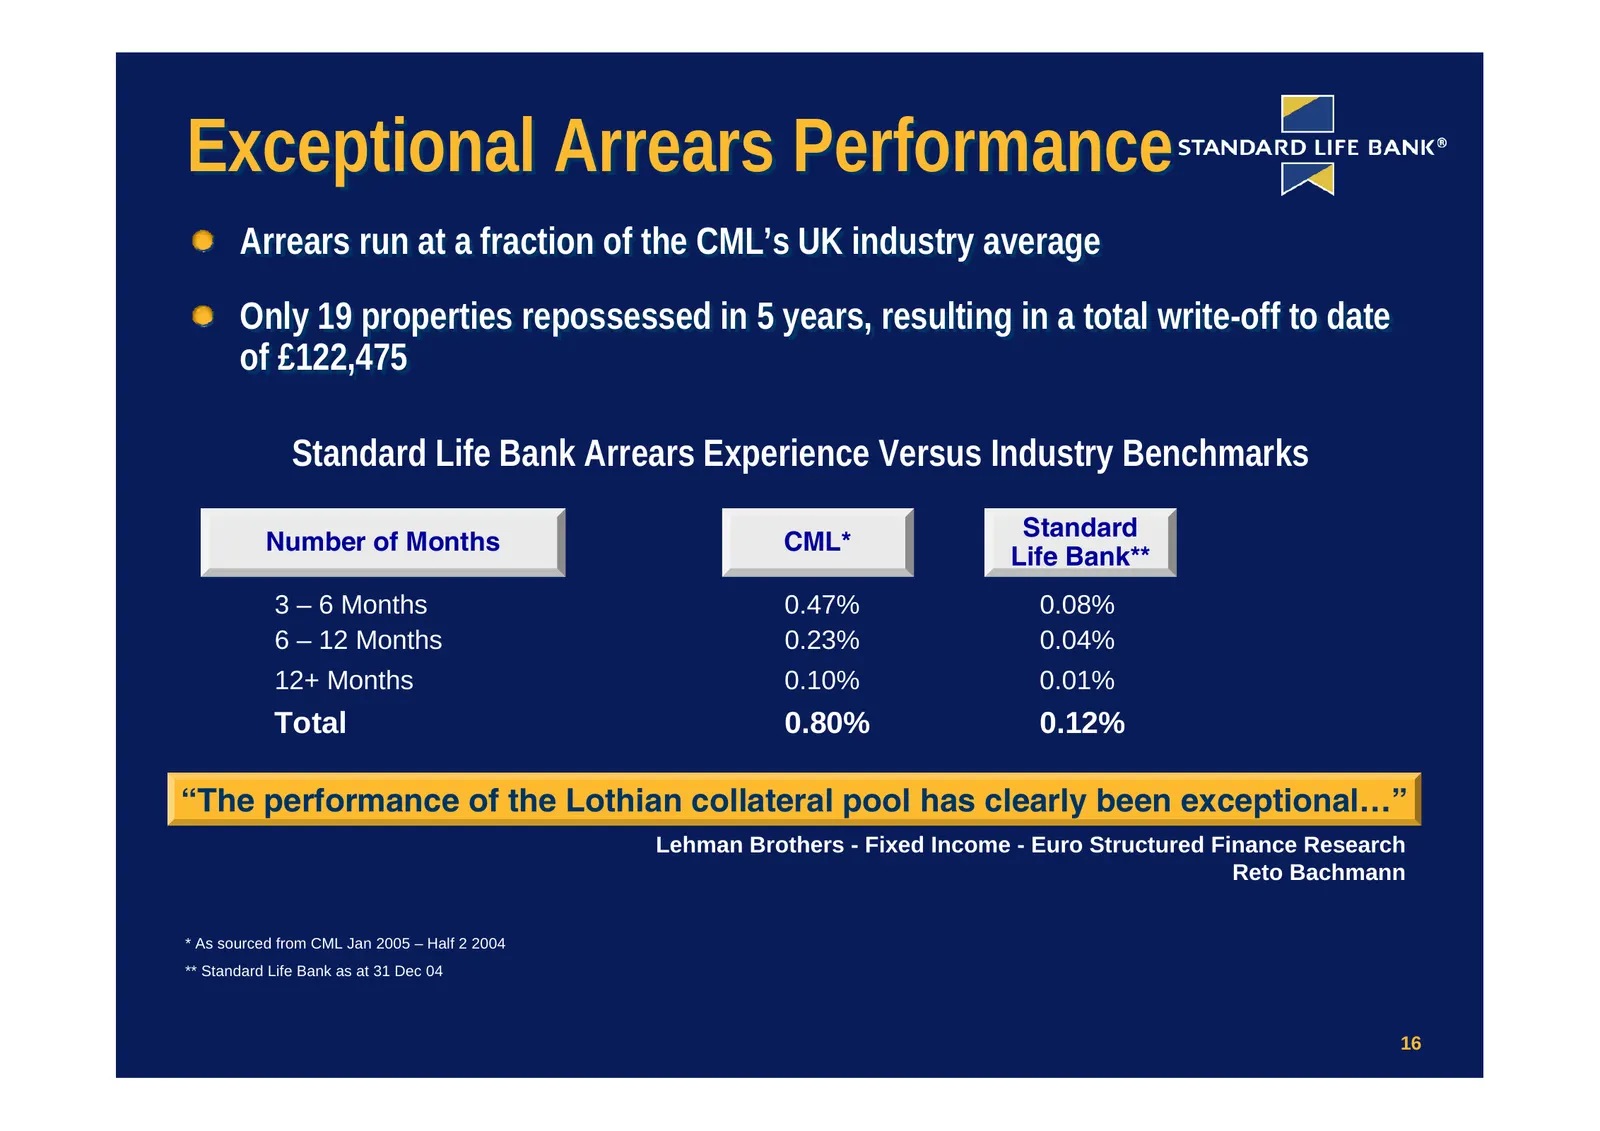
Exceptional Arrears Performance Arrears run at a fraction of the CML’s UK industry average Only 19 properties repossessed in 5 years, resulting in a total write-off to date of £122,475 Standard Life Bank Arrears Experience Versus Industry Benchmarks Standard Number of Months CML* Life Bank** 3 – 6 M
Slide 18: Asset Growth
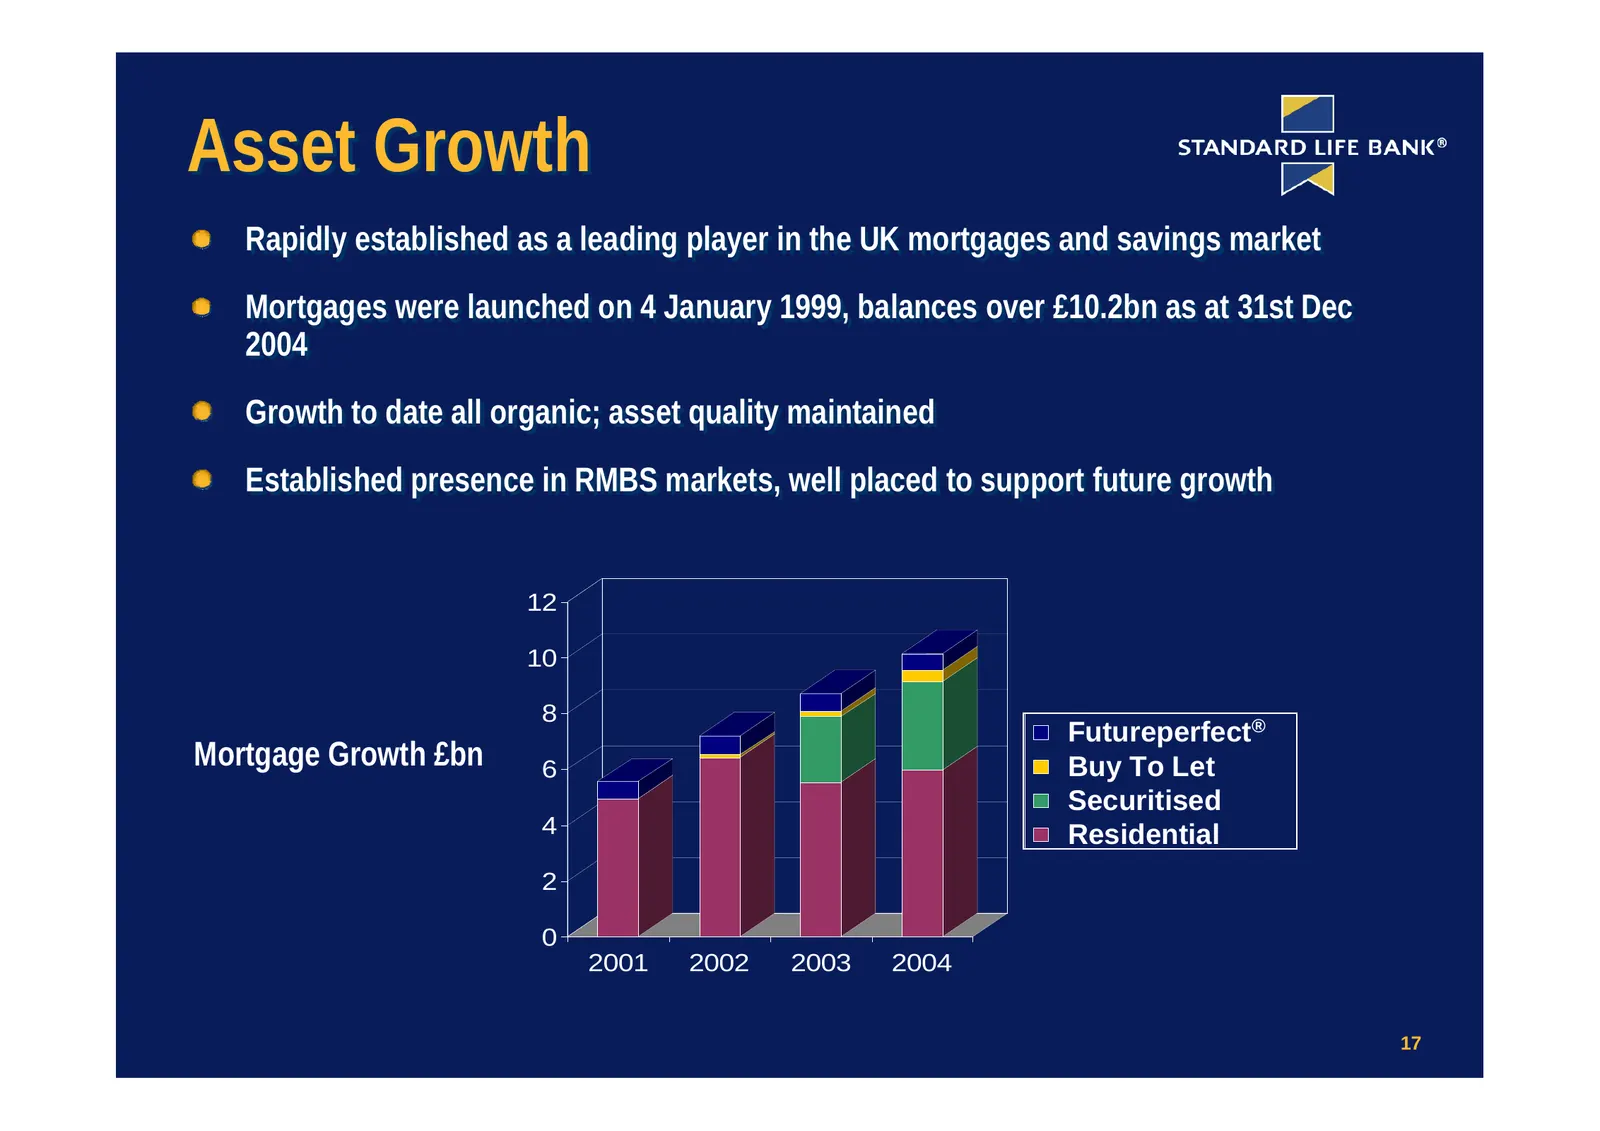
Asset Growth Rapidly Rapidly established established as as aa leading leading player player in in the the UK UK mortgages mortgages and and savings savings market market Mortgages Mortgages were were launched launched on on 44 January January 1999, 1999, balances balances over over £10.2bn £10.2bn a
Slide 19: Increasingly Profitable
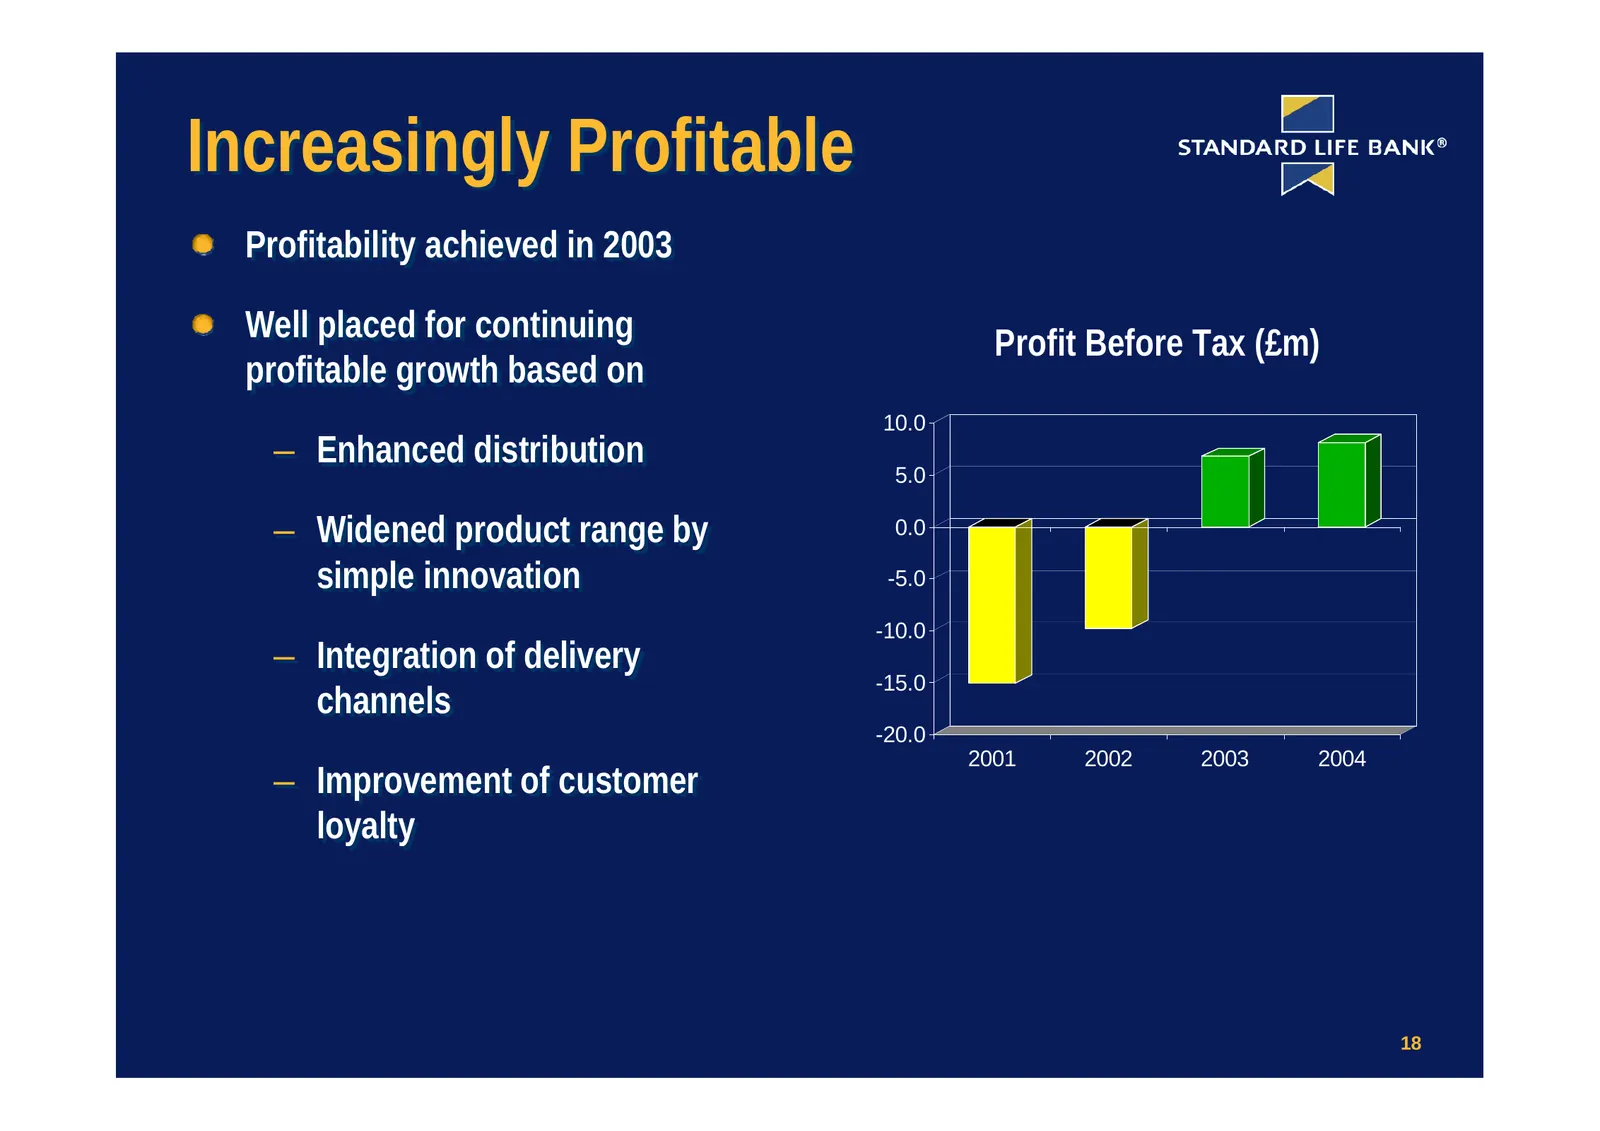
Increasingly Profitable Profitability achieved in 2003 Well placed for continuing Profit Before Tax (£m) profitable growth based on 10.0 – Enhanced distribution 5.0 – Widened product range by 0.0 simple innovation -5.0 -10.0 – Integration of delivery -15.0 channels -20.0 2001 2002 2003 2004 – Improv
Slide 20: Efficiency of Operations
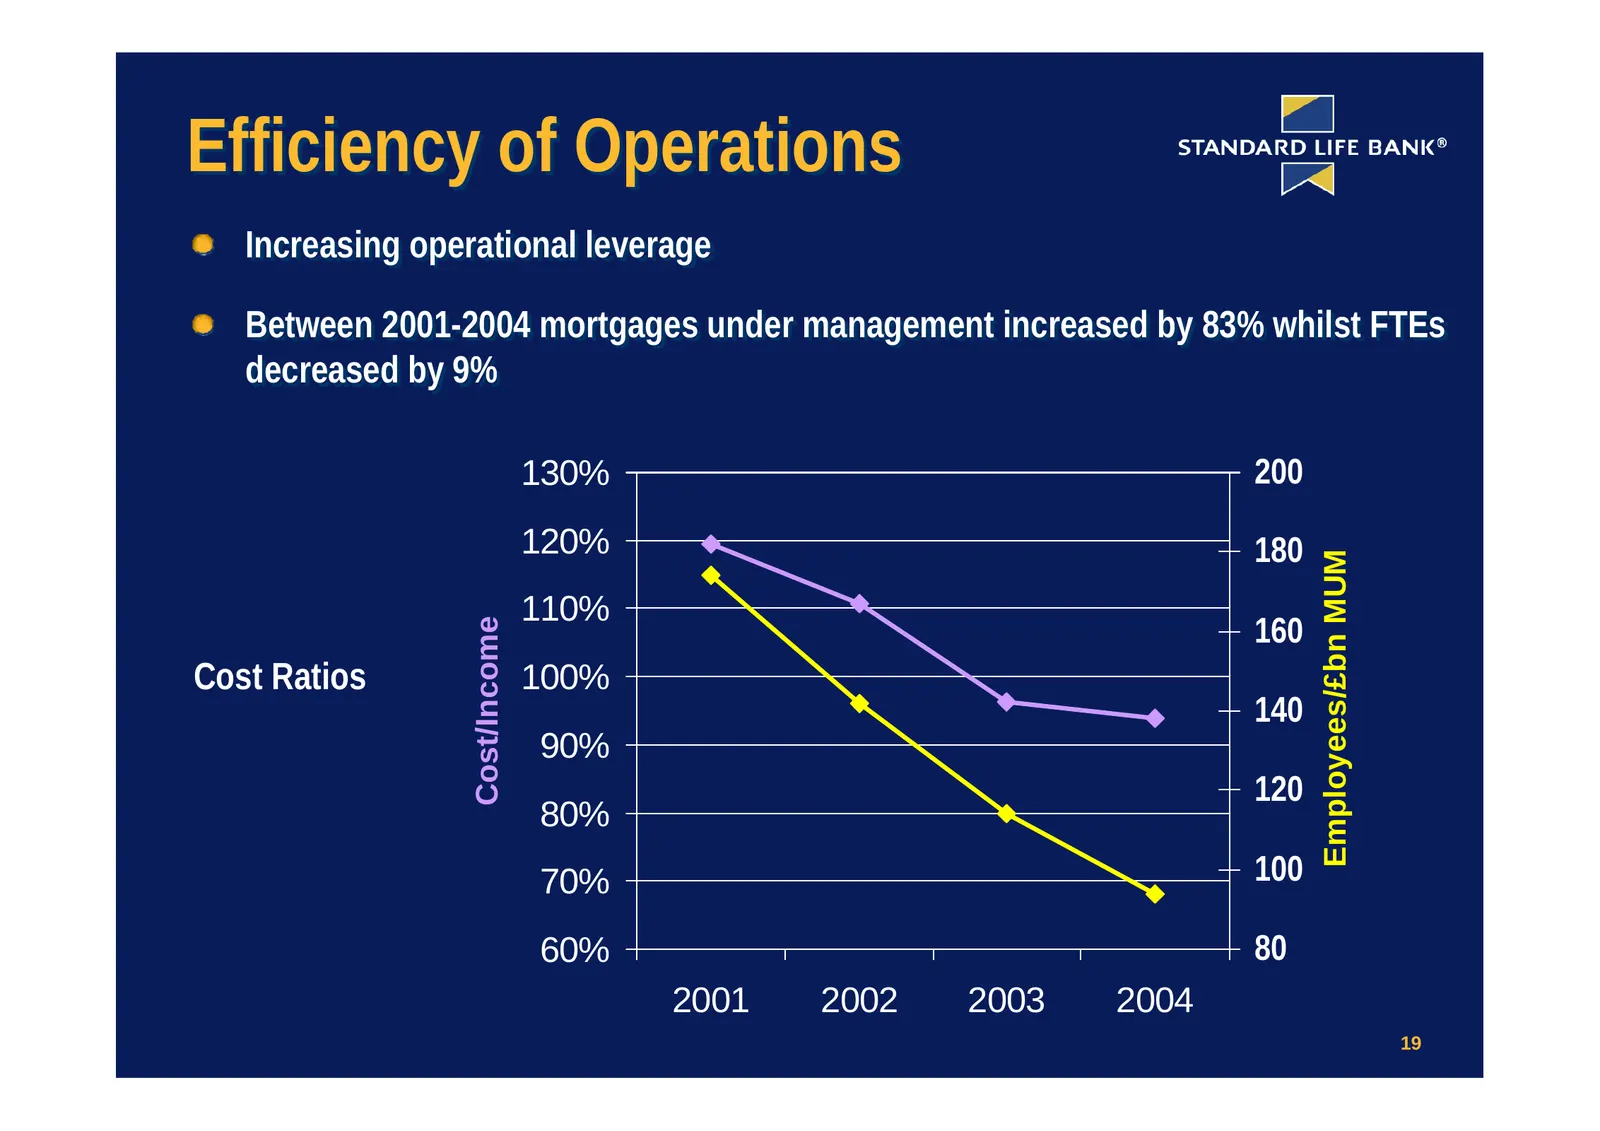
Efficiency of Operations Increasing operational leverage Between 2001-2004 mortgages under management increased by 83% whilst FTEs decreased by 9% 130% 200 120% 180 Employees/£bn MUM 110% 160 Cost/Income Cost Ratios 100% 140 90% 120 80% 70% 100 60% 80 2001 2002 2003 2004 19
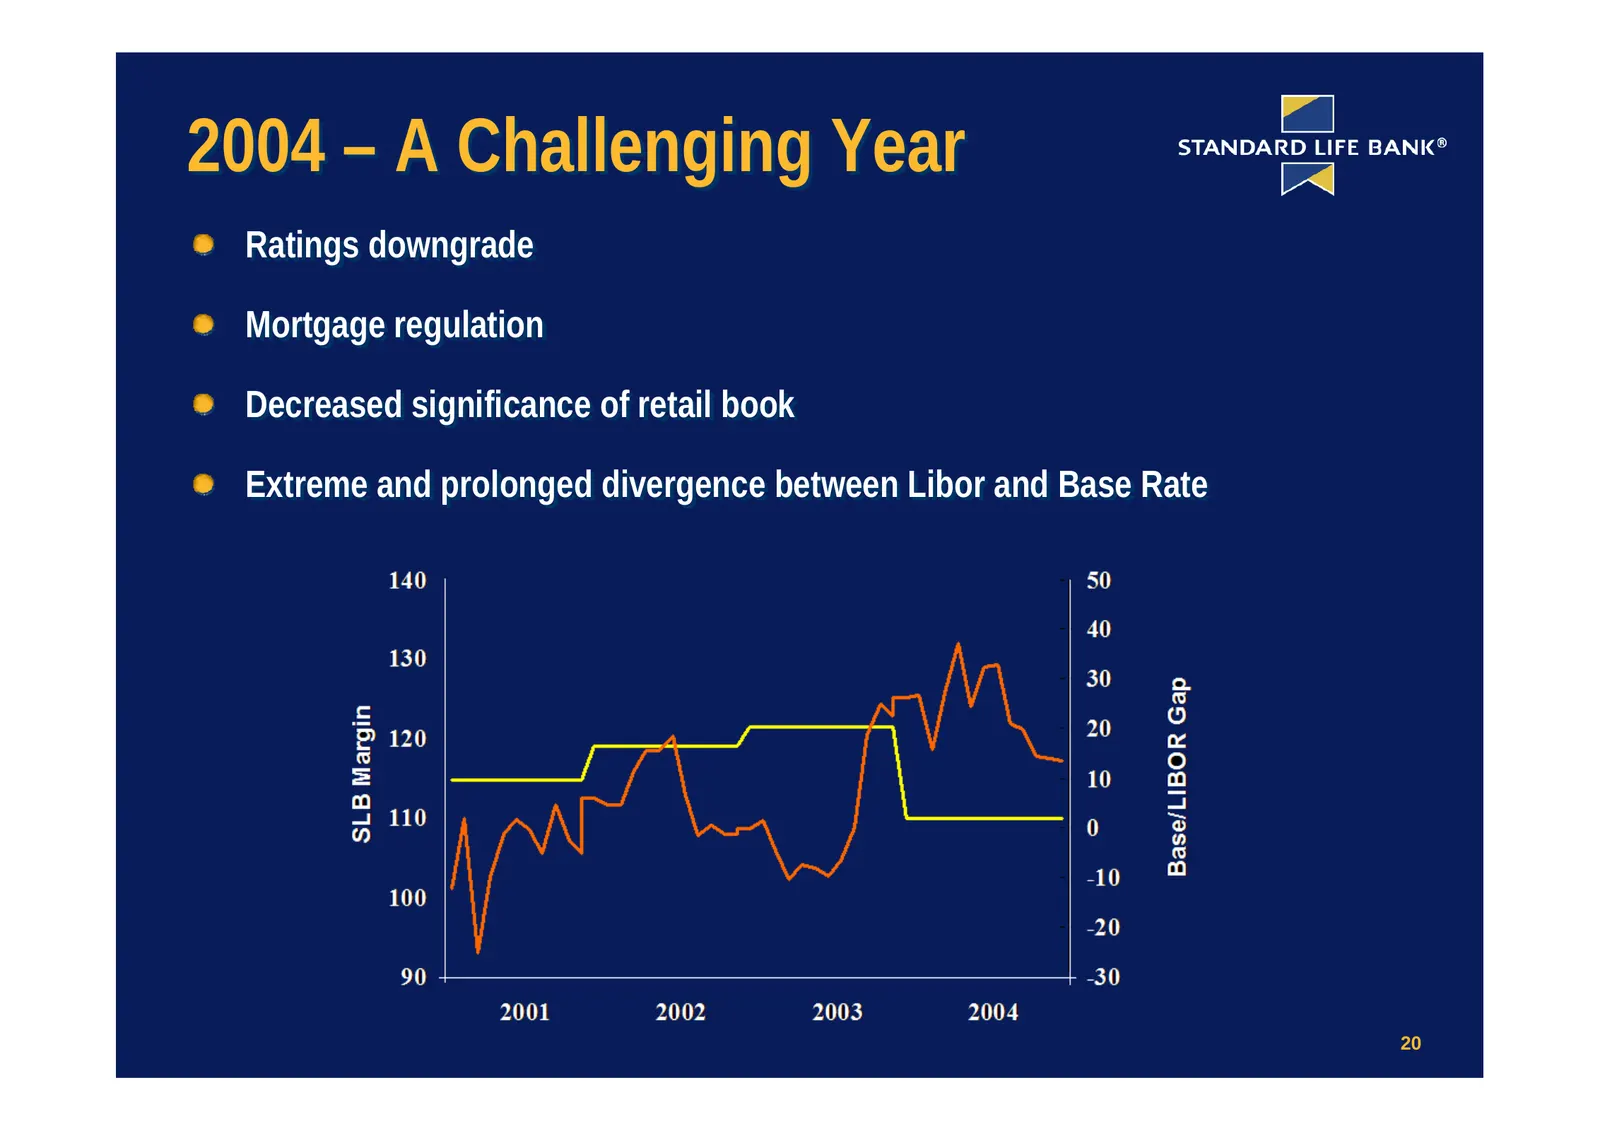
Slide 21: 2004 – A Challenging Year
2004 – A Challenging Year Ratings downgrade Mortgage regulation Decreased significance of retail book Extreme and prolonged divergence between Libor and Base Rate 20
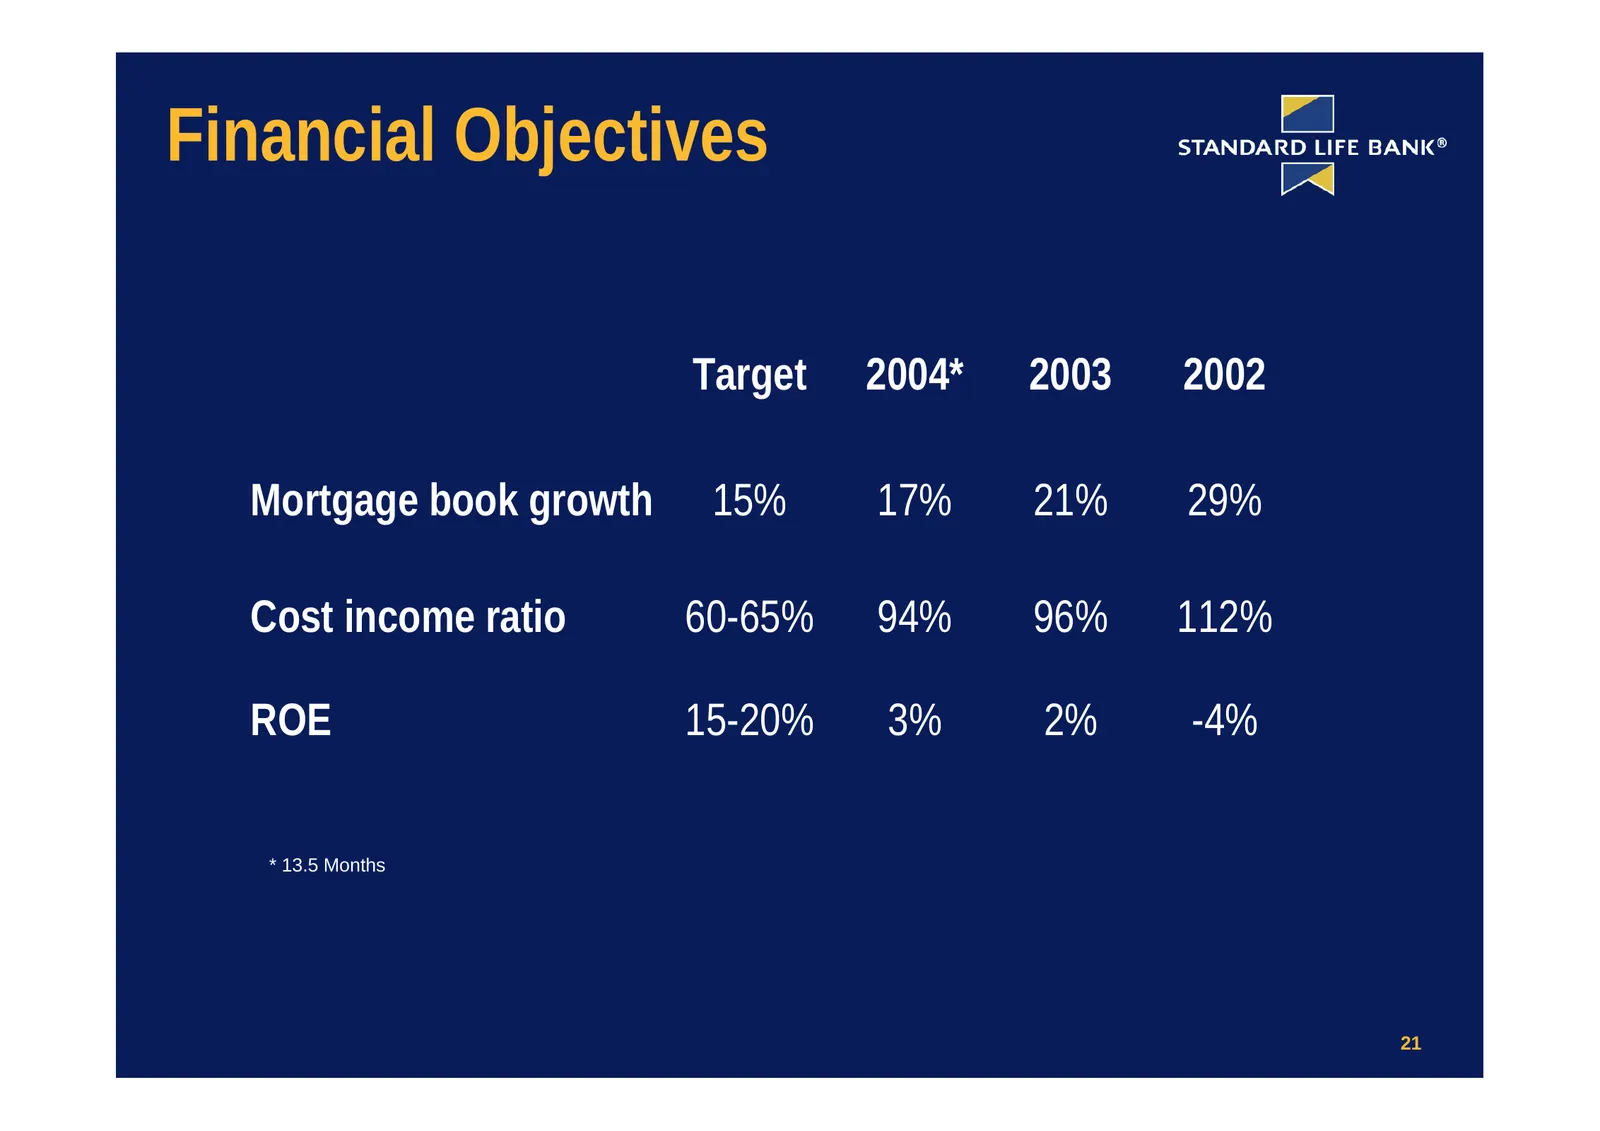
Slide 22: Financial Objectives
Financial Objectives Target 2004* 2003 2002 Mortgage book growth 15% 17% 21% 29% Cost income ratio 60-65% 94% 96% 112% ROE 15-20% 3% 2% -4% * 13.5 Months 21
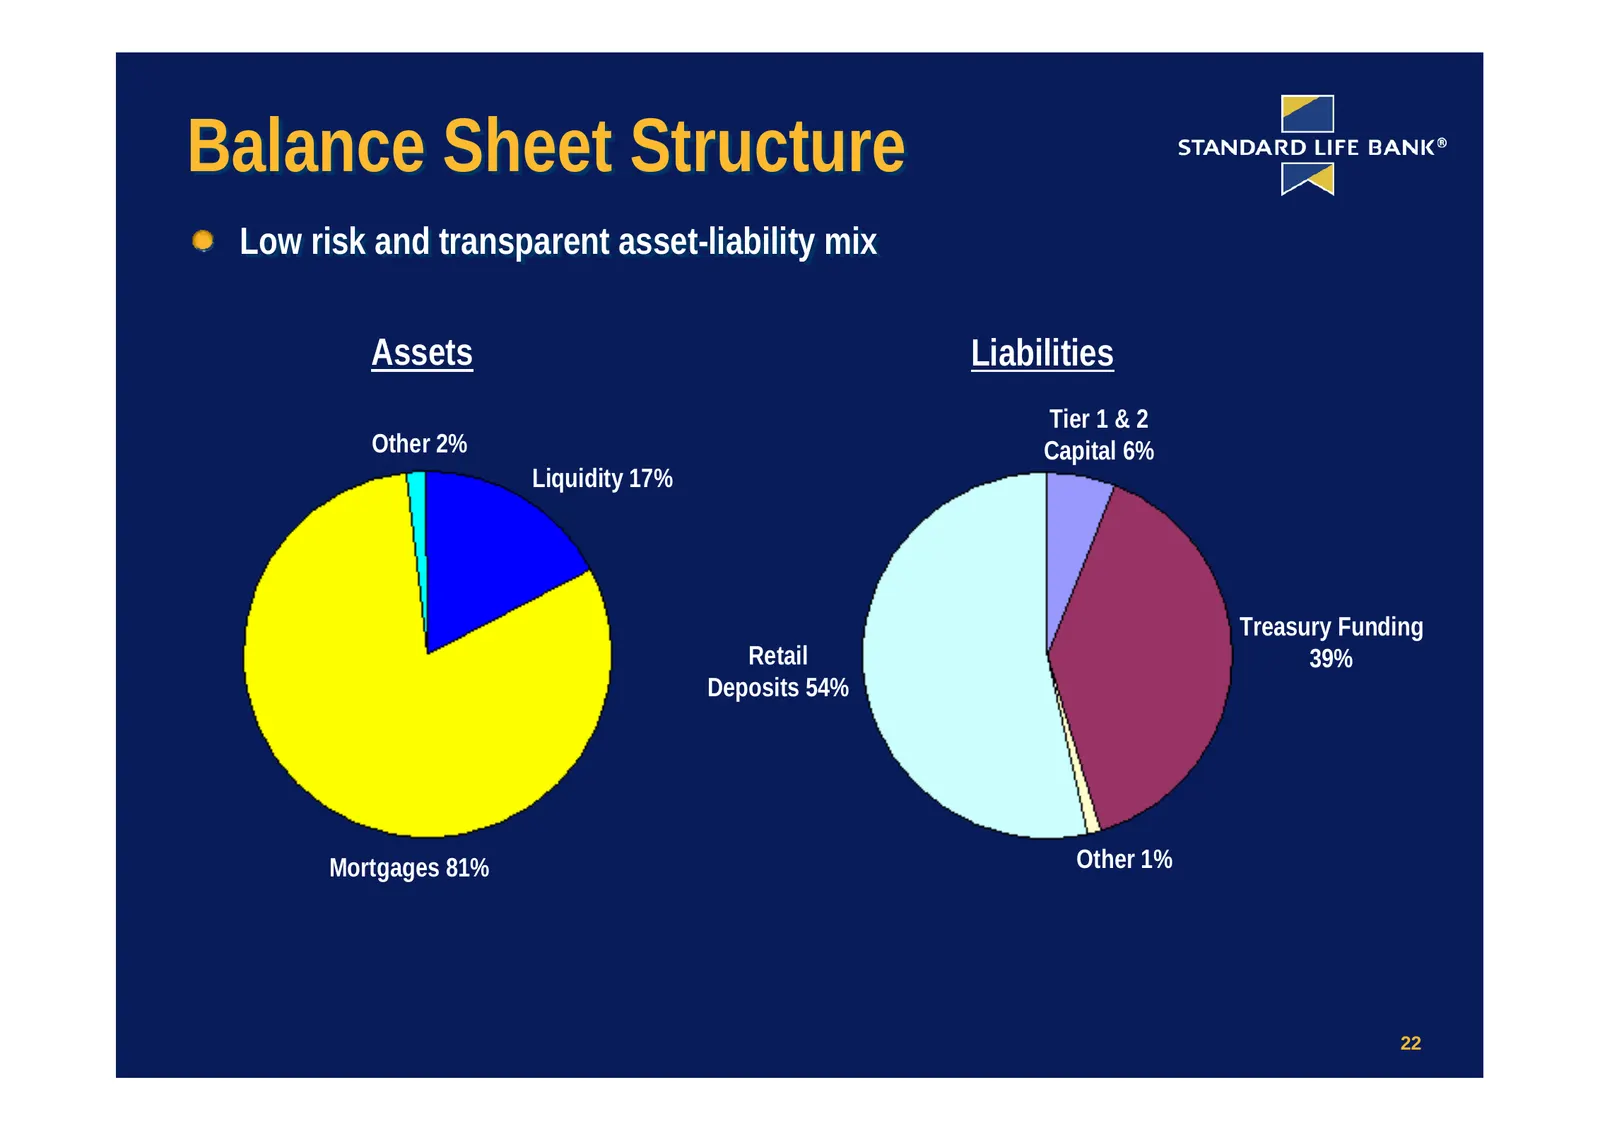
Slide 23: Balance Sheet Structure
Balance Sheet Structure Low risk and transparent asset-liability mix Assets Liabilities Tier 1 & 2 Other 2% Capital 6% Liquidity 17% Treasury Funding Retail 39% Deposits 54% Mortgages 81% Other 1% 22
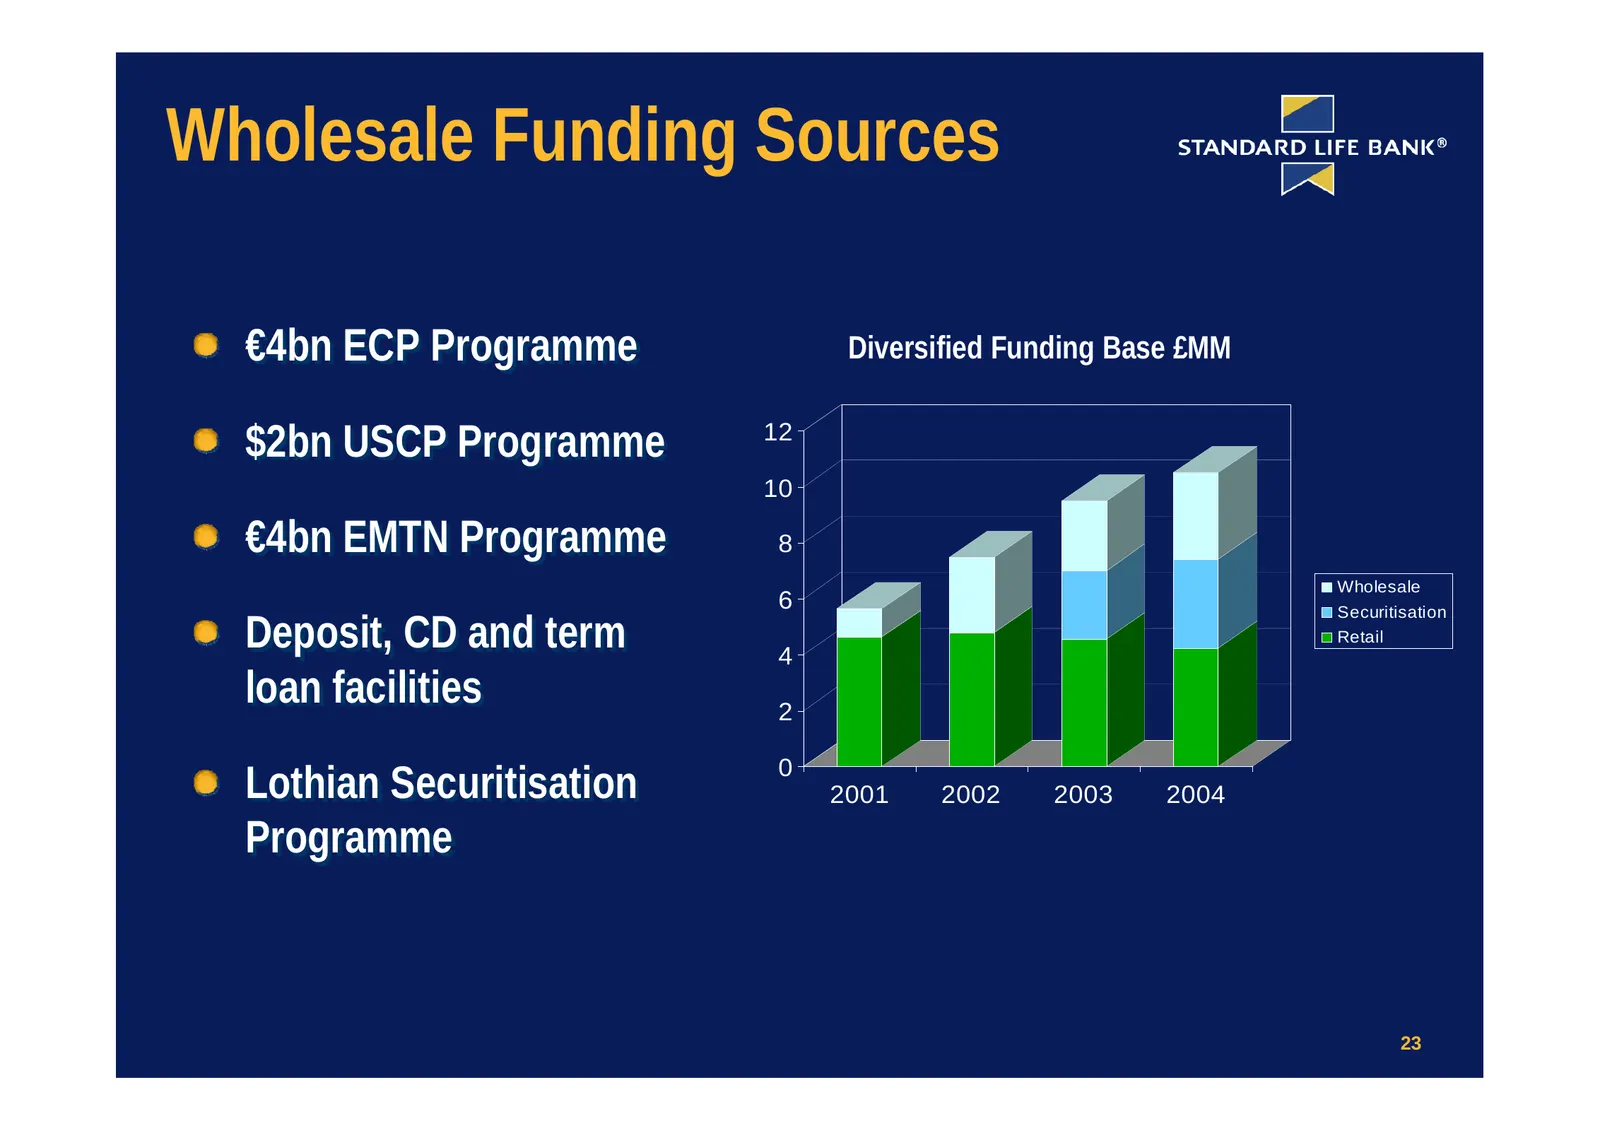
Slide 24: Wholesale Funding Sources
Wholesale Funding Sources €4bn ECP Programme Diversified Funding Base £MM $2bn USCP Programme 12 10 €4bn EMTN Programme 8 Wholesale 6 Deposit, CD and term Securitisation Retail 4 loan facilities 2 Lothian Securitisation 0 2001 2002 2003 2004 Programme 23
Slide 25: Capital Structure
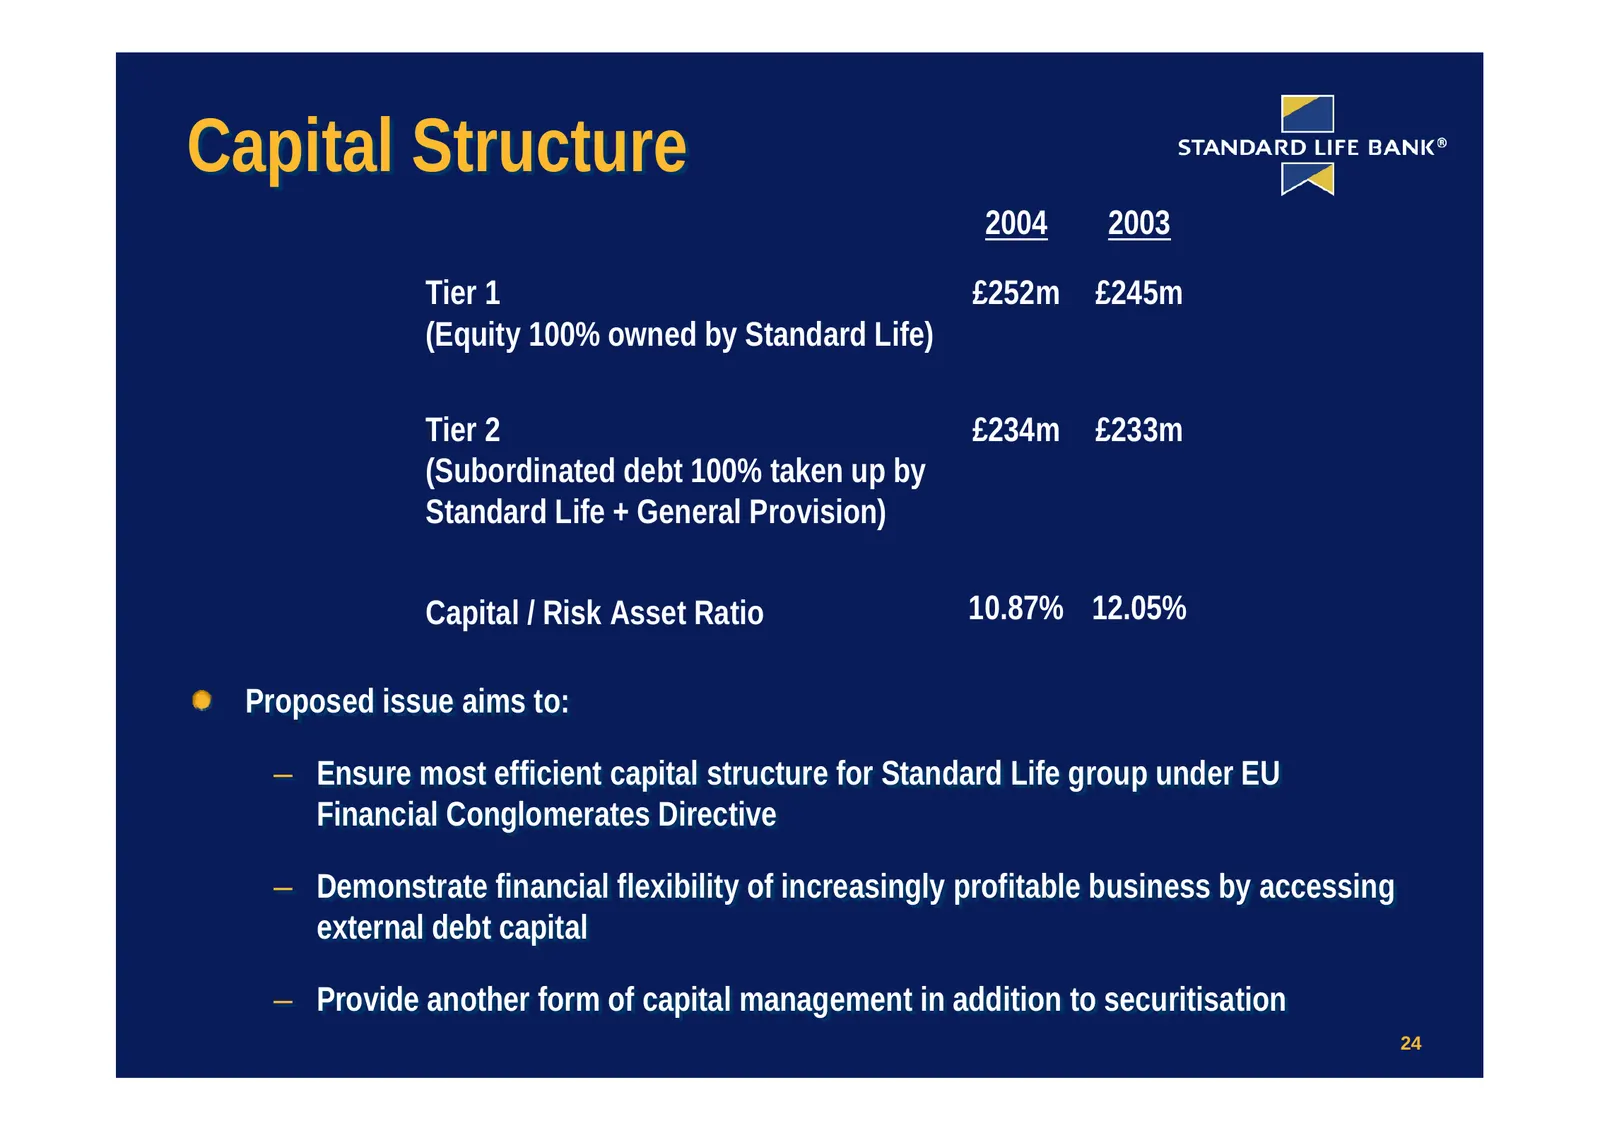
Capital Structure 2004 2003 Tier 1 £252m £245m (Equity 100% owned by Standard Life) Tier 2 £234m £233m (Subordinated debt 100% taken up by Standard Life + General Provision) Capital / Risk Asset Ratio 10.87% 12.05% Proposed Proposed issue issue aims aims to: to: –– Ensure Ensure most most efficient
Slide 26: 4. Strategic Review & Demutualisation
4. Strategic Review & Demutualisation 25
Slide 27: Strategic Review & Demutualisation
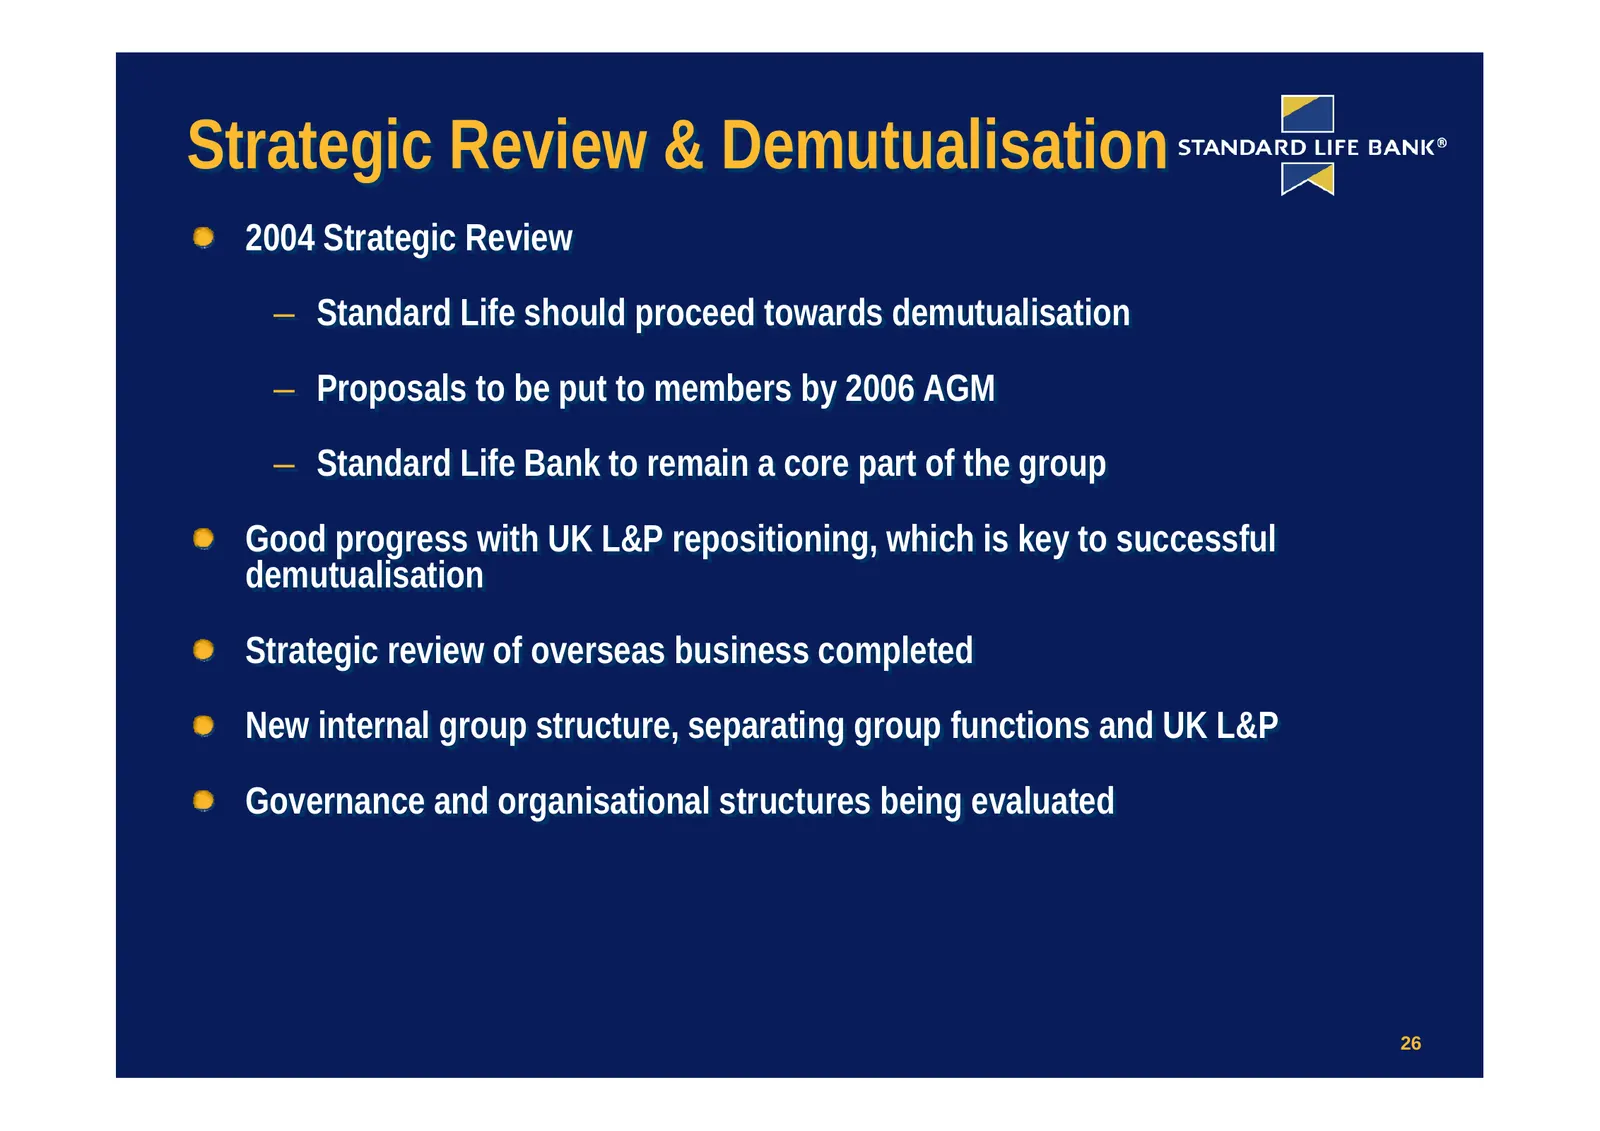
Strategic Review & Demutualisation 2004 Strategic Review – Standard Life should proceed towards demutualisation – Proposals to be put to members by 2006 AGM – Standard Life Bank to remain a core part of the group Good progress with UK L&P repositioning, which is key to successful demutualisation Str
Slide 28: 5. Indicative Terms of the Offering
5. Indicative Terms of the Offering 27
Slide 29: Indicative Terms of the Offering
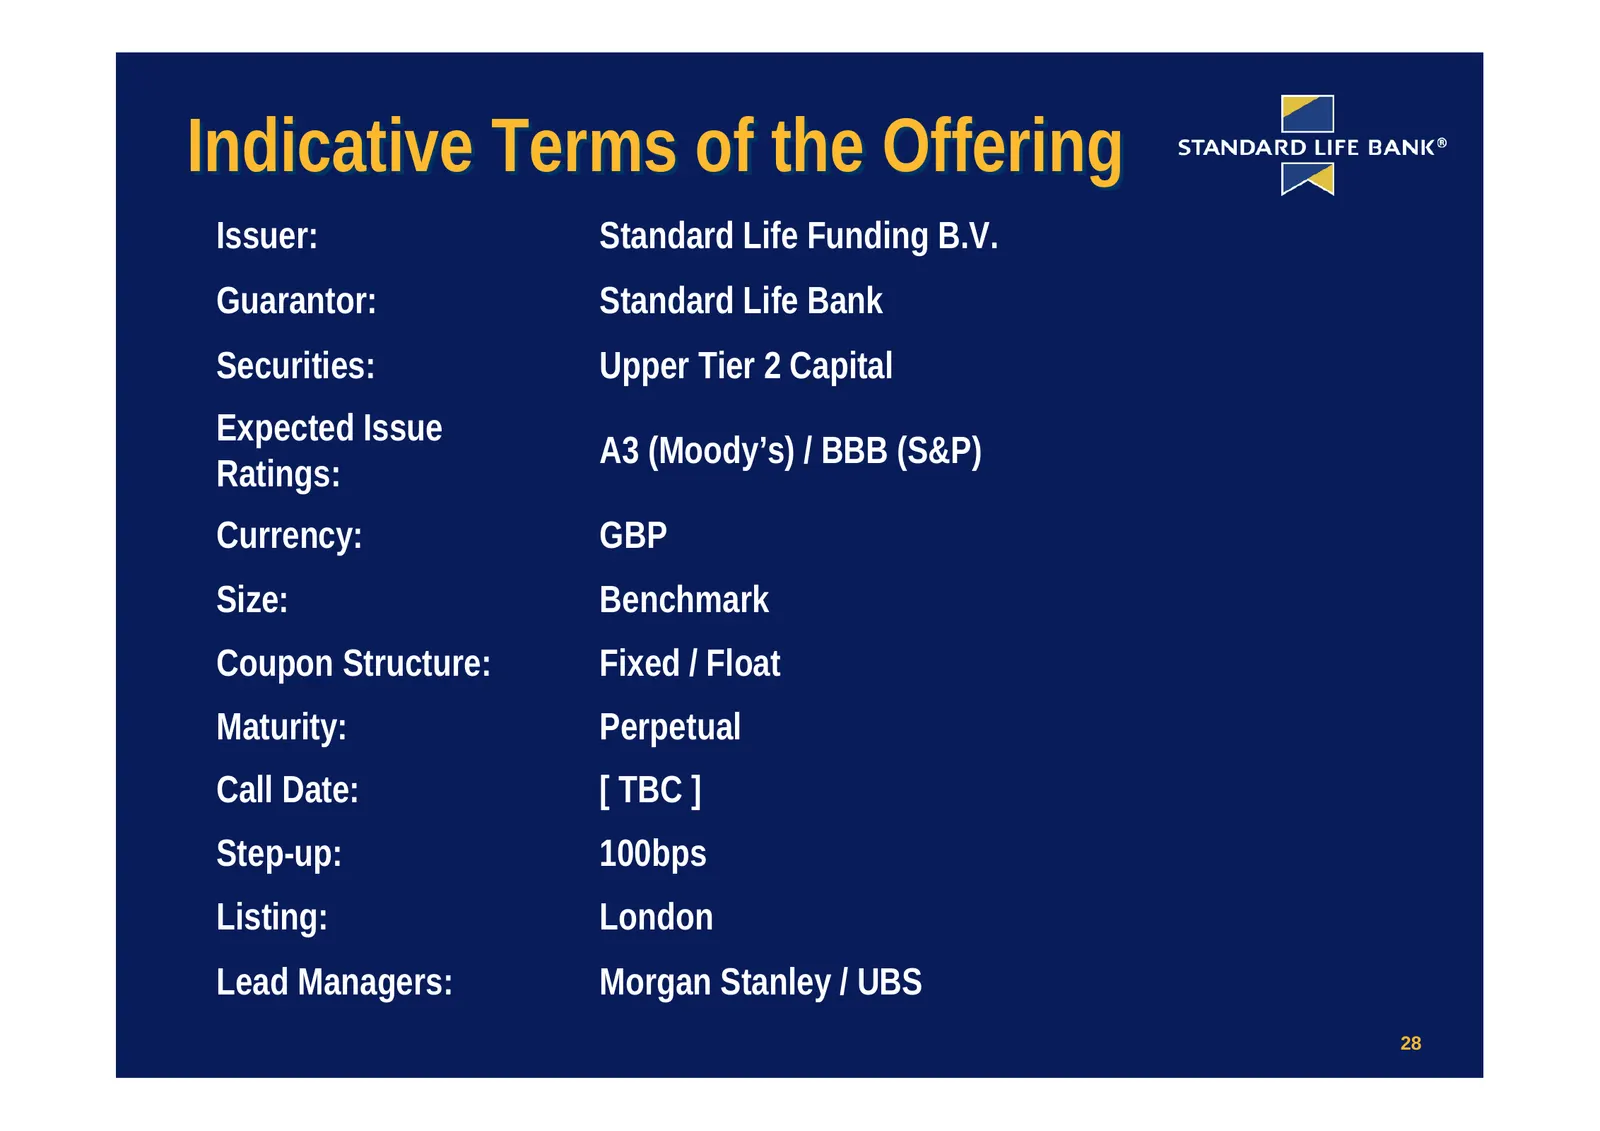
Indicative Terms of the Offering Issuer: Standard Life Funding B.V. Guarantor: Standard Life Bank Securities: Upper Tier 2 Capital Expected Issue A3 (Moody’s) / BBB (S&P) Ratings: Currency: GBP Size: Benchmark Coupon Structure: Fixed / Float Maturity: Perpetual Call Date: [ TBC ] Step-up: 100bps Lis
Slide 30: Investor Relations
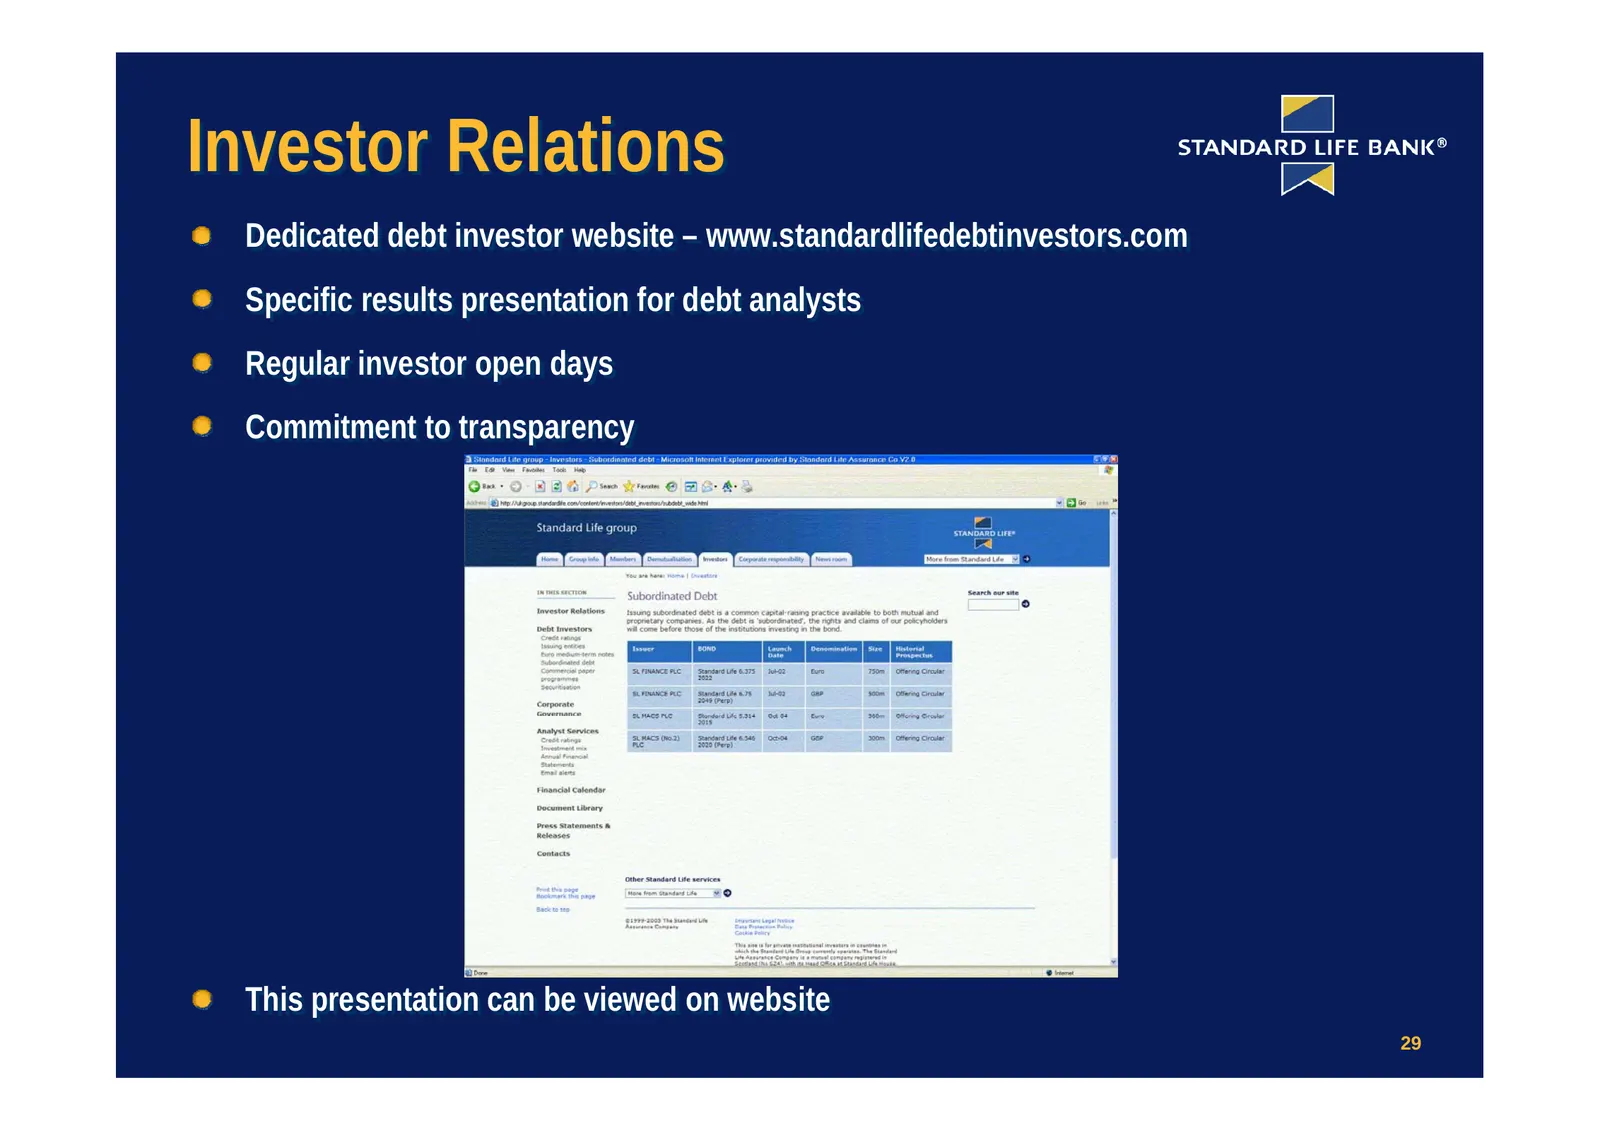
Investor Relations Dedicated Dedicated debt debt investor investor website website –– www.standardlifedebtinvestors.com www.standardlifedebtinvestors.com Specific Specific results results presentation presentation for for debt debt analysts analysts Regular Regular investor investor open open days d
Slide 31: Summary
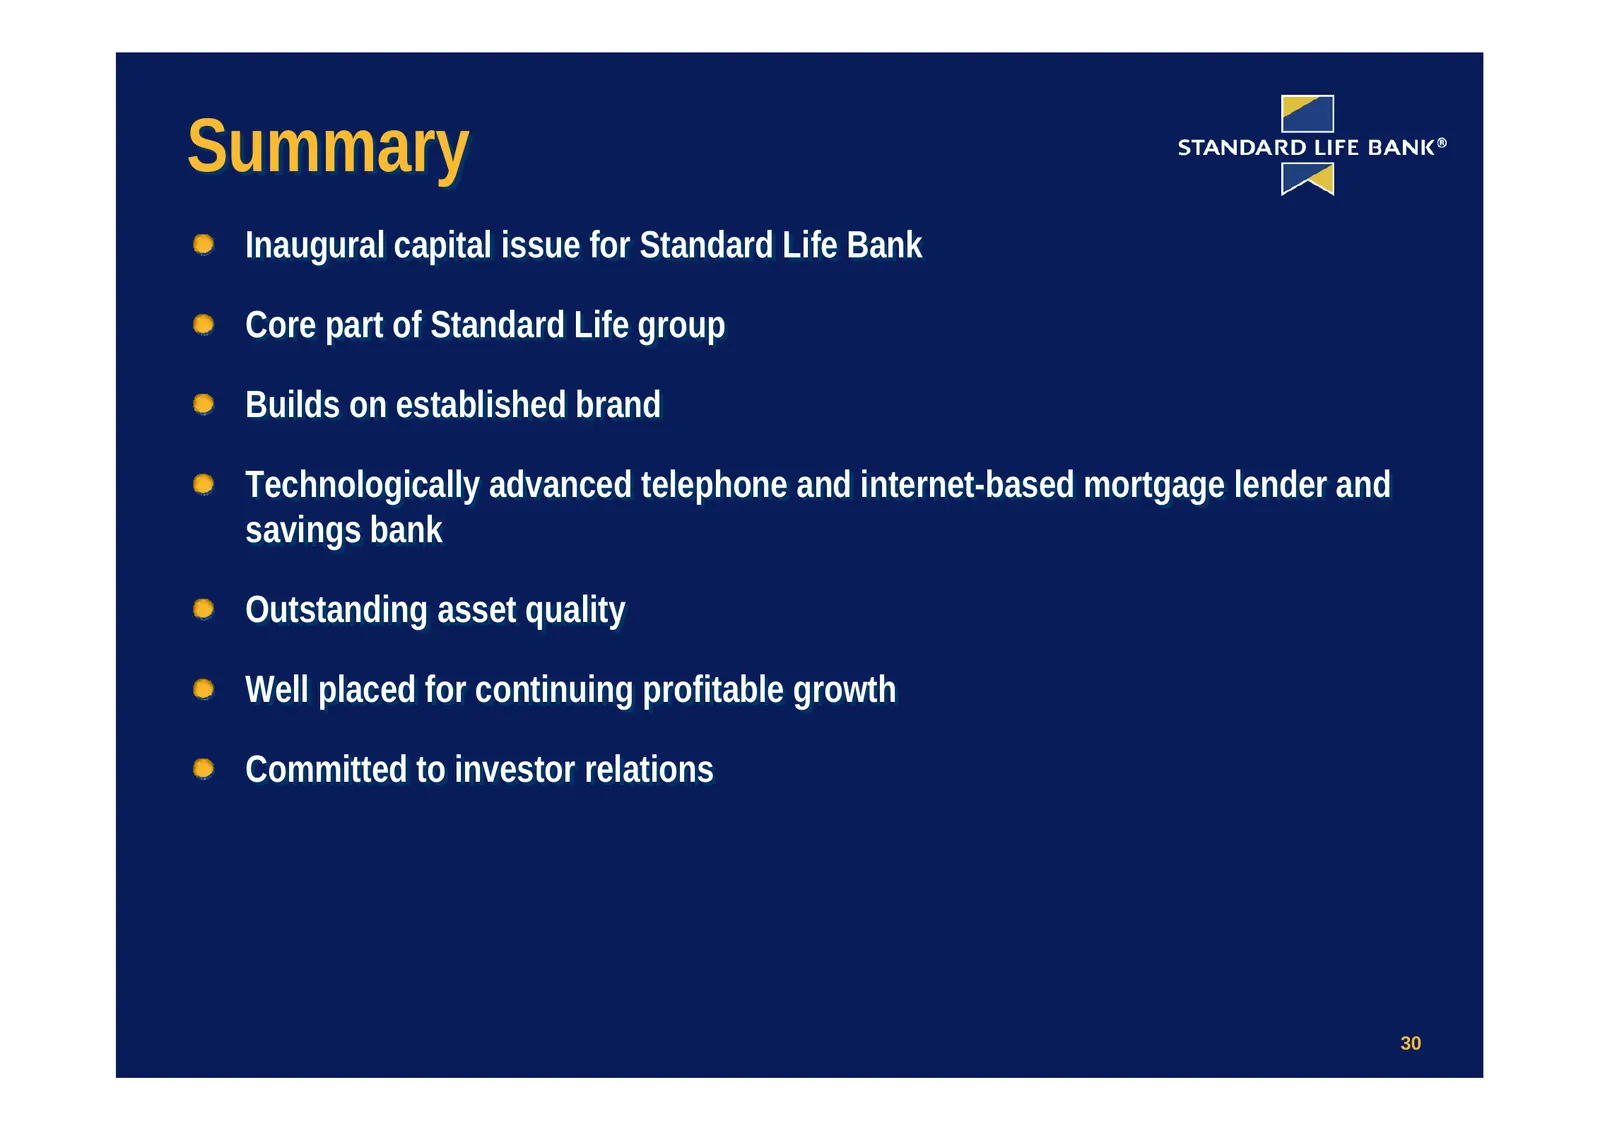
Summary Inaugural capital issue for Standard Life Bank Core part of Standard Life group Builds on established brand Technologically advanced telephone and internet-based mortgage lender and savings bank Outstanding asset quality Well placed for continuing profitable growth Committed to investor rela
Slide 32: Disclaimer
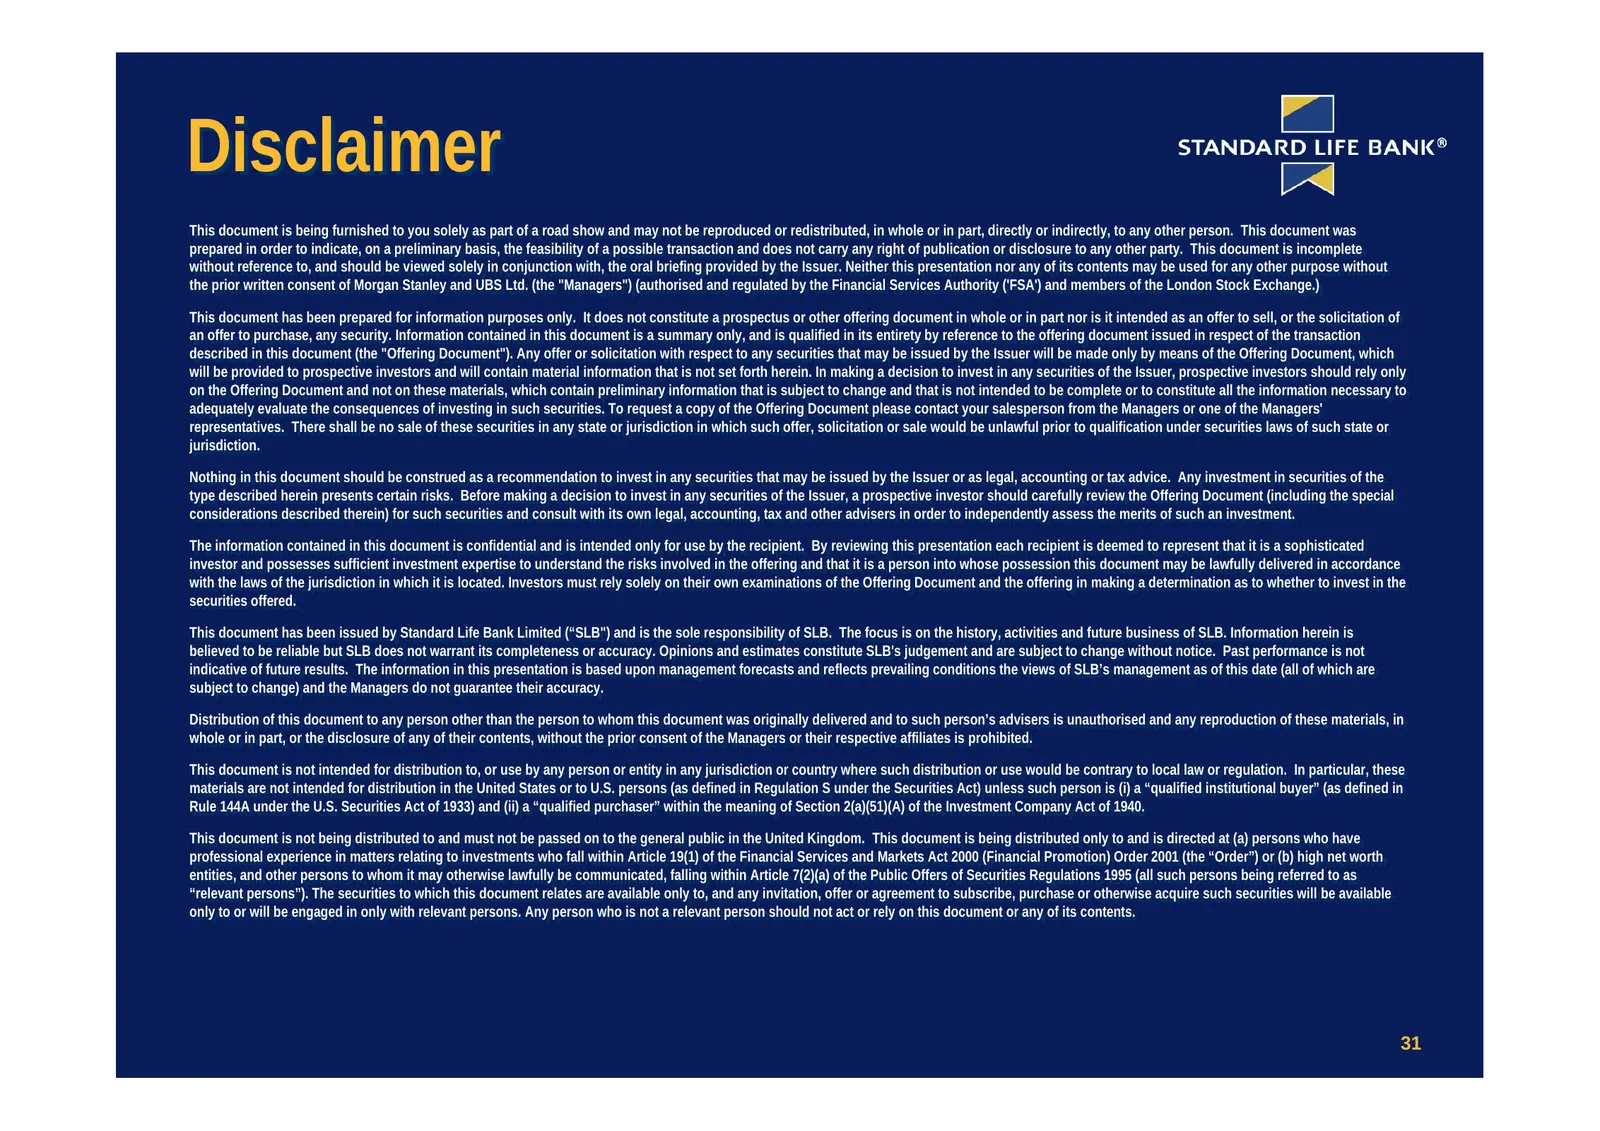
Disclaimer This Thisdocument documentisisbeing beingfurnished furnishedto toyou yousolely solelyas aspart partof ofaaroad roadshow showandandmay maynot notbe bereproduced reproducedororredistributed, redistributed,ininwhole wholeor orininpart, part,directly directlyor orindirectly, indirectly,to toa
Source: Internet Archive copy of standardlife.com
More decks from Aberdeen Group plc
 H1 2026 Earnings Presentation25 slides · Jul 29, 2026
 Investor Day (June 2026)25 slides · Jun 25, 2026
 FY2025 Earnings Presentation33 slides · Mar 3, 2026
 H1 2025 Earnings Presentation27 slides · Jul 30, 2025
 FY2024 Earnings Presentation41 slides · Mar 4, 2025
 H1 2024 Earnings Presentation28 slides · Aug 6, 2024