Duke Realty — 2012 UBS Industrial Real Estate Summit
64 slides from Duke Realty's conference presentation, May 16, 2012
Slide 1: 2012 UBS Industrial Real Estate Summit
RELIABLE. ANSWERS. 2012 UBS Industrial Real Estate Summit May 16 Exhibit 99.1
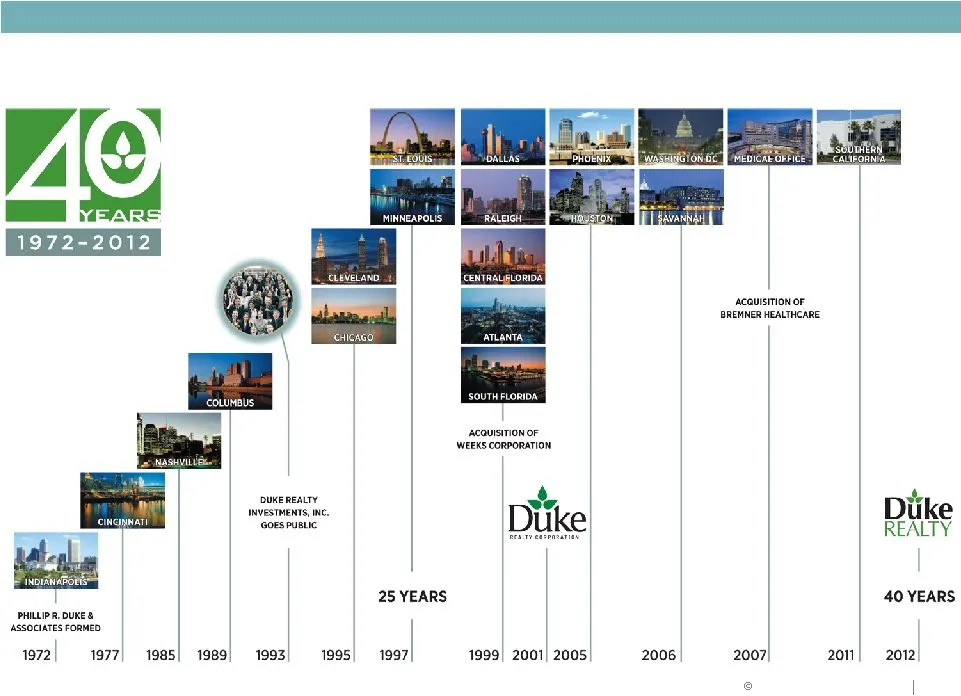
Slide 2: 40 Years Timeline
RELIABLE. ANSWERS . 40 Years Timeline
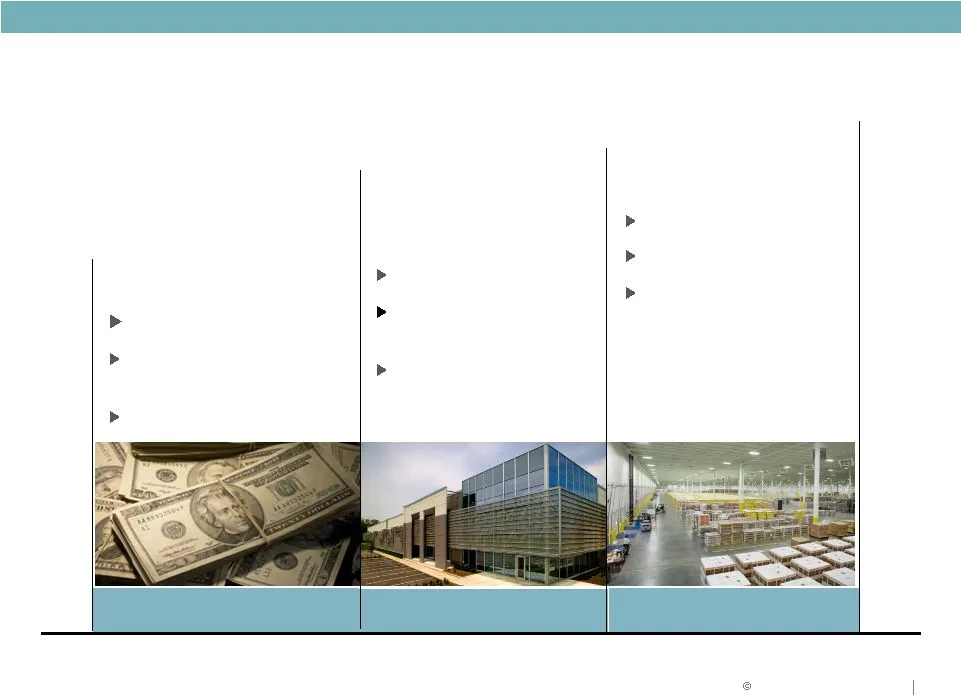
Slide 3: Where we've been and where we're going
RELIABLE. ANSWERS . 2009 2010 and 2011 2012 and beyond FOCUS: Liquidity More than $1.5 billion capital raised Strategy refined FOCUS: Strategy execution Operating fundamentals Balance sheet strength FOCUS: Asset quality Cash flow growth Shareholder return Where we’ve been and where we’re going…
Slide 4: Market Outlook: Office, Medical Office and Industrial
RELIABLE. ANSWERS . Suburban Office Market Still Challenging Economic and federal budget uncertainty limiting business investment and expansion decisions Recovery is very slow, with Q1 overall vacancy declining to 12.7%, down 50 bps from prior year, with class A only space vacancy declining 90 bps f
Slide 5: Industrial Sector Peer Set Drill Down
RELIABLE. ANSWERS . Industrial Sector Peer Set Drill Down • RMZ outperformed S&P 500 in 2011, but has lagged slightly below the S&P 500 in • Industrial Sector Comps have rallied recently . . . Improving key trading metrics and relative valuations • Duke Realty has outperformed, although still underv
Slide 6: Strategies for delivering shareholder value
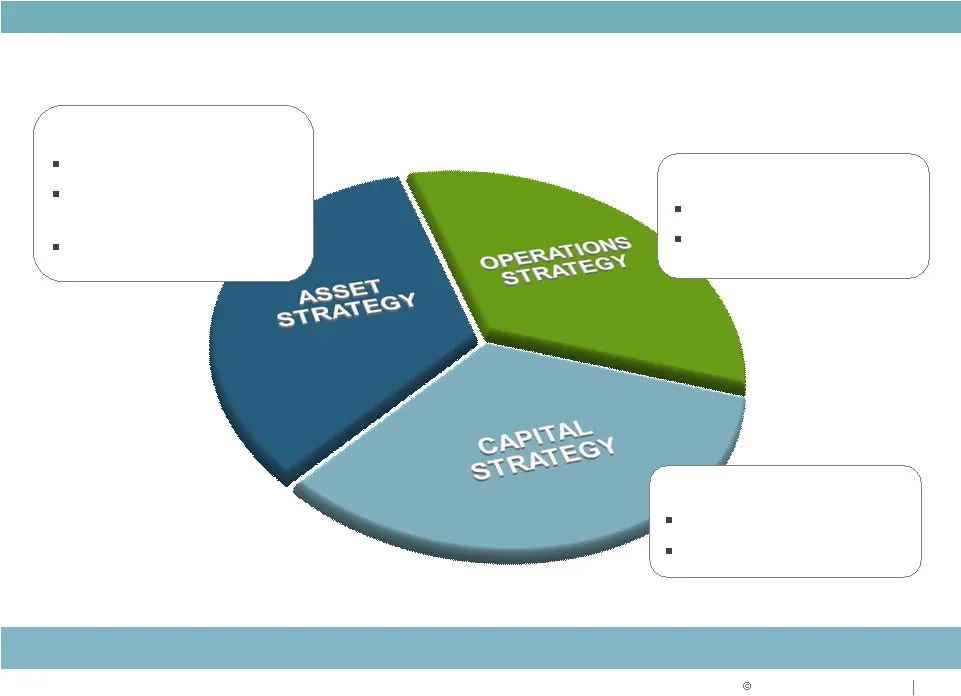
RELIABLE. ANSWERS . Focus on: Increasing cash flow Maximizing return on assets Strategy for Success Focus on: Improving coverage ratios Improving ratings Focus on: Portfolio repositioning Strategic acquisitions & dispositions Development opportunities Strategies for delivering shareholder value
Slide 7: 2012 Goals and Objectives, Q1 2012 Update
RELIABLE. ANSWERS . 2012 Goals and Objectives Q1 2012 Update Solid Q1 start and executing across all three aspects of our strategy Strategic Focus • Lease-up portfolio, manage cap ex; reach positive same property income growth • Balance execution with capital strategy relative to level and quality o
Slide 8: Operations Strategy
OPERATIONS STRATEGY
Slide 9: Focus on Fundamentals
OPERATIONS STRATEGY Focus on Fundamentals LEASING OF PORTFOLIO STRATEGIC NEW DEVELOPMENT AND LAND DISPOSITION AFFO PAYOUT Maximize return on assets
Slide 10: Consistent Operating Performance
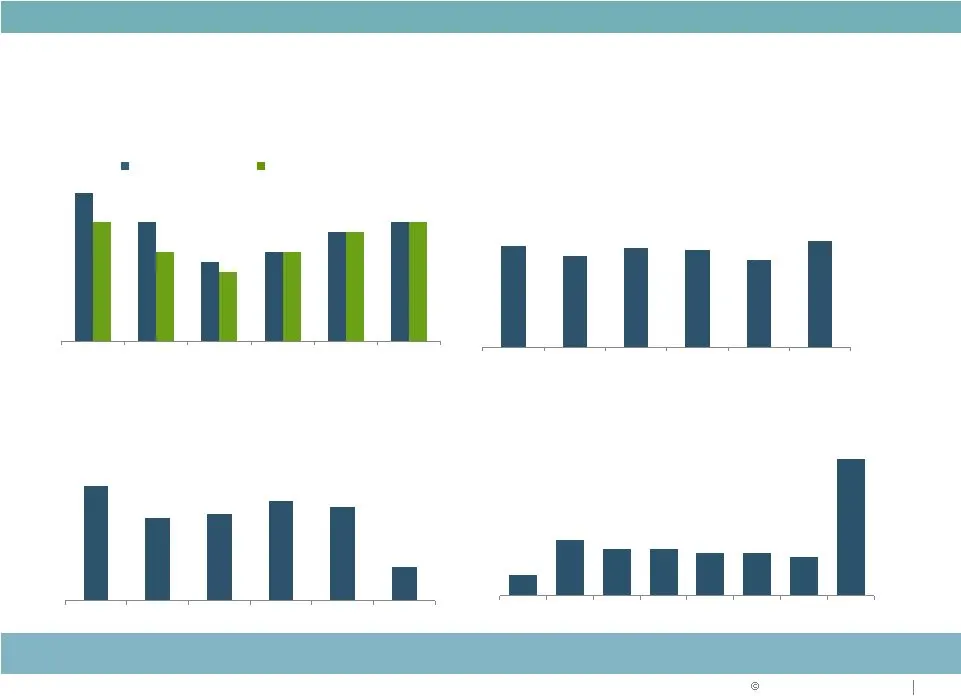
OPERATIONS STRATEGY Consistent Operating Performance Stabilized Occupancy (%) Strong historical stabilized occupancy – fundamentals improving Lease Renewals (%) Strong lease renewal percentages Stabilized occupancy In-service occupancy Leasing Activity New Leases and Renewals – Consistent Execution
Slide 11: Consistent NOI Growth Outperformance
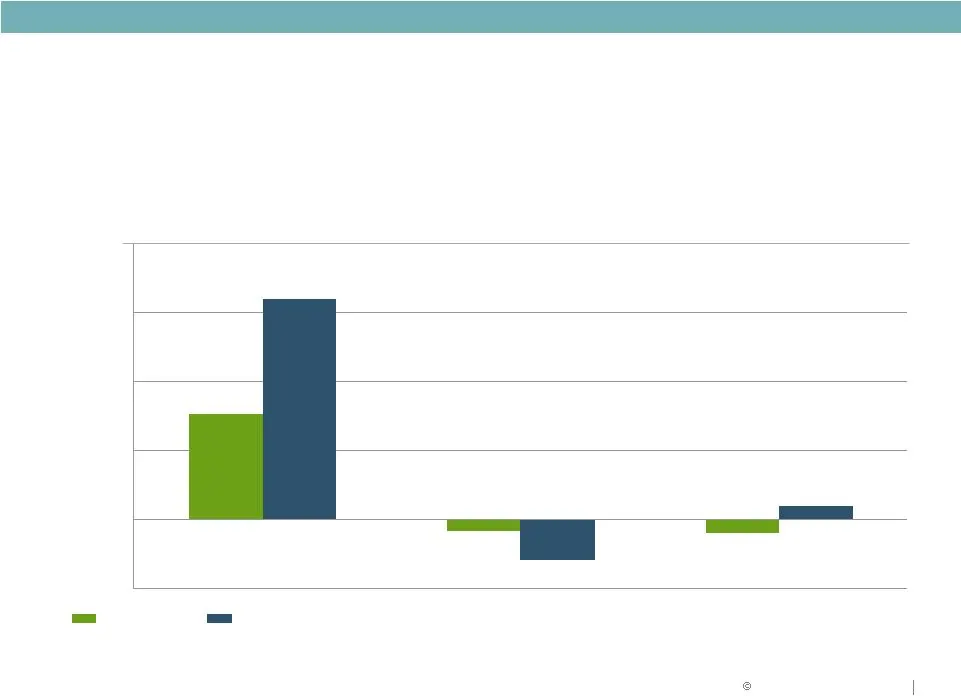
OPERATIONS STRATEGY Notes 1. Based on simple average of year-over-year annual same-property cash NOI growth, includes - 2. Suburban Office Peers include BDN, CLI, HIW, LRY and PKY; weighted by historical market cap 3. Industrial includes DCT, EGP, FR, FPO, PSB, AMB and PLD; weighted by historical ma
Slide 12: Positioned for NAV Growth
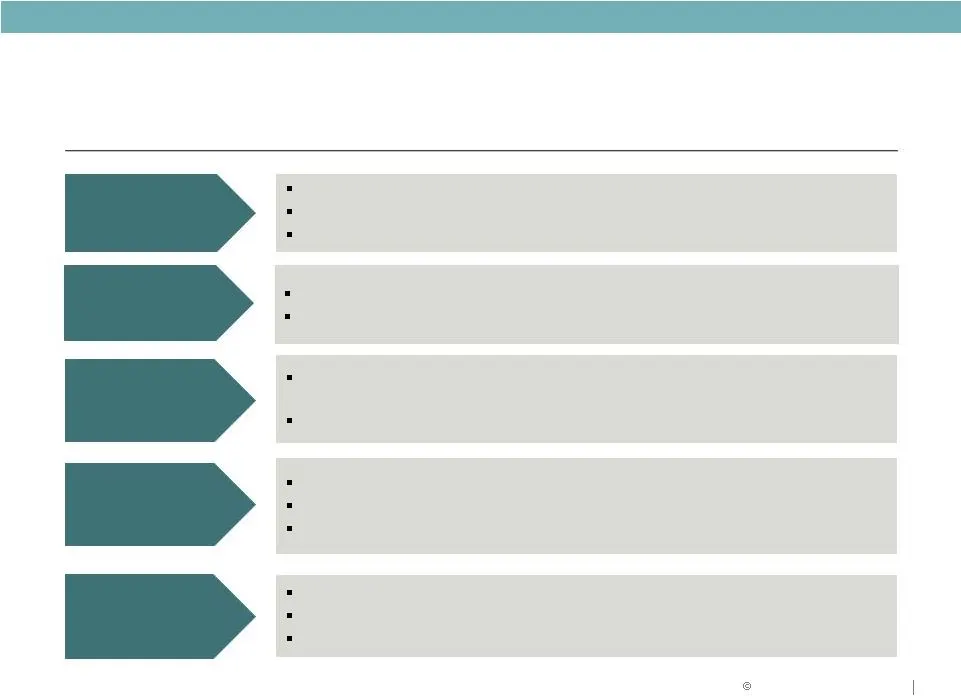
RELIABLE. ANSWERS . Lease up existing vacancy Increase Rents/ Reduced Capex Increased management & service fees Accretive future development Accretive future acquisitions Positioned for NAV Growth KEY NAV GROWTH DRIVERS Source: PPR, Green Street and Duke Realty Portfolio occupancy of 92.1% Strong le
Slide 13: Land and Development Capabilities
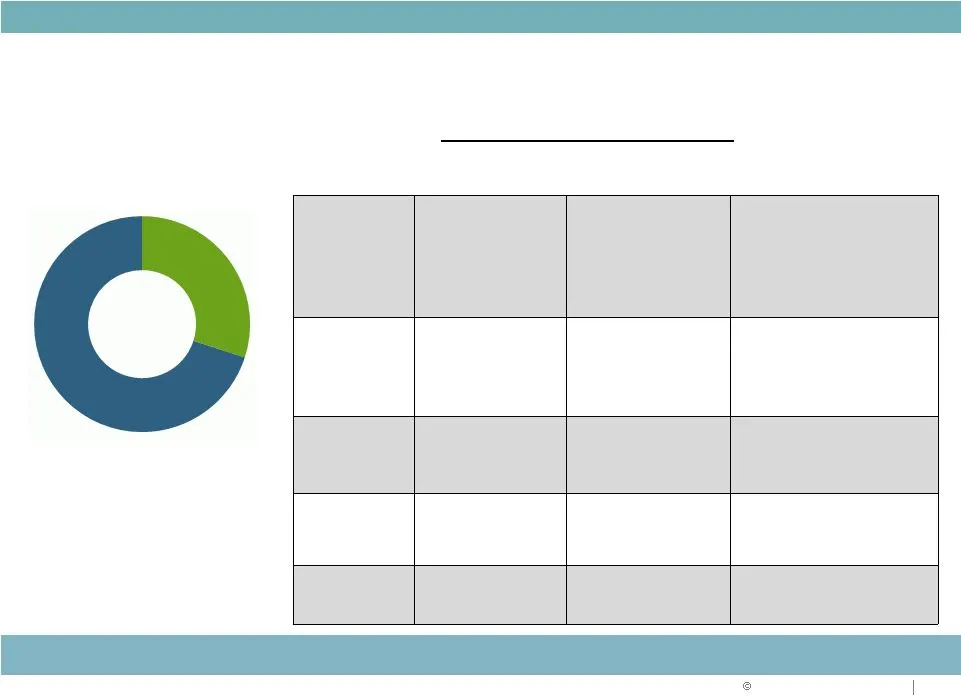
OPERATIONS STRATEGY Office 30% Industrial 70% Land and Development Capabilities $498 million HELD FOR DEVELOPMENT Industrial Office Midwest 26.3 2.8 Indianapolis, Chicago, Cincinnati, Columbus, Minneapolis, and St. Louis major positions East 3.8 2.1 New Jersey, Baltimore, Washington D.C., and Raleig
Slide 14: Indianapolis – Industrial
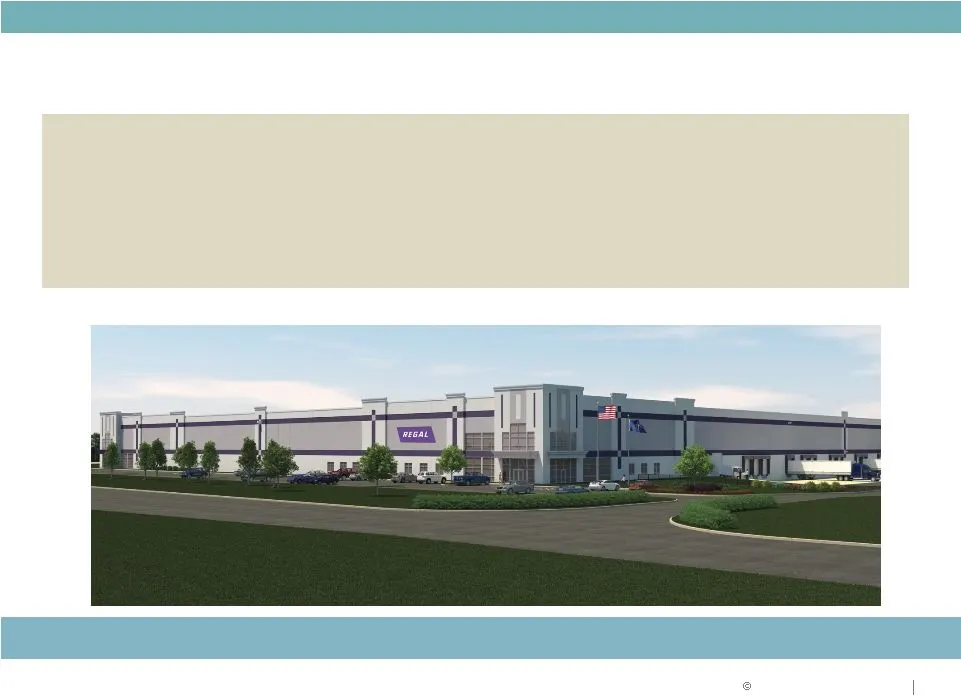
OPERATIONS STRATEGY Indianapolis – Industrial Expand Industrial • Regal Beloit build-to-suit bulk distribution facility • 376,000 square feet, ten year lease term to growing global manufacturing company • 50/50 joint venture with Browning • Monetizes acres of land at our acre AllPoints Midwest bulk
Slide 15: Northeast U.S. – Bulk Industrial Build-to-Suit
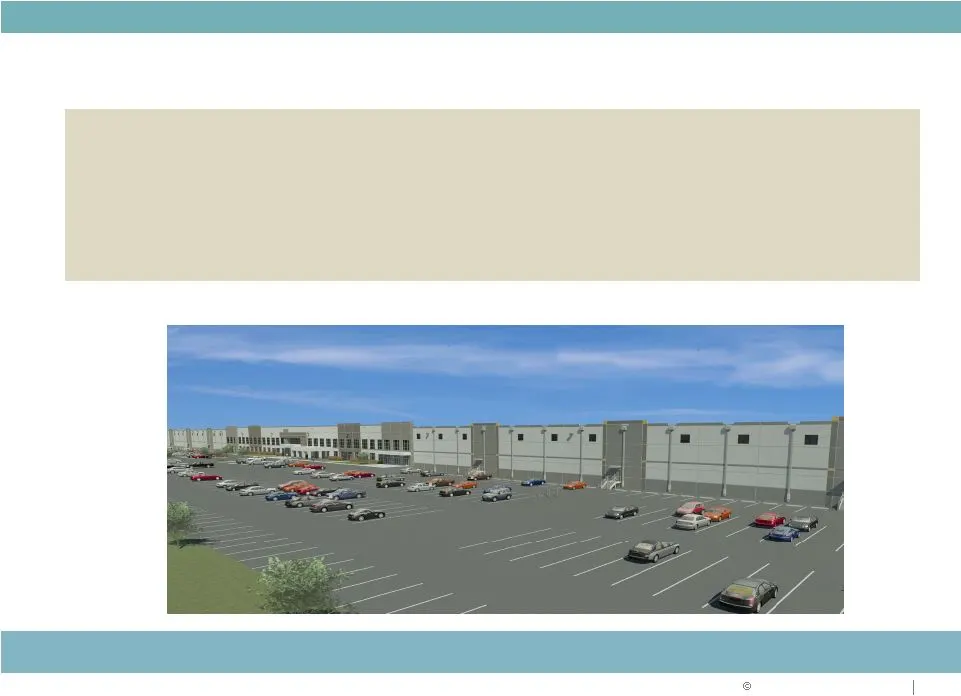
OPERATIONS STRATEGY Northeast U.S. – Bulk Industrial Build-to-Suit Repeat business new development with growing tenant • Regional distribution center build-to-suit in Delaware for Amazon • 1,015,000 square feet • Twelve year lease term • $82 million project • “A” rated credit
Slide 16: Indianapolis – Medical Office
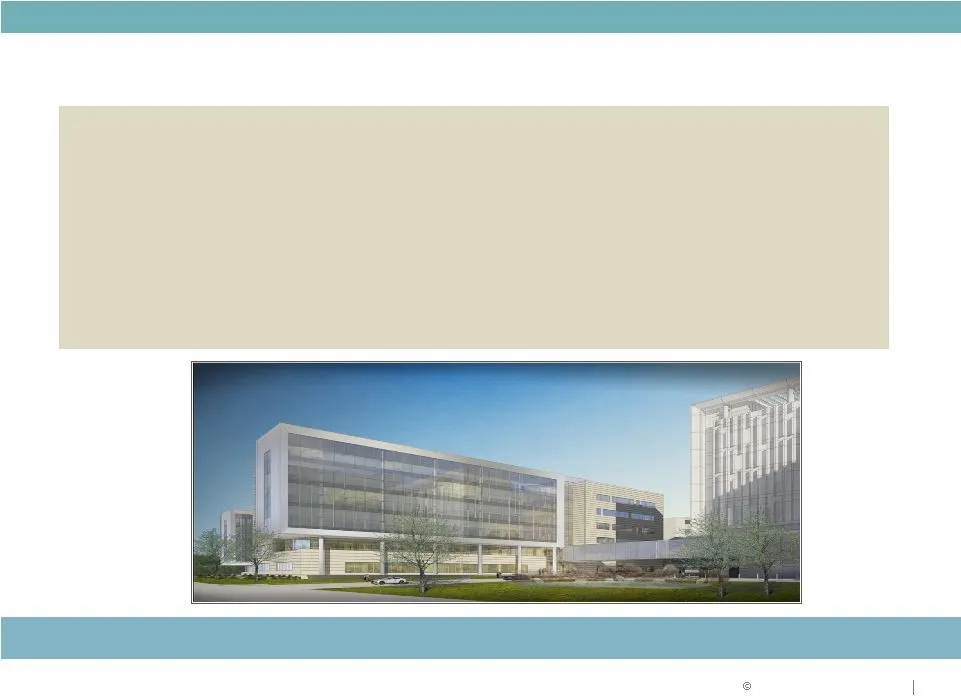
OPERATIONS STRATEGY Indianapolis – Medical Office Grow Medical Office • Wishard Faculty Office Building • Aa2 rated system sponsored by Marion County • 275,000 square feet • Thirty year lease term • 50/50 Joint Venture with Hospital System • On campus of new hospital to open in 2013 • $90 million pr
Slide 17: Tampa – Medical Office
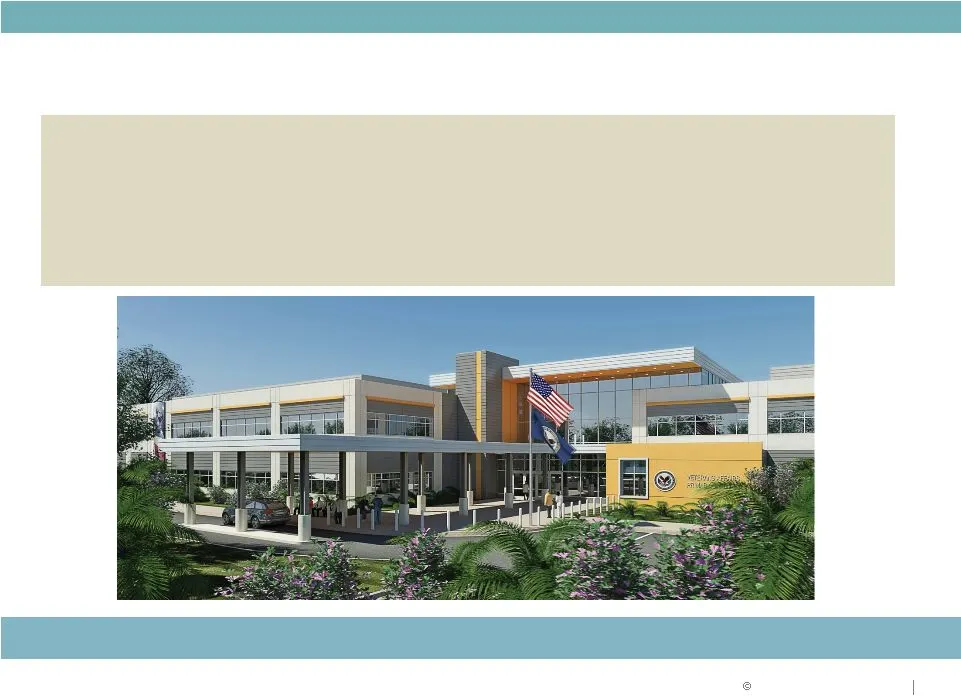
RELIABLE. ANSWERS . Tampa – Medical Office • VA Primary Care Annex at Tampa • Leased to Department of Veterans Affairs • 120,000 square feet • 20 year lease term • $41 million project Grow Medical Office
Slide 18: Quality, well-positioned assets to drive performance
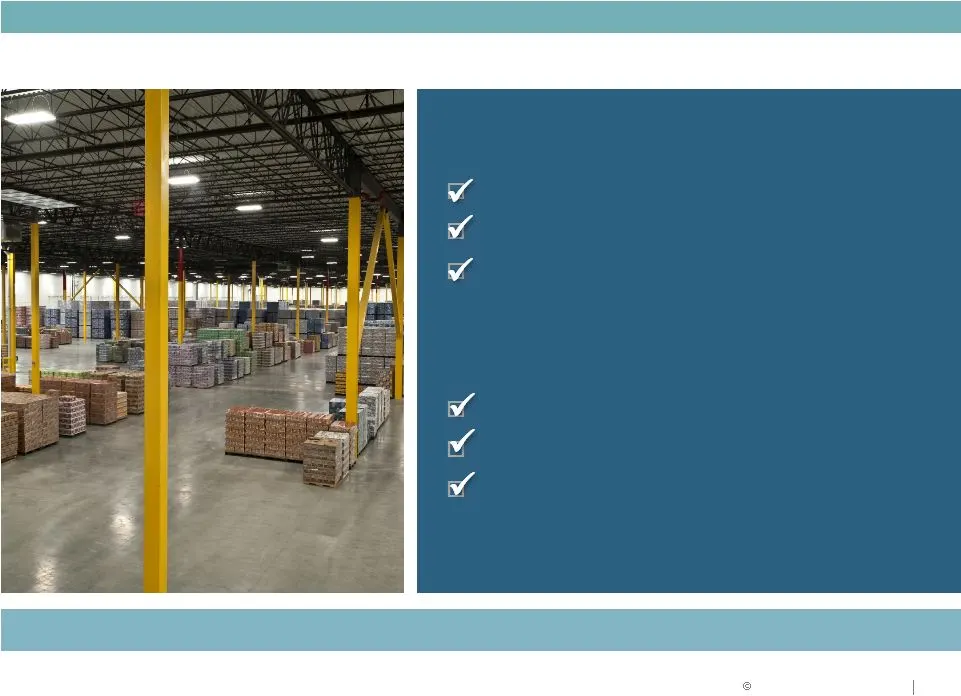
2011 PERFORMANCE Total portfolio occupancy of 90.7% Industrial at 91.9% occupancy Over 24.5 million SF leases 2012 PERFORMANCE YTD: Total occupancy of 92.1% Industrial at 93.6% occupancy Approximately 8.7 million SF leases OPERATIONS STRATEGY Quality, well-positioned assets to drive performance
Slide 19: Asset Strategy
ASSET STRATEGY
Slide 20: Repositioning Track Record
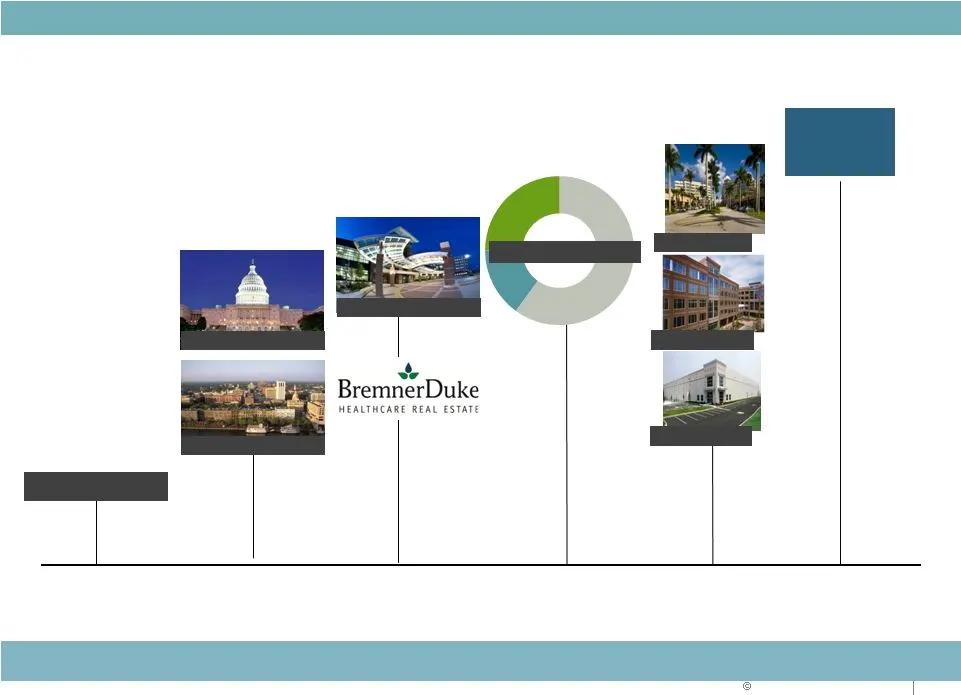
ASSET STRATEGY Flex disposition Washington DC Savannah Healthcare Asset Strategy Premier CBRERT Dugan Suburban Office Disposition $1 Billion Repositioning Track Record $1 Billion Proven ability to execute
Slide 21: Asset Strategy by Product and Geography
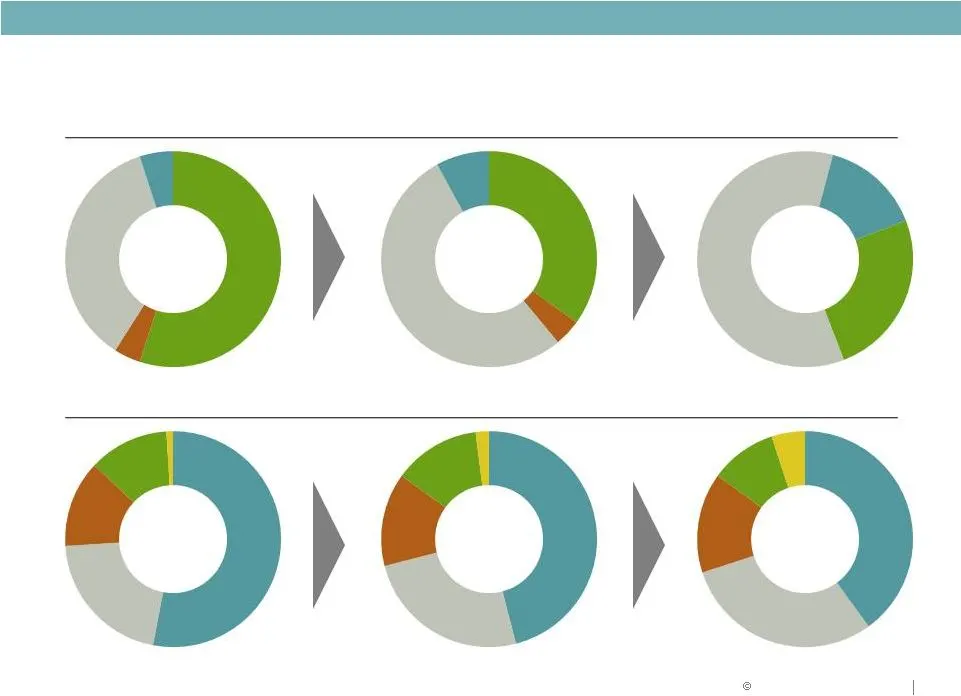
ASSET STRATEGY Asset Strategy March 31, 2012 BY PRODUCT BY GEOGRAPHY Southeast 21% Southeast 24% Southeast 30% Office 55% Retail 4% Industrial 36% Medical Office 5% Office 32% Retail 4% Industrial 53% Medical Office 11% Office 25% Industrial 60% Medical Office 15% Midwest 53% East 13% South 12% West
Slide 22: Asset Strategy: Road Map
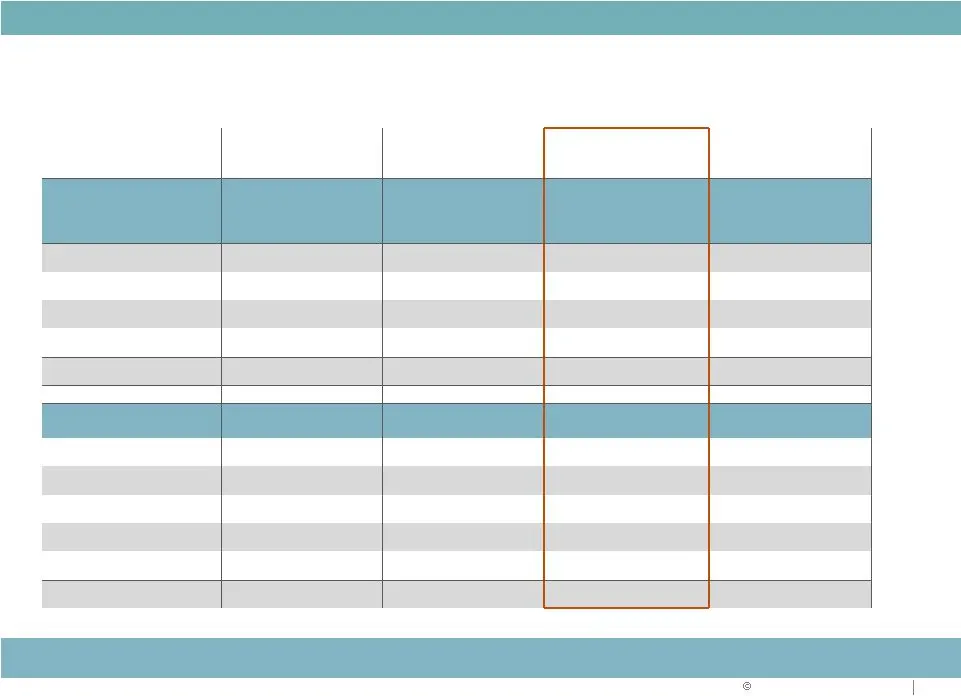
PRODUCT TYPE Amount % Amount % Acquisitions / Developments / Repositioning Amount % REGION ASSET STRATEGY Asset Strategy: Road Map ($ in millions) Investment 12/31/10 Investment 3/31/12 ACTION PLAN Investment Industrial $3,645 45% $4,264 53% $656 $4,920 60% Office 3,770 46% 2,529 32% (479) 2,050 25%
Slide 23: Asset Strategy: Progress To Date
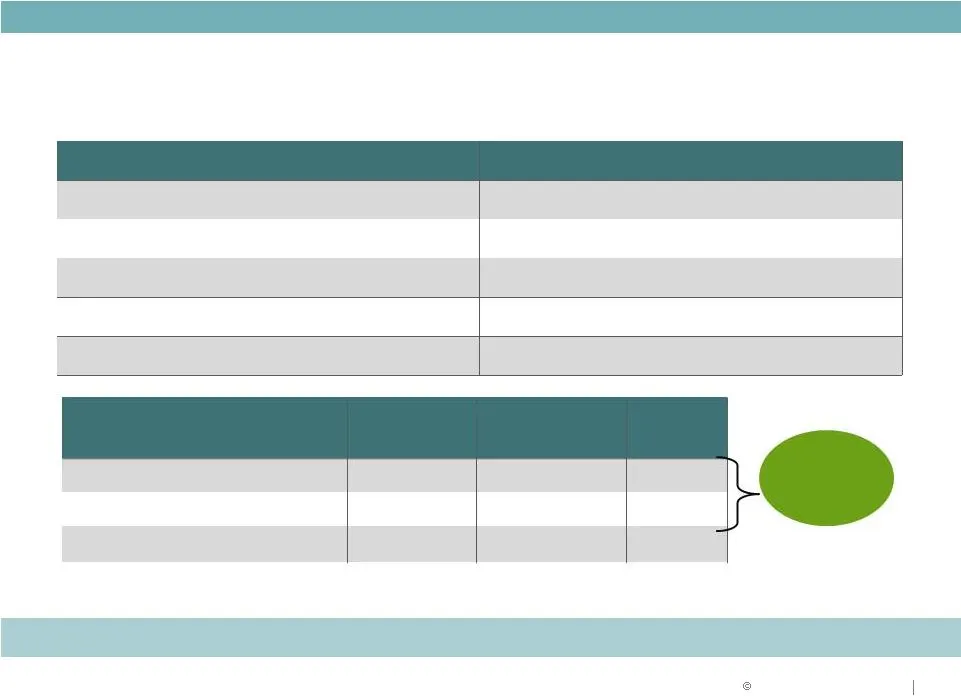
ASSET STRATEGY BUILDING ACQUISITIONS BUILDING DISPOSITIONS PROGRESS TO DATE TOTAL VALUE ASSUMED DEBT NET Asset Strategy: Progress To Date Q4 2009 Q4 2009 1,634 Q1 2012 Total $1,838 Total $2,341 NO DILUTION TO AFFO Matching acquisitions with dispositions . . . limiting earnings impact ($ in millions)
Slide 24: New, High Quality Portfolio with Long-term Leases
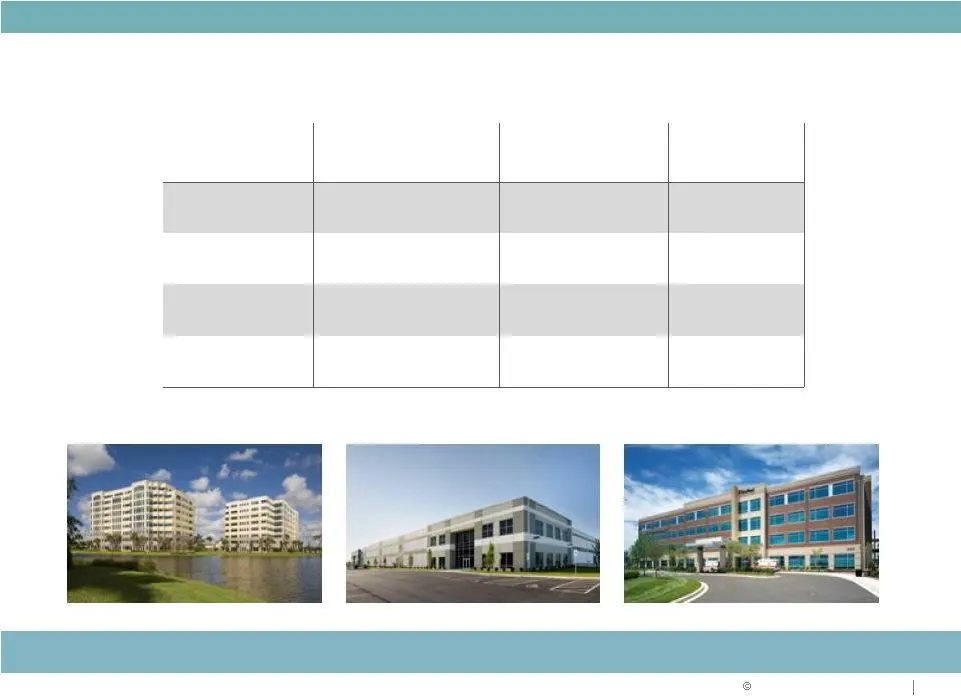
ASSET STRATEGY New, High Quality Portfolio with Long-term Leases Premier portfolio of assets Portfolio average Bulk Industrial Suburban Office Medical Office Property age 10.4 years 13.1 years 4.2 years Property size 221,000 SF 117,000 SF 82,000 SF Lease term 7.1 years 7.3 years 11.7 years Tenant si
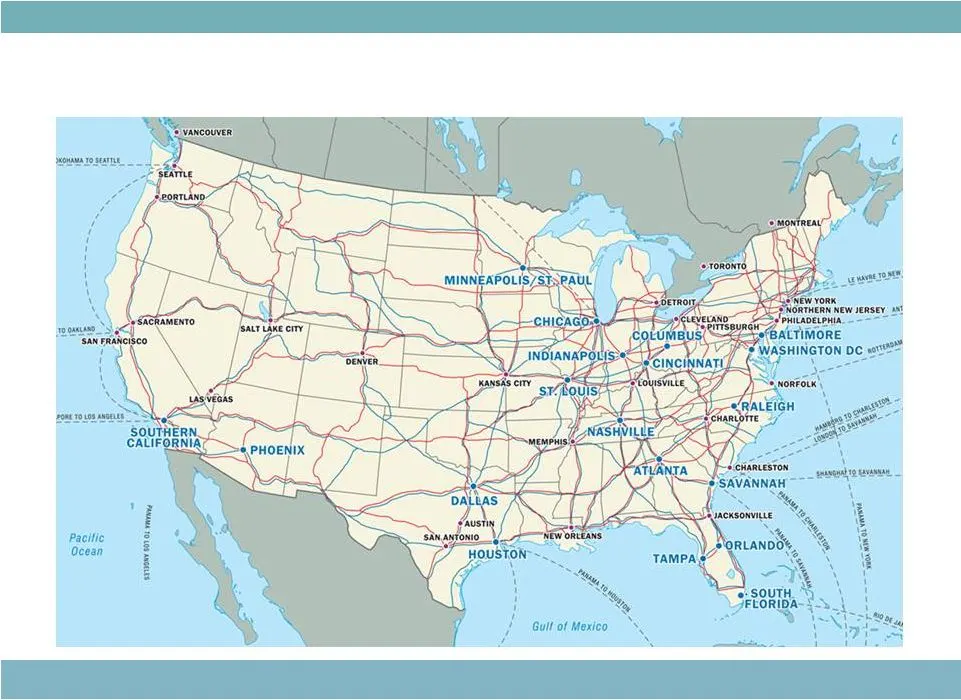
Slide 25: U.S. Rail and Highway Logistics Routes & Corridors
RELIABLE. ANSWERS . U.S. Rail and Highway Logistics Routes & Corridors Duke Realty’s 17 Primary Markets Strategically Placed in Key Distribution Corridors Note: Duke Realty Primary Industrial Markets in Blue
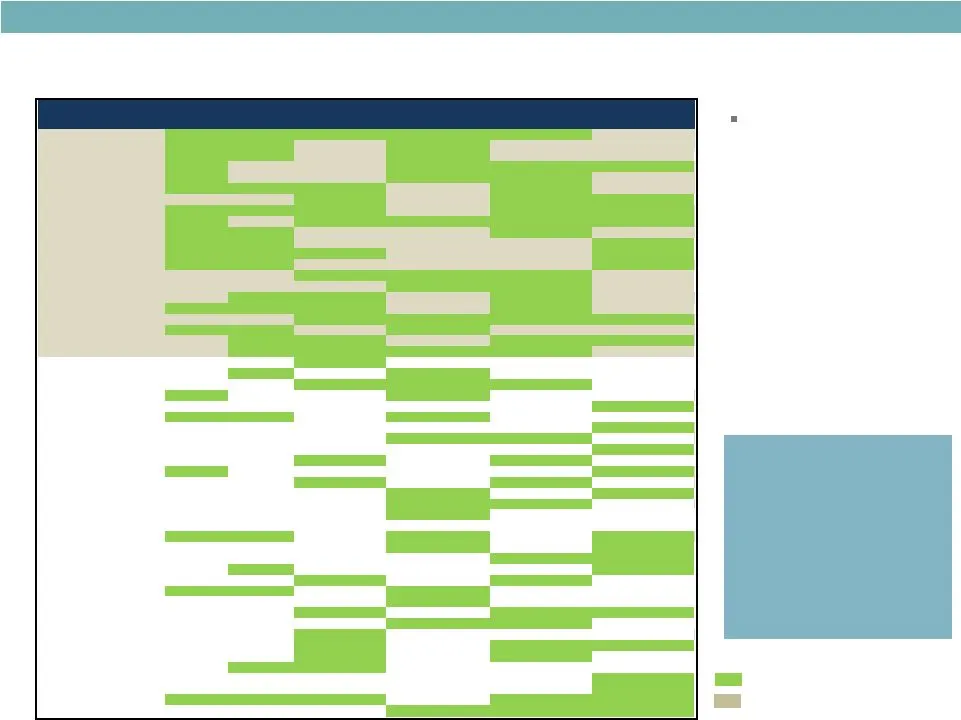
Slide 26: Primary Industrial Markets Data
RELIABLE. ANSWERS . Market Size (MM SF) (Dec. 2011) Population (MM People) (Dec. 2011) Fore. Pop. Growth (Fore. 2011-2016) Pop. w/in 500 miles (as of 2005) Fore. Demand Growth (Fore. 2011-2016) Fore. Vacancy Rates (Fore. Dec. 2016) Atlanta 489.7 5.4 1.8% 25.2% 2.2% 10.4% Baltimore 149.0 2.7 0.5% 36.
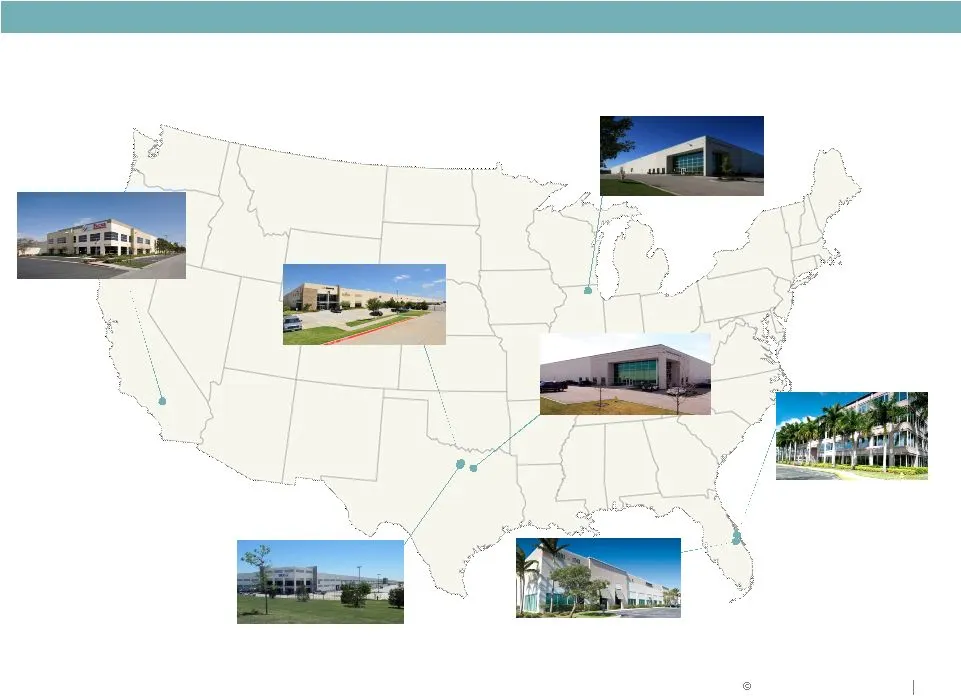
Slide 27: Industrial Market Expansion in 2011
RELIABLE. ANSWERS . Industrial Market Expansion in 2011 Century Distribution Center Los Angeles, CA 323,000 SF, 100% leased Pioneer 161 Solo Dallas, TX 603,000 SF, 100% leased Lakeside Ranch Industrial Dallas, TX 749,000 SF, 100% leased Premier Portfolio Industrial Pompano, FL 1,163,000 SF, 90% leas
Slide 28: Strategy for Industrial Markets
RELIABLE. ANSWERS . Develop in markets where we have land and competitive positions Goal: Increase Shareholder Value Strategy for Industrial Markets Focus industrial expansion in core markets: – South Florida $597 – Chicago – Houston – Dallas – Southern California Develop in markets where we have la
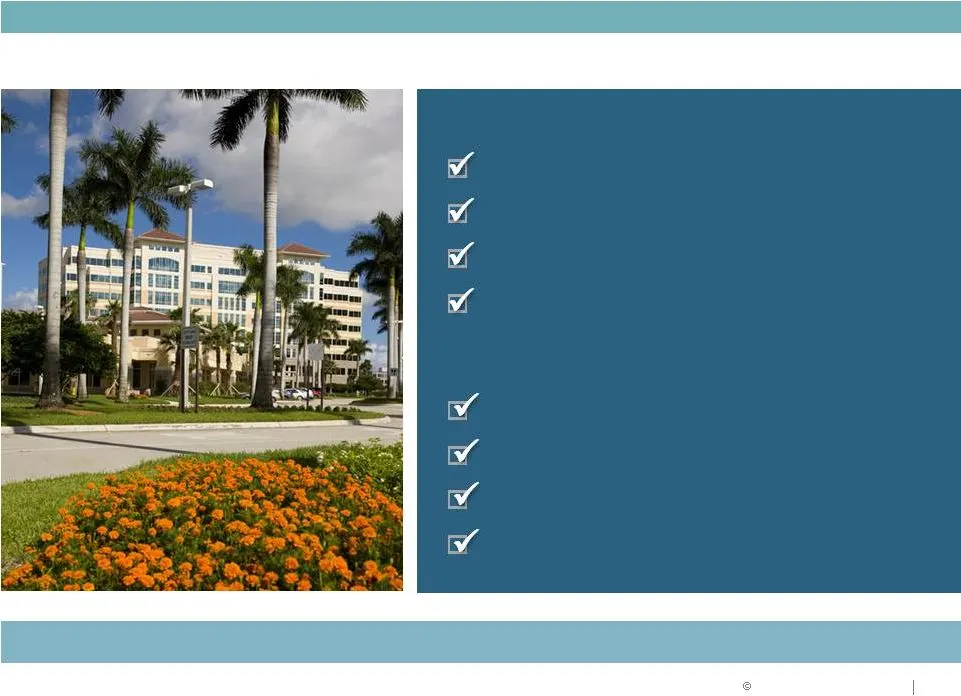
Slide 29: Quality portfolio further improving with asset strategy
$1.6 billion of dispositions $747 million of acquisitions Over $200 million of development starts Made significant progress on strategic plan 2012 PERFORMANCE YTD: $64 million of dispositions $157 million of acquisitions $121 million of development starts Continue making progress on strategic plan A
Slide 30: Capital Strategy and 2012 Guidance
CAPITAL STRATEGY AND 2012 GUIDANCE
Slide 31: Capital Strategy Focus
CAPITAL STRATEGY 1 2 3 4 Capital Strategy Focus Reducing leverage Increasing coverage ratios Maintaining size and quality of unencumbered asset base Executing portfolio repositioning in alignment with capital strategy objectives Further improve balance sheet strength and ratings
Slide 32: Key Metrics & Goals
CAPITAL STRATEGY Key Metrics & Goals Actual Actual Actual 1Q Actual Goal Debt to Gross Assets 44.5% 46.3% 46.8% 47.3 45.0% Debt + Preferred to Gross Assets 54.9% 55.5% 55.6% 54.3 50.0% Fixed Charge Coverage Ratio 1.79 : 1 1.79 : 1 1.82 : 1 1.81:1 2.00 : 1 Debt/EBITDA 6.65 7.31 6.02* 6.56** < 6.00 De
Slide 33: Continue to strengthen balance sheet
CAPITAL STRATEGY Continue to execute on capital strategy objectives CAPITAL SOURCE YTD TOTAL Common Stock $230 - $575 $311 - $150 $1,216 Preferred Stock - $300 - - - - $300 Unsecured Debt $300 $325 $500 $250 - - $1,375 Secured Debt - - $270 - - - $270 Asset Dispositions $785 $475 $300 $533 $1,650 $6
Slide 34: Bond Market Indicative Pricing
RELIABLE. ANSWERS . Reoffer Spread 220.0 bps 240.0 bps Reoffer Yield 2.98% area 4.28% area All-In Cost (Yield) 3.11% area 4.36% area Bond Market Indicative Pricing Credit Markets Responding favorably to Execution of Asset and Capital Strategies Source: Wells Fargo, 5/11/2012 Tenor 5 years 10 years A
Slide 35: RMZ and DRE Price Performance
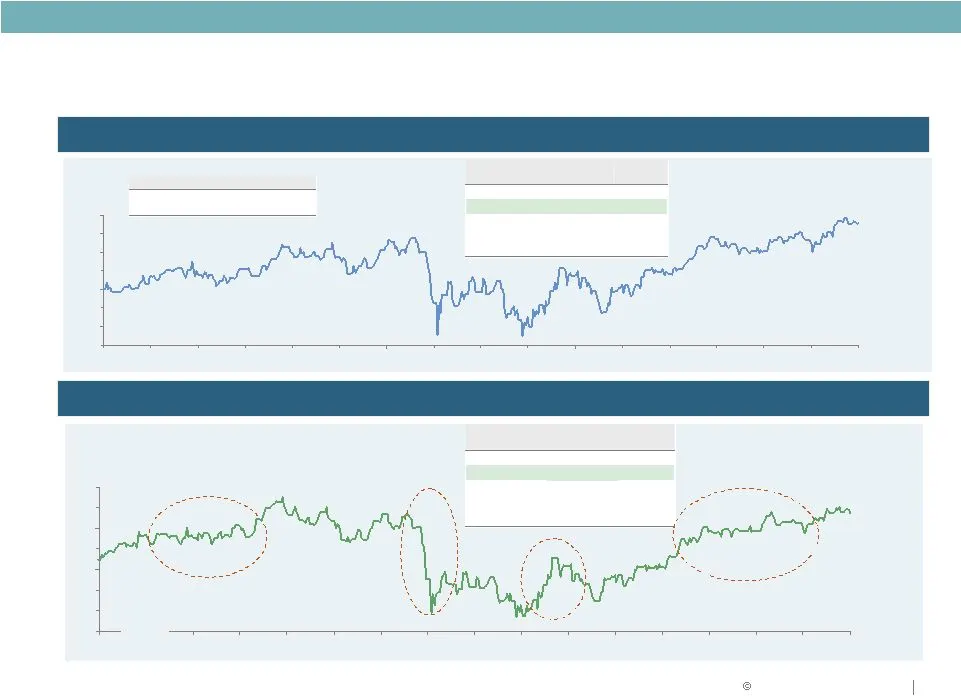
RELIABLE. ANSWERS . RMZ price performance (2011 – 2012YTD) DRE price performance (2011 – 2012YTD) The RMZ outperformed S&P 500 in 2011, but has lagged slightly below the S&P 500 in 2012 Source: J.P. Morgan, Bloomberg, FactSet as of 05/10/12 Based upon 342 total trading days 85% 90% 95% 100% 105% 110
Slide 36: Relative Performance of Duke Realty versus Industrial Comps
RELIABLE. ANSWERS . Relative Performance of Duke Realty versus Industrial Comps only Notes 1. Comparables include DCT, EGP, FR, and PLD; PLD and AMB are included historically, total return for comparable companies figures are calculated on a market cap weighted basis 2. DRE stock price as of end of
Slide 37: Duke Realty and Peers Barra Beta Analysis
RELIABLE. ANSWERS . Notes 1. As of April 30, 2012 2. Includes LRY, HIW, CLI, BDN, and OFC 3. DCT’s beta only available since its IPO. Barra began tracking DCT’s beta in Dec 2006 4. Includes PLD, FR, EGP, DCT, and LRY Duke Realty and Peers Barra Beta Analysis Beta Trends are Slowly Improving Consiste
Slide 38: Liquidity Position
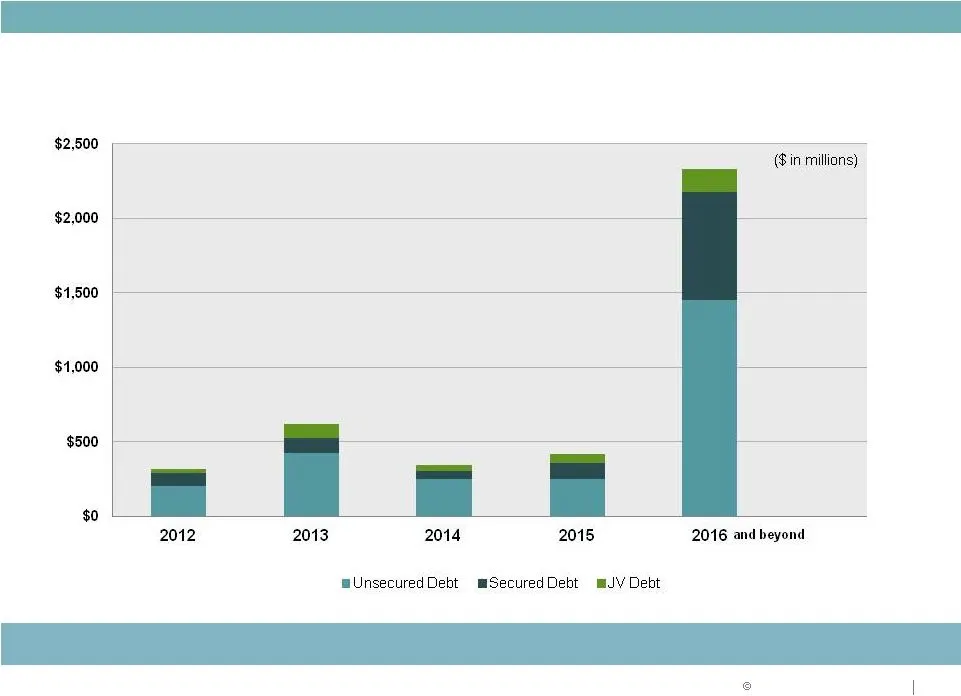
CAPITAL STRATEGY Liquidity Position Manageable debt maturities
Slide 39: 2012 Range of Estimates
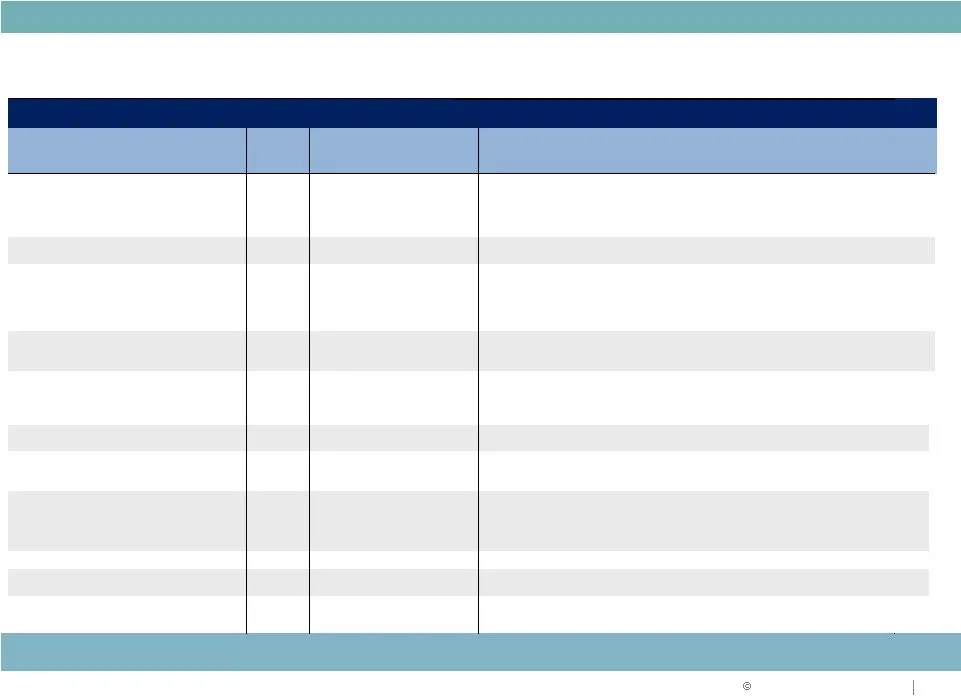
RELIABLE. ANSWERS . 2012 Range of Estimates 2012 Range of Estimates ($ in millions) Leasing Actions Combined with Modest Rental Rate Increases Drive Upside Metrics Actual Q1 2012 Actual Pessimistic Optimistic Key 2012 Assumptions Core FFO per share $1.15 $0.24 $0.94 $1.06 - Blackstone/repositioning
Slide 40: Strong balance sheet executing according to strategy
$1.6 billion of capital raised through asset dispositions Retired $333 million of unsecured bonds Redeemed $109 million of preferred equity Fixed charge ratio of 1.82x and debt to EBITDA of 6.02x* Opportunistically tapped ATM raising $147 million Continue improving coverage ratios Maintaining minima
Slide 41: Midwest Overview
MIDWEST OVERVIEW Performance Update
Slide 42: Midwest Overview: Recent Transactions
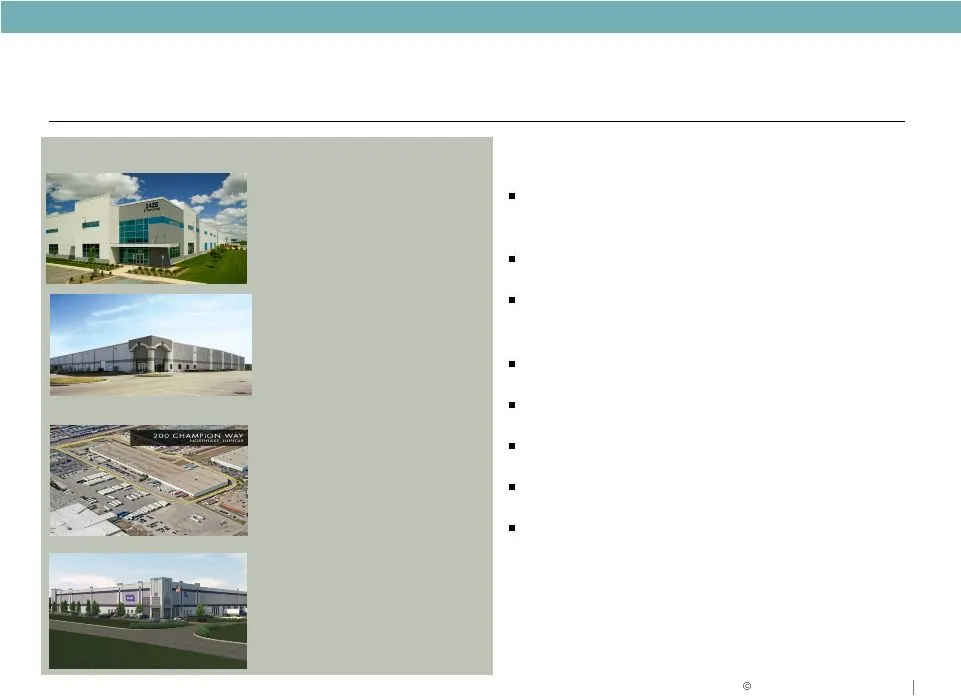
MIDWEST OVERVIEW RECENT TRANSACTIONS Midwest New Lease - Industrial World Park Union Center Cincinnati 191,000 SF Tenant: Ashland Term 6 years Renewal - Industrial Park 100 Bldg 131 Indianapolis 419,000 SF Tenant: Hewlett Packard Term: 1.25 years Strong distribution base: Over 30% of U.S. population
Slide 43: Midwest Overview
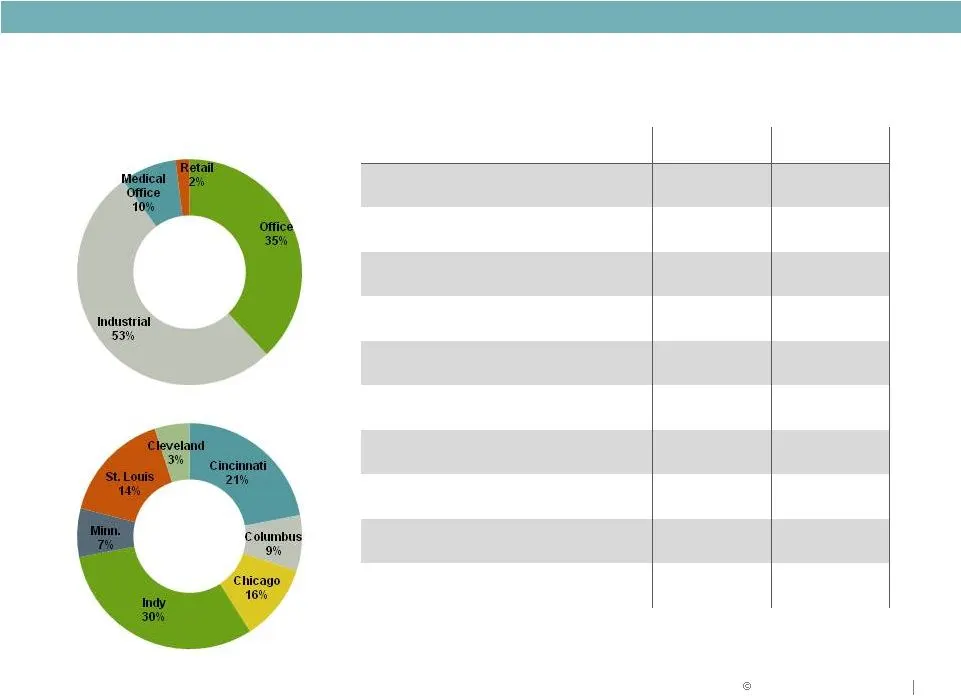
MIDWEST OVERVIEW Midwest Overview Location Product Type Industrial Office Average Age 11.8 years 16.2 years Average Building Size 248,000 SF 125,000 SF Total Square Footage 57 million 12.4 million Current Occupancy 94.8% 83.8% Indianapolis 96.4% 92.6% Chicago 98.0% 88.4% Cincinnati 93.1% 83.4% St. L
Slide 44: Midwest Focus
MIDWEST OVERVIEW Midwest Focus DOMINANT POSITION BULK INDUSTRIAL REDUCE OFFICE CONCENTRATION Enhancing dominant industrial position in Midwest
Slide 45: East & Southeast Overview
EAST & SOUTHEAST OVERVIEW Performance Update
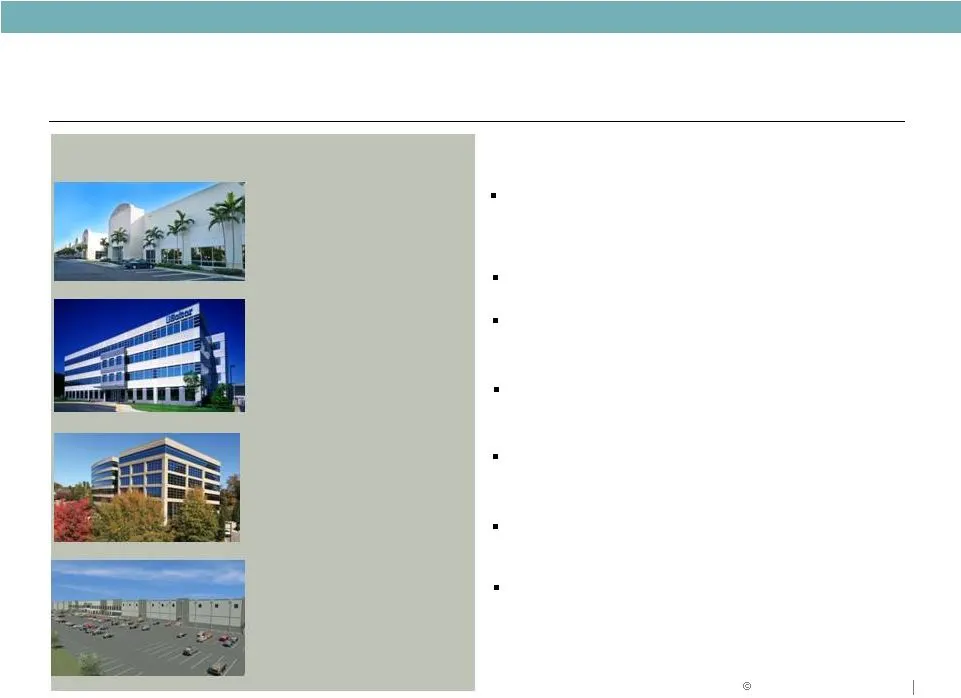
Slide 46: East & Southeast Overview: Recent Transactions
EAST & SOUTHEAST OVERVIEW East & Southeast Overview New Deal – Industrial 625 Braselton Atlanta William Carter Co. 1,061,663 SF Term:11.5 years New/Renewal - Office Liberty Center II Washington, D.C. Scitor Corp 159,000 SF Term: 10 years Disposition – Office Raleigh – 6 Bldgs 427,000 SF 87% leased N
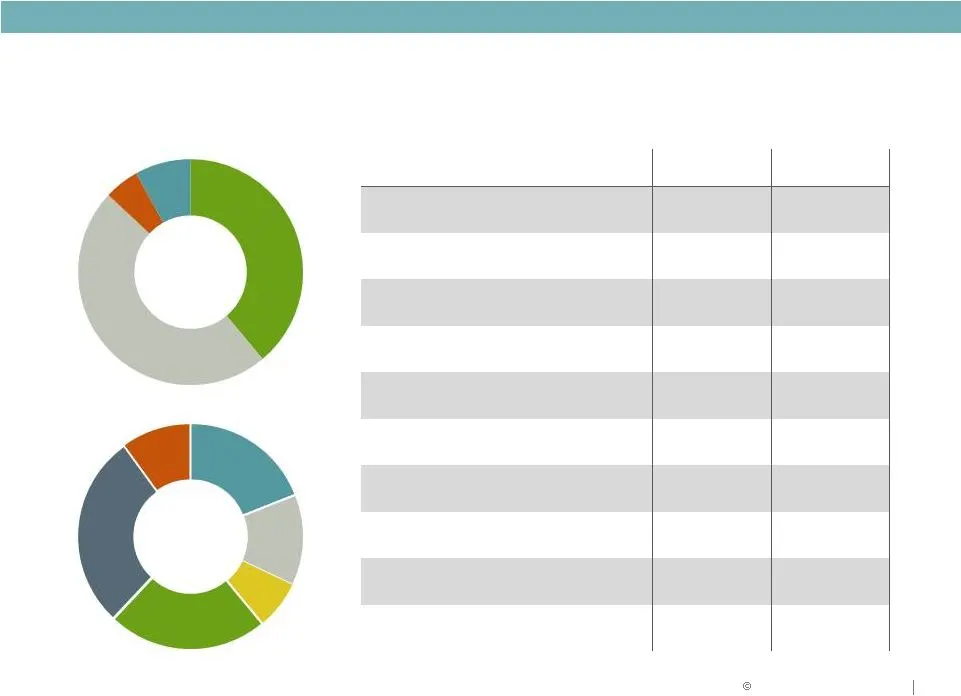
Slide 47: East & Southeast Overview
EAST & SOUTHEAST OVERVIEW East & Southeast Overview Industrial Office Average Age 9.5 years 9.9 years Average Building Size 161,000 SF 110,000 SF Total Square Footage 29.3 million 9.5 million Current Occupancy 91.6% 86.6% Atlanta 90.1% 81.7% South Florida 84.3% 85.7% Raleigh 98.9% 89.4% Washington D
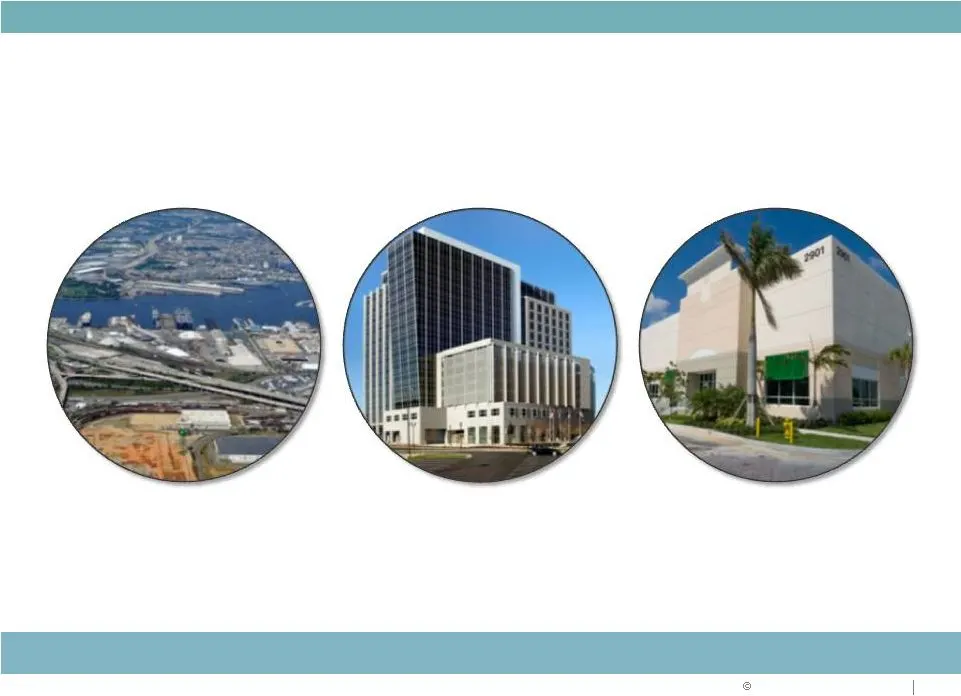
Slide 48: East & Southeast Focus
EAST & SOUTHEAST OVERVIEW East & Southeast Focus BULK INDUSTRIAL/PORTS LEASE UP AND RENT GROWTH ACQUISITIONS & DEVELOPMENT Maximize assets and market position
Slide 49: Southwest Overview
SOUTHWEST OVERVIEW Performance Update
Slide 50: Southwest Overview: Recent Transactions
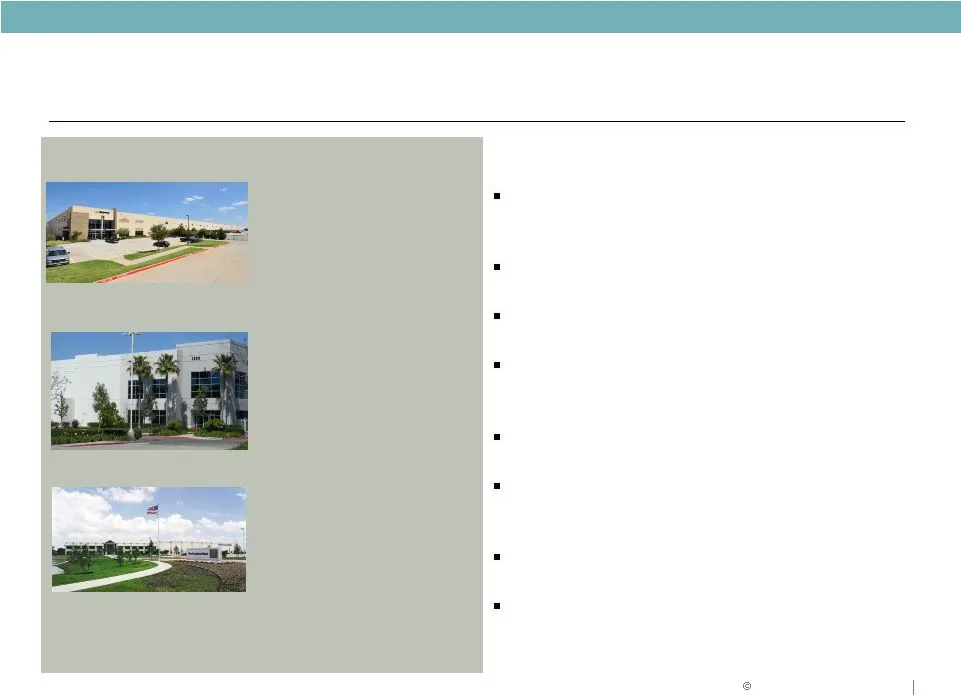
SOUTHWEST OVERVIEW RECENT TRANSACTIONS Southwest New Lease- Industrial Kingsley Dist. Center Service Lighting & Electrical 132, 000 SF Term: 5.5 years New Lease- Industrial Freeport VI VMP Nutrition 114,000 SF Term: 5 years Duke Realty one of top 3 owner/developers in Dallas/Ft.Worth Duke Realty pre
Slide 51: Southwest Overview
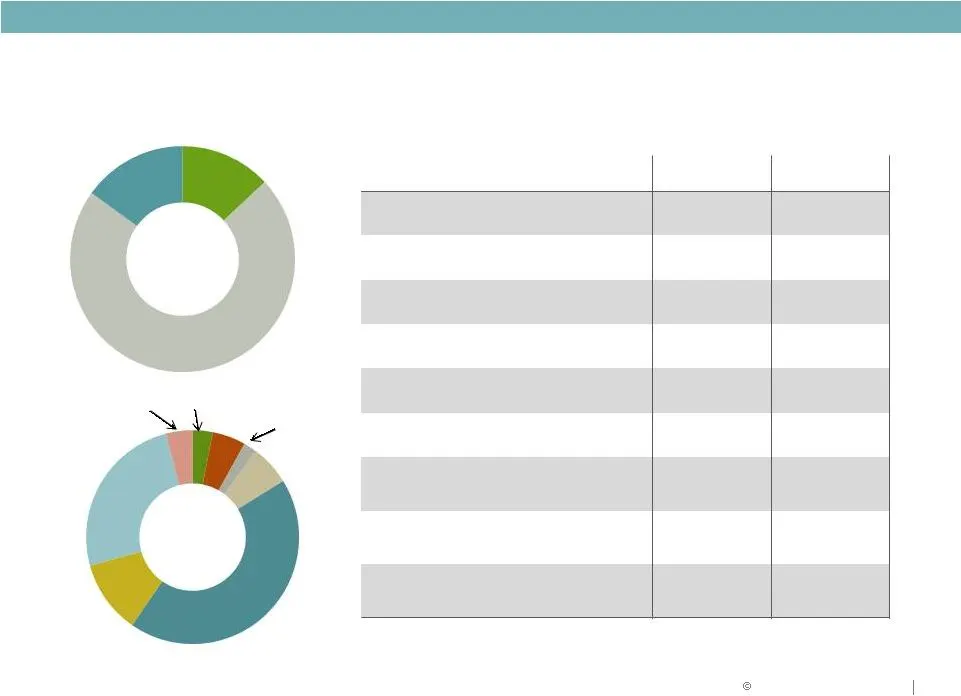
SOUTHWEST OVERVIEW Southwest Overview Location Product Type Seattle 2% Austin 3% Southern CA 5% Dallas 43% Phoenix 6% Houston 12% Nashville 25% San Antonio 4% Office 11% Industrial 68% Medical Office 21% Industrial Office Average Age 8.3 years 7.3 years Average Building Size 272,000 SF 106,700 SF To
Slide 52: Southwest Focus
SOUTHWEST OVERVIEW Southwest Focus DALLAS LEASE-UP HOUSTON INDUSTRIAL PORT DALLAS INLAND PORT SOUTHERN CALIFORNIA EXPANSION Grow
Slide 53: Medical Office Strategy & Performance Update
MEDICAL OFFICE STRATEGY & Performance Update
Slide 54: Medical Office Portfolio at March 31, 2012
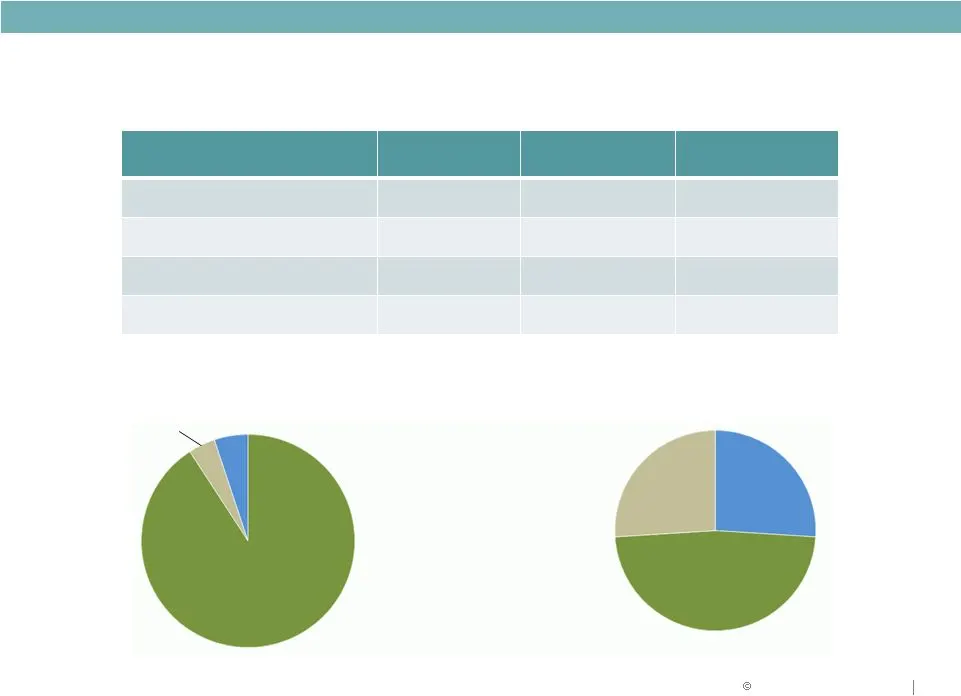
In-Service Under Development Total MEDICAL OFFICE STRATEGY Medical Office Portfolio at March 31, 2012 Properties Investment $ $695 M $145 M $840 M Square Feet 3.59 M 685 K 4.28 M Occupancy 91% 86% 90% Local 15% Regional 55% National 30% Specialty Hospital 7% MOB On- Campus 86% MOB Off-Campus 7% Port
Slide 55: Duke Realty Markets: Demographic Focus
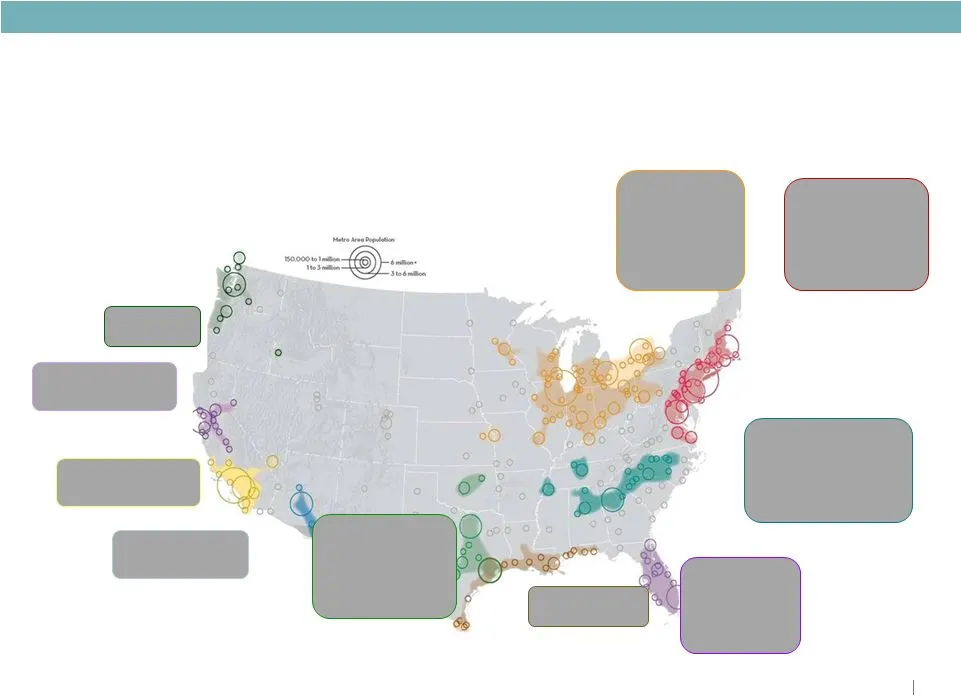
MEDICAL OFFICE STRATEGY major cities that produce more than $100 billion in goods and services. Mega-regions will drive need for healthcare, transportation infrastructure and jobs through 2050 Duke Realty Markets: Demographic Focus * Duke Realty market Map Source: ATLANTA REGIONAL COMMISSION MEGAREG
Slide 56: Healthcare Data Points
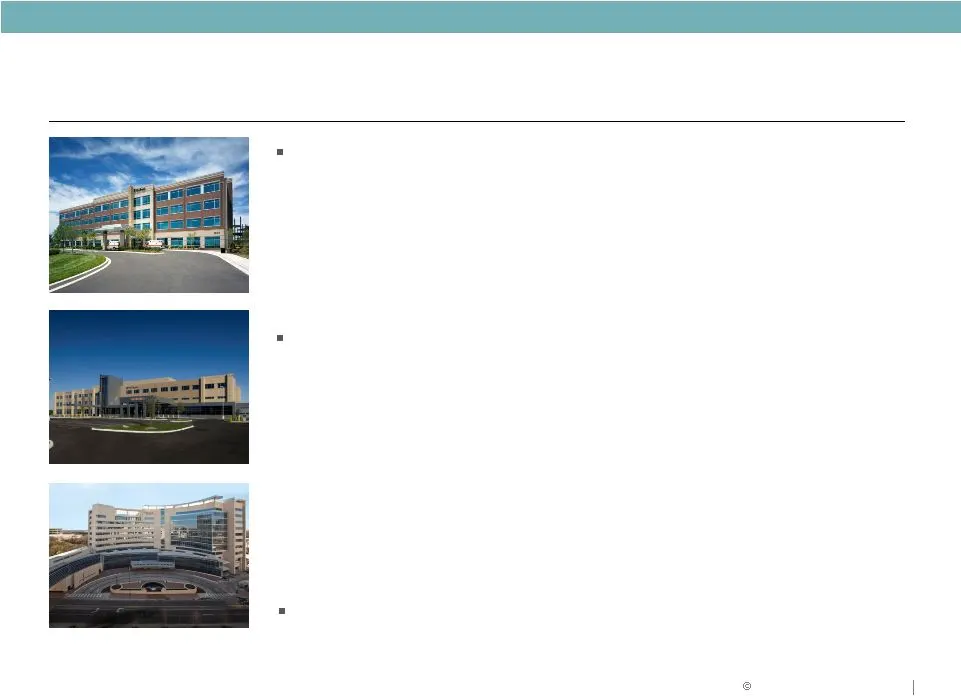
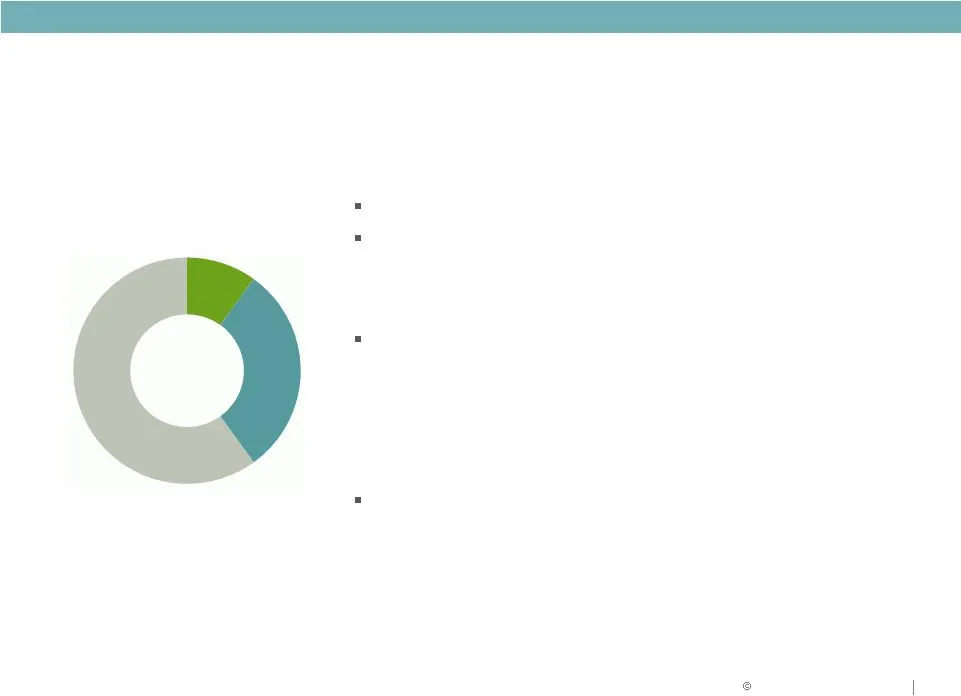
MEDICAL OFFICE STRATEGY Healthcare Data Points The nation’s largest industry • Represents more than 17% of GDP, predicted to exceed 23% by 2020 • Americans spend more than 5% of pre-tax income on healthcare. Lower income brackets pay 15% or more ($7,800 per capita health expenditures in 2008/2009) R
Slide 57: Healthcare Systems and Physician Employment
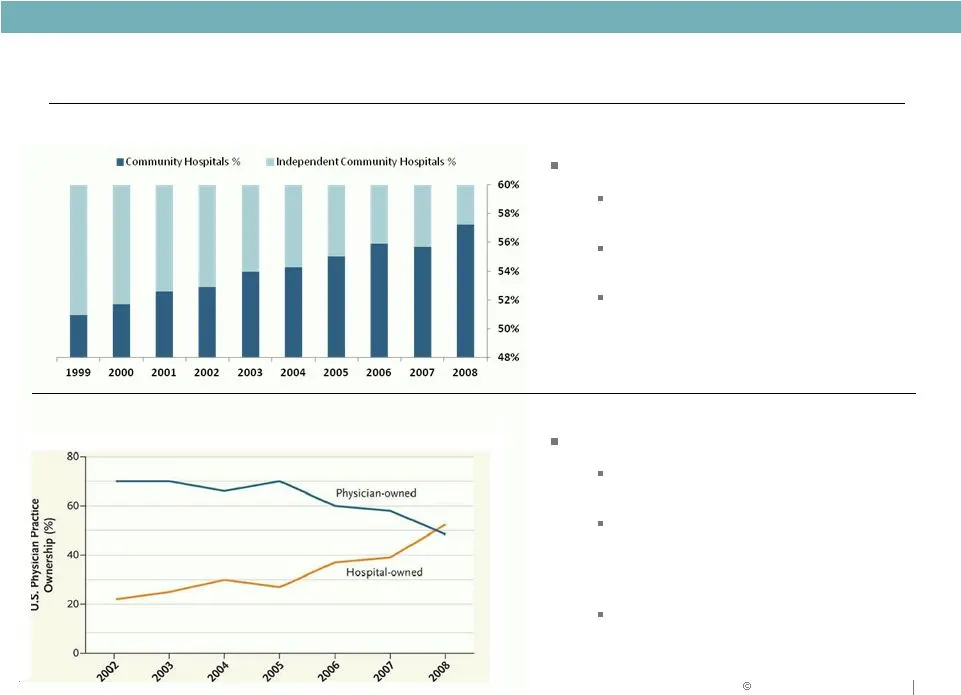
MEDICAL OFFICE STRATEGY Healthcare Systems Consolidation of hospitals into systems continues Hospitals need capital and must grow market share Healthcare systems are drivers for more strategically located outpatient facilities Employment of Physicians More physicians are being employed by hospitals
Slide 58: Development Focus
MEDICAL OFFICE STRATEGY Development Focus ACTION PLAN National brand awareness Be “Experts” – Speak at national conferences (ASHE, BOMA) – Third party references National system relationships – Ascension – Tenet – HCA – Adventist Regional system relationships – Baylor Health – Rex Healthcare – Carol
Slide 59: Healthcare Projects Delivered/Acquired in 2011/2012
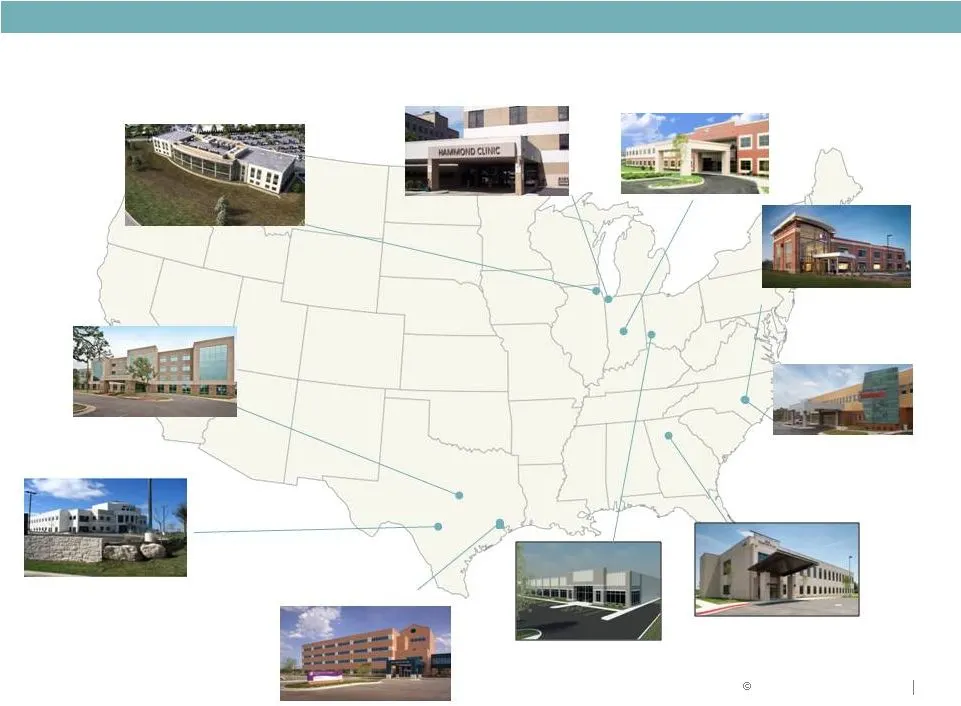
MEDICAL OFFICE STRATEGY Healthcare Projects Delivered/Acquired in 2011/2012 Rex Holly Springs MOB Raleigh, NC 30,000 SF, 100% leased Christus St. Catherine Houston, TX 169,000 SF, 96% leased WakeMed Brier Creek Healthplex Raleigh, NC 48,000 SF, 79% leased Butler County Medical Cincinnati, OH 109, 00
Slide 60: Healthcare Projects Under Development
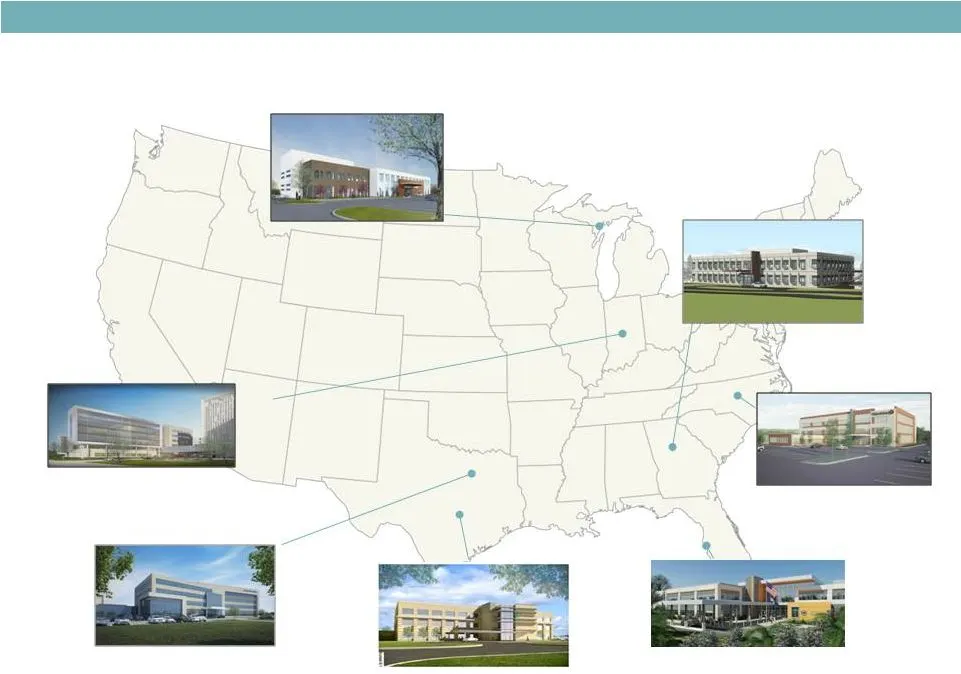
MEDICAL OFFICE STRATEGY Healthcare Projects Under Development at March 31, 2012 Baylor McKinney MOB I McKinney, TX 114,000 SF, 69% preleased WakeMed Raleigh Medical Park Raleigh, NC 86,000 SF, 58% preleased Marquette General Hospital MOB Escanaba, MI 43,000 SF, 100% preleased North Fulton MOB Atlant
Slide 61: Our Plan
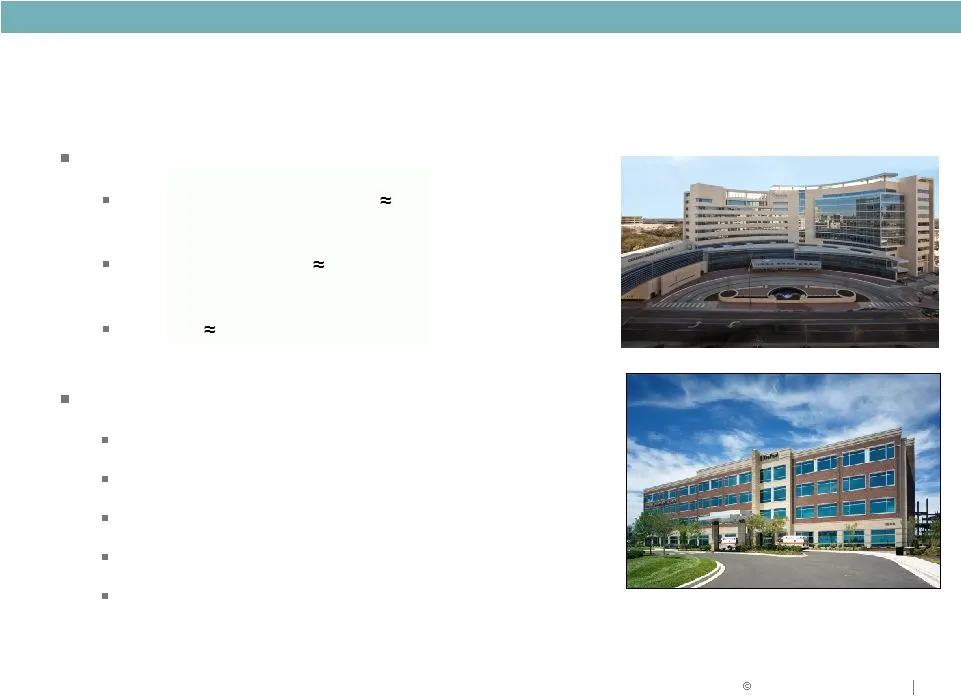
MEDICAL OFFICE STRATEGY Our Plan Existing healthcare assets $840 Million by 3/31/12 New developments $200 Million in and Acquire $200-$250 Million in and Our Focus Goal: Grow Medical Office to $1.23 Billion by 2013 Growth regions (Southeast, South) Health system relationships On-campus assets Class
Slide 62: Why Duke Realty?
MEDICAL OFFICE STRATEGY WHY DUKE REALTY? Quality portfolio improving with asset strategy Solid balance sheet improving with capital strategy Unmatched ability to execute on daily operations Development capabilities in place with existing land bank Talent and leadership depth to execute Delivering on
Slide 63: Vision Road Map – Future Duke Realty
MEDICAL OFFICE STRATEGY What We Will Be Action Plan Vision Road Map – Future Duke Realty Low leverage industrial and office REIT in high growth markets and product segments • Low leveraged • Move from 54% to 45% leverage • Product focused • Become bulk industrial focused Industrial: Increase from 35
Slide 64: Forward-Looking Statement
RELIABLE. ANSWERS . Forward-Looking Statement This slide presentation contains statements that constitute “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934 as amended by the Private Securities Litigation Reform Act of 1995. These fo
Source: SEC EDGAR · 8-K filed May 16, 2012
More decks from Duke Realty Corporation
 Merger or Acquisition (June 2022)14 slides · Jun 13, 2022
 Investor Presentation (June 2021)58 slides · Jun 7, 2021
 Investor Presentation (May 2021)44 slides · May 10, 2021
 Investor Presentation (February 2021)58 slides · Feb 22, 2021
 NAREIT REITworld Virtual Investor Conference 202056 slides · Nov 16, 2020
 B of A Securities 2020 Global Real Estate Conference56 slides · Sep 15, 2020