United Western Bancorp — Q3 2009 Earnings Presentation
29 slides from United Western Bancorp's earnings presentation, Nov 10, 2009
Slide 1: Third Quarter 2009 Investor Presentation
Third Quarter 2009 Investor Presentation
Slide 2: Forward-looking Statement Disclaimer and Prospectus Disclosure
2 2 Forward-looking Statement Disclaimer and Prospectus Disclosure Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 that are subject to significant risks and uncertainties. Forward-looking st
Slide 3: Successful Public Offering
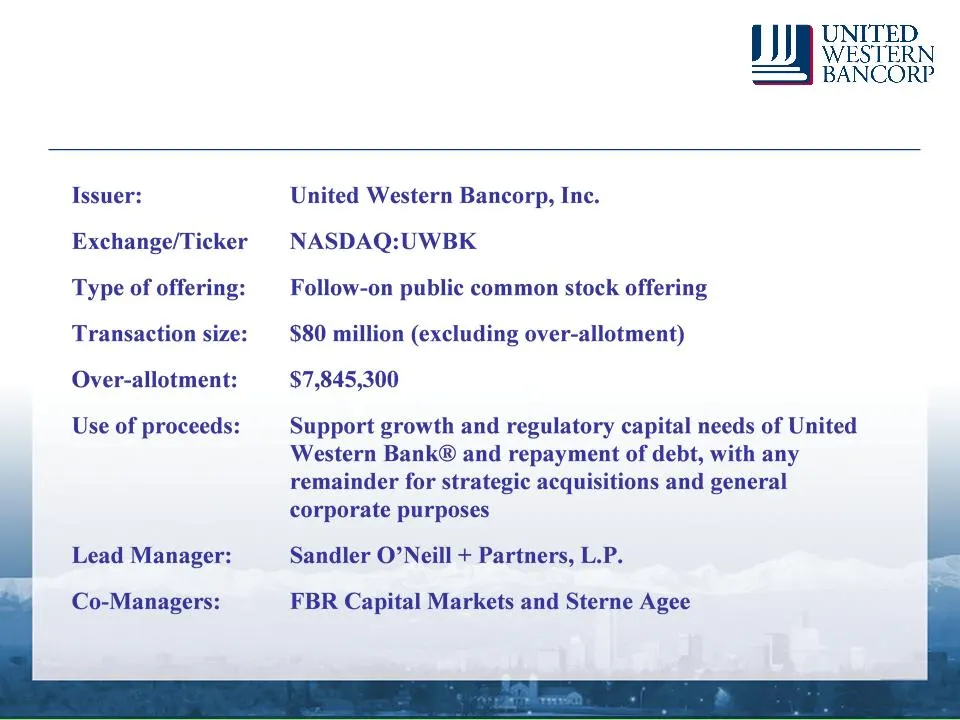
3 Successful Public Offering
Slide 4: Franchise Overview
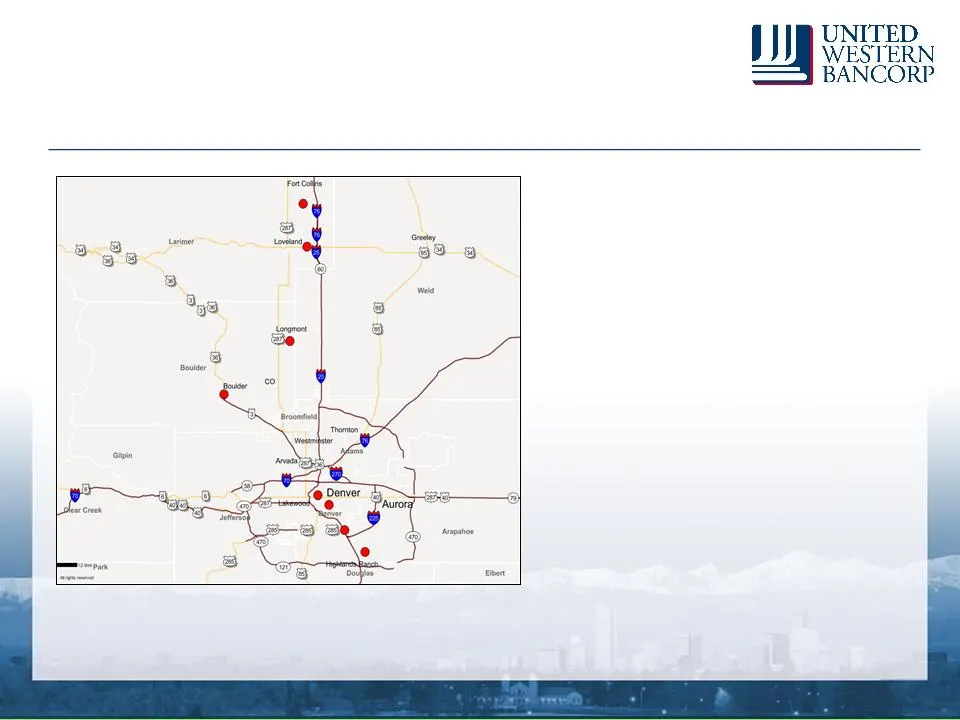
4 Franchise Overview o 3 rd largest federal savings bank in the Western United States o $2.6 billion asset franchise focused on Colorado’s Front Range - Pueblo to Fort Collins including Denver o Traditional community bank - target business first, consumers second o Other services: n National Preferr
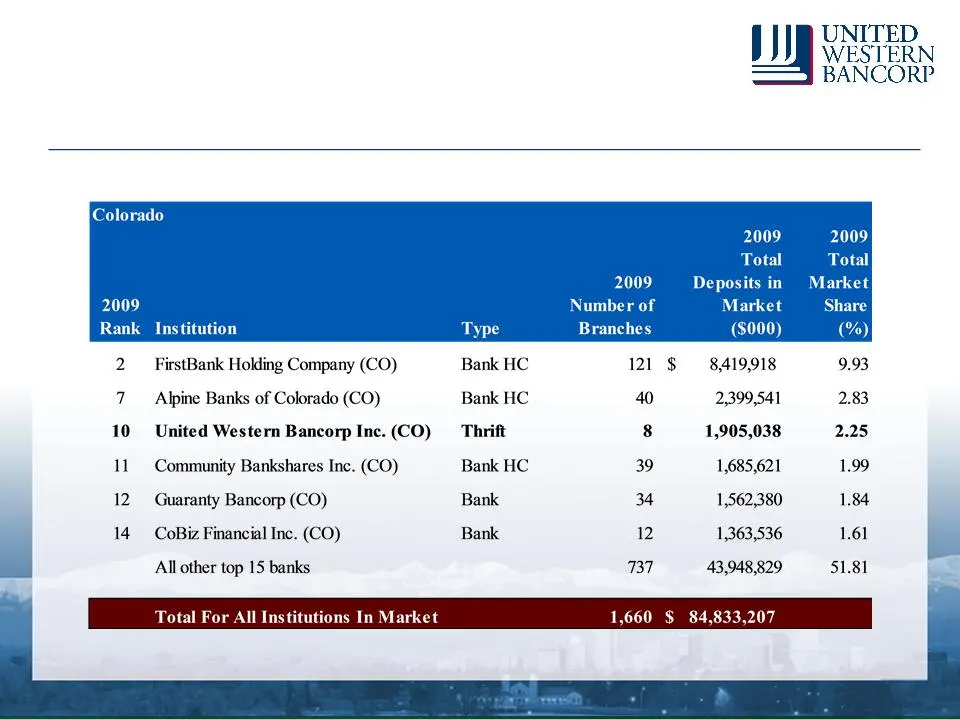
Slide 5: Deposit Franchise Overview: Market Share
5 Source: SNL Financial June 30, 2009 Deposit Franchise Overview o 3 rd largest market share of Colorado based banks and thrifts
Slide 6: Colorado: among strongest economies in US
6 6 Colorado: among strongest economies in US Unemployment Rate Median Home Price Appreciation (YoY) o Case-Shiller®: (11.3%) o Denver: (1.9%) o Boulder: (8.1%) o Ft. Collins: (2.3%) o Aspen/Roaring Fork: (60.1%) o Nationwide: 9.8% o Colorado: 7.0% o Denver: 7.1% o Boulder: 5.5% o Ft. Collins: 5.6%
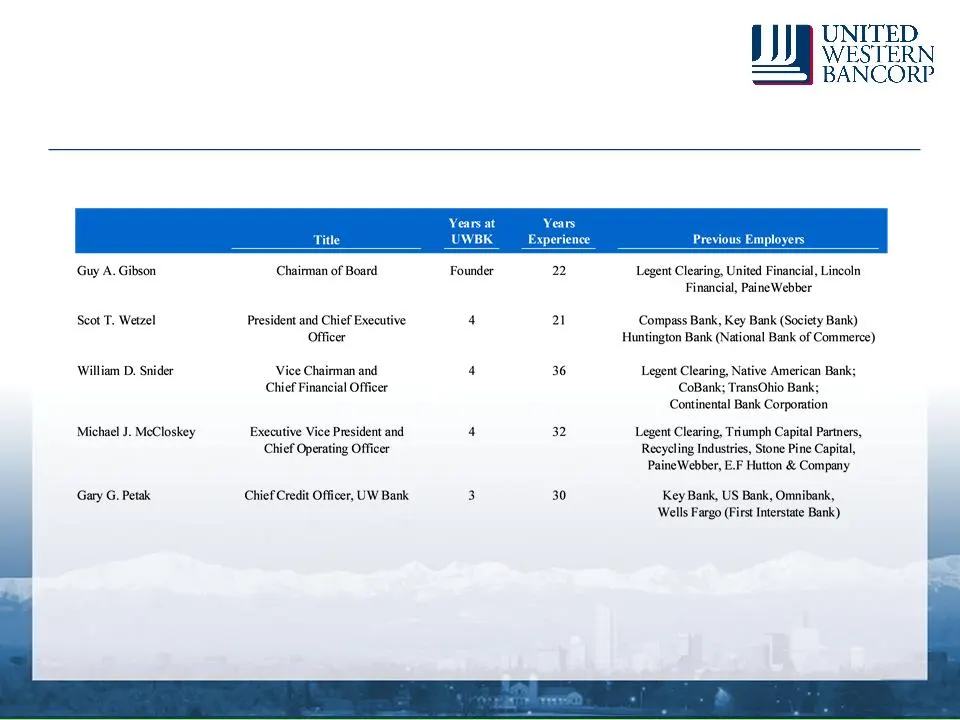
Slide 7: Experienced Management Team
7 Experienced Management Team
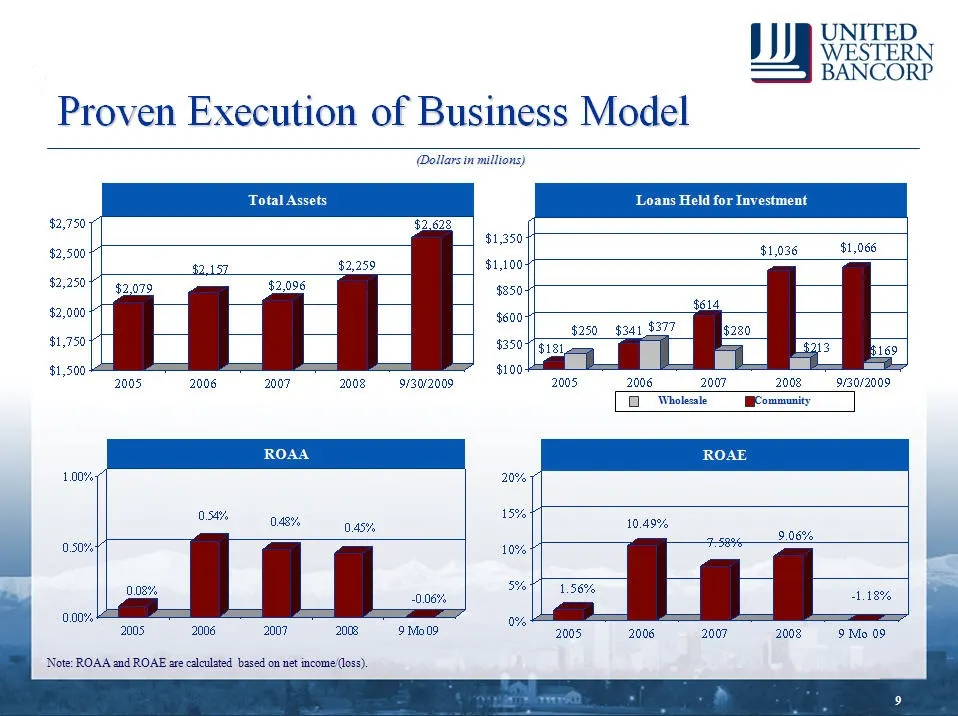
Slide 8: Proven Execution of Business Model
8 Proven Execution of Business Model o Established community bank business plan in 2006 o Redirected legacy company into community banking o Launched United Western brand o Transitioning balance sheet to community banking from wholesale mortgage business o Capitalized on dynamic Colorado banking env
Slide 9: Proven Execution of Business Model
j J J UNITED WESTERN BANCORP Proven Execution of Business Model Total Assets (@ollarsin millions) 2006 2007 1.00%: Loans Held for Investment $1,066 $1,036 $250, 2007, Wholesale 2008, munity 9/30/2009 10.49% O50: oon. 2005 2006 2007 2008 Note: ROAA ad ROAE are calculated based on net income (loss) 20
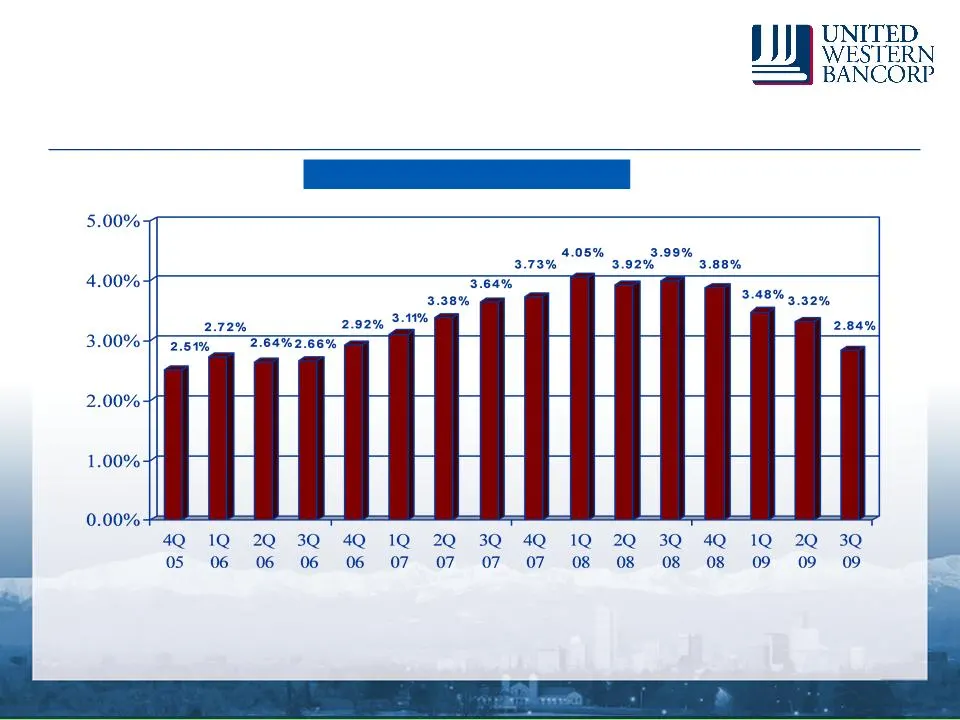
Slide 10: Net Interest Margin
10 Net Interest Margin Proven Execution of Business Model
Slide 11: Focused Branch Network
11 11 Focused Branch Network o “Best” locations - break-even target of 14 months o Smaller distribution network - 10-12 banking centers, not 100 branches o Average tenure of in-market senior bankers is 20 years o Eight full-service locations open in the Front Range and a private banking focused offi
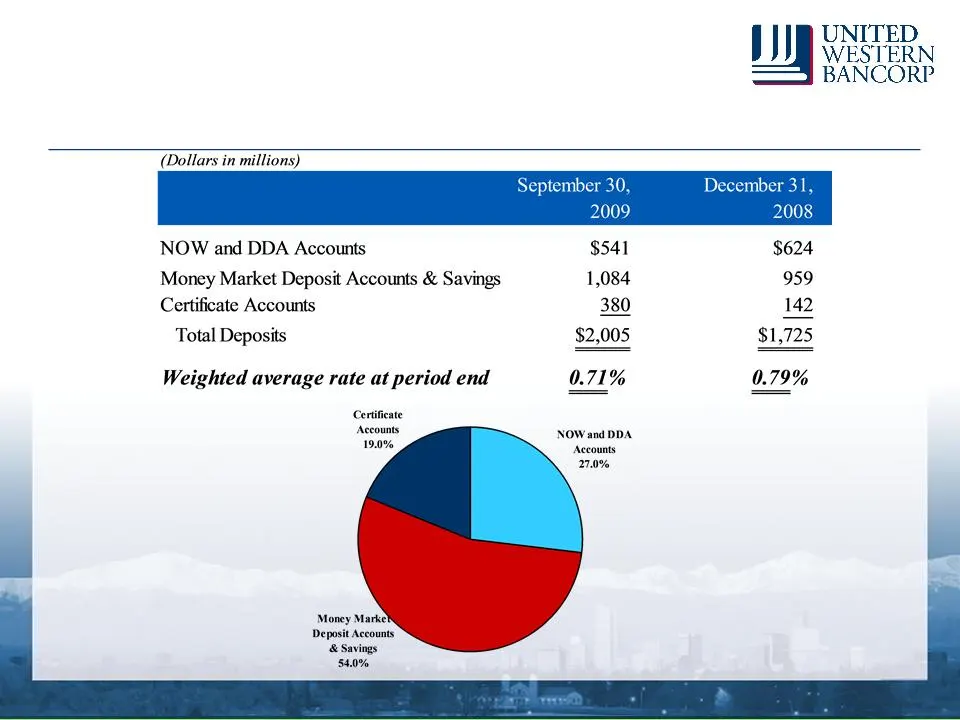
Slide 12: Deposit Franchise Overview
12 Deposit Franchise Overview
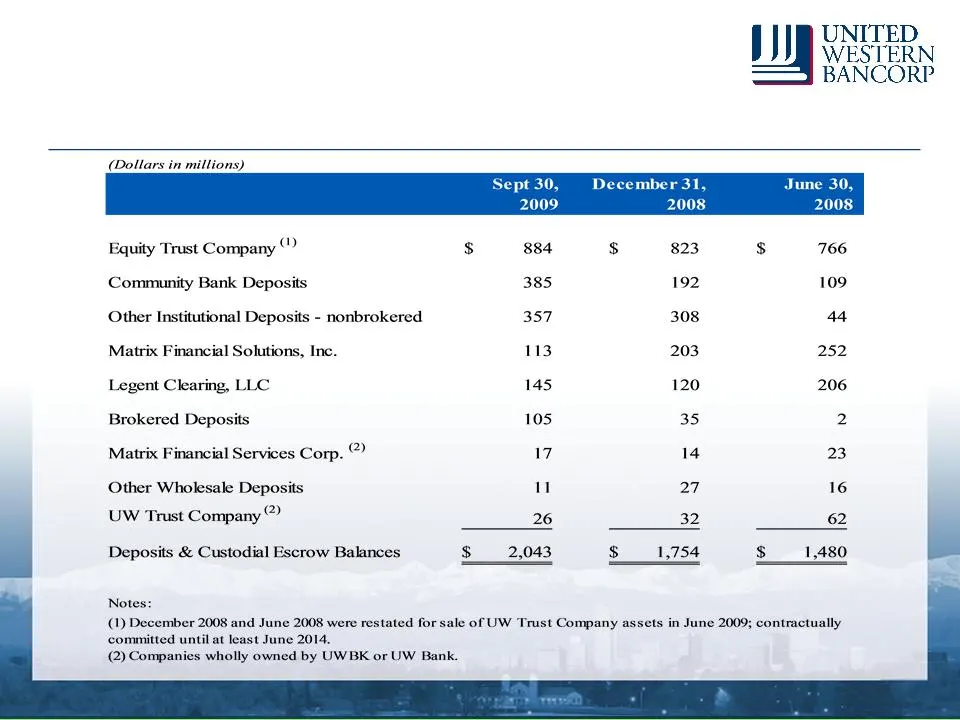
Slide 13: Deposits and Custodial Escrow Balances
WESTERN BANCORP (Dollars in millions) 0, 2008 Equity Trust Company “'? $ 884 $ 823 $ 766 Community Bank Deposits 385 192 109 Other Institutional Deposits - nonbrokered 357 308 44 Matrix Financial Solutions, Inc. 113 203 252 Legent Clearing, LLC 145 120 206 Brokered Deposits 105 35 2 Matrix Financial
Slide 14: Disciplined Credit Culture
14 14 Disciplined Credit Culture o Our philosophy-lend to people we know o Loan administration/workout team created 2006 o Multi-tiered committee based credit approval o Sound lending practices n Traditional/community bank-business credit focus n Colorado focused n Tangible collateral lender n Recou
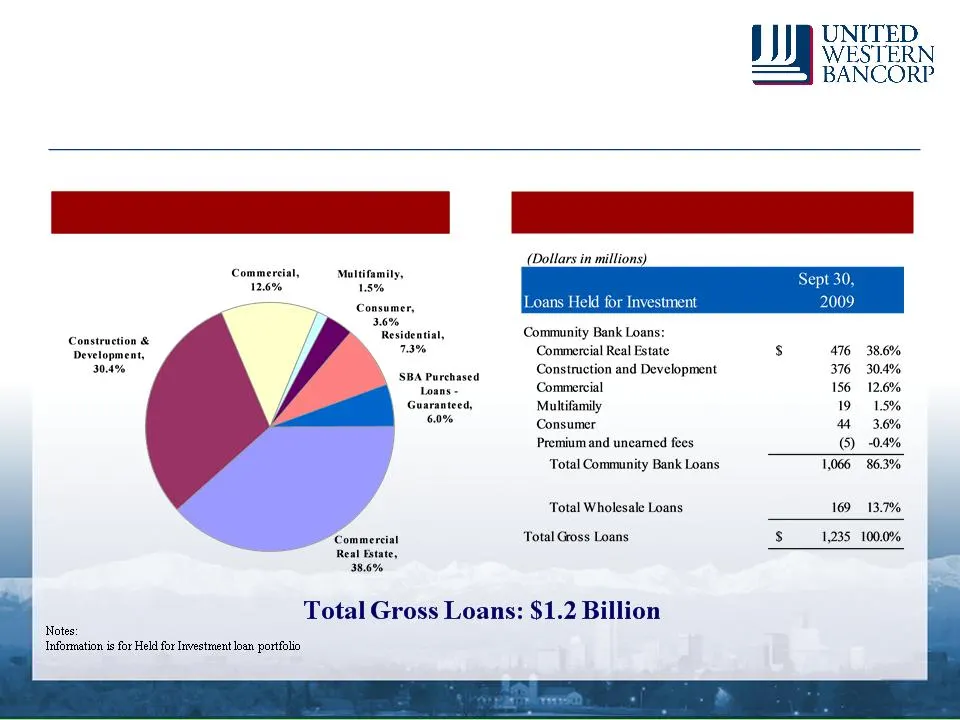
Slide 15: Loan Portfolio Composition and Summary
15 Loan Portfolio Composition Loan Portfolio Summary Data as of September 30, 2009 Source: Company documents Loan Portfolio Summary
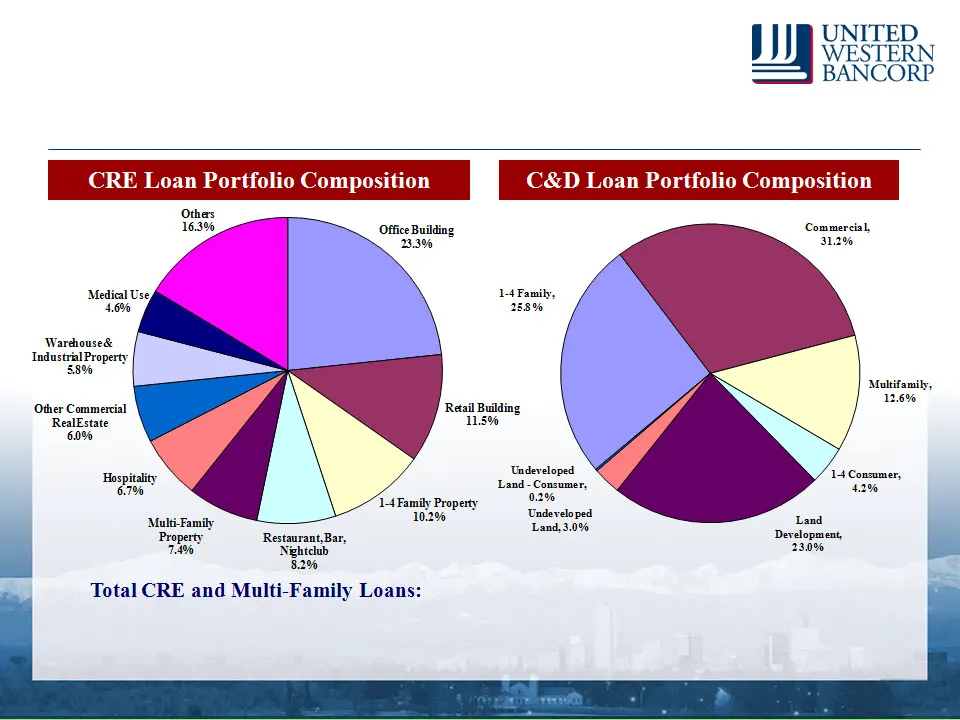
Slide 16: CRE and C&D Loan Portfolio Summary
16 $495 Million Data as of September 30, 2009 Total C&D Loans: $376 Million CRE and C&D Loan Portfolio Summary
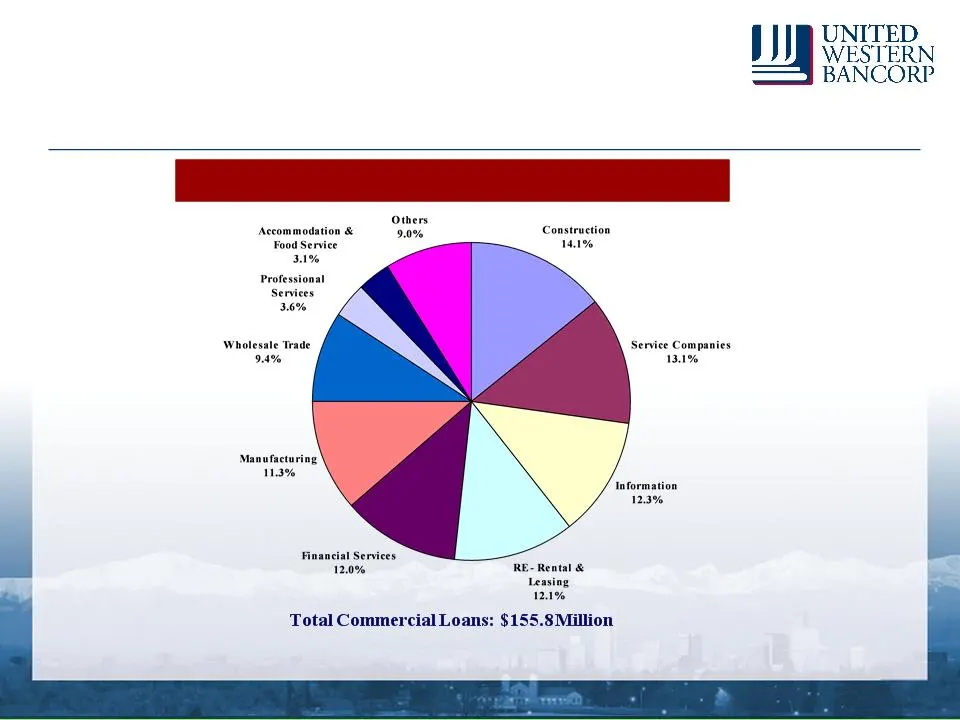
Slide 17: Commercial Loan Portfolio Composition
17 Commercial Loan Portfolio Composition * *Graphic depiction excludes note receivable of $46 million from Equity Trust Company, received as part of sale of UW Trust assets in June 2009. Data as of September 30, 2009 Commercial Loan Portfolio Summary
Slide 18: Single Family Residential Portfolio
18 Single Family Residential Portfolio o $287 million aggregate size across HFI and HFS portfolios o Weighted average loan age-8 years o Average loan size $130,000 o Geographically diverse o Average FICO scores at origination-over 700
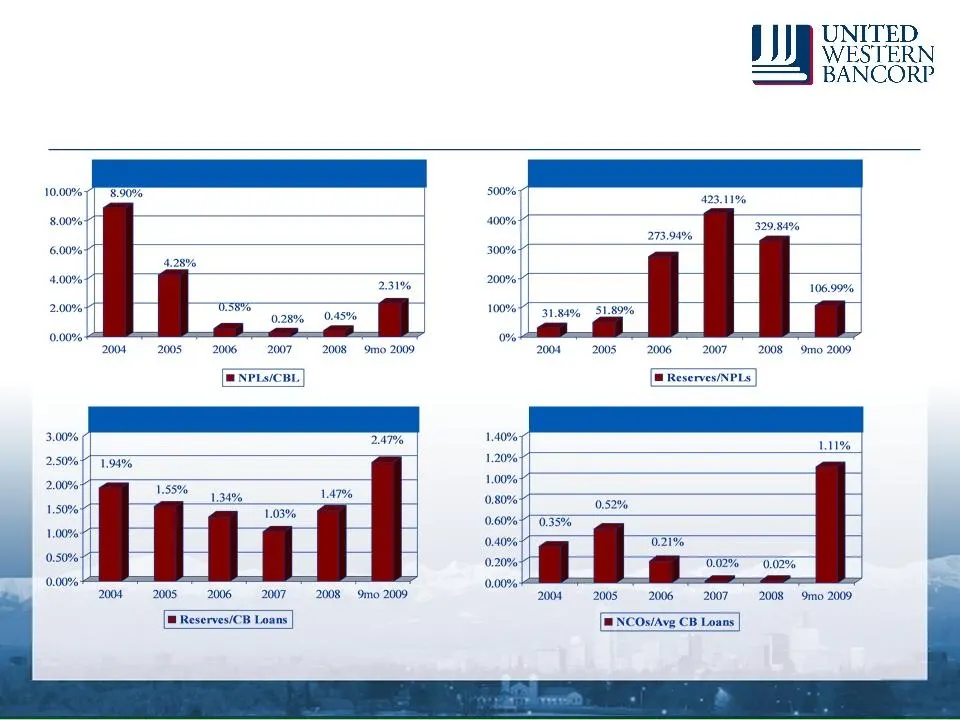
Slide 19: Asset Quality - Community Bank HFI
19 Reserves/NPLs NCOs/ Average Community Bank Loans NPLs/Community Bank Loans Reserves/Community Bank Loans Asset Quality - Community Bank HFI
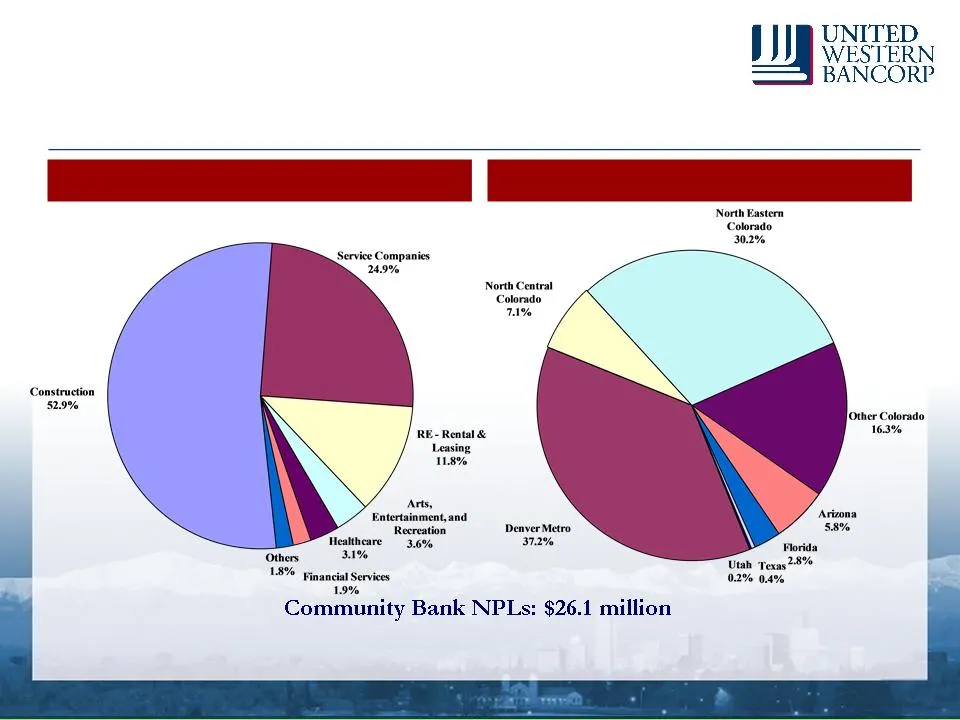
Slide 20: Community Bank NPLs by Location and Composition
20 20 Community Bank NPLs by Location Community Bank NPLs Composition Note: Community Bank NPLs include held for investment Community Bank loans and a held for sale multi-family loan. Source: Company records as of September 30, 2009 Community Bank NPLs
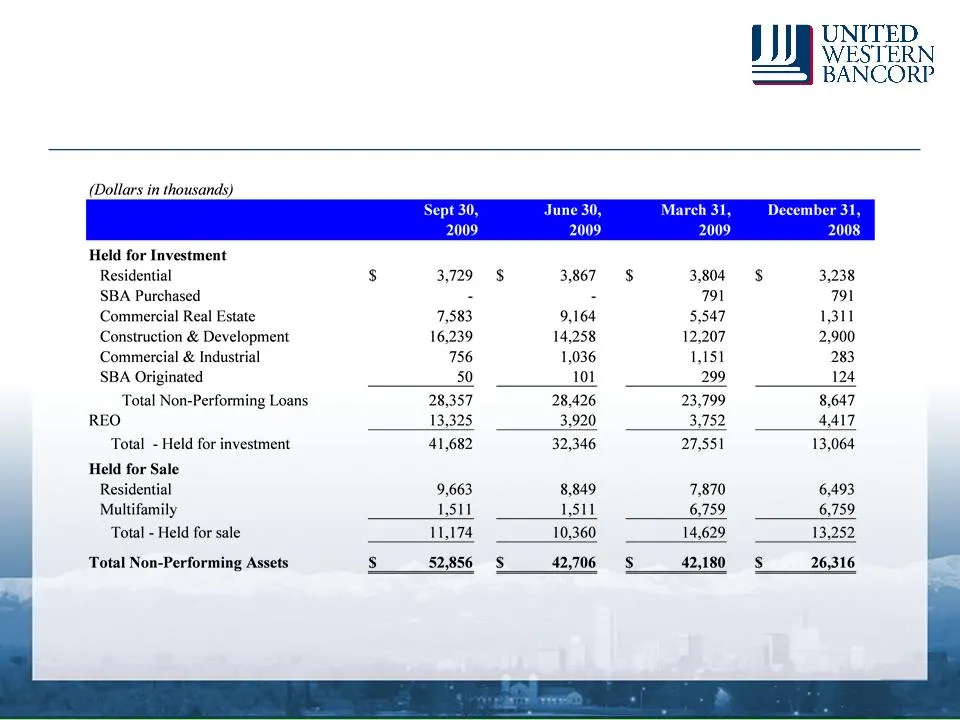
Slide 21: Non-Performing Assets Summary
21 Data as of September 30, 2009 Non-Performing Assets Summary
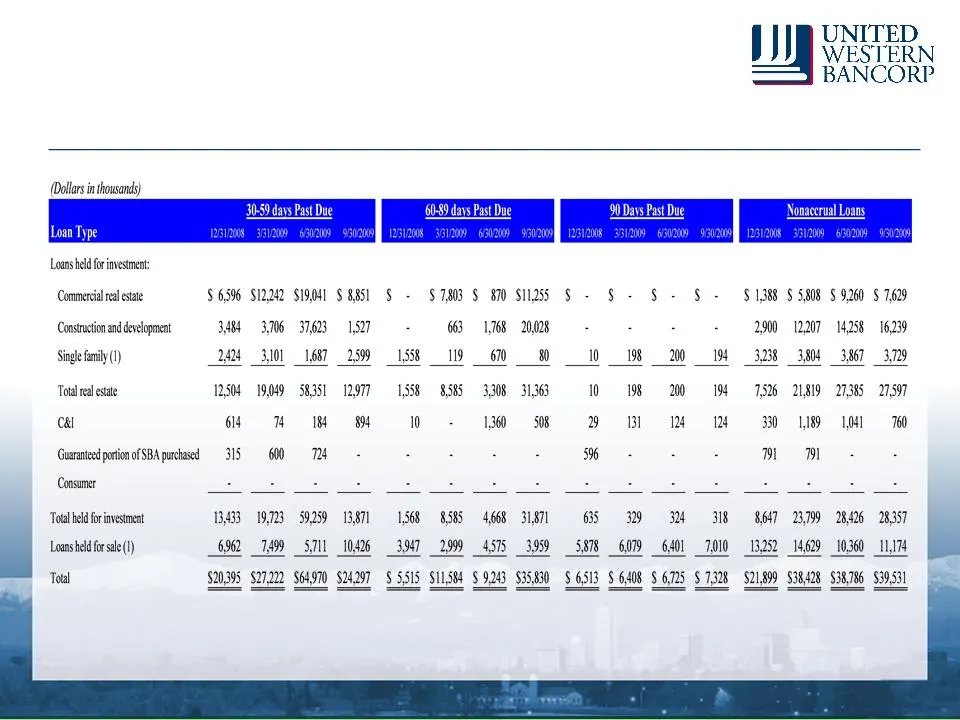
Slide 22: Asset Quality Migration
22 22 (1) Loans over 90 days past due that remain on accrual are guaranteed as to principal and interest by HUD. Asset Quality Migration
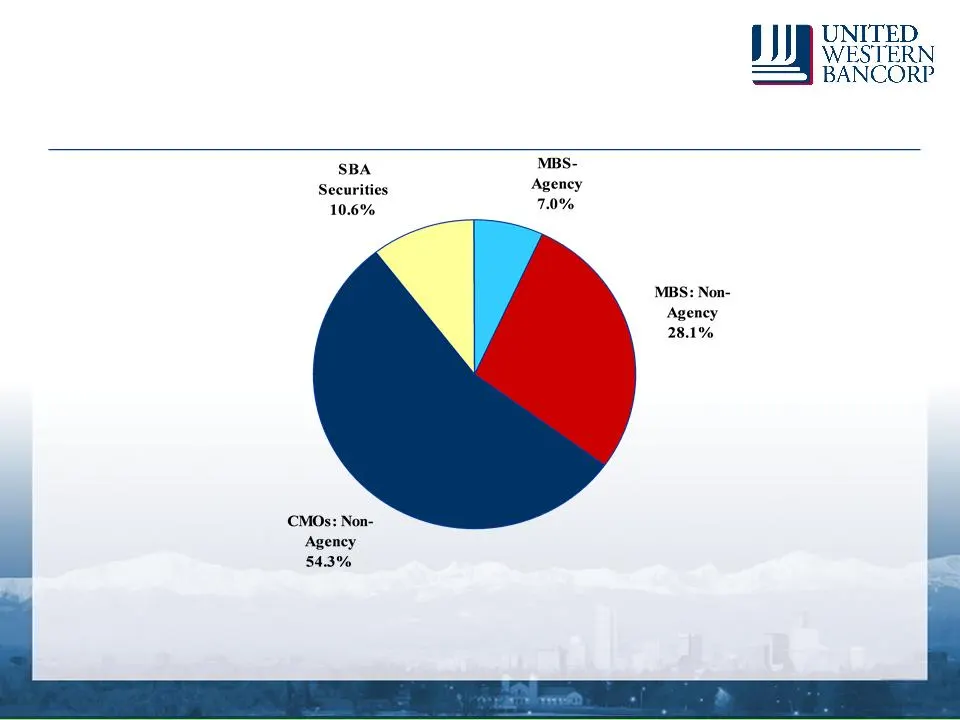
Slide 23: Investment Securities Portfolio
23 Total HTM Securities: $411 million Total AFS Securities: $35 million Data as of September 30, 2009 Investment Securities Portfolio
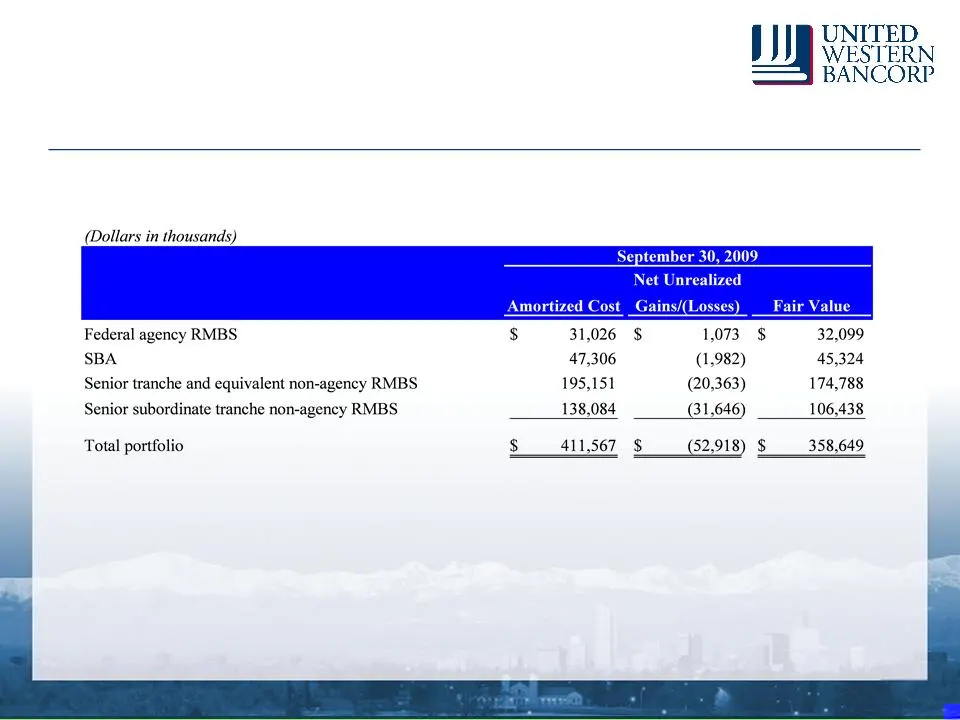
Slide 24: Investment Securities Portfolio: RMBS
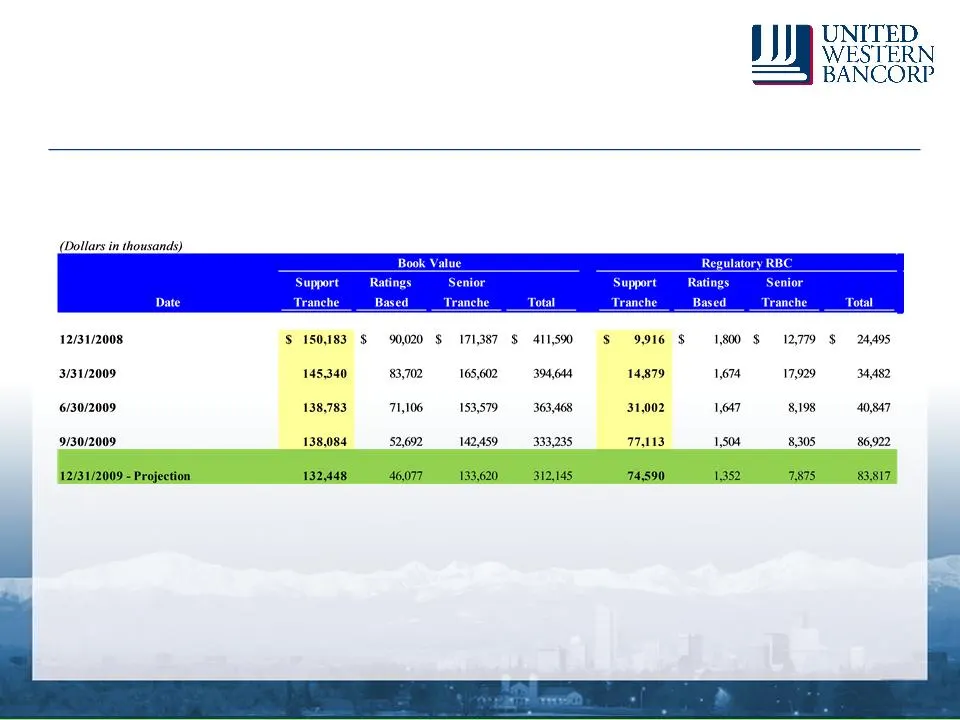
24 Note: Excludes RMBS with amortized cost of $36.8 million at September 30, 2009 held by United Western Bancorp, Inc. and its affiliates other than United Western Bank. This presentation includes both HTM and AFS securities and categorizes the Bank’s securities based on type and regulatory capital
Slide 25: Regulatory Capital Requirements
25 Regulatory Capital Requirements o Non-Agency RMBS: United Western Bank
Slide 26: Investment Securities Portfolio: Non-agency RMBS Run-Off
26 o Portfolio Run-Off: Non-agency RMBS n Reductions average $9.2 million per month for first nine months of 2009 n From December 31, 2008 through September 30, 2009, the portfolio declined $129.9 million, of which $47.3 million was due to sales and $82.6 million due to portfolio pay downs. n Portfo
Slide 27: Opportunities for Growth
27 o Selective expansion of branch network within local markets o Continued ability to attract “disenfranchised” bankers from larger competitors o Branch acquisitions from larger bank overlap/closures o Opportunistic acquisitions of assets or liabilities via FDIC Opportunities for Growth
Slide 28: Investment Considerations
28 o Top performing bank in attractive market - opportunity to grow o Management team track record o Temporary support of regulatory capital to hold our performing non-agency RMBS securities portfolio o Sticky deposit franchise o Performing loan portfolio o Attractive valuation to tangible book valu
Slide 29: Ip yee
Ip yee WESTERN BANCORP | JJ UNITED WESTERN BANCORP al ae |
Source: SEC EDGAR · 8-K filed Nov 10, 2009
More decks from United Western Bancorp Inc
 Shareholder Meeting (July 2010)12 slides · Jul 30, 2010
 Merger or Acquisition (June 2010)16 slides · Jun 15, 2010
 IPO Roadshow (September 2009)38 slides · Sep 8, 2009
 Shareholder Meeting (May 2009)28 slides · May 21, 2009
 Merger or Acquisition (April 2009)6 slides · Apr 10, 2009
 Investor Presentation (March 2009)31 slides · Mar 3, 2009