DDI — Needham 10th Annual Growth Stock Conference 2008
23 slides from DDI's conference presentation, Jan 11, 2008
Slide 1: DDi Corp Needham Growth Conference
Exhibit 99.1 DDi Corp Needham Growth Conference Mikel Williams President and CEO January 11, 2008 1
Slide 2: Safe Harbor
Safe Harbor This presentation may contain information about future expectations, plans and prospects that may constitute forward-looking statements for purposes of the Safe Harbor provisions under the Private Securities Litigation Reform Act of 1995. Actual results or developments may differ materia
Slide 3: Non-GAAP Financial Measures
Non-GAAP Financial Measures This presentation includes ‘adjusted EBITDA,’ ‘adjusted Gross Profit,’ ‘adjusted Operating Income,’ ‘adjusted SG&A’ and other non-GAAP financial measures as defined in Regulation G of the Securities Exchange Act of 1934. Management believes that the disclosure of non-GAAP
Slide 4: DDi Corp. Company Profile
DDi Corp. Company Profile • 29 year operating history • NASDAQ symbol: DDIC, ISS rating of 98.3 • Created the “Time and Technology (Quick Turn)” concept and market • Leader in North American market for time critical, advanced technology PCB engineering and manufacturing services – Preferred OEM sour
Slide 5: DDi Company History
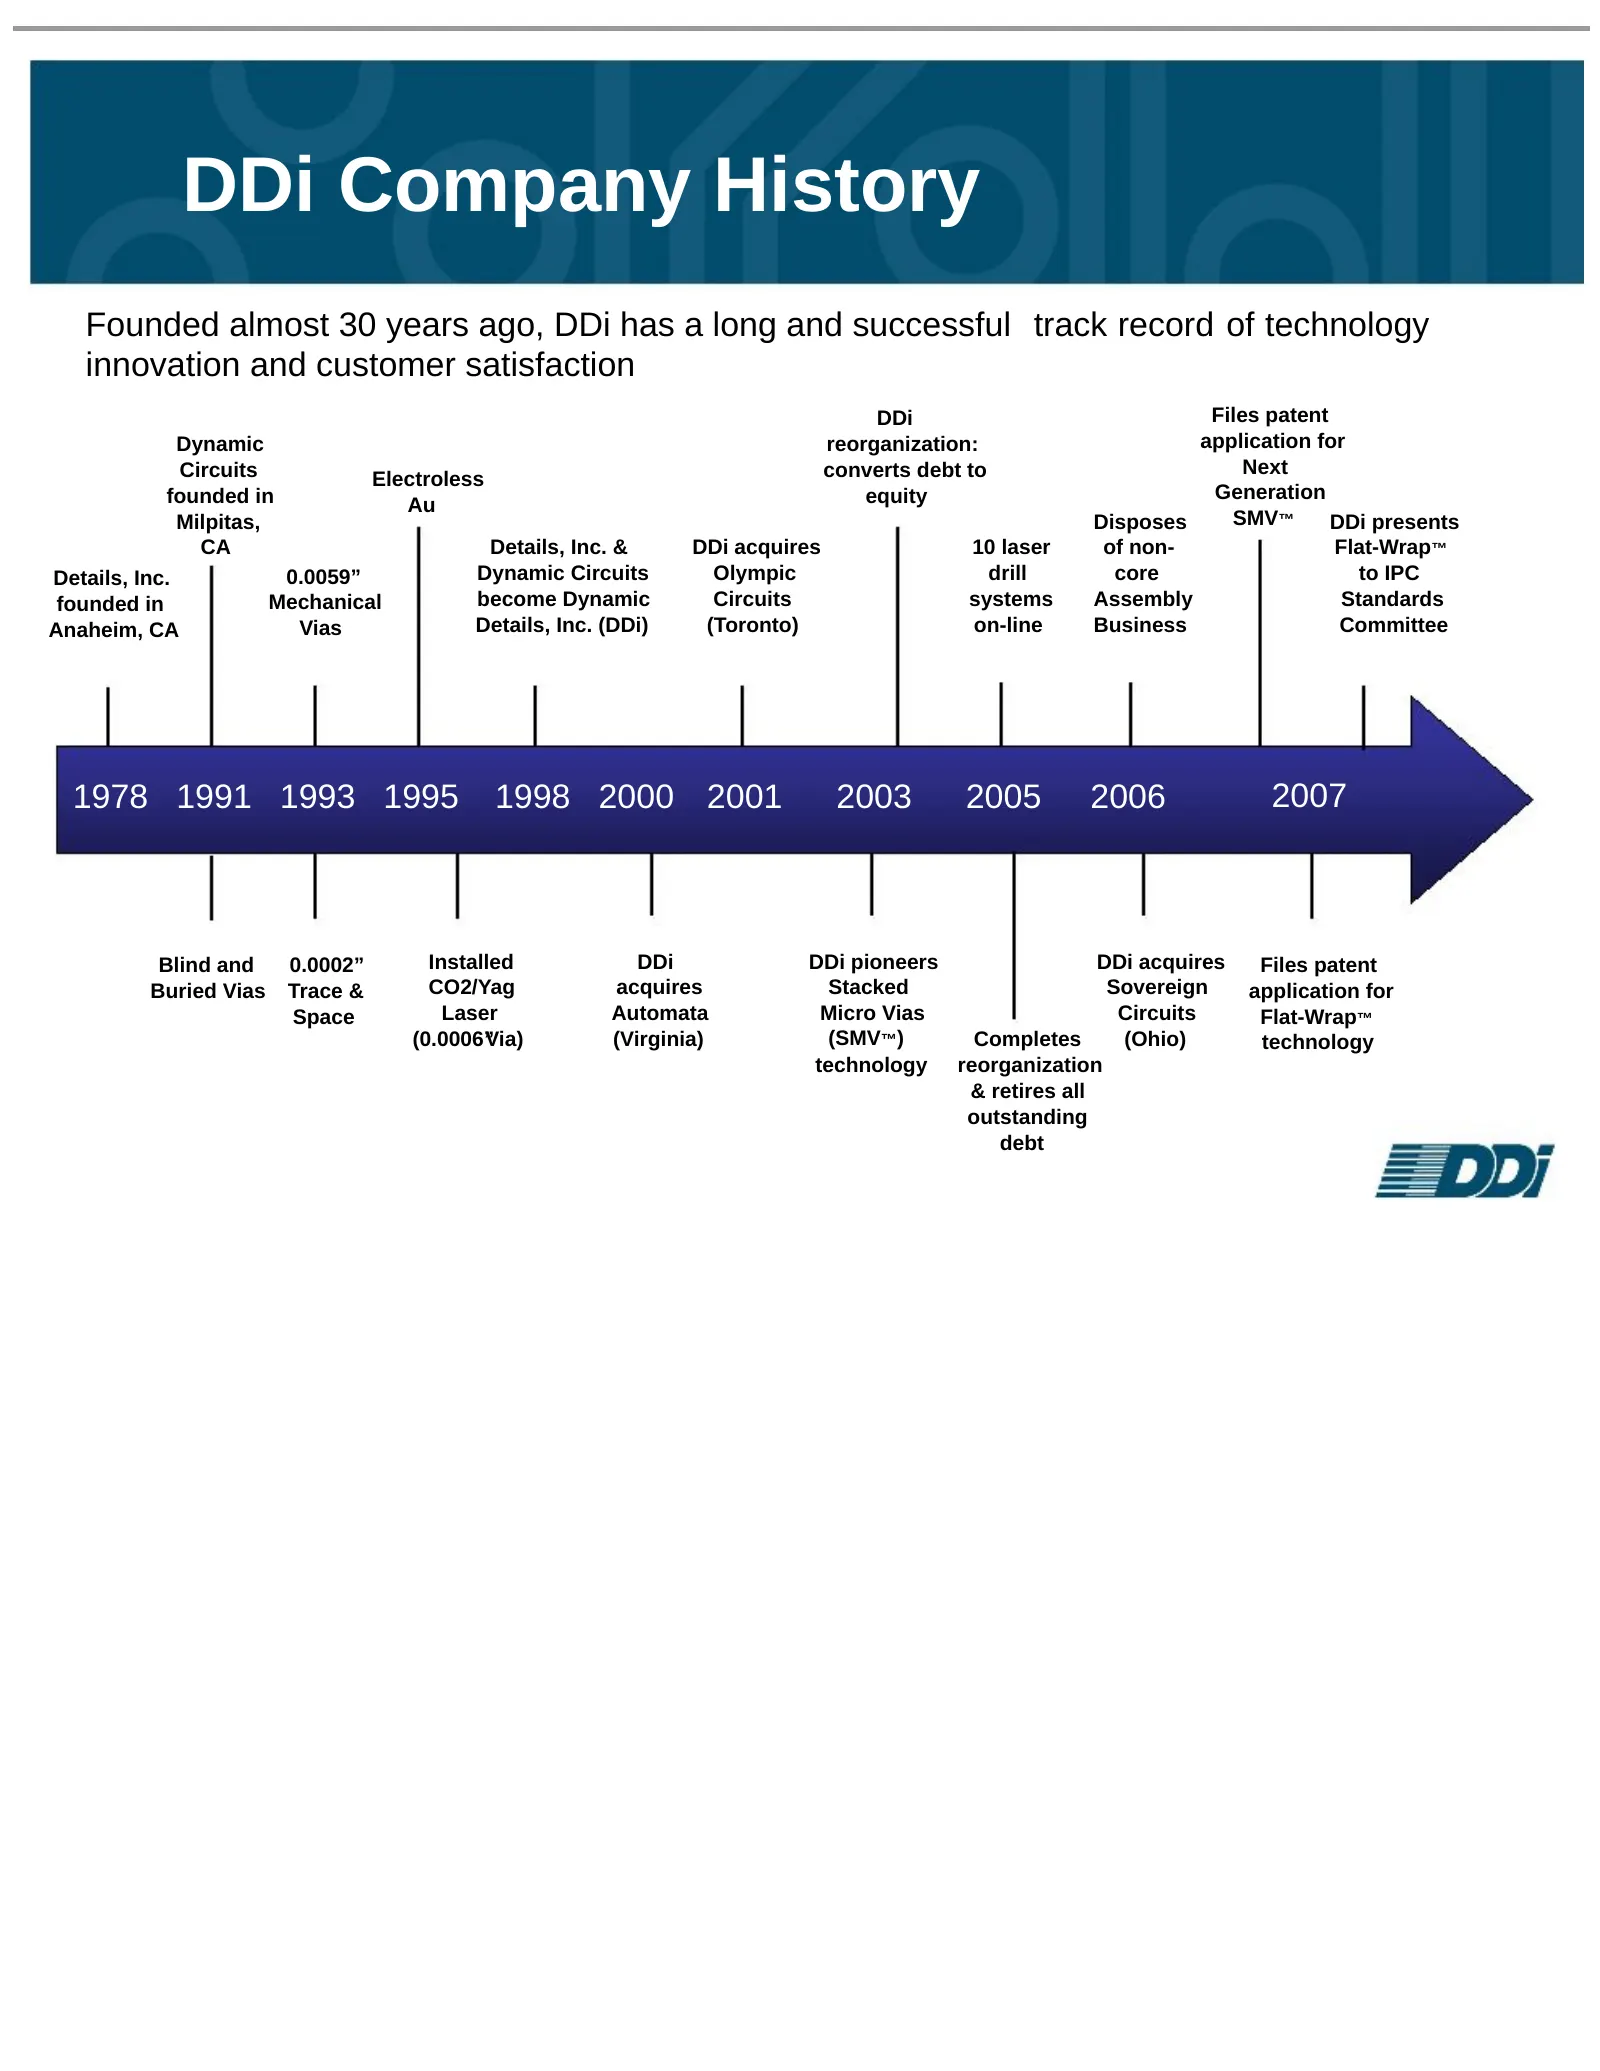
DDi Company History Founded almost 30 years ago, DDi has a long and successful track record of technology innovation and customer satisfaction DDi Files patent Dynamic reorganization: application for Circuits converts debt to Next Electroless founded in equity Generation Au Milpitas, Disposes SMV™ D
Slide 6: Global PCB Market Overview
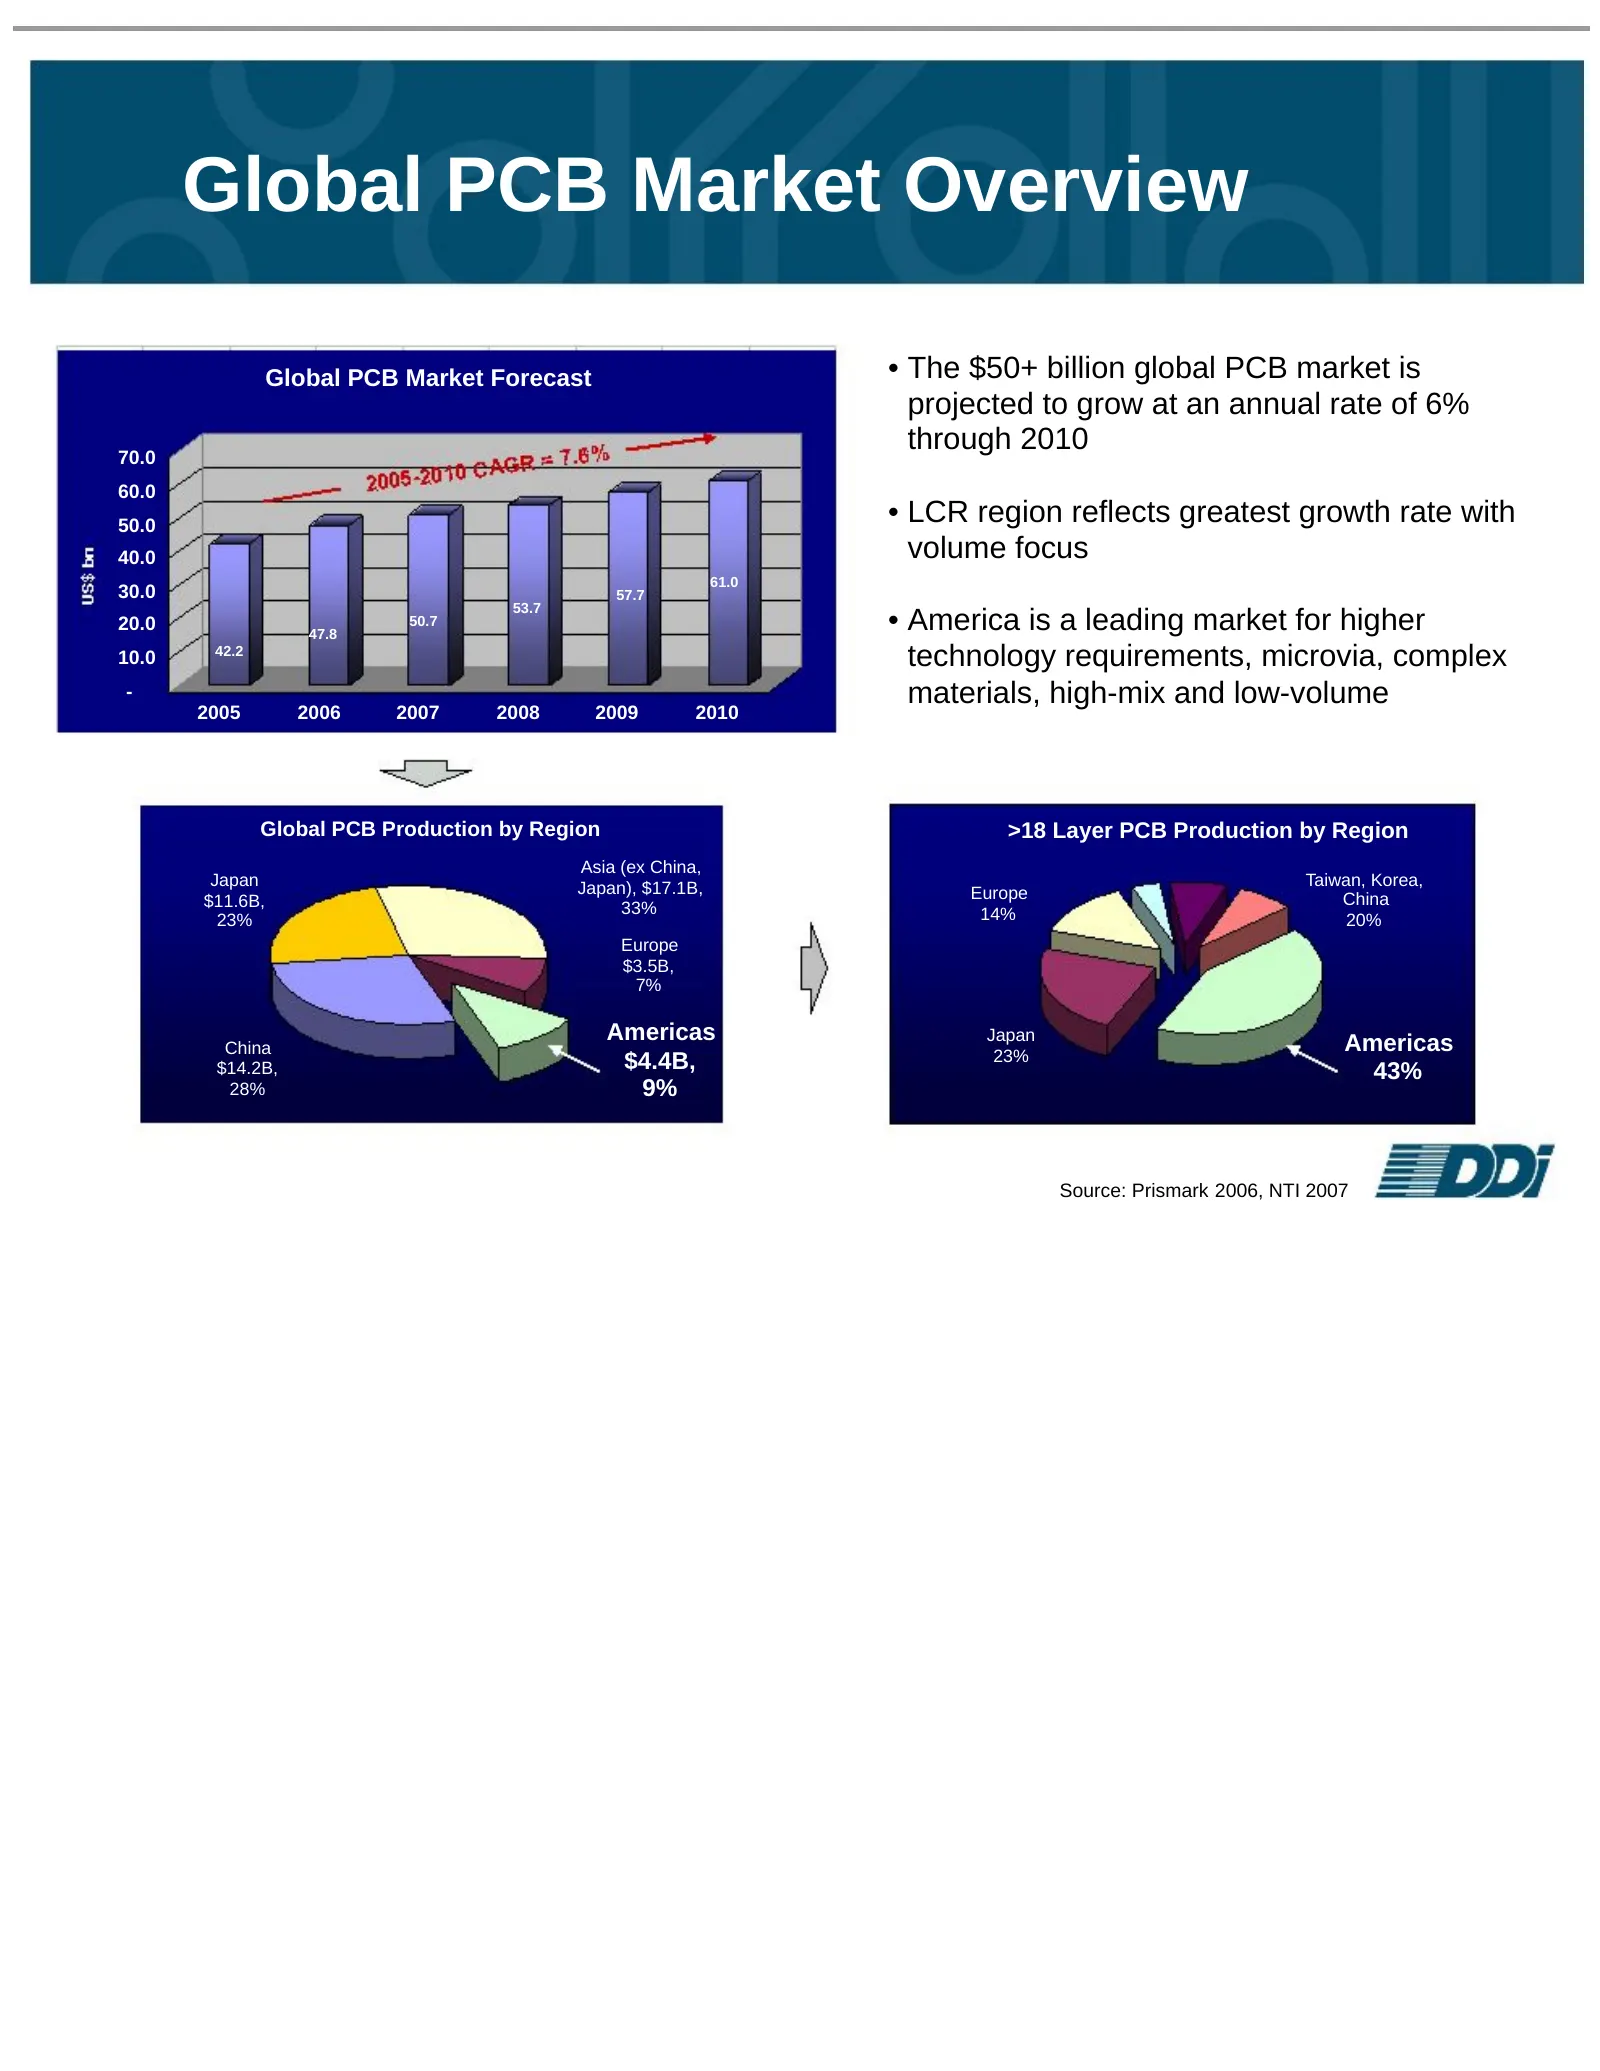
Global PCB Market Overview Global PCB Market Forecast • The $50+ billion global PCB market is projected to grow at an annual rate of 6% 70.0 through 2010 60.0 50.0 • LCR region reflects greatest growth rate with 40.0 volume focus 61.0 30.0 57.7 53.7 20.0 47.8 50.7 • America is a leading market for h
Slide 7: North American PCB Market Overview
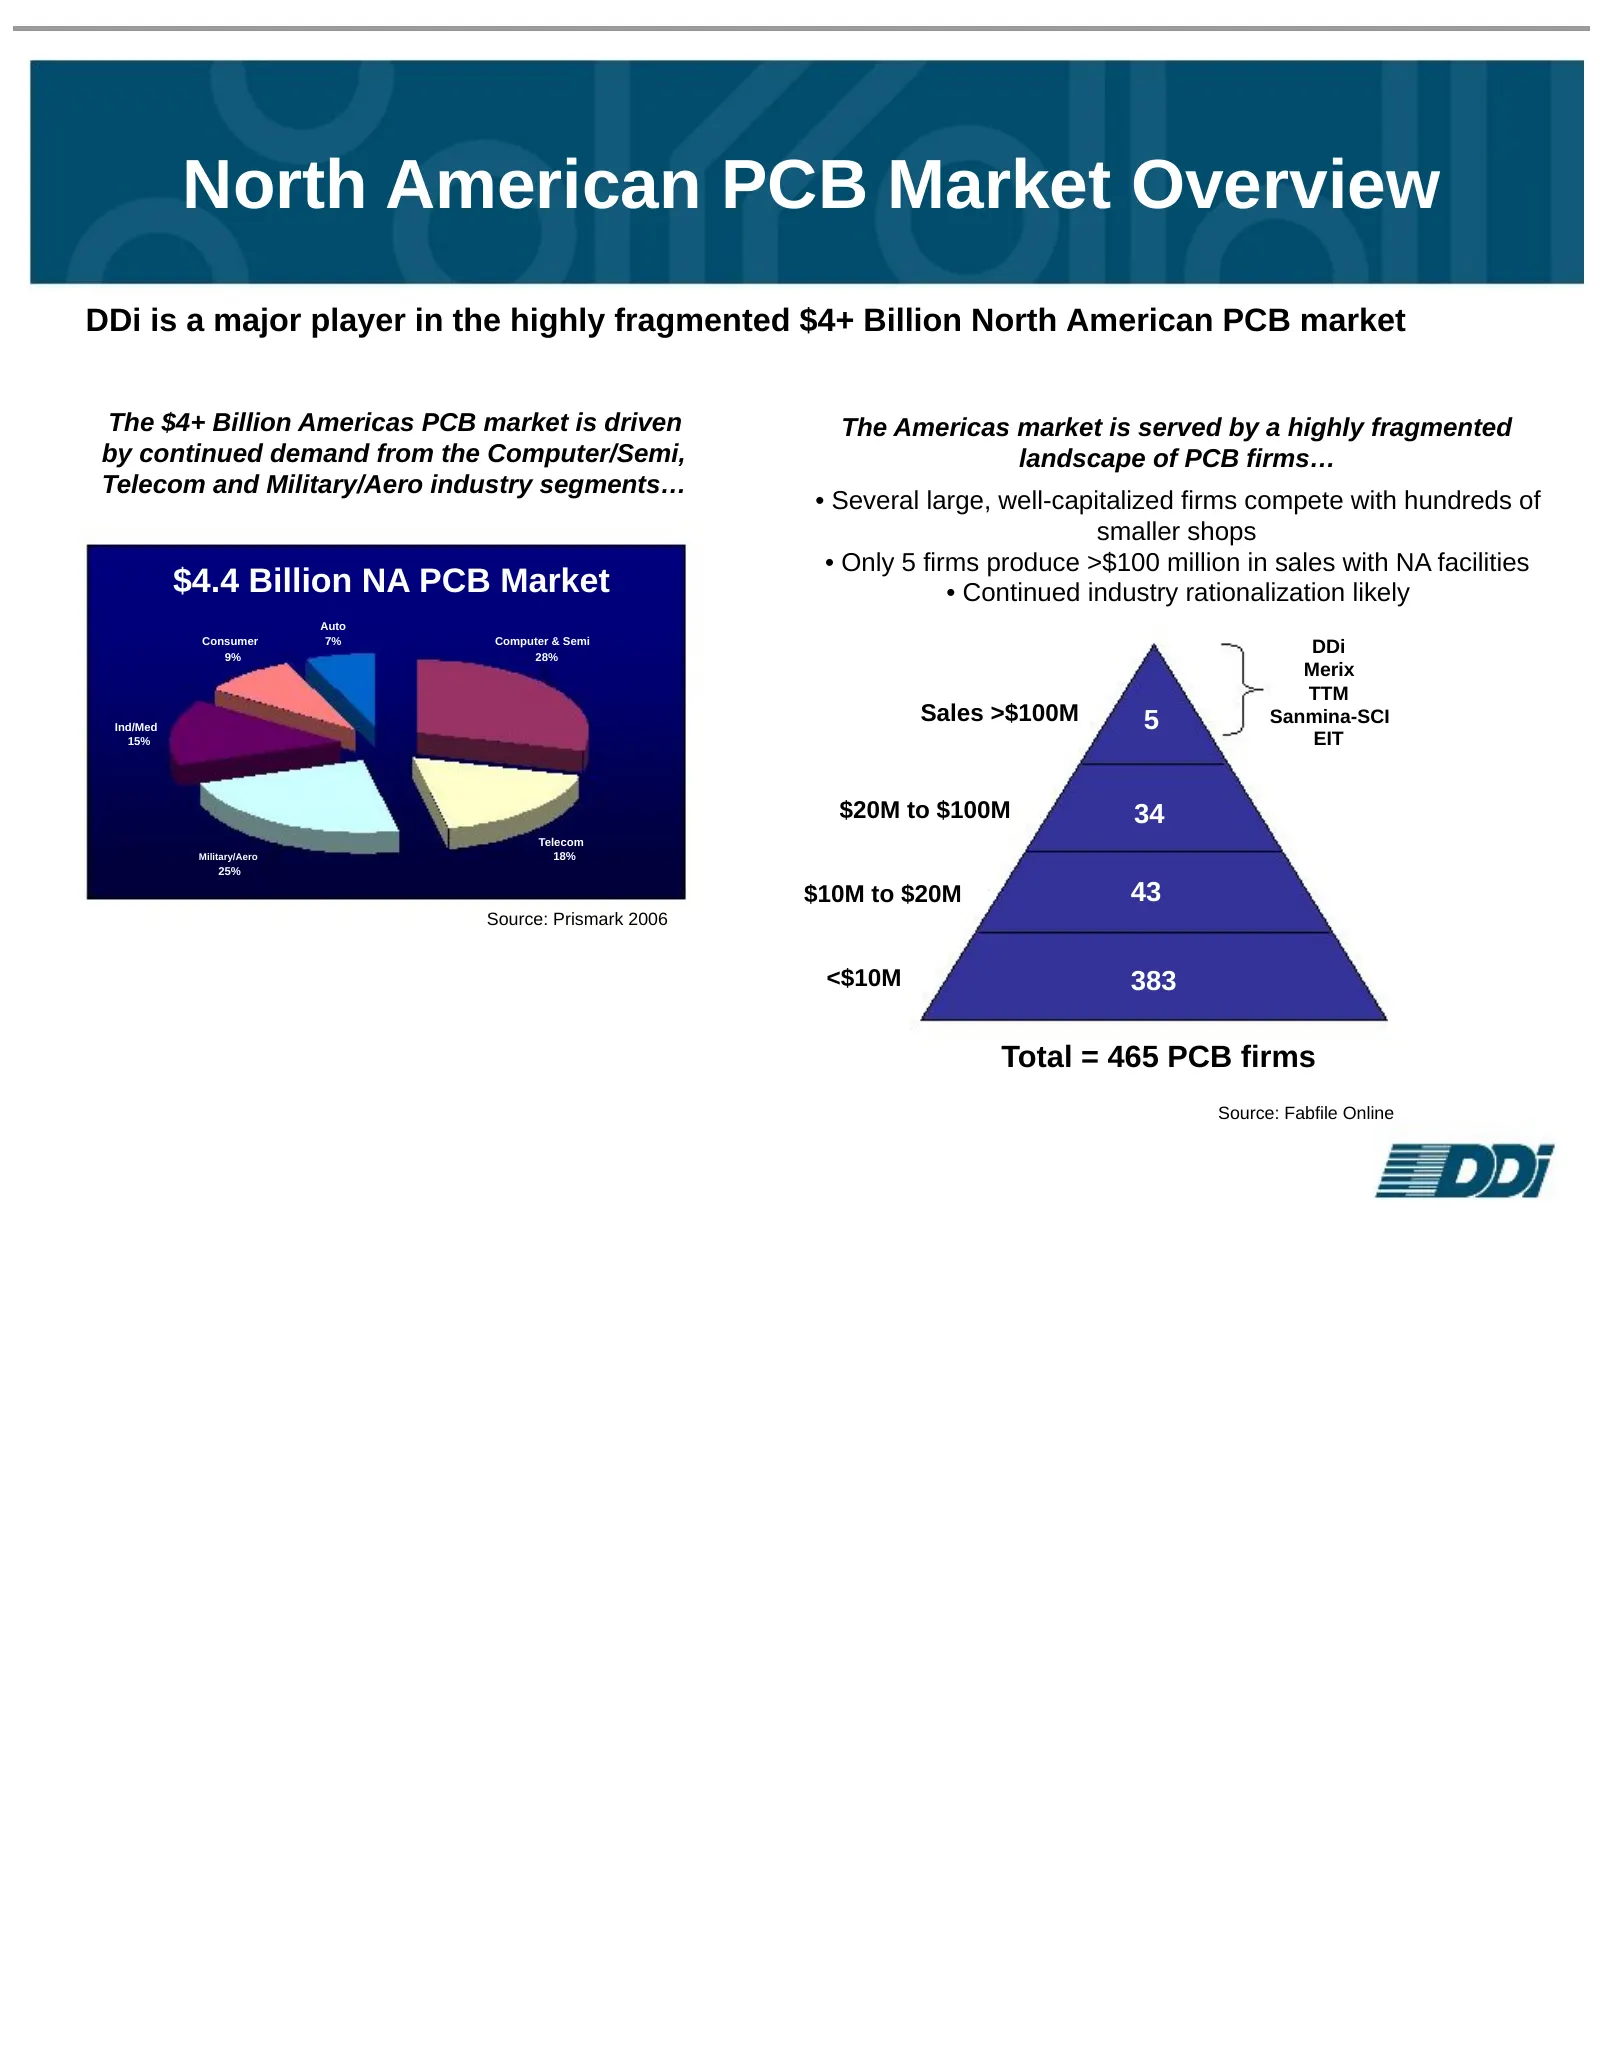
North American PCB Market Overview DDi is a major player in the highly fragmented $4+ Billion North American PCB market The $4+ Billion Americas PCB market is driven The Americas market is served by a highly fragmented by continued demand from the Computer/Semi, landscape of PCB firms… Telecom and M
Slide 8: North American PCB Market Drivers
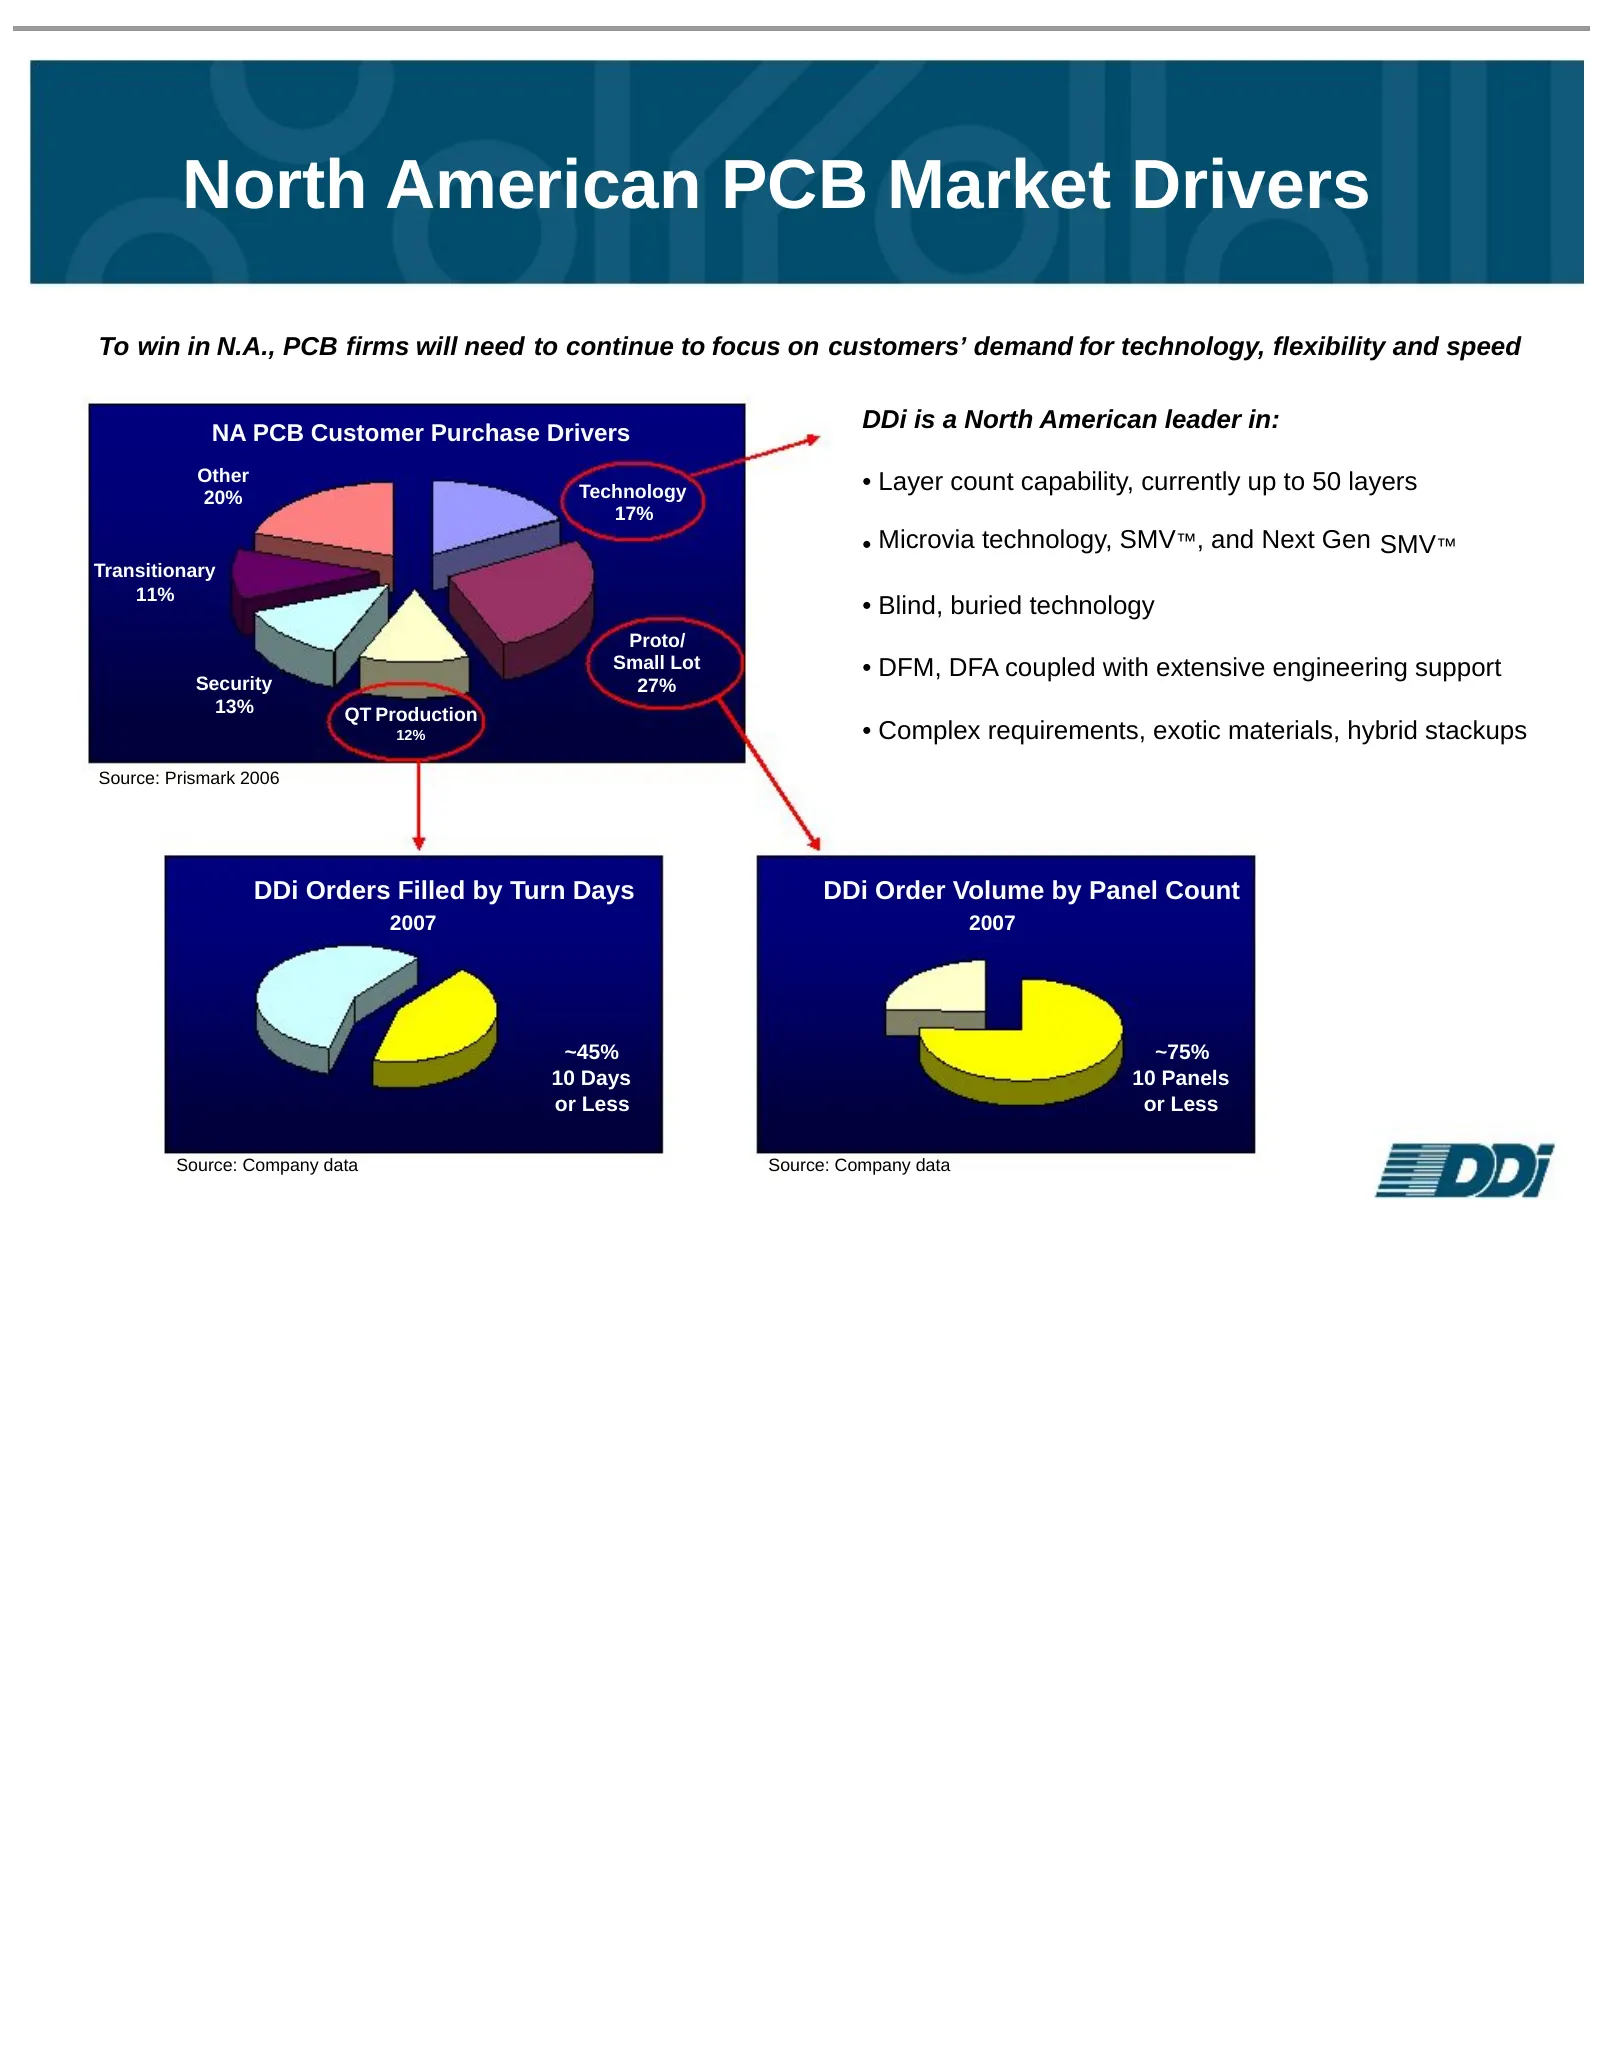
North American PCB Market Drivers To win in N.A., PCB firms will need to continue to focus on customers’ demand for technology, flexibility and speed NA PCB Customer Purchase Drivers DDi is a North American leader in: Other • Layer count capability, currently up to 50 layers 20% Technology 17% • Mic
Slide 9: PCB Product Requirements & Trends
PCB Product Requirements & Trends General product demand trends: • Product life cycles are shortening, NPI time to market is critical • Smaller end-product form factor coupled with high performance requirements • Smaller & more capable semi-conductor devices drives increased functionality • Lead-Fre
Slide 10: Manufacturing Locations & Qualifications
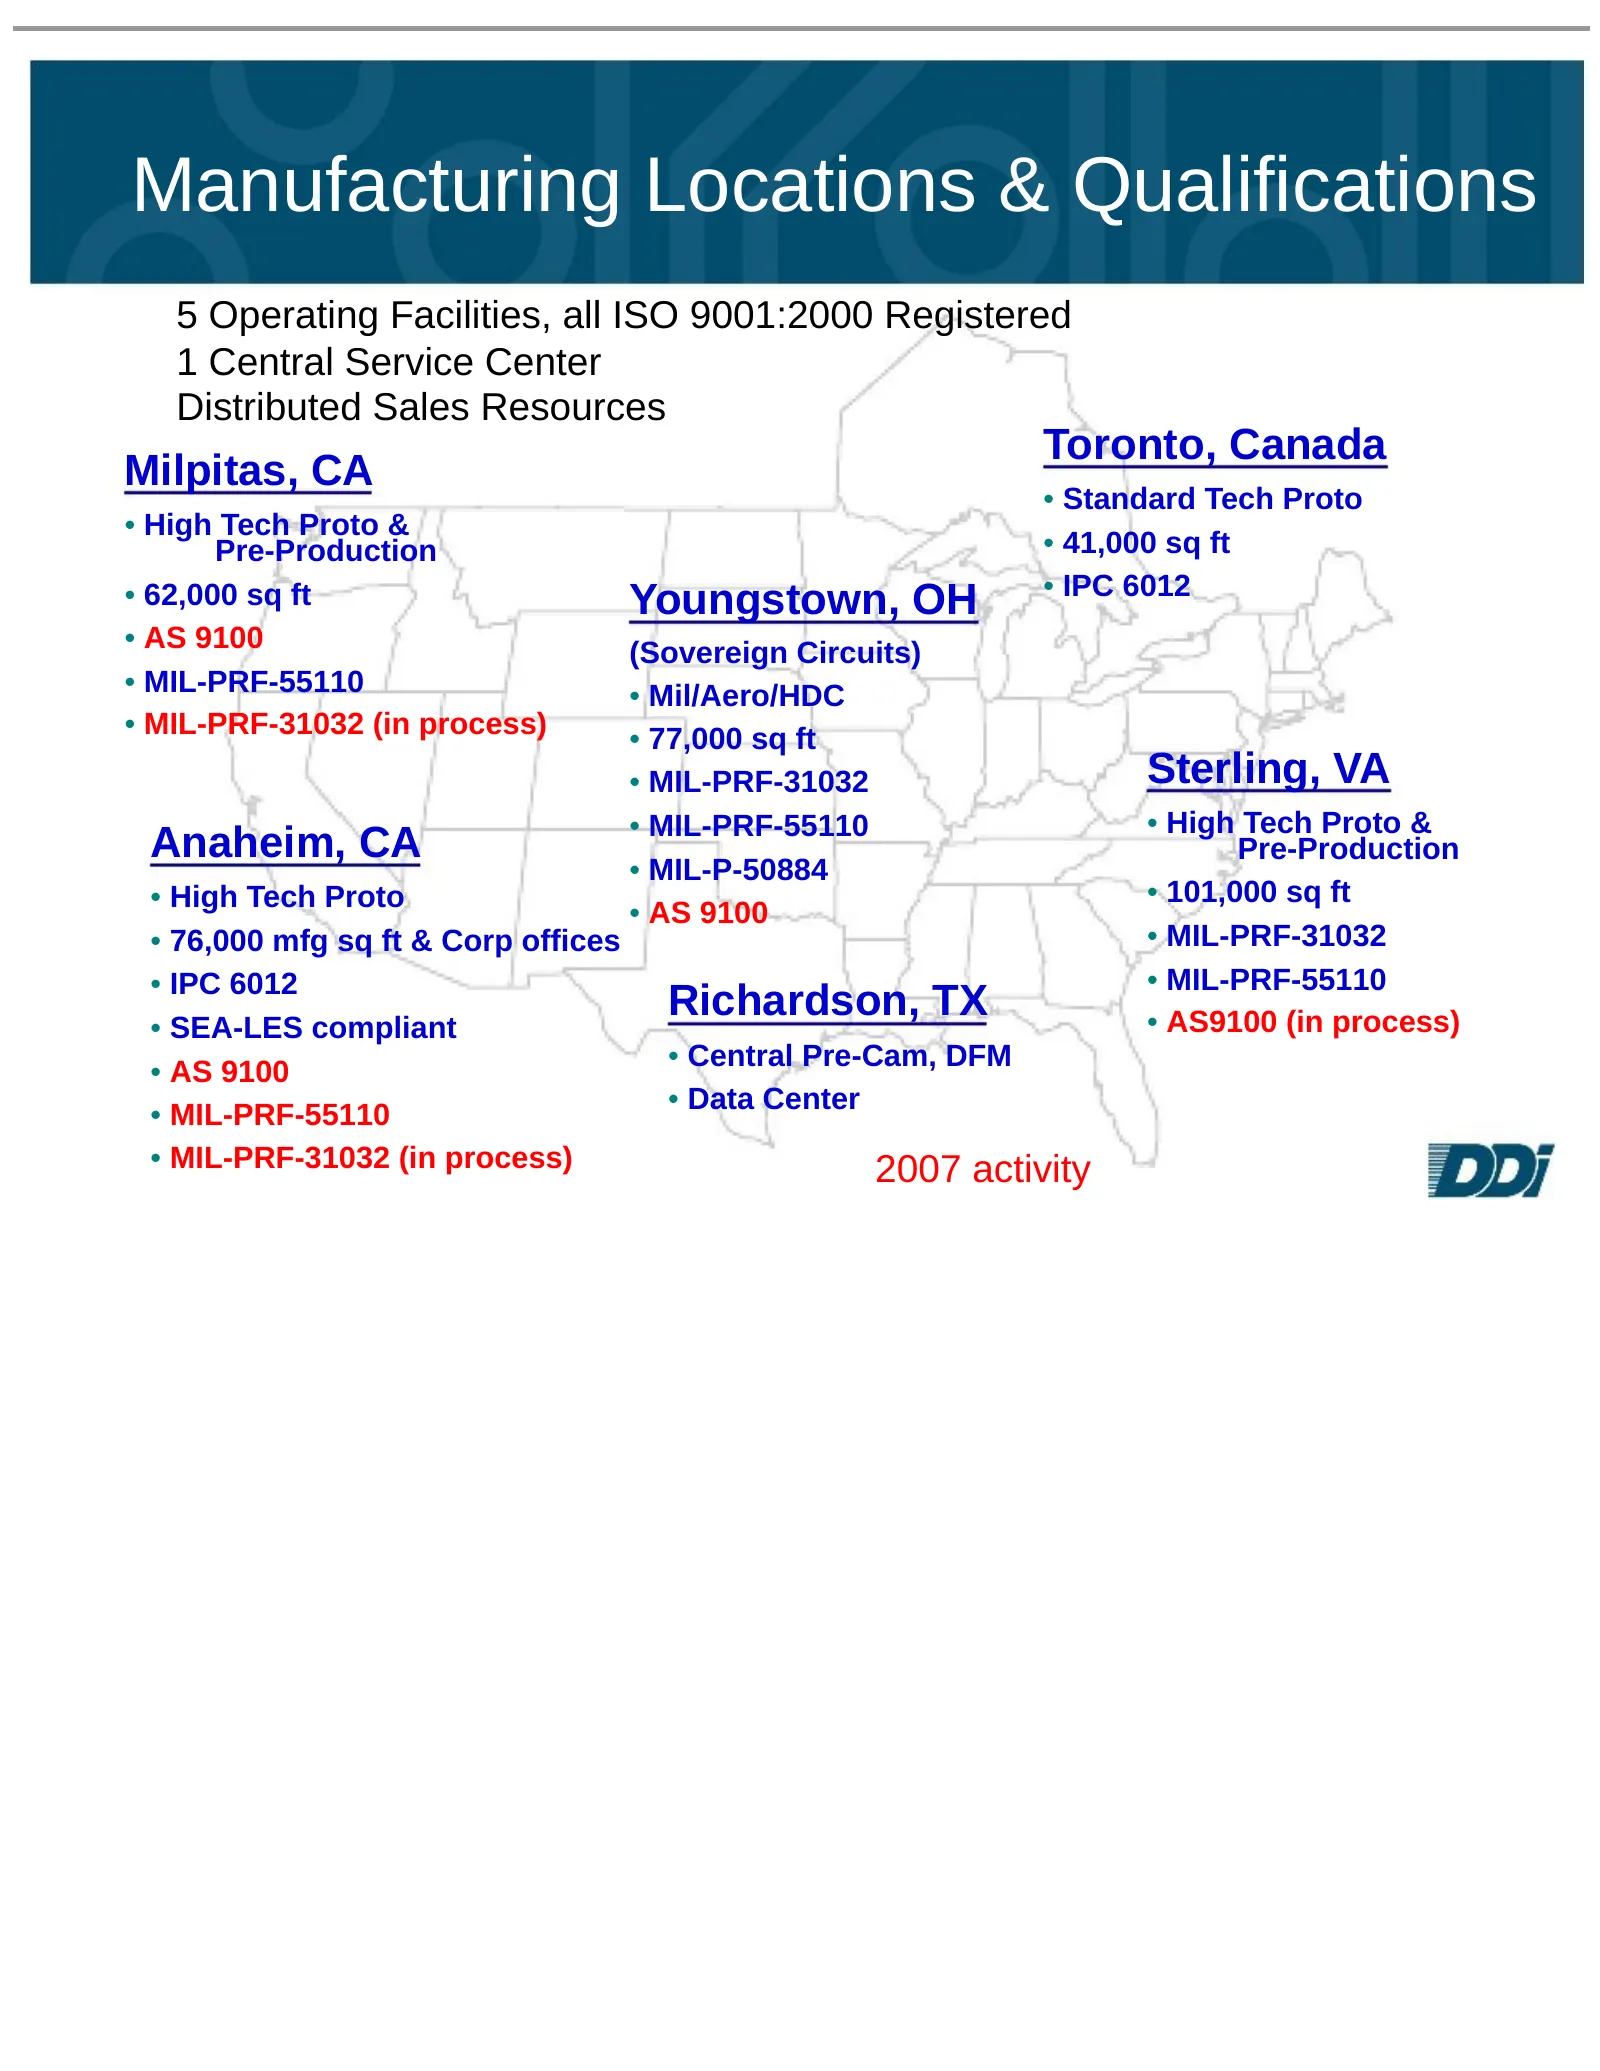
Manufacturing Locations & Qualifications 5 Operating Facilities, all ISO 9001:2000 Registered 1 Central Service Center Distributed Sales Resources Toronto, Canada Milpitas, CA • Standard Tech Proto • High Tech Proto & Pre-Production • 41,000 sq ft • IPC 6012 • 62,000 sq ft Youngstown, OH • AS 9100 (
Slide 11: Technology Leadership
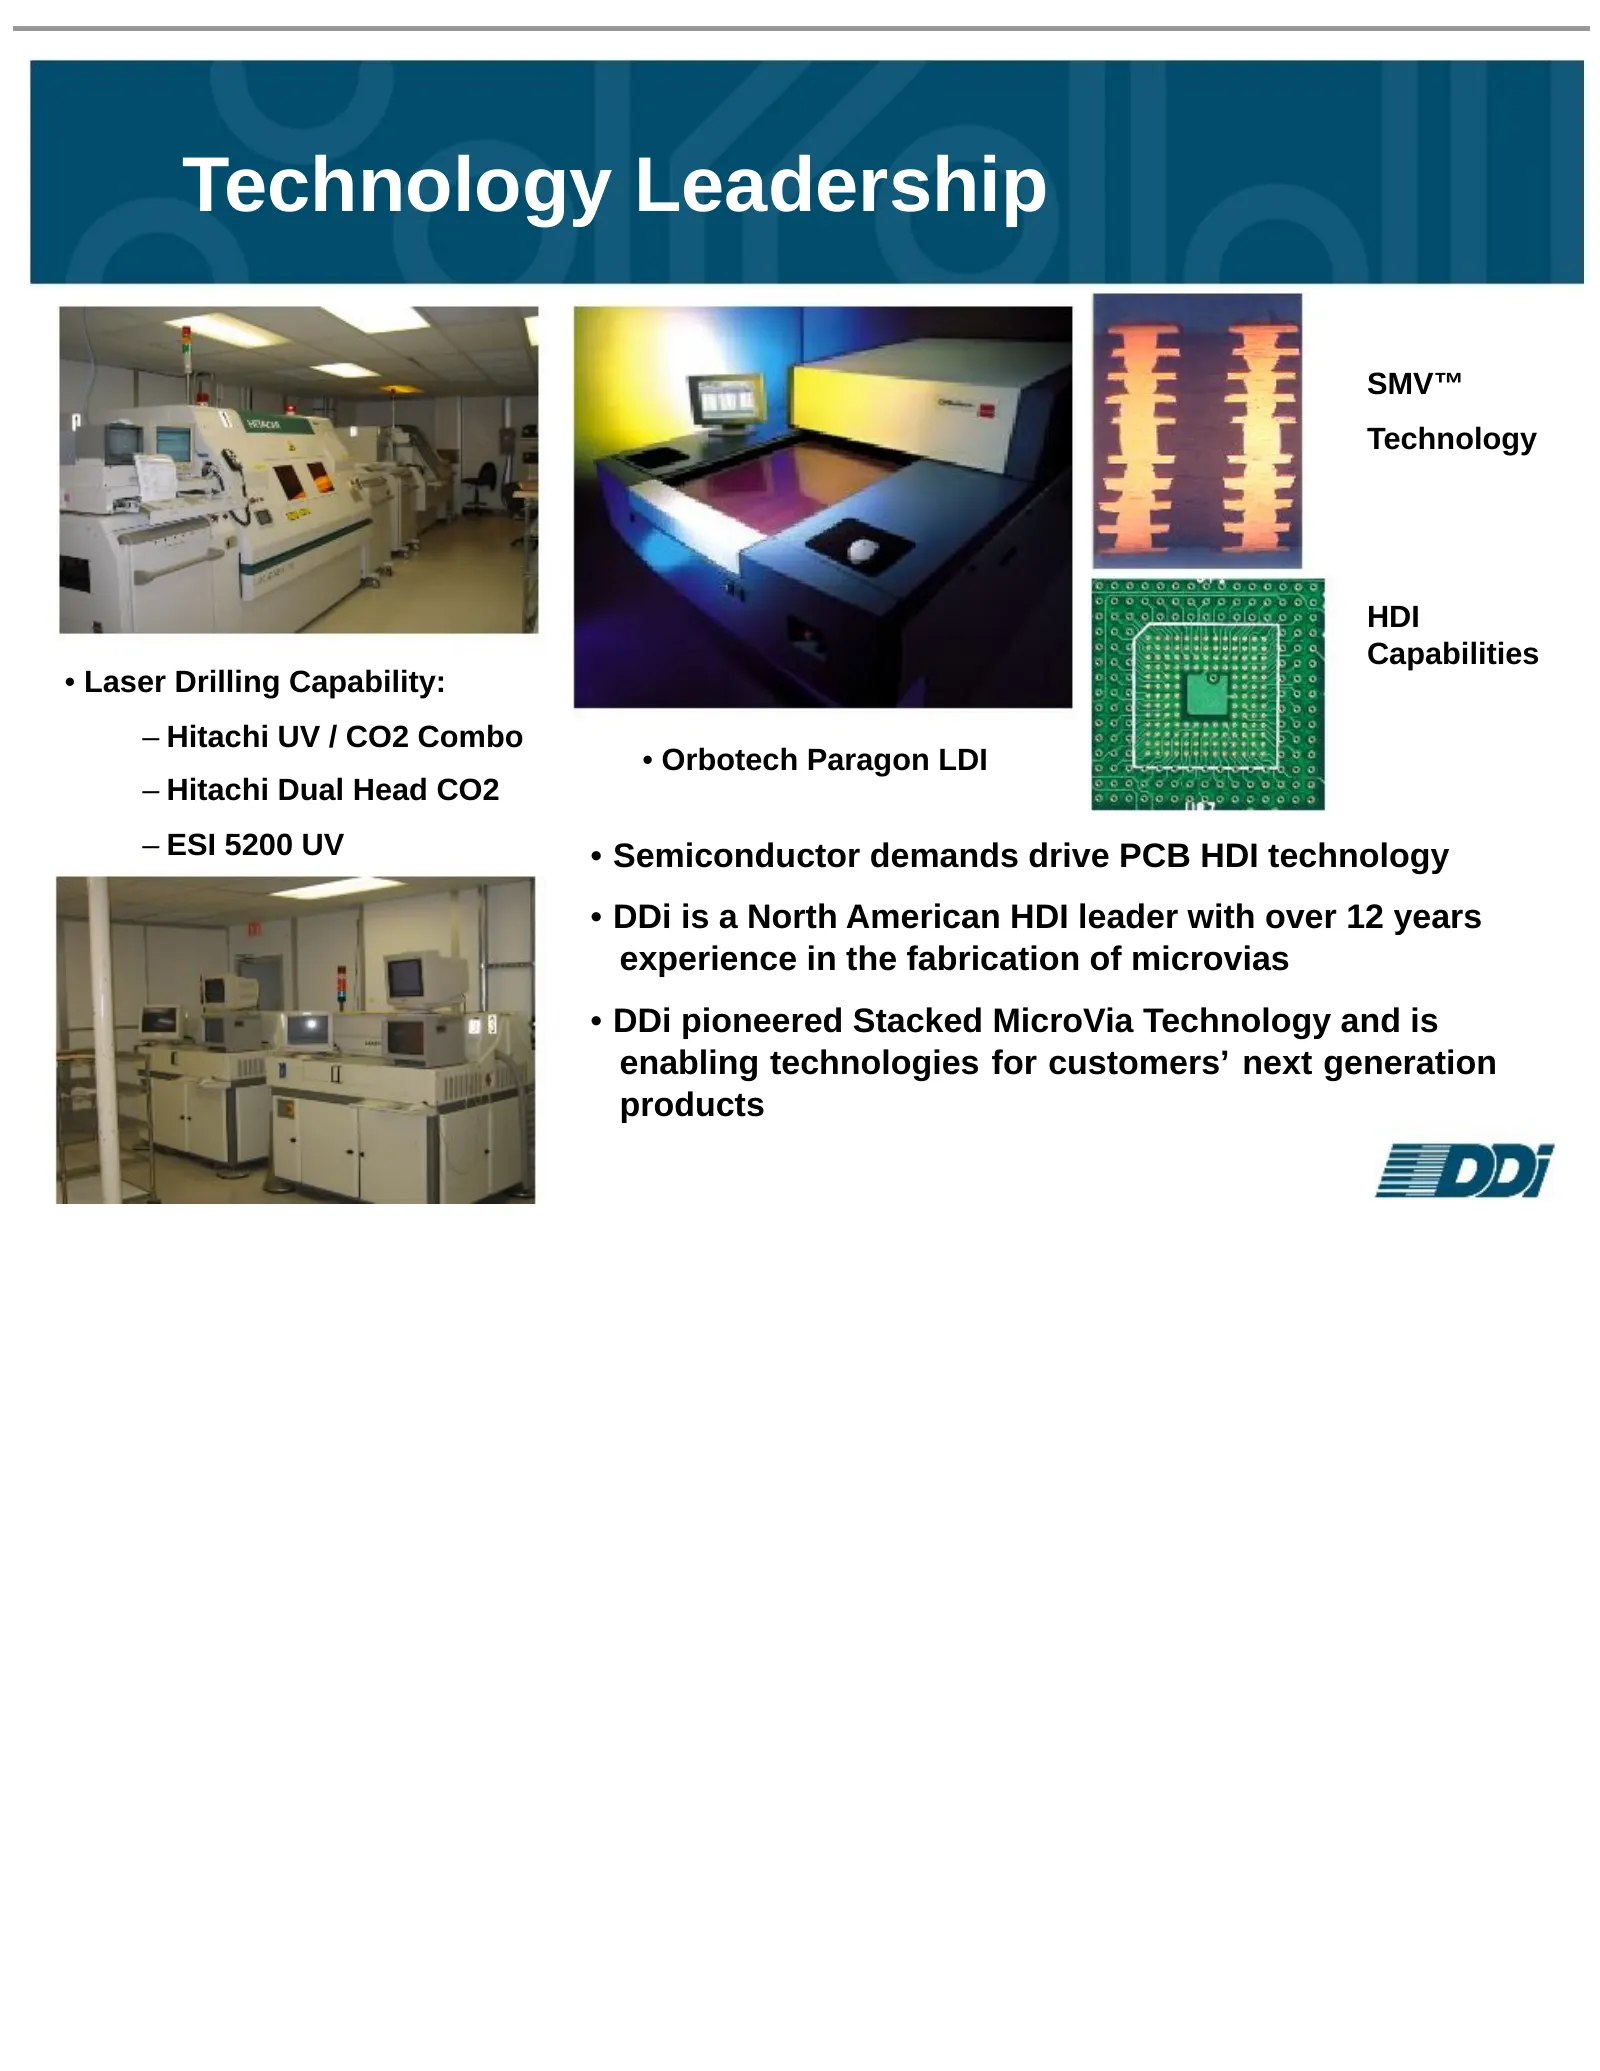
Technology Leadership SMV™ Technology HDI Capabilities • Laser Drilling Capability: – Hitachi UV / CO2 Combo • Orbotech Paragon LDI – Hitachi Dual Head CO2 – ESI 5200 UV • Semiconductor demands drive PCB HDI technology • DDi is a North American HDI leader with over 12 years experience in the fabrica
Slide 12: SMV™ Value Proposition
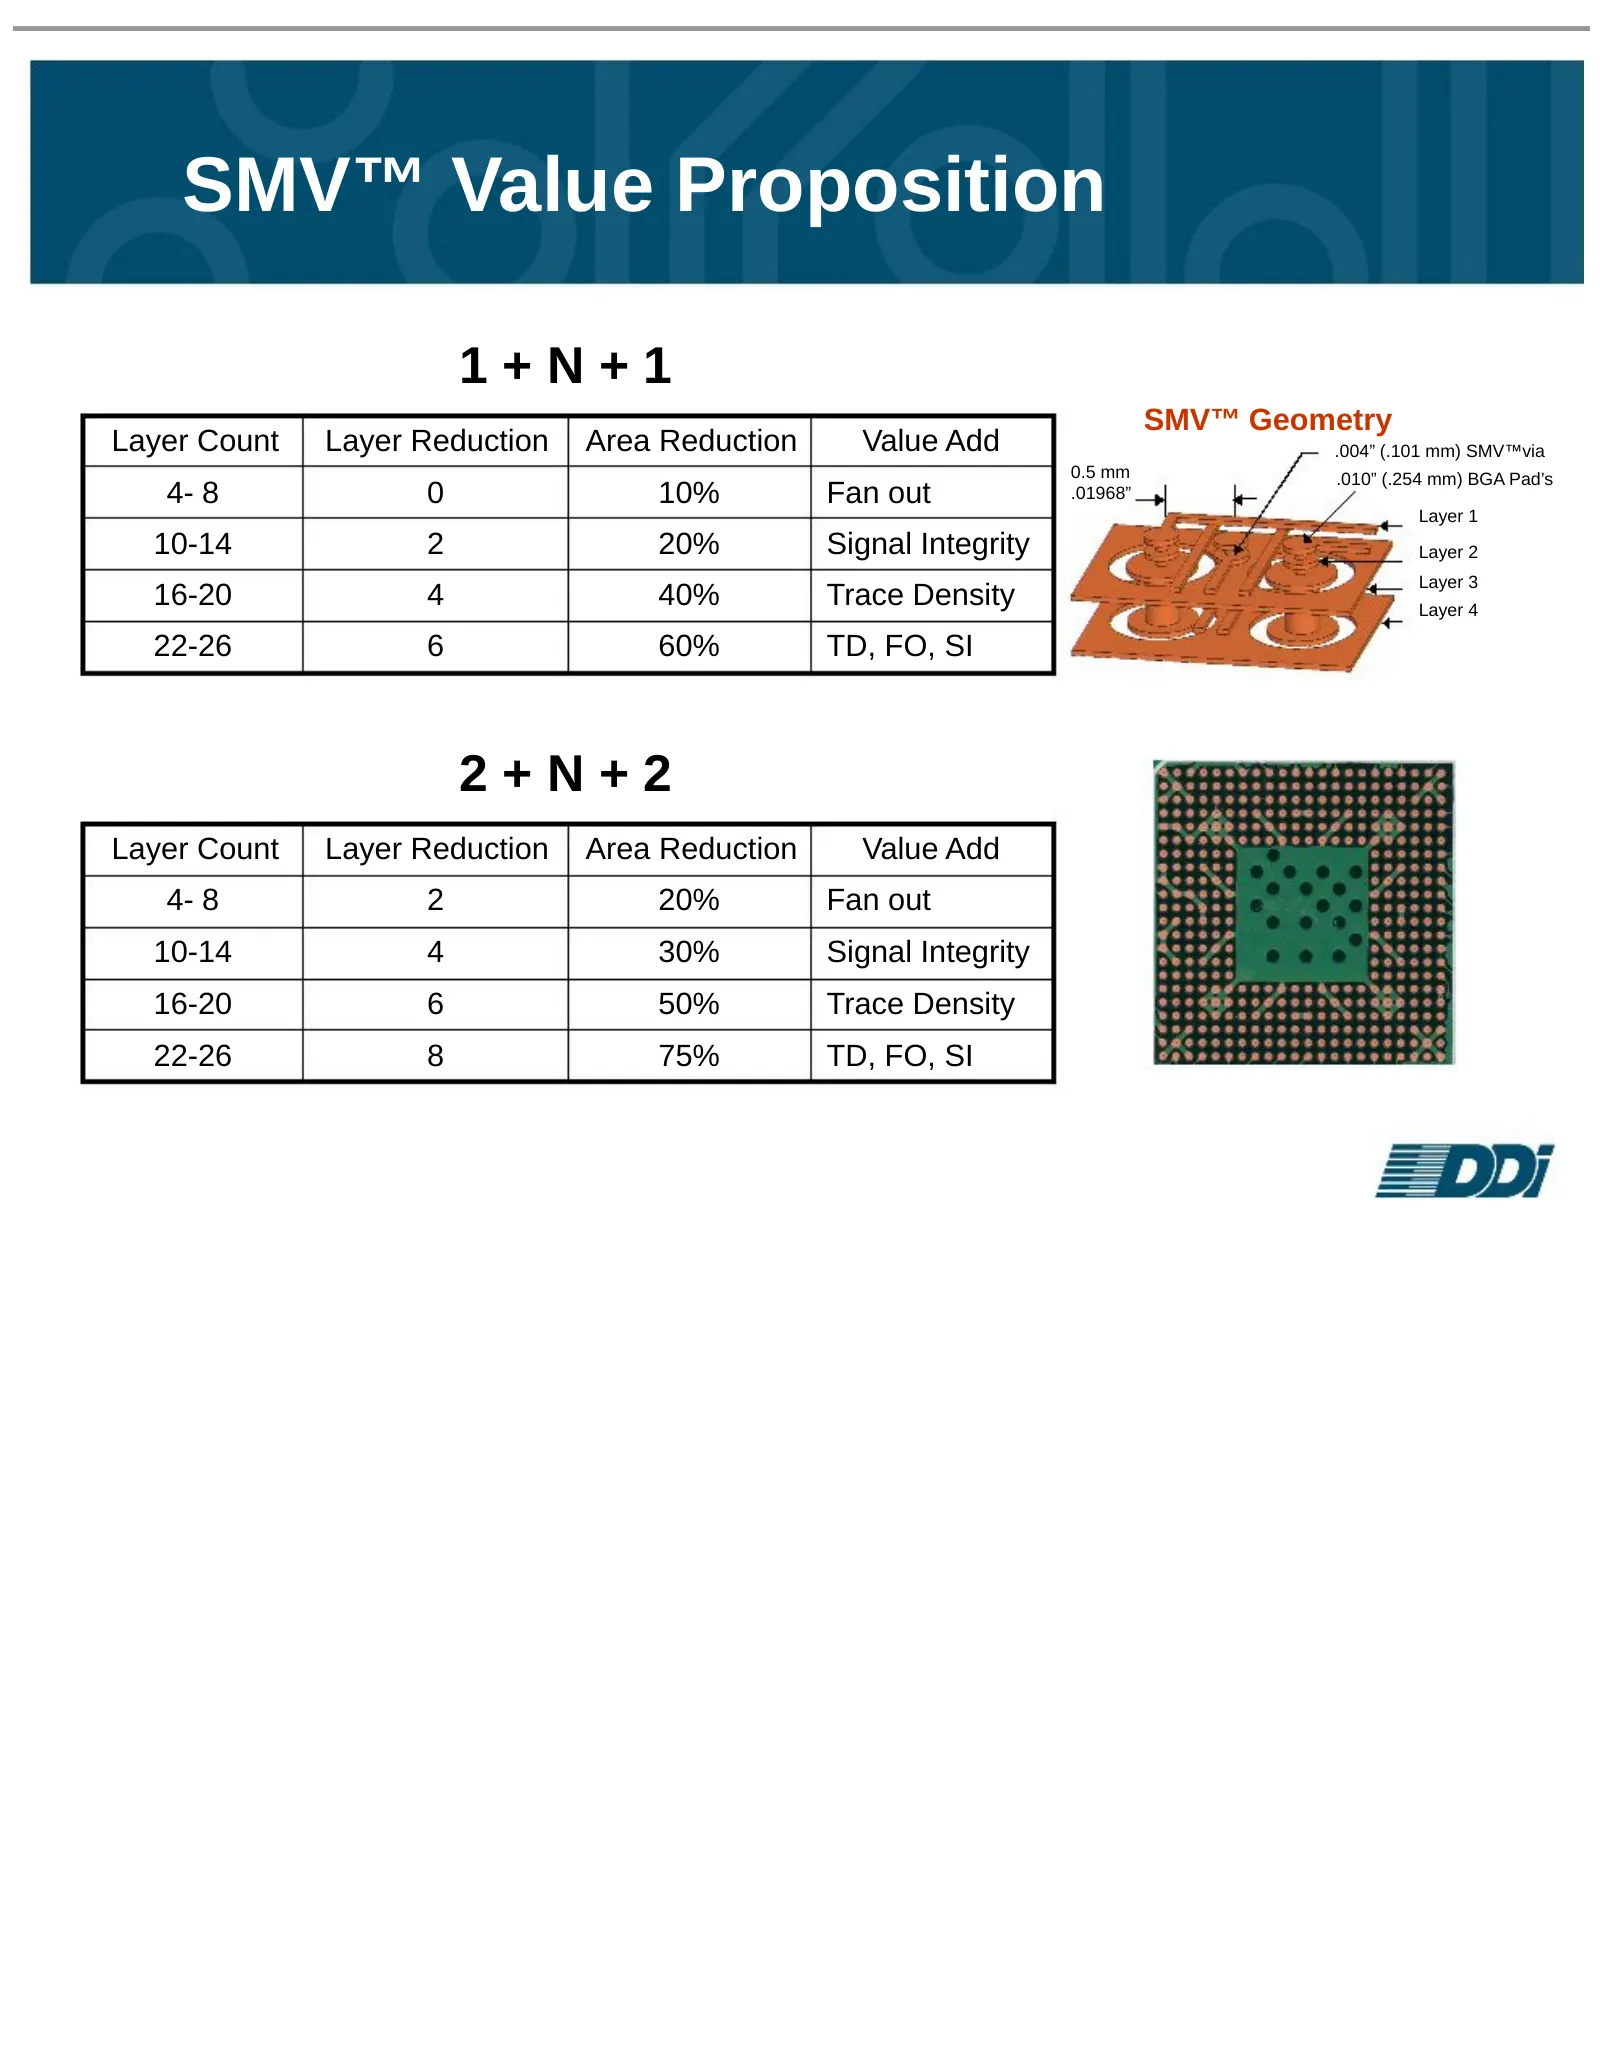
SMV™ Value Proposition 1+N+1 SMV™ Geometry Layer Count Layer Reduction Area Reduction Value Add .004” (.101 mm) SMV™via 0.5 mm .010” (.254 mm) BGA Pad’s 4- 8 0 10% Fan out .01968” Layer 1 10-14 2 20% Signal Integrity Layer 2 Layer 3 16-20 4 40% Trace Density Layer 4 22-26 6 60% TD, FO, SI 2+N+2 Laye
Slide 13: DDi's new FLAT-WRAP™ Technology
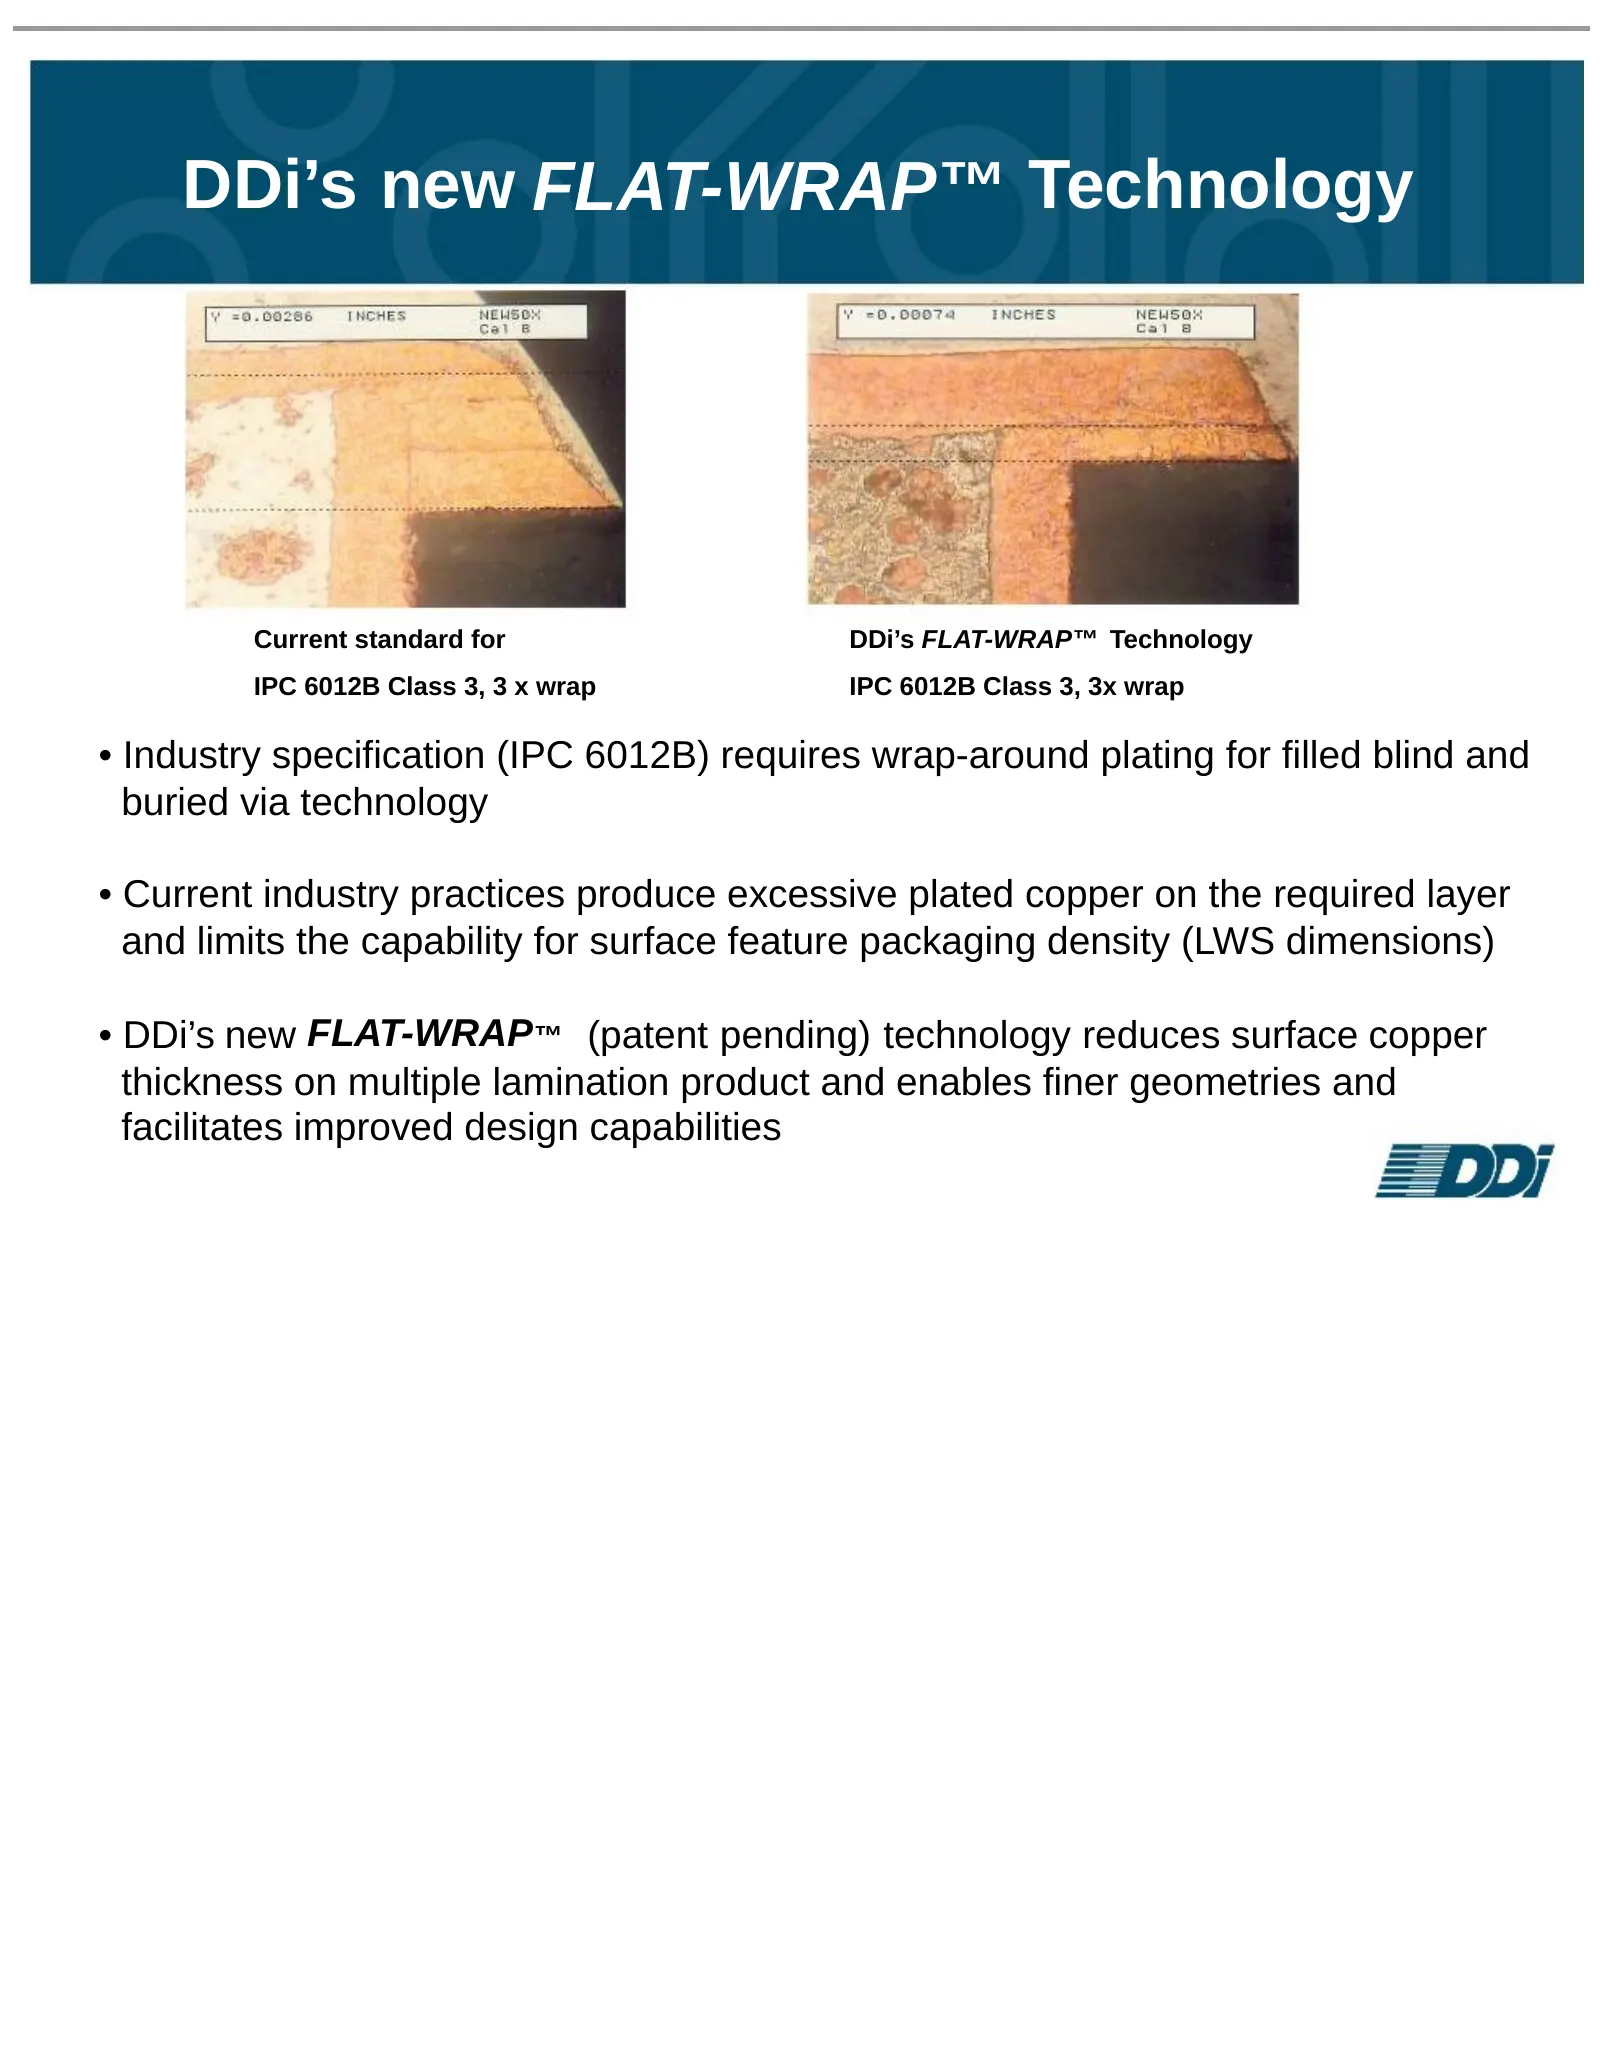
DDi’s new FLAT-WRAP™ Technology Current standard for DDi’s FLAT-WRAP™ Technology IPC 6012B Class 3, 3 x wrap IPC 6012B Class 3, 3x wrap • Industry specification (IPC 6012B) requires wrap-around plating for filled blind and buried via technology • Current industry practices produce excessive plated c
Slide 14: Next Generation - SMV™ Technology
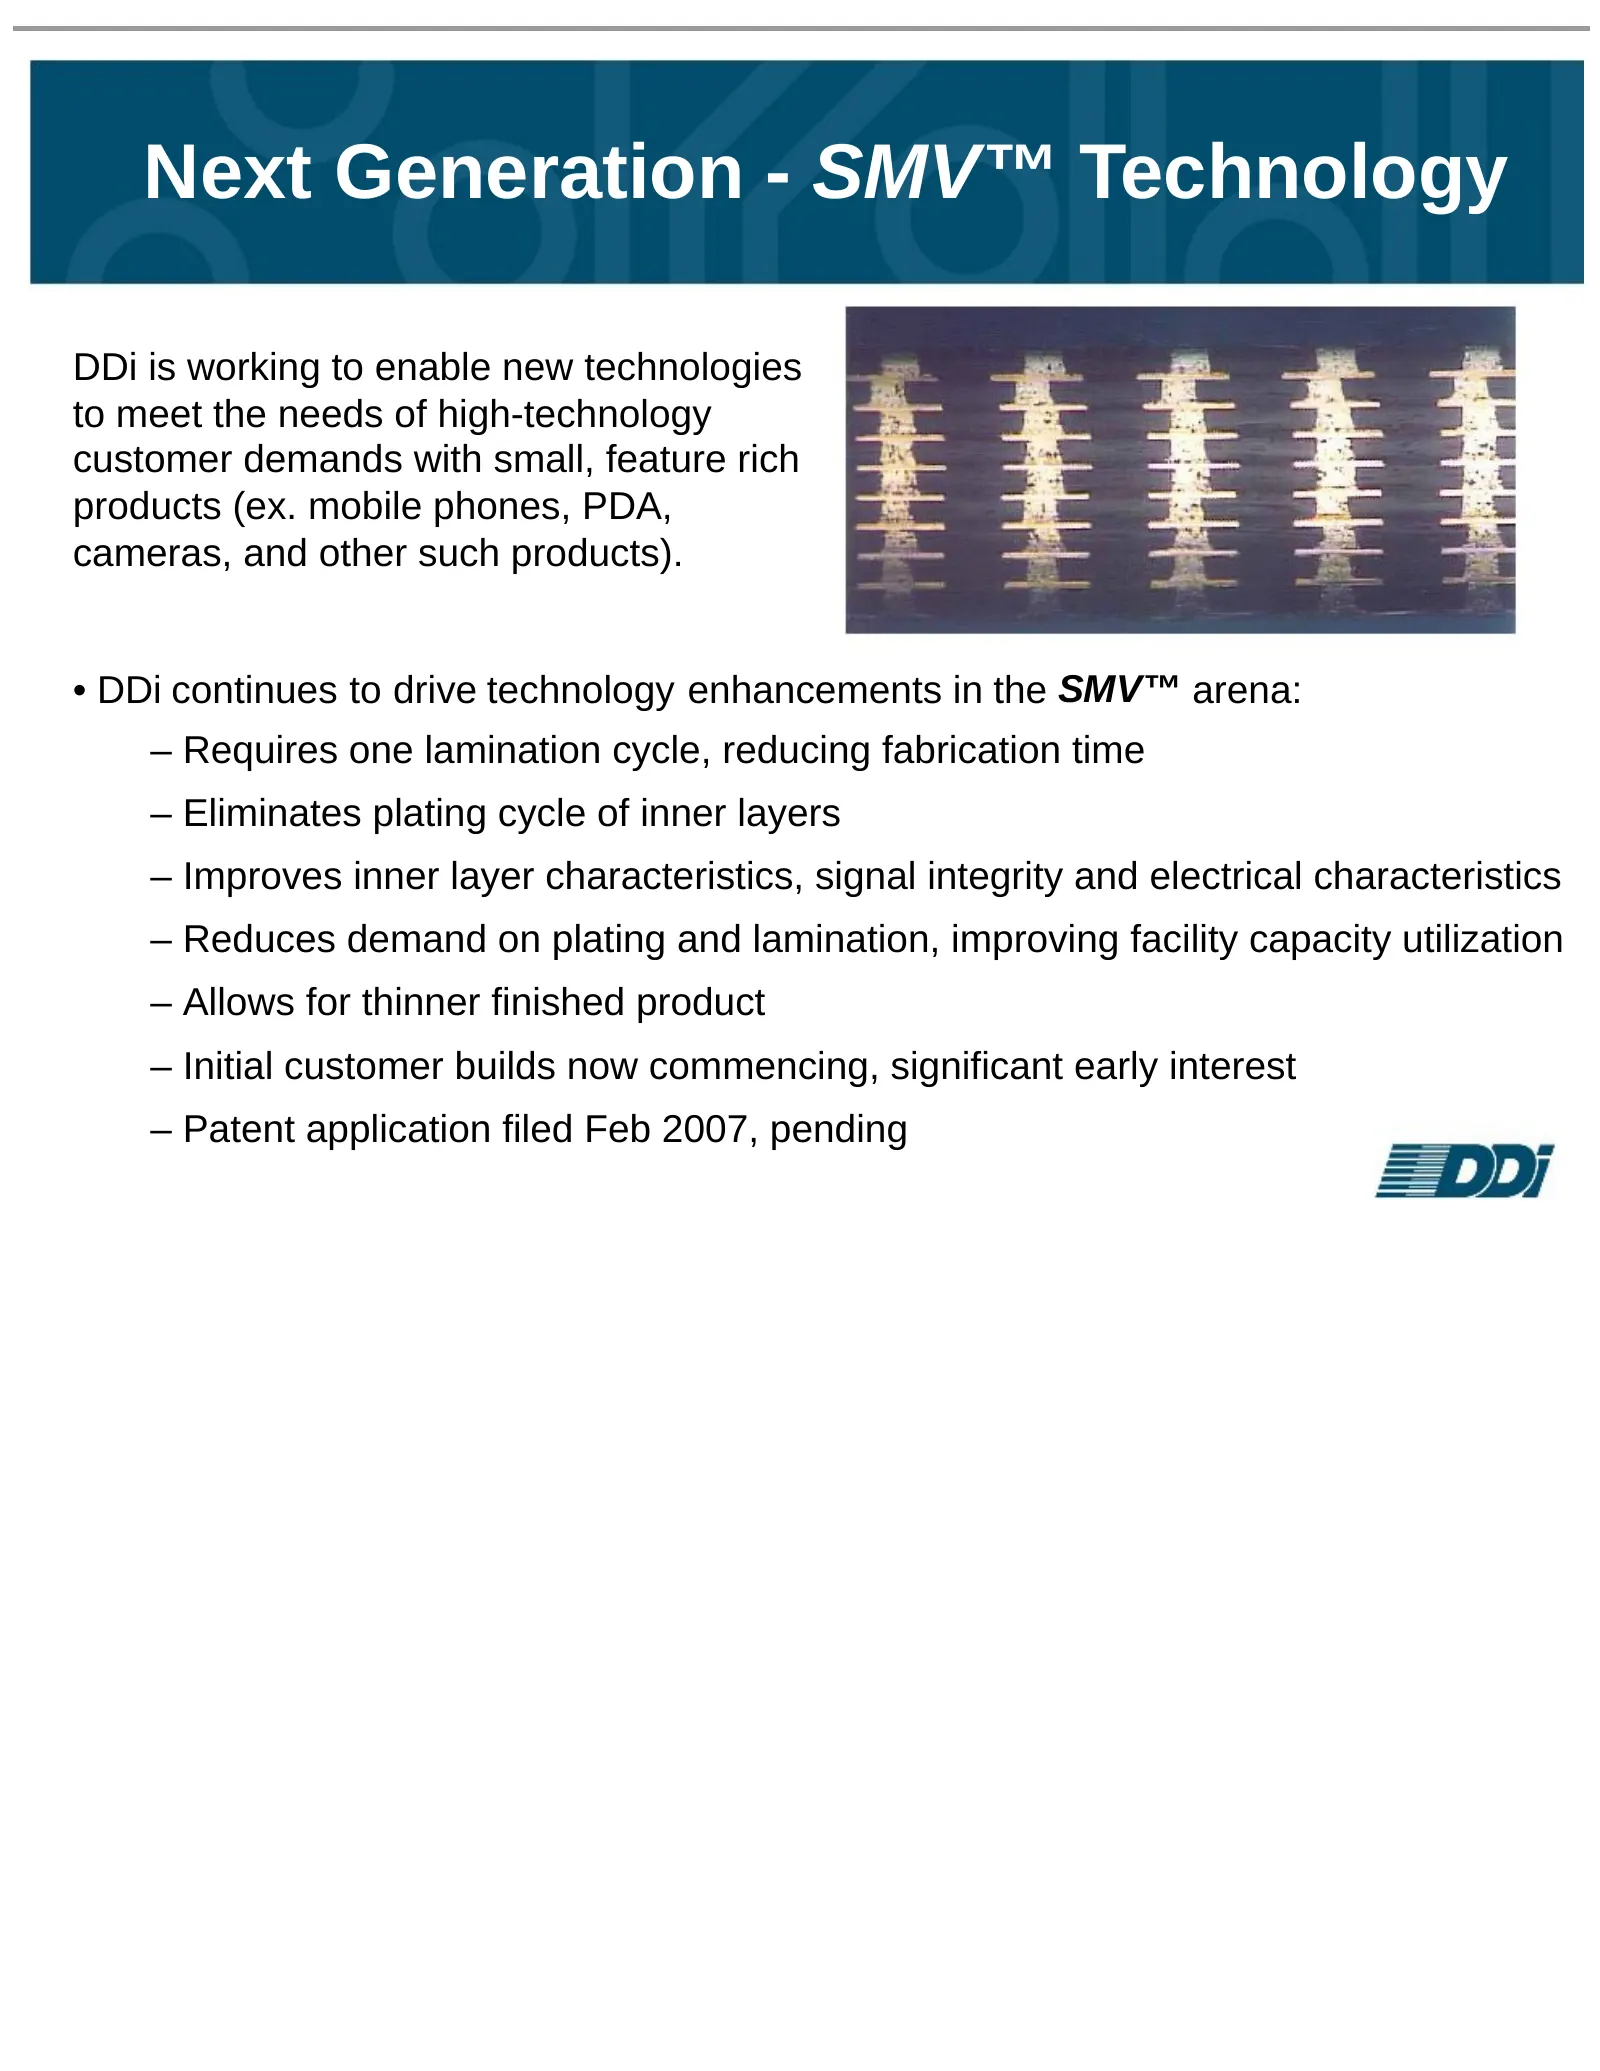
Next Generation - SMV™ Technology DDi is working to enable new technologies to meet the needs of high-technology customer demands with small, feature rich products (ex. mobile phones, PDA, cameras, and other such products). • DDi continues to drive technology enhancements in the SMV™ arena: – Requir
Slide 15: Broad Customer Base and Market Exposure
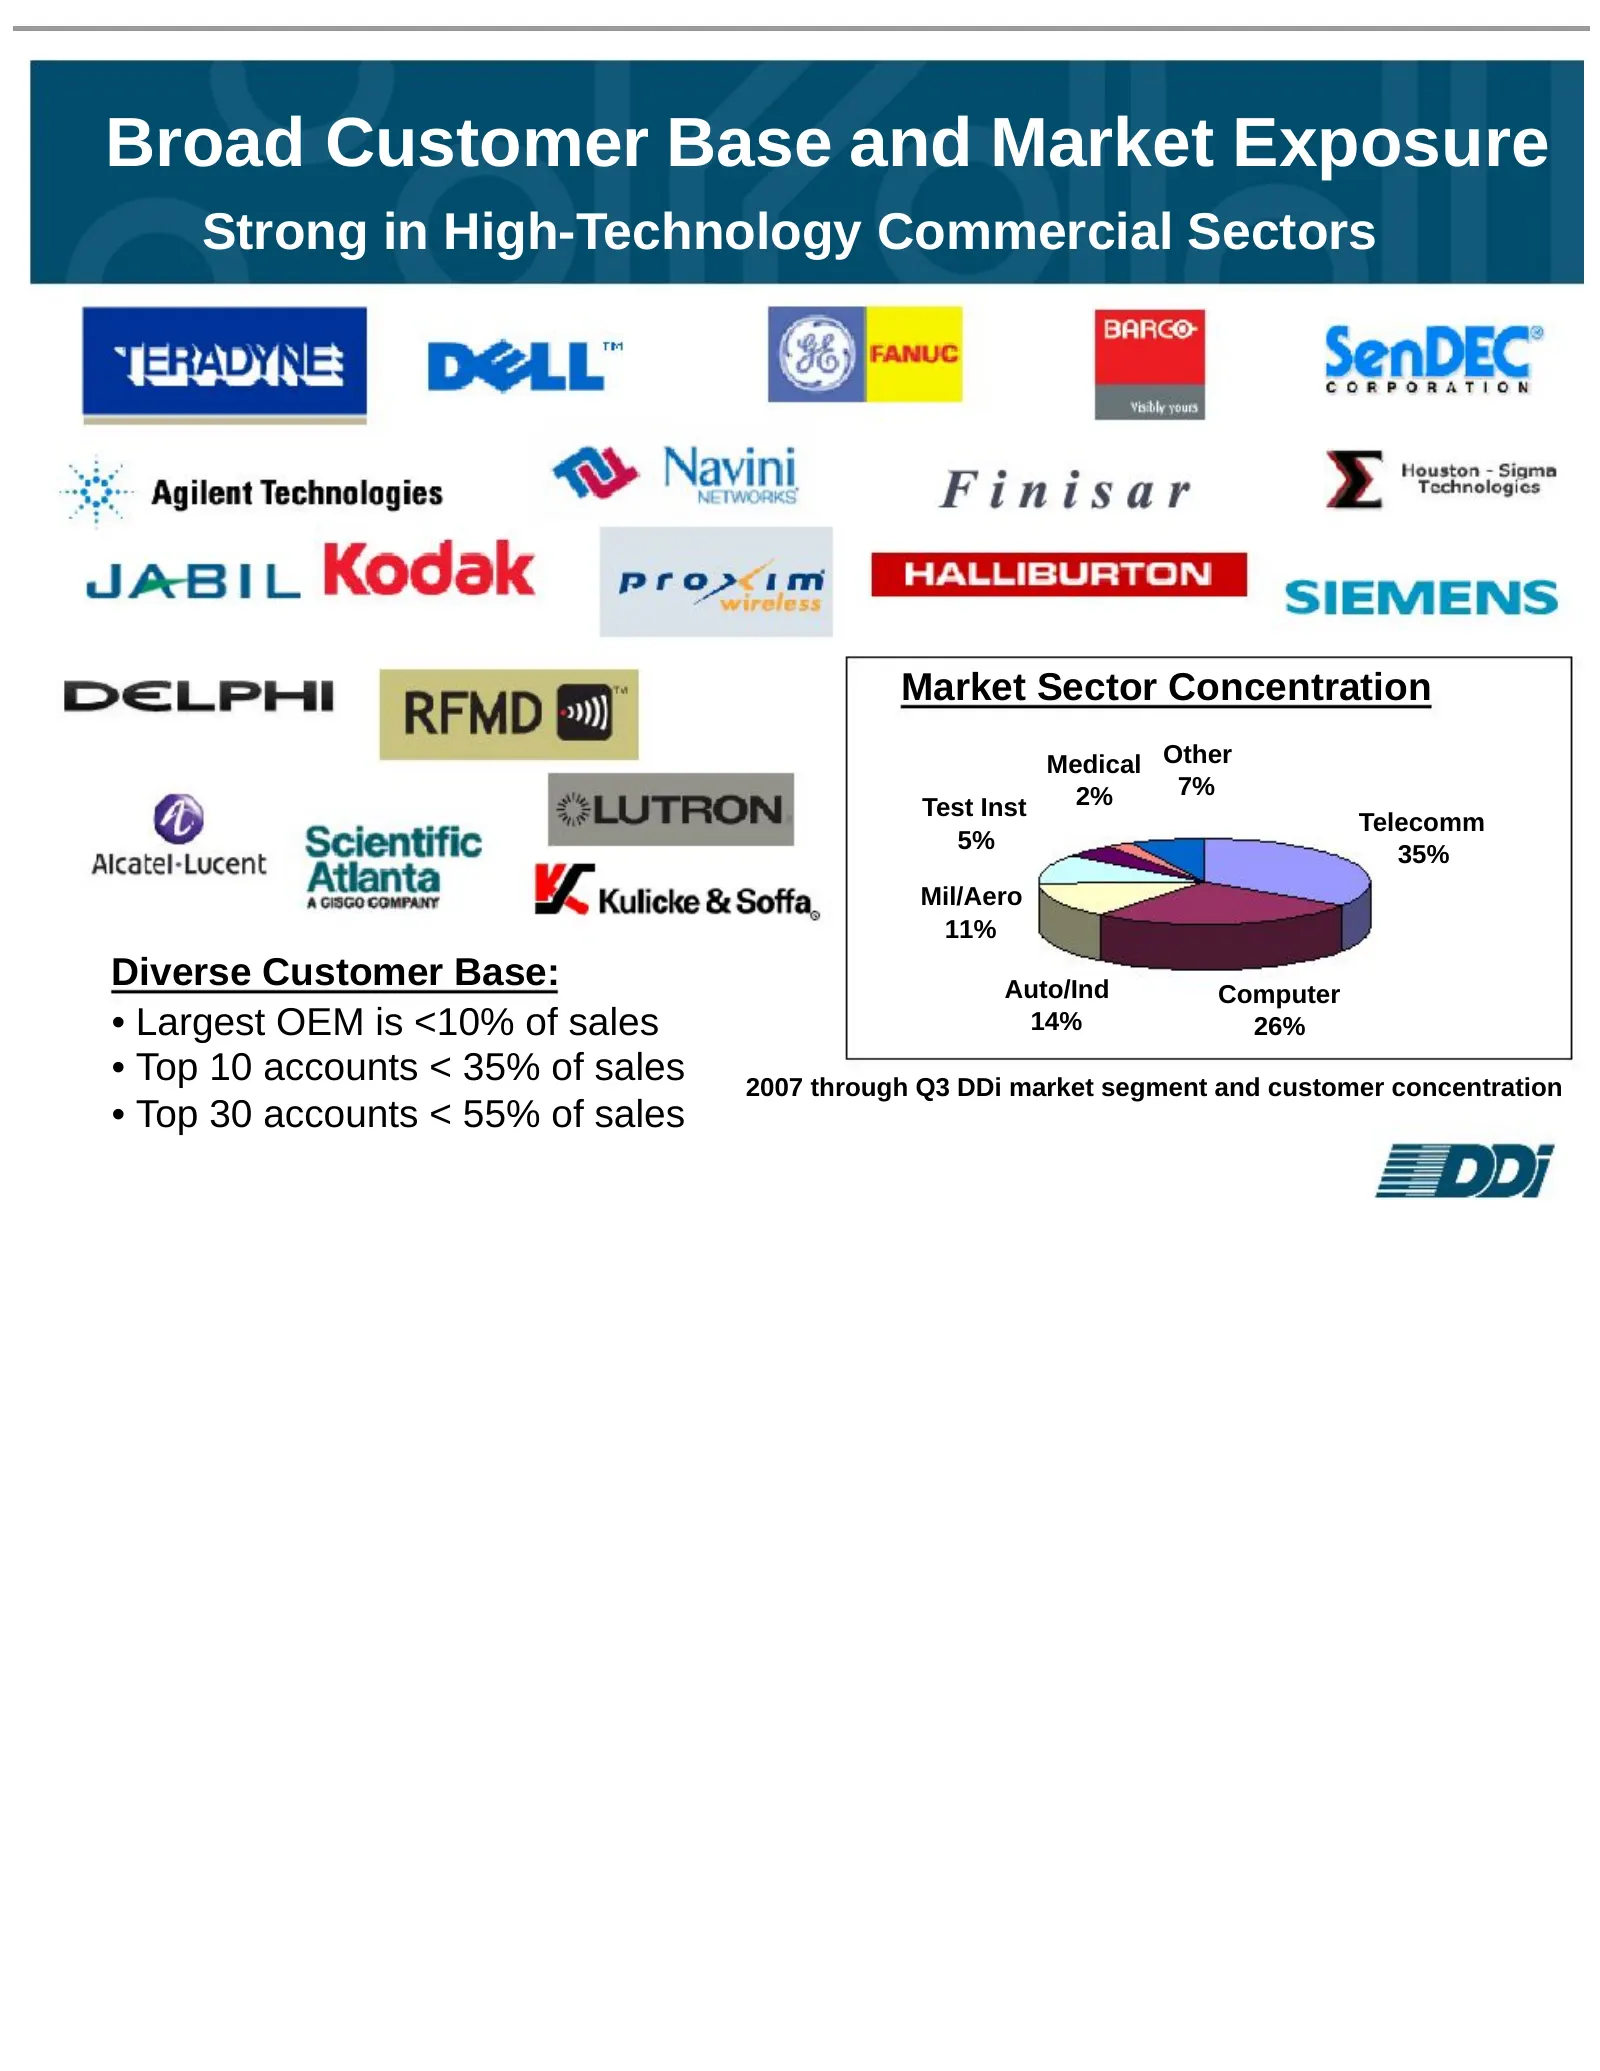
Broad Customer Base and Market Exposure Strong in High-Technology Commercial Sectors Market Sector Concentration Medical Other 2% 7% Test Inst Telecomm 5% 35% Mil/Aero 11% Diverse Customer Base: Auto/Ind Computer • Largest OEM is <10% of sales 14% 26% • Top 10 accounts < 35% of sales 2007 through Q3
Slide 16: Semiconductors Drive PCB Requirements
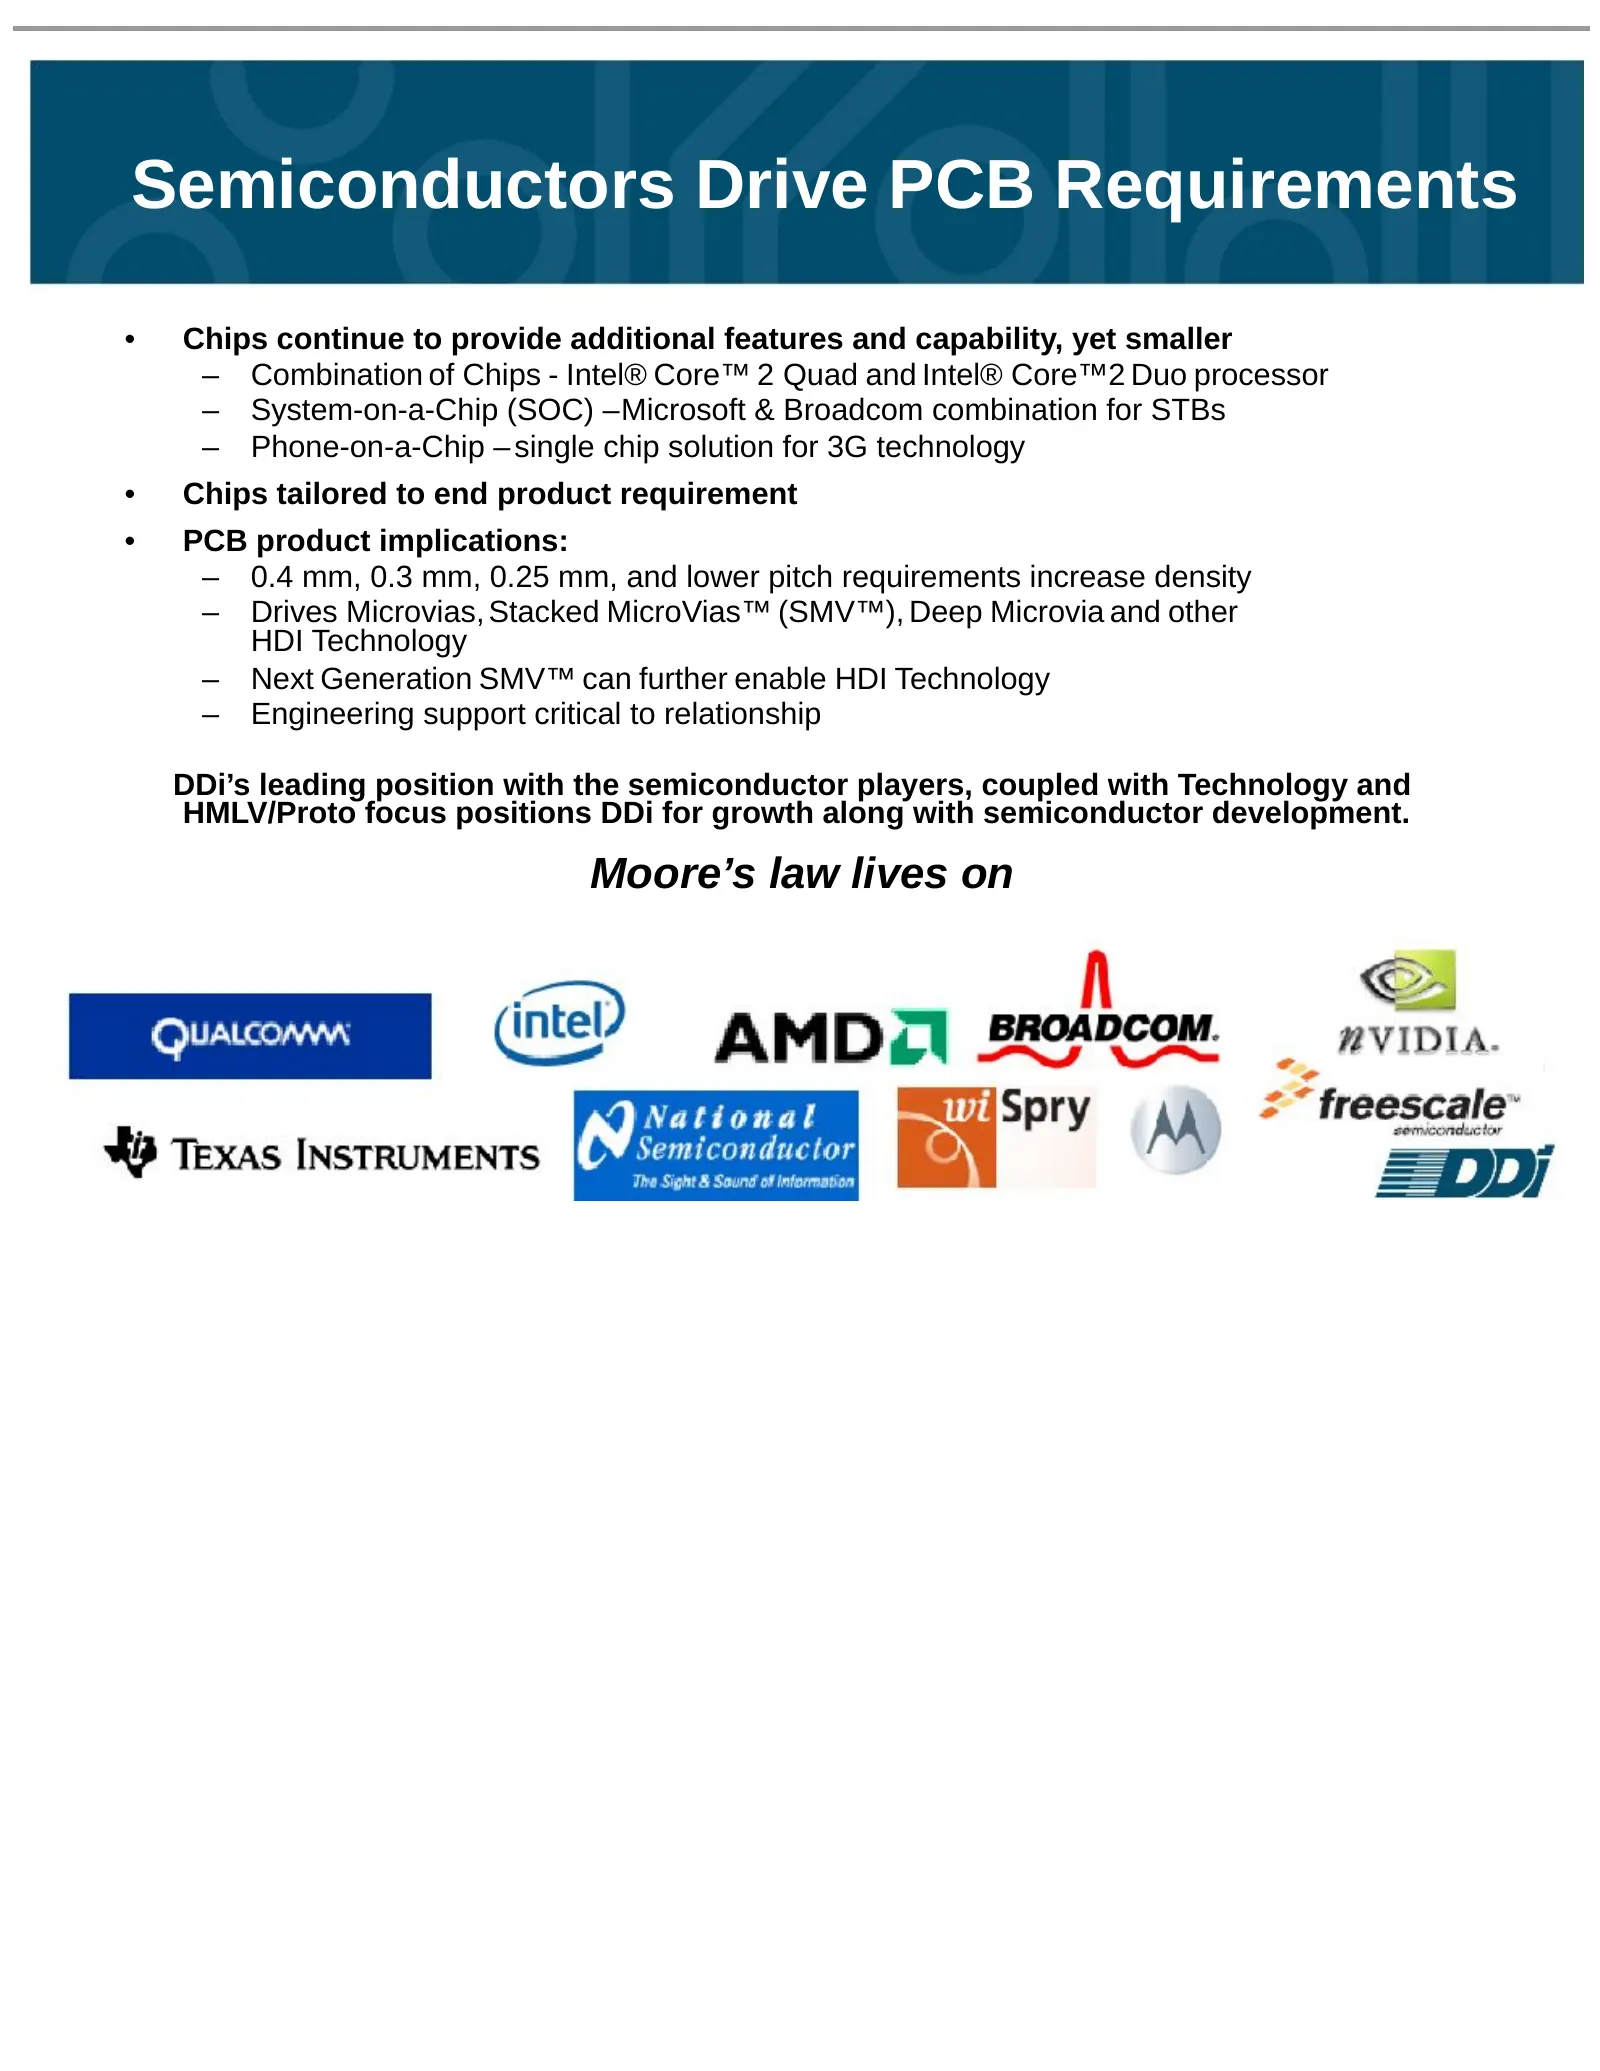
Semiconductors Drive PCB Requirements • Chips continue to provide additional features and capability, yet smaller – Combination of Chips - Intel® Core™ 2 Quad and Intel® Core™2 Duo processor – System-on-a-Chip (SOC) –Microsoft & Broadcom combination for STBs – Phone-on-a-Chip – single chip solution
Slide 17: U.S. Military / Aerospace Market Sector
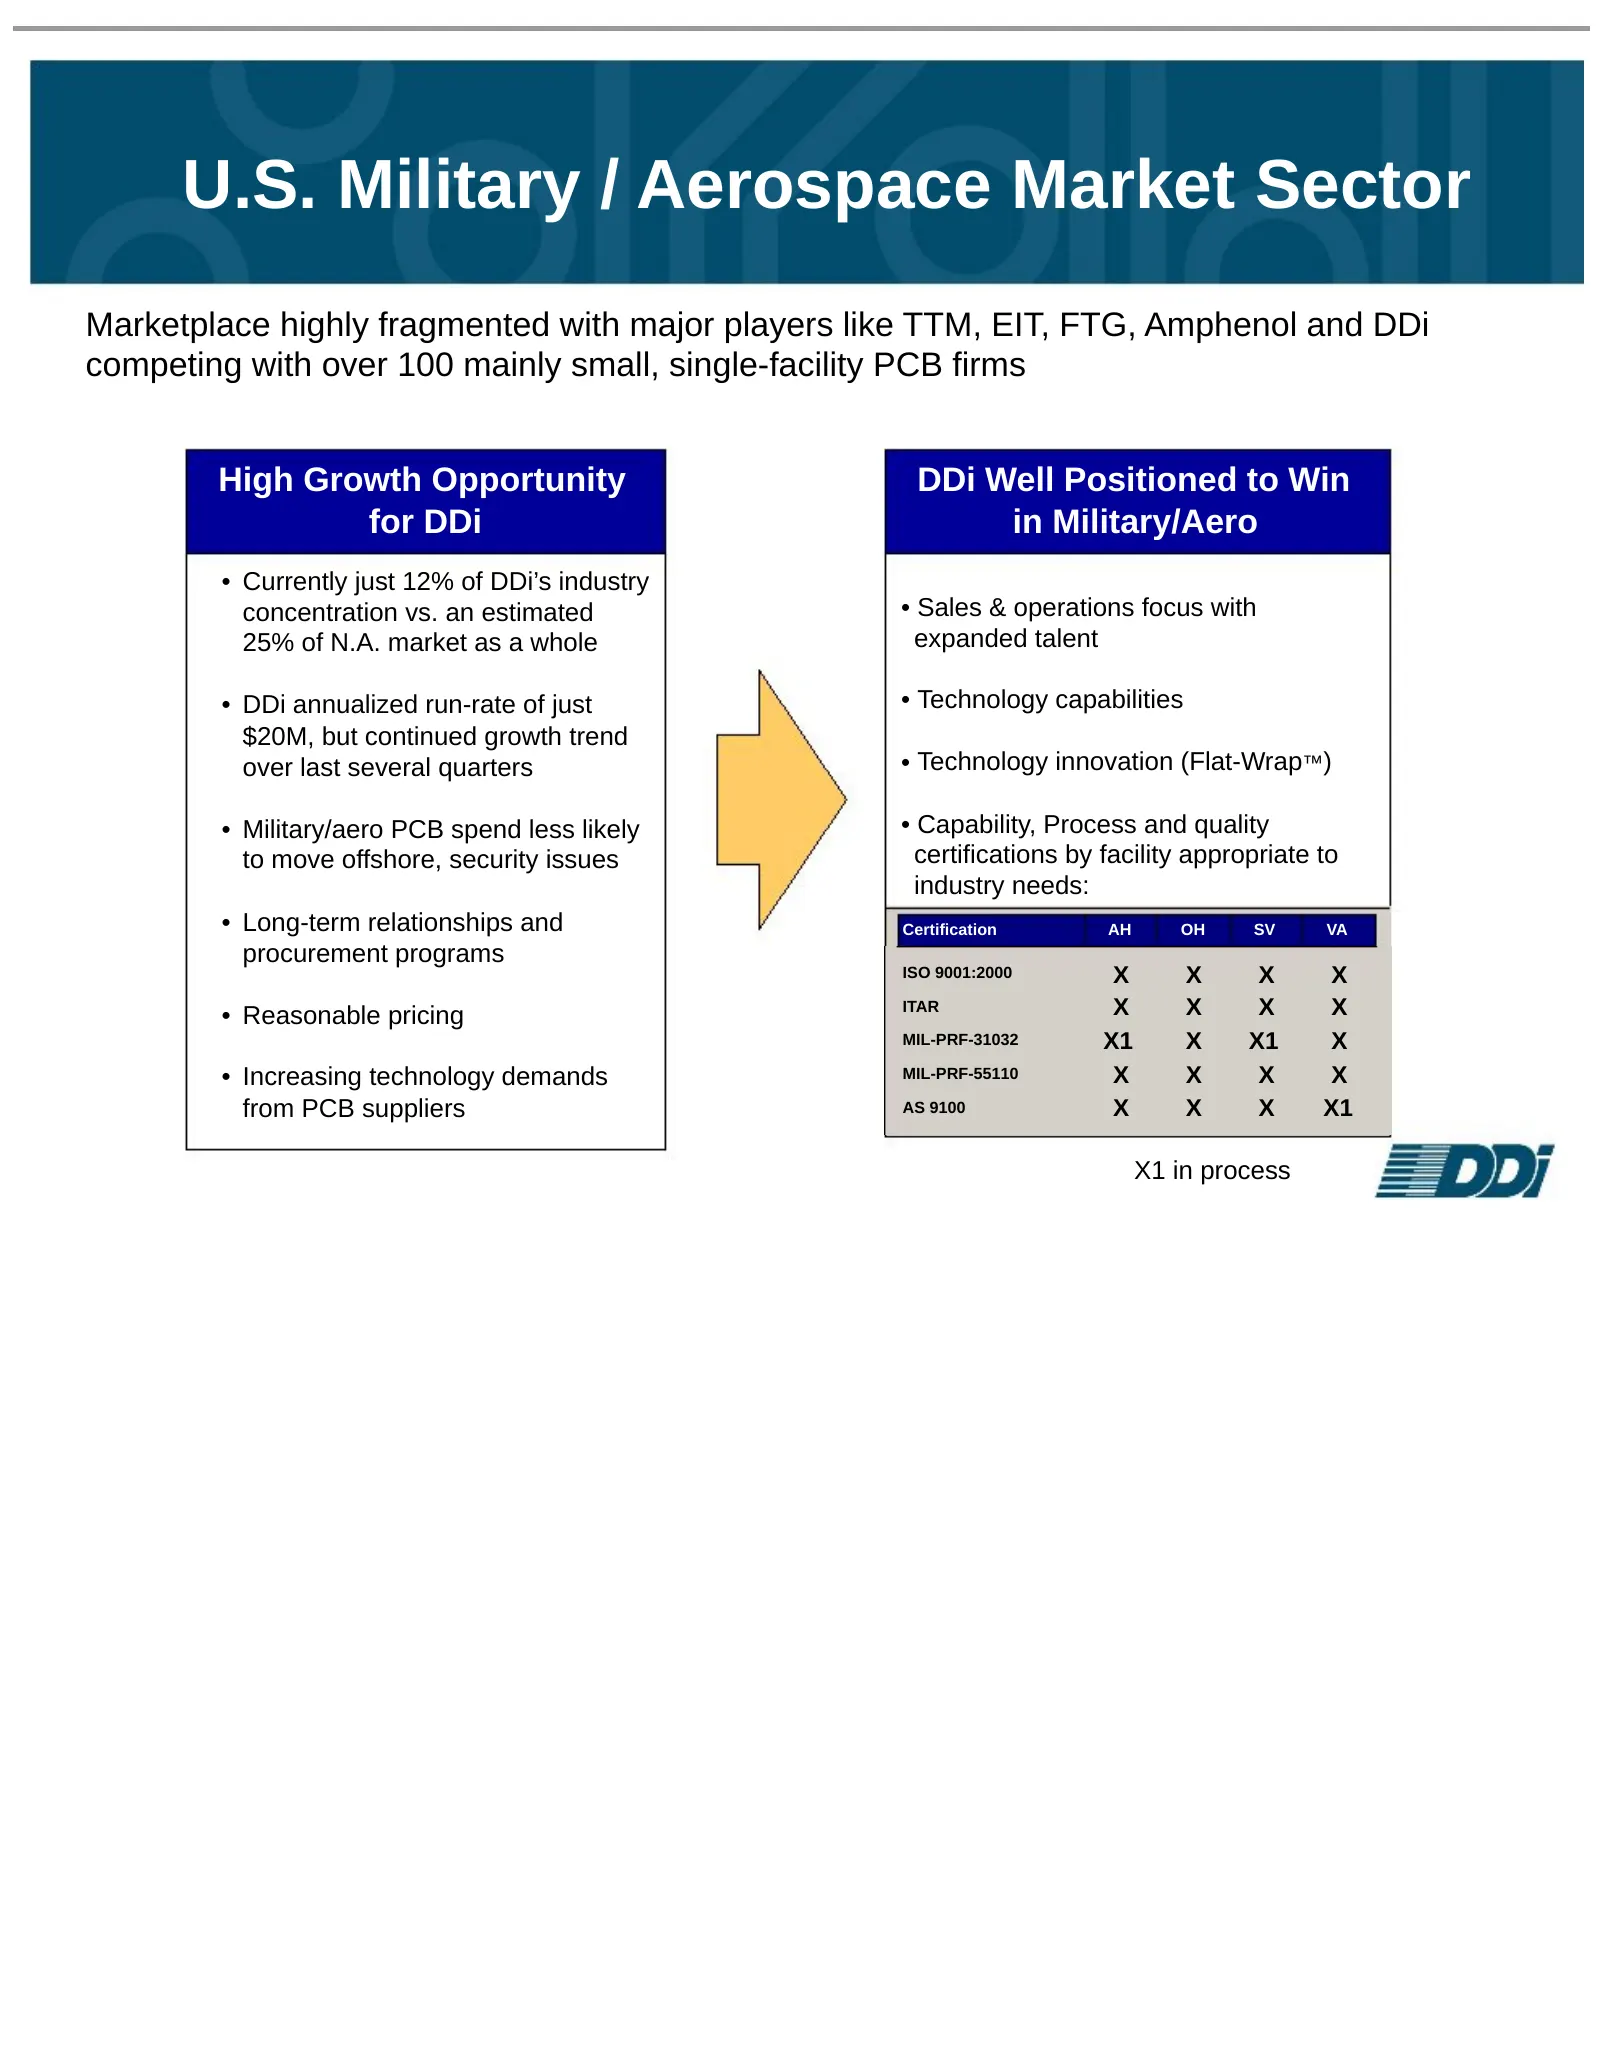
U.S. Military / Aerospace Market Sector Marketplace highly fragmented with major players like TTM, EIT, FTG, Amphenol and DDi competing with over 100 mainly small, single-facility PCB firms High Growth Opportunity DDi Well Positioned to Win for DDi in Military/Aero • Currently just 12% of DDi’s indu
Slide 18: Senior Management Team
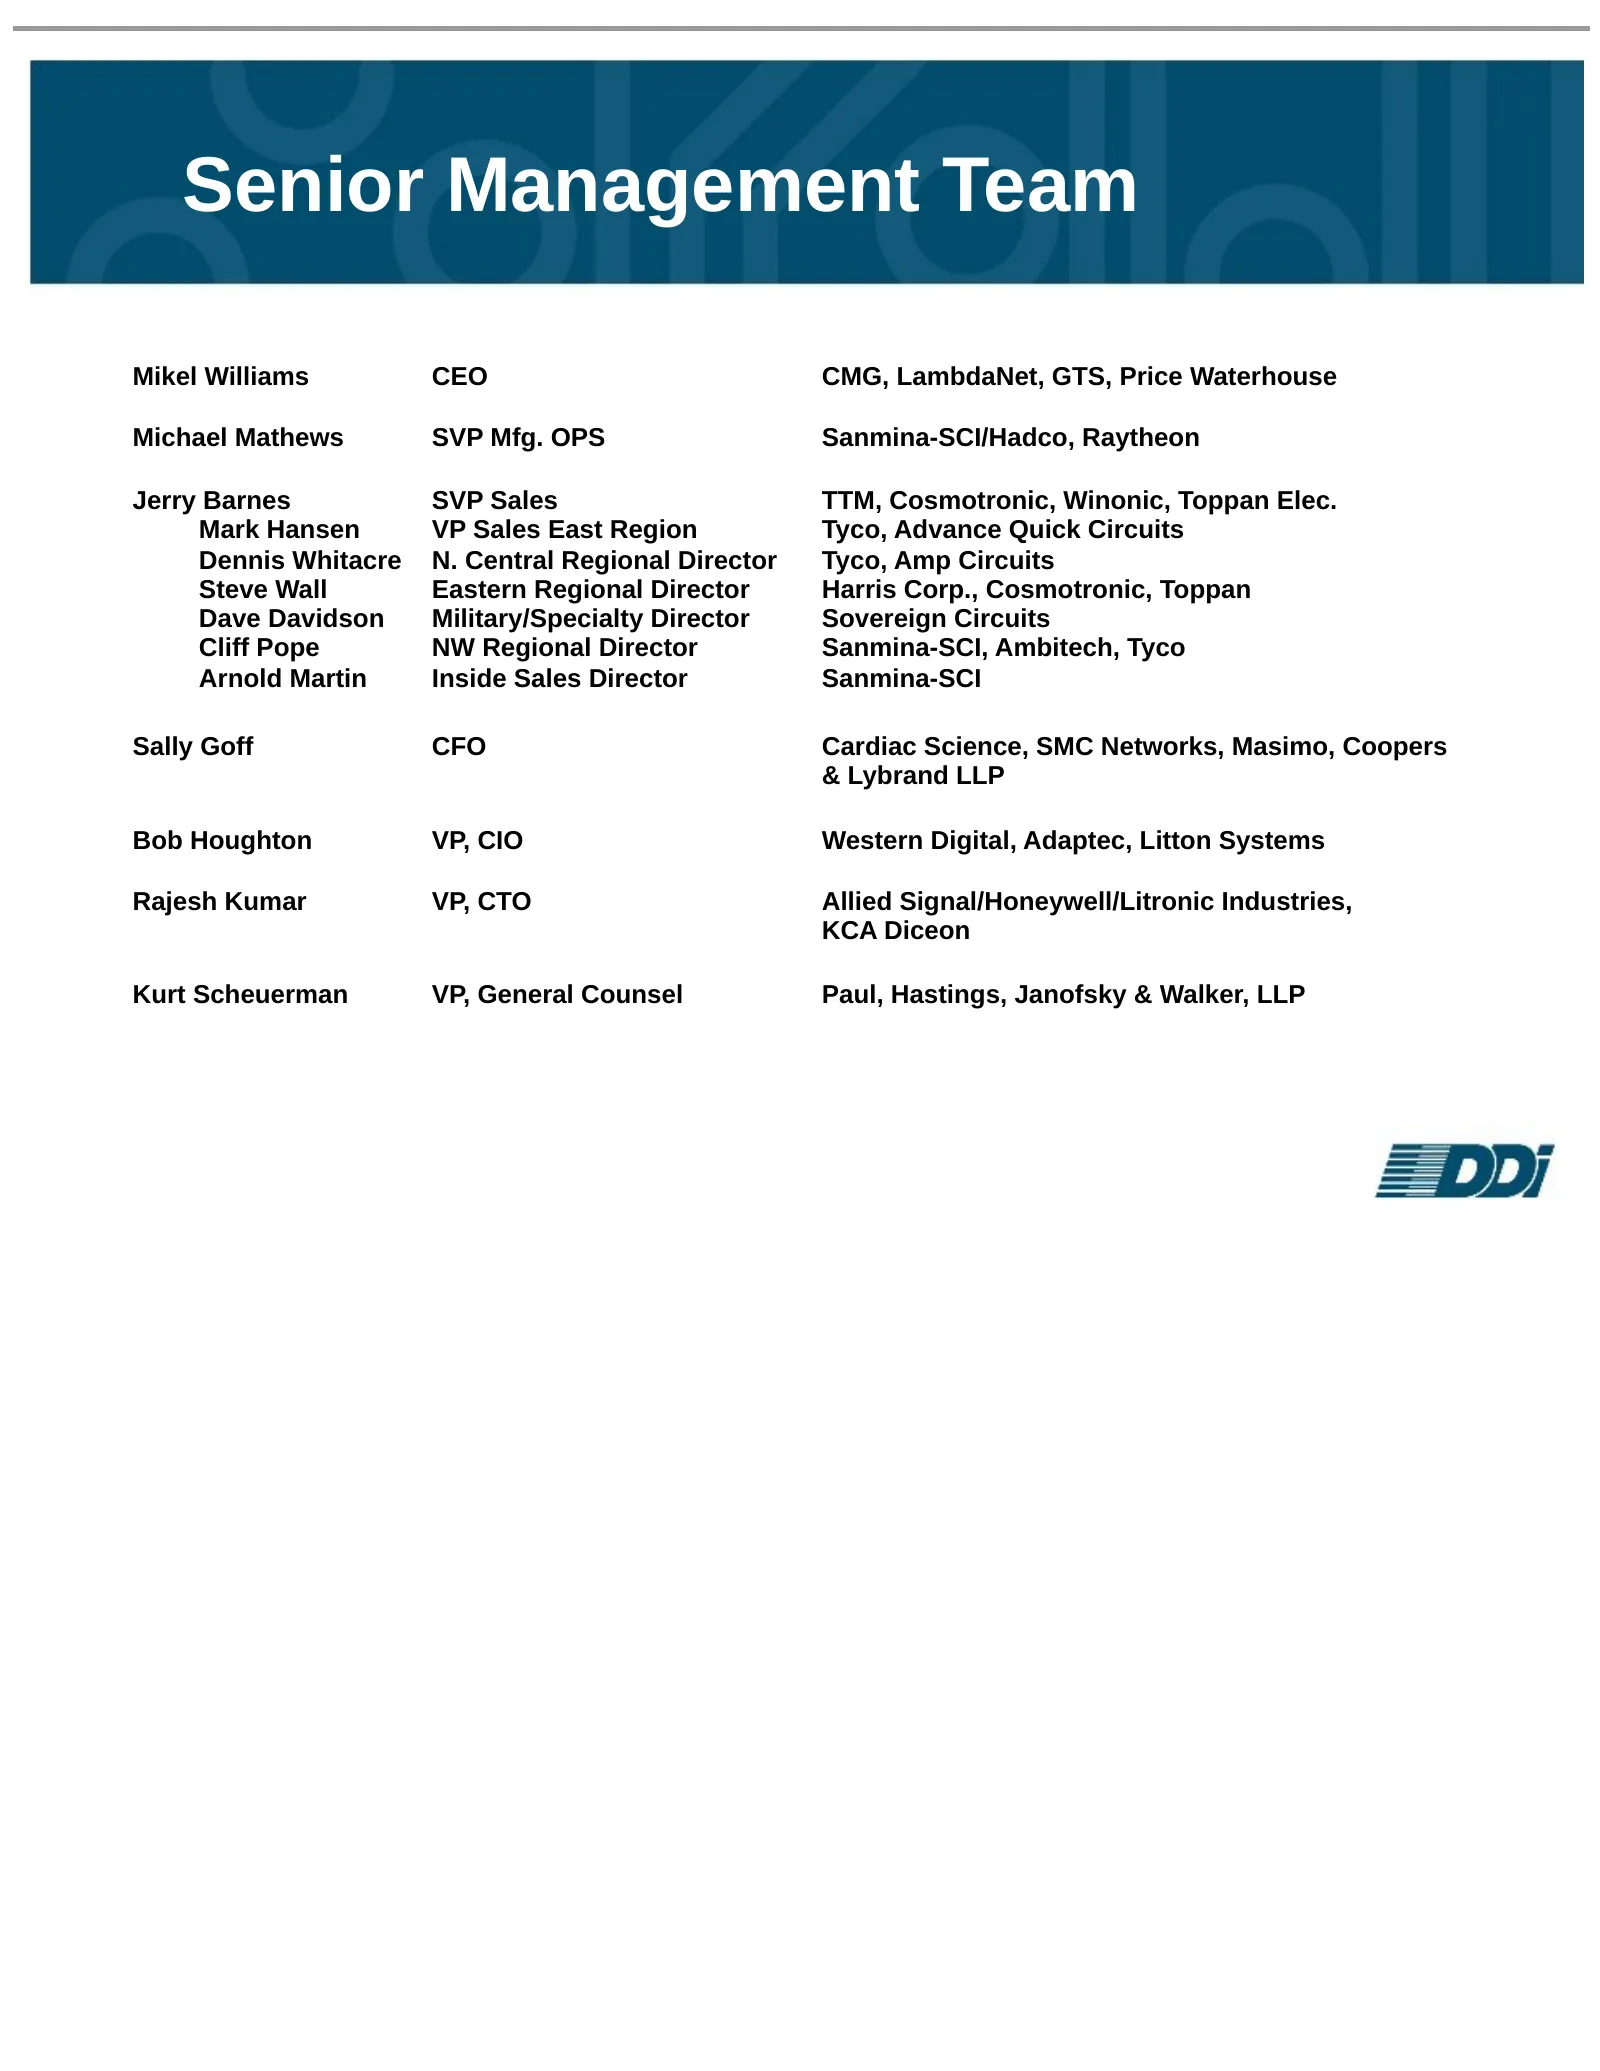
Senior Management Team Mikel Williams CEO CMG, LambdaNet, GTS, Price Waterhouse Michael Mathews SVP Mfg. OPS Sanmina-SCI/Hadco, Raytheon Jerry Barnes SVP Sales TTM, Cosmotronic, Winonic, Toppan Elec. Mark Hansen VP Sales East Region Tyco, Advance Quick Circuits Dennis Whitacre N. Central Regional Di
Slide 19: Improved Capital Structure
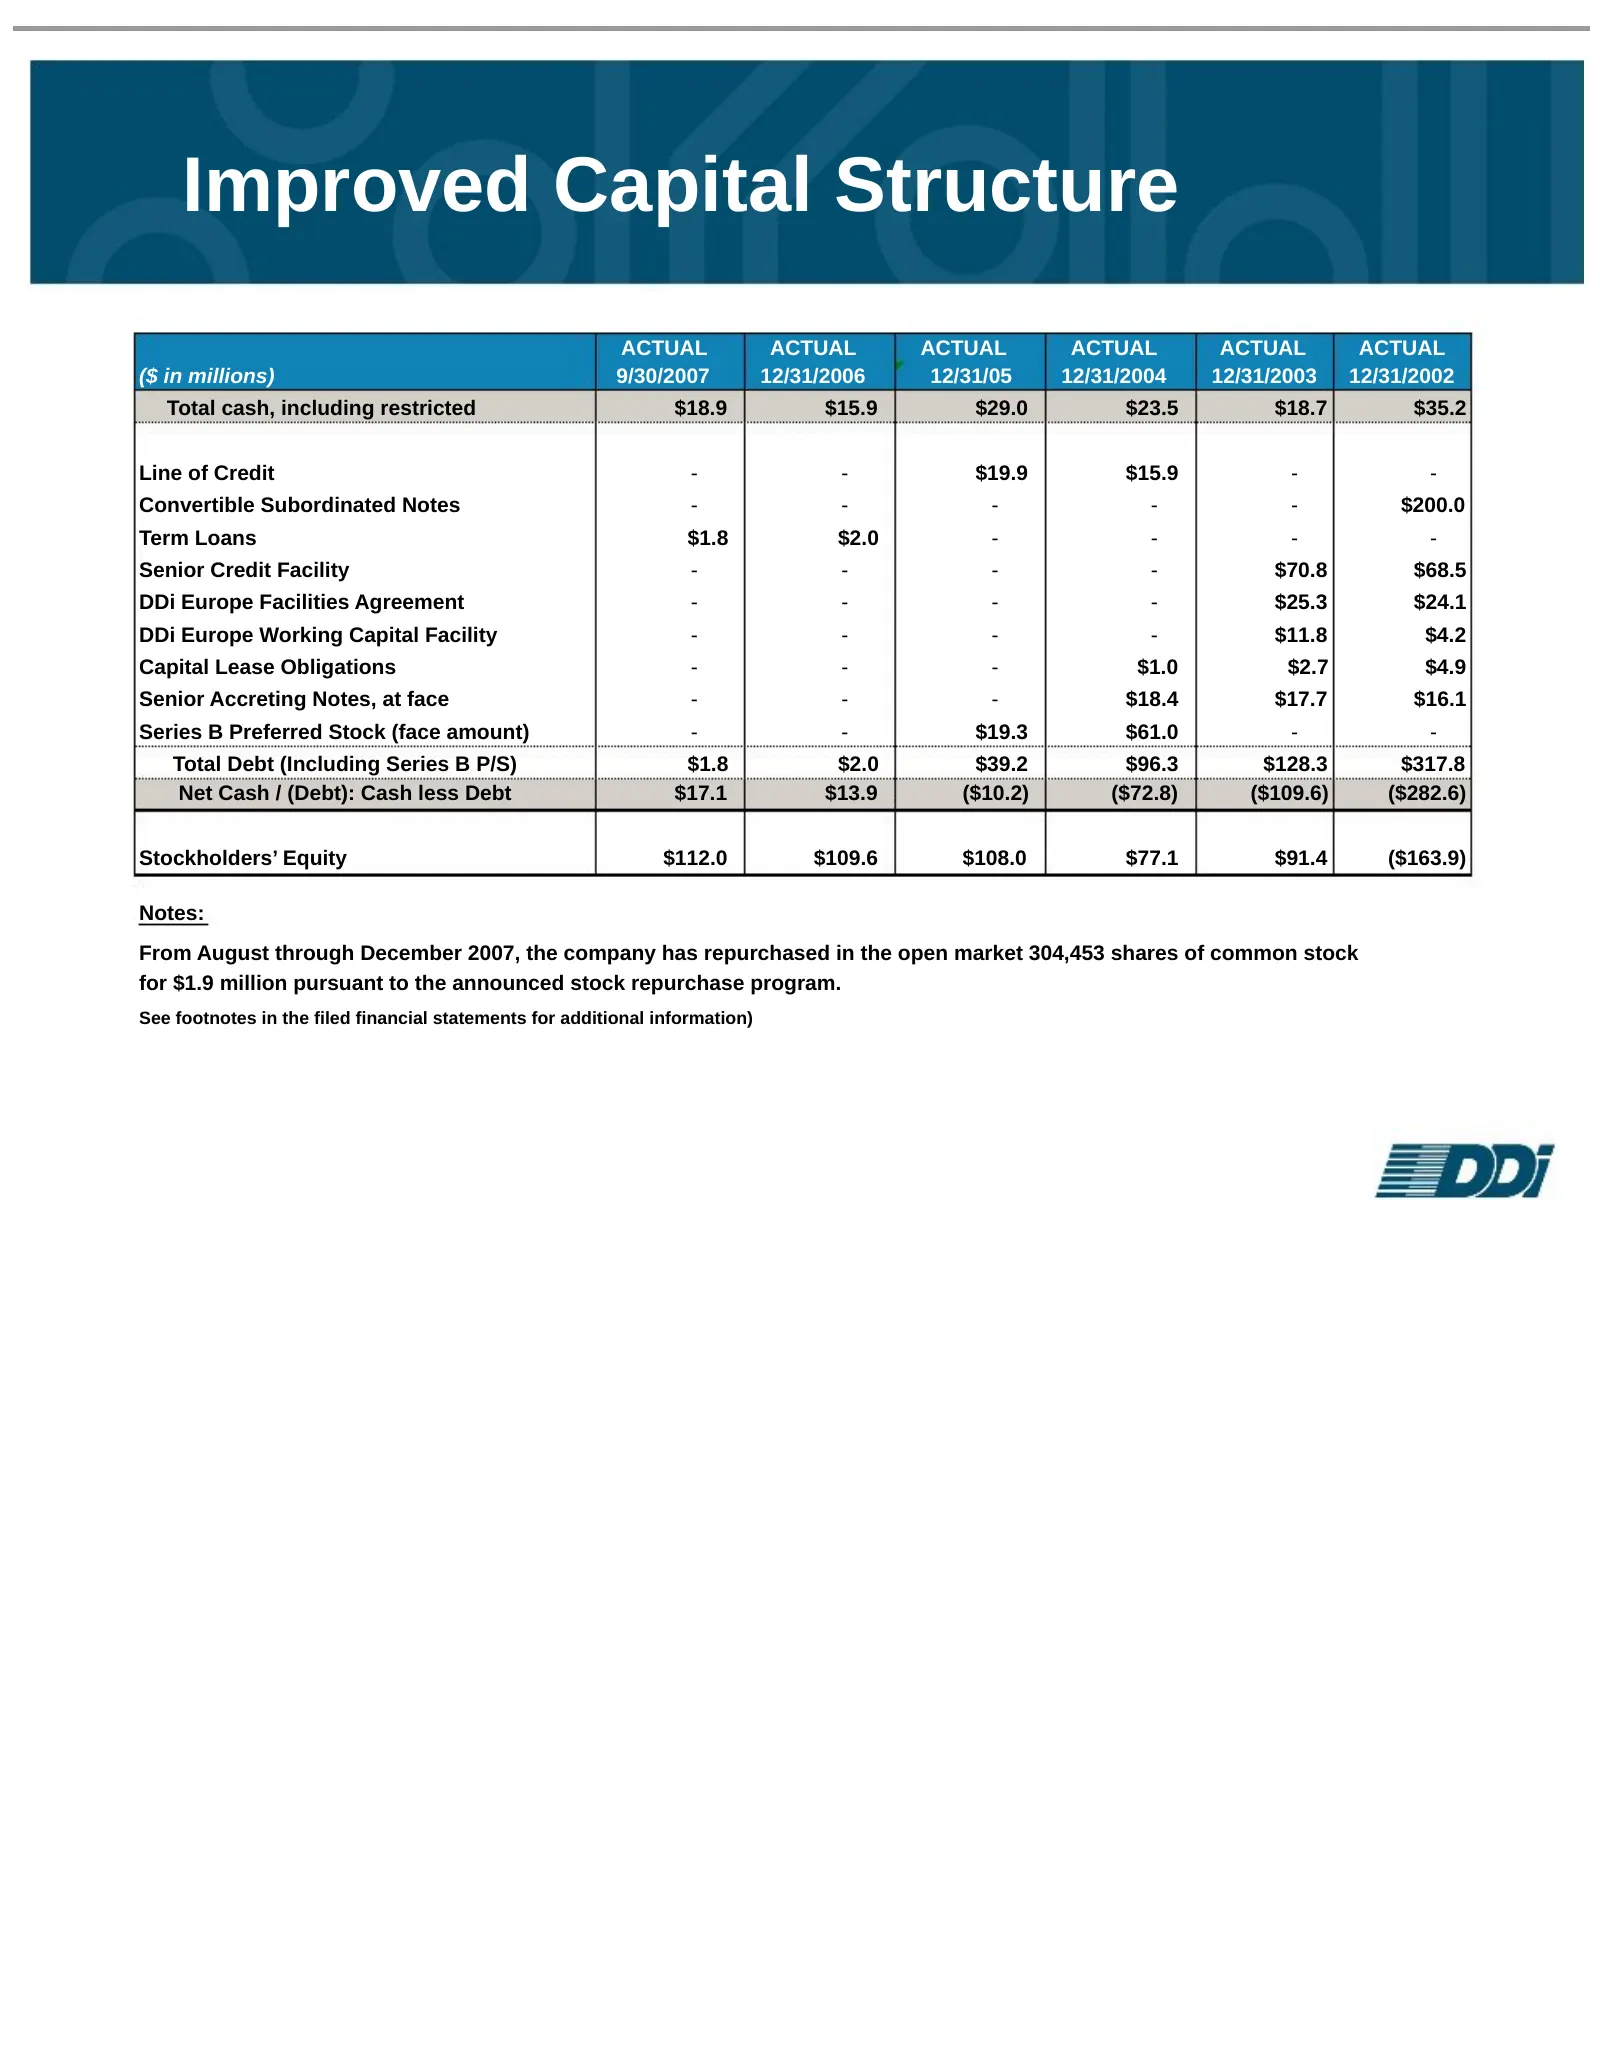
Improved Capital Structure ACTUAL ACTUAL ACTUAL ACTUAL ACTUAL ACTUAL ($ in millions) 9/30/2007 12/31/2006 12/31/05 12/31/2004 12/31/2003 12/31/2002 Total cash, including restricted $18.9 $15.9 $29.0 $23.5 $18.7 $35.2 Line of Credit - - $19.9 $15.9 - - Convertible Subordinated Notes - - - - - $200.0
Slide 20: Trended Operating Results
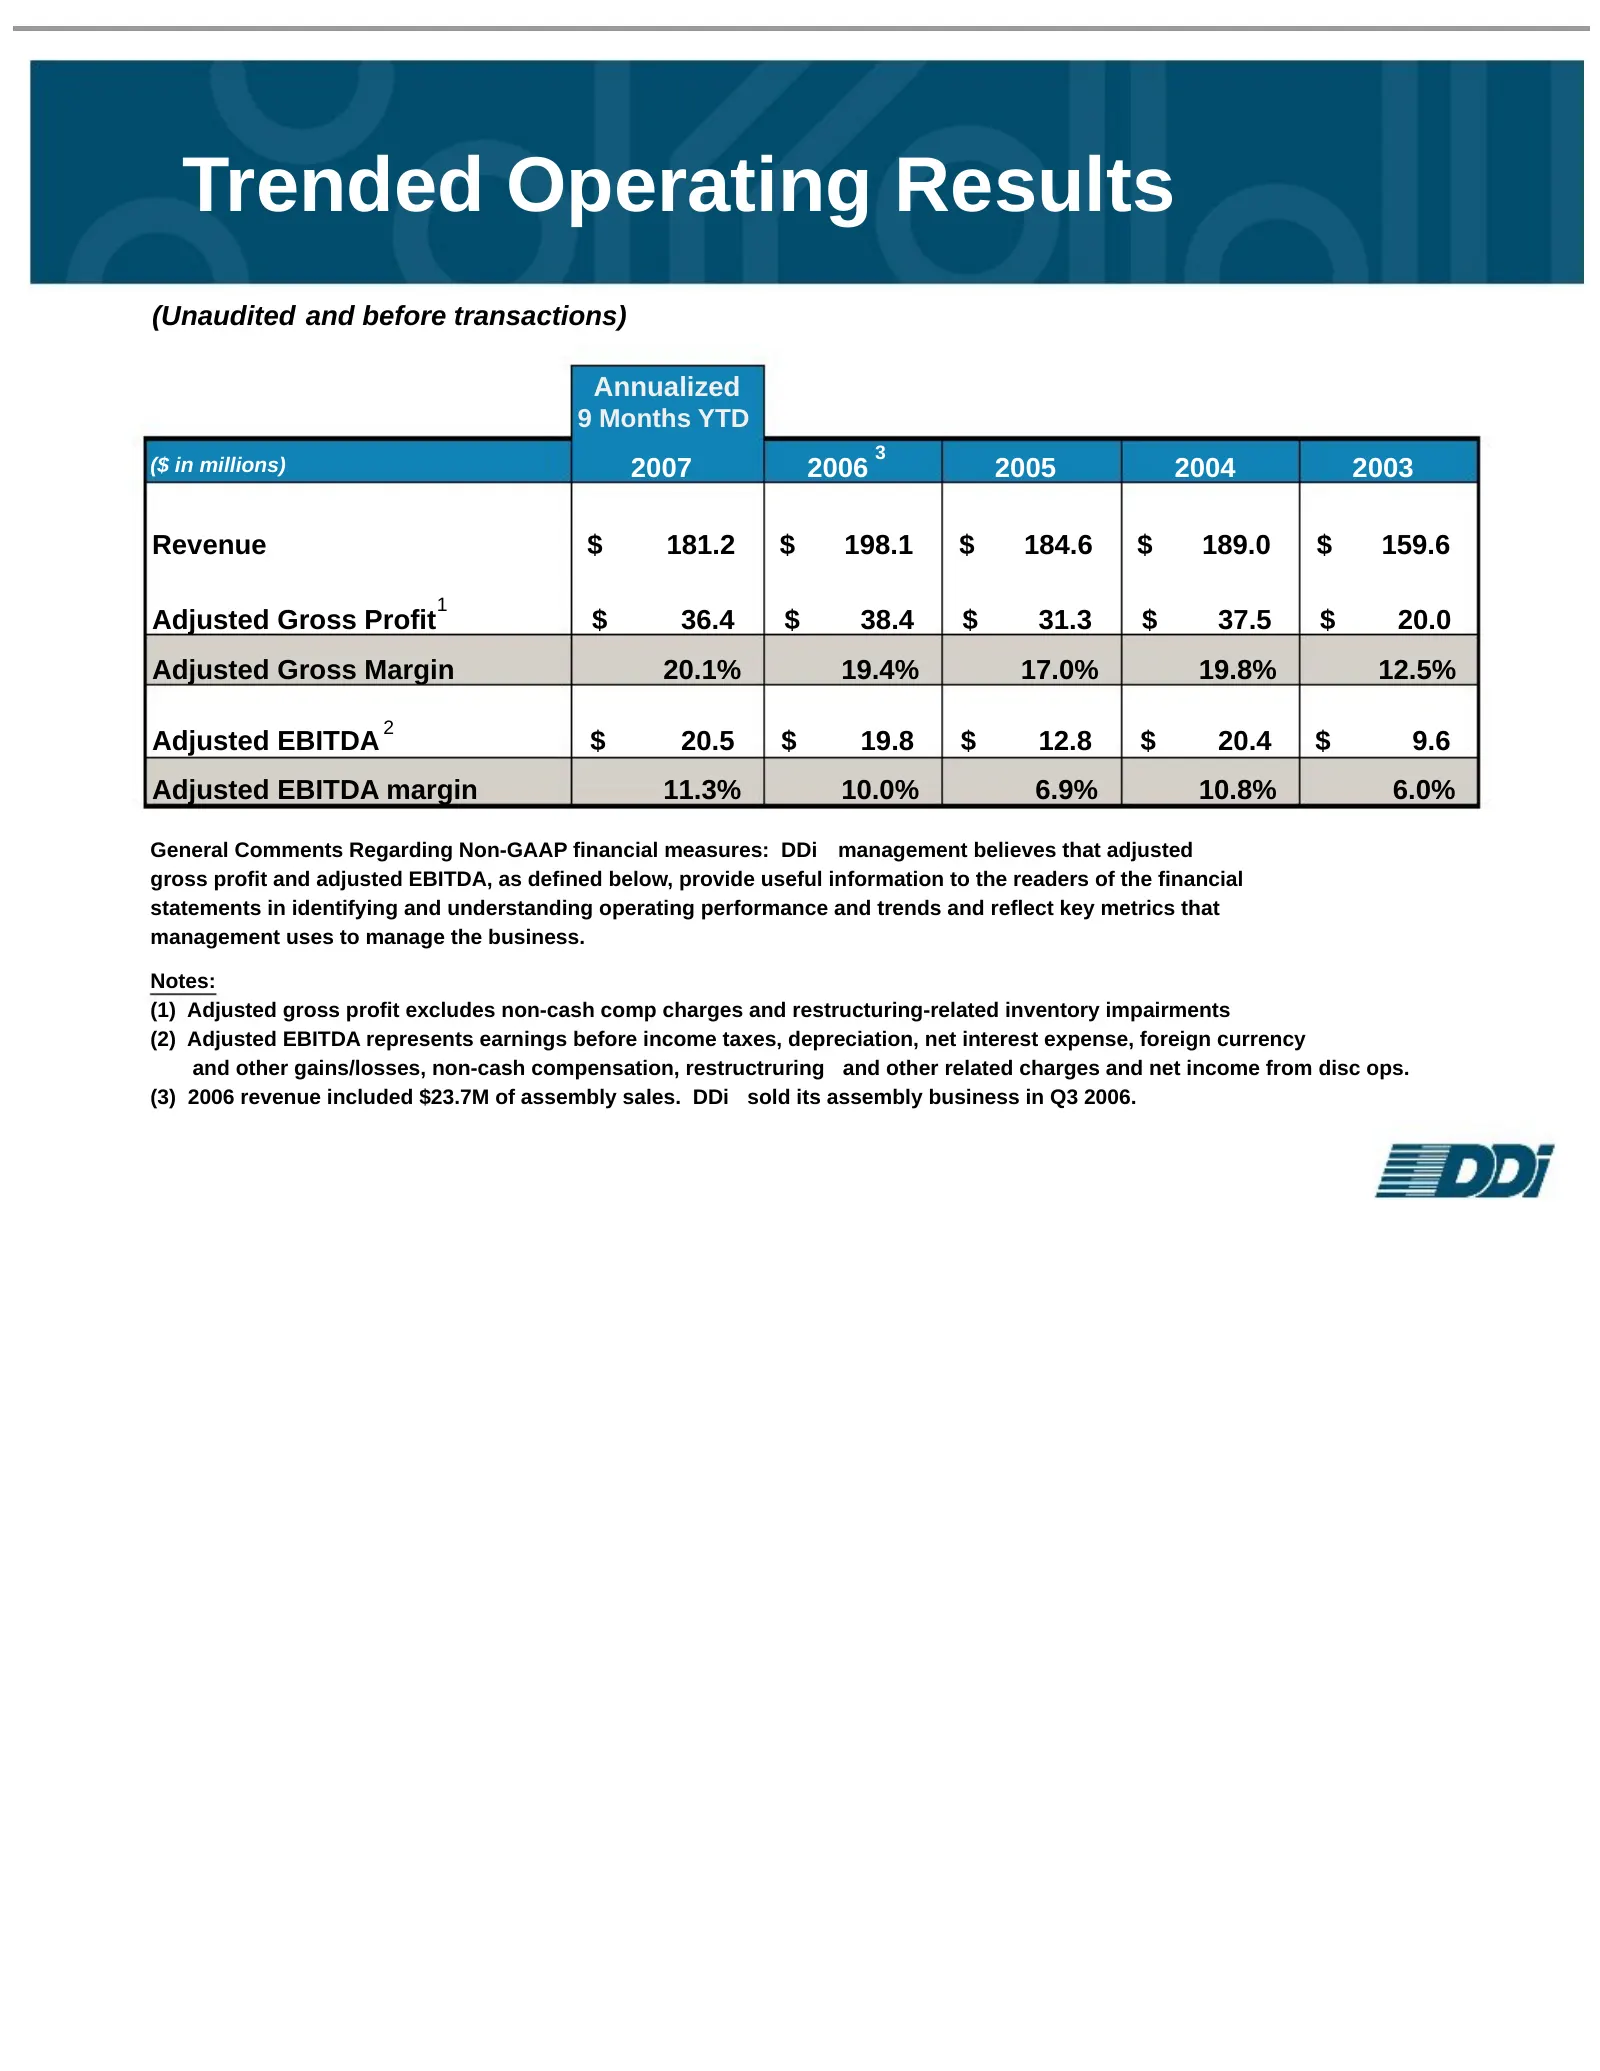
Trended Operating Results (Unaudited and before transactions) Annualized 9 Months YTD 3 ($ in millions) 2007 2006 2005 2004 2003 Revenue $ 181.2 $ 198.1 $ 184.6 $ 189.0 $ 159.6 1 Adjusted Gross Profit $ 36.4 $ 38.4 $ 31.3 $ 37.5 $ 20.0 Adjusted Gross Margin 20.1% 19.4% 17.0% 19.8% 12.5% 2 Adjusted E
Slide 21: DDi PCB Net Sales and Adjusted Gross Margin %
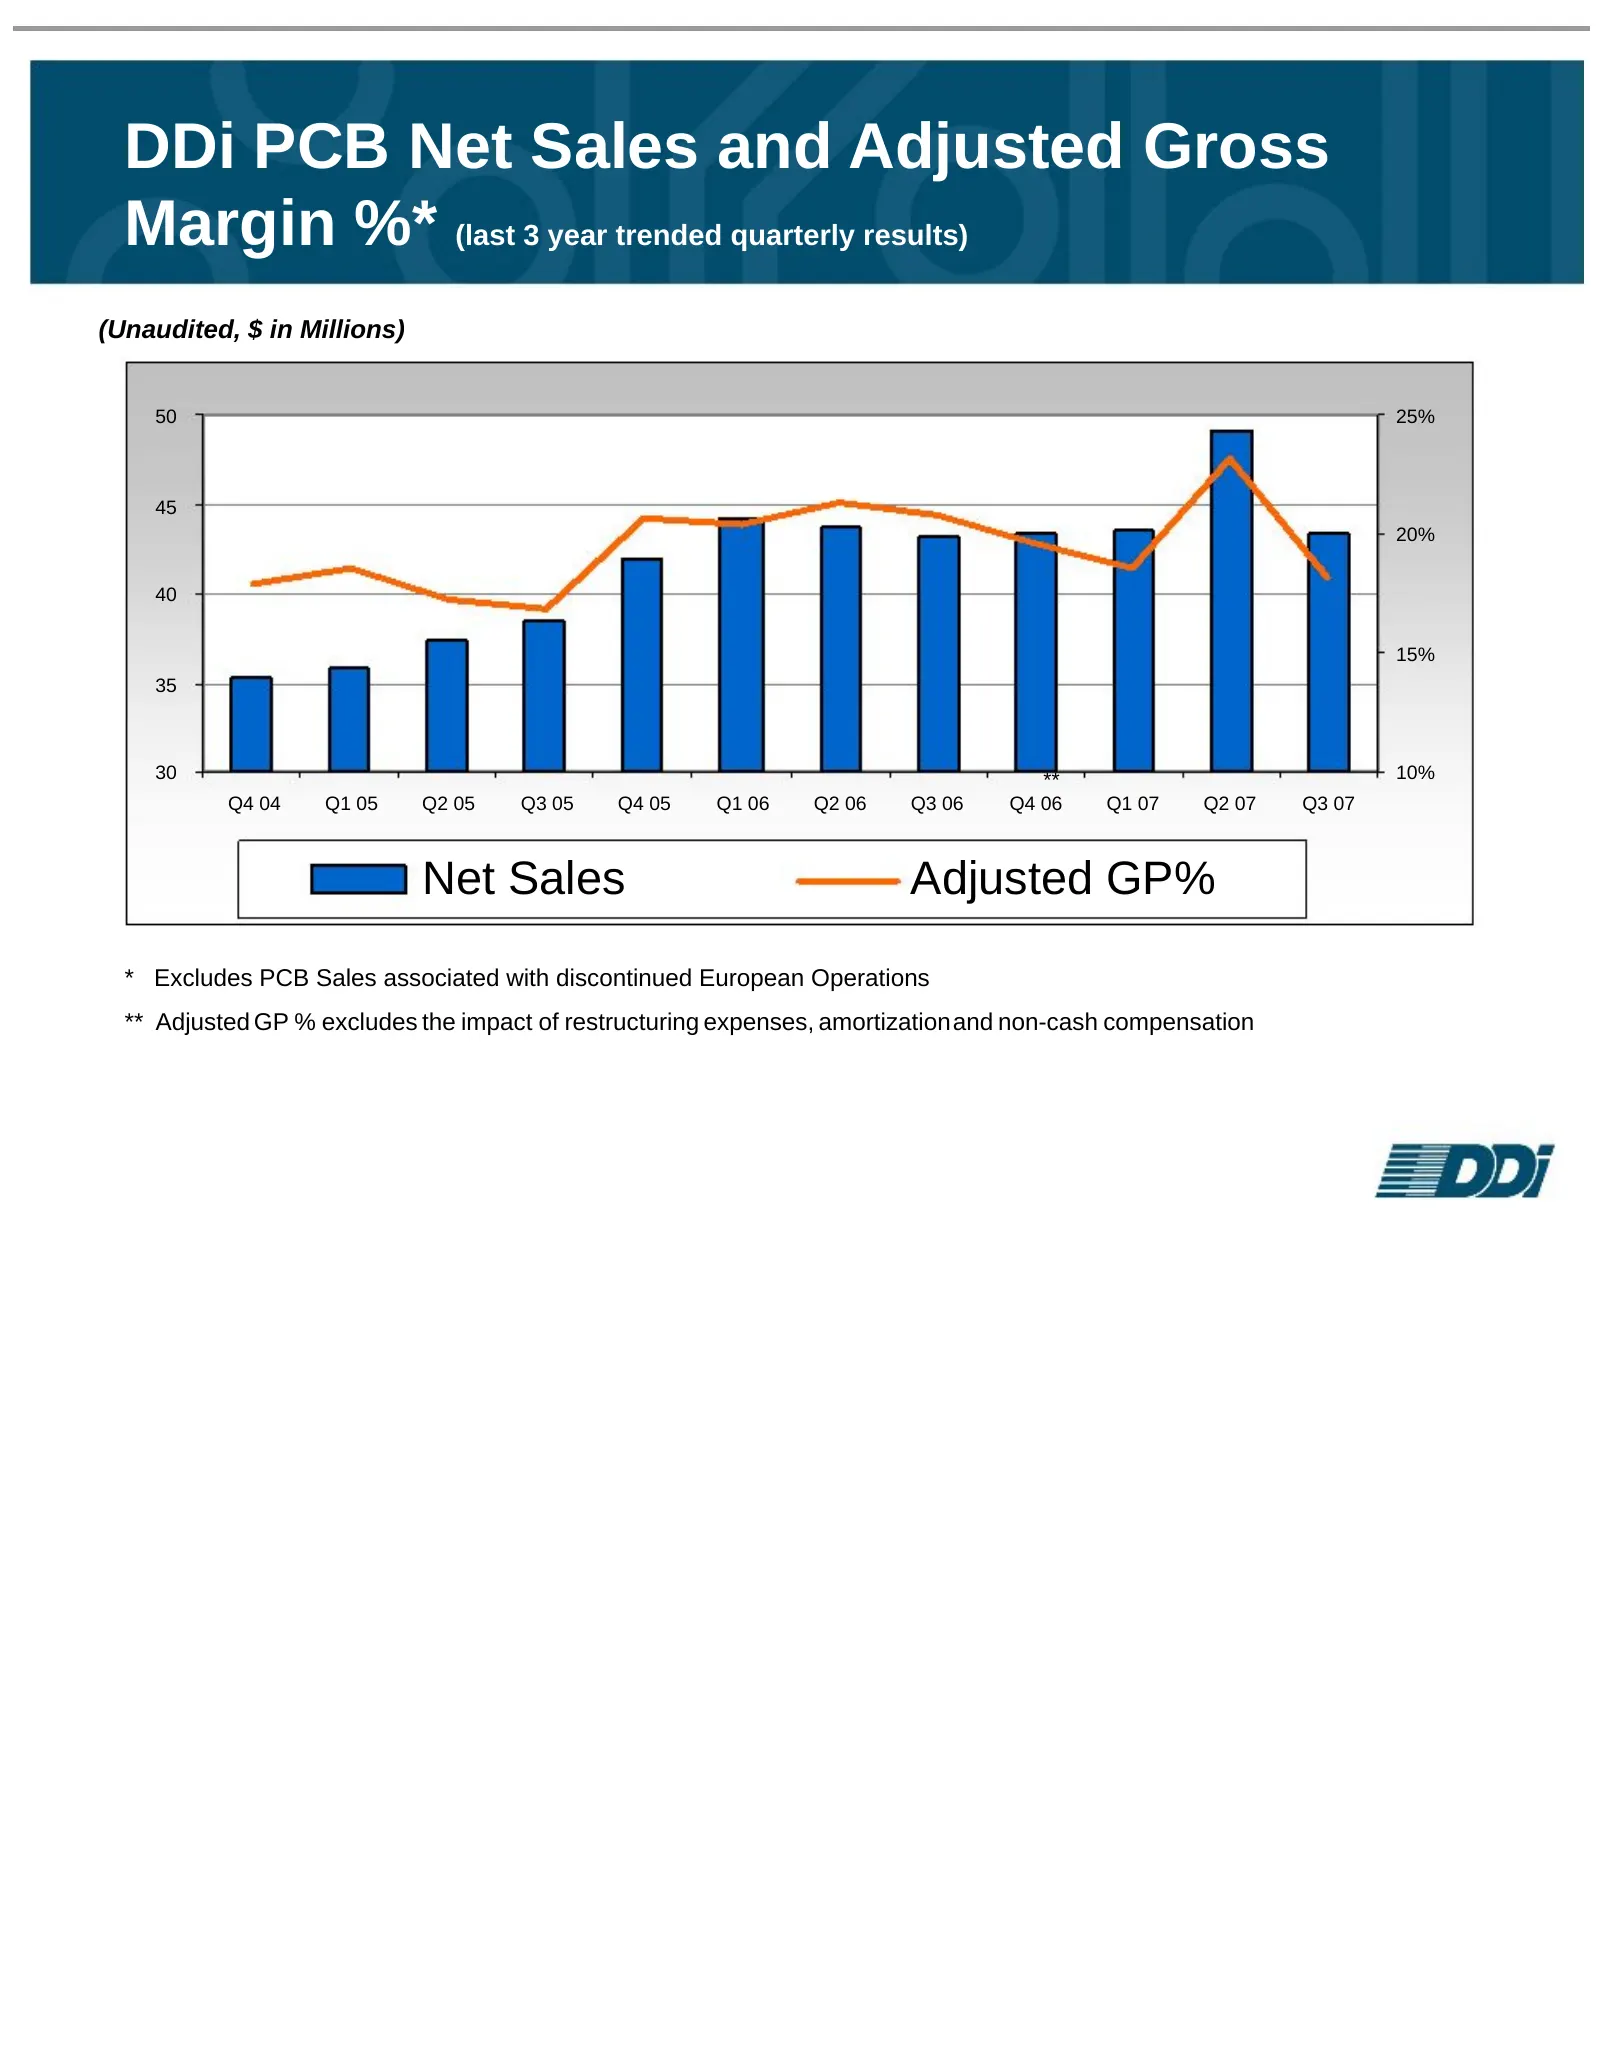
DDi PCB Net Sales and Adjusted Gross Margin %* (last 3 year trended quarterly results) (Unaudited, $ in Millions) 50 25% 45 20% 40 15% 35 30 ** 10% Q4 04 Q1 05 Q2 05 Q3 05 Q4 05 Q1 06 Q2 06 Q3 06 Q4 06 Q1 07 Q2 07 Q3 07 Net Sales Adjusted GP% * Excludes PCB Sales associated with discontinued Europea
Slide 22: Summary: Foundation for Growth
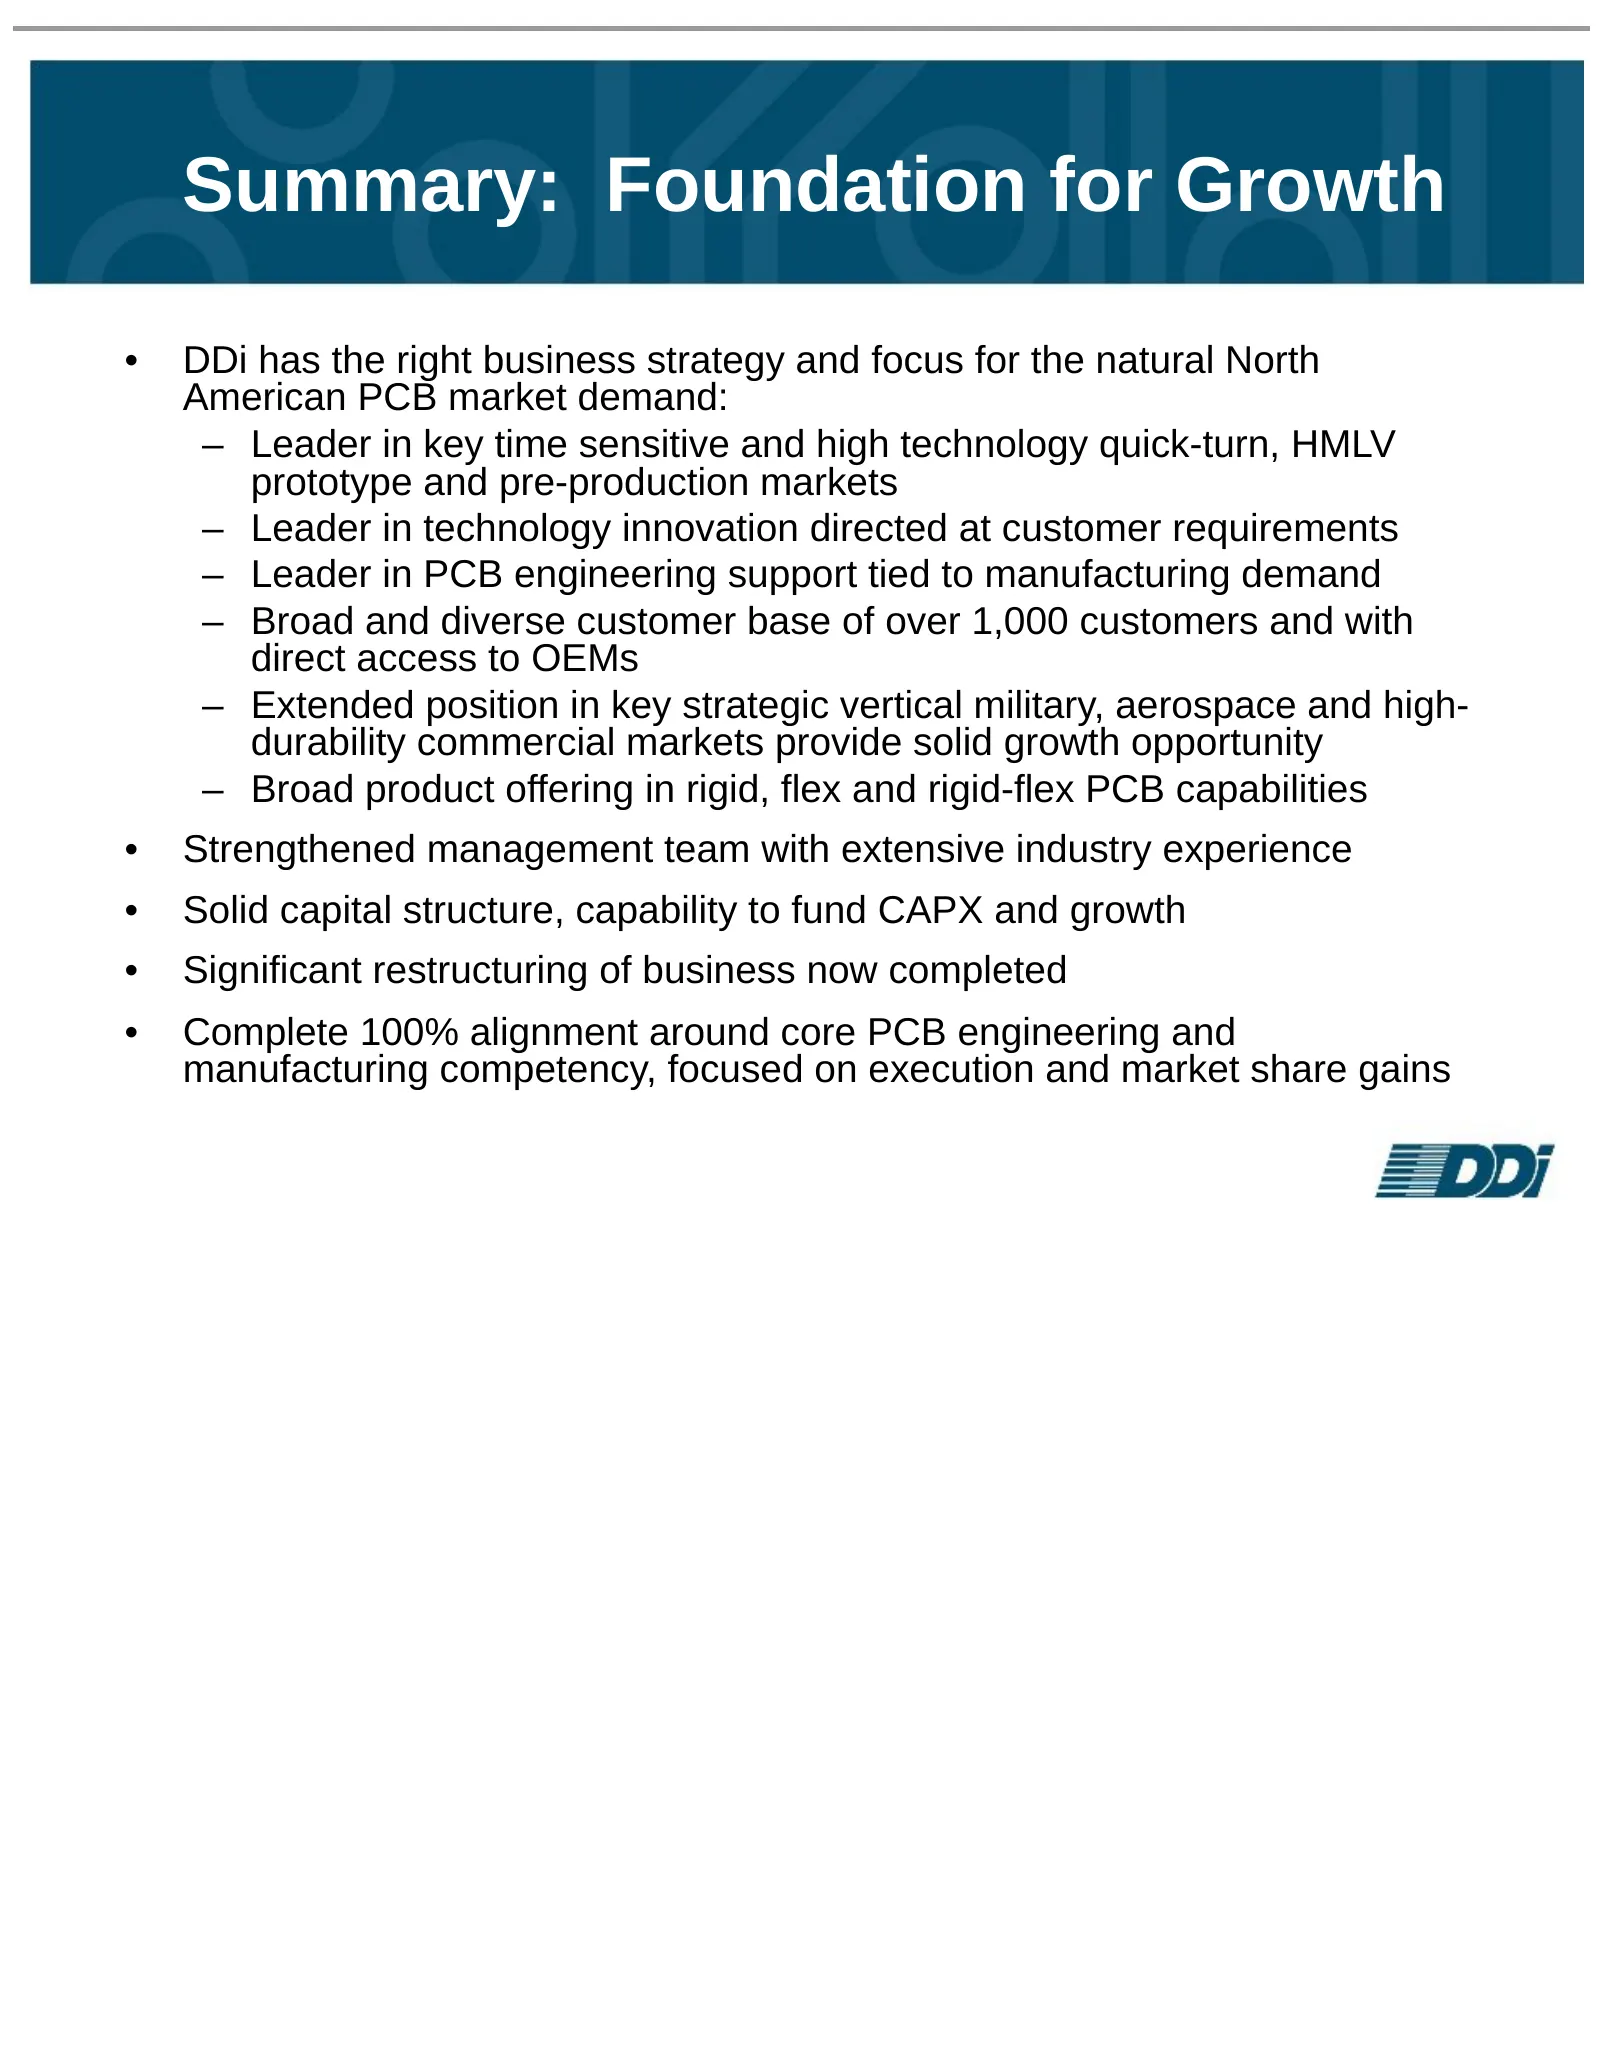
Summary: Foundation for Growth • DDi has the right business strategy and focus for the natural North American PCB market demand: – Leader in key time sensitive and high technology quick-turn, HMLV prototype and pre-production markets – Leader in technology innovation directed at customer requirement
Slide 23: Trended Operating Results
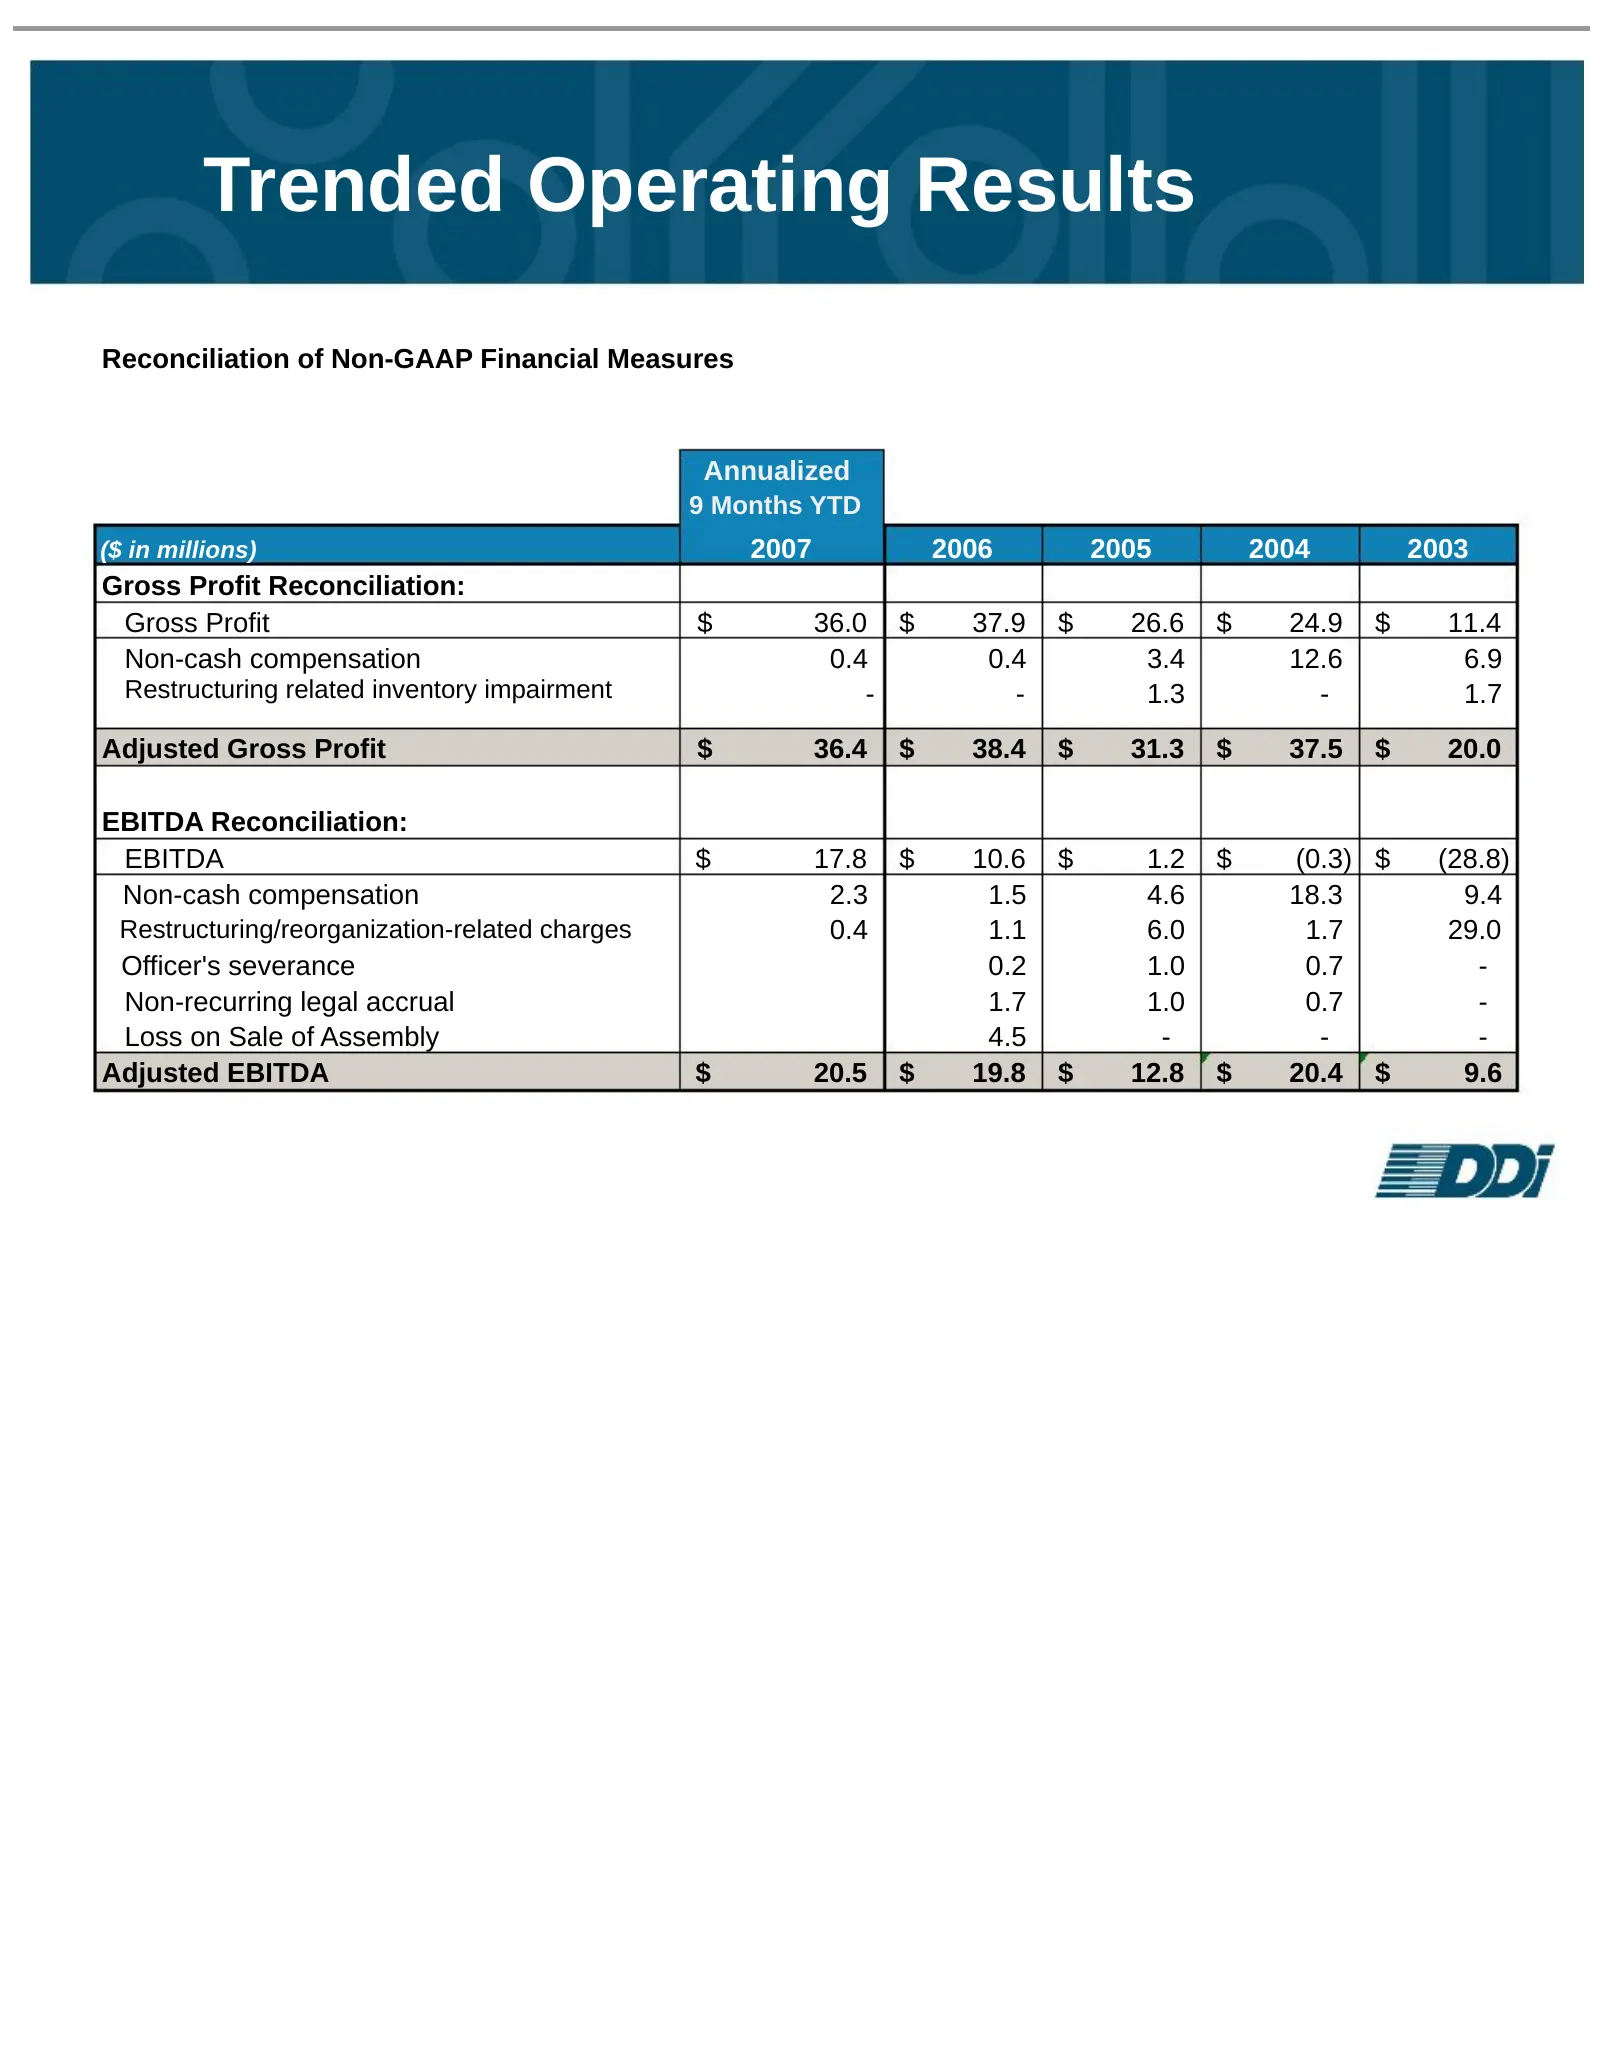
Trended Operating Results Reconciliation of Non-GAAP Financial Measures Annualized 9 Months YTD ($ in millions) 2007 2006 2005 2004 2003 Gross Profit Reconciliation: Gross Profit $ 36.0 $ 37.9 $ 26.6 $ 24.9 $ 11.4 Non-cash compensation 0.4 0.4 3.4 12.6 6.9 Restructuring related inventory impairment
Source: SEC EDGAR · 8-K filed Jan 11, 2008