DDI — Merger or Acquisition (April 2012)
29 slides from DDI's merger presentation, Apr 4, 2012
Slide 1: Viasystems to Acquire DDi Corp.
Exhibit 99.4 Viasystems April Disclaimer 2012 to Acquire DDi Corp.
Slide 2: Disclaimer
This of In forward-looking an Actual Company’s Furthermore, management analytical limitations, impairment Adjusted used 2or 1934, addition, unusual authorized presentation byresults other as EPS EBITDA Net tool, for amended. primarily Form charges, from believes in Income companies. executive could
Slide 3: Disclaimer (cont'd)
Disclaimer Adjusted costs stockholders. Additional DDi or WHEN website, Corporate Participants Viasystems about for Louis, statement (714) 3information given the Corp. associated 688-7200, Viasystems’ MO year IT to atNet for Secretary, BECOMES intends www.sec.gov. Information the (cont’d) 63105, and
Slide 4: Table of Contents
Table I. II. 4III. Transaction Investment Financial of Contents Highlights Summary Highlights
Slide 5: Why We Are Acquiring DDi
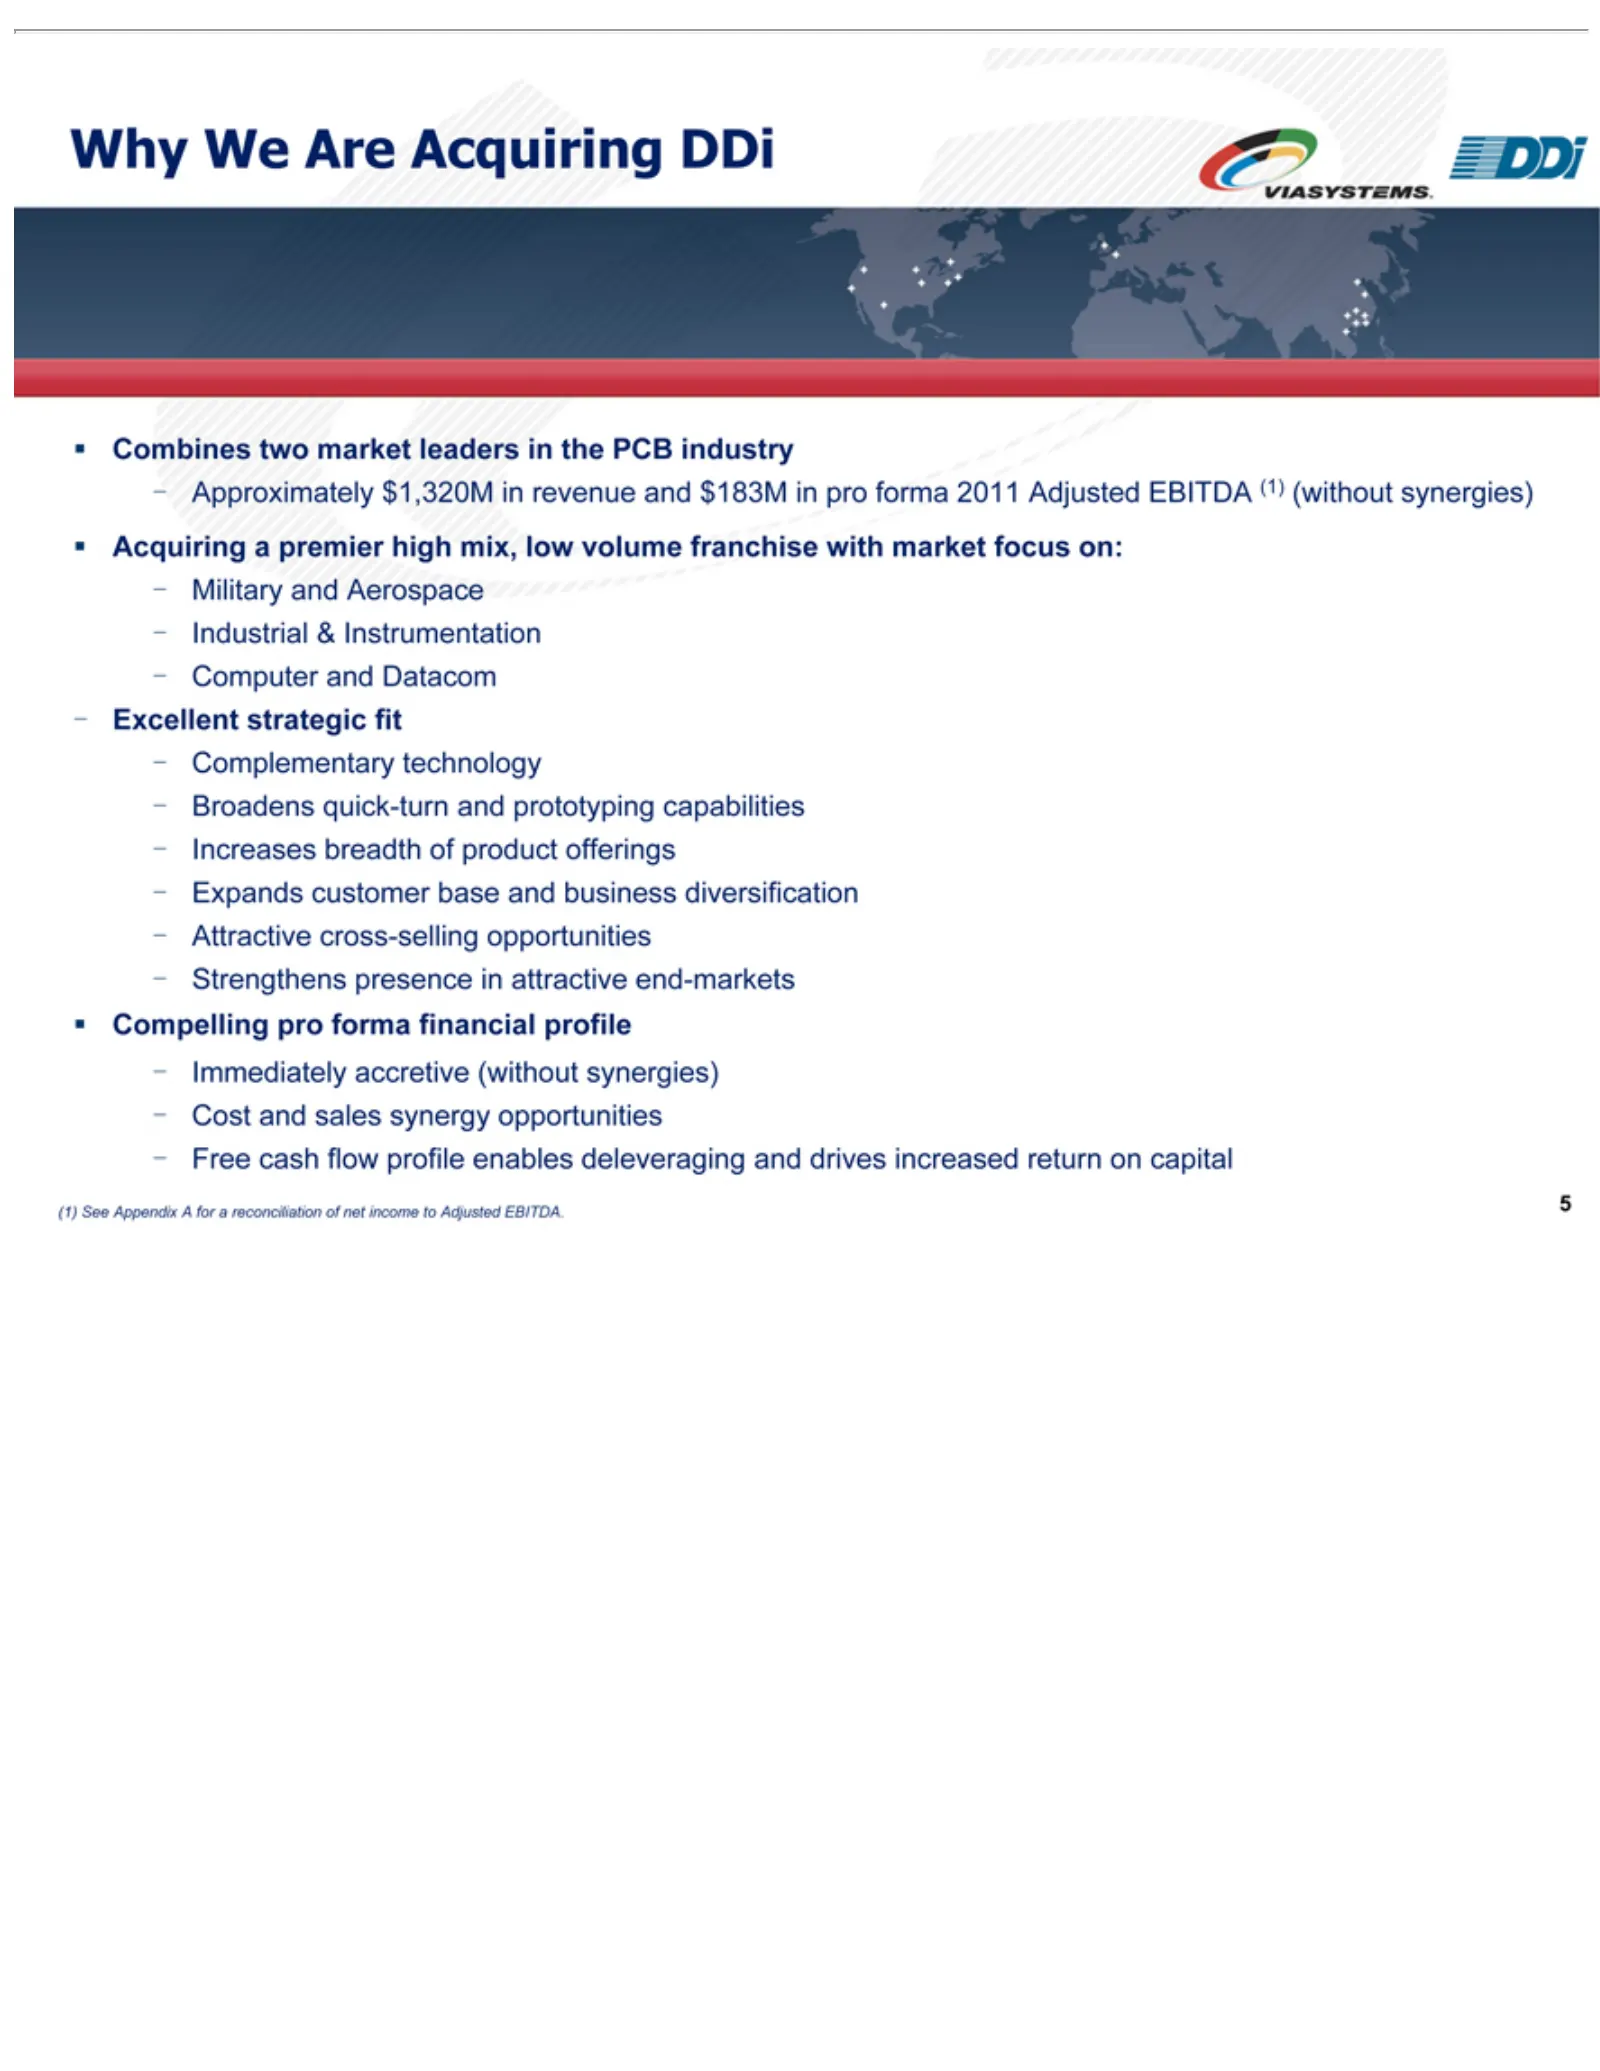
Why Combines Approximately Acquiring Military Industrial Computer Excellent Complementary Broadens Increases Expands Attractive Strengthens Compelling Immediately Cost Free 5(1) See cash and WeAppendix and Are customer sales breadth strategic quick-turn flow &cross-selling and atwo presence pro prem
Slide 6: I. Transaction Summary
C....... Di I. Transaction Summary
Slide 7: Transaction Summary
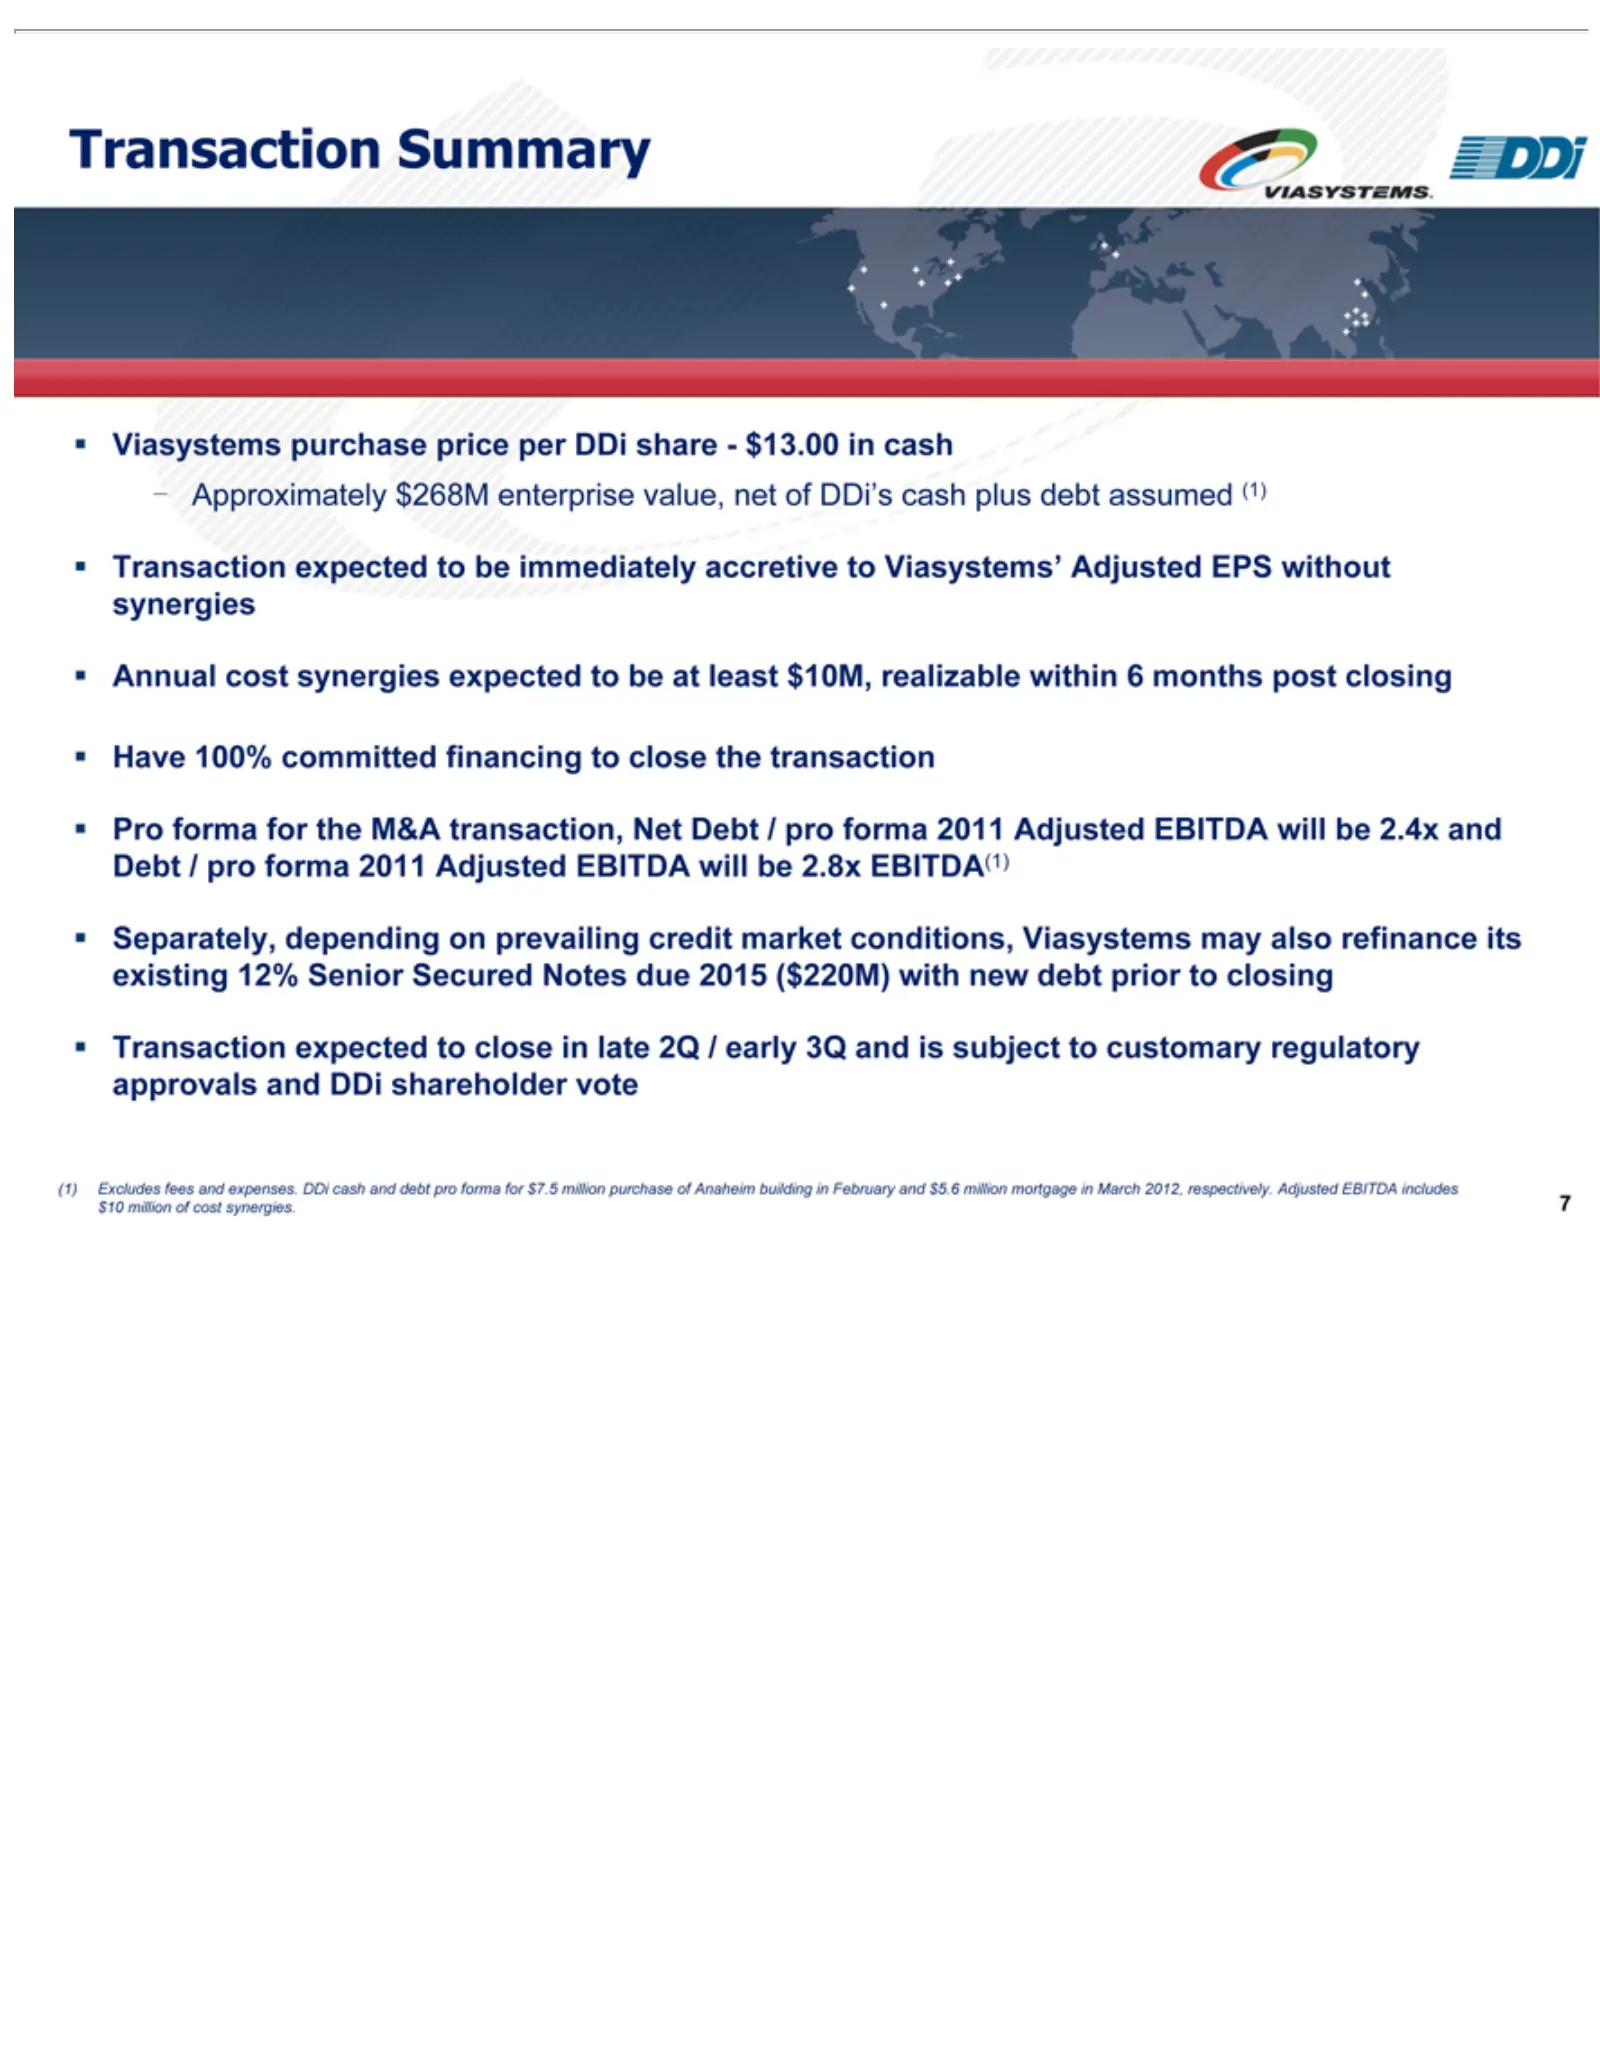
Viasystems Approximately Annual Have Pro Separately, Transaction (1) 7of cost Excludes forma 100% synergies. cost for depending purchase Summary expected committed synergies fees the $268M M&A andprice to expenses. expected on enterprise financing transaction, beprevailing close per immediately inDD
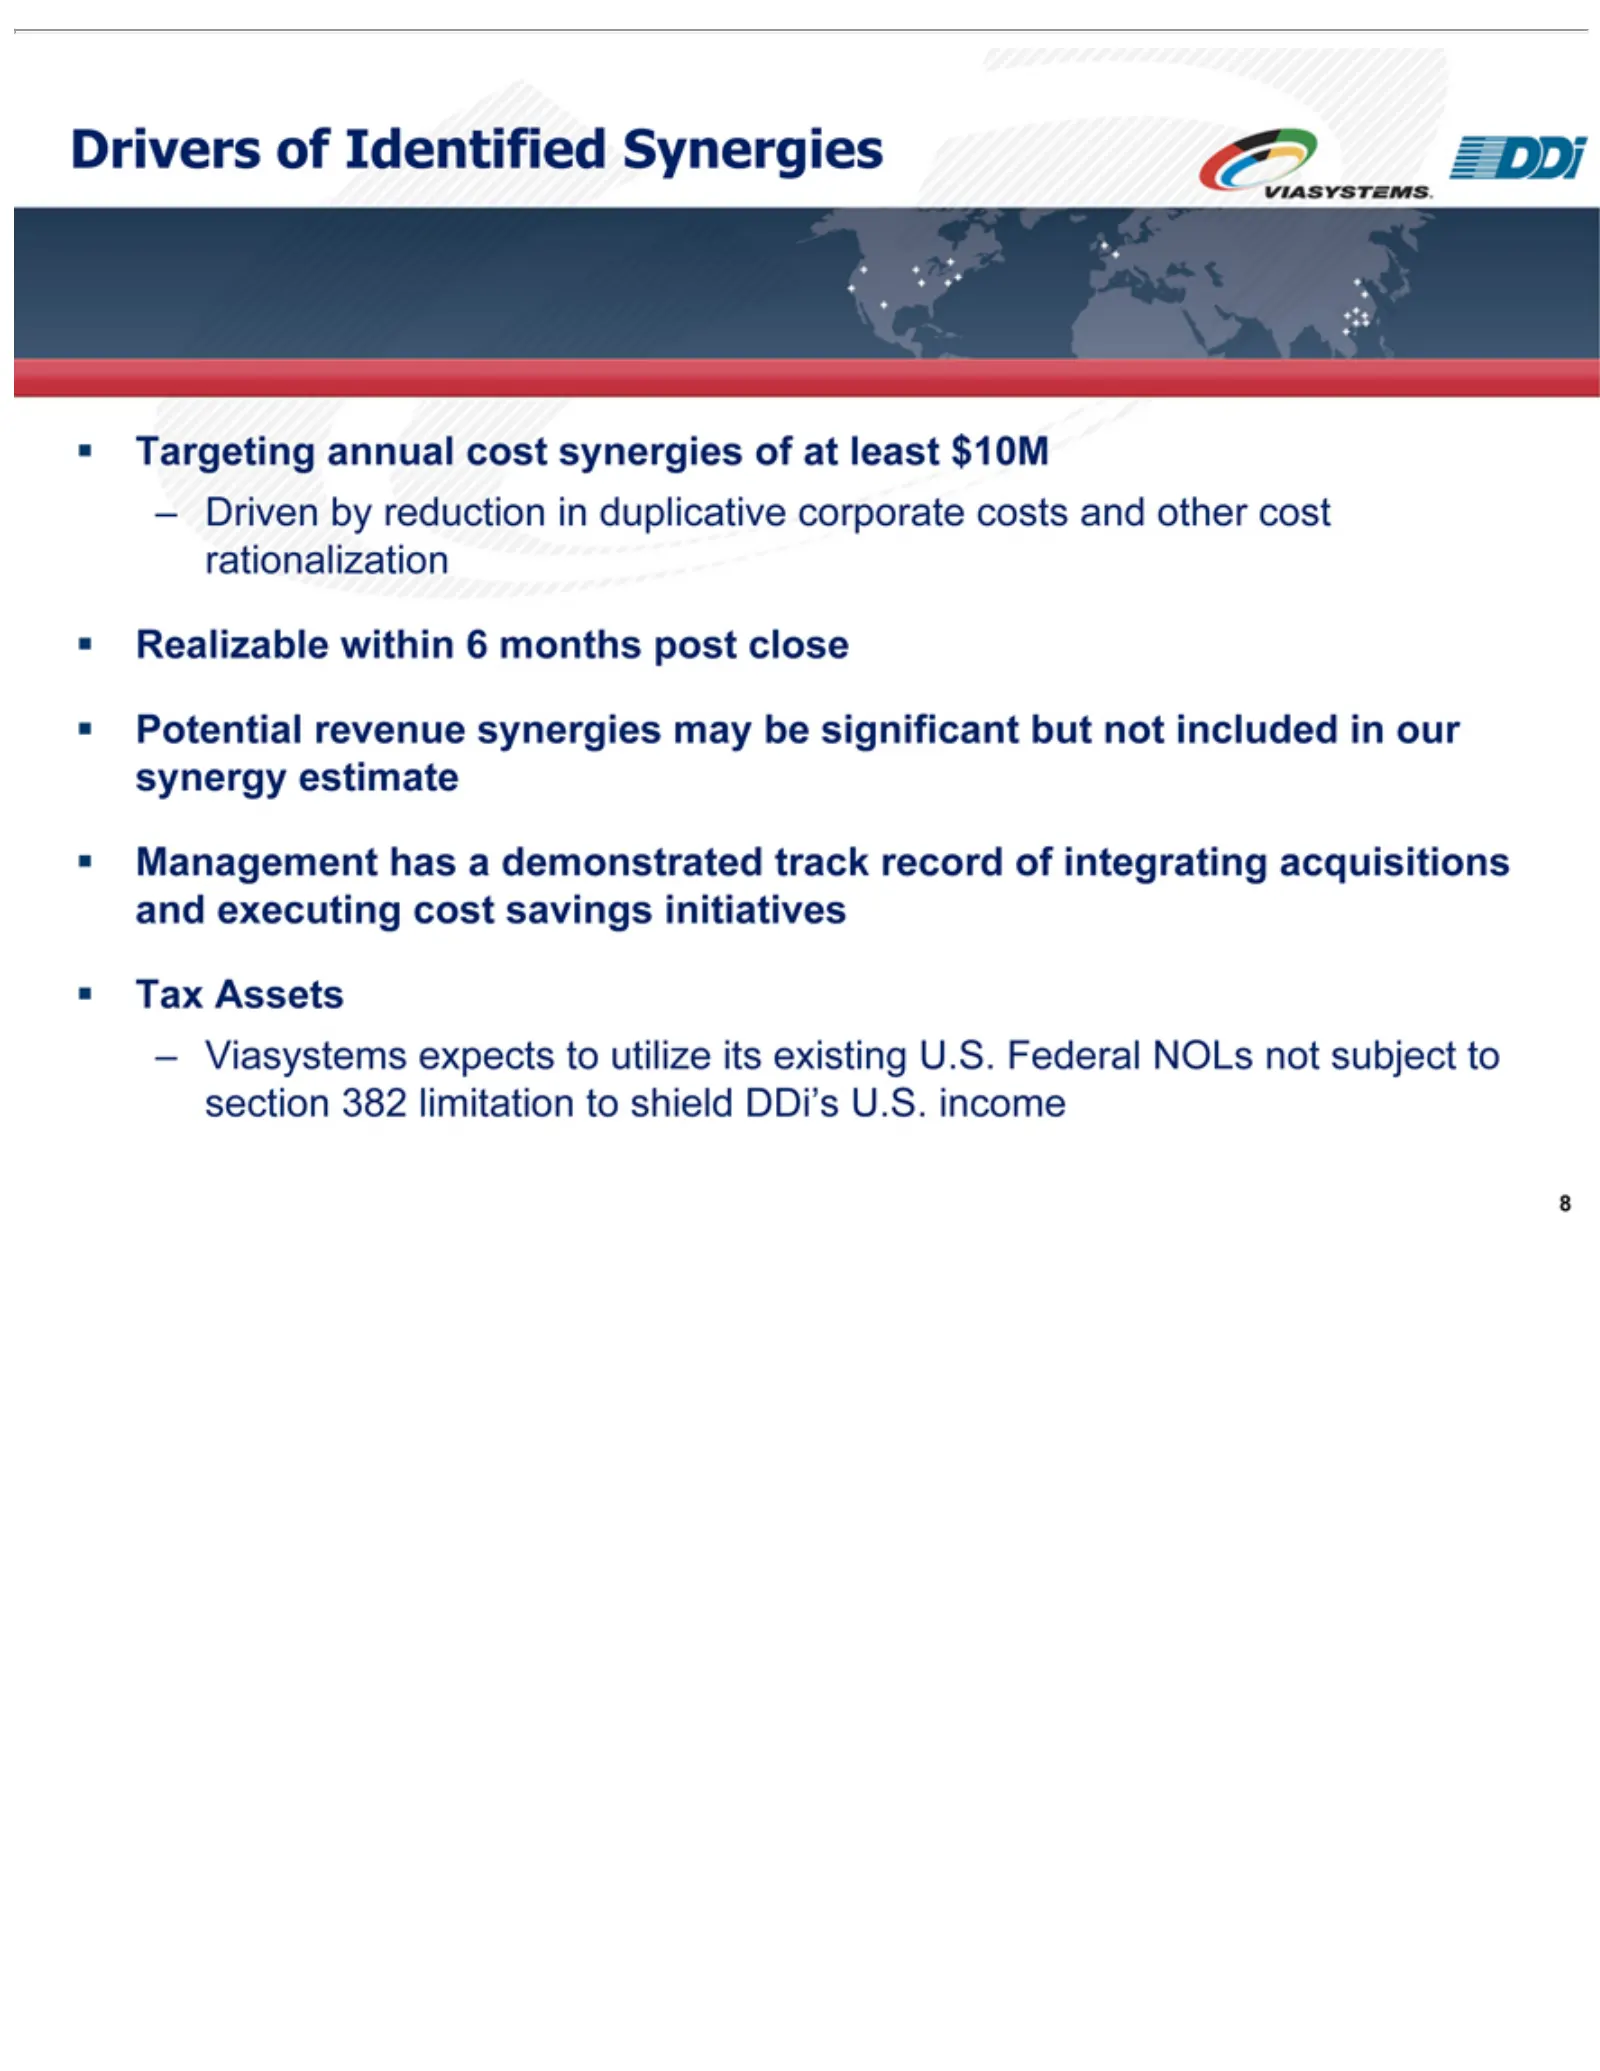
Slide 8: Targeting Realizable Cost Synergies
Drivers Targeting Realizable Potential Management 8–Tax Viasystems Driven Assets ofby revenue annual Identified within reduction has expects cost asynergies 6demonstrated months Synergies to synergies inutilize duplicative post mayits of close be track existing atsignificant corporate least record $
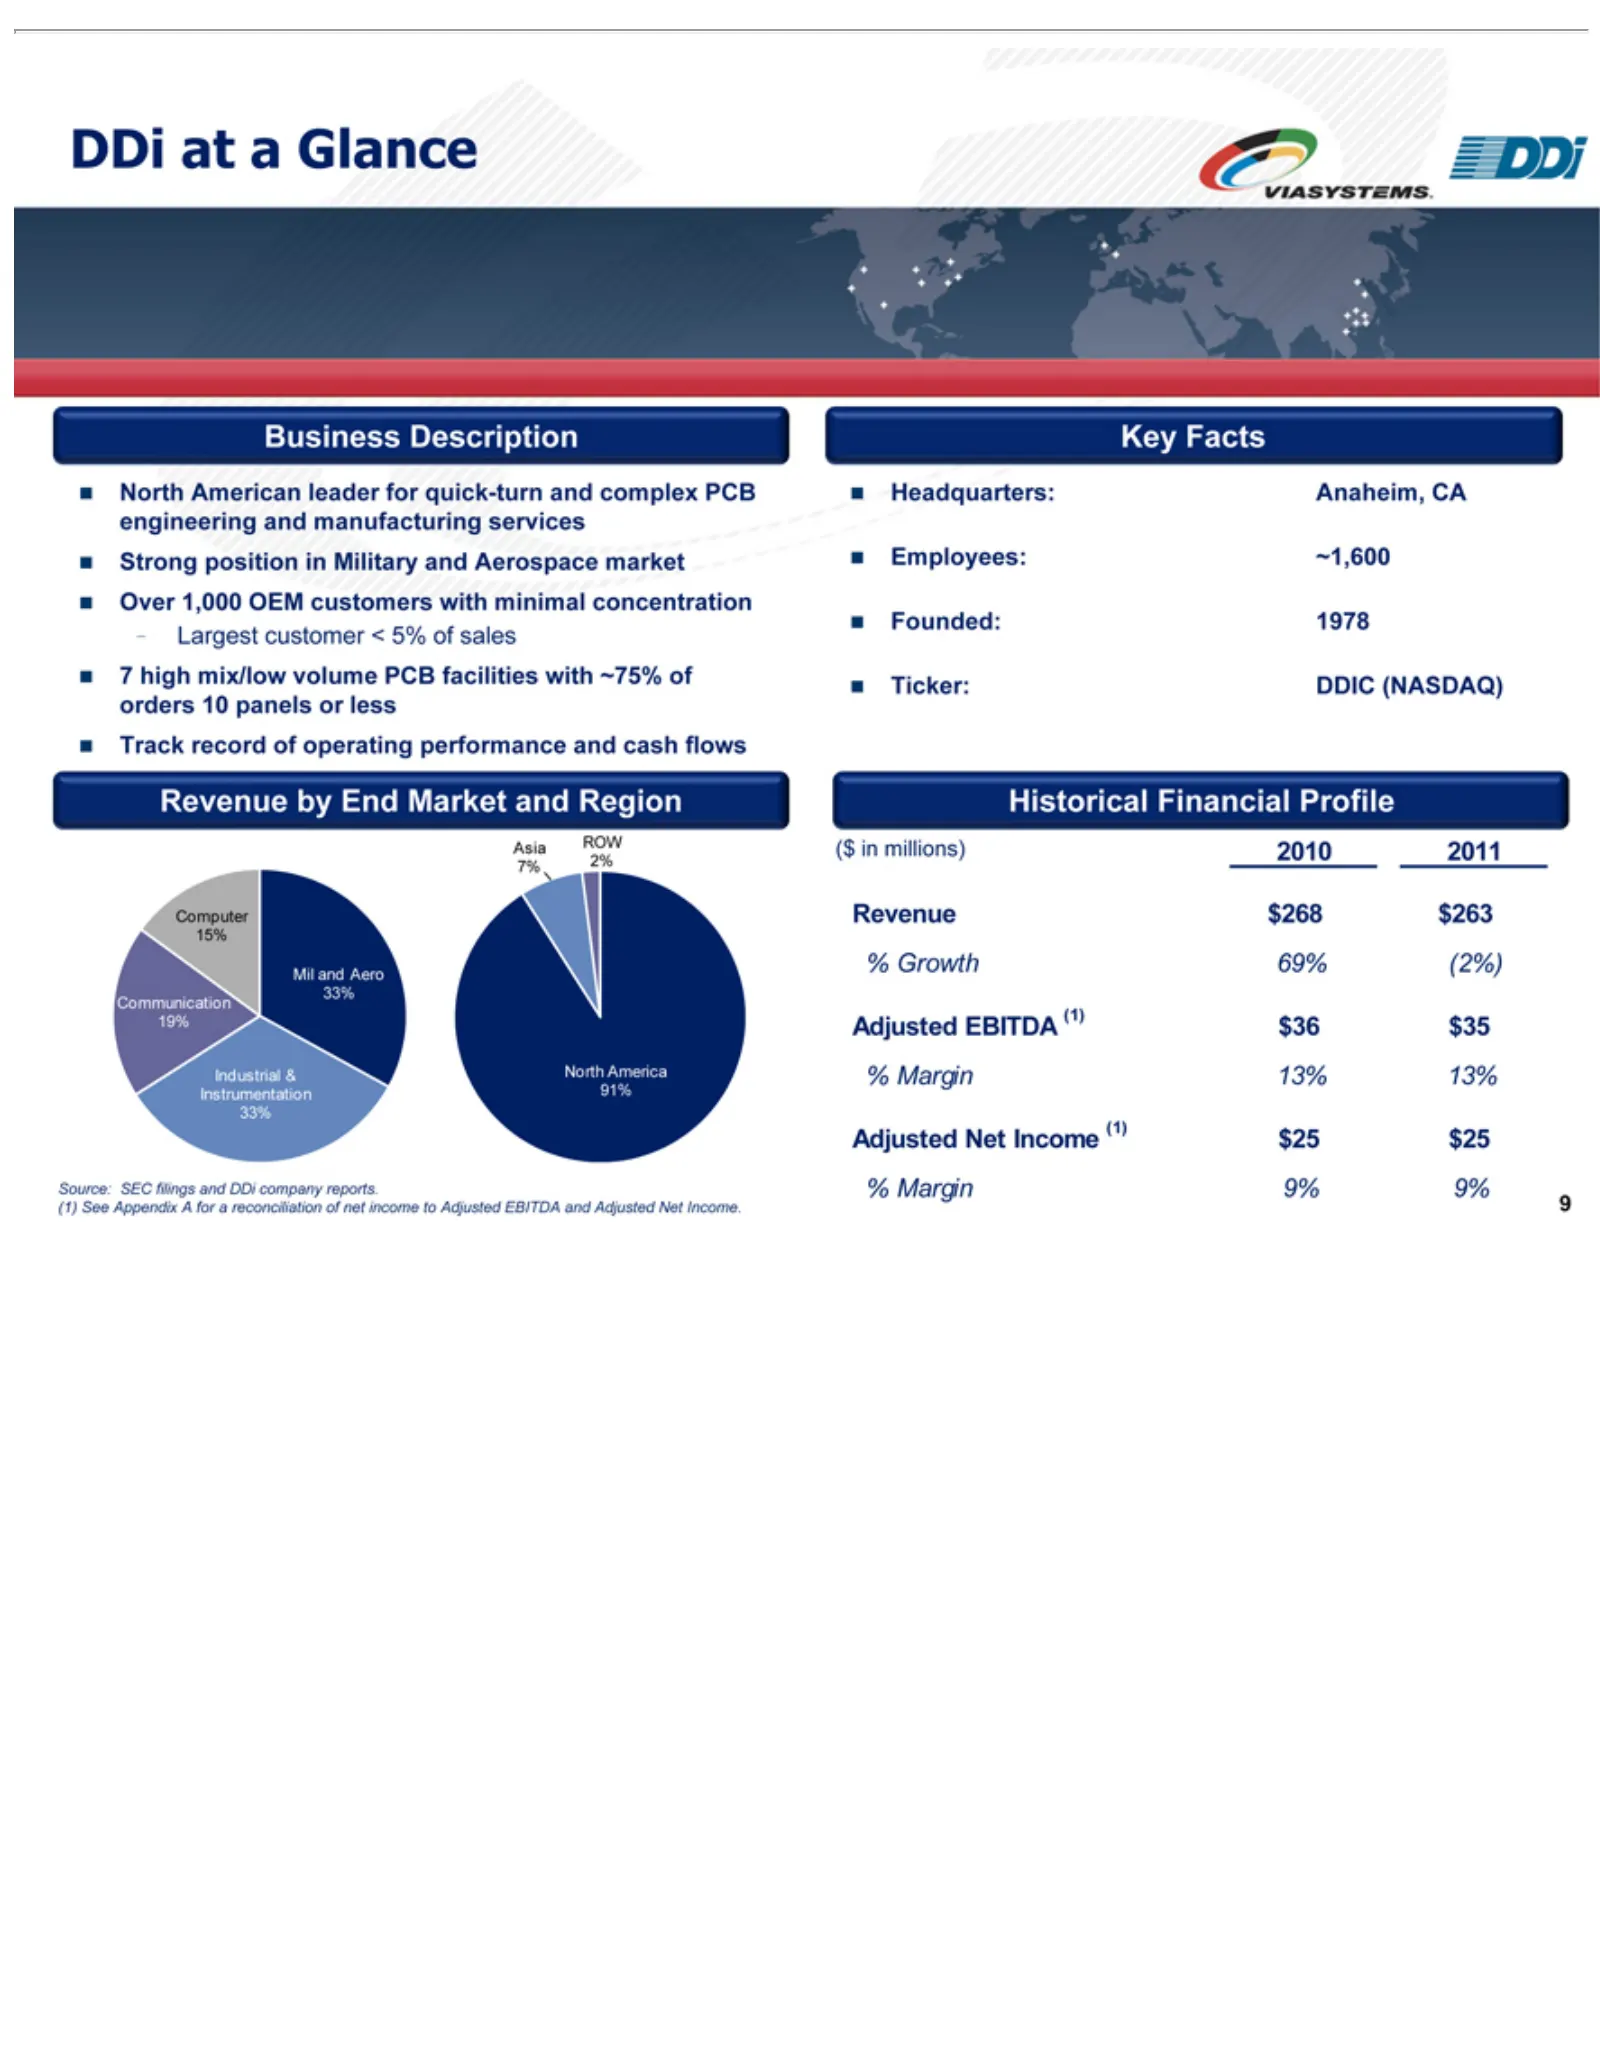
Slide 9: DDi Business at a Glance
DDi Business 7Largest Key Headquarters: Computer Communication Industrial Mil Asia ROW North Source: (1) Historical ($ Revenue Adjusted 9%high inSee Growth Margin and Facts at 7% millions) American America 2% mix/low aAppendix customer SEC Aero Glance by $268 Description EBITDA Net & Financial 15% 1
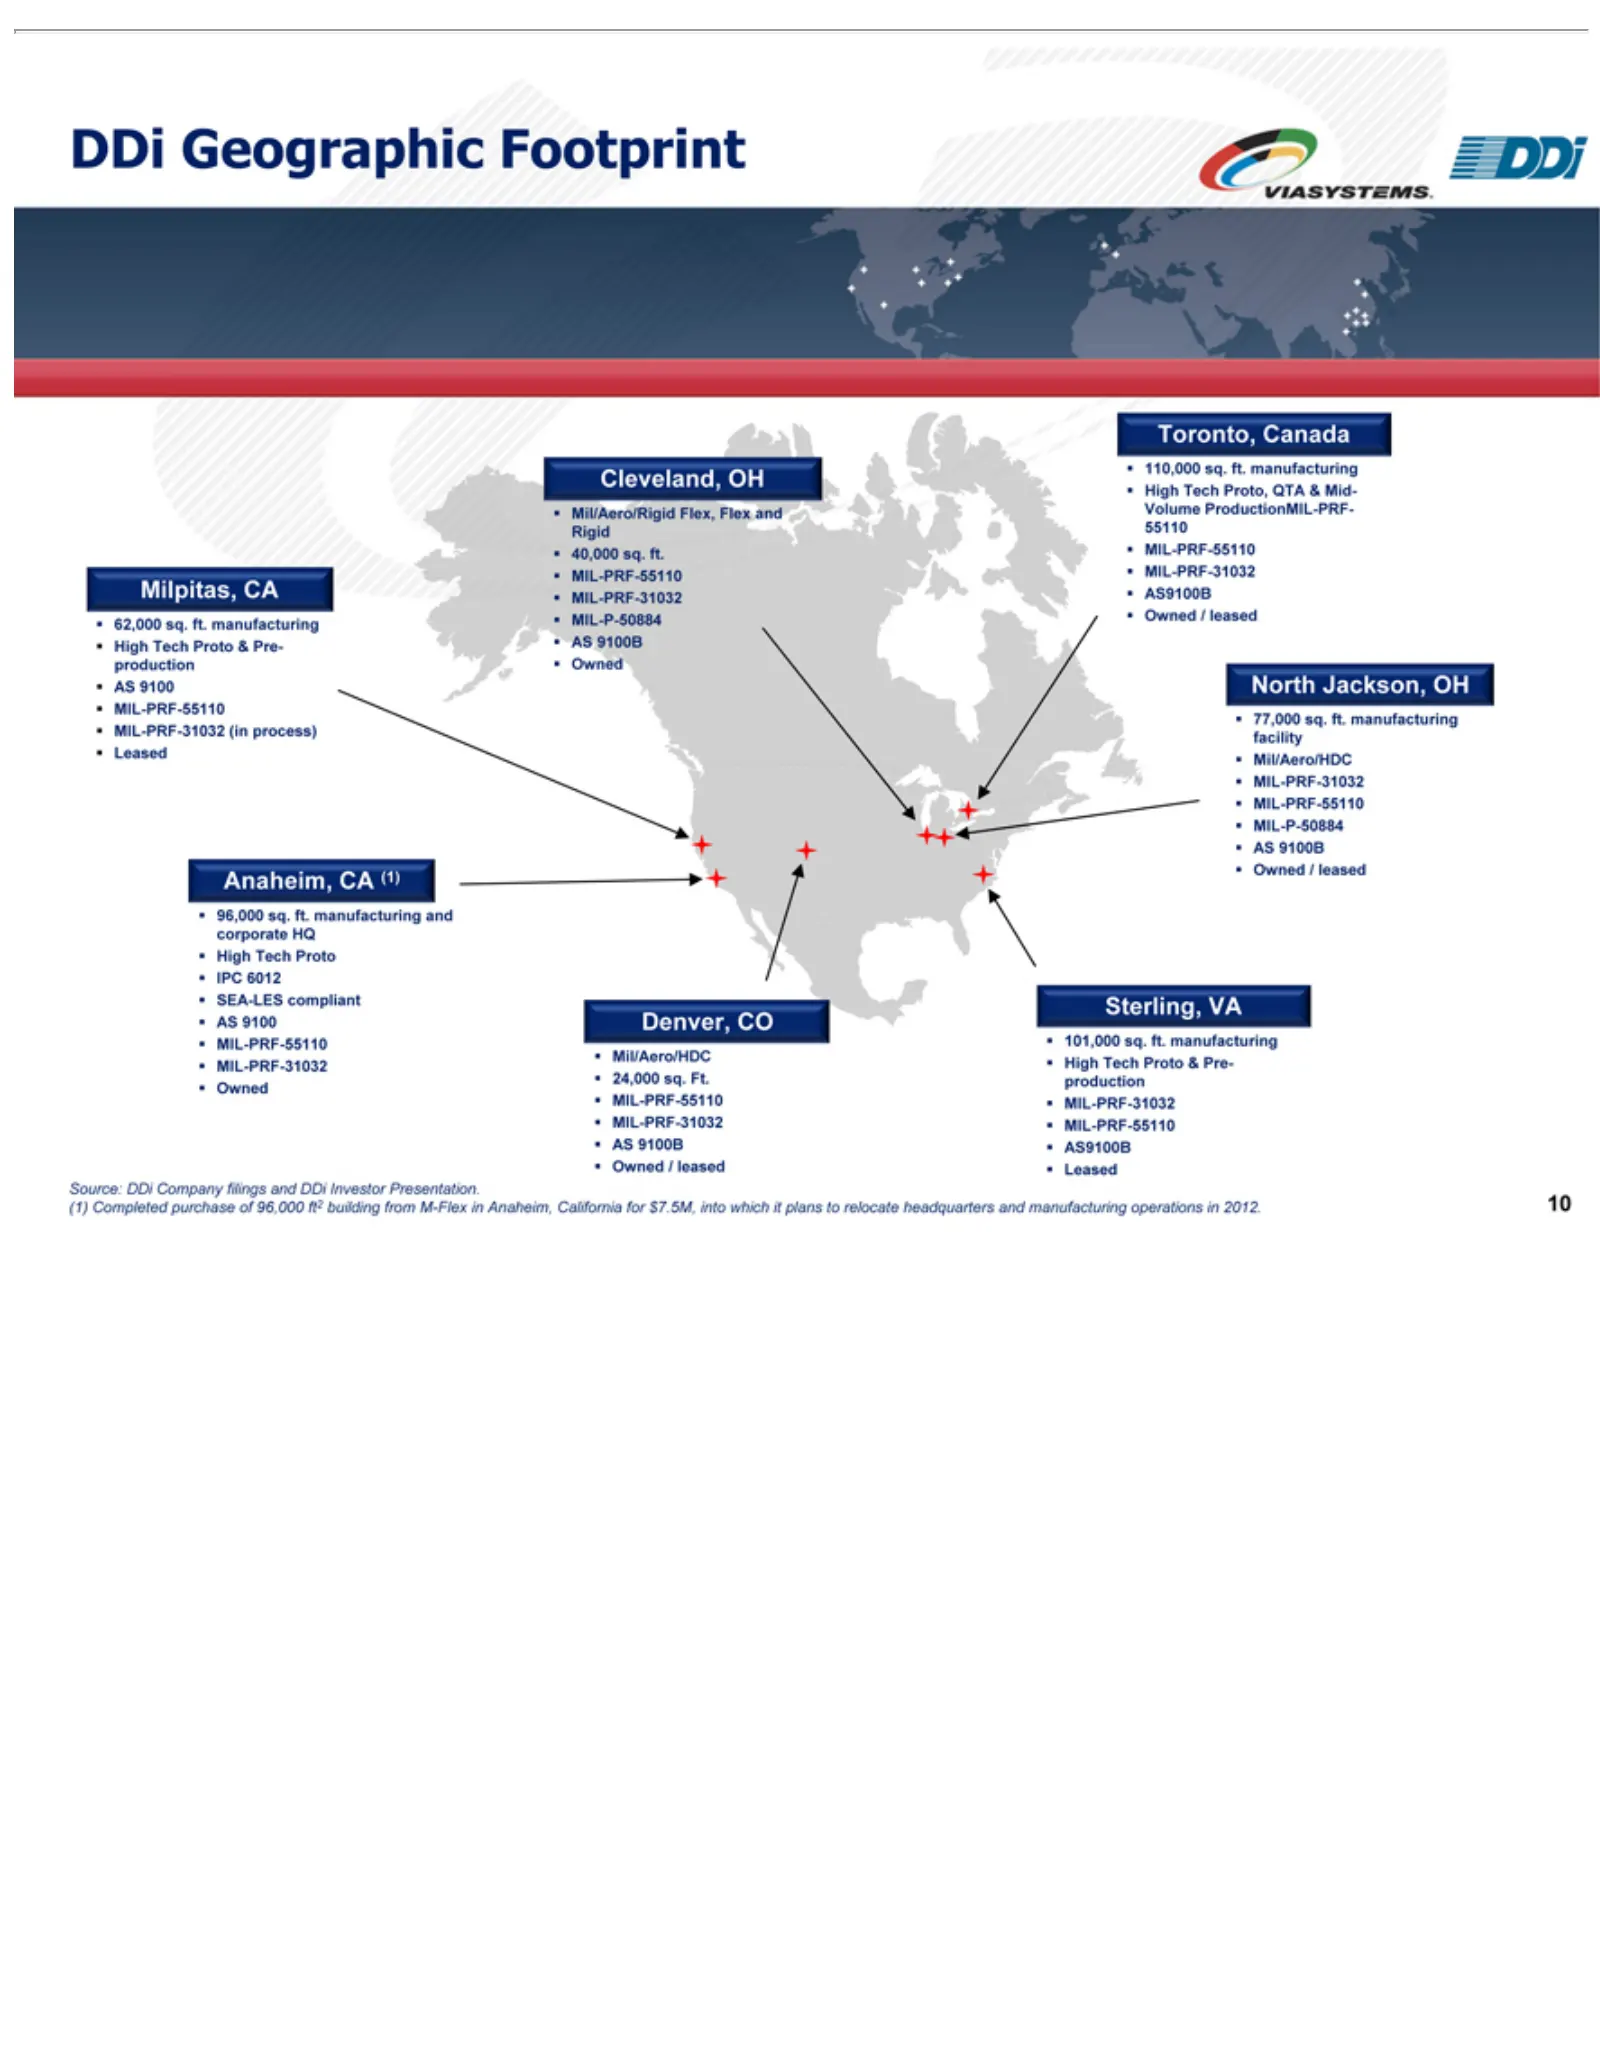
Slide 10: DDi Geographic Footprint
DDiCompleted Cleveland, Mil/Aero/Rigid MIL-PRF-55110 Milpitas, 62,000 Anaheim, 96,000 High Denver, Mil/Aero/HDC Toronto, 110,000 Owned North 77,000 MIL-PRF-31032 Sterling, 101,000 Source: Leased (1) 10 Geographic Tech Jackson, sq. /DDi CO sq. VA Canada leased CA CA ft. Proto OH ft.Company manufactur
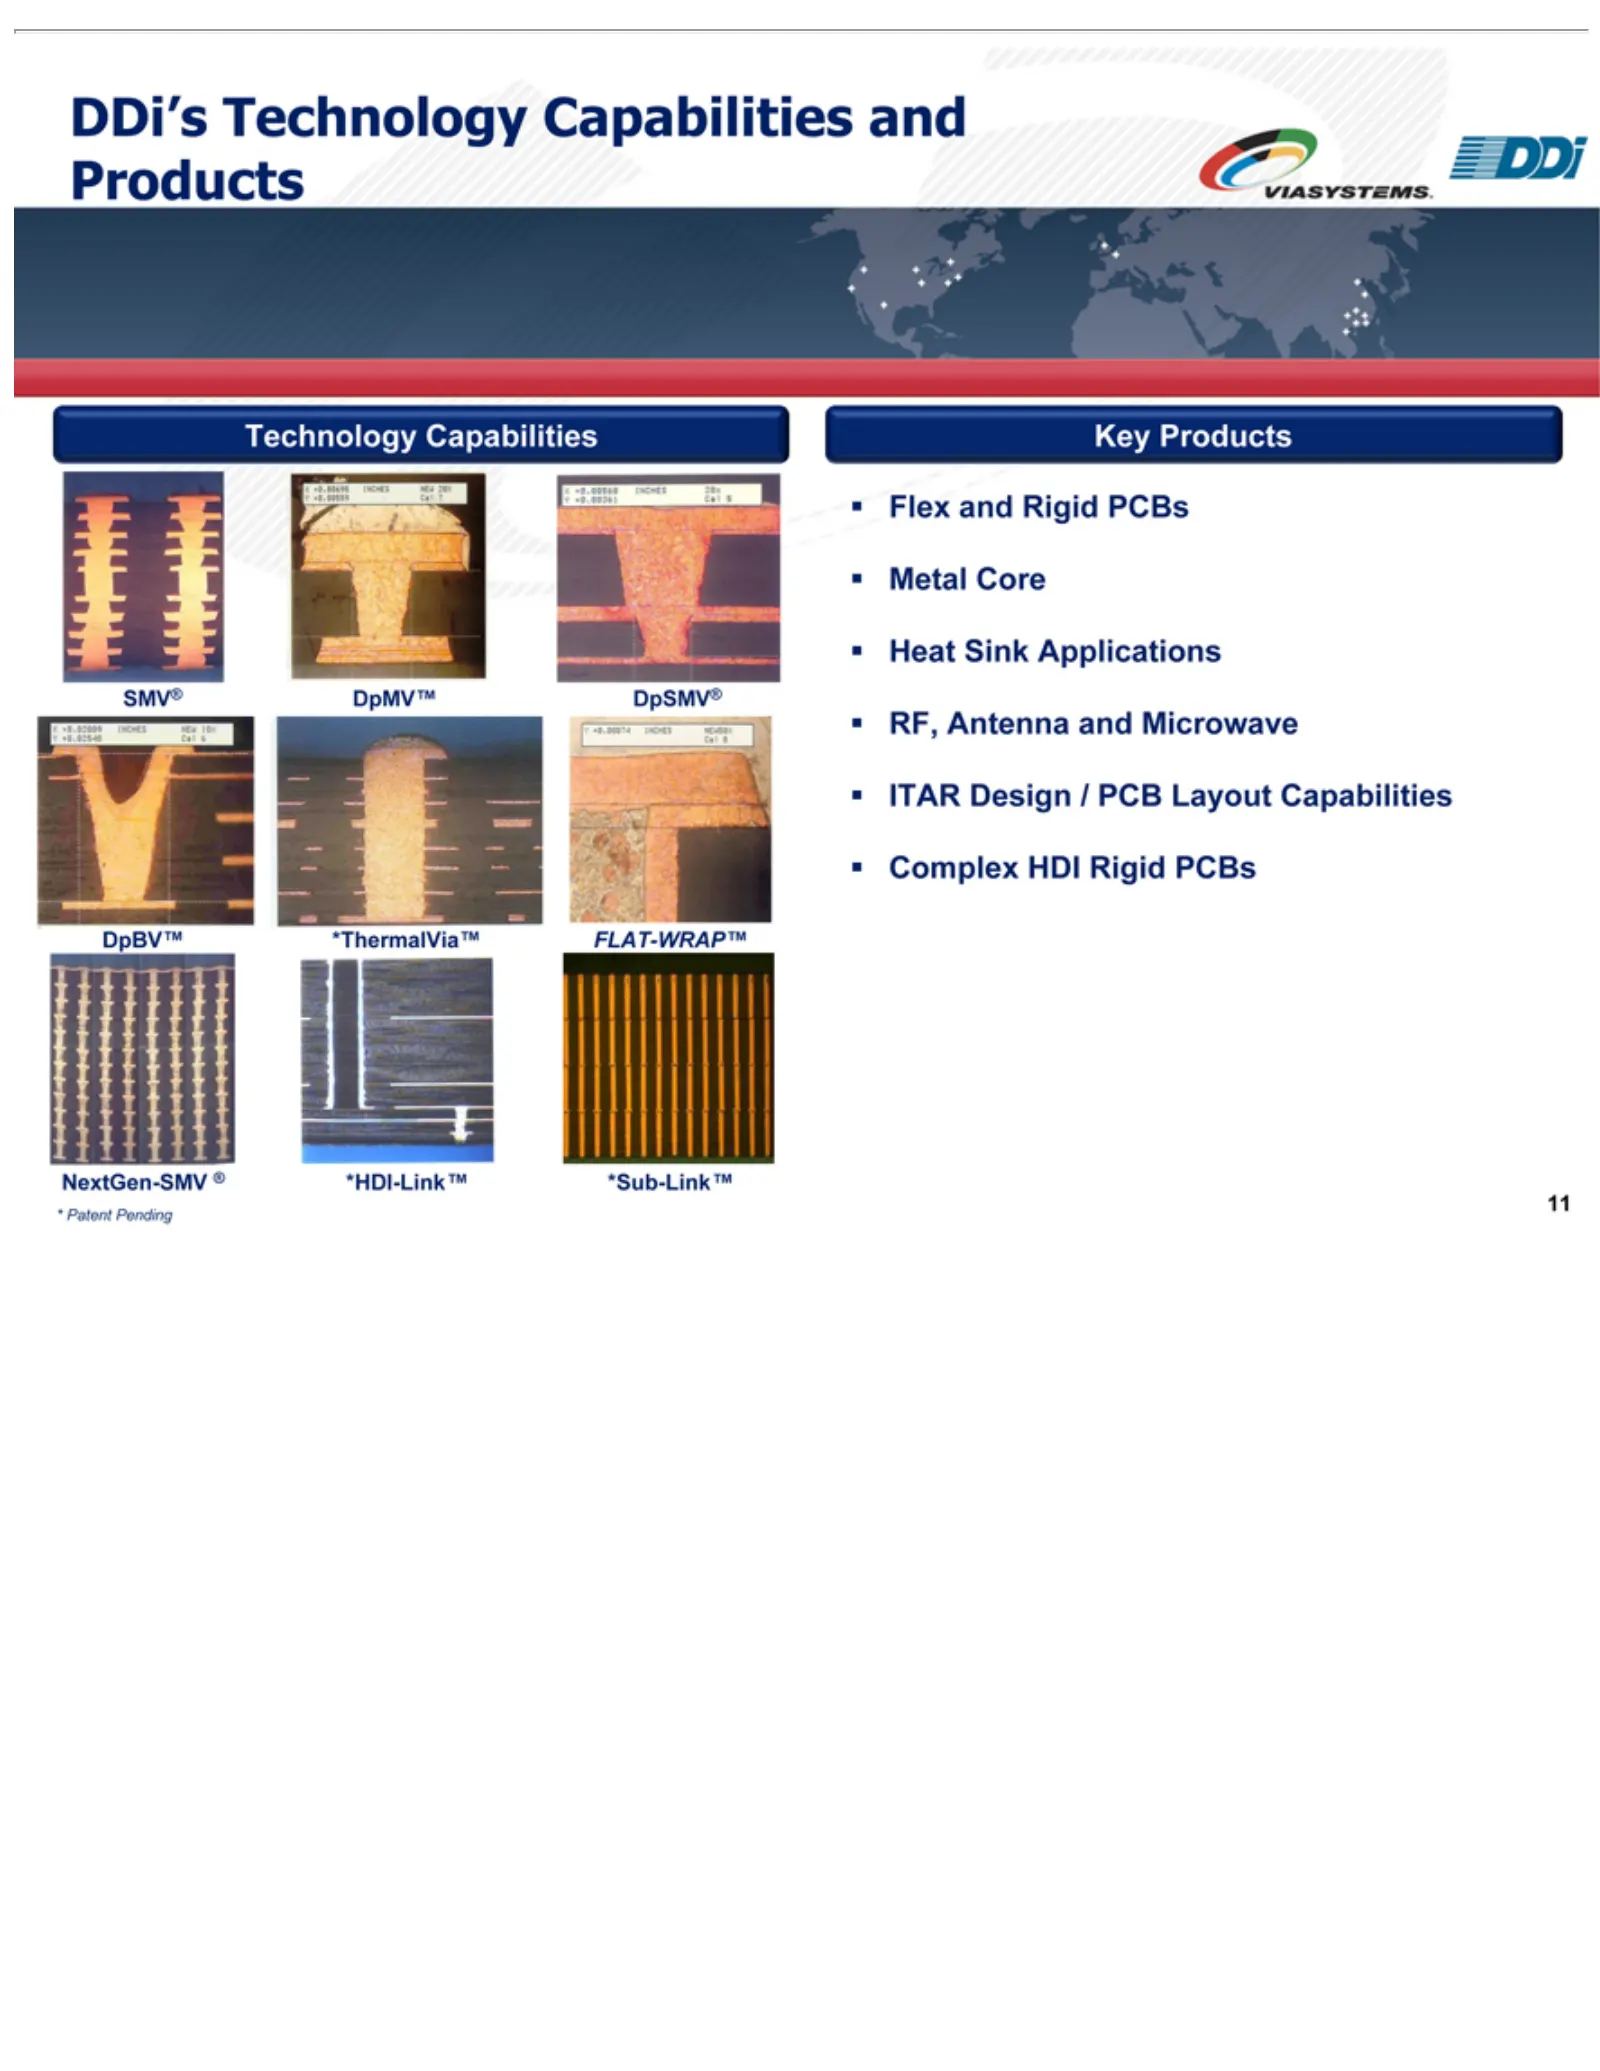
Slide 11: DDi's Technology and Key Products
DDi’s Technology SMV® DpBV™ *NextGen-SMV Key Flex ITAR Complex 11Patent Products and Design Technology DpMV™ Pending Rigid *ThermalVia™ HDI Capabilities / Rigid PCB PCBs ® DpSMV® *HDI-Link™ Capabilities Layout PCBs Metal FLAT-WRAP™ Core Capabilities and *Sub-Link™ Heat Products Sink Applications RF,
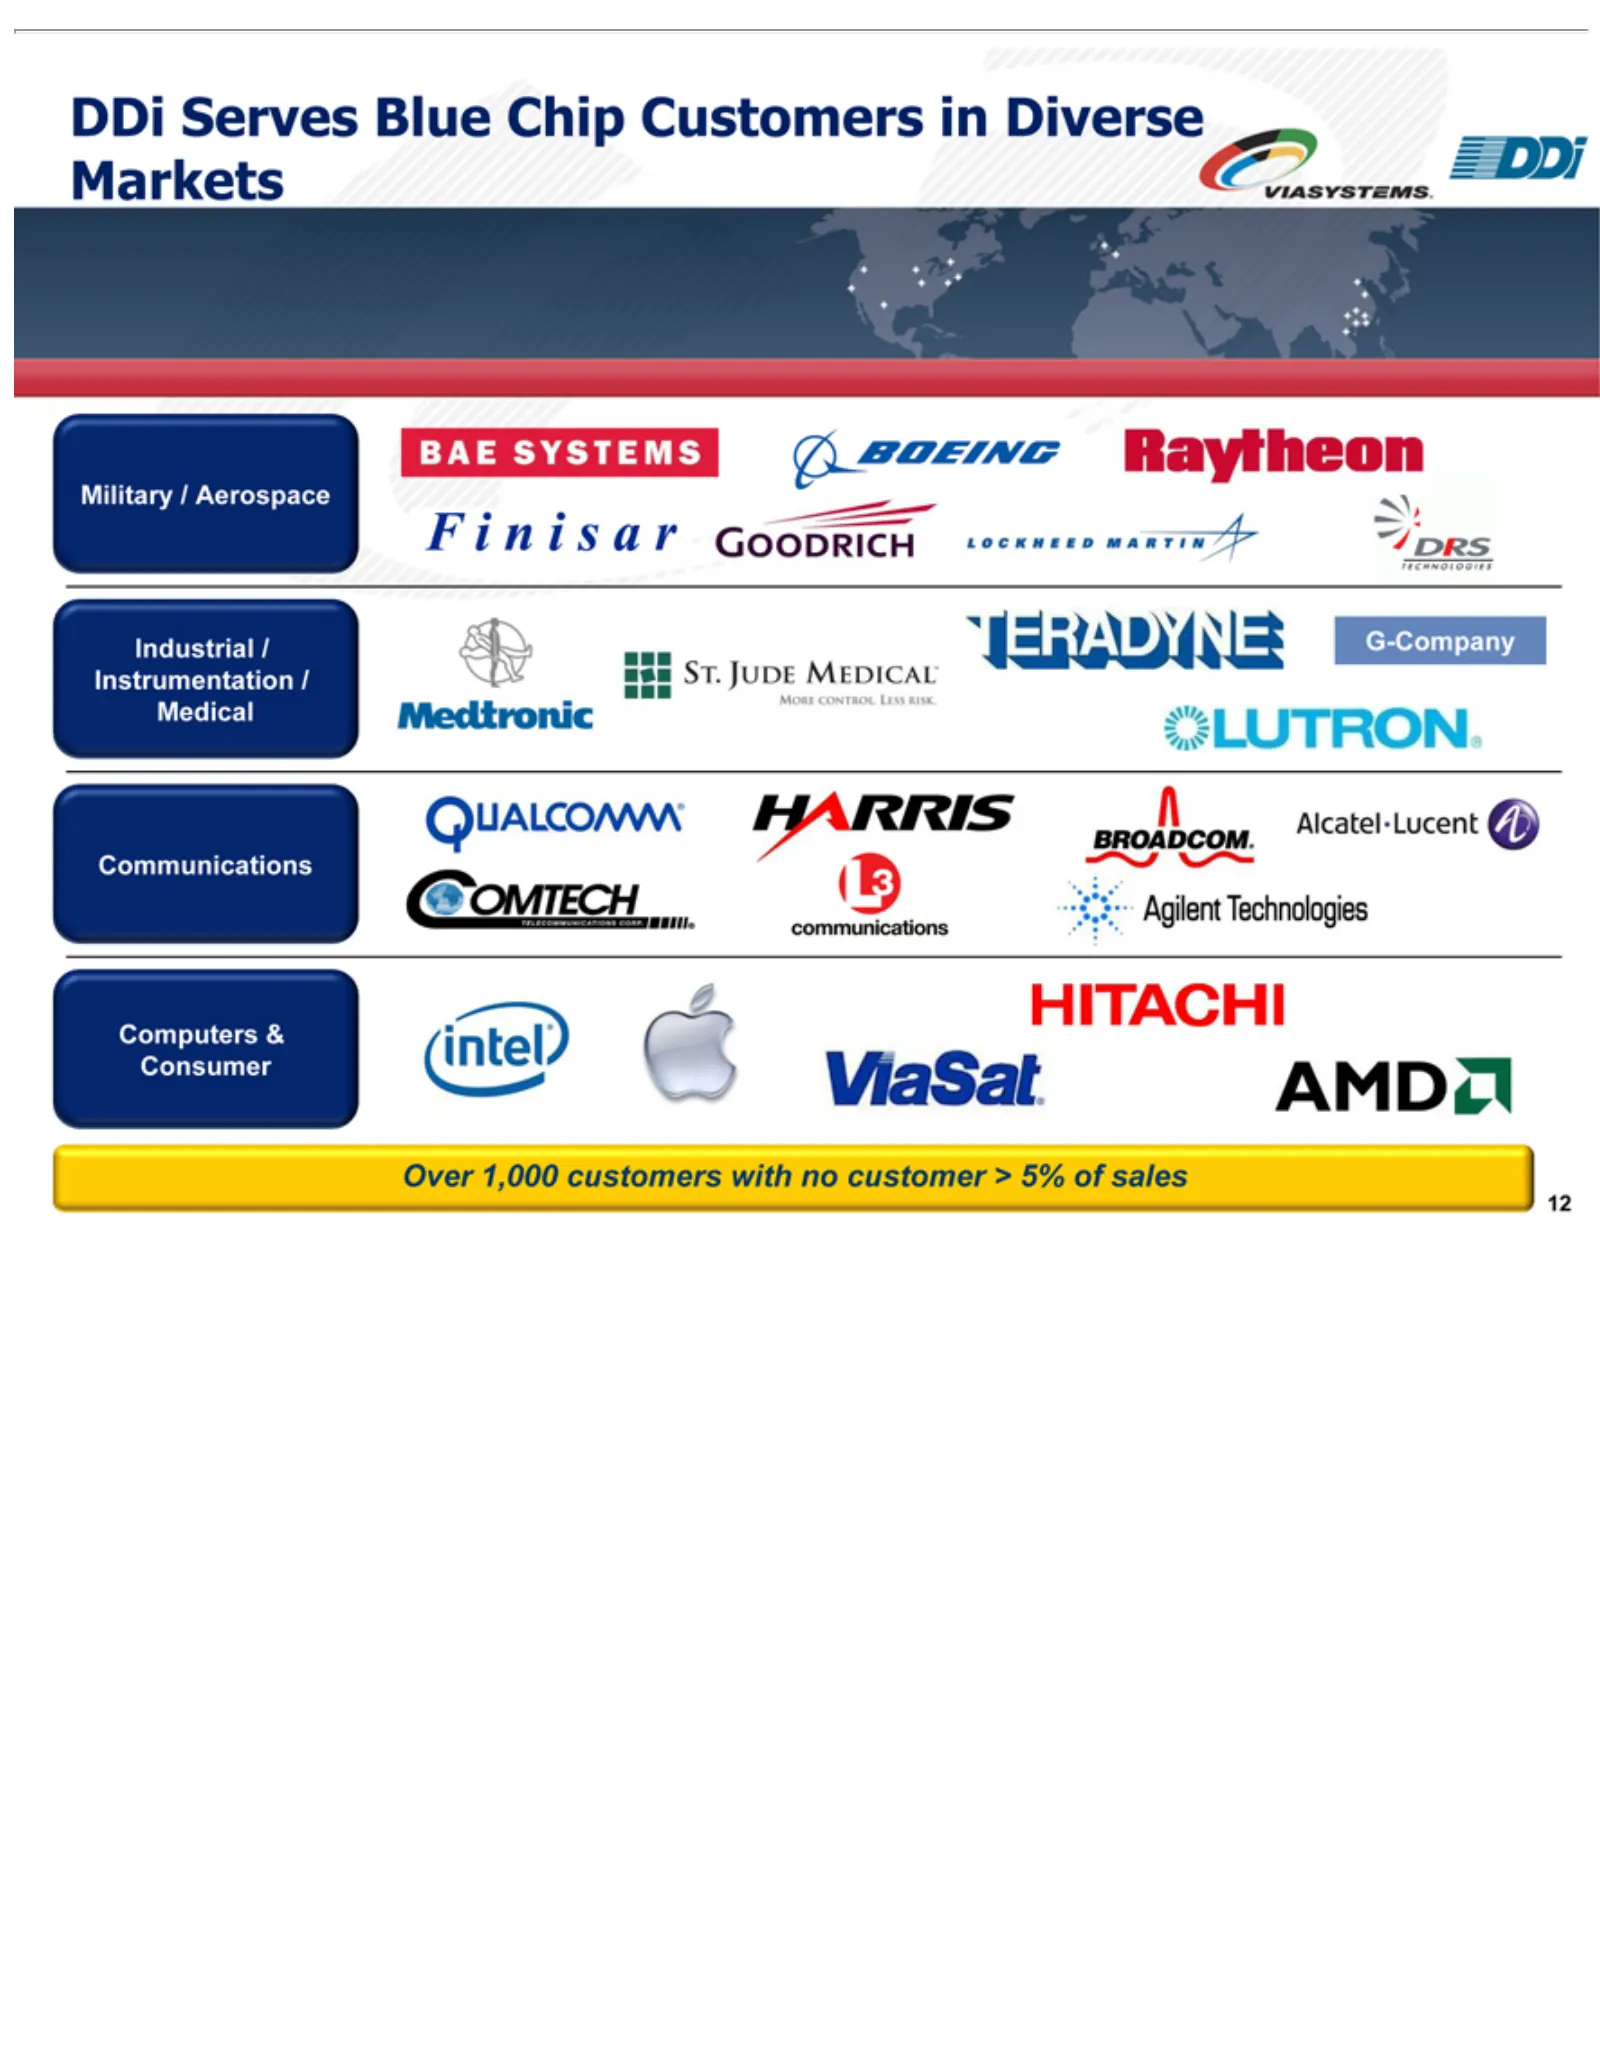
Slide 12: DDi Serves Diverse End Markets
DDi Serves Military Industrial Computers Communications Over 12 1,000 / Aerospace / Instrumentation & customers Blue Consumer Chip with Customers no / Medical customer in Diverse > 5%Markets of sales
Slide 13: II. Investment Highlights
C....... Di ll. Investment Highlights
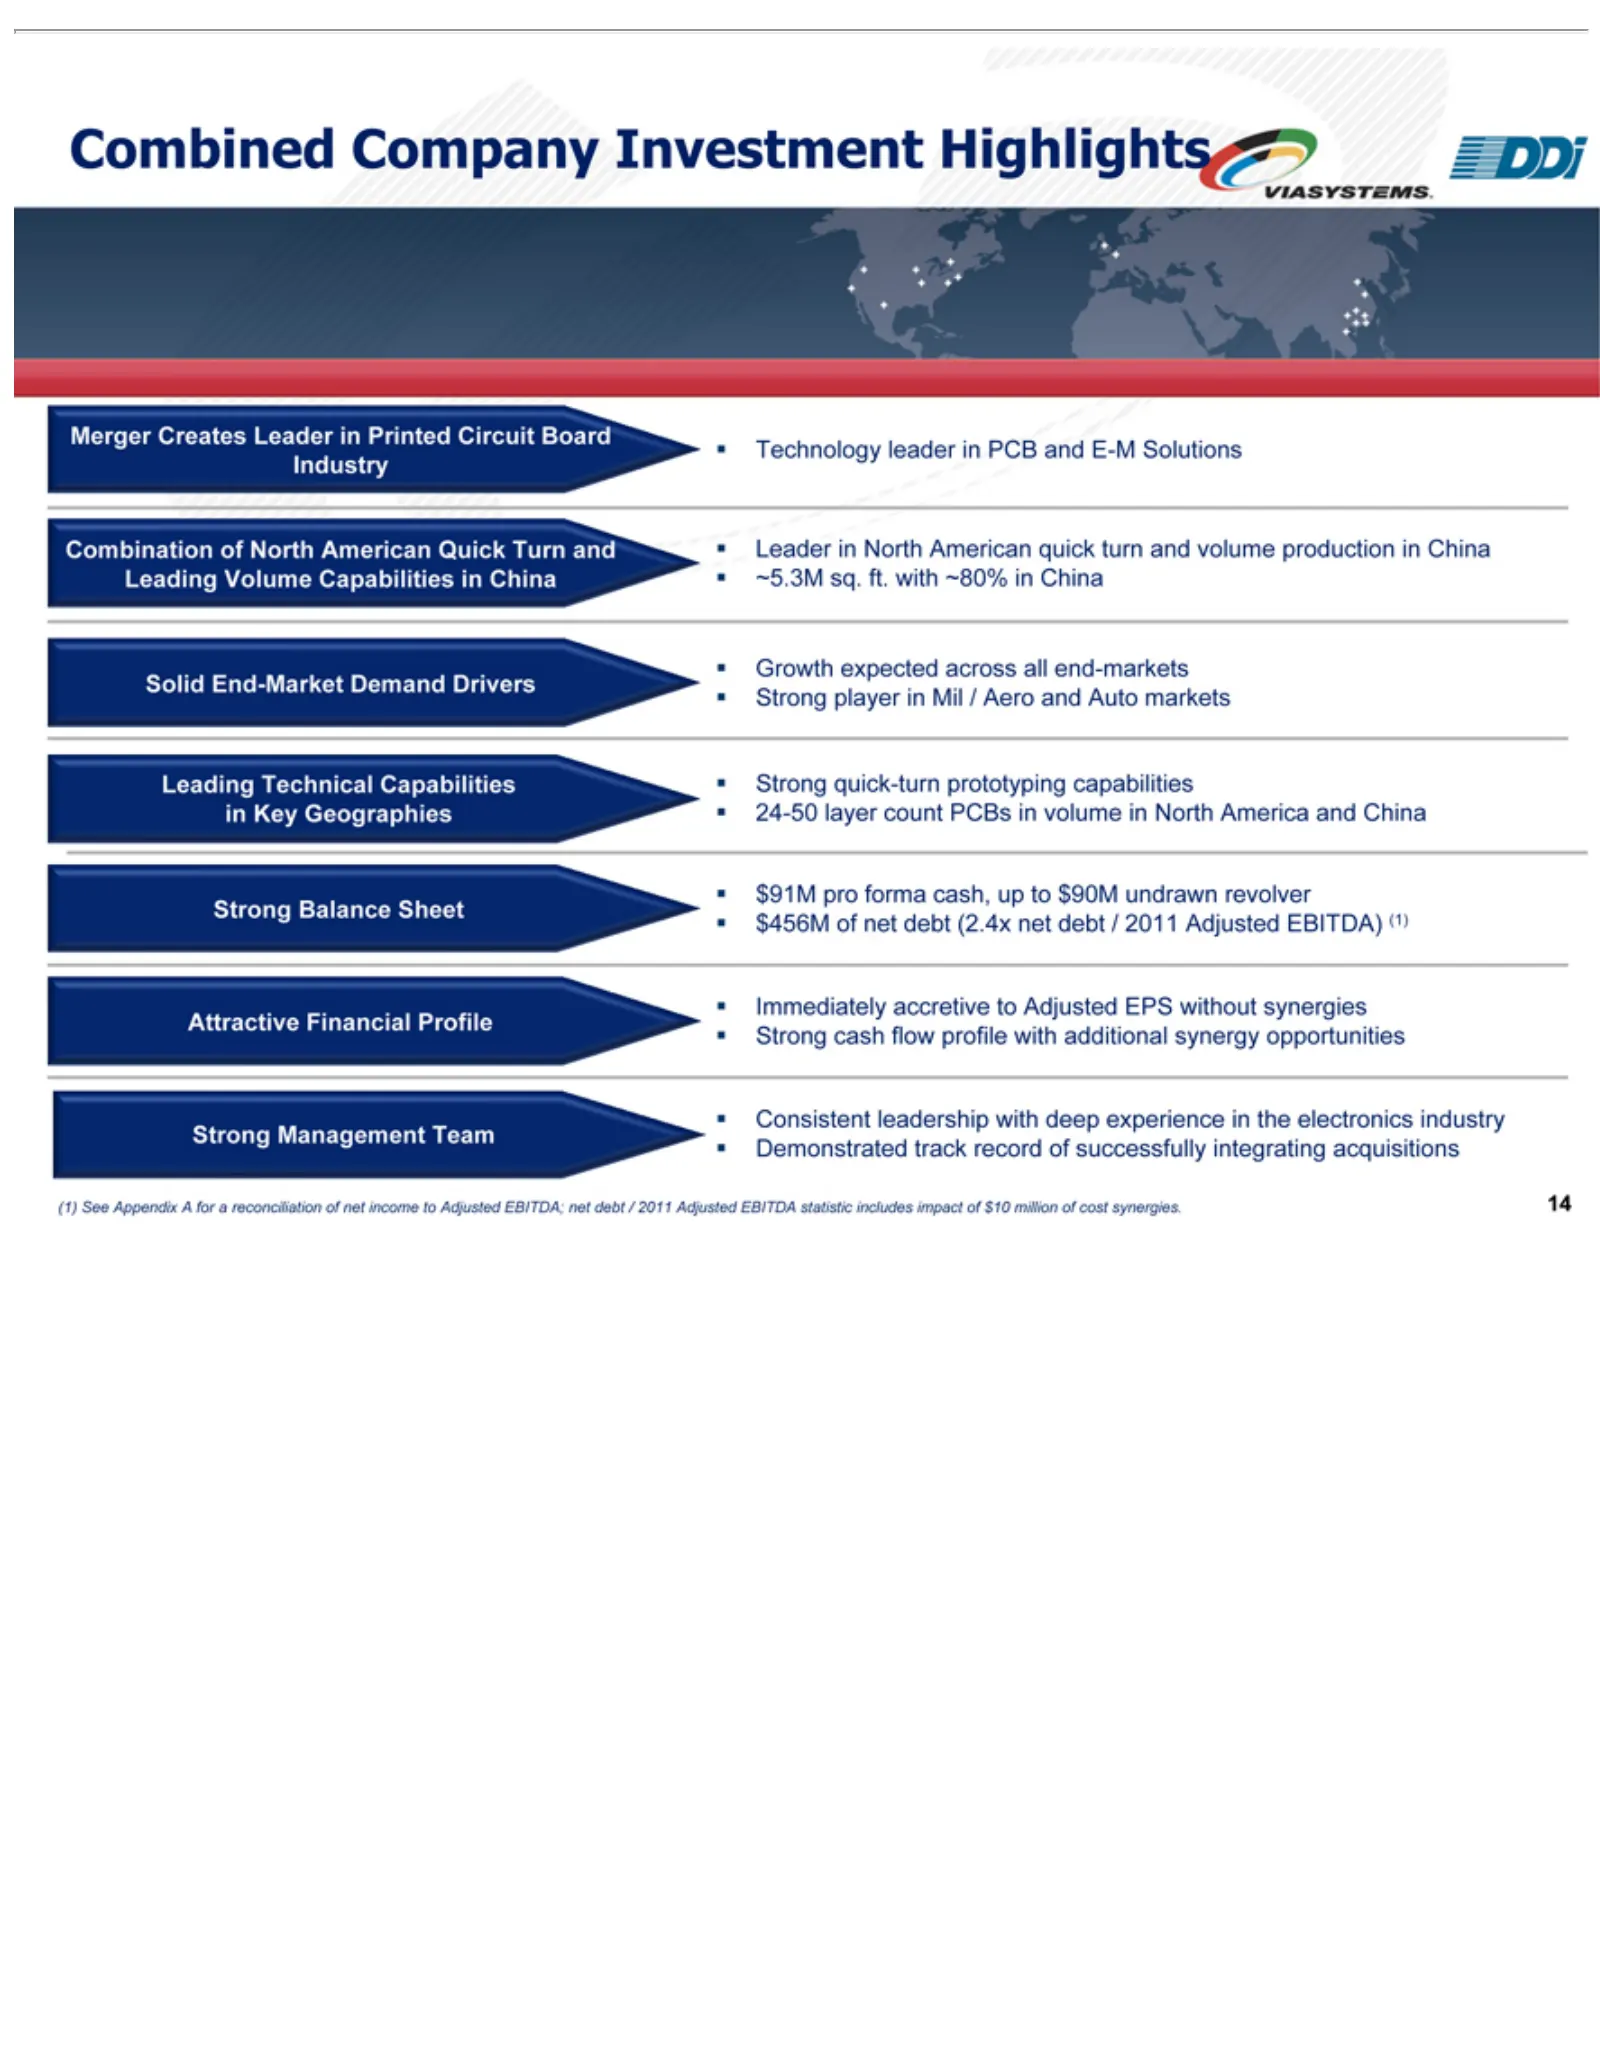
Slide 14: Combined Company Investment Highlights
Combined Merger Combination Solid Leading Technology Leader ~5.3M Growth Strong 24-50 $91M Immediately Consistent (1) 14 SeeEnd-Market layer pro Balance quick-turn sq. in Appendix Creates expected Technical North forma ft. Company leadership count leader accretive with of Sheet Leader North American
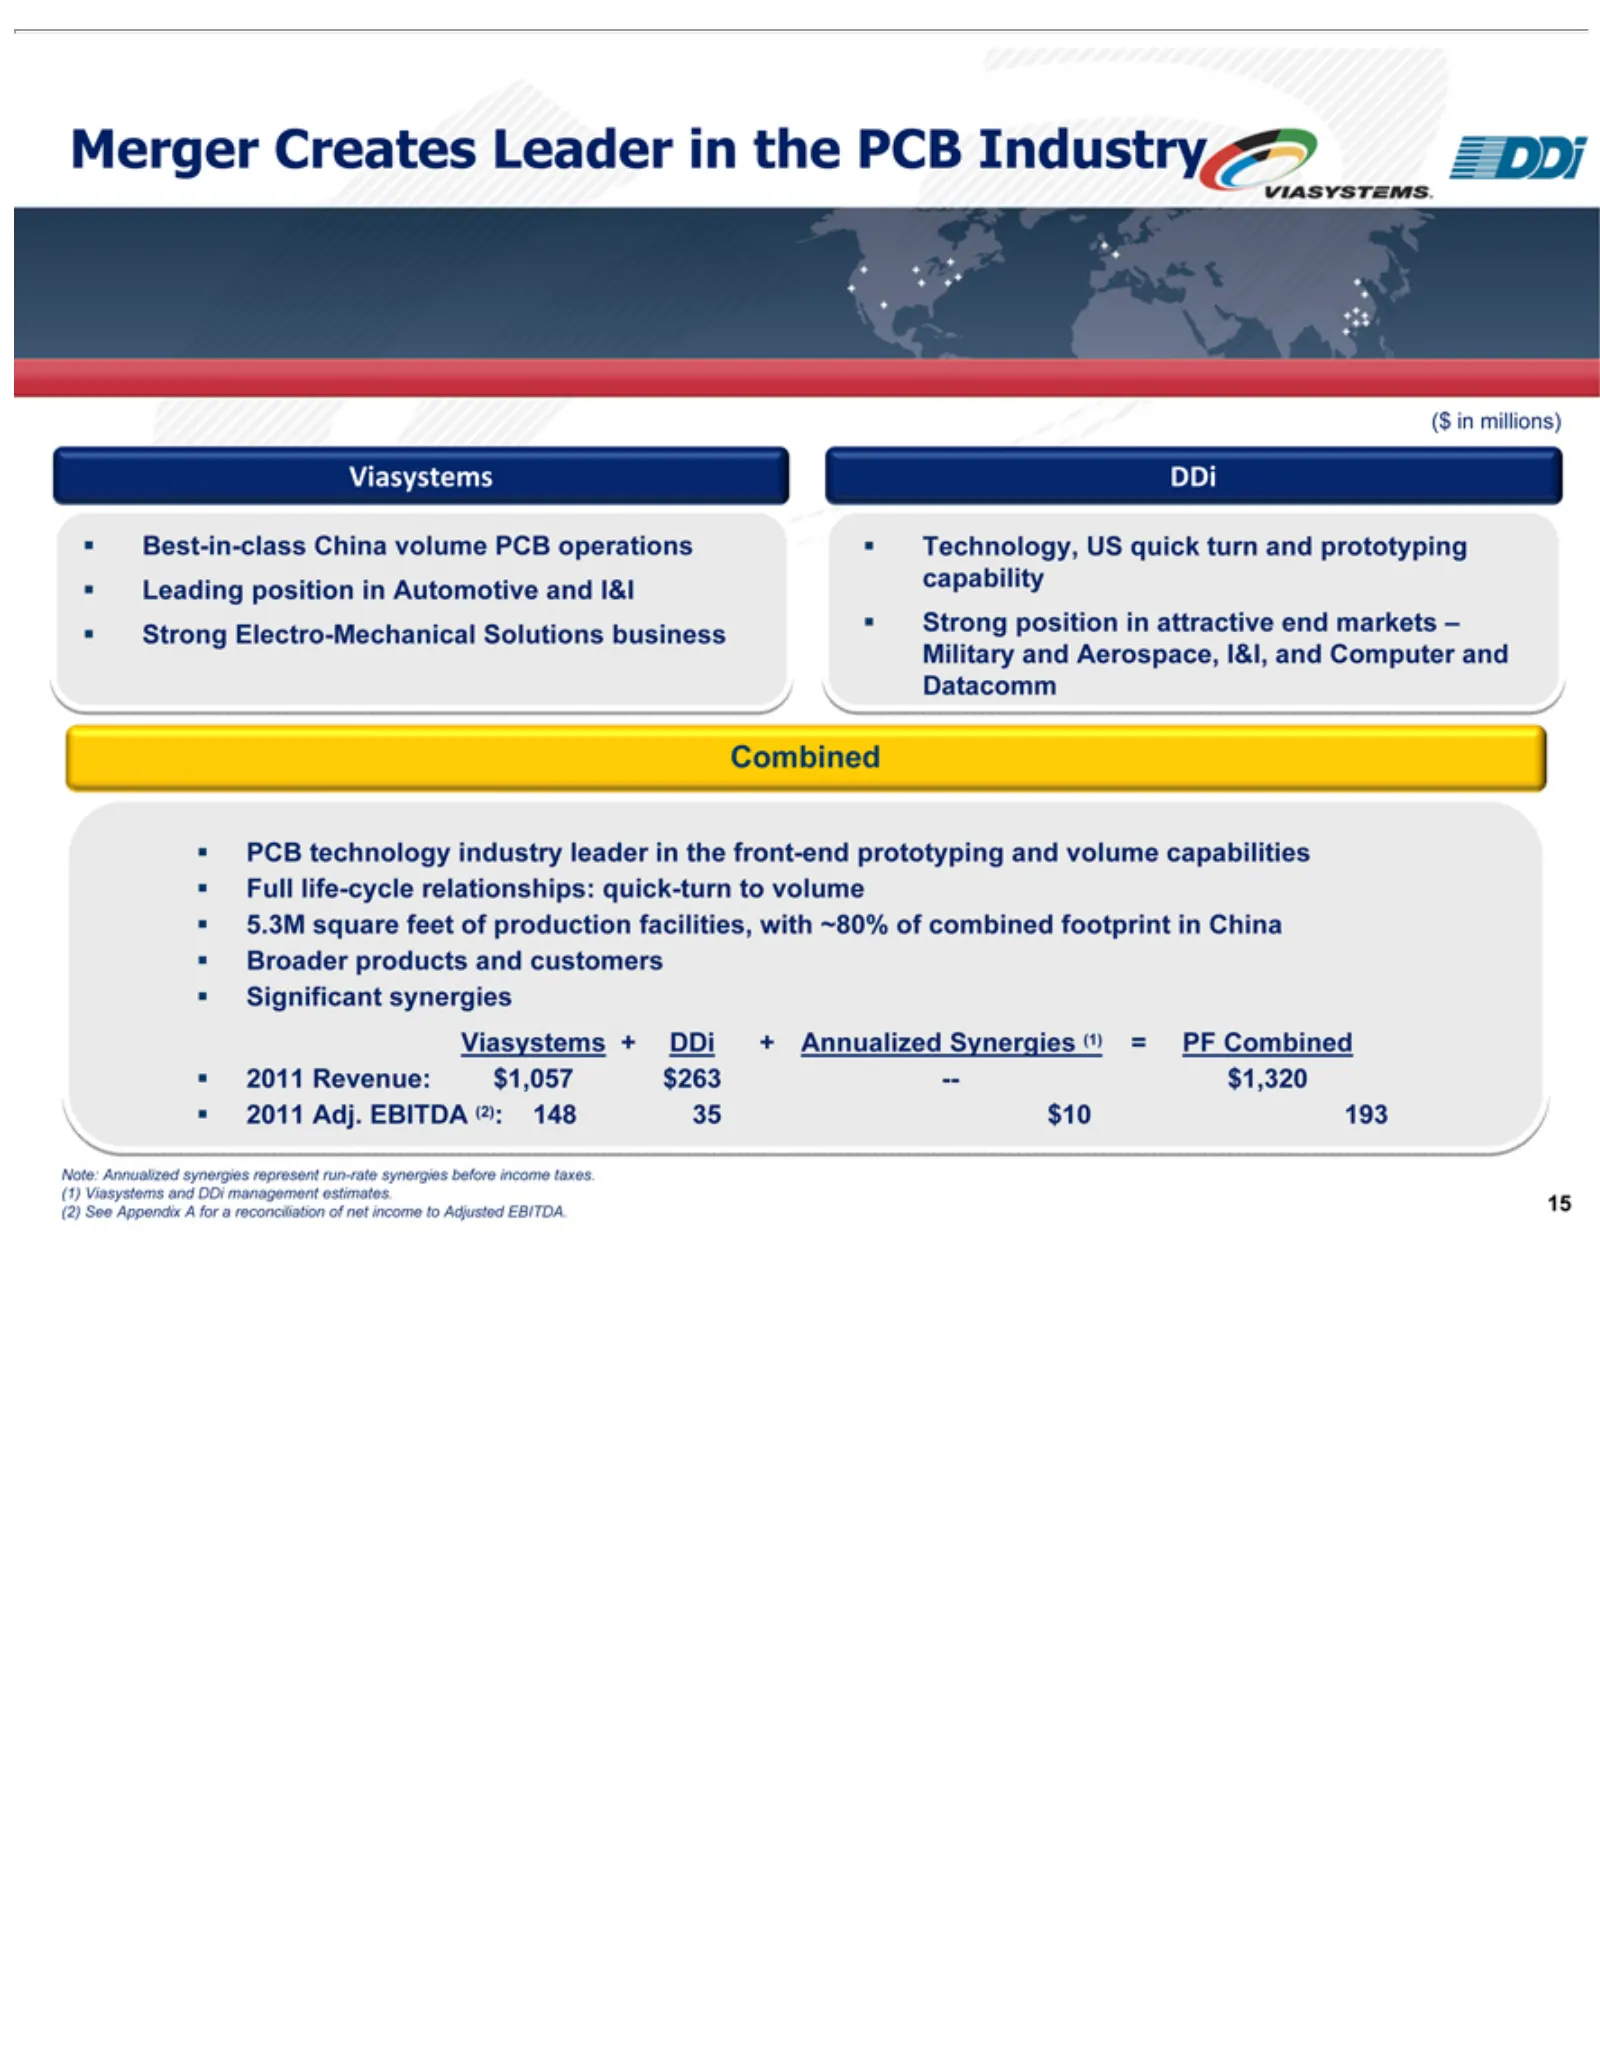
Slide 15: Merger Creates Leader in Quick-turn and Volume PCB
Merger Best-in-class Technology, DDi PCB Combined China Viasystems 2011 Note: (2) 15 See technology Adj. Revenue: Annualized Broader Appendix Creates EBITDA +US China DDi products $1,057 Leader quick industry A synergies +(2): volume for Annualized turn $263 in a148 and reconciliation leader the and
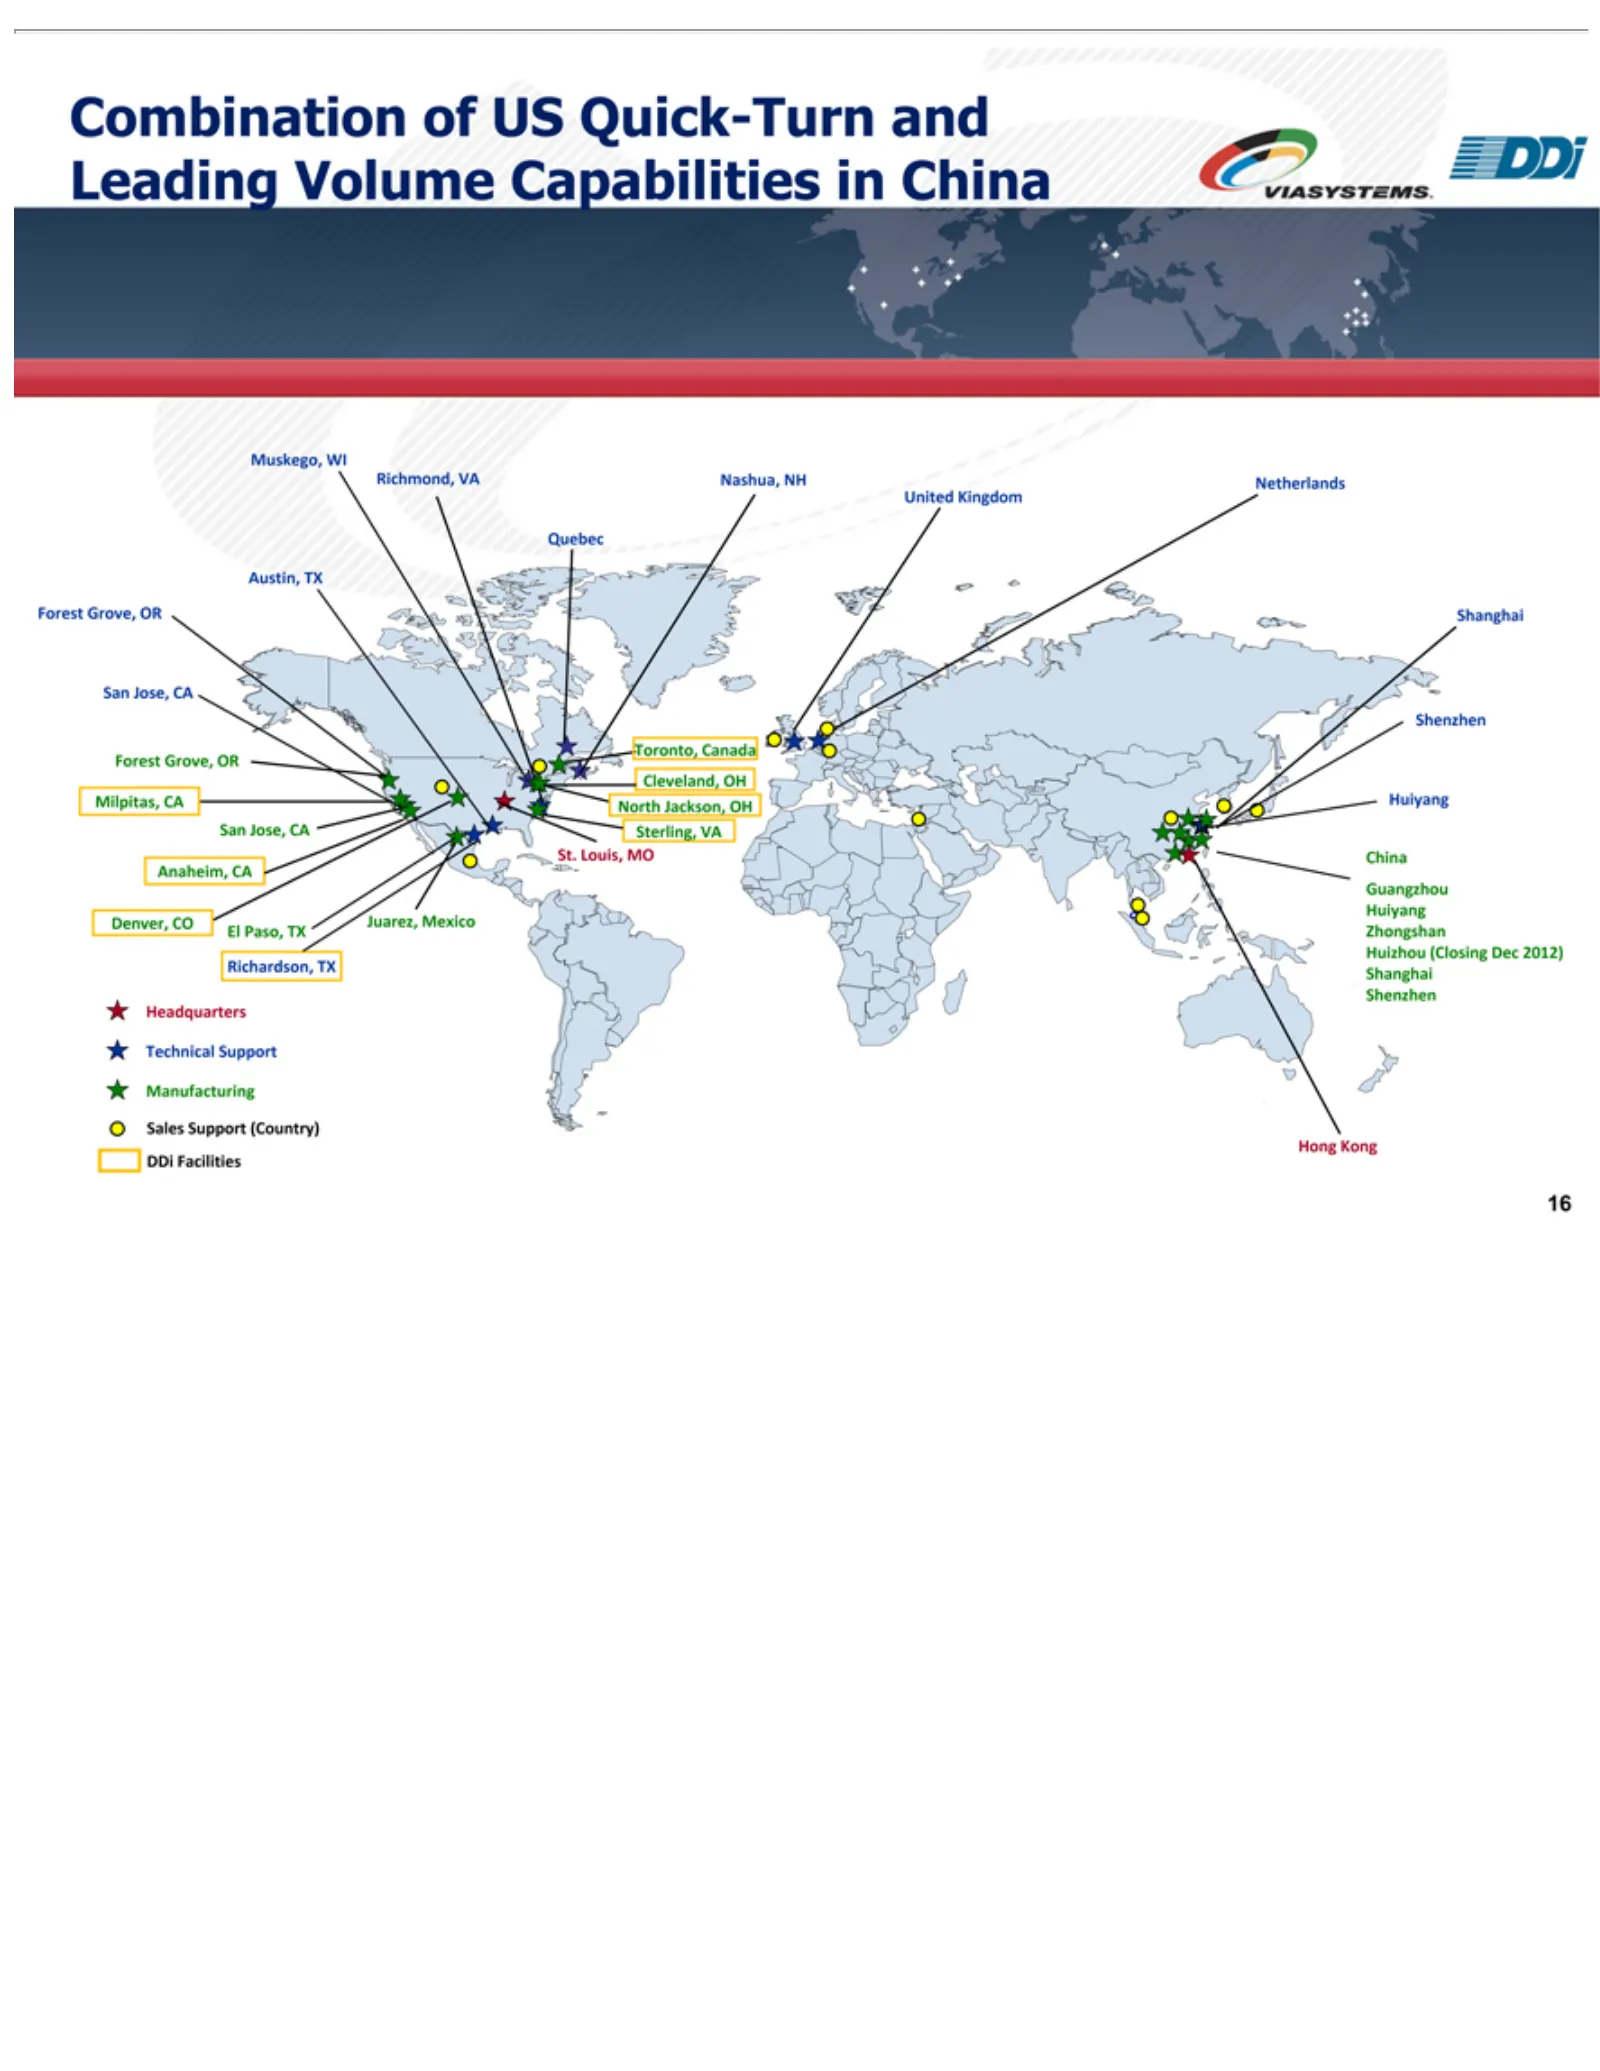
Slide 16: Combination Creates Leading Footprint
Combination Muskego, Richmond, Nashua, Quebec United China Huiyang Shenzhen Shanghai Netherlands Huizhou Toronto, North St. Austin, Forest Milpitas, San Anaheim, Denver, El Richardson, Juarez, Headquarters Sales Hong 16 Paso, Louis, Jose, Support Kong Jackson, Guangzhou Grove, Kingdom Mexico TX CO N
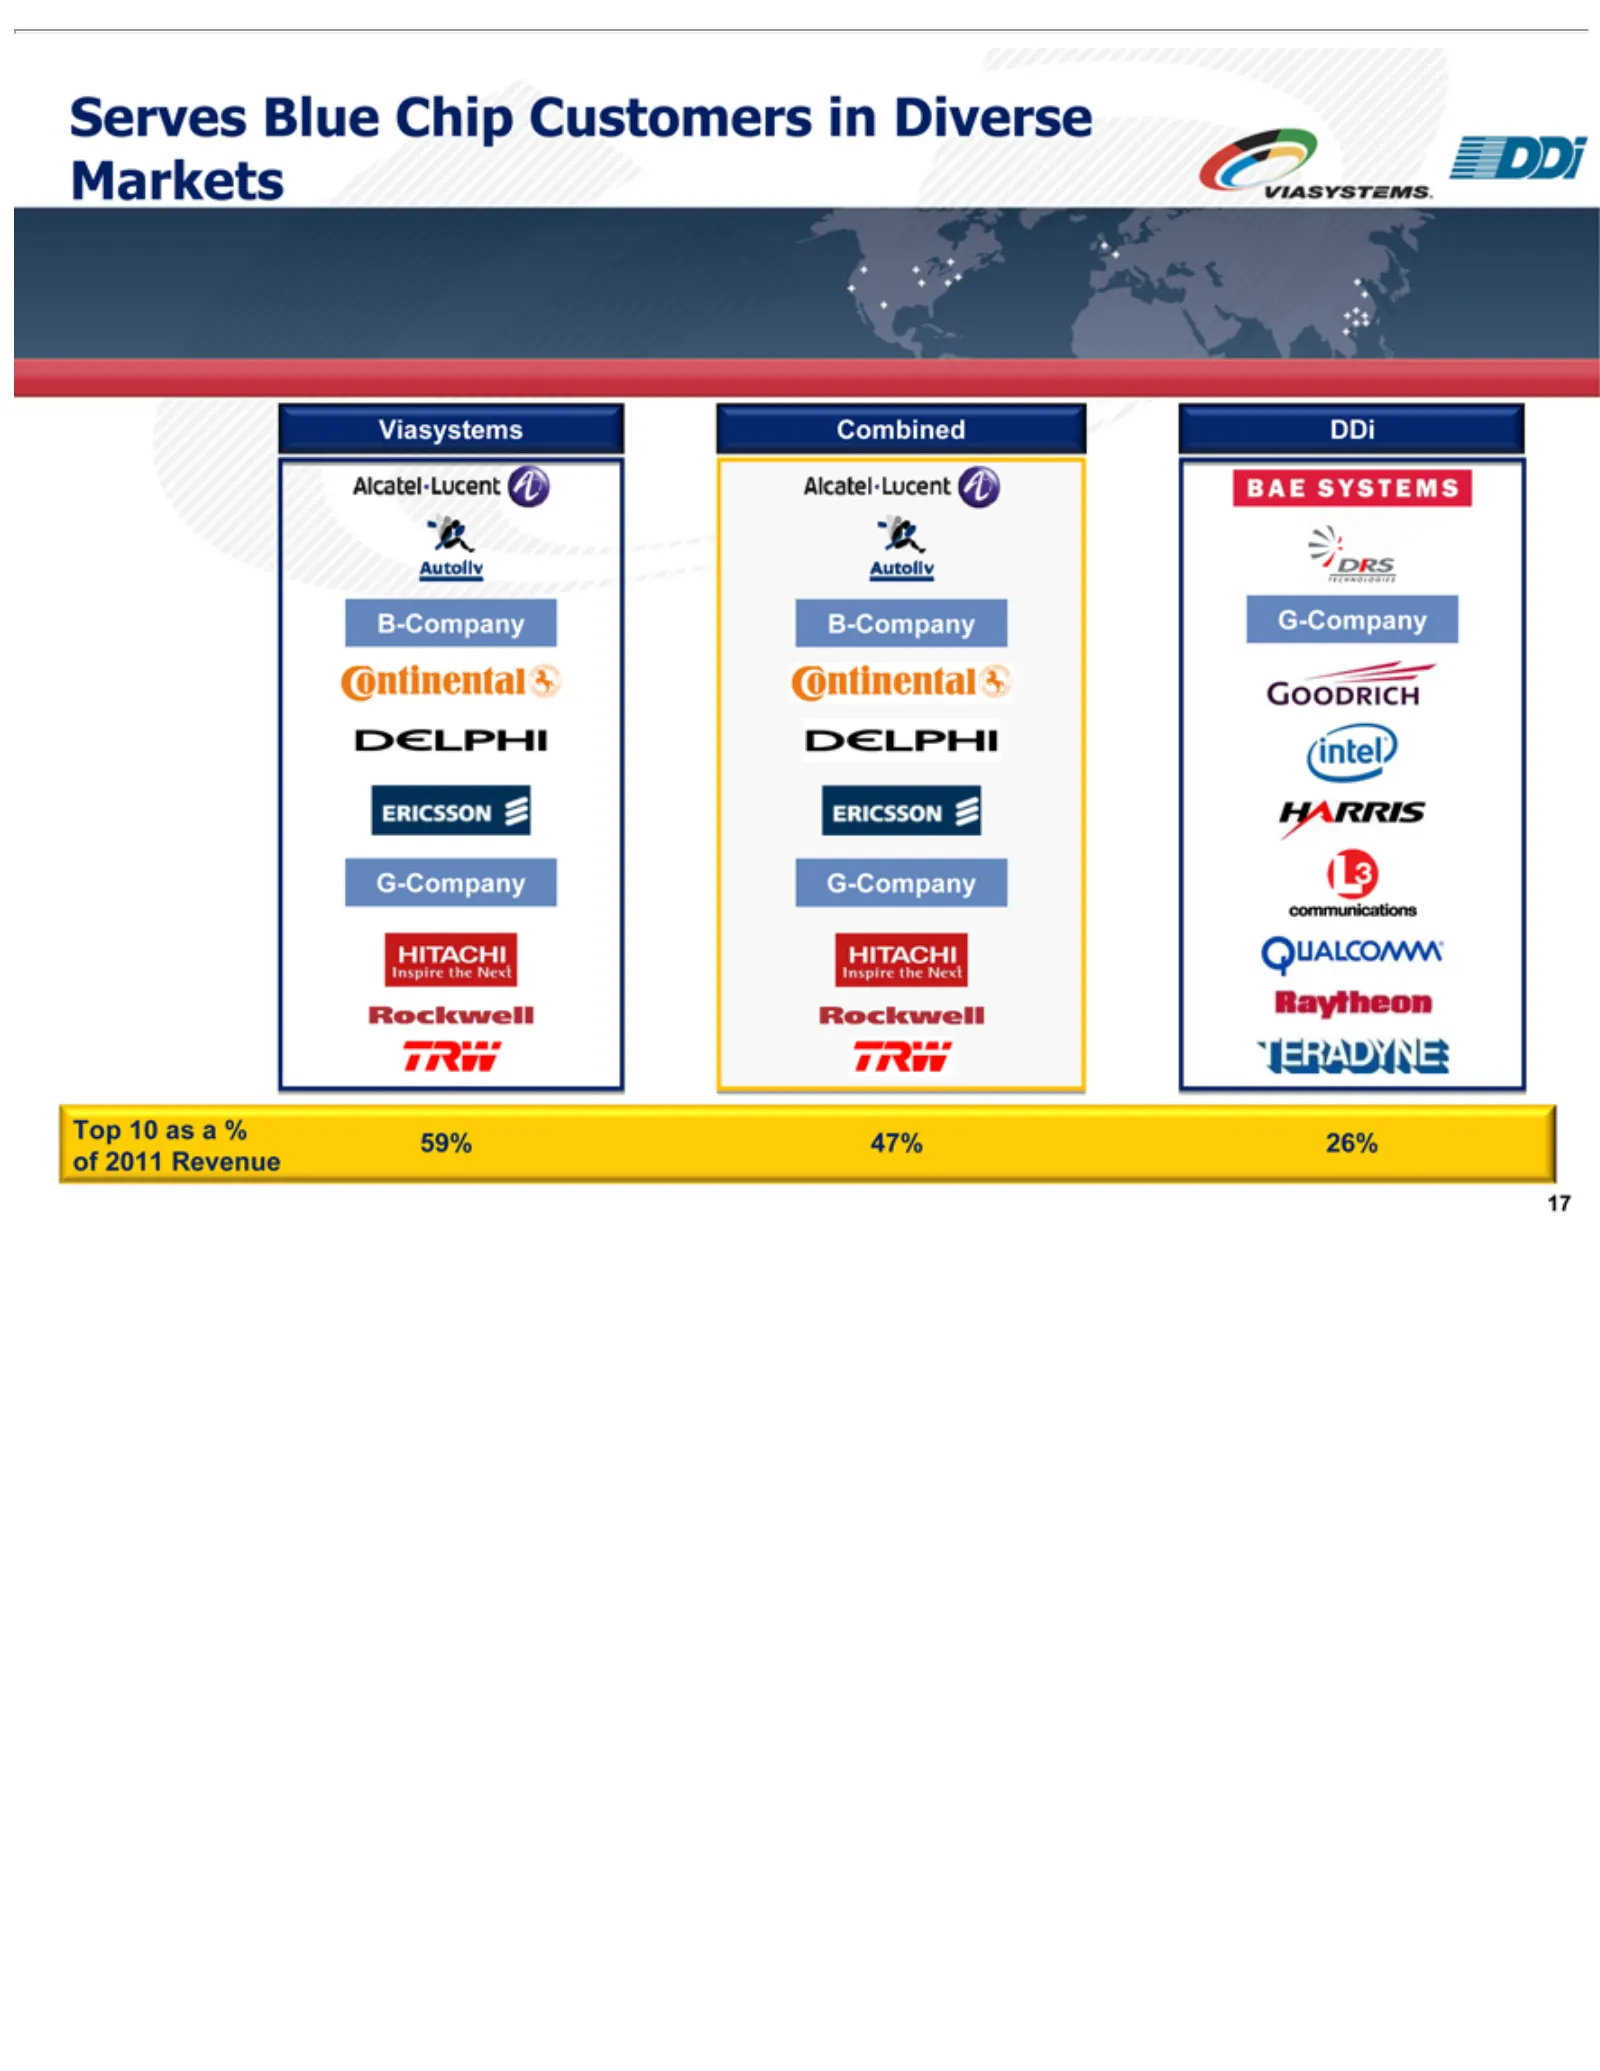
Slide 17: Combined Company Serves Top Customers
Serves Top DDi Combined Viasystems 59% 17 10 47% Blue as a26% %Chip of Customers 2011 Revenue in Diverse Markets
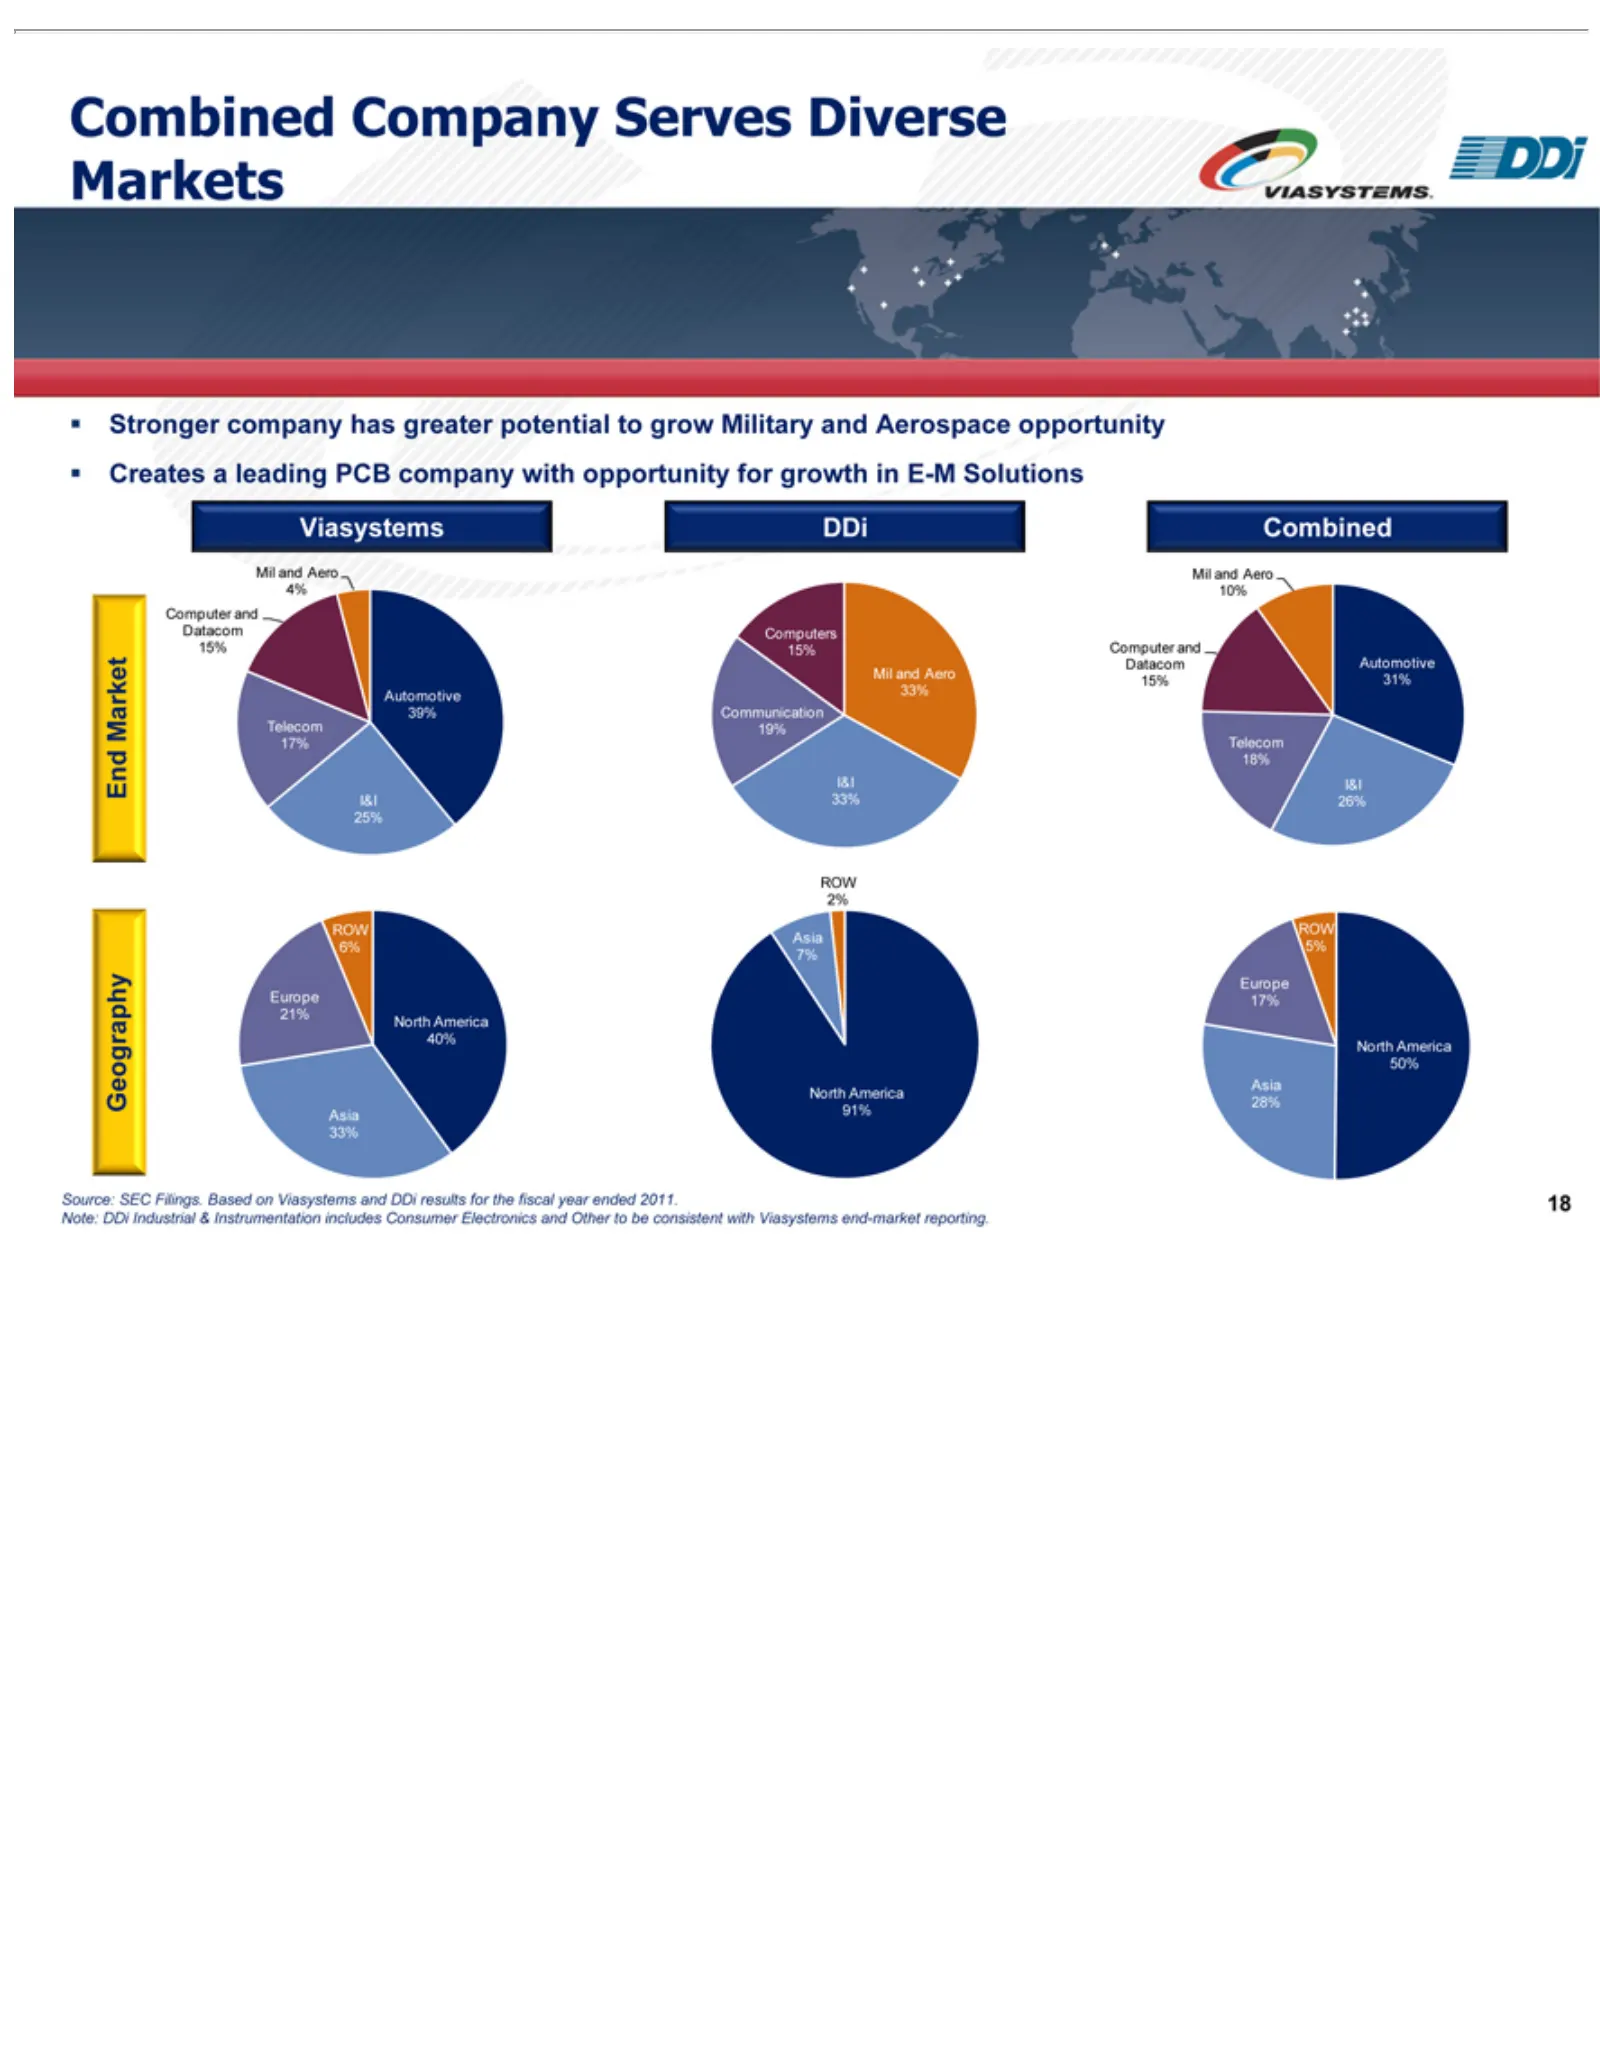
Slide 18: Stronger Combined End-Market Opportunity
Stronger Combined DDi Viasystems Automotive Computers Mil Computer Datacom Telecom I&I End Geography Asia ROW Europe North Source: Note: 18 25% 33% 26% and Market 33% 7% DDi America 6% 2% 5%21% 17% SEC Aero 18% company Automotive and Company Industrial 15% Telecom Filings. 4% 33% 10% 40% 91% 50%Comp
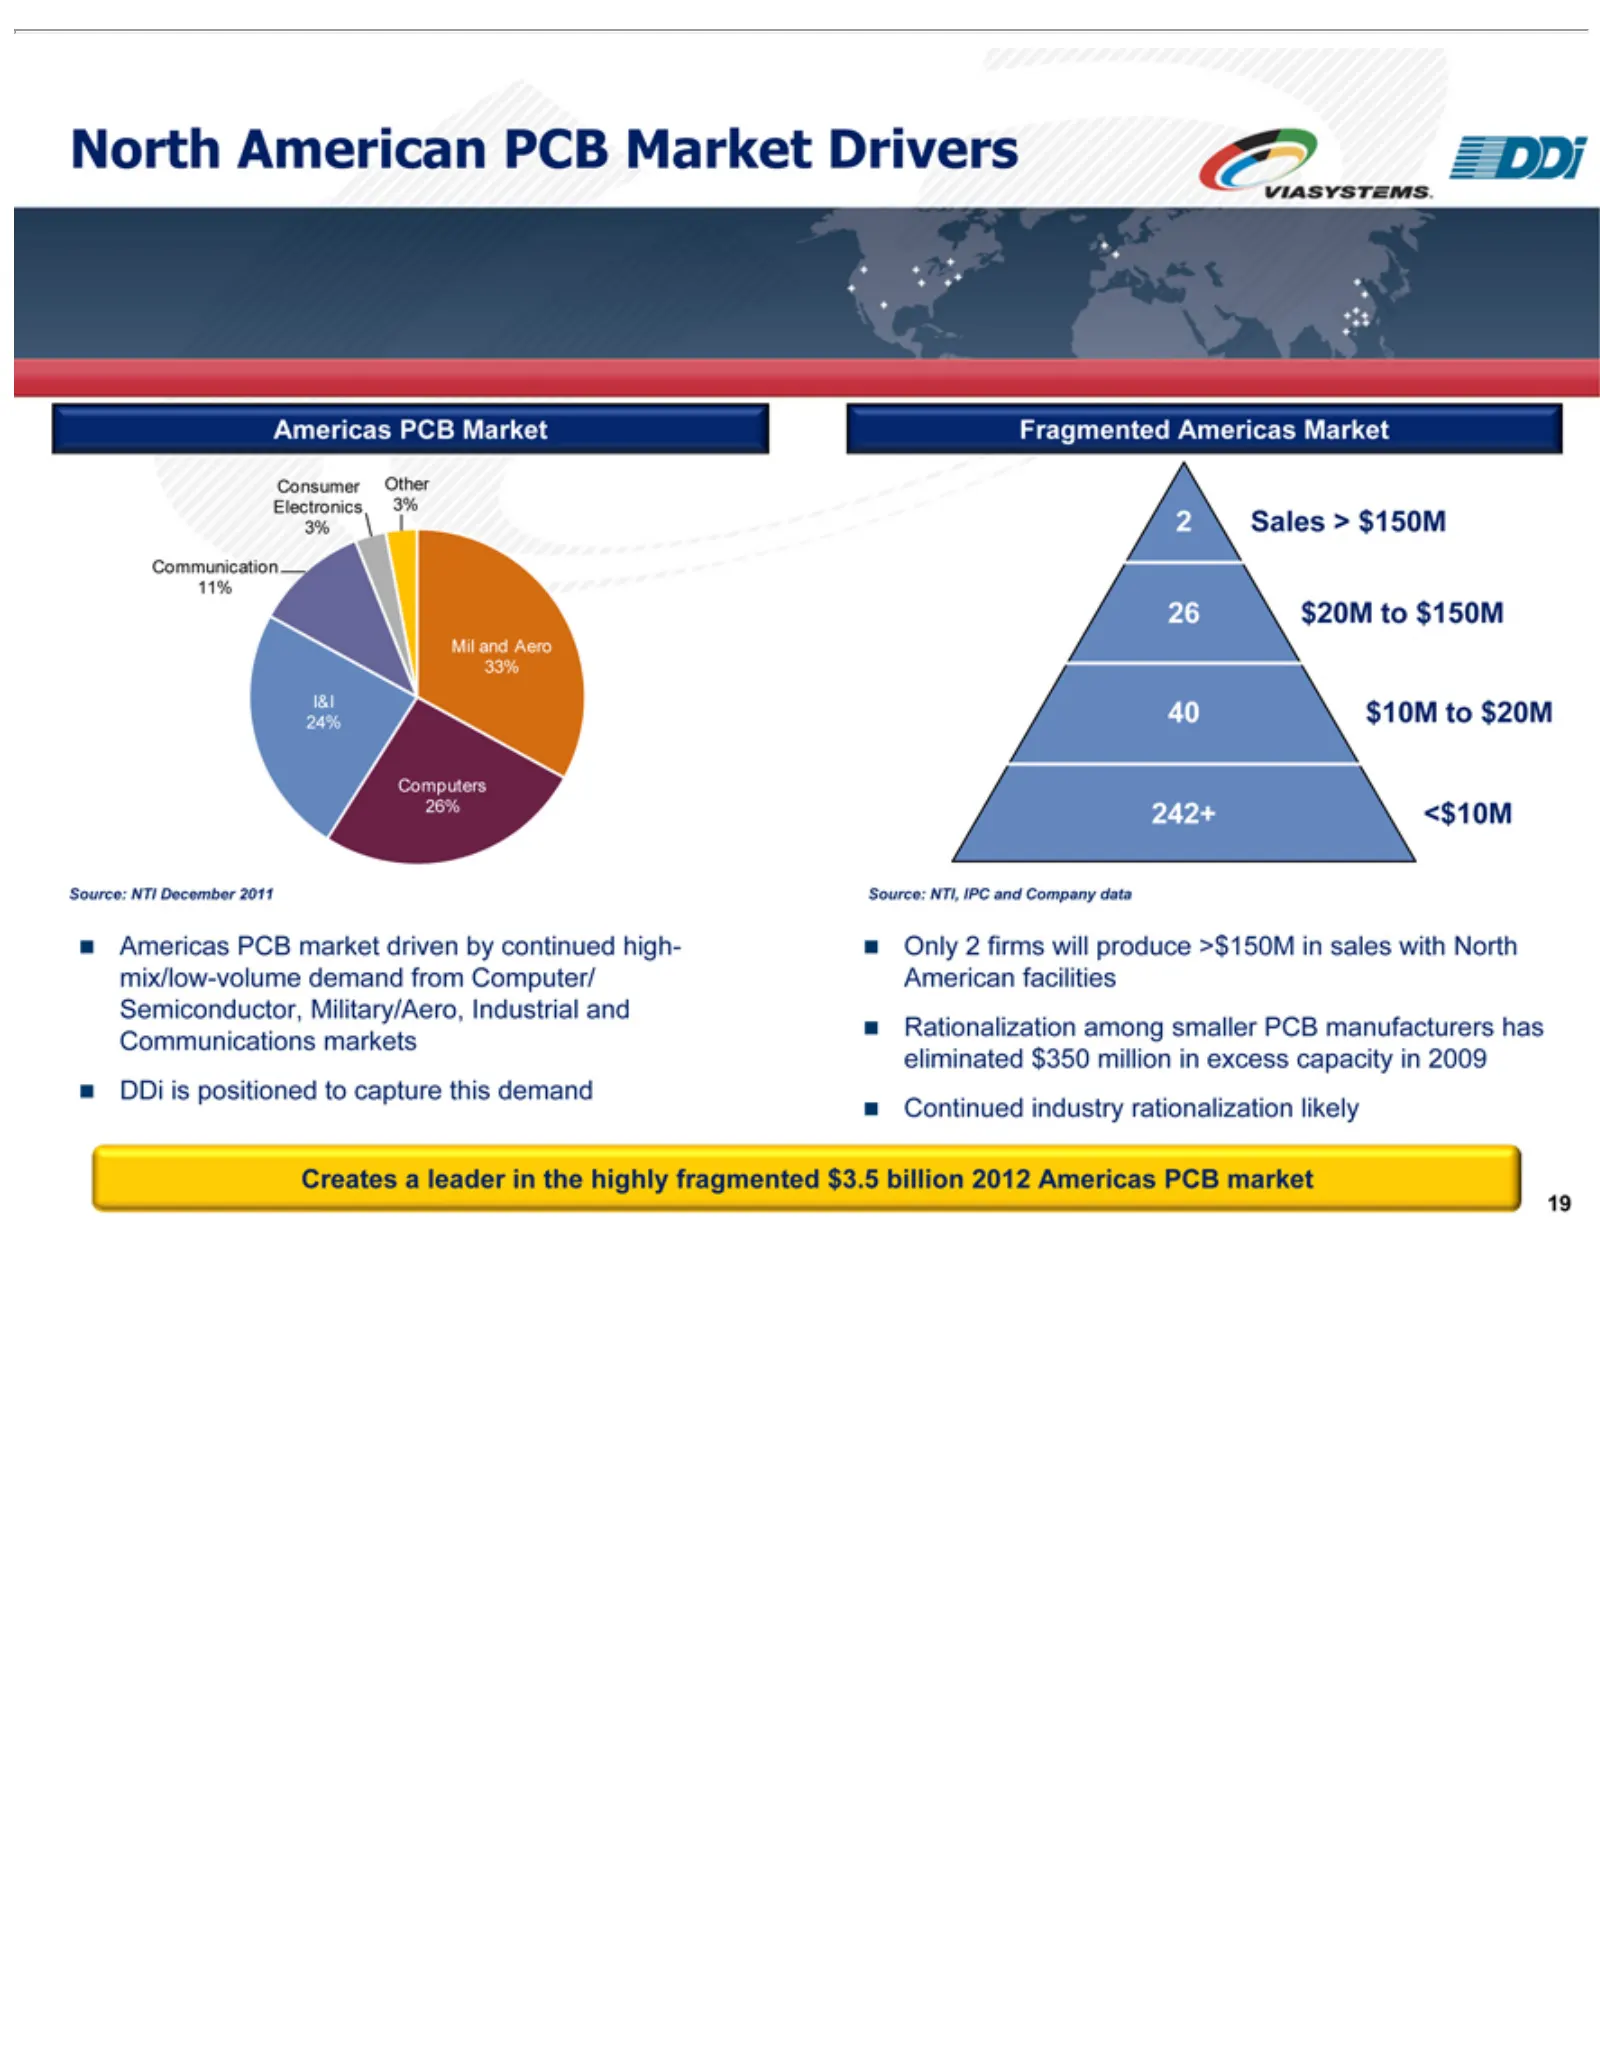
Slide 19: North American PCB Market Drivers
North Consumer Communication Mil Computers 24% 2Fragmented 26 40 242+ Americas DDi Source: Only Rationalization Continued Creates 19Sales $20M $10M and is2<$10M American positioned firms >aNTI, NTI Aero to $150M leader PCB Other industry 26% $150M $20M Americas December will IPC 33% Market market am
Slide 20: Military/Aerospace Market Opportunity
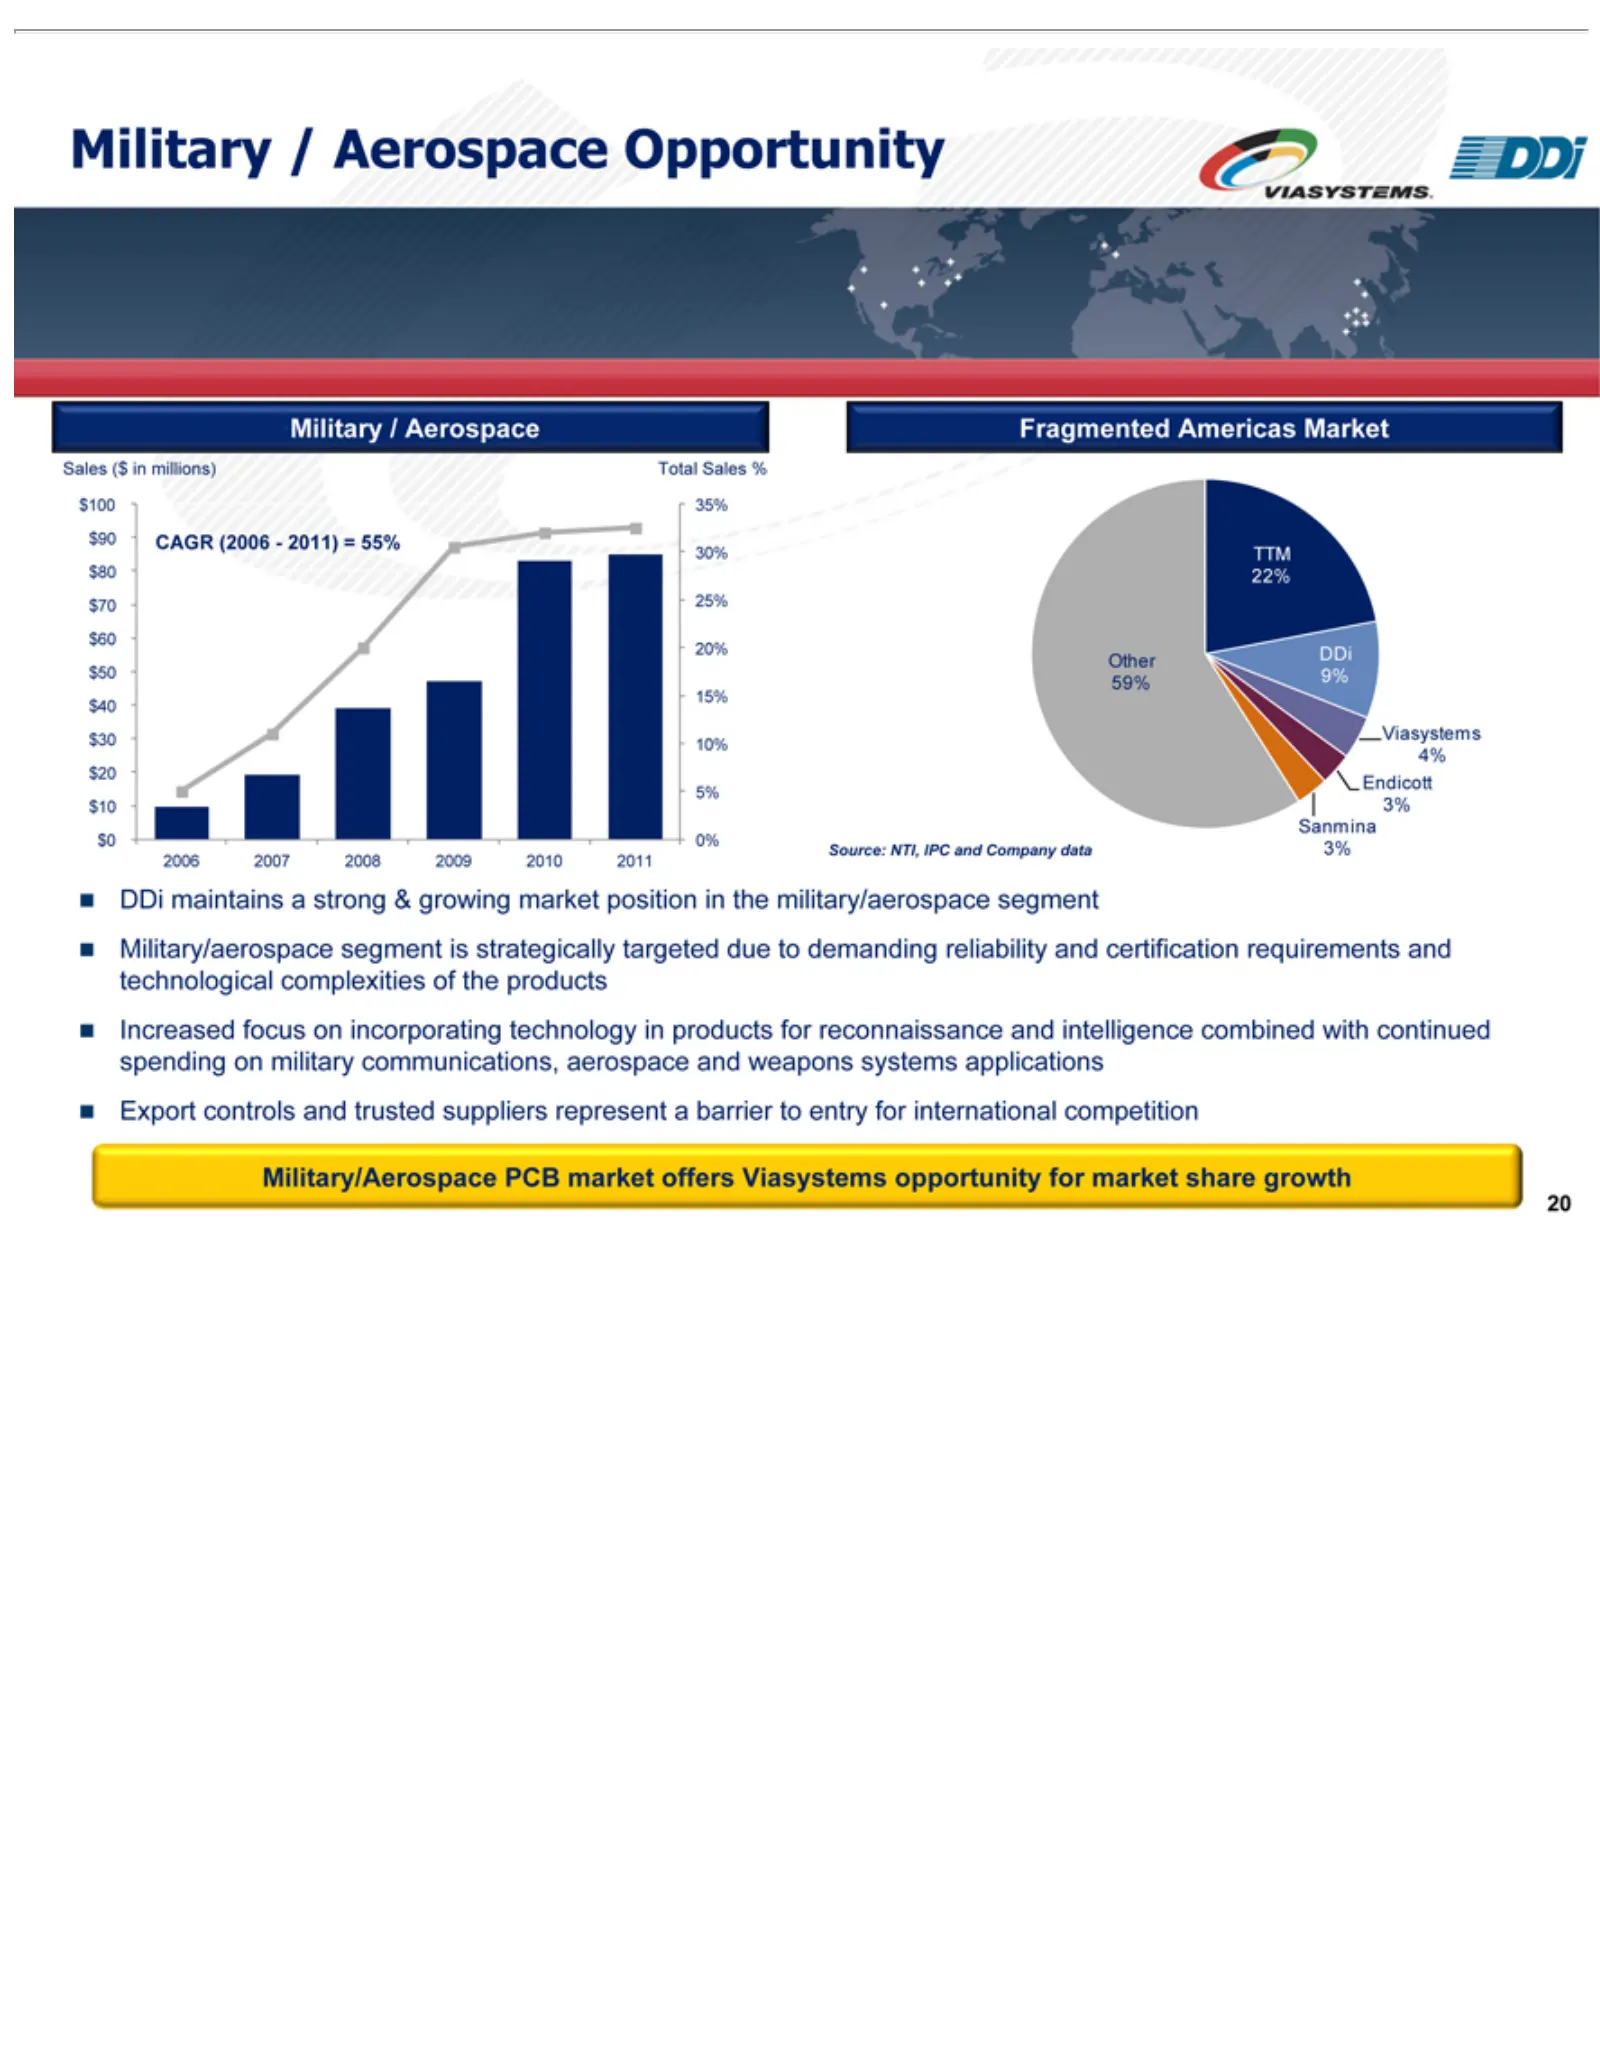
Military •Military Fragmented Sales Total $100 CAGR 2006 35% Source: Other TTM Viasystems Endicott Sanmina DDi Military/aerospace for international Military/Aerospace 20 reconnaissance 9% maintains 30% $90 2007 Sales 22% ($ 59% (2006—2011) NTI, in /3% 3% /$80 Aerospace 25% Aerospace millions) 2008 %
Slide 21: Continued Growth Opportunities for Viasystems-DDi
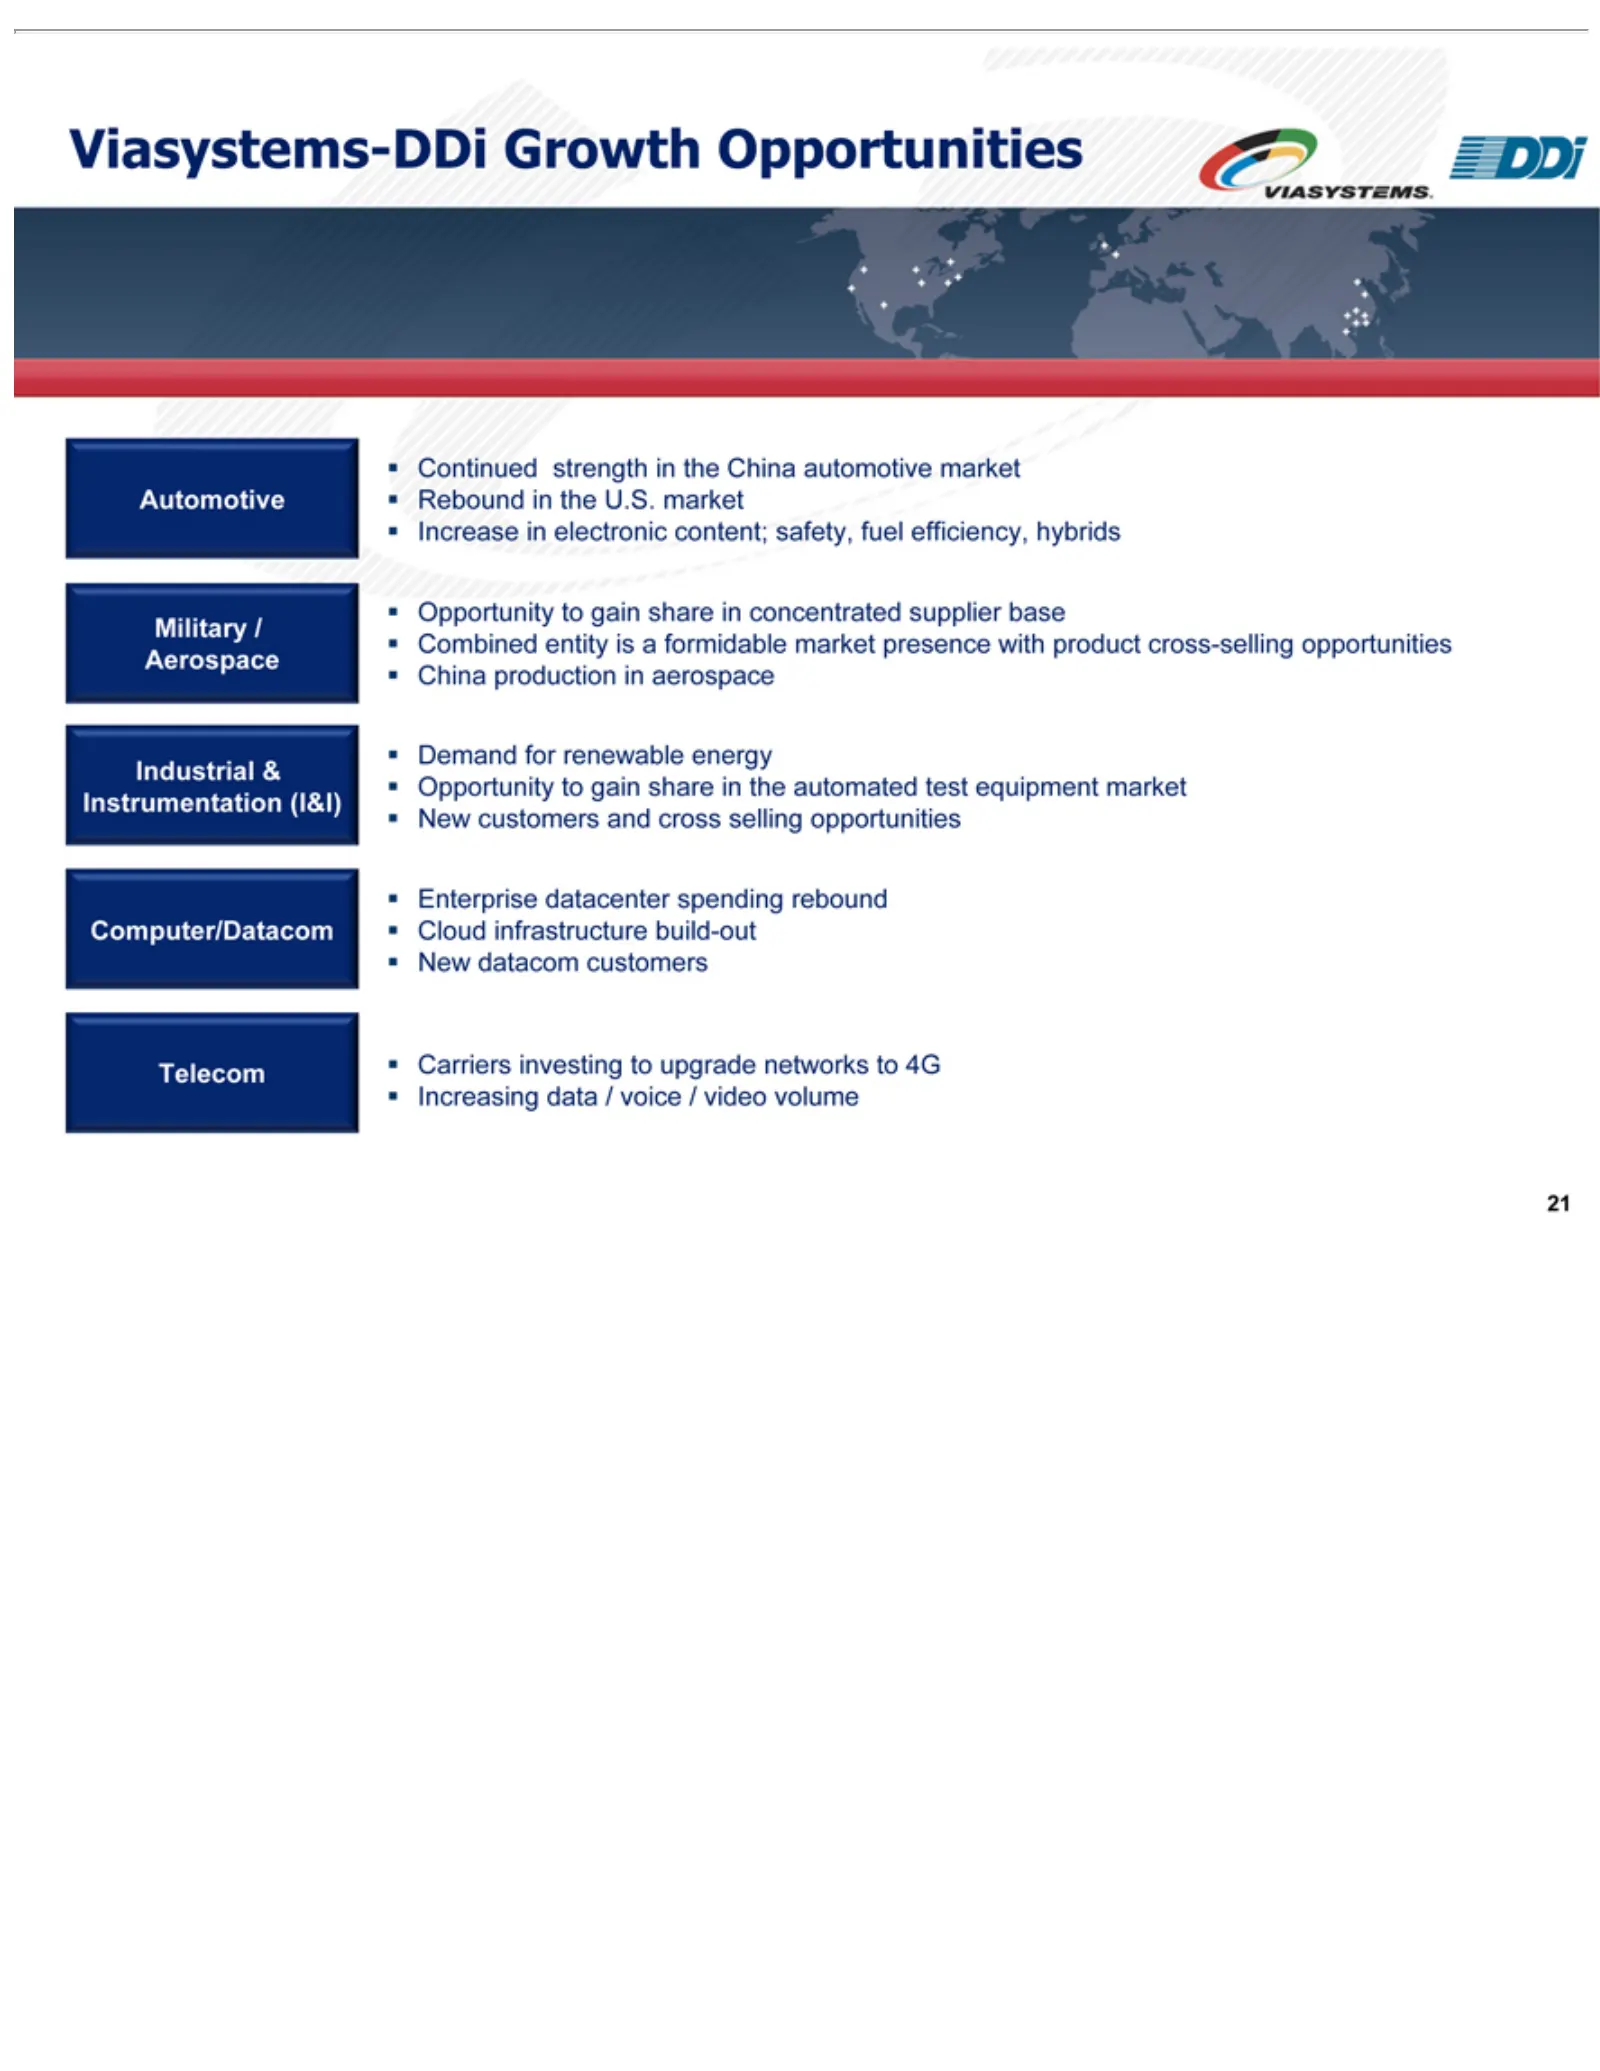
Viasystems-DDi Continued Increase Combined Demand Opportunity Enterprise Carriers 21 investing in fordatacenter strength entity electronic renewable to gain Growth istoain share upgrade formidable spending content; the energy Opportunities China in the concentrated networks safety, rebound automated
Slide 22: III. Financial Highlights
III. Financial Highlights 22
Slide 23: Combined Financials
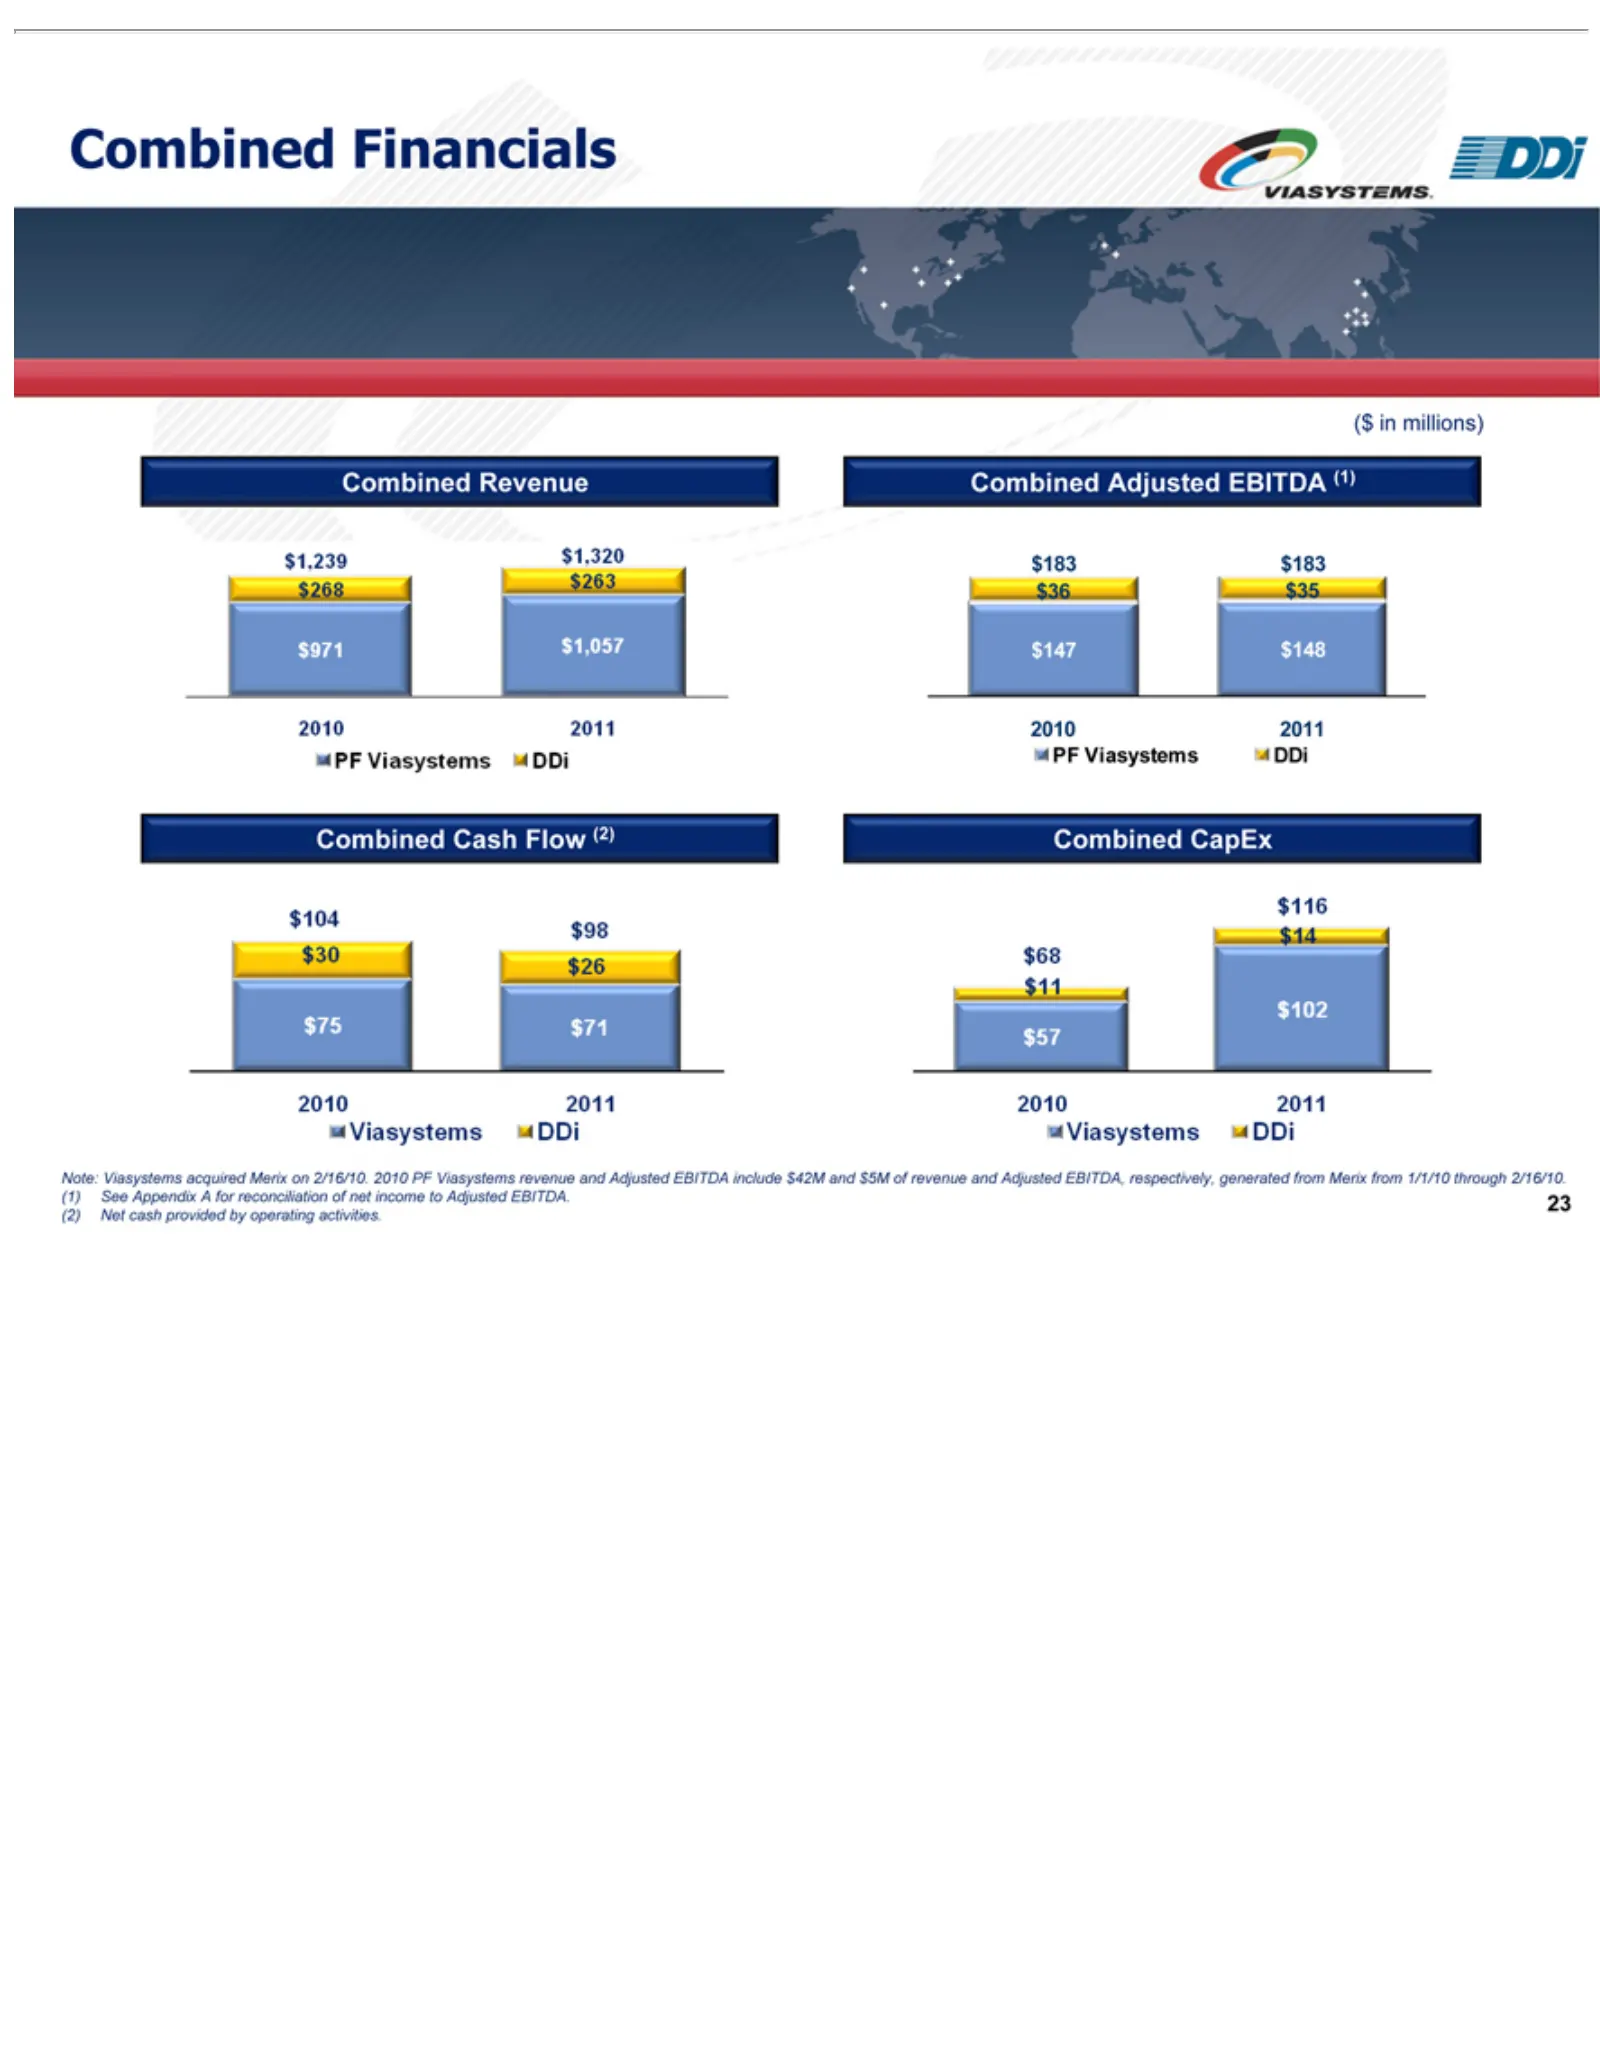
($ in millions) •Combined Combined Note: 2/16/10. 23 Viasystems (1)Adjusted Financials CapEx Revenue Cash See Appendix Flow acquired EBITDA (2) A Merix for (1)reconciliation on 2/16/10. 2010 of netPFincome Viasystems to Adjusted revenueEBITDA. and Adjusted (2) Net EBITDA cash provided includeby $42M
Slide 24: Pro Forma Capitalization
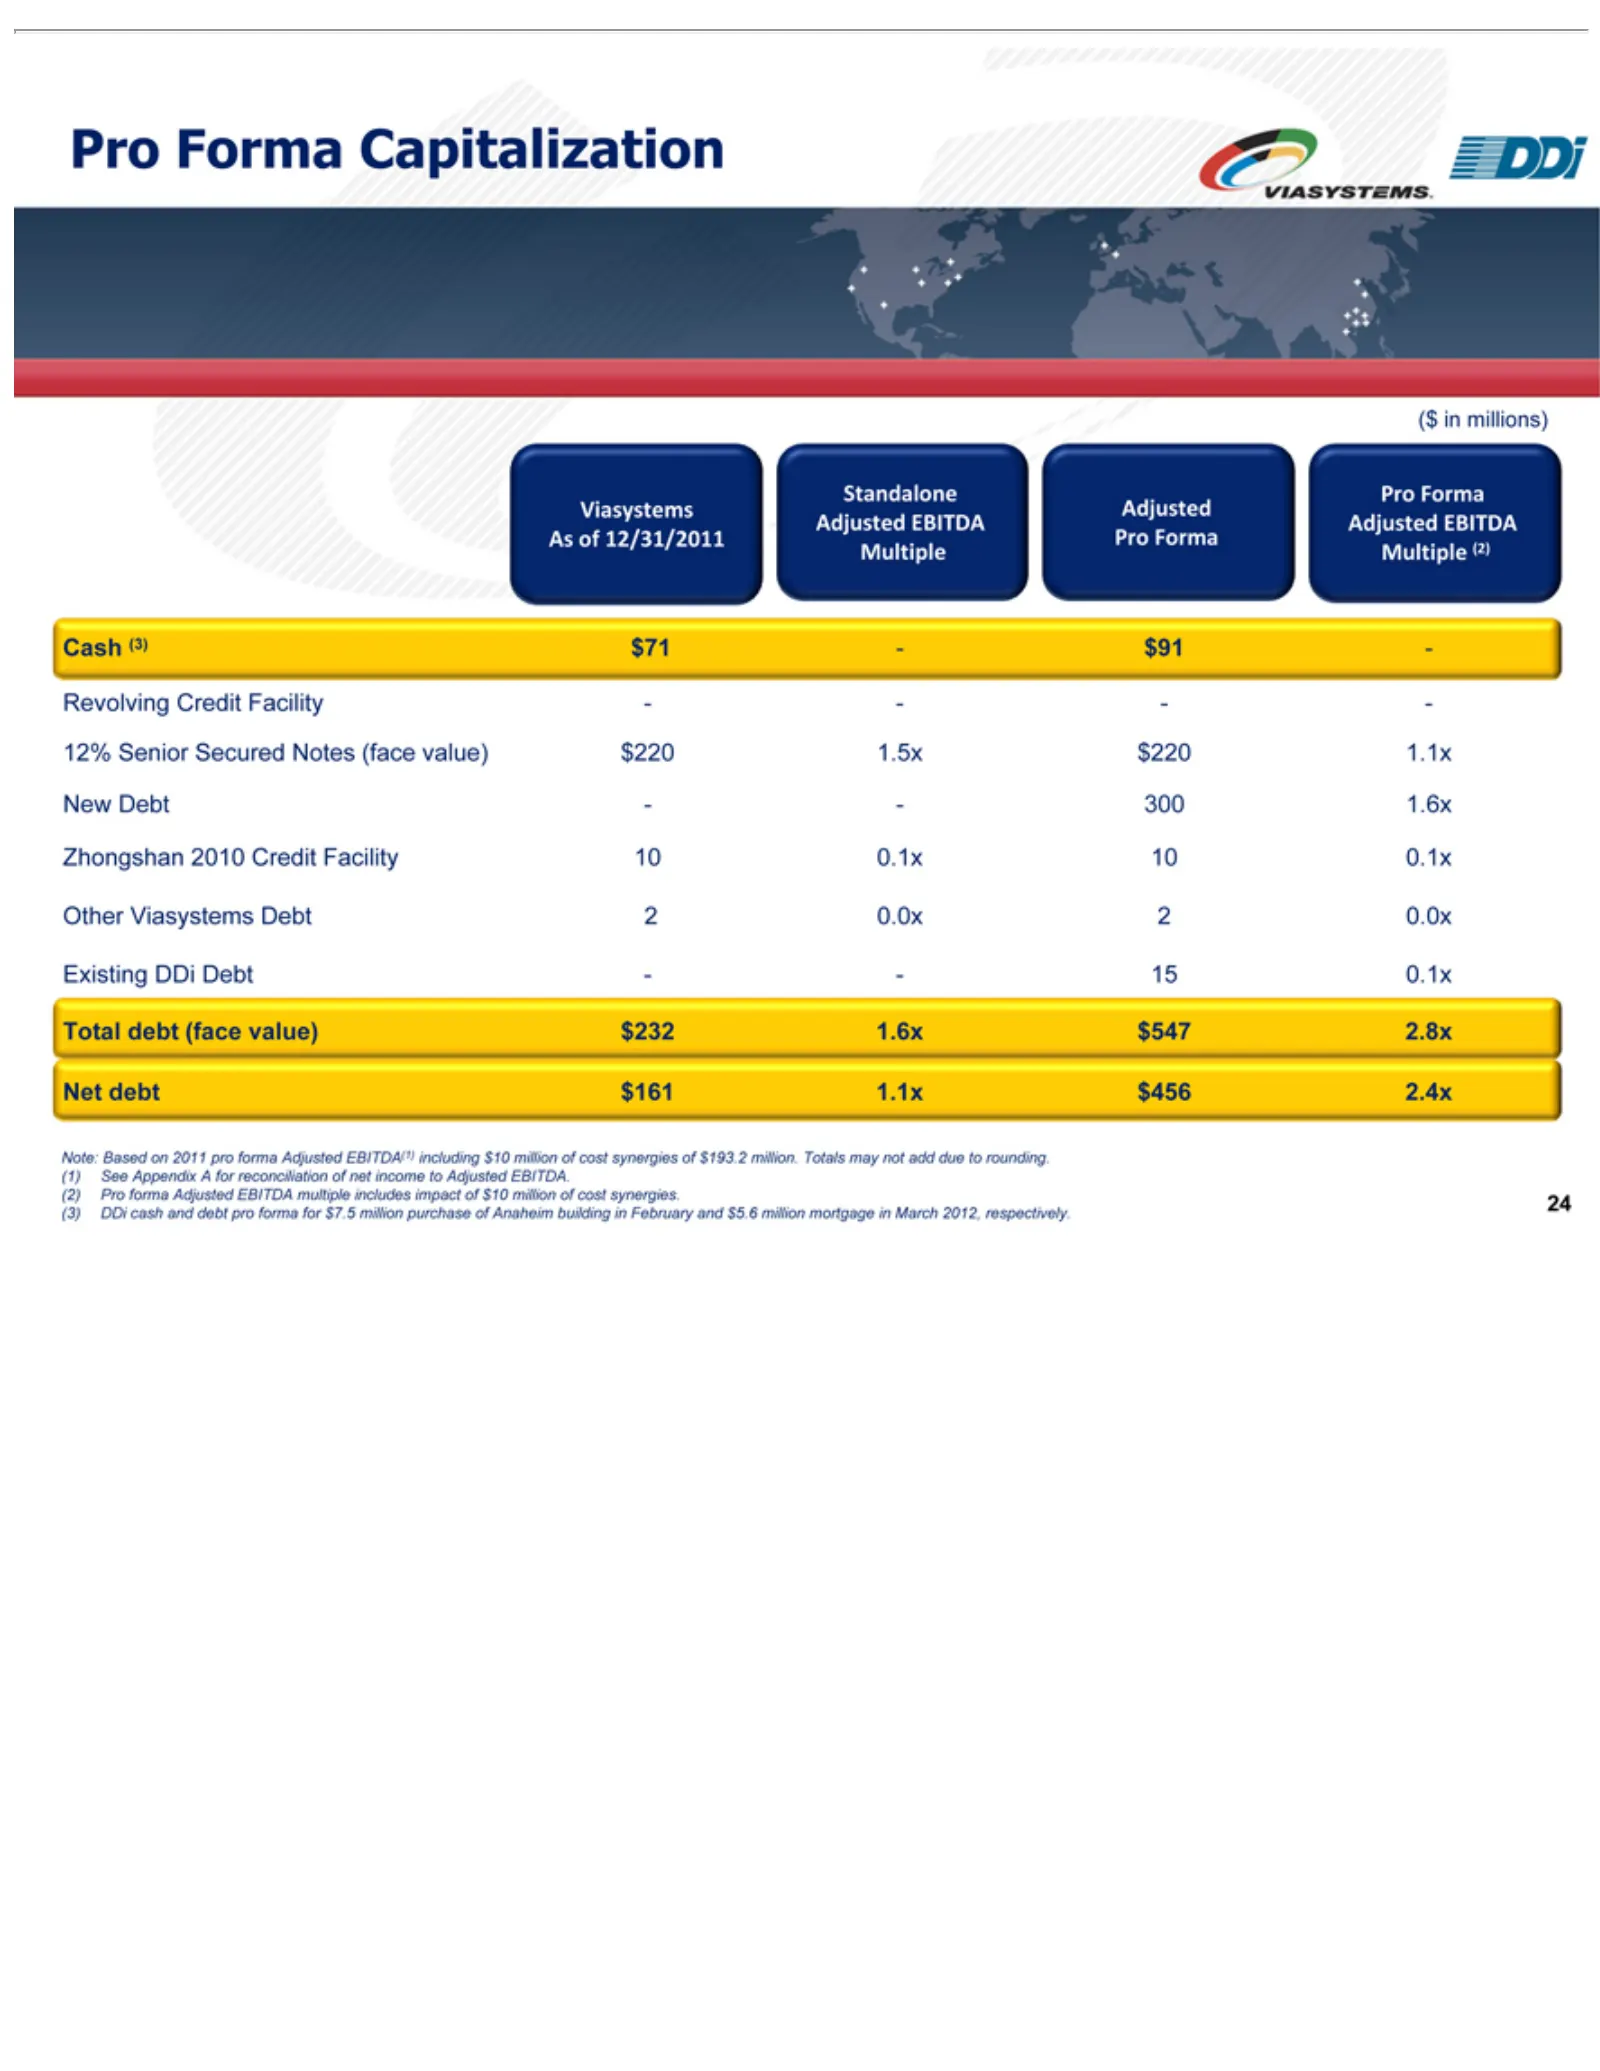
Viasystems Standalone Adjusted Pro Multiple ($ Cash Revolving 12% New Zhongshan Other Existing Total Net Note: (2) EBITDA. (3) 24 inDDi Pro Forma debt Senior millions) Debt—- (3) debt Based Viasystems forma cash DDi $161 $71—$91 (2) Pro (face Credit Adjusted Capitalization Adjusted 2010 As Secured o
Slide 25: Investment Highlights Summary
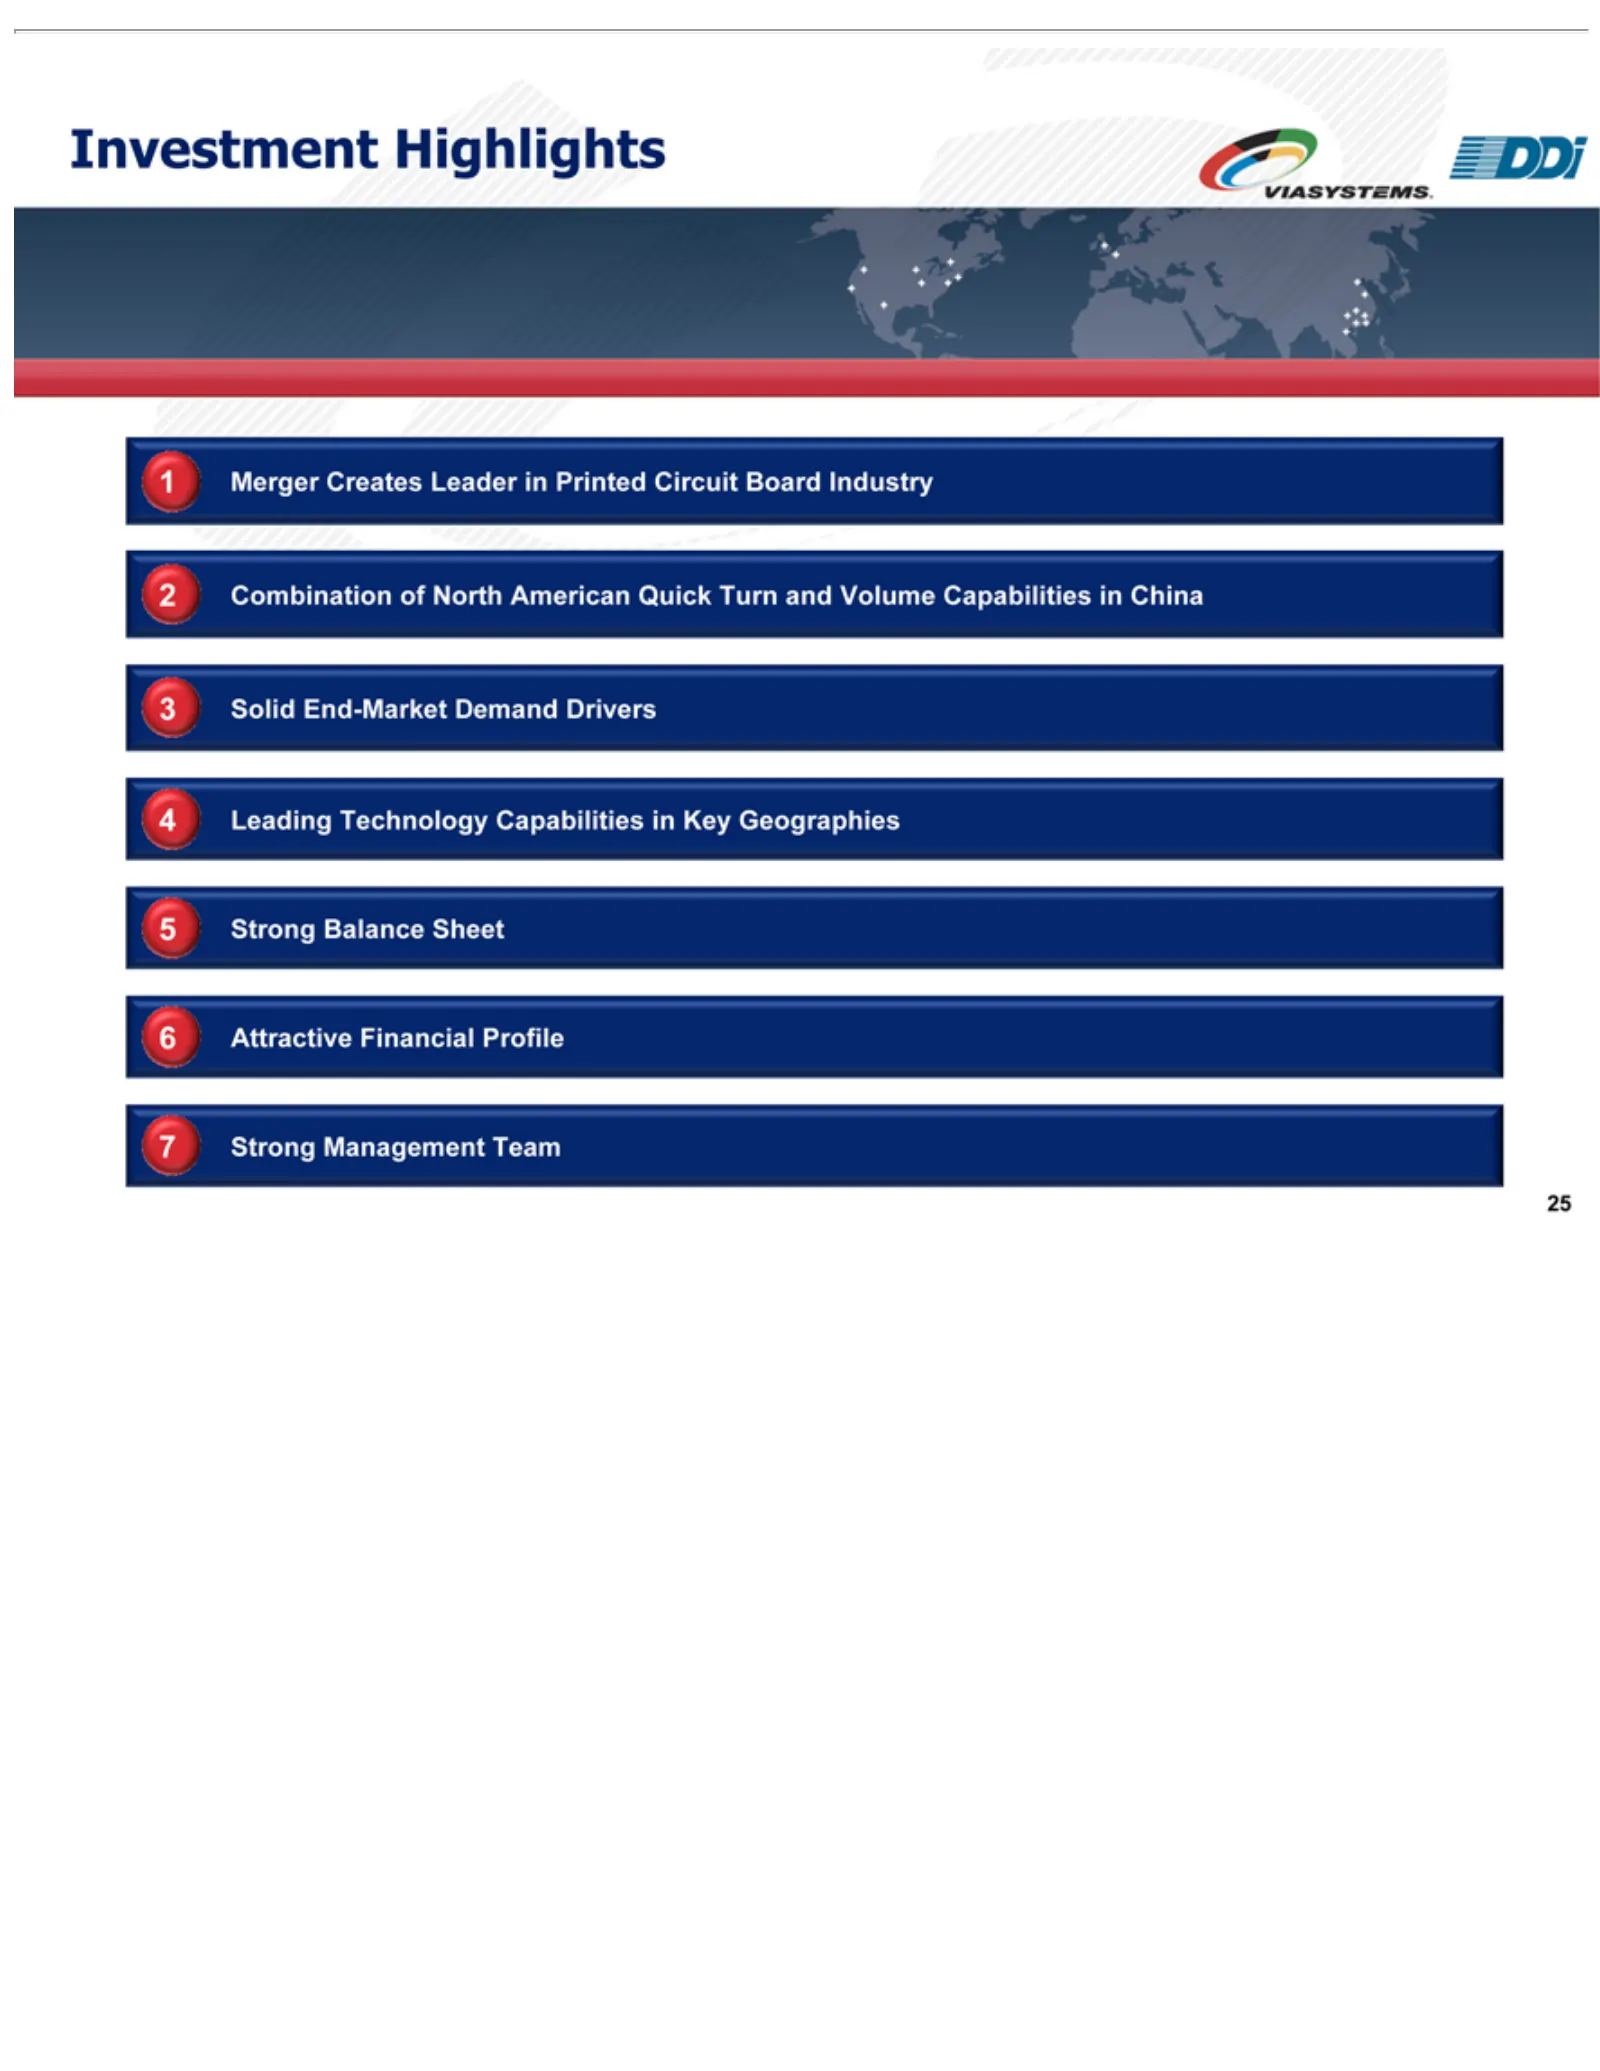
7654321Investment 25Attractive Merger Combination Solid Leading StrongEnd-Market Balance Management Creates Technology Highlights Financial of Sheet Leader North Demand Profile Team Capabilities American in Printed Drivers Quick in Circuit KeyTurn Geographies Board andIndustry Volume Capabilities in
Slide 26: Appendix A. Reconciliation
Appendix A. Reconciliation 26
Slide 27: Viasystems Adjusted EBITDA Reconciliation
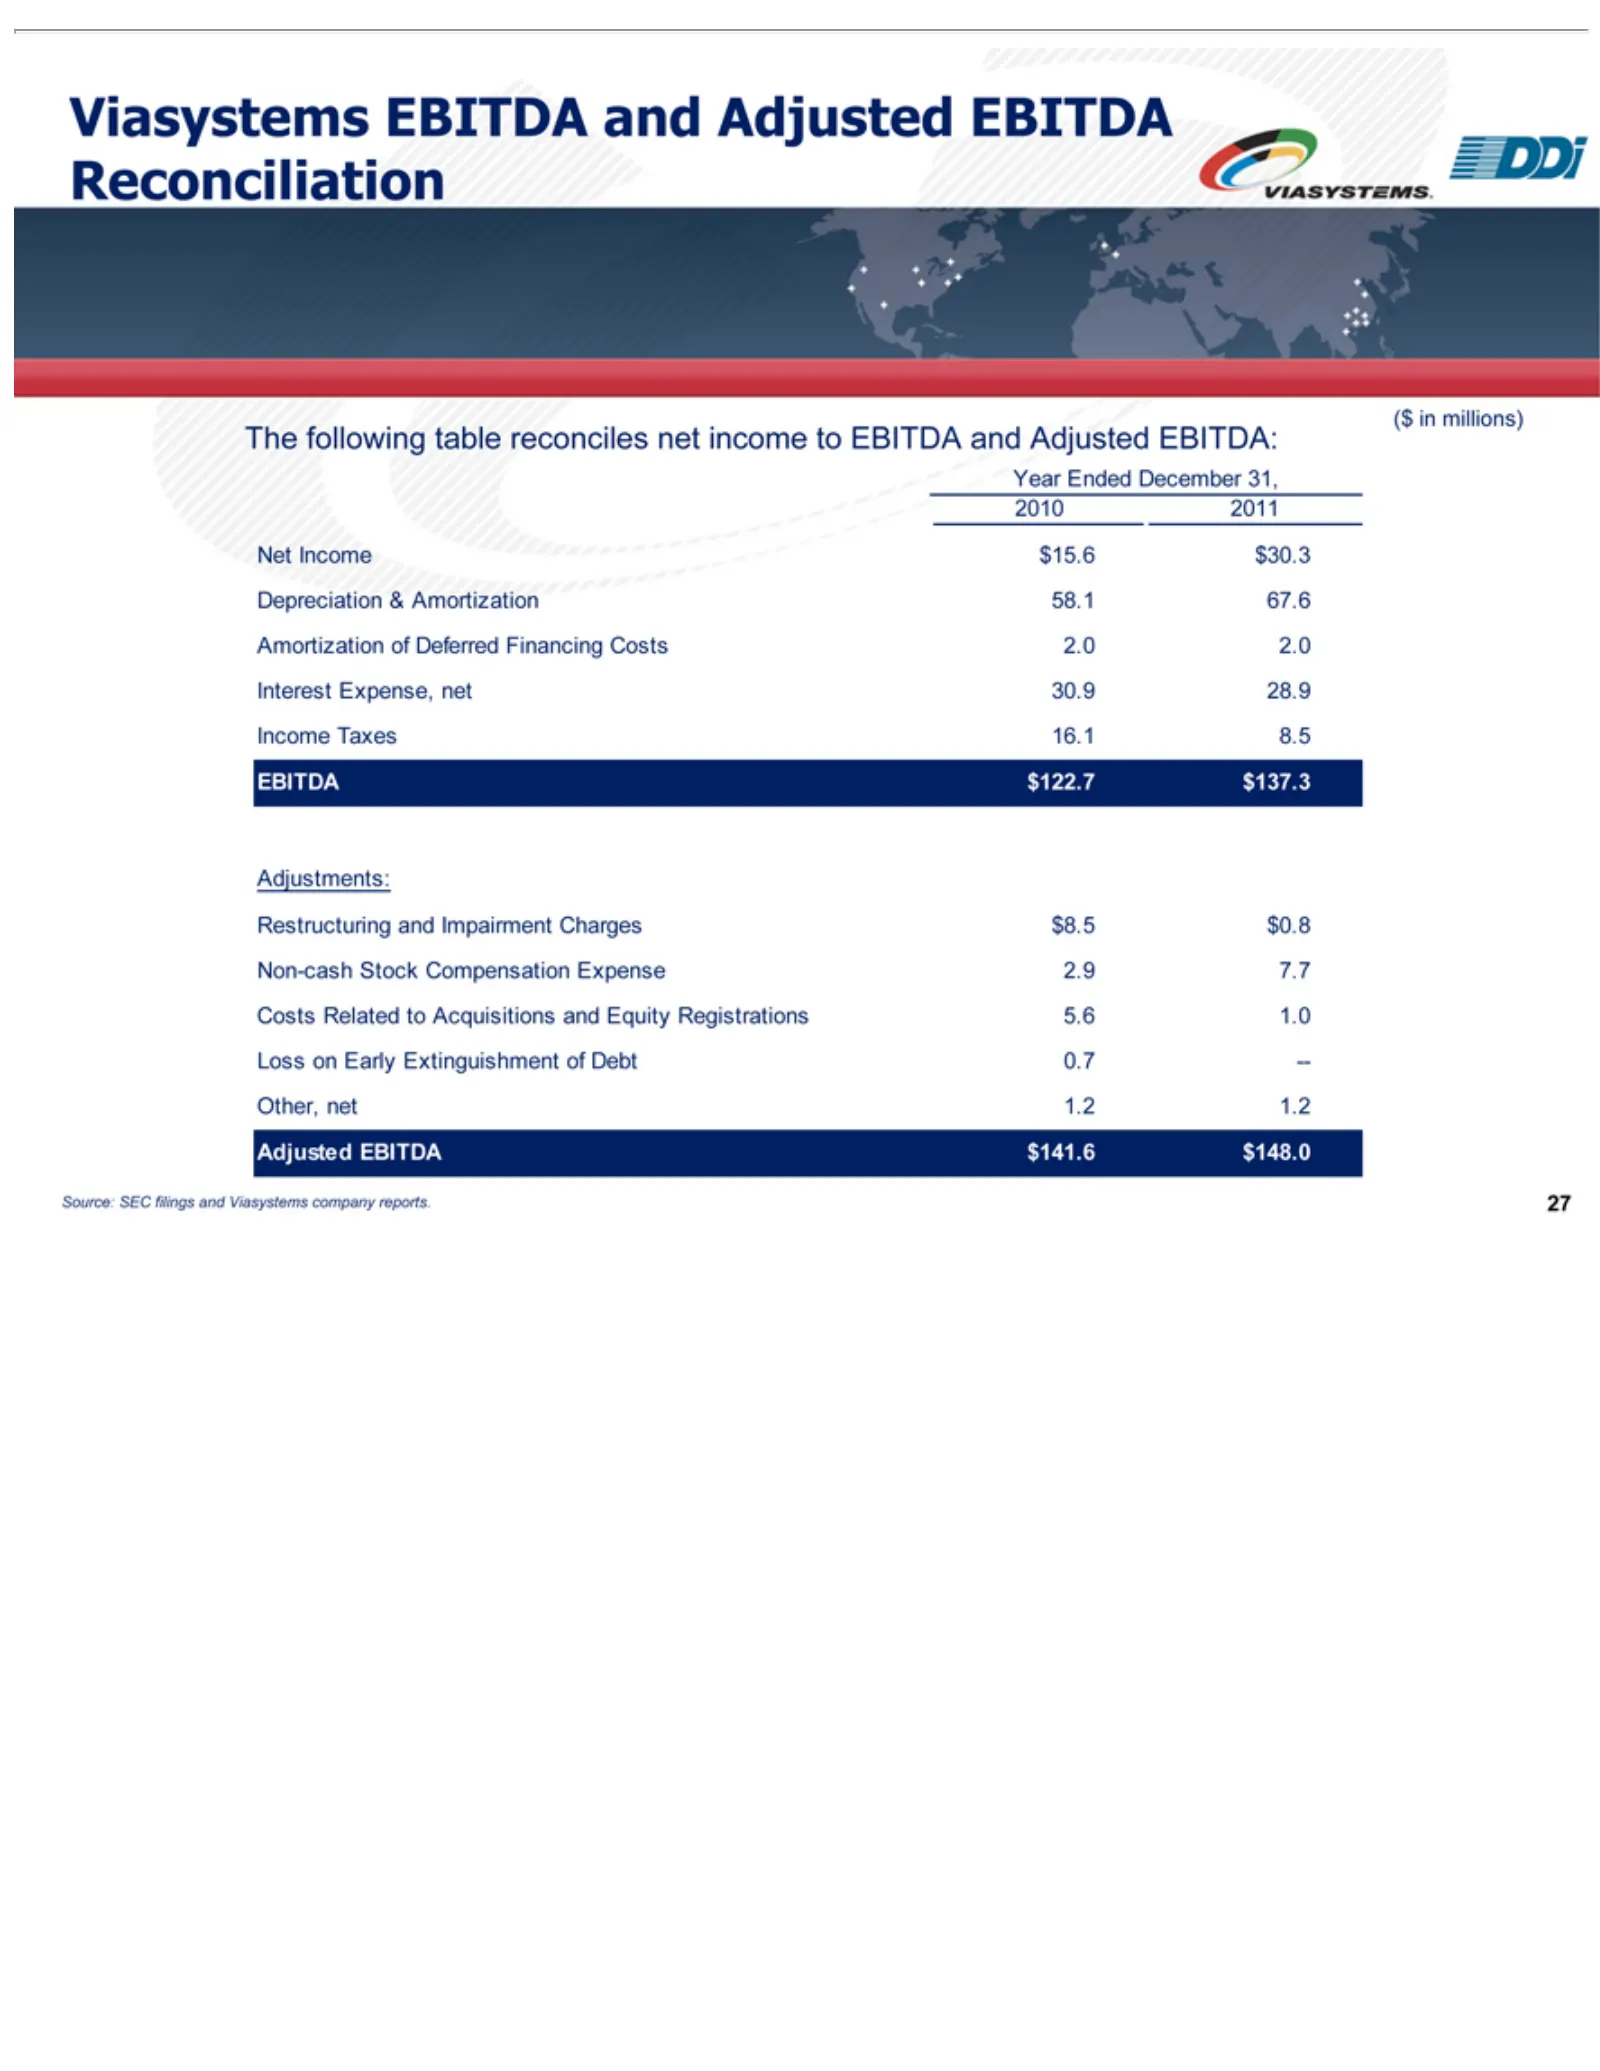
Viasystems ($ The Year Net EBITDA Restructuring Adjustments: 1.2 Adjusted Source: 27 in1.2 Income following Ended millions) SEC $122.7 EBITDA EBITDA December $15.6 filings and table $137.3 Impairment $30.3 $141.6 reconciles and and 31, Viasystems Depreciation Adjusted $148.0 2010Charges net 2011 inc
Slide 28: DDi Adjusted EBITDA Reconciliation
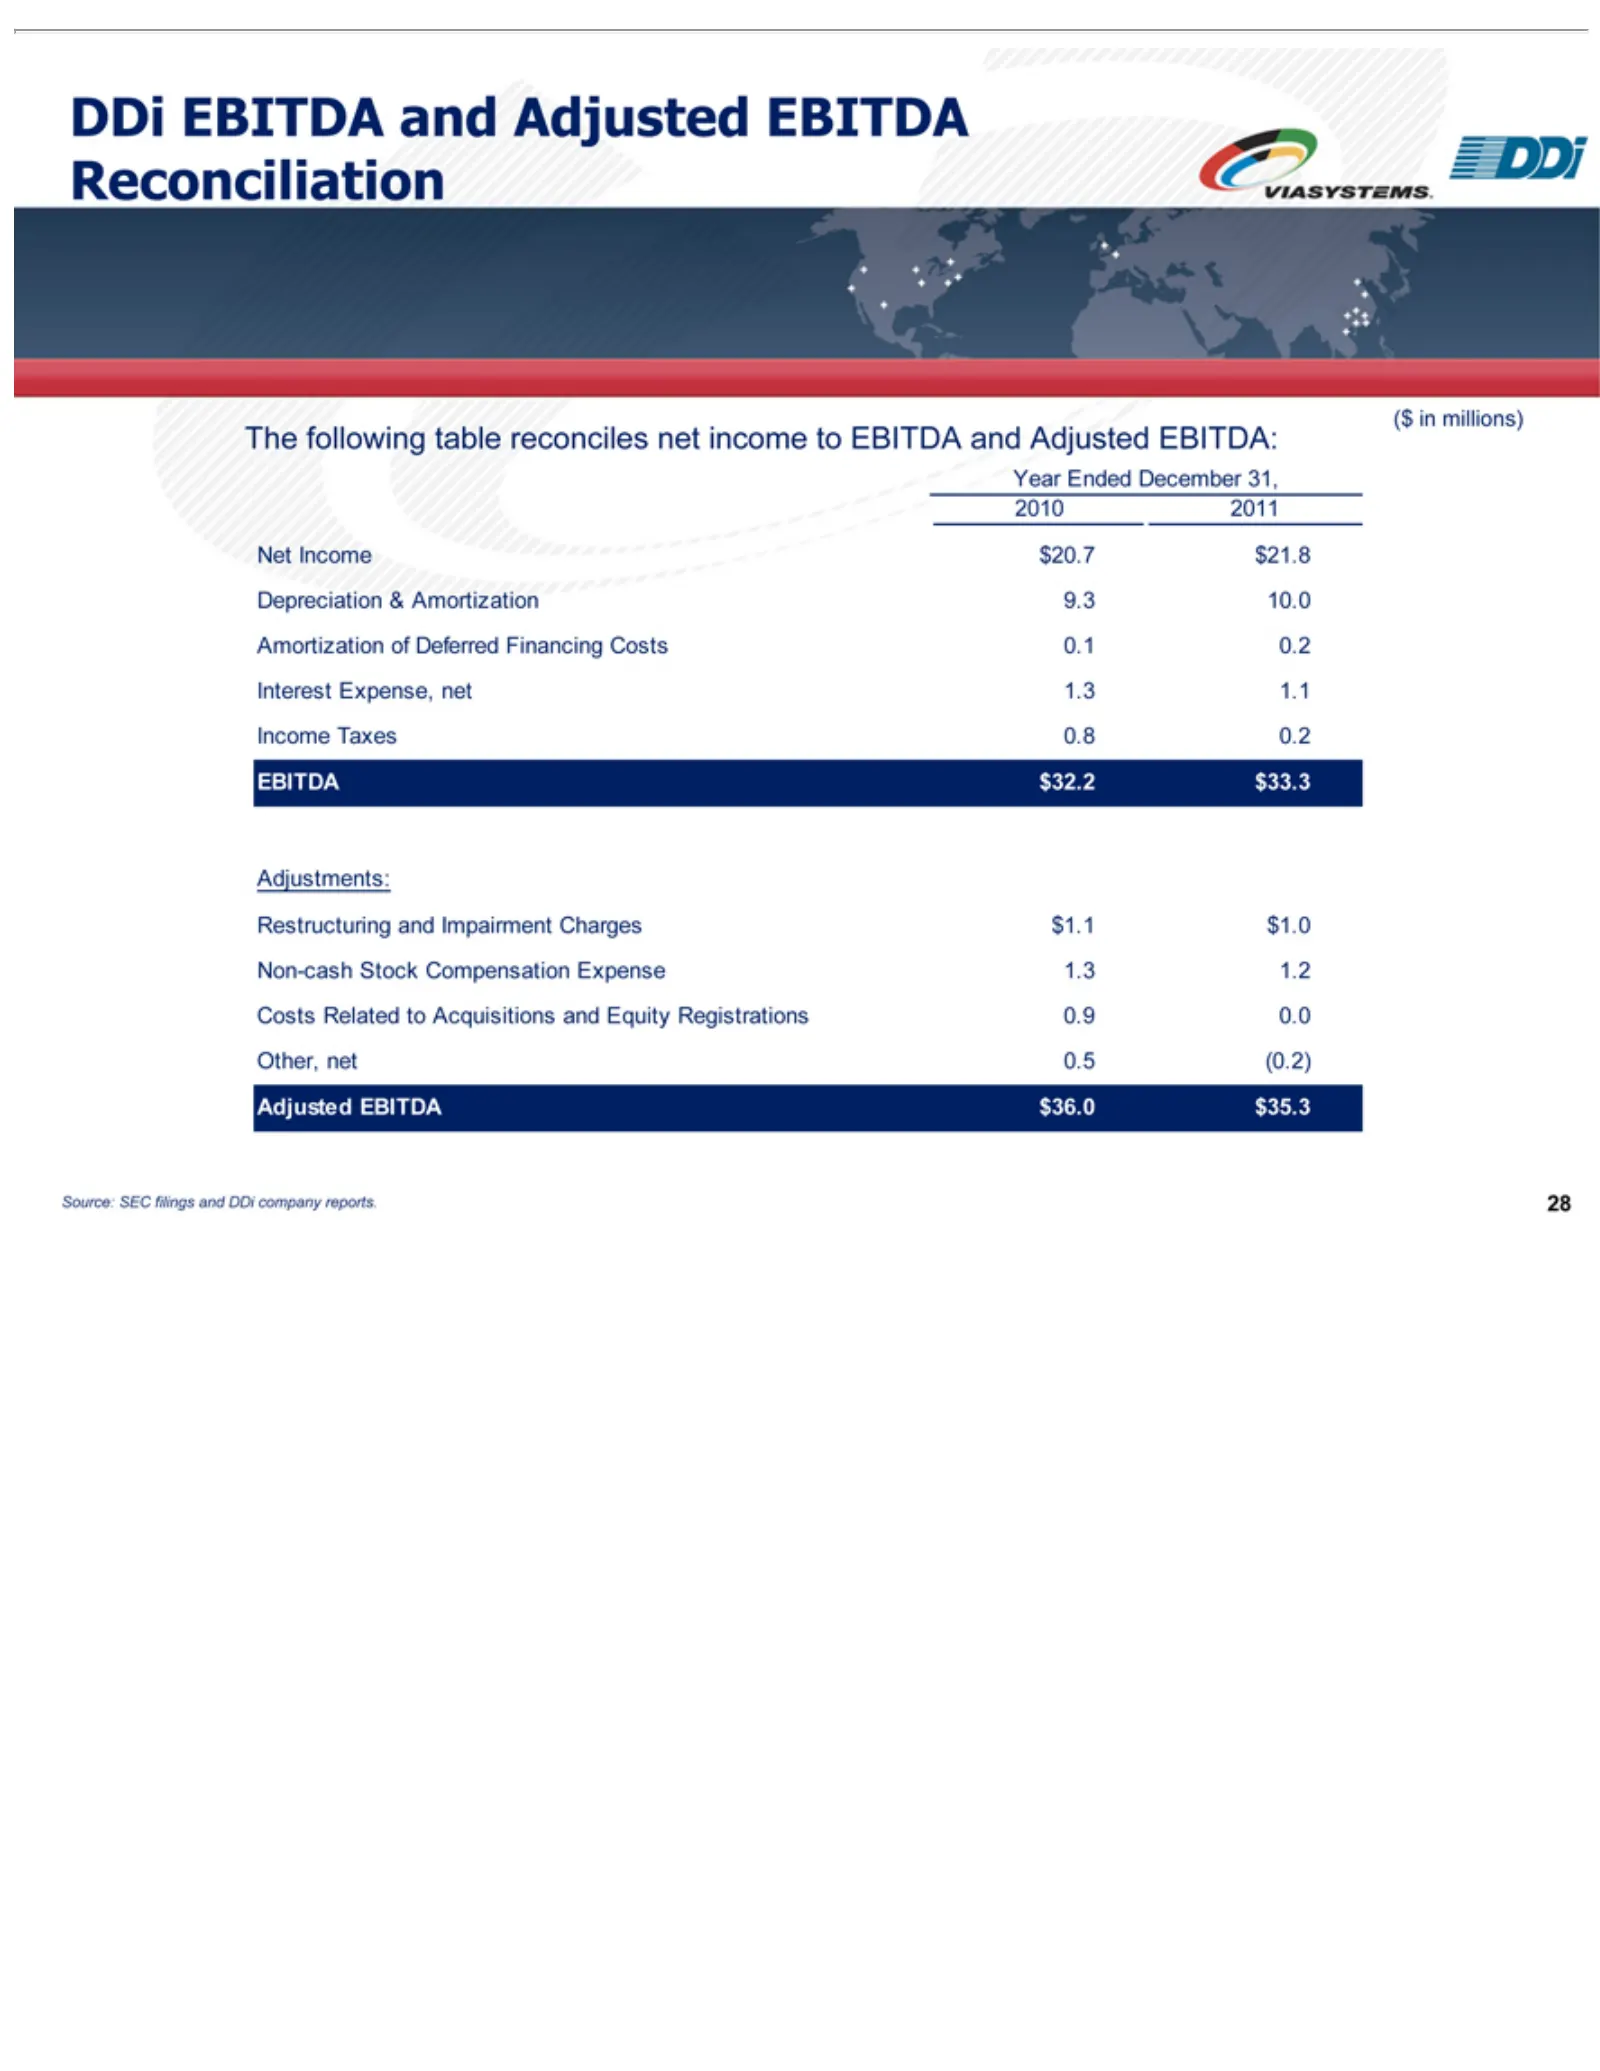
DDi ($ The Year Net EBITDA Restructuring Adjustments: Adjusted Source: 28 inIncome following EBITDA Ended millions) SEC $32.2 EBITDA December $20.7 filings and and table $33.3 Impairment $21.8 Adjusted $36.0 reconciles and31, DDi Depreciation $35.3 2010 EBITDA company Charges net 2011 income Reconci
Slide 29: DDi Adjusted Net Income Reconciliation
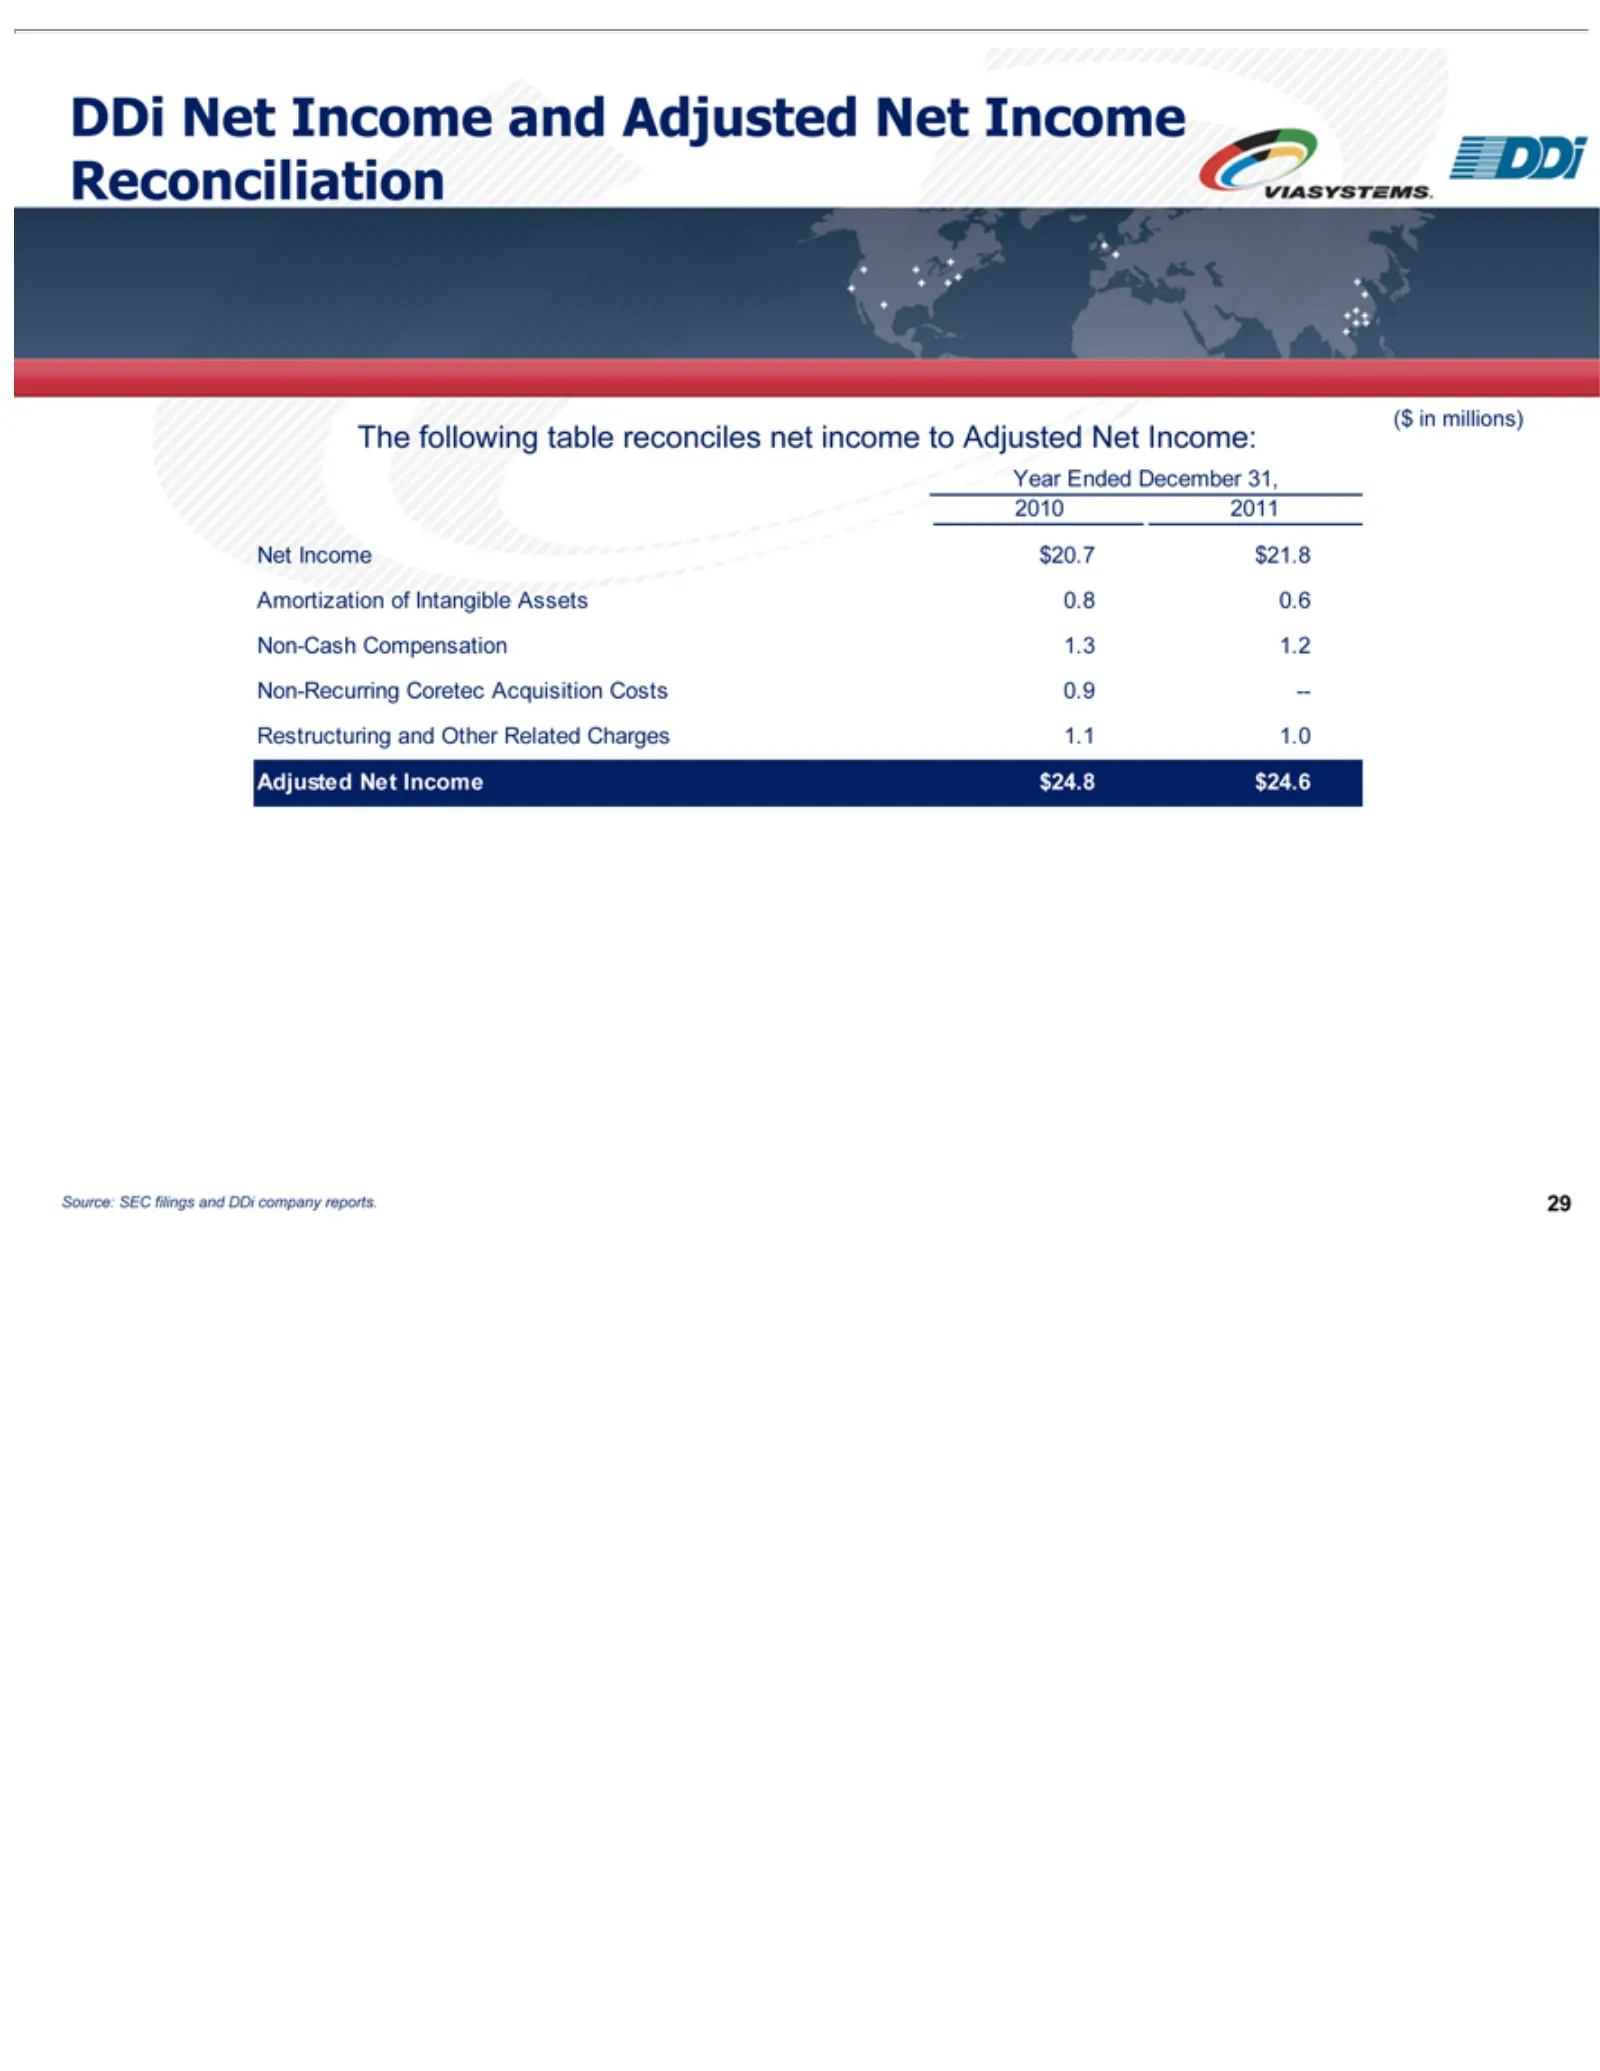
DDi ($ The 3Year Net 3201032011 Amortization Non-Cash Non-Recurring Restructuring Adjusted Source: 29 inIncome3$20.73$21.8 following Net millions) Ended SEC Income Net Compensation31.331.2 filings December Income3$24.83$24.6 of and table Coretec Intangible and Other reconciles and Adjusted Acquisiti
Source: SEC EDGAR · 8-K filed Apr 4, 2012