Gemfields Group Limited · JSE:GML
Gemfields — FY2015 Earnings Presentation
37 slides from Gemfields's earnings presentation, Oct 7, 2015
Slide 1: A leading supplier of responsibly sourced coloured gemstones
A leading supplier of responsibly sourced coloured gemstones Full Year results to 30 June 2015 7 October 2015 Gemfields Plc
Slide 2: Legal disclaimer
Legal disclaimer This document, which has been issued by Gemfields Plc (the “Company”), comprises the This document does not and is not intended to constitute an offer of securities for written materials/slides for a presentation concerning the Company, including its business, distribution or sale i
Slide 3: Gemfields: At a glance
Gemfields: At a glance Gemfields vision A leading supplier of responsibly sourced coloured gemstones Benefiting from Gemfields’ ability to be a price-maker rather than simply a price-taker Key assets Soft assets Hard assets • An experienced team – constantly building on our core • Montepuez (75%), M
Slide 4: Full Year Results 2015: Financial highlights
Full Year Results 2015 Financial highlights Gemfields Plc
Slide 5: Financial highlights
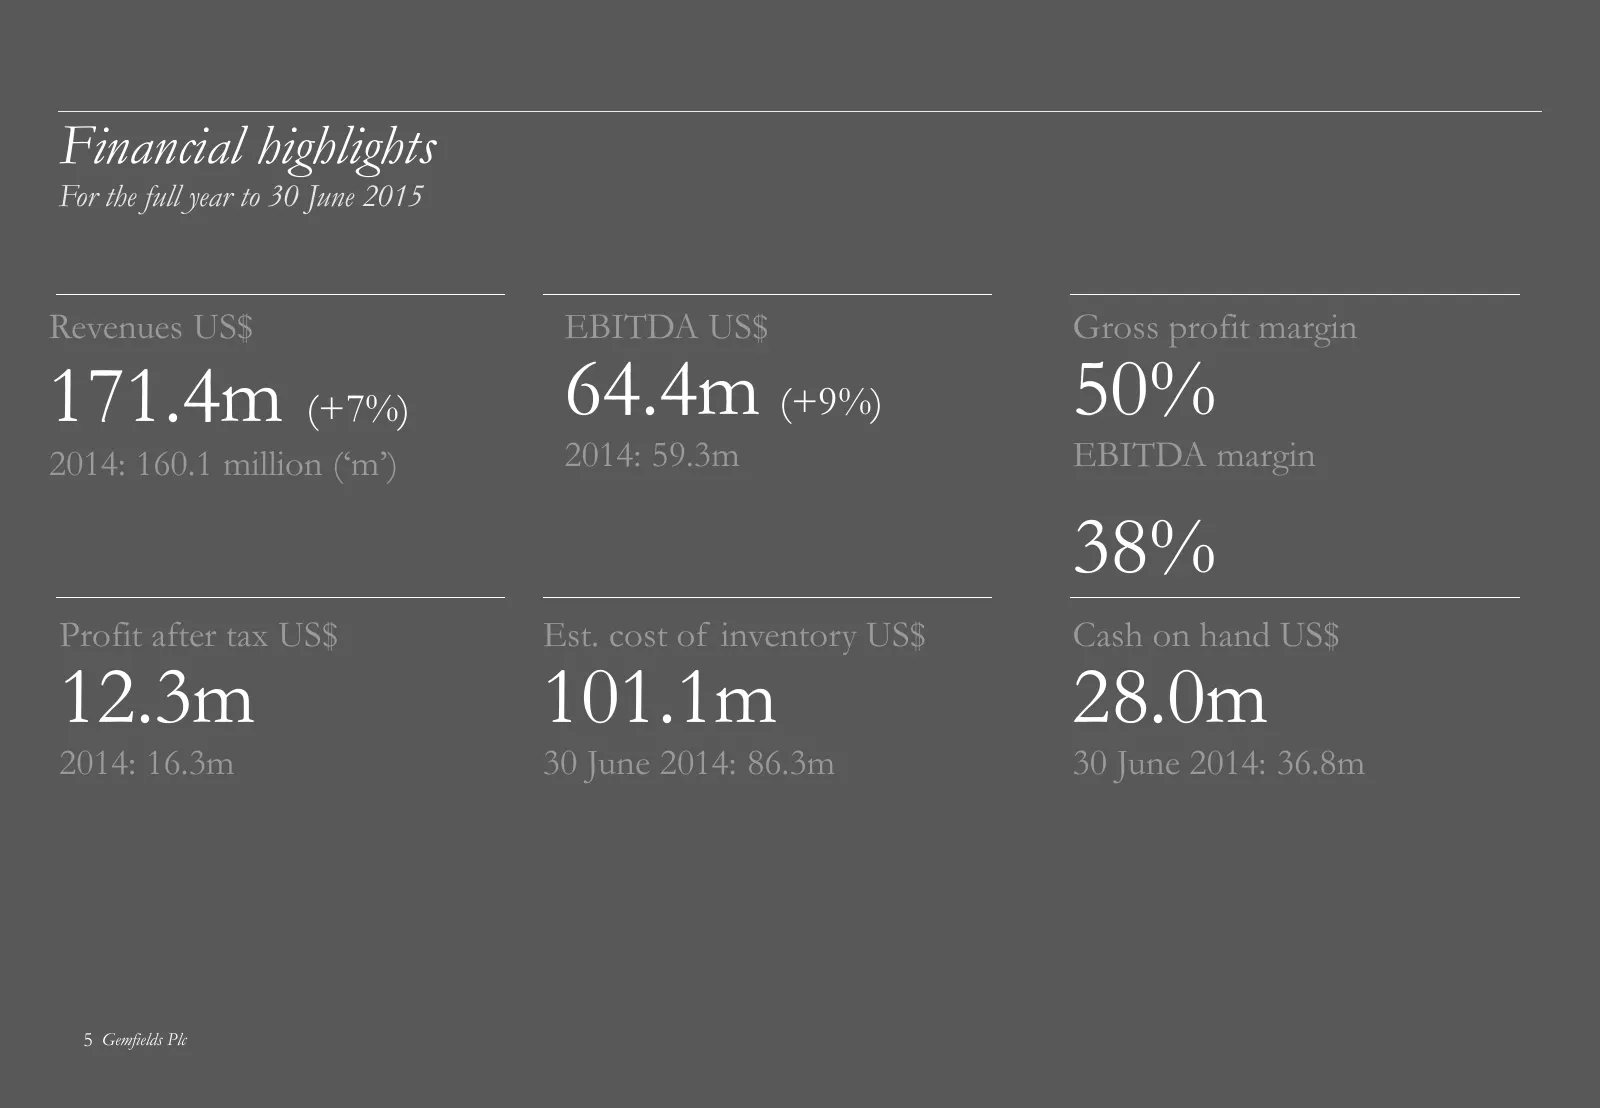
Financial highlights For the full year to 30 June 2015 Revenues US$ EBITDA US$ Gross profit margin 171.4m (+7%) 64.4m (+9%) 50% 2014: 160.1 million (‘m’) 2014: 59.3m EBITDA margin 38% Profit after tax US$ Est. cost of inventory US$ Cash on hand US$ 12.3m 101.1m 28.0m 2014: 16.3m 30 June 2014: 86.3m
Slide 6: Financial highlights - Consolidated income statement
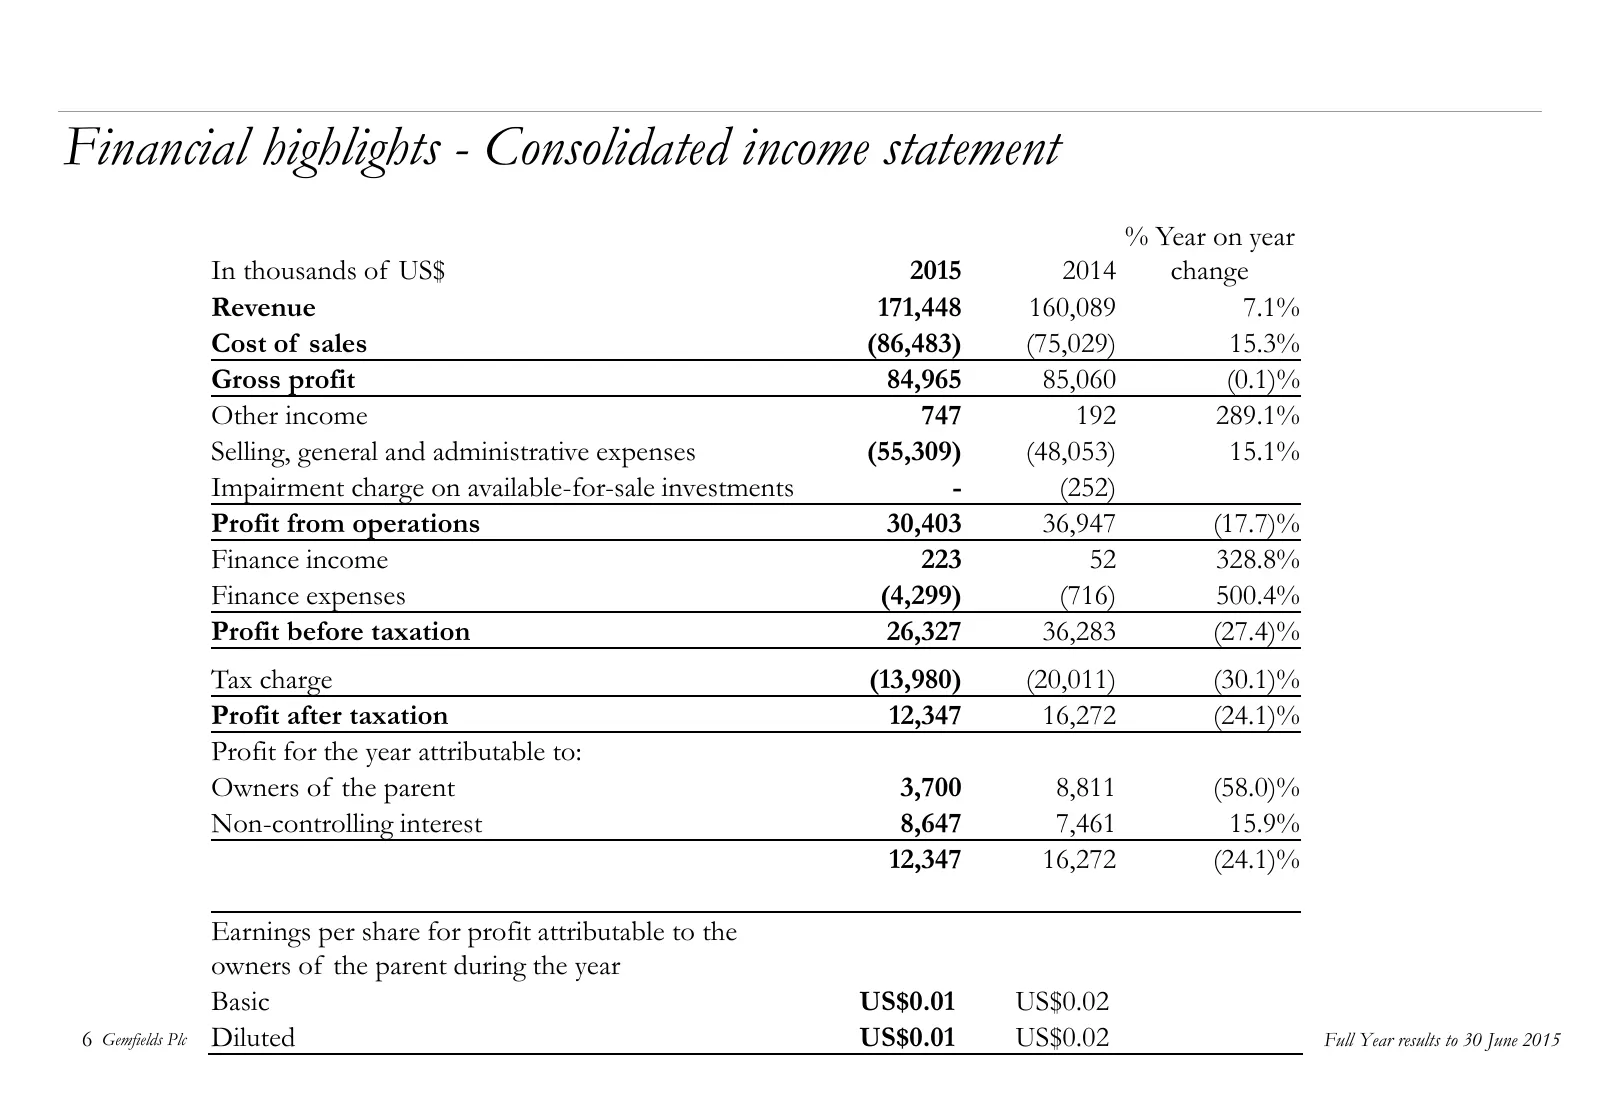
Financial highlights - Consolidated income statement % Year on year In thousands of US$ 2015 2014 change Revenue 171,448 160,089 7.1% Cost of sales (86,483) (75,029) 15.3% Gross profit 84,965 85,060 (0.1)% Other income 747 192 289.1% Selling, general and administrative expenses (55,309) (48,053) 15.
Slide 7: Revenue analysis – six auctions held during the year
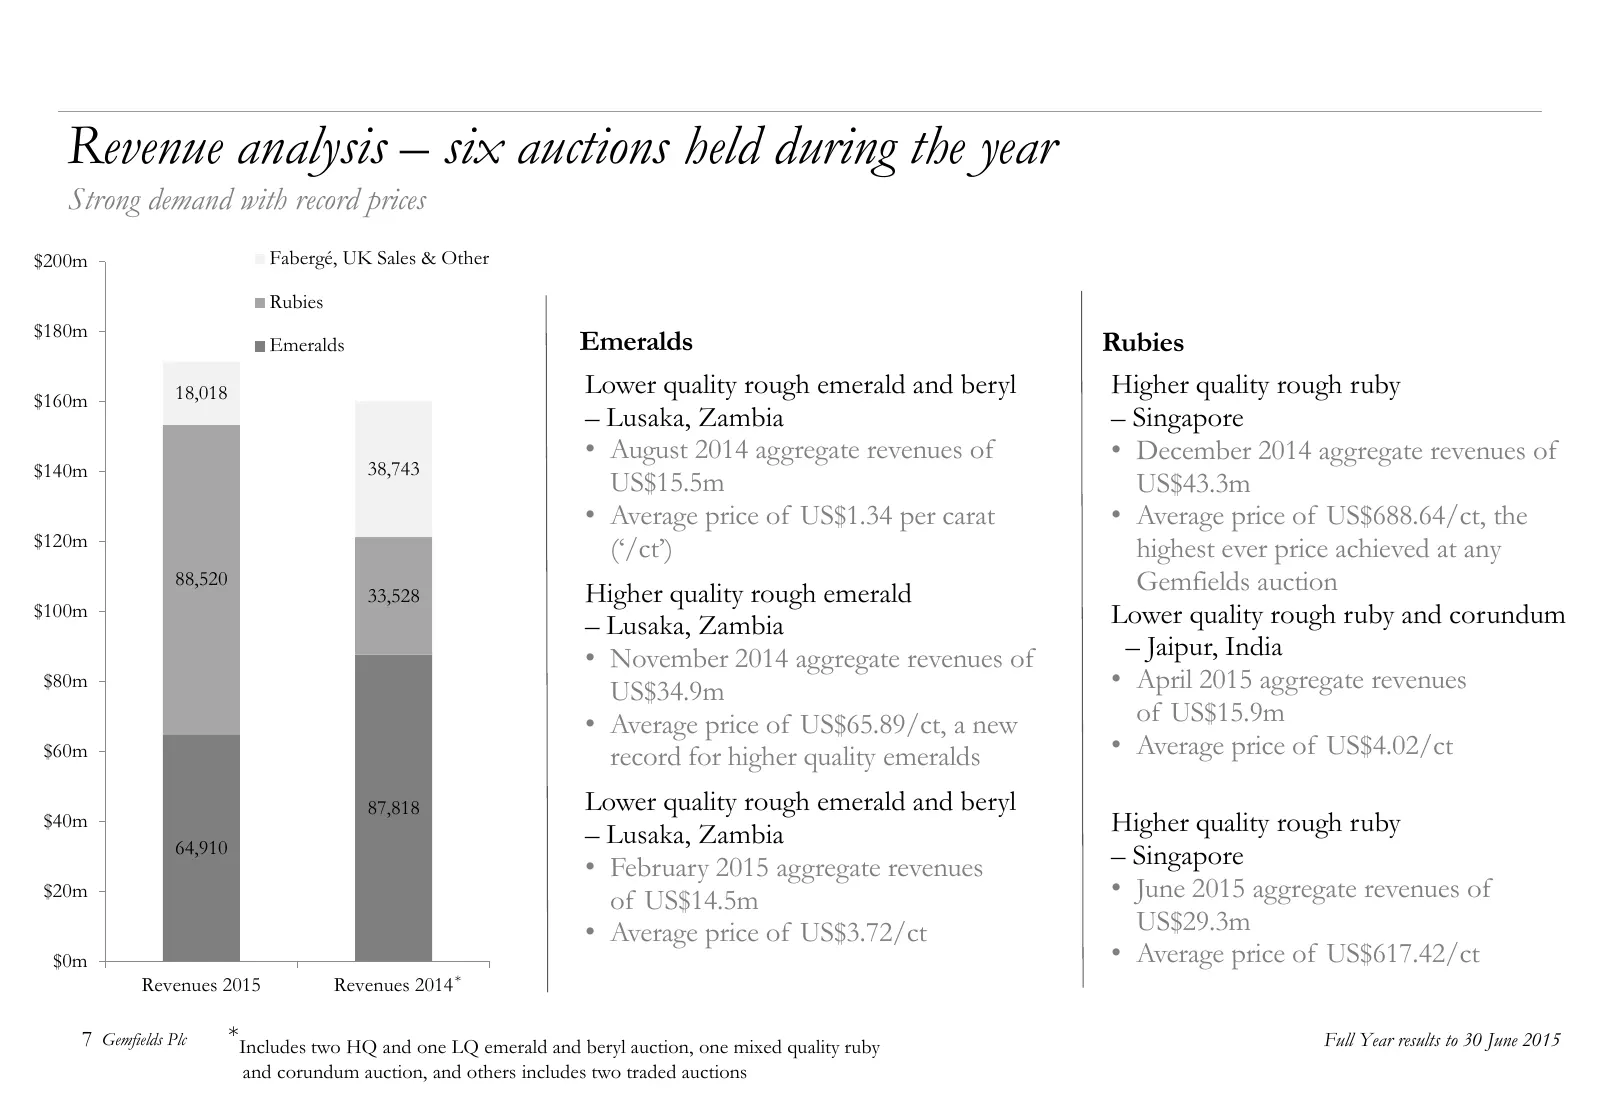
Revenue analysis – six auctions held during the year Strong demand with record prices $200m Fabergé, UK Sales & Other Rubies $180m Emeralds Emeralds Rubies $160m 18,018 Lower quality rough emerald and beryl Higher quality rough ruby – Lusaka, Zambia – Singapore • August 2014 aggregate revenues of •
Slide 8: Financial highlights – Cost of sales and inventory breakdown
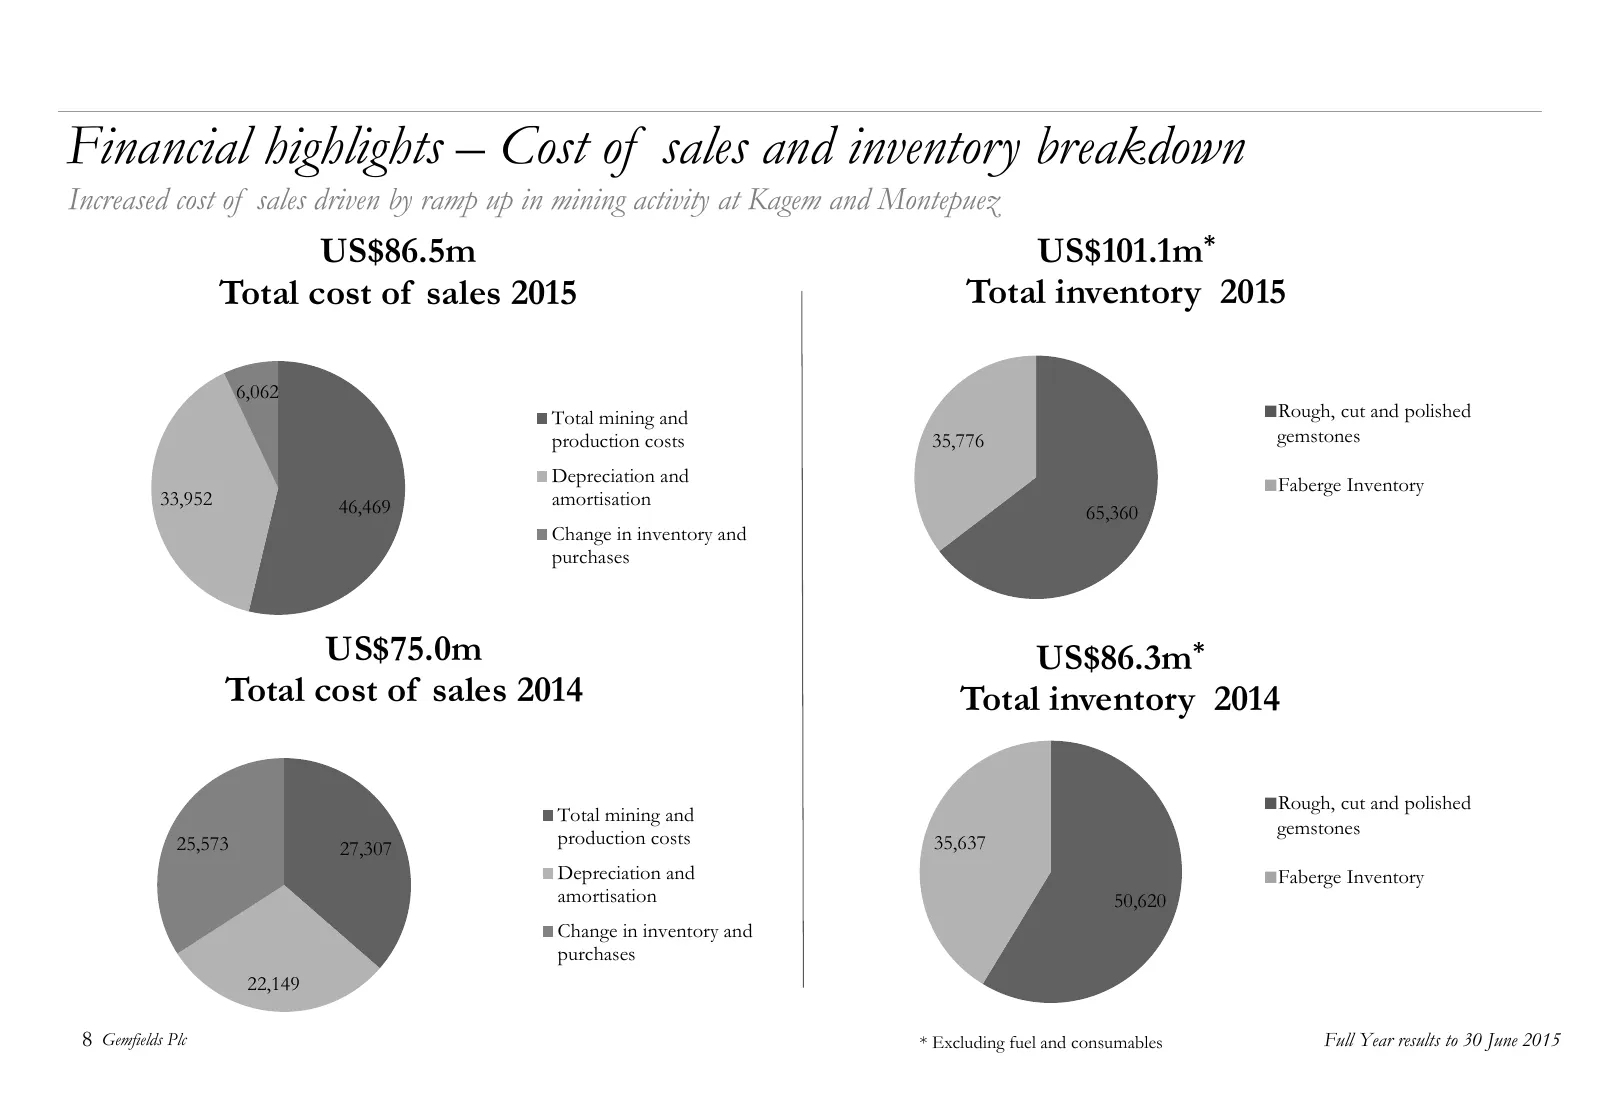
Financial highlights – Cost of sales and inventory breakdown Increased cost of sales driven by ramp up in mining activity at Kagem and Montepuez US$86.5m US$101.1m* Total cost of sales 2015 Total inventory 2015 6,062 Total mining and ■Rough, cut and polished production costs 35,776 gemstones Depreci
Slide 9: Financial highlights – Mining and production costs
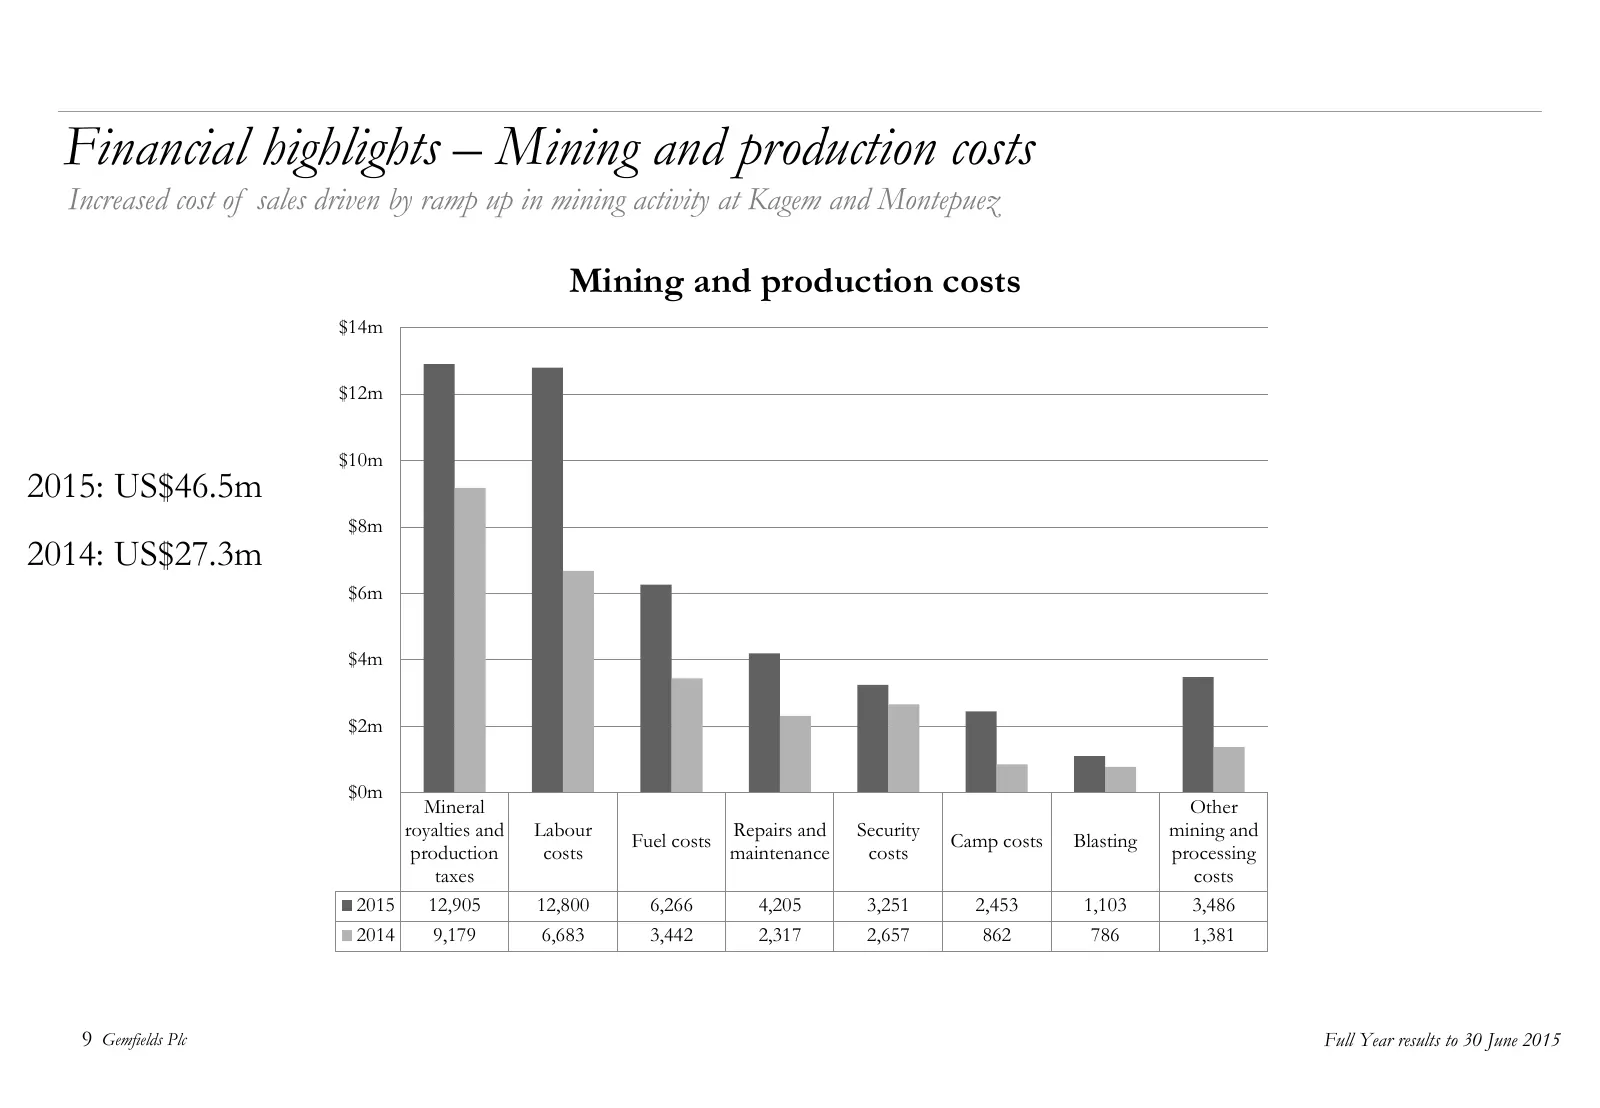
Financial highlights – Mining and production costs Increased cost of sales driven by ramp up in mining activity at Kagem and Montepuez Mining and production costs $14m $12m $10m 2015: US$46.5m $8m 2014: US$27.3m $6m $4m $2m $0m Mineral Other royalties and Labour Repairs and Security mining and Fuel
Slide 10: Mine cost analysis for Kagem, Zambia (75% interest)
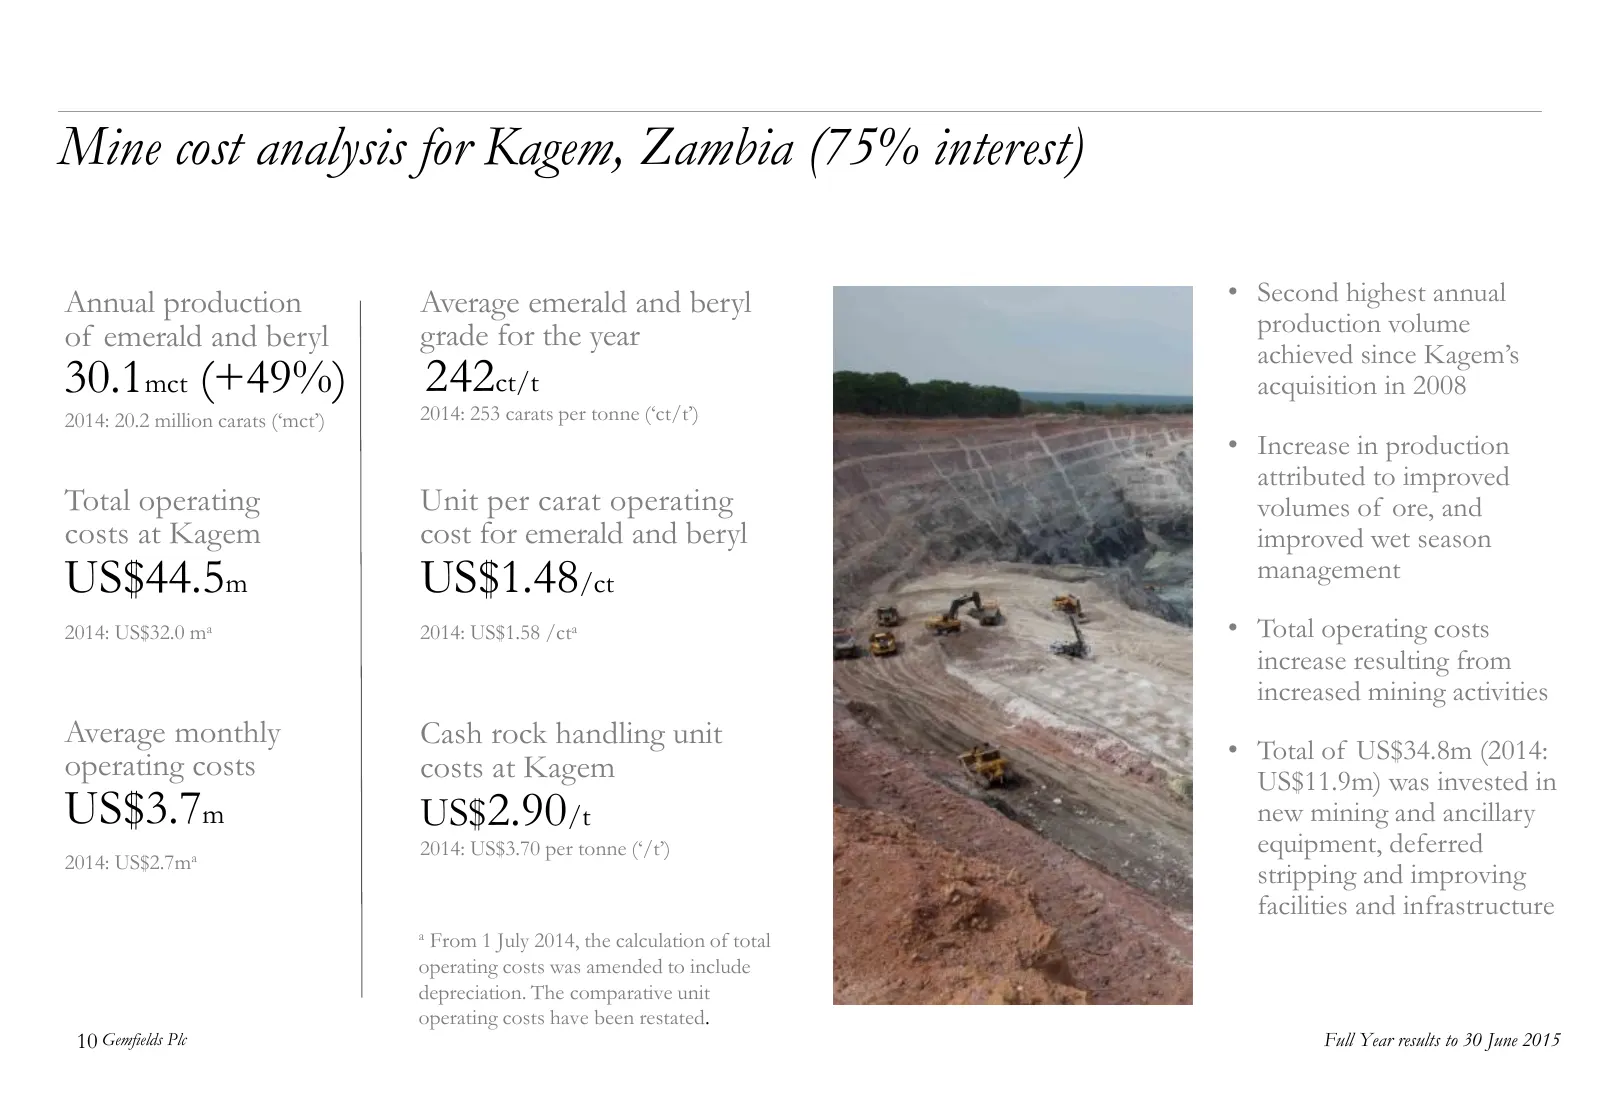
Mine cost analysis for Kagem, Zambia (75% interest) Annual production Average emerald and beryl • Second highest annual of emerald and beryl grade for the year production volume achieved since Kagem’s 30.1mct (+49%) 242ct/t acquisition in 2008 2014: 20.2 million carats (‘mct’) 2014: 253 carats per t
Slide 11: Mine cost analysis for Montepuez, Mozambique (75% interest)
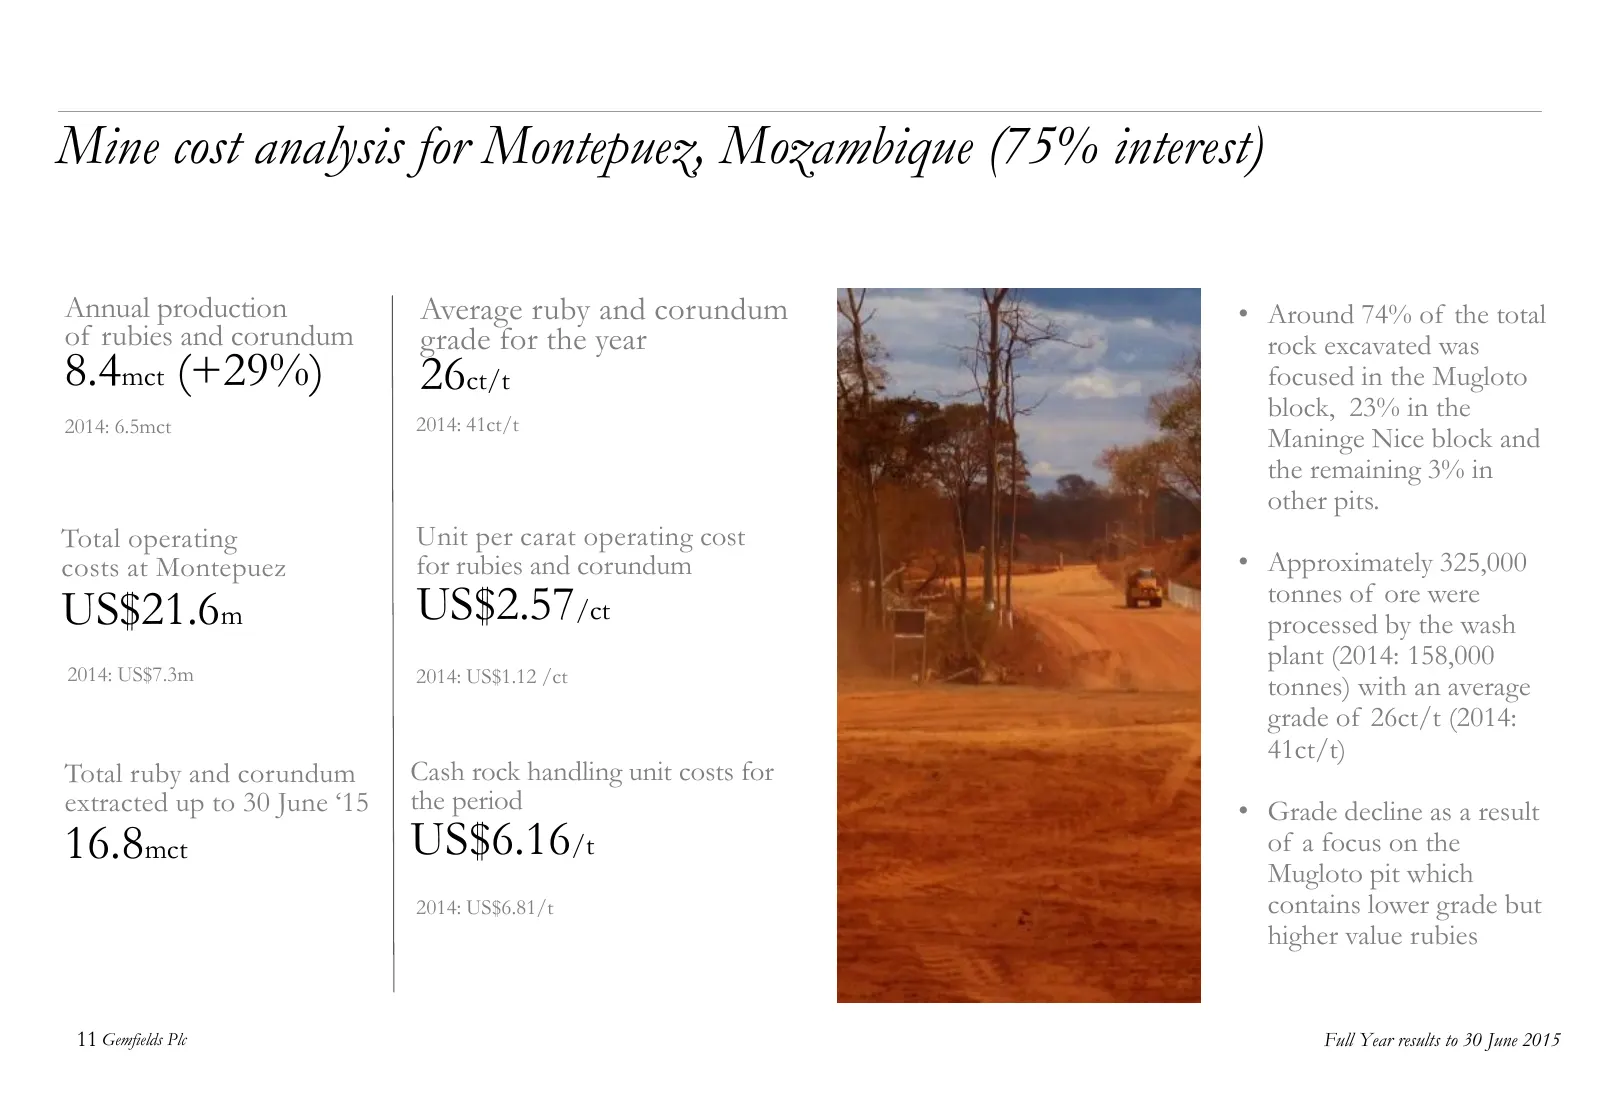
Mine cost analysis for Montepuez, Mozambique (75% interest) Annual production Average ruby and corundum • Around 74% of the total of rubies and corundum grade for the year rock excavated was 8.4mct (+29%) 26ct/t focused in the Mugloto block, 23% in the 2014: 6.5mct 2014: 41ct/t Maninge Nice block an
Slide 12: Financial highlights – Selling, general and administrative expenses
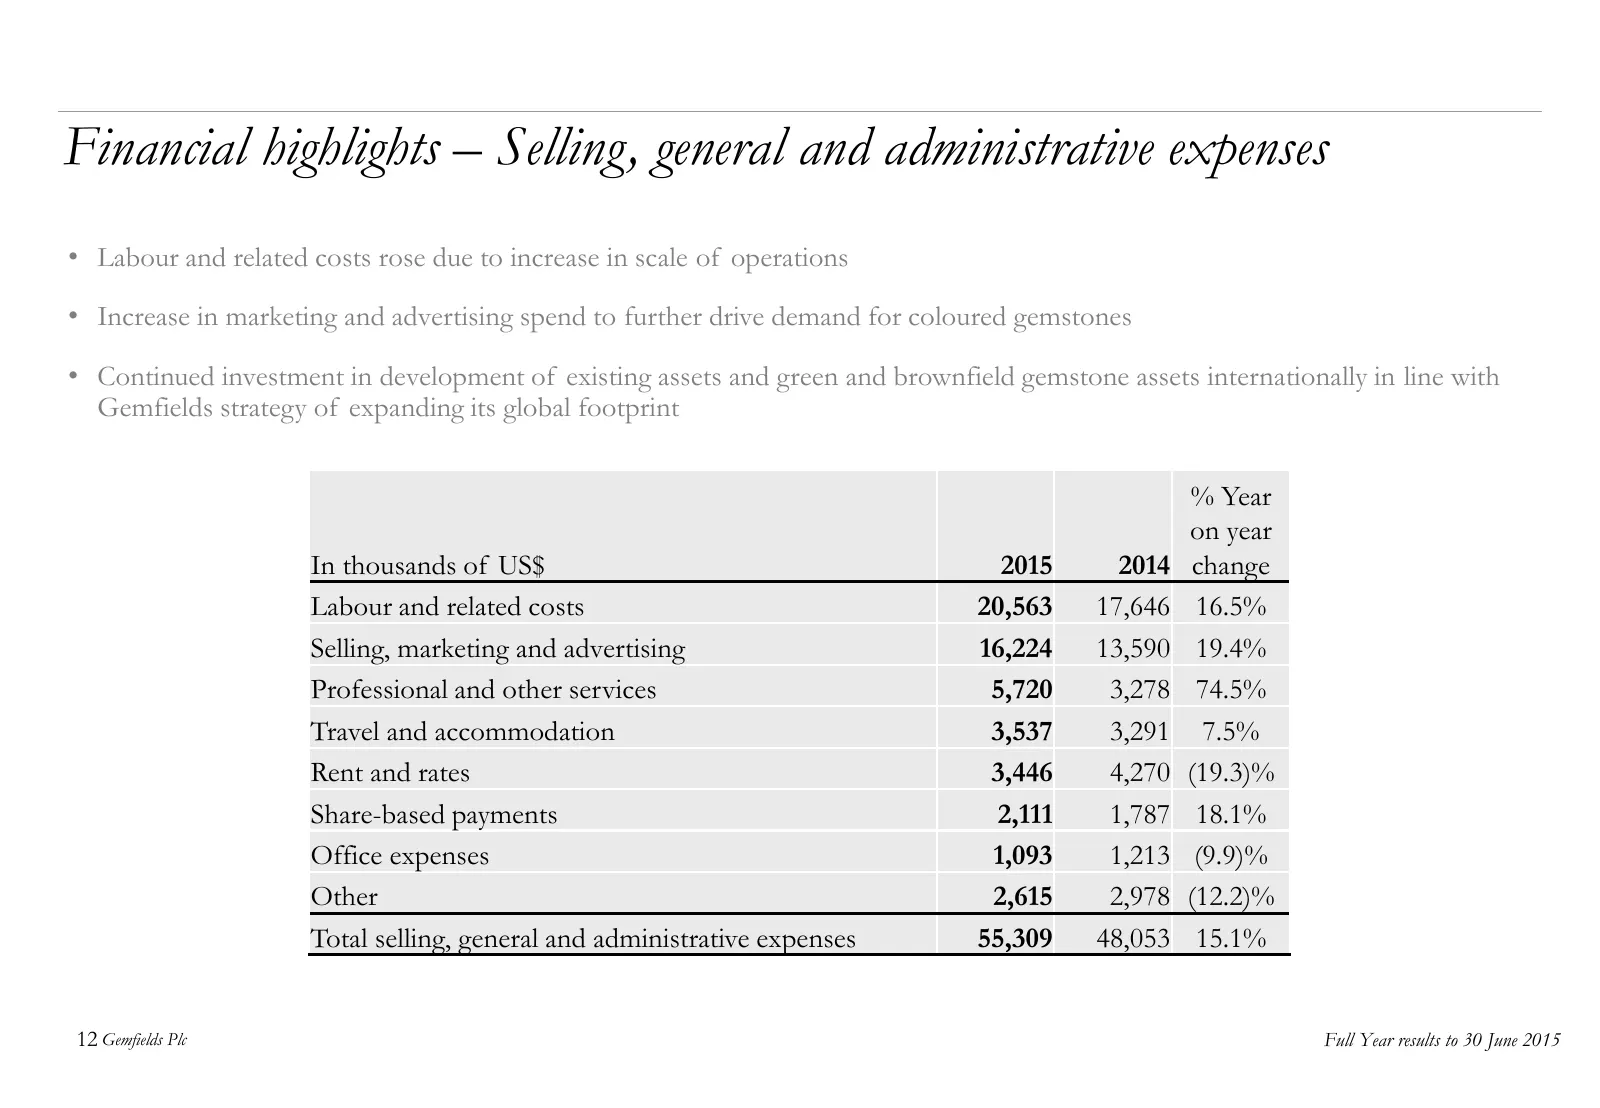
Financial highlights – Selling, general and administrative expenses • Labour and related costs rose due to increase in scale of operations • Increase in marketing and advertising spend to further drive demand for coloured gemstones • Continued investment in development of existing assets and green a
Slide 13: Full Year Results 2015: Operational highlights
Full Year Results 2015 Operational highlights Gemfields Plc
Slide 14: Kagem mine
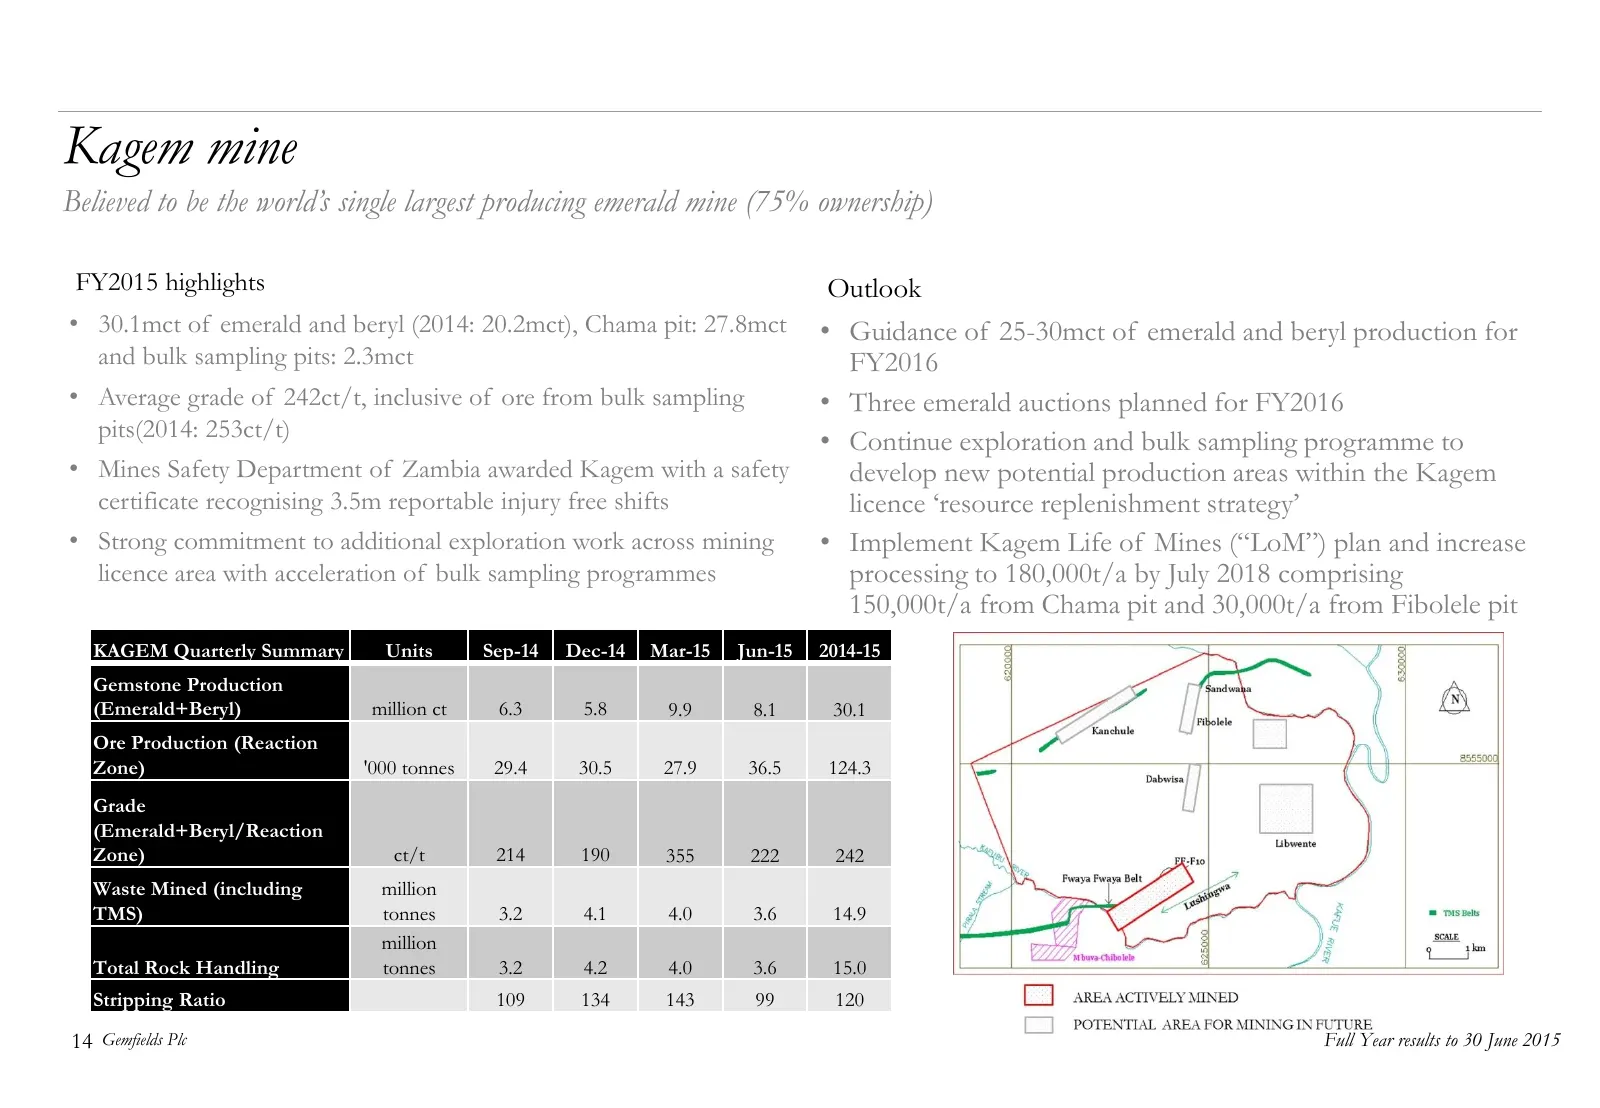
Kagem mine Believed to be the world’s single largest producing emerald mine (75% ownership) FY2015 highlights Outlook • 30.1mct of emerald and beryl (2014: 20.2mct), Chama pit: 27.8mct • Guidance of 25-30mct of emerald and beryl production for and bulk sampling pits: 2.3mct FY2016 • Average grade of
Slide 15: Kagem JORC Resource and Reserves update – Post year end
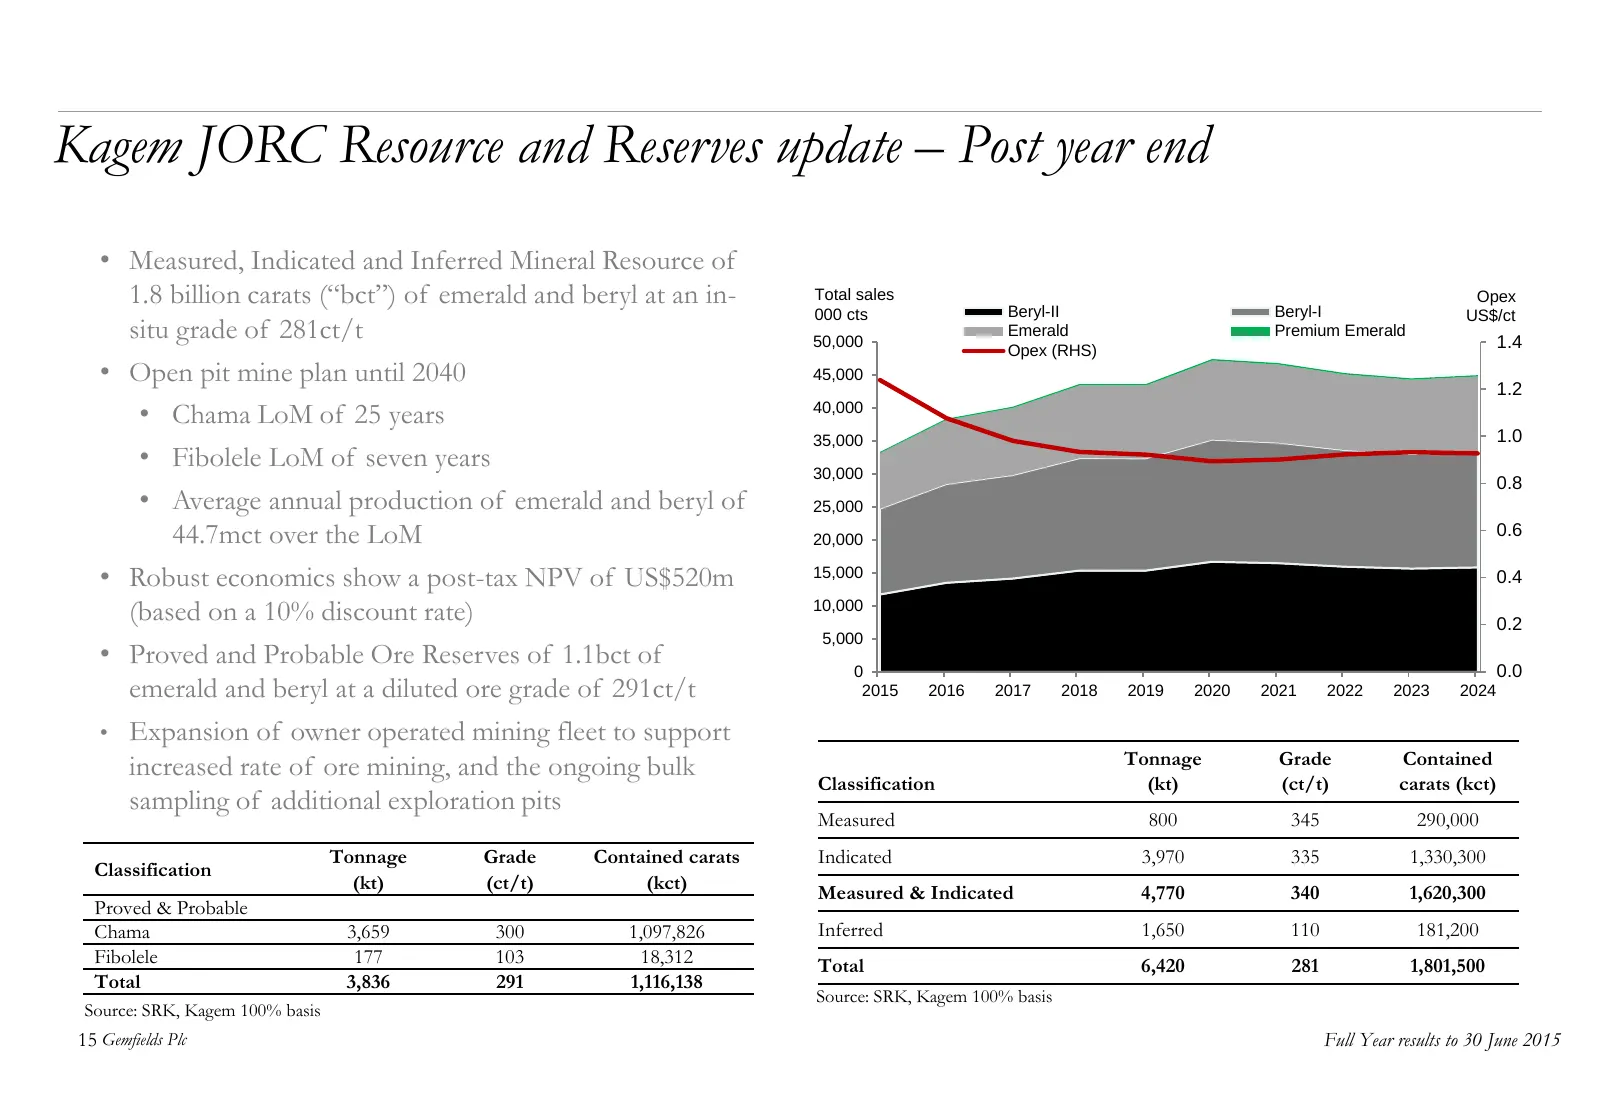
Kagem JORC Resource and Reserves update – Post year end • Measured, Indicated and Inferred Mineral Resource of 1.8 billion carats (“bct”) of emerald and beryl at an in- Total sales Beryl-II Beryl-I Opex 000 cts US$/ct situ grade of 281ct/t 50,000 Emerald Premium Emerald 1.4 Opex (RHS) • Open pit min
Slide 16: Montepuez mine
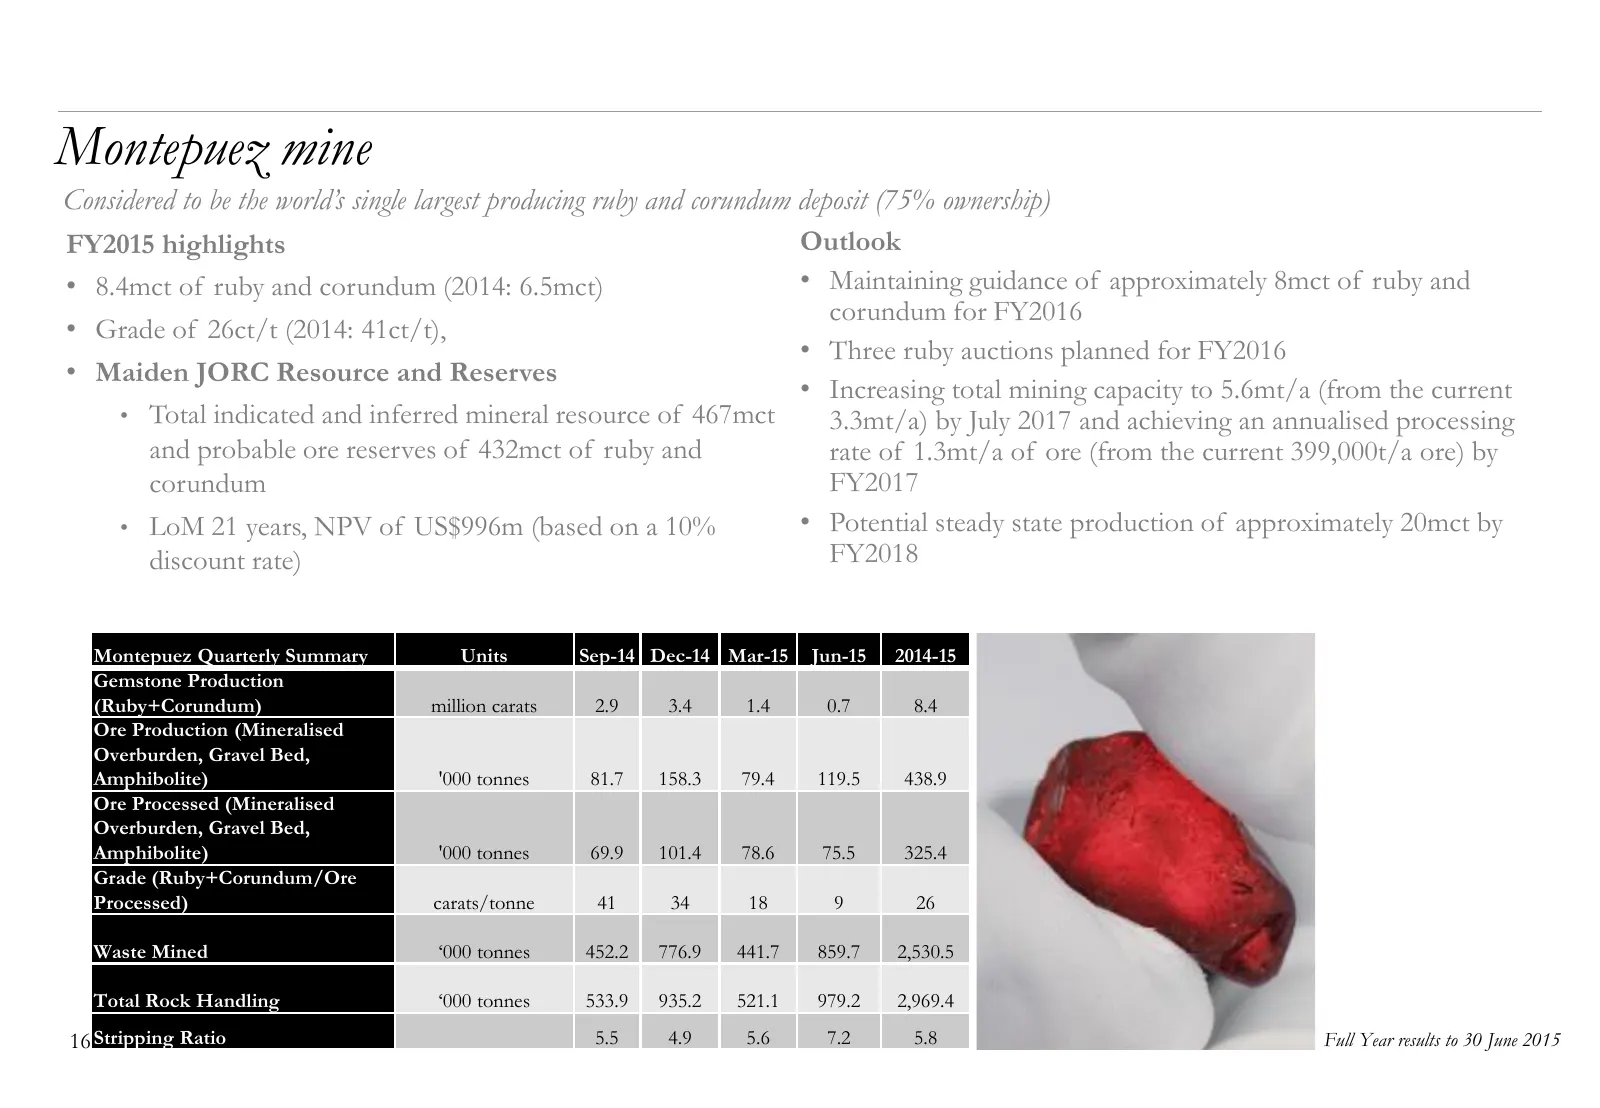
Montepuez mine Considered to be the world’s single largest producing ruby and corundum deposit (75% ownership) FY2015 highlights Outlook • 8.4mct of ruby and corundum (2014: 6.5mct) • Maintaining guidance of approximately 8mct of ruby and corundum for FY2016 • Grade of 26ct/t (2014: 41ct/t), • Three
Slide 17: Montepuez JORC Maiden Resource and Reserves – post year end
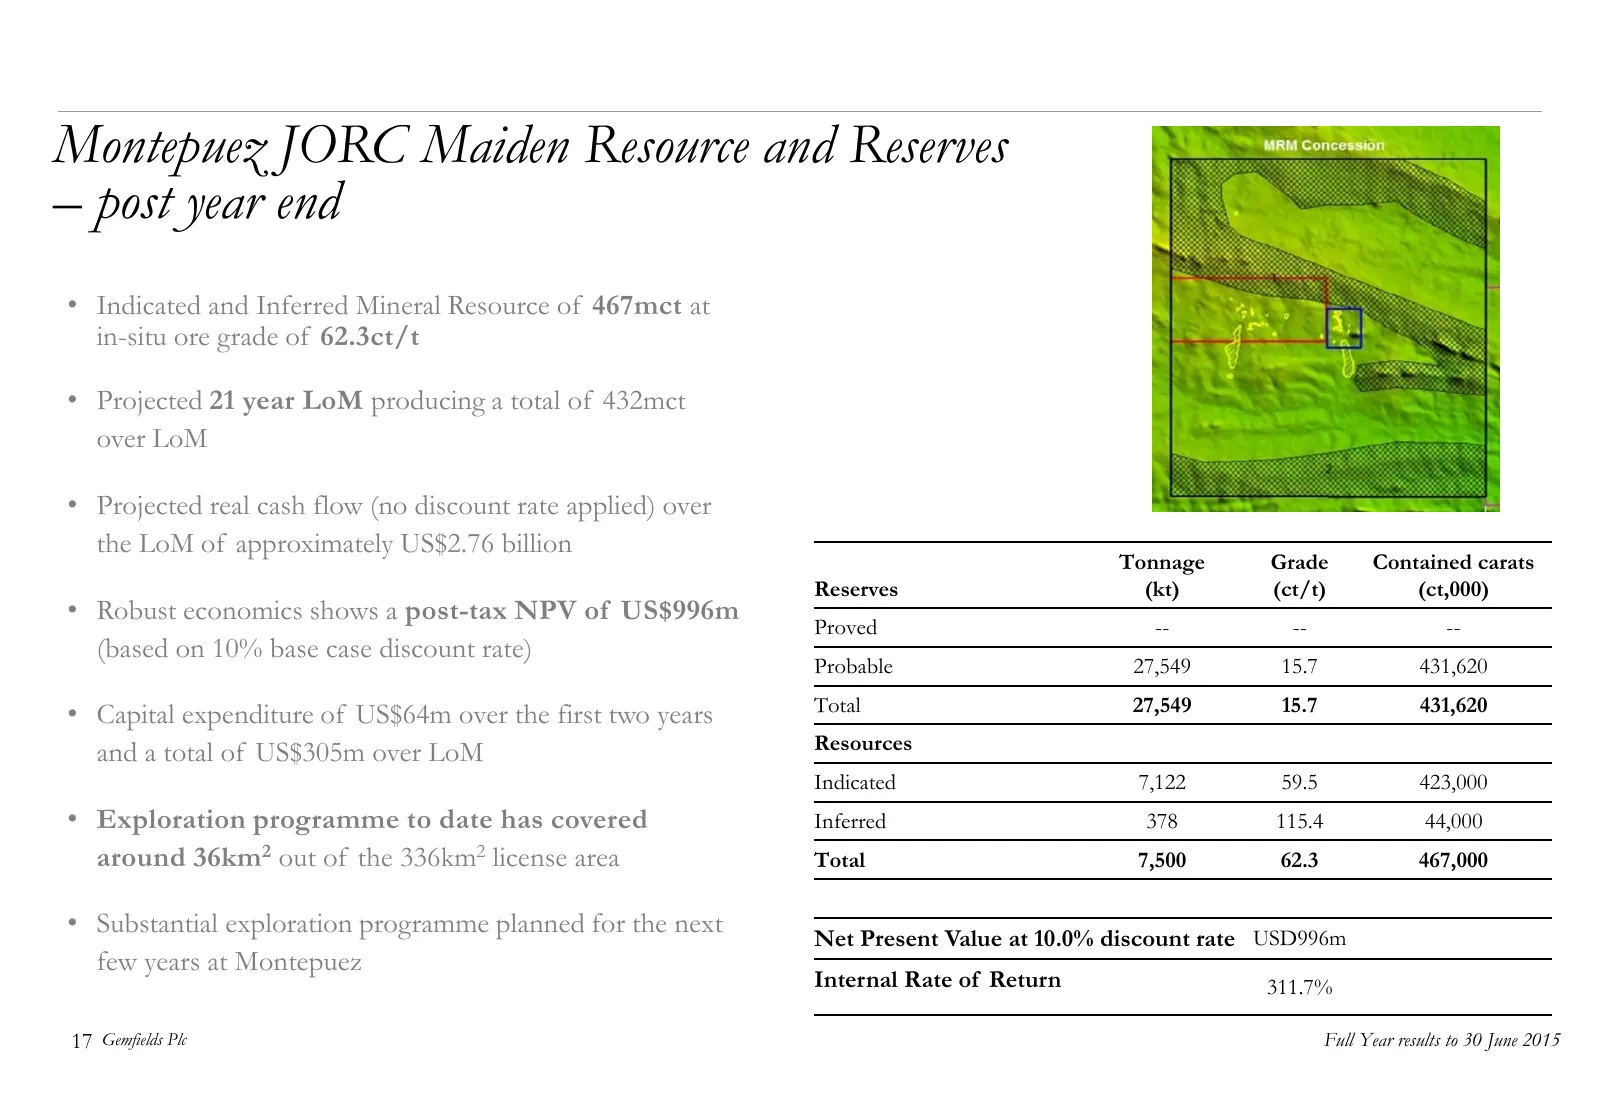
Montepuez JORC Maiden Resource and Reserves – post year end • Indicated and Inferred Mineral Resource of 467mct at in-situ ore grade of 62.3ct/t • Projected 21 year LoM producing a total of 432mct over LoM • Projected real cash flow (no discount rate applied) over the LoM of approximately US$2.76 bi
Slide 18: Amethyst, sapphires and other gemstone opportunities
Amethyst, sapphires and other gemstone opportunities 1. Colombia • In September 2015 Gemfields announced that it has 4. Kariba Minerals, Zambia entered into binding agreements to acquire controlling • 50% interest in world’s single largest producing amethyst interests in two emerald projects with op
Slide 19: Fabergé
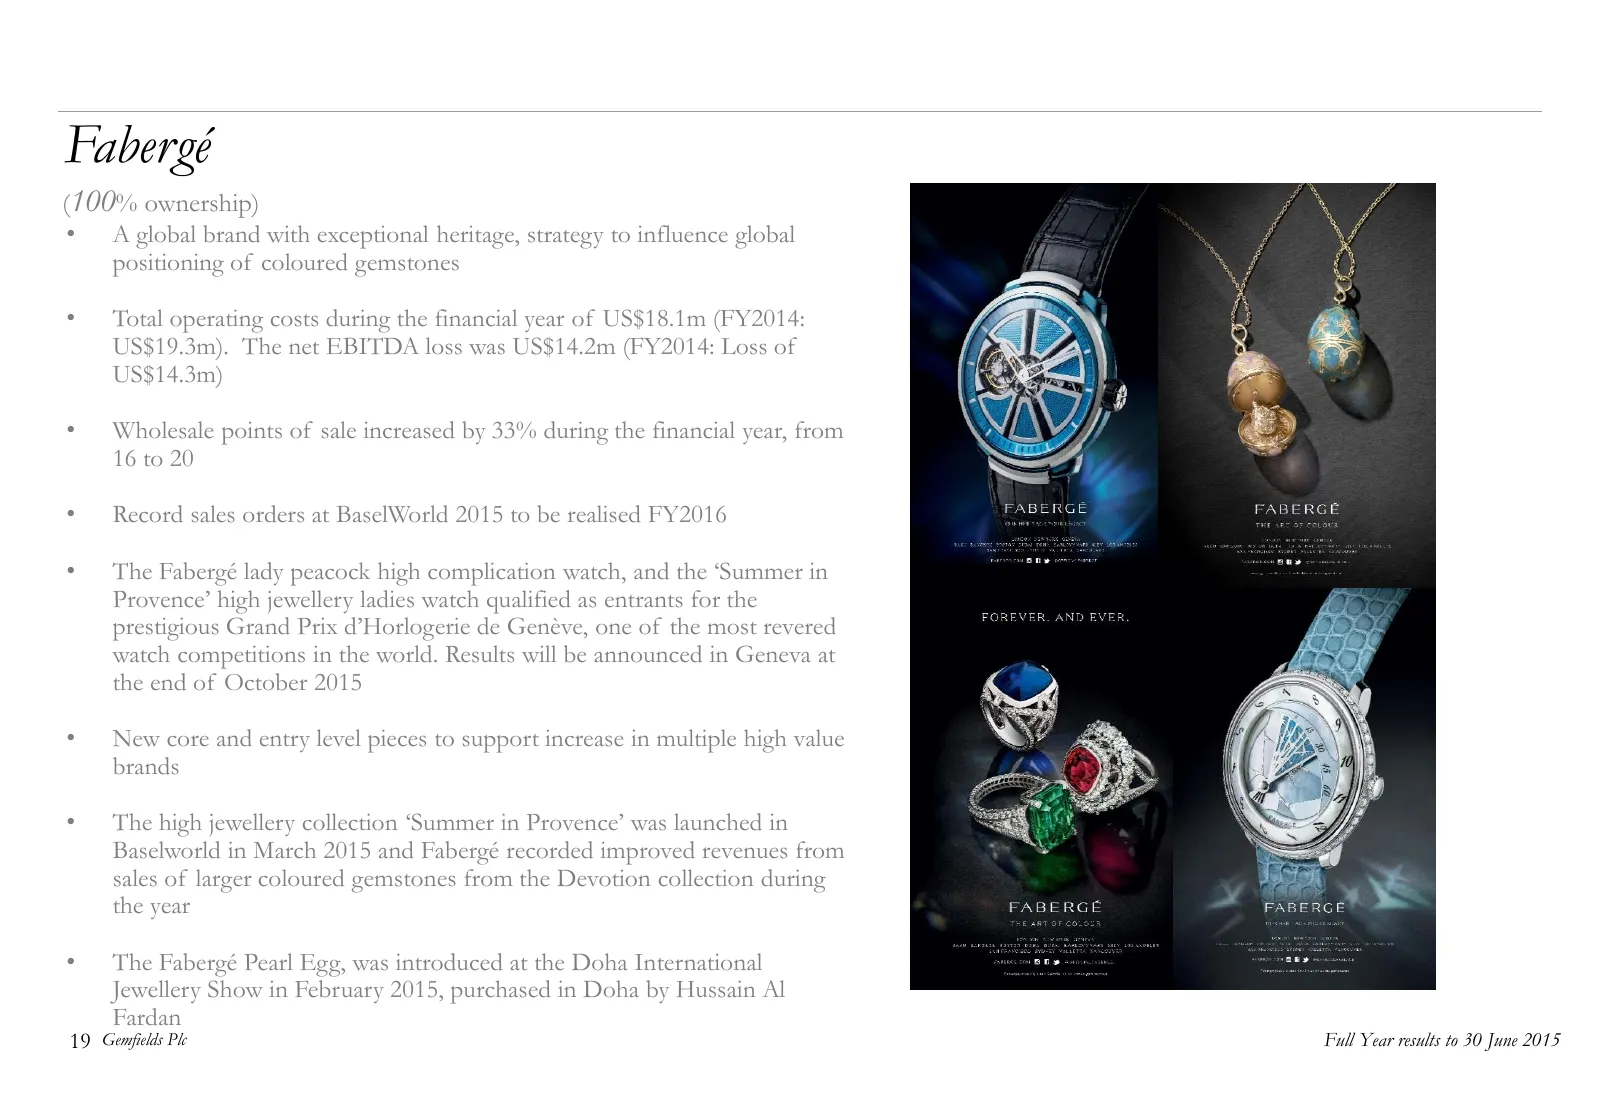
Fabergé (100% ownership) • A global brand with exceptional heritage, strategy to influence global positioning of coloured gemstones • Total operating costs during the financial year of US$18.1m (FY2014: US$19.3m). The net EBITDA loss was US$14.2m (FY2014: Loss of US$14.3m) • Wholesale points of sale
Slide 20: Outlook
Outlook Gemfields Plc
Slide 21: Significant growth opportunities will drive further value
Significant growth opportunities will drive further value Mining Fabergé Kagem • Roll out of new product and distribution strategy • Target of 25-30mct of emerald and beryl per annum for • Become a standalone profitable business unit FY2016 with potential of rising to 40-45mct following new LoM plan
Slide 22: Rough Sales and Marketing
Rough Sales and Marketing Gemfields Plc
Slide 23: Market overview
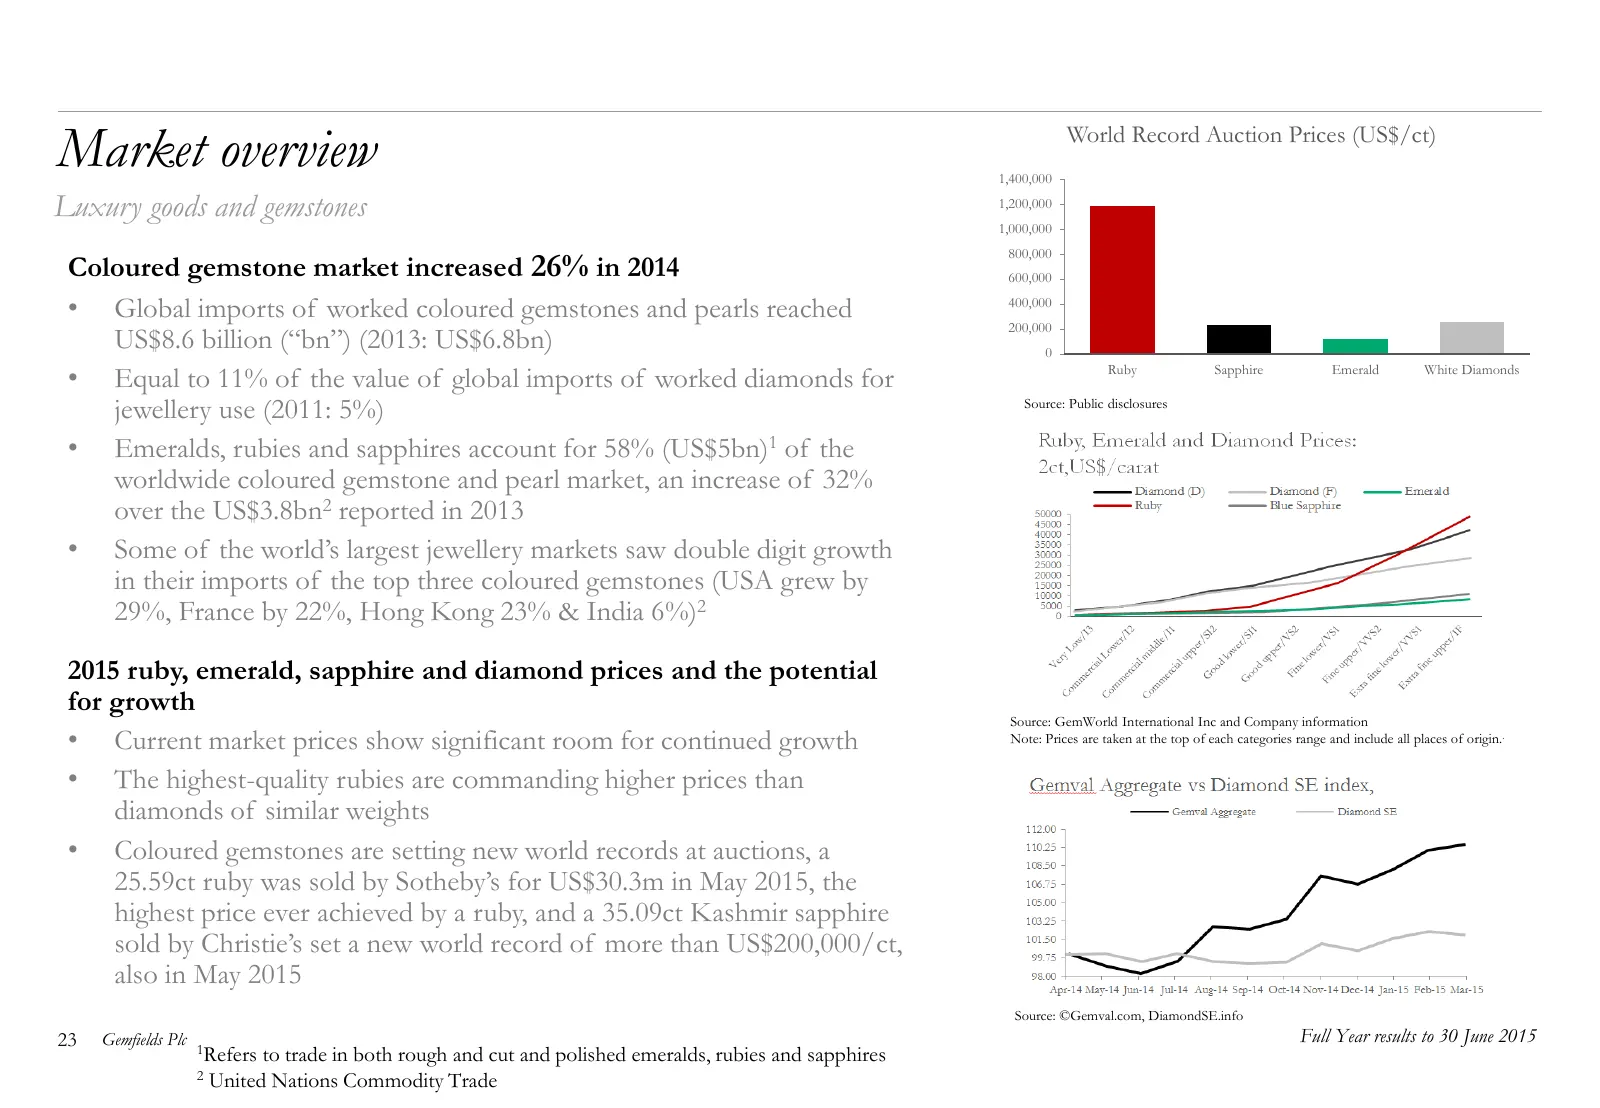
Market overview 1,400,000 World Record Auction Prices (US$/ct) Luxury goods and gemstones 1,200,000 1,000,000 800,000 Coloured gemstone market increased 26% in 2014 600,000 • Global imports of worked coloured gemstones and pearls reached 400,000 200,000 US$8.6 billion (“bn”) (2013: US$6.8bn) 0 • Equ
Slide 24: Gemstone production
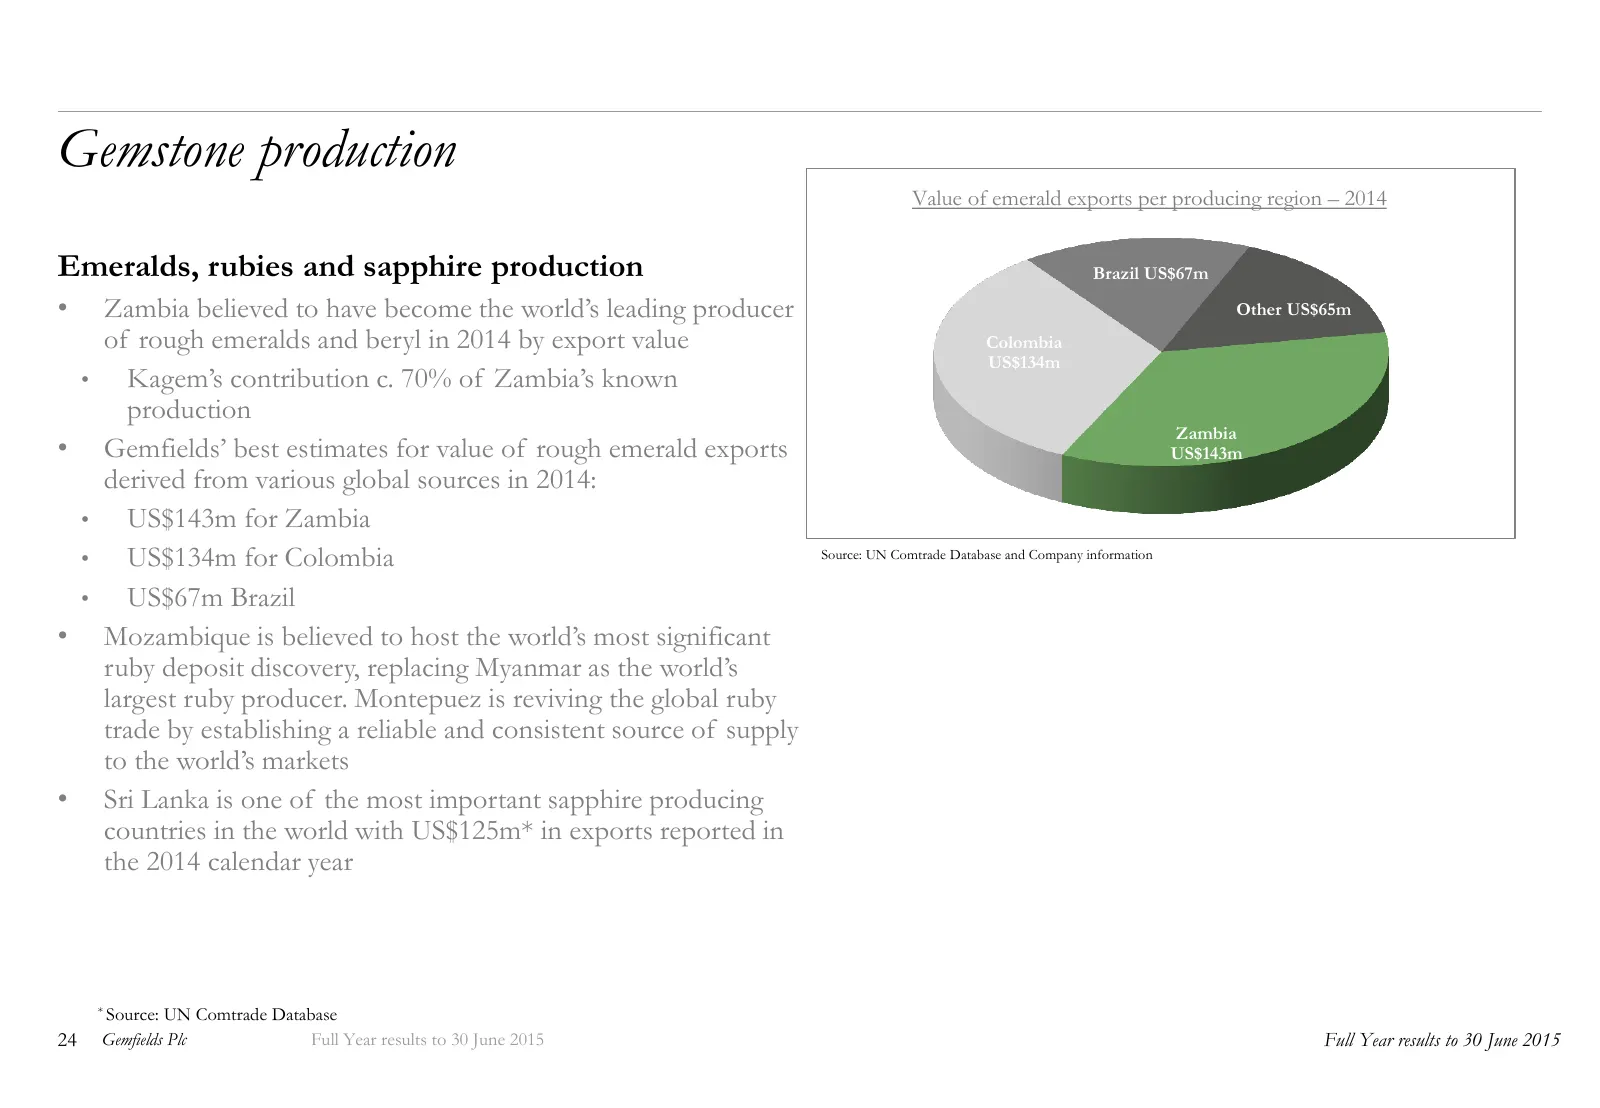
Gemstone production Value of emerald exports per producing region – 2014 Emeralds, rubies and sapphire production Brazil US$67m • Zambia believed to have become the world’s leading producer Other US$65m of rough emeralds and beryl in 2014 by export value Colombia US$134m • Kagem’s contribution c. 70
Slide 25: Rough emerald and beryl sales / Rough ruby and corundum sales
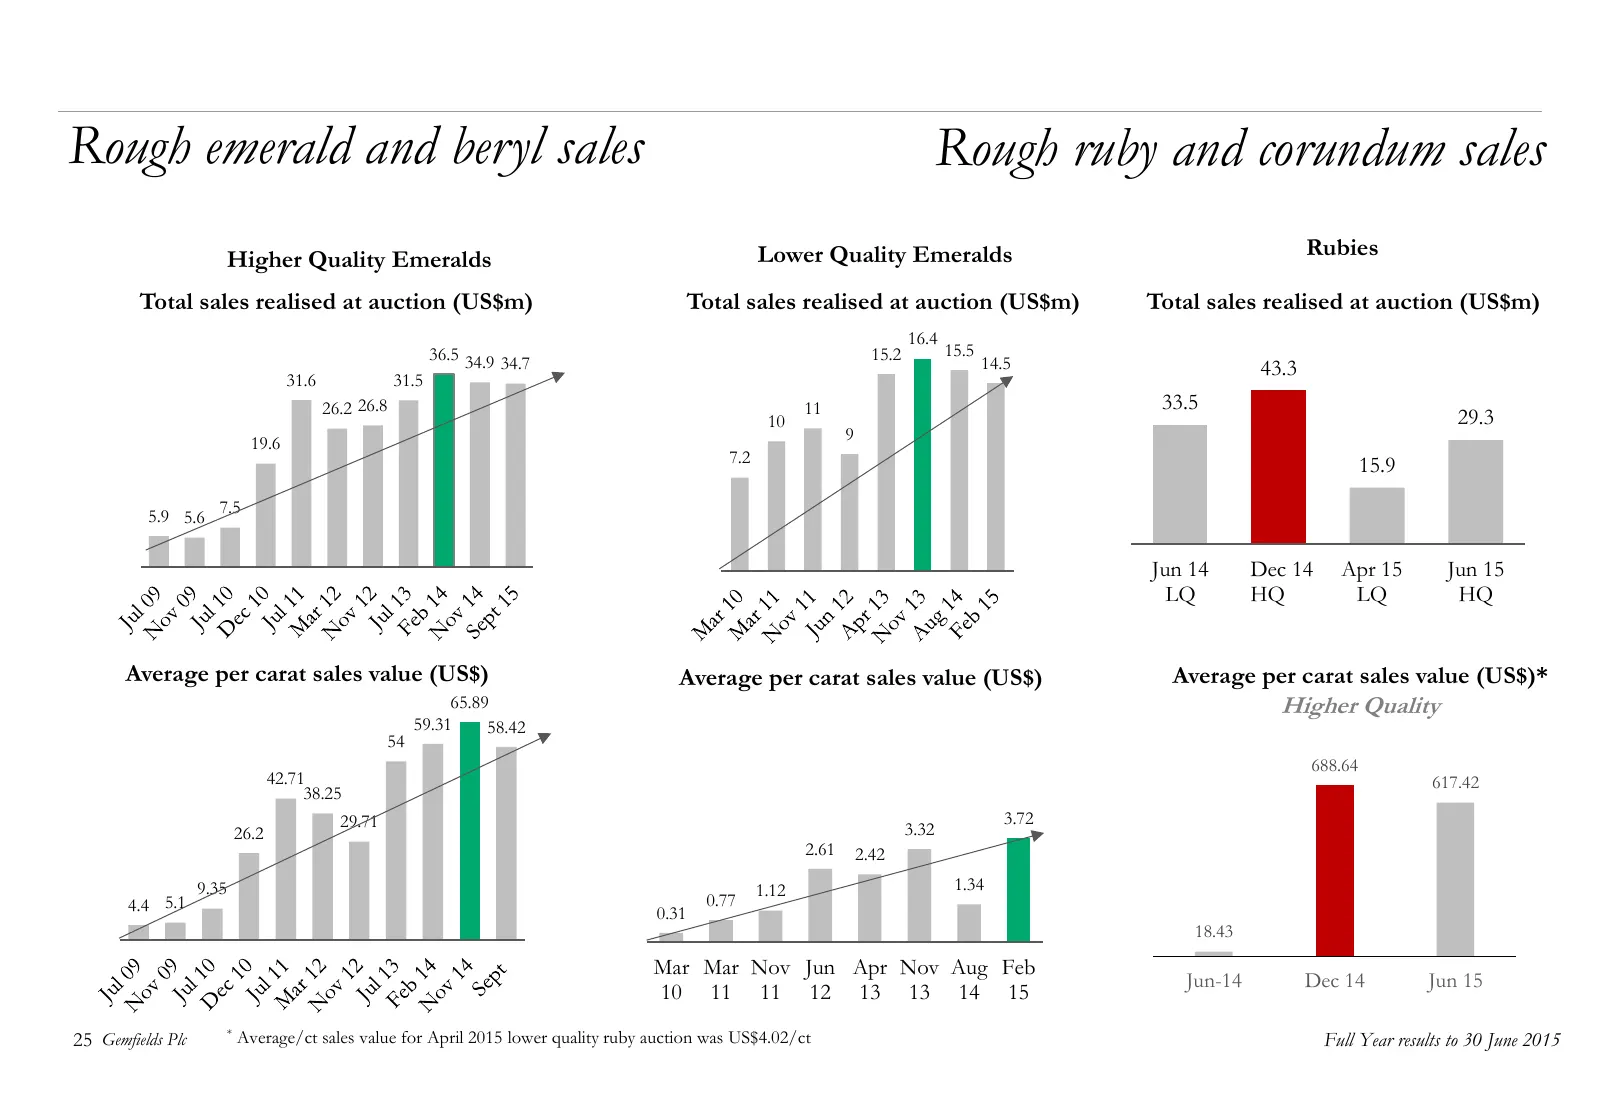
Rough emerald and beryl sales Rough ruby and corundum sales Higher Quality Emeralds Lower Quality Emeralds Rubies Total sales realised at auction (US$m) Total sales realised at auction (US$m) Total sales realised at auction (US$m) 16.4 36.5 34.9 15.2 15.5 34.7 14.5 43.3 31.6 31.5 26.2 26.8 11 33.5 1
Slide 26: Providing a consistent supply
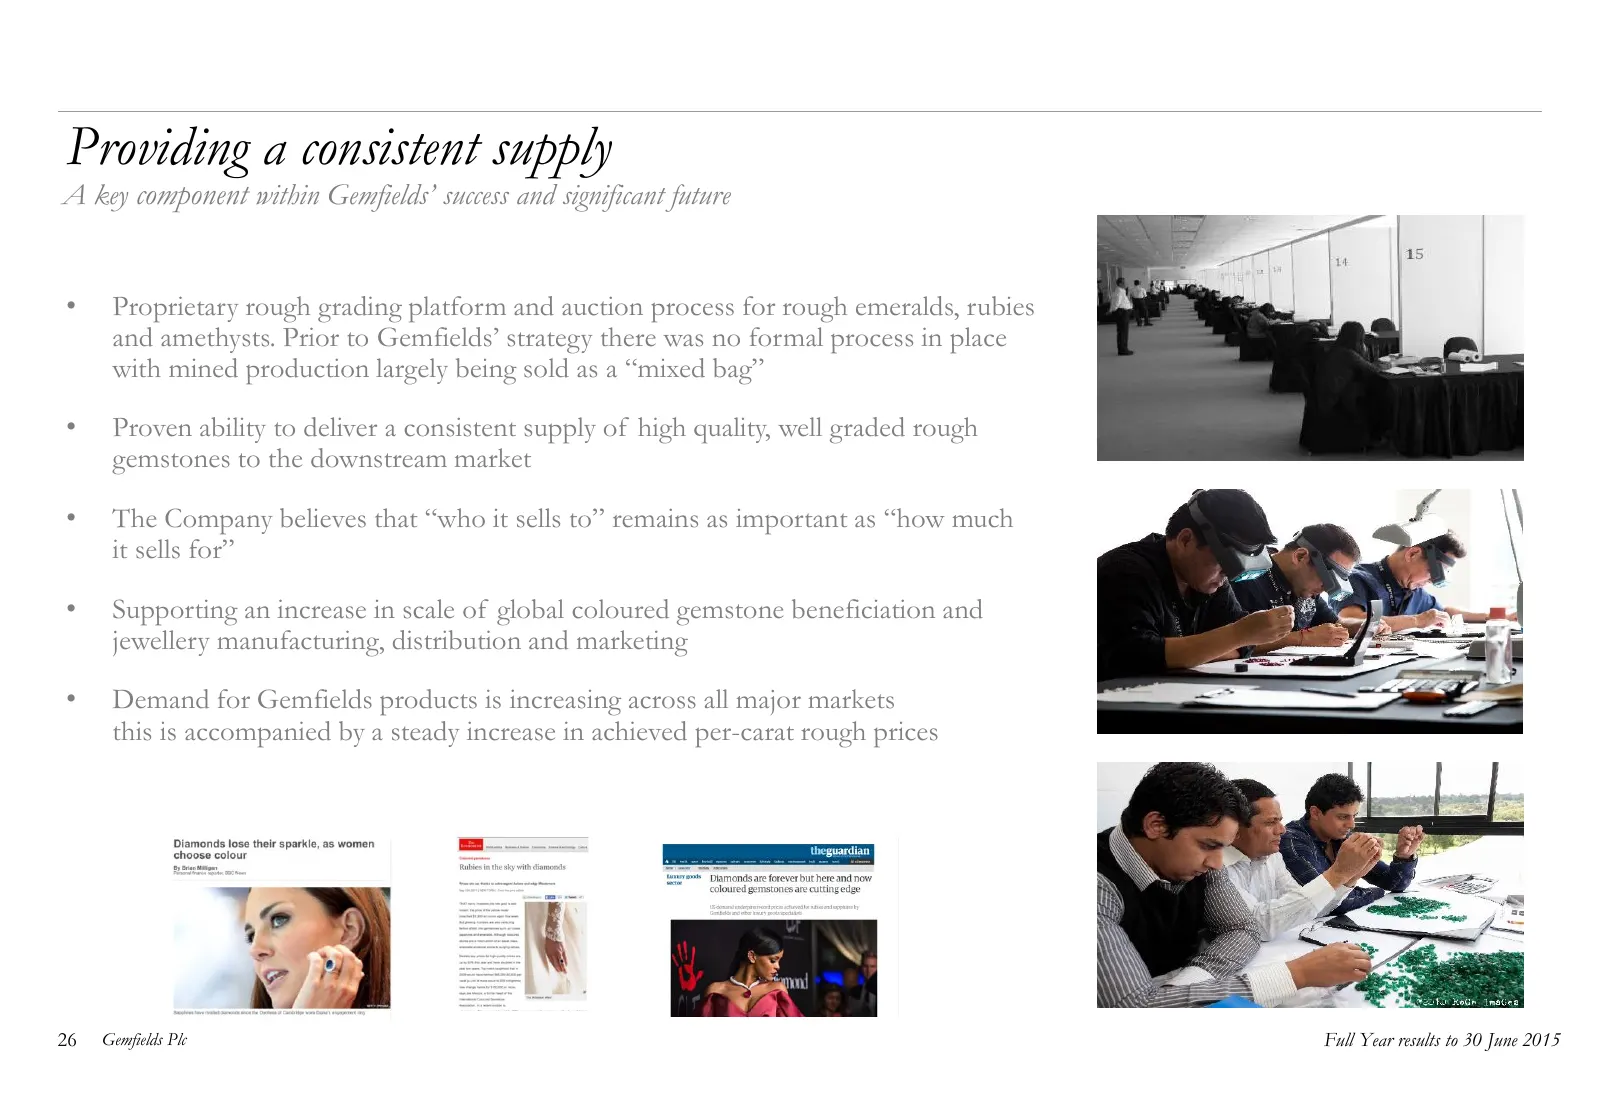
Providing a consistent supply A key component within Gemfields’ success and significant future • Proprietary rough grading platform and auction process for rough emeralds, rubies and amethysts. Prior to Gemfields’ strategy there was no formal process in place with mined production largely being sold
Slide 27: Targeted marketing
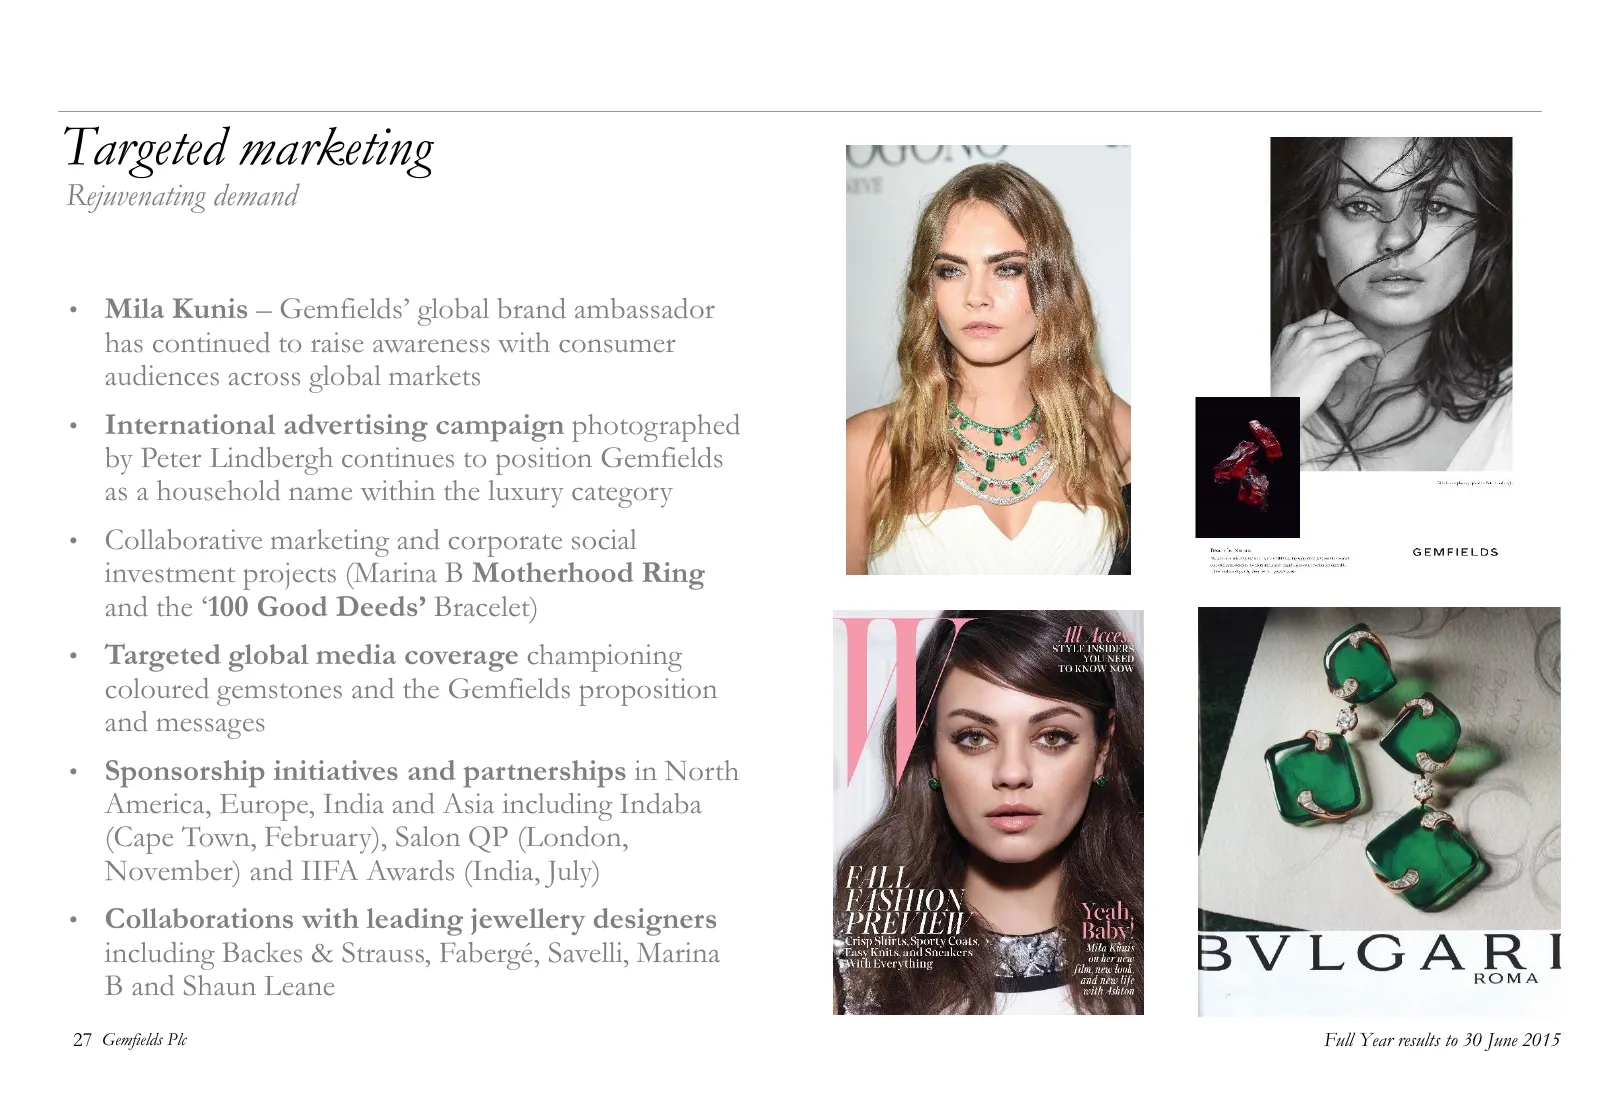
Targeted marketing Rejuvenating demand • Mila Kunis – Gemfields’ global brand ambassador has continued to raise awareness with consumer audiences across global markets • International advertising campaign photographed by Peter Lindbergh continues to position Gemfields as a household name within the
Slide 28: Committed to sustainability
Committed to sustainability Gemfields’ approach: Cause-related initiatives: Addressing sustainability at our operations; societal, In FY2015 we undertook a number of initiatives. These environmental, health & safety, human rights aspects but also, included: crucially, the integrity of our product th
Slide 29: Appendix
Appendix Gemfields Plc
Slide 30: Locations
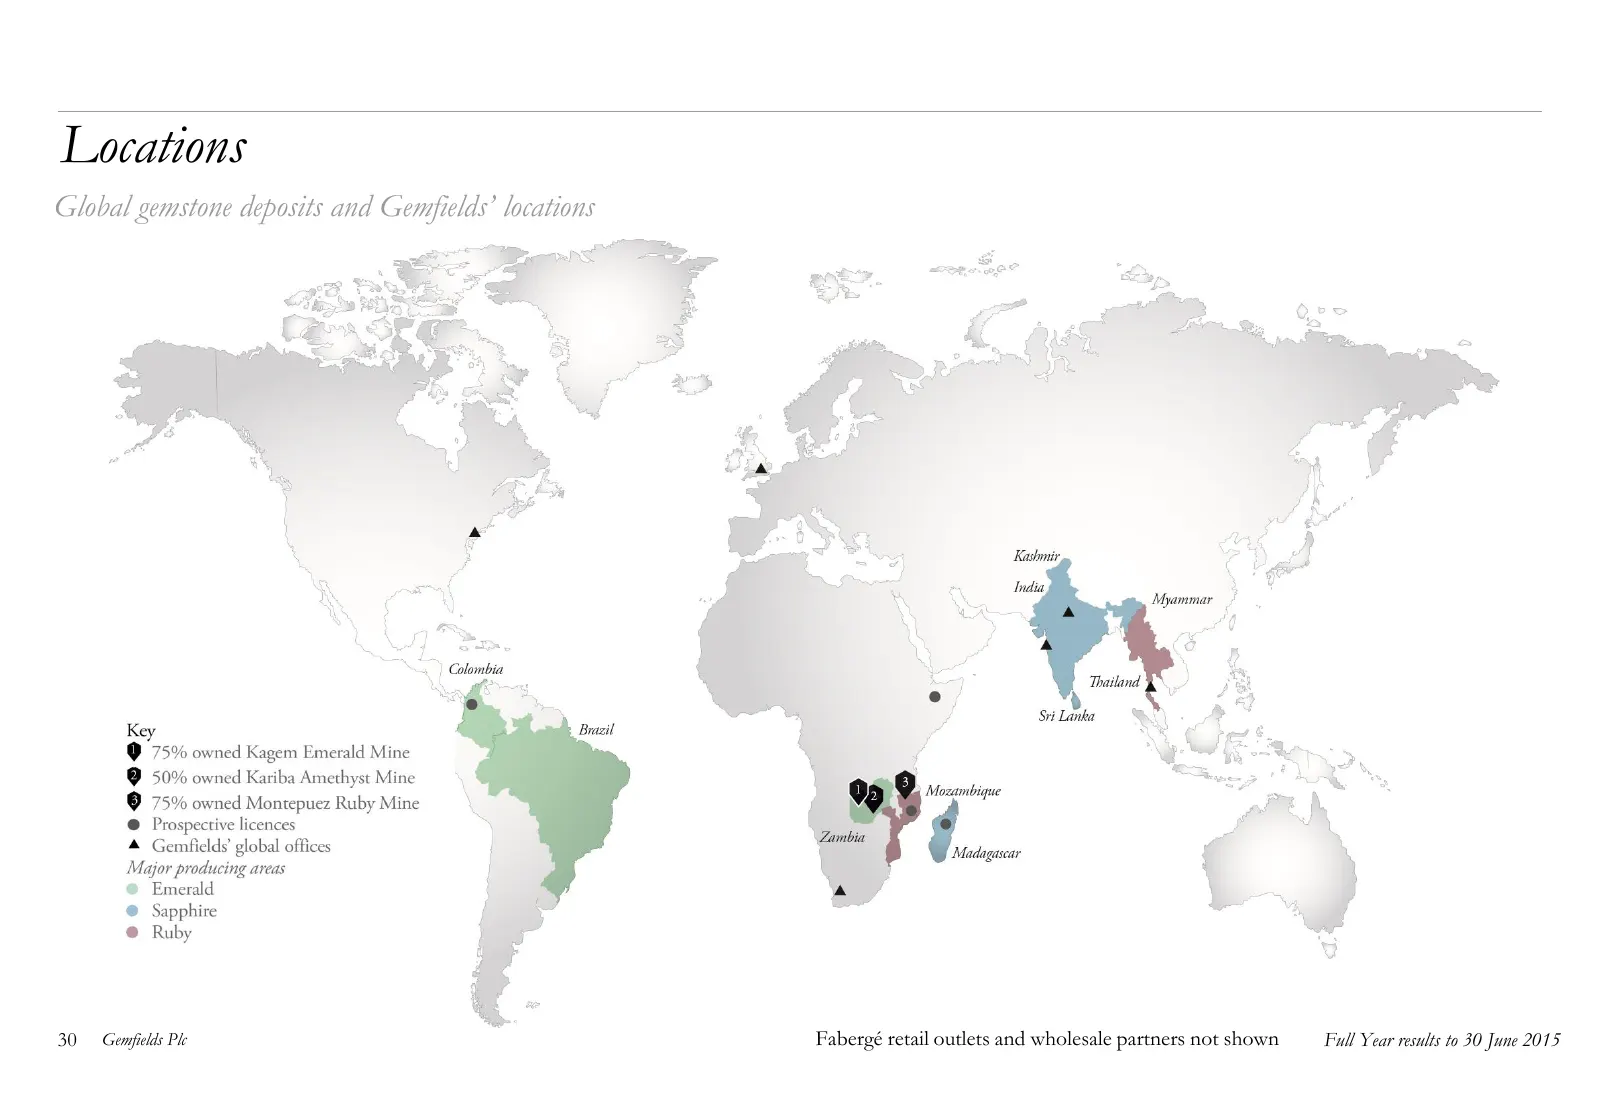
Locations Global gemstone deposits and Gemfields’ locations 30 Gemfields Plc Fabergé retail outlets and wholesale partners not shown Full Year results to 30 June 2015
Slide 31: Company overview
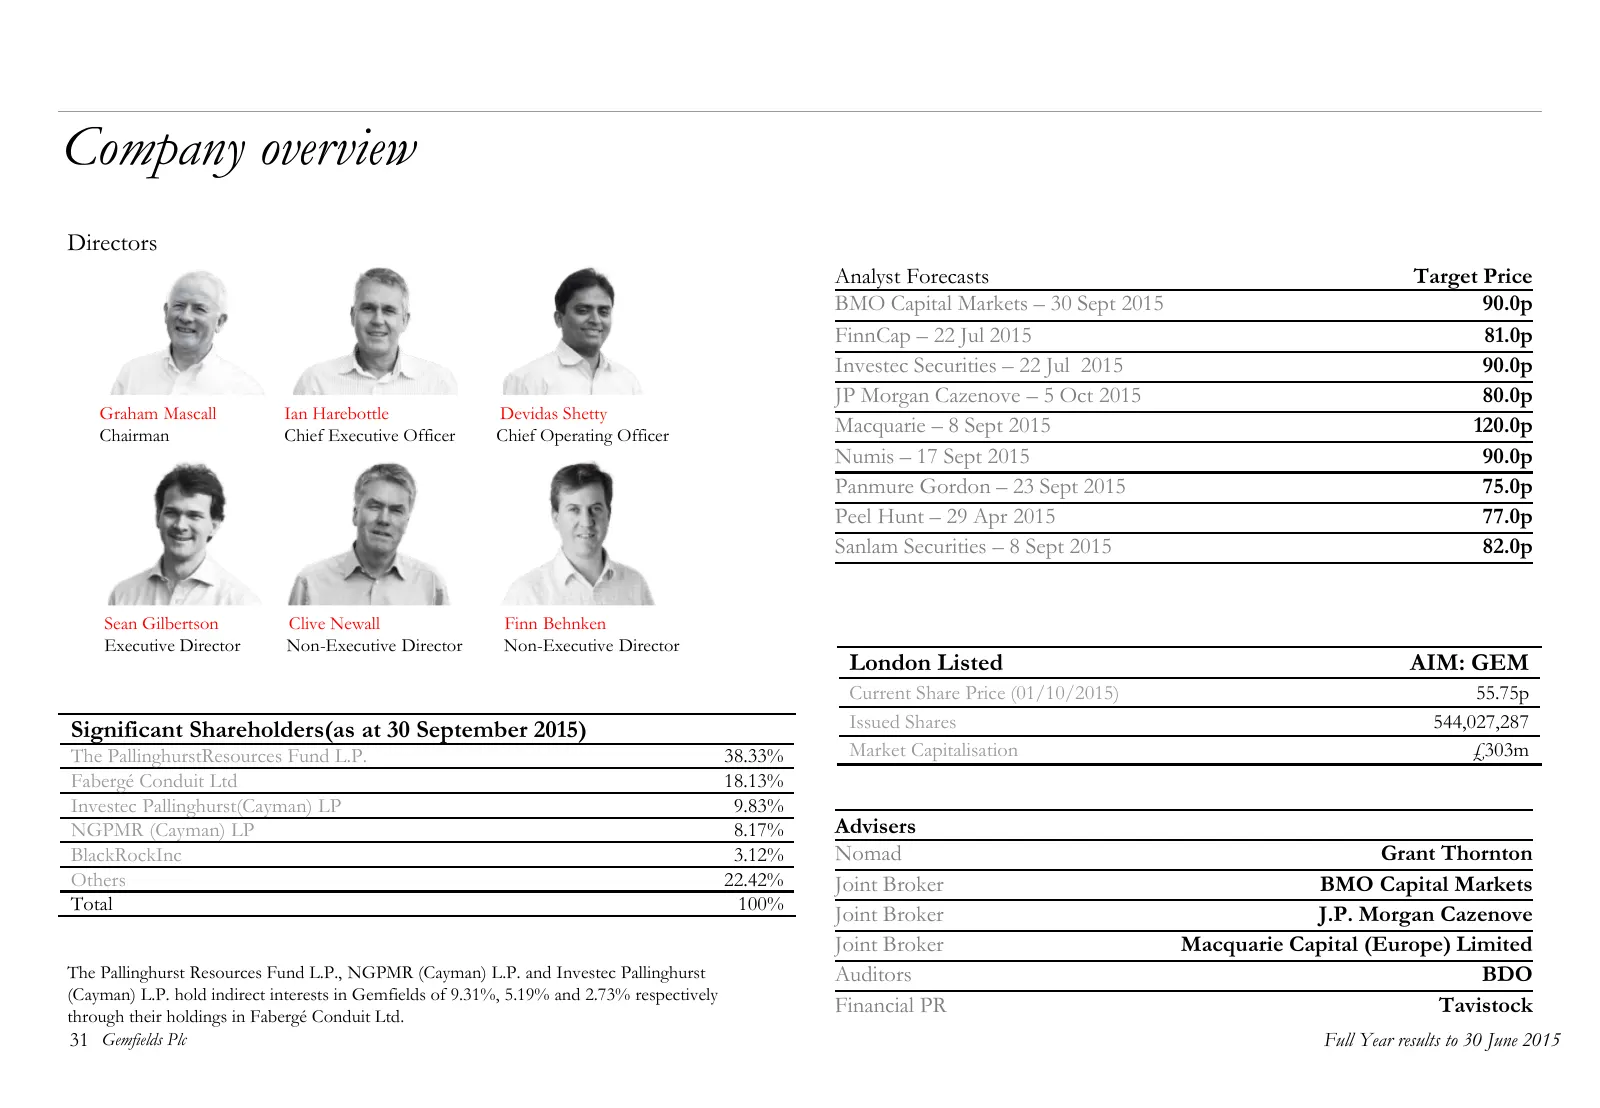
Company overview Directors Analyst Forecasts Target Price BMO Capital Markets – 30 Sept 2015 90.0p FinnCap – 22 Jul 2015 81.0p Investec Securities – 22 Jul 2015 90.0p JP Morgan Cazenove – 5 Oct 2015 80.0p Graham Mascall Ian Harebottle Devidas Shetty Chairman Chief Executive Officer Chief Operating O
Slide 32: Traded emerald auctions
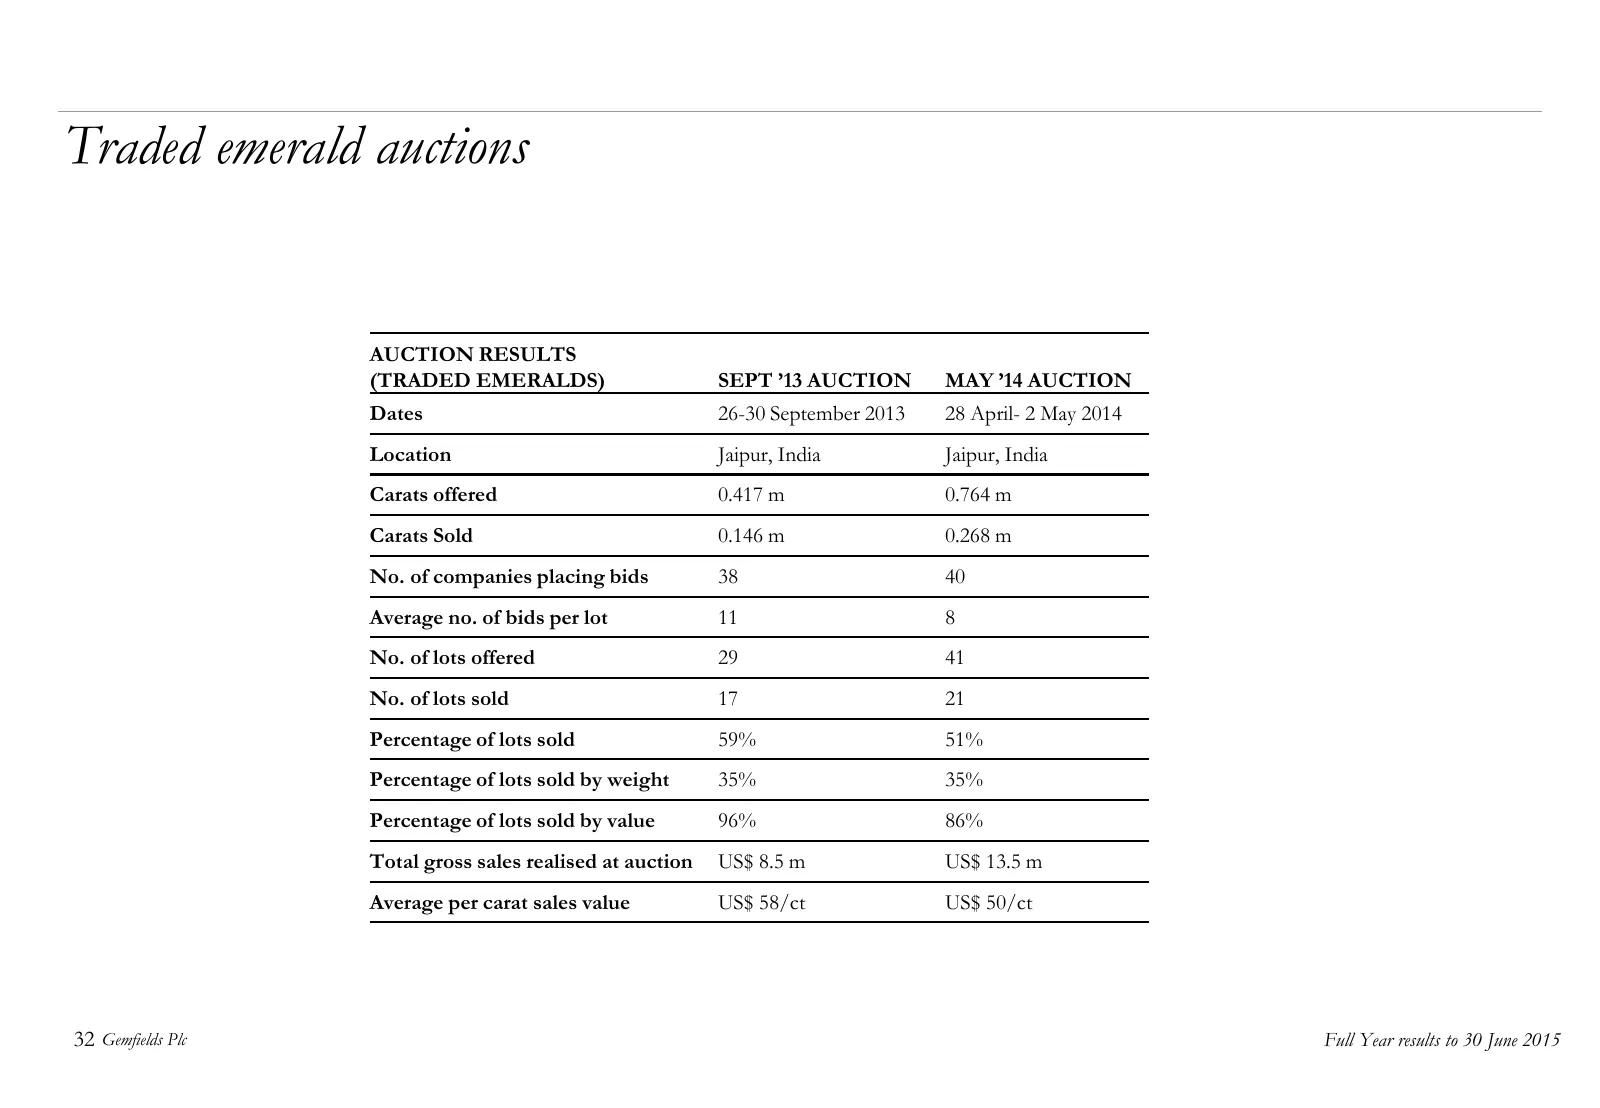
Traded emerald auctions AUCTION RESULTS (TRADED EMERALDS) SEPT ’13 AUCTION MAY ’14 AUCTION Dates 26-30 September 2013 28 April- 2 May 2014 Location Jaipur, India Jaipur, India Carats offered 0.417 m 0.764 m Carats Sold 0.146 m 0.268 m No. of companies placing bids 38 40 Average no. of bids per lot 1
Slide 33: Rough emerald and beryl sales (lower quality)
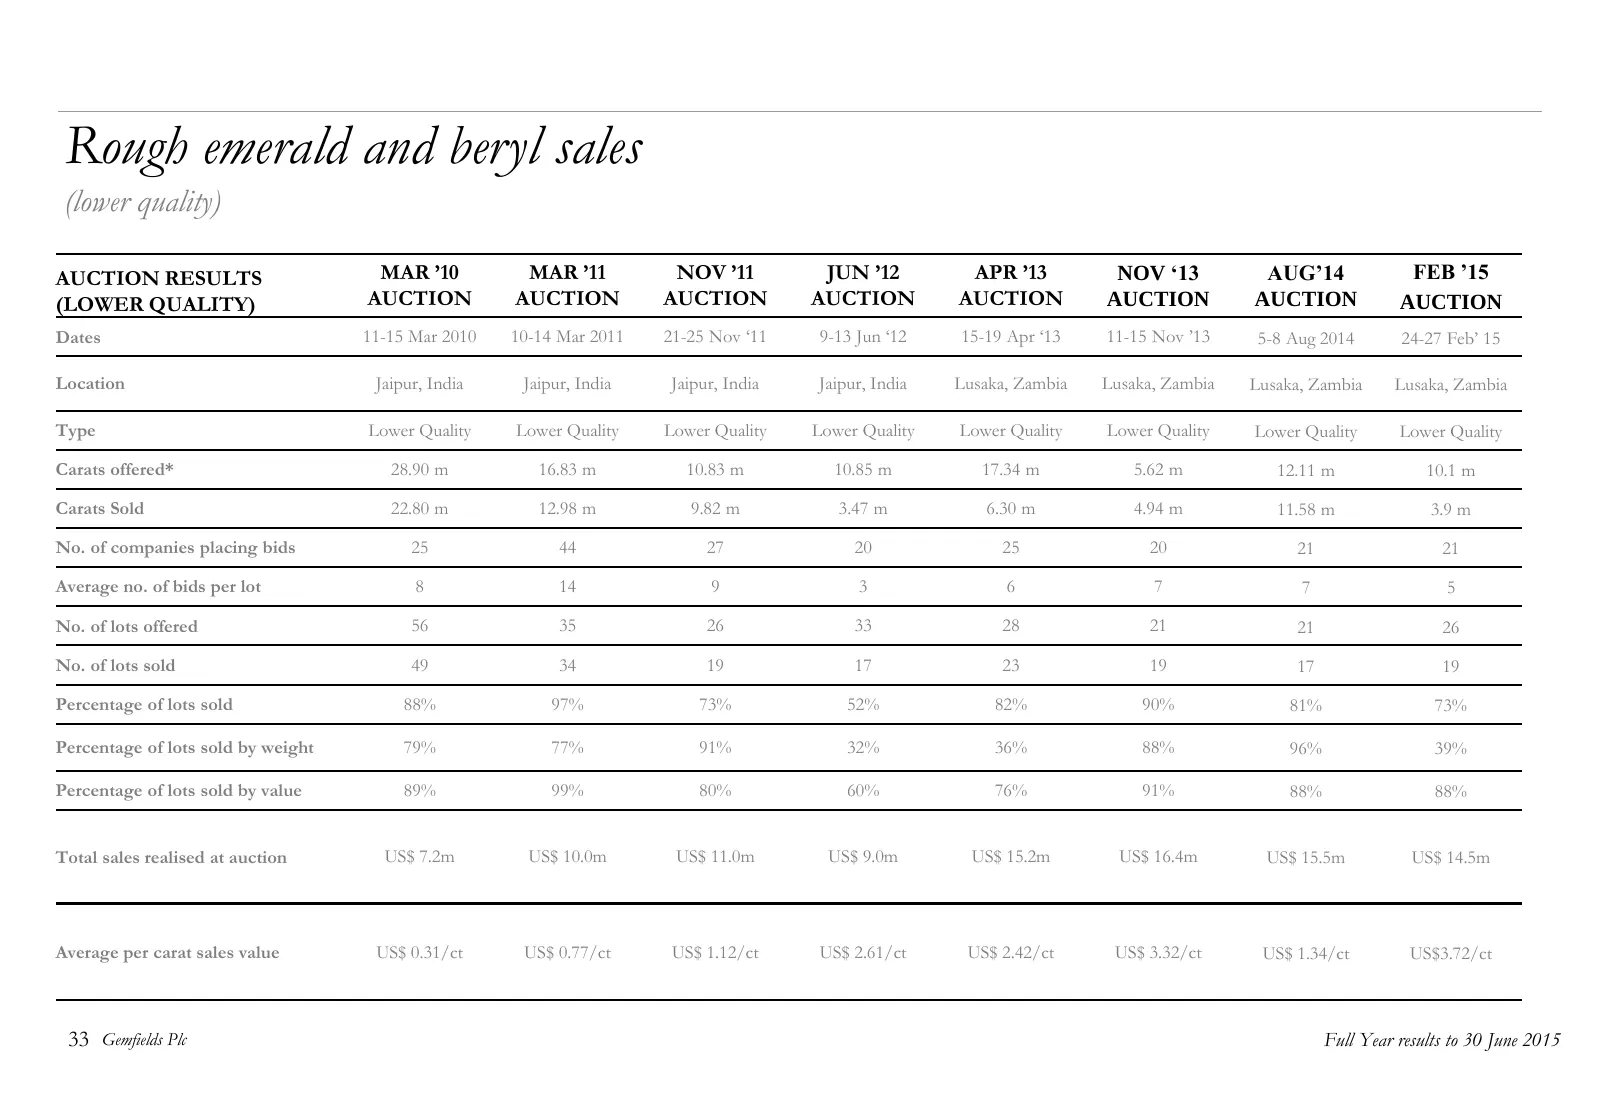
Rough emerald and beryl sales (lower quality) AUCTION RESULTS MAR ’10 MAR ’11 NOV ’11 JUN ’12 APR ’13 NOV ‘13 AUG’14 FEB ’15 (LOWER QUALITY) AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION Dates 11-15 Mar 2010 10-14 Mar 2011 21-25 Nov ‘11 9-13 Jun ‘12 15-19 Apr ‘13 11-15 Nov ’13 5-8
Slide 34: Rough emerald and beryl sales (higher quality)
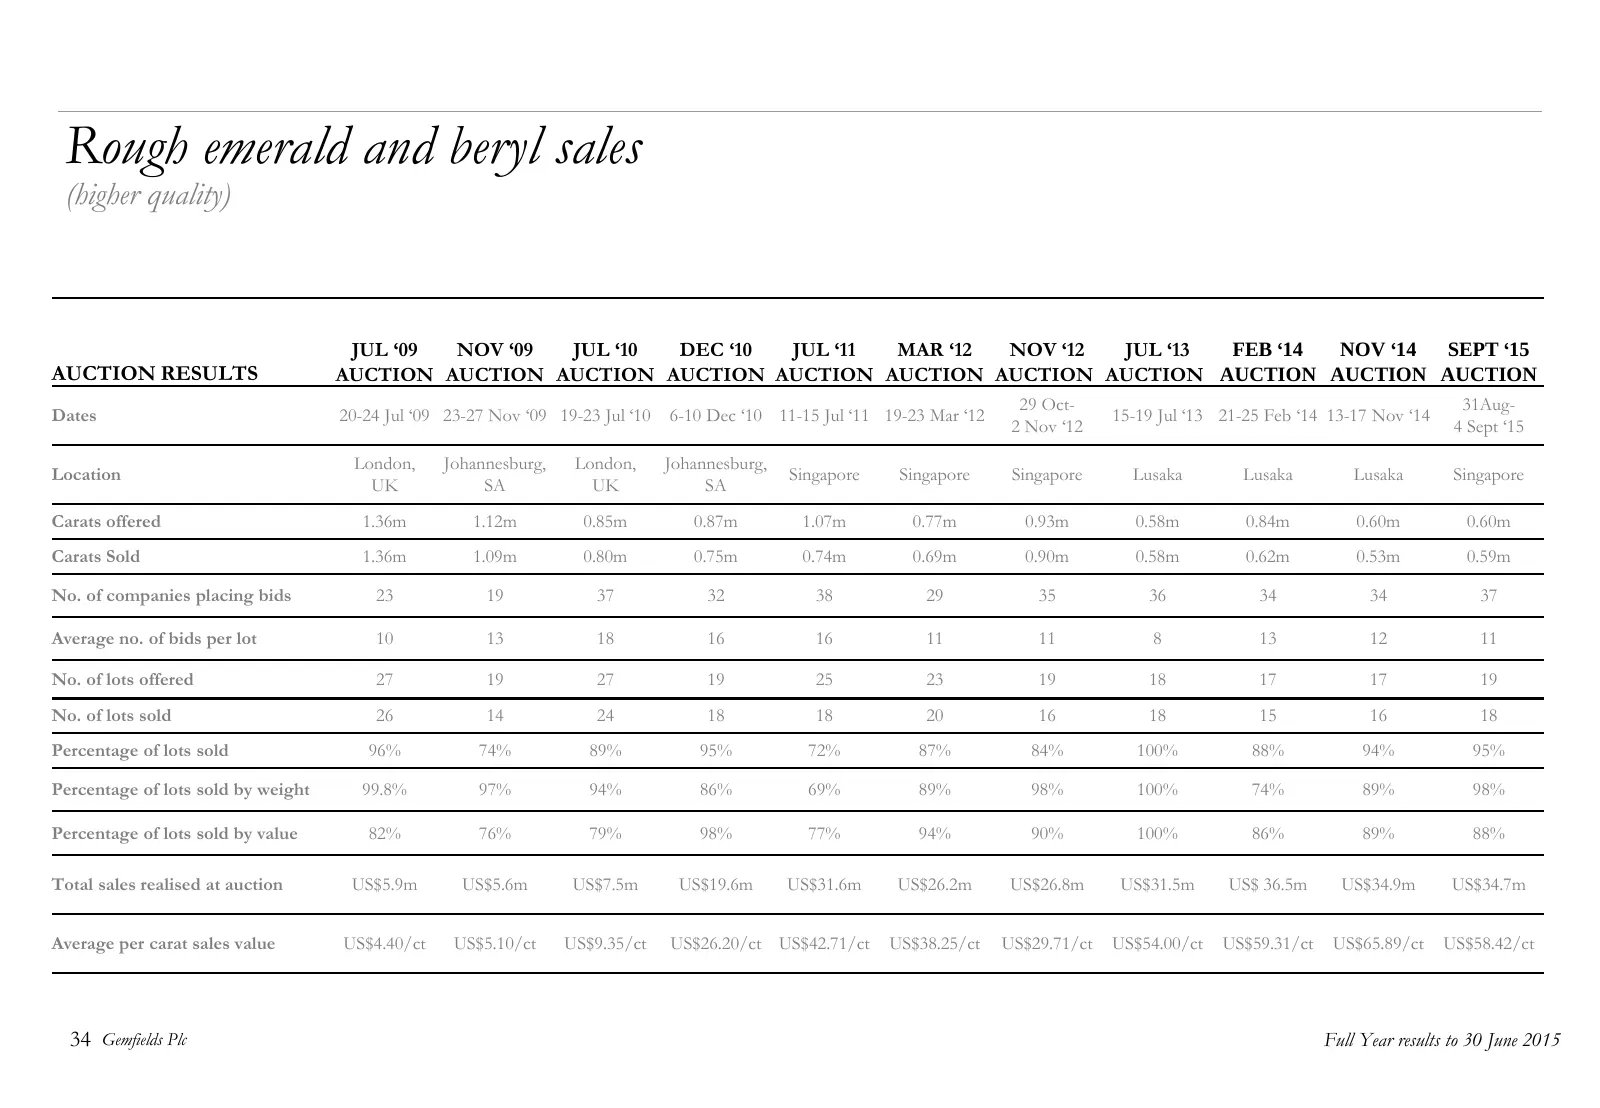
Rough emerald and beryl sales (higher quality) JUL ‘09 NOV ‘09 JUL ‘10 DEC ‘10 JUL ‘11 MAR ‘12 NOV ‘12 JUL ‘13 FEB ‘14 NOV ‘14 SEPT ‘15 AUCTION RESULTS AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION 29 Oct- 31Aug- Dates 20-24 Jul ‘09 23-27 Nov ‘09 19-23 Jul ‘
Slide 35: Rough ruby and corundum auctions
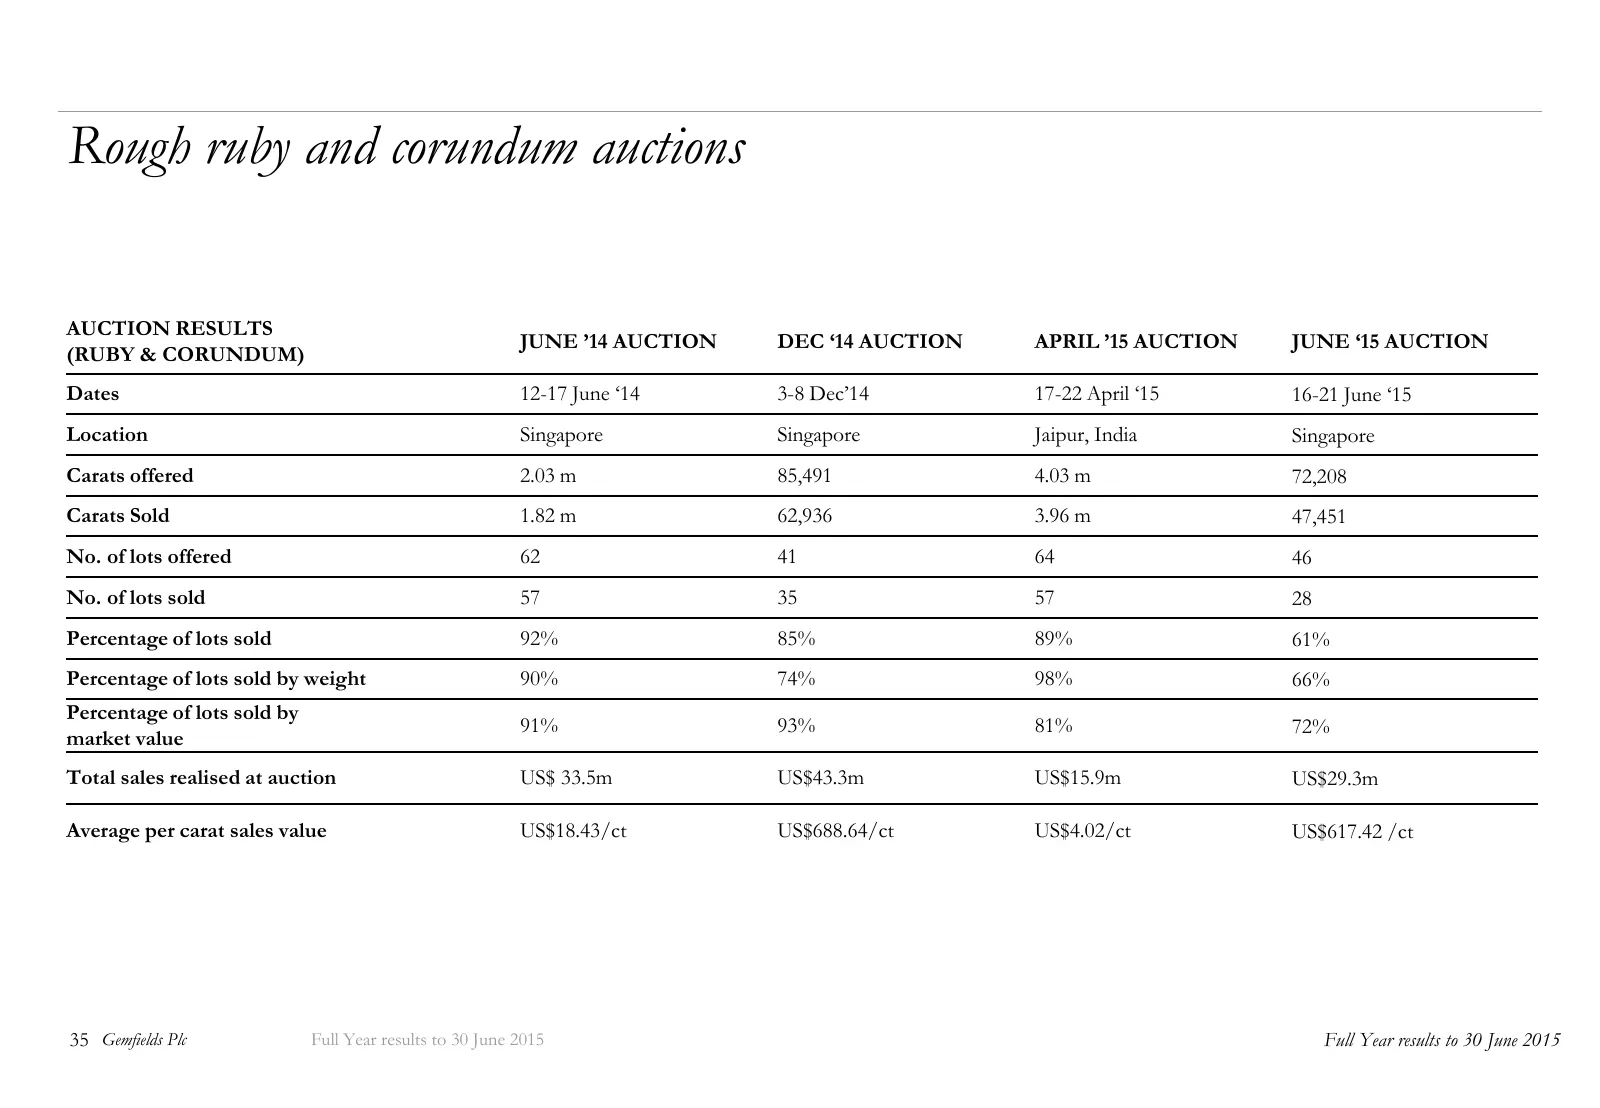
Rough ruby and corundum auctions AUCTION RESULTS JUNE ’14 AUCTION DEC ‘14 AUCTION APRIL ’15 AUCTION JUNE ‘15 AUCTION (RUBY & CORUNDUM) Dates 12-17 June ‘14 3-8 Dec’14 17-22 April ‘15 16-21 June ‘15 Location Singapore Singapore Jaipur, India Singapore Carats offered 2.03 m 85,491 4.03 m 72,208 Carats
Slide 36: World’s leading supplier of responsibly sourced coloured gemstones
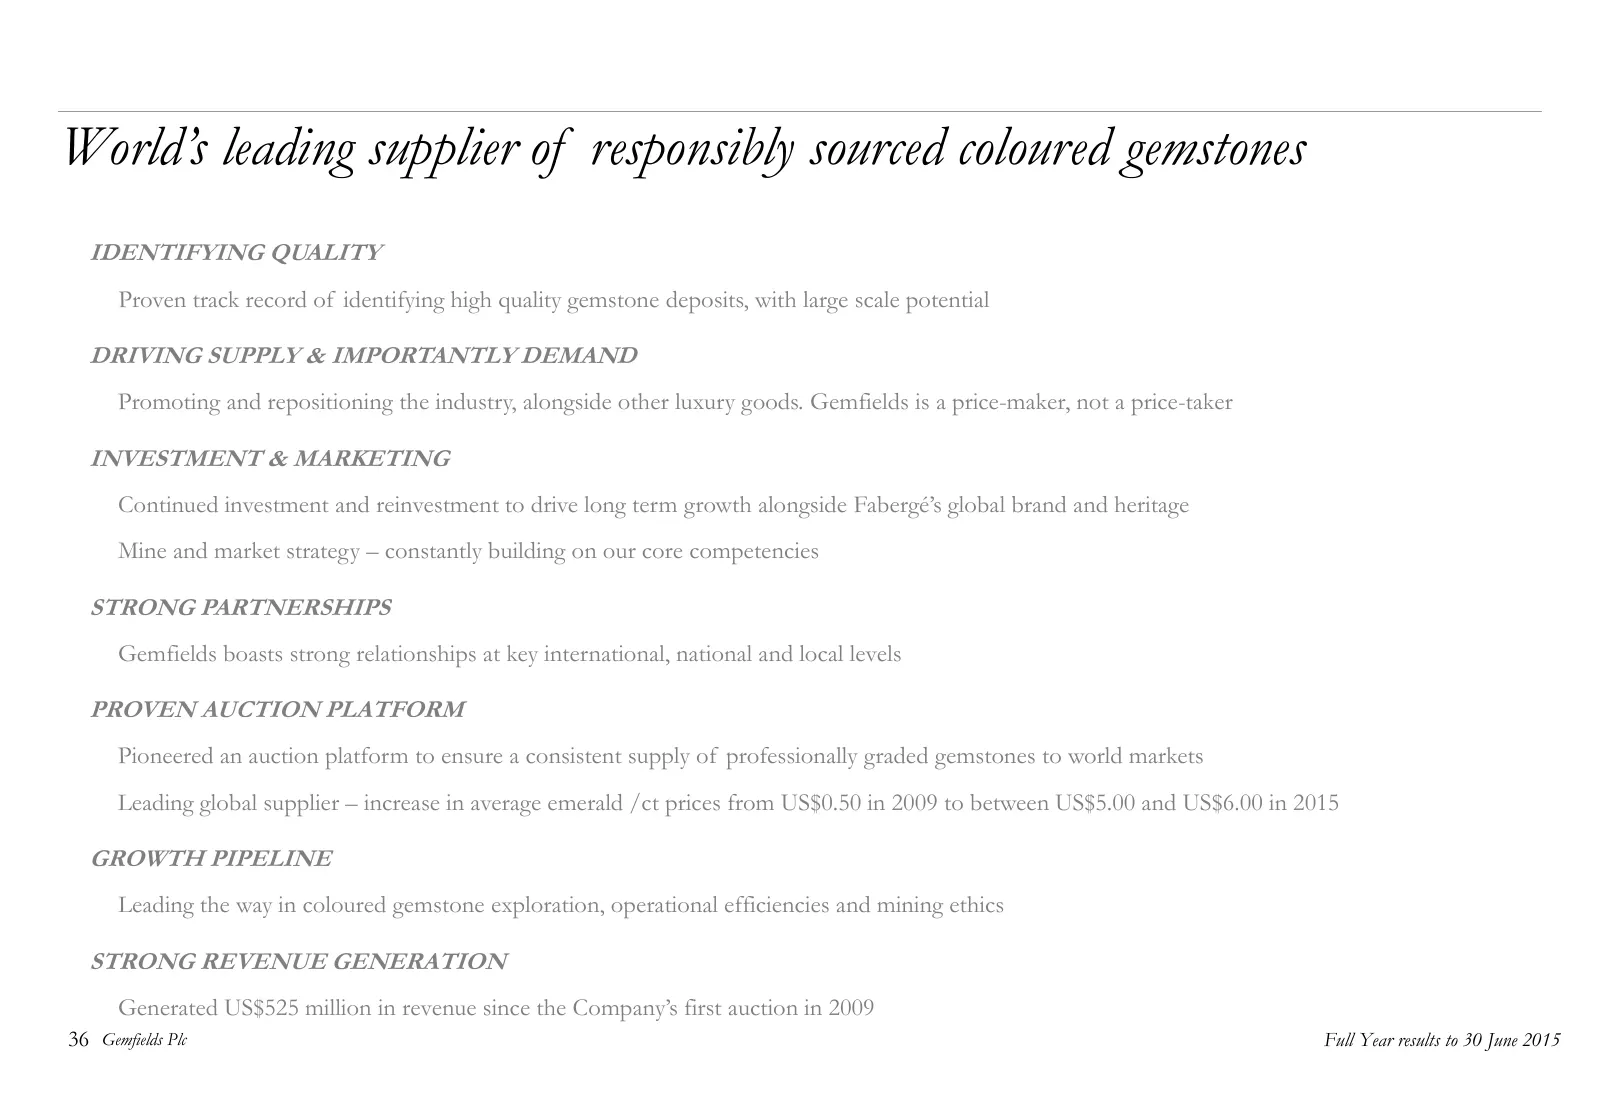
World’s leading supplier of responsibly sourced coloured gemstones IDENTIFYING QUALITY Proven track record of identifying high quality gemstone deposits, with large scale potential DRIVING SUPPLY & IMPORTANTLY DEMAND Promoting and repositioning the industry, alongside other luxury goods. Gemfields i
Slide 37: Contact us
Contact us Gemfields Plc 54 Jermyn Street 8th Floor London SW1Y 6LX United Kingdom Tel: +44 (0)20 7518 3400 Fax: +44 (0) 20 7197 8193 37 Gemfields Plc Full Year results to 30 June 2015
Source: Internet Archive copy of gemfieldsgroup.com
More decks from Gemfields Group Limited
 FY2025 Earnings Presentation26 slides · Mar 26, 2026
 H1 2025 Earnings Presentation74 slides · Sep 26, 2025
 FY2024 Earnings Presentation30 slides · Apr 11, 2025
 Investor Presentation (November 2024)39 slides · November 2024
 FY2023 Earnings Presentation37 slides · Mar 25, 2024
 FY2022 Earnings Presentation71 slides · Mar 24, 2023