Intercorp Financial Services Inc. · NYSE:IFS
Intercorp Financial Services — Q4 2025 Earnings Presentation
57 slides from Intercorp Financial Services's earnings presentation, Feb 12, 2026
Slide 1: 4Q25 IFS earnings presentation
4Q25 IFS earnings presentation is.com.pe
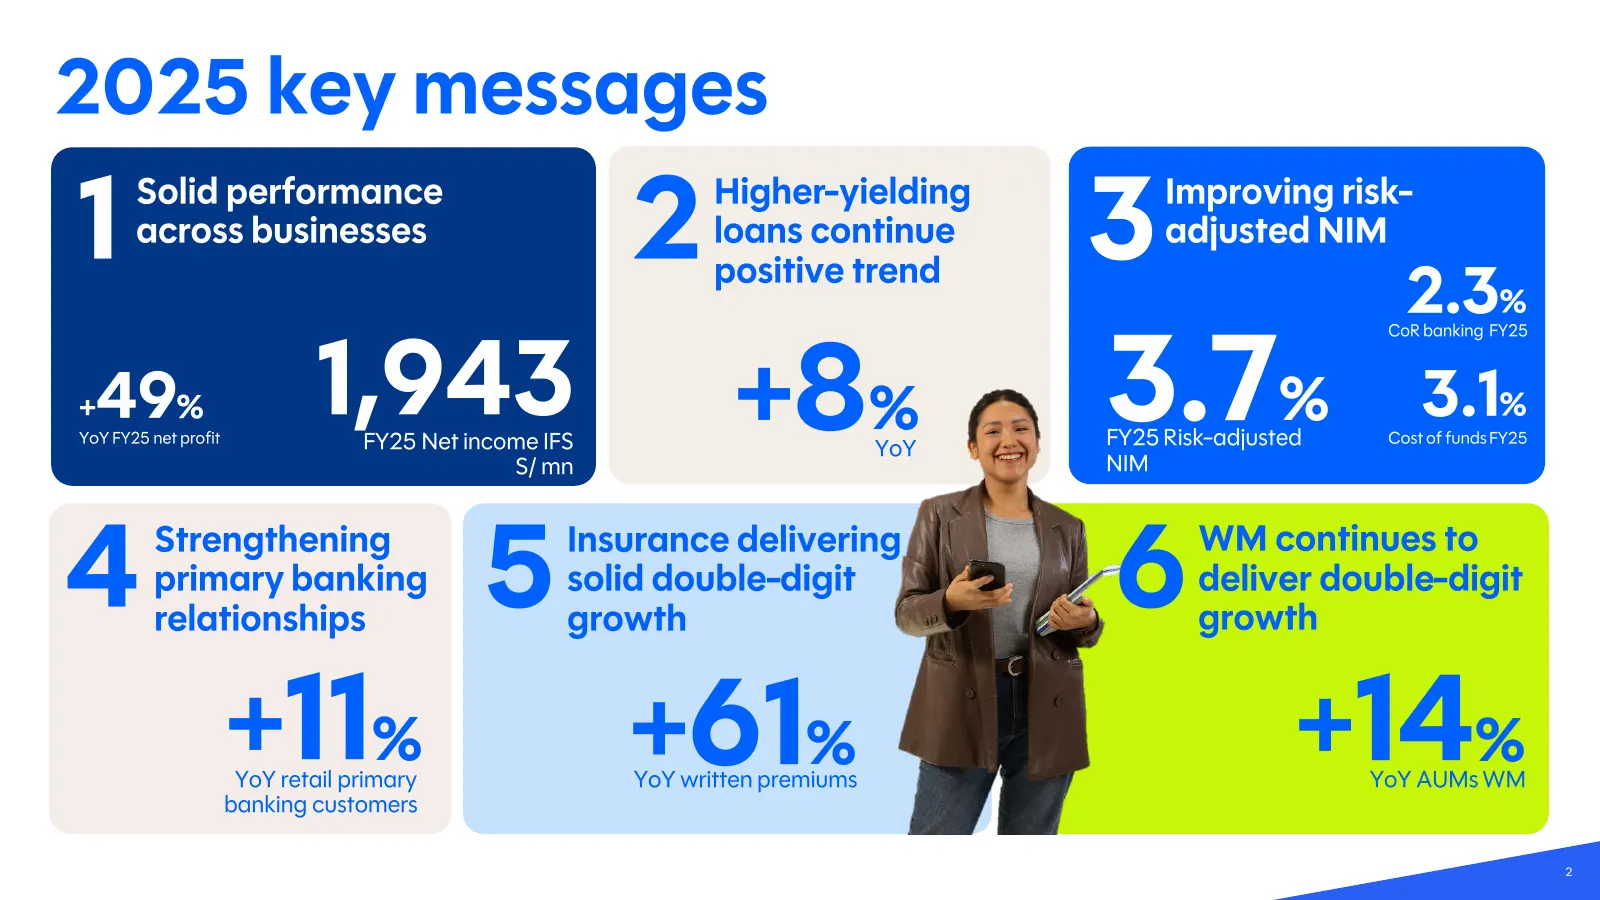
Slide 2: 2025 key messages
2025 k ey messages 1 Solid performance across businesses 2 Higher -yielding loans continue positive trend 3 Improving risk - adjusted NIM 2.3 % CoR banking FY25 + 49 % YoY FY25 net profit 1,943FY25 Net income IFS S/ mn +8 % YoY 3.7 % 3.1 FY25 Risk -adjusted NIM % Cost of funds FY25 4 Strengthening p
Slide 3: Solid performance across businesses
Solid performance across businesses
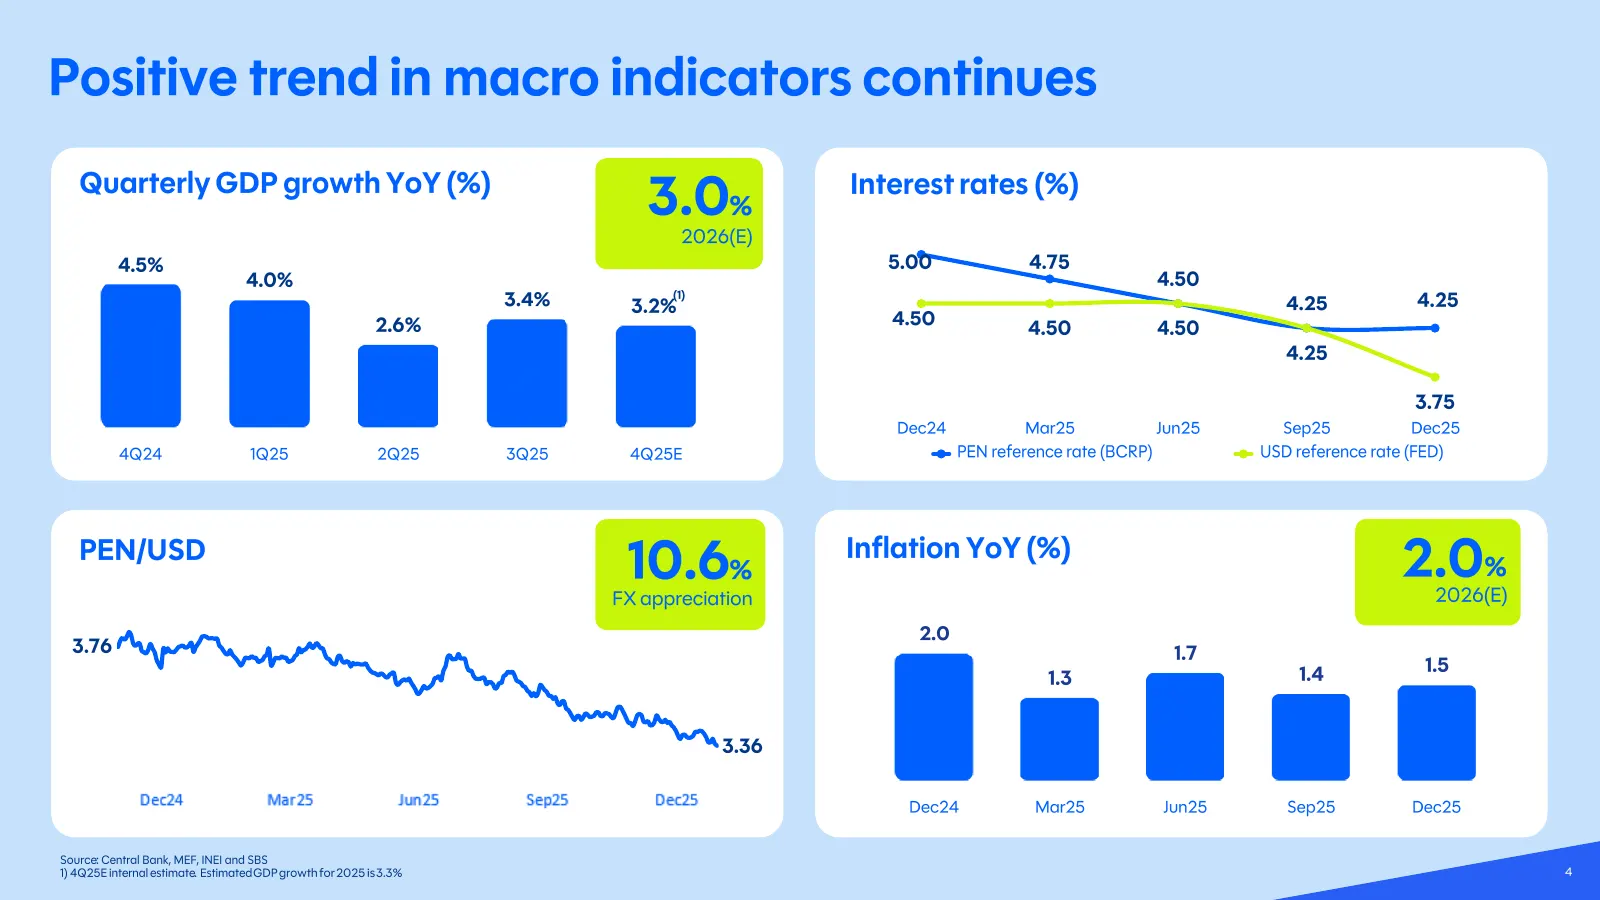
Slide 4: Positive trend in macro indicators continues
Positive trend in macro indicators continues Quarterly GDP growth YoY (%) Interest rates (%) 3.0 % 2026(E) 4.5% 5.00 4.75 4.0% 4.50 (1) 3.4% 3.2% 4.25 4.25 2.6% 4.50 4.50 4.50 4.25 3.75 Dec24 Mar25 Jun25 Sep25 Dec25 4Q24 1Q25 2Q25 3Q25 4Q25E PEN reference rate (BCRP) USD reference rate (FED) PEN/USD
Slide 5: Solid macro fundamentals
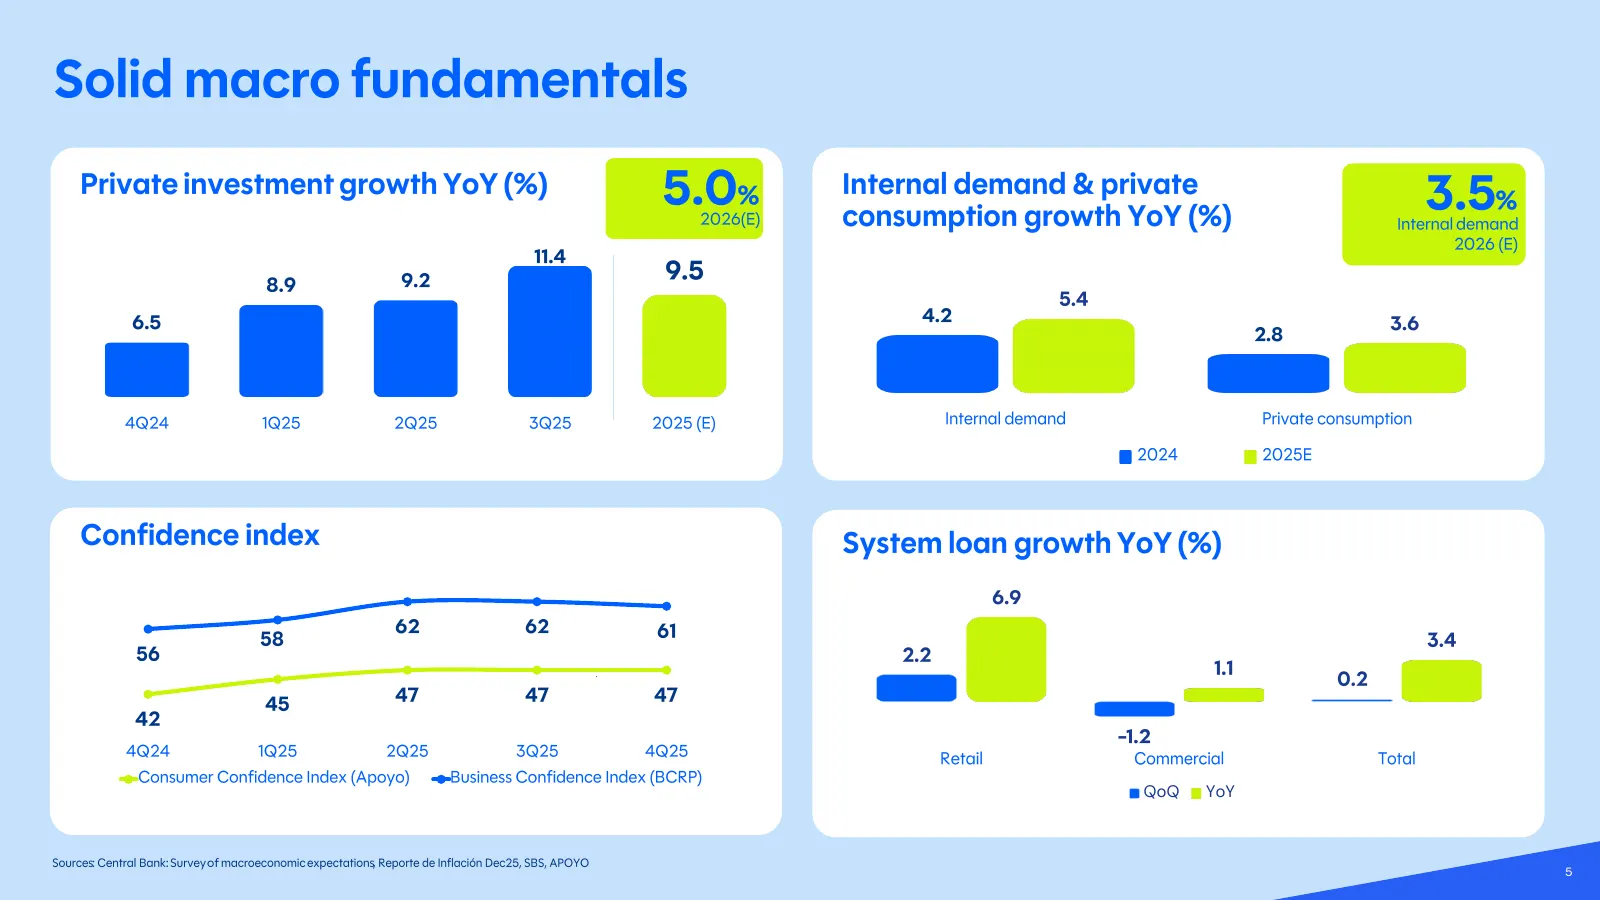
Solid macro fundamentals Private investment growth YoY (%) 5.0 % 2026(E) Internal demand & private consumption growth YoY (%) 3.5 % Internal demand 2026 (E) 11.4 8.9 9.2 9.5 5.4 6.5 4.2 3.6 2.8 4Q24 1Q25 2Q25 3Q25 2025 (E) Internal demand Private consumption 2024 2025E Confidence index System loan g
Slide 6: Drive ROE to 16.8%
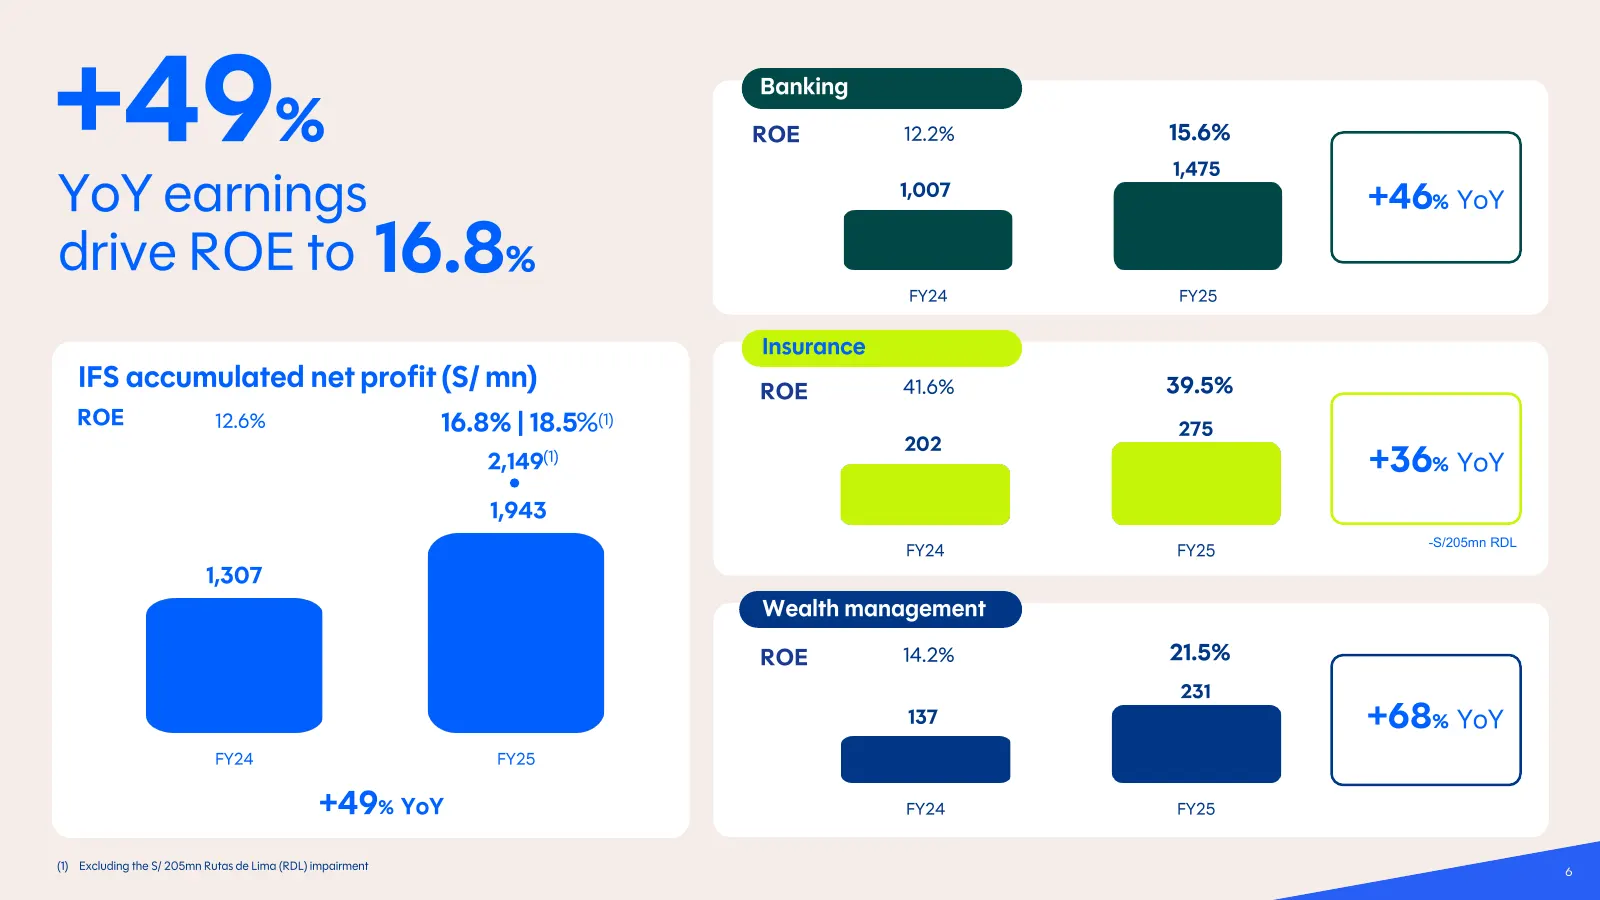
+49 % Banking ROE 12.2% 15.6% 1,475 YoY earnings 1,007 +46 % YoY drive ROE to 16.8% FY24 FY25 Insurance IFS accumulated net profit (S/ mn) ROE 41.6% 39.5% ROE 12.6% 16.8% | 18.5% (1) 275 202 2,149 (1) +36 % YoY 1,943 -S/205mn RDL FY24 FY25 1,307 Wealth management ROE 14.2% 21.5% 231 137 +68 % YoY FY
Slide 7: QoQ earnings despite RDL impact
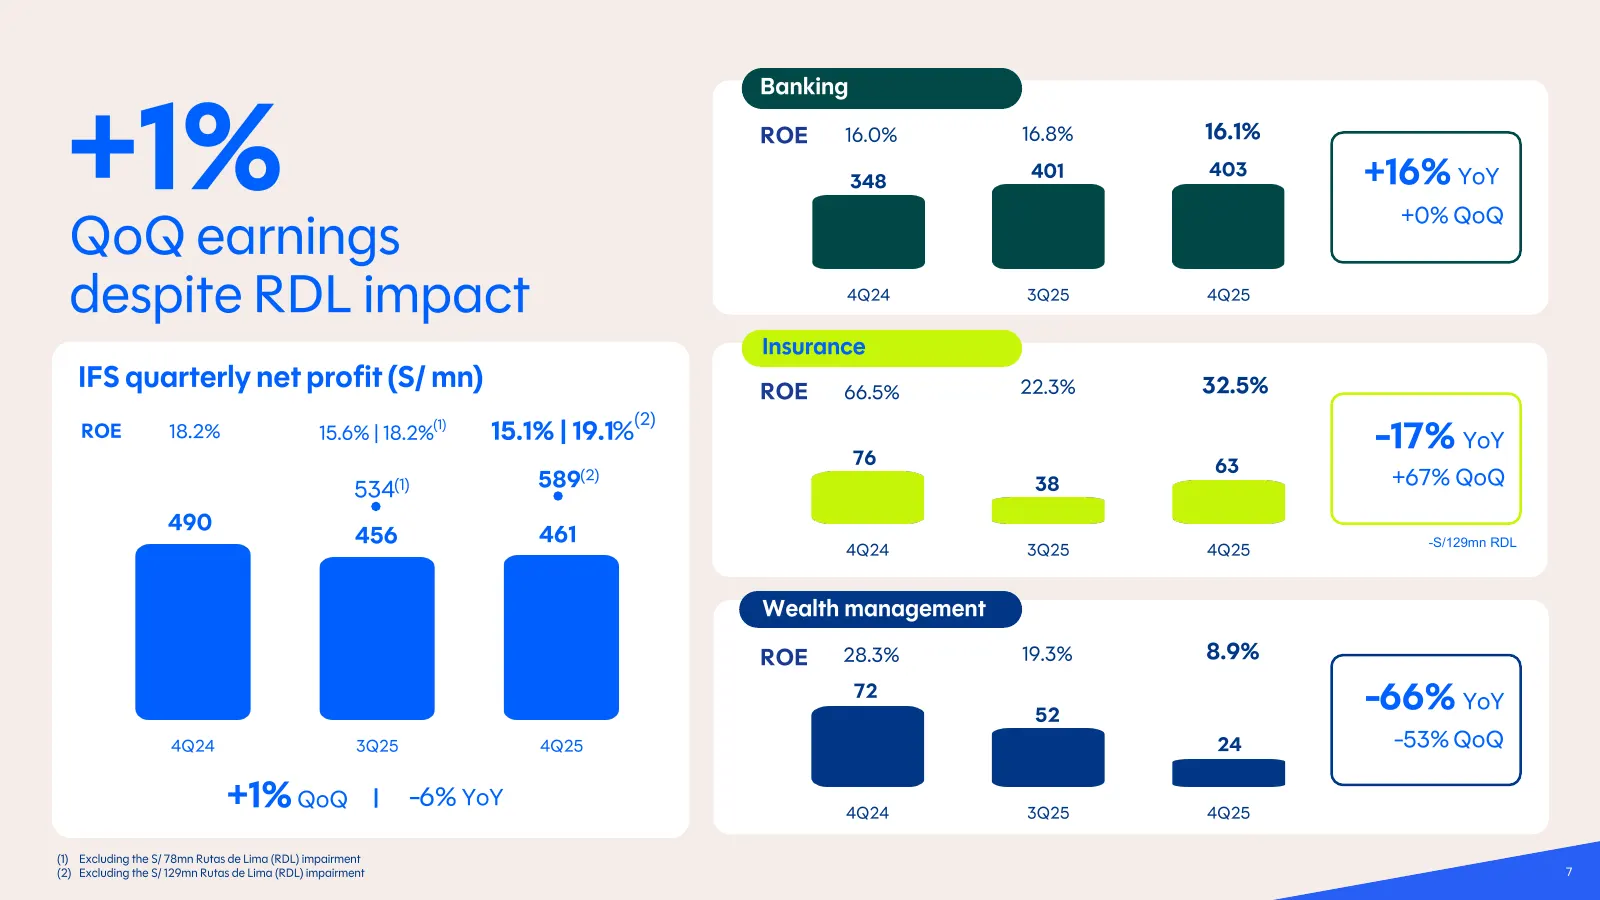
Banking +1% ROE 16.0% 348 16.8% 401 16.1% 403 +16% YoY +0% QoQ QoQ earnings despite RDL impact 4Q24 3Q25 4Q25 Insurance IFS quarterly net profit (S/ mn) ROE 66.5% 22.3% 32.5% (1) (2) ROE 18.2% 15.6% | 18.2% 15.1% | 19.1 % -17% YoY 76 63 589 (2) 38 +67% QoQ 534 (1) 490 456 461 -S/129mn RDL 4Q24 3Q25
Slide 8: Core earnings and ROE recovery continues
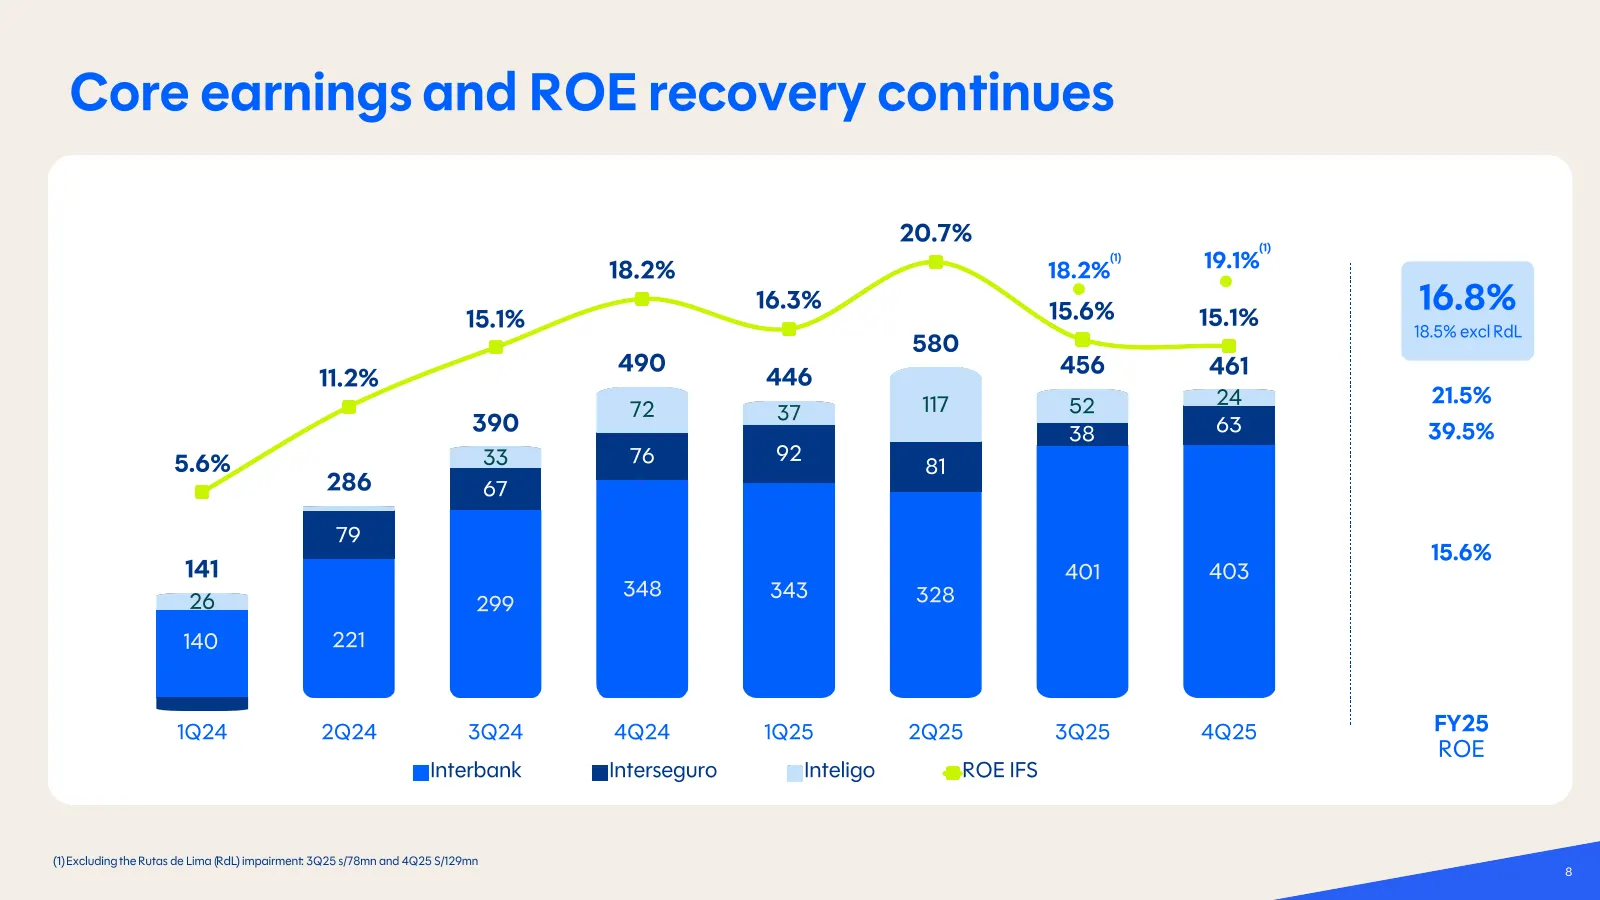
Core earnings and ROE recovery continues 20.7% (1) 18.2% 18.2% (1) 19.1% 20.0% 650 15.1% 16.3% 15.6% 15.1% 16.8% 18.5% excl RdL 550 580 15.0% 490 456 461 11.2% 446 117 52 24 21.5% 450 72 37 390 38 63 10.0% 39.5% 33 76 92 350 5.6% 81 286 67 5.0% 250 79 15.6% 141 401 403 0.0% 348 343 328 150 26 299 14
Slide 9: YoY increase in revenues
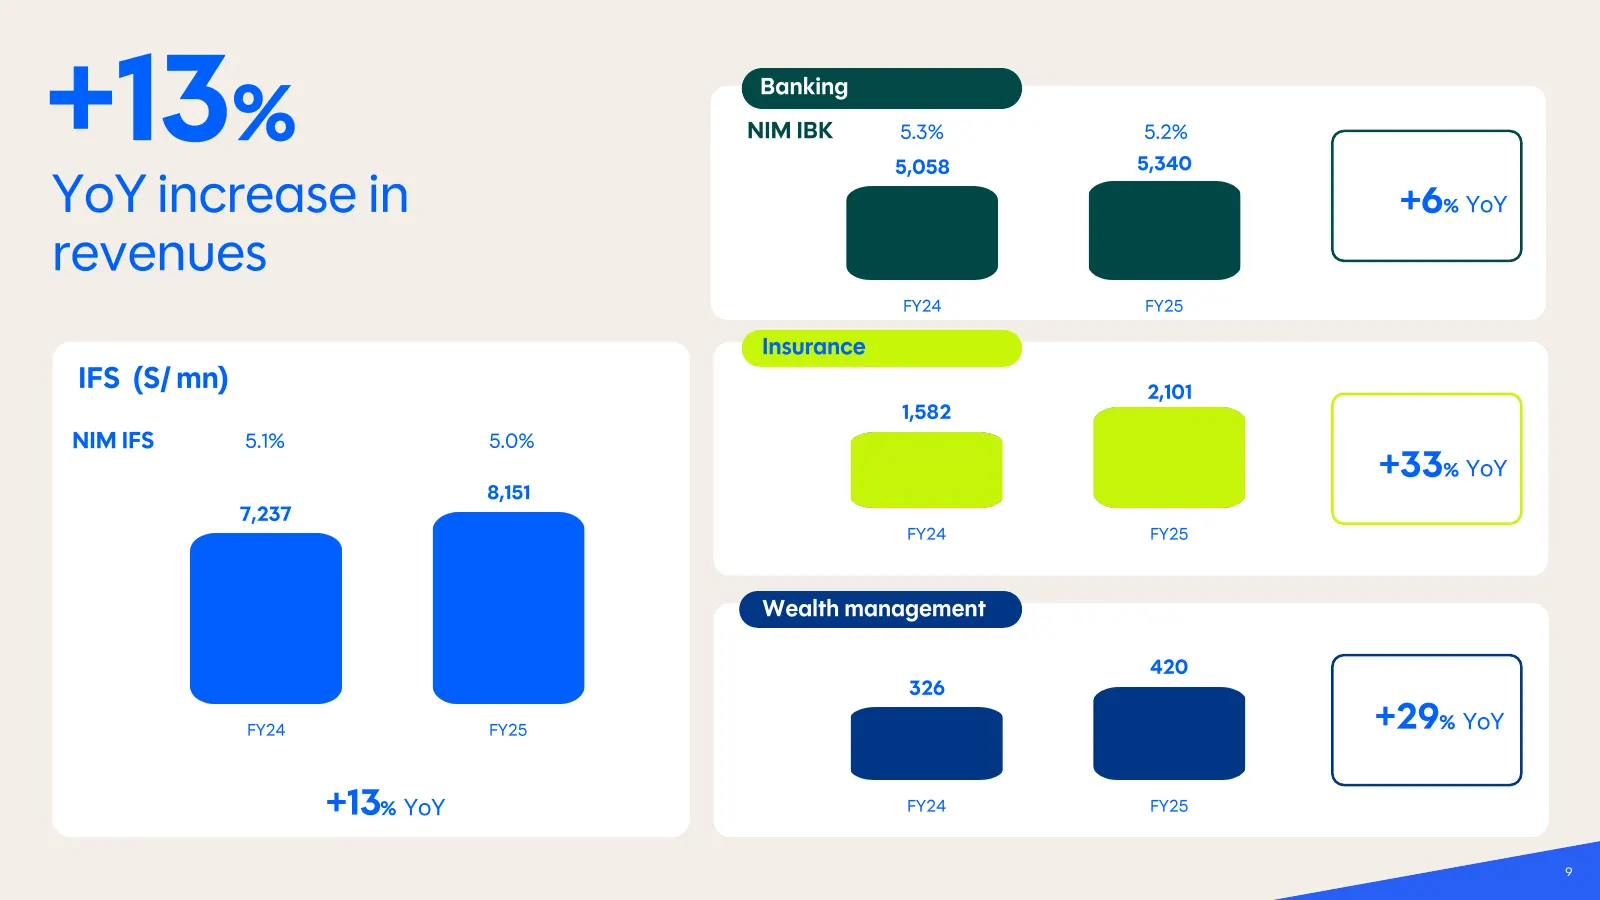
+13% Banking NIM IBK 5.3% 5,058 5.2% 5,340 YoY increase in +6 % YoY revenues FY24 FY25 Insurance IFS (S/ mn) 2,101 1,582 NIM IFS 5.1% 5.0% +33 % YoY 8,151 7,237 FY24 FY25 Wealth management 420 Título del eje 326 FY24 FY25 +29 % YoY +13% YoY FY24 FY25 9
Slide 10: Increasing IT investments, with efficiency as top priority
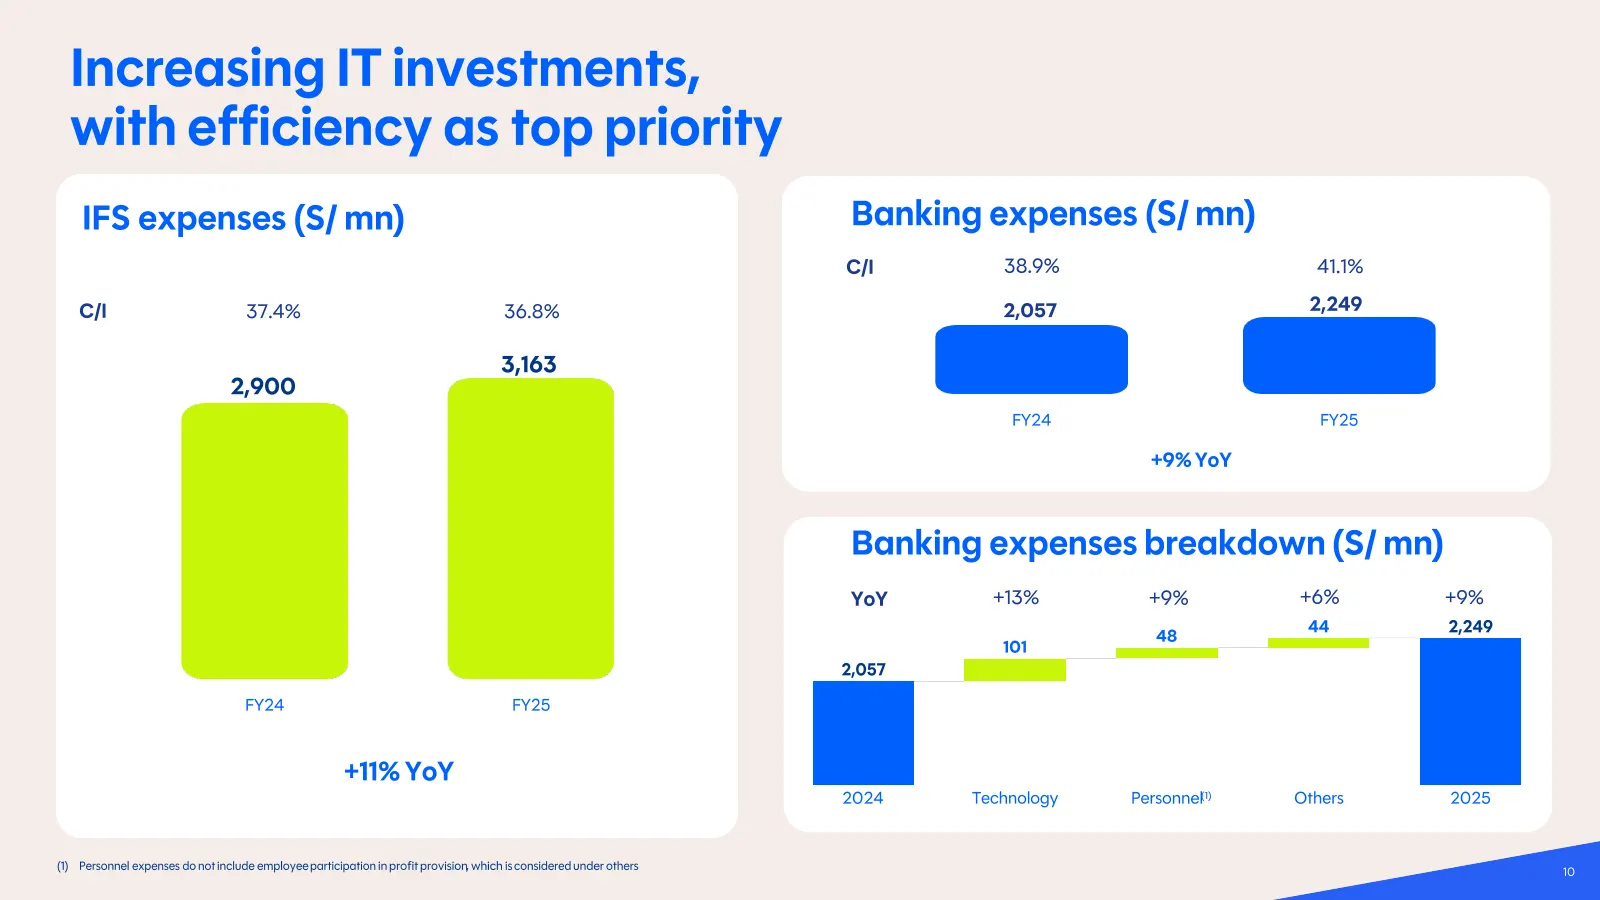
Increasing IT investments , with efficiency as top priority IFS expenses (S/ mn) Banking expenses (S/ mn) C/I 38.9% 41.1% C/I 37.4% 36.8% 2,057 2,249 3,163 2,900 FY24 FY25 +9% YoY Banking expenses breakdown (S/ mn) YoY +13% +9% +6% +9% 44 2,249 48 101 2,057 FY24 FY25 +11% YoY 2024 Technology Personn
Slide 11: Higher-yielding loans continue positive trend
Higher -yielding loans continue positive trend
Slide 12: Increasing dynamism in higher-yielding loans
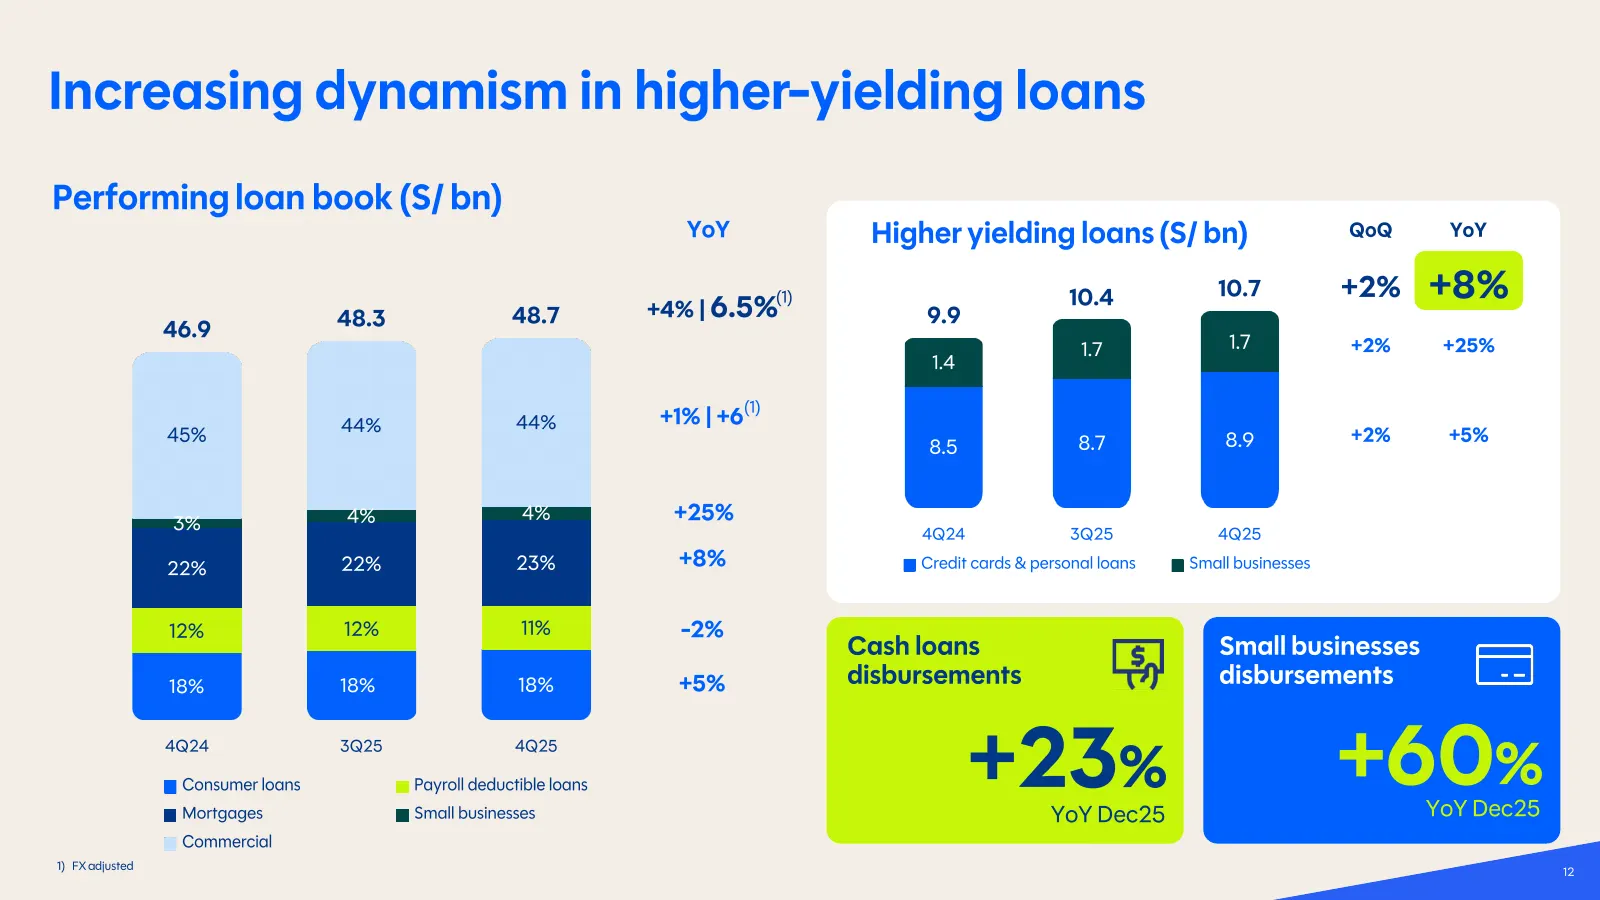
Increasing dynamism in higher -yielding loans Performing loan book (S/ bn) YoY Higher High yielding portfolio -yielding loans (S/ bn) QoQ YoY +4% | 6.5% (1) 10.4 10.7 +2% +8% 48.3 48.7 9.9 46.9 1.7 1.7 +2% +25% 1.4 (1) 44% 44% +1% | +6 45% 8.7 8.9 +2% +5% 8.5 3% 4% 4% +25% 4Q24 3Q25 4Q25 22% 22% 23%
Slide 13: Accelerating credit cards and personal loans
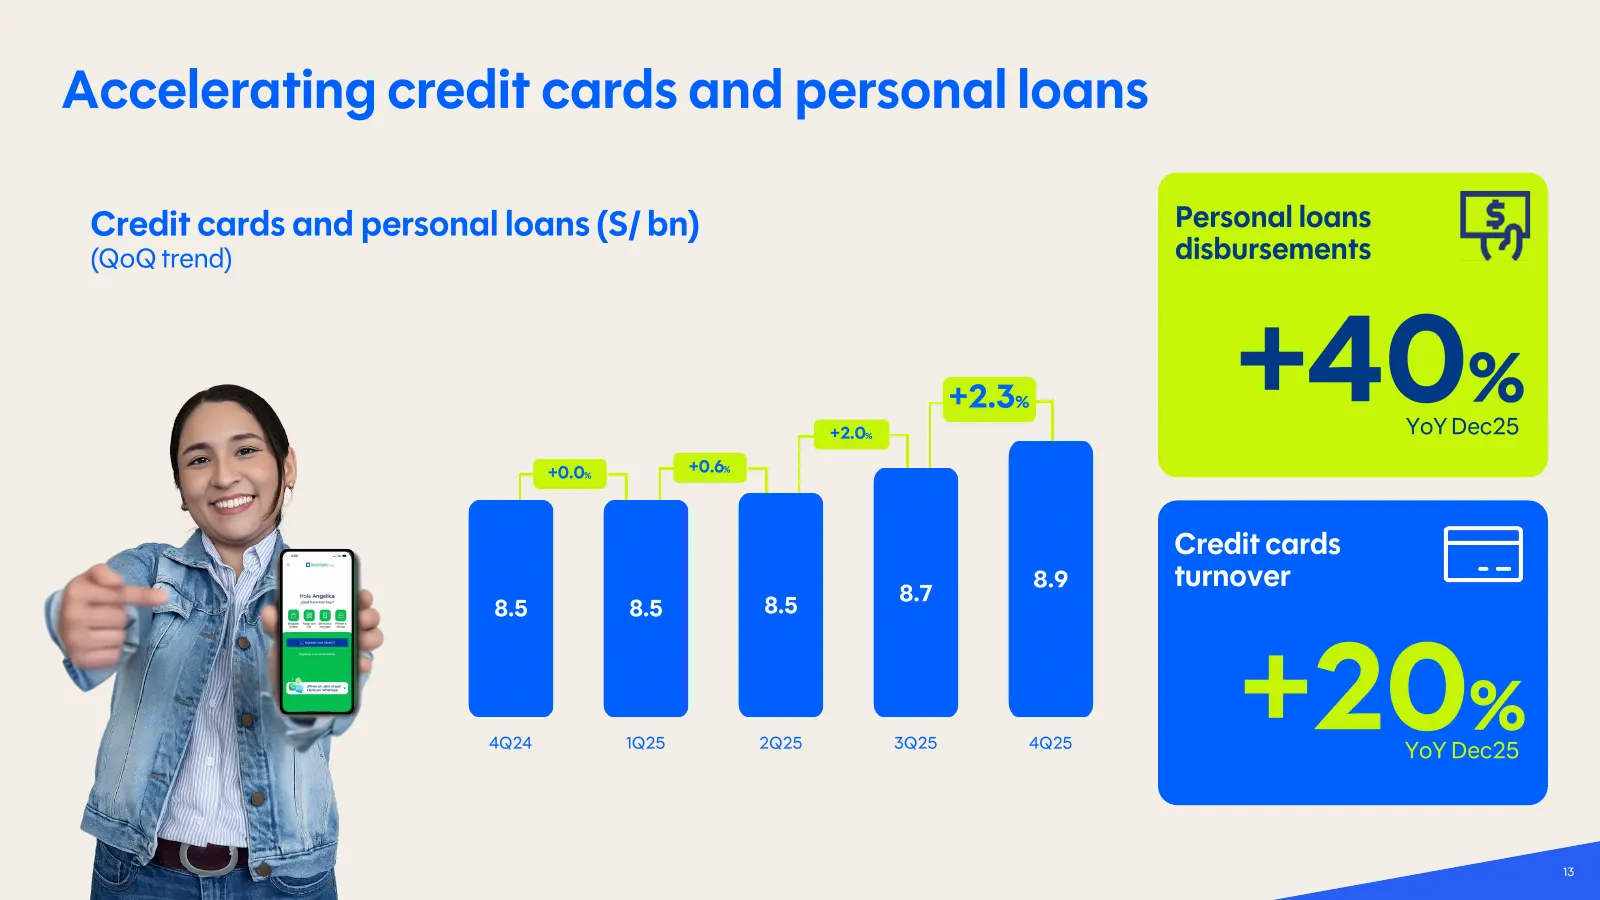
Accelerating credit cards and personal loans Credit cards and personal loans (S/ bn) Personal loans (QoQ trend ) disbursements +2.0 % +2.3 % +40 % YoY Dec25 +0.0 % +0.6 % Credit cards 8.7 8.9 turnover 8.5 8.5 8.5 4Q24 1Q25 2Q25 3Q25 4Q25 +20 % YoY Dec25 13
Slide 14: Improving risk-adjusted NIM
Improving risk - adjusted NIM
Slide 15: +50 bps YoY improvement in risk-adjusted NIM in banking
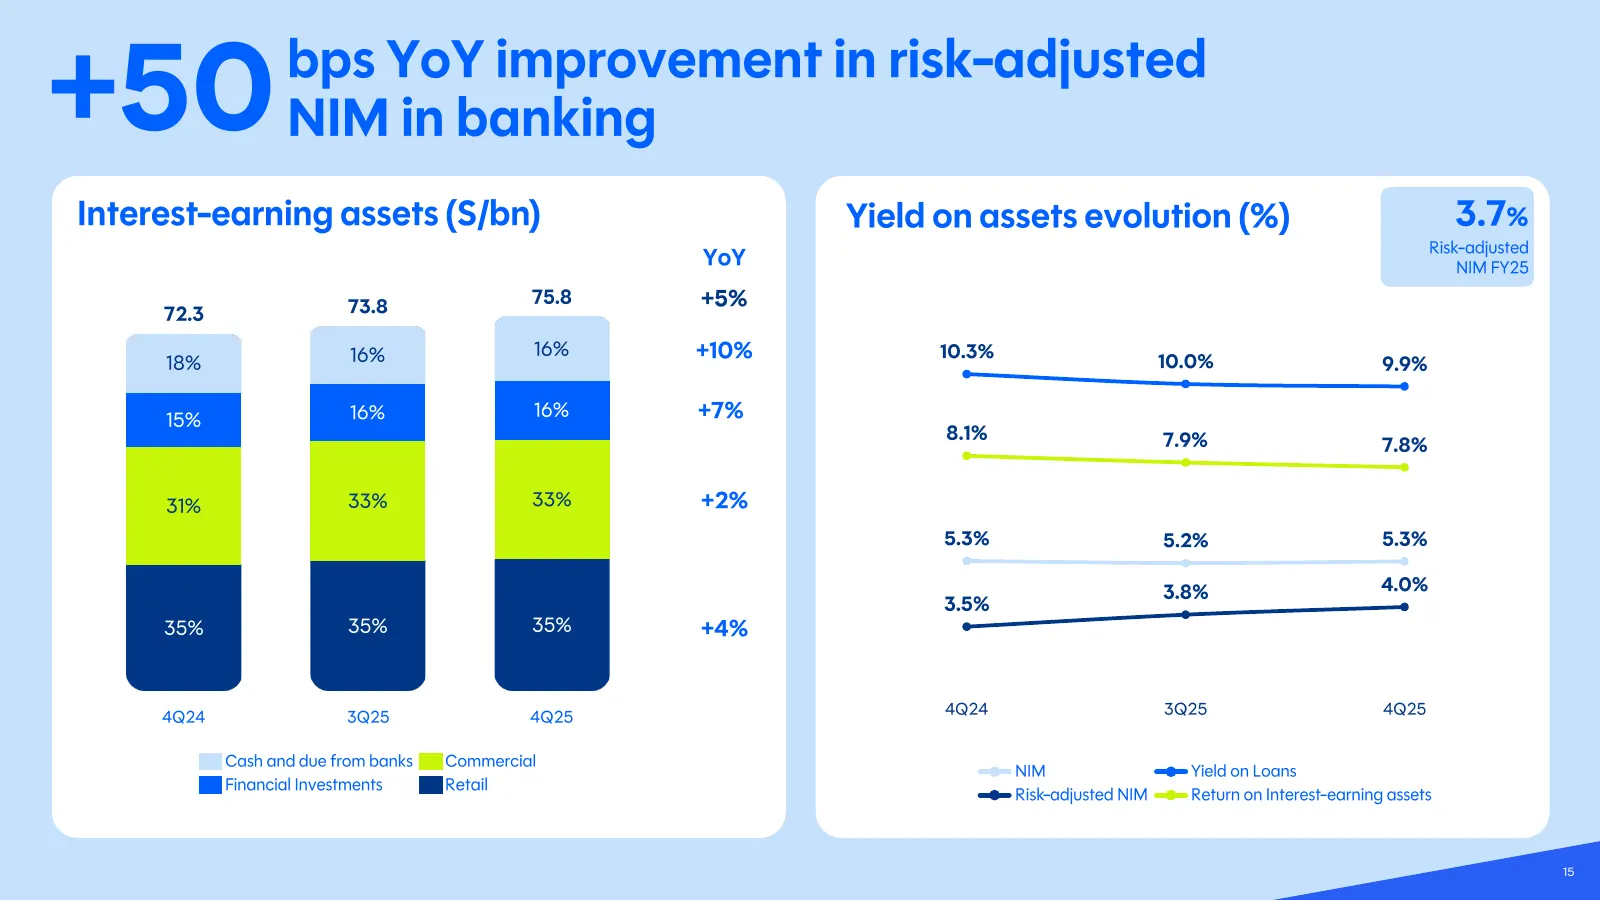
+50 bps YoY improvement in risk -adjusted NIM in banking Interest -earning assets (S/bn) Yield on assets evolution (%) 3.7 % Risk -adjusted YoY NIM FY25 73.8 75.8 +5% 72.3 16% 16% +10% 10.3% 10.0% 18% 9.9% 15% 16% 16% +7% 8.1% 7.9% 7.8% 31% 33% 33% +2% 5.3% 5.2% 5.3% 3.8% 4.0% 3.5% 35% 35% 35% +4% 4
Slide 16: Cost of risk remains at low levels
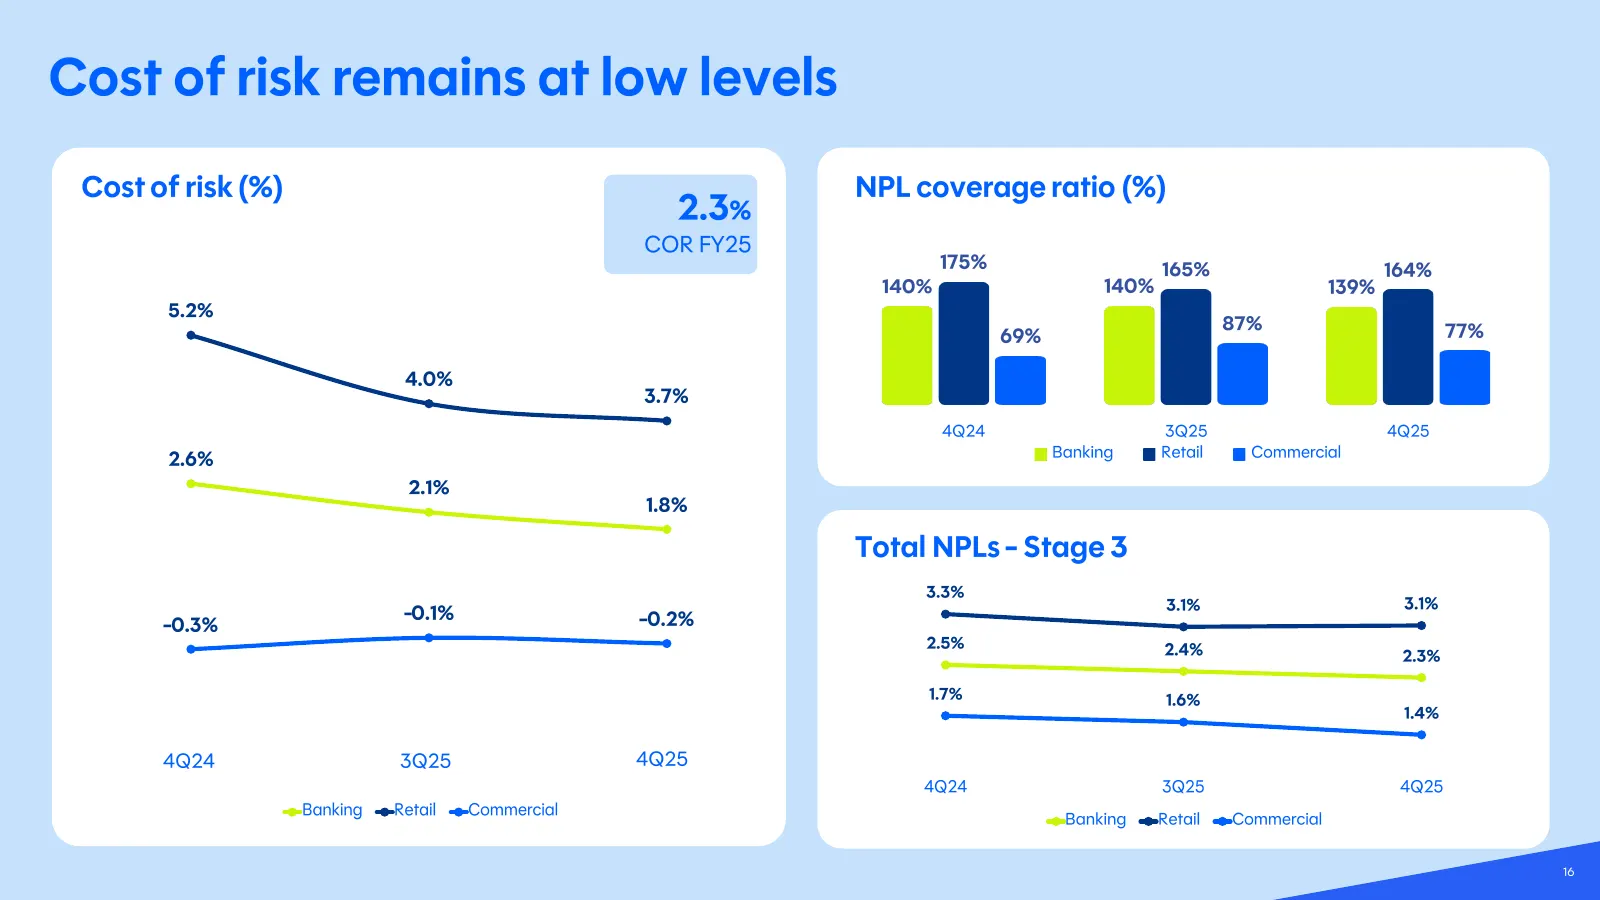
Cost of risk remains at low levels Cost of risk (%) NPL coverage ratio (%) 2.3 % COR FY25 175% 165% 164% 140% 140% 139% 5.2% 87% 77% 69% 4.0% 3.7% 4Q24 3Q25 4Q25 2.6% Banking Retail Commercial 2.1% 1.8% Total NPLs - Stage 3 3.3% 3.1% 3.1% -0.1% -0.2% -0.3% 2.5% 2.4% 2.3% 1.7% 1.6% 1.4% 4Q24 3Q25 4Q2
Slide 17: +20 bps decrease in cost of funds in the year
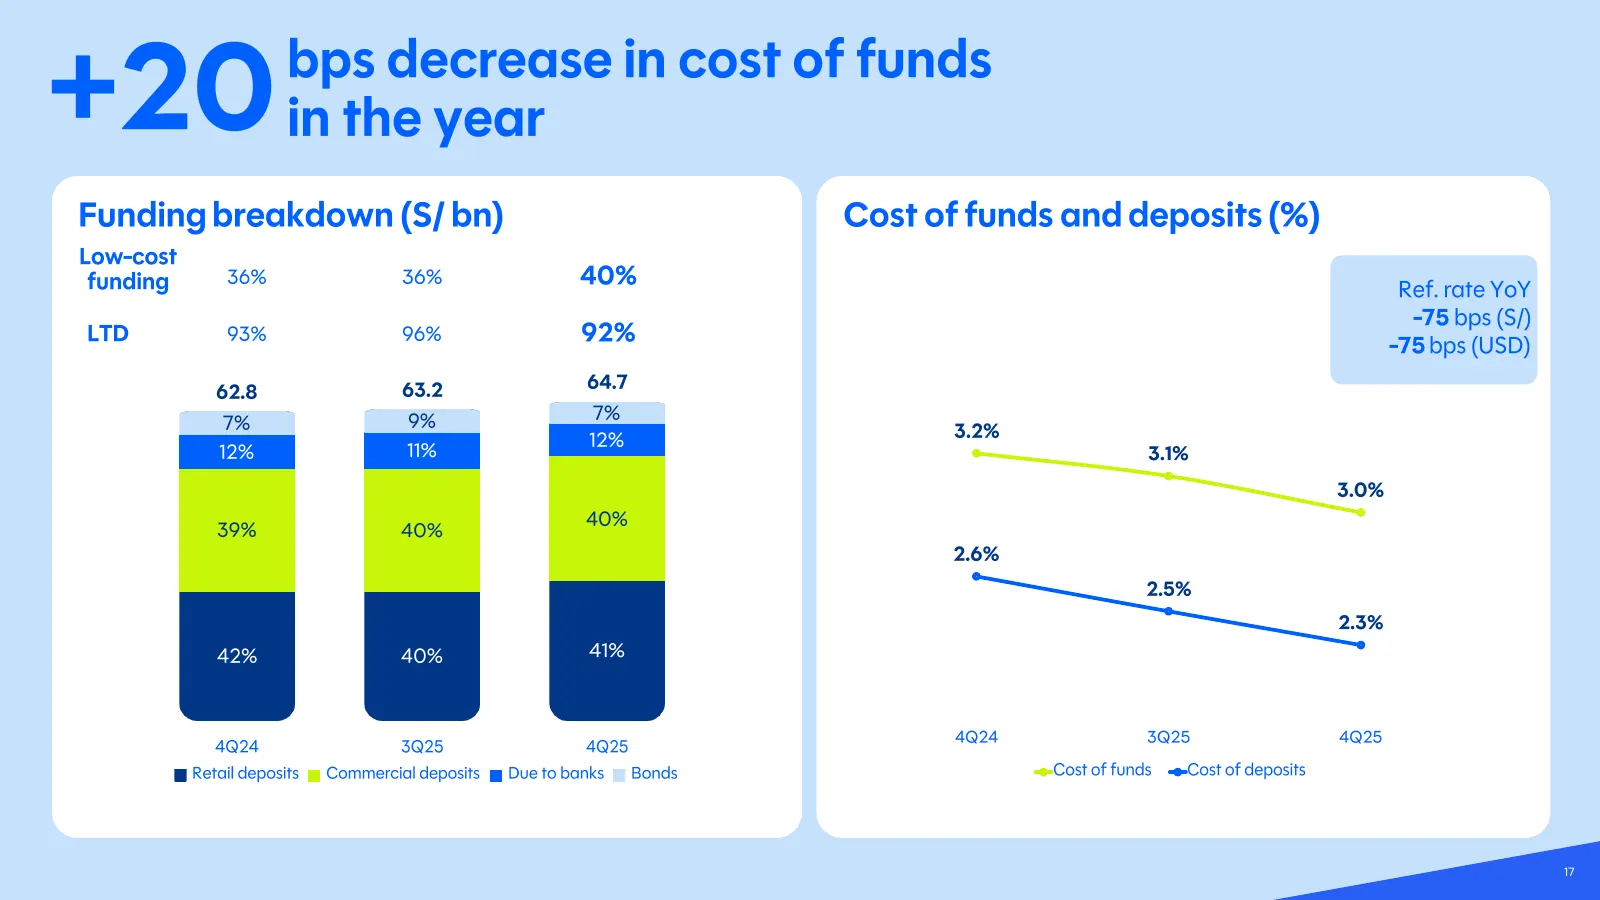
+20 bps decrease in cost of funds in the year Funding breakdown (S/ bn) Cost of funds and deposits (%) Low -cost funding 36% 36% 40% Ref. rate YoY -75 bps (S/) LTD 93% 96% 92% -75 bps (USD) 62.8 63.2 64.7 9% 7% 7% 3.2% 12% 12% 11% 3.1% 3.0% 40% 39% 40% 2.6% 2.5% 2.3% 42% 40% 41% 4Q24 3Q25 4Q25 4Q24
Slide 18: Strengthening primary banking relationships
Strengthening primary banking relationships
Slide 19: Our payments ecosystem as a key driver of low-cost funding
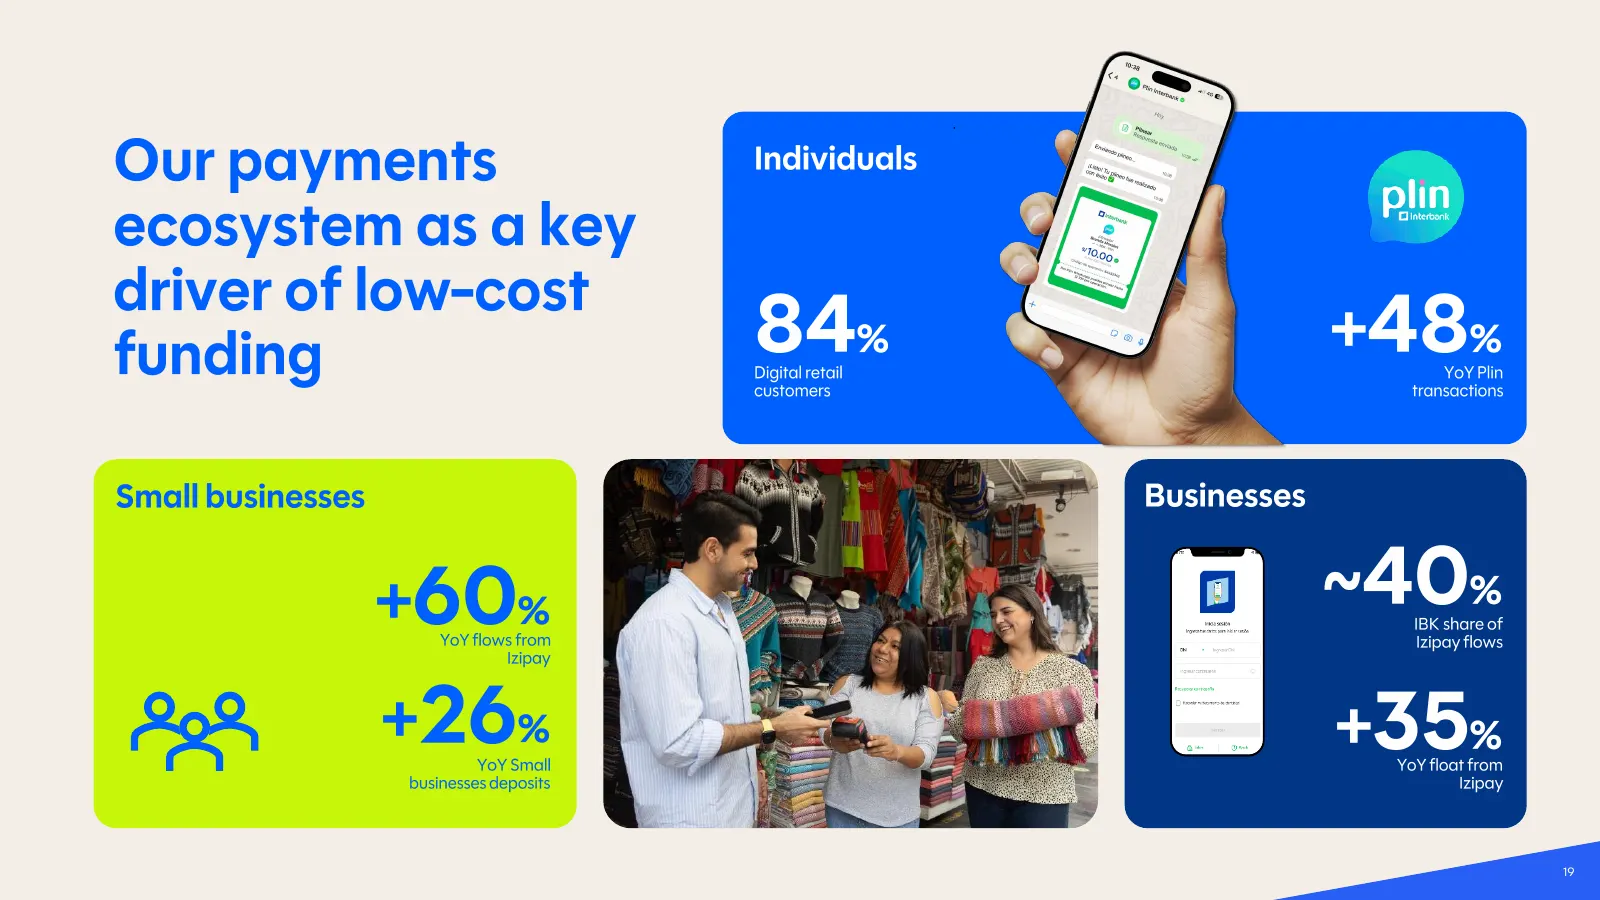
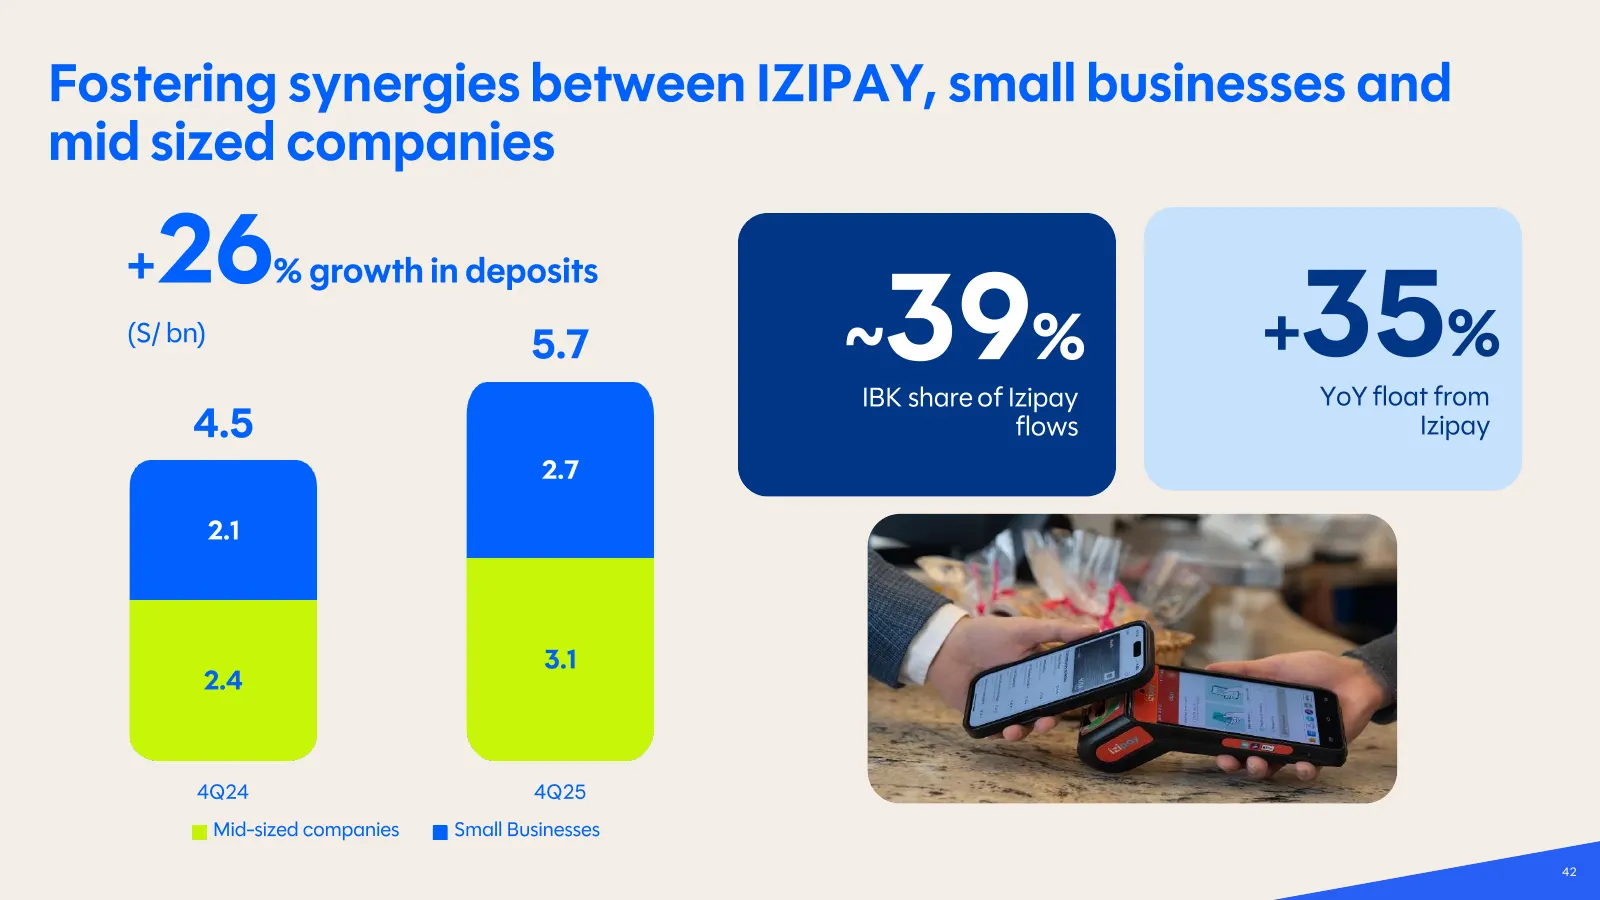
Our payments Individuals ecosystem as a key driver of low -cost funding 84 % Digital retail + 48 % YoY Plin customers transactions Small businesses Businesses + 60 % ~ 40 % IBK share of YoY flows from Izipay flows Izipay + 26 % YoY Small + 35 % YoY float from businesses deposits Izipay 19
Slide 20: Creating stronger primary banking relationships through digital experience
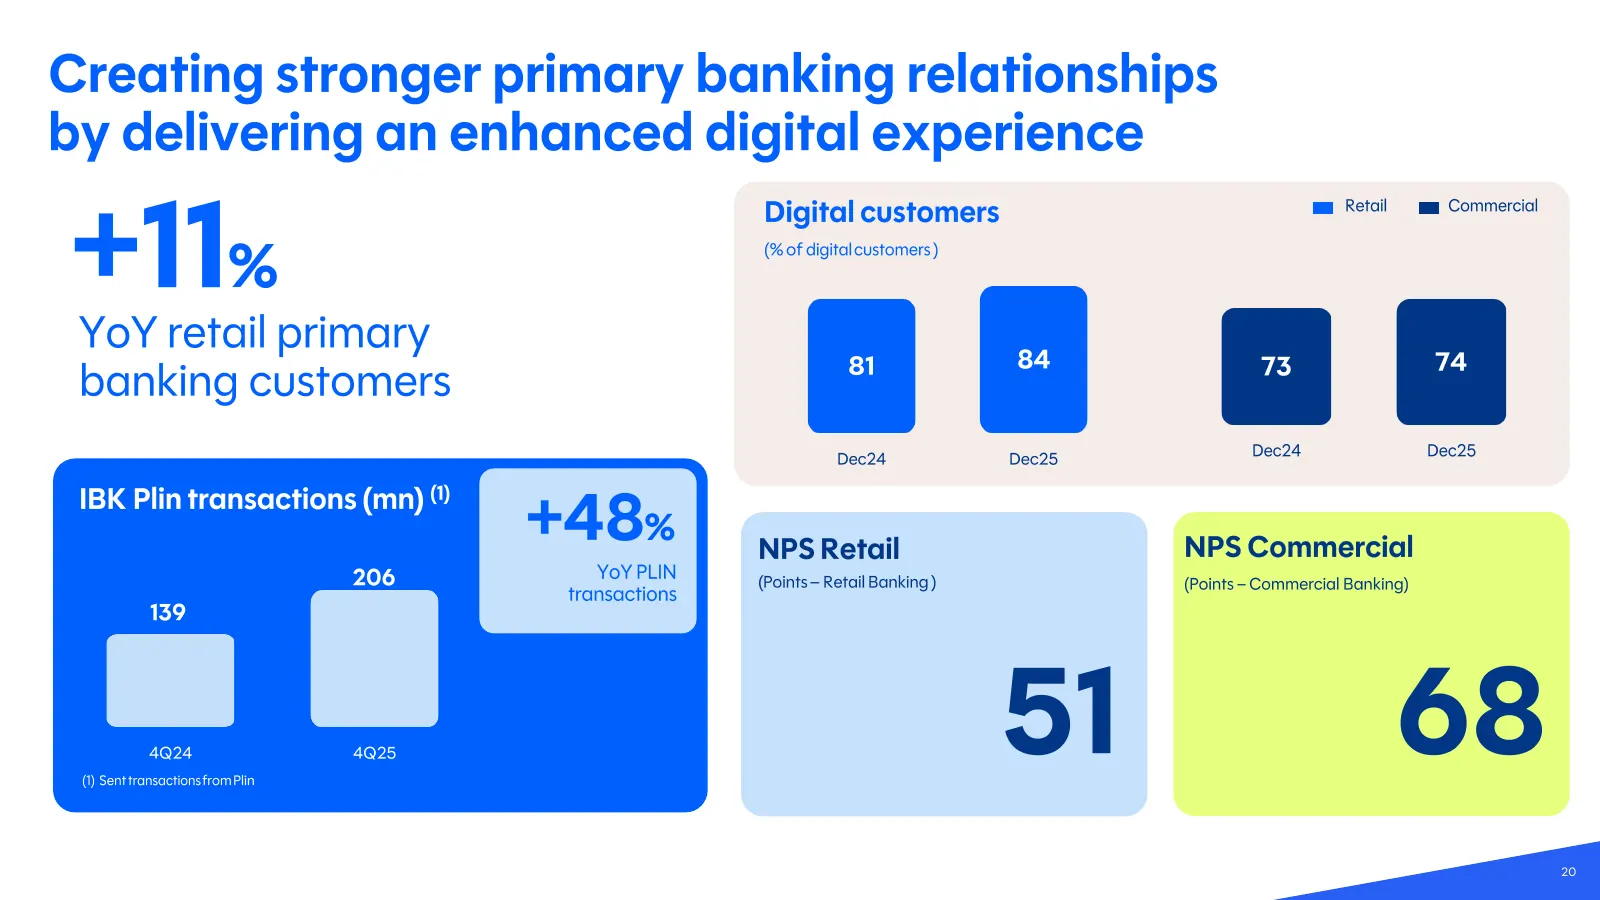
Creating stronger primary banking relationships by delivering an enhanced digital experience +11% Retail Commercial Digital customers (% of digital customers ) YoY retail primary 84 81 73 74 banking customers Dec24 Dec25 Dec24 Dec25 IBK Plin transactions (mn) (1) +48 % NPS Retail NPS Commercial 206
Slide 21: Growing digital engagement across insurance & WM
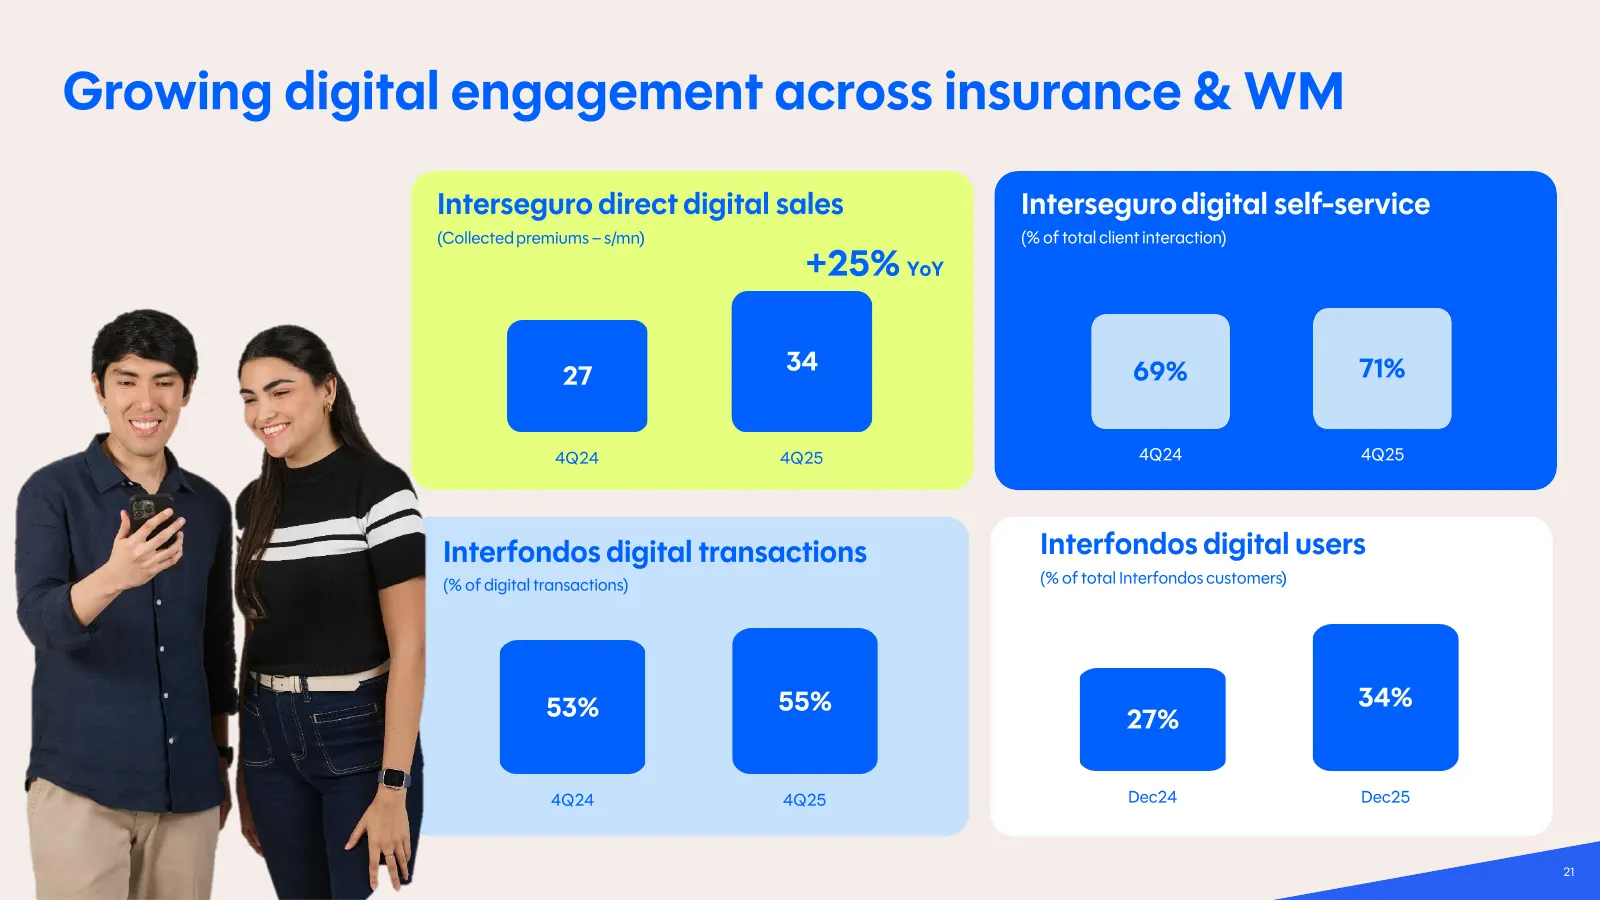
Growing digital engagement across insurance & WM Interseguro direct digital sales Interseguro digital self -service (Collected premiums – s/mn) (% of total client interaction ) +25% YoY 34 69% 71% 27 4Q24 4Q25 4Q24 4Q25 Interfondos digital transactions Interfondos digital users (% of digital transac
Slide 22: Insurance delivering solid double-digit growth
Insurance delivering solid double -digit growth
Slide 23: +22% in long-term insurance
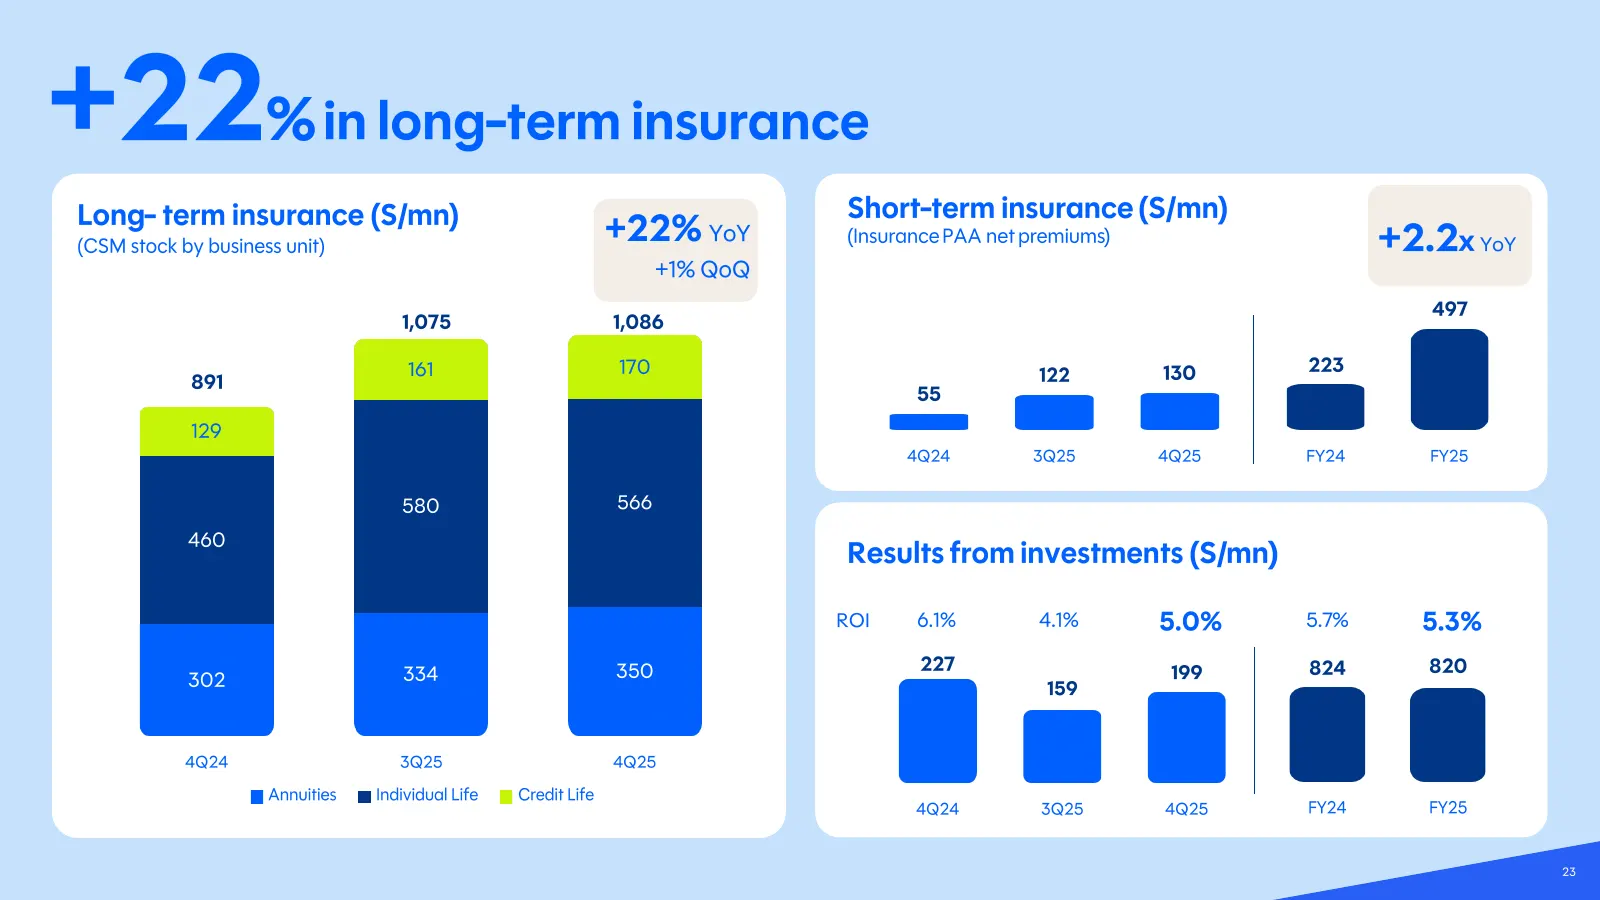
+22 % in long -term insurance Long - term insurance (S/ mn) Short -term insurance (S/mn) (CSM stock by business unit) +22% YoY (Insurance PAA net premiums ) +2.2 x YoY +1% QoQ 497 1,075 1,086 161 170 130 223 891 122 55 129 4Q24 3Q25 4Q25 FY24 FY25 580 566 460 Results from investments (S/mn) ROI 6.1%
Slide 24: WM continues to deliver double-digit growth
WM continues to deliver double -digit growth
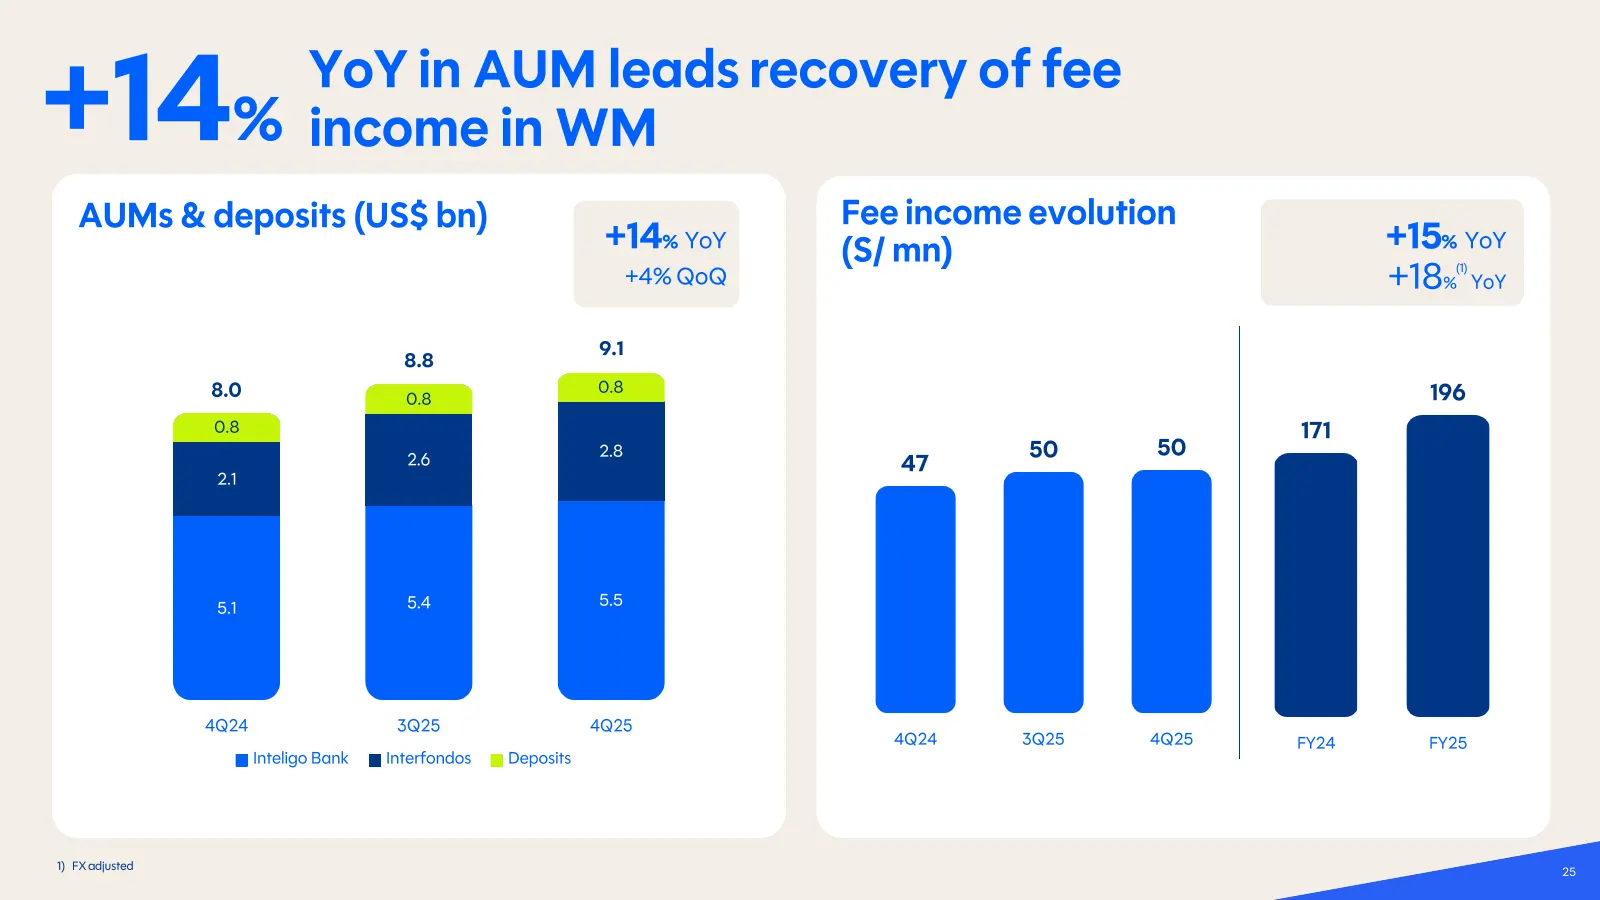
Slide 25: +14% YoY in AUM leads recovery of fee income in WM
+14 YoY in AUM leads recovery of fee % income in WM AUMs & deposits (US$ bn) Fee income evolution +14% YoY (S/ mn) +15% YoY +4% QoQ +18% YoY (1) 9.1 8.8 8.0 0.8 196 0.8 0.8 171 2.6 2.8 50 50 47 2.1 5.1 5.4 5.5 4Q24 3Q25 4Q25 4Q24 3Q25 4Q25 FY24 FY25 Inteligo Bank Interfondos Deposits 1) FX a djusted
Slide 26: Takeaways
Takeaways is.com.pe
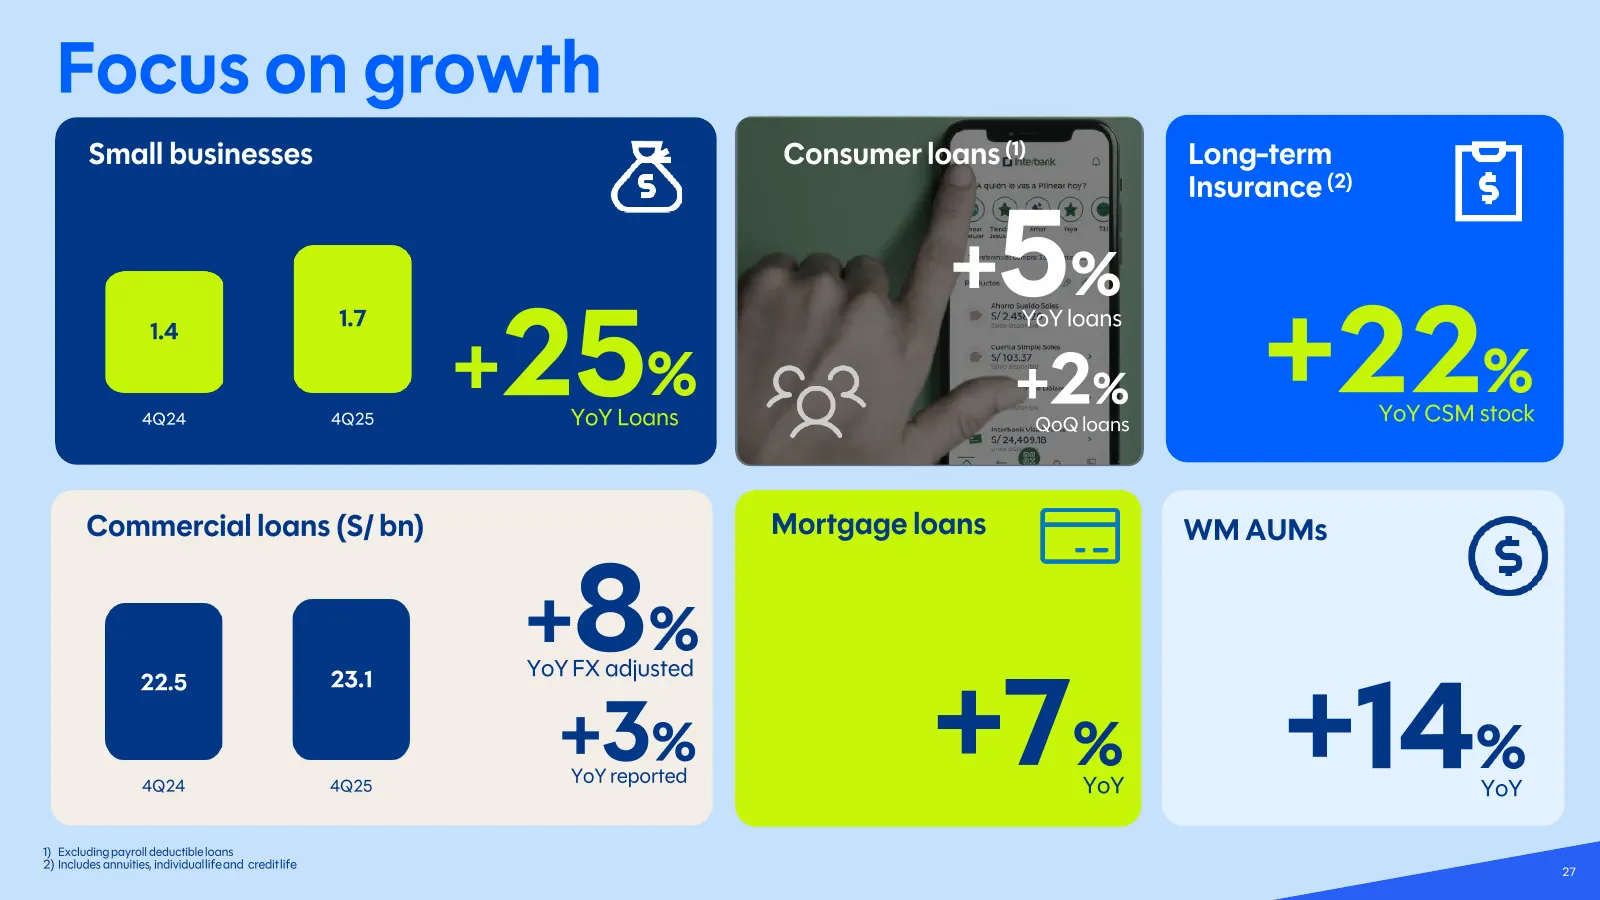
Slide 27: Focus on growth
Focus on growth Small businesses Consumer loans (1) Long -term Insurance (2) +5 % + 25 % +22 % 1.7 YoY loans 1.4 4Q24 4Q25 YoY Loans +2 %QoQ loans YoY CSM stock Commercial loans (S/ bn) Mortgage loans WM AUMs 23.1 +8 % YoY FX adjusted +7 % 22.5 4Q24 4Q25 +3 % YoY reported YoY +14% YoY 1) Excluding p
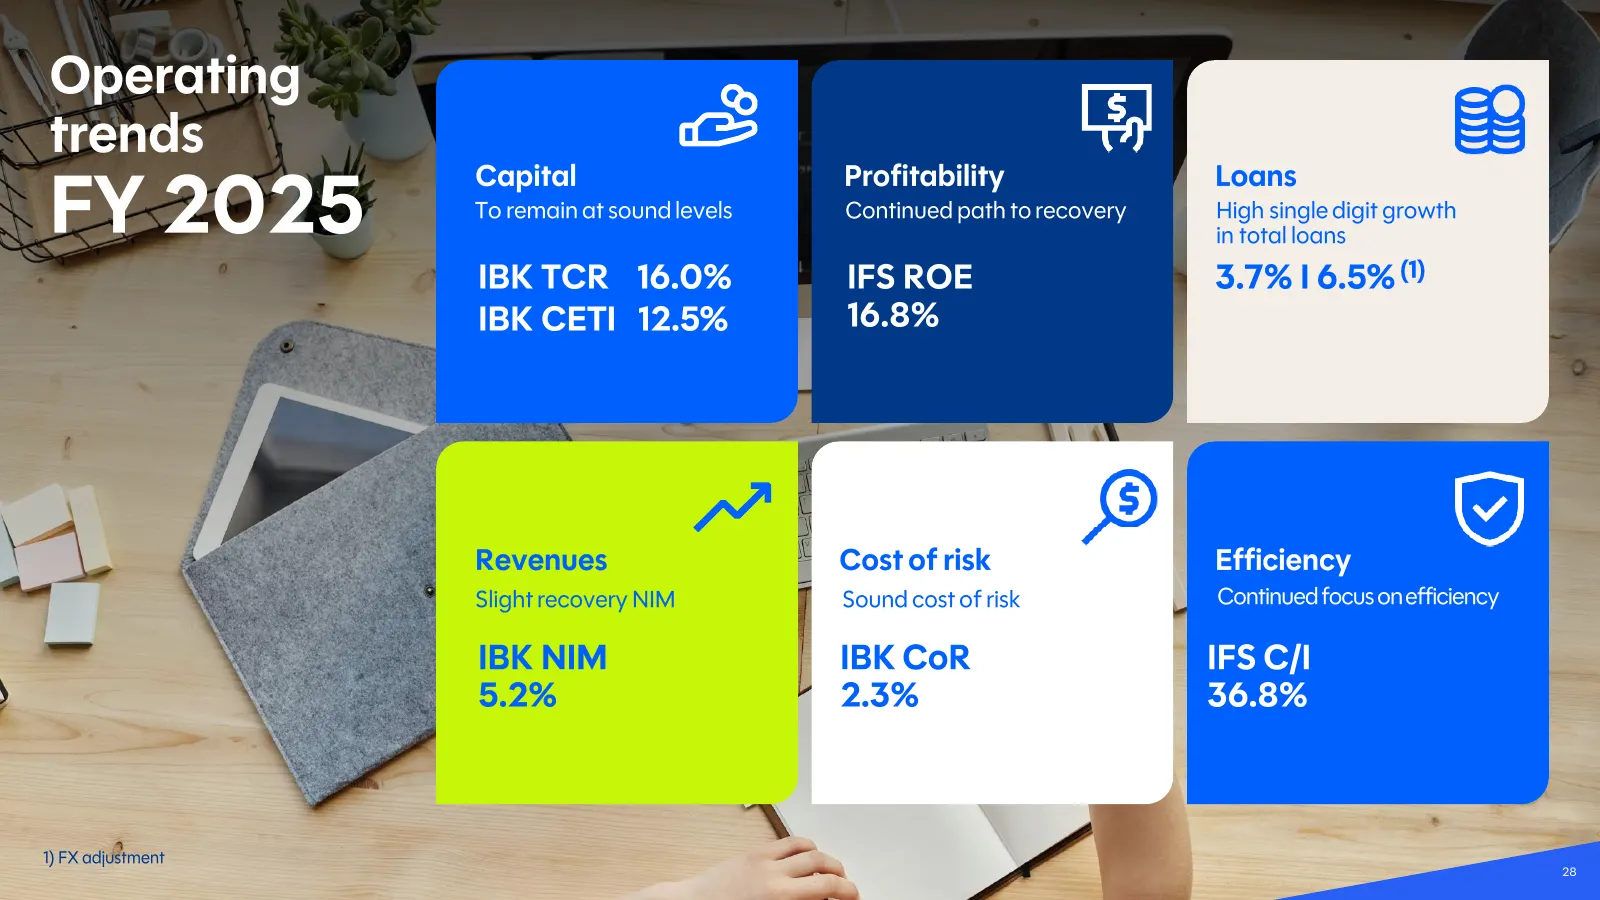
Slide 28: Operating trends
Operating trends Capital Profitability Loans FY 2025 To remain at sound levels Continued path to recovery High single digit growth in total loans IBK TCR 16.0% IFS ROE 3.7% I 6.5 % (1) IBK CETI 12.5 % 16.8% Revenues Cost of risk Efficiency Slight recovery NIM Sound cost of risk Continued focus on ef
Slide 29: Takeaways
Takeaways 1 Solid performance 2 Higher -yielding loans continue positive trend 3 Improving risk-adjusted across businesses NIM 4 Strengthening primary banking relationships 5 Insurance delivering solid double -digit 6 WM continues to deliver double -digit growth growth 29
Slide 30: Appendix
Appendix 30
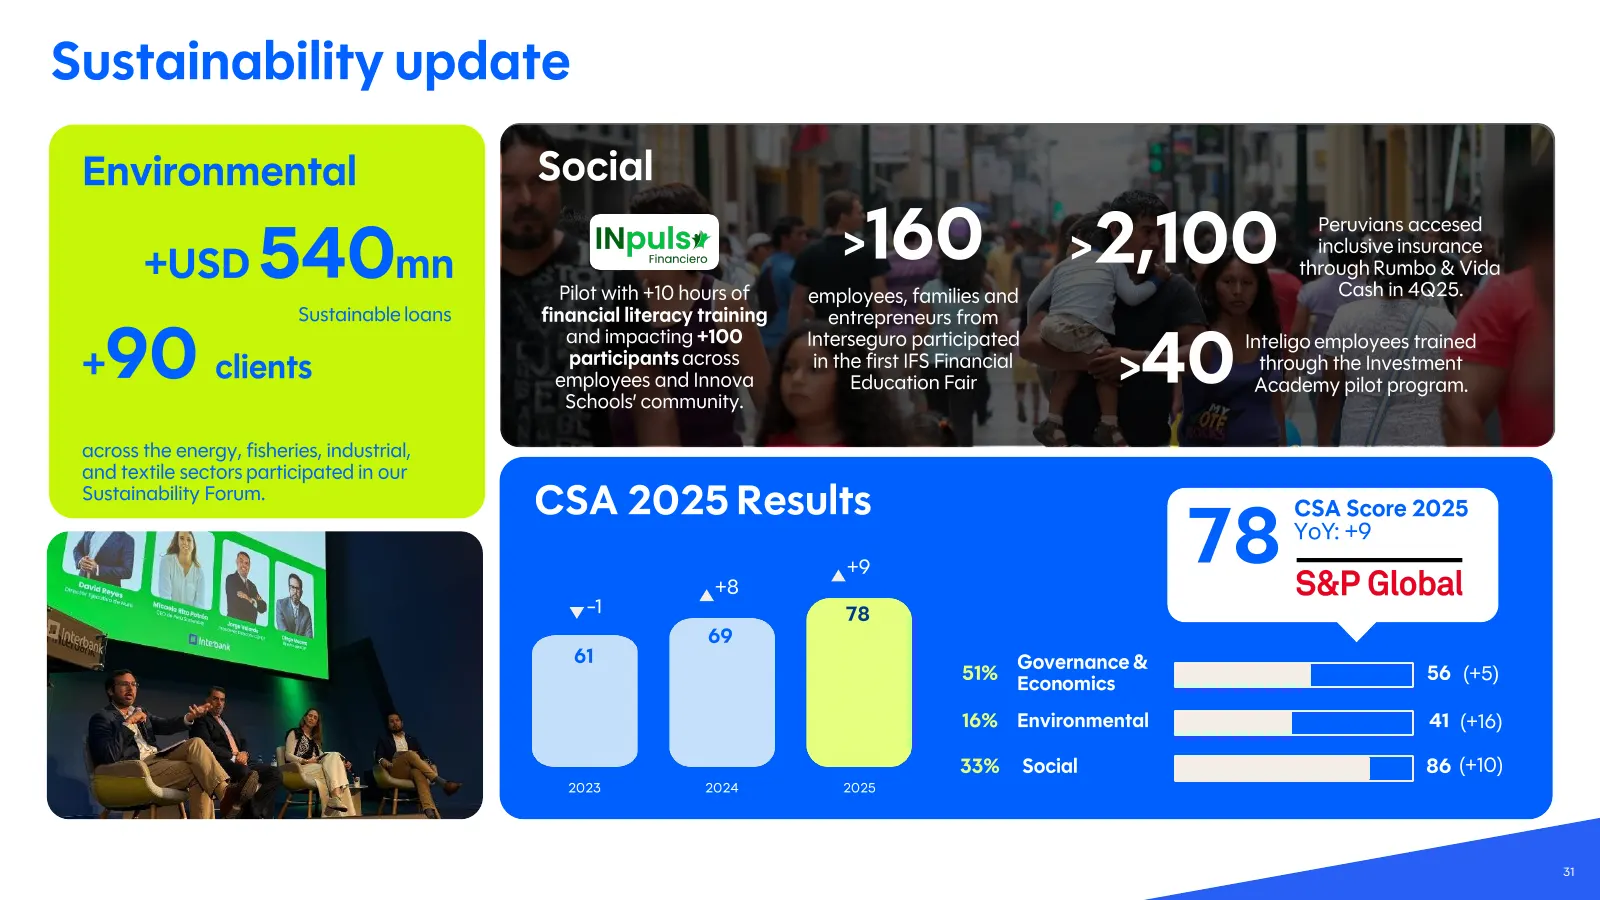
Slide 31: Sustainability update
Sustainability update Environmental Social +USD 540 mn > 160 > 2,100 Peruvians accesed inclusive insurance through Rumbo & Vida Pilot with +10 hours of employees, families and Cash in 4Q25. Sustainable loans financial literacy training entrepreneurs from + 90 clients and impacting +100 participants
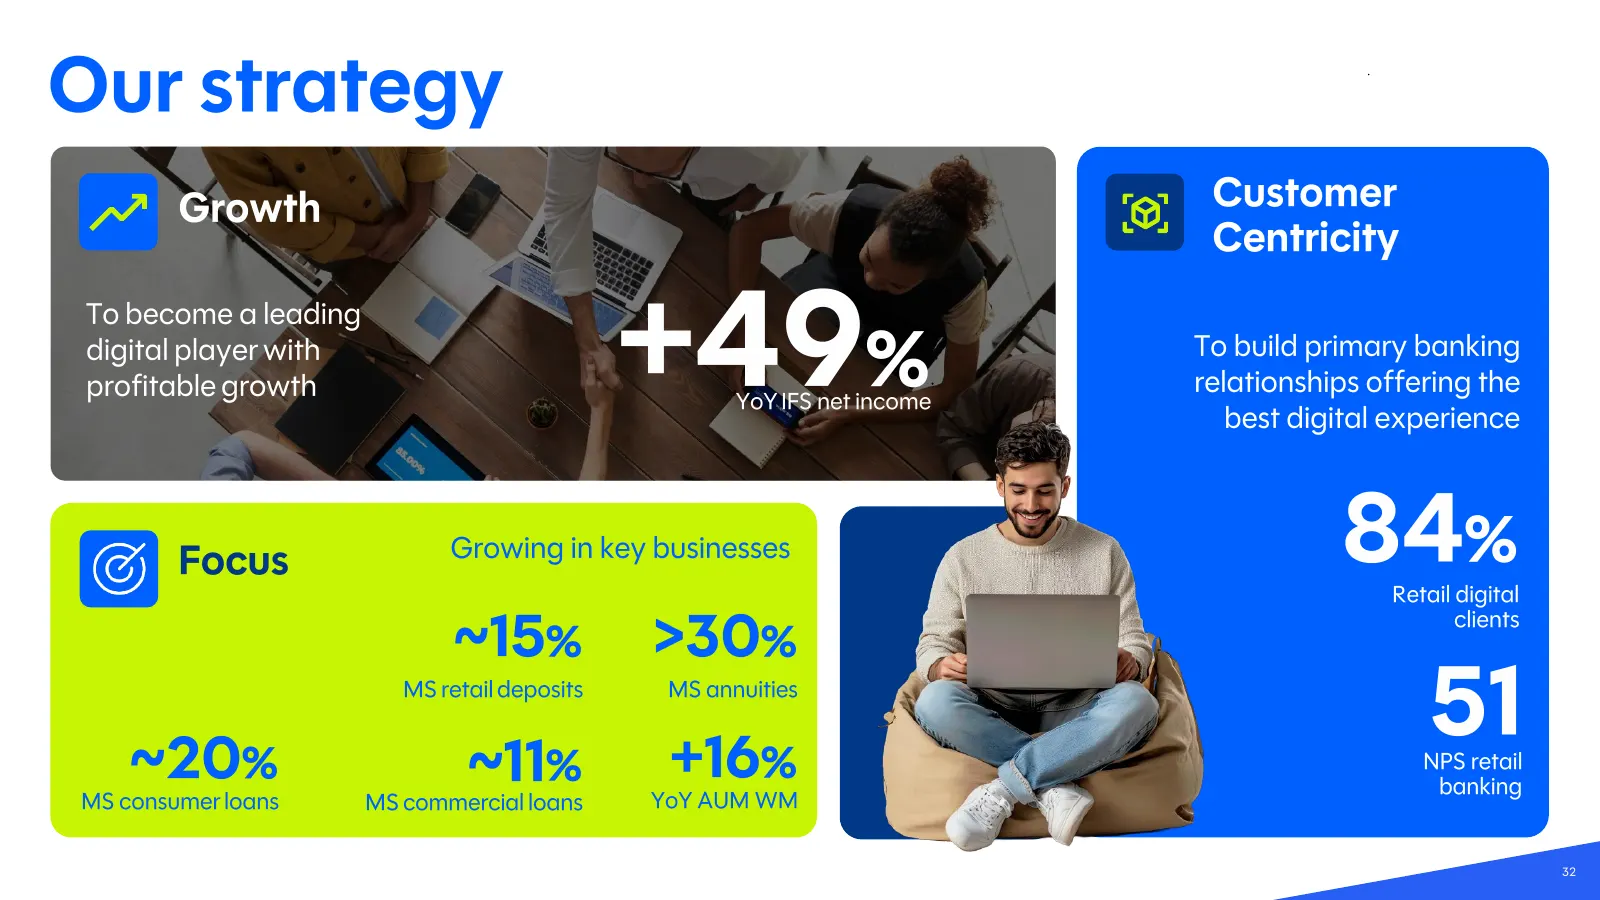
Slide 32: Our strategy
Our strategy Growth Customer Centricity To become a leading digital player with profitable growth +49 % YoY IFS net income To build primary banking relationships offering the best digital experience Focus Growing in key businesses 84 %Retail digital clients ~ 15% >30 % ~ 20 % MS retail deposits ~ 11
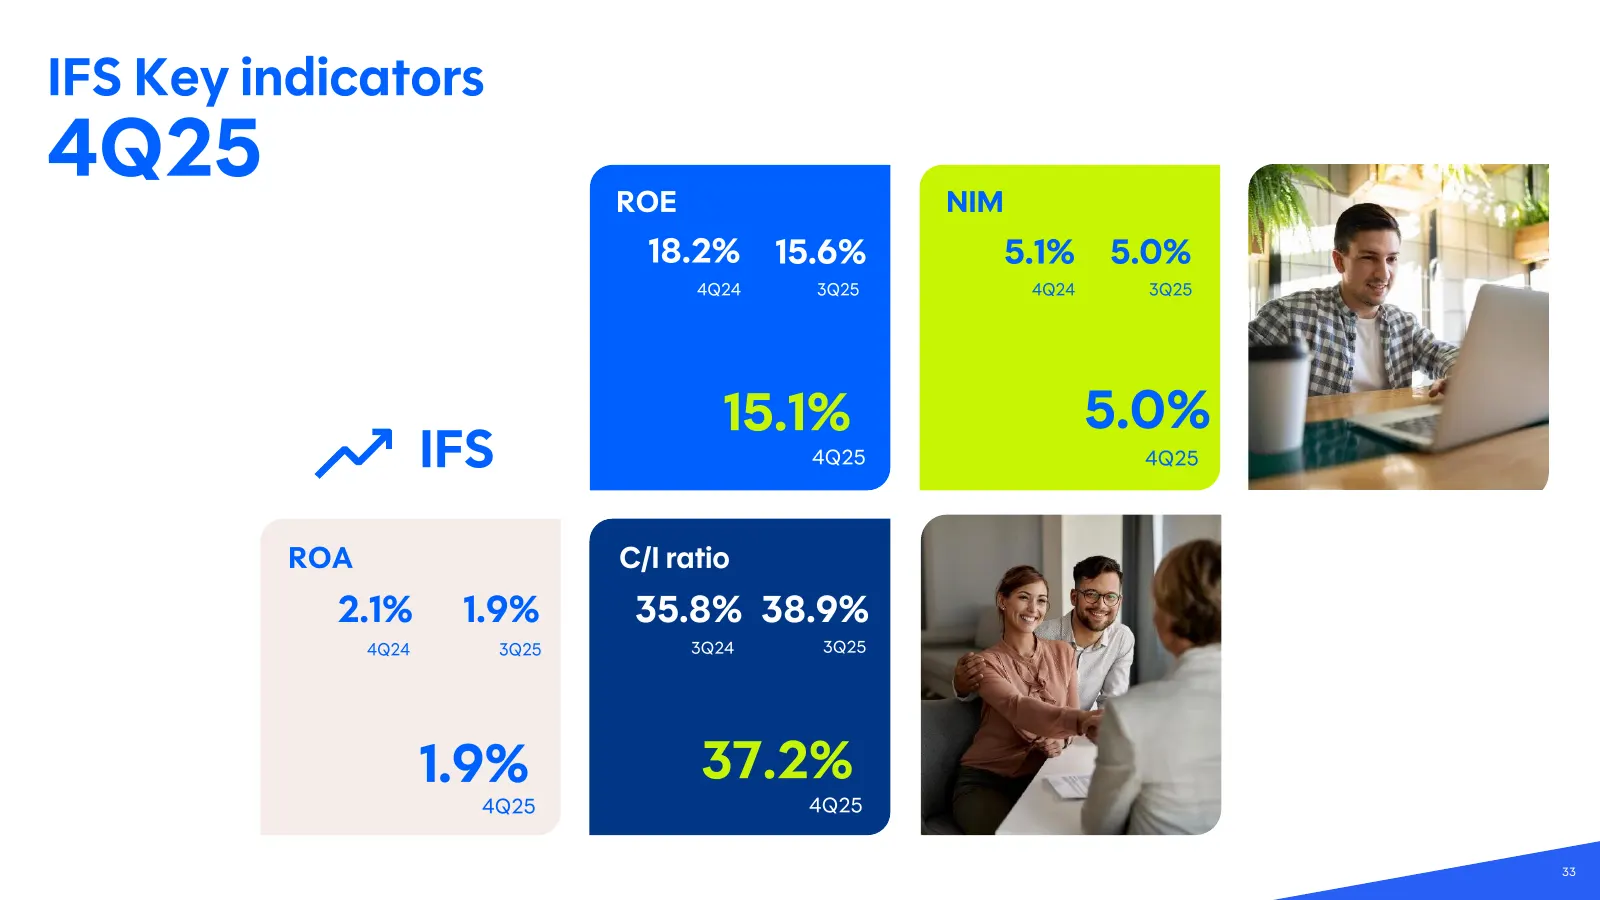
Slide 33: IFS Key indicators 4Q25
IFS Key indicators 4Q25 ROE NIM 18.2% 15.6% 5.1% 5.0% 4Q24 3Q25 4Q24 3Q25 15.1% 5.0% IFS 4Q25 4Q25 ROA C/I ratio 2.1% 1.9% 35.8% 38.9% 4Q24 3Q25 3Q24 3Q25 1.9% 37.2% 4Q25 4Q25 33
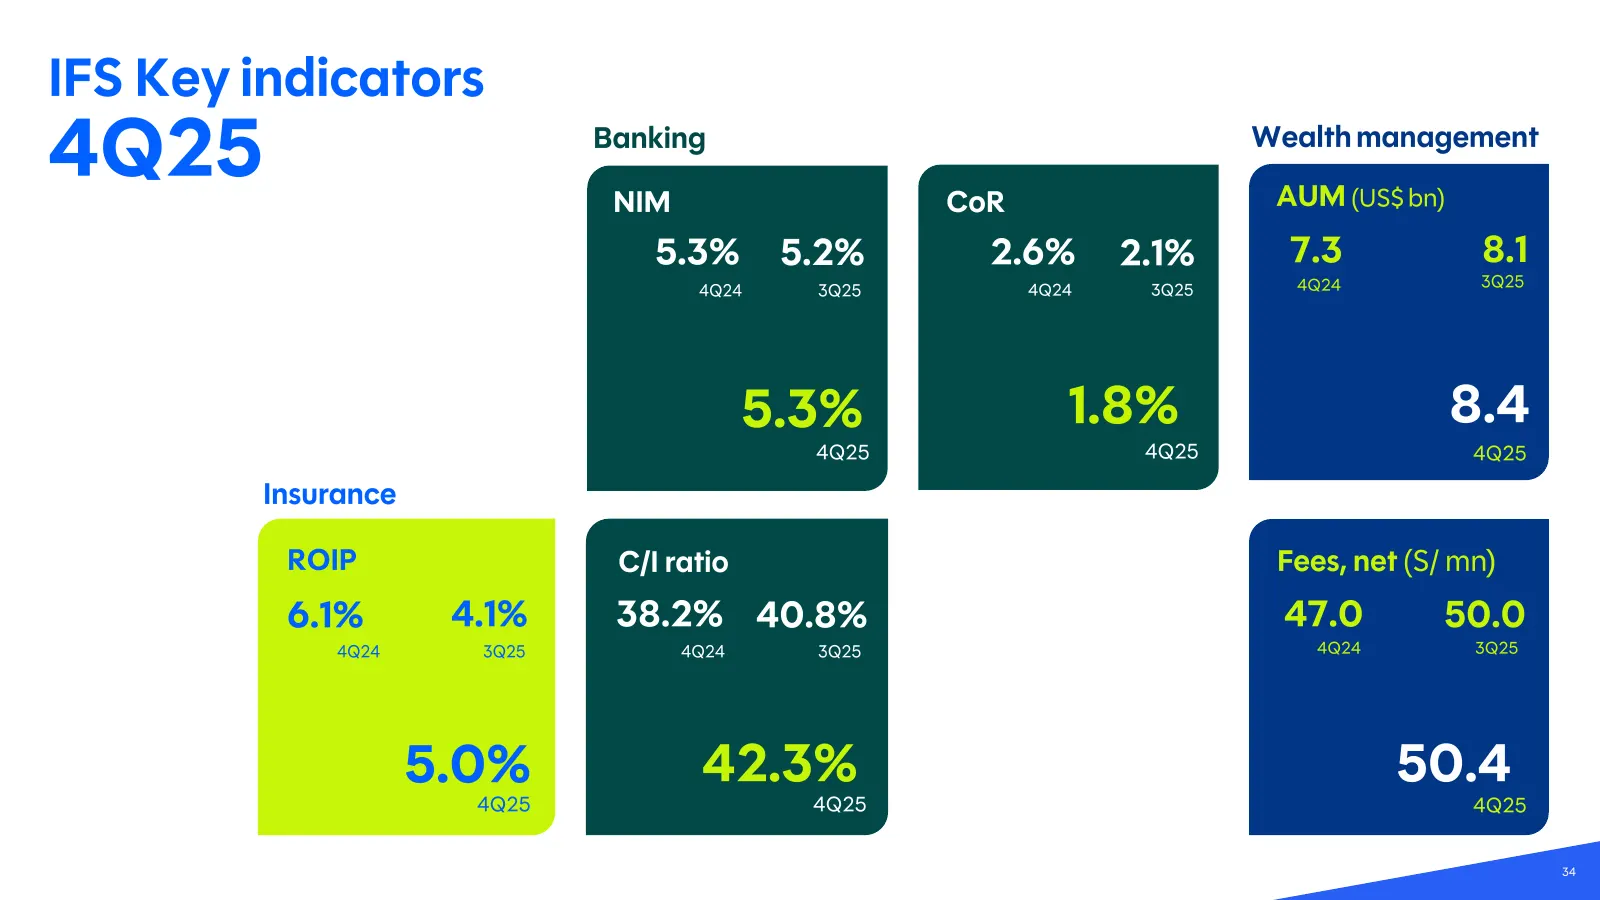
Slide 34: IFS Key indicators 4Q25
IFS Key indicators 4Q25 Banking NIM CoR Wealth management AUM (US$ bn) 5.3% 5.2% 2.6% 2.1% 7.3 8.1 4Q24 3Q25 4Q24 3Q25 4Q24 3Q25 5.3% 1.8% 8.4 4Q25 4Q25 4Q25 Insurance ROIP C/I ratio Fees, net (S/ mn) 6.1% 4.1% 38.2% 40.8% 47.0 50.0 4Q24 3Q25 4Q24 3Q25 4Q24 3Q25 5.0% 42.3% 50.4 4Q25 4Q25 4Q25 34
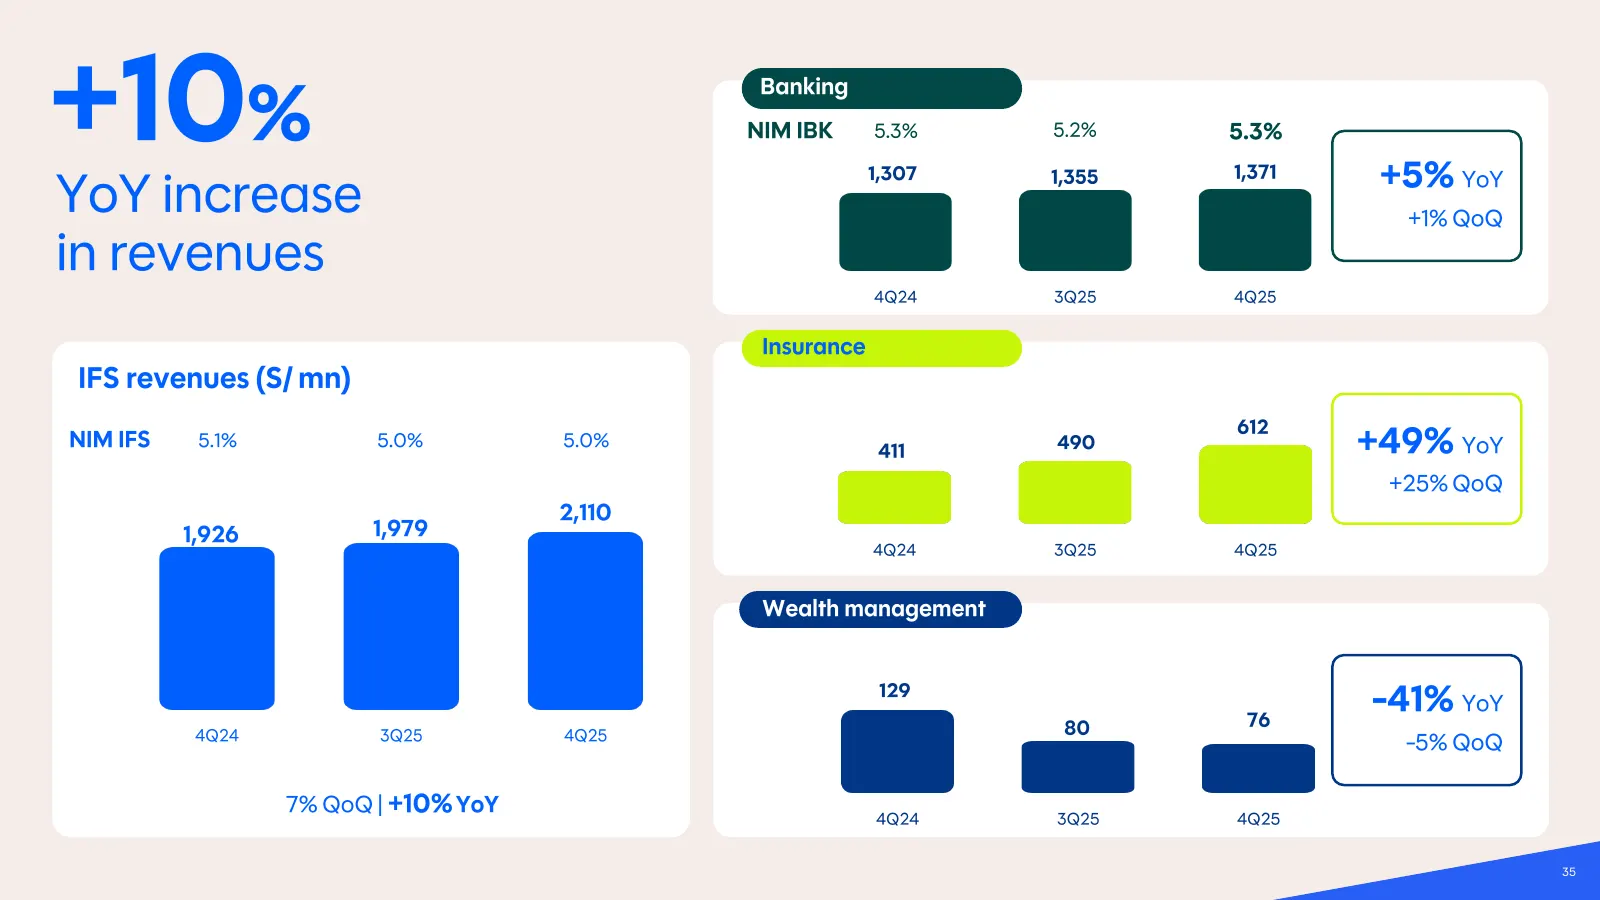
Slide 35: YoY increase in revenues
+10 % Banking NIM IBK 5.3% 1,307 5.2% 1,355 5.3% 1,371 +5% YoY YoY increase +1% QoQ in revenues 4Q24 3Q25 4Q25 Insurance IFS revenues (S/ mn) 612 NIM IFS 5.1% 5.0% 5.0% 411 490 +49% YoY +25% QoQ 2,110 1,926 1,979 4Q24 3Q25 4Q25 Wealth management 129 76 -41% YoY 4Q24 3Q25 4Q25 80 -5% QoQ 7% QoQ |+10%
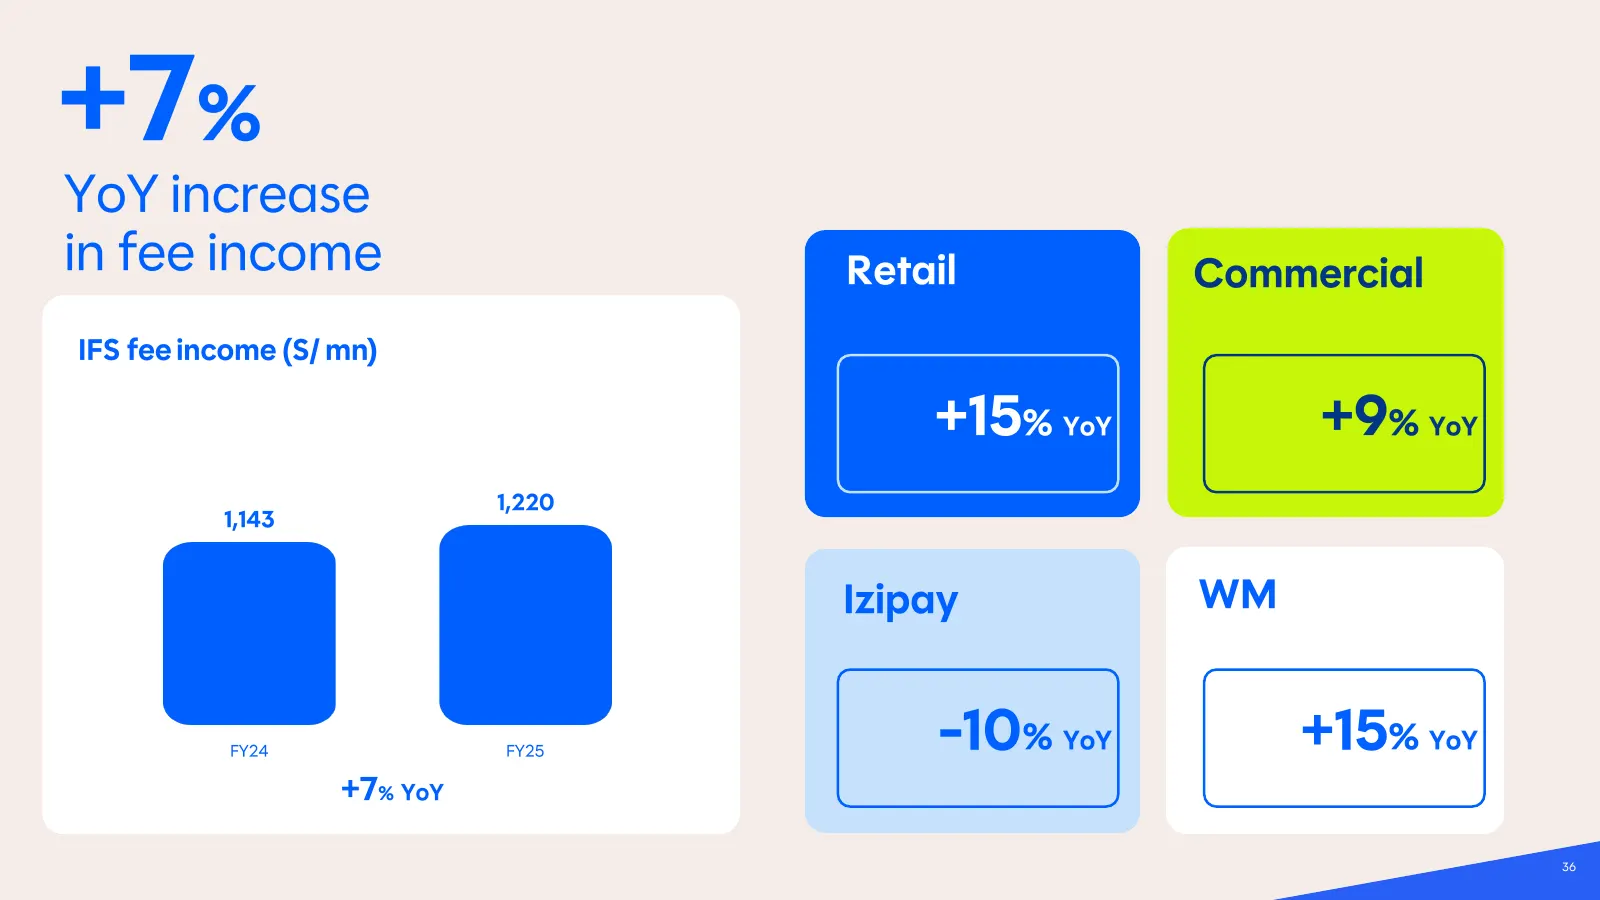
Slide 36: YoY increase in fee income
+7 % YoY increase in fee income Retail C ommercial IFS fee income (S/ mn) +15% YoY +9 % YoY 1,220 1,143 Izipay WM FY24 FY25 -10% YoY +15% YoY +7 % YoY 36
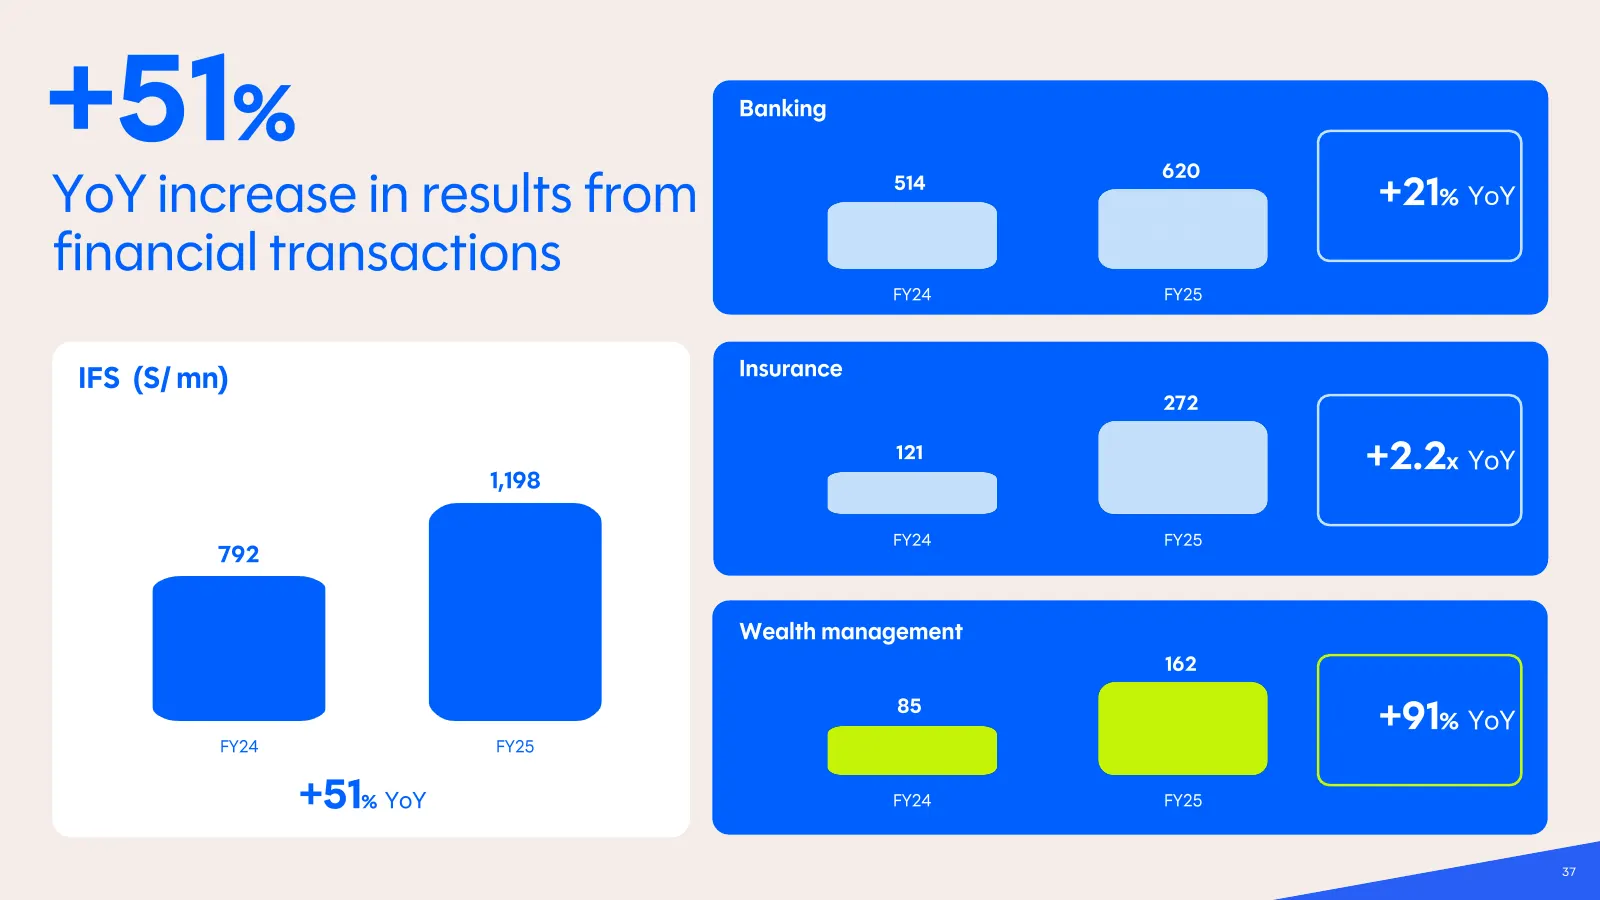
Slide 37: YoY increase in results from financial transactions
+51% Banking 620 YoY increase in results from 514 +21% YoY financial transactions FY24 FY25 IFS (S/ mn) Insurance 272 1,198 121 +2.2 x YoY FY24 FY25 792 Wealth management 162 85 +91% YoY FY24 FY25 +51% YoY FY24 FY25 37
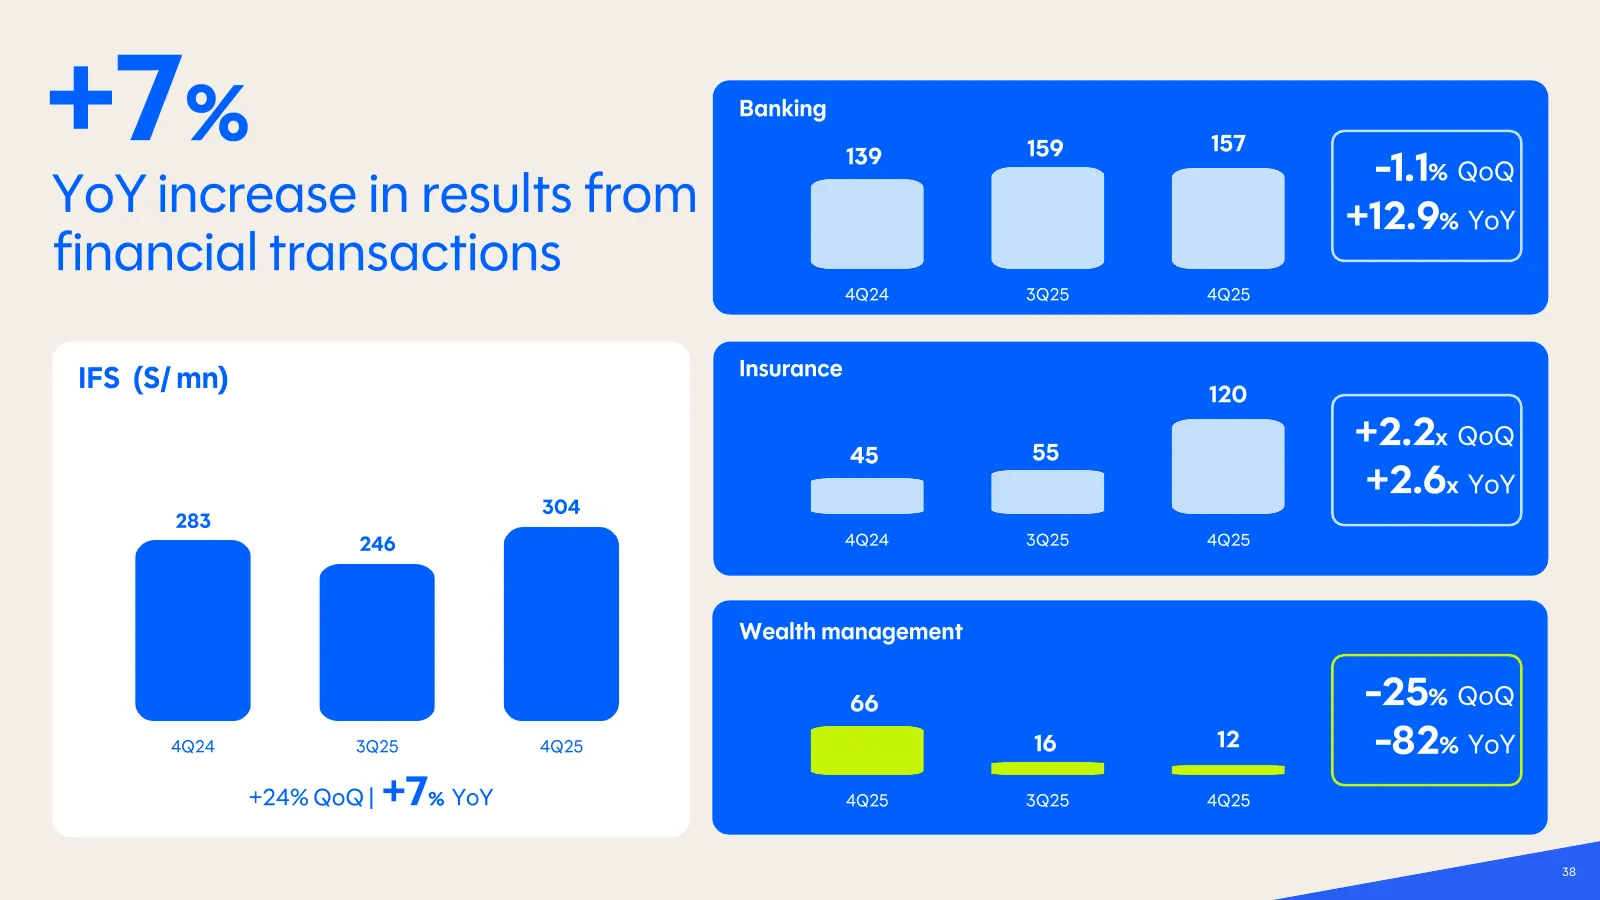
Slide 38: YoY increase in results from financial transactions
+7 % Banking 139 159 157 -1.1% QoQ YoY increase in results from +12.9 % YoY financial transactions 4Q24 3Q25 4Q25 IFS (S/ mn) Insurance 120 45 55 +2.2 x QoQ +2.6 x YoY 304 283 246 4Q24 3Q25 4Q25 Wealth management 66 -25 % QoQ 4Q24 3Q25 4Q25 16 12 -82 % YoY +24% QoQ | +7 % YoY 4Q25 3Q25 4Q25 38
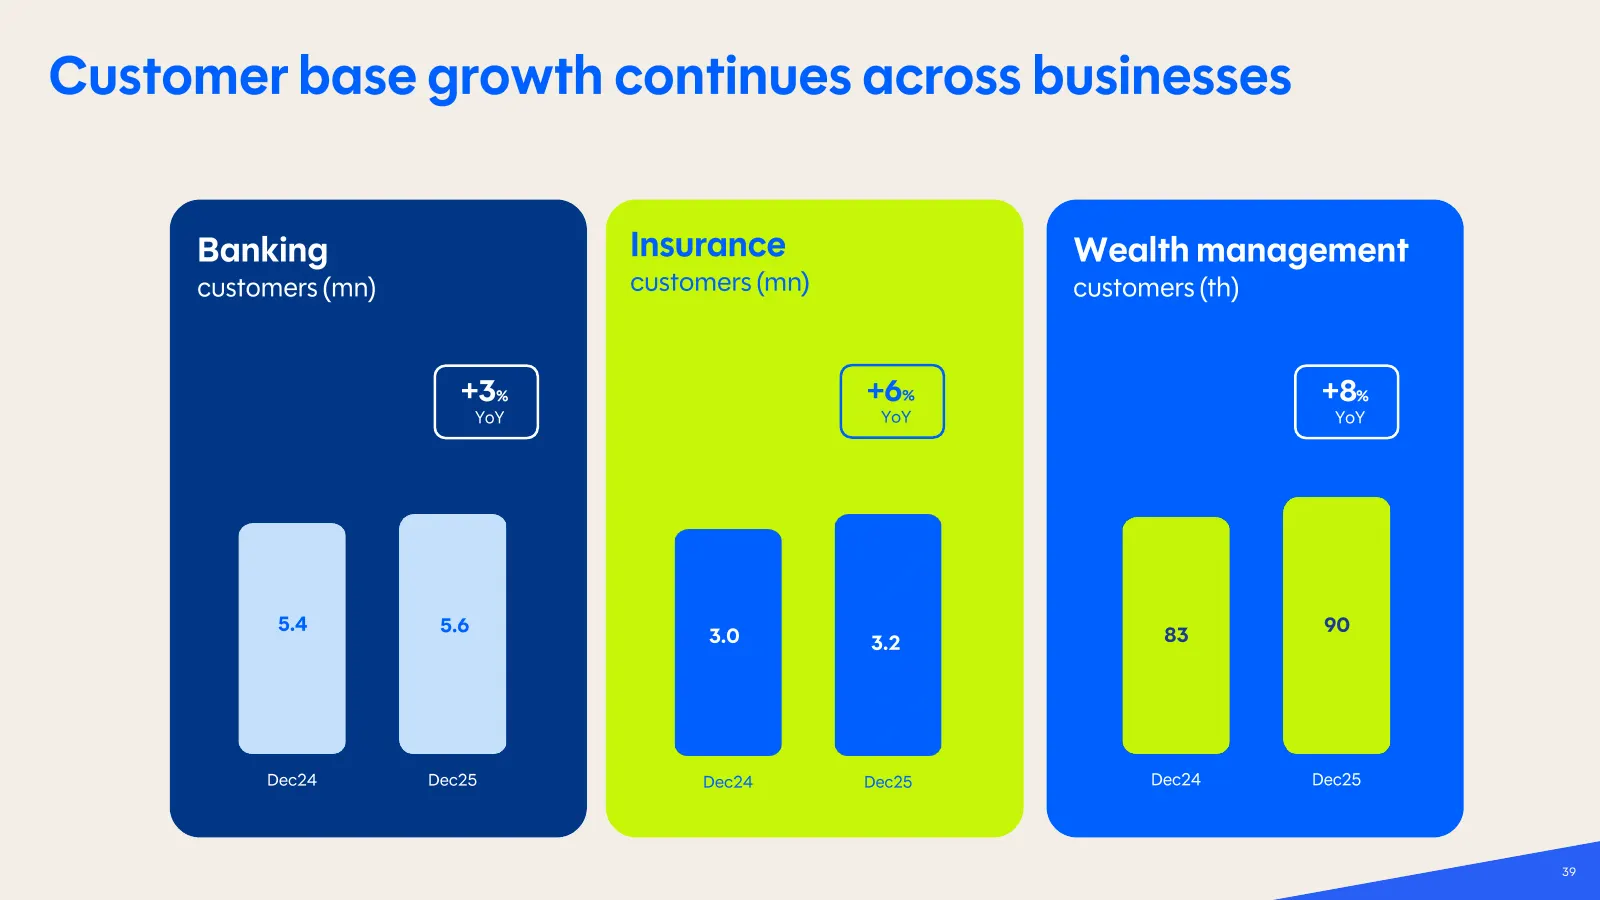
Slide 39: Customer base growth continues across businesses
Customer base growth continues across businesses Banking Insurance Wealth management customers (mn) customers (mn) customers (th) +3 % +6 % +8 % YoY YoY YoY 5.4 5.6 90 3.0 3.2 83 Dec24 Dec25 Dec24 Dec25 Dec24 Dec25 39
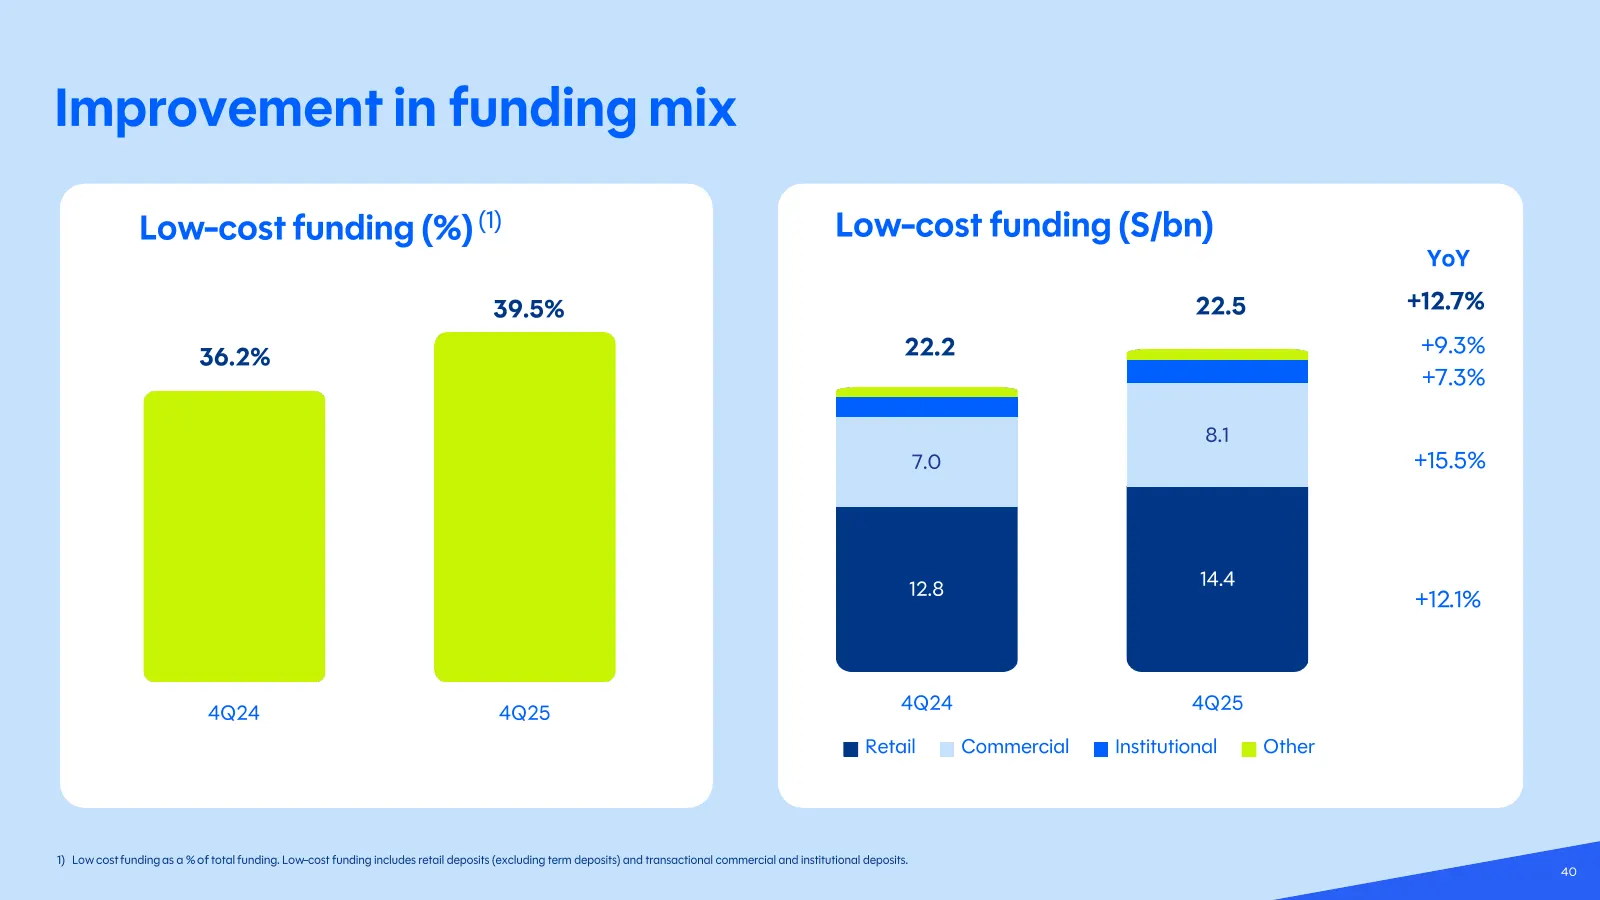
Slide 40: Improvement in funding mix
Improvement in funding mix Low -cost funding (%) (1) Low -cost funding (S/bn) YoY 39.5% 22.5 +12.7% 22.2 +9.3% 36.2% +7.3% 8.1 7.0 +15.5% 14.4 12.8 +12.1% 4Q24 4Q25 4Q24 4Q25 Retail Commercial Institutional Other 1) Low cost funding as a % of total funding . Low -cost funding includes retail deposit
Slide 41: Stable asset quality, CoR at 2.1%
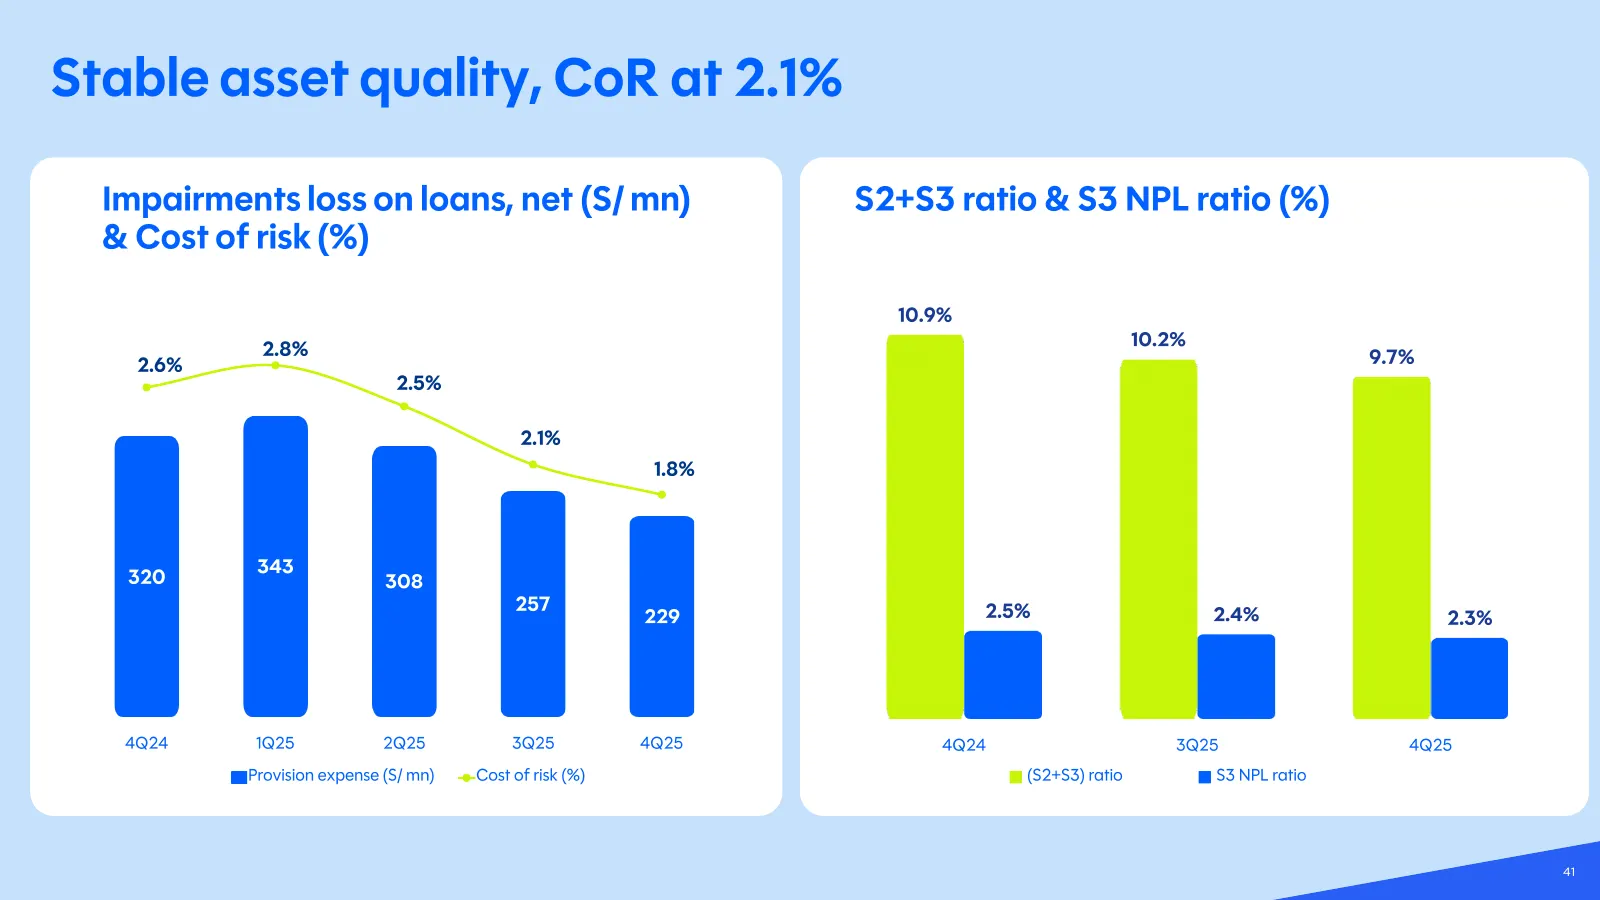
Stable asset quality , CoR at 2.1% Impairments loss on loans , net (S/ mn) S2+S3 ratio & S3 NPL ratio (%) & Cost of risk (%) 10.9% 430 2.8% 3.0% 10.2% 2.6% 9.7% 380 2.5% 2.5% 330 2.1% 280 1.8% 2.0% 230 1.5% 180 343 320 308 130 257 1.0% 2.5% 229 2.4% 2.3% 80 0.5% 30 -20 0.0% 4Q24 1Q25 2Q25 3Q25 4Q25
Slide 42: Fostering synergies between Izipay, small businesses and mid sized companies
Fostering synergies between IZIPAY, small businesses and mid sized companies + 26 % growth in deposits (S/ bn) 5.7 ~ 39 % IBK share of Izipay + 35 % YoY float from 4.5 flows Izipay 2.7 2.1 3.1 2.4 4Q24 4Q25 Mid-sized companies Small Businesses 42
Slide 43: Sound capitalization levels
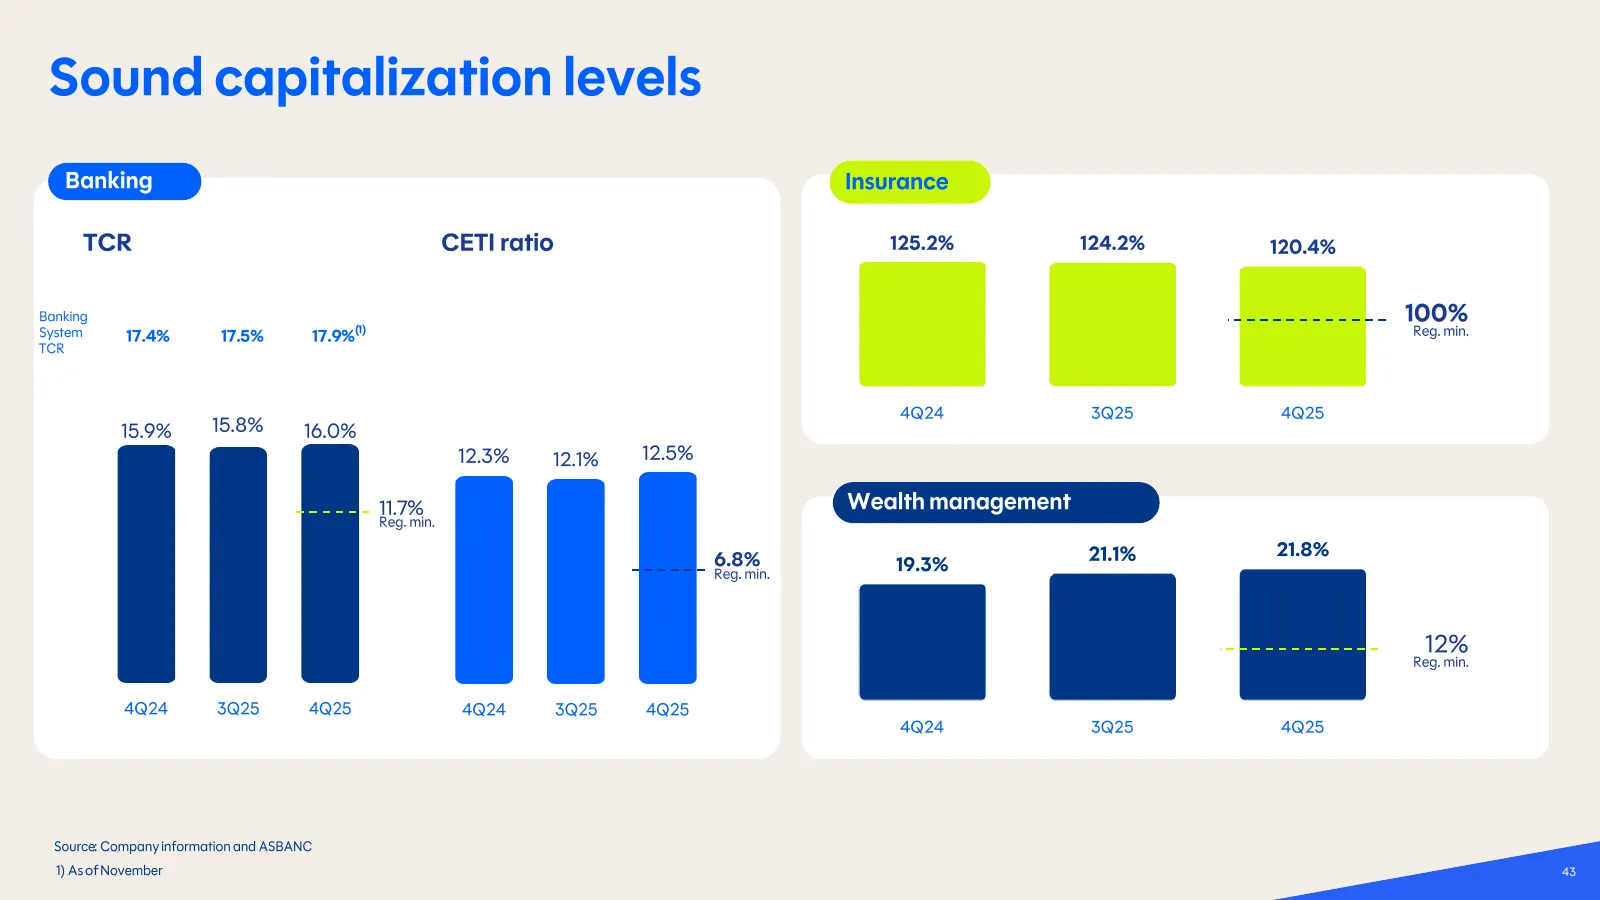
Sound capitalization levels Banking Insurance TCR CETI ratio 125.2% 124.2% 120.4% Banking (1) 100% System 17.4% 17.5% 17.9% Reg. min. TCR 4Q24 3Q25 4Q25 15.9% 15.8% 16.0% 12.3% 12.1% 12.5% 11.7% Wealth management Reg. min. 21.1% 21.8% 6.8% 19.3% Reg. min. 12% Reg. min. 4Q24 3Q25 4Q25 4Q24 3Q25 4Q25
Slide 44: Banking market share evolution
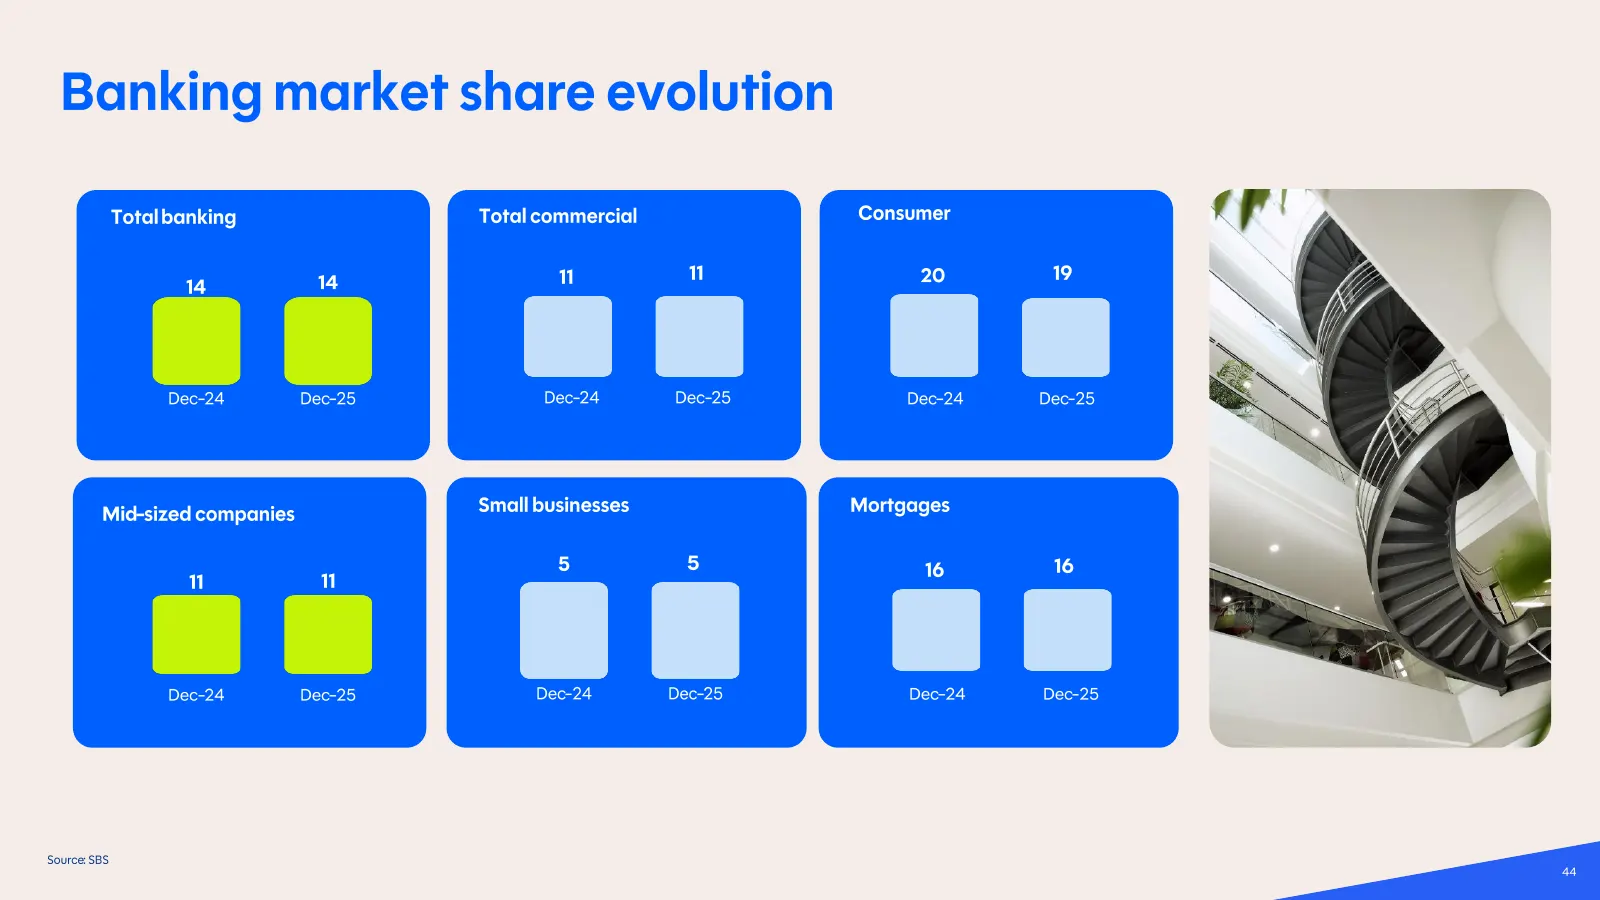
Banking market share evolution Total banking Total commercial Consumer 14 11 11 20 19 14 Dec -24 Dec -25 Dec -24 Dec -25 Dec -24 Dec -25 Mid-sized companies Small businesses Mortgages 5 5 16 16 11 11 Dec -24 Dec -25 Dec -24 Dec -25 Dec -24 Dec -25 Source : SBS 44
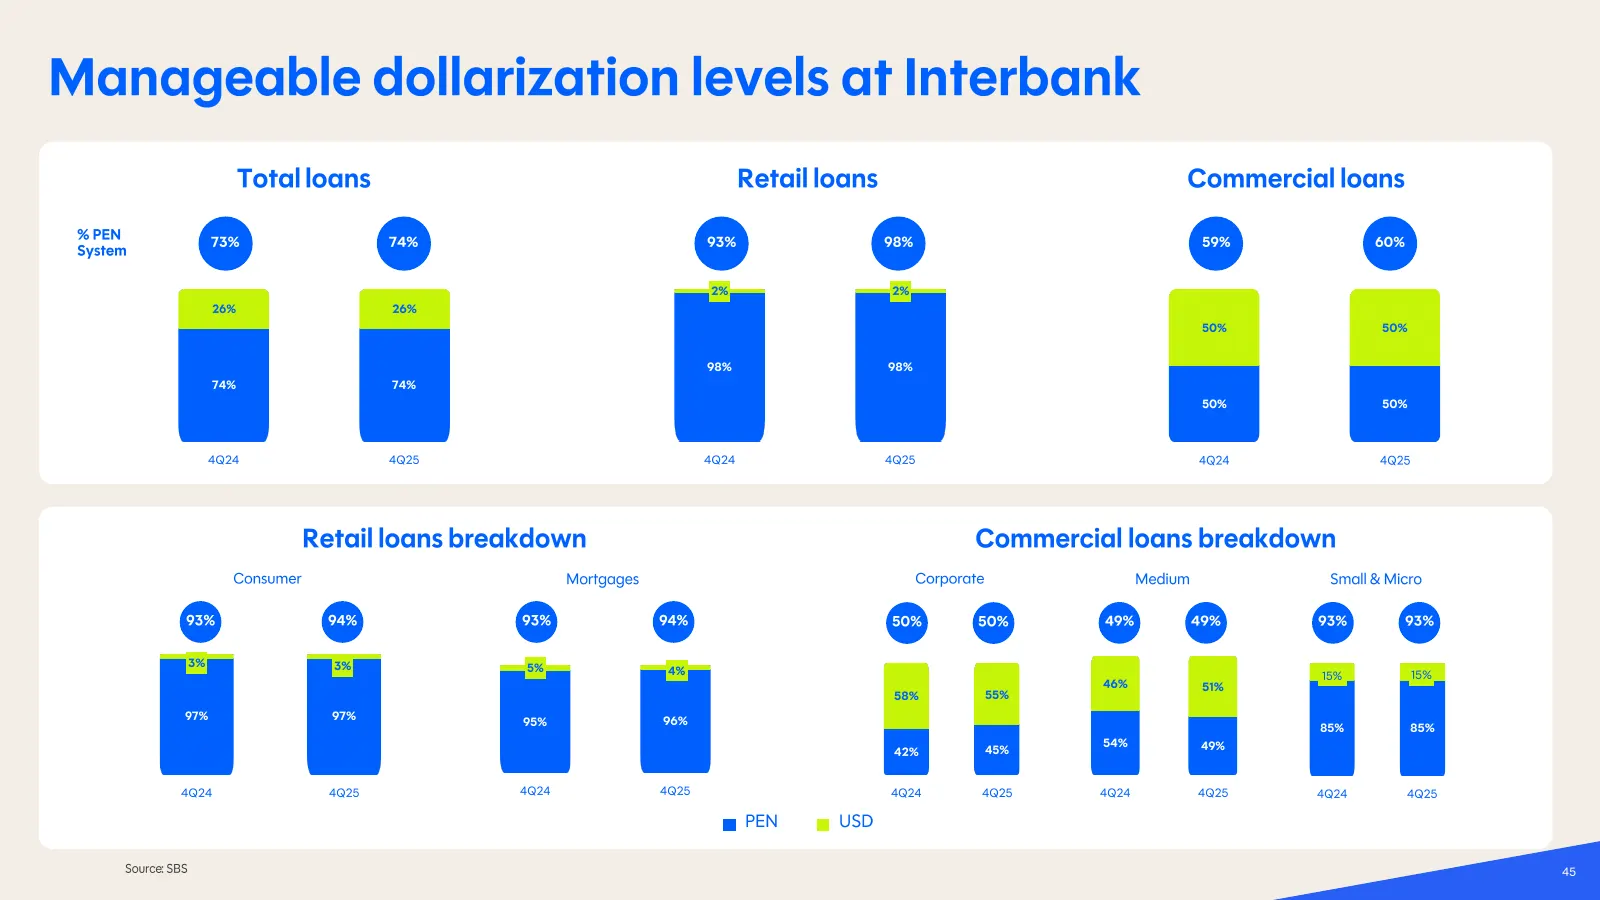
Slide 45: Manageable dollarization levels at Interbank
Manageable dollarization levels at Interbank Total loans Retail loans Commercial loans % PEN 73% 74% 93% 98% 59% 60% System 2% 2% 26% 26% 50% 50% 98% 98% 74% 74% 50% 50% 4Q24 4Q25 4Q24 4Q25 4Q24 4Q25 Retail loans breakdown Commercial loans breakdown Consumer Mortgages Corporate Medium Small & Micro
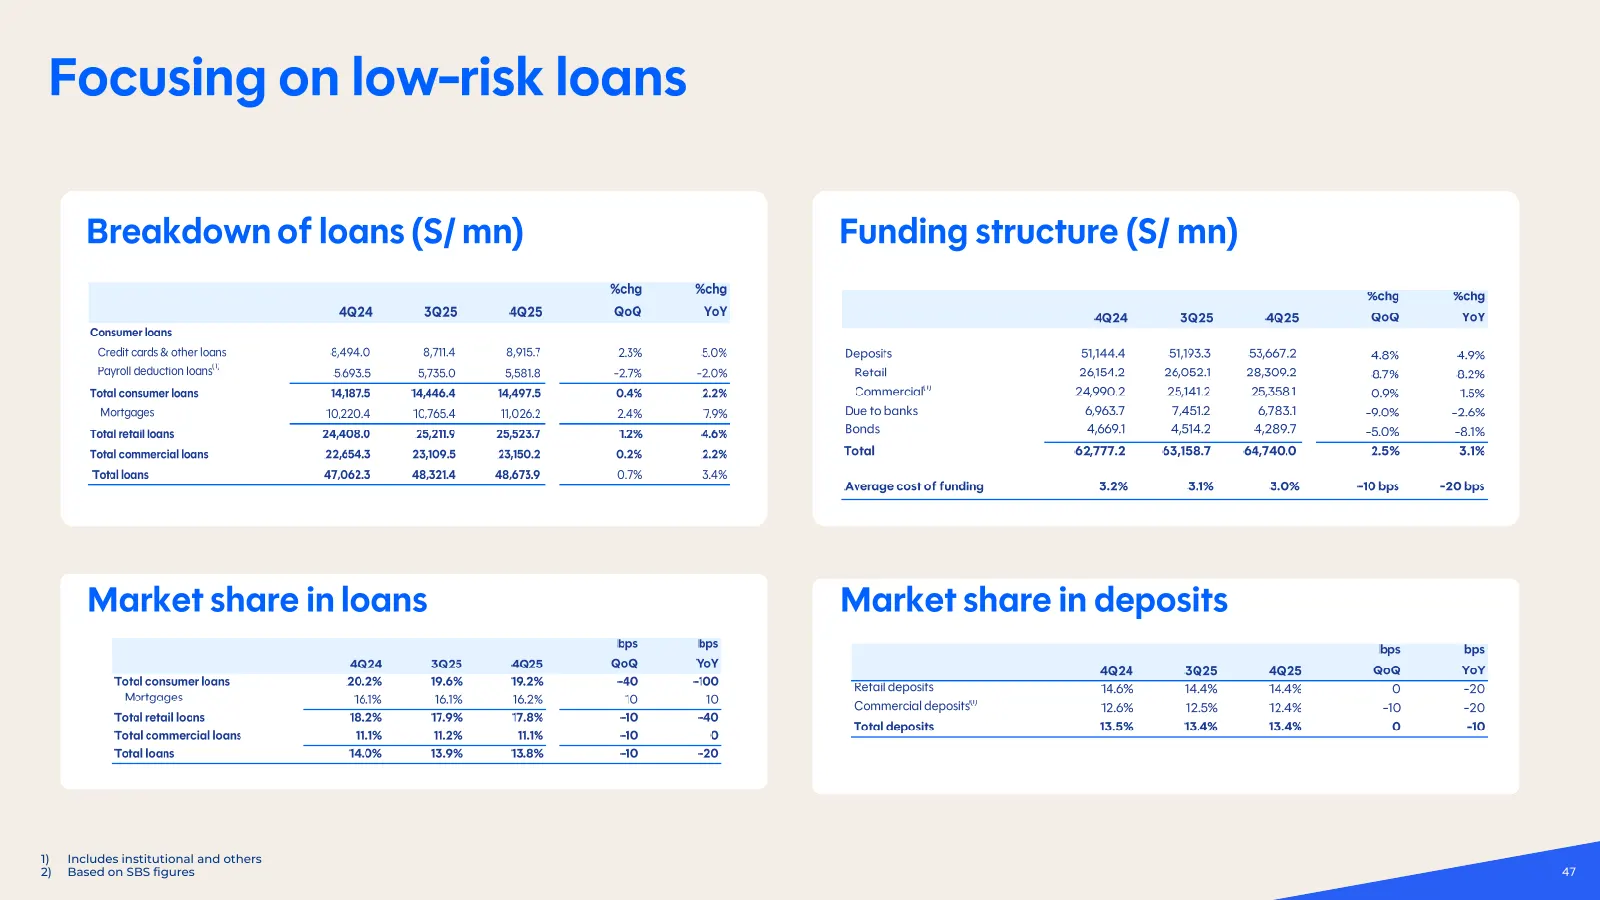
Slide 46: Focusing on low-risk loans
Focusing on low -risk loans Breakdown of loans (S/ mn) Funding structure (S/ mn) %chg %chg %chg %chg 4Q24 3Q25 4Q25 QoQ YoY 4Q24 3Q25 4Q25 QoQ YoY Consumer loans Credit cards & other loans 8,494.0 8,711.4 8,915.7 2.3% 5.0% Deposits 51,144.4 51,193.3 53,667.2 4.8% 4.9% (1) Payroll deduction loans 5,6
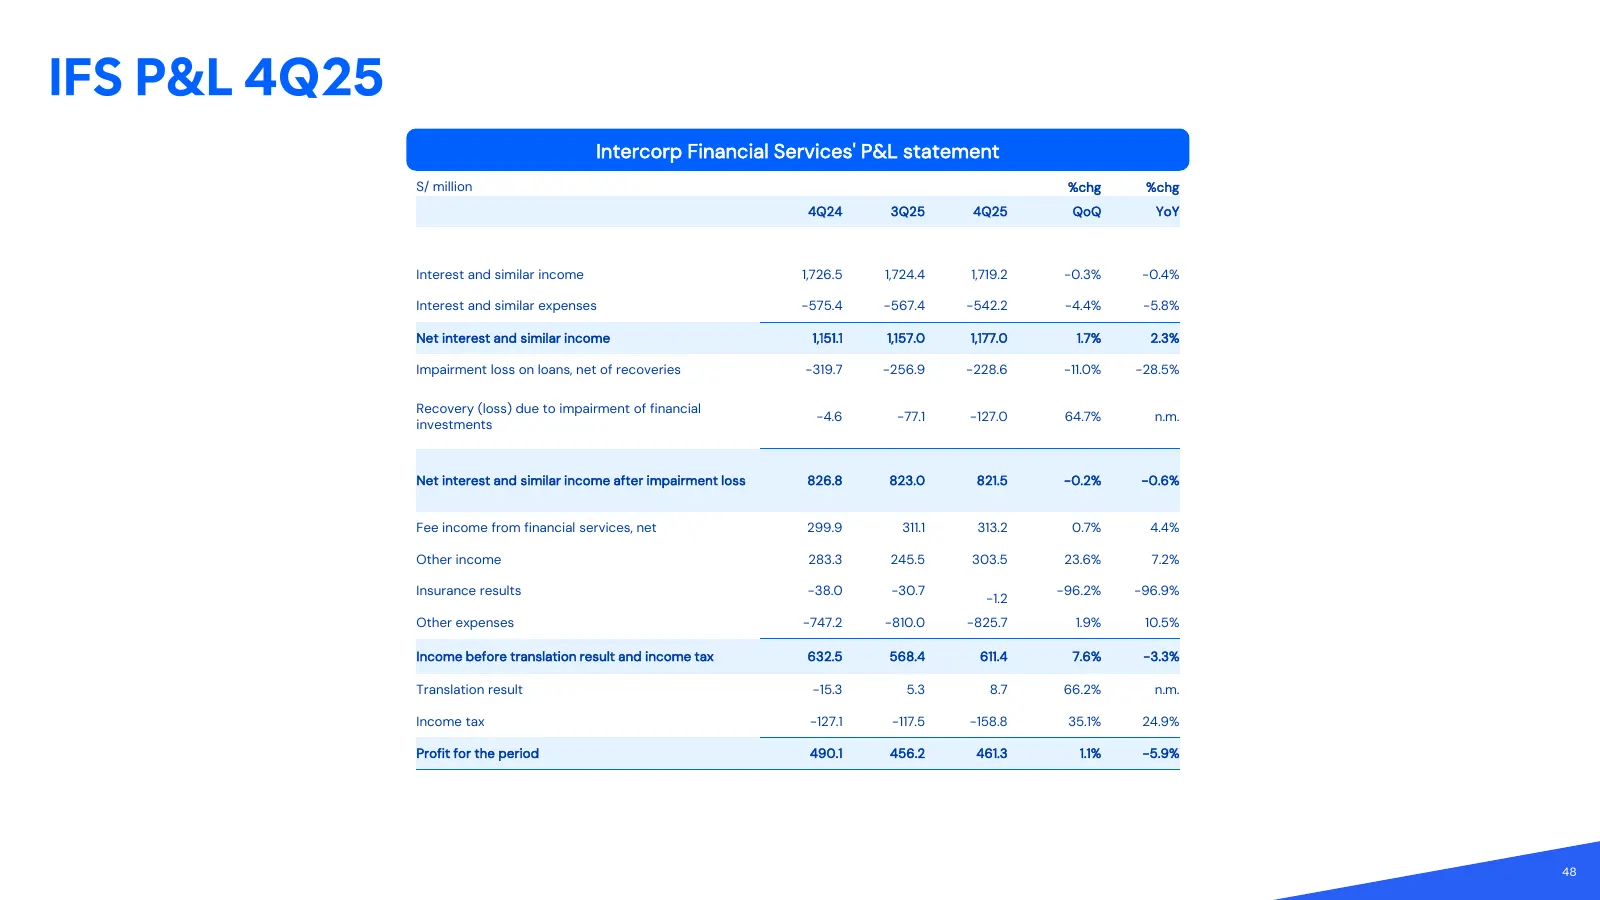
Slide 47: IFS P&L 4Q25
IFS P&L 4Q25 Intercorp Financial Services' P&L statement S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Interest and similar income 1,726.5 1,724.4 1,719.2 -0.3% -0.4% Interest and similar expenses -575.4 -567.4 -542.2 -4.4% -5.8% Net interest and similar income 1,151.1 1,157.0 1,177.0 1.7% 2.3% Impair
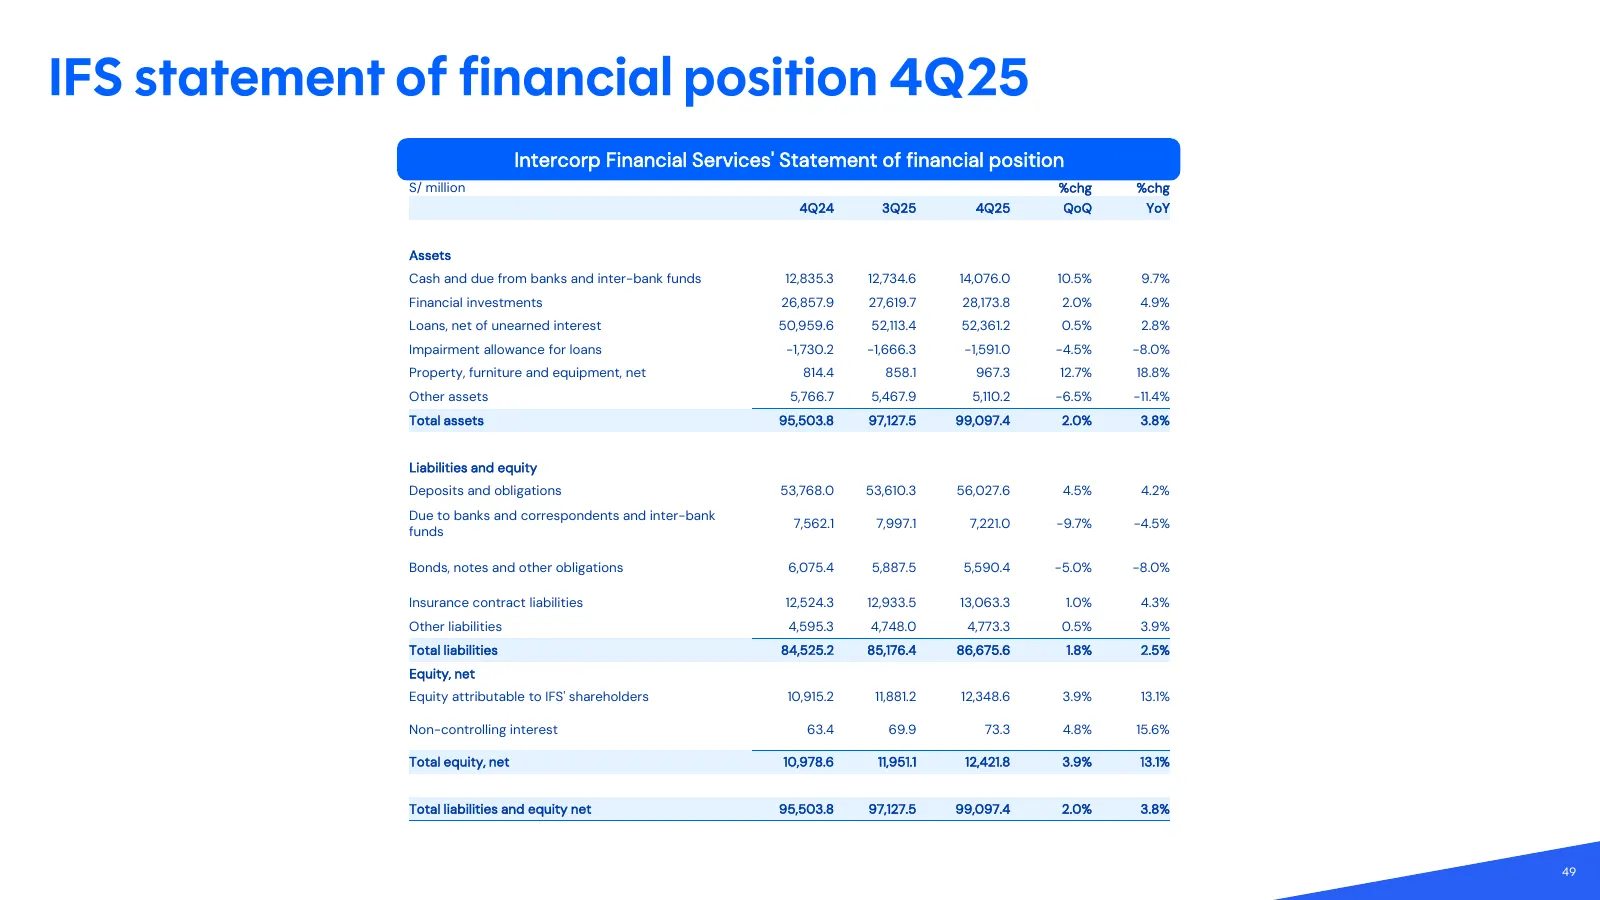
Slide 48: IFS statement of financial position 4Q25
IFS statement of financial position 4Q25 Intercorp Financial Services' Statement of financial position S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Assets Cash and due from banks and inter-bank funds 12,835.3 12,734.6 14,076.0 10.5% 9.7% Financial investments 26,857.9 27,619.7 28,173.8 2.0% 4.9% Loan
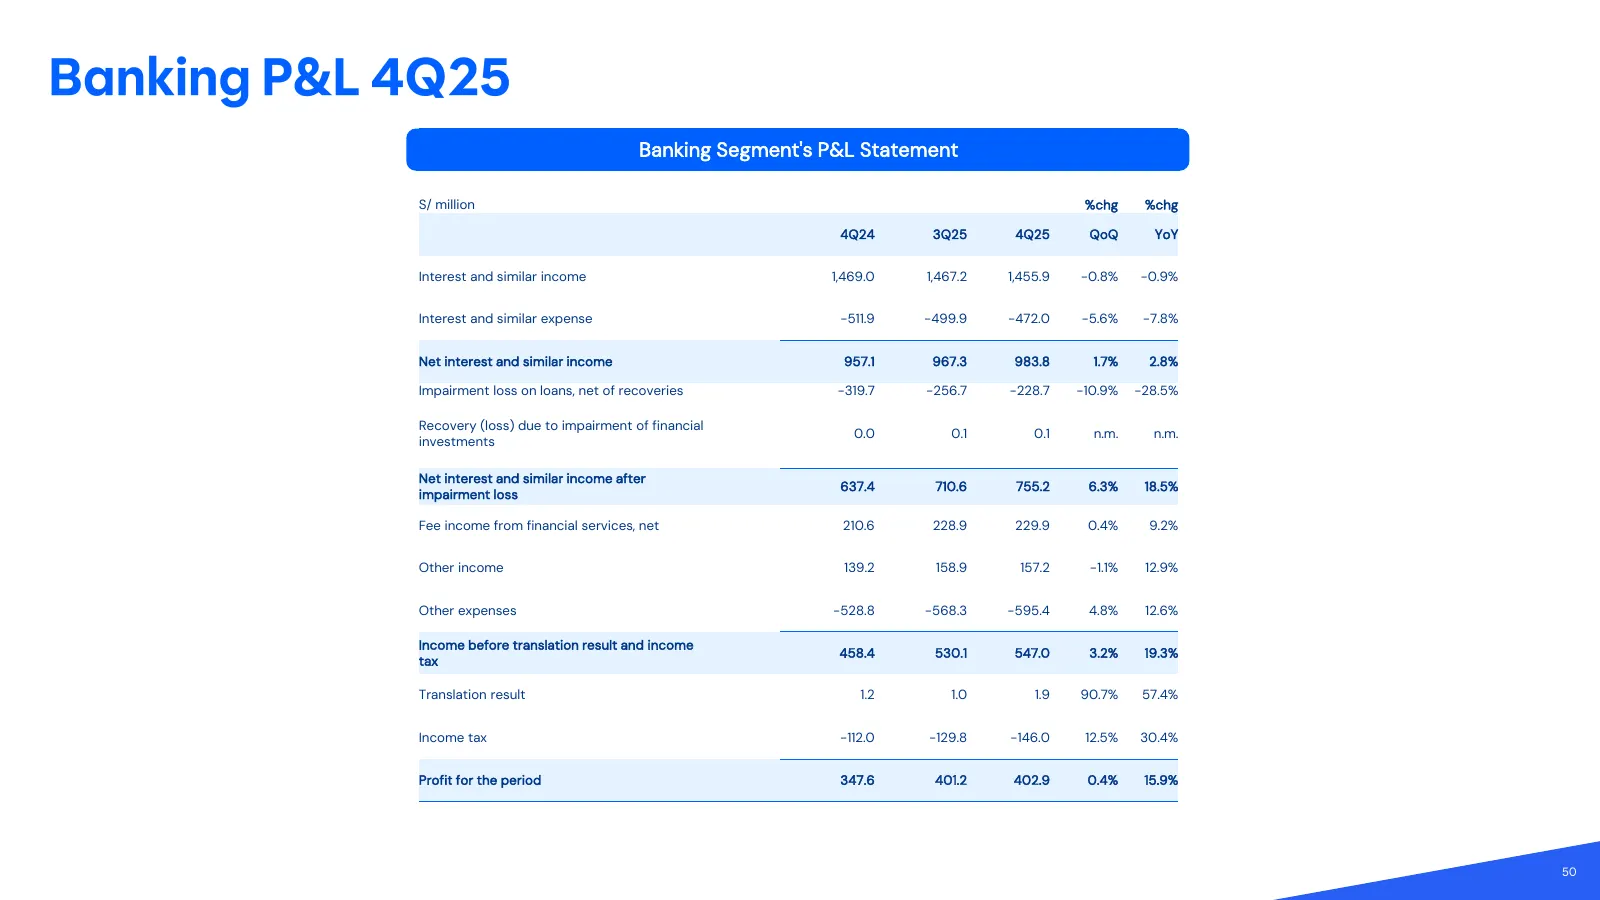
Slide 49: Banking P&L 4Q25
Banking P&L 4Q25 Banking Segment's P&L Statement S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Interest and similar income 1,469.0 1,467.2 1,455.9 -0.8% -0.9% Interest and similar expense -511.9 -499.9 -472.0 -5.6% -7.8% Net interest and similar income 957.1 967.3 983.8 1.7% 2.8% Impairment loss on lo
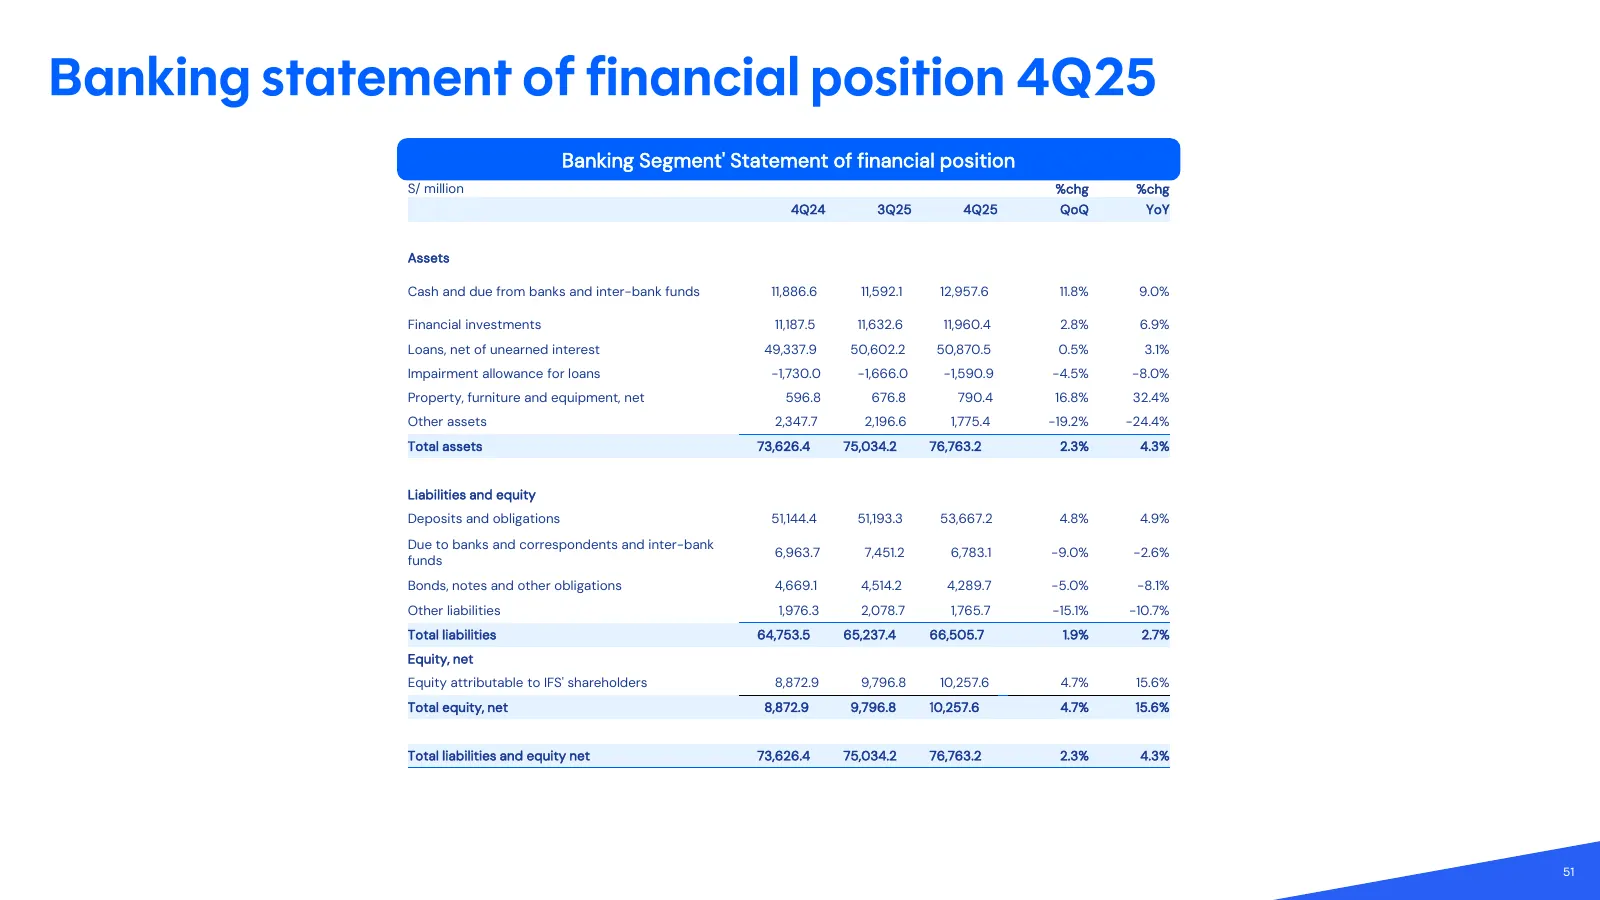
Slide 50: Banking statement of financial position 4Q25
Banking statement of financial position 4Q25 Banking Segment' Statement of financial position S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Assets Cash and due from banks and inter-bank funds 11,886.6 11,592.1 12,957.6 11.8% 9.0% Financial investments 11,187.5 11,632.6 11,960.4 2.8% 6.9% Loans, net of
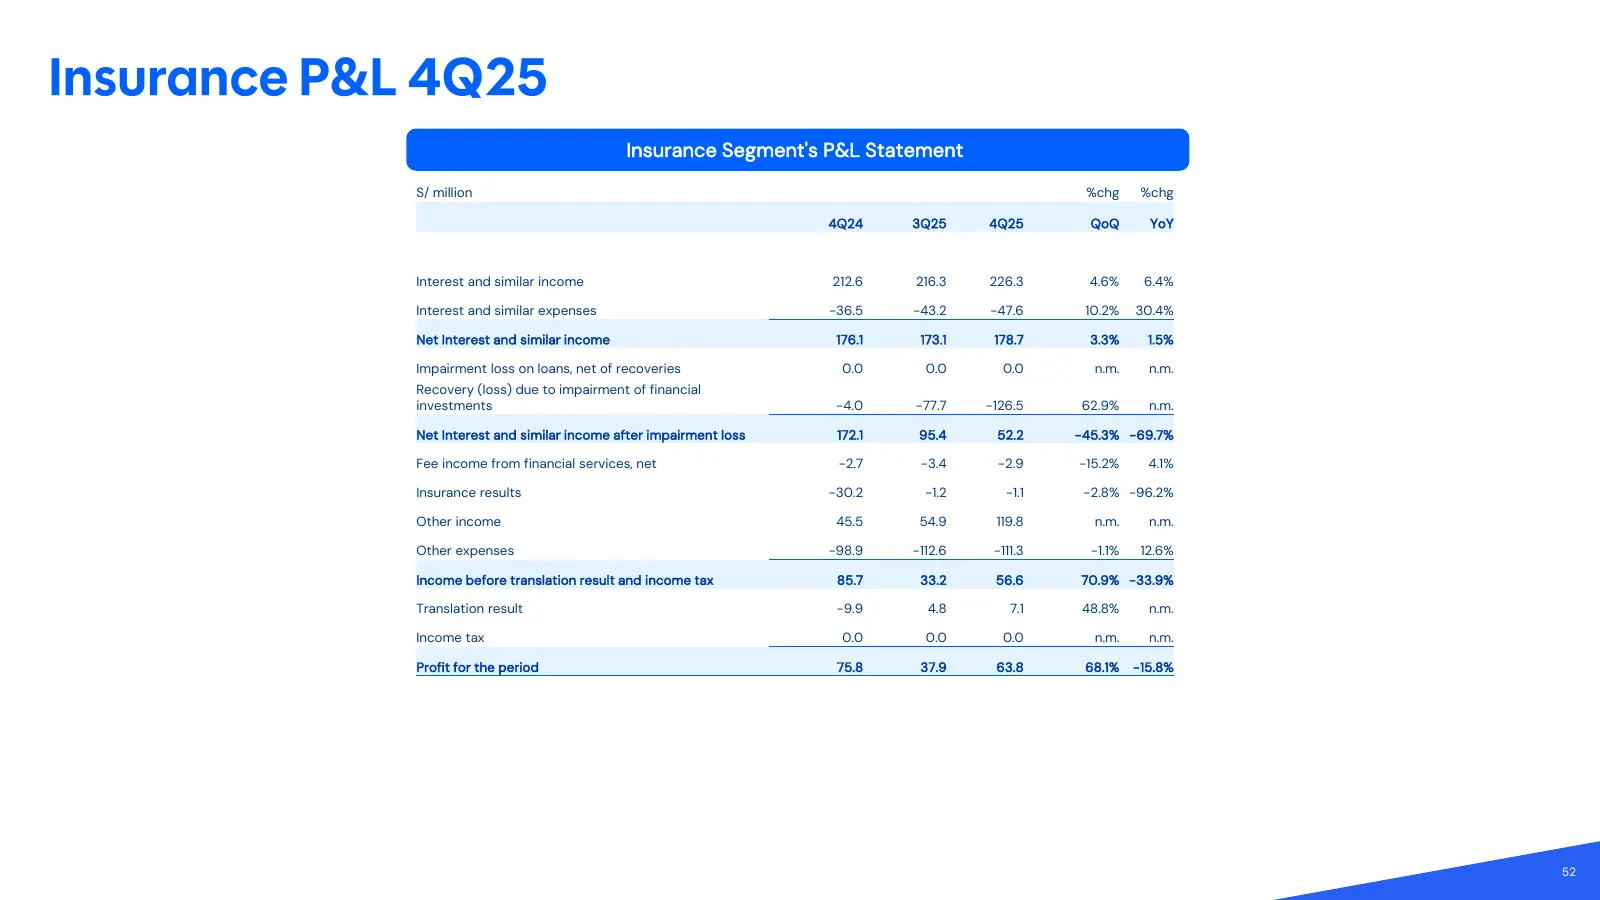
Slide 51: Insurance P&L 4Q25
Insurance P&L 4Q25 Insurance Segment's P&L Statement S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Interest and similar income 212.6 216.3 226.3 4.6% 6.4% Interest and similar expenses -36.5 -43.2 -47.6 10.2% 30.4% Net Interest and similar income 176.1 173.1 178.7 3.3% 1.5% Impairment loss on loans, n
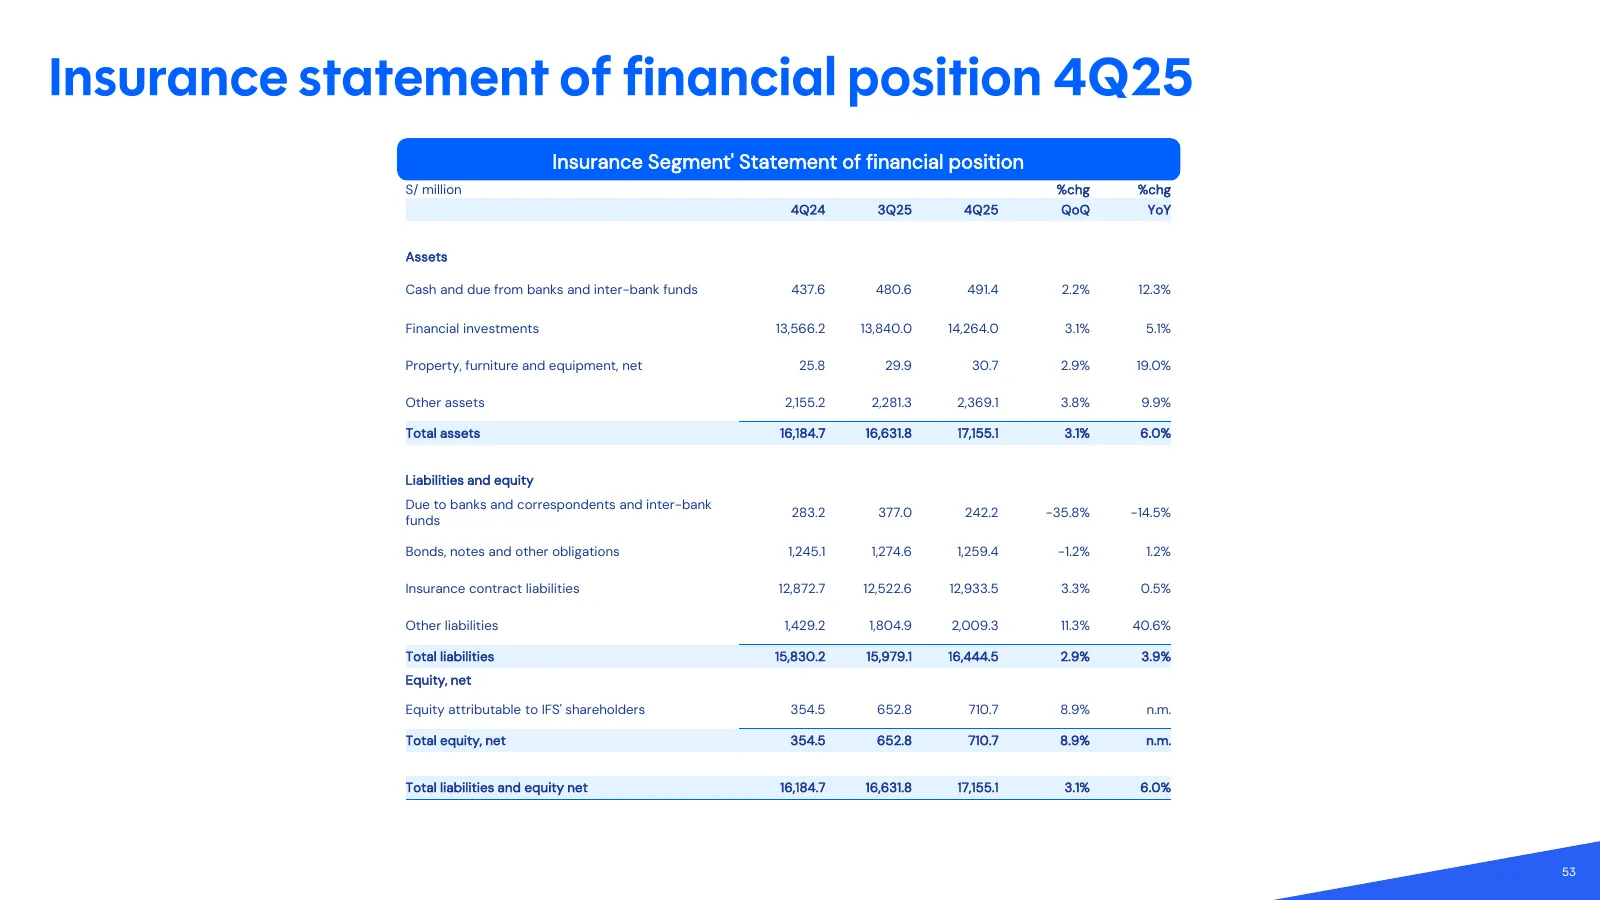
Slide 52: Insurance statement of financial position 4Q25
Insurance statement of financial position 4Q25 Insurance Segment' Statement of financial position S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Assets Cash and due from banks and inter-bank funds 437.6 480.6 491.4 2.2% 12.3% Financial investments 13,566.2 13,840.0 14,264.0 3.1% 5.1% Property, furnitur
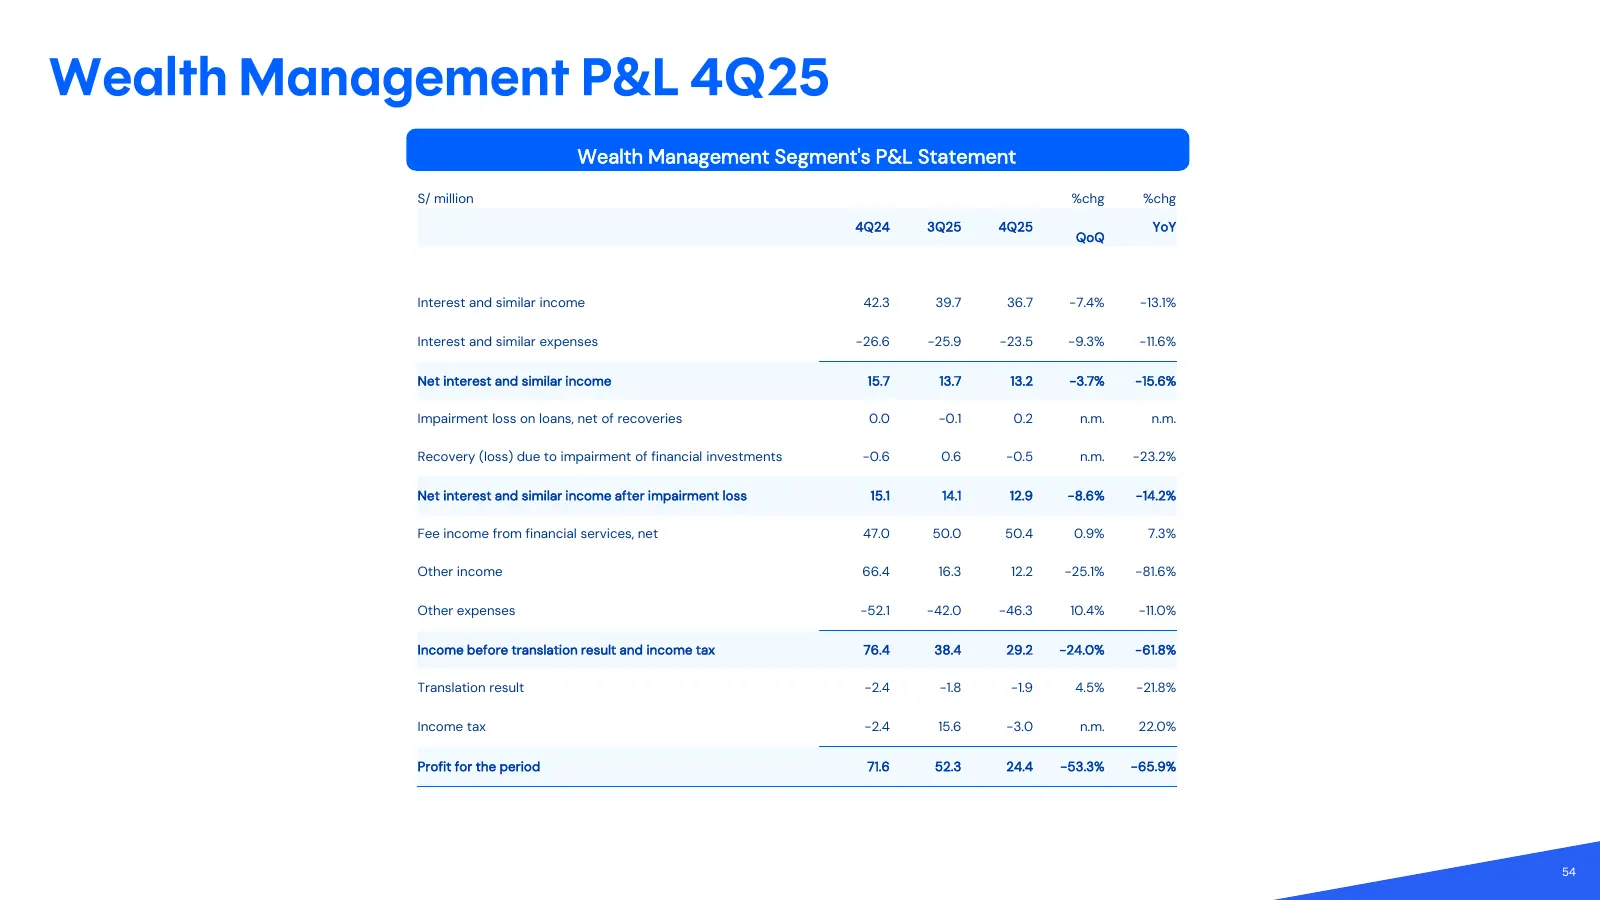
Slide 53: Wealth Management P&L 4Q25
Wealth Management P&L 4Q25 Wealth Management Segment's P&L Statement S/ million %chg %chg 4Q24 3Q25 4Q25 YoY QoQ Interest and similar income 42.3 39.7 36.7 -7.4% -13.1% Interest and similar expenses -26.6 -25.9 -23.5 -9.3% -11.6% Net interest and similar income 15.7 13.7 13.2 -3.7% -15.6% Impairment
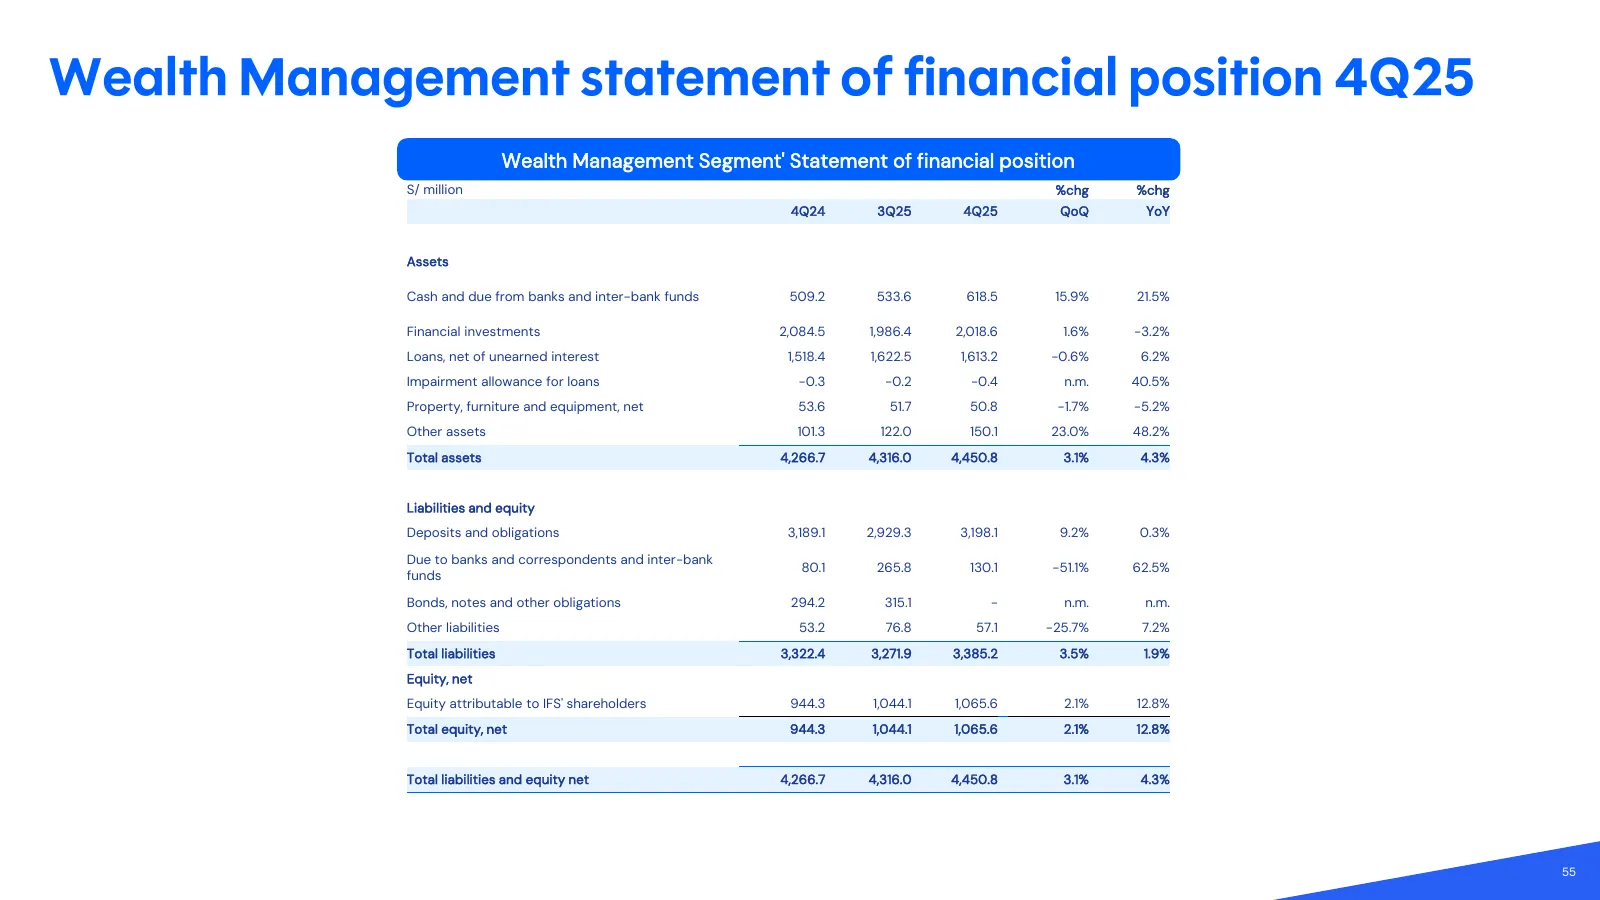
Slide 54: Wealth Management statement of financial position 4Q25
Wealth Management statement of financial position 4Q25 Wealth Management Segment' Statement of financial position S/ million %chg %chg 4Q24 3Q25 4Q25 QoQ YoY Assets Cash and due from banks and inter-bank funds 509.2 533.6 618.5 15.9% 21.5% Financial investments 2,084.5 1,986.4 2,018.6 1.6% -3.2% Loa
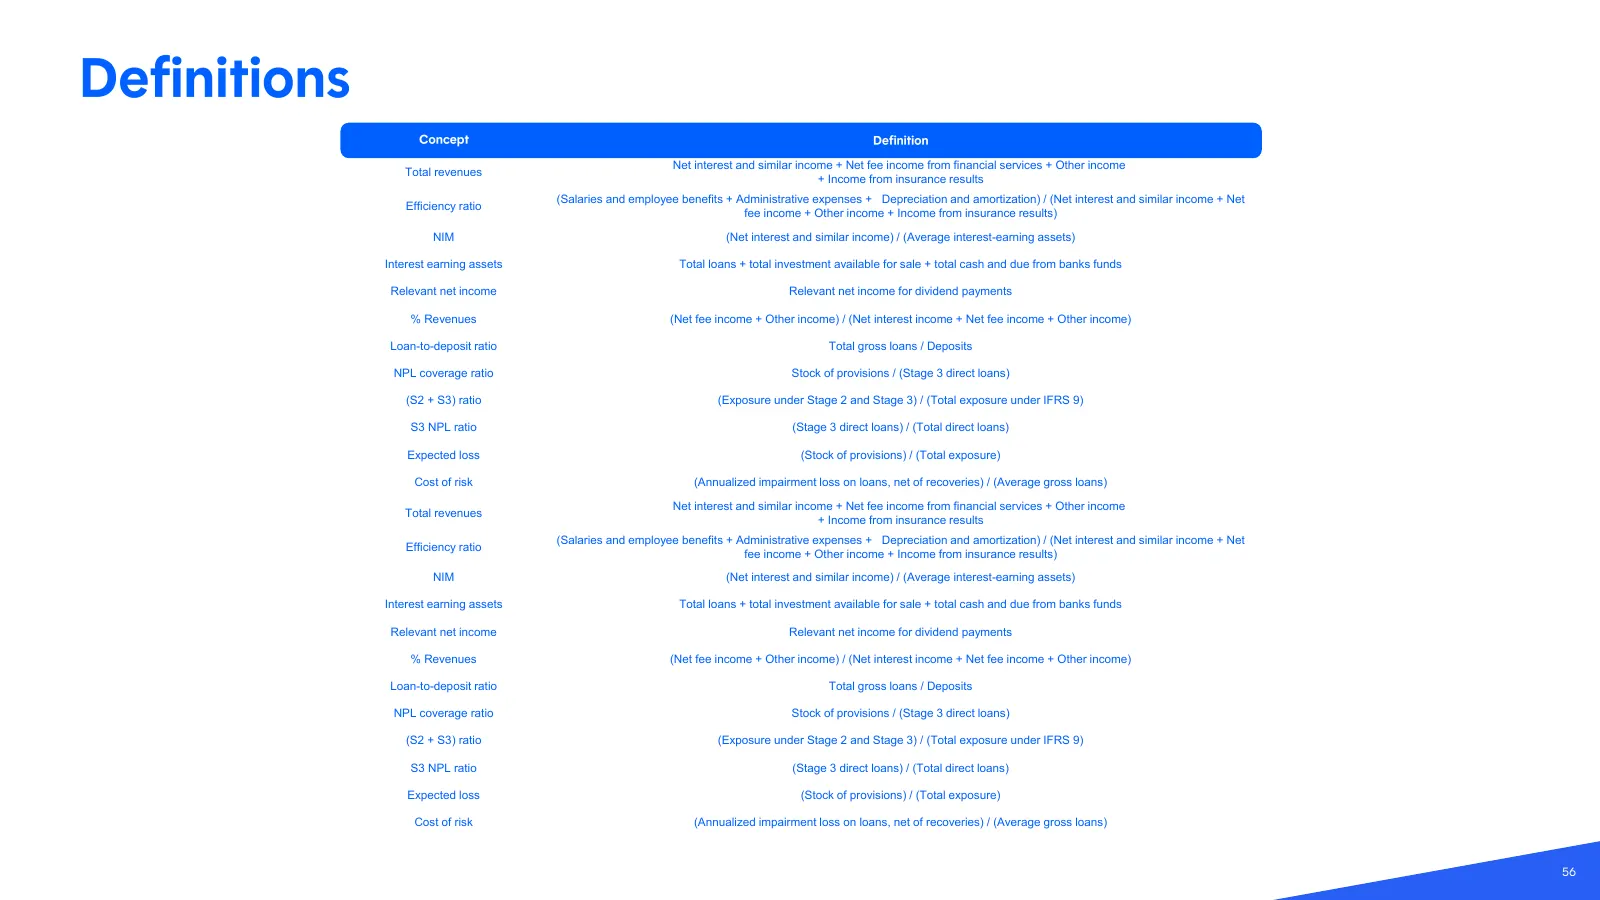
Slide 55: Definitions
Definitions Concept Definition Net interest and similar income + Net fee income from financial services + Other income Total revenues + Income from insurance results (Salaries and employee benefits + Administrative expenses + Depreciation and amortization) / (Net interest and similar income + Net Ef
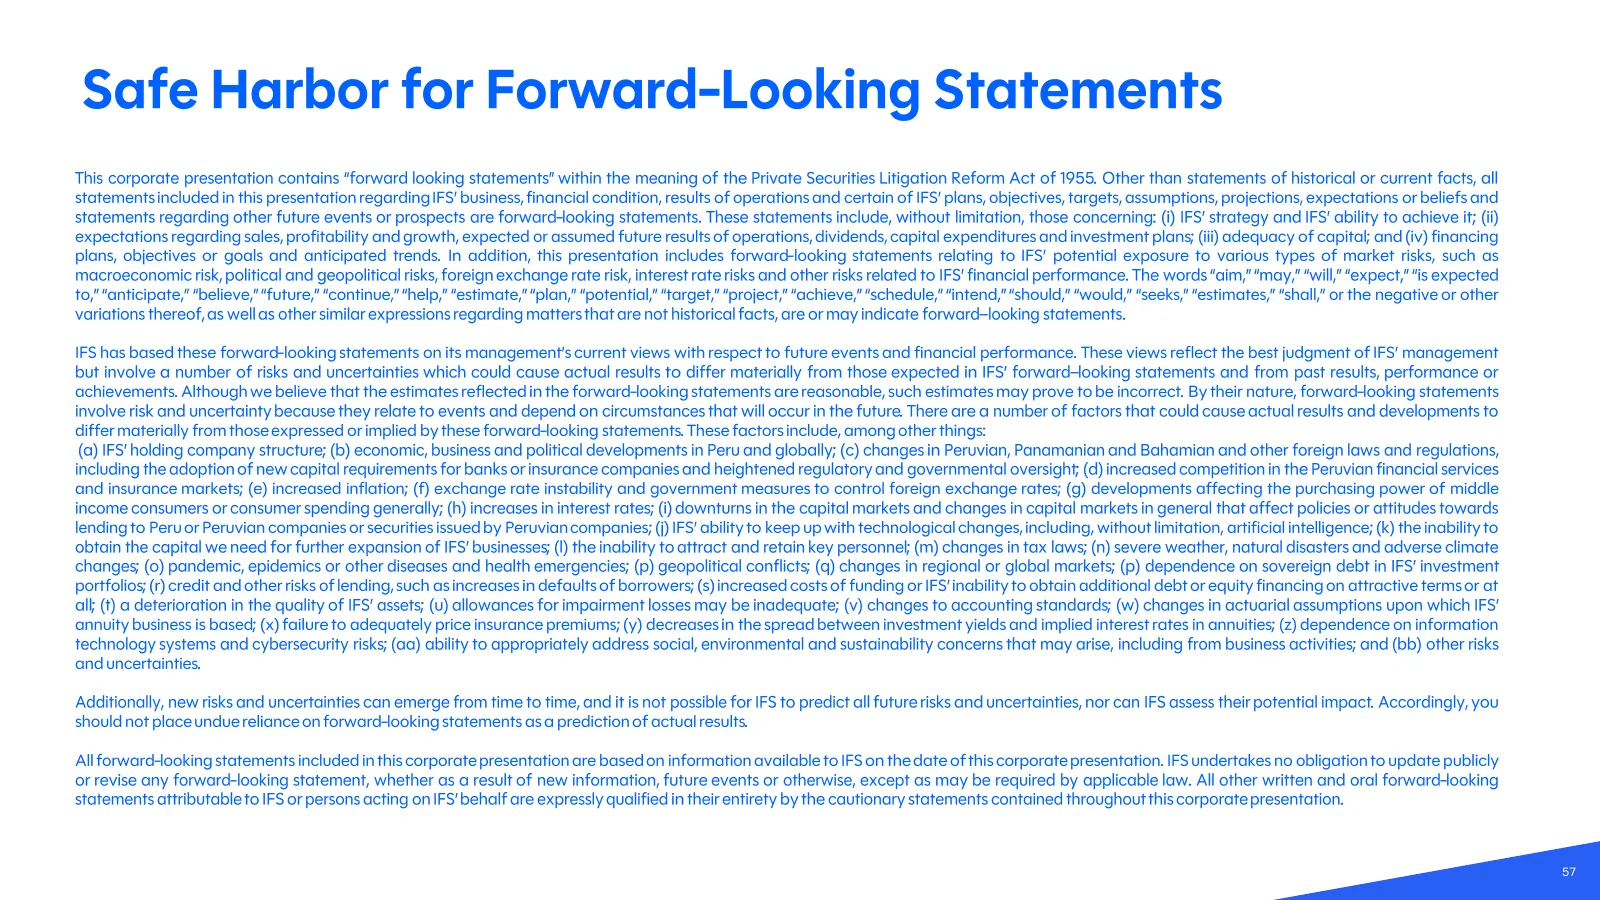
Slide 56: Safe Harbor for Forward-Looking Statements
Safe Harbor for Forward -Looking Statements This corporate presentation contains “forward looking statements” within the meaning of the Private Securities Litigation Reform Act of 1955. Other than statements of historical or current facts, all statements included in this presentation regarding IFS’
Slide 57: 57
57
Source: 6ix earnings call
More decks from Intercorp Financial Services Inc.
 Q3 2026 Earnings Presentation54 slides · November 2026
 Q2 2026 Earnings Presentation54 slides · Aug 12, 2026
 Q2 2026 Earnings Presentation57 slides · August 2026
 Q2 2026 Earnings Presentation38 slides · August 2026
 Q1 2026 Earnings Presentation54 slides · May 12, 2026
 Q1 2026 Earnings Presentation51 slides · May 2026