Aerie Pharmaceuticals — Investor Presentation (February 2019)
25 slides from Aerie Pharmaceuticals's investor presentation, Feb 12, 2019
Slide 1: Company Overview Investor Presentation
Exhibit 99.1 Company Overview Investor Presentation February 2019
Slide 2: Important Information
Important Information The information in this presentation does not contain all of the information that a potential investor should review before investing in Aerie shares. The descriptions of Aerie Pharmaceuticals, Inc. (the “Company” or “Aerie”) in this presentation are qualified in their entirety
Slide 3: Aerie Overview
Aerie Overview Aerie IOP–Reducing Products (IP 2030+) • Rhopressa® (netarsudil ophthalmic solution) 0.02% • Successful U.S. Launch in 2018 • Rocklatan™ (netarsudil/latanoprost ophthalmic solution) 0.02%/0.005% • PDUFA set for March 14, 2019 • GlobalizationPlan Under Way – Europe and Japan Pipeline A
Slide 4: Rhopressa: Market Perspective
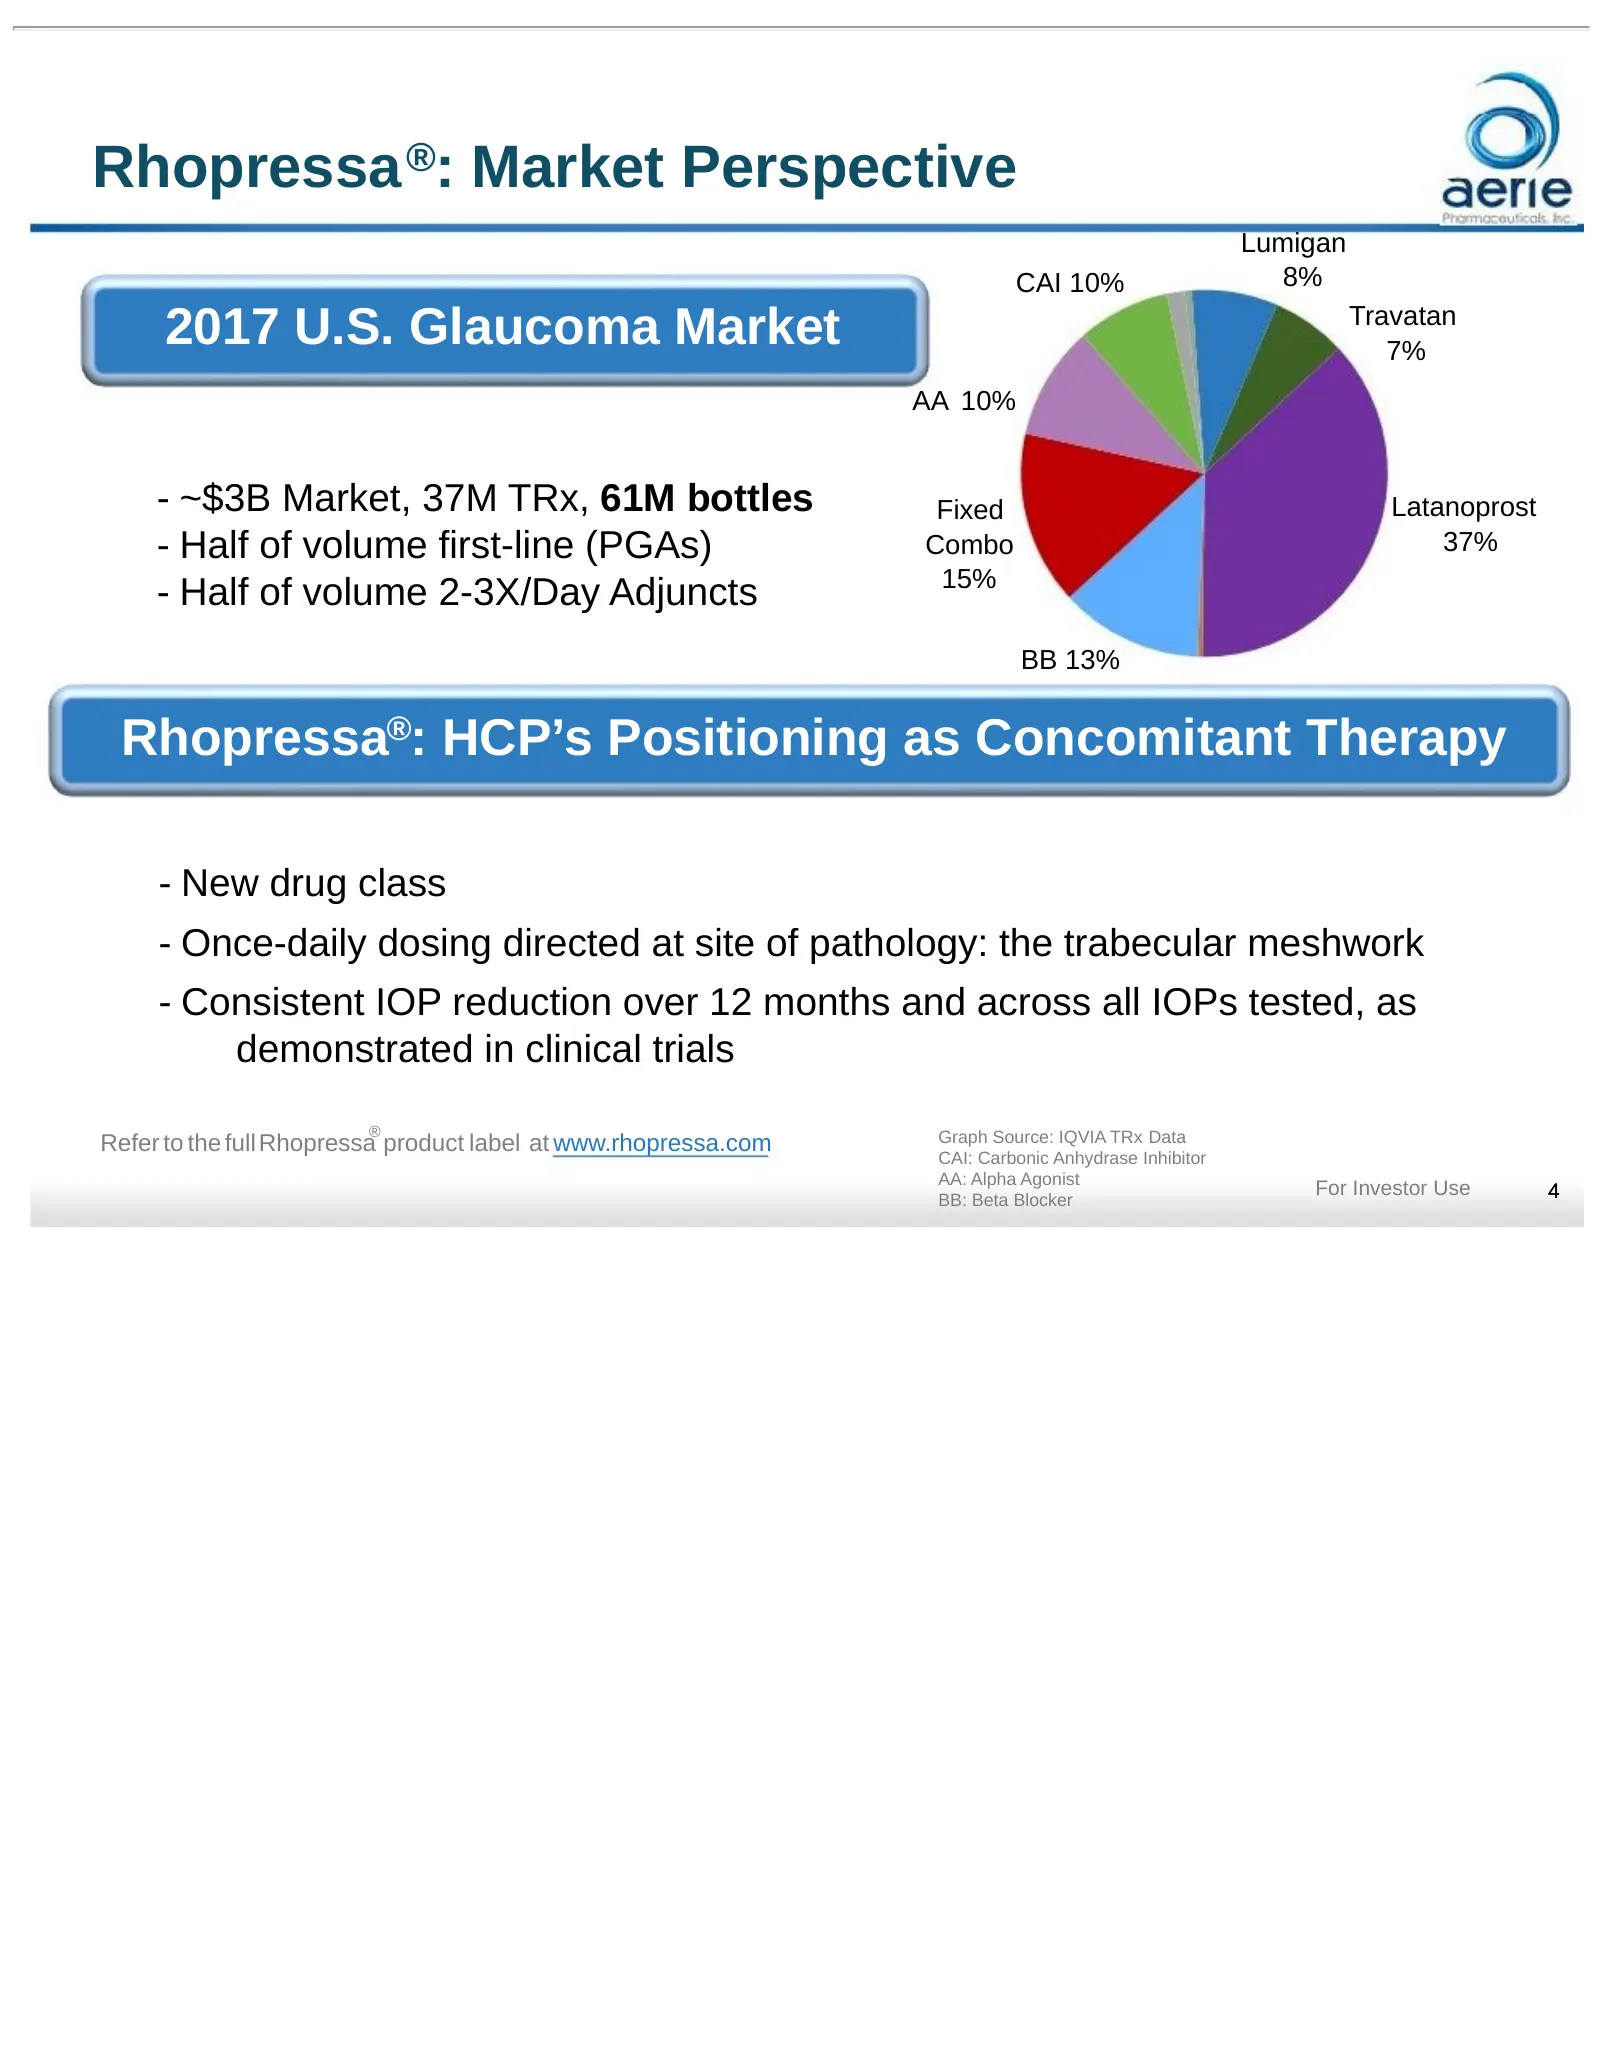
Rhopressa ®: Market Perspective Lumigan CAI 10% 8% 2017 U.S. Glaucoma Market Travatan 7% AA 10% - ~$3B Market, 37M TRx, 61M bottles Fixed Latanoprost - Half of volume first-line (PGAs) Combo 37% 15% - Half of volume 2-3X/Day Adjuncts BB 13% Rhopressa®: HCP’s Positioning as Concomitant Therapy - New
Slide 5: Rhopressa Formulary Coverage Increasing
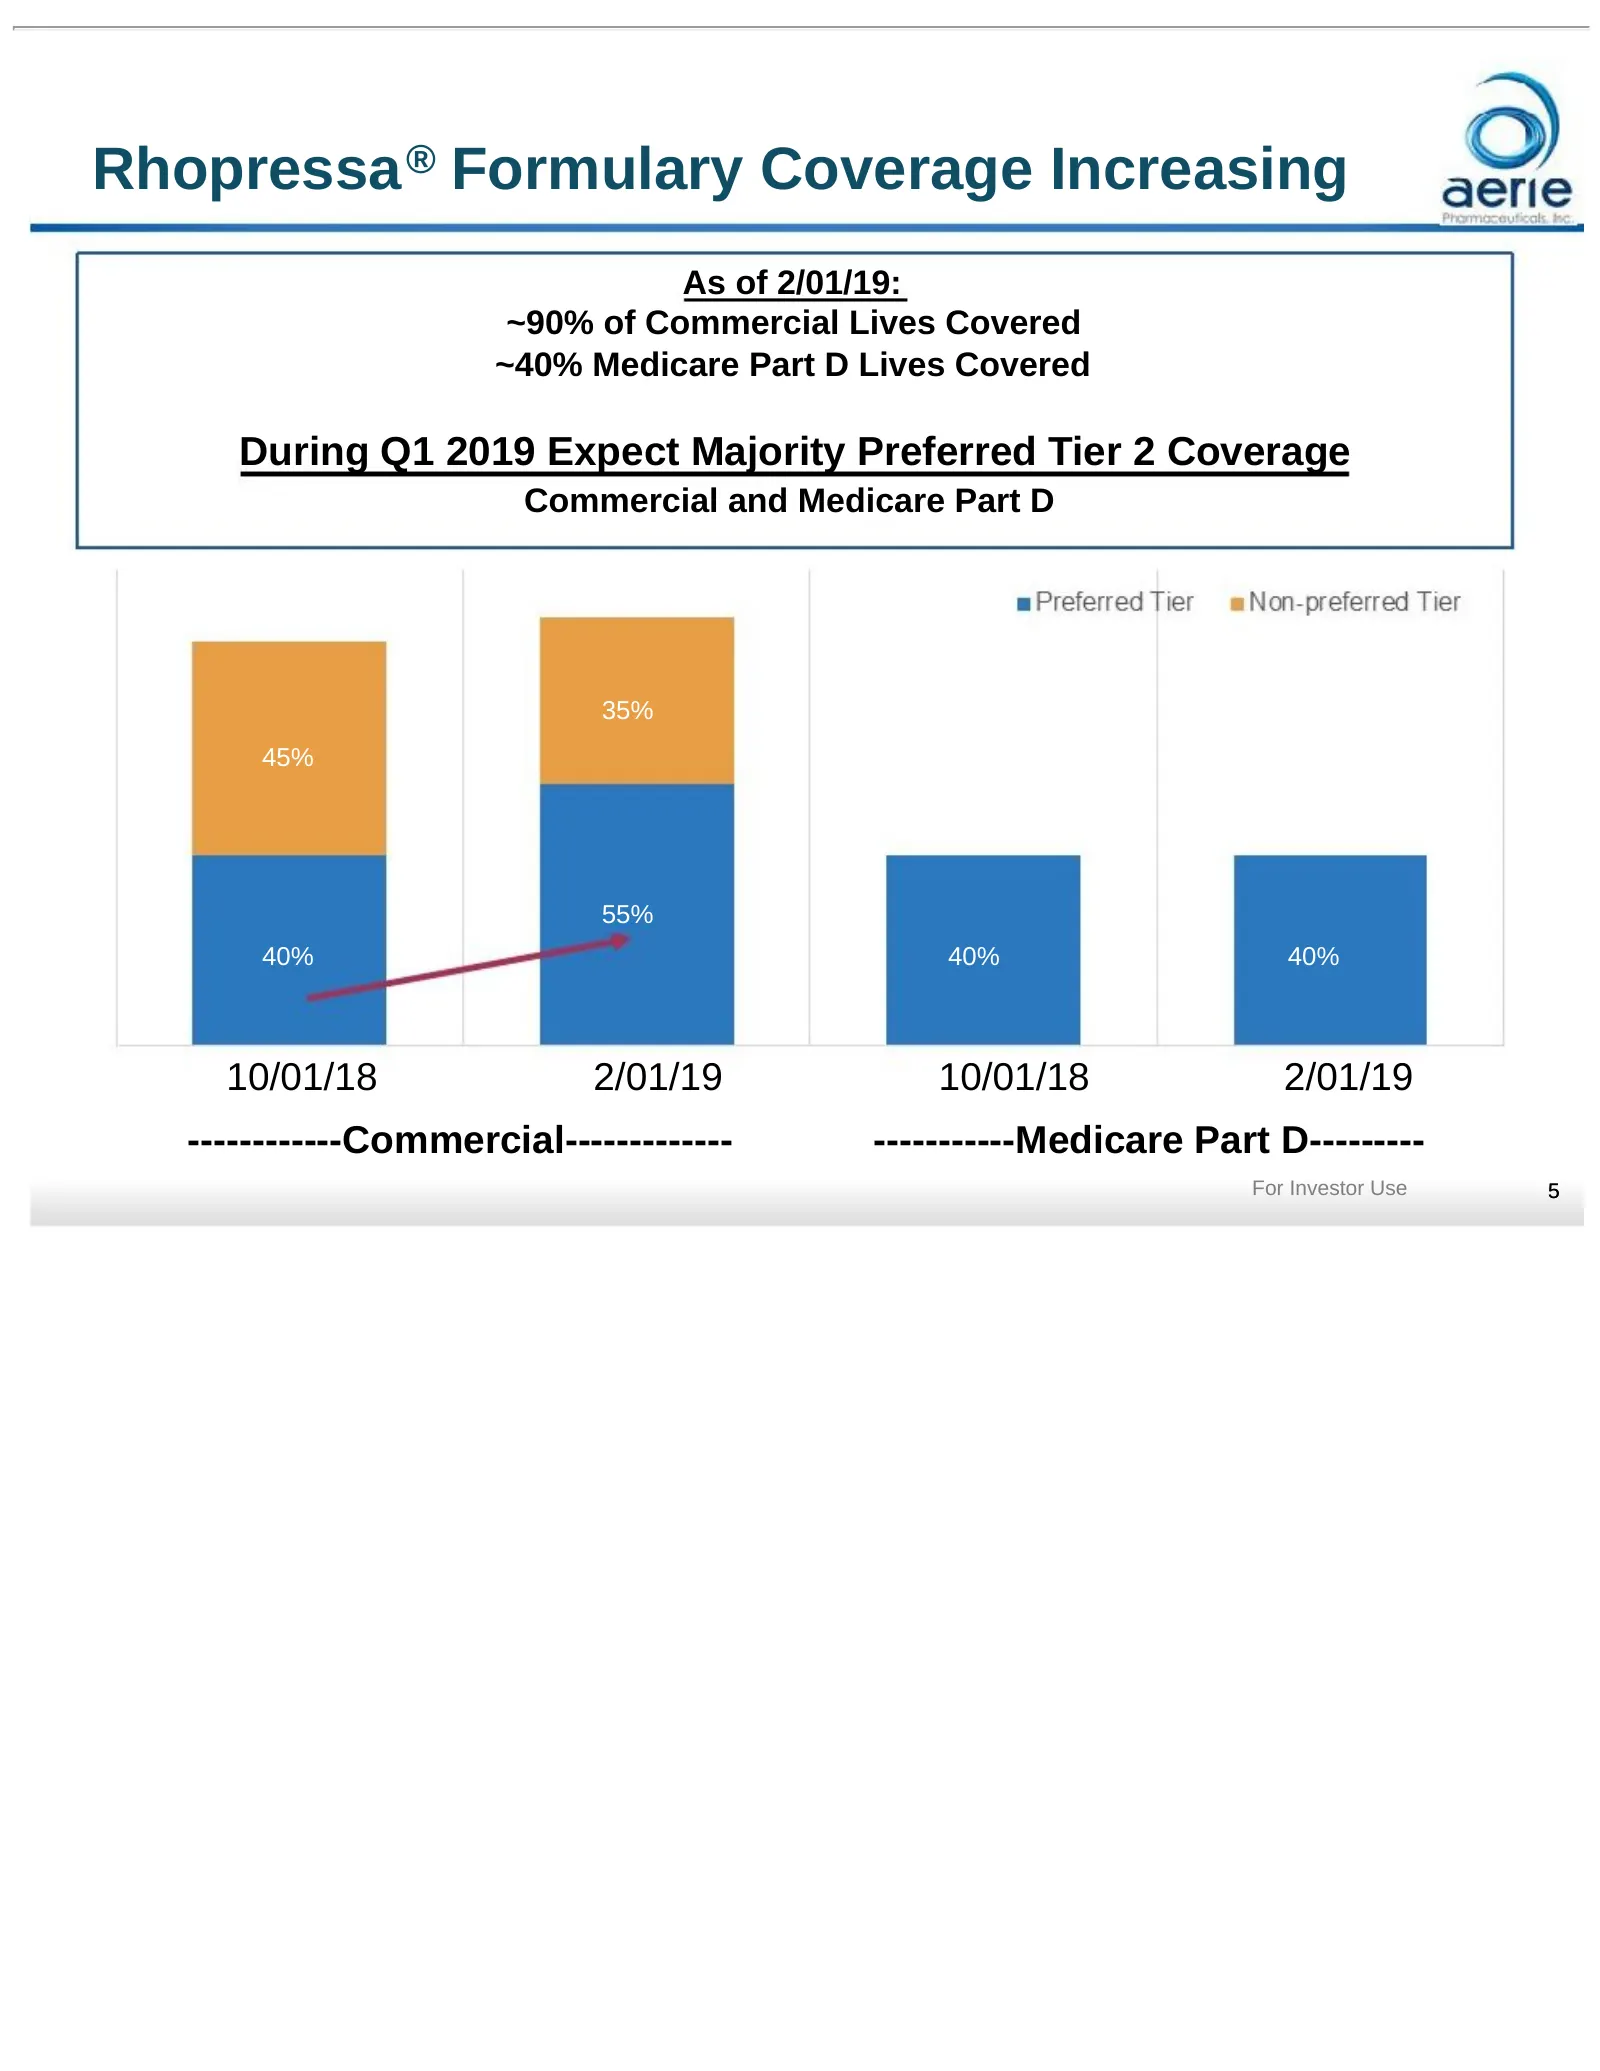
Rhopressa ® Formulary Coverage Increasing As of 2/01/19: ~90% of Commercial Lives Covered ~40% Medicare Part D Lives Covered During Q1 2019 Expect Majority Preferred Tier 2 Coverage Commercial and Medicare Part D 35% 45% 55% 40% 40% 40% 10/01/18 2/01/19 10/01/18 2/01/19 ------------Commercial-------
Slide 6: Rhopressa U.S. Launch Update
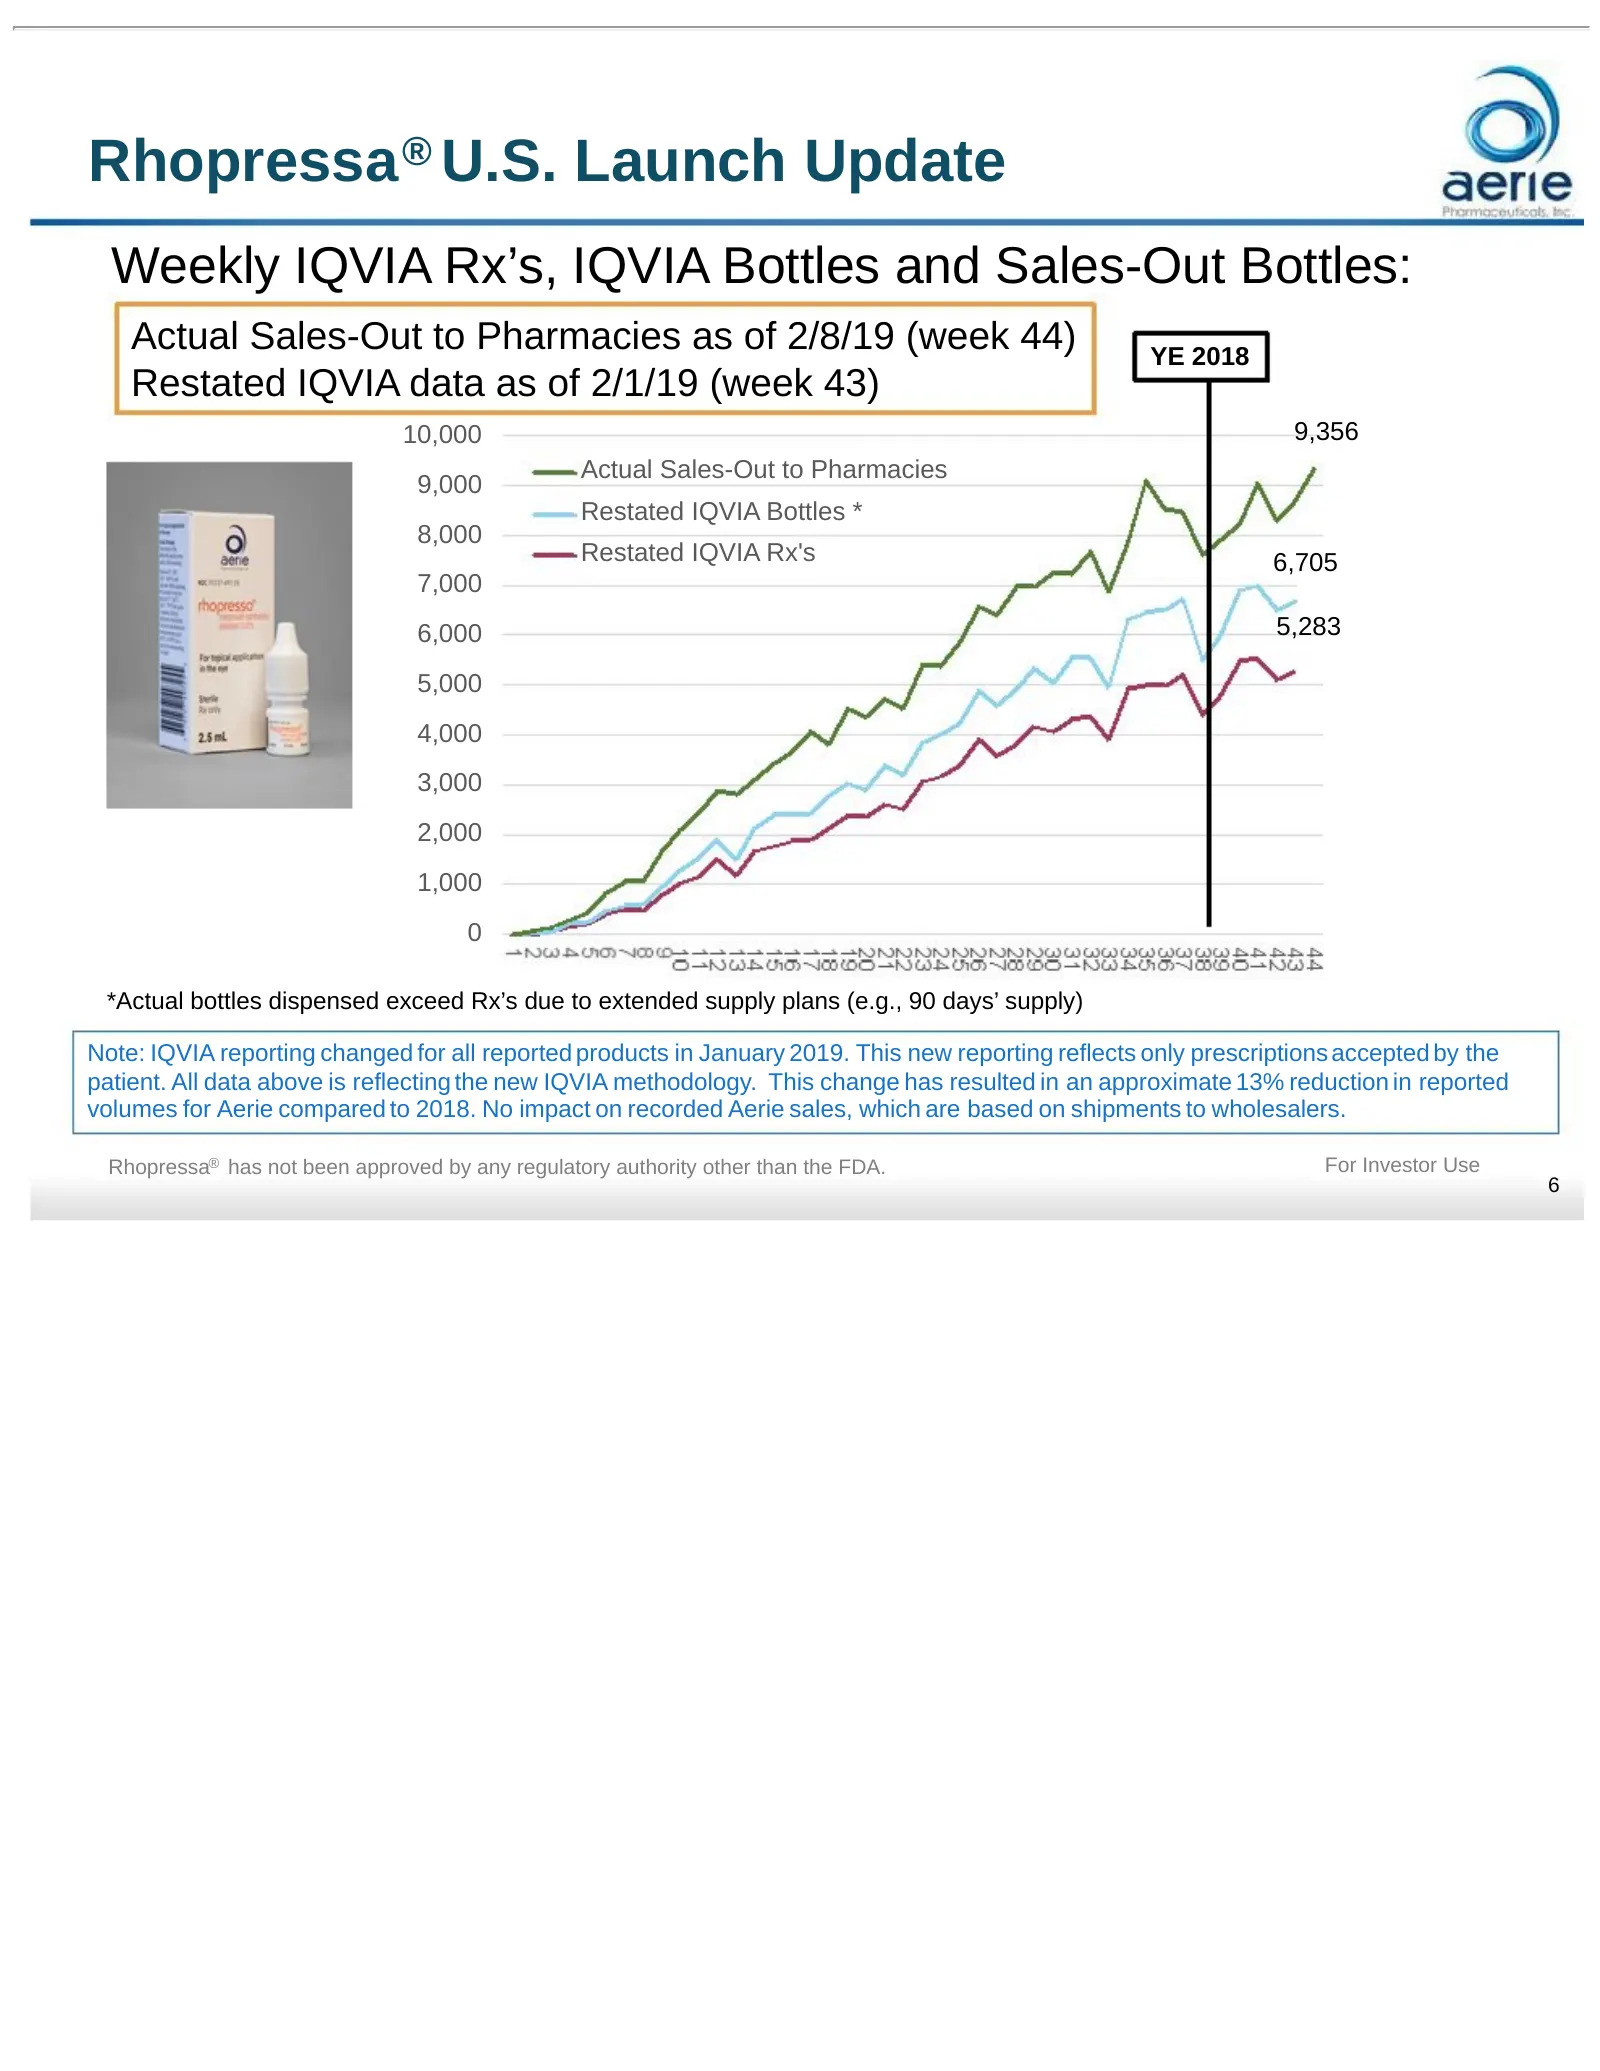
Rhopressa ® U.S. Launch Update Weekly IQVIA Rx’s, IQVIA Bottles and Sales-Out Bottles: Actual Sales-Out to Pharmacies as of 2/8/19 (week 44) YE 2018 Restated IQVIA data as of 2/1/19 (week 43) 10,000 9,356 Actual Sales-Out to Pharmacies 9,000 Restated IQVIA Bottles * 8,000 Restated IQVIA Rx's 6,705 7
Slide 7: Rhopressa U.S. Launch Update
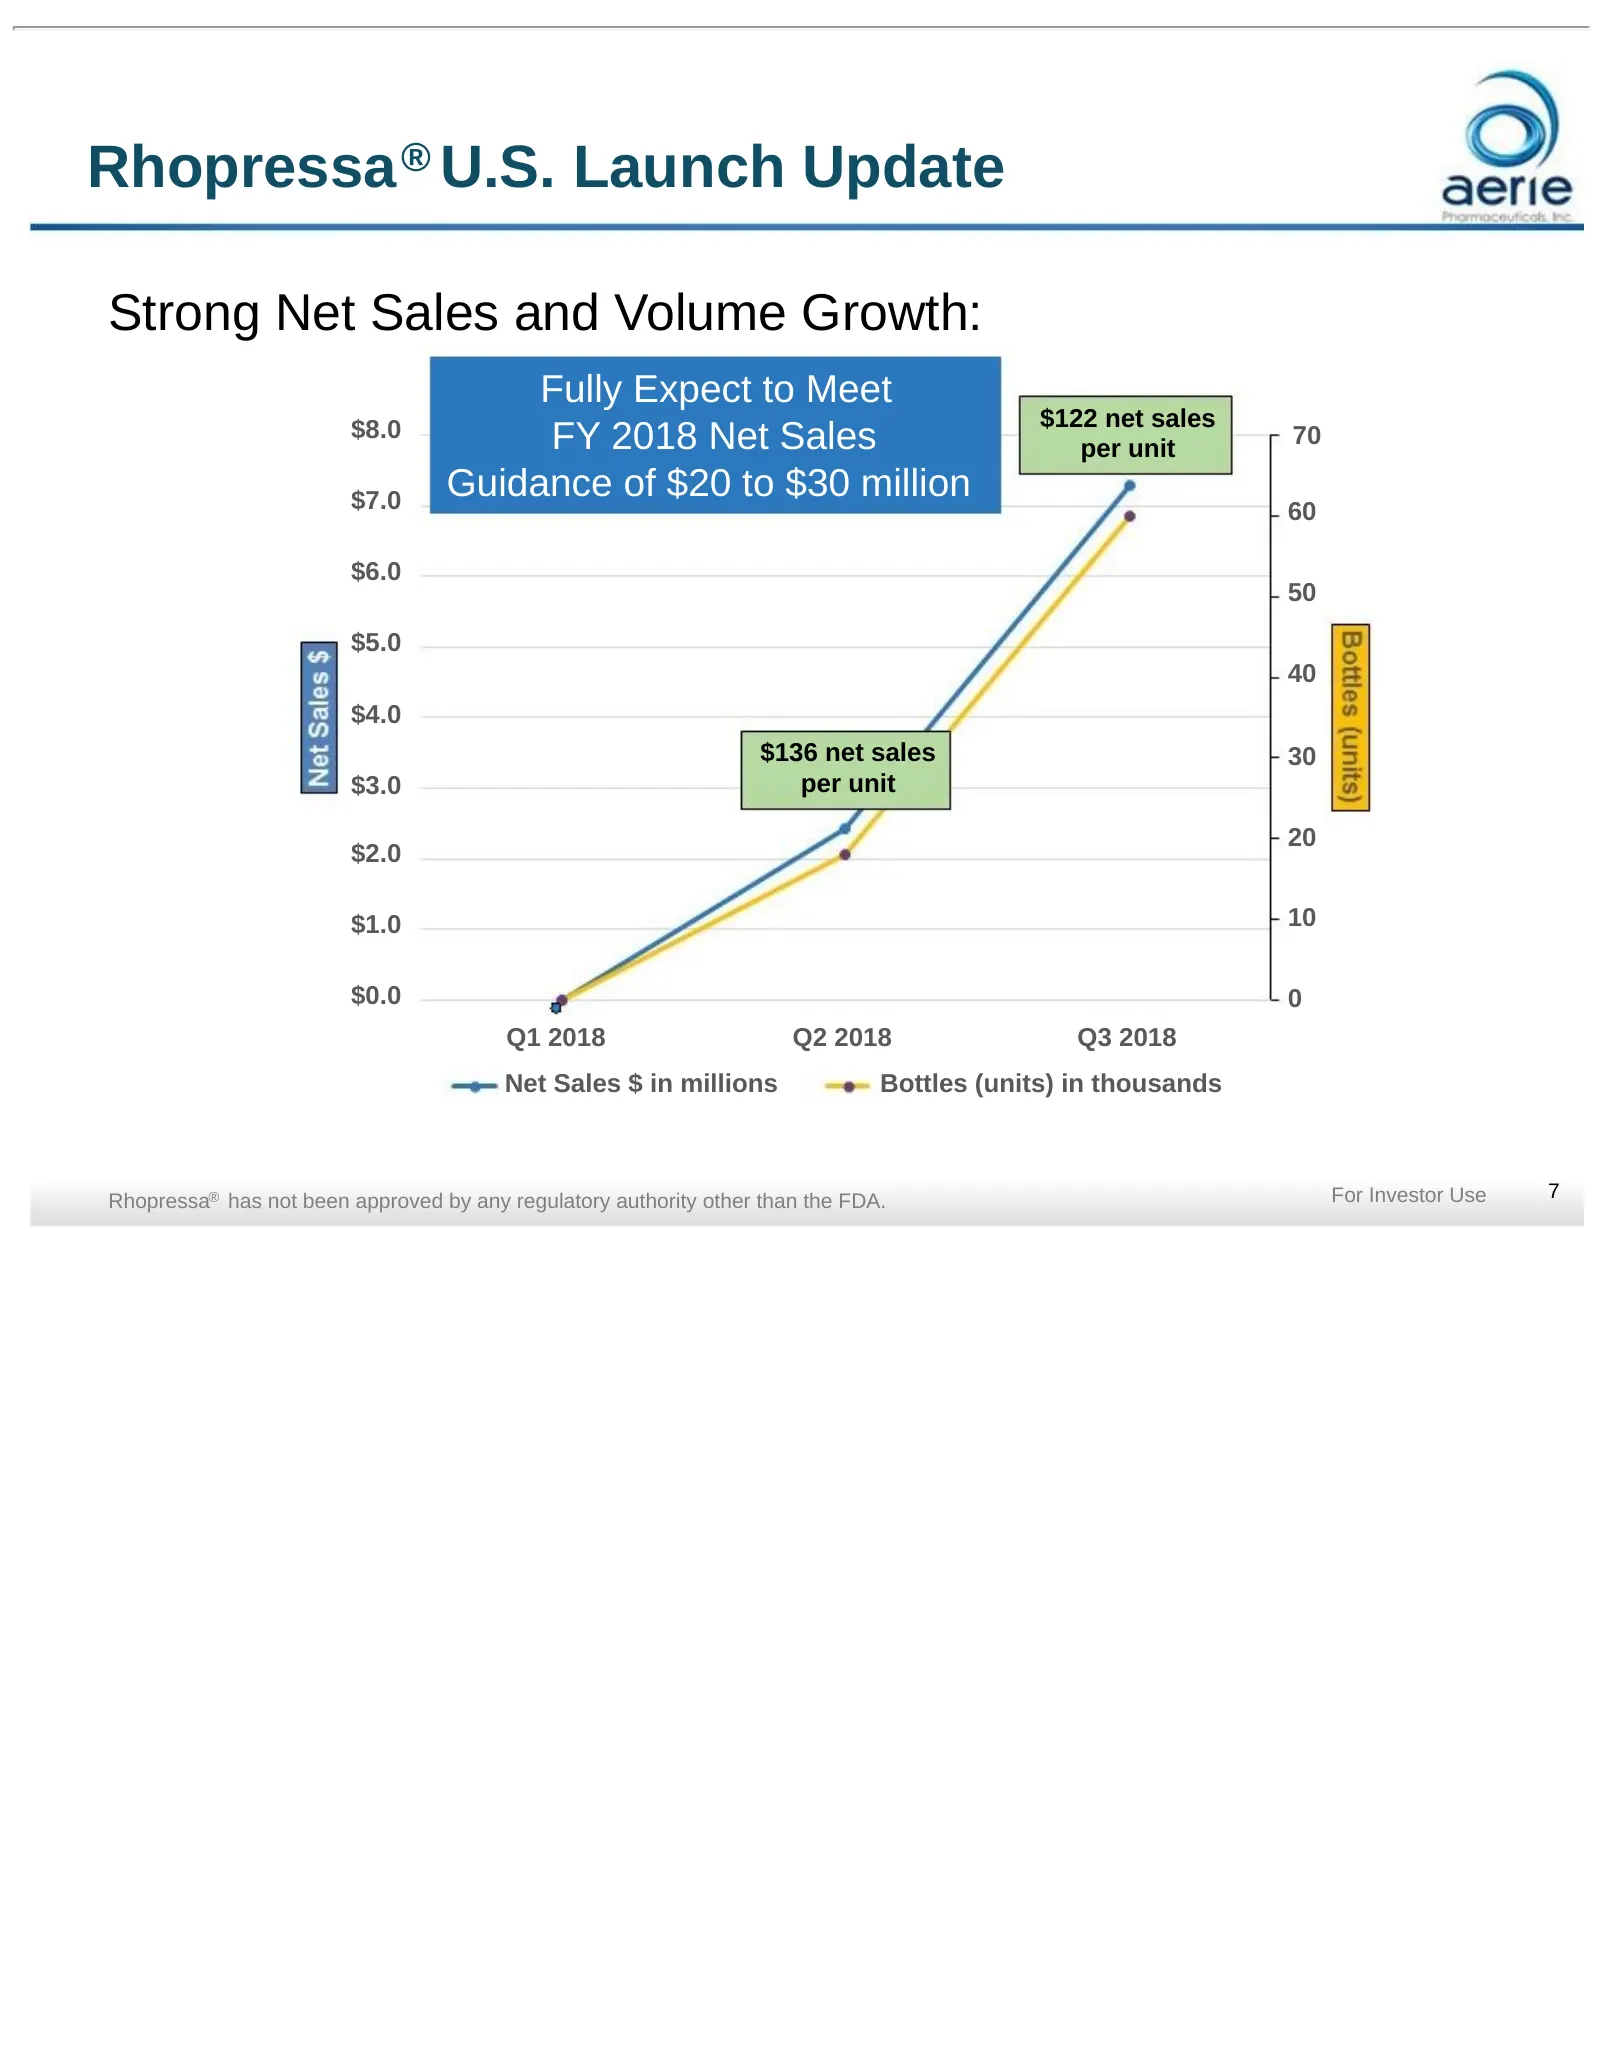
Rhopressa ® U.S. Launch Update Strong Net Sales and Volume Growth: Fully Expect to Meet $122 net sales $8.0 FY 2018 Net Sales per unit 70 $7.0 Guidance of $20 to $30 million 60 $6.0 50 $5.0 40 $4.0 $136 net sales 30 $3.0 per unit 20 $2.0 $1.0 10 $0.0 0 Q1 2018 Q2 2018 Q3 2018 Net Sales $ in millions
Slide 8: Active Engagement at Key Conferences
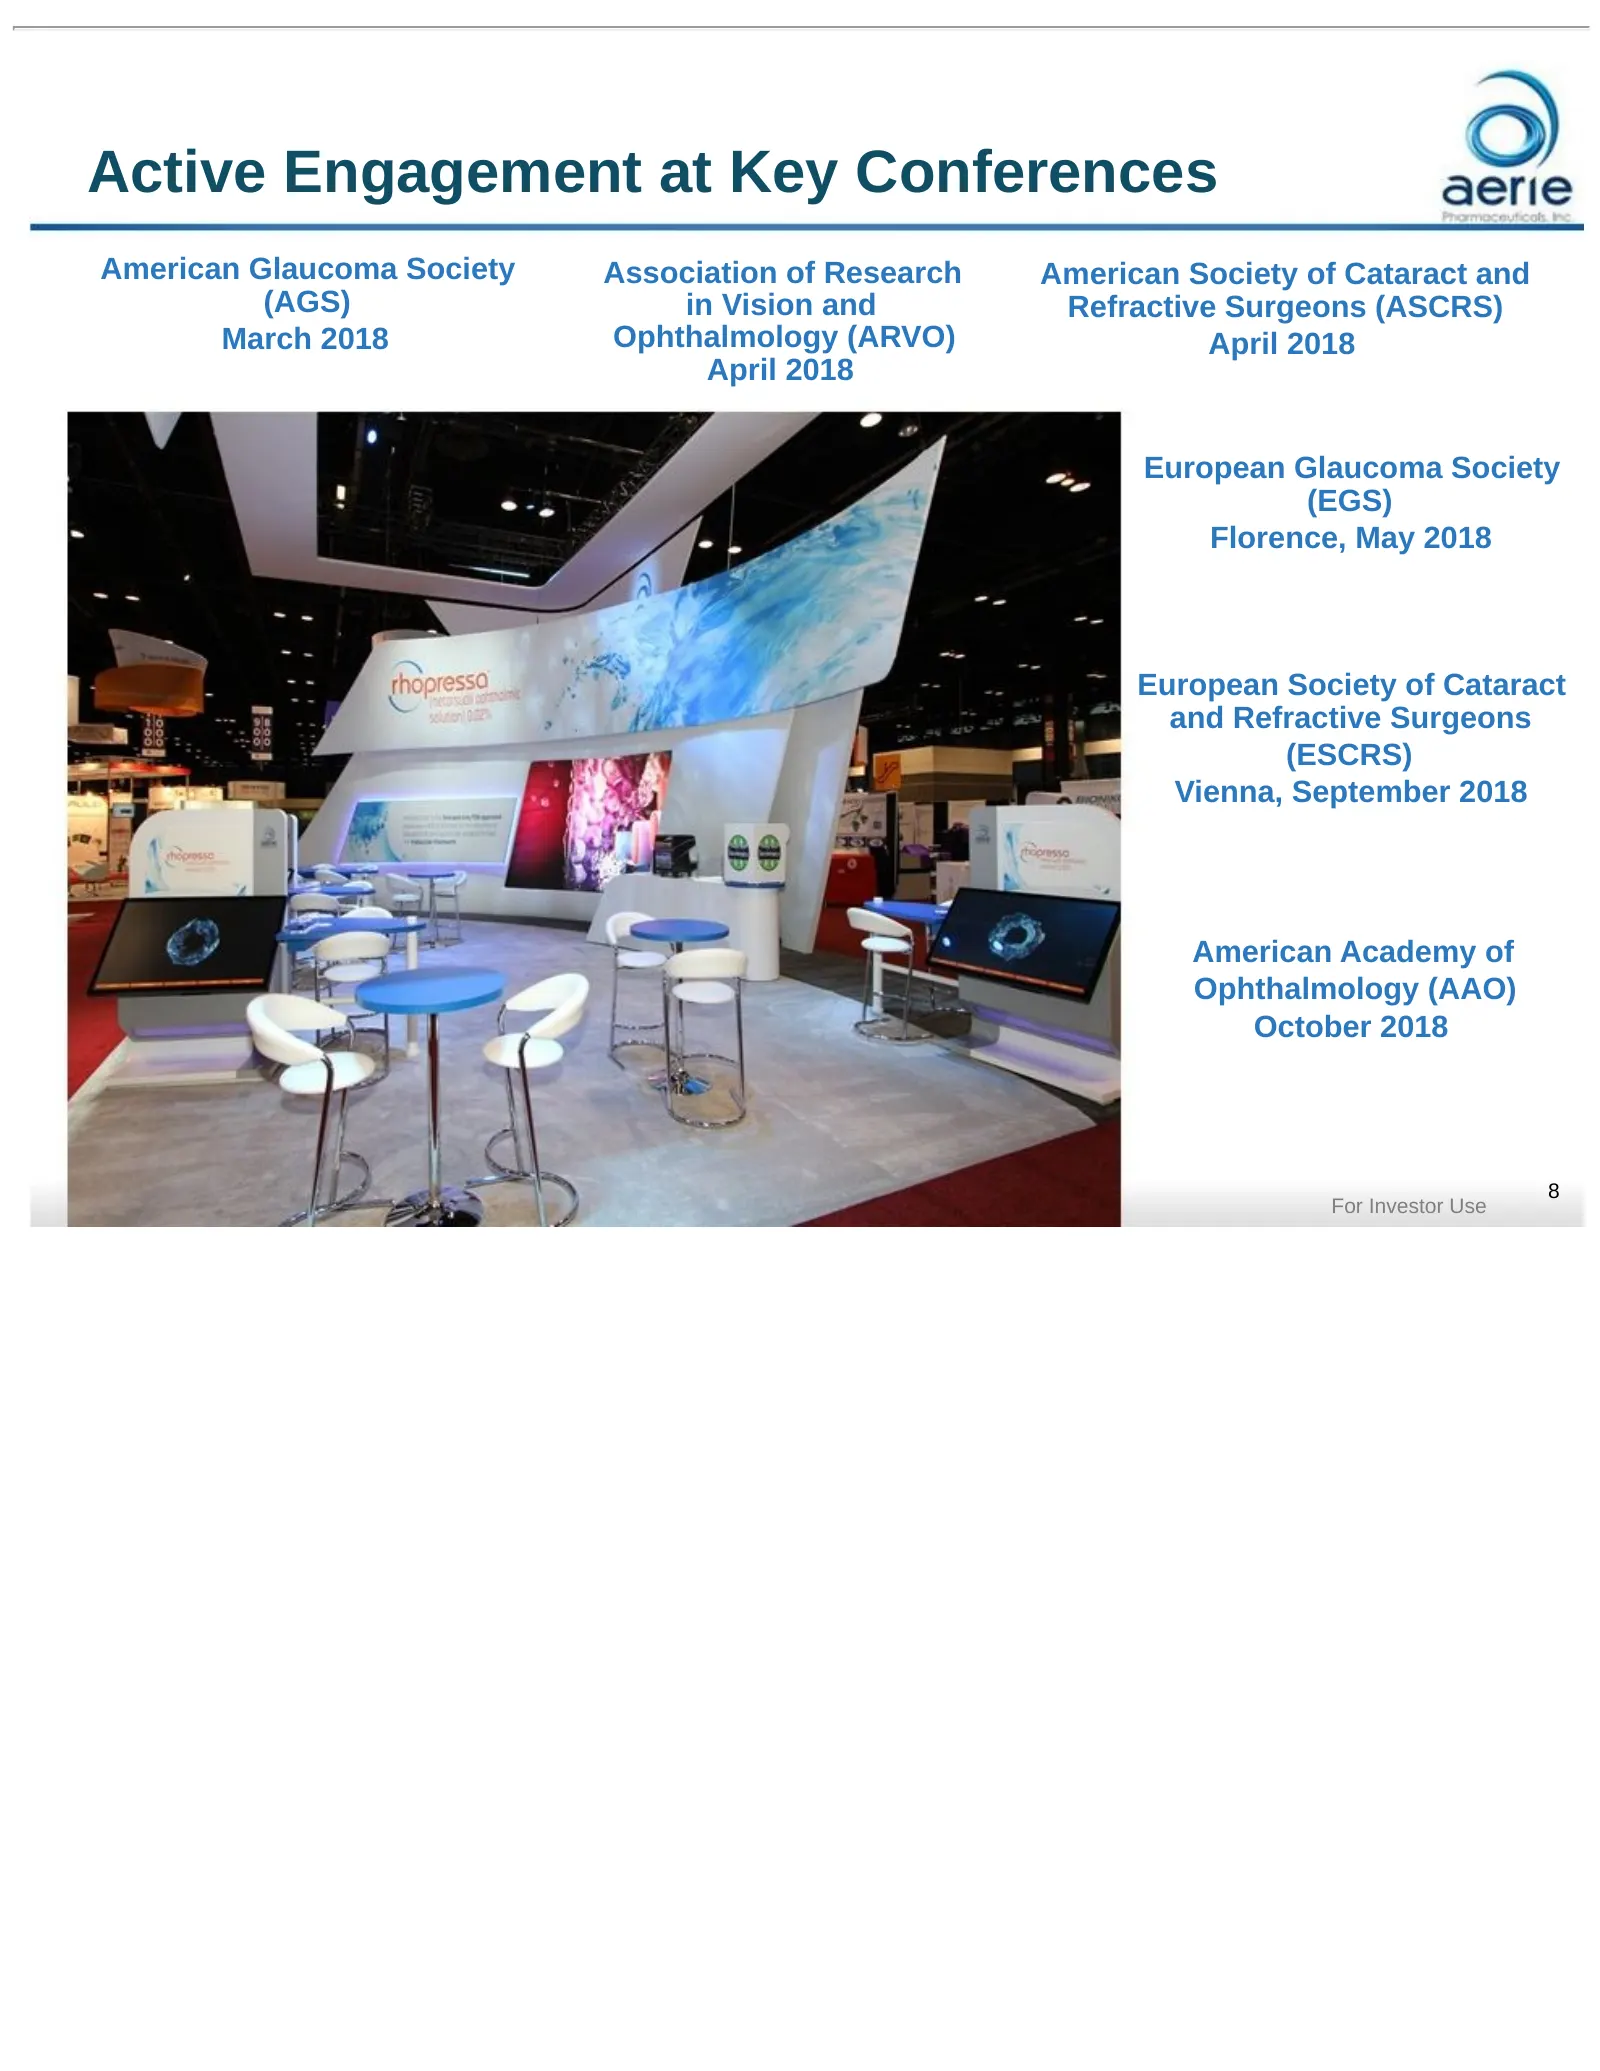
Active Engagement at Key Conferences American Glaucoma Society Association of Research American Society of Cataract and (AGS) in Vision and Refractive Surgeons (ASCRS) March 2018 Ophthalmology (ARVO) April 2018 April 2018 European Glaucoma Society (EGS) Florence, May 2018 European Society of Catarac
Slide 9: Rocklatan Combination Product Candidate
Rocklatan TM Combination Product Candidate TM Rocklatan (netarsudil/latanoprost ophthalmic solution) 0.02%/0.005% Positioning as First Line Therapy: • Benefits of Rhopressa® while also targeting the secondary drain • Achieved statistical superiority to market-leading latanoprost - At each of nine ti
Slide 10: Rocklatan Efficacy and Safety
Rocklatan TM Efficacy and Safety Efficacy: • RocklatanTM demonstrated statistical superiority over its components (market- leading PGA latanoprost and Rhopressa®) in Mercury 1 and 2 Phase 3 trials, at all measured time points • Consistent incremental IOP-reduction over latanoprost and Rhopressa® in
Slide 11: Rocklatan Phase 3 Month 12 Responder Analysis
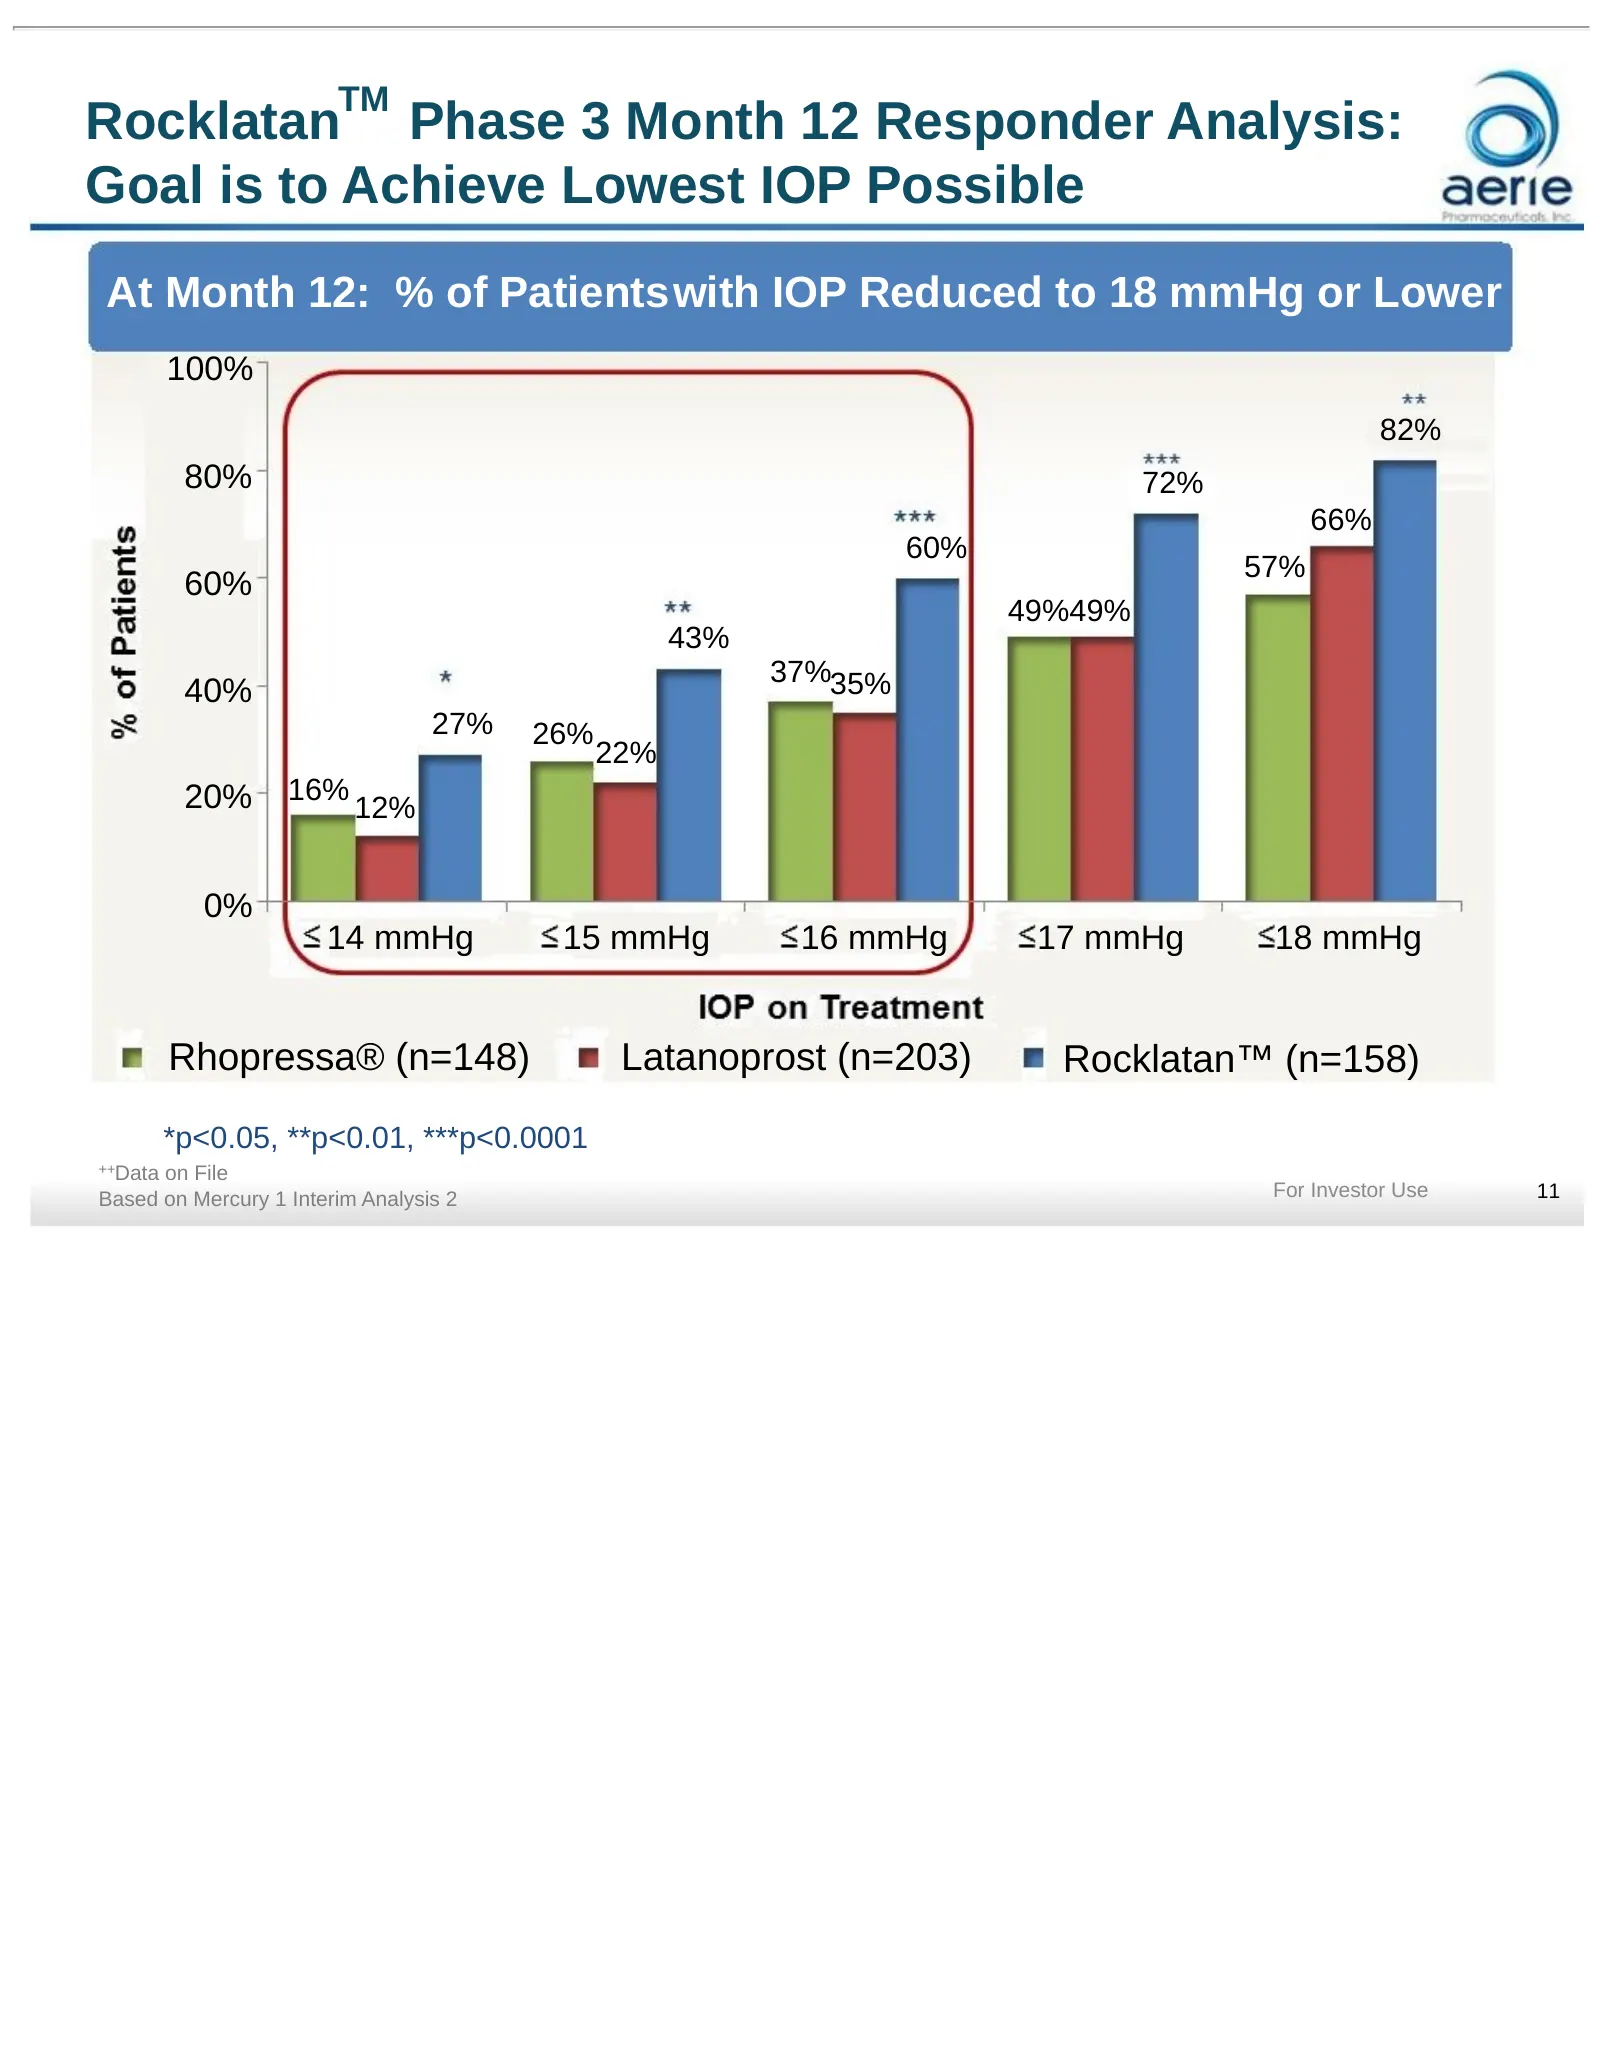
TM Rocklatan Phase 3 Month 12 Responder Analysis: Goal is to Achieve Lowest IOP Possible At Month 12: % of Patientswith IOP Reduced to 18 mmHg or Lower 100% 82% 80% 72% 66% 60% 57% 60% 49%49% 43% 37%35% 40% 27% 26% 22% 20% 16% 12% 0% 14 mmHg 15 mmHg 16 mmHg 17 mmHg 18 mmHg Rhopressa® (n=148) Latanop
Slide 12: Rocklatan Next Steps
Rocklatan™ Next Steps • March 14, 2019 PDUFA TM • Current U.S. sales force is now training for Rocklatan in advance of PDUFA • Medicare Part D formulary submission to payers expected in April 2019 • Commercial and Medicare Part D access expected to be accelerated in comparison to Rhopressa ® For Inv
Slide 13: Expanding Aerie Franchise: Europe and Japan
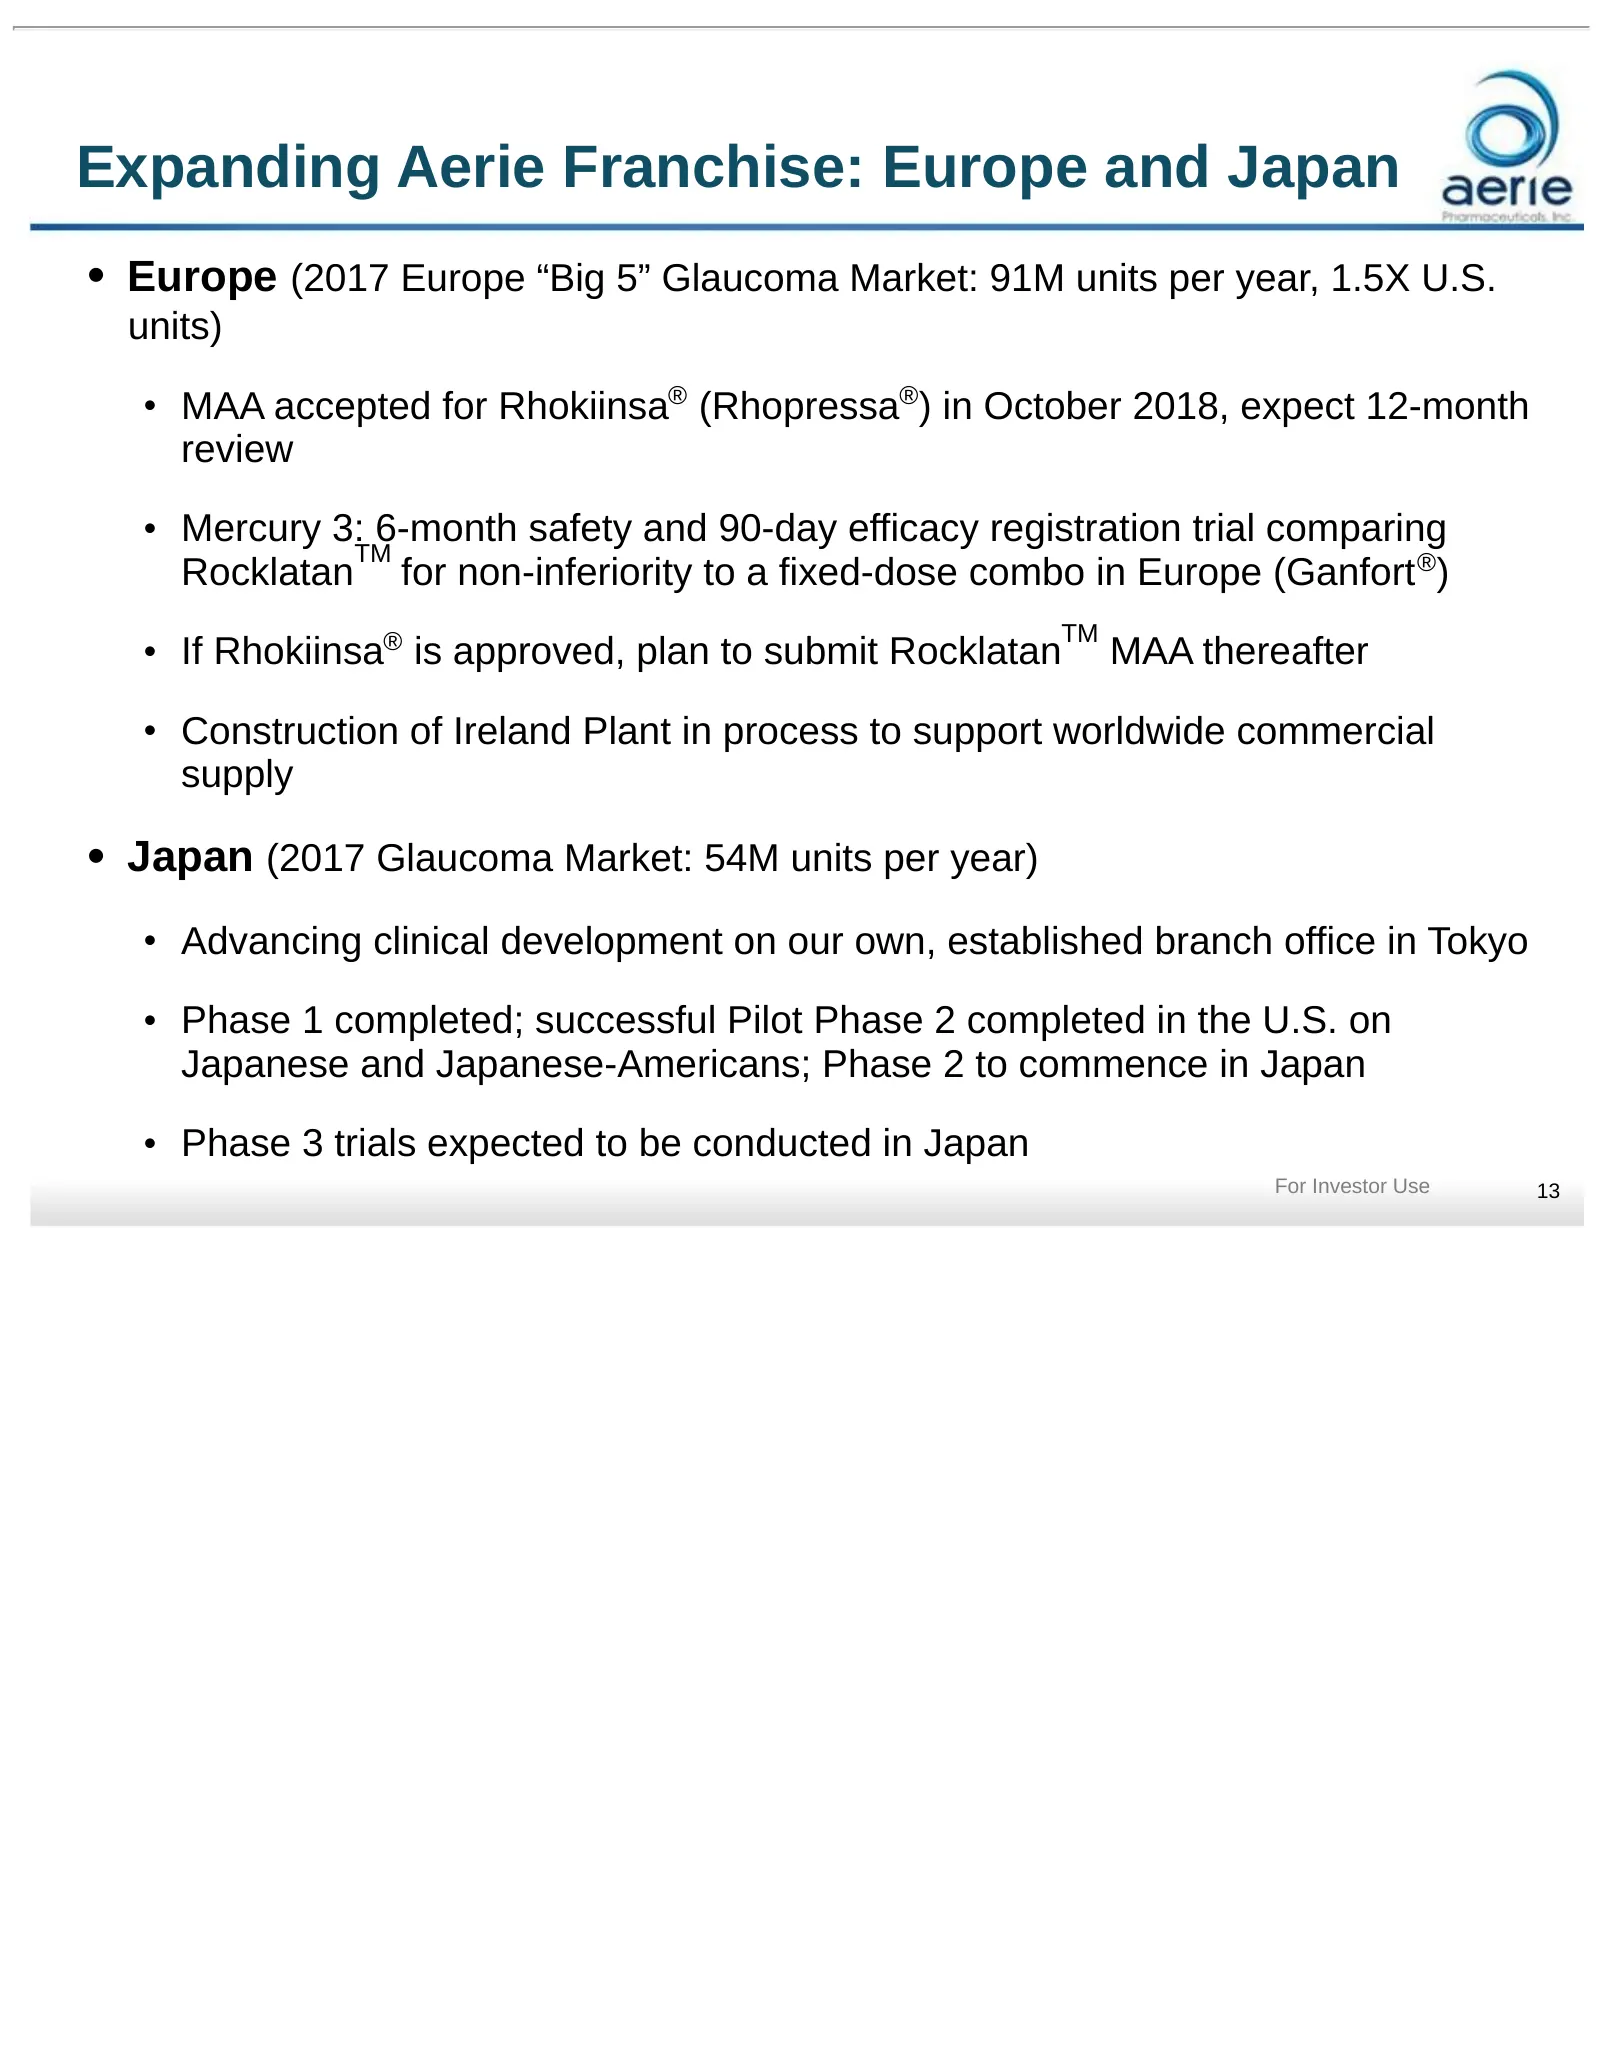
Expanding Aerie Franchise: Europe and Japan • Europe (2017 Europe “Big 5” Glaucoma Market: 91M units per year, 1.5X U.S. units) • MAA accepted for Rhokiinsa® (Rhopressa®) in October 2018, expect 12-month review • Mercury 3: 6-month safety and 90-day efficacy registration trial comparing TM Rocklatan
Slide 14: Europe Glaucoma Market
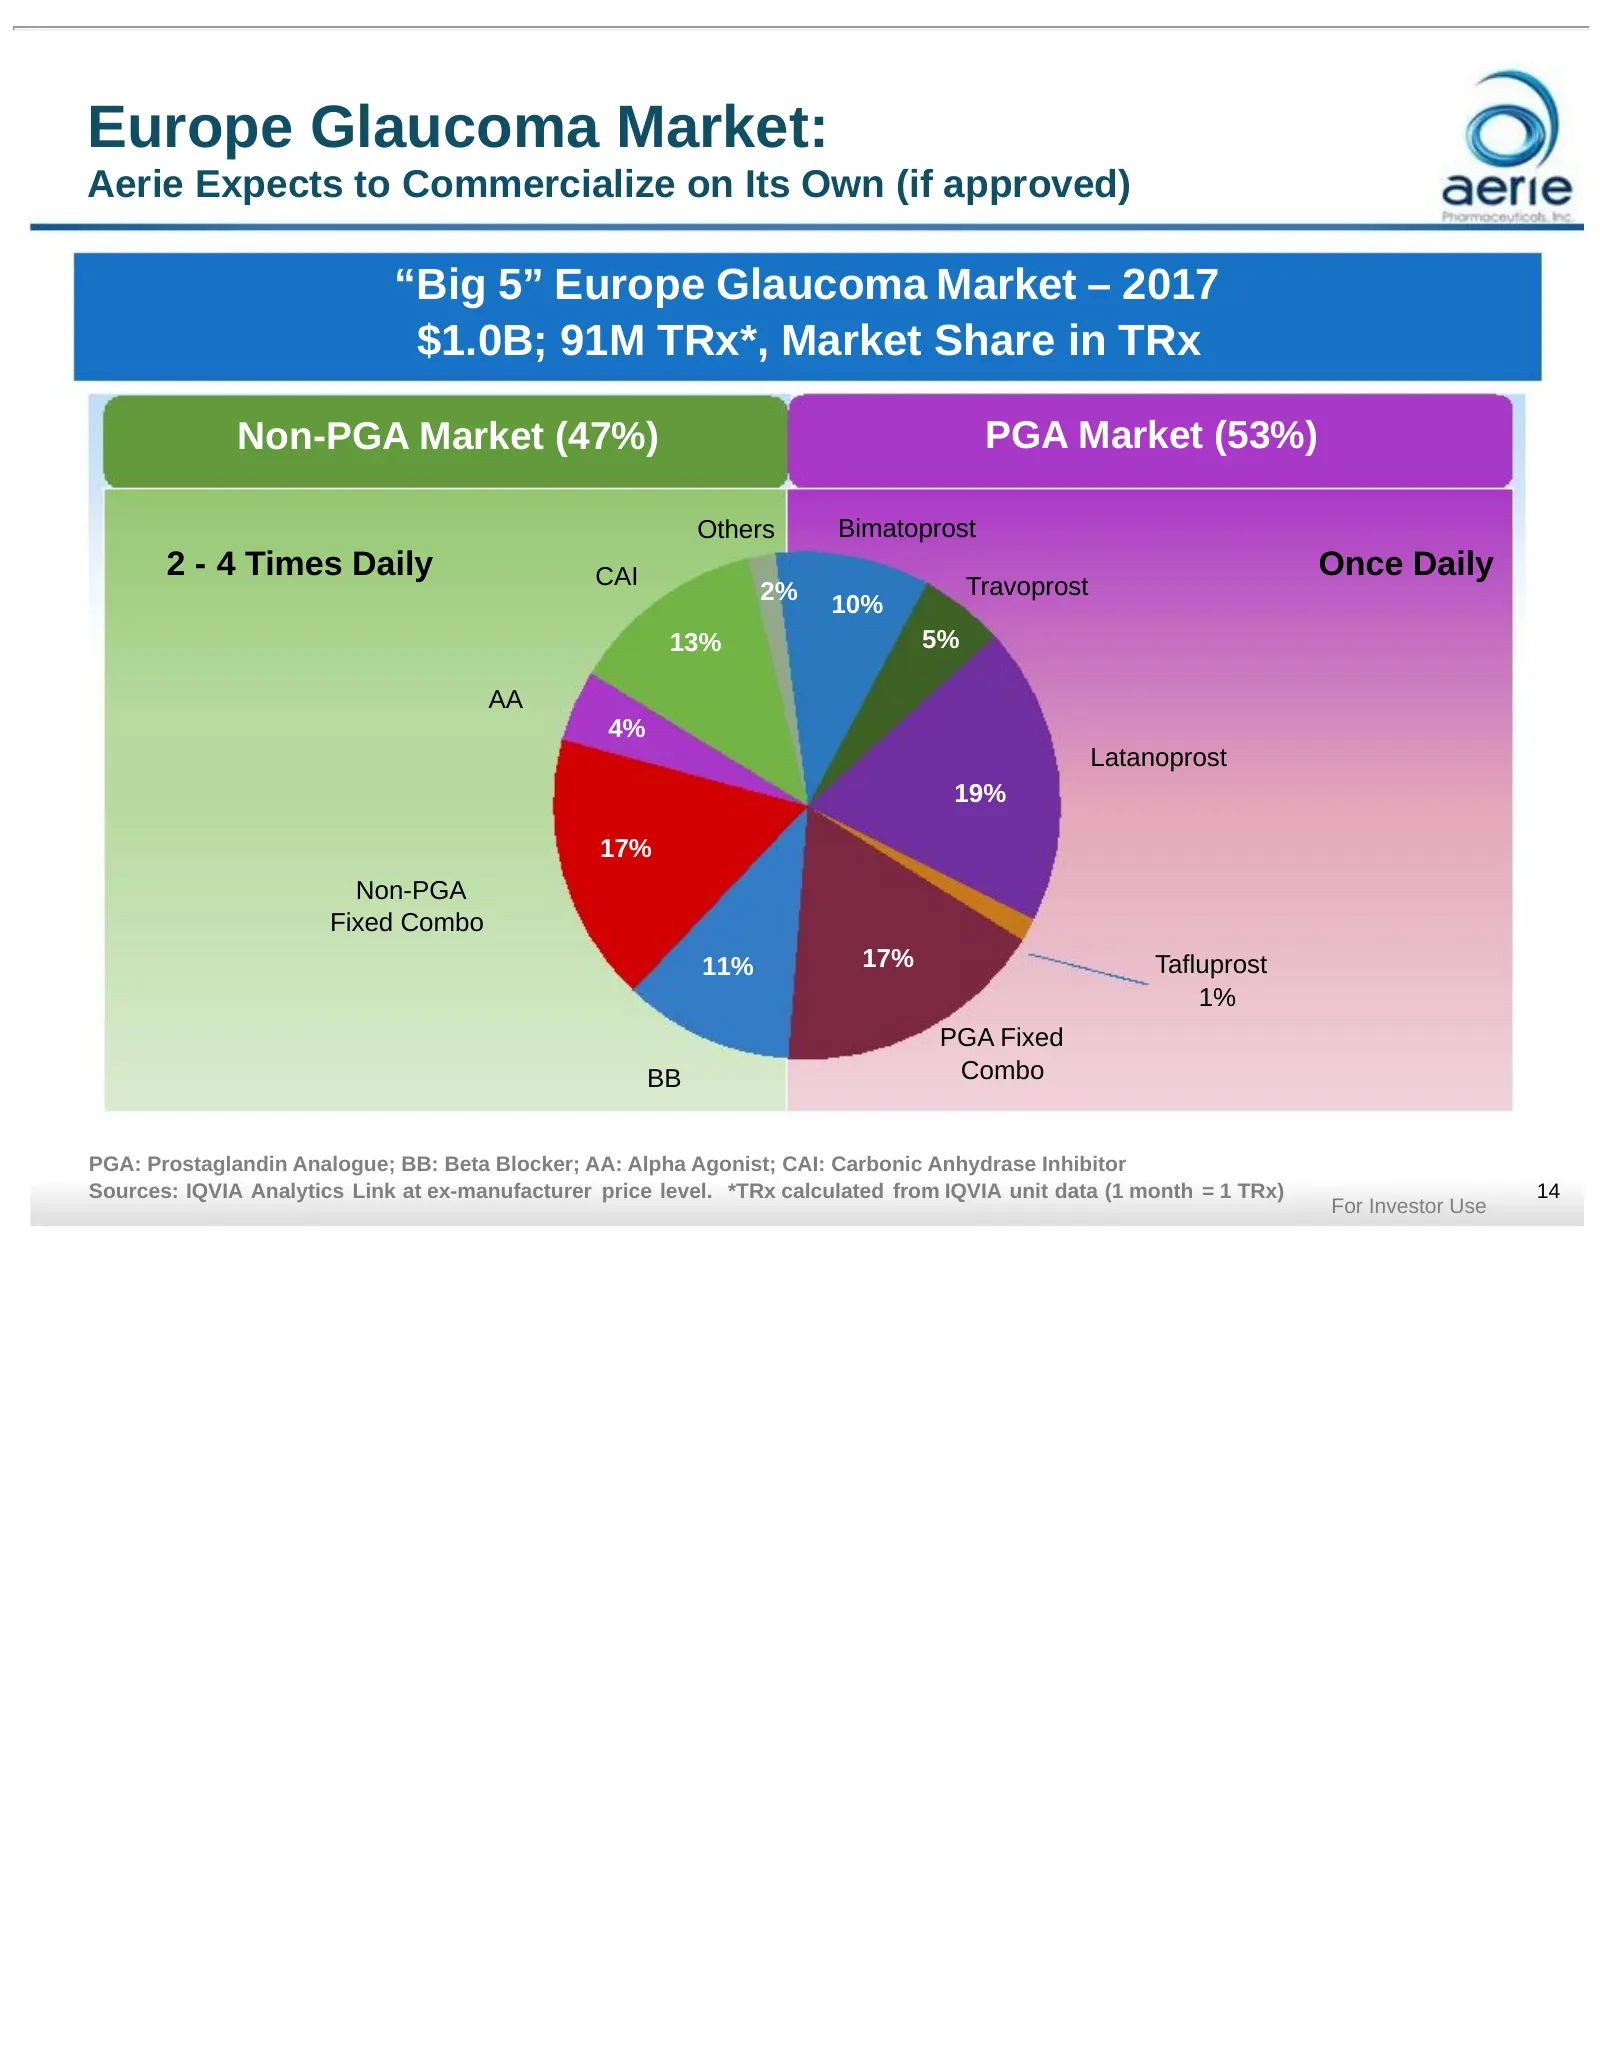
Europe Glaucoma Market: Aerie Expects to Commercialize on Its Own (if approved) “Big 5” Europe Glaucoma Market – 2017 $1.0B; 91M TRx*, Market Share in TRx Non-PGA Market (47%) PGA Market (53%) Others Bimatoprost 2 - 4 Times Daily CAI Once Daily 2% Travoprost 10% 13% 5% AA 4% Latanoprost 19% 17% Non-
Slide 15: Japan Glaucoma Market
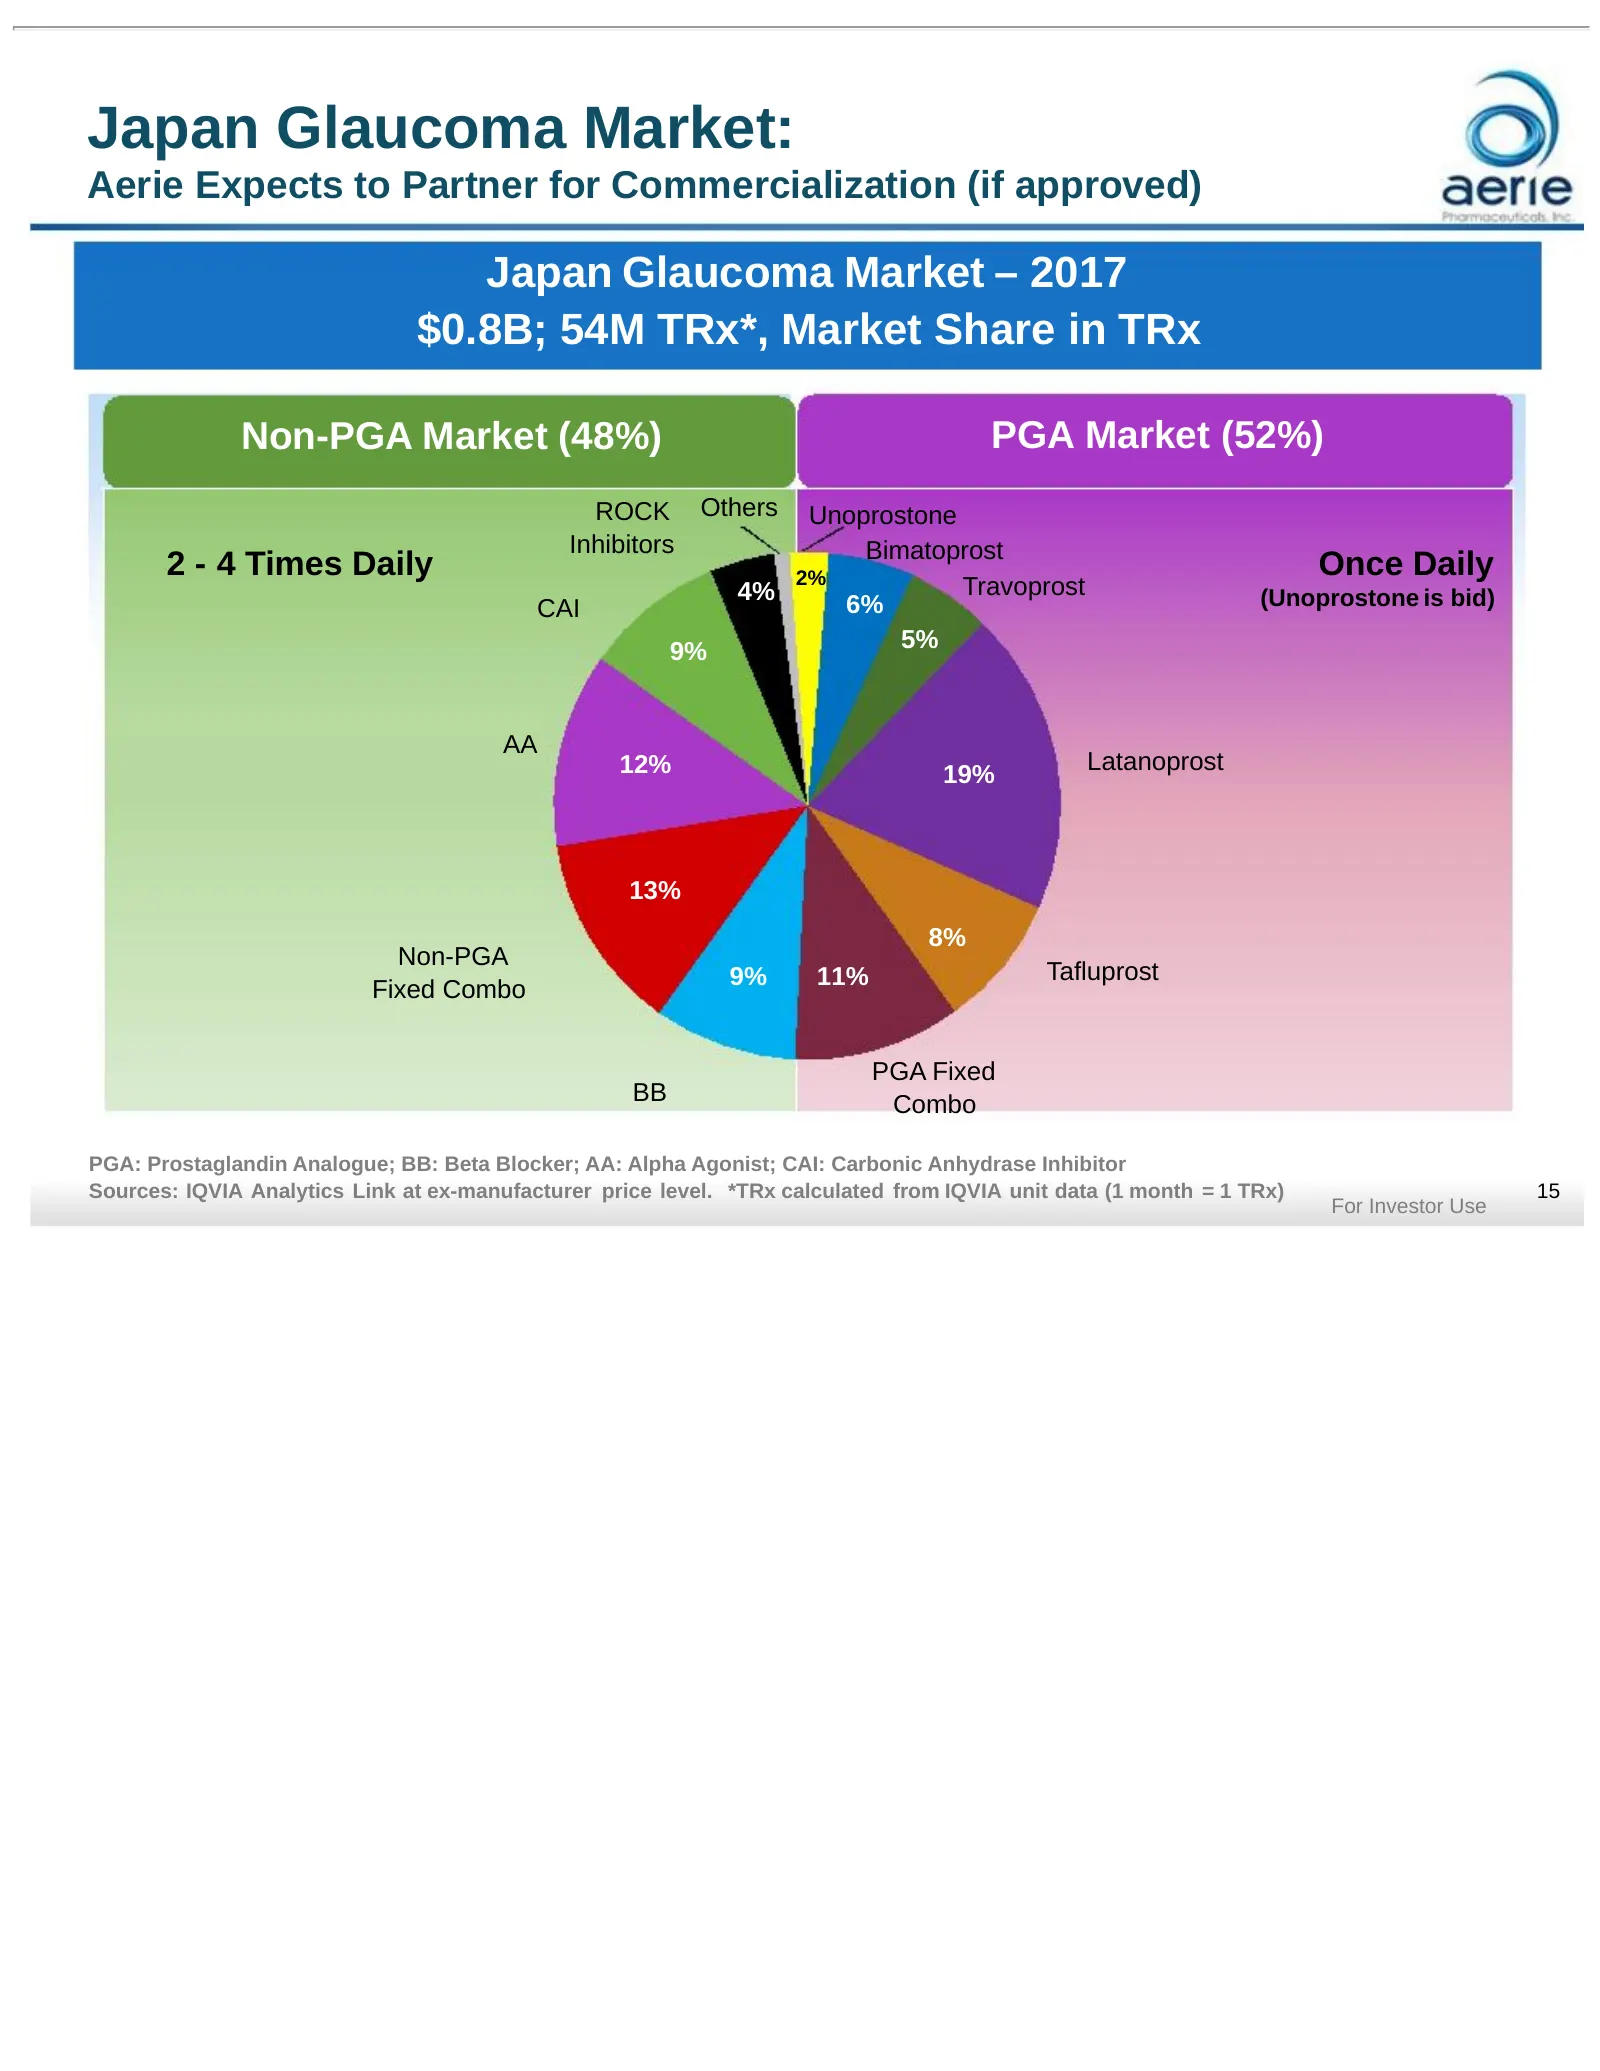
Japan Glaucoma Market: Aerie Expects to Partner for Commercialization (if approved) Japan Glaucoma Market – 2017 $0.8B; 54M TRx*, Market Share in TRx Non-PGA Market (48%) PGA Market (52%) ROCK Others Unoprostone Inhibitors Bimatoprost 2 - 4 Times Daily 2% Once Daily 4% Travoprost (Unoprostone is bid
Slide 16: Advancing the Pipeline
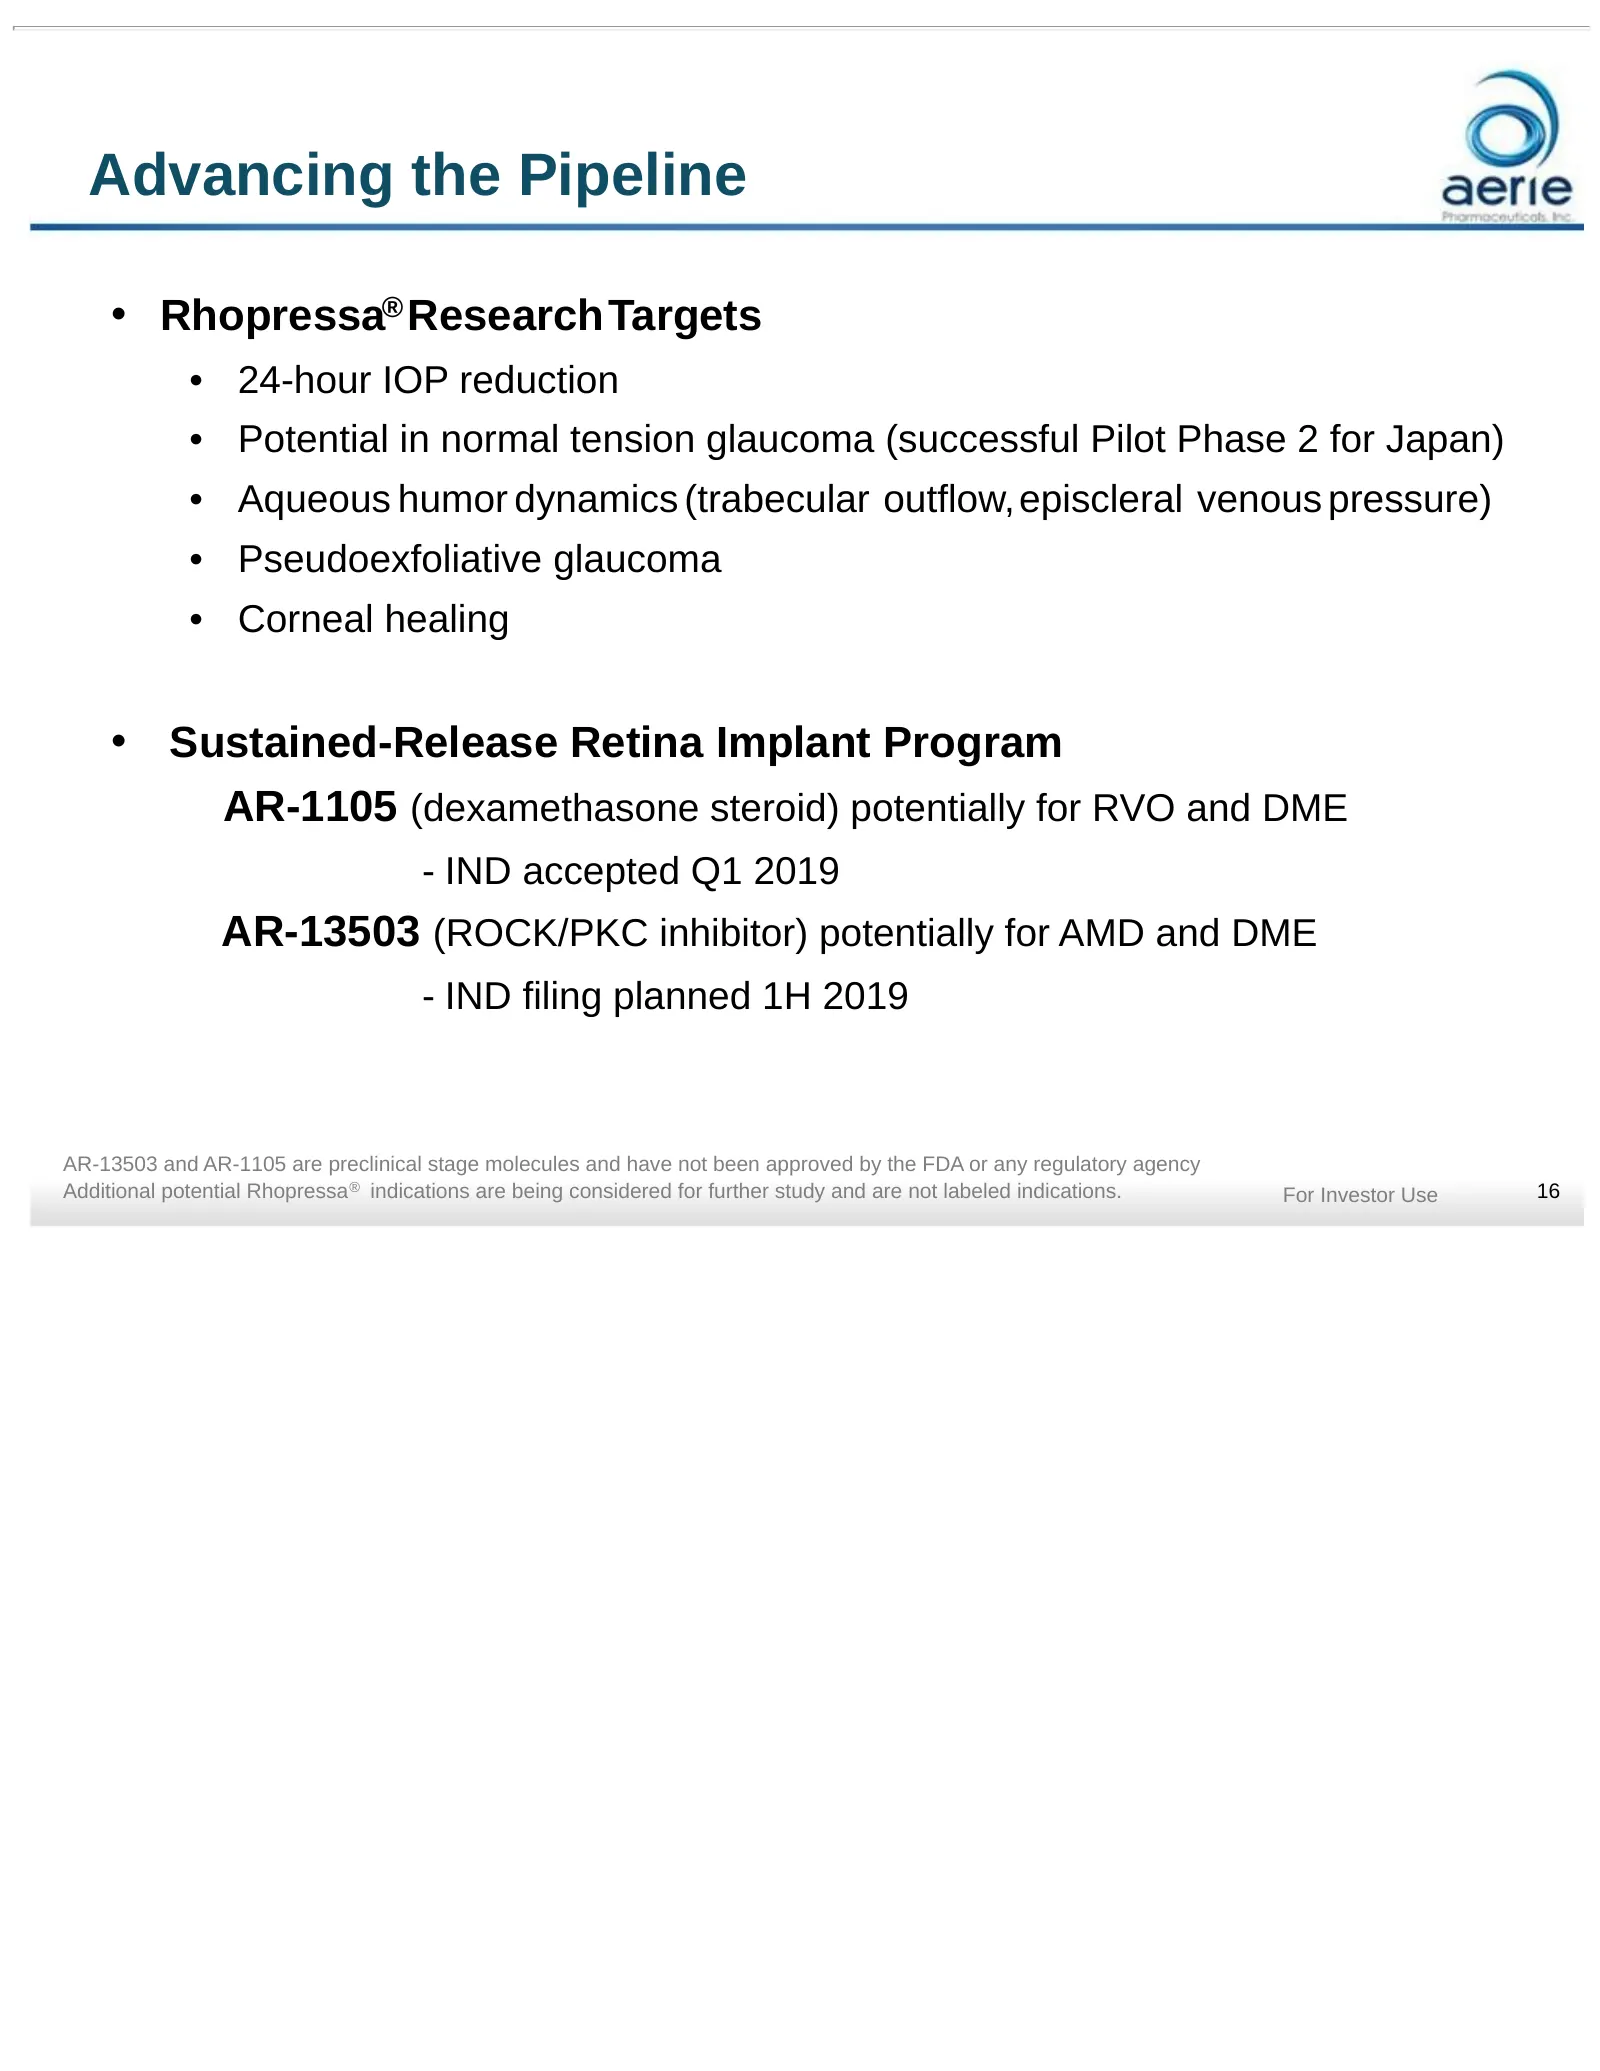
Advancing the Pipeline • Rhopressa® ResearchTargets • 24-hour IOP reduction • Potential in normal tension glaucoma (successful Pilot Phase 2 for Japan) • Aqueous humor dynamics (trabecular outflow, episcleral venous pressure) • Pseudoexfoliative glaucoma • Corneal healing • Sustained-Release Retina
Slide 17: Retinal Eye Diseases – Aerie's Next Chapter
Retinal Eye Diseases – Aerie’s Next Chapter Bringing Small Molecule Therapy to Back of the Eye Most retinal drugs in use and in pipeline are protein therapeutics • Longer half-life allows monthly to bimonthly IVT injections Protein therapeutics address limited number of extracellular targets Small m
Slide 18: 2017 U.S. Retinal Disease Market
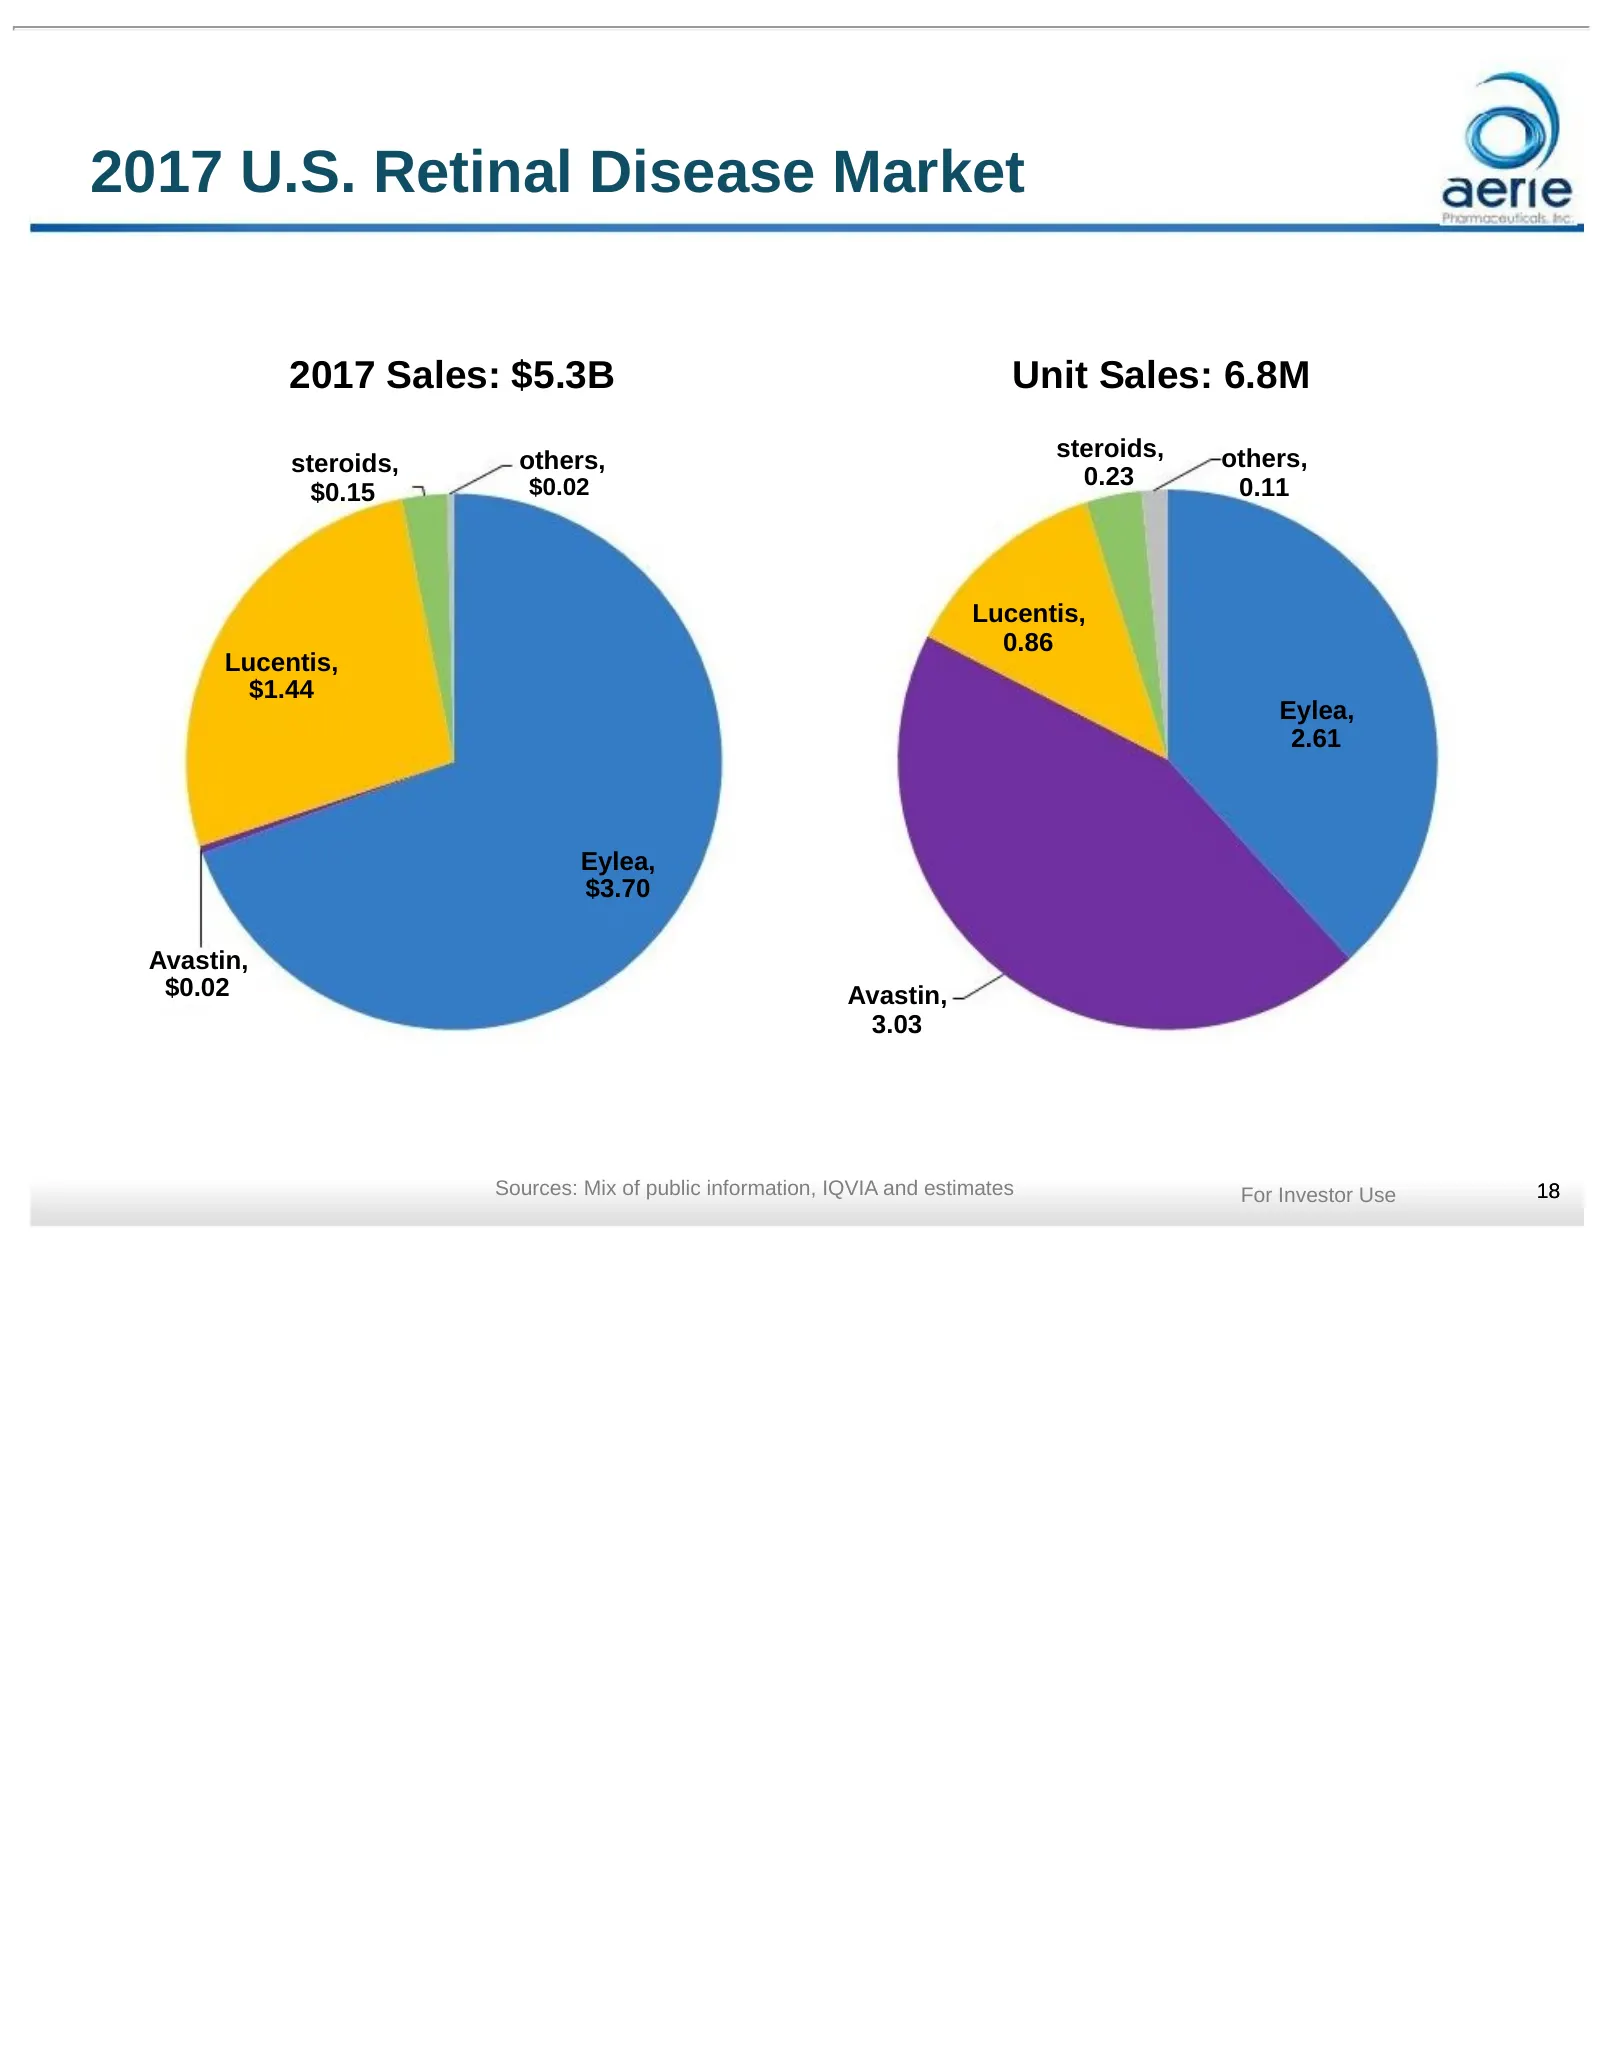
2017 U.S. Retinal Disease Market 2017 Sales: $5.3B Unit Sales: 6.8M others, steroids, others, steroids, 0.23 $0.15 $0.02 0.11 Lucentis, 0.86 Lucentis, $1.44 Eylea, 2.61 Eylea, $3.70 Avastin, $0.02 Avastin, 3.03 Sources: Mix of public information, IQVIA and estimates For Investor Use 18
Slide 19: Aerie's Innovation in Retinal Disease
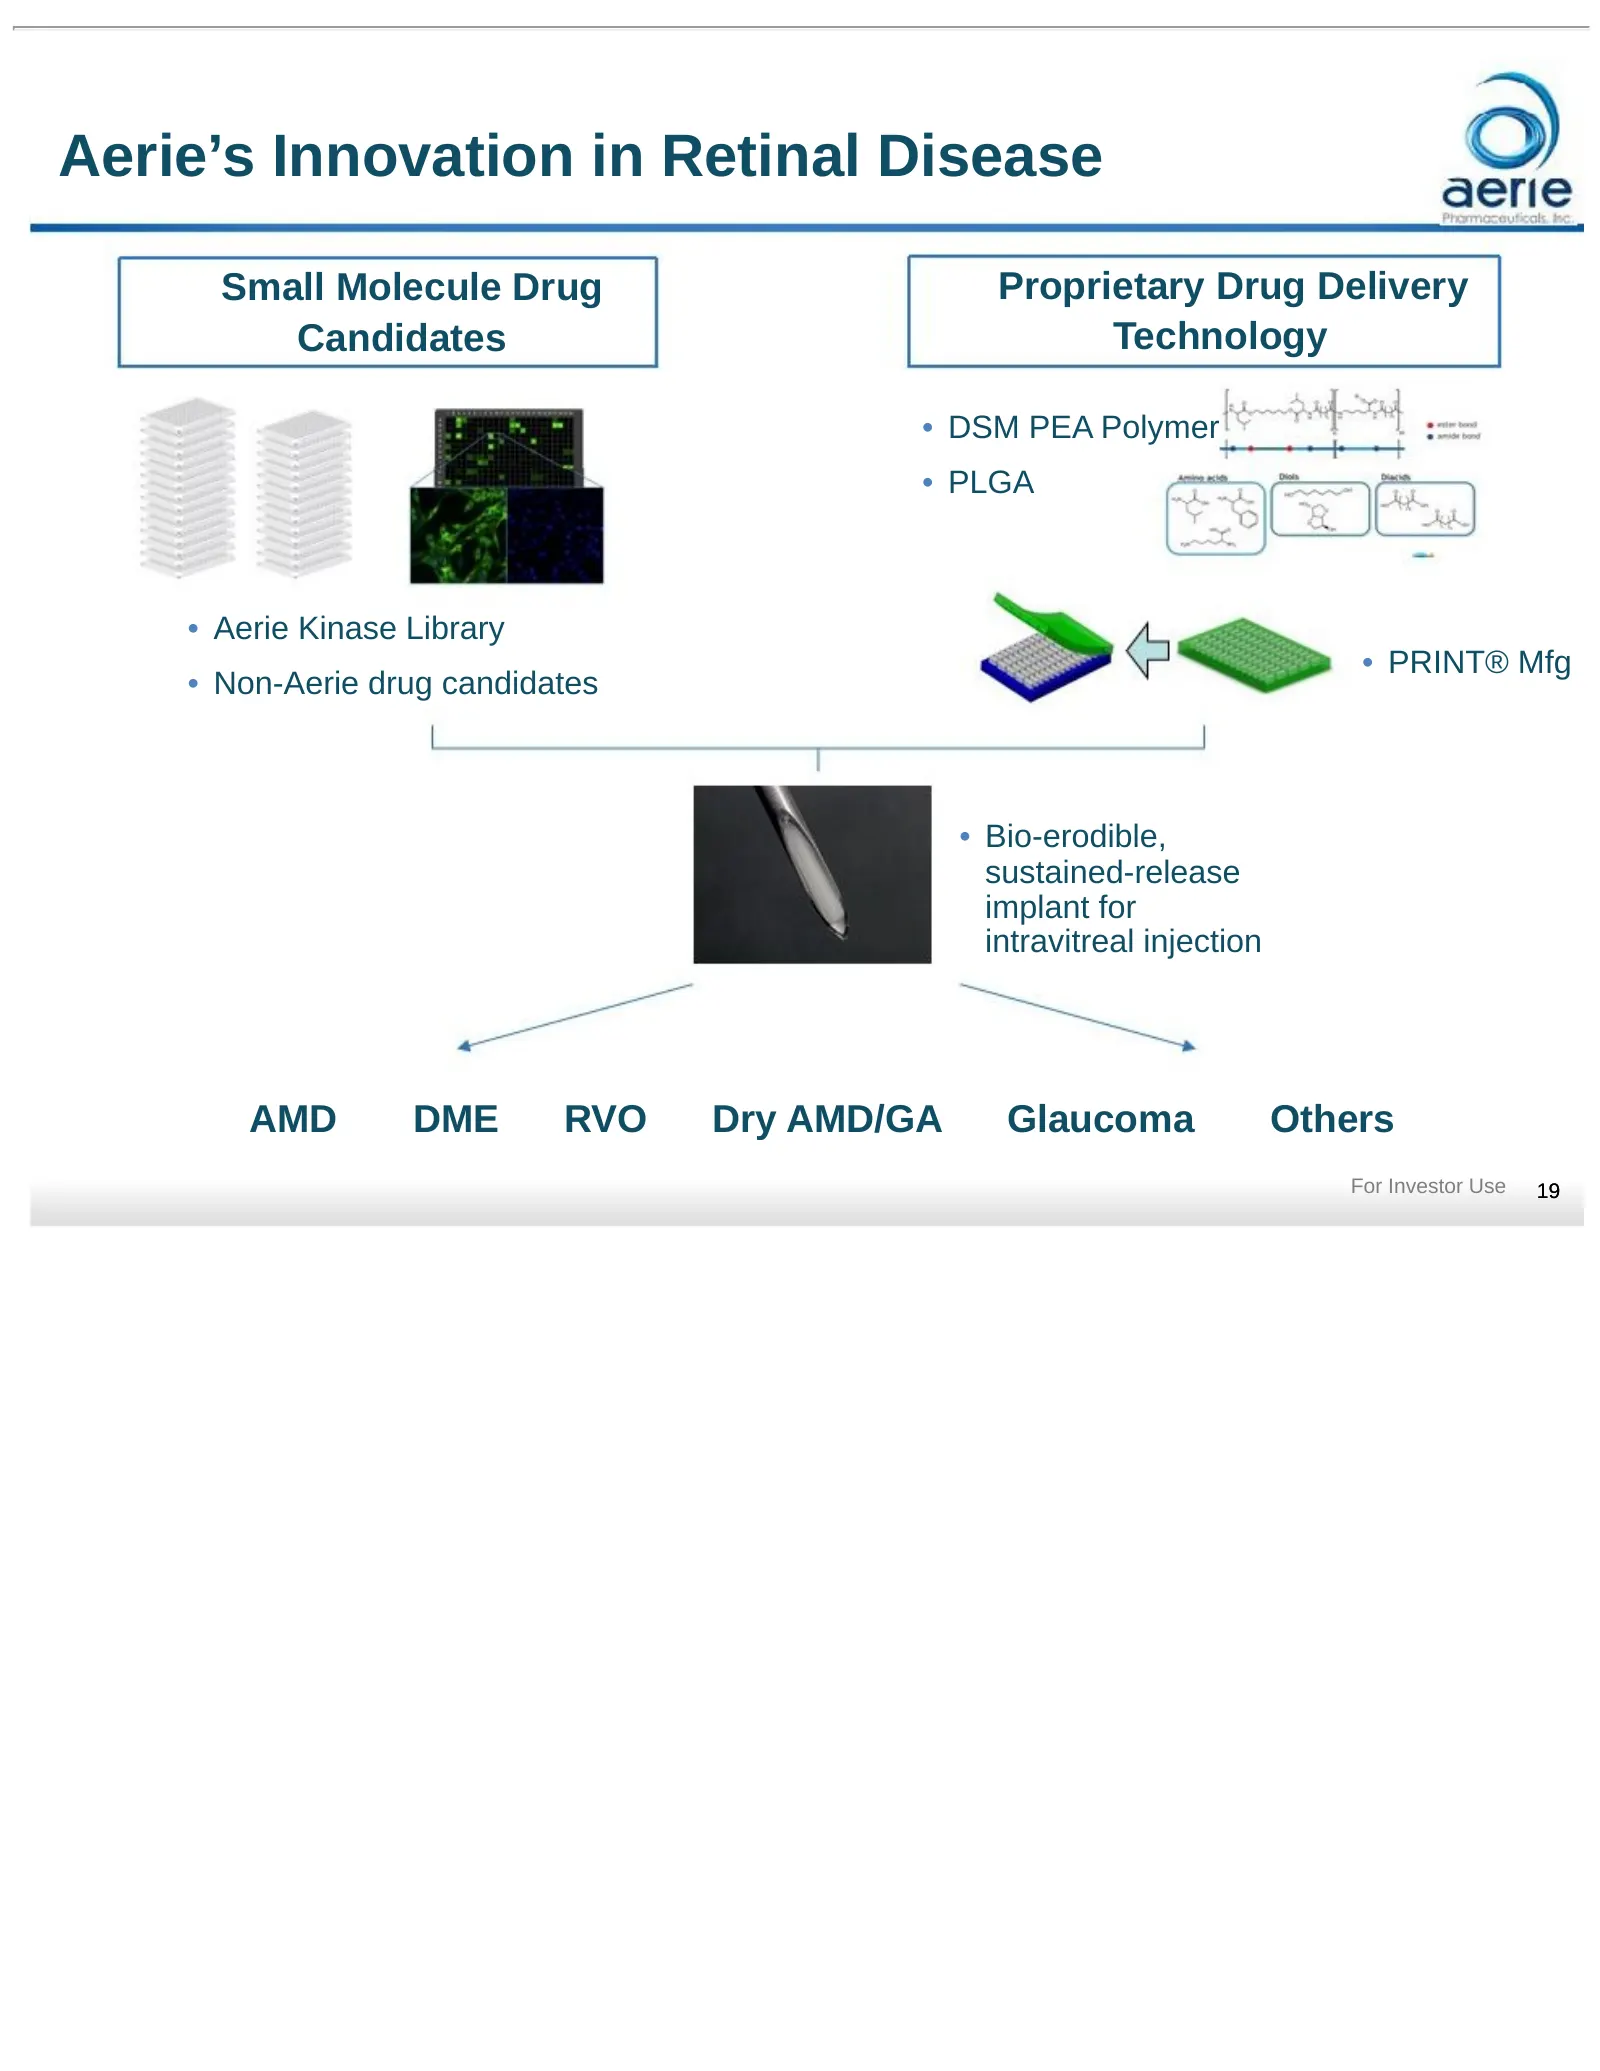
Aerie’s Innovation in Retinal Disease Small Molecule Drug Proprietary Drug Delivery Candidates Technology • DSM PEA Polymer • PLGA • Aerie Kinase Library • PRINT® Mfg • Non-Aerie drug candidates • Bio-erodible, sustained-release implant for intravitreal injection AMD DME RVO Dry AMD/GA Glaucoma Othe
Slide 20: Retinal Eye Disease: Unmet Needs in AMD and DME
Retinal Eye Disease Unmet Needs in AMD and DME Need new treatments to address disease mechanisms beyond VEGF • Complex pathology cannot be addressed by a single drug class Many patients do not achieve and/or maintain sufficient efficacy • AMD: Anti-VEGF efficacy often lost after 5–7 years of treatme
Slide 21: Lead Retina Products
Lead Retina Products AR-1105 (Dexamethasone) Implant • Indications: retinal vein occlusion (RVO) and DME • Target product profile vs. Ozurdex® • Longer duration of efficacy (6 mo vs 3 mo) • Improved administration due to smaller needle • Potential for fewer adverse effects due to lower peak drug lev
Slide 22: Preclinical AR-13503 Provides Efficacy Similar to Eylea
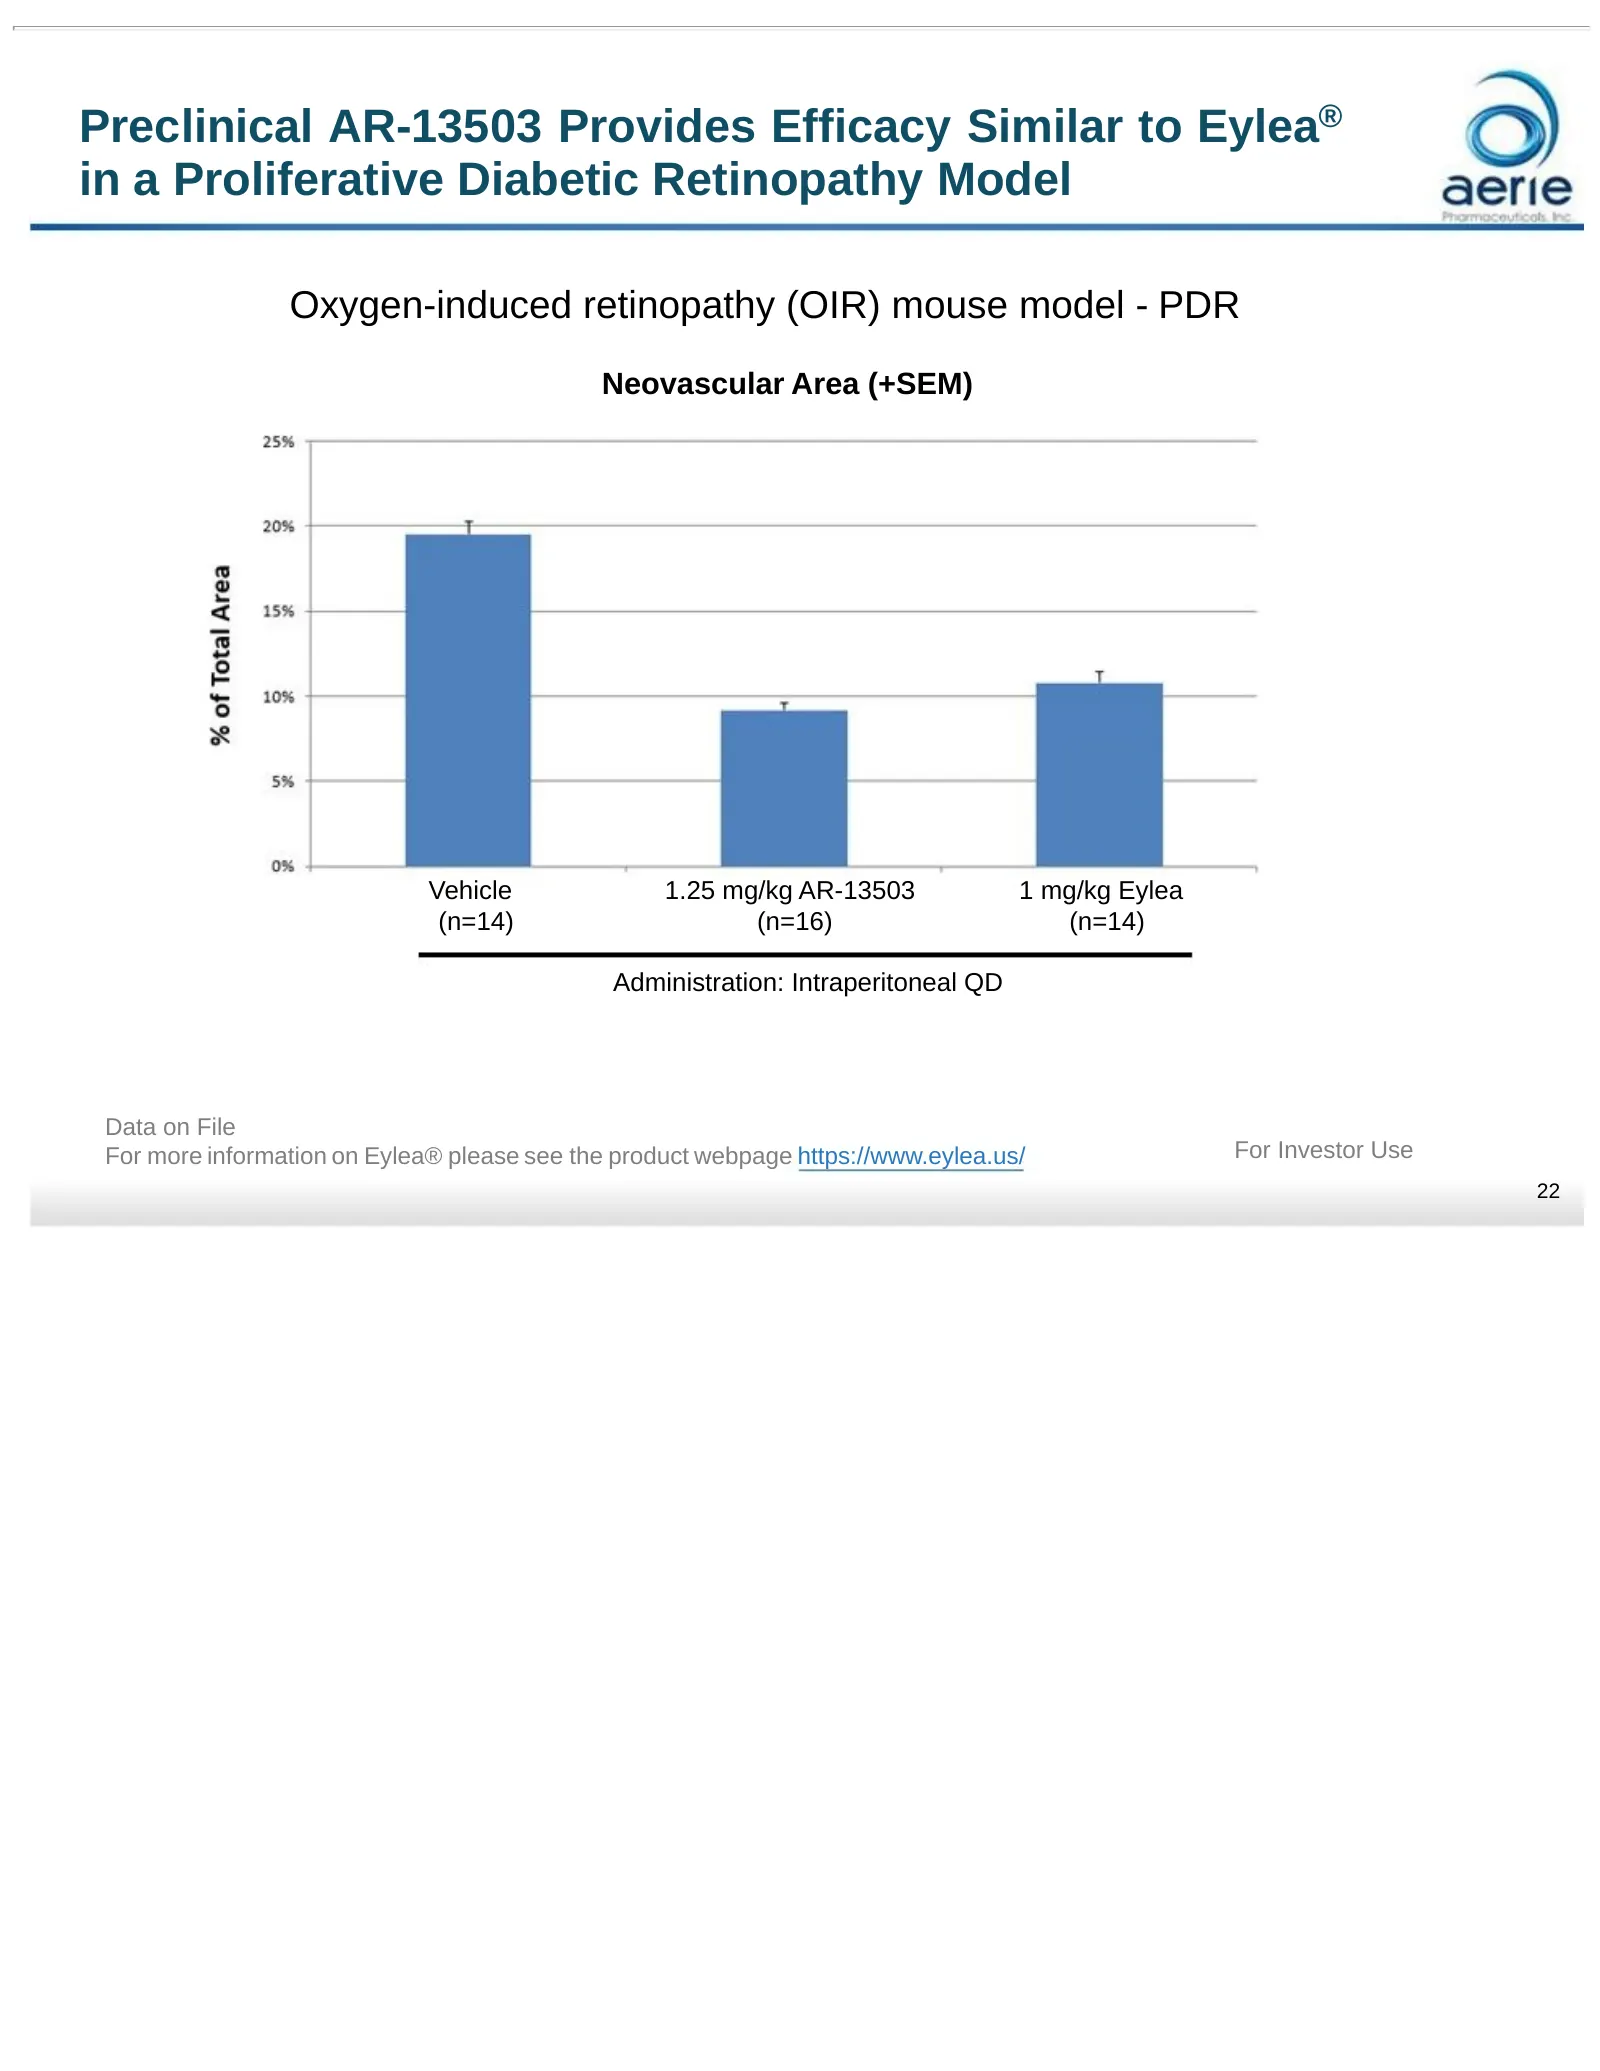
Preclinical AR-13503 Provides Efficacy Similar to Eylea® in a Proliferative Diabetic Retinopathy Model Oxygen-induced retinopathy (OIR) mouse model - PDR Neovascular Area (+SEM) Vehicle 1.25 mg/kg AR-13503 1 mg/kg Eylea (n=14) (n=16) (n=14) Administration: Intraperitoneal QD Data on File For more in
Slide 23: AR-13503 Synergistic to Eylea in Mouse Model
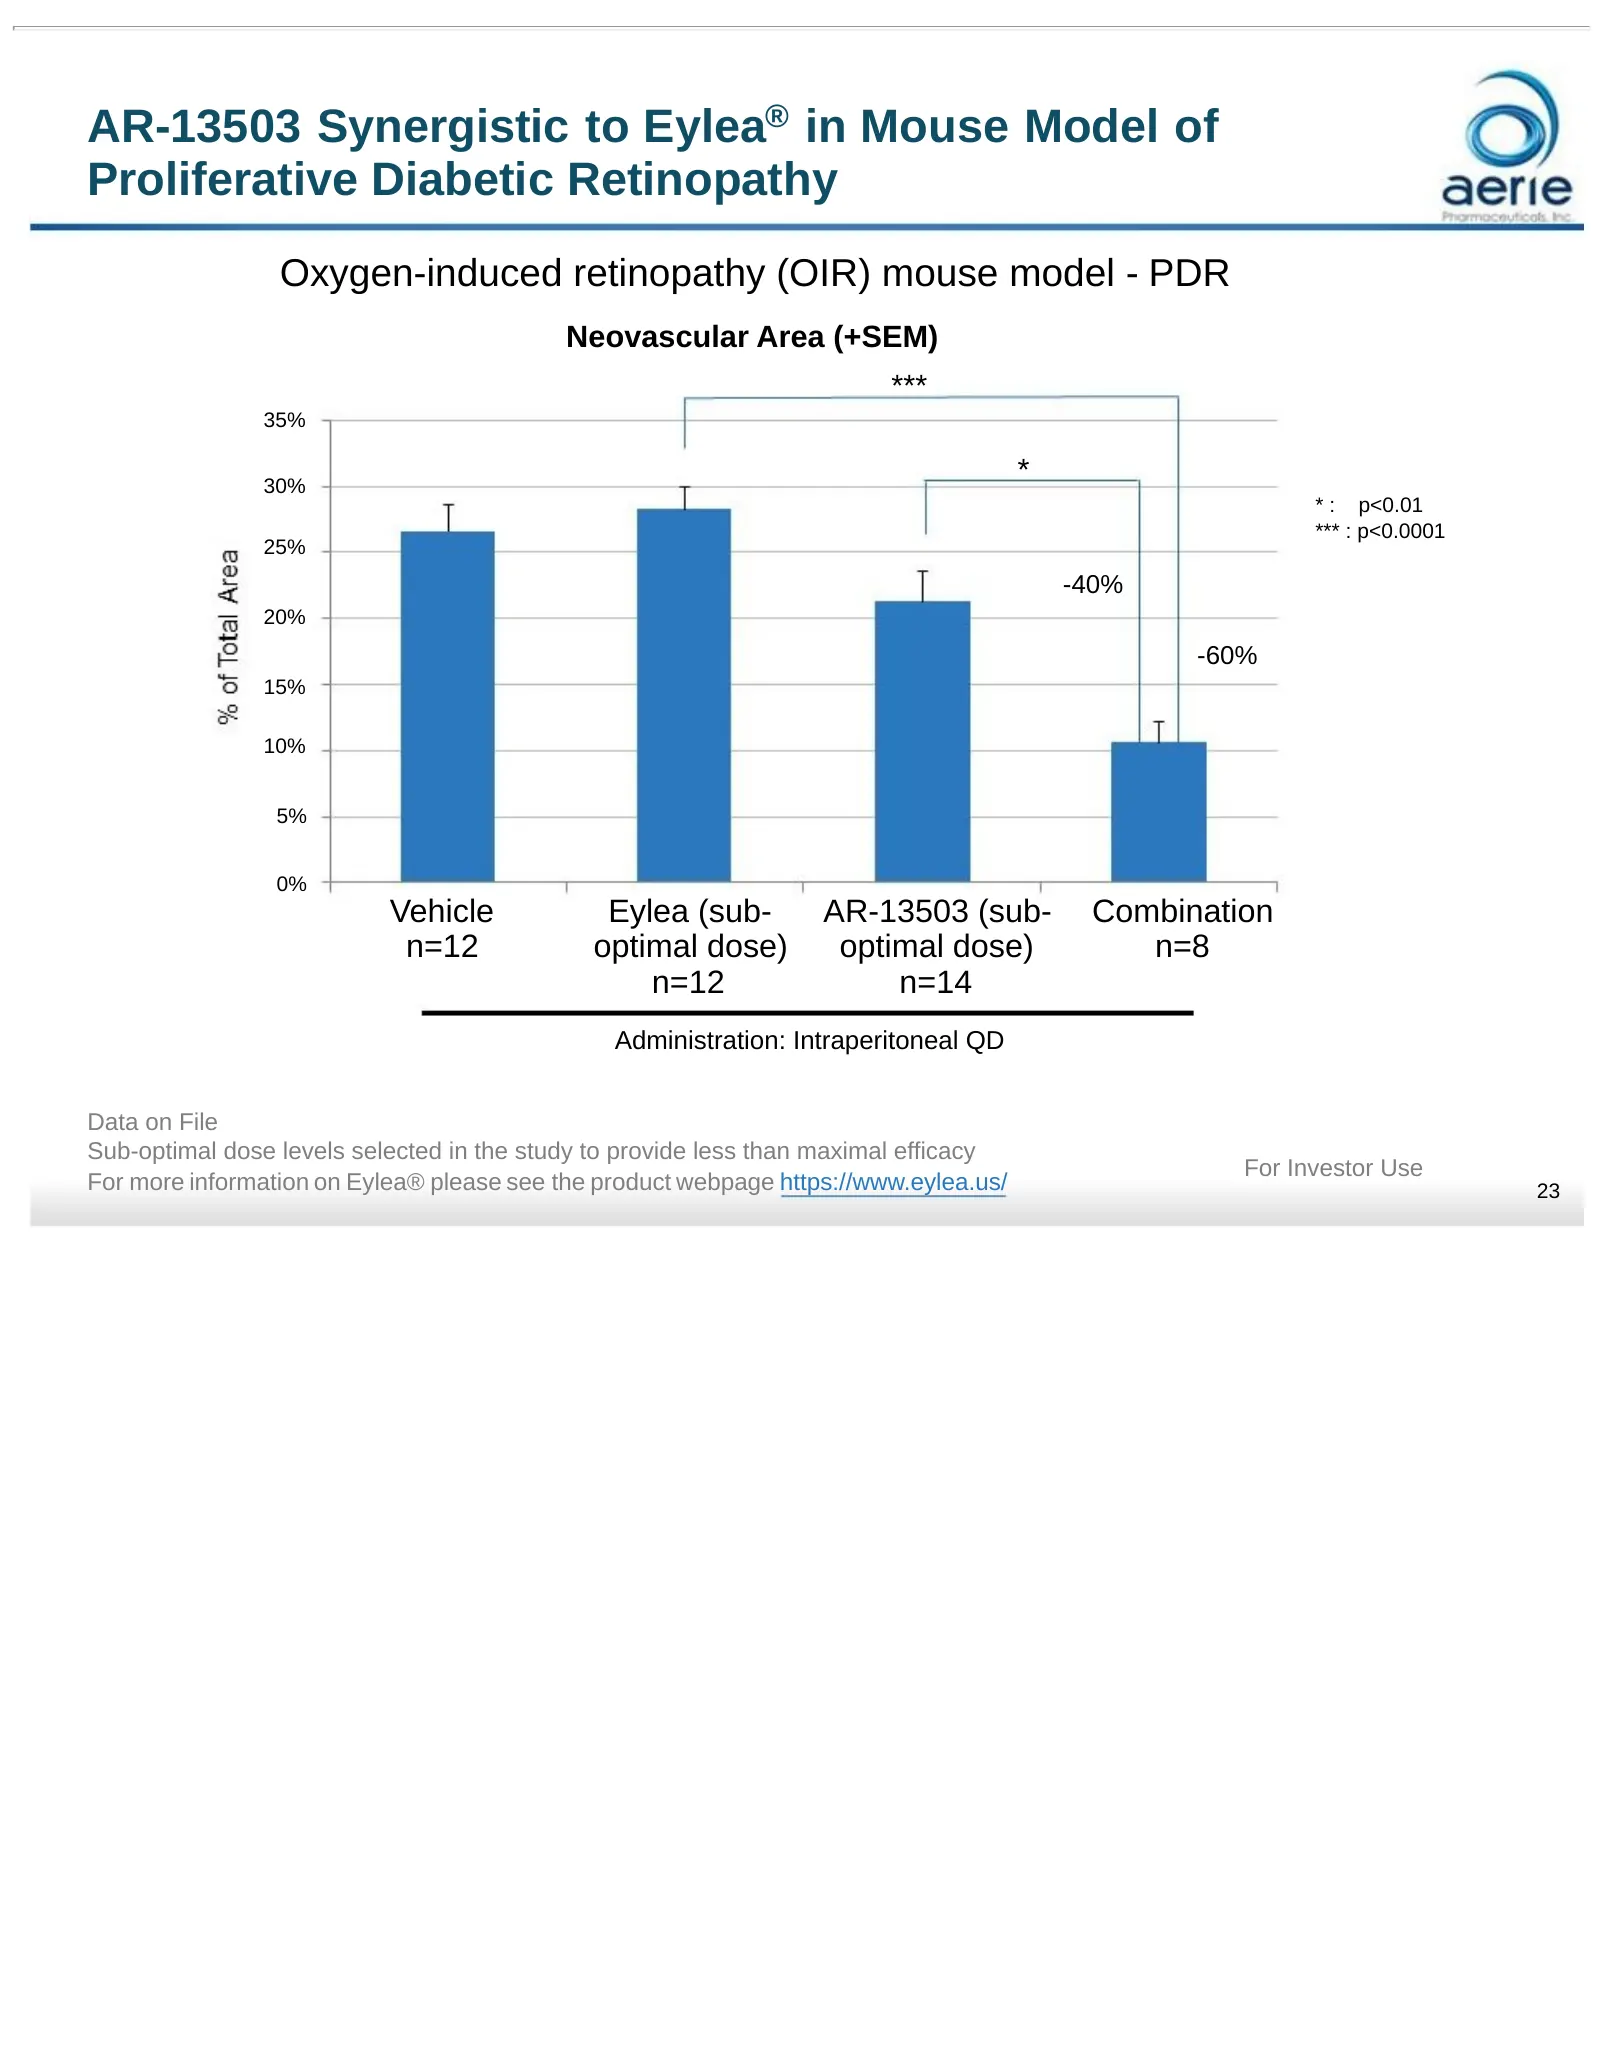
AR-13503 Synergistic to Eylea® in Mouse Model of Proliferative Diabetic Retinopathy Oxygen-induced retinopathy (OIR) mouse model - PDR Neovascular Area (+SEM) *** 35% 30% * * : p<0.01 *** : p<0.0001 25% -40% 20% -60% 15% 10% 5% 0% Vehicle Eylea (sub- AR-13503 (sub- Combination n=12 optimal dose) opt
Slide 24: Evaluating Aerie's 3,500+ Owned Molecules
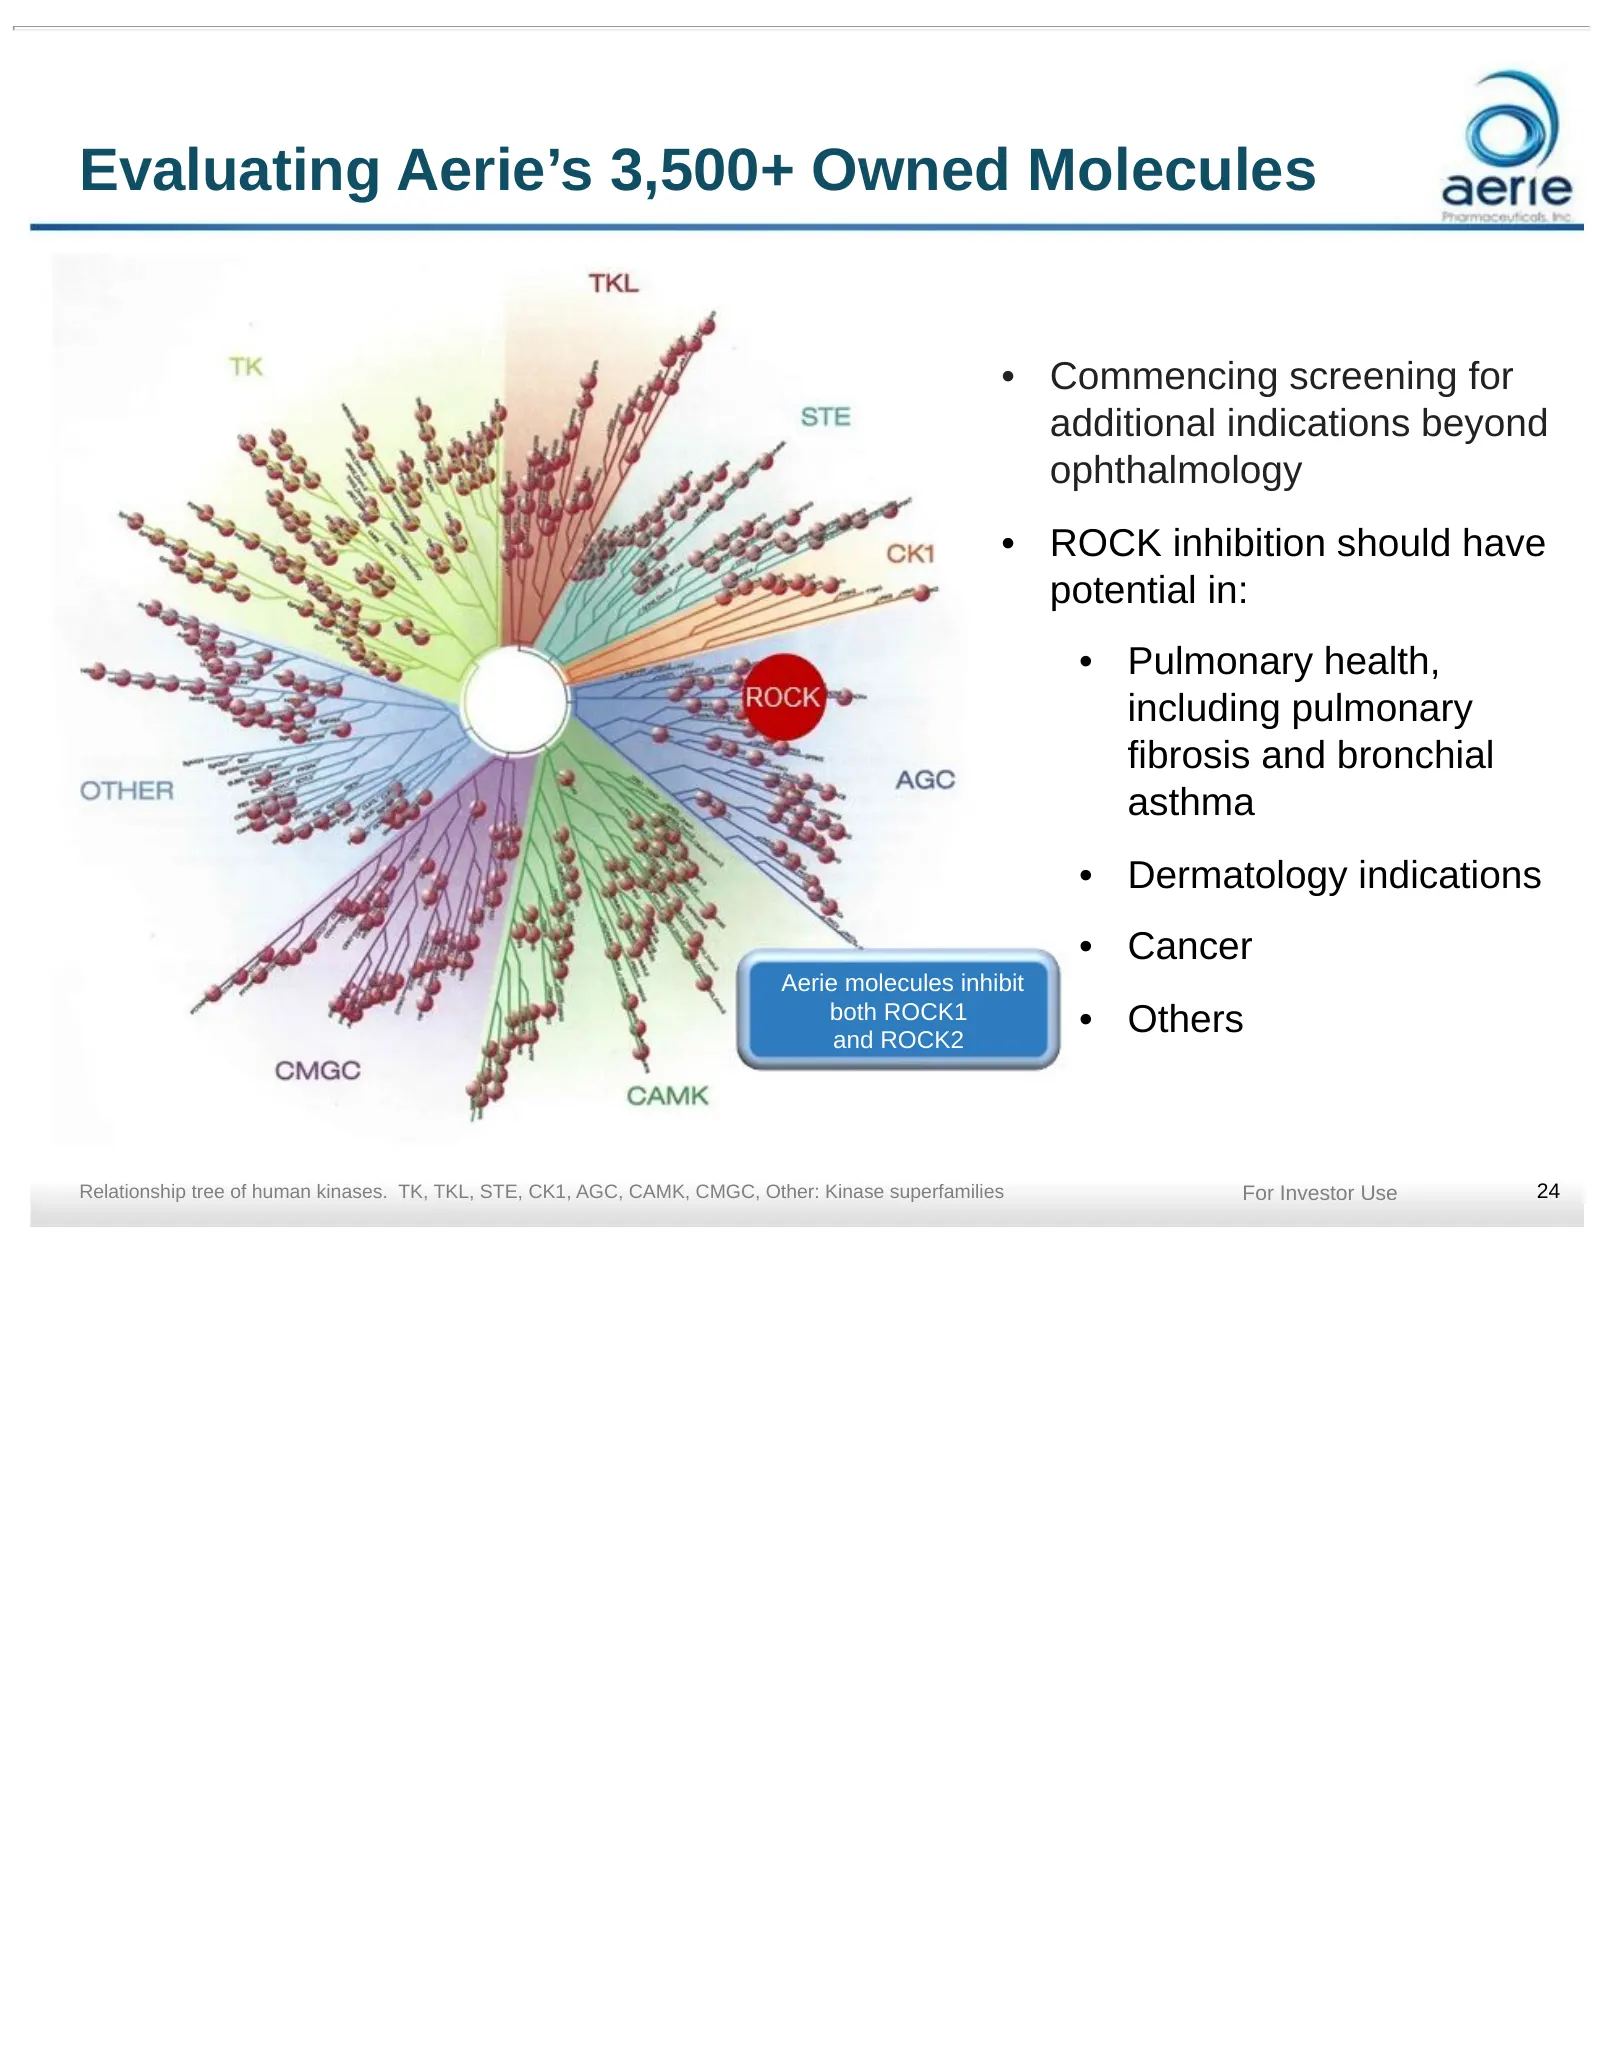
Evaluating Aerie’s 3,500+ Owned Molecules • Commencing screening for additional indications beyond ophthalmology • ROCK inhibition should have potential in: • Pulmonary health, including pulmonary fibrosis and bronchial asthma • Dermatology indications • Cancer Aerie molecules inhibit both ROCK1 and
Slide 25: Summary
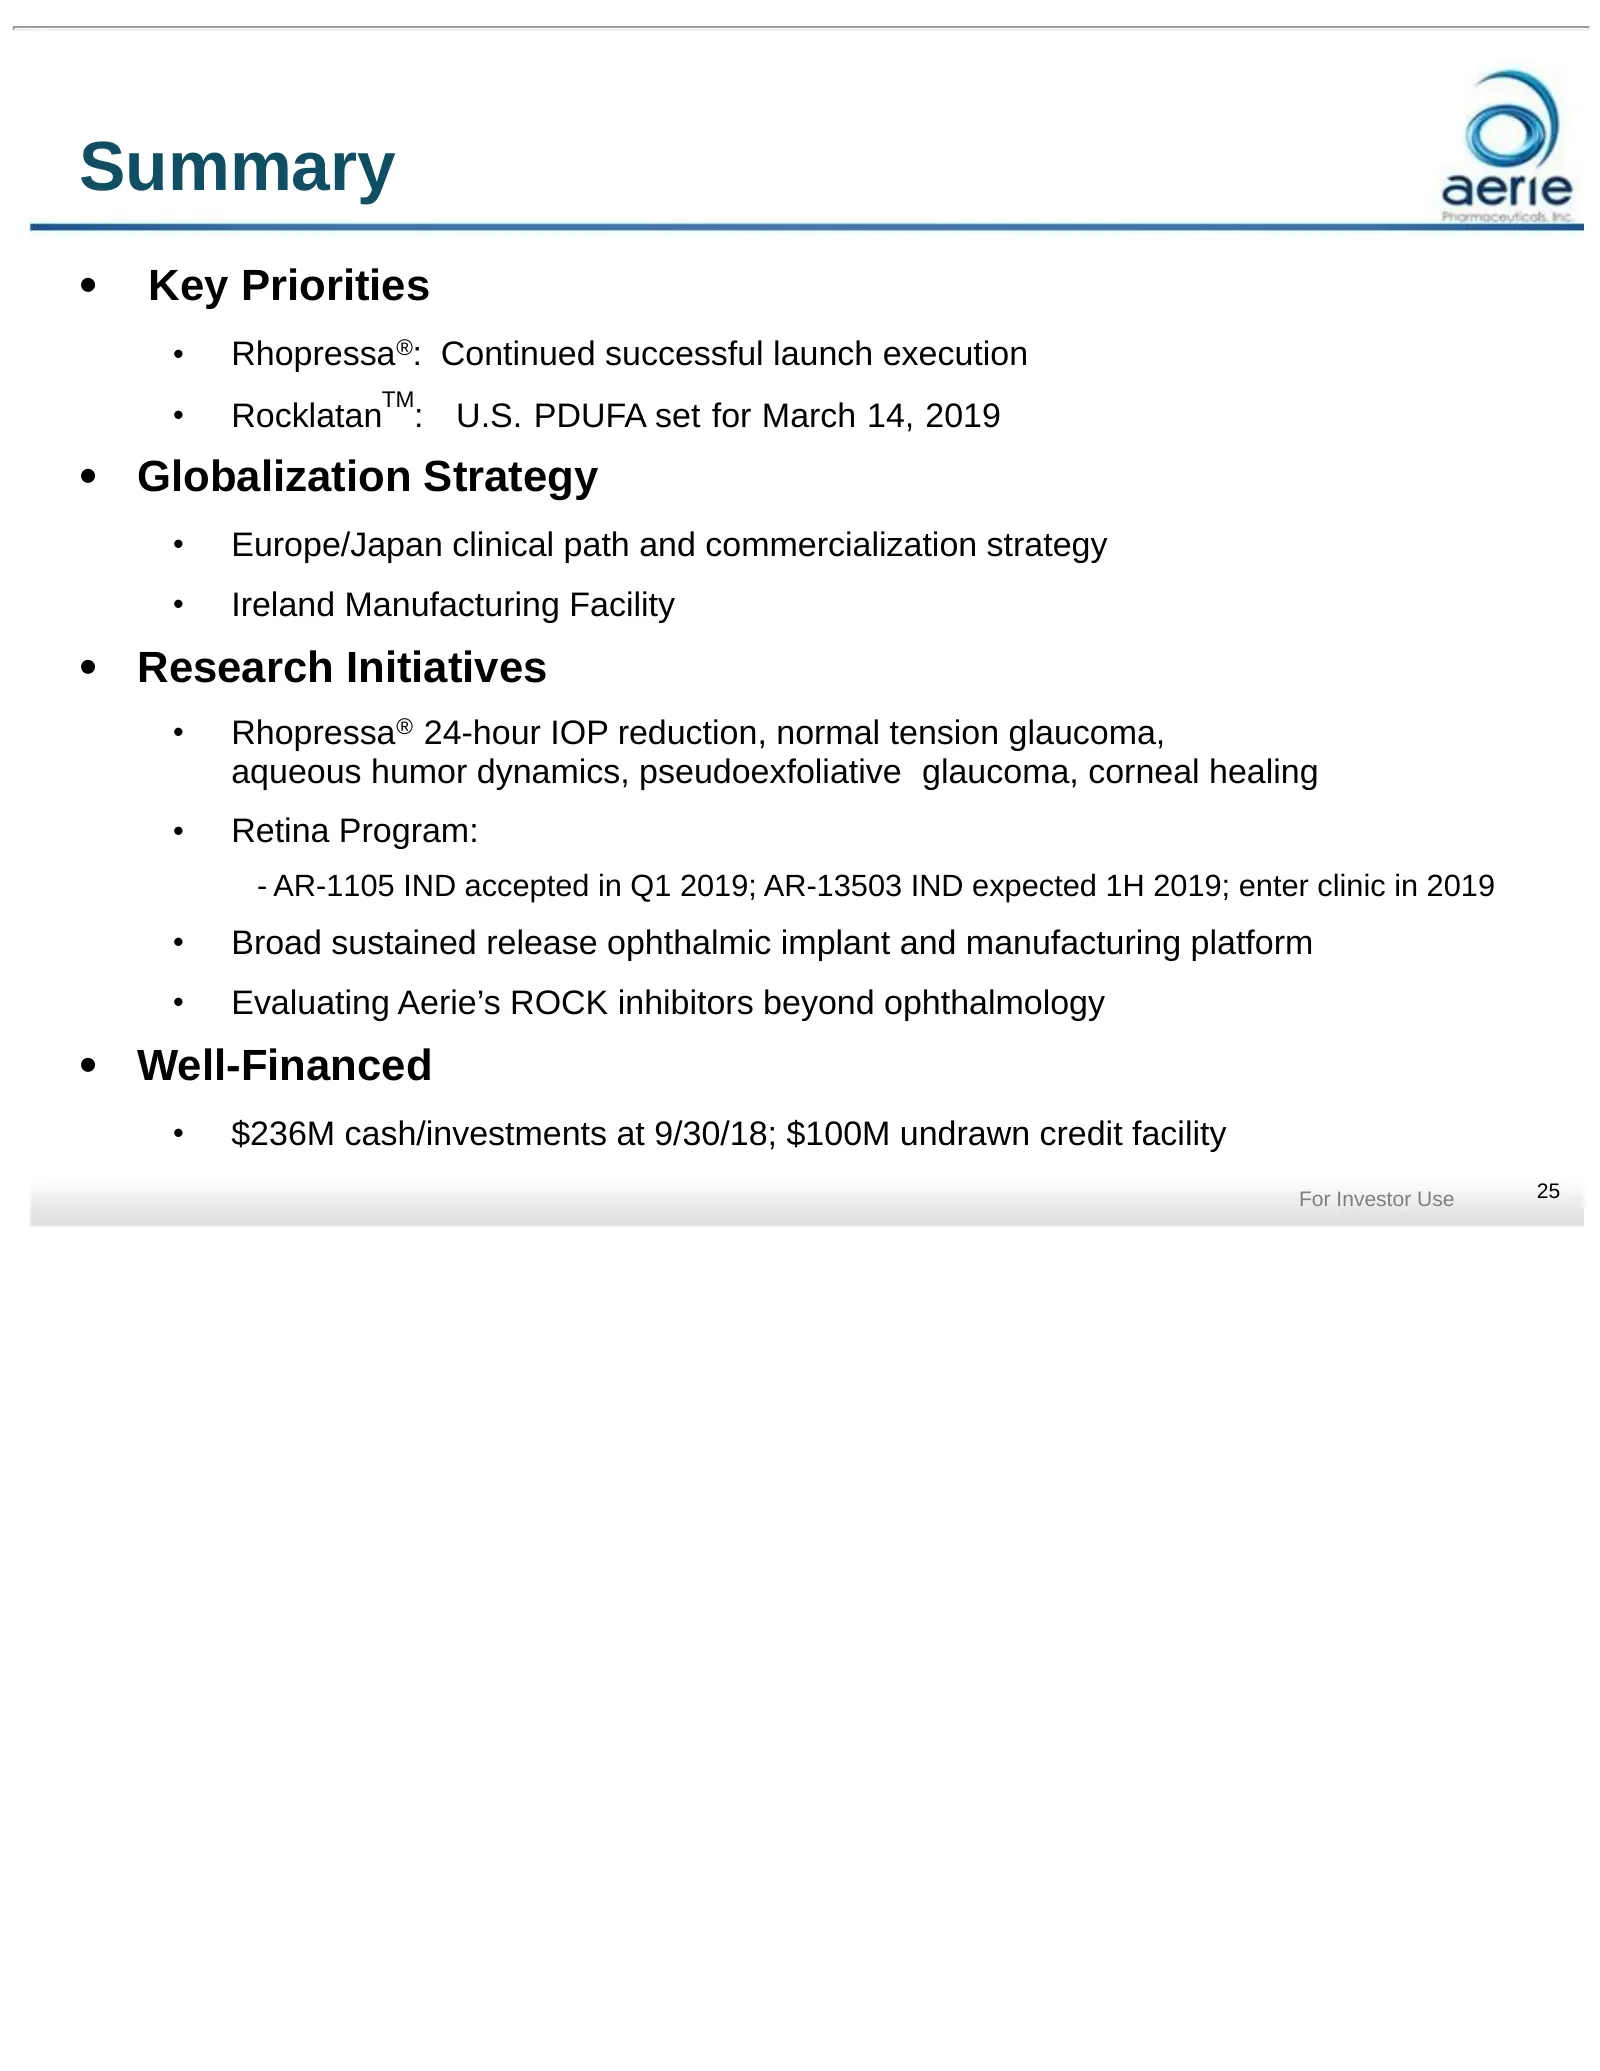
Summary • Key Priorities • Rhopressa®: Continued successful launch execution TM • Rocklatan : U.S. PDUFA set for March 14, 2019 • Globalization Strategy • Europe/Japan clinical path and commercialization strategy • Ireland Manufacturing Facility • Research Initiatives • Rhopressa® 24-hour IOP reduct
Source: SEC EDGAR · 8-K filed Feb 12, 2019
More decks from Aerie Pharmaceuticals Inc.
 Investor Presentation (September 2022)30 slides · Sep 13, 2022
 Merger or Acquisition (August 2022)30 slides · Aug 23, 2022
 Investor Presentation (June 2022)30 slides · Jun 8, 2022
 Investor Presentation (May 2022)28 slides · May 25, 2022
 Investor Presentation (April 2022)25 slides · Apr 11, 2022
 Investor Presentation (January 2022)33 slides · Jan 5, 2022